2024 marks a significant milestone for WDP: listed for 25 years on the stock exchange. During that period, we managed to grow our property portfolio from approximately 100 million euros to approximately 8 billion euros and we recorded an annual total return (including dividends) of the share of +15%, which is significantly better than EPRA indices over the same period.
WDP is a leading European logistics real estate player operating in core locations along key logistics axes in the Benelux, France, Germany and Romania. Our pure player strategy – supported by deep in-house expertise and a strong local presence – allows us to create value for our clients and shareholders. WDP develops, acquires and leases sustainable logistics real estate that is indispensable to our clients’ supply chains. Sustainability and innovation are paramount in our projects. And we respond to the evolving requirements in the sector to contribute to a more efficient and resilient logistics infrastructure. We strive to make sites more self-sufficient and help clients to decarbonise their activities. To this end, we increase green energy production and charging infrastructure for electric transport. Today, WDP is the market leader1 in the Benelux and Romania and manages a unique high-quality and diversified property portfolio worth approximately 8 billion euros. Moreover, we are committed to further scaling up towards a 10+ billion euros European real estate platform.
WDP is listed on Euronext Brussels (BEL 20) and Amsterdam (AMX) and is, among other things, part of the European Real Estate Association (EPRA), MSCI, STOXX, and the Dow Jones Sustainability Index (DJSI). WDP NV/SA has REIT status and is subject to the prudential supervision of the FSMA.
1 Based on square metres of lettable area in the portfolio.


WDP demonstrates versatility in a volatile macro environment thanks to a proactive investment strategy founded on a strong long-term vision. The successful rollout of the #BLEND2027 growth plan is proving its effectiveness. In 2024, WDP has gathered all the building blocks to achieve its 2027 earnings target. Now is the time to execute the 1.1 billion investment euros pipeline.
“
Our growth is the result of expertise, innovation, vision, and high-performing execution of our long-term strategy. This is how WDP is building the future of sustainable logistics, creating value for our clients and shareholders.
Dear shareholders,
Looking back at 2024, I take immense pride in sharing with you the remarkable progress and achievements of WDP in what has been a truly historic year for our company. Once again, we have achieved a robust financial performance and made significant strategic investments. Last year, we laid the groundwork for sustained future growth, which further reinforced WDP’s position as a leading European logistics property platform.
A year of unparalleled growth and execution
2024 was a year of strategic milestones and performance and execution marked by a record investment volume of 1 billion euros across the value chain, boosting our portfolio in Europe. Our EPRA Earnings per share grew by +7% to 1.50 euros, exceeding our initial target, leading to a simultaneous increase in our dividend to 1.20 euros per share. These results testify to our disciplined approach, excellent financial health, and ability to capitalise on market opportunities at the right time. This also demonstrates that our #BLEND2027 strategy of combining multiple drivers in multiple markets is bearing fruit.
By 2024, WDP had established itself as a leading European logistics property platform. The expansion of our footprint in France, doubling our portfolio to 700 million euros, marks a significant milestone in this growth story. Furthermore, the appointment of a dedicated Country Manager for France enables us to accelerate regional growth and further strengthen our position. Our optimized management structure will decisively support our next steps towards further expansion, driving our evolution into a 10 billion euros European logistics platform. Clearly, the #BLEND2027 growth plan is in full swing. We are determined to fostering sustainable growth and create sustained value for our shareholders over the long term.
In a challenging macroeconomic and geopolitical landscape, we are witnessing an inflection point in the rental market at the beginning of the year, which is expected to increase demand and normalise retention rates in 2025. In the longer term, structural trends underpinning demand for logistics real estate continue. We see that deglobalisation is driving diversification and resilience in supply chains, while nearshoring is bringing consumers and producers closer together.
Our financial foundation also stays strong. With a net debt / EBITDA (adj.) of 7.2x and loan-to-value of 38.3%, combined with 1.7 billion euros in available credit lines we have ample balance sheet capacity and liquidity to continue rolling out our growth ambitions. Combined with our unique and unmatched portfolio of critical supply chain infrastructure, the expertise and clout of our in-house teams and backed by a proven track record, we are excellently positioned to capture further growth opportunities.
At WDP, we go beyond developing logistics infrastructure – we help build the future of sustainable and efficient supply chains. Our focused investments in renewable energy, smart infrastructure and client-oriented solutions underline our commitment to innovation and sustainability.
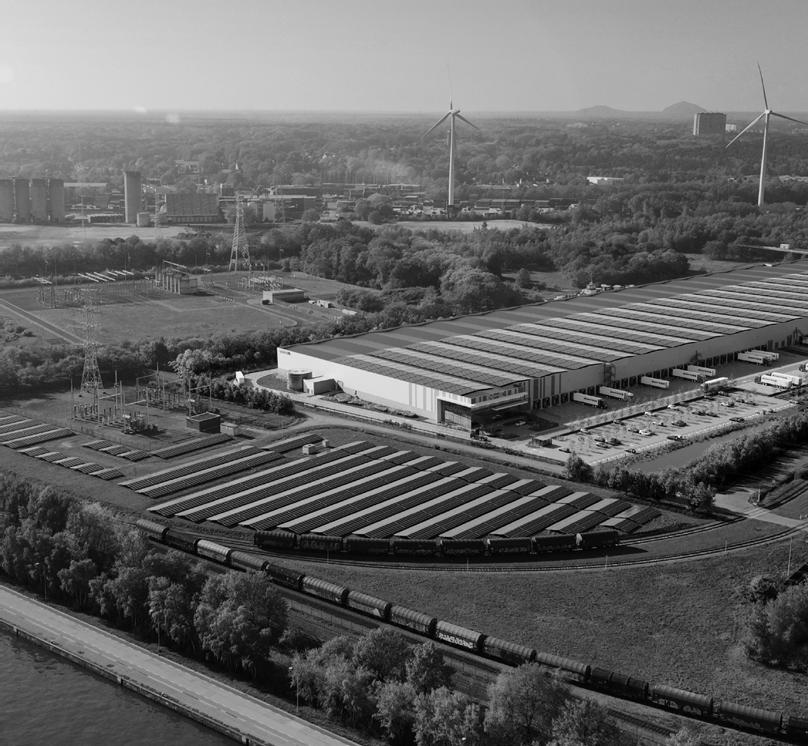
We want to ensure that WDP remains a pioneer in integrated energy solutions for logistics real estate. In 2024, we saw meaningful progress in our energy investments and the realisation of our climate plan. The further expansion of our solar capacity (234 MWp today) and installations under construction, clearly bring the target of a total installed capacity of 350 MWp by 2027, in sight.
Admittedly, our involvement goes beyond solar power. For example, we have initiated solutions for battery storage, including a 60 MW front-of-meter battery park in Belgium. These innovative solutions are key to decarbonising the supply chain, with vehicles powered by fossil fuels gradually being replaced by e-trucks. Although their adoption is still held back by the high cost, there is no doubt that future developments and buildings will need to have fully integrated energy solutions.
Sustainability is also a priority within our team and our corporate culture. Our Great Place to Work® certification reflects our ongoing commitment to an inclusive, safe and entrepreneurial workplace that focuses on the growth and development of our employees.
The growth path towards 2027
Our strategic roadmap, #BLEND2027, is on track: the path to our target of 1.70 euros in EPRA Earnings per share by 2027, representing an underlying annual growth rate (CAGR) of 6%, is clear. With a fully funded investment pipeline of 1.1 billion euros in execution, we have all the essential building blocks in place to create sustainable value for both our shareholders and clients.
Looking ahead to 2025, we also expect an underlying earnings growth of 7%, resulting in an expected EPRA Earnings per share of 1.53 euros per share and a dividend of 1.23 euros per share. This is supported by a minimum occupancy rate of 97% and stable financial metrics.
None of our successes would have been possible without the dedication and expertise of our #TeamWDP. I extend my heartfelt gratitude to all our employees, partners, clients, and stakeholders who continue to support our vision and strategy. To our shareholders: thank you for your trust and confidence in our long-term vision.
After 25 years of listing on the stock exchange, WDP is stronger than ever and wellpositioned for sustainable long-term growth. I am confident that we will continue to execute our strategic ambitions successfully.
This anniversary year also marks the farewell of Tony De Pauw as co-CEO. We would like to thank Tony for his many years of dedication, vision and leadership. He has played a crucial role in the growth and success of WDP and will continue to do so in his role as a board member and advisor.
Together with our team and our partners, we are building the future of efficient and sustainable logistics.
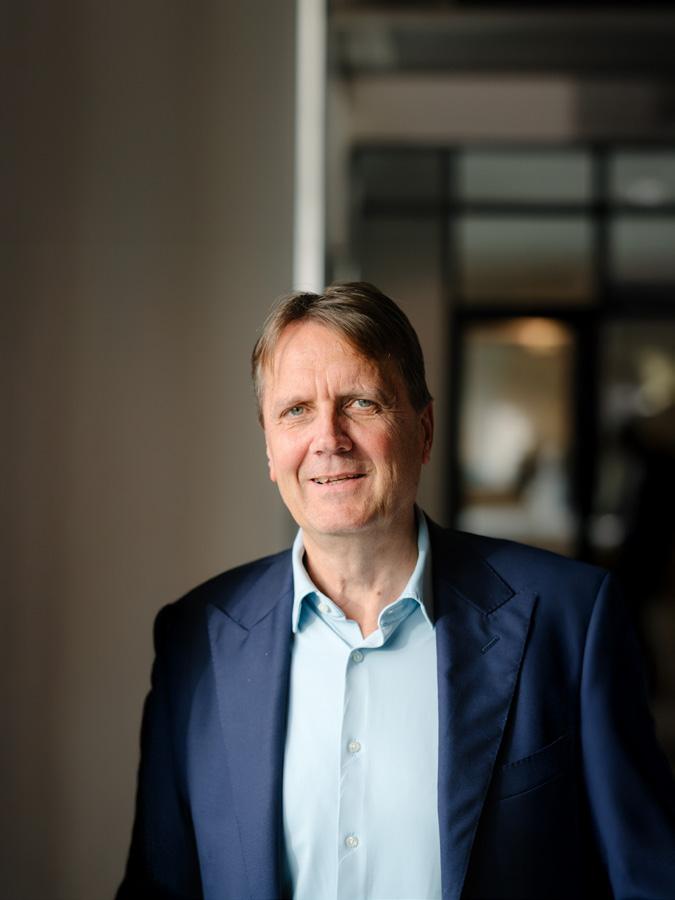
Rik Vandenberghe Chairman of the Board
Continued strong earnings growth thanks to #BLEND2027
The #Blend2027 strategy proves that WDP responds swiftly and dynamically to developments in the market cycle. Value creation through the combination of multiple drivers enables WDP to achieve stable long-term EPS growth in each phase of the market cycle.
Effectively navigating a volatile environment
By proactively investing in multiple growth opportunities, WDP is building a 10+ billion euros European logistics platform. This multi-driver approach reinforces our results and proven resilience in a volatile macroeconomic market.
Fully focused on execution to achieve the 2027 EPS target
Structurally long-term trends remain positive and offer opportunities within the existing portfolio and land reserves. Our strong financial position and exceptional investment pipeline mean that WDP is well positioned to achieve its 1.70 euros EPRA EPS-target in 2027.
1977
Founding of Rederij De Pauw, the company that manages Jos De Pauw’s property portfolio.
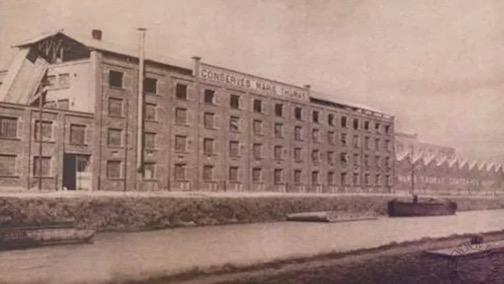
The family-owned group initially restricted itself to a vinegar brewery so it could diversify and include sand mining and inland shipping. Jos De Pauw then saw the potential of older industrial factory buildings that could be modernised into lettable warehouses – the foundation of today’s WDP. In 1999, WDP went public with a portfolio of 100 million euros. Today, WDP has become much more than just a property specialist. Its modern logistics infrastructure is a crucial link within its clients’ supply chains. This is part of a strategy of long-term value creation based on ambitious, delineated and transparent growth plans where we have successfully achieved our objectives to date.
A home for the supply chain
Warehouses are the linchpin in the supply chain for a sustainable future. These are indispensable storehouses for the food on our plates, medication when we are sick, the technological gadgets we cherish, and all the other goods that we depend on every day. They help make the supply chain robust and resilient. Our warehouses are a smart and flexible house that helps our client achieve their operational, social, and climate objectives. They feel at home in the heart of their supply chain. Their home is our home. Our warehouse with brains.
“ A strong and long track record as the foundation for attractive growth in earnings per share. All thanks to our pure player focus, client-oriented approach, ambitious growth plans and capital discipline.

2024 marks a significant milestone for WDP: Listed 25 years in the stock exchange is an impressive track record in earnings growth per share and return on equity.
Accomplishments since the IPO in 1999
>50 x Portfolio growth
% Occupancy rate (average)
growth rate (CAGR)
Historic portfolio growth of €1 billion and €1.1 billion investment pipeline under execution
Growth plan 2019-23
Annual portfolio growth of 10% and 6% EPS increase
Inclusion in BEL 20
Expansion into Germany First ABB by REIT (GVV/SIR)
Issuance of first Green USPP as Belgian REIT (GVV/SIR) (in € billion)
1 million m² of rentable property
Solar panel project launch (30 MWp)
Growth plan 2013-16
+50% portfolio growth and +20-25% EPS increase (cumulative)
Portfolio of €1 billion
Growth plan 2006-09
IPO – listed as a property SICAF
Expansion of the portfolio in France
The Netherlands as a new region
Doubling of portfolio value
Entry into Romania First BREEAMcertified site
Growth plan 2011-13
Growth through leasing, acquisitions and sustainability
WDP named Entrepreneur of the Year®
Conversion from property SICAF to REIT (GVV/SIR)
2024-27
Annual EPS growth of 6% by combining multiple drivers
€300 million ABB and historically strong balance sheet as a foundation for future growth
Delivery of first Green Mobility Hub
Growth plan 2022-25
Annual EPS growth of 8% | External Growth+
First-time issuer credit rating by Fitch (BBB+) and Moody’s (Baa1), both with stable outlook
Inclusion in DJSI Best-in-Class Europe (world in 2022)
€1 billion portfolio growth and +25% EPS increase (cumulative)
Entry into Luxembourg 2016-20
Launch of WDP Climate Action Plan
Mining for the production of construction materials and energy solutions
Production of construction materials and energy solutions
Purchase of construction materials, solar panels and energy solutions
Energy and water supply
Commercialisation
Planning, design and financing
Development and purchasing
Leasing and active asset management
Redevelopment
Warehouse activities by the client
Transport and distribution by the client
Supply chain employee
WDP workplace / #TeamWDP
The double materiality analysis has identified and assessed certain impacts, risks and opportunities (IROs) as material, as well as where these IROs are situated in our own operations or value chain.
Read more in 8. Sustainability report – Material impacts, risks and opportunities
Throughout the value chain, WDP interacts with various stakeholder groups, notably Clients, #TeamWDP, Investors, Financial Institutions, Suppliers, Policymakers and the Community. As part of the double materiality analysis, their interests and views were identified.
Read more in 8. Sustainability report – Stakeholders’ interests and views
Client / Community
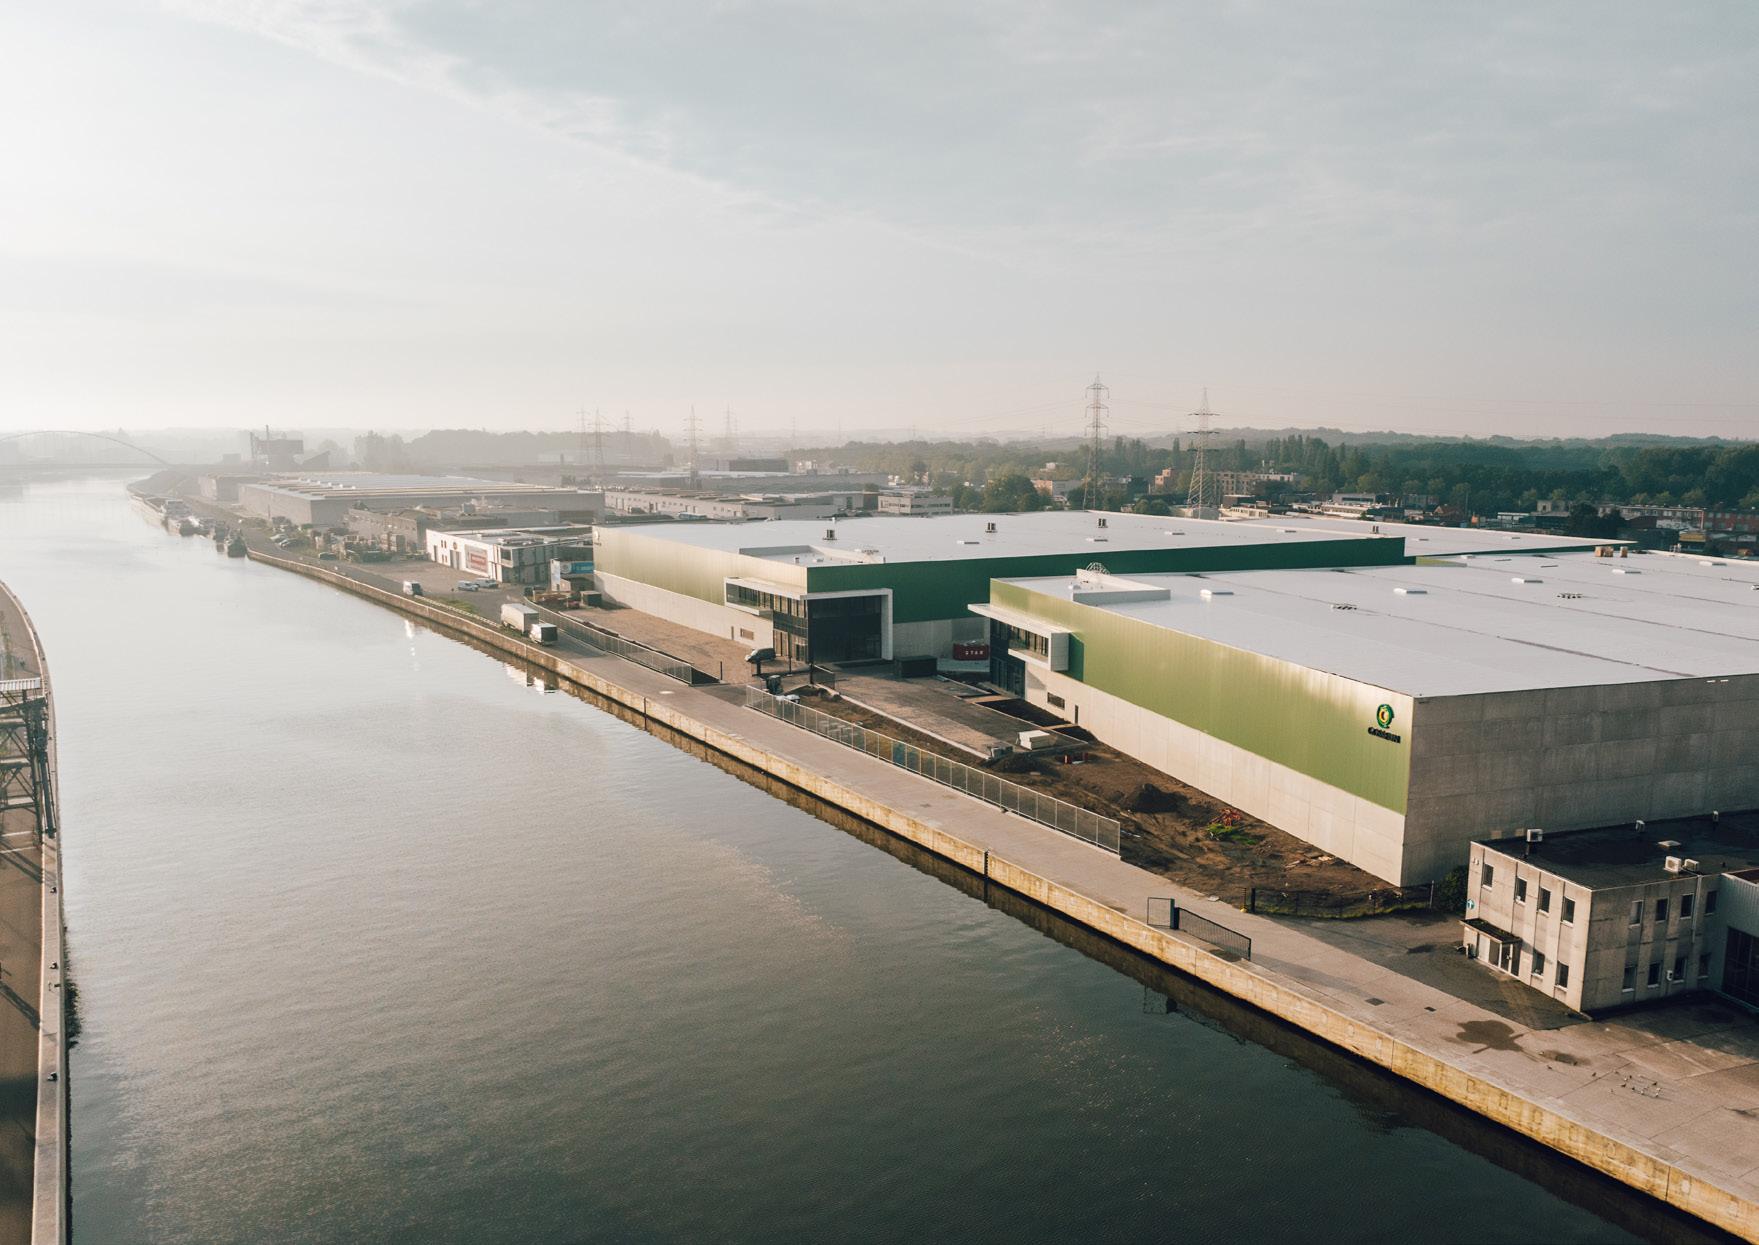
with a focus on client orientation, sustainable growth and innovation, WDP is a leading player in logistics property in the heart of Western Europe with Romania as a strategic gateway to Southeastern Europe.
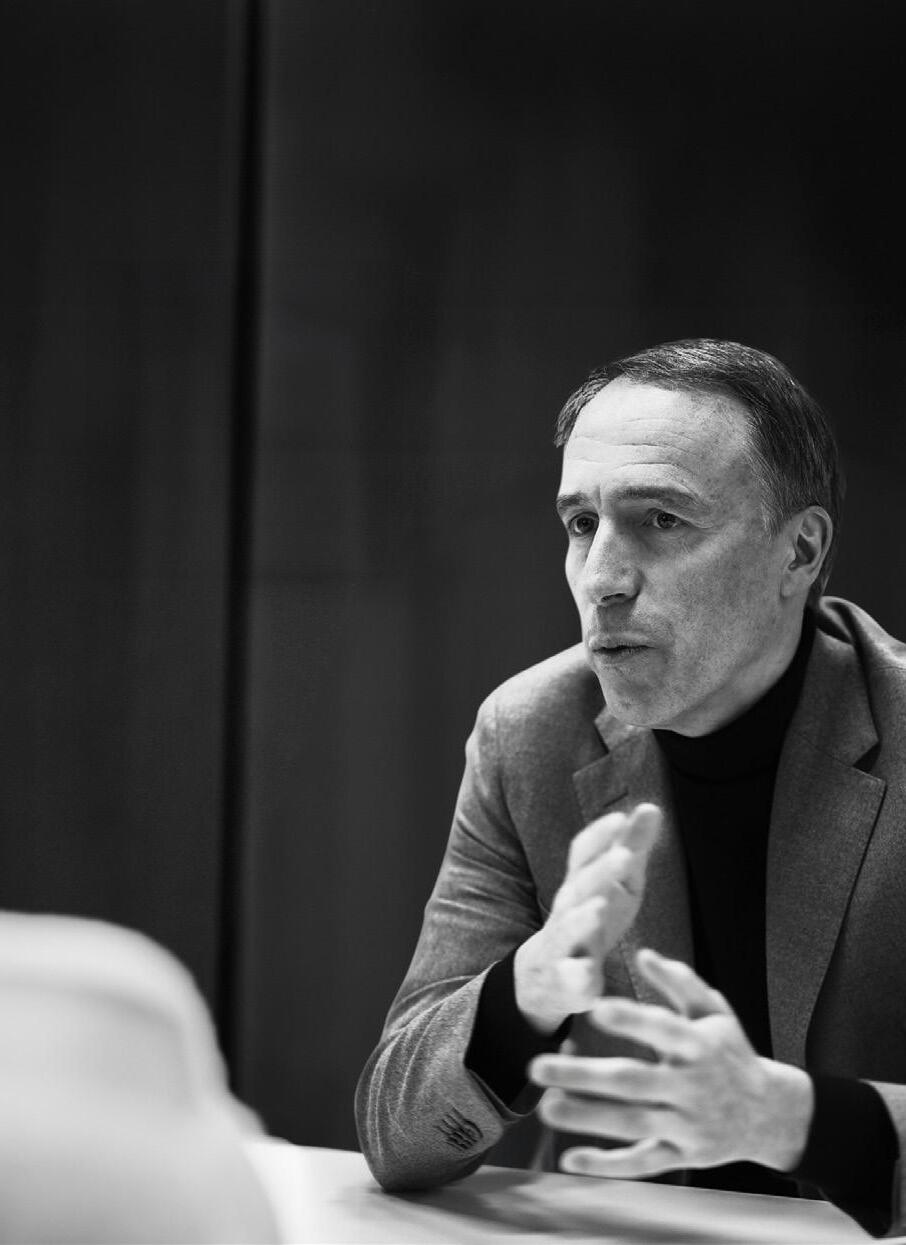
CEO Joost Uwents outlines the company’s vision: “At WDP, we are more than a developer or investor in logistics property. We are a commercial property company with a clear client focus. We do not think in terms of spreadsheets or lease expiry dates, but in terms of solutions that work today and tomorrow. Our philosophy is simple: if our client has a problem, we will solve it right away.”
The transformation of storage to logistics hubs
The logistics sector has changed radically. “It used to be all about grey boxes and cost efficiency,” says Uwents. “Today, those who don’t have their logistics sorted out will not survive. Logistics hubs are also the heart of the supply chain – something that has only become clearer since COVID and other geopolitical upheavals.”
This evolution requires continuous innovation and smart solutions. “Projects, such as Barry Callebaut in Lokeren, demonstrate how automation and highbay buildings not only save space – seven sites were centralised in one place – but also provide new possibilities for clients. Fully automated high-bay buildings allow us to store 80,000 pallets on a fraction of the space needed in a traditional warehouse.”
Historical growth in a larger playing field
WDP took major steps in 2024 to strengthen its position in the heart of Western Europe. “Our expansion in France and Germany has claimed new space among
the biggest players in logistics property,” said Uwents. The portfolio in France doubled to more than 700 million euros. And we also strengthened our position in Germany.
“These are strategic investments that anchor our position in Europe. We intend to do more of the same, and even better at a larger scale. That makes us not only scalable, but agile in a competitive market.”
Superb performance
“More than ever before, we have combined external growth with added value creation within the existing portfolio,” emphasised Uwents. “We get more out of our assets through modernisation and smarter use of available space. For example, we adjusted our proactive strategy to the scarcity of land and rising prices in Western Europe.”
WDP Energy also plays a crucial role in this sustainability. “We use more than 8 million square metres of roof surface to utilise the power of solar energy and large battery solutions combined with innovative solutions, such as batteries and charging infrastructure. So, we not only make logistics buildings more energy-efficient, we also contribute to broader goals, such as the greening of logistics transport – that is, our client activities.”
Client focus as a strategic pillar
“Client orientation is really in our DNA,” explained the CEO. “We don’t see our clients as tenants or occupiers, but as partners. This is how we respond flexibly to their general and logistical needs from temporary storage to fully integrated logistics hubs. The result? Strong client satisfaction and long-term relationships: satisfied clients stay longer, which leads to higher occupancy rates and strong repeat business. In fact, 50% of our growth arises due to projects with existing clients.”
“ WDP uses its client focus, innovation and sustainable growth to make a difference and remain relevant in the logistics property sector as it becomes a 10+ billion euros European platform.
Joost Uwents CEO WDP
Innovation as an engine
WDP’s #BLEND2027 strategy – a combination of external growth, optimisation, innovation and sustainability – is proving its worth. “We thrive as a team in this increasingly complex sector where we constantly strive to make improvements that strengthen our clients. Because a building is not an end point, but a starting point for innovation,” added Uwents. “We develop solutions together with our clients that go beyond storage. For example, solar energy, battery systems and smart technologies, which optimise stock management and deliveries.” So, WDP continues to move forward in a rapidly changing logistics world.
Looking back on his path at WDP so far, the CEO mentioned three milestones that determined the company’s growth and positioning. The IPO in 1999 gave WDP the financial clout to grow into a market leader in logistics property. In 2017, we were named ‘Enterprise of the Year®’. This positioned WDP as more than a property fund or sicav, but as a commercial company with a strong entrepreneurial vision. WDP’s entry into the BEL20 confirmed its position as one of the largest players within the Belgium market.
The CEO would rather look ahead with confidence towards the future. “From an economic cycle perspective, 2024 was not an easy year. Nevertheless, we recorded a historic investment volume and once again strong earnings growth per share. Moreover, since the start of 2025, we see an inflection point in the rental market, with improving dynamics: a normalising retention rate and a gradual recovery in demand through 2025 emphasises confidence in the future. At the same time, structural trends supporting demand for logistics real estate continue. Deglobalisation reinforces the resilience of supply chains, while nearshoring brings consumer and producer closer together. Together with #TeamWDP, we will continue to exploit these developments, seize opportunities and create sustainable value for clients and shareholders.”
Value creation for all stakeholders as a pure player with a strong focus
WDP has a clear mission: provide smart logistics solutions that make the critical infrastructure of the supply chain more efficient and more sustainable, while also creating value for clients, shareholders and society. Our ambition is founded on three pillars: #TeamWDP, Client Focus and Innovative Entrepreneurship
Our team is the beating heart of our company. Their expertise, dynamic approach and clientcentric mindset create our success. They have room to grow and develop innovative solutions due to a flat hierarchy and short decision lines. From commercial advice and sustainable development to operational and executive management: #TeamWDP alleviates clients’ workload and implements impactful solutions. Transparency and honesty are paramount in our business operations, where we balance the different interests and grow long-lasting relationships with both clients and stakeholders.
WDP combines energy-efficient buildings with strategic locations to boost and improve our clients’ growth, processes and supply chain. Our portfolio includes a range of customised solutions for different sectors and operational activities. Their location near the most important logistics axes in the heart of northwest and central Europe optimise the flow of goods and reinforce supply chains. The green energy generation and infrastructure of WDP ENERGY contribute to decarbonisation. This is how we contribute to our clients’ sustainability and also to a greener future.
WDP is forward-thinking with smart financing and innovative solutions. We combine a healthy mix of equity and loan capital with green financing, and reserve earnings to invest sustainably. Each project starts with a clientfocused analysis, which provides pioneering and customised property solutions. We think ahead and with the client to create pioneering futureproof infrastructure founded on concepts that add long-term value.
Purpose
Vision
Warehouses are the linchpin in the supply chain for a sustainable future. These are indispensable storehouses for the food on our plates, medication when we are sick, the technological gadgets we cherish, and all the other goods that we depend on every day. They help make the supply chain robust and resilient. Our warehouses are a smart and flexible house that helps our client achieve their operational, social, and climate objectives. They feel at home in the heart of their supply chain. Their home is our home. Our warehouse with brains.
Mission
Our warehouses with brains boost clients’ growth in the heart of their supply chain.
WDP develops, leases and manages logistics property as the backbone of the supply chain. Our smart warehouses build a sustainable shell around the logistics process. Our #TeamWDP, a client-centric and innovative entrepreneurship enables us to create value for clients, shareholders and society.
For years, WDP has been pursuing a targeted approach to realize sustainable earnings growth per share through multi-year growth plans. These plans are rooted in the longterm strategy, while the multi-year horizon responds to market trends and client needs in the supply chain. As a framework, each growth plan provides a clear roadmap – from strategy to action plan – aimed at delivering earnings growth per share while maintaining a consistently strong capital structure.
Thanks to WDP’s integrated approach as both a developer and long-term investor – with nearly two-thirds of the portfolio consisting of in-house developments, complemented by value-add acquisitions and strategic platform expansion – WDP can remain active as net investor across the cycle and the entire value curve. This enables selective capital deployment and strategic navigation of the risk spectrum, aligned with the market cycle and price dynamics.
#BLEND2027
Doubling of portfolio value
Growth through leasing, acquisitions and sustainability
Growth through acquisitions and our pre-let projects in existing core markets
Growth from pre-let projects supplemented by acquisitions and energy investments
Deepening of core markets and geographical expansion via pre-let projects and energy investments
External Growth+: supply chain investments reinforced by value creation within the existing portfolio and scaling up sustainability investments.
#BLEND2027: earnings growth by combining multiple drivers in multiple (geographical) markets
Whereas logistics property was once solely focused on providing storage space, today’s market is more complex and innovative. At WDP, earnings growth goes beyond developing empty grey boxes. Instead, it is about a well-balanced “blend” of multiple drivers: geographic expansion, innovation, sustainable energy solutions and internal growth based on the existing portfolio. This approach is built on multiple value pillars and is strengthened by seizing opportunities in a broader geographical playing field, with a focus on profitability and solid execution – pushing further and becoming even more international.
Consistent and successful implementation in all phases of the capital cycle
Stable growth focused on long-term value creation
The 2024 recovery in the capital market cycle has set the stage for accretive value-add acquisitions. With demand gradually picking up in 2025, WDP expects balanced growth between own developments and acquisitions.
1 Integrated developer-investor model: Majority of WDP portfolio consists of own in-house developments. Supplemented by value-add acquisitions and strategic platform expansion.
1 Net investor managing the entire value chain: WDP strategically navigates the risk spectrum aligned with price trends within the property cycle.
1 Selective capital use at each stage of the capital cycle.
#Blend2027: multi-driver growth in multiple markets
With #BLEND2027, the four-year growth plan for 2024-27, WDP focuses on both internal and external growth. The plan stands out due to its flexibility in seizing opportunities in a rapidly evolving market. Earnings growth is driven by a blend of factors, including geographical expansion, internal growth, energy-efficient solutions and innovative developments.
The goal? An EPRA Earnings per share of 1.70 euros in 2027, representing an annual growth rate of +6%. This ambitious plan is fully funded thanks to a strong balance sheet and robust cash flow, and provides the foundation for sustainable value creation – for both clients and shareholders.
Robust investment pipeline: € 1.1bn in execution
Organic growth: Full CPI indexation & capturing rent reversion
Funding requirements covered: €1.7bn in funding available with another ca. €600m of equity from retained earnings & scrip dividend expected to be generated in 2025-27
A multi-driver approach in multiple (geographical) markets
BUILD | Continuing structurally positive trends within the logistics property market.
LOAD | Investment through a combination of sustainable developments.
EXTRACT | Added value creation within the existing portfolio.
NEUTRALISE | Sustainability investments help decarbonise the supply chain.
DISCIPLINED | Continued strict capital allocation and strong financial position.
Just one year after its launch, #BLEND2027 is already proving its strength. In 2024, WDP achieved EPRA Earnings of 1.50 euros per share, surpassing guidance. With a historic investment volume of €1 billion, including the doubling of the portfolio in France, a significant step was taken in the European expansion. Additionally, a robust investment pipeline in execution of €1.1 billion provides a solid foundation for further growth.
WDP is strongly positioned to successfully execute #BLEND2027 and is ready to further reinforce its position as a European logistics platform thanks to its robust financial foundation, strategic investments and an ambitious vision.
WDP remains focused on maintaining a stable capital structure with a net debt / EBITDA (adj.) of approximately 8x, in line with the strict capital discipline the company has followed for over a decade. In 2024, WDP also maintained this financial stability with a net debt / EBITDA (adj.) of 7.2x and a loan-to-value of 38%.
Liquidity remained exceptionally strong throughout 2024. WDP reinforced its equity with over 220 million euros1 and maintains a substantial liquidity buffer of 1.7 billion euros in undrawn and confirmed credit lines. Additionally, WDP expects approximately 600 million euros in auto-financing over the next three years, based on retained earnings and optional (stock) dividends.
WDP has an investment pipeline in execution of 1.1 billion euros, a robust balance sheet and is fully financed. With all building blocks in place, WDP is well positioned to achieve its earnings targets of #BLEND2027 and can now fully focus on executing its growth plan.
Net debt / EBITDA (x, adj.)
Our warehouses with brains help our clients to
Operating income
Investment capital
PRODUCED CAPITAL
Property portfolio
New developments
Acquisitions
INTELLECTUAL CAPITAL
In-house expertise and experience
HUMAN CAPITAL
#TeamWDP
Innovative solutions
SOCIAL AND RELATIONSHIP CAPITAL
Stakeholder engagement
Partnerships
Ratings, standards and indices
The high-quality logistics infrastructure we offer facilitates and optimises our clients’ activities and guarantees them quality, sustainability, and continuity.
#TeamWDP
CLIENT FOCUS
INNOVATIVE
WDP strives to achieve balanced growth as a part of its transparent and fair governance. In doing so, we offer answers to economic, social, and environmental needs. This makes us a reliable partner for all our stakeholders and leads to sound financial metrics and attractive, recurring returns.
Just one year after its launch, #BLEND2027 – WDP’s multi-year growth plan is proving its effectiveness by delivering value through multiple drivers across different markets. This makes 2024 a historic year for WDP, underpinned by excellent financial and operational results. Despite persistent macroeconomic and geopolitical uncertainty, WDP has continued to seize opportunities, such as acquisitions in the investment market, further solidifying its position as a leading European logistics platform with a portfolio headed toward a 10+ billion euros platform.
WDP’s ability to generate sustainable EPS growth in each phase of the capital cycle is demonstrated by the effectiveness and responsiveness of its multi-driver strategy. EPRA earnings per share increased by 7% y/y, while WDP secured 1.0 billion euros in new investments across all WDP regions — 85% of which in Western Europe — at a weighted average NOI yield1 of 6.4%2
These investments include 150 million euros in development projects and land reserves (7.5% NOI yield)2, 400 million euros in core+ and value-add acquisitions with redevelopment potential (7.5% NOI yield), 400 million euros in core acquisitions for strategic expansion in France and Germany (5.3% NOI yield), and 75 million euros for energy projects (targeted IRR >10%). The substantial investments in France and Germany, among others, mark a pivotal step in WDP’s European expansion.
1
2 Cost to come: 1.0 billion euros per 31.12.2024. WDP holds all building blocks to achieve its EPRA EPS target of €1.70 by 2027
Additionally, WDP has a robust investment pipeline currently under execution of 1.1 billion euros3. Within our organization, we are also taking targeted steps towards future scaling, which will serve as the backbone for sustainable, profitable long-term growth. Notably, the appointment of a new Country Manager for France, a COO, and an adjusted management structure are key elements of this strategy.
Future earnings growth secured across the value curve
With a strong financial foundation, a disciplined approach to financial management, and an ambitious vision, WDP holds all building blocks to execute #BLEND2027 and further expand its European footprint.
Thanks to the successes of the past year, WDP looks to the future with confidence and reconfirms its position to realize its ambitions for 2027 and beyond. Furthermore, since the beginning of this year, we have seen a turning point in the rental market, with renewed dynamics. Combined with structurally ongoing positive long-term trends, WDP is ready to seize new opportunities and further expand its leading position.
WDP believes all building blocks are in place to achieve the earnings target of 1.70 euros EPRA Earnings per share in 2027 based on the aforementioned investment pipeline in execution, commercial strength and capacity to delivery high-quality projects on time. Moreover, the plan is fully funded based on the loan-to-value of 38.3%, 7.2x net debt / EBITDA (adj.) and a liquidity position of 1.7 billion euros of
WDP distinguishes itself in the logistics property sector with its unique portfolio, robust financial foundation and strategic growth plan that creates value with several drivers. CFO Mickaël van den Hauwe is driven by financial discipline, smart capital management and a targeted approach. He explains how WDP creates sustainable value with a well-considered financial strategy and efficient execution for shareholders and clients.
Essential infrastructure with a growing cash flow
“WDP develops and manages critical infrastructure that is an integral part of the modern economy,” says Van den Hauwe. “Our assets are not just warehouses, but strategic hubs that enable companies to operate more efficiently, more sustainably and more resiliently. For example, in Romania, a lot of foodstuff is transported via our warehouses. It emphasises our social relevance.”
With a record investment of 1 billion euros in 2024, WDP proves that smart financing makes growth possible even in challenging
WDP provides a non-replicable platform with its prime portfolio spread across core locations along key logistics axes. “In Western Europe where land is scarce, we have infrastructure that is impossible to create again,” he adds.
The portfolio’s strong fundamentals resulted in a historic investment volume of 1.0 billion euros in 2024 with an EPRA earnings per share of 1.50 euros and a dividend of 1.20 euros. This is a synchronous increase of 7%. “We have a rental model with solid rent indexation and stable cash flows, which makes us one of the most predictable and attractive players in the sector.”
For Van den Hauwe, financing is not a precondition, but a core part of WDP’s success. “Capital is our raw material. Even the best investments can turn out disastrously without a well-considered financing strategy,” he explains.
WDP is committed to forward-looking financing, a strong balance sheet and an optimal financing mix with sufficient liquidity. “In 2024, WDP managed its balance sheet optimally with a low net debt/EBITDA of 7.2x and superb liquidity with 1.7 billion euros of free credit lines. This is more than ample to finance the #BLEND2027 strategy. Our proactive financial management means we can continue to grow even in challenging market conditions,” says Van den Hauwe. Moreover, this policy offers deal certainty. “When we take on a project, our clients and investors know that we have the means to implement it out successfully and ensure we will honour our commitments.”
Mickaël Van den Hauwe CFO WDP
Strategy is essential, execution makes the difference WDP performs strongly thanks to a sharp focus on execution. “A well-thought-out plan is important, but not enough. It’s even more important to execute it quickly and qualitatively and keep raising the bar,” emphasises Van den Hauwe. “Our track record demonstrates that we consistently deliver according to or above our promises.”
“Financial performance and healthy metrics confirm this approach works. In 2024, WDP achieved an occupancy rate of 98% and we reviewed 500,000 m² GLA in lease contracts, which was on average +12% above the previous level. Just one year after the #BLEND2027 announcement, WDP is well positioned to achieve its 1.70 euros EPRA earnings per share target by 2027.”
#BLEND for value creation via multiple drivers and markets
WDPs #BLEND strategy combines external growth, internal optimisations and sustainability. “We were once a single-driver company completely dependent on external growth,” explains the CFO. “Today, we utilise multiple value creation sources. Acquisitions, project development, renewable energy projects, upgrading the existing portfolio and expansion into new markets.”
The French expansion is a superb example. In 2024, the portfolio doubled to 700 million euros, and the appointment of a new Country Manager and local team is accelerating our growth in this region.
This approach makes WDP agile and future-proof. “External growth is profitable but also inherently highly capital intensive and competitive because of the sector’s appeal. At the same time, we are getting more and more value from our existing portfolio, which requires less capital. This enables us to derive earnings growth from different sources,” says Van den Hauwe. “It makes us stronger, resilient and less dependent on a single economic driver.”
The story behind the numbers? Create value, control risk and… “At WDP, it is more than just figures,” says the CFO. “Our results are due to a thoughtful strategy aimed at sustainable growth. EPRA Earnings, net results and increasing cash flows reflect sound policies, careful risk management and high-performance execution.”
Risk management is essential. “For example, we carefully screen our clients and ensure that our locations and buildings are of the highest quality. By the way, this is reflected in a rental collection rate of 99.75% since our IPO, which is very high.”
In addition, the Corporate Sustainability Reporting Directive (CSRD) or sustainability report is essential for WDP’s financeability and social impact. “Companies averse to transparent reporting and committing to demonstrable progress in sustainability will eventually lose funding.”
The future: responsive, effective and ready
The CFO looks ahead with confidence. "Our #BLEND growth plan for 2024-2027 is on track, and we already see the fruits of our strategy. Despite an environment with a higher cost of capital, we consistently create value with our core business.”
WDP continues to distinguish itself as the market leader with smart financing management, a sharp focus on execution and a non-replicable platform. “Our long-term strategy is clear. Keep doing what we do best within our industry and focus on client and shareholder value.”
EPRA Earnings per share for 2024 increased by +7% year-onyear to 1.50 euros. This earnings growth was driven by pre-let projects and acquisitions, organic rental growth (+2.6%), supported by a stable and sharp financing cost (1.9%) despite the portfolio growth and including +8% in the average number of shares due to capital strengthening in 2023-24. Based on this, WDP proposes a dividend of 1.20 euros per share (also +7% y/y).
Profitability was further supported by a consistently high occupancy rate (98.0% as of 31 December 2024, +20 BPS q/q) and persistent high retention (10% of the lease contracts reached their break, of which 88% were extended).
In 2025, 13% of the leases end on the next due date, of which 70% will be extended. Normally, at the start of the year, we observe a renewal rate of closer to 50% for the current year, indicating that the retention rate or lease renewal rate has normalised.
Within an environment of rising market rents, WDP was able to review 500,000 m² of GLA of contracts and capture an average rental uplift of +12%. Besides, the reversionary potential on the total portfolio amounts to approximately 11%.
WDP completed pre-let projects during 2024 with a total lettable area of around 178,000 m² (approximately 75,000 m² in H2 2024). The NOI yield for all of these completed projects amounts to 6.7%, with an investment amount of approximately 151 million euros. The average lease term is 12 years.
Projects completed in 2024
*Joint venture
Throughout 2024, WDP signed a package of investments amounting to approximately 1 billion euros across activities in all WDP regions (85% Western Europe) with an average NOI yield of 6.4 %1. Throughout 2024, these were either completed or further included in the current investment pipeline in progress. 1 For project developments, excluding land purchases.
Baia Mare Maravet 1Q25
Stefanestii de Jos Metro 3Q25
Sint-Katelijne-Waver Fully let 2Q24
BE Willebroek, Brownfieldlaan Various 0 BE Waregem Balta Industries 3Q24 BE Vilvoorde 0 0
FR Reims Various 2Q25
FR Cross-dock portfolio Various 3Q24
NL Provincie Overrijssel Fully let 1Q27
RO Aricestii Rahtivani Federal Mogul 1Q24
RO Chitila Various 3Q24
RO Constanta Various 3Q24
RO Targu Mures Various 3Q24
and value-add acquisitions
Bollène logistics parc + Puceul Various 4Q24
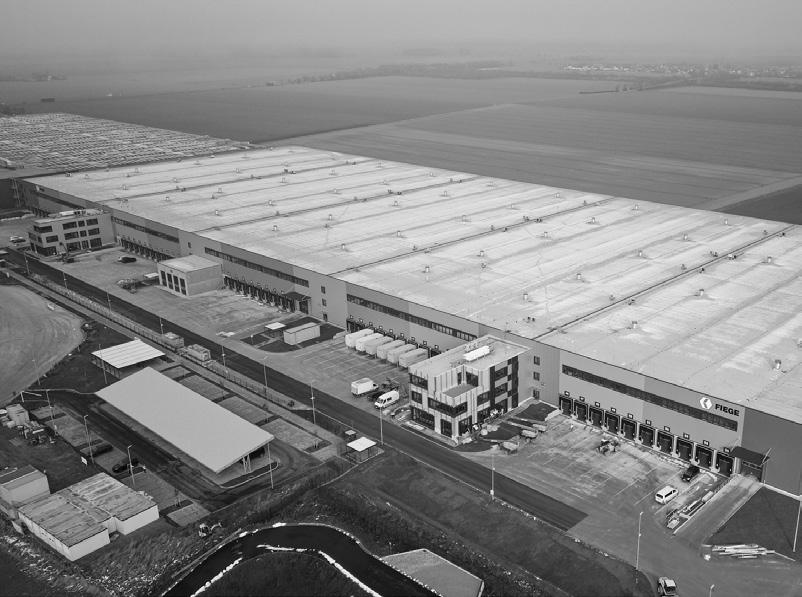
Bollène extension logistics parc Various 4Q26 DE North Rhine-Westphalia Fiege 4Q24
Overview of the investment pipeline of 1.1 billion euros in progress2. This package of investments represents committed investments and deals in exclusive negotiation for an amount of 1.1 billion euros and a NOI yield of 6.6%3
Bornem Capsugel Belgium NV
Genk Martin Mathys
Lokeren In commercialisation
Grimbergen In commercialisation
Willebroek Duomed 1Q26
Vendin-le-Vieil In
4
5
The development projects in progress amounting to approximately 331 million euros with approximately 451,000 m² are 60% pre-let4. The degree of pre-letting for these projects under development showed a temporary decline since Q1 2024. WDP continues to maintain its policy in which it aims to lease the project before development start-up. This temporary decline is attributable to a number of specific factors, including the expansion of existing sites or clusters, brownfield projects with soil remediation, or multi-tenant projects that address the demand for smaller units in specific locations. WDP is confident of successful commercialisation, partly due to the scarcity and decreased development activity in the market. The fall in the fourth quarter of 2024 (Q3 2024: 72%) is due to the early termination of a lease by a client in Romania.5
WDP has a robust investment pipeline with pre-let projects, acquisitions and energy applications, and also continues to boost its growth. In the short term, indexation of lease contracts ensures increasing income, while the rental review potential of currently +11% (contractual rent compared to market rental) contributes to further growth and value creation in the long term. WDP creates room for new developments with a strategic land reserve of 2.1 million m² of developable land (4.9 million m² total land area), which is spread across all regions where the company operates. This combination of short-term actions and long-term strategy reinforces our position in the market.
WDP currently has a land reserve for future development of approximately 2.1 million m² of leasable area spread over the regions in which the company is active.
Our future development potential in Europe
The ongoing structural positive trends within the logistics property market provide opportunities to further help our clients build out critical infrastructure. WDP sees potential here within the existing portfolio and through investment in sustainable developments.
100 %
1
2 The information in this chart is not construed as an earnings forecast or guidance of any kind and thus should not be read as such and is thus solely intended for illustrative purposes. It depicts the
and
Reversionary potential +11%
CPI-indexation of leases Projects under development
1.1 mia €
pipeline in execution +50 mio €
450,000 m²
At the end of 2024, WDP’s total solar capacity was 234 MWp, an increase of 52 MWp. Moreover, as of 31 December 2024, the installation of a capacity of 114 MWp is under development. This aligns with the ambition to achieve an energy capacity via solar panels of 350 MWp by end-2027. The expected annual revenues from solar energy could reach [40] million euros over time.6 Their gradual contribution to the earnings statement should be taken into account due to the increased complexity and lead time of these projects (e.g. grid connection), and lower energy prices. WDP targets an IRR of ~8% for these investments, coupled with a yield on cost of ~10-15%.
The acceleration in electrification and decarbonisation of transport is creating increased demand for investment in its supporting infrastructure. As a property partner, WDP can play a crucial role here for its clients by upgrading its warehouse sites into charging hubs that optimise the client’s energy profile. In fact, e-transport will significantly change that profile. A sophisticated combination of on-site energy generation by solar panels, combined with smart charging facilities and batteries, will provide an answer to this.
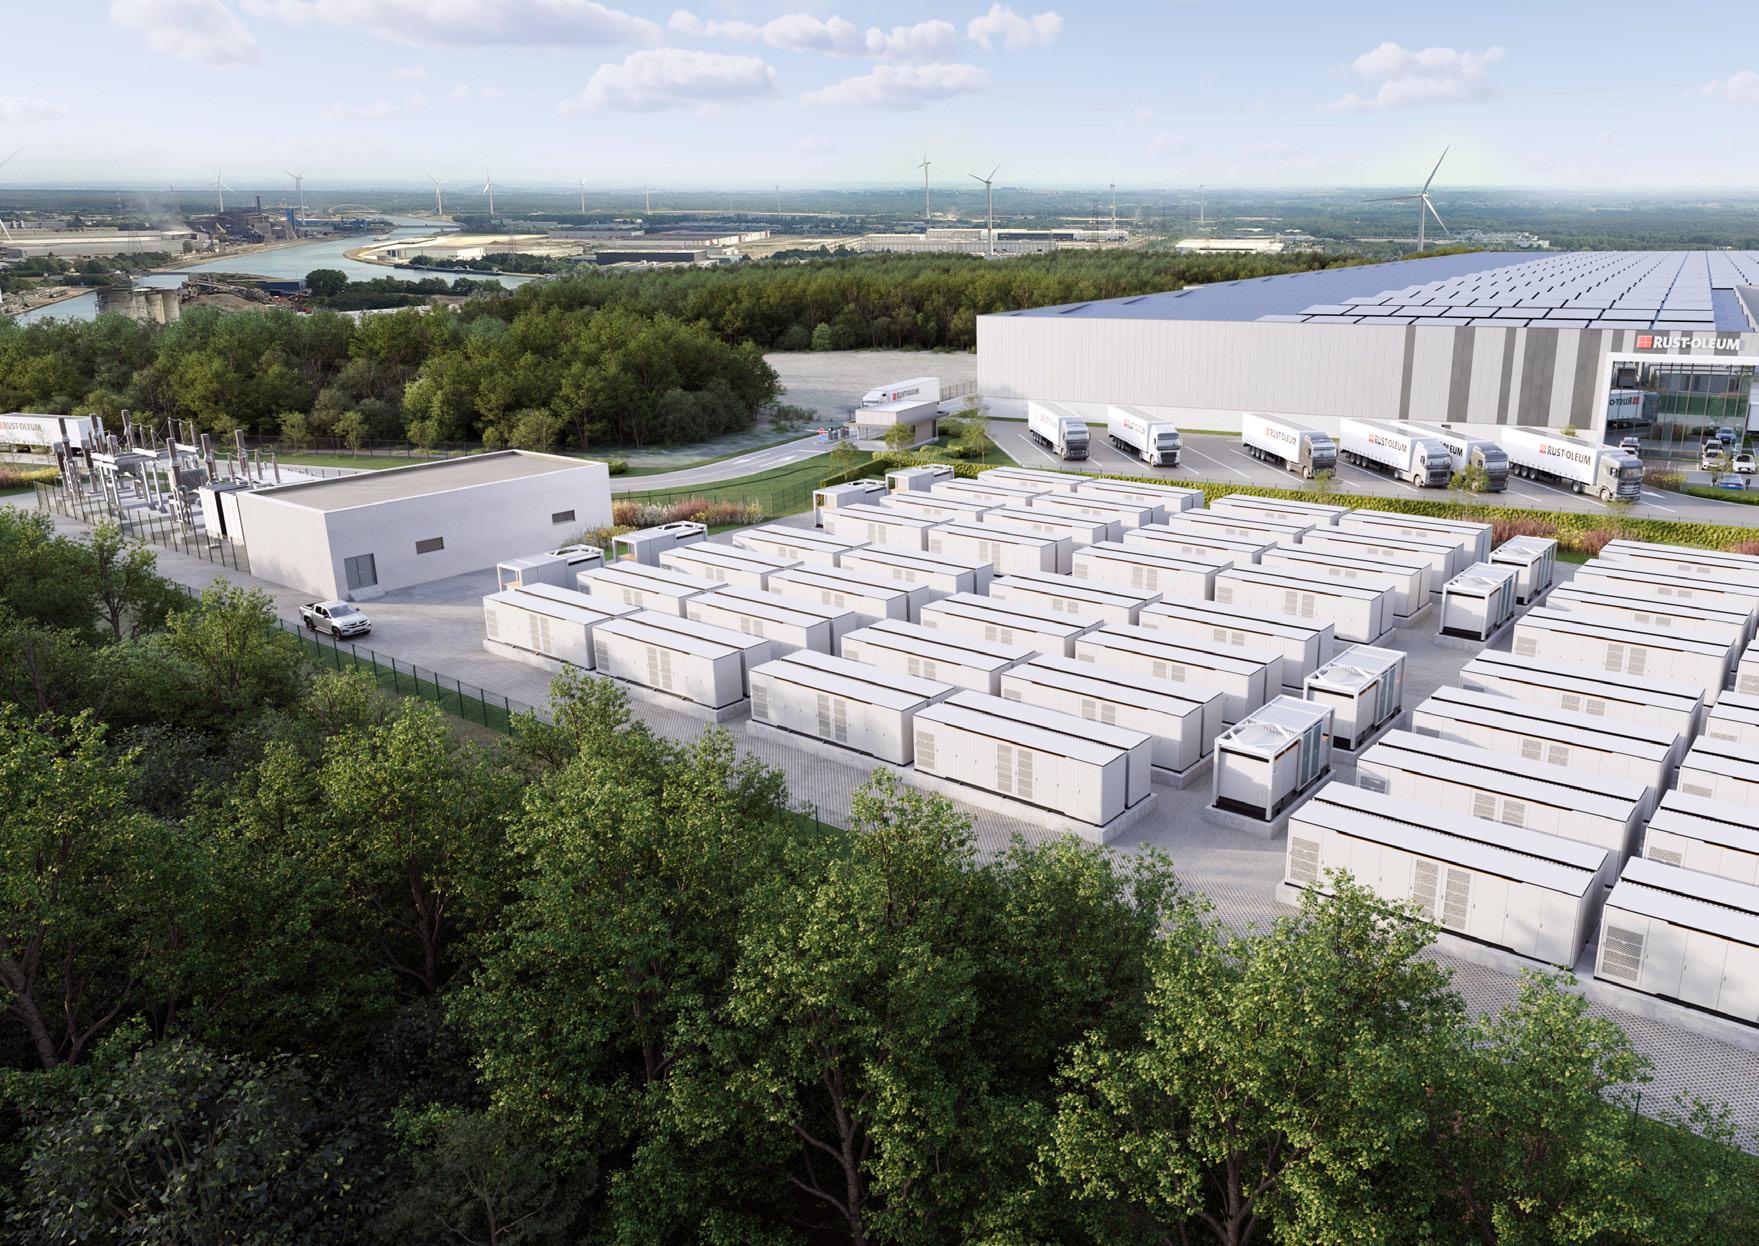
In Belgium (Genk), WDP will invest in an existing site in a large-scale front-of-meter battery park with a capacity of 60 MW (total investment estimated at 65 million euros) targeted for delivery in 2028. In parallel, the installation of some smaller battery projects at other sites in the Belgian portfolio is being rolled out for a capacity of 25 MW and energy storage capacity of 100 MWh, which is an investment of approximately 25 million euros. WDP envisages a project IRR of 10-15%. For more information about these energy projects and investments in the electrification and decarbonisation of our clients’ transport, see Chapter 4. Future logistics
In response to the growing demand for investments that support the electrification of its clients, on-site energy production forms the basis. Furthermore, WDP will focus on the infrastructure required for the decarbonisation of transport.
WDP builds long-term client relationships, leading to consistently high occupancy rates and retention rates averaging over 90% in the past decade.
WDP has a unique position in Belgium and Luxembourg with a 2.5-billion-euros portfolio spread over more than 2.5 million m² of lettable area. These strategically located sites – spread over 110 sites – are located along key core axes. This results in a market penetration equivalent to over 15% market share.
5 locations in Belgium and Luxembourg
WDP occupies a special position in the Netherlands with a 2.9-billion-euros portfolio spread over more than 2.9 million m² of lettable area. These strategically located sites spread across 114 cities are located at crucial logistics hubs. WDP has a market share of more than 6%. Top 5 locations in the Netherlands
WDP’s anchoring in Romania is diversified with a 1.5 billion-euros-portfolio spread across more than 1.9 million m2 of lettable area. This lettable area is spread over 79 strategically located sites. This results in a market penetration equivalent to over 25% market share.
Top 5 locations in Romania
Slatina (Olt), Draganesti 35A – Gebouw 1
Sag 2 (Timis) CF 406546 – Gebouw
Stefanestii de Jos 2 (Ilfov), Sinaia 50B – Gebouw
– Craiova (Dolj) – CF 37091 – Gebouw
(Neamt), Magurei 2, Roman – Gebouw
WDP has reached a significant milestone in France and Germany: the French portfolio will double to 700 million euros. The appointment of a new country manager François Le Levier, supported by a local team from a WDP office in Paris, enables WDP to focus on further growth in this region.
In Germany, WDP took further steps thanks to a sale & lease back transaction concluded with Fiege Group, a managerial European logistics service provider in North Rhine-Westphalia.
WDP offers every building type within the logistics property class. From storage to distribution: each type of warehouse is customised to the client’s specific activities. The robust and high-end construction quality of our buildings goes hand in hand with sustainability and flexibility where performance during the entire life cycle is paramount.
of
8
8 years
Rental income expiry dates (until the first option of termination)
In 2024, 88% of the 10% expiring leases were renewed. By 2025, 70% of the 13% expiring leases had already renewed. Typically, this rate is around 50% at year end. This shows that the retention rate or ‘lease renewal rate’ has normalised.
Historical occupancy rate of the WDP portfolio
“
Our warehouses accommodate many client sectors with a healthy mix of end users and logistics service providers.
The share of e-commerce in WDP’s portfolio (15%)
1
1 Financial performance indicator calculated according to EPRA's (European Public Real Estate Association) Best Practices Recommendations. Please see www.epra.com.
2 Excluding solar panels.
Designated use as of 31 December 2024 2023
3 Calculated by dividing the annualised contractual gross (cash) rents and the rental value of the unlet properties by fair value. The fair value is the value of the property investments after deduction of transaction costs (mainly transfer tax).
How do you make the supply chain run smoother, more sustainable and more efficient? And how do you ensure that a cross-country vision remains relevant for each local market?
At WDP, logistics property goes beyond just stacking and storage. We develop smart hubs that optimise the entire chain for daily goods with energy-efficient warehouses, strategic locations and innovation technologies.
Three experts in their region share how to translate WDP’s international strategy into action and how cross-pollination contributes to European expansion.
“Our breakthrough in France in 2024 was a milestone,” says Kristof De Witte, responsible for Belgium, Luxembourg and – until recently – France. “We have doubled in size thanks to some large and strategic acquisitions. For example, the two multimodal, sustainable new-build logistics platforms of the highest quality (Bollène and Puceul) and six cross-dock warehouses for efficient lastmile deliveries at different locations. This growth opens up perspectives, both for further expansion and for putting together a new team in Paris following the recent appointment of François Le Levier as Country Manager for France. The goal is to serve clients locally and efficiently.”
Markets for new developments remain challenging
However, the challenges remain significant for new developments and are almost identical across countries except for Romania. “Finding suitable land is increasingly difficult, mobility is more and more important, the permit application process requires untold patience and the electricity grid capacity is a challenge. Nevertheless, the 2023 projects are in full swing. These were completed in 2024 such as Gosselin in Schoten and Alfa Gomma in Asse. Or, are almost ready for delivery in 2025, such as the pharmaceutical building for Lonza in Bornem,” says Kristof.
Growth also starts with existing clients
De Witte emphasises that growth does not stop with new square meters. Existing clients are crucial and benefit our occupancy rate, especially in a market subject to a temporary short-term cyclical slowdown.
“A good example is TD SYNNEX (formerly Tech Data) in Aalst, our client for more than twenty years. A thorough renovation and sustainability not only made the site future-proof, it also won us a new nine-year lease for 28,000 m² that extended our collaboration.”
Fortunately, WDP has always been far-sighted in such matters. For example, take the concept of a large-scale battery park in Genk (Bosdel) that will help balance the energy capacity of the public network.
“ Our breakthrough in France in 2024 is a milestone. Strategic acquisitions have doubled our scale, and we are building a local team to serve clients faster and better.
Kristof De Witte Country Manager Belgium and Luxembourg
“
Sustainability is no longer an extra, it is a must-have. In 2024, WDP added 52 MWp of solar panels and launched new energy storage projects. These are essential parts of modern logistics properties.
Michiel Assink COO
and former Country Manager The Netherlands and Germany
Sustainability as a driver of strategy
According to Michiel Assink, COO and former Country Manager Netherlands and Germany, sustainability is no longer an extra, it is a must-have. “In 2024, WDP added 52 MWp of solar panels to our portfolio and we launched new energy storage projects. These are not a nice-to-have, but rather essential parts of modern logistics properties.”
Moreover, the social discussion about the ‘compartmentalising the landscape’ requires making conscious choices. “We have open ears and take responsibility. Our buildings are designed to be architecturally attractive and energy-neutral as well as to add economic value through employment and local cooperation,” says Assink. “This is how we not only serve our clients, but also contribute sustainably to the region in which we are active.”
WDP is also taking strategic steps in Germany. “We completed a complex project with our acquisition of a brand new 61,000 m² pharma hub in Zülpich,” says Assink. “We are also working on various redevelopment projects in the Netherlands. This is in keeping with our ambition to quickly achieve sustainability quality marks, such as BREEAM. And this mirrors exactly what we mean by Effective… making choices that fit our long-term vision and at the same generate earnings.”
Romania, growth through nearshoring Romania plays a key role in WDP’s European strategy. Gijs Klomp, responsible for business development, sees 2024 as a year of taking major steps. “We have expanded our portfolio with an urban logistics cluster in Bucharest (110,000 m²), the acquisition of three existing projects (135,000 m²) in Bucharest, Constanta, and Targu Mures and a strategic land bank of approximately 300,000 m² in Constanta. We have also delivered almost 90,000 m² of developments for both existing (Pirelli, Taparo and Trico) and new clients (Erkurt). And there’s more in the pipeline.”
We develop exactly what the client needs. “
Gijs Klomp business development manager for Romania
According to Klomp, Romania has a unique market. “The manufacturing industry is growing rapidly here both directly (factories) and indirectly (logistics for factories). Nearshoring is an important trend here. Companies want to manufacture closer to their sales markets due to geopolitical tensions and supply chain risks. This creates strong demand for combined production and logistics facilities. And the logistics property market in Romania is still developing. Our flexibility and high standards ensure we deliver exactly what our clients need, where they need it.”
Although sustainability is not dealt with in the same way or is even on some clients’ agenda, WDP uses the same strict standards consistently regardless of location. “Our buildings meet the same standards as elsewhere in Europe. So, we not only anticipate future requirements, but also support our clients in their sustainable transition. As an investor owner, we have every interest in creating long-term value and ensuring that our property portfolio remains future-proof,” he emphasises.
Cross-country collaboration as an asset
WDP’s power is in cross-fertilisation. “We work as one team across regions, and learn from each other’s experiences,” summarises Michiel Assink aptly.
“When it works for renovations in Belgium, we do the same in Romania. And vice versa. We learn from their experience with Nearshoring,” says Assink.
De Witte adds: “When we share knowledge, we serve our clients better and strengthen our team. Every day brings new challenges and opportunities.”
Klomp emphasises the international appeal: “Even though each region has its own dynamics, our joint client-centric approach makes WDP an appealing and strong partner for companies with multinational activities.”
WDP is a company on the move. We continue to grow, learn and innovate to provide the best logistics solutions.
What motivates our colleagues each day?
For Kristof de Witte, the versatility of the work is a huge motivator. “On one day, I work on a strategic acquisition. The next, I work on making an existing building more sustainable. That diversity keeps me sharp and motivated.” Michiel Assink emphasises the importance of teamwork. “Working with motivated people on challenging projects not only makes work fun, it makes the work meaningful and energises you.” For Gijs Klomp, direct client contact is the most inspiring. “We develop properties that really make an impact and perfectly match the processes of our clients.”
Why do clients ‘pick’ WDP?
The unique combination of regional flexibility and cross-country collaboration makes WDP a reliable partner. Kristof boils it down for WDP as client choice: “Innovative and client focus. Our success is built on strong relationships and a future-focused vision.”
Michiel emphasises WDP’s adaptability. “Flexibility. We adapt quickly and offer customised solutions. That makes us reliable and relevant.” Gijs points out the growth potential. “There are still lots of opportunities in Romania and other emerging markets. Our model has been proven, so it will work everywhere. And we are ready to adapt to our client’s requirements.”
WDP’s responsive and effective strategy proves that it is prepared for the challenges of tomorrow.
Our ‘warehouses with brains’ are an indispensable link in the supply chain of our clients. The highquality and future-oriented logistics infrastructure we offer clients facilitates and optimises their activities and guarantees quality, sustainability, and continuity.
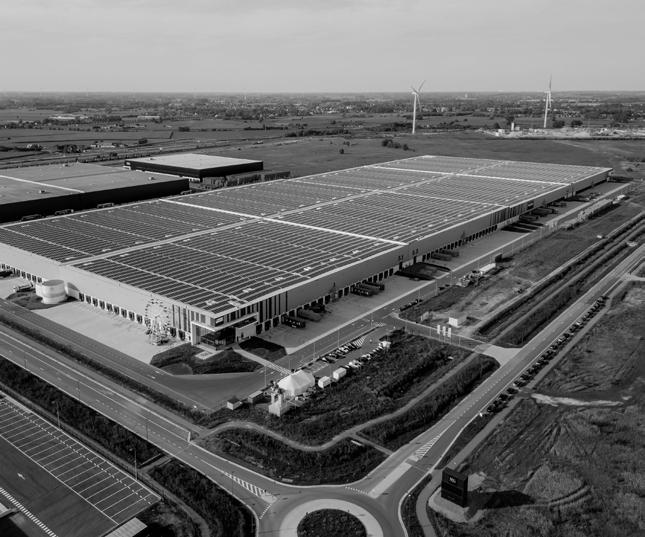
WDP’s answer to the acceleration in electrification and decarbonisation of transport: charging hubs that optimise clients’ energy profiles using a sophisticated combination of on-site energy generation from solar panels combined with smart charging facilities and batteries.
A Front of the Meter (FTM) Battery Energy Storage System (BESS). This will help balance the electricity grid by storing and managing excess energy on the grid, for instance, during sunny or windy periods. WDP is responsible for implementing this project and the investment. It will work with a specialist partner for the operation side. The project should be operational by 2028 (depending on the connection to the high-voltage network).
Charging infrastructure
Barry Callebaut
A challenge for our client: continual use of electric lorries with minimal time to charge.
WDPs integrated energy solution: innovative planning and the installation of high-capacity charging stations, which guarantees continuous 24/7 operations.
Charging infrastructure
Challenge for our client: making their transport more sustainable, but with a quick and efficient system that allows night loading to start the following trip in a timely manner.
WDPs integrated energy solution: investment in charging infrastructure and use of WDPs internal know-how and expertise in fleet electrification, including the use of the Total Cost of Ownership (TCO) tool.
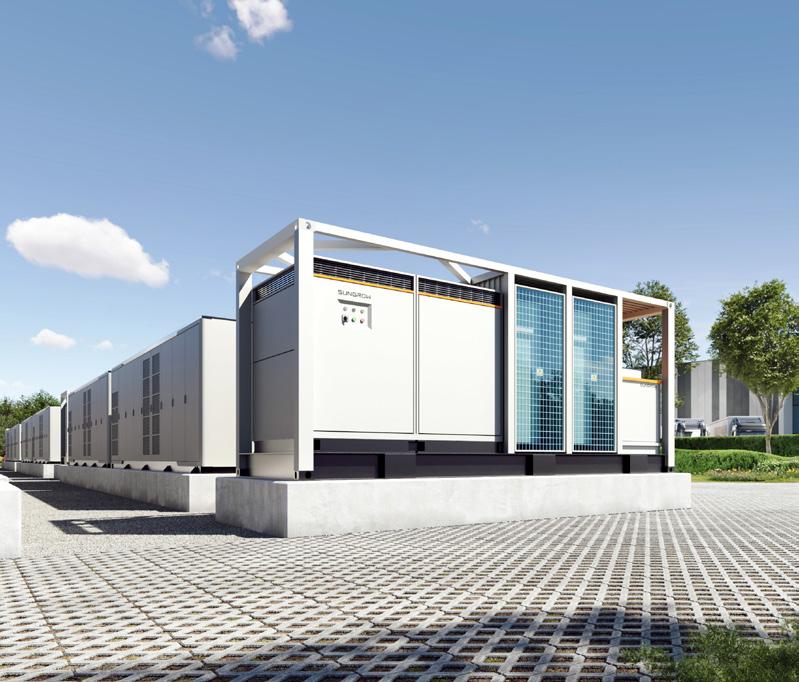
Scaling up renewable electricity production is indispensable for implementing our integrated energy solutions: smart grids, batteries and charging infrastructure for electric vehicles that align with and optimise energy consumption and production.
installations FUTURE LOGISTICS
Green electricity production
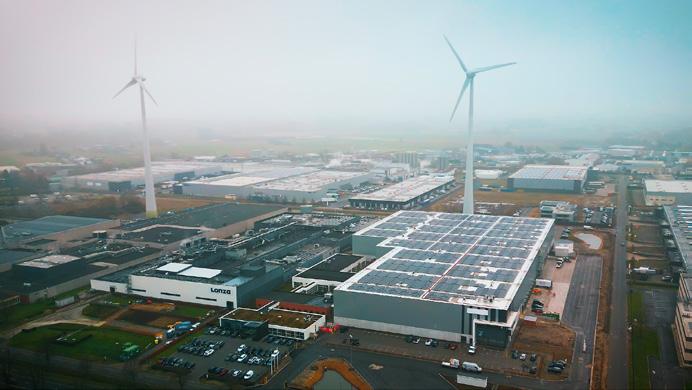
An additional 52 MWp was realised in 2024 giving us a total solar capacity of 234 MWp at year end. We wish to achieve a capacity of 350 MWp by 2027 as part of our Growth Plan #Blend2027 despite the increased complexity and lead time of these projects. This is how we contribute to the decarbonisation of the entire warehouse site and improve the client’s energy consumption (scope 3 downstream).
WDP is convinced that more can be achieved regards the sustainability of buildings and sites by solution-oriented collaborations with clients that allow for their operational activities.
Obviously, WDP understands its construction activities impact the environment and, thus prioritises significantly reducing greenhouse gas emissions. The DECARB+ track from our Climate Action Plan addresses several dimensions that help determine our environmental footprint: land use, material use, our buildings’ resilience, energy consumption, biodiversity, air pollution, water pollution, and soil pollution.
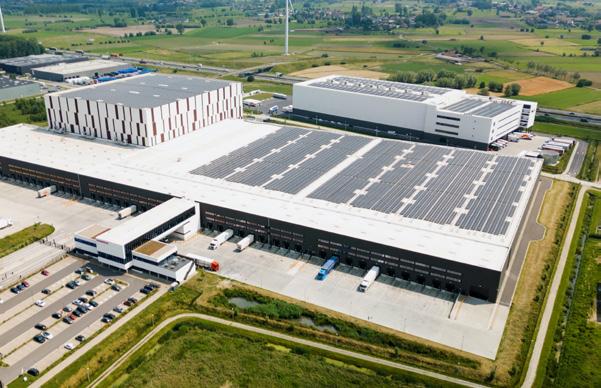
We are committed to sustainable certification of our buildings, specifically through the BREEAM and EDGE certificates. In 2024, we certified 78 additional properties despite the very time and capital-intensive process for our internal (property management) teams.
%
WDP Corporate emissions
WDP commits to reducing scope 1 and scope 2 emissions by 42% by 2030 compared to the baseline year 2020. The net-zero targets were validated by SBTi and approved in April 2022.2
8. Sustainability Statement
Total Scope 1 and 2 emissions (T CO2e market-based)
2 In this validation procedure – valid at the time of notification by WDP in April 2022 – SBTi considers WDP to be a small or medium-sized enterprise (<500 employees). So, initially, only our scopes 1 and 2 near-term targets were validated. A commitment is requested regarding the measuring and reducing of Scope 3 emissions. The Climate Action Plan also includes a net zero target for Scope 3, which is also defined in line with these Science Based Targets.
WDP DECARB+
Integrating biodiversity into the development of our real estate projects allows us to contribute to a healthy and resilient environment. This goes beyond being nature-friendly as it also improves the quality of life of the users of our buildings.
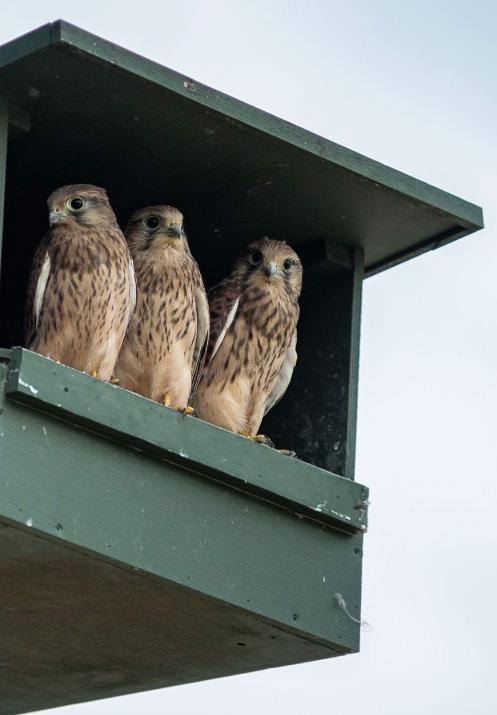
WDP makes a clear commitment to biodiversity in its Biodiversity & Deforestation Policy. Local laws and regulations are observed in the development of projects and renovations. Biodiversity provisions are based on the EU directives, such as the Habitat Directive and the LULCF Directive. Moreover, WDP works closely with landscape architects, contractors, ecologists and biodiversity experts during the permitting process, and design and construction phases of a warehouse.
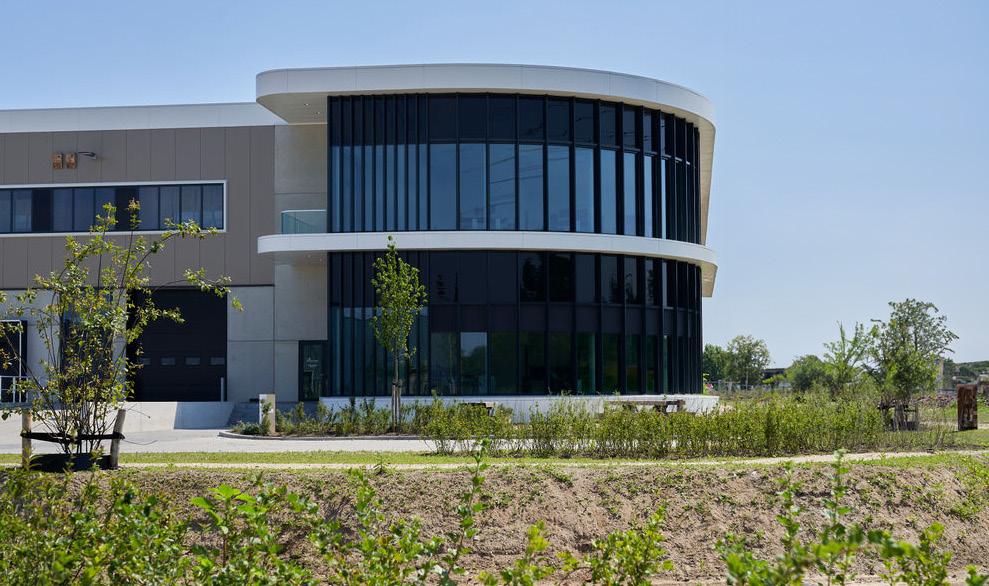
A great deal of attention was paid to biodiversity on this site right from the start of development. The greenery around the building, an eye for water infiltration instead of full paving and natural shelter for birds and animals promote local biodiversity and contribute to the conservation and reproduction of endangered species. Choosing plants that occur naturally in the environment supports local ecology and avoids the negative effects of invasive species.
FUTURE LOGISTICS
WDP DECARB+
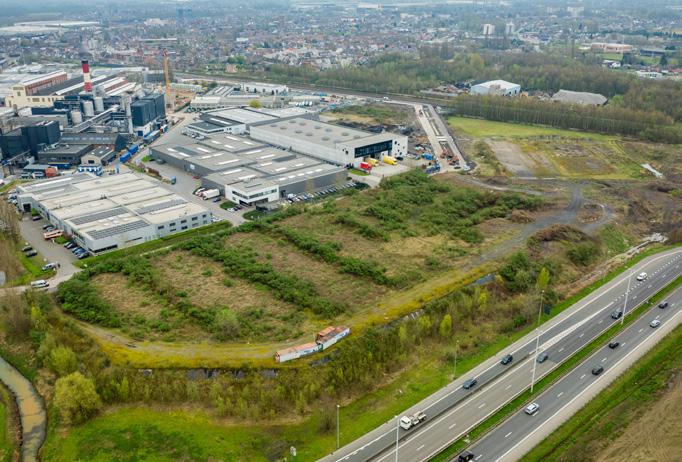
WDP breathes new life into older underused sites. Brownfield developments meet the scarcity of free space.
WDP breathes new life into older underused sites. Brownfield developments meet the scarcity of free space. In addition to redeveloping such sites into modern new-build warehouses with new, sustainable technologies, such projects often also involve cleaning up the (formerly) polluted site. This will reduce the site’s environmental footprint and also contribute to the health of employees who will make use of the premises and surrounding area.
73,024 m²
Brownfield projects under development
16 % of all projects under development
The acquisition of a cluster consisting of a brownfield site for development with a total surface of approximately 48,000 m², and three buildings on a long-term lease of over 10,600 m².
This site is part of the Willebroek-North logistics hotspot with access to and a nicely conspicuous location along the A12 motorway BrusselsAntwerp. After remediation, the vacant plot will be transformed into a high-end sustainable logistics site, where WDP’s leadership in expertise, transaction complexity, partnership with different stakeholders and client-centricity will make the difference.
WDP DECARB+
WDP sees multimodality as the future of logistics. This is why we strategically locate our warehouses at key hubs for (future) road, rail, water, and air transport.
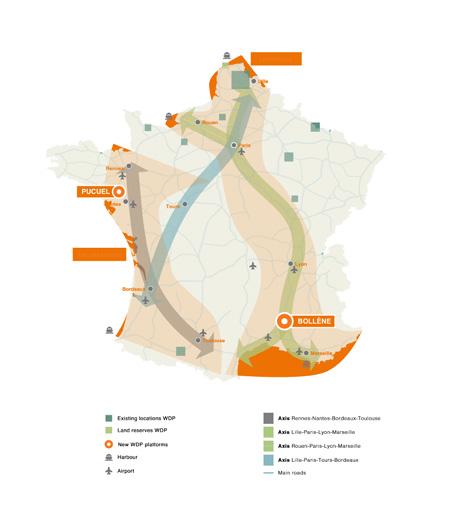
These logistics hubs can generate added value by fostering synergies between clients, regions, cities, ports, and public services. They enable smart solutions, such as freight bundling and agrologistics, and in the future, they could offer opportunities for creating local energy communities.
In 2024, WDP doubled its portfolio in France with the acquisition of two multimodal sustainable logistics sites: Bollène and Puceul. These new-build platforms are exceptionally well located along France’s key logistics corridors in France –La Dorsale and l’Arc Atlantique.
20 % of the entire portfolio
1.6 mio m²
multimodal locations
1 Strategically located next to A7 Motorway, LyonMarseille, with port and rail link Part of La Dorsale, the key economic North-South corridor for logistics with direct link to the Benelux/Germany on the one hand and Spain/Italy on the other hand.
1 3 Class A XXL warehouses of 190,000 m² and 76,000 m² for additional development.
1 BREEAM in-use Excellent, fitted with solar panels.
1 Strategically located on the Arc Atlantique axis with superb visibility and infrastructure for delivery to W-France and a connection to Paris and Bordeaux. Near the Saint-Nazaire harbour and train connection.
1 Newly-built distribution centre of 38,000 m².
1 BREEAM Very Good, fitted with solar panels. Read more
Rennes-Nantes-Bordeaux-Toulouse
axis Lille-Paris-Lyon-Marsille
axis Rouen-Paris-Lyon-Marsille
axis Lille-Paris-Tours-Bordeaux
#WeEducate 18,907 €
Support for training programmes that are in line with the WDP vision.
490 hours for 125 students
AMBITION 2024
Support and guidance for at least 100 students
AMBITION 2025
#WeAre Conscious 79 %
The monitoring of utilities so we contribute to our clients’ sustainable operational management through insight into their energy consumption.
AMBITION 2024
100% coverage energy monitoring system
AMBITION 2025
8.6 /10 ESG targets
Employee satisfaction & engagement
Satisfaction score
AMBITION 2024
Each employee has at least one ESG objective within their individual performance targets.
AMBITION 2024
HRhub
Implementation of the latest module in the digitisation of the HR processes where the onboarding and offboarding processes are integrated. Continued optimisation of HRHub.
AMBITION 2025
247,000 €
Financial and/or material support to local projects and vulnerable groups, including financially favourable terms for MaatWERKbedrijf BWB.
AMBITION 2024
Min. 100,000 euros per year of financial and/or material support to local projects and vulnerable groups.
AMBITION 2025
HSES
Annual audit for existing WDP properties, projects or offices
AMBITION 2025
Psychosocial risk analysis
Annual measurement and action plan follow-up
AMBITION 2025
#TeamWDP is the driving force behind our value creation. So, we are actively committed to the well-being, safety, and development of our employees. We strive to ensure our activities have a positive impact on the immediate surroundings and contribute to the needs of the local communities.
Our response to these key risks Supply chain
Accomplished On track
8.6/10
Overall average satisfaction score
Results in line across regions
Response ratio: 92%
Basis for action plan
In 2024, WDP was certified as a Great Place To Work®. Great Place To Work® is the global authority when it comes to workplace culture. An anonymous employee survey is used to assess staff experiences, how they perceive the workplace, their confidence and the encouragement given to develop both personally and professionally. These insights help WDP continue to improve and make strategic business decisions in line with the worldwide standards for great workplaces. The insights that we gain from the Great Place to Work® assessment provide tangible tools improve our organisational culture and inspire our people to achieve their true potential.
As a growing organisation, WDP must attract the right talent and integrate it into the company and its company culture. Only in this way the future resilience of WDP Group can be guaranteed, the resilience of the company will be increased and growth can be continuously be facilitated.
#TeamWDP was expanded by 11 new employees in 2024 –a +9% increase in headcount.
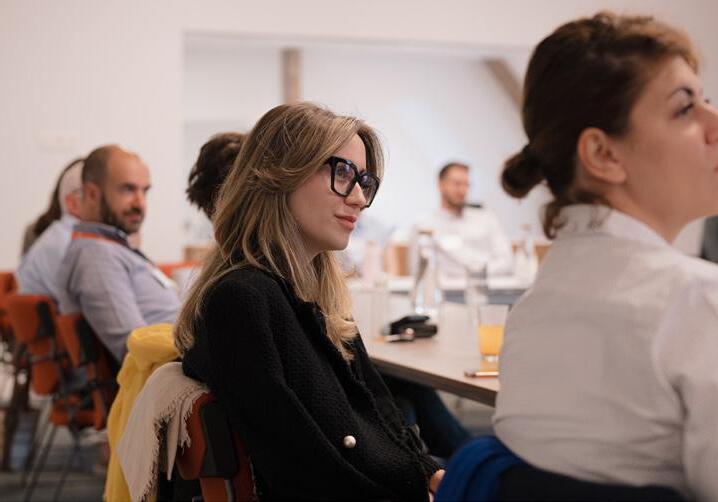
During this day, we welcomed our new colleagues from different countries so they could explore the core of WDP’s activities. During the morning, we delved into the world of logistics property through a fascinating introduction.We also discovered the essence of WDP’s DNA in interesting sessions held by different departments. During the afternoon, we switched from theory to practical experience and set off to explore our impressive warehouses. Read more
1,005 €
training expenditure per FTE (100% coverage)
28 hours
training on average per FTE (100% coverage)
+7 hours
training on average per FTE (y/y)
In 2024, the Learning Management System module was set up in our Online HRHub Tool. All internal training content is centralised here. This platform also provides access to an external learning provider with up-to-date training material in a variety of expertise domains. This helps employees optimise their skills and grow their career. The onboarding training program will be integrated in the LMS in 2025.
1 Attention to ergonomics: organisation of information sessions, purchase of ergonomic office materials, fully adaptation of the office in the Netherlands to the latest standards for ergonomics and workplace experience.
1 Attention for mental well-being: organisation of workshops, individual coaching availability, psychosocial risk analysis.
WDP’s 25th anniversary as a listed logistics property company was the perfect theme this year for its annual international team day.
We organised a three-day team event in Barcelona with all employees from the different countries to celebrate our performance and embrace the #TeamWDP team spirit. There was time for relaxation and team building as well as room for active workshops where cross-country topics were discussed to maintain the alignment within the group and facilitate team engagement between all teams.
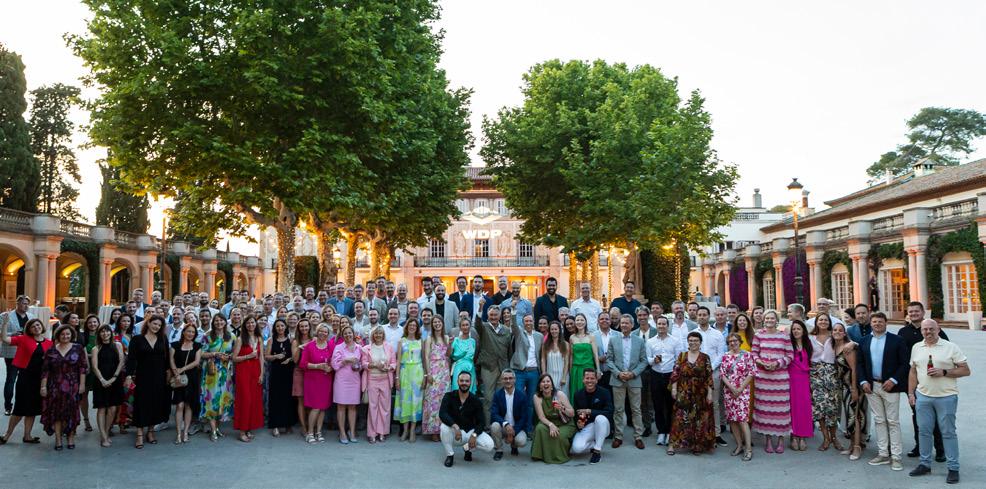
129
Participants
10
Workshops on cross-country topics
4 Participating countries
WDP has a corporate citizenship strategy – #WeMakeADifference –divided into three pillars, #WeCare, #WeAreConscious and #WeEducate. Our strategy aims to create an impact over the long term.
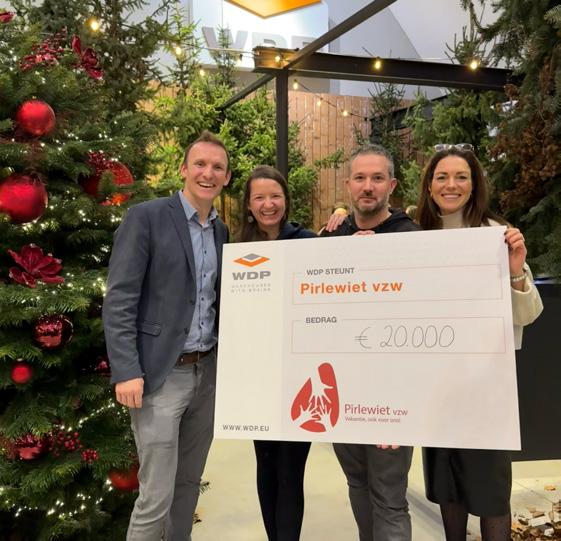
We provide financial and/or material support to local projects and vulnerable groups. This reinforces our relationship with local communities. We also profile ourselves as a reliable partner and company. #TeamWDP raised 20,000 euros in 2024 for Pirlewiet vzw and toys and sweets for the local project “Sint voor ieder1” (St. Nick for everyone). WDP also offers financially favourable terms for the MaatWERKbedrijf BWB. For example, WDP supports this company, which employs people with disabilities.
#WeEducate
We support young students and new workers in the logistics property market. WDP engages in several education programmes, aligned with its business. We support inclusion projects that provide opportunities for young, new workers and, where possible, prevent unemployment among young people. In 2024, we reached more than 100 students with guest lectures for students in logistics property-related training sessions in Belgium and the Netherlands. As part of the EBRD financing, WDP organises an annual theoretical and practical training session for students from the Oil and Gas University Ploiesti (24 in 2024). This includes visits to different WDP sites that are supervised by some Romanian employees.
Long-term partnerships
5.7 years
Average
HSES
Awareness
Roof Safety scan of the entire property portfolio in preparation for a toolbox to raise awareness and educate all building users on safety.
27 %
Repeat business
96 %
Lease renewal
Retention rate as a client satisfaction indicator: the percentage of contracts that mature in the reporting year and are renewed
AMBITION 2024
At least 80% in lease renewal
AMBITION 2025
Supply chain
Supplier Code of Conduct
Our client’s safety and well-being WDP’s Services with Brains offers a full-service solution that, amongst others, increases the safety and well-being of our clients’ employees at a WDP warehouse site.
At least the critical suppliers sign this code and thus formally endorse its principles.
AMBITION 2024
Audit of all WDP offices in Wolvertem, Breda and Bucharest.
AMBITION 2024
Annual HSES audit for existing WDP premises, projects, or offices.
AMBITION 2025
Supply chain management
Further formalisation of supply chain management, taking into account future legal requirements for due diligence in the value chain.
AMBITION 2025
We are committed to a strong and reliable value chain: from our suppliers, who help shape the core product of WDP to our clients who distribute their goods globally. Our strong relationship with our different business partners ensures we can respond to their wishes and challenges. We contribute to the health, safety, and integrity of their staff. Moreover, we take on our responsibility in terms of risk management in our supply chain, including human rights. This is how we ultimately raise WDP’s value creation to a higher level.
Our successful long-term relationships with our clients help us support them in their activities. By listening carefully to the client’s needs, combined with our expertise, years of knowledge of the logistics market and its processes and in-house project and property management, we can offer the most suitable buildings at the most appropriate location and help them develop their strategy crosscountry. The long-term leases, the high occupancy rate, the strong retention rate and the high proportion of repeat business reflect our client’s satisfaction. IMPACT BY RESPONSIBILITY
WDP Services with Brains help clients combine sustainable operational efficiency with top-notch user experience and branding. In close collaboration with our trusted partners, WDP offers a custom full-service solution that relieves our clients of the burdensome work required from design to implementation. This platform facilitates branding solutions, supports welfare and safety, and optimises mobility. It also includes renewable energy and an energy solutions software package and unburdens the client through the Handyman service.
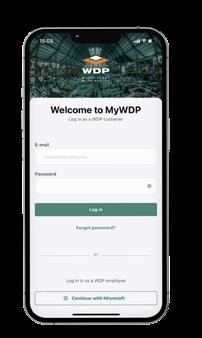
MyWDP combines ease of use with operational efficiency
The MyWDP digital client portal is the intelligent link between our clients and #TeamWDP. This tool transforms real-time data into valuable insights and enables reporting and troubleshooting at the click of a button. It is the one-stop shop that gives access to all crucial information about each warehouse in the portfolio. For example, the client has insight into its energy consumption via real-time energy monitoring. In this way, our client is perfectly aware of his utility consumption and can use this data as a basis for his sustainability strategy.

IMPACT BY RESPONSIBILITY
Everyone’s work environment must comply with relevant health and safety regulations and WDP’s #HealthyAndSafe Statement.
The annually revised HSES Corporate Action Plan developed by the WDP HSES Team entails a thorough analysis of the working environment for all stakeholders, formulates possible improvement actions, and ensures execution of an annual external audit and pushes for awareness among all relevant stakeholders through, for example, white papers or events.
WDP depends on a strong network of business partners, suppliers of materials, products and services. In this selection too, WDP strives for long-term partnerships rather than one-off collaborations.
Such relationships of trust guarantee quality, continuity and proactivity in project development and renovation, ensure high-quality client service and establish a continuous exchange of knowledge and best practices. This will also ensure the further decarbonisation of our product: the WDP warehouse and its infrastructure.
In the long term, WDP intends to organise its supply chain to ensure the required attention is paid at all levels to operational, financial, reputational and sustainability requirements. A management system should enable us to respond to opportunities within the chain and effectively mitigate the risks.
1 This chapter describes how the EPRA core performance indicators are defined and reconciled. Share performance
90.2
2.6 %
(in million euros)
1 This includes the valuation of investments in solar panels at the fair value.
2 The total land area includes concession land.
3
per share (in euros)
Some figures are subject to rounding adjustments. Consequently, it may occur that figures shown as totals in certain tables are not a precise arithmetical totals of foregoing figures.
The Alternative Performance Measures (APM) used by WDP, including the EPRA Key Performance Indicators, are accompanied by a symbol (♦). This chapter also describes how the EPRA core performance indicators are defined and reconciled. The other Alternative Performance Measures can be found in 10. Appendices – Alternative Performance Measures listing the definition and reconciliation.
4 Defined as operating result (before result on the portfolio), divided by interest charges, minus interest and dividend collection, minus compensation for financial leasing and others.
Consolidated results (analytical scheme)
euros x 1,000)
in the fair value of financial instruments – Group
and write-down on solar
Dividend payout ratio (versus EPRA
1 Calculation based on the weighted average number of shares.
2 Calculation based on the number of shares entitled to dividend.
3 The dividend payout ratio is calculated in absolute terms based on the consolidated result. Dividend is distributed based on the statutory result of WDP NV/SA.
The property result amounts to 417.5 million euros for 2024, an increase of 16.8% compared to last year (357.4 million euros). The increase comes from pre-let new construction projects and acquisitions combined with further organic rental growth. The unchanged portfolio saw the level of rental income increase by +2.6%.
The property result also includes 22.8 million euros in solar panel income compared to 24.1 million euros last year. Even though solar energy capacity has increased, revenues slightly decreased due to lower electricity prices and adverse weather conditions. Capacity will continue to grow. But its contribution to the earnings statement should be taken into account gradually, due to the increased complexity and lead time of these projects (e.g. grid connection) and lower energy prices.
Moreover, in the fourth quarter of 2024, WDP received a one-off lease break fee amounting to 11 million euros1. After deducting the tax impact and the minority interest, the impact on EPRA Earnings is approximately 8 million euros, corresponding to a one-off of +0.03 euros in EPRA Earnings per share.
The operating result (before the result on the portfolio) amounts to 376.6 million euros for 2024, an increase of 16.6% compared to the same period last year (323.0 million euros). Property and other general expenses amount to 40.9 million euros over 2024. Its increase by +6.6 million euros or +27% is consistently in line with the +17% growth in the property result. However, this provides an unfavourable basis of comparison due to some positive one-offs in overheads in Q1 2023 amounting to around 2 million euros. There is also an increase in property charges as of Q2 2024 of +2 million euros year-on-year due to the
recent Romanian purchase amounting to 90 million euros2. This purchase provides a high net yield of 12.5%, but the margin is lower due to more intensive management. So, these factors explain the slight decline y/y in the operating margin to 90.2. WDP expects to maintain its high annualised operating margin of above 90%.
The financial result (excluding variations in the fair value of financial instruments) improved from -41.4 million euros last year to -40.7 million euros. The financial result within an environment of high interest rates (Euribor 3 month ranged between 3.9% at the end of 2023 and 2.7% as of 31 December 2024) was kept under control by WDP’s proactive financial management and high degree of hedging (89% at the end of December 2024). This means that WDP kept the average interest cost very low at 1.9% over 2024 and equal to the 2023 level.
This result takes into account +12 million euros of capitalised interest on development properties. This financial result also includes the recurring interest cost for land under concession of -4.4 million euros, which are recognised through the Financial result per IFRS 16.
Together with the increase in the operating result (before the result on the portfolio), this implies a further strengthening of the Interest Coverage Ratio to 6.9x (6.6x as of 31 December 2023).
The result of 15.8 million euros over 2024 mainly involves the contribution following the participation in Catena.
In 2024, WDP continues to draw up its accounts applying the FBI regime for its Dutch operations. Afterwards, the statute will expire, given the change in the law implemented by the Dutch government, which excludes real estate investments from the Dutch FBI regime from 1 January 2025. From 2025, this will lead to an estimated additional annual tax burden on EPRA Earnings of -11 million euros (0.05 euros per share).
Note that the provisions that were provided for 2021-22-23 (when it was assumed that the FBI regime was at risk for these financial years) were reversed in 2023, resulting in a one-off positive impact on EPRA Earnings of approximately 11 million euros (+0.05 euros per share) in 2023.
WDP EPRA Earnings for 2024 amount to 333.7 million euros. This result marks an increase of 15.4% compared to the result of 289.0 million euros in 2023. This result was driven by the impact of pre-let projects, realised acquisitions, organic rental growth and a one-off termination fee. And, this was possible even with a persistently competitive cost of funding (despite high Euribor rates) thanks to quasi-full debt hedging.
EPRA Earnings per share rose +7% to 1.50 euros. This is +0.03 euros higher than the earnings target of 1.47 euros due to a one-off termination fee. Furthermore, this also includes a +7.7% increase in the weighted average number of shares outstanding due to the reinforcing of the capital in 2023-24 by over 500 million euros (via ABB, optional dividend and contribution in kind).
The portfolio result (including the share of joint ventures and after tax) – Group share for 2024 is 140.3 million euros or 0.63 euros per share. For the same period last year, this result amounted to 140.3 million euros or -0.85 euros per share. This breaks down by country as follows: Belgium (+12.5 million euros), the Netherlands (+51.6 million euros), France (+44.1 million euros), Romania (+26.7 million euros), Germany (-0.4 million euros), Luxembourg (-0.8 million euros) and Sweden (+6.6 million euros).
The revaluation of the portfolio (excluding deferred taxes on the portfolio result and the result on sales of investment properties) is +154.9 million euros (Q4 2024: +46 million euros), an increase of +2.0% year-to-date. This is mainly due to latent capital gains on projects and recent acquisitions, as well as asset management initiatives on existing sites, combined with a slight positive revaluation in the existing portfolio driven by the increase in estimated market rental values of +3% over 2024, only marginally offset by an upward yield shift of +8bps). Currently, the portfolio is valued at an EPRA NIY of 5.4%3
The changes in the fair value of financial assets and liabilities – share Group4 are -27.5 million euros or -0.12 euros per share over 2024 (as opposed to -76.0 million euros or -0.37 euros per share in 2023) due to the further decline in long-term interest rates.
The fair value variation has no impact on cash and is an unrealised item, so it is excluded from the financial result in the analytical presentation of results and presented separately in the earnings statement.
The solar panels are valued on the balance sheet at fair value based on the revaluation model in accordance with IAS 16 Tangible fixed assets. In compliance with IAS 16, WDP must include a depreciation component in its IFRS accounts according to the residual service life of the PV installations. The depreciation is calculated based on the fair value from the previous balance sheet date. This newly calculated net book value is subsequently revalued at the fair value. This revaluation is booked directly in the equity capital insofar that it still exceeds the historical cost price, plus accumulated depreciations. If it does not, it is then accounted for in the earnings statement. The depreciation component and write-down is -11.0 million euros. Since this impact of the depreciation and amortisation of solar panels involves a non-cash and unrealised item, it is excluded from the operating result in the analytical presentation of the results and is shown separately in the earnings statement.
The EPRA Earnings along with the result on the portfolio, changes in the fair value of financial instruments and the depreciation and write-down on solar panels result in a net result (IFRS) – Group share of 435.5 million euros in 2024 (compared to the same period last year, when this figure was 22.3 million euros).
The difference between net result (IFRS) – Group share of 435.5 million euros and the EPRA Earnings of 333.7 million euros is mainly due to the slight increase in the value of the portfolio and the negative variation of interest rate hedging instruments.
3 The net reversionary yield is 6.2% based on full letting at market rent..
4 Changes in the fair value of financial assets and liabilities – Group share (a non-cash item) is calculated based on the mark-to-market (M-t-M) value of interest rate hedges concluded.
with respect to EPRA NTA
(in euros x million)
Fair value of the portfolio (including solar panels)¹
Net debt / EBITDA (adjusted)♦
1 Based on 100% of the fair value for the fully consolidated entities (including WDP Romania) and the proportional share for the joint ventures (in particular 55% for Luxembourg, 50% for WDPort of Ghent Big Box) and 29% for GosselinWDP).
2 For the method used to calculate the gearing ratio, refer to the Royal Decree of 13 July 2014 on the GVV/SIR.
According to the independent real estate experts Stadim, JLL, CBRE and BNP Paribas Real Estate, the fair value6 of WDP’s property portfolio per IAS 40, as of 31 December 2024 7,685.1 million euros compared to 6,596.7 million euros at the start of the financial year (including the heading Assets held for sale). Together with the valuation at fair value of the investments in solar panels7 the total portfolio value evolved to 7,869.8 million euros compared to 6,766.6 million euros at the end of 2023.
This value of 7,869.8 million euros includes 7,281.5 million euros in completed properties (standing portfolio)8. Projects under development account for a value of 195.7 million euros. Moreover, WDP has land reserves with a fair value of 207.9 million euros.
The investments made in solar panels were valued on 31 December 2024 at a fair value of 184.7 million euros.
Overall, the portfolio is valued at a gross rental yield of 6.2%9. Currently, the portfolio is valued at an EPRA Net Initial Yield of 5.4%. The current contractual rent is approximately 11% lower than the market rent. The net reversionary yield10 is 6.2% based on full letting at market rent.
5 Under IFRS 11 Joint arrangements, the joint ventures are incorporated using the equity accounting method. With regard to portfolio reporting statistics, the proportionate share of WDP is shown for the portfolio in WDPort of Ghent Big Box (50%), Luxembourg (55%) and Gosselin-WDP (29%).
6 For the exact valuation method, we refer to the BE-REIT press release of 10 November 2016.
7 Investments in solar panels are valued per IAS 16 by applying the revaluation model.
8 Including a right of use of 89 million euros, related to the land held through a concession per IFRS 16.
9 Calculated by dividing the annualised contractual gross (cash) rents and the rental value of the unlet parts by the fair value. The fair value is the value of the investment properties after deducting transaction costs (mainly transfer tax).
10 The reversionary yield is calculated by dividing the estimated market rent value – less non-recoverable property operating costs – by the market value of the property including (estimated) acquisition costs. The reversionary yield relates to the expected return to which the net yield will rise (or fall) once rent reaches the full estimated rental value.
The EPRA NTA per share amounted to 21.1 euros on 31 December 2024. This represents an increase of +1.0 euros (4.7%) versus an EPRA NTA per share of 20.1 euros on 31 December 2023 due to EPRA Earnings generation (+1.50 euros), dividend payment (-1.12 euros), portfolio revaluation (including solar panels) (+0.65 euros) and other (-0.07 euros). This implies a return on equity11 of +10% in 2024.
The IFRS NAV per share12 amounted to 21.0 euros on 31 December 2024, compared to 20.2 euros on 31 December 2023.
In 2024 WDP and its subsidiaries together paid 100.5 million euros in social, fiscal and sector-specific taxes to the treasury.
Balance sheet capacity coupled with strong net debt / EBITDA (adj.) and ICR metrics that measure debt repayment capacity
Validation of solid investment grade credit rating due to track record of prudent financial policies
Fully covered:
refinancing until at least the end of 2026
committed CAPEX
commercial paper
6.9 x ICR 68 % Green financing
Financing needs to implement our growth plan are fully covered
The WDP Group financing policy is geared towards optimal financing of the company with an ideal mix of debt and shareholders’ equity, and the availability of adequate resources to complete ongoing projects and capitalise on any opportunities that arise.
The key objectives within this context are the following:
1 a proactive management of the capital structure;
1 a balanced issuance of minimum 50% equity and maximum 50% debt;
1 a good diversification of the various sources of financing;
1 a good spread of the maturities of the liabilities;
1 a strong liquidity position;
1 a sustainable long-term relationship with all financing partners;
1 an active financial risk control including interest risk, liquidity risk and counterparty risk.
(proportional) (in line with the GVV/SIR Royal
The Alternative Performance Measures (APM) used by WDP, are accompanied by a symbol (
definition and reconciliation can be consulted in Chapter 10. Annexes – Alternative Performance Measures
1 Defined as operating result (before the result on the portfolio) divided by interest charges less interest and dividends collected less the fee for financial leasing and other.
2 Remaining term of debt at fixed rate and interest rate hedges entered into to hedge the debt
fluctuations.
WDP’s financial policy is based on the following KPIs
>18 months Strong access to capital
WDP endeavours as much as possible matching its assets and liabilities throughout the cycle. The chart below shows that minimum 50% of the portfolio growth over the period 2014-2024 is financed by equity.
The portfolio generates a gross yield of 6.2% based on very high visibility with an average lease term of 5.7 years until first break and 6.8 years to final maturity. The debt financing has an average cost of 1.9%, based on a high hedging ratio with long-term hedging instruments (4.8 years on average). This wide margin between yield and cost ensures adequate support to cover the costs of financing, resulting in an interest coverage ratio of 6.9x. Moreover, the visibility on the income and expenses results in a robust revenue flow.
The use of debt is legally limited via the Belgian GVV/SIR Royal Decree. For instance, the gearing ratio cannot exceed 65% (both on a consolidated and statutory level) and moreover, dividend distributions to shareholders are only permitted if the defined limit is not exceeded – given that they must be used at that time to bring the debt ratio back down below 65%. Debt is used to optimise returns for shareholders, but must be applied with prudence taking numerous factors into account, such as access to refinancing capital, capacity to cover interest costs, quality of the portfolio, the term of the leases and the portion of projects under development.
Total financial debt (as per IFRS) increased to 3,063.8 million euros as of 31 December 2024, compared to 2,316.7 million euros at the end of 2023, based on realised investments in 2024. The balance sheet total increased from 7,072.3 million euros as of 31 December 2023 to 8,203.2 million euros as of 31 December 2024.
The loan-to-value, which measures the net financial debt to the value of the portfolio value1, remains low at 38.3% as of 31 December 2024, compared to 33.7% as of 31 December 2023. The (proportional) gearing ratio amounts to 40.5 as of 31 December 2024, compared to 35.8% as of 31 December 2023. Moreover, the net debt / EBITDA (adj.), the key metric of the capital structure, which measures the actual debt repayment capacity, is very strong at 7.2x.
1 Based on IFRS statements including solar panels and receivables from and participations in joint ventures.
The scale on which WDP practises its business activities, in combination with strict regulations, to which a GVV/SIR is subject to, and the high degree of visibility on the rental flows, gives WDP a competitive advantage in the search for appropriate sources of financing. This is extremely important in the continuously changing financing environment where high creditworthiness and diversification are key. The graph below shows a breakdown of the outstanding consolidated financial liabilities across funding sources as of 31 December 2024.
The majority of the credit facilities are bullet type instruments, which implies that over the term, interest charges are due on the principal sum and that full repayment of the capital is due on the final maturity date. The maturity dates are evenly distributed over time. 50% of the debt matures between one and five years and 50% expires after more than five years. The current financial debt of 73.0 million euros includes the short-term straight loans (7.3 million euros) and long-term financing maturing within the year (65.7 million euros). The weighted average maturity of outstanding financial debt is 4.9 years2 as of 31 December 2024.
Composition of the debt portfolio
Maturity of credit facilities
Despite an environment of high interest rates (Euribor 3 month ranged between 3.9% at the end of 2023 and 2.7% as of 31 December 2024), WDP’s proactive financial management ensured debt over 2024 was fully hedged against rising interest rates (the hedge ratio only fell to 89% in December 2024), which succeeded in keeping the interest cost particularly sharp at 1.9% over 2024. Together with the increase in the Operating Result (before the result on the portfolio), this implies a further strengthening of the Interest Coverage Ratio to 6.9x (6.6x as of 31 December 2023).
WDP’s risk policy regarding interest rates aims to minimise fluctuations in interest rates and to optimise the cost of debt. This is done through a centrally managed macrohedging policy, in which interest derivatives are used solely to hedge the financial debt. The Group does not use derivative instruments for speculative purposes nor hold derivatives for trading purposes.
The hedge ratio, which measures the percentage of financial debt at a fixed interest rate or floating interest rate and subsequently hedged via an Interest Rate Swap (IRS) is 89% as of 31 December 2024 with a weighted average maturity of hedges of 4.8 years.
However, WDP’s result is still subject to fluctuations (see also Chapter 5. Financial results and outlook for a sensitivity analysis with respect to short-term interest rates).
Evolution of average cost of debt
Evolution of hedge ratio at constant debt position
MANAGEMENT OF FINANCIAL RESOURCES
Pursing sustainable growth requires funding diversification with a focus on green funding. As a capital intense real estate company, we must secure our access to financing (debt and equity). The clear regulatory shift towards green financing implies a higher demand from investors and financial institutions for green investments and green-certified assets.
WDP has committed to maximum green financing within the framework of the WDP Climate Action Plan. This ambition for more sustainable capital and operations is integrated into the WDP Green pillar of the WDP Climate Action Plan. This sets clear targets for green financing and green certified warehouses. Thus, WDP aims to increase the proportion of green-certified assets in the total property portfolio and the proportion of green financing to minimally 75%.
The WDP Green Financing Framework defines which green projects are eligible to finance and/or refinance, i.e. projects within the Green Buildings, Renewable Energy, Energy Efficiency and Clean Transportation categories.

WDP reports annually on the allocation of the green financing instruments, which is externally verified by independent auditor Deloitte Bedrijfsrevisoren. The auditor confirmed that the amount of outstanding green financing instruments was allocated according to the criteria that were set out in the Green Financing Framework.
For more information about the Green Financing Framework impact indicators, see Chapter 8. Sustainability Statement. All indicators marked with a ✓ were reviewed by Deloitte as part of a limited assurance for 2024.
Credit rating
1 Moody’s reaffirms Baa1 credit rating and upgrades Outlook to Positive3
On 27 June 2024, Moody’s affirmed WDP’s long-term issuer rating of Baa1 and upgraded the Outlook from Stable to Positive. The revised Outlook to Positive reflects Moody’s expectation that WDP will continue to grow its cash flow and maintain good liquidity while retaining high occupancy levels and a balanced growth strategy without compromising the capital structure within a still favourable operating environment.
1 Fitch affirms WDP’s BBB+ Long-Term Issuer Rating with Stable Outlook and A-senior unsecured debt rating.
On 25 July 2024, Fitch affirmed WDP’s Long-Term Issuer Default Rating at BBB+ with a Stable Outlook. The rating is supported by ongoing demand for modern logistics and industrial hubs and rental growth through annual contractual indexation-linked rental uplifts. The rating and outlook are commensurate with WDP’s robust financial profile, strengthened by solid access to capital supporting ongoing investment spending.
The charts below show WDP’s prudent, proactive and disciplined management of capital as the basis of a solid investment grade rating.
Investment grade and positive/stable outlook
1 High-quality portfolio in West Europe and Romania
1 Sustained structural demand and high occupancy rate in the sector
1 Focus on generating long-term cash flows
1 Diversified client base
1 Continued high occupancy rate and stable rental income (indexation linked)
1 Strong balance sheet and interest coverage metrics
1 Solid access to capital through the cycle
Track record of earnings-based leverage ratio target
Financing mix of investments
The contractual terms of the credit facilities generally stipulate that WDP remains qualified as a regulated real estate company (GVV/SIR) in Belgium. Moreover, covenants were entered into regarding a maximum gearing ratio of 65%, a minimum Interest Coverage Ratio of 1.5x, the value of speculative (i.e. without pre-letting) development projects may amount to a maximum of 15% of the book value of the portfolio (i.e. Development Property Ratio) and that the financial debt at subsidiary level may amount to a maximum of 30% of the total outstanding financial debt (i.e. Subsidiary Financial Debt Ratio).
WDP confirms that all of these conditions were met throughout the entire 2024 financial year. The table below summarises the covenants.
Gearing ratio (proportional) (in line with the GVV/SIR Royal Decree) (in %)
In 2024, an investment volume of approximately 1 billion euros was identified consisting of new projects and land as well as acquisitions of existing buildings and investments in energy transition. Besides financing net capital expenditure, liquidity was strengthened in 2024 to a buffer of 1.7 billion euros4 of unused and confirmed long-term credit lines. This provides WDP with ample funds to finance the investment pipeline of 1.1 billion euros and the financing maturing up to the end of 2026 (500 million euros). This excludes retained earnings and the optional dividend (projected approximately 600 million euros cumulatively in 2025-27) and the refinancing of loans. Thanks to its financial strength, WDP has sufficient resources to finance its growth plan.
The company strengthened its financial resources over 2024 as follows:
WDP and the European Investment Bank (EIB) signed a new 250 million euros financing package at the end of July 2024. This package will be used exclusively to finance the renewable energy projects of solar panel installations, batteries and charging infrastructure. The term loan can be drawn in several tranches until the end of 2027 for implementing the projects in Western Europe and Romania.
In the first quarter of 2024, WDP and IFC, a member of the World Bank Group, have concluded a new financing package of approximately 300 million euros. This financing is a sustainability-linked green loan with a term of up to eight years and will be used exclusively to finance the new logistics construction projects in Romania. The interest margin on the loan is linked to the Group’s sustainability strategy. In particular, the further sustainability of the property portfolio and the expansion of installed solar power capacity in Romania.
1 Optional dividend amounting to 103 million euros5
WDP’s shareholders opted to contribute their dividend rights for approximately 60% of their shares in exchange for new shares instead of cash dividend payments. This result led to a capital increase for WDP of approximately 103 million euros by creating 4,363,767 new shares, assuming an issue price of 23.52 euros per share.
4
5
1 Capital increase through contribution in kind for 39.7 million euros6
The sale-and-leaseback transaction of a site in Waregem, Belgium, was realised on 4 September 2024 via contribution in kind in return for 1,737,100 new WDP shares at an issue price of (rounded) 22.85 euros. This transaction resulted in a reinforcement of equity capital by 39.7 million euros.
1 New (re-) financing in 2024
Additionally, in the course of 2024, WDP was able to extend existing credit lines and secure additional financing of around 400 million euros from various Belgian and foreign banks.
Equally in 2024, WDP continuously monitors the potential impact of financial risks and takes the necessary measures to manage these risks. These risks include counterparty risk (insolvency or credit risk affecting financial partners), liquidity risk (non-availability of financing or very expensive financing options). This negative change impacts the fair value of buildings and risks related to interest, budget, agreements and exchange rates.
1 WDP buys out partner in Romania to stay on as Country Manager WDP Romania
After establishing and successfully building WDP Romania for more than 15 years, WDP and its partner in Romania decided to transfer its 15% equity stake in this company to WDP. He retains his position as Country Manager of WDP Romania and will continue to help expand growth in this country. WDP Invest NV/SA, a subsidiary of WDP NV/SA, has therefore concluded a purchase agreement with J.B. Top Pro Invest Srl and Vuurkruisenbizz BV to buy WDP Romania shares, such that WDP Romania is a 100% subsidiary of WDP Invest NV/SA since the end of January. Per GVV/SIR legislation, J.B. Top Pro Invest Srl and Vuurkruisenbizz BV are considered related parties to WDP Invest NV/SA, specifically in their capacity as co-shareholder of WDP Invest NV/SA in WDP Romania. In that context, it is hereby clarified that the acquisition of a minority was completed under normal market terms and at the NAV of the WDP Romania shares as of 31.12.2024 (totalling 91.6 million euros) against payment in cash.
1 Capital increase through contribution in kind for 6.5 million euros7
WDP reinforces cluster at logistics hub next to A12 in Londerzeel. The acquisition of the logistics site in the Londerzeel business park (Belgium) was completed on 19 February 2025 using a contribution in kind of the shares of the company Pielon BV that holds the site in WDP, for a contribution value of approximately 6.5 million euros and this against payment of 311,295 new WDP shares at an issue price of 20.77 euros (rounded). This transaction resulted in a reinforcement of equity capital by 6.5 million euros (rounded).
The forecasts described below contain the expectations for the 2025 financial year regarding the consolidated EPRA Earnings and WDP’s consolidated balance sheet. The basis for their drafting and preparation is similar to that of the outlook for the 2024 and 2023 financial years and is in accordance with the WDP’s accounting policy and IFRS1
These forecasts were drawn up based on information available on 31 December 2024. The forecasts with regard to the consolidated balance sheet and the EPRA Earnings are predictions that will depend on changes in the economy, the financial markets and property markets. This prospective information and these forecasts, opinions and estimates prepared by WDP relating to its currently expected future performance and the market in which WDP operates do not constitute a commitment by the company. By their very nature, ‘forward-looking statements’ imply inherent risks, uncertainties and assumptions (both general and specific), including the risk that these statements will not prove to be accurate.
Assumptions concerning elements that WDP cannot influence directly
1 Organic growth:
• +2.6% increase in rental income due to indexation;
• +0.4% impact of upward rent revisions;
• an occupancy rate of at least 97%.
1 Interest rates: an average level of one, three and six-month Euribor rates of 2.14%, 2.15%, and 2.19% respectively.
1 Financial hedging instruments: given their volatility, variations in their market values were not taken into account. These changes are irrelevant to the forecasts associated with the EPRA Earnings.
1 Electricity prices: an energy price of 80 euros per MWh – based on the 1-year forward market for electricity – is used as a basis for solar energy revenues as of the end of 2024.
1 Valuation of real estate portfolio and solar panels: no predictions are made regarding the variations in the fair value of the real estate portfolio and solar panels. This would be unreliable and subject to many external factors over which the company has no influence. These variations are also not relevant to the outlook for EPRA earnings.
1 External events: it is assumed that no material changes will occur in the (geo)political and/or economic climate which could have a material impact on the Group.
1 Regulatory and tax framework: it is assumed that no material changes occur in tax legislation or regulatory requirements that would affect the Group’s results or its accounting methods.
1 Risks: the outlook may be affected, inter alia, by market, operational, financial and regulatory risks as described in Chapter 7. Risk factors.
1 Net rental result: the increase was mainly driven by external growth and organic growth via indexation of the leases and the impact of rent reviews. The net investment volume of around 950 million euros achieved in 2024 will largely contribute to the result during the 2025 financial year. Moreover, today WDP has a total investment pipeline in execution of around another 1.1 billion euros (of which 400 million euros is currently in an exclusive negotiation phase) that will also contribute to the result in 20252 Regarding organic growth, the indexation of the leases is taken into account (see above). In 2024, 13% of the contracts will come to maturity, of which 70% could already be renewed at the time of the publication of the 2024 results and for which the current rent is therefore known. For the remaining 30%, lease extensions and/or renewals after a possible vacancy period are taken into account. WDP assumes a minimum average occupancy rate of 97% for 2025 and stable client payment behaviour.
1 For the auditor’s report on the EPRA Earnings forecast, see Chapter 10. Appendices – External audit
2
1 Solar power revenue: estimated at approximately 23 million euros, slightly higher compared to 2024. This increase is due to a higher capacity, but is partly tempered by lower electricity prices.
1 Other operating income/expenses: this item includes the net effect of property taxes, the property management fee charged by WDP as well as some non-recurring income.
1 Property costs: these are mainly the net costs (i.e. after any recharges) for maintenance and repairs, insurance contracts and commission. They have been estimated for 2025 based on the current portfolio, the expected investments, and the evolution of the figures from previous financial years.
1 General costs: these costs evolve in line with the portfolio growth, enabling the operational platform to be further developed in a cost-efficient manner, while maintaining a high operating margin above 90%. These costs include WDP’s operating costs, mainly salaries, office rent, fees to external advisors and costs related to the stock exchange listing and external communication.
1 Financial result: the evolution of financial debt is assumed to be dependent on the investment programme. Taking into account the short-term interest rate changes and an 89% hedge ratio as of 31 December 2024, an average cost of debt of 2.3% is assumed for 2025 (based on the current interest rate curve). The assumptions were based on no loans being repaid prematurely, nor that current IRS contracts will be terminated prematurely. The total financial costs were then reduced by capitalised interest included in the investment cost on development properties at an interest rate equivalent to the estimated marginal financing cost. Additionally, the financial charges include the recurring interest cost for land under concession in the amount of 5.1 million euros (for the sites on which WDP does not have bare ownership but does retain usufruct).
1 Taxes: these include the annual corporate income tax depending on the tax status of each entity. In the Netherlands as of 1 January 2025, real estate investments are excluded from the Dutch FBI regime, this will lead to an estimated extra annual tax burden on EPRA Earnings of -11 million euros (-0.05 euros per share).
1 Share of result of joint ventures and associated companies: this result primarily includes the contribution of the participation in Catena, as well as the result of the joint ventures.
1 Minority interests: At the beginning of 2025, WDP acquired the equity participation in WDP Romania of 15% held by the Country Manager of WDP Romania.
Based on the current outlook and the above assumptions, WDP expects EPRA Earnings per share of 1.53 euros (approximately 350 million euros) in 2025. This implies an underlying increase of +7% y/y, based on the one-off return of +0.03 euros per share in 2024 (related to a lease break fee) and the coming into effect of the abolition of the Dutch REIT regime with an impact of -0.05 euros per share from 2025 onwards which were filtered out to get a pure basis of comparison and measure the actual expected business performance.
Based on this outlook, WDP intends to pay a gross dividend per share of 1.23 euros for the financial year 2025 (payable in 2026), taking into account a low payout ratio of 80%.
These forecasts are based on current knowledge and situation and barring unforeseen circumstances within the context of a volatile macroeconomic and geopolitical climate.
Consolidated results (analytical scheme)
3
4 Excluding credit
In the preparation of the balance sheet forecast, factors that could reasonably be estimated were taken into account, such as:
1 Assets – property portfolio: the investments as mentioned above were taken into account.
1 Assets – solar panels: fair value valuation, using the same assumptions as of 31 December 2024, subject to the roll-over of the valuation model by one year3
1 Liabilities – equity capital increase: the 2024 dividend distribution with the assumption of 50% paid out in shares in the form of an optional dividend was taken into account as well as the EPRA Earnings evolution during the 2025 financial year.
1 Liabilities – financial debt: evolution based on the expected investment volume and the portion that is expected to be financed through equity capital (via retained earnings and the optional dividend). Hereby, a loan-to-value – based on the current valuation of the portfolio – of approximately 41% as of 31 December 2025 and an average cost of debt of 2.3% is expected for 2025. As of 31 December 2024, the total undrawn and confirmed long-term credit lines are approximately 1.7 billion euros4. This means WDP has the sufficient liquidity to finance its investment pipeline.
The following table provides a non-exhaustive overview of external and internal factors which have an influence on the key parameters of the company, namely the EPRA Earnings, the gearing ratio and shareholders’ equity.
Sensitivity analysis based on the consolidated figures as of 31 December 2024
Fair value of investment properties and shareholders’ equity (in
Growth plan 2024-27: #BLEND2027 targets confirmed
#BLEND2027, the four-year growth plan for 2024-27, was launched in early 2024 and aims to continue earnings growth per share – capitalising on internal growth opportunities as well as externally through investments in new project developments, selective valueadd acquisitions and energy solutions, as well as the strategic expansion of the platforms in France and Germany.
EPRA Earnings target per share of 1.70 euros confirmed, all building blocks and funding in place
Through 2024, 950 million euros of investments (acquisitions and projects) accrued in the balance sheet. Moreover, today WDP has a total investment pipeline in execution of around another 1.1 billion euros (of which 400 million euros is currently in an exclusive negotiation phase).
In addition, WDP has the balance sheet capacity in place with a loan-to-value of 38%, net debt / EBITDA (adj.) of 7.2x, and, thanks to 1.7 billion euros in unused credit lines, the company has the liquidity to finance this investment pipeline. Moreover, the latter are complemented by cumulatively around 600 million euros of expected auto financing over the next 3 years, based on retained earnings and optional dividends.
With this robust investment pipeline in execution across the breadth of its operations and regions, the robust drivers, supported by a strong balance sheet and full funding, WDP has the required elements to achieve its earnings target of 1.70 euros in EPRA Earnings per share by 2027.
For a detailed explanation of the growth plan #BLEND2027, see Chapter 3. Strategy and value creation
Figures per share
The Alternative Performance Measures (APM) used by WDP, including the EPRA key performance indicators, are accompanied by a symbol (♦). The definition and reconciliation can be consulted in chapter 5. Financial results and outlook and chapter 10. Annexes
1 The number of shares traded divided by the total number of free float shares at the end of the year.
2 IFRS NAV: the IFRS NAV is calculated as shareholder equity as per IFRS divided by the number of dividend-entitled shares on the balance sheet date. It pertains to the net value per share of the public GVV/SIR according to GVV/SIR legislation.
3 On the basis of the pro-rata-temporis basis for the weighted average number of shares over the period.
4 On the basis of the number of shares entitled to dividend at the end of each period.
EURONEXT Brussels en Amsterdam
IPO: 28|06|1999
Notering: continu
ISIN-code: BE0974349814
Liquidity provider: Kempen & Co en KBC Securities

WDP remains committed to generating strong cash flow as the basis for an attractive dividend. The GVV/SIR also firmly believes that the quality of the property portfolio and the tenants continues to point towards a strong future. WDP’s dividend policy is based on offering an annual attractive and recurring dividend yield based on a low pay out rate of 80% and reinvesting the remainder in profitable growth.
WDP achieved an average annual dividend growth of 8.6% over the period 2015-2024 based on strong EPRA Earnings per share growth of 8.6%. In 2024, WDP achieved EPRA Earnings per share of 1.50 euros (+7% year-on-year) and proposes a gross dividend per share of 1.20 euros (payable in 2025) (up +7% from 1.12 euros per share in 2023).
For 2025, WDP expects EPRA Earnings per share of 1.53 euros. This implies an underlying increase of +7% year-on-year, based on the one-off return1 of +0.03 euros in 2024 and the coming into effect of the abolition of the Dutch REIT regime with an impact of -0.05 euros from 2025 onwards which were filtered out to get a pure basis of comparison and measure the actual expected business performance. Based on this outlook, a dividend per share of 1.23 euros gross is projected for 2025 (payable in 2026), taking into account a low payout ratio of 80%.
Share price
The WDP share price in 2024 saw downward pressure in the second half of the year to a closing price of 19.0 euros on 31 December 2024 (compared to the closing price of 28.5 euros on 31 December 2023), but rebounded in January 2025. The total WDP share return2 for 2024 is -29.4% compared to an average return of -2.7% realised in the sector (EPRA index of European real estate shares). This evolution occurs due to external factors, including market volatility, a weakening macroeconomic outlook and heightened geopolitical tensions, such as the US election results that led to the increased sales pressure of the fourth quarter of 2024.
Share price versus EPRA NTA
Share price (in euros per share) EPRA NTA (in euros)
With its robust balance sheet, strong liquidity position and diversified property portfolio with inflation-linked cash flow profile, EPRA figures show that WDP – with a total annualised return of +9.4% since the initial public offer at the end of June 1999 – continues to outperform European property indices (+5.7%), investment properties in the eurozone (+6.4%), and Belgian property investments (+5.8%).
WDP share return versus EPRA indices
FTSE EPRA/NAREIT Belgium/Luxembourg Index Total return (in euros)
FTSE EPRA/NAREIT Euro Zone Index Total return (in euros)
FTSE EPRA/NAREIT Developed Europe Total return (in euros)
WDP Total return (in euros)
The overview below shows share ownership as of 31 December 2024.
shareholders under the statutory treshold²
Jos De Pauw (reference shareholder)³
WDP also relies on the debt capital market to finance its investment projects. This financing as of 31 December 2024 is shown below:
1 The percentage is determined under the assumption that the number of shares has not changed since the most recent declaration of transparency, and taking into account the total number of outstanding shares in WDP.
2 The number of publicly held shares was determined under the assumption that since the declarations of transparency, nothing has changed with regard to the composition of the share portfolio of the shareholders obligated to report major holdings by virtue of the Belgian Law of 2 May 2007 on disclosure of major holdings in issuers whose shares are admitted for trading on a regulated market and with various provisions.
3 On 26 October 2012, the Reference Shareholder, the Jos De Pauw family, assigned all of its shares, held in mutual concert, in joint ownership under the family company structure RTKA, which institutionalised the existing mutual concert. The holders of voting rights are the members of the management body RTKA, to the exclusion of all other right holders in respect to the participation.
16 April 2025 Deadline to register shares for participation in the Annual General Meeting on 30 April 2025
24 April 2025 Deadline to confirm participation in Annual General Meeting on 30 April 2025
25 April 2025 Announcement of Q1 2025 results
30 April 2025 Annual General Meeting on the 2024 financial year
2 May 2025 Ex-date dividend 2024
5 May 2025 Record date dividend 2024
21 May 2025 Payment date 2024 dividend
25 July 2025 Publication of HY 2025 results and publication of the Interim Report
17 October 2025 Publication of Q3 2025 results
30 January 2026 Publication of 2025 annual results
The statutory auditor confirms that the EPRA Earnings, the EPRA LTV, the EPRA NAV indicators, and the EPRA cost ratio were calculated according to the definitions of the
EPRA Best Practices. Recommendations and that the financial data used to calculate these ratios matches the bookkeeping data from the consolidated financial statements. Table EPRA key performance indicator
I. EPRA Earnings
II. EPRA NAV metrics
Recurring earnings from the core operational activities. A key measure of a company’s underlying operating results from its property rental business and an indicator of the extent to which current dividend payments are supported by earnings.
EPRA Net Reinstatement Value (NRV): the aim of the metric is to also reflect what would be needed to recreate the company through the investment markets based on its current capital and financing structure, including real estate transfer taxes.
EPRA Net Tangible Assets (NTA): this is the NAV adjusted to include properties and other investments at their fair value and exclude certain line items that are not expected to take shape in a business model with investment properties over the long term.
EPRA Net Disposal Value (NDV): the EPRA Net Disposal Value provides the reader with a scenario of the disposal of the company's assets resulting in the settlement of deferred taxes and the liquidition of debt and financial instruments.
The EPRA NAV set of metrics make adjustments to the NAV per the IFRS financial statements to provide stakeholders with the most relevant information on the fair value of the assets and liabilities of a real estate investment company, under 3 different scenarios.
IV. EPRA vacancy rate
Annualised rental income based on the cash rents passing at the balance sheet date, less non-recoverable property operating expenses, divided by the market value of the property, increased with (estimated) purchasers’ costs.
This measure incorporates an adjustment to the EPRA NIY in respect of the expiration of rent-free periods (or other unexpired lease incentives such as discounted rent periods and step rents).
A comparable measure for portfolio valuations within Europe. In the past, discussions were held on portfolio valuations in Europe. This measure should make it easier for investors to judge themselves, how the valuation of portfolio X compares with portfolio Y.
Providing detail on the calculation that reconciles the difference between EPRA NIY and EPRA TOPPED-UP NIY.
Estimated Market Rental Value (ERV) of vacant spaces, divided by ERV of the whole portfolio. A pure (in %) measure of investment property space that is vacant, based on ERV.
V. EPRA cost ratio Administrative/operating costs including or reduced by the immediate vacancy costs, divided by gross rental income.
An important criterion to make a meaningful measurement of changes in the operating costs of a property company possible.
VI. EPRA LTV Debt divided by market value of the property. A key (shareholder-gearing) metric to determine the percentage of debt comparing to the appraised value of the properties.
(x 1,000)
Adjustments to calculate the EPRA Earnings, exclude:
I. Changes in value of investment properties, development properties held for investment and other interests
VI. Changes in fair value of financial instruments and associated close-out costs
VIII. Deferred tax in respect of EPRA adjustments
IX. Adjustments (I.) to (VIII.) to the above in respect of joint ventures
X.
euro (x 1.000)
Diluted NAV at fair value (after the exercise of options, convertibles and other equity interests)
Exclude:
Include:
IV. Investment properties – Rental dates and vacancy rate
Reconciliation to the consolidated IFRS profit and loss account Rental
V. EPRA cost ratio
euros (x 1,000)
Include:
I. Administrative/operating expenses (IFRS)
I-1. Impairments of trade receivables
I-2. Recovery of property charges
I-3. Recovery of rental charges and taxes normally paid by the tenant on let properties
I-4. Costs payable by tenants and paid out by the owner for rental damage and refurbishment at end of lease
Exclude (if part of the above): VI.
The EPRA cost ratio reflects operating expenses net of administrative and operating costs capitalised according to IFRS for an amount of 7.0 million euros. Costs capitalised primarily relate to internal employee staff costs of employees directly involved in developing the property portfolio.
VII. Investment properties – Changes in net rental income on a constant baseline
1
1
1 Rights of use to concessions
1 Other adjustments: joint ventures
1
1
1
1
Investment properties – Data related to rental contracts Details on next expiry dates of leases
1 For Luxembourg (55%), WDPort of Ghent Big Box (50%) and Gosselin-WDP (29%) the proportionate share of WDP in the passing rent is indicated.
euros (x 1,000)
1 The overview above shows which investments were included in the balance sheet in the course of 2024. For an overview of all transactions and realisations that were identified in 2024, see chapter 4. Performance and trends
2 This is the net investment for all purchases and disposals executed.
3 This concerns the capitalised interests activated for the project developments.
4 The adjustment for non-cash items of -69.3 million euros for the Group (excluding joint ventures) does not only include the accrual to cash basis adjustment, but also includes an adjustment of -40.0 million euros related to the acquisition realized through a contribution in kind. More information on the acquisition realized in 2024 through contribution in kind can be consulted in chapter 5. Financial results and outlook.
5 The reconciliation with the cash flow statement (see chapter 9. Annual accounts) can be made by abstracting the capitalised interest in the table above, as the capitalised interest is not regarded as an investment activity in the cash flow statement, but as interest paid. Additionally, the reconciliation is influenced this year by the acquisition of several real estate companies. In some cases, not only the real estate but also the liabilities of these companies were acquired. This results in a lower amount presented under ‘Investments’ in the cash flow statement.
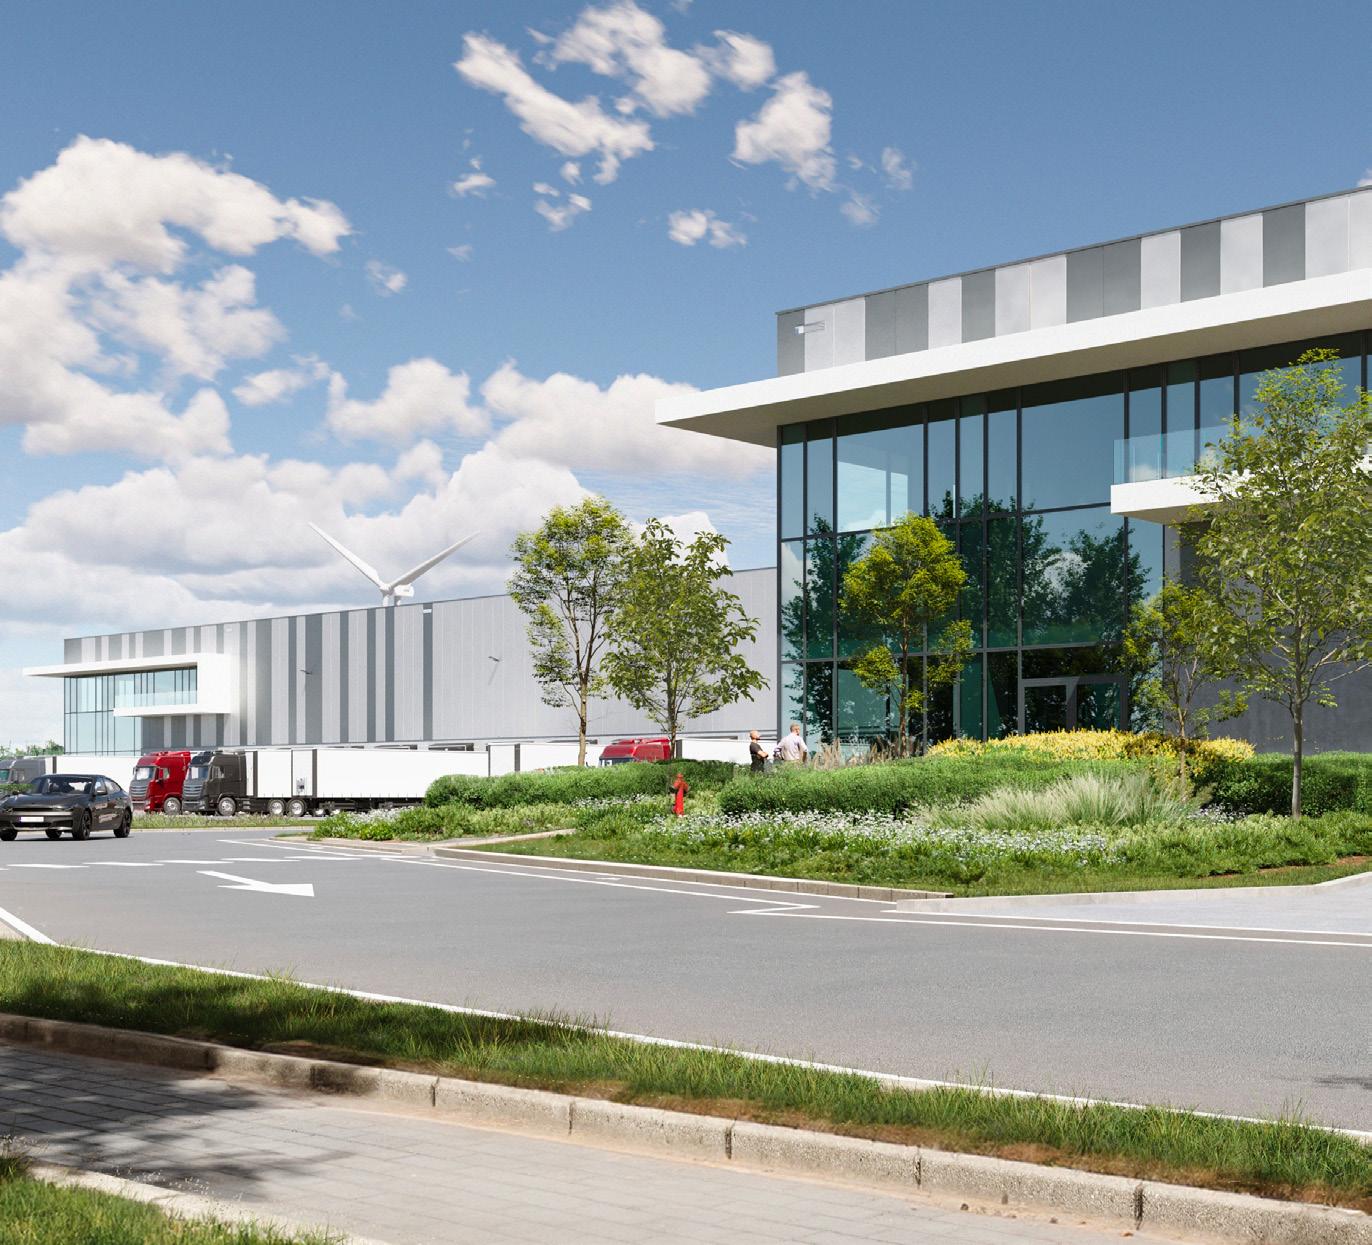
By a decision of the Board of Directors, a Management Committee was formed on 1 October 2019 which acts as an advisory body to the Board of Directors.
STARTING 2025 | The #BLEND2027 growth plan with its multiple-driver strategy should further accelerate WDP towards a fully fledged European logistics platform in the coming years. Paramount here is fidelity to its backbone of client-centricity and innovative entrepreneurship with #TeamWDP as a crucial and powerful link. This strong growth and further internationalisation of the Company requires an appropriate governance framework for decision-making that is one of the building blocks needed to achieve greater ownership and responsibility among the country teams. To this end, on 11 December 2024, the Board of Directors decided to reassess the governance structure. In particular, the Management Committee was terminated with effect as of 1 January 2025. A compact Executive Committee was installed in its place consisting of the CEO, CFO and COO. This Executive Committee facilitates the company’s growth using its decisive geographical platforms which are complemented by shared services.
The Country Managers, who were part of the Management Committee until 31 December 2024, will not be part of the Executive Committee. The COO position is new within WDP where their responsibilities include liaising between the various local teams. The position of CTO will no longer be retained in the new structure and will merge into the position of Head of Project Management.
The current Corporate Governance Statement is used to report on the financial year 2024 governance structure, i.e. with a Management Committee. We start reporting based on the new governance structure with the annual report for financial year 2025.
Since its foundation, WDP has prioritised honest and proper business practices, always based on our core values. WDP strives to meet the highest of standards in the area of corporate governance, out of a firm belief that this contributes to (i) the longterm success of the company and (ii) to protecting the interests of all stakeholders. The Board of Directors monitors to ensure that the corporate governance principles and processes developed for this purpose are suitable for the Company and meet the applicable corporate governance rules or standards at all times.
The Corporate Governance Charter contains all information on the good governance rules that apply within the company, including the principles and processes of the management structure, conflicts of interest prevention policy, remuneration policy, Dealing Code and good conduct policy. This charter is available on our website as are other internal policies.
WDP governance structure
1 Code of Companies and Associations (CCA)
1 Corporate Governance Code 2020 (Code 2020)
1 REIT Regulations
1 EU accounting regulations
1 IFRS
1 EU Market Abuse Regulation
1 EU Prospectus Regulation
1 Euronext Rulebook Internal policies:
1 Corporate Governance Charter
1 Dealing Code
1 Delegation Matrix
1 Employee Code of Conduct
1 Supplier Code of Conduct
1 Remuneration Policy
1 Anti-Bribery and corruption Policy
1 Diversity Policy
1 Grievance Management Procedure
1 Corporate citizenship
1 Enterprise Risk Management Policy
WDP applies the 2020 Belgian Corporate Governance Code per Article 3:6 (§2) CCA and the Royal Decree of 12 May 2019 indicating the mandatory corporate governance code for listed companies. This takes into account the special circumstances related to the GVV/SIR legislation. The 2020 Code is available online at www.corporategovernancecommittee.be
The 2020 Code uses the comply-or-explain principle where deviations from the recommendations must be motivated. As of the date of this Annual Report, WDP is in compliance with the provisions of the 2020 Code, except for the following principles:
Principles 3.19 to 3.21 of the 2020 Code cover the appointment of secretaries in the company.
EXPLAIN | Given the rather small size of the Board of Directors, and to use the strengths within the company with maximum efficiency, for the time being the Board of Directors
has opted not to assign the position of secretary to one specific person. At WDP, the position of secretary is performed by the CFO, who is also present at the Board of Directors’ meetings, and the General Counsel, both of whom have the necessary skills and knowledge with regard to management issues:
1 supporting the Board of Directors and its committees in all governance matters;
1 preparing the Corporate Governance Charter and Corporate Governance Statement;
1 ensuring a proper flow of information within the Board of Directors and its committees as well as between the executive management and the non-executive directors;
1 accurately recording the essence of the discussions and decisions in the board meetings in the minutes; and
1 facilitating initial training and supporting professional development where necessary.
Each director may contact the CFO or General Council individually.
Principle 7.6 of the 2020 Code states that non-executive directors should receive part of their remuneration in the form of shares in the company.
EXPLAIN | WDP deviates from this principle and does not provide remuneration in shares to non-executive directors. Taking into account the current remuneration amounts and the independent nature of the non-executive directors, WDP is of the view that providing part of the remuneration in shares would not necessarily contribute to the objective of the 2020 Code to have these directors act with the perspective of a long-term shareholder.
As a GVV/SIR, WDP strives for robust earnings and dividend per share, in line with the perspective of a long-term shareholder. Since its listing in 1999, WDP has focused on creating stable cash flows over the long-term which, in combination with its high disbursement obligation as a GVV/SIR, makes WDP a fully fledged, profitable and liquid alternative to direct investments in real estate based on rental income. This is the basis of its strategy, as determined by the Board of Directors, which is also clearly reflected in its strategic growth plan.
The remuneration report included in this Corporate Governance Statement gives a summary of the total remuneration for the non-executive directors.
Principle 7.9 of the 2020 Code states that the Board of Directors must set a minimum threshold for shareholdings of members of the Management Committee.
EXPLAIN | WDP deviates from this principle and does not set any explicit minimum threshold for WDP shareholdings for Management Committee members. As a GVV/SIR, WDP strives for robust earnings and dividend per share, in line with the perspective of a long-term shareholder. Since its listing in 1999, WDP has focused on creating stable cash flows over the long-term which, in combination with its high disbursement obligation as a GVV/SIR, makes WDP a fully fledged, profitable and liquid alternative to direct investments in real estate based on rental income. This is the basis of its strategy, as determined by the Board of Directors, which is also clearly reflected in its strategic growth plan. It is this strategy that Management Committee members must roll out operationally. WDP therefore believes that its remuneration policy establishes (i) a clear link with the creation of stable long-term cash flows and (ii) that the Management Committee members act from the perspective of a long-term shareholder. WDP does, however, encourage the members of the Management Committee to build up a shareholding and hold shares in WDP. Several members of the Management Committee have since accumulated such shareholdings.
The remuneration report in this Corporate Governance Statement gives a summary of the shareholdings that the Management Committee members have in their own portfolios. Thus, this is a self-accrued stake in the Company.
On 1 October 2019, after the conversion of WDP from a partnership limited by shares managed by a Statutory Manager into a public limited company with a unitary board (one-tier governance structure), the directors were appointed for the first time in WDP NV/SA, and thus are a legally different entity.
However, this appointment took into account the terms of these directors on the Board of Directors of the former statutory manager of WDP, in the sense that:
1 they were appointed for the remaining period of their term with the former statutory manager; and
1 in drawing up their status as an independent director (Article 7:87 CCA), they also took into account the terms they had as independent and/or non-executive director with the former statutory manager.
At least once every three years, the Board of Directors will evaluate the governance structure it has chosen to determine whether it is still suitable, and if not, it will propose a new governance structure to the General Meeting. A final review of the governance structure by the Board of Directors took place in December 2022 where it was decided that the choice of a unitary board is still the appropriate governance structure for WDP today.
The WDP Articles of Association state that the Company must be run by a Board of Directors consisting of at least three directors. These three directors may be appointed for no more than four years at the General Meeting. The majority of the Board of Directors consists of non-executive directors; it also has a suitable number of independent directors. The Articles of Association per the 2020 Code provide that at least three Directors have the status of independent Directors following the criteria described in the
2020 Code and the CG Charter. Moreover, WDP strives for the majority of the Board of Directors to be independent.
The membership of the Board of Directors enables the management of WDP in accordance with its Articles of Association and its permitted activities (as described in Article 4 of the GVV/SIR Act).
Members of the Board of Directors must meet the requirements set on the GVV/SIR under the applicable law, including membership exclusively comprising natural persons that meet the requirements of Articles 14 and 15 of the GVV/SIR Act (fit-and-proper test for directors).
The membership of the Board of Directors as a whole must provide a combination of experience, knowledge and skills from individual members that enables optimal fulfilment of the role of the Board of Directors. Thus, on the whole, the Board of Directors must offer at least the following characteristics:
1 a proper balance in terms of knowledge, competencies and experience, beginning with the requirements for doing business efficiently in the markets where the company operates;
1 its members must ensure that it functions as an agile and effective body at all times, driven by an entrepreneurial spirit;
1 in decisions regarding its membership, the Board of Directors also strives to achieve diversity (in terms of gender, age, background and nationality) as well as to minimise present or future conflicts of interest between members and the WDP Group (legal, business, economic and ethical conflicts of interest).
The Corporate Governance Charter also sets out the specific qualitative requirements on individual members, including an independent and enterprising personality, an impeccable reputation and proper business ethics.
Moreover, the following principles must also be applied:
1 conformity with diversity requirements (Article 3:6 CCA);
1 conformity with specific gender diversity requirements (Article 7:86 CCA);
1 subject to the age limit set at 70 years whereby a director’s term of office expires at the close of the annual meeting in the year in which he turns 70, unless the Board of Directors decides otherwise on the recommendation of the Nomination Committee;
1 for the non-executive directors: up to 5 appointments as director of a listed company (including their WDP mandate), subject to approval from the Board of Directors (with application of the comply or explain principle).
Today – in keeping with the applicable regulations – no employee representatives are serving on the Board of Directors.
The articles of association of WDP provide for a binding nomination right for any natural person, legal entity or company (with or without legal personality) that individually and directly holds at least 10% of the shares in the company, under specific conditions as described in Article 15 of the Articles of Association of WDP.
By virtue of this binding nomination right, Tony De Pauw was appointed by the Extraordinary General Meeting of WDP of 11 September 2019 as a director of WDP, effective as of 1 October 2019 at the proposal of the current Reference Shareholder of the company, the RTKA partnership. Tony De Pauw was reappointed at the WDP General Meeting in the same capacity as on 26 April 2023 and is thus, at the date of this annual report, the only director appointed based on this binding nomination.
The Board of Directors comprises seven members (natural persons):
1 two executive directors, one of whom has been nominated by the Reference Shareholder (the RTKA partnership): Tony De Pauw; and
1 five non-executive and independent directors within the meaning of Article 7:87 (§ 1) CCA.
1 Date of first appointment within WDP Comm.VA. Each director has been appointed for the first time in WDP SA in October 2019.
2 Patrick O was elected a non-executive independent director by the General Meeting on April 24, 2024. From his appointment, 10 Board meetings were held.
has been the independent, non-executive chair of the Board of Directors of WDP since April 2019 He obtained his degree in Commercial Engineering from the Catholic University of Leuven.
From 2017 to 2021, he was the CEO of the Besix Group, a leading, multidisciplinary construction and property company with operations in twenty-five countries, spanning five continents. In that role, he reinforced the group’s multidisciplinary offering. Before that, he built a 30-year career at ING where he held various management positions. He was also CEO of both ING Luxembourg and ING Belgium. He worked closely with important players in the property market and accrued extensive international experience. At ING Belgium, he headed the Real Estate & Development Financing department (1991-97), a department that also fell under his broader responsibilities until 2007. As CEO, he was also a part of the Risk Committee of ING Luxembourg (2007-13) and the Market Risk Committee of ING Belgium (2013-17).
His experience as chairman of companies like Febelfin and Besix Group and ING subsidiaries, together with his knowledge of real estate, finance and securities markets, entrepreneurial spirit and keen eye for innovation support the management of WDP and the further growth of the company.
has been an independent non-executive director at WDP since April 2015. She obtained a degree in law at the Catholic University of Leuven and an MBA at the Vlerick Business School. She has also taken supplementary courses at the Kellogg School of Management and the University of Cambridge Institute for Sustainability Leadership.
She started her career in the banking sector, where she was Director of Tresorerie between 1980 and 1998, responsible for the Tresorerie, Trading Books and Investment Portfolio. She worked at the Belgian Debt Agency from 1998 to 2019. In 2008, she became the Director of Treasury and Capital Markets. In this role, she defined the financing policy for the Belgian national debt and the organisation of secondary markets. She was also chair of the Market Committee, responsible for the implementation of financing within the risk framework. These positions contributed to gaining extensive knowledge and experience in enterprise risk management. In addition, she has completed a variety of assignments in supranational institutions such as the IMF, the World Bank and the OECD.
Her general management experience, extensive knowledge and expertise regarding financial markets and riskbased, efficient financial management (debt capital markets), provide substantial added value to the financing policy of WDP.
has been an independent non-executive director at WDP since February 2015. She earned her doctorate in Applied Economic Sciences at the Catholic University of Leuven where she is a professor at the Faculty of Economics and Business Studies.
She studied at Yale University and at the University of Chicago and taught at the University of Columbia. In addition, she held the Francqui chair at the University of Ghent. Her academic work focuses on corporate finance, restructuring and governance issues with in-depth expertise in accounting and auditing.
Cynthia’s extensive knowledge and experience in the field of financial management and governance make her a very valuable addition to WDP.
has been an independent non-executive director at WDP since April 2018. He obtained a master’s in Political and Social Sciences and an MBA from the University of Antwerp.
He started his career as investment manager at Dexia Ventures, Dexia’s venture capital fund. He made his name with Clear2Pay, a leading fintech company. Today, he is a managing partner at SmartFin, a venture capital fund which finances and supports growing European technology companies. He is the driving force behind various start-ups and scale-ups, and is one of the founders of SuperNova and The Big Score, two prominent Belgian technology events.
His expertise in financial technology, digital innovation and technology in the broader sense contributes to the growth and future-proofing of WDP.
has been an independent non-executive director at WDP since April 2024. He obtained a degree in industrial engineering.
He started his career at heating manufacturer Sapragaz and then held various positions at Viessmann, including CEO Benelux and an international group position. He also sits on the advisory board of solar shading specialist Harol and the external advisory committee of ING.
Patrick makes an important contribution to the WDP Board of Directors with his expertise in energy transition, electrification and investments in sustainability. His international work experience, and in particular his affinity with the German market, brings valuable insights for WDP’s strategy and further growth.
Born in 1954
has been an executive director since 1999 and represents the Reference Shareholder, the Jos De Pauw family (via the family RTKA partnership). He served as CEO from 1999 until 30 June 2024 and has since joined WDP as a special advisor.
His vast experience and expertise in investing in and managing (logistics) property and the sector as a whole go hand in hand with his entrepreneurship.
Born in 1969
has been a director since 2002 and executive director and CEO since 2010. He is a commercial engineer and holds an MBA.
His banking background gives him strong knowledge of real estate and finance. Before his appointment as CEO, he was CFO of WDP for ten years. Over the years, he has built up expertise in the logistics and supply chain sector. Together with his drive for innovation, his expertise contributes to the expansion of WDP’s sustainable strategy.
Name
Other active terms on 31 December 2024
Rik Vandenberghe Listed companies
–
Non-listed companies
T.P.F., New Vision, Next Day Capital Holding, Next Day Asset Management (Chair), Next Day Investment Management (Chair), Orientalis Next Day Smart Living (Chair), High Five Next Day Smart Living (Chair)
Listed companies
–
Non-listed companies
Terms ending on 31 December 2024, but held in the period from 2019 onwards
as at 31 March 2025
ING Bank Belgium, ING Luxemburg, Entreprises Jacques Delens, Établissements Jean Wust, Franki Foundations Belgium, LUX T.P., Olympiades Brussels Hotel, Socogetra, Different companies within the Besix group, Olympic Invest, Vanhout, Compagnie Belge de Bâtiment (chairman), Six Construct, Watpac, Van den Berg, Les News 24, Besix Group 10,840
BNP Paribas Fortis (risk committee chair), Fluxys Belgium, De Warande, AZ Sint-Maria-Ziekenhuis Halle, Foundation Helios Argenta Bank- en Verzekeringsgroep, Argenta Assuranties, Argenta Spaarbank, KU Leuven (audit committee chair), LRD (audit committee chair), Plexus, UZ Leuven (audit committee chair), Zorg Leuven (audit committee chair)
Cynthia Van Hulle Listed companies
Miko (audit committee chair)
–
Non-listed companies
Argen-Co, Argenta Bank- en Verzekeringsgroep, Argenta Assuranties, Argenta Spaarbank, Rega
Jürgen Ingels
Listed companies
Materialise
–Non-listed companies
Smartfin, Willemen Groep, Ghelamco, GS Pledge CO., Itineris, Bright Analytics, Projective, Mensura, Maria DB, Startups.be/Scaleups.eu, Akinon, Deliverect, Royal Antwerp FC, Recharge.com, Vyncke
Patrick O Listed companies
–
Non-listed companies Harol-Diest, Climafed
Tony De Pauw
Listed companies
–
Non-listed companies
RSC Anderlecht, different mandates in subsidiaries
Joost Uwents
Listed companies
Xior Student Housing, Catena
–
Non-listed companies
nanoGrid, Logistics in Wallonia, EPRA (Advisory Board member), VBO (Strategy Committee member), different mandates in subsidiaries
B_Hive Europe, Trendminer, The Glue, NG Data Europe, Newtec, Silverfin, Exellys, Finsight Solutions, Innovis, Itiviti AB, Unifiedpost Group, Pay-Nxt, Vavato, NG Data 96,719
Viessmann Belgium
Le Concert Olympique, VBO (Strategy Committee member)
Unifiedpost Group, UPPayments
The WDP Board of Directors is authorised to perform all activities that are necessary or useful for achieving the object of the Company, with the exception of activities legally falling to the General Meeting.
The Board of Directors sets the strategy and core values of WDP, decides on investments and the financing strategy and monitors the quality of the management. It prepares the WDP financial statements as well as the Annual Report (including Corporate Governance Statement and remuneration report) and convenes the General Meetings of the company. The Board of Directors decides on the use of the authorised capital. Moreover, it is the Board of Directors that decides on the structure of the management of WDP, and the powers individually or collectively conferred on the CEO and/or other Management Committee members. Finally, the Board of Directors is the body responsible for facilitating effective dialogue with shareholders by means of, for example, transparent communication in press releases, the annual report and other channels.
The Board of Directors, acting as a collegial body, represents the company in all judicial and extrajudicial acts. The company is legally represented by two directors acting jointly in all judicial and extrajudicial acts. The Board of Directors has delegated the day-to-day management to the CEO, who can only act within the meaning of Article 7:121 CCA. The Company may also be represented by a special proxy.
The Board of Directors operating rules are described in detail in WDP’s Corporate Governance Charter.
WDP growth plan New organisational structure to support European growth Growth Plan #Blend2027 targets confirmed
The Board of Directors held 18 meetings in 2024 to discuss, among other things, the items listed below:
1 operating and financial reporting;
1 communications policy;
1 strategy and investment policy;
1 financing policy;
1 risk management policy;
1 composition and evaluation of the Board of Directors (including the nomination of a new director);
1 analysis and approval of the 2024 budget;
1 long-term strategy and analysis of the growth plan #BLEND2027;
1 follow up on the ESG Roadmap, including the concrete targets in the WDP Climate Action Plan;
1 discussion on action plans for the implementation and compliance with CSRD, ESRS, EU Taxonomy;
1 analysis and approval of double materiality analysis under CSRD;
1 analysis and approval of investment, divestment and development dossiers;
1 analysis and approval of credit agreements;
1 internal audit, digitisation, and business processes;
1 new statutory auditor tender process and preparatory proposal to the general meeting;
1 analysis, evaluation and approval of a new governance structure (Executive Committee) with corresponding adjustments in the Delegation Matrix and Corporate Governance Charter;
1 analysis, evaluation and implementation of specific actions with respect to specific risks, such as the tax risk related to the FBI status, cybersecurity, and the general macroeconomic climate;
1 drafting of the Board of Directors reports related to the contribution in kind of a claim (in the context of the optional dividend);
1 capital increases through contribution in kind of immovable property by Balta Industries within the approved authorised capital;
1 completion of the aforementioned transactions and calculation of the resulting capital increase within the authorised capital; and
1 drafting and approving of the 2023 Universal Registration Document.
At least once every three years, the Board of Directors evaluates its own performance, its interaction with the Management Committee and its members, as well as its size, membership and operation and that of its committees.
The evaluation process is led by the chairman and is also monitored by the Nomination Committee. Its objectives include:
1 assessing the operation of the Board of Directors or of the relevant committee;
1 verifying whether important matters are properly prepared and discussed;
1 assessing the effective contribution of each director on the basis of his/her attendance at the Board of Directors meetings or the relevant committee and his/her constructive involvement in the discussions and decision-making. In this evaluation, a minimum individual attendance rate of 75% applies, unless there is a sufficiently substantiated explanation for a lower attendance rate (e.g. health or family circumstances);
1 verifying whether the actual composition of the Board of Directors and committees is appropriate.
The evaluation is conducted through a formal procedure that may or may not be facilitated externally, in keeping with a methodology approved by the Board of Directors.
On the one hand, evaluation of the directors (as members of the Board of Directors and as members of a committee) is ongoing, in particular mutual evaluation among colleagues. If a director has doubts about the contribution of another director, the former director may raise this as an agenda item for the Board of Directors or in the relevant committee, or discuss the matter with the chairman of the Board of Directors. The chairman may then take the necessary steps, at the chairman’s own discretion.
On the other hand, all directors are evaluated individually once a year, and more often where applicable, by the Nomination Committee, taking into account factors such as their attendance rate at the Board of Directors and relevant committee meetings, level of participation in meetings, commitment, suggestions brought forward outside of meetings, provision of innovative ideas based on their experience on other boards or committees, constructive involvement in discussions and decision-making and their sense for risk identification and mitigation. The Nomination Committee also assesses whether the contribution of each director adapts to changing circumstances.
The Board of Directors takes action based on the results of this performance evaluation. Where applicable, this means nominating new members for appointment, proposing that existing members not be reappointed, or taking measures that are considered useful for the effective operation of the Board of Directors.
IN 2024 | The Nomination Committee came to the joint conclusion for 2024 that the current collaboration between the directors is satisfactory and proactive. The Committee also believes that the interaction between the Board of Directors (via its chairman) and
the Management Committee (such as through its CEO and the CFO) is working extremely well, and that there is a steady flow of information. The governance structure appears to have a sound basis. As in previous years, the Board of Directors managed to consult regularly, either remotely or in person, and, if necessary, on an ad hoc basis, depending on the changing market conditions and opportunities.
This was possible thanks to WDP’s coherent and lean governance structure, and also to each director’s significant degree of involvement and flexibility. The Board of Directors, at the recommendation of the Nomination Committee, has concluded that each director individually has fulfilled the role of director in a proper and constructive manner. Discussions and decisions show a high level of commitment, with adequate interest in risk identification and management. Moreover, thanks to their mutually complementary skills, the directors form a formidable collective whole.
Based on the information at its disposal, the WDP Board of Directors states that:
1 the members of the Board of Directors and the Management Committee do not share any kind of familial connections;
1 none of the directors or Management Committee members have been convicted of any fraud-related offences, at least during the past five years;
1 none of the directors or Management Committee members, at least for the last five years, have been the subject of official and public allegations and/or penalties imposed by a statutory or supervisory authority (including a recognised professional organisation), or have ever been declared by a court to be unfit to act as a member of a managerial, supervisory or oversight body of a company or to act within the framework of the management or performance of the activities of a company;
1 no director and no member of the Management Committee has held – for at least the previous five years – an executive function as a senior manager or as a member of the administrative, management or supervisory bodies of any company at the time of its bankruptcy, receivership or liquidation; and
1 none of the directors or Management Committee members have concluded any management or employment contract that provides for a severance payment at the end of the contract, with the exception of what is listed below in the Remuneration report.
The Board of Directors has formed specialised committees to (i) advise on decisions to be taken, (ii) ensure that certain matters are adequately addressed and (iii), if necessary, bring specific matters to the attention of the board. However, decision-taking remains the collective responsibility of the Board of Directors.
The Board of Directors has formed four specialised committees within WDP: the Audit Committee, the Nomination Committee, the Remuneration Committee and the ESG Committee. Each specialised committee has its own internal rules. Insofar required, the composition of these committees complies with the conditions imposed by the Code of Companies and Associations and the Corporate Governance Code. Each committee’s operating rules are described in detail in WDP’s Corporate Governance Charter.
Audit Committee
* At least one member of the Audit Committee must possess the necessary expertise in the field of accounting and auditing and, as an independent director, must meet Article 7:87 CCA. At this time, Cynthia Van Hulle meets these conditions.
Role and responsibilities of the Audit Committee
The Audit Committee supports the Board of Directors in the fulfilment of its monitoring responsibilities, ensuring control in the broadest sense, including risk control.
Activity report of the Audit Committee in 2024
IN 2024 | the Audit Committee mainly discussed the following items in the performance of its duties:
1 quarterly review of accounts, periodic press releases and financial reports;
1 analysis of internal management procedures and independent control function along with effective management (based on the internal audit by the external internal auditor
1 and the audit by the statutory auditor), also with a view to the required reporting to the FSMA;tender process for rotation of the statutory auditor (preparation, analysis, evaluation, proposal to the board of directors);
1 the main risks;
1 monitoring of changes in the law and regulations.
Role and responsibilities of the Nomination Committee
The task of the Nomination Committee is to advise the Board of Directors on appointments of directors, CEO and other members of the Management Committee (on the proposal of the CEO).
Activity report of the Nomination Committee in 2024
IN 2024 | the Nomination Committee mainly discussed the following items in the performance of its duties:
1 evaluating the composition of the current Board of Directors;
1 presenting Patrick O as director;
1 proposal of new organisational structure with an Executive Committee;
1 annual evaluation of the members of the Board of Directors.
ESG Committee Remuneration Committee
Role and responsibilities of the Remuneration Committee
The role of the Remuneration Committee consists of assisting and advising the Board of Directors on all issues concerning the remuneration policy and remuneration techniques for the directors and members of the Management Committee.
Activity report of the Remuneration Committee in 2024
IN 2024 | the Remuneration Committee mainly discussed the following items in the performance of its duties:
1 preparation of the remuneration report of 31 December 2023;
1 new remuneration policy proposal for #BLEND2027;
1 proposal of the targets for the members of the management committee according to their variable remuneration for 2024;
1 proposal of the individual remuneration for the board members and members of the management committee for the 2024 financial year;
Role and responsibilities of the ESG Committee
The role of the ESG Committee is to support and advise the Board of Directors on a wide range of ESG-related topics (including but not limited to good governance, risk management, cybersecurity, programmes on talent development, diversity and inclusion, use of materials, climate, biodiversity, environmental management systems, energy efficiency, etc.).
Activity report of the ESG Committee in 2024
IN 2024 | the ESG Committee mainly discussed the following items in the performance of its duties:
1 advice with respect to the implementation of the Climate Action Plan;
1 monitoring of the implementation of the Climate Action Plan.
1 Analysis and preparation for implementation of CSRD, ESRS and EU Taxonomy.
By a decision of the Board of Directors, a Management Committee was formed on 1 October 2019 which acts as an advisory body to the Board of Directors.
The members are appointed by the Board of Directors on the recommendation of the Nomination Committee. Members of the Management Committee may be either natural persons or legal entities. In the case of a legal entity, it must appoint a single permanent representative who will represent it at Management Committee meetings.
The Board of Directors decides the length of the term of each member of the Management Committee at the time of his appointment.
The remuneration, term and conditions for dismissal of a member of the Management Committee are governed by an agreement between each Management Committee member and the Company (with approvals by the Board of Directors and on the recommendation of the Nomination Committee and Remuneration Committee).
The following pages shows the composition of the Management Committee as of 31 December 2024 where the Management Committee members selected the address of the registered office of WDP NV/SA as their office address, with a view to their role in WDP.
The role of the Management Committee is to consult with the Board of Directors and advise them on the day-to-day management of WDP, and always in accordance with the values, strategy, general policy and business plan determined by the Board of Directors.
The role of the CEO is to work with the other members of the Management Committee on the following:
1 implementing the WDP mission, policy plan and strategic objectives as determined by the Board of Directors;
1 implementing the decisions of the Board of Directors and following up on the performance and results;
1 reporting to the Board of Directors on the progress of all matters and files that fall under the competence of the Board of Directors.
The Board of Directors has delegated the day-to-day management to the CEO and CFO, each of whom may act alone, within the meaning of Article 7:121 CCA. The day-to-day management comprises all actions and decisions that do not extend beyond the needs of the company’s day-to-day proceedings as well as the actions and decisions which, due to their lesser importance or urgency, do not justify the intervention of the Board of Directors.
Each member of the Management Committee is individually responsible for the tasks delegated to them by the CEO and CFO (or, in the case of the CEO and CFO, by the Board of Directors). The Management Committee has no other responsibility than to act as an advisory committee to the Board of Directors.
The Management Committee completes an annual review of its own work, powers and responsibilities. The chairman of the Management Committee shall present and discuss the results of this evaluation with the Board of Directors. The Board of Directors can, if necessary, take appropriate measures. The Management Committee can in turn act on the results of the evaluation by recognising its strengths and improving its weaknesses.
Chief Financial Officer Born in 1981
has been CFO since 2011 and is responsible for Finance, Investor relations and IT & Digitisation. Together with the CTO, he is responsible for Energy & Sustainability. He also sits on the EPRA Regulatory and Taxation Committee on behalf of WDP. He studied at the Solvay Business School (Free University of Brussels) and is a business engineer specialising in Finance. He started his career as a controller at Unilever Bestfoods Belgium and then gained further experience as a buy-side specialist at Delta Lloyd – Bank Nagelmackers. In 2005, he joined Dexia as a sell-side analyst of property shares. Four years later, he became a sell-side analyst for KBC Securities.
Country Manager NL-DE1 Born in 1977
became Country Manager Netherlands for WDP in 2017 and heads the WDP office in Breda. Since 2022, he has coordinated the expansion of the WDP property portfolio in Germany. Previously, he worked at real estate broker CBRE for 13 years, serving in multiple roles, such as Business Unit Director/Senior Industrial & Logistics Director and Associate Capital Markets Director. He holds a BSc in Economics Marketing.
Country Manager BE-LU-FR2 Born in 1967
Country Manager RO Born in 1971
is WDP’s Country Manager Belgium, Luxembourg and France since 2014. His responsibility in this role is to coordinate the commercial team and the property managers. He holds a Master in Business Economics and a Master in Real Estate Management. He is also a member of the Royal Institute of Chartered Surveyors.
Christoffel has over 25 years of experience in commercial property. He started his career as a real estate broker before joining UK logistics REIT Segro, serving in several commercial roles in Belgium over a ten-year period. From 2007 to 2008, he was the Europe Development Director and Belgium Country Manager at US REIT First Industrial. After this, he worked as the Managing Director of Belgian real estate developer MG Real Estate for five years.
After his law studies, Jeroen specialised in export management and logistics. He first spent two years working at the Bar of Antwerp before taking a position as an international legal and financial controller at Den Braven Sealants. In 2001, Jeroen became an international entrepreneur through joint ventures with Romanian, Dutch and Belgian partners. Since 2007, he has been responsible for expanding the WDP property portfolio in Romania as the Country Manager and coshareholder.
Chief Technical Officer3 Born in 1963
as CTO, is responsible for project development and property management in WDP. Together with the CFO, he is also responsible for Energy & Sustainability. He also sits on the EPRA PropTech & Innovation Committee (EPRA) on behalf of WDP. He draws on years of experience in project management and development in numerous positions in renowned companies as a Technical Director at Armonea, Project Manager at Besix, Project Coordinator at UZ Leuven and also internationally as a Project Coordinator for DEME. He studied Applied Sciences (Civil Engineering, Architect) and was an assistant at UGent.
1 Michiel Assink serves as COO within WDP as of 1 January 2025.
2 As of 1 January 2025, WDP has a separate Country Manager for France to provide better support for the strong growth in this market.
3 As of 1 January 2025, the position of CTO was terminated in keeping with the new governance structure.
Co-CEO until 30 June 20244 Born in 1954
Co-CEO and, since 1 July 2024, CEO Born in 1969
We refer to the description above under Board of Directors above. We refer to the description above under Board of Directors above.
Mickaël Van den Hauwe
Other active terms on 31 December 2024 Terms ending on 31 December 2024, but held in the period from 2019 onwards
BE-REIT Association (president), nanoGrid, YUME PROJECTS, different mandates in subsidiaries
Michiel Assink Different mandates in subsidiaries 0
Christoffel De Witte
REALISTIC, BM De Witte, different mandates in subsidiaries Comaan (joint shareholder) Not relevant given no member of Executive committee
Jeroen Biermans J.B. Top Pro Invest, Vuurkruisenbizz, Antonino Invest, Apartementele Trandafirul, Asta Pro Invest, Beltech, Brabuild Invest, Joca Invest, NBR Pro Invest, Paulina Invest, San Carlo Invest, Mills Invest, Lamast Invest, different mandates in subsidiaries Not relevant given no member of Executive committee
Marc De Bosscher Not relevant given no member of Executive committee
Tony De Pauw Listed companies –
Non-listed companies RSC Anderlecht, different mandates in subsidiaries
Joost Uwents Listed companies Xior Student Housing, Catena –
Non-listed companies
nanoGrid, Logistics in Wallonia, EPRA (Advisory Board member), VBO (Strategy Committee member), different mandates in subsidiaries
Group, UPPayments
4 Tony De Pauw was co-CEO of WDP until 30 June 2024. However, he will stay on at WDP, including as a special advisor on the further development of our operations in France and Germany. As of 1 July 2024, Tony De Pauw is no longer part of the Management Committee.
Diversity in all of its facets (cultural, gender, language, professional experience, etc.), equal opportunity and respect for human capital as well as human rights are intrinsic to the WDP company culture. The company firmly believes that these values contribute towards balanced interaction, enrichment of vision and thinking, innovation and an optimal working environment.
WDP has set some diversity guidelines for members of the Board of Directors and the Management Committee. These guidelines are reflected in the internal rules of the Board of Directors and the Nomination Committee, describing the procedure for the nomination and evaluation of directors and members of the Management Committee. The selection process for members of the Board of Directors and Management Committee strives to ensure complementary skills, knowledge, expertise, and diversity in terms of education, knowledge, gender, age, experience, nationality, etc.
This results in a Board of Directors that is highly balanced in its skills, knowledge and experience. The membership of the Board of Directors (two women and five men) also meets the legal provisions on gender diversity (Article 7:86 CCA). The members of the Management Committee also represent a balanced team, each with his own required expertise (see below for their curriculum vitae), albeit with regard to gender. However, it must be taken into account that the Management Committee is assisted by a diversified dedicated team of managers within corporate Shared Services.
WDP relies on a fairly small team with a flat structure, so it is more appropriate to consider diversity across the entire group. At the Team WDP level, there is a nice diversity in terms of gender, nationality, age, seniority and educational background.
#Team WDP
Introduction
This remuneration report was drafted according to the provisions of Article 3:6 (§3) CCA and is a special part of the WDP Corporate Governance Statement. It was also prepared in the spirit of the current draft of the non-binding guidelines of the European Commission for the standardised presentation of the remuneration report.5 This remuneration report describes the remuneration of and the application of the remuneration policy to the members of the Board of Directors and Management Committee, as well as the actual performance of the members of the Management Committee compared to the targets set and covers the period from 1 January 2024 to 31 December 2024.
On April 24, 2024, the General Meeting of WDP approved the current remuneration policy by a large majority (94.63% of those present voted to approve the motion). This remuneration policy went into effect as of 1 January 2024 and is fully aligned with the #BLEND2027 growth plan and is reflected in the Corporate Governance Charter.
In addition, on 24 April 2024, the General Meeting approved the remuneration report for the performance year 2023 with a large majority of 94.93% of the votes present. Moreover, there were no specific comments to be taken into account in the remuneration for the performance year 2024.
Tony De Pauw resigned as co-CEO as of 1 July 2024, which means he was then no longer a member of the Management Committee.6 The remuneration report for performance year 2024 describes Tony De Pauw’s remuneration in his capacity as director, co-CEO and special advisor.
Implementation of the remuneration policy in 2024
Focusing on sustainable business as a long-term real estate partner for the logistics sector
Just like WDP’s strategy of open and transparent communication towards all of its stakeholders
Just like WDP’s business plan, it is always based on defined targets
5 Draft guidelines on the standardised presentation of the remuneration report under Directive 2007/36/EC, as amended by Directive (EU) 2017/828, with regard to the promotion of long-term shareholder engagement.
6 As also stated in the press release of 25 March 2024.
The total remuneration of the non-executive members of the Board of Directors corresponds to the amounts approved by the General Meeting of 26 April 2023. These amounts are in line with WDP’s remuneration policy: a fixed directors’ fee that takes into account each individual director’s responsibilities, and is considered sufficient to attract the right profiles to contribute to WDP’s strategy.
The total remuneration in 2024 of the members of the Management Committee is also in line with the remuneration policy. This remuneration consists of a fixed remuneration and a variable remuneration.
1 The fixed remuneration is in line with the provisions of the remuneration policy and with the amounts set by the Board of Directors (on the recommendation of the Remuneration Committee) in February 2024.
1 The short-term and long-term variable remuneration is also in line with the provisions of the remuneration policy. The criteria for the short-term and long-term variable remuneration are linked to WDP’s financial performance and ESG performance. In this way, the remuneration policy emphasises the creation of stable and sustainable cash flows.
Management Committee remuneration policy
Fixed remuneration
The Board of Directors sets the fixed remuneration annually, taking into account factors such as:
1 position and corresponding responsibilities
1 social security status, experience, competencies
1 local regulations
1 benchmark provided by the Remuneration Committee
The annual remuneration may be reviewed based on changes in the preceding parameters.
Each year, the Board of Directors determines the variable remuneration as a percentage of the annual fixed remuneration.
The annual variable remuneration in cash (i.e. the amount related to the 100% achievement of the targets) amounts to:
1 for the CEOs and CFO: 100% of the annual fixed remuneration;
1 for the other members of the Management Committee: 80% of the annual fixed remuneration.
An overview of the performance targets for 2024 (short-term) and 2024-2027 (long-term) is shown below.
(variable) | 2024
2024: 1.47
Portfolio growth 2024: +500 mio euros
Occupancy rate 2024: 98%
Net debt/EBITDA (adj.) 2024: approx. 8x
Renewable energy 2024: +75 MWp Min. 1 ESG KPI
Min. 1 Risk management policy KPI 2024: Implementation of client-oriented services
Implementation of leadership programme for management positions
Final step for net-zero corporate offices 2025 Further roll-out within WDP Group of the cybersecurity action plan
(adj.) approx. 8x
energy +175 MWp
Expanding leadership in TeamWDP
Progression in net-zero scope 3 downstream 2040
Digital and cyber-secure organisation+
Implementation of non-financial reporting in line with CSRD
The table below sets out the total remuneration of the directors, CEOs, and, on a collective basis, other members of the Management Committee.
1 Executive directors are remunerated only in their capacity as CEO and not in their capacity as members of the Board of Directors.
2 This reflects the total remuneration for performance year 2024 paid to Tony De Pauw in his following capacities (see also the conflicts of interest disclosed in that context): (i) director throughout the year 2024, (ii) co-CEO during the period 1 January 2024 to 30 June 2024, (iii) special adviser during the period 1 July 2024 to 31 December 2024.
3 The base salary for the CEO's and the non-executive directors includes a fixed expense allowance of 5,000 euros per year.
4 The amounts stated here therefore relate to employer contributions to the WDP group insurance (Defined contribution plan) for the year 2024, and are in addition to the variable remuneration received.
5 These additional benefits consist of e.g. a company vehicle and a smartphone, for each of which a benefit in kind is calculated.
6 This represents 40% of the total variable remuneration as foreseen over several years within the 2022-25 growth plan. Given the early realisation of the growth plan 2022-25, the long-term variable remuneration for each member of the Management Committee has been granted and equated to 125% of the long-term bonus initially provided over 4 performance years in the plan. This was paid out for 60% in 2024 and the remaining 40% was paid in 2025 (given that the main targets of that plan 2022-25, namely EPS (1.40 euro) and net debt/EBITDA (<8), were achieved).
7 Patrick O received a remuneration proportional to the base remuneration for 9 months, given that his mandate began in April 2024.
Explanation of the performance of the members of the Management Committee
The fixed remuneration of the members of the Management Committee for 2024 as shown in the above table “Total Remuneration” is equal to the remuneration as approved by the Board of Directors on the recommendation of the Remuneration Committee in February 2024.
The annual variable remuneration is 100% of the annual fixed remuneration for the CEOs and CFO of the annual fixed remuneration, 80% of the annual fixed remuneration for the other members of the Management Committee, upon 100% achievement of the performance targets.
Quantitative performance targets
The short-term targets set by WDP in its #BLEND2027 growth plan are supported by linking the short-term performance targets of the members of the Management Committee to the Company’s financial and sustainable performance, more specifically at least each of the following criteria: EPS, portfolio growth, occupancy rate, net debt/EBITDA; +75 MWp renewable energy. These are weighted to 40% (co-CEOs and CFO) or 50% (other Management Committee members).
PERFORMANCE 2024 | WDP’s financial performance criteria were adopted by the Audit Committee in January 2025. Based on this, the Board of Directors – based on the advice of the Remuneration Committee – determined in January 2025 that the short-term quantitative performance objectives were achieved, overall slightly above target.
The following performance thresholds and ceilings were used: < threshold threshold target maximum 0
Impact by responsibility Net debt/EBITDA (adj.) 2024: approx. 8x
growth Renewable energy 2024: +75 MWp +69 MWp 75% Future logistics
The Board of Directors set at least one performance target for the Management Committee members regarding the implementation of the WDP ESG Roadmap and at least one regarding the implementation of WDP’s risk management policy. Furthermore, objectives were also set for operating activities and business lines (this at both the group and individual level). These are weighted to 20% (co-CEOs and CFO) or 25% (other Management Committee members).
2024 | Based on the achievements in 2024, as explained in detail in this annual report, the Board of Directors – based on the advice of the Remuneration Committee – assessed in January 2025 that the short-term qualitative performance objectives were achieved on target.
Long-term performance targets were linked to achieving the #BLEND27 business plan using both quantitative and qualitative sustainability and financial targets. For more information about the targets set, see p. 128.
Target
Measured performance compared to target Contribution to value pillar Operations
Relative weighting
See 4. Performance and trends on p. 19 and 45
ESG – Implementation of client-centric services
ESG – Implementation of leadership programme for management positions
ESG – Last step for net-zero corporate offices 2025
ESG – Further roll-out within WDP Group of the cybersecurity action plan
See 4. Performance and trends on p. 59
See 4. Performance and trends on p. 197
See 4. Performance and trends on p. 48
See 4. Performance and trends on p. 19
Other Realisation of individual and group objectives
100% Future logistics Sustainable growth
100% Vitally engaged
100% Vitally engaged
100% Future logistics
100% Sustainable growth Impact by responsibility
100% Sustainable growth Future logistics Vitally engaged Impact by responsibility
Note that long-term variable remuneration did not accrue in the 2024 financial year as the long-term performance objectives for 2024 are still included in the settlement of the 202225 growth plan, which was settled early. The Board of Directors – based on the advice of the Remuneration Committee – determined in January 2024 that the overall long-term performance targets of the 2022-25 growth plan were above target and had been met one year early. The long-term variable remuneration was thus granted to each member of the Management Committee and equals 125% of the long-term bonus initially provided over the 4 performance years in the plan. The Board of Directors – based on the advice of the Remuneration Committee – provided for a deferred payment, which is applied more strictly than the deferred payment mechanism provided for in the remuneration policy (66%/34%). Specifically, 60% of the long-term remuneration was already considered vested in January 2024, while 40% of the long-term remuneration would be effectively vested only if the Audit Committee determines in January 2025 that (i) EPS for 2024 equals 1.47 euros and (ii) net debt / EBITDA (adj.) < 8 is achieved. Indeed, these two subtargets have always been considered leading in the 2022-25 growth plan.
Thus, the Board of Directors – based on the advice of the Remuneration Committee –determined in January 2025 that the aforementioned sub-targets were achieved for 2024. Or in other words: 40% of the long-term remuneration (over the 2022-25 growth plan) has now been effectively acquired and was paid out in 2025.
As of the financial year 2025, long-term variable remuneration will be accrued under the current business plan #BLEND27.
As shown in the following table, achieving the quantitative and qualitative performance targets lead to the payout for performance year 2024 (i.e. the short-term variable remuneration for performance year 2024 and 40% of the long-term variable remuneration as provided over several years within the growth plan 2022-25). Joost Uwents and Mickaël Van den Hauwe made use of the option to compensate part of their total variable remuneration in shares per the remuneration policy. To this end, on 30 January 2025, WDP purchased its own shares in accordance with the provisions of Article 7:215, §1, paragraph 3 of the CCA, which allows the Board of Directors to purchase its own shares so it can offer them to staff.
Performance of CEOs and other members of the Management Committee
1 No accrual
De Pauw2
1 No accrual of long-term variable remuneration in financial year 2024. This only starts from financial year 2025 as the long-term performance targets for 2024 are still contained in the settlement of the previous 2022-25 growth plan. See page 123.
2 This reflects the total remuneration for performance year 2024 paid to Tony De Pauw in his following capacities (see also the conflicts of interest disclosed in that context): (i) director throughout the year 2024, (ii) co-CEO during the period 1 January 2024 to 30 June 2024, (iii) special adviser during the period 1 July 2024 to 31 December 2024.
1 No accrual of long-term
remuneration for financial year 2024. This only starts from financial year 2025 as the long-term performance targets for 2024 are still contained in the settlement of the previous 2022-25 growth plan. See page 123.
2 Depending on the position where the CFO has a weighting of 40% and 20% that applies in the short term and 40% in the long term respectively. The other members of the Management Committee have a weighting of 50% and 25% for the short term and 25% for the long term, respectively.
Shareholdings of members of the Management Committee and directors –for its own account
Tony De Pauw¹
For te sake of completeness, please refer to the explanation of the deviation from the recommandations of Code 2020 –principles 7.6 and 7.9.
1 This number corresponds to a multiple of 4.7 times his base remuneration for 2024 (WDP share closing price on 31.12.2024, namely 19.00 euros). Naturally, Tony De Pauw via RTKA Maatschap, as Reference Shareholder, retains the majority of his participating interest in the Company.
2 This number corresponds to a multiple of 5.8 times his base remuneration for 2024 (WDP share closing price on 31.12.2024, namely 19.00 euros).
In 2024, there were no departures from the Board of Directors.
We bid farewell to Mr Marc De Bosscher as the position of CTO will disappear in the new governance structure. In that regard, no severance pay was paid.
The remuneration policy gives an overview of the various departure times and contractually provided severance payments for members of the Management Committee.
No use was made in 2024 of the contractually provided clawback mechanism in the agreements with the co-CEOs and the CFO.
This mechanism entitles WDP to reclaim a variable remuneration from the beneficiary, in full or in part, up to 1 year after its payment, if it turns out that during that period the payment took place based on incorrect information about meeting the performance targets on which the variable remuneration is based, or about the circumstances on which the variable remuneration was made dependent, if such incorrect information was also due to fraud on the part of the beneficiary.
In the implementation of the 2024 remuneration policy, there were no material deviations from the procedures provided for therein, nor were any deviations granted as referred to in Article 7:89/1, §5 CCA.
Total remuneration directors – annual change in % Rik Vandenberghe |
Remuneration Tony De Pauw |
remuneration other members Management Committee (excl. CEOs) –annual change in %³
Ratio highest remuneration of member of the Management Committee / lowest remuneration of employees (in FTE) (Article 3:6 §3 CCA)5
1 The negative fluctuations at the level of the CEOs are entirely due to the fact that an extraordinary bonus was given in 2019 and a settlement took place according to the old remuneration policy. Moreover, as of 2020, a new remuneration policy was in place with a deferred long-term variable remuneration.
2 This increase is explained by the fact that Jürgen Ingels received a remuneration in 2018 proportional to the base salary for 8 months because his mandate commenced in April 2018.
3 As the Management Committee was only formally instituted as of 1.10.2019, the evolution of the total remuneration of the Management Committee is reported as from the financial year 2020.
4 The average employee remuneration is calculated based on Remuneration and direct social benefits divided by the Average number of staff (in FTE) as shown in Note XXIV. Average workforce and breakdown of personnel costs to the financial statements (i.e. on a consolidated basis).
5 The highest remuneration at present is the remuneration of Joost Uwents. The lowest remuneration of employees is calculated based on the workforce (in FTE) as shown in Note XXIV. Average workforce and breakdown of personnel costs to the financial statements (i.e. consolidated basis).
6 The large surges are attributable entirely to the fact that there is a settlement according to the remuneration policy for the growth plan 2019-23 where the long-term variable remuneration for each member of the Management Committee was set to 125% of the long-term bonus initially planned over the 3 performance years in the plan. This will be paid out at a rate of 66% in 2022 and 34% in 2023 in accordance with the same remuneration policy. There was no such long-term variable remuneration in performance year 2020 because the performance period to acquire it was still ongoing at that time.
7 The large surges are attributable entirely to the fact that there is a settlement according to the remuneration policy for the growth plan 2022-25 where the long-term variable remuneration for each member of the Management Committee was set to 125% of the long-term bonus initially planned over the 4 performance years in the plan. This will be paid out at a rate of 60% in 2024 and 40% in 2025 (the latter provided the main targets of that plan, namely EPS (1.40 euro) and net debt/EBITDA (<8), are met). The surges of 10% (total remuneration directors) and 11% (base salary CEO's) result from the one-off indexation of salaries across the entire workforce including members of the Management Committee and independent directors (as approved by the General Meeting of 26 April 2023).
As part of its annual analysis of the remuneration policy and in line with the decisionmaking process provided for in the remuneration policy, the Board of Directors – based on the advice of the Remuneration Committee – decided on 11 December 2024 to submit a new remuneration policy for approval at the General Meeting on 30 April 2025. This is primarily a result of the new organisational structure in which the Management Committee was abolished with effect from 1 January 2025. A compact Executive Committee was installed instead consisting of the CEO, CFO and COO. The Country Managers, who were part of the Management Committee until 31 December 2024, will not be part of the Executive Committee and report directly to the COO.
Short term (variable) | 2025
Subsequently, the proposed remuneration policy that is part of the Corporate Governance Charter is fully aligned with the new organisational structure. However, this is still based on the same principles with respect to remuneration as before.
The performance targets for 2025 et seq. were approved by the Board of Directors – based on the advice of the Remuneration Committee – on 27 January 2025. Remuneration will remain linked to metrics that support WDP in its plan to further differentiate itself within the logistics property market.
1.1 billion euros in investments under development across the breadth of our operations. Climate Action Plan review
Implementation of new organisational structure with Executive Committee
Continued roll out of WDP Group cybersecurity action plan Long-term (variable) | 2024-2027
Expanding leadership in TeamWDP
Progression in net-zero scope 3 downstream 2040
Digital and cyber-secure organisation+
Implementation of non-financial reporting in line with CSRD
With respect to preventing conflicts of interest, the Company is subject to the provisions of the CCA the special provisions of the GVV/SIR legislation regarding an integrity policy, and certain transactions referred to in Article 37 of the GVV/SIR Act. The directors and members of the Management Committee must adhere to all statutory and customary principles relating to conflicts of interest and comply with the prevention policy for conflicts of interest. In any case, WDP imposes on every member of the Board of Directors and Management Committee that the occurrence of conflicts of interest, or the perception of such conflicts, must be avoided as much as possible. When the Board of Directors or the members of the Management Committee take a decision, the members do not pursue their personal interests. Furthermore, they do not use business opportunities that are intended for the company for their own benefit.
The directors have a duty to protect the interests of all shareholders equally. Each director acts according to the principles of reasonableness and fairness. Directors nominated by a Reference Shareholder (based on the binding nomination right) must ensure that the interests and intentions of said shareholder are sufficiently clear and are made known to the Board of Directors in a timely manner.
The rules on the prevention of conflicts of interest are described in detail in the Corporate Governance Charter
Conflicts of interest involving directors (Article 7:96 CCA)
IN 2024 | An excerpt from the minutes of the Board of Directors meeting of 22 January 2024 regarding the determination of the remuneration of the co-CEOs
‘PROPOSAL
The Board of Directors took note of the statements of Mr Tony De Pauw and Joost Uwents per Article 7:96 of the CCA, regarding the interest of a patrimonial nature that could conflict with the decisions mentioned under this agenda item. Tony De Pauw and Joost Uwents refer in their respective statements to the potential conflict of interest of a patrimonial nature in the context of the allocation of the variable remuneration for performance year 2023 and the determination of the remuneration for performance year 2024. Copies of the statements of Tony De Pauw and Joost Uwents are attached to these minutes. Tony De Pauw and Joost Uwents left the meeting before the discussion and decision on this item began.
The chairs of the Remuneration Committee and the Nomination Committee respectively explained their proposals regarding the allocation of the variable remuneration for performance year 2023 to the co-CEOs, as well as regarding the fixed (and resulting variable) remuneration for performance year 2024 with the corresponding short- and long-term performance targets.
After discussion, the Board of Directors decided on:
1 Awarding a variable short-term remuneration for performance year 2022 in line with the remuneration policy in the amount of 513,189.60 euros for Joost Uwents and in the amount of 256,594.80 euros for Tony De Pauw; hereby taking into account the achievement of short-term performance targets where the CEOs achieved the above target.
1 Awarding a variable long-term remuneration due to the early realisation of the 20222025 growth plan (in particular, given the EPRA Earnings projection for 2024 of 1.47 euros per share, the targeted 2025 target of 1.50 euros is within reach one year earlier). Moreover, 125% of the initially provided long-term bonus (over the period 2022-2023-2024-2025) will be settled per the following conditions: (i) 60% of the long-term variable remuneration has vested and will be paid out in 2024; (ii) 40% of the long-term variable remuneration has vested and will be paid out in 2025 provided the Audit Committee determines in January 2025 that (i) EPS over 2024 is at least equal to 1.47 euros and (ii) net debt/EBITDA (adj.) < 8 achieved. Indeed, these two sub-targets have always been considered leading in the 2022-25 growth plan. This amounts to a total variable long-term remuneration of 1,527,847.89 euros for Joost Uwents and 763,923.94 euros for Tony De Pauw.
1 Setting the following performance targets for performance year 2023: EPS, portfolio growth, occupancy rate, adjusted (published) net debt/EBITDA, ESG targets and other quantitative and qualitative performance targets.
1 Setting the fixed remuneration for performance year 2024 at 394,533.94 euros (i.e. 388,780 indexed at 1.48% as approved by the Board of Directors under agenda item 2) for Tony De Pauw (and thus 394,533.94 euros variable as the target amount, i.e. 100% of the fixed remuneration) and at 789,067.89 euros (i.e. 777,560 indexed at 1.48% as approved by the Board of Directors under agenda item 2) for Tony De Pauw (and thus 789,067.89 euros variable as the target amount, i.e. 100% of the fixed remuneration).
IN 2024 | An excerpt from the minutes of the Board of Directors meeting of 22 July 2024 regarding the determination of the remuneration of Tony De Pauw.
The Board of Directors took note of the statement of Mr Tony De Pauw per Article 7:96 of the CCA, regarding the interest of a patrimonial nature that could conflict with the decisions mentioned under this agenda item. Tony De Pauw refer in his 22.01.2024 statement of the potential conflict of interest of a patrimonial nature in the context of the
allocation of the variable remuneration for performance year 2023 and the determination of the remuneration for performance year 2024. He further refers to the possible conflict of interest of a financial nature in the context of entering into a service agreement via TORA BV – where Tony De Pauw is the sole director – with the Company with effect as of 1 July 2024 following the end of his position as CEO. A copy of Tony De Pauw’s statement is attached to these minutes. Tony De Pauw is excused from this Board of Directors and therefore does not participate in either the deliberation or the decisionmaking on this point.
After a discussion, the Board of Directors decided unanimously to approve the service agreement with TORA BV and ratify it with effect as of 1 July 2024. The compensation for services as a special advisor corresponds to ½ of the annual compensation as CEO set out for January 2024. In particular, this means ½ of 394,533.94 euros (fixed remuneration) and ½ of 394,533.94 euros (variable as a target amount, i.e. 100% of the fixed remuneration), minus the pro rata director’s remuneration of 27,500 euros (cf. WDP Remuneration Policy).
Functional conflicts of interest within the context of Article 37 of the GVV/SIR Act
Potential functional conflicts of interest arose, particularly in the context of the optional dividend offered on 24 April 2024 to the shareholders and under which certain directors as well as the Reference Shareholder derived some capital benefit from it, because of their capacity as shareholders of WDP. The Board of Directors approved the optional dividend offer. This is because this transaction was carried out in WDP’s interest. Specifically, the capital increase associated with the transaction strengthens WDP’s equity and thus reduces its (legally capped) gearing ratio. This transaction was also carried out under normal market conditions, with all shareholders treated equally.7
Functional conflicts of interest may have arisen, particularly in the context of the participation in a capital increase of Catena AB, due to the capacity of WDP Invest NV/SA (perimeter company of WDP NV/SA) and Catena AB (a company with which WDP Invest NV/SA has a shareholding structure). WDP Invest NV/ SA wished to perpetuate its existing 10% stake and consequently subscribed pro rata to the capital increases dated 12 March 2024 respectively 28 August 2024 of Catena ABB through an accelerated private placement with the composing of an order book, whereby the issue price and the final number of new shares to be issued were determined by the Catena board of directors in consultation with the joint global coordinators and bookrunners taking into account the provisions in a solicitation, allocation and pricing protocol. The transaction took place under normal market conditions for similar transactions.
The WDP Corporate Governance Charter states very clearly that the members of the Board of Directors, as well as the members of the Management Committee, must exercise the required discretion and, in cases of insider information, the required confidentiality with regard to all information and documentation obtained in the context of their role as a member of the Board of Directors and/or the Management Committee.
The code of conduct for financial transactions are included in a separate business code: the Dealing Code. The Dealing Code is intended to inform its readers of the regulations on market abuse and the resulting obligations on (i) WDP in its capacity as the issuer of financial instruments and (ii) everyone carrying out activities within or for the WDP Group who have access to sensitive information. By means of this policy, WDP strives to prevent market abuse by the persons in question.
Each employee, director and member of the Management Committee who fulfils a role in or on behalf of WDP receives an explanation of this Dealing Code from the compliance officer – as part of the onboarding procedure, and is also asked to sign this Dealing Code as read and agreed.
It is also the compliance officer who must ensure compliance with these rules to limit the risk of market abuse with insider information. For this purpose, the officer maintains insider lists as specified in European regulations and follows the procedures for reporting transactions by supervisors or the questions for trading during blocked or closed periods. The officer does this in consultation with the Market Disclosure Committee. The Corporate Governance Charter also provides for a reporting procedure in case someone would like to report an actual or potential breach of the Dealing Code or other regulations.
IN 2024 | Application of these rules did not result in any kind of difficulties.
WDP organises its internal control and risk management on the basis of the principles of the Enterprise Risk Management (ERM) model developed by COSO (Committee of Sponsoring Organisations of the Treadway Commission). This involves mapping out a control environment, conducting an analysis of the risks to which WDP is exposed and estimating their impact on WDP. It also determines the degree to which WDP has control over these risks and the actions the company is taking to mitigate these risks. Finally, internal control is assessed annually.
When it comes to risk management, WDP applies an integrated approach based on the ‘three lines of defence model’. This model determines how specific responsibilities can be assigned within WDP’s organisation with a view to achieving WDP’s objectives and control of the associated risks.
This methodology contributes to reinforcing the risk culture, taking responsibility for managing risks and internal control and continued optimisation and integration of independent control functions (risk management, compliance, internal audit).
The business itself is responsible for all risks of its own processes and must ensure their identification and effective controls. The business also ensures that the right controls are conducted properly and that the self-assessment by the business is qualitatively adequate. Moreover, the business ensures that risk awareness is sufficient and that adequate capacity is assigned to handle risk matters.
Risk management is an integral part of running the company. It ranges from day-today financial and operational management – including the four-eyes principle – analysis of new investment files and formulation of strategy and objectives, to strict and firmly established decision-making procedures. For this reason, risk management is the responsibility of the entire WDP Group, i.e. across all layers of the organisation, with different responsibilities at each level.
These functions offer support to business and management by applying expertise and formulating an opinion independently of business with regard to the risks facing WDP: risk management function, compliance function, financial control function, IT security function.
These functions offer proper certainty that business itself (via first-line management) has its risks under control. The primary responsibility naturally still lies with the first line. For this, the second line functions serve to identify, measure and report risks.
The internal audit can be understood as an independent assessment function embedded in the organisation, focusing on examination and evaluation of proper functioning, effectiveness and efficiency of the processes, procedures and activities of WDP. This may involve areas such as operational matters (quality and suitability of systems and procedures, organisational structures, policy lines and methods and resources used to meet objectives), financial matters (reliability of accounting, annual financial statements and the financial reporting process), the compliance with applicable accounting and other regulations, management matters (quality of the management function and staff services with respect to company objectives), as well as the compliance function and risk management function.
The Board of Directors set up an Audit Committee, Remuneration Committee, Nomination Committee and an ESG Committee. Starting in October 2019, a Management Committee was used, which was terminated as of 31 December 2024. As of 1 January 2025, an Executive Committee was installed (see introduction of 6. Corporate Governance Statement).
WDP had three operating platforms up until 31 December 20248: Belgium/Luxembourg/ France, the Netherlands/Germany and Romania. Each platform performs the following functions: Sales & Business Development, Property Management, Contracting, Back Office. These teams can count on the support of the following services: Project Development, Finance, IT, Investor Relations, Legal, Marketing, Human Resources and Administration. This structure is explained in an organisational chart and features a clear internal segregation of duties.
Notwithstanding the further professionalisation and considerable reinforcement of the teams in recent years – because of the growth of the company – the size of the team remains limited, where an overbearing structure and excessive formalism must be avoided, in view of factors such as the nature of the activities of the company. A certain degree of flexibility is still indispensable, with people on call to step in for others for specified tasks, according to the urgency of the case at hand. However, the responsibilities are strictly defined and current issues are monitored by means of ongoing daily consultations.
The independent control functions, as also implemented by the GVV/SIR legislation, are fulfilled in a suitable and proportionate manner, and always in accordance with the nature, scope and complexity of WDP’s activities.
1 The independent compliance function is performed by WDP General Counsel Johanna Vermeeren, appointed for an indefinite term. The compliance officer reports directly to the CEO, Joost Uwents.
1 At WDP, CFO Mickaël Van den Hauwe serves in the role of risk manager, appointed for an undetermined period. The risk manager reports directly to the Audit Committee.
1 WDP has entrusted the internal audit function to an external legal entity through the appointment of an independent consultant, namely BDO Advisory BV, permanently represented by a single natural person, Mr Steven Cauwenberghs. In his role as manager bearing final responsibility for the internal audit, Rik Vandenberghe is responsible, on behalf of WDP, for supervision of the internal audit function assigned to the external internal auditor.
The effective leaders (Joost Uwents and Mickaël Van den Hauwe) are responsible for the organisation of internal control under the supervision of the Board of Directors of WDP.
Aside from general organisation of the internal audit structures, the Audit Committee has a special task with regard to internal audit. It supports the Board of Directors in the fulfilment of its monitoring responsibilities, ensuring control in the broadest sense, including risk control. The responsibilities, membership, powers and functioning of this Audit Committee are described in the Internal Rules of the Audit Committee, available in the Corporate Governance Charter.
WDP is convinced that risk management should be an integral part of the company culture to foster an environment in which people are motivated to identify and address risks and ensure the necessary transparency with regard to any possible risks. To this end, WDP has drawn up and implemented a risk management policy that applies equally and fully to its entire operations (i.e. across all WDP entities, geographies, operations, etc.).
A detailed explanation is given in the WDP Enterprise Risk Management Policy
8 Starting as of 1 January 2025, WDP has five operation platforms managed by local Country Managers: Benelux/ Luxembourg, France, The Netherlands, Germany, and Romania.
Top-down
strategic risk management
Board of Directors
1 Set the risk culture
1 Review external environment
1 Monitor the company risk management with an annual in-depth review
1 Determine risk appetite
1 Agree the Enterprise Risk Management Policy and the risk assessment tool
1 Discuss WDP Group’s key risks and emerging risks with the risk manager and Executive Committee
Audit Committee
1 Assist the Board of Directors in balancing risk exposure against risk appetite
1 Review the efficiency of the company’s risk management and internal control processes
operational risk management
Bottom-up
Executive Committee
1 Identify and monitor key risks and emerging risks
1 Evaluate proposed strategies against risk appetite
1 Design, implementation and evaluation of the system of internal control, and for ensuring its operational effectiveness
Risk manager
1 Assist management with the identification and assessment of key risks and emerging risks
1 Aggregate risk information and submit to the Executive Committee and Board of Directors
1 Monitor the risks and response plans in line with the risk appetite
1 Create a general risk framework and common language as well as provide direction on applying that framework
1 Provide guidance and training
1 Facilitate risk escalations
Business units and risk ambassadors
1 Identify and assess risks
1 Respond to risks
1 Monitor risks
1 Ensure operation effectives of key controls
Support roles:
compliance officer, financial controller, IT security
1 Provide guidance/support to the risk manager and the business in identifying, assessing, and reporting
Internal audit
1 Providing assurance on the efficacy of the company’s risk management
1 Test key controls and risk response plans for key risks
Risk identification | risk evaluation | risk management | risk monitoring | risk reporting
Every quarter, the CFO, acting as the risk manager, conducts an analysis and evaluation of the risks that the company may face across departments and different countries with attention to the potential negative impact, the expected value in terms of the realisation of the risk, as well as the degree of control of the risk. This analysis is done in collaboration with the compliance officer and the different risk ambassadors across the business, supported where necessary by specialised (external) advisors.
WDP uses a risk assessment tool to ensure risks are evaluated consistently. Within this context, a scenario analysis is also drawn up based on which (i) the expected value of each scenario is estimated and (ii) the avoidance or mitigation of a risk is focused on as much as possible.
Based on the above evaluation, the implementation of risk management can be done through different methods: prevent, mitigate, share, preserve.
The risk monitoring is embedded in the process of enterprise risk management and the responsibility for monitoring is at the different levels of the organisation: #TeamWDP, the Management Committee, the Board of Directors.
The result of the quarterly analysis, the evaluation of the risks as well as the formulation of concrete recommendations to the other departments of WDP, is formalised in a risk dashboard under the supervision of the risk manager, which is discussed in detail in the Management Committee. Where necessary, the risk dashboard is further adjusted for subsequent submission by the risk manager to the Audit Committee and Board of Directors for pointing out the most significant risks affecting WDP’s strategic goals. Taking into account the input of the risk manager, the Audit Committee and Board of Directors conduct quarterly evaluations of the risks to which WDP is exposed and take the necessary decisions based on these evaluations (such as with regard to setting the interest rate hedging strategy, evaluation of tenant risks, etc.).
WDP values transparency and thus communicates with its stakeholders on this topic of risk and risk management both on an ad hoc basis and via the periodic reporting in the quarterly press releases. The annual report also includes a list of specific and material risk factors with their description and an estimate of the potential impact of these risks, as well as the mitigating factors and some examples of key risk indicators.
The various departments of the Company perform checks in response to the identified risks, as shown in Chapter 7. Risk factors.
1 Lease: constant monitoring of the lease vacancy rate, end dates of lease agreements and the risks and opportunities related to rental income, constant monitoring of the client portfolio and regular analysis of client solvency. Monthly screening of the amounts and validity of the lease deposits of all tenants.
1 Property portfolio: maintenance of a healthy portfolio diversity in various dimensions, such as clients, building types, locations and also continuous monitoring of portfolio quality and sustainability. This is managed based on frequent internal reporting as well as collaboration with renowned construction partners, architects and engineering firms.
1 For each commitment of the company towards third parties, the double signature principle (the four-eyes principle) is applied within the limits of the delegation of powers, for the purchase of property, leases, all types of orders and approvals of invoices and payments.
1 Operational processes, both for the existing portfolio and for new investments, are based on workflows that are harmonised within the WDP Group and are audited regularly.
1 Budget: conducting an extensive quarterly variation analysis (actual versus the preceding period) and updating of this by the Audit Committee and Board of Directors.
1 Purchasing policy: all orders must be preceded by a purchase order and must then be approved by validation of the invoice via a digital approval flow with audit log and application of the four-eyes principle.
1 ERP package: WDP uses SAP Real Estate for accounting, controlling and reporting. SAP contains all accounting and financial aspects and all aspects related to WDP property activities (such as follow-up on lease agreements, settlement of charges, orders, purchases, budget follow-up for new construction projects, etc.).
1 Financing cost: follow-up on the sensitivity of the cost of debt associated with the interest rates based on internal models and using software.
The process for preparing the financial information is structured based on predefined tasks to perform and schedules to meet. WDP uses a detailed checklist of all tasks and sub-tasks to perform for closure of the annual, semi-annual and quarterly accounts of WDP (individually for each entity and consolidated for the Group). Each task is assigned to a manager in the finance department and a mandatory timeframe. Based on this checklist, everyone at the finance department knows what tasks to perform and by when.
This checklist is built around the following dimensions:
1 the types of activity are divided up as follows: pre-closing, closing, consolidation, internal and external reporting and audit;
1 subsequently, for the actual closing and consolidation process, a specific task is linked to each account of the balance sheet and earnings statement, with a SAP transaction code and a description;
1 wherever possible, the tasks are deduplicated and linked to specific deadlines with a responsible person (as well as a backup) in the Finance Department for each task. Moreover, every attempt is made to move tasks forward wherever possible, i.e. before the actual balance sheet date, to guarantee process speed and especially process quality;
1 the above is also linked to standardised templates that serve for control and as a basis for the audit files;
1 WDP and its subsidiaries follow the above procedure.
For efficient performance of the audit process, before the balance sheet date a pre-audit meeting is always held with the statutory auditor, with discussion of all significant trends and special points needing attention over the past period.
Once all accounting tasks are complete and have been processed in the consolidation and reporting set, the figures are checked by the CFO.
This control mainly consists of:
1 a variance analysis between the actual and budgeted figures (the budgeted figures are prepared once a year and updated quarterly based on a forecast);
1 a variance analysis between the actual and historical figures, and
1 an ad hoc analysis of all material amounts and entries.
Once these checks are complete, the figures are submitted to the CEOs of WDP and adopted in mutual consultation with the CFO. The quarterly, semi-annual and annual reports, including corresponding press releases, are submitted to and analysed by the Audit Committee and Board of Directors, which approve them for publication.
The financial reporting is drawn up in accordance with the IFRS (International Financial Reporting Standards) as adopted in the European Union and with the legal and administrative regulations applicable in Belgium. These standards include all new and revised standards and interpretations published by the International Accounting Standards Board (IASB) and the International Financial Reporting Interpretations Committee (IFRIC). Regular discussions are scheduled with the statutory auditor and the required training is arranged for the responsible persons in the organisation in order to meet the accounting standards in their latest versions.
The statutory auditor audits the annual figures (full scope) and semi-annual figures (limited scope). The statutory auditor does not audit quarterly figures.
Over the course of the financial year, the quality of the internal control is assessed by:
1 the statutory auditor: on the one hand within the framework of the audit of the semiannual and annual figures, and on the other hand within the framework of the annual review of underlying processes and procedures. Furthermore, we refer to the statutory auditor’s report (see chapter 10. Appendices). The internal control systems for the key audit matters, i.e. the valuation of the property investments, have been analysed. Based on the recommendations of the statutory auditor, the process is adjusted as needed;
1 the Audit Committee: as indicated above, the Audit Committee performs a special task with regard to internal control and risk management for WDP. The Board of Directors supervises the performance of the tasks of the Audit Committee, using tools such as reports from the Audit Committee to the complete Board of Directors, and
1 internal audit: the company has hired an external internal auditor as a third-line function in the internal audit structure. All critical business processes are audited as part of a three-year cycle. In addition, the compliance function, the risk management function and at least one additional specific process are subject to an annual internal audit. In 2024, an internal audit took place covering revenue recognition of energy investments, the implementation of the Delegation Matrix and the IT lateral network security systems.
Information as per Article 34 of the Belgian Royal Decree of 14 November 2007
In accordance with Article 34 of the Belgian Royal Decree of 14 November 2007 on obligations on issuers of financial instruments admitted for trading on a regulated market, WDP gives a summary and, if applicable, explanation of the following items, to the extent that these items, due to their nature, will have an impact in cases of a public acquisition bid.
capital structure
As of 31 December 2024, the capital of WDP comes to 258,397,378.24 euros, represented by 225,534,676 ordinary shares, each representing 1/225,534,676th of the capital. All shares are fully paid up and are either registered or dematerialised. None of these shares provides special voting or other rights. Each share confers the right to one vote at the General Meeting.
Share transfer provisions under the law, the Articles of Association or by convention
The transfer of shares in WDP is not subject to any provisions under the law or the Articles of Association. All WDP shares are listed on Euronext Brussels and Amsterdam.
Special rights of control
Special rights of control are not granted to any (categories of) shareholders.
Mechanism for auditing a share scheme for employees when rights of control are not exercised directly by employees
WDP does not have a share scheme for employees.
Voting restrictions under the law or the Articles of Association
The law and the Articles of Association do not set any restrictions on voting rights.
Shareholder agreements known to WDP that may give rise to restrictions on share transfers and/or voting rights
As far as WDP is aware, no shareholder agreements exist which could result in restrictions on share transfers or voting rights.
Rules for appointment and replacement of members of the management body and for the amendment of the Articles of Association of WDP
For rules on appointment and replacement of members of the Board of Directors, please refer to the explanatory note in Chapter 6. Corporate Governance Statement, as well as to Article 14 of the Articles of Association of the company, which states that directors are appointed by the General Meeting for a period of four years in principle and that the General Meeting may remove them at any time. Where applicable, the binding nomination right of the Reference Shareholder(s) must be applied in the nomination, as per Article 15 of the Articles of Association.
With regard to the amendment of the Articles of Association of the company, please refer to the GVV/SIR legislation, which provides that any draft amendment of the Articles of Association must be submitted to the FSMA for approval in advance. Moreover, Article 31 of the Articles of Association and the provisions of the Code of Companies and Associations apply.
The powers of the management body, particularly with regard to the option to issue or purchase shares
In accordance with Article 8 of the Articles of Association of the Company, the Board of Directors is authorised, within the constraints of the mandatory provisions contained in the applicable company law, to increase the share capital on the dates and subject to the conditions that it specifies, in one or more increments, up to a maximum amount of:
1 I. 125,703,776.34 euros, if the capital increase to be realised is a capital increase by cash with the possibility for the shareholders of the company to exercise their preferential right or the irreducible allocation right (as referred to in the GVV/SIR legislation); and
1 II. 125,703,776.34 euros if this capital increase is performed in the context of paying an optional dividend; and
1 III. 25,140,755.26 euros, if the capital increase to be realised (a) is a capital increase via a contribution in kind, or (b) a capital increase in cash without the possibility for the Company’s shareholders to exercise the preferential right or the irreducible allocation right (as referred to in the GVV/SIR legislation), or (c) any other form of capital increase; with the proviso that the capital under this authorisation may not be increased by an amount higher than the amount of the capital on the date of the Extraordinary General Meeting which approves the authorisation, being 2 February 2023.
This authorisation is renewable.
Up to the date of this annual report, the Board of Directors has used the authorisation granted to it twice to increase the capital, and thus the available balance of the authorised capital still amounts to:
1 I. 125,703,776.34 euros, if the capital increase to be realised is a capital increase in cash with the option of the company’s shareholders to exercise their preferential right or irreducible allocation right (as referred to in the GVV/SIR legislation);
1 II. 125,703,776.34 euros if this capital increase is performed in the context of paying an optional dividend;
1 III. 22,793,888.21 euros if this capital increase is (a) performed by a contribution in kind or (b) performed by a contribution in cash without the option for company shareholders to exercise their statutory preferential rights or irreducible allocation rights (as referred to in the GVV/SIR legislation) or (c) any other form of a capital increase;
with the understanding that in the context of the authorised capital, for the fiveyear authorisation period, the capital can never be increased beyond an amount of 251,407,552.69 euros.
Under Article 11 of the Articles of Association, WDP may acquire, accept in pledge, and sell its own shares and associated depository receipts in accordance with the applicable company legislation.
In addition, the Board of Directors is authorised to perform the following actions for five years starting on 3 May 2024:
1 acquire shares in the Company and associated depository receipts and accept these in pledge, at a minimum price or countervalue equal to 0.01 euros and at a maximum price or counter value equal to 125% of the closing price on the trading day before the date of the transaction, where the Company shall not be permitted to possess shares in the Company or associated depository receipts that represent more than 10% of the total number of shares;
1 transfer shares in the Company and associated depository receipts, such as to one or more specific persons who are not employees, at a minimum price or countervalue equal to 75% of the closing price of the trading day before the date of the transaction.
On 31 December 2024 and as of the date of this annual report, WDP does not possess any of its own shares.
Major agreements to which WDP is a party that come into force, undergo amendments or expire in cases of a change of control over WDP after a public acquisition bid
The General Meeting held on 24 April 2024 approved the change of control clause per (i) credit agreements dated 22 December 2023 between the Company and Intesa, (ii) credit agreements dated 21 December 2023 between the Company and ICBC, (iii) credit agreements dated 4 December 2023 between the Company and ING, (iv) credit agreements dated 5 September 2023 between the Company and Belfius, (v) credit agreements dated 22 December 2023 between the Company and BNP Paribas, (vi) credit agreements dated 30 November 2023 between the Company and ABN Amro and (vii) credit agreements dated 2 February 2024 between the Company and the International Finance Corporation.
Agreements concluded between WDP and its directors or employees that provide for remuneration if a public acquisition bid results in the resignation of directors or their forced departure without a valid reason or the end of employment of an employee
The agreements concluded with the CEO and the CFO include a clause stating that if the management agreement with the person in question is terminated by either party within six months after a public acquisition bid, in the absence of a serious error, the person in question is entitled to a severance payment of 18 months for the CEO and 12 months for the CFO.
The agreements concluded with other Management Committee members and WDP employees do not include any contractual clauses of this kind.
Group structure as of 31 December 20241
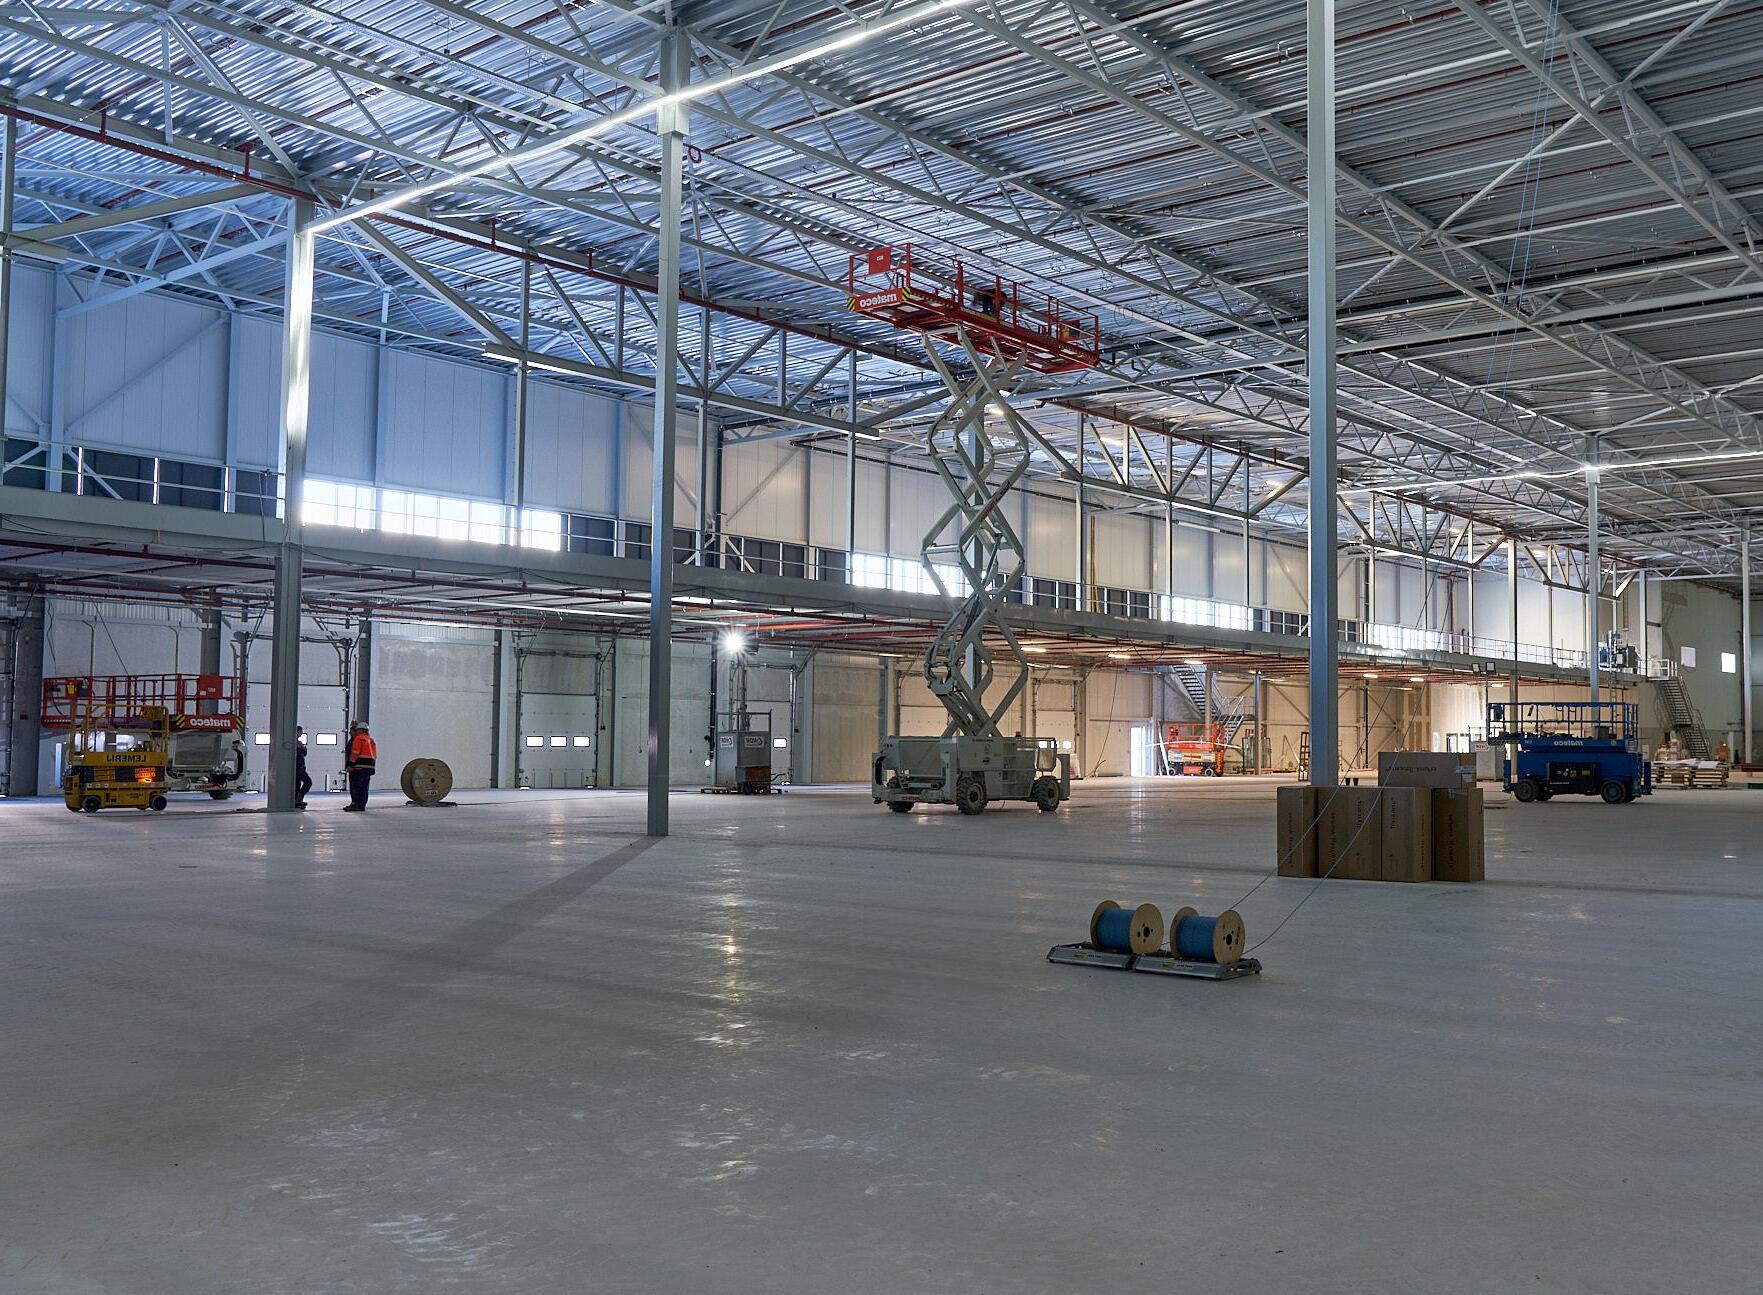
The strategy of WDP is aimed at creating long-term value for its clients, its shareholders and all its stakeholders. WDP aims to create a robust and growing income stream and dividend while safeguarding the long-term value of its properties and solid operational and financial KPIs. WDP’s operations are exposed to a number of internal and external risks or uncertainties that could impact the Group’s ability to achieve its overall strategic objectives.
WDP Group’s risk management focuses on risk awareness and control and/or mitigation of real risks or threats whilst allowing controllable risks (combined with opportunities) in pursuit of generating and protecting value for its shareholders, clients and other stakeholders. Risk management is performed on a continuous basis. Moreover, the Group is convinced that risk management should be an integral part of the company culture to foster an environment in which people are motivated to identify and cope with risks and ensuring the necessary transparency with regard to any possible risks. Risk management is embedded in the Company’s day-to-day business operations so that it can easily adapt to changes that may occur in the environment in which it operates.
Risk management process
Review and identification of (new) risks within the risk register
Risk identification
#TeamWDP Risk ambassadors Risk manager Management Committee Board of Directors
Risk evaluation
Analysis and evaluation of identified risks, taking into account their likelihood and impact Compliance officer Risk ambassadors Risk manager
Active risk management through prevention, mitigation, risk sharing and/or retention of risks
Risk management
#TeamWDP
Continuous monitoring of risk impact and possible changing risks
Risk monitoring
#TeamWDP Risk manager Management Committee Board of Directors
WDP works within the contours of a cautious-to-balanced risk appetite. The near-zero tolerance or cautious appetite relates to legal, regulatory, HSES, compliance, and financial risks. The Group has a limited to balanced risk appetite in pursuing the achievement of its strategic and operational objectives.
The Board of Directors determines the risk level which is acceptable to WDP in order to achieve its strategic objectives and annually reviews the Group’s risk appetite.
Per Regulation (EU) 2017/1121, WDP reports annually on its key risks, which are defined based on their specificity and materiality, taking into account their impact and likelihood. Of course, WDP also faces general risks, which are considered in its risk management assessment, and mapped and monitored within WDP’s risk management system. These risks are not considered as the most significant risks because they are not specific or because their net risk value2 is not considered to be material.
These key risks are presented on the following pages based on their net materiality, i.e. after mitigating actions, ranked per category from high to low and are discussed in detail in this chapter. WDP is aware of the fact that other risks may occur, which are unknown, not significant and/or material at the publication date of this annual report.
To clarify WDP’s risk management process, each of the main risks includes some of their Key Risk Indicators. These Key Risk Indicators can provide an early indication of risk exposure and offer concrete guidelines for risk assessment. The classification and identification of key risks are based on WDP’s Enterprise Risk Management Policy.
1
2 Net risk value (taking into account the mitigating factors) represents the impact x likelihood of each risk.
The key risks for WDP in 2024 are equal to these in the past three years, except for one. The Human capital risk was no longer retained as one of the key risks in 2024, given the qualitative and quantitative expansion of #TeamWDP supporting the operational efficiency and performance of the Company.
Climate transition
Risks related to tightening climate policies and regulations to shift towards a lower-carbon economy
Across the world, we see a tightening of climate policy and regulations to shift the economy away from fossil fuels towards a low-carbon economy.
The consequential requirements through tightening of climate policies can result in restrictions on the development, letting or sale of buildings that do not comply with minimum standards. The same goes for technologically obsolete buildings which may require higher maintenance costs or capex requirements to meet minimum efficiency standards and modern work trends.
Tightening climate policies and regulations can cause shifts in the Company’s entire value chain, going from investors to clients’ demands as this might lead to a reduction in available capital and revenues.
Why is this risk significant to WDP?
1 As a capital intense real estate company, we must secure our access to financing (debt and equity). The clear regulatory shift towards green financing implies a higher demand from investors and financial institutions for green investments and green-certified assets. The WDP Climate Action Plan defines concrete targets for green-certified assets and green financing. For example, we aim to increase the share of green-certified assets in the total property portfolio from the current 56% to at least 75% and ensure that at least 75% of total debt is green financing (2024: 68%).
1 More stringent energy performance and efficiency requirements and ambition to reduce embodied carbon in project developments will incur increasing capex.
1 Land use is critical for logistics development projects. In 2024, WDP will have completed 178,000 m² of developments, representing a land area of approximately 350,000 m².
How does WDP mitigate this risk?
1 Various actions are taken as a part of the WDP Climate Action Plan:
1 analysis of the portfolio’s exposure to transition risk;
1 WDP as a provider of integrated energy solutions;
1 the implementation of an energy monitoring system in the entire property portfolio.
1 WDP participates in various specialised industry organisations, keeping the Company up to date on changes affecting EU and global regulations.
Risk appetite: limited
Which Key Risk Indicators help WDP to monitor this risk?
1 Percentage of green-certified assets.
1 Percentage of green funding.
1 Greenhouse gas emissions (scopes 1, 2, and 3).
1 Percentage of electricity consumption from renewable energy sources for WDP corporate offices and property portfolio.
Risks related to zoning, permits, expropriation
The increasing complexity and uncertainty for obtaining permits, complying with zoning requirements, the lead time of procedures, the opposition of potential stakeholders and the complicated legislation within multiple policy levels and in different regions related to zoning and implantation, pose a risk to WDP.
This might affect the duration of a development project and can therefore lead to significant cost overruns and disruption to the planning of the developments.
Why is this risk significant to WDP?
1 WDP’s growth targets have been driven primarily by investments in pre-let property developments and energy and infrastructure, both of which are subject to permitting processes.
1 In 2024, WDP developed about 178,000 m², representing an investment volume of around 151 million euros. On 31 December 2024, an area of about 451,000 m² was under development, i.e. an investment volume of about 331 million euros.
1 WDP targets an energy capacity via solar panels of 350 MWp by 2027. As of 31 December 2024, the existing capacity was increased to 234 MWp (2024: +52 MWp) and the installation of a capacity of 114 MWp is in execution. In addition, WDP is investing in complementary energy infrastructure and batteries.
How does WDP mitigate this risk?
1 Intensive dialogue and proactive cooperation with stakeholders (authorities, local residents, clients) in both the preparatory and implementation phases of developments.
1 Continuous monitoring of applicable laws and regulations by in-house specialists supplemented by external specialised consultants, if applicable.
1 Long-term partnerships with architects and construction partners.
Risk appetite: cautious
Which Key Risk Indicators help WDP to monitor this risk?
1 Different and/or longer lead time for permits.
1 Number of appeals filed in a licensing process.
1 Divergent and/or delayed delivery of real estate and energy projects.
REIT status
Regulatory risks related to non-compliance with and loss of REIT status
WDP has REIT status in Belgium, the Netherlands3 and France (as GVV/SIR, FBI and SIIC respectively).
To maintain the REIT status – and their fiscally transparent regime – WDP must take into account certain activity restrictions, diversification requirements, restrictions on the level of its subsidiaries, restrictions on its gearing ratio, requirements on earnings distribution, requirements on its shareholder structure, procedures for conflicts of interest, requirements related to corporate gover nance and other specific requirements as set out in the relevant national REIT legislations.
Why is this risk significant to WDP?
1 Potential loss of the fiscally transparent regime causing a significant negative impact on the net result and NAV.
1 On 31 December 2024, WDP had a total of 3,063.8 million euros in outstanding credit facilities. The contractual provisions of these credit facilities generally stipulate that WDP NV/ SA must remain qualified as a regulated real estate company (GVV/SIR) in Belgium.
How does WDP mitigate this risk?
Rigorous internal control procedures. See Chapter 6. Corporate Governance Statement
1 Continuous monitoring of statutory requirements and compliance, assisted by specialist external consultants.
1 Intensive dialogue with the regulator as part of the prudential regulation of REIT regimes.
1 Representation of the Company in organisations that represent the REIT industry.
Risk appetite: cautious
Which Key Risk Indicators help WDP to monitor this risk?
1 Changes in the government’s position related to the REIT status.
1 A regulatory warning for inadequate compliance with REIT regulations.
1 Legal ratios imposed by REIT regulations.
3 WDP is of the opinion that all conditions are met by the Company within the current applicable FBI legislation. So, WDP expects that the FBI regime applies to the 2022, 2023 and 2024 financial years. As of 1 January 2025, the statute has expired given the recent legislative amendment by the Dutch government, which excludes real estate investments from the Dutch FBI regime. For more information, see Chapter 5. Financial results and outlook.
Negative variations in the fair value of the buildings
The fair value of the real estate investments of the WDP Group is subject to change and depends on various factors. Some of these are exogenous and thus potentially beyond the control of the WDP Group (such as decreasing demand or occupancy rates in the respective sub-markets in which the WDP Group is active and changes in expected investment returns or increases in transaction costs related to the acquisition or disposal of real estate).
Why is this risk significant to WDP?
1 A negative impact on net result and EPRA NAV. A 1% decrease in the occupancy rate implies a -4.8 million euros decrease in the EPRA Earnings.
1 A negative change in debt ratio. A 5.0% decrease in the fair value of real estate investments leads to a +2.0% increase in the gearing ratio. See Chapter 5. Financial results and outlook.
1 (Partial) inability for dividend distribution if the cumulative negative change in fair value exceeds the distributable reserves.
See Chapter 9. Annual accounts.
How does WDP mitigate this risk?
1 Investment policy that focuses on high-quality property in strategic logistics hubs or secondary locations with growth potential.
1 Highly diversified portfolio with a maximum risk per building of less than 2.5% in terms of fair value.
1 The property portfolio is evaluated by independent experts on a quarterly basis to identify trends and take timely proactive measures.
1 Prudent, clearly defined management of capital structures. See Chapter 5. Financial results and outlook
1 Sufficient distributable reserves of approximately 1,551 million euros (after payment of the proposed dividend for 2024).
Which Key Risk Indicators help WDP to monitor this risk?
1 Fair value of each building vs. fair value of the total portfolio.
1 Occupancy rate.
1 Average age of the portfolio.
1 Average lease duration.
1 Gearing ratio.
1 Cumulative unrealised profit/loss of the investment property portfolio.
1 Distributable reserves. Risk appetite: cautious
Risk appetite: cautious
As a capital-intensive growth company, WDP’s strategy depends largely on its ability to attain financial resources, in the form of either debt or equity capital so that it can finance its activities and investments. Various negative scenarios (such as disruptions in the international financial debt and share capital markets, a reduction in banks’ lending capacities, a deterioration in the WDP Group’s creditworthiness, and a negative investor perception towards real estate companies) may occur, resulting in difficulties in accessing funding under the existing or new credit facilities or within the capital markets. A material increase of the financing costs of the Company may have an impact on the profitability of the Company as a whole and on new investments.
Why is this risk significant to WDP?
1 An inability to finance acquisitions or projects (both from shareholders’ equity capital and loan capital). As of 31 December 2024, an amount of 168 million euros of identified investments remained to be invested.
1 The unavailability of financial resources (via cash flow or available credit facilities) for interest and operating costs and repayment of outstanding capital on loans and/or bonds on the expiry date.
1 Financing at an increased cost resulting in a decrease in targeted profitability. An increase of 100 basis points in Euribor interest rates implies a negative effect on EPRA Earnings of -3.5 million euros.
1 Potentially increased funding risk for current debt. 7 million euros or 0.2% of the outstanding debt is commercial paper and short-term straight loans.
How does WDP mitigate this risk?
1 Conservative and prudent financing strategy with a balanced spread of maturity dates for debt. See 5. Financial results and outlook
1 Securing sufficient credit lines to finance operating costs and planned investments. As of 31 December 2024, the total amount of undrawn and confirmed long-term credit facilities amounted to approximately 1.7 billion euros after covering the commercial paper programme. See Chapter 5. Financial results and outlook.
1 Protection against interest rate rises with hedging instruments so that 89% of the debt could be hedged. If the rise in interest rates is the result of higher inflation, the indexation of rental income is also a mitigating factor.
1 Continuous dialogue with investors and banking partners to build solid long-term relationships.
1 The commercial paper is fully covered by the backup lines and unused credit facilities that serve as a guarantee for refinancing if the full placement or extension of the commercial paper proves impossible. Backup lines and unused credit facilities also required periodic reviews.
Which Key Risk Indicators help WDP to monitor this risk?
1 Outstanding duration of all drawn and undrawn credit lines.
1 Amount of undrawn and confirmed credit lines.
1 Diversification rate of financing sources.
1 Hedge ratio.
1 Average financing costs.
1 Cost of capital.
Risks related to the investment market cycle
The investment market for logistics property may be negatively impacted by reduced investor demand for real estate. Structural drivers, such as omnichannel, supply chain revision, or sustainability, may lead to significant (negative or positive) changes in the companies’ logistics strategy, hence their real estate.
In addition, an inappropriate response towards an evolving property market will result in investments or disposals by WDP taking place at unfavourable prices or time in the cycle.
Why is this risk significant to WDP?
1 Every 5% decrease in the value of the property portfolio can lead to a -1.7 euros (-8.3%) decrease in the EPRA NAV and a +2.0% increase in the gearing ratio.
1 Acquisitions or disposals at unfavourable yields may affect the Company profitability and negatively impact the targeted EPRA Earnings per share.
How does WDP mitigate this risk?
1 Investment strategy aimed at high-quality buildings that generate stable long-term income, embedded in a multi-year growth plan with defined guidance and yield expectation.
1 Continuous monitoring of property market cycle and possible changing market conditions.
1 High percentage of land reserve in the valuation of the property portfolio (27%), which has withstood decreases in value in the past.
Which Key Risk Indicators help WDP to monitor this risk?
1 Geographical diversification for the entire property portfolio.
1 Initial rental yield of realised acquisitions and project developments.
1 Transactions’ prime yields and take-up volumes in relevant regions.
Volatility in capital markets
Extreme volatility and uncertainty in international markets may negatively impact the cost of capital and can lead to more difficult access to funding, both to share markets to acquire new capital/ shareholders’ equity and to debt financing through existing and/or new loans.
Why is this risk significant to WDP?
1 More difficult access to share markets to retrieve new capital/shareholders’ equity and limitations in the availability of debt financing with regard to existing and/or new credit facilities. On 31 December 2024, total financial debt was 3,063.8 million euros with an appropriate spread of maturities.
1 Volatility and uncertainty in international markets can lead to sharp fluctuations in share price.
1 Financing at an increased cost resulting in a decrease in targeted profitability.
How does WDP mitigate this risk?
1 Extensive and frequent dialogue with capital markets and financial counterparties and transparent communication with clear targets.
1 Strict monitoring and control of any risk which could negatively affect perceptions of the Company by investors and financiers.
1 Aim to build long-term relationships with financial partners and investors.
1 Buffer of 1.7 billion euros of unused and confirmed credit lines in addition to unused credit facilities to cover the commercial paper programme.
1 The Company’s creditworthiness is highlighted by a Baa1 – Positive Outlook (Moody’s) and BBB+ –Stable Outlook (Fitch) credit rating.
Risk appetite: cautious
Which Key Risk Indicators help WDP to monitor this risk?
1 Remaining duration of all drawn and undrawn credit lines.
1 Amount of undrawn and confirmed credit lines.
1 Diversification rate of financing sources.
1 Hedge ratio.
1 Average financing costs.
1 Cost of capital.
1 Credit rating scores.
Rental market cycle
Risks related to the rental market cycle
The rental market may face declining demand for logistics property possibly leading to an oversupply. This may impact the occupancy rate of the property portfolio, which is the main driver of our Company’s operating activities. Additionally, this may have an impact on the ability of pre-letting the project development pipeline and therefore also on the targets predetermined by WDP in its 2024-27 growth plan.
Why is this risk significant to WDP?
1 A decrease in the occupancy rate will affect rental income and vacancy charges. A 1% decrease in the occupancy rate would result in a -4.8 million euros decrease in EPRA Earnings.
1 A decrease in the fair value of the property portfolio and, thus, also of the NAV. Every 5% decrease in the value of the property portfolio decreases the EPRA NAV by -1.7 euros (-8.3%).
1 Inability to pre-let projects and to further develop and yield land potential within the portfolio. As of 31 December 2024, WDP owns a land reserve of approximately 2.1 million m² of lettable space (GLA) with a fair value of 207.9 million euros.
Risks related to the Company’s development activities
Several risks are inherent to developing projects and the rolling out WDP ENERGY: budget, timing, quality, and counterparty.
For example, the quality of the work delivered by the construction partner may pose a risk to the value of the project. Delays can occur during the implementation of the works that lead to a loss of potential revenue. Given the focus on pre-let developments, the time lag between the commercial agreement and the commitment of the construction partner may result in the unavailability of the construction partner and may cause a delay in the implementation of the work. Moreover, the required materials may increase in price due to scarcity, inflation, etc. Subsequently, this may lead to not achieving the intended returns on developments or exceeding investment budgets.
Why is this risk significant to WDP?
1 Within the growth plan, investments are prioritised by the pre-let property developments and roll-out of WDP ENERGY.
1 In 2024, WDP developed about 178,000 m², representing an investment volume of around 151 million euros. As of 31 December 2024, an area of about 452,000 m² was under development, i.e. an investment volume of about 331 million euros.
1 WDP intends to use solar panels to achieve a power capacity of 350 MWp by 2027. As of 31 December 2024, existing capacity was increased to 234 MWp (2024: +52 MWp) and the installation of a 114 MWp capacity is under development. Moreover, WDP is investing in complementary energy infrastructure and batteries.
How does WDP mitigate this risk?
1 Diversified client base with a maximum exposure per client and a wide spread across various tenant sectors (as well as tenants’ clients, especially if they are third-party logistics service providers).
1 Thorough integration in the real estate and logistics market thanks to years of experience and in-house commercial teams.
1 Focus on high-quality sites in strategic logistics hubs or secondary locations with growth potential.
Risk appetite: balanced
Which Key Risk Indicators help WDP to monitor this risk?
1 Occupancy rate.
1 Pre-let rate for development pipeline.
1 Diversification of the client base.
How does WDP mitigate this risk?
1 Long-term partnerships with construction partners with attention to solvency and quality.
1 Strict monitoring of projects under development with the implementation of penalty clauses for non-compliance with contracts by third parties.
1 Specialised internal development team with a strong track record and in-house Energy & Sustainability Team and collaboration with external advisors to mitigate risks.
Risk appetite: balanced
Which Key Risk Indicators help WDP to monitor this risk?
1 Outstanding development pipeline.
1 Timely delivery of project developments and sustainability investments.
1 Budget overrun.
1 Financial situation of partners participating in these realisations.
Portfolio vacancy risk
WDP holds a strategy of long-term leasing of developments and/or acquisitions. WDP keeps the buildings in its portfolio to generate a stable cash flow through leasing, whereby a high and constant occupancy rate is essential for the growth of the Company. Vacancy may arise when expiring lease agreements are not renewed and when lease agreements are terminated before the end date. The occupancy rate of the WDP portfolio at the end of the year amounted to 98.0%. Given the high occupancy rate, the risk of future rental vacancies is higher than the potential to increase the occupancy rate.
Why is this risk significant to WDP?
1 A decrease in the occupancy rate will affect rental income and vacancy charges. A -1% decrease in the occupancy rate would result in a -4.8 million euros decrease in EPRA Earnings.
How does WDP mitigate this risk?
1 Internal property management team and commercial teams.
1 Quality and multi-purpose buildings located at strategic logistics crossroads that facilitate re-letting.
1 Preference for realistic rent levels and long-term rental contracts.
1 Diversified client base with limited exposure towards one tenant and well-spread sector base.
Risk appetite: limited
Which Key Risk Indicators help WDP to monitor this risk?
1 Occupancy rate.
1 Solvency of client portfolio (percentage of rent collection and doubtful debt).
1 Buildings’ spread (geography, building type, age) within the property portfolio.
1 Average lease duration and lease renewal rate.
Client solvency
Client solvency risk (Partial) default of payment by clients can significantly affect the Company’s rental income, cash flow, the portfolio’s occupancy rate, and EPRA Earnings per share.
Why is this risk significant to WDP?
1 As of 31 December 2024, outstanding trade receivables amounted to 28 million euros. An increase of bad debt of 2 million euros would result in a -0.6% decrease in EPRA Earnings.
How does WDP mitigate this risk?
1 Extensive tenant solvency check by internal specialists and external rating agencies before inclusion in the portfolio.
1 Rigorous internal procedure for invoicing and rent collection.
1 Lease strategy that aims for long-term contracts with high-quality stable, solvent tenants and client diversification throughout the property portfolio.
Risk appetite: limited
Which Key Risk Indicators help WDP to monitor this risk?
1 Percentage of rent collection.
1 Days Sales Outstanding.
1 Tenant’s financial situation.
1 Tenants’ diversification throughout the property portfolio.
Supply chain risks related to business continuity, quality, resilience, labour regulations and working conditions
WDP liaises with all kinds of stakeholders who contribute to the operational activities of the Company at various levels within the supply chain. The (re-)development projects (real estate and energy projects) are the focal point of our supply chain. Here, we call on a wide range of service providers (architects, engineering firms, construction companies, etc.), which entails risks in terms of financial stability, ethical misconduct, geopolitical instability, e.g. in certain purchasing regions. Moreover, we are also dependent on the supply chains of (construction) material (potentially disrupted by scarcity, price increases, regulatory changes, and quality control issues). This interaction does not only affect business processes or services, but also entails corporate responsibility and reputation risks.
Why is this risk significant to WDP?
1 Of the projects under development as of 31 December 2024, 60% were pre-let.
1 In 2024, WDP developed about 178,000 m², representing an investment volume of around 151 million euros. On 31 December 2024, an area of about 451,000 m² was under construction, i.e. an investment volume of about 331 million euros.
1 WDP targets an energy capacity through solar panels of 350 MWp by 2027. As of 31 December 2024, the existing capacity was increased to 234 MWp (2024: +52 MWp) and the installation of a capacity of 114 MWp is in execution. In addition, WDP is investing in complementary energy infrastructure and batteries.
How does WDP mitigate this risk?
1 By requiring our suppliers to abide by the WDP Supplier Code of Conduct, we involve them as important stakeholders in achieving our objectives in the area of sustainability.
1 The WDP Grievance mechanism ensures awareness about inappropriate and unlawful practices with the goal of ending and resolving such grievances.
1 Critical suppliers to the Company are subject to regular due diligence.
Risk appetite: cautious
Which Key Risk Indicators help WDP to monitor this risk?
1 Reported breaches of the Supplier Code of Conduct.
1 Changes in regulations related to the Company’s supply chain.
As of the financial year 2025 – and thus the next annual report to be published in March 2026, WDP will be subject to the Corporate Sustainability Reporting Directive (CSRD) and the accompanying European Reporting Standards (ESRS).1
To this end, we chose to prepare the current annual report to comply with the aforementioned regulations. Commensurately, we have taken similar inspiration for this Sustainability Statement. However, not all of the necessary information is available for certain reporting requirements and we indicate this as such in the list of reporting requirements.
General basis for preparation of the sustainability statement
ESRS 2 BP-1
This Sustainability Statement was drawn up based on a consolidated view. The scope of the consolidation is the same as that used for the financial statements.
The Sustainability Statement covers our upstream and downstream value chain per the results of our double materiality analysis. Our policies, actions and goals also extend, where relevant, to our upstream and downstream value chain.
Certain parts of this Sustainability Statement and, by extension, the annual report have been audited. The audited information and data points are clearly marked with a ✓. For the sake of clarity, the external verification has not yet occurred per the requirements of the Corporate Sustainability Reporting Directive. The auditor’s report is included in Chapter 10. External verification, and provides more information about the criteria and audit standards used.
Disclosures in relation to specific circumstances ESRS 2 BP-2
Disclosures stemming from other legislation or generally accepted sustainability reporting pronouncements
Some data points or themes previously reported on fell below the threshold for materiality under the double materiality analysis. Some stakeholders or ESG ratings expect such information, so we have tried to align the representation of such data points with the ESRS reporting structure. More specifically, this concerns:
1 EPRA and GHG environmental performance indicators
1 EPRA social performance indicators
1 EPRA governance performance indicators
1 CAP performance indicators
1 GFF (Green Financing Framework) Impact Report
1 GRI indicators
1 TCFD reporting
to other parts of the annual report
The principle of incorporation by reference is used when information from other parts of this annual report is included. Cross-references are added where relevant.
List of disclosure requirements in ESRS complied with in preparing the Sustainability Statement ESRS 2 IRO-2; BP-2
The following table lists all ESRS reporting requirements in ESRS 2 and the three thematic standards relevant to WDP that led to the preparation of our Sustainability Statement. We have omitted all reporting requirements in thematic standards E2, E3, E5, S1, S2, S3 and S4 because these fall below our materiality thresholds. For E2, E3 and E5, we identified and assessed the impacts, risks and opportunities using the same methodology and process steps as for the topics considered material. However, none of the identified IROs were assessed as material for these topics. Thus, these are not included in the Sustainability Statement.
1 This is subject to any changes under the EU Clean Industrial Deal, as published by the EU Commission dated 26.02.2025.
ESRS E1 – Climate change
E1-5 Energy consumption and mix
E1-6 Gross Scopes 1, 2, 3 and total GHG emissions
E1-7 GHG removals and GHG mitigation projects financed through carbon credits
E1-8 Internal carbon pricing
E1-9 Anticipated financial effects from material physical and transition risks and potential climate-related opportunities
ESRS E4 – Biodiversity and ecosystems
E4-1 Transition plan and consideration of biodiversity and ecosystems in strategy and business model
ESRS 2, SBM 3 Material impacts, risks and opportunities and their interaction with strategy and business model
ESRS 2, IRO-1
E4-2
E4-3
E4-4
Description of processes to identify and assess material biodiversity and ecosystem-related impacts, risks,
E4-5 Impact metrics related to biodiversity and ecosystems change
E4-6 Anticipated financial effects from biodiversity and ecosystems-related risks and opportunities
185;
Partly covered via GHG Protocol and EPRA sBPR reporting
ESRS G1 –
ESRS 2, Gov-1
ESRS 2, IRO-1
Information (fully or partially) incorporated by reference //ESRS2 BP-2 / = information not yet included or not relevant
Strategy, business model and value chain ESRS 2, SBM-1
WDP has a clear mission: provide smart logistics solutions that make the critical infrastructure of the supply chain more efficient and more sustainable, while also creating value for clients, shareholders and society. As a commercial real estate company that puts the client at the heart of its strategy, we build and manage crucial infrastructure via developments, acquisitions, renovations and energy solutions. Development, long-term leasing and stable cash flow are pivotal in our business model.
See 3. Strategy and value creation for strategy and business model
Double materiality analysis ESRS 2 IRO-1, SBM-2
WDP started conducting the organisation’s double materiality analysis in February 2024 following two previous materiality assessments used as the basis for WDP’s corporate sustainability approach. The double materiality analysis defines the sustainability topics that are material for reporting purposes per the European Corporate Sustainability Reporting Directive (CSRD) and the European Sustainability Reporting Standards (ESRS). This analysis assesses the impact of potential material sustainability themes from a twodimensional perspective. Firstly, the financial perspective measures the risks and opportunities for WDP arising from ESG factors. Secondly, the social and environmental perspective measures the impact of WDP’s business activities on the wider society and environment.
The result of the double materiality analysis was approved by the WDP Board of Directors.
This assessment identifies the sustainability themes most relevant to WDP so that a strategy can be implemented that mitigates the potential negative impact and/or increases the potential positive impact on society. And it can be reported transparently and coherently.
Scope and value chain
This assessment covers the WDP Group and all geographical regions in which the Company operates. It takes into account each part of WDP’s value chain: upstream, own operations and downstream. Potential impacts, risks and opportunities were identified for each part of the chain as well as the level of involvement and potential influence WDP can exert on them. ESRS topics and subtopics were then contrasted against these findings.
This analysis is the result of surveying the different stakeholder groups WDP interacts with. The weight assigned to each stakeholder in this exercise was determined based on the Salience Model.
Materiality was determined using a double materiality analysis over the short, medium or long term. From the perspective of impact materiality, actual and/or potential negative impacts were assessed based on scale, scope, irreversibility and likelihood. The actual and/or potential positive impact was assessed based on scale, scope and likelihood. From a financial materiality perspective, WDP assessed actual and/or potential risks and opportunities based on their likelihood and potential scope.
Calculation factors Description Scoring
Impact materiality
Scale Analysis of scope of impact based on geographical spread of WDP on society
Scope Analysis of the scope of WDP’s impact on society
Irremediable character Estimation of capacity to reset negative impact
Likelihood Analysis of expected frequency of impact
Financial materiality
Scope Analysis of the potential financial impact of risks and opportunities
Likelihood Analysis of expected frequency of financial impact
Threshold
From 5 to 0: based on geographical spread; from total impact (at global level) to no impact
From 5 to 0: based on absolute impact to no impact
From 5 to 0: from non-recoverable/irreversible to easily fixable
From 4 to 0: from very high impact (5+ times per year) to very low impact (< 1 time over 10 years)
From 4 to 0: from very high impact (> 10% on EPRA Earnings/Balance sheet) to very long impact (< 1% on EPRA Earnings/Balance sheet)
From 4 to 0: from very high impact (5+ times per year) to very low impact (< 1 time over 10 years)
A threshold is set to distinguish between material and non-material sustainability themes. The threshold is based on three criteria: scope (absolute impact to no impact), scale (based on geographical spread; from total impact (at the global level to no impact) and irremediable character (from non-repairable/irreversible to easily fixable). The threshold determination builds on the methodology used in WDP’s Enterprise Risk Management.
1. Analysis of the business model and value chain
Identification of potential opportunities and risks and positive and negative impacts in each part of the value chain2 and identification of potential ESRS sustainability (sub-) themes.
2. Update on the definition of material topics (sustainability themes)
Redefine sustainability themes used in the previous materiality assessment to ensure alignment with identified (sub-) thematic ESRS sustainability themes and the current environment in which WDP operates. A long list of potential sustainability themes was compiled using various sources, in particular (1) relevant third-party ESG ratings, reporting standards and trend reports (EFRAG, SASB, Sustainalytics, European Commission, Deloitte, MSCI, S&P Global ratings, TCFD, World Economic Forum and WBCSD), (2) material topics reported by peers (Dexus, CTP, Landsec, Prologis, Segro and Gecina), and (3) material topics in WDP’s corporate documentation (such as strategy, materiality matrix 2022, etc.). Internal workshops narrowed down this long list into a shortlist on which stakeholders were then surveyed.
3. Identification and analysis of impacts, risks and opportunities (IROs)
Identification of potential opportunities, risks and impacts for each of the identified sustainability themes. This includes defining a potential or actual IRO and identifying the stakeholders and time horizon involved. The risks and opportunities were then measured against the IIRC Capitals3
4. Stakeholder engagement
Stakeholders identified as representative for the entire value chain were evaluated using:
1 Interviews: clients, investors, financial institutions, suppliers – directly or via their relevant proxy within #TeamWDP
1 Desk research: clients, investors, financial institutions, suppliers, policymakers and communities
1 Business Impact Workshop: senior management team
1 Panel: #TeamWDP
This is how input was collected on stakeholder relevance and the importance stakeholders attach to the selected sustainability themes. Both dimensions were measured. Potential risks, opportunities and impacts were evaluated using the interviews, the Business Impact Workshop and the panel.
5. Composition of materiality matrix
A combination and consolidation of the information obtained to quantify impact and financial materiality.
6. Threshold
A threshold was determined to distinguish between material and non-material sustainability themes. Topics that fall below the set threshold are considered ‘nonmaterial’ for ESRS reporting.
Analysis of the business model and value chain Update on the definition of material topics (sustainability themes) Identification and analysis of impacts, risks and opportunities (IROs)
2
3 Capital identified by the International Integrated Reporting Council (IIRC): financial capital, produced capital, intellectual capital, human capital, social and relationship capital and natural capital. Together, these represent the capital that underpins an organisation’s value creation.
1 Energy efficiency and renewable energy production reduce clients’ costs and emissions and increase WDP’s future resilience and appreciation as a reliable business partner.
2 Decarbonisation strategy reduces costs (e.g. carbon tax) and demonstrates WDP’s commitment to sustainability, which may lead to greater appreciation and loyalty from clients and partners.
4 Resilient buildings for climate resilience, cost savings and strengthening investor and client confidence.
5 Ensuring best practices boost our reputation and shareholder trust and alignment with all employees and partners.
3 An innovative warehouse design to maximise available space and increase flexibility for clients.
2 Not aligned with standards, norms and regulations, resulting in financial penalties, increased operational costs and potential reputational damage.
1 The use of and absence of in-house production of renewable energy increase energy procurement costs and possible loss of clients
5 Ethical misconduct leads to serious damage to the WDP brand resulting in reputational damage, fines and legal consequences.
Attracting and retaining
Occupational health, safety & well-being
Water Stewardship
Local community involvement
Employee Diversity & Inclusion
Material Selection and Scarcity
Human rights
Privacy and Data Security
Biodiversity
Waste management
2 Decarbonisation of the construction process, warehouse operations and WDP’s own operations, reduces the company’s CO2 footprint and benefits the environment.
1 Use of green energy and monitoring ensure avoidance of GHG emissions and lower operational costs.
3 Redevelopment projects for conservation of natural habitats and minimisation of impact on the environment in combination with economic and ecological benefits for the surrounding area.
4 Resilient buildings to mitigate the impact of climate change on the properties’ surroundings and safeguard our strong position in the capital market.
5 Ensure best practices to mitigate the risk of corruption and ensure compliance with financial obligations. Minimises legal and financial risks and strengthens stakeholder trust.
Negative impact
2 Inability to reduce emissions accelerates climate change and negative environmental impacts.
3 Cutting of new land leads to loss of green space, habitat fragmentation, and increased vulnerability of ecosystems to external influences.
To achieve our objectives, we depend on a strong network of business partners and through our activities we interact with numerous stakeholders. WDP continuously keeps its finger on the pulse to keep abreast of their expectations. Moreover, this stakeholder
Key stakeholders and their relationship with the strategy and business model
♦ Contemporary, innovative, energy-efficient logistics property in all its facets
♦ In-house know-how: continuous interaction between our property, project, and commercial managers and (future) clients
♦ Solar panel programme
♦ Energy monitoring system in all WDP warehouses
♦ Energy-efficient measures in the buildings
♦ Leases at market conditions
♦ Property managers respond quickly and flexibly to client demands
♦ Creation of long-term partnerships with mutual dialogue, e.g. on sustainable initiatives
♦ Continuous brainstorming with partners on innovation and sustainable solutions
♦ Sustained profitability with constant EPS and DPS growth according to quantified targets
♦ Stringent capital discipline
♦ Defined growth plan with quantified targets
♦ Transparent communication and financial information via quarterly publications and (interim) annual reports
♦ Participation in and knowledge of the expectations within a selection of reputable ESG questionnaires
♦ Building a solid long-term relationship through constant and intensive dialogue, including via annual roadshows and investor fairs, recurring consultation events and Capital Markets Day
♦ Annual General Meeting
♦ Thorough knowledge of client expectations, the market and geography in which WDP operates and in-house expertise to meet them
engagement exercise as well as recurrent validation of the stakeholder groups are incorporated within the materiality analysis framework (most recently in 2024 ahead of the double materiality matrix). The insights provided by stakeholders within the analysis are shared with the entire #TeamWDP and the Board of Directors via a training session.
♦ Supporting sustainable property in strategic locations with a focus on well-being, safety and the environment
♦ Optimisation and increased energy efficiency of the supply chain and operational activities
♦ Reliable partnership with a clear understanding of client expectations, such as timely project delivery
♦ Positioning as a competent business partner with expertise and know-how
♦ Low-threshold contact between WDP and the client
♦ Supports clients’ contribution to the climate issue
♦ 96% lease renewal
♦ 27% repeat business
♦ Dialogue with the client:
♦ each client meets with the property team at least twice a year
♦ each client meets with the sales team at least once a year
♦ WDP Climate Action Plan
♦ MyWDP, an online and responsive client portal and mobile app
♦ Development of sustainable critical client supply chain infrastructure that supports transport decarbonisation
♦ Project developments delivered as agreed
♦ Value creation and earnings generation
♦ Stable partnership and mutual dialogue
♦ Good ESG ratings score and objective performance benchmarking using reputable ESG questionnaires
♦ Transparent communication and complete information about WDP and its business plan
♦ Development of sustainable properties to ensure high occupancy rates
♦ Land bank for future developments
♦ Profitable growth in line with targets within business plan: earnings target for 2027 confirmed
♦ Stringent capital discipline
♦ One-on-one and group discussions with approximately 350 institutional investors at international roadshows, real estate events, and multiple calls
♦ Biennial Capital Markets Day
♦ Dialogue with the existing shareholder via the General Meeting
♦ Online video call with live Q&A on publication of quarterly results
♦ Shareholder rights
♦ Benchmark performance and proactive interaction with ISS ESG, MSCI, DJSI and CDP
♦ Transparent communication on consensus and analyst expectations
♦ 85% Class A warehouses
♦ WDP Climate Action Plan:
♦ 56% green certified warehouses – all projects under development at least BREEAM Very Good certified
♦ 234 MWp of renewable energy capacity installed
♦ Land bank of ~2.1 million m² of GLA
Key stakeholders and their relationship with the strategy and business model
institutions
Our engagement
♦ Sustained profitability with constant EPS and DPS growth according to quantified targets
♦ Stringent capital discipline
♦ Defined growth plan with quantified targets
♦ Transparent communication and financial information via quarterly publications and (interim) annual reports
♦ Participation in and knowledge of the expectations within a selection of reputable ESG questionnaires
♦ Building a solid long-term relationship through constant and intensive dialogue, including via recurrent consultation opportunities and Capital Markets Day
♦ Pleasant working environment to support creativity, well-being, and motivation for #TeamWDP
♦ Employee Code of Conduct
♦ Corporate engagement activities
♦ #HealthyAndSafe Statement
♦ Open dialogue and regular communication
♦ #SpeakUp
♦ Training and coaching programmes
♦ Annual analysis of the remuneration policy
♦ An open culture with room for constructive feedback and innovation
♦ Collaboration based on clear agreements and interaction
♦ Payment deadline compliance
♦ Creation of a long-term relationship
♦ HSES Team – HSES Corporate Action Plan
♦ Supplier Code of Conduct
♦ #HealthyAndSafe Statement
♦ Collaboration to create sustainable, energy-efficient property
Purpose
♦ Value creation and earnings generation
♦ Stable partnership and mutual dialogue
♦ Good ESG ratings score and objective performance benchmarking using reputable ESG questionnaires
♦ Transparent communication at regular intervals with publications containing accurate and complete information on WDP and its business plan
♦ Contribution to climate issue and clear ESG strategy
♦ Safeguarding human capital
♦ Good rapport between WDP and the environment so that projects can be launched and the client’s activities can be carried out
♦ Good work/life balance and a focus on health and safety
♦ Space for personal and professional development
♦ Attractive salary package
♦ Responsible operations with correct and ethical conduct
♦ Good understanding of any employee concerns
♦ Safeguarding human capital
♦ Minimum score of 8/10 in employee satisfaction score
♦ Ethical conduct
♦ Reliable and long-term partnership
♦ Proper and fair business practices
♦ Safe working environment for suppliers commissioned by WDP
♦ Reducing greenhouse gas emissions
Outcome
♦ Profitable growth in line with targets within business plan: earnings target for 2027 confirmed
♦ Stringent capital discipline
♦ Annual 360° consultations with each partner bank
♦ Biennial Capital Markets Day
♦ Online video call with live Q&A on publication of quarterly results
♦ Benchmark performance and proactive interaction with ISS ESG, MSCI, DJSI and CDP
♦ WDP Climate Action Plan
♦ ESG strategy and results: see 8. Sustainability Statement
♦ 4.9% total employee turnover of which 1.6% voluntary employee turnover
♦ Regular neighbourhood consultations in collaboration with the relevant authorities and the area surrounding the development
♦ 43 building applications in 2024
♦ Training plan for each employee
♦ 28 hours of training on average per FTE in 2024
♦ Average score of 8.6/10 in employee satisfaction score
♦ Annual feedback in open dialogue and interaction for all employee
♦ #SpeakUp related to the Employee Code of Conduct: no reports
♦ Annual international #TeamWDP Day and WDP Academy for newcomers
♦ Digital HRHub: online HR platform for all employees
♦ 4.9% total employee turnover of which 1.6% voluntary employee turnover
♦ Corporate governance policies
♦ Long-term relationships supported by framework contracts with a selection of existing contractors and mirrored by collaboration with a permanent pool of contractors, architects, engineering firms, and legal advisors
♦ Supplier Code of Conduct: due diligence for our most critical suppliers.
♦ #SpeakUp related to the Employee and Supplier Code of Conduct: no reports
♦ WDP Climate Action Plan:
♦ 56% green certified warehouses – all projects under development at least BREEAM Very Good certified
♦ 234 MWp of renewable energy capacity installed
♦ WDP Decarb+
Key stakeholders and their relationship with the strategy and business model Our engagement
♦ Continuous monitoring and compliance with prevailing regulations
♦ Open dialogue through membership of reputable professional organisations
♦ Open dialogue with policymakers in the spirit of transparency and ethical awareness
♦ Open and proactive dialogue with local and national regulating associations during the project development cycle
♦ No monetary contributions to political parties or campaigns
♦ Continuous and mutual dialogue between client, community, and WDP
♦ Direct and transparent contact with the community (e.g. via an information evening) and relevant stakeholders
♦ Corporate citizenship via #WeMakeADifference
♦ Contribution to the infrastructure
♦ Membership of various associations and societies
Purpose
♦ Knowledge of and compliance with prevailing regulations
♦ Long-term partnership and mutual dialogue
Outcome
♦ Neighbourhood consultation or information meeting in collaboration with competent authorities
♦ 43 building applications in 2024
♦ Proactive interaction and dialogue with FSMA and AFM
♦ Proactive consultation with competent authorities
♦ WDP did not make any monetary contributions to political parties or campaigns
♦ Minimal negative impact of WDP’s activities on the immediate environment
♦ Clear communication regarding (the possible impact of) WDP development projects
♦ Measures to reduce ecological impact
♦ Economic growth and job creation
♦ Sustainable operational management
♦ Mutual dialogue
♦ Supporting the community through a corporate citizenship strategy
♦ Sharing knowledge:
♦ Joost Uwents teaches at AMS, is a member of the general council of Vlerick Business School, and is a jury member for a graduation project at ASRE
♦ Joost Uwents is a board member at Logistics in Wallonia, a member of the Advisory Board of EPRA and a member of the strategic committee of VBO
♦ Frank Van Cauwenberge is a member of EPRA’s PropTech Committee
♦ Mickaël Van den Hauwe is Chairman of the BE-REIT Association and a member of the Regulatory & taxation committee of EPRA
♦ Regular neighbourhood consultations in collaboration with the relevant authorities and the area surrounding the development
♦ Collaboration with the Dutch Industrial & Logistics Association (DILAS), which brings together innovative and sustainable stakeholders in the logistics and industrial property chain in the Netherlands
♦ 43 building applications in 2024
♦ Support for students and charities
Material impacts, risks and opportunities ESRS 2, SBM-3
The following tables list our impacts, risks and opportunities (IROs) identified and assessed as material in our double materiality analysis. Each ESRS sustainability theme lists which sub-thematic ESRS relates to the IROs, for example, in ESRS ‘E1 Climate Change’ the subtopics ‘climate mitigation’, ‘climate adaptation’ and ‘energy’ are relevant.
A brief description of material IROs is included here and an indication of where these IROs are located in our own operations or value chain. For impacts, we also show whether they are positive (+), negative (-), actual or potential.
More information on each IRO, including how we manage them, is included in the thematic sections under ‘Environmental Information’, ‘Social Information’ and ‘Governance Information’. Topic Sub-topic
E4-Biodiversity and ecosystems Impacts on the extent and condition of ecosystems
E1-Climate change Climate change adaptation
G1-Business conduct Corporate culture / protection of whistleblowers / management of relationships with suppliers
Land-use Impacts on the extent and condition of ecosystems Impacts on the extent and condition of ecosystems
Impacts on the extent and condition of ecosystems
Adjustment to climate change
Corporate governance & business ethics
change adaptation Climate change adaptation
/ protection of whistleblowers / management of relationships with suppliers
ESG is fully embedded in the company’s day-to-day organisation and governance structure with clear roles and responsibilities assigned to the relevant teams and governing bodies. The continuous interaction between the different levels that unifies a top-down and bottom-up approach is inherent in this governance structure.
We refer to 6. Corporate Governance Statement for more information about the role, responsibilities, and composition of the Board of Directors, the ESG Committee, and the Executive Committee, and also about the risk management policy applicable within WDP.
♦ Approve the proposed ESG strategy (including targets and commitments).
♦ Monitor the implementation of the ESG strategy as well as material IROs.
♦ Twice a year, the Board of Directors receives a progress update on material IROs and strategic priorities and objectives, and delves further into specific ESG topics via deep dives when necessary.
♦ The directors’ expertise in our material IROs is shown in the competences listed in 6. Corporate Governance Statement
♦ Acts as a liaison between the ESG team and the Board of Directors.
♦ Ensures information and education on ESG-related issues are propagated upstream
♦ Advises the Board of Directors – and if applicable, the Audit Committee – about ESG subjects and formulates proposals, recommendations, and reports on these topics, such as target setting, assessment of non-financial information, or information required by prevailing legislation with regard to ESG, material impacts, risks, and opportunities related to the Audit Committee and the Board of Directors.
♦ Aligns the various operational initiatives and the ESG strategy.
♦ Meets at least twice a year.
♦ Submits proposals for the ESG strategy (including targets and commitments) to the ESG Committee based on input from the ESG team.
♦ It is responsible for the continuous evaluation of the ESG strategy and for monitoring its implementation.
♦ It is also responsible for the follow-up and monitoring of material impacts, risks and opportunities.
♦ Forum for the development of the ESG strategy (including objectives and commitments) to be approved by the Executive Committee and Board of Directors.
♦ Ensures complete coordination and necessary interaction between the environmental, social, and governance tracks.
♦ Ensures the information, non-financial or otherwise, required by prevailing ESG legislation is prepared (and reported) to both internal and external stakeholders.
♦ Monitors the progress of ESG strategy implementation.
♦ Composition: Sustainability Manager, Head of Human Resources, General Counsel, Investor Relations. This composition ensures coverage of WDP’s broad ESG topics and, more specifically, the following material IROs: Climate change, Land use, Business behaviour.
♦ Meets monthly.
♦ Responsible for implementing the ESG strategy.
♦ An integrated approach is guaranteed by dedicated interdepartmental working groups focused on specific ESG themes. This is how we make the most of the knowledge of our specialist employees and also ensure ownership of the initiatives and the planned targets.
List of datapoints in cross-cutting and topical standards that derive from other legislation ESRS 2, IRO-2
WDP’s material sustainability themes from the double materiality analysis:
Climate Change Adaptation
Implementation of climate-related risk assessment and adaptation measures to increase the resilience of buildings against climate change and associated severe weather events that can impact WDP facilities.
Energy efficiency
Secure efficient use of energy in our own operations as well as by our tenants through energy monitoring systems, insulation and LED lighting, as well as increasing renewable energy generation. Harnessing the power of batteries and energy storage leading to creation of Logistics Powerhouses. Thereby, providing affordable clean energy for clients to help transition to a lower-carbon economy.
GHG emissions
Adopt strategies to decarbonise WDP’s business and reduce direct and indirect greenhouse gas emissions in our corporate office, car park and our buildings. This includes procurement of green electricity, expanding our renewable energy generation capacity, and decarbonise our upstream (i.e. building processes and redevelopment) and downstream (i.e. client operations).
Land use
Efficient land use to lower the pressure on the environment, as well as dedicating site space towards green space. Ensuring limited changes to land-use, such as fragmentation of habitats.
Material impacts, risks and opportunities and their interaction with the strategy and business model ESRS 2 SBM 3
WDP's Material Sustainability
1 Energy efficiency Energy efficiency measures and renewable energy production Financial opportunity Downstream & Upstream
(i) We reduce our client’s operation al costs and contribute to reducing GHG emissions using energy efficiency measures in our warehouses and integrated energy solutions.
(ii) Renewable energy production reduces our dependence on fossil fuels, lowers costs and reinforces our position as a reliable business partner. Concurrently, we contribute positively to the climate and strengthen our resilience to current and future energy challenges. Short term
WDP's Material Sustainability
matter IRO
Non-renewable energy consumption and production
Financial risk
Downstream & Upstream
Renewable energy consumption and monitoring
Positive impact
Downstream & Upstream
2 GHG emissions
Decarbonisation strategy
Financial opportunity
Downstream & Upstream + Own operations
Misalignment with regulations
Financial risk
Downstream & Upstream + Own operations
No reduction of GHG emissions
Negative impact
Downstream & Upstream + Own operations
Description IRO
Reliance on non-renewable energy increases energy procurement costs, makes operational costs volatile and can deter clients seeking energy efficiency and sustainability in warehouses. A lack of renewable solutions may also damage WDP’s reputation. Investing in renewables and energy efficiency is essential to control costs, maintain competitiveness and ensure customer satisfaction.
Using renewable energy combined with monitoring systems benefits both WDP and the environment. This avoids GHG emissions and reduces dependence on fossil fuels. By investing in renewable energy sources, such as solar power and smart monitoring, WDP contributes to optimising energy consumption, reduced operational costs and a smaller carbon footprint.
Connection to WDP's strategy: #FutureLogistics #ClimateActionPlan
Implementing the decarbonisation strategy can reduce some costs, such as a possible carbon tax. This can also contribute to a stronger position in both logistics and capital markets. Reducing WDP’s carbon footprint demonstrates commitment to sustainability and can increase client and partner appreciation and loyalty.
Failure to reduce emissions can lead to misalignment with different standards, norms and regulations. This increases the risk of significant financial penalties (such as a carbon tax), higher operational costs, and reputational damage.
Failure to reduce emissions within WDP will further accelerate climate change. If WDP does not reduce greenhouse gas emissions, it contributes to global warming and the associated negative environmental impacts, such as more extreme weather events, loss of biodiversity and disruption of ecosystems. So, WDP believes proactive measures are crucial to reduce emissions and contribute to global efforts to slow climate change. This includes implementing sustainable practices, investing in renewable energy sources and optimising energy efficiency in all business activities.
Connection to WDP's strategy: #FutureLogistics #Decarb+
Time horizon
Medium term
Long term
Short term
Medium term
Long term
Decarbonisation strategy
Positive impact
Downstream & Upstream + Own operations
Using the right strategies to decarbonise the construction process, warehouse operations, and WDP’s own operations is essential to reduce the company’s CO2 footprint. In recent years, the focus has been on WDP Energy’s downstream decarbonisation strategy. In the coming years, the Decarb+ strategy will be further developed and optimised to also impact upstream decarbonisation. Continued reductions in GHG emissions benefit both WDP and the environment.
Connection to WDP's strategy: #FutureLogistics #Decarb+
Long term
WDP's Material Sustainability
3 Land-use Optimisation of available space
Financial opportunity
Upstream
Habitat degradation and fragmentation
Negative impact
Upstream
New solutions, such as layout optimisation and multi-storey warehouses, maximise the available space without cutting extra ground. Clients then have more flexibility in handling the growing demand for storage space.
Changes in land use degrade habitats, accelerate the loss of green space and cause fragmentation, creating significant pressure on the environment. Developing new land for warehousing increases the vulnerability of ecosystems to external influences, such as pollution and climate change. Sustainable land use strategies are essential to minimise environmental impacts and preserve the integrity of natural habitats.
Medium term
4 Adjustment to climate change
Redevelopments and brownfield developments
Positive impact
Upstream
Resilient buildings
Financial opporunity
Upstream + Own operations
Resilient buildings
Positive impact
Upstream + Own operations
Connection to WDP's strategy: #FutureLogistics #Decarb+ Medium term
WDP makes optimal use of available space without developing additional land by redeveloping existing buildings and sites. This helps preserve natural habitats and minimise environmental impact. Moreover, redevelopment projects can help revitalise urban areas and improve infrastructure, bringing economic and environmental benefits.
Connection to WDP's strategy: #FutureLogistics #Decarb+
WDP investing in sustainable and climate-resilient construction methods and adequate adaptation measures helps reduce the impact of natural disasters and extreme weather events and saves significantly on costs. This also strengthens investor and client confidence, which is essential for maintaining a strong position in capital markets.
Adopting the right strategies and investments to adapt our buildings will help mitigate the impact of climate change on the environment and residents living near our properties. Targeted investments and proactive measures can help us reduce the impact of natural disasters, such as floods or hurricanes, and strengthen the resilience of the surrounding community.
Connection to WDP's strategy: #FutureLogistics #WDPGreen
Medium term
Medium term
Long term
Strategy ESRS E1-1
WDP has a tradition of pursuing sustainability in its developments. For example, we launched a comprehensive solar panel programme in 2007. In January 2022, we further reinforced that programme. WDP also formally announced its ambition to achieve netzero emissions in Scope 1, Scope 2 and Scope 3 by 2050 at the latest. This is in line with a 1.5°C scenario and the ambitious targets of the EU Green Deal. So, we do not limit our goals to our own business activities. Rather, we wish to decarbonise our real estate portfolio – WDP’s core product – across the entire life cycle (from development through the operational phase to end-of-life) in close cooperation with stakeholders, both upstream (our suppliers) and downstream (our clients).
We have formalised multiple action points in our Climate Action Plan. Moreover, at that time, the validation procedure was carried out at SBTi to validate our scopes 1 and 2 near-term targets. WDP also commits to reducing scope 1 and scope 2 emissions by 42% by 2030 compared to the baseline year 2020.1
Meanwhile, since the summer of 2024, new evolutions in the regulatory landscape and new initiatives occurred in the real estate sector, including SBTi’s Building Sector Criteria. The latter provides an interpretation of the calculation of our emissions related to the development, acquisition and use of our buildings. Obviously, we want to exploit these new opportunities. So, WDP has set up some workflows with internal and external stakeholders that will lead to an update of our Climate Action Plan. We expect to provide a more practical update on this matter in the 2025 annual report.
We believe we create added value with our core product by starting from a businessrelevant context: solution-centric building tailored to the client. Besides years of experience, our employees have real estate expertise and – just as important – an understanding of our clients’ business. We want to play our role as a real estate partner in the global energy and sustainability transition towards a fully sustainable supply chain. That is why we focus on making our sites more sustainable.
The WDP building standard for a new-build warehouse is reviewed and updated annually with its energy efficiency being a priority consideration. We are committed to full insulation of walls and roofs, LED lighting with dimming and motion detection, the greenest and most energy-efficient insulation and heating and air-conditioning systems, and the installation of solar panels and e-mobility.
As part of our Climate Action Plan, we deliberately choose to link the use of the building to practical initiatives. For example, green energy procurement, smart monitoring of energy, water and the circulation of our clients’ employees in the building itself, and implementation of sustainable maintenance strategies. Moreover, since January 2022, every new-build warehouse must be built with (at least) a BREEAM in-use Very Good certificate.
1 In this validation procedure – valid at the time of notification by WDP in April 2022 – SBTi considers WDP to be a small or medium-sized enterprise (<500 employees). So, initially, only our scopes 1 and 2 near-term targets were validated. A commitment is requested regarding the measuring and reducing of Scope 3 emissions. The Climate Action Plan also includes a net zero target for Scope 3, which is also defined in line with these Science Based Targets.
WDP can take a crucial role in its client’s energy transition by tuning its warehouse sites into charging hubs that optimise the client’s energy profile. In doing so, WDP provides the required infrastructure for the further electrification of warehouses. This is required by increased automation, equipment use (such as refrigeration and industrial applications) and the switch to electric transport (for cars, vans and lorries). A solution to this need is a sophisticated combination of on-site energy generation by solar panels and smart charging facilities and batteries.
Scaling up renewable energy production through the installation of solar panels is one driver within our Climate Action Plan. Local energy generation through solar panels creates a solid foundation for the further roll-out of sustainable measures at the warehouse site of the future. For example, smart grids, batteries and electric vehicle charging infrastructure to match and optimise energy consumption and production. Maximising the capacity of our rooftops via renewable energy production help us contribute in the near term to the decarbonisation of the entire warehouse site and our client’s energy consumption (Scope 3 Downstream). It also means that WDP contributes to the EU’s climate ambitions.
In 2018, WDP resolutely put forward the ambition to measure the electricity, water, and gas consumption of the entire WDP portfolio using nanoGrid, a digital real-time utilities and energy monitoring system made by the eponymous energy proptech company. This tool measures the consumption of utilities, such as electricity, gas, and water, as well as solar panel performance, and provides insight into the client’s consumption. Given the increasing importance in the real estate sector of accurate energy monitoring and data analytics, WDP entered into a strategic partnership in 2021 with the energy proptech company nanoGrid by acquiring a 25% stake. We believe that we can make a sustainable difference in energy efficiency when we can assess the total impact of the consumption in our buildings. That includes the tenant’s consumption governed by the utility contracts they entered into.
The nanoGrid data provides our clients with an overall view of their consumption. It also allows us to offer increasingly targeted and integrated solutions and services to our clients, including through MyWDP, the digital client portal. It will also allow us to further address GHG emissions associated with client consumption in our warehouses (Scope 3 Downstream – Leased assets).
Today, nanoGrid has been rolled out across 79% of WDP’s property portfolio. The data we acquire through nanoGrid is the perfect basis for reliable reporting under EPRA’s sustainable Best Practice Recommendations (sBPR). For more information on and interpretation of the EPRA environmental performance indicators, see the appendices of this chapter.
Actions ESRS E1-3
Green electricity production | In 2024, an additional +52 MWp was realised giving us a total solar capacity of 234 MWp at year end. Within the context of our #BLEND2027 growth plan, we are aiming for a total capacity of 350 MWp by 2027. This is a challenging project, especially given the increased complexity and lead time of these projects (e.g. grid connection).
By 2024, our solar panel installations delivered 49,976 MWh of energy (out of the total 159,086 MWh of renewable energy generated) directly on-site to our clients. This corresponds to about 12% of the total electricity demand of all clients (including the consumption by properties that do not have solar panels today). This local consumption is the equivalent of 9,442 T CO2e scopes 1 and 2 emissions avoided by our clients and our own Scope 3 Downstream. The GHG intensity (locationbased) of our property portfolio is approximately 13% lower with these solar panel parks (taking into account a calculation based on absolute figures).
Green electricity procurement | In our Climate Action Plan, we set a target to have 100% green electricity contracts for that part of the property portfolio where WDP directly enters into electricity contracts (instead of with the client). This part of WDP represents an estimated 35% of the total measured energy needs of clients (based on the extrapolated total consumption of our clients). WDP has signed 100% green electricity contracts by the end of 2024, once again achieving one of its targets. Naturally, WDP will continue to pursue this 100% green energy procurement in the coming years.
Landlord-obtained electricity green
Landlord-obtained electricity grey | unknown
Tenant-obtained electricity green
Tenant-obtained electricity grey | unknown
CAP Target 2023 realised and maintained
Green certified buildings | We are committed to sustainable certification of our buildings, specifically through the BREEAM and EDGE certificates. This is a very time-consuming and capital-intensive process for our internal (property management) teams. So, we are very pleased with the positive progress we made this year: a +64% increase in the number of certified assets compared to 2023. In fact, the share of the fair value of green certified assets in the total property portfolio rose to 56%. WDP intends to increase this even more to at least 75% by 2025. This is crucial within the context of our green financing targets and also given the requirements of the EU Taxonomy Regulation.
Multimodal sites | WDP believes that the future of logistics lies in multimodal solutions. This is why WDP strategically plans its warehouses to be sited at locations where road, shipping, rail and air traffic hubs can be or have already been developed. WDP aims to generate added value from these multimodal locations through the creation of synergies between clients, regions, cities, ports, public services, etc. to achieve smart logistics (such as bundling or agrologistics). In the future, this could provide opportunities to create energy communities.
Read more in 4. Performance and trends
Local laws and regulations are observed in the development of projects and renovations. Biodiversity provisions are based on the EU directives, such as the Habitat Directive and the LULCF Directive. Moreover, WDP works closely with landscape architects, contractors, ecologists and biodiversity experts during the permitting process, and design and construction phases of a warehouse.
Read more in 4. Performance and trends
Brownfield projects | WDP breathes new life into older underused sites. Brownfield developments meet the scarcity of free space. In addition to redeveloping such sites into modern new-build warehouses with new, sustainable technologies, such projects often also involve cleaning up the (formerly) polluted site. This will reduce the site’s environmental footprint and also contribute to the health of employees who will make use of the premises and surrounding area.
Read more in 4. Performance and trends
Multilayer warehouse | Vertical development offers a sustainable, efficient and innovative solution to the scarcity of available logistics plots and rising land prices. This vertical innovation minimises the footprint of the buildings and optimises storage and distribution capacity.
Automation | The optimal design of our buildings contributes to more efficient use of warehouse volume. WDP is researching an investment in automation with more and more clients: storing more within the same volumes.
Green leases | WDP makes green investments in its property portfolio at the request of the client or on its own initiative in combination with an adjustment to the lease terms and reduced energy consumption. This is how relighting projects regularly occur in existing buildings.
The actions and pathways outlined in the current Climate Action Plan should result in the net-zero targets for scopes 1, 2 and 3 (base year 2020). So, we map out our entire footprint. And not only our own activities (consumption in our offices and car park), but also the downstream (consumption by our clients in our premises) and upstream (embodied carbon in project developments, renovations and solar panel installations). For the methodology that we used to calculate our WDP climate footprint, we refer to the explanation of the reporting per the GHG Protocol as explained in the appendices of this chapter.
The majority of WDP’s greenhouse gas emissions are contained in the scope 3 emissions linked to the construction and operation of our properties and solar panel installations. Compared to 2023, fewer new construction projects were delivered. This accounted for the decrease in the embodied carbon share from 80% to 64% of WDP’s total emissions. Furthermore, 36% is linked to our clients’ energy consumption and less than 0.20% is linked to scopes 1, 2 and 3 emissions from WDP’s corporate offices, vehicle fleet and business travel.
WDP’s total GHG emissions are 209,073 T CO2e (market-based). This is a 38% decrease compared with 2023, which is primarily due to fewer new construction projects and renovations being delivered (12 in 2024 compared to 20 in 2023).
Scope 1 & 2 | Lead by example
WDP’s absolute emissions linked to office use (Scope 1 and Scope 2) remained stable in 2024 (6.7 T CO2e). Our headquarters in Wolvertem has been fully CO2-neutrally heated and cooled since the summer of 2021. The remaining Scope 1 emissions are from central gas heating in the Romanian office. The remaining Scope 2 emissions are due to the district heating in the office in the Netherlands, which runs on low-carbon biomass. We will consider how to deal with the remaining emissions and/or bring these within a carbon removal strategy.
WDP already implemented a car policy in early 2022 where only hybrid or full-electric company cars can be chosen. As of 2025, only fully electric company cars are allowed as a choice. We believe this choice will allow us to achieve the target of a net-zero car park by 2030. Scope 1 and Scope 2 emissions due to the vehicle fleet decreased slightly. This is largely explained by the further electrification of our vehicle fleet.
Read more in 4. Performance and trends
Scope 3 | More insights
Business travel emissions increased by 33% increased – due to a higher number of flights compared to 2023 – and are now 84 T CO2e. This represents about 20% of total corporate emissions, but remains negligible compared to the other scope 3 emissions (0.04%). For WDP, business travel mainly involves travel to and from our Bucharest office and Investor Relations travel. Smooth collaboration with international teams requires regular travel.
* Extrapolated
The most substantial categories that WDP can directly impact within corporate emissions are linked to transport: our car fleet and business travel, such that this must also occur (partly) within the context of a carbon removal strategy.
Scope 3 embodied carbon | Improved data management
We chose to extrapolate the results of the 2022 embodied carbon analysis – of some reference projects in Belgium, the Netherlands, Romania, Luxembourg and Germany – to the 2024 new construction projects, renovations and solar panel parks. This explains the unchanged CO2 intensity of our buildings and solar panel parks.
In 2024, WDP completed 12 new construction projects and 48 new PV installations (of which 12 on existing properties, 20 on new construction projects and 16 via a property acquisition). Solar projects account for just over 50% of total embodied carbon in 2024.
Maximising embodied carbon reduction in our new construction projects, renovations and PV installations requires a deeper analysis not only of our construction process and related supply chain, but also of the entire life cycle of the buildings and PV installations.
So, we committed in 2023 to hiring an additional Sustainability Manager who developed a roadmap in 2024 for WDP DECARB+. It was drawn up based on pilot projects and the testing of various calculation tools. Our objective here is to move away from the current methodology that relies on extrapolation based on reference projects and progress towards rigorous data management so we can calculate the embodied carbon for each new development, renovation and solar panels project separately. This not only improves the accuracy of our data, but also provides a foundation for detailed studies and improvements in the buildings with a view to decarbonisation, climate adaptation, biodiversity, and circularity.
This year, we once again noted that our clients have become more aware of their energy consumption. Analysis of Heating Degree Days (HDD) – calculated from the difference between average outdoor temperatures and an indoor temperature of 15 degrees Celsius – showed that heating requirements in 2024 are almost the same as in 2023. For Belgium and the Netherlands, it is ~2% lower and, for Romania, 3% higher.
Nevertheless, the Like-for-Like figures show a further decrease in heating energy consumption (-7% energy intensity for heating). This resulted in a 12% decrease in the intensity of greenhouse gas emissions in the portfolio (Like-for-Like comparison of market-based emissions intensity). This could be seen as reaffirming that our clients are more conscious of their energy consumption for heating.
Examining the absolute figures for 2024, we note that total emissions linked to our clients’ energy consumption were 51,206 T CO2e (with a coverage of 69%). Extrapolating to the full portfolio (coverage 100%), this equates to emissions of 74,611 T CO2e. Compared to the extrapolated value for 2023, this shows an increase of 13%. This is mainly explained by the growth of the property portfolio.
WDP Energy
WDP Electricity procurement green | with regard to the contracts that WDP has under its own management
Decarb+
WDP Green
Adoption of recommendations | Compliance with TCFD by 2024 (Annual Report 2023)
1 Total capacity (in MWp) of solar panel parks on WDP property (land or building).
2 Emissions associated with the combustion of fuels and/or production of electricity used in WDP’s car park (leased and owned vehicles) divided by the number of employees with a company car (in kg CO2e/employee).
3 Total fair value of green-certified buildings (currently BREEAM, EDGE) divided by the total fair value of WDP’s entire portfolio (in %).

Methodology
Organisational perimeter
WDP uses the operational control approach for sustainability reporting. WDP manages all of the warehouses in its property portfolio. These warehouses as well as all of the offices where #TeamWDP works (for Belgium in Wolvertem, for the Netherlands in Breda, and for Romania In Bucharest) are included in our sustainability reporting.
Operational perimeter
WDP measures and reports both scope 1, 2, and 3 emissions related to its activities across its value chain.
Interpretation of Scope 1, 2, and en 3
Scope Included Application
Scope 1:
Direct greenhouse gas emissions
Scope 2:
Indirect greenhouse gas emissions
Scope 3:
Indirect greenhouse gas emissions
All direct emissions that result from our activities and are caused by the local combustion of a primary energy source (natural gas, fuel oil, diesel, petrol, etc.).
1 Offices where #TeamWDP is active
1 The car park of WDP
All indirect emissions that result from our activities and that occur at another location during the combustion of a primary energy source. Possible applications are electricity, heating and cooling (DH&C), steam, etc.
All other indirect emissions in our value chain, i.e. the emissions during the production and delivery of building materials and the direct emissions that are caused by the consumption of gas and fuel oil by the tenant, as well as the indirect emissions that are caused by the consumption of electricity and/or district heating and cooling by the tenant. As well as the indirect emissions linked to the electricity consumption of #TeamWDP in the corporate offices and to the business travel of #TeamWDP. The Greenhouse Gas Protocol defines 15 categories of scope 3 emissions. These are further explained below.
1 Offices where #TeamWDP is active
1 The car park of WDP
1 Warehouses in the WDP property portfolio
1 Offices where #TeamWDP is active
1 Business travel #TeamWDP
Since 2017, WDP reports in accordance with the EPRA Best Practice Recommendations for Sustainability Reporting (EPRA sBPR). The EPRA sBPR guidelines are based on the recommendations and methodology of the internationally used Greenhouse Gas Protocol (GHG Protocol). This provides a consistent manner in which listed real estate companies can measure sustainability performance, which contributes to transparency in sustainability reporting. WDP has received a Gold Award for EPRA sBPR every year since 2017.
WDP reports on each relevant EPRA performance indicator for its property portfolio and the offices where #TeamWDP works.
For our data coverage, we report the performance indicators according to their Absolute Performance and their Like-for-Like performance:
1 Absolute Performance (Abs): the Absolute Indicators reflect the gross total of the available data for a specific period (reporting year) and utility (e.g. Elec-Abs, DH&CAbs). In WDP’s reporting, only buildings for which consumption data for a specific utility for the full year 2024 is available were considered for the Absolute performance indicators. For the Energy and GHG figures, the Absolute scope is limited to a perimeter where complete consumption data for each energy supply (i.e. electricity, gas, heating oil, or other heating sources, if present) in a building is available for the entire year 2024 (this means that this scope only contains those buildings for which we have certainty about the full energy consumption data).
1 Like-for-Like performance (LfL): the Like-for-Like indicators reflect the change in performance unrelated to fluctuations in portfolio size (constant boundary) (e.g. ElecLfL, DH&C-LfL). In WDP’s reporting, only buildings with consumption data available for a specific utility for the entire years 2023 and 2024 are considered in the Like-forLike performance indicators. For the Energy and GHG figures, the Like-for-Like scope is limited to a perimeter where complete consumption data for each power supply (i.e. electricity, gas, heating oil, or other heating sources, if present) in a building is available for the full years 2023 and 2024.
Indirect greenhouse gas emissions (both scopes 2 and 3 emissions) are reported according to the location-based and market-based accounting method.
1 For the location-based accounting method, a country-average emission factor from the IEA report1 is used in the calculation.
1 Under the market-based accounting method, the calculations are based on an inventory of the WDP portfolio in which some issues are tracked, such as the responsibility of managing the utilities (whether contractually through WDP or the client); the origin of the electricity (green or grey/unknown). If no specific data is available for utilities, the country-average emission factor is used (as with the locationbased method).
As of 2024, we calculate the total area of the Belgian office based on the actual building plans prepared by an architectural firm. This working method provides more detailed calculations.
The complete reporting on the energy consumption and CO2 emissions of the property portfolio figures is solely based on actual data without estimating or extrapolating consumption data. This is possible because WDP has installed an energy monitoring system (nanoGrid) for its entire property portfolio. Consequently, we use a proprietary data model with consumption data as the source: data from the energy monitoring system.
The complete reporting on energy consumption and CO2 emissions for the offices where #TeamWDP works is based on actual data. No estimate or extrapolation of consumption data is used unless the sources for the consumption data were not yet available as of 31 December 2024. These sources are the invoice data that WDP receives from the office owners and the data from the energy monitoring system (nanoGrid) for the Belgian office.
Limited assurance
All EPRA environmental performance indicators marked with an ✓ have been reviewed by Deloitte Company Auditors as part of a limited assurance check for 2024.
The table below shows the distribution of energy in 2024 per landlord-obtained and tenant-obtained, by origin.
Distribution of Landlord-obtained and Tenant-obtained utilities
Electricity (kWh)
Heating (kWh) Landlord-obtained
Water (L)
PROTOCOL categories (scope 1, 2, and en 3)
Starting with the publication of the Annual Report 2021, WDP annually reports its full GHG climate footprint according to the GHG Protocol methodology.This protocol provides a systematic framework for measuring, managing, and reducing the emissions in our value chain and is a tool for WDP to manage and respond to the risks and opportunities related to these emissions.
The table below provides an overview of the methodology used at WDP and its activiteits throughout the value chain for scope 1, 2, and 3.
GHG Scope Category Included
Scope 1 Scope 1 Yes Emissions from the combustion of fuels used in corporate offices, carpark and service activities of WDP.
Methodology / Justification for exclusion Berekeningsmethode volgens GHG Protocol Activity data source Emission-factor data source
The emissions are calculated according to category by multiplying fuel consumption with a specific emission factor per application.
(1) For our utilities, we refer to our EPRA sBPR methodology on a market-based approach.
(2) We apply a fuel-based method for the fleet, which combines the consumption data from the leasing companies with fuel-specific factors (tank-to-wheel).To ensure data quality and the uniformity of consumption data, we have decided that from 2024 onwards, we will exclusively use data from major leasing companies, such as Arval. For drivers who are not registered through these leasing companies, we will apply extrapolation.
(1) Consumption data of invoices (BE and RO); in NL there are no direct emissions
(2) Actual consumption data regarding fuel filled, directly from the leasing companies.
(1) Location-based: IEAemissionfactors “IEA – Emission Factors: Database Documentation (2024 edition)”
(2) Fuel-specific emissionfactors from “DEFRA 2024" database.
Scope 2 Scope 2 Yes Emissions from the production of electricity and DH&C consumed in corporate offices and car park of WDP.
The emissions are calculated per category:
(1) For the utilities in the offices, we refer to our EPRA sBPR methodology for a market-based approach.
(2) For the vehicle fleet: the electricity at the WDP offices that is used to charge the vehicle fleet is green and therefore has no emissions. We apply market-based emission factors for the energy used to charge the WDP cars outside the WDP offices.
To ensure data quality and the uniformity of consumption data, we have decided that from 2024 onwards, we will exclusively use data from major leasing companies, such as Arval. For drivers who are not registered through these leasing companies, we will apply extrapolation.
(1) Consumption data from invoices (BE, NL and RO) supplemented with monitoring data (BE)
(2) Actual data regarding charged kWhs, directly from the leasing companies.
(1a) Market-based factors: if green electricity (as far as known): no emission; otherwise see 1b
(1b) Location-based: IEAemissionfactors “IEA – Emission Factors: Database Documentation (2024 edition)"
(2) No emissions for the charged kWhs in WDP offices, otherwise country-specific emissionfactors from "IEA 2024".
GHG Scope Category Included
Scope 3 Scope 3
Upstream
cat.1 Purchased goods and services (PG&S) No n/a
cat.2 Capital goods Yes All upstream (cradle-to-gate) emissions released during the construction of our warehouses (including solar panels) via the building materials (embodied carbon), transport of building materials as well as energy consumption on the construction sites.
cat.3 Fuel- and energy-related activities
Yes All upstream losses and emissions linked to transport of electricity to the site (being WDP offices).
Methodology / Justification for exclusion Berekeningsmethode
Not applicable due to inclusion of purchased goods in cat. 2-8 n/a n/a
cat.4 Upstream transportation and distribution
cat.5 Waste generated in operations
No n/a
Yes Emissions related to the waste collection and processing of the activities in the offices of WDP.
The emissions are calculated from a number of reference projects (including a solar project) in BE, NL, RO, LU and DE on the basis of a detailed life cycle assessment in cooperation with an external expert. The listing of material types and quantities is combined with the material-specific emission factor from various material databases.
An extrapolation to the total developed area gives the total emission. This analysis is repeated annually, applied to new developments as well as renovations.
Emissions indirectly linked to electricity production of our offices, for example grid losses.
Bill of materials from reference projects in BE, NL, RO, LU and DE, based on buildings specifications and BREEAM assessments.
Emissionfactors (EF) are based on a combination of two calculationb methods: (1) expenses (spent-based): “EXIOBASE 3” and (2) quantity of materials (quantity-based): “Ecoinvent v3.6”.
Consumption data from invoices (BE, NL and RO) supplemented with monitoring data (BE).
Market-based factors: if green electricity (as far as known): no emission; otherwise application of Location-based factors: IEAemissionfactors “IEA – Emission Factors: Database Documentation (2024 edition)".
These emissions are included in cat. 2 Capital goods because of the cradle-to-gate definition where both the production of construction materials and transport to the site are included.
All waste generated at our headquarters in Wolvertem (Belgium) is recorded based on the Veolia waste register. For paper and cardboard waste, residual waste, and PMD from our headquarters in Belgium, we use actual data. Based on the number of FTEs, we extrapolate these waste quantities for our two other offices in Breda (Netherlands) and Bucharest (Romania). Thanks to this methodology, we have achieved full coverage (100%) of the EPRA Waste-Abs indicator.
Since we do not have exact data on how waste is processed (incineration or recycling) in all countries, we have assumed this year that the waste treatment method used in Belgium also applies to Romania and the Netherlands.
(1) In Belgium, waste data is 100% based on supplier information. The Veolia waste register serves as the basis for the calculations.
(2) For the offices in the Netherlands and Romania, total waste quantities are calculated by extrapolating the registered waste quantities from our headquarters in Wolvertem (Belgium) based on the total number of FTEs.
DEFRA Emission Factors 2024 Condensed Set
GHG Scope Category Included
cat.6 Business travel Yes All flights executed by WDP employees related to their professional activities.
cat.7 Employee commuting Yes Emissions from commuting travel by employees with private transport (car owned by employee).
Methodology / Justification for exclusion Berekeningsmethode volgens GHG Protocol
The methodology is linked to accurate and specialized data, based on the ICAO (International Civil Aviation Organization) calculation tool. In this way, a detailed calculation is carried out for each flight to determine exactly how many kg of CO2e are generated, taking into account the flight type and even the cabin class. Emissions associated with these flights have fallen by 27% and now amount to 63 tonnes of CO2e, which represents approximately 15% of the total corporate. These emissions are expected to increase in the future.
Excluded because of: (1) data not yet available
cat.9 Downstream transportation and distribution No n/a
cat.10 Processing of sold products No n/a
cat.11 Use of sold products No n/a
cat.12 End-of-life treatment of sold products No n/a
cat.13 Downstream leased assets Yes Emissions caused by energy consumption in WDP's property portfolio: electricity, DH&C and fuel.
WDP is a logistics real estate player with a focus on development and renovation for long-term ownership and rental, not on development with the intention of selling.
WDP is a logistics real estate player with a focus on development and renovation for long-term ownership and rental, not on development with the intention of selling.
WDP is a logistics real estate player with a focus on development and renovation for long-term ownership and rental, not on development with the intention of selling.
WDP is a logistics real estate player with a focus on development and renovation for long-term ownership and rental, not on development with the intention of selling.
The emissions are calculated according to category by multiplying energy consumption with a specific emission factor per application. For the specific calculation we refer to our EPRA sBPR methodology for a market-based approach, which is extrapolated to 100% portfolio.
Internal WDP Busisness Travel Registry. The ICAO (International Civil Aviation Organization) calculation tool.
cat.14 Franchises No n/a
cat.15 Investments No n/a
WDP is a logistics real estate player with a focus on development and renovation for long-term ownership and rental, not on development with the intention of selling.
Monitoring data (nanoGrid). Market-based factors: if green electricity (as far as known): no emission; otherwise application of Location-based factors: IEAemissionfactors “IEA – Emission Factors: Database Documentation (2024 edition)".
WDP is a logistics real estate player with a focus on development and renovation for long-term ownership and rental, not on development with the intention of selling. n/a n/a
EPRA environmental performance indicators – WDP corporate offices
WDP corporate offices – Energy & Greenhouse gases
Greenhouse gases (market-based)
WDP corporate offices – Waste1
¹ For the calculation methodology, see p. 182 for the Methodology table concerning GHG Protocol – Category 5 “Waste generated in operations”
EPRA environmental performance indicators – property portfolio
WDP property portfolio – Electricity
WDP property portfolio – Heating
WDP property portfolio – Energy & Greenhouse gases
Greenhouse gases (location-based)
Greenhouse gases (market-based)
Direct | Scope 1 T CO2e GHG-DirAbs GHG-DirLfL
GHGIndir-Abs GHGIndir-LfL
Indir-Abs GHGIndir-LfL
The results of the dual materiality assessment do not identify social sustainability themes as material for reporting. Nevertheless, social sustainability themes remain and are a fundamental part of WDP’s strategy. Obviously, this relevant social information is included in this annual report. However, this is outside the scope of the statutory auditors’ audit and does not adhere to ESRS reporting requirements.
An attractive employer
As a growing organisation, the right talent needs to be attracted and integrated within the company and its company culture. Only in this way the future resilience of WDP Group can be guaranteed, the resilience of the company will be increased and growth can be continuously facilitated. A good mixture of different talents, cultures and personalities is of the utmost importance. As an employer, WDP does not discriminate based on race, colour, sex, religion, political opinion, national origin or social origin. WDP is looking for employees with the right skills that best fit the company culture and activities, with due regard to objective selection procedures and diversity. Our recruitment and selection process is fully aligned with WDP’s Diversity Policy and Human Rights Policy
The family atmosphere within the company ensures that employees are regarded as individuals and are not purely seen in terms of their professional performance. It is vital that everyone on the team feels good and valued and has space to deploy their talents. WDP employees receive leeway for their own initiative, and Management does its utmost to feed and stimulate the ideas of its people, rather than pushing through top-down decisions. The innovative, flat organisational structure ensures a continuous dynamic and fosters involvement, responsibility and ownership.
The search for new talent is supported by an ongoing employer branding campaign that spotlights WDP as an attractive employer via website, LinkedIn or other communication tools within recruiting.
A brief but thorough selection process, clear information and attention to the right match are the basis of successful recruitment.
Recruitment will be followed by an extensive onboarding procedure intended to provide a very in-depth understanding of WDP’s business:
1 an extensive onboarding procedure, a well-equipped workplace and the right tools;
1 an onboarding package for each new employee with attention to the Employee Code of Conduct;
1 allocation of a mentor for each new employee to show them around the company informally;
1 personal introductory talks with colleagues from all departments, including a talk with the compliance officer for a further explanation and a formal introduction to the WDP policies (e.g. Dealing Code, Employee Code of Conduct, and #SpeakUp procedure);
1 a visit to construction sites and/or a visit to clients together with one of the project managers or property managers; and
1 feedback interviews about the quality of the onboarding after one month and six months with the HR Manager.
WDP applies a remuneration policy that is based on three principles: straightforward, transparent and in keeping with the corporate strategy. As is the case with the remuneration of the members of the Management Committee, the remuneration of employees consists of a fixed and a variable remuneration, where relevant supplemented with non-statutory benefits such as a company car, a smartphone and group insurance (defined contribution). The concrete interpretation of these three components always depends, among other things, on the position and social status of the person in question, as well as on the local regulations to which the employee is subject. Obviously, the remuneration is based on the “equal pay for equal work” principle. On an annual basis,
WDP utilises a salary survey to compare its remuneration policy with that of other listed and non-listed real estate companies and other non-real estate companies with a similar scope and importance. To this end, we are currently using the services of an internationally recognised HR agency. In this way, WDP can ensure for market-based remuneration packages.
Variable remuneration for employees consists of:
1 remuneration linked to individual short-term performance targets, at least one of which must be an ESG target.
1 a fee linked to collective short-term performance targets directly arising from WDP’s #BLEND2027 growth plan. For example, the EPRA earnings per share, the occupancy rate, and the continued roll-out of the PV project determine to what extent the collective variable remuneration is granted and paid to the employees.
1 remuneration linked to the collective long-term performance targets from WDP’s growth plan #BLEND2027. This looks at financial targets such as EPRA Earnings per share, occupancy rate, net debt / EBITDA (adj.), as well as non-financial metrics such as WDP Climate Action Plan targets, collaborative, ownership and intrapreneurship programme targets, etc. These objectives apply to all employees. No long-term variable remuneration has been accrued during 2024 because of the early settlement of the 2022-25 growth plan in 2024. This is in line with the recommendation of the Remuneration Committee, as the Board of Directors determined in January 2024 that the overall long-term performance targets of the 2022-25 growth plan were above target and had been met one year early. As a result, 60% of the long-term remuneration was already paid in March 2024, while 40% of the long-term remuneration will only effectively vest after the Audit Committee determines in January 2025 that (i) EPS for 2024 equals 1.47 euros and (ii) net debt / EBITDA (adj.) <8 is achieved. Indeed, these two sub-targets have always been considered leading in the 2022-25 growth plan. Consequently, 40% of the long-term remuneration (on the 2022-25 growth plan) was paid in March 2025. Starting in the 2025 financial year, long-term variable remuneration will be accrued under the current business plan #BLEND2027.
Payment of short-term variable remuneration will be made depending on the place of employment taking into account local legislation and the employee’s position and social status: in cash, by the granting of warrants as part of a warrant plan, by a non-recurring result-related benefit, and/or by a contribution to the group insurance scheme. Longterm variable remuneration is paid in cash.
As is the case with the directors and the members of the Management Committee, there is no share or share option scheme in 2024 for the employees of WDP.
In principle, all our employees are employed based on a permanent employment contract; a fixed-term contract for temporary replacement is provided in exceptional cases. WDP also offers opportunities for part-time work or adapted employment plans.
The continuous development, growth and motivation of all employees ensure that they feel good within the company and that they can continue to expand their competencies. WDP strives to boost the skills of its employees to facilitate a sustainable team and increase capabilities and continuity. However, employee development should not be focused purely on the required job-related skills, but also on the development of soft skills. In 2024, we implemented the online Learning Management System module within the HRHub environment.
Personalised development plans and opportunities for internal mobility promote strong performance and development for both employees and the company. Moreover, WDP also provides individual coaching projects to develop specific competencies, both technical and soft skills. In 2024, a leadership training program has been launched for the management positions in Belgium. Through various workshops different leadership skills could be further developed. In 2025, this track will be further rolled out and implemented in the other countries.
Further development workshops are also organised during the annual International #TeamWDP Day. The objective of the annual team day is to foster overarching cooperation between the countries, strengthen team spirit, inspire each other and work together as one team on the key themes of the long-term growth plan.
Feedback moments
Formal feedback moments are organised annually for all employees with the direct manager. These are organised via the HRHub environment. These annual feedback moments apply to employees working at the time of the annual review period and have been employed for more than six months. In addition to the evaluation and assessment of individual performance targets, these also pay extensive attention to job performance, team atmosphere, work resources, training and further personal development. Regular informal consultation moments allow everyone to offer or receive additional feedback.
Health, well-being and safety
A safe, healthy and carefree working environment
A safe and healthy living and working environment for #TeamWDP, clients, investors, suppliers and the wider community is essential to WDP’s operational management. WDP continues to systematically improve health, physical and mental well-being and safety at work, taking into account specific risks and hazards, always in the spirit of WDP’s #HealthyAndSafe Statement. In each country, the internal prevention service and HR collaborates with an external prevention service to carry out an analysis of the working environment, which includes a proposed local action plan.
All employees, regardless of their position, are expected to help in the identification and prevention of safety and health hazards to create a safe, healthy and carefree working environment for #TeamWDP and all stakeholders. The #SpeakUp procedure provides everyone with the opportunity to report any irregularities.
The Great Place To Work® survey conducted in May 2024 identified the elements of the psychosocial risk assessment in areas, such as work organisation, work content, employment terms, working conditions and interpersonal relationships at work.
Each year, an HSES Corporate Action Plan is rolled out step by step by the WDP HSES Team, which consists of the Health & Safety Manager, property managers (at least one from each platform), a representative of the project managers in countries in which WDP operates, the prevention advisor, and the CTO. The Health & Safety Manager has a leading role in implementing and refining the HSES Corporate Action Plan. Meetings are held with the WDP HSES Team at least on a quarterly basis to implement and discuss the further roll-out of the HSES Corporate Action Plan.
WDP offers adapted employment plans or part-time work opportunities to support an appropriate work/life balance. In Belgium, the Netherlands, Germany and Romania, periods of maternity leave, adoption leave, paternity leave, parental leave, care leave and time credit (in Belgium only) are provided for in law.
Flexible working is allowed using a combination of office work (at least three days a week) or telework.
Every year, staff may avail themselves of the option to get the flu vaccine from the company doctor.
From #TeamWDP, the initiatives of the Office Well-being Team and the Move Team contribute to a healthy and sporty atmosphere in the office – and, of course, to team spirit.
#WeMakeADifference: our social contribution
WDP has a corporate citizenship strategy – #WeMakeADifference – divided into three pillars, #WeCare, #WeAreConscious and #WeEducate. This strategy is fully aligned with the WDP corporate strategy and focuses on initiatives in the vicinity of the property portfolio to contribute to the UN Sustainable Development Goals.
#WeCare
We strengthen our connection with local communities and profile ourselves as a reliable partner and company by providing financial and/or material support to local projects and vulnerable groups.
#WeAreConscious
We encourage our client to increase their awareness of sustainable consumption patterns. We take our sustainable property portfolio and client engagement to the next level by sharing our knowledge on energy monitoring tools and promoting better recycling rates.
#WeEducate
We support young students and new workers in the logistics property market. WDP strives to provide training programmes that align with our corporate culture and we support inclusion projects to provide opportunities for new young workers and combat youth unemployment where possible.
In dialogue with the local community
WDP is aware of the impact that property development has on the surrounding environment and strives to minimise the negative impact of its activities on the immediate surroundings. Thus, the Company shows a clear engagement with the local community, both concerning the impact of activities and to support local well-being and economic growth. To this end, continuous and mutual dialogue between the clients, surrounding area and WDP are paramount.
For all metrics related to #TeamWDP, please refer to 4. Performance and trends – Vitally engaged and 6. Corporate Governance Statement.
The following activities were carried out over the course of 2024:
1 WDP Academy: initiation of an annual training day for new employees in WDP Group.
1 Training and development:
1 our employees received an average of 28 hours of training1, including 13 hours of mandatory training (e.g. on Cyber Security and Non-discrimination Compliance) and 15 hours of voluntary training. Mandatory training courses deal with the exchange of expertise. These are organised in various ways, including in-house Learn@lunch sessions.
1 Integration of a Learning Management System into the online HRHub tool.
1 Annual International #TeamWDP Day: WDP’s 25th anniversary as a listed logistics property company was the perfect theme this year for its annual international team day. Employees enjoyed time relaxing, workshops were organised to discuss crosscountry topics to safeguard continued alignment within the group and facilitate the team engagement of all teams.
1 Health and safety:
1 zero safety and health irregularities reported.
1 one internal prevention advisor for the WDP Group.
1 AED device in every WDP office, coupled with a first aid course that was attended by several employees.
1 HSES Corporate Action Plan
1 38 employees opted to get the flu vaccine.
1 Calculation based on FTEs.
1 Great Place To Work® 2024: WDP was certified for the first time with the Great Place To Work® label based on an anonymous employee survey – Satisfaction Score 8.6/10.
1 Work/life balance: 18% of employees work part-time. 3 employees benefit from an adapted end-of-career employment plan.
1 Sport and health: participation in Immorun and Bouwrun by some Belgian and Dutch colleagues and in the Color Run Night in Romania. During the summer, #TeamBE aligned sports with the charity #WeCare campaign.
1 #WeCare: 247,000 euros in financial and/or material support went to local projects and vulnerable groups, including financially favourable terms for MaatWERKbedrijf BWB.
1 #WeEducate: support for 125 students for training programmes that are in line with the WDP vision.
The following goals were formulated:
1 #WeEducate: support and mentor at least 100 students.
1 #WeCare: min. 100,000 euros per year of financial and/or material support to local projects and vulnerable groups.
1 #TeamWDP employee survey: increase or maintain average satisfaction score.
1 HRHub: implementation of the latest module in the digitisation of the HR processes where the onboarding and offboarding process is integrated. Continued optimisation of HRHub.
WDP’s material sustainability themes from the double materiality analysis:
Corporate governance & business ethics
Ensuring good governance practices to effectively manage sustainability risks and impacts. Upholding the culture of integrity to demonstrate ethical business practices and prevent corruption, insider trading and violations of the code of conduct.
Material impacts, risks and opportunities and their interaction with the strategy and business model ESRS 2 SBM 3
WDP's Material
Sustainability matter IRO
5 Corporate Governance & Business Ethics
Ensuring best practices around ethics and business practices
Financial opportunity
Upstream + Own operations
Ethical misconduct
Financial risk
Upstream + Own operations
Ensuring best practices around ethics and business practices
Positive impact
Upstream + Own operations
Description IRO Time
WDP’s best practices in business ethics and operations, and aligning management’s financial incentives with shareholders’ interests help strengthen our reputation and increase investor confidence. This is essential for maintaining a strong position in capital markets.
Promoting a culture of honesty, integrity and responsibility helps WDP ensure that all employees and partners adhere to high ethical standards. Short term
Ethical misconduct within its own operations and in the value chain can seriously damage the WDP brand. Such risks entail reputational damage, fines and legal consequences. Strict compliance with ethical standards and maintaining consistently high standards is crucial, both internally and with value chain partners. WDP protects its reputation by proactively promoting ethical behaviour and ensuring compliance.
These efforts help eliminate unethical behaviour, reduce the risk of corruption and ensure compliance with financial obligations, such as taxes. Transparent operations and strict ethical standards minimise legal and financial risks, contribute to a fair business environment and strengthen both stakeholder trust and WDP’s reputation in the market. Connection to WDP's strategy: #VitallyEngaged #ImpactByResponsibility
#SustainableGrowth
Short term
Short term
WDP believes that sustainable growth can only be achieved with good governance and ethical business practices. We are regarded as a reliable business partner and continue to safeguard this reputation. This is essential for achieving long-term success and making further progress with the various stakeholders.
The principles of ethics, good governance and corporate social responsibility are formally enshrined in various codes and charters.
The WDP Employee Code of Conduct defines the expectations of staff regarding their actions for or on behalf of the company. The Employee Code of Conduct, in conjunction with the Human rights policy and the Anti-Bribery and Corruption Policy, reinforces the commitment of everyone within #TeamWDP, regardless of contract type or work location, to help build a strong company culture. A culture built on mutual respect, integrity and ethics.
Our Corporate Governance Charter covers and supplements the corporate governance provisions set out in the Belgian Corporate Governance Code. It also describes the role and authority of the compliance officer and risk manager.
The Grievance Mechanism provides a low-threshold for employees, members of the Board of Directors, members of the Executive Committee, suppliers and all other stakeholders to report violations of legal rules and conduct that violate the ethical standards WDP stands for (including zero tolerance for harassment, discrimination and corruption). Concerns can be reported here about (possible) violations of the law, ethical standards or procedures, such as the Corporate Governance Charter, the Employee Code of Conduct, the Supplier Code of Conduct, the Human Rights Policy, etc.
Grievance mechanism
#SpeakUp
1 Online hotline for issues or violations in the workplace, more specifically concerns about (possible) violations of the law, ethical standards or procedures, such as WDP’s Corporate Governance Charter, Employee Code of Conduct, Supplier Code of Conduct, Human Rights Policy, and the Anti-Bribery and Corruption Policy.
1 Compliance with the requirements of the European Whistleblowing Directive.
1 Available to WDP employees and employees of WDP suppliers, among others.
1 Online hotline for complaints regarding WDP (in the broad sense). This is not limited to reporting improper and/or illegal practices, but can also serve to report any dissatisfaction with the activities of WDP and/or its employees.
1 Available to all stakeholders.
Compliance with it or any breaches of the aforementioned codes and charter is closely monitored to prevent any negative impact. This includes annual feedback moments. Furthermore, all new employees follow an extensive onboarding procedure intended to provide a very in-depth understanding of WDP’s business and corporate culture. This includes personal introductory talks with colleagues from all departments, including a talk with the compliance officer for a further explanation and a formal introduction to the WDP policies (e.g. Dealing Code, Employee Code of Conduct, and #SpeakUp procedure). To increase awareness and knowledge on compliance-related issues, we have developed
specific training courses that are available to every employee via the HRHub on topics, such as the Employee Code of Conduct and the Dealing Code. These also cover topics, such as anti-corruption, cybersecurity, and discrimination. These involve courses developed in-house and by an external learning provider. The HR Hub also allows us to monitor course attendance.
Read more in 4. Performance and trends
Moreover, the compliance officer is tasked with promoting the company’s compliance with the laws, regulations and code of conduct applicable to the company. And in particular, the rules relating to the integrity of the company’s activities (as set out in its codes, charters, etc.). WDP’s risk management policies also cover potential compliance risks. These apply to all its activities (i.e. across all WDP entities, geographical areas, operations, etc.). This process involves intense cooperation within WDP between the risk manager, the compliance officer, local risk ambassadors, and if necessary, supported by specialised (external) advisors. The compliance officer also provides regular reports to the Board of Directors on the main compliance risks identified, the measures taken to better manage them and the progress of their implementation.
proactivity in project development and renovation execution, ensure high-quality client service and establish a continuous exchange of knowledge and best practices. In principle, WDP chooses partners with relevant experience (e.g. construction partners familiar with the logistics development sector, with a long history, and a solid track record). WDP works with financially and operationally sound suppliers and – as needed – selects partners experienced with guarantees (e.g. 10-year construction warranty) and financial guarantees. WDP screens its potential partners in advance and not just from a financial perspective. It also screens their activities, quality, reputation, and track record in terms of operations, clients, activities, safety instructions, and corporate social responsibility. More information is available in WDP’s Supply Chain Management process
The WDP Supplier Code of Conduct focuses on both health and safety and human rights. Some suppliers – based on an internal risk assessment of business, social and environmental risks – are asked to formally sign and thus adopt and comply with this code. The principles of this code are recommended to other suppliers.
To achieve our goals, we depend on a strong network of business partners, suppliers of materials, products and services. WDP works every day with construction partners, such as contractors, architects, and engineering firms as well as with specialist consultants and financial partners.
The WDP selection process here is aimed at finding long-term partnerships rather than one-off collaborations. Such trusting relationships guarantee quality, continuity and
As clearly stated in the code, WDP aims to take further steps with suppliers through collaboration, dialogue, and support to ensure compliance with the principles. That is why WDP maintains its very close contact with the suppliers while they are performing their services (whether or not on the construction site). One of the ways we monitor suppliers is with on-site visits by our project manager during the construction of a project. The topics of health and safety and code compliance are also monitored during project site meetings. The WDP Grievance Mechanism allows employees, clients, suppliers and all stakeholders to formally report concerns or breaches in the workplace. A paramount and crucial link in the supply chain is respect for human rights in our operations or by suppliers and clients. WDP strives to avoid all exposure to human rights risks and has formally reflected its commitment in the Human Rights Policy. Such risks are uncovered while performing our proper due diligence that is embedded in the WDP risk management policy.
We are vigilant in our choice of materials in the upstream of our operations. Once again, respect for human rights and health comes into play as well as the possible negative impact certain materials have on ecosystems or biodiversity. The choice of sustainable materials should occur at the design stage of a project in the manner of their origin, transportation, and production impact on water usage, emissions or potential pollution. These materials should be implemented as efficiently as possible while allowing for their sustainability and recyclability. The measures contained in the Supplier Code of Conduct, Human Rights Policy and Climate Action Plan should be respected by all stakeholders.
WDP’s Anti-bribery and corruption policy emphasises WDP’s commitment to its high corporate standards and zero-tolerance approach to fraudulent activity or corrupt behaviour. The policy provides guidelines for detecting corruption and bribery and outlines clear procedures for dealing with incidents, including a specific complaints procedure (#SpeakUp) that ensures a proper assessment is carried out with due discretion and confidentiality.
Per the aforementioned grievance management procedure, irregularities can be reported to the compliance officer and/or to the chairman of the Board of Directors using a specific form available on the WDP website and on WDPConnect! or in person. Following the investigation of the report, the complaints handler provides a recommendation to the Board of Directors, or to the Audit Committee or the Nomination Committee with a conclusion on the merits of the report. Further actions are then outlined per the grievance management procedure.
Internally, this policy is communicated during the onboarding procedure and via the HR Hub. Externally, the policy is shared with the Supplier Code of Conduct and signed by critical suppliers. Standard suppliers are informed of the policy in their contract with WDP.
In 2024, there were no convictions for breaches of anti-corruption and bribery laws. This also means that there are no fines in any amount to report for such infringements nor any notifications of associated penalties.
Moreover, we can report that in 2024 there are no breaches in WDP policies, competition law, insider trading, data regulations nor reports of discrimination or harassment.
We received no reports under the grievance management procedure.
Obviously, our 2025 ambition is zero violations of WDP policies, competition law or insider trading, nor any convictions, data breaches, or reports of discrimination or harassment.
of process regarding conflicts of interest
8. Corporate Governance Statement – Board of Directors –Conflicts of interest
6. Corporate Governance Statement – Board of Directors – Conflicts of interest
In 2017, the Task Force on Climate-related Financial Disclosures (TCFD) established a framework to provide investors and other stakeholders with useful decision-making information on climate-related risks and opportunities relevant to one’s business. The TCFD has structured its recommendations around four thematic areas that represent the core elements of how organisations operate: governance, strategy, risk management, and metrics & targets.
In our WDP Climate Action Plan, we set ourselves the clear target of implementing the recommendations of the TCFD by 2024. With the introduction of the Corporate Sustainability Reporting Directive and the integration of TCFD’s recommendation into these regulations, we decided to include this target in the track within WDP that will align our reporting with CSRD. In the meantime, we will continue to report per TCFD’s recommendations.
In 2021, the focus when beginning this reporting was on the themes of governance, risk management and metrics & targets. With respect to strategy, we carried out an initial identification and analysis of the climate-related risks and opportunities facing WDP in the short, medium, and long term, as well as the impact of these risks on our operations. In the future, we will continue to develop this subject area by further testing the resilience of our strategies based on various climate-related scenarios and to further describe and quantify the impact of climate-related risks and opportunities on our operations, strategy, and financial planning.
We refer to:
1 Chapter 8. Sustainability statement – General Information for further clarification about the decision-making process
1 WDP’s Climate Action Plan
1 Chapter 6. Corporate Governance Statement for WDP’s remuneration policy
1 WDP’s Enterprise Risk Management Policy
Description of the Board of Directors monitoring of climate-related risks and opportunities
In 2022, in combination with the announcement of our Climate Action Plan, the Board of Directors established a dedicated ESG committee to ensure we had a more future-proof approach to ESG. Given the current relevance of sustainability in the European real estate world, it was decided to have the entire Board of Directors sit on the ESG Committee.
Note that the chairman of the ESG Committee, Rik Vandenberghe, is the primary liaison with the ESG team within WDP.
The Board of Directors considered climate as an opportunity and even a driver in WDP’s 2022-25 (Energy as a service) growth plan as well as in the new #BLEND 2024–2027 growth plan. Moreover, in the remuneration policy for the members of the Executive Committee and by extension for #TeamWDP, which is fully in line with the aforementioned growth plan, a clear link has been made to ESG with very concrete short-term and longterm climate-related targets (net-zero targets).
The Board of Directors receives a regular ESG policy update (at least twice a year) that addresses the most relevant sustainability themes. This is the basis used for discussing (climate-related) sustainability risks and opportunities. The reporting is combined with that of the risk management policy and includes a dashboard showing the progress on the different tracks embedded in the Company to achieve the ESG objectives.
Description of management’s role in assessing and managing climate-related risks and opportunities
The primary responsibility for identifying and assessing climate-related risks and opportunities lies with the Head of Energy & Sustainability. At least quarterly, a risk assessment is carried out within the different WDP departments, which also includes climate-related risks. The Head of Energy & Sustainability can rely on input from his team, the risk manager, the risk ambassadors, and the ESG team.
WDP has anchored ESG in the entire organisation for years. The role of the ESG team is to ensure the alignment and necessary interaction between the environmental, social, and governance tracks within WDP. The Head of Energy & Sustainability has ownership over the environmental component, the Head of HR over the social component, and the General Counsel over governance. The Head of External Communication takes the lead in the reporting component. Specifically for the environmental component, the focus is on evaluating and managing climate-related risks and opportunities, following up on the objectives in our Climate Action Plan, evaluating the performance on those objectives, and communicating to internal and external stakeholders.
Our risk management policy includes a reporting process where risks are assessed with our risk assessment tool and reported to the Executive Committee via a risk dashboard. Once the Executive Committee has reviewed the proposed risk strategy, the Energy & Sustainability team jointly with other relevant teams with WDP will be responsible for the operational implementation of that strategy and continued monitoring of the risk.
Risk Management
We refer to:
1 Chapter 7. Risk factors for an overview of WDP’s main risks
1 Chapter 6. Corporate Governance Statement for further explanation about the WDP risk management policy
1 WDP’s Enterprise Risk Management Policy for more information regarding the risk assessment process used in WDP
1 WDP’s Climate Action Plan
Description of WDP’s processes for identifying and assessing climate-related risks
Climate change risks are identified and assessed within our overall risk management policy. This identification is part of a continuous process where the Energy & Sustainability team plays a crucial role with the support of the ESG team and risk ambassadors.
Climate change, both transitional and physical, is considered an increasing risk to WDP’s operations. As previously explained, we consider the risk of climate transition to be one of the key risks for WDP (i.e. both a specific and material risk).
The responsibility for and management of climate-related risks is assigned to the Head of Energy & Sustainability and her team, which ensures the operational implementation of risk response plans, the risk strategy, and continued monitoring of the risk.
For the actions related to managing climate-related risks, we refer to the Climate Action Plan where concrete actions are proposed per track (Decarb+, Green, Energy) to achieve our targets. Here, the input of project managers, property managers, sustainability engineers, and external advisors are essential.
Description of how the processes for identifying, assessing, and managing climate-related risks are integrated into WDP’s overall risk management
Climate change risks are an integral part of our risk management policy and are subject to the same system of identification, control, and monitoring.
As a real estate company, our operations are exposed to both physical and transitional risks and opportunities with respect to climate change.
Description Across the world, we see a tightening of climate policy and regulations to shift the economy away from fossil fuels towards a low-carbon economy. Here, WDP takes into account the obligations and upcoming changes arising from the EU Green Deal, including the EU Taxonomy, EU Directive on sustainability reporting by companies (CSRD), EU Energy Performance of Buildings Directive (EPBD), and EU Emission Trading System.
This can result in restrictions being imposed on the letting or the sale of buildings that do not comply with minimum standards, which can have a negative impact on the Company’s income. The same goes for technologically obsolete buildings which may require higher maintenance costs or capex requirements to meet minimum efficiency standards and modern work trends. Tightening climate policies and regulations can give rise to shifts in the Company’s entire value chain, going from investors to clients’ demands as this might lead to a reduction in available capital and revenues.
How does WDP mitigate this risk?
We consider it as one of the key risks that WDP is exposed to and it is described – both in terms of its specificity and materiality (financial impact) and our current risk mitigation measures – in Chapter 7 Risk factors
Description As a long-term property owner, we must ensure that our buildings can withstand extreme weather conditions (floods or droughts, rising sea levels, extreme winds, hurricanes, etc.) because such events can result in local closures, asset damage, and repair costs. Assets located in risky locations may be subject to higher insurance premiums and higher maintenance and investment costs to increase the resilience of the assets.
How does WDP mitigate this risk?
WDP’s strategy of developing and investing in high-quality assets in the best locations fits in perfectly with our objective of developing a resilient portfolio.
Description WDP considered climate as an opportunity when drawing up its 2024–2027 #BLEND growth plan.
How does WDP incorporate this opportunity into its strategy?
M.A.D.E. for FUTURE
We refer to WDP’s Climate Action Plan, as well as to Chapter 4. Performance and trends.
Moreover, changes in weather patterns associated with rising average temperatures must be taken into account, which can result in higher operating costs (higher cooling requirements, more wear and tear on the building, higher recurring operational costs, and possible property devaluation).
We currently take specific aspects of climate change into account in our development process. For example, all (legally required) measures regarding the flooding risk in the Netherlands (where 50% of WDP’s assets are currently located) are embedded in the construction and maintenance process.
Here, WDP focuses on the energy transition in which the Company wishes to play an important role with its warehouses that can function as decentralised energy plants of the future.
We refer to:
1 WDP’s Climate Action Plan
1 Chapter 6. Corporate Governance Statement for WDP’s remuneration policy
1 Chapter 8. Sustainability Statement – Reporting according to recognised standards for the 2023 and 2024 metrics (sBPR and GHG protocol)
Disclosure of the metrics WDP uses to assess climate-related risks and opportunities in line with its strategy and risk management process.
Climate change and -mitigation
% green-certified assets (as % portfolio value)
Brownfield projects under developments m²
Energy % electricity consumption from renewable energy sources
See p. 177
See p. 50
See p. 173 Energy intensity property portfolio per m² See p. 189
Renewable energy production Total solar energy generated in MWh See p. 173
GHG GHG intensity property portfolio per m² See p. 177
GHG intensity WDP corporate offices per m² See p. 177
Water Water intensity buildings per m² See p. 191
Disclosure of Scope 1, Scope 2, and Scope 3 GHG-emissions in line with the Greenhouse Gas Protocol
See Chapter 8. Sustainability Statement – Reporting according to recognised standards
Description of WDP’s targets for managing climate-related risks and opportunities and its performance against targets
For the targets, we refer to the Climate Action Plan
For the period from 1 January 2023 to 31 December 2023, WDP has reported the information presented in this GRI table of contents with reference to the GRI standards.
GRI 1: Foundation 2021
GRI Standard Disclosure Location
GRI 2: General Disclosures 2021
2-1
Organizational details 5, 225, 292
2-2 Entities included in the organization’s sustainability reporting 141, 159, 178, 225 –Same entities for financial and sustainability reporting
2-3 Reporting period, frequency and contact point
297 – Reporting period for financial and sustainability reporting is 1 January 2024 to 31 December 2024 –Annual reporting – This annual report was published on 31 March 2025
2-4 Restatements of information n/a
2-5 External assurance 277-287 Corporate Governance Charter
2-6 Activities, value chain and other business relationships Front inside flap, 5, 8, 12, 141 – No significant changes from previous reporting year, except for page 141
2-7 Employees 118, 201
2-8 Workers who are not employees 197
2-9 Governance structure and composition 105-113
GRI Standard Disclosure Location
2-10
Nomination and selection of the highest governance body 105-113, 166 Corporate Governance Charter
2-11 Chair of the highest governance body 105-107, 111
2-12 Role of the highest governance body in overseeing the management of impacts 105-118 Corporate Governance Charter
2-13 Delegation of responsibility for managing impacts 105-113, 166 Corporate Governance Charter Delegation matrix
2-14 Role of the highest governance body in sustainability reporting 166
2-15 Conflicts of interest 129-132
2-16 Communication of critical concerns 203-205 Grievance mechanism 0 breaches reported
2-17 Collective knowledge of the highest governance body 105-113, 117-118
2-18 Evaluation of the performance of the highest governance body 110-111 Corporate Governance Charter
2-19 Remuneration policies 119-128 Corporate Governance Charter
2-20 Process to determine remuneration 119-120 Corporate Governance Charter
2-21 Annual total compensation ratio 121
GRI Standard Disclosure Location
2-22 Statement on sustainable development strategy Statement by the Board of Directors and the CEO on sustainability
2-23 Policy commitments WDP policies
2-24 Embedding policy commitments WDP policies
2-25 Processes to remediate negative impacts Supplier Code of Conduct Human Rights Policy Grievance mechanism
2-26 Mechanisms for seeking advice and raising concerns Grievance mechanism
2-27 Compliance with laws and regulations 205 Grievance mechanism 0 breaches reported
2-28 Membership associations Membership in associations and societies
2-29 Approach to stakeholder engagement 162-164
2-30 Collective bargaining agreements Our commitment to equality
GRI 3: Material Topics 2021
3-1 Process to determine material topics 158-161
3-2 List of material topics 161
Material sustainability matters
GRI Standard Disclosure Location
Corporate governance & business ethics
GRI 3: Material Topics 2021 3-3 Management of material topics 202-206 Dealing Code
GRI 205: Anticorruption 2016 205-1 Operations assessed for risks related to corruption Anti-bribery and corruption policy 205-2 Communication and training about anti-corruption policies and procedures Anti-bribery and corruption policy
205-3 Confirmed incidents of corruption and actions taken 0 breaches reported
GRI 415: Public Policy 2016 415-1 Political contributions Membership in associations and societies
Energy Efficiency
GRI 3: Material Topics 2021 3-3 Management of material topics 168-195
GRI 302: Energy 2016 302-1 Energy consumption within the organization 184 302-2 Energy consumption outside of the organization 187-190
302-3 Energy intensity 184, 189
302-4 Reduction of energy consumption 178-192 302-5 Reductions in energy requirements of products and services 177-192
Corporate governance & business ethics – 205-1 Operations assessed for risks related to corruption WDP Group¹ All stakeholders
– 205-2 Communication and training about anti-corruption policies and procedures WDP Group¹ All stakeholders
– 205-3 Confirmed incidents of corruption and actions taken WDP Group¹ All stakeholders
– 415-1 Political contributions WDP Group¹ All stakeholders
Energy efficiency Cert-Tot CRE8
WDP Group¹ Clients
Elec-Abs 302-1 Energy consumption within the organization WDP Group¹
Elec-Abs 302-2 Energy consumption outside the organization – Clients
Elec-LfL 302-1 Energy consumption within the organization WDP Group¹
Elec-LfL 302-2 Energy consumption outside the organization – Clients
Heat-Abs 302-1 Energy consumption within the organization WDP Group¹
Heat-Abs 302-2 Energy consumption outside the organization
Heat-LfL 302-1 Energy consumption within the organization WDP Group¹
Heat-LfL 302-2 Energy consumption outside the organization
DH&C-Abs 302-1 Energy consumption within the organization WDP Group¹ –
DH&C-Abs 302-2 Energy consumption outside the organization – Clients
DH&C-LfL 302-1 Energy consumption within the organization WDP Group¹ –
DH&C-LfL 302-2 Energy consumption outside the organization – Clients
Fuels-Abs 302-1 Energy consumption within the organization WDP Group¹
Fuels-Abs 302-2 Energy consumption outside the organization
Fuels-LfL 302-1 Energy consumption within the organization WDP Group¹
Clients
Fuels-LfL 302-2 Energy consumption outside of the organization – Clients
Energy-Int 302-3 Energy intensity WDP Group¹ Clients
Energy-Int CRE1 WDP Group¹ Clients
– 302-4 Reduction of energy consumption WDP Group¹ Clients
– 302-5 Reductions in energy requirements of products and services WDP Group¹ Clients
Material sustainability matters
Greenhouse gas emissions
GHG-Dir-Abs 305-1 Direct (Scope 1) GHG emissions
GHG- Indir-Abs 305-2 Energy indirect (Scope 2) GHG emissions
– 305-3 Other indirect (Scope 3) GHG emissions
GHG-Int 305-4 GHG emissions intensity
GHG-Int CRE3
– 305-5 Reduction of GHG emissions
Climate change adaptation
Cert-Tot CRE8
Energy-Int 302-3 Energy intensity
Energy-Int CRE1
– 302-4 Reduction of energy consumption
GHG-Int 305-4 GHG emissions intensity
GHG-Int CRE3
Land use
1 See also 6. Corporate Governance Statement – Group structure
within the organisation
WDP Group¹ –
WDP Group¹ –
outside the organisation
WDP Group¹ Clients
WDP Group¹ Clients
WDP Group¹ Clients
WDP Group¹ Clients
WDP Group¹ Clients
WDP Group¹ Clients
WDP Group¹ Clients
WDP Group¹ Clients
WDP Group¹ Clients
WDP Group¹ Clients
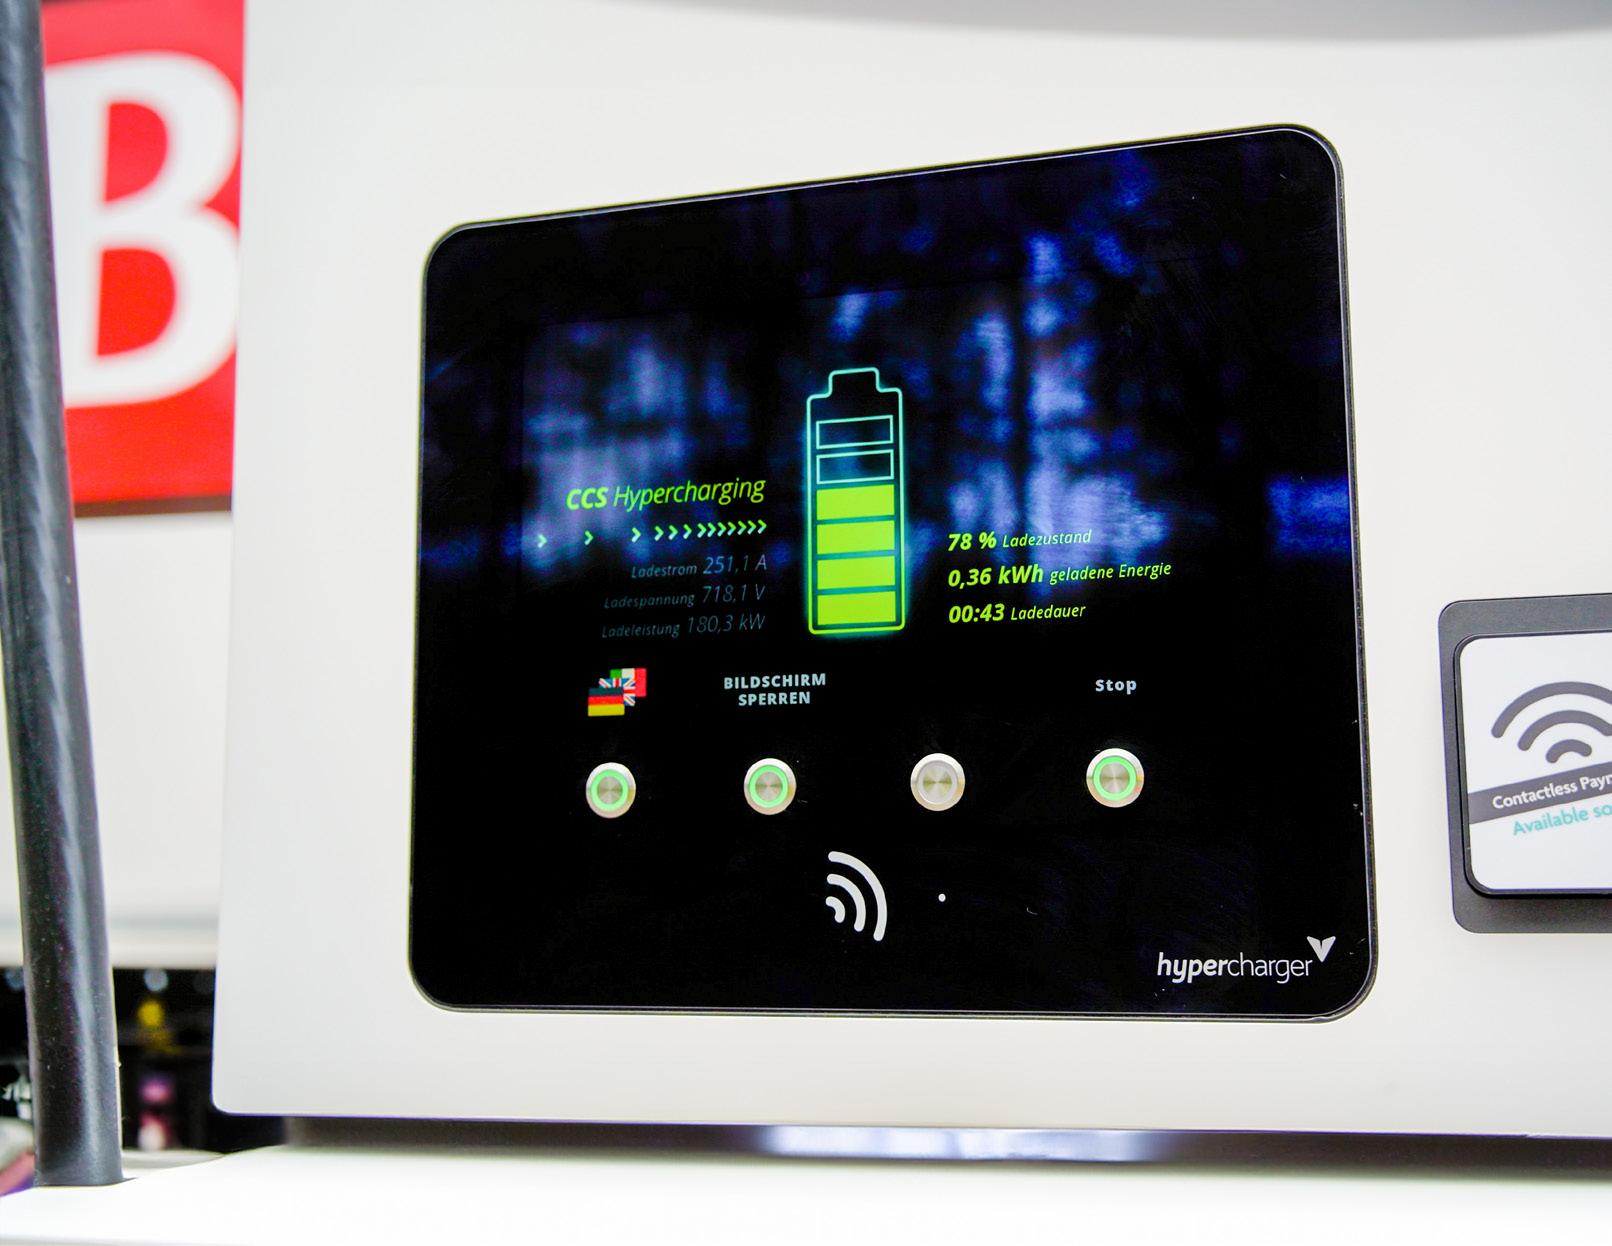
Earnings statement continued
Reserve for the balance of changes in fair value of authorised hedging instruments subject to hedge accounting as defined by IFRS (+/-)
Attributable to: -
1
Allocation of results from the 2023 financial year
in euros (x 1,000)
Reserves for the balance of variations in the fair value of the properties (+/-)
Reserve for the share in the profit or loss in the unrealized results of the participating interests that are not held for 100% by the mother company
Reserves for the balance of variations in the fair value of permitted hedging instruments that are not subject to hedging accounting as defined in IFRS
Reserve for the balance of changes in fair value of authorised hedging instruments subject to hedge accounting as defined by IFRS (+/-)
Reserves for the balance of exchange rate differences for monetary assets and liabilities (+/-)
Reserves for conversion differences arising from the conversion of a foreign activity
Reserves for deferred taxes related to property located abroad
D. Net result of the financial year
Total shareholders’ equity attributable to
Profit for the previous financial year Transfer of result on portfolio¹ Transfer of the result of the participations which are not held for 100% by the mother company
Dividend payments from participating interests that are not held for 100% by the mother company Transfer of variations in the fair value of financial instruments Other
result for the current financial
Allocation of results from the 2022 financial year
euros (x 1,000)
Reserves for the balance of variations in the fair value of the properties (+/-)
Reserve for the share in the profit or loss in the unrealized results of the participating interests that are not held for 100% by the mother company
Reserves for the balance of variations in the fair value of permitted hedging instruments that are not subject to hedging accounting as defined in IFRS
Reserve for the balance of changes in fair value of authorised hedging instruments subject to hedge accounting as defined by IFRS (+/-)
Reserves for the balance of exchange rate differences for monetary assets and liabilities (+/-)
Reserves for conversion differences arising from the conversion of a foreign activity
Reserves for deferred taxes related to property located abroad
Total shareholders’ equity attributable to
Profit for the previous financial year Transfer of result on portfolio¹ Transfer of the result of the participations which are not held for 100% by the mother company
Dividend payments from participating interests that are not held for 100% by the mother company Transfer of variations in the fair value of financial instruments Other
WDP NV/SA is a public regulated real estate company under Belgian law and has the form of an NV/SA under Belgian law. Its registered office is at Blakebergen 15, 1861 Wolvertem (Belgium). The phone number is +32 (0)52 338 400.
The annual consolidated financial statements of the company of 31 December 2024 include the company and its subsidiaries. The annual accounts were prepared and released for publication by the Board of Directors on 26 March 2025.
WDP is listed on Euronext Brussels and Amsterdam.
The annual consolidated financial statements are drawn up in accordance with the IFRS (International Financial Reporting Standards) as adopted in the European Union and with the legal and administrative regulations applicable in Belgium. These standards include all new and revised standards and interpretations issued by the International Accounting Standards Board (IASB) and the International Financial Reporting Interpretations Committee (IFRIC) that apply to the Group’s activities and apply to the financial years as of 1 January 2024.
The annual consolidated financial statements are presented in thousands of euros, rounded to the nearest thousand. The 2024 and 2023 financial years are shown in this document. For historical financial information for the 2022 financial year, please refer to the annual reports for 2023 and 2022.
Accounting methods were consistently applied to the financial years shown.
The Dutch-language version of the annual report was drawn up in accordance with the ESEF (European Single Electronic Format) reporting requirements. According to ESEF requirements, the primary annual accounts are tagged with XBRL tags and the notes to the annual accounts are also block tagged. You can find the annual report in the iXBRL standard at www.wdp.eu. See also 10 Appendices.
Standards and interpretations applicable for the financial year beginning on or after 1 1 January 2024
1 Amendments to IAS 1 Presentation of Financial Statements: Classification of Liabilities as Current or Non-current and Non-current Liabilities with Covenants
1 Amendment to IFRS 16 Leases: Lease obligation in a Sale and Leaseback.
1 Amendments to IAS 7 Statement of Cash Flows and IFRS 7 Financial Instruments: Disclosures: Supplier finance schemes.
New or amended standards and interpretations that are not yet effective
A number of new standards, amendments to standards and interpretations were not yet in force in 2024, but could have been applied earlier. Unless stated otherwise, WDP has not yet adopted these. Below is a description of the potential influence of any new standards, amendments or interpretations relevant to WDP on the consolidated financial statements for 2025 and beyond.
The standards have no or only immaterial impact on the consolidated financial statements, except for IFRS 18. WDP is assessing the attendant impact.
1 Amendments to IAS 21 The Effects of Changes in Foreign Exchange Rates: Lack of Exchangeability (applicable for financial years from 1 January 2025 but not yet approved within the European Union)
1 IFRS 18 Presentation and disclosure in financial statements (applicable for financial years from 1 January 2027 but not yet adopted within the European Union)
1 IFRS 19 Subsidiaries without public accountability – Disclosures (applicable for financial years from 1 January 2027 but not yet approved within the European Union)
1 Amendments to IFRS 9 and IFRS 7 Classification and measurement of financial instruments (applicable for financial years from 1 January 2026 but not yet approved within the European Union)
1 Annual Improvements – Volume 11 (applicable for financial years beginning on or after 1 January 2026, but not yet endorsed in the European Union)
1 Amendments to IFRS 9 and IFRS 7 Contracts related to nature-dependent electricity (applicable for financial years from 1 January 2026 but not yet approved within the European Union)
III. Material accounting principles
Consolidation principles
Subsidiaries
Subsidiaries are entities over which the company exercises control. A company exercises control over a subsidiary if, and only if, the parent company:
1 has control over the shareholding;
1 is exposed to, or has rights to variable revenues, by virtue of its involvement in the participation; and
1 has the ability to use its control over the shareholding to influence the amount of investor returns.
The companies in which the Group has control over the financial and operational policy in order to benefit from its activities are included in full in the Group’s annual consolidated financial statements.
This means that the Group’s assets, liabilities and results are indicated in full. All intragroup transactions and profits are fully eliminated.
Minority interests are holdings in subsidiaries that are not held directly or indirectly by the Group.
Joint ventures are companies over which the Group has joint control, as specified by contractual agreement. Such joint control is applicable when the strategic financial and operational decisions with regard to the business require unanimous agreement from the parties that share the control (the shareholders in the joint venture).
Associated companies are the companies over which it is established that the Group has significant control.
As set out in IAS 28 Investments and joint ventures, the results and balance sheet impact of the joint ventures are incorporated using the equity accounting method. WDP’s proportionate share in the portfolio is still shown in the statistics in the reporting on the portfolio.
The result from transactions with the above joint ventures is not eliminated in the amount of the share of the WDP Group, but rather fully recognised in the result (under the headings Operating result (before the result on the portfolio) and financial result).
If WDP acquires control over an integrated set of activities and assets, as defined in IFRS 3 Business combinations, the identifiable assets, liabilities and contingent liabilities of the acquired company are booked at fair value on the acquisition date. Goodwill is the positive difference between the acquisition costs and the share of the Group in the fair value of the acquired net asset. If this difference is negative (negative goodwill), it is immediately booked in the result after revaluation of the values.
The individual financial statements of each Group member are presented in the currency of the primary economic environment in which the entity operates (its functional currency). For the preparation of the annual consolidated financial statements, the results and the financial position of each entity are expressed in euros, which is the functional currency of the parent company, and the currency used for the presentation of the annual consolidated financial statements.
Transactions in foreign currency are immediately booked at the exchange rate on the transaction date. Monetary assets and liabilities in foreign currency are converted at the closing price.
Realised and unrealised exchange rate differences are recognised in the earnings statement, except when they relate to intra-group borrowing that meets the definition of a net investment in a foreign activity. In that case, the exchange rate differences are included in a separate component of shareholders’ equity and recognised in the earnings statement after disposal of a net investment.
Assets and liabilities are converted at the closing rate, except for properties, which are converted at the historical rate. The earnings statement is converted at the average rate over the financial year.
The resulting conversion differences are included in a separate component of shareholders’ equity. These conversion differences are included in the earnings statement when the foreign entity is disposed of, sold or liquidated.
Land and buildings held to generate (future) rental income over the long term are included as investment properties. On initial recognition, investment properties are valued at the purchase price, including transaction costs, financing costs (per IAS 23) and directly attributable expenses.
Land held for the purposes of initiating property developments with a view to subsequent leasing and long-term increase in value, but for which no specific construction plans or project developments (as referred to in the definition of project development) have been initiated (land reserves), is also deemed to be investment property.
The usage rights recognised in the balance sheet for the concession, ground lease, or similar leases (due to entry into force of IFRS 16) are also considered investment properties.
After initial recognition, the investment properties are valued at fair value, in accordance with IAS 40. From the seller’s perspective, the valuation is after deduction of the registration fees. These transaction costs depend on the geographical area where these properties are located.
This entails that the transaction costs are incorporated into the earnings statement as per IAS 40. According to the GVV/SIR Royal Decree, this must then be included in the designated reserves at the end of the financial year.
After initial recognition, the projects are valued at fair value. The fair value takes substantial development risks into account. In this respect, the following criteria must be met: there must be a clear understanding of the project costs, all permits required for the project development must have been obtained and a substantial part of the project development must be pre-leased (finalised and signed lease). This fair value measurement is based on the valuation by the independent property expert (in accordance with customary methods and assumptions) and takes into account costs to be incurred (including an estimate of unforeseen costs) before the project is finally completed.
The profit/loss realised on the sale is included in the earnings statement under Result on disposal of investment properties. The result is determined as per IAS 40 and is the difference between the sale price and the fair value from the most recent valuation. This achieved result is recognised at the time of execution of the notarial deed for the sale.
These are valuated under the revaluation model as per IAS 16 Tangible fixed assets After initial recognition, assets whose fair value can be reliably established must be booked at the revalued value, which is the fair value at the time of the revaluation, less any subsequent accumulated depreciation and special impairments. The fair value is determined based on the discounting method for future revenues.
The useful life of the solar panels is estimated at thirty years, without taking into account any residual value.
The capital gain when starting a new site is recognised in a separate component of shareholders’ equity. Capital losses are also recognised in this component, unless they have been realised or the fair value drops below the original cost less cumulative depreciation. In the latter case, they are included in the result.
At the start of the lease period, the leases (except for leases with a maximum term of twelve months and leases whose underlying assets are of low value) are recognised on the balance sheet as rights of use and lease liabilities at the present value of the future lease payments. Next, all rights of use that qualify as investment properties are valuated at fair value, in accordance with the valuation rules detailed under Investment properties The minimum lease payments are recognised in part as financing costs and in part as settlement of the outstanding liability, in a manner resulting in a constant periodic interest rate on the remaining balance of the liability. The cost of financing is offset directly against the result. Conditional lease payments are incorporated as costs in the periods in which they were made.
If a lease meets the conditions of a financial lease (according to IFRS 16), WDP as the lessor will recognise the lease from its start date as a receivable in the balance sheet at an amount equal to the net investment in the lease. The difference between this latter amount and the book value of the leased property (exclusive of the value of the residual right held by WDP) at the start of the lease will be recognised in the earnings statement for that period. Each periodic payment made by the lessee will be partly recognised by WDP as a repayment of the capital and partly as financial income based on a constant periodic return for WDP.
The residual right held by WDP will be recognised at its fair value on each balance sheet date. This value will increase every year and will correspond to the market value of the full right of ownership at the end of the lease. These increases will be recognised in Changes in the fair value of investment properties in the earnings statement.
All financial assets are recognised or no longer recognised in the balance sheet on the transaction date if the purchase or sale of a financial asset is based on a contract prescribing conditions for delivery of the asset within the term generally prescribed or agreed on the market in question and initially valued at fair value, plus transaction costs, except for financial assets at fair value with changes in value in the earnings statement, which are initially valued at fair value.
The financial assets are classified in one of the categories provided for in IFRS 9 Financial instruments based on both the business model of the entity for management of the financial assets and the properties of the contractual cash flows of the financial assets and are recorded on their initial recognition. This classification determines the valuation of the financial assets on future balance sheet dates: amortised cost or fair value.
Financial assets are classified at fair value with changes in value through profit or loss if they are held for trading purposes. Financial assets at fair value with changes in value through earnings or loss are valued at fair value, with all resulting income and expenses recognised in the result. Derivatives are also included in the category at fair value with changes in value through earnings or loss, unless they are considered to be hedges and are effective.
Financial assets are classified at fair value with changes in value through shareholders’ equity if they are held for hedge accounting. Financial assets at fair value with changes in value due to shareholders’ equity are valued at fair value, with any resulting income or expenses recognised in shareholders’ equity. Derivatives also belong to the category at fair value with changes in value through shareholders’ equity if they were designated and effective as hedges.
Financial assets at amortised
Financial assets at amortised cost are not derivatives and are retained within a business model geared towards retaining financial assets to receive contractual cash flows (Held to collect) and on certain dates, the contractual conditions of the financial asset give rise to cash flows that are exclusively for settlement of and interest payments on the outstanding principal (Solely Payments of Principal and Interest – SPPI). This category includes cash and cash equivalents, non-current receivables and trade receivables. Cash equivalents are short-term, very often liquid investments that can be immediately converted to cash of a known amount, have an original term of no more than three months and entail no significant risks of impairment. The cash equivalents held by WDP consist of bank deposits and are therefore fully valuated at amortised cost.
Financial liabilities
Financial liabilities are classified as financial liabilities at fair value through profit or loss or as financial liabilities at amortised cost.
Financial liabilities at fair value through profit or loss
Financial liabilities are classified at fair value through profit or loss if they are held for trading purposes. Specifically, for WDP, these are Interest Rate Swaps for which hedge accounting is not applied to the extent that they have a negative fair value. Financial liabilities at fair value through profit or loss are valued at fair value, with all resulting income and expenditures recognised in the result. A financial liability is included in this category if it is primarily acquired for sale in the short term. Derivatives are also included in the category at fair value through earnings or loss, unless they are considered to be hedges and are effective.
Financial liabilities at fair value through shareholders’ equity
Financial liabilities are classified at fair value through shareholders’ equity if these are held for hedge accounting. Financial liabilities at fair value through shareholders’ equity are valued at fair value, with all resulting income or expenses recognised in shareholders’ equity. Derivatives also belong to the category at fair value through shareholders’ equity if these were designated as hedges and are effective.
Financial liabilities valuated at amortised cost
Financial liabilities valuated at amortised cost, including debt, are initially valuated at fair value after deduction of the transaction costs. After initial recognition, they are valuated at amortised cost. The Group’s financial liabilities valued at amortised cost include the non-current financial debt (bank debt, lease debt, bond loans), other non-current debt, current financial liabilities, accounts payable and payable dividends in the other current liabilities.
Revaluations as a result of variations in the foreign currency of the financial obligations valued at amortised cost in foreign currency are a non-cash item and are considered unavailable as such.
Equity instruments issued by the Group are classified based on the economic reality of the contractual agreements and the definitions of an equity instrument. An equity instrument is any contract that includes the remaining interest in the assets of the Group, after deduction of all liabilities. The accounting policies with regard to equity instruments are described below.
Equity instruments issued by the company are recognised for the sum of the amounts received (after deduction of directly attributable issue costs).
The Group uses derivatives to limit risks related to unfavourable interest rates resulting from the operational, financial and investment activities within the framework of its operational management. The Group does not use these instruments for speculative purposes, does not hold any derivatives and does not issue derivatives for trading purposes.
Changes in the fair value of derivatives that do not qualify as hedging transactions are recognised immediately in earnings or loss under the heading Changes in fair value of financial assets and liabilities. Changes in the fair value of derivatives allocated specifically to hedge the variability of cash flows of a recognised asset or liability or a forecast transaction are recognised in Other components in the overall result
Rental income includes rents and revenues directly related to these, such as compensation for early lease termination.
Revenue is valued at the fair value of the received or receivable compensation. Revenue is only recognised if it is likely that the economic benefits will befall the entity and can be determined with sufficient certainty.
Rental income, and other income and expenses, are recognised in the earnings statement in the period to which they pertain.
The fees for premature lease termination are recognised immediately in the result for the financial year.
The proceeds from the sale of green energy to the tenant, the sale of green energy to the lessor and green energy certificates are recognised when the green energy is generated.
Lease-related costs pertain to write-downs and decreases in trade receivables that are recognised in the results if the book value is higher than the estimated realisation value and the rent to be paid on leased assets.
Rental charges and tax on leased buildings and the recovery of these costs pertain to costs that fall to the tenant or lessee by law or custom. Depending on the contractual agreements, the owner may or may not pass these charges on to the tenant.
Other lease-related income and expenses include the passing of management fees on to tenants as well as other revenues that do not fall under rental income (including revenue from investments in energy).
The Overhead costs of the Company are expenses related to the management and general operation of WDP. This includes expenses such as general administrative costs, staff costs for general management, and depreciation of assets used for general management.
Costs related to works performed in the buildings are booked in various ways depending on the type of works:
1 maintenance and repair: maintenance and repair costs are booked as property outgoings for the accounting period, given that these do not increase the expected future economic benefits of the building and do not add any functionality or improve the level of comfort in the building;
1 improvement and renovation: these are works carried out occasionally to add features to the property and considerably increase the expected future economic benefits of the building. The costs of these works (materials, contractor remuneration, technical studies, internal expenses, architect remuneration and interest during the construction period) are capitalised. Examples: installation of a new air conditioning system, new roof, thorough renovation of all or part of the building. Worksites for which costs are being capitalised are identified beforehand according to the abovementioned criteria.
Net interest expense shows the net interest on permitted hedging instruments. They are also shown net in the cash flow statement under Interest paid
GVV/SIR status offers a fiscally transparent status, given that a GVV/SIR is only subject to tax on specific components of the result, such as disallowed expenses and exceptional and gratuitous advantages. No corporate income tax is paid on earnings from leases or realised capital gains.
Tax on the result for the financial year includes taxes due and deductible taxes for the current and previous reporting periods, the deferred tax and the exit tax due. The tax charge is recognised in the earnings statement unless it pertains to components recognised directly in the shareholders’ equity. This latter case also includes the tax on shareholders’ equity.
To calculate the tax on the year’s taxable profit, tax rates applicable on the balance sheet date are used.
Exit taxes – tax on capital gains resulting from a merger of a GVV/SIR with a non-regulated real estate company – are deducted from the established revaluation surplus at merger and if applicable are recognised as a liability.
In general, deferred income taxes (tax receivables) are recognised for all taxable (deductible) temporary differences. Such claims and liabilities are not recorded if the temporary differences result from the initial recognition of goodwill or the initial recognition (other than in a business combination) of other assets or liabilities. Deferred tax liabilities are recognised to the extent that it is likely that a taxable profit will be available against which the deductible temporary difference can be offset. Deferred tax receivables are reduced when it is no longer likely that the associated tax benefit will be realised.
Significant estimates in the drawing up of financial statements
1 Determining whether control, joint control or significant influence is being exercised over investments (see explanatory note III. Material accounting principles). No physical audit was performed on new investments in 2024.
1 Determining whether an entity holding investment property is a business, and thus also determining, in the acquisition of control over an entity of this kind, whether the acquisition is regarded as an IFRS 3 Business combination, is a significant assessment.
The fair value of the investment properties is determined by independent property experts according to the GVV/SIR regulations (see explanatory note XII. Investment properties).
euros (x 1,000)
I. Rental
IV. Recovery of property
V. Recovery of rental charges normally paid by the tenant on let properties
VI. Costs payable by tenants and paid out by the owner for rental damage and refurbishment at end of lease
VII. Rental charges and taxes normally paid by the
VIII. Other income and charges related to
2 The joint ventures are incorporated using the equity accounting method, as per IFRS 11 Joint arrangements. The table shows the operating result based on the proportionate share of WDP and then gives the reconciliation with the proportionate share in the results of these entities, as reported under the equity accounting method as per IFRS.
(x 1,000)
V. Recovery of rental charges normally paid by
VI. Costs payable by tenants and paid out by the owner for rental damage and refurbishment at end of lease
VII. Rental charges and taxes normally paid by the
Other operating income and expenses (depreciation and write-down on solar panels)
XVI. Result on disposals of investment
Variations in the fair value of investment
1 In 2023, income from investments in energy totalled 24.056 million euros against 22.902 million euros in the year 2022. This income was generated in Belgium (10.813 million euros), the Netherlands (10.055 million euros) and Romania (3.187 million euros). The joint ventures WDP Luxembourg and WDPort of Ghent Big Box generated 0.274 million euros and 1.354 million euros in the year 2023. In addition to the income from investments in energy, the property management fees and other operating income/costs are part of the Other income and charges related to leases
2 The joint ventures are incorporated using the equity accounting method, as per IFRS 11 Joint arrangements. The table shows the operating result based on the proportionate share of WDP and then gives the reconciliation with the proportionate share in the results of these entities, as reported under the equity accounting method as per IFRS.
The basis for reporting per segment within WDP is the geographical region. This segmentation basis reflects the geographical markets in Europe in which WDP is active. WDP’s activity is divided into six regions. More information on which subsidiaries are located within the geographical regions can be found in the group structure, see note VII. Information on subsidiaries
This segmentation is important for WDP given that the nature of its business, its clients, etc. represent similar economic characteristics within these segments. Business decisions are taken at this level and different key performance indicators (such as rental income, occupancy rates, etc.) are monitored in this manner.
NV
WDP France SARL
WDP Nederland N.V.
WDP Development NL N.V.1
Love Hungaria NV/SA5
WDPort of Ghent Big Box NV/SA6
NV/SA7
BV8
1 WDP Development NL N.V. was founded in August 2011 as a permanent development company for own account of WDP Nederland N.V.
2 WDP Services NL B.V. was created in June 2023 and is a 100% subsidiary of WDP Nederland NV.
3 On 7 June 2013 WDP acquired 100% of the shares in Eurologistik 1 Freehold BVBA, holding the rights to an existing logistic site in Vilvoorde.
4 As part of the streamlining of the Group and its foreign non-REIT participations, the shares of WDP Romania SRL and WDP Luxembourg SA held by WDP NV/SA were contributed to WDP Invest NV/SA on 22 December 2020 by way of capital increase by contribution in kind. WDP Invest acts as an autonomous investment and financing vehicle for the international activities of the Group as from the aforementioned date. At the beginning of 2025, WDP Invest NV became 100% owner of WDP Romania SRL.
5 This is a joint venture founded in May of 2015 between WDP NV/SA and project developer L.I.F.E. NV/SA with a view to redevelopment of the Hungaria building in Leuven.
6 The joint venture was set up in December 2020 between WDP NV/SA and the co-shareholders Sakolaki and Vendis Capital (shareholders of Exterioo, Juntoo and X²O Badkamers), with regard to the realization of a site in the Port of Ghent that is leased by two of these retailers.
7 The joint venture was set up in June 2023 between WDP NV/SA and the co-shareholder Warehousing & Warehouse Related Services Belgium NV/SA in the context of real estate transactions.
8 In the last quarter of 2021, WDP took a 25%+1 stake in the energy proptech company nanoGrid (founded by Joost Desmedt). The consolidated result before tax of nanoGrid BV amounts to -0.02% of the consolidated result before tax of WDP NV. The consolidated assets of nanoGrid BV amounts to 0.03% of the consolidated assets of WDP NV.
9 This is a joint venture, of which the Luxembourg government owns 45% and of which WDP acquired 55% of the shares on 13 October 2017.
10 On the 18th of December 2019 WDP NV/SA bought, through its fully subsidiary WDP Invest NV/SA, a participation in of 50% in WVI Gmbh, a joint venture with VIB Vermögen. From July 2022, WVI GmbH is a 100% subsidiary of WDP Invest NV, forming WDP Deutschland GmbH. This transaction is not deemed to be a business combination.
11 At the beginning of April 2022, WDP and Catena AB realized a stategic partnership. Joost Uwents was appointed as a director on Catena's Board of Directors at Catena's annual General Meeting.
12 At the end of March 2024, WDP Romania acquired 100% of the shares in the company Expo Market Doraly SRL, which owns a high-yield urban logistics cluster in Bucharest. This transaction is not considered as a business combination. In addition to the real estate, 4 million euros in current assets and 55 million euros in liabilities were acquired. Per 31 December 2024, the net rental result of Expo Doraly SRL contributed for 10.7 million euros and the net result contributed for 20.3 million euros.
13 WDP Deutschland Services GmbH was created in November 2024 and is a 100% subsidiary of WDP Invest NV.
The group structure is shown visually under 6. Corporate Governance Statement.
I love Hungaria NV/SA, WDPort of Ghent Big Box NV, Gosselin-WDP NV/SA, nanoGrid BV and WDP Luxembourg SA are joint ventures in the Group and are consolidated under the equity accounting method. The stake in the associated company Catena AB is also accounted for in the consolidated accounts using the equity accounting method.
In the segmented information, WDP Luxembourg is shown separately, given its geographic distance. I Love Hungaria NV/SA, WDPort of Ghent Big Box NV, GosselinWDP and nanoGrid BV are shown under Other joint ventures
in euros (x 1,000)
Future rental income
less than one year
two to three years
three to four years
four to five years
This table contains an overview of the future rental income under the current agreements. It is based on the non-indexed rents received up to and including the first due date, as set out in the leases.
The impact of the applied indexing of rents amounts to an average of 3.0% and 6.5% for the 2024 and 2023 financial years, respectively.
The future rental income with respect to the previous year rose by 30.8%. This mainly stems from the strong portfolio growth (see also 5. Financial results and outlook) as well as the impact of the indexation of 2024 and 2023 as explained above.
WDP relies on an inflation-resistant cash flow profile thanks to indexation clauses in the leases combined with rising market rents.
Rents are normally paid monthly in advance (sometimes quarterly). They are indexed annually on the anniversary date of the lease.
According to the contractual provisions, taxes and charges (including withholding tax), insurance premiums and collective charges are passed on to the tenant. The tenant must pay a monthly (or quarterly) charge for this. The tenant receives an annual invoice for the actual expenses.
To ensure compliance with the duties that the contract imposes on the tenant, the latter must provide a deposit, usually in the form of a bank deposit equivalent to six months of rent.
At the start of the lease contract, a joint property survey is conducted between the parties by an independent expert. On expiry of the contract, the tenant must return the leased space in the same condition as described in the move-in inspection report, apart from normal wear and tear. A move-out inspection report is prepared. The tenant must pay for repairing any damage that is determined, and should the premises be unavailable during repair.
The tenant is not permitted to carry out any high-risk activities in the spaces it rents, without the prior written approval of WDP. In such cases, WDP may demand that the tenant take certain precautions. Before the end of the contract, tenants who have performed a risk activity during the lease period must have an exploratory soil inspection carried out, and if soil pollution is established, pay for any clean-up operations and consequential damage.
The tenant is responsible for obtaining operational and environmental authorisation. Refusal or withdrawal of such authorisation will not be cause for dissolution or annulment of the contract.
The tenant may not transfer the contract or sublease the leased premises without prior written authorisation from WDP.
If approval is granted to transfer a lease, the original tenant shall remain jointly and severally liable to WDP. The tenant is obligated to register the agreement at its own expense.
in euros (x 1,000)
A capital gain of 0.7 million euros was achieved. The sites sold in 2024 include Beersel – Stationsstraat 230 (Belgium), Voorhout – Loosterweg 33 (The Netherlands), Sibiu –Theodor Mihaly street 3-5 and a part of the site in Leuven – Vaart 25-35 (Belgium).
The comments on the financial result are available under 5. Financial results and outlook.
The financial result (excluding variations in the fair value of financial instruments) improved from -41.4 million euros last year to -40.7 million euros. The financial result within an environment of high interest rates (Euribor 3 month ranged between 3.9% at the end of 2023 and 2.7% as of 31 December 2024) was kept under control by WDP’s proactive financial management and high degree of hedging (89% at the end of December 2024 compared to 119% at the end of December 2023). This means that WDP kept the average interest cost very low at 1.9% over 2024 and equal to the 2023 level.
WDP’s risk policy with respect to the financial policy is explained in 7. Risk factors
(x 1,000)
In 2024, WDP continues to draw up its accounts applying the FBI regime for its Dutch operations. Afterwards, the statute will expire, given the change in the law implemented by the Dutch government, which excludes real estate investments from the Dutch FBI regime from 1 January 2025. From 2025, this will lead to an estimated additional annual tax burden on EPRA Earnings of -11 million euros (0.05 euros per share). Note that the provisions that were provided for 2021-22-23 (when it was assumed that the FBI regime was at risk for these financial years) were reversed in 2023, resulting in a one-off positive impact on EPRA Earnings of approximately 11 million euros (+0.05 euros per share) in 2023.
WDP has REIT status in Belgium, the Netherlands1 and France (as GVV/SIR, FBI and SIIC respectively). More information about these tax transparent statuses can be found in 10. Appendices
1 WDP believes that all conditions are met by the Company within the current applicable FBI legislation. So, WDP expects that the FBI regime applies to the 2022, 2023 and 2024 financial years. As of 1 January 2025, the statute will expire given the recent legislative amendment implemented by the Dutch government, which excludes real estate investments from the Dutch FBI regime. For more information, see Chapter 5. Financial results and outlook
of investment properties by means of share-
properties from associated companies and jont ventures that became a wholly owned subsidiary during the financial year
(x 1,000)
of investment properties by means of sharebased payment transactions
Investment properties from associated companies and joint ventures that became a wholly owned subsidiary during the financial year
Transfers to fixed assets held for sale
1 Land is not included.
Capital expenditures pertain to investments made as part of new acquisitions, in-house project developments, and investments within the existing portfolio (for more information, see 4. Performance and trends).
The property portfolio is valued at fair value. Fair value is based on non-observable inputs, which means assets in investment properties fall under level 3 of the fair value hierarchy as defined in IFRS. No changes in the fair value hierarchy level took place in 2024. For information: Level 1 of the fair-value hierarchy specifies that the fair value is based on listed (non-adjusted) prices in an active market for identical assets or liabilities, while level 2 is based on different information from level 1, which can be determined directly or indirectly for the assets or liabilities in question.
No assets are not valued according to their highest, optimum use, as no assets are being used for less than their optimum use.
The positive variation in the appreciation of the property investments is due to latent capital gains on projects and recent acquisitions, as well as asset management initiatives on existing sites, combined with a slight positive revaluation in the existing portfolio driven by the increase in estimated market rental values of +3% over 2024, only marginally offset by an upward yield shift of +8bps).
In 2023, the variation in fair value was -223 million euros. The negative variation in the valuation of investment properties was due to an upward yield shift of +54 bps in the existing portfolio with the discount rates applied by the property appraisers, partly offset by the increase in estimated rental values of +11%.
2
The gross rental yield, after the addition of the estimated market rent value of the nonleased parts, is 6.2% as of 31 December 2024, compared to 6.1% at the end of 2023.
During 2024, 1.0 billion euros of new investment (including energy projects) were signed across the breadth of operations in all WDP regions (85% in Western Europe): 150 million euros for development projects and land reserve (7.5% NOI yield2)3, 400 million euros core+ and value-add acquisitions with redevelopment potential (7.5% NOI yield), 400 million euros for core acquisitions for strategic expansion in France and Germany (5.3% NOI yield), and 75 million euros for energy projects (targeted IRR >10%). For a detailed description of the various individual acquisitions and the pre-leased and other projects completed and under construction, please see 4. Performance and trends
The following table shows a comparison between the annual rental income for purchased properties and the rental income actually received since the purchase of the properties in the course of 2024 and 2023 (in particular the year of purchase of these properties).
in euros (x 1,000)
Willebroek, Brownfieldlaan 39
Willebroek, Brownfieldlaan 15
Waregem, Roterijstraat 141, 205
Sint-Katelijne-Waver, Fortsesteenweg 19 BE 27 13
Saint-Martin-sur-le-Pré, rue Charles Marie Ravel 25
Saint-Martin-sur-le-Pré, rue Charles Marie Ravel 25
Longvic, Parc d'activité de Beauregard
Rombas, rue Poincaré 24
Rombas, rue Poincaré FR 314 157
Montataire, rue Dheisheh-rue Finsterwalde
Verson, rue du Sault de la Mare 245
Evreux, rue Jean Monnet 676
(x 1,000)
Avenue du coeur de l'ouest 29
Bollène 1, ZAC Pan Europarc 1 – 1780
Route de Lapalud
Bollène 2, ZAC Pan Europarc 2 – 1786
Route de Lapalud
Bollène 3, ZAC Pan Europarc 3 – 1790
Route de Lapalud
Mercatorstraße 1 – 1a
(Expo Market Doraly)
– Constanta – Targu Mures
In 2024, it was also decided to sell some non-strategic sites at Leuven (BE), Beersel (BE), Voorhout (NL) and Sibiu (RO). These sites generated rents in an amount of 217,927 euros in 2024.
The estimation of a site consists of determining its value on a specific date, in other words, the price at which the site would likely be tradable between well-informed buyers and sellers, in the absence of information asymmetries, who wish to perform a similar transaction, without taking account of any particular agreement between them. This value is the investment value when it corresponds to the total price payable by the buyer, plus any transaction costs or VAT, if the purchase is subject to VAT. The fair value, in the sense of the IAS/IFRS reference scheme, can be obtained by deducting an adjusted minimum charge for transaction costs and/or the VAT from the investment value. To calculate the changes in the fair value, the hypothetical local transaction costs are deducted from the investment value. On average, these breakdown as follows by country: Belgium: 2.5%, The Netherlands: 10.4%, France: 3.7%, Germany: 7.8%, Luxembourg: 7% and Romania: 1.5%.
Non-observable inputs in the determination of fair value¹
3
3
3
1 For other non-observable inputs not shown in the above table, please refer to section 5. Financial results and output and
4. Performance and trends
2 For the ERV, only the rents for the available warehouse spaces are taken into account. The wide range (min./max.) is due to the different kinds of storage premises (from outdoor
The sensitivity of the fair value with regard to changes in significant non-observable inputs used in determining the fair value of objects classified as level 3 according to the IFRS fair-value hierarchy, is as follows (ceteris paribus):
Non-observable inputs
Impact on fair value at: Decrease Increase
ERV (in euros/m²) negative positive
Discount rate positive negative
Required yield positive negative
Remaining lease duration (until first break) negative positive
Remaining lease duration (until expiry date) negative positive
Occupation rate (EPRA) negative positive
Projected growth in rent (inflation) negative positive
In addition, it is usually the case that an increase (decrease) in the remaining period of a rental agreement leads to an increase (decrease) in the discount rate (and required yield). An increase (decrease) in the occupancy rate may result in a decrease (increase) in the discount rate (and required yield).
In addition, the sensitivity of the fair value of the portfolio can be estimated as follows (based on a ceteris paribus approach): the effect of an increase (decrease) of 5% of rental income leads to an increase (decrease) in the fair value of the portfolio of approximately 371 million euros (ceteris paribus) with an impact on the decrease (increase) in the gearing ratio of 1.7% and 1.9%.
The effect of an increase (decrease) in the required return of 50 basis points, gives rise to a decrease (increase) in the fair value of the portfolio (and also equity) of -579 million euros and 686 million euros respectively with an impact on the gearing ratio of around 3.1%
The above sensitivity is a reasonable estimate taking into account all parameters known to date.
The valuation process at WDP follows a centralised approach where the policy and procedures with regard to property estimates are determined by the CEO and CFO, after approval by the audit committee. In addition, it is determined which independent property expert will be appointed for the various parts of the property portfolio. Contracts will typically be signed for a renewable term of three years subject to a double rotation obligation according to the Law of 12 May 2014 in the scope of a GVV/SIR. Some examples of the selection criteria would be local market knowledge, reputation, independence and insurance of the highest professional standards. Property expert fees are set for the period of their appointment and are not related to the value of the objects appraised.
Independent property experts are appointed for each country, to ensure proper consideration for the special characteristics of each geographical region and thus also the diversified, pan-European nature of the property portfolio. The property portfolio is valued externally by independent property experts on a quarterly basis. The valuation method is determined by the external expert and is based on a multi-criteria approach. The independent property expert determines the fair market value based on a discounted cash flow model, an income capitalisation method and/or comparable market transactions. In addition, estimates determined in this way are compared to the initial yield and available points of comparison via recent market transactions for comparable objects (including those purchased by WDP itself during that year). The valuation cycle reported covers one financial year. This involves a site visit after which a detailed estimate report is drawn up for each object as well as three desktop reviews in which new information provided by WDP on the lease situation, including any vacancy (with the valuation typically assuming 3 to 12 months of vacancy depending on the market situation and the specificity of the building and the region), and where the most important assumptions about significant non-observable inputs are recognised.
Lang LaSalle
BNP Paribas Real Estate
1 Including the proportionate share of the portfolio in I Love Hungaria NV, Gosselin-WDP NV and WDPort of Ghent Big
The independent property expert has full access to all quantitative and qualitative information with regard to the property portfolio. The Controllers are responsible for continuous contact with and provision of information to the relevant property experts (such as all leases, information on occupancy rate, maturity dates, investments, age of buildings and maintenance and repair costs). Twice a year, the CEO and Country Manager also discuss the asset management plan (such as capital investments and redevelopments) for each object in detail with the property expert. When estimate reports are handed in quarterly, all material differences (positive and negative) are compared in absolute and relative terms with the previous four quarters and analysed by the Controllers and the CFO. Based on this, the CEO and CFO then conduct a detailed discussion with the respective property experts to ensure that all data with regard to the sites are reflected accurately and exhaustively in the estimate, with specific attention to property development projects. The property experts draw up an independent estimate of the future cash flow profile and reflect the risks via a combination of cash flow projections (rental growth, vacancy, incentives, investments, etc.) as well as the applied required yields or discount rates. Next, the final property estimates are submitted to the Audit Committee.
Changes during the financial year
euros (x 1.000)
1 Investments in energy mainly consist of investments in solar energy. Therefore, only these are discussed in the notes to these annual accounts.
2 Other means: Plants, Machinery and equipment, Furniture and rolling stock and Other tangible fixed assets.
1 The revenues consist of the sale of green energy certificates and of green energy to the tenant and/or energy supplier, minus costs associated.
method – Solar panels
Implicit number of sunshine hours
The model assumes an implicit 950 sunshine hours per year. This is based on weather statistics and the available data at the end of the year. On December 31, 2024, the installed capacity was 43 MWp.
The model assumes an implicit 900 sunshine hours per year. This is based on weather statistics and the available data at the end of the year.
On December 31, 2024, the installed capacity was 77 MWp.
The model assumes an implicit 900 sunshine hours per year. This is based on weather statistics and the available data at the end of the year.
On December 31, 2024, the installed capacity was 7 MWp.
The model assumes an implicit 1,250 sunshine hours per year. This is based on weather statistics and the available data at the end of the year.
On December 31, 2024, the installed capacity was 27 MWp.
Green Energy Certificates (GECs)
Energy price
Discount rate
Decrease in yield
Belgium
Green Energy Certificates (GECs) in Flanders are issued to each project by the Flemish Electricity and Gas Market Regulator (the ‘VREG’) at a fixed price per certificate for a fixed period of twenty years. The price of certificates for operational sites vary between 0-450 euros per MWh.
Green energy certificates in Wallonia are issued to each project by the Wallonia Energy Commission (the 'CWaPE') at a guaranteed price per certificate for a fixed period of ten years. The price of certificates for operational sites is at least 65 euros per certificate.
For the energy-price, long-term expectations based on research models are used and an inflation rate of 1.5% per annum.
The required yield is calculated as the weighted average cost of the capital according to long-term interest, market risk premium and country-specific risk.
The yield of the PV installation has decreased by 0.6% per year and will be decommissioned after thirty years. No account was taken here of any possible residual value of the installation, nor of the costs of dismantling the installation.
Maintenance and CapEx Account is taken of the various operational costs related to exploitation as well as a ten-year maintenance cost in order to keep the expected evolution of the operational condition intact.
The Netherlands Luxembourg Romania
Each project receives a subsidy from the Netherlands Enterprise Agency (the ‘RVO’) for a period of fifteen years. The maximum subsidy amount allocated per MWh produced depends on the time of request and is set so the maximum yield including subsidy is 63 to 148 euros per MWh.
Each project receives a subsidy from Creos for a period of fifteen years. The subsidy amount granted per Mwh depends on the monthly market price. The subsidy provides a minimum income of 105 euro per MWh.
Since 2022, green energy certificates (GEC) will no longer be awarded by the ANRE (Romanian Energy Regulatory Authority) for new projects in Romania. The operational installations of 27 MWp at the end of 2024 will receive 6 GEC per MWh of green energy produced for a fixed period of fifteen years, of which ten years have already passed. These certificates can then be sold on the regulated market at a price of 29 euros per certificate. Given the very limited liquidity on the market, WDP today assumes that these GECs can no longer be sold for the remaining term of five years.
For the energy-price, long-term expectations based on research models are used and an inflation rate of 1.5% per annum.
The required yield is calculated as the weighted average cost of the capital according to long-term interest, market risk premium and country-specific risk.
The yield of the PV installation has decreased by 0.6% per year and will be decommissioned after thirty years. No account was taken here of any possible residual value of the installation, nor of the costs of dismantling the installation.
Account is taken of the various operational costs related to exploitation as well as a ten-year maintenance cost in order to keep the expected evolution of the operational condition intact.
For the energy-price, long-term expectations based on research models are used and an inflation rate of 1.5% per annum.
The required yield is calculated as the weighted average cost of the capital according to long-term interest, market risk premium and country-specific risk.
The yield of the PV installation has decreased by 0.6% per year and will be decommissioned after thirty years. No account was taken here of any possible residual value of the installation, nor of the costs of dismantling the installation.
Account is taken of the various operational costs related to exploitation as well as a ten-year maintenance cost in order to keep the expected evolution of the operational condition intact.
For the energy-price, long-term expectations based on research models are used and an inflation rate of 1.5% per annum.
The required yield is calculated as the weighted average cost of the capital according to long-term interest, market risk premium and country-specific risk.
The yield of the PV installation has decreased by 0.6% per year and will be decommissioned after thirty years. No account was taken here of any possible residual value of the installation, nor of the costs of dismantling the installation.
Account is taken of the various operational costs related to exploitation as well as a ten-year maintenance cost in order to keep the expected evolution of the operational condition intact.
The sensitivity of the fair value with regard to changes in significant non-observable inputs used in determining the fair value of objects classified as level 3 according to the IFRS fair-value hierarchy, is as follows (ceteris paribus):
Impact on fair value at:
Non-observable inputs
Implicit number of sunshine hours
Green Energy Certificates (GECs)
Energy price
Discount rate
Efficiency of solar panels
Maintenance and capex
decrease increase
negative positive
negative positive
negative positive
positive negative
negative positive
positive negative
In addition, the sensitivity of the fair value of the solar panels can be estimated as follows (based on a ceteris paribus approach): the effect of an increase (decrease) of the required yield of 25 base points leads to a decrease (increase) in the fair value of the solar panels of approximately 3 million euros.
There is no standardised valuation model for investments in solar panels. The fair value of these assets is calculated by WDP according to a discounted cash flow model based on future cash flows.
The valuation cycle within a financial year consists of a fully detailed estimate update per year end of all assumptions and the expected cash flows as well as three desktop reviews in which a roll forward of the model is performed and the most important assumptions with regard to significant non-observable inputs are recognised.
The data and input with regard to the expected future cash flows are continuously verified with the available statistics over the totality of the PV systems, whereas a consistent, comparable analysis is made of the financial return requirements of investors. The Audit Committee validates the definitive fair value calculations on a quarterly basis.
and deferrals on the
The entirety of the financial instruments of the Group corresponds to levels 1, 2 and 3 in the hierarchy of the fair values. Valuation against fair value occurs regularly.
In the event of bankruptcy of one of both contracting parties, the net position of the derivatives will be considered for the counterparty.
Level 1 in the hierarchy of fair values excludes money investments, funds and cash equivalents regarding which the fair value is based on the share price.
Level 2 in the hierarchy of fair values concerns the other financial assets and liabilities of which the fair value is based on observable inputs and other data that can be determined, directly or indirectly, for the assets or liabilities concerned. The valuation techniques concerning the fair value of the financial instruments at level 2 are as follows: the fair value of the financial assets and liabilities above are valued at the book value, except for bond loans and fixed-rate loans, where fair value is determined under a discounted cash flow model based on quarter-end market interest rates since they are not traded frequently. Because the other financial debt is incurred at a floating interest rate, the fair value is very close to the book value.
Level 3 in the fair value hierarchy retains the property portfolio and financial liabilities recognised in accordance with IFRS 16 whose fair value is determined using nonobservable inputs.
For some of its investments, WDP does not have full ownership, but rather only usufruct through a concession, ground lease, or similar arrangement. Specifically, a financial liability is recognised for this in accordance with IFRS 16. This financial liability is included under Other non-current financial liabilities and Other current financial liabilities. The financial liability is the present value of all future lease payments. The discount rate applied in determining this liability was based on a combination of the interest curve plus a spread according to the WDP credit risk, both in line with the remaining duration of the underlying right of use.
The sensitivity of the calculation of this financial liability can be estimated as follows (based on a ceteris paribus approach): the effect of an increase respectively a decrease in the discount rate of 50 basis points would give rise to a decrease (increase) in the financial liability of 4.5 million euros, respectively 5.2 million euros, with an impact of approximately 0.06% on the gearing ratio (in accordance with the GVV/SIR Royal Decree).
Liquidity requirement on maturity dates associated with non-current loans (contractual cash flows and non-updated interest)
in euros (x 1,000)
Between one and two years 662,491 329,151
Between two and five years 1,259,469 828,813
More than five years 1,706,609 1,701,025
Financial instruments at fair value (as per IFRS 9)
The Group uses derivative financial instruments to hedge the interest rate risk on its financial debt to reduce the volatility of EPRA Earnings (which forms the basis for the dividend) while minimising the cost of debt. Given the high hedge ratio as of year end 2024, both the interest rate risk and the volatility of the EPRA Earnings are limited. These hedges are managed centrally through a macro-hedging policy. The Group does not use derivative financial instruments for speculative purposes and does not hold derivatives for trading purposes.
The hedge ratio, which measures the percentage of financial debt at a fixed or floating interest rate and then hedged via Interest Rate Swaps (IRSes) is 89% with a weighted average hedging term of 4.8 years.
Changes in the fair value of derivatives that do not qualify as hedges are recognised immediately in earnings or loss. Changes in the fair value of derivatives allocated specifically to hedge the variability of cash flows of a recognised asset or liability or a forecast transaction are recognised in the section Other components in the overall result
5
4
In January 2022, the Group entered into two pre-hedges (interest rate swaps) for a total nominal amount of 500 million euros each, which enable the Group to convert the variable interest rate for its expected future debt issues into a fixed interest rate. The pre-hedges were settled on the issuance of the debt (the placement of 500 million euros of green bonds through US private placement4 and the syndicated loan of 440 million euros5). Their fair value was settled in cash at that time.
The Group has determined that these financial instruments meet the conditions for hedge accounting. These instruments were initially recognised at fair value on the date in which the derivatives hedging interest rate risk were entered into, and subsequently valued at their fair values on subsequent closing dates. The pre-hedges were viewed as hedging instruments in a cash flow hedging relationship of a highly probable expected future transaction (debt issuance), changes in the fair value of the pre-hedges were included in the section Other components in the overall result for the period until the pre-hedges were settled. This positive value will be distributed over the profit and loss over the life of the loans issued. These hedges are considered fully effective given that the terms of these pre-hedges are consistent with the characteristics of the debt issued and the prehedges were settled on or around the date of issuance of the debt.
The contracts are valued at fair value as per IFRS 9 on the balance sheet date. This information is received from the various financial institutions and verified by WDP by discounting the future contractual cash flows based on the corresponding interest rate curves.
Fair value is based on observable inputs, and as such, the IRS contracts fall under level 2 in the fair value hierarchy as defined in IFRS. The fair value is calculated based on a discounted cash flow model using the relevant market interest rates indicated in the forward interest curve on the balance sheet date. No changes in the fair value hierarchy level took place in the past year. During this period, no hedging instruments were arranged prior to the maturity date. A number of existing hedging instruments were extended by flattening them over time in a cash-neutral manner.
according to IFRS
The changes in fair value and the valuation of the hedging instruments at fair value on the balance sheet date are as follows:
Besides the above, -21 million euros was also included via Other components in the overall result for pre-hedging instruments.
The table below gives an overview of the impact of the fair value of the IRS if the interest rate rises or falls by maximally 2.00%. Change in the interest rate Impact on the change in fair value of the IRSes as at
For the impact of interest rate changes on EPRA Earnings, please refer to 5. Financial results and outlook.
Liquidity requirement on the maturity dates linked to the derivatives in euros
For a detailed overview of financial and other risks, their limiting factors and control, see Chapter 7. Risk factors. For a discussion of the management of financial risks (including credit risk, liquidity risk, interest risk, counterparty risk), see Chapter
5. Financial results and outlook. Please also refer to the sensitivity analysis in Chapter
5. Financial results and outlook and explanatory note XX. Statement of financial debt
receivables
Trade receivables are payable prior to the regular lease period. The table below shows the past due trade receivables.
debt – mutation table
1 This concerns the historical amount of outstanding trade receivables and not the provision for doubtful debts that was established in the 2024 and 2023 financial years.
The provision for doubtful debt is 3.6 million euros and has decreased compared to last year. An additional provision of 0.393 million euros was made in 2024 compared to 0.968 million euros in 2023. This amount represents 0.1% and 0.3% respectively of the rental income.
A clear procedure is followed to determine provisions to be created for doubtful debt with quarterly estimates of the expected losses on outstanding trade receivables and with the application of corresponding write-downs. Under this method, the book value of the trade receivables approaches their fair value. With regard to the policy on accounts receivable, WDP ensures a regular screening of the creditworthiness of its tenant portfolio. In addition, outstanding client balances are reported internally to all sales and technical employees every month. They can ensure adequate follow-up on rent in arrears by means of their direct contact with the client.
More generally, credit risks are limited by the fact that WDP guarantees an adequate distribution among its tenants. Besides the legal standard of 20%, an in-house goal has been set that no more than 10% of the rental income may come from one client (currently 3%). For the main tenants, see 5. Financial results and outlook. Moreover, credit risks are limited to a maximum risk of 5% per site (currently 2%).
Associated companies and jont ventures that became a wholly owned subsidiary during the financial year
Share in the result of associated companies and joint
1 The share in the result of associated companies and joint ventures mainly comes from Catena (12.7 million euros), WDP Luxembourg (2.5 million euros) and WDPort of Ghent Big Box (1.7 million euros). In addition, 2.5 million euros comes from the other associated company and the joint ventures.
Participation in associated companies and joint ventures is 358 million euros of which approximately 286 million euros consists of the participation in Catena AB. More information on our associate company’s financial information can be found at https:// www.catena.se
Tax receivables in 2024 are mainly related to the recovery of French VAT for purchases during the fourth quarter.
Other current assets are mainly related to short-term receivables from joint ventures.
2018
1
1 Calculated on the weighted average number of shares.
WDP has only one class of shares, namely ordinary shares (without face value). Holders are entitled to receive the declared dividend and have one vote per share at the Annual General Meeting of Shareholders.
All shares are fully paid up and are either registered or dematerialised.
The Board of Directors is authorised, within the limits of the mandatory provisions of the applicable company law, to increase the capital in accordance with the authorisation granted to it regarding authorised capital. On 31 December 2024, the Board of Directors
used the authorisation granted to it on 24 April 2024 for the capital increase via a distribution in kind by Balta Industries (Waregem). For more information on authorised capital authorisation, see chapter 10 Appendices
For the shareholder structure as of the balance sheet date and the proposed dividend payment, see Chapter 5. Financial results and outlook.
The purchase of the shares of the subsidiaries Doraly Expo Market SRL, Black Sea Vision SRL, Targu Mures Logistics Hub SRL and Global Logistics Chitila SRL included 131 million euros in debt in addition to the property. This explains the difference with the sum of loan acquisitions and repayments in the cash flow statement.
For further background information on the financial debt, please refer to Chapter 5. Financial results and outlook
For further information on the applicable financial covenants, see Note XXIV. Rights and obligations not included on the balance sheet. For a complete overview of sensitivity, please refer to the relevant table in Chapter 5. Financial results and outlook
For the calculation of the gearing ratio according to the GVV/SIR legislation, please refer to 10 Appendices
For some of its investments, WDP does not have full ownership, but rather only usufruct through a concession, ground lease, or similar arrangement. The financial liability is the present value of all future lease payments. The table below shows the maturity dates for this liability.
1 FTE stands for Full-Time Equivalents.
For its permanent personnel, WDP has taken out a group insurance contract with a defined contribution plan with an external insurance company. The Company makes contributions to this fund, which is independent of the Company. The company funds the insurance plan contributions. The group insurance contract applies the Vandenbroucke Law on pensions. The insurance company confirmed on 31 December 2024 that the shortfall for guaranteeing the statutory minimum yield is not substantial.
The fees in 2024 of the non-executive directors (316,250 euros6 compared to 275,000 euros last year), the remuneration of Tony De Pauw (974,590 euros compared to 1,114,917 euros last year), the remuneration of Joost Uwents (1,894,001 euros compared to 2,220,916 euros last year) and the remuneration of the members of the Management Committee (3,255,877 euros excluding the remuneration of the two CEOs compared to 3,670,146 euros last year) are explained in the remuneration report in Chapter 6. Corporate Governance Statement
InMarch and August 2024, WDP subscribed to a capital increase of Catena AB using an accelerated exempted private placement. To continue to maintain the 10% stake, 469,763 shares and 548,728 shares for 211 million SEK and 306 million SEK were granted to WDP.
In 2024, transactions also occurred between WDP and its joint ventures I Love Hungaria NV/SA, WDPort of Ghent Big Box NV, Gosselin-WDP NV/SA, nanoGrid BV, WDP Luxembourg SA and its associated company Catena AB. The table below provides an overview of the WDP outstanding receivables for the joint ventures. This primarily involves the long-term receivables, short-term receivables, charged management fee, and financial income booked in WDP and received from I Love Hungaria NV/SA, WDPort of Ghent Big Box NV, Gosselin-WDP NV/SA, nanoGrid BV and WDP Luxembourg SA. The transactions were effected on market terms.
WDP NV/SA and its subsidiaries had bank guarantees in place for a total of 4,665,009 euros as of 31 December 2024, the beneficiaries of which fall under the following categories for the following amounts:
WDP has undertaken several commitments as a part of its ongoing investment programme related to projects and acquisitions, as stated in 4. Performance and trends
Parent company WDP NV/SA has extended the following sureties for its various subsidiaries:
1 A security for the commitments of WDP Nederland S.A. amounting to 25 million euros for ABN AMRO (for the short-term amounts financed through a straight loan of max. 25 million euros, 0.1 million euros of which has been drawn).
1 A security for the commitments of WDP Luxembourg SA amounting to 28.7 million euros in favour of Banque et Caisse d’Epargne de l’Etat.
1 A guarantee as security for the commitments of Gosselin-WDP NV/SA for 10 million euros in favour of KBC Bank NV.
The WDP financing agreements include the following covenants:
1 An Interest Coverage Ratio7 of at least 1.5x. This is 6.9x for 2024.
1 A statutory and consolidated gearing ratio below 65% in line with the GVV/SIR Law. As of 31 December 2024 these are 40.1% and 40.5% respectively.
1 Limitation on projects that have still not been pre-let (development property ratio) to 15% of the book value of the portfolio (excluding land reserves). As of 31 December 2024, this ratio is 0.7%.
1 A maximum of 30% of the financial debt with the subsidiaries compared to the financial debt of the group. As of 31 December 2024, this subsidiary financial debt ratio is 1.7%.
WDP has entered into the following commitments with financiers8:
1 Commitment not to burden the assets with collateral, such as mortgages (negative pledge). WDP confirms that as of 31 December 2024, no mortgages or other collateral are outstanding in the property portfolio or other assets.
1 A commitment that it will continue to qualify as a GVV/SIR. For the conditions on this, please see the Belgian Act of 12 May 2014 and the Royal Decree of 13 July 2014. For more information, see 10. Appendices
1 For some financiers, WDP has agreed to repay the credit if a change of control occurs and the financier consequently asks for repayment.
As of 31 December 2024, WDP complies with all covenants with and commitments to all financiers.
XXV. Financial relations with third parties
Statutory auditor
The statutory auditor(s) and the people with whom they are associated
Pursuant to Article 3:64, §1-5 CCA: without prejudice to the prohibitions arising from Article 3:63 CCA, the statutory auditor may not perform any services other than the assignments entrusted by law or European Union legislation to the statutory auditor, insofar as the total amount of the fees for these services amounts to more than seventy percent of the total amount of the fees referred to in article 3:65, § 2 of the CCA. The 70% rule must be calculated as an average over the duration of the current mandate. The fees for services invoiced by Deloitte Bedrijfsrevisoren BV are considered with regard to this calculation, with the exception of fees for legal assignments entrusted to the statutory auditor of the company. WDP NV has not exceeded the 70% rule as of 31 December 2024.
8
or special assignments that persons associated with the statutory auditor(s) perform within the Company
The management of these climate-related risks is an integral part of the WDP Group’s risk management approach, see Chapter 7. Risk factors. So, WDP launched its ambitious climate plan in January 2022, the WDP Climate Action Plan. The WDP Climate Action Plan is a clear and transparent framework addressing both climate risks and business opportunities (see 4. Performance and trends). In the meantime, WDP has continued to prepare for the implementation of CSRD and thus include Chapter 8. Sustainability statement included in this annual report. This section also currently separately covers the recommendations of the Task Force on Climate-related Financial Disclosures (TCFD). These will be integrated into the Sustainability Statement in the future.
Across the world, we see a tightening of climate policy and regulations to shift the economy away from fossil fuels towards a low-carbon economy. The consequential requirements through tightening of climate policies can result in restrictions on the letting or the sale of buildings that do not comply with minimum standards. The same goes for technologically obsolete buildings which may require higher maintenance costs or CAPEX requirements to meet minimum efficiency standards and modern work trends. This could potentially impact how the market views such risks and how this is reflected in property sales and rentals. The independent property experts include sustainability factors and climate regulations as factors in determining the input parameters of property valuations.
1 WDP buys out partner in Romania to stay on as Country Manager WDP Romania
After establishing and successfully building WDP Romania for more than 15 years, WDP and its partner in Romania decided in early 2025 to transfer its 15% equity stake in this company to WDP. He retains his position as country manager of Romania and will continue to help expand growth in this country. This transaction reflects another step in the internationalisation of WDP Group where WDP’s operations in Romania are experiencing very strong growth in recent years9
1 Contribution in kind
On 19 February 2025, WDP NV/SA acquired the company Pielon BV through a contribution in kind of shares. This resulted in the issuance of 311,295 new shares. The new shares were issued pursuant to a capital increase, following a decision of WDP’s Board of Directors utilising the authorised capital.
9 WDP Invest NV/SA, subsidiary of WDP NV/SA, has therefore concluded with J.B. Top Pro Invest Srl and Vuurkruisenbizz BV to buy WDP Romania shares, such that WDP Romania is a 100% subsidiary of WDP Invest NV/ SA since the end of January. Per GVV/SIR legislation, J.B. Top Pro Invest Srl and Vuurkruisenbizz BV are considered related parties to WDP Invest NV/SA, specifically in their capacity as co-shareholder of WDP Invest NV/SA in WDP Romania. In that context, it is hereby clarified that the acquisition of a minority was completed under normal market terms and at the NAV of the WDP Romania shares as of 31 December 2024 (totalling 91.6 million euros) against payment in cash.
The statutory auditor has issued an unqualified opinion on the statutory annual accounts of WDP NV/SA. These are drawn up in accordance with IFRS as adopted within the
Earnings statement
European Union and as per the Belgian Royal Decree of 7 December 2010. The statutory financial statements had not yet been submitted at the time of publication of this annual report.
V.
hedging instruments that are not subject to hedging accounting as defined in IFRS
Share in the profit or loss and in the unrealised results of subsidiaries, associated shareholding, joint ventures that are administratively processed according to the 'equity'-method
Share in the profit or loss and in het unrealised results of subsidiaries, associated shareholding, joint ventures that are administratively processed according to
Reserve for the balance of changes in fair value of authorised hedging instruments subject to hedge accounting as defined by IFRS (+/-)
Share in the profit or loss and in het unrealised results of subsidiaries, associated shareholding, joint
1 Calculated on the weighted average number of shares.
J.
sheet – Liabilities
Statutory appropriation of results
1. Addition to/withdrawal from the reserve for the (positive or negative) balance of the variations in the fair value of investment properties1
2. Addition to the reserve for the balance of variations in the fair value of permitted hedging instruments that are not subject to hedging accounting as defined in IFRS
3. Withdrawal from the reserve for the balance of variations in the fair value of permitted hedging instruments that are subject to hedging accounting as defined in
4. Addition to the reserve for the balance of variations in the fair value of permitted hedging instruments that are not subject to hedging accounting as defined in IFRS
5. Withdrawal from the reserve for the balance of variations in the fair value of permitted hedging instruments that are not subject to hedging accounting as defined in IFRS
6.
8. Addition
10. Addition to/withdrawal from results carried forward from
1 This item consists out of the result on the portfolio of the 100%-affiliates. Deferred taxes on investment properties are not taken into account.
2 This item mainly includes the result on the portfolio of the participating interests of which WDP holds less than 100%.
WDP applies the look-through approach in its statutory financial statements. This means that as far as 100% subsidiaries are concerned, EPRA Earnings (being the underlying cash earnings of the core activity) are considered to be available and distributable at the level of the parent company, regardless of whether these earnings have flowed up to the parent company as dividends. In this context, the share in the results of these 100% subsidiaries is not fully allocated to the unavailable reserves. Instead, the different
elements that make up these results are considered separately. The share in the result of these 100% participations is allocated to the unavailable and available reserve items as if it were the results of the parent company-GVV/SIR itself (there is, as it were, a consolidation approach in the separate annual accounts at the level of the result processing). The results of non-100% subsidiaries are fully allocated to the unavailable reserves.
obligation in accordance with the GVV/SIR Royal Decree of 13 July 2014
The mandatory distribution in the GVV/SIR legislation only relates to the adjusted net result as shown in the separate annual accounts for the GVV/SIR (drawn up in accordance with the IFRS). The FSMA circular of 2 July 2020 recommends that the look-through approach, when applied, should also be taken into account in determining the mandatory distribution amount. WDP has applied this in the above table for its 100% subsidiaries, which means, in concrete terms, that the EPRA Earnings of these subsidiaries have been included in the calculation of the mandatory distribution amount (also taking into account the company-law rules applicable to the subsidiary concerned; in other words: the parent GVV/SIR is not obliged to distribute any results that cannot be distributed by the subsidiary due mainly to differences between the IFRS and local accounting rules).
gains realised during the financial year that are exempt from the mandatory distrubution provided they are reinvested within a period of four years (-)
Capital gains on property previously exempt from mandatory distribution that is not reinvested within a period of four years (+)
Net capital gains on completion of properties not exempt from mandatory distribution (B)
Non-distributable shareholders’ equity as per Article 7:212 of the Belgian Code of Companies and Associations
capital or, if it is higher, called-up
Reserve for the positive balance of the variations in the fair value of properties2
Reserve for the balance of changes in fair value of authorised hedging instruments subject to hedge accounting as defined by
Reserves for the balance of variations in the fair value of permitted hedging instruments that are not subject to hedging accounting as defined in IFRS (+/-)
Reserve for the translation differences resulting from the conversion of a foreign activity (+/-)
Reserve for the share in the profit or loss and in the unrealised results of non-100% shareholdings that administratively processed according to the 'equity'-method
Other reserves declared unavailable by the General Meeting3
1 The issue premiums issued in 2024 and 2023 were not included here as these are booked on an available account.
2 It relates to the reserve for the positive balance of the variation in the fair value of properties from the mother company and the 100% subsidiaries.
3 Based mainly on the revaluation reserves for the solar panels and the related deferred tax (including variations in the fair value of subsidiaries with regard to solar panels and the related deferred tax) and the impact of IFRS 16 on shareholders’ equity (including variations in the fair value of subsidiaries with regard to IFRS 16), given that these are a non-distributable reserves. This pertains to a non-cash item.
WDP applies the look-through approach in its statutory financial statements. This means that as far as 100% subsidiaries are concerned, EPRA Earnings (being the underlying cash earnings of the core activity) are considered to be available and distributable at the level of the parent company, regardless of whether these earnings have flowed up to the parent company as dividends.
After all, the subsidiaries of the WDP parent company generally draw up their separate financial statements in line with local accounting standards, which often deviate from the IFRS rules applicable to the consolidated (and separate) financial statements of the parent company as a GVV/SIR. As a result, the net result of the subsidiary in its separate annual accounts (on which its distribution of dividends is based) often differs from the contribution of that subsidiary to the consolidated net result. In addition, restrictions apply under local legislation, meaning the full cash earnings of the subsidiaries cannot flow up as dividends, with the latter also effectively being distributed with a one-year delay. Based on the look-through approach, these earnings are considered to be distributable at the level of the parent company, even though they have not yet effectively been realised at the parent company from a statutory perspective.
Given the international character of the WDP group, the company considers it important to be able to apply the look-through approach in the context of its dividend policy. In that context, WDP pays out more as dividends on a consolidated level than what it generates on a statutory level as cash earnings (but realises on a consolidated group level, whereby it has a low pay-out ratio on a consolidated level), by using the look-through approach to view the cash earnings (including distributed profits) of the 100% subsidiaries as distributable at the group level. WDP believes that this does not constitute a problem neither for the parent company nor for the subsidiaries, since they are fundamentally sound and this cash has been effectively realised in the subsidiaries and is also fully available in the parent company (among other things, by accrual through interest, dividends, repayment of loans, etc.).
in euro (x 1.000)
Reserves for the balance of variations in the fair value of the
Reserve for the share in the profit or loss and in the unrealised results of non100% shareholdings that are administratively processed according to the
Reserves for the balance of variations in the fair value of permitted hedging instruments that are not subject to hedging accounting as defined in IFRS (+/-)
Reserve for the balance of changes in fair value of authorised hedging instrumen-ts subject to hedge accounting as defined by IFRS (+/-)
Result carried forward from previous financial years
D.
1 This concerns the changes in fair value of the real estate of WDP NV/SA and the real estate of the participations held for 100%.
2 Including the deferred tax on variations in the fair value of the solar panels.
Statement of shareholders’ equity prior to payment of dividends but after allocation of results
euro (x 1.000)
1 This concerns the changes in fair
of the real estate of WDP NV/SA and the real estate of the participations
in euro (x 1.000)
Reserves for the balance of variations in the fair value of the properties (+/-)
Reserve for the share in the profit or loss and in the unrealised results of non100% shareholdings that are administratively processed according to the 'equity'
Reserves for the balance of variations in the fair value of permitted hedging instruments that are not subject to hedging accounting as defined in
Reserves for the balance of variations in the fair value of permitted hedging instruments that are subject to hedging accounting as defined in IFRS (+/-)
Result carried forward from previous financial years
1 This concerns the changes in fair value of the real estate of WDP NV/SA and the real estate of the participations held for 100%.
2 Including the deferred tax on variations in the fair value of the solar panels.
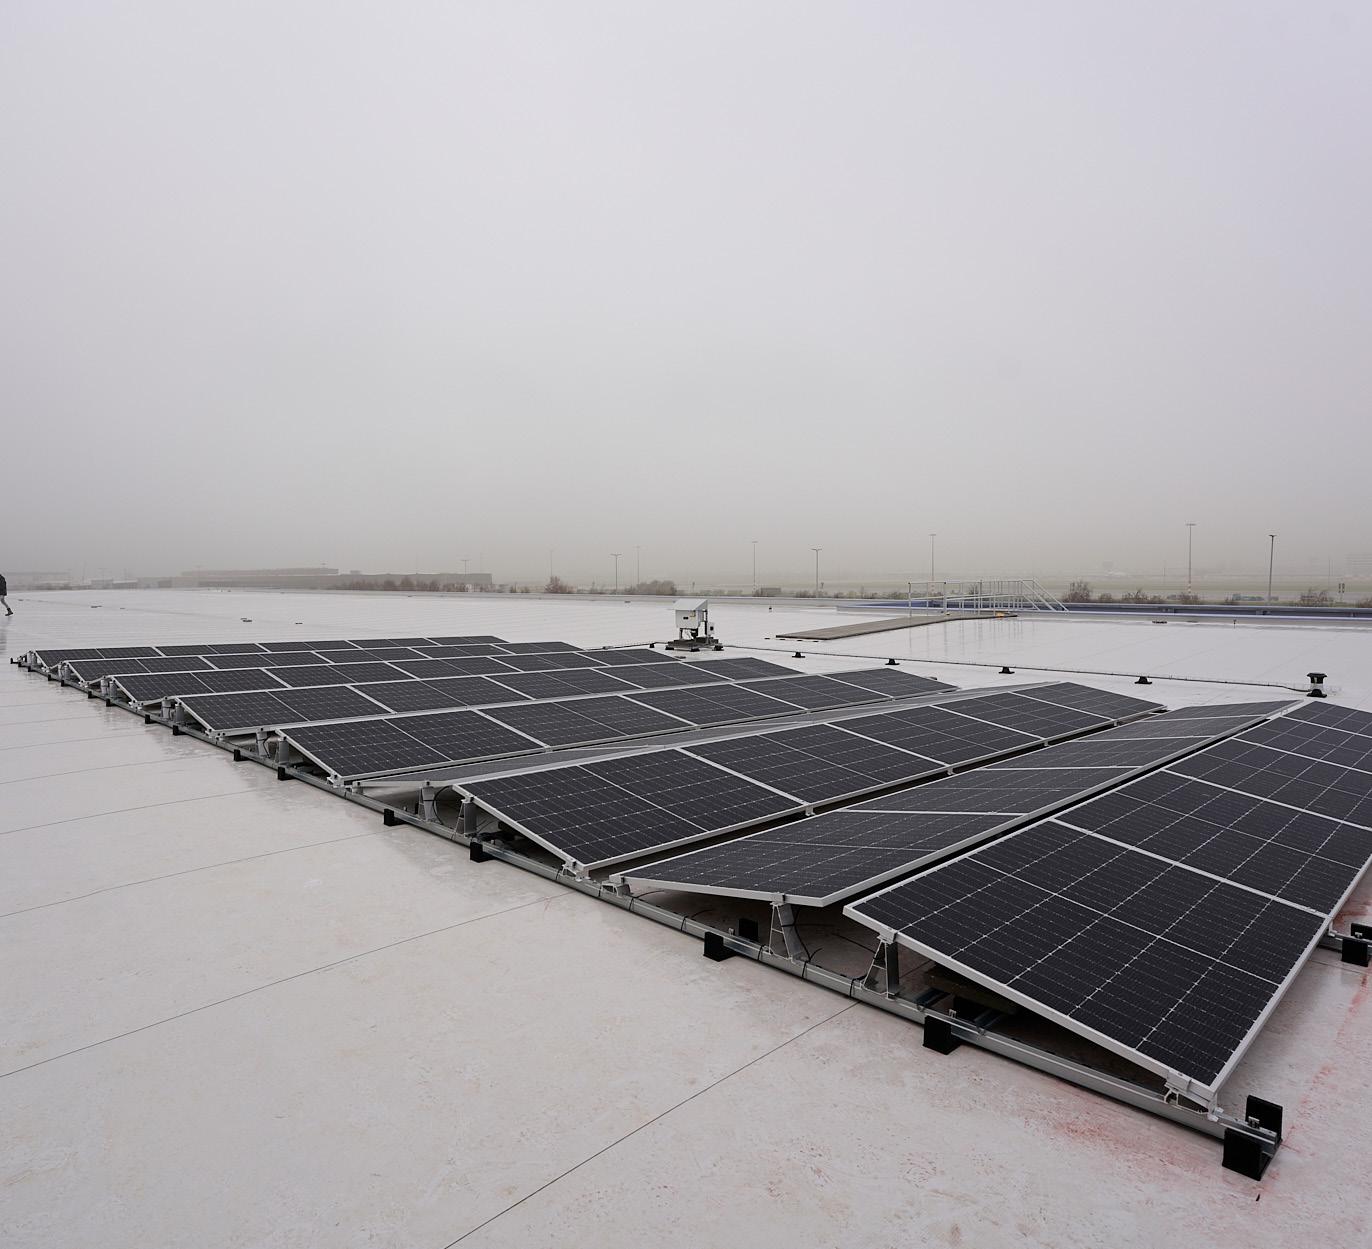
WDP NV appointed eight independent property experts (as defined in art. 26 of the GVV/SIR Law to determine the fair value of various properties within its property portfolio Estimates were made taking into account the assumptions, observations and definitions mentioned in the reports, and the guidelines of the International Valuation Standards issued by the IVSC.
The fair value is defined by the International Accounting Standards Board (IASB) in IFRS 13 as the price that would be received to sell an asset or paid to transfer a liability in an orderly transaction between market participants at the measurement date. IVSC deems these conditions to be met if the above-mentioned definition of fair value is respected. The fair value must reflect the current lease contracts, the reasonable assumptions relating to potential rental income and the expected costs.
Each independent property expert confirms that, for the properties allocated to him or her, he or she possesses relevant and recognized credentials as well as up-to-date experience with properties of a type and location similar to those of the properties in WDP's property portfolio.
In giving an estimate of the properties, the property experts took into account both the current rental agreements and all rights and obligations arising from these agreements. Each property was valuated separately, using comparable recent market transactions on arm’s length terms. The estimates do not account for any potential capital gain or loss that might be realized by offering the portfolio on the market in its entirety. The estimates also do not account for marketing costs specific to a transaction, such as estate agents' fees or publicity costs. In addition to an annual inspection of these properties, the estimates are also based on the information provided by WDP regarding the rental situation, surface areas, sketches or plans, rental charges and taxes associated with each property concerned, compliance and environmental pollution. The information provided was deemed accurate and complete. The estimates assume that undisclosed items are not such that they would affect the value of the property.
Each independent property expert values only a part of WDP’s portfolio and is therefore only responsible for valuing the part of the portfolio that was contractually assigned to him or her. The valuation expert therefore signs only for the accuracy of the figures of the assets he or she values. No further liability for any other valuation expert will be accepted.
Based on the above statements and on the estimates of each individual property expert, we can confirm that the fair value of the property portfolio of WDP (excluding solar panels but including assets held for sale), as set out in the table below, amounted to
7,685,078,886 euros (seven billion six hundred eighty-five million seventy-eight thousand eight hundred eighty-six euros).
Country Property Expert (represented by)
(Céline Janssens) 1,281,319
Hex)
Lang LaSalle Netherlands (Kjell van den Heuvel)
Netherlands CBRE Netherlands (Walter de Geus)
BNP Paribas Real Estate (Jean-Claude Dubois)
CBRE Romania (Ovidiu Ion)
CBRE Germany (Kristine Kühn)
Luxembourg Jones Lang LaSalle Luxembourg (Greet Hex)
Statutory auditor’s report to the shareholders’ meeting of Warehouses De Pauw NV/SA for the year ended 31 December 2024 – Consolidated financial statements
In the context of the statutory audit of the consolidated financial statements of Warehouses De Pauw NV/SA (“the company”) and its subsidiaries (jointly “the group”), we hereby submit our statutory audit report. This report includes our report on the consolidated financial statements and the other legal and regulatory requirements. These parts should be considered as integral to the report.
We were appointed in our capacity as statutory auditor by the shareholders’ meeting of 26 April 2023, in accordance with the proposal of the board of directors (“bestuursorgaan” / “organe d’administration”) issued upon recommendation of the audit committee. Our mandate will expire on the date of the shareholders’ meeting deliberating on the financial statements for the year ending 31 December 2024. We have performed the statutory audit of the consolidated financial statements of Warehouses De Pauw NV/SA for 18 consecutive periods.
Unqualified opinion
We have audited the consolidated financial statements of the group, which comprise the consolidated balance sheet as at 31 December 2024, the consolidated profit and loss account, the consolidated statement of overall result, the consolidated statement of changes in equity and the consolidated statement of cash flow for the year then ended, as well as the summary of significant accounting policies and other explanatory notes. The consolidated balance sheet shows total assets of 8,203,210,000 euros and the consolidated income statement shows a profit for the year then ended of 449,549,000 euros.
In our opinion, the consolidated financial statements give a true and fair view of the group’s net equity and financial position as of 31 December 2024 and of its consolidated results and its consolidated cash flow for the year then ended, in accordance with International Financial Reporting Standards (IFRS) as adopted by the European Union and with the legal and regulatory requirements applicable in Belgium.
We conducted our audit in accordance with International Standards on Auditing (ISA), as applicable in Belgium. In addition, we have applied the International Standards on Auditing approved by the IAASB applicable to the current financial year, but not yet approved at national level. Our responsibilities under those standards are further described in the “Responsibilities of the statutory auditor for the audit of the consolidated financial statements” section of our report. We have complied with all ethical requirements relevant to the statutory audit of consolidated financial statements in Belgium, including those regarding independence.
We have obtained from the board of directors and the company’s officials the explanations and information necessary for performing our audit.
We believe that the audit evidence obtained is sufficient and appropriate to provide a basis for our opinion.
Key audit matters are those matters that, in our professional judgment, were of most significance in our audit of the consolidated financial statements of the current period. These matters were addressed in the context of our audit of the consolidated financial statements as a whole and in forming our opinion thereon, and we do not provide a separate opinion on these matters.
Key audit matters
Valuation of investment properties
1 Investment properties measured at fair value (7 513 487 (000) EUR) represent more than 91 percent of the consolidated balance sheet total as at 31 December 2024. Changes in the fair value of the investment properties have a significant impact on the consolidated net result for the period and equity.
1 The portfolio includes completed investments and properties under construction. Acquisitions and divestments of investment properties are individually significant transactions.
1 The Group uses professionally qualified external valuers to fair value the Group’s portfolio at three-monthly intervals. The valuers are engaged by the Directors and they perform their work in accordance with the International Valuation Standards issued by the ‘IVSC’. The valuers used by the Group have considerable experience in the markets in which the Group operates.
1 The portfolio is valued based on a discounted cash flow model, or income capitalisation model and / or based on comparative market transactions. Development properties are valued by the same methodology with a deduction for all costs necessary to complete the development together with a remaining allowance for risk. The key inputs into the valuation exercise are yields and current market rent, which are influenced by prevailing market forces, comparable transactions and the specific characteristics of each property in the portfolio.
1 Therefore, the audit risk relates to the assumptions and critical judgments linked to those key inputs.
How our audit addressed the key audit matters
1 We considered the internal control implemented by management and we tested the design and implementation of controls over investment properties.
1 We assessed the competence, independence and integrity of the external valuers.
1 We analysed and challenged the valuation process, performance of the portfolio and significant assumptions and critical judgement areas, including yields and estimated rental values.
1 We benchmarked and challenged the key assumptions that were used in the valuation to external industry data and comparable property transactions, in particular the yield.
1 We performed audit procedures to assess the integrity and completeness of information provided to the independent valuers relating to rental income, key rent contract characteristics and occupancy.
1 We agreed the amounts per the valuation reports to the accounting records and from there we agreed the related balances through to the financial statements.
1 As part of our audit procedures performed on the acquisitions and divestments of investment properties, we examined the most significant contracts and documentation on the accounting treatment applied to these transactions.
1 For development properties, we also confirmed that the supporting information for construction contracts and budgets was consistent with the cost to complete deducted from the valuation of development properties. Capitalized expenditure was tested on a sample basis to invoices, and budgeted costs to complete were compared to supporting evidence (for example by inspecting original construction contracts).
1 Furthermore, we assessed the appropriateness of the disclosures provided on the fair values of investment properties.
Reference to disclosures
We refer to the Financial Statements, including notes to the Financial Statements: Note III, Accounting principles and Note XII, Investment properties.
Responsibilities of the board of directors for the preparation of the consolidated financial statements
The board of directors is responsible for the preparation and fair presentation of the consolidated financial statements in accordance with International Financial Reporting Standards (IFRS) as adopted by the European Union and with the legal and regulatory requirements applicable in Belgium and for such internal control as the board of directors determines is necessary to enable the preparation of consolidated financial statements that are free from material misstatement, whether due to fraud or error.
In preparing the consolidated financial statements, the board of directors is responsible for assessing the group’s ability to continue as a going concern, disclosing, as applicable, matters to be considered for going concern and using the going concern basis of accounting unless the board of directors either intends to liquidate the group or to cease operations, or has no other realistic alternative but to do so.
Responsibilities of the statutory auditor for the audit of the consolidated financial statements
Our objectives are to obtain reasonable assurance about whether the consolidated financial statements as a whole are free from material misstatement, whether due to fraud or error, and to issue a statutory auditor’s report that includes our opinion. Reasonable assurance is a high level of assurance, but is not a guarantee that an audit conducted in accordance with ISA will always detect a material misstatement when it exists. Misstatements can arise from fraud or error and are considered material if, individually or in the aggregate, they could reasonably be expected to influence the economic decisions of users taken on the basis of these consolidated financial statements.
During the performance of our audit, we comply with the legal, regulatory and normative framework as applicable to the audit of consolidated financial statements in Belgium. The scope of the audit does not comprise any assurance regarding the future viability of the company nor regarding the efficiency or effectiveness demonstrated by the board of directors in the way that the company’s business has been conducted or will be conducted.
As part of an audit in accordance with ISA, we exercise professional judgment and maintain professional skepticism throughout the audit. We also:
1 identify and assess the risks of material misstatement of the consolidated financial statements, whether due to fraud or error, design and perform audit procedures responsive to those risks, and obtain audit evidence that is sufficient and appropriate to provide a basis for our opinion. The risk of not detecting a material misstatement resulting from fraud is higher than for one resulting from an error, as fraud may involve collusion, forgery, intentional omissions, misrepresentations, or the override of internal control;
1 obtain an understanding of internal control relevant to the audit in order to design audit procedures that are appropriate in the circumstances, but not for the purpose of expressing an opinion on the effectiveness of the group’s internal control;
1 evaluate the appropriateness of accounting policies used and the reasonableness of accounting estimates and related disclosures made by the board of directors;
1 conclude on the appropriateness of the use of the going concern basis of accounting by the board of directors and, based on the audit evidence obtained, whether a material uncertainty exists related to events or conditions that may cast significant doubt on the group’s ability to continue as a going concern. If we conclude that a material uncertainty exists, we are required to draw attention in our statutory auditor’s report to the related disclosures in the consolidated financial statements or, if such disclosures are inadequate, to modify our opinion. Our conclusions are based on the audit evidence obtained up to the date of our statutory auditor’s report. However, future events or conditions may cause the group to cease to continue as a going concern;
1 evaluate the overall presentation, structure and content of the consolidated financial statements, and whether the consolidated financial statements represent the underlying transactions and events in a manner that achieves fair presentation.
1 obtain sufficient appropriate audit evidence regarding the financial information of the entities and business activities within the group to express an opinion on the consolidated financial statements. We are responsible for the direction, supervision and performance of the group audit. We remain solely responsible for our audit opinion.
We communicate with the audit committee regarding, amongst other matters, the planned scope and timing of the audit and significant audit findings, including any significant deficiencies in internal control that we identify during our audit.
We also provide the audit committee with a statement that we have complied with relevant ethical requirements regarding independence, and we communicate with them about all relationships and other matters that may reasonably be thought to bear on our independence, and where applicable, related safeguards.
From the matters communicated to the audit committee, we determine those matters that were of most significance in the audit of the consolidated financial statements of the current period and are therefore the key audit matters. We describe these matters in our report unless law or regulation precludes any public disclosure about the matter.
The board of directors is responsible for the preparation and the content of the directors’ report on the consolidated financial statements.
As part of our mandate and in accordance with the Belgian standard complementary to the International Standards on Auditing (ISA) as applicable in Belgium, our responsibility is to verify, in all material respects, the director’s report on the consolidated financial statements and other matters disclosed in the annual report on the consolidated financial statements, as well as to report on these matters.
In our opinion, after performing the specific procedures on the directors’ report on the consolidated financial statements, this report is consistent with the consolidated financial statements for that same year and has been established in accordance with the requirements of article 3:32 of the Code of companies and associations.
In the context of our statutory audit of the consolidated financial statements we are responsible to consider, in particular based on information that we became aware of during the audit, if the directors’ report on the consolidated financial statements and other information disclosed in the annual report on the consolidated financial statements, i.e.: 1 the required sections of Warehouses De Pauw NV's annual report in accordance with articles 3:6 and 3:32 of the Belgian Companies and Associations Code, as set out in the following sections of the annual report: 3. Strategy and value creation, 4. Performance and trends, 5. Financial results and outlook, 6. Corporate Governance Statement, 7. Risk factors and 9. Annual accounts are free of material misstatements, either by information that is incorrectly stated or otherwise misleading. In the context of the procedures performed, we are not aware of such a material misstatement.
Statements regarding independence
1 Our audit firm and our network have not performed any prohibited services and our audit firm has remained independent from the group during the performance of our mandate.
1 The fees for the additional non-audit services compatible with the statutory audit, as defined in article 3:65 of the Code of companies and associations, have been properly disclosed and disaggregated in the notes to the consolidated financial statements.
In accordance with the draft standard on the audit of the compliance of the financial statements with the Single European Electronic Format ("ESEF"), we have also performed the audit of the compliance of the ESEF format and of the tagging with the technical regulatory standards as defined by the European Delegated Regulation No. 2019/815 of 17 December 2018 ("Delegated Regulation").
The board of directors is responsible for the preparation, in accordance with the ESEF requirements, of the consolidated financial statements in the form of an electronic file in ESEF format (“digital consolidated financial statements”) included in the annual financial report.
Our responsibility is to obtain sufficient and appropriate evidence to conclude that the format and the tagging of the digital consolidated financial statements comply, in all material respects, with the ESEF requirements as stipulated by the Delegated Regulation.
Based on our work, in our opinion, the format and the tagging of information in the official language of the digital consolidated financial statements included in the annual financial report of Warehouses De Pauw NV as of 31 December 2024 are, in all material respects, prepared in accordance with the ESEF requirements as stipulated by the Delegated Regulation.
Other statements
1 This report is consistent with our additional report to the audit committee referred to in article 11 of Regulation (EU) No 537/2014.
Signed at Antwerp.
The statutory auditor
Deloitte Bedrijfsrevisoren BV
Represented by Kathleen De Brabander
To the board of directors of Warehouses De Pauw NV Blakebergen 15 B-1861 Wolvertem
Dear ladies and gentlemen
We report on the forecasted EPRA earnings (as defined in August 2011 (and amended in November 2016) in the report “Best Practices Recommendations Guidelines“ of the European Public Real Estate Association) of Warehouses De Pauw NV/SA (“WDP”, “the Company”) and its subsidiaries (together “the Group”) for the 12 months period ending 31 December 2025 (the “Profit Forecast”). The Profit Forecast, and the material assumptions upon which it is based are set out in chapter 5. Financial results and outlook, paragraph Outlook of the 2024 annual report of the WDP Group (the “Annual Report”) issued by the Company. We do not report on the other elements of the net result nor on the EPRA earnings per share, the projected dividend or the projected balance sheet.
This report is voluntarily required upon request by the board of directors of the Company for the purpose to confirm the Profit Forecast has been compiled and prepared in accordance with elements (a) and (b) as defined under item 11.2 of Annex 1 of the Commission Delegated Regulation (EU) 2019/980 supplementing Regulation (EU) 2017/1129 of the European Parliament and of the Council as regards the format, content, scrutiny and approval of the prospectus to be published when securities are offered to the public or admitted to trading on a regulated market and repealing Commission Regulation (EC) No 809/2004 (the “Commission Delegated Regulation”) and for no other purpose.
It is the responsibility of the directors of the Company (the “Directors”) to prepare the Profit Forecast in accordance with Annex 1 section 11 of the Commission Delegated Regulation.
It is our responsibility to form an opinion as to the proper compilation of the Profit Forecast and to report that opinion to you.
Save for any responsibility arising under art. 26 of the Law of 11 July 2018 to any person as and to the extent there provided, to the fullest extent permitted by law we do not assume any responsibility and will not accept any liability to any other person for any loss suffered by any such other person as a result of, arising out of, or in accordance with this report or our statement, required by and given solely for the purposes of complying with Annex 1 item 1.3 of the Commission Delated Regulation, consenting to its inclusion in the Universal Registration document.
The Profit Forecast has been prepared on the basis stated in chapter 5. Financial results and outlook, paragraph Outlook of the annual report and is based on a forecast for the 12 months to 31 December 2025. The Profit Forecast is required to be presented on a basis consistent with the accounting policies of the Group.
We conducted our work in accordance with the International Standard on Assurance Engagement 3400 “The Examination of Prospective Financial Information” (“ISAE 3400”) issued by the International Auditing and Assurance Standards Board (“IAASB”). Our work included evaluating the basis on which the historical financial information included in the Profit Forecast has been prepared and considering whether the Profit Forecast has been accurately computed based upon the disclosed assumptions and the accounting policies of the Group. Whilst the assumptions upon which the Profit Forecast are based are solely the responsibility of the Directors, we considered whether anything came to
our attention to indicate that any of the assumptions adopted by the Directors which, in our opinion, are necessary for a proper understanding of the Profit Forecast have not been disclosed or if any material assumption made by the Directors appears to us to be unrealistic.
We planned and performed our work so as to obtain the information and explanations we considered necessary in order to provide us with reasonable assurance that the Profit Forecast has been properly compiled on the basis stated.
Since the Profit Forecast and the assumptions on which it is based relate to the future and may therefore be affected by unforeseen events, we can express no opinion as to whether the actual results reported will correspond to those shown in the Profit Forecast and differences may be material.
Our work has not been carried out in accordance with auditing or other standards and practices generally accepted in jurisdictions outside Belgium, including the United States of America, and accordingly should not be relied upon as if it had been carried out in accordance with those standards and practices.
In our opinion, the Profit Forecast has been properly compiled on the basis stated which is comparable with the historical financial information and is consistent with the accounting policies of the Group.
For the purposes of art. 26 of the Law of 11 July 2018 we are responsible for this report as part of the Universal Registration document and declare that we have taken all reasonable care to ensure that the information contained in this report is, to the best of our knowledge, in accordance with the facts and contains no omission likely to affect its import. This declaration is included in the Universal Registration document in compliance with Annex 1 item 1.2 of the Commission Delegated Regulation.
Signed at Antwerp.
The statutory auditor
Deloitte Bedrijfsrevisoren BV
Represented by Kathleen De Brabander
Independent assurance report on selected environmental, social and governance performance indicators published in the Annual Report of Warehouses De Pauw NV for the year ending 31 December 2024
To the board of directors
We have been engaged to conduct a limited assurance engagement on selected environmental, social and governance performance indicators (“Selected Information”) published in the Annual Report of Warehouses De Pauw NV (“the Company”) for the year ending 31 December 2024. In preparing the Selected Information, Warehouses De Pauw NV applied the Best Practices Recommendations for the European Public Real Estate Association regarding sustainability reporting (EPRA sBPR), alongside the Green Bond Principles 2021 by the International Capital Market Association (ICMA) and the Green Loan Principles 2021 by the Loan Market Association (LMA) as delineated in WDP’s Green Financing Framework dated April 2022 with a set of own indicators (“Applicable Criteria”) as included in Chapter 8. Sustainability Statement in the annual report. The Selected Information needs to be read and understood together with the Applicable Criteria. The Selected Information in scope of our engagement is identified with in Chapter 8. Sustainability Statement of the Annual Report.
Based on our work as described in this report, nothing has come to our attention that causes us to believe that the Selected Information identified with in Chapter 8. Sustainability Statement of the Annual Report of Warehouses De Pauw NV per 31 December 2024, has not been prepared, in all material respects, in accordance with the Appliable Criteria.
The board of directors of Warehouses De Pauw NV is responsible for the preparation of the Selected Information and the references made to it presented in the Annual Report per 31 December 2024 as well as for the declaration that its reporting meets the requirements of the Applicable Criteria.
The board of directors is also responsible for:
1 Selecting and establishing the Applicable Criteria.
1 Preparing, measuring, presenting and reporting the Selected Information in accordance with the Applicable Criteria.
1 Designing, implementing, and maintaining internal processes and controls over information relevant to the preparation of the Selected Information to ensure that they are free from material misstatement, including whether due to fraud or error.
1 Providing sufficient access and making available all necessary records, correspondence, information and explanations to allow the successful completion of the Services.
1 Confirming to us through written representations that you have provided us with all information relevant to our Services of which you are aware, and that the measurement or evaluation of the underlying subject matter against the Applicable Criteria, including that all relevant matters, are reflected in the Selected Information.
Our responsibility is to express a conclusion on the Selected Information based on our procedures. We conducted our engagement in accordance with International Standard on Assurance Engagements ISAE 3000 (Revised) Assurance Engagements Other than Audits or Reviews of Historical Financial Information, issued by the International Auditing and Assurance Standards Board (IAASB), in order to state whether anything had come to our attention that causes us to believe that the Selected Information has not been prepared, in all material respects, in accordance with the Applicable Criteria.
Applying these standards, our procedures are aimed at obtaining limited assurance on the fact that the Selected Information do not contain material misstatements. The procedures performed in a limited assurance engagement vary in nature and timing from, and are less in extent than for, a reasonable assurance engagement and consequently, the level of assurance obtained in a limited assurance engagement is substantially lower than the assurance that would have been obtained had a reasonable assurance engagement been performed.
Our work was performed on the data gathered and retained in the reporting scope by Warehouses De Pauw NV as mentioned above. Our conclusion covers therefore only the Selected Information identified with in Chapter 8. Sustainability Statement of the Annual Report and not all information included in the Annual Report. The limited assurance on the Selected Information was only performed on the Selected Information covering the year ending 31 December 2024.
We are required to plan and perform our work to address the areas where we have identified that a material misstatement of the description of activities undertaken in respect of the Selected Information is likely to arise. The procedures we performed were based on our professional judgment. In carrying out our limited assurance engagement on the description of activities undertaken in respect of the Selected Information, we performed the following key procedures:
1 Perform analytical review procedures and consider the risks of material misstatement of the Selected Information.
1 Through inquiries of management, obtain an understanding of the Company, its environment, processes and information systems relevant to the preparation of the Selected Information sufficient to identify and assess risks of material misstatement in the Selected Information, and provide a basis for designing and performing procedures to respond to assessed risks and to obtain limited assurance to support a conclusion.
1 Perform procedures over the Selected Information, including recalculation of relevant formulae used in manual calculations and assessment whether the data has been appropriately consolidated.
1 Perform procedures over underlying data on a statistical sample basis to assess whether the data has been collected and reported in accordance with the Applicable Criteria, including verifying to source documentation.
1 Perform procedures over the Selected Information including assessing management’s assumptions and estimates.
1 Accumulate misstatements and control deficiencies identified, assessing whether material.
1 Read the narrative accompanying the Selected Information with regard to the Applicable Criteria, and for consistency with our findings.
We apply International Standard on Quality Management 1 and, accordingly, maintain a comprehensive system of quality control including documented policies and procedures regarding compliance with ethical requirements, professional standards and applicable legal and regulatory requirements.
In conducting our engagement, we have complied with the independence and other ethical requirements of the Code of Ethics for Professional Accountants issued by the International Ethics Standards Board for Accountants (IESBA), which is founded on fundamental principles of integrity, objectivity, professional competence and due care, confidentiality and professional behaviour. This includes the verification that there are no conflicts of interest with this assurance engagement.
We obtained limited assurance over the preparation of the Selected Information in accordance with the Applicable Criteria. Inherent limitations exist in all assurance engagements.
Any internal control structure, no matter how effective, cannot eliminate the possibility that fraud, errors or irregularities may occur and remain undetected and because we use selective testing in our engagement, we cannot guarantee that errors or irregularities, if present, will be detected.
The self-defined Applicable Criteria, the nature of the Selected Information, and absence of consistent external standards allow for different, but acceptable, measurement methodologies to be adopted which may result in variances between entities. The adopted measurement methodologies may also impact comparability of the Selected Information reported by different organizations and from year to year within an organization as methodologies develop.
Use of our report
This report is made solely to the board of directors of Warehouses De Pauw NV in accordance with ISAE 3000 (Revised) and our agreed terms of engagement. Our work has been undertaken so that we might state to the board of directors those matters we have agreed to state to them in this report and for no other purpose.
Without assuming or accepting any responsibility or liability in respect of this report to any party other than the Company and its board of directors, we acknowledge that the board of directors may choose to make this report publicly available for others wishing to have access to it, which does not and will not affect or extend for any purpose or on any basis our responsibilities. To the fullest extent permitted by law, we do not accept or assume responsibility to anyone other than Warehouses De Pauw NV and its board of directors as a body, for our work, for this report, or for the conclusions we have formed.
Signed at Zaventem.
Deloitte Bedrijfsrevisoren/Réviseurs d’Entreprises BV/SRL
Represented by Sofian
Milad
This relates to the realised and unrealised capital gains/losses with respect to the latest valuation by the property expert, taking into account the effective or deferred capital gains tax due, including WDP’s proportionate share in the portfolio of associated companies and joint ventures and excluding the minority interests.
This is the organic growth of the gross rental income year-on-year on the basis of an unchanged portfolio, excluding development projects, acquisitions and disposals during both periods of this comparison.
The operating margin, obtained by dividing the operating result (before the result on the portfolio) by the property result. Operating margin is a measure of profitability that can indicate how well the company is managing its operating property operations.
This refers to the weighted average yearly interest rate for the reporting period, taking into account the average outstanding debt and the hedging instruments during that same period.
Operating result (before the portfolio result) (excluding depreciation and write-downs on solar panels)
Financial result (excluding changes in the fair value of the financial instruments)
This is the financial result according to IFRS exclusive of the change in fair value of financial assets and liabilities, and reflects the actual financial expenses of the company.
Percentage of fixed-rate and floating-rate debts hedged against interest rate fluctuations by means of derivatives. This economic parameter is not an obligatory parameter under the Belgian regulated real-estate investment companies Law (Wet betreffende de gereglementeerde vastgoedvennootschappen or 'GVV-Wet').
To be excluded:
(excluding the changes in fair value of
and non-current financial debt (IFRS)
Proportional share in joint ventures in current and noncurrent
The loan-to-value is obtained from the IFRS statements by dividing the net financial liabilities by the sum of the fair value of the property portfolio, the fair value of the solar panels and financing to and holdings in associated companies and joint ventures.
Fair value of the real estate portfolio (excluding right of use concessions)
value of the solar panels
Financing of and participations in associated companies and joint ventures
The net debt / EBITDA (adjusted) is calculated starting from the proportional accounts (WDP's joint ventures are included for their proportionate share): in the denominator taking into account the trailing-twelve-months normalized EBITDA and adjusted to reflect the annualized impact of external growth; in the numerator taking into consideration the net financial indebtedness adjusted for the projects under development multiplied by the loan-to-value of the group (as these projects are not yet income contributing but already (partially) financed on the balance sheet). For associated companies only the dividends are taken into account.
1 For the calculation of this APM, it is assumed that the operating result (before the result on the portfolio) is a proxy for EBITDA. TTM stands for trailing 12 months and means that the calculation is based on financial figures for the past 12 months.
2 On a normalized basis and including the annualized impact of organic growth (such as indexation) and external growth (in function of realised disposals, acquisitions and projects).
Active participation in assessments, ratings and reporting according to recognised international standards underlines our ambition to take on a prominent role in all aspects of sustainability. Our selection always keeps in mind the complementarity and versatility of the benchmarks so we can communicate as reliably and transparently as possible
2024 Score
EPRA BPR Gold
EPRA sBPR Gold
Reporting with reference to GRI standards

to the widest possible audience. We are also considering the added value for WDP itself: our participation should enable us to monitor our progress and better assess our performance in the sector as a whole.
Importance for WDP
The EPRA reporting standards are closely aligned with the (real estate) activities of WDP and ensure transparent and consistent reporting on sustainability by real estate companies. Their alignment with the GRI international standard emphasises their relevance.
Reputable standard for relevant stakeholders – investors, policymakers, capital markets, and the community. EPRA aligns its reporting with this standard.
AA MSCI analyses and scores companies on environmental issues. It also does a thorough analysis on governance and social issues. This rating is very well known within the investor community and links it with CDP.
Prime C The ISS ESG Corporate Rating provides investors with a clear picture of the strengths and weaknesses in terms of the sustainability strategy of the companies they have analysed. This rating is widely supported within the investor community. The link with GRI and TCFD is considered a plus by WDP.
Inclusion in Dow Jones Best-in-Class World and Dow Jones Best-in-Class Europe Score 66
B (Climate)
C (Water Security)
Inclusion in Dow Jones Best-in-Class World and Dow Jones Best-in-Class Europe provides autonomous credibility on sustainability and how WDP invests in ESG. The versatility and thorough analysis of all aspects of ESG help WDP to further develop its ESG strategy.
Participation in a CDP (Climate Change Plan) is in keeping given WDP’s efforts towards achieving the objectives of the EU Green Deal. This is how (potential) investors can benchmark WDP’s climate approach in an independent and transparent manner.
1
Information included by way of reference Document¹
Operating activities
Annual Report 2023
2. This is WDP (pp. 4-10)
3. Strategy and value creation (pp. 11-19)
4. Performance and trends (pp. 20-63)
7. Financial results and property portfolio – High quality portfolio (pp. 97-108)
Annual Report 2022
2. This is WDP (pp. 4-10)
3. Strategy and value creation (pp. 11-19)
4. Performance and trends (pp. 20-56)
7. Financial results and property report – Property report – Review of the consolidated property portfolio (pp. 89-96)
Main markets
Annual Report 2023
2. This is WDP – Our position in Europe (p. 6)
7. Financial results and property portfolio – High quality portfolio (pp. 97-108)
7. Financial results and property portfolio – High quality portfolio (pp. 97-100)
11. Annual accounts – 2. Explanatory notes – V. Segmented information – Operating result (pp. 228-230)
11. Annual accounts – 2. Explanatory notes – VI. Segmented information – Assets (p. 231)
11. Annual accounts – 2. Explanatory notes – XII. Investment properties (pp. 236-241)
Annual Report 2022
2. This is WDP – Our position in Europe (p. 6)
7. Financial results and property report – Property report – Review of the consolidated property portfolio (pp. 89-96)
7. Financial results and property report – Property report – Review of the logistics property market (pp. 97-98)
11. Annual accounts – 2. Explanatory notes – V. Segmented information – Operating result (pp. 219-220)
11. Annual accounts – 2. Explanatory notes – VI. Segmented information – Assets (p. 222)
11. Annual accounts – 2. Explanatory notes – XII. Investment properties (pp. 227-232)
Investments Annual Report 2023
Annual Report 2022
Financial condition Annual Report 2023
4. Performance and trends – Sustainable growth (pp. 21-31)
4. Performance and trends – Sustainable growth (pp. 21-30)
4. Performance and trends – Sustainable growth (pp. 21-31)
7. Financial results and property report. (pp. 76-113)
12. Appendices – External audit – Conclusions of the property experts (p. 271)
10. Reporting according to recognised standards – EPRA key performance indicators (pp. 169-178)
11. Annual accounts (pp. 212-269)
12. Appendices – External audit – Statutory auditor’s report on the financial statements (pp. 272-276)
12. Appendices – Alternative Performance Measures (pp. 282-287)
Information included by way of reference Document¹
Annual Report 2022
4. Performance and trends – Sustainable growth (pp. 21-30)
7. Financial results and property report (pp. 70-104)
12. Appendices – External audit – Conclusions of the property experts (p. 263)
10. Reporting according to recognised standards – EPRA key performance indicators (pp. 160-169)
11. Annual accounts (pp. 201-261)
12. Appendices – External audit – Statutory auditor’s report on the financial statements (pp. 264-268)
12. Appendices – Alternative Performance Measures (pp. 274-279)
Historical financial information Annual Report 2023
Annual Report 2022
11. Annual accounts – 1. Consolidated financial statements for the 2023 financial year – Earnings statement (pp. 214-215)
11. Annual accounts – 1. Consolidated financial statements for the 2023 financial year – Balance sheet (p. 217)
11. Annual accounts – 1. Consolidated financial statements for the 2023 financial year – Cash flow statement (p. 218)
11. Annual accounts – 2. Explanatory notes (pp. 221-259)
11. Annual accounts – 1. Consolidated financial statements for the 2022 financial year – Earnings statement (pp. 203-204)
11. Annual accounts – 1. Consolidated financial statements for the 2022 financial year – Balance sheet (p. 206)
11. Annual accounts – 1. Consolidated financial statements for the 2022 financial year – Cash flow statement (p. 207)
11. Annual accounts – 2. Explanatory notes (pp. 210-251)
Statement of the statutory auditor Annual Report 2023
12. Appendices – External audit – Statutory auditor’s report on the financial statements (pp. 272-276) Annual Report 2022
12. Appendices – External audit – Statutory auditor’s report on the financial statements (pp. 264-268)
Dividend Annual Report 2023 7. Financial results and property portfolio – Outlook – Projected consolidated results (pp. 110-111) 7. Financial results and property portfolio – Outlook – Introduction of new growth plan 2024-27 (p. 113) 6. Shares and bonds – The share (pp. 71-73) Annual Report 2022
7. Financial results and property report – Outlook – Projected consolidated results (pp. 100-101)
7. Financial results and property report – Outlook – Growth Plan 2022-25 (pp. 102-103)
6. Shares and bonds – The share (pp. 66-67)
Transactions with affiliated parties Annual Report 2023 11. Annual accounts – 2. Explanatory notes – XXIII. Transactions with affiliated parties (p. 257) Annual Report 2022 11. Annual accounts – 2. Explanatory notes – XXIII. Transactions between related parties (p. 248)
Information on the workforce Annual Report 2023
11. Annual accounts – 2. Explanatory notes – XXII. Average workforce and breakdown of personnel costs (p. 256)
Annual Report 2022 11. Annual accounts – 2. Explanatory notes – XXII. Average workforce and breakdown of personnel costs (p. 248)
1 Reference is always made to the online versions of the documents, as available at https://www.wdp.eu/publications
The annual report is available at the Company’s registered office and can be consulted on the website www.wdp.eu in three languages (Dutch, French and English). The Dutchlanguage version of the annual report was drawn up per the ESEF (European Single Electronic Format) reporting requirements and is therefore the official version of the annual report. This version in ESEF can also be found at the website www.wdp.eu. The electronic versions of the annual reports may not be copied or made available anywhere. It is also prohibited to print the text for further distribution.
Contact persons and additional information:
Joost Uwents, CEO
Mickaël Van den Hauwe, CFO
Joke Cordeels, Head of External Communications
Alexander Makar, Head of Investor relations & Corporate Finance investorrelations@wdp.eu
WDP declares that:
1 the 2024 Annual Report was filed with the FSMA as a Universal Registration Document on the date 31 March 2025, as the competent authority under Regulation (EU) 2017/1129 without prior approval under Article 9 of Regulation (EU) 2017/1129; 1 the Universal Registration Document may be used with a view to offering securities to the public or the admission of securities to trading on a regulated market, provided that it is approved by the FSMA, where applicable, along with any amendments and a securities note and summary approved in accordance with Regulation (EU) 2017/1129.
The information made available via the website is not part of this Universal Registration Document unless such information is included as a reference.
The members of the Board of Directors of WDP NV/SA, the composition of which is described in Chapter 6. Corporate Governance Statement, are responsible for the information provided in this annual report.
Joost Uwents, Managing Director and CEO, declared on behalf of the Board of Directors, the composition of which is described under Chapter 6. Corporate Governance Statement, after taking all measures to guarantee the same, that to his knowledge, the data in this annual report are a fair presentation of reality, and that no information has been omitted which would, if reported, alter the effect of this annual report, and that as far as he is aware:
1 the annual accounts, which have been drawn up in accordance with the applicable standards for annual accounts, give a true and fair view of the group’s equity, financial position and of the results of the issuer and of the companies included in the consolidation;
1 the annual report gives a true overview of the development and the results of the company and of the position of the issuer and the companies included in the consolidation, as well as a description of the main risks and uncertainties they are faced with;
1 no significant changes have occurred in the financial position or financial performance of the Group since 31 December 2024; and
1 subject to what has been publicised with regard to the Dutch REIT status, no government interventions, lawsuits or cases of arbitration exist – or have recently occurred – that could influence WDP’s financial position or profitability. He also declares that, to his knowledge, there are no circumstances or facts that could give rise to such government interventions, lawsuits or arbitrations.
WDP hereby declares that, at least during the period of validity of the Universal Registration Document, the following documents are available for viewing on its website at www.wdp.eu:
1 the latest deed of incorporation and Articles of Association of WDP;
1 the annual reports;
1 the reports, and respectively, the conclusions of the statutory auditor and the property experts;
1 press releases and mandatory financial information. The company’s financial reporting is published in the financial press where required by law;
1 the Corporate Governance Charter;
1 the obligations of the Company and the rights of the shareholders with regard to the General Meeting are published on the Investors section of WDP’s website as of the meeting notice until participation and voting in full. This information remains available on the Company website for a period of at least five years starting from the date of the General Meeting to which it pertains.
In accordance with the relevant provisions of the law, the separate and consolidated financial statements of the Company are deposited with the National Bank of Belgium.
Decisions related to the appointment and dismissal of members of the Board of Directors are published in the Annexes to the Belgian Official Journal.
WDP declares that the information provided by the property experts and the statutory auditor has been faithfully reproduced. To the best of WDP’s knowledge, and based on what it has been able to deduce from the information published by the property experts and the statutory auditor, no facts were omitted that would render the information provided by the property experts or the statutory auditor misleading or incorrectly interpreted. WDP also confirms that the statutory auditor and property experts have given their approval for the content of their report and conclusions respectively to be included in the annual report.
For confidentiality reasons, the full report of the property experts has not been included and cannot be consulted.
In accordance with Articles 3:6 and 3:32 of the Belgian Code of Companies and Associations, the required components of the WDP annual report appear in the following chapters:
1 4. Performance and trends;
1 5. Financial results and outlook;
1 6. Corporate Governance Statement;
1 7. Risk factors; and
1 9. Annual accounts.
This annual report provides an overview of the activities and financial statements for the financial year ending on 31 December 2024.
Company name (Article 1 of the coordinated Articles of Association)
Warehouses De Pauw, or WDP for short.
Place of registration, company number, identification code for legal entities
The Company is registered in the Crossroads Bank for Enterprises, in the district of Brussels, Dutch language division, under the legal entity registration number 0417.199.869. Its identification code for legal entities (LEI – legal entity identifier) is 549300HWDYC5JXC85138.
Legal form, incorporation¹
The Company was founded as a public limited company (‘NV’/'SA') under the name Rederij De Pauw by a deed executed before civil-law notary Paul De Ruyver in Liedekerke on 27 May 1977, published in the Annexes to the Belgian Official Journal on 21 June 1977 under number 2249-1. By means of a general merger and demerger operation, this NV became the holding company bringing together the property portfolios of nine different companies. At the same time, the name of the Company was changed to Warehousing & Distribution De Pauw and was converted into a partnership limited by shares under Belgian law (Comm. VA). The associated amendments to the Articles of Association were provisionally enacted by a deed executed by civil-law-notary Siegfried Defrancq in Asse-Zellik, acting as substitute for civil-law-notary Jean-Jacques Boel in Asse due to his statutory incapacity, on 20 May 1999, subsequently published in the annexes to the Belgian Official Journal on 16 June under number 990616-21, and endorsed in two deeds dated 28 June 1999 by the same civil-law notary, subsequently published in the annexes to the Belgian Official Journal on 20 July under numbers 990720-757 and 758.
The company name was changed during the Extraordinary General Meeting of 25 April 2001 into Warehouses De Pauw, as set out in the deed executed by the aforementioned notary Siegfried Defrancq, replacing the aforementioned notary
1 See also chapter 2. This is WDP. on p. 7.
Jean-Jacques Boel, due to his statutory incapacity, published in the annexes to the Belgian Official Journal on 18 May 2001 under number 20010518-652.
At the Extraordinary General Meeting of 11 September 2019, the legal form of WDP was changed to a public limited company ('naamloze vennootschap') effective as of 1 October 2019, as established in the deed executed before civil-law-notary Tim Carnewal, published in the annexes to the Belgian Official Journal of the following 25 September 2019, under number 19127672.
At the Extraordinary General Meeting on 11 September 2019, it was decided to split the share by a factor of 7. This declaration deed was executed before Civil-Law Notary Eric Spruyt in Brussels and was published in the Annexes to the Belgian Official Journal on 5 February 2020 under number 20020249.
The WDP articles of association were last amended on 4 September 2024 by means of a deed executed by a civil notary Tim Carnewal in Brussels, following the decision to amend the articles of association. This deed was published in the Annexes to the Belgian Official Journal of 20 September 2024 under number 24430030.
BELGIUM: Regulated Real Estate Company (GVV/SIR) status (Article 1 of the coordinated Articles of Association)
Since 28 June 1999, WDP has been registered with the Belgian Financial Services and Markets Authority, (the FSMA), as a fixed-capital Belgian REIT (a Vastgoedbevak/ SICAF). On 16 October 2014 in order to better meet the economic realities, and due to the changes in the legal framework related to our capacity as an operational and commercial real estate company, WDP changed its status to that of a public regulated real estate company under Belgian law (public 'GVV/SIR'). The relevant amendments to the Articles of Association were enacted in a deed executed by the civil-law notary Yves De Ruyver replacing the aforementioned civil-law notary Jean-Jacques Boel, due to his statutory incapacity, as published in the annexes to the Belgian Official Journal on 31 October 2014 under number 14199666. Therefore, WDP is subject to the legal system as determined in the GVV/SIR legislation.
Generally speaking, a public regulated real estate company under Belgian law, and therefore also WDP since 16 October 2014, must satisfy a number of crucial conditions in order to be able to make use of the favourable regime while guaranteeing greater transparency and a limitation of risk for the investor.
A public regulated real estate company under Belgian law:
1 is a real estate company that (i) mainly makes immovable property available to users, (ii) may possess other types of property within the statutory limits (holding rights in fixed capital Belgian REITs (a ‘Vastgoedbevak/SICAF’), holding rights in certain foreign ICBs, shares issued by other REITs, property certificates and holding rights in a FIIS/GVBF), and (iii) within the framework of making immovable property available, may perform any and all activities associated with the construction, conversion, renovation, development (for the company’s own portfolio), acquisition, disposal, management and operation of immovable property and (iv) within the legal limits, may also invest in the infrastructure sector (including through PPPs) and the energy sector (including renewable energy);
1 has a statutory maximum gearing ratio of 65% of its assets;
1 must distribute at least 80% of its earnings to its shareholders;
1 has the obligation of periodic and occasional valuation of the fair value of the property by an independent property expert;
1 diversifies its properties in such a way as to spread the risks appropriately, by type of property, geographic area and category of user or tenant, and no single transaction shall result in more than 20% of its consolidated assets constituting a single property;
1 is subject to corporate income tax at the standard rate, although only on a limited taxable base (i.e. non-deductible professional expenses, abnormal or gratuitous benefits and special assessment of secret commissions). When a GVV/SIR participates in a merger, a demerger or a similar transaction, this transaction shall not benefit from the tax neutrality regime but will give rise to the application of the exit tax at the rate of 15% as of 1 January 2020. As a rule, the dividends paid by a GVV/ SIR to a shareholder give rise to the collection of an immovable property tax at the rate of 30%;
1 follows a strategy intended to retain possession of its properties over the long term;
1 prioritises active management in the performance of its activities, which specifically entails that the company itself is responsible for the development and day-to-day management of the immovable property, and that all other activities that it performs provide added value for these same immovable property or their users, such as offering services that supplement provision of the immovable property;
1 for performance of the aforementioned activities, has its own management structure, administrative, accounting, financial and technical organisation and suitable internal control;
1 is subject to the provisions of the GVV/SIR Act and of the Royal Decree on GVVs/ SIRs;
1 must be incorporated in the form of a public limited company ('NV/SA');
1 is listed, and at least 30% of the shares must be distributed in the market;
1 cannot act (directly or indirectly) as a property developer (other than occasionally);
1 may possess companies in which it owns, directly or indirectly, over 25% of the shares (“perimeter” companies), which may or may not take the status of an institutional GVV/SIR;
1 must adhere to strict rules regarding conflicts of interest and internal auditing structures.
Public or institutional GVV/SIRs fall under the supervision of the FSMA. For more information on the GVV/SIR status, please refer to our website
Aside from Articles 7:96 (conflicts of interest of directors) and 7:97 (conflicts of interest of affiliated companies) of the Belgian Code of Companies and Associations, which apply to all listed companies, special rules apply to GVVs/SIRs regarding functional conflicts of interest (by virtue of Article 37 of the GVV/SIR Act).
For further information on each of these procedures, please refer to Chapter 6. Corporate Governance Statement.
2
Fiscale Beleggingsinstelling (Fiscal Investment Institution) (FBI)
As of 1 November 2010, the FBI (Fiscal Investment Institution) regime applies2 to WDP Nederland S.A., as a result of which the corporate income tax rate of 0% applies. The company must satisfy the following conditions in order to benefit from this regime:
1 WDP The Netherlands must be a B.V., N.V. or a mutual fund.
1 The statutory objective as per the Articles of Association and the actual activities of WDP Nederland S.A. are limited to the investment of capital.
1 Only 60% of the financing of the funds for investment (fiscal book value) can be loan capital, in the case immovable property. For other investments (not related to immovable property), only 20% of the fiscal book value of financing can be loan capital.
1 The operating profit of WDP Nederland S.A. must be provided to the shareholder of WDP Nederland S.A. starting from application of the FBI regime within eight months after the end of the financial year.
1 The distributed profits must be distributed evenly across all shares.
1 75% or more of the shares in WDP Nederland S.A. must be held by a body that is not subject to a tax based on earnings.
1 5% or more of the shares cannot be held directly or indirectly by natural persons.
1 25% or more of the shares cannot be held by funds based abroad for persons residing or legal entities domiciled in the Netherlands.
For more information on the evolution of the FBI status, we refer to Chapter 5. Financial results and outlook on p. 67.
Since 2005, WDP has been under the SIIC regime (Société d’Investissement Immobilier Cotée) via its permanent establishment in France and its subsidiary WDP France SARL, which means that a corporate income tax rate of 0% applies. The company must satisfy the following conditions in order to benefit from this regime:
1 The parent company must have the structure of an NV/SA or any other form of company limited by shares that can be admitted for listing on the stock market. This parent company must be listed on a stock market under EU law.
1 The main activity of the SIIC must be limited to leasing immovable property. Property developments are not permitted to exceed the limit of 20% of the gross book value of the portfolio.
1 No more than 60% of the shares in WDP can be held by a single investor or a group of investors acting in mutual consultation.
1 Earnings originating from the letting of buildings, the capital gains realised on the sale of buildings, the capital gains realised on the sale of securities in the partnerships or subsidiaries that are liable for corporate income tax and that have opted for SIIC status, contributions disbursed through their subsidiaries that have opted for SIIC status and share in the profits in partnerships are exempt from corporate income tax.
1 A disbursement obligation applies to the results for 95% of the tax exempt profit originating from rental income, 60% of tax exempt profit originating from the sale of buildings and securities of partnerships and subsidiaries that are subject to SIIC status and 100% of the dividends that are paid to them by their subsidiaries that are liable for corporate income tax and that have opted for SIIC status.
1 Payment of an exit tax at a rate of 19% on the unrealised capital gains on buildings that are the property of the SIIC or its subsidiaries that are liable for corporate income tax and have opted for SIIC status, and on the securities of partnerships that are not subject to corporate income tax.
Website and e-mail address of the Company (Article 4 of the coordinated Articles of Association)
The Company’s website is: www.wdp.eu
The Company can be contacted at the following e-mail address: shareholdersmeetings@ wdp.eu
Registered office of the Company (Article 3 of the coordinated Articles of Association)
The Company is based in the Flemish Region. The registered offices can be relocated in Belgium by a decision of the Board of Directors, provided the relocation does not require a change in the language of the Articles of Association to comply with applicable language legislation.
Duration (Article 2 of the coordinated Articles of Association)
The duration of the Company is unlimited.
Company objective (Article 5 of the coordinated Articles of Association)
Article 5 of the Articles of Association states that the sole objective of the Company is to:
a) make immovable property available to users, directly or through a company in which it holds an interest in accordance with the provisions of the GVV/SIR legislation and its implementing decrees and regulations; and
b) possess real estate as referred to in Article 2(5°)(i to xi) of the GVV/SIR Act, within the limits of the GVV/SIR legislation.
Real estate shall be understood to mean:
i) immovable property as defined in article 517 and thereafter of the Civil Code and rights in rem to the said immovable property, excluding the immovable property of a forestry, agricultural or mining nature;
ii) shares with voting rights issued by real estate companies, of which the company directly or indirectly retains more than 25% of the capital;
iii) option rights on real estate;
iv) shares in public or institutional GVVs/SIRs, provided in the latter case that the company holds over 25% of the share capital, directly or indirectly;
v) rights arising from contracts giving the company leasehold of one or more assets, or other analogous rights of use;
vi) holding rights in public and institutional real estate investment funds;
vii) holding rights in foreign institutions for collective investment in real estate registered in the list referred to in Article 260 of the Act of 19 April 2014;
viii) holding rights in institutions for collective investment in real estate based in a different Member State of the European Economic Area and not included in the list referred to in Article 260 of the Act of 19 April 2014, insofar as they are subject to equivalent supervision as public real estate investment trusts;
ix) shares or holding rights issued by companies (i) with a legal personality; (ii) governed by the law of another Member State of the European Economic Area; (iii) whose shares may or may not be admitted to trading on a regulated market and which may or may not be subject to a regime of prudential supervision; (iv) the principal activity of which consists of the acquisition or construction of immovable property with a view to placing it at the disposal of users, or the direct or indirect holding of shares in the capital of companies with a similar activity; and (v) which are exempt from tax on income from profits resulting from the activity referred to under (iv) above, subject to compliance with certain legal obligations, and which are obliged to distribute at least part of their income to their shareholders (“Real Estate Investment Trusts” (or “REITs” for short);
x) mortgage debentures as referred to in Article 5(§ 4) of the Act of 16 June 2006;
xi) holding rights in a FIIS/GVBF;
xii) as well as any other goods, shares or rights defined as real estate by the GVV/SIR legislation.
Real estate as referred to in (vi), (vii), (viii), (ix) and (xi) that constitute holding rights in alternative investment funds within the meaning of Directive 2011/61/EU of the European Parliament and of the Council of 8 June 2011 on managers of alternative investment funds and amending Directives 2003/41/EC and 2009/65/EC and of the Regulations (EC) no. 1060/2009 of the European Parliament and the Council of 16 September 2009 on credit rating agencies and (EU) no. 1095/2010 of the European Parliament and of the Council of 24 November 2010 establishing a European supervisory authority (European Securities and Markets Authority) amending Decision no. 716/2009/EC and repealing Commission Decision 2009/77/EC cannot be qualified as voting shares issued by real estate companies, regardless of the amount of the shareholding held directly or indirectly by the company.
c) the long-term conclusion of or accession to one or more of the following, with a public contractor and either directly or by means of a company in which it holds a stake in accordance with the provisions of the GVV/SIR legislation, where applicable in collaboration with third parties:
i) DBF agreements, so-called “Design, Build, Finance” agreements;
ii) DB(F)M agreements, so-called “Design, Build, (Finance) and Maintain” agreements;
iii) DBF(M)O agreements, so-called “Design, Build, Finance, (Maintain) and Operate” agreements; and/or
iv) contracts for public works concessions relating to buildings and/or other real estate infrastructure and associates services, and on the basis of which:
i) the company is responsible for the provision, maintenance and/or operation for a public entity and/or citizens as end users, in order to satisfy a social need and/or to allow the provision of a public service; and
ii) the company, without necessarily having rights in rem, can assume, in whole or in part, the associated financing risks, availability risks, demand risks and/ or operating risks, in addition to any construction risk.
d) the long-term development, incorporation, management and operation, possibly by means of third parties, and provision of the following, either directly or by means of a company in which it holds a stake in accordance with the provisions of the GVV/SIR legislation, where applicable in collaboration with third parties:
i) utilities and storage facilities for the transport, distribution or storage of electricity, gas, fossil or non-fossil fuels and energy in general and associated assets;
ii) utilities for transport, distribution, storage or purification of water and associated assets;
iii) installations for the generation, storage and transport of renewable or nonrenewable energy and associated assets; or
iv) waste and incineration plants and associated assets.
In the context of the provision of immovable property, the Company may exercise all activities related to the incorporation, construction (without infringing the prohibition on acting as a property developer, except for occasional transactions), alteration, fitting out, renovation, development, acquisition, sale, letting, subletting, exchange, inclusion, transfer, subdivision, bringing real estate assets into a system of co-ownership or joint ownership, as described above, the granting or receipt of the right of superficies, the right to the usufruct, long-term lease or other real or personal rights, management and running of immovable property.
In accordance with the GVV/SIR legislation, the Company may also:
1 rent immovable property with or without a purchase option;
1 let immovable property, with or without a purchase option, with the understanding that it is only permitted to let immovable property with a purchase option as a secondary activity;
1 invest in securities other than properties within the meaning of the GVV/SIR legislation, on an occasional or temporary basis. These investments are made in accordance with the risk management policy adopted by the Company and shall be diversified to ensure suitable risk diversification. The Company may also possess unallocated liquid assets. The liquid assets may be held in any currency in the form of demand or term deposits or by any money market instrument susceptible to rapid mobilisation;
1 offer mortgages or any other securities or guarantees for the financing of the real estate activities of the Company or its Group;
1 grant loans;
1 perform transactions on permitted hedging instruments (as defined in the GVV/SIR legislation) to the extent that these transactions are part of a policy defined by the Company to hedge financial risks, with the exception of speculative transactions.
The Company may acquire, lease or rent, transfer or exchange any and all movable or immovable property, materials and necessities, and in general perform all commercial or financial operations directly or indirectly related to its objective and the exploitation of all intellectual rights and commercial properties pertaining to these.
Taking GVV/SIR legislation into account, the Company may obtain a share by contribution in cash or in kind, merger, demerger or other restructuring under company law, subscription, shareholding, financial intervention or by any other means, in all existing companies and enterprises, or those yet to be formed, in Belgium or abroad, whose company objective is similar to its own or which, by its nature, seeks to accomplish or facilitate the accomplishment of its own objective.
Any amendments to the Company’s Articles of Association shall require the prior approval of the FSMA.
capital
Capital (Article 7 of the coordinated Articles of Association)
The capital of WDP NV/SA amounts to 258,754,032.10 euros and is represented by 225,845,971 ordinary shares, each of which represents 1/225,845,971st of the capital.
None of these shares provides special voting or other rights.
Authorised capital (Article 8 of the coordinated Articles of Association)
The Board of Directors is authorised, within the constraints of the mandatory provisions contained in the applicable company law, to increase the capital on the dates and subject to the conditions that it specifies, on one or more occasions, up to a maximum amount of:
i) 125,703,776.34 euros, if the capital increase to be realised is a capital increase by cash with the possibility for the shareholders of the Company to exercise their preferential right or the irreducible allocation right (as referred to in the GVV/SIR legislation); and
ii) 125,703,776.34 euros, if the capital increase to be realised involves a capital increase in the context of paying an optional dividend; and
iii) 25,140,755.26 euros if the capital increase is achieved (a) through a contribution in kind, (b) a contribution in cash without the option for company shareholders to exercise their statutory preferential rights or irreducible allocation rights (as referred to in the GVV/SIR legislation) or (c) any other form of capital increase; with the understanding that the capital under this authorisation may not be increased by an amount exceeding the amount of the capital on the date of the Extraordinary General Meeting which approves the authorisation, being 24 April 2024.
This authorisation is valid for a period of five years commencing as of 3 May 2024 (being the date of publication in the Annexes to the Belgian Official Journal of the decision on the approval of the authorised capital). This authorisation is renewable.
As of the date of this Annual Report, the Board of Directors twice made use of the authorisation granted to it to increase the capital, and thus the available balance of the authorised capital as of the date of this Annual Report:
i) 125,703,776.34 euros, if the capital increase to be realised is a capital increase by cash with the possibility for the shareholders of the Company to exercise their preferential right or the irreducible allocation right (as referred to in the GVV/SIR legislation); and
ii) 125,703,776.34 euros, if the capital increase to be realised involves a capital increase in the context of paying an optional dividend; and
iii) 22,793,888.21 euros if the capital increase is achieved (a) through a contribution in kind, (b) a contribution in cash without the option for company shareholders to exercise their statutory preferential rights or irreducible allocation rights (as referred to in the GVV/SIR legislation) or (c) any other form of capital increase; with the understanding that in the context of the authorised capital, for the fiveyear authorisation period, the capital can never be increased beyond an amount of 251,407,552.69 euros.
Capital increase(s) may be performed by contributions in cash or in kind or the conversion of reserves, including profits carried forward and issue premiums as well as all the equity components in the Company’s individual IFRS annual accounts (compiled based on the GVV/SIR legislation) which can be converted into capital, with or without issuing or creating shares or other securities (of any existing kind), in accordance with the mandatory provisions set out in the applicable company law and the GVV/SIR legislation.
Eventual issue premiums will be shown in one or more separate accounts under shareholders’ equity in the liabilities on the balance sheet. The Board of Directors shall be free to decide to place any issue premiums – possibly after deduction of an amount not exceeding the cost of the capital increase in the meaning of the applicable IFRS rules – to an unavailable account, which shall constitute the third-party guarantee on the
same basis as the capital and cannot under any circumstances be reduced or eliminated except by a resolution of the General Meeting voting as for an amendment to the Articles of Association, except in cases of conversion into capital.
Under the conditions and within the limits set out in paragraphs one to five inclusive of this article, the Board of Directors can create or issue not only shares, but also subscription rights (whether or not attached to another security), convertible bonds, bonds repayable in shares, or other securities (of any existing kind), complying at all times with the mandatory provisions set out in the applicable company law and the GVV/SIR legislation. Without prejudice to the application of the mandatory provisions of the applicable company law and the GVV/SIR legislation, the Board of Directors may limit or cancel preferential rights in this case, even if it benefits one or more persons, other than employees of the company.
The Board of Directors has the power to amend the Company’s Articles of Association in accordance with capital increase(s) performed in the context of the authorised capital.
Share repurchases (Article 11 of the coordinated Articles of Association)
The Company may acquire, accept in pledge and sell its own shares and associated depository receipts in accordance with the applicable company law.
In addition, the Board of Directors is authorised to perform the following actions for five years starting on 3 May 2024:
1 acquire shares in the Company and associated depository receipts and accept these in pledge, at a minimum price or countervalue equal to 0.01 euros and at a maximum price or counter value equal to 125% of the closing price on the trading day before the date of the transaction, without the Company being allowed to own shares of the Company or depositary receipts relating thereto representing more than 10% of the total number of shares;
1 transfer shares in the Company and associated depository receipts, such as to one or more specific persons who are not employees, at a minimum price or countervalue equal to 75% of the closing price of the trading day before the date of the transaction.
On 31 December 2024 at the date of the annual report, WDP NV/SA did not possess any of its own shares.
Changes in capital (Article 12 of the coordinated Articles of Association)
Except for the option to use authorised capital by a decision of the Board of Directors, and taking into account the mandatory provisions in the applicable company law and the GVV/SIR legislation, only an Extraordinary General Meeting can decide to increase or decrease the capital, in the presence of a civil-law notary.
1 Capital increase in cash
Where the capital is increased by a cash contribution and without prejudice to the application of the mandatory provisions of the applicable company law, the preferential right can be restricted or cancelled.
In such cases, if the mandatory provisions of GVV/SIR legislation require the granting of an irreducible allocation right to existing shareholders when new securities are allocated, this irreducible allocation right must at least satisfy the following conditions:
1° it applies to all new securities issued;
2° it is granted to the shareholders in proportion to the share of capital that their shares represent at the time of the transaction;
3° a maximum share price shall be announced by no later than the evening prior to the opening of the public subscription period; and
4° in such cases, the public subscription period must be at least three trading days.
However, a capital increase in cash can also take place with the suspension of the statutory preferential right and without the allocation of an irreducible allocation right, provided that the following conditions are satisfied:
1° the capital increase takes place using the authorised capital;
2° the cumulative amount of capital increases carried out in accordance herewith over a period of twelve months shall not exceed 10% of the amount of the capital at the time of the decision to increase the capital.
This allows a GVV/SIR, among other things, to realise an exempted private offering of new shares by means of an accelerated private placement with an order book (so-called accelerated bookbuilding or ABB).
1 Capital increase in kind
When issuing securities against contributions in kind, the following conditions must be met without prejudice to the mandatory provisions contained in the applicable company law:
1) the identity of the contributor must be disclosed in the special report of the Board of Directors on the capital increase by contribution in kind, and also, where applicable, in the invitations to the general meeting that will decide on the contribution in kind;
2) the issue prices shall be no less than the lower value of (a) a net value per share dated no more than four months prior to the date of the contribution agreement or, at the discretion of the company, before the date of the capital increase deed, and (b) the average closing price of the thirty calendar days before this date;
3) unless the issue price as well as the method used are determined by the working day after conclusion of the contribution agreement and are announced to the public with indication of the timeframe within which the capital increase will actually be complete, the capital increase deed shall be executed within no more than four months; and
4) the report provided for under point 1 above must also explain the impact of the proposed contribution on the position of the earlier shareholders and more particularly on their share in the profits, in the net value per share and in the capital as well as the impact on voting rights.
For the application of point 2 above, an amount may be deducted from the sum specified in clause 2(b) above, that is equal to the part of the undistributed gross dividend to which the new shares may not grant a right. Where applicable, the Board of Directors shall specifically justify the dividend amount deducted, as described above, in its special report, and explain the financial conditions of the transaction in its annual financial report.
The special rules for capital increases in kind, explained above, do not apply to the contribution of a right to a dividend in the context of payment of an optional dividend, insofar as this is effectively open for payment to all shareholders.
1 Mergers, demergers and equivalent operations
The special rules for capital increases in kind, explained above, apply mutatis mutandis to mergers, demergers and similar operations to which the GVV/SIR legislation refers in this specific context. In this case, the “date of the contribution agreement” refers to the date on which the merger or demerger proposal was deposited.
Special rights of control are not granted to any categories of shareholders. WDP currently has only one reference shareholder, who has one representative on the Board of Directors by virtue of the binding right of appointment as set out in Article 15 of the coordinated Articles of Association, an excerpt of which is provided below:
“Notwithstanding the mandatory provisions in the applicable company law and notwithstanding the GVV/SIR legislation, and subject to the conditions and terms of this article, every natural person, legal entity or company (with or without legal personality) that individually and directly holds at least 10% of the shares in the Company (a “Reference Shareholder”), shall have a binding right to appoint one
director at the annual meeting. A Reference Shareholder shall have a binding right, subject to the terms and conditions contained in this article, to appoint one additional director for each block of 10% of the shares that the Reference Shareholder owns individually and directly in the company (…)”
On 25 April 2007, Deloitte Bedrijfsrevisoren, a member of the Belgian Institute of Registered Auditors with offices at Gateway building Luchthaven Brussel Nationaal 1 J, 1930 Zaventem, was appointed as the WDP company auditor.
On 27 April 2016, the statutory auditor, represented by its permanent representative, Kathleen De Brabander, was reappointed until the annual meeting of 2019.
On 6 December 2016, WDP launched an open call for tenders for this term of appointment as statutory auditor in accordance with the European Audit Directive 537/2014/EU. Due to this legislation, the term of Deloitte Bedrijfsrevisoren already ended at the Annual General Meeting of 26 April 2017. This meeting concerned the reappointment of Deloitte Bedrijfsrevisoren, represented by its permanent representative, Kathleen De Brabander, until the annual meeting of 2020.
The Annual General Meeting of 24 April 2019 conducted an internal rotation of the permanent representatives of the statutory auditor in the context of Article 22 (§ 3) of the Act of 7 December 2016 organising the profession and public supervision of company auditors. Kathleen De Brabander was succeeded by Rik Neckebroeck for the remainder of the term, i.e. until the annual meeting of 2020.
The Annual General Meeting of 26 April 2023 conducted an internal rotation of the permanent representatives of the statutory auditor in the context of Article 22 (§ 3) of the Act of 7 December 2016 organising the profession and public supervision of company auditors. Rik Neckebroeck was succeeded by Kathleen de Brabander, for an additional period of two years, i.e. until the annual meeting in 2025.
The duties of the statutory auditor consist of the auditing the consolidated and separate annual accounts of WDP NV/SA and the other Belgian subsidiaries.
In France, Deloitte & Associés SAS, represented by Pierre-Marie Martin, with offices at 6, Place de la Pyramide, 92908 Paris La Défense Cedex, was appointed as statutory auditor for the subsidiary WDP France SARL.
In the Netherlands, Deloitte Accountants B.V., represented by Viona Borreman, with offices at Gustav Mahlerlaan 2970, 1081 LA Amsterdam, the Netherlands, was appointed as the statutory auditor for the WDP Nederland S.A. subsidiaries
In Luxembourg, Deloitte Audit SARL, represented by Ronan Richard, with offices at Boulevard de Kockelscheuer 20, 1821 Luxembourg, was appointed as statutory auditor of the WDP Luxembourg S.A. subsidiary.
In Romania, Deloitte Audit SRL, represented by Claudiu Ghiurluc, with offices at 84-98 and 100-102 Calea Grivitei, The Mark Tower, 9th floor, District 1, 010735 Bucharest, was appointed auditor of the subsidiary Warehouses De Pauw Romania SRL. In addition, KPMG Audit SRL, represented by Vlad-Balanescu Raducu-Bogdan, with offices in DN1, Bucharest-Ploiești Road No. 89a, District 1, 013685 Bucharest, was appointed as the statutory auditor for the subsidiary Expo Market Doraly SRL.
The fees of the statutory auditor are determined based on prices in line with market conditions and independently of WDP as per the code of conduct and the standards of the Belgian Institute of Registered Auditors and in accordance with the applicable provisions with regard to the independence of company auditors set out in the Belgian Code of Companies and Associations.
For further information on statutory auditor fees, please see Chapter 9 Annual accounts on p. 264.
ABN AMRO Bank N.V.
Julie Nollet
Gustav Mahlerlaan 10, P.O. Box 283 (HQ 7212), 1000 EA AMSTERDAM +31 20 628 0647
julie.nollet@nl.abnamro.com
The fees for financial services are determined based on market conditions as a percentage of the volume of the transactions concerned (such as dividend payments, optional dividends, etc.) and are independent of the Company.
For further information on financial service fees, please see Chapter 9. Annual accounts on p. 264.
In accordance with the GVV/SIR legislation, the expert values all buildings of the GVV/ SIR and its subsidiaries at the end of each financial year. The book value of the buildings appearing on the balance sheet is adjusted to these values.
In addition, at the end of each of the first three quarters of the financial year, the independent property expert updates the overall valuation prepared at the end of the previous year based on the development of the market and the individual characteristics of the properties in question. The expert also values the properties of the GVV/SIR and its subsidiaries if the GVV/SIR wishes to perform transactions such as share issues or mergers.
All immovable property that the GVV/SIR or its subsidiaries want to acquire or transfer are valued by the independent property expert prior to the transaction. The valuation of the
expert shall apply as a minimum price (in cases of disposal), or maximum price (in cases of acquisitions) for the GVV/SIR when the counterparty is a person that is closely involved with the GVV/SIR (as determined in the applicable regulations for GVVs/SIRs) or if such persons receive any benefits from the transaction in question.
The GVV/SIR legislation formulates statutory obligations on procedures followed by property experts to ensure the necessary degree of independence of property appraisers in the valuation of the property. It is stipulated that the remuneration cannot be related to the value of the property that forms the subject matter of the expert’s report.
An obligation is also imposed on the GVV/SIR to ensure replacement of the expert(s) that it appoints under a double rotation requirement. Thus, the GVV/SIR may only appoint the expert for a renewable term of three years. Moreover, an expert may only be entrusted with the valuation of a particular property for a maximum period of three years, after which a cooling-off period of three years must be observed. Therefore, an expert who has already served a three-year term may only be appointed for a new three-year term if, for this period, the expert is responsible for valuing a different part of the assets of the public GVV/SIR or its subsidiaries. Special rules apply if the expert is a legal entity.
As of 31 December 2024, the property experts appointed by WDP NV/SA are:
1 Stadim CVBA, Mechelsesteenweg 180, 2018 Antwerp – Belgium, represented (within the meaning of Article 24 of the GVV/SIR Act) by Céline Janssens;
1 Jones Lang LaSalle BV/SRL, Marnixlaan 23, 1000 Brussels – Belgium, represented (within the meaning of Article 24 of the GVV/SIR Act) by Greet Hex;
1 Jones Lang LaSalle BV, Parnassusweg 727, 1077DG Amsterdam – The Netherlands represented (within the meaning of Article 24 of the GVV/SIR Act) by Justin Stortelers;
1 CBRE Valuation & Advisory Services B.V., Anthony Fokkerweg 15, 1059 CM Amsterdam, the Netherlands, represented (within the meaning of Article 24 of the GVV/SIR Act) by Walter de Geus;
1 BNP Paribas Real Estate Valuation France SAS, 50 cours de l’Ile Seguin, 92100 Boulogne-Billancourt, France, represented (within the meaning of Article 24 of the GVV/SIR Act) by Caroline Hussenot;
1 CBRE Real Estate Consultancy SRL, One Tower, 165 Calea Floreasca, 14th Floor, Bucharest, Romania, represented (within the meaning of Article 24 of the GVV/SIR Act) by Ovidiu Ion;
1 Jones Lang LaSalle Luxembourg SCS, rue du Puits Romain 37, L-8070 Bertrange, Luxembourg, represented (within the meaning of Article 24 of the GVV/SIR Act) by Greet Hex;
1 CBRE GmbH, Große Gallusstraße 18, 60312 Frankfurt am Main, Germany, represented (within the meaning of Article 24 of the GVV/SIR Act) by Kristine Kühn.
Remuneration for property experts is not connected to the value of the property and is based on a fixed fee per property valued and/or a variable fee according to the surface area valued. The agreements with the property experts satisfy the relevant regulations.
For further information on the division of the property portfolio or property expert fees, see Chapter 9. Annual accounts on p. 246 and on p. 264.
WDP and its subsidiaries must take out adequate insurance cover for all of their immovable property. The insurance cover must be in line with customary market conditions. All WDP buildings are insured for their new construction value.
For further information on the insured value and the premiums paid for insurance cover, we refer to Chapter 9. Annual accounts on p. 241 and 248 and on p. 265.
3
5
To ensure optimal management of the property portfolio abroad, WDP has subsidiaries and sub-subsidiaries in a number of European countries (these companies do not have the status of an institutional GVV/SIR).
1 The companies in the Group have a number of features in common.
1 The company structure is also the local equivalent of a private limited company (‘BV’) or a public limited company (‘NV/SA’).
1 WDP owns 100% of the shares in all foreign subsidiaries and sub-subsidiaries, except for WDP Romania (85%)3 and WDP Luxembourg (55%).
1 WDP NV/SA is represented in France by its permanent establishment at rue Cantrelle 28, 36000 Châteauroux, France4
1 WDP Nederland S.A. also has two 100% subsidiaries, WDP Development NL S.A., Hoge Mosten 2, 4822 NH Breda and WDP Services NL B.V., Hoge Mosten 2, 4822 NH Breda.
The results of the subsidiaries are subject to local corporate income tax, except for WDP The Netherlands which has FBI status (Fiscale Beleggingsinstelling)5 and WDP France which has SIIC status (Société d’Investissement Immobilier Cotée), with the corresponding fiscal transparency.
More information on the FBI status and the SIIC status is available under REIT status earlier on in this chapter.
The net income can be disbursed to WDP, in which case the withholding tax or exemption depends on the EU Parent-Subsidiary Directive, its implementation in the local legislation of the respective countries and the applicable double taxation agreements between Belgium and the various countries in which WDP is active. Results from foreign subsidiaries are included in the consolidation, after elimination of the depreciation of immovable property and offset of deferred tax receivables.
The choice of financing method (group loans versus bank loans) must always take into account the impact of this financing on the consolidated gearing ratio for WDP (the maximum gearing ratio at the consolidated level must be respected and amounts to 65% as per GVV/SIR legislation. This same maximum gearing ratio also applies to the separate statements of the GVV/SIR). At the consolidated level, subordinate group loans do not affect the Group’s gearing ratio. On the other hand, bank loans do.
For this financing strategy, the main factors to consider (aside from the gearing ratio) are the two key principles of taxation that differ from country to country:
1 the rules on the thin capitalisation obligation for companies;
1 the withholding tax percentage to be deducted on interest payments on outstanding group loans disbursed to the country of origin.
Acquisition price
This refers to the value of the property at the time of purchase. Any transfer costs paid are included in the acquisition price. See also Transfer costs.
Initial yield
The ratio of the (initial) contractual rent of a purchased property to the acquisition price. See also Acquisition price
Accelerated bookbuild (ABB)
An exempt accelerated private placement with international institutional investors with the composition of an order book.
APM (Alternative Performance Measure)
Financial measurement of historic or future financial performance, financial position or cash flow of a company that has not been defined in the customary reporting guidelines. The Alternative Performance Measures (APM) adopted by WDP – including the EPRA key performance indicators – are always accompanied by a symbol (®) and are provided with their definition and reconciliation in the appendices to this report.
CAGR
Compounded annual growth rate.
Contractual rent
The gross rental prices as contractually stipulated in the lease agreements on the date of conclusion.
Derivatives
As a borrower, WDP would like to hedge itself against any interest rate increases. The interest rate risk can be hedged in part by using derivatives (such as interest rate swaps).
Discounted cash flow
This is a valuation method based on a detailed projected revenue flow that is discounted to the current net value at a specific discount rate according to the risk of the asset to be valued.
Due diligence
Extensive investigation conducted within the framework of all acquisitions and/or financial transactions in the areas of real estate, economics, taxation, law, bookkeeping and administration, possibly in association with specialist external advisors.
Fair value
The fair value is defined in IAS 40 as the amount for which the property could be exchanged between two well-informed, willing parties in an arm’s length transaction. The market value must additionally reflect the current rental incomes, the current gross margin for self-financing (or cash flow), the reasonable assumptions regarding potential rental income and the expected costs.
Estimated rental value (ERV)
The estimated rental value is the rental value determined by the independent property experts.
The IAS (International Accounting Standards) and IFRS (International Financial Reporting Standards) apply to the preparation of annual accounts and are drafted by the International Accounting Standards Board (IASB).
IAS 16 Tangible fixed assets
IAS 16 is an IAS/IFRS that applies to the administrative treatment of tangible fixed assets unless a different standard requires or permits different treatment. The main issues arising in the administrative treatment of tangible fixed assets is the recognition of assets, calculation of their book value and depreciation costs and special impairment losses to be recognised in relation to the assets.
IAS 40 Investment properties
IAS 40 is an IAS/IFRS that applies to recognition and measurement of and the provision of information on investment properties. This standard therefore provides the treatment method for investment properties and the corresponding disclosure requirements.
IFRS 9 Financial instruments: recognition and measurement
IFRS 9 is a standard that determines how a company must classify and measure the financial instruments on its balance sheet. Among other things, this standard provides for the obligation that all derivatives must be booked in the balance sheet at their fair value.
Contribution in kind
The assets contributed when a company is incorporated or when its capital is increased, other than by depositing money.
Indexation
The rent is contractually adjusted for inflation annually on the anniversary of the contract start date based on the reference index in each specific country.
Income capitalisation
This is a valuation technique used for valuing real estate where the income stream is discounted in a perpetuity at a certain required rate of return. Subsequently, certain corrections are applied to account for deviations in full occupancy under market conditions (subletting, incentives, vacancies, etc.).
Interest Rate Swap (forward)
An IRS where the start date is in the future.
Interest Rate Swap (IRS)
An interest rate swap is an instrument in which parties exchange interest payments with one another for a set term. WDP uses Interest Rate Swaps to convert floating interest payments into fixed interest payments, to hedge against interest rate increases.
IVSC (International Valuation Standards Council)
An independent body that develops global standards regarding valuations that investors and other third parties or stakeholders should be able to trust.
Quality distribution of the properties in the property portfolio
The quality distribution of the properties within the property portfolio is based on a classification according to Class A green-certified warehouse, Class A warehouse, Class B warehouse and Class C warehouse. This classification is based on the following parameters: age and location of the property, clear height, prospects for expansion and/or development, equipment and parking.
Optional dividend
The transfer of ownership of a property is, in principle, subject to the collection by the state of transfer rights that constitute the bulk of the transaction costs. The amount of these rights depends on the method of transfer, the capacity of the buyer and the geographical location of the property.
Partial demerger
A partial demerger is a legal transaction in which part of the assets of a company (both rights and obligations) is transferred to an existing or new company without dissolution, in exchange for transfer of shares in the acquiring company to shareholders in the demerging company.
Property portfolio
The portfolio value is composed of investment properties, investment properties under development for own account with the purpose of being rented out, assets held for sale and the fair value of the solar panels.
Project development team
Management of construction or renovation projects. WDP has an internal team of project managers working exclusively for the company.
Property management team
Day-to-day management of the property portfolio, more specifically formulation of the policy for management of existing buildings (maintenance, modification and improvement works). WDP has an internal team of property managers working exclusively for the company.
Fair value
See Fair value
Interest hedging
The use of derivative financial instruments to protect existing debt positions against an increase in interest rates.
Gross dividend
The gross dividend per share is the dividend before deduction of the withholding tax. See also Immovable property tax.
Dividend yield
Gross dividend divided by the share price.
Ex-date
Start date of trading the share on the stock market without entitlement to the next dividend distribution, in other words, the cut-off date of the coupon.
Free float
Percentage of shares owned by the public. According to the definition of EPRA and Euronext, this means every individual shareholder that possesses 5% of the total number of shares.
Optional dividend
With an optional dividend, the dividend claim linked to an established number of existing shares provides the right to a new share, at an issue price per share that may include a discount compared to the share price (whether or not an average share price over a certain period). The issue of shares within the framework of the optional dividend is subject to standard company law on capital increases. If, in addition to a contribution in kind within the framework of the distribution of an optional dividend, a contribution in cash is made, the special provisions of article 26, § 1 of the GVV/SIR Act concerning capital increases in cash cannot be declared applicable in the articles of association, insofar as this optional dividend is effectively made payable to all shareholders. The special rules on contribution in kind to a GVV/SIR, as provided for by Article 26, § 2 of the GVV/SIR Act, do not apply either, provided certain conditions are met.
Liquidity
This is the average number of shares traded per trading day measured over a specific period of time.
Market capitalisation
Closing price on the stock market multiplied by the number of shares in circulation on that date.
Net dividend
This is equal to the gross dividend after deduction of the 30% withholding tax. See also Immovable property tax.
Record date
The date on which the positions are closed for identification of shareholders entitled to dividends, also known as the ex-date for short.
Immovable property tax
An advance levy deducted by a bank or financial intermediary on the payment of a dividend. The standard rate of the immovable property tax on dividends in Belgium is fixed at 30%.
BREEAM (Building Research Establishment Environmental Assessment Method)
BREEAM is a sustainability certificate related to the performance of a building over its complete life cycle.
BREEAM is the main and most commonly used sustainability label for buildings in Europe. Unlike other standards, BREEAM applies a multi-criteria approach. The certification process examines not only the energy consumption of a property, but also land use, ecology, the construction process, water use, waste, pollution, transport, materials, health and comfort. As a total score, a building is rated Acceptable (only applicable to BREEAM In-Use), Pass, Good, Very Good, Excellent or Outstanding.
Greenhouse gases (GHG)
Greenhouse gases are a collection of gases expressed in CO2 equivalents that absorb heat from the sun and trap it in the Earth's atmosphere.
Carbon removal
Carbon removal is a process where residual emissions (CO2) are removed from the atmosphere and stored for long periods of time. The removal of GHGs means the removal of greenhouse gases (GHDs) from the atmosphere by deliberate human activities. In other words, in addition to the removal that would occur via the natural carbon cycle or atmospheric chemical processes. Carbon removal is integrated as a part of the strategy to move – after the maximum reduction of greenhouse gas emissions – towards net-zero emissions.
Cradle-to-Grave:
Refers to a full life cycle inventory, including all emissions and disposals of a given product or material starting from its acquisition up to the end of its useful life.
Cradle-to-Gate:
Refers to a partial life cycle inventory, including all emissions and disposals starting from the purchase of the material up to the moment the material reaches the WDP worksite (and thus excluding the use of the end product and end of useful life).
EDGE (Excellence in Design for Greater Efficiencies)
Certification programme for green buildings that focuses on the efficient use of resources. EDGE supports developers and builders to quickly and cost-effectively reduce energy and water consumption or energy absorbed by materials. EDGE certificates are issued worldwide and are an initiative of IFC, part of the World Bank Group.
Embodied carbon
Greenhouse gases released during the production, transport and construction of building materials as well as during the demolition of buildings.
Green Energy Certificates (GECs)
These are granted by the Flemish Electricity and Gas Market Regulator (the 'VREG') in Flanders, the Wallonia Energy Commission (the 'CWaPE') in Wallonia and the Romanian Energy Regulatory Authority (the 'ANRE') in Romania for alternative energy projects, including solar power, with a minimum price per certificate.
Carbon dioxide (CO2)
A greenhouse gas produced by the decomposition of plant-based or animal matter.
PV installation
Photovoltaic or solar panel system.
Scope 1
Direct greenhouse gas emissions caused by sources owned or under direct control of the Group, such as office and transport-related activities.
Scope 2
Indirect greenhouse gas emissions from the generation of purchased electricity or heat. This energy generation occurs outside the Group's control but results in the emission of greenhouse gases.
Scope 3
Indirect greenhouse gas emissions caused by the operating activities of another organisation in the value chain, both from suppliers and customers of the Group.
TCFD
The Task Force on Climate-related Financial Disclosure is a reporting standard that allows companies to report on the financial impact of climate factors on business operations.
Corporate Governance Code 2020
Belgian code drawn up by the Corporate Governance Committee with practices and provisions on good governance that must be met by companies under Belgian law whose shares are traded on a regulated market.
EPRA (European Public Real Estate Association)
EPRA is a pan-European association of listed real estate companies that aims to promote the sector, introduce best practices for bookkeeping, reporting and corporate governance, provide qualitative information to investors and serve as a think tank for challenges facing the sector.
FBI (Fiscale Beleggingsinstelling)
Special fiscal status in the Netherlands available if specific requirements are met. See also 10. Appendices – Permanent document.
FSMA (Financial Services and Markets Authority)
Along with the National Bank of Belgium (the NBB), the FSMA supervises the Belgian financial sector. The powers of the FSMA fall into the following six areas: supervision of financial markets and listed companies, conduct supervision, product supervision, supervision of financial service providers and intermediaries, supervision of supplementary pensions and facilitation of better financial education.
GVV/SIR (Regulated Real Estate Company)
A regulated real estate company is a listed operational real estate company that specialises in making immovable property available to users and meets the legal requirements as set out in the GVV/SIR legislation. It positions itself in an international context as a REIT, characterised by a regime of fiscal transparency. The GVV/SIR is subject to the prudential supervision of the FSMA. See also GVV/SIR legislation
GVV/SIR ROYAL DECREE
Royal Decree of 13 July 2014 on regulated real estate companies and, together with the GVV/SIR Act, i.e. the GVV/SIR legislation. See also GVV/SIR Act, GVV/SIR legislation and REIT.
GVV/SIR Act
Act of 12 May 2014 on regulated real estate companies and, together with the GVV/SIR Act, i.e. the GVV/ SIR legislation. See also GVV/SIR Royal Decree, GVV/SIR legislation and REIT
GVV/SIR legislation
The Act of 12 May 2014 (GVV/SIR Act) and the Royal Decree of 13 July 2014 (GVV/SIR Royal Decree).
Reference shareholder
Any natural person, legal entity or company (possibly with a legal personality) that holds at least 10% of the shares in the Company individually and directly, in accordance with Article 15 of the Articles of Association of the Company.
Regulated Property Companies (GVVs/SIRs)
International designation for listed real estate investment funds with a special tax status (such as in Belgium (see also GVV/SIR), the Netherlands (see also FBI) and France (see also SIIC)).
SIIC (Société d’Investissement Immobiliers Cotée)
Special tax status available in France that listed real estate companies can opt for if the specific requirements are met. See also 10. Appendices – Permanent document.
WDP NV/SA
Blakebergen 15, B-1861 Wolvertem T. +32 (0)52 338 400 info@wdp.eu | www.wdp.eu


www.facebook.com/WDPwarehouses linkedin.com/company/wdp
Company number: BE 0417.199.869 (Register of legal entities of Brussels, Dutch section)
Design and realisation: CF Report I Text and photography: WDP I Translations: ElaN Translations This report has been printed on FSC certified paper.