Q22026 Market Report
CLOSED SALES
2,424
95 DAYS ON MARKET
4% DISCOUNT
Year-to-Year
Quarter-to-Quarter
6,585 INVENTORY
$1,300,000 MEDIAN PRICE +6.1%Year-to-Year
MEDIAN $/SF
$1,428
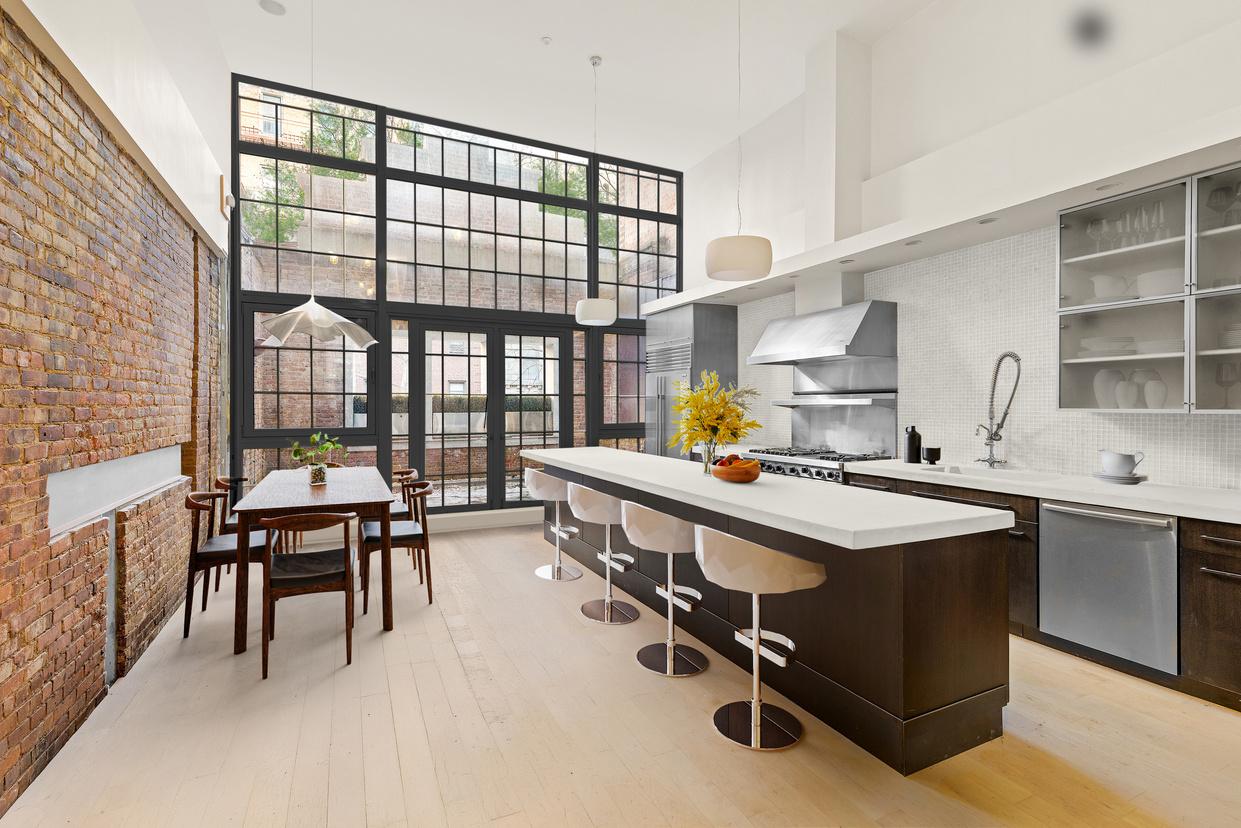
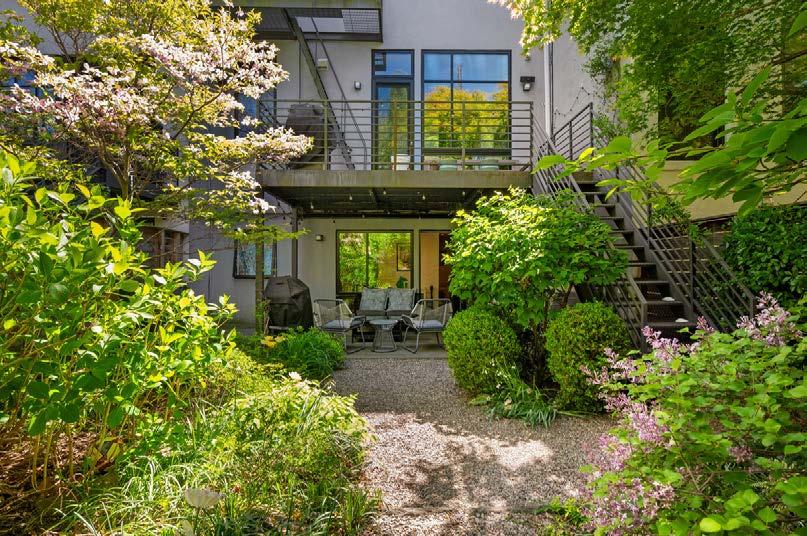
FeaturedListing 150 East 22nd Street, Carriage House

Q22026 Market Report
CLOSED SALES
2,424
95 DAYS ON MARKET
4% DISCOUNT
Year-to-Year
Quarter-to-Quarter
6,585 INVENTORY
$1,300,000 MEDIAN PRICE +6.1%Year-to-Year
MEDIAN $/SF
$1,428
FeaturedListing 150 East 22nd Street, Carriage House
Upper East Side
The Upper East Side was solid but more nuanced than earlier in the year. Resale
condos held steady, while co-ops paused
after a stronger run, suggesting buyers
remain engaged but disciplined.
Townhouses continued to show year-over-
year strength, though a longer time on
market points to the uneven nature of that
segment. Overall, the neighborhood remains well-supported, especially for classic, well-
priced inventory, but sellers still need to
respect where demand actually sits.
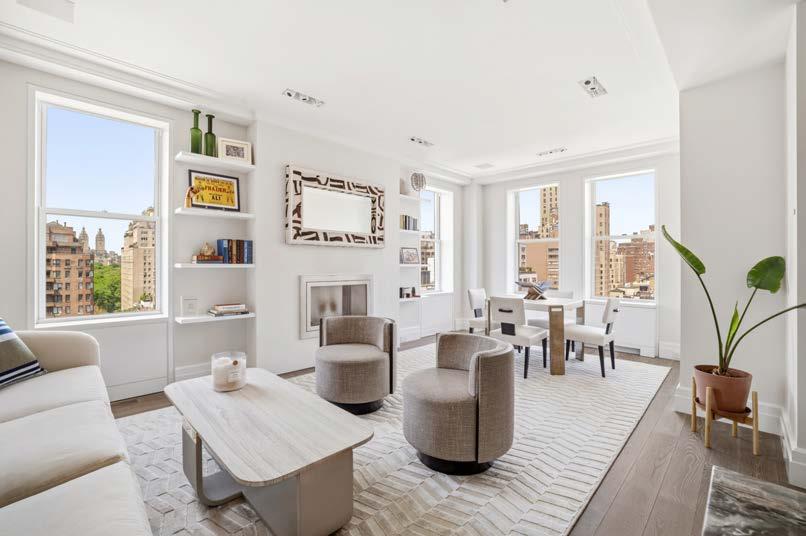
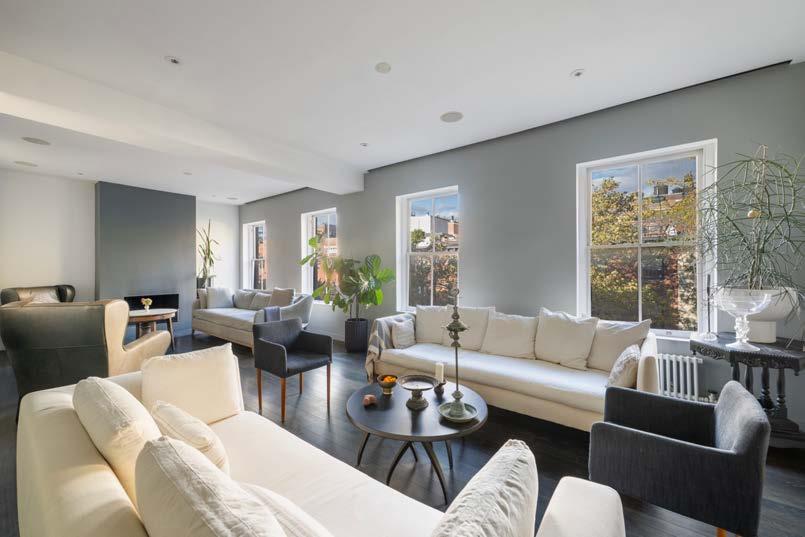
FeaturedListing
784 PARK AVENUE, 14C
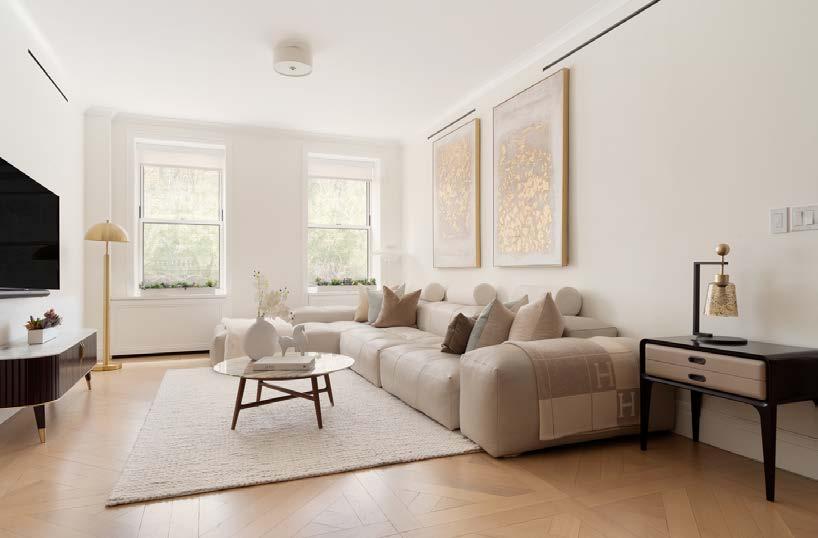
The Upper West Side turned in one of Manhattan ’ s better spring performances. Condo pricing strengthened meaningfully from last year, while co-ops remained steady and continued to draw value-oriented demand. Townhouse results were more volatile, as they often are, but the broader neighborhood tone was positive. The UWS continues to benefit from deep end-user demand, and with more inventory available, buyers had more choice without gaining overwhelming leverage.
FeaturedListing
498 WEST END AVENUE, 3C
Midtown hells kitchen
chelsea
hudson yards
Kips Bay
Turtle Bay
GRAMERCY FLATIRON NOMAD
Stuytown
Sutton Place
Murray Hill
Midtown remained a bit of a patient market, but not a weak one. Condos and co-ops both showed sufficient price stability to
suggest demand remains, even if buyers are
more selective than in stronger lifestyle-
driven neighborhoods. Time on market
remains elevated, underscoring the need for
sharper pricing and clearer product
positioning. The story here is less about
momentum and more about execution:
standout listings can move, but middling
inventory still has to work harder.
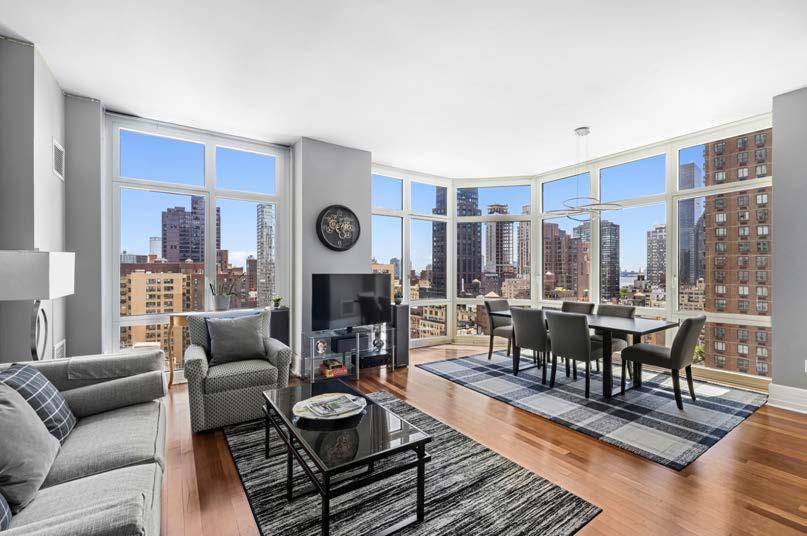
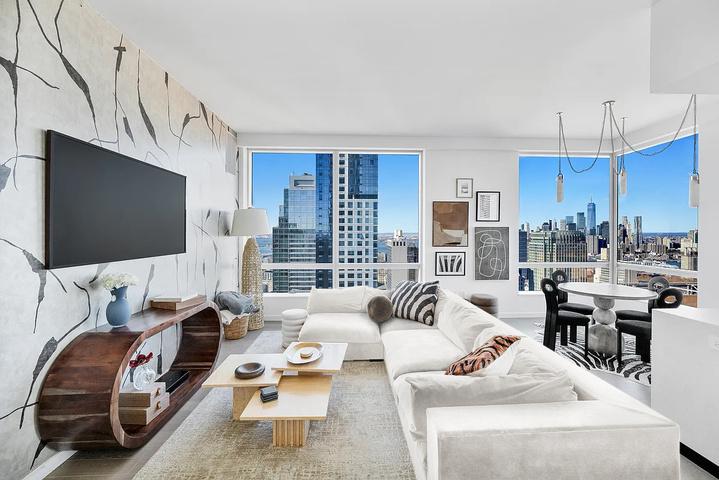
FeaturedListing
300 EAST 55TH STREET, 16D
EAST VILLAGE
West VILLAGE
NOHO/SOHO
TRIBECA
LOWER EAST SIDE
NOLITA/Little Italy
Chinatown
FiDi/Civic Center Battery Park
Two Bridges Seaport Hudson Square
Downtown continues to command attention, especially for quality condos and well-located properties. While pricing did not move in a
straight line, buyers continued to pay for location, finishes, and scarcity. Co-ops
softened on a price-per-foot basis, but, as
always, remain part of the broader value
conversation. As expected, townhouses again
showed the volatility that comes with limited
sales at higher price points. Downtown
remains a market where quality sets the tone
more than averages do.
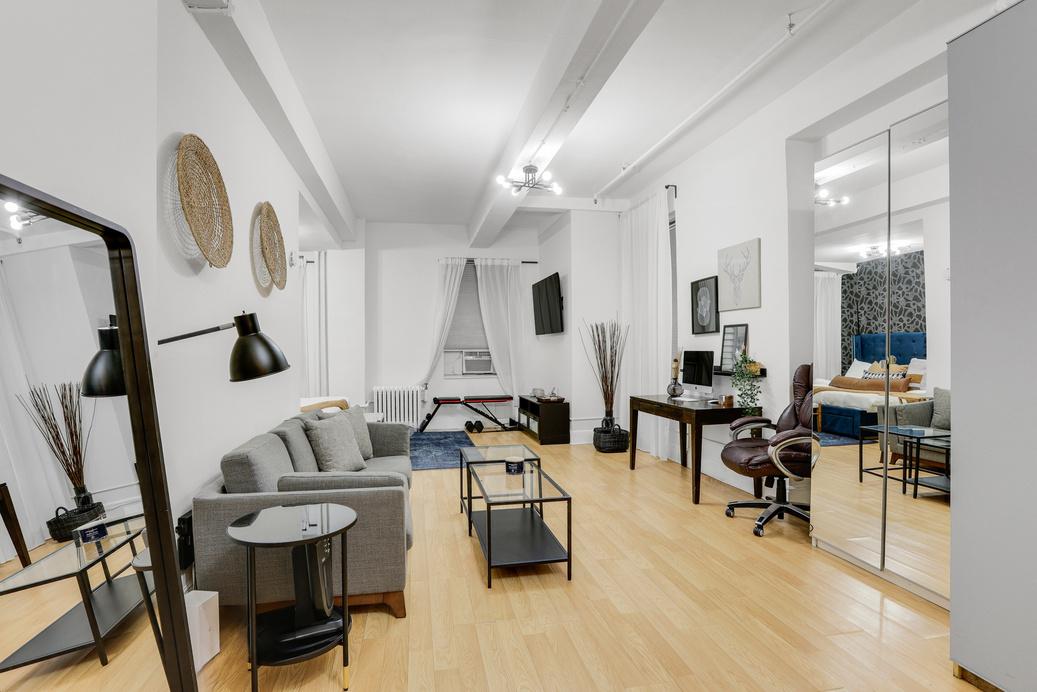
FeaturedListing
12 West 10th Street, 4
CLOSED SALES
1,965
Year-to-Year
Quarter-to-Quarter
71 DAYS ON MARKET
Year-to-Year
Quarter-to-Quarter
3.11% DISCOUNT
Year-to-Year
Quarter-to-Quarter
3,824 INVENTORY
Year-to-Year
Quarter-to-Quarter
$1,050,000
$1,000,000 $1,050,000
$850,000 $900,000 $950,000
Brooklyn Heights
Cobble Hill
Carroll Gardens
Boerum Hill
Park Slope
Fort Greene
Clinton Hill
Prospect Heights
Brownstone Brooklyn remained one of
Brooklyn ’ s strongest spring markets, but the
strength was not evenly distributed. Resale
condos and townhouses did the heavy lifting,
with condo pricing rising sharply and
townhouse medians jumping on both a
quarterly and annual basis. Co-ops were
softer on headline price, though fast
marketing times and full-ask execution
suggest demand remains intact when value is
clea
r. Inventory expanded across product
types, but the market largely absorbed it. The
broader story is familiar: scarce, well-located, well-presented homes in Brownstone
Brooklyn still command attention, even as
buyers remain selective
Listing
191 Baltic Street, 1

DUMBO GOWANUS RED HOOK
Downtown Brooklyn BROOKLYN NAVY YARD
T
N
hwest/Downtown Brooklyn corridor remained mixed but with clear
pockets of strength. Condo prices rose
meaningfully from last year, and co-ops also improved, suggesting buyers continue
to respond to convenience, transit, and, most importantly, relative value.
Townhouses were softer and highly
sample-size dependent. Overall, this
corridor remains a micro-market story:
strong when product/price offerings match
the buyer pool and slower when pricing gets ahead of reality.
FeaturedListing
56 Court Street, 2B
Williamsburg
greenpoint
bushwick
North Brooklyn remained active, though
more balanced than overheated. Condo
inventory expanded, giving buyers more to
choose from, while pricing held reasonably well. Co-ops were more volatile, but the price-per-square-foot signal suggests demand
has not disappeared. Townhouses remained steady, helped by scarcity and continued
neighborhood appeal. The market here feels
healthy, but bu
chasing
ers are no longer blindly
hing.
BedStuy
Crown Heights
Prospect Park South Windsor Terrace Kensington Ditmas Park Dyker Heights
Central and South Brooklyn continued to tell a quietly constructive story. Condo prices improved, townhouses remained in demand, and the broader market showed that valueoriented buyers are still out and about. Coops were mixed, but they continue to play an important role in affordability. While this
part of Brooklyn may not always draw the loudest headlines, it remains one of the steadier areas for practical, end-user demand.
567 Lexington Avenue