BUILDING THE DATA CASE:
INSIGHTS FROM FIRSTHAND REPORTS REVEAL THE VALUE OF CHILD-LENS INVESTING
BUILDING THE DATA CASE:
INSIGHTS FROM FIRSTHAND REPORTS REVEAL THE VALUE OF CHILD-LENS INVESTING
There is a compelling moral and societal case for impact investors and social enterprises seeking to alleviate poverty to center children in their investment and business decision-making. However, their ability to act is constrained by a lack of data that dimensions the scale, nature and magnitude of impact that various investable interventions have in children’s lives.
UNICEF USA’s Impact Fund for Children and Global Partnerships sought to help fill this gap. In 2025, the two organizations collaborated with 60 Decibels, a third-party impact measurement company, and VisionFund International, a global microfinance network, to develop and pilot a child-lens impact assessment approach.
This case study highlights initial findings of the approach applied to housing finance and key implications for social enterprise investees, impact fund managers and investors.
Initial data highlights that allocating capital to housing is a promising pathway for impact on children’s well-being.
The addition of a child lens revealed that tailored housing finance products can be expanded to reach more underserved and marginalized children and families living in poverty.
Applying a child lens can reveal more precise and nuanced analysis of both positive outcomes for children and risks to their well-being.
Decent housing is a dimension of poverty that significantly affects children’s well-being, leading Global Partnerships to pilot the child-lens assessment with investees offering microloans for home construction and improvement, including Fundación Dominicana de Desarrollo.
Children and youth are disproportionately affected by poverty: they are more likely than adults to live on dollars a day,1 and the multifaceted deprivations of poverty often cause more significant and longer-lasting negative effects on children and youth, particularly girls.
Global Partnerships is a nonprofit impact-first fund manager focused on expanding opportunity for people living in poverty. It chose to pilot the child-lens assessment approach with investees tackling inadequate housing because of the magnitude of the problem and evidence pointing to its consequential impact on children and youth. Housing finance constitutes approximately 15 percent of Global Partnerships’ portfolio.2
Globally, 1.6 billion people lack access to adequate shelter.3 Evidence indicates that children’s cognitive development, health and education are significantly affected by the quality of their housing. For the families that Global Partnerships aims to serve (i.e., those living below the $6.85/person per day poverty line), overcrowding, unsafe structures, poor ventilation, dampness and exposure to dust, pests, sewage and extreme heat or rain increase the prevalence of preventable illness and injury. These issues drive missed school days and higher out-ofpocket health costs that further strain household finances. And they are compounded for girls, who often spend more time in the home than boys.4 Nevertheless, there remains persistent underinvestment in decent housing for low-income populations.5
Global Partnerships addresses this challenge through its Home Improvement Finance investment initiative, which has a research-informed thesis that microloans for home improvement and construction6 can improve health, security and sense of well-being for the households it aims to serve. Based on this thesis, Global Partnerships directs investments to microfinance institutions that provide loans and supporting services, such as budgeting and technical assistance from housing engineers, designed to enable families to pursue incremental home improvement or build new homes.
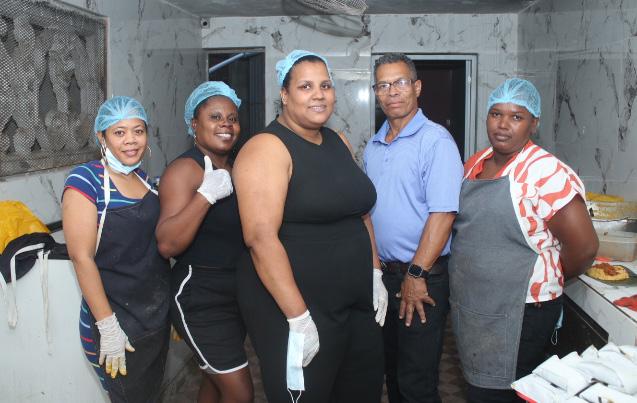
Fundación Dominicana de Desarrollo (FDD) has been a Global Partnerships investee since 2022.7 It is a nonprofit microfinance institution in the Dominican Republic that promotes financial inclusion through loans for microenterprises, housing and other uses, alongside financial and business education. FDD serves more than 16,500 clients, 62 percent of whom are female and 49 percent of whom live in rural areas.8 Around one-fourth of FDD’s clients are using its housing loan product Mi Casa Bonita (“My Beautiful Home”), which is designed to support home-owning families with improvements, repairs, expansions and new construction. FDD tailors the loan size to the project planned by the client, with support from credit officers to ensure appropriate project budgeting. Typical home improvement projects taken on by clients include adding floors, improving roofs, expanding with additional rooms, or enhancing bathroom facilities.
UNICEF USA’s Impact Fund for Children, Global Partnerships and collaborators designed the child-lens impact assessment to leverage data reported by clients of microfinance organizations on child outcomes, which social enterprise investees, impact fund managers and investors can use to understand, optimize and scale their impact.
The impact assessment included:
1. A housing finance survey module, which included five questions related to the enablement and nature of home improvements and perceived changes in household safety, health and climate resilience.
2. A new child-lens survey module, which included four questions9 related to changes in household physical living conditions and children’s well-being.
3. Disaggregation of 60 Decibels 2025 Microfinance (MFI) Index survey results, by households with children and those without, relevant to understanding impact on children, such as health care access, food security and nutrition.
With funding from UNICEF USA, Global Partnerships helped develop and integrate the housing finance and child-lens modules into FDD’s 2025 MFI Index survey to deepen understanding of outcomes enabled for clients and their families. Global Partnerships also worked with FDD post-assessment to interpret findings and identify actionable insights.
FDD’s assessment was based on responses from 28610 of its clients, collected through a mobile, voice-based survey conducted in 2025 by 60 Decibels. Several measures were taken to reduce response bias. Respondents were informed at the outset that the survey was anonymous and conducted by 60 Decibels, an independent research firm, on behalf of their financial service provider. In addition, survey questions were designed to avoid leading or suggestive phrasing. For a more detailed discussion of potential sources of bias and the steps taken to mitigate them, please refer to page 12 of the 60 Decibels 2025 MFI Index Report
FDD saw this study as a valuable opportunity to capture client-level data on the profile, experience and impacts enabled for its housing finance clients to inform the design of the Mi Casa Bonita product and strategic planning for this product’s role in FDD’s portfolio. The inclusion of a child lens increased FDD’s interest, as it believed this data would bring more clarity to aspects of impact evidenced through previous child-centered initiatives.
The findings presented in this case study should be interpreted as directional insights derived from client survey data. Caregiver and non-caregiver households differ across demographic dimensions beyond the presence of children — including age and location — and this should be kept in mind when interpreting comparisons between the two groups. Given that applying a child lens remains an emerging practice across the sector, even modest differences in outcomes across client groups can provide directional insights, which are intended to inform and guide decision-making, rather than establish definitive causal relationships.
Together, Global Partnerships and FDD identified key insights to strengthen and scale impact for children through housing finance. These insights improve decision-making and lay the groundwork for more targeted, evidence-based impact measurement and management.
Investing in housing finance is a promising pathway for impact on children’s well-being.
The assessment suggested that FDD’s housing loans effectively benefit children and contribute to their wellbeing. Sixty-nine percent of surveyed FDD clients reported children in the home (“caregivers”). Among these caregivers, 80 percent reported improved children’s well-being because of their engagement with FDD. Both data points were higher than the Global Partnerships average11 for Latin America and the Caribbean, indicating that the FDD product outperforms other financial inclusion products in the region in reaching and enhancing the well-being of children (Fig. 1).
Fig. 1. Percentage of clients with children in the household (“caregivers”) from the FDD survey compared to the average across Global Partnerships (GP) housing finance investees in Latin America and the Caribbean (LAC) with available data. Percentage of FDD caregivers reporting improved child well-being compared to the average across GP housing finance investees in LAC. Source: 60 Decibels 2025 MFI Index survey for FDD and three additional GP housing finance investees.
The most significant changes clients observed in their children’s lives included improved living conditions, happiness and emotional stability, and security and safety. In fact, 88 percent of caregivers reported improved household safety, whereas only 81 percent of clients without children did. This difference may suggest that households with children are more attuned to safety risks in the home and neighborhood, making housing improvements — such as stronger structures, better lighting, or more secure doors and windows — feel especially consequential for their families. Analysis of survey feedback also suggested that stronger walls and roofs helped families feel safer by reducing the risk of structural failure while children are playing and by lowering the likelihood that housing damage will compromise children’s safety.
My children now sleep peacefully, are more comfortable and are safer in case a thief wants to break in because now there is more security with the windows installed.
ANONYMOUS
FDD and social enterprises like it can use this data to improve communication around child-aligned impact and pursue additional or more attractive impact-aligned capital to scale products like Mi Casa Bonita to more families with children in poverty.
Global Partnerships and other impact fund managers can use this data to make the case for scaling impact capital allocation to client-centered housing finance solutions that deliver impact for children in poverty.
Investors can use this data to make informed decisions about allocating capital to housing finance products as a pathway for impact on children in poverty.
“At Global Partnerships, we recognize microfinance as a sustainable, scalable platform to address the multifaceted needs of the over 3 billion people living on dollars a day, with client-centered design and innovation being key drivers of impact. This data helps crystallize the case for home improvement finance as a credible path for improving the lives of families and children living in poverty. It also provides directional insight into which product and service features enable deeper inclusion and value creation.”
Tara Murphy Forde, Chief Capital and Impact Officer, Global Partnerships
The addition of a child lens revealed that tailored housing finance products can be expanded to reach more underserved and marginalized children and families.
FDD’s Mi Casa Bonita product had a low average loan size compared to similar offerings in Global Partnerships’ portfolio and is unique in that FDD makes the product available to first-time borrowers. Combined with additional data from the study, this suggested the Mi Casa Bonita product is filling a gap in the market for clients in poverty with children in the home.
For example, clients with children in the home appeared to face slightly more limited access to comparable financing than households without children. Forty-seven percent of households with children reported this was the first time they had accessed this type of loan, compared to 45 percent without children. While differences between the groups may seem small, they provide first-time insight into deviations between families with children and those without.
The assessment also found that, relative to other Global Partnerships housing finance investees with available data, FDD demonstrated comparatively strong outreach to clients living in poverty, ranking second in this aspect with an inclusivity ratio of 0.66.12 This indicates meaningful alignment with Global Partnerships’ target market. However, FDD’s performance remains below the average inclusivity ratio of 0.97 observed across Global Partnerships’ broader microfinance portfolio in Latin America and the Caribbean, which includes a more diverse range of loan products. These insights suggest that home improvement finance products tend to serve relatively higher-income segments compared to productive-use loans and underscore the importance of incorporating poverty-informed underwriting practices to enable deeper outreach to lower-income households.
When looked at in concert, this data enhances understanding of how financial products and design features influence the ability of microfinance institutions to responsibly reach underserved populations, which include marginalized children.
FDD can leverage this impact data alongside its operational metrics on financial performance and risk to inform strategic decision-making for its Mi Casa Bonita product, including around opportunities to strengthen inclusivity.
Global Partnerships and other impact-focused fund managers can use these results and insights to guide investment toward financial products that are more effectively and responsibly expanding access for families living in poverty.
Investors can use this data to better target capital toward social enterprises in the housing finance sector that are demonstrably addressing market gaps and reaching underserved families with children.
“These findings are proving crucial for strengthening FDD’s strategy and our products. They will directly inform our strategic planning, help us design new offerings and refine existing ones, and deepen our understanding of our clients’ needs. The results also open new channels to expand client protection communication and campaigns, and they enable us to measure impact more fluidly and transparently using indicators we can now track consistently. We analyzed the results not only through our evolving perspectives but also through the lens of our real impact on the people who are the reason we exist — and how our programs truly benefit them.”
Rosa Marubeny García, Executive Director of FDD
Applying a child lens reveals more precise and nuanced analysis of both positive outcomes for children and risks to their well-being.
FDD has collaborated with other child-aligned organizations in the past to address the risks of child labor within the communities it serves. This assessment reinforced the relevance of those efforts. While it identified strong positive outcomes for children, it also indicated that clients perceive a higher prevalence of child labor in FDD’s operating context compared to other housing finance investees in Latin America and the Caribbean.
In contexts where poverty is prevalent, it is not uncommon for children to contribute to household or family-run activities. Such participation can be appropriate and even beneficial when it is safe, age-appropriate and does not interfere with a child’s well-being, education or safety.
Fig. 2. Percentage of FDD caregivers reporting the noted changes in their children’s participation in labor that may interfere with child well-being, education, or safety compared to the average across Global Partnerships (GP) housing finance investees in Latin America and the Caribbean (LAC) with available data. Source: 60 Decibels 2025 MFI Index survey results for FDD and three additional GP housing finance investees.
As shown in Figure 2, 79 percent of FDD’s clients reported that their children do not engage in work that could negatively affect these factors (Fig. 2). However, this figure is 16 percentage points lower than the average reported across Global Partnerships’ housing finance investees in Latin America and the Caribbean. This gap highlights the importance of further examination around potential risks related to harmful child labor.
Knowing that risks of harmful child labor may exist in its countries of investment, Global Partnerships and many impact investors take proactive measures to mitigate such risks in investment portfolios. As part of environmental and social screening during due diligence, Global Partnerships evaluates whether each potential investee takes context-appropriate measures to mitigate risks of child labor among the investee’s clients’ businesses. FDD, for example, guides loan officers to report instances where they observe minors working at a prospective client’s businesses, and this may be grounds for denial of a loan application.
In the absence of data to dimension the scale and nature of risk, social enterprises and investors apply such risk mitigation practices with limited visibility into risk prevalence or mitigation strategies’ effectiveness. Applying a child lens to impact measurement and management enables a deeper understanding of these risks and helps identify opportunities to better safeguard children’s well-being.
For FDD, this finding reinforces awareness of child risk in its operating context and the value of additional measures it has put in place to mitigate them (e.g., proactive initiatives like training for parents to prevent child labor).
For Global Partnerships, other impact fund managers and investors, this finding is a reminder that the presence of positive outcomes for children does not imply the absence of risks to children. Effective impact underwriting should assess the potential for both positive and negative effects. Impact investors and fund managers should adopt risk mitigation strategies right-sized to the context and capacities of their investees and the nature and magnitude of the risks.
Children are disproportionately exposed to poverty’s harms. They are also natural stakeholders in many impact investing strategies, whether measured or not. Applying a child lens to data capture and analysis makes the effects on children visible, measurable and optimizable. Rather than adding complexity, it increases precision.
In the case of FDD, the application of a child lens to impact measurement and management is helping inform capital allocation, portfolio construction and investee support to optimize impact and mitigate risks. Risks and positive outcomes live side by side and a nuanced understanding of each is essential to maximize impact for children while mitigating potential harms. A child-lens approach to impact measurement and management therefore should be taken across the entire life cycle of an investment, from underwriting to measurement and monitoring.
The data serves as business intelligence for allocators, investment managers and social enterprises who share a desire to scale impact to vulnerable families. FDD and other social enterprises like it can use the data to refine housing loan products, expand outreach and attract aligned capital. Impact fund managers like Global Partnerships can use these insights to integrate child-lens signals into investment theses, portfolio analytics and advisory support. Impact fund managers and investors alike can use it to target investment strategies, align capital structures with the lived realities and needs of families with children living in poverty, and ask more precise questions about who benefits from investments and who may be at risk.
Overall, the assessment signals that the child lens is not just a values-based add-on, it is a material lens for understanding impact depth and risk.
The child-lens impact investment approach is new, and Global Partnerships is piloting it with additional social enterprises that provide working capital loans and education to female micro-entrepreneurs living in poverty. Learnings will be shared through additional case studies. The housing finance and child-lens modules are also being offered by 60 Decibels as add-ons to future MFI Index surveys. Early child-lens applications already show how capital can be better aligned with children’s lived realities and deeper adoption will require patience, partnership and continued evidence-building.
This is one of two case studies developed by UNICEF USA and Global Partnerships.
The Impact Fund for Children (IF4C) is the impact investing arm of UNICEF USA, providing innovative opportunities for donors and social impact investors seeking to help solve the biggest challenges for children around the world. In 2023, UNICEF and UNICEF USA’s Impact Fund for Children, with support from the Government of Finland and Tideline, launched the Child-Lens Investment Framework as a roadmap for investors to frame strategies, develop investment processes and direct capital toward advancing child outcomes and minimizing child harm.
Global Partnerships (GP) is a nonprofit impact-first fund manager dedicated to expanding opportunity for people living in poverty. GP and its affiliated funds provide capital, analytics and impact advisory support to social enterprises that deliver market-based products and services that empower people to earn a living and improve their lives. Each investment it makes starts with the end client and what they need.
60 Decibels is the world’s leading customer insights company for social impact. With a network of more than 1,700 researchers across 110+ countries, they bring reach, speed and repeatability to social performance measurement. Using advanced data collection techniques and AI analytics, 60 Decibels measures and benchmarks impact performance, helping its clients — investors, Fortune 500 companies and NGOs — make informed, data-driven decisions.
Financed by UNICEF USA’s Impact Fund for Children, this case study involved collaboration across UNICEF USA’s Impact Fund for Children, UNICEF’s Innovative Finance Hub, Global Partnerships and 60 Decibels. Analysis by Global Partnerships led by Tara Murphy Forde, Meghan Flaherty, Paola Centeno Duque and Carolina Hernández Cardona.
1. https://blogs.worldbank.org/en/opendata/the-demographic-profile-of-the-global-poor--who-are-the-poor-and
2. Based on data from Global Partnerships as of December 31, 2025.
3. https://unhabitat.org/up-for-slum-dwellers-transforming-a-billion-lives-campaign-unveiled-in-europe
4. https://unhabitat.org/sites/default/files/2022/08/children-cities-and-housing-rights-and-priorities.pdf
5. https://www.ifc.org/content/dam/ifc/doc/2023-delta/factsheet-green-resilient-and-inclusive-housing-finance.pdf
6. Home improvement refers to smaller interventions such as adding floors, improving roofs or adding bathroom facilities. Construction projects refer to the construction of new homes.
7. Fundación Dominicana de Desarrollo was a current borrower of Global Partnerships Impact-First Development Fund, LLC, as of December 31, 2025.
8. Data as of December 31, 2025, as reported by Fundación Dominicana de Desarrollo.
9. At the time of FDD’s survey, the full child-lens module comprised five questions. The survey omitted the fifth question on school attendance as it was not expected to be an outcome of a housing finance loan product.
10. This sample was randomly selected from the relevant client segment and enabled a 90 percent confidence level with a 5 percent margin of error.
11. Global Partnerships compared FDD’s results to averages across its housing finance investees in Latin America and the Caribbean.
12. Inclusivity is measured using an inclusivity ratio at the $6.85 Purchasing Power Parity (PPP)/person/day international poverty line, calculated as FDD’s percentage of clients living below $6.85 PPP/person/day divided by the percentage of the national population living below $6.85 PPP/person/day in its country of operations. A ratio of 1.0 indicates parity with national prevalence; values below 1.0 indicate lower representation of clients living in poverty relative to the national average.
Photographs — Front cover: © UNICEF/MCFARLANE; page 3: © Fundación Dominicana de Desarrollo; page 8: © UNICEF/MCFARLANE; page 10: © UNICEF/MCFARLANE; page 12: © Fundación Dominicana de Desarrollo; page 13: © Fundación Dominicana de Desarrollo; page 15: © Fundación Dominicana de Desarrollo;