Australia & New Zealand Q1 2026
• Rental – Slight increase in face rents
• Incentives – Remain stable
• Land Supply – Constrained development ready land
• Building Supply – Slowing and requires pre-commitment
• Demand – “Wait & see” approach in response to global issues
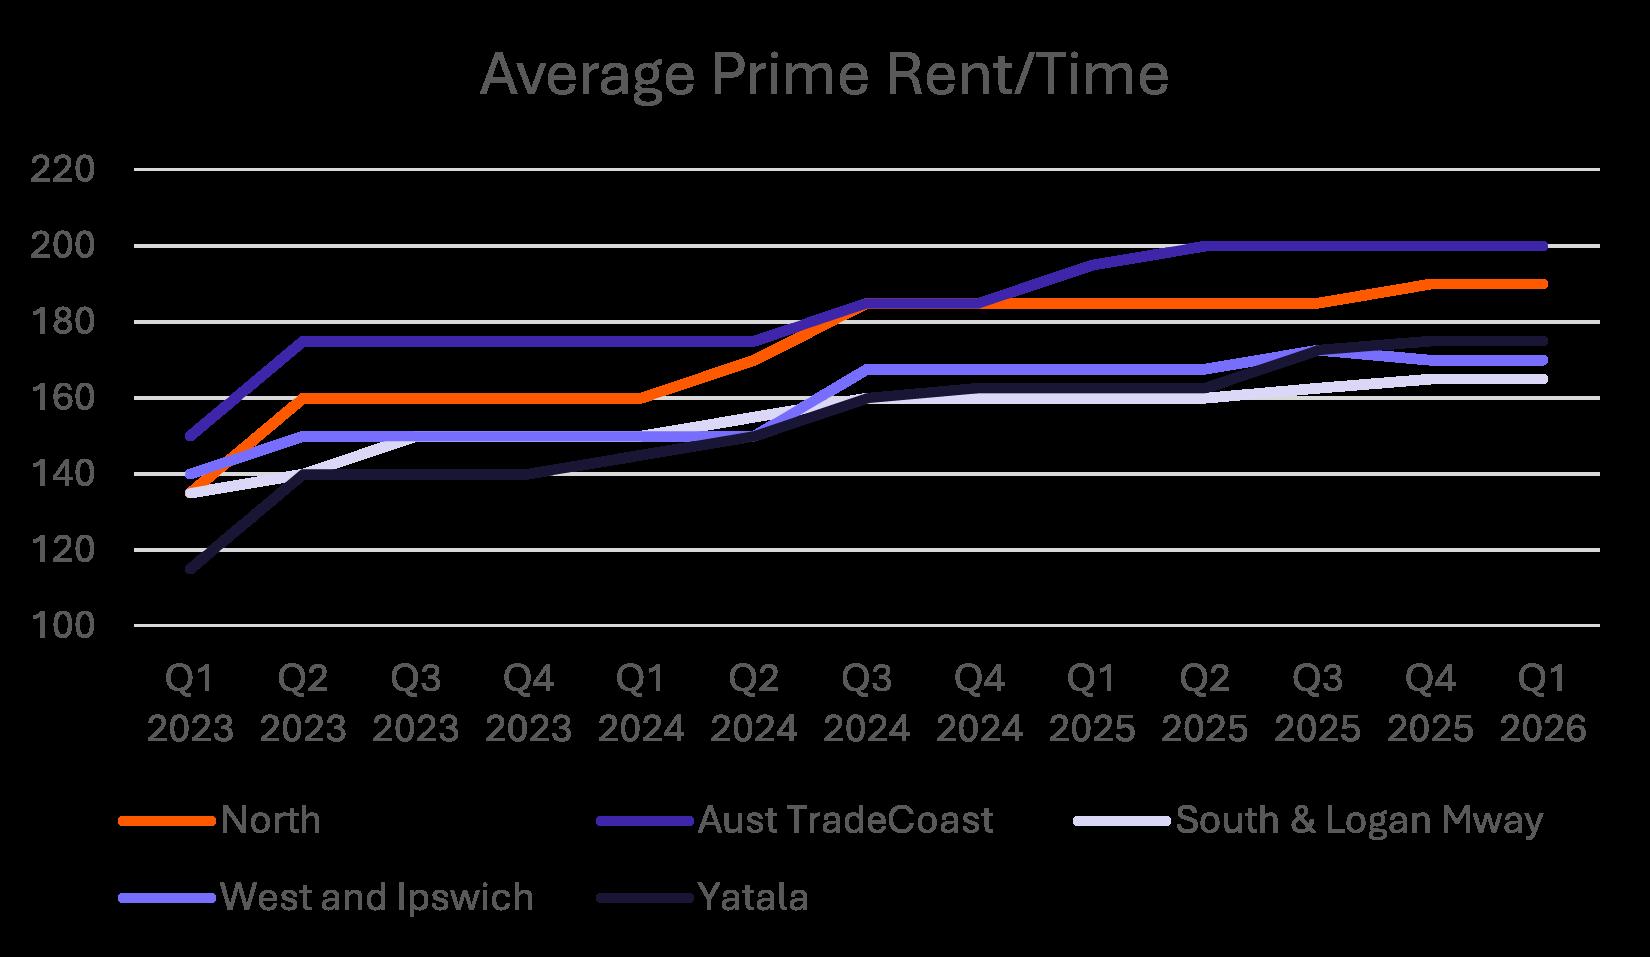
• Rental - Incremental increase in TradeCoast market
• Incentives - Stabilised from last quarter
• Land Supply - Highly constrained in all markets
• Building Supply - Reduced due to take up of last quarter
• Demand - Strong levels of enquiry and activity across markets
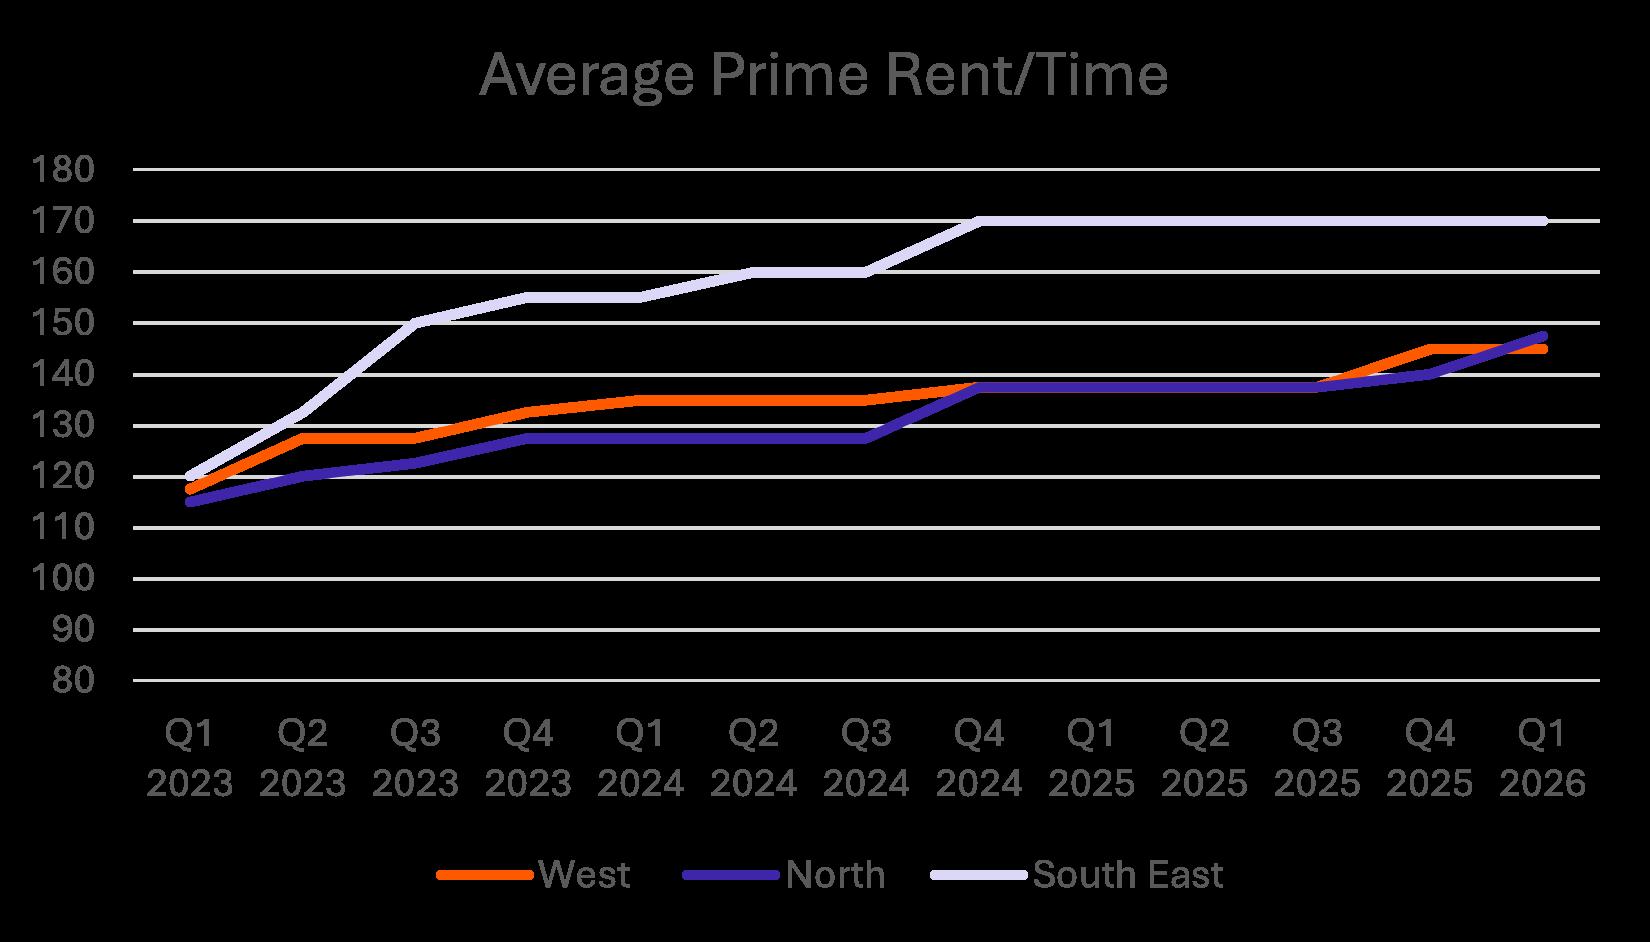
• Rental – Stable
• Incentives – Remain stable
• Land Supply – Concentrated in Outer West
• Building supply – Forecast to increase through 2026
• Demand – Large corporates active; take-up steady
• Rental – Stable through Q1
• Incentives – Remain stable for prime industrial
• Land Supply – New opportunities for Outer North
• Building Supply –Uncommitted specs in Outer North
• Demand – Positive sentiment across general
• Rental – Face rents holding firm
• Incentives – Holding despite reduction in supply
• Land Supply – Remains constrained
• Building Supply – A-Grade supply slowly being taken up
• Demand – Soft demand
• Rental - Stable
• Incentives – Beginning to be offered
• Land Supply – Remains in short supply
• Building supply – Increasing
• Demand – Stabilising
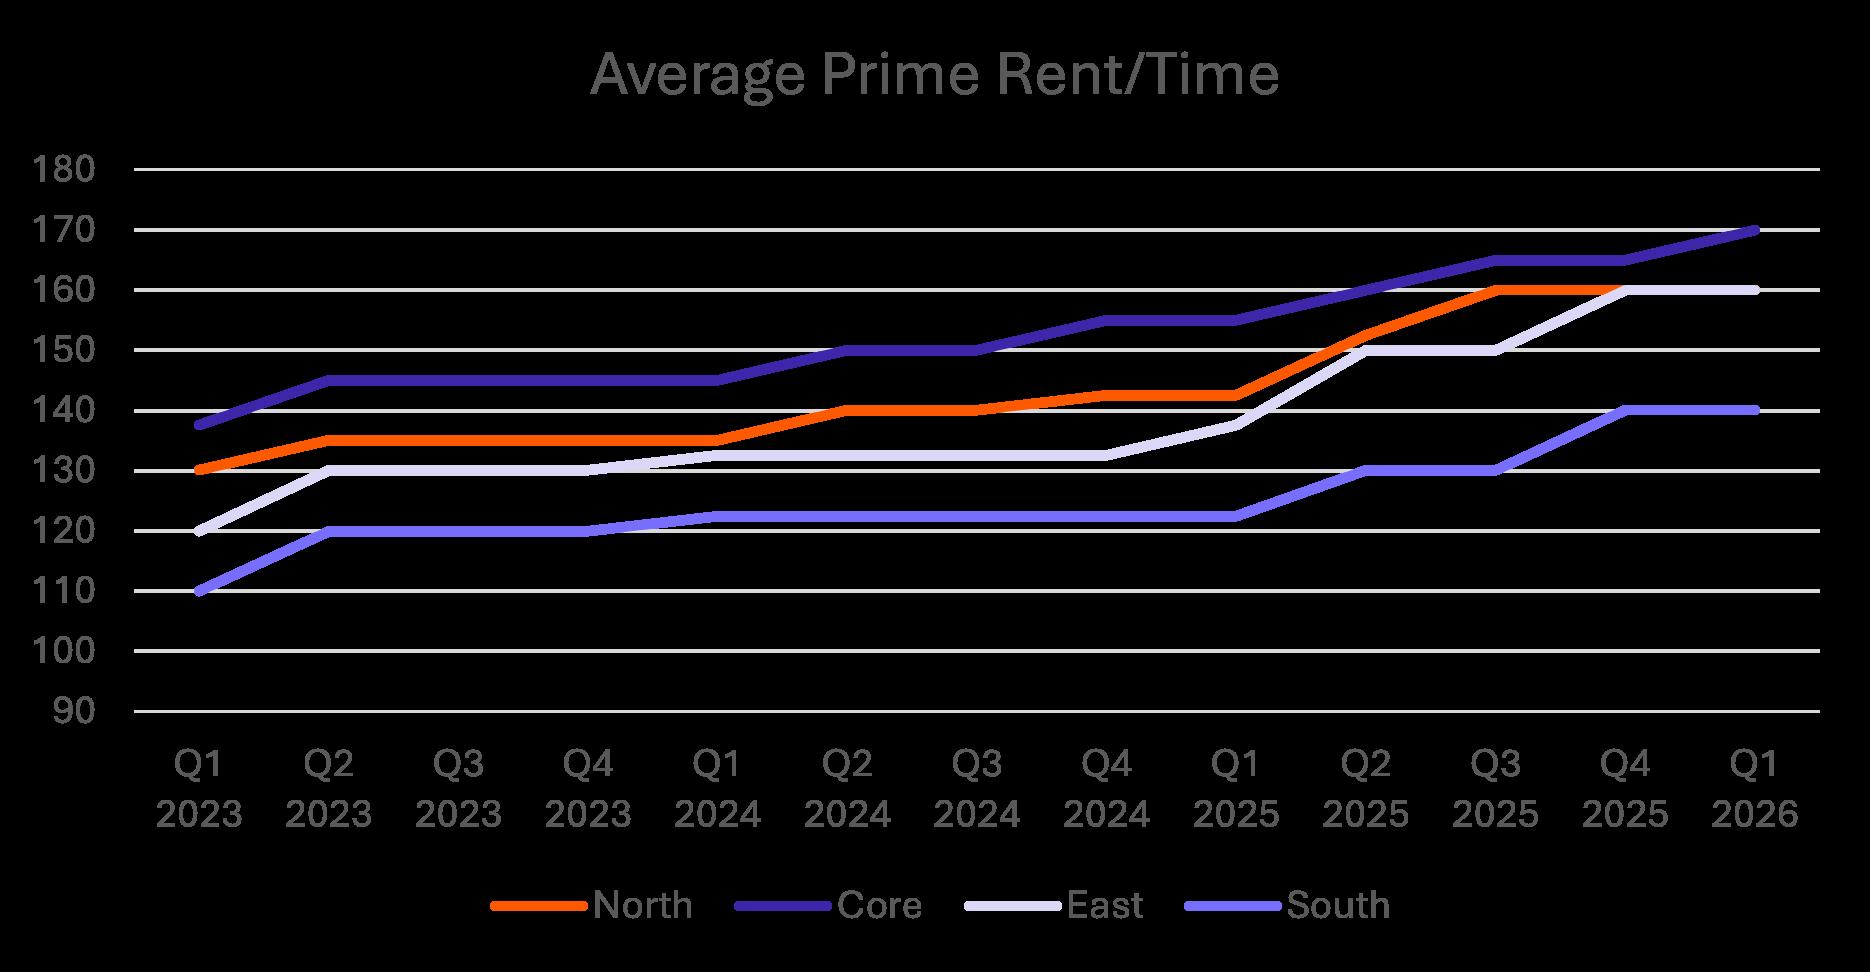
Data in the following pages is based on industrial buildings > 5,000sqm
Prime: Buildings less than 10 years old with internal clearances at or above 13.7m. Buildings showcase design excellence offering ESFR sprinklers, a combination of docks/on-grade doors and sufficient truck articulation for loading/unloading.
Secondary: Buildings generally older than 10 years old but still functional with internal clearances up to 12.6m at the ridge. Buildings typically don’t have high sustainability ratings and may have limitations with warehouse access (no. docks/ on grade doors) and restricted heavy vehicle maneuverability on site.
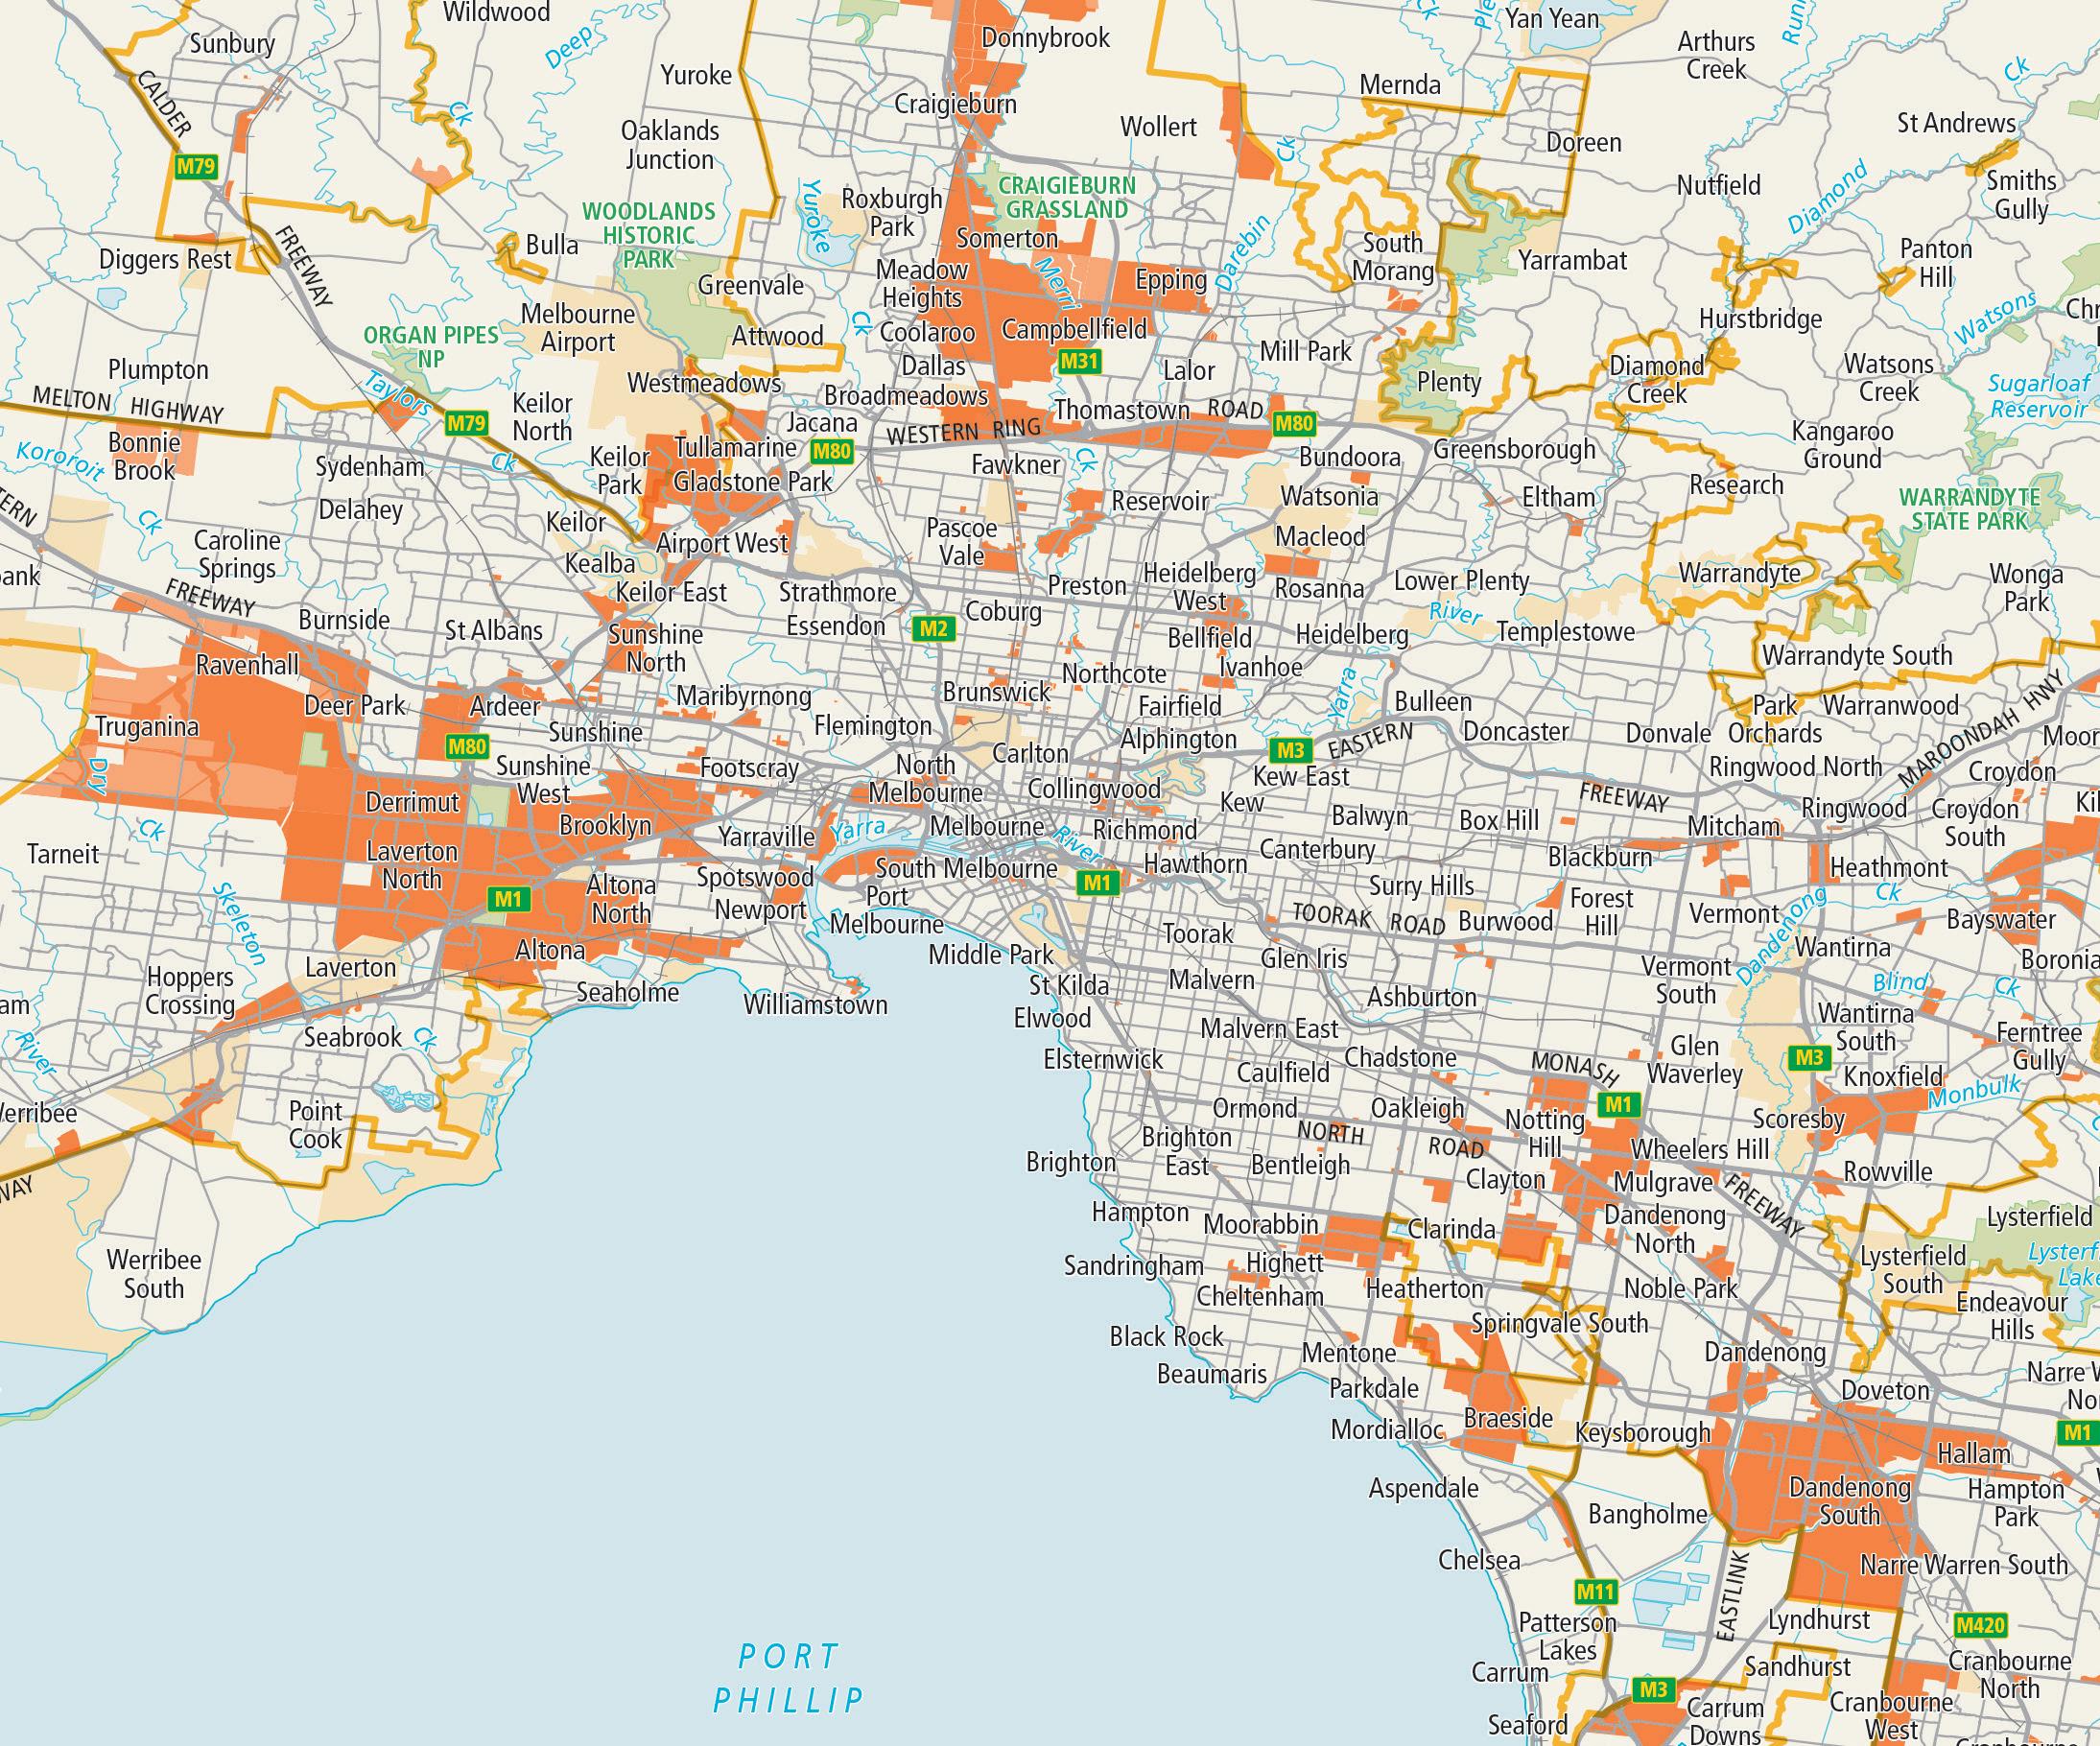
Melbourne Property Market Overview
*Key industrial suburbs only listed
• Altona
• Truganina
• Laverton
• Deer Park
• Tarneit
• Tullamarine/Melbourne Airport
• Epping
• Campbellfield
• Somerton
• Craigieburn
• Mickleham
• Dandenong South
• Cranbourne West
• Keysborough
• Mentone
• Clayton
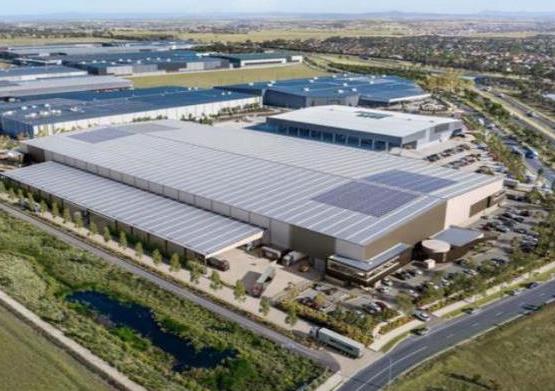
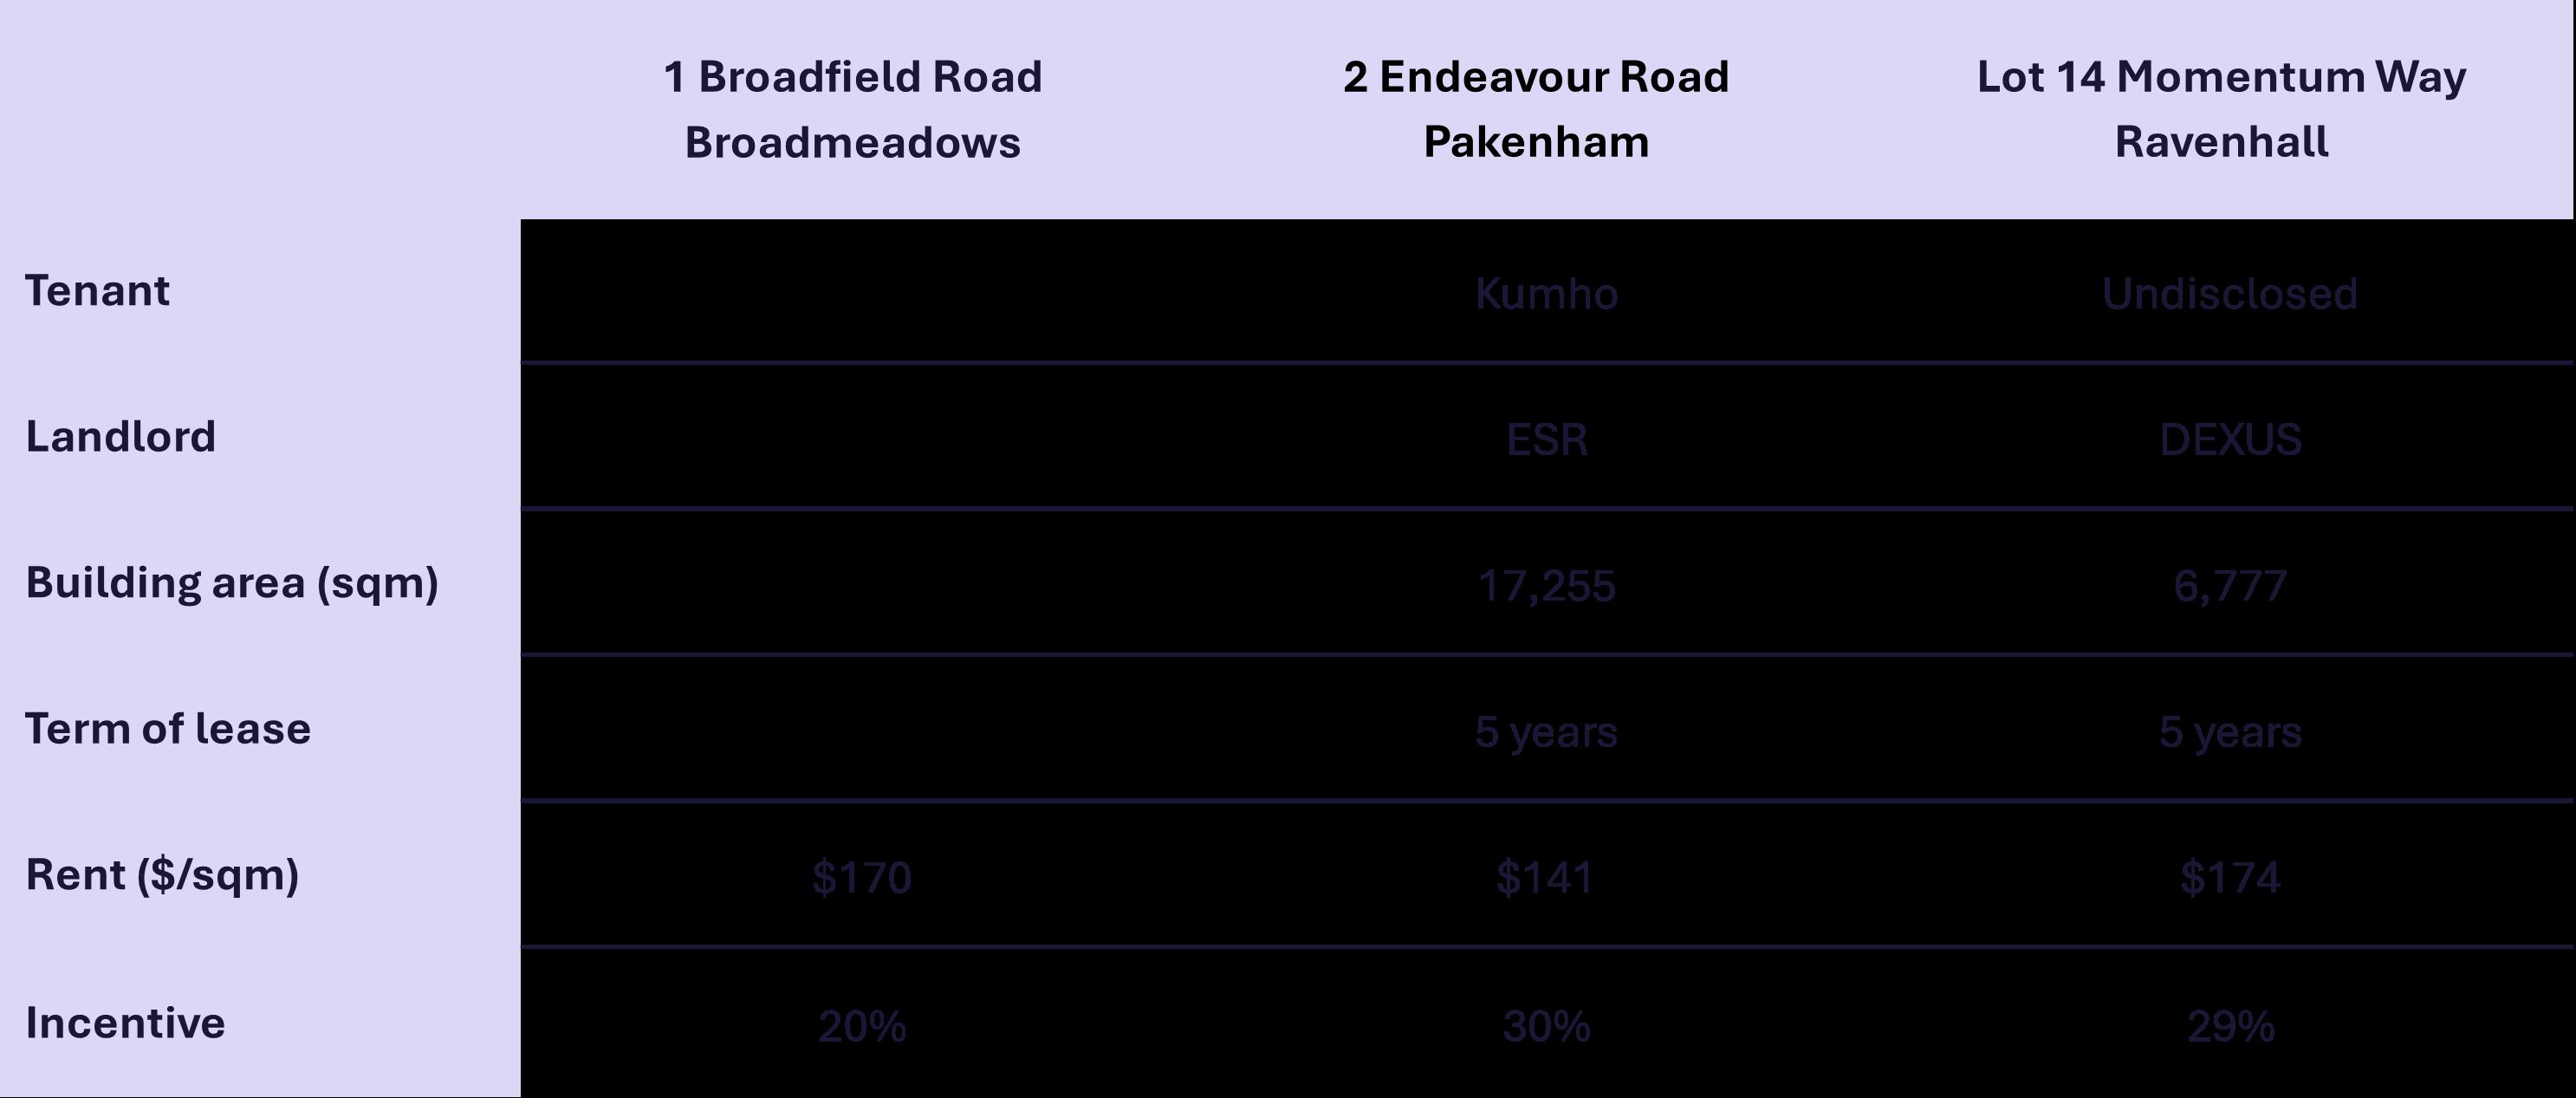
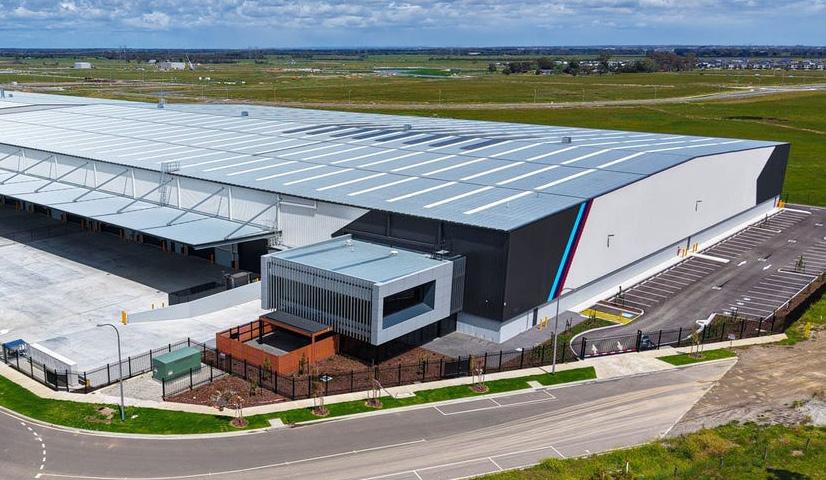
Outgoings continue to increase
New speculative commencements remain limited in all markets
Impact of the fuel supply shock and interest rate rises yet to be priced into the market
Occupiers continue to transform their networks
Flight to quality remains prevalent
Location continues to be a key driver for occupiers
Sydney Property Market Overview
*Key industrial suburbs only listed
• Marsden Park
• Seven Hills
• Glendenning
• Wetherill Park
• Eastern Creek
• Kemps Creek
• Homebush
• Chullora
• Silverwater
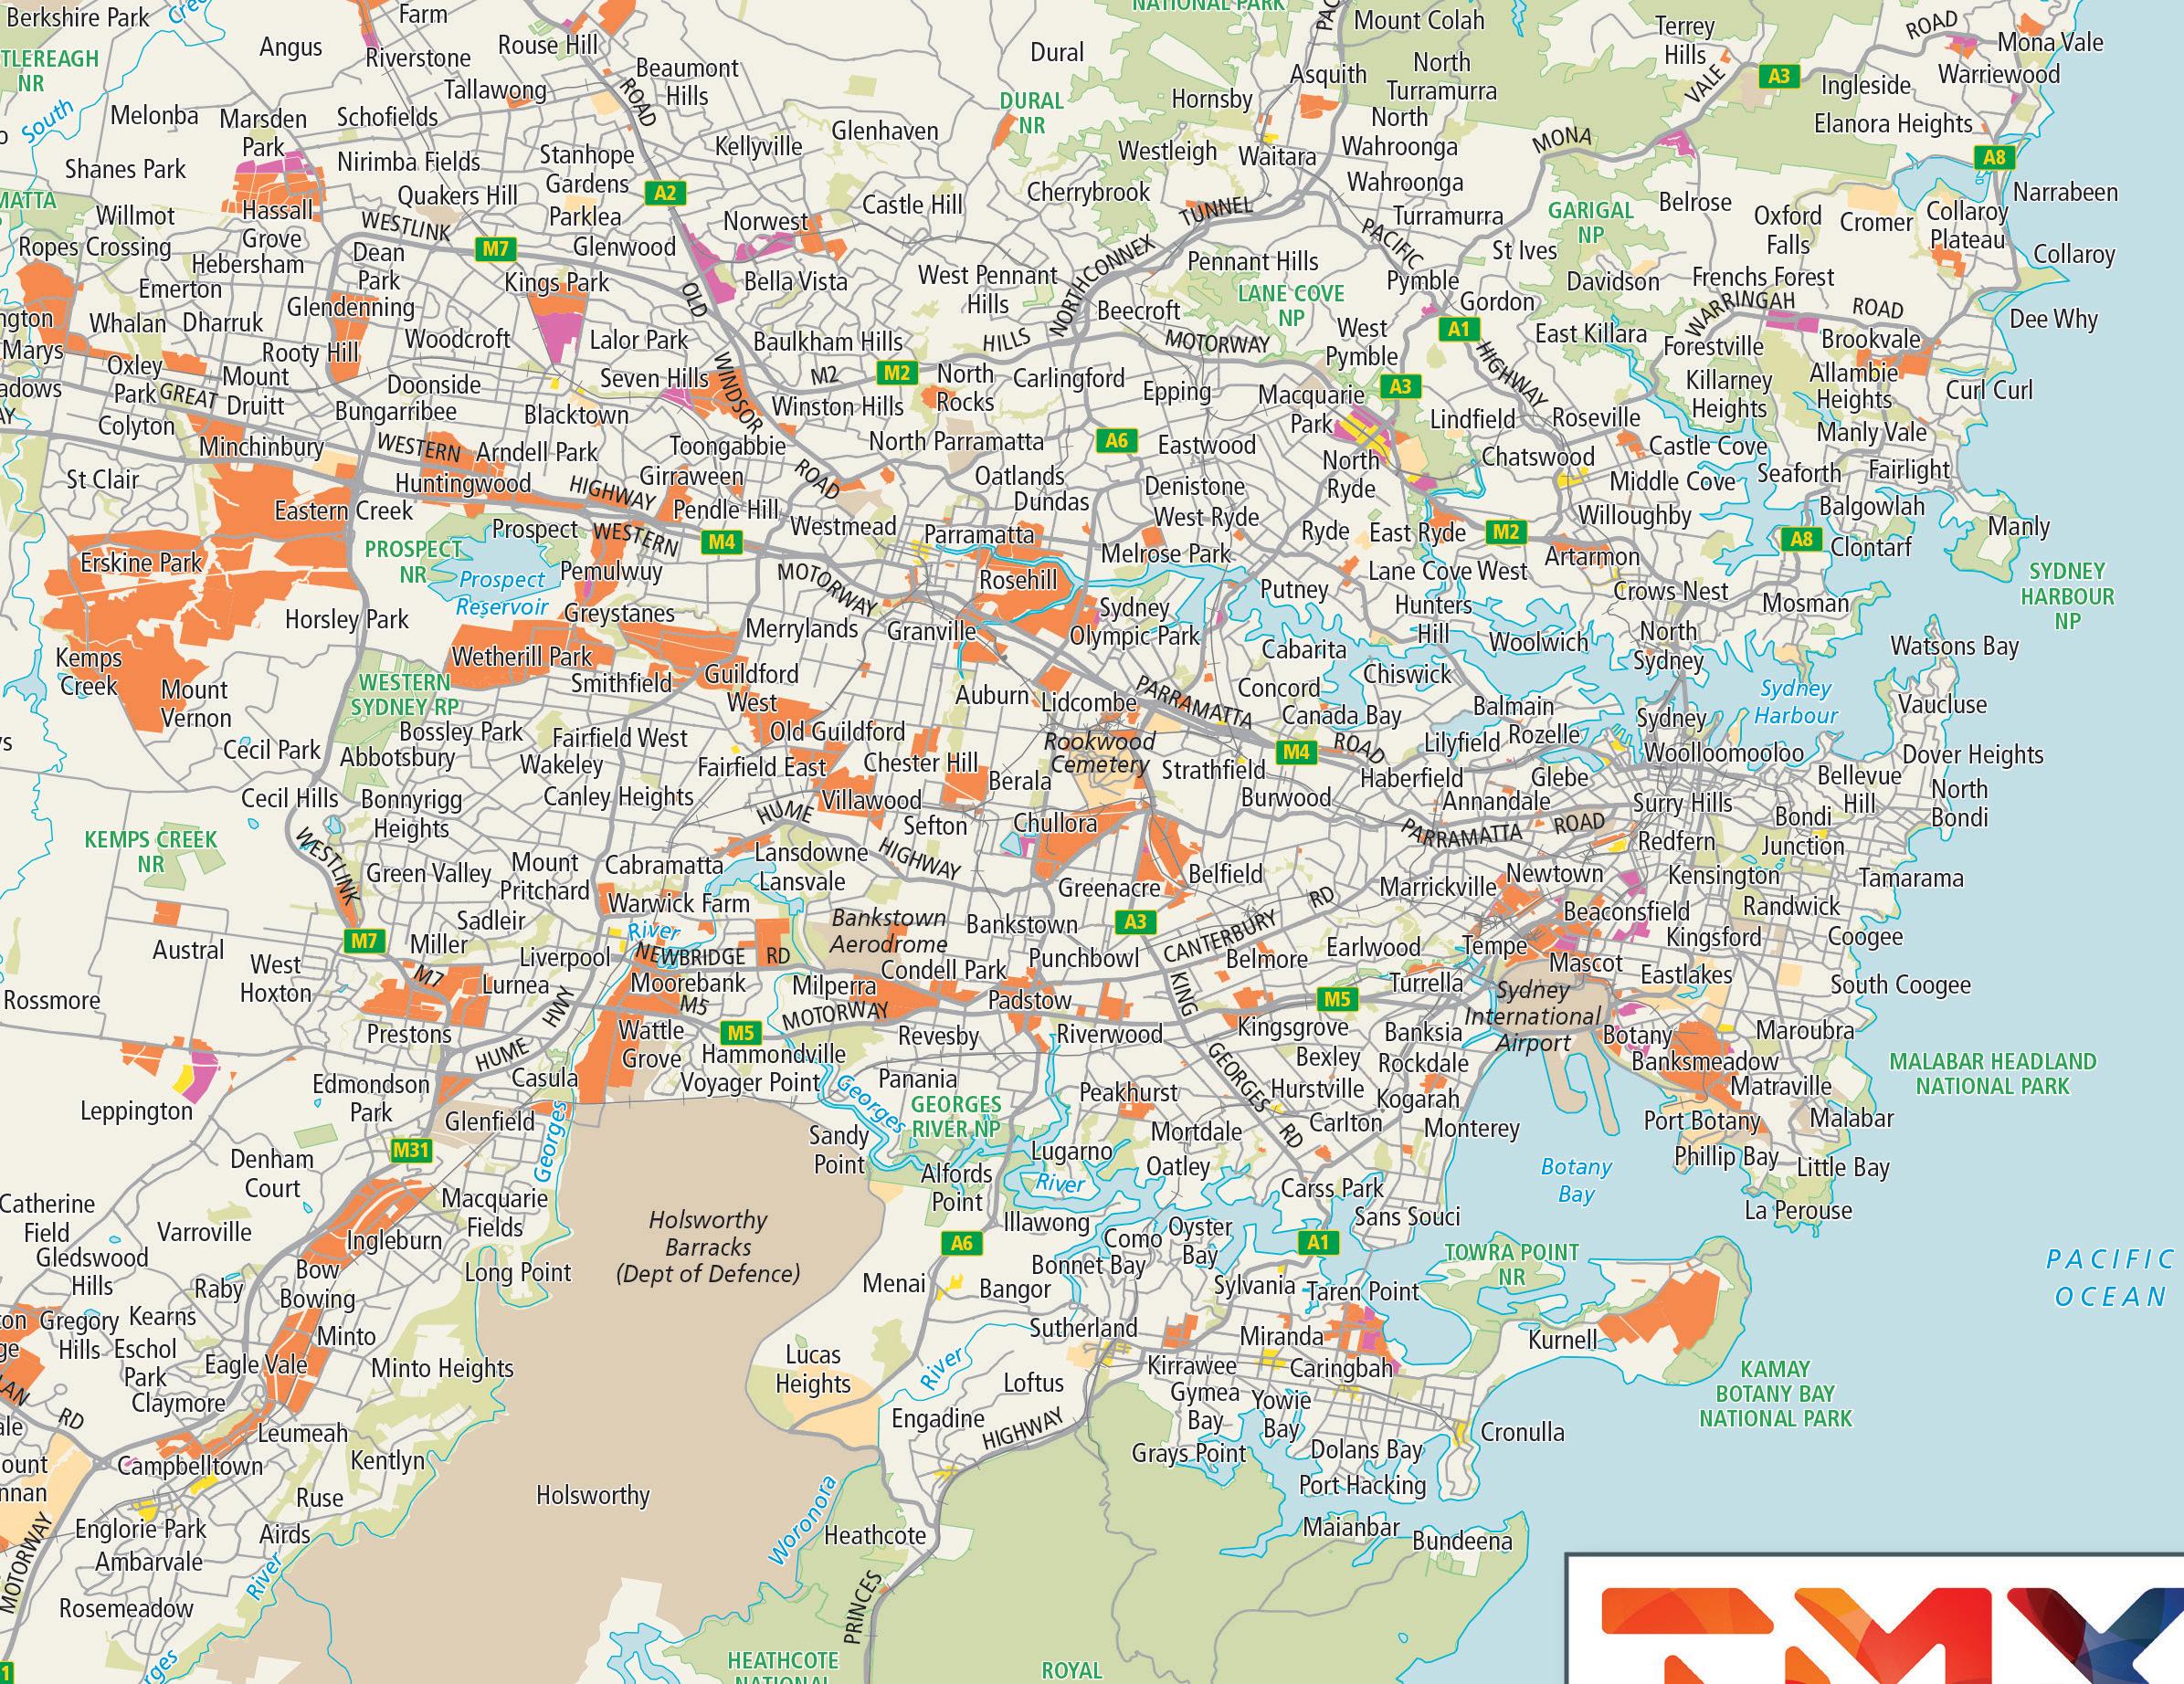
• Ingleburn
• Minto
• Smeaton Grange
• Milperra
• Prestons
• Moorebank
• Alexandria
• Mascot
• Matraville
Q1 2026
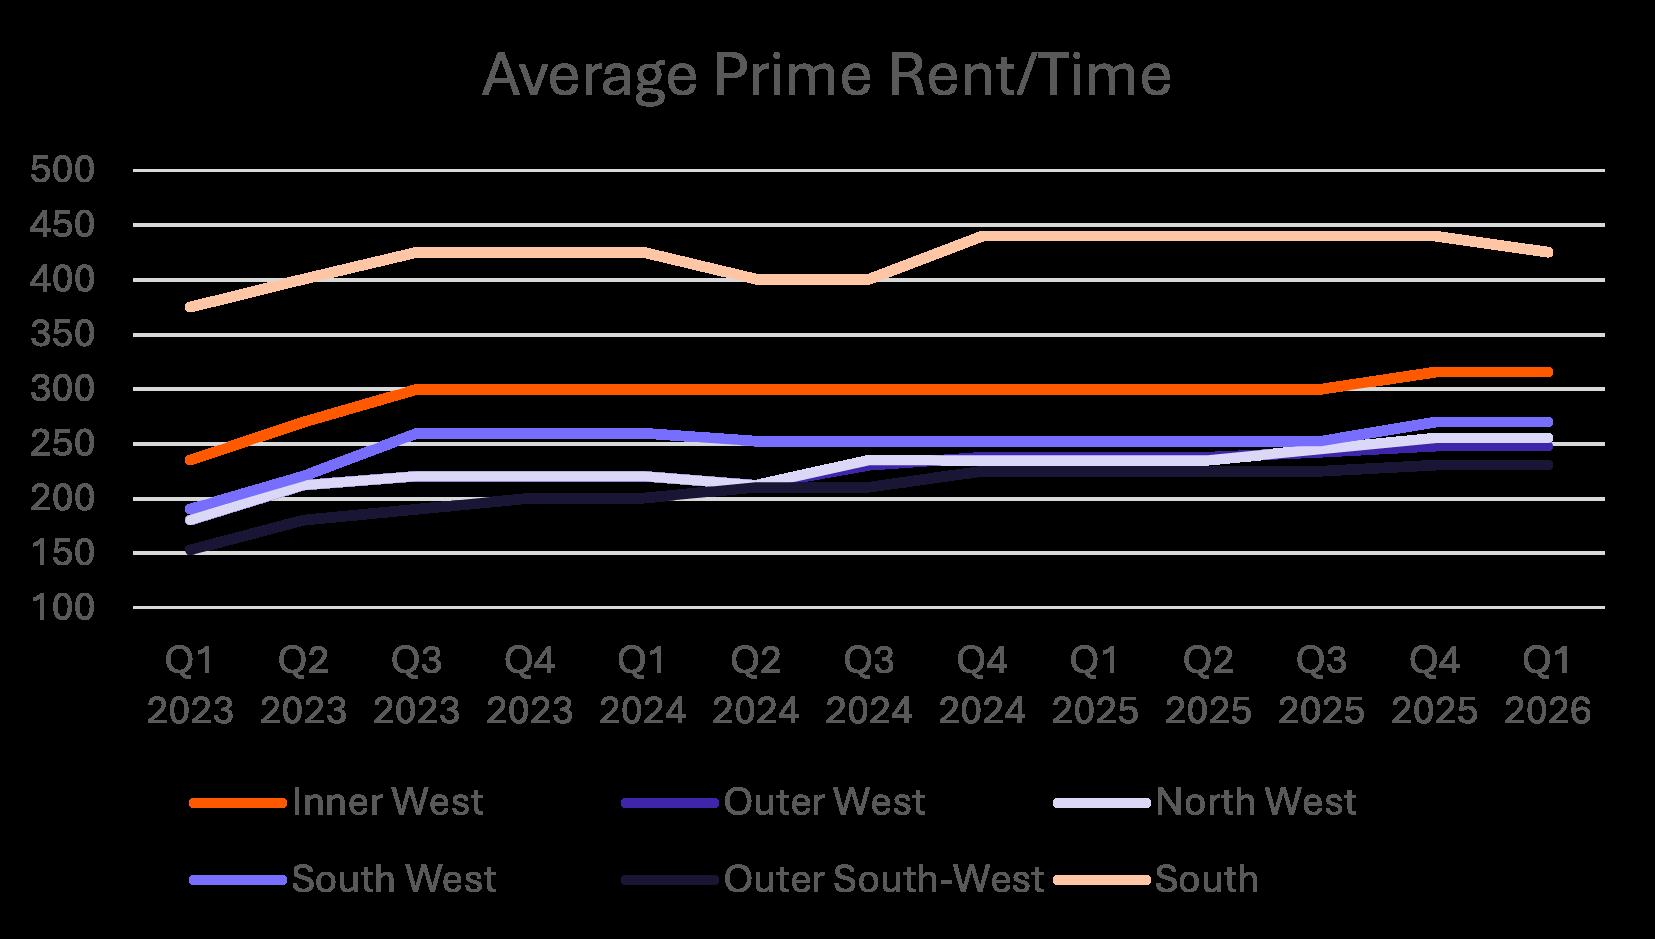
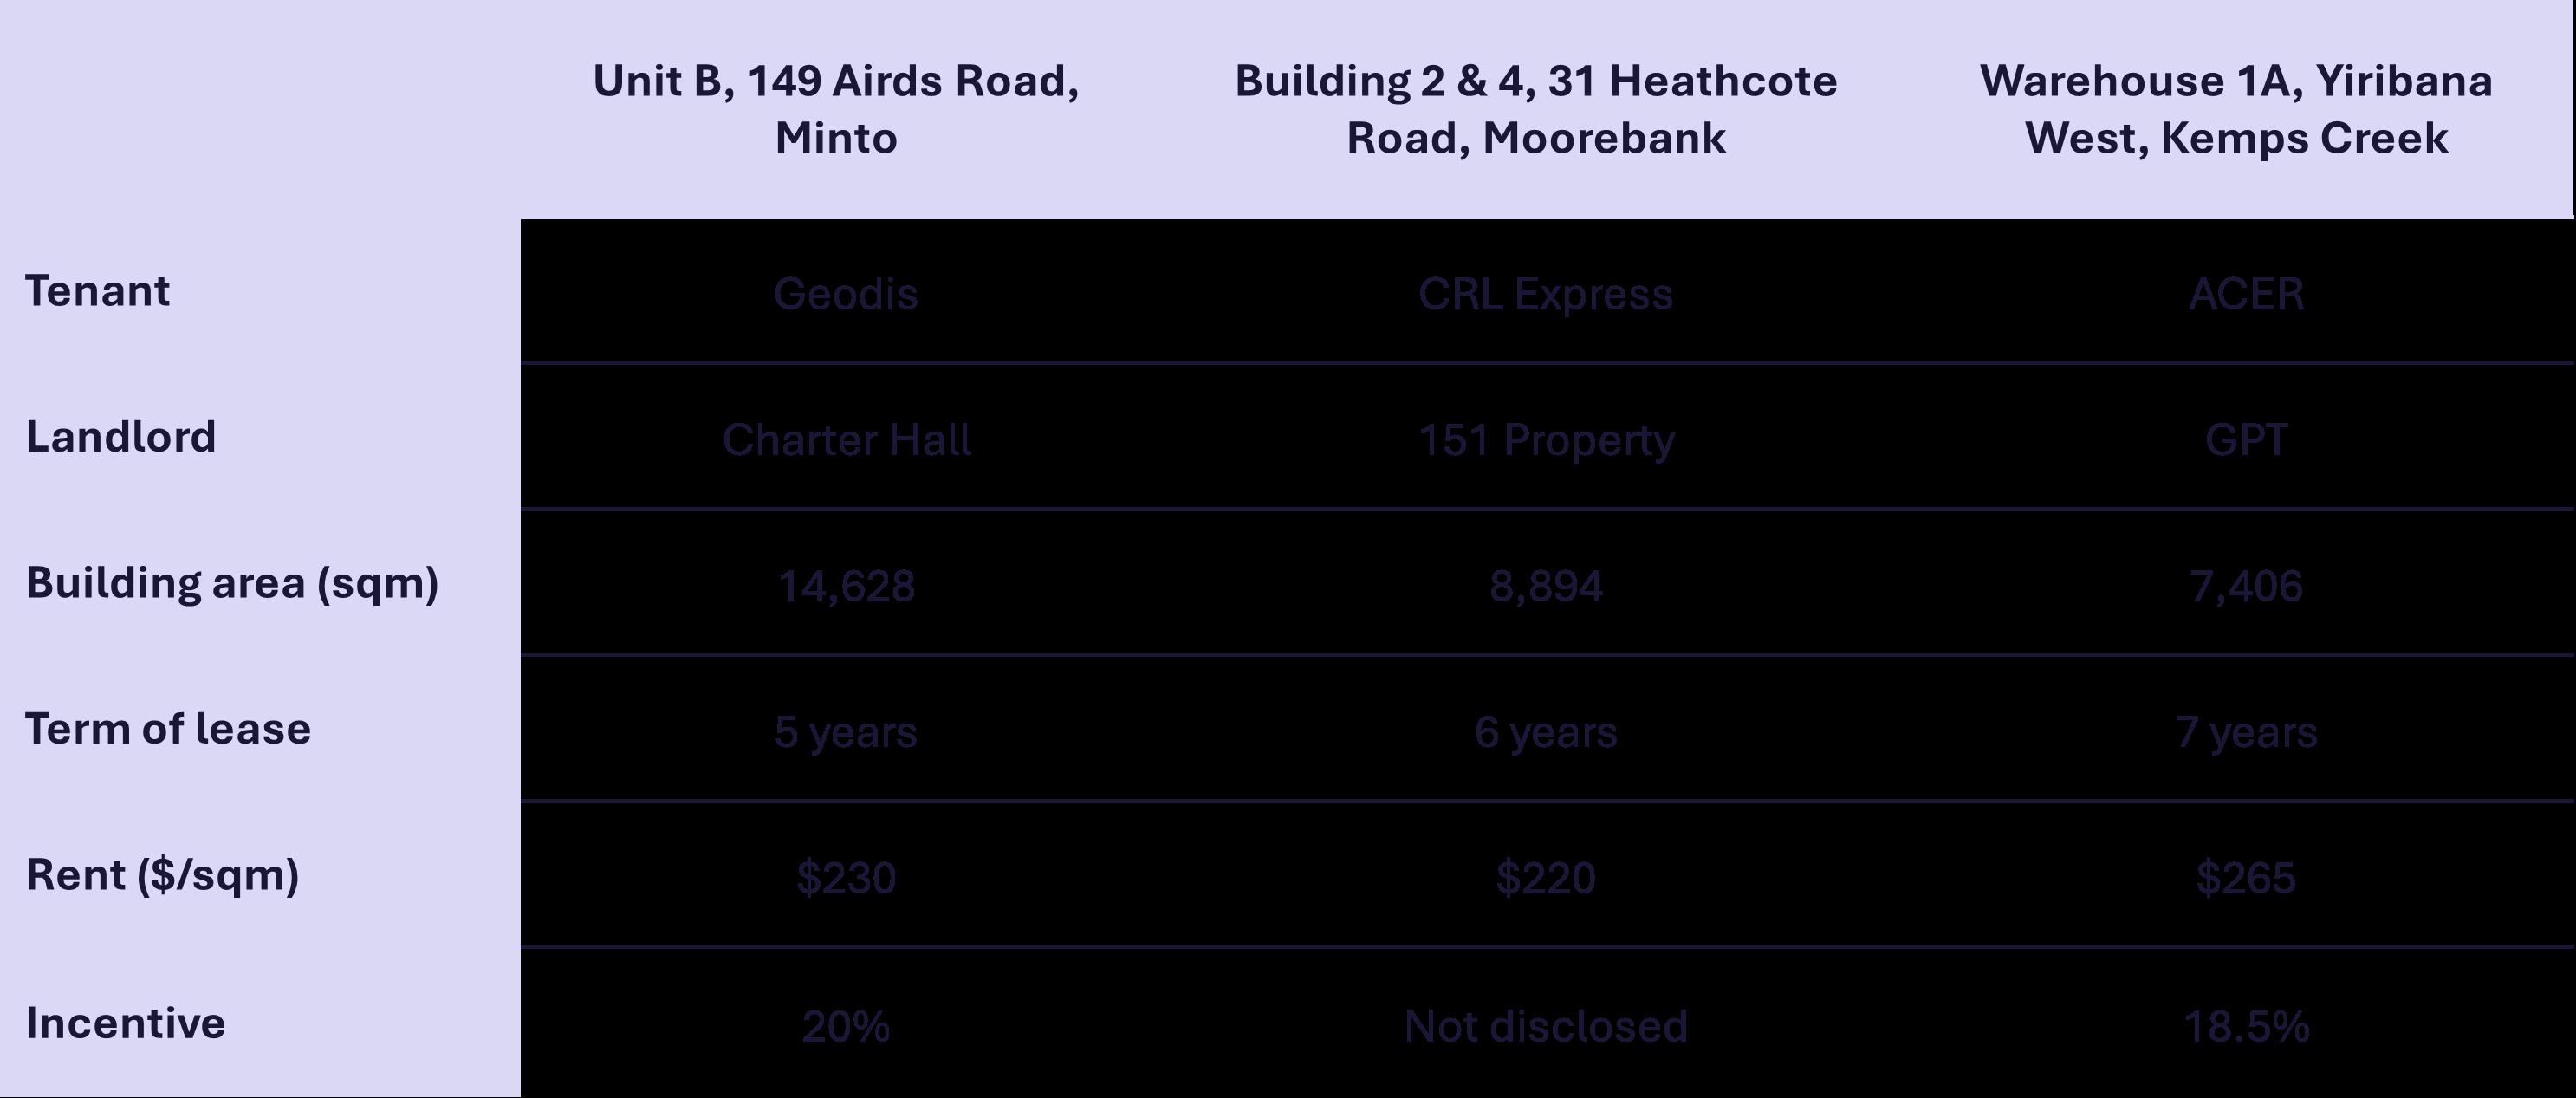
Incentives remain steady around 12.5% to 20% in most locations
Higher development economic rents due to moderate cost pressure in land and build rates
Land values are supported by contrained availability of tradeable land across Sydney, with data centres distorting pricing
Patchy underlying demand, large corporates most active
Vacancy is stable with a pause in the quantity of speculative construction completed in H1 26
Outgoings growth stabilising, though remains a focus for occupiers
Brisbane Property Market Overview
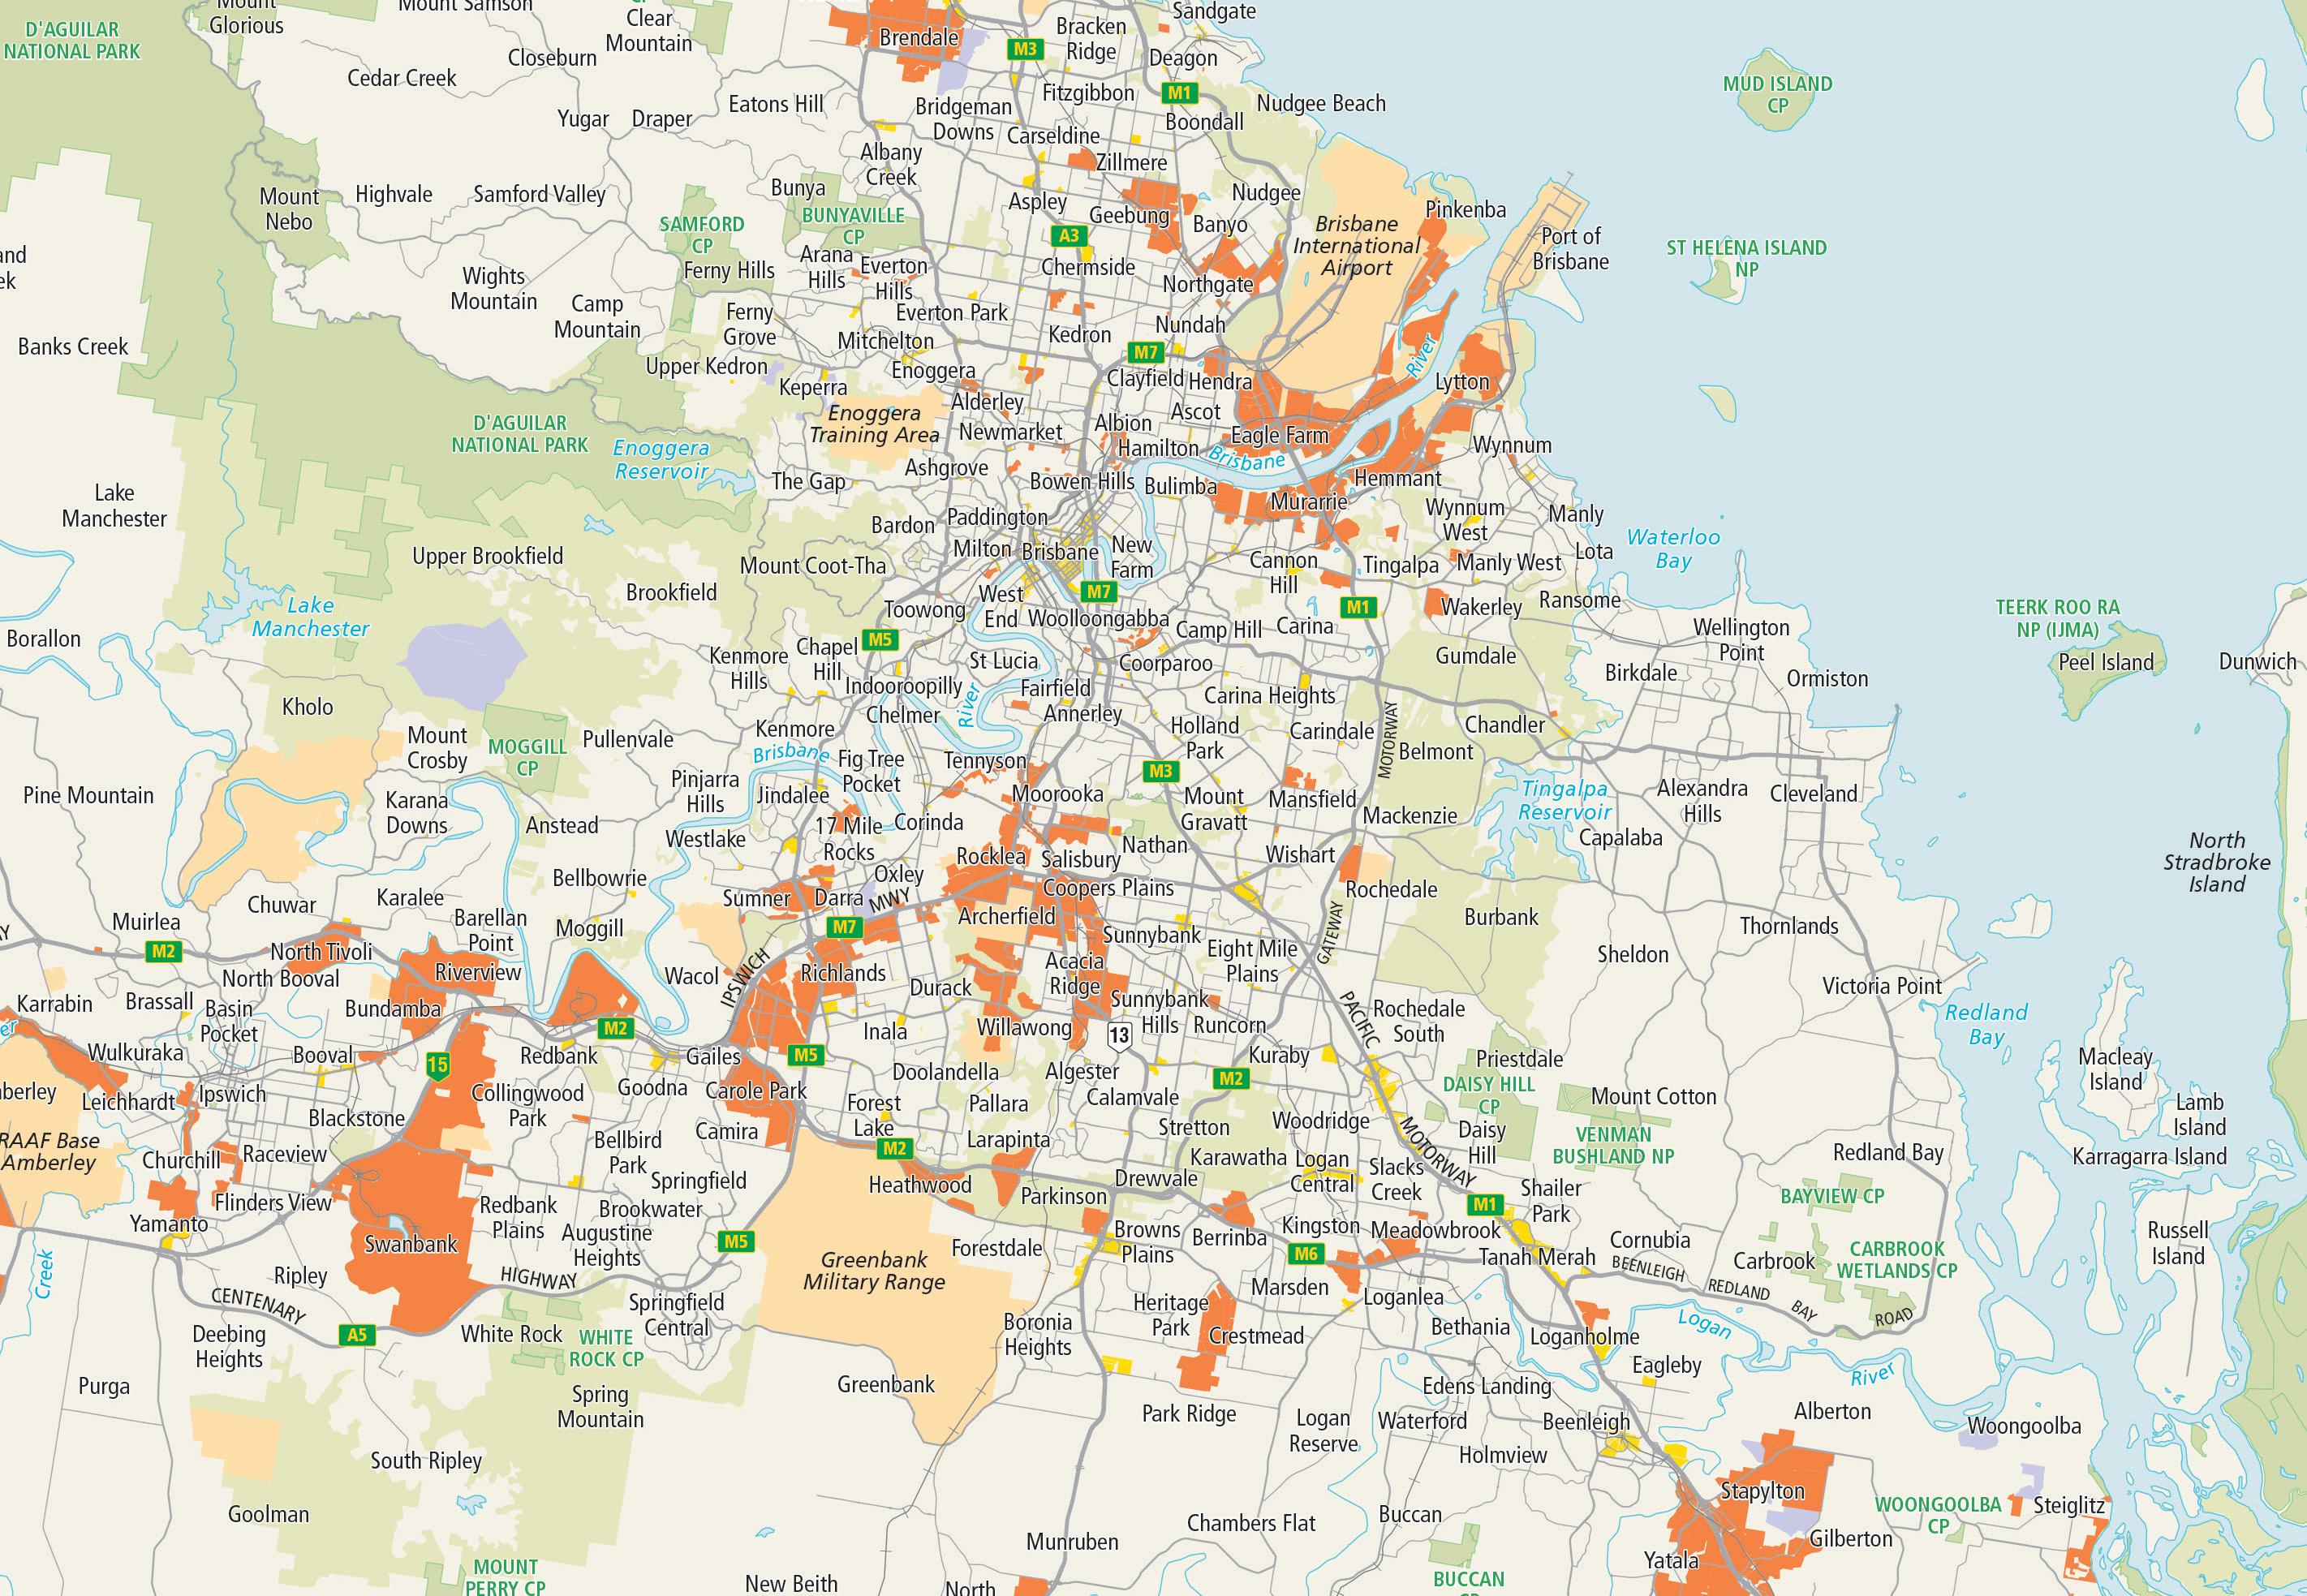
*Key industrial suburbs only listed
*Logan Motorway Corridor includes Heathwood, Larapinta, Berrinba, Parkinson, Meadowbrook, Kingston
• Wacol
• Carole Park
• Redbank
• Bundamba
• Swanbank
• Banyo
• Geebung
• Northgate
• Brendale
• North Lakes
• Eagle Farm
• Brisbane Airport
• Pinkenba
• Murarrie
• Port of Brisbane
• Acacia Ridge
• Archerfield
• Willawong
• Logan Motorway Corridor*
• Crestmead
• Yatala
• Stapylton
• Ormeau
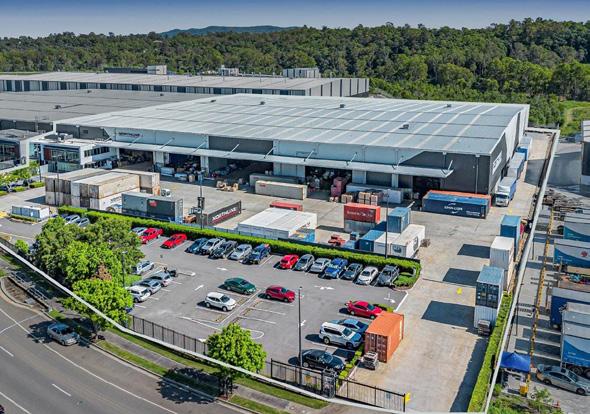
Steady growth and tight market conditions fuel investment and occupier demand
Constrained land supply places upward pressure on economic rents and outgoings
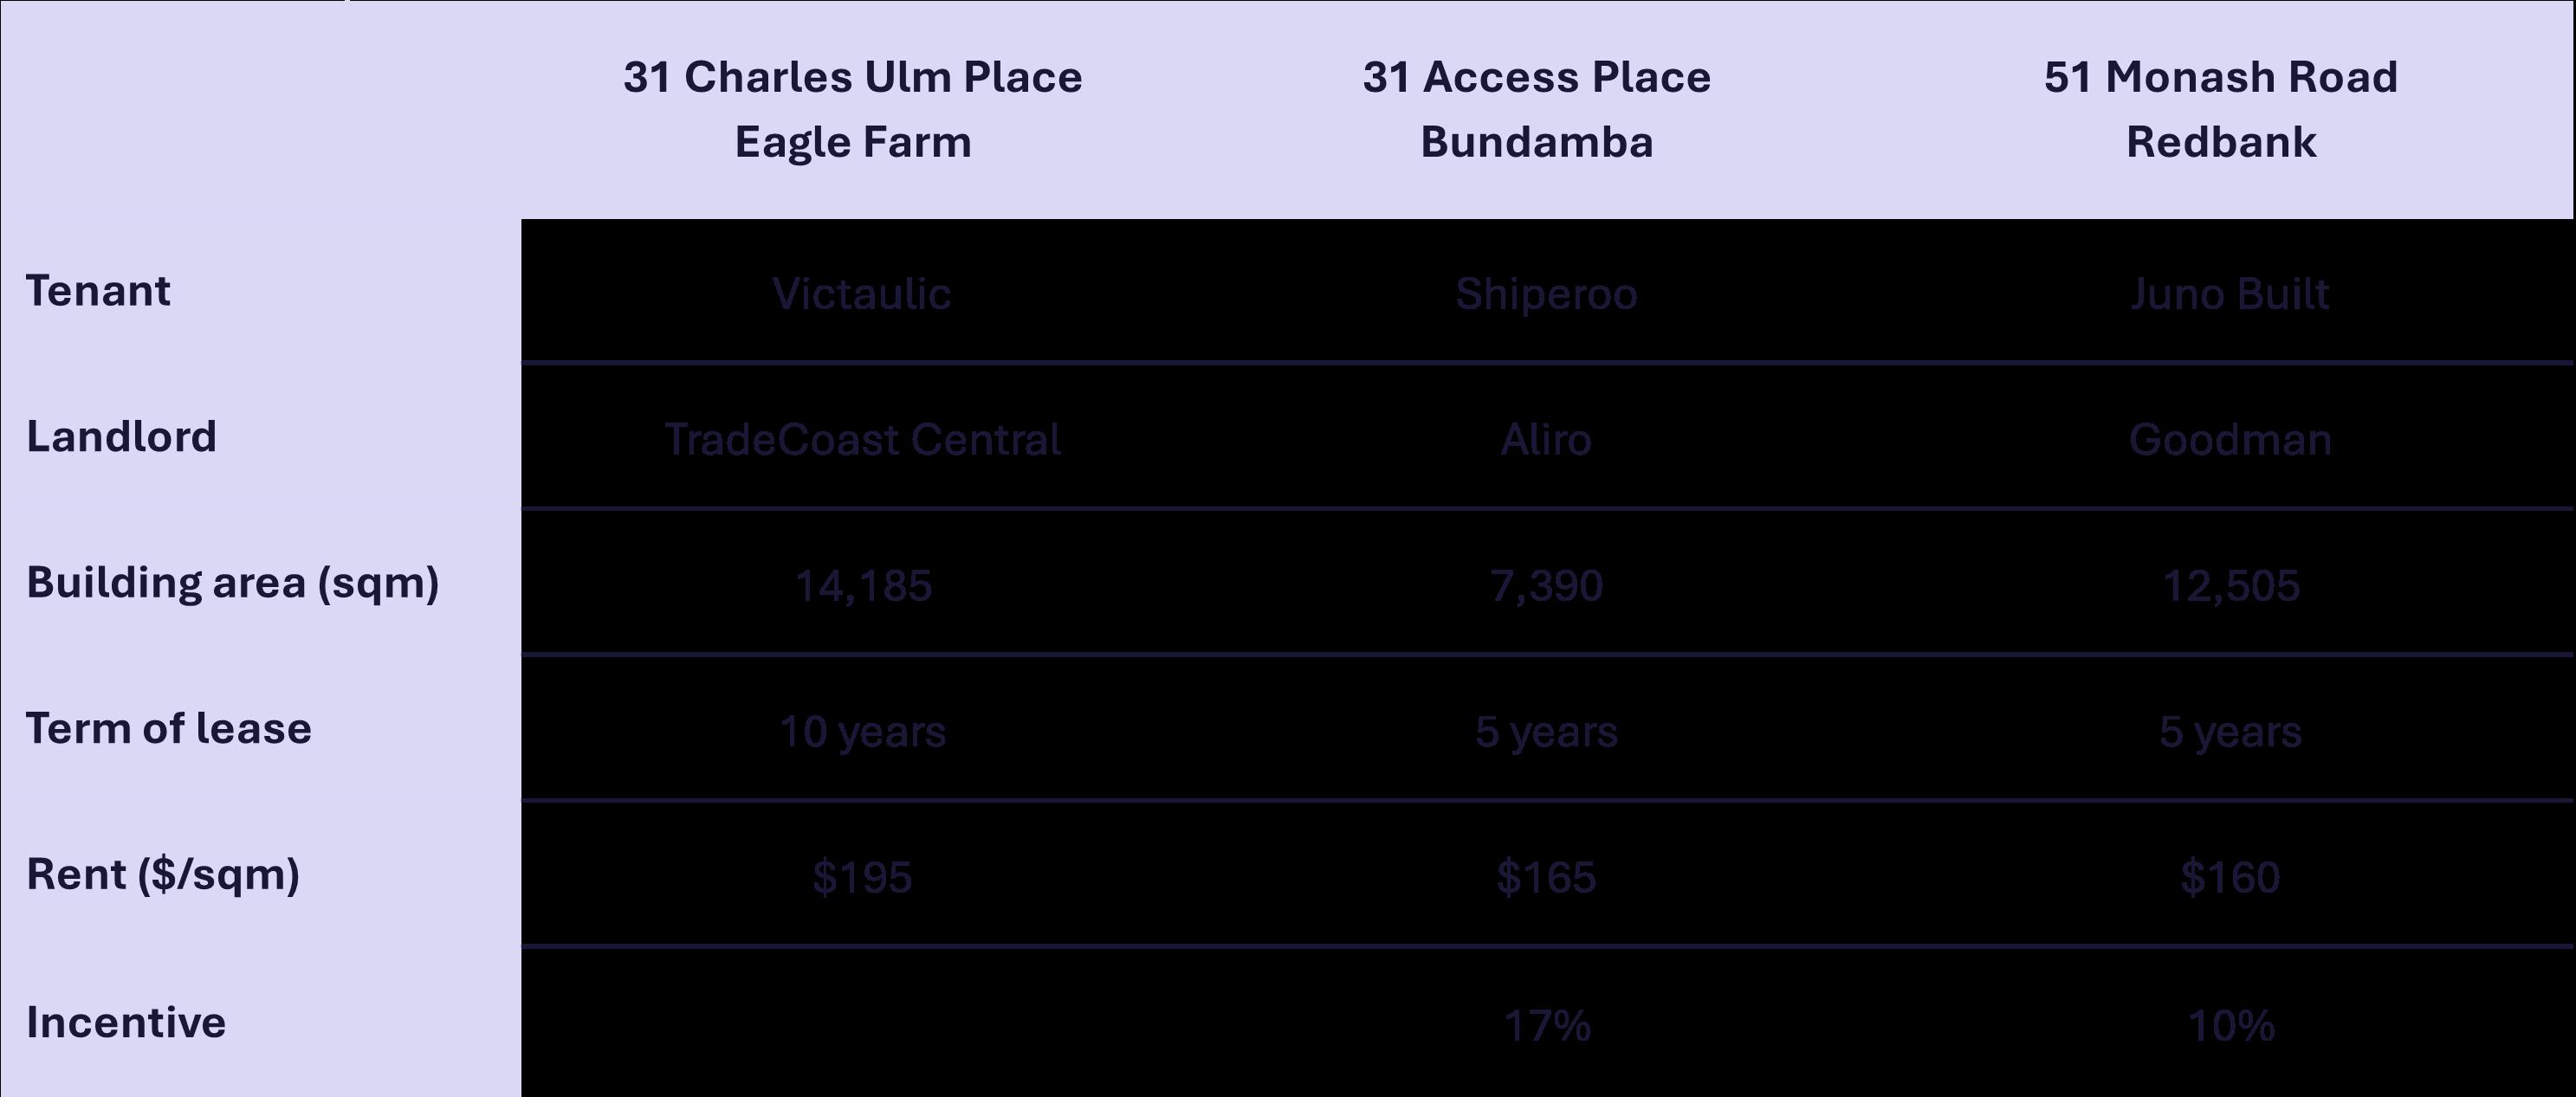
Incentives for existing properties have stabilised at elevated levels

Measured return of speculative development in core markets
Procured & delivered by
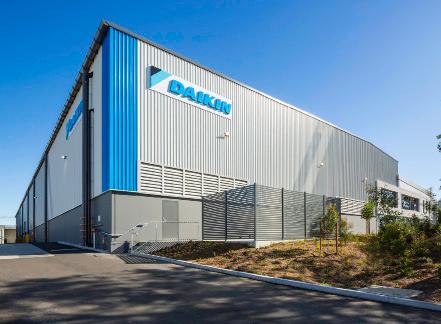
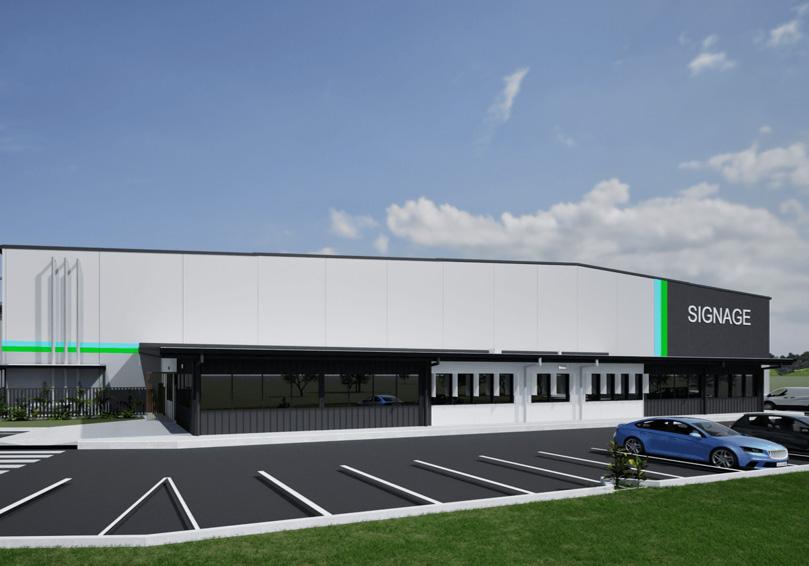
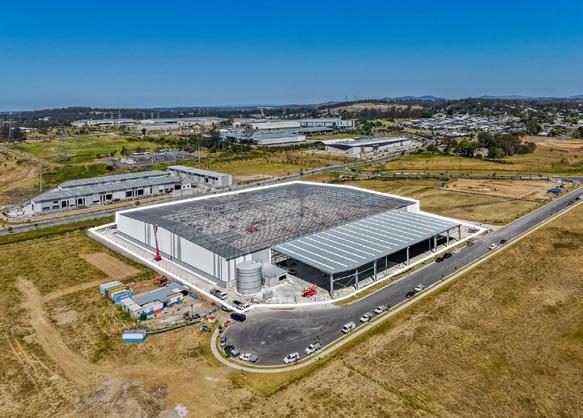
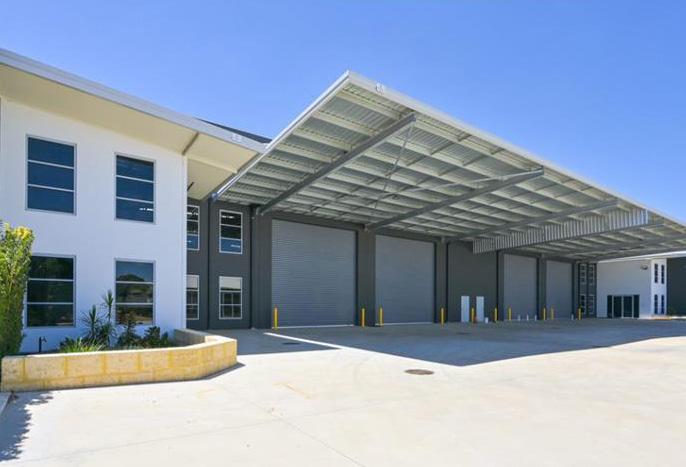
Location: Swanbank, Queensland
Building Area: 30,846sqm
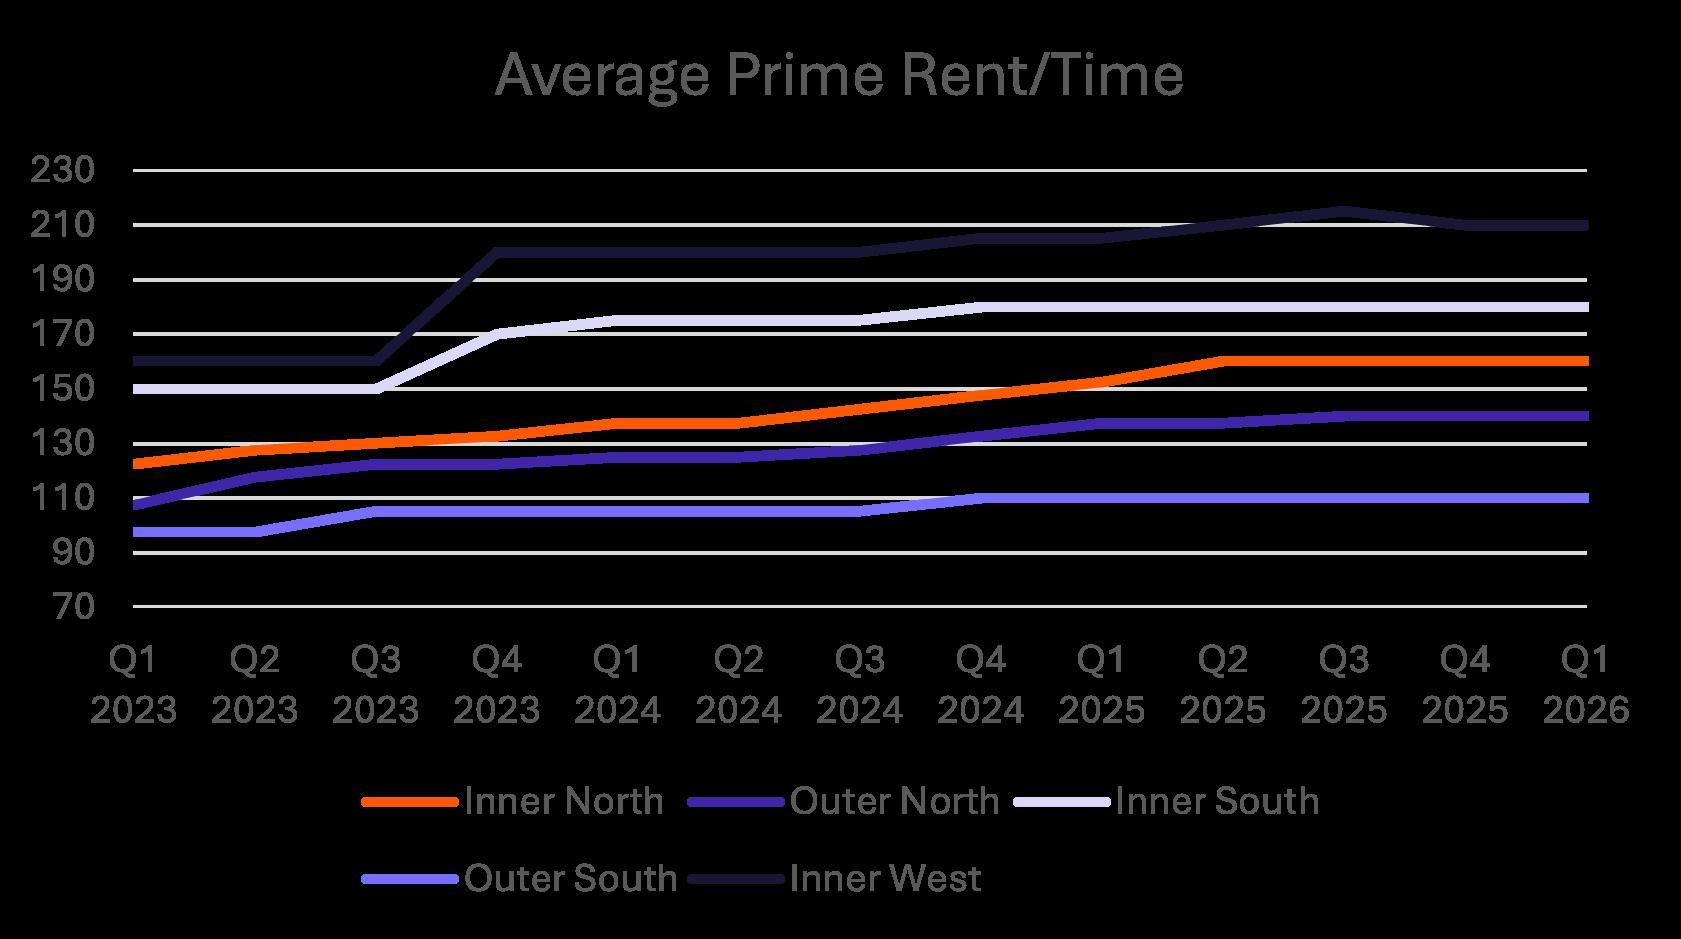
Adelaide Property Market Overview
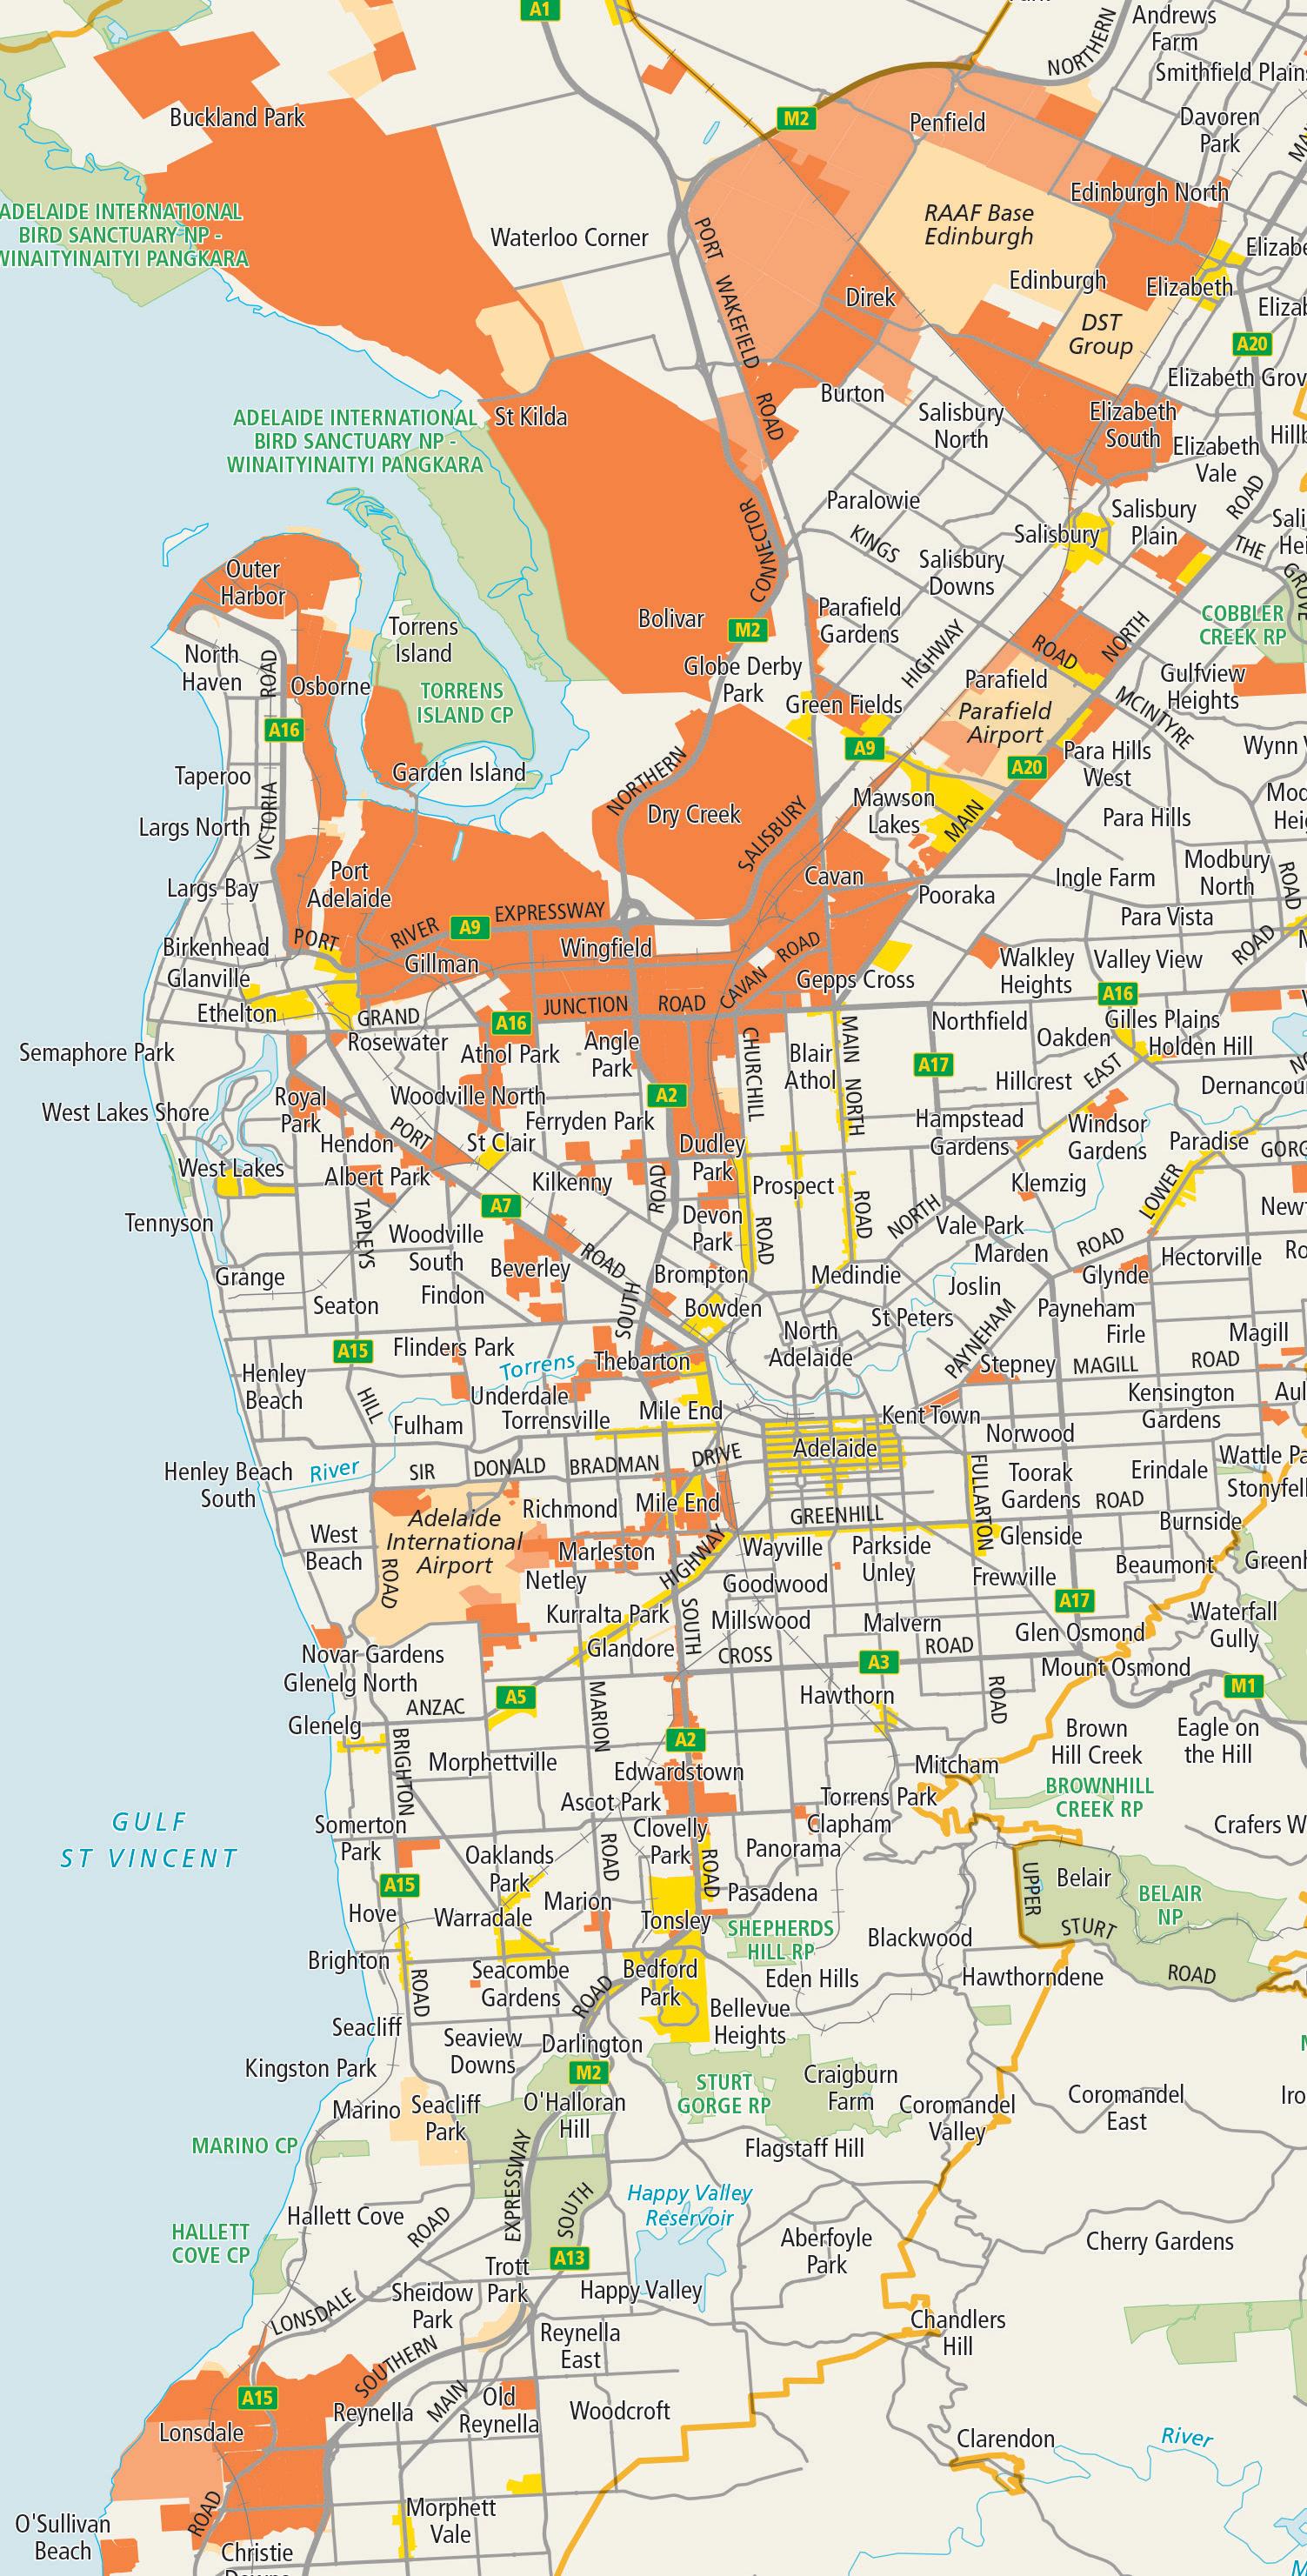
*Key industrial suburbs only listed
OUTER NORTH
• Edinburgh
• Direk
• Regency Park
• Wingfield
• Pooraka INNER NORTH
INNER WEST
• Adelaide Airport
• Mile End
• Torrensville
• Edwardstown
• Glandore
• St Marys INNER SOUTH
OUTER SOUTH
• Lonsdale
Incentives remain unchanged in all markets
Englobo land sales in Outer North create opportunities
Vacancy increasing marginally to 2.5% this quarter
Majority of spec projects concentrated in Northern regions
Pre-lease rents steadily increasing
Impacts of current geopolitical events will be closely monitored
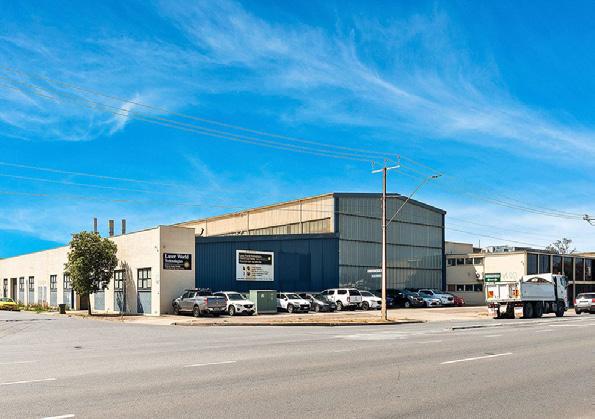
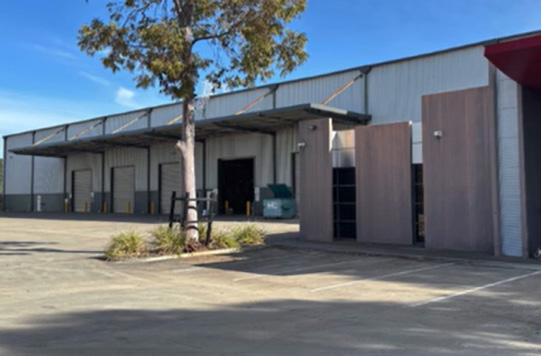
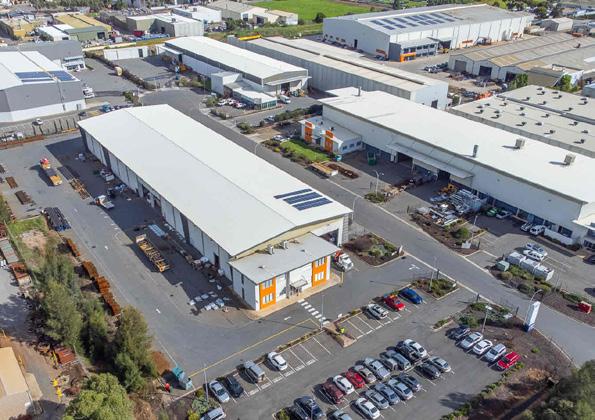
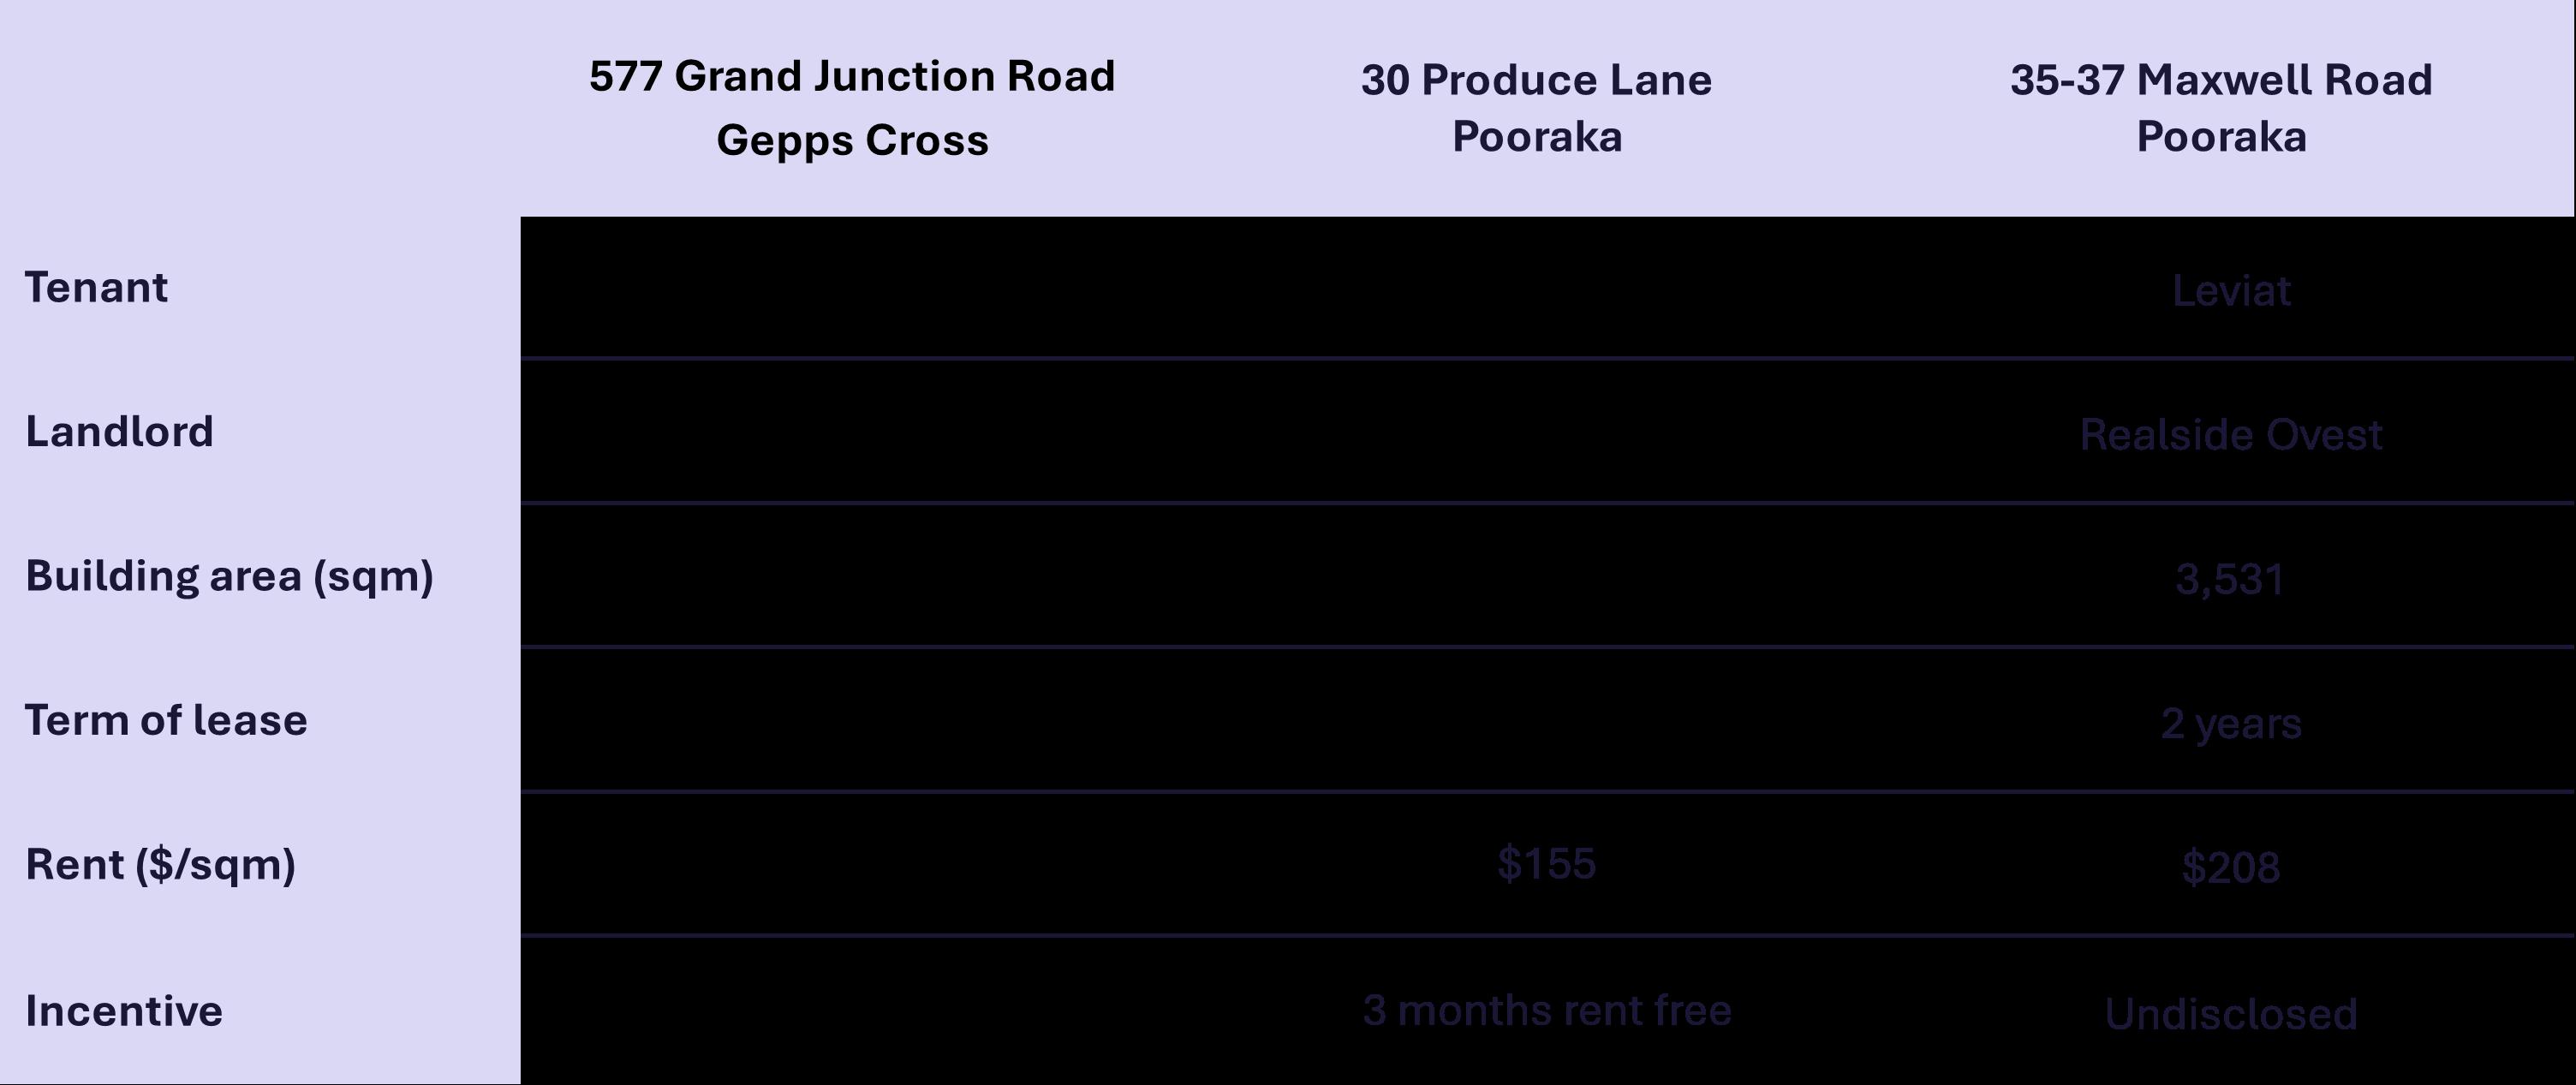
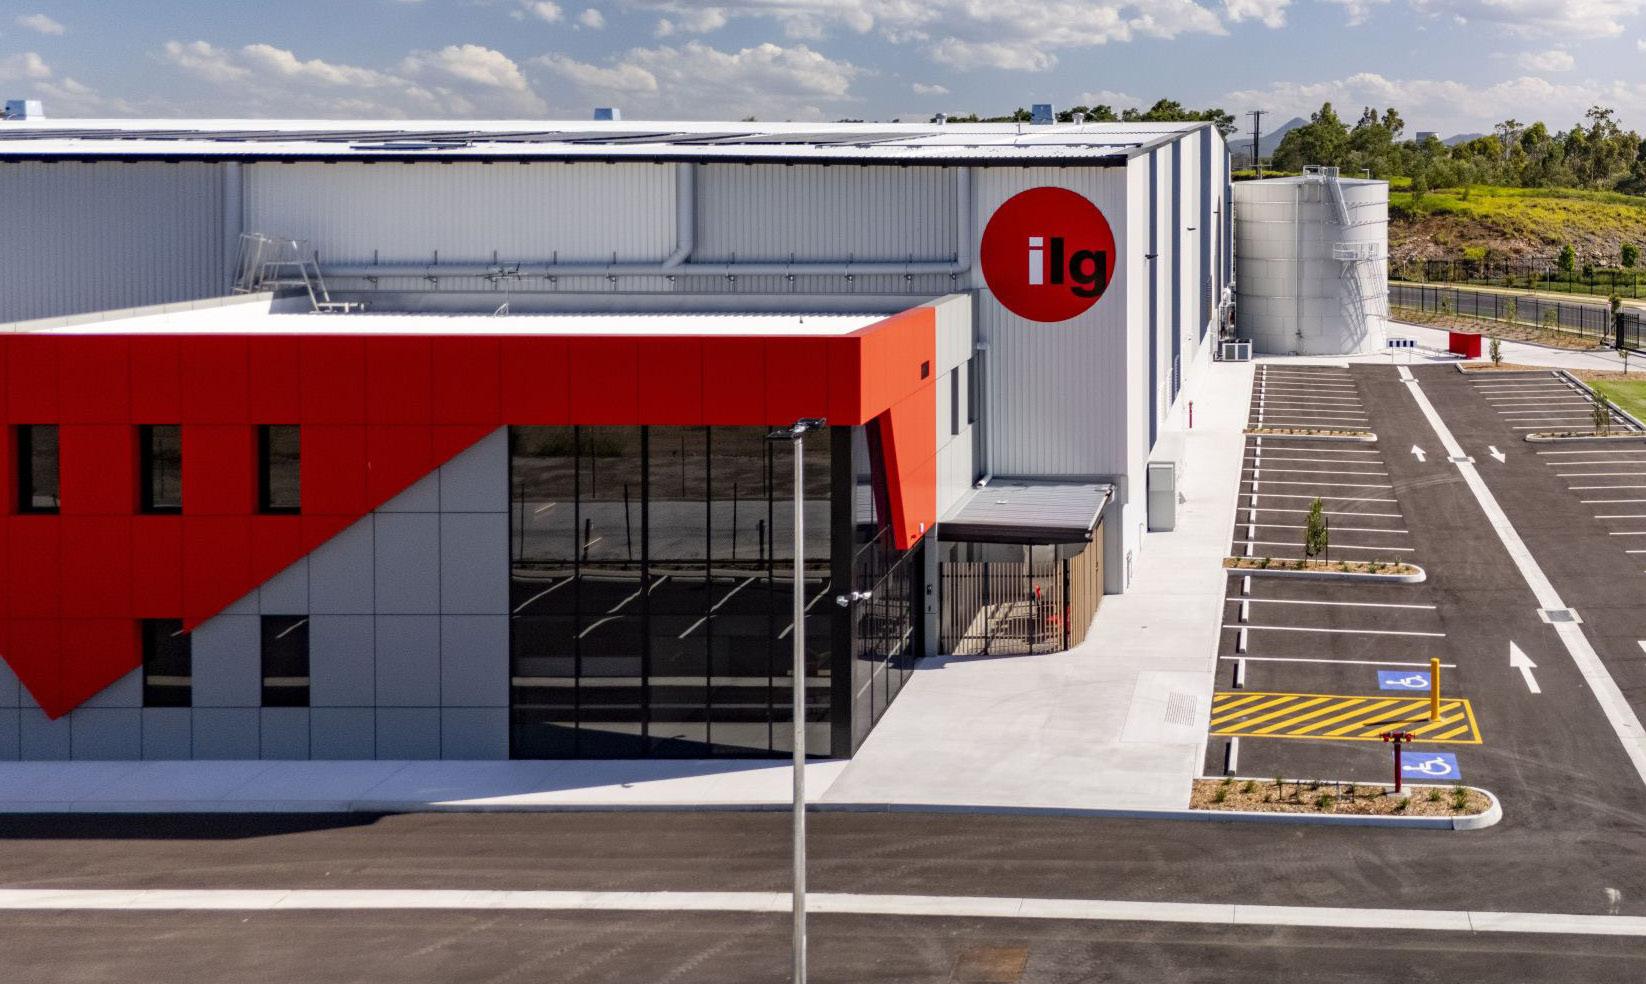
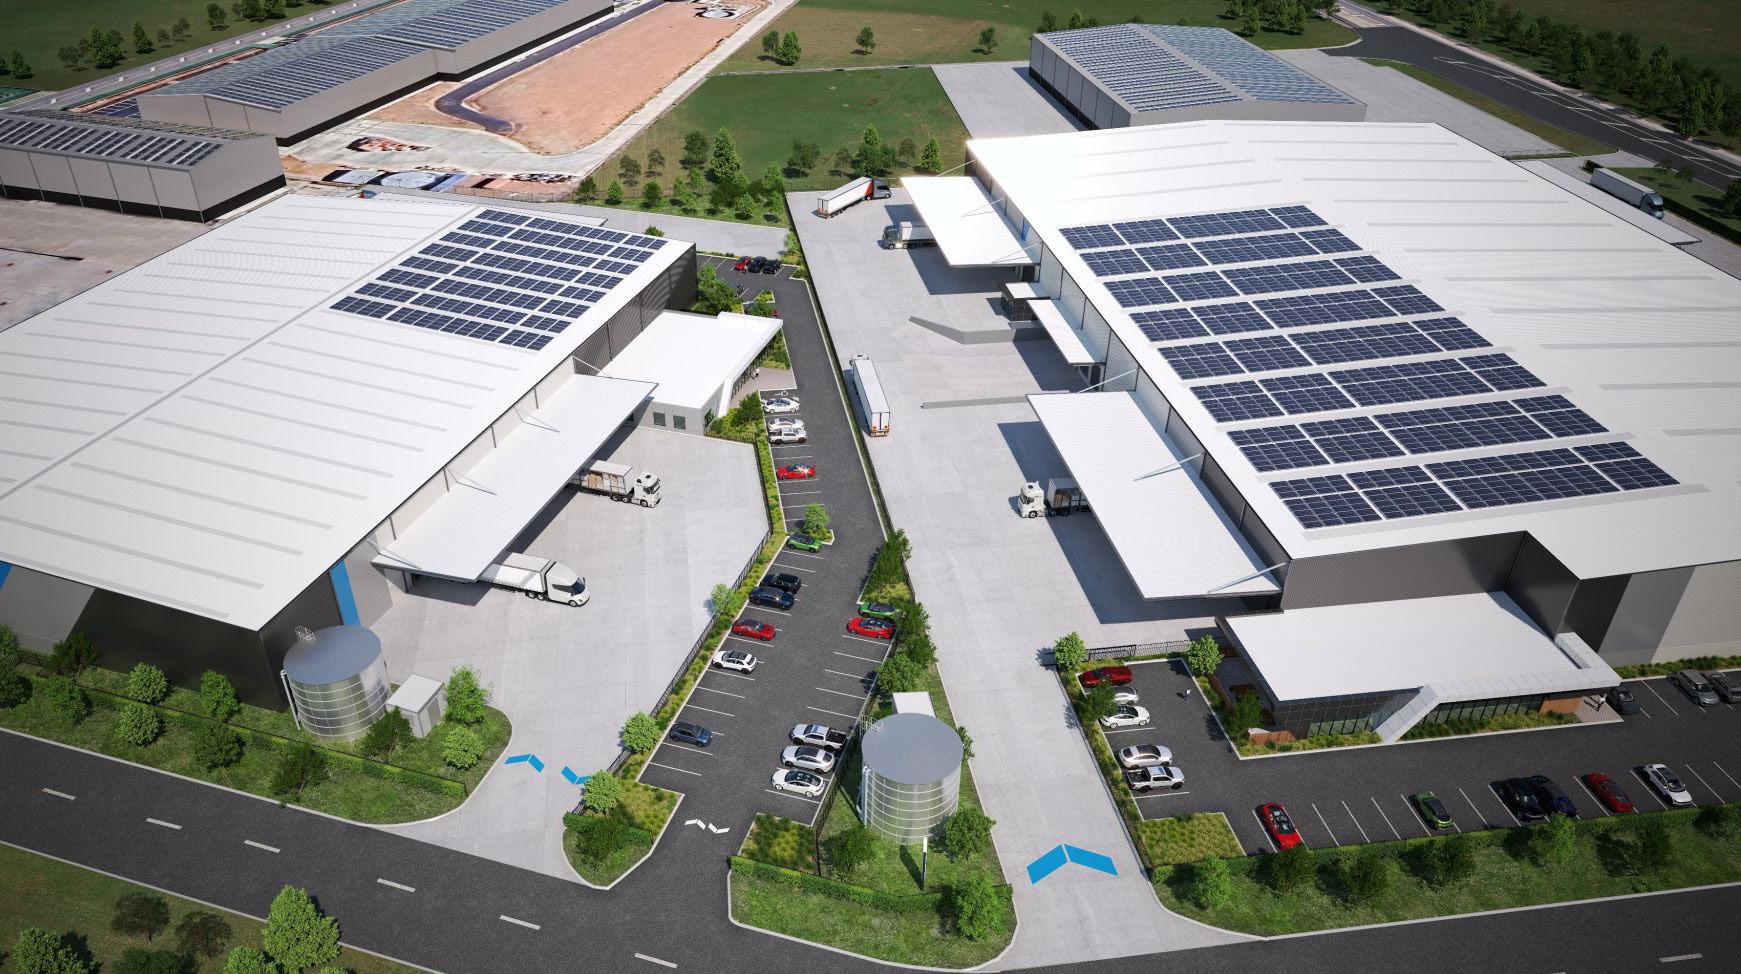
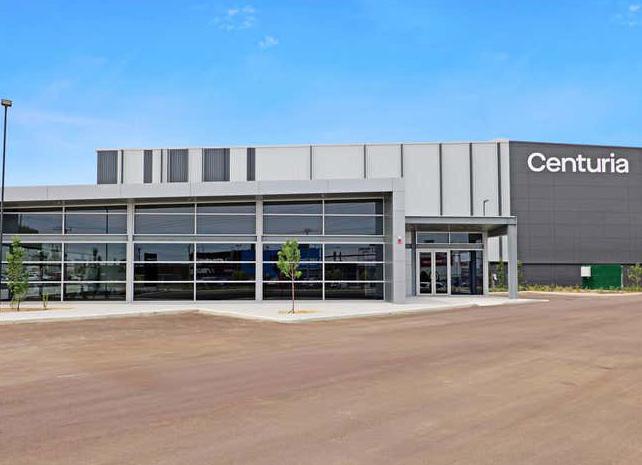
Location: Edinburgh, South Australia
Building Area: 8,920sqm
Perth Property Market Overview
*Key industrial suburbs only listed
• Wangara
• Balcatta
• Malaga
• Perth & Jandakot Airport
• Kewdale
• Welshpool
• Bibra Lake
• Forrestdale
• Brookdale
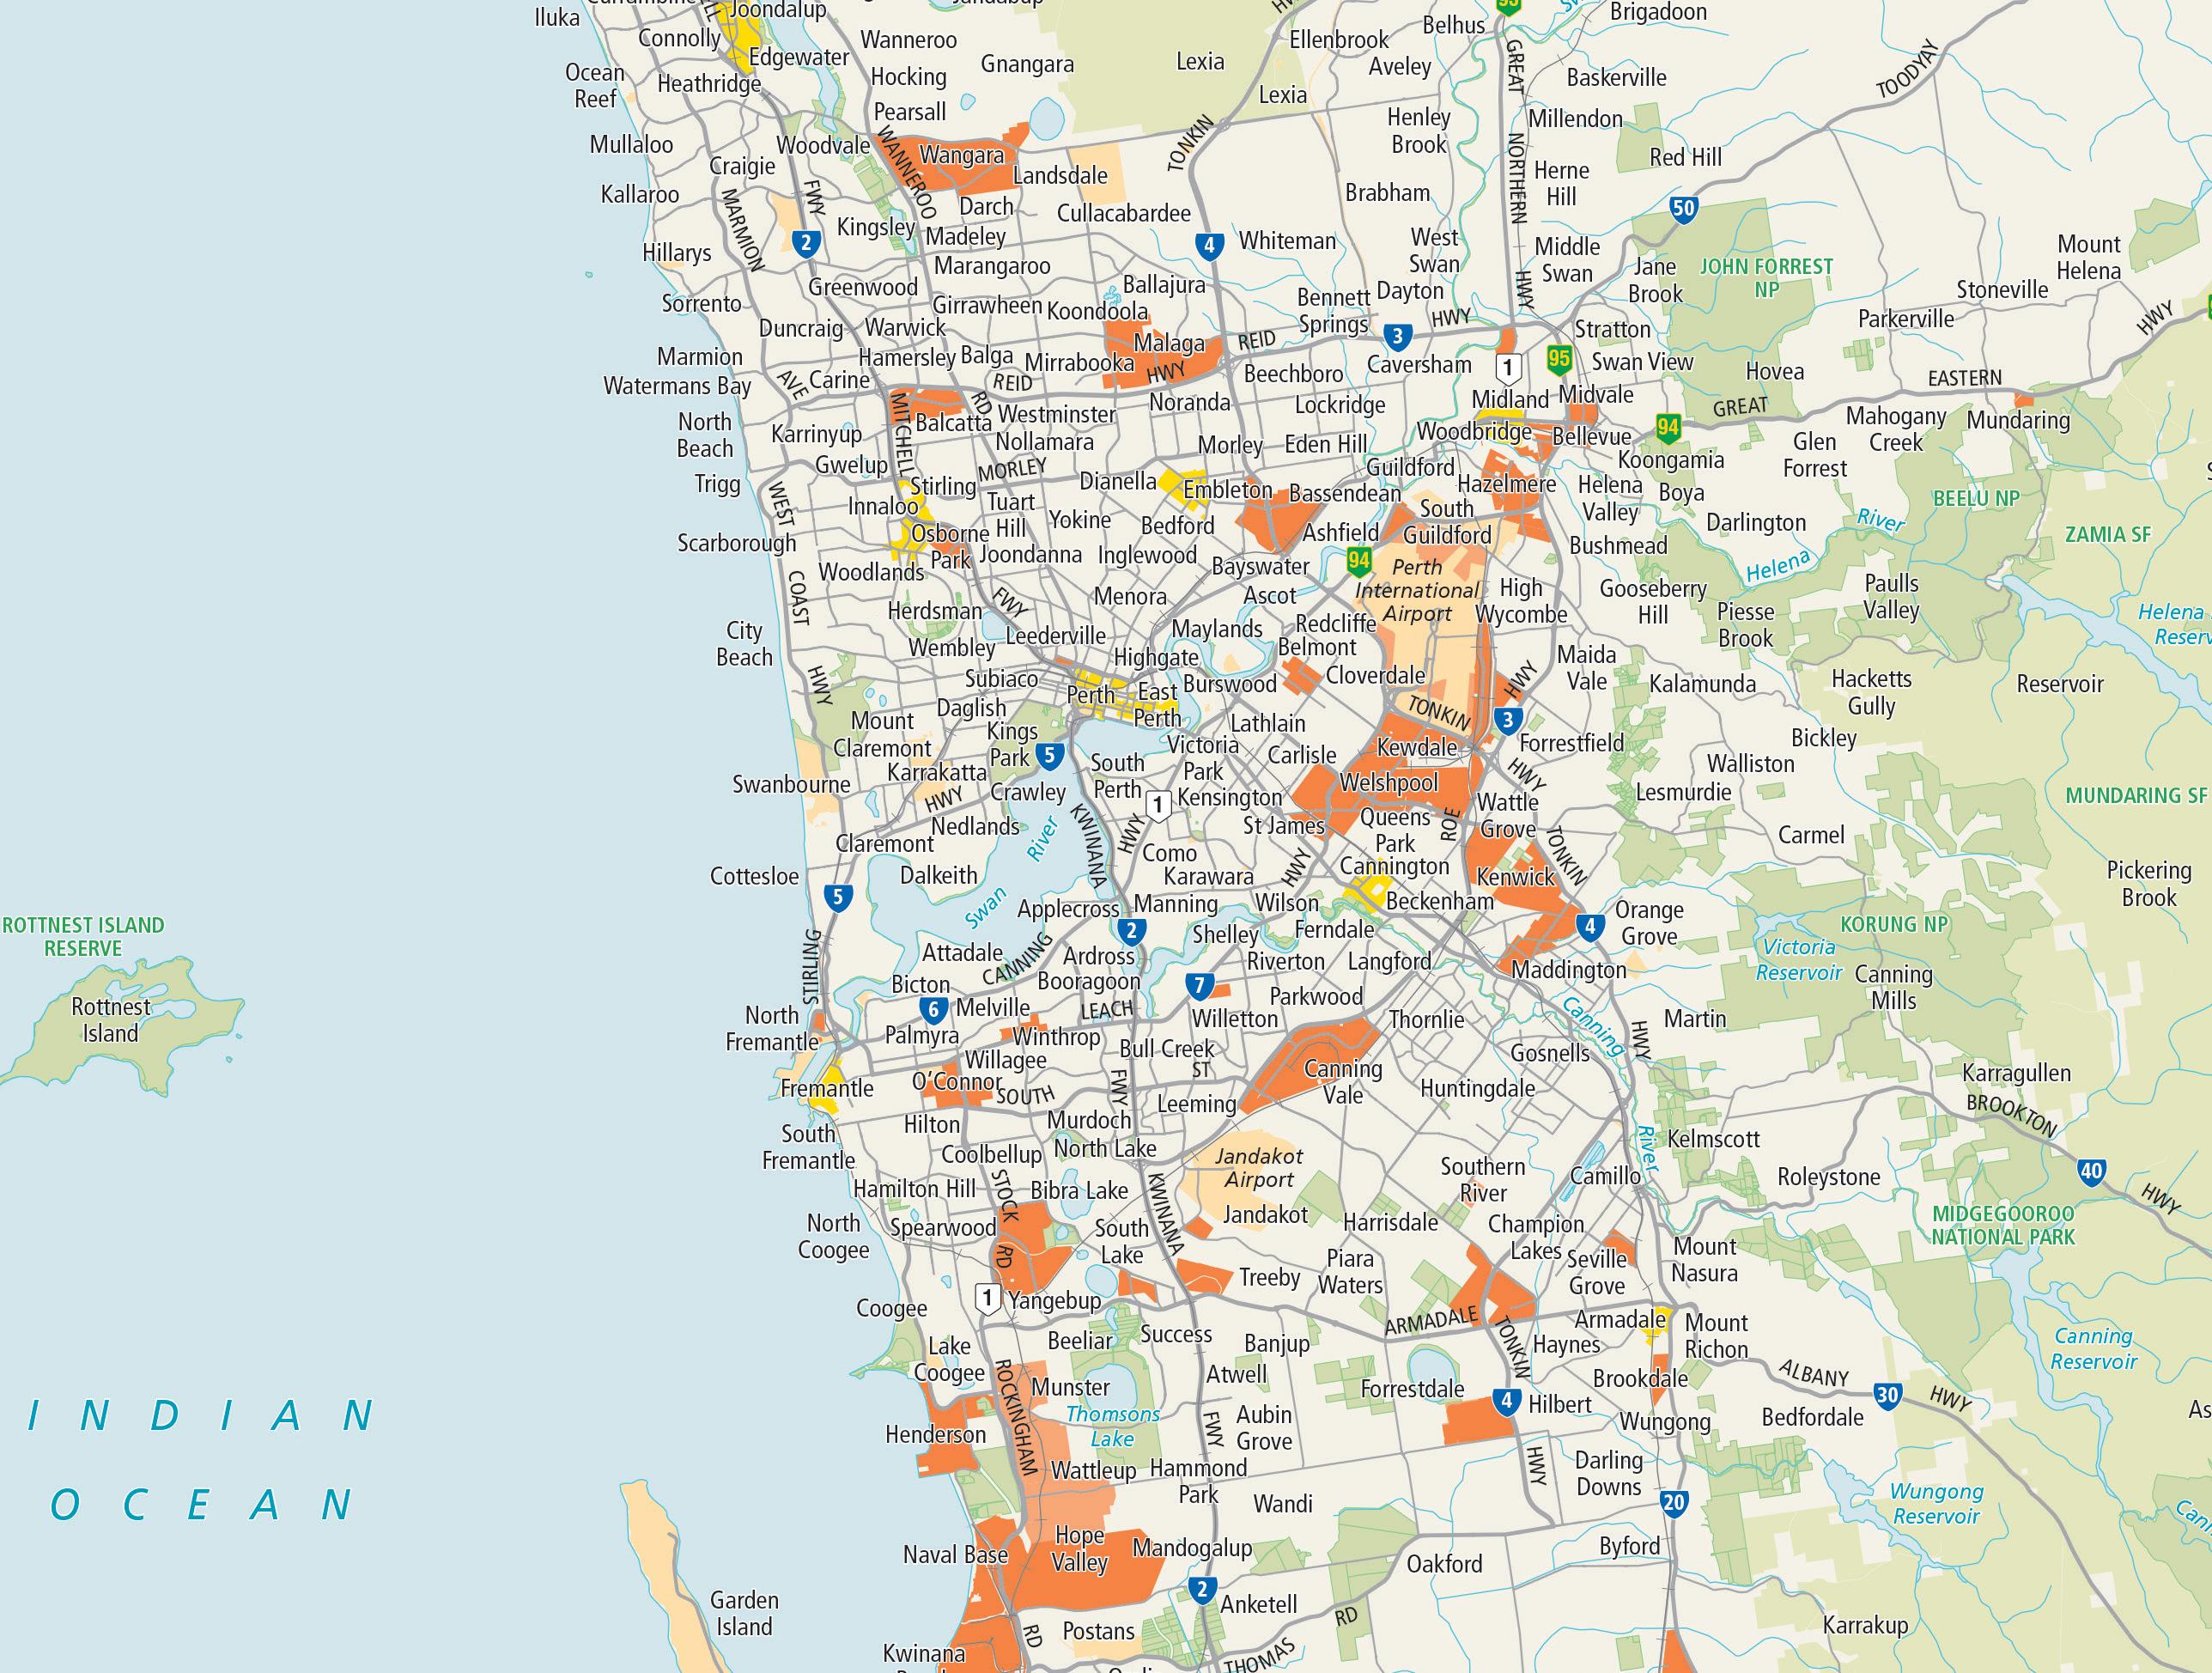
• Henderson
• East Rockingham
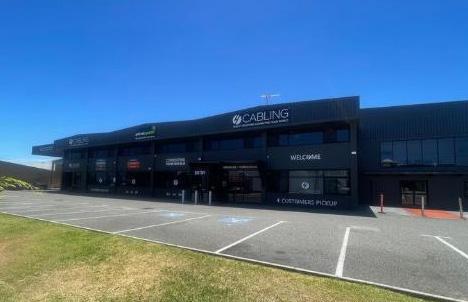
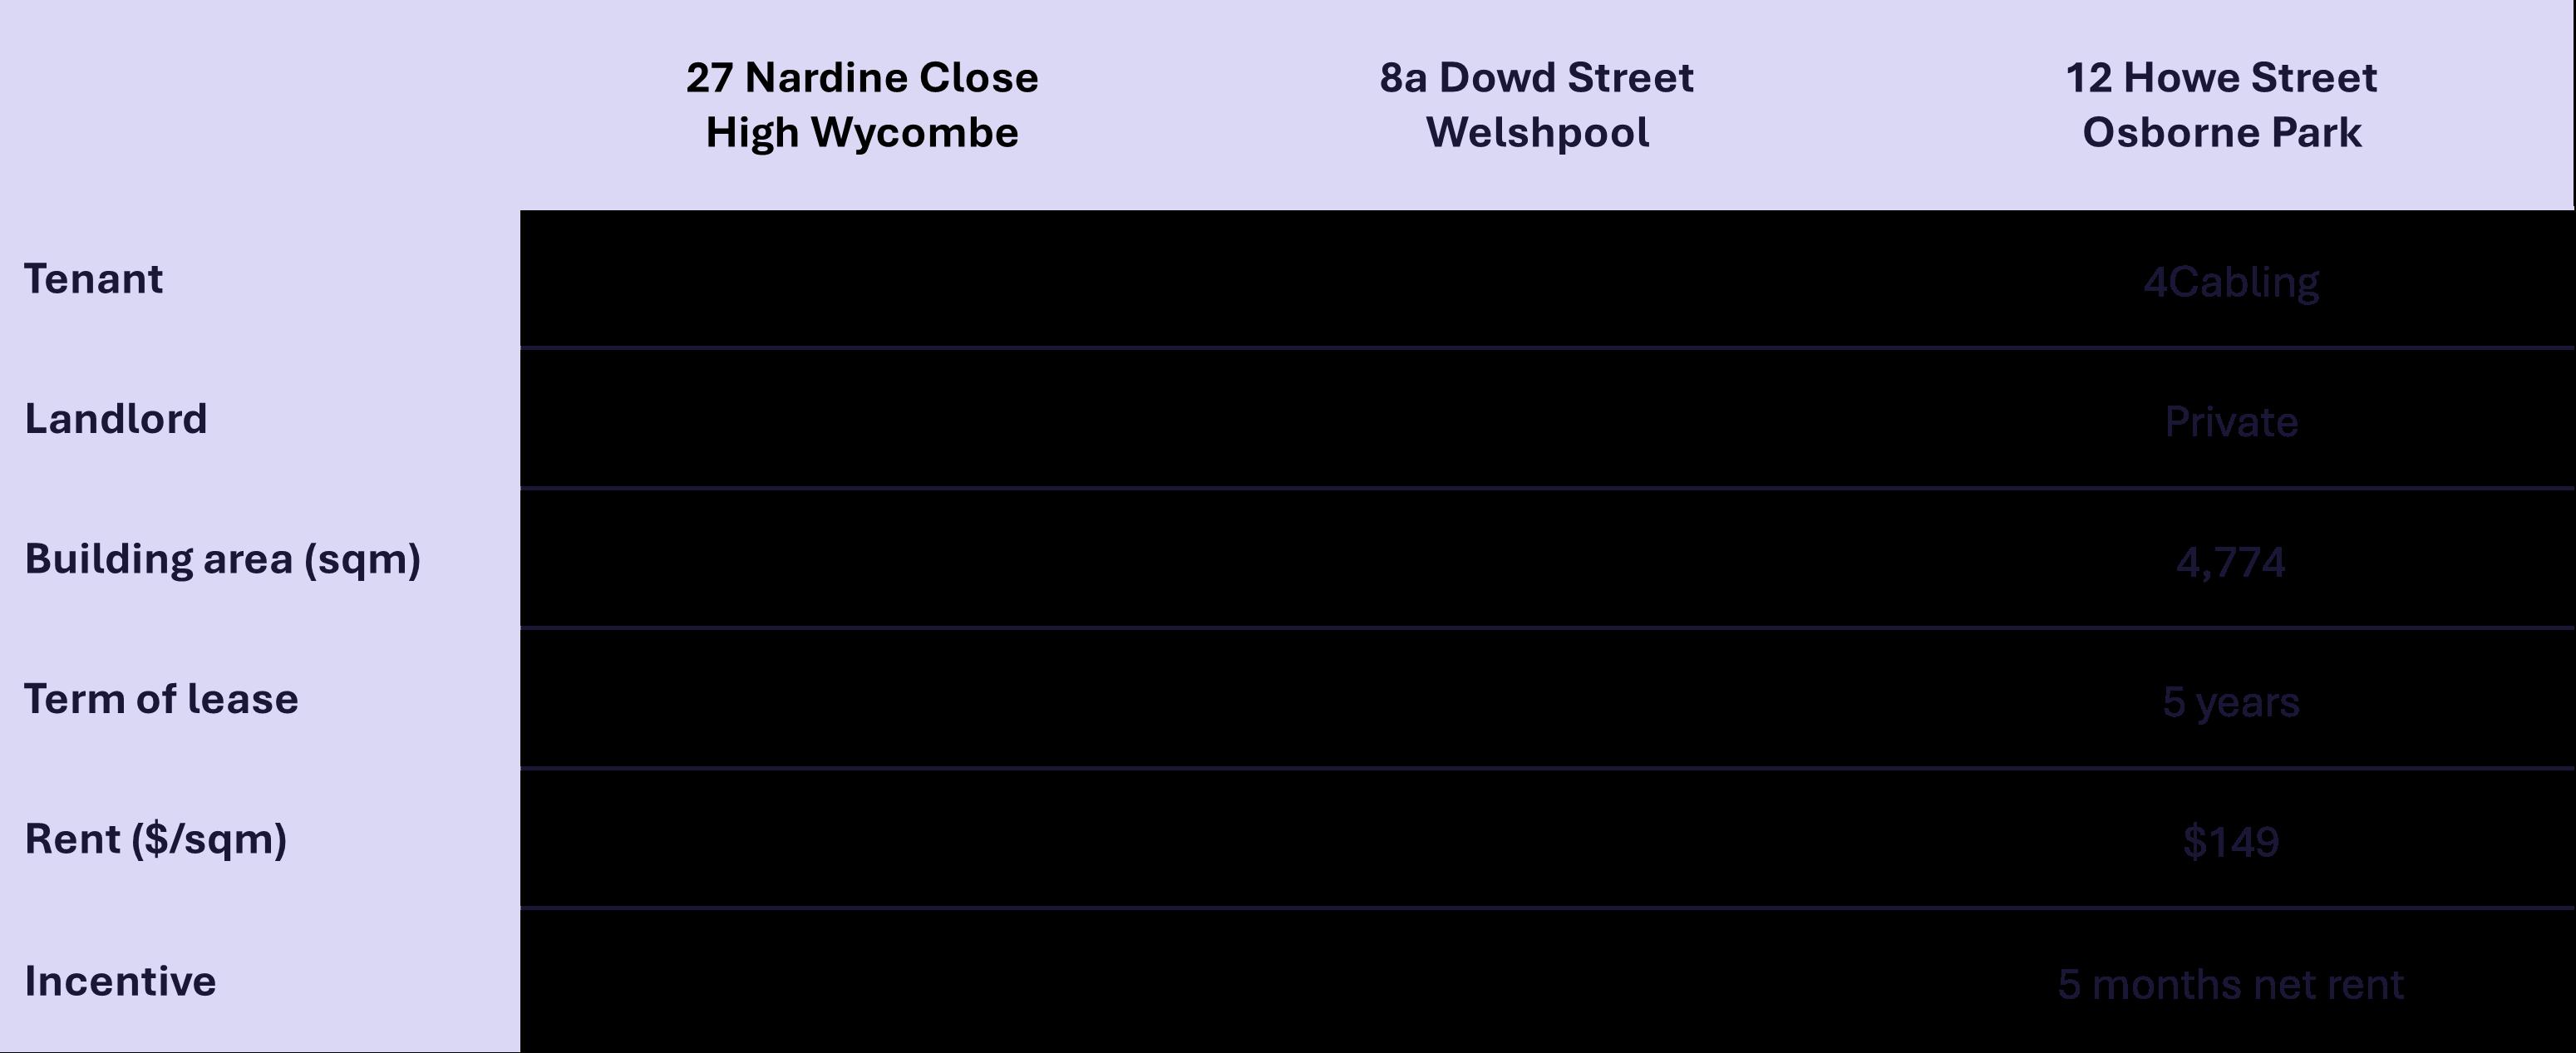
Limited availability of larger warehouses
Increase in lease renewals as occupiers favour staying put over relocating
Consistent leasing demand especially in stock 3,000 –7,000sqm
Development land supply constrained to south
Vacancy remains tight with more availability in the south
Speculative stock construction very low
Positive conditions for increased construction
Increase in stock available for lease
Increased tenant negotiation leverage compared to recent tight market era
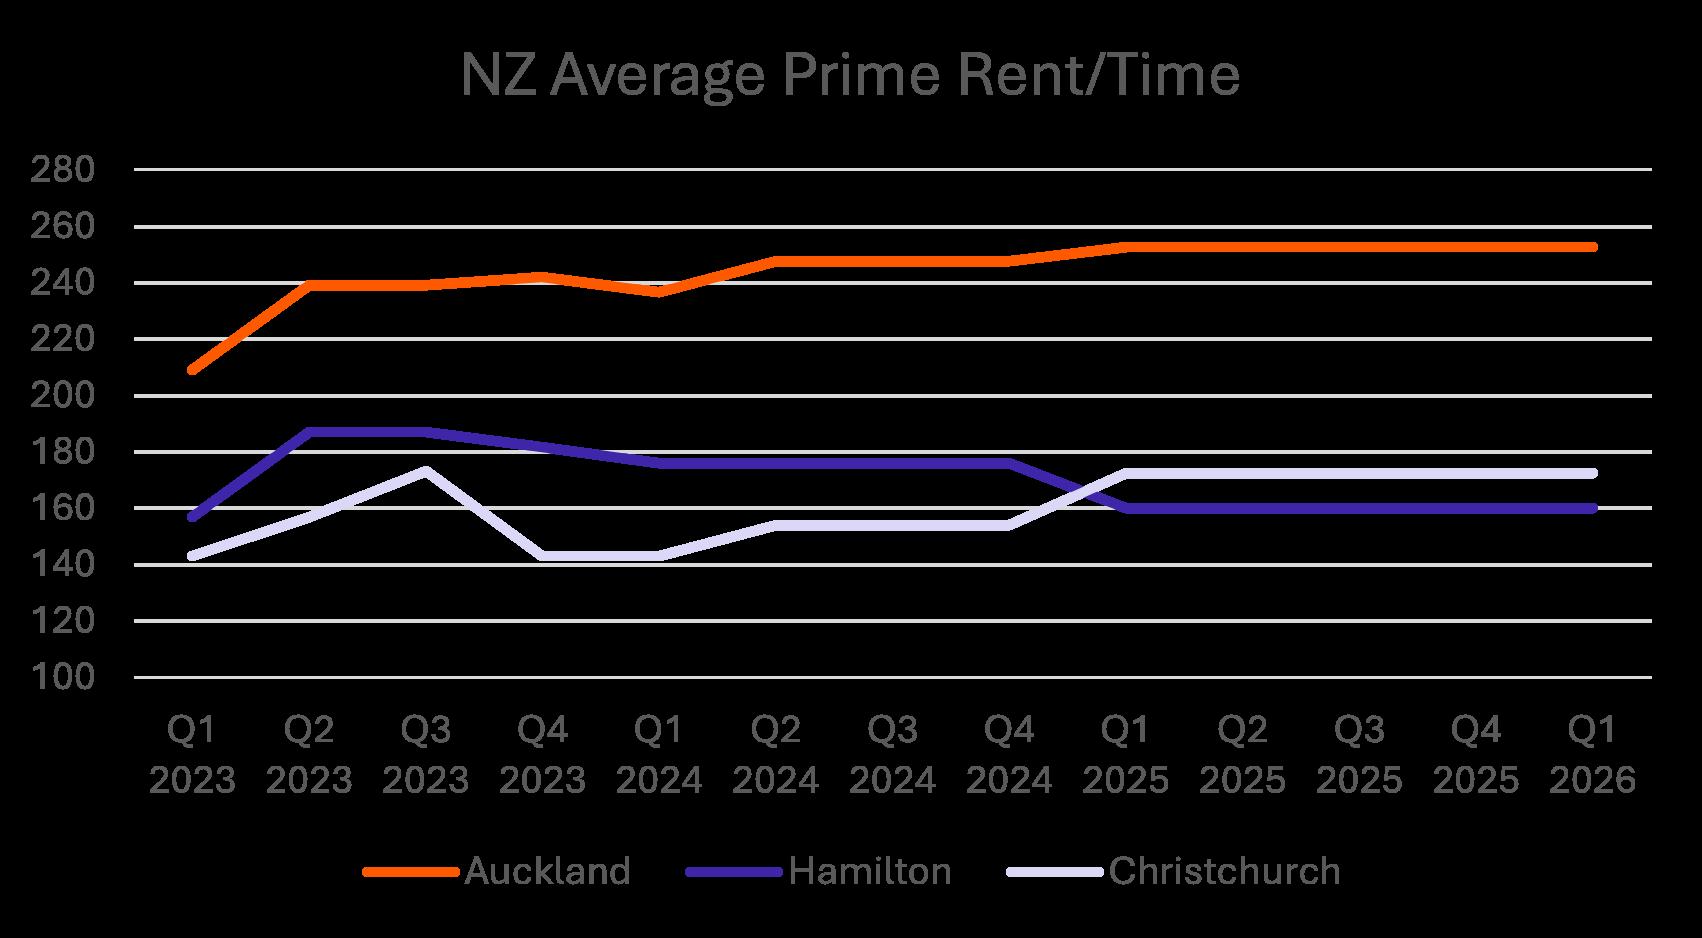
Locational efficiency is still key in NZ markets
Rising enquiry in smaller warehouses in Auckland
Rents holding steady across NZ markets with incentives rising
*NZ typically itemises rents for warehouse, office, canopy, hardstand, yard and parking. Above rents are normalized to reflect overall GLA, as per AU methodology.
Our unique integrated property portfolio service offering allows us to assist with…
• Rent review
• Rental audits
• Benchmarking
• Reviews and reconciliations
• Identify cost saving opportunities
• Capture critical dates
• Document repository
• New and renewed leases
• Make Goods
• Surrender and assignments
• Sale of freehold sites
There have been noticeable increases in outgoings this quarter with Insurance costs growing the fastest and are expected to continue increasing due to climate risk and construction costs. Statutory outgoings are still trending upwards due to general cost of living inflation and government revenue pressures going into 2026.
• Repairs and maintenance responsibilities and negotiations
Occupiers continue to right-size portfolios, focusing on operational efficiency rather than downsizing. Demand is shifting toward modern, automation-ready facilities near urban hubs, with right-sizing driven by optimisation and efficiency rather than cost alone. Working capital and slowing leasing decisions are creating additional friction for relocations and rightsizing initiatives.
Landlords are increasingly requiring bank guarantees of 6-12 months gross rent, driven by heightened tenant credit risk, lender expectations, and rising costs associated with pressure on occupiers. Working capital and slowing leasing decisions are creating additional friction for relocations and right-sizing initiatives.
Looking ahead to Q2 2026, continued pressure from rising outgoings, larger bank guarantee requirements, and ongoing right-sizing initiatives are expected to slow occupier decision-making.
Managing your construction of an industrial warehouse project, from standard facilities through to automated, purpose-built distribution centers.
Working with hundreds of clients in your shoes, we’ve found that a lack of in-house expertise to navigate property procurement and construction journeys, can hinder expansion.
Through our team of industry specialists with end-to-end capabilities, we support this process, ensuring certainty from the business case, through to project delivery.
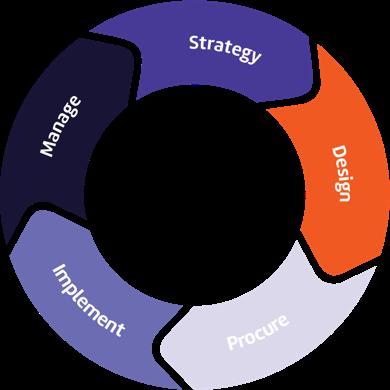
End-to-end Support
Know your costs
Develop a robust base building to avoid variations and unforeseen costs during construction.
Timeline control
Delivery timeline certainty will ensure clarity on transition timeframe and coordination with operations.
Early access
Early access to commence operational fit-out to provide financial benefit to minimize ongoing rental payments.
Ensure optimum quality
Quality of the build will ensure longevity in the asset for the term of the lease.
All below figures are based on a generic 13.7m high warehouse shell including high level services
Given the volatility in oil price driven by the Middle-Eastern disruptions, we are witnessing an increase in construction pricing in the immediate term of 3-5%. The expectation is that this is temporary however timing is uncertain.
Pricing volatility is driven by:
• Fuel levies added to delivery of materials
• Sharp increase in oil-derived products
• Material shortages
*All figures based on past build rates, not a reliable estimate of future costs. Please speak to our Development Team for more accurate cost indications tailored to your requirements.
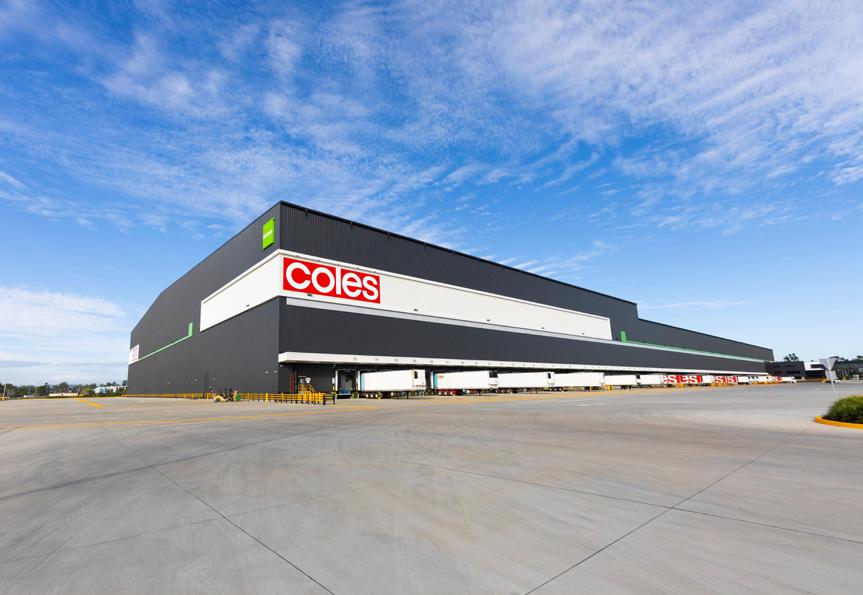
TMX undertook an end-to-end process for Coles, including:
• Developing a detailed technical design document and architectural plans.
• Property procurement facilitated through a developer tender and selection process
• Negotiation of Agreement for Lease
• Complete project management including automation
Angus Perry
Director +61 499 464 213
Nick Ingleby VIC Director +61 448 332 815
Steve Packer
Associate Director
+61 438 922 818
Hugh Vagg
Senior Project Manager
+61 466 743 781
Andrew Walsh
Ben Kilby
Patrick Leong Project Director +61 407 999 140
Nick Cauchi Associate Director +61 415 935 531
Rachelle Eid Project Manager
+61 400 033 544
Cork
Rulla Haifa Director +61 402 640 869
Sarah Thorne Senior Project Manager +61 451 063 991
Nour El-leissy Project Manager +61 424 426 442
Brett Nelson Associate Director +61 434 555 663
Jack Nagle Senior Project Manager +61 418 395 730
Kesty Bindya Senior Project Manager
+61 432 544 126
Addressing challenges at all stages of your digital and physical supply chain.
Supply Chain Strategy
Take a three-sixty-degree view of your supply chain.
Freight & Logistics
Transport your goods from supplier to end customer in the most efficient way.
Advanced Manufacturing
Create value by systematically eliminating waste and inefficiency.
Network Design DC Design & Optimisation
Improve the flow of your products, from source to end consumer.
Merchandise Planning
Carefully curated product ranges, and accurate demand and fulfilment plans.
Design your warehouse solution for now, and in the future.
Program Management
Equip your business with systems to support future growth.
Investment Feasibility
Market-based research customized for your needs.
DISCLAIMER The opinions, estimates and information given in this publication, or otherwise based on or relating to it, are made by TM Insight Operations Pty Ltd
ABN: 41 638 506 340, TMX Global New Zealand Limited
NZBN: 9429047249080, TM Insight Asia Pte Ltd
UEN: 201820336R, TMX (Thailand) Co., Ltd. Registration No. 0105565078465, TMX GLOBAL SOLUTIONS (MALAYSIA)
SDN. BHD Registration No. 202201038479 (1484176A), TMX Global Vietnam Co., Ltd Enterprise Code: 0315853788, TMX GLOBAL UK LIMITED Company Number 14140004, TMX Global North America LLC Employer Identification Number: 93-1462071, trading as TMX Transform and/or its affiliated companies (collectively “TMX”) in their best judgement, in good faith and as far as possible based on data or sources which are believed to be reliable. TMX Transform and each of its officers, employees, consultants, and agents (collectively the “Information Providers”) make no representation or warranty, express or implied, as to the accuracy, reliability, or completeness of the material in this publication and such material is not intended to be a substitute for obtaining individual advice from TMX or another qualified professional advisor able to provide the relevant services. To the maximum extent permitted by law, each Information Provider expressly disclaims any liability (whether foreseeable or not and whether arising from negligence or otherwise, including indirect, special or consequential loss or damage) for, or based on, or relating to any such information. The recipient agrees that it disclaims and waives, and will not take action in relation to, any rights it may have against any Information Provider in relation to such information.
COPYRIGHT TMX Transform all rights reserved. No part of this work may be reproduced or copied in any form or by any means (graphic, electronic or mechanical, including photocopying, recording, recording taping, or information retrieval systems) without the written permission of TMX Transform.