


















It would be remiss of me not to acknowledge just how unse led the geopolitical landscape feels as we move further into 2026 – thanks, in no small part, to a certain orange man.
In fact, readers would be forgiven for thinking the year did not begin a mere few weeks ago. Between ongoing international tensions, volatile markets, and a news cycle that seems to compress months’ worth of drama into a single a ernoon, January felt longer than it had any right to.
For this market, that intensity ma ers. When headlines oscillate so sharply (citing optimism one day, and intense alarm the next) it becomes harder for businesses, lenders and borrowers alike to separate truth from the noise.
The mortgage market does not operate in a vacuum, and while it has shown admirable resilience thus far, confidence is increasingly being shaped by the chaos around us. In this kind of climate, nuance is more important than ever. Affordability conversations naturally become even more layered, lender appetite more conditional, and client needs more complex. Even as rates continue their gradual thaw, major decisions are being filtered through a backdrop of uncertainty that makes ‘one size fits all’ solutions increasingly inadequate.
That is precisely why this month’s focus on specialist finance feels so apt. These are the parts of the market designed to deal with the imperfect, supporting borrowers with complex income streams, property types that do not
www.theintermediary.co.uk
Jessica Bird Managing Editor
Jessica O’Connor Deputy Editor
Marvin Onumonu Reporter
Brian West Sales Director brian.west@astormedia.co.uk
Millie Sweetman Commercial Development Executive
Laura Strelconoka Campaign Manager
Ryan Fowler Publisher
Felix Blakeston Associate Publisher
Helen Thorne Accounts nance@astormedia.co.uk
Orson McAleer
Designer
Bryan Hay Associate Editor Subscriptions subscriptions@theintermediary.co.uk
fit standard criteria, or time-sensitive cases that demand human judgement rather than automation. Indeed, in a world that o en insists on black and white, specialist lending operates in the grey.
Tailored finance solutions sit at the heart of this space. For lenders, that means balancing underwriting flexibility with discipline, and resisting the temptation to retreat to overly rigid criteria when wider conditions become challenging. For brokers, it requires deeper conversations with clients and the confidence to guide them through options that are rarely straightforward.
Throughout this issue, we explore how specialist finance is responding to these pressures in practice. From evolving appetite in shortterm lending, to the role of development and commercial funding in supporting real-world projects, and the continued relevance of asset finance in uncertain times, the common thread is adaptability grounded in experience rather than reaction.
If the wider world currently feels volatile and prone to extremes, I hope this issue serves as a reminder that progress in our market is rarely found at either end of the spectrum.
More o en than not, it is built case-by-case, where experience and common-sense still count for something. I don’t know about you, but right now, that sense of pragmatism certainly feels more welcome than ever. ●
Jessica O’Connor

Aaron Shinwell | Adam Tyler | Alan Fletcher
Alex Alexandrou | Alex Curtis | Alice Harris
Anna ompson | Asher Kenton | Buster Tolfree
Claire Van der Zant | Craig Hall
Dan Narwhal | Dave Harris | David Castling
David Miller | David Travers | Helen Pierson
James Bloom | James Gillam | James Tuck
James Woodfall | Jeremy Duncombe | Jim Boyd
Jonathan Fowler | Jonny Jones | Joy Abisaab
Julie Meehan | Kate Davies | Laura omas
Leanne Ardron | Lee Da ern | Leon Diamond
Lesley White | Lorna Shah | Lottie Dougill
Louisa Ritchie | Manu Dinamani | Martin Temple
Michael Street | Nasar Hussain Neal Moy
Nick Smith | Ollie Popham | Paresh Raja
Pollyanna Puddephat | Rob Stanton
Steve Nobbs | Tanya Elmaz | Tom Worbey








Copyright © 2026 The Intermediary
Cover illustration by Barbara Prada
by Pensord Press
SPECIALIST FINANCE FOCUS ISSUE
Opinion 6
The latest on the specialist market from Paragon, Together, Pallas Capital, LendInvest and more…
Feature 36
FIX AND FLIP APPEAL
Marvin Onumonu on the opportunities for investors with refurbishment-led strategies
REGULARS
A look at the practical realities of being a broker, from attracting the right talent to the monthly case clinic
This month The Intermediary takes a look at the housing market in Stockport
An eye on the revolving doors of the mortgage market: the latest industry job moves
SECTORS AT-A-GLANCE
Residential 42
Buy-to-let 54
Second Charge 60 Technology 64

BDLA
Adam Tyler discusses his recent CEO appointment and the association’s future plans
COHORT CAPITAL
Alex Alexandrou shares insights regarding Cohort’s recent product launch and the rise of bridging nance
NOVUS STRATEGY
Claire Van der Zant talks digital integration and Novus’ plans for growth
ATOM BANK
David Castling discusses Atom’s recent commercial lending milestone and working with brokers
TOGETHER
Dan Narwal on the Premier for Intermediaries launch and what it means for the large loan space
ALTERNATIVE BRIDGING CORPORATION
James Bloom looks at development market trends and the lender’s recent proposition enhancements
AS FINANCIAL
Asher Kenton discusses his move from music promoter to mortgage broker
Protection 69 Later Life 72 52

HARPENDEN BUILDING SOCIETY
James Tuck discusses the challenges and opportunities for BDMs
MANU DINAMANI is director of structured nance at Close Brothers Property Finance
There is no denying that 2025 was a challenging year. The industry has been facing a perfect storm for some time: so ening yields, increased costs of borrowing, and rises in build costs. Even wellcapitalised investors have struggled to deploy funds.
Although structural headwinds persist, the outlook is starting to improve, and the sector has entered 2026 on a cautiously optimistic note. Greater stability in policy, planning and innovation are already creating a more favourable environment.
While the run up to the 2025 Autumn Budget was dominated by negative speculation, market response was muted. If anything, the certainty provided by the Budget has removed the risk of unknown variables, which has helped to instil a degree of confidence.
The “Mansion Tax” generated no shortage of column inches, but its practical impact on housebuilding will be limited. The majority of new homes delivered across the country will fall well below the threshold, meaning it is unlikely to materially affect housing delivery. While the Budget didn’t deliver everything the sector might have hoped for, it avoided major shocks, providing a stable platform for continued investment.
In October, the sector welcomed the new housing support package introduced in partnership with the Mayor of London. The measures included targeted reforms to unlock stalled residential schemes and accelerate affordable housing delivery. As part of the reforms, the Mayor can now review schemes of 50 or more
homes where boroughs are minded to refuse, including development on greenbelt and Metropolitan Open Land (MOL).
One of the most impactful changes is the time-limited planning route that removes the requirement for upfront viability testing on schemes delivering a high proportion of affordable housing. Additionally, schemes that reach first-floor construction by March 2030 are exempt from LateStage Review (LSR), eliminating a key source of future cash flow uncertainty.
The £322m Developer Investment Fund and the £16bn National Housing Bank programme are also welcome, building on the success of the Londoner’s Land Fund. I would anticipate that co-investment structures, guarantees, or mezzanine instruments will be needed to de-risk participation and a ract institutional capital at scale.
Additional financial support for investors and developers includes temporary borough-level Community Infrastructure Levy (CIL) relief of up to 50% for schemes delivering 20% or more affordable housing on brownfield land, with higher relief available for greater affordable provision.
The living sector is becoming increasingly diversified. While traditional single-family homes will remain central to housebuilding targets, diversification across residential asset classes provide scalable opportunities with differentiated risk profiles.
Build to Rent (BTR), co-living, purpose-built student accommodation (PBSA) and senior housing all
address different housing needs. Co-living offers a more affordable alternative to BTR, while PBSA frees up house shares for families and provides students with high-quality accommodation. The exclusion of co-living and PBSA from some of the planning reforms represents a missed opportunity. However, I have every confidence that these sectors will come to play an even greater role in the UK’s housing ecosystem.
Innovation in the capital stack could be a key route to unlocking stalled sites. Blended finance models and partnership-led approaches will be critical to unlocking schemes that would otherwise remain stalled. The sector has increasingly been calling for Government guarantees or other targeted intervention to stimulate a slower sales market and boost confidence amongst investors.
On the whole, I am genuinely optimistic about the outlook for this year. At Close Brothers our deep understanding of the underlying real estate and development process – recognising the nuances of microlocation, the impact of unit mix and product design, and the importance of a partnership-led approach to funding – puts us in a strong position to help unlock funding in 2026 and beyond. I strongly believe that by working closely with developers and stakeholders, and by leveraging collective expertise, we can help deliver not just homes, but resilient, investable communities. ●
The world of specialist finance is complex. Every case has layers: the customer’s story, the numbers behind the deal, the broker’s insight, and the lender’s expertise. And whilst brokers and sales teams are o en the visible face of the journey, the truth is that countless individuals are involved in making each case work. Many of these are people who don’t always appear in the spotlight, but without them deals simply wouldn’t happen.
Take Together’s new Premier for Intermediaries proposition as an example. This service, just launched in 2026, brings together a handpicked team to support brokers handling large, high-value cases over £1m. It provides a bespoke, experience where communication is direct and complex scenarios get the a ention they deserve.
And whilst the Premier team is headed by the exceptional Dan Narwal, even the strongest leaders rely on the strength of the wider operation. Behind every smooth journey sits an ecosystem of specialists; underwriters, case managers, completions experts, risk analysts, valuations teams, and operational colleagues who quietly keep the entire process moving forward.
Underwriters are o en unseen, but brokers certainly feel the impact of their specialist knowledge. They take every detail, document, and nuance of a case and apply an expert lens to it.
For high-value cases, that expertise is even more important. Underwriters assess affordability, analyse risk, challenge assumptions, and ensure that the lending decision works for the customer, the broker, and the business. Their ability to balance commercial opportunity with responsible lending is what
makes complex cases viable. But underwriters don’t simply say “yes” or “no”. They work collaboratively, asking the right questions, spo ing gaps early, and guiding brokers towards solutions that strengthen the case.
In many instances, a skilled underwriter can turn what appears to be a dead end into a constructive path forward. They are the architects of workable lending.
Once a case is in motion, case managers become the heartbeat of the journey. They ensure everything stays on track, documents arrive on time, and all parties; solicitors, valuers, brokers, or customers, stay aligned.
A good case manager removes friction long before it reaches the broker or the client. They spot missing paperwork early, anticipate questions before they’re asked, and raise red flags before they become roadblocks.
In a high value environment, that level of proactive management is essential. It protects timelines, reduces stress, and builds trust. For brokers, it means fewer phone calls chasing updates, and for customers, it means confidence that their significant financial move is in safe hands.
The completions team takes a fully packaged case and turns it into a funded loan, an achievement that is o en underestimated. They handle everything from final checks to coordinating release of funds, ensuring solicitors have what they need, and verifying that all conditions have been met properly.
When completions run smoothly, a broker may never realise how much work went in behind the scenes. But when timelines are tight and expectations are high, the precision and responsiveness of the completions team can make or break a customer’s positive experience. They are the ones who turn “approved” into “delivered.”
TANYA ELMAZ is managing director of intermediary sales at Together
Beyond the customer-facing teams, there are specialists whose expertise shapes the success of every case long before a decision is made.
Valuations teams ensure properties are accurately assessed and reflect true market conditions. Risk analysts protect customers and the business by understanding long-term implications, and operational teams build and refine the systems and processes that allow large, complex cases to move with ease. Without these functions, speed and reliability simply isn’t possible.
For Together, whilst the Premier for Intermediaries team offers a single point of contact and along with great service for brokers dealing with larger loans, they are supported by a network of experts who give that promise substance. It’s their combined knowledge, judgement, and commitment, that enables us to maintain a relationship-first approach to lending.
Those internal teams are the reason businesses can support brokers through challenging cases and help more people achieve their property ambitions, even when the scenarios are far from straightforward.
So, the next time a case completes seamlessly, or a complex scenario turns into a successful outcome, it’s worth remembering the people behind the scenes who made it possible. They might not always be visible, but they are absolutely vital.
These are the unsung heroes of Together, and all other lenders, and every successful case is their achievement too. ●
Islamic finance, also known as Shariah-compliant finance, is a sub-sector of financial services which has been growing rapidly in recent years and is predicted to surpass $4tn in assets globally by 2030.
In the Western world, the UK has emerged as a leader in this space, with over 20 institutions, including five fully Shariah-compliant banks, now providing Islamic finance products. This is more than any other Western nation.
However, despite this promising growth trajectory, there remain lingering misconceptions about the differences between Islamic and conventional finance, as well as who can access these products. For example, according to Gatehouse Bank’s latest ‘Islamic and Ethical Finance Report,’ three in 10 (30%) of UK consumers believe that Islamic finance is only available to those of the Muslim faith.
To ensure the industry can reach its full growth potential and that customers are aware of the opportunities it could afford them, it is important to address these misconceptions and tackle the knowledge gap.
Unlike conventional finance, Shariah-compliant finance does not pay or charge interest, as Shariah principles state that money should not be generated in and of itself. Instead, funds must be put to a good use to generate profit supported by a genuine trade or business-related activity. This is why Islamic savings accounts offer an expected profit rate, which is generated by the profit made by carefully investing customers’ deposits.
Additionally, we make sure that the property finance we provide
and customers’ deposits are not used to support harmful sectors that are against Shariah principles. These include industries such as alcohol, tobacco, gambling, adult entertainment and arms dealing.
Finally, as a Shariah-compliant ethical bank, speculative investments and transactions are prohibited and it is important that in any venture, the risk is always shared and mitigated. As a result, all of our transactions involve real assets, with this approach encouraging trading and enterprise that is stable and transparent.
Shariah-compliant providers such as Gatehouse Bank offer Home Purchase Plans (HPPs), which are commonly known as the Islamic alternative to a mortgage. This involves the customer and the Bank forming a partnership to purchase the property together, with the customer then paying monthly acquisition payments and rent on the share of the property they do not yet own. Once all payments have been made, full ownership of the property is transferred to the customer.
At Gatehouse Bank, we also offer a range of buy-to-let (BTL) Purchase Plans which are available for UK residents, UK expats and international residents. These can be used by prospective or existing landlords just like a conventional mortgage to buy or refinance property, with the final outcome being the same.
Brokers do require additional permissions to submit applications for private home ownership through a HPP, as this is a regulated activity. At Gatehouse Bank, we are still able to assist brokers without these permissions to manage customers seeking Shariah-compliant finance by introducing the case to our direct
LOTTIE DOUGILL is head of home nance distributions at Gatehouse Bank
adviser (DA) team and providing a reduced procuration fee as part of the process. Permissions are not required if a broker is submi ing BTL applications to us, as these products are unregulated.
Despite the misconception remaining that Islamic finance is only available to those of the Muslim faith, the sector is becoming increasingly a ractive to those from all faiths, or none, due to it being guided by the principles of transparency, fairness and ethical venture. This is resonating strongly with a society which is becoming more values-driven and looking to align their values with their financial decisions.
According to our recent research, nearly half (45%) of UK homebuyers would consider using an ethical home finance provider that aligns with Islamic principles and over one in three (37%) said that they would be most interested in opting for a Shariah-compliant provider because funds aren’t invested in unethical industries.
The rise of a more conscious way of accessing finance will be key as we move into 2026 and beyond to ensure providers are still able to deliver the home finance solutions that suit the needs of homebuyers and landlords alike.
Raising awareness, removing misconceptions and working with the Government to level the playing field between Islamic and conventional finance are all key components to ensure it achieves its full growth potential in the UK and in the wider global market and, at Gatehouse Bank, we aim to be part of driving this change forward. ●
The Intermediary speaks with David Castling, head of intermediary distribution at Atom bank about the it’s recent lending milestone and commercial market trends
You recently hit the landmark of reaching £1bn in commercial loans on your balance sheet. How signi cant is that milestone?
It’s a real achievement that demonstrates just how far Atom bank has come within this space.
For a relatively new bank to have built that sort of balance sheet shows that we are meeting a clear need among business borrowers, and delivering the funding that o en isn’t available from high street lenders.
From my perspective, what’s really satisfying is that we’ve managed to hit that milestone while operating with such a small – but perfectly formed – team. We might not have the sheer number of business development managers (BDMs) that some bigger players have, but the Atom BDMs punch well above their weight.
Last year they oversaw a signi cant increase in applications and completions and helped service a panel that had expanded by a third, without any extra resource.
In fact, over the last couple of years we have doubled the size of our commercial loan book, so we have really built some incredible momentum. I don’t believe there’s a BDM team that understands brokers so well, and goes the extra mile as o en, in this industry.
What are brokers looking for from commercial lenders at the moment? How are you making sure they get what they need?
I think all brokers, whether commercial or otherwise, want to feel heard by the lenders they work with. ey are at the coalface, seeing the challenges their clients face in accessing the funding they need, but also the pressure points in the lending process. As lenders, it’s crucial that we
listen to brokers, and act upon their feedback.
We made a host of changes to our commercial proposition last year. ese ranged from improvements to the broker portal to new product developments like the Better Buildings initiative, which means borrowers can access an interest rate discount when raising funds against more energy e cient properties.
In each case, those enhancements have come about because of that close dialogue with brokers, helping us mould a commercial proposition that works for the clients they are seeing on a day-today basis.
I think they are also looking for exibility. e circumstances for each business will be di erent and may not t within neat criteria boxes. What brokers are desperate for are lenders who understand how a business works, will take all of the factors into consideration, and look to structure funding that re ects that particular case. If you are serious about supporting small to medium-sized enterprises (SMEs), as we are at Atom bank, then you have to be adaptable.
It’s important for lenders to remember that our relationships with brokers are symbiotic. We provide them with more choice for their clients, but we also rely on brokers for that distribution.
at’s why building lasting relationships, based on trust, mutual respect and an understanding of what we all need from that partnership, is absolutely key.
Communication is obviously key, but collaboration is just as important in my view. Commercial cases tend to be more complicated, with more moving parts, than residential borrowing.
Every new borrower has their own story, and these stories matter both in helping us understand their objectives, but also where we t in as a lender. e key is nding the alignment between what they want and what we need, and so taking
a rigid ‘tick box’ approach doesn’t really cut it. What’s stood out to me, particularly over the last year, is how a focus on working together and being exible can ensure some cases reach a successful outcome, even when things are a little complicated. If the focus is on nding a way to make a deal work, rather than reasons to block o progress, then you are on the right track as a BDM.
You also need to be available to talk through cases with brokers and borrowers. at personal touch is hugely important – you need to be able to demonstrate that you value the case as much as the borrower does. We had a case last year, our biggest ever loan in Scotland, where that accessibility of the BDM was not only key in securing the deal, but in helping it reach the targeted deadline as well.
e best BDMs act as consultants in e ect, helping brokers ensure the right deals are brought forward, and that they are structured in a way that has the best chance of approval.
You expanded your broker panel last year. What drove that decision, and are there plans for further additions?
2025 was a big year for our broker panel, with the number of rms we work with up by around a third. at was really driven by the level of interest in our commercial lending proposition, with increased awareness of what we are doing, and particularly our expertise in subsectors that other lenders may struggle with, like care homes and pharmacies.
We have always been known for
o ering good value, but we are now building a reputation for outstanding service among brokers, and have maintained that while scaling up our activities, combining an outstanding team with innovative tech
Commerical cases tend to be more complicated, with even more moving parts, than residential borrowing. Every new borrower has their own story, and these stories matter both in helping us understand their objective, but also where we t in as a lender”
solutions. at reputation means more and more brokers are interested in working with us, but we need to ensure that if and when the panel is increased, we are still able to deliver that top level of service. is level of control is crucial, and carried out with the right intentions, though I appreciate it can be frustrating for those waiting on the sidelines.
important
feedback in re ning your commercial proposition?
e dialogue we have with brokers is fundamental to the way we operate. We tap into their expertise to get a better understanding of where cases may slip between the cracks, and where changes can be made which make their job easier.
team with portal, changes have been bigger than others, but they brokers. Another responded to broker feedback, and by introducing a a of exciting plans for 2026, and we look forward to seeing how these their
Over the last year or so we have made more than 150 material improvements to our broker portal, for example, which have come about because of direct feedback. Some of those changes have been bigger than others, but they all add up to a better – and faster – experience for brokers. Another good example was introducing a simpli ed stressed interest rate last year. We responded to broker feedback, and by introducing a simpler way of assessing a ordability, opened up the potential for businesses to improve their borrowing power. at has always been the way we have operated, working with brokers to help us get better. We have a lot of exciting plans for 2026, and we look forward to seeing how these can help brokers and their clients land the funding they need, at a price they want, even quicker. ●
Predatory lending has been in the headlines recently, with The Times revealing that small to medium-sized enterprises (SMEs) are increasingly trapped in cycles of expensive short-term loans. But in a funding landscape where traditional banks’ rigid systems shut out strong SMEs that don’t fit the tick-box model, it’s understandable that some entrepreneurs explore more restrictive options. The fact that ambitious businesses feel they need to consider these loans is a warning sign of a system under strain.
Since the 2008 financial crash, hight street banks have grown increasingly reluctant to fund SMEs – a trend intensified by the Covid-19 pandemic, global instability and stricter compliance frameworks.
Traditional lenders’ slow approvals, rigid structures and blanket refusals of entire sectors mean that ambitious businesses are missing out on opportunities and losing momentum. And this comes at a time when inflation, taxes and government policy are squeezing SMEs tighter and tighter.
The result? Business owners feeling backed into a corner are taking on stacked loans with unclear repayment terms and unsustainable costs. It’s a stark picture of a broken SME funding landscape where an overreliance on rigid systems and red tape lets banks shirk their responsibility to support strong businesses.
This reluctance from traditional lenders is o en labelled as risk avoidance. But when strong, viable businesses are rejected over trivial paperwork, or whole sectors like hospitality are blacklisted, it’s obvious the system is not fit for purpose. The
problem isn’t that SMEs lack ambition or opportunity – far from it.
Across the country, there are exciting entrepreneurs with bold plans who simply need the right financial partner to move forward. The real challenge is that access to responsible capital has not kept pace with the urgency of business reality. Let’s be clear: SMEs aren’t underfunded because they’re high risk. They’re underfunded because the system is too rigid to see their potential.
Remaining responsible
Banks hiding behind process and paperwork comes up all too o en. One Reward client had their high street lender pull funding for a development project because the property was on the proposed HS2 line, despite the scheme being cancelled by the previous Government. With planning permission for the renovation in place and having sought legal insight to understand the risks, we could be pragmatic about the situation. It was clear that in the unlikely event HS2 is reinstated, the risk could be managed collectively with the client.
Inflexible systems saw the situation as too complex, but we worked through to a straightforward solution, supporting the business to complete the project. That deal only worked because we could see the full picture:
NICK SMITH is group managing director at Reward Funding
a client with planning permission, legal clarity and a time-sensitive window. Banks saw a red flag. We saw a viable plan.
With banks stepping back, some less responsible operators have rushed in to fill the gap, but too o en they lack the structure, clarity, or long-term thinking that sustainable funding demands. Running a business in today’s uncertain climate requires finance to be fast and flexible. However, this shouldn’t come at the cost of transparency, responsibility, or long-term viability.
Stuck between rigid banks and unsustainable alternatives, flexible funders are the solid option that can help SMEs avoid facing impossible choices. Behind each funding request is a determined business owner building the economy’s future, and that’s something we should all get behind.
Traditional lenders’ overcautious instincts might seem sensible at face value, but if responsible funding only shows up a er the damage is done, we’ve missed the point. The question is: who’s going to back ambition before it turns into crisis?
Full of drive and conviction, SMEs are the lifeblood of our economy, and they deserve flexible funding to fuel their goals. ●
After a year of extensive planning reforms, I’m hopeful that 2026 will bring the beginning of a long-awaited sea change for small to medium-sized (SME) housebuilders. Housing delivery figures in recent months have been particularly concerning, but the Government’s direction of travel is encouraging with some reassuring signals of support for smaller developers.
The Government’s most recent overhaul of the planning system, announced late last year, focuses on two main aims: fast tracking approvals and prioritising small and medium sites. Updates to the National Planning Policy Framework (NPPF), if the proposals pass Parliament, will introduce a “default yes” for development near transport hubs and minimum density requirements around stations. Once enacted, these changes would allow more small to medium developments to
proceed without the lengthy delays that housebuilders currently have to endure in a volatile planning process, where more often than not, applications have to go through unnecessary appeal processes to gain approval.
However, it could also present somewhat of a double-edged sword for SMEs: on one hand, streamlined processes and Permission in Principle (PIP) for medium sites of between one and 49 homes could open doors to projects previously considered too complex and time consuming to navigate through planning, but on the other hand, it means developers will need to adapt quickly to new viability rules and environmental compliance, under the Planning and Infrastructure Act.
Those that invest in planning expertise early on, and maintain strong relationships with local authorities, will be best placed to navigate new opportunities and capitalise on these opportunities.
In the world of sustainability, the Future Homes Standard (FHS) is likely to become mandatory by the end of the year, requiring a 75% to 80% reduction in carbon emissions for new homes. What does this mean?
Gas boilers are out, whilst heat pumps and low-carbon systems are in. While this aligns with the UK’s net zero ambitions, the impact for SMEs is increased build costs and additional technical skills to implement.
Elsewhere, the Building Safety Act continues to tighten compliance with the introduction of the Building Safety Levy in October, which is set to apply to developments of 10 or more units. For smaller players, these changes mean higher upfront costs and more complex project management. Developers that stand to
gain the most will be those that invest in building the safest and most energy efficient homes, marketing these as selling points.
Outside of bricks and mortar, several financial policy changes will impact SME developers’ bottom line. Late payment reform will introduce statutory caps on payment terms and mandatory interest on overdue invoices. Whilst this will be a positive move for cashflow – and something which Paragon welcomed – it will demand robust invoicing systems.
Making Tax Digital for Income Tax also goes live for those earning over £50,000, adding further administrative burden. Labour costs are rising too, with the National Living Wage jumping to £12.71 per hour in April. All this, combined with changes to capital allowances and tighter margins, means SMEs will need to plan meticulously to maintain profitability.
While these legislative changes aim to level the playing field for housebuilders to speed up delivery and improve living standards, smaller players will be faced with new challenges that require preparation. The good news is that with the right foresight and finance, SMEs have the chance to capitalise on these changes and turn them into genuine opportunities.
In the face of all this change, lenders have a critical role to play for developers – as partners in problemsolving. Access to flexible funding will be essential for time-poor SMEs facing higher build costs, additional administrative complexities and longer lead times.
Products such as development finance with staged drawdowns,
Those that invest in planning expertise early on [...] will be best placed to navigate new opportunities”
revolving credit facilities and green finance options for sustainable projects can be the difference that ensures delivery. Beyond funding –and this is where specialist lenders like Paragon come into their ownlenders can also add value by sharing advice and insights.
What can SME developers do now to get ahead? First things first, invest time to research and engage with local authorities to understand the implications of planning reform and sustainability standards. Strengthen financial planning by factoring in wage increases, compliance costs and tax changes and increase contingency in budgets.
Crucially, leverage partnerships by working with knowledgeable lenders that offer tailored products and sector expertise, and seek advice alongside funding. This is where working with mid-tier lenders like Paragon, our hands on, partnership-led approach, can make all the difference.
Each client we work with is a partner we aim to work with longterm, not a transaction. Finally, embrace sustainability by investing in green building and using it as an opportunity to differentiate yourselves from other players in a competitive market.
This year will test the agility of SME housebuilders. Those who adapt quickly, plan strategically and partner wisely stand to gain the most. ●
There is a real danger in presenting simplistic answers to complex and nuanced problems. We all know that’s an a ention-grabbing technique drawn from political playbooks all around the world, but maybe with housing, just maybe, it is just as simple as... build more.
Looking at the revered problem solving principle of “Occam’s Razor” – where the simplest route and explanation, requiring the fewest assumptions, explains any given phenomenon – it’s not too much of a ‘hot take’ to suggest that there isn’t a single political or buy side interventionist policy that has worked to stimulate the housing market, unless we build more housing in the UK for decades and decades to come. We believe, we need to turn up the volume on this issue, and this sector, to ensure that happens.
There are solid arguments presented that this simplistic approach may not hold, with many new homes designed as speculative investment assets, oversupply in low-demand areas creating stagnation, and the obvious consumption of green space at an unsustainable rate.
There is a great word in German, ‘verschlimmbessern,’ meaning “to worsen by trying to improve,” that we don’t really have a version of in English. But maybe we should, given the number of a empts we have had at manipulating the markets in our favour without realising that free market interventionism rarely, if ever, succeeds. Help to Buy was a great example of this, the good intention was there, a buy side stimulator, that acted as a demand accelerator in a
market choking on scarcity. The ironic thing about the commodification of housing is that ‘choking on scarcity’ drives value creation, so it plays into the hands of investment speculators.
So, what do we mean by that?
Investors understand that this is a politically managed market with a permanently embedded supply-side deficit. This deficit props up longterm demand, limits downside risk and makes any policy intervention unsustainable.
Historically bad policies have created investable conditions, and the challenge we face is to create investment opportunities that benefit the country and investors. Without synergy between profits and purpose, the housing situation will only worsen.
By subsidising purchasing power without unlocking new land or speeding up construction meaningfully, policies such as Help to Buy did exactly what economists foresaw: they pushed prices higher. Developers priced in the subsidy, buyers borrowed a lot more, and affordability didn’t improve; it was simply deferred.
The policy’s defenders argue that it increased new-build supply, and admi edly, it did. But not nearly enough to offset the blizzard of demand it unleashed. This is a recurring pa ern, and the reasoning behind our mission: government policies historically treat access to housing as a finance problem, when it is fundamentally a volume problem.
At its core, we believe the UK housing crisis is brutally simplistic. For decades, population growth, household formation, and investment demand have outpaced new supply.
FLETCHER is partnerships director at Invest&Fund
For most of the post-war period, the UK built housing at a pace roughly in step with population growth and household formation. That alignment broke down in the late 1980s, and it has never recovered. This isn’t a temporary shortfall. It’s a cumulative deficit.
Planning constraints, landbanking incentives, and local political resistance have ensured that homebuilding never comes close to meeting demand. Instead of tackling that, policymakers have repeatedly chosen the easier route: boost demand and hope supply catches up later.
Every major housing policy starts from the same flawed premise, that affordability can be fixed without changing how many homes exist. That assumption underpinned almost every failure that followed, whether in planning reforms, rent controls, tax stimulus, or monetary policy. Help to Buy, shared ownership, Stamp Duty holidays, and mortgage guarantees are not really housing solutions. They are demand accelerants introduced into a market that cannot absorb them without further inflation.
We believe the simplest route is to build. The thousands of smaller homebuilders in the UK have become the survivors in a diminished market, and we need that market to grow. We also believe that empowering the lenders and businesses to encourage more smaller homebuilders back to the table, through providing the liquidity, the products, and the support to do so, is the route to building and finally turning the volume up. ●
PARESH RAJA is CEO at Market Financial Solutions
Labour has commi ed to building 1.5 million homes during this parliament. It was a central pillar of the party’s election-winning manifesto and underlines just how politically important housebuilding has become amid the housing crisis. But many will take such promises with a pinch of salt. These promises have been common from successive prime ministers, and yet annual targets are almost always missed.
If Labour can buck that trend, it will be through a detailed strategy for new-builds, and one is starting to take shape: creating more ‘new towns’. The creation of the New Towns Taskforce, alongside planning reform and sizeable funding commitments, signals a clear intent to accelerate delivery.
There has been some discussion about what this ambition could mean for buyers and sellers. Far less a ention has been paid, however, to what it could mean for brokers. If housebuilding activity follows political rhetoric and picks up in the coming months and years, it could materially change both the shape and volume of demand for property finance.
The concept of new towns is –ironically – not new. Post-war developments such as Milton Keynes and Stevenage were originally designed to relieve pressure on London, pairing large-scale housing delivery with employment, transport and social infrastructure. While their success has varied – they offer a useful lesson.
For investors and developers, large, strategically planned
sites can be highly a ractive. Coordinated infrastructure, longterm development strategies and government backing all point to solid fundamentals. However, previous new towns also show that these schemes should not be viewed as a source of immediate transaction volume. Planning processes, infrastructure delivery and phased construction o en tie up capital long before real value is realised. Exit planning is therefore critical.
Any discussion around new towns must also recognise that their delivery will result in more investors buying new-build properties across the UK. On the surface, this may feel like familiar territory for brokers, but new builds continue to present specific challenges that need careful consideration.
Valuation is one such challenge. New-build properties o en sell at a premium, with Land Registry data from September 2025 showing that the average price of a new build was almost £100,000 higher than that of an existing property. For lenders, this presents elevated risk.
Quality is another important consideration. Recent analysis shows that defects in new homes have increased over the years, raising the risk that a renewed housebuilding drive could lead to investors purchasing properties that incur unexpected costs further down the line.
Timing also remains a challenge. Delays are common, whether due to planning conditions, labour shortages or material supply issues. The UK is currently experiencing a decline in the number of builders. Add to this the fact that planning
permissions fell to their lowest level since 2012 last year, and it is clear that investors purchasing new builds are shouldering some risk.
Increased housebuilding activity is unlikely to translate into a simple rise in straightforward finance needs. Many investors and developers entering the new-build market will face uncertainty around pricing, delivery timelines and exit strategies – factors that fall outside the comfort zone of traditional lenders.
As a result, specialist finance is likely to play a more prominent role. Short-term funding can offer certainty where build schedules are tight, while more flexible structures allow borrowers to adapt as projects evolve.
For brokers, understanding when speed and flexibility ma er more than headline rates will be critical in ensuring clients remain well-positioned.
In essence, advising on finance at the outset is only part of the role. Anticipating delays, structuring funding around multiple exit routes and working closely with lenders will become increasingly important.
As new towns take shape and new-build activity accelerates, the brokers who thrive will be those who embrace complexity, act proactively, and collaborate closely with investors and lenders. By doing so, they can help their clients shape the market and turn the challenges that new towns and new builds present into clear opportunities. ●
The Intermediary speaks with Dan Narwal, intermediary corporate account director at Together, about the launch of Premier for Intermediaries and demand in the large loan market
What gap in the market were you aiming to address with this launch?
Brokers have been telling us for some time that specialist lending is becoming more sophisticated, and that they need a lender that can support larger loans in the same way that we do already across our full product range.
The market hasn’t necessarily adapted to the conditions in the large loan space in the same way that it has in the more traditional borrowing spaces. So, with that in mind, catering to that was the starting point for us.
Obviously last year was turbulent in some sectors of the market, but there was still demand for cases above £1m, which is where our Together Premier for Intermediaries proposition is going to be targeting. Brokers require the support of specialist lenders more and more and the mainstream lenders aren’t in the market to support in the same way that we can as a specialist lender.
decision makers. This team will be experts on the origination function, which will, in turn, allow us to give the brokers definitive answers and increased understanding on the complex inquiries that will be coming our way.
Because we have the knowledge and expertise within the originations and the decision-making functions that we’ve put together for this, it will save brokers time because they’re able to get a definitive decision quickly.
We’re going to put the brokers with specialist senior underwriters, allowing them to do a lot of the structuring of deals at the outset. That’s going to remove a lot of the unnecessary back and forth that happens in this market at the minute.
A lot of lenders in the specialist space try to treat different clients in exactly the same way, but clients are increasingly coming with more complex cases, and they require a deeper knowledge and a deeper expertise. With our processes – where we are able to give brokers access to decision makers – this launch seemed like the natural step for us.
How will this proposition help brokers manage their own time more eff ectively?
Alongside the launch of the proposition, we’re setting up a dedicated team made up of expert
Hopefully they see that as a real positive step. Despite ongoing economic uncertainty, demand for loans above £1m is still strong. We’re still seeing strong appetite, especially from professional investors using existing portfolios to acquire new assets.
In the wider market, there are still lenders scaling back and asking customers to explore refinance opportunities, which gives us an opportunity to step in and support those clients that the high street banks are no longer looking to support.
Are you seeing particular borrower profi les leading this growth in larger funding requirements?
At the moment, we’re seeing a lot of portfolio landlords, family offices, those that are expanding into mixed-use residential and commercial assets or houses in multiple occupation (HMOs) from traditional residential assets. You’ve also got property developers that want flexible solutions. For property investors, we’re comfortable lending to expats and foreign nationals and that often doesn’t fit within the mainstream mould. So,
there’s a few categories there where the bespoke specialist underwriting is required. As well as this, there’s a lot more complex remuneration models for self-employed clients.
How do today’s high-value clients differ from those of five or 10 years ago?
Today’s clients have more diversified income, whether that be through partnerships, corporate dividends, or the way they’re paying themselves as self-employed clients. Assets and portfolios aren’t necessarily just traditional residential assets as they once were.
A lot more property professionals are – as we’ve said – diversifying their portfolio, so they need a lender that can cut across both residential and commercial assets and do so comfortably.
This is where we fit, and clients, especially the experienced property professionals, require that speed and ability to structure a deal with an underwriter and the decision makers that are sanctioning these loans. That’s exactly where specialist lenders like us can help.
There’s a handful of challenges that brokers face with the complex larger loans.
You’ve got the fact that, clients may have multiple income streams and sources that don’t fit your standard box ticking affordability models. Various corporate structures – such as assets within special purpose vehicles (SPVs), assets within trusts, offshore entities – make things more complex.
The ability to achieve finance at speed is also sometimes a challenge for brokers, and that’s one of the things that we’re going to try and correct in the market with this offering. There’s also a lack of clarity from lenders in the market, the clarity of what they can do, how they can support a client, when they can support a client.
cases?
It would be remiss of me to sit here and dismiss technology and dismiss what it can do for
an application. New technology and artificial intelligence (AI) can undoubtedly support efficiency, but can it understand a client’s complex income structure or complex shareholding and ownership structure within their portfolio? I would argue not.
The only people that can understand those nuances are your experienced senior underwriters, who exist to support the broker market with these transactions.
I think with technology, it often forces deals down to a ‘one size fits all’ type approach. This definitely doesn’t fit in this larger loan space. Therefore, the human element remains key, especially in this market, and that’s how we plan to support the broker community going forward.
Do you expect demand for larger lending to continue beyond 2026?
We see it continuing to grow through 2026 and beyond. Across the market as a whole, there’s been a major shift towards specialist lending. That’s not going to stop.
For more and more client types, as we’re seeing with the larger loans that we’re bringing to market, they’re now starting to fall into the specialist lending category, and they require that specialist lenders touch. Over the last three or four years, especially, we’ve seen more and more selfemployed scenarios are becoming specialist, to the point that self-employed clients probably aren’t mainstream clients anymore.
The same goes for international buyers. There probably was once a time where banks were comfortable with that type of lend, but changes in appetites have led us to international clients requiring that specialist approach. That’s only going to continue.
Looking at the wider strategy of the business, Premier is part of our strategy to deliver deeper, more tailored support for our brokers and to cement our position as the leading specialist lender for these larger complex transactions – as well as continuing our position as the leading specialist lender across our existing product range.
We hope to see a strong broker panel that understands and values what we’ve brought to market, faster turnaround on high value cases, higher satisfaction from brokers and clients, and naturally, a meaningful uplift in completions on cases over a million.
And most importantly, we hope that Together, through our Premier for Intermediaries proposition, will earn a reputation for being the lender that brokers want to come to – and have to come to – for their large and complex funding.












Marvin Onumonu speaks with Adam Tyler, CEO at the BDLA, about his new appointment and his plans for the association in 2026
As the Bridging and Development Lenders Association (BDLA) surpasses 100 member firms, its leadership team is also celebrating a significant milestone. Newly appointed Adam Tyler has stepped into the role of CEO, with more than two decades of trade body leadership behind him. Having been involved with the organisation since its inception, he now sets out a refreshed strategy, built on regulatory engagement, fraud prevention, data, and a renewed push on education to support brokers, lenders and their customers.
Tyler first became involved with the association in 2008 as part of the original steering committee that recognised the need for an organisation that wholly represented bridging and development lenders.
At the time, he was CEO of the National Association of Commercial Finance Brokers (NACFB), focused on the broker community. Having a broker trade body alongside a lender association felt, he recalls, like a logical evolution.
He says: “It was a great idea, because then we had a broker association and a lender association. So, I’ve always been close to the BDLA.”
Over the following years, as he moved on to lead other trade bodies including the Financial Intermediary and Broker Association (FIBA), Tyler continued to work alongside the BDLA, then known as the Association of Short-Term Lenders (ASTL), as it grew. When the association recently announced its 100th member, the timing felt significant.
The organisation, he believes, has “got to the point where it can get to the next level.”
Setting out in his new role, Tyler’s priorities mainly revolve around credibility with regulators and confidence in the sector. He sees one of the BDLA’s core functions as representing bridging and development lenders in dialogue with the Financial Conduct Authority (FCA) and ensuring they are seen to be “doing things in the correct way.”
Indeed, the association positions itself as something of a regulatory anchor. As Tyler says: “As a group of lenders, we are providing ourselves with self-regulation. We have a set of standards for our members; that way we are making sure that they do things in the correct way, and that we are also representing those lenders when the important things need to be talked about.”
One of these conversations centres around the 12-month cap for regulated bridging loans. Tyler points out that while a 12-month term was simply “okay” in the past, it no longer reflects reality for many borrowers.
Longer sales pipelines, slower chains and more complex transactions mean even straightforward chain-break cases can need a lot more time.
In light of this, the BDLA is working with the regulator to explore how that term might be extended, so that regulation keeps pace with real-world conditions.
For Tyler, this kind of technical, evidence-based engagement is where he thinks the BDLA can add real value to both lenders and their intermediary partners, thus ensuring products remain fit for purpose while
still delivering the best possible outcomes for end-consumers.
Alongside regulation, fraud prevention sits firmly at the top of Tyler’s agenda, noting this as one of the most important services the association can provide.
He explains: “We run a fraud initiative in partnership with Synectics Solutions, the provider of the SIRA platform – a national fraud prevention database used by high street banks and leading companies to identify fraudulent transactions. Through the SIRA platform, financial institutions can share and analyse information about suspected fraud, making it much easier to detect and prevent criminal activity. We now have a scheme specifically for bridging lenders that’s run through us at the BDLA.”
For Tyler, the power of the initiative lies in collective participation. In his view, that shared intelligence protects not just individual firms, but the integrity of the entire funding chain that sits above them.
He says: “It’s about getting more and more members involved – and the more people feed into that fraud initiative, the better information we’ve got out there to actually combat it.”
Tyler also sees education as a key pillar of the BDLA. The association plays a leading role in the Level 3 Certified Practitioner in Specialist Property Finance (CPSP) qualification, developed in partnership with other trade bodies such as FIBA.
The programme is designed not only for brokers wanting to get involved in bridging, but also for people working within lenders who are new to the sector. Tyler explains: “You’ve got people who are joining a bridging company who don’t understand what bridging looks like, or how it fits in with other lending sectors. Quality education helps with that.”
He adds: “Education like this helps new entrants to the industry, as well as those changing roles within it, to see how everything connects and fits together.”
As testament to this, more than 1,600 people have either completed or are currently enrolled on CPSP to date.
However, Tyler was quick to note that the programme is not just intended for brokers who want to move into bridging, but also for existing industry staff working within lenders – such as underwriters, sales teams and operations people – who need a structured
introduction to how bridging works and how it interacts with buy-to-let (BTL), residential and commercial mortgages.
For Tyler, education is what ties everything together: standards, customer outcomes, regulatory expectations and product design. It is a key lever in making sure the sector grows sustainably and responsibly.
Another area where Tyler believes the BDLA adds unique value is in promoting increased market collaboration.
To support this mission, regular meetings, roundtables and working groups are offered by the association, in a bid to give lenders the chance to share experiences and sense-check their read of the economy.
For Tyler, this kind of shared intelligence is invaluable. He says: “If you get those shared experiences between a group […] you’re learning from them. No single firm can see the entire market in isolation, but an association can aggregate insight across a broad cross-section of lenders.
“For brokers, that ultimately translates into a more informed, and better-calibrated, funding environment.”
When assessing this current market environment, especially that of development finance, Tyler takes a nuanced view.
Construction costs, he says, “have settled down,” which removes at least one source of volatility from project planning. However, he adds that developers still face two major confidence tests, those being the belief in their exit, and ongoing trust in their funders.
He explains: “The issue is the confidence of the property developers. How confident are they, if they’re going to build houses, that their exit is to sell those, and put them into buy-to-let? At the same time, they must be confident in the stability and credibility of the lenders backing them.”
Tyler argues that if a lender is part of the association, subject to its Code of Practice and peer scrutiny, a developer “can see that they have to comply with a certain way of working,” and can therefore be more comfortable borrowing from them.
Where the BDLA cannot directly influence outcomes, however, is in the wider housing market. Nevertheless, Tyler highlights the role of alternative exits – such as development →
exit products and bridge-to-let – where strong collaboration between development and bridging lenders allows projects to move forward even in uncertain conditions.
He says: “Since 2010 I’ve done a lot of work in Westminster as a director of the Genesis Initiative. The Genesis Initiative represents 1.2 million [small and medium-sized enterprises (SMEs)] through 117 trade associations.
“What I’ve always focused on is raising awareness of our sector – raising awareness among end users, whether they’re small business owners, property developers, or property investors – that there’s a whole range of other lenders in the specialist space who are doing things really, really well.”
Tyler believes this is particularly relevant when it comes to the regeneration of high streets and town centres.
He adds: “We’re looking at the bigger picture here, especially when it comes to revitalising city centres where many shops sit empty. Is it possible to turn those unused retail spaces into homes?
“In practice, that’s something you can only achieve with the help of a bridging lender. You’d take an old shop unit with a couple of empty storerooms above and turn it into a couple of attractive flats by using bridging finance, bridge-to-let products, and similar solutions.”
However, he remains frank about the awareness gap: “Many MPs, Treasury officials and even national journalists don’t know we exist.” Raising that awareness, especially among policymakers, media and the public, is therefore a central part of his agenda as he steps into the CEO role.
That lack of awareness is increasingly at odds with the reality of the market Tyler describes. One of the most significant changes he identifies in recent years is the repositioning of bridging from a “short-term funding of last resort” to a mainstream strategic tool for investors and developers.
According to Tyler, bridging is now firmly established within the market, with widespread broker uptake reflecting its new status. He notes: “Bridging is now a mainstream product. That’s why we have so many residential mortgage brokers getting involved in this space.” This evolution is particularly evident among those borrowers who now employ bridging finance in increasingly innovative ways.
He adds: “Some of the most sophisticated borrowers use bridging finance now like
they’ve never used it before, and they’ll use bridging finance because it’s such a great means to an end in their property portfolios, their property development processes, etcetera. It’s easier to get a bridging loan somewhere than it is to get a mortgage. So, it’s become so much more of a tool for everybody, whether you’re sophisticated or not, because it’s not seen as lending of last resort anymore.”
This shift in perception is mirrored by changes in intermediary behaviour. Tyler has witnessed a steady influx of residential mortgage brokers entering the bridging space, often via FIBA and now through the BDLA. For many, bridging is no longer a niche or occasional solution, but an essential and regular component of their client offering.
However, the ‘mainstreaming’ of bridging finance brings new challenges for industry standards and oversight. He highlights the importance of broadening association coverage to safeguard quality and consistency across the sector. Bringing more firms under a shared Code of Practice is, in Tyler’s view, essential if bridging is to maintain and build trust as it continues to grow in prominence.
He says: “If we’ve got 400 bridging lenders in the market, and we’re only representing less than a quarter of those, there’s still 75% out there that we don’t know what they’re – how they behave, and what they’re charging, default fees and so on. So, there’s still a lot of work to do to bring more people in.”
While ongoing innovation has long been a defining feature of bridging, and Tyler expects this trend to continue. The market has already produced a wide range of structures, from bridge-to-let and hybrid options through to increasingly sophisticated refurbishment and semi-commercial propositions.
He highlights semi-commercial as one of the standout growth areas, noting: “One of our members reported to us that they’ve seen an uptick of 41% of semi-commercial valuations undertaken in a 12-month period,” suggesting growing interest in assets that blend residential stability with commercial opportunity.
Looking ahead, he believes the sector needs more depth in commercial and ground-up development finance. He adds: “We don’t have enough commercial bridging lenders; we don’t have enough commercial development lenders.”
He also sees a role for more “halfway house” products – such as 3-year terms that sit between traditional bridging and longer-term investment loans. In his view, this direction of
travel should mean a richer product set for complex cases, particularly where mixed-use, commercial or phased developments demand more tailored funding structures.
Looking toward the remainder of 2026, Tyler sets out a clear set of ambitions for the BDLA. At headline level, he wants to continue growing membership and to cement the association’s position as the default representative body for bridging and development lenders.
Internally, he describes the BDLA as being “on the cusp” of a more mature phase, one that requires “more staff” and a more substantial infrastructure.
One visible step is the move to a London address; until now, the association has been based in Maidenhead. Having a London base is a visible sign of that transition, he notes, bringing the association closer to key stakeholders and reinforcing its status as a national trade body.
For existing members, however, his focus is on deepening involvement with core programmes such as the fraud initiative and data collection, and on making sure that both large and small lenders feel equally represented. He wants the BDLA to be a place where the sector’s biggest brands can sit alongside newer and more specialist players, united by a shared commitment to standards and transparency.
Tyler says: “It’s about encouraging more lenders to participate in these programmes,
but ultimately, it’s about growing our membership overall. As I mentioned earlier, we’re seeing so many more people wanting to join, and as the group gets bigger, it becomes much more powerful.”
Having spent much of his career advocating for brokers, SMEs and now specialist lenders, it is clear that Tyler is driven by the knowledge that entire ecosystems of entrepreneurs, developers and homeowners depend on markets that are often invisible to the general public.
Education, awareness and training are therefore, in his view, the main levers to unlock that potential. When asked for his advice to those starting out in bridging and development finance – whether as lenders, brokers or advisers – he says to invest early in understanding the ecosystem through qualifications like CPSP, engagement with trade bodies and active participation in industry networks. By the end of 2026, Tyler says he wants borrowers, policymakers and the wider financial services community to see the BDLA and its members not as a niche corner of the market, but as an integral and trusted part of the UK’s housing and SME finance solution.
He adds: “Doing things properly is not a burden, it’s an advantage. Firms that embrace robust standards, transparent pricing and responsible customer outcomes, are the ones most likely to attract sustainable funding, build strong broker relationships and thrive through the next phase of the cycle.”
Bridging finance has matured significantly over the past decade, yet parts of the market still treat it as a reactive product, only ever deployed when timelines collapse or conventional funding fails. In reality, bridging has become an integral component of funding strategies across both investment and development-led transactions.
I’ve seen that shi firsthand. Early on, bridging was essentially shorthand for regulated chain break lending— short-term, transactional and usually pulled in at the last minute. But as my experience widened, particularly working with more complex, ultrahigh-net-worth (UHNW) clients, that view quickly changed. It became obvious that bridging wasn’t just a fallback option, but a genuinely flexible funding tool.
Today’s bridging market exists because traditional retail and mainstream commercial lenders are structurally unable to deal with the realities of modern property finance. Planning delays, higher construction costs, slower sales markets and global economic volatility have all contributed to an increase in scenarios where borrowers need speed, flexibility and commercial judgement rather than rigid credit policy. From a broker’s perspective, understanding why bridging is appropriate is just as important as understanding how to place it.
In its simplest form, a vanilla bridge is still driven by speed: auction purchases, unmortgageable assets, chain breaks or time-sensitive acquisitions. In these cases, execution is everything. If a lender cannot deliver within agreed parameters, or communicate clearly throughout,
the product’s purpose is undermined. However, more experienced borrowers are increasingly using bridging as an intentional, structured capital efficiency tool.
Investors may choose to lever short-term finance to avoid tying up cash, while developers use bridging to control sites early, optimise planning outcomes or manage timing mismatches between construction, stabilisation and exit.
Recent interest rate hikes have meant that bridging, impacted bridging as the cost of finance (already at the higher end) overtook achievable margin. Pricing has since stabilised and expectations have reset, resulting in these structures returning, but only where the numbers genuinely stack up.
The most notable growth area remains development-linked bridging. We are seeing increasing use of shortterm facilities for site acquisition, planning upli and development exits. The la er is reflected in lenders increasingly widening their offering and including bespoke products, Pallas Capital included, to cater for developers needing more time to complete projects and, now more than ever, time to sell.
Build costs have increased materially, land values have remained comparatively resilient, and end values have so ened in certain sectors. Against that backdrop, developers are under pressure to preserve margin and avoid distressed sales.
Bridging provides optionality. It’s not just projects and developers needing short-term finance; lease extensions are more common than ever, raising funds for business use, for further property investment, to provide time for be er refinance options… the possibilities are endless
and, in many cases, the cost of shortterm finance is outweighed by the value preserved or created.
For brokers, lender selection has therefore become far more nuanced. Years ago, few advisers would interrogate a lender’s funding model. Today, it should be fundamental. Brokers should be assessing capital certainty, appetite consistency and whether a lender can genuinely support a client’s full funding journey.
When a lender offers bridging alongside term or development finance, and has the expertise to underwrite all stages credibly, there are clear advantages. Due diligence can be streamlined, development assumptions stress-tested early, valuation strategy aligned and costs reduced through continuity. Early repayment mechanics can also be managed pragmatically where facilities transition rather than terminate.
That said, bridging remains highly relationship driven. Integrity, deliverability and communication are critical. Pallas Capital is founded on the basis of a construction background, and here in the UK our leadership team has possess hands-on construction experience and are property developers in their own right, so you can guarantee the loans we assess are done so with full understanding of the asset and funding type.
Bridging finance has moved well beyond its historical role. Used correctly, it is not a sign of distress, but of intent—a tool that empowers borrowers to maximise outcomes. ●
As 2026 begins, the bridging market finds itself at a crossroads. A er an extended period of caution following the recent Budget, activity appears to be accelerating, leading to a surge in deal flow and a record expansion of the sector’s loan book. Reflecting on 2025, the Bridging & Development Lenders Association (BDLA) is reporting another record-breaking year with loan books surpassing £13bn. The continued increase in volume follows from the £10bn generated in 2024.
This momentum confirms what we at LendInvest have long observed. Bridging finance is no longer a niche or reactive solution. Instead, it has matured into a core funding solution, supporting transactions that require speed and flexibility.
The specialist bridging lending sector enters 2026 with sustained confidence and a proven capacity for adaptation. Investor confidence remains strongest in the North and Midlands, where pricing discipline and value-led strategies continue to drive activity. Meanwhile, greater fiscal stability has unlocked transactions that were previously paused, resulting in a strong pipeline entering the year.
In addition, as lenders have refined risk frameworks and invested in digital processes, brokers have increasingly moved into advisory-led roles, structuring more complex and bespoke transactions.
It is clear success in the 2026 market will be defined by agility and capital preservation, with bridging and development finance the primary mechanisms for unlocking value.
From the resurgence of residential chain-breaking to the necessity of ‘green’ refurbishment, the following
four pillars represent the most significant drivers of volume and opportunity for developers and investors alike:
Regulated bridging: No longer just a fallback, it is becoming a mainstream tool for residential buyers navigating chain delays rather than a contingency option. Development exit finance: A strategic lifeline for 2026, allowing developers to avoid distressed sales and hold for the right price while recycling equity into new acquisitions.
The refurbishment “silent engine”: The quiet powerhouse of the industry, fuelled by the urgent need for energy performance certificate (EPC) compliance and the transition to high-performance buy-to-let (BTL) portfolios.
Commercial-to-residential conversions: A high-yield frontier where underused secondary assets are being revitalised into modern homes in multiple occupation (HMOs) through Permi ed Development rights.
While demand in the market remains strong, the operational environment for lenders is becoming more exacting. Rising funding costs and evolving regulation are widening the gap between traditional models and more adaptive lenders. Three structural shi s will shape 2026: Managing the “exit ceiling”: With interest rates stabilising at higher levels, exit viability has become the primary underwriting consideration.
The regulatory thaw: Ongoing dialogue around the Financial Conduct Authority’s (FCA’s) approach to regulated bridging terms reflects a growing recognition of real-life timelines.
The digital efficiency gain: Advanced digital systems have
ARDRON is managing director, shortterm loans at LendInvest
transitioned from a unique selling point to a baseline requirement for the modern lender. At LendInvest, our ‘tech-enabled, expert-led’ model ensures that technology handles the heavy li ing of data and administrative processing. Automated valuation models (AVMs) and digital risk assessments streamline the journey for our brokers and borrowers.
In an era where “cheap capital” is no longer the sole differentiator, the true value of a lender in 2026 is measured by certainty. Investors and brokers need more than just funds; they need a partner who provides the confidence to move decisively and provide support throughout the entire journey.
As we look toward the remainder of 2026, the most successful property professionals will be those who value the durability of their strategy over the marginal gains of a lower interest rate. Value is found in the certainty, speed, and reliability of the capital provider.
Ultimately, the most effective way to have a stable project in 2026 is to partner with a lifecycle lender. A bridge-to-let approach secures an exit at the same moment the bridge is initiated. This strategy does more than just eliminate “exit anxiety”; it provides a significant boost to ROI and progresses property projects at a swi er pace.
Think of bridging finance as a relay race. The most successful projects start with the exit in sight and a trusted partner ready to take the baton. ●
Speedy lending
Speedy

First and second charges
First and second charges
Speedy lending for complex needs www.mercantiletrust.co.uk
Speedy lending for complex needs
Speedy lending for complex needs
Speedy lending for complex needs
First and second charges
First and second charges
Smaller loans from £10,000
Smaller loans from £10,000
Up to 75% LTV
First and second charges
First and second charges
Smaller loans from £10,000 Up to 75% LTV
Up to 75% LTV
Smaller loans from £10,000 Up to 75% LTV
Smaller loans from £10,000 Up to 75% LTV
Smaller loans from £10,000 Up to 75% LTV
Lending across the UK: England, Wales, Scotland, and Northern Ireland
Lending across the UK: England, Wales, Scotland, and Northern Ireland
Lending across the UK: England, Wales, Scotland, and Northern Ireland
Available on: Standard BTL, Holiday Lets, HMOs, MUFB, and Student Lets
Available on: Standard BTL, Holiday Lets, HMOs, MUFB, and Student Lets
Lending across the UK: England, Wales, Scotland, and Northern Ireland
Personal & Limited company borrowers
Personal & Limited company borrowers
Available on: Standard BTL, Holiday Lets, HMOs, MUFB, and Student Lets
Available on: Standard BTL, Holiday Lets, HMOs, MUFB, and Student Lets
Lending across the UK: England, Wales, Scotland, and Northern Ireland
Lending across the UK: England, Wales, Scotland, and Northern Ireland
Funds possible in 48 hours
Personal & Limited company borrowers
Personal & Limited company borrowers
Funds possible in 48 hours
Personal & Limited company borrowers
Funds possible in 48 hours
Funds possible in 48 hours
Funds possible in 48 hours
Funds possible in 48 hours
Available on: Standard BTL, Holiday Lets, HMOs, MUFB, and Student Lets
Available on: Standard BTL, Holiday Lets, HMOs, MUFB, and Student Lets Personal & Limited company borrowers
Contact our team
Contact our team
Vicky
0800 032 5282 SPECIALIST BRIDGING LOANS AND BUY TO LET MORTGAGES
Vicky O'Sullivan
Business Development Manager 01923 280116
Vicky
Business Development Manager 01923 280116
Vicky O'Sullivan Nina Kainth
vicky.osullivan@mercantiletrust.co.uk
vicky.osullivan@mercantiletrust.co.uk
Business Development Manager 01923 280116
Vicky O'Sullivan Business
Development Manager 01923 280116
vicky osullivan@mercantiletrust co uk
Business Development Manager 01923 280116
vicky osullivan@mercantiletrust co uk
Manager 01923 280116
vicky.osullivan@mercantiletrust.co.uk
0800 032 5282

0800 032 5282
0800 032 5282
0800 032 5282

nina.kainth@mercantiletrust.co.uk Contact our team 0800 032 5282
Busines 01923 280297 | 07562 209858
Business Development Manager 01923 280297 | 07562 209858
nina.kainth@mercantiletrust.co.uk
Business Development Manager 01923 280297 | 07562 209858
209858
nina kainth@mercantiletrust co uk
nina.kainth@mercantiletrust.co.uk
www.mercantiletrust.co.uk
www.mercantiletrust.co.uk
www.mercantiletrust.co.uk
www.mercantiletrust.co.uk

The Intermediary sits down with James Bloom, director at Alternative Bridging Corporation, to discuss its revamped proposition and the outlook for residential development finance in 2026
With 2026 now well underway, how would you describe the opportunity for residential developers and their brokers?
The opportunity is still very much there, and that is the starting point.
The housing shortage certainly hasn’t eased, and we see a clear intent across the market to get more schemes moving and ultimately more
homes delivered.
sharper focus on delivery.
However, that opportunity now comes with a Developers and brokers are not just asking whether a scheme stacks up in principle, but whether it can withstand longer timelines
and more cautious sales conditions.
funding structure recognises those pressures from the very outset.
What sorts of challenges are you seeing most often on live development schemes?
Planning reform may help over time, but in the here and now, build-costs, sales-periods and funding certainty are still front of mind.
If you look at live cases, it seems to me that the themes are fairly consistent across the board. Time and cost remain the two biggest pressure points, and they tend to show up in unison rather than in isolation. Typically, it is not that a scheme goes wrong, but that it takes longer than planned. The planning process still takes longer than it should, build programmes can move, or exit-assumptions may no longer quite fit once practical completion is reached. When that happens, otherwise strong schemes can come under some real strain. The issue that we see is that many traditional structures are not built with enough tolerance for that reality, particularly once the build-phase has
that reality, particularly once the build-phase has ended.
So, while the opportunity is real, it
only works if the

How did those observations feed into your recent development fi nance review?
Those challenges were exactly what prompted the review in the first place. When you step back and look at where deals feel most exposed, it is rarely during construction itself. More often, it will be at completion and into exit. Practical completion is often treated as a finish line, but it is just a change in risk. We were seeing schemes perform well up to that point, only for pressure to appear because the funding structure became less flexible just when it was most needed. That disconnect made it clear that the way development finance is traditionally structured no longer holds true in these types of situations.
does the revamped residential development finance proposition look like in practice?
Rather than treating construction and exit as two separate stages, the proposition is structured as a single residential development finance facility that runs from build through to sale. Lending is provided within a clearly defined framework, with scope to support schemes at higher leverage where appropriate.
During the build, a rolling construction float is used to support cash-flow while maintaining visibility over funding throughout the life of the project. Once practical completion is reached, the facility transitions automatically into a development-exit phase, with pricing adjusting to reflect the reduced risk profile.
Because that transition is built into the original structure, there is no need for a separate refinance application at a critical point in the scheme, removing a major source of uncertainty for both brokers and their clients.
How does this structure help brokers support their developer clients more effectively?
I think it changes the very nature of the conversation brokers can have with developer clients at the outset. Rather than focusing purely on the build-loan and leaving exit to be addressed at a later point, brokers can set out a clear, joinedup funding route from start to finish.
This allows developers to plan with greater trust in the process. The extended sales-period is a really good example of this. It gives schemes the headroom to complete sales properly, rather than forcing decisions simply to meet an artificial deadline. Where additional funding is needed mid-scheme, our Alternative Overdraft can be used against under-utilised assets, adding flexibility without undermining the core facility.
does development finance sit within the wider Alternative Bridging proposition?
Development finance has always been central to what we do, and this revamp brings it into closer alignment with the rest of our offering. Looking at the bigger picture, we are spending time looking at how short-term and longer-term funding fit
Developers are active again, but they are planning with a clearer view of timing, cost and risk”
together in cases. That includes development finance, development exit, overdraft-style facilities, and term-loans where a longer hold makes sense. Many schemes float across those categories over time, so it is important that the funding can move with them.
Looking ahead, what should brokers expect from Alternative Bridging Corporation for the remainder of 2026?
This revamp sets the direction. It reflects a wider focus on building products shaped by experience and real-world behaviour, rather than how deals look on day one.
As a result, brokers should expect continued refinement rather than constant change. We will keep building on this integrated approach and strengthening the links between short-term funding and longer-term outcomes, particularly where development, exit and commercial strategies intersect. Any enhancements that we bring to market will be grounded in live cases and the issues brokers raise with us day-to-day, ensuring they exhibit how funding is actually being used across the full life of a scheme.
Finally, how would you sum up the year ahead for development finance as a whole?
There is certainly confidence returning, but it is a more considered type of confidence. Developers are active again, but they are planning with a clearer view of timing, cost and risk.
Our role is to support that sensibly. Where a scheme is well thought-through and the funding structure reflects reality, good projects can still move ahead. This development finance revamp is all about making that easier, giving brokers and developers the clarity and flexibility they need in the current market. ●
In 2026, bridging finance is still doing what it has always done best: stepping in when time ma ers. That core purpose hasn’t changed. What has changed, however, is the level of scrutiny around whether a deal can actually be executed cleanly and repaid within the agreed term.
Volumes across the market remain high, which is broadly positive for brokers and borrowers alike. Liquidity is there, appetite exists, and bridging continues to play a central role in transactions that simply don’t fit the pace of mainstream lending.
But higher volumes also bring a wider spread of deal quality. Alongside strong, well-structured cases, lenders
The aim is not to say ‘no’ more often. It’s to say ‘yes’ to deals that have a clear route to redemption”
are seeing more borderline cases. In reality, the difference between an approved deal and a declined one is rarely speed alone. It comes down to clarity, evidence, and a realistic assessment of risk.
Pricing is an obvious place where this tension shows up. With Bank Rate si ing at 3.75%, funding costs still influence pricing across the market. From an underwriting perspective, the key question is not whether a deal can be priced, but whether that pricing genuinely reflects the risk and the timeframe involved. We look closely at how long the borrower actually needs the funds, how complex the
works or planning position is and how credible the proposed exit looks today.
Price shouldn’t be used as a tool to gloss over uncertainty. If timelines are tight, exits are ambitious, or the asset itself is harder to trade, that risk needs to be addressed in the structure of the deal, rather than assumed away.
Exit strategy remains the fulcrum of most bridging decisions, and while the wider mortgage market has eased compared to previous years, that does not eliminate exit risk. Refinance routes are more achievable than they were, but they still need to stand up to scrutiny.
In 2026, exit assessments are more detailed and forensic. Refinance exits need realistic rental coverage, sensible pay-rate assumptions, and evidence that a suitable term product exists. Sale exits are tested against local demand, comparable sales, and whether the property will be mortgageable in its current and end condition. What underwriters are looking for is not the mere presence of an exit on paper, but confidence that it will complete within the term agreed.
Valuation risk, in this environment, is less about inflated figures and more about misaligned expectations. High deal flow means valuers are generally grounded in the market, but problems arise when assumptions run ahead of reality.
The condition of the property has to support the proposed loan basis. Gross-development-value (GDV) needs to be backed by real, relevant comparables rather than optimistic projections. Time and cost contingencies have to be sensible, particularly where refurbishment or change of use is central to the strategy. Where upli forms part of
JULIE MEEHAN is underwriting manager at Mercantile Trust
the case, the key question is whether the journey from day one to that end value is genuinely achievable within the term and within the borrower’s control.
As the market has become faster and more competitive, the quality of the borrower has taken on even greater importance. Experience ma ers, particularly when the deal involves complexity. Adequate liquidity buffers ma er because unexpected delays are the rule rather than the exception. Clear and consistent documentation ma ers, not as a box-ticking exercise, but as evidence that the borrower understands their own project.
Well-presented cases, with deposits evidenced, works budgets supported by contractor quotes, planning positions clearly explained, and exits properly substantiated, tend to redeem on time.
Poorly evidenced cases are far more likely to dri into extensions and negotiations that could have been avoided.
From a lender’s perspective, saying ‘yes’ in 2026 is not about lowering standards or becoming more cautious for the sake of it. The strongest bridging cases share common traits: they are realistic on timeframes, clear and well evidenced on exits, sensible on value and upli , and led by borrowers who can demonstrate genuine control over the outcome.
The aim is not to say ‘no’ more o en. It’s to say ‘yes’ to deals that have a clear, repeatable route to redemption, without relying on hope, favourable market shi s, or rolling extensions to get them over the line. ●
The bridging market has shown clear signs of momentum in recent months, even as uncertainty continues to shape sentiment across the wider property sector. Based on internal data comparing Q3 2025 with Q4 2025, a number of key trends have emerged that are influencing both broker behaviour and borrower decision-making.
One of the most noticeable developments has been increased competition on pricing. Our data shows a reduction in interest rates: there are four main lenders, all competing at around the 0.55% to
If the property market does dip, there is likely going to be an in ux of investors trying to take advantage of that to get good deals on property”
0.58% per month range on regulated (owner occupied) deals. This is a meaningful shi and reflects a growing willingness among lenders to compete for quality businesses, particularly where affordability, loanto-value and exit strategies are well evidenced.
For brokers, this has helped position bridging as a more accessible shortterm solution for owner-occupiers who may be navigating time-sensitive situations such as chain breaks, auction purchases, or delayed sales. While bridging is still a specialist product, the increased alignment in pricing between lenders has made conversations around cost more
straightforward and transparent. Another clear trend emerging from our data is increased auction activity. This could be due to investors seeking a good opportunity or homeowners trying to get a bargain. With transitions in the wider market o en taking longer to progress, auctions continue to offer certainty of purchase, provided buyers can meet strict completion deadlines.
Bridging finance remains well suited to this environment, offering speed and flexibility where traditional lending routes may struggle to keep pace. Our brokers are increasingly seeing clients who are prepared to act decisively when the right opportunity presents itself, particularly where properties require refurbishment or fall outside mainstream lending criteria.
Market engagement has also improved since the turn of the year. Since the new year, we’ve seen an uptick in enquiries and a more active market. While this does not necessarily point to a full recovery in confidence, it does suggest that borrowers are becoming more willing to explore options rather than delaying decisions definitely.
Despite this increased activity, caution remains a defining feature of the current landscape. There is still hesitation in the property market generally speaking, largely being driven around uncertainty on where the housing market will be in six months’ time. Many clients remain wary of making long-term commitments without greater clarity on pricing, values, and broader economic conditions.
This hesitation is being amplified by negative commentary across the media and online platforms. As noted recently, the Financial Times reported recently about the doom and gloom of mortgage brokers online predicting turnout for the residential market
FERGUS ALLEN is head of bridging at Cli on Private Finance
in 2026. Unsurprisingly, this probably isn’t helping consumer confidence as a whole but even less so for clients looking at the possibility of taking on short-term debt.
However, the way borrowers approach short-term finance is fundamentally different from how they view longterm borrowing. The picture is very different for a client looking at a 12-month term versus a 25-year term. Bridging clients are typically focused on executing a defined strategy over a relatively short timeframe, rather than trying to predict where the market will be several years down the line.
This distinction continues to support demand for bridging, even in periods of uncertainty. The advantage for the bridging industry is that if the property market does dip, there is likely going to be an influx of investors trying to take advantage of that to get good deals on property. Historically, so er market conditions o en encourage experienced investors to act, particularly where speed of completion can secure favourable pricing.
In many cases, this activity may include completing works to a property or the promise of completing quickly by using fast finance such as bridging. For brokers, this highlights the importance of presenting bridging as a proactive tool, one that enables clients to move quickly, manage risk effectively and retain flexibility around their exit. ●
Jessica O’Connor speaks to Alex Alexandrou, head of sales – residential lending at Cohort Capital, about the lender’s recent product launch and borrower demand in an increasingly specialised market
In a specialist lending market that has grown more competitive, lenders are increasingly being judged not just on price, but on how they behave under pressure. While speed remains essential, it is no longer enough on its own. Modern borrowers are looking for certainty, and a sense that decisions are being made by people who truly understand them.
For Cohort Capital, that philosophy has shaped its growth to date. With the launch of its new ResiOne product, the lender is now seeking to bring its same relationship-led approach into the £1m to £6m space.
e Intermediary sat down with Alex Alexandrou, head of sales – residential lending at Cohort Capital, to discuss this new launch, the forces shaping demand for specialist finance, and how Cohort is positioning itself for sustainable growth.
Alexandrou’s route into specialist lending was shaped by an early pull toward property finance. After finishing his degree and working in a property office, he joined Octopus Real Estate, building a solid foundation in property lending that would later inform his approach. It was there that he first crossed paths with Cohort’s founder, Matt Thame.
That certainty ucomes from quick decisionmaking and lenders having, as Alexandrou puts it, “the discretion and mandate” to act. While those core drivers have remained constant, he believes awareness has expanded the market: “Bridging 10 years ago wasn’t a tool that everyone was aware of, whereas nowadays it’s recognised as mainstream.”
The challenge now, he argues, is sustainability. With large volumes of capital entering the market, he sees a divergence emerging between “deep rooted experienced lenders like Cohort that have multiple funding lines and discretionary capital” and newer entrants reliant on franchise-style funding lines.
ALEX ALEXANDROU
Building on that backdrop of sustained demand, Cohort’s launch of ResiOne is rooted less in a sudden gap in the market and more in the confidence that it can operate differently within a space that has become increasingly crowded. On the surface, Alexandrou acknowledges that the market is already well served, as he notes: “At first glance, you could look at the market and say there’s lots of people playing in the £1m to £6m loan sizes.”
Alexandrou explains: “That’s why I had that natural affinity to Cohort – I’ve always kept an eye on what Matt’s been up to. That is what attracted me to the business. I liked that they were a small, experienced and nimble team – deploying a lot of capital in the market across a variety of interesting and quality assets.”
From Alexandrou’s perspective, the same principles that attracted him to the business also underpin demand for unregulated residential bridging more broadly.
“I think demand hasn’t really changed,” he says. “With bridging, that speed is always going to be an element. People need certainty because it’s normally a high-pressure situation. They don’t have time to mess around or be messed around.”
However, he argues, much of that activity sits at the upper limit of lenders’ comfort zones, whereas for Cohort, this bracket is firmly within its natural operating range. Differentiation, however, goes beyond risk parameters. Alexandrou is clear that ResiOne has been designed around borrower need rather than funding constraints.
He adds: “We’re looking to design a product that borrowers actually need, rather than forcing a product that’s been derived from funding lines.”
That philosophy carries through to underwriting, where institutional experience meets flexibility. “We’ve got underwriters that come from institutions long in the tooth, so they’ve got good rigour. But at the same time, we’re a nimble team with that experience, so we can be really agile and pragmatic with our decision making. We’re really trying to avoid any ‘tick box’ style lending.”
Instead, he notes, decisions are made holistically. Alexandrou adds: “We get under the bonnet of a deal and look at the borrower themselves. When we make decisions, we don’t have to go to a big committee in two to three weeks’ time when the borrower is already committed to the deal, we have the decision makers on the front end, ensuring that we make quick decisions at the start.”
Alexandrou sees the clearest opportunities for specialist lenders emerging where mainstream bank appetite has tightened, and borrower strategies have become more deliberate. In the investment market, rising borrowing costs have reshaped behaviour, particularly for long-term holders. He says: “There’s been a lot of pressure on low yielding assets […] many are struggling to meet interest coverage ratio (ICR) covenants.”
Instead, opportunity lies in creating value and increasing yields where best possible. Alexandrou explains: “We focus on supporting clients if they’re looking to do light to heavy refurbishments, convert to houses in multiple occupancy (HMOs), or broaden the asset class,” including semicommercial strategies where yields are stronger. Supporting those strategies, however, depends on balancing pace with discipline. When asked about managing risk, Alexandrou notes that the most important thing is the strength of the team around you.
“The starting point is the team line-up,” he says. “We’ve got a really experienced team, and I think that’s super important. Totting up the years, we’ve got over 100 years of combined real estate experience.”
Crucially, Cohort’s underwriting looks beyond bricks and mortar. He continues: “We don’t just look at the asset. We carry weight towards the sponsor themselves,” he says.
“I think that’s really important. It’s understanding, are they the right person to back? And who can deliver the strategy that they’re looking to do? Because everything’s always a short-term A to B strategy with bridging.”
That emphasis on partnership extends into how Cohort positions itself alongside its intermediary partners. For Alexandrou, supporting brokers is not a ‘bolt-on’ to the proposition, but a central principle. He points first to product development itself, stressing that getting this right means ensuring “it’s a product that there’s demand for in the market.”
That focus then extends into delivery. While Cohort has built what he describes as “a really
good process,” Alexandrou is conscious that growth can easily dilute the qualities that made it effective in the first place.
He says: “As we grow and evolve, we need to ensure that we maintain a streamlined process, and we keep what has been imperative to our success today, which is being nimble and quick.”
Alongside structure, communication plays an equally important role. “There’s no point having a really good offering if we’re not out there speaking to people,” Alexandrou explains, acknowledging that in the intermediary world “out of sight, out of mind is a big thing.”
As a result, Cohort invests time in detailed broker engagement, spending time with introducers to understand “their client flow, what their typical demographic is,” and then mapping Cohort’s appetite against that reality. As Alexandrou notes, this ensures that brokers are equipped with “a compelling and competitive offering for their clients.”
Looking ahead, Alexandrou frames the months to come as a period where risk and opportunity will sit side by side. While inflationary pressure has not disappeared, ongoing uncertainty around interest rates continues to weigh on borrower behaviour, particularly for those approaching the end of fixedrate terms.
He notes that “a lot of people are taking on mortgages that potentially now they’re struggling to afford,” while rising construction and refurbishment costs are also testing the viability of schemes across the market.
Layered onto this are planning delays, regulatory change and the implementation of the Renters’ Rights Act, which he describes as “a natural regulation that we need to keep an eye on.”
Add to that a volatile geopolitical backdrop and it would be easy for lenders to retreat into rigid processes and defensive appetites.
Yet Alexandrou believes this environment plays to Cohort’s strengths. He explains: “There’s a big opportunity for businesses like Cohort, where we really get under the bonnet of a deal and understand the strategy, what the client’s looking to achieve, the strength of the asset in isolation. That’s where we’ll start to start to pull away from the rest of the crowd.”
It is within that context that his vision for Cohort’s residential business comes into focus: continuing to build on its reputation in larger debt quantum transactions while deliberately expanding into the £1m to £6m space through ResiOne. As he puts it: “The vision is to become a market leader in this space. That to me, that tells me the product has been a success.” ●
Over the last few years, many brokers have noticed the same pa ern. Deals that would once have sailed through mainstream lenders are now ge ing delayed, reshaped, or declined altogether. Criteria has tightened, risk appetite has narrowed, and as a result, more deals are finding their way into the bridging space.
That doesn’t mean bridging finance has become a fallback option. In many cases, it’s becoming the most practical solution earlier in the process.
Traditional lenders are taking a more cautious approach across the board. That shows up in stricter affordability assessments, slower credit processes, and less flexibility around property type or borrower profile.
Non-standard assets are a common sticking point, as properties with short leases, unusual construction, mixed-use elements, or planning considerations o en struggle to fit neatly into mainstream boxes.
Borrowers themselves are also more complex. Self-employed income, multiple businesses, portfolio structures, or time pressure can all introduce friction, even when the underlying deal is sound. For brokers, that can mean longer conversations, more back and forth, and less certainty on outcomes.
Stepping in earlier
Bridging finance is designed to deal with complexity and time pressure. That’s not new. What’s changed is how early it’s being used. Rather than waiting for a decline, brokers are increasingly using bridging as a proactive tool, allowing a purchase
or refinance to complete while a longer-term solution is lined up in the background.
This is particularly common where speed ma ers, such as auction purchases, chain breaks, or opportunities tied to planning or refurbishment.
Bridging offers a way to keep momentum without forcing a deal through criteria that no longer fits.
It’s also a reflection of how value and risk are being assessed more rigidly in parts of the mainstream market. Automated processes and standardised credit models leave less room for nuance, meaning deals that are fundamentally sound can still struggle to progress.
In contrast, specialist lenders are o en able to take a more rounded view, considering the full context of the borrower, the asset, and the wider strategy behind the transaction.
Not every deal suits bridging finance. It works best when there’s a clear, realistic exit and a defined reason for using short-term funding. Used well, it buys time and flexibility. Used poorly, it creates pressure.
That’s why early sense-checking is so important. Understanding the borrower’s objectives, the property fundamentals, and the exit strategy helps to make sure bridging is being used for the right reasons. It’s also why honest conversations ma er. Bridging isn’t about stretching deals beyond what’s sensible, but instead solving specific problems in a controlled way.
Tighter criteria isn’t going away anytime soon, which means brokers need more options, not fewer.
DAVID TRAVERS is CEO of ScotLend
Used thoughtfully, bridging helps keep deals moving in a more cautious lending environment”
Bridging finance is increasingly part of that toolkit, as a strategic choice where timing, complexity, or flexibility are key. The strongest outcomes tend to come from early understanding; knowing whether a deal suits bridging, how it can be structured, and how it exits avoids wasted time later.
For brokers, this shi places greater emphasis on early positioning and expectation-se ing. Introducing bridging as a considered option rather than a last resort can help clients be er understand the role it plays within a broader funding strategy. That clarity upfront o en leads to smoother transactions, fewer surprises, and stronger long-term relationships.
As lending criteria continues to evolve, bridging finance is playing a more visible role in ge ing deals over the line. Not because deals are weaker, but because the market is different. Used thoughtfully, bridging helps keep deals moving in a more cautious lending environment. If you’re seeing more deals caught between tightened criteria and tight deadlines, a quick conversation early on can help. The ScotLend team are always happy to sense-check a deal and give a clear view on whether bridging finance is the right fit for your needs. ●

Plan A is turning itself off and on again.
It’s time for Plan Alternative.
When your usual lending strategy keeps stalling, the original alternative is here.
by Marvin Onumonu
As the housing sector contends with evolving regulation and unpredictable economic conditions, a new wave of transformation has the potential to reshape property markets up and down the country. Across city terraces and rural high streets alike, run-down and ‘unmortgageable’ properties are being bought with the purpose of being renovated quickly and resold for profit.
This strategy, known as ‘fix and flip’, is increasingly facilitated by nuanced and flexible auction finance and refurbishment bridging loans, which have the potential to transform not only the pace of property transactions, but the foundations of UK property investment.
So why do neglected homes, shops, and vacant offices have the chance to become hot commodities? How are specialist lenders, intermediaries, and auction houses enabling investors to seize opportunity amid regulatory change and market pressure?
The answers lie in a new era of speed, certainty and entrepreneurial vision.
The fix and flip movement is inseparable from the evolution of bridging finance. While once seen as a niche, high-cost resource for distressed sellers, bridging has become a driving force behind modern property investment.
Within this, auction finance – a form of bridging designed for the rapid timeframes of property auctions – and refurbishment bridging loans have emerged as popular specialist options.
Steve Matthews, head of residential lending at Octopus Capital, says: “Bridging finance has evolved significantly through better technology,
improved automated valuation models (AVMs), and product innovation, all of which support rapid decision-making and delivery of funds.”
He adds: “Specialist lenders are structured to meet tight deadlines. Competitive funding markets have also helped keep pricing keen, making fast, flexible capital more accessible for investors acting on time-sensitive opportunities.”
Narinder Gill, head of bridging at Coreco, has also seen this shift in perception. He observes: “Auction and refurbishment finance have really come into their own since the Covid-19 pandemic. There has been an abundant increase in lenders and products available to both experienced developers and, more importantly, novice and first-time developers.”
Indeed, with bridging no longer seen as a last resort – but instead, a strategic tool for unlocking opportunities – it serves to empower a new generation of property investors and developers.
Andrew Cappaert, group head of national accounts at Brightstar Financial, reinforces this point.
He adds: “Auction finance has always been a major factor in fix and flip activity, and we have definitely seen over the past two to three years an increase in refurb bridging, creating a proactive, rather than reactive, usage of bridging finance.”
Cappaert notes that the main obstacles for these transactions are speed and property condition. He explains that traditional lenders are generally unwilling to finance unmortgageable or severely dilapidated properties, and when they do, the process is often too slow to meet auction deadlines or allow for competitive bidding. Bridging addresses this gap by enabling purchases to complete within weeks



















rather than months, and by providing lending on properties that require significant work before they become mortgageable or rentable.
This opens up opportunities for a wider pool of investors who are confident in their ability to act quickly and add value. According to Cappaert, over the past 12 months, participation has widened to include first-time or ‘accidental’ investors, as well as portfolio landlords moving into heavier refurbishments.
Cappaert adds: “[Our] role is to structure these deals, match clients with the right lenders, and navigate criteria, valuations, and exit strategies.”
Auction sales are, by their very nature, time sensitive. Buyers must pay a deposit and complete within weeks of purchase, often for properties that fail standard mortgage criteria due to poor condition or legal complexity. Auction finance addresses time-sensitive funding gaps, providing fast, flexible funding that can be arranged in just days.
As Sonia Mann, head of sales at Roma Finance, explains: “Speed is critical in today’s market. Auction finance and refurbishment bridging loans give investors the confidence to move decisively and meet tight completion deadlines, which can make the difference between securing a deal or missing out."
“We’re also seeing increased use of revolving credit facilities and capital-raise bridging to support this approach,” she adds.












Stuart Collar-Brown, president of NAVA Propertymark, notes that “sellers continue to value the speed and certainty that an auction offers when compared to private treaty sales,” adding that the legal certainty provided, with completion typically within 28 days, remains a key driver.
Cappaert emphasises: “Speed and flexibility are often the difference between winning and losing a deal. Auction purchases come with strict completion deadlines, with vendors favouring buyers who can demonstrate funds and certainty. Lenders have responded by increasing flexibility, with some now offering up to 85% gross loans and the ability to fund up to 100% of works, giving clients far greater leverage on value-add projects.”
He adds that, for many, bridging is more than just a source of funding; it is a strategic tool that enables clients to act with the speed of cash buyers while still making the most of their capital – hence its reputation as the “Swiss-army knife” of finance.
In light of this, many brokers now specialise in securing pre-auction approvals and rapid due diligence, enabling clients to commit with confidence and complete transactions that would otherwise have been out of reach.
For properties that cannot be mortgaged in their current state – those lacking kitchens, bathrooms, or Energy Performance Certificate
(EPC) compliance, for instance – refurbishment loans provide a short-term solution. This strategy allows lenders assess the post-refurbishment value and thus lend against the investor’s plan to bring the property up to standard.
That shift in how value is assessed is influencing investor behaviour.
Matthews notes this move away from simpler strategies over the past year, as investors respond to tighter margins and higher borrowing costs by pursuing more ambitious projects.
He says: “Demand has shifted toward value-add projects, with investors moving away from straightforward ‘light touch’ refurbishments into more substantial schemes."
He adds: “Conversions to houses in multiple occupation (HMOs), serviced accommodation, co-living, and commercial-to-residential projects have all increased due to stronger yields and profit potential. Borrowers today tend to be more experienced and professional, reflecting the increased complexity of the projects they pursue.”
This evolution has also altered how investors view transactions themselves. Certainty is now central to deal-making, particularly where sellers are motivated.
Matthews continues: “Sellers typically prioritise speed, offering attractive pricing to achieve quick transactions, and investors increasingly understand the opportunity to add value through refurbishment rather than relying on market appreciation alone. In this environment, certainty of execution matters more than minor differences in rate.”
That emphasis on confidence in execution is reflected in the types of assets being targeted. Mann points to the condition and composition of much of the stock currently coming to market, where refurbishment is not optional, but fundamental to the investment case.
into pricing rather than treated as deal-breakers, creating opportunities for buyers with the experience and funding to act decisively.
With mainstream lenders unable to participate in this trend, cash buyers and those using bridging finance have, as a by-product, become the natural risk-takers in this segment of the market.
Jonathan Rolande, founder of NAPB, says: “We are seeing a clear shift in what buyers will move quickest on. Anything unmortgageable, structurally defective, or with legal quirks used to sit around because mainstream lenders would not touch it.”
He adds: “Now it often trades faster because the cash buyer pool is ready and decisive. Cash buyers, developers, landlords and bridgingbacked purchasers can act immediately, and they are actively hunting for stock where the discount is obvious.”

She says: “Much of this property requires work – from layout changes and EPC improvements to full modernisation – which naturally lends itself to auction finance and refurbishment-led funding. The focus has shifted away from volume and towards buying well, adding value and futureproofing assets. Loan purposes are increasingly centred on meaningful refurbishment rather than short-term, cosmetic upgrades.”
The result is a market driven by investors prepared to undertake more intensive works.
Unmortgageable properties undoubtedly sit at the sharper end of the risk spectrum. However, that risk is no longer being avoided – it is being actively assessed. Issues around condition, structure or legal complexity are now factored
If risk is being reassessed, price is where that judgement becomes visible. As more buyers grow comfortable operating outside traditional lending constraints, assets that might once have been caught in protracted renegotiation are now moving straight to auction, where certainty of outcome often matters more than squeezing every last pound from the sale.
As Richard Worrall, past president of NAVA Propertymark, notes: “Prices achieved have been strong without being overinflated, and we have seen good levels of interest across all price ranges."

He adds: "Buyer sentiment appears more positive, the certainty of sale at auction is becoming increasingly appealing to sellers, and we are now selling far more properties to ‘end users’ than at any point in my career.”
That balance between realism and opportunity is particularly evident in properties requiring the most significant work. These assets often trade well below their post-refurbishment value, reflecting the risk and capital required to bring them up to standard, but also leaving meaningful headroom for those able to act quickly and execute effectively.

Rolande adds: “A run-down property is simpler, it is priced for work, the issues are visible, and the upside is clearer. Auctions also create urgency and certainty, which suits sellers who want a clean exit and buyers who want a quick win.”
For lenders, pricing risk is not just about the asset, but about the borrower’s ability to move at pace. Bridging finance has become a key enabler, allowing experienced investors to compete decisively in fast-moving situations.
As Mann points out: “With a revolving credit facility in place, experienced investors can often

draw down funds within as little as 48 hours, giving them a real advantage at auction or when pursuing off-market opportunities.”
That speed feeds directly back into auction dynamics. Matt Burrows, NAVA Propertymark advisory panel member, says: “Well-priced lots continued to attract strong interest, particularly where reserves were realistic and guidance was clear. Demand from cash buyers and experienced investors remain consistent, reinforcing the relevance of auctions in uncertain market conditions.”
Across the market, what began as a predominantly residential strategy has expanded into a broader range of asset classes.
Fix and flip activity now spans traditional buy-to-let (BTL), mixed-use buildings, commercial property, and small to medium-sized enterprise (SME) development, as investors search for value beyond increasingly competitive residential stock. Homeowners, small landlords, and professional investors alike are able to use refurbishment bridging to acquire auction properties, improve them, and either sell them at a profit or refinance onto longer-term funding. As access to straightforward BTL opportunities tightens, more would-be landlords are going to be willing to take these labour intensive risks.
This, in turn, has opened the door to larger, more complex schemes.
Gill adds: “SME developers who might once have just looked at ground developments are now looking at larger-scale office-to-residential conversions. Commercial developers will typically look to sit and manage office blocks, repurpose them, or improve covenants within commercial stock and property, for example on high streets.”
Bridging finance is also enabling smaller developers to scale more quickly by funding multiple projects simultaneously.
With bridging no longer seen as a last resort [...] it serves to empower a new generation of investors and developers"

Mann notes: “In the SME sector [...] they’re acquiring premises, completing works, or refinancing quickly to keep projects moving. The most interesting deals tend to come from borrowers who look beyond the property as it is today, and consider what it could become with the right funding and a bit of imagination.”
However, Cappaert adds nuance, noting that strategy execution varies significantly by sector. He explains: “Fix and flip looks quite different across sectors. In residential, the focus is often on speed, cosmetic and structural upgrades, and creating mortgageable, attractive homes for resale or refinance. Commercial and SME activity is more varied and often more innovative.”

Gill says: “We have seen an increase from what we would have described in previous times as your more 'hands-off' or 'armchair' investors now looking at auction and refurb finance requirements. As there is a lesser amount of stock available in the BTL market, investors are now looking to purchase properties where they can add capital and rental value.”
According to Mann, residential remains the most common entrypoint, but diversification is becoming a defining feature of more experienced investors’ strategies. “As margins tighten, many experienced buyers are diversifying into mixeduse and light commercial properties, where there’s still scope to add real value", she notes.
In addition, the pandemic accelerated the decline of certain retail and office spaces, pushing more commercial stock into auctions and creating opportunities for repositioning.
Collar-Brown says: “We are seeing commercial investors step in. Councils, for example, are releasing garage sites and similar assets, which often provide greater longevity and stability than short-term residential tenancies, making them a safer investment.”
He adds: “We’re seeing projects that convert offices or retail into residential, reconfigure mixed-use blocks, or modernise small industrial and trade units. SME clients might be owneroccupiers improving premises or investors repositioning assets for new uses.
“The innovation tends to cluster around mixeduse and alternative sectors: co-working; flexible retail; or hybrid live-work spaces, where creative design and planning can unlock significant value. These deals can be more complex, with layered income streams and planning risk, so specialist bridging and a knowledgeable intermediary become even more important.”

Nowhere are these dynamics more visible than in the BTL sector. As landlords are increasingly looking to diversify, with capital growth remaining uncertain, rental income has become a key motivator for many, helping to justify investment in tired or unmortgageable properties, particularly where upgrades also address looming EPC requirements.
Matthews notes: “Rising rents support the economics of projects such as HMOs and p
serviced accommodation, but they’re generally not the primary driver of refurbishment activity. EPC improvements are often a by-product of wider works rather than the sole motivation, though investors are increasingly aware that strong EPC ratings can support higher valuations and marketability.
"Ultimately, investors focus on cost control and delivering a product that maximises value.”
Rather than chasing top-end energy performance, some landlords seem to be targeting pragmatic upgrades that align with rental returns and future saleability.
Indeed, according to Rolande, as rents continue rise, the margin for intervention widens. He says: “Higher achievable rents can justify heavier refurb budgets. That is why we are seeing more buyers willing to take on tired stock, even if it is unmortgageable on day one.”
At the same time, EPC considerations have moved from the margins into the core of investment decision-making.
According to David Leary, NAVA Propertymark advisory panel member, there has been “a noticeable increase in flats and converted houses being offered at auction, driven in part by regulatory and legislative changes such as the Renters’ Rights Act and changes to Section 21.”
Mann agrees, noting that “while rents have made refurbishment projects financially more attractive again [...] EPC requirements are encouraging a longer-term perspective.”
She explains: “The savvier landlords aren’t just asking: ‘What’s the rent today?’ They’re considering: ‘Will this property still perform in five or 10 years?’”
Cappaert adds: “The real shift over the past year has been the surge in landlords using bridging specifically to tackle EPC-driven upgrades.”
can quickly undermine otherwise sound investments. Mann cautions that the practical realities of delivery now matter as much as the underlying asset.
She explains: “The challenges come from the narrower margin for error. Build costs, labour, and timescales all need careful planning, as delays can become expensive very quickly. Successful deals are the ones where borrowers are realistic, allow for overruns, and don’t rely on everything going perfectly to make the numbers work.”
That pressure is particularly acute for landlords attempting to scale up or enter unfamiliar submarkets. Gill adds that contingency planning is "no longer optional," especially where resale or refinance depends on local demand.
He continues: “This dual dynamic (strong rental demand and regulatory pressure) has pushed refurb-focused bridging to the forefront. Instead of financing cosmetic improvements, facilities are increasingly being used for deep, compliance-led upgrades that protect long-term value, reduce running costs, and ensure portfolios remain viable in a tightening regulatory landscape.”
For investors embracing refurbishment-led strategies, the opportunity is real – but so is the execution risk.
As projects become more capital-intensive and compliance-driven, success increasingly hinges on discipline rather than optimism. The margin for error has narrowed, and small miscalculations around cost, timing, or exit

He notes: “Time and cost overruns can severely affect the profitability and viability of a project, and it is important to allow for a sufficient contingency to mitigate against this.
"Another huge challenge is understanding the strength of your exit. Your exit has to be rock solid; we typically advise to have a primary, secondary and tertiary exit.”
In fact, the divide between successful and unsuccessful projects is often operational, rather than conceptual.
According to Rolande, success is afforded to “the professionals who cost it properly and get work completed fast.”
He adds: “The losers underestimate compliance and timelines as well as escalating costs.”
Despite these challenges, the underlying opportunity remains compelling for investors who approach fix and flip as a structured business rather than a speculative trade.
More specialised strategies, such as multiunit conversions or targeting specific tenant groups, can deliver strong returns, but they also introduce additional layers of complexity. Higher interest rates have made holding costs more punitive, increasing lender scrutiny around experience, planning, and exit viability. As a result, professionalism has become a key differentiator.
Cappaert adds: “Successful clients are the ones who treat projects like a business: detailed appraisals, realistic timelines, strong professional teams, and a clear ‘Plan B’ if the preferred exit (sale or refinance) takes longer than expected.”
Matthews reinforces the point that value creation alone is not enough if fundamentals are weak. Especially for newer entrants, he warns that preparation is key.
He notes: “Projects face real risks: build-cost volatility, planning constraints, and a flat sales market can all impact profitability.
"Investors must have a clear exit strategy, robust costings, and reliable contractors.
“Thorough due diligence is essential. Investors should analyse their figures carefully, understand their exit, and avoid emotional decisions that drive unnecessary spending.”
Despite tighter regulation and a more demanding operating environment, the fix and flip model could emerge as a key fixture in the market in 2026 and beyond.
Rental pressures, housing shortages and the growing pool of stock requiring intervention should underpin demand, while auctions remain a key route for assets that no longer fit mainstream lending criteria.
When asked about the future of the trend, Collar-Brown remains optimistic. He says: “As we head into the new year, we are expecting to see more properties in need of refurbishment and commercial investments coming to auction.”
Activity, however, is becoming more selective. As Mann notes: “I expect the market to remain busy but disciplined. Opportunities will be strongest for borrowers who understand their numbers and focus on adding real value, particularly through refurbishment and energy efficiency. The biggest risk is over-optimism –assuming costs will fall quickly or exit values will always rise.”
On the funding side, competition remains intense. Gill cites increased lender activity as they continue to diversify their funding lines.
He explains: “There are attractive yields and returns to these investors and funders, so this will continue to fuel and keep heating up the market until there is not enough business to support all of these lenders, at which point we will start to see some exiting the market.”
Looking ahead, Cappaert says: “Auction finance and refurb bridging are likely to remain central tools for active investors.
Average gross pro t per ip £22,000 in Q1 2025
Peak gross pro t £38,000 in 2022; average pro t has halved since then
Pro t margin Average gross pro t declined from 17% in Q1 2015 to 10% in Q1 2025
"The ability to buy well, add value, and create compliant, efficient stock will be more important than relying on passive capital growth.”
While demand for finance tied to EPC upgrades, conversions and underperforming assets is expected to remain strong, lenders are tightening scrutiny around experience, costings and exit viability. In that environment, execution will remain the key differentiator for market players.
Cappaert concludes: “The opportunity lies in professionalism: those who treat fix and flip and refurb as a disciplined, numbers-driven business [...] are best placed to thrive in the next phase of the market.”
Proportion of ips in transactions
2.3% of all sales in England and Wales in Q1 2025
Flips making a pro t after Stamp Duty 66% of ips in Q1 2025 were pro table after Stamp Duty
Regional shift 61% of ips occurred in the Midlands, North of England, or Wales in Q1 2025, up from 50% a decade ago
North East hotspot 4.7% of all homes sold in the North East in Q1 2025 were ips, double the national average
Highest cash return by region Average pro t per ip in London was £93,730 in 2022, despite lowest ip proportion
Most pro table region proportionally
Wales saw a typical 39% (£42,310) gain per ip in 2022
Typical refurbishment spend Majority of ippers spent £11,000 to £25,000 per project
Completion speed 68% of ips took less than six months from purchase to resale
Source: Hamptons
MARTIN TEMPLE is an economist at Leeds Building Society
At Leeds Building Society, we’re driven by our purpose of ge ing more people into bricks and mortar that they own. We know that affordability remains the biggest barrier to homeownership. The latest data released by the Office for National Statistics (ONS) on UK house prices showed that property prices remain high, with annual growth of 2.5% to the end of November, which is encouraging for the market overall. It is interesting to note that there continues to be a divergence in the relative strength of property markets in the North of England and the South East and London – with average house prices rising by 7% in the North East over the last year but falling by 1% in the nation’s capital.
Other recent data suggests that buyers are being more cautious, but importantly they haven’t disappeared altogether, and are starting to return to the market following the removal of pre-Budget uncertainty. For first-time buyers (FTBs), continued collaboration across the mortgage industry remains vital, ensuring that aspirational homeowners continue to receive the support they need.
The first weeks of 2026 have been dominated by unse ling headlines and it’s understandable that many may be worried about how geopolitical uncertainty could affect interest rates and their personal finances.
Headlines around the potential for higher US tariffs or a full-blown trade war between the EU and the US returned in the middle of January, this time linked to UK and European support for Greenland. However,
whilst announcements on significant levels of tariffs on imports in the US last April triggered sharp market reactions, the latest developments have had a much more muted impact.
Despite all the noise, financial markets have been relatively steady and changes to interest rate expectations have been minimal. Recent moves in rates seem to be more closely linked to so er national employment data in both the US and the UK rather than fears of escalating trade tensions. The biggest market reactions have instead been seen across commodity markets, with gold prices
continuing to reach record highs and oil prices remaining weak.
For now, developments in the news are not currently feeding through into borrowing rates in the UK, but markets will continue to monitor the situation closely and I am reassured by the fact that the market has remained stable.
Having bought my own first home at a time also dominated by worrying headlines – albeit related to the fallout from the dot-com crash – I understand that it can feel disheartening and unse ling when there is an almost constant stream of potential worrying news. But ge ing on the property ladder is rarely about perfect timing, it’s about having the right support.
Many may be worried about how geopolitical uncertainty could a ect interest rates and their personal nances”
We offer a range of products designed to help tackle some of the barriers to homeownership, such as minimum income requirements, loan size, and deposit requirements. These options allow people to borrow responsibly while widening their access to the housing market.
I know from my own experience of buying my first home that affordability ma ers a lot, particularly in the current economic climate. That’s why it’s important for people to understand the basics around interest rates and how they might be impacted by what’s going on in the world.
As 2026 progresses, I expect to see a calmer, more balanced housing market, assuming no material external shocks actually materialise. Property prices are broadly stable, rather than surging, and buyer interest remains steady, albeit sensitive to mortgage affordability. With this in mind, we’re looking forward to continuing to work with our intermediary partners, and by extension more aspirational homeowners, throughout 2026 –whatever it may bring. ●
Aer several years in which first-time buyers (FTBs) were the most exposed cohort in a higherrate environment, 2025 delivered a more encouraging outcome. Transaction volumes recovered strongly, with FTBs once again accounting for a significant share of purchase activity. According to UK Finance figures, this share is almost 20%, despite Bank Base Rate (BBR) reductions arriving more slowly than markets initially predicted.
Underwriting standards have remained robust throughout, and the recovery has been underpinned by lender innovation and greater regulatory clarity around affordability. As a result, demand has proved durable.
There are also reasons to believe this momentum will continue into 2026. Further cuts from the Bank of England are widely anticipated, mortgage rates are already well below their recent peaks and recent changes to affordability rules are beginning to feed through into lending decisions. Together, these factors point to gradually improving access to mortgage finance for would-be FTBs. However, stronger recent performance should not be mistaken for a full recovery. IMLA’s ‘Mortgage Affordability Paradox’ research shows that FTB numbers have consistently fallen short of historical norms, even during periods when affordability appeared strong.
During the ultra-low interest rate years from 2013 to 2022, mortgage payments as a share of income were close to record lows, yet FTB volumes averaged around 330,000 a year –well below the levels seen in earlier decades. The result is a cumulative
shortfall of around 3.5 million households who, based on past trends, would have been expected to buy since the financial crisis but have not.
The resilience seen in FTB numbers in 2024 and 2025 reflects this substantial pool of pent-up demand rather than a resolution of the underlying barriers to ownership. Recent momentum is welcome, but it has only begun to address a much deeper deficit.
One consequence of this long-term underperformance is the growing number of households remaining in the private rented sector (PRS) for longer than planned.
Research by Barra Developments suggests that a lack of understanding has become the single biggest barrier to ownership for Gen Zs. Nearly 30% of aspiring buyers in this group said that ignorance of the buying process ranked higher than either saving for a deposit or qualifying for a mortgage.
That finding is instructive, as it implies that many renters are not simply constrained by income or access to products, but by uncertainty about the mechanics of home buying. While the research focuses on process, it points to a broader issue around confidence.
For many renters, mortgage borrowing is still framed primarily as risk rather than as a structured means of investing in a long-term asset. Repayments are viewed as exposure rather than equity accumulation. This perception can deter engagement even where borrowing would be sustainable and appropriate.
For an intermediary-led market, this ma ers. Too many exclude themselves from homeownership based on outdated assumptions
KATE DAVIES is executive director at the Intermediary Mortgage Lenders Association
about income multiples, deposit requirements or what constitutes ‘acceptable’ affordability.
This is where the value of advice extends beyond product selection. Advisers play a critical role in demystifying the home buying process, reframing mortgage borrowing in its proper long-term context. Doing so is not about encouraging unsuitable borrowing, but about ensuring that households are not deterred by misplaced fear.
The outlook for FTBs in 2026 is more positive than it has been for some time. But if the industry is serious about addressing the shortfall in homeownership, improved market conditions alone will not be enough.
There remains a compelling case for a targeted, time-limited successor to Help to Buy to support FTBs and, crucially, housing delivery. A more tightly targeted version could support access to homeownership while aligning with wider policy goals on supply and affordability.
Supporting FTBs is not just a social good, it is a practical lever for unlocking supply and sustaining a functioning housing market. Sustained progress will depend on whether we collectively do more to improve understanding, build confidence and encourage engagement with advice.
FTBs have already shown that demand is there. The next challenge is ensuring that lack of understanding, rather than lack of affordability, does not remain the biggest barrier to turning that demand into homeownership. ●




At Magnet Capital, we’re always looking for ways to help your clients level up. That’s why we’ve enhanced our development finance offering, including increasing our LTV to up to 70%. That means more flexibility, more support, and even more power to get your clients’ projects off the ground.
We’re still the same expert team with the same straight-talking approach - just with more powerful funding that stacks up exactly how you need it to.
Ready to level up your client’s next project? Let’s talk.
Product Features:
• LTV Day 1: 70%
Loans from £250k - £4m
Gross LTGDV: up to 65%
• 100% of development costs funded
• Max number of units: 20
hello@magnetcapital.co.uk
020 8075 3255
In conversations we are having with brokers and others across the mortgage sector, it’s clear there is a sense of optimism running through the market in the early part of this year. With the uncertainty created by the Autumn Budget now behind us, confidence has started to return to the market.
There are several factors which are likely contributing to this. Mortgage rates are at their lowest level since 2022, buyer borrowing power has increased following the Financial Conduct Authority (FCA) ‘clarification’ of stress rates, and more flexibility with loan to income multiples. And there’s more to come, with the FCA commi ing to a series of reforms which should support first-time buyers, later life lending, and the rollout of new technology and other innovations.
The need for expert advice will only increase given this changing landscape. The support and advice of a good broker through the homebuying journey can save thousands over the lifetime of a mortgage. This is true of those buying for the first time and those remortgaging at the end of their current deal. This year an estimated
Optimism alone won’t deliver better outcomes [...] because even in an improving rate environment, many borrowers still struggle to access a mortgage”
1.8 million fixed-rate mortgages are due to expire, according to UK Finance’s mortgage market forecast.
Across the market, lenders are responding – not only by reducing interest rates but looking at other ways to improve access for borrowers. In our case, that has included price changes, simplifying criteria for self-employed applicants, widening our approach to future income, and providing greater flexibility around borrower profiles. We believe optimism alone won’t deliver be er outcomes unless it is paired with continued innovation in how we lend, how we assess risk, and how we support borrowers whose circumstances don’t fit neatly into traditional boxes.
Why? Because even in an improving rate environment, many borrowers still struggle to access a mortgage. Not because they can’t afford it, but because the system has difficulty in recognising how they earn, spend, and manage money in today’s world.
These borrowers include the aforementioned self-employed and contractors, those with variable income, older demographics, or those whose financial resilience doesn’t present itself neatly on a payslip. Many of these borrowers demonstrate strong payment behaviour every month through rent, bills or childcare costs, yet those behaviours don’t always carry enough weight in underwriting.
That’s where lenders, working closely with brokers, continue to play a vital role in making sure that rigid processes and assessment models do not create barriers.
If we’re serious about widening access, we need to collectively embrace a more holistic measure of financial
AARON SHINWELL is chief lending o cer at Nottingham Building Society
resilience. Be er use of data and alternative verification can reduce the amount of uploading, re-uploading, and explaining that borrowers are asked to do, without removing the checks that protect both customer and lender.
Innovation should be about practical change that removes friction and improves outcomes. On the product side that means greater flexibility around income assessment, term structures, and later-life lending. But innovation isn’t just about what we lend, it’s about how we lend.
Application journeys are still o en too slow and cumbersome and too document-heavy for customers who already feel anxious about the process. The adoption of artificial intelligence (AI) will help streamline these processes for brokers and lenders alike – we’re already seeing the benefits of investment in this area which will only gather more pace through the year.
For brokers, clarity is just as important as speed. A healthy market is one where advisers can clearly see which paths are viable for “unique but credible” cases rather than spending time navigating opaque criteria or unnecessary dead ends.
This year brings genuine reasons to be positive. Lower rates, returning confidence, and strong remortgaging volumes give the market momentum and will open more doors. But optimism should be matched with responsibility. Innovation must continue so that underserved borrowers don’t miss out. If we can do that, this year won’t just be a be er year for volumes, it will be a be er year for outcomes across the market. ●
2026 has already started with the usual a ermath of the festive period.
People deciding to bite the bullet and list their home for sale a er realising that their current home is too cramped to cater for extended family. Or, ears begin to prick up when lenders reduce rates which makes that extension potentially viable once again. Being just a few weeks into the year, here at Fowler Smith Mortgages & Protection, we’ve already seen an influx in enquiries and submissions. Indeed, it looks as though 2026 is going to be a very busy one for mortgage advisers.
We’re currently seeing predictions of the Bank of England’s base rate being cut at least twice throughout the year. Off the back of this, we’ve already seen a number of lenders reducing fixed rates. This ultimately gives borrowers more spending power and will drive them to borrow, whether that be to move or to stay put and extend.
With a potential boost in property activity, we might in turn see an increase in property prices throughout the year. Something that isn’t the most welcomed by the first-time buyer (FTB) market, but with lower rates and many lenders offering some form of incentive for FTBs in the form of cashback, increased lending multiples or free valuation surveys, then it hopefully shouldn’t cause too much of a detriment to the market as a whole.
As much as I’m feeling positive about the residential market, I equally feel the same way about buy-to-let (BTL). As we know, that market has taken a bit of a hammering in the past 18 months or so. Increased Stamp
Duty, impending energy performance requirements, Renters’ Rights Act and more.
But, again, if a yield presents itself in a way that is beneficial to a landlord, they’re going to invest. With lower rates, lenders opening criteria, and even some lenders completely rebranding to put a focus on more specialist BTL cases, there’s not too much of an argument remaining as to why someone wouldn’t consider a BTL for 2026.
Besides, if interest rates are decreasing, then we’re going to be seeing a spike in enquiries where people somewhat ‘flirt’ with the idea of property investment. They might not see the same strong returns from keeping their funds locked away in a savings account.
Considering the positivity for the property market this year, I’d really like to see some lender improvements, too. One of the main ones that I’m seeing at the moment is inconsistency with property valuations, especially in the new build space for smaller developers. For instance, we have seen one apartment unit value up, while the one next door sees a he y down valuation. You can try to contest it, but ultimately, you’ll get nowhere.
Equally, with regards to the more traditional house purchase or remortgage, automated valuation models (AVMs) might be great for speed, but when they don’t work, it’s a real pain. For instance, a house that has been significantly improved through renovation, that then gets down-valued due to an automated survey based on the house price index, can severely impact that purchaser or remortgaging client and have a really detrimental effect on the
With a potential boost in property activity, we might in turn see an increase in property prices throughout the year”
overall transaction. You then ask for a physical survey and the lender can just say ‘no’ as they don’t need it. This can impact borrowers deposit amounts, the amount they are able to pull out of their existing property or just halt the transaction altogether. What’s even worse is if it’s then a empted with another lender, and they also decide an automated survey is all that’s needed again. The cycle continues.
I understand from a lender’s perspective that speed is vital, and automation helps manage demand; but sometimes, it is just necessary to have a human approach and consider what is fair, not just fast.
While certain issues within the market certainly still exist, it is clear that 2026 will be busy in all aspects –we’re seeing it already in just the first couple of weeks of the year. I, for one, remain optimistic, as I think we as advisers can work closely with lenders to make the year even be er than we anticipated. ●
The market continued to expand in 2025, and with that growth brings an even sharper focus on how lenders assess risk. At the center of this risk assessment, of course, is valuation, and in a complex lending environment where loan security underpins every decision, I would argue that a physical valuation remains one of the most reliable ways to understand the true condition of a property.
Within this, sectors such as bridging, second charge and equity release have all contributed to this growth, which means that the role of the valuation is even more relevant than ever across these individual markets.
In bridging, The Bridging & Development Lenders Association (BDLA) reported that completions reached £2.5bn in Q3 2025, up 9.6% on Q2 and 42% higher than the same period in 2024. Lender loan books also hit £13.7bn, more than 50% higher year-on-year. In such a fast-moving market where even the smallest delays
in the valuation stage can cause cases to fall away, an early, in-depth physical inspection can prevent surprises and support cleaner exits.
The same pa ern can be seen in the second charge sector. According to the Finance & Leasing Association (FLA), in November 2025, volumes were 27% higher than the previous year, and the value of new business was 28% higher too. In fact, the second charge mortgage market has reported growth in new business volumes in all but one month in 2025.
Equity release continues to grow as well. The Equity Release Council said that total lending reached £639m in Q3 2025, slightly higher than Q2 and 4% up on Q3 2024.
Despite this growth, many borrowers across the market are still holding on to low fixed rates, so valuation plays a major role in determining what they can raise. When past improvements have never been inspected on site, an automated valuation model (AVM) may not give a fair view of the current value. Older properties and mixed
JAMES GILLAM is managing director at Pure Panel Management
construction types are common in this market, and a physical visit can o en highlight issues that influence affordability and advice.
That’s not to say that physical valuations are the only way; automated valuation models (AVMs) are now part of everyday lending. They offer speed and can support simpler cases, but they are still generating information based solely on historic data, not a live inspection. They cannot see internal conditions, judge the quality of works or comment on the wider se ing.
As lending grows, the limits of AVMs become clearer, especially when our housing stock gets older and older. I say this as the UK has the oldest housing stock in Europe, with around 38% of all properties built before 1946. This significant proportion of older homes can contain hidden defects that only appear on a full inspection, where only the eyes of a trained valuer can spot structural movement, insulation issues or signs of past repairs that affect both value and risk.
Growth across many areas of the property market is expected to continue. With that expansion comes a greater need for accurate assessments and consistent outcomes.
Physical valuations do not slow lending when used at the right stage. They can protect cases from avoidable delays, help brokers set expectations and give borrowers a clearer understanding of their property.
AVMs will continue to play a role, but in a market built on complex scenarios, physical valuations still provide a level of assurance that desktop models cannot match.





Find innovative solutions here, to help your first-time buyer clients break through the barriers they’re facing:

• Track Record mortgages - if your client can afford to rent, they may be able to afford to buy.
• Income Booster - your clients could boost their affordability through family and friends with no relationship restrictions.
• Delayed Start mortgages - now available for up to 1, 2 or 3 months and can be used alongside Track Record and Shared Ownership.
Subject to affordability and lending criteria.

Throughout 2025, the mortgage market continued to demonstrate real resilience. Arrears continued to trend downwards throughout the year across both residential and buy-to-let (BTL) sectors – adding further merit to the view that many borrowers may have finally been able to stabilise their finances a er extended pressure.
While possessions did increase – most likely suggesting greater difficulty in the higher arrears bands – they still represent a very small proportion of cases and further proves that it is still a last resort for lenders.
On the ground, we see the proactive work of lenders firsthand, engaging early with borrowers to provide tailored support and if necessary, flexible exit strategies to ensure good outcomes are still achieved. The positive results of the past 12 months show that not only are conditions improving, but the strategies of lenders and their third-party suppliers are clearly working.
Recent economic data has given further cause for optimism, most notably improving inflation and further cuts to the Bank of England base rate throughout 2025. We did see inflation creep back up in December’s data, but the hope is that this is more of a seasonal or temporary blip.
While this may make further base rate cuts more unlikely, there is still growing expectation among economists that there will be two more cuts in 2026 – which will certainly help the overall arrears picture. The signs are promising for new borrowers, particularly as lenders continue to support improvements in innovation and affordability with changes to products and criteria.
This is being evidenced already, as Moneyfacts reports that product choice has continued to rise to its highest point since 2007. Higher loanto-value (LTV) options – which are particularly needed among first-time buyers (FTBs) – are at their highest level for nearly 19 years. There’s plenty for mortgage brokers to be shouting about and plenty of reasons for potential borrowers to be positive.
At the same time though, it’s certainly reason for caution. It’s important to stress that we are not out of the woods just yet. Product choice at such a high level is likely to make those in the industry with longer memories slightly nervous. This is particularly true in the geopolitical and economic climate we currently find ourselves in, with a fragile economy, unemployment at a four-year high and wage growth slowing.
Despite its recent blip, the belief is that inflation will return to the hallowed 2% target. That does of course depend on so many factors – whether it’s government policy at home or any further escalations abroad.
There’s no question that lessons have been learned over the last decade, and lenders are in much be er shape to loosen rules and relax their approach to risk. To put more keys in the hands of buyers and enable the housing market to play its significant role in driving economic growth, we need to innovate as an industry.
At the same time, we have to remain vigilant and keep a laser focus on arrears. We have to be conscious of the factors in play around us to make sure we support both new and existing borrowers and make sure we catch any challenges early.
DAVID MILLER is divisional director at Spicerhaart Corporate Sales
My message to mortgage lenders is that we need to keep up the good work on forbearance and continue to implement strategies to support borrowers in difficulty.
A prime example is Assisted Voluntary Sale (AVS), which provides a viable exit strategy for all parties. Lenders work with an asset manager to market the property and achieve the best possible price in the shortest amount of time. Not only does this avoid the stress of repossession, but it is also possible for the borrower to maximise equity from the sale. We’re increasingly seeing lenders adopt this strategy and partner with expert asset managers to look a er this process from start to finish.
It does rely on lenders staying close to their mortgage book. With an accurate view of both the value and potential risk of their property portfolio, lenders are able to make informed decisions much earlier. Asset managers play a critical role too, with regular reviews of the mortgage book to identify any red flags. The ultimate strategy is to enhance the intelligence you may already have from automated valuation models (AVMs) with boots on the ground to fully determine the property’s current state and potential value.
Keeping up the good work on arrears and ensuring repossession remains that last resort requires lenders to stay fully focused. Above all, they need to leverage the right intelligence and industry partners to understand the full picture around their property portfolio, and to be able to provide early intervention where it’s needed most. ●
Building Society

The Intermediary speaks with James Tuck, business development manager at Harpenden Building Society
How and why did you become a BDM?
I had already been with Harpenden Building Society (HBS) for almost two years when I transitioned into my role as a business development manager (BDM) in January 2026. Previously I worked within our product team, identifying and developing growth opportunities.
When the BDM position came up, I saw it as a unique opportunity to use the knowledge and skills I had developed within product management, and in turn, apply them to expanding our intermediary relations strategy, further contributing towards our growth ambitions. As I’m still new to the role, I am also looking forward to representing the society nationally and communicating our expansive
criteria to brokers, especially to those who may never have worked with us before.
brought
I returned home from Australia in January 2024 and was keen to begin working within the nancial services industry. Having grown up in Harpenden, I was already aware of the strong reputation the society had; therefore, I saw it as an ideal opportunity.
e society has actively supported me, helping me develop my understanding of the industry and allowing me to progress to become a BDM! Additionally, the size of HBS provides a really great opportunity to work across di erent business areas
and develop a greater understanding of the complete journey of both the broker and the customer.
makes
Building Society stand out from the crowd?
Our manual underwriting process means that we can take a commonsense approach to cases which may be instantly declined in a more automated process. Additionally, the ways in which people receive income has changed and our expansive range of accepted income, alongside this common-sense approach to verifying income, means that we are able to successfully adapt and best support borrowers in this changing environment.
We are also actively and regularly developing our proposition, allowing

us to apply our expansive criteria to new product areas. We have an impressive roadmap of product development for 2026 – so watch
particularly those operating within the specialist market to play a pivotal role in identifying and developing new areas of growth.

this space!


In 2026, brokers have more choice than ever before, with lenders competing not only on pricing, but also on product exibility, service levels, and technology. is increasingly competitive landscape means that, as BDMs, we must be far more deliberate and strategic in how we engage the market. We can no longer rely on a small, established group of brokers to deliver the majority of our business.

Instead, success requires a targeted approach to identify and develop relationships with broker rms whose client base, product mix, and growth ambitions closely align with our own lending proposition. By focusing our time and e ort on partners where there is a genuine strategic t, we can build deeper, more sustainable relationships, drive mutual growth, and ensure we remain relevant and competitive in a crowded market.
ere has been signi cant growth in specialist mortgage lending in recent years, including areas such as limited company buy-to-let (BTL), complex self-employed income, and foreign income cases. is trend is being driven by changing borrower pro les, evolving employment structures, and increasing demand for exible underwriting solutions.
Importantly, expansion into specialist product areas shows no signs of slowing and is likely to accelerate further, especially as brokers seek lenders who can accommodate more complex client needs. is environment presents a clear opportunity for BDMs,
By leveraging broker insight and market feedback, BDMs can help pinpoint unmet demand and emerging niches, and work closely with internal stakeholders such as underwriting, product, and credit teams to bring new solutions to market. In doing so, BDMs move beyond a purely relationship-based role and become key contributors to product innovation, proposition development, and long-term business growth.
I begin by building a complete understanding of the customer’s background, assessing what could derail the case but also identifying the primary strengths. is enables us to informally pre-underwrite tricky cases, sense checking that income, loan-to-value (LTV), property and criteria t our requirements. is means that we can ensure that all cases that go through to a formal application have already been preliminary reviewed, reducing the number of declined applications further down the line, saving valuable time for both the broker and the borrower.
I think it is also highly important to be clear on criteria, including grey areas. Being honest about where exibility ends therefore allows the broker to have a complete understanding of our position, before submitting a formal application.
Particularly in the specialist mortgage market, being honest about your pro le is key. It’s important to be open about your income or deposit source, unusual
properties and credit blips (even historical ones) from the start. is means that alongside the broker, we can work through complex situations and nd the best solution from the start, reducing the number of surprises that will get found later in the underwriting process. Fundamentally, this will save borrowers valuable time and ensure that they end up with a mortgage which is best suited to their needs.
What would you like people to know about you outside of work?
Outside of work I am a keen rugby enthusiast. I am part of a team which has achieved strong success over the last couple of years, and we are now looking forward to backing that up as we move into the second half of the season. Building trust amongst teammates on a rugby pitch is fundamental, knowing exactly how one another works and backing each other up when things go wrong. I think the same is true in the intermediary market. It is important for us as BDMs to build trust with our broker partners, nding solutions to complex cases and building towards mutual success.
Harpenden Building Society
Established in 1953
Products
◆ Residential and self-build
◆ BTL, limited company BTL and holiday lets
◆ Large loans of £3.5m for residential and £2m for self-build
◆ Complex income borrowers
◆ Unusual property types, including up to three properties on one title
Contact details
brokerteam@harpendenbs.co.uk 01582 463133
As the rental market continues to evolve, houses of multiple occupancy (HMOs) are undergoing a quiet but significant transformation. Once viewed as a niche or transitional asset class, HMOs are now firmly embedded in the strategies of professional landlords.
Over the past decade, the evolution of the HMO sector has been gradual but deliberate. Changes to buy-to-let (BTL) mortgage tax relief in 2020 were a clear catalyst, prompting many landlords to reassess how they generate income from property. For a growing number, HMOs offered a way to offset higher costs through stronger yields. Since then, wider market forces including rising rents, changing tenant behaviour and increased regulation have accelerated the professionalisation of the sector.
The pandemic initially introduced uncertainty, but demand rebounded strongly in its a ermath. As people returned to offices, demand grew for affordable and flexible accommodation in commutable locations. HMOs naturally meet this need, offering lower individual rents and shorter commitments that appeal to a more mobile workforce.
Crucially, today’s HMO tenants are not the same as those of the past. While students remain part of the picture, the tenant base increasingly includes young professionals and shi workers, particularly NHS staff. Expectations have risen sharply. Tenants are no longer willing to compromise on quality and are seeking larger rooms, ensuite bathrooms and reliable ultra-fast broadband. It is no longer just about providing facilities, but about delivering them to a high standard.
This shi in expectations has driven the rebranding of many schemes towards co-living. Higher-end HMOs
and new-build developments are increasingly positioned this way, but improvements are being made across the wider HMO market as landlords invest more capital to a ract professional tenants.
Professionalisation is now one of the defining characteristics of the sector. Far fewer landlords operate a single HMO as a standalone asset. Most are running portfolios and treating their investments as businesses. That brings higher standards, but also higher costs, from refurbishment and ongoing management to compliance. Licensing, in particular, can be complex, with requirements varying significantly between local authorities.
This complexity does raise the bar, but it does not close the door. HMOs can still deliver strong returns, even for newer entrants, provided the right structures are in place. Experienced managing agents can play a vital role in reducing day-today operational risk. From a lending perspective, stronger rental coverage is o en required where borrowers are new to the sector. This helps ensure the property can comfortably service the debt while experience is built. As portfolios grow and track records are established, those requirements can ease.
For brokers, this presents a real opportunity to add value. As more landlords enter or evolve within the HMO market, understanding which lenders’ criteria align with a client’s objectives is essential. Some lenders are be er suited to first-time HMO investors, while others are more appropriate for experienced operators. Brokers who recognise these distinctions are be er placed to secure funding that genuinely supports their clients’ strategies.
At Redwood Bank, we o en talk about being ‘Experts for Experts’.
TOM WORBEY is senior product manager (lending) at Redwood Bank
HMOs and complex BTL lending demand specialist understanding on both sides. We take time to understand each case, the asset and the borrower’s experience. That approach allows us to support professional landlords operating in an evolving market; while giving brokers confidence. Looking ahead, brokers should be engaging clients early to gain a clear understanding of their goals, rental income and managing costs. Using tools such as commercial mortgage calculators and detailed product guides, and being willing to explore more specialist opportunities, can significantly improve outcomes. Making the maths work is fundamental to achieving a higher likelihood of acceptance.
The HMO market has moved well beyond its traditional image. It is now a professional, highly specialised segment of the BTL market.
While London remains popular, growth is accelerating in cities such as Leeds and Manchester, as well as commuter locations like Cambridge. Affordability pressures continue to shape rental demand, with HMOs increasingly meeting the needs of younger working professionals, not just students or shi workers.
Graduates moving into cities are seeking well-located, high-quality shared accommodation with strong amenities and access to social and professional hubs. This shi is influencing how investors approach HMO assets, placing greater emphasis on quality, longevity and compliance. In this environment, partnering with a specialist lender that understands the nuances of complex BTL and HMO lending is essential to supporting sustainable growth. ●



Making Tax Digital (MTD) for Income Tax is no longer a future change that landlords can safely park for another year. From 6th April, it becomes mandatory for a large number of unincorporated landlords and sole traders, and advisers should already be thinking about how this impacts their landlord clients.
Any individual landlord or sole trader with qualifying income above £50,000 will need to comply with MTD for Income Tax from April, and HM Revenue and Customs (HMRC) will not enrol people automatically. That places real importance on awareness and preparation.
For advisers, this is not simply a technical tax change to note and move on from. It is another area where landlords will need support.
MTD for Income Tax is a new way for individuals to report income and expenses to HMRC. It applies to sole traders and landlords who complete self-assessment and whose total income from self-employment and property exceeds £50,000 a year. This includes landlords who hold property in their own name, but it does not include limited companies at this early stage.
From April, those within scope will need to keep digital records using recognised so ware rather than paper records or basic spreadsheets. They will also need to send quarterly updates to HMRC through that so ware. These updates are not tax returns, and they do not trigger tax payments. They are simply summaries showing income and expenses for each three-month period.
The annual tax return will still be required, and any tax due will still be payable by 31st January following the end of the tax year. One common
misunderstanding is that MTD means paying tax quarterly, but that is not the case.
Many landlords will assume that MTD does not apply to them, particularly those who do not see themselves as running a business. In reality, many advisers will have clients who are likely to fall within scope without realising it.
This includes landlords with several properties, those with a mix of rental income and self-employed income, and those close to the £50,000 threshold who may cross it as rents increase. It may also affect joint borrowers where one party has qualifying income in their own name.
Mortgage advisers themselves may also be impacted if they operate as sole traders, as perhaps will other selfemployed clients advisers work with.
HMRC sets out a clear process for those who need to use MTD. The first step is working out qualifying income, as this determines whether the rules apply.
The next step is confirming when an individual needs to start using the service. HMRC provides an online tool to help with this. A er that, suitable so ware must be chosen, as HMRC does not provide its own system. There are a wide range of options available, and the right choice will depend on how complex someone’s income is and how confident they are with digital tools.
Once prepared, individuals need to sign up to MTD and then use the system throughout the year. This includes keeping records up to date, submi ing quarterly updates, and completing the annual return through the same so ware.
Advisers are not expected to give tax advice unless they are qualified to do so, but they are well placed to help
LOUISA RITCHIE is national account manager at Fleet Mortgages
landlord clients understand what is changing and why it ma ers. Simply raising MTD during a review or remortgage discussion could prompt action far earlier than landlords might otherwise take.
Advisers can also add value by signposting clients towards appropriate solutions, whether that is accounting support, digital record-keeping tools or bank accounts designed to help separate personal and property income and link with accounting so ware.
For advisers, this fits naturally within the wider set of added services that landlord clients now expect. Helping clients prepare for MTD supports be er organisation, clearer affordability discussions and stronger long-term relationships. In some cases, there may also be opportunities to introduce clients to third-party services where appropriate.
Landlords are already dealing with regulatory change, cost pressures and shi ing market conditions, and MTD adds another layer to manage. Advisers who understand the rules now, and who start these conversations, will be be er placed to support clients through the change and demonstrate value beyond the mortgage itself.
In a market where strong adviser relationships ma er more than ever, that proactive support can make a real difference. ●
Nearly two months into 2026 and it already feels like a very significant year for the buy-to-let (BTL) market. A large cohort of landlords are now coming up for product maturity, in a much more price-competitive mortgage market. And that’s before we have even mentioned the Renters’ Rights Act, and its potential increase in purchase business.
All of these factors point to a year where BTL activity will grow and a more focused and professionalised landlord base will continue to seek opportunities and secure portfolio growth.
Industry data supports this view. The Intermediary Mortgage Lenders Association (IMLA) estimates BTL gross lending reached £39bn in 2025 and forecasts this will rise to £44bn this year. Crucially, the bulk of this activity is expected to come from remortgaging and product transfers (PTs) rather than new purchases.
IMLA forecast remortgage volumes of around £28bn in 2026, rising to £29bn in 2027. Our own landlord survey, carried out at the end of December and start of January, fits neatly within this picture. Many landlords are reviewing their options, assessing affordability and thinking about how best to bolster property portfolios in a changing market.
One of the most important dynamics which will shape activity is the gap between where pricing is now, and the rates and products landlords are si ing on or coming to the end of. According to Twenty7tec, at the time of writing
the average BTL 2-year fixed rate sits at 5.19%, with the average 5-year fix at 5.54%. Our survey shows many landlords are still on deals priced above 5%, and a meaningful number on rates of 6% or more, secured two or three years ago when pricing was at its peak.
Today’s reality is different. There are deals currently available at rates well below those averages. In our own Premier range at Landbay, we have rates currently starting with a two. This is therefore a healthier market to refinance into. Monthly payments could be lower. Cash flow can improve. And for some landlords, affordability improvements means access to equity becomes more realistic again.
For advisers, the remortgage conversation also presents a very clear opportunity. Many landlords are thinking about wider issues. Ownership structure. Future tax changes. Portfolio growth. And of course, the cost of meeting new responsibilities under the Renters’ Rights Act.
Much of the focus has been on compliance and cost, but IMLA highlighted a less discussed potential outcome. The Act could increase property churn; smaller landlords may well sell up, with their properties likely to be bought by portfolio operators. That could support purchase lending over the next two years. But even here, remortgaging and release of stored equity will o en sit behind those purchases. Again, advisers are central to that process.
Our survey also highlighted an important behavioural trend. Around
ROB STANTON is sales and distribution director at Landbay
three-quarters of landlords told us they would use the same adviser again for their next buy-to-let mortgage. That is hugely positive. But of those who would not, the most common reason was not necessarily dissatisfaction, it was direct access to PTs.
Of that group, 34.4% said they would normally PT with the same lender. In a market where pricing has improved, this ma ers. Le to their own devices, some landlords may default to what they could deem, an ‘easy option’. In doing so, they are going to miss out on access to a wider range of products and options that be er suit their longer-term plans.
At Landbay, our product transfers are adviser-only. Advisers remain involved, ensuring speed does not come at the expense of advice or choice. In a year where remortgaging and PTs will account for the majority of activity, that distinction ma ers.
The message for 2026 is clear. This is not a market in retreat. It is a market adjusting to a new phase and likely to move forward at some pace. Pricing is more competitive. Volumes are rising. Landlords are engaged and planning ahead.
But advisers will need to work at these relationships. If they do not, others will fill the gap. By staying close to landlord clients, reviewing options early and explaining what is now achievable, this looks like a year with real opportunity to deliver positive outcomes for both advisory firms and across landlords BTL portfolios. ●
The Renters’ Rights Act 2025 (RRA) is set to transform the private rented sector (PRS). It brings in a regulatory framework that will, among other measures, abolish fixedterm tenancies and Section 21 ‘no-fault evictions’. The RRA will be introduced in phases, with the most significant changes taking effect from 1st May this year.
However, a number of changes are already in force. At this preliminary stage, local authorities have already gained new investigatory powers and reporting duties to deal with non-compliance with legislation. In addition, new exemptions have been introduced for Housing Act 1988 tenancies, meaning that tenancies for more than 21 years can no longer be ‘Assured Tenancies’ and they will fall outside of the new regime.
The headline change introduced by the Act is the abolition of Section 21 ‘no-fault’ evictions, preventing any further use of the most used process for regaining possession.
The last date to serve a Section 21 notice is 30th April 2026, although landlords are strongly advised not to leave the service of Section 21 notice until the last minute, and the final date for commencing possession claims on existing notices is 31st July.
Under the RRA, landlords will still be able to reclaim possession of
their properties but will need to rely on amended and expanded Section 8 grounds, such as a genuine intention to sell or move into the property or where there has been antisocial behaviour, property damage or serious rent arrears.
Most notably, the RRA changes the threshold for mandatory possession due to rent arrears to three months from two months, with an increased notice period of four weeks rather than the existing two weeks’ notice. In addition, where landlords seek to sell the property or move themselves or family members into the property, there is a 12-month protected period before those grounds can be relied on and a four-month notice period must be provided.
The extension of notice periods under the Section 8 possession grounds significantly extends the process for landlords and careful planning around these notice periods will be required.
Obtaining possession will be increasingly court-dependent, with potential delays exacerbated by an already burdened system. An online possession claim service is expected to be introduced in April 2027, but interim delays are already being experienced, and further delays are likely once the new rules come into force in May.
Fixed term tenancies will become a thing of the past. All new and existing tenancies automatically transition
into Assured Periodic Tenancies, rolling indefinitely on a monthly basis until the tenant gives notice to leave or the landlord obtains possession under the Section 8 grounds. Notice periods for tenants are two months unless the landlord has agreed to a shorter notice period.
All new tenancies from 1st May will require a written statement of terms (covering mandatory details like names, rent, deposits and repair duties) to be provided to tenants before they sign.
The RRA also sees the introduction of significant controls on rental pricing. From 1st May, landlords may increase rent only once per year, on two months’ notice via a prescribed Section 13 notice. Tenants may challenge excessive rises through a simple process with the First Tier Tribunal, and such challenges can be brought within the first six months of a tenancy or after a Section 13 notice has been served.
This provides clearer predictability for tenants, however, the elimination of the ability for landlords to increase rents to respond to fast-moving market conditions will need to be carefully managed by setting realistic and appropriate rent levels from the outset.
The RRA also prohibits advanced rent and bidding wars. Landlords cannot accept any higher offers than the advertised rent. Payment of advance rent for new tenancies after
1st May will be limited to one month’s rent, which is payable before the tenancy begins.
Another major change is the removal of blanket bans on tenants with pets or children. Landlords must not unreasonably refuse requests by tenants to have a pet in the property. In the same vein, anti-discrimination rules now prevent landlords from rejecting applicants based on benefit status or having children.
While these immediate changes will certainly impact the sector, there is
also significant change scheduled for further down the line. In late 2026, the Private Rented Sector Database will be rolled out. This means all landlords must register their properties and tenancies and pay a membership fee, and failure to do so will restrict access to possession routes and lead to potential fines.
The RRA also supports future reforms aimed at improving safety and energy efficiency. Energy Performance Certificate (EPC) C standards are anticipated to be implemented by 2030, and the Decent Homes Standard is set to apply to the private rented sector from 2035 to 2037.
In addition, Awaab’s Law will impose mandatory timeframes on repairing dangerous hazards, namely that of black mould, and from 2026 to 2028, the Private Landlord Ombudsman will launch in phases, creating a free and binding dispute
resolution mechanism to deal with issues and disputes raised by tenants.
Ultimately, the RRA represents a decisive shift in the balance of power within the PRS. While tenants gain stronger rights, landlords face higher compliance burdens and more constrained financial modelling assumptions. For brokers, lenders, conveyancers and advisers, the RRA is not merely regulatory reform, but a new operating framework.
The coming years will be testing but reward those who adapt early: updating internal policies, reviewing portfolios, preparing for compliance, and navigating this transformed landscape with clarity and foresight. ●
The beginning of the year is o en a time for reflection. It brings fresh starts, new goals, and New Year’s resolutions, some of which focus on improving personal finances. A er the pressures of Christmas spending, it’s common for people to step back and reassess their financial position, considering what they could do differently to start the year on a stronger footing.
As a result, in Q1 we typically see a notable increase in clients looking to consolidate their debts, and second charge mortgages are o en a suitable solution to achieve this.
Statistics from the Finance and Leasing Association (FLA) consistently show that second charge mortgages are primarily used for debt consolidation, home improvements, or a combination of both. While this trend is usually evident throughout the year, demand is o en more pronounced in the first few months.
Many households emerge from the festive period with a desire to simplify their finances, reduce monthly outgoings, and regain control early in the year. When approached correctly, second charge mortgages can play a valuable role in helping clients achieve desired outcomes, without disrupting an existing mortgage that still works well for them.
With more lenders entering the second charge market and criteria becoming increasingly competitive, it’s more important than ever for brokers to recognise when this type of lending is appropriate and genuinely adds value for the client. At The Loans
Second charges can play a valuable role in helping clients achieve desired outcomes”
Engine, we place a strong emphasis on opportunity spo ing, and we regularly support brokers through training and case reviews to ensure potential solutions for their clients aren’t overlooked. In practice, there are several common scenarios where a second charge mortgage may be worth considering. Declined for a further advance:
One of the most frequent situations we see is where a client has been declined for a further advance, o en because the purpose of borrowing is debt consolidation. Some lenders are restricted in this area, whereas second charge lenders are typically far more flexible. In these cases, a second charge mortgage can allow the client to consolidate debts, reduce overall monthly commitments, and thus, simplify their finances – all while retaining their existing mortgage.
Protecting a preferential rate or avoiding early repayment charges (ERCs): Another common scenario involves clients who don’t want to remortgage to raise extra funds. They may be benefiting from a highly competitive rate or face significant early repayment charges if they switch too early. A second charge mortgage can provide access to additional funds without disturbing the client’s current deal. This o en results in a more costeffective and practical solution than
STEVE NOBBS is director at e Loans Engine
remortgaging, particularly where their existing mortgage is currently fit for purpose.
Unsecured borrowing is not meeting their needs: Some clients explore unsecured personal loans but find they can’t raise sufficient funds or are offered unfavourable terms. In contrast, a second charge mortgage may allow them to borrow the required amount over a longer term, o en resulting in a lower monthly commitment and more manageable repayments.
Second charge mortgages won’t be suitable for every client, but when used in the right circumstances, they can play a valuable role in delivering positive customer outcomes. They can help simplify finances, ease pressure on monthly budgets, and provide clients with a practical route to regain control of their finances, particularly at the start of the year, when many are reassessing their financial position. For brokers, this reinforces the importance of considering second charge lending alongside all other available options, allowing them to be er support their clients in achieving their financial goals. ●
The second charge market has entered 2026 in a strong position with the sector reported to have experienced significant growth in 2025. As the Finance and Leasing Association (FLA) reported there was a 27% increase in new business volumes in November last year compared to the previous year. What was once regarded as a niche, tactical product, seconds have started to become a mainstream part of holistic mortgage advice, used to unlock trapped equity and provide flexibility in a higher-for-longer rate environment.
Volumes, lender participation and broker confidence have all grown materially. The real question now isn’t whether the second charge market will continue to expand – it’s how it grows, and whether the competitive changes we’re seeing genuinely prioritise good customer outcomes or simply focus on driving profit.
The fundamentals are compelling. Millions of borrowers remain on historically low first-charge fixed rates, many unwilling – or unable – to refinance at today’s higher pricing. At the same time, household budgets are under pressure from the higher cost of living and in other scenarios a wish to carry out home improvements, fund private schooling and support laterlife borrowing needs.
Second charges sit neatly in this gap. They preserve a favourable first-charge rate, provide speed and flexibility, and increasingly allow advisers to deliver be er overall cost outcomes than a full remortgage. From a pure advice perspective, they are now a core consideration rather
than a contingency. It is no surprise, then, that new lenders continue to enter the space.
Increased lender choice has undoubtedly improved pricing, and product breadth. But with that comes a risk the market must acknowledge: too many lenders chasing the same borrowers can distort behaviour.
We are already seeing signs of margin compression, increasingly nuanced credit policy flexing, and in some cases, a subtle reframing of risk to justify volume. That should give senior professionals pause.
Second charge lending is a regulated mortgage business. Yet, I have a growing concern that some propositions are being positioned in a way that feels closer to unsecured lending than to fully aligned mortgage advice under Mortgage Conduct of Business (MCOB) principles.That is not an accusation, but it is something the industry should keep an eye on.
The industry must guard against allowing competitive pressure to dilute standards. Key questions advisers and lenders alike should be asking include:
Are affordability assessments robust under stressed scenarios, not just today’s rate?
Is the customer genuinely be er served by layering secured debt rather than restructuring?
Are loan terms, consolidations and future flexibility being explained clearly – or merely justified? Would this recommendation stand up to scrutiny from the customer, the regulator and our peers?
The risk is not that second charges are inappropriate – far from it. The risk is that they become too easy to justify,
BUSTER TOLFREE is managing director –mortgages, BTL and bridging at United Trust Bank
particularly in complex cases where speed, equity and short-term relief are prioritised over long-term outcomes.
The second charge market has benefited enormously from clear regulatory oversight by the Financial Conduct Authority (FCA) and from the professionalism brought by advisers who understand MCOB inside out.
As competition intensifies, the industry should resist the temptation to view regulation as a box-ticking exercise or an obstacle to innovation. Instead, it should be the anchor that differentiates high-quality lenders and advisers from volume-driven entrants. Markets that forget this lesson tend to relearn it the hard way.
Second charges are no longer proving their relevance – they are proving their maturity. With that comes responsibility. For lenders, it means pricing for sustainability, not just market share. For brokers, it means advice that is demonstrably holistic, not transactional. For the industry as a whole, it means ensuring growth does not come at the expense of trust.
If the sector gets this right, second charges will continue to earn their place as a respected, regulated and customer-centric solution. If it doesn’t, the risk is not regulatory intervention alone, but reputational damage that takes far longer to repair. 2026 will show which side of that line the second charge market chooses to stand on. ●
For much of its history, second charge lending has been defined by product rates, criteria, loan-to-values (LTVs) and speed. Access to capital was the story, and innovation focused on expanding who could borrow, how quickly decisions could be made, and how flexibly equity could be unlocked.
But as we look forward in 2026, something quieter, and arguably more significant, is happening in the background. The competitive advantage in second charge lending is no longer access. It is perspective.
In today’s market, borrowers are not short of options. Product ranges are broad, technology has streamlined processes, and advisers can source faster than ever.
What you could argue is becoming harder is understanding which option genuinely delivers the best outcome for a customer when navigating increasingly complex financial lives. This is where the real shi lies.
Second charge lending now sits at an intersection of multiple pressures: first charge fixes that borrowers are reluctant to disturb due to an uncertain market, rising living costs, and an ageing homeowner population si ing on high equity. Yet consumer credit figures are rising, and this short-term available credit, together with high living costs, is creating a storm.
These are not simple borrowing decisions. Customers are weighing trade-offs between short-term affordability and long-term costs, between certainty and flexibility, and between immediate need and future resilience. In this context, the value of second charge lending is
not simply that it exists, but that it is properly understood.
Objectivity ma ers because second charge is rarely the obvious answer. It is the considered one.
But it is a sector that is growing; based on historic Finance and Leasing Association (FLA) numbers and our own market insights, Q4 2025 saw the market 35% up on the same time last year and a massive 80% higher than two years ago. We believe that the growth is sustainable and likely to be achieved.
As product and lender choice has expanded, the role of advice has become more central, not less. The best outcomes increasingly depend on advisers being able to step back, assess the full picture, and explain not just what a customer can do, but why one route may be more suitable than another.
That places a growing responsibility on the entire market ecosystem –lenders included.
Lenders are uniquely placed to influence outcomes through how they structure propositions and how they work with advisers to navigate more complex cases: customers with vulnerabilities, layered credit histories, or changing circumstances that do not fit neatly into automated models.
It means recognising that in a mature, regulated market, the strongest partnerships are built around shared responsibility for outcomes, not just approvals.
The regulatory framework in the UK already points in this direction. The Consumer Duty has sharpened the industry’s focus on foreseeable
JONNY
JONES is CEO at Interbridge Mortgages
Perspective [...] and prioritising long-term outcomes is where the real di erentiation now sits”
harm and customer understanding. But beyond regulation, there is a commercial reality; lenders who consistently support be er outcomes will earn trust, loyalty and sustainability.
Complaints and reputational damage are o en the delayed symptoms of poor understanding earlier in the journey. Investing in clarity, perspective and advice led processes is not a cost, it is risk management in the highest order. Second charge lending, when done well, can be transformative. When done poorly it can be misunderstood. The difference lies in how decisions are framed, explained and supported.
None of this diminishes the importance of competitive products. But as we progress through 2026, the leaders in the second charge market will be those who recognise that products are only the starting point. Perspective, understanding the customer’s broader context, adviser judgement, and prioritising longterm outcomes, is where the real differentiation now sits. It is a quieter shi than new product launches, or technology announcements. But it is one that, I believe, will define the next chapter of second charge lending in the UK. ●
One of the key trends of second charge lending at this time of year is the number of enquiries from advisers whose clients want to raise funds to pay January tax calls. It might seem odd that businesspeople have not planned their tax money accordingly, so we insist on knowing why they didn’t have enough squirreled away to pay, and how they will pay next year. In most cases, as we discovered, many businesspeople simply reinvested profits, which in turn le them short when it came to handling tax calls. In a market where annual lending now totals close to £2bn, tens of thousands of new agreements such as these are completed each year.
The seconds market has grown by more than 30% since 2020, making it one of the fastest-growing specialist lending sectors. In fact, there is evidence that second charge lending is beginning to rival bridging finance in terms of volume. Second charge mortgages have also outperformed some traditional mortgage segments in growth, including certain buy-to-let (BTL) and home mover categories.
Rising house prices over recent years have increased available homeowner equity, making second charge mortgages a viable funding option. Higher interest rates on firstcharge remortgages have encouraged borrowers to look at alternatives rather than refinance their main mortgage and financial advisers are beginning to understand the advantages of a second charge option as the product is increasingly seen as a flexible financial planning tool rather than a last resort option.
As a side note, second charge mortgage new business volumes grew by 27% in November 2025 according to the Finance & Leasing Association (FLA). Not only did business volumes grow significantly that month, but
the second charge mortgage market has reported growth in new business volumes in all but one month in 2025. The trend looks like it is going to continue in 2026.
However, rapid growth in the second charge mortgage market inevitably puts pressure on speed, accuracy and risk management. It is against this backdrop that technology, particularly artificial intelligence (AI), is beginning to play a more prominent role.
AI and its effect on the mortgage market is a topic which has already had plenty of airing. From our perspective as a major lender in the second charge sector, we see the benefits of AI, but it would be foolish not to acknowledge the other side of the coin; how AI can mask significant potential drawbacks.
On the face of it, AI looked like the answer to the perennial issues surrounding the need to speed up the mortgage process. Its ability to help package applications more quickly and accurately means that efficiency can be boosted. It provides underwriters with tools that, when blended with their human expertise, creates a more robust framework for ge ing applications through to completion. For brokers AI will help streamline processes surrounding the packaging of cases and make the whole exercise more efficient. Affordability
assessments become easier to prove –especially useful when professional landlords are relying on accurate assessments of their property portfolios, for example.
However, in all the hype about the crucial role that AI can perform to support the mortgage process, we must remember that there are also some negatives to consider. The prospect of AI contributing to a higher risk of fraud needs to be taken into account. AI, while being a particular benefit to the mortgage industry can also be used to increase the risk of an increase in fabricated wage slips and other supporting documentation. This means that lenders are going to have to be more aware of the potential for false documents being presented to support applications.
So, AI can become a double-edged sword unless it can be controlled properly. The next few years will reveal whether or not AI can police itself, allowing lenders and brokers to extract the maximum benefit and minimise the more negative aspects of how it can be used. ●
If I had to name the two biggest trends shaping the intermediary mortgage market today, they would be the rise of artificial intelligence (AI) and the growing demand for tailored advice. At first glance, these might seem contradictory. One is about technology and automation; the other is about human insight and personal service. But look closer and it’s clear they complement each other perfectly. Together, they create a significant opportunity for brokers and borrowers, provided advisers overcome any innate fear of technology they may have, and embrace its benefits. Those who do could benefit from a rare chance to grow their businesses without having to grow their wage bill and help more borrowers secure the homes they want.
This matters because the market is more complex than ever. Borrowers face high house prices, cost-of-living pressures, and often have multiple or non-traditional income sources. Advisers need quick access to a wide range of information and time to understand individual circumstances. Meeting these demands, alongside rising regulatory requirements, has been tough – especially for smaller firms. Technology can help. From research to routine admin, digital tools free brokers to focus on what matters most.
So why the hesitation? Many brokers worry that “AI will take our jobs,” “borrowers will use tech to do it all themselves,” or “I don’t have time to learn how to use it.” It’s human nature to fear change. The fight-or-flight instinct kicks in, and their inner voice
starts listing worst-case scenarios. But the evidence shows AI is more friend than foe. In fact, when used well, it can make brokers indispensable.
Recent research we conducted found that nearly half (47%) of brokers are optimistic about technology’s role and 39% feel relaxed about it. Most see AI and digital tools as ways to enhance –not replace – their advice.
Many already use tech to cut admin and improve service. For example, we’ve introduced a digital booking system for business development managers (BDMs) via our customer relationship management (CRM) platform. Brokers can book appointments directly using a simple link, with real-time diary access and location details, avoiding the usual back-and-forth emails.
Since launch, this has enabled hundreds of appointments and freed BDMs to provide more proactive support instead of admin.
Still, 24% of advisers remain concerned about AI. Brokers see the benefits but struggle to find time to embed new tools; ironically, the very tools that would save them time.
So, what’s the answer? There’s no single fix or silver bullet. But brokers can start by identifying which tools will make the biggest difference in line with their own business priorities, whether they are streamlining admin, improving data management or enhancing client insight.
Adopting changes gradually can help them manage cost and avoid overwhelm – think of it as tackling the challenge in chunks; starting with the areas that will deliver the most immediate impact and then building from there. The benefits go beyond efficiency, too. AI can help brokers
JEREMY DUNCOMBE is managing director at Accord Mortgages
analyse complex borrower profiles faster, spot patterns, and match clients to lenders more accurately. It can even support marketing by identifying trends and helping brokers target the right audiences.
Used wisely, technology becomes an enabler, not a threat. Our freeto-access Growth Series information resource can help, providing relevant content including blogs on the best AI tools for brokers, and how brokers can unlock AI’s full potential.
Of course, none of this replaces the human touch. Borrowers still want reassurance, empathy, and guidance through what is often the biggest financial decision of their lives.
Technology can’t replicate that. But it can give brokers the time and tools to deliver it better. In fact, the savviest brokers will use tech to supercharge their advice, reach more clients, and grow their businesses.
The mortgage market isn’t getting any simpler. Economic pressures, and evolving borrower needs mean advisers are more essential than ever. But being essential doesn’t guarantee success. Brokers who embrace technology will have a competitive edge. They’ll be faster, more informed, and more available to their clients.
Ultimately, whether brokers view AI as an opportunity or a threat is up to them. But the evidence is clear: technology is here to stay.
The tools exist. The benefits are proven. The question is whether brokers are ready to take the first step. ●
For years, the mortgage industry has talked about digitisation as progress.
Paper forms became PDFs. Wet signatures became e-signatures. Yet brokers are still spending days clarifying information that has already been submitted through a form. Digitising a broken process does not fix it. It simply makes people hit friction faster.
Nowhere is this clearer than in specialist lending. These complex cases do not fail because brokers lack information. They fail because systems were never built to understand nuance. As a result, lenders are forced to revert to manual processes to make sense of it all. As we move into 2026, lenders need infrastructure that can interpret policy and precedent, not just move data around.
One of the biggest barriers to adopting artificial intelligence (AI) in secured and specialist lending is trust. Brokers and underwriters are rightly sceptical of black box decisions, particularly in a regulatory environment shaped by Consumer Duty.
Intelligent infrastructure cannot replace judgement. It must support it. In a specialist case, technology should do the analysis while humans verify and confirm the outcome. It should handle the mundane but critical underwriting work that does not require specialist judgement, such as calculating usable income for a selfemployed applicant based on trading history, determining how much variable income like bonuses can be relied on, or flagging cases where rental income does not meet interest coverage requirements.
The underwriter can then apply expertise immediately, with evidence in front of them. Removing the basic challenges of transforming data for an
underwriter frees up mental capacity to focus on what actually matters: assessing the case based on the evidence provided, while maintaining a clear audit trail.
Specialist lending, like vanilla lending, is still weighed down by documents. Bank statements, accounts, payslips, company structures. Most systems treat these as files to be stored. Intelligent platforms treat them as structured data.
When a broker uploads a document, the system should extract, verify, and cross-check the information against lender policy instantly. This removes the endless back-and-forth caused by missing data or avoidable queries, ensuring cases are fully and correctly packaged upfront.
We are seeing lenders process specialist applications up to three times faster when structured, verified data replaces manual checks. That speed is not about rushing decisions. It is about eliminating unnecessary friction.
Specialist lenders need to innovate continuously, whether through new products, evolving policy, or more sophisticated affordability assessments. Yet legacy technology means even simple changes can take months to implement. That is not innovation. It is constraint, dressed up as progress.
True agility comes from no-code infrastructure. Credit and policy teams should be able to update rules themselves and see them live immediately.
If a system cannot reflect a policy change within days, brokers will feel the gap long before IT catches up and will move to lenders who respond faster.
Intelligent technology removes the administrative burden. This frees brokers to advise and underwriters to assess risk properly.
JOY ABISAAB is CEO at Mast
The next evolution is agentic underwriting. Data is automatically collated, structured, and assessed against underwriting policy, informed by previous decisions and lenderspecific risk logic. A first layer of reasoning is applied before the case ever reaches a human. The system arrives with a recommended outcome, the supporting evidence, and the policy rationale already applied. Only then does the underwriter step in. Not to gather information, but to confirm, challenge, and apply judgement where it truly matters When technology handles execution and pre-analysis, underwriting timelines that once took weeks can be reduced to days without compromising risk. For brokers, this means faster decisions, fewer resubmissions, and more reliable outcomes for clients. For lenders, it creates a genuine and defensible competitive edge.
This is not about removing brokers or underwriters. Final decisions still sit with people. It is about stripping away repetitive, low-judgement manual work that is prone to error and too often mistaken for risk management. When systems apply policy, learn from precedent, and present a complete, evidenced recommendation, humans are freed to do what machines cannot: exercise judgement.
In specialist lending, speed without intelligence creates risk. Intelligence without human oversight creates mistrust. Agentic underwriting delivers both. In specialist lending, the future belongs to systems that think first and humans who decide last. ●
Marvin Onumonu speaks with Claire Van der Zant, CEO of Novus Strategy, about horizonal digital integration and the firm’s strategic direction following her appointment
When Claire Van der Zant was appointed CEO of Novus Strategy in April 2025, she joined the business at a time of increasing complexity across property and advisory markets. With transactions becoming more layered and decision-making more time critical, her focus has been on strengthening Novus Strategy’s role as a strategic partner to its clients, rather than a generalist consultancy.
Her route into the role was anything but linear. Having spent years in financial services and payments – including leading growth for a legal sector payments startup – she first encountered Novus through founder Chris Williams.
Van der Zant says: “I was ready to step back from the chaos, but I didn’t want something safe or incremental. The conversations with Chris made it clear that Novus had a genuinely unique vantage point across the home buying and selling infrastructure. The opportunity was to take that and apply relentless focus to a single, critical problem.”
Her first months in the role were about combining that vantage point with a much sharper definition of what Novus would – and would not – do. Van der Zant adds: “When I joined, Novus had this incredible expertise in home buying and selling, but it hadn’t always had the sharpest focus. The early priority was to be really clear and build a clear education drive into the market.”
As property transactions grow more complex, Novus Strategy’s advisory role has expanded beyond traditional models of consultancy. Rather than focusing solely on single organisations or vertical systems, clients increasingly require support that spans structure and execution across the entire transaction journey.
Van der Zant says: “Where we are now is what we call the second phase of transformation. The first phase was about everyone in the transaction going on a digital maturity journey internally. Now
the challenge is in the handoffs between actors – the bits in between estate agency, broking, lending, and conveyancing. That’s where the friction lies.”
Those handoffs, she notes, are where brokers most noticeably feel the pain. She adds: “If you think about a broker’s daily experience, it’s manual rekeying, a lack of clarity from lenders, inconsistent requirements and decisioning, and chasing information that sits somewhere else in the chain. Brokers are fantastic at providing advice and supporting customers; lenders can design products. The problems sit in the communication and data flow between them.”
This shift has reinforced the firm’s focus on integrated thinking, helping clients align commercial, operational, and digital considerations throughout the transaction process.
She explains that the strategies that brought success in the past will not necessarily drive future growth. Traditionally, organisations have focused narrowly on their own systems – like core banking, origination platforms, and broker customer relationship management systems (CRMs). Now, she says, they need to broaden their perspective and consider their role across the entire transaction process.
A key element of this approach is Horizontal Digital Integration (HDI). Novus Strategy uses HDI as a strategic framework to connect systems and stakeholders across a transaction.
Van der Zant says: “HDI isn’t a platform, it’s a framework. It’s about how organisations integrate and connect into the ecosystem so they can deliver a simple, predictable, certain transaction to customers. The technology exists – the problem has never really been inside the individual actors; it’s in the handoffs. HDI helps businesses understand where the industry is going, what the priorities are, and what the sequence is to get there.”
For Van der Zant, the point is not to add yet another system, but to make existing investments work harder. She adds: “We’re not saying,
‘Throw everything away and start again.’ Most organisations already have substantial technology estates and data assets. HDI gives them a lens to say: what do we already have, how do we surface the right data at the right time, and how do we connect into an emerging ecosystem of data standards and trust frameworks?”
The result, she says, is greater clarity, improved collaboration and more informed decision making for clients navigating complex property transactions. She states: “It’s there to unlock value quickly against real pain points –manual rekeying, missing or out of date information, lack of predictability. It doesn’t compete with large transformation programmes; it protects them and gets proof of concepts into market using real data and real partnerships”.
Collaboration remains central to the firm’s model, particularly with lenders, conveyancers, proptechs and other professional partners. Although Novus has not yet been directly engaged by brokers, much of its work is designed with their experience in mind.
the value of cross-sector insight in shaping future strategy.
She notes: “We put that immersion tour on very deliberately, because HDI can sound theoretical. Aviation embodies HDI.
“Any two pilots can work together; they may never have met, but the processes, data, information, and communication are universal. You cross borders and nothing stops – the whole system flows because the industry-built processes, not just systems, on shared data and standards. We wanted people to touch and feel that, see for themselves how powerful that level of integration can be.”
The experience, she says, helps industry stakeholders visualise what a fully integrated property ecosystem could feel like. She argues: “That’s the kind of predictability and calm we should be aiming for in home buying and selling – a journey where the complexity is expertly managed behind the scenes, not pushed onto brokers and consumers.”
Van der Zant says: “We do a lot of work with lenders and with proptechs. A big part of that is in service of making the broker role simpler. When information doesn’t move clearly across the transaction, brokers end up being the human glue in the middle – explaining delays they haven’t caused.”
For brokers specifically, her message is to stay close to how the infrastructure is evolving. According to Van der Zant, those individuals and companies who help shape the next stage – by influencing how data standards are applied and how trust frameworks work day-to-day –will find their positions strengthened rather than undermined.
Regulation, she adds, is a constant backdrop. She explains: “The regulatory drum never stops beating. Things like the Smart Data Bill and Consumer Duty absolutely shape what we need to consider in the home buying and selling industry. We’re closely plugged into that ecosystem, but we don’t position ourselves as regulatory transformation consultants. We work with clients on how these changes intersect with the customer journey.”
Looking forward, Van der Zant says that Novus continues to broaden its perspective. An example of this is through initiatives such as the Spring Aviation Immersion experience, reflecting
By the end of 2026, the ambition is for Novus Strategy to be recognised for its integrated, strategic approach to complex decision making, and for its tangible improvements in the customer journey.
Van der Zant explains: “This year is about execution. For a long-time there have been shiny new things claiming to solve everything overnight in a very fragmented, heavily regulated market. There is no silver bullet. But we have now landed on how to rewrite the fabric of this industry – and this is going to work.
“The job is to get proof of concepts and pilots into market that prove against outcomes, not just reskinning journeys that still rely on manual rekeying.”
Van der Zant says she wants Novus to be known as the team that helped the industry progress from its initial phase of digitalisation to full HDI. She also sees a clear, grounded role for artificial intelligence (AI) within that future.
She adds: “AI is exposing the same structural problems brokers have been dealing with for years. It only works when the underlying data and handoffs work. It’s an AI capability, not an independent thinker.
“Where it can have real impact is decision speed, case progression visibility, and predictability around service level agreements (SLAs). It’s not here to wipe out jobs. If anything, leaning in and understanding what AI can and can’t do will help relieve pressure on brokers, lenders, and conveyancers alike.” ●
Everyone is talking about artificial intelligence (AI). And who can blame them? Automation has incredible benefits. When implemented correctly, AI and technology mean faster, smarter, more powerful ways of working.
But as the industry accelerates towards an AI-enabled future, a more uncomfortable question is emerging: What happens when technology advances faster than the people using it? Because right now, the industry is aligning automation with progress, and if we’re not careful, customer success could pay the price.
The industry could do better AI and automation absolutely belong in mortgage technology. They remove friction and enable brokers to focus on advice rather than admin. However, while smarter systems may streamline workflows, they do not reduce the need for human support.
As platforms become more sophisticated, they also become more complex. Without equal investment in customer success, automation will generate more problems than it solves. We might be able to reduce paperwork and admin with AI, but without dedicated customer support to help brokers, we risk replacing inefficiency and admin with under-utilisation and frustration.
2026 research from Accenture into the future of banking highlights a striking trend: even as financial services become more digital, people are increasingly nostalgic for human interaction. If that’s true in everyday banking, it is even more true in mortgages.
Mortgages are complex, regulated and emotionally charged. Brokers don’t just need powerful systems –they need confidence in how those systems support advice, compliance and client outcomes. That confidence cannot come from technology alone.
One of the most overlooked assumptions in mortgage technology is that customer support is a cost to be managed. In reality, customer success is part of the product itself.
Customer success is not about fixing issues if something breaks. It’s about ensuring brokers consistently realise value from the technology they invest in. As platforms evolve, the gap between what technology can do, and what brokers actually use, widens. Without proactive, well-resourced customer success, even excellent technology risks being perceived as difficult, frustrating or poor value. And once that perception sets in, it’s a tricky road back.
In practice, there are clear signs that technology is genuinely supporting advisers, rather than simply automating tasks. One indicator is whether advisers have multiple ways of ge ing help when they need it, whether they are mid-case and able to jump on live chat, pick up the phone or follow up by email. Another is whether support fits around the working day. Access to training videos, guides and FAQs allows advisers to revisit information in the evening or quickly find an answer without having to wait for a response.
Strong customer success also shows up in proactive education, not just reactive support. Regular live webinars or walkthroughs of new
PUDDEPHAT is head of marketing at Mortgage Brain
features help advisers understand how technology should be used, rather than discovering changes through trial and error.
Who delivers that support is just as important. A dedicated customer success team is be er placed to understand how advisers actually work than a generic helpdesk, particularly when dealing with complex or time-sensitive cases.
Clear, reliable communication should underpin all of this, so that advisers are not le guessing about updates or changes but are given clear guidance on what improvements mean in practice for their workflow and, ultimately, for their clients.
As AI becomes embedded across mortgage technology, featurelevel differentiation will become an outdated prospect. Platforms will look increasingly similar on paper. What will not be easy to replicate is excellent, human-centred customer success.
Providers who invest properly in customer success send a clear signal: we are invested in broker outcomes. That commitment shows up in smoother onboarding, stronger adoption, greater confidence and longer-term relationships. Technology should amplify human expertise, not a empt to replace it.
The companies that lead the next phase of mortgage technology will be those that stop treating customer success as an operational necessity and start treating it as a strategic advantage. ●
With the market expected to strengthen this year, fuelled by lower interest rates, advisers are expected to see demand rise as property transactions pick up. Alongside this, 2026 is shaping up to be a significant year for client remortgages and product transfers.
Within this environment, general insurance (GI) presents a powerful opportunity to deepen client relationships, support good customer outcomes, and generate additional income.
Our latest annual adviser research highlights both the opportunity and the challenge. In 2025, we surveyed 485 financial advisers and found that 83% want to grow the volume of GI business they write. However, half admi ed they sometimes miss opportunities to discuss or sell GI.
As the year gathers pace and good intentions risk slipping down the priority list, the focus should be on turning GI into a habit. Beyond simply remembering to raise the subject, here are some tips for effective GI conversations today, so that advisers can ensure more of their clients benefit.
Even with all the integrations and automated quotes available, nothing replaces the benefits of a meaningful conversation. Fact-finding remains the foundation of good advice, but effective GI conversations go beyond basic property details. Asking the right questions helps advisers connect insurance back to what ma ers most to the client.
Questions such as “what’s important to you about your insurance?”,
“what do you expect this policy to do for you?” and “are there any items you’d want to be absolutely sure are covered?”, demonstrate genuine interest and encourage meaningful dialogue. Clients should feel understood, not funnelled towards a standard product.
For remortgage clients in particular, it’s essential to check whether circumstances have changed. Have they purchased any high-value items? Started working from home? Have they renovated or extended their home, or are they planning any building work soon? These prompts help advisers quickly assess whether existing cover is still appropriate and competitive.
Crucially, advisers should be led by what the client tells them. For example, if a client mentions a child moving out for university, it creates a natural opportunity to discuss relevant features - such as Paymentshield policies that include up to £10,000 of contents cover for household members living away from home.
Home insurance premiums have risen across the market in recent years, largely due to higher rebuilding costs. While prices are now easing (Consumer Intelligence reports a 1% average decrease in the last three months and a 4.8% fall in Q3 2025), premiums remain above pre-2024 levels. As a result, some clients may gravitate towards more slim-line policies. This is where advisers can add real value.
Clients appreciate guidance on where savings make sense and where they don’t. Discussing optional extras such as home emergency or personal possessions cover, and explaining their
benefits, helps clients make informed decisions rather than simply cu ing cover. Using real-world examplessuch as the cost and disruption of a boiler breakdown - can make these discussions more tangible.
For advisers who don’t feel like they have the time or resource to handle GI in-house, referring to a trusted partner is a straightforward mechanism to still help drive good customer outcomes. It’s a route growing in popularity: our referral volumes increased by almost 40% in 2025 compared to 2024.
However, consistency is key. If GI discussions are o en missed with remortgage or product transfer clients, for example, building referral into the standard process can help close that gap. Quality also ma ers. Clients should be warmed up and expecting contact, as this significantly improves engagement.
At its heart, GI is about connection: connecting advice to real lives and policies to priorities. Advisers who build strong GI habits don’t just reduce missed opportunities - they reinforce their role as trusted partners throughout the home-owning journey and beyond.
By asking be er questions, linking cover back to what ma ers and using referral where appropriate, advisers can ensure GI remains a natural and integral part of the client relationship. ●
Ask most advisers about protection and you will hear the same thing.
Clients generally know it ma ers, but they rarely feel any urgency until something forces the issue. By that point, options can be more limited or more expensive.
That gap between awareness and action sits at the heart of many protection conversations. Mortgage advisers and appointed representatives (ARs) working across the protection industry see it regularly, particularly where life cover or income protection plans have not been reviewed for several years.
Employer benefits are o en the first assumption. Clients will point to death-in-service or basic accident cover and assume it fills the gap. In practice, those benefits are usually limited, tied to employment, and rarely aligned with real household costs. Once mortgages, childcare, or long-term commitments are factored in, the shortfall becomes obvious.
Product confusion plays a role too. Accident-only income protection is a common example. Clients hear the phrase “income protection” and assume broad cover, without appreciating how narrow accidentonly policies can be.
Whole of life policies raise different questions, o en around why they were set up in the first place and whether they still make sense within the wider insurance market. None of this is unusual. These are recurring conversations, not edge cases.
Protection tends to land be er when it is linked to something tangible. A new mortgage, a growing family, or a
change in employment status usually sharpens focus, particularly when conversations turn to life insurance as part of the lending discussion.
Mortgage advisers are already involved at these moments, which makes protection a natural extension of the discussion rather than a bolt-on.
Where things o en fall down is treating protection as a single conversation. Many clients need time to sit with the idea. Revisiting life cover or income protection plans later, once the immediate transaction has se led, o en leads to more realistic decisions.
Advisers who are comfortable returning to the topic usually find the conversation becomes easier over time. Confidence comes from repetition, not from perfectly phrased explanations.
Cost is the objection advisers hear most, but it is not always what it seems. Clients are o en reacting to uncertainty rather than the premium itself. When the cover is presented as a single figure with li le context, it feels expensive by default.
Breaking protection down helps. Layering life cover with income protection, adjusting benefit levels, or explaining how accident cover fits into the picture can make premiums easier to digest.
Talking openly about loaded premiums, renewal commissions, and the potential impact of clawbacks also removes suspicion.
In practice, clients commit when the numbers feel proportionate and when they understand what the cover would actually do if it were needed.
The regulatory regime shapes how advice is delivered, whether advisers like it or not.
OLLIE POPHAM is senior manager, sales at Cavendish
Con dence comes from repetition, not from perfectly phrased explanations”
Consumer Duty has changed how protection advice is scrutinised, particularly within larger distribution channels where consistency is more closely monitored. In practice, this can create tension for advisers who are trying to follow the process without le ing conversations feel rehearsed.
Clients are usually less interested in the regulatory framework behind a recommendation and more interested in why it makes sense for them at that point in their lives.
Most clients are not chasing ideal solutions. They want reassurance that their financial security would hold up under pressure.
This is where advisers earn trust. Real examples, plain explanations, and a willingness to revisit protection conversations over time tend to have more impact than detailed product comparisons. When protection is treated as part of the broader advice relationship, rather than something squeezed in alongside specialist lending cases or bridging finance, engagement improves.
Protection rarely dominates meetings, but when it is ignored, it is o en missed later. Advisers tend to understand this instinctively, even when clients are reluctant to engage with it. ●
While 2007 is o en seen as the high-water mark for the mortgage market, with gross lending peaking at £363bn, 2026 has the potential to be the busiest year on record for brokers.
UK Finance forecasts £300bn of new lending and £261bn of product transfers (PT) this year, meaning total lending could hit an astonishing £561bn in total. With PTs only becoming a significant part of the market in the past decade, it means that total activity in 2026 should eclipse 2007 by some margin.
We are now nearly six years on from the pandemic and the ‘race for space’ and lending spike that followed it. As a result, an astonishing 1.8 million fixed rates are due to expire this year.
Therefore, the most obvious opportunity this year for brokers lies in the refinance market. However, what has largely gone underappreciated is how this refinance boom also offers up a significant protection opportunities for advisers and clients alike.
Of those 1.8 million projected borrowers, nearly a million will be rolling off sub-2% 5-year fixed rates and are likely to see a significant increase in their monthly repayments, according to the latest Financial Conduct Authority (FCA) data.
Many of these borrowers may not have considered their cover in over five years. In that time, their circumstances may have changed significantly, due to marriage, moving jobs or perhaps starting a family. Therefore, a review is important. Some of these borrowers may also
need to extend their mortgage term to afford their increased outgoings.
This is where it is important to have deeper conversations with your clients, delving into what workplace sickness and employee benefits they have in place through their employers, as well as what savings provisions they have to cover their outgoings if they were unable to work due to illness or incapacity.
The remaining 800,000 or so borrowers will be on 2- or 3-year fixed rates, meaning they have already refinanced onto a higher rate since the Bank of England started hiking borrowing costs in early 2022. In most cases, these borrowers can look forward to a noticeable reduction in their monthly repayments when they refinance this year. This creates a different, but equally compelling, protection opportunity for brokers.
For borrowers, a drop in monthly repayments can feel like a windfall a er years of ongoing pressure on household finances.
The instinct may be to pocket the cash or rebuild savings, which is, of course, sensible. But having adequate protection in place is arguably just as important to safeguard income and family finances if the worst were to happen.
CRAIG HALL is director, strategic partnerships at LSL Financial Services
Over the past two years, the average fixed rate mortgage has fallen by around 1.12%, according to Moneyfacts data. On a typical £250,000 repayment mortgage over 25 years, that equates to a saving of roughly £163 a month.
Even using a portion of these savings could fund meaningful additional cover. For those who thought they couldn’t afford protection previously, framing it this way may make them realise that, actually, now they can.
Viewed this way, protection shi s from an additional cost or sacrifice to a pain-free way of strengthening a client’s financial resilience.
The refinance boom may dominate headlines over the coming 12 months, but it also offers a rare opportunity to demonstrate the broader value of advice. In a year when many borrowers face higher repayments and others enjoy falling costs, advisers will need to navigate multiple client scenarios, priorities and risks. That is where professional advice becomes indispensable.
With such divergent borrower experiences converging at once, the value of sound advice in 2026 will be huge. ●
This year, 1.8 million fixed rate mortgages are due to expire, according to a recent forecast from UK Finance.
That’s 12.5% more than the 1.6 million that matured in 2025 – which was already a big year for refinancing. As a result, many brokers around the country already have their work cut out scouring the market for the best available deals to suit their clients’ circumstances.
Affordability is a pertinent issue. Many borrowers with deals maturing this year will have been benefi ing from historically low pandemic rates of around 2%. Switching on to a new 4% or 5% deal will be a shock for many households, with monthly repayments likely to increase by hundreds of pounds per month.
Of those 1.8 million mortgages, many will be held by borrowers either at or approaching retirement age. These individuals are now likely to be in a very different financial position compared with the start of their previous mortgage term, making affordability an even bigger issue.
Bespoke assessments
Assessing a client’s affordability at this stage in life can also seem a complex undertaking. While they may have le – or be planning to leave – full-time employment, they could still have a part-time job, pension, savings and income from other sources like rental properties and investments. They may also have additional pensions and savings pots that they can draw from at a later date. However, these are assets that many lenders will fail to consider, preferring to take a one-size-fits-all approach that ultimately leads to a client’s rejection.
For this age group, affordability can be further impacted if a client is going through a divorce or separating from a partner they previously shared mortgage repayments with. They
might also still be supporting younger family members, helping them to get on to the property ladder or easing university costs.
So, it is important for brokers to find options from lenders willing to take an agile, holistic approach to lending to individuals who are at or approaching retirement age. O en, with a ‘can-do’ a itude and an underwriter willing to consider a client’s entire story, a solution can be found that fits the borrower’s needs and provides the necessary capital required.
It’s also not all about rates when dealing with later life clients. Instead, research should be carried out into the product options available as pairing a client with the right product o en makes a big difference to the maximum borrowing and rate available to them. Options available to later life clients now reach much further than equity release products (otherwise known as lifetime mortgages). Standard or retirement interest-only (RIO) mortgages are o en a far more appropriate fit for those only just entering retirement.
Education is key for advisers with clients in this age bracket, as properly understanding the products available
LEON DIAMOND is founder and CEO at LiveMore Mortgages
in this space as well as the individual lenders’ affordability criteria and accepted income streams can make the difference between delivering the best available solution for your client and failing to deliver a solution entirely.
At LiveMore, we offer later life products for anyone over the age of 50 and accept a wide range of income streams including self-employed, buy-to-let (BTL) and room rental income, with no minimum income requirement. Thanks to our LiveMore Mortgage Matcher® technology, in a few easy steps, we can take an instant and accurate snapshot of a client’s current and future affordability and put forward a range of suitable products with a maximum borrowing amount.
When it comes to advising on later life lending it’s all about looking beyond the high-street lenders’ cookiecu er approach to affordability and searching for solutions that maximise affordable borrowing – making every client’s dream of a comfortable retirement a reality.
Later life lending is no longer a side discussion outside of the mortgage mainstream. The needs expectations and financial behaviour of older homeowners have already shi ed, and now, regulation is starting to follow that reality, rather than work against it.
One of the clearest signs that later life lending is shi ing into the mainstream is the growing overlap between traditional mortgages and later life products for customers over-55. Many borrowers now take out mortgages that run well into retirement, o en without a clear plan for how those loans will be managed as income changes or pension provision falls short of expectations.
At the same time, lifetime mortgages and retirement interestonly (RIO) products have evolved, with greater flexibility, voluntary repayments and hybrid features that make them relevant far earlier in later life than was once the case. The old idea that there is a sharp line between ‘normal’ mortgages and later life solutions is becoming less credible by the day.
The Financial Conduct Authority (FCA) has been clear in its recent work that this blurring of markets is not a future problem but a current one. Its focus on enhancing later life lending, improving market readiness and considering holistic advice reflects a recognition that the system needs to adapt to how customers actually live, rather than how regulation has historically been structured.
Despite this shi , the structure of the market deserves a ention. There are around 179 active lenders in the wider mortgage market, compared with around 16 active lenders in the equity release space. There are estimated to be more than 35,000
mortgage advisers, yet only 6,000 or so hold the qualification to advise on equity release, with industry estimates suggesting only 2,000 are active.
This imbalance ma ers because it shapes customer outcomes. Large numbers of older homeowners are advised within a framework that naturally steers conversations towards mainstream products, even where a later life option may be more suitable or more aligned with the client’s wider needs.
The FCA’s intention to how advice silos may be reduced means this gap should begin to disappear. Advisers do not all need to become later life specialists, but they will need to be far be er at recognising when later life lending should be part of the conversation.
Wider financial planning trends are also pushing later life lending into the centre of advice. Recent research from Air highlights a sharp rise in pension withdrawals, underlining how many clients are already drawing on retirement pots earlier or more heavily than expected.
For advisers, this reinforces the holistic advice future; the need to look at the full picture, including income, pensions, property and family support, rather than treating the mortgage as a standalone decision. Clients increasingly expect joinedup conversations, and regulation is moving in the same direction, with outcomes, not product labels, becoming the key test.
As later life lending moves from niche to norm, advisers face a choice. They can wait for regulatory change to force a shi in approach, or they can start adapting now by improving front-end triage, asking be er questions of older clients and building clearer routes into specialist support where needed.
This is not about adding complexity for the sake of it. It is about reducing risk, improving suitability and ensuring clients are not denied access to options simply because of how advice is structured. Firms that engage early will be be er placed as regulatory expectations sharpen and as consumer demand continues to rise.
At more2life, we believe later life lending should sit naturally within modern mortgage advice, supported by clear information, practical tools and strong adviser partnerships. Our focus has always been on helping advisers understand where later life solutions fit, how they compare with mainstream options, and how they can be used responsibly to meet real client needs.
Through ongoing education, practical support and technology that improves certainty and confidence at an early stage, we aim to make later life lending easier to engage with, whether advisers are active in the sector or simply need to know when to refer.
We aim to track how the move from niche to norm continues to unfold, driven by regulation, demographics and client behaviour. The shi is already under way, and the pace will only increase.
Advisers who recognise this now, and who take steps to adapt their approach, will be be er placed to deliver good outcomes for older clients and to operate with confidence as expectations change. Those who wait may find that the market, and the regulator, have already moved on. ●
The first babies born in post-war Britain celebrated a milestone birthday recently, as the ‘Baby Boomer’ generation reached 80. Nine months on from Victory in Europe (VE) Day on 8th May 1945, the country’s birth rate started to surge. This demographic phenomenon –known as the ‘baby boom’ – resulted in almost one million births in 1946.
Approximately 470,000 baby boomers will mark their 80th birthday this year, according to our analysis. They join one of the UK’s oldest and fastest growing cohorts; the UK’s over-80 population is expected to hit 4,934,490 in 2036 and reach 6,234,990 by 2046.
As living standards, medicine and technology have improved, life expectancy has grown. The most recent official period life expectancy data from the Office for National Statistics (ONS), published December 2025, shows male life expectancy of 79 years at birth in the UK and 83 years for women. Female life expectancy at birth in 1946 was 69 years, while men’s life expectancy was just 64 years.
There are now approximately 15,300 centenarians (people aged 100 years and over) in England and Wales, a number that has doubled from only 7,280 in 2003. In 1946, there were fewer than 300 centenarians across both countries.
While only 1.7% of the male baby boomers who turn 80 this year can expect to live to 100, 3.8% of women can expect to live long enough to receive a le er from Buckingham Palace on their 100th birthdays in 2046.
Since the Second World War, the UK’s financial landscape has
changed fundamentally. The average UK house price was £1,459 in 1946 (approximately £53,503 in today’s money) compared to £271,000 today.
The financial landscape has changed a great deal, too. The UK State Pension – officially the retirement pension under the National Insurance Act 1946 – was introduced in July 1948, so there was no contributory State Pension in 1946 itself. But in 1948, a married couple’s State Pension was £2 2s – around £66.86 in today’s money. For people reaching State Pension age on or a er 6th April 2016, the full New State Pension is £230.25 per week – or £11,973 per year.
Despite increased real-terms spending, 1.9 million pensioners still live in poverty. Those aged 80 or over are the most in need of care – yet few have saved sufficient funds to meet their care costs, and poverty among pensioners continues to affect a significant number of older households. Almost four in every 10 future retirees (38%) are on track for a retirement income below the Pensions UK ‘minimum standard’.
This is one of the key drivers of the equity release market, which grew 11% in 2025, according to our research, while total annual lending increased from £2.3bn in 2024, to £2.57bn in 2025. The astonishing growth rate highlights the role housing wealth is playing in supporting financial resilience in later life. Indeed, Fairer Finance expects that, by 2040, 51% of UK households aged 60-plus will need to use housing wealth to support their retirement spending.
Equity release allows older people to access the wealth in their homes, without needing to sell or move. Lifetime mortgages make
JIM BOYD is CEO at the Equity Release Council
up more than 99% of the market. These mortgages let people borrow against their homes without making repayments unless they choose to. The loan and interest are paid when the customer dies or goes into long-term care. Equity release is proving increasingly vital to meeting people’s social and economic needs. Demographic and economic pressures mean the demand is there – and it is likely to grow.
This is being reinforced by product design. Innovations from lenders are making modern equity release more secure and more a ractive to consumers. Modern products are more flexible.
Growth driven by innovative supply and demographic demand will be supported by collaboration across the later life lending sector and regulatory engagement.
The Financial Conduct Authority (FCA) is set to launch a focused later life lending market study later this year, examining how mortgages and property-based solutions can be er support consumers borrowing into retirement.
Brokers need to be aware that this is an important step, reflecting the reality that borrowing in later life is becoming more common and that the market must continue to evolve to deliver the right consumer outcomes. That regulatory focus, combined with collaboration and continued product innovation, gives us confidence in the sector’s long-term direction. We have never had a be er opportunity to bridge the retirement later life funding gap. ●
We o en speak of the implications of living longer lives, with people working for longer and having to make their retirement income stretch further.
It’s partly because of our longer lifespans that the exit from the workforce and into retired life is no longer a single milestone moment for many, but a phased exit. But that’s not the only milestone moment that is increasingly taking place in later life. L&G’s research has shown that just under a fi h (17%) of all divorces take place in later life.
Those who decide to separate at this stage in life can find themselves in a difficult position as they draw closer to retirement and their ability to earn decreases.
The financial impact of later life divorce is stark. A quarter (23%) of those who divorce at age 50 or over expect to live on a lower income in retirement than originally planned, a third (32%) will need to downsize their
home as a result, and one in five (20%) say they may no longer be able to leave an inheritance.
Equally, despite the significant financial challenge a divorce in later life can pose for those approaching retirement, only a quarter (25%) of those who divorce in later life include pensions in se lement discussions, and almost a third (31%) waive rights to their partner’s pension entirely.
While divorce is a highly emotional time, it’s crucial to consider its financial impact from all angles. This is particularly the case with property wealth for separating couples.
Property is top of mind as an asset for divorcing couples, with 63% of those who divorced aged 50 and over considering it as part of the separation process. Not only is the family home a place of financial value, it also holds significant sentimental value.
L&G’s research also found property wealth (including via equity release) plays a key role for some in the separation process, with 14% of those who divorced in later life using the money from a property (either its sale or via equity release) to fund their separation. For some (5%), equity release played an important role in allowing them to stay in the home they had grown to know and love, as they used it to buy their partner out so they could keep the property.
While it’s clear that property wealth plays a key role in the separation process, it’s important that divorcing couples are well informed at every juncture. L&G’s research found that just 8% of those who divorce at 50 or over seek financial advice before making these decisions. Seeking
LORNA SHAH is managing director at L&G Retail Retirement
financial advice enables separating couples to ensure they’re considering all avenues and opting for the best of course action for them. This is particularly the case as the later life lending space undergoes ongoing product innovation.
While drawing on property wealth may make sense for some people who find their retirement income stretched following a divorce in later life, it may not be right for everyone. For some people, downsizing may make more sense, and this is the juncture in which financial advisers can really demonstrate their value.
Working with a financial adviser allows divorcing couples to ensure that if they do decide to draw on the money tied up in their home – either as part of the divorce process or to fund requirements during their retirement – they are doing so in a way that best suits their individual circumstances.
Everyone’s needs are unique, and this is even more important for those approaching retirement as they consider what their goals are and what a rewarding retirement looks like. While later life divorces can be financially challenging, ensuring that clients are set up to have the right conversations with the right people at the right time can be er position them to achieve their retirement goals, supporting them to explore every avenue from their pensions to their property. ●
In
financial services, HR is no longer a back-office support function. Increasingly, it is being treated as a core part of business performance, governance and risk management. Until the robots take over, people remain central to regulated businesses, which is why more firms are now employing full-time HR managers rather than relying on outsourced support or part-time administration.
At Loans Warehouse, this became increasingly clear during 2025. With a workforce of around 40 employees, the demands of recruitment, employee relations and wellbeing had grown significantly, both in volume and complexity. For directors focused on growth, performance and regulatory obligations, maintaining oversight of employment law developments and workforce risk alongside core business responsibilities has become increasingly challenging.
Across the sector, employees are now far more informed about their statutory and contractual rights, supported by easier access to external advice and guidance. While this greater awareness can promote fairness and transparency, it has also led to a higher volume of formal processes being initiated earlier in the employment relationship.
According to ACAS, requests for early conciliation have risen steadily year-on-year, with tens of thousands of claims raised annually, many within the first year of employment. A significant proportion of these cases relate not to serious misconduct or long-term performance issues, but to misunderstandings, communication breakdowns or mismatched expectations.
This environment is also one of the reasons many businesses are increasingly exploring automation and artificial intelligence (AI). That interest is not purely about efficiency. Reducing people-related friction and risk is becoming a strategic priority in its own right, particularly in highly regulated sectors.
The shi has been particularly noticeable over the last two decades, according to Ma Tristram, cofounder of Loans Warehouse. “Having owned Loans Warehouse for two decades, I’ve seen a real change in employee expectations, not just around pay and progression, but flexibility, wellbeing, communication and how quickly issues are escalated formally,” he said. “Employment rights and processes have become far more complex, and in many cases heavily weighted in favour of the employee, even at the earliest stages of employment. That means businesses
have to operate with far greater structure, documentation and consistency than they did years ago.”
Post-pandemic workforce dynamics have also evolved. Many organisations are reporting higher levels of turnover, shorter average tenure and increased expectations around flexibility. In financial services, where continuity, accountability and competence are critical, these trends can introduce operational risk if not managed properly, particularly where HR support is limited or stretched across multiple priorities.
Employee expectations have shi ed as well. Across the sector, staff increasingly view HR as a source of guidance, reassurance and clarity, particularly around fairness, wellbeing and process. That shi is pushing firms away from reactive, transactional HR support and towards consistent, visible and accessible inhouse HR leadership.
This view is increasingly reflected at senior levels across the wider financial services industry. United Trust Bank’s recent appointment of a chief people officer reinforces the idea that dedicated HR leadership is now being treated as a business necessity rather than an optional extra.
As employment regulation continues to evolve and employee awareness increases, firms that want to remain high-performing will need to invest in robust HR capability. Not as a defensive measure, but as a foundation for strong culture, effective risk management and sustainable growth.
When my administration manager first asked if her team could have more days off but get paid the same, I’ll admit, I was incredibly sceptical. I couldn’t imagine asking my manager that question when I was a rookie adviser back in the nineties. But everyone must move with the times, and so must our business. So, we put the ke le on, and I listened to what she had to say.
The admin department is where many people in our industry start their careers. They get trained up, earn their experience and o en move on to another role within the business. For El, our admin team manager, that means she is forever interviewing staff to fill vacancies.
More and more, she came across candidates asking what flexible working benefits we offered. To be frank, there were none. And, as a growing business operating within the competitive mortgage industry, we need more than ever to stand out among our competitors to a ract the best staff to support our continued growth.
Our admin team is required to be in the office from Monday to Friday. But having some form of flexibility during the working week is a perk that most people are now looking for in a job, with some naming it a priority.
So before coming to me, El did her research and looked into schemes that other companies operated, choosing one that would fit with the needs of the business. She proposed a nineworking day fortnight with a day off every two weeks.
As a growing business operating within the competitive mortgage industry, we need more than ever to stand out among our competitors to attract the best sta to support our continued growth”
Staff can use their rest day to catch up on all the things that life throws at us, which we’d rather not or can’t deal with over the weekend; an MOT, a trip to the dentist, nipping to the dry cleaners or, heaven forbid, just a bit of quiet time while the kids are in school.
To earn the extra day off, they must work an extra 50 minutes a day. The team is split into two rotas. Those working a five-day week are rostered from 8:40am to 5:30pm to make sure our phones are manned until we close for the day. Those on a four-day week can choose to do the same, or work from 8:10am until 5pm.
We trialled this model for three months between September and November and got great results, both for the business and team morale. Prior to the flexi-working trial between May and September, we were averaging 43 offers per month that exceeded our 15-day target turnaround period. Since the introduction of compressed hours this has reduced to
HELEN PIERSON is director at Mortgage Advice Bureau New Homes
an average of 27 offers per month that exceed target.
That’s a 37% reduction in a ma er of months and those remaining outside our desired service levels were largely beyond administrative control, for example outstanding documents, down valuations or affordability issues.
Our operational continuity has been maintained on non-working days, with diaries and case notes consistently updated, allowing work to be picked up without service disruption.
In fact, El has noticed that her team are communicating more effectively and writing clearer case notes now their cases must be handed over once a fortnight for someone else to manage. And those with tricky cases si ing in the pipeline are speaking up more to ask for help on how they can be moved forward quickly.
It seemed like an obvious win for me, so from 1st January, we implemented the condensed working week for the admin team permanently.
The whole experience says a lot about the culture that myself and the other senior leaders have worked hard to cultivate. We want our staff to feel empowered to make decisions and if they want to improve something, come with a solution like El did, not just a problem.
Of course, not every idea has legs but certainly a er this experience, we have happier staff, improved performance and a competitive edge as an employer and recruiter within the mortgage industry. It pays to listen. ●
Marvin
led to you becoming a broker?
I retrained as a mortgage broker during the Covid‑19 pandemic. Before that I was an events manager and, prior to that, a music promoter. When I was put on furlough quite early on, I started to worry about the long‑term future of the events industry with all the lockdowns. While I was at home, I used the time to study for my CeMAP exams. I started around June, passed in October, and then began looking for a new role. I called a number of well‑reviewed broker firms in London and managed to secure a job at AS Financial. That was about five years ago.
What is something outside of work
that people might like to know
about you?
Outside of work I run a music promotions company called Portals.
We promote alternative and mostly rock‑based music events, from gigs to festivals.
That was my original background before moving into mortgages. Becoming a broker was ultimately a more financially secure way to use the transferable skills I’d developed through organising events and private functions.
How have you found the transition from the events industry to the mortgage industry?
The transition has been very positive. It’s nice to be in an industry the Government clearly cares about, given how closely the property market is tied to the wider economy, whereas music and events often feels overlooked despite its cultural and economic importance.
The mortgage industry offers better long‑term career prospects and stability, but it still allows me to spend most of my day with clients and building relationships, which
I’ve always enjoyed. There is also a strong problem‑solving element because every case is different. I’ve found helping first‑time buyers (FTBs) who thought they’d never be able to purchase a home particularly rewarding.
What sets your fi rm apart?
At AS Financial we tend to build personal, goals‑based relationships with our clients, and we see ourselves more as advisers than brokers. Rather than trying to compete purely on rate, when most whole‑of‑market advisers have access to broadly the same products, we focus on the quality of our advice and service.
We manage the entire process for the client from start to finish, rather than simply arranging a deal and stepping away. I want clients to leave the first meeting confident enough to go out and make offers knowing what to expect at each stage. The advice is holistic and tailored to each client’s circumstances, supported
by the use of technology to keep applications progressing smoothly and helping clients manage their mortgage properly over time.
The biggest opportunities are still relationship‑driven, particularly personal referrals. If you do an excellent job and build strong connections, clients will often sing your praises and recommend you to friends and family.
One of my first clients was from Myanmar, with very complex income and limited English, and it was a difficult case.
We eventually got it through, and he went on to recommend five or six friends, who then recommended others. From that one relationship I’ve developed a small cluster of very friendly and appreciative Burmese clients.
It shows that when you do the basics well, go above and beyond, and genuinely fight for your clients, one good outcome can snowball into many more.
One major issue is how hard landlords have been hit by tax changes, which has pushed many of them to sell properties even though some portfolio landlords are taking the opposite approach and expanding while they see value.
Another big challenge is the lack of housing supply. There simply are not enough homes being built, which means the market is not as liquid as it could be and transactions do not move as quickly as they might otherwise.
Despite these headwinds, there are still opportunities for investors and brokers who are willing to go slightly against the grain and think long term.
Two key areas are broker support and valuations. On the support side, getting hold of business development managers (BDMs) or helplines can be very difficult. You might be working on a complex case, sit on hold for half an hour and then be cut off, only get a response a day or two later when your attention has moved elsewhere. Live chat is often promoted as an alternative, but the quality of guidance can be inconsistent.
On valuations, there can be a worrying disconnect between what valuers say and what properties are actually worth. I have seen the same property valued by two different firms with more than a 40% difference between them, and both insisted they were correct.
When you have years of tenancy agreements showing a certain rental level and the valuation does not reflect that, it is very hard to explain to a client, especially when it kills a deal they have worked on for months. Greater transparency in how valuations are reached and more willingness from lenders to challenge valuations, where the evidence supports it, would make a real difference.
My aim in the first meeting is always that clients leave feeling confident enough to make offers on properties and with a clear understanding of what will happen at each stage of the process. I take time to walk them through the full journey from initial enquiry to completion in a way that is specific to their circumstances, rather than simply showing them a couple of rate options.
That explanation is then backed up by the way we work as a firm, with dedicated people handling different parts of the journey, so that clients
always know what is going on and are supported throughout.
What are your views on the use of artificial intelligence (AI) in the
I think AI is already improving certain aspects of what we do and will continue to do so. Interestingly, we have started to see leads come through ChatGPT, where people have asked it to recommend a good broker in London and it has suggested AS Financial. At the same time, I do not believe AI will replace human‑to‑human mortgage advice. There is still a risk of incorrect or incomplete advice if you rely solely on AI, and it cannot replicate the personal connection, reassurance and availability that clients value, especially when something goes wrong and needs fixing quickly. In the short to medium term, I see AI as a set of tools to enhance our work rather than a replacement for good advisers who build those strong relationships.
My priority is to keep building on what already works: strong relationships, detailed advice and a willingness to fight for clients. AS Financial has grown every year for the last five years and continues to grow, which reinforces my belief that there will always be space for advisers who put clients first.
Brokers or advisers should treat every client as if they are your most important client. Build trust by seeing things from their perspective, give thoughtful, high‑quality advice and really fight their corner. In my experience, combining determination and persistence with strong relationship‑building has led to steady growth year after year, and there will always be room in this industry for committed human advisers who look after their clients properly. ●
Want
Professional with foreigndenominated savings
Aclient is looking to buy a flat worth
£285,000 with deposit of 20%. Their deposit is held partly in a UK savings account and partly in an account overseas in Canada, where they previously worked.
They earn approximately £48,000 in the UK and have been a resident here for over 14 months. They have a thin but clean UK credit file and use their UK current account daily. However, they hold no loans or credit cards.
They also need to transfer the remainder of their deposit to the UK prior to completion of their purchase.
We accept funds from Canada, subject to understanding the source and providing evidence of transfer and origin and eligibility depends on their profession.
If they qualify under our Professional range, an enhanced affordability up to 6x income could apply. Otherwise, our Key Worker range is also an option, and offers up to 5.5x income.
However, on our standard terms (4.5x income), the loan may fall short.
United Trust Bank (UTB) requires applicants to be resident with a credit footprint in the UK for at least the last three years, so unfortunately, we would not be able to help this applicant.
Firstly, we would recommend that they move their deposit over to a UK bank account as soon as they can. We would also need to see the money in their account and see an explanation regarding how they accumulated those funds.
Assuming they are a UK national, this case would be acceptable subject to all of our normal checks. If they are a foreign national, however, we would need to see a valid visa at the point of application and to take a look at their credit profile.
This is an ideal circumstance for the broker to get in touch ahead of the application to chat through the details and try to get any necessary exceptions in place.
We credit check rather than credit score, so a limited credit history is acceptable for us. Deposits originating outside the UK are generally accepted, provided that the funds are held in the applicant’s UK bank account before the application is submitted.
As part of the application process, an explanation of how the funds were acquired must also be provided.
The society is unable to accept any deposit from overseas, however, the society could lend to 90% loan-to-value (LTV).
In addition, in order for this case to be acceptable, the applicants would also need to be returning British citizens.
This is certainly a case that the Harpenden Building Society could consider.
However, we would need the source of deposit to be referred to our underwriters early on in the process in order to ensure it is acceptable.
Together could support this applicant provided they possess the right to reside and any relevant visas. Deposits from Canada can also be accepted, subject to the standard legal checks on the source and origin of funds.
We could offer up to 75% LTV – potentially using an online valuation – assuming the flat is not in a building over six floors. If it is, the maximum LTV we could offer would be 65% LTV.
If the client is a British national returning to the UK, then we could consider this on our Standard range, subject to a full underwriting and a verification of the deposit.
However, if they are a foreign national on an appropriate visa, they will need to have been residing in the UK for at least 24 months before we could consider lending to them.
Joint application with one applicant on probation
Acouple are aiming to purchase a property worth £350,000 with a 5% deposit. The first applicant earns £39,000 a year and has been in their role for eight months.
The second applicant earns approximately £45,000 but only started in a new job two weeks ago. In light of this, they are still in a six-month probation period.
Both applicants have good credit conduct, but savings outside the deposit are limited. Despite this, the couple are keen to proceed quickly before their landlord increases rent.
Our maximum LTV available is 90%. If an applicant is in their probation period and a first-time buyer (FTB), we require at least six months in the role and their income is disregarded.
If not in probation, and with a minimum of three months employment history, income can also be accepted.
UTB will not consider using income from an applicant in a probation period. Therefore, whilst
still able to be party to the application, their income is ignored. In this case, the first applicant’s income on its own would be insufficient for the loan they require.
For this case to work, the second applicant will need to show 12 months’ track record of a similar income level in a similar role.
With this (and subject to our normal underwrite), Gen H would be happy to lend.
If the second applicant is in the same line of work as they were previously, we can take a view on the probation period.
If this is not the case, we would wait until the probation period is completed before proceeding.
The society may be able to consider this application; however, completion would be subject to confirmation that the applicant has successfully passed their probationary period. This would form a condition of the mortgage offer.
Alternatively, a Joint Borrower Sole Proprietor (JBSP) arrangement could be explored if a family member is able to support, provided there is a suitable exit strategy in place.
Under this option, the probationary requirement could be bypassed, however, the LTV would be capped at 90%.
This is unlikely to be a case for us, as our max LTV is 85%.
If this could work, we would need a minimum of three years’ working history for the second applicant due to the short timeframe in their current role.
Both could apply for lending with Together. We accept applicants still in work probationary periods, provided they have been in continuous employment for the previous 12 months and also supply us with their first payslip.
We could offer up to 75% LTV on a standard build property.
West One can accept applicants who are still in their probationary period, however the second applicant will need to have been in the role for at least a month, in which case a referral
would be needed. We would also accept the second applicant after three months in the role without referral.
At a loan-to-income (LTI) of just under 4x income, once the required time-in-employment is met, West One would easily assist if everything else checks out.
AA client hopes to buy their ‘dream home’ which is worth £310,000. They currently hold a 10% deposit.
The client earns a base salary of £50,000 but contributes 15% of this to a workplace pension, reducing their net monthly income noticeably. In light of this, the client is seeking the longest possible term to reduce monthly payments.
Pension contributions are not deducted from verified gross income when assessing affordability. Therefore, we can consider borrowing up to 6x income. However, this will be subject to professional eligibility and commitments.
In turn, a term of up to 40 years may be possible, depending on the applicant’s age and occupation – for instance, if their role consists of manual or non-manual work.
The applicant’s income is insufficient to consider lending due to not meeting our minimum LTI requirements for a 90% LTV application.
However, had the income been sufficient, we would deduct the monthly pension contribution when calculating our monthly affordability assessment.
We would not deduct the pension from the LTI calculation, but we may include a deduction for the pension if it were needed to fund the pension that will eventually repay the mortgage into retirement.
However, the LTI ratio for this case is 5.89x, which is above our maximum.
Nevertheless, if the buyer has any family who could consider joining the case as an income
booster, this could make the required loan affordable – in which case we would be happy to support the applicant with this case.
This is something that The Stafford Building Society could consider. If the client can confirm the minimum pension contribution that they are required to make, and that they would reduce to this level in times of financial strain, we could work on the lower contribution figure.
We can use earned income up to the age of 75 and have no further income multiple restrictions. Each case is assessed on its individual affordability to the client, making this one something that we could help with.
All pension contributions must be deducted from the income assessment.
In light of this, the society could consider a mortgage term of up to 40 years, based on earned income. This would also be subject to plausibility and the applicant’s stated intention to work until age 75.
Beyond this age, affordability would need to be supported solely by pension income.
Our max LTV is 85%, but if this could work for the clients, we could consider this case. This would also depend on how the pension contributions affect affordability, as they will need to be deducted from the income.
We can accept non-manual working income up to the of age 75 and even look to stretch the term beyond this point if affordability will still be met by subsequent retirement income.
Together would assess affordability based on net income, initially using standard ONS outgoings, but can consider actual stated outgoings if needed.
Our maximum term is up to age 70 on earned income, or pushed up to age 85 if the pension income supports affordability.
However in this case, we could offer up to 75% LTV.
We would have to factor the pension contribution into our affordability calculations.
However, if that is acceptable to the applicant, we would likely be able to assist the case on our Residential Extra range as the LTI is between 5x and 6.5x income.
Looking back at 2025, a year characterised by a challenging economic climate, restructuring, and large-scale technological shi s, one thing is clear: emotional intelligence (EI) is no longer optional for advisers and brokers.
As we continue in 2026 to ride the waves of volatility across markets and adapt to fast evolving artificial intelligence (AI), clients will be looking for advice from professionals who can understand the pressure they’re under and offer a human element that AI cannot. In a profession built by numbers, it will be an adviser’s response to emotions that sets them apart.
Recent findings confirm just how much financial and emotional pressure many people are under. A 2025 study by Zellis found that 92% of UK employees experienced financial worry in the past year. What’s more, according to Royal London, 81% of advisers reported noticing increased client anxiety ahead of the 2025 Autumn Budget announcement.
This background of uncertainty and irregularity proves that technical know-how alone is no longer sufficient to support clients and employees effectively. Businesses have to be able to recognise and respond to emotions, and it’s EI that makes the difference. In fact, professionals with higher EI o en perform be er.
One of the most common challenges I see advisers face is the instinct to respond to emotion with explanation. While well-intentioned, jumping straight into facts and figures can feel dismissive to a client who is already under pressure.
Those with high EI will know that acknowledging emotion first, before offering solutions, o en leads to more productive and trusting conversations – showing that simply changing one’s approach to clients can make a big
difference in the long run. As clients gain easier access to information, they have the potential to be more informed, be er able to manage their own investments and make decisions about what to do financially.
However, when people are worried about the future, fearful of making a wrong decision, or time-poor, they will still seek – and need – advice from professionals.
This is where EI comes in, providing the ability to connect with clients, build relationships, and increase retention because clients feel heard and understood. The real client value is in the human side of advice.
Clients will be looking for advice from professionals who can understand the pressure they’re under and o er a human element that AI cannot”
Data from Talent Smart also indicates that EI accounts for approximately 58% of a leader’s effectiveness, speaking to the advantage that EI can also provide for professionals when it comes to skills such as reading the room, securing relationships, and developing one’s team.
Furthermore, as AI and automation begin to take over more routine tasks, even global CEOs such as Microso CEO Satya Nadella are acknowledging that empathy and social intelligence are essential skills, and not just “nice-to-haves.” With the future looking less admin focused thanks to technology an adviser’s time and value should shi towards delivering support with the emotional outcomes clients are seeking.
So, what steps can companies and advisers take to embed emotional intelligence into their 2026 strategy? Here are three steps I would recommend implementing to make the most of this human advantage: Investing in EI training, embedding EI in culture and leadership, and leveraging EI as a business asset.
Developing EI across all levels of an organisation leads to measurable benefits in communication, collaboration, and client relationships. Bring on board consultants and coaches to offer practical EI training and equip employees with the right skills to build relationships, spot changes in client behaviour, and support them through challenging times.
In my experience, EI training only delivers real value when it’s practical, evidence-based, and not a one-off workshop with good intentions. Focus on developing self-awareness, emotional regulation, and empathy, as this not only equips advisers and brokers to recognise subtle shi s in client behaviour and respond more effectively, but also to recognise their own stress responses, biases, and communication skills under pressure. A particularly useful set of skills during times of volatility.
Leaders set the tone in their organisation. The most effective
programmes involve leadership, so that emotionally intelligent behaviour is modelled and reinforced culturally.
The best leaders use self-awareness and empathy to build trust, reduce friction, exhibit healthy behaviours, and make be er decisions with their team and clients.
It’s when EI becomes part of how firms train, coach, and lead – a core part of organisational culture visible in day-to-day processes – that behaviour actually changes.
Driving business growth
Research demonstrates that EI delivers much more than what’s considered ‘so skills’; it also increases sales, referrals, retention, and profitability, making it a crucial component of business strategy. These outcomes stem from increased trust in adviser-client relationships and effective communication.
Referrals tend to increase because clients find it easier to communicate emotional outcomes, describing how an adviser made them feel during difficult moments.
Internally, EI can also reduce burnout and improve adviser stress because they can understand and respond to their own triggers, which directly affects capacity and performance. To further reap the business benefits, training success metrics should be aligned with broader organisational goals.
While companies o en invest in new systems, platforms, and technology, it’s clear that business growth doesn’t just come from processes; it comes from people. In 2026, organisations can no longer afford to overlook the importance of developing their employees’ emotional intelligence. Not only will this improve communication skills, both in and outside the organisation, it can have a powerful impact on your bo om line and client relationships. Those who prioritise it today will be best positioned to thrive this year and beyond. ●
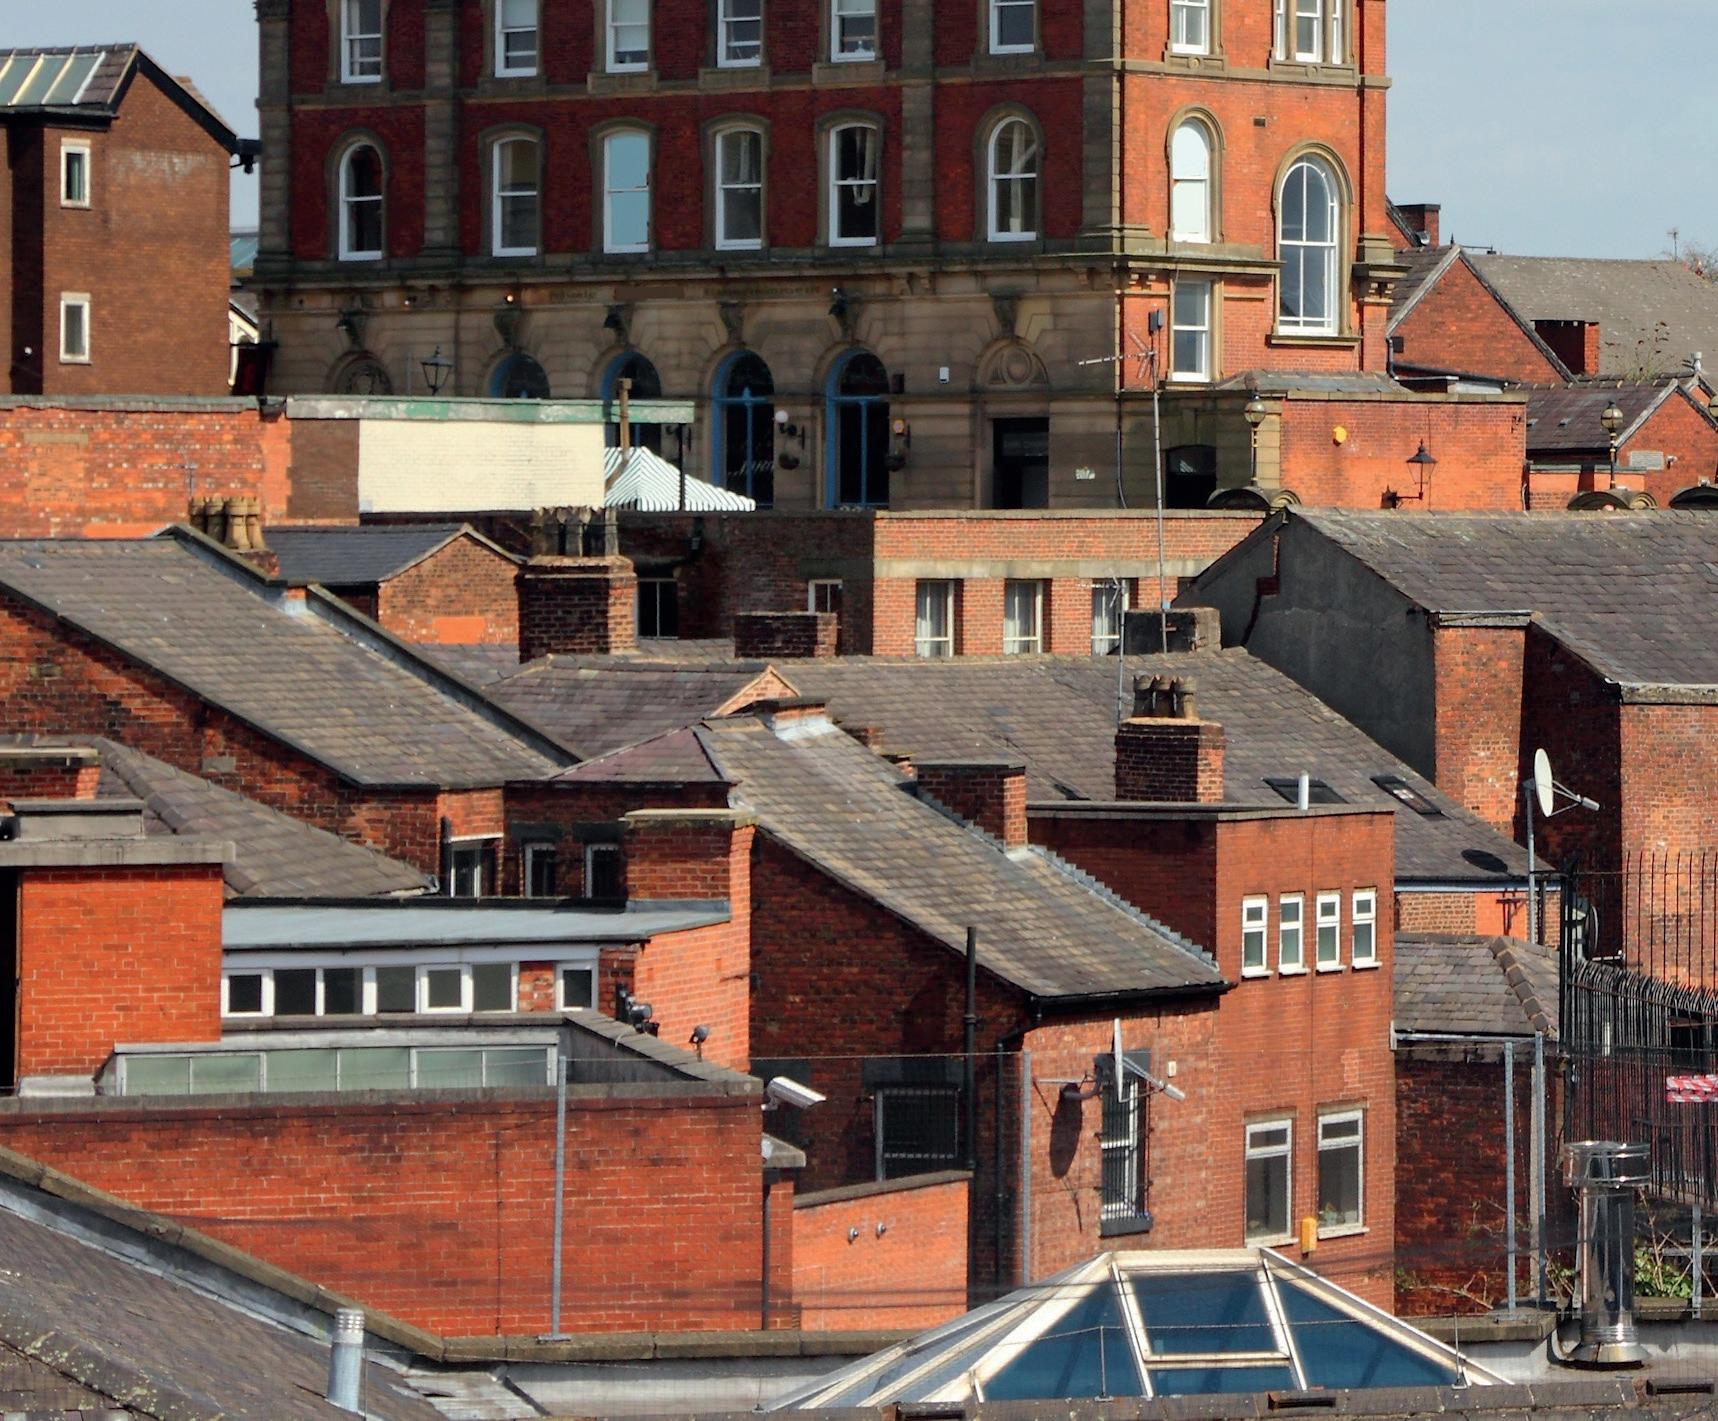
Each
month, The Intermediary takes a close-up look at the housing market in a specific region and speaks to the experts supporting the area to find out what makes their territory unique
As 2026 gets underway, Stockport’s housing and mortgage market is entering a more considered phase. Transitioning from ultra-low rates to the recent turbulent recalibrations that tested even the most seasoned adviser’s mettle, the era of dramatic market swings appears to be giving way to something more measured.
For local intermediaries, the dialogue with clients has matured in recent months. The focus has moved on from blunt ‘rate war’ comparisons to a stronger emphasis on suitability and long-term planning. Demand for homeownership remains resilient, but buyers and remortgagers are engaging with finance in more nuanced ways, all the while lenders have been quietly redrafting their playbooks, behind the scenes.
Looking ahead, the mood is one of cautious optimism. In Stockport – a market long underpinned by commuter appeal and connectivity to Manchester – change is certainly on the horizon. In this edition of Local Focus, The Intermediary examines how the local market is adapting at
pace, exploring the trends influencing borrower behaviour and the opportunities emerging for advisers as the year unfolds.
Stockport’s housing market continues to demonstrate resilience. The average property price across the postcode area now stands at £342,000, with a median of £280,000. Values have edged upwards over the past year, rising by £8,100, or 2%.
That said, activity levels have cooled, as approximately 8,100 transactions were recorded over the past 12 months, representing an 11.2% reduction, or around 1,100 fewer sales, compared with the previous year. Demand remains most concentrated in the core of the market, with the £300,000 to £400,000 bracket accounting for 1,499 sales (18.5%), followed closely by homes priced between £200,000 and £250,000, which saw 1,319 transactions (16.3%).
At postcode level, price variation remains pronounced, with SK1 3 emerging as the most affordable pocket at an average of £138,000, while SK10 4 sits firmly at the top end with average values of £912,000.
By property type, the established pecking order holds firm, as detached homes average at approximately £582,000, semi-detached properties fetch £334,000, terraced houses and flats come in at £239,000 and £183,000, respectively.
Residentially, the mood on the ground is one of quiet confidence. According to Michael Street, founding partner at Word On The Street: “Stockport continues to be a very attractive ‘valueto-Manchester’ market.”
Demand, he notes, remains broadbased, with “steady demand across most price bands.” In his view, this is
JESSICA O’CONNOR is deputy editor at e Intermediary
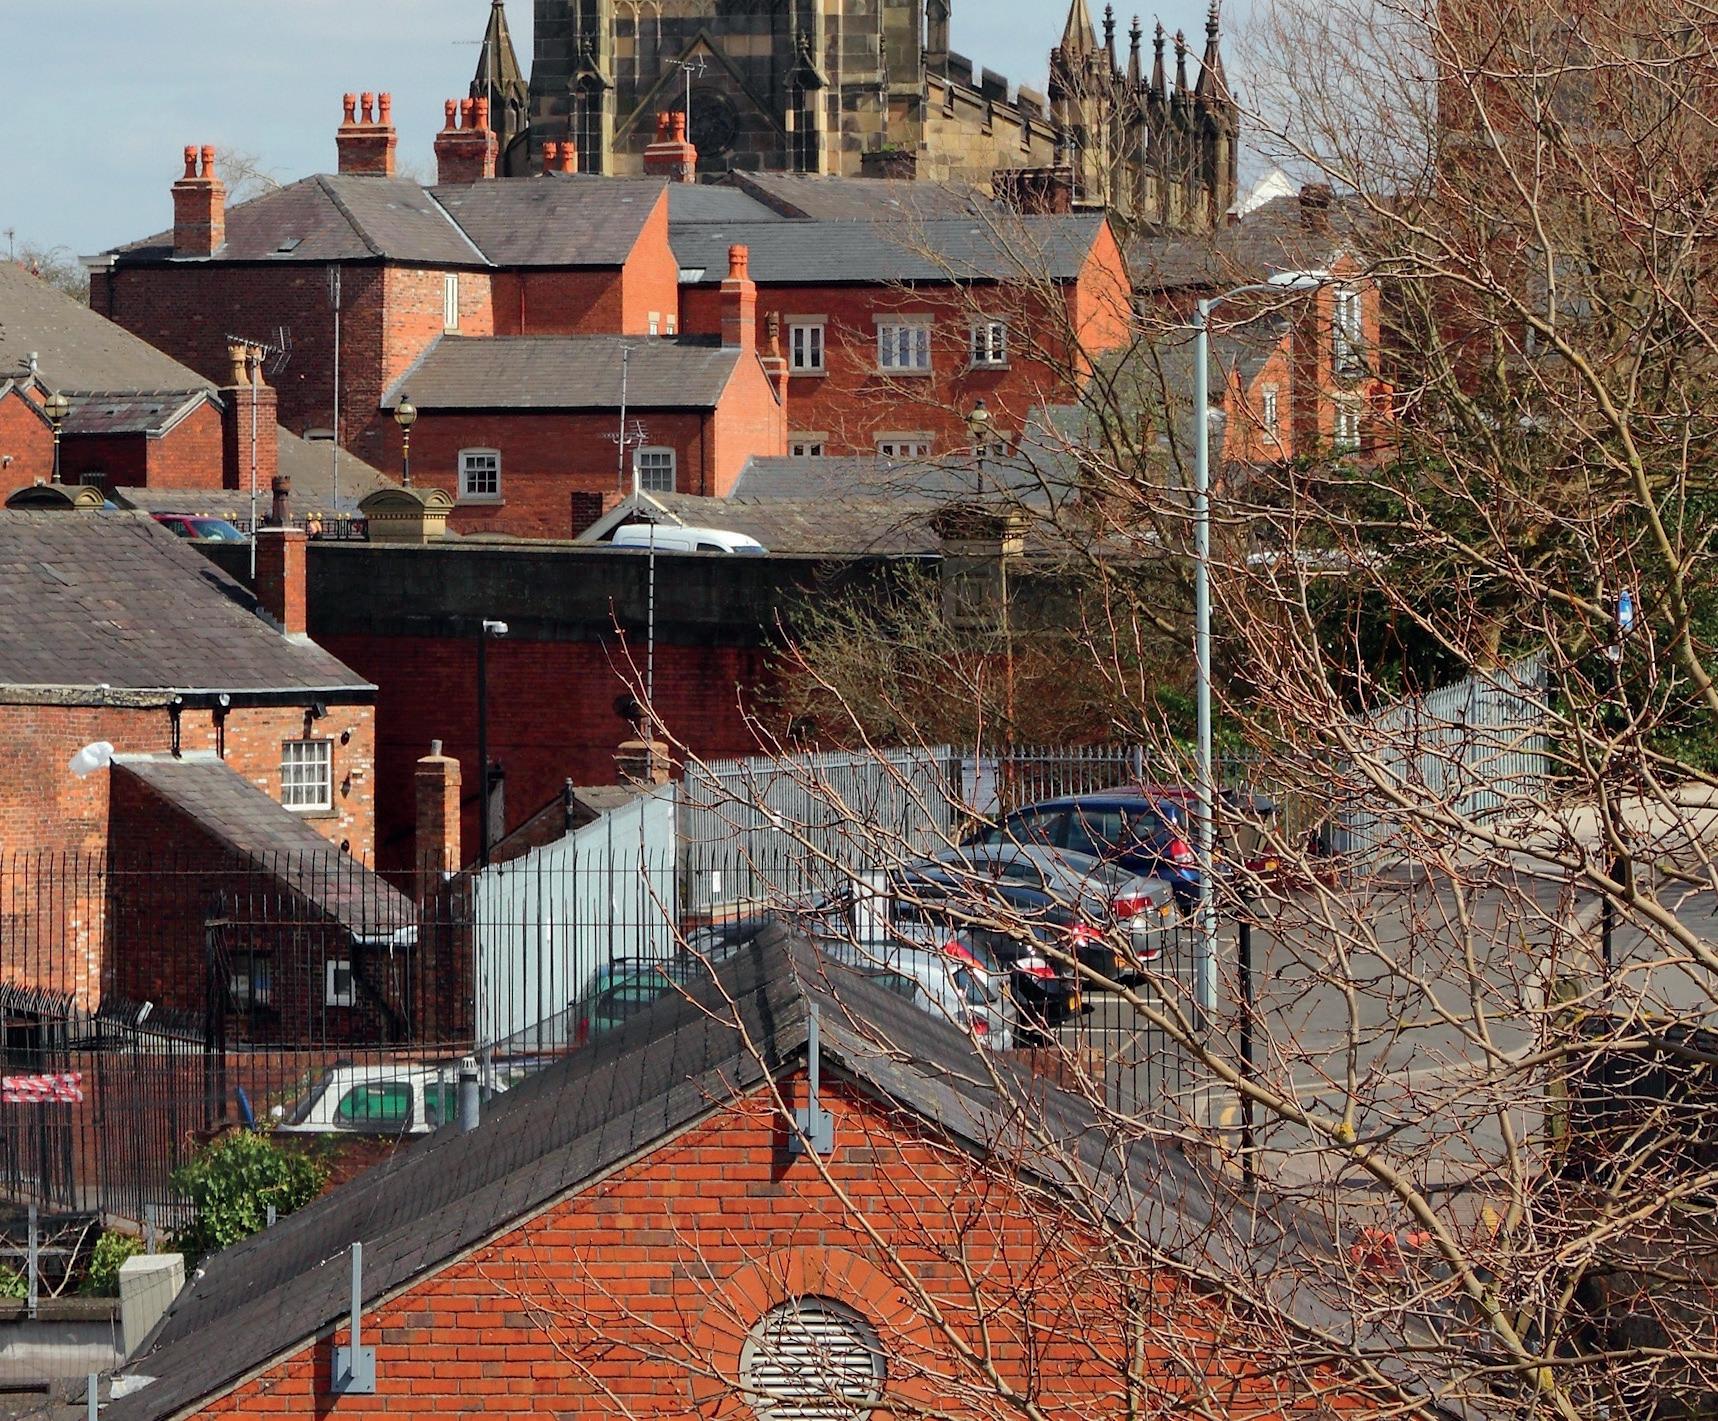
particularly pronounced “in family homes and good commuter locations –particularly where there’s easy access to rail and tram links and the M60.”
That demand, however, is operating in a recalibrated environment. Street adds: “Pricing feels more balanced than it was at the peak and sellers are having to be realistic, but wellpresented homes in the right areas are still moving.”
From a complementary perspective, Lee Daffern, protection and mortgage broker at Just Mortgages, describes a market that “remains healthy but moderate,” with prices “still on the rise but not rapidly increasing.”
However, he is also quick to emphasise that “buyers are as cautious as ever.” In fact, affordability constraints continue to underpin Stockport’s appeal, with Daffern noting “the area remaining affordable compared with central Manchester or East Cheshire,” particularly
for family buyers. According to Daffern, this is most evident in the competition for “well-priced three- or four-bedroom homes” in areas like Cheadle, Heaton Moor, Bramhall, and Hazel Grove. It is the properties in these areas that Daffern says, “often attract multiple buyer interest and sell quickly,” sometimes pushing prices higher and prompting the question of “how long will these types of homes remain affordable.”
Against a backdrop, Street notes that “overall, it feels like a market that’s stabilised rather than stalling,” with buyers simply taking longer to decide, before proceeding with greater intent.
That more deliberate approach is also shaping how borrowers and advisers are engaging with the market at a practical level. As Street notes: “People are stress-testing affordability more carefully and asking better questions about management costs, ongoing bills, and future rate movements.”
This is, in turn, feeds directly into product choice with Street citing “more clients weighing up 2-year versus 5-year fixes based on portfolio growth plans and aspirations, rather than defaulting to one option.”
Capital strategy is also evolving, as advisers report a marked push from borrowers to get to the next loanto-value (LTV) bracket to improve pricing – whether through private investor funds or delaying a purchase to build deposit.
Alongside these forward-looking decisions, the broader tone remains measured. Daffern describes conditions as “still relatively healthy however people are still being cautious,” a balance that is particularly visible in borrower behaviour. Rather than trading up, he notes that “remortgage activity remains strong with more people willing to remain and improve rather than sell and upsize.”
Borrower and buyer demographics in Stockport continue to reflect its broad population base. With around 634,000 residents across the postcode area, an average age of 42.4 years, not to mention a population growth of 8.4% since the early 2000s, the area naturally lends itself to longer-term ownership and portfolio building, rather than short-term churn.
This is borne out in adviser experience. As Street explains: “Our core demographic is typically formed of a mix of professional investors and landlords, property developers, property traders – those looking to capitalise on profits and begin to build out a portfolio – and landlords with small-to-medium portfolios.”
Over the past year, however, that profile has subtly shifted in tone if not composition, with Street noting “a slight shift towards clients wanting more certainty – more remortgage reviews ahead of time, more appetite for structured debt, and more questions around affordability
and futureproofing.” On the owneroccupier side, Daffern notes a parallel change in mindset, observing that “Buyers are far more price-conscious in recent years. Overpriced homes are sitting longer, more price reductions are appearing, and well-priced and marketed property is selling much quicker.”
This growing financial literacy is also influencing how buyers assess risk. Daffern adds: “I would also suggest that buyers are becoming smarter with their money and are putting more focus on stress-testing their affordability, something I do with all my clients. They are also starting to pay more attention to the property energy performance
certificate (EPC) rating.”
When it comes to lender selection in the local market, flexibility and fit appear to trump brand loyalty. As Street explains: “We work across the market and place business with a wide range of mainstream and specialist lenders depending on the client’s needs,” a necessity in an area characterised by varied borrower profiles and increasingly nuanced cases.
Established high-street names and challenger banks remain a core part of the mix, with Street noting that “the established high-street and challenger bank lenders remain active across buy-to-let,” particularly for more straightforward scenarios. However,
ILEE
DAFFERN protection and mortgage broker at Just Mortgages
feel the Stockport market remains healthy but moderate, with house prices still on the rise but not rapidly increasing. Buyers are as cautious as ever.
I would say affordable family homes are still in high demand, with the area remaining affordable compared with central Manchester or East Cheshire. For example, well-priced three- or four-bedroom homes in areas like Cheadle, Heaton Moor, Bramhall, and Hazel Grove often attract multiple buyer interest and sell quickly. This can drive the price up so how long will these types of homes remain affordable.
Also, Stockport is currently benefiting from long-term infrastructure improvements and regeneration, with improvements in train and new tram links to Manchester and surrounding areas, as well as other town centre regeneration projects. This creates demand for properties near transport hubs such as Stockport Station, Heaton Chapel, Davenport, the result of which is stronger rental demand and resale values.
However, I think there is a significant shortage of affordable homes relative to demand.
There are currently several significant up-and-coming areas and major development projects in Stockport, especially focused on town centre regeneration and the supply of new housing. These will influence the property market whilst creating potential opportunities for new buyers, renters, and investors.
I would say it is still relatively healthy however people are still being cautious. Remortgage activity remains strong with more people willing to remain and improve rather than sell and upsize.
Yes, I would say that buyers are far more price-conscious in recent years. Overpriced homes are sitting longer, more price reductions are appearing, and well-priced and marketed property is selling much quicker.
I would also suggest that buyers are becoming smarter with their money and are putting more focus on stress-testing their affordability, something I do with all my clients. They are also starting to pay more attention to the property Energy Performance Certificate (EPC) rating.
specialist lenders continue to play a critical role, and are “regularly used for complex income, self-employed clients, and cases involving adverse credit or non-standard properties.”
In this environment, lender choice is less about chasing headline rates and more about alignment, with Street emphasising that “for clients, the ‘best’ lender is usually the one whose criteria and service levels align with the scenario.”
Infrastructure investment and new development continue to play an increasingly influential role in shaping Stockport’s property landscape. Newly built homes now command a notable premium, averaging £438,000 compared with £338,000 for established stock, and having seen a sharp uplift in value over the past year.
Geographically, SK7 1 has emerged as a particular hotspot for new-build completions and sales over the past 12 months. This appetite is closely tied to wider regeneration efforts. As Street notes: “Stockport’s continued regeneration is a big talking point, particularly the ongoing investment in the town centre and transport connectivity,” with “increased interest in areas that benefit from improved links and local amenities.”
From a lending perspective, Street adds that “where regeneration is visible and sustained, it seems to be supporting both owner-occupier demand and rental demand.”
Daffern echoes this view. He notes: “Stockport is currently benefiting from long-term infrastructure improvements and regeneration,” including enhanced rail services and new tram links, which are driving demand around transport hubs such as Stockport Station, Heaton Chapel and Davenport, and contributing to stronger rental and resale values. However, this momentum is not without its pressures, as Daffern cautions that there is still a significant shortage of affordable homes relative to demand.
He explains: “There are currently several significant up-and-coming areas and major development projects in Stockport, especially focused on town centre regeneration and the supply of new housing.”
SMICHAEL STREET founding partner at Word On The Street
tockport continues to be a very attractive ‘value-to-Manchester’ market. We’re seeing steady demand across most price bands, with the strongest activity in family homes and good commuter locations (particularly where there’s easy access to rail and tram links and the M60). Pricing feels more balanced than it was at the peak and sellers are having to be realistic, but well-presented homes in the right areas are still moving.
Overall, it feels like a market that’s stabilised rather than stalling, with buyers taking a bit more time and doing more due diligence. Stockport has and continues to see significant investment from local authority and private venture capitalists.
We’ve seen an uplift in enquiries and applications for buy-to-let (BTL) and specialist BTL mortgages from people who had paused decisions and are now re-engaging, both first-time landlords and professional investors. Clients are still rate-sensitive, but they’re increasingly focused on getting the ‘right fit’ overall.
We work across the market and place business with a wide range of mainstream and specialist lenders depending on the client’s needs. In the area, the established high-street and challenger bank lenders remain active across buy-to-let, and we also regularly use specialist lenders for complex income, self-employed clients, and cases involving adverse credit or non-standard properties.
For clients, the ‘best’ lender is usually the one whose criteria and service levels align with the scenario, that’s where our broker guidance and support adds the most value.
Stockport’s continued regeneration is a big talking point, particularly the ongoing investment in the town centre and transport connectivity. We’re also seeing increased interest in areas that benefit from improved links and local amenities, it all feeds into buyer confidence and longterm demand. From a mortgage perspective, where regeneration is visible and sustained, it seems to be supporting both owner-occupier demand and rental demand (subject to pricing and yields stacking up
Buy-to-let has been more selective. The landlords who are active are typically experienced and numbers-led are focusing on yields, realistic rental demand, and factoring in higher interest rates and running costs.
We’ve seen landlords being more strategic: some are refinancing to optimise portfolios, others are buying where the yield comfortably works, and some are pausing purchases if the deal doesn’t stack up. Rental demand locally remains strong, but affordability caps and compliance costs mean it’s not a ‘buy anything and it works’ market –it’s about choosing the right property and structuring the finance correctly. It’s most certainly a ‘buyer’s market’.
This regeneration-led activity is also shaping the buy-to-let market. Private rented stock in Stockport accounts for 17.4% of homes, well below the England and Wales average of 23.6%, a dynamic that continues to underpin tenant demand. As Street observes: “Buy-to-let has been
more selective. The landlords who are active are typically experienced and numbers-led are focusing on yields, realistic rental demand, and factoring in higher interest rates and running costs.”
This has led to a more strategic approach across portfolios, where “some are refinancing to optimise
Source: www.plumplot.co.uk
portfolios, others are buying where the yield comfortably works, and some are pausing purchases if the deal doesn’t stack up.”
While local rental demand remains strong, Street cautions that affordability ceilings and rising compliance costs mean “it’s not a ‘buy anything and it works’ market,” but rather one “about choosing the right property and structuring the finance correctly.”
In that context, and despite the competition for well-located stock, the prevailing view is that it is “most certainly a ‘buyer’s market’,” favouring informed landlords who are prepared to be selective.
As the Stockport market looks ahead to 2026, it is clear that local emphasis has shifted from speed to substance, with residential homebuyers and landlords alike approaching decisions with greater clarity.
Speaking to local brokers, it appears that lending strategies have become even more bespoke in light of recent volatility, with client expectations more grounded.
In addition to these shifting dynamics, ongoing regeneration continues to provide a steady tailwind rather than a speculative rush. In this environment, investment opportunity has not disappeared in the area – in fact far from it – it has simply become more selective and better defined. As Daffern aptly puts it, going forward, this evolving landscape “will influence the property market whilst creating potential opportunities for new buyers, renters, and investors.”
MSP Capital appoints Ben Arnold as director of property services
MSP Capital has appointed Ben Arnold as director of property services.
Arnold brings more than 25 years’ experience across residential and commercial property, valuation, development land and planning. He qualified as a chartered surveyor in 2005 before joining Savills, where he progressed to development director and head of its south coast valuation team. In 2017, he moved to housebuilder Pennyfarthing Homes as land and planning director.
On his move to MSP Capital, Arnold said: “I’ll be utilising my past experiences in a range of property roles to lead and support the team and our customers to help deliver their projects to a successful conclusion.”

SLeigh Bartle , chief executive officer at MSP Capital, said: “Ben brings extensive knowledge in development, planning and valuation.
kipton Business Finance has strengthened its leadership team with the appointment of Kim Hughes as head of asset-based lending (ABL).
director and head of its south


Santander UK appoints Ben Merritt as head of mortgage trading
Santander UK has appointed Ben Merri , as head of mortgage trading. Merri has over 20 years of experience in financial services, with the last 15 in the mortgage industry. Previously, he was director of mortgages at Yorkshire Building Society and executive director at Accord.
In his new role, Merri will be responsible for leading Santander’s mortgage strategy, with a focus on sustainable lending growth.
Merri said: “I’m excited to bring my experience from the past 15 years to Santander and find ways we can develop its mortgage offering for its new and existing customer base.
“I’m looking forward to showcasing how Santander’s products can truly help their clients on their homeownership journey.”




David Morris said: “I am delighted to welcome Ben to the team. I know his expertise will be instrumental as we continue to evolve our mortgage proposition."
"His skills and insight will help strengthen our relationshipled lending and the benefits we bring to our clients through robust, flexible lending solutions.”

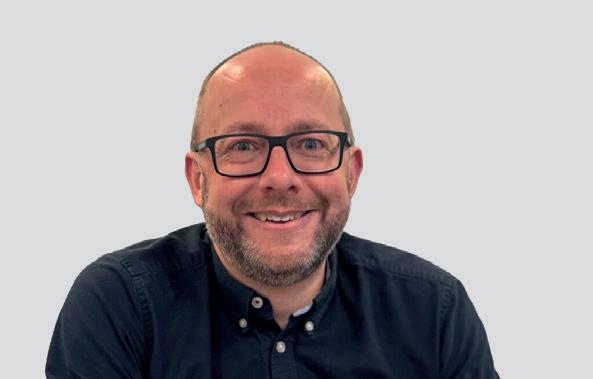
lending solutions.”
Pallas Capital appoints Phil Mabb as senior originator
Pallas Capital has appointed Phil Mabb as senior originator a er launching into the UK non-bank lending market last month. Mabb brings over 25 years’ experience in specialist property finance, including time in senior lending roles, independent broking and advisory work.
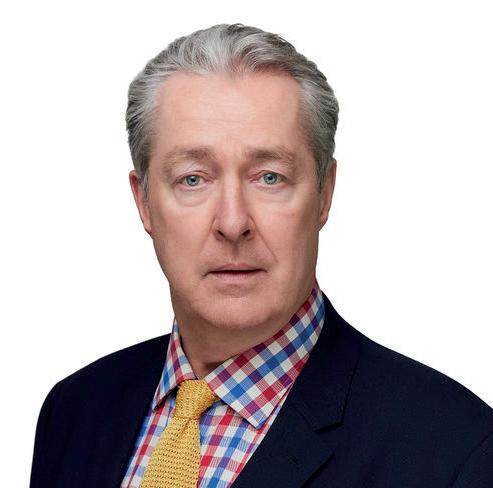
Mabb said: “This is a tough market, but that’s exactly why it’s such a good opportunity. Strong lenders establish themselves when conditions are challenging, not when everything is easy. Pallas is well funded, commi ed and built for long-term growth, which makes now the right time to be here."
Ben Keenan, chief credit officer said: “Phil brings a rare combination of broker credibility, lending experience and market judgement. As we grow, his insight will be invaluable in delivering the consistency and professionalism that define Pallas globally.”
She began her banking career at Yorkshire Bank before joining RBS as senior relationship manager in the specialist restructuring team. Since 2018, she has held senior assetbased lending positions, most recently head of asset management and first line underwriter at ABN AMRO Commercial Finance. In her new position, Hughes will support the asset-based lending team and take part in the credit process.
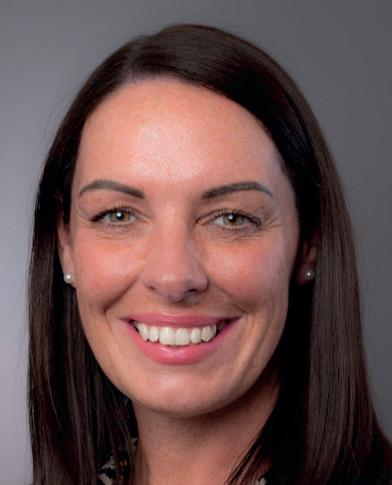
Hughes said: “I’m delighted to be joining Skipton Business Finance at such an exciting time. SBF has a strong reputation for providing flexible, relationship-led funding, and I’m looking forward to working with the team to further develop our ABL proposition and help more businesses achieve their growth ambitions.”
Michelle Wilson, chief operating officer at Skipton Business Finance, said: “We’re thrilled to welcome Kim to Skipton Business Finance.
"Her extensive ABL experience, strategic insight, and proven track record in delivering sophisticated funding solutions make her a fantastic addition to our team.”