
Sample Read
© Taxmann
Price : ` 4295
(For a set of two volumes)
Case Laws reported till 16th November, 2025 are covered
Published by : Taxmann Publications (P.) Ltd.
Sales & Marketing : 59/32, New Rohtak Road, New Delhi-110 005 India
Phone : +91-11-45562222
Website : www.taxmann.com
E-mail : sales@taxmann.com
Regd. Office : 21/35, West Punjabi Bagh, New Delhi-110 026 India
Printed at :
Tan Prints (India) Pvt. Ltd.
44 Km. Mile Stone, National Highway, Rohtak Road Village Rohad, Distt. Jhajjar (Haryana) India
E-mail : sales@tanprints.com
Disclaimer
Every effort has been made to avoid errors or omissions in this publication. In spite of this, errors may creep in. Any mistake, error or discrepancy noted may be brought to our notice which shall be taken care of in the next edition. It is notified that neither the publisher nor the author or seller will be responsible for any damage or loss of action to any one, of any kind, in any manner, therefrom. It is suggested that to avoid any doubt the reader should cross-check all the facts, law and contents of the publication with original Government publication or notifications.
No part of this book may be reproduced or copied in any form or by any means [graphic, electronic or mechanical, including photocopying, recording, taping, or information retrieval systems] or reproduced on any disc, tape, perforated media or other information storage device, etc., without the written permission of the publishers. Breach of this condition is liable for legal action.
For binding mistake, misprints or for missing pages, etc., the publisher’s liability is limited to replacement within seven days of purchase by similar edition. All expenses in this connection are to be borne by the purchaser. All disputes are subject to Delhi jurisdiction only.
Chapter-heads v
List of Cases Digested
List of Cases Affirmed/Reversed/Overruled/Approved/ Disapproved
List of Cases against which SLP Dismissed/Granted/ Notice issued by Supreme Court
List of Circulars & Notifications Judicially Analysed by Supreme Court/High Courts
SECTION 2
Charge of income-tax
SECTIONS 10 TO 10C
Income received from units [Section 10(35)] 113-114
Compensation received on compulsory acquisition of Rural Agricultural Land [Section 10(37)] 115
Transfer of certain long-term securities [Section 10(38)] 116-123
Certain body, authority, board, etc., constituted for benefit of general public [Section 10(46)] 124
Newly established undertakings in free trade zone, etc. [Section 10A] 125-130
Newly established units in special economic zones [Section 10AA] 131-132
Newly established 100% export-oriented undertakings [Section 10B] 133-138
SECTIONS 11 TO 13
purpose [Section 2( 15 )]
of income from property held under charitable/ religious trust [Section 11]
for applicability of sections 11 and 12 [Section 12A]
for registration [Sections 12AA & 12AB]
[Section 13]
SECTION 13A
SECTIONS 15 TO 17
SECTIONS 22 TO 27
SECTIONS 28 & 29
SECTION
SECTION
SECTION
SECTION
SECTION
SECTION
SECTION
Special
& doubtful debts [Section 36(1)(viia)]
applicability of section 36(1)(vii) & 36(1)(viia)
SECTION 36(1)(viii)
SECTIONS 40, 40A & 43B
SECTIONS 45 TO 55A
SECTIONS 56 TO 59
SECTION 69
SECTION 69A
SECTION 69B
SECTION 69C
SECTIONS 70 TO 80
SECTIONS 80A TO 89A
SECTION 90
of Double Taxation [Article 23 of OECD Model Convention]
Agreement Procedure (MAP) [Article 25 of OECD Model Convention]
SECTIONS 92 TO 92F & 144C
SECTIONS 95 TO 102
SECTION 115BBE
SECTIONS 115J TO 115JB
SECTIONS 119, 124 & 127
SECTIONS 131 TO 138
SECTION 139AA
SECTION 142
SECTIONS 143 & 144
SECTION 144B
SECTIONS 145 & 145A
SECTIONS 147 TO 153
Procedure before issuance of notice u/s 148 [Section 148A] 1150-1184
Time limit for notices u/ss 148 & 148A [Section 149] 1185-1237
Assessment is in pursuance of an order on appeal, etc. [Section 150] 1238-1239
Exception to section 150(1) 1240
Sanction for issue of notice [Section 151] 1241-1262
Faceless reassessment [Section 151A] 1263-1286
Time limit for completion of assessment, reassessment and recomputation [Section 153] 1287-1295
SECTIONS 153A TO 153D
Assessment of Search or Requisition cases
General 1296-1297
Assessment in case of search or requisition [Section 153A] 1298-1303
Time limit for completion of assessment [Section 153B] 1304-1305
Assessment of income of any other person [Section 153C] 1306-1332
Prior approval necessary for assessment [Section 153D] 1333 SECTION 154
SECTIONS 158B TO 158BI
[Section 158BC] 1342-1344 Undisclosed income of any other person [Section 158BD] 1345 Time limit for completion of block assessment [Section 158BE] 1346
SECTIONS 159 TO 179
Liability in special cases Legal representatives [Section 159] 1347
Charge of tax where share of beneficiaries unknown [Section 164] 1348-1349
of directors of private company [Section 179] 1350
SECTIONS 184 TO 189A
Special provisions applicable to firms
Joint and several liability of partners for tax payable by firm [Section 188A] 1351
SECTIONS 190 TO 206C & 234E
Deduction/Collection of tax at source (TDS/TCS)
[Section 194A]
[Section 194-I]
on acquisition of certain immovable property [Section 194LA]
[Section 195]
[Section 197]
[Section 234E]
SECTIONS 220 TO 226
Collection and recovery of tax
When tax payable and when assessee deemed in default [Section 220] 1396-1428
to TRO [Section 222] 1429-1432
[Section 226] 1433
CASE NOS.
SECTIONS 234A TO 234C
Interest, chargeable as
Defaults in furnishing return of income [Section 234A] 1434
Defaults in payment of advance tax [Section 234B] 1435-1436
Refunds
SECTIONS 237 TO 245
Refunds [Section 237] 1437-1449
Form of claim for refund and limitation [Section 239] 1450-1451
Withholding of refund [Section 241A] 1452
Interest on refunds [Section 244A] 1453-1462
Set off and withholding of refunds [Section 245] 1463-1470
SECTIONS 245A TO 245M
Settlement Commission
Application for settlement of cases [Section 245C] 1471-1477
Procedure on receipt of an application under section 245C [Section 245D] 1478-1482
Powers and Procedure [Section 245F] 1483
Power to grant immunity from prosecution and penalty [Section 245H] 1484-1486
SECTION 245MA
Dispute Resolution Committee (DRC)
Opportunity of hearing 1487
SECTIONS 246 TO 251
Commissioner (Appeals) & Joint Commissioner (Appeals)
Appealable orders before Commissioner (Appeals) [Section 246A] 1488-1492
Form of appeal and limitation [Section 249] 1493-1494
Procedure in appeal [Section 250] 1495-1504
Others 1505
SECTIONS 252 TO 255
Appellate Tribunal Appeals [Section 253] 1506-1514
CASE NOS.
Orders [Section 254] 1515-1520
Procedure [Section 255] 1521-1525
Appeals to High Court
SECTIONS 260A & 260B
Territorial jurisdiction 1526
Substantial question of law 1527-1530
Condonation of delay [Section 260A(2A)] 1531-1532
Opportunity of being heard 1533
Code of Civil Procedure, 1908, applicability of [Section 260A(7)] 1534
Power to Review/Recall 1535-1536
Remarks on Members of Tribunal 1537
SECTIONS
261 & 262
Appeals to Supreme Court
Dispute Settled under Vivad se Vishwas Scheme 1538
SECTIONS 263 & 264
Revision of orders
Revision of orders prejudicial to revenue [Section 263] 1539-1545
Revision of other orders [Section 264] 1546-1553
SECTION 268A
Filing of appeal by income-tax authority
Circular No. 3/2018, dated 11-7-2018 1554-1555
Circular Nos. 5/2024 & 9/2024, dated 15-3-2024 & 17-9-2024 1556-1563
SECTION 269ST
Mode of undertaking transactions
Scope of provision 1564
Apex Court guidelines for strict implementation of provision 1565
SECTIONS 269U TO 269UP
Purchase by Central Government of immovable properties in certain cases of transfer
Final and conclusive order of appropriate authority [Section 269UN] 1566
CASE NOS.
SECTIONS 270A TO 275
Penalties imposable
Under-reporting and misreporting of income [Section 270A] 1567-1569
Concealment of income [Section 271(1)(c)] 1570-1592
Failure to keep and maintain information and document, etc., in respect of certain transactions [Section 271AA] 1593
Search cases [Section 271AAA] 1594-1596
Failure to get accounts audited [Section 271B] 1597
Failure to deduct TDS [Section 271C] 1598-1601
Failure to comply with provisions of section 269SS [Section 271D] 1602-1605
Failure to comply with provisions of section 269ST [Section 271DA] 1606
Failure to comply with provisions of section 269T [Section 271E] 1607-1608
Failure to furnish information or document under section 92D [Section 271G] 1609
Power to grant immunity from penalty [Section 273AA] 1610
SECTIONS 275A TO 279A
Offences & Prosecution
Failure to pay tax to credit of Central Government under Chapter XII-D or XVII-B [Section 276B] 1611-1616
Wilful attempt to evade tax, etc. [Section 276C] 1617-1626
Failure to furnish return of income [Section 276CC] 1627-1629
Punishment not to be imposed in certain cases [Section 278AA] 1630-1631
Offences by companies [Section 278B] 1632-1633
Presumption as to culpable mental state [Section 278E] 1634
Prosecution to be at instance of Chief Commissioner [Section 279] 1635-1642
SECTION 281
Certain transfers to be void
Valid transfer 1643-1644
SECTION 281B
Provisional attachment to protect revenue in certain cases
Attachable property 1645
Time-limit for provisional attachment order 1646-1647
Release of attached property 1648
SECTION 282 Service of notice generally
SECTION 292BB Notice deemed to be valid in certain circumstances
SECTION 293
of suits in civil courts Suit 1652
OTHER ACTS /RULES/SCHEMES
Black Money (Undisclosed Foreign Income and Assets) and Imposition of Tax Act, 2015 1653-1654
Chartered Accountants Act, 1949 1655-1657
Direct Tax Dispute Resolution Scheme, 2016 1658
Direct Tax Vivad se Vishwas Act, 2020 1659-1676
Direct Tax Vivad se Vishwas Scheme, 2024 1677-1684 Expenditure-Tax Act, 1987 1685-1686 Gift Tax Act, 1958 1687 Income Declaration Scheme, 2016 1688-1689
Indian Revenue Service Rules, 2015 1690
Interest-Tax Act, 1974 1691-1692
Prohibition of Benami Property Transactions Act, 1988 1693-1695
Specified Bank Notes (Cessation of Liabilities) Act, 2017 1696
Wealth-tax Act, 1957 1697
WORDS AND PHRASES
Income-Tax Act, 1961 1698-1715
Direct Tax Vivad se Vishwas Act, 2020 1716 Prohibition of Benami Property Transactions Act, 1988 1717 PAGE NO. SUBJECT INDEX 1121
Chapter-heads
List of Cases Digested
List of Circulars & Notifications Judicially Analysed by Tribunal I-115-I-128
SECTION 2
SECTION 4
SECTION 9
Income deemed to accrue or arise in India
Permanent
[Article 5 of OECD Model Convention]
SECTIONS 10 TO 10C
Educational institutions [Section 10(23C)(iiiab)/(iiiad)/(vi)]
Hospitals [Section 10(23C)(iiiac)/(iiiae)/(via)]
Approved charitable fund/institution or approved public religious/ charitable trust [Section 10(23C)(iv)/(v)] 342-344
Investment income of VCC/VCF in VCU [Section 10(23FB)]
Certain incomes of infrastructure capital fund/company [Section 10(23G)]
individual [Section 10(26AAA)]
Agricultural produce market committee/board [Section 10(26AAB)]
back of shares [Section 10(34A)]
Income received from units [Section 10(35)]
Compensation received on compulsory acquisition of agricultural land [Section 10(37)]
of certain long-term securities [Section 10(38)]
SECTIONS 11
TO 13
trusts
purpose [Section 2(15)]
of income from property held under charitable/ religious trust [Section 11] 417-504 Conditions for applicability of sections 11 and 12 [Section 12A] 505-532 Procedure for registration [Sections 12A(1)(ac), 12AA & 12AB] 533-623
of exemption [Section 13] 624-637
SECTION 14A
Expenditure incurred in relation to income not includible in total income
of expenditure 682-715
SECTIONS 15 TO 17
SECTIONS 22 TO 27
SECTIONS 28 & 29
SECTION 35DDA
SECTION 35E
SECTION 36(1)(vii), (viia) & 36(2)
Bad debts and provision for bad & doubtful debts
Bad debts [Section 36(1)(vii) & 36(2)] 992-1005
Provision for bad & doubtful debts [Section 36(1)(viia)] 1006-1019
Simultaneous applicability of section 36(1)(vii) & 36(1)(viia) 1020-1022
SECTION 36(1)(viii)
Special reserve created and maintained by specified entities
finance
This provision vis-à-vis section 36(1)(viia)
SECTION 37(1)
Business expenditure
Allowability 1030-1267 Year in which deductible 1268-1274
SECTIONS 40, 40A & 43B
Business disallowance
Interest, etc., paid to non-residents without deducting TDS [Section 40(a)(i)] 1275-1279
Interest, etc., paid to residents without deducting TDS [Section 40(a)(ia)] 1280-1303
Rates or taxes [Section 40(a)(ii)] 1304-1305
Fees/charges levied exclusively on or any appropriations from State Government undertaking by State Government [Section 40(a)(iib)] 1306
Interest, salary, etc., paid by firm to partner [Section 40(b)] 1307-1308
Excessive/Unreasonable expenditure [Section 40A(2)] 1309-1318
Cash payment exceeding prescribed limit [Section 40A(3), (3A) & (4)] 1319-1328
Gratuity provision [Section 40A(7)] 1329-1330
Employer’s Contribution for employee’s benefit to funds, trust, etc. [Section 40A(9)] 1331
Certain deductions to be only on actual payment [Section 43B] 1332-1359 CASE NOS.
SECTION 41
Profits chargeable to tax
Remission/Cessation of trading liability [Sub-section (1)] 1360-1375
Withdrawal from special reserve [Sub-section (4A)] 1376
SECTION 43
Definitions of certain terms relevant to income from profits and gains of business or profession
[Clause (1)]
transaction [Clause (5)]
SECTION 43A
SECTION 43CA
Special provision for full value of consideration for transfer of assets other than capital assets in certain cases
SECTION 43CB
SECTION
SECTION
SECTION
SECTION
SECTION
SECTIONS 45 TO 55A
Capital gains Capital asset [Section 2(14)] 1423-1436
[Section 2(47)] 1437-1443
gains, chargeable as [Section 45] 1447-1467
as transfer [Section 47] 1472-1475
Computation of capital gains [Sections 48, 49 & 55] 1476-1513
Special provision for computation of capital gains in case of depreciable assets [Section 50] 1514-1522
Computation of capital gains in case of slump sale [Section 50B] 1523
Special provision for computation of full value of consideration [Section 50C] 1524-1549
1550-1619
SECTIONS 56 TO 59
Income from other sources
from other sources, chargeable as [Section 56] 1620-1695
[Section 57] 1696-1710 SECTION 68
SECTION 69
SECTION 69A
SECTION 69B
Unexplained expenditure
SECTION 69C
Bogus purchases, examination/verification of 1926
Opportunity of being heard 1927
Non-consideration of assessee’s reply 1928-1929
Non-compliance of section 133 notice 1930-1931
Illustrations 1932-1953
Taxable on whom 1954
Quantum of addition 1955-1964
SECTIONS 70 TO 80
Set off, or Carry forward and set off, of Losses
Set off of losses under same head of income [Section 70] 1965-1971
Set off of losses under any other head of income [Section 71] 1972-1973
Business losses [Section 72] 1974-1976
Accumulated loss and unabsorbed depreciation allowance in amalgamation or demerger, etc. [Section 72A] 1977-1978
Accumulated loss and unabsorbed depreciation allowance in business reorganisation of co-operative banks [Section 72AB] 1979
Losses under head “capital gains” [Section 74] 1980-1981
Submission of return for losses [Section 80] 1982-1984
SECTIONS 80A TO 89A
Deductions, Rebates & Reliefs
Deductions to be made in computing total income [Section 80A] 1985-1987
Deduction not to be allowed unless return furnished [Section 80AC] 1988
Deduction in respect of life insurance premia, etc. [Section 80C] 1989-1990
Donation to certain charitable institutions, etc. [Section 80G] 1991-2048
Political contributions by companies [Section 80GGB] 2049
Political contributions by other persons [Section 80GGC] 2050
Profits retained for export business [Section 80HHC] 2051-2056
Profits and gains from industrial undertakings or enterprises engaged in infrastructure development, etc. [Section 80-IA] 2057-2068
Profits and gains by an undertaking or enterprise engaged in Development of SEZ [Section 80-IAB] 2069
Profits and gains from industrial undertakings other than Infrastructure development undertakings [Section 80-IB] 2070-2073
Certain undertakings/enterprises in certain special category states [Section 80-IC] 2074-2087
Certain undertakings in north-eastern states [Section 80-IE] 2088
Employment of new employees [Section 80JJAA] 2089-2091
Inter-Corporate dividends [Section 80M] 2092
Income of co-operative societies [Section 80P] 2093-2111
Rebate of income-tax in case of certain individuals [Section 87A] 2112
Relief available when salary is paid in arrears or in advance [Section 89] 2113-2114
Relief from taxation in income from retirement benefit account maintained in a notified country [Section 89A] 2115
SECTION 90
Double taxation relief where Agreement exists
Overriding effect of DTAA [Section 90(2)] 2116 Taxes covered [Article 2 of OECD Model Convention] 2117
Elimination of double
[Article 23 of
vention] 2118-2136
SECTIONS 92 TO 92F & 144C
enterprise [Section 92A] 2142-2144
transaction [Section 92B] 2145-2176 Specified domestic transaction [Section 92BA] 2177-2185
Arm’s length price, computation of [Section 92C] 2186-2535
Reference to TPO [Section 92CA] 2536-2543
Advance pricing agreements [Sections 92CC & 92CD] 2544-2551
Accountant’s report [Section 92E] 2552
Reference to dispute resolution panel [Section 144C] 2553-2573
SECTION 94B
Limitation on interest deduction in certain cases
Fresh claim of deduction before appellate authority 2574 CASE NOS.
SECTION 112
SECTION 115A Tax on dividends, royalty and technical service fees in case of foreign companies
in shares of Indian subsidiary
SECTION 115BAA
SECTION 115BAC
SECTION 115BBC
SECTION 115BBE
SECTION 115-O
SECTIONS 115QA TO 115QC
Tax on distributed income of domestic company for buy-back of
SECTION 115U
SECTIONS 115V TO 115VZC
SECTIONS 120, 124 & 127
SECTIONS 131 TO 138
Inquiry before assessment
SECTION 142
Special audit 2647
SECTIONS 143 & 144
Assessment
Summary assessment [Section 143(1)] 2648-2657
Scrutiny assessment [Section 143(2) & (3)] 2658-2683
Best judgment assessment [Section 144] 2684-2686
SECTION 144B
Faceless assessment
Method of accounting
General [Section 145]
SECTIONS 145 & 145A
2688-2725
Valuation of inventory [Section 145A] 2726-2732
SECTIONS 147 TO 153
Reassessment Income escaping assessment [Section 147] 2733-2747 Notice for reassessment [Section 148] 2748-2758
Procedure before issuance of notice u/s 148 [Section 148A] 2759-2762
Prior approval for assessment, reassessment or recomputation in certain cases [Section 148B] 2763
Time limit for notices u/ss 148 & 148A [Section 149] 2764-2781
Sanction for issue of notice [Section 151] 2782-2804
Faceless reassessment [Section 151A] 2805-2806
Time Limit for completion of assessment, reassessment and recomputation [Section 153] 2807-2808
SECTIONS 153A TO 153D
Assessment of search or requisition cases
General 2809
Assessment in case of search or requisition [Section 153A] 2810-2822
Time limit for completion of assessment [Section 153B] 2823-2825
CASE NOS.
Assessment of income of any other person [Section 153C] 2826-2830
Prior approval necessary for assessment [Section 153D] 2831-2844
Rectification of mistake
SECTION 154
Reasonable opportunity of being heard [Sub-section (3)] 2845-2846
Illustrations 2847-2849
Time-Limit for making rectification order [Sub-section (8)] 2850
SECTION 156A
Modification and revision of notice in certain cases
Resolution plan not finalised 2851-2852
SECTIONS 158BC & 158BD
SECTIONS 159 TO 179
Liability in special cases
Legal representatives [Section 159] 2854
Charge of tax where share of beneficiaries unknown [Section 164] 2855-2863
Charge of tax where shares of member in AOPs or BOIs unknown, etc. [Section 167B] 2864-2865
Executors [Section 168] 2866
SECTIONS 190 TO 206C
Deduction/Collection of Tax at Source (TDS/TCS)
Salary [Section 192] 2867
Interest other than interest on securities [Section 194A] 2868-2877
Contractors, payment to [Section 194C] 2878-2889
Insurance commission [Section 194D] 2890
Commission or brokerage [Section 194H] 2891-2900
Rent [Section 194-I] 2901-2904
Transfer of certain immovable property other than agricultural land [Section 194-IA] 2905-2907
Joint development agreement [Section 194-IC] 2908-2909
Fees for professional/technical services [Section 194J] 2910-2917
Interest on certain bonds and government securities [Section 194LD] 2918
Payment by E-Commerce operator to E-Commerce participant [Section 194-O] 2919
Purchase of goods [Section 194Q] 2920
Non-residents [Section 195] 2921-2933
Certificate for deduction at lower/nil rate [Section 197] 2934
Credit for tax deducted [Section 199] 2935-2955
Processing of statements of TDS & other statements [Section 200A] 2956
Consequences of failure to deduct/pay tax [Section 201] 2957-2965
Requirement to furnish PAN [Section 206AA] 2966 Collection of tax at source [Section 206C] 2967-2968
SECTIONS 207 TO 219
2969
for advance tax [Section 219] 2970
SECTION 226
When tax payable when assessee deemed in default
Interest [Sub-section (2)] 2971-2972
Stay of Demand [Sub-section (6)] 2973
SECTIONS
234A TO 234C
Interest, chargeable as
Defaults in furnishing return of income [Section 234A] 2974
Defaults in payment of advance tax [Section 234B] 2975-2979
Deferment of advance tax [Section 234C] 2980-2984
SECTIONS
237 TO 245 Refunds Refunds [Section 237] 2985 Interest on refunds [Section 244A] 2986-2990
SECTIONS 246 TO 251
Commissioner (Appeals) & Joint Commissioner (Appeals)
Appealable orders before Commissioner (Appeals) [Section 246A] 2991
CASE NOS.
Form of appeal and limitation [Section 249] 2992-2999
Procedure in appeal [Section 250] 3000-3004
Powers [Section 251] 3005-3015
Appellate Tribunal
SECTIONS 252 TO 255
Appeals [Section 253] 3016-3023
Orders [Section 254] 3024-3026
Procedure [Section 255] 3027-3029
Revision of orders
SECTIONS 263 & 264
Revision of orders prejudicial to revenue [Section 263] 3030-3037
Revision of other orders [Section 264] 3038
SECTION 268A
Filing of Appeal by Income-Tax Authority
Circular No. 3/2018, dated 11-7-2018 3039
Circular Nos. 5/2024 & 9/2024, dated 15-3-2024 & 17-9-2024 3040-3042
SECTIONS 269SS, 269ST, 269T, 271D, 271DA & 271E
Mode of acceptance, payment or repayment in certain cases to counteract evasion of tax
Mode of taking or accepting certain loans, deposits and specified sum [Section 269SS] 3043-3049
Mode of undertaking Transactions [Section 269SS] 3050
Mode of repayment of certain loans or deposits [Section 269T] 3051-3053
Penalties imposable
SECTIONS 270A TO 275
Under-reporting and misreporting of income [Section 270A] 3054-3063
Concealment of income [Section 271(1)(c)] 3064-3086
Failure to keep, maintain or retain books of account, documents, etc. [Section 271A] 3087
Failure to keep and maintain information and document, etc., in respect of certain transactions [Section 271AA] 3088-3091
Search cases [Section 271AAB] 3092-3096
Unexplained income, etc. [Section 271AAC] 3097
SECTION 9
Income deemed to accrue or arise in India
Extra-territorial income 39
Permanent Establishment (PE) [Article 5 of OECD Model Convention]
Existence of PE in India 40
Fixed place PE
Dependant Agent PE (DAPE) 41-45
Liaison office 46-48
Secondment of employees 49
Strategic oversight services agreement 50
Insurance PE 51
Reassessment 52
Business profits [Article 7 of OECD Model Convention]
Profits attributable to PE, computation of 53
Global net loss 54
Arm’s length transfer 55
Related party transactions 56
Credit card fees 57
Withholding tax rate 58
Absence of PE 59
Dividend [Article 10 of OECD Model Convention]
MFN clause impact 60
Interest [Article 11 of OECD Model Convention]
Notional interest 61
Royalty/fees for technical services [article 12 of OECD Model Convention]
Royalty Advertisement charges 62
Cross-cost charges 63
Inter-connect services 64-65
Satellite transponder services 66-67
Software 68-72
Fees for technical/included services (FTS/FIS)
Access to online content 73
Advisory services 74
Centralised services 75-76
Export commission 77
Logistic support services 78
Management support services 79
Marketing services 80
Reimbursement of expenses
81-82
Repair & maintenance services 83
Secondment of employees 84
Software 85
Testing services 86
Training workshops 87
Royalty or FTS/FIS
Database 88
Software 89
Reassessment 90
Capital gains [Article 13 of OECD Model Convention]
Sale of shares 91
Reassessment 92-94
EXTRA-TERRITORIAL INCOME
39. Income-tax authorities in India do not have jurisdiction to bring to tax income arising from extra-territorial source, that is outside India, in respect of business carried on by foreign companies outside India [Assessment years 2008-09 to 2015-16] [In favour of assessee] [Article 12 of OECD Model Convention]
Vodafone Idea Ltd. v. Dy. DIT, (International Taxation) [2023] 152 taxmann.com 575/457 ITR 189 (Kar.)
Assessee was an ILD license holder and responsible for providing connectivity to calls originating/terminating outside India. It had entered into an agreement with NTOs for international carriage and connectivity services. Assessee had also entered into a capacity transfer agreement with a Belgium entity (Belgacom) which had certain arrangement with Omantel for utilisation of bandwidth. Assessing Officer passed an assessment order holding assessee as ‘defaulter’ for failure to deduct TDS while making payments to the said company. Equipments and submarine cables were situated overseas and Belgacom did not have any ‘permanent establishment’ in India.
Held that the income-tax authorities have no jurisdiction to bring to tax income arising from extra-territorial source. Further, withholding tax liability should not be levied at a higher rate. Since, in the instant case, facilities were situated outside India and agreement was with a Belgium entity which did not have any presence in India, tax authorities in India would have no jurisdiction to bring to tax income arising from extra-territorial source.
Case review : SLP dismissed in Dy. CIT (International Taxation) v. Vodafone Idea Ltd. [2025] 173 taxmann.com 695/304 Taxman 594 (SC); Dy. CIT, International Taxation v. Vodafone Idea Ltd. [2025] 176 taxmann.com 626/306 Taxman 267 (SC)
PERMANENT ESTABLISHMENT (PE) [ARTICLE 5 OF OECD MODEL CONVENTION]
EXISTENCE OF PE IN INDIA
40. Where Commissioner invoked revisionary proceedings on ground that Assessing Officer had not conducted necessary inquiries to verify claim of assessee, a Singapore based company, that it had no PE in India and to verify whether any commercial substance existed in Singapore, since said tentative opinion that assessee was a conduit company formed to obtain tax benefits of India-Singapore DTAA were not put to assessee and assessee was not given any opportunity of hearing, revisionary order was to be set aside [Assessment year 2017-18] [In favour of assessee] [Article 12 of DTAA between India and Singapore]
CIT, International Taxation - 3 v. Zebra Technologies Asia Pacific Pet. Ltd. [2024] 169 taxmann.com 187/[2025] 302 Taxman 380/472 ITR 745 (Delhi)
Assessee, a company incorporated in Singapore, was engaged in the business of wholesale distribution of electronic products as well as services related to after sales, repairs, and technical support services to customers in various parts of world including India. Assessee had received certain amount for rendition of technical support, repair, and maintenance services. Assessee filed its income tax returns for relevant assessment year, inter alia, claiming that it had no PE in India and was not liable to pay tax in respect of aforesaid receipts. Assessing Officer accepted assessee’s claim. Commissioner opined that Assessing Officer had not verified the relevant details to ascertain whether assessee had a PE in India and to ascertain whether any commercial substance existed in Singapore or assessee was merely a conduit company. Accordingly, Commissioner initiated proceeding under section 263 by issuance of a show cause notice. Tribunal set aside the revisionary order on the ground that assessee was not afforded an opportunity to counter allegation. It was noted that Commissioner had faulted Assessing Officer for not undertaking certain enquiries. However, Commissioner had not put the issue regarding treaty shopping to assessee.
Held that there was no fault with the decision of the Tribunal in setting aside the revisionary order passed by the Commissioner.
Case review : Zebra Technologies Asia Pacific Pte. Ltd. v. CIT (International Taxation) [2023] 150 taxmann.com 467/201 ITD 87 (Delhi - Trib.) affirmed
FIXED PLACE PE
Dependant Agent PE (DAPE)
41. Where assessee, a foreign company, had established a liaison office in India which was followed by incorporation of a fully owned subsidiary in India, since revenue had abjectly failed to prove that said subsidiary stood conferred with authority to bind or conclude contracts on behalf of assessee, no DAPE could be said to have come into existence and, thus, assessee could not be said to have a fixed place PE in India [Assessment years 1997-98 and 1998-99] [In favour of assessee] [Article 5 of the DTAA between India and Finland]
CIT, International Taxation v. Nokia Network OY [2025] 171 taxmann. com 757/479
ITR 515 (Delhi)
Assessee, a foreign company, was engaged in manufacture of advanced telecommunication systems and equipment. It had established a liaison office in India in 1994 which was followed by incorporation of a fully owned subsidiary, NIPL, in India. Assessee filed its return of income taking a position that offshore supplies were not exigible to tax. Assessing Officer held that NIPL was liable to be treated as Dependent Agent Permanent Establishment (DAPE). He further held that 70 per cent of total equipment revenue was attributed towards sale of hardware and 30 per cent of the same was attributed towards supply of software and same was taxed as royalty. It was noted that NIPL was pursuing an independent line of business with Indian telecom operators. Revenue had abjectly failed to prove that NIPL stood conferred with authority to bind or conclude contracts on behalf of assessee. NIPL was not generating any revenue or income for the assessee. Onshore activities of NIPL were totally disconnected with supply contracts of assessee. There was, thus, a clear and discernible distinction between the activities undertaken by NIPL and supply contracts executed by assessee.
Held, on facts, that no DAPE could be said to have come into existence and, thus, assessee could not be said to have a fixed place PE in India. Further, income derived from sale of equipment and licensing of software in India could not be taxed in the hands of assessee.
42. Where MIPL was not performing additional function, in absence of material, it could not be taken as dependant agency PE to assessee, a non-resident company [Assessment year 2009-10] [In favour of assessee] [Article 5 of DTAA between India and Japan]
CIT (International Taxation)-2 v. Mitsui and Co. [2025] 170 taxmann. com 827 (Delhi)
Where MIPL was not performing additional function, in the absence
of material, it could not be taken as dependant agency PE to assessee (a non-resident company) liable to tax in India.
Case review : Dy. CIT (International Taxation) v. Mitsui & Co. [2022] 141 taxmann.com 128/94 ITR(T) 34 (Delhi - Trib.) affirmed and SLP dismissed in CIT International Taxation 2 v. Mitsui and Co. [2025] 170 taxmann.com 828/303 Taxman 331 (SC).
43. Where Assessing Officer initiated reassessment proceedings against assessee, a US based company, on ground that assessee had fixed place PE and dependent agent PE in India and was, therefore liable to pay tax in India, since there was no tangible material to establish existence of a PE in India for relevant assessment years, impugned reassessment proceedings were to be quashed [Assessment years 2013-14 to 2016-17] [In favour of the assessee] [Article 5 of DTAA between India and USA]
GE Renewables Grid LLC v. Asstt. CIT [2025] 174 taxmann.com 460 (Delhi)
Assessee, a US-based company, was engaged in development of power grid transmission and distribution management software and engineering services, was issued reassessment notices under section 148 based on survey findings alleging existence of dependent agent PE and fixed place PE in India. It was noted that reasons recorded for reopening did not contain any tangible material to substantiate existence of PE in India for the relevant assessment years.
Held that in the absence of any cogent material to establish existence of PE in India, reassessment proceedings initiated under section 148 were to be quashed.
44. Where Assessing Officer initiated reassessment proceedings against assessee, a foreign company, on ground that assessee had fixed place and dependent agent PE in India and, thus, it was liable to pay tax in India, since reasons as recorded in support of formation of opinion that income had escaped assessment had not alluded to any facts specific to assessment years 2013-14 to 2017-18, impugned reassessment proceedings were to be quashed [Assessment years 2013-14 to 2017-18] [In favour of assessee] [Article 5 of DTAA between India and Finland]
Grid Solutions OY (Ltd.) v. Asstt. CIT, International Taxation [2025] 170 taxmann.com 498/303 Taxman 288/477 ITR 698 (Delhi)
Assessee, a foreign company, was engaged in the business of manufacturing products for efficient power transmission, reactive power compensation and harmonic filtering, as well as related project engineering. Assessee had been awarded a contract by Indian company to supply equipments from outside India. Assessee claimed to have received payment of only 10 per cent advance during the year from
Indian company and, accordingly, had shown nil income. Assessment was completed under section 143(3) accepting income as shown by assessee. Subsequently, a survey under section 133A(2A) was conducted upon GE group which had taken over grid business of assessee in the year 2015. Based on the said survey, impugned reassessment proceedings were initiated against the assessee on the ground that the nature of activities by assessee would establish that assessee had fixed place and dependent agent permanent establishment in India and, thus, it was liable to pay tax in India on income earned from the said contract. It was noted that the Assessing Officer had merely proceeded to adopt and reiterate what was found in the course of survey.
Held that since reasons as recorded in support of formation of opinion that income had escaped assessment had not alluded to any facts specific to assessment years 2013-14 to 2017-18, impugned reassessment proceedings were to be quashed.
45. Where Assessing Officer issued reopening notice against assessee, a foreign company, on ground that a survey conducted on a company revealed that assessee had fixed place and dependent agent PE in India and, thus, it was liable to pay tax in India, since revenue had woefully failed to establish that formation of opinion was based on any independent inquiry or material that Assessing Officer might had collated for purposes of forming an opinion as to whether income in relevant AYs had escaped assessment, impugned reassessment notice was to be set aside [Assessment years 2013-14 to 2017-18] [In favour of assessee] [Article 5 of DTAA between India and Switzerland]
GE Grid (Switzerland) GMBH v. Asstt. CIT [2025] 172 taxmann. com 227 (Delhi)
Assessee-company was incorporated and registered under the laws of Switzerland. It was engaged in the business of supplying equipments and spares to Indian entities. A survey was conducted upon company GE in June, 2019 which revealed that assessee had a business connection as per the Income-tax Act as well as a PE in India as per India-Switzerland DTAA and, thus, a part of its business profits arising from India was to be taxed in India as income of PE. Accordingly, Assessing Officer issued a reassessment notice. It was noted that revenue had woefully failed to establish that formation of opinion was based on any independent inquiry or material that Assessing Officer might had collated for the purposes of forming an opinion as to whether income in AYs 2013-14 to 2017-18 had escaped assessment. As was ex facie evident from a reading of reasons which stood assigned for invoking section 148, solitary basis was survey conducted in June 2019.
Held, on facts, that the impugned reassessment notice issued against the assessee was to be set aside.
Liaison office
46. Where assessee, a US based company, engaged in business of rendering money transfer services, established a liaison office (LO) in India, since activities undertaken by LO were merely preparatory or auxiliary in character and far removed from core business of assessee, LO would not constitute a PE [Assessment years 2001-02 to 2004-05, 2006-07, 2007-08, 2011-12, 2013-14 and 2015-16] [In favour of assessee] [Article 5 of the DTAA between India and USA]
DIT (International Taxation) v. Western Union Financial Services Inc. [2024] 169 taxmann.com 461/[2025] 472
ITR 220 (Delhi)
Assessee, a US-based company, was engaged in the business of rendering money transfer services. For the said purpose, it had entered into agreements appointing agents in India. In terms of agency agreements, assessee had established a liaison office (LO) in India. Assessing Officer opined that assessee had a fixed place of business which constituted a ‘Fixed Place’ PE. Tribunal held that the activities undertaken by LO were merely preparatory or auxiliary in character and, thus, it would not constitute a PE.
Held that the permission granted by RBI proscribed LO from undertaking any commercial, trading or industrial activity in India and since activities undertaken by LO were far removed from core business of assessee, tests of ‘preparatory’ and ‘auxiliary’ as embodied in Article 5(3)(e) stood satisfied and, thus, LO would not constitute a PE. Further, since LO did not have any authority to conclude contracts, it could not be classified as a DAPE. Furthermore, since software merely constituted a medium of communication which enabled Indian agents to talk and communicate with servers of assessee housed in USA, deployment of software would not result in creation of a PE.
47. Where Liaison Office (LO) of assessee in India did not finalize and transact a business deal on its own or in name of head office, activities carried out by LO could not be said to be preparatory or auxiliary in nature and, thus, LO did not constitute Permanent Establishment of assessee [Assessment year 2009-10] [In favour of assessee] [Article 5 of DTAA between India and Japan]
CIT (International Taxation)-2 v. Mitsui and Co. [2025] 170 taxmann.com 827 (Delhi)
Where liaison office of assessee, a Japanese company, in India did not finalize and transact a business deal on its own or in the name of head
office, activities carried out by LO could not be said to be preparatory or auxiliary in nature and, thus, LO did not constitute Permanent Establishment, liable to tax in India.
Case review : Dy. CIT (International Taxation) v. Mitsui & Co. [2022] 141 taxmann.com 128/94 ITR(T) 34 (Delhi - Trib.) affirmed and SLP dismissed in CIT International Taxation 2 v. Mitsui and Co. [2025] 170 taxmann.com 828/303 Taxman 331 (SC).
48. Where Assessing Officer issued reopening notice based on materials gathered during survey conducted for earlier assessment years at Indian LO of non-resident assessee, and held that LO constituted a fixed place PE of assessee in India and income attributable to such PE was taxable in India, since assessee did not assert that facts in relevant assessment year were distinct from those which had fallen for detailed examination of revenue and had ultimately culminated in passing of a judgment by High Court in earlier assessment years, impugned reassessment proceedings were justified [Assessment year 2009-10] [In favour of revenue] [Articles 5 and 7 of DTAA between India and Italy]
GE Nuovo Pignone S.P.A v. CIT (International Taxation) [2024] 167 taxmann.com 351/[2025] 477 ITR 659 (Delhi)
Assessee was a non-resident company incorporated in Italy and part of GE group. A survey was conducted at LO of assessee’s group company and based on material gathered in the course thereof, notices under section 148 came to be issued to various entities of GE Group including assessee for assessment years 2001-02 to 2008-09. Thereafter, Assessing Officer issued reopening notice for the relevant assessment year on the ground that LO constituted a fixed place PE of assessee in India and income attributable to such PE was taxable in India. Assessee contended that the entire reassessment action was based upon the survey report and material which had been gathered and collated for assessment years other than the relevant assessment year and could not have justifiably formed the basis for invocation of section 148. It was noted that assessee did not assert that the facts in the relevant assessment year were distinct or distinguishable from those which had fallen for detailed examination of revenue in litigation which had ensued and had ultimately culminated in passing of a judgment by the High Court in earlier assessment years holding that assessee had a PE in India.
Held that the impugned reassessment proceedings were justified. Case review : GE Nuovo Pignone SPA v. Deputy CIT (IT) [2019] 101 taxmann. com 402 (Delhi - Trib.) affirmed
Secondment of employees
49. Where assessee, a South Korean company, had seconded employees in India, however, those employees were not discharging functions or performing activities connected with global enterprise of assessee and their placement in India was with objective of facilitating activities of Indian subsidiary, those employees would not meet qualifying benchmarks of a PE [Assessment years 2007-08 to 2009-10, 2011-12 to 2015-16 and 2017-18] [In favour of assessee] [Article 5 of DTAA between India and South Korea]
Pr. CIT, International Taxation v. Samsung Electronics Co. Ltd. [2025] 170 taxmann.com 417/303 Taxman 212/478 ITR 271 (Delhi)
Assessee, a South Korean company, was engaged in manufacturing and sale of electronic goods. It had two wholly owned subsidiaries in India. Assessing Officer held that Indian subsidiary was liable to be considered as a PE per se. He also held that the said subsidiary met tests of DAPE as well as service PE. Tribunal noted that seconded employees were not discharging functions or performing activities connected with the global enterprise of assessee. Their placement in India was with the objective of facilitating activities of Indian subsidiary and, thus, collection of market information, collation of data for development of products, market trend studies or exchange of information would not meet the qualifying benchmarks of a PE.
Held that the Tribunal was justified in interfering with the opinion formed by DRP which had spoken of a deemed PE having come into being merely on account of secondment of employees.
Case review : Samsung Electronics Co. Ltd. v. Dy. CIT (Int. Taxation) [2018] 92 taxmann.com 171/64 ITR(T) 99 (Delhi - Trib.) affirmed.
Strategic oversight services agreement
50. Where assessee, a Dubai based company, entered into an agreement with Indian hotel to provide strategic planning and ‘know-how’ to ensure that hotel was developed and operated efficiently, since assessee exercised pervasive and enforceable control over hotel’s strategic, operational, and financial dimensions, hotel premises satisfied criteria required to be classified as a “fixed place of business” or PE within meaning of article 5(1) of DTAA and, thus, income received under SOSA was attributable to such PE and was taxable in India [Assessment years 2009-10 to 2017-18] [In favour of revenue] [Articles 5 and 7 of the DTAA between India and UAE]
Hyatt International Southwest Asia Ltd. v. Addl. DIT [2025] 176 taxmann.com 783/306 Taxman 241/478 ITR 238 (SC)
Assessee, a company incorporated in Dubai, entered into two Strategic Oversight Services Agreements (SOSA) with ASL, India. Under the
said agreement, assessee agreed to provide strategic planning and ‘know-how’ to ensure that hotel was developed and operated efficiently. Assessing Officer passed assessment orders taxing hotel related services rendered by assessee, inter alia, on the ground that assessee had a PE in India in form of place of business under article 5(1) of DTAA. High Court upheld the order passed by the Assessing Officer. It was noted from contractual provisions detailed in SOSA that assessee exercised pervasive and enforceable control over hotel’s strategic, operational, and financial dimensions. It was also noted that assessee’s executives and employees made frequent and regular visits to India to oversee operations and implement SOSA.
Held that the 20-year duration of SOSA, coupled with assessee’s continuous and functional presence, satisfied the tests of stability, productivity and dependence and, thus, hotel premises clearly satisfied the criteria required to be classified as a “fixed place of business” or PE. Furthermore, assessee’s ability to enforce compliance, oversee operations, and derive profit-linked fees from hotel’s earnings demonstrated a clear and continuous commercial nexus and control with hotel’s core functions which satisfied conditions necessary for constitution of a fixed place PE under Article 5(1) of India-UAE DTAA. Thus, assessee had a fixed place PE in India within the meaning of article 5(1) of DTAA and income received under SOSA was attributable to such PE and taxable in India.
Case review : Hyatt International-Southwest Asia Ltd. v. Addl. DIT [2024] 158 taxmann.com 136/297 Taxman 497/464 ITR 508 (Delhi) affirmed.
51. Where assessee, an insurance company, made payments towards reinsurance premium to Non-Resident Reinsurers (NRRs) without deducting tax at source, since brokers were acting as independent entities merely playing role of facilitators, no tax at source was to be deducted on these payments, thus, impugned payments made by assessee to NRRs could not be disallowed under section 40(a)(i) [Assessment years 2005-06 to 2010-11, 2013-14 and 2014-15] [In favour of assessee] [Article 5 of the DTAA between India and Switzerland]
Pr. CIT - 4 v. Cholamandalam MS General Insurance Company Ltd. [2025] 175 taxmann.com 452 (Mad.)
Assessee was an insurance company carrying on reinsurance business. It made payments towards reinsurance premium to non-resident reinsurers (NRRs) without deducting tax at source. Assessing Officer disallowed such payments under section 40(a)(i) for non-deduction of TDS under section 195. It was noted that the discussion in the order
of Tribunal sat out the relevant facts making it clear that brokers were acting as independent entities merely playing the role of facilitators. Tribunal, thus, concluded that brokers did not either constitute a business connection in terms of Explanation 2 to section 9(1)(i) or a Permanent Establishment in terms of article 5 of relevant DTAAs.
Held that no material was produced by the Department before the court to dislodge factual findings rendered by the Tribunal. Thus, the impugned payments made by assessee to NRRs could not be disallowed under section 40(a)(i).
REASSESSMENT
52. Where reassessment proceedings were initiated against assessee on ground that non-resident parent company and its affiliates had a business connection and a PE in India and, thus, assessee was liable to deduct tax under section 195 on payments made by it to them, since subsequent order passed under section 201(1) found that except for one, all other affiliates did not have a PE in India, impugned reassessment proceedings were to be quashed [Assessment years 2006-07 and 2007-08] [In favour of assessee] [Article 5 of OECD Model Convention]
Honda Cars India Ltd. v. Dy. CIT [2024] 166 taxmann.com 623/301
Taxman 653 (Delhi)
Assessee-company was engaged in the business of manufacturing and selling of cars in India. It filed its return of income which was accepted and an assessment order was passed. Subsequently, a survey was conducted upon assessee and on the basis of same, reassessment proceedings were initiated against the assessee on the ground that nonresident parent company and its affiliates had a business connection and a PE in India and, thus, assessee was liable to deduct tax under section 195 on payments made by it to them and since assessee had failed to do so, provisions of section 40(a)(i) were attracted and amount claimed as expenditure was liable to be disallowed under section 40(a) (i). Assessee submitted that subsequent order dated 10-12-2018 passed under section 201(1) found that except for one, all other affiliates did not have a PE in India.
Held, on facts, that the impugned reassessment proceedings initiated against the assessee were to be quashed.
BUSINESS PROFITS [ARTICLE 7 OF OECD MODEL CONVENTION]
PROFITS ATTRIBUTABLE TO PE, COMPUTATION OF
53. Where issue regarding attribution of profit to AE on merits already stood concluded in favour of assessee by Court in earlier year, questions raised in Revenue’s appeal having become academic, appeal under section 260A was not maintainable [Assessment year 2011-12] [In favour of assessee]
CIT, International Taxation-3 v. Travelport LP [2025] 179 taxmann. com 613 (Delhi)
Assessing Officer held that assessee had a PE in India and profit of 100% was attributed to the assessee. Tribunal, however, held that the provisions of section 144C with all its sub-section did not apply to assessee, and so assessment order was void ab initio. Tribunal also held that even on the merits of the case, assessee had to succeed inasmuch as findings given by the Assessing Officer was totally based upon findings given in earlier assessment years and assessee was not responsible to explain recipients of receipts shown in Form No. 26AS. It was noted that in assessee’s case for earlier AYs, namely, CIT, International Taxation v. Travelport L.P. USA [2024] 158 taxmann.com 351 (Delhi), it was held that since assessee had not deployed any assets in India and major part of business activities took place in USA, Appellate Authority was justified in holding that 15 per cent of assessee’s profit was to be attributed to India.
Held that since the issue on merits already stood concluded in favour of assessee by Court in earlier year, questions raised in Revenue’s appeal having become academic, appeal under section 260A was not maintainable.
Global net loss
54. For computing profits attributable to Indian PE of assessee, net profit margins of assessee were to be applied and since assessee recorded a global net loss in relevant assessment year, no profit/income would be attributable to PE [In favour of assessee] [Articles 5 and 7 of the India-Finland DTAA]
CIT (International Taxation) v. Nokia Solutions and Networks OY [2023] 147 taxmann.com 165/455 ITR 157 (Delhi)
For computing the profits attributable to Indian PE of assessee, a Finland based company, net profit margins of assessee were to be applied and since assessee recorded a global net loss in the relevant assessment year, no profit/income would be attributable to PE.
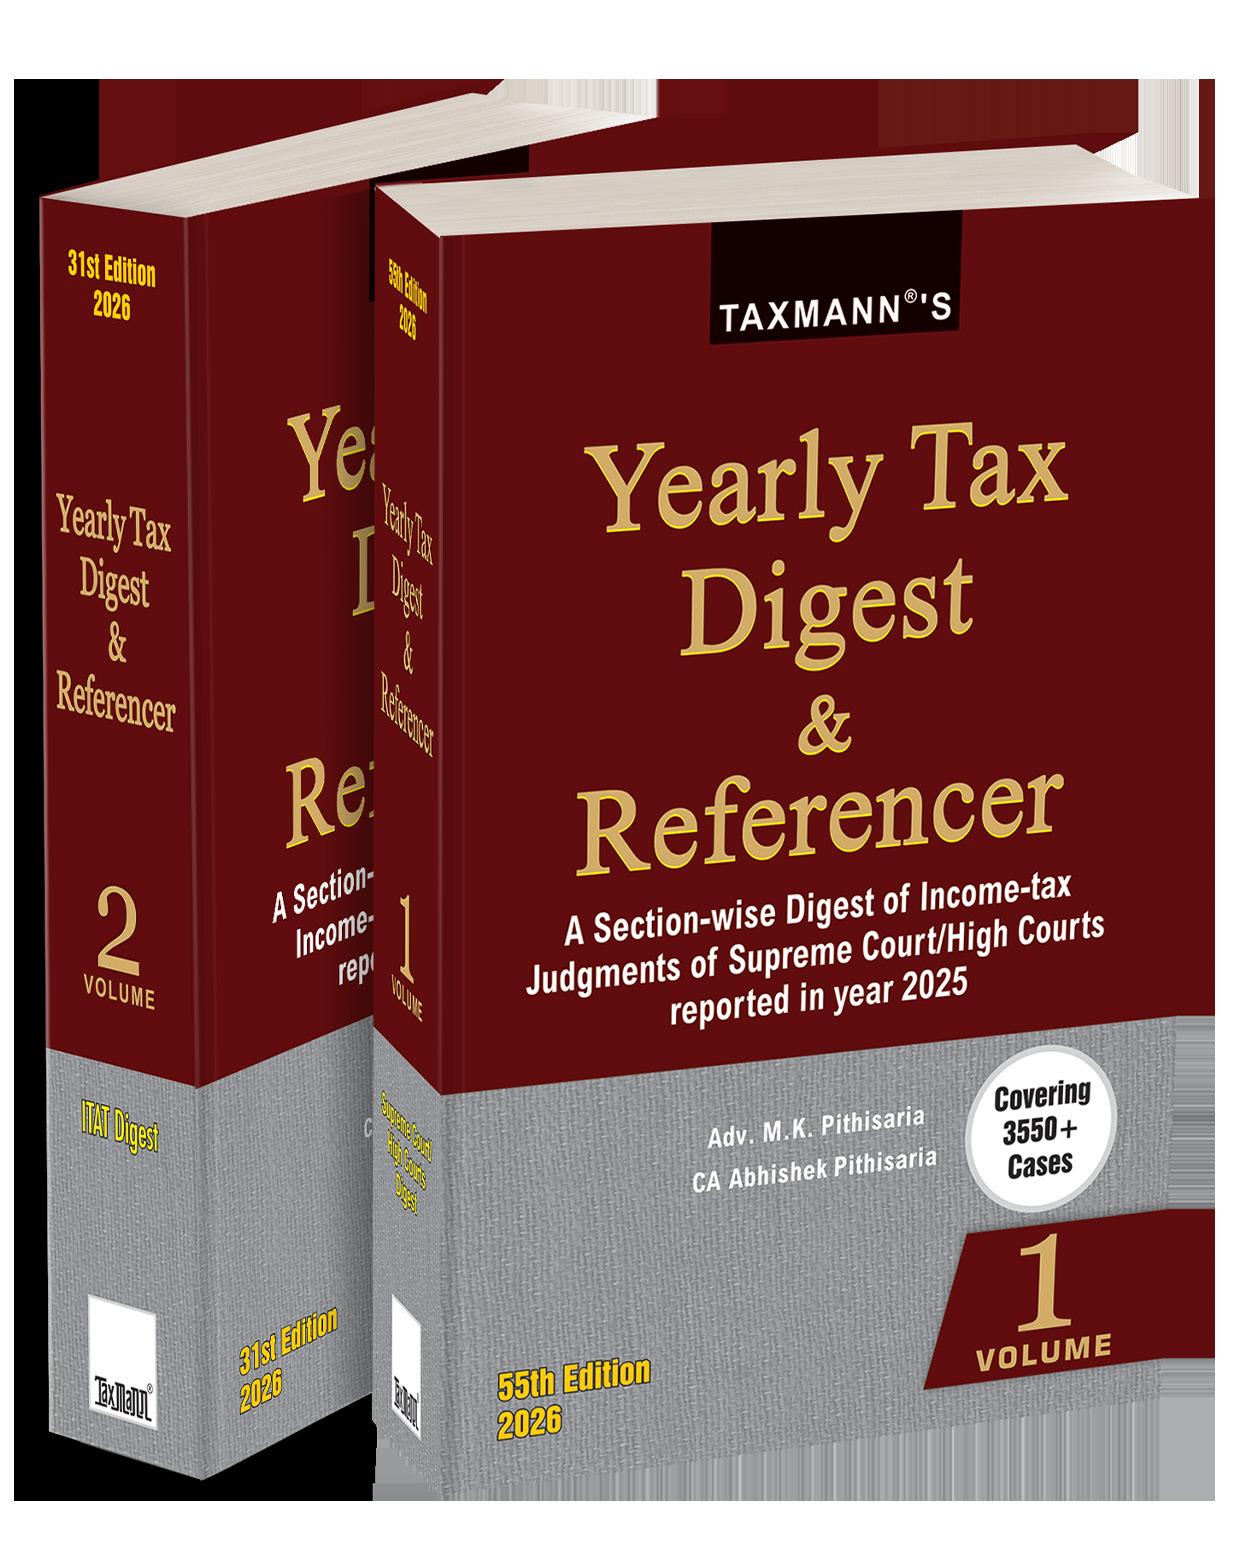
Yearly Tax Digest & Referencer
AUTHOR : M.K. Pithisaria, Abhishek Pithisaria
PUBLISHER : Taxmann
DATE OF PUBLICATION : January 2026
EDITION : Vol I : 55th Edition
Vol II : 31st Edition
ISBN NO : 9789375613749
No. of Pages : 2808
BINDING TYPE : Hardbound
4,295
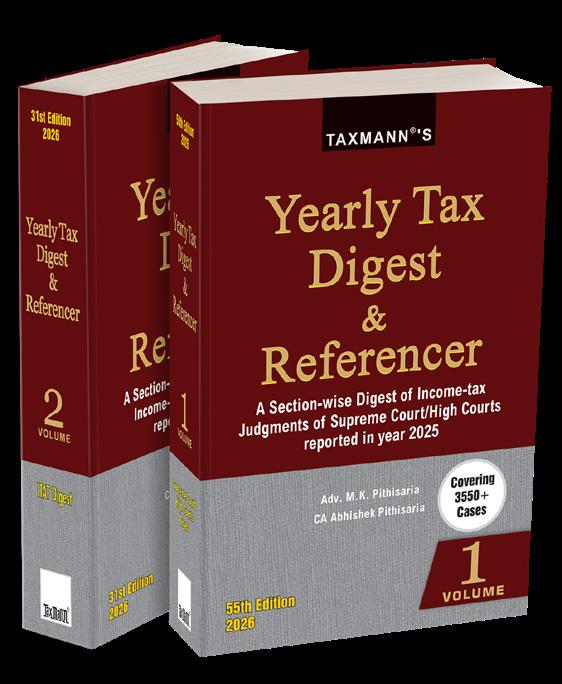
DESCRIPTION
Yearly Tax Digest & Referencer is Taxmann’s flagship annual jurisprudence compendium that presents a complete, section-wise record of income-tax litigation in India. The 2026 Edition consolidates 3,550+ incometax rulings reported in 2025, covering decisions of the Supreme Court, High Courts, and the Income-tax Appellate Tribunal (ITAT). Designed as a pure judicial digest, the publication enables professionals to quickly determine what the judiciary has held on specific income-tax provisions and how those rulings may be reliably cited and applied in practice. The Digest is structured as a two-volume set, distinctly separating higherjudiciary precedents from tribunal jurisprudence, while following a uniform, section-wise and issue-wise research framework across both volumes.
This publication is indispensable for professionals who work with case law as a daily decision-making tool, including:
• Tax Litigators & Advocates
• Chartered Accountants & Tax Consultants
• In-house Tax & CFO Teams
• Departmental Representatives & Revenue Officers
• Researchers & Advanced Students
The Present Publication is the 55th Edition (Volume 1) & 31st Edition (Volume 2), edited by Adv. M.K. Pithisaria & CA. Abhishek Pithisaria. It incorporates all Case Laws reported till 16th November 2025 for the year 2025. The key features of the book are as follows:
• [Complete Annual Judicial Record] Comprehensive consolidation of income-tax rulings reported during 2025
• [Court-segregated Architecture] Separate volumes for Supreme Court/High Courts and ITAT
• [Section-wise & Issue-wise Digesting] Every ruling is mapped to the relevant statutory provision and litigation issue
• [Precedent-status Intelligence] Tools to identify cases affirmed, reversed, overruled, or pending before the Supreme Court (Volume 1)
• [Circulars & Notifications in Litigation] Dedicated lists of CBDT circulars and notifications judicially analysed
• [Neutral, Non-Commentarial Presentation] Objective summaries without editorial opinion
• [Multi-layer Navigation] Case lists, subject indices, and issue taxonomies for quick access