
Sample Read
© All rights reserved
Price : ` 1175
Fourteenth Edition : February 2026
Published by :
Taxmann Publications (P.) Ltd.
Sales & Marketing : 59/32, New Rohtak Road, New Delhi-110 005 India
Phone : +91-11-45562222
Website : www.taxmann.com
E-mail : sales@taxmann.com
Regd. Office : 21/35, West Punjabi Bagh, New Delhi-110 026 India
Printed at :
Tan Prints (India) Pvt. Ltd.
44 Km. Mile Stone, National Highway, Rohtak Road Village Rohad, Distt. Jhajjar (Haryana) India
E-mail : sales@tanprints.com
Disclaimer
Every effort has been made to avoid errors or omissions in this publication. In spite of this, errors may creep in. Any mistake, error or discrepancy noted may be brought to our notice which shall be taken care of in the next edition. It is notified that neither the publisher nor the author or seller will be responsible for any damage or loss of action to any one, of any kind, in any manner, therefrom. It is suggested that to avoid any doubt the reader should cross-check all the facts, law and contents of the publication with original Government publication or notifications.
No part of this book may be reproduced or copied in any form or by any means [graphic, electronic or mechanical, including photocopying, recording, taping, or information retrieval systems] or reproduced on any disc, tape, perforated media or other information storage device, etc., without the written permission of the publishers. Breach of this condition is liable for legal action. For binding mistake, misprints or for missing pages, etc., the publisher’s liability is limited to replacement within seven days of purchase by similar edition. All expenses in this connection are to be borne by the purchaser. All disputes are subject to Delhi jurisdiction only.

7.1 BLOCK CREDIT UNDER SECTION 17(5)
Q.1.ABC company Ltd. of Bengaluru is manufacturing and registered supplier of machine. It has provide the following details for the month of November 2021
Detail of GST paid on inward supplies during the months:
Health insurance of factory employees.20,000
Raw material for which invoice has been received and GST has also been paid for full amount but only 50% of material has been received, remaining 50% will be received in next month
of manufacturing machine directly send to job worker’s premises under challan.
Purchase of car used by director for the business meeting only 25,000 Outdoor catering service availed for business meeting. 8,000
ABC Company Ltd. provided service of hiring of machines along with man power for operation. As per the trade practice machines are always hired out along with operators and also operators are supply only when machine are hired out.
Receipt on outward supplied (exclusive of GST) for the month of November 2021 are also followed:
Assumed all the transactions are inter-State and the rates of IGST to be as under:
(i) Sales of machine 5%
(ii) Services of hiring of machine 12%
(iii) Supply of man power operator service 18%
Compute the amount of input tax credit available and also the net GST payable for the month of November 2021 by giving necessary explanations for treatment of variable items.
Note - Opening balance of input tax credit is nil. [MTP, May/Nov. 2018, 10 Marks]
Gross GST liability [Refer working note (2) below]91,200
Less: Input tax credit [Refer working note (1) below]62,000
Net GST liability29,200
Working Notes:
(1) Computation of Input Tax Credit (ITC) available with ABC Company Ltd. in the month of November 2021.
Health insurance of factory employees
(As per section 17(5)(b)(iii) of the CGST Act, 2017 ITC of health insurance is blocked in the given case since said services are not notified by Government as obligatory for employer to provide to its employees under any law.)
Raw material received in factory
(Where the goods against an invoice are received in lots/instalments, ITC is allowed upon receipt of the last lot/instalment vide first proviso to section 16(2) of the CGST Act, 2017. Therefore, ABC Company Ltd. will be entitled to ITC of raw materials on receipt of second instalment in December, 2021.)
Works contract service used for installation of plant and machinery
(As per Section 17(5)(c) of CGST Act, 2017 provides that ITC on works contract services is blocked when supplied for construction of immovable property (other than plant and machinery) except when the same is used for further supply of works contract service.
Though in this case, the works contract service is not used for supply of works contract service, ITC thereon will be allowed since such services are being used for installation of plant and machinery.)
Manufacturing machinery directly sent to job worker’s premises under challan
(As per Section 19(5) of CGST Act, 2017 ITC on capital goods directly sent to job worker’s premises under challan is allowed)
Purchase of car used by director for business meetings only
1. (Section 17(5)(a) of CGST Act, 2017 ITC on motor vehicles is allowed only when the same are used:
(1) for making taxable supply of - (i) further supply of such vehicles, (ii) transportation of passengers, (iii) imparting training on driving, flying, navigating such vehicles and (iv) motor vehicle having seating capacity > 13 persons
(2) for transportation of goods.
12,000
50,000
Since ABC Company Ltd. is a supplier of machine and it does not use the car for transportation of goods, ITC thereon will not be available.) Nil
Outdoor catering service availed for business meetings
(Section 17(5)(b)(i) of CGST Act, 2017 ITC on outdoor catering is blocked except where the same is used for making further supply of outdoor catering or an element of a taxable composite or mixed supply.
Since ABC Company Ltd. is a supplier of machine, ITC thereon will not be available.) Nil
Total ITC available62,000
(2) Computation of gross GST liability
charges for supply of manpower operators
Gross GST liability91,200
Notes:
Since machine is always hired out along with operators and operators are supplied only when the machines are hired out, it is a case of composite supply, wherein the principal supply is the hiring out of machines [Section 2(30) of the CGST Act, 2017 read with section 2(90) of that Act]. Therefore, service of supply of manpower operators will also be taxed at the rate applicable for hiring out of machines (principal supply), which is 12%, in terms of section 8(a) of the CGST Act, 2017.
In the above answer, the amounts given in the second table of the question have been taken as “Receipts on outward supply”. If the same are taken as GST paid, the gross GST liability will be ` 7,60,000 (5,25,000 + 2,35,000) and the same can be directly set off against input tax credit available. Thus, net GST liability will work out to ` 6,98,000 (7,60,000-62,000).
Q. 2.With reference to the provisions of section 17 of the CGST Act, 2017, examine the availability of input tax credit under the CGST Act, 2017 in the following independent cases:—
(i) MBF Ltd., an automobile company, has availed works contract service for construction of a foundation on which a machinery (to be used in the production process) is to be mounted permanently.
(ii) Shah & Constructions procured cement, paint, iron rods and services of architects and interior designers for construction of a commercial complex for one of its clients.
(iii) ABC Ltd. availed maintenance & repair services from “Jaggi Motors” for a truck used for transporting its finished goods.
Ans.
Statutory ProvisionIn the given case
(i)Section 17(5)(c) of the CGST Act, 2017:- Input tax credit is blocked in respect of works contract services when supplied for construction of an immovable property (other than plant and machinery) except where it is an input service for further supply of works contract service.
Further, the term “plant and machinery” means apparatus, equipment and machinery fixed to earth by foundation or structural support that are used for making outward supply of goods and/ or services and includes such foundation or structural support but excludes land, building or other civil structures, telecommunication towers, and pipelines laid outside the factory premises.
ITC is available in respect of works contract service availed by MBF Ltd. as the same is used for construction of plant and machinery which is not blocked under section 17(5)(c) of the CGST Act, 2017.
(ii)Section 17(5)(d) of the CGST Act, 2017:- Input tax credit is blocked on goods and/or services received by a taxable person for construction of an immovable property (other than plant and machinery) on his own account even though such The taxable person has used the goods and services for construction of immovable property for some other person and not on its own account. Hence, ITC in this case will be allowed.
Statutory ProvisionIn the given case goods and/or services are used in the course or furtherance of business.
(iii)As per section 17(5) of the CGST Act, 2017:ITC is allowed on repair and maintenance services relating to motor vehicles, which are eligible for input tax credit. Further, as per section 17(5)(a) ITC is allowed on motor vehicles which are used for transportation of goods. Yes, ITC is allowed.
Q. 3.A company has entered to an agreement with a customer for the manufacture and supply of cement pipes for their exclusive use. A company manufactured the product but before receiving the inspection certificate, their customer rejected some quantity of goods on the grounds of quality. As per agreement, the rejected quantity will be destroyed in front of the customer and shall not be sold. Examine the issue in the light of statutory provisions and suggest future course of action to the assessee as to whether any liability arises as per the provisions of GST law. [Nov. 2018, Old, 4 Marks]
Ans. Section 17 of the CGST Act, 2017 blocks ITC in respect of destroyed goods.
Accordingly, since in the given case the cement pipes have been destroyed, ITC attributable to such pipes will not be allowed [Section 17(5)(h) of the CGST Act, 2017].
Thus, in the given case, if the credit has already been availed, the same will need to be reversed.
Q. 4.A company has entered into an agreement with a customer for the manufacture and supply of cement pipes for their exclusive use. A company manufactured the product but before receiving the inspection certificate, their customer rejected some quantity of goods on the grounds of quality. As per agreement the statutory provisions and suggest future course of action to the assessee as to whether any liability arises as per the provisions of GST law. [Nov. 2018-OS, 4 Marks]
Ans. Fact Before receiving the inspection certificate, their customer rejected some quantity of goods on the grounds of quantity.
Provision The scope of term supply has been given under section 7 of CGST Act, 2017. As per section 7(1)(a), Supply includes all forms of supply of goods or services or both such as sale, transfer, barter, exchange, license, rental, lease or disposal made or agreed to be made for a consideration by a person in the course or furtherance of business.
Decision The company will not be liable to pay GST on the rejected quantity of the cement pipes which were destroyed in front of customer. However, the company will be required to reverse input tax credit so taken in respect of destroyed goods since the same fall under the ambit of blocked credit under section 17(5)(h) of the CGST Act, 2017.
7.2 BLOCK CREDIT UNDER SECTION 17(5) & CONDITIONS FOR AVAILING ITC [SECTION 16]
Q. 5.PQR Company Ltd., a registered supplier of Bengaluru (Karnataka), is a manufacturer of goods. The company provides the following information pertaining to GST paid on input supplies during the month of April, 2022:
(iii)Raw materials purchased which are used for zero rated outward supply.
(iv)Works contractor’s service used for repair of factory building which is debited in the profit and loss account of company.
(v)Company purchased the capital goods for ` 4,00,000 and claimed depreciation of ` 44,800 (@ 10%) on the full amount of ` 4,48,000 under Income-tax Act, 1961.
Other Information:-
(i) In the month of September, 2021, PQR Company Ltd. availed input tax credit of ` 2,40,000 on purchase of raw material which was directly sent to job worker’s premises under a challan on 25-09-2021. The said raw material has not been received back from the Job worker up to 30-04-2022.
(ii) All the above input supplies except (ii) above have been used in the manufacture of taxable goods.
Compute the amount of net Input Tax Credit available for the month of April, 2022 with necessary explanations for your conclusion for each item. You may assume that all the other conditions necessary for availing the eligible input tax credits have been fulfilled. [Nov. 2018, 7 Marks]
Ans. Computation of Input Tax Credit (ITC) available with PQR Ltd. for the month of April, 2022 Particulars
Insurance premium paid by the company on the life of factory employees [Note 1]
materials purchased [Note
materials used for zero rated outward supply [Note 3]50,000
contractor’s service [Note 4]30,000
goods purchased wherein the depreciation is claimed on the tax component [Note 5]
Notes:
(1) As per Section 17(5) of the CGST Act, 2017:- ITC on life insurance service is available only when the same is notified by the Government as being obligatory for an employer to provide to its employees under any law for the time being in force. In the absence of any information, it is assumed that such services have not been notified in the instant case and thus, the ITC thereon is blocked.
(2) As per Section 16 of the CGST Act, 2017:- ITC cannot be taken since invoice is missing and delivery challan is not a valid document to avail ITC.
(3) As per Section 16 of the IGST Act, 2017:- ITC can be availed for making zero-rated supplies, notwithstanding that such supply may be an exempt supply.
(4) As per Section 17(5) of the CGST Act, 2017:- ITC is blocked on works contract services for construction of an immovable property except when
It is input service for further supply of works contract service
Immovable property is plant and machinery
Construction includes reconstruction, renovation, additions or alterations or repairs, to the extent of capitalization, to the said immovable property.
ITC on expenses incurred on re-construction, renovation, additions or alterations and repairs would be allowed in case such expenses are charged to revenue and not capitalized.
(5) As per Section 16(3) of the CGST Act, 2017:- ITC is not available when depreciation has been claimed on the tax component of the cost of capital goods under the Income-tax Act.
(6) As per Section 19 of the CGST Act, 2017:- The principal is entitled to take ITC of inputs sent for job work even if the said inputs are directly sent to job worker. However, where said inputs are not received back by the principal within a period of 1 year of the date of receipt of inputs by the job worker, it shall be deemed that such inputs had been supplied by the principal to the job worker on the day when the said inputs were received by the job worker.
Hence, the ITC taken by PQR Company Ltd. in September, 2021 is valid and since 1 year period has yet not lapsed in April, 2022, there will be no tax liability on such inputs.
Q. 6.Siddhi Ltd. is a registered manufacturer engaged in taxable supply of goods. Siddhi Ltd. purchased the following goods during the month of January, 2022. The following particulars are provided:
1.Capital goods purchased on which depreciation has been taken on full value including input tax thereon
2.Goods purchased from Ravi Traders (Invoice of Ravi Traders is received in month of January, 2022, but goods were received in month of March, 2022) 20,000
3.Car purchased for making further supply of such car. Such car is destroyed in accident while being used for test drive by potential customers 30,000
4.Goods used for setting up telecommunication towers being immovable property 50,000
5.Goods purchased from Pooja Ltd. (Full payment is made by Siddhi Ltd. to Pooja Ltd. against such supply, but tax has not been deposited by Pooja Ltd. 10,000
6.Truck purchased for delivery of output goods80,000
Determine the amount of Input Tax Credit (ITC) available by giving necessary explanations for treatment of various items as per the provisions of the CGST Act, 2017. You may assume that all the necessary conditions for availing the ITC have been complied with by Siddhi Ltd. [May 2019, (Old), 5 Marks]
Ans.Computation of ITC available with Siddhi Ltd.
Sl. No.
1.Capital goods [Since depreciation has been claimed on the tax component of the value of the capital goods, ITC of such tax cannot be availed in terms of section 16 of the CGST Act, 2017.]
2.Goods purchased from Ravi Traders [ITC in respect of goods not received cannot be availed (Section 16 of the CGST Act, 2017). Since the goods have been received in the month of March, 2020, ITC thereon can be availed in March, 2020 and not January 2022 even though the invoice for the same has been received in January 2022]
3.Cars purchased for making further supply [Though ITC on motor vehicles used for further supply of such vehicles is not blocked, ITC on goods destroyed for whichever reason is blocked (Section 17(5) of the CGST Act, 2017).]
4.Goods used for setting telecommunication towers [ITC on goods used by a taxable person for construction of immovable property on his own account is blocked even when such goods are used in the course or furtherance of business (Section 17 of the CGST Act, 2017).]
5.Goods purchased from Pooja Ltd. [Note 1].
However, the claim will get confirmed only when the tax charged in respect of such supply has been actually paid to the Government.]
6.Trucks purchased for delivery of output goods [ITC on motor vehicles used for transportation of goods is not blocked (Section 17(5) of the CGST Act, 2017).]
80,000
Total ITC available with Siddhi Ltd.80,000
NOTE-1 In this case, the provisions of Rule 36(4) are applicable:
Step-1 Segregation of ITC on the basis of uploading of corresponding GSTR 1 by supplier. Eligible ITC regarding invoices by supplierGST (`)
Step-2Eligible ITC regarding NOT furnished invoices:
As per Rule 36(4), the ITC in respect of which details have not been uploaded by suppliers in GSTR-1 Registered Person (Siddhi Ltd.) cannot claim ITC.
Q. 7.Pari Ltd. of Jodhpur (Rajasthan) is a registered manufacturer of cosmetic products. Pari Ltd. has furnished following details for the month of April, 2022:
(A)Receipts (Details of Sales) (i) Sales in Rajasthan 8,75,000 (ii) Sales in States other than Rajasthan 3,75,000 (iii) Export under bond6,25,000
(B)Payments
(1)Raw materials
(i) Purchased from registered suppliers located in Rajasthan 1,06,250
Particulars
(ii) Purchased from unregistered suppliers located in Rajasthan 37,500
(iii) Purchased from Punjab from registered supplier 1,00,000
(iv) Integrated tax paid on Import from USA22,732
(2)Consumables purchased from registered suppliers located in Rajasthan including high speed diesel (Excise and VAT paid) worth ` 31,250 for running the machinery in the factory 1,56,250
(3)Monthly rent for the factory building to the owner in Rajasthan 1,00,000
(4)Salary paid to employees on rolls6,25,000
(5)Premium paid on life insurance policies taken for specified employees. Life insurance policies for specified employees have been taken by Pari Ltd. to fulfil a statutory obligation in this regard. The Government has notified such life insurance service under section 17(5)(b)(iii)(A). The life insurance service provider is registered in Rajasthan. 2,00,000
All the above amounts are exclusive of all kinds of taxes, wherever applicable. However, the applicable taxes have also been paid by Pari Ltd.
The balance of Input Tax Credit (ITC) with Pari Ltd. as on 1st April, 2022 is
CGST ` 20,000
SGST ` 15,000
IGST ` 15,000
Assume CGST, SGST and IGST rates to be 9%, 9% and 18% respectively, wherever applicable. Assume that all the other necessary conditions to avail the eligible input tax credit have been complied with by Pari Ltd., wherever applicable.
Compute eligible input tax credit and net GST payable (CGST and SGST or IGST as the case may be) by Pari Ltd. for the month of April, 2022. [Nov. 2018, 10 Marks] Ans.Computation of eligible input tax credit available with Pari Ltd. in the month of April, 2020
No.
`
` IGST ` 1.Raw Material:
Purchased from local registered suppliers [Note 1(i)] (` 1,06,250 × 9%) 9,562.509,562.50
Purchased from local unregistered suppliers [Note 1(ii)] NilNil
Purchased from Punjab from registered supplier [Note 1(i)] (` 1,00,000 × 18%) 18,000
Raw material imported from USA [Note 1(iii)]22,732
2. Consumables [Note 2] [(1,56,250-31,250) × 9%]11,25011,250
3. Monthly rent for the factory building to the owner in Rajasthan [Note 3] 9,0009,000
4. Salary paid to employees on rolls [Note 4]NilNilNil
5. Premium paid on life insurance policies taken for specified employees [Note 5] (` 2,00,000 × 9%) 18,00018,000Total47,812.5047,812.5040,732
Add: Opening balance of ITC on 01-4-202020,00015,00015,000
Eligible ITC [Note 7]67,812.5062,812.5055,732
Computation of net GST payable for the month of April, 2020
Exports under bond [Note 6]NilNilNil
Less: Eligible ITC67,812.5062,812.5055,732
Net GST payable10,937.5015,937.5011,768
Notes:
1. (i) As per section 16 of the CGST Act:- Credit of GST paid on raw materials used in the course or furtherance of business is available.
(ii) All intra-State procurements made by a registered person from an unregistered supplier have been exempted from GST. Therefore, since no GST is paid on such raw material purchased, there does not arise any question of Input Tax Credit (ITC) on such raw material.
(iii) As per section 16 of the CGST Act:- IGST paid on imported goods qualifies as input tax in terms of section 2(62) of CGST Act, 2017. Therefore, credit of IGST paid on imported raw materials used in the course or furtherance of business is available.
2. ITC on consumables, being inputs used in the course or furtherance of business, is available. However, since levy of GST on high speed diesel has been deferred till a date to be notified by Government, there cannot be any ITC of the same.
3. ITC on monthly rent is available as the said service is used in the course or furtherance of business.
4. As per section 7 read with Schedule III to the CGST Act:- Services by employees to employer in the course of or in relation to his employment is not a supply. Therefore, since no GST is paid on such services, there cannot be any ITC on such services.
5. As per section 17(5) of the CGST Act, 2017:- ITC on life insurance service is available only when the same is notified by the Government as being obligatory for an employer to provide to its employees under any law for the time being in force.
6. As per section 16 of the IGST Act:- Export of goods is a zero rated supply. A zero rated supply under bond is made without payment of IGST, supplies includes zero rated supply.
7. Since export of goods is a zero rated supply, there will be no apportionment of ITC and full credit will be available.
Q. 8.State whether input tax credit is available in the following cases:
(i) Motor car purchased by driving school for imparting training to the customers. Whether your answer would be different if the motor car is purchased by a manufacturing company to be used by its Managing Director for official purposes (sitting capacity is 5 persons)?
(ii) Amount spent for construction of factory building.
(iii) Gift articles purchased on the occasion of Diwali to be distributed among the employees.
Ans. (i) As per Section 17(5) of CGST Act, 2017:- Motor car purchased by driving school for imparting training to the customers is an exception to the blocked credit item. Hence, ITC is available.
Yes, motor car purchased by a manufacturing company to be used by its managing director is a blocked credit item as per Section 17(5)(a) of CGST Act, 2017. Hence, ITC is not available.
(ii) As per Section 17(5) of CGST Act, 2017:- Amount spent for construction of factory building is an item for which input tax credit is not available.
(iii) As per Section 17(5) of CGST Act, 2017:- Input tax credit shall not be available for goods disposed of by way of gift or free samples.
Q. 9.V-Supply Pvt. Ltd. is a registered manufacturer of auto parts in Kolkata, West Bengal. The company has a manufacturing facility registered under Factories Act, 1948 in Kolkata. It procures its inputs indigenously from both registered and unregistered suppliers located within as well as outside West Bengal as also imports some raw material from China. The company reports the following details for the month of November, 20XX:
All the above amounts are exclusive of all kinds of taxes, wherever applicable. However, the applicable taxes have also been paid by the company. Further, following additional details are furnished by the company in respect of the payments and receipts reported by it:
(i) Raw material amounting to ` 0.80 lakh is procured from Bihar and ` 1.5 lakh is imported from China. Basic customs duty of ` 0.15 lakh and integrated tax of ` 0.29781 lakh are paid on the imported raw material. Remaining raw material is procured from suppliers located in West Bengal. Out of such raw material, raw material worth ` 0.30 lakh is procured from unregistered suppliers; the remaining raw material is procured from registered suppliers. Further, raw material worth ` 0.05 lakh purchased from registered supplier located in West Bengal has been destroyed due to see page problem in the factory and thus, could not be used in the manufacturing process.
(ii) Consumables are procured from registered suppliers located in Kolkata and include diesel worth ` 0.25 lakh for running the generator in the factory.
(iii) Transportation charges comprise of ` 0.60 lakh paid to Goods Transport Agency (GTA) in Kolkata and ` 0.10 lakh paid to horse pulled carts. GST applicable on the services of GTA is 5% and taxable under RCM.
(
(
iv) Life insurance policies for specified employees have been taken by the company to fulfil a statutory obligation in this regard. The Government has notified such life insurance service under section 17(5)(b)(iii)(A). The life insurance service provider is registered in West Bengal.
(
(
v) Audit fee is paid to M/s Goyal & Co., a firm of Chartered Accountants registered in West Bengal, for the statutory audit of the preceding financial year.
vi) Telephone expenses pertain to bills for landline phone installed at the factory and mobile phones given to employees for official use. The telecom service provider is registered in West Bengal.
vii) Bank charges are towards company’s current account maintained with a Private Sector Bank registered in West Bengal.
(
viii) The break up of sales is as under:
Sales in West Bengal - ` 7 lakh
Sales in States other than West Bengal - ` 3 lakh
Export under bond - ` 5 lakh
The balance of input tax credit with the company as on 1.11.20XX is:
CGST - ` 0.15 lakh
SGST - ` 0.08 lakh
IGST - ` 0.10 lakh
Compute eligible input tax credit and net GST payable [CGST, SGST or IGST, as the case may be] by V-Supply Pvt. Ltd. for the month of November 20XX.
Note—
(
i) CGST, SGST & IGST rates to be 9%, 9% and 18% respectively, wherever applicable.
(ii) The necessary conditions for availing input tax credit have been complied with by V-Supply Pvt. Ltd., wherever applicable.
You are required to make suitable assumptions, wherever necessary. [MTP, May 2018, 10 Marks]
Ans.Computation of input tax credit available with V-Supply Pvt. Ltd. in the month of November 20XX
1.Raw Material
Raw material purchased from Bihar [Refer Note 1(i)] 14,40014,400
Raw material imported from China [Refer Note 1(ii)] 29,78129,781
Raw material purchased from unregistered suppliers within West Bengal [Refer Note 1(iii)]
Raw material destroyed due to see page [Refer Note 1(iv)]
Remaining raw material purchased from West Bengal [Refer Note 1(i)] 7,6507,65015,300
Total7,6507,65044,18159,481
Indirect Tax Laws (IDT) | CRACKER
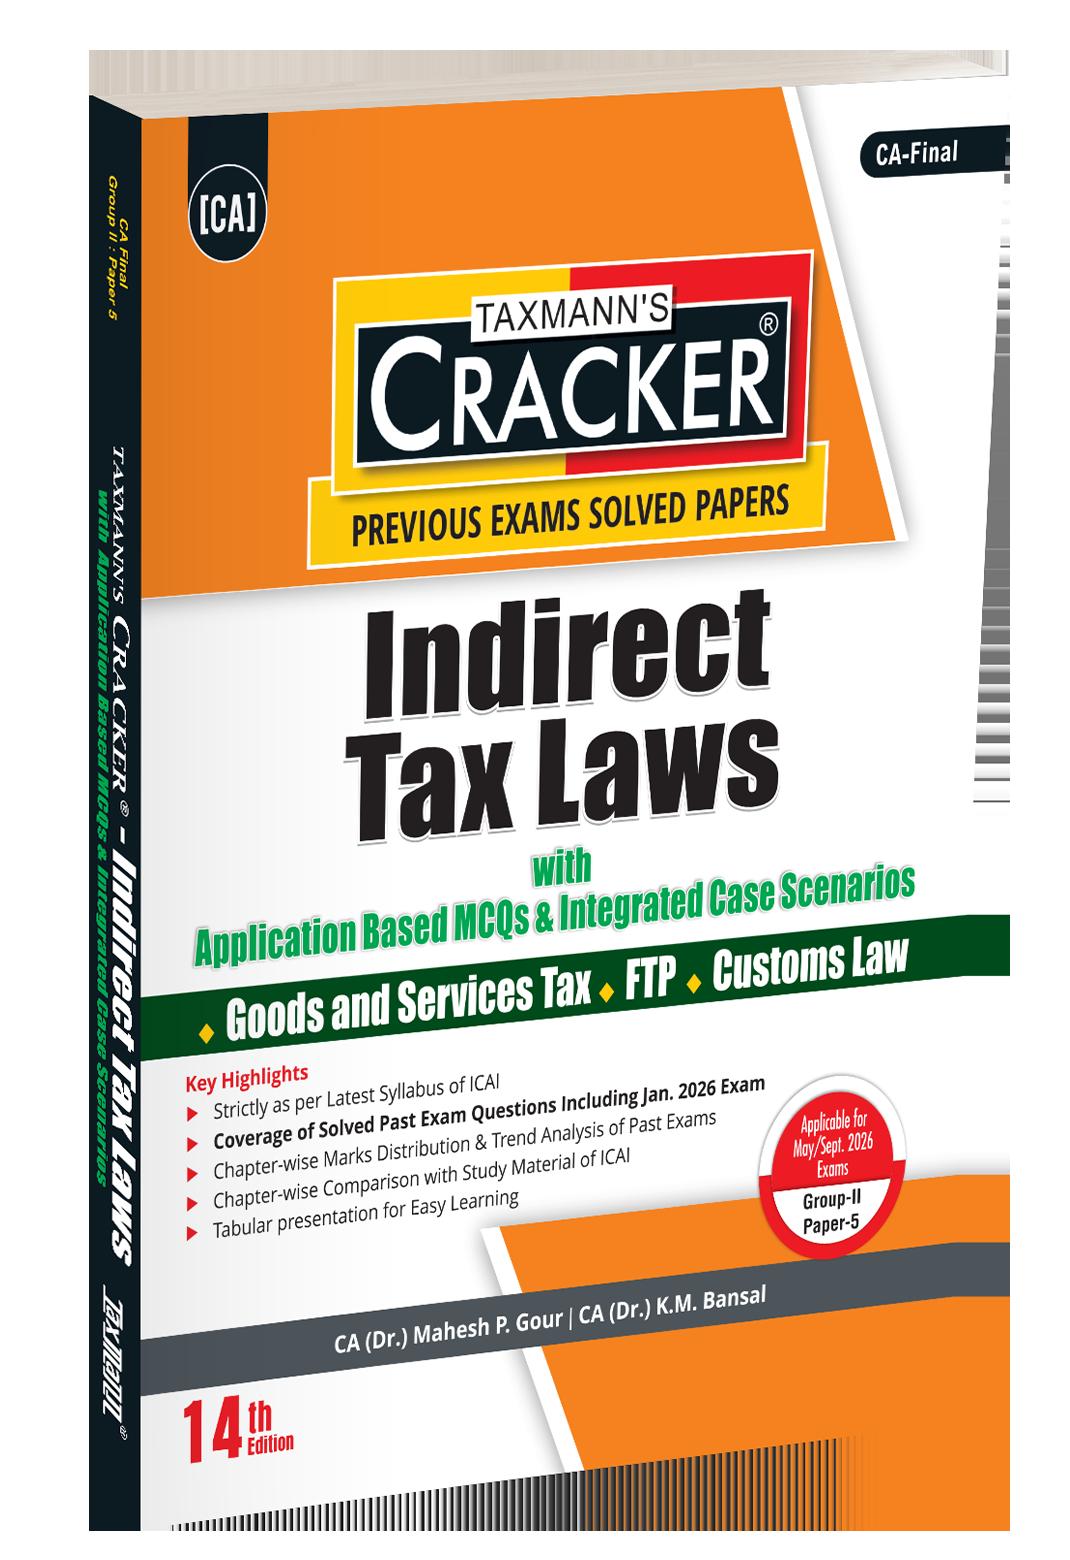
AUTHOR : Mahesh P. Gour, K.M. Bansal
PUBLISHER : Taxmann
DATE OF PUBLICATION : February 2026
EDITION : 14th Edition
ISBN NO : 9789375617792
No. of Pages : 620
BINDING TYPE : Paperback
Rs. 1,175
DESCRIPTION
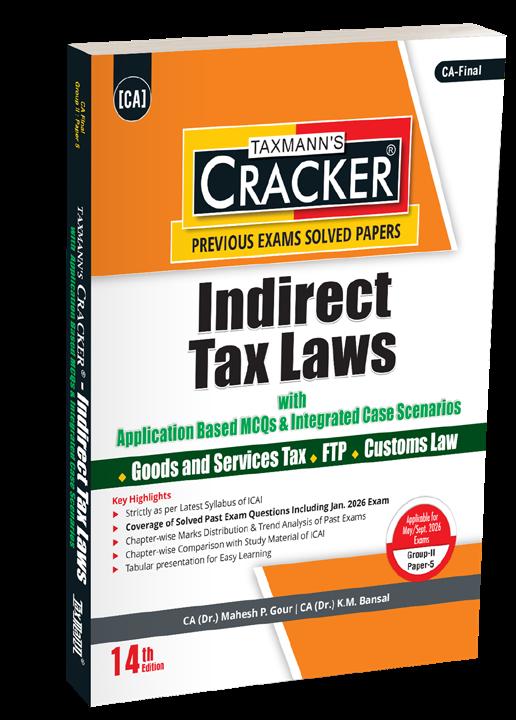
Indirect Tax Laws – CRACKER is a structured, exam-intelligence–driven preparation manual for CA Final –Group II | Paper 5, covering GST, Customs Law, and Foreign Trade Policy (FTP). Aligned with the latest ICAI syllabus and updated to include all amendments and solved past examination questions up to January 2026, this Edition is designed as a scoring system rather than a conventional reference text. It converts ICAI’s testing patterns—chapter weightage, compulsory structures, theory–practical mix, and MCQ orientation—into a focused exam-execution strategy, training students to apply and present answers precisely in the format ICAI evaluates.
The Present Publication is the 14th Edition, authored by CA. (Dr) Mahesh Gour & CA. (Dr) K.M. Bansal. This book incorporates the following noteworthy features:
• [Strictly as per Latest ICAI Syllabus] Fully aligned with the revised Paper 5 syllabus and examination structure
• [Solved Past Exam Questions including Jan. 2026] Comprehensive coverage of previous attempts reflecting the latest examiner approach
• [Chapter-wise Marks Distribution] Attempt-wise weightage analysis to identify high-yield and frequently tested areas
• [Previous Exams Trend Analysis] Insight into compulsory/optional patterns and theory–practical allocation
• [Chapter-wise Comparison with ICAI Study Material] Direct cross-mapping for focused and efficient revision
• [Application-based MCQs] Concept-driven MCQs aligned with ICAI’s evolving assessment methodology
• [Integrated Case Scenario MCQs] Multi-provision caselets simulating real examination complexity
• [Structured Answer Presentation] Solutions drafted under logical heads—facts, provisions, analysis, conclusion
• [Tabular & Comparative Format] Key provisions and procedural requirements presented for quick retention