
Sample Read
DIVISION ONE
DIVISION TWO
DIVISION THREE
SECTION PAGE
DIVISION FOUR
DIVISION FIVE
Repairs and insurance of machinery, plant and furniture.
231. 3In respect of repairs and insurance of machinery, plant or furniture used for the purposes of the business or profession, the following deductions shall be allowed— (i)the amount paid on account of current repairs4 thereto ; (ii)the amount of any premium paid in respect of insurance against risk of damage or destruction thereof.
5[Explanation.—For the removal of doubts, it is hereby declared that the amount paid on account of current repairs shall not include any expenditure in the nature of capital expenditure.]
Depreciation.
632. (1) 7[In respect of depreciation of— (i)buildings8, machinery8, plant8 or furniture, being tangible assets; (ii)know-how, patents, copyrights, trade marks, licences, franchises or any other business or commercial rights of similar nature8, being intangible assets acquired on or after the 1st day of April, 1998, 9[not being goodwill of a business or profession,] owned8, wholly or partly, by the assessee8 and used8 for the purposes of the business8 or profession, the following deductions shall be allowed—]
2.See also Circular No. 26-D(XLVII-22), dated 10-10-1966 (In case of tea companies, etc.). For details, see Taxmann’s Master Guide to Income-tax Act.
3. For relevant case laws, see Taxmann’s Master Guide to Income-tax Act.
4. For the meaning of the expressions “current repairs” and “repairs”, see Taxmann’s Direct Taxes Manual, Vol. 3.
5. Inserted by the Finance Act, 2003, w.e.f. 1-4-2004.
6.See also Circular No. 9, dated 23-3-1943 (Leased assets), Circular No. 29-D(XIX-14), dated 31-8-1965 (Allowance of depreciation when profit is estimated), Letter [F.No. 10/14/66IT(A-I)], dated 12-12-1966 (Equipments provided at employees’ residences), Circular No. 609, dated 29-7-1991, Circular No. 622, dated 6-1-1992, Circular No. 652, dated 14-61993 (Foreign motor cars used by tour operators/travel agents), Circular No. 2/2001, dated 9-2-2001 (Finance Lease Agreements - Effect of publication of Accounting Standards on allowability of depreciation), Circular No. 9/2014, dated 23-4-2014 (Treatment of expenditure incurred for development of roads/highways in BOT Agreements), Circular No. 15/2016, dated 19-5-2016 (Additional depreciation u/s 32(1)(iia) to printers) and Circular No. 20/2019, dated 19-8-2019 [Treatment of Farm-in expenditure incurred by Oil Exploration and Production (E&P) Companies]. For details, see Taxmann’s Master Guide to Income-tax Act. For relevant case laws, see Taxmann’s Master Guide to Income-tax Act.
7. Substituted for the opening portion beginning with the words “In respect of depreciation of buildings, machinery, plant or furniture owned, wholly or partly,” and ending with the words and figures “section 34, be allowed—” by the Finance (No. 2) Act, 1998, w.e.f. 1-4-1999. Prior to its substitution, the quoted portion was amended by the Finance (No. 2) Act, 1996, w.e.f. 1-4-1997.
8. For the meaning of the terms/expressions “buildings”, “machinery”, “plant”, “business or commercial rights of similar nature”, “owner”, “owned by the assessee”, “assessee”, “used” and “used for the purposes of the business”, see Taxmann’s Direct Taxes Manual, Vol. 3.
9. Inserted by the Finance Act, 2021, w.e.f. 1-4-2021.
10[(i)in the case of assets of an undertaking engaged in generation or generation and distribution of power, such percentage on the actual cost thereof to the assessee as may be prescribed11;]
(ii) 12[in the case of any block of assets, such percentage on the written down value thereof as may be prescribed13:]
14[***]
15[Provided 16[***] that no deduction shall be allowed under this clause in respect of—
(a)any motor car manufactured outside India, where such motor car is acquired by the assessee after the 28th day of February, 1975 17[but before the 1st day of April, 2001], unless it is used— (i)in a business of running it on hire for tourists ; or (ii)outside India in his business or profession in another country ; and
(b)any machinery or plant if the actual cost thereof is allowed as a deduction in one or more years under an agreement entered into by the Central Government under section 42 :]
18[Provided further that where an asset referred to in clause ( i) or clause ( ii) 19[or clause (iia)] 20[or the first proviso to clause (iia)], as the case may be, is acquired by the assessee during the previous year and is put to use for the purposes of business or profession for a period of less than one hundred and eighty days in that previous year, the
10. Inserted by the Income-tax (Amendment) Act, 1998, w.e.f. 1-4-1998. Earlier, original clause (i) was substituted by the Taxation Laws (Amendment) Act, 1975, w.e.f. 1-4-1976 and later on omitted by the Taxation Laws (Amendment & Miscellaneous Provisions) Act, 1986, w.e.f. 1-4-1988.
11.See rule 5(1A) and Appendix IA of the Income-tax Rules.
12. Substituted for “in the case of buildings, machinery, plant or furniture, other than ships covered by clause (i), such percentage on the written down value thereof as may in any case or class of cases be prescribed :” by the Taxation Laws (Amendment and Miscellaneous Provisions) Act, 1986, w.e.f. 1-4-1988.
13.See rule 5(1) and Appendix I of Income-tax Rules.
14. First proviso omitted by the Finance Act, 1995, w.e.f. 1-4-1996. Prior to its omission, first proviso was inserted by the Finance Act, 1966, w.e.f. 1-4-1966 and later on amended by the Finance Act, 1983, w.e.f. 1-4-1984.
15. Substituted by the Finance (No. 2) Act, 1991, w.e.f. 1-4-1992. Prior to its substitution, second proviso was inserted by the Finance Act, 1975, w.e.f. 1-4-1975 and amended by the Taxation Laws (Amendment and Miscellaneous Provisions) Act, 1986, w.e.f. 1-4-1988.
16. Word “further” omitted by the Finance Act, 1995, w.e.f. 1-4-1996.
17. Inserted by the Finance Act, 2001, w.e.f. 1-4-2002.
18. Substituted by the Income-tax (Amendment) Act, 1998, w.e.f. 1-4-1998. Prior to its substitution, second proviso was inserted by the Finance (No. 2) Act, 1991, w.e.f. 1-4-1992 and later on amended by the Finance Act, 1995, w.e.f. 1-4-1996.
19. Inserted by the Finance Act, 2002, w.e.f. 1-4-2003.
20. Inserted by the Finance Act, 2015, w.e.f. 1-4-2016.
deduction under this sub-section in respect of such asset shall be restricted to fifty per cent of the amount calculated at the percentage prescribed for an asset under clause ( i) or clause ( ii) 21[or clause (iia)], as the case may be :]
22[Provided also that where an asset referred to in clause (iia) or the first proviso to clause (iia), as the case may be, is acquired by the assessee during the previous year and is put to use for the purposes of business for a period of less than one hundred and eighty days in that previous year, and the deduction under this sub-section in respect of such asset is restricted to fifty per cent of the amount calculated at the percentage prescribed for an asset under clause (iia) for that previous year, then, the deduction for the balance fifty per cent of the amount calculated at the percentage prescribed for such asset under clause (iia) shall be allowed under this sub-section in the immediately succeeding previous year in respect of such asset:]
23[Provided also that where an asset being commercial vehicle is acquired by the assessee on or after the 1st day of October, 1998 but before the 1st day of April, 1999 and is put to use before the 1st day of April, 1999 for the purposes of business or profession, the deduction in respect of such asset shall be allowed on such percentage on the written down value thereof as may be prescribed.
Explanation.—For the purposes of this proviso,—
(a)the expression “commercial vehicle”24 means “heavy goods vehicle”, “heavy passenger motor vehicle”, “light motor vehicle”, “medium goods vehicle” and “medium passenger motor vehicle” but does not include “maxi-cab”, “motor-cab”, “tractor” and “roadroller”;
(b)the expressions “heavy goods vehicle”25, “heavy passenger motor vehicle”25, “light motor vehicle”25, “medium goods vehicle”25, “medium passenger motor vehicle”25, “maxi-cab” 25, “motorcab”25,“tractor”25 and “road roller” shall have the meanings respectively as assigned to them in section 2 of the Motor Vehicles Act, 1988 (59 of 1988):]
26[Provided also that, in respect of the previous year relevant to the assessment year commencing on the 1st day of April, 1991, the deduction in relation to any block of assets under this clause shall, in
21. Inserted by the Finance Act, 2002, w.e.f. 1-4-2003.
22. Inserted by the Finance Act, 2015, w.e.f. 1-4-2016.
23. Inserted by the Income-tax (Second Amendment) Act, 1998, w.e.f. 1-4-1999.
24. For the meaning of the expression “commercial vehicle”, see Taxmann’s Direct Taxes Manual, Vol. 3.
25. For definitions of “heavy goods vehicle”, “heavy passenger motor vehicle”, “light motor vehicle”, “medium goods vehicle”, “medium passenger motor vehicle”, “maxi-cab”, “motorcab” and “tractor”, respectively, see Appendix
26. Inserted by the Taxation Laws (Amendment) Act, 1991, w.e.f. 15-1-1991.
the case of a company, be restricted to seventy-five per cent of the amount calculated at the percentage, on the written down value of such assets, prescribed under this Act immediately before the commencement of the Taxation Laws (Amendment) Act, 1991:]
27[Provided also that the aggregate deduction, in respect of depreciation of buildings, machinery, plant or furniture, being tangible assets or know-how, patents, copyrights, trademarks, licences, franchises or any other business or commercial rights of similar nature, being intangible assets allowable to the predecessor and the successor in the case of succession referred to in 28[clause (xiii), clause (xiiib) and clause (xiv)] of section 47 or section 170 or to the amalgamating company and the amalgamated company in the case of amalgamation, or to the demerged company and the resulting company in the case of demerger, as the case may be, shall not exceed in any previous year the deduction calculated at the prescribed rates as if the succession or the amalgamation or the demerger, as the case may be, had not taken place, and such deduction shall be apportioned between the predecessor and the successor, or the amalgamating company and the amalgamated company, or the demerged company and the resulting company, as the case may be, in the ratio of the number of days for which the assets were used by them.]
29[Explanation 1.—Where the business or profession of the assessee is carried on in a building not owned by him but in respect of which the assessee holds a lease or other right of occupancy and any capital expenditure is incurred by the assessee for the purposes of the business or profession on the construction of any structure or doing of any work in or in relation to, and by way of renovation or extension of, or improvement to, the building, then, the provisions of this clause shall apply as if the said structure or work is a building owned by the assessee.
Explanation 2.—For the purposes of this 30[sub-section] “written down value of the block of assets” shall have the same meaning as in clause* (c) of sub-section† (6) of section 43.]
31[Explanation 3.—For the purposes of this sub-section, 32[the expression “assets”] shall mean—
27. Fifth proviso substituted by the Finance Act, 1999, w.e.f. 1-4-2000. Prior to its substitution, fifth proviso was inserted by the Finance (No. 2) Act, 1996, w.e.f. 1-4-1997 and later on amended by the Finance (No. 2) Act, 1998, w.e.f. 1-4-1999.
28. Substituted for “clause (xiii) and clause (xiv)” by the Finance Act, 2010, w.e.f. 1-4-2011.
29. Inserted by the Taxation Laws (Amendment and Miscellaneous Provisions) Act, 1986, w.e.f. 1-4-1988.
30. Substituted for “clause” by the Finance Act, 2002, w.e.f. 1-4-2003.
31. Inserted by the Finance (No. 2) Act, 1998, w.e.f. 1-4-1999.
32. Substituted for ‘the expressions “assets” and “block of assets”’ by the Finance (No. 2) Act, 2009, w.e.f. 1-4-2010.
*Should be read as ‘sub-clause’.
†Should be read as ‘clause’.
(a)tangible assets, being buildings, machinery, plant or furniture; (b)intangible assets, being know-how, patents, copyrights, trade marks, licences, franchises or any other business or commercial rights of similar nature33 34[, not being goodwill of a business or profession].
Explanation 4.—For the purposes of this sub-section, the expression “know-how” means any industrial information or technique likely to assist in the manufacture or processing of goods or in the working of a mine, oil-well or other sources of mineral deposits (including searching for discovery or testing of deposits for the winning of access thereto).
35[Explanation 5.—For the removal of doubts, it is hereby declared that the provisions of this sub-section shall apply whether or not the assessee has claimed the deduction in respect of depreciation in computing his total income;]
36[(iia)in the case of any new machinery or plant (other than ships and aircraft), which has been acquired and installed37 after the 31st day of
33. For the meaning of the expression “any other business or commercial rights of a similar nature”, see Taxmann’s Direct Taxes Manual, Vol. 3.
34. Inserted by the Finance Act, 2021, w.e.f. 1-4-2021.
35. Inserted by the Finance Act, 2001, w.e.f. 1-4-2002.
36. Substituted by the Finance Act, 2005, w.e.f. 1-4-2006. Clause (iia), was originally inserted by the Finance (No. 2) Act, 1980, w.e.f. 1-4-1981 and omitted by the Taxation Laws (Amendment and Miscellaneous Provisions) Act, 1986, w.e.f. 1-4-1988. Prior to its substitution, clause (iia), as inserted by the Finance (No. 2) Act, 2002, w.e.f. 1-4-2003 and amended by the Finance (No. 2) Act, 2004, w.e.f. 1-4-2005, read as under :
‘(iia)in the case of any new machinery or plant (other than ships and aircraft), which has been acquired and installed after the 31st day of March, 2002, by an assessee engaged in the business of manufacture or production of any article or thing, a further sum equal to fifteen per cent of the actual cost of such machinery or plant shall be allowed as deduction under clause (ii) :
Provided that such further deduction of fifteen per cent shall be allowed to—
(A)a new industrial undertaking during any previous year in which such undertaking begins to manufacture or produce any article or thing on or after the 1st day of April, 2002; or
(B)any industrial undertaking existing before the 1st day of April, 2002, during any previous year in which it achieves the substantial expansion by way of increase in installed capacity by not less than ten per cent:
Provided further that no deduction shall be allowed in respect of—
(a)any machinery or plant which, before its installation by the assessee, was used either within or outside India by any other person; or
(b)any machinery or plant installed in any office premises or any residential accommodation, including accommodation in the nature of a guest house; or
(c)any office appliances or road transport vehicles; or
(d)any machinery or plant, the whole of the actual cost of which is allowed as a deduction (whether by way of depreciation or otherwise) in computing the income chargeable under the head “Profits and gains of business or profession” of any one previous year:
(Contd. on p. 1.261)
March, 2005, by an assessee engaged in the business of manufacture37 or production of any article or thing 38[39[or in the business of generation, transmission or distribution] of power], a further sum equal to twenty per cent of the actual cost of such machinery or plant shall be allowed as deduction under clause (ii) :
40[Provided that where an assessee, sets up an undertaking or enterprise for manufacture or production of any article or thing, on or after the 1st day of April, 2015 in any backward area notified41 by the Central Government in this behalf, in the State of Andhra Pradesh or in the State of Bihar or in the State of Telangana or in the State of West Bengal, and acquires and installs any new machinery or plant (other than ships and aircraft) for the purposes of the said undertaking or enterprise during the period beginning on the 1st day of April, 2015 and ending before the 1st day of April, 2020 in the said backward area, then, the provisions of clause (iia) shall have effect, as if for the words “twenty per cent”, the words “thirty-five per cent” had been substituted:]
Provided 42[further] that no deduction shall be allowed in respect of— (A)any machinery or plant which, before its installation by the assessee, was used either within or outside India by any other person; or
(Contd. from p. 1.260)
Provided also that no deduction shall be allowed under clause (A) or, as the case may be, clause (B), of the first proviso unless the assessee furnishes the details of machinery or plant and increase in the installed capacity of production in such form, as may be prescribed along with the return of income, and the report of an accountant, as defined in the Explanation below sub-section (2) of section 288 certifying that the deduction has been correctly claimed in accordance with the provisions of this clause.
Explanation.—For the purposes of this clause,—
(1)“new industrial undertaking” means an undertaking which is not formed,— (a)by the splitting up, or the reconstruction, of a business already in existence; or (b)by the transfer to a new business of machinery or plant previously used for any purpose;
(2)“installed capacity” means the capacity of production as existing on the 31st day of March, 2002;’
37. For the meaning of the expressions “acquired and installed” and “manufacture”, see Taxmann’s Direct Taxes Manual, Vol. 3.
38. Inserted by the Finance Act, 2012, w.e.f. 1-4-2013.
39. Substituted for “or in the business of generation or generation and distribution” by the Finance Act, 2016, w.e.f. 1-4-2017.
40. Inserted by the Finance Act, 2015, w.e.f. 1-4-2016.
41. For notified backward areas, see Taxmann’s Master Guide to Income-tax Act.
42. Inserted by the Finance Act, 2015, w.e.f. 1-4-2016.
(B)any machinery or plant installed in any office premises or any residential accommodation, including accommodation in the nature of a guest-house; or
(C)any office appliances or road transport vehicles; or
(D)any machinery or plant, the whole of the actual cost of which is allowed as a deduction (whether by way of depreciation or otherwise) in computing the income chargeable under the head “Profits and gains of business or profession” of any one previous year;]
43[(iii)in the case of any building, machinery, plant or furniture in respect of which depreciation is claimed and allowed under clause (i) and which is sold, discarded, demolished or destroyed in the previous year (other than the previous year in which it is first brought into use), the amount by which the moneys payable in respect of such building, machinery, plant or furniture, together with the amount of scrap value, if any, fall short of the written down value thereof :
Provided that such deficiency is actually written off in the books of the assessee.
Explanation.—For the purposes of this clause,—
(1)“moneys payable” in respect of any building, machinery, plant or furniture includes—
(a)any insurance, salvage or compensation moneys payable in respect thereof;
(b)where the building, machinery, plant or furniture is sold, the price for which it is sold,
so, however, that where the actual cost of a motor car is, in accordance with the proviso to clause (1) of section 43, taken to be twenty-five thousand rupees, the moneys payable in respect of such motor car shall be taken to be a sum which bears to the amount for which the motor car is sold or, as the case may be, the amount of any insurance, salvage or compensation moneys payable in respect thereof (including the amount of scrap value, if any) the same proportion as the amount of twenty-five thousand rupees bears to the actual cost of the motor car to the assessee as it would have been computed before applying the said proviso;
(2)“sold” includes a transfer by way of exchange or a compulsory acquisition under any law for the time being in force but does not
43. Inserted by the Finance (No. 2) Act, 1998, w.r.e.f. 1-4-1998. Earlier, original clause (iii) was amended by the Finance Act, 1966, w.e.f. 1-4-1966 and the Finance (No. 2) Act, 1967, w.e.f. 1-4-1967 and later on omitted by the Taxation Laws (Amendment and Miscellaneous Provisions) Act, 1986, w.e.f. 1-4-1988.
1.263 CH. IV - COMPUTATION OF BUSINESS
include a transfer, in a scheme of amalgamation, of any asset by the amalgamating company to the amalgamated company where the amalgamated company is 44[an Indian company or in a scheme of amalgamation of a banking company, as referred to in clause (c) of section 5 of the Banking Regulation Act, 1949 (10 of 1949) with a banking institution as referred to in sub-section (15) of section 45 of the said Act, sanctioned and brought into force by the Central Government under sub-section (7) of section 45 of that Act 45, of any asset by the banking company to the banking institution.]]
(iv) 46[***]
(v) 47[***]
(vi) 48[***]
(1A) 49[***]
50[(2) Where, in the assessment of the assessee, full effect cannot be given to any allowance under sub-section (1) in any previous year, owing to there being no profits or gains chargeable for that previous year51, or owing to the profits or gains chargeable51 being less than the allowance, then, subject to the provisions of sub-section (2) of section 72 and sub-section (3) of section 73, the allowance or the part of the allowance to which effect has not been given, as the case may
44. Substituted for “an Indian company” by the Finance Act, 2005, w.e.f. 1-4-2005.
45. For text of section 5(c) and section 45 of the Banking Regulation Act, 1949, see Appendix
46. Clause (iv) was omitted by the Taxation Laws (Amendment & Miscellaneous Provisions) Act, 1986, w.e.f. 1-4-1988. Original clause (iv) was amended by the Finance Act, 1983, w.e.f. 1-4-1984, the Finance Act, 1978, w.e.f. 1-4-1979, the Finance Act, 1976, w.e.f. 1-4-1977 and the Finance Act, 1966, w.e.f. 1-4-1966.
47. Clause (v) was omitted by the Taxation Laws (Amendment & Miscellaneous Provisions) Act, 1986, w.e.f. 1-4-1988. Original clause (v) was inserted by the Finance (No. 2) Act, 1967, w.e.f. 1-4-1968 and later amended by the Finance Act, 1983, w.e.f. 1-4-1984.
48. Clause (vi) was omitted by the Taxation Laws (Amendment and Miscellaneous Provisions) Act, 1986, w.e.f. 1-4-1988. Original clause (vi) was inserted by the Direct Taxes (Amendment) Act, 1974, w.e.f. 1-4-1975 and later amended by the Finance Act, 1976, w.e.f. 1-4-1976.
49. Sub-section (1A) was omitted by the Taxation Laws (Amendment & Miscellaneous Provisions) Act, 1986, w.e.f. 1-4-1988. Original sub-section (1A) was inserted by the Taxation Laws (Amendment) Act, 1970, w.e.f. 1-4-1971.
50. Substituted by the Finance Act, 2001, w.e.f. 1-4-2002. Prior to its substitution, sub-section (2), as amended by the Taxation Laws (Amendment and Miscellaneous Provisions) Act, 1986, w.e.f. 1-4-1988, Direct Tax Laws (Amendment) Act, 1987, w.e.f. 1-4-1989 and Finance Act, 1992, w.e.f. 1-4-1993, substituted by the Finance (No. 2) Act, 1996, w.e.f. 1-4-1997 and further amended by the Finance Act, 2000, w.e.f. 1-4-2001, read as under : ‘(2) Where in the assessment of the assessee full effect cannot be given to any allowance under clause (ii) of sub-section (1) in any previous year owing to there being no profits or gains chargeable for that previous year or owing to the profits or gains being less than the allowance, then, the allowance or the part of allowance to which effect has not been given (hereinafter referred to as unabsorbed depreciation allowance), as the case may be,—
(Contd. on p. 1.264)
be, shall be added to the amount of the allowance for depreciation for the following previous year and deemed to be part of that allowance, or if there is no such allowance for that previous year, be deemed to be the allowance for that previous year, and so on for the succeeding previous years.]
52[Investment allowance.53
32A. (1) In respect of a ship or an aircraft or machinery or plant specified in sub-section (2), which is owned by the assessee and is wholly used for the purposes of the business54 carried on by him, there shall, in accordance with and subject to the provisions of this section, be allowed a deduction, in respect of the previous year in which the ship or aircraft was acquired or the machinery or plant was installed54 or, if the ship, aircraft, machinery or plant is first put to use54 in the immediately succeeding previous year, then, in respect of that previous year, of a sum by way of investment allowance equal to twenty-five per cent of the actual cost of the ship, aircraft, machinery or plant to the assessee : S.
(Contd. from p. 1.263)
(i)shall be set off against the profits and gains, if any, of any business or profession carried on by him and assessable for that assessment year ;
(ii)if the unabsorbed depreciation allowance cannot be wholly set off under clause (i), the amount not so set off shall be set off from the income under any other head, if any, assessable for that assessment year;
(iii)if the unabsorbed depreciation allowance cannot be wholly set off under clause (i) and clause (ii), the amount of allowance not so set off shall be carried forward to the following assessment year and—
(a)it shall be set off against the profits and gains, if any, of any business or profession carried on by him and assessable for that assessment year ;
(b)if the unabsorbed depreciation allowance cannot be wholly so set off, the amount of unabsorbed depreciation allowance not so set off shall be carried forward to the following assessment year not being more than eight assessment years immediately succeeding the assessment year for which the aforesaid allowance was first computed :
Provided that the time limit of eight assessment years specified in sub-clause (b) shall not apply in the case of a company for the assessment year beginning with the assessment year relevant to the previous year in which the said company has become a sick industrial company under sub-section (1) of section 17 of the Sick Industrial Companies (Special Provisions) Act, 1985 (1 of 1986) and ending with the assessment year relevant to the previous year in which the entire net worth of such company becomes equal to or exceeds the accumulated losses.
Explanation.— For the purposes of this clause, “net worth” shall have the meaning assigned to it in clause (ga) of sub-section (1) of section 3 of the Sick Industrial Companies (Special Provisions) Act, 1985 (1 of 1986).’
51. For the meaning of the expressions “no profits or gains chargeable for that previous year” and “chargeable”, see Taxmann’s Direct Taxes Manual, Vol. 3.
52. Inserted by the Finance Act, 1976, w.e.f. 1-4-1976.
53.Vide Notification No. SO 233(E), dated 19-3-1990, no investment allowance shall be allowed in respect of any new ship or aircraft acquired or any new machinery or plant installed after 31-3-1990. For details, log on to www.taxmann.com.
54. For the meaning of the expressions “wholly used for the purposes of the business”, “installed” and “put to use”, see Taxmann’s Direct Taxes Manual, Vol. 3.
55[Provided that in respect of a ship or an aircraft or machinery or plant specified in sub-section (8B), this sub-section shall have effect as if for the words “twentyfive per cent”, the words “twenty per cent” had been substituted :]
Provided 55[further] that no deduction shall be allowed under this section in respect of—
(a)any machinery or plant installed in any office premises56 or any residential accommodation, including any accommodation in the nature of a guest house ;
(b)any office appliances56 or road transport vehicles56 ;
(c)any ship, machinery or plant in respect of which the deduction by way of development rebate is allowable under section 33 ; and
(d)any machinery or plant, the whole of the actual cost of which is allowed as a deduction (whether by way of depreciation or otherwise) in computing the income chargeable under the head “Profits and gains of business or profession” of any one previous year.
55[Explanation.—For the purposes of this sub-section, “actual cost” means the actual cost of the ship, aircraft, machinery or plant to the assessee as reduced by that part of such cost which has been met out of the amount released to the assessee under sub-section (6) of section 32AB.]
(2) The ship or aircraft or machinery or plant referred to in sub-section (1) shall be the following, namely :—
(a)a new ship or new aircraft acquired after the 31st day of March, 1976, by an assessee engaged in the business of operation of ships or aircraft ;
(b)any new machinery or plant installed57 after the 31st day of March, 1976,—
(i)for the purposes of business of generation or distribution of electricity or any other form of power ; or
58[(ii)in a small-scale industrial undertaking59 for the purposes of business of manufacture or production59 of any article or thing59 ; or
(iii)in any other industrial undertaking59 for the purposes of business of construction59, manufacture or production59 of any article or thing59, not being an article or thing59 specified in the list in the Eleventh Schedule :]
55. Inserted by the Direct Tax Laws (Amendment) Act, 1989, w.e.f. 1-4-1989.
56. For the meaning of the expressions “office premises”, “office appliances” and “road transport vehicles”, see Taxmann’s Direct Taxes Manual, Vol. 3.
57. For the meaning of the expression “installed”, see Taxmann’s Direct Taxes Manual, Vol. 3.
58. Substituted by the Finance (No. 2) Act, 1977, w.e.f. 1-4-1978.
59. For the meaning of the terms/expressions “industrial undertaking”, “construction”, “manufacture”, “production” and “article or thing”, see Taxmann’s Direct Taxes Manual, Vol. 3.
60[Provided that nothing contained in clauses (a) and (b) shall apply in relation to,—
(i)a new ship or new aircraft acquired, or (ii)any new machinery or plant installed, after the 31st day of March, 1987 but before the 1st day of April, 1988, unless such ship or aircraft is acquired or such machinery or plant is installed in the circumstances specified in clause (a) of sub-section (8B) and the assessee furnishes evidence to the satisfaction of the Assessing Officer as specified in that clause ;]
61[(c)any new machinery or plant installed after the 31st day of March, 1983, but before the 62[1st day of April, 1987], for the purposes of business of repairs to ocean-going vessels or other powered craft if the business is carried on by an Indian company and the business so carried on is for the time being approved63 for the purposes of this clause by the Central Government.]
Explanation.—For the purposes of this sub-section and 64[sub-sections (2B) 65[, (2C)] and (4)],—
66[(1)(a)“new ship” or “new aircraft” includes a ship or aircraft which before the date of acquisition by the assessee was used by any other person, if it was not at any time previous to the date of such acquisition owned by any person resident in India ;
(b)“new machinery or plant” includes machinery or plant which before its installation by the assessee was used outside India by any other person, if the following conditions are fulfilled, namely :—
(i)such machinery or plant was not, at any time previous to the date of such installation by the assessee, used in India ;
(ii)such machinery or plant is imported into India from any country outside India ; and
(iii)no deduction on account of depreciation in respect of such machinery or plant has been allowed or is allowable under the provisions of the Indian Income-tax Act, 1922 (11 of 1922), or this Act in computing the total income of any person for any period
60. Inserted by the Direct Tax Laws (Amendment) Act, 1989, w.e.f. 1-4-1989.
61. Inserted by the Finance Act, 1983, w.e.f. 1-4-1984.
62. Substituted for “1st day of April, 1988” by the Finance Act, 1986, w.e.f. 1-4-1987.
63. For approved company, see Taxmann’s Direct Taxes Circulars.
64. Substituted for “sub-section (4)” by the Finance (No. 2) Act, 1977, w.e.f. 1-4-1978.
65. Inserted by the Finance Act, 1983, w.e.f. 1-6-1983.
66. Substituted by the Taxation Laws (Amendment & Miscellaneous Provisions) Act, 1986, w.e.f. 1-4-1988.
prior to the date of the installation of the machinery or plant by the assessee,]
(2)an industrial undertaking shall be deemed to be a small-scale industrial undertaking, if the aggregate value of the machinery and plant (other than tools, jigs, dies and moulds) installed, as on the last day of the previous year, for the purposes of the business of the undertaking 67[does not exceed,—
68[(i)in a case where the previous year ends before the 1st day of August, 1980, ten lakh rupees ; (ii)in a case where the previous year ends after the 31st day of July, 1980, but before the 18th day of March, 1985, twenty lakh rupees; and
(iii)in a case where the previous year ends after the 17th day of March, 1985, thirty-five lakh rupees,]] and for this purpose the value of any machinery or plant shall be,—
(a)in the case of any machinery or plant owned by the assessee, the actual cost thereof to the assessee ; and (b)in the case of any machinery or plant hired by the assessee, the actual cost thereof as in the case of the owner of such machinery or plant.
69[(2A) The deduction under sub-section (1) shall not be denied in respect of any machinery or plant installed and used mainly for the purposes of business of construction, manufacture or production of any 70article or thing, not being an article or thing specified in the list in the Eleventh Schedule, by reason only that such machinery or plant is also used for the purposes of business of construction, manufacture or production of any article or thing specified in the said list.]
71[(2B) Where any new machinery or plant is installed after the 30th day of June, 1977, but before the 1st day of April, 72[1987], for the purposes of business of manufacture or production of any article or thing and such article or thing— (a)is manufactured or produced by using any technology (including any process) or other know-how developed in, or (b)is an article or thing invented in, 1.267
67. Substituted for “does not exceed ten lakh rupees” by the Finance Act, 1981, w.e.f. 1-4-1981.
68. Substituted by the Finance Act, 1986, w.r.e.f. 1-4-1985.
69. Inserted by the Finance (No. 2) Act, 1977, w.e.f. 1-4-1978.
70. For the meaning of the term “article”, see Taxmann’s Direct Taxes Manual, Vol. 3.
71. Inserted by the Finance (No. 2) Act, 1977, w.e.f. 1-4-1978.
72. Substituted for “1982” by the Finance Act, 1982, w.e.f. 1-4-1982.
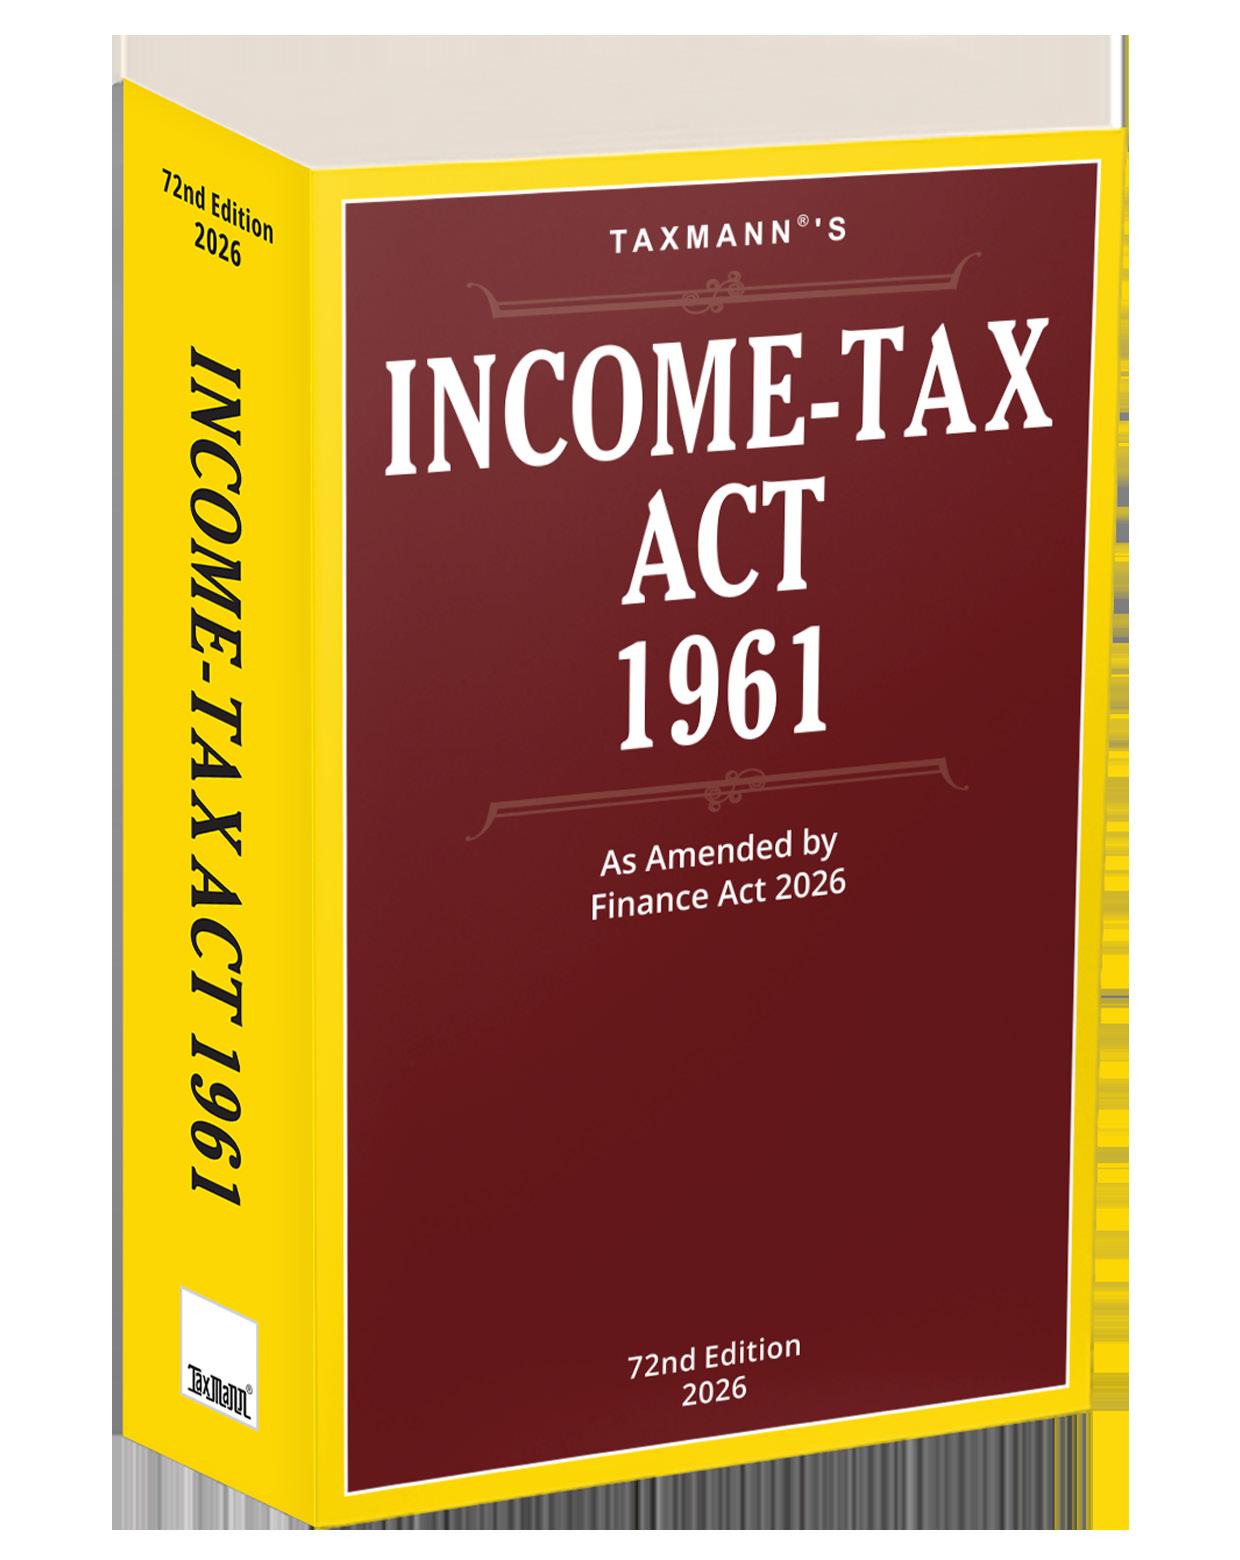
Income-Tax Act 1961
AUTHOR : Taxmann’s Editorial Board
PUBLISHER : Taxmann
DATE OF PUBLICATION : April 2026
EDITION : 72nd Edition | 2026
ISBN NO : 9789371264778
No. of Pages : 1888
BINDING TYPE : Paperback
Rs. 2,995
DESCRIPTION
Income-Tax Act 1961 is the most authoritative and complete Edition of India’s principal direct tax statute, now in its 72nd consecutive annual Edition. At 1,800+ pages and spanning five self-contained Divisions, this Edition presents the full text of the Income-tax Act 1961 as it stands after every amendment effected by the Finance Act 2026.
The Edition is designed to serve simultaneously as a legislative reference, a compliance tool, a research base, and a professional quick-reckoner. Its architecture—dual section-page indexing, exhaustive amendment-history footnoting, and an integrated Appendix of allied provisions—makes it functional as a complete single-volume direct tax library for most day-to-day professional needs.
This title is essential for every category of direct tax professional and student:
• Tax Practitioners and Chartered Accountants
• Advocates and Tax Lawyers
• Company Secretaries, CFOs, and In-House Tax Teams
• Revenue Officers and ITAT Members
• CA Final, LL.B., and Allied Examination Candidates
• Legal Researchers and Academics
The Present Publication, in its 72nd Edition | 2026, upholds its tradition of unmatched accuracy and reliability. It is updated to incorporate the latest amendments introduced by the Finance Act 2026. The book is authored and edited by Taxmann’s Editorial Board, continuing its legacy as a cornerstone in Direct Tax, with the following noteworthy features:
• [Complete, Section-by-Section Amended Text] Every section across all 23 Chapters, every Rule, and every Schedule is reproduced in full as currently in force. Provisions inserted, substituted, or omitted by each amending statute since 1961 are clearly indicated inline
• [Exhaustive Amendment-History Footnoting] Numbered footnotes on each page record the amending statute, effective date, and the exact nature of every change—allowing practitioners to reconstruct the law as it stood at any point in time, critical for reassessment proceedings and prior-year appeals
• [Full Text of Finance Act 2026 as a Separate Division] Reproduced in Division Two with its own Arrangement of Sections, eliminating the need for a separate purchase
• [Dual-Statute Coverage] The Finance Act 2026 amends both the Income-tax Act 1961 and the Income-tax Act 2025 (Act No. 30 of 2025). This Edition captures both sets of amendments, making it the essential reference during the current transitional period
• [Revised STT Rates Integrated] Finance Act 2026 revisions—options in securities (0.15%), exercise of options (0.15%), and futures (0.05%)—are captured in Division Three with full footnote history
• [Foreign Assets of Small Taxpayers Disclosure Scheme 2026 — New Division] Full text of Sections 130–144 of the Finance Act 2026. The Scheme covers taxpayers with aggregate undisclosed foreign assets/income not exceeding ₹1 crore, prescribes tax at 30% on asset fair market value plus 30% on undisclosed income plus a 100% surcharge, and grants full immunity from penalty and prosecution upon compliance
• [Section–Page Dual-Column Index] Every Division opens with a section-number and page-number index for immediate navigation
• [Comprehensive Allied Acts Appendix] Full text of provisions from 50+ allied statutes cross-referenced within the Act—including the Companies Act 2013, IBC, IRDAI Regulations, IFSC Authority Regulations, LLP Act, Patents Act, PFRDA Act, RBI Act, RERA, and SARFAESI Act
• [Subject Index] A detailed alphabetical and topical Subject Index supporting keyword-based and topic-led navigation