
Sample Read
© Taxmann
Price : ` 125
Law stated in this book is as updated till 8th January, 2026
Published by : Taxmann Publications (P.) Ltd.
Sales & Marketing :
59/32, New Rohtak Road, New Delhi-110 005 India
Phone : +91-11-45562222
Website : www.taxmann.com
E-mail : sales@taxmann.com
Regd. Office :
21/35, West Punjabi Bagh, New Delhi-110 026 India
Printed at :
Tan Prints (India) Pvt. Ltd.
44 Km. Mile Stone, National Highway, Rohtak Road Village Rohad, Distt. Jhajjar (Haryana) India
E-mail : sales@tanprints.com
Disclaimer
Every effort has been made to avoid errors or omissions in this publication. In spite of this, errors may creep in. Any mistake, error or discrepancy noted may be brought to our notice which shall be taken care of in the next edition. It is notified that neither the publisher nor the author or seller will be responsible for any damage or loss of action to any one, of any kind, in any manner, therefrom. It is suggested that to avoid any doubt the reader should cross-check all the facts, law and contents of the publication with original Government publication or notifications.
No part of this book may be reproduced or copied in any form or by any means [graphic, electronic or mechanical, including photocopying, recording, taping, or information retrieval systems] or reproduced on any disc, tape, perforated media or other information storage device, etc., without the written permission of the publishers. Breach of this condition is liable for legal action.
For binding mistake, misprints or for missing pages, etc., the publisher’s liability is limited to replacement within seven days of purchase by similar edition. All expenses in this connection are to be borne by the purchaser. All disputes are subject to Delhi jurisdiction only.

HEALTH SECURITY se
NATIONAL
SECURITY CESS RULES, 2026
MISCELLANEOUS
Health Security se National Security Cess Act, 2025
[NO.
35 OF 2025]1
An Act to augment the resources for meeting expenditure on national security and for public health, and to 2[levy] a cess for the said purposes on the machines installed or other processes undertaken by which specified goods are manufactured or produced and for matters connected therewith or incidental thereto.
BE it enacted by Parliament in the Seventy-sixth Year of the Republic of India as follows:—
CHAPTER I
PRELIMINARY
Short title and commencement.
1. (1) This Act may be called the Health Security se National Security Cess Act, 2025.
(2)It shall come into force on such date3 as the Central Government may, by notification in the Official Gazette, appoint.
Definitions.
2. In this Act, unless the context otherwise requires,—
(a)“adjudicating authority” means the concerned proper officer appointed or authorised under the respective provisions to pass orders under this Act after adjudication, but does not include the Board, the revisional authority and the appellate authority;
(b)“appellate authority” means an authority appointed or authorised to hear appeals under section 29;
(c)“Appellate Tribunal” means the Customs, Excise and Service Tax Appellate Tribunal constituted under section 129 of the Customs Act, 1962 (52 of 1962);
1.Dated 15-12-2025.
2.As corrected by Corrigenda, dated 8-1-2026.
3. NOTIFICATION NO. S.O. 6153(E), DATED 31-12-2025: In exercise of the powers conferred by the sub-section (2) of section 1 of the Health Security se National Security Cess Act, 2025 (35 of 2025), the Central Government hereby appoints the 1st day of February, 2026 as the date on which the provisions of the said Act, shall come into force.
(
(d) “Board” means the Central Board of Indirect Taxes and Customs constituted under section 3 of the Central Boards of Revenue Act, 1963 (54 of 1963);
(
e) “cess” means the Health Security se National Security Cess levied under section 4;
(f) “factory” means any premises, including the precincts thereof, wherein or in any part of which—
(
i) the specified goods are manufactured; or
(ii) any manufacturing process connected with the production of the specified goods are being carried on or is ordinarily carried on;
(
g) “machine” for the purposes of manufacture or production of the specified goods includes all types of Form, Fill and Seal Machines and Profile Pouch Making Machines, by whatever name called, whether vertical or horizontal, with or without collar, single track or multi-track, and any other type of packing machine used for packing of the specified goods in pouches, tins or other containers;
(
h) “manufacture” includes—
(i) any process incidental or ancillary to the completion of the specified goods; and
(ii) the process of packing or repacking of such goods in a pouch or tin or other container or labelling or re-labelling thereof including the declaration or alteration of retail sale price on it or adoption of any other treatment on the goods to render the specified goods marketable to the consumer, whether or not such process is the only process undertaken;
(i) “notification” means a notification published in the Gazette of India and the expression “notify” with its grammatical variation and cognate expressions shall be construed accordingly;
(j) “pan masala” means goods falling under tariff item 2106 90 20 of the First Schedule to the Customs Tariff Act, 1975 (51 of 1975);
(k) “prescribed” means prescribed by rules made under this Act;
(l) “proper officer” means any officer of the Central Government entrusted with such powers or assigned with specific functions under the provisions of this Act by the Board;
m) “process” means any manual, mechanical, electrical, electronic, automated or hybrid operation, or any other activity by which the specified goods are manufactured or produced, whether wholly or in part;
(n) “revisional authority” means an authority appointed or authorised under section 28 for revision of an order of the adjudicating authority;
(o) “Schedule” means a Schedule annexed to this Act;
(p) “specified goods” means the goods as specified in Schedule I to this Act or such other goods as the Central Government may, by notification, specify;
(q) “State” includes a Union territory with Legislature;
(r) “taxable person” shall mean a person referred to in section 3; and
(s) “weight” means the maximum weight of the specified goods that is capable of being packaged in each pouch, tin or other container by the relevant machine or process.
COMMENTS
SECTION NOTES
2.1 Definition of “Adjudicating Authority” [Section 2(a)]
Adjudicating authority refers to the concerned proper officer who is appointed or authorized under the respective provisions of this Act.
The primary function of this officer is to pass orders under the Act after the process of adjudication.
2.1-1 Exclusions from the Definition
The definition of adjudicating authority specifically excludes:
The Board.
The revisional authority.
The appellate authority.
2.2 Definition of “Factory” [Section 2(f)]
Factory means any premises, which includes the precincts of such premises.
Activities determining a factory
A premises is considered a factory if, within any part of it:
The specified goods are manufactured.
Any manufacturing process connected with the production of the specified goods is being carried on or is ordinarily carried on.
2.3 Definition of “Machine” [Section 2(g)]
For the purposes of manufacturing or producing specified goods, “machine” includes: All types of Form, Fill, and Seal Machines.
Profile Pouch Making Machines, regardless of the name by which they are called.
Technical variations included
The definition encompasses machines whether they are:
Vertical or horizontal in orientation.
Equipped with or without a collar.
Single track or multi-track in operation.
Inclusion of packing equipment
The term includes any other type of packing machine that is used for packing the specified goods into:
Tins.
Other containers.
2.4 Definition of “Manufacture” [Section 2(h)]
Manufacture includes any process that is incidental or ancillary to the completion of the specified goods.
Inclusion of packing and marketability processes
Manufacture includes the process of:
Packing or repacking of such goods in a pouch, tin, or other container.
Labelling or re-labelling of the goods.
Declaring or altering the retail sale price on the goods.
Adopting any other treatment on the goods intended to render the specified goods marketable to the consumer.
Application regardless of process extent
The listed processes are considered manufacture whether or not such a process is the only process undertaken.
CHAPTER II TAXABLE PERSON
Taxable person.
3. (1) For the purposes of this Act, “taxable person” means any person who owns, possesses, operates, manages, or is otherwise in control of the machine or undertakes any process by which specified goods are manufactured or produced, whether directly or through job-workers, employees, hired labour, or through any other person acting on his behalf under any arrangement.
(2) A person shall be treated as a taxable person under this section irrespective of whether he has opted for, or is availing of, any composition scheme, concessional levy, or any other alternate scheme of taxation applicable to the specified goods, under any law for the time being in force.
(3) For the purposes of this section,—
(a) the ownership, possession, or control over the machine or processes shall be sufficient to constitute a person as a taxable person, irrespective of the actual quantity manufactured;
(b) where a machine or process, is owned, possessed, leased, hired or otherwise placed at the disposal of one or more persons manufacturing or producing the specified goods, every such person shall be regarded as a taxable person; and
(c) where the production or manufacture of the specified goods are divided into stages or processes carried out by different persons, such person undertaking the final process that results in the completion or rendering of the specified goods marketable, shall be deemed to be the taxable person.
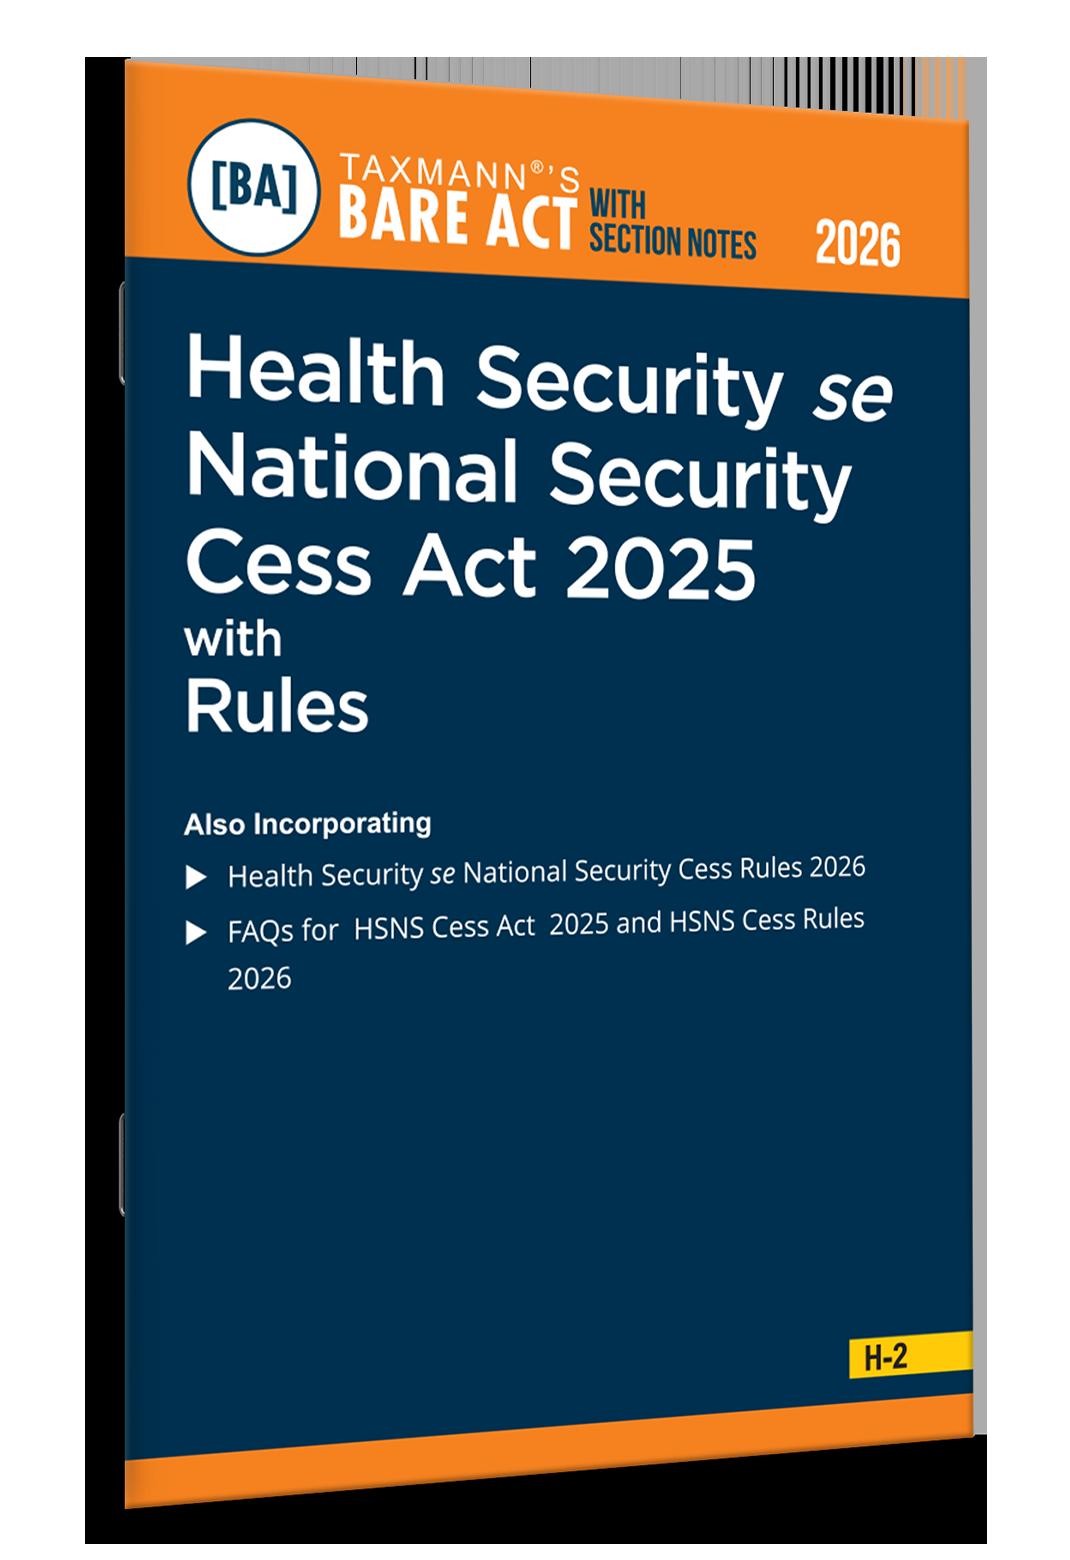
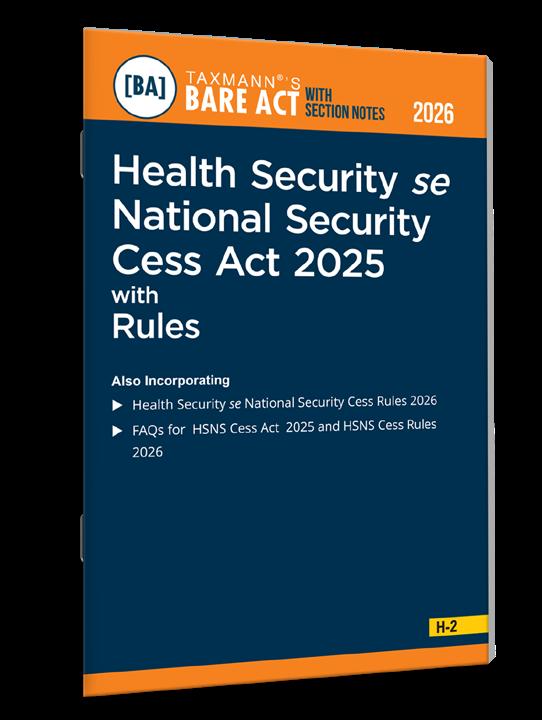
Health Security se National Security Cess Act 2025 with Rules – Bare Act with Section Notes
AUTHOR : Taxmann’s Editorial Board
PUBLISHER : Taxmann
DATE OF PUBLICATION : January 2026
EDITION : 2026 Edition
ISBN NO : 9789375613855
No. of Pages : 92
BINDING TYPE : Paperback
DESCRIPTION
Health Security se National Security Cess Act 2025 with Rules [Bare Act with Section Notes] by Taxmann is an authoritative statutory publication documenting India’s newly introduced machine-capacity–based cess regime, enacted to augment funding for national security and public health. This publication goes beyond the bare statutory text by presenting the law as an operational compliance framework, integrating the principal Act, the Health Security se National Security Cess Rules 2026, section-wise explanatory notes, Schedules, statutory Forms, and FAQs. It is designed to enable readers to understand the computation, administration, enforcement, audit, penalty, and appellate mechanisms under the HSNS Cess regime, with a specific focus on capacity-based assessment, machine verification, abatement, and enforcement powers. This publication is intended for professionals and institutions that require a precise and defensible understanding of the HSNS Cess framework, including:
• Manufacturers of Specified Goods
• Industry Compliance Teams
• Chartered Accountants, Cost Accountants & Company Secretaries
• Indirect Tax Consultants and Litigation Professionals
• Corporate Legal Departments and Regulatory Advisors
• Tax Authorities, Enforcement Officers, and Policy Analysts
• Courts, Tribunals, and Academic Institutions
The Present Publication is the 2026 Edition, covering the amended and updated text of the Health Security se National Security Cess Act [Act No. 35 of 2025] and Rules, with the following noteworthy features:
• [Complete Legislative Architecture in One Volume] Act, Rules, Schedules, Forms, and FAQs presented in a single consolidated reference
• [Section-wise Explanatory Notes] Clarifies key definitions, compliance triggers, and enforcement thresholds
• [Capacity-based Levy Explained with Precision] Statutory tables detailing cess computation based on:
o Maximum rated speed of machines
o Weight of pouches/tins/containers
o Fixed monthly cess slabs (machine-based and manual)
• [Machine & Process Governance Framework] Coverage of machine registration, declarations, calibration, physical verification, and Chartered Engineer certification
• [Abatement Mechanism with Illustrations] Pro-rata abatement rules for non-operational machines with formulas and illustrations
• [Strong Enforcement & Surveillance Provisions] Inspection, search, seizure, confiscation, arrest, prosecution, and mandatory CCTV requirements
• [Comprehensive Compliance Forms] Statutory forms for registration, declaration, payment, returns, appeals, bonds, and certifications
• [Practical FAQs] Clarifies operational issues such as mid-month installation, sealing/desealing, delayed payments, abatement eligibility, and audit exposure