
Sample Read
© Taxmann
Price : ` 4895 (for a set of Two Volumes)
Law stated in this book is as updated till 1st February, 2026
Published by :
Taxmann Publications (P.) Ltd.
Sales & Marketing : 59/32, New Rohtak Road, New Delhi-110 005 India
Phone : +91-11-45562222
Website : www.taxmann.com
E-mail : sales@taxmann.com
Regd. Office :
21/35, West Punjabi Bagh, New Delhi-110 026 India
Printed at :
Tan Prints (India) Pvt. Ltd.
44 Km. Mile Stone, National Highway, Rohtak Road Village Rohad, Distt. Jhajjar (Haryana) India
E-mail : sales@tanprints.com
Disclaimer
Every effort has been made to avoid errors or omissions in this publication. In spite of this, errors may creep in. Any mistake, error or discrepancy noted may be brought to our notice which shall be taken care of in the next edition. It is notified that neither the publisher nor the author or seller will be responsible for any damage or loss of action to any one, of any kind, in any manner, therefrom. It is suggested that to avoid any doubt the reader should cross-check all the facts, law and contents of the publication with original Government publication or notifications.
No part of this book may be reproduced or copied in any form or by any means [graphic, electronic or mechanical, including photocopying, recording, taping, or information retrieval systems] or reproduced on any disc, tape, perforated media or other information storage device, etc., without the written permission of the publishers. Breach of this condition is liable for legal action.
For binding mistake, misprints or for missing pages, etc., the publisher’s liability is limited to replacement within seven days of purchase by similar edition. All expenses in this connection are to be borne by the purchaser. All disputes are subject to Delhi jurisdiction only.
DIVISION FIVE
DIVISION SIX
GST Tariff Notifications (Rate of Tax and Exemptions)
GST Tariff Notifications (Rate of Tax and Exemptions)
*See Volume 2.
CHAPTER 24
TOBACCO AND MANUFACTURED TOBACCO SUBSTITUTES; PRODUCTS, WHETHER OR NOT CONTAINING NICOTINE, INTENDED FOR INHALATION WITHOUT COMBUSTION; OTHER NICOTINE CONTAINING PRODUCTS INTENDED FOR THE INTAKE OF NICOTINE INTO THE HUMAN BODY
[SEE ALSORATESSPECIFIEDINOTHERACTS:DIVISIONTWO]
Notes:
1.This Chapter does not cover medicinal cigarettes (Chapter 30);
2.Any products classifiable in heading 2404 and any other heading of the Chapter are to be classified in heading 2404.
3.For the purposes of heading 2404, the expression “inhalation without combustion” means inhalation through heated delivery or other means, without combustion.
Sub-heading Note:
For the purposes of sub-heading 2403 11, the expression “water pipe tobacco” means tobacco intended for smoking in a water pipe and which consists of a mixture of tobacco and glycerol, whether or not containing aromatic oils and extracts, molasses or sugar, and whether or not flavoured with fruit. However, tobacco-free products intended for smoking in a water pipe are excluded from this sub-heading.
Supplementary Notes:
For the purposes of this Chapter :
(1) “tobacco” means any form of tobacco, whether cured or uncured and whether manufactured or not, and includes the leaf, stalks and stems of the tobacco plant, but does not include any part of a tobacco plant while still attached to the earth.
(2)“cut-tobacco” means the prepared or processed cut-to-size tobacco which is generally blended or moisturised to a desired extent for use in the manufacture of machine-rolled cigarettes.
(3)“smoking mixtures for pipes and cigarettes” of sub-heading 2403 10 does not cover “Gudaku”.
1. Reverse charge on following supplies of goods, i.e., tax shall be paid on reverse charge basis by recipient of supply [Notification No. 4/2017-Central Tax (Rate), dated 28-6-2017/Notification No. 4/2017-Union Territory (Rate), dated 28-6-2017/Notification No. 4/2017-Integrated Tax (Rate), dated 28-6-2017] : Tariff item, sub-heading, heading or Chapter Description of supply of Goods Supplier of goodsRecipient of supply 2401Tobacco leavesAgriculturist Any Registered Person
2401 20 70---Tobacco for manufacture of cigar and cheroot
2401 20 80---Tobacco for manufacture of hookah tobacco
2401 20 90---Other
2401 30 00-Tobacco refuse
2402 Cigars, cheroots, cigarillos and cigarettes, of tobacco or of tobacco substitutes
2402 10- Cigars, cheroots and cigarillos, containing tobacco :
2402 10 10---Cigar and cheroots
2402 10 20---Cigarillos
2402 20- Cigarettes, containing tobacco:
2402 20 10---Other than filter cigarettes, of length not exceeding 65 millimetres
2402 20 20---Other than filter cigarettes, of length exceeding 65 millimetres but not exceeding 70 millimetres
2402 20 30---Filter cigarettes of length (including the length of the filter, the length of filter being 11 millimetres or its actual length, whichever is more) not exceeding 65 millimetres
2402 20 40---Filter cigarettes of length (including the length of the filter, the length of filter being 11 millimetres or its actual length, whichever is more) exceeding 65 millimetres but not exceeding 70 millimetres
2402 20 50---Filter cigarettes of length (including the length of the filter, the length of filter being 11 millimetres or its actual length, whichever is more) exceeding 65 millimetres but not exceeding 75 millimetres
2402 20 90 ---Other
2402 90- Other :
or UTGST : 2402 : Cigars, cheroots, cigarillos and cigarettes, of tobacco or of tobacco substitutes
2402 90 10---Cigarettes of tobacco substitutesTu20%20%40%
2402 90 20---Cigarillos of tobacco substitutes
2402 90 90---Other
TariffItemDescriptionofgoodsUnitCGSTSGST/ UTGST IGST (1)(2)(3)(4)(5)(6)
2403Other manufactured tobacco and manufactured tobacco substitutes; “homogenised” or “reconstituted” tobacco; tobacco extracts and essences
18% IGST/9% CGST/9% SGST or UTGST: Heading No. 2403 1921, 2403 1929: Biris
40% IGST/20% CGST/20% SGST or UTGST : 2403 : Other manufactured tobacco and manufactured tobacco substitutes; “homogenised” or “reconstituted” tobacco; tobacco extracts and essences (other than biris)
- Smoking tobacco, whether or not containing tobacco substitutes in any proportion
2403 11-- Water pipe tobacco specified in Subheading Note to this Chapter:
TariffItemDescriptionofgoodsUnitCGSTSGST/ UTGST
(1)(2)(3)(4)(5)(6)
2404
Products containing tobacco, reconstituted tobacco, nicotine, or tobacco or nicotine substitutes, intended for inhalation without combustion; other nicotine containing products intended for the intake of nicotine into the human body
18% IGST/9% CGST/9%
SGST or UTGST : 2404 12 00 : Products containing nicotine and intended for inhalation without combustion
18% IGST/9% CGST/9%
SGST or UTGST : 2404 91 00, 2404 92 00, 2404 99 00 :
Products for oral application or transdermal application or for application otherwise than orally or transdermally, containing nicotine and intended to assist tobacco use cessation
40% IGST/20% CGST/20%
SGST or UTGST : 2404 11 00 : Products containing tobacco or reconstituted tobacco and intended for inhalation without combustion
40% IGST/20% CGST/20%
SGST or UTGST : 2404 19 00 : Products containing tobacco or nicotine substitutes and intended for inhalation without combustion - Products intended for inhalation without combustion: 2404 11 00--Containing tobacco or reconstituted tobacco kg.20%20%40% 2404 12 00--Other, containing nicotinekg.9%9%18% 2404 19 00--Otherkg.20%20%40% - Other :
2404 91 00--For oral applicationkg.9%9%18% 2404 92 00--For transdermal applicationkg.9%9%18% 2404 99 00--Otherkg.9%9%18%
RATE OF TAX AND EXEMPTION NOTIFICATIONS FOR GOODS
(SEE DIVISION SIX)
1.CGST/IGST/SGST or UTGST Rate Schedule for Goods.—Notification No. 9/2025-Central Tax (Rate), dated 17-9-2025/Notification No. 9/2025-Integrated Tax (Rate), dated 17-92025/Notification No. 9/2025-Union Territory Tax (Rate), dated 17-9-2025
2. List of CGST/IGST/SGST or UTGST exempt goods (Nil rated goods). Notification No. 10/2025-Central Tax (Rate), dated 17-9-2025/Notification No. 10/2025-Integrated Tax (Rate), dated 17-9-2025/Notification No. 10/2025-Union Territory Tax (Rate), dated 17-92025
3.Concessional CGST/IGST/SGST or UTGST rate for supplies of goods to specified petroleum and other explorations and productions under various Schemes.—Notification No. 3/2017-Central Tax (Rate), dated 28-6-2017/Notification No. 3/2017-Integrated Tax (Rate), dated 28-6-2017/Notification No. 3/2017-Union Territory Tax (Rate), dated 28-6-2017
4.Refund of 50% of CGST/IGST/SGST or UTGST on Supplies of Goods to Canteen Stores Department (CSD) under Ministry of Defence.—Notification No. 6/2017-Central Tax (Rate), dated 28-6-2017/Notification No. 6/2017-Integrated Tax (Rate), dated 28-6-2017/ Notification No. 6/2017-Union Territory Tax (Rate), dated 28-6-2017
5.Exemption to Supplies of Goods by Canteen Stores Department (CSD) under Ministry of Defence to Unit Run Canteens and Supplies of Goods by CSD/Unit Run Canteens to authorised customers.—Notification No. 7/2017-Central Tax (Rate), dated 28-6-2017/Notification No. 7/2017-Integrated Tax (Rate), dated 28-6-2017/Notification No. 7/2017-Union Territory Tax (Rate), dated 28-6-2017
6.Exemption to intra-State supplies of goods or services or both received by a TDS deductor under section 51 from an unregistered supplier.—Notification No. 9/2017-Central Tax (Rate), dated 28-6-2017/Notification No. 9/2017-Union Territory Tax (Rate), dated 28-6-2017
7.Exemption to intra-State supplies of second hand goods received by a registered person from an unregistered supplier.—Notification No. 10/2017-Central Tax (Rate), dated 28-62017/Notification No. 10/2017-Union Territory Tax (Rate), dated 28-6-2017
8.Notified supplies which shall be treated neither as a supply of goods nor as a supply of services.—Notification No. 14/2017-Central Tax (Rate), dated 28-6-2017/Notification No. 11/2017-Integrated Tax (Rate), dated 28-6-2017/Notification No. 14/2017-Union Territory Tax (Rate), dated 28-6-2017
9.Notified specialised agencies entitled to claim a refund of taxes paid on supplies of goods or services or both received by them.—Notification No. 16/2017-Central Tax (Rate), dated 28-6-2017/Notification No. 13/2017-Integrated Tax (Rate), dated 28-6-2017/Notification No. 16/2017-Union Territory Tax (Rate), dated 28-6-2017
10.Composition Levy - Notified rate of tax, turnover, conditions & restrictions - Notification No. 14/2019-Central Tax, dated 7-3-2019
11.Exemption from Compensation Cess to intra-State supplies of second hand goods received by a registered person from an unregistered supplier.—Notification No. 4/2017-Compensation Cess (Rate), dated 20-7-2017
12.Reverse Charge on certain specified supplies of goods.—Notification No. 4/2017-Central Tax (Rate), dated 28-6-2017/Notification No. 4/2017-Integrated Tax (Rate), dated 28-6-2017/ Notification No. 4/2017-Union Territory Tax (Rate), dated 28-6-2017
13.Exemption to intra-State/inter-State supply of taxable goods by a registered supplier to a registered recipient for export, from so much of the CGST/IGST/SGST or UTGST tax leviable thereon, as is in excess of the amount calculated at the CGST rate of 0.05 per cent/IGST rate of 0.1 per cent/SGST or UTGST rate of 0.05 per cent.—Notification No. 40/2017-Central Tax (Rate), dated 23-10-2017/Notification No. 41/2017-Integrated Tax (Rate), dated 23-10-2017/Notification No. 40/2017-Union Territory Tax (Rate), dated 23-102017
14.Notified rate of tax to be levied on specified first intra-State supplies of goods or services. Notification No. 2/2019-Central Tax (Rate), dated 7-3-2019/Notification No. 2/2019-Union Territory Tax (Rate), dated 7-3-2019
15. Refund of applicable Tax to retail outlets established in the departure area of International Airport beyond the Immigration counters making tax free supply of goods to an outgoing International Tourist.—Notification No. 11/2019-Central Tax (Rate), dated 29-6-2019/ Notification No. 10/2019-Integrated Tax (Rate), dated 29-6-2019/Notification No. 11/2019-Union Territory Tax (Rate), dated 29-6-2019
16. Exemption on supply of goods by a retail outlets established in the departure area of an International Airport beyond Immigration counters to an outgoing International Tourist.— Notification No. 11/2019-Integrated Tax (Rate), dated 29-6-2019
17. Exemption of goods supplied to Food and Agricultural Organisation (FAO) of the United Nations.—Notification No. 19/2019-Central Tax (Rate), dated 30-9-2019/Notification No. 18/2019-Integrated Tax (Rate), dated 30-9-2019/Notification No. 19/2019-Union Territory Tax (Rate), dated 30-9-2019
18. Notified supplies which shall be treated neither as supply of goods nor as supply of services. Notification No. 25/2019-Central Tax (Rate), dated 30-9-2019/Notification No. 24/2019-Integrated Tax (Rate), dated 30-9-2019/Notification No. 25/2019-Union Territory Tax (Rate), dated 30-9-2019
19. Exemption on goods and services compensation cess on supply of goods by a retail outlets established in the departure area of an International Airport beyond Immigration Counters to an outgoing International Tourist.—Notification No. 1/2019-Compensation Cess (Rate), dated 29-6-2019
20. Notified goods in respect of which no refund of unutilised Input Tax Credit of Compensation Cess shall be allowed.—Notification No. 3/2019-Compensation Cess (Rate), dated 30-9-2019
21.Notified registered persons who shall pay tax on reverse charge basis on certain specified supplies of goods or services or both received from an unregistered supplier.—Notification No. 7/2019-Central Tax (Rate), dated 29-3-2019/Notification No. 7/2019-Integrated Tax (Rate), dated 29-3-2019/Notification No. 7/2019-Union Territory Tax (Rate), dated 29-3-2019.
22.Levy of IGST/CGST/SGST or UTGST on inter/intra-State supplies notified goods.— Notification No. 14/2025-Central Tax (Rate), dated 17-9-2025/Notification No. 14/2025Integrated Tax (Rate), dated 17-9-2025/Notification No. 14/2025-Union Territory Tax (Rate), dated 17-9-2025.
LATEST CLARIFICATIONS
Biris, all biris attract 28% GST.—PIB Press Release, dated 24-7-2017. Biris, handmade, in addition, handmade biris attract NCCD of Rs.1 per thousand. Machine made biris attract NCCD of Rs. 2 per thousand.—PIB Press Release, dated 24-7-2017. NCCD shall continue to be levied on tobacco and tobacco products at the rates as applicable prior to 1st July, 2017.—PIB Press Release, dated 24-7-2017.
NCCDs, since NCCD is a duty of excise, the valuation for the purposes of charging NCCD shall be as per the Central Excise Law read with the Valuation Rules under Central Excise Law.— PIB Press Release, dated 24-7-2017.
Nicotine Polacrilex gum which is commonly applied orally and is intended to assist tobacco use cessation is appropriately classifiable under tariff item 2404 91 00 with applicable GST rate of 18%.—Circular No. 179/11/2022-GST, dated 3-8-2022.
Tobacco leaves, for GST rate of 5%, tobacco leaves means leaves of tobacco as such or broken tobacco leaves or tobacco leaves stems.—CBEC’s Clarifications, dated August 2017.
E-WAY BILL
E-WAY BILL NOT REQUIRED TO BE GENERATED WHERE FOLLOWING GOODS ARE TRANSPORTED
S. No. ChapterorHeading orSub-headingor
Tariffitem
DescriptionofGoods
1.Any ChapterSupplies of goods by Canteen Stores Department (CSD) under Ministry of Defence to Unit Run Canteens and supplies of goods by CSD/Unit Run Canteens to authorised customers
LATEST CASE LAWS
NameofProductHeadingNo.Citation
Chewing tobacco
Dried tobacco leaves
Gudakhu
Herbal Smokes
Herbal smokes - Cigarettes of tobacco substitute
Manufactured Tobacco
Raula Gundi
Sun cured tobacco leaves
2403
2401
2403 99 90
2402 90 10
2402
2403 9910
2403
2401
Jainish Anantkumar Patel, In re [2021] 123 taxmann. com 279 (AAR - Gujarat)/Dindayal Colloids (P.) Ltd., In re [2024] 167 taxmann.com 754 (AAR- Rajasthan)
Shalesh Kumar Singh, In re [2018] 94 taxmann.com 36 (AAR - New Delhi)
Aravind Kumar Agrawal, In re [2019] 107 taxmann. com 8/Prabhat Gudakhu Factory, In re [2019] 102 taxmann.com 408 (AAAR - Odisha)
Aorom Herbotech, In re [2025] 171 taxmann.com 186 (AAAR-Gujarat)
Aorom Herbotech, In re [2022] 136 taxmann.com 26 (AAR - Gujarat )
Kavi Cut Tobacco, In re [2020] 120 taxmann.com 389 /[2021] 83 GST 232 (AAAR - Tamilnadu)
Das & Sons, In re [2023] 146 taxmann.com 16/71 GSTL 210 (AAR - Odisha)
Suresh G., In re [2019] 104 taxmann.com 37/23 GSTL 483 (AAR - Kerala)
NameofProductHeadingNo.Citation
Tobacco leaves 2401
Tobacco mixed with lime 2403
Tobacco product 2401
Pragathi Enterprises, In re [2018] 99 taxmann.com 96; Alliance One Industries India (P.) Ltd., In re [2019] 111 taxmann.com 504; Michailides ML Oriental Tobacco (P.) Ltd., In re [2019] 111 taxmann.com 499; K.S. Subbaih Pillai & Co. (India) (P.) Ltd., In re [2019] 112 taxmann.com 8; VST Industries Ltd., In re [2019] 111 taxmann.com 497; Maddi Lakshmaiah and Company (P.) Ltd., In re [2019] 111 taxmann.com 503/[2020] 32 GSTL 277; M.L. Agro Products (P.) Ltd., In re [2019] 111 taxmann.com 498/[2020] 32 GSTL 438; Polisetty Somasundaram, In re [2019] 112 taxmann.com 9; Polisetty Somasundaram Tobacco Threshers (P.) Ltd., In re [2019] 111 taxmann.com 506; M.L. Tobacco Developers (P.) Ltd., In re [2019] 111 taxmann.com 505/[2020] 32 GSTL 311 (AAR - Andhra Pradesh); Devendrakumar Rambhai Patel, In re [2023] 153 taxmann.com 252 (AAR - Gujarat)
Dindayal Colloids (P.) Ltd., In re [2024] 167 taxmann. com 754 (AAR- Rajasthan)
Gyankeer Products (P.) Ltd., In re [2022] 144 taxmann. com 191/95 GST 103 (AAR - Rajasthan)
Tobacco leaves/bhukko with coating 2401 JCP Agro Process (P.) Ltd., In re [2023] 149 taxmann. com 285/77 GSTL 149 (AAR - Gujarat)
Tobacco leaves, dried 2401
Tobacco leaves procured at tobacco auction platforms 2401
Tobacco leaves, sun cured 2401 10 20
Shalesh Kumar Singh, In re [2018] 94 taxmann.com 36 (AAR - New Delhi)
ML Exports, In re [2019] 111 taxmann.com 496 (AAR - Andhra Pradesh)
Sringeri Yogis Pai, In re [2019] 110 taxmann.com 444/Suresh G., In re [2019] 104 taxmann.com 37 (AAR - Karnataka)
CASE LAWS/DEPARTMENTAL CLARIFICATIONS UNDER OLD REGIME
NameofProductHeadingNo.Citation
Biris, hand-made2403
Chewing Tobacco 2401 00
Chewing Tobacco (Flavoured)2403 99 10
Cigarettes, tipper-gold tipped brand 2403.11
Mangalore Ganesh Beedi Works v. CCE 2007 (213) ELT 621 and 2007 (217) ELT 257 (CESTAT) *CCE v. Hindustan Biri Mfg. Co. 2007 (215) ELT 407 (CESTAT)
CCE v. Ravindra & Company 2000 (120) ELT 699 (CEGAT)
Flakes-N-Flavourz v. CCE 2015 (327) ELT 435 (CESTAT)
CCE v. International Tobacco Co. Ltd. 2008 (231) ELT 207 (SC)
NameofProductHeadingNo.Citation
Gutka Chapter 24
Kimam Chapter 24
Kimam, perfumes additive mixture ofChapter 24
Misri, Shaheen Misri and Kokan MisriChapter 24
Pan masala containing tobaccoChapter 24
Kuber Tobacco Products Pvt. Ltd. v. CCE 2004 (168) ELT 58 (CESTAT)
Dharampal Satyapal v. CCE 2005 (183) ELT 241 (SC); Gulab Gandhi Tobacco Co. v. CCE [2017] 87 taxmann.com 12/64 GST 360 (New Delhi - CESTAT)affirmed in Gulab Gundhi Tobacco Co. v. CCE [2018] 94 taxmann.com 215 (SC)
CCE v. Dharampal Prem Chand Ltd. 2011 (265) ELT 81 (CESTAT)
CCE v. Borsad Tobacco Co. Pvt. Ltd. 2004 (165) ELT 352 (CESTAT)
Shree Canesh International v. CCE 2004 (167) ELT 479 (CESTAT) * CCE v. Virat Crane Industries Ltd. 2007 (208) ELT 262 (CESTAT)
Snuff preparation made by adding menthol, perfumes etc.
Chapter 24
Tobacco cured by treating with jaggery water 2401
Tobacco, jarda 2401
Tobacco leaf, rawSub-heading 2401 10
Tobacco mix with lime 2403 99 10
Tobacco, preparations containing snuff of
Chapter 24
CCE v. Khetu Ram Bishamber Dass 1998 (102) ELT 65 (CEGAT)
CCE v. Muthuvelappa Gounder & Sons 2010 (256) ELT 320 (CESTAT)
V.H. Patel Tobacco Pvt. Ltd. v. CCE 1999 (113) ELT 962 (CEGAT)
Yogesh Associates v. CCE 2006 (195) ELT 196 (CESTAT) - affirmed by SC 2006 (199) ELT A221 (SC)
Hira Packaging v. CCE [2017] 87 taxmann.com 65/64 GST 344 (New Delhi - CESTAT)
CCE v. Khetu Ram Bishamber Dass 1998 (103) ELT 653 (CEGAT) *Sona Udyog Ltd. v. CCE 2001 (128) ELT 137 (CEGAT) - confirmed by SC 2004 (163) ELT A115 (SC)
Tobacco, raw, treated with quimam and perfumes
Sub-heading 2401 10
Tobacco, unmanufactured2403
Zarda Chapter 24
Suresh Enterprises v. CCE 2006 (203) ELT 432 (CESTAT)
CCE v. Parveen Tobacco Co. (P) Ltd. 2013 (288) ELT 433 (CESTAT).
B.S. Patel v. CCE 1999 (113) ELT 166 (CEGAT)
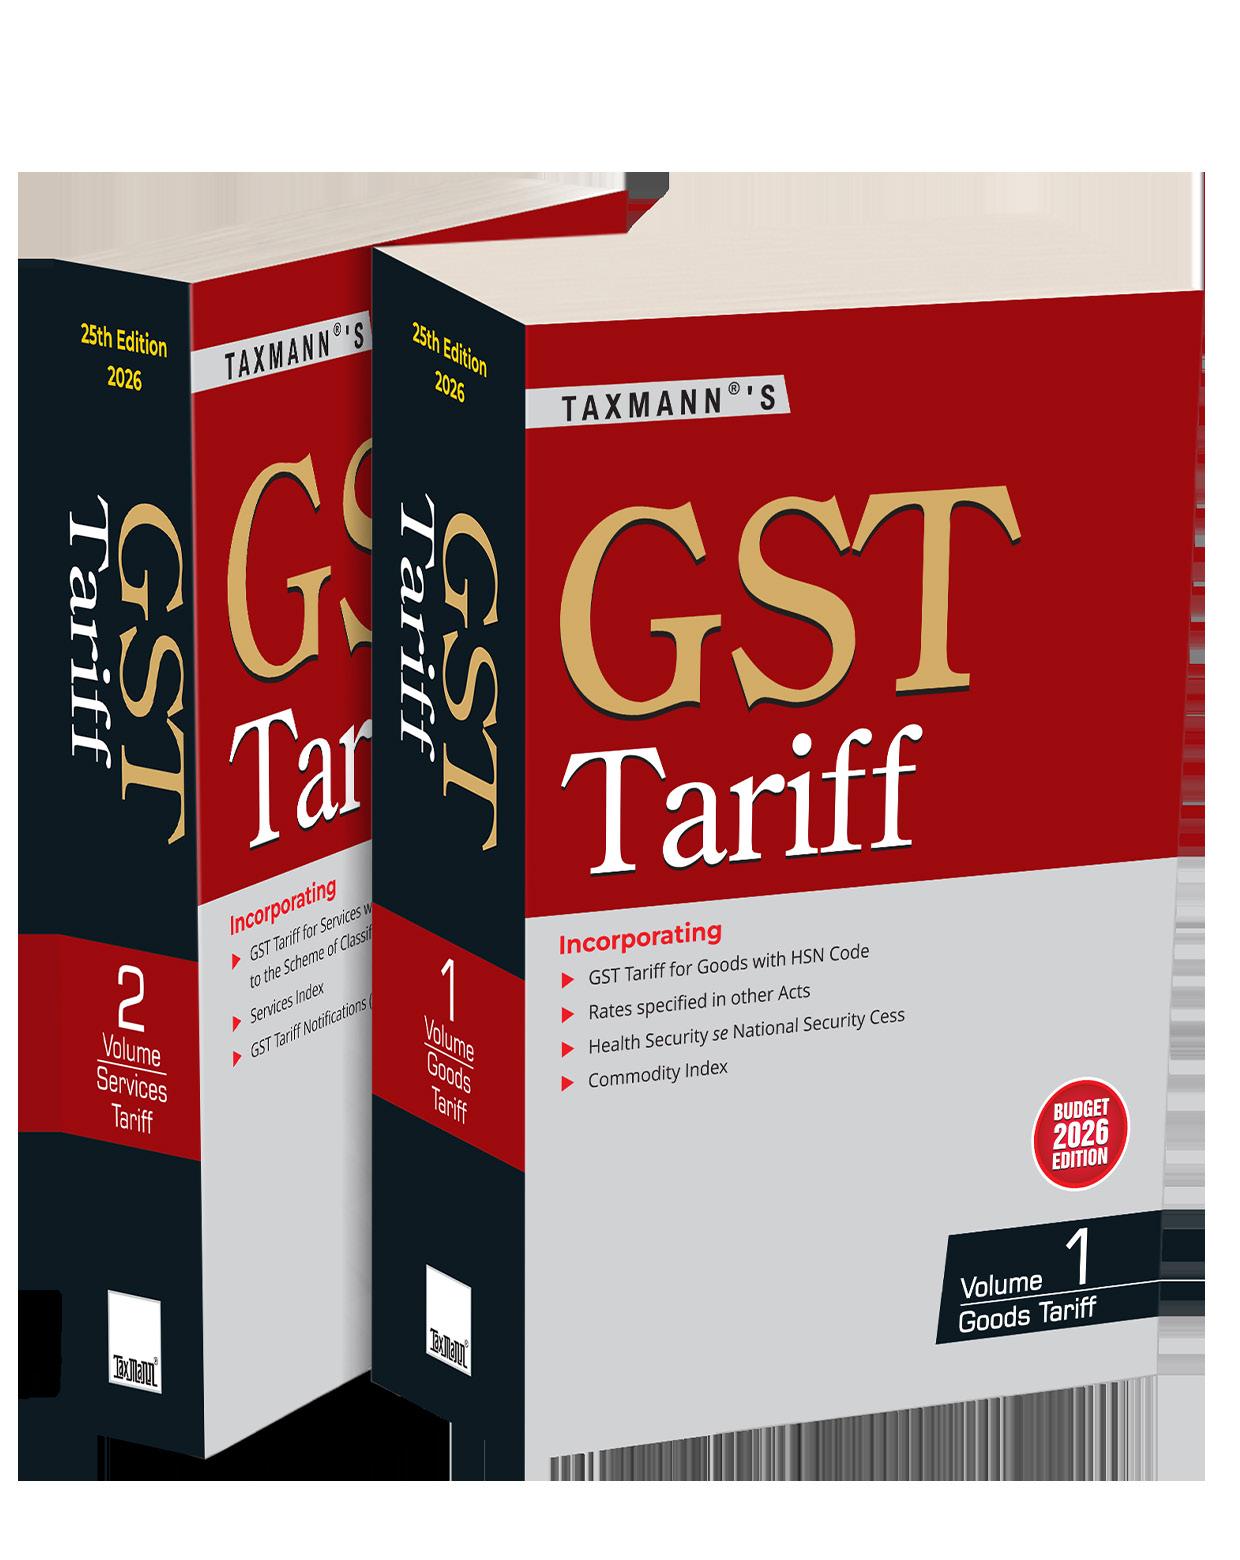
GST Tariff
AUTHOR : Taxmann’s Editorial Board
PUBLISHER : Taxmann
DATE OF PUBLICATION : February 2026
EDITION : 25th Edition | 2026
ISBN NO : 9789375610809
No. of Pages : 3384
BINDING TYPE : Paperback
4,895
DESCRIPTION
GST Tariff (Budget 2026 Edition) is a comprehensive, execution-oriented GST classification and rate-determination manual, presented as a meticulously structured two-volume statutory tariff system covering Goods (HSN-based) and Services (Service Code-based) under the GST regime. This Edition reflects the law as applicable post-Budget 2026, incorporating Finance Bill–linked amendments, newly introduced cesses, revised rates, and the complete, contemporaneous notification framework. Editorially designed as a classification-to-rate operating system, the publication enables professionals to determine—with statutory certainty, audit traceability, and litigation defensibility—the correct GST rate, exemption status, reverse charge applicability, and special levy implications for any supply of goods or services. By integrating tariff schedules, interpretative rules, explanatory notes, rate and exemption notifications, special cesses, and exhaustive indices into a single, navigable framework, the book functions as a reliable day-to-day decision tool for practical GST application. This publication is specifically intended for users who must apply GST tariffs accurately in live transactions and compliance environments, including:
• Chartered Accountants, Cost Accountants, Company Secretaries, and GST Practitioners
• Indirect Tax and Compliance Teams
• Manufacturers, Traders, Importers, Exporters, and Supply-Chain Professionals
• Service-sector Businesses
• Tax Advisors and Litigators
• GST Departmental Officers, Auditors, and Assessment Authorities
• Academicians and Advanced Students
The Present Publication is the 25th Edition, updated till 1st February 2026. This book is edited by Taxmann’s Editorial Board, with the following noteworthy features:
• [Budget 2026 ‘Change-First’ Architecture] The Goods volume opens with Finance Bill 2026 relevant extracts, Notes on Clauses, the Explanatory Memorandum, and TRU letter extracts, followed by notifications and corrigenda—enabling users to understand legislative changes before applying the consolidated tariff framework
• [Two-volume Functional Segregation] Separate and exhaustive treatment of Goods and Services ensures clarity, avoids interpretational overlap, and mirrors actual GST practice
• [HSN-based Goods Classification with Interpretative Text] Complete chapter-wise goods tariff supported by the General Rules for Interpretation of the Schedule, enabling defensible classification in complex cases
• [Service Code-based Services Tariff with Explanatory Notes] Services are supported by structured explanatory notes defining scope, inclusions, and exclusions—critical where classification determines taxability
• [Integrated Rate, Exemption, and Notification Framework] Consolidates GST rates, exemption notifications, reverse charge provisions, e-commerce operator liabilities, and no-refund-of-unutilised-ITC provisions in a unified reference
• [Inclusion of Allied Levies and New Cess Regimes] Incorporates rates specified under other Acts and the complete Health Security se National Security Cess framework, including the Act, Rules, amendments, and FAQs
• [Practitioner-grade Indexing] Extensive Commodity Index and Services Index enable rapid lookup by common descriptions
• [Notification Traceability] Structured List of Notifications with amendment histories and page references ensures auditand litigation-ready traceability