5 Input Tax Credit when exempted as well as taxable supplies made
5.1 Proportionate ITC when partly used for business or taxable supplies
Pri nci pl e of VAT i s t hat i np ut t ax cr e di t i s avail a bl e o nl y whe n t ax i s paya bl e o n hi s o ut p ut. I f s o me of s uppli es ar e t axa bl e a nd s o me ar e e xe mpt, t he t axa bl e pers o n c a n t a ke o nl y pr oporti o nat e i np ut t ax cr e di t.
Thi s pri nci pl e a ppli es t o i np ut g oo ds, i np ut s er vi ces a nd c a pi t al g oo ds. Thes e ar e pr ovi de d i n s ecti o n 17 of C GS T Act.
Wher e t he g oo ds or s er vi ces or bot h ar e us e d by t he r e gi st er e d t axa bl e pers o n partl y f or t he p ur pos e of a ny busi ness a nd partl y f or ot her p ur pos es, t he a mo unt of i np ut t ax cr e di t s hall be r est ri ct e d t o s o muc h of t he i np ut t ax as i s att ri b ut a bl e t o t he p ur pos es of hi s b usi ness - s ecti o n 17( 1) of C GS T Act.
Wher e t he g oo ds a nd/ or s er vi ces ar e us e d by t he r e gi st er e d pers o n partl y f or eff ecti ng t axa bl e s uppli es i ncl udi ng z er o r at e d s uppli es under C GS T or I GS T Act a nd partl y f or eff ecti ng e xe mpt s uppli es, t he a mo unt of cr e di t s hall be r est ri ct e d t o s o muc h of t he i np ut t ax as i s att ri b ut a bl e t o t he t axa bl e s uppli es i ncl udi ng z er o- r at e d s uppli es - s ecti o n 17( 2) of C GS T Act.
The Ce nt r al or a St at e Gover n me nt may, by noti fic ati o n i ss ue d i n t hi s be hal f, pr es cri be t he ma nner i n whi c h t he pr oporti o nat e i np ut t ax cr e di t i s t o be t a ke n - s ecti o n 17( 6) of C GS T Act.
Thi s pr ovi si o n i s si mil ar t o r ul e 6 of Ce nvat Cr e di t Rul es.
Taxable supply“ Taxa bl e s uppl y ’’ me a ns a s uppl y of g oo ds or s er vi ces or bot h whi c h i s l e vi a bl e t o t ax under C GS T Act – s ecti o n 2( 109) of C GS T Act.
Non-taxable supply‘ No n- t axa bl e s uppl y ’ me a ns a s uppl y of g oo ds or s er vi ces or bot h whi c h i s not l e vi a bl e t o t ax under C GS T
Act or I GS T Act – s ecti o n 2( 78) of C GS T Act.
Supply of alcoholic liquor is non-taxable supply and hence is exempt supply - Suppl y of al c o holi c li q uor i s a no n- t axa bl e s uppl y a nd he nce i ncl ude d i n defi ni ti o n of ‘ e xe mpt s uppl y ’Karnani
FNB Specialities LLP, In re ( 2023) 97 GS T 783 = 73 GS TL 653 = 148 t ax ma nn. c o m 217 ( AA R- WB). I n t hi s c as e, t he ass ess ee was pr ovi di ng r est a ur a nt s er vi ce a nd was al s o s uppl yi ng al c o holi c li q uor. It was hel d t hat pr oporti o nat e r e vers al of I T C i s r e q ui r e d - vi e w c o nfi r me d i n
Karnani FNB Specialities LLP, In re ( 2023) 77 GS TL 92 = 9 Ce nt ax 202 ( AAA R- WB).
Zero rated supply“ Zer o- r at e d s uppl y ” me a ns a s uppl y of a ny g oo ds or s er vi ces or bot h i n t er ms of s ecti o n 16 of I GS T Act – s ec - ti o n 2( 23) of I GS T Act.
Ex port of g oo ds or s er vi ces or bot h a nd s uppli es of g oo ds or s er vi ces or bot h t o S EZ uni t or S EZ de vel oper will be z er o r at e d s uppl y - s ecti o n 16( 1) of I GS T Act.
Cr e di t of i np ut t ax may be avail e d f or ma ki ng z er o- r at e d s uppli es, e ve n i f s uc h s uppl y i s e xe mpt e d s uppl y - s ecti o n 16( 2) of I GS T Act.
The r e gi st er e d pers o n ma ki ng z er o r at e d s uppl y c a n cl ai mr ef und under ei t her of t wo opti o ns - ( a) s uppl y g oo ds under bo nd or L UT w i t ho ut pay me nt of I GS T a nd cl ai mr ef und of un utili z e di np ut t ax cr e di t or ( b) s uppl y g oo ds o n pay me nt of I GS T a nd cl ai mr ef und of I GS T pai d o n g oo ds a nd s er vi ces. The r ef und will be i n acc or da nce w i t h s ecti o n 54 of C GS T Act - s ecti o n 16( 3) of I GS T Act.
5.1-1 Calculation of value of ‘exempt supply’
“ Exe mpt s uppl y ” me a ns s uppl y of a ny g oo ds or s er vi ces or bot h whi c h att r act s nil r at e of t ax or whi c h may be wholl y e xe mpt f r o mt ax under s ecti o n 11 of C GS T Act or under s ecti o n 6 of I GS T Act, a nd i ncl udes no n- t axa bl e s uppl y - s ecti o n 2( 47) of C GS T Act.
‘ No n- t axa bl e s uppl y ’ me a ns a s uppl y of g oo ds or s er vi ces or bot h whi c h i s not l e vi a bl e t o t ax under C GS T Act or I GS T Act – s ecti o n 2( 78) of C GS T Act.
Exempt supply cannot include activities included in Schedule III of CGST Act, except value of land, buildings and securities –The‘ e xe mpt s uppl y ’ a nd‘ no n- t axa bl e s uppl y ’ c a n o nl y c over g oo ds or s er vi ces whi c h ar e ‘ s uppl y ’ . Thes e c a nnot i ncl ude a ny acti vi t y whi c h i s not ‘ s uppl y ’ at all. Th us, ‘ Exe mpt s uppl y ’ c a nnot i ncl ude acti vi ti es i ncl ude d i n Sc he d ul e III of C GS T Act, as t he acti vi ti es s peci fie d i n Sc he d ul e III ar e nei t her s uppl y of g oo ds nor s uppl y of s er vi ces. The e xce pti o n i s what i s s peci fie d i n s ecti o n 17( 3) of C GS T Act, i. e. val ue of l a nd, c o mpl et e d b uil di ngs ( e xce pt wher e s uppl y i s ma de bef or e c o mpl eti o n of b uil di ng) a nd s ec uri ti es.
Exempt supply to include value of land, building and securitiesAs per s ecti o n 17( 3) of C GS T Act, val ue of e xe mpt s uppl y s hall i ncl ude – ( a) s uppl y wher e GS Ti s paya bl e o n r e vers e c har ge basi s ( b) t r a ns acti o ns i n s ec uri ti es ( c) s al e of l a nd ( d) s al e of b uil di ng ( e xce pt c o nst r ucti o n of c o mpl e x wher e s uppl y i s ma de bef or e o bt ai ni ng c o mpl eti o n certi fi c at e).
For det er m i ni ng t he val ue of a n e xe mpt s uppl y as per s ecti o n 17( 3) of C GS T Act-- ( a) t he val ue of l a nd a nd b uil di ng s hall be t a ke n as t he s a me as a dopt e d f or t he p ur pos e of payi ng st a mp d ut y, a nd ( b) t he val ue of s ec uri t y s hall be t a ke n as 1 % of t he s al e val ue of s uc h s ec uri t y –
Rul es, 2017.
Explanation under Rul e 45 of C GS T a nd S GS T
Reversal of common input services for mutual fund investment is required – Mut ual f unds ar e s ec uri ti es. Tr a ns acti o n i n s ec uri - ti es i s ‘ e xe mpt s uppl y ’ . Re vers al of c o mmo n i np ut s er vi ces f or mut ual f und i nvest me nt i s r e q ui r e d as per r ul e 42. Re de mpti o n of mut ual f und uni t s i s c o mmer ci all y e q ui val e nt t o s al e –Zydus
Lifesciences Ltd. In re ( 2025) 180 t ax ma nn. c o m 233 ( AAA R- Guj ).
Apportionment of ITC between taxable supply and exempt supply on basis of value except in case of real estate servicesSecti o n 17( 3) of C GS T Act e nvi s ages t hat a pporti o n me nt of I T C bet wee n e xe mpt s uppl y a nd t axa bl e s uppli es i ncl udi ng z er o r at e d s uppli es s hall be o n basi s of val ue.
Ho we ver, as per s c he me of GS T o n s er vi ce of r e al est at e of r esi de nti al a nd c o mmer ci al a part me nt s w . e. f. 1- 4- 2019, i t i s e nvi s age d t hat s uc h a pporti o n me nt s hall be o n basi s of ar e a of c o nst r ucti o n of c o mpl e x. He nce, Re moval of D i ffi c ul ti es Or der No. 04/2019- CT dat e d 29- 3- 2019 pr ovi des t hat s uc h a pporti o n me nt s hall be o n basi s of ar e a of c o nst r ucti o n of c o mpl e x.
Activities and transactions covered under Schedule III are not ‘exempt supply’ except covered in paragraphs 5 and 8(a) of Schedule III - For p ur pos e of s ecti o n 17( 3) of C GS T Act ( pr oporti o nat e r e vers al of I T C whe n t axa bl e pers o n i s ma ki ng bot h t axa bl e a nd e xe mpt s uppl y) , t he e x pr essi o n “ val ue of e xe mpt s uppl y ” s hall not i ncl ude t he val ue of acti vi ti es or t r a ns acti o ns s peci fie di n Sc he d ul e III of C GS T Act, except (i) the value of activities or transactions specified in paragraph 5 of the said Schedule; and (ii) the value of such activities or transactions as may be prescribed in respect of paragraph 8(a) of the said Schedule – Ex pl a nati o n t o s ecti o n 17( 3) of C GS T Act as a me nde d vi de Fi na nce Act, 2023 f r o m 1- 10- 2023 by s ubsti t uti ng wor ds i n i t ali cs.
The earlier words were –‘ e xce pt t hos e s peci fie d i n par agr a p h 5 of t he s ai d Sc he d ul e ’ .
Sc he d ul e III of C GS T Act s peci fi es t r a ns acti o ns or acti vi ti es whi c h s hall be t r e at e d nei t her as s uppl y of g oo ds nor s uppl y of s er vi ces.
Par agr a p h 5 of Sc he d ul e III of C GS T Act pert ai ns t o s al e of l a nd or s al e of b uil di ng aft er c o mpl eti o n certi fi c at e i s o bt ai ne d.
Par agr a p h 8( a) of Sc he d ul e III of C GS T Act pert ai ns t o s uppl y of war e ho us e d g oo ds t o a ny pers o n bef or e cl e ar a nce f or ho me c o ns u mpti o n. Th us, pr ovi si o ns r el ati ng t o pr oporti o nat e r e vers al of I T C will a ppl y t o s uppl y of g oo ds f r o m d ut y f r ee s hops at ar - ri val t er m i nal aft er 1- 10- 2023Explanation 3 t o r ul e 43 of C GS T
Rul es, i ns ert e d w . e. f. 1- 10- 2023.
Value of exempt supply shall include value of supply of goods from Duty Free Shops at arrival terminal w.e.f. 1-10-2023 - For t he p ur pos e of r ul e 42 a nd r ul e 43, t he val ue of acti vi ti es or t r a ns - acti o ns me nti o ne d i n Sc he d ul e III par agr a p h 8( a) of t he C GS T Act whi c h i s r e q ui r e d t o be i ncl ude d i n t he val ue of e xe mpt s uppli es under cl a us e ( b) of t he
Explanation t o s ecti o n 17( 3) of t he C GS T Act s hall be t he val ue of s uppl y of g oo ds f r o m Dut y Fr ee Shops at arri val t er m i nal i n i nt er nati o nal ai r port s t o t he i nc o m i ng pass e ngersExplanation 3 t o r ul e 43 of C GS T Rul es, i ns ert e d w . e. f. 1- 10- 2023.
Electricity is exempt supply - El ect ri ci t y i s ‘ e xe mpt s uppl y ’ .
Interest is not exempt supply for purposes of rules 42 and 43 i.e. no reversal of ITC required - I nt er est o n l oa ns, de posi t s a nd
borr o w i ngs ar e e xe mpt, t ho ug h i t i s s uppl y of s er vi ce. Ho we ver, i t i s not ‘ e xe mpt s uppl y ’ f or p ur pos es of r ul es 42 a nd 43 of C GS T Rul es. The e xact wor di ng i n r ul es i s as f oll o ws -
For t he p ur pos es of r ul es 42 a nd 43 of C GS T Rul es, i t i s her e by cl ari fie d t hat t he aggr e gat e val ue of e xe mpt s uppli es s hall e xcl ude
t he val ue of s er vi ces by way of acce pti ng de posi t s, e xt e ndi ng l oa ns or a dva nces i n s o f ar as t he c o nsi der ati o n i s r e pr es e nt e d by way of i nt er est or di s c o unt, e xce pt i n c as e of a ba nki ng c o mpa ny or a fina nci al i nsti t uti o n i ncl udi ng a no n- ba nki ng fina nci al c o mpa ny, e ngage d i n s uppl yi ng s er vi ces by way of acce pti ng de posi t s, e xt e ndi ng l oa ns or a dva nces -
Explanation 1( b) t o r ul e 43( 2) of C GS T Rul es, i ns ert e d w . e. f. 23- 1- 2018 [Explanation r e- n u mber e d as Explanation 1 w . e. f 1- 4- 2019].
Si nce i t i s o nl y cl ari fic ati o n, i t s ho ul d a ppl y w i t h r et r os pecti ve eff ect f r o m 1- 7- 2017.
Exempt Supply shall not include supply of services to Nepal and Bhutan for purpose of reversal of ITC upto 1-2-2019 – Val ue of ‘ Exe mpt Suppl y ’ f or p ur pos es of r ul es 42 a nd 43 of C GS T Rul es ( r e vers al of I T C) s hall exclude t he val ue of s uppl y of s er vi ces t o Ne pal a nd Bh ut a n wher e pl ace of s uppl y i n Ne pal or Bh ut a n e ve n whe n pay me nt i s r ecei ve d i n I ndi a n r upees [ Thes e s er vi ces ar e e xe mpt vi de Noti fic ati o n No. 42/2017- I T ( Rat e) dat e d 27- 102017] –Explanation ( a) t o r ul e 43( 2) of C GS T Rul es, i ns ert e d w . e. f. 15- 11- 2017 a nd a me nde d o n 23- 1- 2018. Thi s
Explanation ( a) has bee n o m i tt e d w . e. f. 1- 2- 2019, as no w , i n c as e of e x port of s er vi ces, c o ndi ti o n of r ecei pt of pay me nt i n f or ei g n e xc ha nge does not a p - pl y wher e RBI all o ws r ecei pt of pay me nt i n I ndi a n Rupees, as per s ecti o n 54( 8)( c) of C GS T Act i ns ert e d w . e. f. 1- 2- 2019.
Si nce i t i s o nl y cl ari fic ati o n, i t s ho ul d a ppl y w i t h r et r os pecti ve eff ect f r o m 1- 7- 2017.
Aft er 1- 2- 2019, s uppl y t o Ne pal a nd Bh ut a n will q uali f y as ‘ e x port’ e ve ni f pay me nt i s r ecei ve di n I ndi a n Rupees. It will be ‘ z er o r at e d ’ . He nce, t he q uesti o n of t r e ati ngi t as ‘ Exe mpt s uppl y ’ does not ari s e.
Exempt supply shall include outward freight from India to outside India for reversal of ITC w.e.f. 1-10-2023 - For t he p urpos es of r ul es 42 a nd 43 of C GS T Rul es, i t i s her e by cl ari fie d t he
aggr e gat e val ue of e xe mpt s uppli es s hall e xcl ude t he val ue of s uppl y of s er vi ces by way of t r a ns port ati o n of g oo ds by a vess el f r o mt he c ust o ms st ati o n of cl e ar a nce i n I ndi a t o a pl ace o ut si de I ndi a–
1( c) t o r ul e 43 of C GS T Rul es, i ns ert e d w . e. f. 15- 11- 2017 a nd o m i tt e d w . e. f. 1- 10- 2023. Th us, aft er 1- 10- 2023,
Explanation
Exempt supply shall include o ut war d f r ei g ht f r o mI ndi a t o o ut si de I ndi a f or r e vers al of I T C .
Exempt supply shall not include value of duty credit scrips – For t he p ur pos es of r ul es 42 a nd 43 of C GS T Rul es, ‘ Exe mpt s uppl y ’ s hall not i ncl ude val ue of s uppl y of d ut y cr e di t s cri ps s peci fie d i n t he noti fic ati o n of t he Gover n me nt of I ndi a, M i ni st r y of Fi na nce, De part me nt of Re ve n ue No. 35/2017- Ce nt r al Tax ( Rat e), dat e d t he 13t h Oct o ber, 2017 –
Explanation 1( d) t o r ul e 43 of C GS T Rul es, i ns ert e d w . e. f. 5- 7- 2022 – c o nfir me d i n Kaveri Exports, In re [ 2023] 152 t ax ma nn. c o m 273 = 8 Ce nt ax 151 ( AA R- Tel a nga na).
5.2 Special provisions in respect of Banks, FI and NBFC
A ba nki ng c o mpa ny or a fina nci al i nsti t uti o n i ncl udi ng a no nba nki ng fina nci al c o mpa ny, e ngage d i n s uppl yi ng s er vi ces by way of acce pti ng de posi t s, e xt e ndi ng l oa ns or a dva nces s hall have t he opti o n t o ei t her c o mpl y w i t h t he pr ovi si o ns of s ecti o n 17( 2) of C GS T Act, or avail of, e ver y mo nt h, a n a mo unt e q ual t o fift y per ce nt of t he eli gi bl e i np ut t ax cr e di t o n i np ut s, c a pi t al g oo ds a nd i np ut s er vi ces i n t hat mo nt h - s ecti o n 17( 4) of C GS T Act.
The opti o n o nce e xer ci s e d s hall not be w i t hdr a wn d uri ng t he r e mai ni ng part of t he fina nci al ye ar - first proviso t o s ecti o n 17( 4) of C GS T Act.
The 50 % r est ri cti o n s hall not a ppl y t o t he t ax pai d o n s uppli es ma de by o ne r e gi st er e d pers o n t o a not her r e gi st er e d pers o n havi ng s a me PA N n u mber - s ec o nd pr ovi s o t o s ecti o n 17( 4) of C GS T Act.
Thi s pr ovi si o n a ppli es whe n Ba nk/ FI / NBF Ci n o ne St at e pr ovi des s er vi ces ( or s uppli es g oo ds) t o i t s o wn br a nc h i n a not her St at e.
I n most of t he c as es, Ba nk, FI or NBF C may find i t e as y a nd pr o fit a bl e t o avail 50 % of i np ut t ax cr e di t i nst e a d of availi ng i np ut t ax cr e di t o n pr oporti o nat e basi s as per s ecti o n 17( 2) of C GS T Act.
Co-operative society accepting deposits and granting loans is Financial InstitutionA c o- oper ati ve s oci et y, c arr yi ng o n b usiness of fi na nci ng by acce pti ng de posi t s a nd gr a nti ng l oa ns or a dva nces, q uali fi e d t o be a “ fi na nci al i nsti t uti o n” as per RBI Act, 1934 a nd c o ns e q ue ntl y al s o under s ecti o n 17( 4) of C GS T Act. He nce, t he s oci et y i s eli gi bl e f or availi ng opti o n pr ovi de d under s ecti o n 17( 4) whi c h pr es cri bes t o avail a n a mo unt e q ual t o 50 % of eli gi bl e cr e di t of i np ut t ax o n i np ut s, c a pi t al g oo ds a nd i np ut s er vi ces i n t hat mo nt h a nd r est s hall l a ps eKnanaya Multi Pur-
pose Co-operative Credit Society Ltd., I n r e [ 2020] 119 t ax ma nn. c o m 65 ( AA R - Ker al a).
5.2-1 Procedure to claim of credit by a banking company or a financial institution
A ba nki ng c o mpa ny or a fina nci al i nsti t uti o n, i ncl udi ng a no nba nki ng fina nci al c o mpa ny, e ngage d i n s uppl y of s er vi ces by way of acce pti ng de posi t s or e xt e ndi ng l oa ns or a dva nces t hat c hoos es not t o c o mpl y w i t h t he pr ovi si o ns of s ecti o n 17( 2), i n acc or da nce w i t h t he opti o n per m i tt e d under s ecti o n 17( 4) of C GS T Act, s hall f oll o w t he pr oce d ur e s peci fie d bel o w
( a ) t he s ai d c o mpa ny or i nsti t uti o n s hall not avail t he cr e di t of (i ) t ax pai d o n i np ut s a nd i np ut s er vi ces t hat ar e us e d f or no nb usi ness p ur pos es a nd (ii ) t he cr e di t att ri b ut a bl e t o s uppli es s peci fie di n s ecti o n 17( 5), i n f or m GS T R- 2 [i.e. i neli gi bl e I np ut Tax Cr e di t]
(b ) t he s ai d c o mpa ny or i nsti t uti o n s hall avail t he cr e di t of t ax pai d o n i np ut s a nd i np ut s er vi ces r ef err e d t o i n t he s ec o nd pr ovi s o t o s ecti o n 17( 4) a nd not c over e d under cl a us e ( a) [i. e. s er vi ces s uppli e d by o ne br a nc h or di vi si o n t o a not her i. e. w i t h s a me I nc o me Tax PA N]
( c ) fift y per ce nt of t he r e mai ni ng i np ut t ax s hall be t he i np ut t ax cr e di t a d m i ssi bl e t o t he c o mpa ny or t he i nsti t uti o n a nd s hall be f ur ni s he d i n f or m GS T R- 2.
(d ) t he a mo unt r ef err e d t o i n cl a us es ( b) a nd ( c) s hall, s ubj ect t o t he pr ovi si o ns of s ecti o ns 41, 42 a nd 43, be cr e di t e d t o t he el ect r o ni c cr e di t l e dger of t he s ai d c o mpa ny or t he i nsti t uti o n - Rul e 38 of C GS T a nd S GS T Rul es, 2017. [ s ecti o ns 41 t o 43
pr ovi de f or pr ovi si o nal cr e di t, mat c hi ng a nd r e vers al of I T C a nd o ut p ut t ax li a bili t y].
5.3 Determination of input tax credit when partly used for taxable supply and partly for exempt supply
The det ail e d mo de of c al c ul ati o n has bee n pr es cri be d i n r ul e 42 of C GS T Rul es. I ni ti all y, i np ut t ax us e d e xcl usi vel y f or t axa bl e or e xe mpt s uppli es ar e s e gr e gat e d. The n, f or c o mmo n i np ut t ax, eli gi bl e cr e di t i s c al c ul at e d o n r ati o basi s. No n- eli gi bl e I T C i s r e vers e d.
Fi nal c al c ul ati o ns ar e ma de at e nd of fina nci al ye ar of eli gi bl e I T C bef or e t he d ue dat e f or fili ng t he r et ur n f or t he mo nt h of Se pt e mber f oll o w i ng t he e nd of t he fina nci al ye ar, o n s a me basi s.
5.3-1 Final calculations at end of financial year of eligible ITC
Except in case of supply of services covered by clause (b) of paragraph 5 of the Schedule II of the CGST Act , t he i np ut t ax cr e di t det er m i ne d under r ul e 42( 1) of C GS T a nd S GS T Rul es ( as a bove) s hall be c al c ul at e d fi nall y f or t he fi na nci al ye ar bef or e t he d ue dat e f or fili ng t he r et ur n f or t he mo nt h of Se pt e mber f oll o w i ng t he e nd of t he fi na nci al ye ar t o whi c h s uc h cr e di t r el at es, i n t he s peci fi e d ma nner [ Rul e 42( 2) of C GS T a nd S GS T Rul es, 2017]. [ a me nde d w . e. f. 1- 4- 2019]
5.3-2 Final calculations of eligible ITC in case of real estate projects where no transition of ITC
Rul es 42( 3) t o 42( 6) of C GS T Rul es i ns ert e d w . e. f. 1- 4- 2019 ma ke pr ovi si o ns f or fi nal c al c ul ati o ns of eli gi bl e I T Ci n c as e of r e al est at e pr oj ect s or r esi de nti al a nd c o mmer ci al a part me nt s.
5.3-3 Calculation of commercial portion of ITC of real estate project other than RREP
I n cas e of s uppl y of s er vi ces c over e d by par agr a p h 5( b) of Sc he dul e II of t he Act, t he i np ut t ax det er m i ne d under r ul e 42( 1) s hall be c al c ul at e d fi nall y, f or c o mmer ci al porti o n i n e ac h pr oj ect, ot her t ha n r esi de nti al r e al est at e pr oj ect ( RREP), whi c h under we nt
t r a nsi ti o n of i np ut t ax cr e di t c o ns e q ue nt t o c ha nge of r at es of t ax o n t he 1st April, 2019 i n acc or da nce w i t h noti fi c ati o n No. 11/2017Ce nt r al Tax ( Rat e), dat e d t he 28t h J une, 2017, p ubli s he d vide GS R No. 690( E) dat e d t he 28t h J une, 2017, as a me nde d f or t he e nti r e peri o d f r o mt he c o mme nce me nt of t he pr oj ect or 1st J ul y, 2017, whi c he ver i s l at er, t o t he c o mpl eti o n or fi rst occ upati o n of t he pr oj ect, whi c he ver i s e arli er, bef or e t he d ue dat e f or f ur ni s hi ng of t he r et ur n f or t he mo nt h of Se pt e mber f oll o w i ng t he e nd of fi na nci al ye ar i n whi c h t he c o mpl eti o n certi fi c at e i s i ss ue d or fi rst occ upati o n t a kes pl ace of t he pr oj ect, i n t he s peci fi e d ma nner.
5.3-4 Final calculations of ITC in real estate projects not required in case of RREP
I np ut t ax det er m i ne d under r ul e 42( 1) s hall not be r e q ui r e d t o be c al c ul at e d fi nall y o n c o mpl eti o n or fi rst occ upati o n of a n RREP whi c h under we nt t r a nsi ti o n of i np ut t ax cr e di t c o ns e q ue nt t o c ha nge of r at es of t ax o n 1st April, 2019 i n acc or da nce w i t h noti fi c ati o n No. 11/2017- Ce nt r al Tax ( Rat e), dat e d t he 28t h J une, 2017, p ubli s he d vide GS R No. 690( E) dat e d t he 28t h J une, 2017, as a me nde dr ul e 42( 5) of C GS T Rul es i ns ert e d w . e. f. 1- 4- 2019. [i. e. who opt e d f or 1 %/5 % s c he me] - r ei t er at e d i n FA Q( Part II) No. 21 i ss ue d by C BI &C vide ci r c ul ar F No. 354/32/2019- T RU dat e d 14- 5- 2019.
5.3-5 Assignment of input tax when used for several projects
Wher e a ny i np ut or i np ut s er vi ce ar e us e d f or mor e t ha n o ne pr oj ect, i np ut t ax cr e di t w i t h r es pect t o s uc hi np ut or i np ut s er vi ce s hall be assi g ne d t o e ac h pr oj ect o n a r e as o na bl e basi s a nd cr e di t r e vers al pert ai ni ng t o e ac h pr oj ect s hall be c arri e d o ut as per r ul e 42( 3)r ul e 42( 6) of C GS T Rul es i ns ert e d w . e. f. 1- 4- 2019.
5.4 Determination of input tax credit in respect of capital goods used partly for taxable supply and partly for exempt supply
I f c a pi t al g oo ds ar e partl y us e d f or t axa bl e g oo ds a nd partl y f or exe mpt goods, t he I TC on capi t al goods i s avail a bl e on pr oporti onat e basi s [j ust li ke I T C o n c o mmo n i np ut g oo ds a nd i np ut s er vi ce]. The c al c ul ati o ns s ee m q ui t e cl u ms y, b ut basi c c o nce pt i s si mpl e.
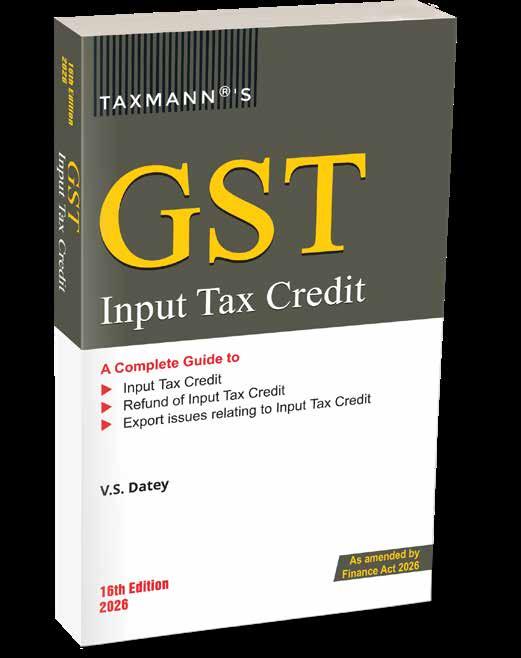
GST INPUT TAX CREDIT
AUTHOR : V.S. Datey
PUBLISHER : Taxmann Publications
DATE OF PUBLICATION : April 2026
EDITION : 16th Edition | 2026
ISBN NO : 9789375617242
NO. OF PAGES : 520
BINDING TYPE : Paperback
1,595
DESCRIPTION
GST Input Tax Credit by V.S. Datey is the definitive single-subject practitioner reference on the Input Tax Credit regime under India's GST law. Now in its 16th Edition, updated annually since GST's inception, the book goes beyond statutory text to integrate the CGST Act, IGST Act, CGST Rules, CBI&C circulars, departmental clarifications, AAR/AAAR decisions, CESTAT precedents, and High Court and Supreme Court judgments into a unified, topic-wise treatment. Where the law is unsettled or advance rulings conflict across states, the author identifies the disagreement and offers his own assessment of the defensible position—a dimension that sets it apart from a bare commentary. This is an advanced practitioner text, not an introductory guide to GST. The reader is assumed to have working knowledge of GST law and its procedural architecture. Specifically, this book is suited for:
• Tax Professionals and Advisors
• GST Litigators and Advocates
• Finance and Indirect Tax Heads in Business
• Exporters and Merchant Exporters
• Banks, NBFCs, and Financial Institutions
• Real Estate Developers
• Companies with Multi-State Operations
• Tax Authorities and Quasi-Judicial Officers
The Present Publication is the 16th Edition | 2026, amended by the Finance Act 2026. This book is authored by V.S. Datey with the following noteworthy features:
• [Finance Act 2026—Fully Integrated] All amendments woven into the substantive discussion at the point of relevance, with the author's commentary on whether each change is in force or pending notification—covering post-sale discount liberalisation, 90% provisional refund for inverted duty structure, IGST refund below ₹1,000 for small exporters, and the nine-year intermediary place-of-supply anomaly finally corrected
• [Mandatory ISD—Both Regimes Covered] The transition from optional to mandatory ISD from 1st April 2025 is addressed in two distinct sections, enabling practitioners to advise on legacy cross-charge positions and current compliance in parallel
• [Section 17(5)—Exhaustive with Conflicting Rulings Assessed] Every blocked credit category analysed with precision; where AAR and AAAR decisions across states conflict, the book identifies the disagreement and flags the more defensible position
• [Author's Own Views—Clearly Flagged] Interpretive positions that are the author's own are consistently identified, including disagreements with advance rulings, departmental practice, or anomalous drafting—a practitioner candour rare in reference texts
• [CBI&C Circulars—Embedded, Not Appended] Circular clarifications appear at the precise sub-section they govern, making the book usable as a standing desk reference without parallel access to a circular repository
• [Case Law—Selectively and Critically Applied] Landmark decisions—Thirumalakonda Plywoods, Landmark Cars East, Troikaa Pharmaceuticals, CMS Info Systems—referenced where they drive the legal position, not cited for volume; pre-GST CESTAT precedents included where the principle survives
• [ITC Flow Diagram] Visual diagram mapping credit flow from imports, inter-state, and intra-state procurement through to IGST, CGST, and SGST/UTGST utilisation, including the mandatory utilisation sequence
• [Refund Forms and Timelines—Operationally Complete] Every refund category covered with the applicable formula, GST RFD form reference, timeline, post-adjudication procedure, PFMS bank account validation mechanics, and interest computation on delayed refunds