Sample Read
© All rights reserved
Price : ` 845
Thirteenth Edition : May 2026
Published by :
Taxmann Publications (P.) Ltd.
Sales & Marketing : 59/32, New Rohtak Road, New Delhi-110 005 India
Phone : +91-11-45562222
Website : www.taxmann.com
E-mail : sales@taxmann.com
Regd. Office : 21/35, West Punjabi Bagh, New Delhi-110 026 India
Printed at :
Tan Prints (India) Pvt. Ltd.
44 Km. Mile Stone, National Highway, Rohtak Road Village Rohad, Distt. Jhajjar (Haryana) India
E-mail : sales@tanprints.com
Disclaimer
Every effort has been made to avoid errors or omissions in this publication. In spite of this, errors may creep in. Any mistake, error or discrepancy noted may be brought to our notice which shall be taken care of in the next edition. It is notified that neither the publisher nor the author or seller will be responsible for any damage or loss of action to any one, of any kind, in any manner, therefrom.
No part of this book may be reproduced or copied in any form or by any means [graphic, electronic or mechanical, including photocopying, recording, taping, or information retrieval systems] or reproduced on any disc, tape, perforated media or other information storage device, etc., without the written permission of the publishers. Breach of this condition is liable for legal action.
For binding mistake, misprints or for missing pages, etc., the publisher’s liability is limited to replacement within seven days of purchase by similar edition. All expenses in this connection are to be borne by the purchaser. All disputes are subject to Delhi jurisdiction only.

CHAPTER
SUMMARY
1. Capital Structure: Capital structure is the combination of capitals from different sources of finance.
2. Capital Structure Theories:
CAPITAL STRUCTURE THEORIES
Capital Structure Relevance Theory
Net Income Approach (NI)
Capital Structure Irrelevance Theory
Capital Structure Other Theory Traditional Approach
Operating Income Approach (NOI)
Modigliani Miller Approach (MM)
The Trade Off Theory
Pecking Order Theory
3. Net Income Approach (NI): According to this approach, capital structure decision is relevant to the value of the firm. An increase in financial leverage (Debt Proportion) will lead to decline in the Weighted Average Cost of Capital (WACC), while the value of the firm as well as market price of ordinary share will increase.
As per NI Approach:
Kd and K e will remain constant.
K o will decrease with the help of use of Debt.
MV of Equity and Firm will increase with the help of use of Debt.
Formulae:
Value of shares (S) = e EBITInterest K Or = V – D
Value of Debt (D) = Face Value of Debt
Value of Firm (V) = o EBIT K Or = V + D
Overall cost of capital = o EBIT K
Cost of Equity = EBITInterest S × 100
Note: K e and K o of unlevered firm are same.
4. Traditional Approach: This approach favours that as a result of financial leverage up to some point, cost of capital comes down and value of firm increases. However, beyond that point, reverse trends emerge.
As per Traditional Approach: Kd, Ke, Ko and MV of Equity and MV of Firm are variable Company has to select capital structure with lowest Ko or highest MV of Firm
5. Net Operating Income Approach (NOI): According to this approach, capital structure decisions of the firm are irrelevant. Any change in the leverage will not lead to any change in the total value of the firm and the market price of shares, as the overall cost of capital is independent of the degree of leverage.
As per NOI Approach:
Kd, K o and MV of Firm will remain constant in case of without tax structure.
Kd will remain constant in case of with tax structure, with the increase in Debt, MV of firm will increase and Ko will decrease
Value of firms as per NOI Approach (in case of tax):
Step 1: Calculate Value of Unlevered Firm:
Value of Unlevered Firm (VU) =
Step 2: Value of Levered Firm:
Value of Levered Firm = Value of unlevered firm
Value of firm as per NOI Approach (in case of tax):
Step 1: Calculate value of Unlevered Firm:
Value of Unlevered Firm (VU) = EBITInterest K o () 1t
Step 2: Value of Levered firm
Value of unlevered firm + (Debt × t)
6. Modigliani-Miller Approach (MM): The NOI approach is definitional or conceptual and lacks behavioural significance. However, Modigliani-Miller approach provides behavioural justification for constant overall cost of capital and therefore, total value of the firm.
Assumptions of MM Approach
Capital markets are perfect
All information is freely available
There are no transaction costs
All investors are rational
Firms can be grouped into ‘Equivalent risk classes’
Non-existence of corporate taxes
Note: Solution of practical problems are same under NOI and MM Approaches
7. The Trade Off Theory:
Trade Off Theory
8. Pecking Order Theory:
First use retained earnings for financing, then use debt capital and if further capital required, use equity share capital.
9. Arbitrage Process: Capital structure arbitrage refers to a strategy used by companies and individual where they take advantage of the existing market mispricing across all securities to make profits. In this strategy, there is buying share of undervalued firms and sell shares of overvalued firm. The main objective is to make use of the pricing inefficiency to make a profit. There is anticipation that the pricing difference, will at some point cancel out or reach at equilibrium.
10. Proforma Statement Showing EBIT, EPS & MPS:
Note:
MPS = EPS × PE Ratio
Number of Equity Shares = Existing Shares + New Shares
New Equity Shares = Additional Funds Raised through Equity Net Proceeds from One Equity Share
Net Proceeds from Share = Issue Price - Issue Expenses
Note: If nothing is specified in the question, MPS is assumed to be Issue Price.
11. Selection of plan on the basis of EPS or MPS (New company):
Statement of EPS & MPS
Less: Tax @ 50%(XXX)(XXX)(XXX)
Preference Dividend--(XXX) Earning For EquityXXXXXXXXX
12. Selection of plan on the basis of EPS or MPS (Existing company): Statement of EPS & MPS
Less: Interest:
Less: Tax @ 50%(XXX)(XXX)(XXX)
Particulars
Less: Preference Dividend:
13. Indifference Point: Indifference point refers the level of EBIT at which EPS under two different options are same.
EPS under option 1 = EPS under option 2
If expected EBIT < Indifference PointSelect option having lower Fixed Financial Burden
If expected EBIT = Indifference PointSelect any option
If expected EBIT > Indifference PointSelect option having higher Fixed Financial Burden
14. Financial Break Even Point: It is the level of EBIT at which EPS will be zero.
EBIT = Interest + Preference Dividend (1t)
15. Indifference Point in case of Equal Number of Share:
Indifference Point in Case of Equal Number of Shares
Situation 1
No EBIT will provide same EPS under both plans
There is no indifference point between two plans
Plan having lower financial fixed burden will dominate other plan
Situation 2
Each and every EBIT will provide same EPS under both plans
Each and every EBIT is indifference point between two plans
No plan will dominate
FORMATS AND FORMULAS
ALTERNATIVE FINANCING PLAN
Earnings per share (EBIT – Interest) (1 – t) – Preference dividend/No. of shares
Market price per share EPS x PE Ratio
Best Alternative plan
Step 1
Step 2
Step 3
EPS Basis: Plan which gives higher EPS MPS Basis: Plan which gives higher MPS
Assume EBIT = X
EPS formula plan I = EPA formula plan II
Calculate X
DIFFERENT APPROACHES OF CAPITAL STRUCTURE
Net Income
Net Operating Income
(1) Optimum capital structure = Which use high debt
(2) Ke remain constant at all capital structure
(1) Optimum capital structure = All Capital structure are optimum
(2) Market value of firm and overall cost of capital remain constant
(3) Ke increases with increase in debt in total capital
MM (No tax) Same as NOI
Traditional
Note:
Optimum capital structure = At which market value of firm is maximum or overall cost of capital is minimum
(1) Optimum capital structure: Market value of firm is maximum or overall cost is minimum
(2) Market value of firm = Market value of equity + Debt
(3) Market value of equity = EBIT – Interest/Ke
(4) Overall cost of capital = EBIT/Market value of firm × 100
MM APPROACH WITH TAX
(1) Market value of unlevered firm = EBIT (1 – t)/Ke
(2) Market value of levered firm = Market value of unlevered firm + (Debt × tax rate)
(3) Overall cost of capital = Calculate same as WACC
(4) Optimum capital structure: Which use high debt
THEORY QUESTIONS
Q1. What is Net Operating income theory of capital structure? Explain the assumptions on which the NOI theory is based. (May 2012, 4 Marks)
Ans. Net Operating Income (NOI) Theory of Capital Structure: According to NOI approach, there is no relationship between the cost of capital and value of the firm i.e. the value of the firm is independent of the capital structure of the firm.
Assumptions:
1. The corporate income taxes do not exist.
2. Debt Equity mix is irrelevant for computation of market value of firm.
3. With the increase in debt proportion, financial risk and expectations of shareholders increase.
Financial Management & Strategic Management (FM and
| CRACKER
AUTHOR : Rakesh Rathi, Vivek Panwar
PUBLISHER : Taxmann
DATE OF PUBLICATION : June 2026
EDITION : 13th Edition
ISBN NO : 9789375613534
No. of Pages : 764
BINDING TYPE : Paperback
Rs. 845
DESCRIPTION
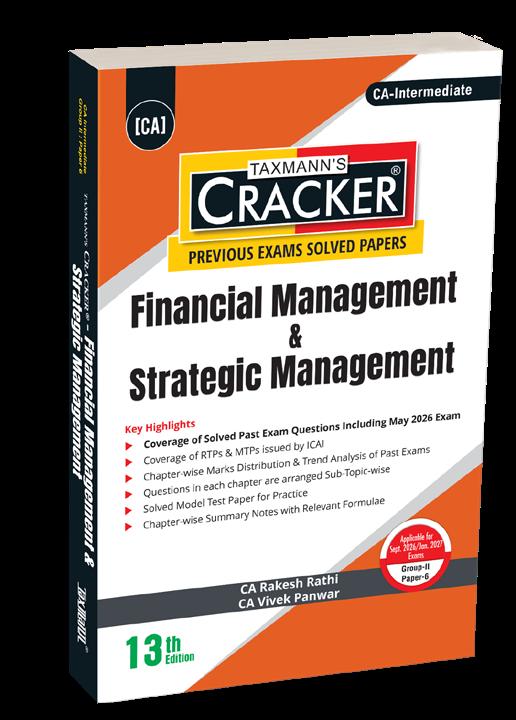
Financial Management & Strategic Management – CRACKER is an exam-oriented, solved question bank for CAIntermediate (New Syllabus), Group II, Paper 6. Rather than reteaching the syllabus, it turns it into writing-ready practice: each chapter opens with a point-wise summary, then works through theory questions, subtopic-wise practical problems, and ICAI RTP questions—each with a full solution linked to its source attempt. The book mirrors the 100-mark paper exactly—Financial Management (50) and Strategic Management (50)—and closes with a fully solved Model Test Paper and four solved recent papers in ICAI’s current case-scenario format, carrying a student from revision to answer-practice to self-assessment in one volume.
The Present Publication is the 13th Edition, authored by CA. Rakesh Rathi and CA. Vivek Panwar, with the following noteworthy features:
• [Solved Past Exam Questions] Past-exam questions integrated chapter-wise across a long run of ICAI attempts, with the most recent papers—up to and including May 2026—reproduced as fully solved papers
• [Coverage of ICAI RTPs] Revision Test Paper questions integrated chapter-wise with full solutions
• [Chapter-wise Marks Distribution] A chapter-wise marks break-up from May 2024 to May 2026, with perchapter averages
• [Previous-Exams Trend Analysis] A question-by-question analysis capturing marks, the compulsoryquestion flag, and a Practical/Theory tag
• [Comparison with ICAI Study Material] Each chapter mapped to the corresponding ICAI Study Material chapter for cross-referencing
• [Relevant Formulae] Formulae for the Financial Management chapters presented as tables, decision rules and step-wise procedures
• [Solved Model Test Paper] A fully solved Model Test Paper for timed self-assessment
• [Solved Suggested-Answer Papers] Four fully solved papers—May 2025, September 2025, January 2026 and May 2026—in ICAI’s current case-scenario pattern
• [Case-study/Application Questions] Strategic Management chapters carry case-study and application questions matching the exam’s application focus
• [Exam-tagged Questions] Every question carries its attempt and marks, showing recency and weightage at a glance