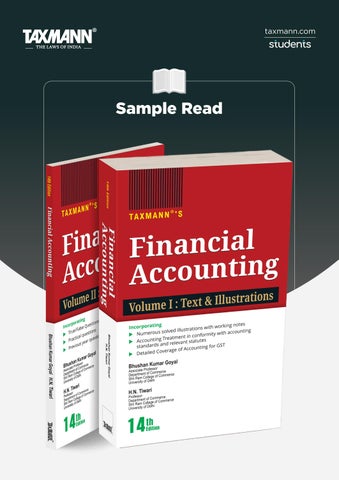
Sample Read
© Bhushan Kumar Goyal
Printing and publishing rights with the publisher
Fourteenth Edition : June 2026
Price : ` 1145 (For a set of two volumes)
Published by :
Taxmann Publications (P.) Ltd.
Sales & Marketing : 59/32, New Rohtak Road, New Delhi-110 005 India
Phone : +91-11-45562222
Website : www.taxmann.com
E-mail : sales@taxmann.com
Regd. Office :
21/35, West Punjabi Bagh, New Delhi-110 026 India
Printed at :
Tan Prints (India) Pvt. Ltd.
44 Km. Mile Stone, National Highway, Rohtak Road Village Rohad, Distt. Jhajjar (Haryana) India
E-mail : sales@tanprints.com
Disclaimer
Every effort has been made to avoid errors or omissions in this publication. In spite of this, errors may creep in. Any mistake, error or discrepancy noted may be brought to our notice which shall be taken care of in the next edition. It is notified that neither the publisher nor the author or seller will be responsible for any damage or loss of action to any one, of any kind, in any manner, therefrom.
No part of this book may be reproduced or copied in any form or by any means [graphic, electronic or mechanical, including photocopying, recording, taping, or information retrieval systems] or reproduced on any disc, tape, perforated media or other information storage device, etc., without the written permission of the publishers. Breach of this condition is liable for legal action.
For binding mistake, misprints or for missing pages, etc., the publisher’s liability is limited to replacement within seven days of purchase by similar edition. All expenses in this connection are to be borne by the purchaser. All disputes are subject to Delhi jurisdiction only.
About the Authors
Preface to Fourteenth Edition
Acknowledgement
Syllabus
CHAPTER 1
ACCOUNTING SYSTEM
CHAPTER 2
CAPITAL AND REVENUE EXPENDITURES AND RECEIPTS
CHAPTER 3
EVENTS OCCURRING AFTER THE BALANCE SHEET DATE
CHAPTER 4
EXTRAORDINARY ITEMS, PRIOR PERIOD ITEMS, ACCOUNTING
ESTIMATE, ACCOUNTING POLICIES AND FAIR VALUE
CHAPTER 5
PROVISIONS, CONTINGENT LIABILITIES AND CONTINGENT ASSETS
CHAPTER 6
FINANCIAL ACCOUNTING PRINCIPLES
CHAPTER 7
INTRODUCTION TO ACCOUNTING STANDARDS AND IND AS
CHAPTER 8
ACCOUNTING PROCESS : JOURNAL AND LEDGER
CHAPTER 9
ACCOUNTING PROCESS : SUBSIDIARY BOOKS, LEDGER AND TRIAL BALANCE
CHAPTER 10
ACCOUNTING FOR GOODS AND SERVICES TAX
CHAPTER 11
MEASUREMENT OF BUSINESS INCOME AND REVENUE RECOGNITION
CHAPTER 12
ACCOUNTING FOR PROPERTY, PLANT, EQUIPMENT AND DEPRECIATION
CHAPTER 13
ACCOUNTING FOR INTANGIBLE ASSETS
CHAPTER 14
INVENTORY VALUATION
CHAPTER 15
CHAPTER 16
CHAPTER 17
ACCOUNTING FOR INLAND BRANCHES
CHAPTER 18
DEPARTMENTAL ACCOUNTING
CHAPTER 19
LEASE ACCOUNTING
CHAPTER 20
COMPUTERIZED ACCOUNTING SYSTEM
15 CHAPTER FINANCIAL STATEMENTS OF NON-CORPORATE BUSINESS ENTITIES
Learning Objectives
After studying this chapter, the learners will be able to understand:
Trading Account
Profit and Loss Account
Balance Sheet
Adjustments
Graded Illustrations
Manufacturing Account
Worksheet
Limitations of Financial Statements
Set off of GST ad Financial Statements with GST
Traditionally, financial statements of business enterprises engaged in trading or manufacturing activities consist of: (1) Income Statement and (2) Balance Sheet. These statements are also called Final Accounts. But now-a-days a third statement namely, Cash Flow Statement, if applicable, is also prepared. As per AS-3, preparation of Cash Flow Statement is mandatory in respect of certain types of enterprises mentioned therein such as listed companies, banks, financial institutions, insurance companies, and other business enterprises whose turnover exceed a certain specified limit.
Income statement of a sole trader is divided into two parts: the first part reveals gross profit/gross loss and the second part shows the net profit/net loss. It may be prepared in form of a statement or in the form of an account i.e. ‘T’ form account. The first part of the Income Statement is called Trading Account and the second part is called the Profit and Loss Account. In case of partnership, a third part is also prepared known as Profit and Loss Appropriation Account.
Balance Sheet shows assets, liabilities and equity as on the last date of the accounting period. In this chapter, preparation of Trading Account, Profit and Loss Account and Balance Sheet of non-corporate business entities which follow the double entry system of book-keeping has been discussed.
TRADING ACCOUNT
Preparation of Trading Account is the first stage in the process of the preparation of Final Accounts. Trading Account shows the results of buying and selling of goods and/or rendering of services. It is prepared to calculate the Gross Profit or Gross Loss of a business for a specific period of time, normally an accounting year. The cost of goods sold and/or services rendered is matched with the sale proceeds of goods sold and/or services rendered. If the sales are more than the cost of goods sold and/or services rendered, the difference between the two is Gross Profit. On the other hand, if the cost of goods sold and/or services rendered, is more than the sales, the difference is Gross Loss. In case of a trading concern, it is shown as follows:
Gross Profit = Sales - Cost of Goods Sold
Gross Profit = Net Sales - (Opening Stock + Net Purchases + Direct Expenses - Closing Stock)
Gross Profit = Net Sales - Opening Stock - Net Purchases - Direct Expenses + Closing Stock
Opening Stock + Net Purchases + Direct Expenses + Gross Profit = Net Sales + Closing Stock
The items shown on the left side of the last equation namely Opening Stock, Purchases, Direct Expenses are entered on the debit side of the Trading Account and items shown on the right side of the last equation namely, Sales and Closing Stock are entered on the credit side of the Trading Account. If the total of the credit side is more than that of the debit side, the difference is Gross Profit which is entered on the debit side of the Trading Account. If the total of the debit side is more than that of the credit side, the difference is Gross Loss which is entered on the credit side of the Trading Account. The contents of the Trading Account are explained below:
1. Opening Stock: Closing Stock of unsold goods of the previous accounting period becomes the opening stock of the current accounting period. Thus it is brought forward in the current accounting year from the previous accounting year. In case of a trading concern opening stock consists of various types of finished goods. But in case of manufacturing concern it consists of raw materials, work in progress and finished goods. It usually appears in the Trial Balance. If there was opening stock and it is not shown in the Trial Balance, it means that it has already been adjusted through Purchases Account by debiting Purchases Account and crediting Opening Stock Account. In case of new business, there will be no Opening Stock.
2. Purchases: Purchases refers to the goods bought for cash and on credit for resale. This items appears in the Trial Balance. From the total amount of purchases
the following items are deducted in the inner column of the Trading Account and the net balance is shown in the Amount Column of the Trading Account:
(i) Returns Outward or Purchases Returns
(ii) Goods withdrawn by the proprietor for personal use
(iii) Goods distributed by way of free samples
(iv) Goods given as charity
(v) Goods sold on hire purchase
When the goods purchased have not been received, i.e., they are still in transit, it is recorded by debiting the Goods-in-transit Account and crediting the supplier’s account (by name). Goods-in-transit in this case will be shown as an asset in the Balance Sheet and supplier’s account as a liability in the Balance Sheet. Trading Account is not affected by this. On actual receipt of the goods at a later date, Purchases Account will be debited and Goods-in-transit will be credited. Goods received on consignment basis are not included in purchases. Similarly, the goods received on sale or return basis are not included in purchases until the property in goods (ownership of goods) is transferred by acceptance or failure to return within the time specified or if no time is specified within reasonable time. If the goods have been received but the relevant invoice has not been received by the date of closing of the accounting year, Purchases Account should be debited and the supplier’s account should be credited with the cost of goods. If this entry is not passed, these goods should be excluded from the closing stock, but this course is usually not adopted.
‘Duty drawbacks’ and ‘subsidies’ are incentives offered by the Government to the enterprises in certain sectors. Duty drawbacks are the incentives given to the exporters in the form of refund of duties levied on purchases made by them. Subsidy is the cash assistance received from the Government on purchase of certain goods or services. Duty drawback and subsidies should be deducted from purchases. AS-2 states that duty drawback and other similar items are deducted in determining the costs of purchases. In practice, duty drawbacks and cash subsidies are accounted for on cash basis by the business entities and are generally shown as part of “Other Income.” However, preferable approach is the deduct these from purchases.
“As explained earlier in the Chapter Accounting for Goods and Services Tax” GST Paid on purchases is ‘Input GST’. On intra state purchases of goods, input CGST and Input SGST are paid and on inter state purchases of goods, Input IGST is paid.
Following Journal entry is passed at the time of purchase of goods: Purchases A/c Dr. Input CGST A/c (for intra state purchases) Dr.
Input SGST A/c (for intra state purchases)
Input IGST A/c (for inter state purchases)
To Cash A/c/Bank A/c/Creditor
Dr.
Dr.
In Case of purchases return, the following journal entry is passed:
Cash A/c/Bank A/c/Creditor
To Purchases Returns A/c
To Input CGST A/c (for intra state)
To Input SGST A/c (for intra state)
To Input IGST A/c (for inter state)
Dr.
When goods are given as Charity out of purchases made by the firm, the following journal entry is passed:
Charity A/c
To Purchases A/c
To Input CGST A/c (for intra state purchases)
To Input SGST A/c (for intra state purchases)
To Input IGST A/c (for inter state purchases)
Dr.
Goods given as Charity will be deducted from purchases and Charity Account will be closed by transferring to Profit and Loss Account.
Similarly, when goods are distributed as free samples, the following journal entry is passed:
Goods Distributed as Free Samples A/c
To Purchases A/c
To Input CGST A/c (for intra state purchases)
To Input SGST A/c (for intra state purchases)
To Input IGST A/c (for inter state purchases)
Dr.
Goods distributed as free samples will be deducted from purchases and Goods Distributed as Samples Account will be closed by transferring to Profit and Loss Account.
Again when goods are withdrawn by the proprietor for personal use, the following journal entry is passed:
Drawing A/c
To Purchases A/c
To Input CGST A/c (for intra state purchases)
To Input SGST A/c (for intra state purchases)
To Input IGST A/c (for inter state purchases)
Dr.
3. Direct Expenses: Direct expenses, in case of a trading concern, are the expenses directly attributable to the acquisition of goods and bringing them in a saleable condition. In case of manufacturing concern, cost of conversion of raw materials into finished goods are also included in direct expenses. Direct expenses are debited to the Trading Account. These expenses include: Freight or carriage inwards, wages, power, fuel, factory lighting, factory rent and rates, import duty, dock dues and clearing charges, other non-refundable taxes on purchases, royalty, primary packing charges, and consumable stores. These are explained below:
(
a) Freight inwards, carriage inwards and cartage inwards: These are incurred to bring the goods or raw materials to the place of the business or to the firm’s godown and make them available for use. If freight or cartage is paid on an asset like machinery or furniture, it is added to the cost of the asset and not debited to the Trading Account.
(
b) Wages: Wages are paid to workers in the factory. It is a direct expense. If there is one combined account titled “Wages and Salaries” it is treated as direct expense. If wages are paid for installation or erection of machinery, it should be added to the cost of asset. If wages paid for installation of an asset has been debited to wages account instead of debiting the asset account, a rectification entry is made by debiting the asset account and crediting the wages account.
(
c) Factory expenses: Factory expenses include power, factory lighting, factory rent and rates. Power is the electricity consumed to run the machines. It is a direct expense. Similarly fuel which is used to run the boiler or other machines is direct expense. Factory lighting is the electricity consumed for providing light in the factory or to run fans. It is a direct expense. Factory Rent is the rent paid for the factory premises. Factory Rates are the municipal taxes or charges for water. If factory and office are in the same premises, then Factory Lighting and Office Lighting; and Factory Rent and Rates and Office Rent and Rates should be suitably apportioned between the two. Gas, fuel, water are other examples of factory expenses.
(
d) Import duties, dock dues and clearing charges: Import Duties are the duties paid on import of goods. This is a direct expense. Dock dues and Clearing charges are paid on imported goods. These are debited to the Trading Account. Import duties, inter alia, includes basic customs duty, anti-dumping duty, goods and services tax. Basic customs duty is levied by the Central Government on value of goods at a specified rate under the Customs Tariff Act, 1975. Similarly, anti-dumping duty is levied by the Central Government. Thus, GST would be applied to imports in addition to Basic customs duty.
(
e) Octroi: Octroi is paid when goods enter municipal limits. Octroi paid on goods purchased is a direct expense. Octroi is now included in GST.
(
f) Royalties: Royalties are the payments which are made for acquiring the right to use patents. It is treated as a direct expense if it is based on the number of unit produced.
(
g) Consumable stores: These include lubricating oil and grease, cotton waste, cleaning materials, coolants. These are necessary to keep the machines in good working condition.
(
h) Primary packing materials and charges: These are essential to bring the goods in a saleable condition and therefore, treated as direct expenses. For example, packing of cigarettes in the packets of ten or twenty is essential to bring the goods in a saleable condition. Similarly packing of liquid in containers such as bottles, tins etc. is a direct expense. But the expenses incurred on packing the goods for their safe despatch to customers or fancy packing for the purpose of advertisement are treated as indirect expenses and therefore debited to the Profit and Loss Account.
4. Sales: It refers to the total of cash and credit sales of goods bought for resale. The following items are shown by way of deduction from the total sales:
(i) Returns inward or Sales returns.
(
ii) Sale of an asset like machinery, furniture etc. should not be included in Sales. If it has been included in Sales, it should be deducted by debiting Sales Account and crediting the particular Asset Account.
(
iii) Goods sent on approval (sale or return basis) or goods sold on consignment or on hire purchase should be recorded separately. If these are included in Sales, these should be deducted. In case goods sold on consignment have been included in sales, Sales Account should be debited and Goods Sold on consignment Account should be credited.
(iv) Value added tax, where GST is not applicable, should be deducted from sales if the sales figure includes Value Added Tax (formerly known as sales tax).
(v) Where GST is applicable, the firm shall charge Goods and Services Tax on the goods sold by it. The GST (CGST, SGST or IGST) is collected on sales. This GST is called Output GST (CGST, SGST or IGST).
At the time of sale, following journal entry is passed: Cash A/c / Bank A/c / Debtor (with sales value + GST) Dr.
To Sales A/c (With sales value)
To Output CGST A/c (In case of intra state sales)
To Output SGST A/c (In case of intra state sales)
To Output IGST A/c (In case of inter state sales)
Output GST is set off against Input GST. Set off of Output GST against Input GST has been explained in the chapter on Accounting for Goods and Services Tax and also later in this chapter.
Output GST (CGST, SGST or IGST) collected on sales is reversed in case of sales returns.
5. Closing Stock: It refers to the stock of unsold goods at the end of the current accounting year. In case of a trading concern, the closing stock consists of different type of goods meant for resale. In case of manufacturing concern, it consists of raw materials, work-in-progress and finished goods. It is valued at cost or market price whichever is less.
Closing stock is usually given as an additional information or adjustment outside the Trial Balance. To incorporate the closing stock in the books. Closing Stock Account is debited and the Trading Account is credited by the amount of unsold stock at the end. Closing Stock appears as an asset on the asset side of the Balance Sheet.
If the closing stock appears in the Trial Balance, it means that it has already been adjusted through purchases by debiting the Closing Stock Account and crediting the Purchases Account. In this case closing stock will not be shown on the credit side of the Trading Account and it will be shown as an asset on the asset side of the Balance Sheet.
If the goods have been sent on approval basis to customers and the customer has the right to return the goods on the last day of the accounting year, the cost of the goods should be included in the closing stock. Further the cost of the abnormal loss of goods is also credited to the Trading Account or deducted from purchases as the abnormal loss of goods should not affect the Gross Profit.
Closing Entries and Adjusting Entries: Closing entries are journal entries that transfer the balances in the temporary accounts [i.e. revenue accounts (including other income and gains), expense accounts (including losses) and drawings account] to Trading Account, Profit and Loss Account and Capital Account as the case may be. Temporary accounts pertain to the current period and are not carried forward to the next year. Therefore, at the end of the accounting period the balances of these are reset to zero. For example, small opening stock account, purchases account, various direct expenses accounts and sales account are transferred to Trading Account. Indirect expenses accounts, various types of other income accounts are transferred to Profit and Loss Account. Balance of the Profit and Loss Account and Drawings Account are transferred to Capital Account.
Adjusting Entries are the entries which are passed for incorporating closing stock, outstanding expenses, prepaid expenses, accrued income and income received in advance, etc. at the end of the accounting period.
JOURNAL ENTRIES
The following entries are passed to prepare the Trading Account (First four entries are closing entries and the fifth is an adjusting entry):
(i) For closing the Purchases Returns Account (Returns Outward Account)
Purchases Returns AccountDr.
To Purchases Account/Trading Account
(ii) For closing Opening Stock Account, Purchases Account and Accounts of Direct Expenses
Trading AccountDr.
To Opening Stock Account
To Purchases Account
To Wages Account
To Fuel and Power Account
To Factory Rent and Rates Account
To Freight on Purchases Account
To Factory Lighting, etc.
(iii) For closing Sales Returns Account (Returns Inward Account)
Sales Account/Trading AccountDr.
To Sales Returns Account
(iv) For closing Sales Account
Sales AccountDr.
To Trading Account
(v) If Closing Stock appears outside the Trial Balance then the following adjusting entry is passed:
Closing Stock Account Dr.
To Trading Account
If the credit side is more than the debit side, the difference is Gross Profit; and if the debit side is more than the credit side, the difference is Gross Loss. For transferring the Gross Profit, the following closing entry is passed which will close the Trading Account:
Trading AccountDr.
To Profit and Loss Account
In case of Gross Loss, the following entry is passed: Profit and Loss AccountDr.
To Trading Account
FORMAT OF TRADING ACCOUNT
A simple format of the Trading Account is as follows:
TRADING ACCOUNT OF ………
Dr. for the year ended …… Cr.
Particulars ` Particulars `
To Opening Stockx x xBy Salesx x x
To Purchasesx x x
Less: Sales Returnsx x xx x x
Less: Purchases Returnsx x xx x xBy Closing Stock
To Wagesx x xBy Abnormal Loss of Stock (at cost) x x x
To Fuel and Powerx x xBy *Gross Loss transferred to
To Factory Rent and Ratesx x xProfit and Loss A/c (bal. fig.)x x x
To Freight on Purchasesx x x
To Carriage Inwardsx x x
To Consumable Storesx x x
To *Gross Profit transferred to Profit and Loss A/c (bal. fig.) x x x
*Either Gross Profit or Gross Loss will appear:
Advantages of Trading Account: The following are the advantages of preparing Trading Account:
1. It provides information about gross profit ratio.
2. It also provides information about net purchases and net sales. This helps in knowing the percentage of goods, returned by the customers.
3. It provides information about various direct expenses. This information is important for control of these expenses.
4. Sales figure of the current accounting period can be compared with that of the previous periods and thus the growth of the company in terms of sales can be judged.
5. Significant changes, if any, in stock may be investigated to find out the reasons for the change.
ILLUSTRATION 1:
From the following balances extracted from the books of Mr. A. Naidu:
(i) Ascertain the cost of goods sold.
(ii) Give necessary journal entries to prepare the Trading Account.
(iii) Prepare the Trading Account for the year ending 31st March, 2026. ``
Closing Stock on March 31, 2026 was ` 1,43,000.
SOLUTION:
(i) Cost of Goods Sold = Opening Stock + Purchases - Purchases Returns + Direct Expenses - Closing Stock = ` 1,50,000 + 1,80,000 - 2,000 + 10,000 + 3,000 - 1,43,000 = ` 1,98,000 (ii)
JOURNAL ENTRIES
DateParticularsL.F.Dr.(`)Cr.(`) 2026
March 31Trading A/c
Wages A/c10,000
Freight Inwards A/c3,000 To Sales Returns A/c3,000
(Being the transfer of items to be written on the debit side of the Trading A/c) Sales A/cDr.2,50,000 Closing Stock A/cDr.1,43,000 Purchases Returns A/cDr.2,000 To Trading Account3,95,000
(Being the transfer of items to be written on the credit side of the Trading Account)
Trading A/cDr.49,000 To Profit and Loss A/c49,000
(Being the transfer of gross profit to the P & L A/c)
TRADING ACCOUNT OF MR. A. NAIDU
Dr. for the year ended 31st March, 2026 Cr.
PROFIT AND LOSS ACCOUNT
Profit and Loss account means an account which is prepared to determine the net profit earned or net loss incurred during an accounting period. After preparing the Trading Account, the next step is to prepare the Profit and Loss Account. This account is prepared to ascertain the net profit earned or net loss incurred by the business entity during the accounting period which is usually an year. As pointed out earlier, the balance of the Trading Account (Gross Profit or Gross Loss, as the case may be) is transferred to the Profit and Loss Account. Thus, the Profit and Loss Account starts with the Gross Profit on the credit side. In case of Gross Loss it is entered on the debit side of the Profit and Loss Account. Due to this reason the Trading Account can be treated as part or sub-section of the Profit and Loss Account. In case of companies, Trading and Profit and Loss Account is named Statement of Profit and Loss as per the Companies Act, 2013.
All the indirect expenses and losses are shown on the debit side of the Profit and Loss Account. In other words, all those expenses and losses which have not been entered in the Trading Account are entered on the debit side of the Profit and Loss Account. Revenues and gains, other than sales are shown on the credit side of the Profit and Loss Account. It should be noted that expenses and losses which relate to the current year (i.e., revenue expenditure) are entered on the debit side of the Profit and Loss Account. Similarly, on the credit side of the Profit and Loss Account revenue and gains of the current year are entered. If the total of the credit side is more than the total of the debit side, the difference is Net Profit for the period. On the other hand, if the total of the debit side is more than the total of the credit side, the difference is Net Loss for the period.
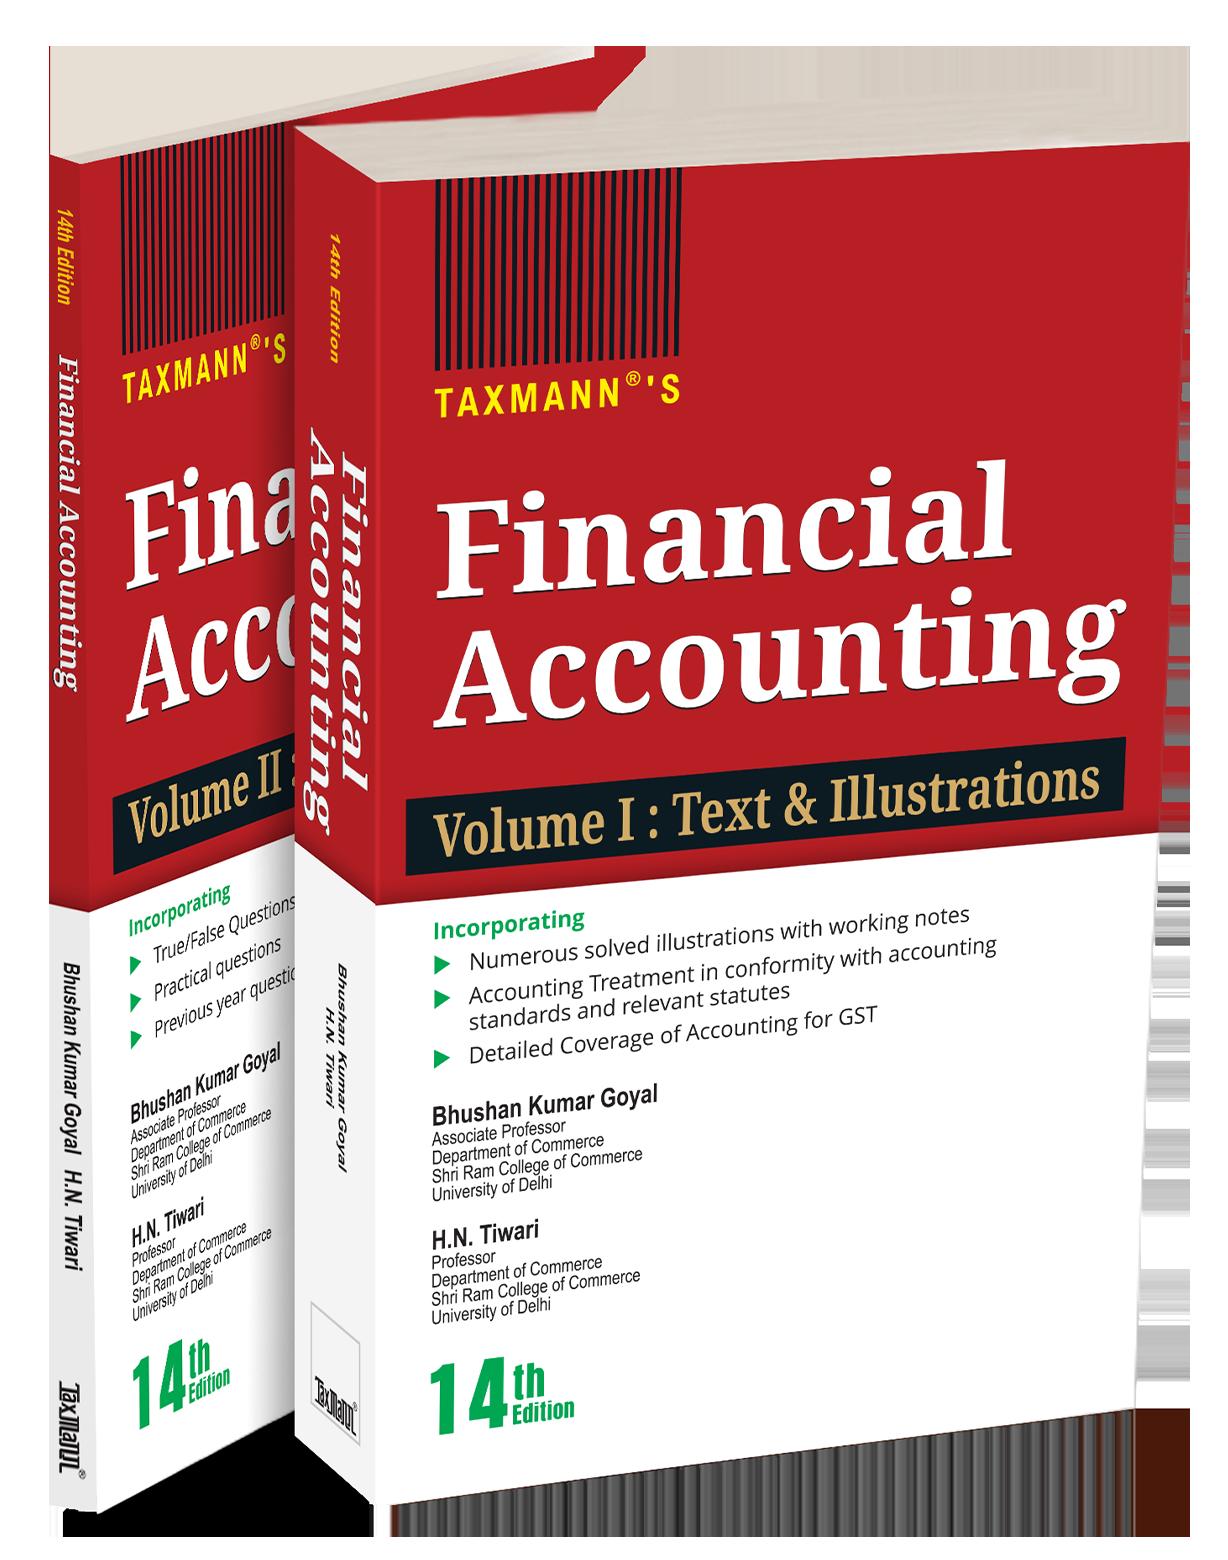
Financial Accounting
AUTHOR : Bhushan Kumar Goyal, H.N. Tiwari
PUBLISHER : Taxmann
DATE OF PUBLICATION : June 2026
EDITION : 14th Edition
ISBN NO : 9789375616634
No. of Pages : 1236
BINDING TYPE : Paperback
Rs. 1,145
DESCRIPTION
Financial Accounting is a comprehensive two-volume textbook integrating the theory, procedure, and practice of accounting. Written for undergraduate commerce students, it is fully aligned with the Undergraduate Curriculum Framework (UGCF) under the National Education Policy (NEP) and suits B.Com. and B.Com. (Hons.) programmes at universities across India.
The book is student-oriented throughout—concepts are explained in simple language and built up systematically, with special care over the points students find difficult. Theory is anchored to an extensive body of solved illustrations with working notes, and the major standards-based topics are presented under the relevant Accounting Standard (AS) and, where applicable, set against their Ind AS counterparts.
It is delivered across two complementary volumes—Volume I (Text & Illustrations) carrying the conceptual and workedexample content, and Volume II (Assignments) carrying objective questions, practical problems, and previous-year question papers—keeping study and self-assessment distinct yet coordinated.
This book is intended for the following audience:
• Undergraduate Commerce Students Pursuing B.Com. and B.Com. (Hons.)
• Candidates of Other Undergraduate and Postgraduate Programmes
• Students of Management Courses
• Aspirants to Professional Accountancy Qualifications
• Students of the School of Open Learning (SOL) and the Non-Collegiate Women’s Education Board (NCWEB)
The Present Publication is the 14th Edition, authored by Bhushan Kumar Goyal and Dr H.N. Tiwari, and includes several noteworthy features:
• [Solved Illustrations with Working Notes] A large number of fully solved illustrations, each with detailed working notes that show the complete reasoning behind every solution
• [Graded Problem Progression] Illustrations that progress from elementary to advanced, building competence before examination-standard problems
• [AS-versus-Ind AS Comparisons] Dedicated comparisons at the relevant topics—AS 4 with Ind AS 10; AS 5 with Ind AS 8; AS 29 with Ind AS 37; AS 26 with Ind AS 38; AS 2 with Ind AS 2; and AS 19 with Ind AS 17—with Ind AS 115 (Revenue from Contracts with Customers) introduced by way of an overview
• [Standards-Compliant Treatment] Accounting treatment given throughout in conformity with the Accounting Standards and relevant statutes
• [Accounting for GST] Detailed, worked coverage of GST, including its integration into the final accounts
• [Latest Examination Questions] Most questions from the December 2025 examination of the University of Delhi reproduced and solved, alongside fresh illustrations added in this edition
• [Student-Friendly Exposition] Simple language and a step-by-step build-up, with emphasis on the points students find difficult
• [Dedicated Assignment Volume] Volume II carrying True/False questions with reasoned answers, practical questions, and previous-year papers for self-assessment
• [Revised for the UGCF/NEP Syllabus] Thoroughly revised in line with the UGCF syllabus under NEP, incorporating suggestions from the faculty of the University of Delhi