Sample Read
© All rights reserved
Price : ` 695
Third Edition : June 2026
Published by :
Taxmann Publications (P.) Ltd.
Sales & Marketing : 59/32, New Rohtak Road, New Delhi-110 005 India
Phone : +91-11-45562222
Website : www.taxmann.com
E-mail : sales@taxmann.com
Regd. Office : 21/35, West Punjabi Bagh, New Delhi-110 026 India
Printed at :
Tan Prints (India) Pvt. Ltd.
44 Km. Mile Stone, National Highway, Rohtak Road Village Rohad, Distt. Jhajjar (Haryana) India
E-mail : sales@tanprints.com
Disclaimer
Every effort has been made to avoid errors or omissions in this publication. In spite of this, errors may creep in. Any mistake, error or discrepancy noted may be brought to our notice which shall be taken care of in the next edition. It is notified that neither the publisher nor the author or seller will be responsible for any damage or loss of action to any one, of any kind, in any manner, therefrom.
No part of this book may be reproduced or copied in any form or by any means [graphic, electronic or mechanical, including photocopying, recording, taping, or information retrieval systems] or reproduced on any disc, tape, perforated media or other information storage device, etc., without the written permission of the publishers. Breach of this condition is liable for legal action.
For binding mistake, misprints or for missing pages, etc., the publisher’s liability is limited to replacement within seven days of purchase by similar edition. All expenses in this connection are to be borne by the purchaser. All disputes are subject to Delhi jurisdiction only.
SECTION B MANAGEMENT AUDIT
MODULE 9 BASICS OF MANAGEMENT AUDIT
SECTION C
LAUNDERING
PREPARATION AND FILING OF COST AUDIT REPORT
8.1
INTRODUCTION
A QUICK REVIEW
The primary responsibility of preparation of the Annexures to the Cost Audit Report lies with the company. However, the same should be prepared in consultation with the cost auditor to ensure that the reporting conforms to the prescribed rules and at the same time the report is in conformity with the cost accounting records. If, as a result of the examination of the books of the accounts, the cost auditor wants to point out any material deficiency or give a qualified report, he shall indicate the same against the relevant paragraph in the prescribed form of the cost audit report giving details of discrepancies noticed by him. It implies that the cost auditor should put his comments in the respective paragraphs of the cost audit report itself.
The report, suggestions, observations and conclusions given by the cost auditor shall be based upon data duly verified, and reference to which shall be made in the report and shall be included after an opportunity is given to the company to comment on them. The cost auditor is required to point out any deficiency or reservation to the management first. In case he is satisfied with the response of the management, he may decide to drop the issue. However, if he is not satisfied with the explanation of the management, he may decide to qualify the report to that extent.
8.2
CRITICAL ELEMENTS OF COST AUDIT REPORT AND RELATED EVIDENCES (PHYSICAL AND DIGITAL)
A QUICK REVIEW
A cost audit comprises the following:
Verification of the cost accounting records such as the accuracy of the cost accounts, cost reports, cost statements, cost data and costing technique Examination of these records to ensure that they adhere to the cost accounting principles, plans, procedures and objective.
Cost audit helps in detection of errors and frauds. The management gets accurate and reliable data based on which they can make day-to-day decisions like price fixation, margin, continuity or outsourcing, make or buy etc. It helps in cost control and finding avenues of cost reduction.
The Cost Audit and requirement of details are informative for better and clear understanding of the Users of Report.
Accordingly, the prescribed Format (Ref. CRA -3) i.e. the Cost Audit Report includes Unit-wise, Product/Service- wise Cost Statements and Schedules, deviation for the same need to be reported. Part – D of CRA-3 is a measure towards performance orientation which includes the following aspects:
u Product and Service profitability statement
u Profit reconciliation
u Value addition and distribution of earnings
u Financial position and ratio analysis
It is needless to point out that appropriate documentation (Working papers, Files, process document in physical or electronic form/mode) and additional supporting, if any, to be to be filed along with XBRL.
The following critical elements must be stated in the cost auditor’s report:
u Whether the machines and labour remained idle during the year because of the shortage of raw materials.
u Whether a large quantity of raw materials were stocked which remained unutilized for a long time, thereby locking up the working capital of the company.
u He should state whether the cost records maintained by the company were adequate for the purpose of audit.
u He should state whether the broad policy laid down by the management was faithfully followed.
u The report should concentrate more on the cost of production, comparative profitability, and operating efficiency of different lines in which the company is engaged rather than the routine statistical or financial information.
u The cost auditor should state if there has been a rise in the cost of production as compared to that of the previous year. He should analyse the causes of such a rise. He should clearly point out where the problem originates from.
u The report should state if there has been any wastage during the process of manufacture and how it could be avoided.
u The cost auditor should also mention the areas in which it is possible to reduce the cost of production.
u He should state whether or not the cost statement reveals a true and fair view of the cost of production.
Every Company covered under this rules, within a period of 30 days from the receipt of the cost audit report to submit/upload in XBRL Format the detail and report with full information and explanations on every reservations or quantification contained therein in CRA-4 as specified in the Companies’ Filing of Documents and Forms in
XBRL Rules 2015 in MCA Portal. This helps Companies to integrate Financial and Cost datum across all operational areas for better control.
PAST EXAMINATION QUESTION
OBJECTIVE QUESTION
Q. 1 Which of the following particulars relating to wages and salaries is/are to be included in Cost Auditor’s Report to the Director of the company?
(a) Total wages and salaries paid
(b) Total man days of direct labour available and actually worked
8.3
(c) A brief explanation of variances in items
(d) All of the above [June 2025, 2 Marks]
Ans. (d) All of the above
QUALIFIED AUDIT REPORT
A QUICK REVIEW
A qualified audit report is given by the cost auditor when the cost statements are materially misstated due to misstatement in one particular cost element, class of transaction or disclosure that does not have pervasive effect on the cost statements and when the cost auditor is unable to obtain audit evidence regarding particular cost element, its allocation and apportionment, class of transaction or disclosure that does not have pervasive effect on the cost statements.
A qualified audit report issued when the cost auditor encounters any of these situations which do not comply with the generally accepted cost accounting principles and is not in conformity with the principles laid down in CRA-1.
PAST EXAMINATION QUESTION
CASE STUDY
Q.1 Your friend who has been appointed as cost auditor of a company has sought your advice on under what circumstances a qualified audit report is to be issued? [June 2023, 4 Marks]
Ans. : A qualified audit report is issued when the cost auditor concludes that there is a limitation or deviation in the audit that materially affects the cost statements, but is not pervasive to the extent of rendering them misleading as a whole. The report in which Cost Auditors express a qualified view of cost statements is a qualified audit report. It means that the company’s cost records are not maintained in accordance
with Generally Accepted Accounting Principles (GAAP) but no misinterpretations are involved.
u Non-compliance with Cost Accounting Standards: If the company fails to follow mandatory CAS without justification.
u Improper Maintenance of Cost Records: When records are incomplete, inaccurate, or not maintained as prescribed under the Companies Act and Cost Audit Rules.
u Material Misstatements or Omissions: Errors or omissions in cost statements that affect decision-making.
u Non-availability of Information: If necessary records or explanations are not provided by the company despite repeated requests.
u Discrepancies in Resource Utilization: If there is excessive wastage or inefficiency not addressed by the management.
u Conflict with Financial Statements: If cost data materially differs from financial records without reconciliation.
A qualified audit report is issued when the cost auditor encounters any of these situations which do not comply with the generally accepted cost accounting principles and is not in conformity with the principles laid down in CRA-1.
8.4
ADVERSE AUDIT REPORT
A QUICK REVIEW
An adverse audit report on the cost accounting records and cost statements of a company means that the cost statements are materially misstated and such misstatements have pervasive effect on the cost of production, cost of sales and margin of the products. An adverse opinion is issued when the cost auditor determines that the cost statements of an auditee are materially misstated and when considered as a whole, do not conform to the generally accepted cost accounting principle. It is considered the opposite of an unqualified or clean opinion, essentially stating that the information contained is materially incorrect, unreliable, and inaccurate in order to assess the company’s operational results. 8.5
A QUICK REVIEW
Rule 6(6), of the Companies (Cost Records and Audit) Rules, 2014, as amended by the Companies (Cost Records and Audit) Amendment Rules, 2016,
“Every company covered under these rules shall, within a period of thirty days from the date of receipt of a copy of the cost audit report, furnish the Central Government with such report along with full information and explanation on every reservation or qualification contained therein, in Form CRA-4 in Extensible Business Reporting Language format in the manner as specified in the Companies (Filing of Documents and Forms in Extensible Business Reporting language) Rules, 2015 along with fees specified in the Companies (Registration Offices and Fees) Rules, 2014.”.
Accordingly, all the cost audit reports have to be filed online, with MCA, in XBRL format, attached to the prescribed Form CRA-4. XBRL international, and the MCA portal, provide detailed information about XBRL and its applications. The necessary information and procedure for understanding XBRL in general and filing of cost audit report in that format, as extracted from these portals is briefly recited below:
XBRL is the open international standard for digital business reporting, managed by a global not for profit consortium called “XBRL International”. XBRL is used around the world, in more than 50 countries. Millions of XBRL documents are created every year, replacing older, paper-based reports with more useful, more effective and more accurate digital versions. The change from paper, PDF and HTML based reports to XBRL is like the change from film photography to digital photography, or from paper maps to digital maps.
XBRL makes reporting more accurate and more efficient. It allows unique tags to be associated with reported facts, allowing:
u People publishing reports to do so with confidence that the information contained in them can be consumed and analysed accurately.
u People consuming reports to test them against a set of business and logical rules, in order to capture and avoid mistakes at their source.
u People using the information to do so in the way that best suits their needs, including by using different languages, alternative currencies and in their preferred style.
u People consuming the information to do so confident that the data provided to them conforms to a set of sophisticated pre-defined definitions.
Potential uses of XBRL
XBRL can be applied to a very wide range of business applications including financial and cost data. XBRL has applications in the following areas:—
u Reporting for internal and external purposes by an entity involving financial and costing data/information.
u Business reporting to all types of regulators, including tax and financial authorities, central banks and governments.
u Filing of loan reports and applications; credit risk assessments.
u Exchange of information between government departments, institutions and banks.
Benefit from using XBRL
All types of organizations can make use of XBRL to automate their process of data collection and distribution to various stakeholders. It helps in saving costs and improving the efficiency in managing business information - financial or cost. XBRL being extensible and flexible, can be adapted to a wide variety of requirements. All stakeholders whether they are preparers, transmitters or users of business data in the financial information supply chain can benefit from the use of XBRL.
Future of XBRL
XBRL has a bright future ahead of it that goes way beyond the current focus on regulatory reporting and compliance. Businesses that are now creating XBRL filings for regulatory bodies should be thinking about how they can leverage their investment in understanding and using XBRL to drive more consistent and comparable internal reporting. By tagging data at the account/transaction level, by investigating how XBRL can help to deliver new holistic reports that integrate and connect financial and non-financial data, and by leveraging emerging online XBRL data streams for better industry performance and peer group analytics, every business can power its own journey towards financial transformation.
Benefits of having cost related data in XBRL Format
Government and Regulators require cost data of different sectors for policy making. The availability of cost data [without compromising on the confidentiality] in XBRL format enables informed decision making and for sectoral studies. With full adoption of XBRL, companies would be able to integrate its financial and cost data across its operational areas and exercise better control on its activities.
Costing Taxonomy
Costing Taxonomy is a dictionary of all cost elements required in the cost audit report. The costing taxonomy contains the properties and interrelationships of all these cost elements for the purposes of capturing the required reporting data in XBRL format.
Conversion of cost audit report into the XBRL format
XBRL is an open source technology. Any of the following methods can be adopted to create the instance document required for filing of the respective reports.
u XBRL-enabled software packages developed by different software vendors which support the creation of cost reports in XBRL format can be used to create the necessary document.
u Various elements of Cost Audit Report can be mapped into XBRL tags of the costing taxonomy using specialised XBRL software tools specifically designed for this purpose.
u Different third party packages can be integrated into the existing accounting systems to generate XBRL Cost statements.
u There are various web based applications available that take input reports in various formats viz. Microsoft Excel etc. and transform them into XBRL format.
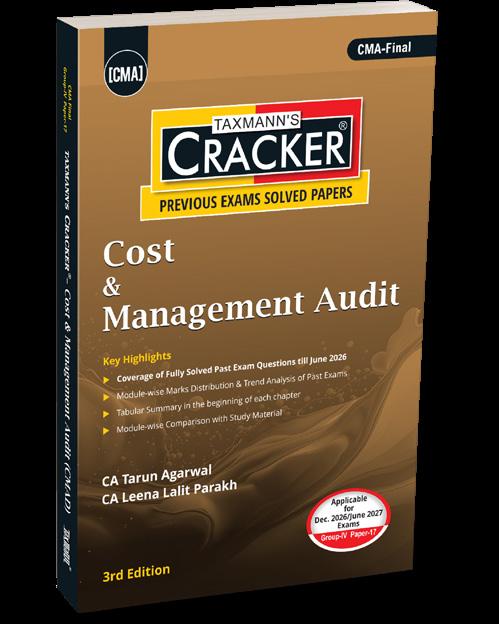
COST & MANAGEMENT AUDIT (CMAD) | CRACKER
AUTHOR : Tarun Agarwal, Leena Lalit Parakh
PUBLISHER : Taxmann
DATE OF PUBLICATION : June 2026
EDITION : 3rd Edition
ISBN NO : 9789375617228
NO. OF PAGES : 596
BINDING TYPE : Paperback
Rs. 695
DESCRIPTION
Cost & Management Audit – CRACKER is a past-examination-driven question-and-answer companion for CMA-Final, Group-IV, Paper-17, part of Taxmann's CRACKER 'Previous Exams Solved Papers' series. Rather than re-teaching the subject, it recasts the entire Paper-17 syllabus into a fully solved question bank arranged module-by-module in the institute's study order, so candidates revise the way the examiner sets the paper. Each topic opens with a quick conceptual recap, followed by the actual questions that have appeared in the examination—objective and descriptive alike—with model answers, fully worked numerical solutions, and the sitting and marks tagged against every question. The result is a practice-first revision instrument that shows exactly how each area is examined, where the marks concentrate, and how answers are expected to be framed—built for the final stretch of preparation and intended to be worked alongside the official study material, not in place of it.
The Present Publication is the 3rd Edition | June 2026, authored by CA. Tarun Agarwal and CA. Leena Lalit Parakh, with the following noteworthy features:
•[Fully Solved Past Questions (Up to June 2026)] Questions are segregated into Objective Questions (1–2 mark short-answer, fill-in-the-blank and select-the-option items) and Theory Questions (descriptive and analytical, largely 7-mark across a 4–10 mark range), each tagged with its sitting and marks for instant weightage
•[Step-by-Step Worked Numericals] Numerical and practical problems are solved in full—cost statements, prime-cost build-ups, make-or-buy and export-decision evaluations, ratio and profitability computations, with supporting working notes
•[Tabular 'Quick Review' in Every Chapter] A concept summary opens every chapter and sub-chapter—tabular or diagrammatic for rule- and standard-based topics, concise prose for conceptual ones
•[Module-wise Marks Distribution] Across the June and December sittings from 2023 through 2026, with per-module averages, to steer effort toward high-scoring areas
•[Previous Exams Trend Analysis] A question-by-question map of recent papers (December 2023 to June 2026) recording the compulsory question, chapter, marks, and whether the item was theoretical or practical—revealing recurring patterns
•[Module-wise Comparison with the Study Material] Every module and chapter mapped to the corresponding ICMAI/CMA institute module, for gap-free movement between this CRACKER and the official content
•[Latest Solved Papers (December 2025 & June 2026)] Module-wise solved papers for the two most recent sittings, with suggested answers, on full, current papers
•[Updated for Current Rules & Standards] Reflects the Companies (Cost Records and Audit) Rules 2014, the relevant provisions of the Companies Act, 2013, the Cost Accounting Standards and GACAP, and the Cost Auditing and Assurance Standards, with XBRL-based reporting addressed