
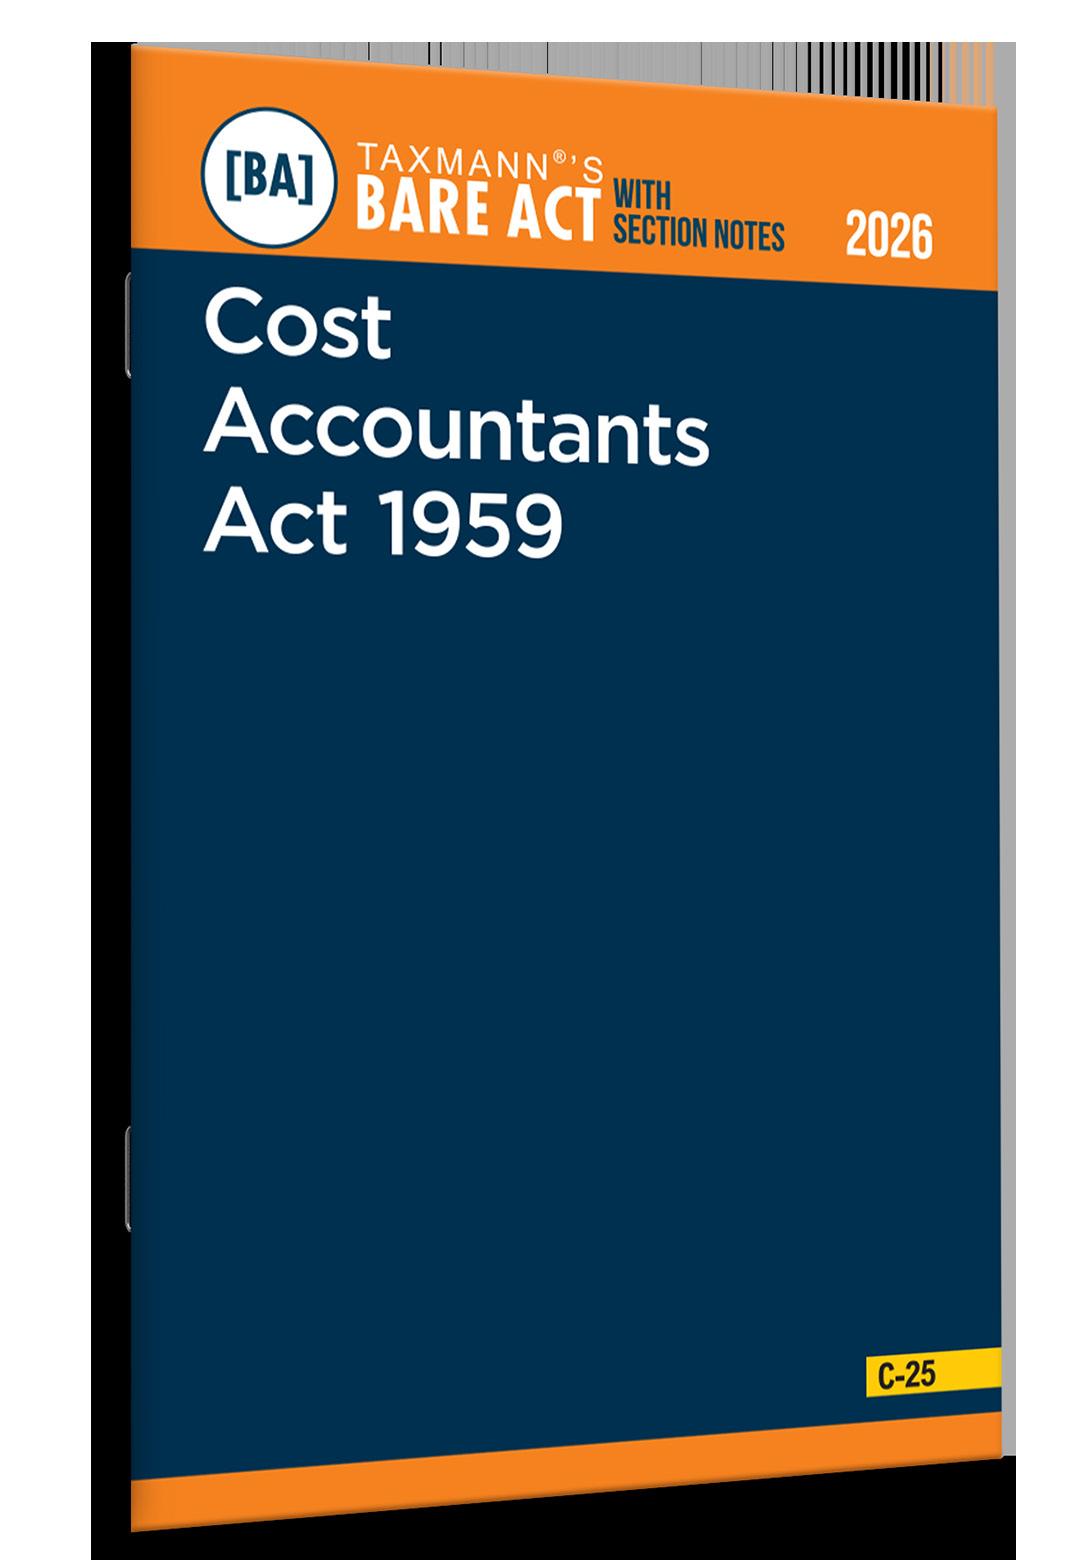
Sample Read
© Taxmann
Price : ` 125
Law stated in this book is as updated till 25th December, 2025
Published by : Taxmann Publications (P.) Ltd.
Sales & Marketing :
59/32, New Rohtak Road, New Delhi-110 005 India
Phone : +91-11-45562222
Website : www.taxmann.com
E-mail : sales@taxmann.com
Regd. Office :
21/35, West Punjabi Bagh, New Delhi-110 026 India
Printed at :
Tan Prints (India) Pvt. Ltd.
44 Km. Mile Stone, National Highway, Rohtak Road Village Rohad, Distt. Jhajjar (Haryana) India
E-mail : sales@tanprints.com
Disclaimer
Every effort has been made to avoid errors or omissions in this publication. In spite of this, errors may creep in. Any mistake, error or discrepancy noted may be brought to our notice which shall be taken care of in the next edition. It is notified that neither the publisher nor the author or seller will be responsible for any damage or loss of action to any one, of any kind, in any manner, therefrom. It is suggested that to avoid any doubt the reader should cross-check all the facts, law and contents of the publication with original Government publication or notifications.
No part of this book may be reproduced or copied in any form or by any means [graphic, electronic or mechanical, including photocopying, recording, taping, or information retrieval systems] or reproduced on any disc, tape, perforated media or other information storage device, etc., without the written permission of the publishers. Breach of this condition is liable for legal action.
For binding mistake, misprints or for missing pages, etc., the publisher’s liability is limited to replacement within seven days of purchase by similar edition. All expenses in this connection are to be borne by the purchaser. All disputes are subject to Delhi jurisdiction only.

CHAPTER IV
REGISTER OF MEMBERS
MISCONDUCT
CHAPTER VI
REGIONAL COUNCILS
1[Cost Accountants] Act, 1959
[23 OF 1959]
An Act to make provision for the 2[regulation and development of the profession of cost accountants].
BE it enacted by Parliament in the Tenth Year of the Republic of India as follows:—
CHAPTER I
PRELIMINARY
Short title, extent and commencement.
1. (1) This Act may be called the 1[Cost Accountants] Act, 1959.
(2)It extends to the whole of India 3[***];
(3)It shall come into force on such date* as the Central Government may, by notification in the Official Gazette, appoint.
Definitions and interpretation.
2. (1) In this Act, unless the context otherwise requires,—
(a) “associate” means an associate member of the Institute;
4[(aa) “Authority” means the Appellate Authority referred to in section 22A; (aaa) “Board” means the Quality Review Board constituted under section 29A;]
*With effect from 28-5-1959.
1.Substituted for “Cost and Works Accountants” by the Chartered Accountants, the Cost and Works Accountants and the Company Secretaries (Amendment) Act, 2022, w.e.f. 10-5-2022.
2.Substituted for “regulation of the profession of cost and works accountants”, ibid.
3.Words “except the State of Jammu and Kashmir” omitted by the Central Laws (Extension to Jammu and Kashmir) Act, 1968, w.e.f. 15-8-1968.
4.Inserted by the Cost and Works Accountants (Amendment) Act, 2006, w.e.f. 8-8-2006.
5[(ab) “Board of Discipline” means the Board of Discipline constituted under sub-section (1) of section 21A;
(ac) “Companies Act” means the Companies Act, 2013 (18 of 2013) or any other previous company law as defined in clause (67) of section 2 of the said Act;]
(b) “cost accountant” means a person who is a member of the Institute;
(
c) “Council” means the Council of the Institute 5[constituted under section 9;]
5[(ca) “Director (Discipline)” means the Director (Discipline) referred to in section 21 and includes Joint Director (Discipline);
(cb) “Disciplinary Committee” means the Disciplinary Committee constituted under sub-section (1) of section 21B;
(cc) “Disciplinary Directorate” means the Disciplinary Directorate established under sub-section (1) of section 21;]
(d) “dissolved company” means the Institute of Cost and Works Accountants registered under the Companies Act 6 [***];
7[(e) “fellow” means a fellow member of the Institute;]
8[(ea) “firm” shall have the meaning assigned to it in section 4 of the Indian Partnership Act, 1932 (9 of 1932), and includes,—
(i) the limited liability partnership as defined in clause (n) of sub-section (1) of section 2 of the Limited Liability Partnership Act, 2008 (6 of 2009); or
(ii) the sole proprietorship, registered with the Institute;]
(f) “Institute” means the 9[Institute of Cost Accountants of India] constituted under this Act;
10[(fa) “notification” means a notification published in the Official Gazette and the term “notify” shall be construed accordingly;]
8[(fb) “partner” shall have the meaning assigned to it in section 4 of the Indian Partnership Act, 1932 (9 of 1932) or in clause (q) of sub-section (1) of
5. Inserted by the Chartered Accountants, the Cost and Works Accountants and the Company Secretaries (Amendment) Act, 2022, w.e.f. 10-5-2022.
6. Figures “1956” omitted, ibid.
7. Substituted, ibid. Prior to its substitution, clause (e) read as under:
‘(e) “fellow” means a fellow of the Institute;’
8. Inserted by the Cost and Works Accountants (Amendment) Act, 2011, w.e.f. 1-2-2012.
9. Substituted for “Institute of Cost and Works Accountants of India”, ibid
10. Substituted by the Chartered Accountants, the Cost and Works Accountants and the Company Secretaries (Amendment) Act, 2022, w.e.f. 10-5-2022. Prior to its substitution, clause (fa) as inserted by the Cost and Works Accountants (Amendment) Act, 2006, w.e.f. 8-8-2006, read as under:
‘(fa) “notification” means a notification published in the Official Gazette;’
section 2 of the Limited Liability Partnership Act, 2008 (6 of 2009), as the case may be;
(fc) “partnership” means—
(A) a partnership as defined in section 4 of the Indian Partnership Act, 1932 (9 of 1932); or
(B) a limited liability partnership which has no company as its Partner;]
(g) “prescribed” means prescribed by regulations made under this Act;
(h) “President” means the President of the Council;
11[(i) “Register” means the Register of members of the Institute maintained under section 19 or Register of firms of the Institute maintained under section 20B, as the case may be;]
12[(ia) “specified” means specified by rules made by the Central Government under this Act;
13[(iaa) “sole proprietorship” means an individual who engages himself in the practice of cost accountancy or offers to perform services referred to in clauses (ii) to (iv) of sub-section (2);]
14[(iaaa) “Standing Committee” means a Standing Committee constituted under sub-section (1) of section 17;]
(ib) “Tribunal” means a Tribunal established under sub-section (1) of section 10B;]
(j) “Vice-President” means the Vice-President of the Council;
(k) “year” means the period commencing on the 1st day of April of any year and ending on the 31st day of March of the succeeding year.
(2) Save as otherwise provided in this Act, a member of the Institute shall be deemed “to be in practice” when, individually or in partnership with one or more members of the Institute in practice 13[or in partnership with members of such other recognised professions as may be prescribed], he, in consideration of remuneration received or to be received,—
(i) engages himself in the practice of 15[cost accountancy]; or
(ii) offers to perform or performs services involving the costing or pricing of goods or services or the preparation, verification or 16[certification or
11. Substituted by the Chartered Accountants, the Cost and Works Accountants and the Company Secretaries (Amendment) Act, 2022, w.e.f. 10-5-2022. Prior to its substitution, clause (i) read as under:
‘(i) “Register” means the Register of members maintained under this Act;’
12. Inserted by the Cost and Works Accountants (Amendment) Act, 2006, w.e.f. 8-8-2006.
13. Inserted by the Cost and Works Accountants (Amendment) Act, 2011, w.e.f. 1-2-2012.
14. Inserted by the Chartered Accountants, the Cost and Works Accountants and the Company Secretaries (Amendment) Act, 2022, w.e.f. 10-5-2022.
15. Substituted for “Cost and Works accountancy”, by the Cost and Works Accountants (Amendment) Act, 2011, w.e.f. 1-2-2012.
16. Substituted for “certification of cost accounting and related statement or holds himself out to the public as a cost accountant in practice”, ibid.
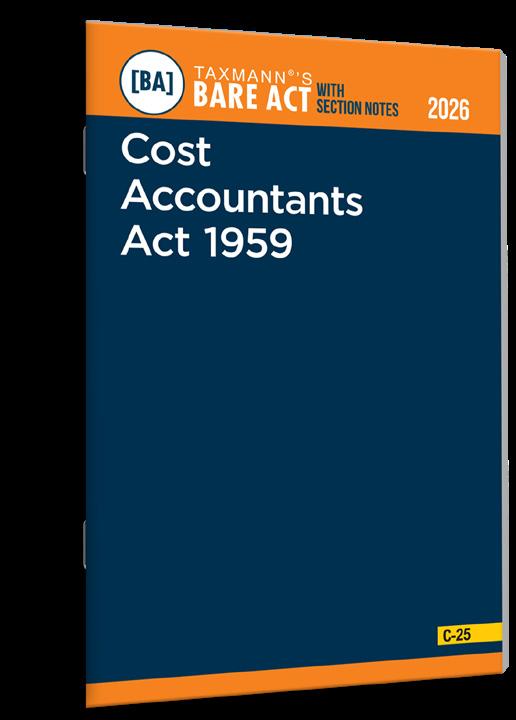
Cost Accountants Act 1959 – Bare Act with Section Notes
AUTHOR : Taxmann’s Editorial Board
PUBLISHER : Taxmann
DATE OF PUBLICATION : January 2026
EDITION : 2026 Edition
ISBN NO : 9789371267571
No. of Pages : 76
BINDING TYPE : Paperback
Rs. 125
DESCRIPTION
Cost Accountants Act 1959 [Bare Act with Section Notes] by Taxmann is a concise and authoritative statutory publication that presents the complete text of the Act governing the regulation, development, and professional discipline of cost accountants in India. The 2026 Edition reproduces the bare legislation in full, supplemented with brief, section-wise explanatory notes that clarify statutory intent and practical application, while preserving the integrity of the legislative text. The law is stated as updated to date, ensuring reliability for professional, academic, and institutional reference.
This book is intended for the following audience:
• Cost Accountants (CMA)
• Students of CMA/Cost & Management Accountancy
• Advocates & Legal Practitioners
• Regulators & Government Officials
• Academicians & Researchers
The Present Publication is the 2026 Edition, covering the amended and updated text of the Cost Accountants Act [Act No. 23 of 1959], with the following noteworthy features:
• [Complete Text of the Cost Accountants Act 1959] Provides the full and updated statutory text of the Act as amended up to date
• [Section-wise Notes] Concise explanatory notes placed immediately below the relevant sections for quick and accurate understanding
• [Pre-amendment Provisions] Incorporates pre-amendment text through statutory footnotes to trace legislative changes and historical applicability
• [Easy-to-Refer Format] Chapter-wise and section-wise arrangement with a clear, reader-friendly layout for efficient navigation
• [Comprehensive Coverage of Amendments] Includes all significant amendments affecting professional regulation, disciplinary mechanisms, institutional governance, and penalties
• [Subject Index] A detailed subject index for fast and precise location of provisions and concepts