Sample Read
© All rights reserved
Price : ` 1225
(For a set of Two Volumes)
Seventh Edition : May 2026
Published by :
Taxmann Publications (P.) Ltd.
Sales & Marketing :
59/32, New Rohtak Road, New Delhi-110 005 India
Phone : +91-11-45562222
Website : www.taxmann.com
E-mail : sales@taxmann.com
Regd. Office :
21/35, West Punjabi Bagh, New Delhi-110 026 India
Printed at :
Tan Prints (India) Pvt. Ltd.
44 Km. Mile Stone, National Highway, Rohtak Road Village Rohad, Distt. Jhajjar (Haryana) India
E-mail : sales@tanprints.com
Disclaimer
Every effort has been made to avoid errors or omissions in this publication. In spite of this, errors may creep in. Any mistake, error or discrepancy noted may be brought to our notice which shall be taken care of in the next edition. It is notified that neither the publisher nor the author or seller will be responsible for any damage or loss of action to any one, of any kind, in any manner, therefrom. It is suggested that to avoid any doubt the reader should cross-check all the facts, law and contents of the publication with original Government publication or notifications.
No part of this book may be reproduced or copied in any form or by any means [graphic, electronic or mechanical, including photocopying, recording, taping, or information retrieval systems] or reproduced on any disc, tape, perforated media or other information storage device, etc., without the written permission of the publishers. Breach of this condition is liable for legal action.
For binding mistake, misprints or for missing pages, etc., the publisher’s liability is limited to replacement within seven days of purchase by similar edition. All expenses in this connection are to be borne by the purchaser.
All disputes are subject to Delhi jurisdiction only.
Paper – May 2026 Exams (Suggested Answers – Descriptive Questions)
Preliminary
1.1 - Definitions
Q.1 X Industries Ltd. is a company in which 25% of shareholding is held by Central Government; 10% shareholding is held by Government of Maharashtra and 15% shareholding is held by Central Government and Government of Rajasthan jointl y. Examine whether, X Industries Ltd. is a government company.
Ans.: Government Company:
Conclusion
Q.2 The statutory auditors of a company were required to issue a certificate on the net worth of the company as per the requirement of the management as of 30 September 202 6 computed as per the provision of section 2(57) of the Companies Act, 2013.
The company had fair valued its property, plant and equipment in the current year which was mistakenly taken into retained earnings of the company in its books of account. Please advise whether this fair valuation would be covered in the net worth of the company as per the legal requirements.
Ans.: Computation of Net Worth:
Conclusion:
Q.3 A Pvt. Ltd. is wholly owned subsidiary of AB Ltd., a public company incorporated under the Companies Act, 2013. A Pvt. Ltd. wanted to avail exemptions as provided to private companies. Examine whether A Pvt. Ltd. can do so.
Ans.: Status of wholly owned private subsidiary company:
Conclusion
Q.4 Examine the below mentioned situation and answer whether the entities are related parties for the purpose of Sec. 188:
(i) XYZ Pvt. Ltd. has two subsidiary companies, Y Pvt. Ltd. and Z Pvt. Ltd.
(ii) XYZ Ltd. a public company, has two subsidiary companies, Y Pvt. Ltd and Z Pvt. Ltd.
Ans.: Related Parties: (viii) (viii)
Conclusion
Q.5 The paid-up share capital of Saras Private Limited is ₹ 1 crore, consisting of 8 lacs Equity Shares of ₹ 10 each, fully paid -up and 2 lacs Cumulative Preference Shares of ₹ 10 each, fully paid-up. Jeevan (JVN) Private Limited and Sudhir Private Limited are holding 3 lacs Equity Shares and 50,000 Equity Shares respectively in Saras Private Limited. Jeevan Private Limited and Sudhir Private Limited are the subsidiaries of Piyush Private Limited.
Q.6
With reference to the provisions of the Companies Act, 2013 examine whether Saras Private Limited is a subsidiary of Piyush Private Limited? Would your answer be different if Piyush Private Limited has 8 out of 9 Directors on the Board of Saras Private Limited? [RTP-May 18, May 19]
Ans.: Status of Subsidiary company:
MNP Private Ltd. is a company registered under the Companies Act, 2013 with a, Paid Up Share Capital of ₹ 8 crores and turnover of ₹ 120 crores. Explain the meaning of the “Small Company” and examine the following in accordance with the provisions of the Companies Act, 2013:
(i) Whether the MNP Private Ltd. can avail the status of small company?
(ii) What will be your answer if the turnover of the company is ₹ 90 crores? [May 18 (6 Marks), MTP-Oct. 20]
Ans.: Determination of Status of Small Company:
Conclusion
Q.7 What does the term Financial Statements include in relation to a company under the Companies Act, 2013? Which companies need not prepare a cash flow statement? [Nov. 18 (4 Marks)]
Ans.: Financial Statements:
Companies Not requiring to prepare cash flow statement
Q.8 SKP Limited (Registered in India), a wholly owned subsidiary company of Herry Limited decided to follow different financial year for consolidation of its accounts outside India. State the procedure to be followed in this regard assuming that Herry Limited is a foreign company. [Nov. 19 (2 Marks)]
Ans.: Financial year in case of a foreign company
Q.9 The information extracted from the audited Financial Statement of Smart Solutions Private Limited as at 31st March, 202 5 is as below:
(1) Paid-up equity share capital ₹ 50,00,000 divided into 5,00,000 equity shares (carrying voting rights) of ₹ 10 each. There is no change in the paid-up share capital thereafter.
(2) The turnover is ₹ 2,00,00,000.
It is further understood that Nice Software Limited, which is a public limited company, is holding 2,00,000 equity shares, fully paid -up, of Smart Solutions Private Limited. Smart Solutions Private Limited has filed its Financial Statement for the said year with the Registrar of Companies (ROC) excluding the Cash Flow Statement within the prescribed time line during the financial year 202526.The ROC has issued a notice to Smart Solutions Private Limited as it has failed to file the cash flow statement along with the Balance Sheet and Profit and Loss Account.
You are to advise on the following points explaining the provisions of the Companies Act, 2013:
(i) Whether Smart Solutions Private Limited shall be deemed to be a small company whose significant equity shares are held by a public company?
(ii) Whether Smart Solutions Private Limited has defaulted in filing its financial statement?
[July 21 (6 Marks); MTP-Oct. 23, March 24 , April 26]
Ans.: Determination of Status of Small Company:
Conclusion
Default in filing the financial statements
Conclusion
Q.10 Johnson Limited goes for public issue of its shares. The issue was oversubscribed. A default was committed with respect to allotment of shares by the officers of the company. There were no Managing Director, Whole time Director or any other officer/person designated by the Board with the responsibility of complying with the provisions of the Act. State, who are the persons considered as officers in default under the Companies Act, 2013. Examine who will be considered in default in the instant case ? [July 21 (5 Marks)] Ans.: Officer in Default:
Conclusion
Q.11 New Private Ltd. is a company registered under the Companies Ac t, 2013 with a paid -up share capital of ₹ 70 lakh and turnover of ₹ 142 crores. Explain the meaning of the “Small Company” and examine the following in accordance with the provisions of the Companies Act, 2013:
(i) Whether the New Private Ltd. can avail the status of small company?
(ii) What will be your answer if the turnover of the company is ₹ 90 crore and the capital is same as ₹ 70 lakh? [MTP-Oct. 21]
Ans.: Determination of Status of Small Company:
Conclusion
Q.12 Kapila Limited issued equity shares of ₹ 1,00,000 (10,000 shares of ₹ 10 each) on 01.04.202 6 which have been fully subscribed, whereby Kusha Limited holds 4000 shares and Prem Limited holds 2000 shares in Kapila Limited. Kapila Limited is also holding 20% equity shares of Red Limited before the date of issue of equity shares stated above. Red Limited controls the composition of Board of Directors of Kusha Limited and Prem Limited from 01.08.202 6.
Examine with relevant provisions of the Companies Act, 2013:
(i) Whether Kapila Limited is a subsidiary of Red Limited?
(ii) Whether Kapila Limited can hold shares of Red Limited? [MTP- March 22]
Ans.: Status of Subsidiary company:
Q.13
Conclusion
AJD Pvt. Ltd. is having paid up share capital of ₹ 45 0 Lakhs and annual turnover of ₹ 1850 Lacs. It is a wholly owned subsidiary of K Ltd., a listed company. Can AJD Pvt. Ltd. be called a small company as per the provisions of the Companies Act, 2013. [MTP-April 22]
Ans.: Determination of Status of Small Company:
Conclusion
Q.14 Following are some of the securities, issued by different companies related with each other, as follows:
Company Securities Issued
Kleshrahit Ltd.
Indriyadaman Ltd.
Sajagta (P) Ltd.
Listed non-convertible redeemable preference shares issued on private placement basis in terms of relevant SEBI Regulations.
Listed non-convertible debt securities issued on private placement basis in terms of relevant SEBI Regulations.
Listed non-convertible debt securities issued on private placement basis in terms of relevant SEBI Regulations.
Remarks
Has the power to appoint 2/3rd directors in Indriyadaman Ltd.
Holding 60% voting power in Sajagta (P) Ltd.
The company holds 52% equity shares in Pratibodh Ltd. as an investment on behalf of another company in a capacity of a trustee.
Equity shares issued by the Kleshrahit Ltd. and Indriyadaman Ltd. are not listed in any of the recognized stock exchanges.
In the context of aforesaid facts, answer the following question(s):
(a) Whether the aforesaid companies can be considered as listed company(ies)?
(b) Explain the relationship between the aforesaid companies? [RTP-May 22] Ans.: (a) Listed Company: Provided
Preliminary Chapter 1
Conclusion
Kleshrahit Ltd. (a)
Indriyadaman Ltd.
Sajagta (P) Ltd.:
(b)Relationship between the aforesaid companies:
Provided (i) (ii)
Conclusion
Relationship between Kleshrahit Ltd. & Indriyadaman Ltd.
CORPORATE & OTHER LAWS (LAW) | CRACKER
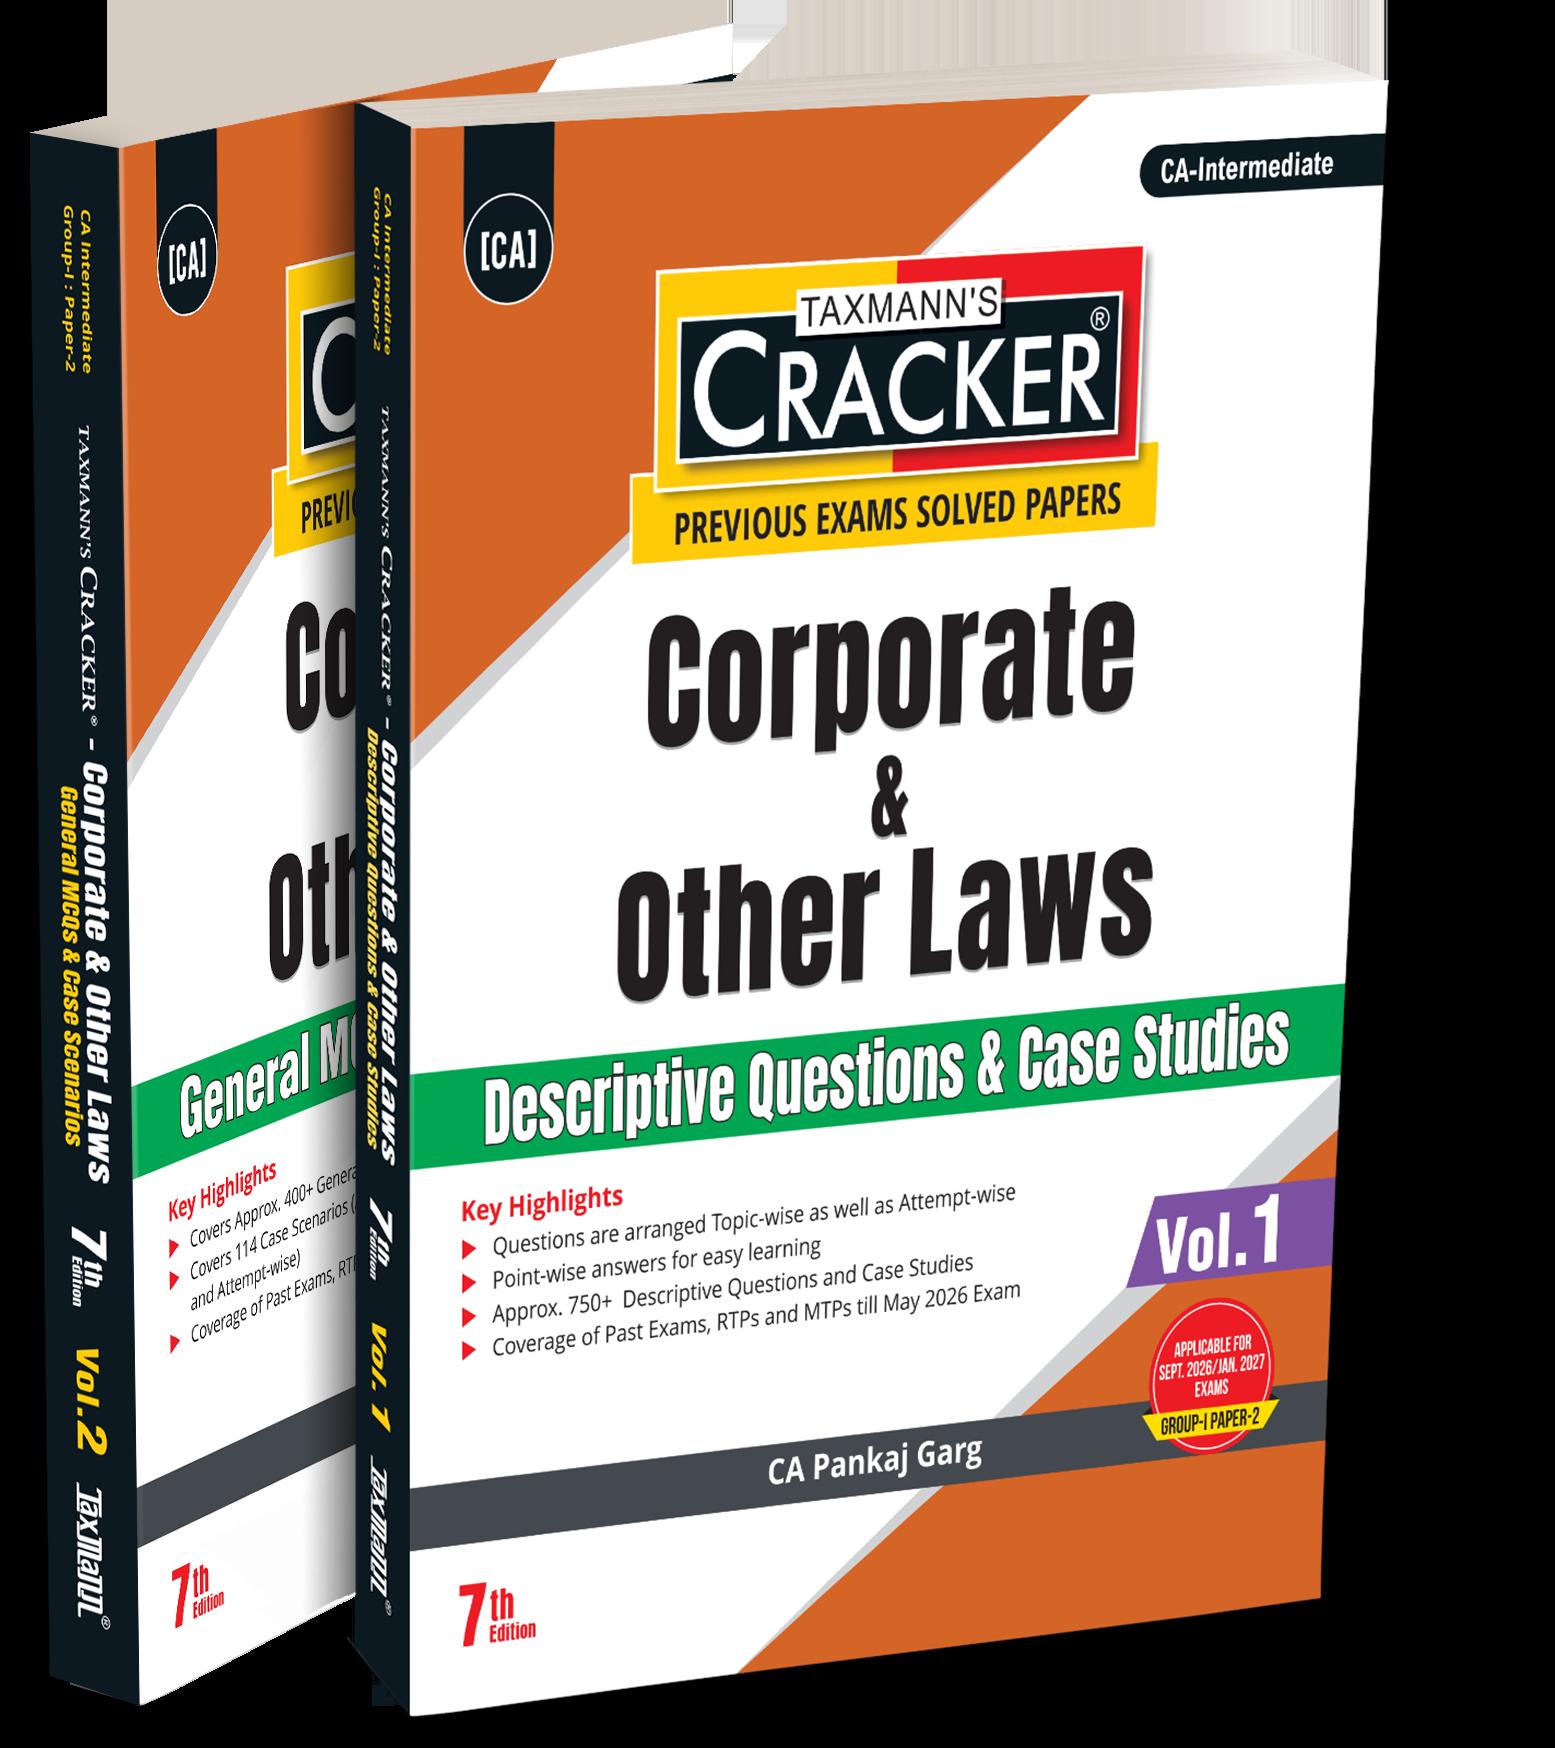
AUTHOR : Pankaj Garg
PUBLISHER : Taxmann
DATE OF PUBLICATION : June 2026
EDITION : 7th Edition
ISBN NO : 9789375615163
NO. OF PAGES : 808
BINDING TYPE : Paperback
Rs. 1,225
DESCRIPTION
Corporate & Other Laws – CRACKER is the dedicated question-and-answer companion to CA-Intermediate | Group I – Paper 2, built for revision and rehearsal rather than first-time learning. It converts the full syllabus into solved, exam-ready questions arranged section-by-section under each chapter, so practice tracks the exact provision being tested. Its two-volume design mirrors the two halves of the paper—the descriptive component and the objective component (independent MCQs plus integrated case studies)—allowing candidates to rehearse both answer writing and rapid application against the same syllabus spine.
The Present Publication is the 7th Edition, authored by CA. Pankaj Garg, with the following noteworthy features:
• [Section-Anchored Organisation] Questions sit under numbered sub-topics tied to the specific provisions they test
• [Point-Wise Descriptive Answers] Subjective solutions broken into scannable points for fast recall and marks-friendly reproduction
• [Explained MCQ Keys] Objective answers carry supporting reasoning, turning a wrong attempt into a learning point
• [Dual Indexing] Questions arranged both topic-wise and attempt-wise to trace how each provision has been examined
• [Current Question Base] Drawn from past exams, RTPs and MTPs up to and including the May 2026 cycle
• [Weightage Visibility] Separate chapter-wise marks-distribution matrices for the descriptive and MCQ formats
• [Latest Solved Paper] The May 2026 paper reproduced with suggested answers in both volumes