Under the Income-tax Act, certain categories of income are taxed at the Maximum Marginal Rate (MMR) rather than the normal slab rates or other rates otherwise applicable to the assessee. The concept of MMR was introduced as an anti-avoidance measure to discourage high-income taxpayers from reducing their tax burden by distributing income among multiple entities, such as private trusts, Associations of Persons (AOPs), or Bodies of Individuals (BOIs), that might otherwise be eligible for lower tax rates.
By taxing such income at the MMR, the Act seeks to ensure tax neutrality and discourage tax avoidance, particularly in cases where the shares of beneficiaries or members are indeterminate or where the legislature considers taxation at the highest rate appropriate.
The provisions relating to MMR apply to specified entities and circumstances, including certain trusts, AOPs/BOIs, business trusts, Alternative Investment Funds (AIFs), and registered Non-Profit Organisations (NPOs). The table below summarises the principal provisions under which income is chargeable to tax at the MMR.
Section Description
223 of the ITA 2025 (115UA of the ITA 1961)
224 of the ITA 2025 (115UB of the ITA 1961)
307 of the ITA 2025 (164 of the ITA 1961)
308 of the ITA 2025 (164A of the ITA 1961)
309 of the ITA 2025 (167B of the ITA 1961)
Income of a business trust, other than capital gains covered under Sections 196, 197 and 198 of the ITA 2025 (corresponding to Sections 111A, 112 and 112A of the ITA 1961), is taxable at MMR.
Business income of a Category-I or Category-II Alternative Investment Fund (AIF) that is not registered as a company or firm is taxable at the MMR.
Income of a private discretionary trust is taxable at the MMR where the beneficiaries’ shares are indeterminate.
Income of an oral trust is taxed at the MMR.
Income of an AOP or BOI is taxable at the MMR where the members’ shares are indeterminate or unknown. Income of an AOP or BOI is also taxable at the MMR where the members’ shares are determinate, but the total income of any member (excluding the member’s share from the AOP or BOI) exceeds the basic exemption limit.
352 of the ITA 2025 (115TD of the ITA 1961)
The accreted income of an NPO registered under Chapter XVII-B of the ITA 2025 (corresponding to Section 12AA or Section 12AB of the ITA 1961) is taxable at the MMR if the NPO converts into a non-charitable organisation, merges with a non-charitable organisation, or transfers its assets on dissolution to a non-charitable organisation.
Note – Under the ITA 1961, Section 161 provides that profits and gains from the business of a private trust are taxable at the MMR, except where the trust is declared by will exclusively for the benefit of a relative dependent on the settlor for support and maintenance and is the only such trust declared by him. This provision is no longer available under the ITA 2025.
Section 2(70) of the ITA 2025 (corresponding to Section 2(29C) of the ITA 1961) defines the term MMR as the income tax rate (including surcharge on income tax) applicable to the highest slab of income for an individual, AOP, or BOI, as specified in the Finance Act for the relevant year.
The new tax regime was introduced under Section 115BAC of the Income-tax Act, 1961, and continues under Section 202 of the ITA 2025 with substantially similar provisions and conditions. From Assessment Year 2024-25 onwards, the new tax regime became the default tax regime for individuals, HUFs, AOPs, BOIs and Artificial Juridical Persons (AJPs). This has repeatedly raised a question about the MMR during return filing, namely, whether it should be 39% or 42.744%, which is calculated as follows:
Note – The surcharge rate differs significantly between the old and new tax regimes. Under the old regime, the surcharge is levied at four rates, with the maximum rate of 37% applying when total income exceeds Rs. 5 crore. In contrast, under the new regime, the surcharge has been streamlined and capped at 25%.
Note – The surcharge rate is capped at 15% for an AOP comprising only companies as its members, resulting in an MMR of 35.88% (30% + 15% surcharge + 4% cess). Consequently, such an AOP may be subject to an MMR lower than the generally applicable rate of 39%.
From the foregoing discussion, it follows that the applicable MMR depends on the tax regime applicable to the concerned entity. Since the new tax regime is the default regime, the MMR would ordinarily be 39%. A higher rate would apply only where specifically mandated by law.
For example, Section 311 of the ITA 2025 (corresponding to Section 167B of the ITA 1961) creates an exception to the general rule applicable to AOPs and BOIs. The provision
provides that where any member is chargeable to tax at a rate higher than the MMR applicable to the AOP or BOI, the relevant income of the AOP or BOI shall be taxed at that higher rate.
Accordingly, if a member is chargeable to tax at 42.744% under the old tax regime, the relevant income of the AOP or BOI will also be chargeable to tax at 42.744% and not at 39%.
The Maximum Marginal Rate is 39% under the default tax regime and rises to 42.744% only when the old tax regime applies. In the case of an AOP or BOI, if any member is chargeable to tax at 42.744% under the old tax regime, the relevant income of the AOP or BOI may also be taxed at that higher rate, even if the AOP or BOI itself is otherwise taxable under the default regime. Therefore, before determining whether the effective rate is 39% or 42.744%, taxpayers should first identify the applicable tax regime and the relevant surcharge threshold.
Founded 1972
Evolution From a small family business to a leading technology-oriented Publishing/Product company
Expansion
Launch of Taxmann Advisory for personalized consulting solutions
Aim
Achieve perfection, skill, and accuracy in all endeavour
Growth
Evolution into a company with strong independent divisions: Research & Editorial, Production, Sales & Marketing, and Technology
Future
Continuously providing practical solutions through Taxmann Advisory
Editorial and Research Division
Over 200 motivated legal professionals (Lawyers, Chartered Accountants, Company Secretaries)
Monitoring and processing developments in judicial, administrative, and legislative fields with unparalleled skill and accuracy
Helping businesses navigate complex tax and regulatory requirements with ease
Over 60 years of domain knowledge and trust
Technology-driven solutions for modern challenges
Ensuring perfection, skill, and accuracy in every solution provided
Income Tax
Corporate Tax Advisory
Trusts & NGO Consultancy
TDS Advisory
Global Mobility Services
Personal Taxation
Training
Due Diligence
Due Dilligence
Advisory Services
Assistance in compounding of offences
Transactions Services
Investment outside India
Goods
Transaction Advisory
Business Restructuring
Classification
Due Diligence
Training
Advisory
Trade Facilitation Measures
Corporate
Corporate Structuring
VAT Advisory
Residential Status
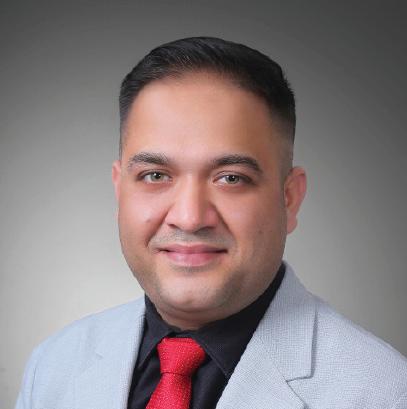
Naveen Wadhwa Research and Advisory [Corporate and Personal Tax]
Chartered Accountant (All India 24th Rank)
14+ years of experience in Income tax and International Tax
Expertise across real estate, technology, publication, education, hospitality, and manufacturing sectors
Contributor to renowned media outlets on tax issues
Vinod K. Singhania
Expert on Panel | Research and Advisory (Direct Tax)
Over 35 years of experience in tax laws
PhD in Corporate Economics and Legislation
Author and resource person in 800+ seminars
V.S. Datey
Expert on Panel | Research and Advisory [Indirect Tax]
Holds 30+ years of experience
Engaged in consulting and training professionals on Indirect Taxation
A regular speaker at various industry forums, associations and industry workshops
Author of various books on Indirect Taxation used by professionals and Department officials
S.S. Gupta
Expert on Panel | Research and Advisory [Indirect Tax]
Chartered Accountant and Cost & Works Accountant
34+ Years of Experience in Indirect Taxation
Bestowed with numerous prestigious scholarships and prizes
Author of the book GST – How to Meet Your Obligations', which is widely referred to by Trade and Industry
Manoj Fogla
Expert on Panel | Research and Advisory [Charitable Trusts and NGOs]
Over three decades of practising experience on tax, legal and regulatory aspects of NPOs and Charitable Institutions
Law practitioner, a fellow member of the Institute of Chartered Accountants of India and also holds a Master's degree in Philosophy
PhD from Utkal University, Doctoral Research on Social Accountability Standards for NPOs
Author of several best-selling books for professionals, including the recent one titled 'Trust and NGO's Ready Reckoner' by Taxmann
Drafted publications for The Institute of Chartered Accountants of India, New Delhi, such as FAQs on GST for NPOs & FAQs on FCRA for NPOs.
Has been a faculty and resource person at various national and international forums
the UAE
Chartered Accountant (All India 36th Rank)
Has previously worked with the KPMG
Taxmann Delhi
59/32, New Rohtak Road
New Delhi – 110005 | India
Phone | 011 45562222
Email | sales@taxmann.com
Taxmann Mumbai
35, Bodke Building, Ground Floor, M.G. Road, Mulund (West), Opp. Mulund Railway Station Mumbai – 400080 | Maharashtra | India
Phone | +91 93222 47686
Email | sales.mumbai@taxmann.com
Taxmann Pune
Office No. 14, First Floor, Prestige Point, 283 Shukrwar Peth, Bajirao Road, Opp. Chinchechi Talim, Pune – 411002 | Maharashtra | India
Phone | +91 98224 11811
Email | sales.pune@taxmann.com
Taxmann Ahmedabad
7, Abhinav Arcade, Ground Floor, Pritam Nagar Paldi
Ahmedabad – 380007 | Gujarat | India
Phone: +91 99099 84900
Email: sales.ahmedabad@taxmann.com
Taxmann Hyderabad
4-1-369 Indralok Commercial Complex Shop No. 15/1 – Ground Floor, Reddy Hostel Lane Abids Hyderabad – 500001 | Telangana | India
Phone | +91 93910 41461
Email | sales.hyderabad@taxmann.com
Taxmann Chennai No. 26, 2, Rajan St, Rama Kamath Puram, T. Nagar
Chennai – 600017 | Tamil Nadu | India
Phone | +91 89390 09948
Email | sales.chennai@taxmann.com
www.taxmann.com
Taxmann Bengaluru
12/1, Nirmal Nivas, Ground Floor, 4th Cross, Gandhi Nagar
Bengaluru – 560009 | Karnataka | India
Phone | +91 99869 50066
Email | sales.bengaluru@taxmann.com
Taxmann Kolkata Nigam Centre, 155-Lenin Sarani, Wellington, 2nd Floor, Room No. 213
Kolkata – 700013 | West Bengal | India
Phone | +91 98300 71313
Email | sales.kolkata@taxmann.com
Taxmann Lucknow
House No. LIG – 4/40, Sector – H, Jankipuram Lucknow – 226021 | Uttar Pradesh | India
Phone | +91 97924 23987
Email | sales.lucknow@taxmann.com
Taxmann Bhubaneswar
Plot No. 591, Nayapalli, Near Damayanti Apartments
Bhubaneswar – 751012 | Odisha | India
Phone | +91 99370 71353
Email | sales.bhubaneswar@taxmann.com
Taxmann Guwahati
House No. 2, Samnaay Path, Sawauchi Dakshin Gaon Road
Guwahati – 781040 | Assam | India
Phone | +91 70866 24504
Email | sales.guwahati@taxmann.com