Sample Read
©
NATIONAL INSTITUTE OF SECURITIES MARKETS, MUMBAI, 2026
PRINTING AND PUBLISHING RIGHTS WITH THE PUBLISHER
All rights reserved. No part of this publication may be reproduced, stored in or introduced into a retrieval system, or transmitted in any form or by any means (electronic, mechanical, photocopying, recording or otherwise), without the prior written permission of National Institute of Securities Markets.
Any person who does any unauthorised act in relation to this publication may be liable to criminal prosecution and civil claims for damages.
While every care has been taken in compiling the information contained in this publication, National Institute of Securities Markets accepts no responsibility for any errors or omissions.
Workbook Version : March 2026
Price : ` 740
Published by :
Taxmann Publications (P.) Ltd.
Sales & Marketing :
59/32, New Rohtak Road, New Delhi-110 005 India
Phone : +91-11-45562222
Website : www.taxmann.com, E-mail : sales@taxmann.com
Mumbai
35, Bodke Building, Ground Floor, M.G. Road, Opp. Railway Station, Mulund (West), Mumbai-400080
Mobile : 09322247686, 9619668669, 7045453844/45/48/51
E-mail : sales.mumbai@taxmann.com; nileshbhanushali@taxmann.com
Regd. Office :
21/35, West Punjabi Bagh, New Delhi-110 026 India
Printed at :
Tan Prints (India) Pvt. Ltd.
44 Km. Mile Stone, National Highway, Rohtak Road, Village Rohad, Distt. Jhajjar (Haryana) India
E-mail : sales@tanprints.com
DISCLAIMER
The contents of this publication do not necessarily constitute or imply its endorsement, recommendation, or favoring by the National Institute of Securities Markets (NISM) or the Securities and Exchange Board of India (SEBI). This publication is meant for general reading and educational purpose only.
The statements/explanations/concepts are of general nature and may not have taken into account the particular objective/move/aim/need/circumstances of individual user/reader/organization/institute. Thus NISM and SEBI do not assume any responsibility for any wrong move or action taken based on the information available in this publication.
Therefore before acting on or following the steps suggested on any theme or before following any recommendation given in this publication user/reader should consider/seek professional advice.
The publication contains information, statements, opinions, statistics and materials that have been obtained from sources believed to be reliable and the publishers of this title have made best efforts to avoid any errors. However, publishers of this material offer no guarantees and warranties of any kind to the readers/users of the information contained in this publication.
Since the work and research is still going on in all these knowledge streams, NISM and SEBI do not warrant the totality and absolute accuracy, adequacy or completeness of this information and material and expressly disclaim any liability for errors or omissions in this information and material herein. NISM and SEBI do not accept any legal liability what-so-ever based on any information contained herein.
While the NISM Certification examination will be largely based on material in this workbook, NISM does not guarantee that all questions in the examination will be from material covered herein.
CHAPTER 2
TIME VALUE OF MONEY
CHAPTER 3
CHAPTER 4
DEBT MANAGEMENT AND LOANS
INDIAN FINANCIAL MARKETS
CHAPTER 5
INTRODUCTION TO INVESTMENT
CHAPTER 8
INVESTING IN
CHAPTER 9
INVESTING IN FIXED INCOME SECURITIES
9.7
CHAPTER 10
UNDERSTANDING DERIVATIVES
MODULE 4: INVESTMENT THROUGH MANAGED PORTFOLIO
CHAPTER 11
MUTUAL FUNDS
CHAPTER 12
PORTFOLIO MANAGER
CHAPTER 13
MODULE 5: PORTFOLIO CONSTRUCTION, PERFORMANCE MONITORING AND EVALUATION
CHAPTER 14
CHAPTER 15
CHAPTER
CHAPTER 17 OPERATIONAL ASPECTS OF INVESTMENT MANAGEMENT
CHAPTER 18
CHAPTER 19
CHAPTER 20
GRIEVANCE REDRESS MECHANISM
CHAPTER 8
INVESTING IN STOCKS
LEARNING OBJECTIVES:
After studying this chapter, you should know about:
Ø Understand Equity as an investment
Ø Diversification of risk through equity instruments - Cross sectional versus time series
Ø risks of equity investments
Ø Overview of Equity Market
Ø Know the equity research and stock selection
Ø Understand combining relative valuation and discounted cash flow models
Ø Know about Technical Analysis
Ø Qualitative evaluation of stocks
8.1 Equity as an investment
There are two broad types of securities that are issued by seekers of capital from investors: Equity and Debt. Equity securities are issued by companies providing ownership to the investor in their company, and Debt securities are issued by companies providing the rights of a lender to the investor. The features of both these securities differ due to the inherent difference in the claim of the investors on the company.
Equity investors, also known as shareholders, have residual claim7 in the business. Because they are the owners of the company and not lenders, the company which issues equity securities, is not contractually obligated to repay the amount it receives from the shareholders. It is also not contractually obligated to make periodic payments to shareholders for the use of their funds, like interest payments in the case of lenders. Equity investors get voting rights. When equity investors own a sizable amount of shares in a company, they get an opportunity to participate in the management of the business.
Investors who purchase equity shares look for capital appreciation and dividend income. There is no assurance of either by the company to the equity investor. While dividend payment depends on the profitability of the company, capital appreciation depends on the conditions of the stock market. Because all residual benefits of deploying capital in a business go to the equity investor, It is usually expected that the return to equity investors should be higher than that of the debt investors (lenders).
Choosing between equity and debt is a trade-off for investors. Investors desiring lower risk choose debt, at the cost of lower but stable returns. However, if they seek a higher returns they choose equity investment, but they may not be able to earn it without taking on the additional risk of the equity investment. Most investors tend to allocate their capital between these two choices, depending on their expected return, their investing time period, their risk appetite and their needs.
8.2 Diversification of risk through equity instrumentsCross sectional versus time series
Equity is inherently riskier compared to bonds and many other asset classes. However, there are ways to mitigate the risks in stocks. The most meaningful way to risk reduction is through diversification – both on cross sectional (i.e. across business sectors and industries) as well as on time series basis (i.e. across various time periods).
Empirical research has demonstrated that a significant portion of risk can be reduced through diversification. Conceptually, it is achieved due to the relatively less correlated
7 Claim on the company’s net assets, i.e. the value of assets after all liabilities have been paid.
behaviour of various business sectors which underlie each equity investment. This is what the old adage ‘Don’t put all your eggs in one basket’ means.
Cross sectional risk diversification is reducing risk by holding equities in many different kinds of businesses at a point in time and also across various geographies of the world.
Reaping the benefits of time diversification requires investing in equities for a long period of time. The belief is that bad times will get cancelled out by good times. This is why “time in the market” is suggested for equity investment as against “timing the market”.
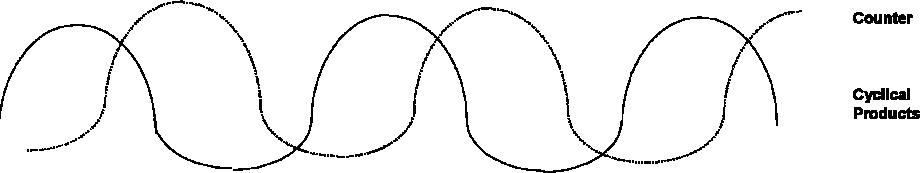
Underlying the word ‘diversification’ is the concept of business cycles and countercyclical businesses, and the phenomenon of lag and lead between the behaviour of investments returns and countries’ economic performance.
In the Figure 8.1, a business cycle is shown as a dark line. Some businesses may be at peak when the business cycle is in its trough, as shown by the broken line. These products or businesses are called ‘counter-cyclical’ or defensive businesses. Businesses that do better in a recession are called ‘recession-proof’ businesses. Some products, sectors or countries come out of a recession faster than others (these are called as leading sectors); other products, sectors or countries may go into recession later than others(these are called lagging sectors).
Figure 8.1 Counter-cyclical products
8.3 Risks of equity investments
Equities are often regarded as riskier than other asset classes. The main types of risks discussed in the context of equity investments are discussed below:
8.3-1 Market risk
Market risks arise due to the fluctuations in the prices of equity shares due to various market related dynamics. These factors affect all the listed, market-traded assets, irrespective of their business sector. The degree of impact may be different. Beta is a proxy measure for market risk. Market risks cannot be diversified away, though it can be hedged.
8.3-2 Sector specific risk
Risks due to sector specific factors are not part of market risks. These risks can be diversified away by investing in different business sectors. Sector specific risks arise due to factors that affect the performance of businesses in a particular sector/industry. Factors affecting certain sectors might not impact certain other sectors. Such risks are also called “idiosyncratic risks”. Say for instance there are restrictions on the movement of international tourists, the airline industry and hospitality industry are going to be affected. But industries and business sectors dependent on domestic customers are not affected by such restrictions.
8.3-3 Company specific risk
Risks arising due to company specific factors are also non-market risks. These risks can also be diversified away by investing in different companies. Company specific risk arises due to factors that affect only the performance of a single company and other firms might not be affected by them. Though, overall, the airline industry goes through turbulent times, time and again, certain airlines withstood the rough weather and other exited helplessly. Such corporate debacles are due to company specific factors. Same is now being seen in telecom sector.
8.3-4 Transactional risk
Risks due to the other party not fulfilling the terms of the contract while buying or selling equities is often referred to as transactional risk. This can happen when the other person is either not able to pay the money or deliver the shares. This type of risk can be mitigated by transacting through the stock exchange where there are robust risk mitigation procedures present to take care of such situations.
8.3-5 Liquidity risk
Liquidity risk is the risk of not being able to find a buyer or seller for the equity holdings. Liquidity risk is measured by impact cost. The impact cost is the percentage price movement caused by a particular order size (let’s say an order size of Rs.1 Lakh) from the average of the best bid and offer price in the order book snapshot. The impact cost is calculated for both, the buy and the sell side. Less liquid stocks are more thinly traded, and a single large trade can move their prices considerably. Such stocks have high impact costs. A lower market impact implies the stock is more liquid.
8.3-6 Currency Risk
Prima Facie it appears that currency risk is not directly related to prices of equity. However, once the financial markets are open to the international investors currency risk sets in. Currency risk arises due to uncontrollable, unpredictable and volatile exchange rates of various pairs of currencies. When a significant proportion of players in a financial market belong to the international institutional investors groups, then that financial market is bound to be related to exchange rate movements. Many times we here that stock market reacts to FPIs’ buy and sell pressure, and FPIs move in and move out of a country with changes in their home country interest rates, or due sudden unfavourable exchange rate movements, like deep depreciations in their host countries or due to any other socio-politico-economic, industry or market shocks. Apart from the above most prominent risks, all other macro-economic factors like inflation, fuel prices, interest rates, economic growth, economic slowdown, do influence stock markets.
8.4 Overview of Equity Market
Equity securities represent ownership claims on a company’s net assets. A thorough understanding of the equity market is required to make optimal allocation to this asset class. The equity market provides various choices to investors in terms of riskreturn-liquidity profile. There are opportunities in listed as well as unlisted equity space available. Investments in listed companies are relatively more liquid than
investment in unlisted companies. Listed companies have to abide by the listing norms, making this investment space more regulated with better disclosures.
8.5 Equity research and stock selection
As there are thousands of opportunities available to investors in the equity market, equity research and stock selection process plays a very important role in identifying stocks which suit the risk-return-liquidity requirements of the investors. Equity research involves thorough analysis and research of the companies and its environment. Equity research primarily means analysing the company’s financials and non-financial information, studying the dynamics of the sector the company belongs to, competitors of the company, economic conditions etc. The idea behind equity research is to come up with intrinsic value of the stock to compare with market price and then decide whether to buy or hold or sell the stock. There are many frameworks/methodologies available for stock selection. Analysts use fundamental analysis - top-down approach or bottom-up approach - quantitative screens, technical indicators etc., to select stocks.
8.5-1 Buy side research versus Sell Side Research
Though both Sell-side and Buy-side researchers and analysts take up similar works, but they differ in terms of for whom they work, their objectives, and for what are they paid.
Sell-side analysts work for firms that provide investment banking, broking, advisory services for clients. They typically publish research reports on the securities of companies or industries with specific recommendation to buy, hold, or sell the subject security. These recommendations include the analyst’s expectations of the earnings of the company and future price performance of the security (“price target”). In essence the sell-side analysts are paid for providing useful information to be acted upon. In this regard the expectations from the sell-side research is broad guidance on multiple sectors, rather than accurate price predictions.
Buy-side analysts work for fund managers like those of mutual funds, hedge funds, pension funds, or portfolio managers that purchase and sell securities for their own investment accounts or on behalf of their clients. These analysts generate investment recommendations for their internal consumption viz. use by the fund managers
INVESTING IN STOCKS
within organization. Research reports of these analysts are generally circulated among the top management/investment managers of the employer firms as these reports contain recommendations about which securities to buy, hold or sell. Therefore, the buy-side researchers need to be more accurate and they are paid for their investment recommendations.
8.5-2 Fundamental Analysis
Fundamental analysis is the process of determining intrinsic value for the stock based on the fundamentals that drive its intrinsic value. These values depend on underlying economic factors such as future earnings or cash flows, interest rates, and risk variables. By examining these factors, intrinsic value of the stock is determined. Investors should buy the stock if its market price is below intrinsic value and do not buy, or sell, if the market price is above the intrinsic value, after taking into consideration the transaction cost. Investors who are engaged in fundamental analysis believe that intrinsic value may differ from the market price but eventually market price will merge with the intrinsic value. An investor or portfolio manager who can do a superior job of estimating intrinsic value will generate above-average returns by acquiring undervalued securities. Fundamental analysis involves Economy Analysis, industry analysis, company analysis.
Top-Down approach versus Bottom up Approach
Analysts follow two broad approaches to fundamental analysis – top down and bottom up. The factors to consider are economic (E), industry (I) and company (C) factors. Beginning at company-specific factors and moving up to the macro factors that impact the performance of the company is called the bottom-up approach. Scanning the macro-economic scenario and then identifying industries to choose from and zeroing in on companies, is the top-down approach.
EIC framework is the commonly used approach to understanding fundamental factors impacting the earnings of a company, scanning both micro and macro data and information.
8.5-3 Stock Analysis Process
The value of an investment is determined by its expected cash flows and the investor’s/ analyst’s required rate of return (i.e., its discount rate). The expected cashflows as
INVESTING IN STOCKS
well as required rate of return are influenced by the economic environment. The analyst needs to have a good understanding of important economic variables and economic series. The macroeconomic analysis provides a framework for developing insights into sector and company analysis.
Economy Analysis
Macro-economic environment influences all industries and companies within the industry. Monetary and fiscal policy influences the business environment of the industries and companies. Fiscal policy initiatives like tax reduction encourages spending while removal of subsidies or additional tax on income discourage spending. Similarly, monetary policy may reduce the money supply in the economy affecting the expansionary plans and working capital requirements of all the businesses. Hence a thorough macro-economic forecast is required to value a sector/firm/equity.
Any macro-economic forecast should include estimates of all of the important economic numbers, including:
Ø Gross Domestic Product
Ø Inflation rates
Ø Interest rates
Ø Unemployment
The most important thing an analyst does is to watch for releases of various economic statistics by the government, Reserve Bank of India and private sources. Especially, they keep a keen eye on the Index of economic indicators like the WPI, CPI, monthly inflation indices, Index of Industrial Production, GDP growth rate etc. Analysts assess the economic and security market outlooks before proceeding to consider the best sector or company. Interest rate volatility affects different industries differently. Financial institution or bank stocks are typically placed among the most interest-sensitive of all sectors. Sectors like pharmaceuticals are less affected by interest rate change.
The economy and the stock market have a strong and consistent relationship. The stock market is known as a leading economic indicator. A leading economic indicator is a measure of economic recovery that shows improvement before the actual economy does because stock price decisions reflect expectations for future
INVESTING IN STOCKS
economic activity, not past or current activity. Sometimes, though, the market can run ahead or lag behind the economy, driven by sentiments and cash flows.
Industry/Sector Analysis
Industry analysis is an integral part of the three steps of top-down stock analysis. Industry analysis helps identify both unprofitable and profitable opportunities. Industry analysis involves conducting a macro analysis of the industry to determine how different industries relate to the business cycle.
Performance of industries is related to the stage of the business cycle. Different industries perform differently in different stages of the business cycle. On the basis of the relationship different sectors share with the business cycles, they are classified as cyclical and noncyclical sectors. For example, banking and financial sector perform well towards the end of a recession. During the phase of recovery, consumer durable sectors like producers of cars, personal computers, refrigerators, tractors etc., become attractive investments. Cyclical industries are attractive investments during the early stages of an economic recovery. These sectors employ high degree of operating costs. They benefit greatly during an economic expansion due to increasing sales, as they reap the benefits of economies of scale. Similarly, sectors employing high financial leverage also benefit during this phase, as debt is good in good times.
At the peak of the business cycle, inflation increases as demand overtakes supply. Inflation impacts different industries differently. There are industries, which are able to pass on the increase in the costs of products to their consumers by increasing prices. Their revenue and profits may remain unaffected by inflation. Industries producing basic materials such as oil and metals benefits the situation. Rising inflation doesn’t impact the cost of extracting these products. These industries can increase prices and experience higher profit margins. However, there are industries that are not able to charge the increased costs of production to their consumers. Their profitability suffer due to inflation.
During a recession phase also, some industries do better than others. Defensive industries like consumer staples, such as pharmaceuticals, FMCG, outperform other sectors. Even though the spending power of consumer is going down, people still spend money on necessities.
Analysts also see the stage of the Industry is in its life cycle. The number of stages in the life cycle of the industry are depicted in Figure 8.2:
INVESTMENT ADVISER (LEVEL 1)
AUTHOR : National Institute of Securities Markets (NISM) | An Educational Initiative of SEBI
PUBLISHER : Taxmann
DATE OF PUBLICATION : June 2026
EDITION : Workbook Version - March 2026
ISBN NO : 9789375613008
NO. OF PAGES : 496
BINDING TYPE : Paperback
Rs. 740
DESCRIPTION
Investment Adviser (Level 1) by NISM takes the reader from first principles to practitioner-grade competence. It moves from personal financial planning and the mathematics of money, through the full menu of investment products—equity, fixed income, derivatives, and managed vehicles—to portfolio construction and evaluation, the operational machinery of investing, the regulatory code, and the ethical and fiduciary standards of the profession. It assumes no prior advisory background, yet treats valuation, bond mathematics, and portfolio theory with real rigour, serving equally as an examination text and a standing reference for the advisory desk.
This book is intended for the following audience:
• Individuals Seeking SEBI Registration as an Investment Adviser
• Persons Associated with Investment Advice
• Candidates Preparing for the NISM-Series-X-A
• Financial Planners, Wealth Managers, Relationship Managers, and Advisory-Desk Professionals
• Students and Job Aspirants
• Practising Advisers and Advisory Firms
The Present Publication is the March 2026 Workbook Version, developed in collaboration with the NISM Certification Team and subject-matter experts—Arnav Pandya, Pratap Giri, Rachana Baid, Rama Iyer, Sunita Abraham, Sundar Sankaran, and Joydeep Sen. It is published exclusively by Taxmann, with the following noteworthy features:
•[Authoritative, Peer-Reviewed Authorship] Developed by NISM's Certification team with recognised industry experts and vetted by the Series X-A Examination Committee, ensuring technical accuracy and tight alignment to the live examination
•[Learning Objectives] Each chapter opens with a defined set of outcomes, letting candidates anchor their reading and self-test against explicit goals
•[Concept-to-Application Method] Theory is grounded in worked numericals and household and client scenarios, so ideas such as the time value of money, bond pricing, and risk-adjusted return translate directly into practice
•[Spreadsheet-Based Computation] Quantitative chapters are built around step-by-step calculations for Microsoft Excel/LibreOffice, mirroring the test-centre environment
•[Regulatory Grounding Through Real Cases] Compliance material is reinforced with illustrative SEBI enforcement actions showing how breaches by registered advisers are treated and penalised
•[Self-Assessment] Sample multiple-choice questions and caselets are embedded throughout in the exact format of the examination
•[Precise Syllabus and Weightage Mapping] Chapter sequence and depth correspond exactly to the official NISM syllabus and module-wise marks