MARKET RESEARCH BRIEFING · BULK CHEMICALS
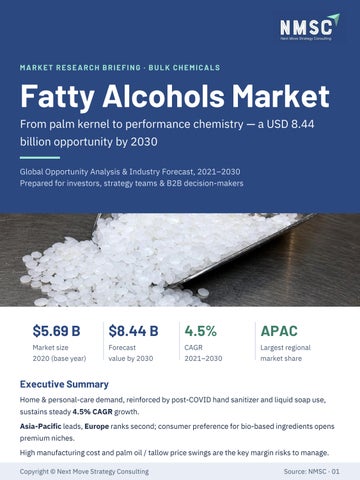
Fatty Alcohols Market From palm kernel to performance chemistry — a USD 8.44 billion opportunity by 2030 Global Opportunity Analysis & Industry Forecast, 2021–2030 Prepared for investors, strategy teams & B2B decision-makers
$5.69 B
$8.44 B
4.5%
APAC
Market size
Forecast
CAGR
Largest regional
2020 (base year)
value by 2030
2021–2030
market share
Executive Summary Home & personal-care demand, reinforced by post-COVID hand sanitizer and liquid soap use, sustains steady 4.5% CAGR growth. Asia-Pacific leads, Europe ranks second; consumer preference for bio-based ingredients opens premium niches. High manufacturing cost and palm oil / tallow price swings are the key margin risks to manage. Copyright © Next Move Strategy Consulting
Source: NMSC · 01
01 · MARKET LANDSCAPE
Market Size, Share & Ecosystem A USD 2.75 B value pool added over the decade Global market size (USD billion)
+48%
➞
8.44
5.69
4.5%
CAGR, 2021–2030 Base year 2020 · values in USD
Regional market share ranking Asia-Pacific — lion's share; China
#1 soap & detergent hub
Europe — strict detergent chemical
#2 rules
North America — steady rise in
2020
2030F
▲ surfactant demand
Industry ecosystem: feedstock to end-use
SOURCE
PRODUCT
TYPE
APPLICATION
Tropical oils Animal fats Soft oils Petrochemical (ethylene)
C6–C10 C11–C14 C15–C22
Pure Midcut Long chain Short chain
Soaps & detergents Cosmetics & personal care Food & bev · Pharma Textile & leather
Straight-chain primary alcohols (C4–C26) used as non-ionic surfactants, emollients, thickeners & emulsifiers. Dual natural vs. petrochemical routes define cost structure and sustainability positioning.
Copyright © Next Move Strategy Consulting
Source: NMSC · 02
02 · GROWTH DRIVERS & OPPORTUNITIES
What Is Fuelling Demand Hygiene & personal care pull — bio-based push ▲ DRIVERS
▼ RESTRAINTS
★ OPPORTUNITIES
Home & personal care —
High manufacturing cost
Bio-based shift —
shampoo, conditioner,
compresses producer
consumers move away from
shower gel, deodorants,
margins. Volatile feedstock — palm
toxic petrochemical
lipstick. Post-COVID hygiene — surge in hand sanitizers & liquid soaps. Industrial breadth —
detergents, inks, plasticizers, pharma &
oil, tallow & rapeseed oil
substitutes. R&D-led specialty grades
prices fluctuate. Supply concentration —
and capacity additions.
82% of palm oil from two
plants by Sasol & KLK Oleo.
China build-outs — new
countries.
nutrition.
High-potential segments to watch Cosmetics & Personal Care
Soaps & Detergents
Emollient, thickener & emulsifier role in skincare
Surfactant base for home care; China is the
formulations
manufacturing hub
Tropical-Oil Sourced Grades
Pharma, Food & Nutrition
Natural-route products aligned with bio-based
Diversified, higher-value applications beyond
demand
home care
Feedstock risk: palm oil supply is concentrated Indonesia — 57% (45.5 MMT)
82% from two countries
Malaysia — 25% (20.2 MMT)
Rest of world — 18% Natural-route producers benefit from upstream integration and hedging. World output 81.44 MMT, MY2025/26 (USDA FAS).
Copyright © Next Move Strategy Consulting
Source: NMSC; USDA FAS · 03
02 · GROWTH DRIVERS & OPPORTUNITIES
Regional Opportunity Map Asia-Pacific leads; Europe and North America follow #2 EUROPE
▲ NORTH AMERICA
#1 ASIA-PACIFIC
Lion's share of demand
REST OF WORLD
Asia-Pacific · Dominant
Europe · Second largest
Cosmetics, personal care & surfactant demand;
Strict regulations on chemicals in detergents
rising incomes in China, Japan, South Korea;
favour compliant, high-purity and bio-based
China leads detergent output.
grades.
North America · Steady rise
Rest of World · Emerging
Demand spike in surfactants, home-cleaning
Coverage spans UAE, Saudi Arabia, South Africa
products and sanitizers during and after COVID-
and Brazil — early-stage pockets for distribution
19.
partnerships.
INVESTOR TAKEAWAY Anchor capacity near Asia-Pacific feedstock and demand; use Europe's regulatory bar to command premiums for certified bio-based grades. Copyright © Next Move Strategy Consulting
Source: NMSC · 04
03 · COMPETITIVE SCENARIO
Who Leads & How They Compete Competitive positioning matrix
Value-chain role → integrated
KLK Oleo
Sasol Limited
NATURAL · INTEGRATED
SYNTHETIC · INTEGRATED
VVF LLC
Shell plc BASF SE
Emery Oleochemicals
Kao Corp. NATURAL · SPECIALTY
P&G Chemicals
Univar Solutions
DISTRIBUTION / CHANNEL
Berg+Schmidt ← Natural / oleochemical feedstock
Petrochemical / synthetic route →
Key strategic moves: expansion, partnerships, M&A Company
Strategic move
Type
Date
KLK Oleo
Zhangjiagang, China plant lifted to 500,000 t/yr
Expansion
Jul 2024
Sasol
Nanjing, China alkoxylation plant, ~150 ktpa
Expansion
Jul 2019
Kao Corp.
Apical Kao JV, Indonesia — ~100 kt/yr fatty acids
Joint venture
May 2019
BASF SE
Acies Bio tie-up: fermentation-route fatty alcohols
Partnership
Nov 2024
Emery Oleo.
Asia-Pacific business sold to Edenor Technology
M&A
Nov 2021
Univar Solutions
Acquired by Apollo funds, USD 8.1 B
M&A
Aug 2023
Shell plc
Singapore chemicals park divested to CAPGC
Divestment
Apr 2025
Read-across: Asian capacity build-outs and bio-based R&D partnerships define the leaders, while portfolio reshaping shifts assets toward focused owners.
Copyright © Next Move Strategy Consulting
Source: NMSC; company releases · 05
04 · LET'S CONNECT
Thank You Connect with our analysts for in-depth insights, custom segment forecasts and strategic guidance on the fatty alcohols value chain.
WEBSITE
www.nextmsc.com
PHONE
+1 857 758 5017
info@nextmsc.com
Click here for the complete report ➞ Full report includes: 2021–2030 segment forecasts · player market shares · SWOT & Porter's Five Forces · value chain analysis
Follow Us gen-dedup-d5e9abffec46a0141c75e700f7e2805b.png
gen-dedup-ea95884bb212514fd09367ef2d66bcb4.png
Copyright © Next Move Strategy Consulting
gen-dedup-6637f24827c319bdcadcbdc1dc5e70dc.png
YouTube
gen-dedup-52add9f1793d715ab35aac8ba0396838.png
gen-dedup-3c8902be6c32917f73e7864ebf73854f.png
06