
In late 2025, homes sat on the market for an average of 39 days and received an average of 2.2 offers.*
*January 2026 REALTORS® Confidence Index Survey
Urgency has become a defining force of modern buyer behavior. With mortgage rates shifting daily, many feel the intense pressure to act fast before borrowing costs climb again, or before the next offer is submitted on the home they really want.
“It felt high-stakes, fast-moving and uncertain, with pressure to make the right choice.”
- Male, Gen Z
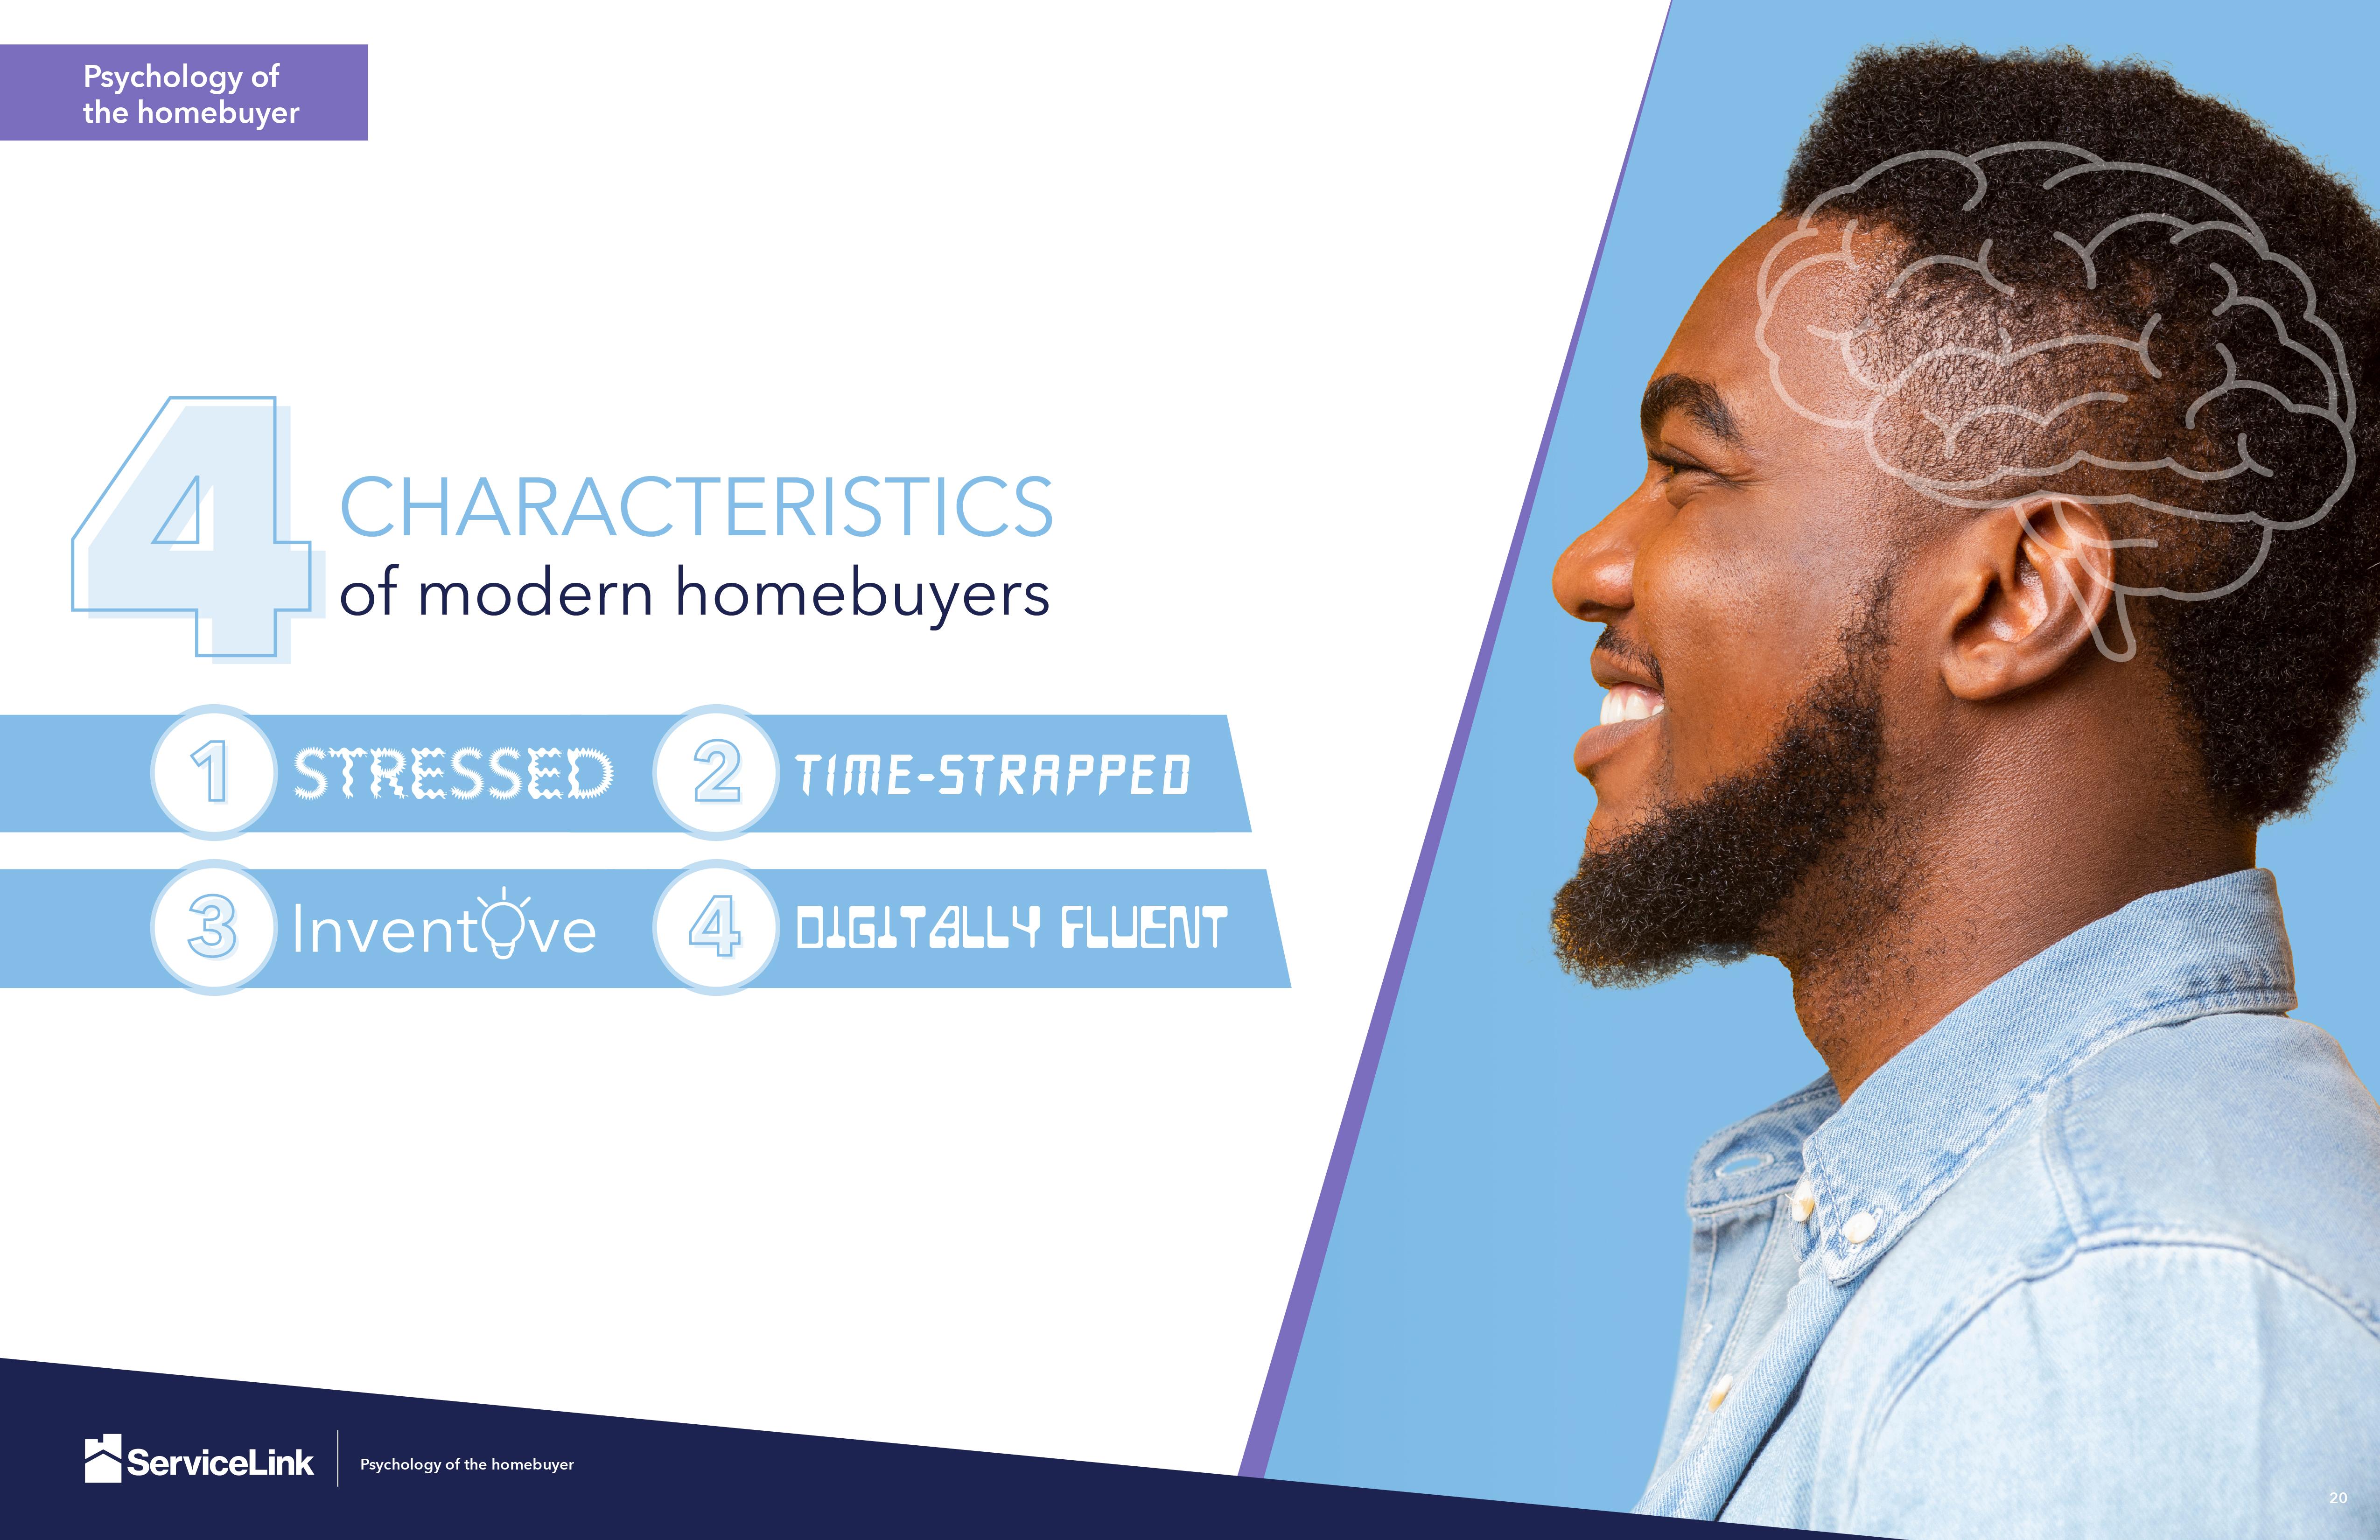
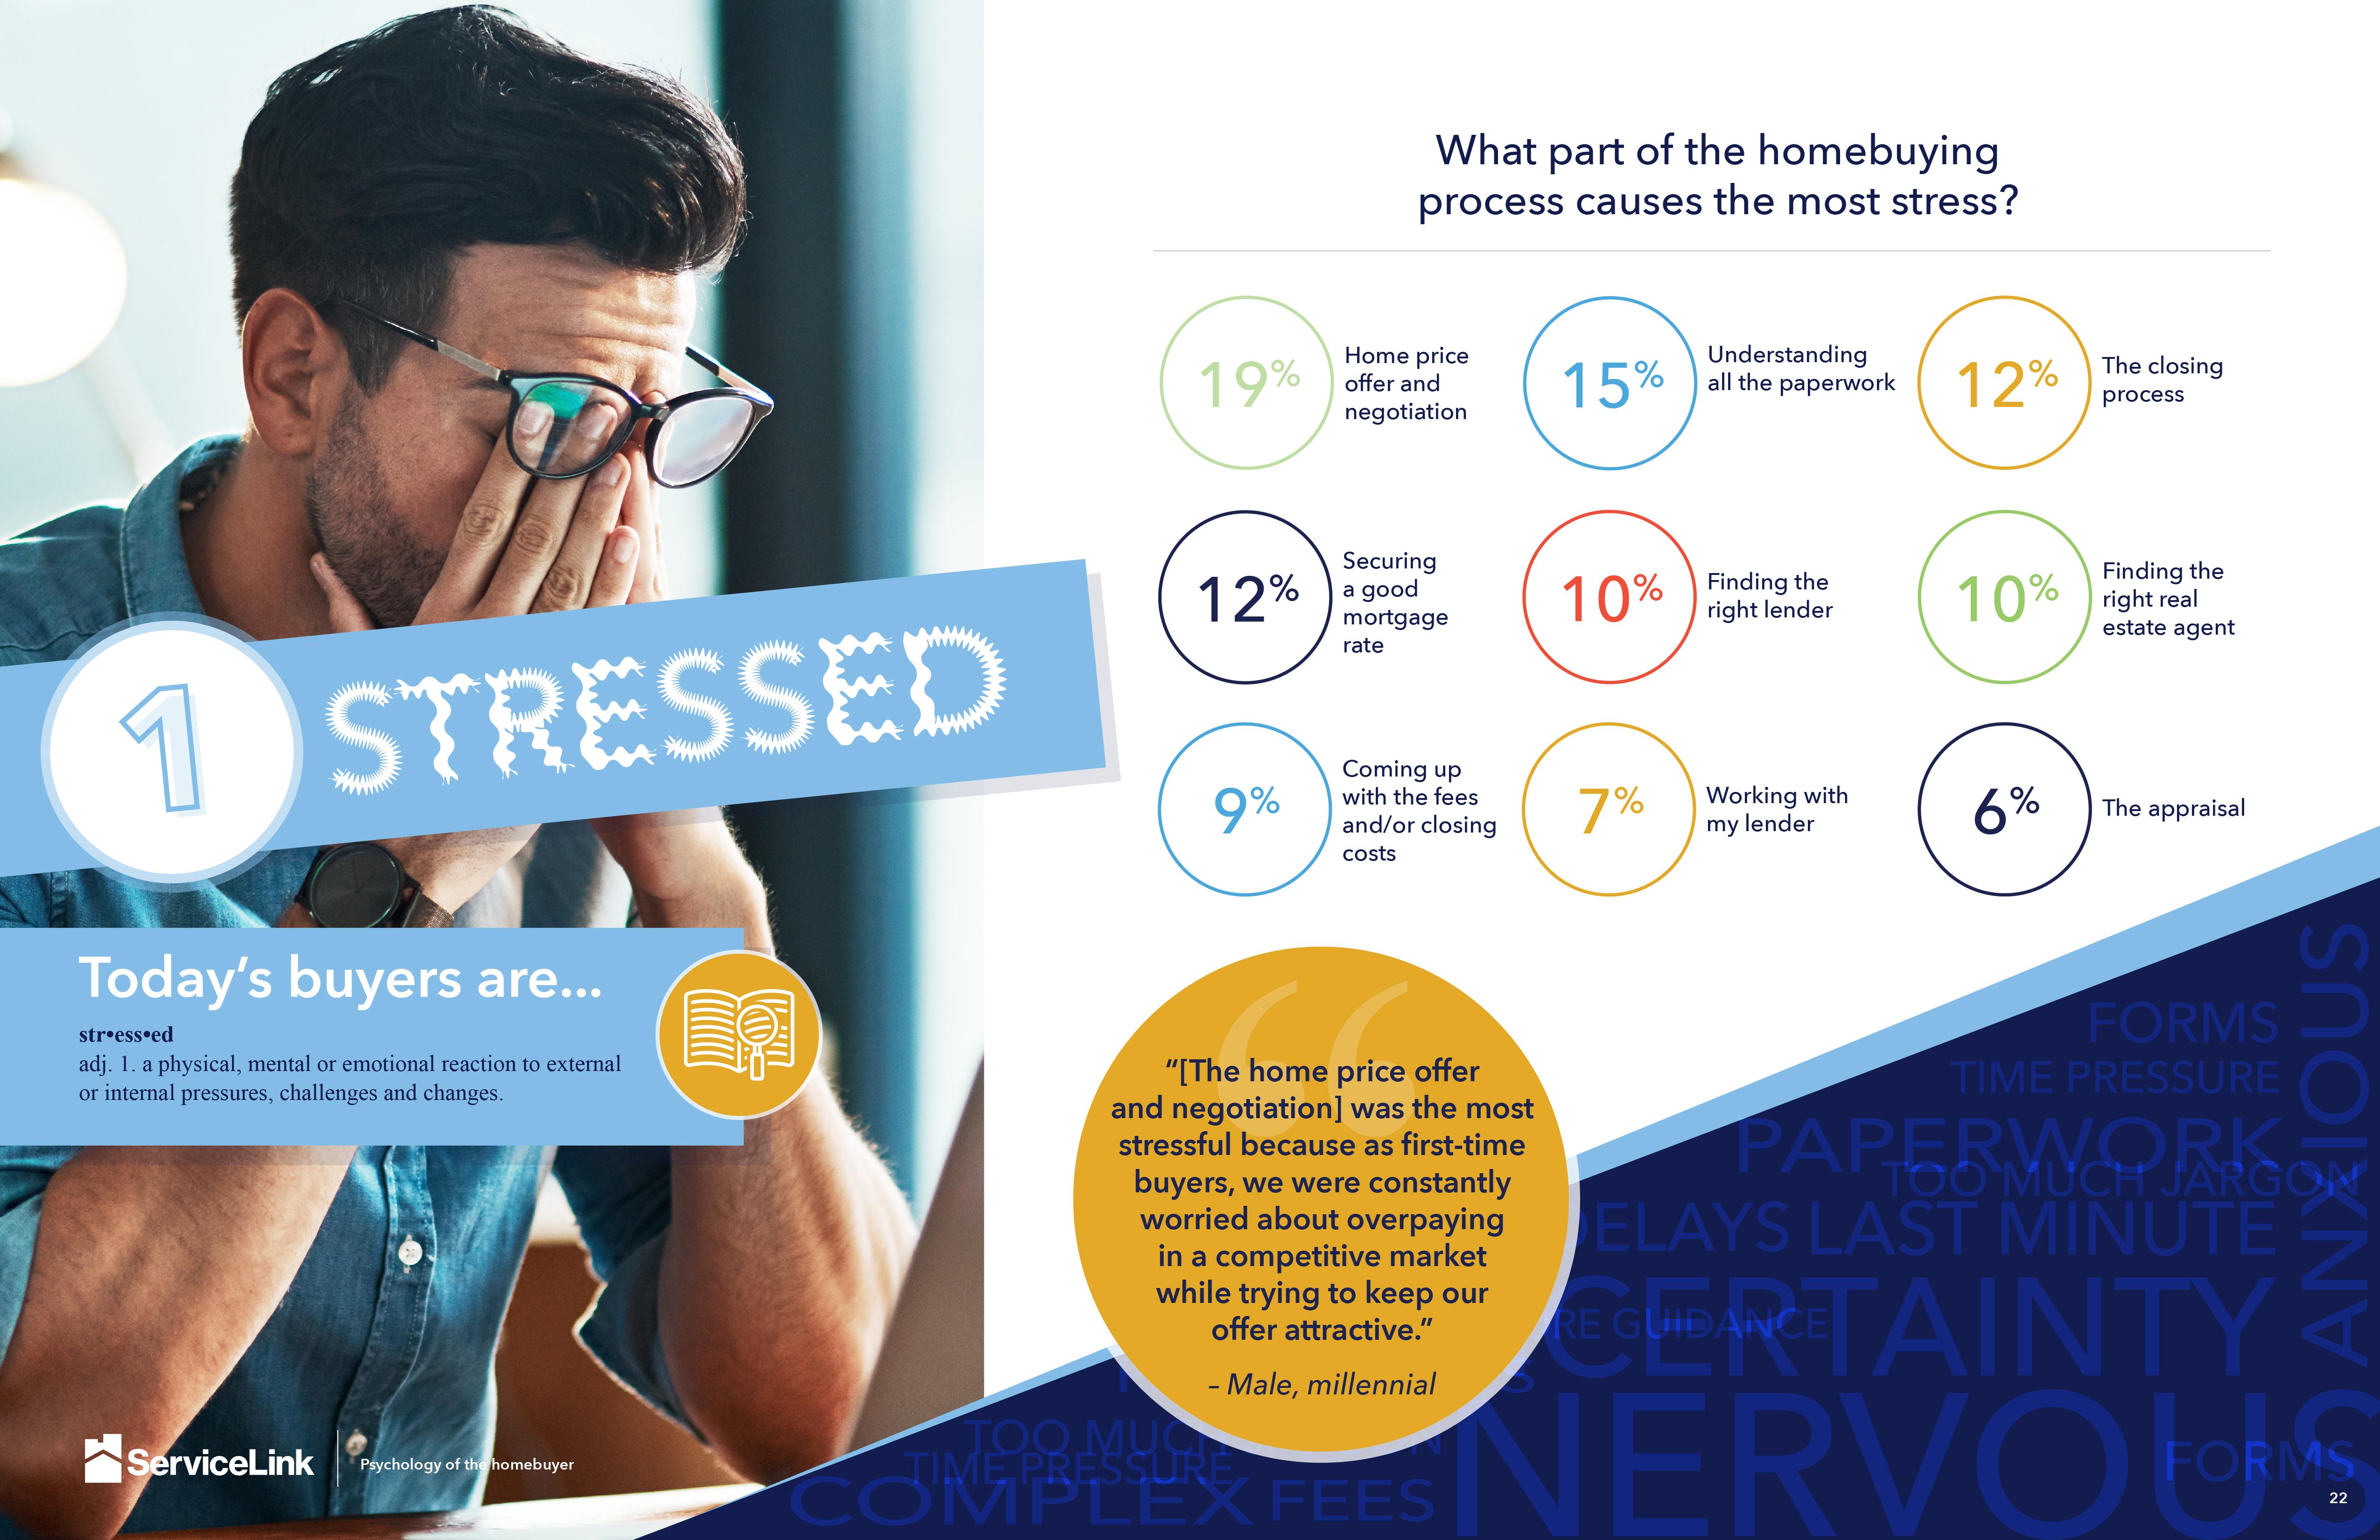
Today’s buyers are...
“Customers want more time to make decisions. With high bids and quick transaction times, customers complain about how they wish they could take their time on purchases.”
- Male, Pennsylvania time-strapped adj. 1. a person who has very limited time available. It implies being pressed for time, often to the point where completing tasks feels rushed or difficult.
More than one in three respondents think it should take two weeks or less to close on a home
If you were purchasing a new home, how long do you think it should take to close?
Loan officers also cited borrowers' need for speed on the path to close. When asked how quickly their borrowers expected to close on a purchase transaction, based on their experiences, 43% said within two weeks or less, not far off from respondents’ expectations (35%). While the industry average is around 30-40 days at the time of writing this report, the youngest respondents - Gen Z and millennials – are more likely to expect 1-2 week closings than older generations, who lean more toward 3-4 week expectations.
faster processing times as areas make the mortgage for borrowers.
Loan officers know there’s of slow processing and loan officers in open-ended
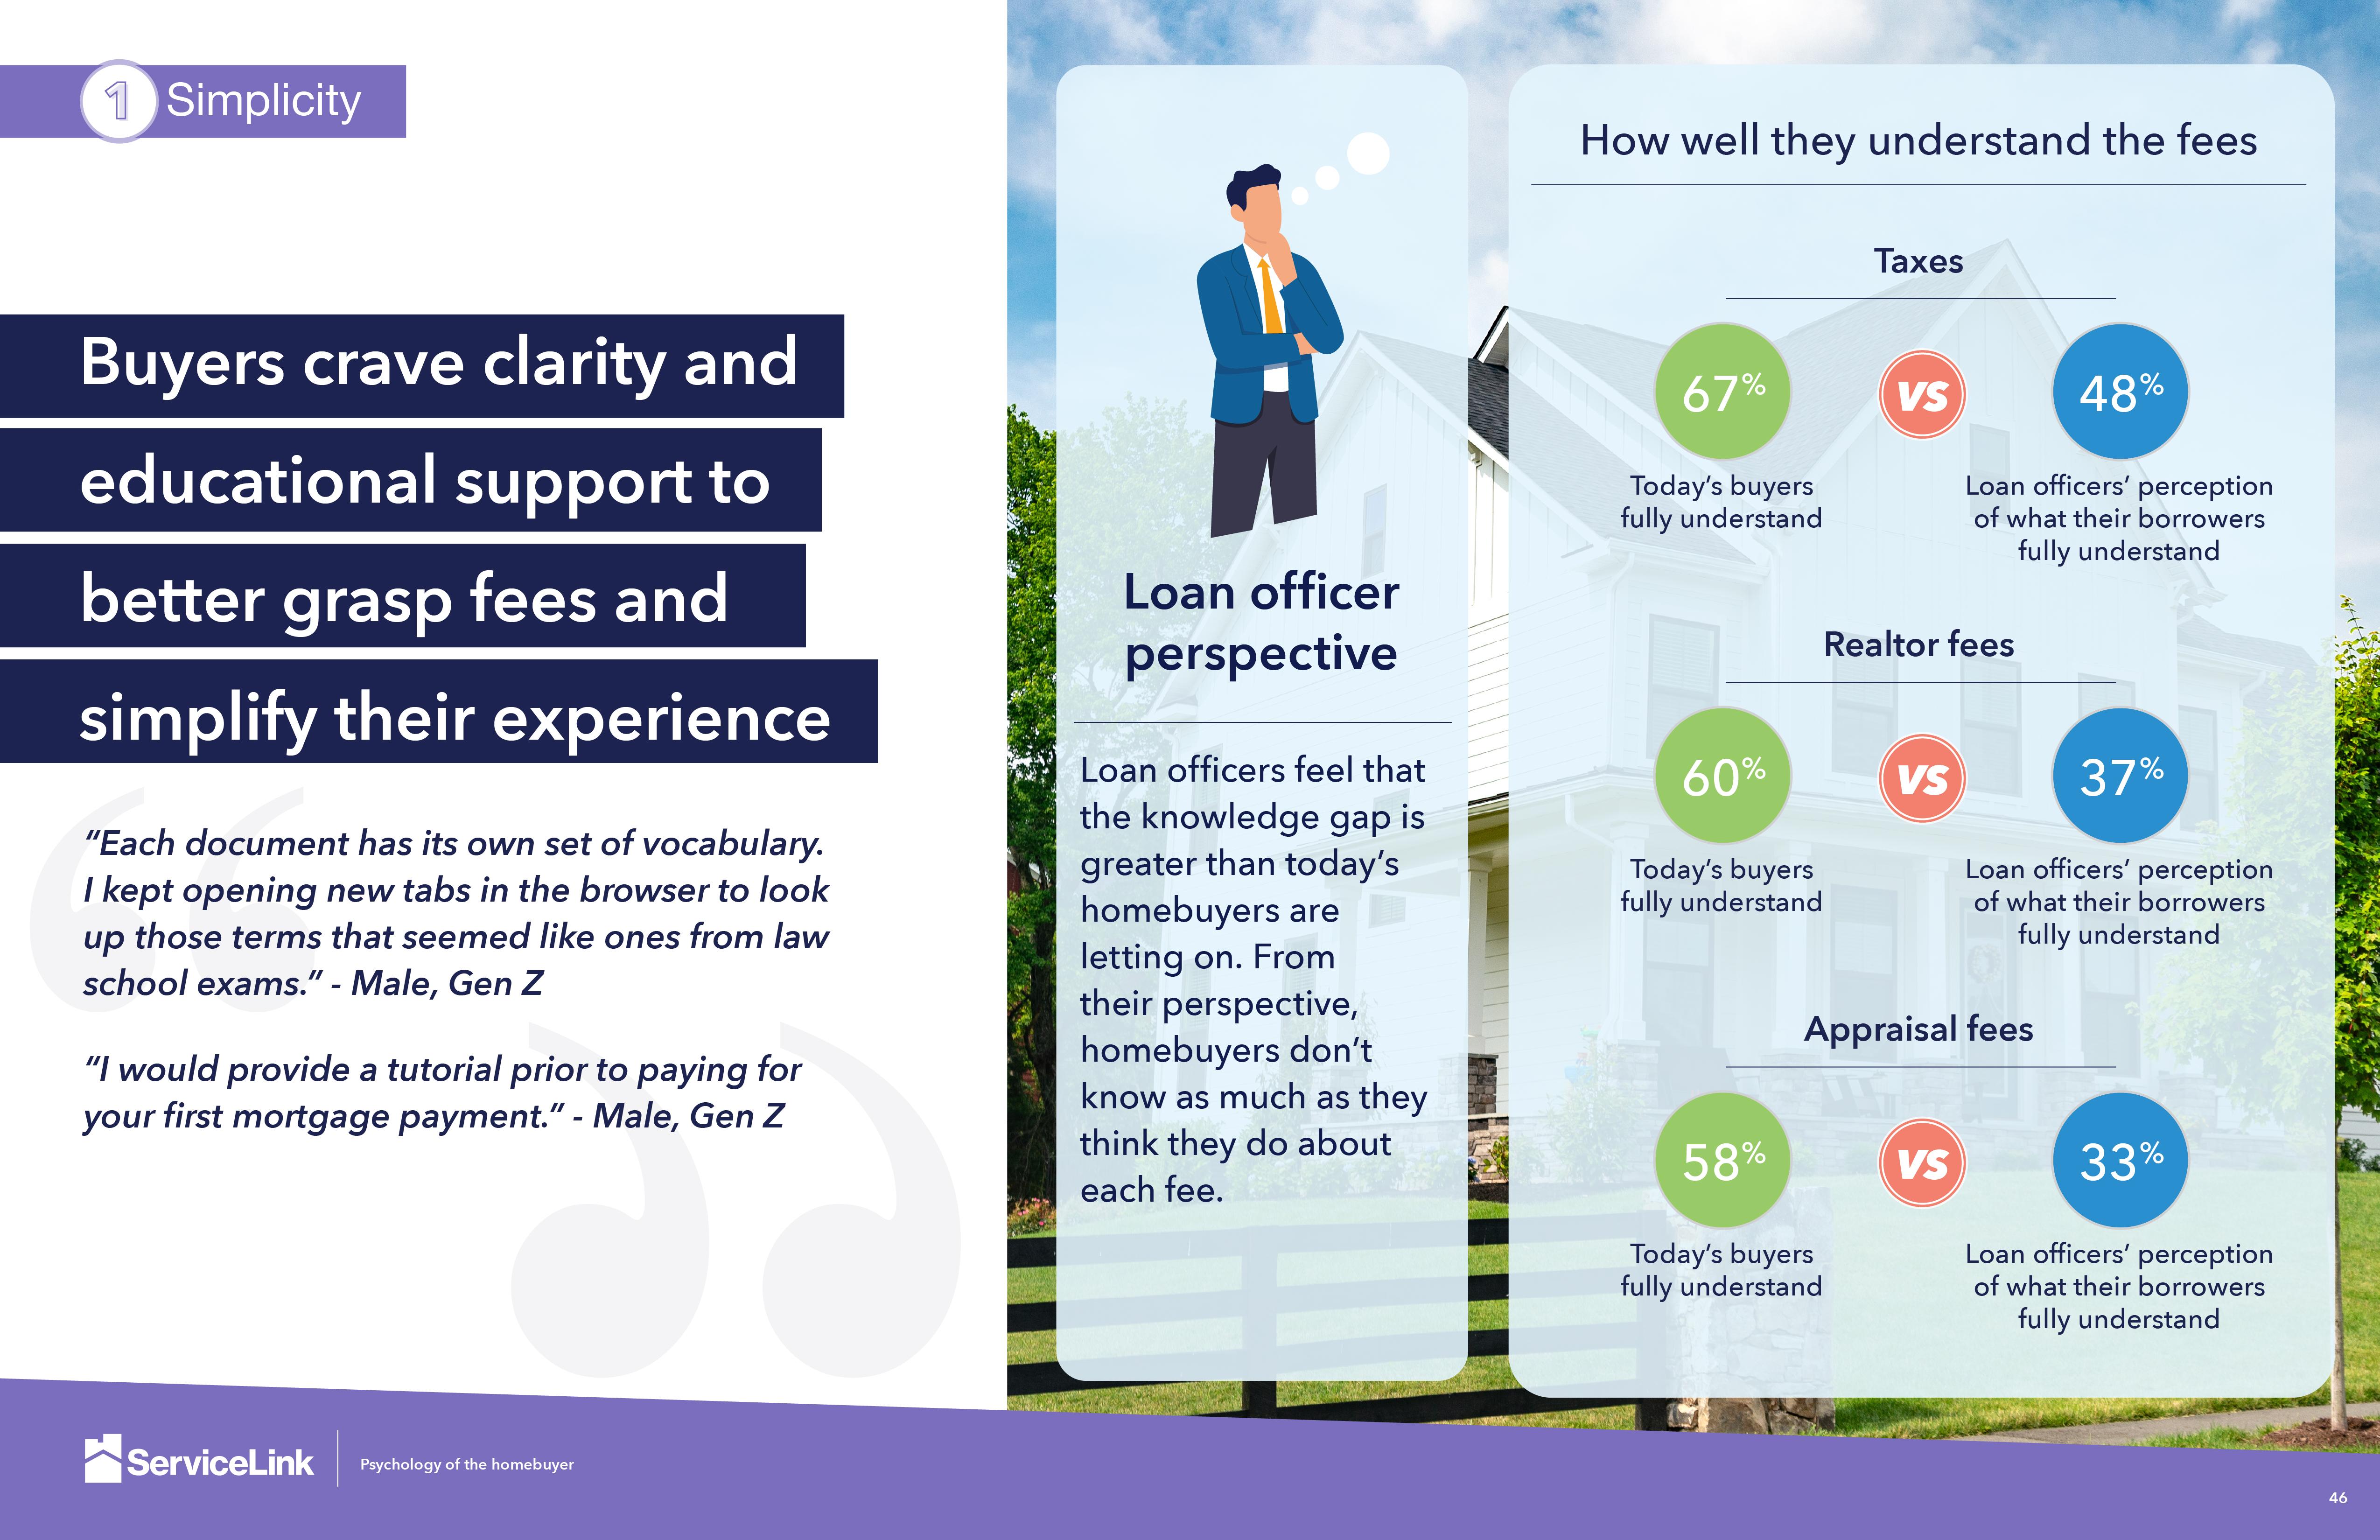
Loan officer perspective
Respondents cited faster approvals, processing and faster response areas where lenders can mortgage process better borrowers.
there’s room for improvement, too. Instances and approvals were mentioned by 40% of open-ended responses.
What are the most common complaints from your borrowers throughout the entire homebuying process?
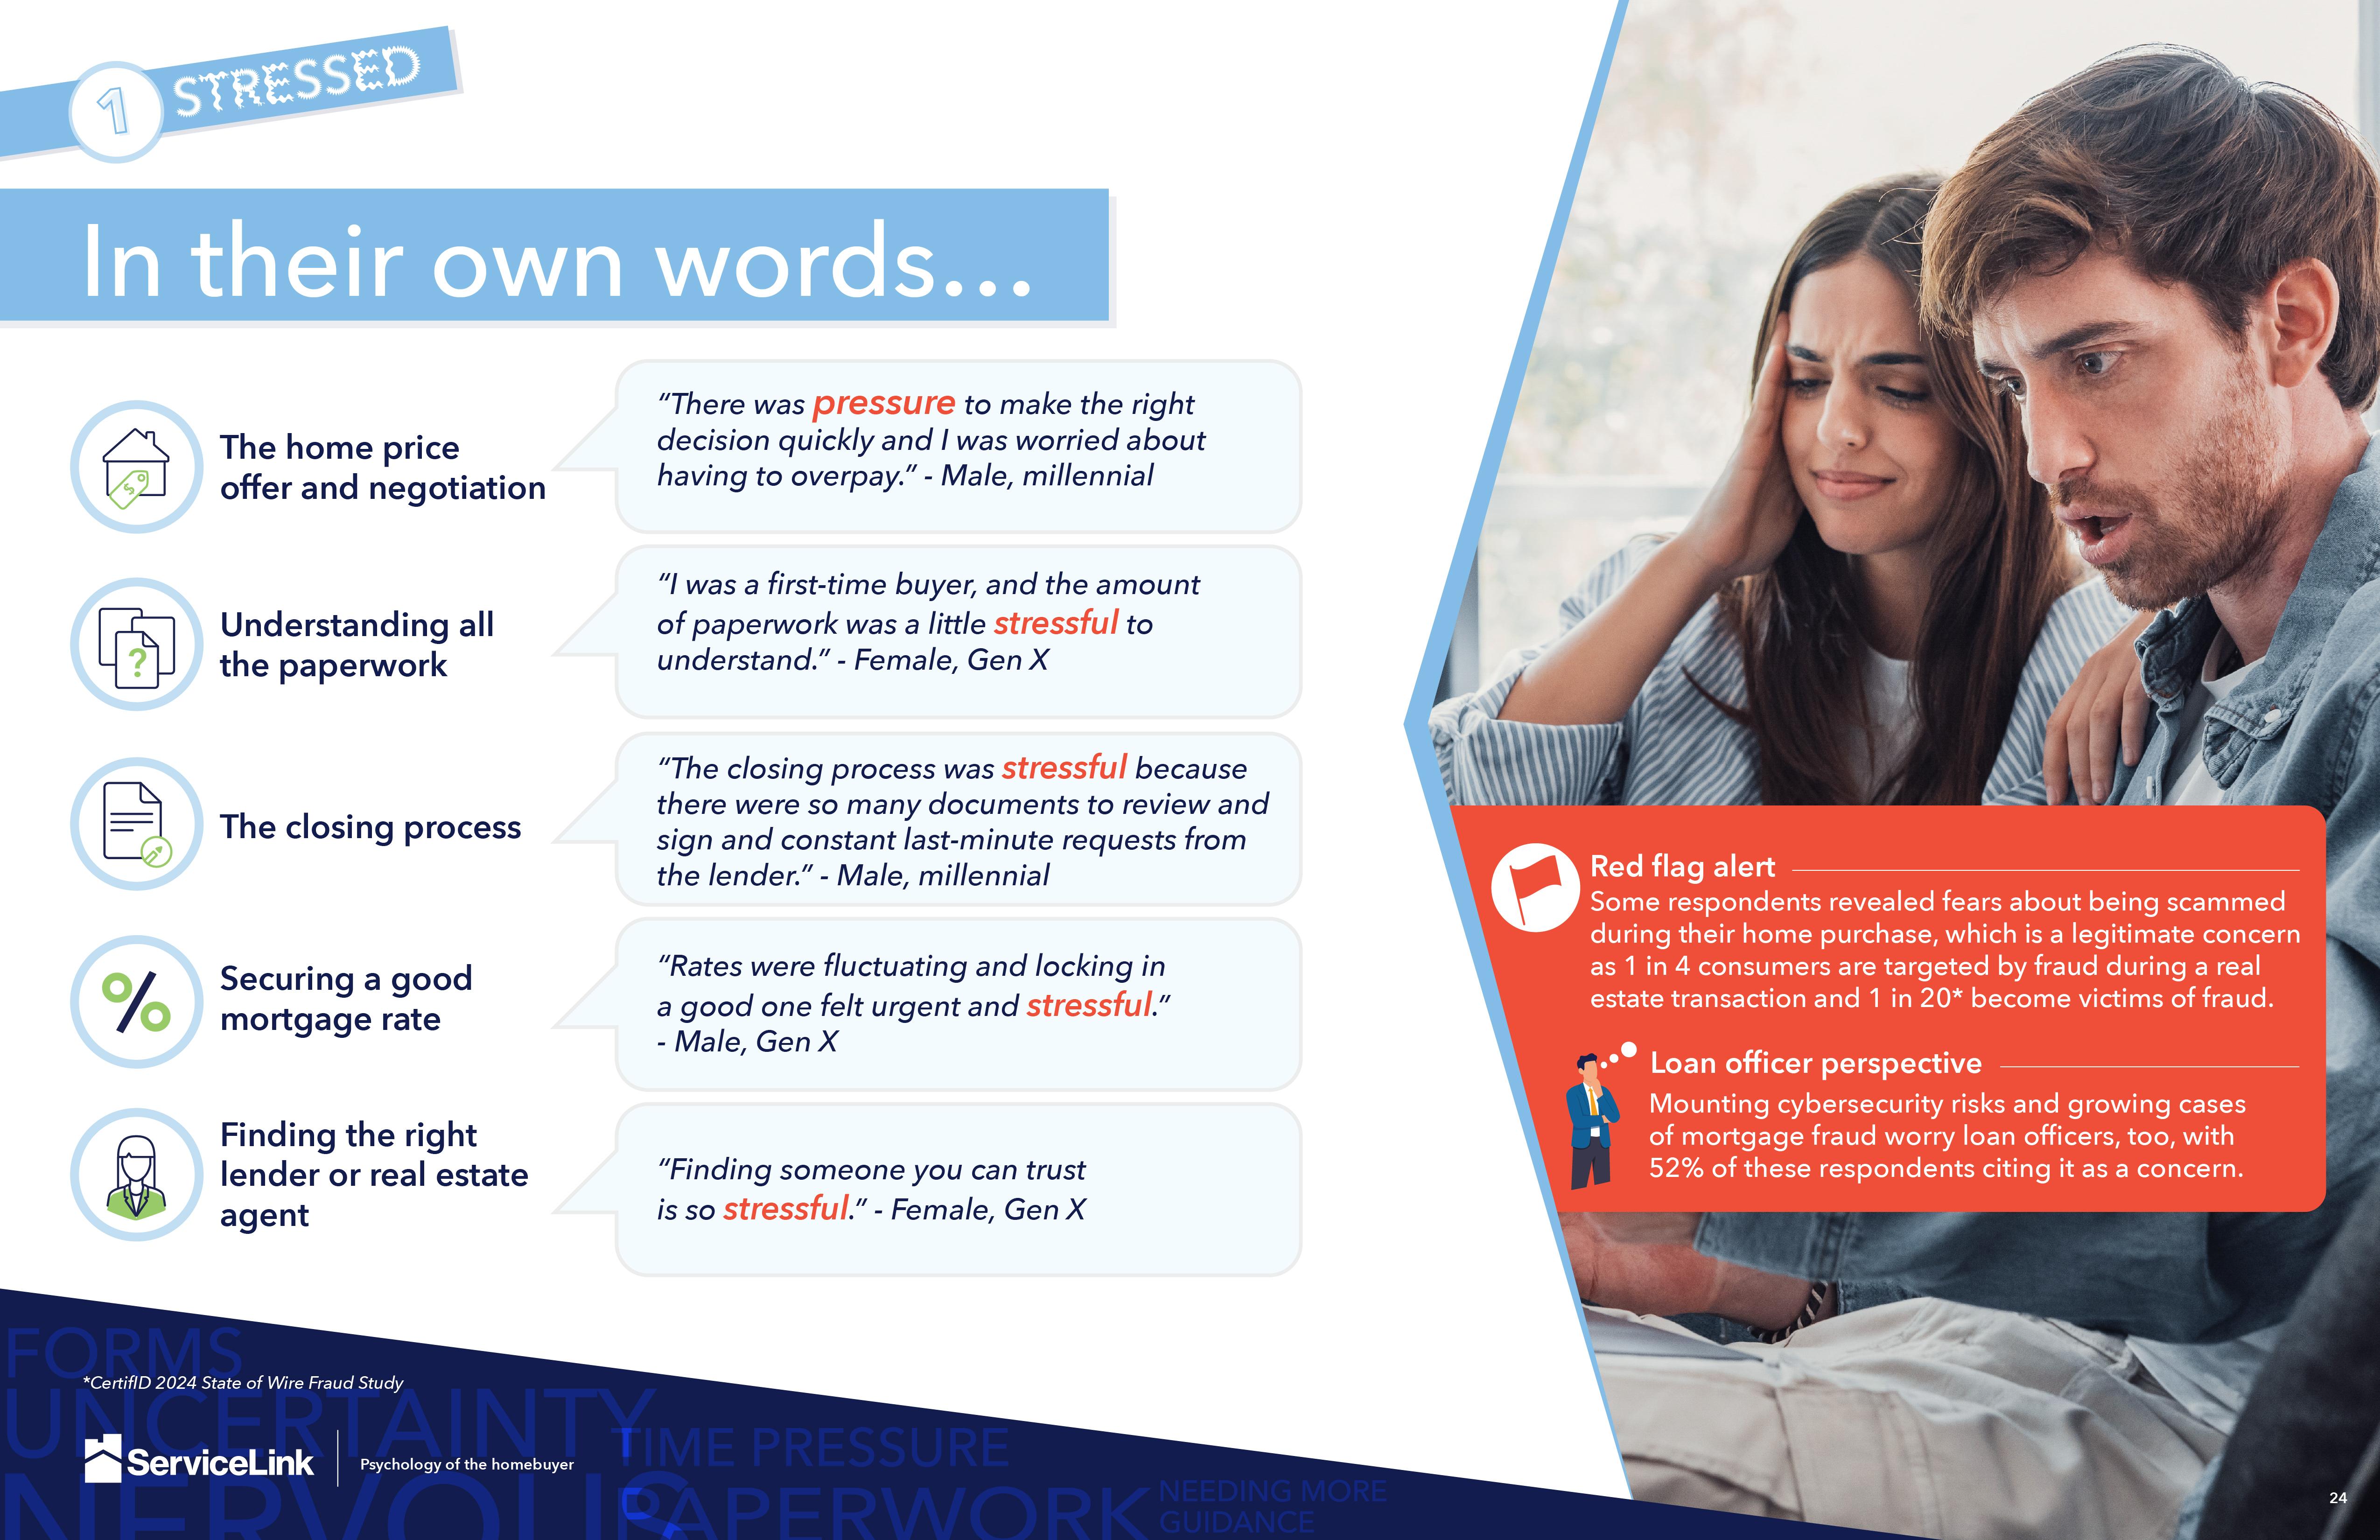
“Borrowers most often complain about slow or unclear communication, feeling overwhelmed by repeated document requests and the process taking longer than they expected. They also get frustrated by unexpected costs, appraisal delays and having to coordinate between multiple parties like the lender, agent and title company.”
- Female, credit union, Texas
“Faster response times would help — a few hours of silence can leave me stuck and unsure what the next step is.”
- Male, Gen Z
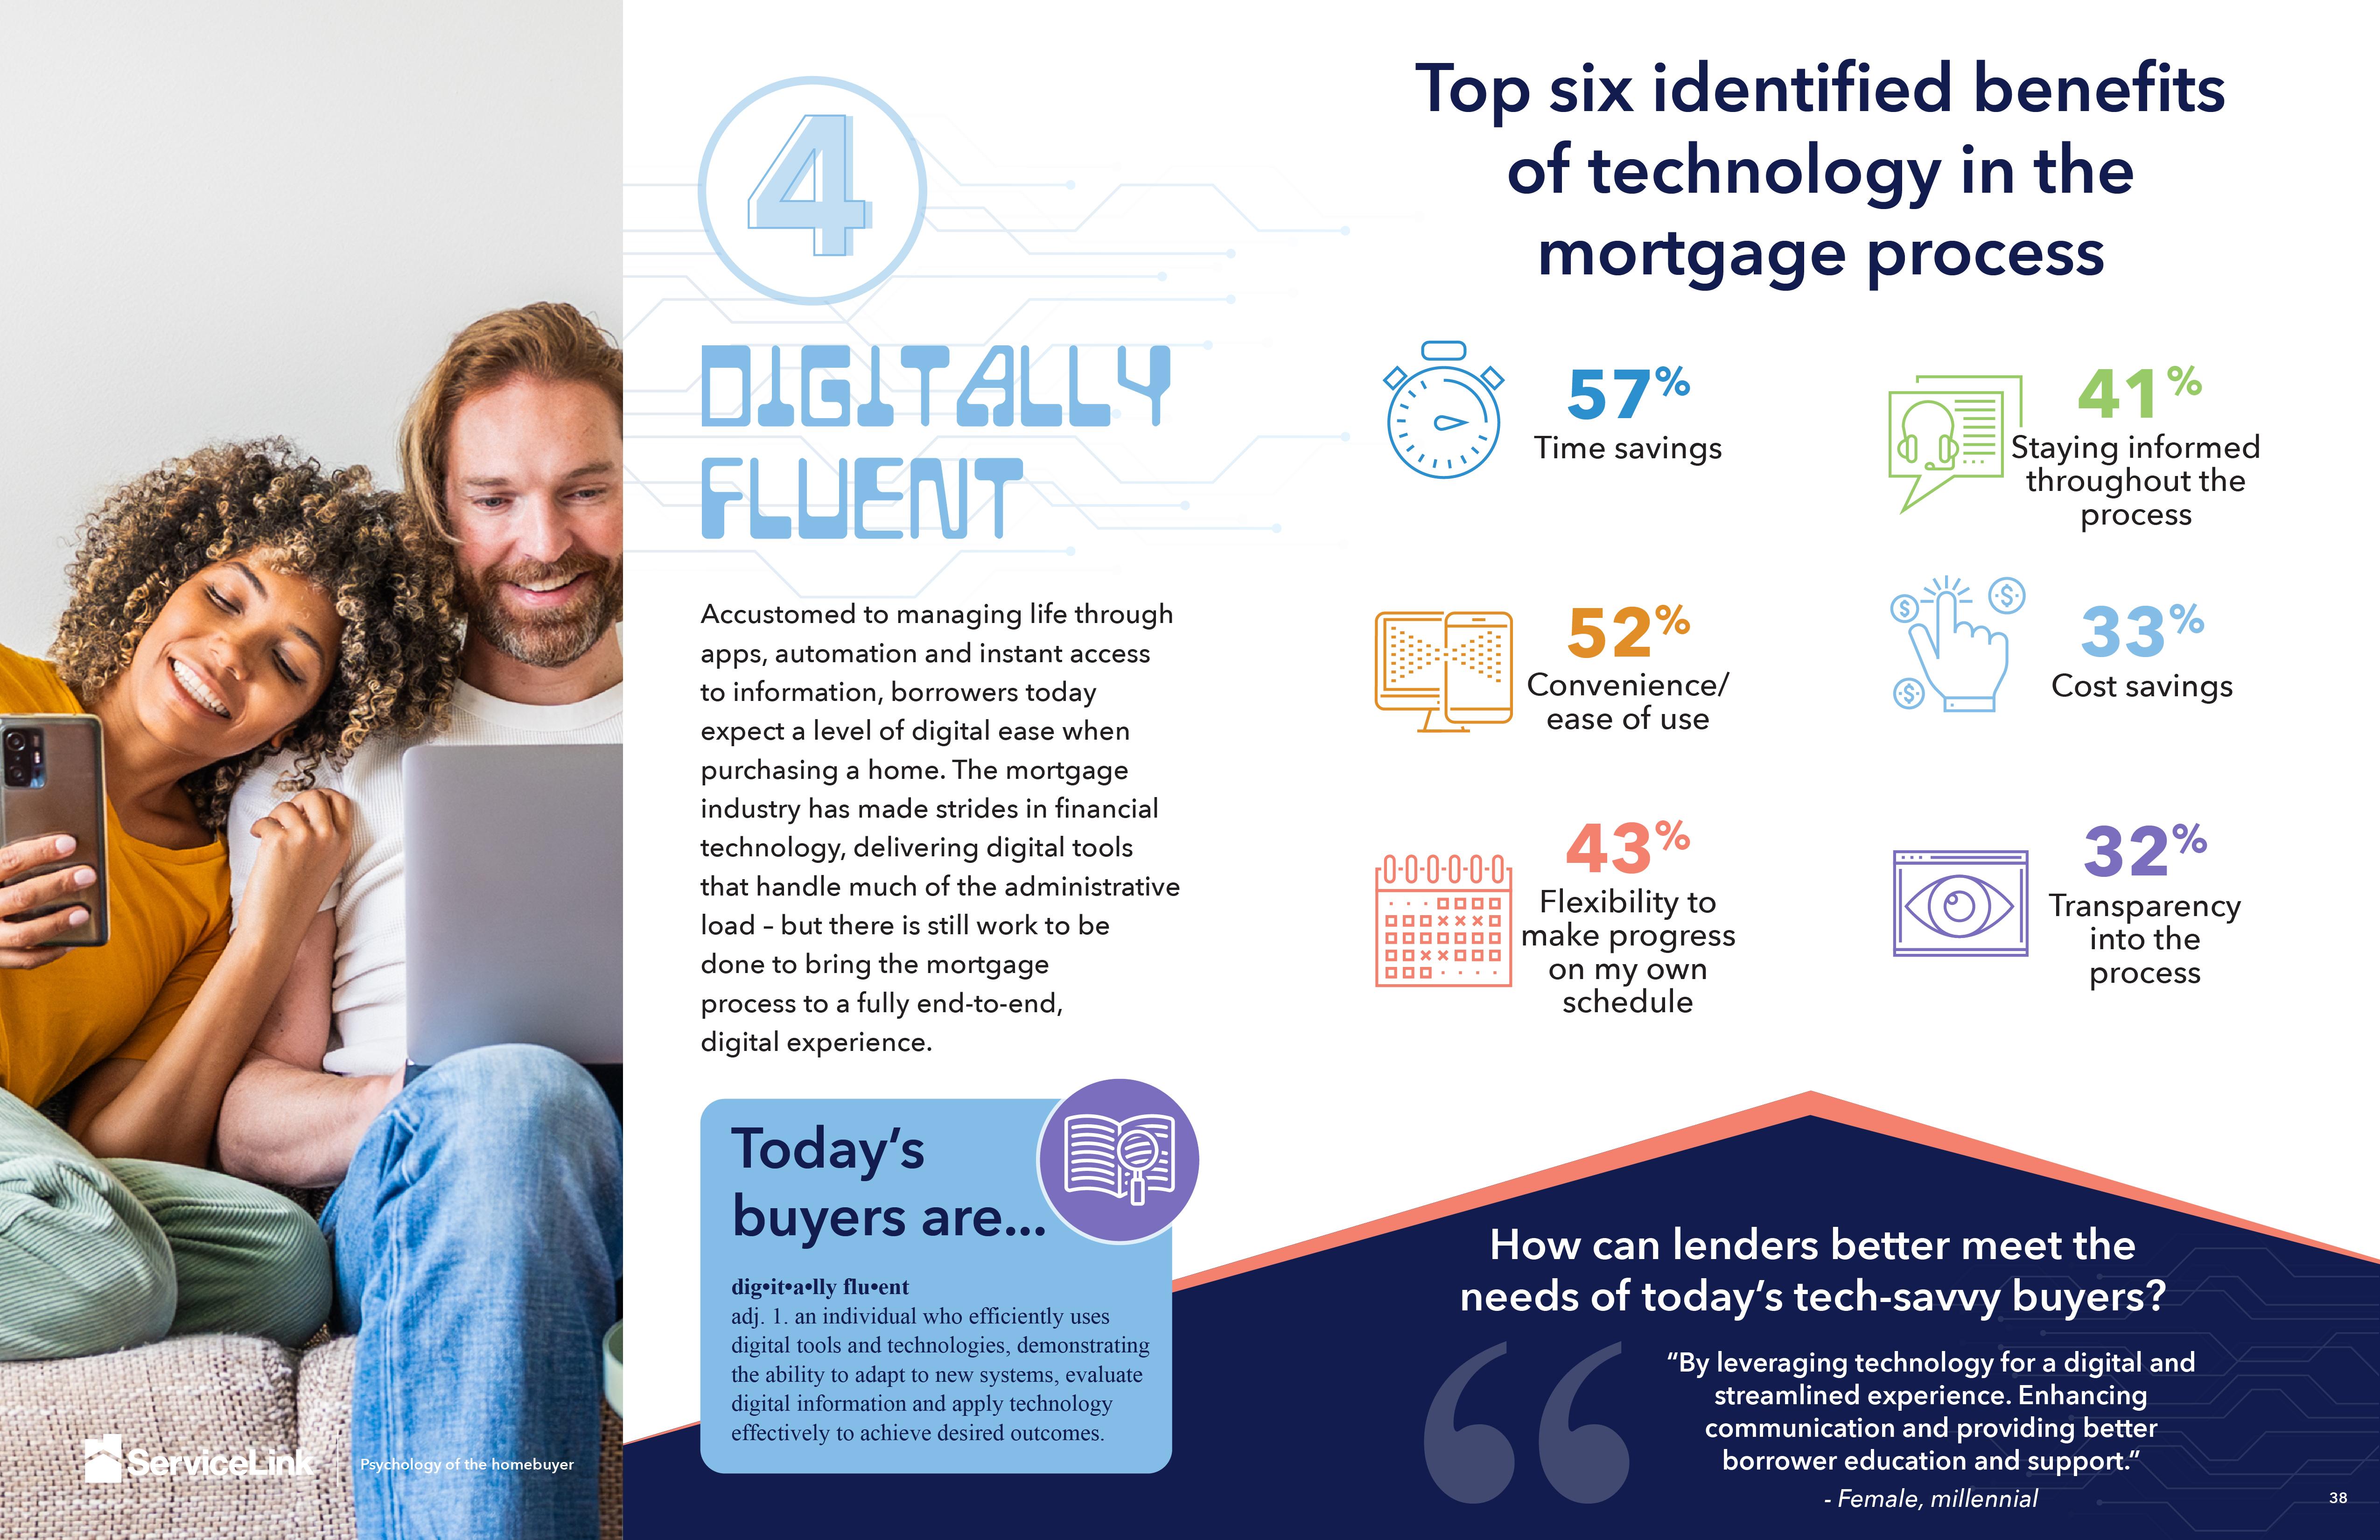
The top technologies that would influence respondents’ decision to work with a specific lender
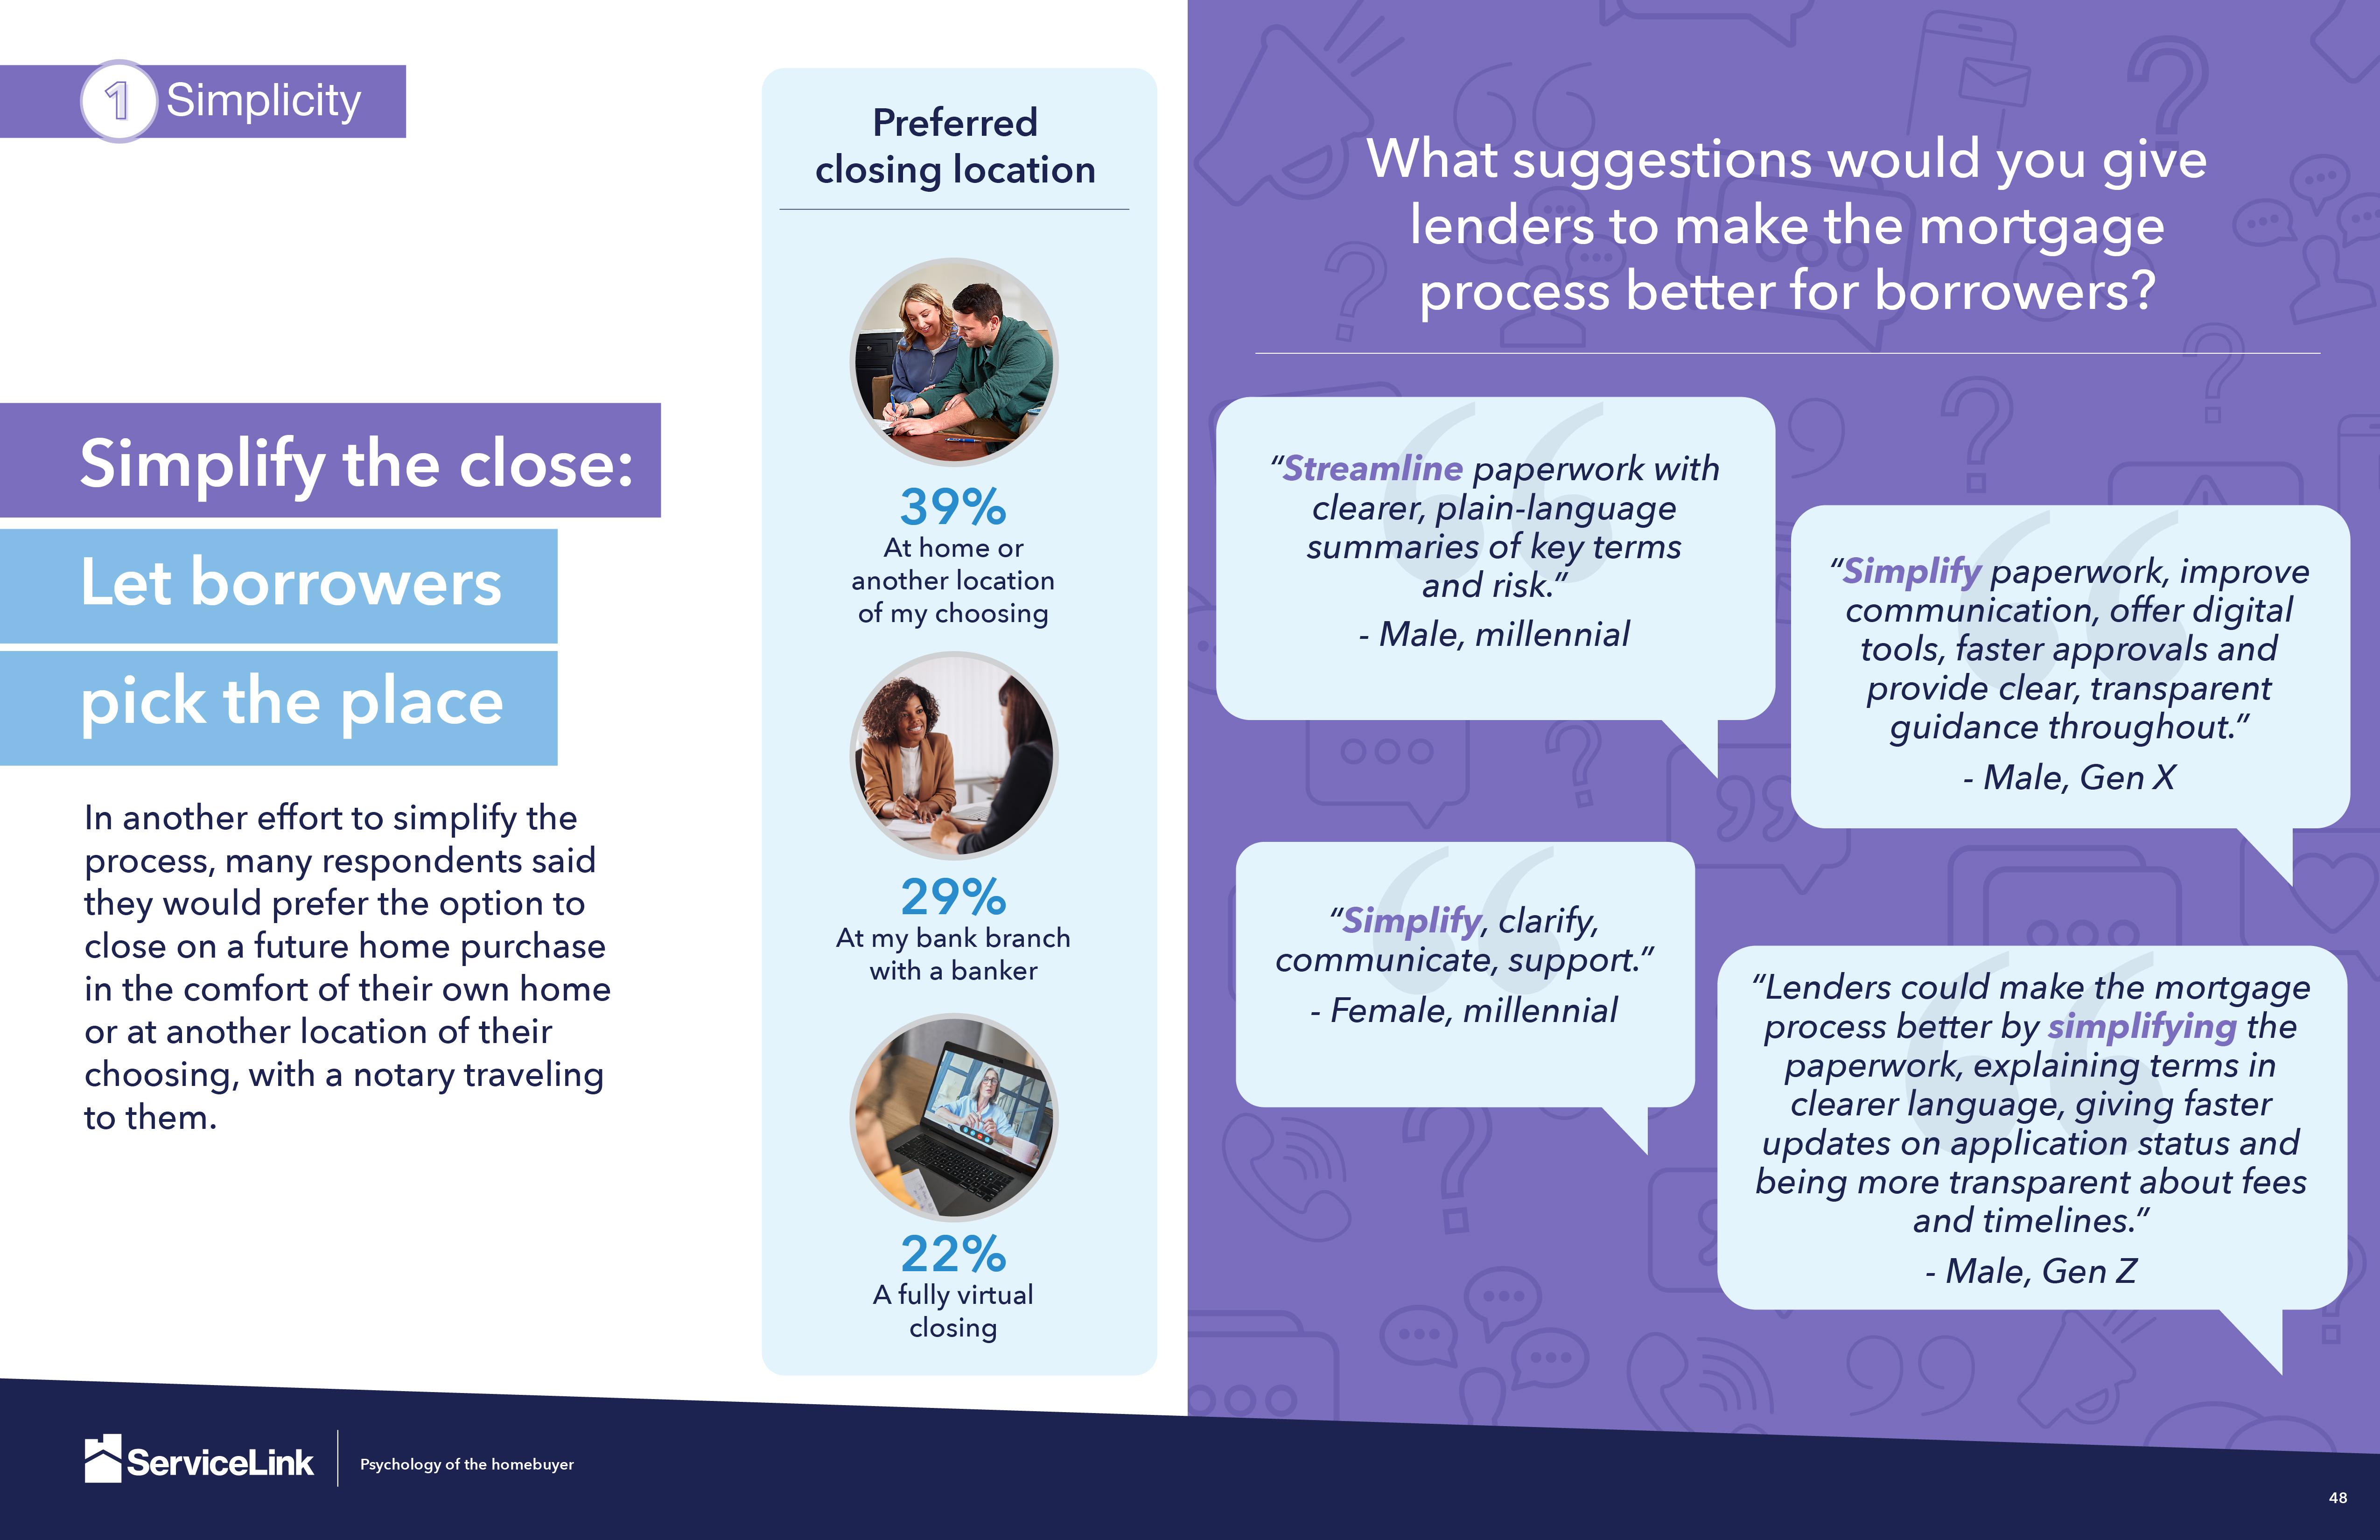
The opportunity to eSign some or all closing documents Most popular among millennials (92%) and Gen X (91%)
An option to use my phone/tablet to self-schedule an appraisal or closing appointment for the exact date and time that I desire
Most popular among millennials (91%) and Gen X (91%)
The opportunity to hold the closing virtually Most popular among millennials (87%)
A range of AI tools and technology that move the process forward and create fewer steps while reducing the timeline to close Most popular among millennials (88%)
The opportunity to conduct the entire process digitally with no in-person appointments Most popular among millennials (84%)
• A deeper dive
62% of baby boomer respondents say they used eSigning technology on some or all of their closing documents, more than the other generations.
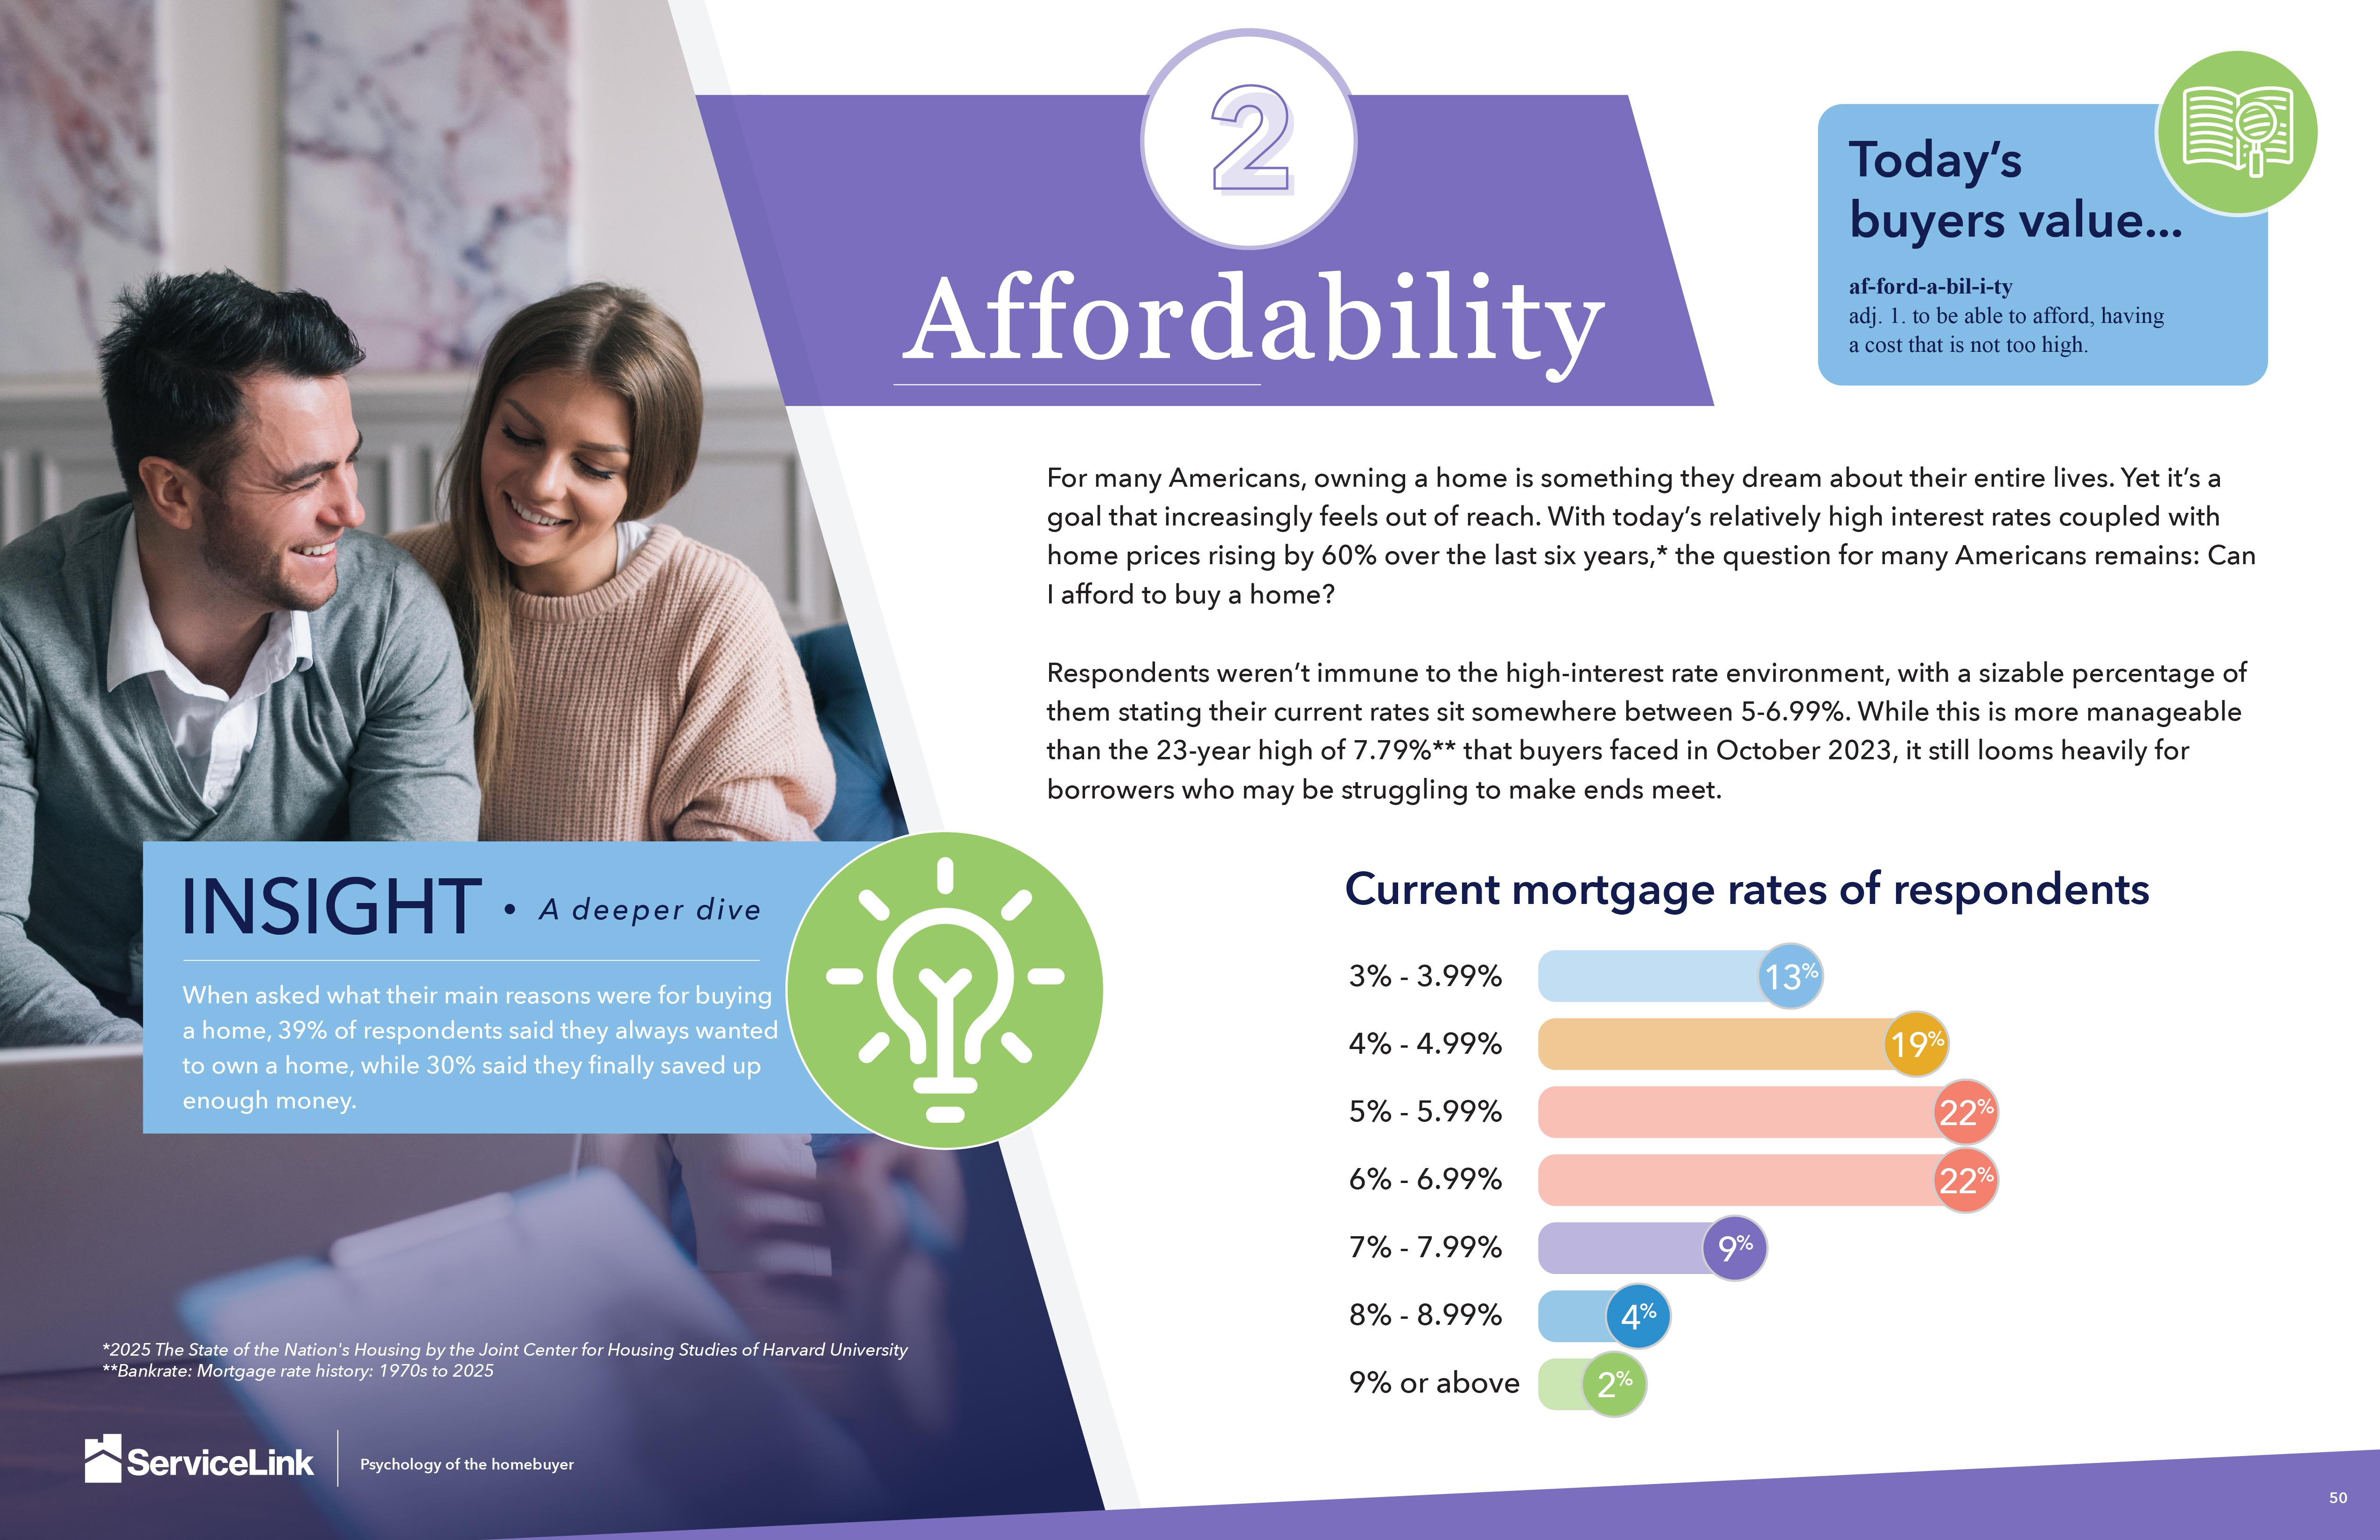
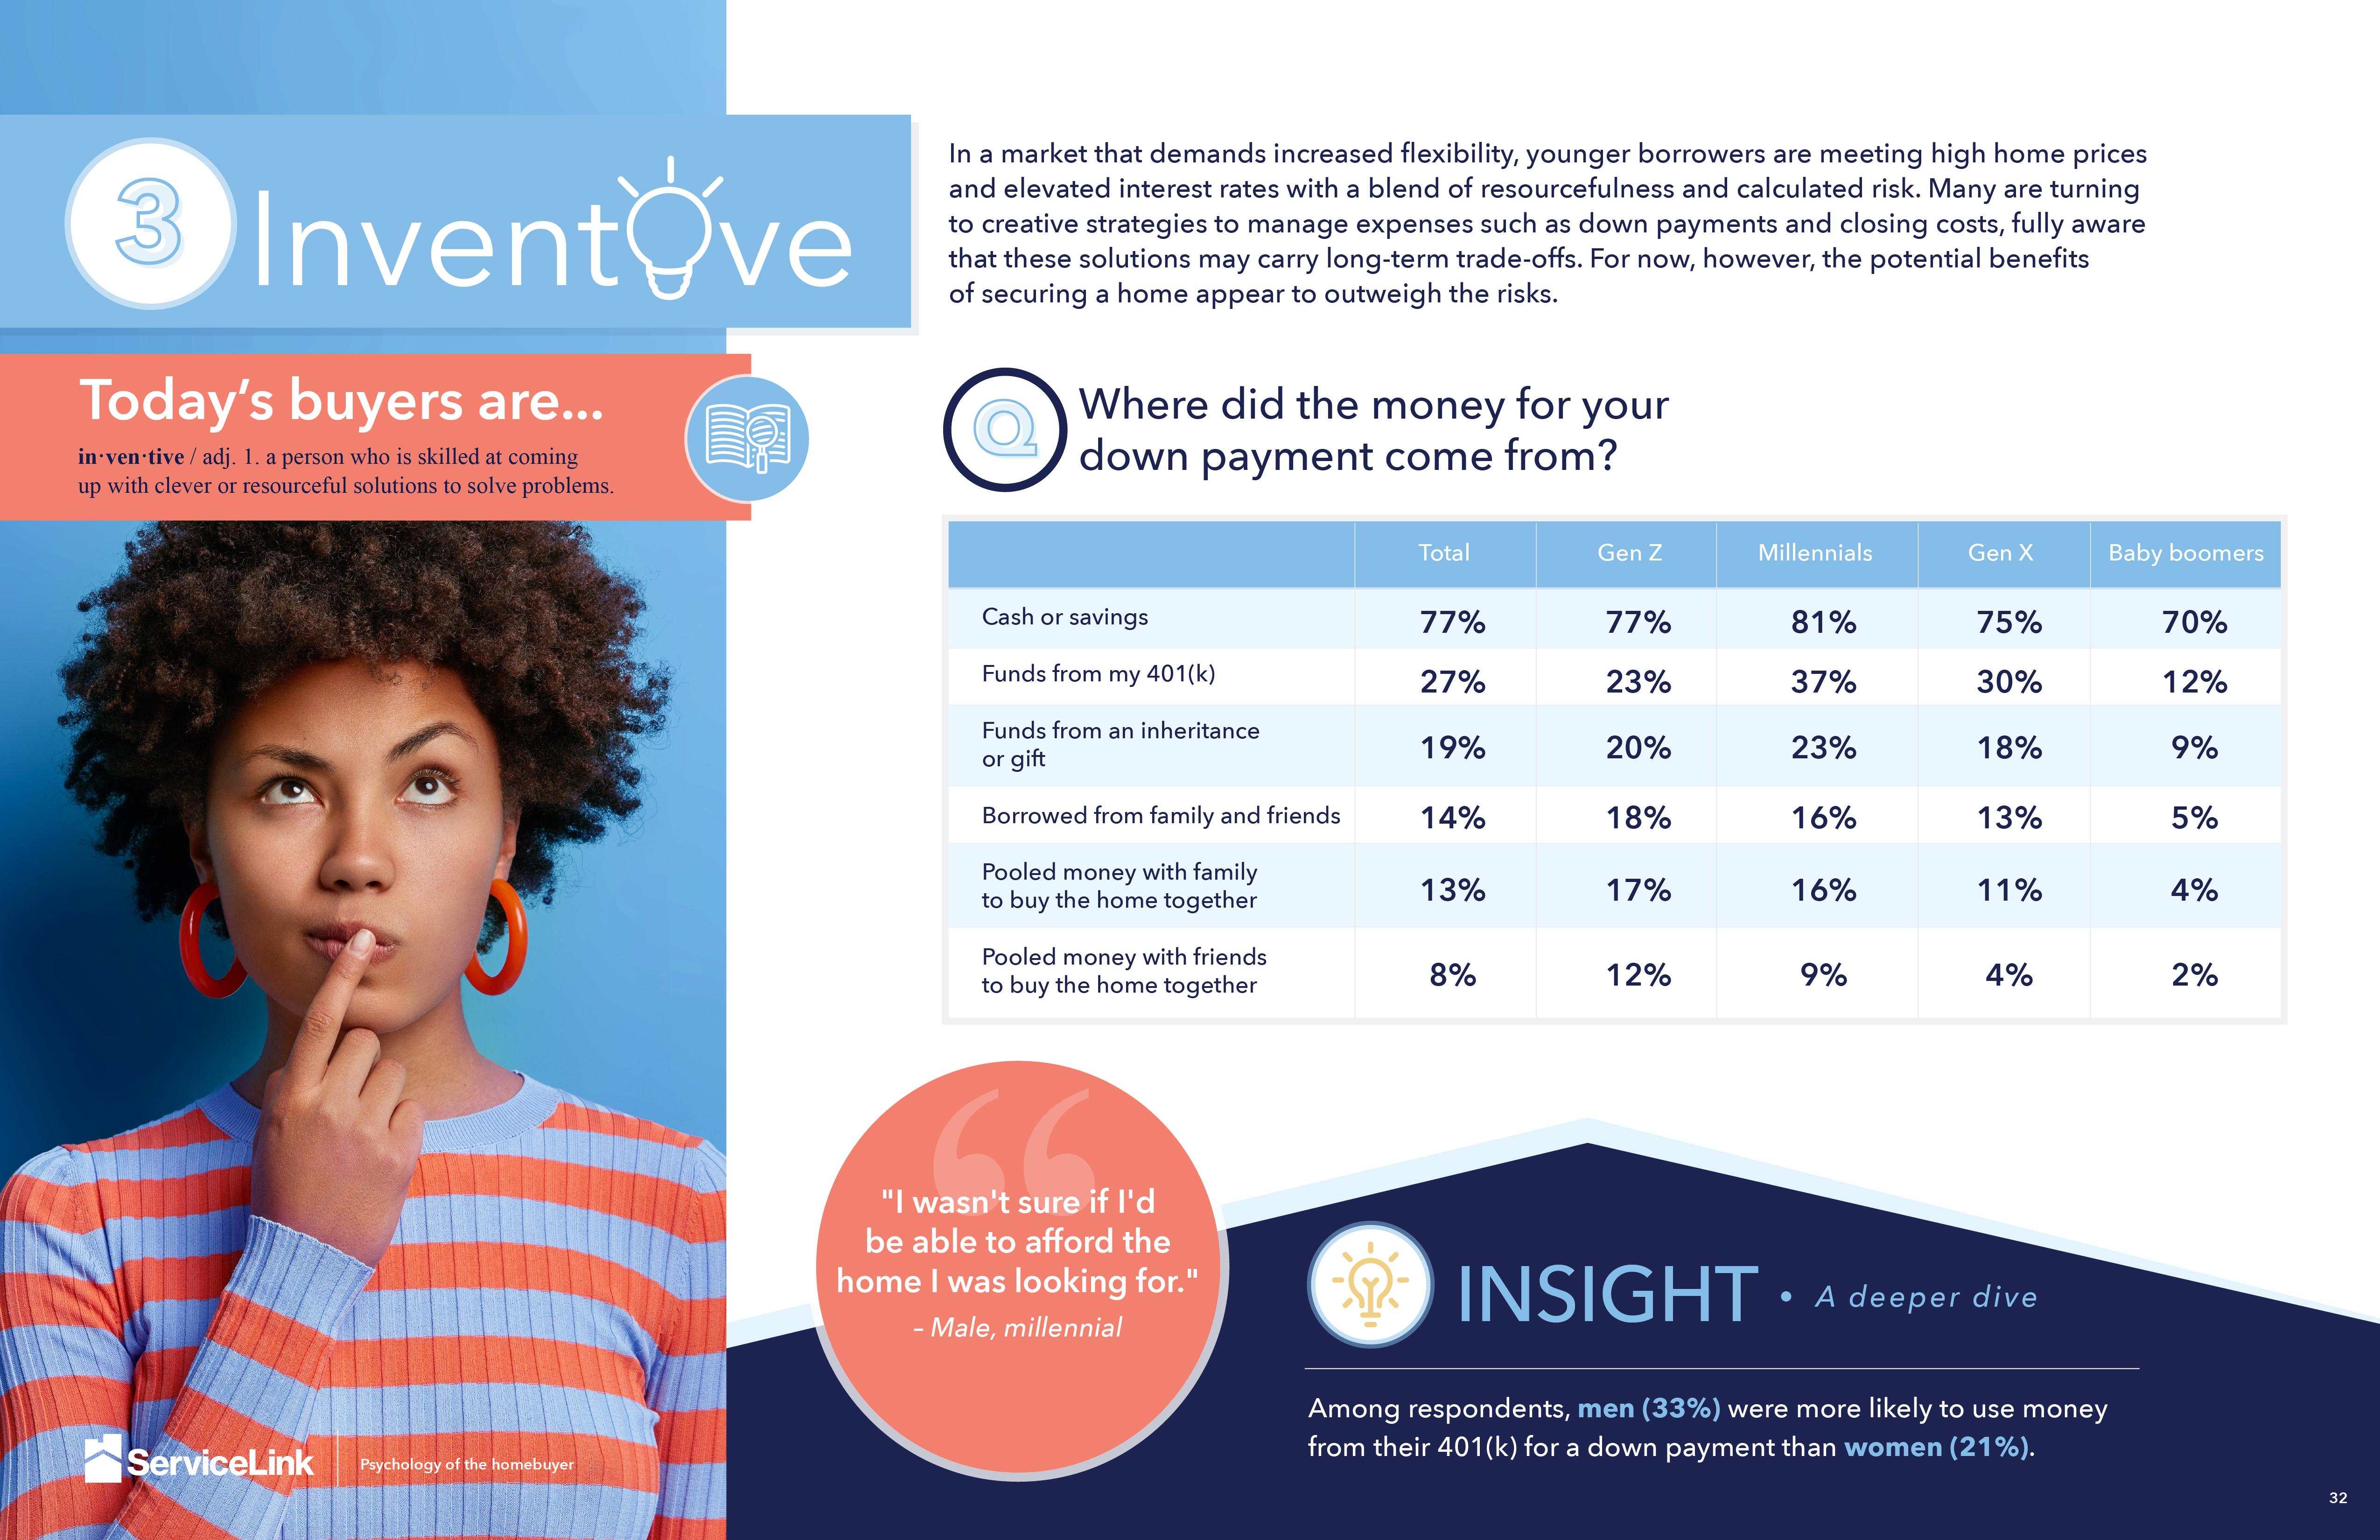
If today’s buyers were currently in the market for a new home, many would accept an interest rate higher than what they’re currently paying – but not by much. Gen Z and millennials have the highest tolerance for higher rates, where they would accept a 0.5% to 0.7% higher interest rate than they are currently paying. Each generation’s tolerance for higher rates has remained relatively the same in the last year.
Despite the increase in mortgage rates over the last three years, many recent buyers say they’re happy with their current rate
I’m unhappy with my rate I’m happy with my rate 64%
I’m indifferent about my rate
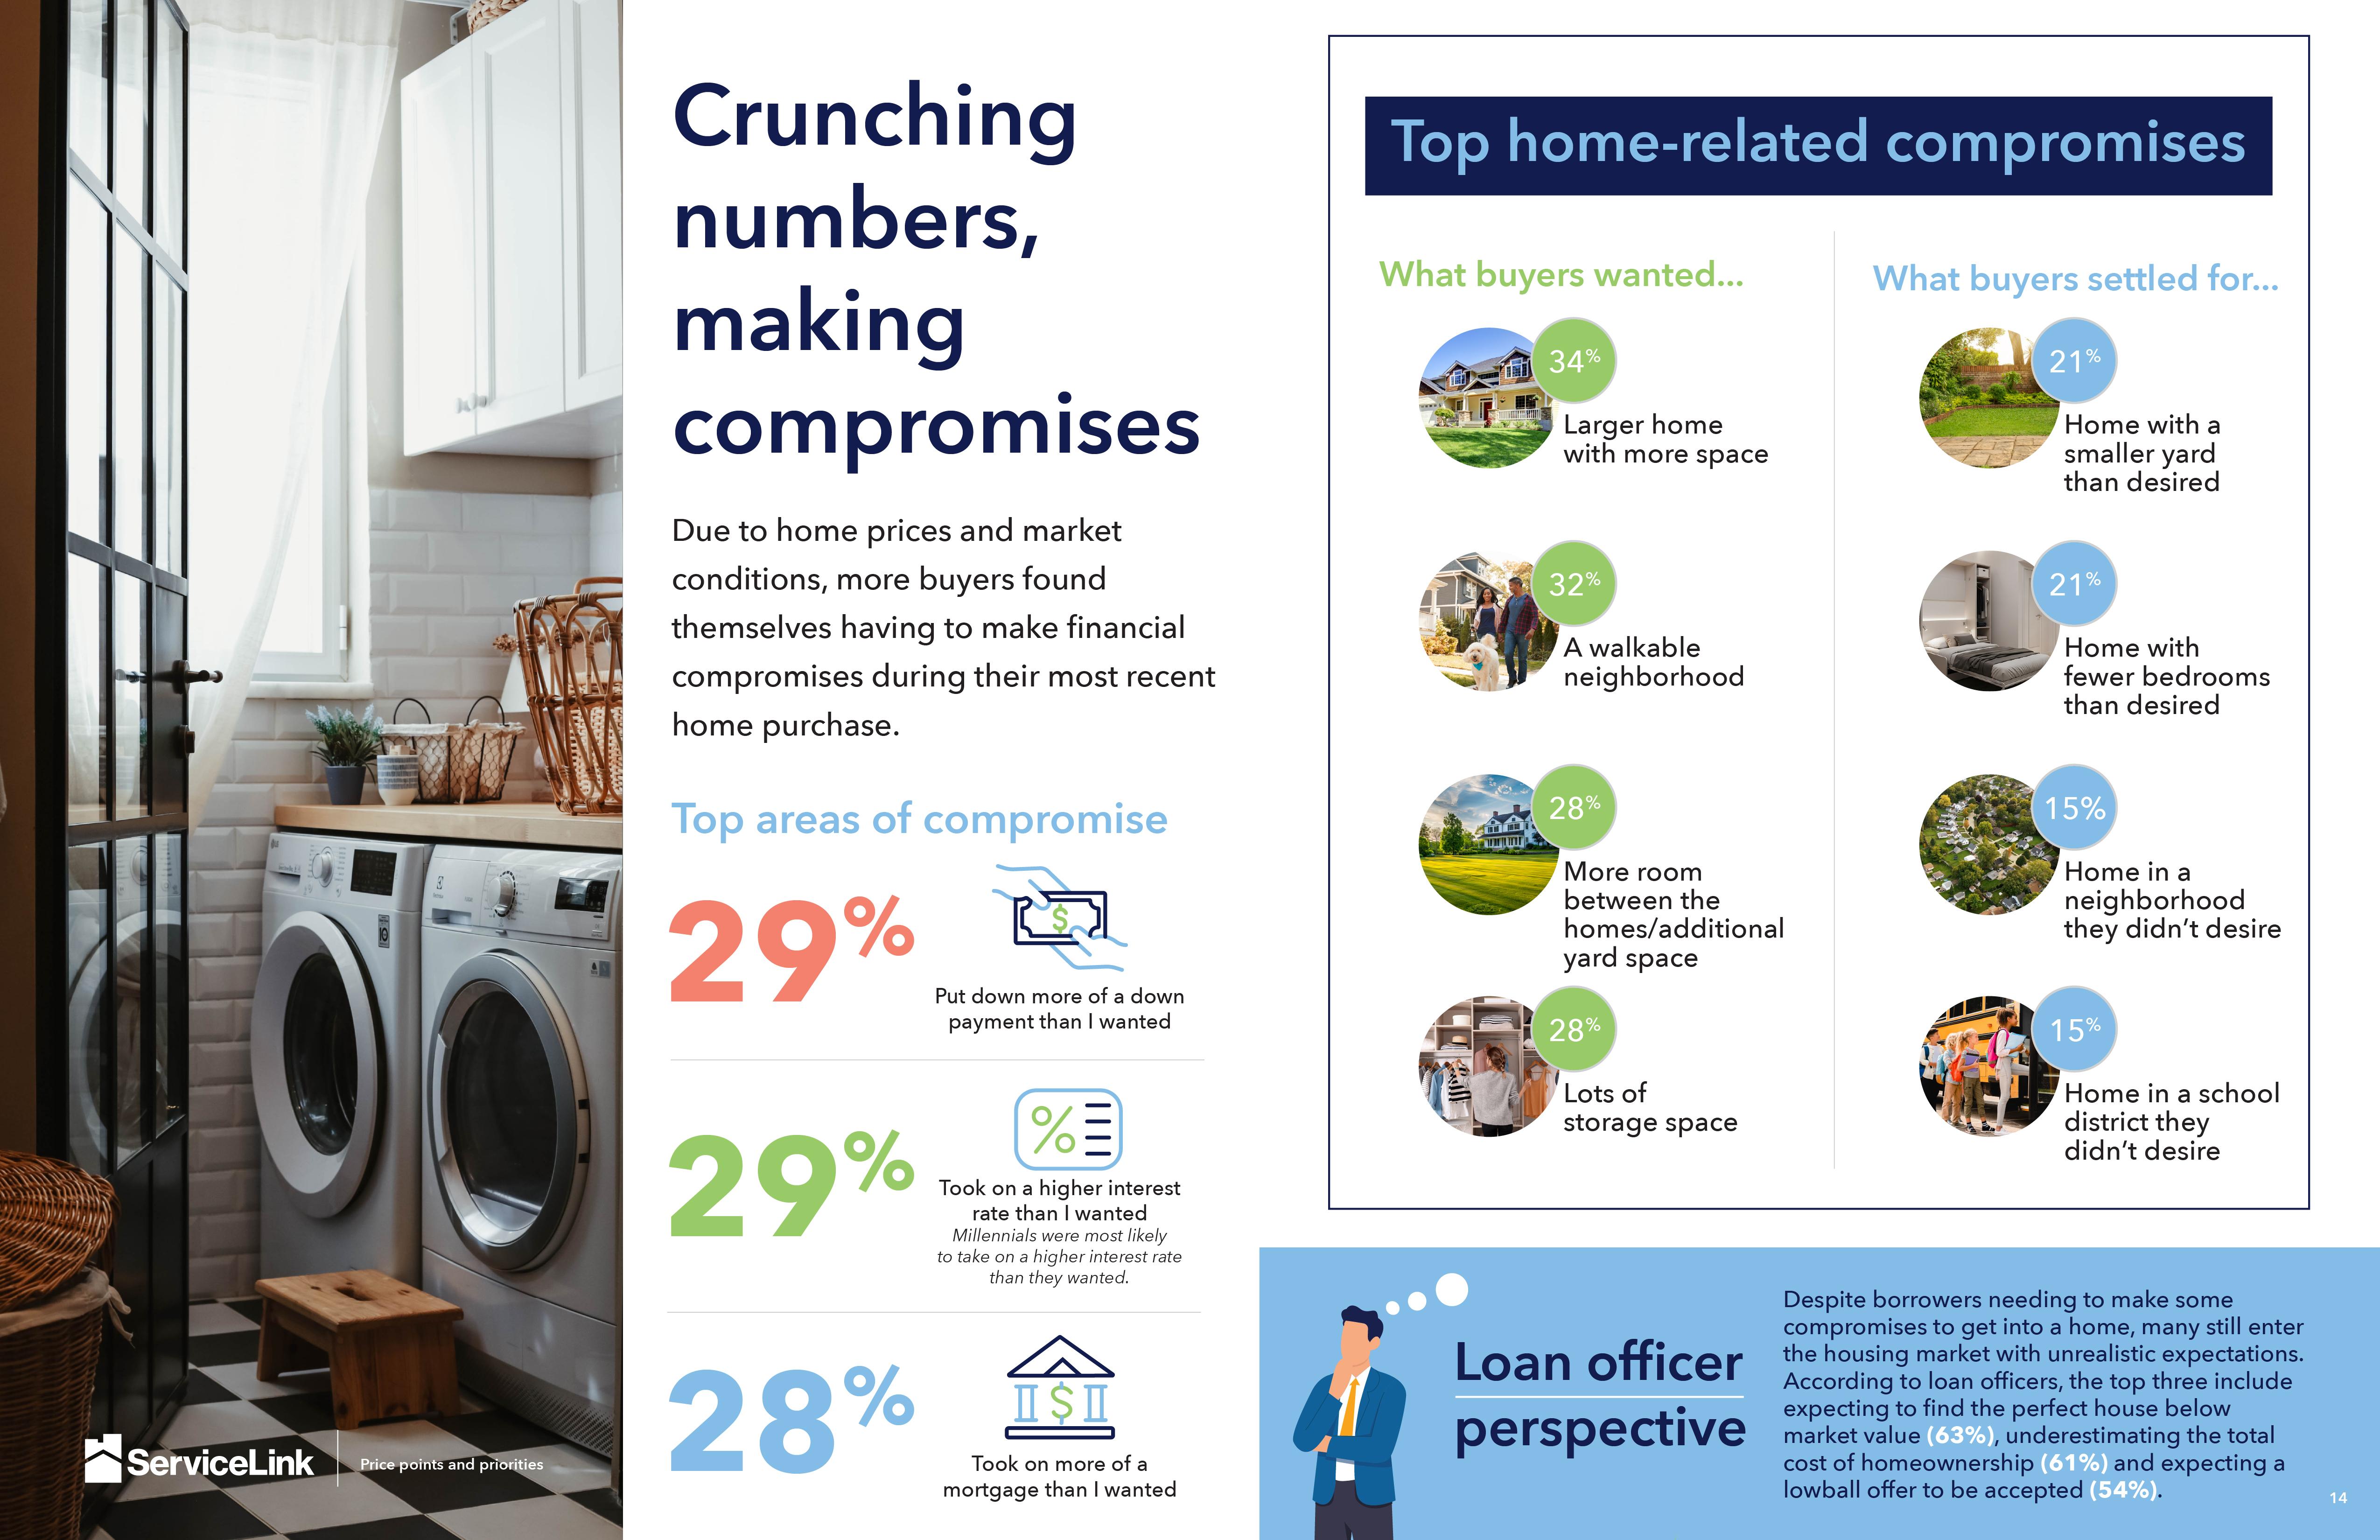
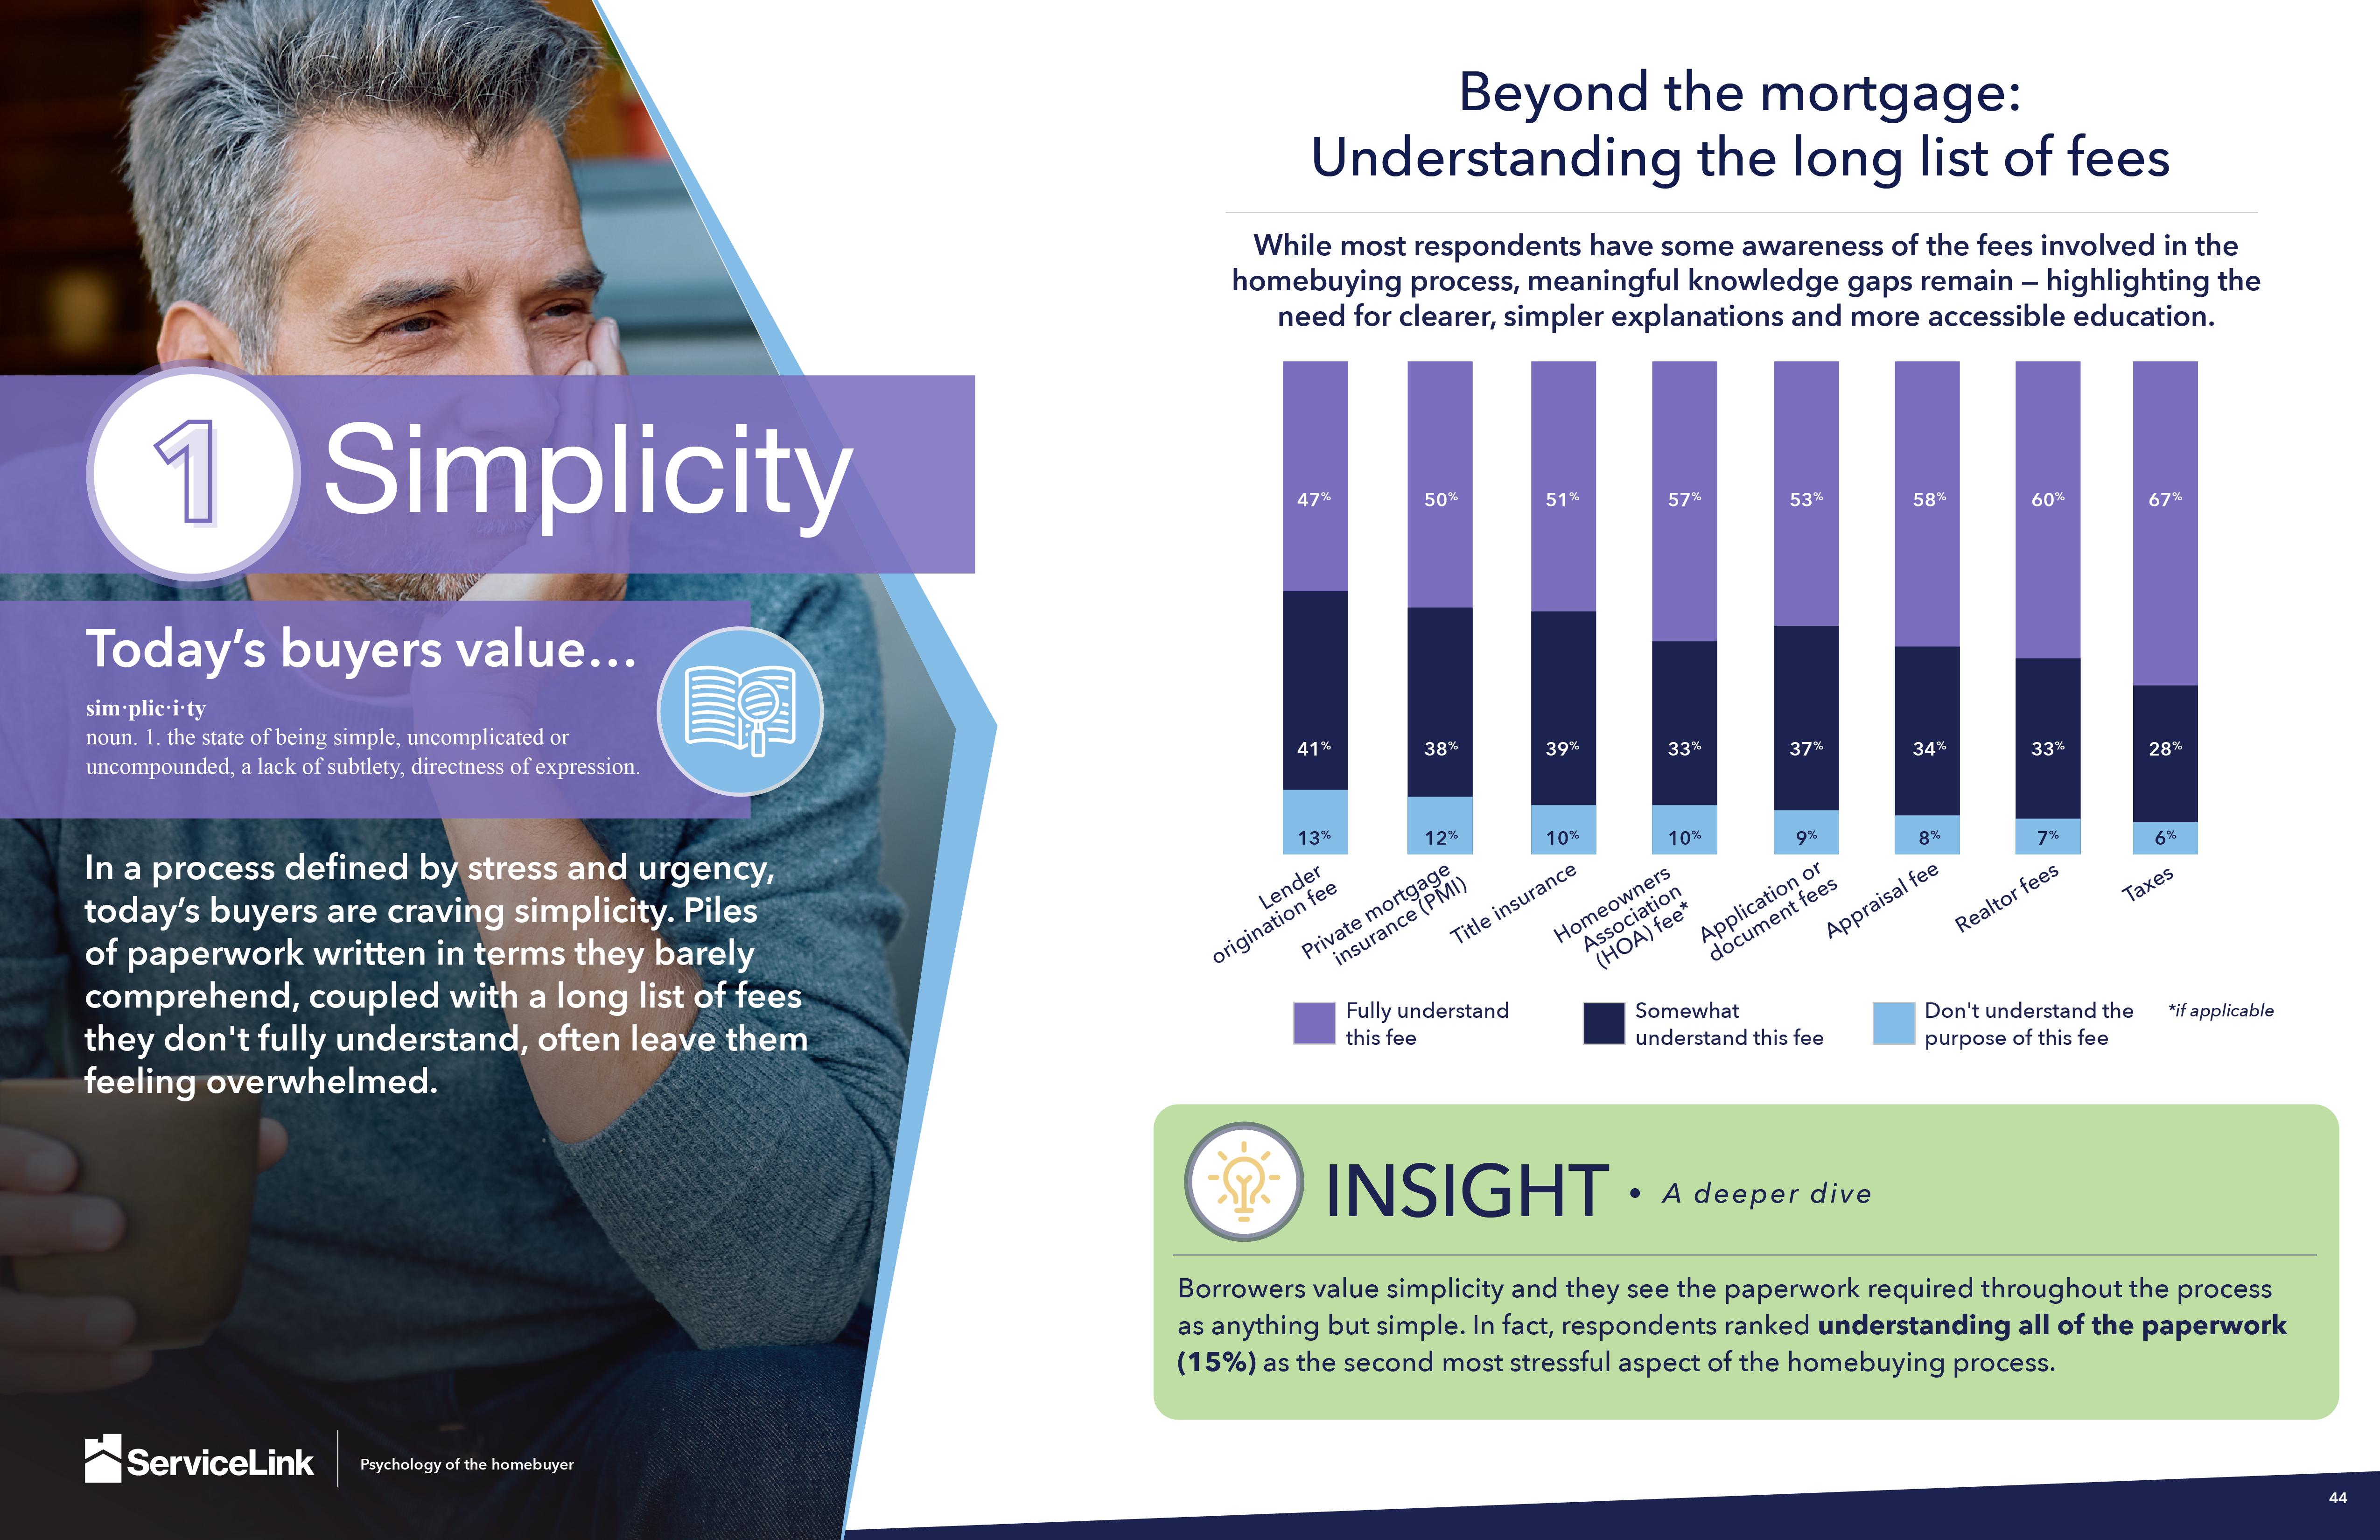
While most recent buyers say they’re happy with their current rate, many still list lower interest rates, along with lower down payments than required, as things they would change about the mortgage process. These also serve as one of their biggest stressors throughout the homebuying process.
“The fear of paying too much or losing the dream home created a high-stakes, no-win pressure.”
- Male, Gen X
“High interest rates were the hardest part for us.”
- Female, millennial
38% of loan officers said home affordability, specifically qualifying borrowers for a loan, keeps them up at night.
25% of loan officers said volatile interest rates keep them up at night.
What are the biggest challenges for today's borrowers?
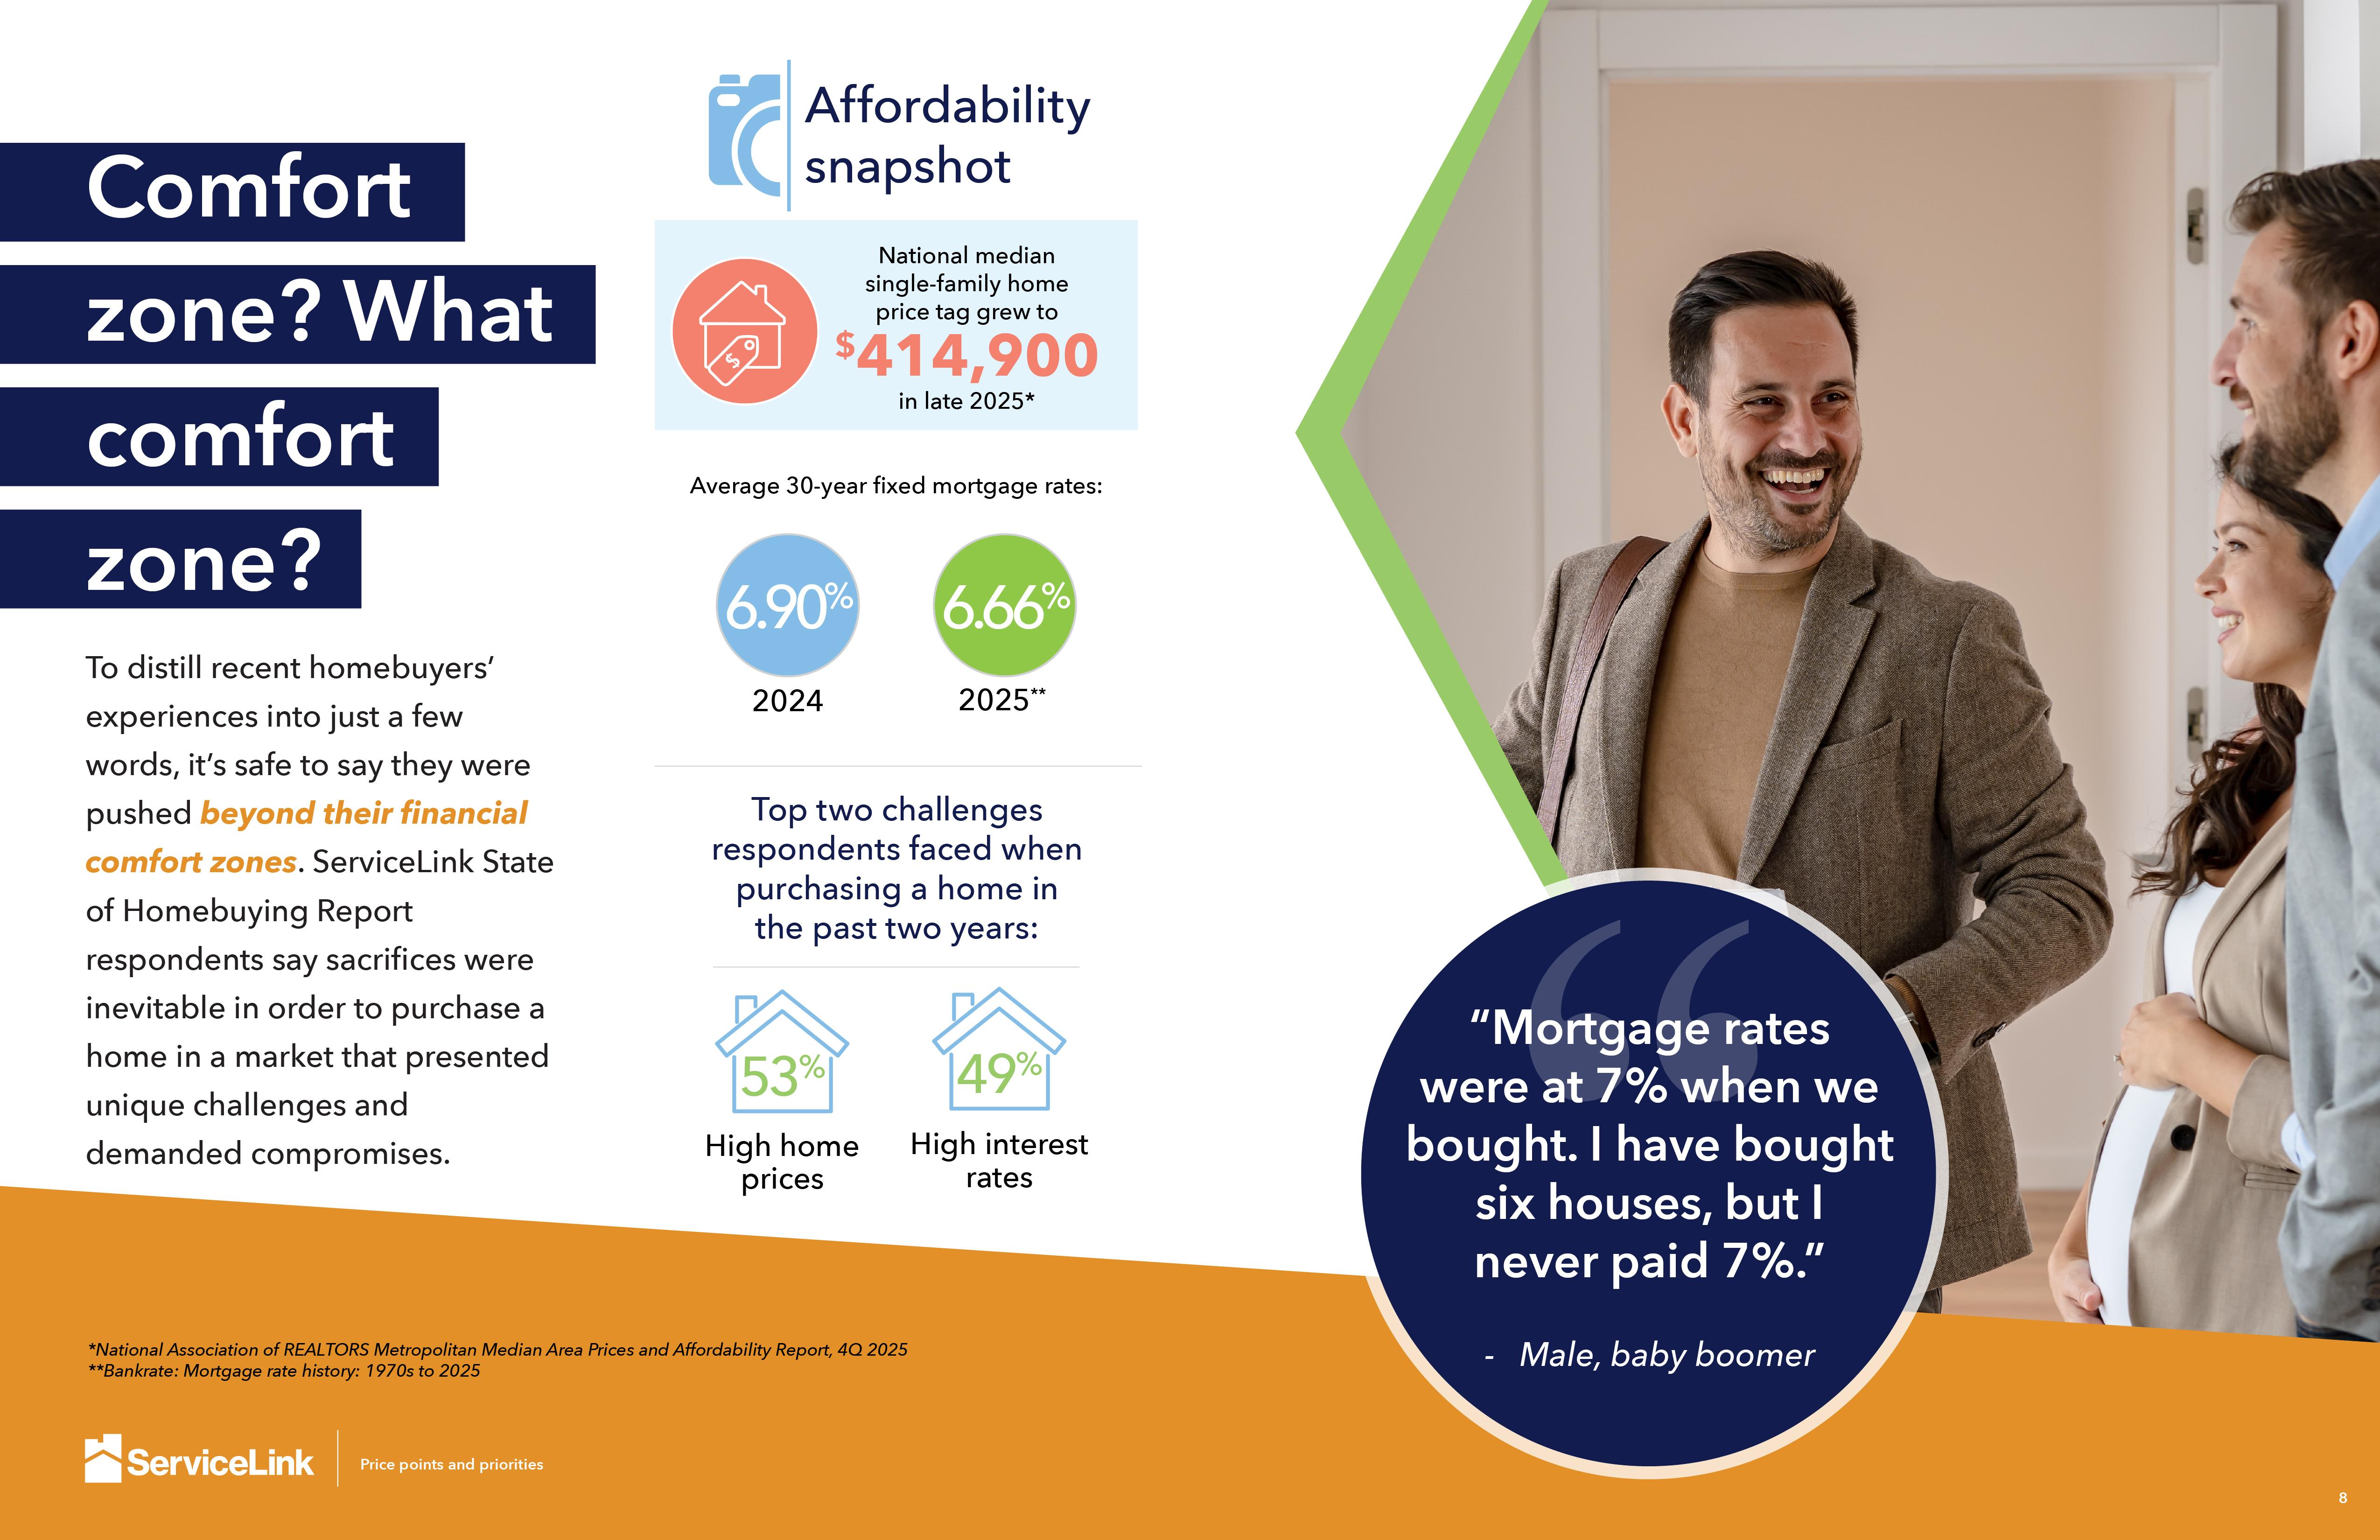
High interest rates
64% Loan officers
49% Homebuyers
Loan officers and homebuyers agree that finances are one of the greatest challenges of the homebuying process. In fact, loan officers see it as an even bigger challenge for their buyers than the buyers themselves see it.
High home prices
57% Loan officers
53% Homebuyers
Lack of money for a down payment
42% Loan officers
22% Homebuyers
Getting pre-approved for a loan
35% Loan officers
24% Homebuyers
Poor credit
34% Loan officers
14% Homebuyers
Lack of housing volume
24% Loan officers
27% Homebuyers
Bidding wars
17% Loan officers
24% Homebuyers