VIC Greenfield Market Report
Luke Kelly
National Managing Director Built Form
luke@rpmgrp.com.au
Victoria’s housing demand has remained resilient in the face of mounting headwinds. The state is gaining population, affordability relative to other state markets has improved, and owner occupier activity is holding up. The question now is whether buyers can bridge the gap between what they desire in a home and what they can afford to build in the current environment.
Housing demand remains resilient. The challenge is bridging the gap between what buyers desire and what they can afford.
In our Q&A session, ANZ Associate Director of Property Daniel Gradwell notes that while conditions aren’t grinding things to a halt, concern around construction cost is elevated across every developer conversation. It is not a supply chain story; materials are available, but excavation, civil works, and road infrastructure are all costing more. The upside in the near term is that much of the titled stock currently on the market was serviced before those cost increases landed. Looking further out, those pressures compound on top of challenges the industry is already navigating.
This is also shaping how developers approach land transactions. With PSP approvals slowing, available sites smaller and more fragmented, and competition for well located land intensifying, developers’ margins for error have narrowed. RPM National Strategy Manager of Transactions & Advisory, Tim Hyland outlines how a data first methodology is driving better acquisition outcomes across residential and commercial asset classes in the current cycle.
This report explores these and other dynamics in detail, unpacking the latest data and sentiment shifts shaping the Victorian greenfield market. We hope it provides a clear view of where demand is headed, what buyers are seeking, and how the industry is adjusting.
For more information, please visit: www.rpmgrp.com.au
For a detailed market analysis or a tailored report, email the team at: contactus@rpmgrp.com.au
RPM’s Market Intelligence division provides in-depth analysis on current local and overseas economic and property market conditions. The team consists of economists, property experts, and GIS analysts that provide real-time market intelligence, and analytical and strategic advice.
Our knowledge and expertise are an invaluable resource for RPM’s developer clients, empowering them to make intelligent, informed, and strategic decisions when evaluating residential developments and investment opportunities.
Our data and analysis help clients maximise their marketing efforts and achieve sales targets on their estates. Each month we collect extensive data on approximately 350 estates in Victoria, 180 estates in Queensland and 180 in New South Wales, providing our clients with a comprehensive understanding of the market dynamics. This also underpins the core strategic decision-making of our own business.
We profile every lot including lot size, price, orientation, sqm rate and title status, monitoring through to final sale.
RPM is also the founding data partner of Terralytics, an independent, next-generation data intelligence platform built for developers, builders, planners, government bodies and industry partners across Australia’s greenfield land markets.
For more information, please visit: terralytics.com.au
This rich data helps our team and clients to better understand:
Volume of lots sold
Dollar per sqm rates
Stock release levels
Volume of stock returned to market
Your dedicated Market Intelligence team:
Michael Staedler General Manager Market Intelligence
Distribution of lots of a particular size
Distribution of price points
Activity levels by market, product & developer
Stock level fluctuations
Andrew Raponi Senior Research Manager Market Intelligence
Rao Research Manager - VIC Market Intelligence
4.35%
The third rate rise this year. May 2026
Unemployment Rate 4.30%
Edged higher during 2026, although remains low from a long term sense. Mar 2026
Annual Wage Growth Index
3.20%
Victoria’s 3.2% annual wage growth to Q4 2025 sits slightly below the national average of around 3.4%. Dec 2025
GDP
0.80
Australia’s economy grew 0.8% in Q4 2025 and 2.6% over the year, indicating a gradual recovery. Dec 2025 AUS Annual Inflation
4.60%
Inflation remains above the target band, highlighting persistent cost pressures across the economy. Mar 2026
The household savings ratio increased to 6.9% in Q4 2025, up from 6.1% in Q3 2025 and 5.5% a year earlier. Dec 2025 Exchange Rate AUD/USD $0.66
Reflecting moderate strength supported by commodity prices but still sensitive to movements from the RBA. Mar 2026
Avg. Weekly Earnings $2,080 A solid 4.4% annual gain, above the national average. Nov 2025
Increased during 2026, to be the highest among all states and territories. Mar 2026 Melb. Median House Price
$991,500 Rising 1.9% from December 2025 and 7.7% year-on-year. Mar 2026 VIC State Final Demand
0.69% SFD keep increased 0.69% in Q4 2025, moderating from 1.59% in Q3 2025. Dec 2025
Employment Participation
67.3%
Remains elevated indicating a strong share of the population is either employed or actively seeking work. Mar 2026 All information is as of the latest available datasets.
Daniel Gradwell
Associate Director of Property
Victoria will become the fastest-growing state in terms of population now that we’re not losing people to other parts of the country.
How do Victoria’s market fundamentals look heading into the second half of 2026?
Melbourne is the only capital city where affordability has improved over the last couple of years. If you want to buy a house in Melbourne, you need around 45% of average income to service a typical mortgage. In Sydney, that figure is 68%, and even Adelaide and Brisbane are sitting in the mid-50s now.
That affordability bonus of moving interstate has basically completely vanished. People aren’t leaving Victoria like they were a couple of years ago, and the outflow has stopped. I think Victoria will become the fastest-growing state in terms of population now that we’re not losing people to other parts of the country.
What is Melbourne’s relative affordability doing for first home buyer activity?
We can see first home buyers coming into the market at a better rate than most other parts of the country, and that’s been the case for a couple of years now. The first home buyer guarantee scheme is also making a material difference, and we can see that across the entire country.
How are construction cost pressures and rising rates affecting feasibility and staging decisions?
It’s coming up in every single conversation we’re having with development clients right now. It’s not at the point where it’s grinding things to a halt, but concern is definitely elevated. The difference from Covid is that supply is largely available. It’s not a supply chain story; it’s just that we have to pay more for the product.
You’ve got excavators running on diesel, pipes going in for water and sewerage, bitumen for local roads, all of that is costing more.
The good news is that a lot of the titled stock in the market right now was serviced before those cost increases landed, so that land isn’t going to incur the recent uptick in servicing costs. Looking further out though, it doesn’t help, and it kind of compounds on top of other issues the industry is already facing into.
What’s your overall outlook for the Victorian greenfield market?
Affordability looks quite good right now, and that’s supporting first home buyer demand and keeping population in Victoria.
Victoria looks set to become the fastest-growing state in the country, and that underlying population growth means the demand for new housing will grow. The opportunity is there to meet that demand, but the challenge is how do we actually bring it to market, given uncertainty, interest rates increasing, construction costs increasing and so on.
Tim Hyland
National
Strategy Manager
Transactions & Advisory
tim@rpmgrp.com.au
Victoria’s development land pipeline has tightened considerably over recent years. PSP approvals have slowed, available stock is comprised of smaller and more fragmented parcels, and competition for well located sites is intensifying. The margin for error has narrowed with it, particularly for developers still applying the same acquisition processes they used in a more forgiving cycle.
The projects that perform well across both residential and commercial sectors tend to share a common thread. The initial site acquisitions were supported by a more rigorous process where the data comes first, then drives the key decisions.
Strategies that pinpoint high growth opportunities and emerging development hotspots.
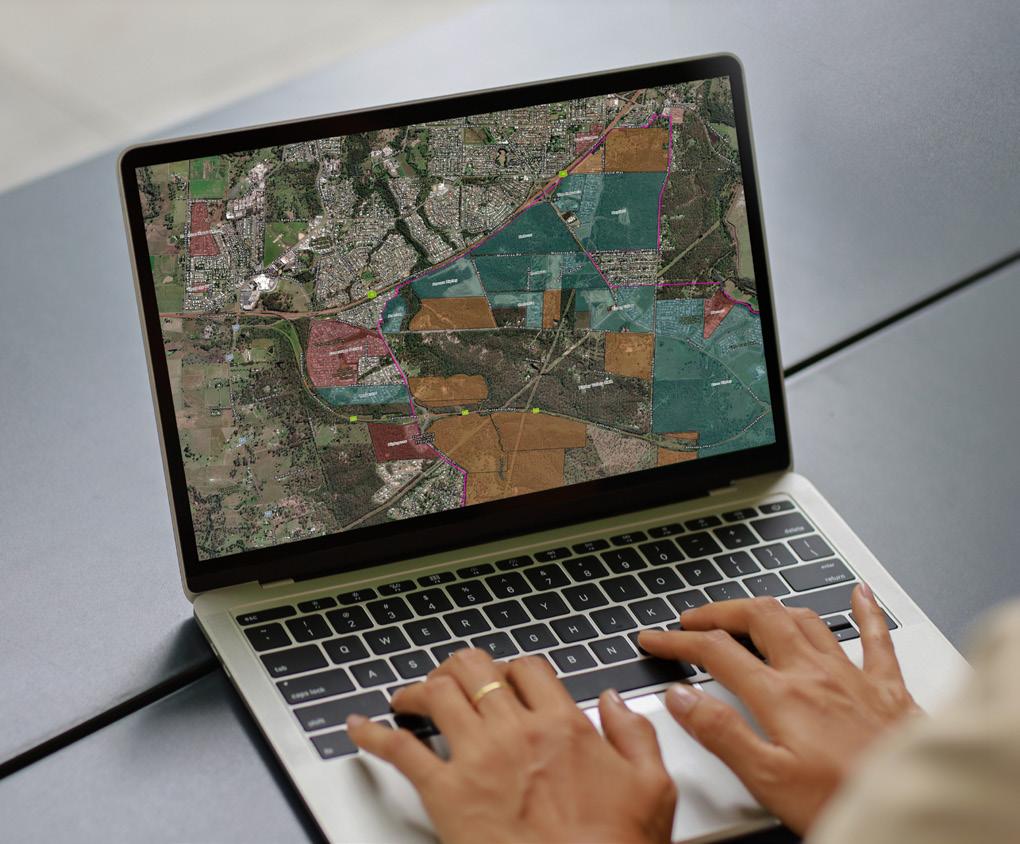
RPM Transactions & Advisory (T&A) layers GIS mapping across designated growth areas, infrastructure constraints, and landholding data to more accurately reveal a site’s true value. Historical transaction data and real time market trends narrow the field further, pinpointing high growth opportunities and emerging development hotspots before they are widely recognised.
Predictive modelling then stress tests each opportunity against planning controls, market demand, and projected population growth, producing a sharper picture of where genuine development potential exists.
Proximity to transport, employment, and community amenity shapes absorption and end buyer demand in ways that are measurable well before a residential site goes to market. The developers consistently making strong acquisitions understand that this analysis belongs at the beginning of the process, not appended to a feasibility after an agreement is signed.
RPM T&A extends this analytical framework across all asset classes. In the data centre sector, power grid capacity and network infrastructure are mapped to identify sites viable for digital infrastructure both now and into the future, with connectivity, energy availability, and planning considerations all assessed as part of the site selection process.
For childcare centres and school sites, demographic modelling of birth rates, family density, and catchment supply gaps produces a far clearer picture of where demand will be in five years than any current survey can offer. This is the methodology that has underpinned several of RPM’s record breaking transactions in recent years.
Whether residential or commercial, the underlying discipline is consistent: translate complex datasets into a clear view of where opportunity is, enabling smarter, faster, and more strategic acquisition decisions. Opportunities that once generated modest interest are now producing genuine competitive tension.
For more information on development site opportunities, contact
Tim Hyland
tim@rpmgrp.com.au
Rod
Anderson National Managing Director Communities rod@rpmgrp.com.au
Purchaser sentiment softened through Q1 2026, with gross lot sales of 3,515 across metropolitan and regional growth areas representing a 30% quarterly decline and sitting 3% below the same period in 2025.
The quarterly pullback reflects both the direct impact of two consecutive RBA rate rises in February and March and the broader deterioration in consumer confidence as household cost pressures intensified through the quarter.
The affordability tailwind that sustained momentum through 2025 has reversed. Three rate cuts delivered through last year, combined with wage growth outpacing inflation for most of the period, had materially improved borrowing conditions. The February and March hikes have unwound a meaningful portion of that improvement, reducing borrowing capacity and reintroducing uncertainty around the rate outlook. Developer end-of-year campaigns that helped drive Q4 activity have also wound down, removing a layer of short-term demand stimulus from the market.
Sequential rate rises through early 2026 tempered the momentum built through 2025, with buyers recalibrating against a more uncertain interest rate and cost of living environment.
Titled stock continues to influence sales activity, though its share has moderated. Across metropolitan growth areas the proportion remains lower than regional corridors, where titled lot dominance (particularly in Geelong and Ballarat) continues to defer new stage releases. Melbourne’s median lot price lifted 3.4% over the quarter to $398,250, breaking toward the $400,000 mark that has acted as a ceiling for six consecutive quarters, while the median lot size held steady at 350sqm.
Average trading days for lots sold in Melbourne improved further to 157 days, down 6% on the prior quarter and 14% annually — the continuation of a trend that points to more efficient stock absorption in metropolitan estates despite the softer headline sales result.
Smaller product lots, including townhomes, small lot housing code product and conventional lots between 300 and 450sqm in regional areas, continued to account for a growing share of transactions as affordability constraints directed buyers toward more efficient configurations.
Lots Sold (All Regions)
$398,250
Source: RPM Market Intelligence
$700-750k
$650-700k
$600-650k
$550-600k
$500-550k
$450-500k
$400-450k
Source: RPM Market Intelligence and Terralytics - as at Q1 2026. All differences are expressed as changes from the previous quarter. Price figures have been rounded to the nearest ‘000’.
Note: Locations are approximate only
Source: RPM Market Intelligence and Terralytics
The Western growth corridor recorded 937 gross lot sales in Q1 2026, down 40% from Q4 2025’s 1,566. Despite the pullback, the West remained one of Melbourne’s most active corridors, with family buyer participation and steady underlying enquiry holding firm. Established estates with stronger amenities continued to outperform newer releases.
Titled stock again shaped activity, with buyers favouring immediate build readiness and shorter delivery timelines. Builder promotions across Wyndham’s northern precincts helped offset softer demand periods through the quarter.
New supply eased modestly in Q1 2026, with 726 lots released across Wyndham and Melton, down 8% on Q4 2025. Developers focused on absorbing existing titled and near titled stock rather than pushing new supply into a softening sales environment.
Stock returns declined again, pointing to improved buyer retention despite two rate rises through the quarter. Active estates fell to around 126 by quarter’s end, their lowest level in over two years. That consolidation reduces head to head competition between projects and supports a more stable pricing environment heading into the rest of 2026.
Price & Size - Q1 2026
$379,500
Median lot pricing lifted 4% in Q1 2026, from $365,000 in Q4 2025 to $379,500, while the median lot size held steady at 350sqm. Per sqm rates improved in line with the price movement.
At $379,500 for 350sqm, the Western corridor offers the strongest value per sqm of any major Melbourne growth corridor. For price sensitive buyers, the gap is meaningful and continued to drive enquiry even as borrowing conditions deteriorated through the quarter.
Price growth is expected to remain moderate through 2026, with upward pressure most likely if titled stock tightens further across Wyndham and Melton’s key precincts.
The Northern growth corridor recorded 981 gross lot sales in Q1 2026, down 29% on Q4 2025’s 1,385. Hume continued to anchor performance, supported by consistent absorption across large masterplanned communities. Whittlesea and Mitchell also delivered stable monthly sales, buoyed by continued interest from entry-level purchasers. Demand remained strongest for well-located stages offering flexible deposits and stronger builder alignment. Trading days improved as several leading estates progressed through titles, providing clearer construction timelines and strengthening buyer confidence in a time of growing uncertainty.
The corridor’s house and land packages demand profile remained a distinguishing feature, enabling developers to maintain momentum even as other corridors saw a tilt back toward titled lots. This reinforces the North’s strong position among first-home buyers who remain drawn to the region’s attainable price points and the established scale of its masterplanned communities.
New supply pulled back through Q1 2026, with 856 lots released across the corridor — a 21% decline on Q4 2025’s 1,089. Releases remained concentrated across Hume and Mitchell, with no significant new estate launches through the quarter, keeping supply broadly aligned with underlying demand. Stock returns declined again, reinforcing continued purchaser commitment.
Active estates declined to 91 over Q1, down 33% from the Q2 2023 peak of 135. With fewer projects competing for the same buyer pool, remaining estates are operating in a less fragmented market — a dynamic that supports pricing discipline and reduces pressure to discount or over incentivise.
Available stock edged lower by quarter end, leaving the North with one of the tighter supply pipelines across Melbourne’s growth corridors. Combined with the consolidation in active estates, this positions the corridor well for more stable release activity through 2026, provided demand conditions hold.
Median lot pricing lifted 1.6% in Q1 2026, moving from $384,000 in Q4 2025 to $390,000. The median lot size held steady at 350sqm, consistent with Q4 2025. Per sqm rates improved modestly in step with the price movement.
At $390,000 for 350sqm, the North sits at a slight premium to the Western corridor on a per sqm basis. What justifies that premium is the scale and maturity of its masterplanned communities — established amenity, likely stronger builder networks, and a forward sales pipeline that gives firsthome buyers certainty in an uncertain environment. Buyers aren’t just purchasing land, they’re buying into a functioning community with a clearer path to build.
Price growth should remain moderate through 2026, with more meaningful movements likely to emerge only if supply tightens materially across Hume and Mitchell’s key precincts and the lending environment shows some sign of improvement or at least stabilise.
Gross Sales - Q1 2026
The South East corridor recorded 688 gross lot sales in Q1 2026, a 31% decline on Q4 2025’s result of 994. Casey again led the region, with Cardinia attracting continued interest across the more affordable eastern estates. While activity softened, the corridor retained broad buyer appeal across both the upgrade and entry-level cohorts.
Trading days improved as titled product was absorbed more readily, with Officer and Cranbourne estates active. Local demand remained the dominant driver, with investors largely absent from the mix.
Despite the quarterly decline, the South East retained a consistent upgrader cohort, with buyers less impacted by the worsening lending environment and taking advantage of clearer construction timeframes. This underpinned a reliable baseline of monthly sales activity through Q1.
New supply lifted 27% in Q1 2026, with 827 lots released compared to 650 in Q4 2025. Casey drove the bulk of this increase, delivering additional releases across staged communities as developers responded to tightening stock conditions. Stock returns rose to 110 lots, up from a recent low of 72 recorded in Q4 2025, though the movement remains within normal seasonal ranges rather than signalling any deterioration in buyer commitment.
Active estates contracted to 66 in Q1, continuing a gradual consolidation that has kept the South East’s supply environment more structured than in prior years. With fewer projects competing for the same buyer pool, well-located estates are facing less direct competition — a dynamic that continues to support pricing discipline across the corridor.
Available stock remained tight by quarter-end despite the lift in releases, reflecting consistent absorption through the back half of 2025. High-amenity estates continued to outperform, maintaining competitive conditions for well-located land across Casey and Cardinia.
$448,000
Median lot pricing rose 3% in Q1 2026, moving from $435,000 in Q4 2025 to $448,000. The median lot size increased to 376sqm, up 26sqm on the prior quarter, with the size shift reflecting a change in the mix of stock transacting rather than a fundamental product pivot. Per sqm rates remained broadly stable as price and size movements largely offset each other.
Premium precincts across Berwick South, Cranbourne East and Officer South continued to command higher values, reinforcing strong spatial segmentation within the corridor. Buyers showed continued willingness to pay for proximity to established amenity and transport infrastructure.
With stock remaining tight and releases only modestly lifting, upward pricing pressure in select locations is likely to persist through 2026, particularly across high-amenity estates with limited forward supply.
Gross Sales - Q1 2026
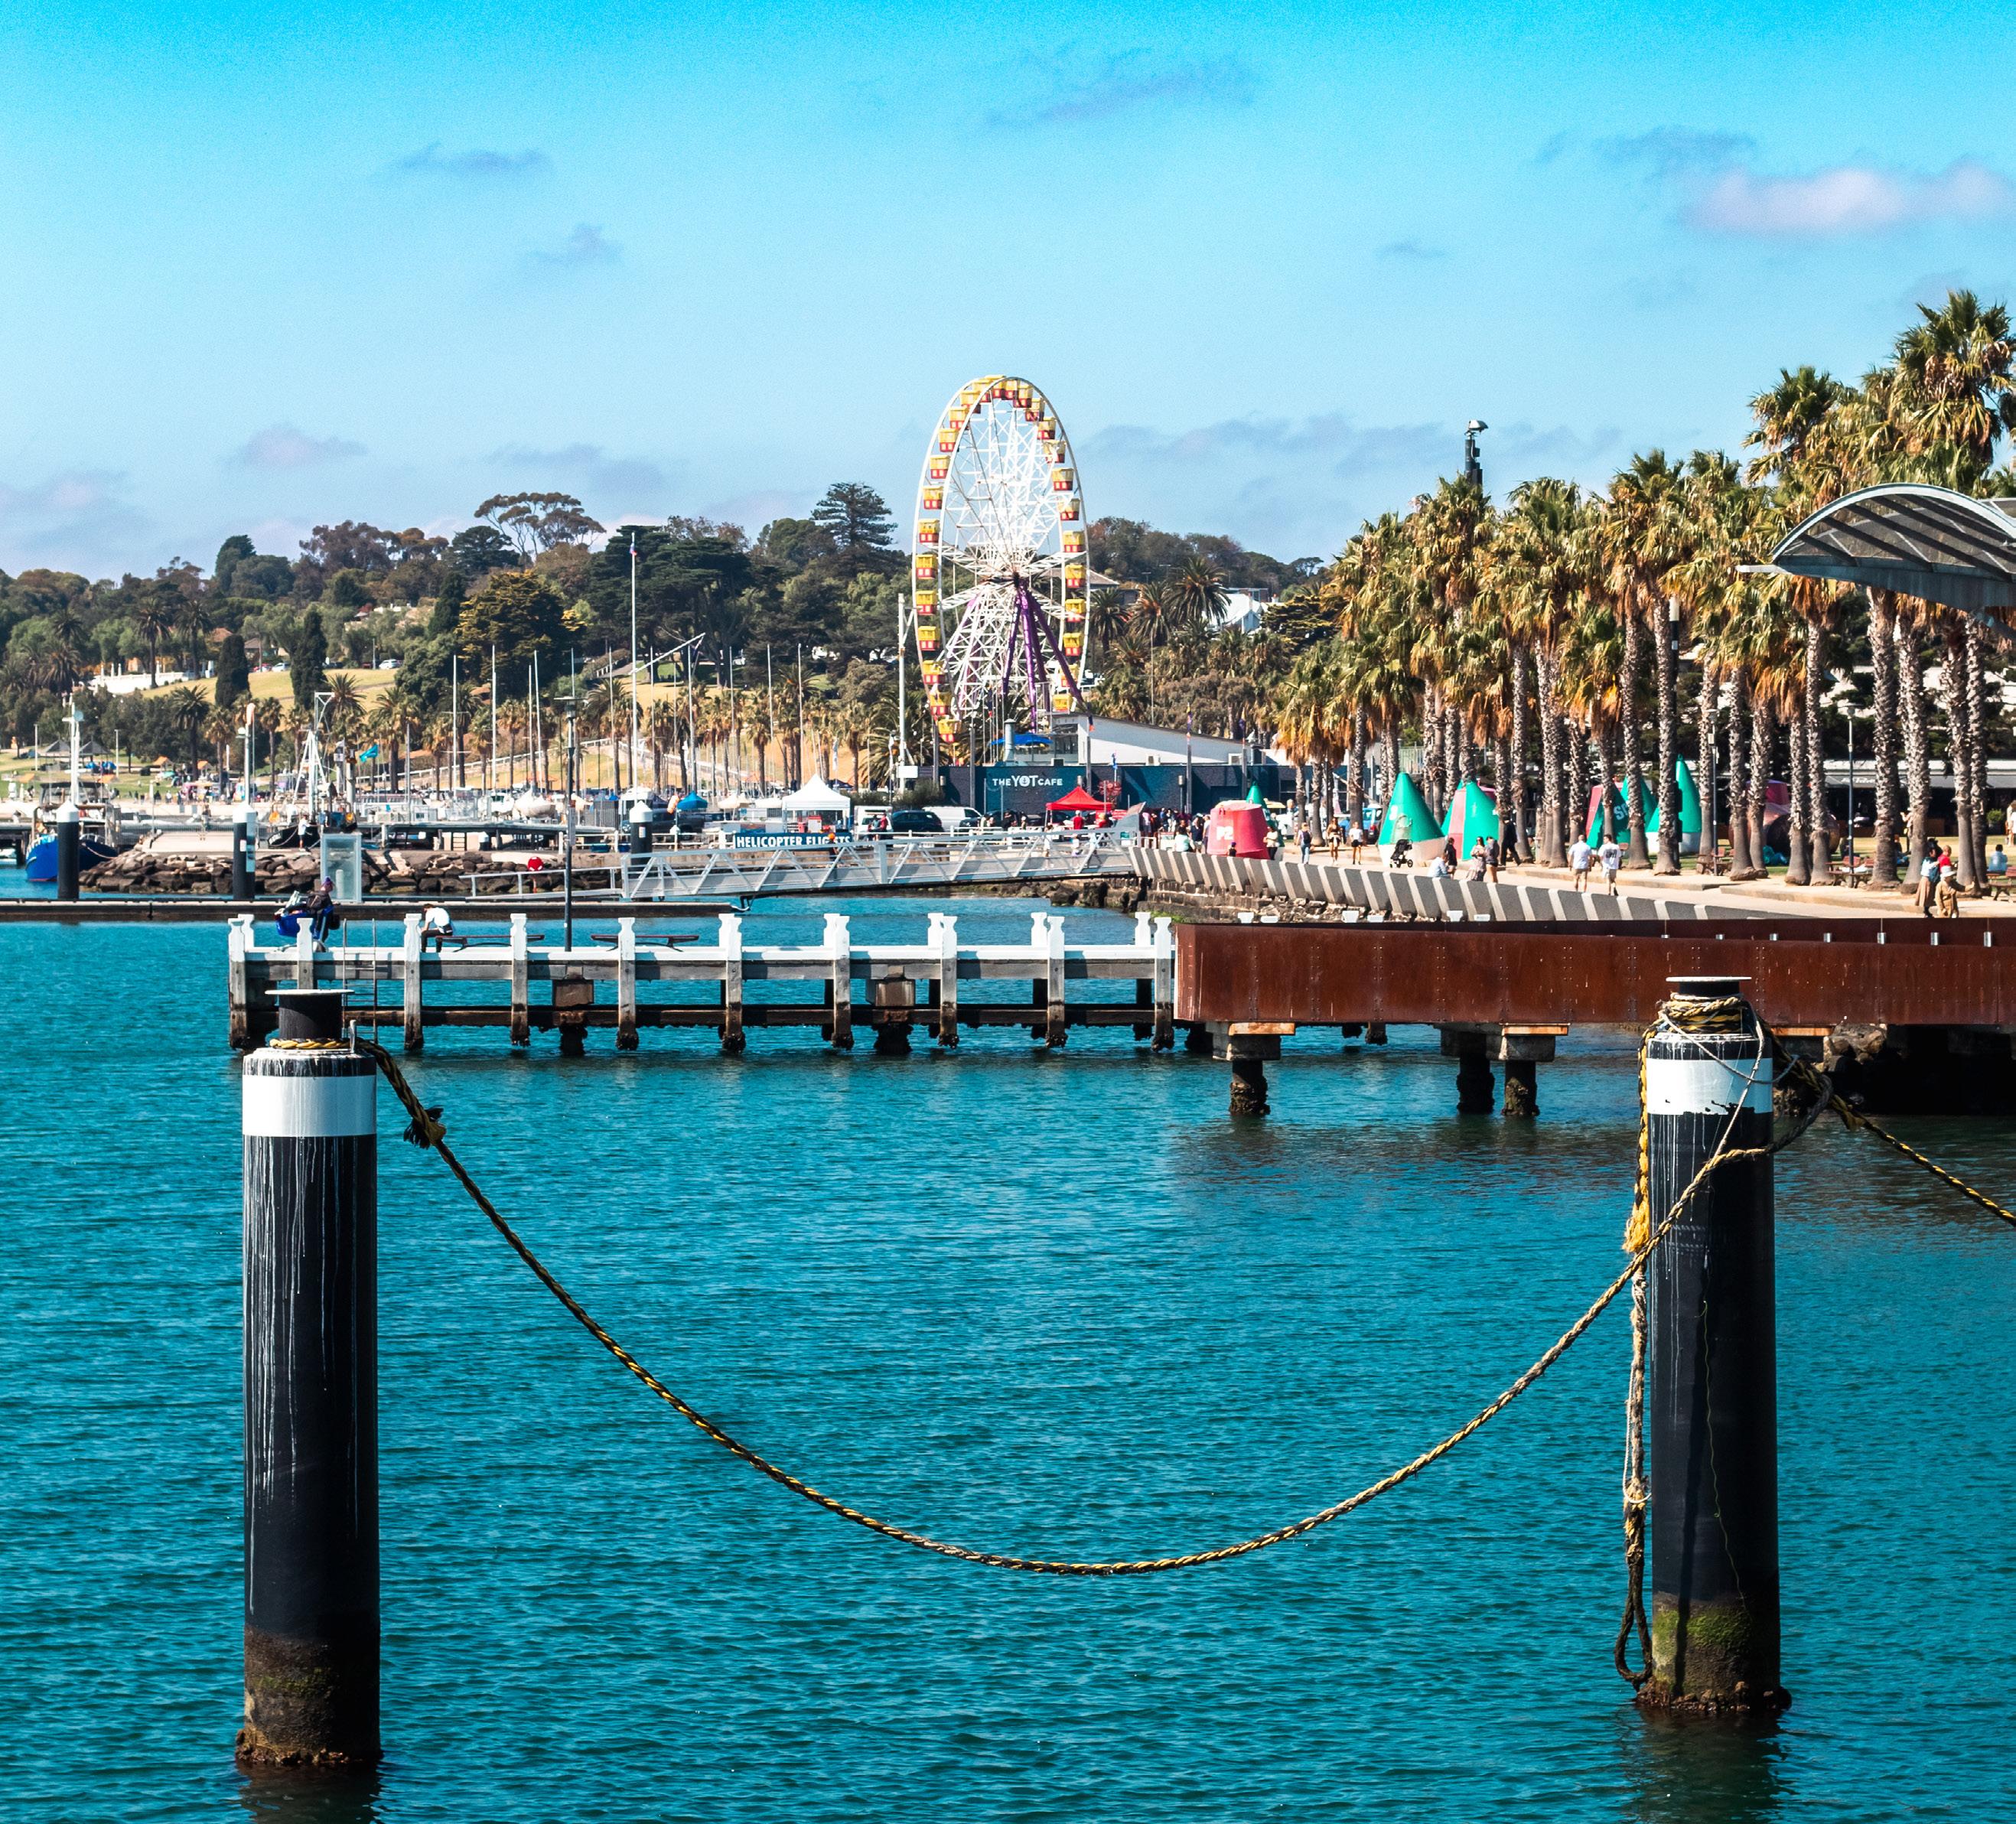
Greater Geelong recorded 471 gross lot sales in Q1 2026, a 10% decline on Q4 2025’s result of 526. Armstrong Creek continued to anchor performance, supported by strong builder alignment and sustained demand for titled stock. Enquiry held up across several high-activity estates through the quarter despite the broader seasonal softening.
Lara and adjacent precincts continued to deliver consistent volumes, benefitting from relative affordability and access to established transport links. Buyers remained sensitive to build timelines but responded positively to clearer delivery pathways.
Market sentiment remained constructive through Q1, despite the higher lending environment, with improving construction lead times offsetting this and leading to support upgrader driven enquiry across the corridor.
New supply lifted 20% in Q1 2026, with 268 lots released compared to 224 in Q4 2025. The increase was measured, with fewer new estates coming to market relative to Melbourne’s growth corridors. Stock returns fell to 58 lots — the lowest reading in the series — pointing to strengthening buyer retention and minimal cancellation activity through the quarter.
Active estates held steady at 65, consistent with the corridor’s pattern over the past three years — a more stable supply base than what’s been seen across Melbourne’s growth corridors through the same period.
Supply conditions remained broadly balanced, as developers remained focused on clearing titled and near-titled stock ahead of larger release programs scheduled through 2026, a strategy that continues to preserve pricing stability across Armstrong Creek and Lara’s key precincts.
Price & Size - Q1 2026
$385,000
Median lot pricing edged up 0.8% in Q1 2026, rising from $382,000 in Q4 2025 to $385,000. The median lot size increased marginally to 400sqm, up 1sqm on the prior quarter, reflecting continued buyer preference for slightly larger lot formats across key Armstrong Creek stages. The per sqm values remained broadly stable as a result.
The corridor continued to attract value driven buyers seeking larger lot formats at more accessible prices than Metropolitan Melbourne alternatives. This supported steady absorption and a consistent sales profile through Q1.
Pricing is expected to remain steady throughout the remainder of 2026, with more meaningful upward pressure only likely if supply conditions tighten across Armstrong Creek and Lara’s key release pipelines.
Gross Sales - Q1 2026
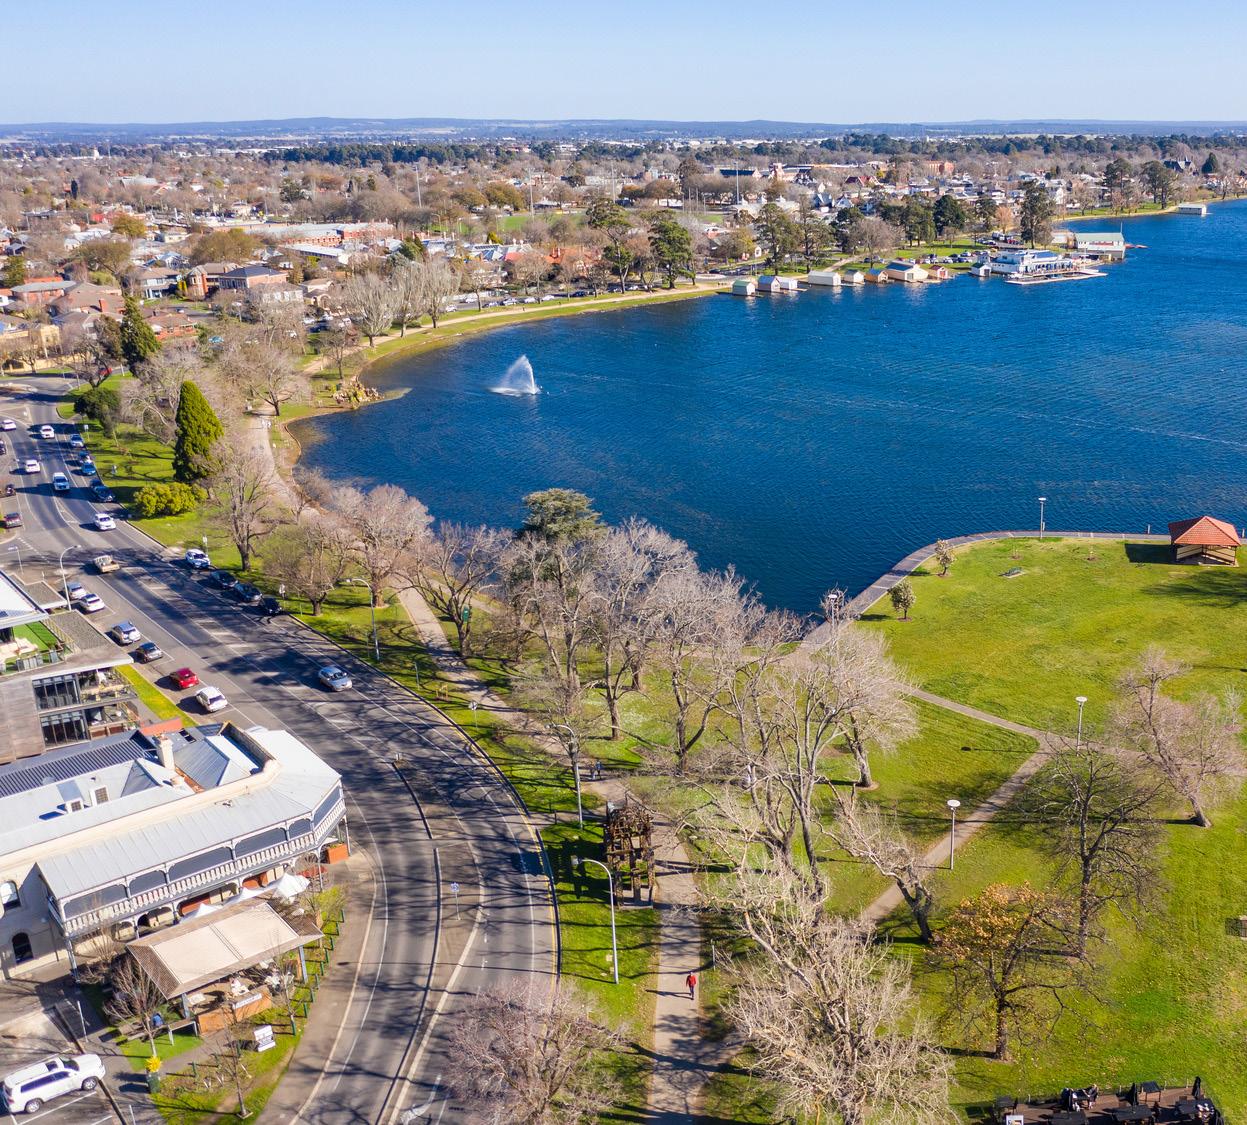
Ballarat recorded 174 gross lot sales in Q1 2026, a 28% decline on Q4 2025’s result of 240. Sales remained concentrated in the western growth precinct, continuing a trend seen throughout 2024–25, with smaller but steady contributions from the southern precinct. The eastern and northern regions continued to operate at low but stable levels.
Buyer enquiry held up through the quarter, supported by a combination of builder incentives and continued clearing of titled stock. While the volume pullback was notable, the underlying demand base remained intact with first-home buyers and upgrader families continuing to drive the majority of activity.
Borrowing stability and improving construction leadtimes continued to support sentiment through Q1, with no material deterioration in buyer confidence despite the softer headline number.
New lot releases lifted sharply in Q1 2026, with 52 lots coming to market compared to just 31 in Q4 2025 — a 68% increase. The lift reflected developers responding to improved absorption conditions and a more balanced stock position entering the year. Stock returns fell to 19 lots, the lowest in recent time, pointing to strong buyer retention and minimal cancellation activity through the quarter.
Active estates eased to 46, continuing a modest drift lower over the past 12 months. The market remains well-structured with no signs of oversupply, and the gradual consolidation in active projects is keeping competitive pressure between developers contained.
Total available stock declined further as absorption continued to outpace new supply on a net basis. Ballarat enters the remainder of 2026 with one of its more balanced supply positions in recent memory, reducing the risk of meaningful price discounting across key precincts.
Median lot pricing surged 23% in Q1 2026, jumping from $245,000 in Q4 2025 to $302,250. The median lot size also increased materially to 491sqm, up 47sqm on the prior quarter, suggesting the price movement was at least partly driven by a shift in the mix of stock transacting toward larger, higher value lots rather than broad based price inflation across the market.
Despite the headline jump, Ballarat remains one of regional Victoria’s most affordable new-home locations on an absolute basis, continuing to attract first-home buyers and upgrader families priced out of metropolitan corridors.
The durability of this price movement warrants monitoring through Q2 — if the lot size mix normalises, some price moderation is likely. If larger lots continue to dominate transactions, the new pricing level may prove more sustainable.
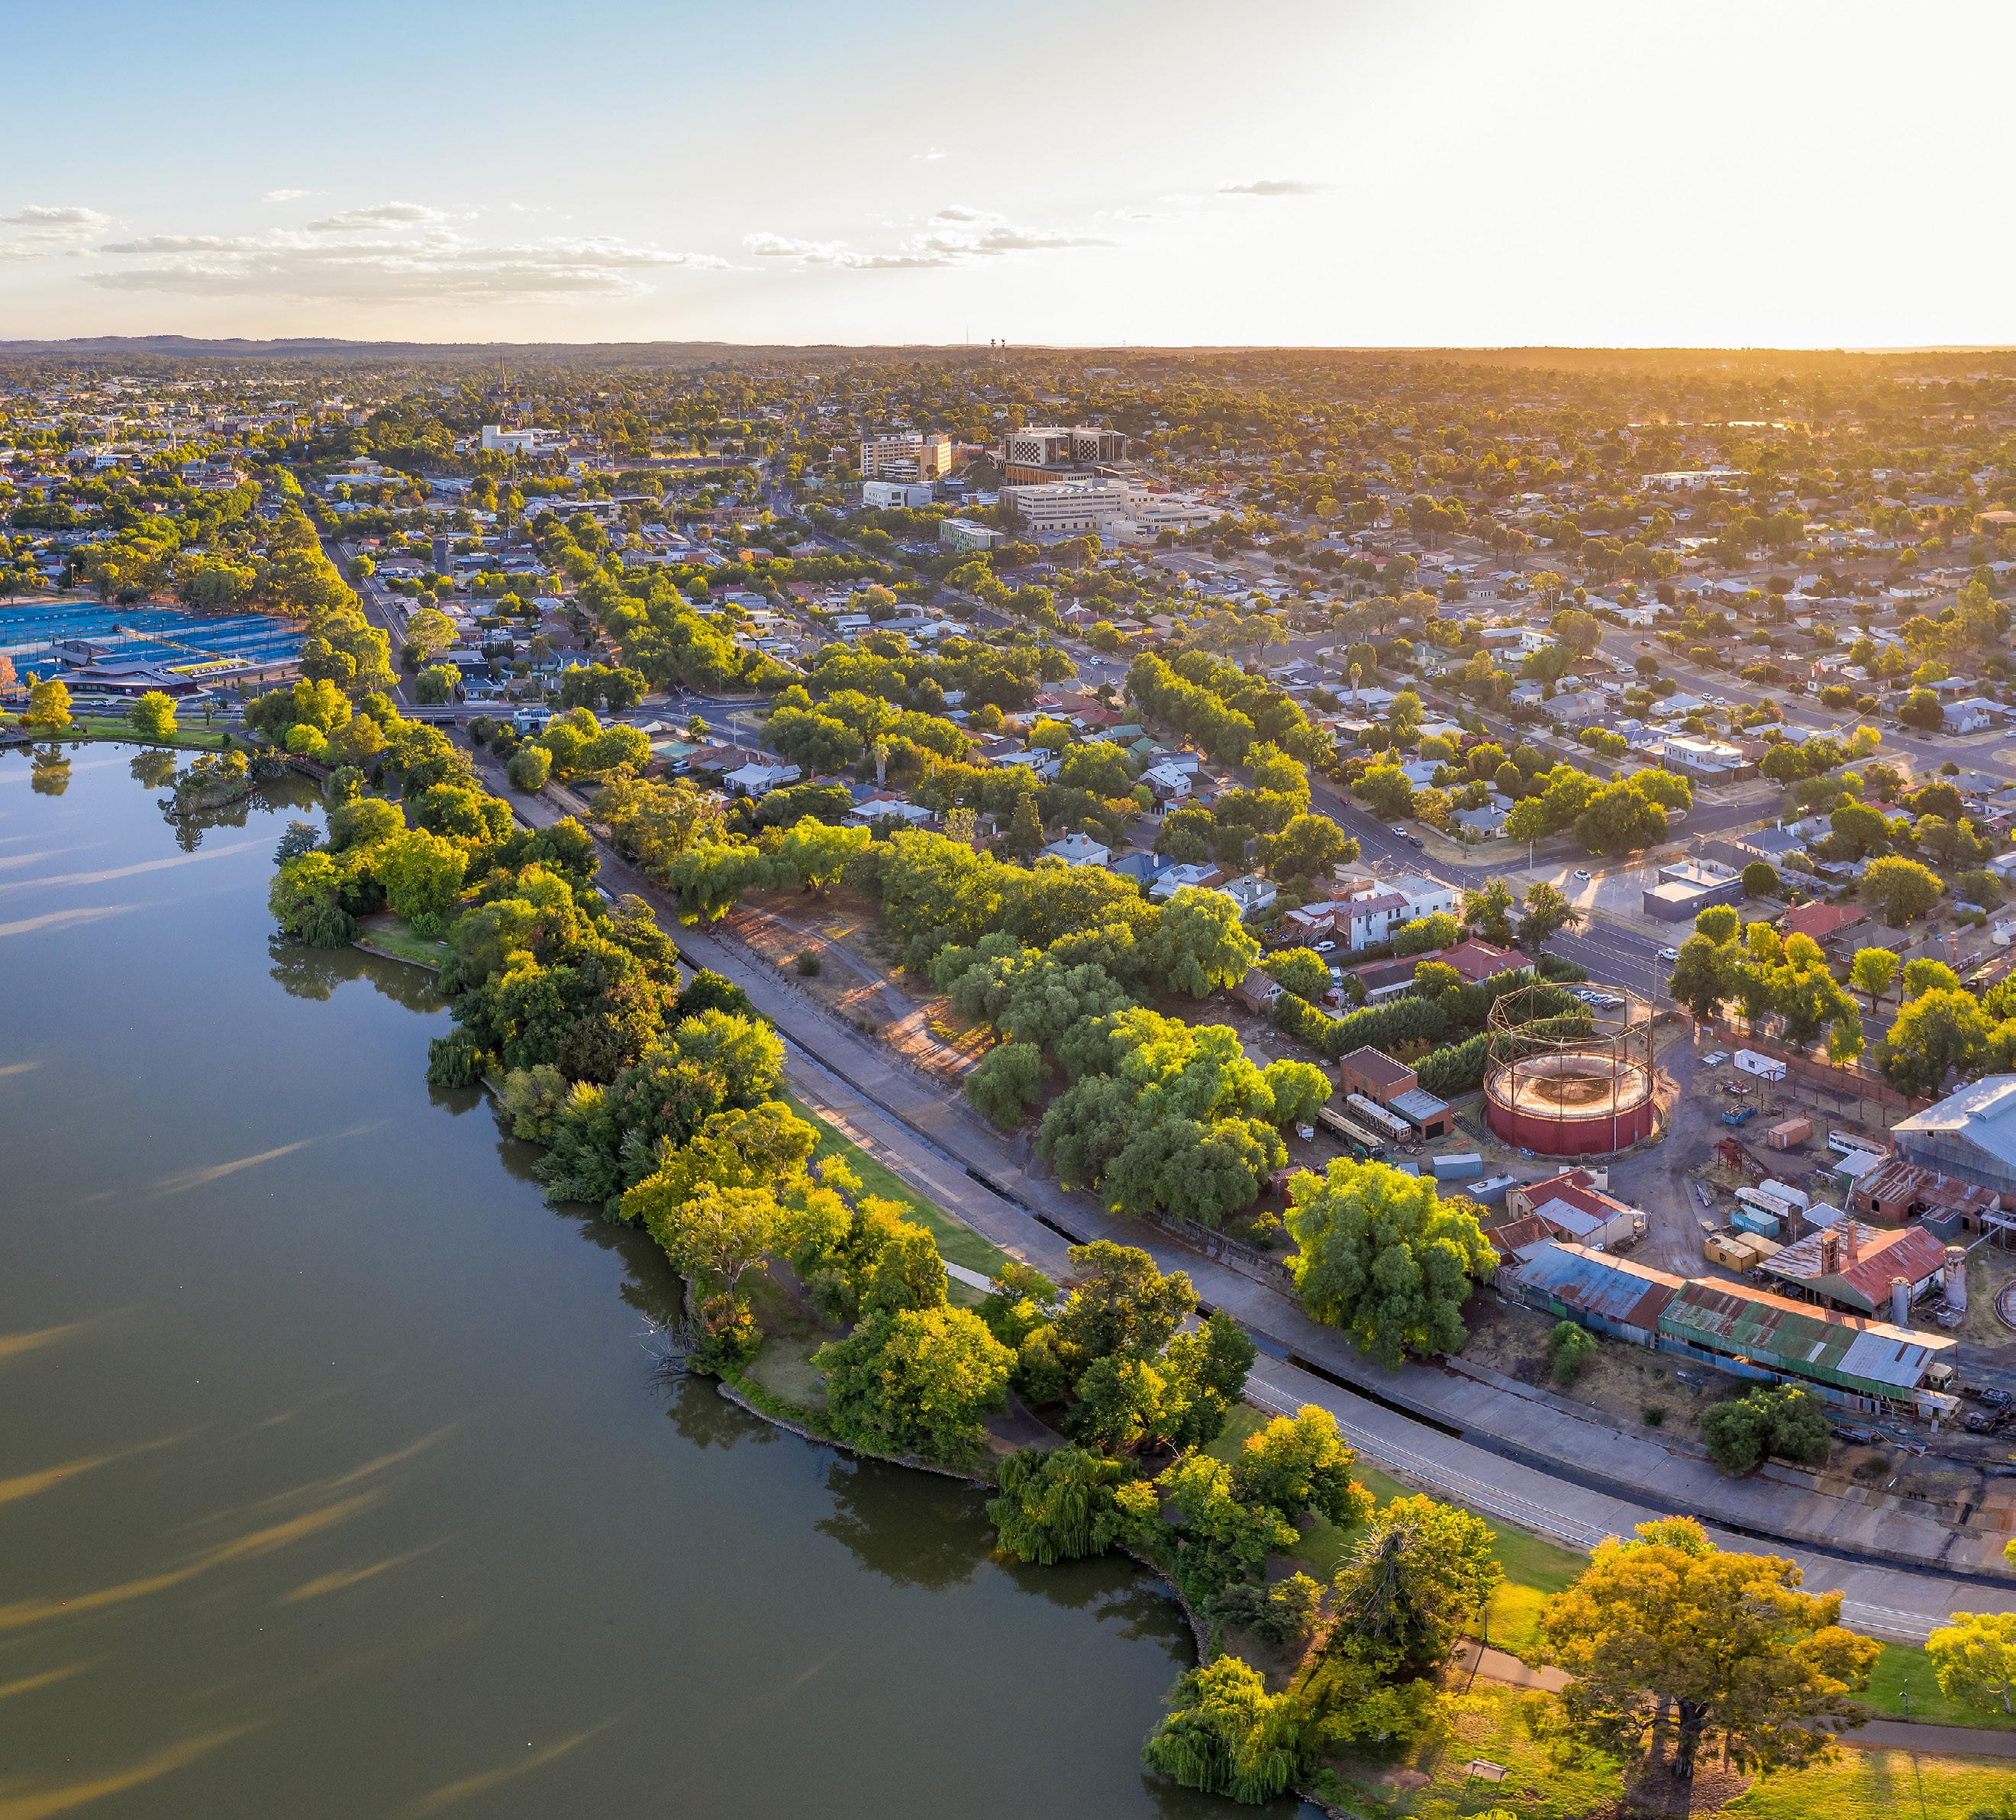
Bendigo recorded 100 gross lot sales in Q1 2026, a 30% decline on Q4 2025’s result of 143. While the quarterly pullback was meaningful, sales remained 8% higher than Q1 2025’s 92 lots, suggesting the region is holding a healthier baseline than a year prior. Activity was again led by Bendigo’s northern corridor, while the southern and western precincts continued to operate at subdued but stable levels.
Buyer enquiry remained selective through the quarter, with purchasers continuing to favour well-priced titled stock with clear construction pathways. Builder incentives played a supporting role in maintaining engagement through what is typically a softer seasonal period.
Despite the headline decline, Bendigo’s demand fundamentals remain intact. Affordability relative to metropolitan and other regional markets continues to underpin interest from first-home buyers and tree-changers, providing a consistent floor beneath activity levels.
New lot releases lifted 42% in Q1 2026, with 105 lots coming to market compared to 74 in Q4 2025. The increase reflects developers responding to tighter stock conditions, with total available inventory having compressed through the back half of 2025. Stock returns fell to just 3 lots — the lowest through this cycle — pointing to exceptionally strong buyer retention.
Active estates held steady at 46, consistent with Q4 2025 and part of a gradual expansion over the past three years. While Melbourne’s growth corridors have seen meaningful consolidation in active projects — the Northern corridor alone has contracted from 135 to 91 estates over the same period — Bendigo has been moving in the opposite direction, quietly growing its active project base as developer confidence in the region’s long-term demand profile builds.
The combination of rising releases, record-low stock returns and an expanding estate base kept supply conditions manageable through the quarter, with no meaningful overhang emerging despite the softer sales environment.
$265,000
Median lot pricing eased 1.9% in Q1 2026, slipping from $270,000 in Q4 2025 to $265,000. The median lot size also contracted slightly to 534sqm, down 4sqm on the prior quarter. The per sqm rates held broadly steady as the price and size movements were modest and largely offsetting.
The Q4 2025 price spike — driven by a compositional shift toward larger northern lots — has partially unwound, with Q1 transactions reflecting a more normalised product mix. This brings pricing back in line with Bendigo’s longer-run trend rather than signalling any fundamental deterioration in values.
Bendigo remains one of regional Victoria’s most competitively priced growth markets, continuing to attract buyers seeking larger lots at price points well below metropolitan alternatives. Stability rather than growth is the more likely near-term pricing outlook.
Macedon & Mitchell recorded 78 gross lot sales in Q1 2026, a 5% decline on Q4 2025’s result of 82. While the quarterly dip was modest, the corridor maintained solid footing relative to earlier 2025 levels, with continued engagement across both Kilmore and Wallan precincts supporting a consistent baseline of activity.
Sales held up reasonably well given the broader market softening seen across most corridors in Q1. Buyer interest remained anchored by the region’s lifestyle appeal and relative affordability compared to Melbourne’s outer metropolitan growth areas.
Several established masterplan stages continued to deliver steady absorption through the quarter, with enquiry holding up in precincts offering clearer build timelines and stronger builder alignment.
New lot releases lifted 24% in Q1 2026, with 72 lots coming to market compared to 58 in Q4 2025. The increase reflected developer confidence in the region’s improving demand profile, with both shires contributing to the uplift. Nevertheless, stock returns spiked with 48 lots — a sharp jump from just 13 in Q4 2025. The cause of that movement warrants monitoring; at this scale it is difficult to attribute purely to seasonal factors and may reflect some softening in buyer commitment or settlement delays across select contracts.
Active estates held steady at 36, consistent with where the corridor has operated throughout the past three years. The stability in project numbers reflects the corridor’s more contained development footprint relative to Melbourne’s growth areas.
Total available stock rose modestly as a result of the returns but remained manageable overall. The lift did not materially disrupt pricing through the quarter.
Price & Size - Q1 2026
$372,000
Median lot pricing lifted 3% in Q1 2026, rising from $361,200 in Q4 2025 to $372,000. The median lot size held broadly steady at 611sqm, down just 1sqm on the prior quarter, keeping per-sqm rates stable through the period.
Price levels remain broadly aligned with the corridor’s longterm average, with the Q1 movement reflecting genuine demand support rather than compositional distortion. Macedon & Mitchell continues to offer one of the more distinctive value propositions in Victoria’s growth markets — larger lots at prices that remain accessible relative to the lifestyle premium the region commands.
Near-term pricing is expected to remain stable, with upside more likely to emerge through improved sales velocity than any supply-side squeeze, given the corridor’s comparatively modest release volumes.
Gross Sales - Q1 2026
Drouin & Warragul recorded 86 gross lot sales in Q1 2026, a 21% decline on Q4 2025’s result of 109. Despite the quarterly softening, activity remains significantly above early-2024 levels, supported by the corridor’s affordability advantage relative to Melbourne’s fringe growth areas. Warragul continued to dominate activity, with Drouin contributing steady but comparatively lower volumes through the quarter. Builder incentives helped sustain enquiry through what is typically a softer seasonal period, with momentum holding reasonably well into the new year. The corridor continues to benefit from relocation trends, with buyers drawn by lifestyle appeal and access to Gippsland transport connections providing a consistent floor beneath demand.
New lot releases lifted 11% in Q1 2026, with 80 lots coming to market compared to 72 in Q4 2025. Developers maintained a measured approach to release timing, keeping supply broadly aligned with underlying demand. Stock returns held low at 10 lots, consistent with the improved buyer retention seen through the back half of 2025 and pointing to minimal cancellation activity through the quarter.
Active estates recovered to 20 through the quarter, returning to 2023 levels after bottoming out at 16 through late 2024 and early 2025. The rebound in active projects reflects growing developer confidence in the corridor’s demand outlook, with the re-entry of projects that had previously paused release activity now adding depth to the supply pipeline without creating meaningful oversupply pressure. Supply conditions remained stable and well structured through Q1, with the combination of low stock returns and a recovering estate base providing a sound platform for consistent release activity through the remainder of 2026.
Median lot pricing eased 1.1% in Q1 2026, slipping from $318,500 in Q4 2025 to $315,000. The median lot size contracted to 497sqm, down 13sqm on the prior quarter, with Warragul’s smaller lot formats continuing to influence the corridor’s overall size and pricing profile. The per sqm rates held broadly steady as the modest price and size movements largely offset each other.
Pricing movements remain modest and continue to reflect variations in the mix of lots transacting rather than any fundamental shift in underlying values. The corridor’s affordability relative to Melbourne’s growth areas remains its primary demand driver and continues to attract pricesensitive buyers seeking larger format land.
Near-term pricing is expected to remain stable, with the corridor unlikely to see meaningful upward pressure until sales velocity improves more consistently across both Warragul and Drouin precincts.
Michael Staedler
General Manager
Market
Intelligence
m.staedler@rpmgrp.com.au
Three consecutive RBA rate increases in February, March, and May moved the cash rate from 3.60% to 4.35%, reversing all of the monetary easing that had supported buyer activity through 2025. The impact was immediate and broad-based, with sales volumes contracting across every Victorian growth corridor in Q1.
Borrowing capacity has been materially reduced, and the prospect of further tightening in coming months is sustaining uncertainty at a point in the cycle where confidence is already fragile.
According to the latest NAB Consumer Sentiment Survey, consumer conditions deteriorated sharply through the quarter. Household stress reached its highest level since 2014, driven by compounding cost
Rate rises, cost pressures and cautious buyers — the greenfield market’s path through 2026 narrows.
pressures across mortgage servicing, utilities and essential spending. Spending intentions have shifted from selective restraint to broad-based caution — a pattern that historically precedes more sustained demand weakness. First-home buyers, who represent the dominant demand cohort across the greenfield corridors, are disproportionately exposed to rate movements and the associated compression in borrowing capacity.
Supply-side cost pressures continue to constrain lot delivery economics. According to the Colliers Engineering & Design 2026 Cost Per Lot Report, Victoria’s average civil development cost per lot eased 4.3% to approximately $127,000 in 2025, but statutory charges now represent approximately 40% of total per-lot costs and continue to rise. That relief is also under threat, with the same report noting that geopolitical instability is reintroducing materials cost volatility across fuel and petroleum-dependent inputs.
Nevertheless, Melbourne’s greenfield market retains a meaningful affordability advantage over established housing and other eastern seaboard markets, and government incentives and low deposit schemes continue to underpin entry-level demand. The trajectory of inflation and the RBA’s response to it will be the dominant variable shaping market outcomes through the second half of 2026.
For more information, please visit: www.rpmgrp.com.au
Our Market Intelligence Services create bespoke reports crafted to your specifications, translating rich data into in-depth analysis. For a bespoke report, email the team at: contactus@rpmgrp.com.au
Market Intelligence
Michael Staedler
General Manager
Market Intelligence m.staedler@rpmgrp.com.au
Andrew Raponi
Senior Research Manager a.raponi@rpmgrp.com.au
Laurence Rao
Research Manager - VIC laurence@rpmgrp.com.au
Simon Brinkman
Research Manager - QLD simon@rpmgrp.com.au
Executive, Sales and Marketing Leadership
Paul McMahon
Chief Operating Officer paul@rpmgrp.com.au
Imogene Schaefer
General Manager
Marketing imogene@rpmgrp.com.au
Tim Hyland
National Strategy Manager
Transactions & Advisory tim@rpmgrp.com.au
Luke Kelly
National Managing Director Built Form luke@rpmgrp.com.au
Michael Vilar
General Manager
Medium Density - VIC michaelv@rpmgrp.com.au
Rod Anderson
National Managing Director Communities rod@rpmgrp.com.au
Greg Rankin
General Manager
Communities - VIC gregr@rpmgrp.com.au
Peter Grant
National Managing Director
Business Development peter@rpmgrp.com.au
Johnathon Driessen
General Manager
Communities - VIC johnathon@rpmgrp.com.au
For detailed insights or custom reporting, contact the team at: contactus@rpmgrp.com.au