ROCKY MOUNTAIN PUBLISHING PO Box 740, Fort Collins, CO 80522 (970) 221-9210 www.RMPublish.com
Northern Colorado Home Buyers Guide 2026 is a special publication of Rocky Mountain Publishing, Inc. Publication of this magazine does not constitute an endorsement of the products or services advertised. RMP reserves the right to refuse any advertisement for any reason. The opinions expressed by contributors or writers do not necessarily reflect the opinions of Rocky Mountain Publishing.
Northern Colorado can feel financially daunting, especially in a competitive market where prices and interest rates remain elevated. But traditional 20 percent down payment models are no longer the only path to homeownership. Today’s buyers have access to a range of creative financing tools designed to lower upfront costs, expand eligibility, and make monthly payments more manageable. From statewide down payment assistance programs through the Colorado Housing and Finance Authority to rural lending options backed by the U.S. Department of Agriculture and flexible, member-focused solutions offered by local institutions such as Canvas Credit Union and Elevations Credit Union, prospective homeowners have more options than they might realize. Understanding these opportunities can make the difference between waiting indefinitely and confidently stepping into homeownership.
Down Payment Assistance Programs—Stretching Your Savings
One of the most impactful ways to reduce upfront costs when buying a home in Northern Colorado is to tap into down payment
assistance (DPA) programs. These programs offer grants or low-interest second loans that help eligible buyers cover part or all the down payment and even closing costs. At the state level, the Colorado Housing and Finance Authority (CHFA) offers programs such as SmartStep and SmartStep Plus, which pair a 30-year mortgage with up to $25,000 in assistance either as a grant or zero percent second lien, depending on income
and eligibility criteria.
Locally, organizations like the Impact Development Fund provide down payment assistance for first-time buyers in Larimer and Weld Counties (including Fort Collins, Loveland, and Greeley). These funds can match up to 20 percent of the purchase price or $30,000 when paired with a primary mortgage, helping buyers who meet income thresholds get their foot in the door.
USDA Rural and GovernmentBacked Loans—Lower Barriers, Flexible Terms
If you’re interested in homes just outside urban cores or in more rural areas, you might qualify for governmentbacked alternatives such as the USDA Rural Housing programs. USDA Section 502 Direct Home Loans provide long-term, low-interest mortgages for very-low- and low-income buyers, often with payment assistance to reduce monthly costs.
What makes these programs creative is how they reduce traditional barriers: often no down payment is required, interest rates are subsidized based on income, and the loans can be used to purchase, build, or improve property in eligible rural areas.
Credit Unions: Member-Focused Lending with Local Advantage
Working with a local credit union can offer meaningful advantages for Northern Colorado homebuyers.
• Relationship-Based Underwriting. Credit unions are member-owned, not shareholder-driven. That often translates into more flexibility in underwriting and a willingness to look at the full financial picture— particularly helpful for firsttime buyers, self-employed borrowers, or those with nontraditional income.
• Competitive Rates and Lower Fees. Because credit unions are not-forprofit financial institutions, they frequently offer lower origination fees and competitive interest rates compared to larger national banks. Even small rate differences can save thousands of dollars over the life of a loan.
• Portfolio Lending Options. Unlike lenders that immediately sell loans on the secondary market, credit unions may retain loans in-house. This allows for more customized mortgage structures, including adjustable-rate options, lower down payment products, or the more custom, creative refinancing strategies.
FIVE STAR SERVICE FIVE STAR RESULTS
“Jeff was a rock star agent! He not only worked exceptionally hard on selling our house, but he also became a dear friend in the process. He was honest and open and offered great advice. He went above and beyond helping us. A “must have” person when selling, or buying a home in the Ft. Collins area.” - Tim H
“Both myself and my wife are in our eighties. We have bought and sold 7 homes. Never in all of those sales have we had a real-estate agent as helpful and pleasant as Jeff has been. He went above and beyond what was necessary and helped us resolve problems involving our age and abilities to get things done. For this and his professionalism we are truly grateful.” - Judy & Terry H
“Jeff is the BEST!! He is proactive in a not-so-great market. Jeff was very innovative with his marketing strategies. He is very smart. He helped me get my home on the market by literally moving furniture, boxes, etc. He gives great detailed feedback. He offers to help all the way through the process. He is also one of the kindest human beings. I would recommend Jeff to anyone for the greatest experience of selling your house because he cares!! If there are fivestar ratings, Jeff is an 8. He is the BEST!!” - Kathleen G
WHY CLIENTS CHOOSE JEFF
• Comprehensive Expertise: I provide solutions tailored to your unique stage of life.
• Specialized Senior Support: As a Seniors Real Estate Specialist® (SRES®), I understand the unique needs of seniors and their families.
• Investment Strategies: I can guide you through using a self-directed IRA to invest in real estate, helping to diversify your retirement portfolio beyond the stock market.
• Business Insight: With an MBA in Marketing and decades of experience, I bring a strong foundation in strategy, negotiation, and market knowledge.
I can help you buy, sell, or invest with confidence and peace of mind.
JEFF BITTERMAN Broker Associate/Partner
Current homebuying trends
Interest rates and a balanced market
Dan England
SINCE COVID-19 and the chaos that followed in real estate (along with everywhere else), Marshall Massaro is enjoying his deep breath offered by Northern Colorado’s current homebuyers market.
Stability isn’t a word Relators have used very often for Colorado’s market, especially during and immediately after COVID-19, when homes would sell, on average, two weeks after they went on the market, and sometimes the same day.
But things appear to be calm for now, says Massaro, a broker for C3 Real Estate Solutions, given that interest rates have hovered around 6 percent for at least a year, if not more, and the market doesn’t appear to favor buyers or sellers as much as it used to.
“Honestly, it’s the best kind of market for everyone,” Massaro says. “It’s not a frenzy. You can see homes and take your time.”
Interest rates
Rising interest rates calmed the chaotic homebuyers market, and since then, they’ve remained fairly steady, even after the past year, when they went down a percent.
“That’s making houses a lot more affordable for buyers,” Massaro says of the rate cut.
It may not feel that way, given that many homes won’t sell for less than $500,000, but Massaro says interest rates are still historically low.
“They’re really not too bad, considering,” Massaro says.
In fact, the rates and steady market have helped renters move out of apartments and into homes, townhomes or condos, something that may not have been possible a few years ago.
“People are definitely moving out of rentals right now,” Massaro says. “It’s nice to be able to build equity instead of paying into a landlord’s pocket.”
Home prices are still high, and they probably always
will be in Northern Colorado, but the steady rates help establish reasonable monthly payments.
“It still makes it hard for single-income families to afford homes,” he says, “but lower interest rates make them more affordable.”
A balanced market
Statistically, it’s still a seller’s market: Less than four months of inventory is considered a seller’s market, Massaro says, and Northern Colorado generally has a three-month supply at most. But with prices staying high
and interest rates stabilizing, Massaro calls it a balanced market.
Sellers can likely still get a good price for their home and likely make a sizeable profit, but they’re also more willing to make concessions than they were a few years ago. This gives buyers more options.
“Prices are high, but there’s a lot of sellers willing to negotiate or offer incentives,” Massaro says.
There are a lot of new products on the market, from condos to single-family homes, Massaro says, and there are advantages to both.
An existing home may need some work, but prices can reflect that, and they’re generally with well-established yards and neighborhoods.
“If you put in a little sweat-equity and work on a home, you can save,” Massaro says. “But it’s also a home that will have everything ready.”
That may not be true of a new home, Massaro says, but sometimes those can be cheaper.
“There’s not the competition of an existing home as much, so they’re really good for first-time homebuyers,” he says. “There’s the stigma of a new build, and they can take longer to sell than an existing home.”
Of course, it also depends on where you buy, Massaro says. Prices are cheaper east of I-25, such as Johnstown, Evans and Greeley, and those cities also offer a good mix of new homes and existing houses. Fort Collins is less affordable but also offers a lot of outdoor recreation. Loveland is a good balance between some outdoor recreation and more affordable houses.
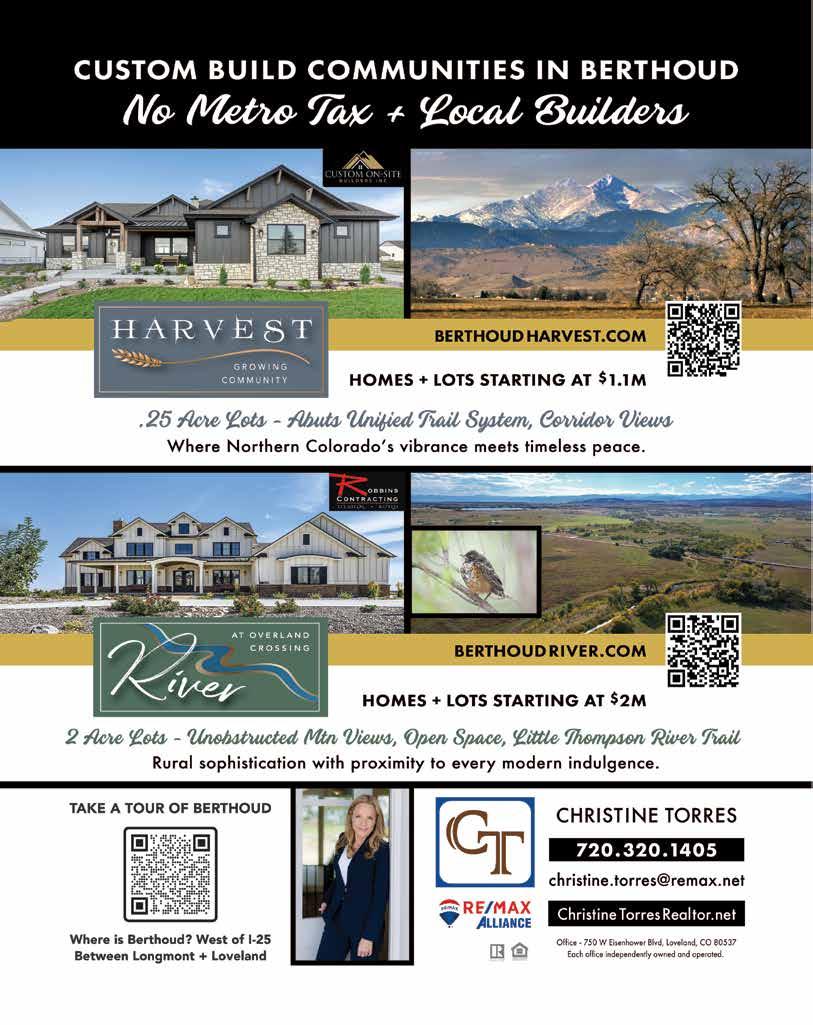
There are also lots with acreage, such as some offered in Berthoud, where Massaro lives.
“Those are a hot commodity,” Massaro says.
Make outdoor spaces shine
Tips for growing curb appeal
Emily Zaynard
WHEN PUTTING YOUR HOME on the market there are so many things to take care of that it can feel like an endless to-do list. While checking items off and preparing your home to look its best, be sure to include the great outdoors.
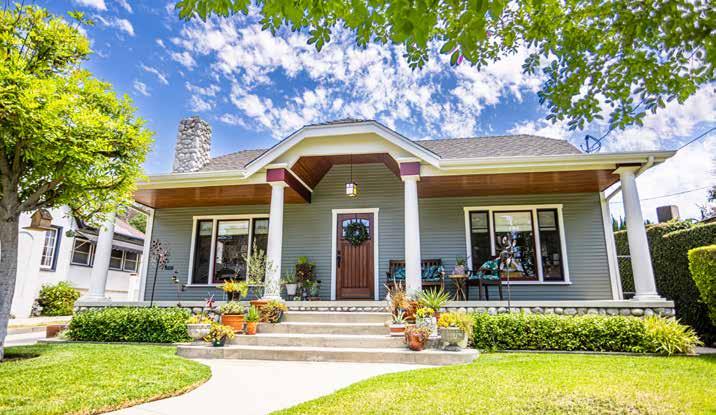
“Curb appeal” is how your home looks to potential buyers from the street curb. First impressions can mean that potential buyers have a favorable opinion of your home even before they cross the threshold. Ideally, you’ll be marketing your home in a season that allows your landscaping to shine. If this
isn’t the case don’t fear, there are a few “hacks” that you can use to spiff up the first impressions that buyers have of their potential new home.
Prune
Prune back hedges, dead trees, and overgrown shrubbery to give the house a “haircut.” Can’t see the front porch from the street because of an overly-enthusiastic juniper? Trim down that shrub and highlight an open and welcoming entryway that can be appreciated as potential buyers approach.
Tree maintenance can make
a big visual impact. When buyers approach your home, dead branches and trees that are tottering on collapse look like additional costs and potential safety hazards.
Jesse Eastman, President of Fort Collins Nursery, doesn’t mince his words when he tells us, “Hire an arborist!” Professional pruning can improve the health of the tree and avoid the lopping off of limbs, both human and arboreal. Avoid the haunted house feel of a scraggly tree and call a professional to safely trim those branches.
Patch
Give your lawn some love, depending on the season. When selling a home you might be tempted to take on all those DIY-projects that you’ve been meaning to do. Keep in mind that you are
selling your home so putting in an extraordinary amount of time and effort just doesn’t make sense. When it comes to a patchy lawn you have a sod vs. seed vs. something else decision on your hands.
Re-sodding can be a relatively low maintenance solution for patches of bare earth. “It’s lower-maintenance than seeding, more resilient and more forgiving than seed.” Eastman relates. A tidy patch of lawn can also make your home look more traditionally inviting to buyers.
Re-seeding a patch of bare earth requires the right season and a commitment to watering and maintaining the growth. Reseeding is the highest-maintenance option because of these factors. As an alternative, Eastman suggests the practice of over seeding. “Over seeding means you spread seed over a patchy lawn to fill in the bald spots.” he explains. Inexpensive seed makes this a less costly option.
There is something else that can resolve issues with patchy lawn growth. That “something else” is: Be okay with it. Potential buyers might not consider a lush lawn to be a required selling point. Many people are embracing native grasses and flora for landscaping. Xeriscaping is enjoying popularity as well as a potential tax incentive from the city. A less-than-perfect lawn isn’t likely to be a deal-breaker.
Plant
If you are putting your home on the market during a warmer season tuck some
flowers into those beds! Highlight your yard’s potential by putting bright pops of color along the path edges and near the entryway. Eastman recommends you “Look for full size plants that are large or mature enough to have an immediate impact.”
Don’t have any space for flower beds? Consider putting lush potted plants or flowers on the front porch to transform it into a “nature nook” that serves as a low maintenance, warm welcome for buyers.
Potential
From gardening to grilling to firepits and paddle pools, outdoor living space is in demand. To make your space shine, identify where your property has potential and visually define it. This gives buyers a glimpse of their future dream yard. Inexpensive mulch can transform unused flower beds into a gardener’s paradise. That dusty patch by the back gate? With the addition of seating, it becomes a perfect place for a fire pit. Repurposing what you have or using inexpensive materials to define areas in your yard makes room for buyers to see a potential haven of relaxation and leisure.
The housing market can be volatile so do your best to make your property welcoming to buyers even before they look inside. Use the tips above to prune, patch, plant and “potential” your way to an outstanding showing. A beautiful home, both inside and out, will inspire buyers to make that offer.
Buyers: Make the market work for you in 2026
Get preapproved and be ready to act
Katie Harris
WITH NORTHERN COLORADO’S
real estate market finally offering some breathing room, buyers have a window of opportunity—if they’re ready to act.
“Our current market doesn’t necessarily favor buyers over sellers,” says RE/MAX Alliance agent Christine Torres. “Who it does favor is the buyer who is prepared and ready to take advantage of the opportunities that are available.”
Talk to a lender
The first step to being prepared is talking to a lender. Torres says sellers are more likely to consider offers from buyers who have been financially vetted.
This can mean prequalification—you’ve had an initial conversation with a lender about your finances and buying power, or preapproval—your income and credit have been reviewed and a lender has conditionally approved you for a specific loan amount.
A knowledgable lender can also walk you through options to improve affordability. These might include down payment assistance, first-time buyer programs, solutions for buyers with lower credit scores or the ability to buy down your interest rate by paying more upfront.
Ask for seller concessions
Buyers who understand their budget and are preapproved are in a stronger position to negotiate. In a balanced market this can mean opportunities for seller concessions.
Torres explains that concessions can take several forms. A seller may agree to cover some or all of the buyer’s closing costs, contribute funds to buy down the buyer’s mortgage rate or take care of the cost of repairs or upgrades. In some cases, sellers may also agree to cover the
buyer’s agent commission— something that was standard before 2024 but is now negotiable.
Be aware of ongoing costs
Purchase price is only part of the financial picture. Torres encourages buyers to research the long-term costs associated with a specific property.
“Find out whether the area you’re buying in has a metro tax,” she advises. “If so, what does it cover? And is the cost worth it to you?”
In Colorado, metro districts are government
entities which fund roads, water systems and neighborhood amenities through property taxes. These taxes are ongoing and reflected in the property’s mill levy.
Homeowner’s associations, in contrast, are private organizations run by a board of neighborhood residents. Dues are collected to fund road maintenance and amenities, and members vote on fee increases and budget. Because metro districts and homeowners associations work differently, it’s
important to understand their financial implications and which is present in your desired neighborhood.
Torres recommends reviewing the property tax certificate on the county assessor’s website with your realtor for any property you’re considering so that you understand which mill levies apply, including metro, fire and water districts.
Know the area
If you’re considering moving to a new city or town, local expertise is essential. Local amenities, infrastructure and school boundaries can influence property values as well as quality of life, so it’s important to understand the area’s trajectory.
“You need someone who understands city projects: Where are new parks planned? What is the long-term water outlook?” Torres says. “A Realtor who is immersed in the community can tell you about local events, help you find information on schools and discuss the area’s pros and cons.”
New builds work differently
If you’re shopping for a newly constructed home there are a few more things to take into consideration before you make a purchase. Builder’s contracts work differently than standard resale contracts and are typically worded to protect the builder’s interests.
“Contracts vary
significantly between builders,” Torres says. “A Realtor familiar with how these contracts work can explain what you’re agreeing to and serve as your advocate.”
Builders may recommend using their in-house lender, and Torres notes this can be beneficial. She says builders’ preferred lenders often offer rate incentives and a more streamlined process. Torres recommends that buyers work with their realtor to compare terms and make sure the offer aligns with their goals.
Don’t wait for perfect
Torres describes the outlook for 2026 as positive and dynamic, with more movement likely on both the buying and selling sides. In fact, she says she has more inventory preparing to hit the market than at this point in any other year since the Covid-era.
“People are ready to sell and they’re ready to buy,” she says. “But factors like the economy, interest rates and politics are fluid and can change the market pretty quickly.”
Torres says waiting for the perfect home at the perfect rate could mean missing out on opportunities. Buyers who are realistic about their budget, armed with a lender’s pre-approval, and ready to act will have the edge in this year’s market.
Join us
We are the trusted business champion, catalyst and convener creating shared economic prosperity for Northern Colorado.
Join 1 , 203 businesses at more than 150 events designed to create connections while driving a strong, vibrant local economy.
Service Directory
MORTGAGE LENDERS
Cornerstone Home Lending
Fort Collins, 970-206-4663
2809 E. Harmony Rd., Ste. 200
Greeley, 970-313-1330
6500 W. 29th St., Ste. 230
Longmont, 303-547-3442
1925 Pike Rd. Ste. 201
Tom Beck, 970-313-1330
NMLS 280374
Beau Couch, 970-674-2626
NMLS 280375
Patti Dirks, 303-717-4176
NMLS 278909
Lonnie Jenkins, 303-513-1915
NMLS 258988
Shanna Keller, 970-481-6158 NMLS 265565
Bill Rodriguez, 303-877-6323
NMLS 279673
Justin Smith, 970-797-3308 NMLS 269167
Elevations Credit Union
2025 S. College Ave. Fort Collins, 970-667-8585
Excel Financial Group
Fort Collins, 970-818-9280
123 N. College, Ste. 230
Robert Castle, 970-690-3883
NMLS 375348
Flat Branch Home Loans
300 E. Horsetooth Rd., #103 Fort Collins, 630-730-9431
FNBO Mortgage Fort Collins 970-494-6200 fnbo.com/mortgage
PROPERTY MANAGEMENT
Faith Pro LLC
375 E. Horsetooth Rd., Bldg. 1, Fort Collins 970-224-4446 or 970-377-1626