PLAN YEAR:
JULY 1, 2026 - JUNE 30, 2027

PLAN YEAR:
JULY 1, 2026 - JUNE 30, 2027
May 1, 2026 - May 15, 2026
PLAN YEAR & EFFECTIVE DATES: ANNUAL ENROLLMENT DATES:
July 1, 2026 - June 30, 2027
• Employees working 30 hours or more per week are eligible for benefits.
Congratulations on your new employment! Your employment means more than just a paycheck. Your employer also provides eligible employees with a valuable benefits package. Above you will find eligibility requirements and below you will find information about how to enroll in these benefits as a new employee.
Colonial Life Insurance Products - Please call PGB’s Employee Services within 30 days of your date of hire and a PGB Benefits Representative will help you enroll in benefits. The Employee Services number is located in the contact section of this guide.
All Other Benefits - Please reach out to your Benefits Department within 30 days of your date of hire.
Be sure to also review your group’s custom benefits website, that allows for easy, year-round access to benefit information, live chat support, benefit explainer videos, plan certificates and documents, and carrier contacts and forms.
Health Savings Account HSA Bank
- Individual Maximum: $4,400/year Max
-Family Maximum: $8,750/year Max
HSA plans can only be established in conjunction with a qualified High-Deductible Health Plan (HDHP)
Flexible Spending Accounts Ameriflex
- Dependent Care Reimbursement: $7,500/year Max
*You will need to re-enroll in the Flexible Spending Accounts if you want them to continue next year.
If you do not re-enroll, your contribution will stop effective June 30, 2026.
When do my benefits start? The plan year for Colonial Life Insurance Products, The Local Choice Benefits (Anthem Health, Delta Dental of VA, and Anthem Blue View Vision), HSA Bank Health Savings Accounts, Ameriflex Flexible Spending Accounts, Delta Dental (Stand-Alone Policy), Anthem Blue View Vision (Stand-Alone Policy) and CHUBB Long Term Care runs from July 1, 2026, through June 30, 2027.
When do my deductions start? Deductions for The Local Choice Benefits (Anthem Health, Delta Dental of VA, and Anthem Blue View Vision), Delta Dental (Stand-Alone Policy) and Anthem Blue View Vision (Stand-Alone Policy) start June 2026 for all enrolled employees. Deductions for Colonial Life Insurance Products, HSA Bank Health Savings Accounts, Ameriflex Flexible Spending Accounts and CHUBB Long Term Care start July 2026 for all enrolled employees.
Why have my Medical Bridge benefits not started yet? The Health Screening Rider on the Colonial Medical Bridge plan has a 30-day waiting period for new enrollees. Coverage, therefore, will not begin until July 31, 2026.
How do Dependent Care Account (DCA) funds work and when do they need to be used? Dependent Care Accounts are like FSA accounts and allow you to request reimbursement up to your current balance. However, you cannot receive more reimbursement than what has been deducted from your pay. After the plan year ends, an employee has 3 months to submit claims for incurred qualified dependent care expenses. Claims cannot be submitted after the date of employment termination. Any remaining funds in your DCA account must be utilized before the deadline. Failure to use all allotted funds in the DCA account will result in a “Use It or Lose It” scenario.
When will I get my card? If you will be receiving a new debit card, whether you are a new participant or to replace your expired card, please be aware that it may take up to 30 days following your plan effective date for your card to arrive. Your card will be delivered by mail in a plain white envelope. During this time you may use manual claim forms for eligible expenses. Please note that your debit card is good through the expiration date printed on the card.
I want to sign my family up for benefits as well, what information will I need? If signing up for any coverage on your spouse and/or children, please have their dates of birth and social security numbers available when speaking with the Benefits Representative.
What does Pre-Tax vs. Post-Tax Change? Pre-Tax benefits take funds directly from your paycheck to cover benefits before going through State and Federal taxing process. Post-Tax collects funds for benefits after taxes have been taken out. Please be aware there are certain coverages that may be subject to federal and state tax when premium is paid by pretax deduction or employee contribution.
Can I change my benefit elections outside of the enrollment period? Elections made during this enrollment period CANNOT BE CHANGED AFTER THE ENROLLMENT PERIOD unless there is a family status change, otherwise known as a qualifying life event (Mid-Year Events), as defined by the Internal Revenue Code. Examples of Mid-Year Events can be found in the chart on the next page. Once a Mid-Year Event has occurred, an employee has 30 days to notify PGB’s VA Employee Services at 1-800-387-5955 to request a change in elections.
I have a pre-existing condition. Will I still be covered? Some policies may include a pre-existing condition clause. Please read your policy carefully for full details.
The benefit elections you make during Annual Enrollment or as a New Hire will remain in effect for the entire plan year. You will not be able to change or revoke your elections once they have been made unless a Mid-Year Event (status change) occurs. The summary of events that allow an employee to make benefit changes and instructions for processing those life event changes can be reviewed in the chart below.
Make elections within 30 days of hire date. Documentation is required.
Add your new spouse to your elections within 30 days of the marriage date. A copy of the marriage certificate must be presented.
Birth or Adoption of a Child
Remove the former spouse within 30 days of the divorce. Proof of the divorce will be required. A copy of the divorce decree must be presented.
You and your dependents are not eligible until the next Annual Enrollment period.
Dependent Aging Out
Enroll the new dependent in your elections within 30 days of the birth or adoption date, even if you already have family coverage. A copy of the birth certificate, mother’s copy of birth certificate, or hospital discharge papers must be presented. Once you receive the child’s Social Security Number, don’t forget to update your child’s insurance information record.
Your spouse is not eligible until the next Annual Enrollment period.
Remove or update dependent elections within 30 days of the dependent aging out. For more information and assistance, please call PGB Employee Services at 800-387-5955.
Benefits are not available for the divorced spouse and will be recouped if paid erroneously.
Death of a Spouse or Dependent
Remove the dependent from your elections within 30 days from the date of death. Death certificate must be presented.
The new dependent will not be covered until the next Annual Enrollment period.
Change in Spouse’s Employment or Coverage
Add or drop benefits from your elections within 30 days of the event date. A letter from the employer or insurance company must be presented.
Coverage for the dependent will end at the time of the dependent aging out and the policyholder must remove/update the dependent elections in order for the change to be reflected in the employee’s deductions.
You could pay a higher premium than required and you may be overpaying for coverage required.
You will not be able to make changes until the next Annual Enrollment period.
The examples included in this chart are not all-inclusive. Please speak to a Benefits Representative to learn more.
Mid-Year Event
Part-Time to Full-Time or Vice Versa
Transferring Employers
Change your elections within 30 days from the employment status change to receive COBRA information or to enroll in benefits as a full-time employee. Documentation from the employer must be provided.
If you are transferring from one PGB client to another, some benefits may be eligible for transfer. Please call PGB Employee Services at 800-387-5955 for more information and assistance.
Benefits may not be available to you or your dependents if you wait to enroll in COBRA. Full-time employees will have to wait until the next Annual Enrollment period.
Loss of Government or Education Sponsored Health Coverage
Entitlement to Medicare or Medicaid
If you, your spouse, or a dependent loses coverage under any group health coverage sponsored by a governmental or educational institution, you may be eligible to add additional coverage for eligible benefits.
You may lose the opportunity to transfer benefits.
Non-FMLA Leave
If you, your spouse, or dependent becomes entitled to or loses coverage under Medicare or Medicaid, you may be able to change coverage under the accident or health plan.
You and your dependents are not eligible until the next Annual Enrollment period.
You and your dependents are not eligible until the next Annual Enrollment period.
An employee taking a leave of absence, other than under the Family & Medical Leave Act, may not be eligible to re-enter the Flexible Benefits program until next plan year. Please contact your Benefit Administrator for more information.
Your individual supplemental/voluntary policies through Colonial Life are portable! To move them from payroll deduction to direct billing, please complete and submit the Payment Method Change Form to Colonial Life within 30 days of retiring. You are also eligible for post-employment Dental, Vision, and Telemedicine benefits through PGB. Please visit: www.piercegroupbenefits.com/ individualcoverage or call our Employee Services at 800-387-5955 for more information and assistance.
You and your dependents are not eligible until the next Annual Enrollment period.
If you do not transfer your policies from payroll deduction to direct billing, Colonial Life will terminate your policies resulting in a loss of coverage.
The examples included in this chart are not all-inclusive. Please speak to a Benefits Representative to learn more.
During your annual enrollment period, a PGB Benefits Representative will be available by appointment to meet with you one-on-one to help you evaluate your benefits based on your individual and family needs, answer any questions you may have, and assist you in the enrollment process. If you prefer, you may also self-enroll online following the instructions on the next page of this guide.
YOU CAN MAKE THE FOLLOWING BENEFIT ELECTIONS DURING THE ANNUAL ENROLLMENT PERIOD:
• Enroll in, change, or cancel The Local Choice benefits (Anthem Health, Delta Dental of VA, and Anthem Blue View Vision).*
• Enroll in, change, or cancel Health Savings Accounts.
• Enroll/Re-Enroll in Flexible Spending Accounts.+
• Enroll in, change, or cancel Dental Insurance (Stand-Alone Policy).**
• Enroll in, change, or cancel Vision Insurance (Stand-Alone Policy).**
• Enroll in, change, or cancel Long Term Care Benefits.
• Enroll in, change, or cancel Colonial coverage.
+You will need to re-enroll in the Flexible Spending Accounts if you want them to continue each year.
*The Local Choice benefits are not available for self-enroll. Please see your HR Representative to enroll sign up or make changes.
**The Delta Dental and Anthem Blue View Vision stand alone plans are for employees who have waived coverage under a The Local Choice (Health, Dental and Vision) plan. Members enrolled in a TLC plan may not enroll in the Dental or Vision Stand-Alone plans.
You can view details about what benefits your employer offers, view educational videos about all of your benefits, download forms, chat with one of our knowledgeable Benefits Representatives, and more on your personalized benefits website. To view your custom benefits website, visit:
www.PierceGroupBenefits.com/PrinceGeorgeCountyPublicSchools
Below is a series of instructions outlining the enrollment process. Please have the following information available before you begin:
• Username, pin, and enrollment website URL from this page
• Social security numbers of the spouse or any dependents you wish to enroll
• Dates of birth for the spouse and any dependents you wish to enroll
• Beneficiary names and social security numbers
• If you are a new employee, please refer to the New Hire information on the Eligibility Requirements page of this guide or contact PGB Employee Services at 800-3875955 between 8:30am and 5:00pm for assistance.
• If you are an existing employee and unable to log into the online system, please contact PGB Employee Services at 800-387-5955, or speak with the Benefits Representative assigned to your location.
Enter your Username: Social Security Number with or without dashes (ex. 123-45-6789 or 123456789)
Enter your Pin: Last 4 numbers of your Social Security Number followed by last 2 numbers of your Date of Birth year (ex. 678970)
To login, visit: harmony.benselect.com/pgs
The screen prompts you to create a NEW PIN.
Choose a security question and enter answer.
Confirm (or enter) an email address.
Click on ‘Save New PIN’ to continue to the enrollment welcome screen.
From the welcome screen click ‘Next’.
The screen shows ‘Personal Information’. Verify that the information is correct and enter the additional required information (marital status, work phone, e-mail address). Click ‘Next’.
The screen allows you to add family members. It is only necessary to enter family member information if adding or including family members in your coverage. Click ‘Next’.
The screen shows ‘Benefit Summary’. Review your current benefits and make changes, and selections for the upcoming plan year.
Click ‘Sign & Submit’ once you have decided which benefits to enroll in.
Review your coverage. If any items are ‘Pending’, you will need to decide whether to enroll or decline this benefit.
Click ‘Next’ to review and electronically sign the authorization for your benefit elections.
Click ‘Download & Print’ to print a copy of your elections, or download and save the document. Please do not forget this important step! Click ‘Log Out’.
Review the confirmation, then if you are satisfied with your elections, enter your PIN and click ‘Sign Form’.
Lifetime Maximum Covered Services
Doctor's Visits (Outpatient or In-Office)
Primary Care Physician Visits -
Chiropractic, Spinal Manipulations (30 visit limit)
Specialist Visits -
Chiropractic, Spinal Manipulations (30 visit limit)
Shots - Allergy or Therapeutic Injections -
Doctor's Office, ER, or Outpatient Setting
Diagnostic Tests, Labs, and X-Rays
Specific conditions/diseases at doctor's office, ER, or
Outpatient Setting
Preventive Care Visits
Emergency Room Visits
Hospital & Other Services (Pre-certification may be required)
Ambulance Services
Inpatient Hospital Services
Outpatient Hospital Services
Outpatient Diagnostic Test, Labs, and X-Rays
Outpatient Therapy Services - Occupational, Speech, Physical, Cardiac, Chemotherapy, Radiation, Infusion, & Respiratory
Diabetic Equipment
Maternity
Prenatal & Provider Services- PCP
Prenatal & Provider Services - Specialist
Hospital Services for Delivery
Diagnostic Tests, Labs, and X-Rays
Behavioral Health
Inpatient Treatment/Residential Treatment
Partial Hospitalization (Day) Program
Outpatient Professional Provider Services
Prescription Drug Benefit*
Pharmacy (up to a 34-day supply)
Deductible - Individual/Family
Anthem can help you make the most of your benefts so you can be your healthiest. Take advantage of these wellness programs and services included in your health plan.
The SydneySM Health mobile app gives you a quick connection to beneft information, tools, and helpful resources. Download the app today and log in using your anthem.com username and password to:
• View your ID card.
• See all your medical and pharmacy benefts and claims.
• Easily chat with customer service.
• Connect quickly to virtual care and wellness resources.
• Track your health goals and ftness.
Simplify your healthcare by downloading Sydney Health today
Anthem Health Guides are specially trained to answer your health plan questions and steer you to the right programs and support for your unique needs. Your guide will also remind you of any screenings or routine exams that are due, help you save money on your prescription drugs, compare costs for care, and fnd in-network doctors in your area. Call 800-552-2682, Monday to Friday 8:00 a.m. to 6:00 p.m.
Life can be challenging, and Anthem EAP is here to help. Your EAP includes up to 4 free, confdential counseling sessions per issue per plan year for you, your covered dependents, and members of your household. It’s also a valuable source for information about emotional well-being, childcare and elder care resources, fnancial and legal issues, and smoking cessation. Go to anthemeap.com, and log in using Commonwealth of Virginia as your company, and then select The Local Choice, or call 855-223-9277.
Using the Sydney Health app, you can have a private, secure, video visit wherever you are with a doctor.
Urgent care virtual visits are available on demand 24/7. Virtual appointments can also be scheduled to meet with a therapist, psychologist, psychiatrist, or a sleep specialist, Monday to Friday 9 a.m. to 9 p.m. Eastern time.
No cost for Key Advantage Plans. Twenty percent coinsurance, after deductible for HDHP plans.
24/7 NurseLine has registered nurses ready and willing to help you at any time of the day. They are excellent resources for:
• Minor health issues that can be handled at home.
• Directing you to the correct doctor, health professional, or specialist.
• Determining which facility type is the best choice for your issue.
Call 800-337-4770 anytime day or night. Your call is always free and completely confdential.
Enroll in Future Moms by calling 800-828-5891 within the frst 16 weeks of pregnancy for free pre- and post-natal support that can help ensure a healthy pregnancy. Once your baby is born, use LiveHealth Online for virtual visits with a certifed lactation consultant, counselor, or registered dietitian at no extra cost through the Future Moms with Breastfeeding Support program. Key Advantage Expanded or Key Advantage 250 members: Enroll within the frst 16 weeks and your plan will waive the hospital copayment for delivery.
Extra support for members with:
• Asthma
• Diabetes
• Coronary artery disease
• Heart failure
• Chronic obstructive pulmonary disease (COPD)
• Hypertension
ConditionCare provides Nurse Care Managers who work with you or a covered
family member to help you better understand and manage a condition and meet personalized health goals. Call 844-507-8472 to enroll or we may call you to see if you would like to participate.
During those moments when you feel overwhelmed, your Employee Assistance Program (EAP) is here for you with real-life tips, tools, articles, webinars, and links to helpful resources. As always, your EAP is private, confidential, and included as part of your benefits.1 EAP is available to all employees and household members or dependents, even if you are not enrolled in an Anthem medical plan.
Connect with a mental health professional for a variety of matters, including in moments of crisis. In-person and virtual options are available. Virtual options are offered through Headway, Talkspace or LiveHealth Online.
Find resources for career, parenting, healthy communication, and balancing work and family.
Talk with a professional and find resources that can help you take charge of your finances.
For questions or issues, you have access to your EAP 24/7. Contact your EAP by calling 855-223-9277 or visit anthemeap.com/the-local-choice
Access on-line resources and legal help in-person or by phone for each issue, each year, at no added cost.2 You or eligible family members can call EAP and request a consultation for each separate issue, with a network attorney at no cost.
Emotional Well-being resources connect you to one-on-one coaching, self-help digital tools and access to articles, podcasts, and webinars for help with depression, anxiety, relationships, and alcohol use.
Take self-assessments to get personalized recommendations on the best resources for your needs.
You have an allowance for eyeglass lenses or contact lenses every plan year. You pay the remaining cost for frames and lenses after Your Health Plan’s Reimbursement.
Covered Services
Routine eye exam
Standard eyeglass lenses (in lieu of contact lenses)
Polycarbonate lenses included at no additional cost for children under 19 years old
Eyeglass frames
Contact lenses1 (in lieu of eyeglass lenses)
Elective Conventional2
Elective Disposable2
Non-Elective2
Retinal Imaging
At member’s option can be performed at time of eye exam
Lens options
UV coating, tints, standard scratch-resistant
Blue View Vision Network (once per plan year)
You pay $15 copayment
You pay $20 copayment
Plan pays up to $100* retail allowance
Plan pays up to $100 allowance then 15% discount off remaining balance
Plan pays up to to $50
Plan pays up to: $50 single lenses; $75 bifocal; $100 trifocal
Plan pays up to $80
Plan pays up to $80
Plan pays up to $100 allowance (no additional discount)Plan pays up to $80
Covered in full
Not more than $39
You pay $15
Standard polycarbonate (Adult) You pay $40
Standard progressive (in addition to bifocal copayment)
Standard anti-reflective
Other add-ons
(i.e. high index lenses, anti-fog coating)
You pay $65
You pay $45
You pay 20% off retail
*You may select a frame greater than the covered allowance and receive a 20% discount for any additional cost over the allowance.
Plan pays up to $210
Not available
Not available
Not available
Not available
Not available
1 Declining Balance. Your plan has a declining balance allowance. This means if you do not use your allowance all at once, the remainder will be available for you to use at a later time. However, any remaining balance will not carry over to the next benefit year. All services or supplies using the declining balance for a benefit period must be received In-Network based on where the first paid claim is incurred..
2 Elective contact lenses are typically elected in lieu of eyeglass lenses. Non-Elective contact lenses are medically necessary contacts when glasses are not an option for vision.
Enrollment in a HDHP allows you to set up a personal Health Savings Account (HSA) through a bank or other financial institution to help you manage healthcare expenses or save for retirement. HSAs were created as part of Medicare reform legislation in 2003. An HSA is a tax-favored account that allows those covered by a HDHP to pay for certain qualified medical expenses. It can help you save on the cost of your health insurance and healthcare expenses, and also help pay for covered services before you satisfy the health plan deductible. If you decide to set up an HSA to work with your HDHP, confer with your tax advisor, bank or other financial institution.
The following web sites are a good place to start learning more about HSAs.
• www.treasury.gov – Provides an overview of HSAs, answers to frequently asked questions and important IRS forms and applications. Search using keyword HSA.
• www.irs.gov – Provides information about how HSAs impact your Federal taxes and qualified medical expenses (Publications 969 and 502). Search using keyword HSA.
• www.hhs.gov – Provides general information about HSAs and other tax-favored health plans. Search using keyword HSA.
Note: If you have an HSA, you cannot also have a Flexible Spending Account unless it is limited in scope. More information is available from tax consultants or financial institutions.
You have an allowance for eyeglass lenses or contact lenses every plan year. You pay the remaining cost for frames and lenses after Your Health Plan’s Reimbursement.
Routine eye exam
Standard eyeglass lenses (in lieu of contact lenses)
Polycarbonate lenses included at no additional cost for children under 19 years old
Eyeglass frames
Contact lenses1 (in lieu of eyeglass lenses)
Elective Conventional2
Elective Disposable2
Non-Elective2
Retinal Imaging
At member’s option can be performed at time of eye exam
Lens options
UV coating, tints, standard scratch-resistant
Blue View Vision Network (once per plan year)
You pay $40 copayment
You pay $20 copayment
Plan pays up to $100* retail allowance
Plan pays up to $100 allowance then 15% discount off remaining balance
Plan pays up to $100 allowance (no additional discount)
Plan pays up to $250 allowance
Not more than $39
You pay $15
Standard polycarbonate (Adult) You pay $40
Standard progressive (in addition to bifocal copayment)
Standard anti-reflective
Other add-ons (i.e. high index lenses, anti-fog coating)
You pay $65
You pay $45
You pay 20% off retail
*You may select a frame greater than the covered allowance and receive a 20% discount for any additional cost over the allowance.
Plan pays up to to $50
Plan pays up to:
$50 single lenses;
$75 bifocal;
$100 trifocal
Plan pays up to $80
Plan pays up to $80
Plan pays up to $80
Plan pays up to $210
Not available
Not available
Not available
Not available
Not available
1 Declining Balance. Your plan has a declining balance allowance. This means if you do not use your allowance all at once, the remainder will be available for you to use at a later time. However, any remaining balance will not carry over to the next benefit year. All services or supplies using the declining balance for a benefit period must be received In-Network based on where the first paid claim is incurred..
2 Elective contact lenses are typically elected in lieu of eyeglass lenses. Non-Elective contact lenses are medically necessary contacts when glasses are not an option for vision.
How to make the most of your pharmacy benefits
Your prescription coverage is an important part of your benefit plan. Your prescription drug benefits are administered by Anthem Pharmacy, delivered by IngenioRx.
First things first. Have you registered at anthem.com yet?
It’s the fastest and easiest way to get all of your personalized pharmacy benefits information. At anthem.com you can do things like:
} Find a pharmacy.
} Compare drug costs.
} Switch to home delivery or refill a prescription.
} Check your claims status and history.
} Check your deductible or coinsurance amounts.
There’s an app for all of that, too. The Sydney mobile app makes it easy to manage your pharmacy benefits from wherever you are. You can find it at the Apple Store® (iOS) or on Google Play (Android).
} Hundreds of drugs covered by your plan
} Some preventive drugs at little or no cost to you
} Specialty drugs if you have an ongoing health issue or serious illness
This is a list of prescription drugs covered by your plan. It’s made up of hundreds of generic and brand-name drugs.
Through in-depth research, we find high-quality drugs with the best success rates. Sometimes we update the drug list when new drugs come to market or if new research becomes available. To check if a drug you need is on the list, call Member Services at 1-800-552-2682 or visit anthem.com
Your drug plan is a mandatory generic program. This means if you or your doctor requests a brand name drug when a generic is available, you will pay the brand coinsurance plus the difference between the allowable charge for the generic and brand name drug after the deductible.
You have plenty of choices about how and where to get your medicine, including local pharmacies in your plan or convenient home delivery.
Your plan includes nearly 70,000 pharmacies nationwide. The network includes most chains and some local, independent pharmacies. To make sure your pharmacy is in the network call the pharmacy or Anthem Pharmacy Member Services at 1-833-267-3108
Simply show your member ID card at your network pharmacy and get up to a 34-day supply of covered drugs at a network retail pharmacy. Once your deductible has been met, pay the coinsurance at the time of purchase.
If you use a pharmacy out of the network you’ll pay the full cost of your drug when you pick it up, and then file a Prescription Drug Claim Form to get reimbursed. You may be responsible for the difference between the pharmacy’s charge and the plan’s allowable charge for the drug.
This is a convenient, cost-saving way to get a 90-day supply of medications you take on a regular basis. You pay the appropriate coinsurance for a three-month supply of drugs, and the medication is delivered right to your home.
Call 1-833-267-3108 and a representative will help you with your order. Or you can sign up at anthem.com.
Your pharmacy plan includes access to home delivery of specialty drugs — drugs that may need special handling or that you may get by injection or infusion — through IngenioRx Specialty Pharmacy.
Call 1-833-267-3108 and a member of the specialty pharmacy care team will help you get started with your specialty pharmacy order.
You can also obtain your specialty drugs from a participating retail pharmacy for up to a 34-day supply by paying the appropriate coinsurance.
} Take medicines on your plan’s drug list
} Find out if there are generic or over-the-counter options that may work for you.
} See how much your cost could be with our Price a Medication tool at anthem.com
} Use a pharmacy in your plan
} Get 90-day supplies of the medicines you take regularly.
Remember to always talk to your doctor before making any change in your medicine.
Some medications require taking certain steps before they’re covered by your plan. Here are a few you need to know about:
} Prior authorization (PA). You may need to get our approval before a pharmacy can fill your prescription for certain medications.
} Step therapy (ST). You may need to try one or more other drugs before we’ll cover the one your doctor wants you to take.
} Quantity limits (QL). Your plan may limit how much of a medicine you can get each month to help protect your health.
} Dose optimization (DO). You may be able to switch from taking a drug twice a day to taking it once a day at a higher strength. We’re
July 1, 2026 - June 30, 2027 Employee Contribution Schedule
The Local Choice Package includes health, dental, and vision coverage

Group Number: 00000006107 • Effective Date: July 1, 2026
(Applies
For the services listed below, Delta Dental will pay the stated percentage of the plan allowance based on the dentist’s participation with Delta Dental.
Diagnostic and Preventive Services
• Oral exams and cleanings Twice in a 12-month period
• Periodontal Cleanings Twice in a 12-month period .
• Fluoride applications Twice in a 12-month period for enrollees under age 19.
• X - rays Bitewing X - rays are limited to once in a 12-month period ; limited to a maximum of four films or a set ( seven to eight films) of vertical bitewings. Full - mouth X - rays are limited to once in a five - year period.
• Sealants One per tooth every 5 years for members under age 16 on first and second permanent molars.
Basic Services
• Fillings One per surface in a 24 - month period; c omposite (white) fillings are limited to upper and lower six front teeth .
• Simple extractions
• Denture repair and recementation
• Endodontic services R oot canal therapy .
• Periodontic services T reatment for gum disease
• O ral surgery Surgical extractions and other surgical procedures
Major Services *
• Crowns One per tooth in a 84 - month period for members age 12 and older.
• Prosthodontics/dentures and bridges Once in a 84 - month period for members age 16 and older.
• Implants One per site for members age 16 and older.
*Other Basic services have a 12 month waiting period.
*Major services have a 12 month waiting period.
Additional b enefits included in your plan :
MaxOver ™ Allows a portion of a member ’s annual maximum to roll over to next year to use for future dental services.
Healthy Smile, Healthy You ® Provides additional cleanings , fluoride and/or sealants for members with certain health conditions. Visit DeltaDentalVA.com to learn more or to download an enrollment form.
Right Start 4 Kids® Covers children up to age 13 at 100% with no deductible when you visit an in - network dentist. (For services outlined in the plan, up to the annual maximum. Subject to any limitations, exclusions and waiting periods).
Special Health Care Needs Benefit Provides additional benefits for members with special needs. To learn more about this benefit , visit DeltaDentalVA .com/special - health - care - needs - resources.
Coverage is available for:
• Dependent children, only to the end of the month when they reach age 26 (the “limiting age”).
Convenient, eco - friendly options available :
At Delta Dental of Virginia, we are committed to taking actionable measures to minimize our environmental footprint. Join us as we step toward reducing paper waste and promoting sustainability by signing up to receive your Delta Dental of Virginia explanation of benefits (EOB) digitally at DeltaDentalVA.com/members
You may select the dentist of your choice. However, t o get the most value from your dental benefits, make sure your dentist participates in the network listed at the top of your Delta Dental ID card With Delta Dental PPO Plus Premier ™, you have the option of visiting any dentist. However, your out - of - pocket costs may be lowest if you see a Delta Dental PPO ™ network dentist and highest if you choose an out - ofnetwork dentist. Delta Dental network dentists agree to discount their fees, submit claims on your behalf and not bill you for the difference. Visit DeltaDentalVA.com to find a participating dentist in your area
If you visit an out - of - network dentist, Delta Dental will pay its portion of the bill and you are responsible for any coinsurance and deductible (if applicable), as well as the difference between the nonparticipating dentist’s charge and Delta Dental’s payment. Payment will be made to you , unless state law requires otherwise.
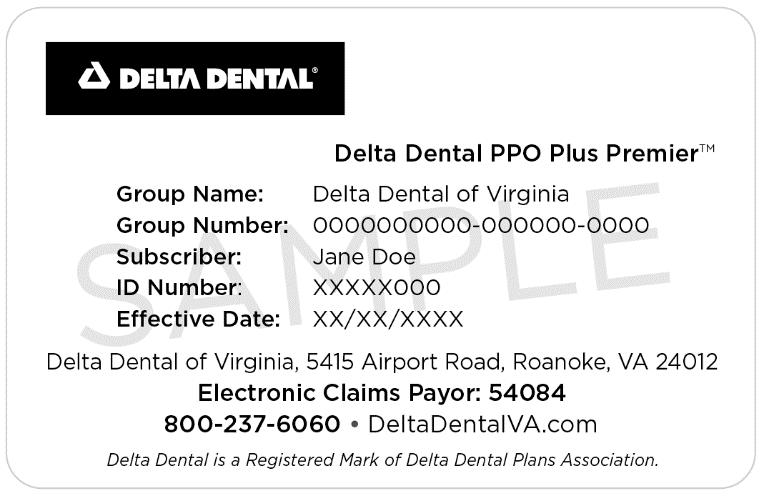
This fact sheet is a brief description of dental services covered under your plan and is not designed to serve as an Evidence of Coverage. If you have questions about specific benefits or limitations under your plan, call Delta Dental’s Benefit Services at 800.237.6060 or visit DeltaDentalVA.com /members to register for an account .
Group Number: 00000006107 • Effective Date: July 1, 2026
For the services listed below, Delta Dental will pay the stated percentage of the plan allowance based on the dentist’s participation with Delta Dental.
and Preventive
• Oral exams and cleanings Twice in a 12-month period
• Periodontal Cleanings Twice in a 12-month period
• Fluoride applications Twice in a 12-month period for enrollees under age 19.
• X - rays Bitewing X - rays are limited to once in a 12-month period ; limited to a maximum of four films or a set ( seven to eight films) of vertical bitewings. Full - mouth X - rays are limited to once in a five - year period.
• Sealants One per tooth every 5 years for members under age 16 on first and second permanent molars.
• Fillings One per surface in a 24 - month period; c omposite (white) fillings are limited to upper and lower six front teeth
• Simple extractions
• Denture repair and recementation
Other Basic Services *
• Endodontic services R oot canal therapy
• Periodontic services T reatment for gum disease
• O ral surgery Surgical extractions and other surgical procedures
Major Services *
• Crowns One per tooth in a 84 - month period for members age 12 and older.
• Prosthodontics/dentures and bridges Once in a 84 - month period for members age 16 and older.
• Implants One per site for members age 16 and older.
Orthodontic Services
• Treatment for the proper alignment of teeth For dependent children under age 19.
*Other Basic services have a 12 month waiting period.
*Major services have a 12 month waiting period.
Continued on next page
Additional b enefits included in your plan :
MaxOver ™ Allows a portion of a member ’s annual maximum to roll over to next year to use for future dental services.
Healthy Smile, Healthy You ® Provides additional cleanings , fluoride and/or sealants for members with certain health conditions. Visit DeltaDentalVA.com to learn more or to download an enrollment form.
Right Start 4 Kids® Covers children up to age 13 at 100% with no deductible when you visit an in - network dentist. (For services outlined in the plan, up to the annual maximum. Subject to any limitations, exclusions and waiting periods).
Special Health Care Needs Benefit Provides additional benefits for members with special needs. To learn more about this benefit , visit DeltaDentalVA .com/special - health - care - needs - resources.
Coverage is available for:
• Dependent children, only to the end of the month when they reach age 26 (the “limiting age”).
Convenient, eco - friendly options available :
At Delta Dental of Virginia, we are committed to taking actionable measures to minimize our environmental footprint. Join us as we step toward reducing paper waste and promoting sustainability by signing up to receive your Delta Dental of Virginia explanation of benefits (EOB) digitally at DeltaDentalVA.com/members
You may select the dentist of your choice. However, t o get the most value from your dental benefits, make sure your dentist participates in the network listed at the top of your Delta Dental ID card With Delta Dental PPO Plus Premier ™, you have the option of visiting any dentist. However, your out - of - pocket costs may be lowest if you see a Delta Dental PPO ™ network dentist and highest if you choose an out - ofnetwork dentist. Delta Dental network dentists agree to discount their fees, submit claims on your behalf and not bill you for the difference. Visit DeltaDentalVA.com to find a participating dentist in your area
If you visit an out - of - network dentist, Delta Dental will pay its portion of the bill and you are responsible for any coinsurance and deductible (if applicable), as well as the difference between the nonparticipating dentist’s charge and Delta Dental’s payment. Payment will be made to you , unless state law requires otherwise.
This fact sheet is a brief description of dental services covered under your plan and is not designed to serve as an Evidence of Coverage. If you have questions about specific benefits or limitations under your plan, call Delta Dental’s Benefit Services at 800.237.6060 or visit DeltaDentalVA.com /members to register for an account .
Did you know that cavities are the most chronic childhood disease? Cavities are five times more common than asthma. Children with pain from tooth decay may miss more school and have lower grades than their peers, not to mention the lost work hours for parents. But cavities are nearly 100% preventable, and it’s easy to protect your child’s oral health and ensure better overall health.
Right Start 4 Kids from Delta Dental is a benefit that helps remove cost barriers to dental care for children up to age 13. This program provides 100% coverage for diagnostic and preventive and basic and major services, with no deductible, when you visit an in-network dentist.* Coinsurance levels apply when visiting an out-of-network dentist.**
Want to learn more about your child’s oral health and why it’s so important to take care of it? Visit DeltaDentalVA.com/members for more oral health and wellness resources.
Welcome to your Blue View Vision plan!
You have many choices when it comes to using your benefits. As a Blue View Vision plan member, you have access to one of the nation’s largest vision networks. You may choose from many private practice doctors, local optical stores, and national retail stores including LensCrafters®, Target Optical®, and most Pearle Vision® locations. You may also use your in-network benefits to order eyewear online at Glasses.com and ContactsDirect.com. To locate a participating network eye care doctor or location, log in at anthem.com, or the Sydney app. You may also call member services for assistance at 1-866-723-0515
Out-of-Network – If you choose to, you may instead receive covered benefits outside of the Blue View Vision. Just pay in full at the time of service, obtain an itemized receipt, and file a claim for reimbursement up to your maximum out-of-network allowance.
Your vision plan includes coverage for routine eye exams and prescription eyewear from your choice of eye care providers.
Routine Eye Exam
A comprehensive eye examination
Eyeglass Frames
One pair of eyeglass frames
Eyeglass Lenses (instead of contact lenses)
One pair of standard plastic prescription lenses
Single vision lenses
Bifocal lenses
Trifocal lenses
Eyeglass Lens Enhancements
$15 Copay
$140 Allowance, then 20% off any remaining balance
$25 Copay
$25 Copay
$25 Copay
Reimbursed Up To $30 Once every calendar year
Reimbursed Up To $45
Once every calendar year
Reimbursed Up To $25
Reimbursed Up To $40
Reimbursed Up To $55
Once every calendar year
When obtaining covered eyewear from a Blue View Vision provider, you may choose to add any of the following lens enhancements at no extra cost
Lenses (for a child under age 19)
Standard polycarbonate (for a child under age 19)
Factory Scratch Coating
Contact Lenses (instead of eyeglass lenses)
$0 Copay
$0 Copay
$0 Copay
No allowance when obtained out-of-network
Same as covered eyeglass lenses
Contact lens allowance will only be applied toward the first purchase of contacts made during a benefit period. Any unused amount remaining cannot be used for subsequent purchases in the same benefit period, nor can any unused amount be carried over to the following benefit period.
Elective conventional (non-disposable) OR
Elective disposable OR
Non-elective (medically necessary)
Contact lens fit and follow-up
$140 Allowance, then 15% off any remaining balance
$140 Allowance (no additional discount)
Covered in full
Reimbursed Up To $105
Reimbursed Up To $105 Reimbursed Up To $210
Once every calendar year
A contact lens fitting and up to two follow-up visits are available to you once a comprehensive eye exam has been completed.
Standard contact lens fitting
Premium contact lens fitting
exclusions, are contained in the
$0 Copay 10% off retail price, then apply $55 allowance Reimbursed Up To $35 Reimbursed Up To $35
policy, which shall control in the event of a conflict with this overview. This
overview is only one piece of your entire enrollment package. EXCLUSIONS & LIMITATIONS (not a comprehensive list – please refer to the member Certificate of Coverage for a complete list) Combined Offers. Not to be combined with any offer, coupon, or in-store advertisement.
Once every calendar year
Excess Amounts. Amounts in excess of covered vision expense. Sunglasses. Plano sunglasses and accompanying frames. Safety Glasses. Safety glasses and accompanying frames. Not Specifically Listed. Services not specifically listed in this plan as covered services. Lost or Broken Lenses or Frames. Any lost or broken lenses or frames are not eligible for replacement unless the insured person has reached his or her normal service interval as indicated in the plan design. Non-Prescription Lenses. Any non-prescription lenses, eyeglasses or contacts. Plano lenses or lenses that have no refractive power. Orthoptics. Orthoptics or vision training and any associated supplemental testing
(Discounts are not covered benefits under your vision plan and will not be listed in your certificate of coverage.)
Retinal Imaging - at member’s option, can be performed at time of eye exam
Eyeglass lens upgrades
When obtaining eyewear from a Blue View Vision provider, you may choose to upgrade your new eyeglass lenses at a discounted cost. Eyeglass lens copayment applies.
Additional Pairs of Eyeglasses
Anytime from any Blue View Vision network provider
Eyewear Accessories
Conventional Contact Lenses (non-disposable type)
More Than
lenses (Adults)
Standard Polycarbonate (Adults)
Tint (Solid and Gradient)
UV Coating
Progressive Lenses1
Standard
Tier 2
Tier 3
Anti-Reflective Coating2
Premium Tier 1
Premium Tier 2
Other Add-ons (i.e. high index lenses, anti-fog coating)
Complete Pair
Eyeglass materials purchased separately
Items such as non-prescription sunglasses, lens cleaning supplies, contact lens solutions, eyeglass cases, etc.
Discount applies to materials
1 Please ask your provider for his/her recommendation as well as the available progressive brands by tier.
2 Please ask your provider for his/her recommendation as well as the available anti-reflective brands by tier. Cannot be combined with any other offer. Discounts are subject to change without notice. Discounts are not covered benefits under your vision plan and will not be listed in your certificate of coverage. Discounts will be offered from in-network providers except where State law prevents discounting of products and services that are not covered benefits under this plan. Discounts on frames will not apply if the manufacturer has imposed a no discount on sales at retail and independent provider locations. Some of our in-network providers include:S
Savings on items like additional eyewear after your benefits have been used, non-prescription sunglasses, hearing aids and even LASIK laser vision correction surgery are available through a variety of vendors. Just log in at anthem.com, select discounts, then Vision, Hearing & Dental. * Discounts cannot be used in conjunction with your covered benefits.
OUT-OF-NETWORK
If you choose to receive covered services or purchase covered eyewear from an out-of-network provider, network discounts will not apply and you will be responsible for payment of services and/or eyewear materials at the time of service. Please complete an out-of-network claim form and submit it along with your itemized receipt to the fax number, email address, or mailing address below. To download a claim form, log in at anthem.com, or from the home page menu under Support select Forms, click Change State to choose your state, and then scroll down to Claims and select the Blue View Vision Out-of-Network Claim Form. You may instead call member services at 1-866-723-0515 to request a claim form.
TO FAX: 866-293-7373
TO EMAIL: oonclaims@eyewearspecialoffers.com
TO MAIL: Blue View Vision Attn: OON Claims P.O. Box 8504 Mason, OH 45040-7111
A Health Savings Account, or HSA, is a tax-advantaged savings account you can use for healthcare expenses. Along with saving you money on taxes, HSAs can help you grow your nest egg for retirement.
• Contribute to your HSA by payroll deduction, online transfer or personal check.
• Pay for qualified healthcare expenses for yourself, your spouse and your dependents. Both current and past expenses are covered if they’re from after you opened your HSA.
• Use your Benefits Card to pay directly, or pay out of pocket for reimbursement or to grow your HSA funds.
• Roll over any unused funds year to year. It’s your money — for life.
• Invest your HSA funds and potentially grow your savings.¹
You’re most likely eligible to open an HSA if:
• You have a qualified high-deductible health plan (HDHP).
• You’re not covered by any other non-HSAcompatible health plan, like Medicare Parts A and B.
• You’re not covered by TriCare.
• No one (other than your spouse) claims you as a dependent on their tax return.
The IRS limits how much you can contribute to your HSA every year. This includes contributions from your employer, spouse, parents and anyone else.2
You can use your HSA funds to pay for any IRS-qualified healthcare expenses, like doctor visits, hospital fees, prescriptions, dental exams, vision appointments, over-the-counter medications and more.
Visit hsabank.com/QME for a full list.
You may be eligible to make a $1,000 HSA catch-up contribution if you’re:
• Over 55.
• An HSA accountholder.
• Not enrolled in Medicare (if you enroll midyear, annual contributions are prorated).
A huge way that HSAs can benefit you is they let you save on taxes in three ways.
1 You don’t pay federal taxes on contributions to your HSA.3
2 Earnings from interest and investments are tax-free.
3 Distributions are tax-free when used for qualified healthcare expenses.
¹ Investment accounts are not FDIC insured, may lose value and are not a deposit or other obligation of, or guarantee by the bank. Investment losses which are replaced are subject to the annual contribution limits of the HSA.
2 HSA contributions in excess of IRS limits are subject to penalty and tax unless the excess and earnings are withdrawn prior to the tax filing deadline as explained in IRS Publication 969.
3 Federal tax savings are available regardless of your state. State tax laws may vary. Consult a tax professional for more information.
Visit hsabank.com or call the number on the back of your debit card for more information
• The largest selection of guaranteed HSAeligible products
• Phone and live chat support available 24 hours a day / 7 days a week
• Fast and free shipping on orders over $50
• Use your HSA card or any other major credit card for purchases
Eligibility List
Search comprehensive list of eligible products and services.
FSA Calculator
Estimate how much you can save with an HSA.
Learning Center
Easy tips and resources for living with an HSA.
Savings Center
Your funds go further with the HSA Store rewards program.
Take control of your health and wellness with guaranteed HSA-eligible essentials. Pierce Group Benefits partners with the HSA store to provide one convenient location for Heath Savings Account holders.
Click or Scan to Shop Now
Click on the video below to learn more about Dependent Care Accounts!
Set aside tax-free money for daycare and dependent care services
Use the below information to determine if a Dependent Care Account (DCA) is right for you and how to best take advantage of an DCA account.
When you enroll in a Dependent Care Account (DCA) you get to experience tax savings on expenses like daycare, elderly care, summer day camp, preschool, and other services that allow you to work full time.
• Save On Eligible Expenses: You can use a DCA to pay for qualifying expenses such as daycare, summer day care, elder care, before and after school programs, and pre-school.
• Keep More Money: The funds are taken out of your paycheck "pre-tax" (meaning they are subtracted from your gross earnings before taxes) throughout the course of the year. Let’s say you earn $40,000 a year and contribute $1,500 to an DCA; so, only $38,500 of your income gets taxed. That means you are increasing your take-home pay simply by participating!
• Easy Spending and Account Management: You will receive an Ameriflex Debit Mastercard linked to your DCA. You can use your card for eligible purchases everywhere Mastercard is accepted. Account information can be securely accessed 24/7 online and through the mobile app.
The IRS determines what expenses are eligible under a DCA. Below are some examples of common eligible expenses:
For a full list of eligible expenses, go to myameriflex.com/eligibleexpenses.
How to Access Your Ameriflex Account:
Go to MyAmeriflex.com and click “Login” from the upper right hand corner. When prompted, select “Participant.”
How to Register Online For Your Ameriflex Spending Account:
Click the register button atop the right corner of the home screen.
1.As the primary account holder, enter your personal information.
• Choose a unique User ID and create a password (if you are told that your username is invalid or already taken, you must select another).
• Enter your first and last name.
• Enter your email address.
• Enter your Employee ID, which in most cases, will be the account holder’s Social Security Number(no dashes or spaces needed).
2.Check the box if you accept the terms of use.
3.Click 'register'. This process may take a few seconds. Do not click your browser’s back button or refresh the page.
4.Last, you must complete your Secure Authentication setup. Implemented to protect your privacy and help us prevent fraudulent activity, setup is quick and easy. After the registration form is successfully completed, you will be prompted to complete the secure authentication setup process:
Step 1: Select a Security Question option, and type in a corresponding answer.
Step 2: Repeat for the following three Security Questions, then click next.
Step 3: Verify your email address, and then click next.
Step 4: Verify and submit setup information,
5.The registration process is complete! Should you receive an information error message that does not easily guide you through the information correction process, please feel free to contact our dedicated Member Services Team at 888.868.FLEX (3539).
Download the MyAmeriflex mobile app, available through the App Store or Google Play.
Your credentials for the MyAmeriflex Portal and the MyAmeriflex Mobile App are the same; there is no need for separate login information!
Click on the video below to learn more about Long Term Care Benefits!
Learn more about our 7702(b) Qualified Long Term Care offering, with favorable interest rates and benefits to ensure your clients are better protected.
LBT provides a tax-qualified LTC Benefit that complies with this provision of the tax code and may satisfy future state mandates as Qualified Long Term Care.
After 10 years, paid-up benefits begin to accrue. At any point thereafter, if you stop paying the premium, a reduced paid-up benefit is issued and can never lapse.
Based on a 3% interest rate and mortality assumptions, the full death benefit is designed to last through age 99 for non-tobacco users and age 95 for tobacco users.
Our Life Insurance premiums never change and are only due until age 100. And as long as premiums are paid, coverage won’t lapse, lasting until employees reach their 121st birthday.
Pays benefits for Long Term Care services
and
Employees can take these benefits with them, even if they change jobs.
Chubb’s Workplace Benefits product series is designed to empower you with innovative and flexible benefits solutions to better meet your customer’s needs.
For about the same premium, LifeTime Benefit Term (LBT) provides higher death benefits than permanent life insurance and lasts to age 121. Plus offers additional benefits.
LBT’s innovative design provides life time guarantees at a fraction of the cost of permanent life insurance. And flexibility allows you to customize benefits for Long Term Care (LTC) and double or triple the policy value.
Death Benefit is guaranteed 100% when it is needed most—during the working years when a family is relying on income. While the policy is in force, the death benefit is 100% guaranteed
The full death benefit is designed to last through age 99 for nontobacco users and age 95 for tobacco users based on the current interest rate and mortality assumptions.
Chubb is the marketing name used to refer to subsidiaries of Chubb Limited providing insurance and related services. This insurance product is underwritten by Combined Insurance Company of America, Chicago, IL, a Chubb company. www.chubbworkplacebenefits.com
When employees need LTC, death benefits can be paid early for home health care, assisted living, adult day care and nursing home care. Early payments equal 4% of the death benefit per month for up to 25 months. Premiums are waived while this benefit is being paid.
Once the full death benefit has been paid in advance for LTC, payments can be extended. Choose between 25 and 50 months of LTC Benefit Extension to double or triple the value.
Accelerating the life coverage for LTC benefits can reduce the death benefit to $0. This rider restores the life coverage to either 25% or 50% of the death benefit on which the LTC benefits were based, therefore assuring a death benefit available up to the insured’s age 121.
Lifelong protection with premiums beginning as low as $3 per week.
Dependable
Guaranteed life insurance premium and death benefits last a lifetime.
Fully Portable and Guaranteed Renewable for Life
Employee coverage cannot be cancelled as long as premiums are paid as due.
LifeTime Benefit Term protects families with money that can be used any way they need. Often it is used to pay for mortgage or rent, education for children and grandchildren, family debt and final expenses.
Long Term Care is expensive, and LifeTime Benefit Term can help. It pays death benefits in advance for home health care, assisted living, adult day care and nursing home and waives life insurance premiums. And with Extension of Long Term Care, benefits can last for more than 6 years, in essence, tripling the policy value
Life insurance premiums will never increase and are guaranteed through age 100.
After 10 years, paid-up benefits begin to accrue. At any point thereafter, if premiums stop, a reduced paid up benefit is guaranteed. Flexibility is perfect for retirement.
After coverage has been in force for two years, employees can receive 50% of their death benefit immediately, up to $100,000, if they are diagnosed as terminally ill.
Waiver of Premium Benefit
Waives premium if employee becomes totally disabled.
For the same premium, LifeTime Benefit Term provides higher benefits than permanent life Insurance and lasts to age 121.
* LTC and Extension of Benefits premiums may be adjusted based upon the experience of the group or other group characteristics that may affect results. Premiums will not be increased solely because of an independent claim.
This document is only a brief description of Group Policy Form No. P34544. See the policy for complete details about features, benefits, exclusions and limitations that may vary by state. The availability of this product, riders or optional benefits are subject to underwriting approval.
Click on the video below to learn more about Cancer Benefits!
Hopefully, you and your family will never face cancer. If you do, a financial safety net can help you and your loved ones focus on what matters most — recovery.
If you were diagnosed with cancer, you could have expenses that medical insurance doesn’t cover. In addition to your regular, ongoing bills, you could have indirect treatment and recovery costs, such as child care and home health care services.
Cancer coverage from Colonial Life & Accident Insurance Company can help protect the lifestyle you’ve worked so hard to build. It provides benefits you can use to help cover:
■ Loss of income
■ Out-of-network treatment
■ Lodging and meals
■ Deductibles and co-pays
Travel expenses
When the couple traveled several hundred miles from their home to a top cancer hospital, they used the policy’s lodging and transportation benefits to help with expenses.
Paul and Kim were preparing for their second child when they learned Paul had cancer. They quickly realized their medical insurance wouldn’t cover everything. Thankfully, Kim’s job enabled her to have a cancer insurance policy on Paul to help them with expenses.
Out-of-pocket costs
The policy’s benefits helped with deductibles and co-pays related to Paul’s surgery and hospital stay.
■ Coverage options are available for you and your eligible dependents.
■ Benefits are paid directly to you, unless you specify otherwise.
■ You’re paid regardless of any insurance you may have with other companies.
■ You can take coverage with you, even if you change jobs or retire.
Experimental care Follow-up evaluations
Paul used his plan’s benefits to help pay for experimental treatments not covered by his medical insurance.
Paul has been cancer-free for more than four years. His cancer policy provides a benefit for periodic scans to help ensure the cancer stays in check.
Our cancer insurance offers more than 30 benefits that can help you with costs that may not be covered by your medical insurance.
Treatment benefits (inpatient or outpatient)
■ Radiation/chemotherapy
■ Anti-nausea medication
■ Medical imaging studies
■ Supportive or protective care drugs and colony stimulating factors
■ Second medical opinion
■ Blood/plasma/platelets/ immunoglobulins
■ Bone marrow or peripheral stem cell donation
■ Bone marrow or peripheral stem cell transplant
■ Egg(s) extraction or harvesting/ sperm collection and storage
■ Experimental treatment
■ Hair/external breast/voice box prosthesis
■ Home health care services
■ Hospice (initial or daily care)
■ Surgical procedures
■ Anesthesia
■ Reconstructive surgery
■ Outpatient surgical center
■ Prosthetic device/artificial limb
■ Transportation
■ Companion transportation
■ Lodging
■ Hospital confinement
■ Private full-time nursing services
■ Skilled nursing care facility
■ Ambulance
■ Air ambulance
Additional benefits
■ Family care
■ Cancer vaccine
■ Bone marrow donor screening
■ Skin cancer initial diagnosis
■ Waiver of premium
For an additional cost, you may have the option of purchasing additional riders for even more financial protection against cancer. Talk with your benefits counselor to find out which of these riders are available for you to purchase.
■ Diagnosis of cancer rider — Pays a one-time, lump-sum benefit for the initial diagnosis of cancer. You may choose a benefit amount in $1,000 increments between $1,000 and $10,000. If your dependent child is diagnosed with cancer, we will pay two and a half times ($2,500 - $25,000) the chosen benefit amount.
■ Diagnosis of cancer progressive payment rider — Provides a lump-sum payment of $50 for each month the rider has been in force and before cancer is first diagnosed.
■ Specified disease hospital confinement rider — Pays $300 per day if you or a covered family member is confined to a hospital for treatment for one of the 34 specified diseases covered under the rider.
If cancer impacts your life, you should be able to focus on getting better — not on how you’ll pay your bills. Talk with your Colonial Life benefits counselor about how cancer insurance can help provide financial security for you and your family.
We will not pay benefits for the diagnosis of internal cancer or skin cancer that is a pre-existing condition, nor will we pay benefits for the treatment of internal cancer or skin cancer that is a pre-existing condition unless the covered person has satisfied the six-month pre-existing condition limitation period shown on the Policy Schedule. Pre-existing condition means a condition for which a covered person was diagnosed prior to the effective date of this policy, and for which medical advice or treatment was recommended by or received from a doctor within six months immediately preceding the effective date of this policy.
We will not pay benefits for cancer or skin cancer:
■ If the diagnosis or treatment of cancer is received outside of the territorial limits of the United States and its possessions; or
■ For other conditions or diseases, except losses due directly from cancer.
The policy and its riders may have additional exclusions and limitations. For cost and complete details of the coverage, see your Colonial Life benefits counselor. Coverage may vary by state and may not be available in all states. Applicable to policy form CanAssist-VA and rider forms R-CanAssistIndx-VA, R-CanAssistProg-VA and R-CanAssistSpDis-VA.
Cancer insurance helps provide financial protection through a variety of benefits. These benefits are not only for you but also for your covered family members.
For more information, talk with your benefits counselor.
Air ambulance
Transportation to or from a hospital or medical facility [max. of two trips per confinement]
Ambulance
Transportation to or from a hospital or medical facility [max. of two trips per confinement]
Anesthesia
Administered during a surgical procedure for cancer treatment
■ General anesthesia
■ Local anesthesia
Anti-nausea medication
$2,000 per trip
$250 per trip
25% of surgical procedures benefit
$50 per procedure
$60 per day administered or Doctor-prescribed medication for radiation or chemotherapy [$240 monthly max.] per prescription filled
Blood/plasma/platelets/immunoglobulins
A transfusion required during cancer treatment [$10,000 calendar year max.]
Bone marrow donor screening
Testing in connection with being a potential donor [once per lifetime]
Bone marrow or peripheral stem cell donation
Receiving another person’s bone marrow or stem cells for a transplant [once per lifetime]
Bone marrow or peripheral stem cell transplant
Transplant you receive in connection with cancer treatment [max. of two bone marrow transplant benefits per lifetime]
Cancer vaccine
An FDA-approved vaccine for the prevention of cancer [once per lifetime]
Companion transportation
Companion travels by plane, train or bus to accompany a covered cancer patient more than 50 miles one way for treatment [up to $1,500 per round trip]
Egg(s) extraction or harvesting/sperm collection and storage
Extracted/harvested or collected before chemotherapy or radiation [once per lifetime]
■ Egg(s) extraction or harvesting/sperm collection
■ Egg(s) or sperm storage (cryopreservation)
Experimental treatment
Hospital, medical or surgical care for cancer [$15,000 lifetime max.]
Family care
Inpatient or outpatient treatment for a covered dependent child [$3,000 calendar year max.]
Hair/external breast/voice box prosthesis
Prosthesis needed as a direct result of cancer
Home health care services
Examples include physical therapy, occupational therapy, speech therapy and audiology; prosthesis and orthopedic appliances; rental or purchase of durable medical equipment [up to 100 days per covered person per lifetime]
Hospice (initial or daily care)
An initial, one-time benefit and a daily benefit for treatment [$15,000 lifetime max. for both]
■ Initial hospice care [once per lifetime]
■ Daily hospice care
$250 per day
$50
$1,000
$10,000 per transplant
$50
$0.50 per mile
$1,500
$500
$300 per day
$60 per day
$500 per calendar year
$175 per day
$1,000
$50 per day
Hospital confinement
Hospital stay (including intensive care) required for cancer treatment
■ 30 days or less
■ 31 days or more
$350 per day
$700 per day
Lodging $80 per day
Hotel/motel expenses when being treated for cancer more than 50 miles from home [70-day calendar year max.]
Medical imaging studies
Specific studies for cancer treatment [$450 calendar year max.]
Outpatient surgical center
Surgery at an outpatient center for cancer treatment [$1,200 calendar year max.]
Private full-time nursing services
Services while hospital confined other than those regularly furnished by the hospital
Prosthetic device/artificial limb
A surgical implant needed because of cancer surgery [payable one per site, $6,000 lifetime max.]
Radiation/chemotherapy
[per day with a max. of one per calendar week]
■ Injected chemotherapy by medical personnel
■ Radiation delivered by medical personnel
[per day with a max. of one per calendar month]
■ Self-injected
■ Pump
■ Topical
■ Oral hormonal [1-24 months]
■ Oral hormonal [25+ months]
■ Oral non-hormonal
Reconstructive surgery
A surgery to reconstruct anatomic defects that result from cancer treatment [min. $350 per procedure, up to $3,000, including 25% for general anesthesia]
$225 per study
$400 per day
$150 per day
$3,000 per device or limb
$60 per surgical unit
Second medical opinion $300
A second physician’s opinion on cancer surgery or treatment [once per lifetime]
Skilled nursing care facility
Confinement to a covered facility after hospital release [up to 100 days per covered person per lifetime]
Skin cancer diagnosis
A skin cancer diagnosis while the policy is in force [once per lifetime]
Supportive or protective care drugs and colony stimulating factors
Doctor-prescribed drugs to enhance or modify radiation/chemotherapy treatments [$1,600 calendar year max.]
Surgical procedures
Inpatient or outpatient surgery for cancer treatment [min. $350 per procedure, up to $6,000]
$175 per day
per day
$70 per surgical unit
Transportation $0.50 per mile
Travel expenses when being treated for cancer more than 50 miles from home [up to $1,500 per round trip]
Waiver of premium Is available
No premiums due if the named insured is disabled longer than 90 consecutive days
The policy has limitations and exclusions that may affect benefits payable. Most benefits require that a charge be incurred. Coverage may vary by state and may not be available in all states. For cost and complete details, see your benefits counselor.
This chart highlights the benefits of policy forms CanAssist-NJ and CanAssist-VA. This chart is not complete without form 101505-NJ or 101481-VA.
THE POLICY PROVIDES LIMITED BENEFITS. For cost and complete details of the coverage, see your Colonial Life benefits counselor. Coverage may vary by state and may not be available in all states. Coverage is dependent on answers to health questions. Applicable to policy forms CanAssist-VA and rider forms R-CanAssistIndx-VA, R-CanAssistProg-VA and R-CanAssistSpDis-VA.
Cancer Insurance Benefits
Level 1Level 2Level 3Level 4
$2,000$2,000$2,000$2,000
Maximum trips per confinement 2222
Ambulance, per trip
Anesthesia, General Air Ambulance, per trip
$250$250$250$250
Maximum trips per confinement 2222
Anesthesia, Local, per procedure Anti-Nausea Medication, per day
Maximum per month
Blood/Plasma/Platelets/Immunoglobulins, per day
Maximum per year
Bone Marrow or Peripheral Stem Cell Donation, per lifetime
Bone Marrow or Peripheral Stem Cell Transplant, per transplant
25% of Surgical Procedures Benefit
$25$30$40$50
$25$40$50$60
$100$160$200$240
$150$150$175$250
$10,000$10,000$10,000$10,000
$500$500$750$1,000
$3,500$4,000$7,000$10,000
Maximum transplants per lifetime 2222
Companion Transportation, per mile
Maximum per round trip
Egg(s) Extraction or Harvesting or Sperm Collection, per lifetime
Egg(s) or Sperm Storage, per lifetime
Experimental Treatment, per day
Maximum per lifetime
Family Care, per day
Maximum per year
Hair/External Breast/Voice Box Prosthesis, per year
Home Health Care Services, per day
$0.50$0.50$0.50$0.50
$1,000$1,000$1,200$1,500
$500$700$1,000$1,500
$175$200$350$500
$200$250$300$300
$10,000$12,500$15,000$15,000
$30$40$50$60
$1,500$2,000$2,500$3,000
$200$200$350$500
$50$75$125$175
Benefit payable for at least and not more than 100 days per covered person per lifetime
Hospice, Initial, per lifetime
Hospice, Daily
Maximum combined Initial and Daily per lifetime
Hospital Confinement, 30 days or less, per day
Hospital Confinement, 31 days or more, per day
$1,000$1,000$1,000$1,000
$50$50$50$50
$15,000$15,000$15,000$15,000
$100$150$250$350
$200$300$500$700
Benefit payable for up to 365 days per covered person per calendar year.
Lodging, per day
$50$50$75$80
Maximum days per year 70707070
Medical Imaging Studies, per study
Maximum per year
Outpatient Surgical Center, per day
Maximum per year
Private Full-time Nursing Services, per day
Prosthetic Device/Artificial Limb, per device or limb
Maximum per lifetime
$75$125$175$225
$150$250$350$450
$100$200$300$400
$300$600$900$1,200
$50$75$125$150
$1,000$1,500$2,000$3,000
$2,000$3,000$4,000$6,000
Radiation/Chemotherapy
Benefit payable period can exceed but will not be less than 365 days per covered person per lifetime
Injected chemotherapy by medical personnel, per day with a maximum of one per calendar week
Radiation delivered by medical personnel, per day with a maximum of one per calendar week
Self-Injected Chemotherapy, per day with a maximum of one per calendar month
Pump Chemotherapy, per day with a maximum of one per calendar month
Topical Chemotherapy, per day with a maximum of one per calendar month
Oral Hormonal Chemotherapy (1-24 months), per day with a maximum of one per calendar month
Oral Hormonal Chemotherapy (25+ months), per day with a maximum of one per calendar month
Oral Non-Hormonal Chemotherapy, per day with a maximum of one per calendar month
Reconstructive Surgery, per surgical unit
Minimum per procedure
Maximum per procedure, including 25% for general anesthesia
Second Medical Opinion, per lifetime
Skilled Nursing Care Facility, per day, up to days confined
$250$500$750 $1,000
$250$500$750 $1,000
$150$200$300 $400
$150$200$300 $400
$150$200$300 $400
$150$200$300 $400
$100$150$250 $350
$150$200$300 $400
$40$40$60 $60
$100$150$250$350
$2,500$2,500$3,000$3,000 $150$200$300 $300
$50$75$125 $175
Benefit payable for at least and not more than 100 days per covered person per lifetime
Skin Cancer Initial Diagnosis
Supportive/Protective Care Drugs/Colony Stimulating Factors, per day
Surgical Procedures
Transportation
Waiver of Premium
Additional Riders may be available at an additional cost
What is not covered by the policy
Pre-Existing Condition Limitation
$300$300$400 $600
$50$100$150
We will not pay benefits for the diagnosis of internal cancer or skin cancer that is a pre-existing condition nor will we pay benefits for the treatment of internal cancer or skin cancer that is a preexisting condition, unless the covered person has satisfied the six-month pre-existing condition limitation period.
Pre-existing condition means a condition for which a covered person was diagnosed prior to the effective date of the policy and for which medical advice or treatment was recommended by or received from a doctor within six months immediately preceding the effective date of the policy.
We will not pay benefits for cancer or skin cancer:
■ If the diagnosis or treatment of cancer is received outside of the territorial limits of the United States and its possessions; or
■ For other conditions or diseases, except losses due directly from cancer.
Click on the video below to learn more about Critical Illness Benefits!
Chris was mowing the lawn when he suffered a stroke. His recovery will be challenging and he's worried, since his family relies on his income. HOW
The lump-sum payment from his critical illness insurance helped pay for:
When life takes an unexpected turn due to a critical illness diagnosis, your focus should be on recovery — not finances. Colonial Life’s group critical illness insurance helps provide financial support by providing a lump-sum benefit payable directly to you for your greatest needs. Coverage amount:
For illustrative purposes only.
Available coverage for spouse and eligible dependent children at 50% of your coverage amount
Cover your eligible dependent children at no additional cost
Receive coverage regardless of medical history, within specified limits
Works alongside your health savings account (HSA)
Benefits payable regardless of other insurance
Subsequent diagnosis of a different critical illness2
If you receive a benefit for a critical illness, and are later diagnosed with a different critical illness, 100% of the coverage amount may be payable for that particular critical illness.
Subsequent diagnosis of the same critical illness2
If you receive a benefit for a critical illness, and are later diagnosed with the same critical illness,3 25% of the coverage amount may be payable for that critical illness.
For more information, talk with your benefits counselor.
Preparing for the unexpected is simpler than you think. With Colonial Life, youʼll have the support you need to face lifeʼs toughest challenges.
1. Refer to the certificate for complete definitions of covered conditions.
2. Dates of diagnoses of a covered critical illness must be separated by more than 180 days.
3. Critical illnesses that do not qualify include: coronary artery disease, loss of hearing, loss of sight, loss of speech, and occupational infectious HIV or occupational infectious hepatitis B,C,or D.
THIS INSURANCE PROVIDES LIMITED BENEFITS
Insureds in MA must be covered by comprehensive health insurance before applying for this coverage.
EXCLUSIONS AND LIMITATIONS FOR CRITICAL ILLNESS
We will not pay the Critical Illness Benefit, Benefits Payable Upon Subsequent Diagnosis of a Critical Illness or Additional Critical Illness Benefit for Dependent Children that occurs as a result of a covered person’s: alcoholism or drug addiction; felonies or illegal occupations; intoxicants and narcotics; suicide or injuring oneself intentionally, whether sane or not; war or armed conflict; or pre-existing condition, unless the covered person has satisfied the pre-existing condition limitation period shown on the Certificate Schedule on the date the covered person is diagnosed with a critical illness.
PRE-EXISTING CONDITION LIMITATION
We will not pay a benefit for a pre-existing condition that occurs during the 12-month period after the coverage effective date. Pre-existing condition means a sickness or physical condition for which a covered person was treated, had medical testing, received medical advice or had taken medication within 12 months before the coverage effective date.
This information is not intended to be a complete description of the insurance coverage available. The insurance or its provisions may vary or be unavailable in some states. The insurance has exclusions and limitations which may affect any benefits payable. Applicable to policy form GCI6000-P and certificate form GCI6000-C (including state abbreviations where used, for example: GCI6000-C-TX). For cost and complete details of coverage, call or write your Colonial Life benefits counselor or the company.
Rebecca
When life takes an unexpected turn, your focus should be on recovery — not finances. Colonial Life’s group critical illness insurance helps relieve financial worries by providing a lump-sum benefit payable directly to you to use as needed. Coverage amount: ____________________________
Available coverage for spouse and eligible dependent children at 50% of your coverage amount
Cover your eligible dependent children at no additional cost
Receive coverage regardless of medical history, within specified limits
Works alongside your health savings account (HSA)
Benefits payable regardless of other insurance
For more information, talk with your benefits counselor.
Subsequent diagnosis of a different critical illness2
If you receive a benefit for a critical illness, and are later diagnosed with a different critical illness, 100% of the coverage amount may be payable for that particular critical illness.
Subsequent diagnosis of the same critical illness2
If you receive a benefit for a critical illness, and are later diagnosed with the same critical illness,3 25% of the coverage amount is payable for that critical illness.
Reoccurrence of invasive cancer (including all breast cancer)
If you receive a benefit for invasive cancer and are later diagnosed with a reoccurrence of invasive cancer, 25% of the coverage amount is payable if treatment-free for at least 12 months and in complete remission prior to the date of reoccurrence; excludes non-invasive or skin cancer.
Preparing for the unexpected is simpler than you think. With Colonial Life, youʼll have the support you need to face lifeʼs toughest challenges.
1. Refer to the certificate for complete definitions of covered conditions.
2. Dates of diagnoses of a covered critical illness must be separated by more than 180 days.
3. Critical illnesses that do not qualify include: coronary artery disease, loss of hearing, loss of sight, loss of speech, and occupational infectious HIV or occupational infectious hepatitis B,C,or D.
THIS INSURANCE PROVIDES LIMITED BENEFITS
Insureds in MA must be covered by comprehensive health insurance before applying for this coverage.
EXCLUSIONS AND LIMITATIONS FOR CRITICAL ILLNESS
We will not pay the Critical Illness Benefit, Benefits Payable Upon Subsequent Diagnosis of a Critical Illness or Additional Critical Illness Benefit for Dependent Children that occurs as a result of a covered person’s: alcoholism or drug addiction; felonies or illegal occupations; intoxicants and narcotics; suicide or injuring oneself intentionally, whether sane or not; war or armed conflict; or pre-existing condition, unless the covered person has satisfied the pre-existing condition limitation period shown on the Certificate Schedule on the date the covered person is diagnosed with a critical illness.
EXCLUSIONS AND LIMITATIONS FOR CANCER
We will not pay the Invasive Cancer (including all Breast Cancer) Benefit, Non-Invasive Cancer Benefit, Benefit Payable Upon Reoccurrence of Invasive Cancer (including all Breast Cancer) or Skin Cancer Initial Diagnosis Benefit for a covered person’s invasive cancer or non-invasive cancer that: is diagnosed or treated outside the territorial limits of the United States, its possessions, or the countries of Canada and Mexico; is a pre-existing condition, unless the covered person has satisfied the pre-existing condition limitation period shown on the Certificate Schedule on the date the covered person is initially diagnosed as having invasive or non-invasive cancer. No pre-existing condition limitation will be applied for dependent children who are born or adopted while the named insured is covered under the certificate, and who are continuously covered from the date of birth or adoption.
PRE-EXISTING CONDITION LIMITATION
We will not pay a benefit for a pre-existing condition that occurs during the 12-month period after the coverage effective date. Pre-existing condition means a sickness or physical condition for which a covered person was treated, had medical testing, received medical advice or had taken medication within 12 months before the coverage effective date. This information is not intended to be a complete description of the insurance coverage available. The insurance or its provisions may vary or be unavailable in some states. The insurance has exclusions and limitations which may affect any benefits payable. Applicable to policy form GCI6000-P and certificate form GCI6000-C (including state abbreviations where used, for example: GCI6000-C-TX). For cost and complete details of coverage, call or write your Colonial Life benefits counselor or the company.
SC
For more information, talk with your benefits counselor.
The first diagnosis building benefit rider provides a lump-sum payment in addition to the coverage amount when you are diagnosed with a covered critical illness or invasive cancer (including all breast cancer). This benefit is for you and all your covered family members.
First diagnosis building benefit
Payable once per covered person per lifetime
¾ Named insured
¾ Covered spouse/dependent children
Accumulates $1,000 each year
Accumulates $500 each year
The benefit amount accumulates each rider year the rider is in force before a diagnosis is made, up to a maximum of 10 years.
If diagnosed with a covered critical illness or invasive cancer (including all breast cancer) before the end of the first rider year, the rider will provide one-half of the annual building benefit amount. Coronary artery disease is not a covered critical illness. Non-invasive and skin cancer are not covered cancer conditions.
This information is not intended to be a complete description of the insurance coverage available. The insurance or its provisions may vary or be unavailable in some states. The insurance has exclusions and limitations which may affect any benefits payable. Applicable to policy form GCI6000-P and certificate form GCI6000-C (including state abbreviations where used, for example: GCI6000-C-TX) and rider form R-GCI6000-BB. For cost and complete details of coverage, call or write your Colonial Life benefits counselor or the company.
The sudden onset of an infectious or contagious disease can create unexpected circumstances for you or your family. The infectious diseases rider provides a lump sum which can be used toward health care expenses or meeting day-today needs. These benefits are for you as well as your covered family members.
1. Refer to the certificate for complete definitions of covered diseases.
THIS INSURANCE PROVIDES LIMITED BENEFITS.
EXCLUSIONS AND LIMITATIONS FOR INFECTIOUS DISEASES RIDER
We will not pay benefits for a covered infectious disease that occurs as a result of a covered person’s: alcoholism or drug addiction; felonies or illegal occupations; intoxicants and narcotics; suicide or injuring oneself intentionally, whether sane or not; war or armed conflict; or pre-existing condition, unless the covered person has satisfied the pre-existing condition limitation period shown on the Certificate Schedule on the date the covered person is diagnosed with a covered infectious disease.
PRE-EXISTING CONDITION LIMITATION
We will not pay a benefit for a pre-existing condition that occurs during the 12-month period after the coverage effective date. Pre-existing condition means a sickness or physical condition for which a covered person was treated, had medical testing, received medical advice or had taken medication within 12 months before the coverage effective date. This information is not intended to be a complete description of the insurance coverage available. The insurance or its provisions may vary or be unavailable in some states. The insurance has exclusions and limitations which may affect any benefits payable. Applicable to policy form GCI6000-P and certificate form GCI6000-C (including state abbreviations where used, for example: GCI6000-C-TX) and rider form R-GCI6000-INF. For cost and complete details of coverage, call or write your Colonial Life benefits counselor or the company.
For more information, talk with your benefits counselor.
The debilitating effects of a progressive disease not only impact you physically, but financially as well. Changes in lifestyle may require home modification, additional medical treatment and other expenses. These benefits are for you as well as your covered family members.
Payable for each covered progressive disease once per covered person per lifetime
This benefit is payable if the covered person is unable to perform two or more activities of daily living2 and the 90-day elimination period has been met.
1. Refer to the certificate for complete definitions of covered diseases.
2. Activities of daily living include bathing, continence, dressing, eating, toileting and transferring.
THIS INSURANCE PROVIDES LIMITED BENEFITS.
EXCLUSIONS AND LIMITATIONS FOR PROGRESSIVE DISEASES RIDER
We will not pay benefits for a covered progressive disease that occurs as a result of a covered person’s: alcoholism or drug addiction; felonies or illegal occupations; intoxicants and narcotics; suicide or injuring oneself intentionally, whether sane or not; war or armed conflict; or pre-existing condition, unless the covered person has satisfied the preexisting condition limitation period shown on the Certificate Schedule on the date the covered person is diagnosed with a covered progressive disease.
PRE-EXISTING CONDITION LIMITATION
We will not pay a benefit for a pre-existing condition that occurs during the 12-month period after the coverage effective date. Pre-existing condition means a sickness or physical condition for which a covered person was treated, had medical testing, received medical advice or had taken medication within 12 months before the coverage effective date. This information is not intended to be a complete description of the insurance coverage available. The insurance or its provisions may vary or be unavailable in some states. The insurance has exclusions and limitations which may affect any benefits payable. Applicable to policy form GCI6000-P and certificate form GCI6000-C (including state abbreviations where used, for example: GCI6000-C-TX) and rider form R-GCI6000-PD. For cost and complete details of coverage, call or write your Colonial Life benefits counselor or the company.
Help protect your paycheck with Colonial Life’s short-term disability insurance.
You use your paycheck mainly to pay for your home, your car, groceries, medical bills and utilities. What if you couldn’t go to work due to an accident or sickness?
My Coverage Worksheet (For use with your Colonial Life Benefits Counselor)
Who’s being covered?
You only
You and your spouse
You and your dependent children
You, your spouse and your dependent children
How much
do I need?
When will my benefits start?
After
How much will it cost?
Your
In addition to disability coverage, this plan also provides employees with benefits for medical fees related to accidents, hospital confinement, accidental death and dismemberment, as well as fractures and dislocations.
Even if you’re not disabled, the following benefits are payable for covered accidental injuries:
Pays in addition to disability benefit.
l Benefits begin on the first day of confinement in a hospital for a covered accident or sickness. Up to 3 months .................................................................................................................... $1,200/month ($40/day)
The Hospital Confinement benefit increases to $6,000/month ($200/day) when the Total Disability benefit ends at age 70
Complete Dislocations
closed reduction with anesthesia
For a fracture or dislocation requiring an open reduction, your benefit would be 11/2 times the amount shown.
Additional Features
l Waiver of Premium
l Worldwide Coverage
You may cover one or all of the eligible dependent members of your family for an additional premium.
Medical Fees for Accidents Only
Hospital Confinement Benefit for Accident or Sickness l
Accidental Death and Dismemberment Benefits l
Will my disability income payment be reduced if I have other insurance?
You’re paid regardless of any other insurance you may have with other insurance companies. Benefits are paid directly to you (unless you specify otherwise).
Totally disabled means you are:
l Unable to perform the material and substantial duties of your job;
l Not, in fact, engaged in any employment or occupation for wage or profit for which you are qualified by reason of education, training or experience; and
l Under the regular and appropriate care of a doctor.
What if I want to return to work part-time after I am totally disabled?
You may be able to return to work part-time and still receive benefits. We call this “Partial Disability.” This means you may be eligible for coverage if:
l You are unable to perform the material and substantial duties of your job for more than 20 hours per week,
l You are able to work at your job or your place of employment for 20 hours or less per week,
l Your employer will allow you to return to your job or place of employment for 20 hours or less per week; and
l You are under the regular and appropriate care of a doctor.
The total disability benefit must have been paid for at least one full month immediately prior to your being partially disabled.
The Total Disability Benefit will end on the policy anniversary date on or after your 70th birthday. The Hospital Confinement benefit increases when the Total Disability Benefit ends.
A pre-existing condition is when you have a sickness or physical condition for which you were treated, had medical testing, received medical advice, or had taken medication within 12 months testing, or before the effective date of your policy.
If you become disabled because of a pre-existing condition, Colonial Life will not pay for any disability period if it begins during the first 12 months the policy is in force.
If you change jobs or leave your employer, you can take your coverage with you at no additional cost. Your coverage is guaranteed renewable for life as long as you continue to pay your premiums when they are due.
You may choose the amount of coverage to meet your needs (subject to your income). You can elect more or less coverage which will change your premium. Colonial Life can change your premium only if we change it on all policies of this kind in the state where your policy was issued.
What is a covered accident or a covered sickness?
A covered accident is an accident. A covered sickness means an illness, infection, disease or any other abnormal physical condition, not caused by an injury.
A covered accident or covered sickness:
l Occurs after the effective date of the policy;
l Occurs while the policy is in force;
l Is of a type listed on the Policy Schedule; and
l Is not excluded by name or specific description in the policy.
We will not pay benefits for injuries received in accidents or sicknesses which are caused by or are the result of: alcoholism or drug addiction; flying; giving birth within the first nine months after the effective date of the policy; felonies or illegal occupations; having a pre-existing condition as described and limited by the policy; psychiatric or psychological condition; committing or trying to commit suicide or injuring yourself intentionally; being exposed to war or any act of war or serving in the armed forces of any country or authority.
For cost and complete details, see your Colonial Life benefits counselor. Applicable to policy form ED DIS 1.0-VA. Coverage may vary by state and may not be available in all states. This is not an insurance contract and only the actual policy provisions will control.
If you are in an accident, your focus should be on recovery, not how you’re going to pay your bills. Colonial Life Accident Insurance can pay benefits directly to you to use however you like — from medical costs to everyday expenses — offering financial support when you need it.
coverage includes:
• Benefits payable directly to you
• No medical questions to qualify for coverage
• Coverage for simple and complex injuries
• Benefits payable regardless of other insurance
• Worldwide coverage
• Works alongside your Health Savings Account (HSA)
Olivia was driving to the store when she got into a car accident. Olivia’s accident benefits helped cover her annual deductible and co-payments.
Olivia arrived by ambulance at the nearest emergency room and received immediate care.
The doctor ordered an X-ray and discovered Olivia had fractured her thigh (femur). He also ordered a CT scan of her head to check for a brain injury.
Olivia was admitted to the hospital for surgery on her leg. She was confined for three days.
Olivia had eight sessions of physical therapy to help regain the strength in her leg.
Over the next several weeks, she had six follow-up appointments with her doctor.
For illustrative purposes only for covered accidents. Benefit amounts may vary and may not cover all expenses.
• Ambulance
•
• X-ray
• Medical imaging (CT) • Thigh fracture — femur (surgical)
• Hospital admission
• Surgery (exploratory/arthroscopic)
• Hospital confinement (3 days)
• Physical therapy (8 days)
• Medical equipment (crutches)
follow-up treatment (6 visits)
Benefits are per covered person per covered accident unless stated otherwise.
Accident emergency treatment......................... $125
Hospital emergency room, urgent care facility or physician’s office
Accidental injury due to an automobile accident1 ........ $250
Air ambulance ..................................... $2,400
Ambulance — ground or water ......................... $250
Observation room .............................. $175 per day
(up to two days per calendar year)
X-ray................................................. $40
Burn ....................................... $1,000–$15,000 (based on size and degree)
Burn — skin graft .............. 50% of applicable burn benefit
Coma ............................................. $15,000
(lasting for seven or more consecutive days)
Concussion $200
Dislocation — separated joint
• Non-surgical — repair .......................
$125–$2,750
Examples: elbow: $600 | ankle: $1,250 | hip: $2,750
• Incomplete dislocation — or dislocation without anesthesia 25% (payable as a % of the applicable dislocation benefit)
• Surgical — repair ............................ $250–$5,500 Examples: elbow: $1,200 | ankle: $2,500 | hip: $5,500
Emergency dental work .......................... $125–$350
Dental extraction or dental crown, denture or implant
Eye injury — with surgical repair or removal of a foreign object ............................ $350
Fracture — complete
• Non-surgical — repair $300–$3,750 Examples: hand/foot: $475 | collarbone: $775 | leg: $1,250
• Chip fracture ....................................... 25% (payable as a
Hearing-loss injuries2 .................................. $140
Knee cartilage — torn — with surgical repair ............. $800
Laceration ...................................... $30–$750 (based on repair and length)
Ruptured disc — with surgical repair $950
Tendon/ligament/rotator cuff — with surgical repair
• One ............................................... $800
• Two or more ...................................... $1,600
Hospital admission
$1,250
Hospital confinement $300 per day (up to 365 days)
Hospital sub-acute intensive care unit confinement ............................. $400 per day (up to 30 days)
Intensive care unit admission
$2,500
Intensive care unit confinement $550 per day (up to 15 days)
Blood/plasma/platelets — transfusion
$400 Surgery $250–$1,900 (based on type of repair and surgery)
Transportation for hospital confinement .. $700 per round trip (up to three round trips, 50+ miles from home)
Lodging–companion .......................... $150 per day (up to 30 days)
Accident follow-up treatment, including transportation/telemedicine
$55 (up to six benefits per covered person per covered accident and up to 12 benefits per covered person per calendar year)
Medical equipment
• Tier 1...............................................
$40
Arm sling, cane, medical ring cushion, neck brace or wrist/ankle splint
• Tier 2 $125
Bedside commode, cold therapy system (cryotherapy), crutches, leg brace, shower chair, walker or walking boot
• Tier 3 ............................................. $250
Back brace, body jacket, continuous passive movement (CPM), halo, electric scooter, hospital bed (including rental), knee scooter, stair lift chair or wheelchair
Medical imaging study — CT, CAT scan, EEG, EMG, MR or MRI. .
(one per calendar year)
$250
Pain management for epidural anesthesia — non-surgical $125
Post-traumatic stress disorder (PTSD) ................. $250
Prosthetic device/artificial limb
• One ............................................... $950
• More than one .................................... $1,900
• Repair/replacement3 .......................... $475/$950
Rehabilitation unit confinement $175 per day (up to 15 days, not to exceed 30 days per calendar year)
Therapy — occupational, physical or speech ...... $45 per day (up to 10 days)
Accidental dismemberment ................. $1,050–$40,000
• Loss, loss of use or paralysis – hand, arm, foot, leg, sight of eye
• Loss, loss of use – finger, toe, partial dismemberment of finger or toe
Accidental death
• Named insured, spouse .......................... $40,000
• Child $10,000
Accidental death common carrier
Examples of common carriers are mass transit trains, buses and planes
• Named insured, spouse .......................... $160,000
• Child ........................................... $30,000
For more information, contact your Colonial Life benefits counselor.
1 Requires transportation by a licensed professional air ambulance or ambulance (ground or water).
2 One benefit for each injured ear per covered person per lifetime.
3 One repair or replacement per prosthetic device/artificial limb per covered person per lifetime.
HEALTH SAVINGS ACCOUNT (HSA) COMPATIBLE
This plan is compatible with HSA guidelines and any other HSA plan in which a covered family member may participate. It may also be offered to employees who do not have HSAs.
THIS POLICY PROVIDES LIMITED BENEFITS.
This coverage is a supplement to health insurance. It is not a substitute for essential health benefits or minimum essential coverage as defined in federal law. Insureds in some states must be covered by comprehensive health insurance before applying for this coverage.
EXCLUSIONS
We will not pay benefits for losses that are caused by, contributed to by or occur as the result of a covered personʼs felonies or illegal occupations, sickness, suicide or injuries which any covered person intentionally does to himself, war or armed conflict.
This information is not intended to be a complete description of the insurance coverage available. The policy or its provisions may vary or be unavailable in some states. The policy has exclusions and limitations which may affect any benefits payable. Applicable to policy form IAC4000-VA. For cost and complete details of the coverage, call or write your Colonial Life benefits counselor or the company.
Underwritten by Colonial Life & Accident Insurance Company, Columbia, SC. © 2024 Colonial Life & Accident Insurance Company. All rights reserved. Colonial Life is a registered trademark and marketing brand of Colonial Life & Accident Insurance Company.
This benefit increases the amount you receive by 20% for your covered eligible benefits, giving you more financial protection for the unexpected.
The active lifestyles benefit is available to you with accident coverage, as well as all your covered family members.
Eligible benefits1
• Concussion
• Dislocation
• Emergency dental work
• Eye injuries
• Fractures
• Knee cartilage (torn)
• Laceration
• Medical imaging study
• Ruptured disc with surgical repair
• Surgery
‐ cranial, open abdominal, thoracic/hernia
‐ exploratory and arthroscopic
• Tendon/ligament/rotator cuff with surgical repair
• X-ray
Example of a benefits calculation
$2,500 Eligible benefits
$2,500 x 20% $500 Eligible benefit amount Active lifestyles benefit Active lifestyles benefit calculation
$2,500 + $500
$3,000 Eligible benefit amount Active lifestyles benefit
Total
For illustrative purposes only
To learn more, talk with your Colonial Life benefits counselor.
1 Active lifestyles benefit applies to any combination of these injuries or services due to a covered accident.
HEALTH SAVINGS ACCOUNT (HSA) COMPATIBLE
This plan is compatible with HSA guidelines and any other HSA plan in which a covered family member may participate. It may also be offered to employees who do not have HSAs.
THIS POLICY PROVIDES LIMITED BENEFITS.
This coverage is a supplement to health insurance. It is not a substitute for essential health benefits or minimum essential coverage as defined in federal law. Insureds in some states must be covered by comprehensive health insurance before applying for this coverage.
ADDITIONAL DISCLOSURES FOR KENTUCKY
Eligibility for benefits: We will pay benefits for a covered accident if any covered person sustains an injury as a result of a covered accident if:
• the covered accident occurs while the policy is in force;
• the covered accident occurs on or after the policy coverage effective date;
• the covered accident is an accident type listed on the policy schedule; and
• the covered accident is not excluded by name or specific description in the policy.
Noncancellable: This policy is noncancellable. We have no right to change the premiums we charge on this policy. Any riders attached to this policy may be subject to a change in premium. The premium can be changed following the approval of the Commissioner of Insurance only if we change it on all riders of the same kind in force in the state where the policy was issued.
What is not covered by this policy: We will not pay benefits for losses that are caused by, contributed to by or occur as a result of the covered person’s felonies or illegal occupations, hazardous avocations, racing, semi-professional or professional sports, sickness or injuries which any covered person intentionally does to himself, war or armed conflict. In addition, we also will not pay the Accidental Dismemberment due to Catastrophic Accident benefit for injuries that are caused by or are the result of birth or intoxicants, narcotics and hallucinogencis.
This information is not intended to be a complete description of the insurance coverage available. The policy or its provisions may vary or be unavailable in some states. The policy has exclusions and limitations which may affect any benefits payable. Applicable to policy form IAC4000 (including state abbreviations where used, for example: IAC4000-TX). For cost and complete details of coverage, call or write your Colonial Life benefits counselor or the company. An insurance producer may contact you.
Underwritten by Colonial Life & Accident Insurance Company, Columbia, SC. © 2024 Colonial Life & Accident Insurance Company. All rights reserved. Colonial Life is a registered trademark and
These benefits can help with medical costs related to a hospital stay for a covered sickness, including costs that your health insurance may not cover, such as co-pays and deductibles.
The sickness hospital confinement rider is optional coverage available to you and all your covered family members.
Daily sickness hospital confinement
To learn more, talk with your Colonial Life benefits counselor.
$100 per day
Up to 30 days per covered person per confinement for a covered sickness
Re-confinement for the same or related condition within 90 days of discharge is considered a continuation of a previous confinement.
HEALTH SAVINGS ACCOUNT (HSA) COMPATIBLE
This plan is compatible with HSA guidelines and any other HSA plan in which a covered family member may participate. It may also be offered to employees who do not have HSAs.
THIS POLICY PROVIDES LIMITED BENEFITS.
This coverage is a supplement to health insurance. It is not a substitute for essential health benefits or minimum essential coverage as defined in federal law. Insureds in some states must be covered by comprehensive health insurance before applying for this coverage.
EXCLUSIONS AND LIMITATIONS
We will not pay benefits for losses that are caused by, contributed to by or occur as the result of accidental injuries, alcoholism or drug addiction, dental procedures, elective procedures and cosmetic surgery, felonies or illegal occupations, psychiatric or psychological conditions, intoxicants and narcotics, psychiatric or psychological conditions, suicide or injuries which you intentionally do to yourself, war or armed conflict and well baby care.
PRE-EXISTING CONDITION LIMITATION
Pre-existing condition means a sickness or physical condition, whether diagnosed or not, for which a covered person was treated, had medical testing, received medical advice, or had taken medication within 12 months before the rider coverage effective date shown on the rider schedule. After this rider has been in force for 12 months from the rider coverage effective date shown on the rider schedule, we will pay benefits as stated in the rider for any loss as the result of a pre-existing condition not excluded by name or specific description if the covered loss began at least 12 months after the rider coverage effective date.
STATE VARIATIONS FOR EXCLUSIONS AND LIMITATIONS
AK: Replace “alcoholism or drug addiction” with “intoxicants or narcotics.”
DE: Replace “alcoholism or drug addiction” with “substance abuse.”
FL: Replace “psychiatric or psychological conditions” with “mental or nervous disorders.”
IL: Pre-existing Condition Limitation definition also includes “produced symptoms.”
LA: Replace “alcoholism or drug addiction” with “intoxicants and narcotics.”
ME: Pre-existing Condition Limitation definition does not include “had taken medication.”
MO: Replace “alcoholism or drug addiction” with “substance abuse.”
MT: Pre-existing Condition Limitation definition does not include “whether diagnosed or not” or “had medical testing.”
NC: Pre-existing Conditions Limitation definition also includes “If a covered person is 65 or older when this policy is issued, pre-existing conditions for that covered person will include only conditions specifically eliminated by rider.”
OK: Replace “psychiatric or psychological conditions” with “mental or emotional conditions.”
SC: Replace “psychiatric or psychological conditions” with “mental or emotional disorders.”
SD: Not applicable to “alcoholism or drug addiction.”
UT: Replace “psychiatric or psychological conditions” with “mental or nervous disorders.”
VT: Not applicable to “alcoholism or drug abuse, psychiatric or psychological conditions, well baby care,” or the limitation for giving birth within the first nine months after the rider coverage effective date.
ADDITIONAL DISCLOSURES FOR THE STATE OF KENTUCKY
Eligibility for Benefits: We will pay the benefits for a covered accident if any covered person sustains an injury as a result of a covered accident if:
• The covered accident occurs while the policy is in force;
• The covered accident occurs on or after the policy coverage effective date;
• The covered accident is on an accident type listed on the policy schedule; and
• The covered accident is not excluded by name or specific description in the policy.
What is not covered by this policy: We will not pay benefits for losses that are caused by, contributed to by or occurs as a result of the covered person’s felonies or illegal occupations, hazardous avocations, racing, semi-professional or professional sports, sickness or injuries which any covered person intentionally does to himself, war or armed conflict. In addition, we also will not pay the Accidental Dismemberment due to Catastrophic Accident benefit for injuries that are caused by or are the result of birth or intoxicants, narcotics, and hallucinogenics.
Termination of this Rider: This rider will terminate on the earliest of: the date the policy to which this rider is attached terminates; the date premium for this rider is not paid by the end of the grace period; or the date we receive your written request to terminate this rider.
Noncancellable: This policy is noncancellable. We have no right to change the premiums we charge on this policy. Any riders attached to this policy may be subject to a change in premium. The premium can be changed following the approval of the Commissioner of Insurance only if we change it on all riders of the same kind in force in the state where the policy was issued. This information is not intended to be a complete description of the insurance coverage available. The policy or its provisions may vary or be unavailable in some states. The policy has exclusions and limitations which may affect any benefits payable. Applicable to policy form IAC4000 and rider form R-SHC4000 (including state abbreviations where used, for example: IAC4000-AL). For cost and complete details of coverage, call or write your Colonial Life benefits counselor or the company.
Underwritten by Colonial Life & Accident Insurance Company, Columbia, SC.
© 2024 Colonial Life & Accident Insurance Company. All rights reserved. Colonial Life is a registered trademark and marketing brand of Colonial Life & Accident Insurance Company.
Click on the video below to learn more about Medical Bridge Benefits!
For more information, talk with your benefits counselor.
Our Individual Medical BridgeSM insurance can help with medical costs that your health insurance may not cover. These benefits are available for you, your spouse and eligible dependent children.
Hospital confinement $
Maximum of one benefit per covered person per calendar year
Observation room..................................................................................
Maximum of two visits per covered person per calendar year
Rehabilitation unit confinement
$100 per visit
$100 per day
Maximum of 15 days per confinement with a 30-day maximum per covered person per calendar year
Waiver of premium
Available after 30 continuous days of a covered hospital confinement of the named insured
Health savings account (HSA) compatible
This plan is compatible with HSA guidelines. This plan may also be offered to employees who do not have HSAs.
Colonial Life & Accident Insurance Company’s Individual Medical Bridge offers an HSA compatible plan in most states.
THIS POLICY PROVIDES LIMITED BENEFITS.
EXCLUSIONS
We will not pay benefits for losses which are caused by: alcoholism or drug addiction, dental procedures, elective procedures and cosmetic surgery, felonies or illegal occupations, pregnancy of a dependent child, psychiatric or psychological conditions, suicide or injuries which any covered person intentionally does to himself or herself, war, or giving birth within the first nine months after the effective date of the policy. We will not pay benefits for hospital confinement of a newborn who is neither injured nor sick. We will not pay benefits for loss during the first 12 months after the effective date due to a pre-existing condition. A pre-existing condition is a sickness or physical condition for which a covered person was treated, had medical testing, received medical advice or had taken medication within the 12 months before the effective date of the policy. For cost and complete details, see your Colonial Life benefits counselor. Applicable to policy number IMB7000 (including state abbreviations where used, for example: IMB7000-TX). Coverage may vary by state and may not be available in all states. This is not an insurance contract and only the actual policy provisions will control.
For more information, talk with your benefits counselor.
Our Individual Medical BridgeSM insurance can help with medical costs that your health insurance may not cover. These benefits are available for you, your spouse and eligible dependent children.
Hospital confinement $
Maximum of one benefit per covered person per calendar year
Observation room
Maximum of two visits per covered person per calendar year
Rehabilitation unit confinement
$100 per visit
$100 per day
Maximum of 15 days per confinement with a 30-day maximum per covered person per calendar year
Waiver of premium
Available after 30 continuous days of a covered hospital confinement of the named insured
Diagnostic procedure
Tier 1 $250
Tier 2
Maximum of $500 per covered person per calendar year for all covered diagnostic procedures combined
Outpatient surgical procedure
Tier 1 $
Tier 2 $
Maximum of $___________ per covered person per calendar year for all covered outpatient surgical procedures combined
The following is a list of common diagnostic procedures that may be covered.
Tier 1 diagnostic procedures
Breast
– Biopsy (incisional, needle, stereotactic)
Diagnostic radiology
– Nuclear medicine test
Digestive
– Barium enema/lower GI series
– Barium swallow/upper GI series
– Esophagogastroduodenoscopy (EGD)
Ear, nose, throat, mouth
– Laryngoscopy
Gynecological
– Amniocentesis
– Cervical biopsy
– Cone biopsy
– Endometrial biopsy
– Hysteroscopy
– Loop electrosurgical excisional procedure (LEEP)
Tier 2 diagnostic procedures
Cardiac
– Angiogram
– Arteriogram
– Thallium stress test
– Transesophageal echocardiogram (TEE)
Liver – biopsy
Lymphatic – biopsy
Miscellaneous
– Bone marrow aspiration/biopsy
Renal – biopsy
Respiratory
– Biopsy
– Bronchoscopy
– Pulmonary function test (PFT)
Skin
– Biopsy
– Excision of lesion
Thyroid – biopsy
Urologic
– Cystoscopy
Diagnostic radiology
– Computerized tomography scan (CT scan)
– Electroencephalogram (EEG)
– Magnetic resonance imaging (MRI)
– Myelogram
– Positron emission tomography scan (PET scan)
The surgeries listed below are only a sampling of the surgeries that may be covered. Surgeries must be performed by a doctor in a hospital or ambulatory surgical center. For complete details and definitions, please refer to your policy.
Tier 1 outpatient surgical procedures
Breast
– Axillary node dissection
– Breast capsulotomy
– Lumpectomy
Cardiac
– Pacemaker insertion
Digestive
– Colonoscopy
– Fistulotomy
– Hemorrhoidectomy
– Lysis of adhesions
Skin
– Laparoscopic hernia repair
– Skin grafting
Ear, nose, throat, mouth
– Adenoidectomy
– Removal of oral lesions
– Myringotomy
– Tonsillectomy
– Tracheostomy
– Tympanotomy
Tier 2 outpatient surgical procedures
Breast
– Breast reconstruction
– Breast reduction
Cardiac
– Angioplasty
– Cardiac catheterization
Digestive
– Exploratory laparoscopy
– Laparoscopic appendectomy
– Laparoscopic cholecystectomy
Ear, nose, throat, mouth
– Ethmoidectomy
– Mastoidectomy
– Septoplasty
– Stapedectomy
– Tympanoplasty
Eye
– Cataract surgery
– Corneal surgery (penetrating keratoplasty)
– Glaucoma surgery (trabeculectomy)
– Vitrectomy
EXCLUSIONS
Gynecological
– Dilation and curettage (D&C)
– Endometrial ablation
– Lysis of adhesions
Liver
– Paracentesis
Musculoskeletal system
– Carpal/cubital repair or release
– Foot surgery (bunionectomy, exostectomy, arthroplasty, hammertoe repair)
– Removal of orthopedic hardware
– Removal of tendon lesion
Gynecological
– Hysterectomy
– Myomectomy
Musculoskeletal system
– Arthroscopic knee surgery with meniscectomy (knee cartilage repair)
– Arthroscopic shoulder surgery
– Clavicle resection
– Dislocations (open reduction with internal fixation)
– Fracture (open reduction with internal fixation)
– Removal or implantation of cartilage
– Tendon/ligament repair
Thyroid
– Excision of a mass
Urologic
– Lithotripsy
We will not pay benefits for losses which are caused by: alcoholism or drug addiction, dental procedures, elective procedures and cosmetic surgery, felonies or illegal occupations, pregnancy of a dependent child, psychiatric or psychological conditions, suicide or injuries which any covered person intentionally does to himself or herself, war, or giving birth within the first nine months after the effective date of the policy. We will not pay benefits for hospital confinement of a newborn who is neither injured nor sick. We will not pay benefits for loss during the first 12 months after the effective date due to a pre-existing condition. A pre-existing condition is a sickness or physical condition for which a covered person was treated, had medical testing, received medical advice or had taken medication within the 12 months before the effective date of the policy. For cost and complete details, see your Colonial Life benefits counselor. Applicable to policy number IMB7000 (including state abbreviations where used, for example: IMB7000-TX). Coverage may vary by state and may not be available in all states. This is not an insurance contract and only the actual policy provisions will control.
Individual Medical BridgeSM insurance’s health screening benefit can help pay for health and wellness tests you have each year.
Health screening $_____________
Maximum of one health screening test per covered person per calendar year; subject to a 30-day waiting period
Blood test for triglycerides
Bone marrow testing
Breast ultrasound
CA 15-3 (blood test for breast cancer)
CA 125 (blood test for ovarian cancer)
CEA (blood test for colon cancer)
Carotid Doppler
Chest X-ray
Colonoscopy
Echocardiogram (ECHO)
Electrocardiogram (EKG, ECG)
Fasting blood glucose test
Flexible sigmoidoscopy
Hemoccult stool analysis
Mammography
Pap smear
PSA (blood test for prostate cancer)
Serum cholesterol test for HDL and LDL levels
Serum protein electrophoresis (blood test for myeloma)
Skin cancer biopsy
Stress test on a bicycle or treadmill
Thermography
ThinPrep pap test
Virtual colonoscopy
For more information, talk with your benefits counselor.
Individual Medical BridgeSM offers two optional benefit riders – the daily hospital confinement rider and the enhanced intensive care unit confinement rider. For an additional cost, these riders can help provide extra financial protection to help with out-of-pocket medical expenses.
Daily hospital confinement rider
Per covered person per day of hospital confinement
Maximum of 365 days per covered person per confinement
Enhanced intensive care unit confinement rider
Per covered person per day of intensive care unit confinement
Maximum of 30 days per covered person per confinement
Re-confinement for the same or related condition within 90 days of discharge is considered a continuation of a previous confinement.
$100 per day
$500 per day
EXCLUSIONS
We will not pay benefits for losses which are caused by: alcoholism or drug addiction, dental procedures, elective procedures and cosmetic surgery, felonies or illegal occupations, pregnancy of a dependent child, psychiatric or psychological conditions, suicide or injuries which any covered person intentionally does to himself or herself, war, or giving birth within the first nine months after the effective date of the rider. We will not pay benefits for hospital confinement of a newborn who is neither injured nor sick. We will not pay benefits for loss during the first 12 months after the effective date due to a pre-existing condition. A pre-existing condition is a sickness or physical condition for which a covered person was treated, had medical testing, received medical advice or had taken medication within the 12 months before the effective date of the rider. For cost and complete details, see your Colonial Life benefits counselor. Applicable to rider numbers R-DHC7000 and R-EIC7000 (including state abbreviations where used, for example: R-DHC7000-TX and R-EIC7000-TX). Coverage may vary by state and may not be available in all states. This is not an insurance contract and only the actual policy or rider provisions will control.
|
which Colonial Life is the marketing brand.
Life insurance needs change as life circumstances change. You may need different coverage if you’re getting married, buying a home or having a child.
Term life insurance from Colonial Life provides protection for a specified period of time, typically offering the greatest amount of coverage for the lowest initial premium. This fact makes term life insurance a good choice for supplementing cash value coverage during life stages when obligations are higher, such as while children are younger. It’s also a good option for families on a tight budget — especially since you can convert it to a permanent cash value plan later.
n A beneficiary can receive a benefit that is typically free from income tax.
n The policy’s accelerated death benefit can pay a percentage of the death benefit if the covered person is diagnosed with a terminal illness.
n You can convert it to a Colonial Life cash value insurance plan, with no proof of good health, to age 75.
n Coverage is guaranteed renewable up to age 95 as long as premiums are paid when due.
n Portability allows you to take it with you if you change jobs or retire.
Two options are available for spouse coverage at an additional cost: You may add a Children’s Term Life Rider to cover all of your eligible dependent children with up to $20,000 in coverage each for one premium.
1. Spouse Term Life Policy: Offers guaranteed premiums and level death benefits equivalent to those available to you –whether or not you buy a policy for yourself.
2. Spouse Term Life Rider: Add a term rider for your spouse to your policy, up to a maximum death benefit of $50,000; 10-year and 20-year are available (20-year rider only available with a 20- or 30-year term policy).
The Children’s Term Life Rider may be added to either the primary or spouse policy, not both.
How much coverage do you need?
£ YOU $ ___________________
Select the term period:
£ 10-year
£ 15-year
£ 20-year
£ 30-year
£ SPOUSE $ ___________________
Select the term period:
£ 10-year
£ 15-year
£ 20-year
£ 30-year
Select any optional riders:
£ Spouse term life rider
$ _____________ face amount for ________-year term period
£ Children’s term life rider
$ _____________ face amount
£ Accidental death benefit rider
£ Critical illness accelerated death benefit rider
£ Waiver of premium benefit rider
At an additional cost, you can purchase the following riders for even more financial protection.
Your spouse may receive a maximum death benefit of $50,000; 10-year and 20-year spouse term riders are available.
You can purchase up to $20,000 in term life coverage for all of your eligible dependent children and pay one premium. The children’s term life rider may be added to either your policy or your spouse’s policy – not both.
The beneficiary may receive an additional benefit if the covered person dies as a result of an accident before age 70. The benefit doubles if the accidental bodily injury occurs while riding as a fare-paying passenger using public transportation, such as ridesharing services. An additional 25% will be payable if the injury is sustained while driving or riding in a private passenger vehicle and wearing a seatbelt
If you suffer a heart attack (myocardial infarction), stroke or end-stage renal (kidney) failure, a $5,000 benefit is payable.1 A subsequent diagnosis benefit is included
Premiums are waived (for the policy and riders) if you become totally disabled before the policy anniversary following your 65th birthday and you satisfy the six-month elimination period.3
1 Any payout would reduce the death benefit. Benefits may be taxable as income. Individuals should consult with their l egal or tax counsel when deciding to apply for accelerated benefits.
3 You must resume premium payments once you are no longer disabled.
If the insured dies by suicide, whether sane or insane, within two years (one year in ND) from the coverage effective date or the date of reinstatement, we will not pay the death benefit. We will terminate this policy and return the premiums paid without interest, minus any loans and loan interest to you.
This information is not intended to be a complete description of the insurance coverage available. The policy or its provisions may vary or be unavailable in some states. The policy has exclusions and limitations which may affect any benefits payable. Applicable to policy forms ICC18-ITL5000/ITL5000 and rider forms ICC18-R-ITL5000-STR/RITL5000- STR, ICC18-R-ITL5000-CTR/R-ITL5000-CTR, ICC18-R-ITL5000-WP/R-ITL5000-WP, ICC18-R-ITL5000-ACCD/RITL5000- ACCD, ICC18-R-ITL5000-CI/R-ITL5000-CI, ICC18-R-ITL5000-CC/R-ITL5000-CC. For cost and complete details of the coverage, call or write your Colonial Life benefits counselor or the company.
You can’t predict your family’s future, but you can prepare for it.
Help give your family more peace of mind and coverage for final expenses with Colonial Life Individual Whole Life Plus insurance.
Benefits and features
Choose the age when your premium payments end — Paid-Up at Age 70 or Paid-Up at Age 100
Stand-alone spouse policy available even without buying a policy for yourself
Ability to keep the policy if you change jobs or retire
Built-in terminal illness accelerated death benefit that provides up to 75% of the policy’s death benefit (up to $150,000) if you’re diagnosed with a terminal illness1
Immediate $3,000 claim payment that can help your designated beneficiary pay for funeral costs or other expenses
Provides cash surrender value at age 100 (when the policy endows)
Spouse term rider
Cover your spouse with a death benefit up to $50,000, for 10 or 20 years.
Juvenile Whole Life Plus policy
Purchase a policy (Paid-Up at Age 70) while children are young and premiums are low — whether or not you buy a policy for yourself. You may also increase the coverage when the child is 18, 21 and 24 without proof of good health.
Children’s term rider
You may purchase up to $20,000 in term life insurance coverage for all of your eligible dependent children and pay one premium. The children’s term rider may be added to either your policy or your spouse’s policy — not both.
• Permanent life insurance coverage that stays the same through the life of the policy
• Premiums will not increase due to changes in health or age.
• Accumulates cash value based on a nonforfeiture interest rate of 3.75%2
• Policy loans available, which can be used for emergencies
• Benefit for the beneficiary that is typically tax-free
Your cost will vary based on the amount of coverage you select.
For use with your benefits counselor
How much coverage do you need?
YOU $
Select the option:
Paid-Up at Age 70
Paid-Up at Age 100
SPOUSE $
Select the option:
Paid-Up at Age 70
Paid-Up at Age 100
DEPENDENT STUDENT
$
Select the option:
Paid-Up at Age 70
Paid-Up at Age 100
Select any optional riders:
Spouse term rider
$ face amount for -year term period
Children’s term rider
$ face amount
Accidental death benefit rider
Critical illness accelerated death benefit rider
Guaranteed purchase option rider
An additional benefit may be payable if the covered person dies as a result of an accident before age 70, and doubles if the injury occurs while riding as a farepaying passenger using public transportation. An additional 25% is payable if the injury occurs while driving or riding in a private passenger vehicle and wearing a seatbelt.
If you suffer a heart attack, stroke or end-stage renal (kidney) failure, a $5,000 benefit is payable.1 A subsequent diagnosis benefit is included.
This rider allows you to purchase additional whole life coverage — without having to answer health questions — at three different points in the future. The rider may only be added if you are age 50 or younger when you purchase the policy. You may purchase up to your initial face amount, not to exceed a total combined maximum of $100,000 for all options.
Policy and rider premiums are waived if you become totally disabled before the policy anniversary following your 65th birthday and you satisfy the six-month elimination period. Once you are no longer disabled, premiums will resume.
* Whole Life Plus is a marketing name of the insurance policy filed as “Whole Life Insurance” in most
Waiver of premium benefit rider states.
1 Any payout would reduce the death benefit. Benefits may be taxable as income. Individuals should consult with their legal or tax counsel when deciding to apply for accelerated benefits.
2 Accessing the accumulated cash value reduces the death benefit by the amount accessed, unless the loan is repaid. Cash value will be reduced by any outstanding loans against the policy.
This life insurance does not specifically cover funeral goods or services and may not cover the entire cost of your funeral at the time of your death. The beneficiary of this life insurance may use the proceeds for any purpose, unless otherwise directed.
To learn more, talk with your benefits counselor.
EXCLUSIONS AND LIMITATIONS: If the insured dies by suicide, whether sane or insane, within two years (one year in ND) from the coverage effective date or the date of reinstatement, we will not pay the death benefit. We will terminate this policy and return the premiums paid without interest, minus any loans and loan interest to you.
This information is not intended to be a complete description of the insurance coverage available. The policy or its provisions may vary or be unavailable in some states. The policy has exclusions and limitations which may affect any benefits payable. Applicable to policy forms ICC19-IWL5000-70/ IWL5000-70, ICC19-IWL5000-100/IWL5000-100, ICC19-IWL5000J/IWL5000J and rider forms ICC23IWL5000-LTC/IWL5000-LTC, ICC19-R-IWL5000-STR/R-IWL5000-STR, ICC19-R-IWL5000-CTR/RIWL5000-CTR, ICC19-R-IWL5000-WP/R-IWL5000-WP, ICC19-R-IWL5000-ACCD/R-IWL5000-ACCD, ICC19-R-IWL5000-CI/R-IWL5000-CI, ICC19-R-IWL5000-CC/R-IWL5000-CC, ICC19-R-IWL5000GPO/R-IWL5000-GPO (including state abbreviations where applicable). For cost and complete details of the coverage, call or write your Colonial Life benefits counselor or the company.
Underwritten by Colonial Life & Accident Insurance Company, Columbia, SC. © 2023 Colonial Life & Accident Insurance Company. All rights reserved. Colonial Life is a registered trademark and marketing brand of Colonial Life & Accident Insurance Company.
Dreaming of the day with no financial stress? With FinPath, we can help you achieve your goals with our confidential, no-cost sessions.
Financial Coaches work with you every step of the way toward financial self-discovery so you can focus more on your family and spend less time on your wallet.
They help identify your financial goals, develop a plan of action, and keep track of your success with each session.
Most importantly, coaching sessions are provided at no cost to you.
We can address topics like:
Understanding your credit
Creating a budget that sticks
Facing your student loans
Working toward a debt-free life
Faster service than calling/emailing
Confirmation when a claim has been submitted
Simplified bill payment and management Answers to frequently asked questions and live chat assistance if you don’t see what you are looking for.
Find out how simple your claims and benefits experience can be by learning more about the Colonial Life for Policyholders portal. Just visit ColonialLife.com to see what this online account administration platform can do for you.
Colonial Life for Policyholders is an online portal created with you in mind. It’s the most convenient and efficient way to file a claim and manage your benefits.
File claims with a simple, guided form
Set up direct deposit for approved payments
BECOME A MEMBER TODAY:
View claim status or policy details anytime
Opt for instant alerts by email or text
Update your personal info & preferences
Go to ColonialLife .com/access to register. Click “create an account”, fill out the required information and click Submit Enjoy faster service and improved benefits awareness.
Filing online means never waiting for mail or dealing with fax machines and complex paper forms . Our guided question wizard walks you through the process and checks for missing information that could cause delays. Opting for direct deposit can also get approved payments to you up to a week faster than paper check.
Check your claim status by logging into your account at ColonialLife .com/access. You can also sign up for text or email alerts so you know instantly if status changes or more information is needed. For your convenience, you can login anytime with a mobile device to photograph and upload documents with your camera.
For the purpose of evaluating my application(s) for insurance submitted during the current enrollment and eligibility for benefits under an y insurance issued including checking for and resolving any issues that may arise regarding incomplete or incorrect information on my application(s), I hereby authorize the disclosure of the following information about me and, if applicable , my dependents, from the sources listed below to Colonial Life & Accident Insurance Company (Colonial) and its duly authorized representatives.
Health information may be disclosed by any health care provider or institution, health plan or health care clearinghouse that has any re cords or knowledge about me including prescription drug database or pharmacy benefit manager, or ambulanc e or other medical transport service. Health information may also be disclosed by any insuranc e company, Medicare or Medicaid agencies or the Medical Information Bureau (MIB). Health information includes my entire medical record, but does not include psychotherapy notes. Non-health information including earnings or empl oyment history deemed appropriate by Colonial to evaluate my application may be disclosed by any person or organization that has these records about me, including my employer, employer representative and compensation sources, insurance company, financial institution or governmental entities including departments of public safety and motor vehicle departments.
Any information Colonial obtains pursuant to this authorization will be used for the purpose of evaluating my application(s) for insu rance or eligibility for benefits. Some information obtained may not be protected by certain federal regulations governing the priva cy of health information, but the information is protected by state privacy laws and ot her applicable laws. Colonial will not re- disclose the information unless permitted or r equired by those laws. Re-disclosed information may no longer be protected by federal privacy laws.
This authorization is valid for two (2) years from its execution and a copy is as valid as the original. A copy will be included with my contract(s) and I or my authorized representative may request access to this information. This authorization may be revoked by me or my authorized representative at any time except to the extent Colonial has relied on the authorization prior to notice of revocation or has a legal right to contest coverage under the contract(s) or the contract itself. If revoked, Colonial may not be able to evaluate my application(s) for insurance or eligibility for benefits as necessary to issue my contract(s). I may revoke this authorization by sending written notice to: Colonial Life & Accident Insurance Company, Underwriting Department, P. O. Box 1365, Columbia, SC 29202.
You may refuse to sign this form; however, Colonial may not be able to issue your coverage. I am the individual to whom this authorization applies or that person's legal Guardian, Power of Attorney Designee, or Conservator.
(Printed name of individual (Social Security (Signature) (Date Signed) subject to this disclosure) Number)
If applicable, I signed on behalf of the proposed insured as ____________________(indicate relationship). If legal Guardian, Power of Attorney Designee, or Conservator.
(Printed name of legal representative) (Signature of legal representative) (Date Signed)
Group Long Term Disability (LTD) insurance from The Standard helps provide financial protection for insured members by promising to pay a monthly benefit in the event of a covered disability.
This Group Short Term Disability (STD) program is provided for VRS Hybrid Plan Participants and administered by The Standard. This benefit helps provide financial protection for covered members by promising to pay a weekly benefit in the event of a covered disability.
Questions about your VACORP Short and Long Term Disability can be submitted one of two ways: Please refer to the plan summary document and your employee handbook for specific plan details, eligibility definitions, limitations, and exclusions.
By calling: 1-844-404-2111
Or by visiting their website: www.vacorp.org/coverage/hybrid-disability
Group health plans and health insurance issuers generally may not, under federal law restrict benefits for any hospital length of stay in connection with childbirth for the mother or newborn child to less than 48 hours following vaginal delivery, or less than 96 hours following a cesarean section. However, federal law generally does not prohibit the mother’s or newborn’s attending provider, after consulting with the mother, from discharging the mother or newborn earlier than 48 hours (or 96 hours as applicable). In any case, plans and issuers may not, under federal law, require that a provider obtain authorization from the plan or the issuer for prescribing a length of stay not in excess of 48 hours (or 96 hours).
In October 1998, Congress enacted the Women’s Health and Cancer Rights Act of 1998. This notice explains some important provisions of the Act. Please review this information carefully. As specified in the Women’s Health and Cancer Rights Act, a plan participant or beneficiary who elects breast reconstruction in connection with a covered mastectomy is also entitled to the following benefits: 1. All stages of reconstruction of the breast on which the mastectomy has been performed: 2. Surgery and reconstruction of the other breast to produce a symmetrical appearance; and 3. Prostheses and treatment of physical complications of the mastectomy , including lymphedemas. Health plans must provide coverage of mastectomy related benefits in a manner to determine in consultation with the attending physician and the patient. Coverage for breast reconstruction and related services may be subject to deductibles and insurance amounts that are consistent with those that apply to other benefits under the plan.
Premium Assistance Under Medicaid and the Children’s Health Insurance Program (CHIP)
If you or your children are eligible for Medicaid or CHIP and you’re eligible for health coverage from your employer, your state may have a premium assistance program that can help pay for coverage, using funds from their Medicaid or CHIP programs. If you or your children aren’t eligible for Medicaid or CHIP, you won’t be eligible for these premium assistance programs but you may be able to buy individual insurance coverage through the Health Insurance Marketplace. For more information, visit www.healthcare.gov.
If you or your dependents are already enrolled in Medicaid or CHIP and you live in a State listed below, contact your State Medicaid or CHIP office to find out if premium assistance is available.
If you or your dependents are NOT currently enrolled in Medicaid or CHIP, and you think you or any of your dependents might be eligible for either of these programs, contact your State Medicaid or CHIP office or dial 1-877-KIDS
NOW or www.insurekidsnow.gov to find out how to apply. If you qualify, ask your state if it has a program that might help you pay the premiums for an employer sponsored plan.
If you or your dependents are eligible for premium assistance under Medicaid or CHIP, as well as eligible under your employer plan, your employer must allow you to enroll in your employer plan if you aren’t already enrolled. This is called a “special enrollment” opportunity, and you must request coverage within 60 days of being determined eligible for premium assistance. If you have questions about enrolling in your employer plan, contact the Department of Labor at www.askebsa.dol.gov or call 1-866-444-EBSA (3272).
ALABAMA - MEDICAID
Website: myalhipp.com
Phone: 1-855-692-5447
ALASKA - MEDICAID
The AK Health Insurance Premium Payment Program
Website: myakhipp.com
Phone: 1-866-251-4861
Email: CustomerService@MyAKHIPP.com
Medicaid Eligibility: dhss.alaska.gov/dpa/Pages/ medicaid/default.aspx
ARKANSAS - MEDICAID
Website: myarhipp.com
Phone: 1-855-MyARHIPP (855-692-7447)
CALIFORNIA - MEDICAID
Website: www.dhcs.ca.gov/services/Pages/ TPLRD_CAU_cont.aspx
Phone: 916-440-5676
COLORADO - HEALTH FIRST COLORADO (MEDICAID) & CHILD HEALTH PLAN PLUS (CHP+)
Health First Colorado Website: www.healthfirstcolorado.com
Health First Colorado Member Contact Center: 1-800-221-3943/State Relay 711
CHP+: www.colorado.gov/pacific/hcpf/childhealth-plan-plus
CHP+ Customer Service: 1-800-359-1991/State Relay 711
Health Insurance Buy-In Program (HIBI): www.colorado.gov/pacific/hcpf/health-insurancebuy-program
HIBI Customer Service: 1-855-692-6442
GEORGIA - MEDICAID
Website: medicaid.georgia.gov/health-insurance premium-payment-program-hipp
Phone: 678-564-1162, ext. 2131
INDIANA - MEDICAID
Healthy Indiana Plan for Low-Income
Adults 19-64
Website: www.in.gov/fssa/hip
Phone: 1-877-438-4479
All other Medicaid Website: www.in.gov/medicaid
Phone: 1-800-457-4584
Medicaid Website: dhs.iowa.gov/ime/members
Medicaid Phone: 1-800-338-8366
Hawki Website: dhs.iowa.gov/Hawki
Hawki Phone: 1-800-257-8563
KANSAS - MEDICAID
Website: www.kdheks.gov/hcf/default.htm
Phone: 1-800-792-4884
KENTUCKY - MEDICAID
Kentucky Integrated Health Insurance
Premium Payment
Program (KI-HIPP) Website: chfs.ky.gov/agencies/dms/member/Pages/kihipp.aspx
Phone: 1-855-459-6328
Email: KIHIPP.PROGRAM@ky.gov
KCHIP Website: kidshealth.ky.gov/Pages/index.aspx
Phone: 1-877-524-4718
Kentucky Medicaid Website: chfs.ky.gov
Website: www.medicaid.la.gov or www.ldh.la.gov/lahipp
Website: www.flmedicaidtplrecovery.com/flmedicaidtplrecovery.com/hipp/index.html
Phone: 1-877-357-3268 FLORIDA - MEDICAID
Phone: 1-888-342-6207 (Medicaid hotline) or 1-855-618-5488 (LaHIPP)
MAINE - MEDICAID
Website: www.maine.gov/dhhs/ofi/public assistance/index.html
Phone: 1-800-442-6003
TTY: Maine Relay 711
- MEDICAID AND CHIP
Website: www.mass.gov/eohhs/gov/departments/ masshealth
Phone: 1-800-862-4840
MINNESOTA - MEDICAID
Website: mn.gov/dhs/people-we-serve/children-and-families/health-care/health-care-programs/programs-and-services/medical-assistance.jsp [Under ELIGIBILITY tab, see “What if I have other health insurance?”]
Phone: 1-800-657-3739
KANSAS - MEDICAID
Website: www.kdheks.gov/hcf/default.htm
Phone: 1-800-792-4884
MISSOURI - MEDICAID
Website: www.dss.mo.gov/mhd/participants/ pages/hipp.htm
Phone: 573-751-2005
MONTANA - MEDICAID
Website: dphhs.mt.gov/MontanaHealthcarePrograms/HIPP
Phone: 1-800-694-3084
NEBRASKA - MEDICAID
Website: www.ACCESSNebraska.ne.gov
Phone: 1-855-632-7633
Lincoln: 402-473-7000
Omaha: 402-595-1178
NEVADA - MEDICAID
Medicaid Website: dhcfp.nv.gov
Medicaid Phone: 1-800-992-0900
NEW HAMPSHIRE - MEDICAID
Website: www.dhhs.nh.gov/oii/hipp.htm
Phone: 603-271-5218
Toll free number for the HIPP program: 1-800-852-3345, ext. 5218
NEW JERSEY - MEDICAID AND CHIP
Medicaid Website: www.state.nj.us/humanservices/dmahs/clients/medicaid
Medicaid Phone: 609-631-2392
CHIP Website: www.njfamilycare.org/index.html
CHIP Phone: 1-800-701-0710
NEW YORK - MEDICAID
Website: www.health.ny.gov/health_care/ medicaid
Phone: 1-800-541-2831
NORTH CAROLINA - MEDICAID
Website: medicaid.ncdhhs.gov
Phone: 919-855-4100
NORTH DAKOTA - MEDICAID
Website: www.nd.gov/dhs/services/medicalserv/medicaid
Phone: 1-844-854-4825
OKLAHOMA - MEDICAID & CHIP
Website: www.insureoklahoma.org
Phone: 1-888-365-3742
OREGON - MEDICAID & CHIP
Website: healthcare.oregon.gov/Pages/index.aspx
Phone: 1-800-699-9075
PENNSYLVANIA - MEDICAID
Website: www.dhs.pa.gov/providers/Providers/ Pages/Medical/HIPP-Program.aspx
Phone: 1-800-692-7462
RHODE ISLAND - MEDICAID AND CHIP
Website: www.eohhs.ri.gov
Phone: 1-855-697-4347 or 401-462-0311
(Direct RIte Share Line)
SOUTH CAROLINA - MEDICAID
Website: www.scdhhs.gov
Phone: 1-888-549-0820
SOUTH DAKOTA - MEDICAID
Website: dss.sd.gov
Phone: 1-888-828-0059
TEXAS - MEDICAID
Website: gethipptexas.com
Phone: 1-800-440-0493
UTAH - MEDICAID
Medicaid Website: medicaid.utah.gov
CHIP Website: health.utah.gov/chip Phone: 1-877-543-7669
VERMONT - MEDICAID
Website: www.greenmountaincare.org Phone: 1-800-250-8427
VIRGINIA - MEDICAID AND CHIP
Website: www.coverva.org/hipp
Medicaid Phone: 1-800-432-5924
CHIP Phone: 1-855-242-8282
WASHINGTON - MEDICAID
Website: www.hca.wa.gov Phone: 1-800-562-3022
WEST VIRGINIA - MEDICAID
Website: mywvhipp.com
Toll-free phone: 1-855-MyWVHIPP (1-855-699-8447)
WISCONSIN - MEDICAID AND CHIP
Website: www.dhs.wisconsin.gov/badgercareplus/p-10095.htm Phone: 1-800-362-3002
WYOMING - MEDICAID
Website: wyequalitycare.acs-inc.com Phone: 307-777-7531
To see if any other states have added a premium assistance program since July 31, 2020, or for more information on special enrollment rights, contact either:
U.S. Department of Labor
Employee Benefits Security Administration www.dol.gov/agencies/ebsa 1-866-444-EBSA (3272)
U.S. Department of Health and Human Services Centers for Medicare & Medicaid Services www.cms.hhs.gov 1-877-267-2323, Menu Option 4, Ext. 61565
According to the Paperwork Reduction Act of 1995 (Pub. L. 104-13) (PRA), no persons are required to respond to a collection of information unless such collection displays a valid Office of Management and Budget (OMB) control number. The Department notes that a Federal agency cannot conduct or sponsor a collection of information unless it is approved by OMB under the PRA, and displays a currently valid OMB control number, and the public is not required to respond to a collection of information unless it displays a currently valid OMB control number. See 44 U.S.C. 3507. Also, notwithstanding any other provisions of law, no person shall be subject to penalty for failing to comply with a collection of information if the collection of information does not display a currently valid OMB control number. See 44 U.S.C. 3512. The public reporting burden for this collection of information is estimated to average approximately seven minutes per respondent. Interested parties are encouraged to send comments regarding the burden estimate or any other aspect of this collection of information, including suggestions for reducing this burden, to the U.S. Department of Labor, Employee Benefits Security Administration, Office of Policy and Research, Attention: PRA Clearance Officer, 200 Constitution Avenue, N.W., Room N-5718, Washington, DC 20210 or email ebsa.opr@dol.gov and reference the OMB Control Number 1210-0137.
INTRODUCTION: You’re getting this notice because you recently gained coverage under a group plan. This notice has important information about your right to COBRA continuation coverage, which is a temporary extension of coverage under the Plan. This notice explains COBRA continuation coverage, when it may become available to you and your family, and what you need to do to protect your right to get it. When you become eligible for COBRA, you may also become eligible for other coverage options that may cost less than COBRA continuation coverage.
The right to COBRA continuation coverage was created by a federal law, the Consolidated Omnibus Budget Reconciliation Act of 1985 (COBRA). COBRA continuation coverage can become available to you and other members of your family when group health coverage would otherwise end. For more information about your rights and obligations under the Plan and under federal law, you should review the Plan’s Summary Plan Description or contact the Plan Administrator.
You may have other options available to you when you lose group health coverage. For example, you may be eligible to buy an individual plan through the Health Insurance Marketplace. By enrolling in coverage through the Marketplace, you may qualify for lower costs on your monthly premiums and lower out-of-pocket costs. Additionally, you may qualify for a 30-day special enrollment period for another group health plan for which you are eligible (such as a spouse’s plan), even if that plan generally doesn’t accept late enrollees.
What Is Cobra Continuation Coverage?: COBRA continuation coverage is a continuation of Plan coverage when it would otherwise end because of a life event. This is also called a “qualifying event.” Specific qualifying events are listed later in this notice. After a qualifying event, COBRA continuation coverage must be offered to each person who is a “qualified beneficiary.” You, your spouse, and your dependent children could become qualified beneficiaries if coverage under the Plan is lost because of the qualifying event. Under the Plan, qualified beneficiaries who elect COBRA continuation coverage [choose and enter appropriate information: must pay or aren’t required to pay] for COBRA continuation coverage.
If you’re an employee, you’ll become a qualified beneficiary if you lose your coverage under the Plan because of the following qualifying events:
• Your hours of employment are reduced, or
• Your employment ends for any reason other than your gross misconduct.
• If you’re the spouse of an employee, you’ll become a qualified beneficiary if you lose your coverage under the Plan because of the following qualifying events:
• Your spouse dies;
• Your spouse’s hours of employment are reduced;
• Your spouse’s employment ends for any reason other than his or her gross misconduct;
• Your spouse becomes entitled to Medicare benefits (under Part
A, Part B, or both); or
• You become divorced or legally separated from your spouse. Your dependent children will become qualified beneficiaries if they lose coverage under the Plan because of the following qualifying events:
• The parent-employee dies;
• The parent-employee’s hours of employment are reduced;
• The parent-employee’s employment ends for any reason other than his or her gross misconduct;
• The parent-employee becomes entitled to Medicare benefits (Part A, Part B, or both);
• The parents become divorced or legally separated; or
• The child stops being eligible for coverage under the Plan as a “dependent child.”
Sometimes, filing a proceeding in bankruptcy under title 11 of the United States Code can be a qualifying event. If a proceeding in bankruptcy is filed with respect to Prince George County Public Schools and that bankruptcy results in the loss of coverage of any retired employee covered under the Plan, the retired employee will become a qualified beneficiary. The retired employee’s spouse, surviving spouse, and dependent children will also become qualified beneficiaries if bankruptcy results in the loss of their coverage under the Plan.
When is COBRA continuation coverage available?
The Plan will offer COBRA continuation coverage to qualified beneficiaries only after the Plan Administrator has been notified that a qualifying event has occurred. The employer must notify the Plan Administrator of the following qualifying events:
• The end of employment or reduction of hours of employment;
• Death of the employee;
• The employee’s becoming entitled to Medicare benefits (under Part A, Part B, or both).
For all other qualifying events (divorce or legal separation of the employee and spouse or a dependent child’s losing eligibility for coverage as a dependent child), you must notify the Plan Administrator within 60 days after the qualifying event occurs. You must provide this notice to: Wendy Livingston at 804-733-2700. Applicable documentation will be required i.e. court order, certificate of coverage etc.
How is COBRA continuation coverage provided?
Once the Plan Administrator receives notice that a qualifying event has occurred, COBRA continuation coverage will be offered to each of the qualified beneficiaries. Each qualified beneficiary will have an independent right to elect COBRA continuation coverage. Covered employees may elect COBRA continuation coverage on behalf of their spouses, and parents may elect COBRA continuation coverage on behalf of their children.
COBRA continuation coverage is a temporary continuation of coverage that generally lasts for 18 months due to employment termination or reduction of hours of work. Certain qualifying events,
or a second qualifying event during the initial period of coverage, may permit a beneficiary to receive a maximum of 36 months of coverage.
There are also ways in which this 18-month period of COBRA continuation coverage can be extended:
Disability extension of 18-month period of COBRA continuation coverage: If you or anyone in your family covered under the Plan is determined by Social Security to be disabled and you notify the Plan Administrator in a timely fashion, you and your entire family may be entitled to get up to an additional 11 months of COBRA continuation coverage, for a maximum of 29 months. The disability would have to have started at some time before the 60th day of COBRA continuation coverage and must last at least until the end of the 18-month period of COBRA continuation coverage.
Second qualifying event extension of 18-month period of continuation coverage: If your family experiences another qualifying event during the 18 months of COBRA continuation coverage, the spouse and dependent children in your family can get up to 18 additional months of COBRA continuation coverage, for a maximum of 36 months, if the Plan is properly notified about the second qualifying event. This extension may be available to the spouse and any dependent children getting COBRA continuation coverage if the employee or former employee dies; becomes entitled to Medicare benefits (under Part A, Part B, or both); gets divorced or legally separated; or if the dependent child stops being eligible under the Plan as a dependent child. This extension is only available if the second qualifying event would have caused the spouse or dependent child to lose coverage under the Plan had the first qualifying event not occurred.
Are there other coverage options besides COBRA Continuation Coverage?: Yes. Instead of enrolling in COBRA continuation coverage, there may be other coverage options for you and your family through the Health Insurance Marketplace, Medicare, Medicaid, Children’s Health Insurance Program (CHIP), or other group health plan coverage options (such as a spouse’s plan) through what is called a “special enrollment period.” Some of these options may cost less than COBRA continuation coverage. You can learn more about many of these options at www.healthcare.gov.
Can I enroll in Medicare instead of COBRA continuation coverage after my group health plan coverage ends?: In general, if you don’t enroll in Medicare Part A or B when you are first eligible because you are still employed, after the Medicare initial enrollment period, you have an 8-month special enrollment period to sign up for Medicare Part A or B, beginning on the earlier of
• The month after your employment ends; or
• The month after group health plan coverage based on current employment ends.
If you don’t enroll in Medicare and elect COBRA continuation coverage instead, you may have to pay a Part B late enrollment penalty and you may have a gap in coverage if you decide you want Part B later. If you elect COBRA continuation coverage and later enroll in Medicare Part A or B before the COBRA continuation coverage ends, the Plan may terminate your continuation coverage. However, if Medicare Part A or B is effective on or before the date of
the COBRA election, COBRA coverage may not be discontinued on account of Medicare entitlement, even if you enroll in the other part of Medicare after the date of the election of COBRA coverage.
If you are enrolled in both COBRA continuation coverage and Medicare, Medicare will generally pay first (primary payer) and COBRA continuation coverage will pay second. Certain plans may pay as if secondary to Medicare, even if you are not enrolled in Medicare.
For more information visit https://www.medicare.gov/medicare-and-you.
If you have questions: Questions concerning your Plan or your COBRA continuation coverage rights should be addressed to the contact or contacts identified below. For more information about your rights under the Employee Retirement Income Security Act (ERISA), including COBRA, the Patient Protection and Affordable Care Act, and other laws affecting group health plans, contact the nearest Regional or District Office of the U.S. Department of Labor’s Employee Benefits Security Administration (EBSA) in your area or visit www.dol.gov/ebsa. (Addresses and phone numbers of Regional and District EBSA Offices are available through EBSA’s website.) For more information about the Marketplace, visit www.HealthCare. gov.
Keep your Plan informed of address changes: To protect your family’s rights, let the Plan Administrator knowabout any changes in the addresses of family members. You should also keep a copy, for your records, of any notices you send to the Plan Administrator.
Plan Contact Information
Prince George County Public Schools
ATTN: Wendy Livingston Phone: 804-733-2700
Email: wlivingston@pgs.k12.va.us
Dental and Vision COBRA Administrator: Interactive Medical Systems P.O. Box 1349
Wake Forest, NC 27588
Physical Address: 11635 Northpark Dr., Suite 330 Wake Forest, NC 27588 (800) 426-8739
We collect Non Public Information (NPI) about our customers to provide them with insurance products and services. This may include telephone number, address, date of birth, occupation, income and health history. We may receive NPI from your applications and forms. medical providers, other insurers, employers, insurance support organizations, and service providers.
We share the types of NPI described above primarily with people who perform insurance, business, and professional services for us, such as helping us pay claims and detect fraud. We may share NPI with medical providers for insurance and treatment purposes. We may share NPI with an insurance support organization. The organization may retain the NPI and disclose it to others for whom it performs services. In certain cases, we may share NPI with group policy holders for reporting and auditing purposes. We may share NPI with parties to a proposed or final sale of insurance business or for study purposes. We may also share NPI when otherwise required or permitted by law, such as sharing with governmental or other legal authorities. When legal necessary, we ask your permission before sharing NPI about you our practices apply to our former, current and future customers.
Please be assured we do not share your health NPI to market any product or service. We also do not share any NPI to market non financial products and services. For example, we do not sell your name to catalog companies.
The law allows us to share NPI as described above (except health information) will affiliates to market financial products and services. The law does not allow you to restrict these disclosures. We may also share with companies that help us market our insurance products and services, such as vendors that provide mailing services to us. We may share with other financial institution to jointly market financial products and services. When required by law, we ask your permission before we share NPI for marketing purposes.
When other companies help us conduct business, we expect them to follow applicable privacy laws.
We do not authorize them to use or share NPI except when necessary to conduct the work they are performing for us or to meet regulatory or other governmental requirements.
Our affiliated companies, including insurers and insurance service providers, may share NPI about you with each other. The NPI might not be directly related to our transaction or experience with you. It may include financial or other personal information such as employment history. Consistent with the Fair Credit Reporting Act, we ask your permission before sharing NPI that is not directly related to our transaction or experience with you.
We have physical, electronic and procedural safeguards that protect the confidentiality and security of NPI. We give access only to employees who need to know the NPI to provide insurance products or services to you.
You may request access to certain NPI we collect to provide you with insurance products and services, You must make your request in writing and send it to the address, telephone number and policy number if we have issued a policy. If you request, we will send copies of the NPI to you. If the NPI includes health information, we may provide the health information to you through a health care provider you designate. We will also send you information related to disclosures. We may charge a reasonable fee to cover our copying costs. This section applies to NPI we collect tor provide you with coverage. It does not apply to NPI we collect in anticipation of a claim or civil or criminal proceeding.
If you believe NPI we have about you is incorrect, please write us. Your letter should include your full name, address, telephone number and policy number if we have issued a policy. Your letter should also explain why you believe the NPI is inaccurate. If we agree with you, we will correct the NPI and notify you of the correction. We will also notify any person who may have received the incorrect NPI from us in the past two years if you ask us to contact that person.
If we disagree with you, we will tell you we are not going to make the correction, We will give the reason(s) for our refusal. We will also tell you that you may submit a statement to us.
Your statement should include the NPI you believe is correct. It should also include the reasons(s) why you disagree with our decision not to correct the NPI
in our files. We will file your statement with the disputed NPI. We will include your statement any time we disclose the disputed NPI. We will also give the statement to any person designated by your if we may have disclosed the disputed NPI to that person int he past two years.
Information regarding your insurability will be treated as confidential. Colonial or its reinsure(s) may, however, make a brief report thereon to the Medical Information Bureau, a nonprofit membership organization of life insurance companies which operates an information exchange on behalf of its members. If you apply to another Bureau member company for life or health insurance coverage, or a claim for benefits is submitted to such company, the Bureau, upon request, will supply such company with the information in its file.
Upon receipt of a request from you, the Bureau will arrange disclosure of any information it may have in your file. If you question the accuracy of information in the Bureau’s file, you may contact the Bureau and seek a correction in accordance with the procedure set forth in the federal Fair Credit Reporting Act. The address of the Bureau’s information office is: 50 Braintree Hill Park, Suite 400, Braintree, MA 02184-8734, telephone (617) 4263660.
Colonial or its reinsure may also release information in its file to other life insurance companies to whom you may apply for life or health insurance or to whom a claim for benefits may be submitted.
We are committed to being there for you and your family at every stage of life. Pierce Group Benefits makes it easy to stay protected!
The following benefits can be self-enrolled online or by contacting PGB Employee Services, with Individual and Family coverage options available for most plans. You are eligible to sign-up the first day after the end date of your employer-sponsored plan.
Your individual supplemental/voluntary policies through Colonial Life are portable! To transfer your benefits from payroll deduction to direct billing or automatic bank draft, please call Employee Services at 800-387-5955 within 30 days of becoming unemployed, switching careers, or retiring.
If you are transferring from a current PGB client to another, some benefits may be eligible for transfer. Please call Employee Services at 800-387-5955 for assistance.
Please visit www.piercegroupbenefits.com/individualcoverage or call 800-387-5955 for more information on these policies, as well as to enroll/continue your benefits.
Pierce Group Benefits is a leading full-service employee benefits administration and consulting agency serving employer groups across the Southeast. By leveraging market strength, exclusive partnerships, and industry expertise, we deliver trusted advice, products, and solutions that benefit employers and employees alike; delivered by one team and driven by one purpose — together we can do more.