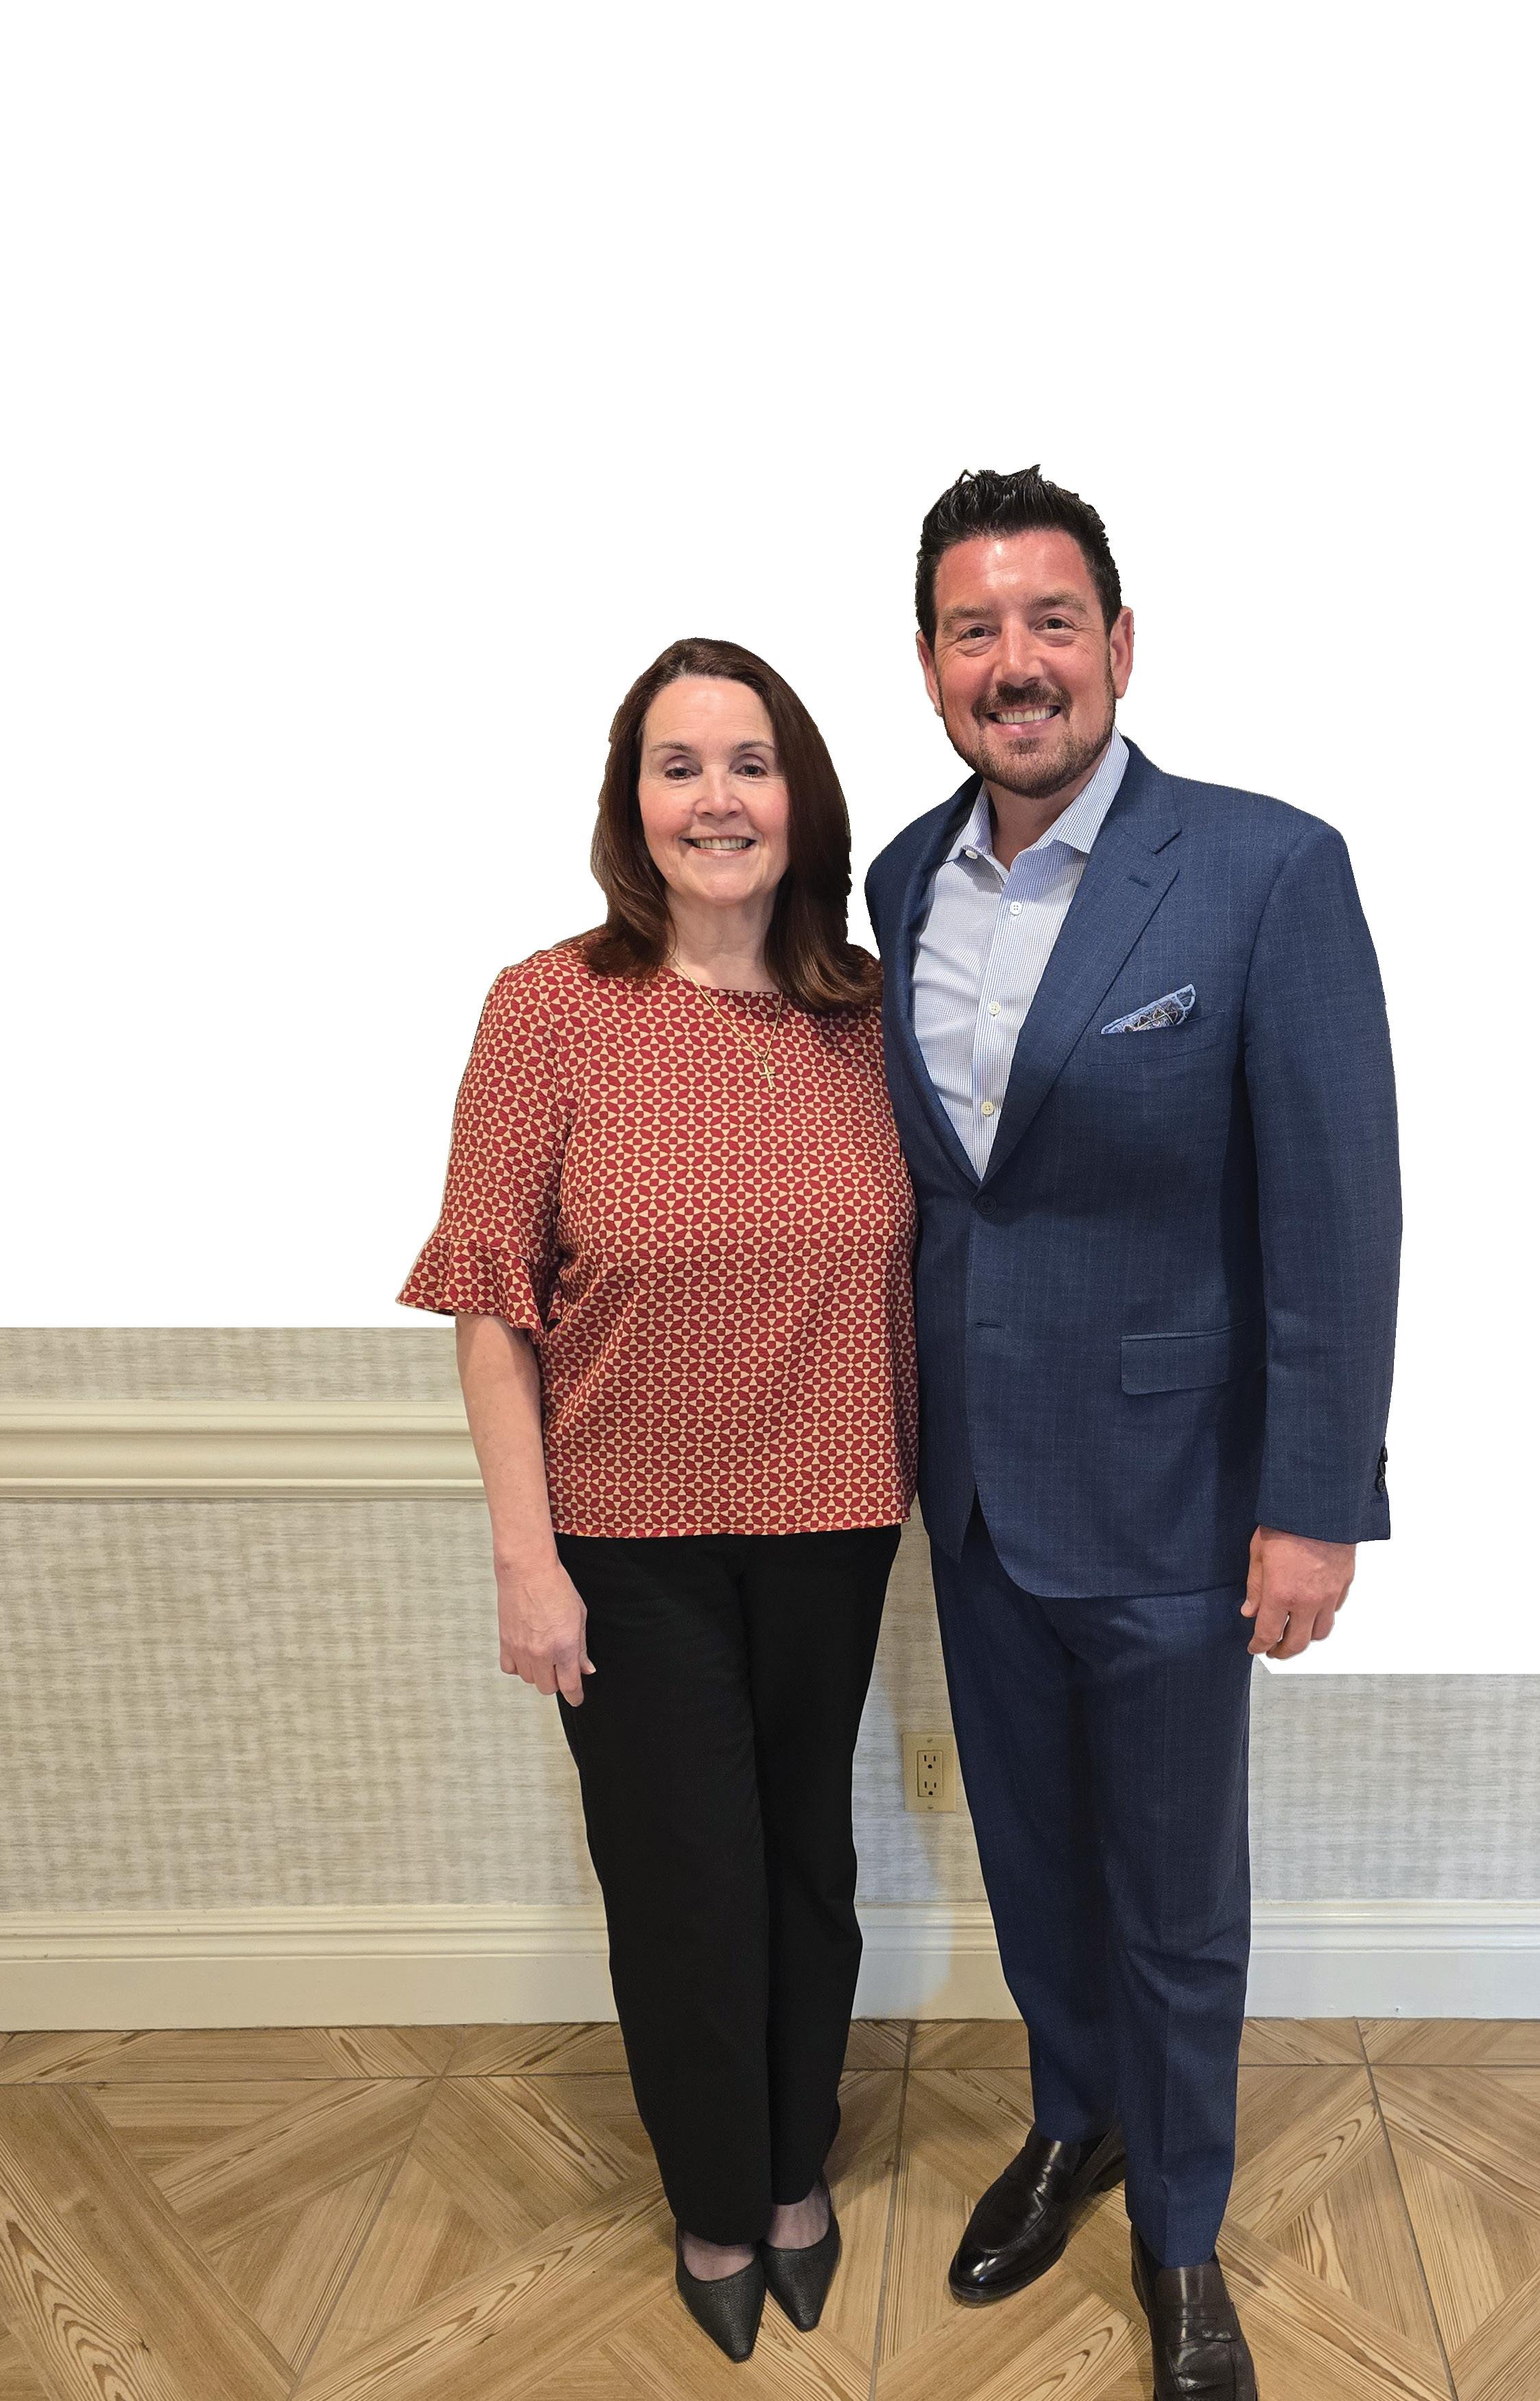
We are proud to recognize Aaron Levine as the newly appointed President of PIANJ.
As a dedicated agent with NJAN/SIAA , Aaron brings a unique perspective— bridging two highly respected and successful organizations within the insurance industry. His leadership reflects a commitment to collaboration, innovation, and strengthening the independent agency system.
Join us in congratulating Aaron on this well-deserved achievement.
NJAN Power Stats
Serving New Jersey since 1994 (30+ years of continuous growth and leadership)
Backed by 5,200+ agencies nationwide through SIAA
Part of a national platform with $18+ billion in premium through SIAA
SIAA Power Stats
49 Master Agencies nationwide delivering local support with national scale
$16.7+ billion in total in-force premium (2024)
Represents approximately 13% of all independent insurance agencies in the U.S.
When you think about how you develop your agency’s customer strategy, remember that it all starts with attracting and growing a dedicated client base.
When you are considering your agency’s customer strategy, here are some best practices.
Clients want to be treated well. This just doesn’t end at the hospitality you may offer them in your one-on-one interactions until you sell them an insurance policy. Rather it extends to other parts of the business as well. This may include:
• Clear lines of communication, such as email or instant messaging, throughout the year not just at renewal time.
• The user-friendliness of your website, which helps your clients find the information they need.
• Detailed and informative product descriptions, and a knowledgeable agency staff.
There are few things that are quite as potent as word of mouth. You can draw in even more people by having clients who can speak directly about the quality of service your agency can provide. Encourage them to leave reviews and provide referrals.
Definition—Brand advocacy: the organic promotion of a business by loyal customers and employees, primarily through word-of-mouth and social media. Examples: referral programs, user-generated content and online reviews.
In 2022, PWC found that 37% of insurance consumers switched products because of bad customer service.
A study from LIMRA International showed that referrals can account for 40%-60% of new business for insurance agents.
Today, it’s impossible to ignore the power and reach of online marketing. You already may have implemented a few strategies in your agency, including:
• Creating a website for your business.
• Creating content and promotion opportunities.
• Establishing a presence on multiple social media channels (e.g., LinkedIn, Facebook or Instagram).
Because engagement strategies on the internet can rapidly change, it’s important to keep up with the latest trends to keep drawing new customers.
The value of Instagram
If your agency has been active on social media, but it does not have an Instagram account consider this:
• Instagram has over 2 billion monthly users
• You can reach the up-and-coming, insurance-buying crowd: 63% of Instagram users are between the ages of 18-34 .
• Video content can capture attention and communicate brand values through powerful imagery.
• It has cross-posting capabilities with Facebook.
Some of Instagram’s pros: high engagement rates, targeting advertising and influencer collaborations.
Some of Instagram’s cons: high competition, constant need for content (consider posting 3-5 times a week), and the platform has frequent updates that change its algorithm.
It can take time, effort and plenty of connections, but by tapping into a niche insurance market you can greatly expand your customer base. Consumers who have an interest in a niche market tend to be passionate about it. And, passionate people tend to be dedicated people. If you have a niche you are passionate about insuring, it could lead to business growth opportunities for your agency.
You may have heard of customer-led growth as something you can incorporate into your agency’s business plans, but what is it? It involves reorienting your business to focus on and address your customers’ needs to grow it, which is the opposite of product-led growth (oriented around a product to drive growth).
To begin this shift into customer-led growth, you can start by collecting feedback from your clients, analyzing it, then applying it to your own agency. Instead of focusing only on new leads (regardless of who they are), your agency can concentrate on creating high-value experiences that can turn existing clients into advocates for your agency. Clients who advocate for your agency believe in the agency—and what it is offering them. They are more likely to stick around and be lasting clients, rather than short-term clients who are only interested in the cheapest insurance policy.
Independent insurance agents have a leg up over online insurance providers and direct writers—they attract clients who are looking for someone who can explain the world of insurance to them without the jargon, and who can be a trusted insurance consultant. People who value this type of service tend to be loyal customers.
That’s good news! There are people looking for you and your agency. You just need to know the best way to find them. To build a dedicated client base, you must define your specific target audience, deliver exceptional personalized service and foster trust through communication.
Start with your current client list. Examine their demographics (e.g., age, location, interests), but don’t forget to include psychographics (e.g., values, needs). Establish who your ideal current clients are. Then determine how your agency can best reach those prospects who fit your definition of an ideal client.
Don’t be afraid to lose the clients who don’t fit into your target audience—especially if they require more of your time, but offer little value to your agency. Instead, focus on nurturing the relationships with the clients who are looking to grow with your agency.
When you build trust with clients you can foster long-term loyalty, which can help you to avoid those clients who are looking for the lowest price, and who will move to the next agent or company that can offer a better deal at renewal time. Make clients feel valued by offering personalized, attentive service. Use your agency management system to remember details about your clients’ lives—and ask them questions about their families and interests. Keep track of your clients’ life-changing events that might create the need for additional insurance, and reach out to them proactively about making the necessary changes to their policies.
Stay in touch—not just at renewal time, but throughout the year. If you see an insurance trend that may affect your clients—either personally or commercially—bring the issue to their attention, so that they aren’t blindsided by an increase in premium or a decrease in coverage. If possible, help them to create a new insurance plan that may be able to help them mitigate any changes.
Be available to your clients and make sure they know how to reach you. Be active on social media, but don’t just post commercials for your agency. Instead include information that your clients can interact with, and that establish your agency as a place where people can turn to if they have a question about insurance. Use videos to explain insurance coverages—but don’t make statements that can be viewed as promises or guarantees—or answer frequently asked insurance questions.
As your client base continues to evolve, so should your agency. Keep reviewing your client list for new opportunities to approach new prospects and grow your agency. Listen to client feedback—if people keep mentioning the same thing, find out why. If it’s positive, make sure all your clients know about it. If it’s negative, find a way to fix the issue. Don’t forget to let those individuals who brought the issue to your attention know that you’ve addressed the problem. People like to know when they’ve been helpful. Remember, don’t just grow your agency to grow. Make sure each decision makes sense for your agency, and that it won’t harm the dedicated client base that your agency already has.
If you see an insurance trend that may affect your clients … bring the issue to their attention, so that they aren’t blindsided by an increase in premium or a decrease in coverage.
Joseph Ritchie Coordinator of government & industry affairs, PIA Northeast
Consider this scenario: Brian is a first-time auto insurance buyer in a state with strict coverage requirements. He opens an app, compares a few quotes, and selects the cheapest option he can find. Within minutes, he has coverage and proof of insurance. Simple, fast and done. A few months later, Brian misses a payment, and he does not realize his policy has been canceled.
One day he gets pulled over while driving. Since his insurance is lapsed, he is no longer legally allowed to be on the road. Now he faces fines, a suspended license and additional fees just to get his insurance policy reinstated. What started as a quick purchase has turned into a costly situation.
This is not an unusual problem, and it’s easily preventable. An independent agent would have explained the importance of continuous coverage, what happens when a policy lapses and how to avoid it. More importantly, Brian would have had someone to call before the situation escalated.
That is the difference between an app and an agent. Not just selling a policy but making sure the client understands how it works before something goes wrong.
For younger consumers, insurance often is their first complex financial decision. They are comfortable navigating apps and comparing prices, but many do not understand coverage, limits or legal requirements. That gap creates an opportunity for independent agents. The challenge is reaching younger buyers before they make avoidable and often costly mistakes.
Most young insurance buyers are not intentionally taking risks. They simply do not know what to look for. Without guidance, first-time buyers often make decisions that can have long-term consequences. They may choose minimum limits without realizing how quickly those limits can be exceeded, misunderstand what their policies actually cover, or overlook important protections altogether. In some cases, they do not recognize the importance of maintaining continuous coverage until it is too late.
This is where independent agents stand apart from apps and direct writers. The value is not just placing coverage. It is helping clients understand what they are buying, why it matters, and what can go wrong if it is structured incorrectly.
They need to understand that missed payments or policy lapses can trigger serious consequences—including license suspensions, registration revocations and costly reinstatement fees—and these consequences can vary from state to state.
They are used to purchasing anything based on price and convenience. Independent insurance agents need to let them know that insurance does not work that way. A lower premium often means less protection or higher out-ofpocket costs.
For many first-time insurance buyers, the insurance policies are tied to a life event: buying a car, moving into an apartment or starting a new job. These moments move quickly, and insurance becomes a box to check rather than a decision to understand.
This is where independent agents stand apart from apps and direct writers. The value is not just placing coverage. It is helping clients understand what they are buying, why it matters, and what can go wrong if it is structured incorrectly.
Agents bring context to the decision. They can explain the difference between minimum limits and meaningful protection, walk through real-world scenarios and identify gaps that a firsttime buyer may not recognize. They also provide something younger buyers often do not realize they need until it is too late—ongoing support.
A simple conversation can prevent a costly mistake. An agent who explains how a deductible can impact a claim, what could happen if coverage lapses or how liability limits should apply in an accident can change how clients approach their policies. These are critial discussions.
Independent agents also offer choice. Unlike direct channels, which present a single option, agents can compare multiple carriers and tailor coverage to fit the client’s situation. That flexibility allows for better alignment between price and protection, rather than forcing a tradeoff between the two.
Agents can take this further by being intentional about how they engage first-time buyers. Creating a simple Insurance 101 experience can set the foundation early. This does not need to be complex. A short onboarding conversation, a basic guide or a series of clear explanations can help clients understand the fundamentals before they ever need to use their policy.
Some agents also may benefit from having a dedicated resource in their agency for younger or first-time clients. Someone who can answer questions, explain
coverage in plain language and serve as a consistent point of contact. For a new buyer, knowing who to call can be just as valuable as the policy itself.
These are small adjustments, but they reinforce the role of the agent as an adviser, not just a transaction point.
If the goal is to attract a younger demographic, timing matters. Too often, agents enter the conversation after a policy already has been purchased or after a problem has occurred. By then, the opportunity to guide the initial decision has passed.
Reaching younger buyers means showing up earlier, and being visible before that first purchase is made. Start by identifying key entry points (e.g., first cars, first apartments, new jobs). These are moments when insurance becomes relevant, and they create a natural opportunity to introduce guidance rather than just a quote.
It also requires meeting younger buyers where they are. Short-form videos, quick explainers and simple posts on platforms like TikTok or Instagram can make complex topics more accessible. A 30-second explanation of what happens if insurance lapses or what minimum coverage means can have more impact than a brochure.
The goal is not to go viral. It is to be useful. Agents who consistently show up with clear, practical guidance position themselves differently. They are not just another option when it is time to buy. They become a trusted source before the decision is made. That early connection is what turns a first-time buyer into a long-term client.
Consistent education builds familiarity. When it is time to purchase a policy, that familiarity can turn into trust.
Communicate in a way that resonates with clients
How agents communicate matters. Younger buyers respond to clarity. Industry jargon and technical explanations can create confusion. Plain language and real-life examples are more effective. A simple explanation of what happens if coverage lapses will resonate more than a technical description of policy conditions. The objective is understanding, not complexity.
Attracting younger clients is a longterm strategy. First-time buyers who have positive experiences are more likely to stay, ask questions, and expand their coverage over time. This can lead to multipolicy households and referrals.
It also leads to better outcomes. Clients who understand their coverage are less likely to be surprised at claim time.
The role for independent agents is not just to compete. It is to lead. Younger buyers are not rejecting guidance. They are making decisions before they receive it.
Agents who show up early, simplify complex concepts and use technology to support real conversations will stand apart. A quick explanation today can prevent a costly mistake tomorrow. This is not about replacing digital tools. It is about adding meaning to them.
The agents who win with the next generation of insurance buyers will be the ones who educate first, advise clearly and build trust before a policy is even bound. Getting there first is not a strategy. It is the advantage!
AFCO Direct interrupts our standard monthly ad to bring you this fun premium finance word search.
1. Find all the words.
2. Send a photo of your completed puzzle to solutions@afcodirect.com by June 16th, 2025.
3. Earn a $25 Grubhub lunch certificate on us.
• Insurance
• Premium
• Service
• Risk
• Investment
• Agency
• Rate
• Payment
• Coverage
• Capital
• Renewal
• Revenue
• Partner
• Finance
• Compliance
• Solution
• Technology
• Value
• Strength
• Trustworthy
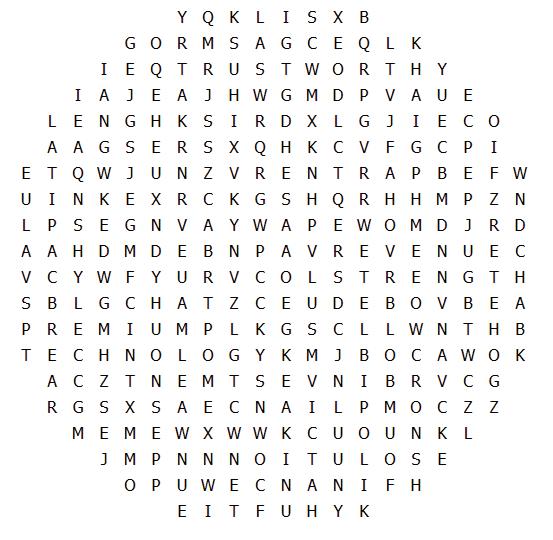
Having a premium finance partner you can rely on gives you more time for brain breaks like this.
Foremost®, part of Farmers Insurance®, has a legacy of more than 70 years of industry leadership and excellent service. Built from decades of experience, we deliver customizable coverages for autos, homes, motorcycles, off-road vehicles and much more.
With our flexible payment plans, numerous discounts and 24/7 claim service, we’re here to help make insurance easier. Your customers can live confidently knowing Foremost has their back with above-and-beyond service and exceptional coverage for their homes, vehicles and passions..
Kimberly A. Kennedy Chief operating officer, personal lines, The Hanover
Customer service expectations have never been higher. Real-time updates, immediate access to information and on-demand services are now the norm, and insurance customers expect the same speed, simplicity and levels of support they get with other digital tools they use every day.
To meet expectations, independent agents rely on carrier customer service centers to enhance the service they provide. These service centers help maximize their time, provide extended hours, deliver expert support for coverage questions, and help augment their insurance portfolios with proper protection. These centers can operate as seamless extensions of the agencies, improving customer retention, premium per account and overall profitability.
As carriers scale these models, many are turning to artificial intelligence to further streamline operations and reduce friction. While speed and efficiency are essential, the real opportunity lies in how AI is used. When thoughtfully embedded within carrier service centers, AI doesn’t replace the customer connection—it strengthens it. By shifting repetitive, lower-value tasks into the background, AI can create space for more empathetic, personalized and meaningful interactions—benefiting both the agency and the customer.
The most effective carrier service centers now use AI to enable stronger human connections. Insurance interactions are rarely routine—whether discussing a claim, a premium or a coverage option, these moments often carry emotional weight tied to customers’ homes, livelihoods and security. Customers want efficient service, but not at the expense of empathy. Therefore, the independent agency channel’s competitive advantage is not speed alone, but speed delivered with personability and care.
Here are four ways leading carriers are using AI to support people-first service experiences.
No. 1: AI as an assistant. AI acts as assistants to carriers’ service professionals. If you’ve ever tried to capture copious notes while truly listening, you know how one compromises
the other. In a service center environment, generative AI tools can listen to an entire call, draft clean summaries, categorize the reason for the interaction, and capture the recommendations and agreed upon next steps in seconds.
There’s a growing empirical basis for this assistance. In a study published in The Quarterly Journal of Economics, researchers tracked more than 5,000 customer support agents and found access to a generative AI assistant increased the number of issues resolved per hour by 15% on average.1 Greater efficiency saves customers time and drives greater service satisfaction, and it frees up service center professionals to focus on the person. This means less manual work and more meaningful work. Professionals stay engaged in the conversation, ask more curious and clarifying questions, meet customers where they’re at and effectively address concerns in real time.
Carriers that focus on personability in their service centers elevate daily interactions with agents and customers, to ensure customers feel heard, understood and supported in ways that leave them with lasting, positive impressions that deepen their relationship with the agency.
No. 2: Consistency that builds trust. Carriers are using AI to ensure consistency in the responses of their service professionals. Consistency is a perennial challenge in any service organization. As teams grow and roles expand, even small variations in how people interpret a coverage term or process can lead to different answers for customers. AI-powered knowledge tools reduce that variability by providing a single source of truth, accessible in real time, enabling service center professionals to surface the latest guidance in seconds.
A seasoned service professional might use an analogy to explain replacement cost; a newer colleague might stick closer to the script. Both arrive at the same accurate answer. This ensures all customers get the same information and guidance, no matter who is taking care of them. Some carriers already have implemented real-time knowledge management tools
and job aids for their service agents. From intuitive look-up capabilities to voice AI automatic computer screen pop-up recommendations, these innovations are increasing both the speed and accuracy of information provided to each caller.
No. 3: Voice tools that ensure natural conversations. Carriers are leveraging voice-enabled assistants to retrieve relevant information in the background while conversations continue uninterrupted, proving some of the most practical applications of AI are also the least visible. Carrier insurance professionals can quickly surface what they need without placing customers on hold, which creates more productive and meaningful interactions.
These tools also enable insurance professionals to become more available for the next customer call. The ability to quickly review, refine if needed, and approve the automated summary significantly reduces manual work after each call. Some carrier service centers instantly share call notes with enrolled agents, who value the consistent, natural-language summaries. As a result, when agents engage with customers, those conversations reflect seamless communication and collaboration, reinforcing that the agent and the carrier service center operate as one highly effective team on the customer’s behalf.
No. 4: Data-driven insights that better protect customers. Carriers use AI-driven analytics to identify portfolio gaps. Some service teams can surface insights in real time to help identify next best actions—such as additional coverages—that would provide enhanced insurance protection for customers. For example, a customer calls in with a question about an auto policy. After that question is addressed, data-driven capabilities allow insurance professionals to become immediately aware
of opportunities to add value. The customer may have a watercraft, or may not have cyber liability insurance, or may want to increase umbrella coverage due to an upcoming life event.
These data-backed tools foster more proactive, better informed and smarter conversations. Intelligent-servicing capabilities help deliver a higher level of consultation and recommendations that ensure customers are aware of and stay ahead of emerging risks. Customers who work with independent agents value having a trusted adviser, and the best carriers understand that service centers are an extension of their independent agents’ teams, so they must provide valued insurance counsel in their customer interactions, too.
Going beyond a basic assistant, carriers can use large language models to capture sentiment analysis. By analyzing tone, pace and language patterns, AI can flag when customers become frustrated or confused—such as when understanding a rate change or interpreting an unfamiliar policy term. Those insights support smarter coaching, clearer training materials and greater professional development for insurance professionals, so difficult conversations become easier to navigate, and result in a better customer experience—greater clarity, increased productivity and more personability.
The ability for a carrier to ascertain the emotional reaction of its stakeholders in each interaction is powerful because it ultimately leads to more effective business decisions, thoughtful change management and improved communications.
Change is inevitable, but growth is optional. Agents don’t need to leverage every new technology trend, but they can
rely on top carriers that are investing in and scaling advanced technologies to enhance their agency’s employee and customer experiences. AI can help offer the speed and precision today’s agents and customers expect, which frees agency staff to focus on relationship building to maintain and improve their competitive edge and grow.
The real differentiator becomes how carriers culturally adopt these tools. Successful implementations keep people at the center of their operating models. AI can suggest next steps, summarize calls or serve as an assistant, but it is not a replacement for authentic human connections. AI’s real value is in enhancing relationships—not replacing them—and the best carriers are leveraging this technology to help bring people together.
Agents who leverage carrier service centers for their agencies, and who have embraced these AI tools will be better equipped to deliver faster, more insightful service, deepen client relationships, and deliver as customer expectations evolve. Digitizing the ordinary to humanize the extraordinary is good for everyone and for business. Currently, Kennedy serves as chief operating officer and vice president of personal lines and enterprise operations at The Hanover Insurance Group. In this role, she partners closely with all stakeholders to translate business strategy into action and deliver innovative and exceptional service capabilities, offerings, and experiences for the company’s independent agents and policyholders. Kennedy has nearly three decades of experience leading insurance professionals through transformational, organizational change, and she holds a master’s degree in business process engineering and a bachelor’s degree in communications.
1 Oxford Academic, 2025 (tinyurl.com/536bsrsy)
Auto
Cabinet/Floor
Electrical
Grocery/Deli/Supermarkets
Landscapers
Masonry Program
Simplified
Trusted
Competitive
Roger Butler for all your hard work.
Aaron Levine. We look forward to all that 2026 has in store!
Plymouth Rock proudly supports our Independent Agents and PIA of New Jersey and New York.
Thank you for all that you do for the industry.
ANUPAM GUPTA CHIEF PRODUCT OFFICER, APPLIED SYSTEMS
Your data knows what your clients need
Turn internal data into smarter, more strategic client conversations
Every independent agency sits on a goldmine of client intelligence. Policy histories, claims records, renewal timelines, coverage limits, endorsement selections—the data is already there, accumulated over years of doing business. The challenge has never been a lack of information; it has been the impracticality of synthesizing it into something an agent can use in the 10 minutes before a client walks through the door or picks up the phone. Agents always have faced a difficult balancing act: the desire to deliver deeply personalized advice weighed against the operational reality of limited time and bandwidth.
Artificial intelligence is tipping that balance decisively in the agent’s favor. Not by replacing the agent’s judgment, expertise or relationship skills, but by doing the heavy analytical lifting that no human could reasonably accomplish at scale. AI gives agents the ability to walk into every conversation—renewals, risk assessments, new business pitches, coverage reviews—armed with insights that once would have taken hours of manual file review to assemble. The result is a fundamental shift in how independent agents deliver value: from reactive service providers to proactive, consultative advisers.
The advisory gap that AI can close Independent agents in the Northeast know the value of relationships. Agencies across New York, New Jersey, Connecticut, New Hampshire and Vermont have built their reputations on trust, local expertise, and the kind of personalized attention that direct writers simply cannot match. Yet, even the best agents face a persistent tension between the depth of service they want to deliver and the operational realities of running an agency.
The average commercial lines account involves dozens of data points: multiple policy types, varying renewal dates, evolving exposure profiles, claims history and carrier-specific nuances. A thorough prerenewal review of even a mid-market account could take an experienced agent 30 to 45 minutes of file analysis before the client conversation even begins. Multiply that across a full book of business, and the math becomes unforgiving. Agents end up triaging—focusing their deepest preparation on the largest accounts and handling smaller ones with less rigor, not out of negligence, but out of necessity.
AI eliminates that trade-off. It can analyze an entire book of business continuously, flagging coverage gaps, identifying cross-sell opportunities, benchmarking limits against industry norms, and surfacing risk factors that deserve attention—all in the time it takes to pour a cup of coffee. The agent’s role does not diminish. It evolves. The agent is no longer the person sifting through data. The agent is the strategist who interprets the findings and translates them into the advice that matters to the client.
Renewal season has long been the backbone of agency revenue—and one of the most operationally demanding periods
of the year. Too often, renewal conversations default to a familiar script: review the expiring terms, present the new premium, discuss any rate changes, and secure the signature. The exchange is transactional, efficient and forgettable.
AI makes a different kind of renewal conversation possible. Imagine sitting down with a commercial client and opening with a specific observation: “Your property values have increased 18% over the past three years, but your building limits have remained flat. You may be significantly underinsured.” That is not a generic talking point. That is a data-driven insight, generated by an AI system that compared the client’s current coverage against valuation trends and flagged the discrepancy automatically.
This kind of specificity transforms renewals from administrative checkpoints into genuine advisory sessions. The agent is not just asking whether the client wants to renew. The agent is demonstrating a deep understanding of the client’s evolving risk profile, and is recommending adjustments that protect the client’s interests. Clients notice the difference. They feel known, understood and valued—which is precisely the experience that drives long-term retention.
Also, AI can prioritize the renewal pipeline itself. It can identify which accounts have the highest likelihood of shopping their coverage based on factors like premium increases, claims frequency or length of relationship. Armed with that intelligence, agency principals can allocate their teams’ time and energy where it will have the greatest impact on retention.
The most powerful statement an agent can make to a client is, “I was thinking about your account and noticed something you should know about.” That kind of proactive outreach builds trust faster than any marketing campaign or loyalty program ever could. AI makes proactive outreach scalable.
Consider the personal lines side of the business. AI can monitor a book of personal auto and homeowners policies, and identify clients whose coverage profiles suggest they may have unaddressed exposures. A client with a homeowners policy and two auto policies but no umbrella is an obvious candidate for a conversation about personal liability protection. An AI system can surface that gap, draft talking points, and even suggest an appropriate umbrella limit based on the client’s asset profile—all without the agent having to manually cross-reference multiple policy records.
On the commercial side, the opportunities are equally compelling. An AI tool analyzing a contractor’s account might flag that the client added three new vehicles to the fleet over the past year—a clear sign of expanded operations—yet the client has not updated the inland marine coverage to account for the additional tools and equipment now traveling to more job sites. AI also might flag that a restaurant client’s liquor liability limits have not been reviewed since the original policy inception, despite two expansions of the dining area. These are the kinds of insights that distinguish an exceptional agent from a merely competent one—and AI makes them available systematically rather than leaving them to chance.
Winning new business in a competitive market requires more than quoting the lowest premium. Prospects want to know that their agents understand their industries, their risks and their specific situations. AI gives agents a significant edge in preparing for these conversations.
For example, an agent preparing to meet with a prospect in the manufacturing sector can use AI to analyze anonymized portfolio data and identify the most common coverage gaps among similar businesses. The agent walks into the meeting not just with a quote but with a risk assessment that demonstrates sector expertise. The conversation shifts from “Here is what I can offer …” to “Here is what I have learned about businesses like yours, and here is how I would protect you.” That consultative posture wins accounts.
AI also can help agents identify new business opportunities within their existing relationships. A cross-referencing analysis might reveal that a significant percentage of commercial clients do not carry employment practices liability insurance, or that many personal lines clients lack adequate flood coverage despite living in moderate-risk zones. These are not cold leads. These are warm conversations with clients who already trust the agency, presented with a recommendation that genuinely serves their interests.
There is a common misconception that AI is about replacing people. In the independent agency channel, the opposite is true. AI is most valuable when it handles the tasks that prevent talented people from doing their best work. Think about how much time agency staff spend on data entry, certificate issuance, routine policy checking and other
administrative tasks. These are necessary functions, but they are not the reason clients choose an independent agent over a direct writer or an online platform. Clients choose independent agents for the expertise, the advocacy and the relationship. Every hour an agent spends on administrative work is an hour not spent strengthening those bonds.
AI-driven automation can take on much of that operational burden. Automated data extraction, intelligent workflow routing, predictive analytics for workload management— these capabilities free up hours each week that agents can reinvest in client-facing activities. The agency does not need fewer people. It needs its people spending their time on higher-value work.
Agency principals should think about AI adoption not as a technology project but as a talent strategy. The question is not “How do I automate my agency?” The question is “How do I give my best people the tools they need to operate at the top of their capability?” AI is the answer to that question.
Adopting AI does not require a massive technology overhaul or a six-figure budget. Many agents can begin leveraging their agency’s AI capabilities through the management systems and platforms they already use. The key is to start with a clear objective and build from there.
A strong first step is to focus on renewal preparation. Identify the top 20% of accounts by revenue and use AI-powered analytics to generate prerenewal insight reports for each one. Train your producers and account managers to use those insights as conversation starters rather than relying on the standard renewal script. Measure the results—track retention rates, round-out success, and client satisfaction scores—and let the data guide your expansion.
The second priority should be cross-sell identification. AI can analyze your entire book of business and produce a prioritized list of clients with coverage gaps that represent both a protection need and a revenue opportunity. Assign those conversations to your team with specific talking points and track the conversion rate. Most agents who undertake this exercise are surprised by the volume of opportunity sitting within their existing client base.
Finally, invest in your team’s comfort with AI tools. The technology is only as effective as the people using it. Build training into your regular team meetings. Share success stories internally. Celebrate the wins that come from
AI-informed conversations. The goal is to make AI a natural part of your agency’s workflow, not an additional burden on already-busy professionals.
The insurance industry is evolving rapidly, and client expectations are evolving with it. Investment in digital capabilities across every distribution channel continues to accelerate. Innovation in InsurTech is raising the bar for streamlined buying experiences in small commercial and personal lines. Clients across every demographic increasingly expect the kind of personalized, data-informed service they receive from other industries.
AI is how independent agents meet that moment. Not by becoming technology companies, but by using technology to amplify the qualities that have always made independent agencies indispensable: deep expertise, genuine care for clients, and the ability to provide counsel that no algorithm can replicate on its own. The agents who embrace AI as a tool for human empowerment—rather than viewing it with suspicion or treating it as a passing trend—will be the ones that thrive in the years ahead.
The data your agency has accumulated over years of serving clients is not just a record of past transactions. It is a strategic asset. AI is the key that unlocks its full potential, transforming raw information into the kind of actionable intelligence that drives better conversations, stronger relationships and measurable business results. The opportunity is here. The technology is ready. The only question is whether you will seize it for your agency.
Gupta is chief product officer at Applied Systems Inc. He is responsible for the company’s product vision and product management teams. Formerly CPO at 4C Insights, a sophisticated Data & Analytics SaaS provider to the AdTech/MarTech industries, which was acquired by Mediaocean, the mission-critical platform for omnichannel advertising with more than $200 billion in annualized media spend managed through its software, connecting the ecosystem of agencies, brands, media, technology and data. As CPO of the combined companies, he spearheaded their product transformation to the cloud, adding new products fueled by data and intelligence infused in the core workflow. Previously, he led product organizations for several tech companies, including at Vubiquity, Mixpo and Microsoft.
Invest in Your CPIA Designation Today.
Register for all four CPIA sessions and receive a discount.
Tuesday, Sept. 1, 2026—How to Turn Your Technical Knowledge into Dollars ($75 member/$150 nonmember)
Thursday, Sept. 24, 2026 CPIA 1: Position for Success ($190 member/$255 nonmember)
Thursday, Oct. 15, 2026 CPIA 2: Implement for Success ($190 member/$255 nonmember)
Tuesday, Nov. 10, 2026—CPIA 3: Sustain Success ($190 member/$255 nonmember)
Register online at: www.pia.org/category/education
Carolyn Smith, APR, CRA, TRA Chief training officer, Beyond Insurance
Let’s start with a hard truth: Clients are far less patient than they used to be. In fact, according to the Zendesk CX Trends 2026 report, 85% of customers will walk away after just one unresolved issue. One dropped ball. One unanswered email. One moment when they feel like no one is really listening.
At the same time, those same customers say they’re overwhelmed with communication. Nearly 70% say they’re receiving so many messages that they tune most of them out—even when the information might matter.
So, independent agents are facing a strange paradox midyear. Clients want:
• More attention, but fewer interruptions.
• More responsiveness, but less noise.
• More personalization, but faster service.
And, all of this is happening while clients are navigating a world that feels increasingly uncertain with economic pressure, rising premiums, global instability and constant change.
People feel it. They’re tired of it. And when they pick up the phone to call their insurance adviser, they’re not just looking for a policy explanation. They’re looking for someone steady. Someone who can help them make sense of what matters.
Customer expectations haven’t simply increased. They’ve reset. Clients expect immediacy, accuracy and service that moves at the pace of their concerns. They want agents to anticipate needs, remove friction, and use data and context to smooth the experience before problems appear.
Yet, Zendesk research finds that 74% of customers are frustrated when they must repeat themselves, and 81% expect conversations to pick up exactly where they left off.
For clients navigating claims, renewals or complex risks, starting over each time isn’t just annoying—it breaks trust. In many ways, this moment is quietly returning the insurance profession to its roots. The agents who are standing out today are not necessarily the loudest or the most technologically flashy. They’re the ones who communicate clearly, anticipate problems, and show up with calm authority when clients feel overwhelmed.
Here are some case studies that demonstrate what this looks like in practice.
Staying close to clients when the ground keeps moving underneath them
Earlier this year, Kevin McKiernan, CIC, CPIA, president of Abercrombie, Burns, McKiernan & Co., and immediate past president of PIACT, began noticing something subtle in his conversations with clients.
The expectations weren’t louder, but they were sharper. Clients wanted answers faster. They wanted reassurance sooner. And more than anything, they wanted to feel that their agent was present—not just available.
For ABMCK, that realization carried weight. The agency has been providing service to clients since 1952, and its reputation was built on something that never really goes out of style: strong relationships, thoughtful advice, and a deep commitment to protecting people rather than simply placing policies.
Even as the industry races toward automation and artificial intelligence, ABMCK has chosen a slightly different path. Technology matters, but relationships matter more.
McKiernan and his teams have leaned into a concierge-level client experience—one in which clients feel known, understood and guided through uncertainty, rather than left to navigate it alone.
He says the message from clients is clear. They want an agent who communicates like a partner, not a vendor. That means consistent outreach, clear explanations and proactive conversations—especially when renewals approach or pricing pressures begin to surface.
To support this approach, the firm recently implemented a new client experience platform that is integrated with its agency management system and email tools. Routine service requests now can be handled instantly, which frees the team to spend more time doing what actually builds relationships: talking with clients.
However, technology is just one piece of the strategy. What defines ABMCK’s model is how deliberately the agency shows up as a strategic risk adviser.
Teams design tailored programs and guide clients through a proprietary risk navigator framework, which helps organizations identify, understand, implement and continuously monitor the risks surrounding their operations.
For ABMCK’s nonprofit clients, this kind of guidance has become especially valuable. Events happening halfway across the world can suddenly affect supply chains, infrastructure stability, cyber security exposure and regulatory oversight.
McKiernan explained that ABMCK’s structured planning process helps nonprofit clients address security threats, reputational risk, operational disruption, and compliance issues before they escalate.
“Telling our story and explaining our risk management process is how we reduce anxiety, anchor relationships, and help clients understand the value of our guidance,” McKiernan explained.
The result is something every client quietly wants: confidence.
Founded in 1917 and now operating under fifth-generation leadership, PIANJ member Nottingham Insurance has watched the insurance industry reinvent itself repeatedly. Markets harden and soften. Technology evolves. Risks appear that no one saw coming.
Nottingham has long been recognized as a Best Practices Agency, built on disciplined operations and a deeply people-focused culture. Its competitive advantage is surprisingly simple. When a client calls, a person answers. When business owners have questions, they reach an adviser who already understands their operations. And when a claim disrupts a client’s world, an experienced team steps in to guide the situation.
It’s service that feels personal rather than procedural. However, even for an agency with a century of history, expectations have changed. Business owners want faster answers, earlier insights and guidance before problems appear. Responsiveness has become one of the clearest measures of value.
Managing Partner Jack Blair said, “People still want to talk to a person, and we still want to talk to our clients and bring them more value more quickly. If you are not using technology on both sides of that equation, then your responsiveness will fall behind.”
With that reality in mind, Nottingham is redesigning its internal service model. The goal is straightforward: empower licensed professionals to focus on the work that creates value and deepens the client relationship.
Administrative friction is stripped away. Repetitive processing is automated. Advisers gain immediate access to the information they need, allowing them to spend less time navigating systems and more time helping clients understand exposures and evaluate options.
The results are noticeable. Responsiveness stops being a struggle. Instead, it becomes a competitive advantage. Technology decisions also are intentional. Instead of adding tools that slow teams down, the agency is replacing outdated processes with systems designed for today’s service environment.
One key addition was a workflow platform that automates document handling, routing and communication. By reducing manual tasks and eliminating duplicate data entry, the platform helps the team stay focused where it matters most—on the client.
Blair said, “We have intentionally broadened our network of insurance and tech professionals to be as proactively involved in helping our clients manage their risk as possible.”
That approach transforms the agency from a transaction provider into something more valuable: a strategic business partner helping clients navigate rising costs and complex exposures.
While much of the industry entered the year bracing for disruption, Chuck Gohn, president of Associates of Glens Falls—a PIANY member—saw something else entirely: a moment where discipline would outperform drama. A year in which the agency staff who had done the hard work early—set expectations, educated clients and communicated consistently—would finally see the payoff.
“The market isn’t behaving very differently from what we anticipated or communicated to clients,” Gohn said.
“We told them that 2026 would likely be a year of softening, and that’s largely been true. What matters most is that none of this has been a surprise to our clients.”
Gohn understands that surprise creates anxiety, while clarity creates trust. In a world in which clients are already carrying more uncertainty than they can comfortably hold, trust is everything.
AOGF has built that trust not through complexity, but through consistency and years of telling the truth about market cycles, even when the message wasn’t easy to hear—through conversations that focused less on transactions and more on understanding, and through a discipline of showing up before clients had to ask.
However, there’s another layer to what’s happening in 2026, one that Gohn is watching closely. Experience is thinning. Underwriting teams are turning over, and those individuals with institutional knowledge are
retiring. In many cases, it’s being replaced by process, automation, and systems that can move data but not always judgment. Decisions take longer. Nuance gets lost. Conversations become more transactional. When that happens, the AOGF’s advisory role becomes even more important.
The agency’s response has been intentional. The team has doubled down on fundamentals that don’t expire: active listening, disciplined communication and visible advocacy. Because when clients can see the work, they can feel the value.
Of course, technology plays a role, but AOGF uses AI where it makes sense: with policy checking and contract review, or with eliminating bottlenecks that slow service teams down. It removes friction and creates space, but it doesn’t replace judgment, relationships or trust.
In a year of uncertainty, AOGF is showing up early, explaining what’s coming, and documenting every conversation so nothing gets lost.
As Gohn puts it, “Agencies that win in 2026 will be the ones that get ahead of renewals, explain what’s coming, and show clients that negotiation is happening on their behalf.”
Strip away the noise—platforms, dashboards, buzzwords— and what’s left is surprisingly human. Clients don’t want more information—they want understanding, better communication and confidence in the decisions they’re making.
The agents who win in 2026 won’t be the ones doing more. They’ll be the ones doing the right things earlier, more intentionally and more consistently. How can you make that happen?
No. 1: Get ahead of the renewal by months, not weeks. The renewal should never be the first real conversation of the year. Strong agencies start 90-120 days out, not with pricing, but with perspective. What’s changing? What pressures are emerging? What should clients be thinking about now? When clients feel included early, they react far less to outcomes later.
No. 2: Eliminate “start over” conversations. Nothing erodes trust faster than making clients repeat themselves. Every interaction should pick up where the last one ended. That requires disciplined documentation—not just notes, but context. Who is this client? What matters to the person? What’s changed since the last conversation?
No. 3: Prioritize relevance over volume. Agents at top-tier agencies avoid mass communication in favor of purposeful,
substantive messaging. Every interaction should either answer clients’ existing questions or proactively address a need they haven’t yet voiced.
No. 4: Make your work visible. Clients don’t see negotiations, market resistance or advocacy happening behind the scenes. Show them. Share strategy, obstacles and wins transparently so they understand the value you are delivering.
No. 5: Use technology to create time, not distance. Automate what slows your team down. Remove duplication and friction. Then, reinvest that time where it matters most: listening, advising and thinking ahead with clients.
No. 6: Set expectations early and repeat them. The most trusted advisers prepare clients for reality. Explain market cycles before they hit pricing. Talk about uncertainty before it shows up. Give clients language to understand what’s coming.
No. 7: Lead with calm, not urgency. Clients are overwhelmed already. They don’t need urgency—they need clarity. So pause, translate and communicate in a way that steadies the situation instead of amplifying anxiety.
No. 8: Tell your story clearly. If you don’t define your value, clients will—and they’ll define it too narrowly. Explain how you think, plan and advocate. Confidence builds over time through understanding.
The agents who win show up early, document so nothing gets lost, use AI to remove friction—not relationships—and communicate with intention, not urgency. Clients aren’t measuring you by systems or tools. They’re measuring you by how confident they feel after talking to you.
Presence is the advantage. Disciplined. Proactive. Unmistakably human. And in uncertain times, that kind of presence doesn’t just win business—it keeps it.
Smith is chief training officer at Beyond Insurance, where she leads the strategy, design and delivery of high-impact training programs, such as the Trusted Risk Advisor® certification, for the insurance and risk management community. For more information, PIA Northeast members can log on to www.pia.org/EDU/ traprogram. Her expertise spans producer development, client experience, leadership, communication and advanced consultative selling, with a focus on high-accountability, skill-building programs that address the industry’s most pressing challenges. Smith began her career as a journalist for the Santa Monica News, she has served as an instructor in the extracurricular marketing certificate program at the University of Texas-Austin, and she previously worked in international branding and marketing.
of clients would drop their broker over poor communication.
With handbook reviews, regulatory deadlines, and new effective dates hitting this summer, the brokers who show up now earn the trust that holds at renewal. The ones who go quiet? They're the ones getting replaced. See what your clients actually expect — and where your opportunity is.
Utica National Insurance Group E&O Risk Management
Video proposals are becoming a popular way for insurance agents to explain coverage options, personalize the sales process, and stand out in a competitive market. Agents are using short, recorded videos to walk prospects through quotes, renewal options and coverage highlights—often replacing or supplementing traditional in-person meetings and written proposals.
While video proposals can improve engagement and efficiency, they also introduce new professional liability considerations. Once recorded, a video proposal is no longer a casual conversation—it becomes a permanent sales communication that may be replayed, shared and scrutinized later.
What a video proposal is
From a risk perspective, a video proposal is recorded sales material. Even when personalized, recorded explanations of coverage options function as formal sales communications. This means statements made on video can later be evaluated the same way as written proposals or other marketing materials.
Before you use video proposals in your agency, there are some standards that should be used to avoid possible errors-and-omissions concerns later:
Apply the same standards to video proposals as written ones. The conversational nature of video can create a false sense of informality. Agents may unintentionally oversimplify coverage or use language that sounds definitive. To reduce E&O exposures, agents should avoid absolute phrases, guarantees or promises, and focus on describing options rather than outcomes.
Never let the video replace the written proposal—and standardize the disclaimer. Video proposals should supplement—not replace—written proposals and policy documents. One of the most common contributors to E&O claims is reliance on verbal explanations that are not clearly tied back to the written record. Disclaimers help reinforce that
distinction and manage expectations—particularly when used consistently across all client communications.
Rather than relying on each agent to verbally state a disclaimer at the start of every recording, you should consider embedding standardized disclaimer language directly into the video itself. Using a visual disclaimer creates consistency, reduces the risk of omissions or paraphrasing, and it demonstrates a systematic agency practice. All disclaimers must be clear, conspicuous and reasonably noticeable.
Best practice guidance includes:
• Use a single, standardized disclaimer approved by compliance and legal.
• Display the disclaimer as a persistent footer throughout the video or, at minimum, during the opening segment for long enough to be read and in legible font size and contrast.
• Do not rely solely on verbal statements made during the video, include written ones as well.
• Keep the language broad, neutral and nontechnical.
Sample video disclaimer language: This video is provided for general informational purposes only. Coverage is subject to the terms, conditions, limitations and exclusions of the written proposal and issued policy. This video does not amend, extend or guarantee coverage.
Disclaimers do not prevent E&O claims on their own, but consistent and visible use helps demonstrate reasonable care, reinforces documentation discipline and reduces ambiguity about what the video is—and is not—intended to do.
Be cautious when explaining coverage gaps and exclusions. Video proposals are effective for highlighting value, but they can increase risk when used to interpret exclusions or limitations. Agents should use video to flag that exclusions exist and encourage follow up discussions for complex exposures, rather than attempting to resolve nuanced coverage questions on camera.
Assume every video will be replayed out of context. Unlike live meetings, video proposals can be replayed, shared internally, and viewed long after they are recorded. Agents should record with the assumption that the video may later be reviewed without additional explanation or context.
Store and retain video proposals like other sales records. Video proposals should be stored alongside written proposals, emails and client communications. Applying the same retention standards used for other sales documentation helps support consistent recordkeeping and E&O defense.
Train producers on risk awareness— not just technology. Most training on video proposals focuses on delivery and presentation. Agents also should train producers on risk awareness, emphasizing what not to say on video, how to rely on written documentation and why consistency matters.
Agent checklist—before you hit record:
Does the video have a standardized disclaimer visibly displayed?
Does the verbiage avoid guarantees or absolute statements?
Does the video align with the written proposal?
Does the video clearly reference the written proposal and policy?
Does the video avoid oversimplifying exclusions or coverage gaps?
Is the tone professional and clear?
Is the video stored in a retrievable system and subject to retention guidelines?
If the video is viewed years later, would there be any cause for concern?
Effective risk management doesn’t resist new tools—it puts guardrails around them. Video proposals can improve client understanding and
engagement, but only when they are supported by clear documentation, visible disclaimers and consistent agency practices. Independent agents who treat video proposals as structured sales communications—not informal conversations—are better-positioned to defend their process if a dispute arises. This information and any attachments or links are provided solely as an insurance risk management tool. They are derived from information believed to be accurate. Utica Mutual Insurance Company and the other member insurance companies of the Utica National Insurance Group (“Utica National”) are not providing legal advice or any other professional services. Utica National shall have no liability to any person or entity with respect to any loss or damages alleged to have been caused, directly or indirectly, by the use of the information provided. You are encouraged to consult an attorney or other professional for advice on these issues.
PIA technical staff
Have a question? Ask PIA at resourcecenter@pia.org.
Q. One of my carriers offered me the opportunity to participate in a marketing support program, where I can purchase $50 and $150 movie theater passes for $25 and $75, respectively. I am encouraged to offer these passes to my clients for several reasons including: policy purchase incentives and referral gifts. Is this legal? What are my options? What can I do with them?
A. PIA applauds carriers for supporting their agents with marketing initiatives, but the association cautions agents that they should acquaint themselves with the relevant laws governing their ability to offer valuable consideration to current or prospective clients.
To answer the first part of your question: yes, it is legal for an insurer to offer discounted items of merchandise to an agent for the agent to use in a marketing campaign. However, the agent should be aware that in New Jersey, N.J.A.C. 11:17A-2.3 states that it is prohibited to “offer, make or give or permit to be offered, made or given, to any person directly or indirectly, an inducement to purchase insurance other than that plainly expressed in the insurance contract.” The law states that this prohibition applies only to any favor, advantage, object, valuable consideration or anything other than money that has a cost of or a redeemable value greater than $100. Thus, you could offer the $50 cards to your existing or prospective clients with no restriction. However, the $150 cards can pose problems. Even though you paid less than $100 for the passes, their redeemable value is $150—thus they are subject to the restrictions in the law. Even though they cannot be offered as freely, you still have many options.
First, you may offer them in exchange for referrals, so long as the referral is not a disguised rebate—namely one offered to an existing or prospective client in a manner calculated to skirt the restrictions on rebating.
Second, a producer can offer them to members of the general public, so long as the offer is open to all (not just existing or prospective clients), and the offer is not conditioned on the recipient getting a quote, sitting down for a coverage review, or similar interactions with the agency intended to lead to the purchase of insurance.—Lachut
Q. Is it permissible for a producer or an insurer to advertise that it provides “free rate quotes” for automobile insurance?
A. Yes. The New Jersey Insurance Law and regulations do not prevent this type of advertising, as long as fees (e.g., motor vehicle abstract fees) are not charged.—Lachut
Q. Our agency wants to run a raffle to increase our visibility. We plan to reach out to our existing homeowners insurance customers, and give away a cruise vacation package worth $1,000 if they allow us to quote their auto insurance. Is this permissible in New Jersey? What about the other states in the PIA Northeast footprint?
A. PIA analyzed this proposed raffle with guidance from the New Jersey Department of Banking and Insurance and concluded that the planned raffle is not allowable as it is currently designed.
Generally speaking, New Jersey law prohibits a producer from offering any valuable consideration or item worth more than $100 to an insured, as it can be construed as an illegal premium rebate or inducement to insurance. However, a producer or agency may hold a raffle for an item valued above $100, so long as the following conditions are met:
• the raffle must be truly open and advertised to the public, such as by being advertised in a newspaper of general circulation—it cannot be promoted or advertised solely to existing clients; and
• the entry into the raffle must not be contingent on the sale, solicitation or negotiation of insurance.
PIA has communicated with the insurance departments of the various states listed below and it has confirmed that the law’s operation regarding sale, solicitation or negotiation extends to and embodies the quotation process. This means that entry into the raffle cannot be contingent on submitting information to receive a quote.
Connecticut, New Hampshire, New York and Vermont have similar laws regarding the regulation of raffles held by insurance agencies. For more information, see the following:
Connecticut. PIA Northeast members can access Connecticut’s rebating and referral fee requirements (QS06056) in the PIA QuickSource library;
New Hampshire. PIA Northeast members can access New Hampshire rebating requirements (QS28009) in the PIA QuickSource library;
New York. PIA Northeast members can access Promotional program to get referrals (Ask PIA 310241) in the Ask PIA library; and
Vermont. Vermont Statute 8 V.S.A. Section 4724.—Lachut
Q. Do I need permission to send marketing text messages to prospective clients?
A. According to the Federal Communications Commission Telephone Consumer Protection Act, to send marketing text messages to nonclients, you must get prior, written consent. This could be as simple as asking interested parties to text a number to receive the text messages, or asking interested parties to input information into a website form to indicate that they wish to receive marketing text messages from you. You also must offer an opt-out option so people can stop receiving your messages if they no longer want to receive them.
Marketing messages to clients can be sent without prior written consent because a business relationship exists. However, you must offer clients the ability to opt out of receiving the messages if they choose to do so.
For a sample electronic consent form, PIA Northeast members can access Sample electronic delivery consent form (QS90802) in the PIA QuickSource library. You can learn more about the FCC Telephone Consumer Protection Act rules at tinyurl.com/muts36hk.—Ritchie
Q. We’d like an interpretation of Coverage B–Personal and Advertising Injury Liability of the ISO commercial general liability coverage form. We had a situation in which a woman was told to leave the grounds of a public town green. We want to know if our client’s policy should respond to her claim of wrongful eviction. Our client was sponsoring an event on the green, and the client asked security to remove the woman because of her disruptive behavior. The carrier is balking because it was a public space.
A. Under the terms of the policy, “‘personal and advertising injury’ means injury, including consequential ‘bodily injury,’ arising out of one or more of the following offenses: c. The wrongful eviction from, wrongful entry into, or invasion of the right of private occupancy of a room, dwelling or premises that a person occupies, committed by or on behalf of its owner, landlord or lessor.”
There is no requirement that the premises be privately owned for wrongful eviction to apply, which means that coverage should apply under these circumstances.—Lachut
Join your Small Business Team for an exclusive session and learn more about product, appetite, and how we can help your agency grow by getting a direct appointment with The Hartford.
• Pick up strategies to grow your agency’s small business book.
• Take the opportunity to network with your local sales team.
• Discover our Small Business definition and appetite—where we win and how to qualify opportunities.
• How to navigate our Electronic Business Center (EBC) with ICON quoting and issuing capabilities.
• We have two convenient options available - morning or afternoon.
Agency principals, producers and account managers who are currently not appointed with The Hartford and interested in our Small Business offering.
Event Details
July 15, 2026 at the Courtyard Edison Woodbridge 3105 Woodbridge Avenue, Edison, NJ 08837
Two sessions available: 10am -12pm or 2pm-4pm
RSVP to Sheree Williams at Sheree.Williams@thehartford.com
OFFICERS
President
Roger C. Butler, CIC Barclay Group Riverton, NJ
President-elect
Aaron Levine, CIC
LG Insurance Agency
Long Branch, NJ
Vice President
Lisa Hamm, CIC Clyde Paul Agency Summit, NJ
Vice President
Michael Beckerman, CPCU Acrisure of New Jersey Iselin, NJ
Secretary/Treasurer
Christopher J. Powell Hardenbergh Insurance Group Marlton, NJ
Immediate Past President
Andrew Harris Jr., CIC, AAI, CISR Liberty Insurance Associates Inc. Millstone Township, NJ
PIA NATIONAL DIRECTOR
Paul Monacelli, CIC, CPIA Veterans Insurance Agency Inc. Randolph, NJ
DIRECTORS
Lydia Bashwiner, Esq. Otterstedt Insurance Agency Inc. Englewood Cliffs, NJ
Yossi Bolanos
Yossi United Insurance Agency LLC Clifton, NJ
Kenneth Bull, CIC, AU Ironpeak Hillsborough, NJ
Walter Conroy, CISR Liberty Insurance Associates Inc. Millstone Township, NJ
Alyssa Delaney KRH Consulting Hazlet, NJ
Maria N. Escalona, CPIA Jimcor Agencies Inc. Montvale, NJ
Becky Mateus, CIC, CPIA, ANFI, CFM
World Insurance Associates LLC Iselin, NJ 08830
Josh McManigal LG Insurance Agency Long Branch, NJ
William J. McMahon III, CIC, CWCA
McMahon Agency Inc. Ocean City, NJ
Shanna Muscavage Ironpeak Lancaster, PA
Logan True, CRIS The True Agency LLC Mendham, NJ
Casey Yarger, CIC, CRM Acrisure of New Jersey Fairfield, NJ
DIRECTOR/YIP LIAISON
Tim Latimer
JS Braddock Agency Medford, NJ
ACTIVE
PAST PRESIDENTS
Anthony F. Bavaro, CIC, CRM Liberty Insurance Associates. Inc. Millstone Township, NJ
Louis Beckerman, CIC, CPCU Acrisure of New Jersey Iselin, NJ
Bruce Blum, CPIA, TRA Blum & Walsh Group Inc. c/o TE Freuler Agency Inc. Somerset, NJ
Rip Bush, CPIA Keer & Heyer Inc. Point Pleasant Beach, NJ
Charles J. Caruso, CIC, CPIA AssuredPartners Jamison Cranford, NJ
Donna M. Cunningham, CPIA ADP Partners Insurance Agency Inc. Florham Park, NJ
Michael DeStasio Jr., TRIP AssuredPartners of NJ Cranford, NJ
Donald F. LaPenna Jr. DFL Consulting Group Naples, FL
John A. Latimer, Esq. Barclay Group Riverton, NJ
Connie Mahoney Mark Anthony Associates Mountainside, NJ
Steven C. Radespiel Insurance Center of New Jersey Hillsdale, NJ
Keith A. Savino, CPIA Broadfield Group Trucordia Warwick, NY
William R. Vowteras Fraser Brothers Group LLC Edison, NJ
11 AFCO Direct
BC Applied Underwriters
8 Venbrook Group
12 Foremost
37 The Hartford
2 NJAN/SIAA
15 JENCAP
7 Omaha National
22 PIA Education
30 PIA E&O Insurance
34 PIA Members’ Choice
16 PIA NumberONE Comp
32 PIWA Spring Reception
17 Plymouth Rock Assurance
23 Preferred Mutual
24 Selective Insurance
33 SIAA
29 Zywave
For more information about an advertiser, email ads@pia.org, or call (800) 424-4244