Photo by Charlie Day, used under the Creative Commons License
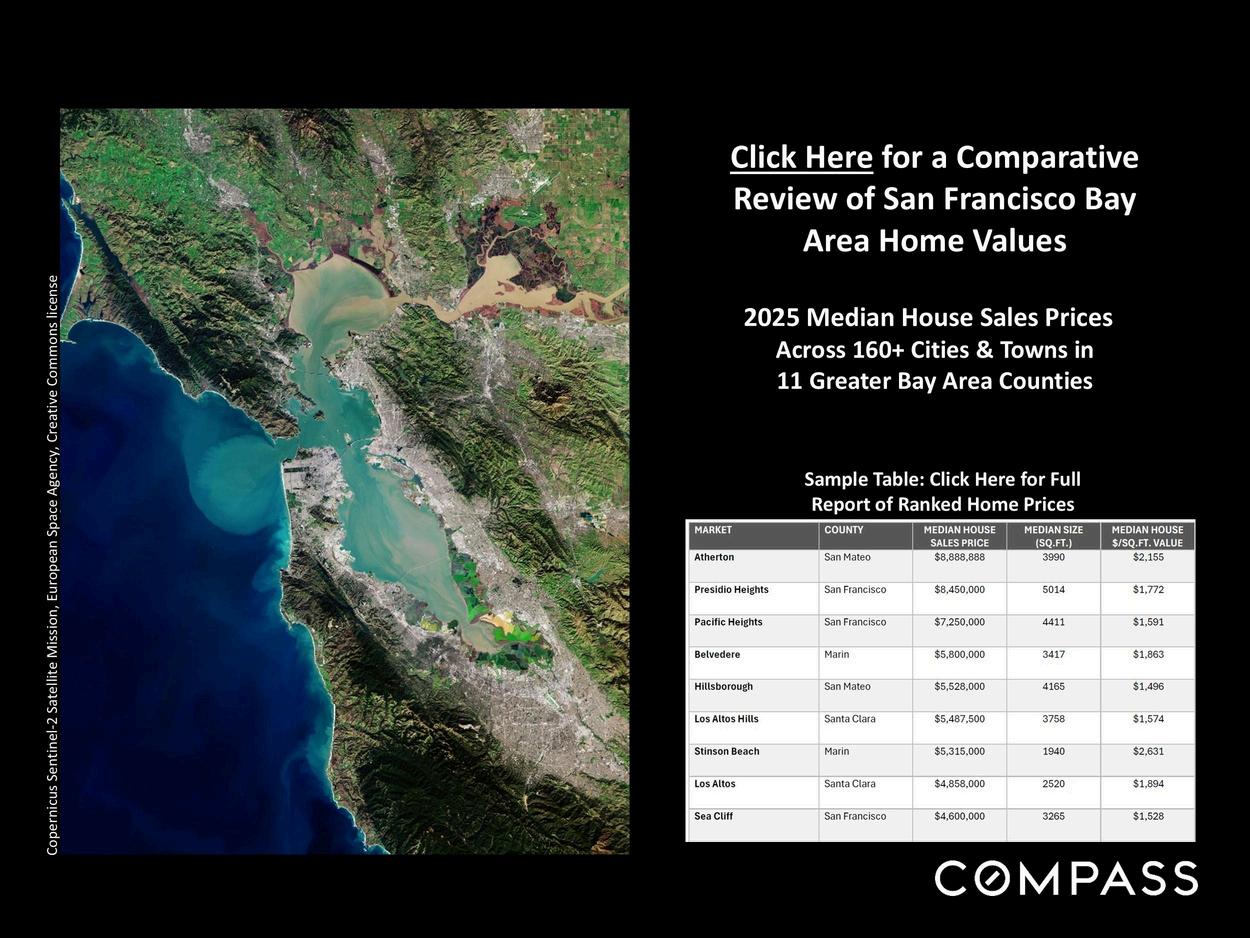
In 2025, Bay Area real estate markets started the year with strong buyer demand but had much of the wind taken out of their sails by the political/economic uncertainty that soared in early spring. Then, in mid-late summer, stock markets rebounded to hit new highs, and interest rates began a sustained decline, initiating a shift in the psychology of buyers and sellers that is still developing. Still, national consumer confidence readings showed a significant split between the outlooks of more and less affluent households, and that affected market segments in different ways. Generally speaking, more expensive markets, powered by rising demand from affluent buyers seeing substantial increases in household wealth from stock market gains, performed better than more affordable markets, which tended to be more impacted by concerns regarding inflation, affordability and employment. Santa Cruz County benefited from its proximity to the AI boom in Silicon Valley. Most of the analyses in this report focus on annual statistics, which, of course, summarize a year of changing economic conditions. Overall, the 2025 real estate market was somewhat cooler than in 2024, but the median house price was essentially unchanged. Fueled by more listings, the number of sales rose 8% year over year, but luxury home sales jumped 45%. As 2026 begins, interest rates are near multi-year lows and stock markets are at or close to all-time peaks. Early in the new year, it is common for buyers, re-energized to move forward with major life decisions, to jump back into the market faster than sellers list their homes for sale. This disparity of increasing demand versus a low supply of new listings usually runs through the spring, typically making these months the most heated selling season of the year. Last year, this was upended by the tariff shock. Barring new, unexpected economic alarms, we expect this spring to be much stronger. NOTE: This report includes an image link to our comprehensive review of city and town home values and market dynamics.
Report createdingood faithusing data fromsources deemedreliable but may containerrorsand subject to revision. Last period figures are preliminary estimates based on data available early in the following month. All numbers approximate and may change with late-reported activity.
Mortgage
Interest Rates in 2025 – 2026 YTD
30-YearConformingFixed-RateLoans,WeeklyAverageReadings* price, borrower and lender.
Per Freddie Mac (FHLMC), on January 8, 2026, the weekly average, 30-year, conforming-loaninterest rate was 6.16%, very close to its 2-year low.
*Freddie Mac (FHLMC), 30-Year Fixed Rate Mortgage Weekly Average: https://www.freddiemac.com/pmms. Data from sources deemed reliable. Different sources of mortgage data sometimes vary in their determinations of daily and weekly rates. Data from sources deemed reliable but may contain errors. All numbers approximate.
Financial
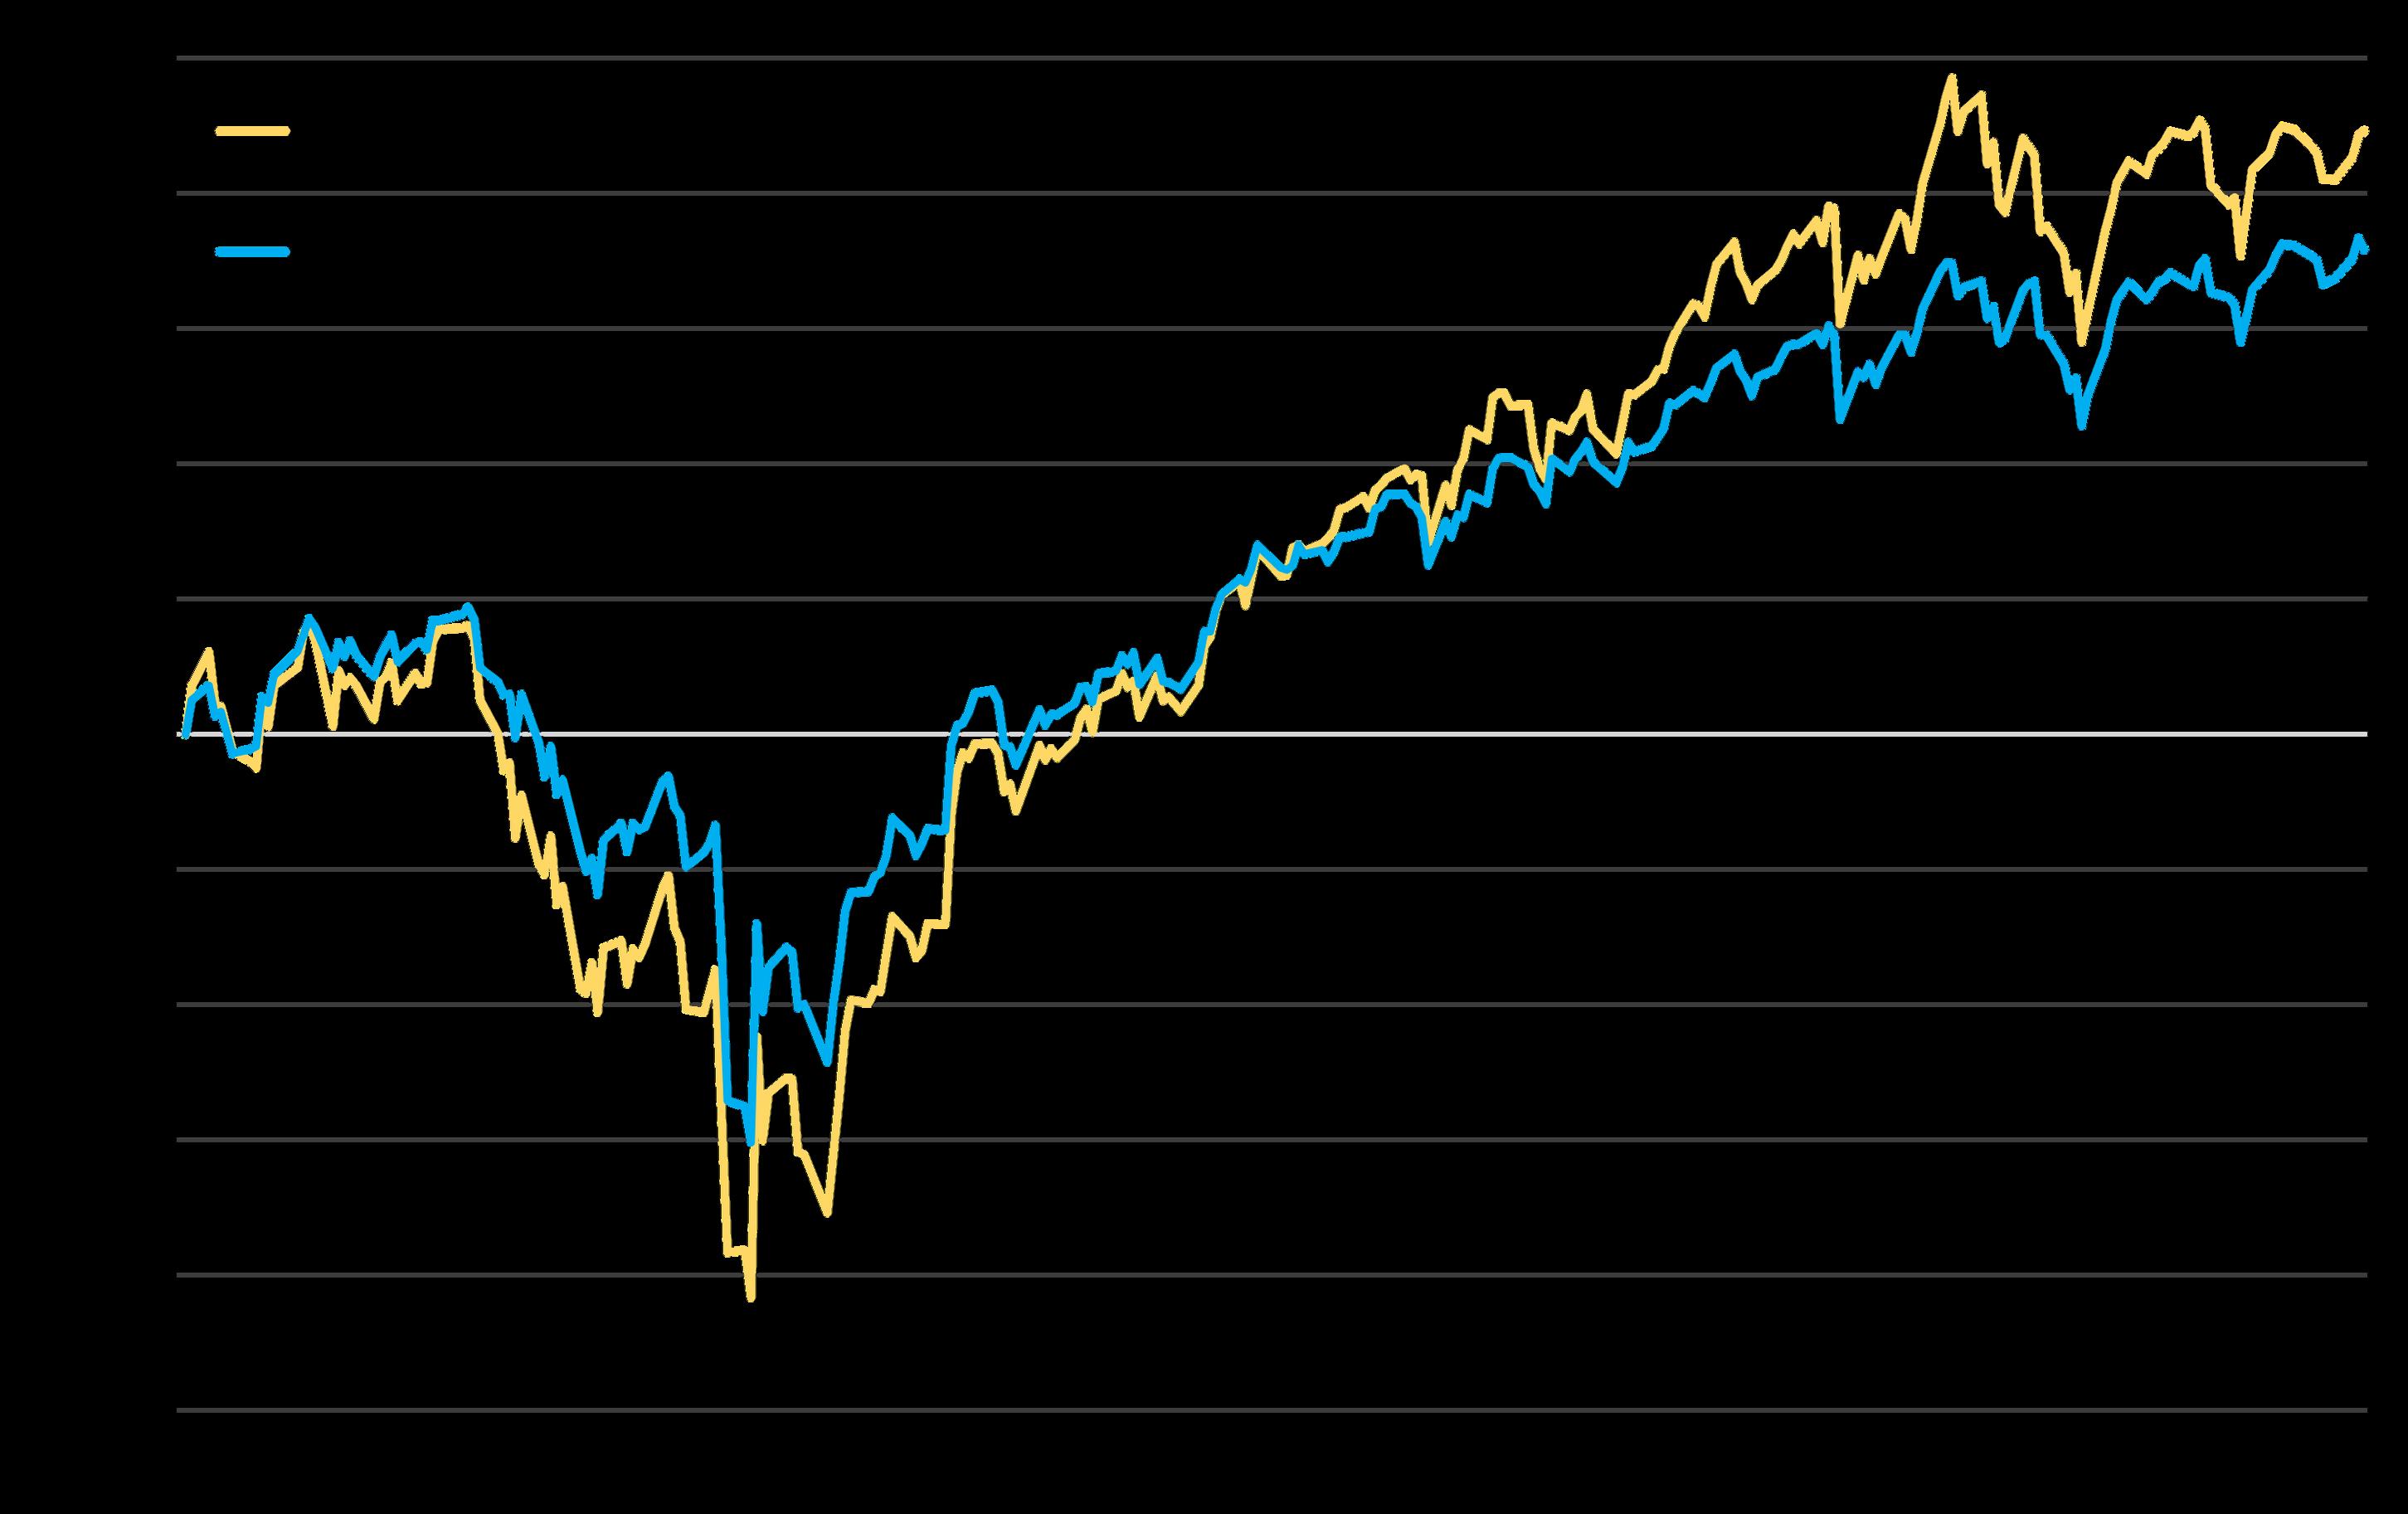
Markets, 2025 – 2026 YTD
Percentage Increases in S&P 500 & Nasdaq since 1/2/25
Nasdaq Index: % Change since 01/25
S&P 500 Index: % Change since 01/25
Large changes in stock markets can dramatically affect household wealth, consumer confidence and housing markets, especially more affluent markets.
Tariff shock
►
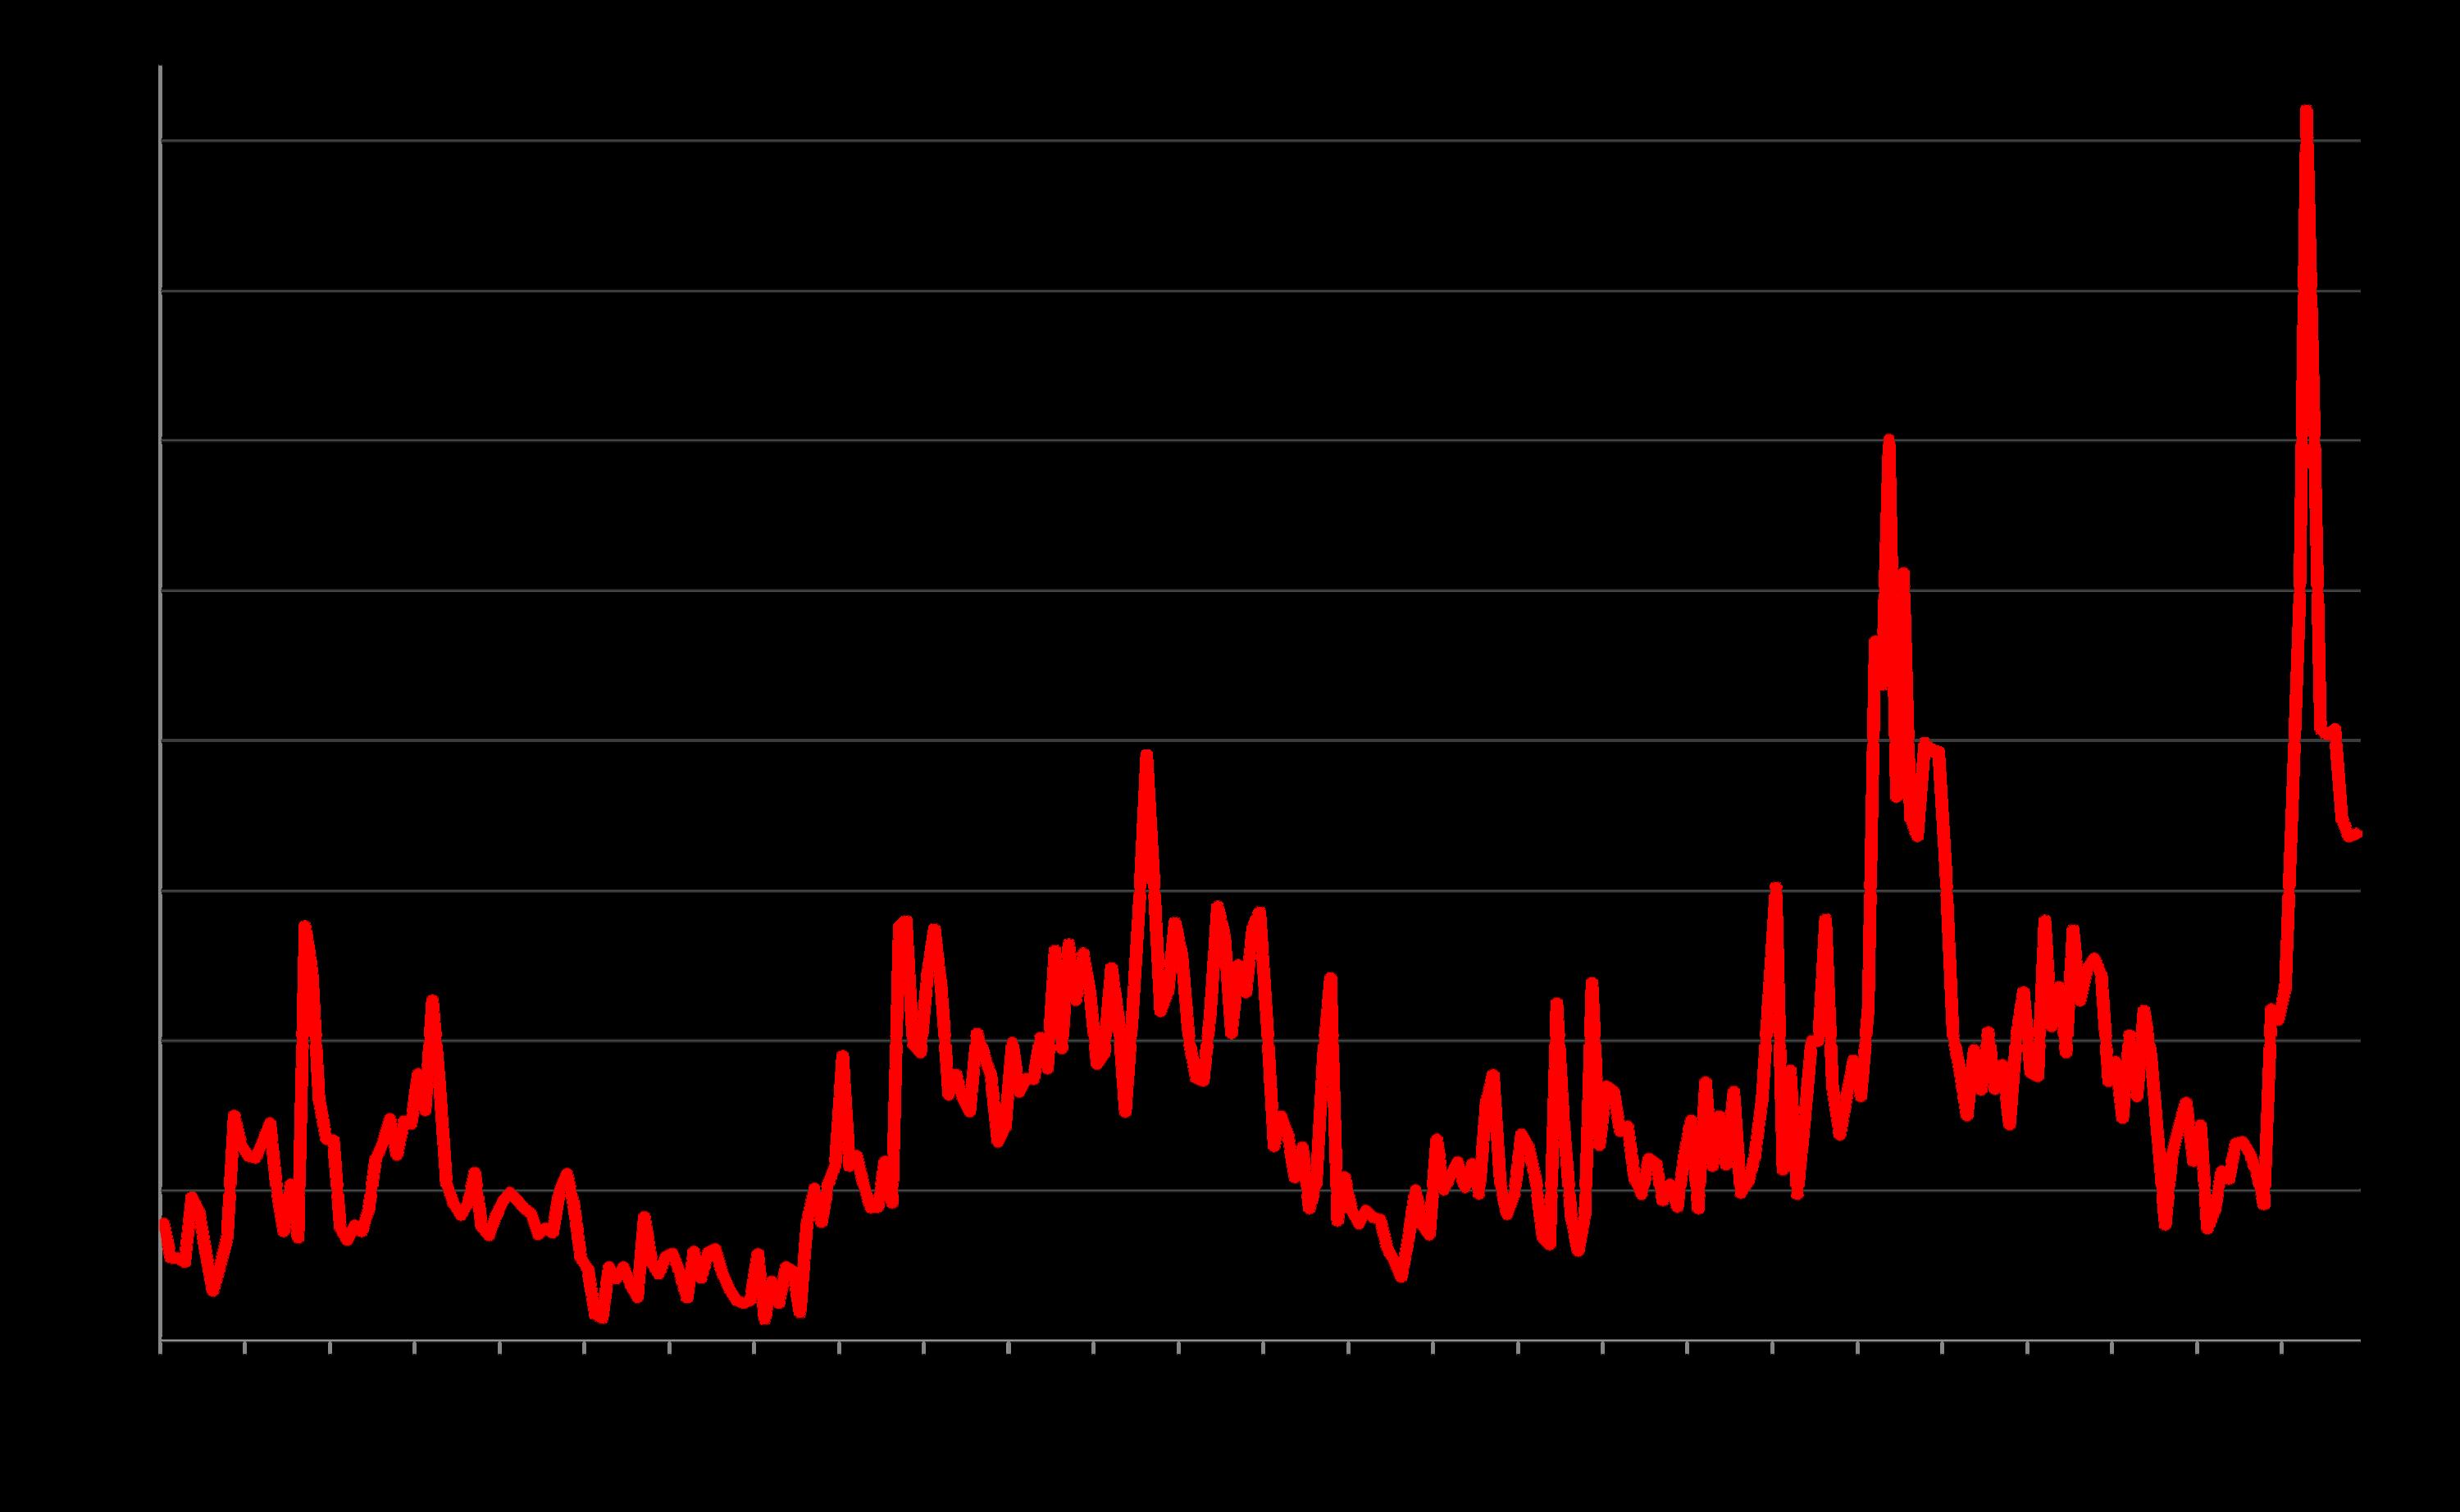
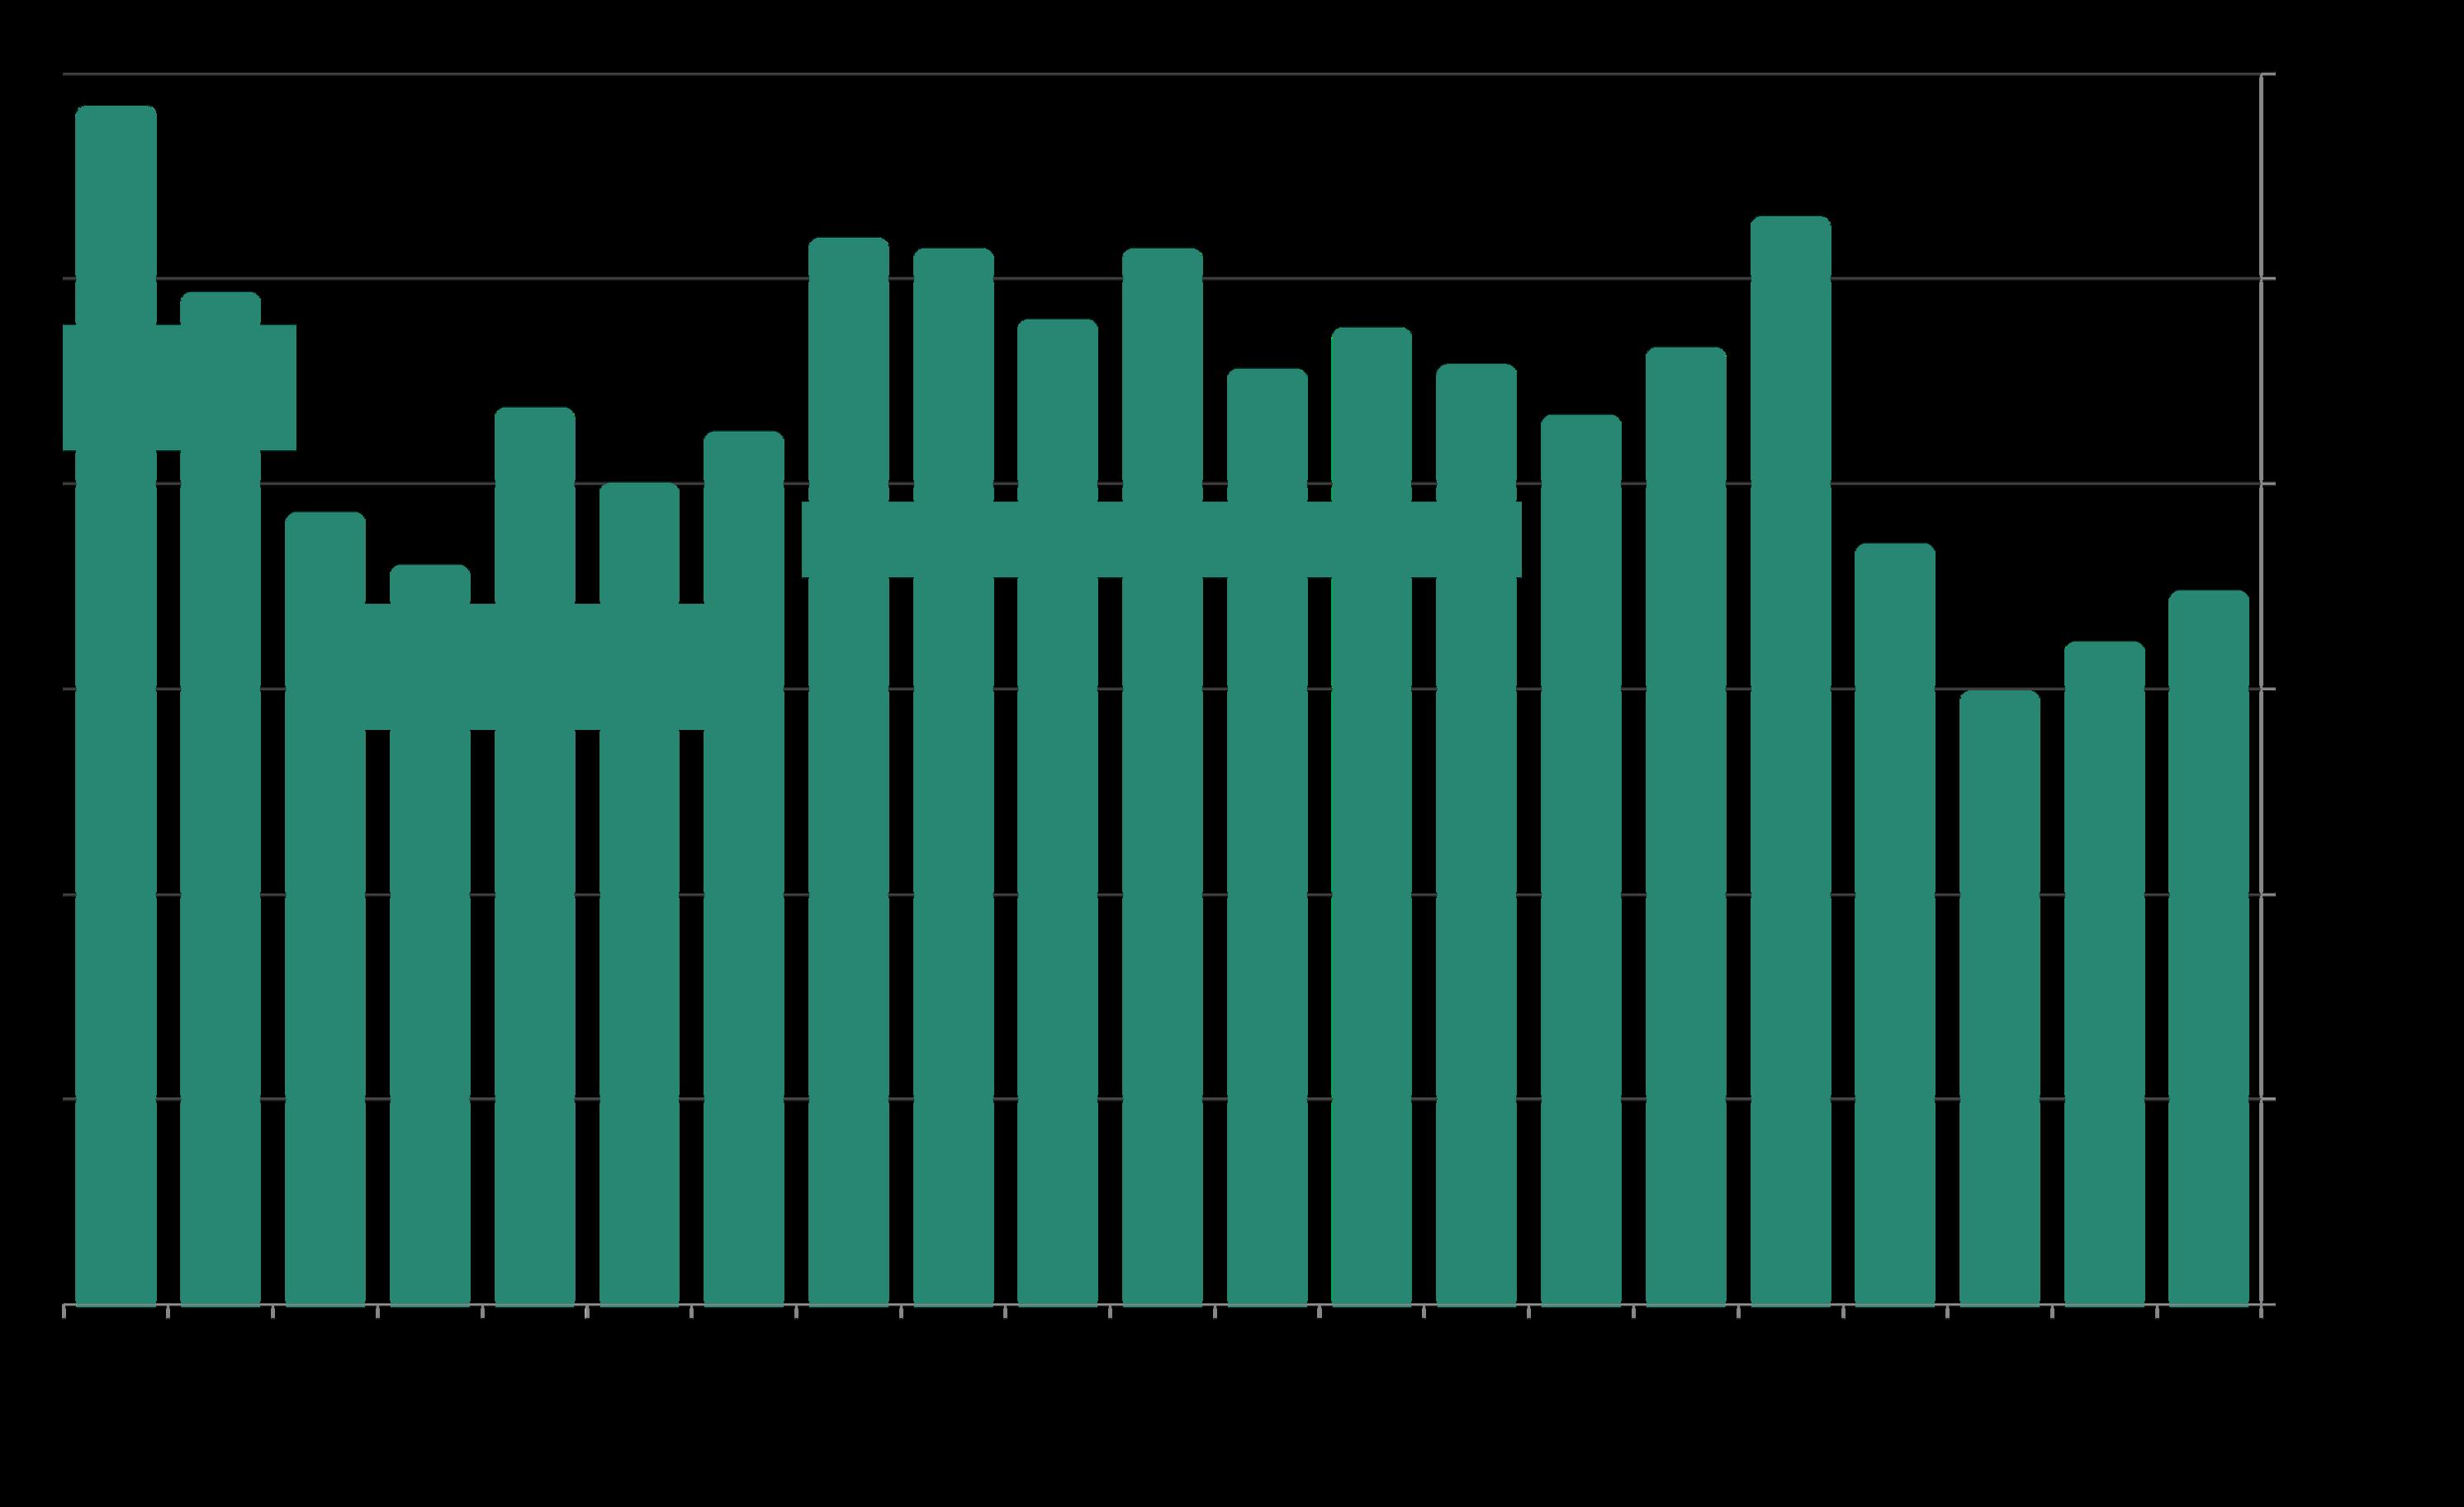
Economic Policy Uncertainty Index*
By Month since January 2000
The Economic Policy Uncertainty Index reading in November 2025 ticked up slightly. It has plummeted since April’s tariff shock, though remains elevated by long-term norms.
The Economic Uncertainty Index is constructed from data analysis of 1) an index of search results from 10 large newspapers for terms related to economic and policy uncertainty, 2) reports by the Congressional Budget Office, and 3) the Federal Reserve Bank of Philadelphia's Survey of Professional Forecasters.*
*Source: 'Measuring Economic Policy Uncertainty' by Scott Baker, Nicholas Bloom and Steven J. Davis, 3component index, www.PolicyUncertainty.com, https://www.policyuncertainty.com/us_monthly.html.
from sources deemed reliable, but numbers to be considered approximate and subject to revision.
Santa
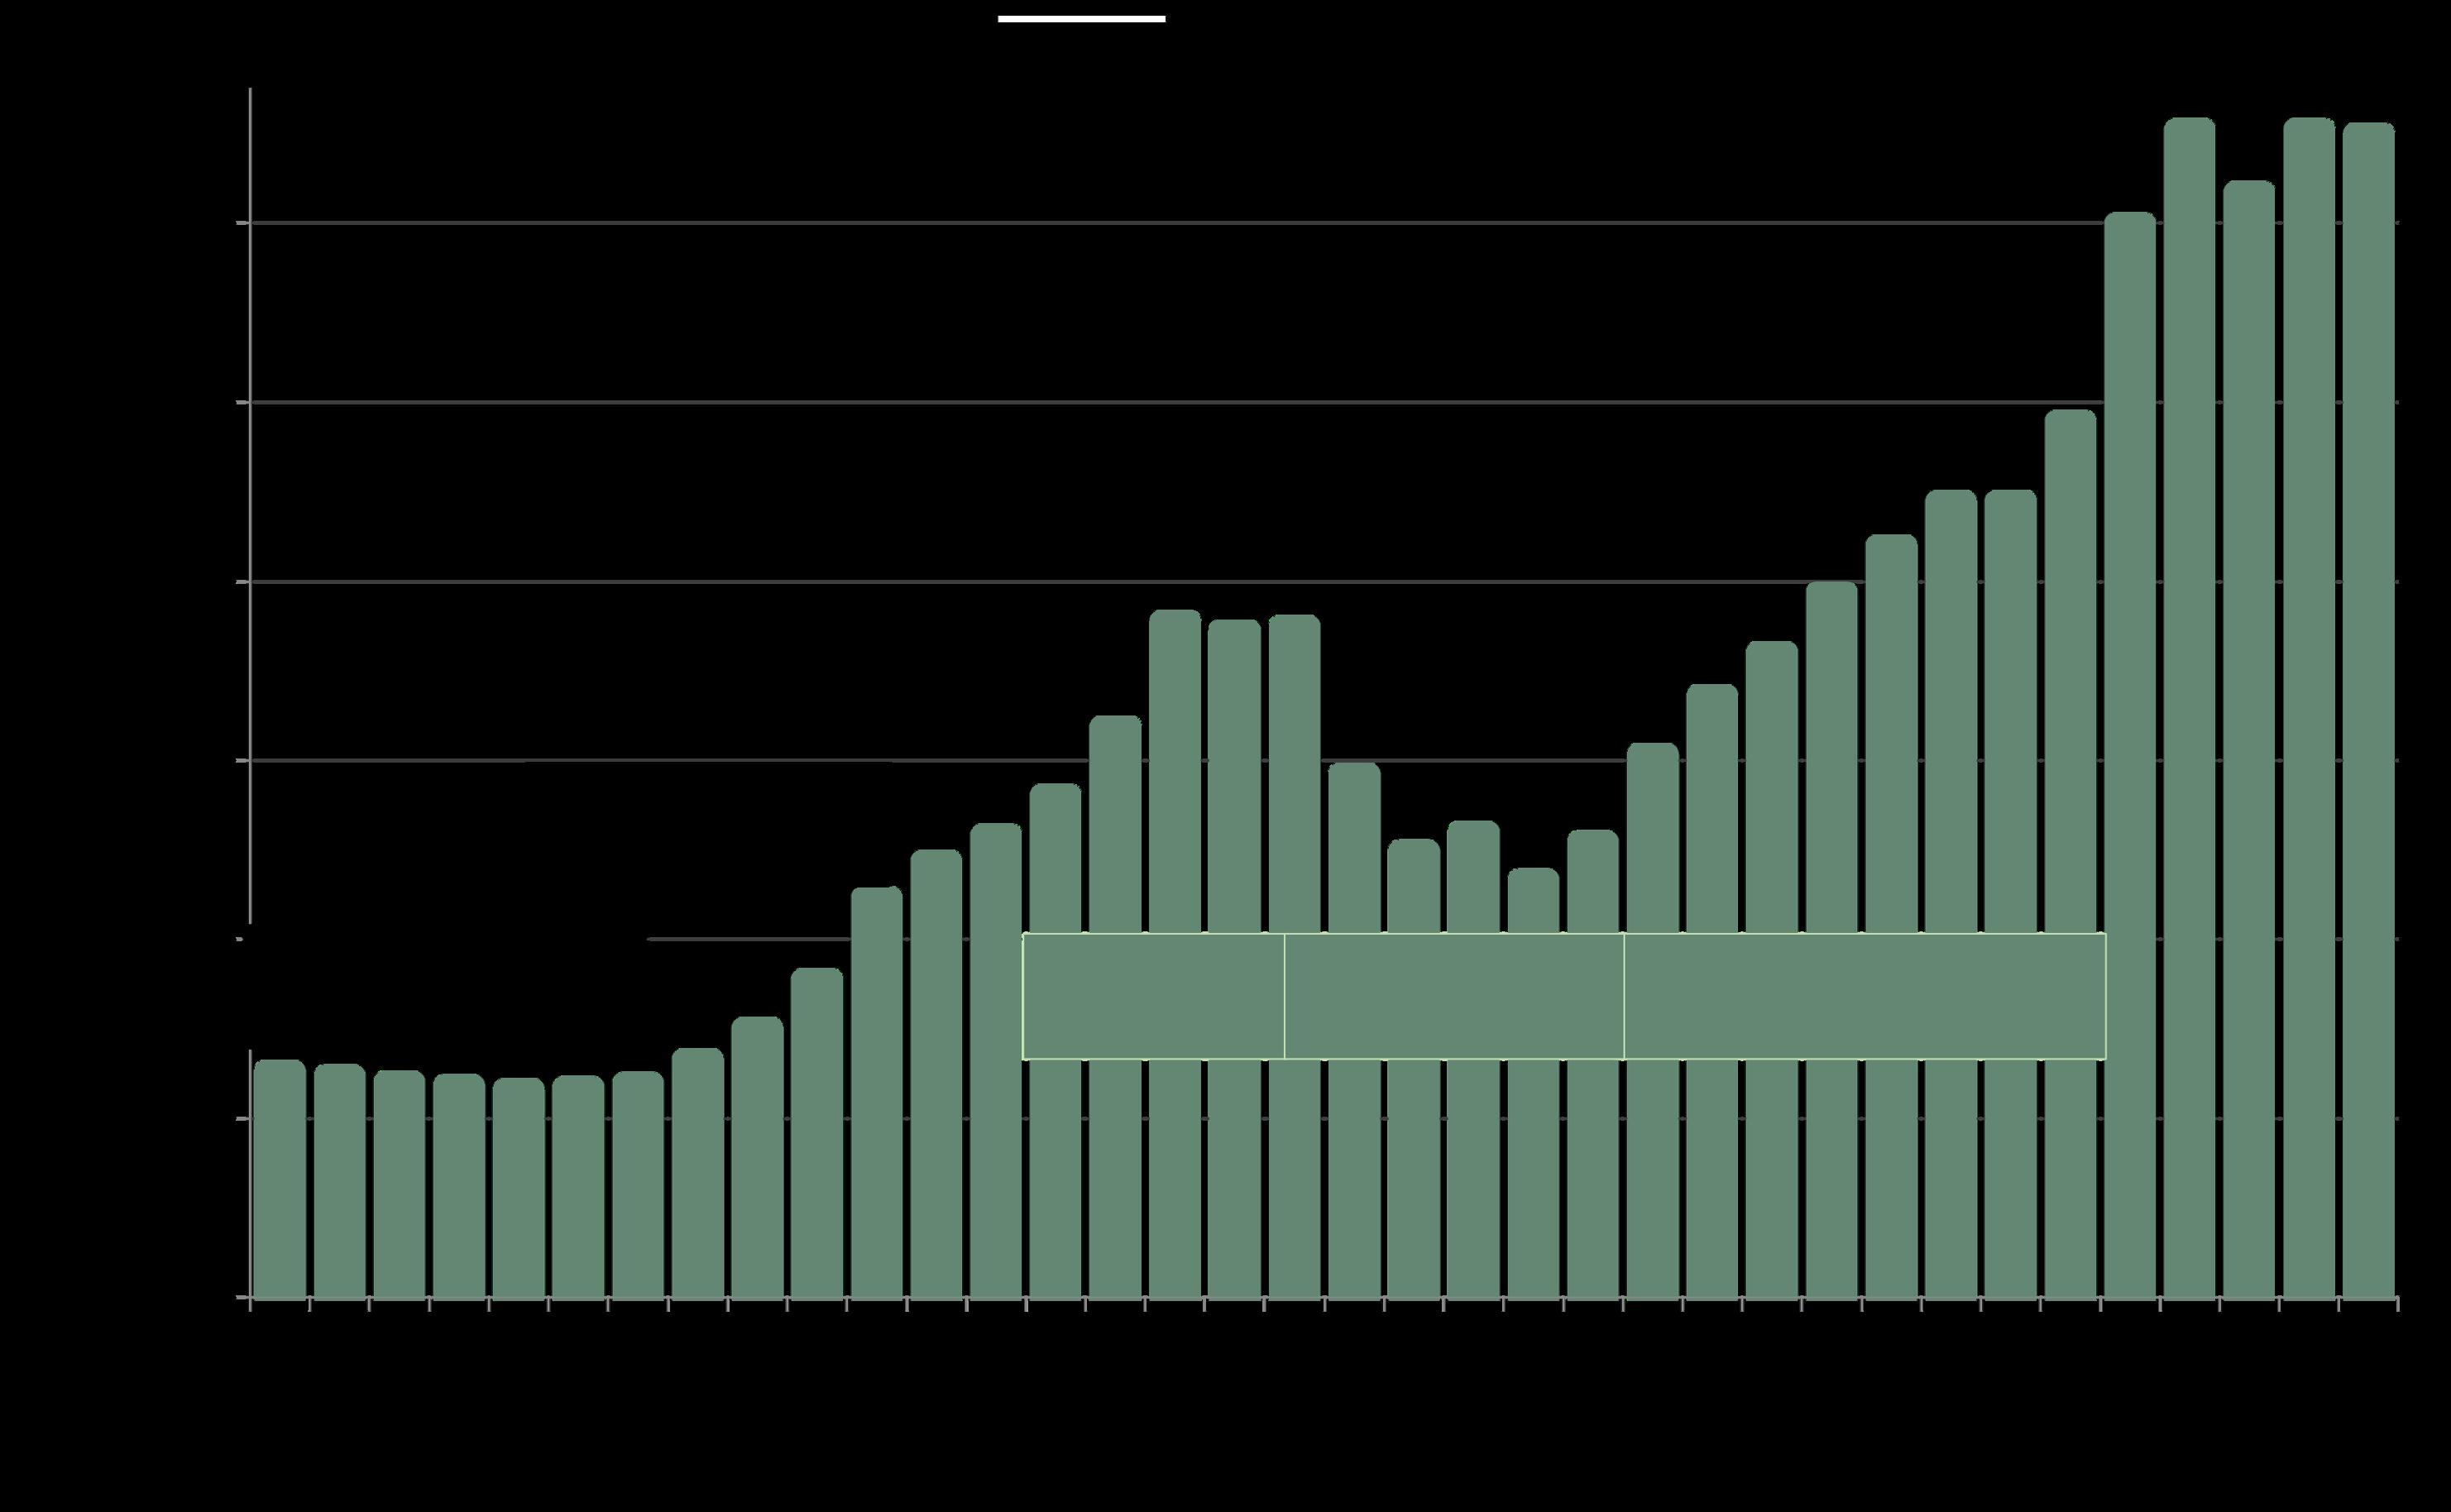
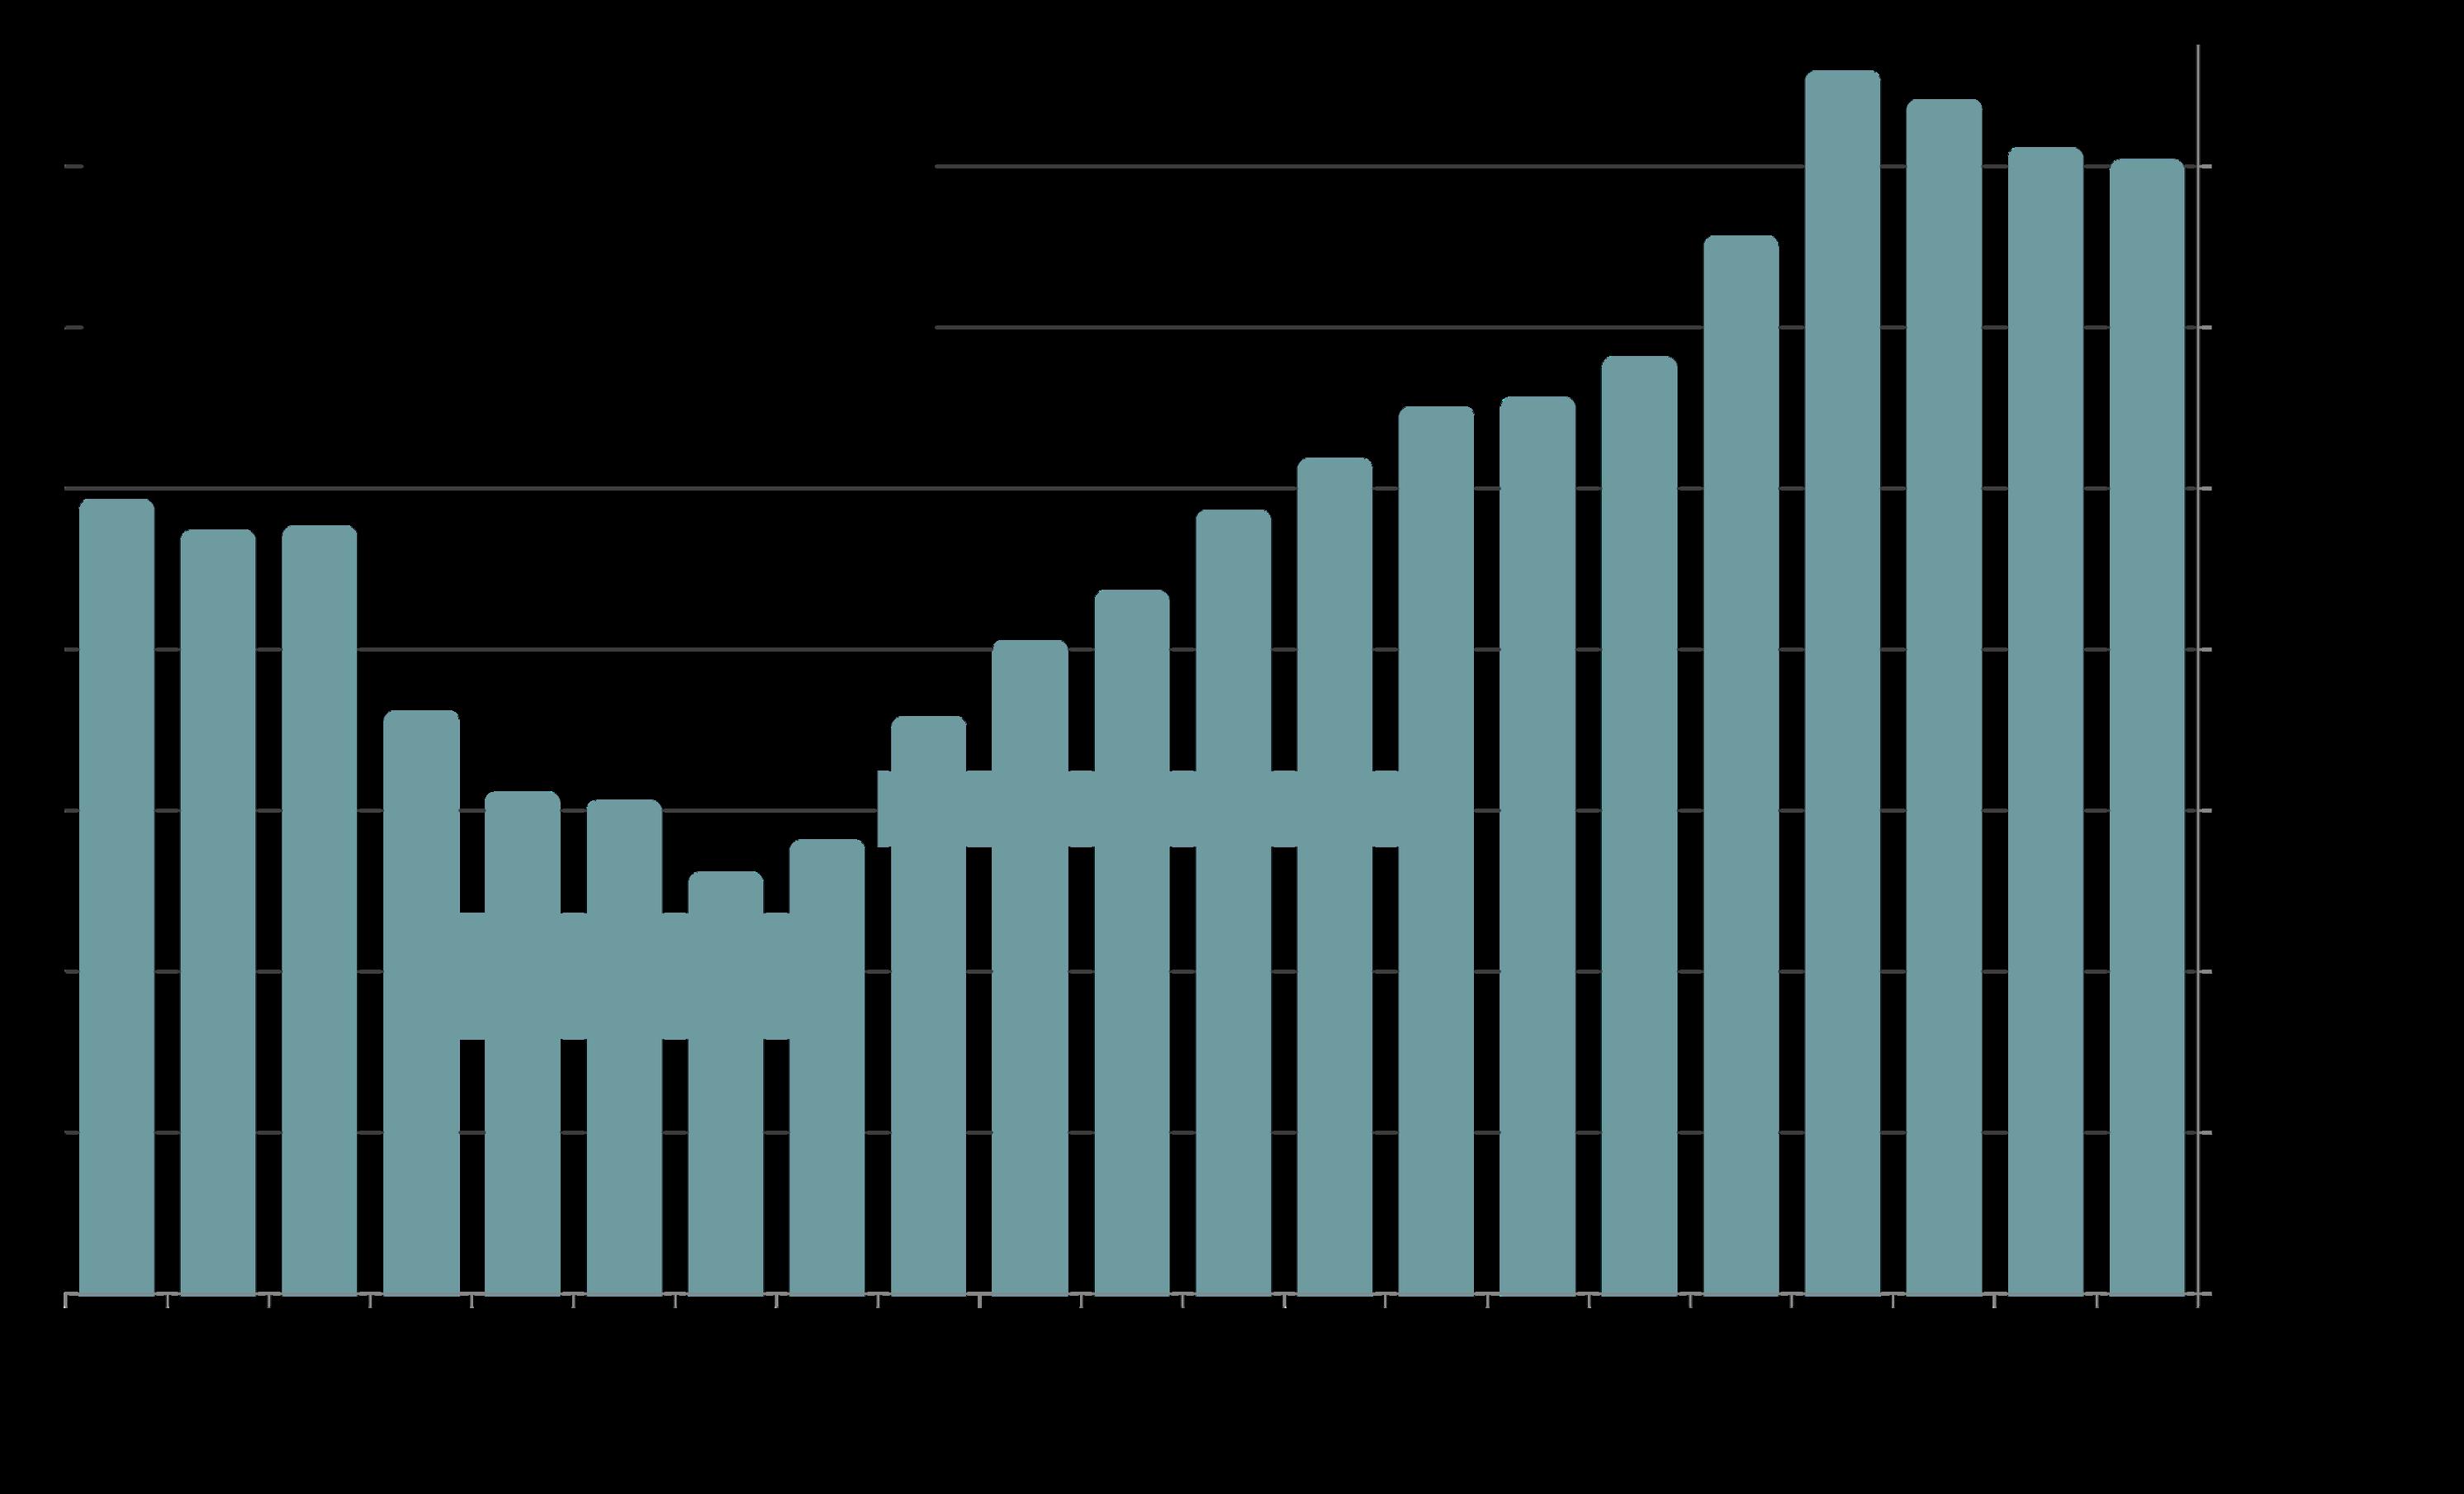
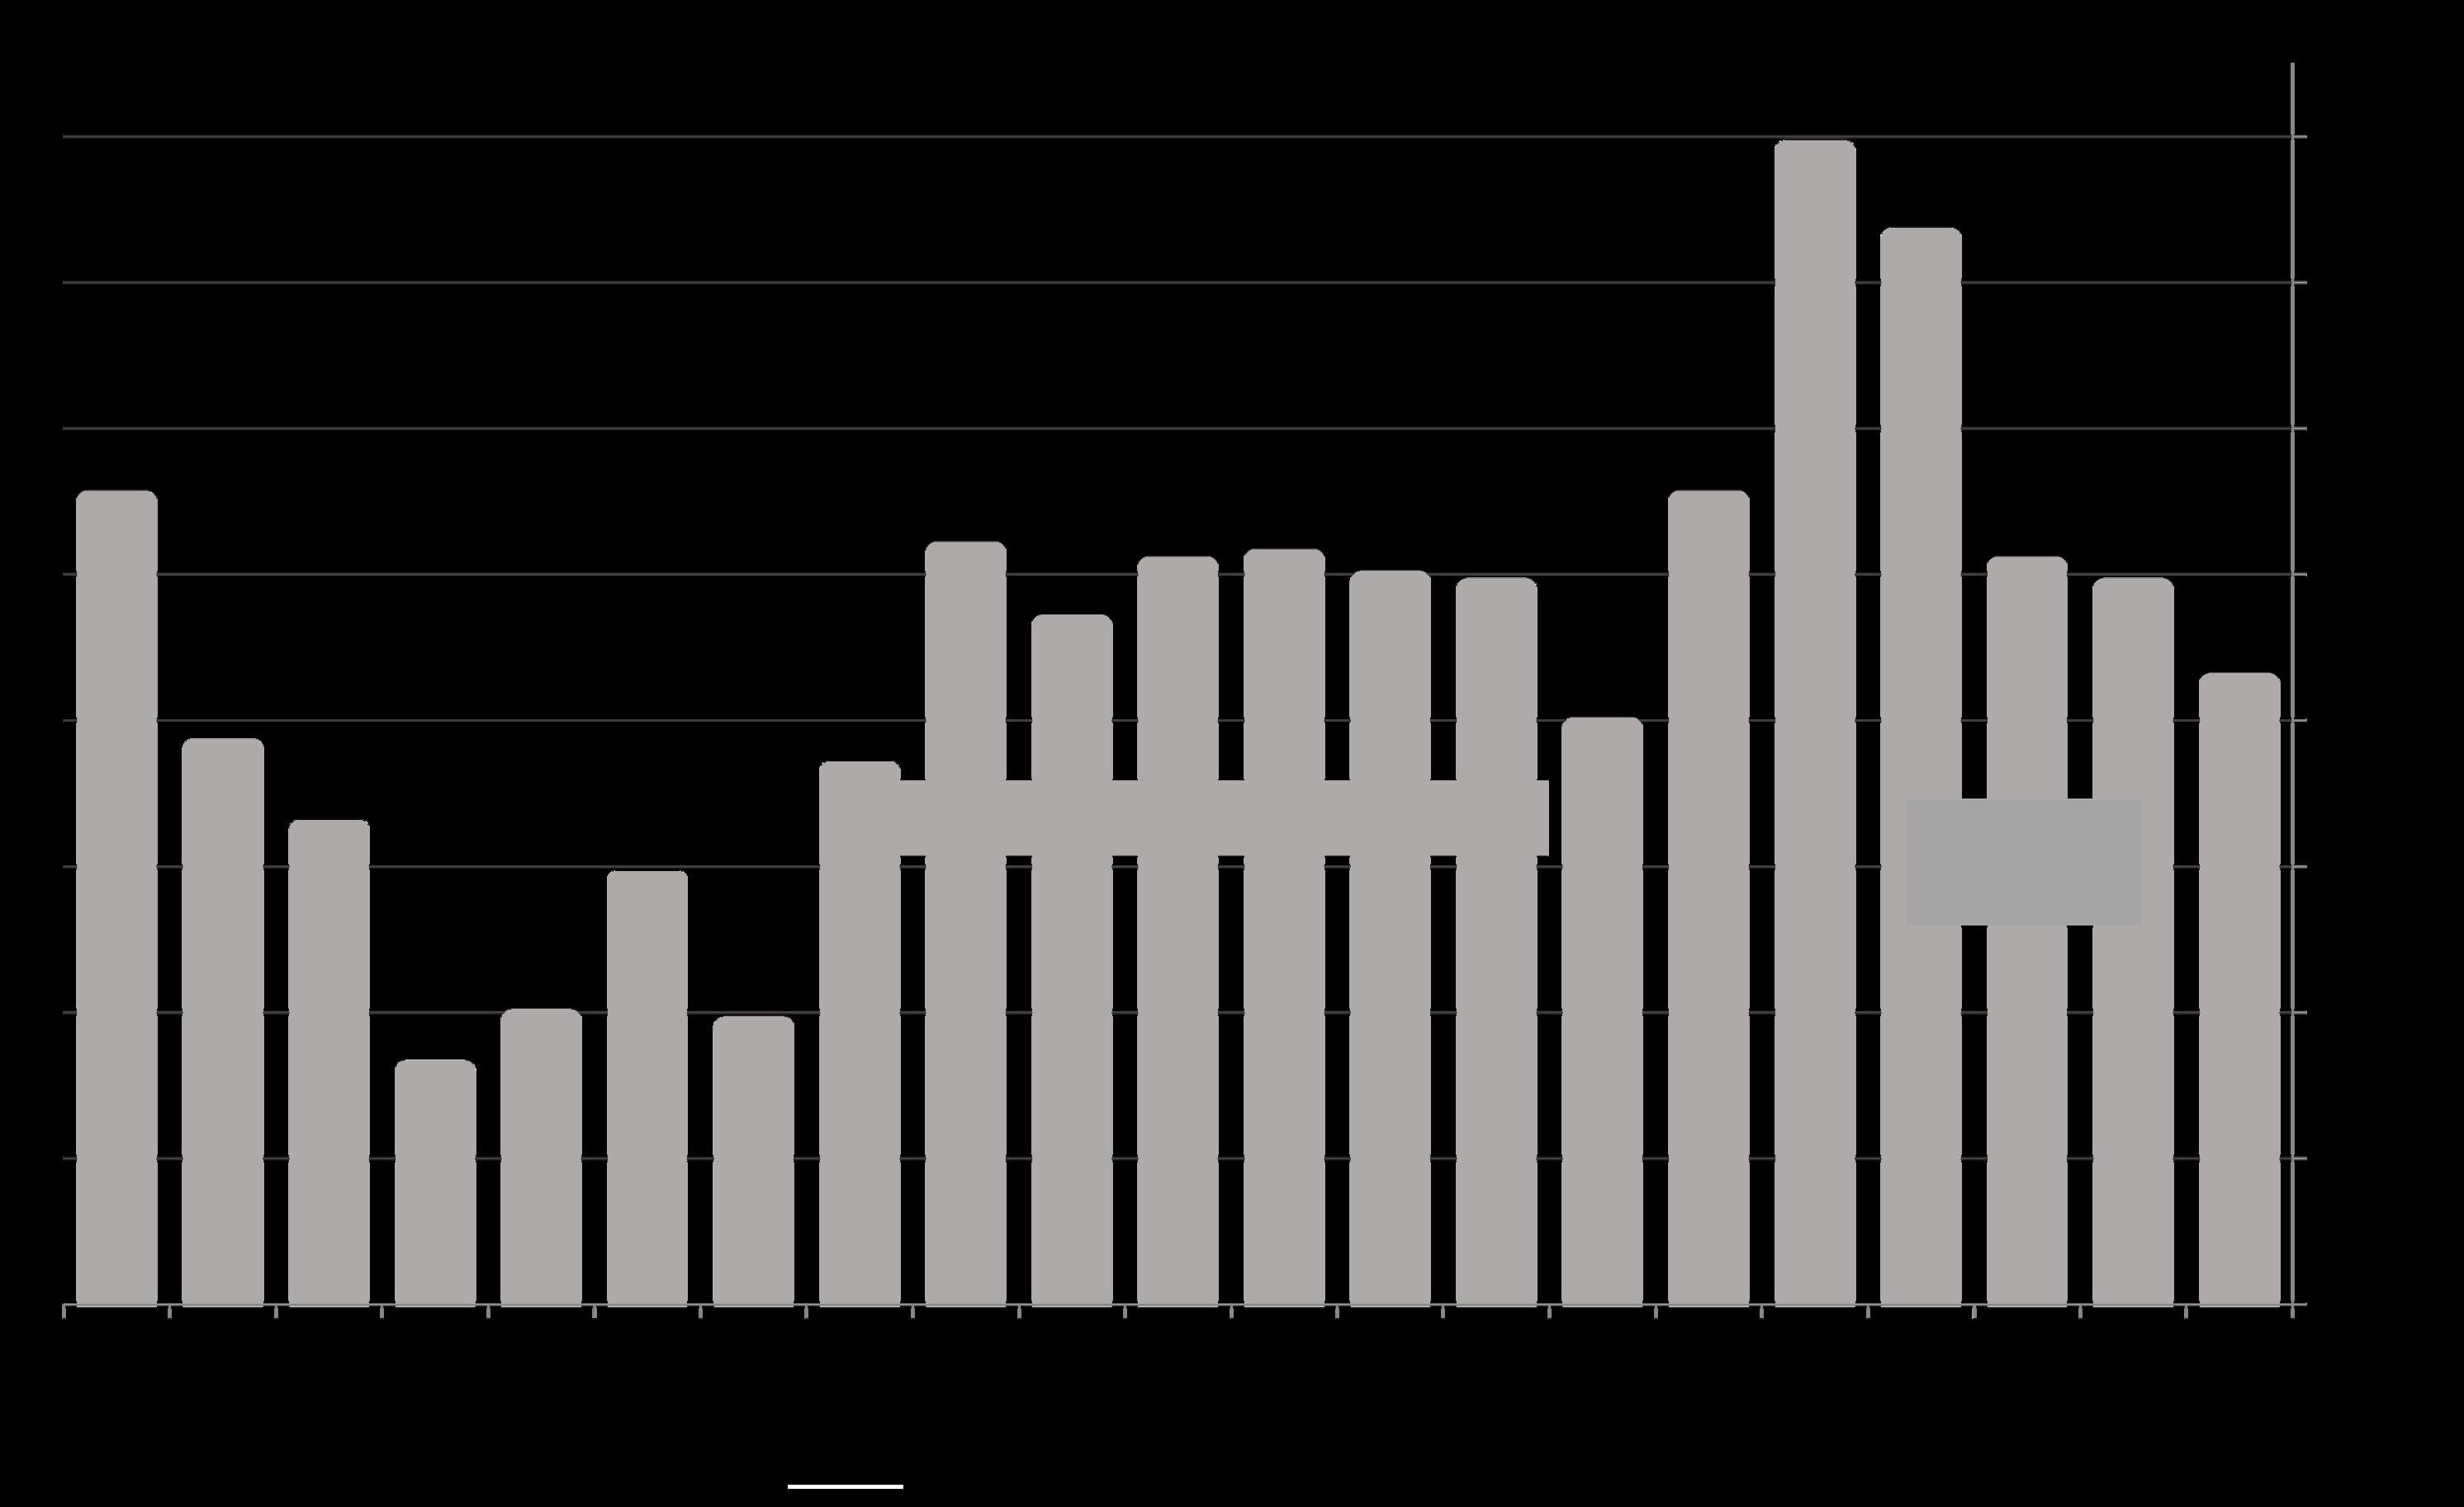
The 2025 median house sales price was essentially unchanged from 2024.
$1,000,000
$1,200,000 $800,000 $600,000 $400,000 $200,000 $0 to dotcom boom
Median prices are generalities, most useful to discern broad market trends. They can be affected by other factors besides changes in fair market value. The county contains cities, towns and neighborhoods of widely varying values.
Mid-90’s recovery
Early 90’s recession, after 80’s boom
*Per CA. Association of Realtors annual historical survey for existing single-family dwellings. 2025 an estimate based on sales reported to NorCal MLS Alliance by early Jan. 2026. Data from sources deemed reliable but may contain errors and subject to revision. All numbers approximate and may change with late-reported sales. Various sources of data may calculate median sales prices slightly differently.
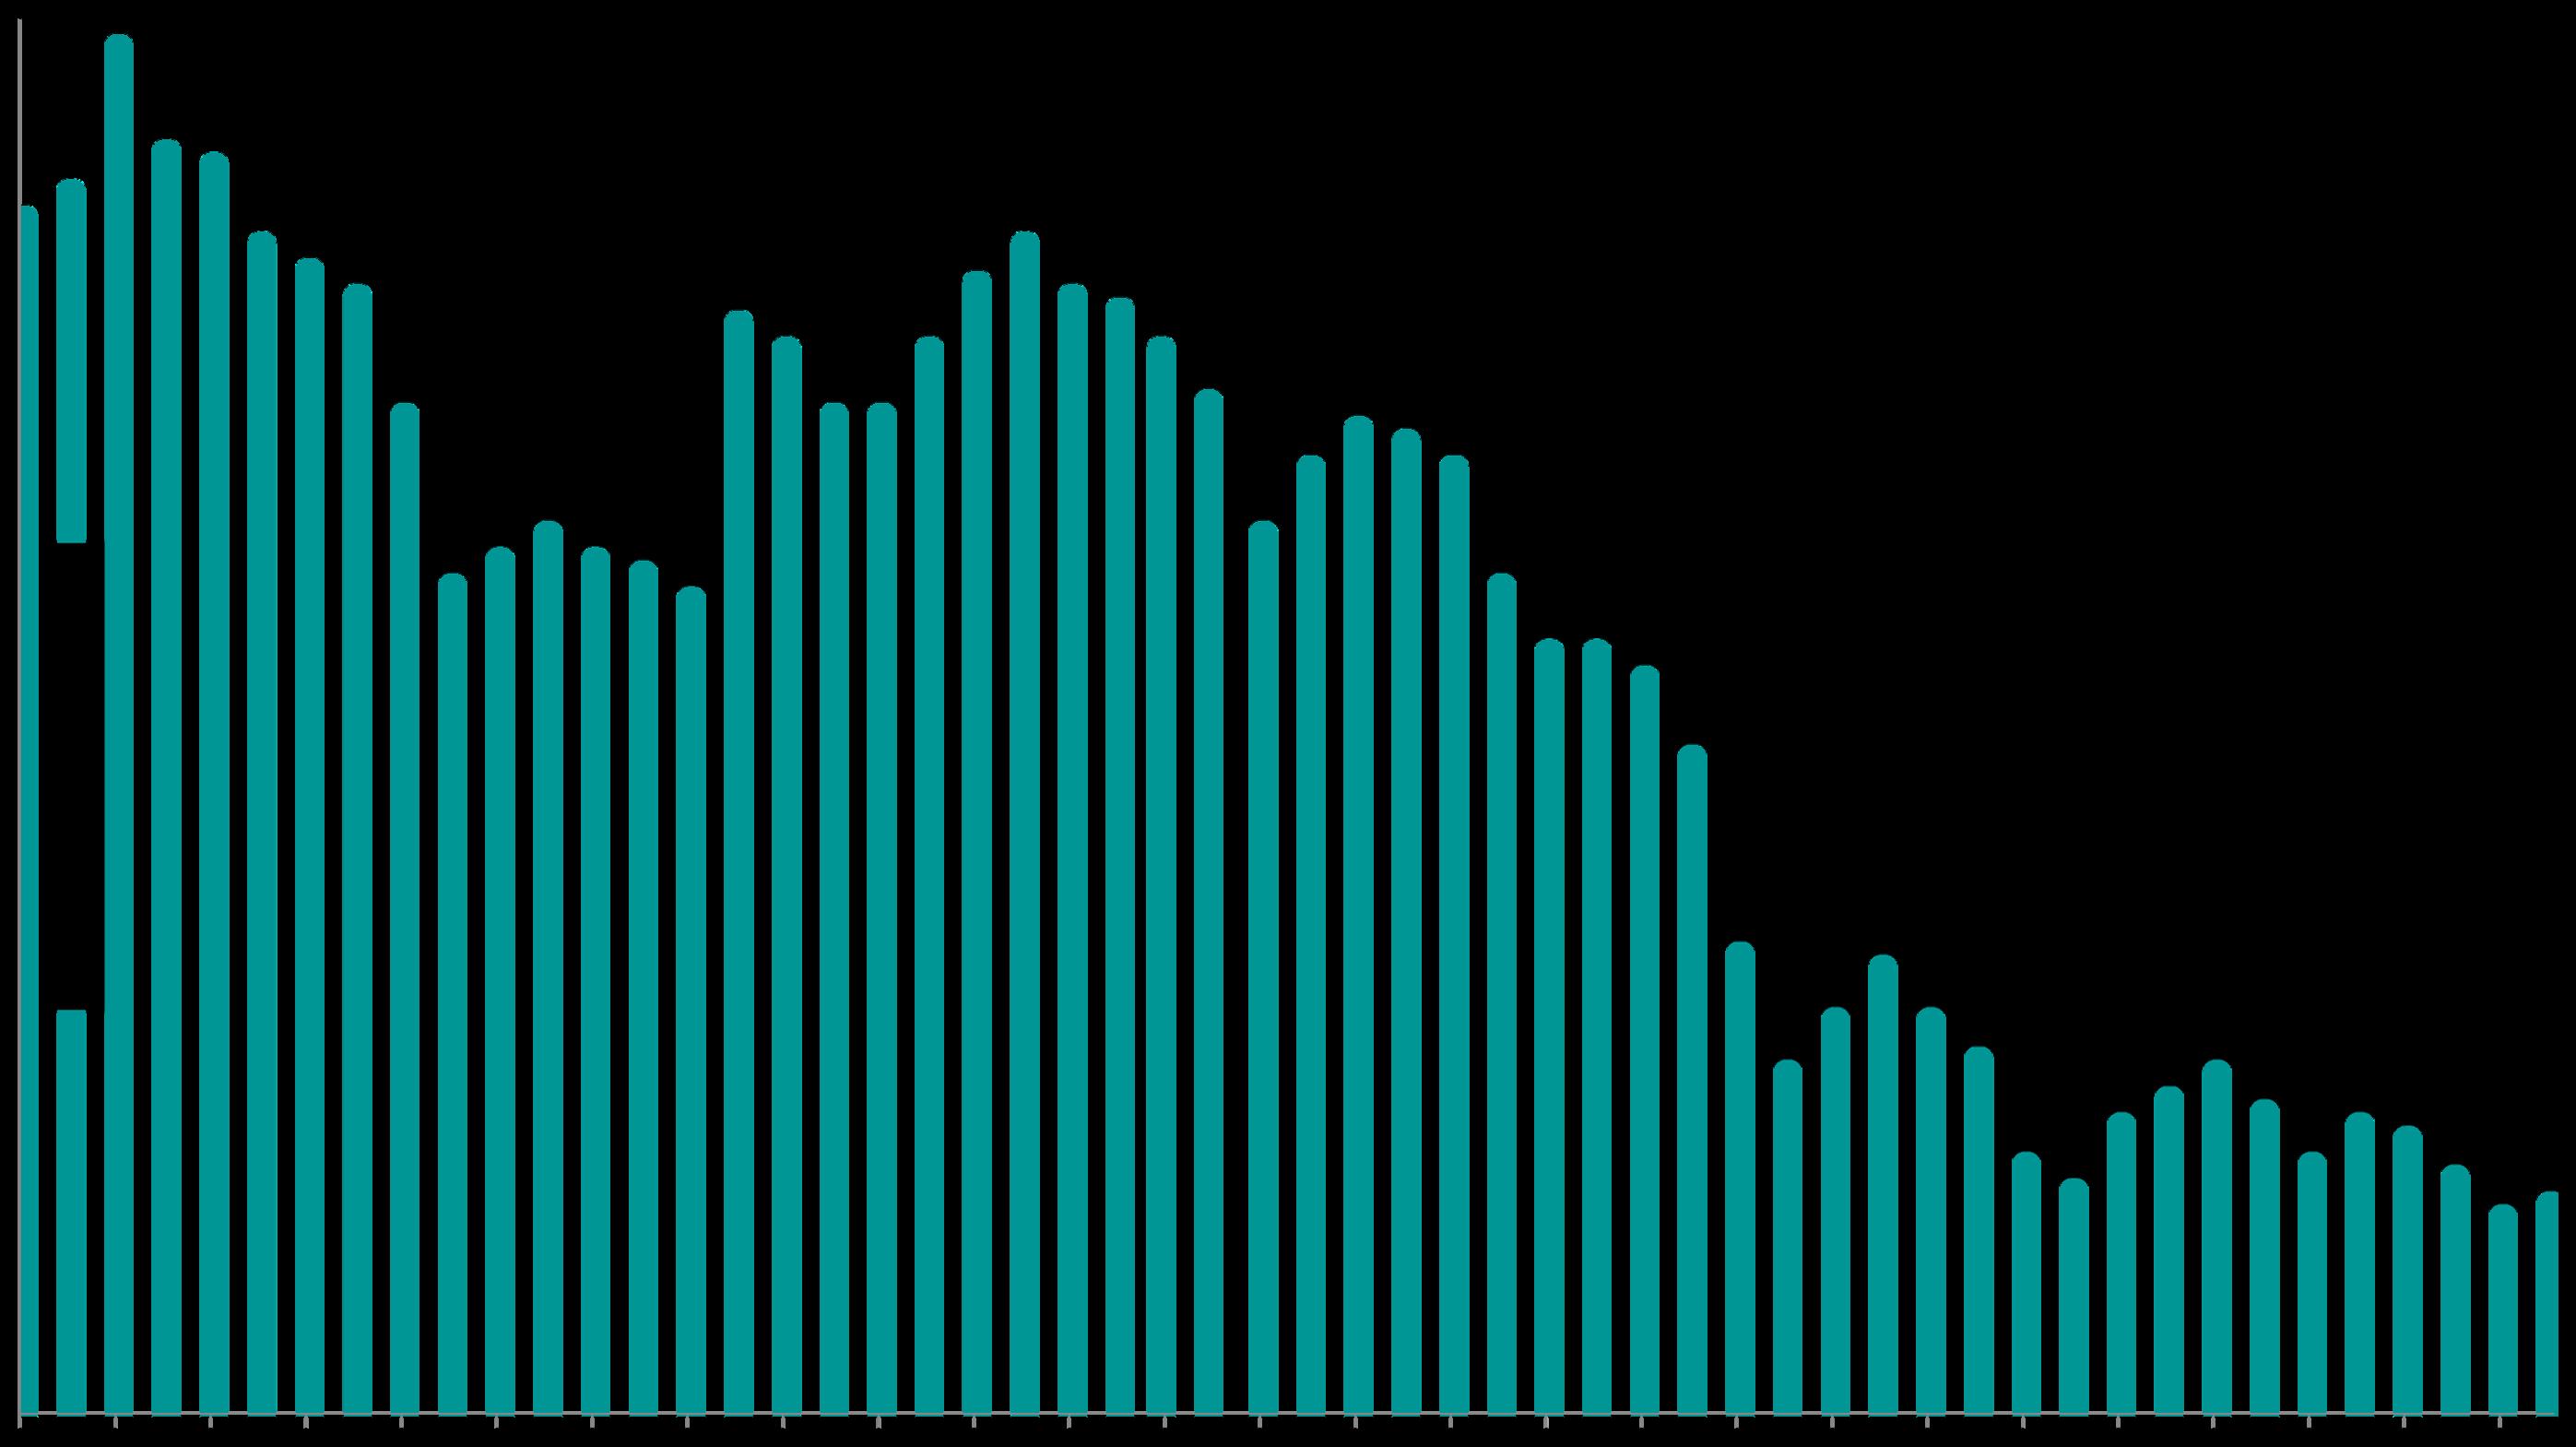
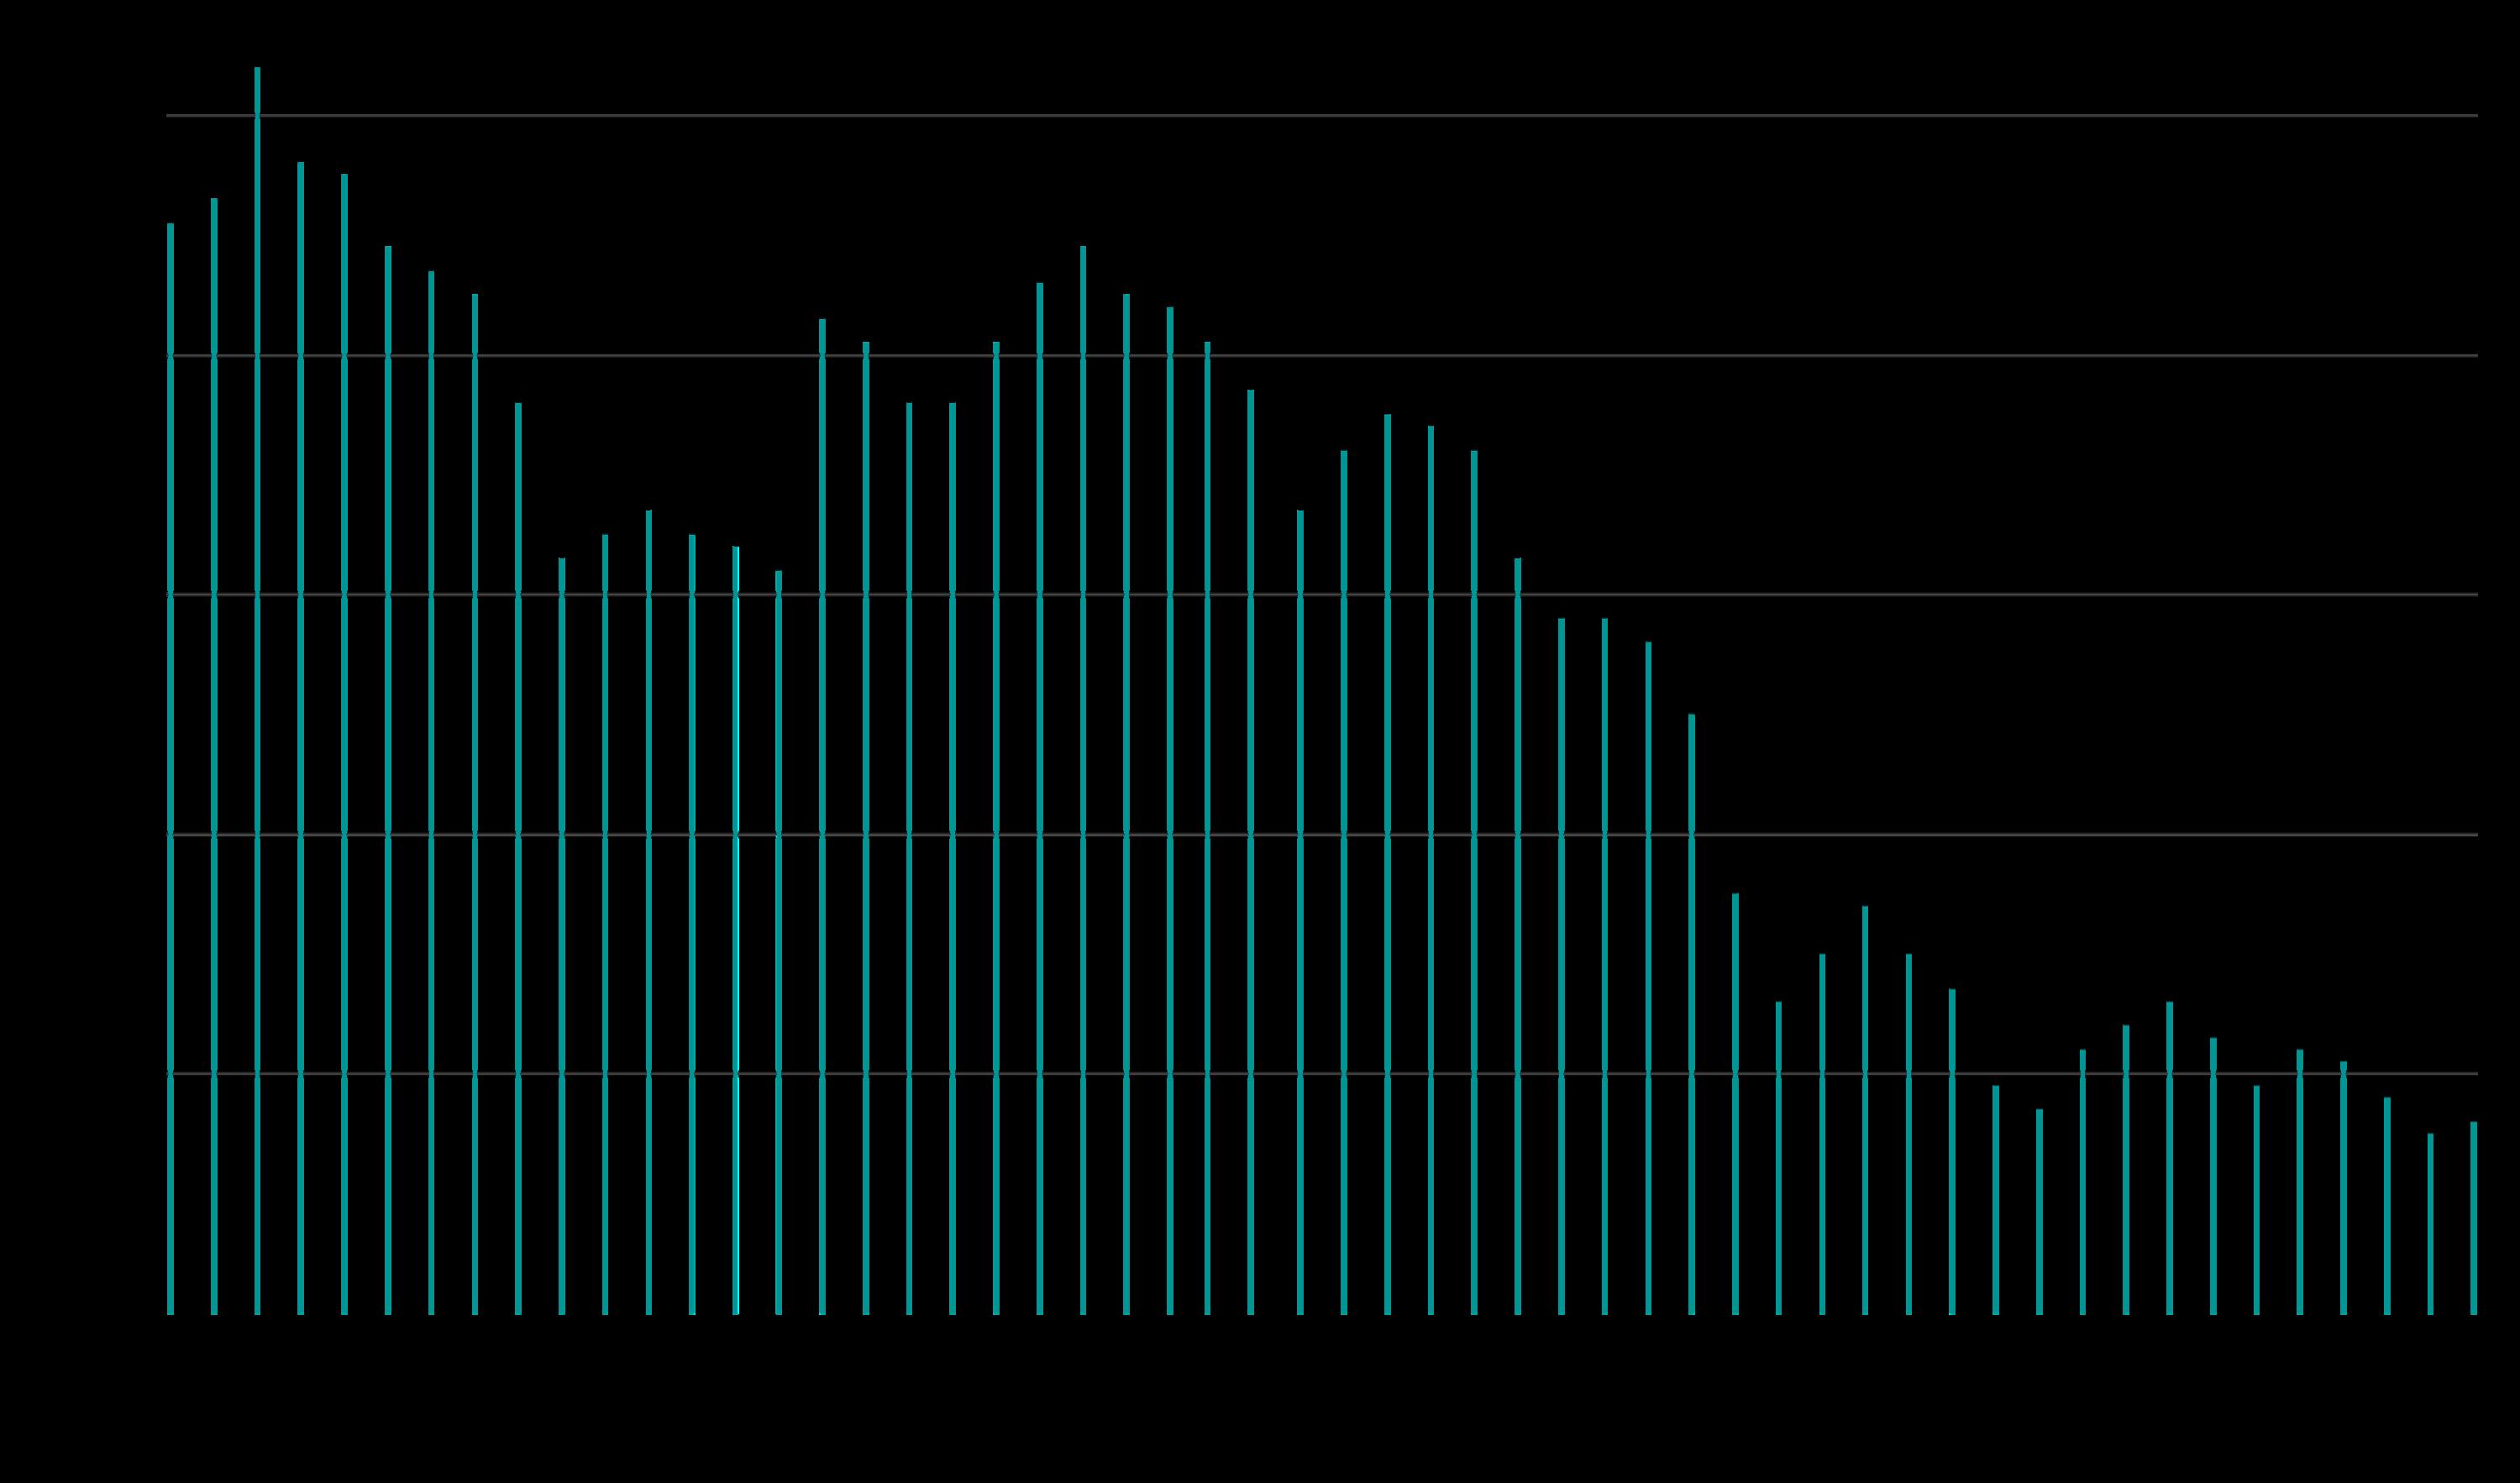
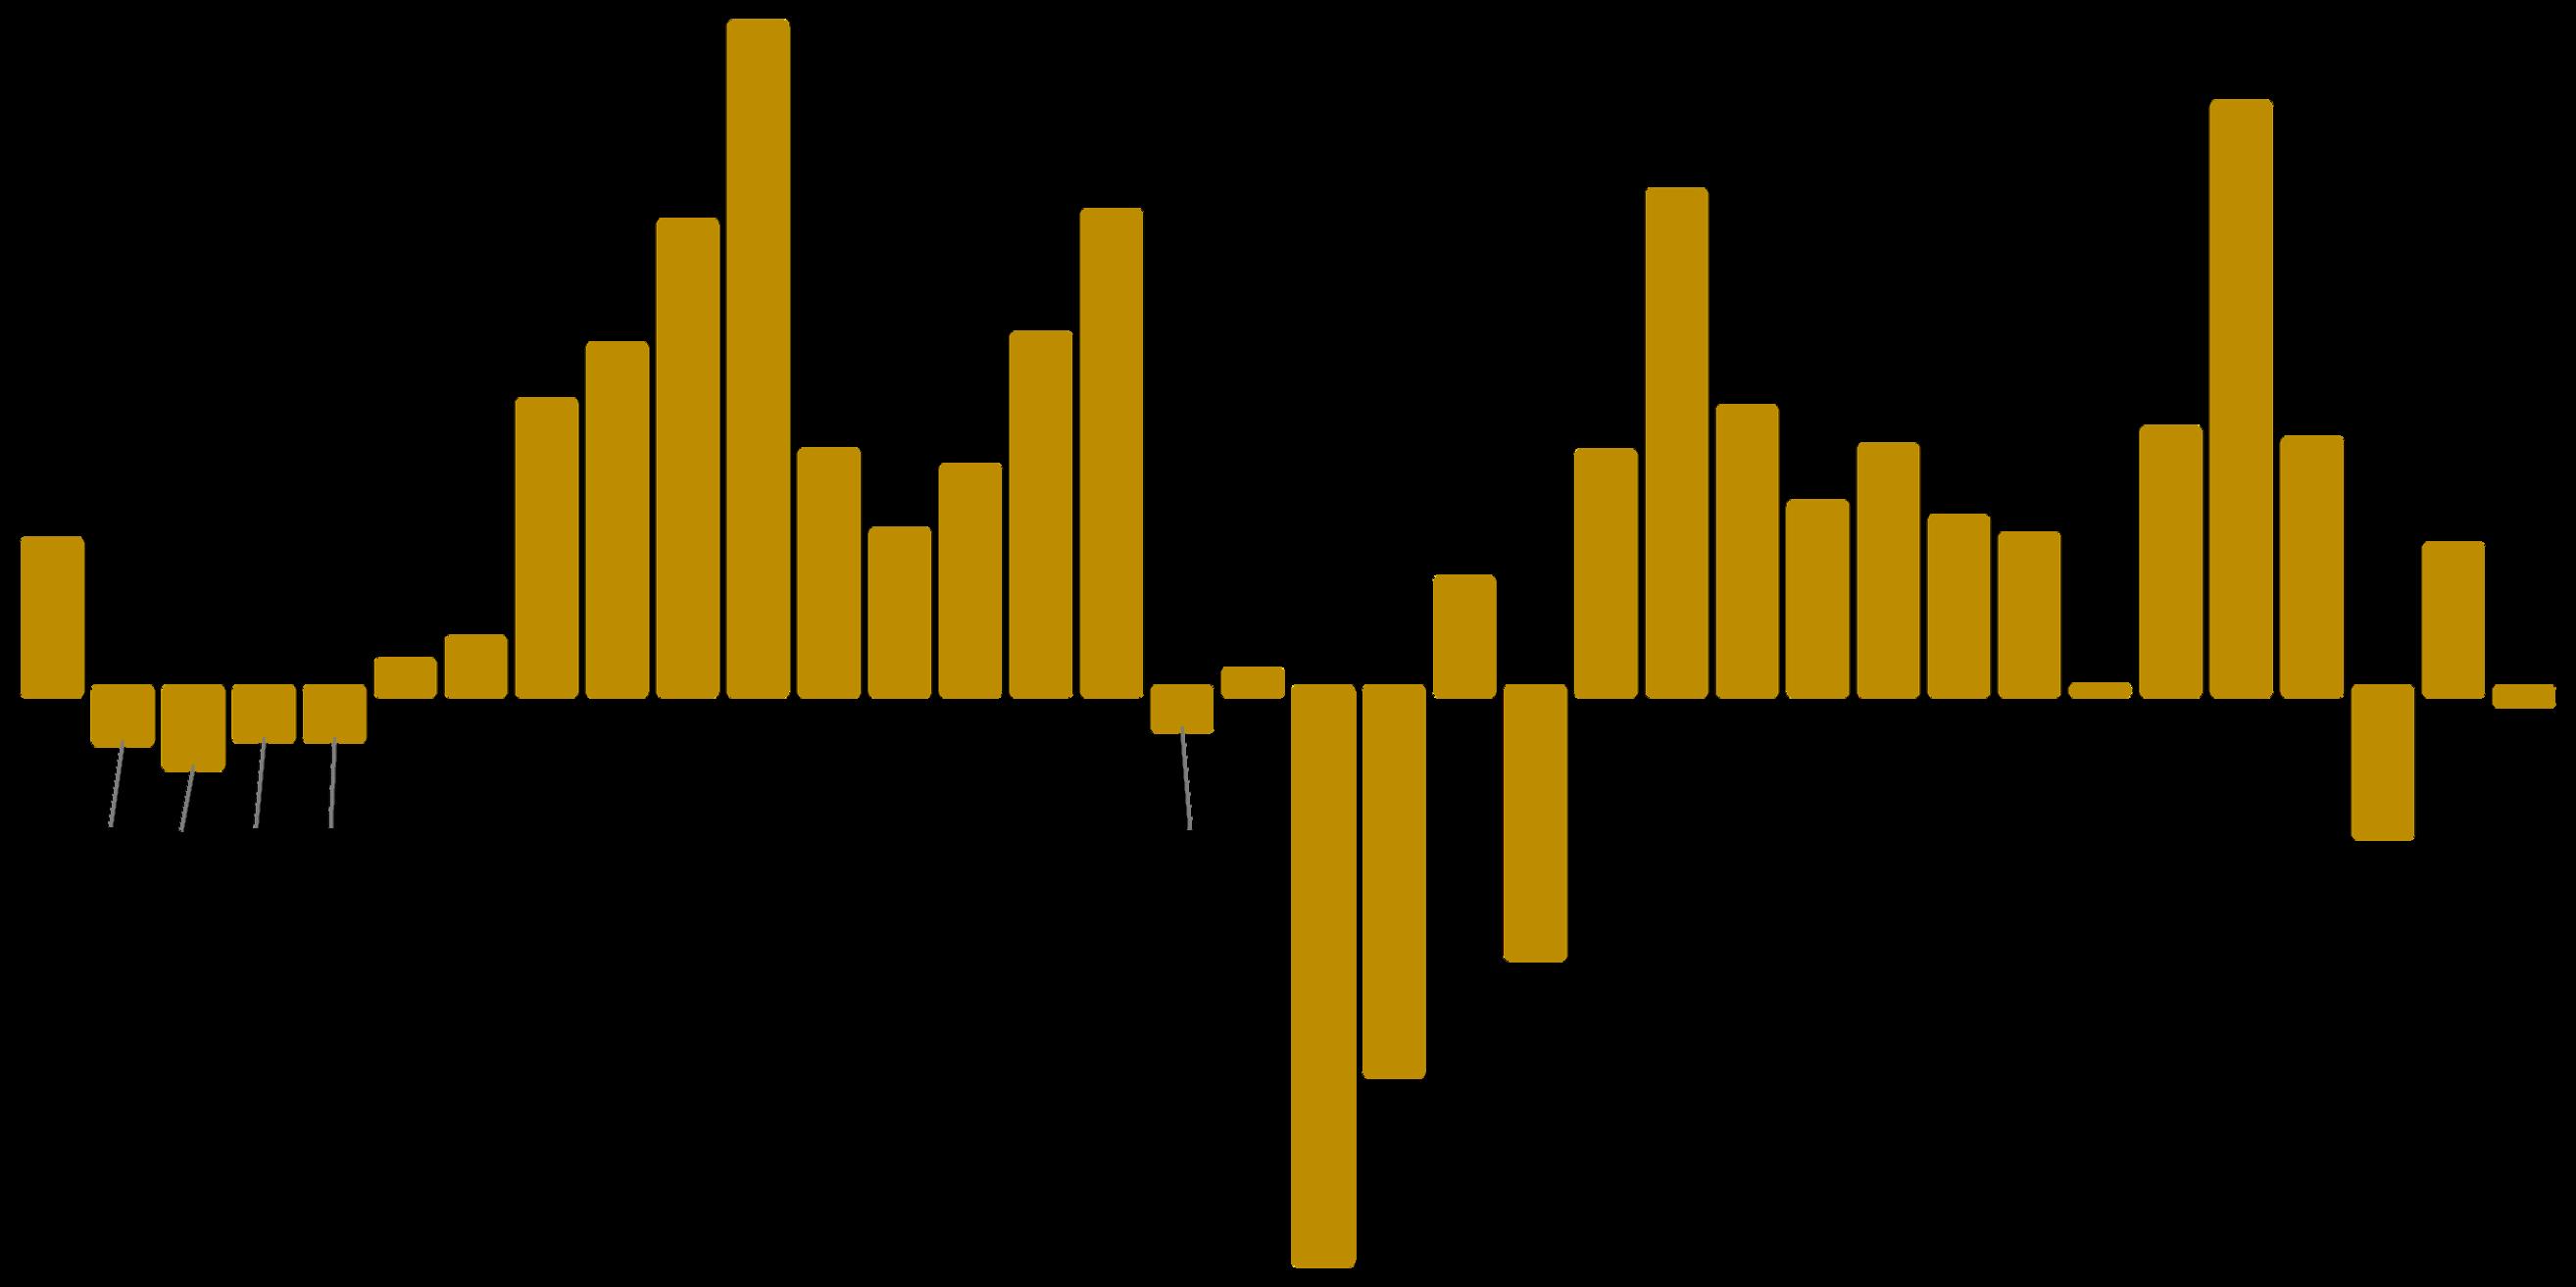
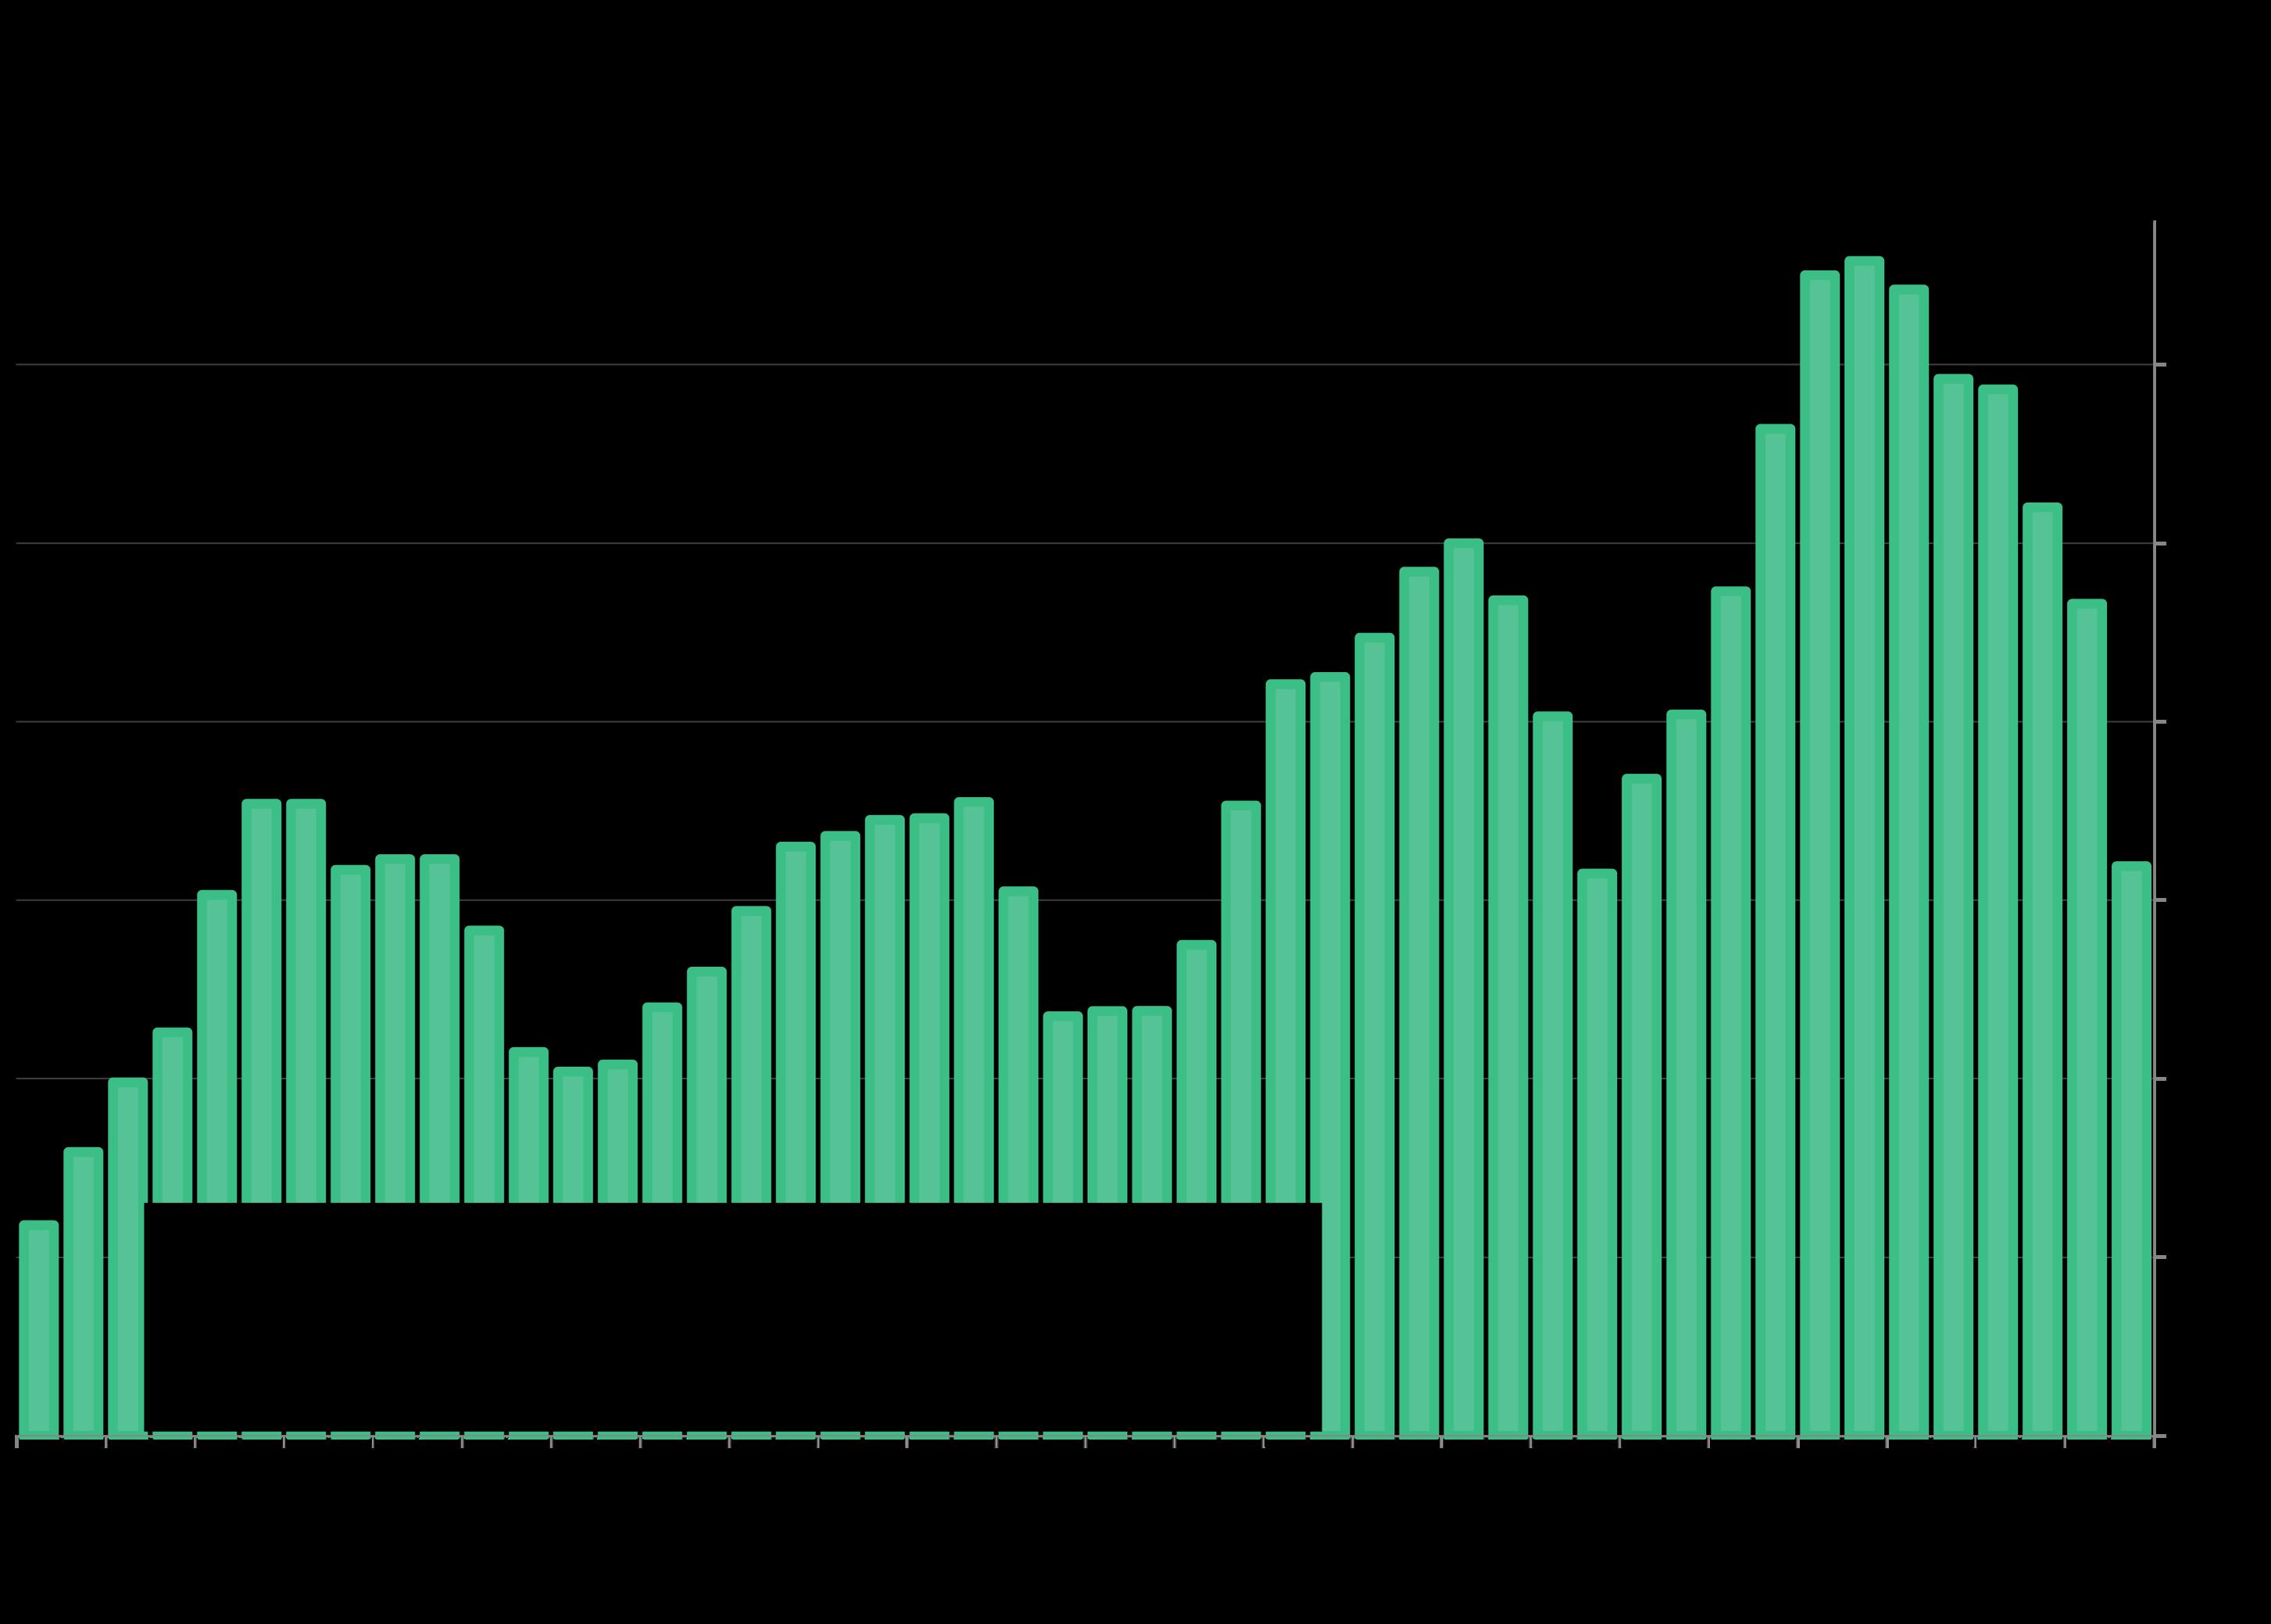
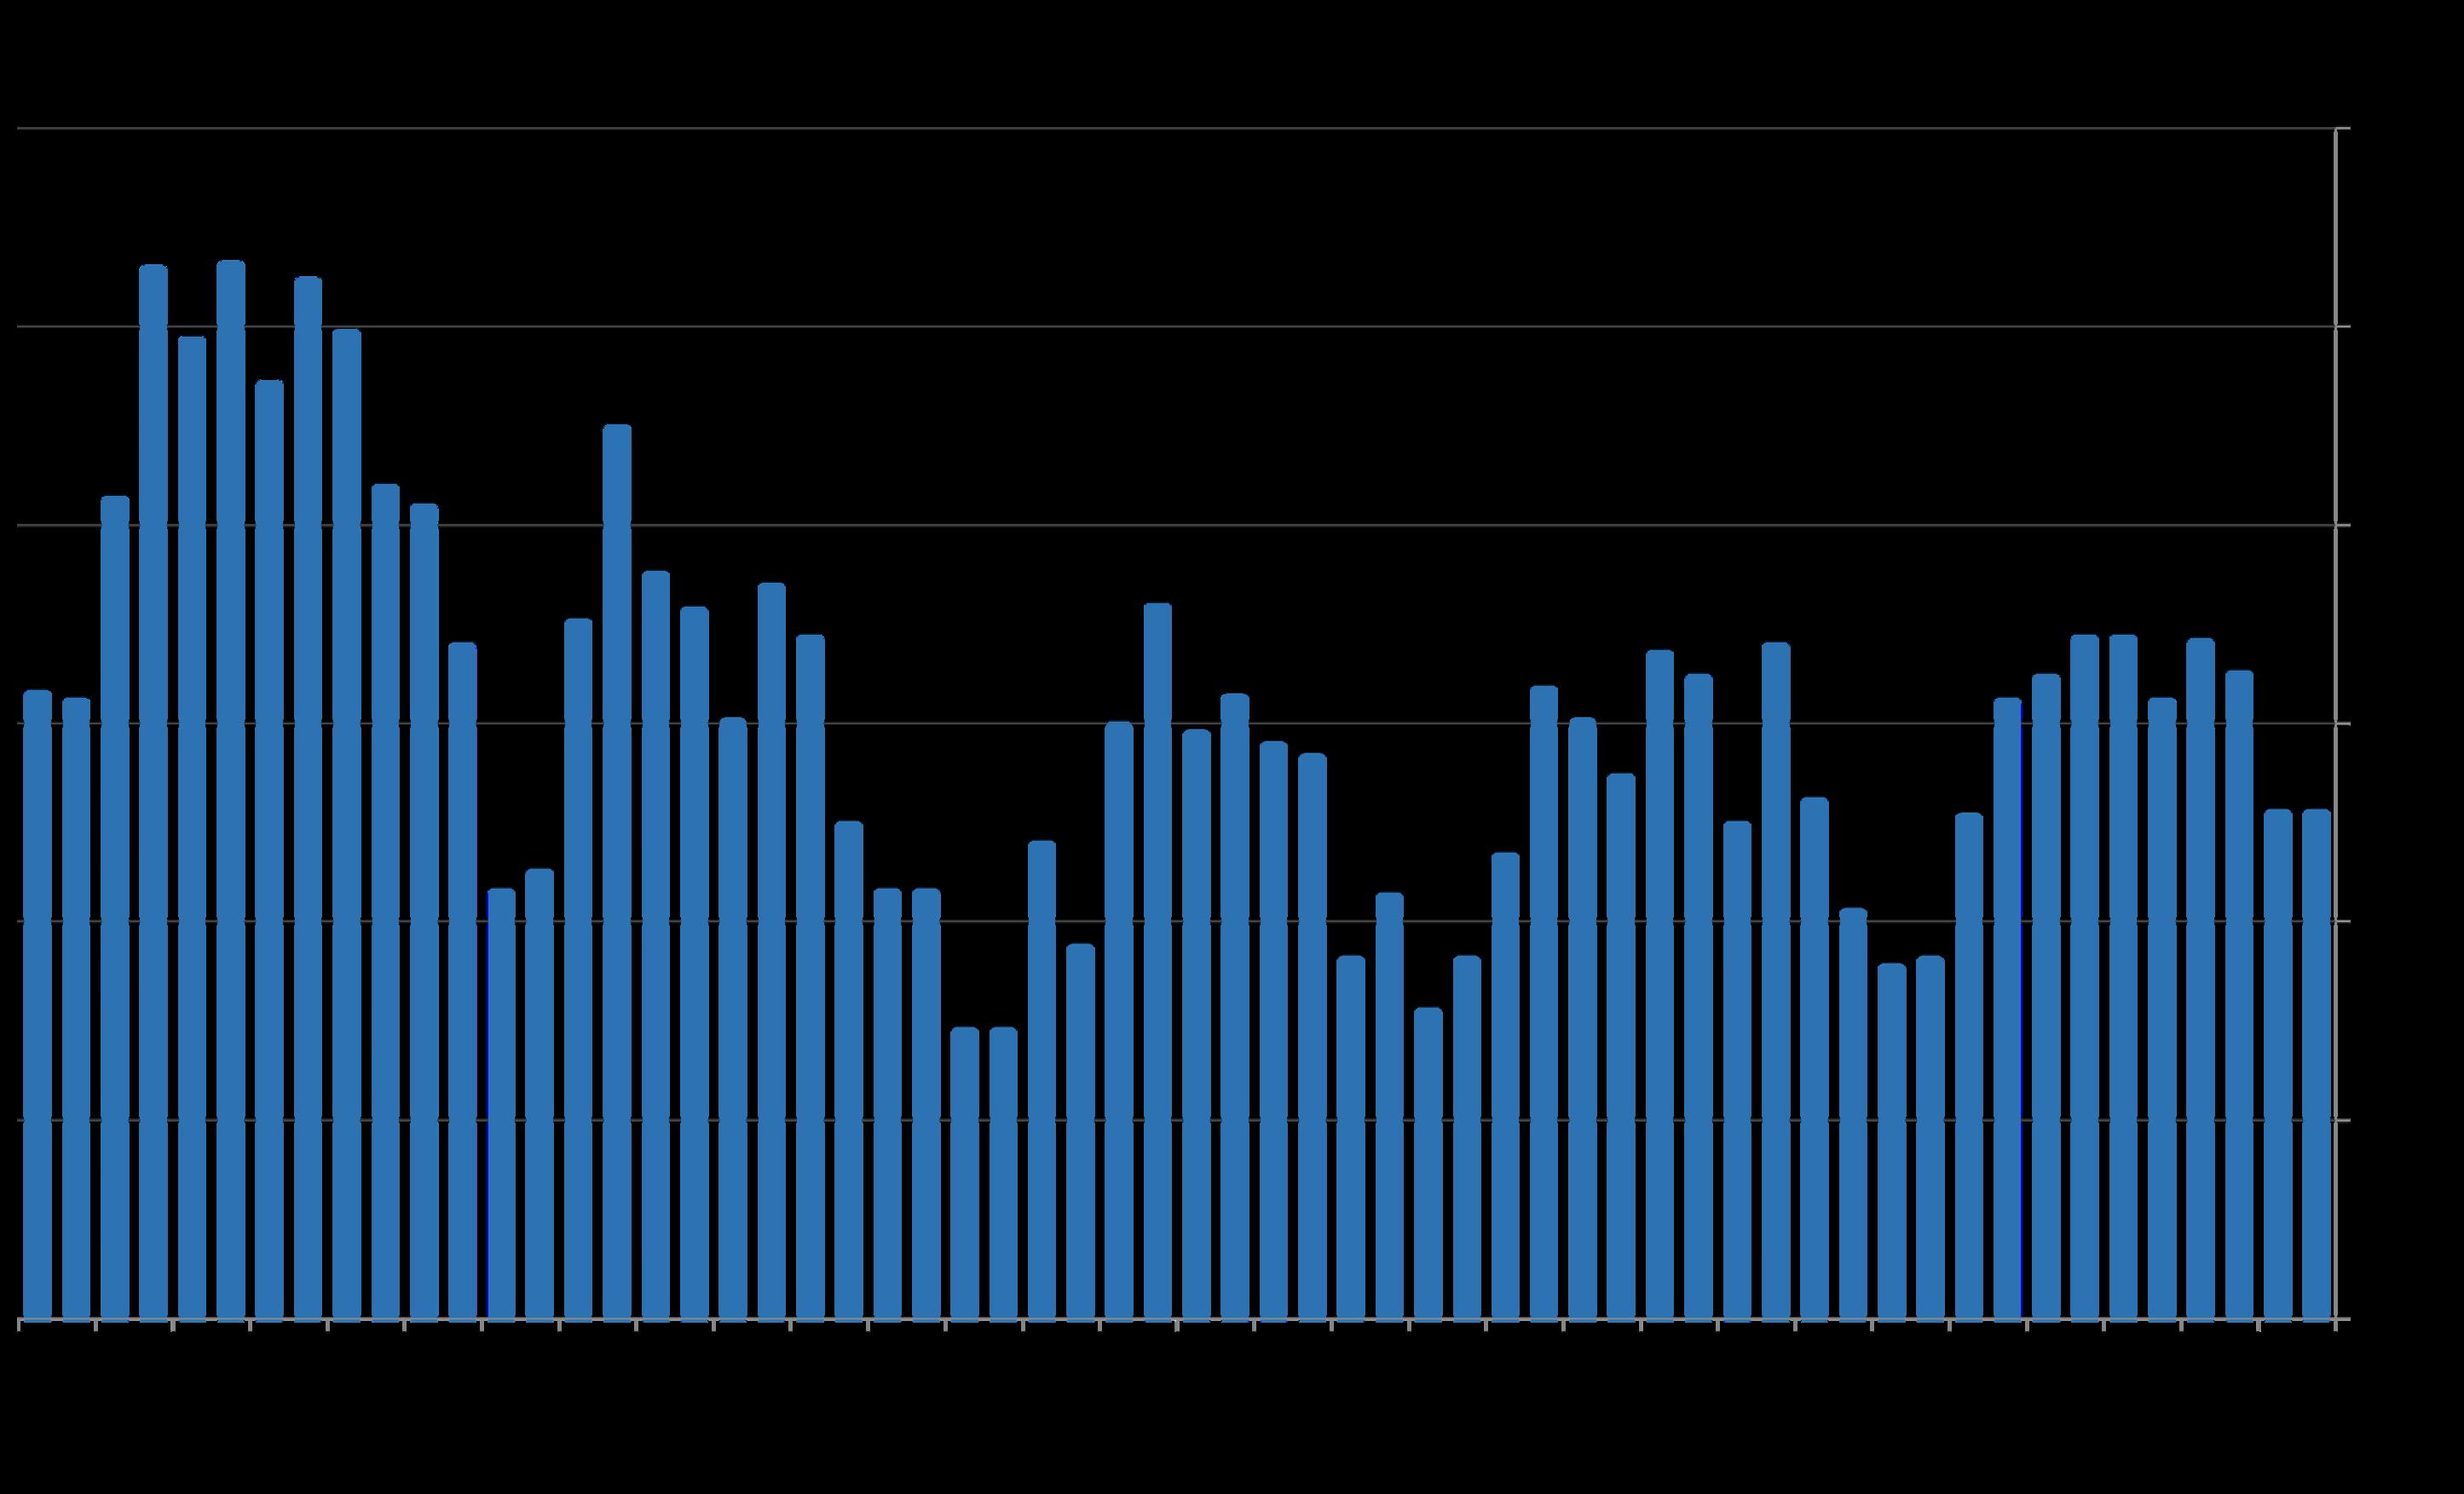
Santa Cruz County Year-over-Year Appreciation Rates since 1990
Y-o-Y Percentage Change in Annual Median HOUSE Sales Price*
Annual appreciation rates often varied widely between submarkets within the county. How this chart applies to any particular property is unknown without a specific comparative market analysis.
*Sales reported to MLS: median existing house sales price appreciation rates, per CA Association of Realtors Annual Historical Survey or NorCal MLS Alliance. 2025 estimated from MLS sales reported by early January 2026. Percentage-change labels typically rounded to nearest full percentage point. All numbers approximate, may contain errors and subject to revision, and may change with late-reported sales.
Median values are generalities, most useful to discern broad market trends. They can be affected by other factors besides changes in fair market value. Values vary widely across submarkets within the county.
Santa
Median prices are generalities, most useful to discern broad market trends. They can be affected by other factors besides changes in fair market value. Annual data can disguise significant changes that occur within the calendar year.
Subprime bubble
*Per sales reported to NorCal MLS Alliance. Median sales price is that price at which half the sales occurred for more and half for less. Data from sources deemed reliable but may contain errors and subject to revision. All numbers approximate and may change with late-reported sales. The median condo sales price in 2025 dropped about 1% from 2024.
Santa Cruz County House Values
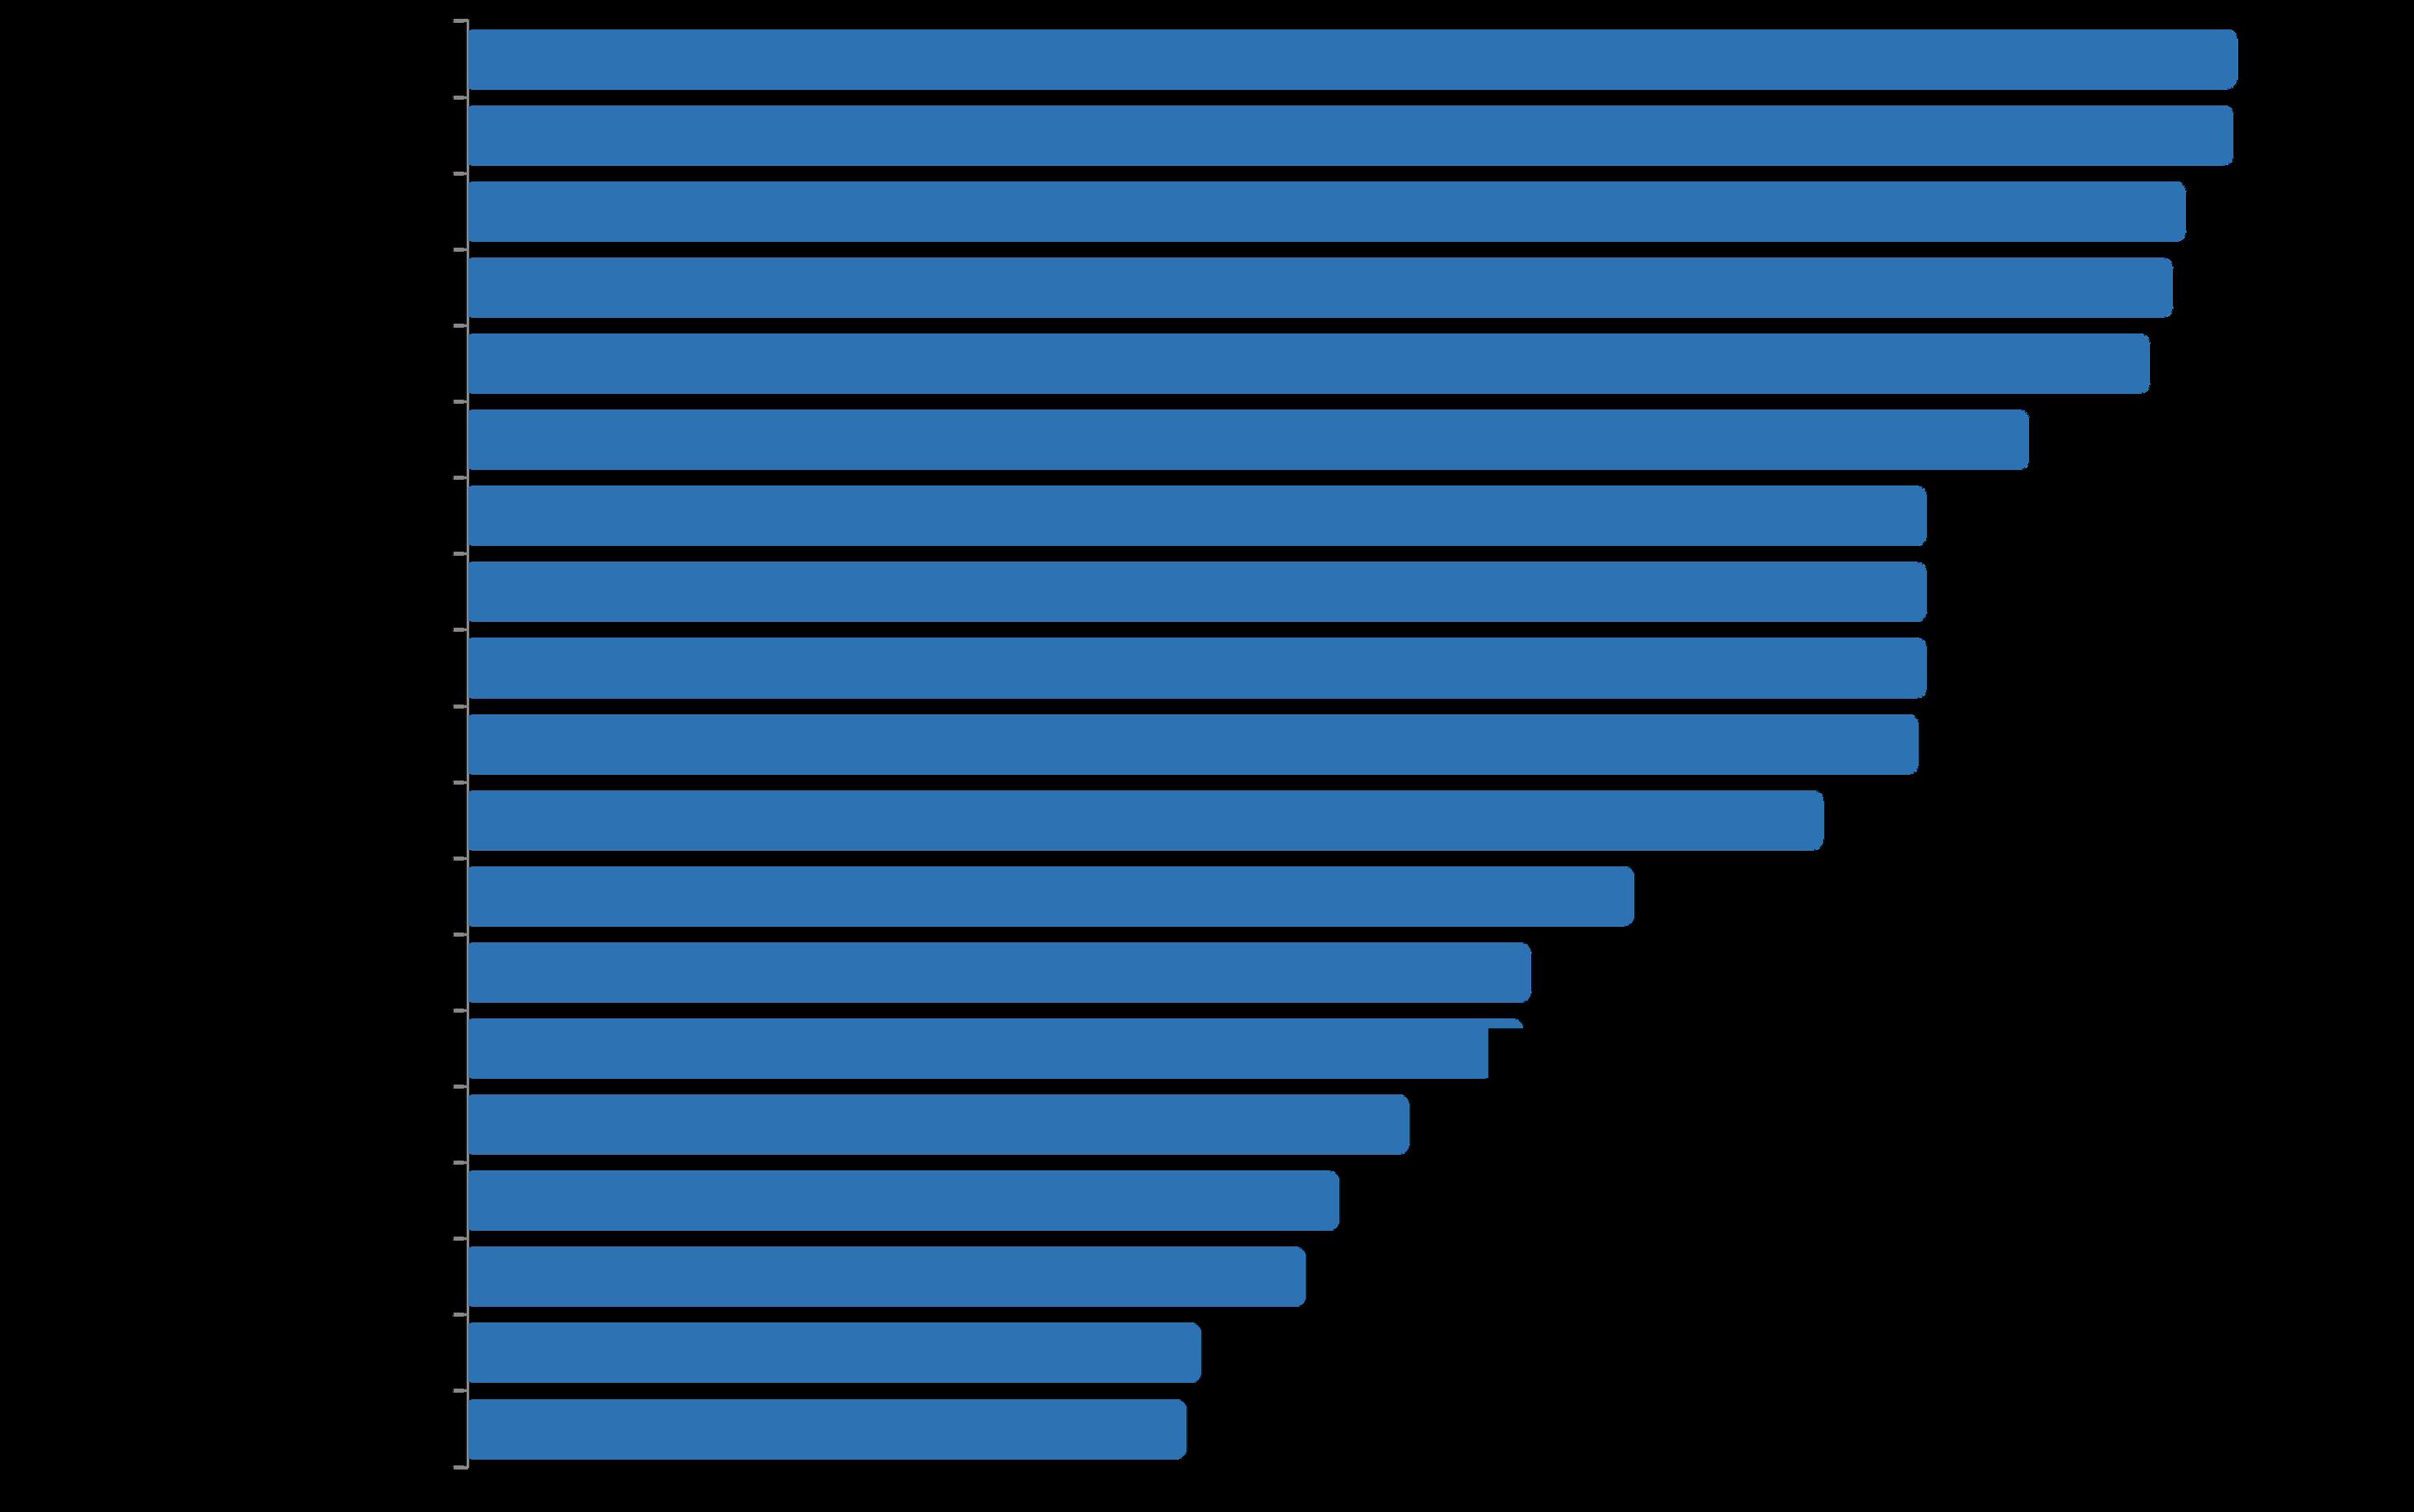
MedianHouseSalesPrices,12MonthsSales, High Sales $4m+*
Capitola
Rio del Mar/Seascape
West Santa Cruz (city)
La Selva Beach
Live Oak
Soquel
Central Aptos
Scotts Valley
East Santa Cruz (city)
Los Gatos Mtns
Seacliff
Larkin Valley
Ben Lomond
Corralitos
Felton
Amesti/Green Vly
Central Watsonville
Boulder Creek
Lompico/Zayante
$1,700,000
$1,696,500
$1,650,000
$1,637,500
$1,615,500
$1,499,000
$1,400,000
$1,400,000
$1,400,000
$1,392,000
$1,300,000
$1,117,500
$1,017,500
$1,010,000
$900,000
$832,500
$800,000
$699,000
$685,000
East and West Santa Cruz refer to the City of Santa Cruz. Scotts Valley includes 3 MLS areas. All areas delineated are MLS areas.
12 months sales through mid-December 2025
Median sales price is that price where half the homes sold for more and half for less. It is a general statistic that typically disguises a wide range of prices in the underlying sales. This chart pertains to HOUSE sales. The median condo sales price was $697,500, and for townhouses, $896,000.
Santa Cruz County Homes Market
As is the normal seasonal trend, the number of listings for sale on January 1st fell to its annual low count. Inventory will now start to rapidly increase as the market wakes up.*
The # of active listings on a given day is affected by 1) the # of new listings coming on market, 2) how quickly buyers put them into contract, 3) the sustained heat of the market over time, and 4) sellers pulling their homes off the market without selling.
* Active/Coming-Soon listings posted to NorCal MLS Alliance. Data from sources deemed reliable but may contain errors and subject to revision. Not all listings are posted to MLS. All numbers approximate. The number of active listings constantly changes.
0 5,000 4,000 3,000 2,000 1,000
Sales in one month mostly reflect accepted offers in the previous month. The number of sales in December 2025 was substantially higher year over year. January typically sees the annual low count, reflecting the holiday market slowdown in December and early January.
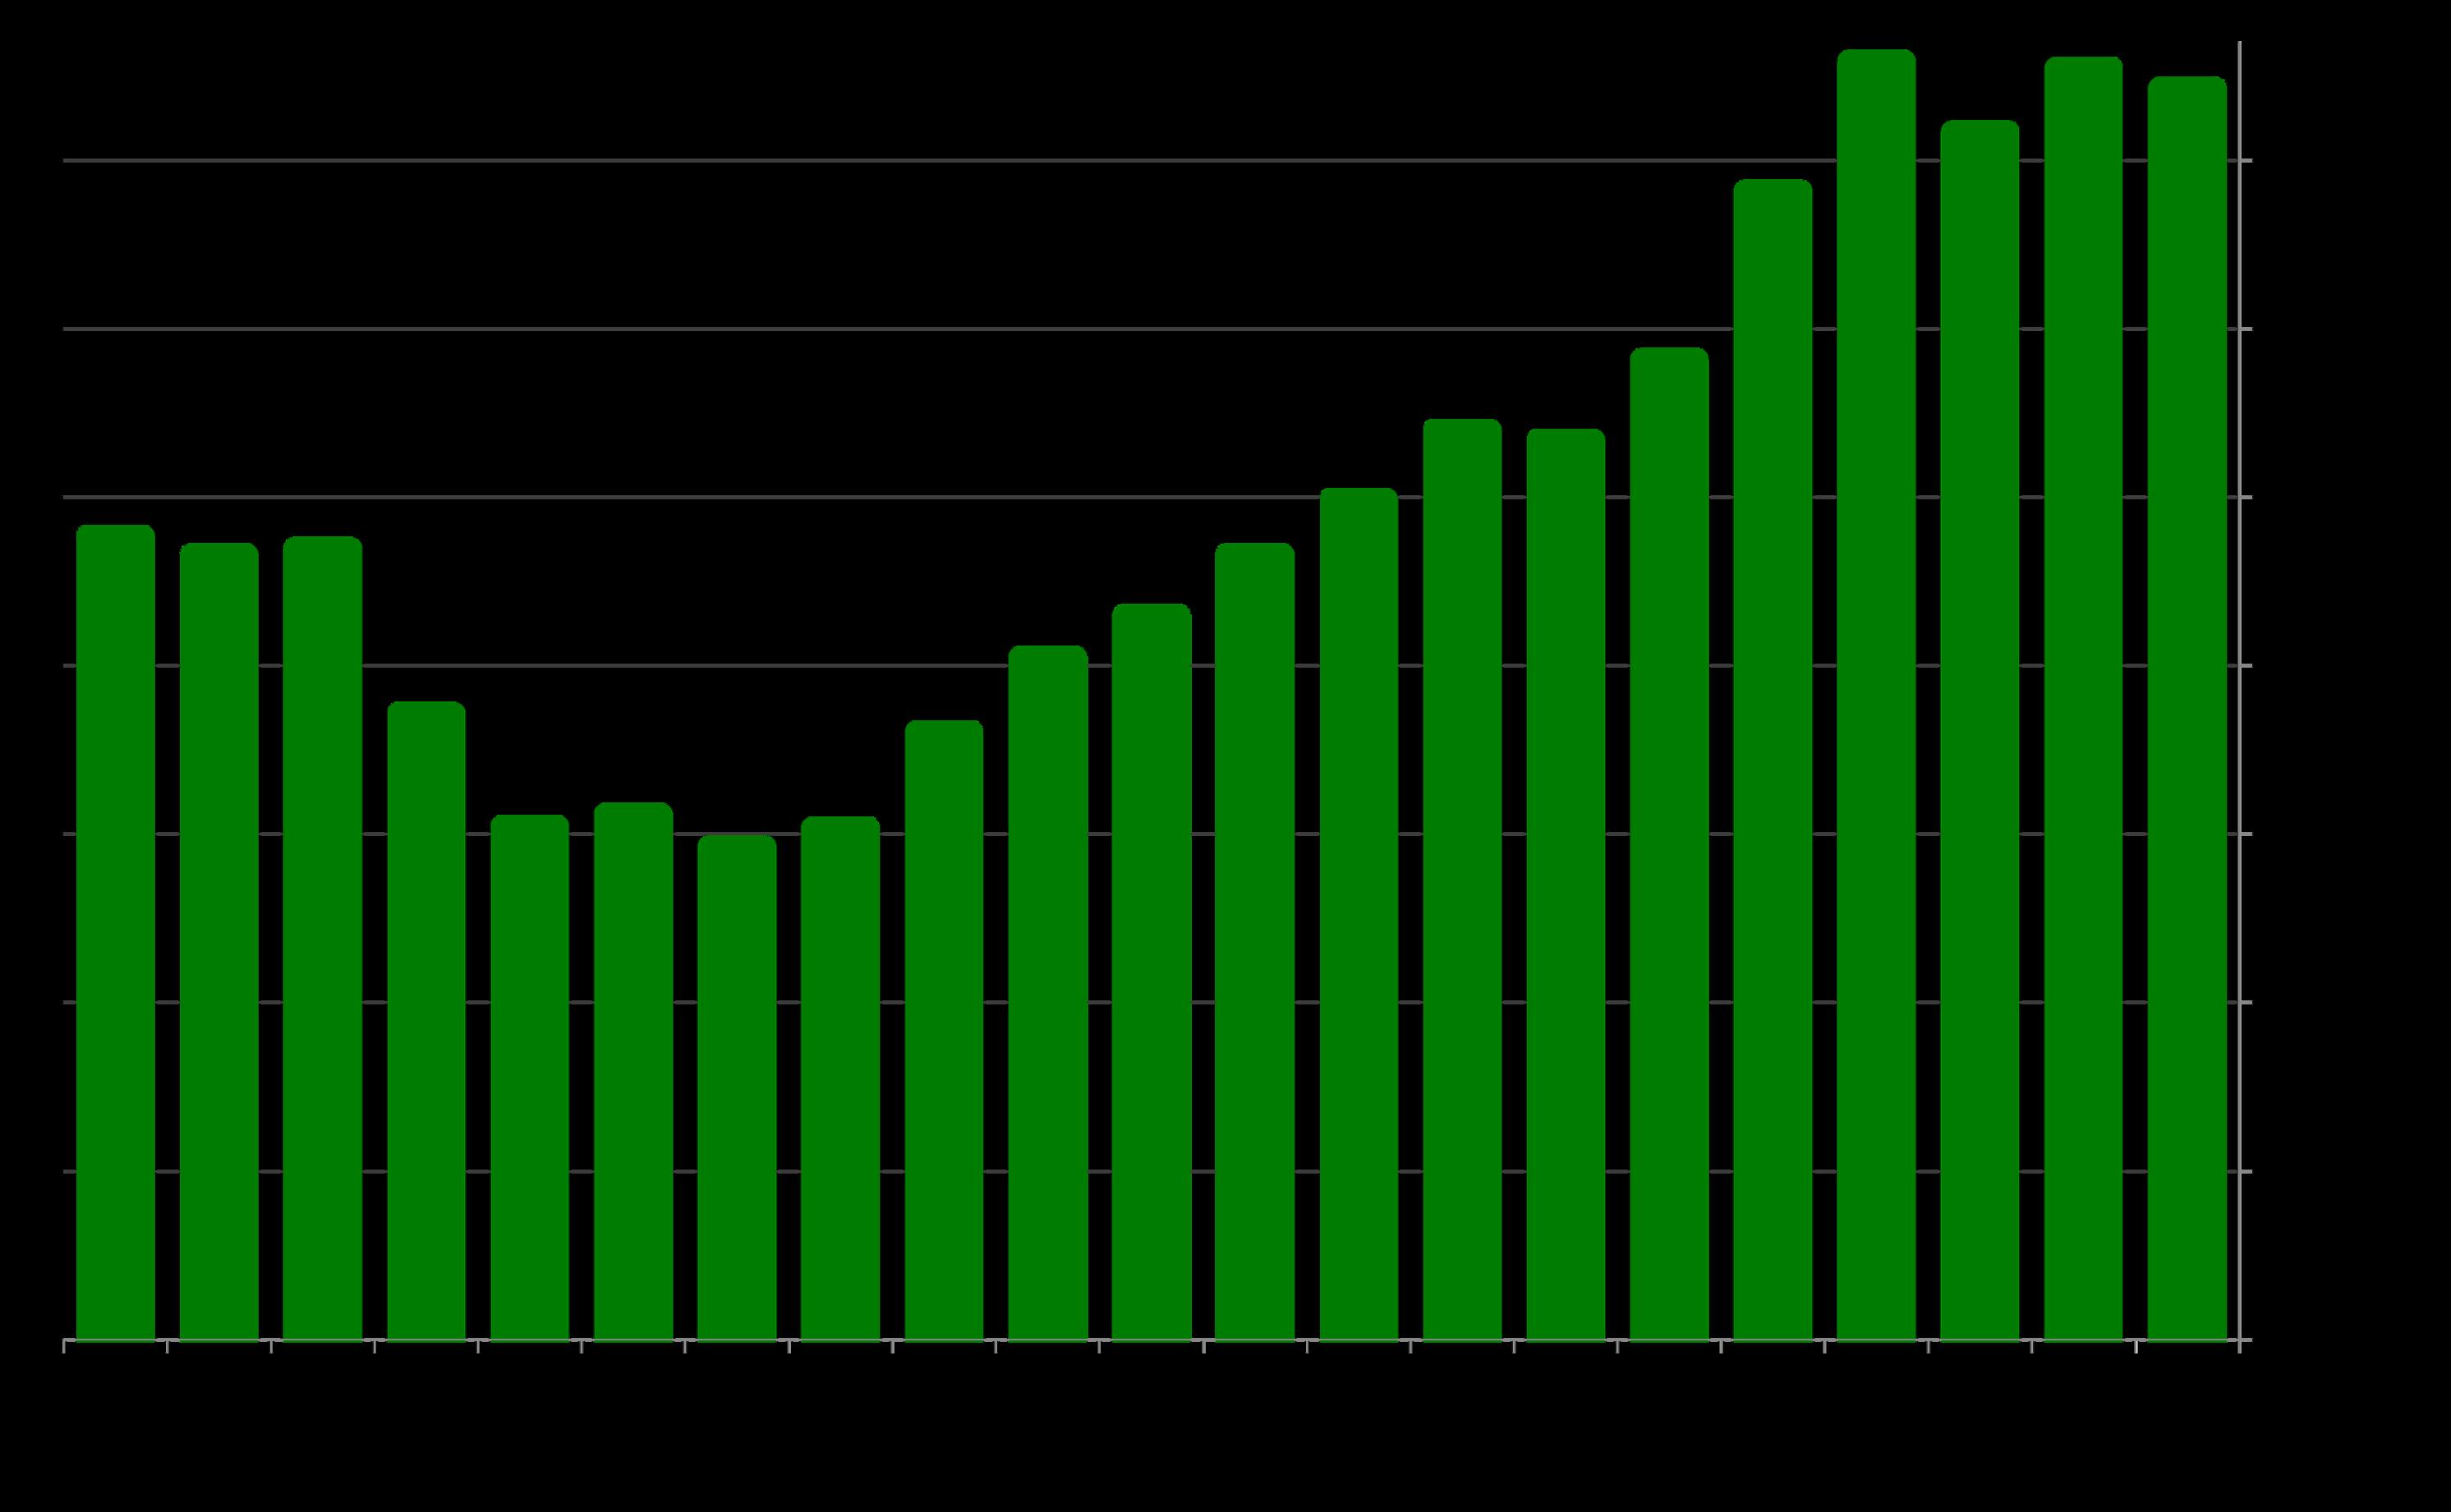
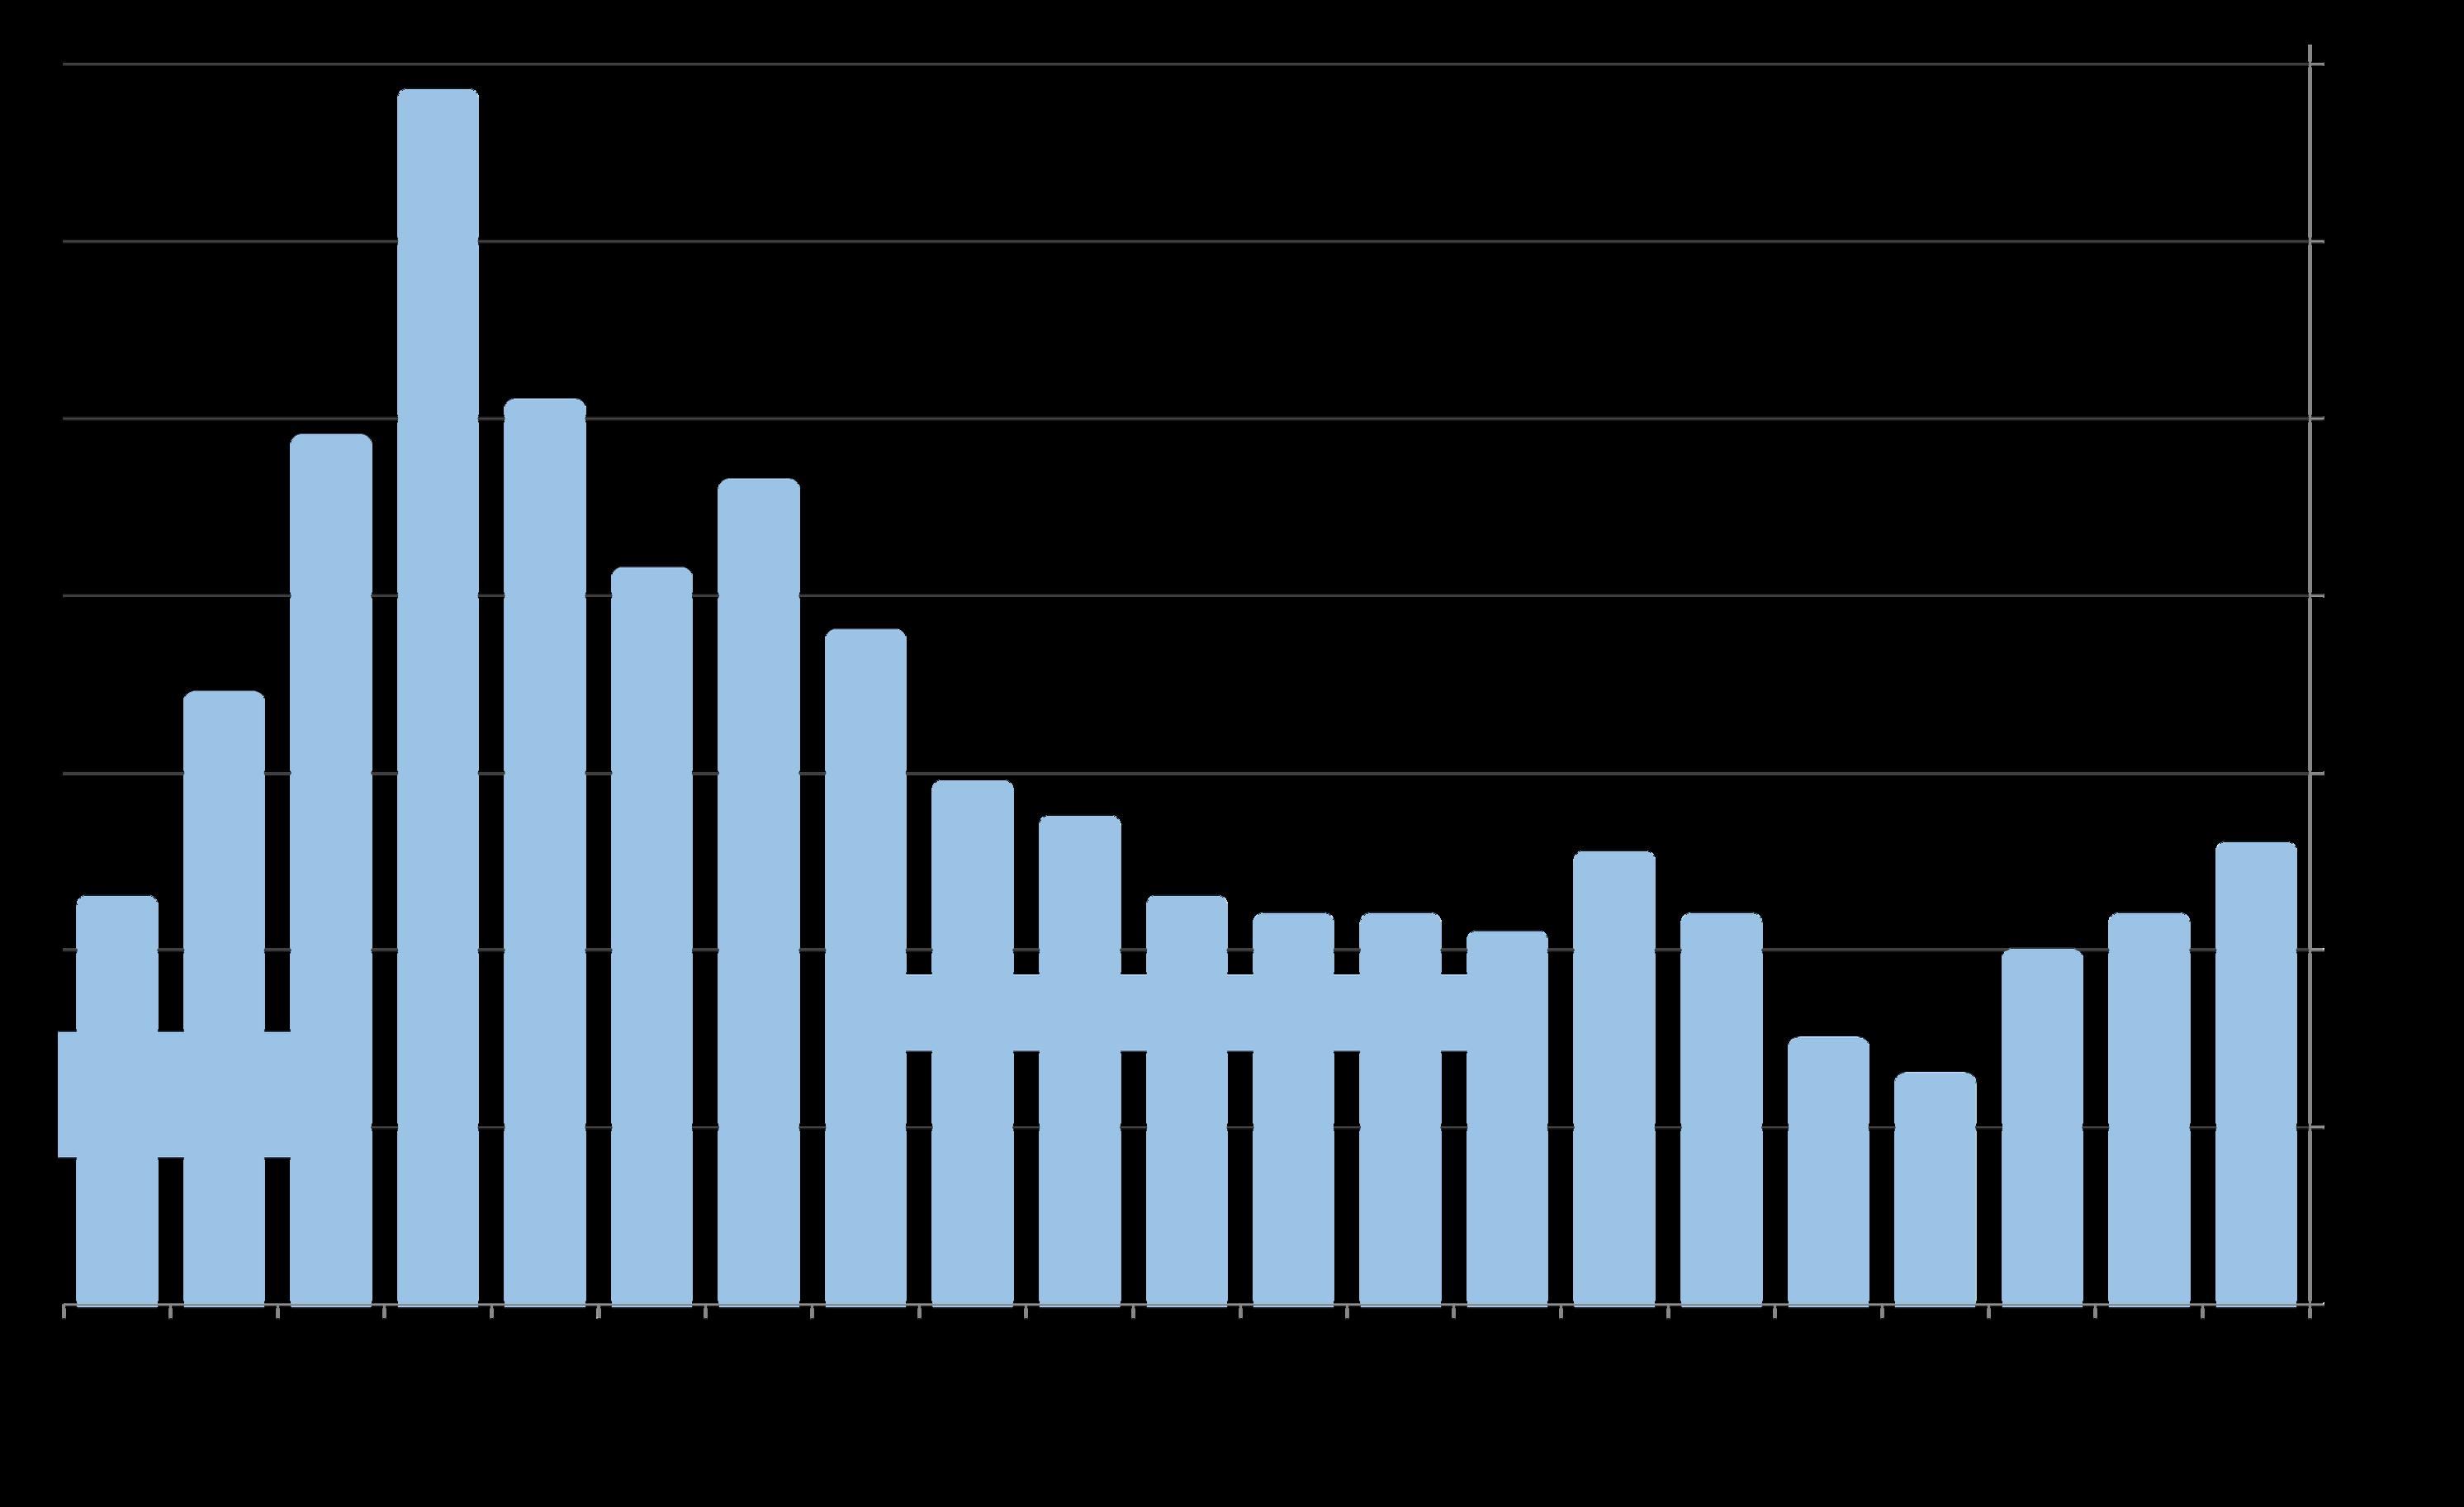
Santa Cruz County Annual Sales Volume
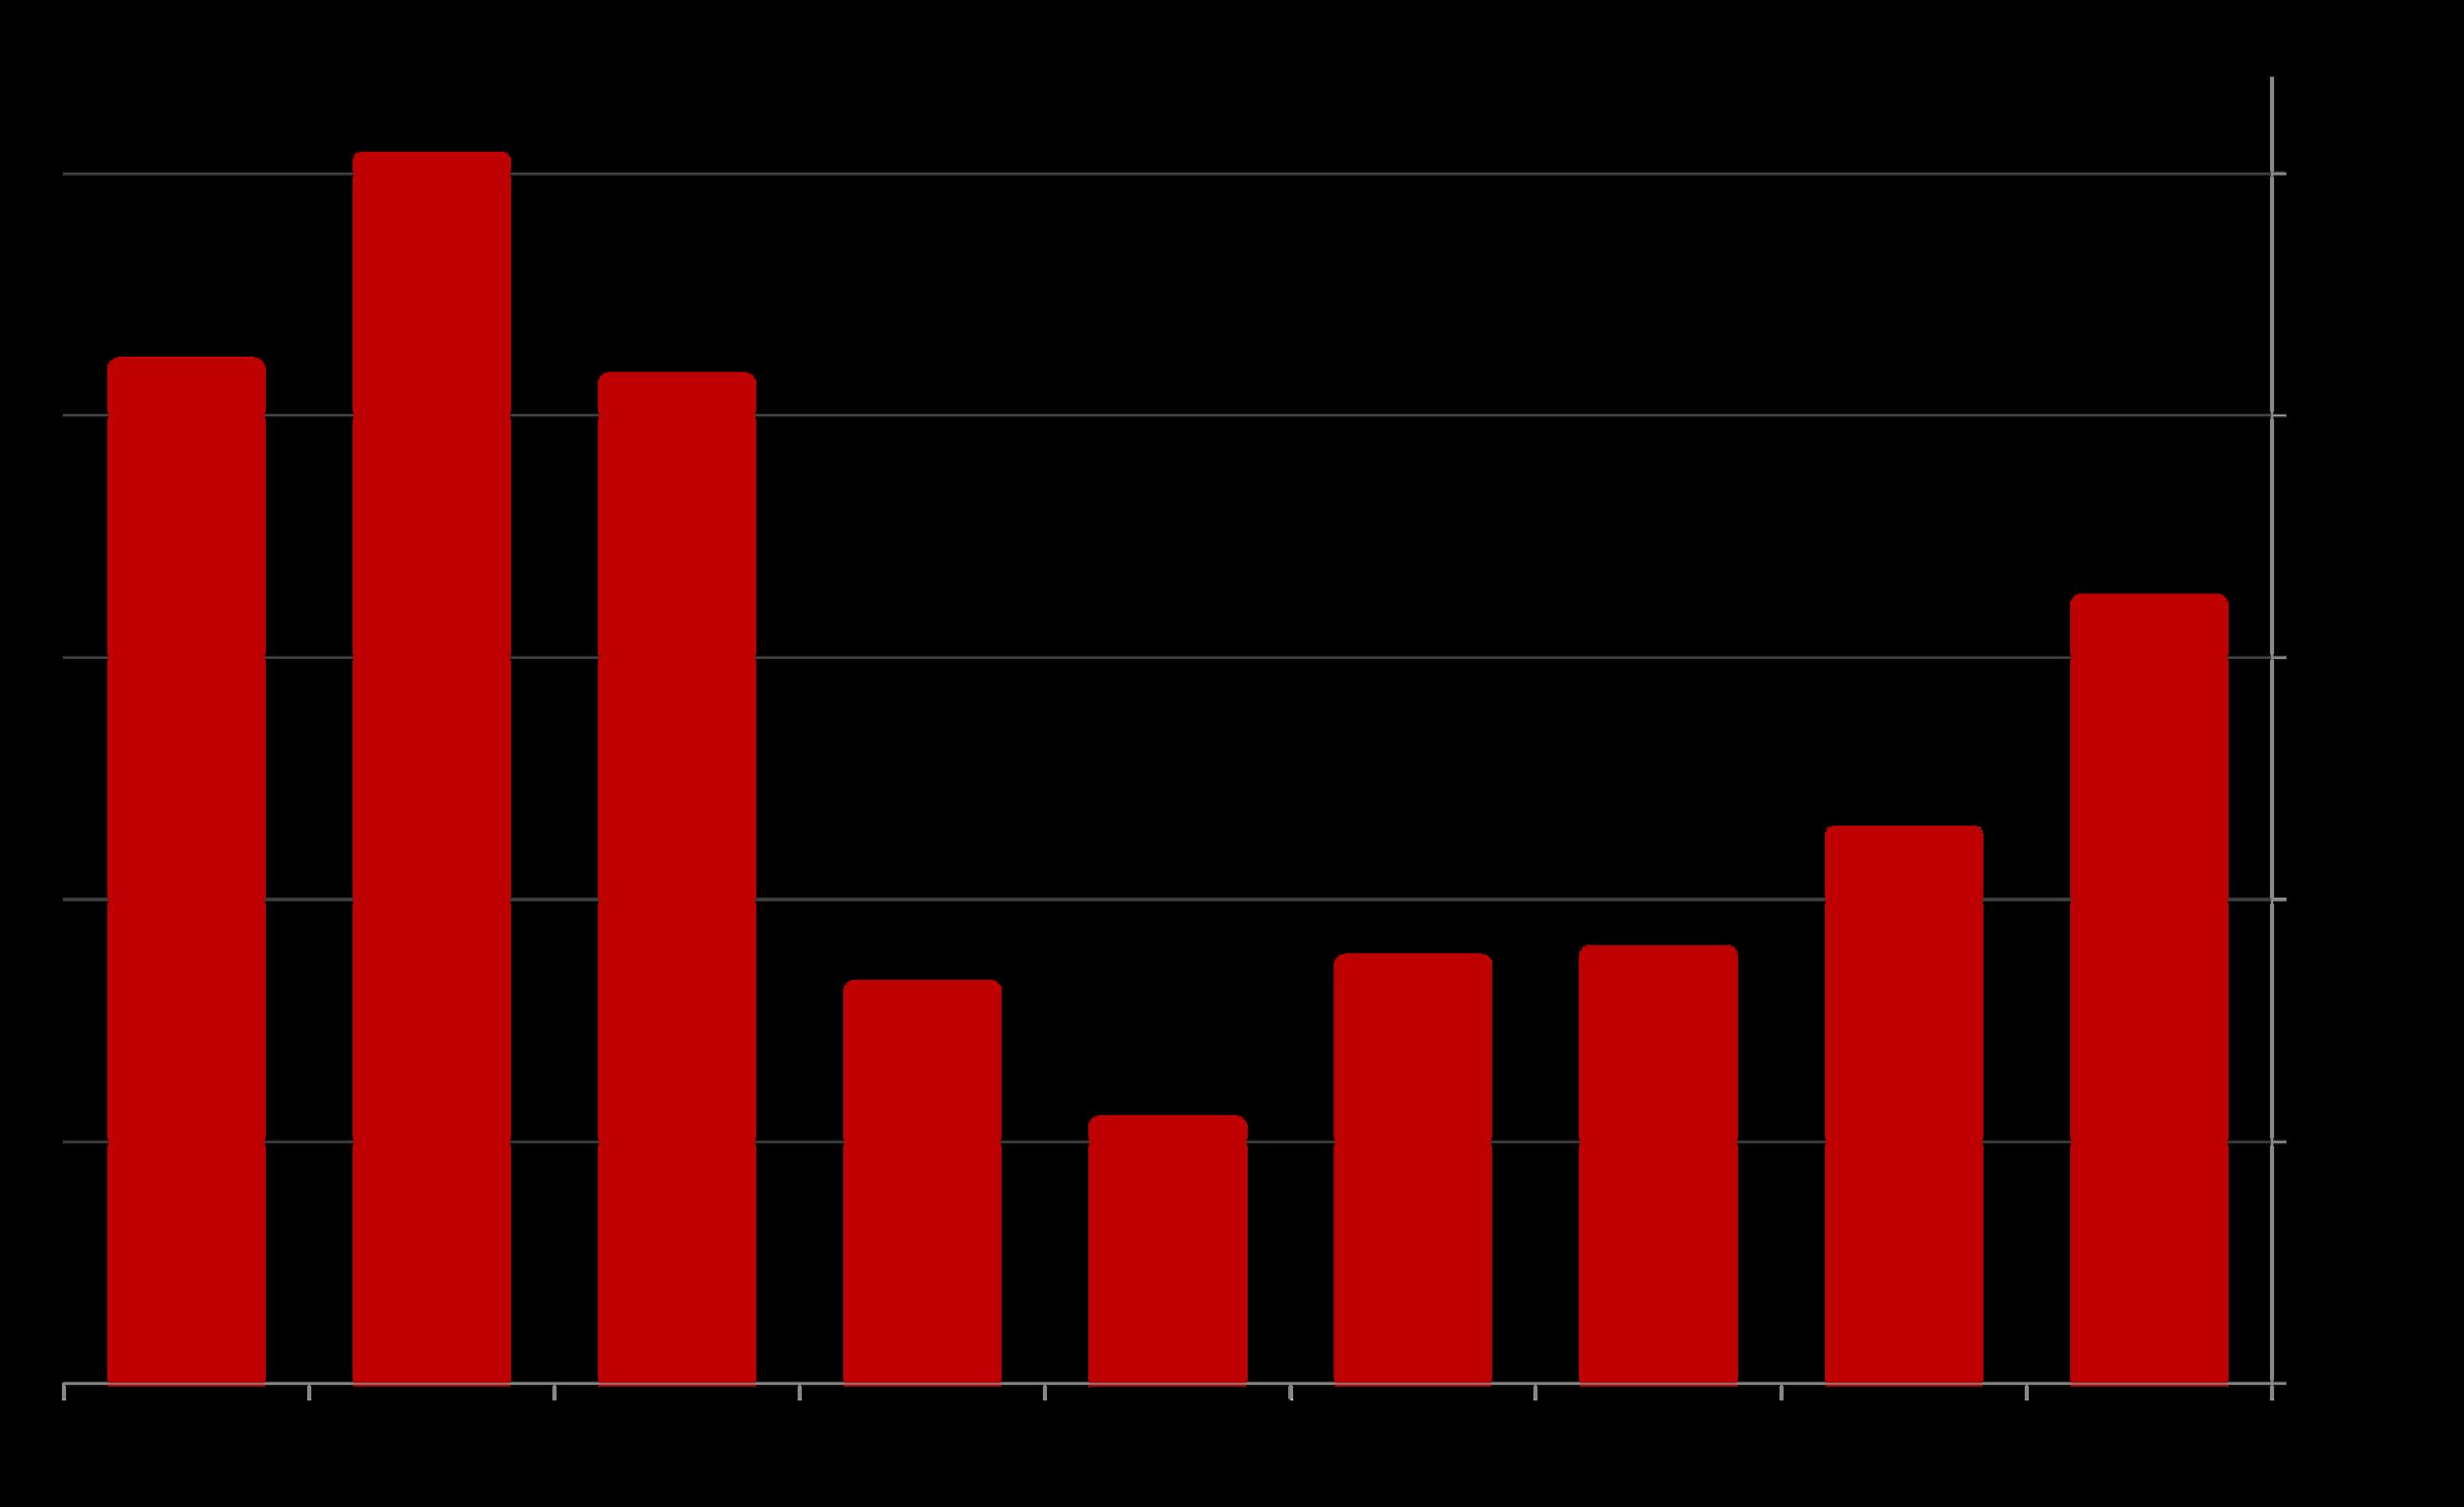
e asre deeply number of listings available t impacted by positive and negative economic conditions. 2025 sales volume increased about 8% from 2024 but remained very low by historical standards.
Salesvolume isaffected by both buyer demand and the
pnunrcuhaasel, wSha
*All attached and detached residential home sales reported to NorCal MLS Alliance per Infosparks calculations. Data from sources deemed reliable but may contain errors and subject to revision. All numbers approximate, with last year’s total estimated based on available data in early January and may change due to late-reported sales. Not all sales are reported to
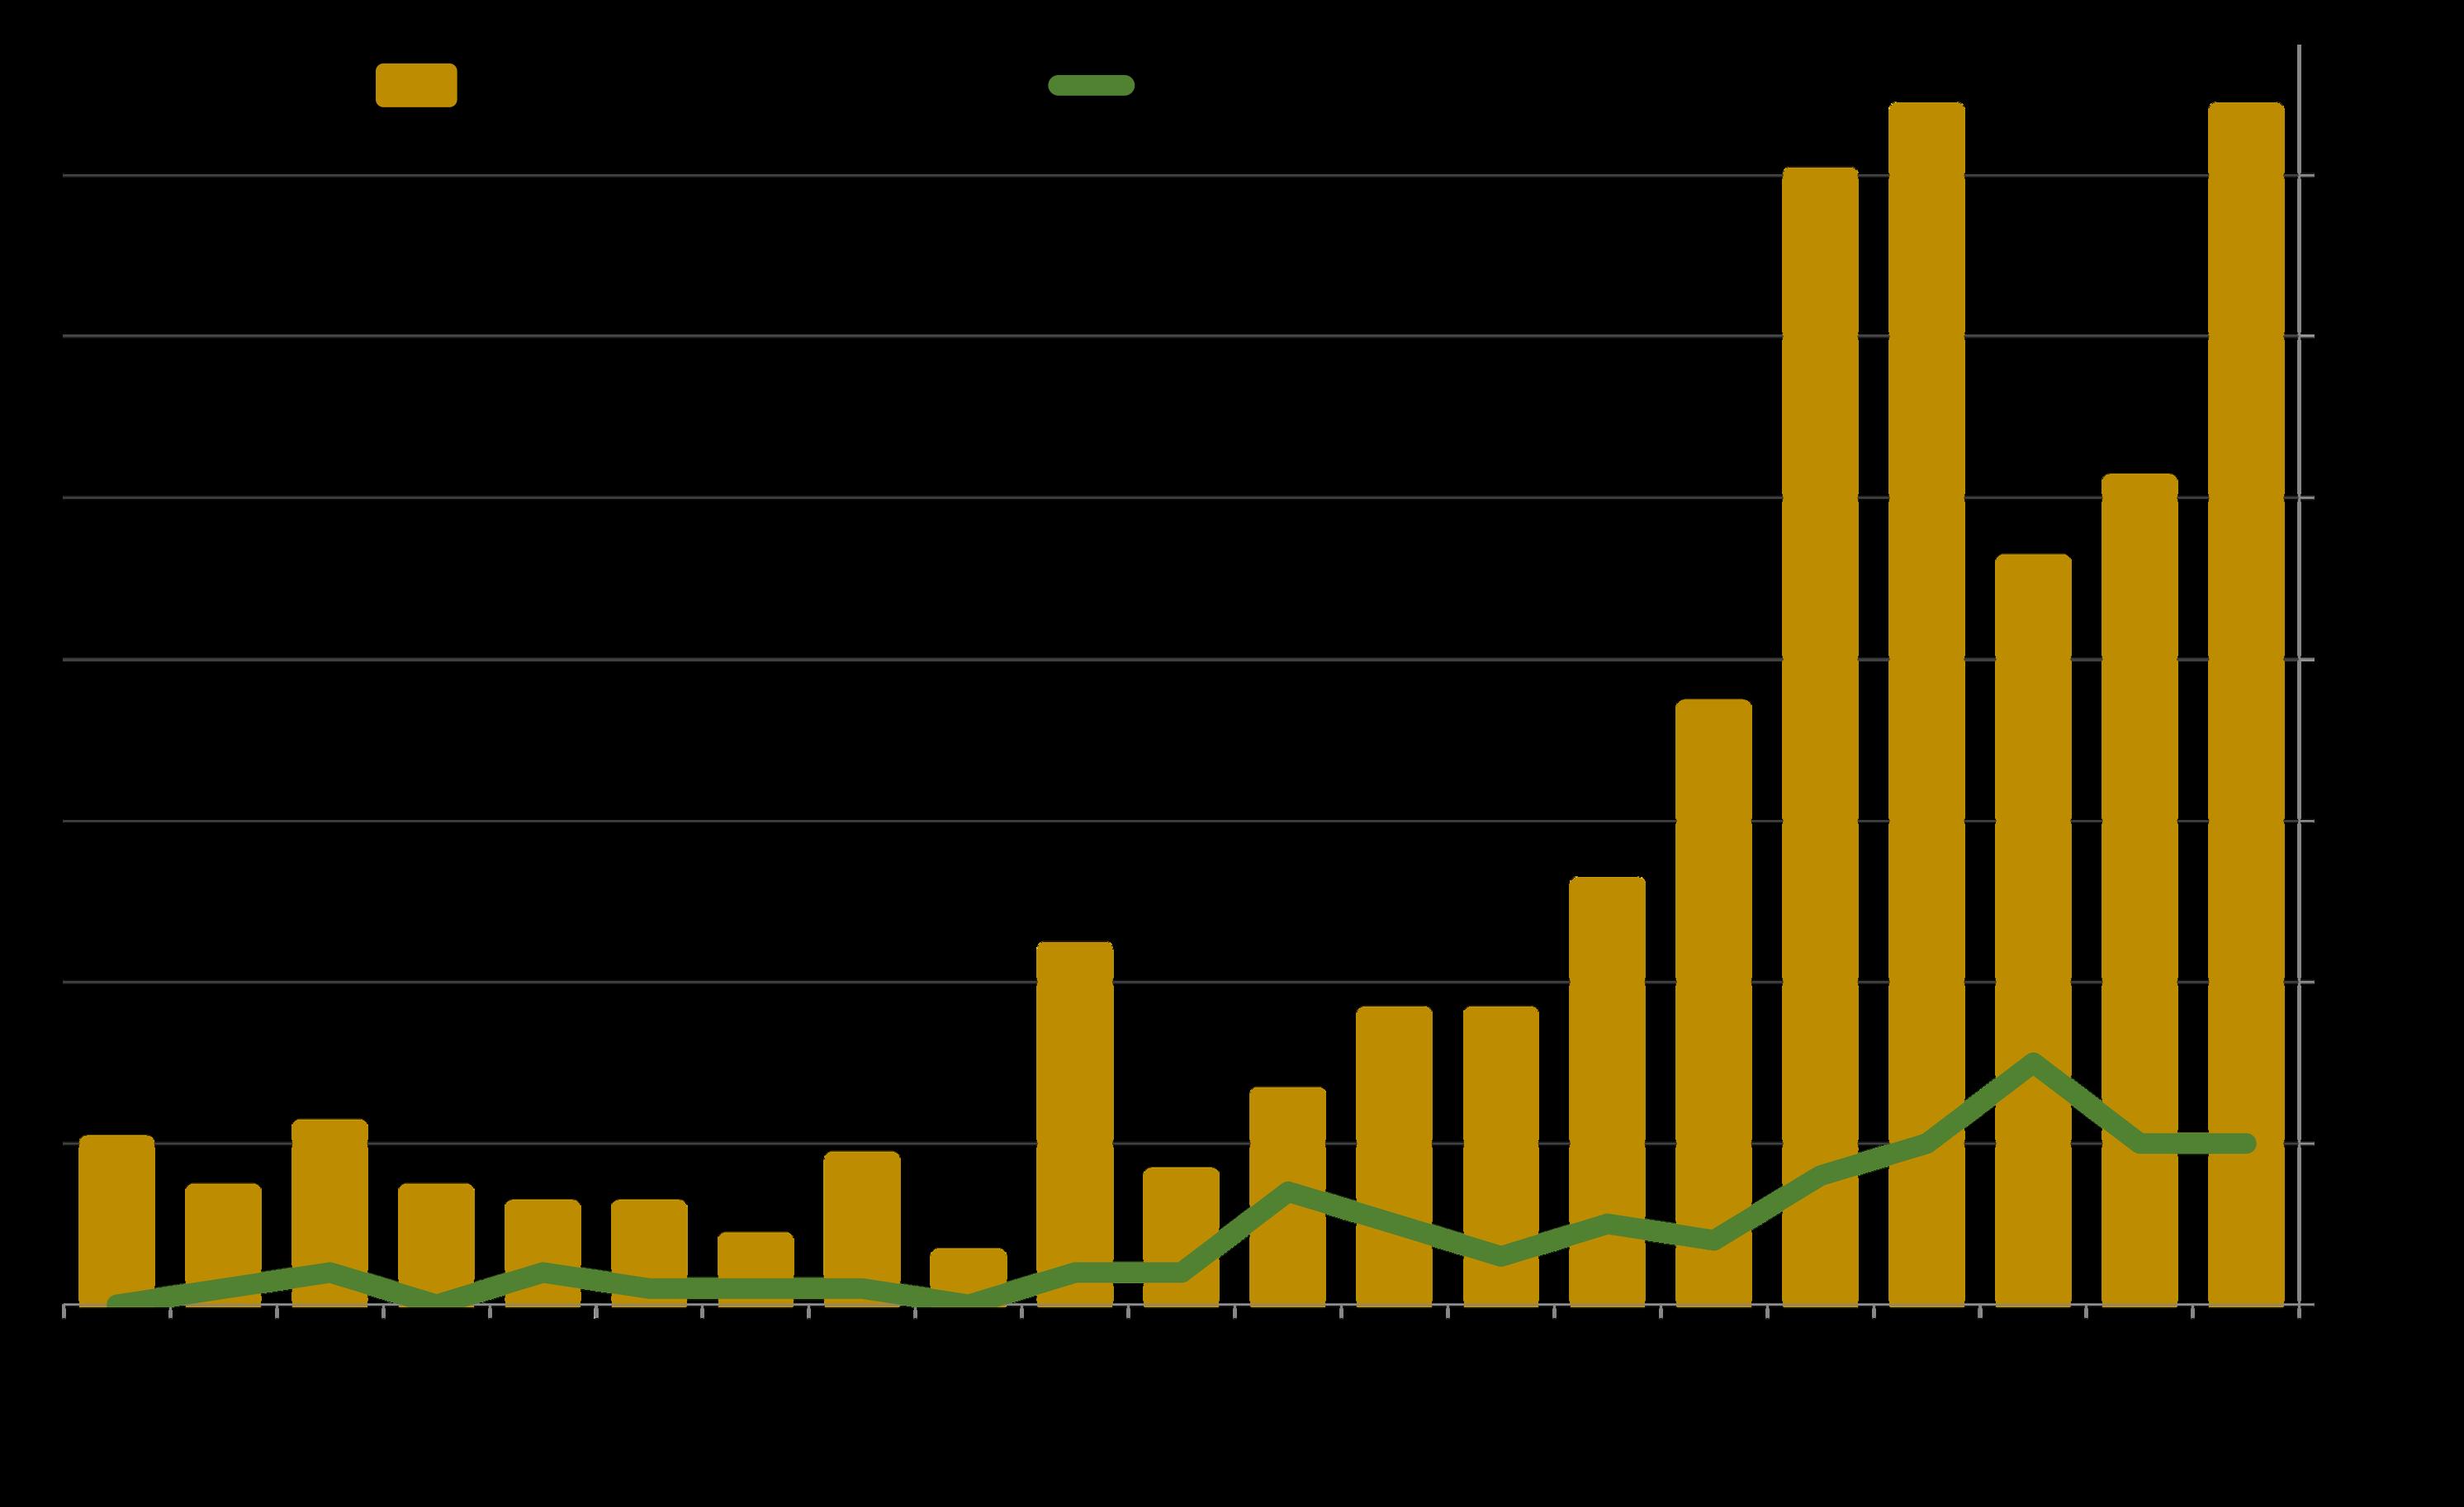
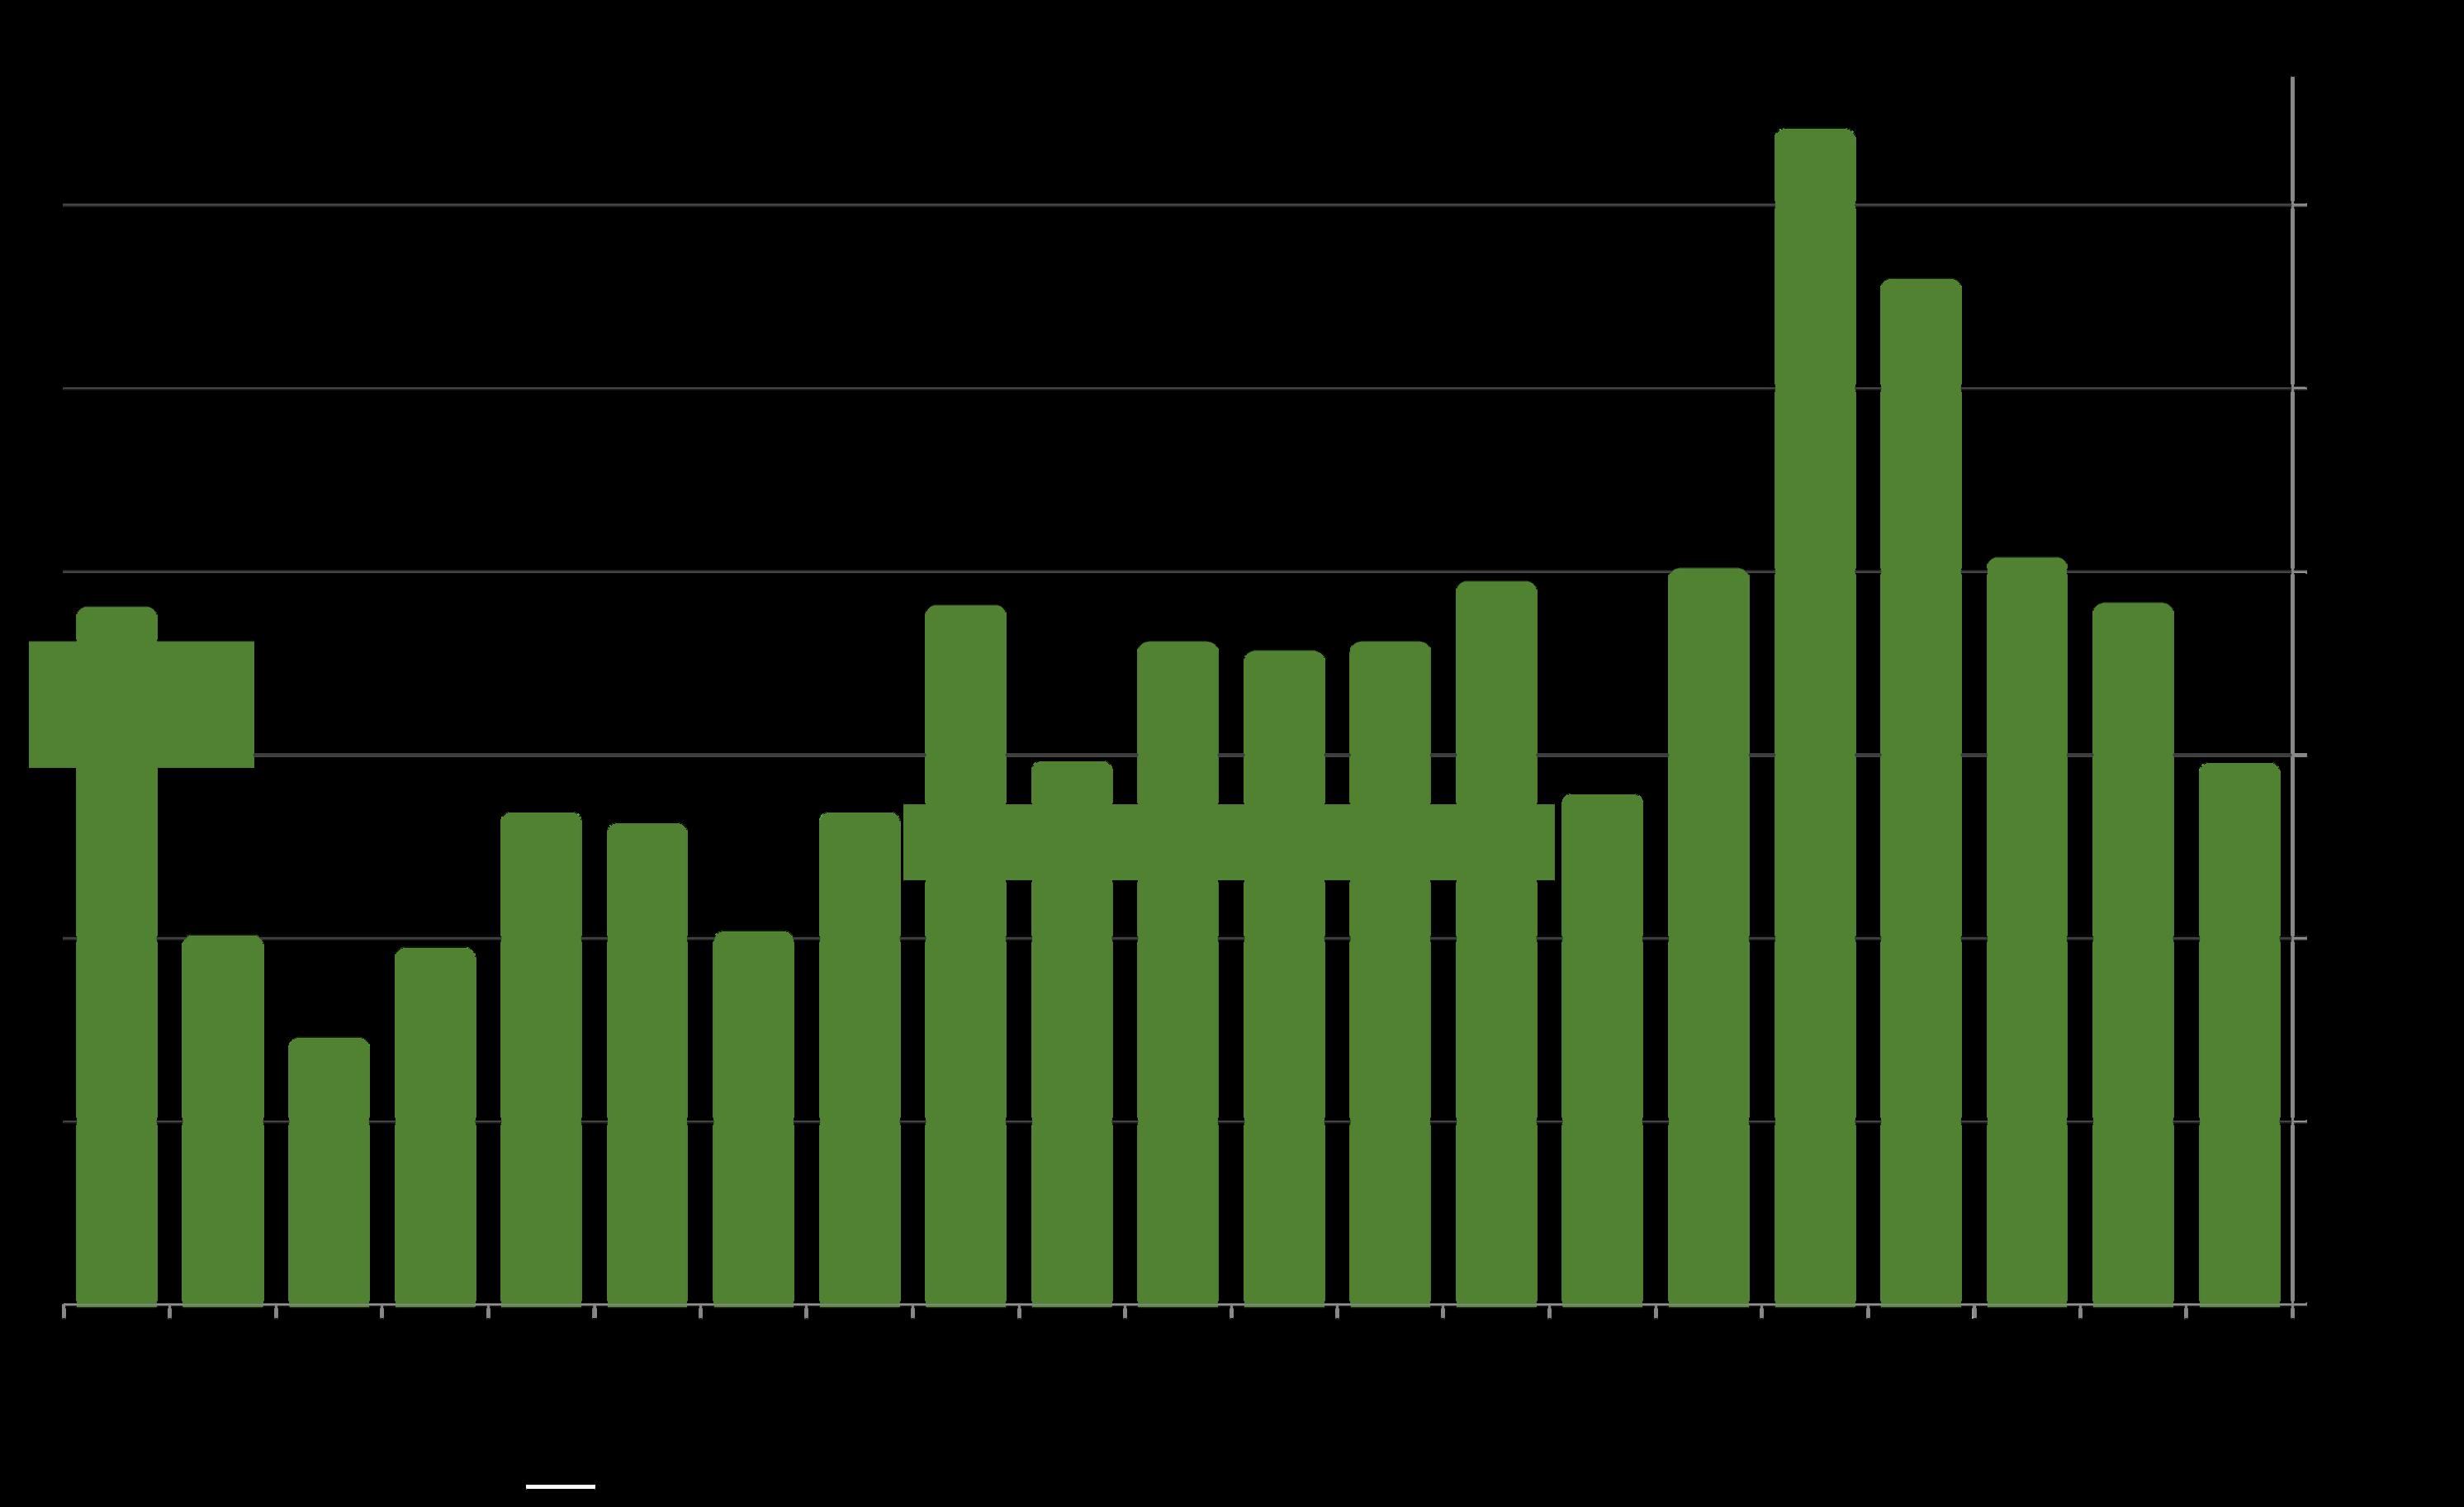
Cruz County: Annual Sales - $3,000,000+
Number of Luxury Home Sales by Year, since 2005*
Sales of higher-price homes are affected by buyer demand, the number of listings available to
and appreciation trends –all of which are impacted by economic and demographic conditions. As appreciation occurs over time, homes that would have sold for under $3 million, then sell for over that
(and vice versa if
Santa Cruz County Residential Market
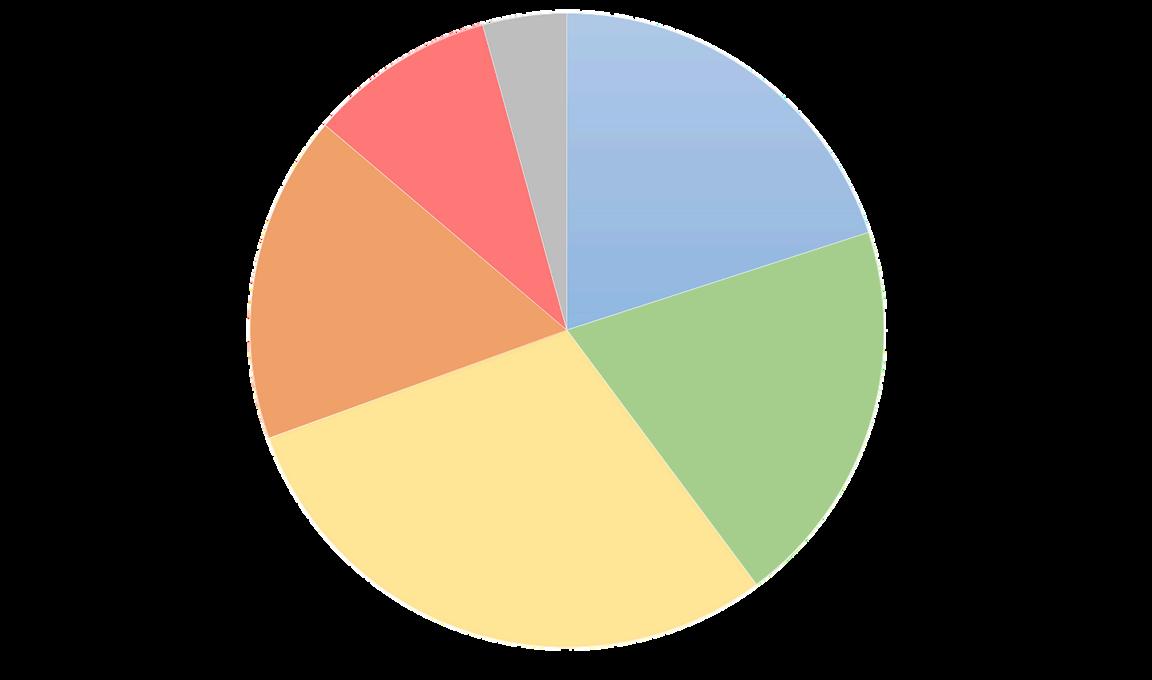
2025 Home Sales by Price Segment*
$2,000,000 - $2,999,999
$1,500,000
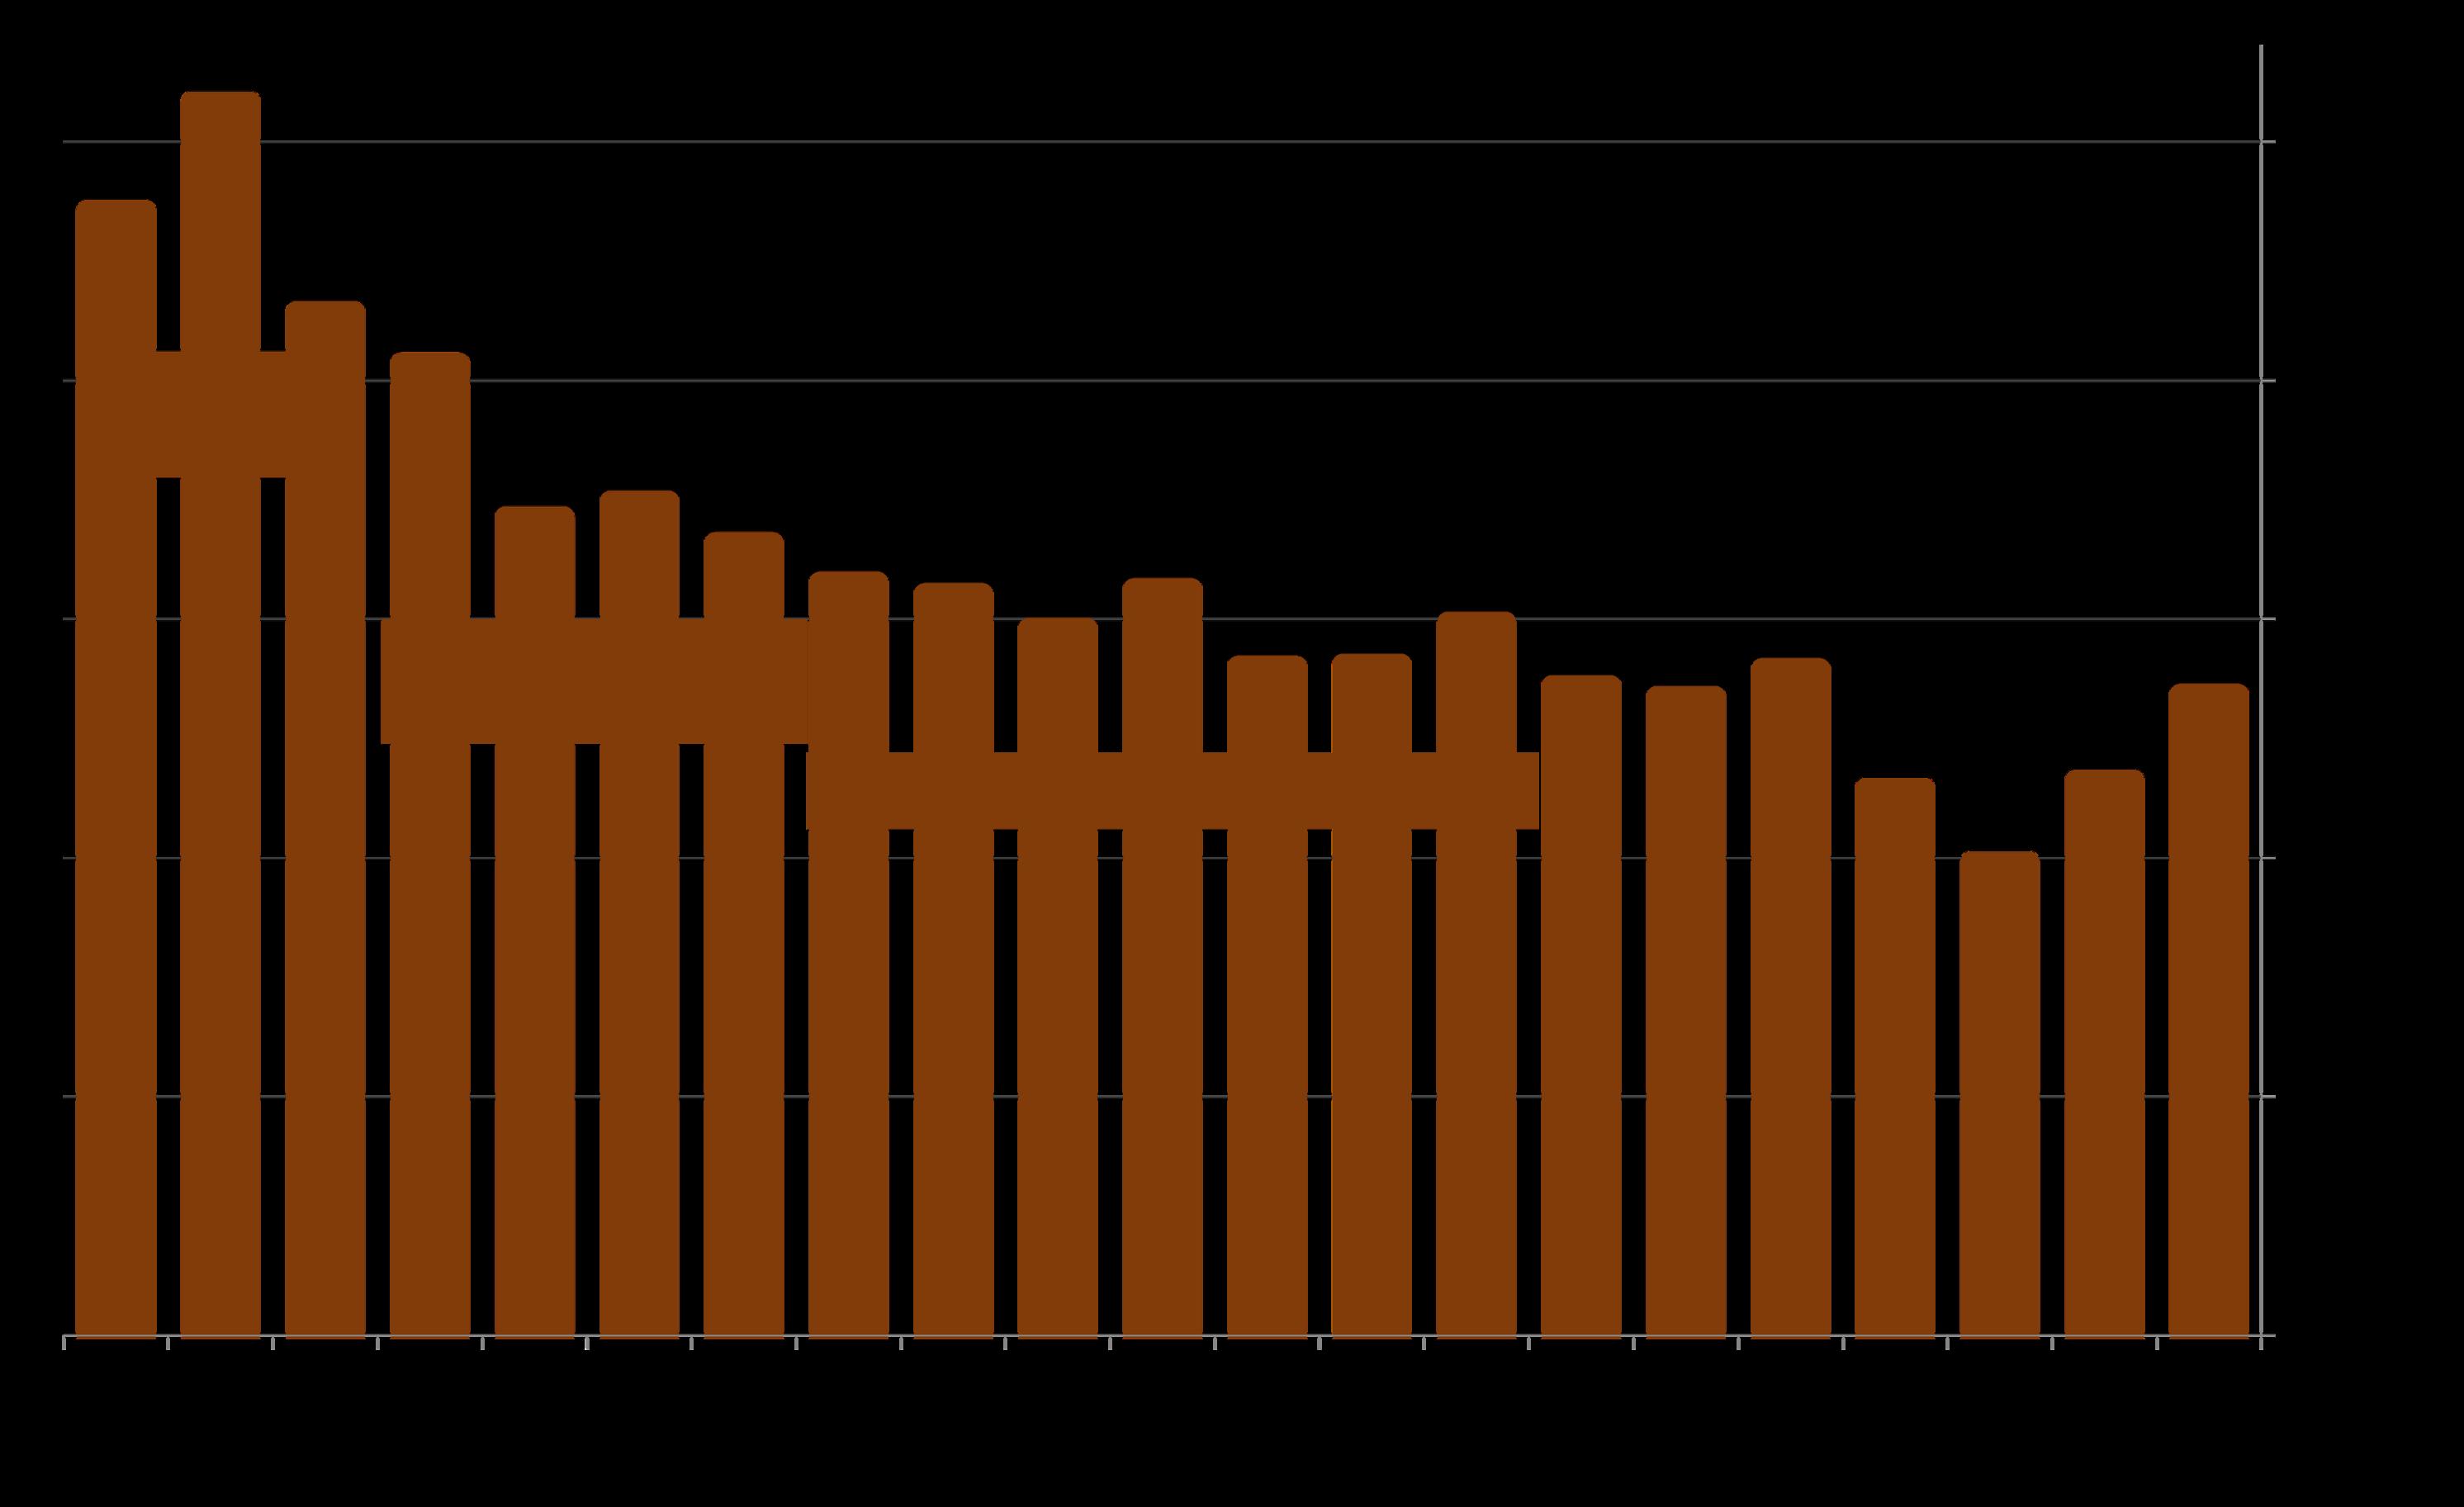
Annual DOM
This statistic is an indicator of the strength of buyer demand vs. the supply of homes for sale, measuring – for homes sold – the average time between a listing coming on market and offer acceptance.
The market typically sees substantial seasonal variations in this metric, which do not appear in this annual trend chart. On average, more expensive homes usually take longer to sell than more affordable homes.
Santa Cruz County – Overbidding Asking Price
Generally speaking, the stronger the demand as compared to the supply of homes for sale, the more buyers compete to win the sale by overbidding asking price.
*Sales over final list price: All attached and detached residential home sales reported to NorCal MLS Alliance per Infosparks calculations. Data from sources deemed reliable but may contain errors and subject to revision. All numbers approximate and may change due to late- reported sales. Not all sales are reported to MLS.
Santa Cruz County: Overbidding & Underbidding
*The ratio of sales price to the original list price: All attached and detached residential home sales reported to NorCal MLS Alliance per Infosparks calculations. Data from sources deemed reliable but may contain errors and subject to revision. Percentages rounded, all numbers approximate and may change due to late-reported sales. Not all sales are reported to MLS. 100% = an average sales price at original asking price; 104% = an average price 4% above asking; 98% = 2% below asking.
Annual Number of Price Reductions
Bay Area Median House Values by County
2025 Sales By Bedroom/Bath Count*
County
In alphabeticalorder
4 Bedroom, 3 Bath Houses
$1,626,500 $1,075,000
$1,905,000
Monterey County
How these values apply to any particular home is unknown without a specific comparative market analysis.
Sonoma County
$1,110,000
$2,200,000
$2,622,500
$2,210,000
$1,550,000
$739/sq.ft.
$478/sq.ft.
5+ Bedroom, 4+ Bath Houses, 3000+ sq.ft.
$4,000,000
$941/sq.ft.
$1232/sq.ft.
$1023/sq.ft.
$677/sq.ft.
$317/sq.ft.
$423/sq.ft.
*Sales reported toNorCal MLS Alliance in 2025 through mid-December 2025. Counties contain submarkets of widely varying values. “Fixer-uppers” excluded. Median values fluctuate for reasons besides changes in fair market value. Counties with low sales volumes, such as Napa, can see large fluctuations in values. Data from sources deemed reliable but may contain errors and subject to revision. All numbers approximate, and data constantly changes as new sales occur. Not all sales are reported to MLS.
Bay Area Median House Values by County
2025 Sales By Bedroom/Bath Count*
County
In alphabeticalorder
Alameda County
Contra Costa
Marin County
Monterey County
Napa County
San Francisco
San Mateo County
Santa Clara County
Santa Cruz County
Solano County
Sonoma County
2 Bedroom, 1-2 Bath Houses
Median value is that value at which half the sales occurred for more and half for less. It is a very general statistic.
*Sales reported to NorCal MLS Alliance in 2025 through mid-December 2025. Counties contain submarkets of widely varying values. “Fixer-uppers” excluded. Median values fluctuate for reasons besides changes in fair market value. Data from sources deemed reliable but may contain errors and subject to revision. Numbers approximate, and data constantly changes as new sales occur. Not all sales are reported to MLS.
$528/sq.ft.
$859/sq.ft.
$573/sq.ft.
$597/sq.ft.
$1005/sq.ft.
$1153/sq.ft.
$1249/sq.ft.
$758/sq.ft.
$388/sq.ft.
$532/sq.ft.
Bay Area Median Condo & Townhouse Values
2025 Sales By Property Type & Bedroom/Bath Count*
2 Bedroom, 2 Bath Condos
3 Bedroom, 2-3 Bath Townhouses County In alphabeticalorder $600,000
$558/sq.ft.
$497/sq.ft.
$661/sq.ft.
$642/sq.ft.
$929/sq.ft.
$1051/sq.ft.
$742/sq.ft.
$694/sq.ft.
$652/sq.ft.
$340/sq.ft.
$398/sq.ft.
$608/sq.ft.
$524/sq.ft.
$561/sq.ft. MedianDollar
$580/sq.ft.
$887/sq.ft.
Statistics are generalities, essentially summaries of widely disparate data generated by dozens, hundreds or thousands of unique, individual sales occurring within different time periods. They are best seen not as precise measurements, but as broad, comparative indicators, with reasonable margins of error. Anomalous fluctuations in statistics are not uncommon, especially in smaller, expensive market segments. Last period data should be considered estimates that may change with late-reported data. Different analytics programs sometimes define statistics – such as “active listings,” “days on market,” and “months supply of inventory” – differently: what is most meaningful are not specific calculations but the trends they illustrate. Most listing and sales data derives from the local or regional multi-listing service (MLS) of the area specified in the analysis, but not all listings or sales are reported to MLS and these won’t be reflected in the data. “Homes” signifies real-property, single-household housing units: houses, condos, co-ops, townhouses, duets and TICs (but not mobile homes), as applicable to each market. City/town names refer specifically to the named cities and towns, unless otherwise delineated. Multi-county metro areas will be specified as such. Data from sources deemed reliable, but may contain errors and subject to revision. All numbers to be considered approximate.
Many aspects of value cannot be adequately reflected in median and average statistics: curb appeal, age, condition, amenities,
views, lot size, quality of outdoor space, “bonus” rooms, additional parking, quality of location within the neighborhood, and so on. How any of these statistics apply to any particular home is unknown without a specific comparative market analysis.
Median Sales Price is that price at which half the properties sold for more and half for less. It may be affected by seasonality, “unusual” events, or changes in inventory and buying trends, as well as by changes in fair market value. The median sales price for an area will often conceal an enormous variety of sales prices in the underlying individual sales.
Dollar per Square Foot is based upon the home’s interior living space and does not include garages, unfinished attics and basements, rooms built without permit, patios, decks or yards (though all those can add value to a home). These figures are usually derived from appraisals or tax records, but are sometimes unreliable (especially for older homes) or unreported altogether. The calculation can only be made on those home sales that reported square footage.
Photo use under the Creative Commons License: https://creativecommons.org/licenses/by-sa/2.0/
Compass is a real estate broker licensed by the State of California, DRE 01527235. Equal Housing Opportunity. This report has been prepared solely for information purposes. The information herein is based on or derived from information generally available to the public and/or from sources believed to be reliable. No representation or warranty can be given with respect to the accuracy or completeness of the information. Compass disclaims any and all liability relating to this report, including without limitation any express or implied representations or warranties for statements contained in, and omissions from, the report. Nothing contained herein is intended to be or should be read as any regulatory, legal, tax, accounting or other advice and Compass does not provide such advice. All opinions are subject to change without notice. Compass makes no representation regarding the accuracy of any statements regarding any references to the laws, statutes or regulations of any state are those of the author(s). Past performance is no guarantee of future results.