THE ECONOMY IN MOTION: WHAT NEWTON’S LAWS CAN TEACH US ABOUT GROWTH, INFLATION & THE ECONOMY
SPECIAL REPORT: INSIDE THE IPO MARKET
A WAR, A MARKET RALLY, & THE QUARTER THAT FEW EXPECTED
OUR INVESTMENT COMMITTEE’S TOP PREDICTIONS FOR THE REMAINDER OF 2026
A Letter from Our Chief Investment Officer
If you had told me on February 27, 2026, the U.S. would start a war with Iran the next day AND the S&P 500 would rally over 15% during the second quarter of 2026, I would have thought you were crazy. After all, weren’t we afraid a war with the Iranians would or could get really ugly really quickly? That the price of crude oil would skyrocket? Taking the global economy along with it?
Or so we thought.
To be sure, the mess in the Middle East hasn’t been as clean as this American would have liked. Theocracy hasn’t fallen yet, but the conflict hasn’t really spread as much as many may have feared. To be sure, crude oil prices shot up in March and April, but they came back down pretty sharply in May and June.
As for the economy, the Bureau of Economic Analysis (BEA) announced in June the U.S. economy grew at a 2.1% annualized rate during the first quarter of 2026. (1) Unless all the economic data we have seen since the end of March has been wrong, the economy likely grew modestly during the second quarter as well.
Put another way, IF war with Iran was expected to significantly weaken the U.S. economy, we didn’t appear to get the message. That, or it was garbled in transmission.
To say it was one of the more bizarre quarters in my professional career would be an understatement. Sure, the fourth quarter of 2018 was a whopper, as were pretty much all of them in 2008. However, those were bad times. Last quarter was good. Great, even.
What wasn’t to like? War with Iran? Higher crude oil prices for much of the time? Continued bellicosity in Eastern Europe? Ongoing domestic strife and never-ending tiffs with Europe? Surprisingly stubborn inflation, turning potential rate cuts into potential rate hikes? Slightly higher long-term rates? Already high market multiples getting higher?
In essence, at the start of April, I could have made a much more coherent argument for a negative stock market during the second quarter than I could for double-digit returns. Don’t get me wrong. I wasn’t calling for blood in the streets. I was hopeful we could squeeze a ‘little more blood out of the turnip’ during the quarter.
But returns north of 15%, as David McGrath points out in his equity commentary? Nope. I didn’t see that coming. So, what does it mean for the remainder of the year? In our Predictions section, I state the following:
“With future rate cuts appearing more unlikely, corporate America will likely to have exceed expectations in order for stocks to outperform their strong results of the last several years. It will be a pretty neat trick if it can pull it off.”
If economic and market conditions evolve broadly in line with current expectations, much of this year’s strongest market advance may already be behind us, reflecting the significant gains already realized, current equity valuations and a more balanced outlook for corporate earning sand monetary policy.
Of course, that last statement assumes the market will behave somewhat normally moving forward. Arguably, it didn’t during the second quarter of 2026. So, perhaps I should quit looking proverbial gift horses in the mouth, and just be happy for the strong
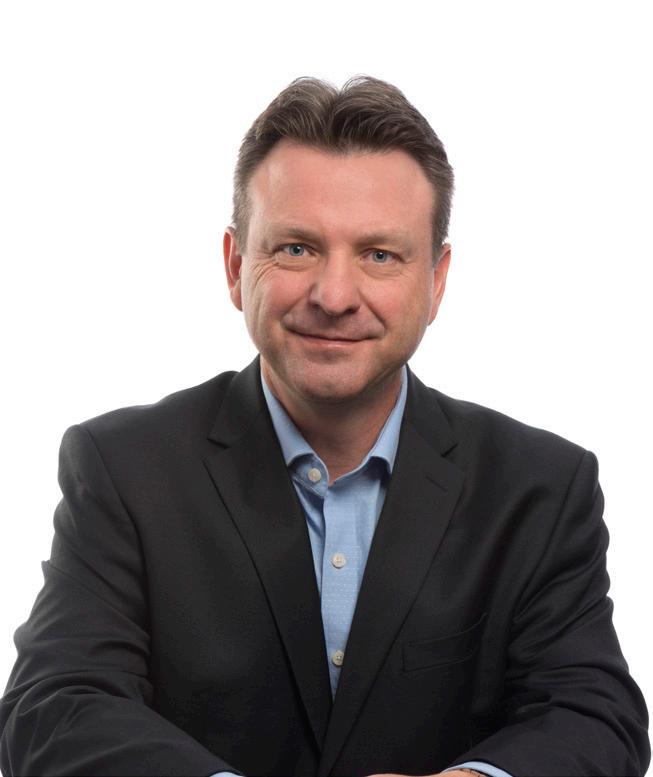
John Norris Chief Economist and Chief Investment Officer
Chief Investment Officer
JOHN NORRIS
Oakworth Asset Management Investment Committee
Catch More From Our Investment Committee Experts
SOURCES:
READ OUR BLOG: Common Cents
Started over 20 years ago, Common Cents is a weekly blog written by Chief Economist John Norris, detailing and explaining the events that impact our economy. John distills the latest information, making it easy to understand how these events affect daily life.
LISTEN TO OUR PODCAST: Trading Perspectives
In this weekly podcast, Chief Economist John Norris and Portfolio Manager Sam Clement exchange perspectives on the driving factors influencing our economy. Trading Perspectives can be found on Apple Podcasts, Spotify, Google Play, YouTube and all other major podcast outlets.
1. U.S. Bureau of Economic Analysis, Gross Domestic Product, First Quarter 2026 (Third Estimate), released June 25, 2026.
2. Source for all other generic statements would be Bloomberg Financial unless otherwise noted.
Advisory services, including investment management and financial planning, are offered through Oakworth Asset Management LLC, an SEC-registered investment adviser and a wholly owned subsidiary of Oakworth Capital Bank, Member FDIC and Equal Housing Lender. Registration with the U.S. Securities and Exchange Commission does not imply a certain level of skill or training.
Investment products and services offered through Oakworth Asset Management LLC are not deposits, are not FDIC insured, are not bank guaranteed, may lose value, and are not insured by any federal or state government agency. Due to the ownership relationship between Oakworth Capital Bank and Oakworth Asset Management LLC, conflicts of interest may exist to the extent that either entity recommends the services of the other. Additional information regarding Oakworth Asset Management LLC, including its services, fees, and conflicts of interest, is available in the firm's Form ADV at www.adviserinfo.sec.gov.
This communication is provided for informational and educational purposes only and should not beconstrued as investment, legal, tax, accounting, or other professional advice. The views and opinions expressed are those of the author(s) as of the publication date and are subject to change without notice. The information presented is general in nature and is not intended to address the specific objectives, financial situation, or particular needs of any individual investor, account, or client relationship.
Nothing contained herein constitutes a recommendation to buy, sell, or hold any security,investment product, or investment strategy, nor should any information presented be relied upon as the basis for making an investment decision. References to specific securities, companies, industries, sectors, market indices, economic conditions, political developments, or geopolitical events are provided solely for informational and illustrative purposes and should not be interpreted as investment recommendations, endorsements, or predictions of future investment results. Investment strategies discussed may not be suitable for all investors. Individuals should consult their own financial, legal, tax,
accounting, and other professional advisers before making any financial decisions.
This communication contains general information that may not be suitable for every investor and may be based on assumptions, estimates, opinions, and forward-looking statements that are subject to change. Actual results may differ materially from those expressed or implied, and no assurance can be given that any expectations, forecasts, or opinions discussed herein will be realized.
Investing involves risk, including the possible loss of principal. Past performance is not indicative of future results and should not be relied upon as a predictor of future performance. There is no guarantee that any investment strategy will achieve its objectives or avoid losses.
Any references to market indices are provided for illustrative purposes only. It is not possible to invest directly in an index. Index performance reflects the reinvestment of dividends, where applicable, but does not reflect the deduction of fees, expenses, or transaction costs, which would reduce returns. It should not be assumed that any client account will achieve returns comparable to any index discussed.
Information contained herein may be obtained from third-party sources believed to be reliable; however, Oakworth Asset Management LLC and Oakworth Capital Bank do not warrant or guarantee the accuracy, completeness, or timeliness of such information. References or links to third-party content are provided solely as a convenience and do not constitute an
Portfolio Manager
CHRIS COOPER Associate Managing Diredtor
SAM CLEMENT Managing Director
DAVID McGRATH ®
SECOND-QUARTER KEY TAKEAWAYS
Oakworth Investment Committee
The second quarter was shaped by a wide range of developments— from inflation, interest rates and AI to geopolitical events, private credit and evolving market sentiment.
Using Newton's Laws of Motion as an analogy, this article examines why economies often maintain their trajectory unless acted upon by significant external forces.
Initial public offerings tend to arrive in waves, often reflecting broader market conditions and investor sentiment rather than simply the strength of the companies going public.
From inflation and interest rates to AI investment, commodities and global events, the Investment Committee highlights the developments it believes could influence markets and the economy in the months ahead.
850 Shades Creek Parkway Birmingham, Alabama 35209
Phone: (205) 263-4700
South Alabama Office
1 St. Louis Street, Suite 3200 Mobile, Alabama 36602
Phone: (251) 375-7800
Central Carolinas Office
6000 Fairview Road, Suite 125
Charlotte, North Carolina 28210
Phone: (704) 901-7250
Middle Tennessee Office
5511 Virginia Way, Suite 110
Brentwood, TN 37027
Phone: (615) 760-1000
About Macro & Market Perspectives:
This communication is provided for informational and educational purposes only and should not be construed as investment, legal, tax, accounting or other professional advice. The views and opinions expressed are those of the author(s) as of the publication date and are subject to change without notice. The information presented is general in nature and is not intended to address the specific objectives, financial situation or particular needs of any individual investor, account, or client relationship. Nothing contained herein constitutes a recommendation to buy, sell or hold any security, investment product or investment strategy, nor should any information presented be relied upon as the basis for making an investment decision. References to specific securities, companies, industries, sectors, market indices, economic conditions, political developments or geopolitical events are provided solely for informational and illustrative purposes and should not be interpreted as investment recommendations, endorsements or predictions of future investment results. Investment strategies discussed may not be suitable for all investors. Individuals should consult their own financial, legal, tax, accounting and other professional advisers before making any financial decisions. This communication contains general information that may not be suitable for every investor and may be based on assumptions, estimates, opinions and forwardlooking statements that are subject to change. Actual results may differ materially from those expressed or implied and no assurance can be given that any expectations, forecasts or opinions discussed herein will be realized. Investing involves risk, including the possible loss of principal. Past performance is not indicative of future results and should not be relied upon as a predictor of future performance. There is no guarantee that any investment strategy will achieve its objectives or avoid losses. Any references to market indices are provided for illustrative purposes only. It is not possible to invest directly in an index. Index performance reflects the reinvestment of dividends, where applicable, but does not reflect the deduction of fees, expenses or transaction costs, which would reduce returns. It should not be assumed that any client account will achieve returns comal arable to any index discussed. Information contained herein may be obtained from third-party sources believed to be reliable; however, Oakworth Asset Management LLC and Oakworth Capital Bank do not warrant or guarantee the accuracy, completeness or timeliness of such information. References or links to third-party content are provided solely as a convenience and do not constitute an endorsement of any thirdparty views, products, or services. Oakworth Asset Management LLC does not provide legal or tax advice. Individuals should consult their attorney, accountant, or tax adviser regarding their specific circumstances.
About Oakworth:
Oakworth Capital Bank, Member FDIC, Equal Housing Lender, provides commercial and private banking, wealth management and advisory services. Advisory Services, including investment management and financial planning, are offered through Oakworth Asset Management LLC, a registered investment advisor. Oakworth Asset Management LLC is owned by Oakworth Capital Bank. Investment products and services offered via Oakworth Asset Management LLC are independent of the products and services offered by Oakworth Capital Bank, and are not FDIC insured, may lose value, have no bank guarantee, and are not insured by any federal or state government agency. Because of the ownership relationship and involvement by Oakworth Asset Management LLC associates with Oakworth Capital Bank, there exists a conflict of interest to the extent that either party recommends the services of the other. Oakworth Asset Management LLC does not provide tax or legal advice. You should consult your tax advisor, accountant, and/or attorney before making any decisions with tax or legal implications. For additional information about Oakworth Asset Management LLC, including its services and fees, visit adviserinfo.sec.gov.