For many business owners, a company is far more than just a source of income. It may represent years of hard work, personal sacrifice and longterm planning. If a marriage breaks down, however, a business can become one of the most significant assets considered during divorce proceedings.
Many entrepreneurs are surprised to learn that shares in a company are generally treated as assets within a divorce settlement. Whether you own a family business, a professional practice or a small or medium-sized enterprise (SME), it is important to understand how divorce can affect your company and the steps you can take to protect both your personal and commercial interests.
When a couple divorces, the Court will consider all their assets, including business interests. A company’s value can form part of the overall marital wealth and may be considered when determining a financial settlement. The extent to which a business is affected will depend on several factors, including:
• Whether the business was established before or during the marriage;
• The role, if any, that a spouse has played within the company;
• How the business has grown during the marriage;
• Whether it provides the family’s primary source of income; and
• The value of the couple’s other assets.
Every case is different, and the Court has considerable discretion when deciding how financial resources should be divided.
How the Court deals with business assets
The Family Court has wide-ranging powers when dealing with business assets during divorce proceedings. Depending on the circumstances, the Court may order:
• The transfer of shares from one spouse to another;
• A lump sum payment funded from business assets or profits;
• Greater allocation of non-business assets to the non-owning spouse;
• Full disclosure of company accounts and financial records;
• Orders preventing assets from being transferred or dissipated; and, in exceptional circumstances,
• The sale of a business.
Although a forced sale of a company is relatively uncommon, it can occur where there is no practical alternative to achieve a fair settlement. Courts are generally mindful that a business often provides future income for one or both parties, but protecting the viability of the company does not automatically take precedence over achieving fairness.
One of the most complex aspects of any divorce involving a company is establishing its value. Business owners often assume that the valuation prepared by their accountant will be sufficient. However, in many cases, the Court may appoint an independent forensic accountant or valuation expert to assess the business. These experts may review company accounts, management information, assets, liabilities, future earnings and market conditions before providing an independent valuation.
This process can be time-consuming and may require the disclosure of highly sensitive commercial information, including details of shareholders, directors, future business plans and, in some cases, potential sale discussions. For this reason, business owners should seek specialist legal advice at an early stage to minimise disruption and protect confidential information wherever possible.
When both spouses are involved in the business
Divorce can become particularly challenging where both spouses are directors, shareholders or employees of the same company. Many couples structure their business affairs jointly for tax efficiency, with dividends, salaries or directors’ loan accounts supporting the family’s lifestyle. Once the relationship breaks down, these arrangements may no longer be appropriate.
When separating spouses continue to have a shared interest in a business, tensions can sometimes extend beyond the personal relationship and into the workplace. Questions often arise around ownership, decision-making and future involvement in the company.
A well-drafted Shareholders’ Agreement can help provide clarity, setting out the rights and obligations of each shareholder and reducing the risk of disputes affecting the day-to-day running of the business.
While no one enters a marriage expecting it to end, forward planning can significantly reduce risk. When establishing or restructuring a company, business owners should consider whether their corporate documents provide adequate protection in the event of divorce.
Key measures may include:
• Reviewing and updating the company’s Articles of Association;
• Including compulsory transfer provisions for shares;
• Introducing drag-along rights to facilitate future business sales;
• Putting a comprehensive Shareholders’ Agreement in place; and
• Ensuring ownership structures align with wider family wealth planning objectives.
These steps can help maintain control of the business and reduce uncertainty if personal circumstances change in the future.
The role of pre and post-nuptial agreements
A pre-nuptial or post-nuptial agreement can provide an additional layer of protection. These agreements allow couples to set out how business assets should be treated if the marriage later breaks down. While not automatically binding in England and Wales, Courts increasingly recognise and uphold properly prepared nuptial agreements where they have been entered into freely and fairly. Nuptial agreements can be particularly valuable for family businesses, helping to preserve ownership across generations and reducing the risk of future disputes.
Where a business forms part of a broader family wealth strategy, these agreements can often sit alongside estate planning, tax planning, trusts, wills and Family Investment Company structures.
Beware of moving assets before divorce When a relationship starts breaking down, concerns about the future of a business can lead to hasty decisions.
However, transferring shares or other assets to protect them from a future financial claim can create significant difficulties.
The Family Court has wide powers to scrutinise transactions that appear designed to reduce the assets available for a financial settlement. Depending on the circumstances, the Court may freeze assets, reverse transactions or take the value of those assets into account when determining the overall settlement.
Seeking specialist advice at an early stage can help avoid unintended consequences and ensure that any business decisions are made appropriately and transparently.
advice early
Every family and every business is different. Seeking specialist advice at an early stage can provide clarity and reassurance. At Myerson, we have extensive experience advising business owners through divorce, helping them protect both their personal wealth and the businesses they have worked hard to build.
The Renters’ Rights Act 2025 marks the most significant reform of England’s private rented sector in decades. In force from 1 May 2026, it fundamentally reshapes the legal relationship between landlords and tenants.
The legislation aims to strengthen tenant security, raise housing standards, and promote fairness, while preserving landlords’ ability to recover possession where justified. This article highlights the key changes and what they mean in practice.
Section 21 has been abolished. Landlords can no longer evict tenants without giving a reason and must instead rely on the section 8 procedure to prove a statutory ground for possession. This significantly enhances tenant security. Transitional provisions apply, and for any section 21 notices served before 1 May 2026, possession proceedings must be issued by 31 July 2026.
Assured shorthold tenancies (ASTs) have been abolished. All tenancies are now periodic (usually weekly or monthly) and open-ended, with no fixed term. Existing ASTs converted automatically on 1 May 2026, removing fixed end dates. Landlords were required to provide a government information leaflet by 31 May 2026, with financial penalties for noncompliance.
Tenants must give at least two months’ written notice, typically expiring at the end of a rental period. This creates a clear and consistent framework for ending tenancies.
With section 21 notices abolished, possession depends entirely on the landlord satisfying one of the statutory grounds. Key grounds include the sale of the property, landlord or family occupation of the property, rent arrears, and anti-social behaviour.
Notable changes include:
• A higher threshold for mandatory possession based on rent arrears (minimum three months);
• Safeguards where rent arrears arise from delayed Universal Credit payments;
• Restrictions on sale and occupation grounds, including a 12-month exclusion period at the start of a tenancy and a four-month notice requirement.
Where possession is obtained on sale or occupation grounds, landlords are subject to a 12-month restriction on re-letting or marketing the property, calculated from a defined statutory point.
Deposit protection requirements are now critical. Courts will generally refuse possession unless the deposit has been properly protected and prescribed information served, or the deposit has been returned or resolved.
Rent increases must follow the statutory section 13 procedure, with at least two months’ notice and limited to once per year. Increases are prohibited during the first 12 months, and tenants can challenge abovemarket rents.
Landlords cannot require rent before a tenancy is agreed and may take no more than one month’s rent in advance after signing.
It is now unlawful to refuse tenants on the basis that they receive housing benefits or have children, strengthening protection against discriminatory practices.
Tenants have a qualified right to request that pets can stay at the property. Landlords must consider requests reasonably and provide reasons for refusal.
Landlords must provide clearer documentation, including a Renters’ Rights Act Information Sheet for existing tenants and written terms where none exist.
Local authorities have enhanced enforcement powers. Rent Repayment Orders have been strengthened, with the maximum repayment increased to 24 months’ rent.
Further measures will be introduced in phases, including:
• A Private Rented Sector Ombudsman;
• A national landlord database;
• Expansion of the Decent Homes Standard;
• Awaab’s Law-style protections for serious hazards.
The Act represents a clear shift towards greater tenant protection and regulation. By abolishing no-fault evictions, introducing open-ended tenancies, and strengthening enforcement, it aims to rebalance the landlord–tenant relationship. Now, landlords must adapt to a more structured regime, while tenants benefit from increased security and clearer rights.
Whether you are purchasing your first buy-to-let property or growing an established portfolio, financing and refinancing decisions can play an important role in achieving your long-term investment goals. Specialist legal advice is key to ensuring the process runs smoothly and your transaction completes efficiently.
Whilst your broker may be best placed to advise on buy-to-let mortgage products, bridging options or commercial finance, we can help you complete the legal process efficiently, whether you are releasing equity or securing new funding. We work closely with a range of leading buy-to-let finance providers, including Paragon Bank, Barclays and Handelsbanken, and are skilled in reviewing their offers and satisfying their special conditions.
Whether you are refinancing a singular dwelling or a portfolio of investment properties, our solicitors typically manage the transaction in the following stages:
Upon receipt of your mortgage offer, we will review the terms, and track and satisfy the special conditions. These can include requirements to provide planning consent and building regulations approval for renovation works and conversion to HMO status. We will draft a mortgage report setting out the key terms and invite you to sign the mortgage deed/legal charge.
Obtain the title documents from the Land Registry and conduct a title check on behalf of the lender. This will include checking to see if there are any restrictions which may need to be satisfied before the refinance can take place. If the property is leasehold, we would also check the management arrangements and obtain the necessary information from the freeholder and management company.
Order searches in line with your lender’s requirements.
Once all the lender’s conditions have been satisfied, we will take your instructions on a completion date. If you are refinancing, we will request a final redemption statement from your lender outlining the amount required to redeem the existing mortgage in full. We will then arrange for completion of the new mortgage to take place on the same day as the redemption.
Post-completion, we will register the new mortgage against your property at the Land Registry promptly and provide you with the updated title documents upon receipt.
At Myerson, we look beyond the legal transaction itself. A refinance is often part of a wider strategy, such as transferring equity or incorporating a portfolio into a limited company. As a full-service law firm, our Residential Property team works closely with colleagues in our Commercial Property, Corporate and Private Client teams to deliver joined-up advice. We can guide you through the legal transaction and provide you with practical advice which touches on the following:
• Portfolio size and associated tax implications;
• Personal guarantees and corporate liability;
• Redemption and early repayment charges;
• Statutory compliance, ensuring that you have the correct certification for renovation work and that you comply with your obligations under the Companies Act as to the recording of the transaction.
We work closely with a trusted network of mortgage brokers, letting agents, accountants and tax advisers to provide joined-up support throughout your transaction. Unlike bulk conveyancing providers, we work to your timescales, delivering the personal service and attention to detail that complex investment transactions deserve.
Pension rules are due to change, which could result in thousands of pounds in additional Inheritance Tax (IHT) for your estate. This article explores the proposed changes and the practical steps you can take to ensure your estate is structured as tax efficiently as possible.
Currently, most pensions are excluded from your estate for IHT purposes at death. This is because pensions are typically distributed at the discretion of Pension Scheme Administrators (PSAs), who are guided by a Beneficiary nomination form that you complete during your lifetime.
From 6 April 2027, however, undrawn pension funds will be included in your Estate for IHT purposes. This represents a big shift because, instead of being outside your Estate for IHT purposes, they will be aggregated with your other assets and subject to IHT at a rate of 40%. This is a huge shift because it will increase the value of your taxable Estate by the value of your pensions and result in more IHT, as shown in the following case study:
Scenario: A dies with an Estate worth £700,000 and a pension worth £300,000. A has a Will and tax-free thresholds of £500,000.
Before 6 April 2027: As the pension is outside the Estate for IHT purposes, the IHT liability on the Estate will be £80,000 with £620,000 available for distribution under the Will, and £300,000 available for distribution under the pension.
After 6 April 2027: As the pension is included in the Estate for IHT purposes, the IHT liability on the Estate will be £200,000 (an additional £120,000 of IHT) with £560,000 available for distribution under the Will, and £240,000 available for distribution under the pension.
Not only is the overall IHT burden higher, but you can see that the distribution of assets also shifts because the total IHT liability is apportioned between the Estate and the pension. This could create issues when the beneficiaries of the pension and the Estate differ, particularly when charitable beneficiaries are involved.
The changes also introduce additional complexity for Personal Representatives (PRs). PRs will be liable for IHT attributable to the pensions, despite having no control over how, or crucially when, those funds are distributed. PRs will need to act swiftly to liaise with PSAs to establish pension values and assess any IHT liability. Where a liability arises, PRs can notify PSAs to withhold up to 50% of pension funds for up to 15 months and PRs will be able to direct PSAs to pay any IHT due on the pensions to HMRC.
However, the six-month deadline for paying IHT (from the end of the month of death) remains unchanged and penal interest of 7.75% will accrue on unpaid tax after this point. Although PSAs are expected to provide information within four weeks of a request, there are concerns that increased demand for information may lead to delays that could result in missed IHT payment deadlines and premature distribution of pension funds before PRs have finalised the IHT liability.
Further complications may arise if previously unknown pensions come to light after the IHT has been paid, and even after distribution. PRs would still be responsible for recalculating the IHT position across the entire estate and this may require recovering funds from beneficiaries to meet additional IHT. While insurance and financial asset searches can mitigate this risk, they will increase the estate’s overall cost. So, how can you prepare for these changes and mitigate the associated risks?
• Start planning now: Review and, where appropriate, consolidate your pensions with your financial advisor. This will make it easier for your PRs to identify and value assets after your death.
• Review your choice of beneficiaries: Pensions have historically been a taxefficient way to pass wealth down generations, but you may wish to change beneficiaries to maximise spouse and civil partner exemptions. Whilst working with your legal and financial advisors, it is also important to ensure alignment between your pension nominations and your Will so that your beneficiaries receive what you intend.
• Review Charitable Beneficiaries: If your Will includes a gift of 10% of your Estate to charities to secure a reduced IHT rate, the clause should be reviewed because 10% of your Estate may now be a much greater sum and result in your non-exempt beneficiaries getting much less than intended.
• Review your Personal Representatives: Ensure you have a valid Will appointing Executors, and that they are best placed to manage the complexity of your Estate. You may wish to appoint professional Executors, such as Myerson Trust Corporation, who has experience with dealing with PSAs and IHT.
• Lifetime planning: Review options with your financial advisor for how best to use your pensions, and consider gifting options to reduce the overall value of your Estate to preserve all the available reliefs and mitigate IHT.
The proposed changes mean pensions can no longer be treated in isolation from the rest of your Estate, nor relied upon as a tax-efficient means of passing on wealth. You should act now by seeking advice on the legal aspects from us and advice on wider financial planning from a suitable financial adviser.
At Myerson, we can assist by reviewing your Will and IHT position to ensure your Estate is structured tax efficiently and that your PRs are equipped to manage the additional responsibilities these changes will bring.
Call 0161 941 4000 Email lawyers@myerson.co.uk
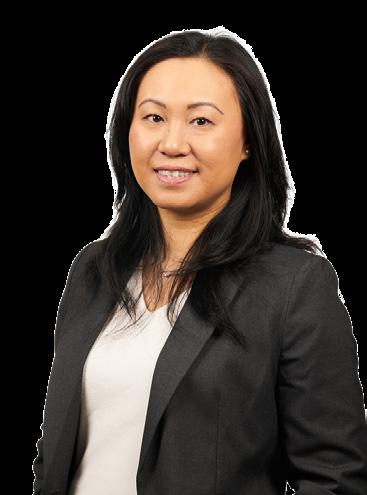
At Myerson, we understand that wealth isn’t just about numbers; it’s about legacy, responsibility, and peace of mind. That’s why our Private Wealth team, led by the nationally recognised Bik-ki Wong, delivers clear, compassionate legal guidance to help you protect what matters most.
Bik-ki Wong, a Partner in our Wills, Trusts and Probate team, is one of the region’s most respected names in private wealth law. She is ranked in the Chambers High Net Worth Guide, where clients highlight her “approachable demeanor” and her exceptional ability to make complex legal matters simple and easy to understand.
Our team are experts in structuring and protecting your personal wealth and assets, whether in the UK or overseas. Making you and your family the heart of everything we do means establishing long-term relationships with our clients and their families across the generations.
Wills & Succession Planning
Secure your legacy with well-structured, tax-efficient estate plans.
Trusts & Asset Protection
Protect family wealth with carefully tailored trust structures.
Tax & Estate Planning
Plan ahead to reduce tax exposure and ensure long-term financial security.
Ensure your wishes are upheld if life takes an unexpected turn.
Business Wealth Advice
Wealth structuring and succession planning tailored to business owners.
Probate & Estate Administration
Sensitive, expert support through the legal and emotional complexity of estate matters. Need advice?
Scan the QR Code for Wealth Protection
Contact our team today for discreet and first-class support. or visit www.myerson.co.uk/wealth
Providing financial support to family members or friends is increasingly common, whether to help them onto the property ladder, fund education, support a business venture or assist more generally.
However, how that support is structured is just as important as the support itself. Outright gifts have traditionally been popular, particularly for parents helping children through the “Bank of Mum and Dad”. Increasingly, however, families are considering more structured arrangements, such as private loans with agreed terms from the outset.
Although gifts and loans can both provide financial assistance, they have different legal, financial and tax implications. Understanding these differences is key to deciding which option is most appropriate.
In the context of Inheritance Tax (IHT), a lifetime gift is any transfer of money, property or assets by an individual during their lifetime. Examples of common lifetime gifts can include:
• Parents giving money to a child, to help them purchase a home;
• Grandparents contributing towards a grandchild’s education;
• Family members gifting cash, towards a wedding or other celebration;
• The transfer of jewellery, artwork or other personal property.
Lifetime gifts are often attractive because of their simplicity. They allow you to provide immediate financial support without the need for formal documentation and can also form part of your wider estate planning. People often choose to make a lifetime gift to help family or friends without strings attached, whether to fund a property
purchase, education or another significant expense, while seeing the benefit during their lifetime.
However, whilst straightforward, lifetime gifts can have important legal, financial and tax implications, including:
Making an outright gift during your lifetime has long been an effective way to reduce the value of your estate for IHT purposes. With careful planning, passing assets on early can reduce the potential tax burden on your estate and ensure more of your wealth reaches your loved ones sooner.
For IHT purposes, a lifetime gift to an individual from capital is a Potentially Exempt Transfer (PET). The transfer is potentially exempt because, if you survive for seven years from the date the gift is made, its value will fall outside of your estate for IHT purposes. If you do not survive for seven years, the value of the gift may be brought back into account when calculating the value of your estate for IHT.
Every individual has a Nil Rate Band of £325,000, which can be passed on free of IHT. The Nil Rate Band can also be used by lifetime gifts if you do not survive for seven years and the value of those gifts is brought back into account. If an individual makes lifetime gifts exceeding the Nil Rate Band within the seven years before their death, IHT may be payable on those gifts at a rate of up to 40%.
There are various other exemptions individuals can use when making lifetime gifts to reduce potential Inheritance Tax liability.
Gifts are irrevocable. Once a gift has been made, you are no longer in control of the funds or assets that have been given away. For example, you may gift a sum of money with the expectation that it will be used to purchase a property. However, unless conditions are put in place, once the funds leave your account, the recipient is free to use them as they wish.
The individual making the gift may later experience financial difficulties and regret having made it. As gifts are irrevocable, recovering the assets may not be possible. Before making a gift, you should be satisfied that you are financially secure and can afford the reduction in the value of your estate. It is important not to deprive yourself of assets and to ensure you have sufficient funds to maintain your standard of living and meet any future needs, including care fees. If a local authority considers that a gift was made to avoid paying for care, it may investigate the circumstances and treat the assets accordingly.
Large undocumented gifts can create tension among family members, particularly if another family member feels aggrieved or believes they have been treated unequally.
If the recipient is married or contemplating marriage, you should also consider the potential implications if that marriage ends in divorce and how the gifted assets may be treated. Without a pre or post nuptial agreement, those assets could form part of the financial settlement.
Similarly, if you are gifting money to help with a house purchase and the recipient is buying with another person, you should consider what would happen if the relationship were to break down. Without appropriate protection, such as a declaration of trust, there is a risk that the gifted funds may not be returned in full to the recipient.
You should also consider whether the recipient is financially stable or whether there is a risk of bankruptcy and the implications this could have for the gifted assets.
Instead of making a lifetime gift, it is possible to introduce structure and greater protection by making a loan, with the terms recorded in writing. In simple terms, a loan is a financial arrangement in which one person, the lender, provides funds to another, the borrower, who agrees to repay them at a later date. Although people often associate loans with mortgages or commercial lending, individuals can also enter into private loan agreements with each other.
Private loans commonly occur between family members, friends, business partners, shareholders and companies, and private investors and borrowers. A written loan agreement can set out the terms clearly and provide protection for both parties.
There are several factors to consider when deciding whether a loan arrangement is suitable:
When making a loan, the funds or assets subject to the loan will remain repayable in accordance with the terms of the loan agreement. The loan itself should be documented formally, in written terms and should set out any terms for repayment, including any interest terms. A properly drafted loan agreement should also set out default provisions, explaining what happens if any repayments are missed.
Loans are generally more flexible, as the arrangement can be tailored to your needs and circumstances. For example, the loan could be structured so that it is repayable on demand or when certain conditions are met and can be waived in the future, although there are IHT implications associated with waiving a loan, summarised below.
Some loans are secured against property or other assets, giving the lender additional protection, particularly if the borrower fails to repay the loan. Loans secured against residential property may be subject to the Financial Services and Markets Act 2000, if certain criteria are met. The circumstances of each arrangement need to be assessed on a case-by-case basis.
Both parties should sign the agreement to record their intentions, obligations and acceptance of the agreed terms. This helps reduce the risk of future disputes by ensuring each party has a clear understanding of their respective rights and responsibilities.
A documented loan agreement may help demonstrate that the funds were intended to be a loan rather than a gift, particularly in the event of divorce, relationship breakdown, bankruptcy or family disputes.
Where a loan agreement is entered into, the value of the loan remains part of your estate for IHT purposes. The loan is treated as an asset rather than a reduction in the value of your estate. Subject to the terms of the agreement, any repayments will generally return value to your estate. If the loan is later written off, the amount written off may be treated as a gift at that point. If estate planning is your primary objective, a loan may therefore not be the most appropriate option.
Whilst loan agreements offer clear benefits, they also carry risks. Discussions around lending and repayment obligations can create tension, particularly where family members or friends are involved. If the borrower defaults, legal action may be required, resulting in additional cost, stress and the potential to further strain relationships. Before entering a loan arrangement, both parties should seek appropriate legal and tax advice. Whether a loan is the right option will depend on the particular circumstances, your intentions and your objectives.
Myerson supports farming families, landowners and rural enterprises across the North West and nationally.
Our Agricultural and Rural Business team is ranked Tier 1 in The Legal 500, bringing together specialists from across the firm and a trusted network of professional advisers.
Although outright gifts and private loan agreements both involve transferring money or assets, they serve very different purposes. The right option will depend on your objectives, financial circumstances and long-term intentions. Whatever you choose, taking advice and documenting the arrangement properly can help protect everyone involved.
To discuss whether an outright gift or a private loan is right for you, please contact our Banking or Private Client teams on 0161 941 4000.
Wills, trusts, succession & inheritance tax planning
Estate administration
Land sales & property
Business structures & diversification
Dispute resolution Promotion agreements
Family issues
Employment

We understand the unique challenges facing rural businesses and families. Our practical, straight-talking advice helps you plan for the future with confidence.”
Head of Agricultural and Rural Business
Andrew Brown 0161 941 4000 andrew.brown@myerson.co.uk
Although a person is generally free to leave their estate to whomever they choose, there are circumstances in which a Will can be challenged, or a claim can be brought against an estate. This article explains the most common grounds for doing so in England and Wales.
Lack of testamentary capacity
For a Will to be valid, the person making it must have had testamentary capacity. The legal test for this is set out in the case of Banks v Goodfellow, which confirms that the testator must:
• Understand they are making a Will and what it means;
• Understand the size of their estate;
• Consider those who might have a claim on the estate, such as family members or partners;
• Not be suffering from any disorder of the mind which influences their decision-making.
If any of these requirements are not met, the testator will not have had testamentary capacity, and their Will would then be invalid. Concerns often arise when a person was elderly, unwell, or living with conditions such as dementia. It is important to note, however, that the existence of dementia does not automatically invalidate a Will - someone can be suffering from this condition but still be able to make a Will. The question comes down to whether they had the requisite testamentary capacity at the time of making their Will. In these cases, evidence, such as medical records, is particularly important.
Even where someone had testamentary capacity, they must also have understood and approved the contents of their Will. Issues can arise where the Will is complex, the person had difficulty with reading or was blind, or when a beneficiary was heavily involved in preparing the Will. If there are unusual or suspicious circumstances, those relying on the Will may need to show that it truly reflected the person’s intentions.
Undue influence is where the testator was coerced into making a Will that they did not want to make. It is important to note that it is common for family members to discuss and even influence decisions. However, a Will can be challenged if the influence went too far and overpowered the person’s free will.
These claims are serious and so the burden of proof is high. This means that compelling evidence needs to be obtained to be able to successfully pursue a claim. Suspicions alone are not enough to invalidate the Will. Undue influence cases can be complex, but warning signs often include sudden or unexpected changes in a Will, especially where one individual benefits significantly compared to others.
Fraudulent calumny occurs when someone deliberately tells the testator something which is untrue about a potential beneficiary in order to turn the testator against them so that they change how the estate is left. An example of this is where a person falsely tells a testator that their child stole money from them which leads to a falling out and the child being cut out of the Will. The key element is dishonesty rather than pressure. If the person making the representation genuinely believed it to have been true, then this would not amount to fraudulent calumny.
Although relatively rare, a Will can be challenged if it is not genuine. Examples include where someone else forged the testator’s signature, where the Will has been altered after it was signed or if the person was misled into what they were signing. Again, fraud is a serious allegation and accordingly requires strong supporting evidence which can include an expert handwriting report. These reports can help to confirm whether the signature on the Will was the testator’s or someone else’s.
There are strict legal requirements for executing a Will which are:
• The Will must be in writing;
• It must be signed by the person making it or by someone else in their presence and at their direction;
• The testator must have intended their signature to give effect to the Will;
• The testator must either sign or acknowledge their signature in the presence of two witnesses who are present at the same time and;
• The witnesses must sign the Will or acknowledge their signature in the presence of the testator.
If these formalities are not followed correctly, the Will would be invalid, even if it reflects the person’s wishes.
Sometimes the concern is not whether the Will is valid, but whether it makes reasonable financial provision for an individual. Under the Inheritance (Provision for Family and Dependants) Act 1975 (“the Act”), certain people can make a claim against an estate for provision to be made for them. This includes spouses or civil partners, children and any individual who was financially dependent on the deceased. The court has the power under the Act to adjust how an estate is distributed to ensure reasonable provision is made.
All categories of claimant other than spouses/civil partners must have a maintenance need to be able to pursue a claim. This means they must be in some financial difficulty. Claimants who are comfortable or well off would not have strong claims. A claim under the Act is subject to a strict time limit. You must begin court proceedings within six months of the date of the Grant of Representation. If you miss this time limit, you may not be able to pursue the claim any further.
If you are concerned about a Will, there are some important points to consider:
• Act promptly: some claims are subject to strict time limits;
• Evidence matters: documents, medical records, and witness accounts can be crucial in determining your claim;
• Costs and proportionality: it is important to weigh the likely costs you will incur against the value of the claim;
• Settlement is common: many disputes are resolved through negotiation without going to court.
Concerns about a Will can be both legally complex and emotionally challenging, particularly when family relationships are involved. Our experienced contentious probate team is here to guide you through the process with clear, practical advice tailored to your circumstances.
If you are worried about the validity of a Will or whether you have a potential claim for provision from an estate, you should seek advice at an early stage. This can help you understand your position and take the right steps to protect your interests.
The Employment Rights Act 2025 (ERA 2025) represents one of the most significant overhauls of UK employment law in decades. Whilst much of the commentary has focused on the enhancement of general employee protections, the reforms may particularly improve the negotiating position of senior executives in relation to both contractual terms on appointment and exit from employment.
The key changes affecting senior executives
The removal of the unfair dismissal compensation cap
One of the most significant changes for senior executives is the planned removal of the statutory cap on the compensation awarded for a successful unfair dismissal claim.
Under the current regime, compensation for unfair dismissal is limited to 12 months’ gross pay or around £123,000 (whichever is lower). For many senior executives, whose remuneration package is often made up of various incentives and deferred benefits, the statutory cap has meant that compensation doesn’t fully compensate for the financial loss suffered.
From 1 January 2027, the statutory cap will be removed, allowing compensation to be awarded at any level to reflect the loss
suffered. Although executives will still have an obligation to seek new work and reduce their losses, and the tribunals can still reduce compensation for various reasons, the absence of a statutory cap could significantly increase employer exposure and become a powerful negotiating tool for senior executives. In particular:
• Unfair dismissal claims that previously had limited financial value, and thus were not commercially worthwhile, may now warrant active pursuit;
• Litigation risk may become a more significant factor in board decisionmaking when considering executive exits and employers may face greater pressure to resolve disputes through negotiated settlements;
• Executives may, therefore, have stronger leverage when negotiating severance terms, treatment of incentive awards and the relaxation of restrictive covenants.
The ERA 2025 will reduce the qualifying period for unfair dismissal protection from two years to six months. This change is also expected to take effect from 1 January 2027.
For many executives, the initial couple of years in a new role represents a vulnerable period of employment - the current delay in obtaining statutory protection gives time for strategic priorities to shift, boards to change composition and leadership teams to be restructured, all before the executive has acquired protection. Reducing the qualifying period to six months materially shortens this vulnerability window.
Whilst this may create additional scrutiny of the executive in the first six months of employment and early intervention or implementation of formal processes, it may also mean that executives have clearer objectives, role profiles and key performance indicators. It may also create enhanced job security, given that organisations are likely to place greater emphasis on getting appointments right the first time. Similarly, the reform may give executives a stronger bargaining position at exit, especially when the reasons for dismissal relate to factors outside the executive’s control.
From October 2026, most employment tribunal time limits will increase from three months to six months. As most senior executive departures often involve complex negotiations concerning incentive arrangements, restrictive covenants and reputational considerations, the extension should allow executives more time to obtain appropriate legal advice, assess potential claims, gather evidence, and engage in meaningful and strategic negotiation before commencing formal proceedings.
How can senior executives use the reforms to strengthen contractual protections?
Although statutory rights are improving under the ERA 2025, contractual
protections remain an important safeguard for senior executives to consider, particularly to mitigate against the vulnerabilities in the early stages of employment. The best opportunity to negotiate contractual terms is before the contract is signed. Therefore, executives considering a move can use the changing legal landscape to negotiate various contractual protections.
Longer notice periods can provide substantial financial security if a role ends unexpectedly. However, they can also restrict an executive’s ability to move quickly to alternative employment and so should be carefully balanced.
In all circumstances, it is important to scrutinise restrictive covenants, ensuring that they are appropriately tailored to the role and proportionate to the legitimate business interests they are intended to protect.
The removal of the compensatory cap may create greater scope for executives to negotiate post-termination restrictions at the outset of employment, particularly assessing the practical impact that such restrictions will have on the executive’s future employment and earning ability.
Executives in senior positions are often headhunted for new roles. They may also –now more than ever - be subjected to more extensive recruitment processes. In those circumstances, probationary periods may not be appropriate.
If a probationary period cannot be avoided, then careful consideration should be given to mitigate its practical effect as far as possible. In particular, senior executives should be empowered to negotiate notice entitlements (both during and after the probationary period), limit the company’s ability to extend the probationary period and ensure that any performance expectations and objectives are articulated clearly at the earliest opportunity.
As part of the offer to join a new business, senior executives are often incentivised with bonus opportunities, deferred compensation and equity awards. Given the reforms, companies are likely to subject the executive to additional scrutiny in the early months of employment. As a result, executives may have greater bargaining power to ensure that such incentives are clearly documented in the contract and that they are afforded adequate protection. In particular, executives should pay particular attention to the circumstances under which incentives are earned, retained or forfeited. Where possible, executives may wish to negotiate greater certainty around payment terms, treatment on termination and any clawback provisions.
These protections will be key, particularly when a senior executive is giving up valuable rights or benefits in leaving an existing role.
How can senior executives use the reforms to their advantage?
Executives should seek clarity on how performance will be measured in practice and how success will be evidenced. Any applicable KPIs and targets should be reasonable, and executives will likely want to be involved in their creation.
Executives may benefit from seeking greater clarity around performance expectations, including regular (and documented) feedback and contemporaneous records of achievement. This facilitates objective
decisions to be made, based on evidence. It also allows the executive the ability to obtain legal advice on documented facts, at an early stage, should it be necessary.
A long-term consequence of the ERA 2025 reforms might be increased executive mobility. Historically, many executives have remained in roles longer than they otherwise might have, because changing employers required surrendering valuable statutory protection and accepting significant employment risk. Whilst economic conditions and increased employment costs may cause employers to hire more selectively, executives who are prepared, understand the reforms and are properly advised, may find that the ERA 2025 reforms provide greater certainty and flexibility when considering career moves, as well as a stronger platform from which to negotiate key contractual protections.
If you, or someone you know, is moving into a senior role, or you are a business owner seeking to understand how the reforms could affect your business, recruitment or performance management processes, please get in touch with our specialist Employment team.
Section 284 of the Insolvency Act 1986 places restrictions on what an individual can do with their assets once a bankruptcy petition has been presented against them, or they have applied for their own bankruptcy. From that point onwards, any transfer or disposal of property will generally be void unless the court approves the transaction by granting a validation order.
These rules are designed to protect creditors by preventing assets from being transferred or one creditor from being treated more favourably than others before a trustee in bankruptcy takes control of the estate.
What happens if a validation order is not obtained?
If an individual transfers or disposes of assets without first obtaining a validation order, and a bankruptcy order is later made, the trustee in bankruptcy may seek to recover the property. This can apply even if the asset has already been transferred to someone else.
Are third parties protected?
Not necessarily. However, someone who received money or property in good faith, gave value for it and had no notice of the bankruptcy petition may have protection. Even if the trustee recovers the asset, they may still be able to prove in the bankruptcy as a creditor.
Validation orders can arise in a variety of situations. Common examples include:
• Selling or transferring a property;
• Repaying a creditor after a bankruptcy petition has been presented;
• Making payments into an overdrawn bank account;
• Transferring assets as part of divorce or financial remedy proceedings; and
• Transactions where property is transferred for significantly less than its market value.
Even where section 284 does not apply, a transaction may still be challenged under other insolvency legislation, such as where assets have been transferred at an undervalue.
A validation order is obtained by applying to the court. The application must explain the proposed transaction and why it should be approved. The application should be supported by an application notice, draft order and witness statement.
Unless there are exceptional circumstances, notice of the application should also be given to the petitioning creditor and, where appropriate, any other creditors with an interest in the bankruptcy proceedings.
Each application is considered on its own facts. The court will usually expect evidence that the individual is solvent and able to pay their debts as they fall due, or that the proposed transaction will benefit, or at least not prejudice, the interests of unsecured creditors. Where approval is sought after a transaction has taken place, the court will balance the interests of the recipient against those of the bankrupt’s creditors. Validation orders are often granted where transactions were entered into in good faith before either party became aware that a bankruptcy petition had been presented.
Validation orders can be crucial when a transaction needs to proceed after a bankruptcy petition has been presented. Obtaining legal advice at an early stage can help avoid delays, protect the transaction and reduce the risk of it being challenged at a later date.
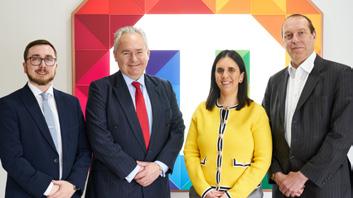





Our Core Values define what we stand for and the standards we set for ourselves every day. They shape the way we work, ensuring our clients’ best interests are always at the heart of what we do. That’s what makes Myerson an ALL TOGETHER DIFFERENT law firm.



Since our last edition, we’ve had plenty to celebrate, with Myerson receiving four awards recognising our private client expertise and workplace culture.

At the Private Client Modern Law Awards 2026, we were delighted to be named Private Client Team of the Year – North of England and Private Client Trusts, Tax & Wealth Planning Team of the Year. Our Probate & Estate Administration Team was also Highly Commended, reflecting the dedication and expertise of our Private Client specialists.
We were also proud to receive Corporate Culture and Wellbeing Champions of the Year at the Manchester Legal Awards. We believe that when our people feel valued and supported, they’re able to provide the very best service to our clients.
While it’s always an honour to receive recognition from the legal profession, what matters most to us is the trust our clients place in us every day. These awards reflect the care, commitment and expertise our teams bring to every conversation, whether we’re helping you plan for the future, support your family, administer an estate or resolve a dispute.
Thank you for continuing to choose Myerson.
Our recent awards
• Private Client Team of the Year – North of England
• Private Client Trusts, Tax & Wealth Planning Team of the Year
• Highly Commended – Probate & Estate Administration Team of the Year
• Corporate Culture and Wellbeing Champions of the Year
See our full list of Awards & Accreditations at www.myerson.co.uk/about/our-awards
Join Myerson’s Family Law experts and guest specialists as they explore the real issues behind family and relationship challenges.
Clear advice. Practical support. Real conversations.
Listen now – search “MyFamily Pod” on your favourite platform.
Family life isn’t always simple. We’re here to help. Follow