EXPERIENCE • TRUST • EXPERTISE
Peace of mind
for your client and you.
We’ve mastered “the art” of closing. Experience peace of mind with Cottonwood Title. We’ve perfected our process and handle all the details to make every transaction a masterpiece. When real estate agents want to create a perfect closing for their clients, they choose Cottonwood Title.
MURRAY • MIDVALE • SALT LAKE • ST. GEORGE • OREM • LEHI • LAYTON • CENTERVILLE | COTTONWOODTITLE.COM
Together we can reach your goals.
Having an accountability partner increases your chance of success to 95%. Team up with us for an active partnership to grow your business this year.
HelpYourClient@snmc.com SecurityNational Mortgage Company complies with Section 8 of RESPA and does not offer marketing services in exchange for referrals or the expectation of referrals. This is not a commitment to make a loan. Loans are subject to borrower and property qualifications. Contact loan originator listed for an accurate, personalized quote. Interest rates and program guidelines are subject to change without notice. SecurityNational Mortgage Company is an Equal Housing Lender NMLS 3116. snmc.com/disclaimer snmc.com/state-licensing
Turning houses into homes.
Table of Contents Features 8
From Family Business to Board Leadership
12 Mortgage Rates Are Falling but Owners Still Won't Sell Nicole Friedman | The Wall Street Journal
John©/Adobe Stock
14 Top 10 Homebuying Hot Spots for 2026 The National Association of Realtors®
14
16 Why January Is the Best Time to Kickstart Your 2026 Home Search The Lighter Side of Real Estate
18 Oregon Tops U.S. Inbound Migration as Americans Move for Family and Work
Top 10 Homebuying Hot Spots for 2026
20 Been Dreaming About Becoming a House Flipper? Here's Why Now Might Be Your Best Chance
The Lighter Side of Real Estate 24 Mortgage Rates Dip, Prices Cool–Yet U.S.
SeanPavonePhoto©/Adobe Stock
Homes Stay Historically Unaffordable
18
Oregon Tops U.S. Inbound Migration as Americans Move for Family and Work
Columns 5
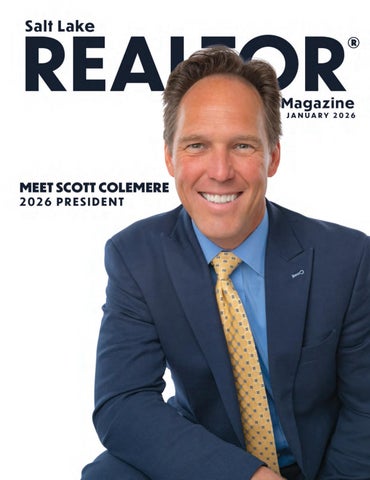
Why Real Estate Is Still About People, Not Just Properties J. Scott Colemere – President’s Message
Departments 6
Happenings
6
In the News
28 Housing Watch
On the Cover: Jo Ann Snover©/Adobe Stock
Cover Photo: 2026 Board President J. Scott Colemere
20 Been Dreaming About Becoming a House Flipper? Here's Why Now Might Be Your Best Chance
This Magazine is Self-Supporting Salt Lake Realtor® Magazine is self-supporting. The advertisers in this magazine pay for all production and distribution costs. Help support this magazine by advertising. For advertising rates, please contact Mills Publishing at 801.467.9419. The paper used in Salt Lake Realtor® Magazine comes from trees in managed timberlands. These trees are planted and grown specifically to make paper and do not come from parks or wilderness areas. In addition, a portion of this magazine is printed from recycled paper.
Salt Lake
REALTOR slrealtors.com
®
Maga zine
January 2026 volume 86 number 1
slrealtors.com 4 | Salt Lake Realtor ® | January 2026
The Salt Lake REALTOR® (ISSN 2153 2141) is published monthly by Mills Publishing, located at 772 E. 3300 South, Suite 200 Salt Lake City, Utah 84106. Periodicals Postage Paid at Salt Lake City, UT. POSTMASTER: Send address changes to: The Salt Lake REALTOR,® 772 E. 3300 South, Suite 200 Salt Lake City, Utah 84106-4618.
Salt Lake
REALTOR
®
Maga zine
slrealtors.com
PRESIDENT J. SCOTT COLEMERE Colemere Realty Assoc. 1ST VICE PRESIDENT JANICE SMITH CB Realty (Union Heights) 2ND VICE PRESIDENT KIM FARBER Eleven11 Real Estate LLC
KRISTEL GOUGH Summit Sotheby's (Draper) LORI KHODADAD CB Realty (Union Heights) DONNA POZZUOLI BHHS UP (N. Salt Lake) CARLYE WEBB Summit Sotheby's INT (Draper) BRYAN HURD Real Broker, LLC
TREASURER RUSS ORCHARD Century 21 Everest PAST PRESIDENT CLAIRE LARSON Woodside Homes of Utah LLC MEMBERS MORELZA BORATZUK RealtyPath (South Valley) ERIC SANTISTEVAN Engel & Volkers (Holladay)
TRISH NICHOLS CB Realty (SL-Sugarhouse) APPOINTED BOD TONY KETTERLING Equity RE (Advantage) LINDA MASCHER Realtypath LLC (Advisors) PAST PAST PRESIDENT DAWN STEVENS Real Broker, LLC
Advertising information may be obtained by calling (801) 467-9419 or by visiting www.millspub.com
Managing Editor Dave Anderton Publisher Mills Publishing, Inc. www.millspub.com President Dan Miller Office Administrator Cynthia Bell Snow Art Director Jackie Medina Graphic Design Ken Magleby Patrick Witmer
Sales Staff Paula Bell Dan Miller
Salt Lake Board: (801) 542-8840 e-mail: dave@saltlakeboard.com Web Site: www.slrealtors.com
Why Real Estate Is Still About People, Not Just Properties At its best, real estate is not about transactions—it’s about transformation. Every month, because of Realtors®, thousands of families across our country become homeowners. They gain stability, build wealth, and take a meaningful step toward the American Dream. That doesn’t happen by accident. It happens because of professionalism, education, cooperation, and a commitment to serving others— especially when the road is difficult. And if there’s one thing most Realtors® understand, it’s that this business can be difficult. Like many of you, my start in real estate was far from smooth. I had ambition, but I lacked experience. I made mistakes—some of them painful. Transactions fell apart. Markets shifted. Certain years tested not only my business, but my confidence and resolve. There were moments when quitting would have been easier. What carried me forward was not luck. It was mentorship, support, and the structure of organized real estate. I was fortunate to learn from people who believed in me before I fully believed in myself—parents, mentors, brokers, and fellow Realtors® who modeled professionalism even when conditions were tough. They taught me that setbacks are not signals to stop; they are opportunities to grow. Professionalism is never more visible than during adversity. It shows up when a deal falls apart and you still communicate clearly and honestly. It shows up when a client is scared or frustrated and you choose patience over pressure. It shows up when markets slow and, instead of cutting corners, you double down on education, ethics, and service. Some of the most meaningful moments of my career came during challenging markets. I’ve seen buyers lose hope after multiple failed offers, only to succeed because we stayed disciplined and strategic. I’ve seen sellers face unexpected obstacles and walk away grateful—not because everything went perfectly, but because they felt protected, informed, and well represented. That is the quiet power of professionalism. As we begin 2026, my message is simple: we succeed together.
The Salt Lake Board of REALTORS® is pledged to the letter and spirit of U.S. policy for the achievement of equal housing opportunity throughout the nation. We encourage and support the affirmative advertising and marketing program in which there are no barriers to obtaining housing because of race, color, religion, sex, handicap, familial status, or national origin. The Salt Lake REALTOR® is the monthly magazine of the Salt Lake Board of REALTORS®. Opinions expressed by writers and persons quoted in articles are their own and do not necessarily reflect positions of the Salt Lake Board of REALTORS®. Permission will be granted in most cases, upon written request, to reprint or reproduce articles and photographs in this issue, provided proper credit is given to The Salt Lake REALTOR®, as well as to any writers and photographers whose names appear with the articles and photographs. While unsolicited original manuscripts and photographs related to the real estate profession are welcome, no payment is made for their use in the publication. Views and opinions expressed in the editorial and advertising content of the The Salt Lake REALTOR® are not necessarily endorsed by the Salt Lake Board of REALTORS®. However, advertisers do make publication of this magazine possible, so consideration of products and services listed is greatly appreciated.
OFFICIAL PUBLICATION OF THE SALT LAKE BOARD OF REALTORS ® REALTOR® is a registered mark which identifies a professional in real estate who subscribes to a strict Code of Ethics as a member of the NATIONAL ASSOCIATION OF REALTORS®. October 2005
Attend classes. Join committees. Mentor a new Realtor®. Support RPAC. Thank our staff. Show up—for each other. When we invest in professionalism, we invest in our clients’ futures. When we lean into education and cooperation, we turn difficult markets into opportunities for growth. And when we remember why we do this work— to help people achieve homeownership—we reconnect with our purpose. I am proud to be a Realtor®. I am proud to be part of this Realtor® family. Together, we are poised to make 2026 a year of impact—for our clients, our communities, and each other.
J. Scott Colemere President January 2026 | Salt Lake Realtor ® | 5
Happenings
In the News
First-Time Homebuyer Age Hits 40, Lautz Tells Housing Forecast Audience Dr. Jessica Lautz, deputy chief economist and vice president of research at the National Association of Realtors®, delivered the keynote address at the 2026 Housing Forecast event at The Little America Hotel in downtown Salt Lake City. Lautz said the median age of today’s first-time homebuyer is now 40—about a decade older than the historical average— and noted that first-time buyers are more likely to purchase single-family homes in the suburbs. She added that baby boomers are now the largest generation of homebuyers, with the median age of today’s repeat buyer at 62 compared with a historical norm of 36, highlighting a sharp contrast between millennials struggling to achieve homeownership and boomers often able to buy with cash. James Wood, Ivory-Boyer Senior Fellow at the Kem C. Gardner Policy Institute, said 2026 will be a year of “running in place,” projecting Salt Lake County’s median single-family home price will remain near $620,000 while multi-family homes rise 3% to $440,000.
Realtors® Unite for RPAC Bingo and Prizes Members of the Salt Lake Board of Realtors® gathered at the Realtor® Campus for an RPAC Bingo Night, where dozens of prizes were awarded—including a Vizio 55-inch television won by Brittney Cornia, a Realtor® with Cannon and Co. The Realtors® Political Action Committee (RPAC) works to protect and promote the real estate industry through voluntary contributions from Realtors®, helping elect candidates at the local, state, and federal levels who support homeownership and private property rights.
6 | Salt Lake Realtor ® | January 2026
Sundry Photography©/Adobe Stock
President Donald Trump announced Jan. 7 he is moving to block large investors from purchasing single-family homes, according to Realtor.com. “I am immediately taking steps to ban large institutional investors from buying more single-family homes, and I will be calling on Congress to codify it,” Trump wrote in a Truth Social post. “People live in homes, not corporations.” Trump added that homeownership, which has long been the “pinnacle of the American Dream,” has become increasingly out of reach for many Americans, particularly younger ones. Trump said he will address the proposal and additional housing affordability measures during a speech at the World Economic Forum in Davos, Switzerland, beginning Jan. 19. Details of how the ban would be implemented were not immediately clear, including what legal authority or legislative mechanisms would be used to restrict corporate purchases. Since the 2008 Great Recession, investors large and small— including major firms such as Blackstone and JPMorgan Chase—have purchased homes to rent for profit, a trend that peaked in 2022 before mortgage rates began rising. In recent years, institutional investors have drawn bipartisan criticism from housing advocates and lawmakers, who argue their buying activity reduces available inventory and contributes to higher home prices.
Photos: Dave Anderton
From Family Business to Board Leadership A conversation with Scott Colemere, 2026 president of the Salt Lake Board of Realtors®. 1. Tell us about your family’s real estate business, Colemere Realty. How did you get your start, and how many generations has the company been in business? My real estate company is called Colemere Realty. It was founded by my grandfather, Burgess, in 1953. My father joined the business in 1971 and took over shortly after. I joined in 1997, and after a bit of an early struggle, I got serious, committed fully, and never looked back. My brother Bryan joined in 2008, and in 2016 we bought my parents out. Bryan and I are both third-generation Realtors®. For most of the company’s history, it has been a small family business. Over the years, we’ve had both large and small teams, and there are pros and cons to each. The bottom line is that this business has been very good to our family. We’ve always tried to treat our clients like family, and in return, they’ve come back again and again— often for generations. 8 | Salt Lake Realtor ® | January 2026
2. What challenges have you faced throughout your real estate career and in life more broadly, and how have those experiences shaped you? This is a tough question, because I could write an entire book in response—but I’ll try to be brief. My start in the real estate business, despite my father’s best efforts as a mentor, was rocky. I was young—only 24—and my inexperience and lack of understanding of how the business truly works made things difficult. At its heart, real estate is a prospecting business. When agents stop prospecting, their business dies. Once I fully learned that prospecting is the lifeblood of the business, I began to succeed. That said, both Bryan and I survived the 2008 recession while staying full-time in real estate by working harder and longer than our competition. I remember many mornings waking up at 5 a.m. to flyer neighborhoods with new listings or to solicit buyer business—then
working all day, often battling bank short-sale departments to make transactions happen. To make matters more difficult, my wife and I suffered the loss of a child early in the recession. It was devastating, but we both understood the importance of continuing forward. Life throws difficult things at all of us, and one thing I love about this industry is that it gives us the opportunity to learn and grow through hardship.
Realtor® will continue to be central to the real estate transaction. I love AI, and I love technology tools. Ultimately, they are exactly that—tools that help us be more effective at what we do: helping buyers buy homes and helping sellers sell homes.
3. What are your primary goals and priorities as president of the Salt Lake Board of Realtors®? My primary goal as president this year is to keep this ship moving forward. The Salt Lake Board is run extremely well—we have an outstanding CEO and staff, and we’re in a strong financial position. We’re poised to continue supporting Realtors® in their businesses. If I could focus on one thing, it would be helping Realtors® who are less engaged truly understand what they’re missing and how much this organization supports them. I would encourage every Realtor® to get involved by taking a class (preferably in person), joining a committee, attending an event, and engaging with fellow Realtors® about the value of RPAC. Every member should also contribute to RPAC. It supports Realtors® and protects and promotes real property rights. 4. How do you see the future of the real estate profession evolving as technology such as AI and automation plays a larger role? I believe the value of a knowledgeable, professional
Burgess Colemere
January 2026 | Salt Lake Realtor ® | 9
5. What advice would you give to new agents who are just starting out in the profession? I remember starting in this business like it was yesterday. Real estate is often described as an “easy business” or an “easy entry” business, and while both can be true, it is a very hard business to stay in and succeed unless a new agent is committed to lifelong learning, connected to a quality mentor, and—most importantly—committed to daily prospecting. Prospecting is the lifeblood of this business. 6. In your view, what qualities or habits make a Realtor® successful? Consistent prospecting, continuous learning, and the discipline to keep improving. 7. What improvements can be made within the Realtor® Association? Where do you see our greatest strengths and our biggest opportunities for growth? We can always improve. That said, because SLBR is such a well-run organization, our improvements tend to come in small increments. One of our biggest opportunities is continuing to increase member involvement—because that’s where great ideas, feedback, and progress come from. One thing that’s so great about this industry is that when Realtors® engage, their energy is contagious and their synergy becomes unstoppable. We can continue to be creative and adaptive as we work to provide housing solutions in an ever-changing real estate market.
8. How has a career in real estate shaped your life personally and professionally? A career in real estate has made me who I am. It has influenced how I parent, how I interact with my spouse, and how I carry myself professionally. In short, it runs very deep in me. This profession has taught me not only how to be an effective Realtor®, but also how to be a better father and a better husband. I’ve learned conflict resolution, negotiation strategies, and principles for working with people. My family also jokes that—especially in the early years, when I was constantly on the phone—“Dad is making money right now.” We still laugh about that today. It was honestly one of the only ways I could get them to stay quiet sometimes when I was working on a difficult transaction at a family event. 9. What interests or hobbies do you enjoy outside of real estate? What do you like to do for fun? Besides spending time with my wife and children, I really have two major interests. First, I love studying stories of endurance and overcoming challenges. Second, I love participating in activities that push me to my physical limits. A few years ago, I had the opportunity to summit Mount Kilimanjaro, and it was an incredible experience. I also really enjoy endurance sports—especially Ironman
10 | Salt Lake Realtor ® | January 2026
triathlons. I love them because through preparation and sustained effort, we can accomplish incredibly difficult feats. 10. What steps can be taken to make homeownership more affordable, particularly for first-time buyers? One of the most important steps we can take as an industry is to continue supporting efforts that help reduce interest rates. This is best done through donations to RPAC, which help Realtor® organizations influence decision-makers who impact these outcomes. We likely won’t be able to lower housing prices significantly—many forecasts predict they will continue to rise. But we can help educate buyers, especially firsttime buyers, so they’re prepared with proper savings, budgeting, and income stability to meet the realities of homeownership.
stabilized pricing. There is opportunity for buyers to jump into the market.
11. Looking ahead, where do you see the housing market heading in 2026?
Some suggest we’re headed for a downturn or that the market is unstable, but I disagree. Days on market remain low. Inventory is improving, and sellers are getting the message that they need to present their homes well to attract buyers. Buyers are negotiating harder and securing discounts.
I think we have great things ahead in 2026, with downward pressure on interest rates and more
Overall, we have a very healthy market—and I expect it to heat up in 2026.
This responsibility is ongoing, and as Realtors® we must continually stay informed so we can continually educate buyers on the best approach to homeownership.
January 2026 | Salt Lake Realtor ® | 11
Mortgage Rates Are Falling but Owners Still Won’t Sell Nearly 30 million households, or 54% of primary mortgage-holders, have mortgage rates at or below 4%. By Nicole Friedman The Wall Street Journal Mortgage rates have fallen to their lowest level in a year, but millions of homeowners are still locked into ultralow mortgage rates they don’t want to give up.
Realtor.com. “People can’t afford to move.” Other factors continue to unsettle the market. Nearrecord home prices are leading many buyers to give up. Expenses related to homeownership, including home insurance and property taxes, have also risen in many places.
Due to limited rights, this story is only available in the print issue of But mortgage rates remain a major stumbling block, the Salt Lake Realtor® magazine. despite having fallen in recent months. Now, many of those who want to move don’t feel it is article A copy of this available Rates is are unlikely to fall far enough to persuade many worth it to buy a home and take on mortgage rates that of those homeowners who want to sell to take on a on the Wall Street far Journal website have doubled. more expensive loan. Economists don’t expect significant declines in mortgage rates in the next This “lock-in effect” has helped freeze the housing but charges may apply. year. The Mortgage Bankers Association forecast in market for three straight years, suppressing the number Nearly 30 million households, or 54% of primary mortgage-holders, have mortgage rates at or below 4%, according to Intercontinental Exchange. They were able to buy homes or refinance their mortgages when rates fell to 3% or lower in 2020 and 2021.
of U.S. homes for sale and keeping inventory well below historic levels for most of that period.
December that the 30-year fixed mortgage rate would average 6.4% in 2026.
“We don’t expect to see this massive influx of home buyers, especially while mortgage rates are above 6%,” said Hannah Jones, senior economic research analyst at
The Federal Reserve cut short-term interest rates this month but signaled it might be done with further rate cuts for now. Mortgage rates edged lower to 6.21%
12 | Salt Lake Realtor ® | January 2026
Jaskaran Kooner©/Adobe Stock
this week, holding near the one-year low reached in October, Freddie Mac said.
climbed, especially in the South and West, giving buyers more negotiating power.
Kenneth Chen started a new job in northern Virginia last year, but it doesn’t make financial sense to sell his Chicago-area home and buy a new one in Virginia, he said. Chen is renting an apartment in Virginia but his wife and children still live in Illinois.
Existing-home sales rose in November for the third straight month. Mortgage purchase applications in the week ended Dec. 12 rose 13% from a year earlier, according to the MBA.
Other locked-in homeowners would face similar increases. A homeowner paying the current typical mortgage payment of $1,291 would have needed to pay $2,236, or 73% more, to buy a median-priced home in October 2025, according to a Realtor.com analysis. (News Corp, parent of The Wall Street Journal, operates Realtor.com.)
home-buying costs.
Due to limited rights, this story is “For buyers, you’re not getting a house as cheap as people got them in 2020, but Chen’s mortgage rate on his Illinois house is under in the only available print issue of it’s cheaper than it was in 2024 and 2023 and most of 2022,” said Mischa Fisher, 3%. He estimated that buying an equivalent house in thecostSalt Realtor® magazine. chief economist at Zillow. northern Virginia today would him atLake least $1,500 a month more. But overall purchase activity remains muted, and A copy of this article is available existing-home sales are on track for their third straight “It’s just too big of a jump on a monthly basis—it would near 30-year lows. really impact our budget,” he “I’m just waitingStreet year onsaid.the Wall Journal website for the interest rate to drop” before buying a home in Economists say it could take years for affordability to but charges may apply. Virginia, he said. improve significantly, as rising incomes catch up to
Home-buying activity has picked up recently. Declining mortgage rates, along with falling home prices in some parts of the country, are convincing some buyers to make a move. The inventory of homes for sale has also
“The people who have to move for a job, or whatever family reason, they are selling. But that’s just very few people,” said Chen Zhao, Redfin’s head of economics research. “The ones who have more discretion are electing not to sell. They’re staying put.” Write to Nicole Friedman at nicole.friedman@wsj.com. Reprinted by permission of The Wall Street Journal, Copyright © 2025 Dow Jones & Company, Inc. All Rights Reserved Worldwide. License number 6178350666879.
January 2026 | Salt Lake Realtor ® | 13
Top 10 Homebuying Hot Spots for 2026 With a young population and improving inventory, Salt Lake City earned a spot among the top 10 homebuying hotspots for 2026. By The National Association of Realtors® The National Association of Realtors® unveiled the top 10 homebuying hot spots for 2026 in a new report, Housing Hot Spots for 2026: The Markets Poised for New Buyer Opportunities. The 10 markets were selected based on economic, demographic and housing factors. NAR Chief Economist Lawrence Yun revealed the homebuying hot spots and provided a 2026 real estate and economic forecast during NAR’s seventh annual Real Estate Forecast Summit: The Year Ahead.
The 10 Top Housing Hot Spots for 2026 (in alphabetical order) • • • • • • •
Charleston, South Carolina Charlotte, North Carolina–South Carolina Columbus, Ohio Indianapolis, Indiana Jacksonville, Florida Minneapolis–St. Paul, Minnesota–Wisconsin Raleigh, North Carolina
14 | Salt Lake Realtor ® | January 2026
• • •
Richmond, Virginia Salt Lake City, Utah Spokane, Washington
Salt Lake City is a young, fast-growing, and ratesensitive area. Salt Lake City’s youthful demographics and improving inventory make it one of the biggest beneficiaries of lower rates in 2026. •
Nearly 25,000 additional households in Salt Lake City would qualify for a median-priced home with mortgage rates easing to 6%
•
Millennial households represent 40.9% of all households in the area
•
Income growth 6.5% higher than the previous year
•
1.8% job growth from a year ago
•
Listings increasingly aligned with local incomes: 20.7% higher than a year ago
•
9.8% more mortgage originations in 2024
John©/Adobe Stock
The top 10 housing hot spots consist of markets that outperform the average market in the U.S. on at least five of 10 economic, demographic, and housing indicators, have populations above 250,000, and demonstrate meaningful 2026 opportunities for homebuyers and agents who are Realtors®. “Lower mortgage rates and larger inventory will attract buyers back to the market in 2026,” said NAR Chief Economist Lawrence Yun. “The top 10 housing hot spots for 2026 have a combination of strong demand potential, projected improvements in affordability, and, most critically, a housing stock that matches the budgets of the buyers who are returning to the market.”
National Outlook for 2026 • • • •
Existing-home sales are forecast to increase by 14% Home prices are expected to rise by about 4% Mortgage rates are projected to decline toward 6% Job growth is expected to remain moderate with roughly 1.3 million new jobs
“After three years of flat home sales, a solid doubledigit percentage increase is expected in 2026,” Yun said. “In 2026, we expect higher inventory, modest improvements in affordability, and more accommodating monetary policy from the Federal Reserve will help more Americans buy their next home.”
Methodology NAR identified the 2026 housing hot spots by analyzing how each area performs relative to the national level across the following 10 key economic, demographic and housing factors: 1. Share of Millennial Households 2. Household Income Growth 3. Job Growth 4. Impact of Lower Mortgage Rates 5. Domestic Migration as a Share of Population 6. Share of Sales with Price Cuts 7. Listings-to-Income Alignment Score (and YoY Change) 8. Mortgage Payment vs. Rent Ratio 9. Single-Family Permits Growth 10. Mortgage Originations Growth
About the National Association of Realtors® The National Association of Realtors® is involved in all aspects of residential and commercial real estate. The term Realtor® is a registered collective membership mark that identifies a real estate professional who is a member of the National Association of Realtors® and subscribes to its strict Code of Ethics. For free consumer guides about navigating the homebuying and selling transaction processes – from written buyer agreements to negotiating compensation – visit facts.realtor. January 2026 | Salt Lake Realtor ® | 15
Jesse Bettencourt/peopleimages.com©/Adobe Stock
Why January Is the Best Time to Kickstart Your 2026 Home Search Conditions are unusually favorable for buyers — and that’s not something to assume will stick around. By The Lighter Side of Real Estate It’s a new year, and if buying a home in 2026 is on your mind, there’s one simple piece of advice worth hearing first: get started now. Not in March. Not in spring. Not “when the weather gets better.” Now. Why? For starters, buying a home takes time. A recent Realtor.com article suggests getting started at least six months before you plan to close. That doesn’t mean starting in January automatically puts you on track for a June closing. In fact, if you get started now, there’s a good chance you could be in a home much sooner than that. On the flip side, even if you don’t plan to move until later in the year, beginning the process early still puts you in a far stronger position when you’re ready to make offers. You’re almost always better off starting sooner rather than later. There’s a lot involved beyond simply finding a house you like. Financial preparation, getting pre-approved for a mortgage, understanding what you can truly afford, getting a handle on the existing inventory, touring homes, writing offers, negotiating terms, and finally closing — all of that takes time. And that’s before 16 | Salt Lake Realtor ® | January 2026
factoring in local competition and inventory. But as we head into this new year, there’s another reason starting early matters even more — and it has everything to do with what’s happening in the market right now…
It’s Finally a Buyer’s Market in Many Areas… But It Might Not Last One of the biggest reasons to begin in January is where the market stands right now. In many areas, conditions are unusually favorable for buyers — and that’s not something to assume will stick around. According to recent housing market data, there were roughly 37% more sellers than buyers across the U.S. in November 2025, one of the largest gaps on record going back to 2013. A gap that large can give buyers more negotiating power. It often leads to more options, more time to consider choices, and greater leverage when it comes to price, terms, and requests for seller concessions. But that gap can easily close. Many buyers put off looking for a home until the spring
market “officially” begins. That’s in quotation marks because there really is no official date for when the spring market begins. But at some point in the next few months, there will likely be a surge of buyers entering the market. When that happens, competition will increase and many of the advantages buyers enjoy early in the year will likely begin to shrink. Buyers who wait may find themselves facing more multiple-offer situations, tighter negotiations, and less room to ask for concessions. Getting started in January doesn’t just give you a head start — it gives you a shot at taking advantage of conditions that may look very different just a few months from now.
The First Thing to Do After the First of the Year If you’re even just thinking about buying a home in 2026, the most productive first step after the new year isn’t scrolling listings or heading out to open houses — it’s having a conversation with a local real estate agent.
target price range, and whether sellers are negotiating or still holding firm. They can also help you come up with a timeline and strategy based upon your personal situation and the current market conditions.
The Takeaway: Buying a home almost always takes longer than people expect. That’s why many experts recommend starting the process at least six months before you plan to move. That doesn’t mean it has to take that long — plenty of buyers find and close on a home much sooner. But it does mean that giving yourself time is rarely a bad idea. Starting as early in the year as possible is always smart, but starting early in 2026 may be even smarter. With roughly 37% more sellers than buyers — the largest gap we’ve seen since 2013 — today’s market is offering buyers opportunities that may not last once more people jump in later this year. Waiting until spring could mean more competition and fewer advantages than buyers see right now.
National headlines are helpful for understanding broad trends, but real estate is extremely local. Conditions can vary dramatically from one city to the next, from one neighborhood to another, and even from one price range to another within the same town.
If you’re even thinking about buying in 2026, getting the ball rolling in January can put you in a much stronger position. And the best first step isn’t browsing listings — it’s talking with a local real estate agent who can explain what’s happening in your market, help you set realistic.
An agent can walk you through what inventory looks like right now, how competitive buyers are in your
Source: The Lighter Side of Real Estate. Check out their content marketing services at lightersideofrealestate.com.
January 2026 | Salt Lake Realtor ® | 17
SeanPavonePhoto©/Adobe Stock
Oregon Tops U.S. Inbound Migration as Americans Move for Family and Work Family became the top reason Americans crossed state lines in 2025, fueling 29% of moves. The American moving map is shifting again, but the familiar story of people fleeing northern winters for southern sunshine is giving way to something more complicated: a mix of family ties, job hunting and affordability pressures that is pushing migrants toward smaller metros and away from high-cost states. That is the picture emerging from United Van Lines’ 49th Annual National Movers Study, which tracks household relocations handled by its parent company, UniGroup, across the contiguous U.S. and Washington, D.C. The study found that Oregon led the nation in inbound migration for the first time, with 65% of United Van Lines moves into the state, a sharp rise from its No. 8 inbound ranking a year earlier. New Jersey remained the top outbound state for the eighth consecutive year, with 62% of moves leaving the state. The reasons Americans are packing up are also changing. According to United, the top driver for interstate relocation in 2025 was not work but 18 | Salt Lake Realtor ® | January 2026
family—29% of movers said they relocated primarily to be closer to relatives. Company transfers and new jobs accounted for 26%, while retirement represented 14%. “Interstate relocation is no longer a linear calculation,” said Michael A. Stoll, an economist and public policy professor at UCLA, describing moves as increasingly shaped by competing pressures— especially housing costs.
A Move Toward Smaller Metros The migration trend appears to be intensifying outside major cities, with movers increasingly targeting medium-size markets where housing is cheaper and the pace of life slower. Among metro areas measured in United’s dataset, Eugene–Springfield, Ore., ranked as the most inbound market, with 85% of moves headed in. United attributed part of Springfield’s appeal to a lower cost of living relative to Portland and proximity to larger employment hubs.
This shift aligns with broader post-pandemic preferences for lower-density living, economists said, but it also reflects the reality that prices in many top “destination” states have climbed sharply, squeezing newcomers as well as longtime residents.
New Jersey: Losing Residents, Attracting Young Workers New Jersey’s position as the country’s leading outbound state masks a demographic nuance: the state is still drawing younger adults, even as it loses retirees and households seeking lower costs elsewhere. United reported that 21% of inbound movers to New Jersey were ages 18 to 34, reinforcing the state’s role as a career and income “launch” point—especially for workers tethered to the New York City labor market— before moving again later in life. The dynamic is playing out across other high-cost states, including New York and California, which continue to attract job seekers while simultaneously seeing residents depart for retirement and affordability.
Southern Magnets Cool Perhaps the most notable signal in the 2025 results is not just where people are going, but where migration has cooled. Historically high-growth states such as Texas and Florida now fall into United’s “balanced” category, meaning inbound and outbound moves are roughly equal—a change United attributed to rising housing costs, which are beginning to constrain even traditionally attractive markets. For the first time in more than a decade, Illinois also landed in the balanced category, no longer appearing among the most outbound states.
Where Americans Moved United’s list of top inbound states included: 1. Oregon 2. West Virginia (62% inbound) 3. South Carolina (61% inbound) 4. Delaware 5. Minnesota 6. Idaho 7. North Carolina 8. Arkansas 9. Alabama 10. Nevada The top outbound states included: 1. New Jersey 2. New York 3. California 4. North Dakota 5. Colorado 6. Mississippi 7. Massachusetts
A Migration Pattern in Transition United said its total number of residential moves in 2025 was similar to 2024, but the underlying motivations continue to diverge by age and household type. “We’re seeing much greater complexity in why people move,” said Eily Cummings, vice president of corporate communications at United Van Lines. Taken together, the findings suggest that the U.S. migration story has entered a new phase: still driven by the pull of jobs and warm-weather states, but increasingly shaped by family proximity and affordability, with smaller metros positioned as the biggest winners.
lucky–photo©/Adobe Stock
January 2026 | Salt Lake Realtor ® | 19
Been Dreaming About Becoming a House Flipper? Here’s Why Now Might Be Your Best Chance Flipping houses isn’t as easy as TV makes it look. But that doesn’t mean it’s out of reach. By The Lighter Side of Real Estate
Flipping houses for a profit is one of those ideas that feels exciting the moment it pops into your head. On TV it looks fun—even when things go wrong, the disasters usually get wrapped up in a neat 60-minute storyline with a big reveal and a happy ending. It’s easy to see why so many people daydream about doing it. But it isn’t just television that makes flipping sound enticing. Real estate has always carried a certain appeal for people who want to invest in something solid and tangible. At the same time, once you start thinking about it in real terms instead of just as a “what if,” the whole thing can suddenly feel overwhelming and lead to a lot of questions… •
How do you even get financing for the purchase?
20 | Salt Lake Realtor ® | January 2026
•
What about the money for renovations?
•
Do you hire contractors or roll up your sleeves and tackle the work yourself?
•
Is this even a good time to try flipping?
•
And if it is, are there really any deals out there you can actually compete for—ones that leave enough room to make a profit when (not if ) things don’t go exactly as planned?
If you’ve been asking yourself those questions, that’s a good sign. It means you’re thinking about flipping in a realistic way rather than just getting swept up in the hype. While they’re not an entire list of questions you need to answer for yourself, they’re a solid place to start.
When the Pros Step Back, the Door Opens for First-Timers The flippers who are pulling back right now have legitimate reasons. Higher costs, tricky financing, and slower price growth make the math a lot tighter. But there are always risks in real estate. There’s never a time when flipping is a guaranteed win. The question is whether the balance of risk and opportunity is shifting in your favor. And right now, it might be. For years, flippers have been trying to buy in a market where homes flew off the shelf in days and often sold for well above asking price. That’s great once you’ve renovated a flip and are in the process of selling, but not so great when you’re trying to snag a property that leaves any room for profit in the first place. Today, things look a little different: •
Prices in many areas are leveling off, and in some places, even dipping.
•
Homes are sitting on the market longer, which means sellers may be more open to negotiation.
•
And with some seasoned flippers hitting pause, there’s less competition snapping up every fixerupper the minute it’s listed.
Put all of that together and you’ve got an opening. More time to analyze deals. More chances to buy at a discount. And less pressure from bidding wars that used to make flipping feel impossible for newcomers.
Jo Ann Snover©/Adobe Stock
But interestingly, one of them might have a more encouraging answer right now than it has in years… even if it doesn’t sound like it at first.
Why Seasoned Flippers Are Hitting Pause Right Now According to a recent report from Realtor.com, home flipping has slowed down. A lot of the seasoned flippers—the ones who’ve been snapping up fixeruppers for years—are stepping back right now. Why? A mix of things. Renovation costs have gone up. Interest rates make it more expensive to borrow. And home prices in many areas aren’t shooting up the way they were, which makes it harder to guarantee a big profit margin at the end of the project. Add those factors together, and plenty of investors are deciding it’s just not worth the risk at the moment. On the surface, that doesn’t sound encouraging for anyone who’s been thinking about getting into flipping. If the pros are backing away, shouldn’t you do the same?
That doesn’t mean you should just rush out and scoop up the first “bargain” you see. The opportunity is real, but so are the risks. The key is being prepared, patient, and strategic so you end up with a project that actually makes sense.
How to Set Yourself Up for a Successful First Project Every successful flipper has one thing in common: at some point, they had to dive in and do their very first project. That first one can be the toughest because you don’t yet have the experience to lean on. But you can set yourself up to make smarter decisions from the start. Here are a few steps that will put you in the best position to find—and actually pull off—your first flip: 1.
Find the right real estate agent. This is a big one. Many would-be flippers make the mistake of casually telling every agent they meet, “Hey, let me know if you see a good deal.” The reality? That doesn’t work. What you want is one agent who knows the investment side of real estate and is willing to really partner with you. The right agent won’t just send you listings; they’ll help you figure out what to pay, what kind of updates will actually add value, and what projects to walk away from.
But their hesitation could be exactly why this is a smart time for first-time flippers to step in. January 2026 | Salt Lake Realtor ® | 21
4Max©/Adobe Stock
2.
3.
4.
Get your financing squared away. If you’ve got cash for the whole purchase plus renovations and carrying costs, you’re ahead of the game. But if you need financing, don’t worry— there are options. Talk with lenders about loans designed for fixer-uppers. And get preapproved before you start shopping so you know exactly what you can afford and can move quickly when the right property comes along. Be ready to look at a lot of houses—and pass on most of them. Not every “cheap” house is a good flip. Some will need too much work. Some won’t leave enough profit margin once the dust settles. Sometimes the smartest move you can make is to walk away. Patience is part of the process. The flip you don’t buy could save you more money than the one you do. Learn to spot the right opportunities. As you look at houses, practice running the numbers. What will it cost to fix? What can it realistically sell for? What’s left over after carrying costs and commissions? The more you practice, the better you’ll get at spotting the deals worth jumping on.
22 | Salt Lake Realtor ® | January 2026
The goal isn’t to buy as many properties as possible right out of the gate—it’s to buy the right one. Get that first flip successfully under your belt, and you’ll be in a much stronger position the next time around.
The Takeaway: Flipping houses isn’t as easy as TV makes it look, and it’s definitely not a guaranteed path to quick riches. But that doesn’t mean it’s out of reach. With many experienced flippers stepping back because of higher costs, tighter margins, and tougher financing, the market is a little less crowded than it has been in years. That creates space for first-timers who are willing to be patient, strategic, and prepared. The key is not to jump in blindly. Line up the right agent, get your financing in place, and learn how to separate a true opportunity from a money pit. If you take the time to approach your first flip carefully, you could find yourself buying smart, renovating wisely, and selling for a profit while others sit on the sidelines. And by the time the headlines start announcing a “flipping comeback,” you’ll already have valuable experience under your belt. Source: The Lighter Side of Real Estate. Check out their content marketing services at lightersideofrealestate.com.
Mortgage Rates Dip, Prices Cool—Yet U.S. Homes Stay Historically Unaffordable In 99% of the 594 counties ATTOM analyzed for its fourth-quarter affordability report, a median-priced home remained less affordable than historical norms.
After three years of punishing home prices and high mortgage rates, the U.S. housing market ended 2025 with signs of easing. Mortgage rates drifted down through the quarter. Price growth softened in pockets of the country. The national affordability crisis, however, barely budged. In 99% of the 594 counties ATTOM analyzed for its fourth-quarter affordability report, a median-priced home remained less affordable than historical norms, the data firm said. That result mirrors the prior two quarters and comes with the national median home price still hovering near a record high—$365,185 in the fourth quarter.
24 | Salt Lake Realtor ® | January 2026
There was improvement, but it was incremental. Affordability improved quarter over quarter in 86% of counties, ATTOM said, as mortgage rates and monthly ownership costs edged lower. “Many Americans were priced out of buying a home in 2025, and affordability remains worse than historic norms in most markets,” said ATTOM Chief Executive Rob Barber. “Still, modest, quarter-over-quarter affordability improvements in many markets at the end of the year offered some encouragement.”
A Paycheck Problem as Much as a Price Problem The country’s affordability stress is the product of a widening gap between wages and home values—one that has grown steadily since 2020.
StockPick©/Adobe Stock
Over the past five years, the median sales price of a home has risen 54%, ATTOM said, while typical wages increased 29%, based on federal wage data available through the second quarter of 2025. In practical terms, that imbalance has reshaped what “affordable” means. Even if prices stabilize, buying power in 2026 will depend heavily on borrowing costs and the broader economy, Barber said.
The 28% Rule Still Doesn’t Hold in Most Counties ATTOM’s model measures affordability by estimating the share of local income required to cover major monthly costs on a median-priced home, including mortgage payments, mortgage insurance, property taxes and homeowners insurance. It assumes a 20% down payment and uses a 28% front-end debt-toincome ratio as the affordability threshold. By that standard, the typical county still fails the test. In 74.1% of counties, the major costs of homeownership consumed more than 28% of local wages, ATTOM said. Nationally, those costs required 31.4% of wages in the fourth quarter—down from 33.3% in the third quarter, according to Realtor.com.
Brooklyn Is Least Affordable; California Dominates the Bottom The least affordable county in the analysis was Kings County, N.Y., better known as Brooklyn, where ownership costs consumed 103% of median wages, effectively placing the median home out of reach for the median worker. California followed close behind. Marin County required 97% of typical wages, and Santa Cruz County required 94%, ATTOM said. In fact, the state dominates the country’s least affordable markets: 14 of the 25 least affordable counties were in California, ATTOM said, followed by three each in New York and New Jersey. The pressure shows up in large metro areas as well. Among the most populous counties where costs exceeded the 28% threshold were: •
Los Angeles County, Calif. (67.5%)
•
San Diego County, Calif. (67.4%)
•
Orange County, Calif. (90.3%)
•
Miami-Dade County, Fla. (43.6%)
January 2026 | Salt Lake Realtor ® | 25
trongnguyen©/Adobe Stock
•
Maricopa County, Ariz. (38.1%)
Where the Math Still Works The most affordable county in the report was Cambria County, Pa., where major homeownership expenses required just 13% of typical local income, according to the Realtor.com recap. Several major counties also remained below the standard affordability threshold, including: •
Harris County, Texas (21.9%)
•
Cook County, Ill. (26.4%)
•
Dallas County, Texas (27.6%)
•
Philadelphia County, Pa. (19.2%)
•
Cuyahoga County, Ohio (19.6%)
A Market That’s Cooling, Not Resetting The quarter ended with modest relief in financing costs. ATTOM reported the average 30-year fixed mortgage rate fell from 6.34% at the beginning of October to 6.15% at year-end. The typical monthly cost of mortgage payments, taxes and insurance fell as well, to $2,015 in the fourth
quarter—down 2% from the prior quarter and 1% from the prior year, ATTOM said. Yet even with those improvements, the affordability baseline remains historically strained. In nearly onethird of counties (29.5%), major homeownership expenses exceeded 43% of typical wages, a level ATTOM classifies as “seriously unaffordable.” That is the defining reality of the late-2025 housing market: conditions can improve, and still remain far from normal. Bottom Line The latest data suggests the market is loosening at the edges—lower rates, slightly improved ratios, and affordability gains in most counties quarter over quarter. But the core problem persists. Home values remain elevated, wage growth has lagged, and even a “better” quarter still leaves ownership costs above traditional affordability thresholds in most of the country. A cooling market isn’t the same as an affordable one. Sources: ATTOM, Realtor.com
November November2025 2025Housing HousingWatch Watch Salt Lake County’s Market Shifts: Buyers Take Their Time Salt Lake County’s Market Shifts: Buyers Take Their Time
Home sales in Salt Lake County totaled 795 units in November, down 10% from 888 sales a year Homeaccording sales in Salt Lake County totaled The 795 decline units in was November, down 10% sales a year earlier, to UtahRealEstate.com. driven largely by a from sharp888 slowdown in earlier, according to UtahRealEstate.com. The decline was driven largely by a sharp slowdown multifamily activity: single-family home sales slipped nearly 3%, while multifamily sales—in multifamily activity: condominiums single-family home sales slipped nearly including townhomes, and twin homes—fell more3%, thanwhile 27%. multifamily sales— including townhomes, condominiums and twin homes—fell more than 27%. Despite the monthly drop, year-to-date single-family sales remain steady. Over the first 11 months monthly drop, year-to-date single-family Over flat the compared first 11 months ofDespite the year,the 7,776 single-family homes were sold in Saltsales Lakeremain County,steady. essentially to of the year, the 7,776 single-family were in Salt Lake County, essentially flatofcompared 7,719 during same period lasthomes year. Even so,sold activity remains well below the pace the recentto 7,719 during same period last year. Evenfirst so, 11 activity remains wellbefore below the the pace of the recent peak: sales are the down 32% compared to the months of 2021, Federal Reserve peak:raising sales are downrates 32%incompared to the first 11 months of 2021, before the Federal Reserve began interest 2022. began raising interest rates in 2022. Prices, meanwhile, continued to climb. The median price for all homes sold in November was Prices, meanwhile, continued climb. TheThe median price for for all homes sold inhomes November was $543,000, up nearly 6% from a to year earlier. median price single-family rose to $543,000, nearlyof6% yearyear. earlier. Thealso median price for single-family homes roseinto $616,500, anup increase 4%from year aover Homes took longer to sell. The typical property $616,500, an increase of 4% year over year. Homes also took longer to sell. The typical property Salt Lake County spent 42 days on the market, compared with 36 days a year ago—an indicationin Saltbuyers Lake County spent 42 days market,iscompared 36choice. days a year ago—an indication that are taking more time on andthe inventory providingwith more that buyers are taking more time and inventory is providing more choice. New supply was steady. In November, 1,008 new listings entered the market, nearly unchanged New supply wasearlier. steady. In overall November, 1,008improved: new listings entered the market, nearly had unchanged from 1,014 a year But selection as of Nov. 30, Salt Lake County 2,987 from 1,014 a year earlier. But overall selection improved: as of Nov. 30, Salt Lake County had 2,987 active listings, up 20% from 2,496 at the same time last year. active listings, up 20% from 2,496 at the same time last year. National Trends Mirror Local Shifts National Trends Mirror Local Shifts Across the U.S., existing home sales fell 1% year over year in November, according to the National Across the U.S., existing home sales fell 1% year over the National Association of Realtors® (NAR). The national median sales year pricein forNovember, all housingaccording types wasto $409,200, up Association of Realtors® (NAR). The national median sales price for all housing types was $409,200, 1% from a year ago and marking the 29th consecutive month of annual price increases. Mortgage ratesup 1% fromsome a yearrelief. ago and 29thfixed-rate consecutive month of annual price increases. Mortgage provided The marking average the 30-year mortgage was 6.24% in November, accordingrates to provided some relief. The average 30-year fixed-rate mortgage was 6.24% in November, according to Freddie Mac, slightly down from 6.25% in October and well below 6.81% one year earlier. Freddie Mac, slightly down from 6.25% in October and well below 6.81% one year earlier. “Existing-home sales increased for the third straight month due to lower mortgage rates this “Existing-home forLawrence the thirdYun. straight monthinventory due to lower mortgage rates to this autumn, ” said NARsales Chiefincreased Economist “However, growth is beginning autumn, ” said NAR Chief Economist Lawrence Yun. “However, inventory growth is beginning stall. With distressed property sales at historic lows and housing wealth at an all-time high, home-to stall. With distressed property at historic lowsthe andwinter housing wealth owners are in no rush to list theirsales properties during months. ” at an all-time high, homeowners are in no rush to list their properties during the winter months.” Yun noted that affordability has improved, at least modestly, as wages have risen faster than Yun prices. noted “Wage that affordability has improved, least modestly, as wageshousing have risen faster than home growth is outpacing home at price gains, which improves affordability. home prices. “Wage growth outpacing home price gains, which housing Still, future affordability couldisbe hampered if housing supply failsimproves to keep pace withaffordability. demand,” Still, future affordability could be hampered if housing supply fails to keep pace with demand,” he said. he said. Single-family homes continued to outperform condominiums in November, Yun added. While Single-family homes continued to outperform condominiums November, Yun added. the typical condo sold for 13.5% less than the typical single-familyinhome, that price gap canWhile be the typical“The condo sold for 13.5% less than the typical single-family home,fees, thatwhich price gap can be misleading. purchase price does not include condominium association are rising misleading. “The purchases purchase price not include condominium association fees, which are rising and making these moredoes expensive, ” he said. and making these purchases more expensive,” he said. 28 | Salt Lake Realtor ® | January 2026
“Wage growth is “Wage growth is outpacing home outpacing home price gains, which price gains, which improves housing improves housing affordability.” affordability.”
Lawrence Yun Lawrence Yun Chief Economist Chief Association Economist National National Association of Realtors® of Realtors®
Salt Lake County
Source: UtahRealEstate.com
Local Market Update for November 2025 KEY METRICS
NUMBER OF SALES
MEDIAN SOLD PRICE
NEW LISTINGS
UNDER CONTRACT LISTINGS
ACTIVE LISTINGS AS OF NOV. 30
All Housing Types Single Family Multi Family
795 582 197
$543,000.00 $616,500.00 $415,000.00
1,008
889
2,987
$514,450.00 $591,795.00 $423,700.00
1,014
919
2,496
5.55% 4.17% -2.05%
-0.59%
-3.26
19.67%
COMPARISON TO LAST YEAR 2024
All Housing Types Single Family Multi Family
888 597 271
COMPARISON TO LAST YEAR -% DIFFERENCE
All Housing Types Single Family Multi Family
888
-10.47% -2.51% -27.31%
NO. OF SALES 795
NEW LISTINGS
1,008
-0.59%
ALL HOUSING TYPES NOV 2024
42 36 16.67%
5.55%
ALL HOUSING TYPES NOV 2025
1,014
$543,000
$514,450
-10.47%
ALL HOUSING TYPES NOV 2024
MEDIAN DAYS ON MARKET
MEDIAN SOLD PRICE
ALL HOUSING TYPES NOV 2025
ALL HOUSING TYPES NOV 2024
ALL HOUSING TYPES NOV 2025
UNDER CONTRACT LISTINGS
919
ALL HOUSING TYPES NOV 2024
ALL HOUSING TYPES NOV 2025
ACTIVE LISTINGS AS OF NOV. 30
2,987
889 2,496
-3.26%
ALL HOUSING TYPES NOV 2024
19.67%
ALL HOUSING TYPES NOV 2025
ALL HOUSING TYPES NOV 2024
January 2026 | Salt Lake Realtor ® | 29
ALL HOUSING TYPES NOV 2025
Pamela Abbott Robert Davis Judy Allen Brian De Haan Suzanne Allred Babs De Lay George Anastasopoulos Lynn Despain Brent Anderson Jerard Dinkelman Clay Anderson Darlene Dipo Diane Anderson Sally Domichel Sue Avalos Rebecca Duberow Margaret Averett James Dunn Laurence Bailess Carol Edgmon Les Bailey Douglas Edmunds Brent Barnum Michael Evertsen Veda Barrie-Weatherbee Bijan Fakhrieh Edward Belka Robert Farnsworth Ken Bell Jack Fisher Raymond Bennett Gale Frandsen Richard C. Bennion David Frederickson Steven Benton Howard Freiss Gregg Bohling Brent Gardner Russell Booth Heidi Gardner Virginia Bostrom Paul Gardner Robert Bowles Linda Geer Mary Ann Brady Sheila Gelman Stephen Bryant J. Carolyn Gezon Barbara Burt Richard Grow Hedy Calabrese Klair Gunn Gary Cannon James Haines Tracey Cannon John Hamilton Julie Carli Mark Handy Carol Cetraro Grant Harrison Scott Chapman Michael Hatch Garn Christensen Thomas Haycock Byron Christiansen Bill Heiner David Clark Jeffrey Helotes Deborah Clark Marvin Hendrickson Terry Cononelos Terry Hill-Black Jeffery Cook Lynda Hobson Philip Craig Sheryl Holmes
Carol Howell Gary Huntsman Blake Ingram Kent Ingram Esther Israelson Kevin Jensen Ron Jenson Jeffrey Jonas Steve Judd David Kenney Henry Kesler Douglas Knight Peggy Knight Randall Krantz Leah Krueger Gary Larson Teresa Larson Vann Larson Fred Law Michael Lawrence Shauna Leake Kaye LeCheminant Daniel Lindberg Michael Lindsay Mildred Llewelyn Don Louie Ted Makris Margaret Malherbe Al Mansell David Mansell Dennis Marchant Susan Mark-Lunde Paul Markosian Ronnald Marshall Susie Martindale Christopher McCandless Curtis McDougal Miriam McFadden
John McGee Russell McKague Andrew McNeil Elizabeth Memmott Uwe Michel Gordon Milar Kyle Miller Preston Miller David Moench Gary Monk H.Craig Moody Randal Moore Thomas Morgan Charles Mulford Melanie Mumford Jacqueline Nicholl John Nielson Robyn Nielson Victor Oishi Joseph Olschewski Brent Parsons Joan Pate Yvonne Pauls Derk Pehrson Douglas Pell Robert Plumb David Read George Richards W. Kalmar Robbins Emilie Rogan Marie Rosol Christopher Ross David Sampson Mark Schneggenburger Gary Shiner Jeff Sidwell Kent Singleton Debra Sjoblom
Elizabeth Smith Kenneth Smith Rick Smith Skip Smith Lorenzo Spencer Kenneth Sperling Anna Grace Sperry Robert Spicer Trudi Stark Lee Stern Sandra Straley Gary Strang John Strasser Kevin Strong Thomas Swallow Sonny Tangaro Joan Taylor Rosanne Terry Martin Vander Veur Craig Vierig Hilea Walker H. Blaine Walker Dana Walton Jerry Webber William Wegener David Weissman Jeffrey Wells Jeff White Clayton Wilkinson Thomas Wilkinson Kimball Willey Douglass Winder Robert Wiskirchen James Witherspoon Linda Wolcott Cynthia Wood Sherrill Wood Margene Wrigley
X3
THE
DISCOVER THE ADVENTURE-READY, CITY-SAVV Y 2025 BMW X3. When you pair “adventure ready” with “city savvy,” you’ll find a vehicle that lives at the intersection of downtown avenues and mountain roads: the BMW X 3. With a reimagined design and sporty handling, the latest iteration of this icon doesn’t just tackle any journey with ease; it draws attention while doing it. And it wouldn’t earn the X 3 name without versatility at its heart and a premium interior that makes it unmistakably BMW. Visit BMW of Murray or BMW of Pleasant Grove for exceptional offers on the BMW X 3.
BMW of Murray 4735 S. State Street Murray, Utah 801-262-2479 bmwofmurray.com
BMW of Pleasant Grove 2111 West Grove Parkway Pleasant Grove, Utah 801-443-2000 bmwofpg.com
©2025 BMW of North America, LLC. The BMW trademarks are registered trademarks.
2026
If the new year has you thinking bigger, it’s time to elevate your business and the service you deliver to your clients. At Windermere, we back our agents with the tools, expertise, and support needed to make 2026 your strongest year yet.
Grady Kohler PRINCIPAL BROKER
grady@winutah.com | 801.815.4663
Brad Hansen GENERAL MANAGER
brad@winutah.com | 801.230.5236
W I N D E R M E R E R E A L E S TAT E – U TA H
Monica Draper VP BUSINESS DEV
monica@winutah.com | 435.313.7905
winutah.com/joinus