NOVEMBER 2019 | FUTUREOFBUSINESSANDTECH.COM
An Independent Supplement by Mediaplanet to USA Today
FINANCIAL PLANNING & INSURANCE
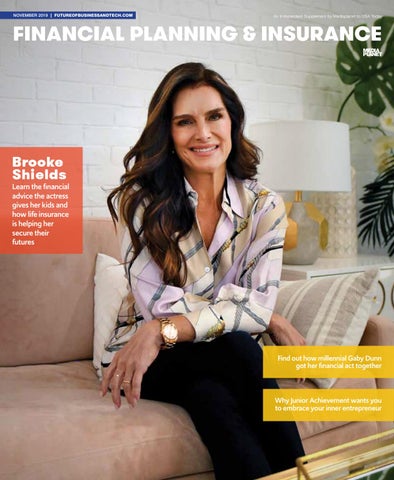
Brooke Shields
Learn the financial advice the actress gives her kids and how life insurance is helping her secure their futures
Find out how millennial Gaby Dunn got her financial act together
Why Junior Achievement wants you to embrace your inner entrepreneur
5 Things We Can Learn From Baby Boomers About Managing Our Finances The baby boomers know a thing or two about changing financial trends. Here’s what they can teach us about saving for retirement.
The Secret to Good Financial Planning
The baby boomer generation has developed a unique approach to finances over the years. What can we learn from them? 1 How not to retire Departing from earlier generations, 66 percent of boomers plan to work past age 65 or not retire at all, in order to to keep their income and benefits and maintain their lifestyles.
3 How to pay yourself first Boomers are choosing saving for retirement over funding a child’s college education. After all, their child has longer to pay off loans than they have to build adequate savings. 4 How to save without a pension The responsibility of funding retirement has shifted from employer to employee during the boomers’ lifetime. Only 2 percent of workers now have a pension plan — down from 28 percent in 1979. “Defined contribution” plans have forced boomers to develop retirement savings with little or no help from employers. 5 How to enjoy retirement Boomers are using retirement to pursue dreams or give back, often spending more in their first years of retirement than in the years leading up to it. Decumulation strategies help fund their retirement lifestyles. Evelyn M. Zohlen, CFP, President, Financial Planning Association
PHOTO: TINNETTA BELL
2 How to handle competing pressures Boomers are supporting their children and aging parents while trying to meet personal monetary obligations. Creating financial plans with all parties has helped address the burden.
When it comes to budgeting for retirement, financial educator Tiffany Aliche says automation is the key.
T
iffany Aliche, an award-winning financial educator for women, otherwise known as “The Budgetnista,” has one key piece of financial advice: “When it comes to a budget, automation is the new discipline,” she said. “For each aspect of your budget, try to automate it.” Aliche believes people owe it to themselves to plan for retirement. “If you don’t set aside for retirement, you’re not going to have any money,” she said. Be kind to your future self Aliche proposes a thought
experiment: re-name your future self and imagine that person in retirement. “My older self’s name is Wanda,” Aliche said. “I imagine Wanda rocking on the porch and think, if I make bad choices now, how will they affect Wanda?” Planning for your financial future is harder now, Aliche admits. “You used to have one person working in a household making $50,000 a year, and you would still be able to send your kids to school, buy a car, and go on vacation,” she said. “Now, people make double that
and still cannot sustain basic life.” Online social groups are great places to start a financial education, like her own free programs called, "Live Richer Challenges." Over 800,000 women have taken at least one challenge. The four stages of automation But automation is key. Aliche breaks it down into four stages. “First is retirement,” she said. “Ideally, you’d put aside 10 percent or more of your gross income — and more than that for women.” Even if 10 percent is unachievable now, she says, “Start with 1 percent. Then every six months, call HR and add another 1 percent until you get to 10 or more.” Second, arrange for automatic payments to your checking account. Third, separate your bill money. “You should have two checking accounts at the same bank,” Aliche said. “One where your money lands, and one where you pay bills from.” Lastly, automate savings transfers. “Keep your savings in an online-only bank, because most big banks will only give small returns,” she said. Aliche stresses that detailed financial planning is not about wealth. “Money is really not a goal,” she said. “It’s just one tool to achieve your goal, which is really a richer, more fulfilling, more connected, healthier life.” n Ross Elliott
Publisher Tom Zwicke Business Developer Jordan Hernandez Managing Director Luciana Olson Lead Designer Tiffany Pryor Designer Tiffany Jackson Lead Editor Mina Fanous Copy Editor Marjie Shrimpton Director of Sales Shannon Ruggiero Head of Business Development Jourdan Snyder Director of Product Faye Godfrey Content Strategist Vanessa Rodriguez Cover Photo LIFE Happens All photos are credited to Getty Images unless otherwise specified. This section was created by Mediaplanet and did not involve USA Today. FOLLOW US: @MEDIAPLANETUSA
2 • FUTUREOFBUSINESSANDTECH.COM
INQUIRIES: US.EDITORIAL@MEDIAPLANET.COM AND US.ADVERTISE@MEDIAPLANET.COM
PLEASE RECYCLE
fits. These additional benefits allow the consumer to access the death benefit of their policy during their lifetime for additional financial help, in the event they are diagnosed with a serious illness.
Why It’s Important for Millennials to Buy Life Insurance Now SPONSORED
A monthly payment for life insurance costs about the same as a monthly subscription for a streaming service, yet many millennials either don’t have life insurance or don’t have enough coverage. “This is not necessarily on the radar for the majority of millennials,”
says Erika George, director at National Life Group, and a millennial herself. “Think about the competing priorities millennials are faced with, such as student debt and rising costs of living, etc. Yet, it’s best to get life insurance when time is on your side and you are young and healthy.” What you should know It’s important to know the difference between term life insurance and permanent life insurance. Term insurance provides a death benefit for a specified period of time,
such as 10 or 20 years. Some term policies can be extended after the term, but typically at much higher costs. The death benefit is only paid if the insured dies while the policy is in effect. Permanent life insurance continues for the life of the insured person, as long as all premiums are paid. Plus, it has the potential to build cash value that the policy owner can access during their lifetime via policy loans and withdrawals. But it doesn’t stop there; some types of life insurance include living bene-
Priorities Six in 10 people reported not buying life insurance because they said they have other financial priorities, according to the 2018 Insurance Barometer Study by LIMRA of 2,082 individuals, including millennials. But managing those “other financial priorities” after a loved one’s death would be challenging without life insurance. That same survey found 35 percent of all households said they would feel adverse financial impacts within one month of a primary wage-earner’s death. “Life insurance should just be one of those things you budget for,” says Faisa Stafford, president of Life Happens, who says it’s more affordable than people think. “Millennials overestimate the cost of life insurance,” she says, explaining that 42 percent of millennials surveyed thought a $250,000 life insurance policy for a 30-year-old was over $1,000. It’s actually only $160 per year. The process can be easy too. In many cases, with simplified underwriting, many consumers can
qualify without doctors’ visits or lab work. Buy it now It’s smart to buy life insurance when you are younger in order to lock in your insurability. The longer you wait, the more expensive it can get, and you may not be eligible later on due to health reasons. “We spend so much time planning for that dream vacation or wedding, our first home, and so on,” says Colleen Tuohy, principal industry consultant at Hearsay Systems. “Oftentimes we don’t adequately prepare for the unexpected.” Don’t rely on a crowdsourced fundraiser like GoFundMe to help your family pay for your final expenses. With life insurance, you help your family stress less over current and future expenses. Tuohy urges millennials to take a protection-first approach. She is encouraged that 6 in 10 millennials say they’d consult a financial professional and the internet for information on individual insurance products, according to the 2018 Insurance Barometer Study. Looks like the old ideas about life insurance may be changing just in time for the millennial generation. n Kristen Castillo
National Life Group® is a trade name of National Life Insurance Company, Montpelier, VT, Life Insurance Company of the Southwest, Addison, TX and their affiliates. Each company of National Life Group is solely responsible for its own financial condition and contractual obligations. Life Insurance Company of the Southwest is not an authorized insurer in New York and does not conduct insurance business in New York. Living benefits are provided by no-additional premium accelerated benefit riders. Payment of Accelerated Benefits will reduce the Cash Value and Death Benefit otherwise payable under the policy. Receipt of Accelerated Benefits may be a taxable event, may affect your eligibility for public assistance programs, and may reduce or eliminate other policy and rider benefits. Please consult your personal tax advisor to determine the tax status of any benefits paid under this rider and with social service agencies concerning how receipt of such a payment will affect you. Riders are supplemental benefits that can be added to a life insurance policy and are not suitable unless you also have a need for life insurance. Riders are optional, may require additional premium and may not be available in all states or on all products. Policy loans and withdrawals reduce the policy’s cash value and death benefit and may result in a taxable event. Surrender charges may reduce the policy's cash value in early years. MEDIAPLANET • 3
How Life Insurance Can Help Secure Millennials’ Finances Despite student debt and dwindling social security, millennials remain optimistic about their financial futures. Life insurance helps, and here’s why. The oldest millennials are celebrating their 20th anniversary in the workforce this year. It’s true! The millennial generation, born 1981-1996, is already the largest generation in the U.S. labor force. Millennials today As millennials today make decisions about housing, starting families, and career advancement, they also encounter momentous financial decisions impacting their futures. But their financial pasts have seen hard times; as the most educated generation in American history, millennials endured college education costs that far outpaced inflation. Recession and resilience Subsequently, many of those college grads entered the workforce during the recession, when jobs were scarce. But despite mountains of student loans, millennials remain resilient and optimistic about their financial futures. Protect it all with life insurance If you are a millennial, take these steps to secure your future: • Protect your capacity to work with disability income insurance. Your earning power is your most valuable asset and should be safeguarded. • Protect your family. More than 1 million millennials are becoming firsttime moms each year — life insurance equals assurance for growing families. • Protect the second half of your life. If a millennial is healthy at 30, they’re likely to live to 90. Life insurers offer solutions to help save for retirement and provide income for a lifetime. Susan K. Neely, President and CEO, American Council of Life Insurers 4 • FUTUREOFBUSINESSANDTECH.COM
How Brooke Shields Teaches Her Daughters Their Worth Brooke Shields shares her love of motherhood and the value of passing on sound financial advice. Brooke Shields has been a household name since the actress and model starred in the 1978 film “Pretty Baby.” But the 54-year-old celebrity has a behindthe-scenes job she considers even more important: being a mom. “It’s a labor of love, and one of the toughest, most challenging, and rewarding jobs I’ve ever had. I think that with most jobs, it’s important to earn it. Just because you have a baby doesn’t mean you’re a good mother,” Shields said. Paying it forward For Shields, being a good mom to daughters Rowan Henchy, 16, and Grier Henchy, 13, includes talking about family finances. She explained that her own mother viewed money only as a means to an end; she didn’t tend to the details. “The way my mother looked at things was: If I did a movie, we could buy a house; if I did this job, we could get a car. There was never any, ‘Let’s sit down and understand this.’” “It was working to live, not working for the future,” she continued. “At one point, we were incredibly cash-poor but had properties everywhere. When
I took over my finances, I realized I had to do things I really didn’t like but that were very important.” Now with their children, Shields and her husband, 55-year-old Chris Henchy, are making sure to pass on critical money lessons their daughters can carry into adulthood. “I’m trying to give my daughters respect for money earned, not wasted,” Shields said. “They have summer jobs, an allowance, and are learning to save. So when they ask for something, we can say, ‘Well, find out what it costs and if you have enough saved to buy it, or how long it’ll take to save for it.’” Planning for the future Teaching them the importance of independence is also key. “They know that both mom and dad work, and both mom and dad earn. That’s an important lesson — not to be dependent on anybody without knowledge or a safety net,” she said. One of the ways Shields is creating a safety net for her family is through a quality life insurance plan, something she’s raising awareness about with the organization Life Happens.
PHO
TO :
M O N TA
N A P R I TC H A
RD
“Protecting my family financially means everything, and life insurance is an important piece of that,” Shields said. “I think people shy away from [getting] a will and life insurance. But once you’ve gone through those few, uncomfortable conversations, then it’s basically done, and those you’ve promised to take care of will be provided for financially.” The time and attention she’s paid toward being a good mom — financial wisdom included — is no doubt paying dividends in her relationship with her daughters. One day recently Rowan offered some encouraging words to help lift Shields’ spirits. “[Rowan] said, ‘Mom,you’ve got this. Hang in there! I’m really proud of you,’” Shields recounted.“It stopped me in my tracks, because over the years I’ve been working at being her mother, somewhere along the line, love and respect have been built up. Receiving that type of good will from your children is a huge gift." n Melinda Carter MEDIAPLANET
Protect Your Belongings With Renters Insurance Landlords might cover repairs, but who has your back in a break-in? Learn how renters insurance can save your belongings and your bank account. If you’re a renter, you might think, “Why do I need insurance?” After all, your landlord is responsible for any problems with the building. However, if anything is damaged or stolen, your personal belongings won’t be covered by your landlord’s insurance. Get covered Most policies provide two types of coverage: personal property and liability. Personal coverage pays to repair or replace personal belongings if they’re damaged or stolen. Liability insurance covers against claims resulting from bodily injury or property damage caused to others while on the policyholder’s property. Cost concerns Thankfully, renters insurance isn’t expensive. An average policy costs only $15-$30 a month. Replacing all your possessions or paying liability costs would likely cost much more. Sold on security Once you’ve decided to purchase renters insurance, you’ll need to decide between actual cash value or replacement cost coverage. Actual cash value will reimburse the cost of the personal property at the time of the claim. Replacement cost will reimburse the full value of a comparable new item. Prevention pays Always ask about discounts — many insurers will reduce premiums if you have alarms, extinguishers, deadbolts, etc., and some offer discounts if you take out more than one policy. Lastly, remember an insurance policy is a contract. Make sure you understand what’s covered and what’s not before you buy a policy. Eric A. Cioppa, President, National Association of Insurance Commissioners; Superintendent, Maine Bureau of Insurance 6 • FUTUREOFBUSINESSANDTECH.COM
Life Insurance Experts Bust the Myths and Discuss Why You Need It Now The idea of life insurance makes many think “why” or “when.” These experts answer your questions and share how it can help the lives of loved ones forever. In short, why is life insurance necessary? Dennis Martin: Peace of mind. When people are younger, life insurance helps protect families from a sudden loss of income. Later in life, it helps optimize retirement plans and establish a legacy. Steve Sanders: Our human capital is our greatest asset. We insure our homes and cars, so why not our income? We all have a plan for our lives and how the future will unfold, and those plans require time and years of earnings. Life insurance helps ensure our loved ones can maintain their life plans in the event of an untimely death. Who feels the effects if disaster happens and the affected does not have life insurance? DM: Unfortunately, the people that you love the most — spouses, children, business partners, etc. Life insurance is one way to show you care for them. SS: Anyone you provide for. Think about all the things your income covers. Whether childcare, bills, groceries, a mortgage, or retirement, suddenly those short-term expenses and long-term plans may become near impossible for your loved ones to take on.
Dennis Martin President, Individual Life and Financial Services, OneAmerica
SS: Another myth is “I’m too young to need it.” In fact, it’s often best to get life insurance in your 20s and 30s, because we tend to be healthiest at these ages, and the younger and healthier you are, the better the price of insurance. How do you see future generations looking at life insurance?
Steve Sanders Vice President, Life Distribution, F&G Life How has life insurance changed your life? DM: My mother passed away suddenly at age 50. Her life insurance provided a comfort to us as we grieved and planned her funeral. It also helped my dad plan his own financial future. Once I experienced the difference a life insurance policy can make to those grieving a loss, I wanted to help provide that peace of mind to other people. What are some common myths consumers believe about life insurance? DM: One of the biggest myths is that it’s too expensive. There are many options for protection, and you don’t have to be wealthy to protect your loved ones.
DM: It stands the test of time. Families may be forming later, but protecting loved ones is a basic human desire and that isn’t going to change. The cost does go up with age, so waiting increases the risk of not qualifying due to health changes as you get older. SS: Some of today’s most popular life insurance products provide “living benefits,” which offer access to your policy values during your lifetime. For some, it becomes retirement income; for others, it helps pay for healthcare for a terminal or chronic illness. As we live longer, future generations will likely see their parents managing longer retirements with rising healthcare expenses, which brings even more value to having a life insurance agent. They stay on top of the latest policies and provide multiple options for every situation. n
How We Can Empower Young Girls to Be Financially Independent Financial literacy is a gamechanger for career success, but it’s often not taught to women. It’s time to empower young girls in finance early on.
Author and Activist Gaby Dunn on Millennial Money Matters Gaby Dunn didn’t plan on becoming a finance expert. But the podcast host who talks sex realized she should talk about another topic: money. "I cried about money more than I cried about anything else,” says Gaby Dunn, 31. “All these people like me for my honesty, yet my biggest secret is that I cry about money at least once a week, and I don’t tell anybody about it.” It never stopped Like many millennials, Dunn was worried about medical and student debt, fixing her car, and affording a cell phone. She also stressed about making ends meet if her freelance clients didn’t pay. She often wished for a 24-hour break from worry-
ing about debt, but says, “It just felt like it never stopped.” The solution has been talking about it. In the few years she’s been doing her “Bad With Money” podcast — which was named one of the top 10 podcasts of 2016 by The New York Times — Dunn has realized that having money issues is not an isolated problem. “The audience has followed me learning, and I think they’ve learned along the way because I’m asking the stupid questions,” Dunn says. She encourages consumers, especially millennials, to be politically engaged so they can work to improve financial wellness in the country. No shame The author of “Bad with Money: The Imperfect Art of Getting Your Financial
PHOTO: ROBYN VAN SWANK
Look around an average classroom and likely half the kids will be girls. Look around a typical corporate boardroom, though, and likely only 1 in 5 directors will be women. Why? Because girls often aren’t taught about finances. Studies show only 12 percent of women feel confident making financial decisions, and they defer to others more than men do.
Sh*t Together,” says it’s OK to ask for financial advice. “Money is already hard,” she says. “You don’t need to add shame. Just talk to each other.” Dunn uses the “You Need a Budget” app and an Excel spreadsheet. Plus, she keeps a handwritten list of financial data including her tax information, which she prints and highlights. She also recommends printing out your bank statement so you can see what you’re spending your money on and what you don’t need. For example, she realized she was overpaying at parking meters. “It’s taking your head out of the sand, and saying, ‘What’s going on?’” she says. “It’s your money — you’re the only person who’s going to care about it.” n Kristin Castillo
Turning the tide Thankfully, young women can now take matters into their own hands with these foundational financial skills: Advocate for yourself. Always negotiate job offers and don’t hesitate to ask for a raise. Be independent. Don’t assume someone else knows more about money than you. Have confidence. There’s no career or goal you can’t tackle. Be thrifty. Start a nest egg early to support your goals for many years. Invest in girls There are simple steps parents, schools, and corporate leaders can take to ensure girls’ success, too: Offer personal finance classes for boys and girls in high school. Financial literacy changes the way girls operate in the world. Encourage girls to ask questions. Research shows girls need to feel safe and comfortable to learn best. Introduce girls to women executives, boardrooms, and workplaces in school. Access to female role models accelerates change and fosters confidence. Girls can and should feel empowered to make financial decisions for their personal lives and their careers just as boys do. It’s time to even the odds. Betsy Kelder, Executive Director, Invest In Girls MEDIAPLANET • 7
YOU F&G provides annuities and life insurance for over 700,000 Americans. We work with your financial and insurance professional to ensure your prosperity, provide stability and security, and help you plan for a better tomorrow. F&G is collaborative & transparent, dynamic & trustworthy. Together, we’ll make a great team. fglife.com “F&G� when used herein refers to Fidelity & Guaranty Life, the marketing name for Fidelity & Guaranty Life Insurance Company issuing insurance in the United States outside of New York. Life insurance and annuities issued by Fidelity & Guaranty Life Insurance Company, Des Moines, IA.
19-0248