










Q: My husband and I have been renting this house in Suisun City for almost four years. We started renting during the pandemic. When we agreed to lease the property, the owner told us that, when we were financially able to purchase it, he would sell it to us at a fair market price. We have been working with a loan officer for the past six months and we were just getting ready to contact him when we got a notice to move out in 60 days. He says he has relatives who he’s going to let live here. We both love this house and have been planning to buy it for all these years. Now we don’t know what to do. We want to sue him and make him sell us the house. We really need your advice.
A: This type of agreement all but died in the past decade, but became more common during the pandemic when people still needed homes, but getting loans was difficult.
But there’s a right way, and a wrong way, to go about it.
When you rented the property you “agreed” and the owner “said,” but is there anything in writing? As you’ll see, that’s a critical question.
The name for such an arrangement is a
Lease/options are really two separate, but related contracts.
Everyone knows what a lease is. It is a contract in which you agree to pay rent and abide by certain rules and the owner of the property agrees to let you live there. Option agreements are contracts in which the potential buyer is given an exclusive right to purchase the property. In other words, the buyer doesn’t have to buy, but the seller does not have the right to sell the property to someone else as long as the option agreement
If the agreement was in writing, as it certainly should have been, you don’t have a problem. Simply presenting the contract at an eviction trial will keep you in the house.
If he won’t sell it to you, you can file a lawsuit to make him abide by the terms of the deal.
But since the landlord has given you the statutory 60-day notice to vacate, I’m assuming that the written option has expired, or, most likely, it
See Jones, Page 6









In Solano and Yolo County, first-time homebuyers and middle class move-up buyers are often buying homes with barely enough money to close.
TED ROSSMAN BANKRATE.COM
TJim Porter
First-time homebuyers around here rarely have more than 5% down and most firsttime buyers have less than 3.5% of the sales price, which is the down payment required to qualify for an FHA loan, the easiest loan to qualify for when it comes to FICO scores and debt ratios.
Cash to close is always the biggest challenge for renters that are living paycheck-to-paycheck that lack savings or parents with money to gift. Veterans can buy with zero down and CALHFA qualified buyers can get a down payment assistance loan for the down payment, which leaves these buyers with nothing more than the recurring and nonrecurring closing costs to come up with at the end of the 21to 45-day residential purchase agreement (RPA).
The recurring costs are the things that you have to pay once and then again for the rest of your life, like property taxes, homeowner insurance and mortgage interest.
When you buy a house with 5% down or less, the lender requires you to have an impound account for property tax and insurance to be paid monthly and included with your mortgage payment. If you buy a home
See Porter, Page 6
here aren’t enough homes for sale. Exist ing homeowners have self-imposed golden handcuffs in the form of 3% mort gage rates, and they aren’t in a hurry to move.
We keep hearing that the U.S. needs more housing inven tory, which is true, but that lament is geographic. In fact, some markets are experiencing an overbuilding phenomenon. And builders, eager to rid them selves of inventory, do a good job of enticing homebuyers with few other options to gobble up those homes.
An impatient homebuyer could find themselves tempted into an inadvisable purchase.
Florida is the epicenter of this trend. Punta Gorda build ing permits hit an all-time record in late 2021. At the peak, permit activity tripled pre-pandemic levels and was 15-20 times the levels typical throughout most of the 2010s.
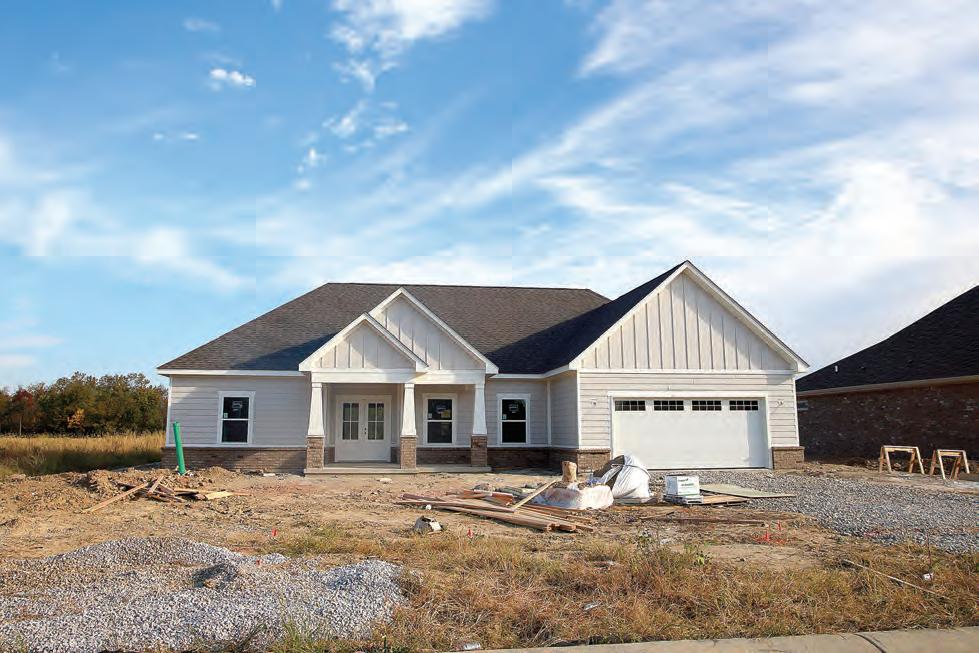
New homes are currently cheaper than existing homes, but that’s partly because of builder incentives that may not measure up over time.
But from January 2025 to January 2026, Punta Gorda experienced the largest drop in home prices in the nation, according to Realtor.com. Active housing market inventory in Punta Gorda is 76% higher than pre-pandemic levels. The homebuilding boom that took place over the past few years has backfired, leaving some of those enthusiastic homebuyers from a few years ago holding housing supply in a market with not enough demand.
What does all of this mean for today’s homebuyers? It means understanding exactly what you’re getting in a new build and doing your research to control all the aspects of the homebuy-
ing process that you can.
Last year, the Wall Street Journal proclaimed that Cape Coral, near Punta Gorda, was “the worst housing market in America.” Reasons included the most underwater homeowners in the nation (that is, people who owe more than their home is worth), along with declining home prices and a glut of unsold inventory. Many of today’s coldest housing markets are in the
South. The Sun Belt, particularly places like Florida, Texas and Tennessee, lured relocators with the promises of warm weather, affordable housing and low taxes. Earlier this decade, home prices rose dramatically in places like Nashville; Austin, Texas; and all across the Sunshine State. But now we’re seeing that what goes up can come down, particularly when too much new construction goes up too quickly.
The potential mistake was thinking that an object in motion stays in motion. And that no price is too high for markets experiencing seemingly insatiable demand. Like a diner at an all-
you-can-eat buffet, prospective homebuyers need to know when enough is enough. There should be a limit to how much you’re willing to pay. Home prices go up and down, particularly in the short term.
Newly built homes offer a certain appeal to buyers. It’s nice to be able to customize your living space, and you’re not inheriting someone else’s problems, like an
See Beware, Page 7
TOTAL SALES: 6
LOWEST AMOUNT: $360,000
HIGHEST AMOUNT: $1,235,000
MEDIAN AMOUNT: $702,500
AVERAGE AMOUNT: $791,667
195 East B Street - $700,000
04-10-26 [3 Bdrms - 1544 SqFt - 1982 YrBlt], Previous Sale: 10-25-22, $680,000
900 Cambridge Drive #95 - $360,000
04-07-26 [2 Bdrms - 1087 SqFt - 1984 YrBlt], Previous Sale: 04-10-08, $217,500
1190 Church Street - $1,100,000
04-06-26 [3 Bdrms - 2075 SqFt - 1968 YrBlt], Previous Sale: 04-12-19, $765,000
358 Mccall Drive - $1,235,000
04-10-26 [3 Bdrms - 3485 SqFt - 2004 YrBlt], Previous Sale: 07-09-08, $591,000
879 Oxford Way - $650,000
04-07-26 [4 Bdrms - 1919 SqFt - 1981 YrBlt]
1811 Pacifica Court - $705,000
04-08-26 [3 Bdrms - 1239 SqFt - 1958 YrBlt]
TOTAL SALES: 9
LOWEST AMOUNT: $495,000
HIGHEST AMOUNT: $875,000
MEDIAN AMOUNT: $590,000
AVERAGE AMOUNT: $621,556
620 North 2nd Street - $495,000
04-09-26 [2 Bdrms - 1260 SqFt - 1984 YrBlt], Previous Sale: 03-03-20, $360,000
689 West C Street - $699,000
04-09-26 [2 Bdrms - 2127 SqFt - 1954 YrBlt]
525 Fruit Tree Road - $610,000
04-08-26 [3 Bdrms - 2024 YrBlt], Previous Sale: 09-11-24, $571,500
745 Jasmine Street - $875,000
04-10-26 [3 Bdrms - 2935 SqFt - 2022 YrBlt], Previous Sale: 08-29-22, $868,000
440 Mckenzie Drive - $515,000
04-07-26 [3 Bdrms - 1512 SqFt - 1970 YrBlt]
950 Norton Court - $590,000
04-07-26 [3 Bdrms - 1606 SqFt - 2003 YrBlt], Previous Sale: 04-19-04, $359,500
630 Sierra Drive - $500,000
04-10-26 [3 Bdrms - 1328 SqFt - 1965 YrBlt], Previous Sale: 00/1989, $112,000
1200 Tufts Lane - $810,000
04-08-26 [3 Bdrms - 2022 YrBlt], Previous Sale: 11-02-22, $670,000
230 East Walnut Street - $500,000
04-09-26 [3 Bdrms - 1082 SqFt - 1964
YrBlt], Previous Sale: 09-15-23, $450,000
TOTAL SALES: 18
LOWEST AMOUNT: $235,000
HIGHEST AMOUNT: $849,500
MEDIAN AMOUNT: $598,000
AVERAGE AMOUNT: $581,417
346 East Alaska Avenue - $486,000
04-08-26 [3 Bdrms - 1287 SqFt - 1968 YrBlt], Previous Sale: 10-29-08, $134,000
497 Americano Way - $560,000
04-08-26 [4 Bdrms - 2253 SqFt - 1986 YrBlt]
1724 Autumn Meadow Drive - $591,000
04-07-26 [3 Bdrms - 1307 SqFt - 1997 YrBlt]
2913 Balsam Court - $540,000
04-06-26 [4 Bdrms - 1590 SqFt - 1987 YrBlt], Previous Sale: 08-26-05, $435,000
4764 Brookside Circle - $640,000
04-09-26 [4 Bdrms - 1638 SqFt - 1993 YrBlt], Previous Sale: 12-17-20, $540,000
3327 Colonial Court - $810,000
04-06-26 [4 Bdrms - 2474 SqFt - 1988 YrBlt],
Previous Sale: 06-18-03, $450,000
3896 Doral Drive - $750,000
04-10-26 [4 Bdrms - 2146 SqFt - 1999 YrBlt],
Previous Sale: 01-04-05, $540,000
1661 Fairfield Avenue - $605,000
04-09-26 [4 Bdrms - 2212 SqFt - 1980 YrBlt],
Previous Sale: 03-25-25, $455,000
2076 Harte Court - $285,000
04-10-26 [3 Bdrms - 1204 SqFt - 1976 YrBlt],
Previous Sale: 01-23-13, $164,500
2952 Inspiration Drive - $683,000
04-09-26 [4 Bdrms - 2194 SqFt - 2020 YrBlt], Previous Sale: 02-20-20, $542,000
5001 Lakeview Circle - $627,000
04-06-26 [3 Bdrms - 1281 SqFt - 1988 YrBlt], Previous Sale: 01-21-26, $479,000
506 Palo Alto Court - $405,000
04-10-26 [4 Bdrms - 2942 SqFt - 1997 YrBlt],
Previous Sale: 05-11-01, $405,000
1844 Stockbridge Drive - $790,000
04-08-26 [5 Bdrms - 2755 SqFt - 2005 YrBlt], Previous Sale: 12-21-05, $710,500
1312 Sutter Court - $525,000
04-06-26 [3 Bdrms - 1438 SqFt - 1976 YrBlt], Previous Sale: 03-02-12, $163,000
4017 The Masters Drive - $663,000
04-10-26 [3 Bdrms - 2449 SqFt - 2004 YrBlt], Previous Sale: 10-30-24, $480,000
3343 Ticonderoga Place - $421,000
04-10-26 [3 Bdrms - 1703 SqFt - 1997 YrBlt]
2059 Tilden Court - $235,000
04-09-26 [3 Bdrms - 1438 SqFt - 1974 YrBlt], Previous Sale: 05-18-05, $425,000 2707 Tuckaway Court - $849,500
04-08-26 [5 Bdrms - 2874 SqFt - 1993 YrBlt], Previous Sale: 08-25-06, $765,000
TOTAL SALES: 6
LOWEST AMOUNT: $205,000
HIGHEST AMOUNT: $486,000
MEDIAN AMOUNT: $380,000
AVERAGE AMOUNT: $367,000
350 Canyon Springs Drive - $486,000
04-10-26 [2 Bdrms - 2302 SqFt - 2002 YrBlt], Previous Sale: 04-23-03, $328,000
307 Crystal Downs Drive - $295,000
04-08-26 [2 Bdrms - 1439 SqFt - 2003 YrBlt]
600 Falconcrest Way - $456,000
04-09-26 [2 Bdrms - 1837 SqFt - 2016 YrBlt],
Previous Sale: 12-31-15, $389,000
914 Laurel Way - $205,000
04-10-26 [2 Bdrms - 858 SqFt - 1951 YrBlt],
Previous Sale: 00/1989, $75,000
2235 Reunion Lane - $410,000
04-08-26 [2 Bdrms - 1686 SqFt - 2021 YrBlt], Previous Sale: 06-30-21, $451,000
372 Shadow Creek Drive - $350,000
04-09-26 [2 Bdrms - 1359 SqFt - 2003 YrBlt]
TOTAL SALES: 4
LOWEST AMOUNT: $484,000
HIGHEST AMOUNT: $575,000
MEDIAN AMOUNT: $525,000
AVERAGE AMOUNT: $527,250
329 Ridgecrest Circle - $484,000
04-07-26 [2 Bdrms - 1058 SqFt - 1991 YrBlt], Previous Sale: 02-15-05, $350,000 904 Shelduck Court - $520,000
04-09-26 [4 Bdrms - 1544 SqFt - 1981 YrBlt], Previous Sale: 07-20-11, $145,000
1706 Ventura Way - $530,000
04-08-26 [3 Bdrms - 1334 SqFt - 1988 YrBlt], Previous Sale: 12-17-19, $413,500
1109 Waxwing Drive - $575,000
04-10-26 [4 Bdrms - 1720 SqFt - 1977 YrBlt],
Previous Sale: 09-17-25, $370,000
TOTAL SALES: 23
LOWEST AMOUNT: $255,000
HIGHEST AMOUNT: $1,205,000
MEDIAN AMOUNT: $570,000
AVERAGE AMOUNT: $604,022
309 Adobe Drive - $469,000
04-09-26 [3 Bdrms - 1012 SqFt - 1968 YrBlt]
160 Bristol Drive - $599,000
04-06-26 [4 Bdrms - 1799 SqFt - 1974 YrBlt], Previous Sale: 09-07-16, $285,000
2030 Broom Grass Court - $1,200,000
04-08-26 [4 Bdrms - 2736 SqFt - 2017 YrBlt], Previous Sale: 02-07-17, $743,500
448 Corte Lagos - $650,000
04-07-26 [4 Bdrms - 2048 SqFt - 1976 YrBlt]
901 El Camino Avenue - $450,000
04-08-26 [3 Bdrms - 1369 SqFt - 1979 YrBlt], Previous Sale: 10-01-19, $344,000
291 Ginger Street - $850,000
04-06-26 [4 Bdrms - 2843 SqFt - 2015 YrBlt], Previous Sale: 02-21-22, $855,000
700 Granada Lane - $680,000
04-09-26 [4 Bdrms - 1851 SqFt - 1974 YrBlt]
285 Hemlock Street - $362,000
04-10-26 [3 Bdrms - 1294 SqFt - 1957 YrBlt]
122 Isle Royale Circle - $420,000
04-09-26 [2 Bdrms - 1488 SqFt - 1964 YrBlt], Previous Sale: 08-15-00, $159,900
115 Isle Royale Circle - $410,000
04-10-26 [2 Bdrms - 1152 SqFt - 1964 YrBlt],
Previous Sale: 00/1989, $105,000
692 Linwood Street - $570,000
04-06-26 [3 Bdrms - 1695 SqFt - 1975 YrBlt]
1801 Marshall Road #407 - $255,000
04-06-26 [1 Bdrms - 714 SqFt - 1986 YrBlt],
Previous Sale: 12-10-15, $132,000
206 Millbrook Way - $480,000
04-06-26 [5 Bdrms - 2043 SqFt - 1976 YrBlt]
481 South Orchard Avenue - $560,000
04-07-26 [3 Bdrms - 1329 SqFt - 1958 YrBlt],
Previous Sale: 11-15-16, $360,000 708 Owl Drive - $769,000
04-07-26 [4 Bdrms - 2331 SqFt - 1988 YrBlt], Previous Sale: 11-02-15, $485,000
761 Pintail Court - $1,205,000
04-09-26 [5 Bdrms - 3191 SqFt - 1999 YrBlt],
Previous Sale: 01-18-18, $742,000
336 Primrose Drive - $650,000
04-07-26 [4 Bdrms - 1860 SqFt - 2020 YrBlt], Previous Sale: 02-20-20, $513,000
121 Sequoia Drive - $320,000
04-07-26 [1 Bdrms - 728 SqFt - 1964 YrBlt],
Previous Sale: 09-19-12, $68,000 1025 Swift Court - $770,000
04-07-26 [4 Bdrms - 37 SqFt - 2022 YrBlt], Previous Sale: 12-01-22, $853,500
525 Trinity Drive - $520,000
04-06-26 [4 Bdrms - 1602 SqFt - 1969 YrBlt],
Previous Sale: 10-18-02, $270,000
307 Trinity Drive - $493,500
04-07-26 [3 Bdrms - 1296 SqFt - 1971 YrBlt],
Previous Sale: 02-21-02, $221,000
880 Trysail Court - $575,000
04-10-26 [4 Bdrms - 1417 SqFt - 1973 YrBlt],
Previous Sale: 10-08-25, $402,000
206 Windjammer Court - $635,000
04-09-26 [4 Bdrms - 1967 SqFt - 1988 YrBlt],
Previous Sale: 12-11-03, $415,000
TOTAL SALES: 20 LOWEST AMOUNT: $298,500 HIGHEST AMOUNT: $1,590,000
MEDIAN AMOUNT: $495,000
AVERAGE AMOUNT: $572,800
110 Fremont Street - $510,000
04-07-26 [3 Bdrms - 1101 SqFt - 1973 YrBlt] 2019 Georgia Street - $450,000
04-06-26 [2 Bdrms - 910 SqFt - 1949 YrBlt], Previous Sale: 10-01-25, $290,000 2751 Georgia Street - $447,000
04-10-26 [2 Bdrms - 1196 SqFt - 1940 YrBlt], Previous Sale: 01-17-23, $360,000 317 Glenn Street - $530,000
04-10-26 [2 Bdrms - 1102 SqFt - 1925 YrBlt],
Previous Sale: 06-25-25, $320,000
1009 Glenwood Street - $415,000
04-09-26 [2 Bdrms - 860 SqFt - 1942 YrBlt],
Previous Sale: 09-21-15, $215,000
431 Hilton Avenue - $330,000
04-07-26 [2 Bdrms - 800 SqFt - 1971 YrBlt],
Previous Sale: 12-23-19, $250,000
1355 Jack London Drive - $460,000
04-07-26 [4 Bdrms - 1536 SqFt - 1971 YrBlt]
127 Jackson Way - $540,000
04-09-26 [3 Bdrms - 1622 SqFt - 1951 YrBlt]
509 Keats Drive - $655,000
04-10-26 [4 Bdrms - 2004 SqFt - 1970 YrBlt],
Previous Sale: 01-13-14, $330,000
408 Lakeside Drive - $490,000
04-09-26 [3 Bdrms - 1228 SqFt - 1961 YrBlt],
Previous Sale: 07-12-01, $199,000
1720 Louisiana Street - $500,000
04-10-26 [2 Bdrms - 660 SqFt - 1924 YrBlt],
Previous Sale: 04-16-25, $420,000 2580 Marshfield Road - $979,000
04-10-26 [3 Bdrms - 3084 SqFt - 2001 YrBlt], Previous Sale: 10-31-22, $950,000 1537 Mini Drive - $425,000
04-07-26 [3 Bdrms - 1106 SqFt - 1954 YrBlt]
2890 Redwood Parkway #46174$298,500
04-09-26 [2 Bdrms - 1095 SqFt - 1981 YrBlt],
Previous Sale: 02-24-12, $50,000
117 Shoal Drive - $601,500
04-08-26 [3 Bdrms - 1753 SqFt - 2002 YrBlt], Previous Sale: 02-15-17, $465,000 5011 Staghorn Drive - $675,000
04-10-26 [3 Bdrms - 2580 SqFt - 2002 YrBlt], Previous Sale: 09-28-12, $330,000
208 Sunfish Court - $400,000
04-07-26 [5 Bdrms - 2088 SqFt - 1987 YrBlt], Previous Sale: 08-06-09, $206,000 3011 Tennessee Street - $1,590,000
04-09-26 [3 Bdrms - 1431 SqFt - 1955 YrBlt], Previous Sale: 09-27-12, $148,000
401 Valle Vista Avenue - $785,000
04-10-26 [3 Bdrms - 3000 SqFt - 1964 YrBlt] 1037 Virginia Street #1035 - $375,000 04-10-26
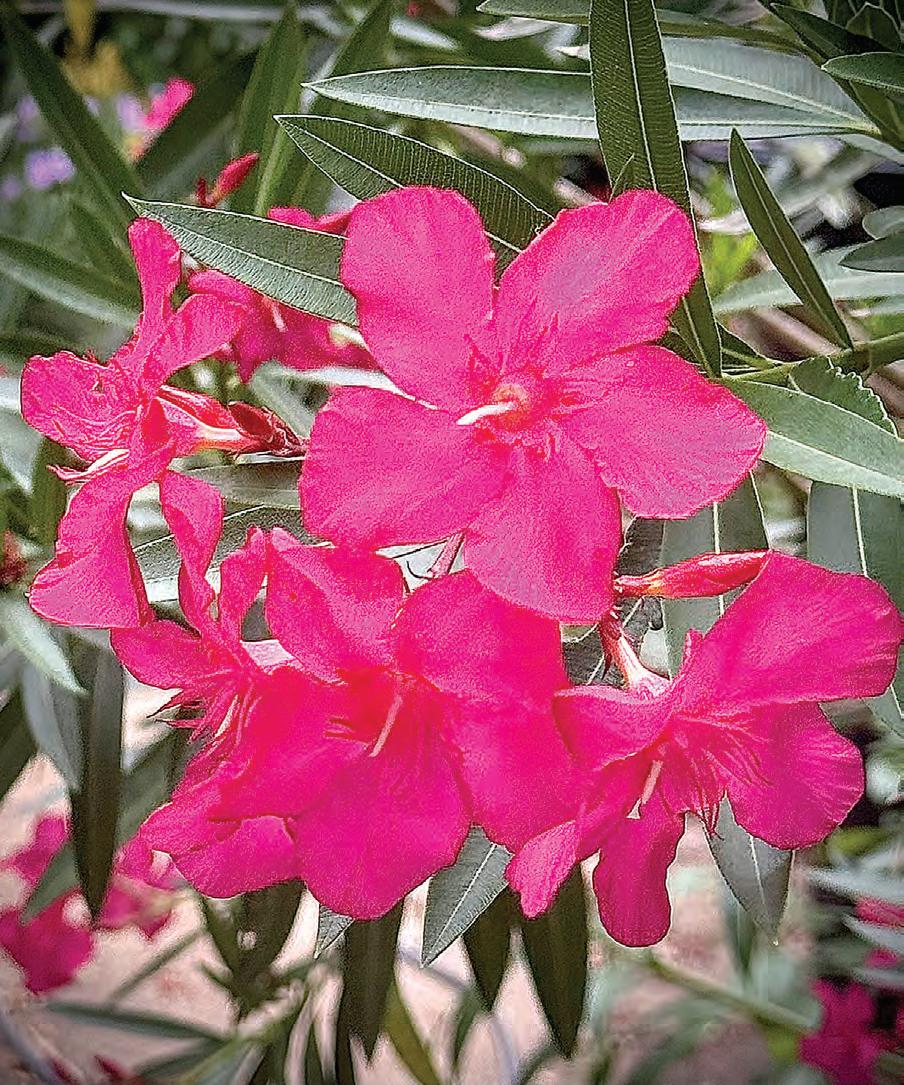
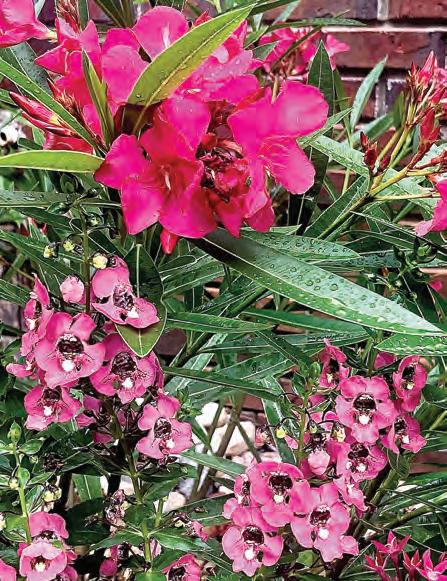
If you’ve got sun and want a touch of the tropics and baskets full of blooms, then Austin Pretty Limits oleander is for you.
Let’s address your cold hardiness con cerns first. Austin Pretty Limits is cold hardy from zones 8 and up. That’s a large swath of the country that can grow the shrub with ease. The rest of the country can grow Austin Pretty Limits in contain ers by the pool or on the porch, patio or deck.
You might be thinking that’s a pretty large shrub, and in some respects you might be right. Austin Pretty Limits, however, is in that 5- to 6-foot height range with a 4-foot spread. Now The Garden Guy lives in a virtual forest with decreasing sunlight. My Austin Pretty Limits oleander is in one of the sunniest locations in the landscape and has me wishing for more.
perhaps enhancing my shrub’s height.
One of the most valued traits of Austin Pretty Limits is a long bloom season, especially in regions farther south. By this I mean that if it’s not always showing blooms, it will seem that way. I’m in zone west Georgia and mine started blooming the last week of April and is still blooming with no end apparent. It is reported to bloom on old wood and new wood.
As you might guess, The Garden Guy is not content with just planting a shrub but searches out combinations. The first years, I tried various annuals like Sunstar Pentas and Angelface angelonias or summer snapdragons.
I say that to tell you that I still get incredible blooms (but maybe not like friends in absolute full sun). My growth habit is slightly open, and I feel the branches reach for the sun,
Then I added a rose bush, Oso Easy Peasy. I placed it at the rear of the bed in an effort to keep the neighborhood deer population from noticing it. It syncs with the oleander in bloom some, but so far not an easy photo.
But now I am into perennials around the Austin Pretty Limits.
From Page 5
I’ve got Luscious Citrus Blend lantana, Summerific Valentine’s Crush hibiscus, Rockin Playin’ The Blues salvia and Estrellita Little Star bouvardia or firecracker bush. They all give wonderful blooms but no combo photo. It may come in a few weeks.
As is legendary, oleanders are NOT to be eaten or ingested. If you feel the need to prune, wear gloves as the sap ooze is also toxic and DO NOT BURN the refuse as the smoke is toxic.
While these warnings may sound scary, simply know and teach. Then enjoy the incredible blooms and evergreen texture that Austin City Limits oleander has to offer the landscape.
Besides sun, good drainage is essential as the oleander is not a bog plant. If you are searching for a screen or blooming hedge type shrub, the Austin Pretty Limits oleander should certainly be considered. Planting season is at hand, and search out Austin City Limits oleander.
Norman Winter is a horticulturist, garden speaker and author of “Captivating Combinations: Color and Style in the Garden.”
From Page 3
that closes on July 15, your first payment will be due Sept. 1. To make the 360-month amortization accurate, the lender will collect 16 days of prepaid interest on July 15 so when Sept. 1 rolls around there will be an even 30 days of interest due.
Recurring closing costs for prepaid interest, the first-year home insurance premium and setting up the property tax impound account can add up to $10,000 for a $650,000 house depending on the cost of the fire insurance and the property tax rate.
The non-recurring closing costs are the fees that happen once and never again like loan originations fees, discount buydown points, appraisal, termite, roof and whole house inspections, title insurance and escrow fees, recording fees and, in some cases, transfer taxes and home
warranty fees. Non-recurring closing costs on a $650,000 house can vary and range from as little as $7,500 to as much as $25,000 depending on the loan costs.
A few weeks ago, I wrote about new home builders and “concessions galore.” A Realtor asked me the other day if he should have his buyer ask for a $10,000 seller credit for closing costs or $10,000 less on the price for a home that has been on the market for 30 days. In this case, his buyer was putting down 40% of the sales price so it did not make sense to pay the higher price for a closing cost credit. The lower price meant lower property taxes and closing costs and, unlike the new home builders, it made no sense to artificially inflate the price for future sellers to use this home as a comparable sale. Now if his buyer was squeaking in with barely enough funds to close escrow, then the seller’s credit of $10,000 can make the dream a reality for his buyer.
The guidelines for seller
From Page 2
was never in writing in the first place.
That’s OK, since month-tomonth leases do not have to be in writing to be enforceable.
Unfortunately, that’s not the case with option agreements. In order to be enforceable, options must be in writing and signed by the seller. An oral promise to sell you the property, some day, when you are able to buy it would not be specifically enforceable. In other words, you wouldn’t be able to get a court to order him to sell the property to you.
However, even if the option agreement was in writing, the option must expire after a certain period of time. If
credits are as follows: On VA loans the maximum seller contribution for buyer closing costs is 4% of the sales price, on FHA it is a generous 6% and on Freddie and Fannie conventional financing for buyers with less than 10% down it is 3% of the sales price and the seller can never credit the buyer more than the total non-recurring and recurring closing costs.
A seller’s credit for closing costs can help a buyer become a homeowner with only $1 out of her pocket. Realtors in our market have been doing this for 50 years. One dollar moves you in!
Jim Porter, NMLS No. 276412, is the branch manager and senior loan adviser of Solano Mortgage, NMLS No. 1515497, a division of American Pacific Mortgage Corporation, NMLS No. 1850, licensed in California by the Department of Financial Protection and Innovation under the CRMLA / Equal Housing Opportunity. Jim can be reached at 707-449-4777.
no expiration period is stated in the written agreement, the court will imply that all three of you intended the contract to last for a reasonable period of time.
What’s reasonable? That’s something two attorneys can make a living arguing about.
But in your case, four years would be a tough sell to a judge or jury. It’s hard to believe that the seller, without more facts, intended to tie-up his right to sell the property for four whole years.
I’m afraid that if the agreement isn’t in writing you’re pretty much out of luck.
Tim Jones, Esq., is a real estate attorney in Fairfield. If you have any real estate questions you would like to have answered in this column, you can send an email to AllThings RealEstate@TJones-Law.com.























$784,000
$790,000





ADOBE
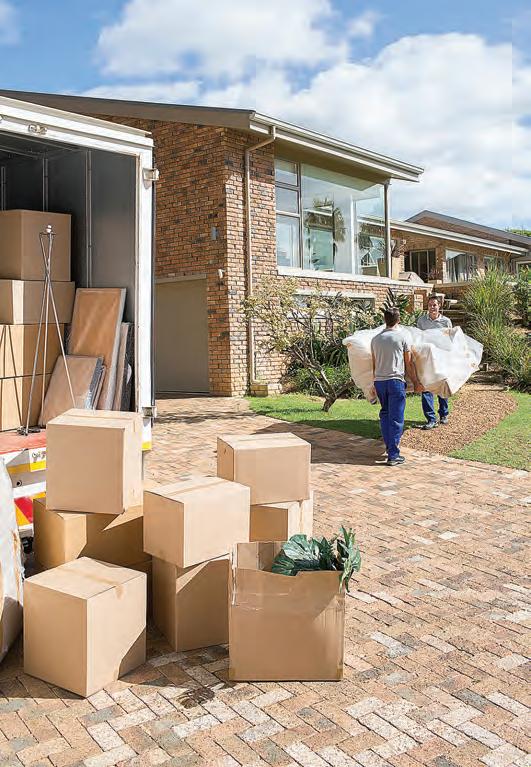
Hiring movers offers convenience, speed and a handsoff experience, while moving yourself gives you more control and comes at a lower price point.
If you have a move coming up, you know one of the biggest decisions is whether you should hire movers or try to tackle the moving process yourself. Unfortunately, there’s no one-size-fits-all approach to moving – your answer will depend on your budget, timeline, preferences and whether or not you have the physical ability to move your belongings. Hiring movers can be a great option for people who don’t have the time or ability to move themselves. Working with reputable, professional movers can make your move faster, more convenient and less stressful. Hiring movers is also a highly customizable process, allowing you to pick and choose which parts of the move you want to do yourself. For example, you can hire movers only for the loading and unloading process, or you can hire full-service movers to
help with the entire moving process, from packing to loading and unloading to driving the moving truck. If you’re short on time but watching your budget, consider hiring movers for one aspect of the move, but managing the rest of the move yourself. The main downside of hiring movers is the cost. Professional movers can be expensive, especially for long-distance moves. Moving costs can vary a lot depending on the company you go with, so I recommend reaching out to several companies to get in-person quotes before making your decision. If you want to save a little money when hiring
movers, plan for a weekday move in the middle of the month. This will help you avoid peak pricing. Another downside is that movers may not know which items need extra care due to sentimental value. I recommend moving Grandma’s china and other sentimental, fragile items yourself to be safe.
While hiring movers offers convenience and ease, DIYing your move also has its advantages. The main benefit is that moving yourself is much cheaper than hiring movers. Instead of paying for a moving company, you only need to rent a moving truck and pay for materials like boxes, tape, moving blankets, dollies and bubble wrap. DIYing your move can also give you full control over the moving process, allowing you to move at your own pace and ensure things are done exactly the way you want them.
If you go the DIY route, there are a few things you can do to make the moving process go as smoothly as possible. Start packing far in advance, label your boxes clearly and try to disassemble large furniture before moving day. You should also budget for the move ahead of time, keeping the cost of materials in mind so there are no surprises. If your friends and family are helping you move, make sure you confirm dates a few weeks ahead of time to avoid any last-minute changes. Whether you plan on hiring movers or tackling the move yourself, the key is to plan ahead and know what you’re getting yourself into. The more prepared you are, the smoother your move will be.
Tweet your home care questions with #AskingAngi and we’ll try to answer them in a future column.
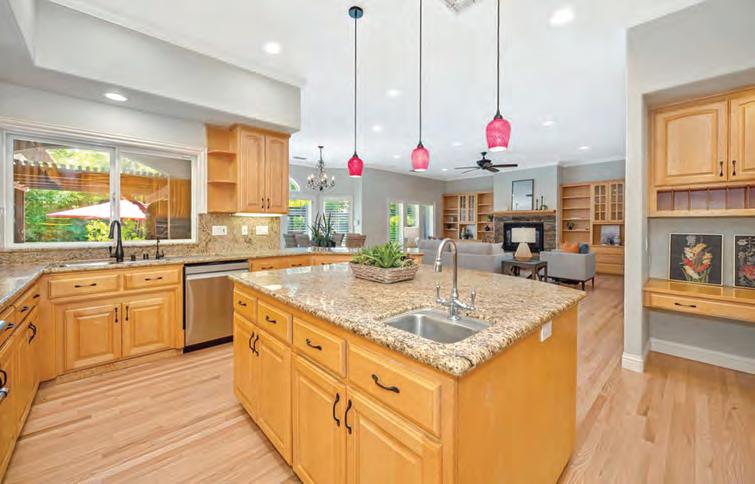
99 active properties on the market and 37 pending properties in Davis.
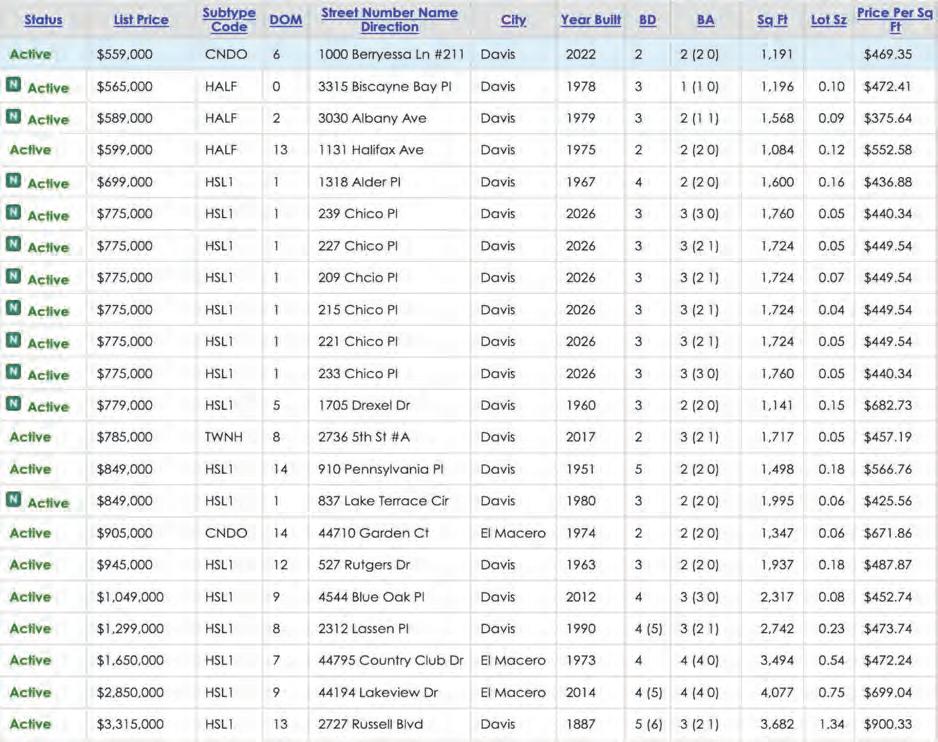
Over the past two weeks:
Active
Twenty-two new listings of which four have already gone pending.
Closed
Twenty-five listings closed escrow.
Median closed price $802,000 (Average $848,440).
Twelve closings received multiple offers including four on Alpine.
For the full newsletter subscribe here: or visit our website below!
Elevent closings were cash and the remainder were conventional financing.