


















Q: We have a tree problem Mr. Jones. We own a house in an older part of Fairfield. There’s a big tree, I’m not sure what kind, that sits more-or-less on the property line between the side of our prop erty and my neighbor’s. The tree looks like it used to be only on my property but, over the decades, has grown so big around that some of it is clearly growing out of the ground on my neighbor’s side. The fence stops at one side of the tree and continues from the other side. The branches are huge and at this time of year, when the leaves are coming out and the branches get heavy and subject to getting grabbed by the wind, branches often come down.
Last year, I had a tool shed that was damaged. Roots are yet another problem as they tear up our concrete. I got some bids to remove the tree. I told the neighbor that the removal may damage our fence, but that I’d pay to make any repairs after the tree was gone. That’s when my neighbor started yelling and claiming it was his tree and I’d better not touch it. The tree company we were going to use says they won’t touch it if there’s a dispute between my neighbor and me. We don’t know what to do at this point.
A: Ah, springtime! It is always right around this time of year when my inbox starts getting filled with tree questions. So let’s take a look at California tree law which, as you might guess, isn’t nearly as easy as it should be.
Your first step is to understand who owns the tree. If the tree is yours, you can do what you want with it; more or less.
And maybe some longgone previous owner of your home originally planted the tree on what is now your property. But once the tree grew big enough that the trunk crossed the property line, your neighbor became a co-owner in the tree.
It doesn’t even matter what percentage of the tree is growing out of your neighbor’s ground. If any of it is, he owns half of the tree. As such, you can’t remove the tree without his permission. Period. The same laws that control the rights and liabilities of co-owners of a house control co-ownership of a tree. Each coowner has a legal duty not to damage the co-owned property.
If you really want to remove the tree and your neighbor won’t sign off, you’re going to have to go to court and try to get an order from a judge allowing the removal of the tree for everyone’s safety. But frankly, that may be putting the proverbial cart in front of the horse.
What you may really want is simply to remove the branches and roots that are threatening your property. If you can cut the overhanging branches without damaging the tree itself, you’re free to do so. Same goes for the roots.
But here’s where it gets into a very, very gray area.
Before 1994, the law was pretty simple. If it was on your property, you could remove it or sue the tree’s actual owner for damages. Then a case called Booska v Patel was decided that said you can’t do anything without considering the consequences to your neighbor’s tree. Removing too many branches
See Jones, Page 6
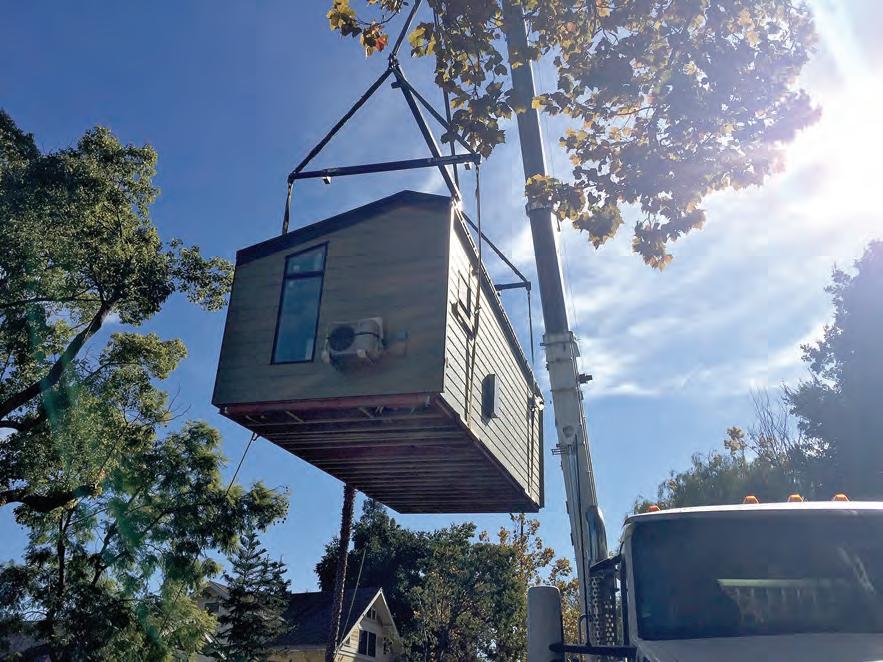
A crane maneuvers an accessory dwelling unit, or ADU, over South
TRIBUNE CONTENT AGENCY
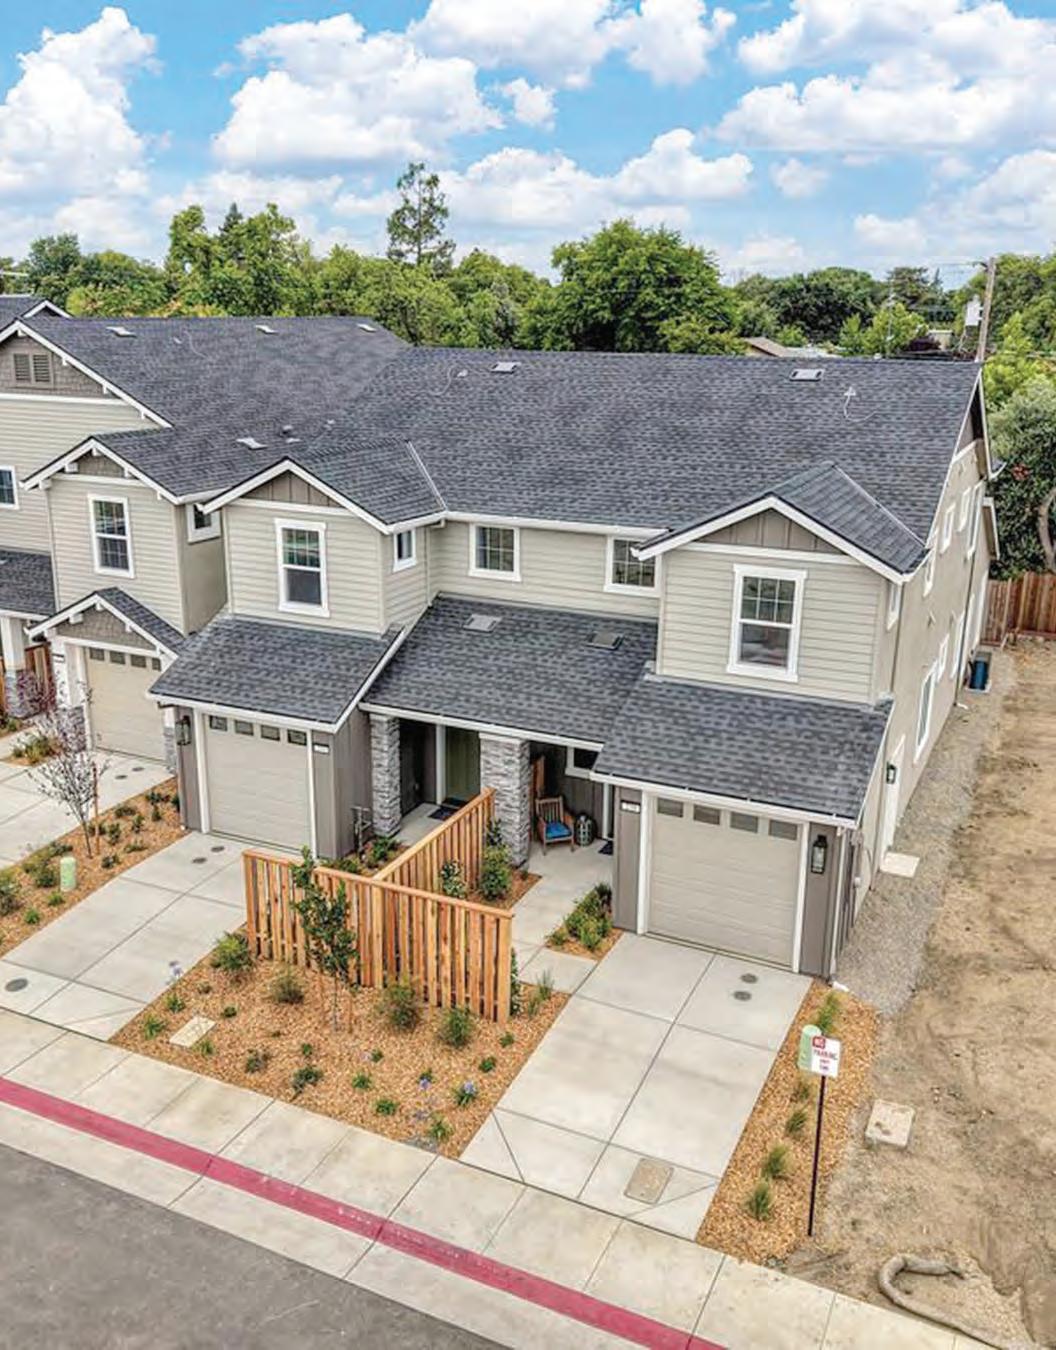
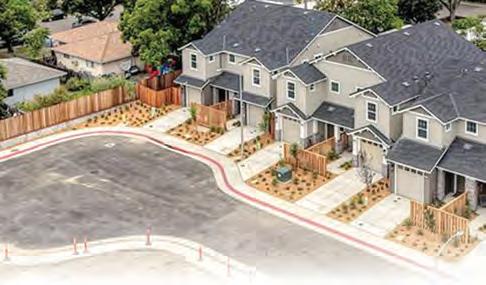
San Jose is home to the first accessory dwelling unit sold as a separately owned condo in California, city officials said, setting a potential template for a more affordable path to homeownership. But a lengthy rollout raises questions about whether the model can become a scalable solution to the state’s housing crisis – the sale comes more than two years after the state made such transactions possible.
fornia Association of Realtors.
Real estate brokerage Redfin last month listed San Jose among the 10 most expensive U.S. housing markets, based on the share of median income needed to afford to buy a home.
ADUs, also known as in-law units or granny flats, typically have up to 1,200 square feet of living space and must include a kitchen sink, cooking appliance and separate bathroom.
require an HOA agreement with the primary homeowner for common elements, such as roofs or driveways.
The 749-square-foot, two-bedroom ADU on Josefina Street near downtown closed last month for $530,000. That’s about a quarter of Santa Clara County’s eye-popping $2.1 million median single-family home price in May, according to the Cali-
The sale was made possible by a state law passed in 2023, AB 1033, which allows homeowners to convert ADUs into condos and sell them separately from the main property, rather than just renting them out. Under the law, ADU condos come with their own property tax bills, but
City officials said the Josefina property is one of two ADU condos approved in San Jose, with two more under review. Officials expect more conversions in the future but declined to provide an estimate. It’s unclear how many ADU condo conversions and sales have been completed statewide. The state does not appear to track that data.
To boost ADU condo construction and sales, San Jose has sought to streamline permitting for construction and conversions. The city has also assigned two building department employees
to being lowered into a backyard of a residence. See ADU, Page 6
Helping a family achieve the American Dream of homeownership with a mortgage is a rewarding achievement for a loan officer team.
The licensed originator, processor, underwriter, document drawer and funder all work together to provide the financing required to meet the terms of the residential purchase agreement (RPA) that the Realtor negotiated for the homebuyer with the seller.
that get buried in credit card, automobile, second mortgage and unsecured loan debt.
Most first-time home buyers are buying with 5% or less down so when they are paying $550,000 for the house, they are buying a 30-year mortgage for more than $500,000.
Nowadays, the median age of a California first-time homebuyer is over 45, an all-time high, so selling a mortgage is not as easy as it used to be now that the buyer will be 75 when they make the final mortgage payment.
Selling mortgages is a huge responsibility and this is especially true for selling cash-out refinances because when a person refinances a mortgage, in most cases, the lender sells the client a whole new 30-year fixedrate mortgage, which obviously can extend that final mortgage payment from age 75 to 85 or 90.
There is absolutely nothing wrong with doing a cash-out refinance when the cash out is being used for home improvements or something financially beneficial. One common reason for doing a cash-out refi that banks, credit unions and mortgage bankers sell is debt consolidation, which is often necessary for people
A cash-out refi to payoff $100,000 worth of high rate and high monthly payment debt can be a financial life saver or a financial disaster. If the borrower pays off the $100,000 in debt and reduces their monthly outgo by $1,200 per month and then invests the $1,200 per month in an IRA or pays an extra $1,200 per month toward the mortgage balance, thus reducing the term of the loan, then this is a winning strategy. But if the borrower spends the $1,200 at the casino every month and runs up the debt again, this will be a disaster and something that happens all the time.
Converting unsecured debt to debt secured against a residence can be a huge mistake, because sadly, sometimes a chapter 13 or 7 bankruptcy is the right solution to avoid losing the house.
Buying a mortgage loan should be done with a local loan officer that cares more about the referrals they will get from you over the next 10 years than one bonus or commission they will make on the one mortgage sale.
Jim Porter, NMLS No. 276412, is the branch manager and senior loan adviser of Solano Mortgage, NMLS No. 1515497, a division of American Pacific Mortgage Corporation, NMLS No. 1850, licensed in California by the Department of Financial Protection and Innovation under the CRMLA / Equal Housing Opportunity. Jim can be reached at 707-449-4777.


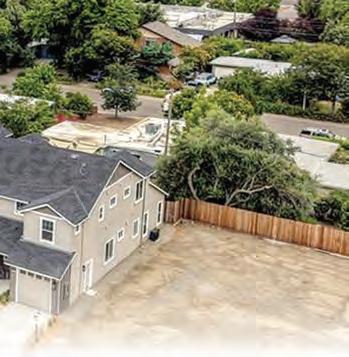
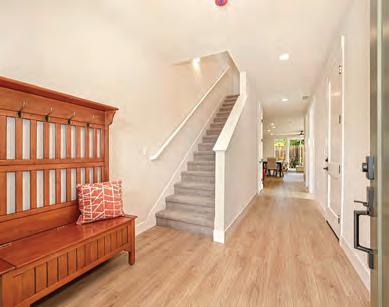
All O ered at $775,000





TOTAL SALES: 9
LOWEST AMOUNT: $290,000
HIGHEST AMOUNT: $1,200,000
MEDIAN AMOUNT: $800,000
AVERAGE AMOUNT: $771,944
639 East 5th Street - $908,000
05-04-26 [2 Bdrms - 1247 SqFt - 1935 YrBlt]
249 Baker Street - $920,000
05-05-26 [4 Bdrms - 1874 SqFt - 1975 YrBlt],
Previous Sale: 01-10-18, $575,000
387 Columbia Circle - $514,500
05-07-26 [2 Bdrms - 1500 SqFt - 1992 YrBlt],
Previous Sale: 08-04-23, $605,000
563 Cooper Drive - $885,000
05-04-26 [3 Bdrms - 2039 SqFt - 1980 YrBlt], Previous Sale: 07-29-24, $815,000
1196 Grove Circle - $635,000
05-04-26 [2 Bdrms - 1130 SqFt - 1979 YrBlt],
Previous Sale: 00/1991, $159,000
494 Mills Drive - $795,000
05-04-26 [4 Bdrms - 2192 SqFt - 1977 YrBlt]
900 Southampton Road #142 - $290,000
05-08-26 [2 Bdrms - 853 SqFt - 1977 YrBlt],
Previous Sale: 10-03-24, $282,000
105 Woodstock Court - $800,000
05-08-26 [3 Bdrms - 1667 SqFt - 1972 YrBlt]
446 York Drive - $1,200,000
05-06-26 [4 Bdrms - 2569 SqFt - 1977 YrBlt], Previous Sale: 07-19-16, $687,000
TOTAL SALES: 5
LOWEST AMOUNT: $486,000
HIGHEST AMOUNT: $787,000
MEDIAN AMOUNT: $600,000
AVERAGE AMOUNT: $625,600
1355 Estates Drive - $680,000
05-05-26 [4 Bdrms - 2217 SqFt - 1987 YrBlt],
Previous Sale: 12-18-12, $360,000
1520 Gill Court - $787,000
05-04-26 [5 Bdrms - 2987 SqFt - 1993 YrBlt], Previous Sale: 04-13-21, $655,000
1155 Mulberry Lane - $600,000
05-04-26 [4 Bdrms - 1798 SqFt - 1978 YrBlt], Previous Sale: 03-28-05, $485,000
450 Priddy Drive - $486,000
05-04-26 [4 Bdrms - 1216 SqFt - 1971 YrBlt],
Previous Sale: 03-24-20, $183,000
1825 Whiting Court - $575,000
05-05-26 [4 Bdrms - 1676 SqFt - 1996 YrBlt]
TOTAL SALES: 24
LOWEST AMOUNT: $350,000
HIGHEST AMOUNT: $1,010,000
MEDIAN AMOUNT: $562,500
AVERAGE AMOUNT: $575,333
587 Abbey Drive - $744,000
05-05-26 [4 Bdrms - 2169 SqFt - 1998 YrBlt],
Previous Sale: 12-08-99, $271,900
3482 Astoria Circle - $610,000
05-05-26 [5 Bdrms - 2392 SqFt - 1977 YrBlt]
3537 Augusta Court - $530,000
05-05-26 [4 Bdrms - 1926 SqFt - 1981 YrBlt]
2429 Baltic Drive - $450,000
05-07-26 [3 Bdrms - 1256 SqFt - 1973 YrBlt],
Previous Sale: 03-15-22, $495,000
300 Begonia Boulevard - $501,000
05-05-26 [4 Bdrms - 1559 SqFt - 1971 YrBlt]
58 Del Prado Circle - $371,000
05-04-26 [2 Bdrms - 1224 SqFt - 1983 YrBlt], Previous Sale: 08-31-21, $408,000 1464 Descanso Lane - $585,000
05-05-26 [3 Bdrms - 1516 SqFt - 2021 YrBlt],
Previous Sale: 06-13-24, $610,000
219 Hamilton Drive - $390,000
05-08-26 [2 Bdrms - 785 SqFt - 1956 YrBlt]
1700 Hemlock Street - $530,000
05-08-26 [4 Bdrms - 1600 SqFt - 1959 YrBlt], Previous Sale: 05-02-18, $395,000
751 Hillcrest Court - $532,000
05-08-26 [3 Bdrms - 1684 SqFt - 1973 YrBlt]
682 Hillside Drive - $550,000
05-08-26 [3 Bdrms - 1866 SqFt - 1985 YrBlt], Previous Sale: 00/1989, $165,000
883 Inverness Court - $350,000
05-07-26 [3 Bdrms - 1177 SqFt - 1972 YrBlt],
Previous Sale: 11-15-01, $180,000
2611 Lilac Street - $570,000
05-08-26 [4 Bdrms - 1474 SqFt - 1969 YrBlt],
Previous Sale: 11-28-00, $175,000
3280 Mustang Circle - $615,000
05-04-26 [4 Bdrms - 2127 SqFt - 1990 YrBlt], Previous Sale: 12-16-09, $283,000
3451 Nantucket Drive - $699,000
05-04-26 [5 Bdrms - 2392 SqFt - 1984
664 K St, $675,000
06-23-26, (3 bdrms – 1086 sqft – 1951 yrblt),
Previous Sale N/A
233 University Ave, $950,000
06-17-26, (6 bdrms – 1380 sqft – 1920 yrblt), Previous Sale N/A
35 Parkside Dr, $1,420,000
06-15-26, (3 bdrms – 1872 sqft – 1954 yrblt), Previous Sale N/A
1703 Donner Ave #1, $410,000
06-17-26, (2 bdrms – 780 sqft – 1971 yrblt),
Previous Sale $225,000 2-8-16
116 Huerta Pl, $470,000
06-23-26, (2bdrms – 900 sqft – 1981 yrblt),
Previous Sale $342,000 3-12-15
1661 Spring St #443, $615,000
06-26-26, (2-3 bdrms – 1431 sqft – 2020 yrblt), Previous Sale N/A
1000 Berryessa Ln #224, $705,000
06-25-26, (3 bdrms – 1761 sqft – 2018 yrblt),
Previous Sale $716,000 4-3-24
717 Bianco Ct, $750,665
06-22-26, (3 bdrms – 1784 sqft – 1977 yrblt),
Previous Sale N/A
39872 Barry Rd, $1,075,000
06-23-26, (3 bdrms – 1925 sqft – 1973 yrblt),
Previous Sale N/A
1037 Forbes Ln, $1,105,000
06-15-26, (5 bdrms – 2511 sqft – 2016 yrblt),
Previous Sale N/A
1769 Cannery Loop, $1,300,000
06-23-26, (4 bdrms – 2999 sqft – 2015 yrblt),
Previous Sale N/A
2617 Loyola Dr, $599,500
06-25-26, (3 bdrms – 960 sqft – 1972 yrblt),
Previous Sale N/A
1807 Raintree Pl, $731,000
06-18-26, (4 bdrms – 1428 sqft – 1975 yrblt),
Previous Sale N/A
1007 Vanderbilt Ter, $900,000
06-16-26, (5 bdrms – 1972 sqft – 2026 yrblt),
Previous Sale N/A
1049 Ginkgo Cir, $980,000
06-18-26, (4 bdrms – 2031 sqft – 2026 yrblt),
Previous Sale N/A
2436 Elendil Ln, $945,549
06-17-26, (3 bdrms – 1677 sqft – 1976 yrblt),
Previous Sale N/A
912 Los Robles, $725,000
06-18-26, (4 bdrms – 1456 sqft – 1973 yrblt),
Previous Sale N/A
44031 S El Macero Dr, $1,095,000
06-22-26, (4 bdrms – 2415 sqft – 1973 yrblt),
Previous Sale N/A
29 N Ashley Ave, $433,000
06-17-26, (3 bdrms – 1000 sqft – 1972 yrblt),
Previous Sale N/A
940 Lexington Way, $525,000
06-17-26, (4 bdrms – 1949 sqft – 1999 yrblt),
Previous Sale N/A
1008 Greenwood Dr, $620,000
06-1-26, (3 bdrms – 1680 sqft – 1966 yrblt),
Previous Sale $425,000 12-14-18
933 Wendell Way, $750,000
06-15-26, (4 bdrms – 2190 sqft – 1977 yrblt),
Previous Sale N/A
511 4th St, $537,000
06-16-26, (3 bdrms – 16823 sqft – 1935 yrblt), Previous Sale $305,000 12-29-15
1206 Carriage Dr, $430,000
06-24-26, (2 bdrms – 927 sqft – 1988 yrblt),
Previous Sale $289,900 10-21-04
1963 Stephens Ln, $500,000
06-22-26, (3 bdrms – 1324 sqft – 1996 yrblt),
These are the local homes sold recently, provided by California Resource of Lodi. The company can be reached at 209.365.6663 or CalResource@aol.com.
YrBlt], Previous Sale: 04-04-11, $299,000
2833 Prestwick Court - $1,010,000
05-04-26 [3 Bdrms - 2316 SqFt - 1997 YrBlt], Previous Sale: 03-11-16, $558,000
559 Princeton Way - $565,000
05-07-26 [4 Bdrms - 1549 SqFt - 1972 YrBlt],
Previous Sale: 04-23-25, $450,000 1463 Quail Drive - $455,000
05-08-26 [3 Bdrms - 1208 SqFt - 1974 YrBlt]
2770 Seabreeze Drive - $560,000
05-08-26 [3 Bdrms - 1603 SqFt - 1989 YrBlt], Previous Sale: 01-26-15, $284,000 2236 Silver Fox Circle - $676,000
05-05-26 [3 Bdrms - 1958 SqFt - 1989 YrBlt], Previous Sale: 05-22-03, $370,000 1318 Taft Street - $430,000
05-07-26 [3 Bdrms - 1046 SqFt - 1956 YrBlt]
661 Vintage Valley Drive - $940,000
05-08-26 [3 Bdrms - 2416 SqFt - 1999 YrBlt],
Previous Sale: 05-10-23, $899,000 413 Violet Court - $575,000
05-05-26 [4 Bdrms - 1625 SqFt - 1969 YrBlt], Previous Sale: 09-30-25, $365,000
2045 Wylie Court - $570,000
05-04-26 [4 Bdrms - 1618 SqFt - 1976 YrBlt], Previous Sale: 02-13-26, $400,000
TOTAL SALES: 2
LOWEST AMOUNT: $420,000
HIGHEST AMOUNT: $470,000
MEDIAN AMOUNT: $445,000
AVERAGE AMOUNT: $445,000
395 Del Monte Drive - $420,000
05-05-26 [2 Bdrms - 1359 SqFt - 2003 YrBlt], Previous Sale: 04-11-05, $356,000
506 Rutland Drive - $470,000
05-08-26 [2 Bdrms - 2528 SqFt - 2013 YrBlt], Previous Sale: 04-01-13, $359,000
TOTAL SALES: 4
LOWEST AMOUNT: $375,000
HIGHEST AMOUNT: $615,500
MEDIAN AMOUNT: $563,000
AVERAGE AMOUNT: $529,125
1294 Mayfield Circle - $615,500
05-04-26 [3 Bdrms - 2206 SqFt - 1989 YrBlt], Previous Sale: 11-19-19, $479,000
1109 Pheasant Drive - $375,000
05-07-26 [3 Bdrms - 1138 SqFt - 1977 YrBlt]
607 Seagull Drive - $561,000
05-07-26 [3 Bdrms - 1466 SqFt - 1977 YrBlt], Previous Sale: 02-09-26, $391,000
117 Summertime Lane - $565,000
05-08-26 [4 Bdrms - 1972 SqFt - 2008 YrBlt], Previous Sale: 01-15-16, $340,000
AMOUNT: $580,000
AMOUNT: $597,659
See Solano, Page 14
These are the local homes sold recently, provided by Yolo County Association of Realtors. They can be reached at 530.666.4253 or www.yolorealtors.com.
Previous Sale N/A
990 Garcia Dr, $535,000
06-23-26, (4 bdrms – 1575 sqft – 2002 yrblt),
Previous Sale $444,000 4-28-06
1060 Powers Cir, $580,000
06-17-26, (4 bdrms – 2110 sqft – 1995 yrblt), Previous Sale N/A
793 Laugenour Dr, $610,000
06-25-26, (4 bdrms – 2500 sqft – 2002 yrblt),
Previous Sale $296,900 5-3-02
46 Epperson Ct, $710,000
06-26-26, (4 bdrms – 2281 sqft – 1998 yrblt), $540,000 8-16-22
1732 Casa Nueva St, $610,000
06-18-26, (3 bdrms – 1410 sqft – 1976 yrblt),
Previous Sale $320,500 4-14-15
1828 Sander St, $550,000
06-23-26, (3 bdrms – 1690 sqft – 2019 yrblt),
Previous Sale N/A
2366 Ortiz Ave, $635,000
06-17-26, (3-4 bdrms – 1904 sqft – 2006 yrblt), Previous Sale N/A
1525 Griffith Dr, $660,000
06-15-26, (5 bdrms – 2713 sqft – 2017 yrblt),
Previous Sale $540,490 1-23-18
2004 Shafer Pl, $700,000
06-18-26, (4 bdrms – 2119 sqft – 2021 yrblt),
Previous Sale $710,000 4-4-24
2029 Smith Dr, $777,000
06-148-26, (3 bdrms – 2192 sqft – 2022 yrblt), Previous Sale N/A 33318 Merganser Ct, $859,000 06-15-26, (6 bdrms – 4973 sqft – 2005 yrblt), Previous Sale $430,000 5-13-09
7588 Highway 16, $205,000 06-24-26, (1 bdrm – 1064 sqft – 1927 yrblt), Previous Sale $300,000 9-3-21
16400 County Road 85b, $700,000 06-26-26, (3 bdrms – 2566 sqft – 1959 yrblt), Previous Sale N/A
105 Colby Ln, $550,000
06-22-26, (3 bdrms – 1284 sqft – 1994 yrblt), Previous Sale N/A
500 1st St, $580,000
06-26-26, (3 bdrms – 1600 sqft – 1967 yrblt), Previous Sale N/A
JEFF OSTROWSKI BANKRATE.COM
any Americans believe the dream of homeownership is out of reach, but a Bankrate survey revealed that at least some of those frustrations may be due to misconceptions that make homeownership seem harder than it really is.
The public opinion poll, fielded earlier this year, found that 41% of U.S. adults think now is a “bad time” to buy a home, and 26% say they’ll “never” be able to afford their dream home. It also showed that many have over-inflated perceived barriers to getting a home loan, such as less-thanstellar credit.
Here are the most common myths revealed in the survey, and how they stack up to reality.
The survey found 39% of Americans believe a home buyer needs “excellent” credit to get a mortgage. While it’s true that excellent credit will help you qualify for the best deal, it’s quite possible to land a mortgage with a credit score of less than 700.
According to Equifax, credit score of 800 or higher qualifies as “excellent.” “Very good” means 740 to 799, which is still quite creditworthy. A credit score of 670 to 739 is considered “good,” while 580 to 669 is “fair.”
The reality is that borrowers with credit scores as low as 620 can qualify for Federal Housing Administration (FHA) loans, while the requirements for loans through the U.S. Department of Veterans Affairs (VA) can go as low as 580.
“Someone with a 620 credit
score or higher is eligible for many of our first-time homebuyer programs,” says Scott Linder, senior vice president at TD Bank.
You will pay more as a borrower with a lower credit score – FHA and VA loans carry higher fees than conventional loans. But you still can qualify for a mortgage with a score well below the excellent range.
With home prices still at record levels, many potential buyers are pessimistic they can afford down payments and closing costs. According to Bankrate’s survey, 39% believe a buyer needs a 20% down payment.
A 20% down payment indeed helps qualify you for the best combination of mortgage rate and fees, but many people qualify for a mortgage with less than 20% down. FHA loans require just 3.5% down, while VA loans require nothing down. You can get a conventional loan with less than 20% down, although you’ll have to pay private mortgage insurance (PMI) in that case.
That’s good news, because the typical home price nationally is around $400,000, and most firsttime buyers don’t have $80,000 to devote to the down payment.
It’s possible that Americans know they can qualify for a loan with less than 20% down but simply don’t think it’s wise, says Brad Case, chief residential economist at Homes.com.
“People have different ways of interpreting the question,” he says. “It may be that 19% of them think that’s a requirement, and the other 20% think they shouldn’t buy with less than 20% down. You’re signing up for the biggest loan you’ll ever take, and it lasts for 30 years. So you’re taking on a lot of risk.”
Unlike the other two, this last myth doesn’t speak to the barriers of homeownership as much
Buying a home is one of the largest purchases most people will make in their lives, and taking out a home loan is a common way to finance the purchase. This primer on home loans explains the mortgage basics, including what a mortgage is, typical types of loans, and the concept of shopping for a lender.
A mortgage is a loan used to purchase a home or other real estate. The term mortgage may also be used to indicate the amount of money you borrow, with interest, to purchase your house. The mortgage amount is usually the purchase price of the home minus your down payment.
Before taking out a mortgage, it’s important to understand the upfront and ongoing costs of homeownership, including closing costs, property taxes, insurance, and maintenance. If you fall behind on your mortgage payments and can’t resolve the delinquency, your lender may begin foreclosure proceedings, which could result in losing your home.
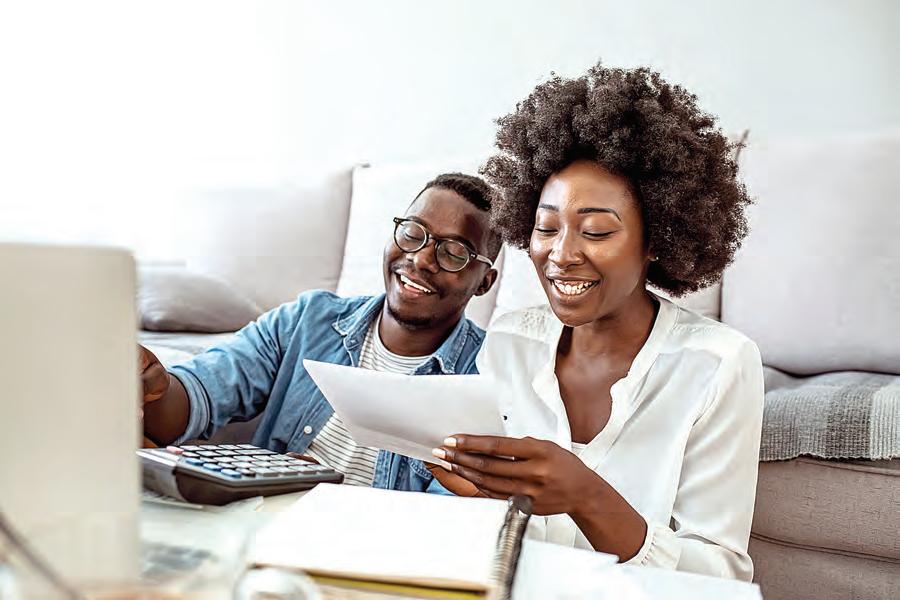
Prospective homebuyers review financial documents as they explore mortgage options. Understanding loan types, interest rates and lending requirements can help first-time buyers make confident decisions.
Consider the loan term, which is the length of time it will take you to repay your loan. Your loan term will affect your interest rate, monthly payment and the total amount of interest you will pay over the life of the loan.
Long-term mortgages, such as the most common 30-year term, typically have:
• Smaller monthly payments than short-term mortgages, making your mortgage more affordable month by month.
• Higher mortgage rates,
meaning you’ll pay more in interest over the life of the loan.
Short-term mortgages, which typically come in the form of 10, 15 or 20 years, generally have:
• Lower interest rates than long-term mortgages, meaning
See Beginner’s, Page 11
From Page 2
and/or roots might not only damage the viability of the tree, but could create an increased risk of the tree falling down on someone. If you did that, you would not only be liable for any damage to life or property, but to your neighbor for half of the value of the tree as well.
Which takes us right back to your plea, “We don’t know what to do at this point.”
First, hire an arborist to look at the tree and give you an opinion regarding how many branches and roots can be safely removed. Make sure you get that opinion in writing. If the arborist’s recommendations would work for you, then go ahead and have the work done.
However, if following the arborist’s recommendations would still leave dangerous branches and damaging roots, I’m afraid you’ll have to head for court. Your lawsuit would be based on the theory the tree is causing what’s called a private nuisance that interferes with your enjoyment of your property. You’d have to make the claim that the only reasonable way to mitigate the nuisance is to remove the tree.
From Page 2
to help homeowners navigate the process.
City officials were unable to make the unit’s buyer and seller available Monday.
While ADU condos may offer a new opportunity for first-time homebuyers and others struggling to afford a home in the Bay Area, potential roadblocks remain.
For one, cities must opt in to
AB 1033 to allow the conversions.
And even after San Jose became the first city to greenlight ADU condos in July 2024 – the state law took effect at the start of 2024 – it took another two years to complete the initial sale.
Part of the delay may be that homeowners are still learning that selling an ADU as a condo is an option. Some may also be deterred by the need and cost of obtaining easements, subdivisions and other permitting requirements for a sale.
“These are extra steps that a homeowner has to take in addi-
tion to building an ADU,” said David Garcia, deputy director of the UC Berkeley Terner Center for Housing Innovation.
Homeowners also sometimes struggle to secure loans to build ADUs, Garcia said.
Despite the financing challenges, new state housing laws have helped spur an ADU boom statewide in recent years. In 2025, California cities and counties permitted nearly 32,000 ADUs, up from about 9,000 in 2018, according to data from the state housing department. San Jose approved 502 last year, up from 192 in 2018.
Even so, many local governments, including San Jose, are behind schedule in meeting their state-mandated housing goals, particularly for low- and middleincome housing.
Overall, the Bay Area is on the hook for approving more than 441,000 new units between 2023 and 2031. At the end of last year, a quarter of the way through the eight-year housing cycle, the region had permitted only about 14% of that goal, according to the housing department data.
There are only two arguments your neighbor can make against you. Either the tree doesn’t pose a nuisance, which it obviously does, or there is a less destructive yet reasonable way to get rid of the nuisance.
That’s why you want your arborist’s opinion in hand.
Tim Jones, Esq., is a real estate attorney in Fairfield. If you have any real estate questions that you would like answered in this column, you can send an email to AllThingsRealEstate@ TJones-Law.com.
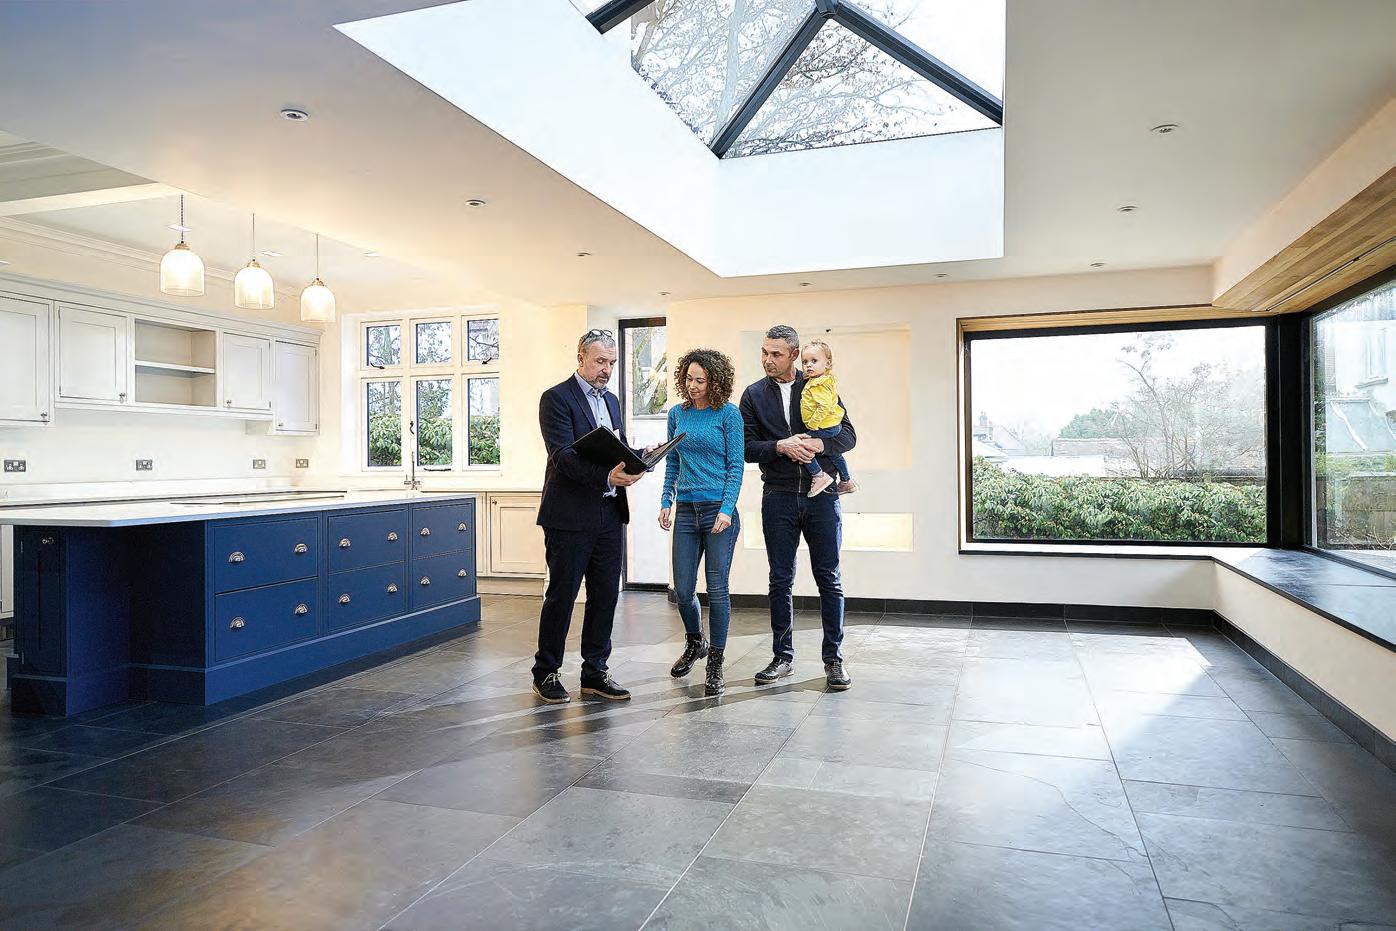
Choosing a home with the right amount of space for your lifestyle, budget and future plans can lead to greater comfort and long-term financial stability.
Shopping for a new home is an exciting experience. As prospective buyers shop around and attend open houses, they are likely to fine-tune their list of what they need and what they want in their next home.
One choice buyers will be faced with is how much home to buy. Determining how much square footage an ideal home should have can be difficult. While many home buyers can envision themselves enjoying a palatial estate, square footage is a significant variable in regard to home prices. When trying to determine how much home to buy, prospective home buyers can ask themselves a range of questions to help make that decision.
Home buyers’ budgetary considerations should extend beyond the asking price of a home and into what they will be able to afford should they purchase a particular property. Projected monthly mortgage payments can be easy to determine, but utilities can fluctuate considerably from home to home. Energy prices are fluid, but the more square footage a home has, the higher utility bills are likely to be. When determining how much home you should buy, you first need to identify what you can afford, and that mock budget should include estimates regarding monthly utilities. In addition, upgrading and renovating a larger property is likely to cost more, so that’s another budget-related variable to con-
sider when determining how much home to buy.
Seasoned homeowners know that the work required to own a home never ceases. First-time buyers must keep that in mind when shopping for a home. A home with lots of square footage will require more daily and longterm maintenance than a smaller home. If you don’t have the time, the means or the will to keep up with maintaining a property, then perhaps a home with a small footprint in terms of square footage is for you. If taking care of the home is not a concern, then extra square footage may not be a deterrent.
Another variable to consider when determining square footage is the ZIP code of a home. Selling might not be foremost on the minds of prospective buyers, but a large home in a town with a poor school district and safety concerns is unlikely to generate as great a return on investment as a smaller home in a town with a reputation for great schools and little crime. However, the real estate market is forever in flux, so prospective buyers who prefer a larger home but don’t want to break the bank to purchase one are urged to work with a real estate professional to identify areas that might be upand-coming and offer the best of
both worlds. That’s no small task, but local real estate agents and realtors can be invaluable assets in such pursuits.
Of course, how much home a buyer needs is a unique and important variable. But this also is a difficult question to answer. Buyers who plan to grow their families will need enough space to accommodate everyone who eventually lives under their roof. Couples buying a home together who discuss how big a family they want to have can use that discussion to inform how large a home to buy.
The ideal amount of square footage in a home varies from buyer to buyer.
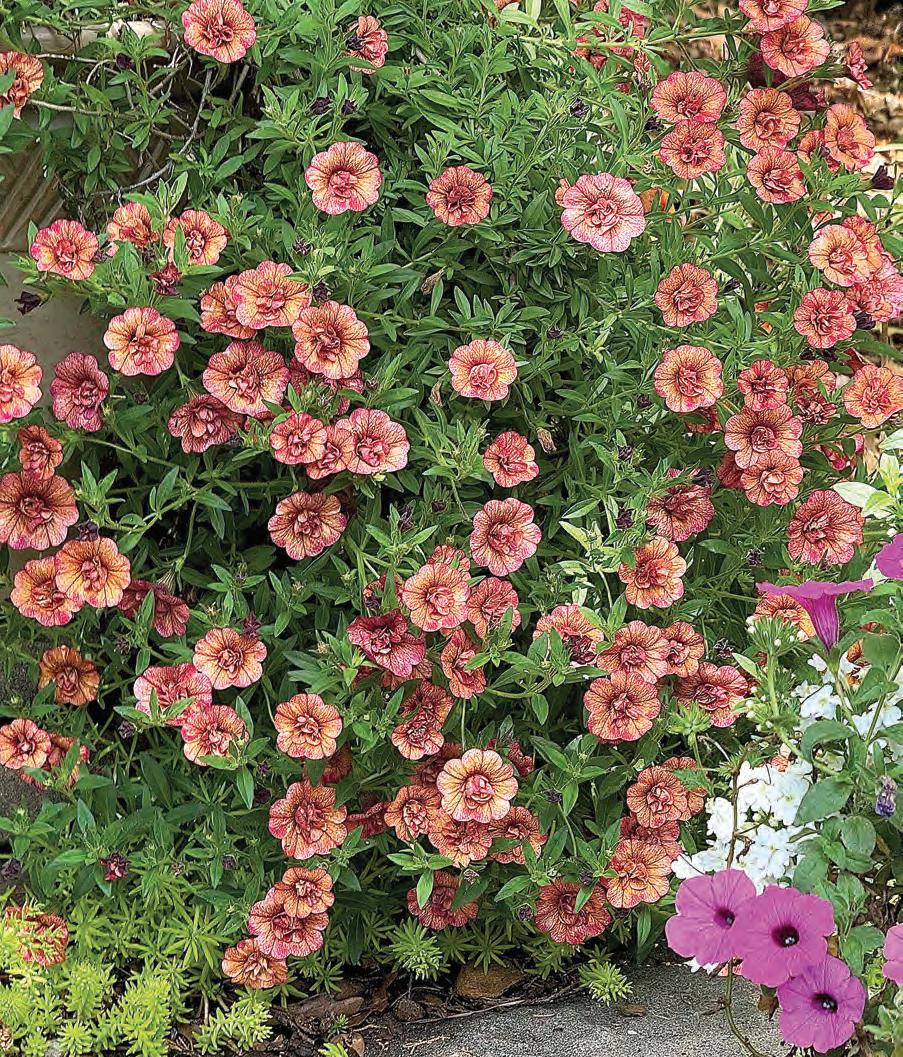
ABOVE: Double calibrachoas have dazzled the garden with incredible new varieties like Superbells Double Vintage Coral in 2025. NORMAN WINTER/TNS
RIGHT: This year, Superbells Magic Double Grapefruit calibrachoa has mystified gardeners with changing colors that begin with lemon yellow and mature to deep rose pink.
COURTESY OF CREEKSIDE NURSERY/TNS
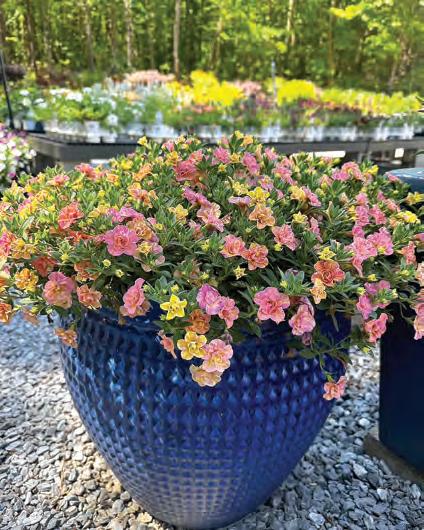
hen Superbells calibrachoas made their debut, no one could have imag ined where we would be today, not only in colors but with the addition of double-flow ered selections. Last year Superbells Double Vintage Coral made its debut with an incredible nos talgic look, but with a color that is ever so rare in the garden.
This year a tip of the hat goes to Superbells Magic Double Grapefruit, which is absolutely mystifying as it changes colors right before your eyes, aging from a lemon yellow to a deep rose pink. And in 2027 you will gleefully be shouting “Laissez les bons temps rouler!” (Let the good times
Norman Winter See Winter, Page 12
























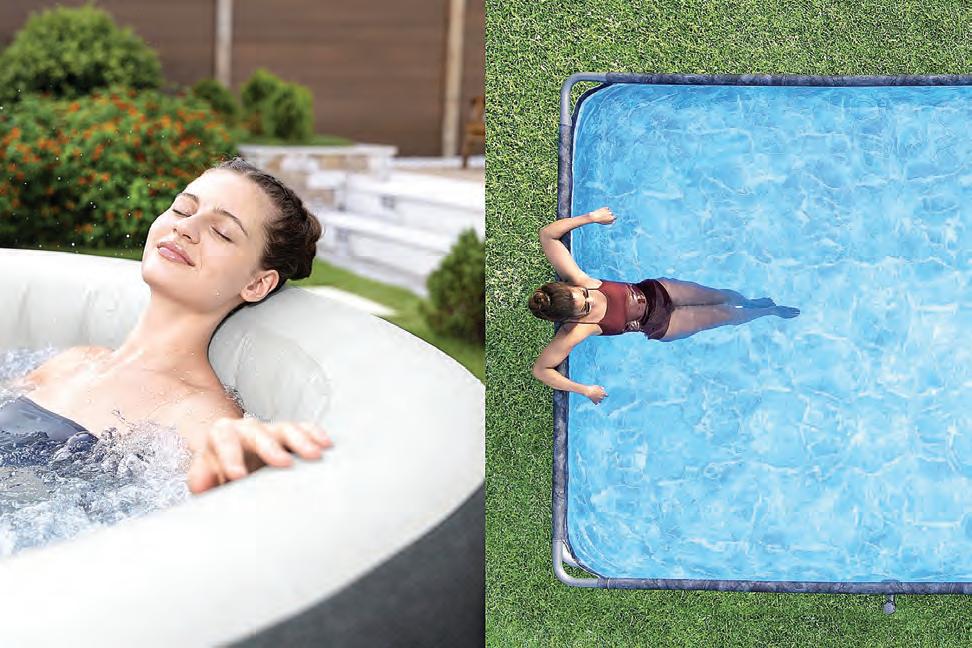
Whether you’re splashing under the sun with family or hosting a pool party with friends, having a pool or spa in your backyard is a guaranteed memory-maker.
It doesn’t matter how big your backyard is or how many people will be splashing or relaxing – a pool, spa or even both can turn your backyard into an oasis. On a mission to bring the fun to every household worldwide, Bestway is offering advice for picking the right pool or spa for your lifestyle.
For the self-care experts: The SaluSpa Hot Springs Inflatable Hot Tub fits up to four adults and offers a relaxing massage via 120 air jets for a spa-like retreat at home. Its EnergySense insulated walls and cover are up to 40% more energy efficient than similar hot tubs, while a multifunction pump controls the AirJet massage system, inflation, heating and filtration. Plus, a Power-Saving Timer allows you to control the temperature of the water up to 40 days in advance.
From soaking in a spa to cooling off in a pool, outdoor living spaces designed for comfort and relaxation can help homeowners create their own backyard oasis.
Want the same spa-at-home experience with more friends? A larger model accommodates six and features 140 AirJets for a soothing massage experience all around.
For space-saving families: Perfect for compact backyards, the Steel Pro MAX 10’ x 6’7’ x 33’ Oval Above Ground Swim-
ming Pool Set is quick to fill and easy to maintain, giving families a refreshing way to enjoy summer without taking up too much room. Its durable, punc-
ture-resistant construction makes it a great choice for both relaxation and active play. A larger model in the same line, the Steel Pro MAX 14’ x 8’2” x 39.5” Oval
Above Ground Swimming Pool Set features a safety ladder, quick assembly, and long-lasting use summer after summer.
For the family fun enthusiast: Holding 2,700 gallons of water, the Bestway Steel Pro MAX 14’ x 33” Round Above Ground Swimming Pool Set is the perfect size for large families. With its durable construction, corrosionresistant steel frame and quick, tool-free assembly, it’s built for hassle-free summer fun.
For the year-round pool party host: Create lasting summer memories with the APX 365 18’ x 9’ x 52” Rectangular Pool Set. Built with a corrosion-resistant galvanized steel frame and a first-of-its-kind Polar-Shield liner protection system, this pool is designed to withstand the elements and stay up year-round. Its spacious design provides plenty of room for family gatherings, pool parties, and everyday fun.
For more information about pools and spas, visit BestwayUSA. com or Bestway’s Amazon store. Nothing says ultimate summer oasis like a pool or spa in your own backyard. The right option can transform your outdoor space into a destination for relaxation, entertainment, and family fun all season long.
Page 6
you’ll pay less interest over the life of the loan.
• Higher monthly payments than long-term mortgages.
There are two basic types of mortgages:
Fixed-rate mortgages (FRM) lock in one interest rate for the life of the loan. This means your monthly mortgage payment
will remain the same for the entire loan term.
Adjustable-rate mortgages (ARM) have an interest rate that will change over the life of the loan, and rates typically start off lower than those of a fixed-rate mortgage. After an initial hold period, ranging from six months to 10 years, your interest rate will change based on market conditions.
Once you determine which mortgage best fits your financial situation and goals, it’s time to shop for a lender. Your lender is
an important part of your homebuying team, and will help guide you through the rest of the mortgage process.
You can obtain estimates from many types of lenders, including loan officers at banks and credit unions, mortgage brokers and non-bank lenders. Different lenders will offer different terms and interest rates and charge different fees. That’s why it’s important to explore your options. Freddie Mac research shows that getting just one additional rate quote could save homebuyers an average of $1,500 over the life of the loan, and getting five
more quotes saved an average of about $3,000.
Because mortgage rates change frequently, be sure to compare loans on the same day to accurately judge loan estimates. It’s also best to do your mortgage shopping swiftly, as multiple credit inquiries outside a 45-day period could lower your credit score.
Freddie Mac’s personalized tools and resources include a loan term calculator for exploring whether a short-term or long-term mortgage may be
better for you; a loan type calculator for understanding whether a fixed- or adjustable-rate mortgage better meets your needs; and a loan comparison calculator to help you determine the differences between multiple loan estimates. To access these calculators, along with other free resources and information, visit https://myhome.freddiemac.com. A mortgage is a long-term commitment and a legally binding contract. Before borrowing, be sure to understand the ins and outs of how home loans work, and your financial responsibilities in the years ahead.
From Page 8
roll!) as Superbells Mardi Gras calibrachoa will be showing up at garden centers everywhere.
Like the others, Superbells Magic Mardi Gras will reach 6 to 12 inches in height with a spread of 24 inches. The tag nails its description, saying it’s the first of its kind, as the double-flowered calibrachoa blooms prolifically in lavender purple with fun splashes of yellow and white.
Your first reaction may be: These look like dainty little flowers. But as Proven Winners said, they are prolific and before you realize it, they have exploded with blooms. This explosion was front and center on a raised bed display planting at Young’s Plant Farm Annual Garden Tour this past June in Auburn, Alabama.
The colors will trigger those artistic design talents you may have been hiding for way too long. The Garden Guy immediately chose partners like Supertunia Tiara Blue petunias, which showed a magical attraction for each other in the first container. But it was made even better with the addition of Superbells Yellow calibrachoa. This meant that all colors in the new Superbells Double Mardi Gras echoed in the companions.
The next container I did featured the Supertunia Double Mardi Gras calibrachoa with Supertunia Mini Vista Indigo petunia, again a dreamy combo on its own. I did, however, add a third companion: the Luscious Royale Red Zone lantana. One color we have mentioned is white and it makes its appearance in the Mardi Gras. Hence the addition of the Luscious Royale Red Zone lantana gives an overall patriotic look to the mix.
While Young’s Plant Farm Annual Garden Tour certainly demonstrated the Superbells’ ability to dazzle in raised beds, for a floral ground cover look
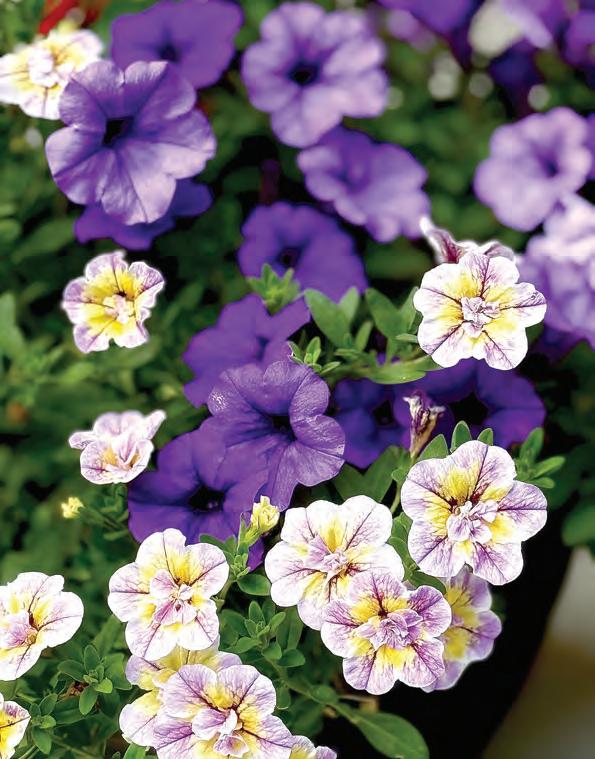
Superbells Double Mardi Gras will make its debut in 2027, offering gardeners a first of its kind as the double flowered calibrachoa blooms prolifically in lavender purple with fun splashes of yellow and white. Here it is partnered with Supertunia Mini Vista Indigo petunia.
you may find it more suitable to grow them in baskets, boxes and containers. In these situations, you give the plants the ability to spill and tumble over the rim or edge to really stand out, creating a Kodak moment.
So, choose a good lightweight potting soil that has controlled released granular fertilizer incorporated and kick-start your new transplants. Typically, we water daily, which will leach out your nutrients. So, plan on making fertilization a regular garden regimen. I either use a dilute water-soluble mix every two to three weeks or add the granular fertilizer per label instructions.
It seems that at some point during the summer, the flowers look a little tired and need to be
From Page 5
as it illustrates a general misunderstanding about financing a home purchase.
According to the survey, just 18% of American adults agreed that renting is cheaper than owning a home, even though it’s generally the case in much of the country. According to Realtor.com’s March Rental Report, renting is more affordable than buying in all 50 of the largest U.S. metro areas, with an average monthly savings of $920 compared to buying.
In some places, the gap is massive. In Northern California, you’ll spend about $6,000 more a month owning versus renting, according to Bankrate data. In only a couple of metro areas is the math even close: In Detroit, where the average rent was $1,481 and the average homeownership cost was $1,515 last year, and in Pittsburgh, where the typical rent was $1,452 a month and the typical homeownership cost was $1,601.
“Renters who are intentional about saving have a real opportunity to build toward a down payment faster than they might think,” says Danielle Hale, chief economist at Realtor.com. One reason to buy a home: Households that purchase their first home by age 30 see a 22.5% higher net worth by midlife compared to those who wait until their 40s, according to Realtor.com. That corresponds with the well-worn notion that renting amounts to throwing away money each month, while owning is akin to paying yourself.
cut back. So, use a sharp pair of scissors and remove about a third of the foliage to generate new blooming stems that will carry you into fall.
I live in zone 8 Georgia and love to plant fresh Superbells, Supertunias and Superbenas in September and October when I find them. Tell your garden center you want to try the new Superbells Double Mardi Gras calibrachoas then plan on getting a supply.
Norman Winter is a horticulturist, garden speaker and author of “Tough-as-Nails Flowers for the South” and “Captivating Combinations: Color and Style in the Garden.” Follow him on Facebook @ NormanWinterTheGardenGuy.
That doesn’t mean homeownership is not a valid goal. You could view savings from a rental as an opportunity to build toward tomorrow’s purchase.
This study was conducted by SSRS on its Opinion Panel Omnibus platform. The SSRS Opinion Panel Omnibus is a national, twice-per-month, probability-based survey. Data collection was conducted from January 16 – January 20, 2026, among a sample of 1,007 respondents. The survey was conducted via web (n=977) and telephone (n=30) and administered in English. The margin of error for total respondents is +/-3.5 percentage points at the 95% confidence level. All SSRS Opinion Panel Omnibus data are weighted to represent the target population of U.S. adults ages 18 or older.





05-04-26 [3 Bdrms - 2120 SqFt - 2010 YrBlt],
Previous Sale: 05-21-21, $515,000 1030 Fox Hound Road - $635,000
05-08-26 [3 Bdrms - 1856 SqFt - 1989 YrBlt], Previous Sale: 00/1991, $178,500 938 Fruit Stand Circle - $706,000
214 Albany Avenue - $585,000
05-05-26 [3 Bdrms - 1642 SqFt - 2022 YrBlt], Previous Sale: 10-14-25, $450,000 172 Arrowhead Drive - $532,000
05-07-26 [4 Bdrms - 1402 SqFt - 1971 YrBlt], Previous Sale: 04-26-12, $145,000
257 Bantry Drive - $880,000
05-06-26 [4 Bdrms - 2389 SqFt - 1995 YrBlt], Previous Sale: 05-23-18, $570,000
401 Buck Avenue - $667,500
05-04-26 [3 Bdrms - 1684 SqFt - 1958 YrBlt], Previous Sale: 04-06-23, $650,000
196 Caldwell Drive - $560,000
05-04-26 [4 Bdrms - 2073 SqFt - 1977 YrBlt], Previous Sale: 01-19-24, $665,000 839 Calico Trail - $660,000
05-05-26 [4 Bdrms - 1951 SqFt - 1989 YrBlt]
117 Carlsbad Circle - $355,000
05-04-26 [2 Bdrms - 1296 SqFt - 1968 YrBlt]
212 Coulter Way - $575,000
05-08-26 [4 Bdrms - 47 SqFt - 2022 YrBlt],
Previous Sale: 06-30-22, $760,500
697 Harvard Court - $680,000
05-08-26 [4 Bdrms - 2501 SqFt - 1990 YrBlt], Previous Sale: 00/1990, $260,000
7937 Heather Lane - $865,000
05-06-26 [4 Bdrms - 1755 SqFt - 1978 YrBlt]
406 Lupine Circle - $620,000
05-05-26 [3 Bdrms - 1889 SqFt - 2018 YrBlt], Previous Sale: 02-22-22, $640,000
139 Maple Street - $505,000
05-04-26 [2 Bdrms - 1359 SqFt - 1948 YrBlt],
Previous Sale: 06-22-18, $350,000
460 Oak View Drive - $655,000
05-06-26 [4 Bdrms - 2001 SqFt - 1970 YrBlt]
236 Plum Street - $518,000
05-06-26 [3 Bdrms - 1160 SqFt - 1961 YrBlt],
Previous Sale: 11-01-17, $395,000
276 Ponderosa Drive - $530,000
05-05-26 [4 Bdrms - 1284 SqFt - 1977 YrBlt], Previous Sale: 07-15-08, $218,000
If spring and summer are seasons when homeowners focus their renovation energy on outdoor living spaces, that attention shifts back inside upon the arrival of fall. People tend to spend much more time indoors than outside come late fall and throughout the winter. The ambiance inside in fall and winter is notably different, as fewer hours of daylight can darken interior spaces. Finding ways to brighten home interiors can make spaces more inviting in late fall and throughout the winter.
• Layer with sheer and blackout curtains. The simplest way to brighten interior spaces is to allow natural light to illuminate them, but that can be difficult in homes with blackout curtains. Blackout curtains are highly effective at keeping light out, but they won’t do much to brighten interior spaces in the winter. Layer blackout curtains with sheer curtains so you can still get some privacy but brighten interior spaces with natural light at the same time.
• Add lighting wherever possible. The days when interior lighting was limited to floor lamps and overhead fixtures are long gone. Various types of lighting can now be used to brighten interior spaces throughout winter. Recessed lighting is a relatively inexpensive upgrade that can brighten any room in a home at any point in a day.
343 Portsmouth Avenue - $540,000
05-08-26 [4 Bdrms - 1860 SqFt - 1985 YrBlt]
448 Potters Lane - $550,000
05-08-26 [3 Bdrms - 2033 SqFt - 2022 YrBlt], Previous Sale: 03-16-22, $625,000 113 Richard Place - $560,000
05-05-26 [3 Bdrms - 1260 SqFt - 1975 YrBlt], Previous Sale: 05-12-23, $585,000 123 Sequoia Drive - $365,000
05-04-26 [2 Bdrms - 993 SqFt - 1964 YrBlt], Previous Sale: 00/1992, $89,500
1073 Villaggio Circle - $605,000
05-05-26 [3 Bdrms - 1570 SqFt - 2004
YrBlt], Previous Sale: 07-04-05, $454,500
TOTAL SALES: 20
LOWEST AMOUNT: $272,000
HIGHEST AMOUNT: $1,470,000
MEDIAN AMOUNT: $550,000
AVERAGE AMOUNT: $576,800
1900 Alice Drive - $500,000
05-05-26 [3 Bdrms - 1323 SqFt - 1965
YrBlt], Previous Sale: 01-28-11, $120,000
1408 Arkansas Street - $385,000
05-08-26 [2 Bdrms - 821 SqFt - 1942 YrBlt],
Unlike a traditional overhead fixture where the light emanates from a single source, recessed lighting can be installed in various points in the ceiling so each corner of a room can be lit up. In addition to recessed lighting, under cabinet lighting in kitchens and on bookshelves can brighten spots that traditional fixtures typically fail to illuminate. Layering the lighting so light comes from various sources can create a brighter feel.
• Use color to your advantage. Color is another tool that can be used to brighten interior spaces in the winter. If homeowners are reluctant to paint walls with new and brighter colors, then accents can lend rooms a lighter feel. Vibrantly colored throw pillows, blankets and fixtures can create a lighter feel when residents and guests enter a room. Artwork with light colors also can help to brighten interior spaces.
• Wash the windows. They are easily overlooked, but dirty windows can block natural light and greatly reduce the amount of light entering a home through the windows. Clean the interior and exterior of your windows prior to winter so any grime that has built up in recent months and years is not preventing light from entering your home.
It can be a challenge to keep interior spaces bright over the winter. But there are many ways homeowners can illuminate interior spaces.
Previous Sale: 06-11-20, $335,000 8356 Bennington Court - $590,000
05-05-26 [3 Bdrms - 1665 SqFt - 2005
YrBlt], Previous Sale: 07-08-21, $595,000 1023 Caldwell Avenue - $340,000
05-08-26 [4 Bdrms - 1290 SqFt - 1950 YrBlt] 7817 Caracena Court - $500,000
05-08-26 [3 Bdrms - 1448 SqFt - 2003
YrBlt], Previous Sale: 03-06-20, $450,000
312 Central Avenue - $378,000
05-06-26 [2 Bdrms - 1025 SqFt - 1932
YrBlt], Previous Sale: 04-30-10, $110,500
242 College Avenue - $425,000
05-08-26 [3 Bdrms - 1104 SqFt - 1963 YrBlt],
Previous Sale: 08-05-14, $225,500
444 Corcoran Avenue #4 - $272,000
05-06-26 [3 Bdrms - 1032 SqFt - 1972 YrBlt], Previous Sale: 02-05-26, $155,000
136 Evergreen Way - $639,000
05-05-26 [3 Bdrms - 1898 SqFt - 1978
YrBlt], Previous Sale: 05-23-22, $700,000
227 Haviture Way - $615,000
05-07-26 [3 Bdrms - 1805 SqFt - 1991 YrBlt], Previous Sale: 01-31-07, $400,000
100 Justin Court - $655,000
05-06-26 [4 Bdrms - 2030 SqFt - 1980 YrBlt], Previous Sale: 03-06-19, $550,000
100 Marquette Avenue - $600,000
05-04-26 [4 Bdrms - 1536 SqFt - 1966 YrBlt], Previous Sale: 11-26-13, $230,000 4288 Melody Lane - $600,000
05-06-26 [4 Bdrms - 1914 SqFt - 2000 YrBlt], Previous Sale: 05-09-13, $290,500
47 Muller Street - $460,000
05-08-26 [3 Bdrms - 1220 SqFt - 1935 YrBlt], Previous Sale: 02-15-13, $145,000 863 Oakwood Avenue - $500,000
05-04-26 [3 Bdrms - 1020 SqFt - 1951 YrBlt], Previous Sale: 09-05-17, $330,000
6206 Pebble Beach Drive - $787,000
05-04-26 [5 Bdrms - 3487 SqFt - 2000 YrBlt], Previous Sale: 11-09-21, $820,000
143 Primrose Lane - $710,000
05-08-26 [4 Bdrms - 1819 SqFt - 1978 YrBlt]
129 Revere Street - $510,000
05-04-26 [3 Bdrms - 987 SqFt - 1942 YrBlt],
Previous Sale: 10-07-25, $360,000
215 Roney Avenue - $1,470,000
05-05-26 [3 Bdrms - 1639 SqFt - 1951 YrBlt],
Previous Sale: 07-23-13, $165,000
449 Topsail Drive - $600,000
05-07-26 [4 Bdrms - 1430 SqFt - 1987 YrBlt], Previous Sale: 09-19-16, $370,000
$1,349,000
$1,395,000 4 427 Glencannon
$2,195,000
$729,000 1763 E St Napa 2 1/0 957 0.18 325099689
$738,000 7937 Sunkist Dr Oakland 4 3/0
market,with37propertiespending.
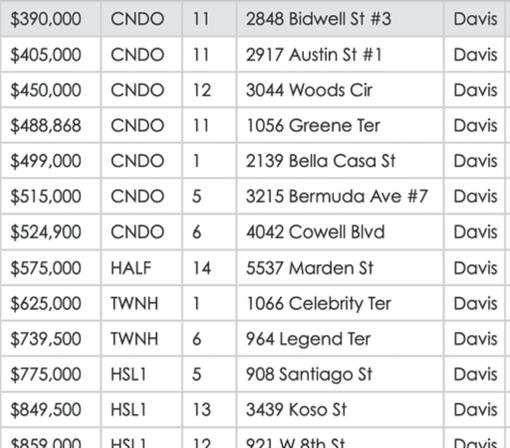
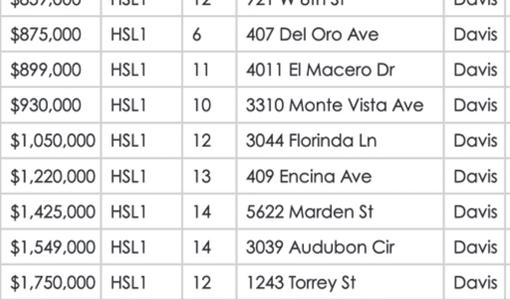
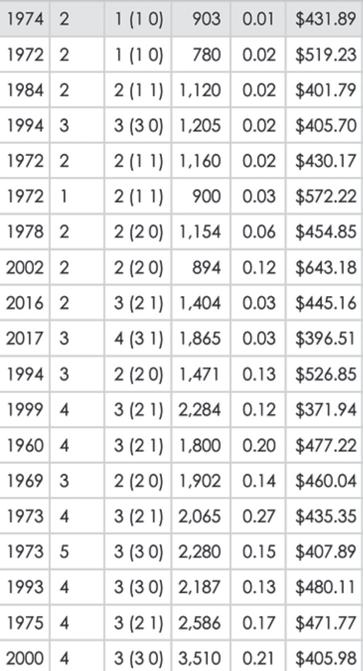
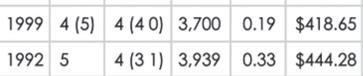
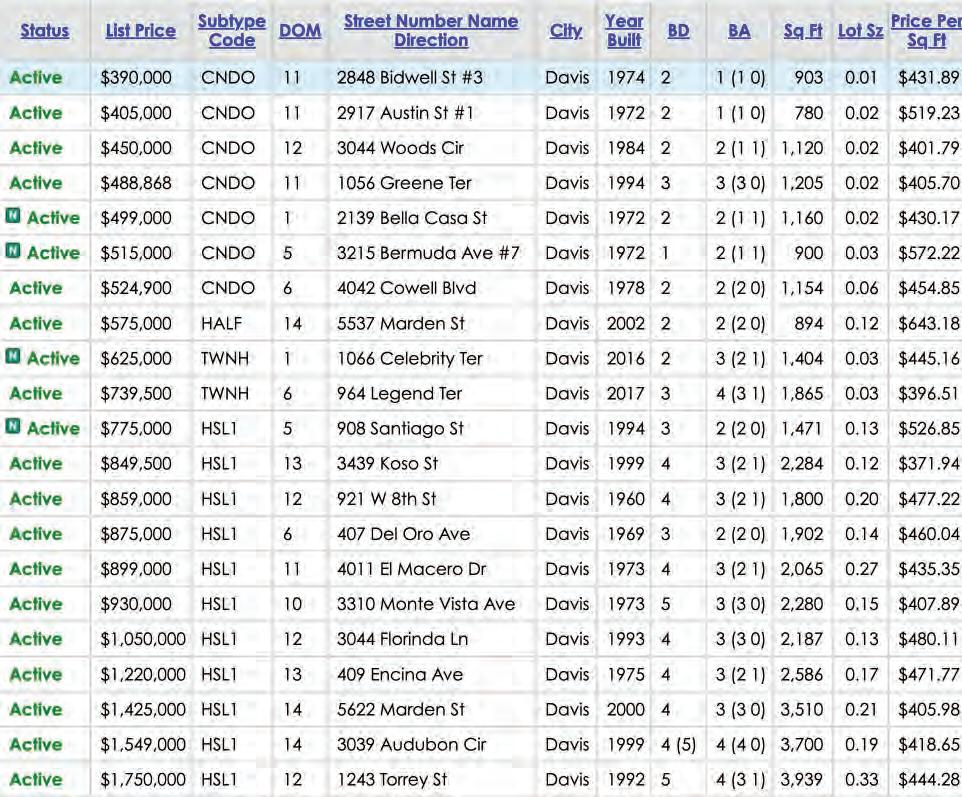
Overthepasttwoweeks:
Active
Twenty-sevennewlistings cameonthemarket.Six havealreadygonepending.
Medianactiveprice
$775,000(Avg.$828,000).
Eighteenlistingsclosed escrow.
Medianclosedprice
$715,000(Avg.$907,500). Twoclosingsreceived multipleoffers. Nineclosingswereunder thelistprice;fivewereover. Elevenclosingwere conventionalfinancing,the remainderwerecash.