Week of August 21, 2026 DailyRepublic.com DavisEnterprise.com
Serving SServin ing SSolano l & Yolo Y l C Counties ti
Kathy Salling BROKER ASSOCIATE, DRE #01925196
707.330.9913
www.KathySallingHomes.com
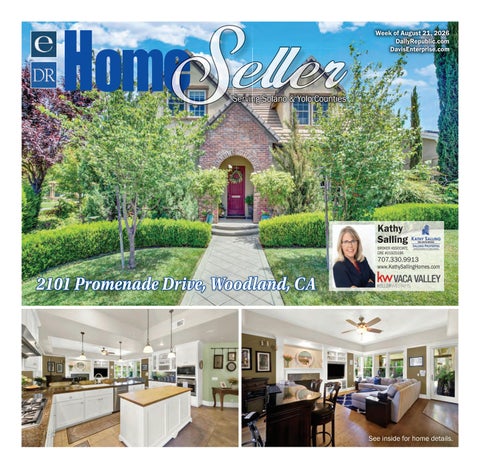
2101 Promenade Drive, Woodland, CA
See inside for home details.
2 Friday, August 21, 2026 — McNAUGHTON MEDIA
ALL THINGS REAL ESTATE
Tricky part of buying infested estate home the property. Q: I bought a home However, there is an this spring from a guy exception to the rule. whose mother had If a trustee or execupassed away and he was tor – now known as the selling it as part of her “personal representaestate. It looked like tive” in order to make a very well-kept older home. Last week we had Tim Jones the position gender neutral – is selling the a swarm of flying terproperty for a deceased person, mites invade the inside of the there is no requirement that a house. When I called a termite TDS be given to the buyer. The company to come out they distheory is that such a representacovered that the home had probably been infested for many tive cannot be expected to know anything about the property but years. They checked the previis only acting as a seller for the ous pest reports on file with the purpose of administering the state and discovered that the estate of the deceased. guy’s mother knew about the Check your deed to see if it infestation two years ago when is a grant deed from the son, she had a report done. The or something else like a trustcost to get rid of the bugs and ee’s deed or a grant deed repair the damage is going to from “Sonny Boy as Succesbe close to $25,000. A neighbor sor Trustee of Mom’s Trust.” then told me the son knew all If the deed is from son as an about the termites and that, on executor, trustee or personal several occasions, he had purchased over-the-counter termite representative, the exception to the disclosure laws should remedies and tried to solve the protect him. problem himself. Nobody ever However, there is also an disclosed the house had terexception to the exception. mites. What should I do next? A personal representative A: That depends upon who has no duty to disclose unless actually sold you the house. they go ahead and make a discloIf the son inherited the home sure anyway. If they do, they are and then sold it to you, the guy liable for the accuracy of that is liable to you for failing to disdisclosure. There are two ways close the problem. He’s the one this sometimes happens. who had better come up with the For example, if during the $25,000. However, if the son was sale, the son or his Realtor had acting in the capacity of a trustee said to you something to the or executor for his mother’s effect that he doesn’t know of estate, the repair bill is probaany defects or, “their ain’t no bly all yours. bugs in this house,” then the son In California, a seller must waived the protections of the give a buyer a document known disclosure statutes and mom’s as a Transfer Disclosure Stateestate would be liable for the ment, or TDS for short. You cost of repair. can think of the TDS as being Some Realtors just don’t the mother of all disclosures. know there is an exception to the Failure to give the buyer a TDS TDS disclosure laws for almost automatically makes the seller liable for any defects in See Jones, Page 4
4 Beds | 3 Baths | 3,057 Sq. Ft. 0.20 Acre Lot | 3-Car Garage
7KLV FXVWRP KRPH KDV IRXU EHGURRPV LQFOXGLQJ RQH VSDFLRXV JXHVW URRP DQG D IXOO EDWK ORFDWHG RQ WKH VW IORRU (QWHU WKH IR\HU FHQWHUHG EHWZHHQ WKH IRUPDO GLQLQJ URRP DQG D VLWWLQJ URRP FXUUHQWO\ GHVLJQHG ZLWK D VSRUWV PRWLI 3URFHHG WR D EHDXWLIXO IDPLO\ URRP DGMRLQHG WR WKH VSDFLRXV FKHIuV NLWFKHQ ZLWK ODUJH LVODQG DQG D SHQLQVXOD IRU FDIH GLQLQJ $ VHFRQG GLQLQJ DUHD LV DOVR DGMDFHQW WR WKH NLWFKHQ 7DNH WKH VWDLUZD\ WR DQRWKHU OLYLQJ DUHD DQG WKUHH XSVWDLUV JXHVWURRPV 7KH OX[XULRXV PDVWHU VXLWH ZLWK D ZDON LQ FORVHW KDV D VSD OLNH HQVXLWH EDWK $PSOH XSVWDLUV VWRUDJH LV DYDLODEOH IRU VHDVRQDO GHFRU RU SHUVRQDO LWHPV 'RZQVWDLUV WKHUH LV DFFHVV WR WKH FRYHUHG SDWLR IURP WKH IDPLO\ URRP RU WKH GRZQVWDLUV EHGURRP 7KH EDFN\DUG JDUGHQ KDV VSDFH IRU JDWKHULQJ IULHQGV DQG IDPLO\ 7KH GHWDFKHG FDU JDUDJH KDV WDQGHP SDUNLQJ &RQYHQLHQWO\ ORFDWHG QHDU &5 WR 'DYLV , WR 6DFUDPHQWR DQG +LJKZD\ WR , View Listing at www.listing4.com/2101promenadedr
New Price $875,000
Kathy Salling BROKER ASSOCIATE, DRE #01925196
707-330-9913
www.KathySallingHomes.com
McNAUGHTON MEDIA — Friday, August 21, 2026 3
‘Buy now, refinance later,’ they said.
SOLANO REAL ESTATE SCENE
Market update for August
T
he Resale Market: Zillow is reporting 1,285 active listings; Realtor.com reports 1,628 total listings including new construction and foreclosures; and MLS shows 1,179; and according to Redfin Solano County trends, 369 homes sold in June and 401 sold in July. Both inventory and the Jim Porter number of sales are up over last year. The median list price is sitting around $575,000, and homes are taking an average of 38 to 49 days to sell. Thanks to the low overall supply of houses for sale, Solano is still technically considered a sellers’ market, but buyers currently enjoy significantly more negotiating leverage this year over the last few. The national average for a 30-year fixed rate conventional mortgage hit 6.75% this week. However, with house prices down by 2.5% since this time last year, first time homebuyers are keeping local mortgage loan officers and real estate agents alive. I do not have the exact numbers handy, but I remember very clearly that it was almost impossible to find starter homes under $530,000 in Solano County over the last five years, and today there are more than 450. The New Home Builder Market: Nationwide, the new home builders are suffering with the cost to build and the affordability issues for buyers dealing with rates approaching 7%, but they are still making profits because they can simply slow down for a while till the market improves and profit See Porter, Page 6
MORTGAGE RATES SAID OTHERWISE JEFF OSTROWSKI
M
BANKR ATE.COM
illions of Americans will move forward with home purchases this year, despite mortgage rates that won’t budge from their perch above 6% and home prices that continue to break records. Some of these buyers are banking on mortgage rates falling in the near future so that they can refinance into more affordable monthly payments. Here’s the problem if you’re among those buyers: If rates don’t fall, you could be stuck with a monthly mortgage payment that weighs down your budget and leaves no easy options for managing the ongoing costs of home ownership, such as repairs and potential jumps in homeowners insurance and property taxes. This risk is especially pronounced for buyers who stretch their budgets to afford homeownership. You can’t necessarily count on your real estate agent or lender to let you in on the risks. In fact, lenders and agents coined the cute tagline for this strategy: “Marry the house, date the rate.” Take Justin Dance’s experience. He and his wife bought a house in Idaho in September 2023. Mortgage rates had risen to 7%, well above their pandemic lows of less than 3%. The consensus in the housing industry at the time was that rates would drop back to the 5% range. “We thought, ‘There’s no way rates are going to be this high in two years,’” Dance recalled. Of course, they’re still that high. Dance’s disappointment illustrates just one way reality can
ADOBE STOCK
Some home buyers are banking on mortgage rates falling in the near future so that they can refinance into more affordable monthly payments. If mortgage rates don’t fall, they could be stuck with a monthly mortgage payment that weighs down their budget and leaves no easy options for managing the ongoing costs of home ownership. get in the way of well-intentioned refinance plans.
‘Significant’ risks for homebuyers While “buy now, refi later” has become a mantra for some in the housing industry in recent years, you don’t have to look far for an expert who urges caution. “I am not a fan of ‘marry the house, date the rate,’ never was,” says Nicole Rueth, senior vice president at CrossCountry Mortgage in Englewood, Colorado. “It
put a lot of people in tough situations now that rates have been higher for nearly four years.” Say you stretch your housing budget now in hopes of saving $100 to $200 a month at some point in the future. If the refi doesn’t happen, you’re stuck with a higher payment that could hamper other financial goals, such as saving for retirement, building an emergency fund or stashing away money for your children’s education. American homebuyers, especially first-time buyers, have been facing an affordability
squeeze. U.S. home values have been setting one record after another – in May, the median price of existing homes sold in the U.S. rose to $429,300, the most ever for the month, according to the National Association of Realtors. At the same time, mortgage rates are stuck above 6% and the job market is weaker than it was a few years ago. Meanwhile, home prices have risen faster than Americans’ incomes. As of April, buying a median-priced U.S. home See Rates, Page 6
4 Friday, August 21, 2026 — McNAUGHTON MEDIA
Solano real estate transactions BENICIA
TOTAL SALES: 6 LOWEST AMOUNT: $500,000 HIGHEST AMOUNT: $900,000 MEDIAN AMOUNT: $835,500 AVERAGE AMOUNT: $784,167.
1449 West 2nd Street - $839,000
06-17-26 [3 Bdrms - 1724 SqFt - 1987 YrBlt], Previous Sale: 11-24-10, $445,000
1920 East 3rd Street - $765,000
06-18-26 [3 Bdrms - 1080 SqFt - 1965 YrBlt], Previous Sale: 09-18-19, $460,000
284 Carlisle Way - $832,000
06-18-26 [4 Bdrms - 2569 SqFt - 1975 YrBlt]
270 West K Street - $900,000
06-15-26 [3 Bdrms - 1540 SqFt - 1964 YrBlt], Previous Sale: 06-26-18, $550,000
231 Panorama Drive - $869,000
06-16-26 [4 Bdrms - 1874 SqFt - 1975 YrBlt], Previous Sale: 01-05-00, $260,000
347 East T Street - $500,000
06-15-26 [2 Bdrms - 1254 SqFt - 1981 YrBlt], Previous Sale: 02-23-21, $440,000
DIXON TOTAL SALES: 3 LOWEST AMOUNT: $559,500.00 HIGHEST AMOUNT: $630,000.00 MEDIAN AMOUNT: $600,000.00 AVERAGE AMOUNT: $596,500.00
120 Victoria Court - $600,000
06-17-26 [4 Bdrms - 1599 SqFt - 1993 YrBlt], Previous Sale: 03-10-23, $600,000
1065 Wesleyan Court - $630,000
06-16-26 [4 Bdrms - 2366 SqFt - 2020 YrBlt], Previous Sale: 01-11-21, $506,000
1170 Woodman Way - $559,500
06-15-26 [3 Bdrms - 1790 SqFt - 1985 YrBlt]
FAIRFIELD TOTAL SALES: 16 LOWEST AMOUNT: $323,500.00 HIGHEST AMOUNT: $995,000.00 MEDIAN AMOUNT: $524,500.00 AVERAGE AMOUNT: $578,156.00
YrBlt], Previous Sale: 06-01-18, $806,000
2466 Cinnabar Drive - $625,000
06-17-26, Previous Sale: 03-09-23, $604,500
231 East Colorado Street - $425,000
06-17-26 [3 Bdrms - 985 SqFt - 1952 YrBlt]
5025 Ellis Godfrey Drive - $790,000
06-18-26 [4 Bdrms - 2787 SqFt - 2019 YrBlt], Previous Sale: 11-12-19, $622,000
1220 Illinois Street - $425,000
1001 Camellia Court - $416,000
2973 Orchid Street - $519,000
927 Freedom Drive - $510,000
06-18-26 [4 Bdrms - 2281 SqFt - 1998 YrBlt], Previous Sale: 08-19-21, $685,000 06-17-26 [2 Bdrms - 656 SqFt - 1920 YrBlt], Previous Sale: 03-16-11, $72,000 06-17-26 [3 Bdrms - 1276 SqFt - 1973 YrBlt]
4925 Paramount Way - $960,000
06-15-26 [5 Bdrms - 4260 SqFt - 2008 YrBlt], Previous Sale: 03-24-09, $500,000
489 Pear Tree Lane - $325,000
06-15-26 [3 Bdrms - 1256 SqFt - 1964 YrBlt]
648 San Lorenzo Street - $530,000
06-17-26 [3 Bdrms - 1841 SqFt - 1965 YrBlt]
1419 Shelby Drive - $645,000
06-18-26 [4 Bdrms - 1827 SqFt - 1977 YrBlt], Previous Sale: 03-26-02, $292,000
600 East Tennessee Street - $400,000
06-18-26 [3 Bdrms - 1138 SqFt - 1958 YrBlt], Previous Sale: 04-28-20, $368,000
1032 Tyler Street - $323,500
06-16-26 [3 Bdrms - 936 SqFt - 1952 YrBlt], Previous Sale: 10-07-21, $405,000
2177 Vista Del Rancho - $590,000
06-18-26 [3 Bdrms - 1470 SqFt - 1977 YrBlt], Previous Sale: 06-12-00, $225,000
RIO VISTA TOTAL SALES: 4 LOWEST AMOUNT: $336,000.00 HIGHEST AMOUNT: $480,000.00 MEDIAN AMOUNT: $414,500.00 AVERAGE AMOUNT: $411,250.00
390 Edgewood Drive - $336,000
06-18-26 [2 Bdrms - 1382 SqFt - 2000 YrBlt], Previous Sale: 01-20-09, $162,000
209 Begonia Boulevard - $519,000
510 Twin Pines Drive - $385,000
2866 Birkham Court - $995,000
06-15-26 [4 Bdrms - 3803 SqFt - 2006
Jones From Page 2 personal representatives and will have their client execute a TDS out of habit. Once the representative has voluntarily
TOTAL SALES: 8 LOWEST AMOUNT: $325,000 HIGHEST AMOUNT: $541,000 MEDIAN AMOUNT: $511,500 AVERAGE AMOUNT: $470,938
817 Blue Bill Way - $522,500
570 Turnberry Terrace - $444,000
06-15-26 [4 Bdrms - 1583 SqFt - 1964 YrBlt], Previous Sale: 04-02-13, $150,000
SUISUN CITY
2129 Fieldcrest Avenue - $805,000
499 Apple Tree Lane - $374,000
06-18-26 [3 Bdrms - 926 SqFt - 1962 YrBlt]
Previous Sale: 10-23-03, $338,170
06-16-26 [2 Bdrms - 1864 SqFt - 1999 YrBlt] 06-18-26 [2 Bdrms - 1391 SqFt - 2004 YrBlt], Previous Sale: 02-03-21, $340,000
06-18-26 [3 Bdrms - 1320 SqFt - 1976 YrBlt], Previous Sale: 03-04-10, $170,000
Previous Sale: 09-12-02, $160,000
160 Bergwall Way - $630,000
06-18-26 [3 Bdrms - 1130 SqFt - 2001 YrBlt], Previous Sale: 03-25-04, $352,000
362 De Anza Drive - $480,000
06-18-26 [4 Bdrms - 1626 SqFt - 1965 YrBlt]
464 Evelyn Circle - $579,000
06-17-26 [4 Bdrms - 1794 SqFt - 1988 YrBlt], Previous Sale: 02-12-21, $555,000
1259 Fulton Avenue - $730,000
149 Dewberry Drive - $552,500 149 Donner Drive - $420,000
719 Greenhaven Drive - $625,000 8018 Kenai Court - $715,000
06-17-26 [4 Bdrms - 2502 SqFt - 2015 YrBlt]
06-18-26 [3 Bdrms - 1487 SqFt - 1960 YrBlt], Previous Sale: 08-29-24, $626,000 06-18-26 [3 Bdrms - 1677 SqFt - 1958 YrBlt] 06-18-26 [4 Bdrms - 1547 SqFt - 1983 YrBlt], Previous Sale: 11-18-09, $155,000 06-17-26 [4 Bdrms - 2597 SqFt - 2008 YrBlt], Previous Sale: 04-23-09, $190,000
128 Lassen Circle - $417,000
705 Georgia Street - $825,000
443 Mandarin Circle - $430,000
137 Hastings Avenue - $505,000
619 Placer Lane - $530,000
332 Plantation Court - $526,000
148 Kathy Ellen Court - $590,000
341 Ridgecrest Circle - $410,000
142 Plymouth Court - $500,000
1109 Kentucky Street - $610,000
401 Shoveller Drive - $541,000
197 Rainier Circle - $295,000
319 Ladera Drive - $390,000
06-16-26 [3 Bdrms - 1588 SqFt - 1989 YrBlt], Previous Sale: 07-27-01, $234,000 06-19-26 [3 Bdrms - 1590 SqFt - 2005 YrBlt], Previous Sale: 04-20-09, $190,000 06-16-26 [3 Bdrms - 1405 SqFt - 1984 YrBlt], Previous Sale: 07-31-23, $262,000 06-18-26 [3 Bdrms - 1427 SqFt - 1991 YrBlt], Previous Sale: 00/1991, $146,000 06-15-26 [4 Bdrms - 1904 SqFt - 1976 YrBlt], Previous Sale: 02-14-02, $227,000
06-16-26 [2 Bdrms - 1152 SqFt - 1964 YrBlt], Previous Sale: 01-10-23, $385,000 06-16-26 [2 Bdrms - 1395 SqFt - 1999 YrBlt], Previous Sale: 05-10-99, $162,000 06-15-26 [4 Bdrms - 2043 SqFt - 1978 YrBlt], Previous Sale: 12-14-22, $590,000 06-16-26 [3 Bdrms - 1000 SqFt - 1977 YrBlt], Previous Sale: 02-24-20, $390,000
TOTAL SALES: 18 LOWEST AMOUNT: $295,000 HIGHEST AMOUNT: $1,400,000 MEDIAN AMOUNT: $539,250 AVERAGE AMOUNT: $577,750
407 Alyssum Drive - $659,000
06-16-26 [4 Bdrms - 1860 SqFt - 2018 YrBlt], Previous Sale: 03-12-20, $510,000
1124 Araquipa Court - $585,000
1081 Madrone Avenue - $710,000
06-17-26 [4 Bdrms - 1860 SqFt - 1989 YrBlt], Previous Sale: 00/1992, $184,000
107 Mayo Avenue - $455,000
06-15-26 [5 Bdrms - 3693 SqFt - 1966 YrBlt], Previous Sale: 06-30-17, $800,000
156 Morningside Avenue - $540,000
742 Violet Lane - $652,000
160 Wykoff Drive - $1,400,000
VALLEJO TOTAL SALES: 23 LOWEST AMOUNT: $175,000 HIGHEST AMOUNT: $825,000 MEDIAN AMOUNT: $541,500 AVERAGE AMOUNT: $550,978
1457 Alabama Street - $465,000
06-16-26 [3 Bdrms - 2189 SqFt - 2022 YrBlt], Previous Sale: 05-04-22, $734,500
1024 Atherton Street - $510,000
06-17-26 [4 Bdrms - 2265 SqFt - 1996 YrBlt], Previous Sale: 03-16-15, $487,000
178 Baxter Street - $623,000
961 Cedar Brook Lane - $757,000 128 Del Rio Court #4 - $340,000
delivered a TDS to the buyer he too has waived the protections afforded him in the law. So take a look at your file and see if the exception, or the exception to the exception, applies in your case. And finally, there is an exception to the exception to the
exception for fraud. It’s sometimes, though rarely, a chance to prove in court that the personal representative committed actual fraud by failing to disclose something he knew about. But courts want to protect the personal representative generally and making out a claim for fraud can
06-18-26 [3 Bdrms - 1056 SqFt - 1973 YrBlt],
06-18-26 [3 Bdrms - 1080 SqFt - 1958 YrBlt]
06-16-26 [3 Bdrms - 1722 SqFt - 1972 YrBlt]
06-16-26 [3 Bdrms - 1518 SqFt - 1996 YrBlt], Previous Sale: 04-11-23, $538,000
4019 Barrel Court - $715,000
06-18-26 [4 Bdrms - 2394 SqFt - 1918 YrBlt], Previous Sale: 04-03-17, $105,000
216 Los Gatos Avenue - $580,000
500 Thomas Circle - $513,000
VACAVILLE
06-16-26 [4 Bdrms - 3028 SqFt - 1988 YrBlt], Previous Sale: 06-07-05, $522,000
06-18-26 [4 Bdrms - 1512 SqFt - 1975 YrBlt], Previous Sale: 01-10-13, $157,500
360 Spindrift Way - $430,000
06-18-26 [3 Bdrms - 1226 SqFt - 1985 YrBlt], Previous Sale: 01-17-24, $500,000
06-17-26 [4 Bdrms - 1285 SqFt - 1965 YrBlt], Previous Sale: 07-26-12, $99,000
333 Lamont Court - $410,000
178 Richard Place - $381,000
06-18-26 [4 Bdrms - 2925 SqFt - 1899 YrBlt], Previous Sale: 09-03-15, $405,000
06-18-26 [4 Bdrms - 2984 SqFt - 1900 YrBlt], Previous Sale: 08-15-18, $829,000
06-19-26 [2 Bdrms - 1152 SqFt - 1964 YrBlt], Previous Sale: 06-15-26, $280,000
205 Solano Street - $325,000
341 Watson Hollow Drive - $480,000
06-16-26 [2 Bdrms - 2031 SqFt - 2003 YrBlt],
These are the local homes sold recently, provided by California Resource of Lodi. The company can be reached at 209.365.6663 or CalResource@aol.com.
06-17-26 [3 Bdrms - 1308 SqFt - 1959 YrBlt], Previous Sale: 09-28-17, $400,000 06-18-26 [3 Bdrms - 1299 SqFt - 1954 YrBlt] 06-16-26 [4 Bdrms - 2630 SqFt - 2005 YrBlt], Previous Sale: 03-25-26, $600,000 06-16-26 [2 Bdrms - 999 SqFt - 1925 YrBlt], Previous Sale: 01-05-26, $300,000 06-16-26 [2 Bdrms - 1556 SqFt - 1939 YrBlt]
355 Parkview Terrace #1 - $175,000
06-18-26 [2 Bdrms - 918 SqFt - 1973 YrBlt]
914 Pine Street - $541,500
06-16-26 [3 Bdrms - 1798 SqFt - 1949 YrBlt], Previous Sale: 01-15-26, $355,000
316 Sea Mist Drive - $704,000
06-18-26 [4 Bdrms - 1430 SqFt - 1987 YrBlt], Previous Sale: 05-19-14, $300,000
06-17-26 [3 Bdrms - 1017 SqFt - 1939 YrBlt], Previous Sale: 11-09-16, $400,000
1151 Sereno Drive - $355,000
06-18-26 [3 Bdrms - 1509 SqFt - 1950 YrBlt], Previous Sale: 04-06-17, $351,000
6753 Sunriver Lane - $815,000
06-15-26 [3 Bdrms - 1576 SqFt - 1961 YrBlt], Previous Sale: 03-26-24, $510,000
2008 Tuolumne Street - $450,000
06-16-26 [3 Bdrms - 1082 SqFt - 1955 YrBlt], Previous Sale: 05-31-00, $175,000 06-17-26 [4 Bdrms - 3583 SqFt - 1999 YrBlt], Previous Sale: 06-21-19, $600,000 06-17-26 [2 Bdrms - 844 SqFt - 1953 YrBlt]
be very difficult. Tim Jones, Esq. is a real estate attorney in Fairfield. If you have any real estate questions you would like to have answered in this column, you can send them to AllThingsRealEstate@ TJones-Law.com.
To advertise here, call 707-427-6927
McNAUGHTON MEDIA — Friday, August 21, 2026 5
ASK ANGI
Are your windows making your home less energy efficient?
W
indows play a maintained. Fortunately, major role in your homeowners don’t home’s comfort always need to replace and energy efficiency. every window to improve Identifying small issues efficiency. A quick during the summer can inspection during the help homeowners lower summer can help idencooling costs now and Angie Hicks tify small issues before prepare their homes they become larger and for cooler weather ahead. more expensive problems as the As summer temperatures seasons change. climb, many homeowners One of the first things homeexpect their air conditioners owners should look for is air to work a little harder. But if leaks. Even when windows are your home never seems to cool closed, worn weatherstripping, down, certain rooms always cracked caulk or small gaps feel warmer than others, or around the frame can allow cool your energy bills continue to air to escape while letting hot climb, your windows, not your outdoor air seep inside. That HVAC system, could be part of forces your air conditioner to the problem. run longer to maintain a comWindows are one of the fortable temperature, increasing biggest sources of energy loss wear on your HVAC system and in a home, especially if they’re driving up energy costs. Replacolder or haven’t been properly ing weatherstripping or applying
fresh caulk is often an affordable way to improve efficiency and comfort. It’s also worth checking how well your windows operate. If they’re difficult to open or close, won’t lock properly or show signs of moisture trapped between panes of glass, they may no longer be performing as intended. Condensation between double-pane windows can indicate a failed seal, reducing the window’s insulating ability. In some cases, repairing the window may be enough, while older or extensively damaged windows may be better candidates for replacement. Summer is also an ideal time to inspect the exterior of your windows. Look for cracked caulking, peeling paint, damaged trim or gaps where moisture could eventually make its way
inside. Addressing these issues now can help prevent water damage, improve insulation and leave your home better prepared for fall rains and cooler temperatures. While replacing windows can improve energy efficiency, it’s not always necessary to replace every window at once. Many homeowners choose to make repairs or replace the windows that receive the most direct sunlight or show the greatest signs of wear first. Small improvements made today can provide immediate comfort while helping homeowners spread larger investments over time. If you’ve noticed your cooling bills increasing despite regular HVAC maintenance, your windows may deserve a closer look. A qualified window profes-
sional can inspect your home’s existing windows, identify areas where energy is being lost and recommend repairs or replacements based on your home’s needs and budget. Your windows do much more than let in natural light. They help regulate indoor temperatures, improve comfort, protect against the elements and contribute to your home’s overall energy efficiency. Taking a little time this summer to inspect and maintain them can help homeowners stay more comfortable now, lower energy costs and head into fall with greater confidence. Tweet your home care questions with #AskingAngi and we’ll try to answer them in a future column.
6 Friday, August 21, 2026 — McNAUGHTON MEDIA
Rates From Page 3 required income of $122,775, well above the median household income of $85,994, according to the Federal Reserve Bank of Atlanta. Given that ongoing squeeze, many buyers are paying more than they want – and hoping for the best. A 2025 survey by Truework, a company that verifies applicants’ income and employment on behalf of mortgage lenders, found that 56% of recent homebuyers were banking on lower rates to create breathing room in their budgets. Buyers continue to make that bet, which Ethan Winchell, co-founder and president of Truework, calls a “significant financial risk.” “It’s a sticky situation,” Winchell says. “The whole industry has been expecting rates to fall. When there’s so much groupthink around a topic, it feels like a safe bet.”
The mortgage rate reality Mortgage rates soared from less than 3% in early 2021 to more than 8% in late 2023. This dramatic swing prevented many Americans from buying homes, and sales volumes have been well below historical levels since 2023. Mortgage rates fell below 3% for only a brief period during the pandemic, but the memory of super-cheap money is powerful, and many Americans expect it to return in the near future. The reality so far has been much different. Since September 2022, mortgage rates have remained between 6% and 8%, according to Bankrate’s national survey of lenders. Housing economists don’t expect much relief in the coming months. According to Fannie Mae’s May forecast, rates will stay above 6.3% for the rest of 2026. The Mortgage Bankers Association’s outlook calls for rates at 6.5% in the back half of 2026. As of June 24, the average rate on a
30-year loan was 6.48%, according to Bankrate’s national survey of lenders. “Rates may not return to where they were, possibly ever,” Rueth says. “Many economists expect rates to stay in a narrow range for years to come.”
Calculating the break-even rate Deciding whether to refinance is all about calculating the break-even period. That’s the point at which the lower monthly payment has covered your closing costs – which can include lender fees, title insurance, an appraisal and other costs. “I look at it as you’re buying the house for yourself again,” says Jim McMahan, president of Benchmark Mortgage in Dallas. “You’re recertifying the title insurance, you’re updating the appraisal. There’s a cost to that.” Say you’ve got a $400,000 loan at 7.25%, for a monthly principal and interest payment of $2,729. If rates fall to 6.25%, your new payment would be $2,463, or a savings of $266 a month. If your closing costs are $8,000 – not unreasonable, given that closing costs typically total 2% or more of the loan amount – you’d break even on the refinancing costs in 30 months. That’s far from a slam dunk. McMahan advises borrowers to aim for a break-even period of less than 18 months.
The risks of dating the rate The “date the rate” mantra wasn’t designed to lead borrowers astray – when the phrase was coined, many in the housing industry assumed rates were destined to fall. However, homeowners and would-be buyers now are learning that even a well-intentioned bit of advice might not work out as planned. “Outside of Shakespeare, a rhyming couplet is somebody’s marketing slogan,” Winchell says. Beyond the possibility that rates don’t fall in the future, there are other potential pitfalls
that accompany counting on a future refinance: Risk 1: Rates do fall, but not enough to justify the costs of a refi If you’re lucky enough to refinance when rates have declined significantly, your break-even period could fall within McMahan’s guideline of 18 months. But if current mortgage rates are only marginally lower than the rate on your original loan, the math gets tricky. In some cases, lenders won’t require a new appraisal or new title insurance, and those savings can tip the decision in your favor. But some states – including Florida and New York – impose taxes on refinancing that can push the break-even point far into the future. Rate-related risks underscore the importance of shopping around for your mortgage, ideally with at least three lenders. Offers can vary from one lender to the next, even on the same day. And because you might be stuck with a loan for a while, you want to grab the best deal you can. Risk 2: Rates fall, but so does your income While borrowers like to remember the pandemic’s 3% rates as the good old days of mortgage finance, the reality is that mortgage rates plunged because the economic news was terrible. The global economy was on the verge of collapse. If mortgage rates fall dramatically again, the move will likely be the result of a recession – and there would be no guarantee that you’d still have enough income to qualify for a refinance. “Qualifying to refinance requires the same financial health as qualifying to purchase,” Rueth says. “Job changes, income fluctuations or a dip in credit can close that door entirely.” Risk 3: Your home’s value falls, and you no longer have 20% equity Say you paid $500,000 for a home a couple of years ago, put down 20% and borrowed $400,000. If your home is in Florida, Texas or another area where home
values have dipped, your house may no longer be worth $500,000. And if it has fallen by even 5% – to $475,000 – the small mortgage principal payments in the early years of an amortization schedule may mean that you now have less than 20% equity in your home. Refinancing could require you to take on private mortgage insurance or to come out of pocket to make up the difference between 80% of the old value and 80% of the new value.
What you can do Because there’s no guarantee that you’ll be able to refinance into a better deal in the future, focus on buying a house that fits your financial means today. And since you may be stuck with the same rate for awhile, be sure to compare offers from at least three lenders, ideally more. “Ultimately, ‘marry the house, date the rate’ works best when buyers purchase a home they can comfortably afford under today’s terms and view any future refinancing opportunity as a bonus, rather than a requirement for the purchase to make financial sense,” says Anthony O. Kellum, president of Kellum Mortgage in Roseville, Michigan. “The phrase can be a useful mindset for buyers who find the right home and are financially prepared for ownership, but it should never be treated as a guarantee that refinancing opportunities will materialize in the near future.” Dance, the Idaho homeowner, kept that advice in mind when he bought his home in 2023. As a result, he said, higher rates were “annoying but not burdensome.” It’s possible that in a few years, mortgage rates will be lower, your income will be higher and your home will be worth more. But you want to make sure you’re on solid ground even if those things don’t pan out. “One of the biggest caveats I share with borrowers,” Kellum says, “is that they must be comfortable with the payment they are accepting today, not the payment they hope to have tomorrow.”
Porter From Page 3 margins return. The local builders are doing the same thing as builders across the country incentivizing buyers with closing cost credit and free upgrades. Lagoon Valley has already sold $125 million worth of homes and is being marketed as Northern California’s first true “conservation community.” Eight-five percent of the 2,400 acres are permanently preserved as natural open wilderness. Lennar has a large twostory with a full ADU downstairs with its own door entry and full kitchen. This is a home worth looking at for a two-generation family, if you can afford $1.2 million and the property taxes. According to the internet AI, both Lagoon Valley and One Lake are doing “exceptionally well.” These big home builders all own a mortgage company, and all the incentives they offer are only given when the buyer uses the builder lender. Yes, it hurts when one of our preapproved buyers goes with the builder’s lender, but if our client is selling their existing home to move up to the dream home; this is good for our market because we have first time home buyers that want to buy that home. Jim Porter, NMLS No. 276412, is the branch manager and senior loan adviser of Solano Mortgage, NMLS No. 1515497, a division of American Pacific Mortgage Corporation, NMLS No. 1850, licensed in California by the Department of Financial Protection and Innovation under the CRMLA / Equal Housing Opportunity. Jim can be reached at 707-449-4777.
McNAUGHTON MEDIA — Friday, August 21, 2026 7
Upgrades to ensure a home stays safe and secure
A METRO
spaces in a home.
home can never be too safe or secure. When residents of a home leave or go to bed at night, a wide range of safety and security features can protect them and their belongings. In-home amenities also can make homes safer for residents with mobility issues or other limitations. Homeowners indeed have no shortage of options when seeking to make their homes safer and more secure. An assortment of safety and security features can help homeowners plan for nearly every situation that could put residents in jeopardy.
Entry point security features
Age-related safety features Various features can help seniors age in place. The National Institute on Aging recommends installing grab bars in showers and bathtubs to reduce the risk of falls when bathing. Such features also can help seniors balance themselves while they bathe and get in and out of showers and tubs. Nonslip strips can be installed on bathroom and kitchen floors in areas that might be vulnerable to spills or puddling. The NIA also recommends fixing all carpets firmly on the floors, which may necessitate the removal of all area rugs. Adding handrails on staircases so there’s something to grab onto on each side the staircase also can enhance the safety of these potentially risky
Deadbolts, security cameras and/or smart doorbells make it easier to keep strangers out and monitor entryways. Smart doorbells may deter criminals from approaching a property. Locks and sensors also can be installed on all windows, and especially those on the first floor that can be accessed from the ground. Locks on sliding doors can be reinforced with secondary locks that further prevent the door from being opened from the outside once the locks are engaged.
Fire safety features The National Fire Protection Association notes that the death rate in home structure fires is approximately 60 percent lower in homes with working smoke alarms than in homes with no alarms or in homes where alarms are not working. The NFPA adds that smoke alarms monitor for smoke and control the speaker that emits the sounds that notify occupants of the presence of smoke. The NFPA recommends both ionization smoke alarms and photoelectric smoke alarms, as each employs a different type
of sensor. The combination of both in a home ensures people are alerted in the case of both flaming fires (ionization alarms) and smoking, smoldering fires (photoelectric alarms). A functioning fire extinguisher also is a must (disposable extinguishers typically last between 10 and 12 years), as is a carbon monoxide detector.
Lighting Sufficient lighting in a home and around the exterior of a home and even the property can be another important safety and security measure. Exterior lighting deters intruders because it makes them more visible to residents while they’re awake and makes them easier to see on overnight security cameras, which can be enough to keep them away. Interior lighting makes it easier to navigate a home at twilight and at night. Hallway night lights can make trips to the bathroom safer, and lighting alongside stairways can make these spaces easier to navigate when the rest of the home is dark. There’s no shortage of ways to make homes safer and more secure, which should be a priority for homeowners of all ages.
YOUR RENTAL EXPERTS! 44 Years in Business! 912 5th Street, Suite 200 • Davis 530-753-0121 kingproperties.com
THE DR DELIVERS. Call 707-427-6989 to subscribe.
METRO
Security cameras and other smart-home upgrades can help homeowners keep a watchful eye on their property and improve overall home security.
Your Home. Your Equity. Your Freedom.
Enjoy the retirement you’ve worked for without leaving the home you love.
A Division of American Pacific Mortgage Corporation MLS 1850
785 Alamo Drive, Ste. 120, Vacaville
707-449-4777 CALL US TO SCHEDULE YOUR FREE, NO-OBLIGATION CONSULTATION
We are local experts here to serve you. Solano Mortgage NMLS # 1515497 is a division of American Pacific Mortgage Corporation NMLS #1850 is licensed in California by the Dept. of Financial Protection and Innovation under the CRMLA © 2024 American Pacific Mortgage Corporation DRE #0121593 For informational purposes only. This is not an offer to extend credit or a commitment to lend. All loans subject to underwriting approval. Some products may not be available in all states and restrictions may apply. Equal Housing Opportunity.
8 Friday, August 21, 2026 — McNAUGHTON MEDIA
ON GARDENING
Heart to Heart Lemon Blush stuns with a rare spring return M
suppose this is common- horticulturist and not an agronany of you are familiar with place in warmer zones. omist or meteorologist, but I the term “surSoil structure, temperafeel like the drought played a prise lilies.” This name ture and moisture levels helpful role with the dormant is mostly attributed to no doubt played a role. caladium bulbs. members of the Lycoris The pathway was The perfect drainage during genus. In the South the created by the previous the winter of 2025-2026 partred Lycoris radiata owner and is comprised Norman nered with sparse rains meant and yellow Lycoris of flagstone and fine pea the bulbs really didn’t suffer Winter aurea are two of the gravel over a loamy soil any rot. While the winter was most treasured surbase. I planted the calacold, the overhead forest canopy prise lilies. We are approaching dium bulbs in May 2025. provided just enough winter their season of bloom. Georgia was in a two-year protection. If you aren’t familiar with the drought, but the caladiums In the front yard where I have term surprise lily, here’s why flourished in 2025 thanks to my “river of caladiums,” I had they are called that: We forget supplemental irrigation. The some Heart to Heart Radiance about them, including where drought broke in May and June they were planted, but suddenly of 2026. The Garden Guy is a See Winter, Page 11 as school approaches, they begin to bloom in glorious displays. But have you heard of surprise caladiums? As the old country song goes, what I am about to tell you is my story and I am sticking to it. Truth be told, I suppose there are no surprise caladiums. Oh, there are always one or two in my zone 8. But in the 2026 garden year, I had dozens of surprise caladiums. It started in 2025 when I planted Heart to Heart Lemon Blush on each side of a walkway on a slope leading up to our wooden swing. The sides of the Two homes on 30 private acres – the main residence has walkway are also lined with a one-of-a-kind design, plus there’s a 3-bed farmhouse. Soprano impatiens, Let’s Dance Views for miles, pool, sport court, chef’s kitchen. hydrangeas and Shadowland This one you really need to see in person. hosta varieties. Heart to Heart Lemon Blush was Proven Winners’ Caladium of the Year in 2024. This caladium is a multi-award winner including Director’s Select at Penn State University. Lemon Cal DRE Lic# 01231287 Blush is a fancy leaf shade intro(707) 249-2702 duction with rose red centers and wide chartreuse margins. ReneeNeuman.com The huge surprise is that almost all of the Heart to Heart Lemon Blush caladiums returned in the spring of 2026. I
8560 & 8565 Holmes Ln, Winters • $1,599,000
Want to take a tour? I’d love to show you around!
Renee Neuman
NORMAN WINTER/TNS FILE
Heart to Heart Lemon Blush caladium is an award-winning fancy leaf selection made for the shade. This photo taken in June 2025 shows them lining a hillside pathway.
10 Friday, August 21, 2026 — McNAUGHTON MEDIA
REAL ESTATE
*DOOHU\
Choosing the Right REALTOR® Does Make A Difference
DAVE FRANZONI
REALTOR®
Executive Council Cal BRE #1748267
I live and work in Solano County REALTOR® for over 20 years Top Producer Smart Home Specialist Executive Council of REALTORS® #1 Company in the Nation 6 Offices for your convenience
(707) 410-9003 DaveFranzoni.com
5071 Business Center Drive Fairfield, CA 94534
2280 ROCKVILLE ROAD • GREEN VALLEY-FAIRFIELD, CA 94534 • LIC#01035560 OUR FAMILY ESTABLISHED COUNTRY ESTATES, INC IN 1982
LONEY & WORLEY TEAM
Scott C. Loney Alicia N. Worley
OWNER/BROKER ASSOCIATE BRE# 01146887
(707) 290-0556
REALTOR®
BRE# 01322884
(707) 344-1300
Use A BROKER/REALTOR® That Will Help You Make The Right Choice Based On Your Individual Needs!
Jim & Darla are both past Presidents of the Northern Solano County Association of REALTORS.® Having been in business since 1978 we are one of the few remaining Independent Real Estate Companies in Fairfield. Born and raised in Solano County... we know the area. We strive to meet the specialized needs of each client, using the highest ethical standards.
BIGGER GGER IS NOT ALWAYS BETTER.
JIM M STEVER REALLTY
STEVER & ASSOCIATES Serving Solano County Since 1978!
vogelpohl real estate consulting & sales ( 7 07 ) 373-6949 Annie@AnnieVogelpohl.com
$QQLH 9RJHOSRKO
BROKER, CAL DRE #00705450
Successfully moving mobiles to mansions. Contact me for current market conditions.
OPEN 7 DAYS A WEEK! 690 E. Tabor Ave., Ste. F, Fairfield www.JimSteverRealty.com
(707) 421-1000
Need to Sell Your Home? Looking For A New Home? Call one of these Real Estate Professionals to help you with your housing needs today!
Jim & Darla Stever BROKER/REALTOR®/Owner Cal BRE#01085687
McNAUGHTON MEDIA — Friday, August 21, 2026 11
Winter From Page 11 and Heart to Heart Splash of Wine return, but nothing compared to the hillside path in the backyard. This area I call the river has good soil, but it is a little heavier and no pea gravel. In no way am I suggesting Heart to Heart caladiums will be perennial outside of their zone, which the tag clearly states is zone 10 and warmer. But this happened to The Garden Guy in 2026 in a most rare and enjoyable experience. This has been an incredible year for caladiums, and you need to get on the bandwagon. When you want to seek the cool indoors to escape the August heat, caladiums will be the plants giving you the look of the islands out in the landscape. Norman Winter is a horticulturist, garden speaker and author. Follow him on Facebook @ NormanWinterTheGardenGuy.
STATEPOINT
Lawn striping creates crisp, eye-catching patterns while promoting a healthier, more attractive lawn with proper mowing techniques.
Boost curb appeal, grass health with lawn striping L
STATEPOINT
NORMAN WINTER/TNS
In a rare occurrence for zone 8 in Columbus, Georgia, almost all Heart to Heart Lemon Blush caladiums returned in 2026. This June 2026 photo shows them partnered with Let’s Dance hydrangeas and Shadowland hostas.
awn striping isn’t just a terrific way to elevate curb appeal, it’s key to a healthier lawn. “With lawn striping, you can add some dimension and interest to your lawn and give it a ‘finished’ professional-quality look. At the same time, lawn striping benefits the overall health of your grass,” says Lenny Mangnall, marketing manager at Exmark. Not sure how to mow stripes? The secret is alternating patterns. Stripe east to west one week, cut diagonally the next. Because you’re reverse cutting and changing the pattern, you’re
not stressing the grass as much as a typical cut. This will reduce soil compaction, ruts, and scalping, and stop grass from lying down, inviting in light, air, nutrients and water, and preventing the buildup of unhealthy thatch. While a striping kit will push the grass over farther, you don’t actually need one to achieve the look. Any mower can be used for striping, although zero turn and riding mowers will make complicated patterns, like diamonds, easier. One simple trick for the best results is to mow your lawn about half an inch higher than usual, as longer blades will bend more.
To tailor the look of your striped lawn, first, decide which direction you want your stripes to run. Stripes that are perpendicular to the street will be more noticeable than ones that are horizontal. Start on an edge of the lawn and mow a straight line; to keep your pass straight, look about 10 feet in front of the mower, not at the ground right in front of you. At the end of your row, be sure to lift the mower deck as you turn. Mow in a straight line next to the first stripe. You might also consider mowing in a checkerboard or diamond pattern. No matter what pattern you choose, remember
that it’s supposed to be fun, so enjoy yourself! It’s always best to start with healthy, lush grass. Find lawn care tips and additional insights on lawn striping at Backyard Life, a unique multimedia destination with a focus on helping homeowners improve their outdoor living spaces. The knowledgeable tips and DIY projects found on Backyard Life, along with Exmark Original Series videos, make it easy to make meaningful improvements to your outdoor living experience. For thicker growth and a healthier lawn, get outside, start mowing and “earn your stripes.”
12 Friday, August 21, 2026 — McNAUGHTON MEDIA
How to find the right real estate professional METRO
B METRO
Could refinancing your mortgage now help lower your monthly payment or save on interest?
Is now the time to refinance?
R METRO
efinancing a home may be on the minds of many as mortgage interest rates continue to drop from the heights they reached just a short while ago. Data from the Freddie Mac Primary Mortgage Market Survey showed average 30-year fixed mortgage rates hovering around 6.51% as of late May 2026. The rates are a notable step down from the almost 8% peaks in late 2023. Norada Real Estate Investments says traditional advice on refinancing is to wait for a full 2% drop in interest rates. However, modern market dynamics may require a far less rigid approach. Homeowners who bought homes with peak rates during the postpandemic surge are recognizing that small shifts are now opening opportunities to refinance and save money. Consideration of various factors can help homeowners determine if now is the time to refinance.
The need to refinance Before determining if it’s the right time to refinance, homeowners should assess why they want to. First Savings Mortgage Corpo-
ration says people refinance for various reasons. For some, they want to shorten the loan term to save on overall interest. Others need access to cash and use a cash-out refinance to tap into their home equity. Someone who has an adjustable-rate mortgage may want to refinance to switch to a fixed-rate one. People who need relatively fast access to cash may be looking to refinance more quickly than those who are doing so to switch a mortgage type or shorten terms.
Rate reductions According to mortgage analysis from AmeriSave Mortgage Corporation, an interest rate reduction of just 0.75% to 1% is often enough to justify a refinance. On a $400,000 loan balance, dropping the rate from 7.5% to 6.5% can cut roughly $260 off the monthly principal and interest payment. So, even though rates aren’t historically low, if they are lower than when the original loan was initiated, it may be prudent to refinance.
The break-even point Refinancing comes with certain costs that homeowners will have
to pay. Data from Rocket Mortgage indicates that closing costs typically range between 3% and 6% of the total loan amount, and include title searches, property appraisals, loan origination, and underwriting. Timing a refinance should occur at the break-even point, or the exact month when the homeowner’s accumulated monthly savings surpasses the upfront costs of securing the new loan, says Norada.
Removing PMI Private mortgage insurance is added to the mortgage when a borrower presents a down payment that is less than 20% of the loan’s value. Conventional borrowers will have the PMI removed once they have reached 20% equity, but others may want to refinance to have the PMI removed sooner if the home’s value has risen significantly since purchase. Removing PMI can improve cash flow. Timing a refinance requires consideration of factors unique to each homeowners. Working with a reputable lender can help homeowners identify and weigh the pros and cons of refinancing.
uying and selling a home are multifaceted processes that often are made much easier with the help of a qualified real estate professional. Indeed, the complexity of a housing transaction inspires the vast majority of buyers and sellers to seek expert assistance. Data from the National Association of Realtors 2025 Profile of Home Buyers and Sellers indicates that 88% of buyers and 91% of sellers use a real estate agent to facilitate their transactions. However, one must first navigate the vast landscape of licensed professionals, and selection of the right professional is crucial. Here’s how to do just that.
Seek personal referrals One of the first places to start is with friends, neighbors or family members. Housingwire says about 40% of people find their agents through a referral. A personal referral typically offers insight about real estate pros that can inform if the person is communicative and reliable. Superior negotiation
skills also might be best advertised by former clients than online profiles.
Prioritize experience A professional’s level of experience is important. The market often is saturated with part-time or inexperienced intermediaries because the industry typically has low barriers to entry and relies on fixed commission structures. Although there are some anomalies, veteran real estate pros who have been active for many years tend to close sales more successfully than novices. HomeLight data suggests topperforming professionals can sell homes for up to 10% more than average.
Prepare questions It’s wise to interview a couple of professionals before settling on one. The NAR urges individuals to prioritize experience, honesty and trustworthiness. When interviewing, ask about current client load, marketing strategies, experience, and how a professional handles challenges like bidding wars or low inventory.
4M\ =[ 0MTX AW] -VPIVKM <PM *MI]\a 7N AW]Z 0WUM ?M XZW^QLM \PM PQOPM[\ Y]ITQ\a XZWL]K\[ _Q\P \WX VW\KP [MZ^QKM \PZW]OPW]\ \PM _PWTM XZWKM[[
.QJMZOTI[[ ?QVLW_[ IVL 8I\QW ,WWZ[ 7ٺMZ ;]XMZQWZ 8MZNWZUIVKM + .QJMZOTI[[ ;MZQM[
AMIZ[ .IUQTa 7_VML 7XMZI\ML +) 4QKMV[M
/M\ AW]Z .ZMM 9]W\M <WLIa
McNAUGHTON MEDIA — Friday, August 21, 2026 13
Celebrating 30 years in business!
PROFESSIONAL SERVICES DIRECTORY
Remodeling, Design & Construction KIRIVEP GSRXVEGXSV PMG
p WWW 3EDILLO#OMPANY COM
BLINDS • SHUTTERS • SHADES REMODEL LIGHTING INDUSTRIAL RESIDENTIAL
SOLAR DESIGN SERVICE COMMERCIAL
(707) 448-8222 Lic. #1066269
Come See Our Store!
Design & Build Services! www.loraindesign.com
Licensed, Insured, and Bonded
VEelectric.com
"DDVNVMBUJPO PG QPMMFO MFBWFT EVTU XJMEmSFT BOE NPSF XJMM BGGFDU QBOFMT BOE DBVTF UIFJS FGmDJFODZ UP ESPQ 8F BMTP PGGFS CJSE OFUUJOH FTUJNBUFT BOE TFSWJDFTÑ
2ZQHUV (ULF 3DXOD 5LFK
530-760-6625
2300 FIFTH ST | 530.756.4187 | DAVISHOMETRENDS.COM
,-;1/6 *=14, -627A
$BMM UPEBZ GPS BO FTUJNBUF UP DMFBO ZPVS TPMBS QBOFMT
Great Prices!
Top Soil Pavers Bark
Come See Us for All Your 150 East H St., Dixon Landscaping (707) 678-8200 Needs! www.dixonlandscape.com
&DOOHQ 6WUHHW 9DFDYLOOH
! ! " " ]YVK\L_^VO\VVM MYW
Davis Native Since 1969, Your Local Builder Designing Building Remodeling in Davis Over 30 Years
)RU WKH EHVW SULFH DQG TXDOLW\ HTXLSPHQW FDOO WKH ´1RQ &RPPLVVLRQHG *X\V µ &DOO 7RGD\ IRU D )5(( (VWLPDWH
Great Selections t ons att
ZZZ EODNHVKYDF FRP /LF
Fair Price, Quality Work! We build A.D.U.'s!
(530) 756-6061 • eisele-construct@sbcglobal.net Lic. #628459
Cobbles Sand / Gravel Flagstone Sod Retaining Walls Bricks Decorative Rocks
THIS SPOT CAN BE YOURS! )RU ,QIRUPDWLRQ RQ $GYHUWLVLQJ 3OHDVH &RQWDFW 'HEELH .HQQHG\ 'HEELH#'DYLV(QWHUSULVH FRP
14 Friday, August 21, 2026 — McNAUGHTON MEDIA
DESIGN RECIPES
Begin with basics when designing from scratch CATHY HOBBS
Y
TRIBUNE NE WS SERVICE
ou have just moved into your dream home. Now what? As you stare at the blank walls and empty rooms, it all may seem so overwhelming. Believe it or not, even professional designers experience this same feeling when launching a new interior design project. But what sets a pro apart from a novice is having the education and experience to understand key design elements such as space, size, scale and color.
Getting started As a professional interior designer, I always advise clients to begin with the basics; in other words start big and then small. Imagine a tree. You should start with the trunk before moving to the branches and ultimately the leaves. The same is true for home décor. It is critical to begin with what I call “foundation” pieces; these are elements such as sofas and even rugs. Sofas and rugs also help to anchor a room, so it is important to choose these elements early in the design process. When choosing rugs, I often suggest choosing them either first, for color, graphic or design inspiration, or last to tie everything together.
Defining your style I always suggest that when looking for the “springboard” for design inspiration to focus on two key elements, your favorite color and your “favorite things.” These two defined design elements can easily be the foundation to begin your design path. Beyond this, taking photographs of designs you love either
ZINA ZAVAL/GENERATED WITH AI/ADOBE STOCK
Nautical elements help to set the tone in a lake house bedroom. on your everyday travels or on vacation, perusing magazines and in person or on-line retailers will help you to hone in on what speaks to you and help to create a starting point for your design journey.
Working with a professional interior designer Once you reach a point where you believe you want to hire a professional designer, it is an investment that one should not take lightly. A designer typically charges either hourly or flat fees for their time and often a percentage of the furniture budget. Aspects such as shopping, emails and even phone calls are often con-
sidered to be billable services. Keep in mind that an interior designer should be qualified in their field and often this means they have earned qualifications recognized as industry standards such as ASID (American Society of Interior Designers) or IIDA (International Interior Design Association). Within professional organizations that provide accreditations to professional interior designers are directories that list professionals who have earned qualifications; this is a great place for someone to begin their search for a professional designer. Beyond this, consumer events such as trade shows, showcases and local events can provide
insight into the work of some of the professionals in your area. Once you begin working with an interior designer, most work in phases such as the design phase (when your design is planned and formulated), procurement or purchase phase (when the purchasing of furniture, artwork and accessories occurs) and the installation phase (when the design vision becomes a reality).
Save versus splurge When should you save? And when should you splurge? In other words where should you and should you not spend your money? When it comes to making that first big purchase, make it a
well-crafted sofa or bed. These are literally foundation pieces that will be well used and should last for an extended period, not a year or two. Look for elements such as solid hardwood in materials such as walnut and oak versus softer woods such as pine or veneered pieces with particle board. As for sofas and upholstered pieces in general, as a designer, I always suggest using commercial or hospitality grade fabrics; they cost a bit more than regular fabrics but will go a long way as far as longevity with minimal care and maintenance. Cathy Hobbs is the owner of Cathy Hobbs Design Recipes, a home staging company based in New York City.
McNAUGHTON MEDIA — Friday, August 21, 2026 15
Solano County Listings: Homes, land for sale PRICE
ADDRESS
$430,000 $484,000 $765,000 $190,000 $190,000 $440,000 $449,900 $450,000 $474,000 $510,000 $540,000 $549,000 $549,900 $549,900 $569,977 $580,000 $585,000 $599,500 $599,900 $622,999 $629,000 $675,000 $685,000 $690,000 $699,950 $729,999 $734,000 $739,000 $790,000 $799,000 $815,000 $850,000 $899,000 $1,250,000 $1,345,000 $1,857,000 $2,195,000 $2,695,000 $495,000 $869,000 $525,000 $635,000 $665,000 $729,000 $469,000 $499,000 $499,000 $550,000 $595,000 $1,000,000 $672,500 $340,000 $235,000 $295,000 $359,000 $459,900 $479,000 $479,900 $499,900 $500,000 $515,000 $530,000 $540,000
1841 Shirley Drive Benicia 2139 Bella Casa St Davis 1133 Decatur Ct Davis 1625 Park Lane #17 Fairfield 1625 Park Lane #23 Fairfield 1210 Coolidge Street Fairfield 1500 Harrison Street Fairfield 1701 Utah St Fairfield 2038 San Gabriel St Fairfield 806 Meadowlark Dr Fairfield 2714 Tribeca Place Fairfield 381 Lily St Fairfield 2402 Gulf Dr Fairfield 713 Dogwood Cir Fairfield 2936 Teton Ln Fairfield 1559 Tommy Ln Fairfield 3278 Inwood Pl Fairfield 509 Clearwater Oak Court Fairfield 843 Coventry Lane Fairfield 2351 Hanson Dr Fairfield 2405 Topgallant Ct Fairfield 911 Walden Ct Fairfield 1328 Horizon Cir Fairfield 3045 Balance Cir Fairfield 3257 Mustang Circle Fairfield 5850 Maroon Pl Fairfield 5131 Duren Cir Fairfield 4538 Avondale Cir Fairfield 844 Crescendo St Fairfield 3202 Del Monte Ct Fairfield 556 Yarrow Ct Fairfield 3225 Bear Creek Dr Fairfield 3109 Sonoma Valley Dr Fairfield 3114 Lomita Ct Fairfield 4427 Glencannon Dr Fairfield 5304 Ravenridge Place Fairfield 23 Country Club Drive Fairfield 1783 Green Acres Lane Fairfield 2289 Rutland Ct Fairfield 3581 Young Ave Napa 165 Country Club Ln Napa 1406 Thomas Dr Napa 828 Laguna St Napa 1763 E St Napa 220 Long St Suisun City 1110 Waxwing Dr Suisun City 233 Maple St Suisun City 519 Crested Dr Suisun City 1000 Worley Road Suisun City 301 Morgan St Suisun City 305 Mayfield Cir Suisun City 643 Beelard Dr Vacaviile 1801 Marshall Rd #506 Vacaville 630 Arcadia Dr Vacaville 723 Beelard Drive Vacaville 113 Fairoaks Dr Vacaville 1109 Syracuse Cir Vacaville 313 Trellis Ln Vacaville 442 Yellowstone Dr Vacaville 266 Fairview Drive Vacaville 1913 Southwood Drive Vacaville 214 Ash St Vacaville 432 S Orchard Avenue Vacaville
CITY
BEDS
BA (F/H) SQ. FT.
2 2 5 2 2 3 4 3 3 3 3 4 3 3 3 3 2 3 4 4 3 4 4 4 4 4 4 5 5 3 4 4 4 4 3 4 4 5 4 3 3 3 3 2 3 4 3 4 4 4 4 2 1 2 4 2 3 2 3 3 3 3 3
2/0 1/1 2/0 1/0 1/0 2/0 2/0 2/0 1/0 2/0 2/1 2/0 3/0 2/0 2/0 2/1 2/0 2/0 2/1 3/0 2/0 2/1 3/0 3/0 2/1 3/0 3/0 2/1 3/0 3/0 3/0 2/1 3/0 2/2 2/1 4/0 4/0 5/1 3/0 2/0 2/0 1/0 2/0 1/0 2/0 2/0 2/0 2/0 2/0 2/0 3/0 2/0 1/0 1/0 2/1 3/0 2/0 2/0 2/0 2/0 2/0 2/0 2/0
LOT/AC MLS #
873 858 1,160 1,615 0.1607 794 condo 794 condo 1117 5,227 1425 5,663 1,117 960 1,300 1890 1,638 1,474 1,900 1,661 1,578 1,854 1,409 1328 4,251 2608 0.16 2,214 0.0728 1,541 2,087 2,578 0.0806 2,065 0.1043 2253 10,023 2,371 2,974 3,611 2,387 2,411 1,860 0.1716 2,303 2,492 3,200 2,409 4972 13,521 3806 18,731 7065 94,961 2,160 0.0484 1,688 900 0.2336 1,015 0.1416 1,374 0.14 957 0.1751 1,176 1,279 1,176 1,308 1984 6,970 2,977 2,574 0.1637 1,044 0.0300 714 0.0161 998 1552 1,306 1,445 0.04 1,370 0.06 1,222 1,588 1318 5,663 1345 5,663 1,800 1329 6,098
326047214 226082590 226085832 326055292 326056030 326061746 326013761 326065531 326055871 326034479 326053371 326047655 326070293 326058163 326068703 326060957 326064423 326052007 326059984 326031631 326047879 326065616 326043108 325089067 326059972 326065594 326060488 326064600 326069790 326043426 326045422 326060270 326050793 325051938 326017869 326002990 326048204 326002065 326048588 326038367 326047836 326065424 325099692 325099689 326042058 326058959 326067347 326068494 326035461 326069457 326016867 326070054 326062143 326024039 326060119 326060724 326041034 326007338 326025738 326063807 326048902 326063113 326037241
PRICE
ADDRESS
CITY
BEDS
BA (F/H) SQ. FT.
$549,000 $569,500 $569,900 $585,000 $585,000 $589,000 $595,000 $619,000 $619,900 $620,000 $630,000 $649,999 $674,000 $675,000 $675,000 $680,000 $695,000 $695,000 $699,000 $700,000 $729,900 $769,900 $775,000 $1,150,000 $1,649,000 $1,750,000 $550,000 $779,000 $1,150,000 $419,999 $465,000 $565,000 $590,000 $625,000 $649,900 $748,000 $525,000 $960,000 $1,599,000 $518,000 $674,900 $714,000
1648 Alamo Dr 387 Colonial Cir 137 Barbera Court 240 N West St 701 Oak Brook Drive 178 Arroyo Ct 613 Isabella Ct 185 Midvale Dr 573 Westwood Ct 214 Gentry Cir 393 Limerick Way 206 Millbrook Way 773 Blue Ridge Ln 226 N Alamo Drive 7018 Westminster Ct 451 Sandstone Dr 107 Bald Eagle Dr 745 Broadfork Circle 140 Alamo Dr 419 Iverness Way 212 Wrentham Dr 413 Crownpointe Cir 700 Maxwell Road 4049 N Kappel View Ln 4157 Shelly Ln 3370 Cotting Ln 101 Barbera Ct 312 Hibiscus St 4851 Udell Rd 1112 Sonata Dr 168 Fairmont Avenue 1208 Amador St 279 Clearpointe Circle 873 Knights Circle 221 Parkview Ter 171 Ancheta Pl 613 Manzanita Way 8412 Tubbs Rd 8560 Holmes Ln 1165 Chapman St 1009 Hillview Ln 1108 Hiramatsu Ln
Vacaville Vacaville Vacaville Vacaville Vacaville Vacaville Vacaville Vacaville Vacaville Vacaville Vacaville Vacaville Vacaville Vacaville Vacaville Vacaville Vacaville Vacaville Vacaville Vacaville Vacaville Vacaville Vacaville Vacaville Vacaville Vacaville Vacaville Vacaville Vacaville Vallejo Vallejo Vallejo Vallejo Vallejo Vallejo Vallejo Winters Winters Winters Winters Winters Winters
4 4 3 3 3 3 3 4 4 5 4 3 4 4 3 3 4 4 4 4 4 5 5 3 4 4 3 4 4 2 2 2 4 3 4 4 3 3 4 4 4 4
2/0 2/0 2/1 2/0 2/0 2/0 3/0 2/0 2/0 2/1 2/1 2/0 2/0 2/0 3/0 2/1 3/0 2/0 2/1 3/0 3/0 3/0 3/0 2/0 4/0 3/0 3/0 3/0 3/0 2/0 1/0 1/1 2/1 2/1 2/0 2/1 2/0 2/0 4/2 2/0 3/0 3/0
LOTS & LAND
PRICE
$80,000 $110,000 $185,000 $185,000 $550,000 $975,000 $299,000
ADDRESS
CITY
224 Jasmine Ct 1109 Headlands Dr 6674 State Highway 128 517 Suisun St Liberty Ln 58 Cernon St 2030 Pinecrest Court
Napa Napa Napa Suisun City Vacaville Vacaville Vacaville
ADDRESS
CITY
MOBILE / FLOATING
PRICE
$130,000 $139,000 $159,000 $167,232 $119,999 $135,000 $180,000
75 Goya Dr Fairfield 157 zafra Dr Fairfield 48 Goya Dr Fairfield 45 Goya Dr Fairfield 6004 Monticello Rd #10 Napa 6004 Monticello Rd #7 Napa 1740 Broadway Street, #39 Vallejo
LOT/AC
12066 0.34 20.04 0.1500 25.44 1.01 0.55 BR
2 1 3 2 2 3 2
LOT/AC MLS #
1,218 1,257 0.13 1791 3,022 1,635 0.12 1478 6,094 1,561 1,460 1,635 2,265 2,043 2,060 1,851 0.21 1,851 1795 9,583 1,809 0.1104 1,961 2,247 1779 7,540 2,818 1,993 0.1943 2,102 2,452 0.17 2637 6,399 1,976 3,500 3.23 2,703 1,631 0.0827 2,501 0.0918 2,311 4.58 1,167 647 6,098 1,275 2761 8,686 1236 4,822 2,100 2,450 1,135 1,152 2,505 1,438 0.1180 2,360 0.1587 2,320 0.1372 SUB TYPE SQ. FT.
Res 12,064 Res 14,810 AG/RES 872,942 Res 6,534 Res 1,108,166 Comm 43,996 RESL BA
2/0 1/0 2/0 2/0 2/0 2/0 2/0
SQ. FT.
1,440 800 1,020 1,248 1,344 1,260 1100
326067348 326037138 326064042 326062666 326012658 326061999 326068258 326061430 326044896 326055505 326066088 326060086 326045341 326066543 326064226 326057439 326062710 326012658 326053643 326068076 326057233 326048797 326063131 326049110 326023878 326052360 326069806 326062165 326044825 326054606 326066821 326021075 326047099 326028528 325097957 326019153 226097756 326062798 325002680 226093084 226090397 226071646 MLS#
326011416 326021197 326039942 326069920 326049023 32603359 326019347 MLS#
326056171 326059911 326049659 326023801 326008213 326008207 326041256
16 Friday, August 21, 2026 — McNAUGHTON MEDIA
Davis currently has 112 active properties on the market and 36 pending properties. Over the past two weeks: Active s Thirty-one new listings came on the market, five have already gone pending. s Median active price $847,000 (average $826,000). Closed s Eleven listings closed escrow. s Median closed price $950,000 (average $932,727). s Four closings received multiple offers.
For the full newsletter subscribe here:
or visit our website below!
/RUL 3UL]PLFK '5( ORUL#ORULSUL]PLFK FRP ZZZ 7KH/RUL3UL]PLFK7HDP FRP
0DULD :HVW
0DUFHOD &DUGHQDV
'5(
'5(
s Two closings were cash, one VA, one private and the remainder were conventional financing.