For decades, we have built a real estate practice unparalleled in the US. Now, as the global legal powerhouse HSF Kramer, we are so much more. As the only law firm ranked in Chambers Band 1 on three continents, we continue to transform skylines and reshape landscapes. Please visit our website to learn more. Kramer Levin is now HSF Kramer

TO BENEFIT:
Golf • Tennis & Pickleball • Cards & Games
Shopping & Lunch • Cocktails & Dinner
Join Us To Celebrate Two Decades of Bringing Joy to Children with Cancer & Their Siblings!
MONDAY, AUGUST 3, 2026
The Seawane Club | Hewlett Harbor, NY
Rockaway Hunting Club | Lawrence, NY
Hempstead Golf & Country Club | Hempstead, NY
Brian Diffendale, M&T Bank
Christopher Hagen, Green Art Plumbing Supply
Carl Oliveri, Grassi Advisors
RECOGNIZING
Rich Schaffer
Plumbing Contractors Association of LI with the Joe Weksler Memorial Community Service Award
LUNCHEON HONOREE
Joan Copell Grant
For further information, please contact Deborah Lom at 516.634.4171 or deborah.lom@sunriseassociation.org Scan the QR code or visit our website to learn more! www.levinegolfouting.org
GOLF OUTING SPONSOR
Sunrise Day Camp–Long Island is a proud member of the Sunrise Association, whose mission is to bring back the joys of childhood to children with cancer and their siblings worldwide. Sunrise accomplishes this through the creation and oversight of welcoming, inclusive summer day camps, year-round programs and in-hospital recreational activities, all offered free of charge. Sunrise Day Camp–Long Island is a program of the Friedberg JCC, a beneficiary agency of UJA-Federation of New York.
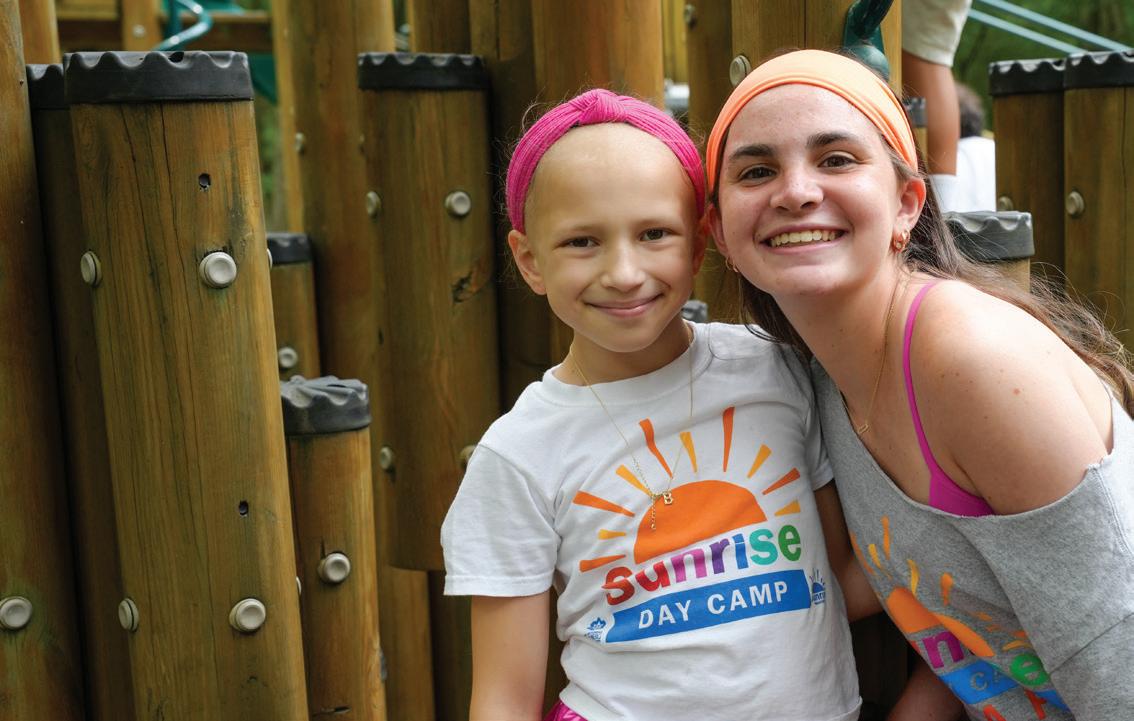




EDITORIAL
Editor
Debra Hazel
Director of Communications and Marketing
Penelope Herrera
Director of Newsletter Division
Kristen Pooran
PRESIDENT/CEO
Jeff Mann
ART
Art Director
Virginia Sanchez
Cover Photography
Isaiah Gill
Eric Bernstein
Eric Bramlett
Lauren Dennison
Pamela Eyring
Joel Horwitz
Kris Kiser
Bob Knakal
Ernest Rrika
Stuart Saft
Carol A. Sigmond
Michale Siino
Nicole R. Sinatra
Technology Consultant Eric Loh
Distribution Mitchell’s Delivery Service
DIGITAL MEDIA
Designers
Virginia Sanchez
Editors
Debra Hazel
Penelope Herrera
Rose Leveen
Web Developer
CS Designworks
West Coast Office: 578 Washington Blvd., Suite 827
Marina Del Rey, CA 90292 866-306-MANN (6266) mannpublications.com


East Coast Office: 450 7th Ave, Suite 2306 New York, NY 10123 212-840-MANN (6266)
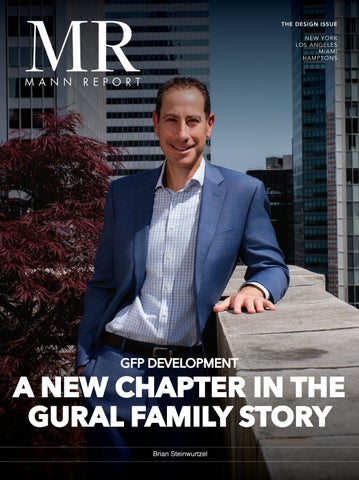
The real estate business is frequently a family business, especially in New York City, and my family and I have been privileged to call many of these leaders friends. One especially close example is the Gural family, first of Newmark and, now, GFP Real Estate. For decades, our families have celebrated major life events together — even my own bar mitzvah.
New generations continuing that legacy in real estate would seem logical and maybe even easy. But that’s not true of the Gurals, now in their third generation of leadership, who continually challenge their family members to reinvent their business while remaining true to their core values. I’m delighted and honored to feature Brian Steinwurtzel, part of that third generation, as he takes on the leadership of GFP Development, which will build new projects around our area. It’s a story of family, persistence and innovation.
Meanwhile, we celebrate other types of legacy in our Events pages, including the Real Estate Board of New York’s Residential Deal of the Year Awards and ULI’s Annual Awards for Excellence. Both celebrate how current work will become a part of New York City’s skyline for decades to come.
This is our summer double issue, so the Mann team will have a break to enjoy some sun and fun. We’ll be back in August, so until then, Happy Summer and a safe and Happy 4th of July!
“Design is not for philosophy. It's for life.” — Issey Miyake
At Peninsula Property Management (PPM), we do more than manage properties—we elevate them. With a leadership team that is deeply involved, hands-on, and responsive, PPM is redefining the standard for property management in New York City. Our mission is simple: deliver results with integrity, precision, and a hospitality-first approach.
Proactive Management
Stop issues before they start — from Local Law 97 to vendor oversight.
Financial Clarity
Clean, timely financials. No surprises –just strategic planning and transparency.
NYC Compliance Expertise
DOB, HPD, LL88, LL97, FISP we navigate every regulation so you don’t have to.
New Development Services
Schedule B, TCO phasing, hiring of staff, punch-list, insurance implementation.
Smart Cost Control
Energy savings, bulk contracts, vendor negotiations we cut waste, not corners.
Track requests, tasks, and reports live through our integrated digital platform.
Beauty may be nice, but it’s nothing without creating value, as we learn in this, our Design Issue!
Vocon’s Lauren Dennison explains how office design has evolved, and become critical to the sector’s future. CBIZ’s Michael Siino tells us how sustainable design shapes long-term value. Look at the beautiful blend of New York style and Miami flair at the NoMad Residences Wynwood, the first residential expansion of the hotel brand. And check out the latest retail trends and concerns in my report from ICSC@Las Vegas.
Speaking of retail — in the early 20th century, department store legend John Wanamaker was credited with the classic marketing phrase, “Half the money I spend on advertising is wasted; the trouble is I don’t know which half.” In the 21st century, Synter’s Joel Horwitz helps us solve that age-old dilemma with an insightful piece on AI-powered advertising.
Meanwhile, because this is our summer double issue, all of us at Mann Publications will be taking a break, too. Happy summer, and see you in August with our Proptech Issue!
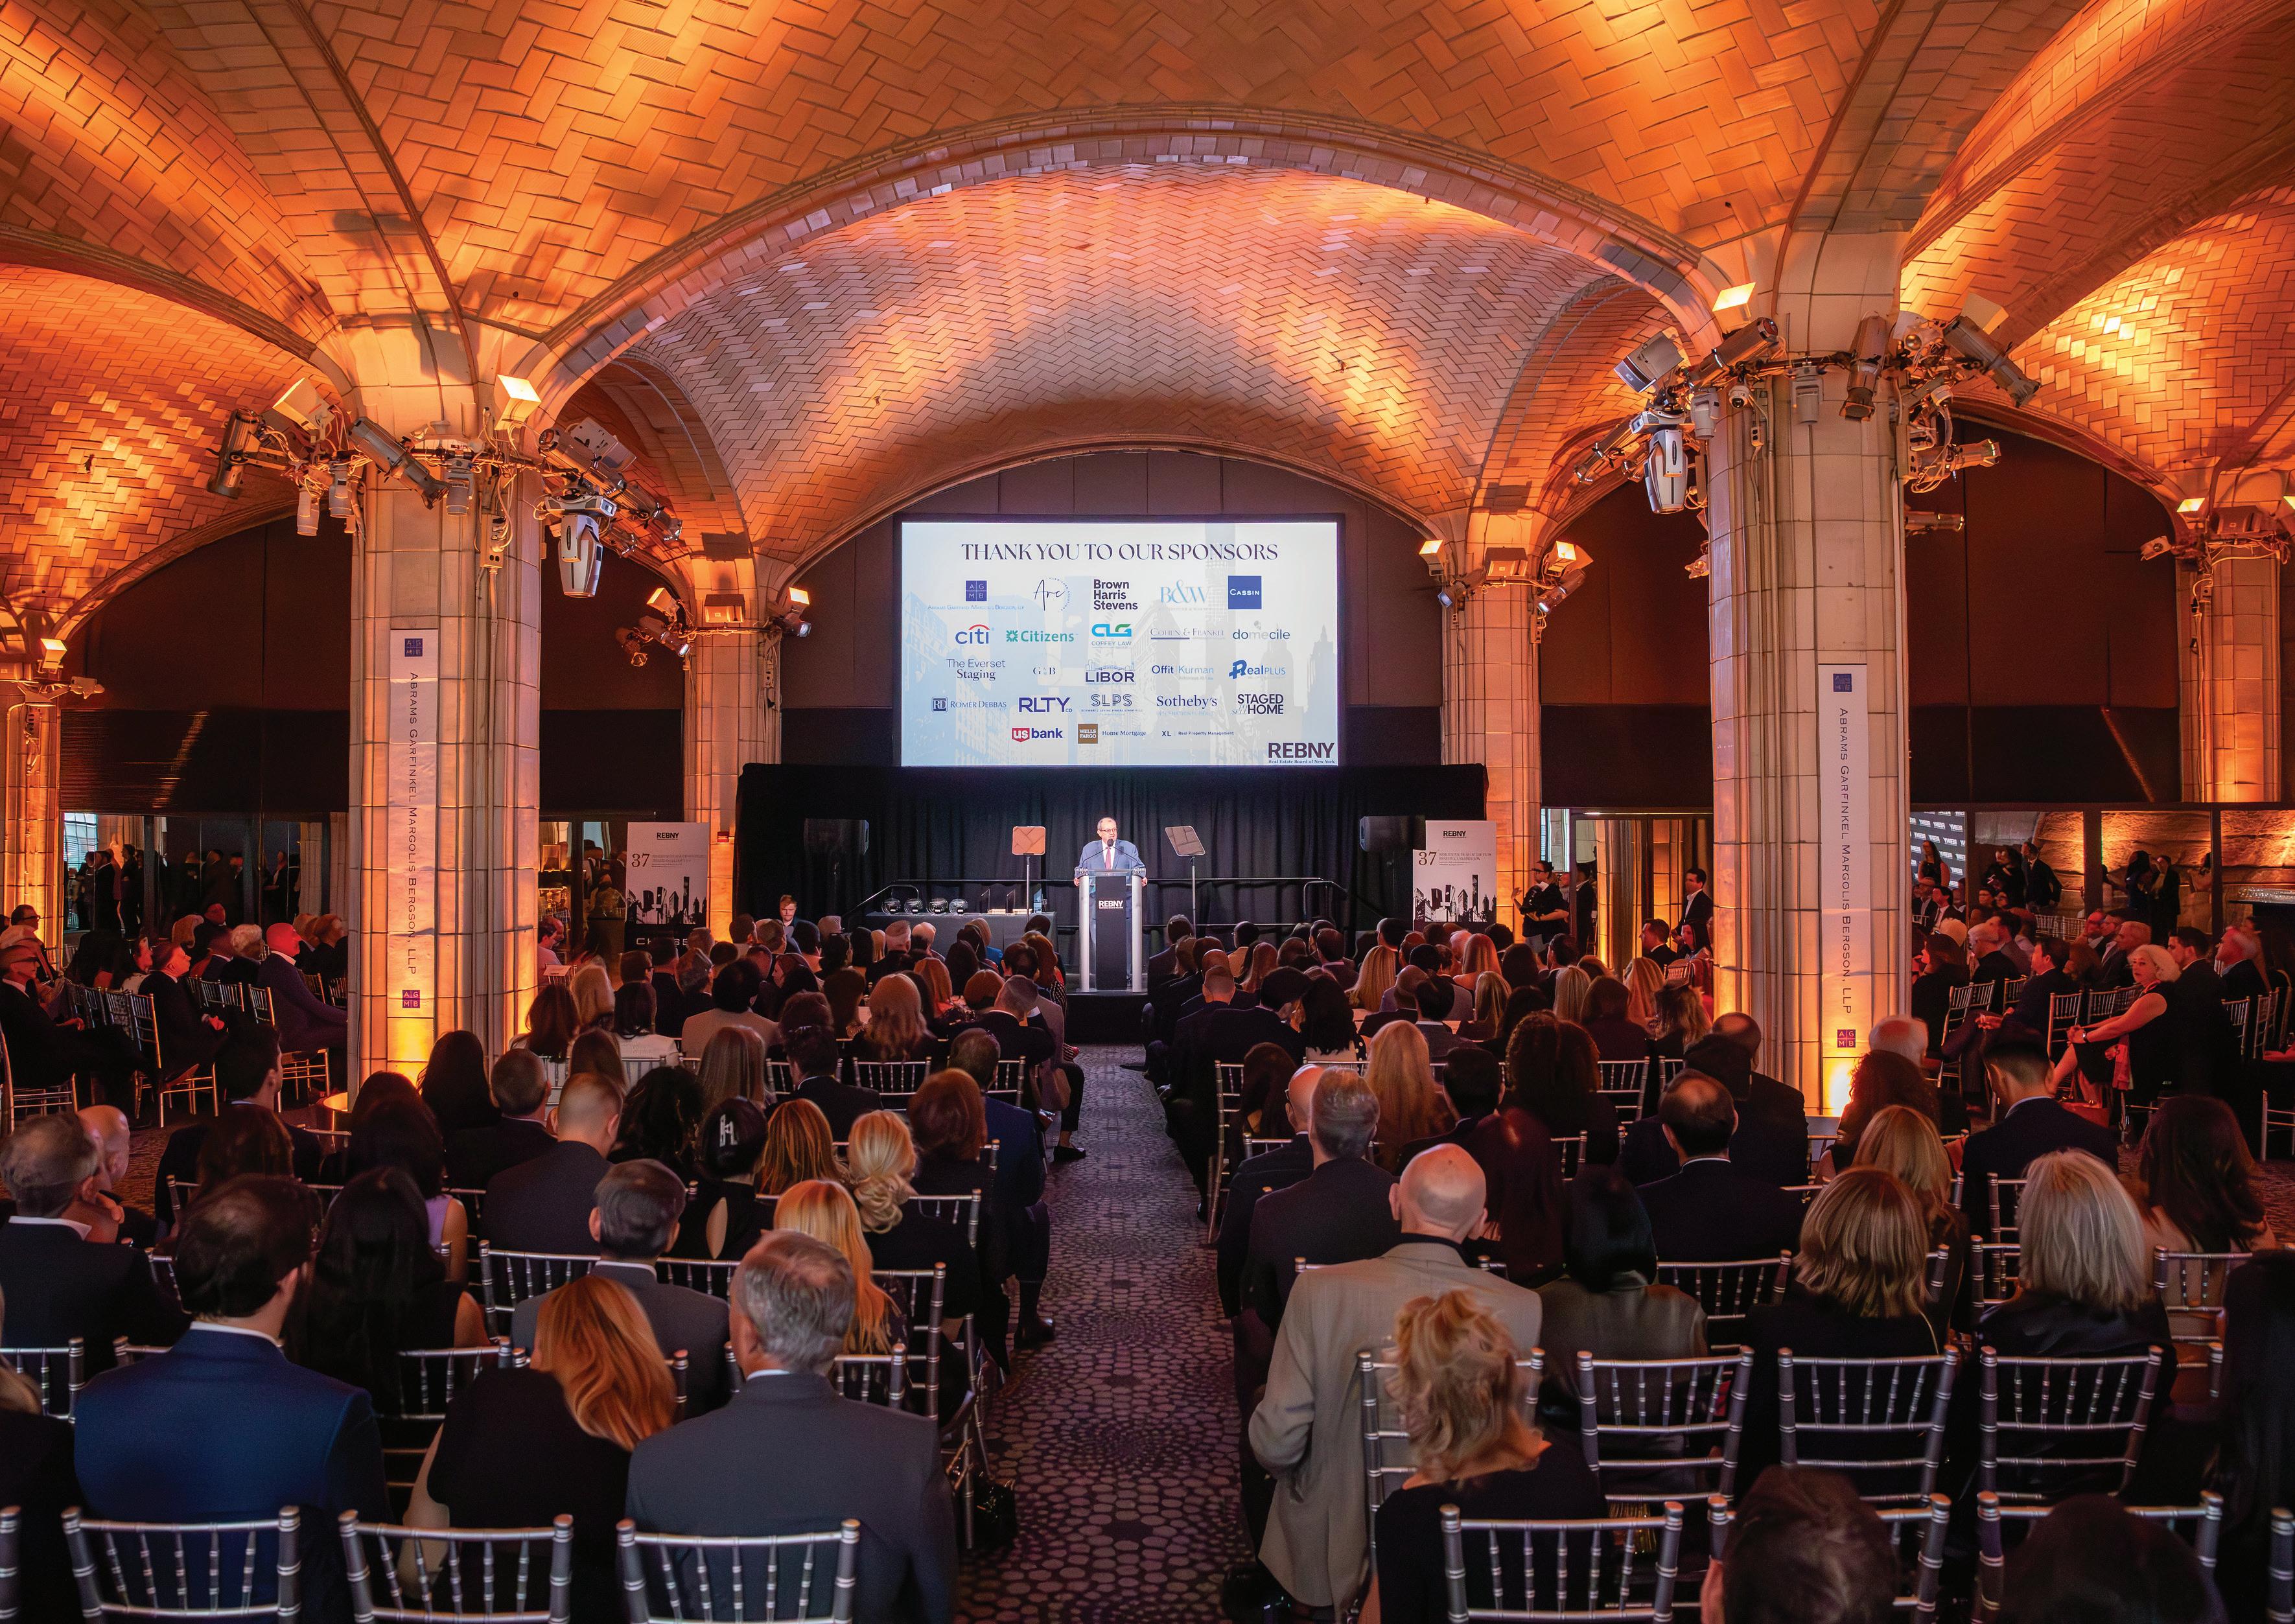
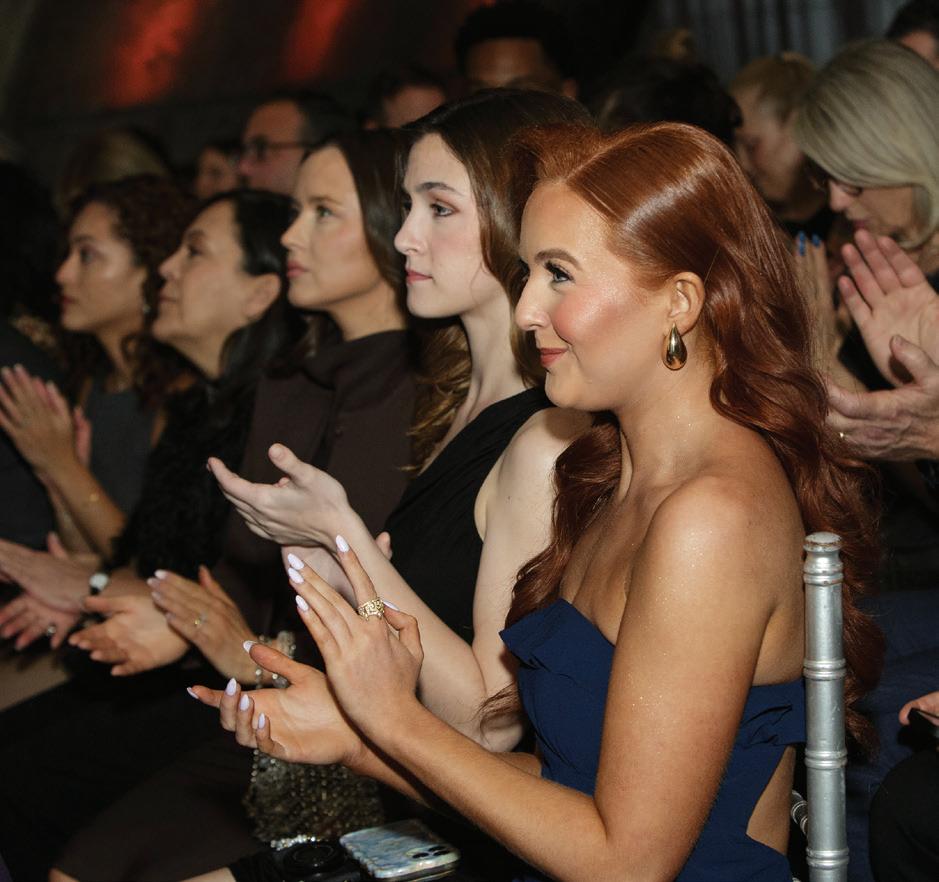
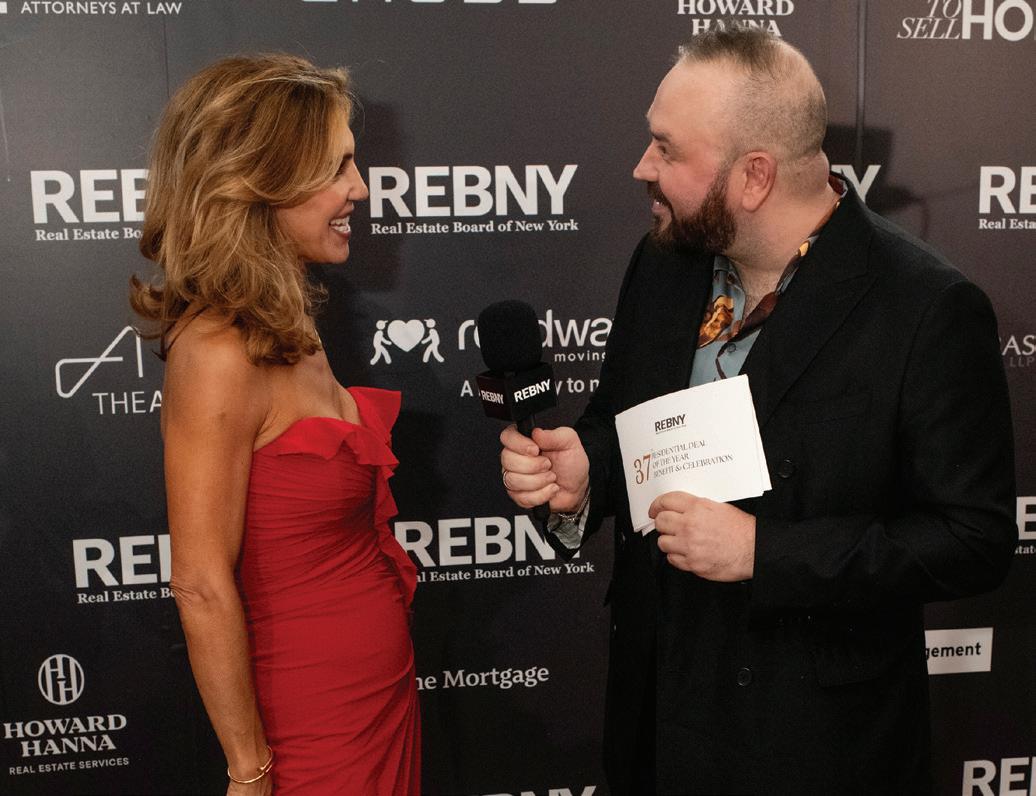
The Real Estate Board of New York (REBNY) hosted its 37th Annual Residential Deal of the Year Benefit & Awards at Guastavino’s, bringing together approximately 360 members of New York City’s residential brokerage community to celebrate industry excellence.
The event recognized standout residential sales and rental transactions from 2025, along with professionals whose leadership, integrity and service have made a lasting impact on the industry.
Proceeds from the evening benefited the REBNY Member in Need Fund, which provides financial assistance to brokers and agents


facing unexpected hardship.


facing unexpected hardship. Honorees included leading brokers from Compass, Corcoran, Sotheby’s International Realty, Brown Harris Stevens, Alta Real Estate and others.

Henry Forster Memorial


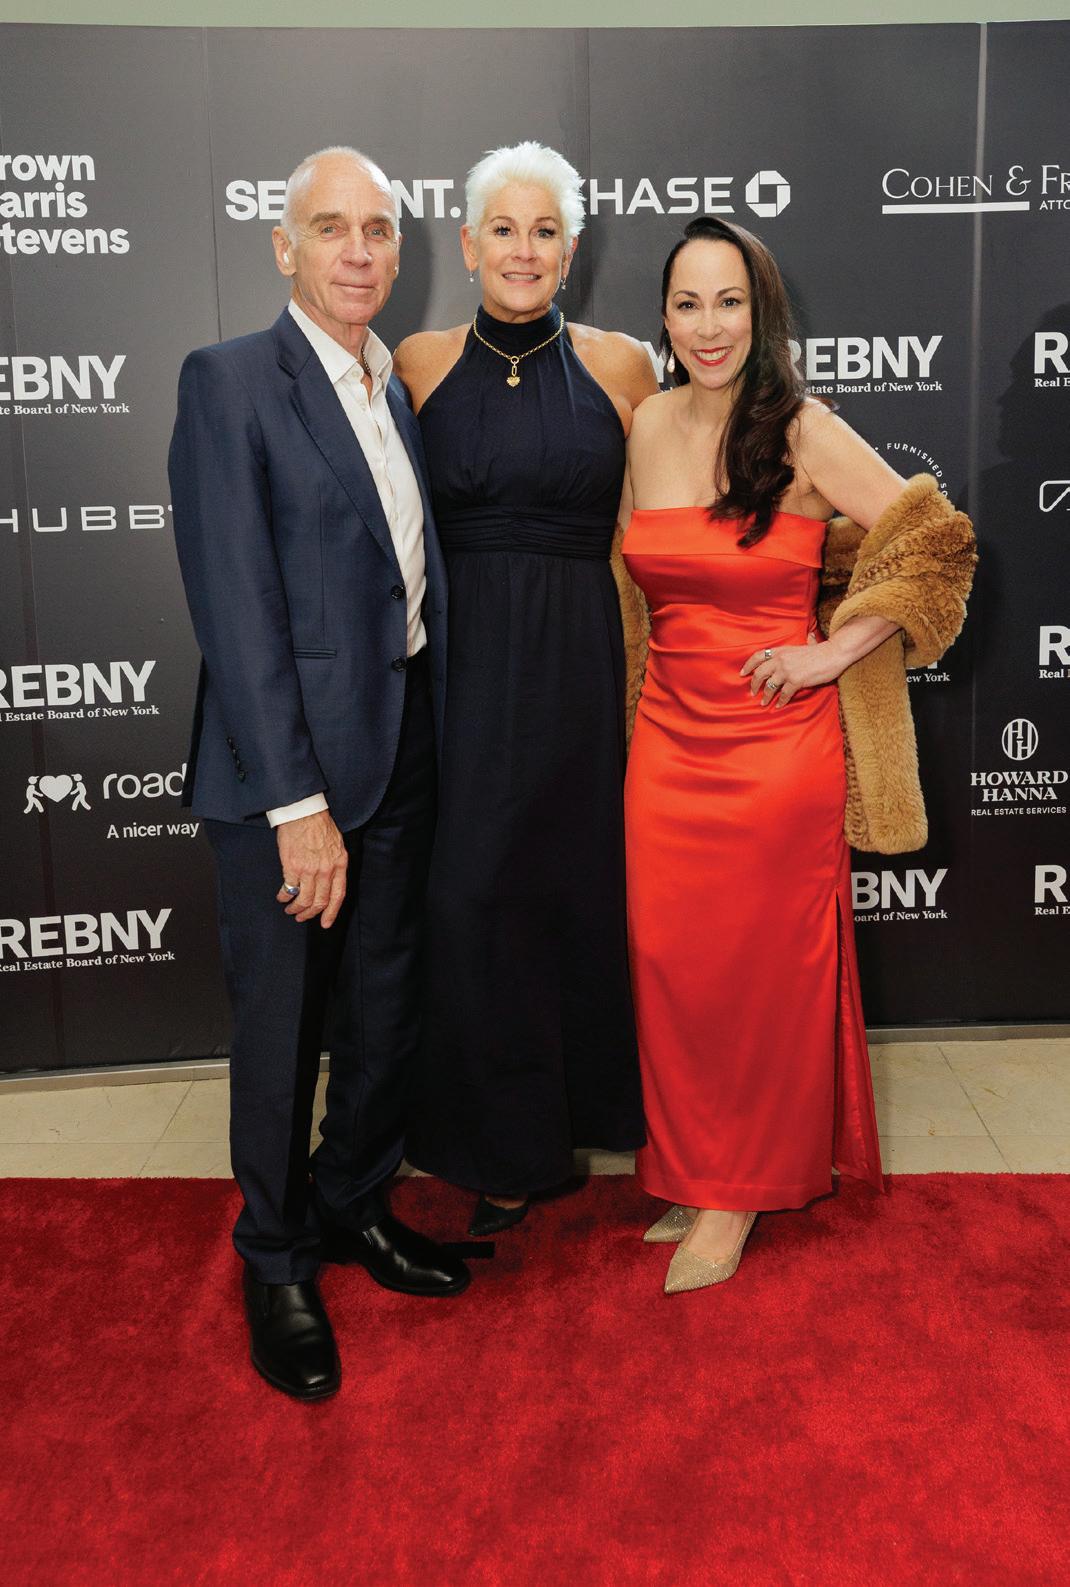
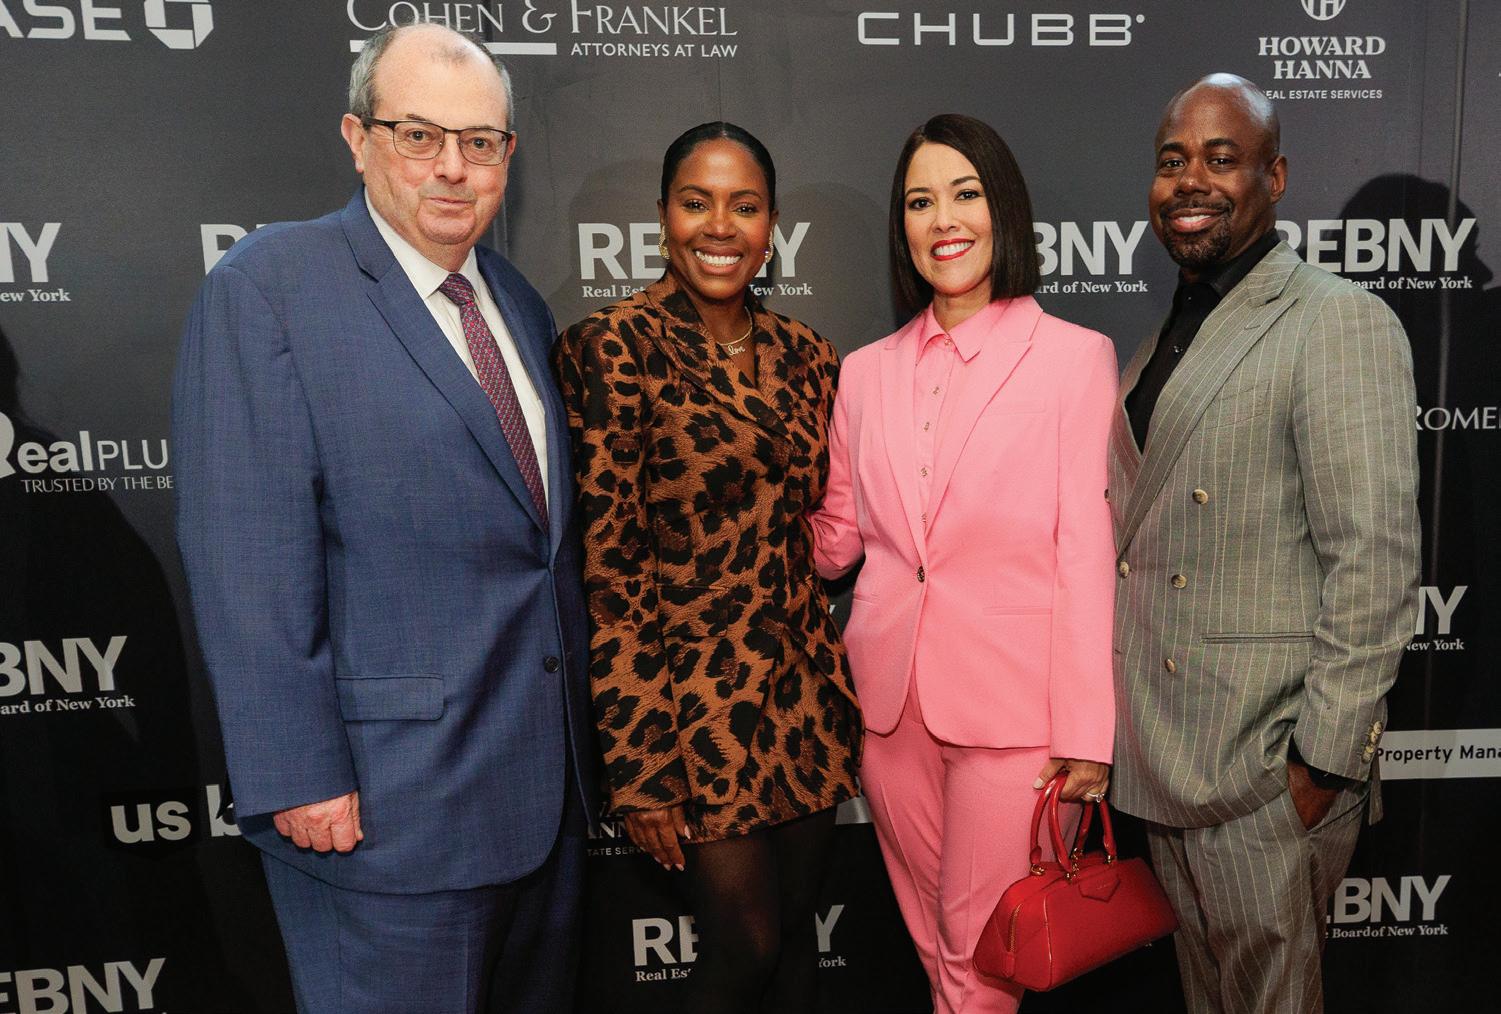
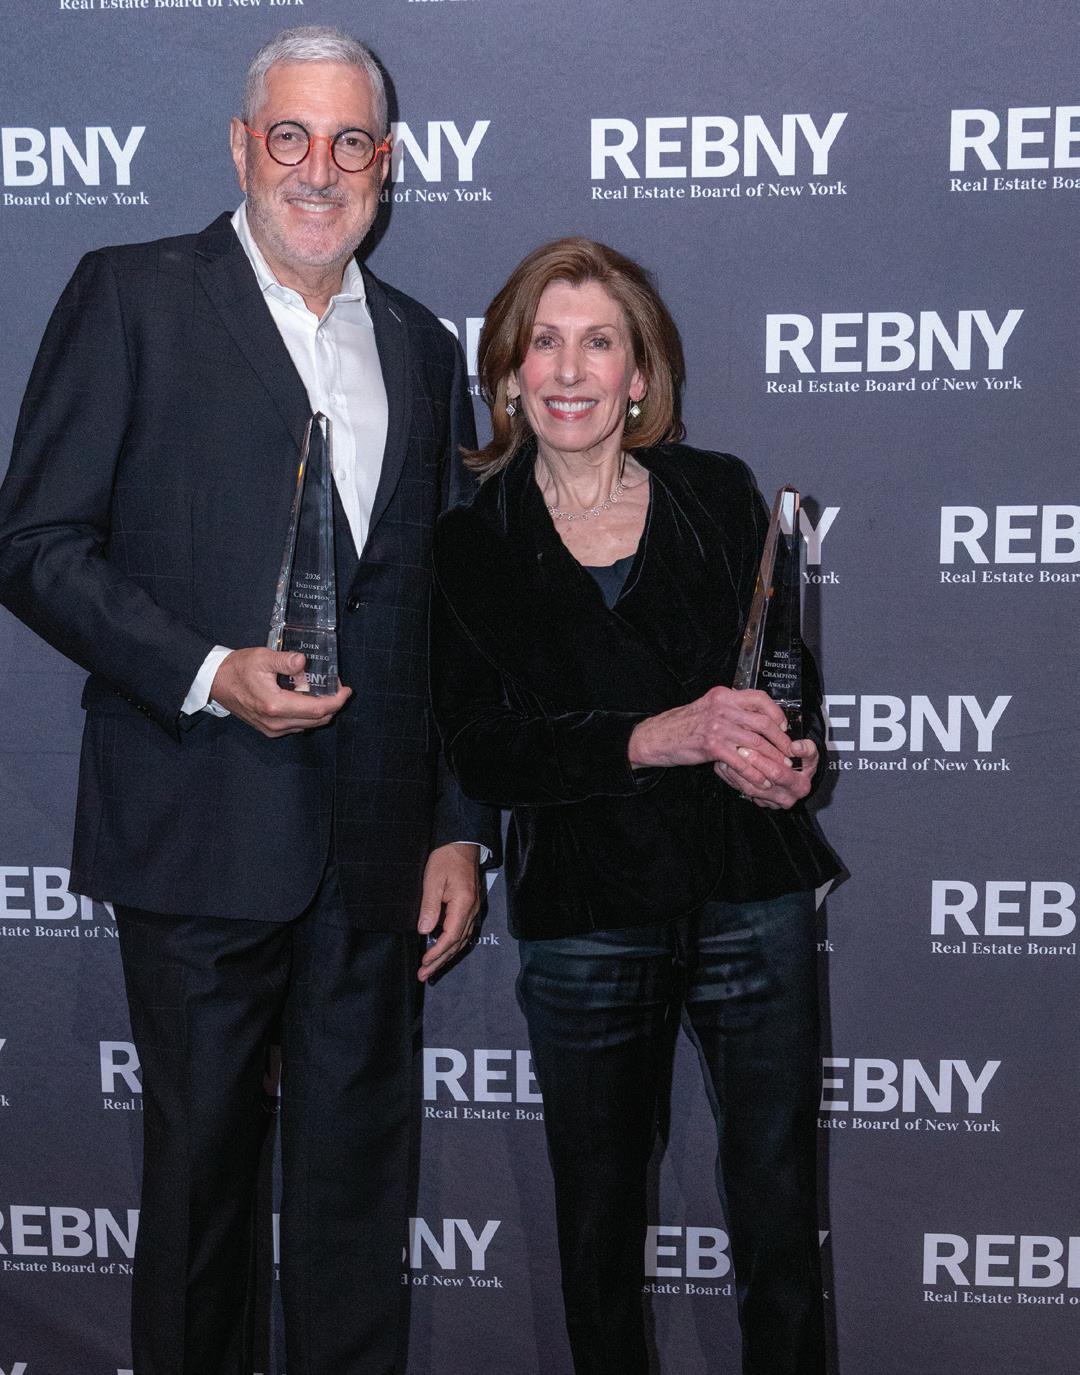
Bess Freedman of Brown Harris Stevens received the Henry Forster Memorial Award for Lifetime Achievement, William Abramson of Buchbinder & Warren was honored with the Eileen Spinola Award for Distinguished Service, and Beth Gittleman of Compass was named Residential Agent of the Year.



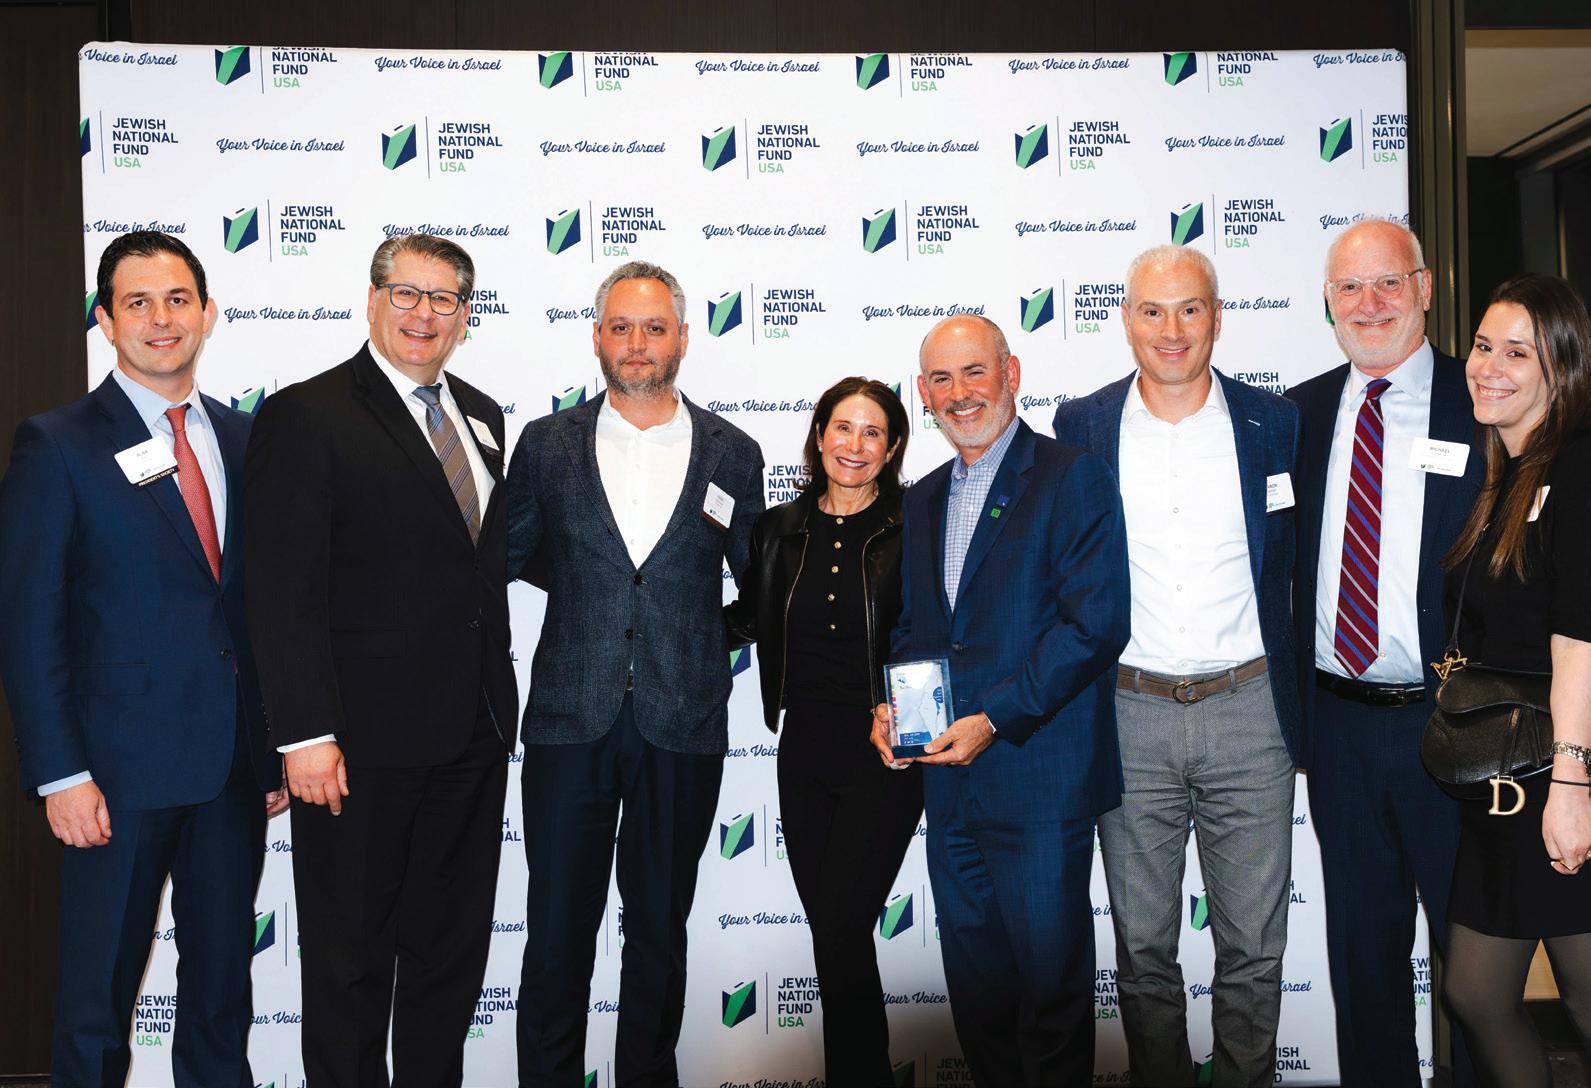
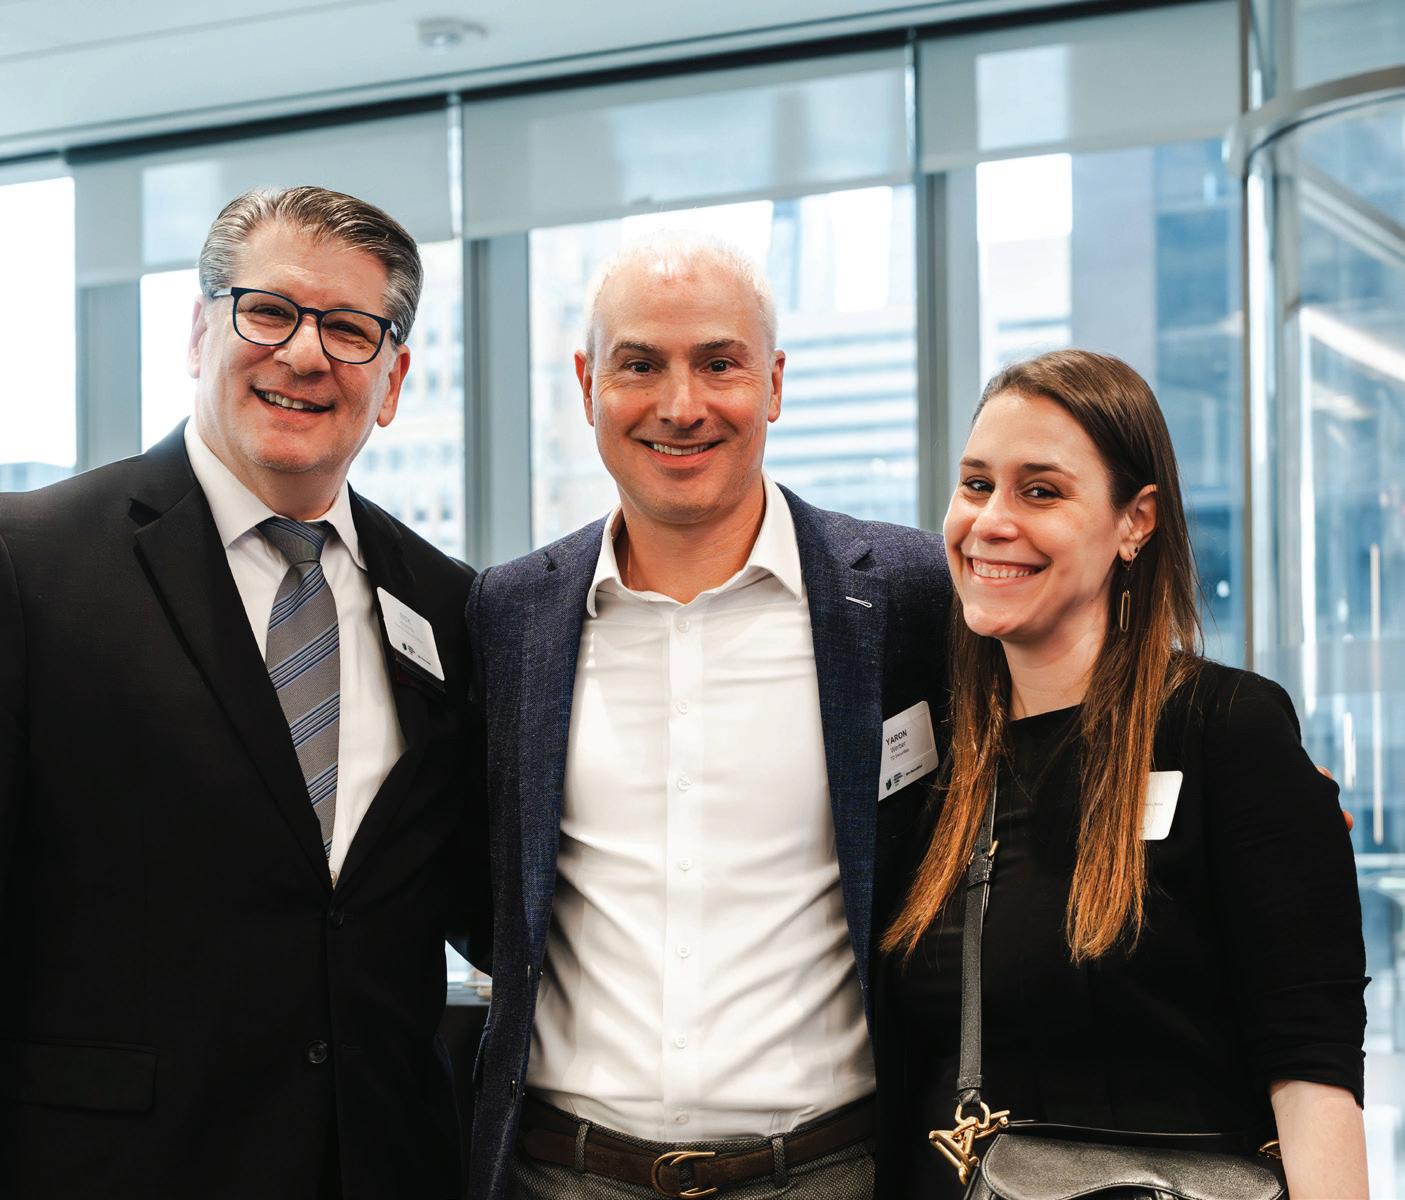
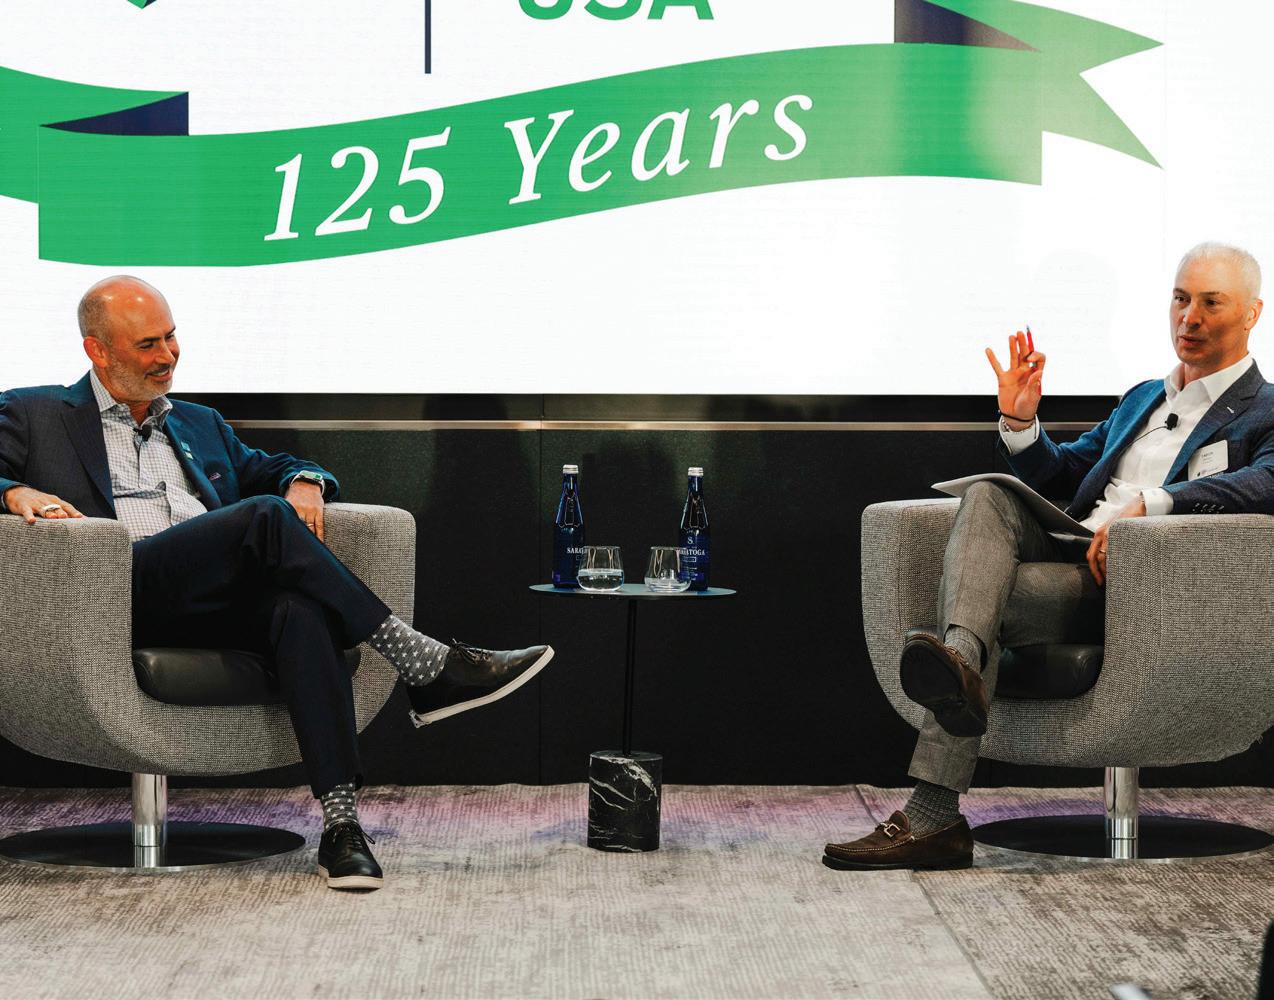
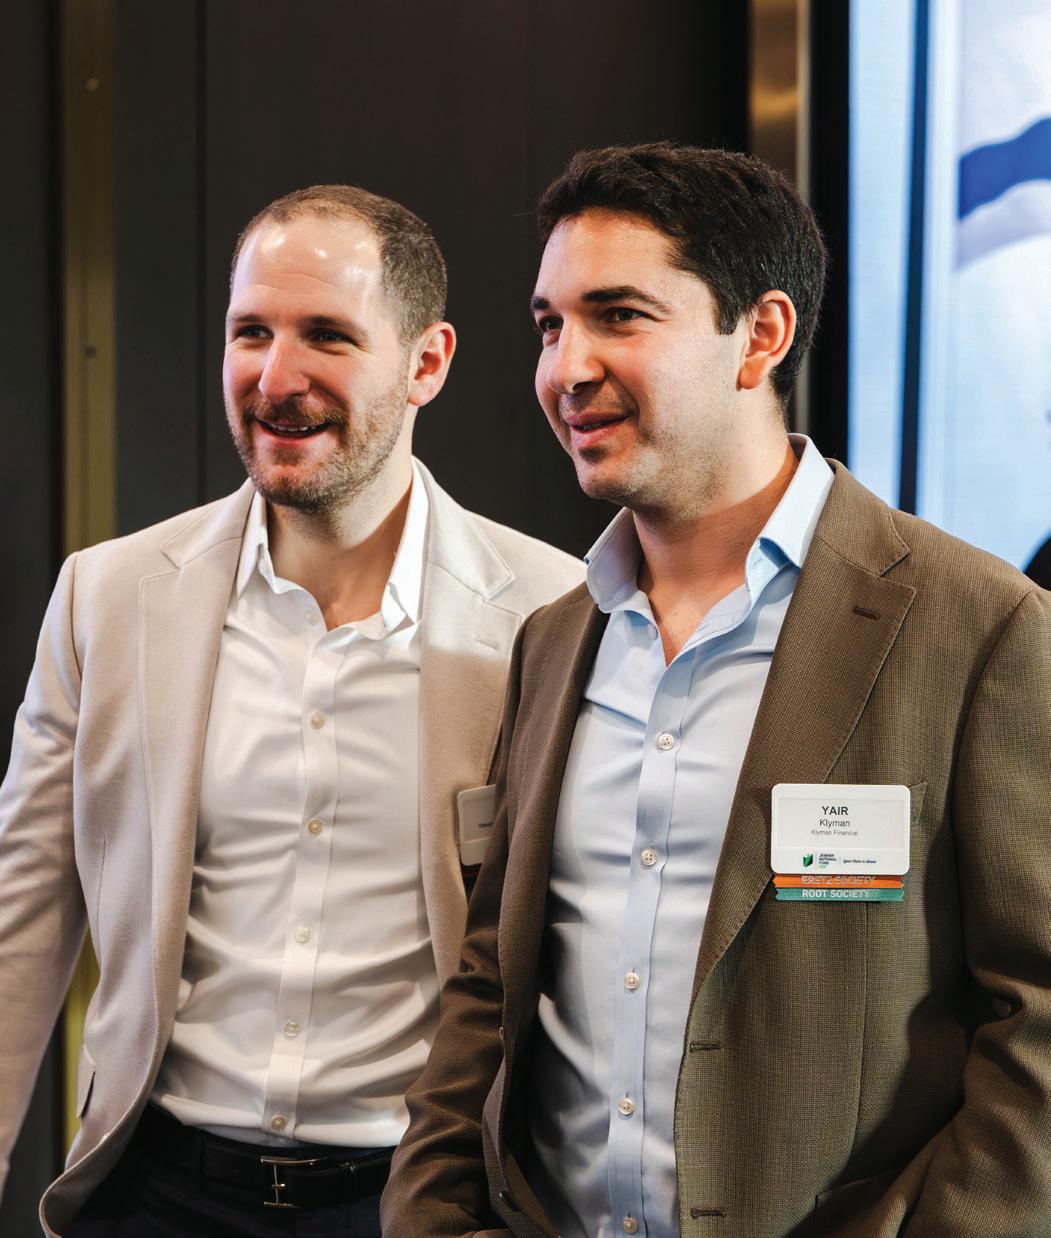
Nearly 100 business professionals in the finance, legal and real estate industries came together at Jewish National Fund-USA’s Finance for Israel and Lawyers for Israel event, “Supporting Israel in the Public Eye,” held at TD. The evening of advocacy and community focused on the importance of maintaining professional integrity while publicly supporting the land and people of Israel, and the collective impact professionals can make in strengthening communities in Israel’s North and South.
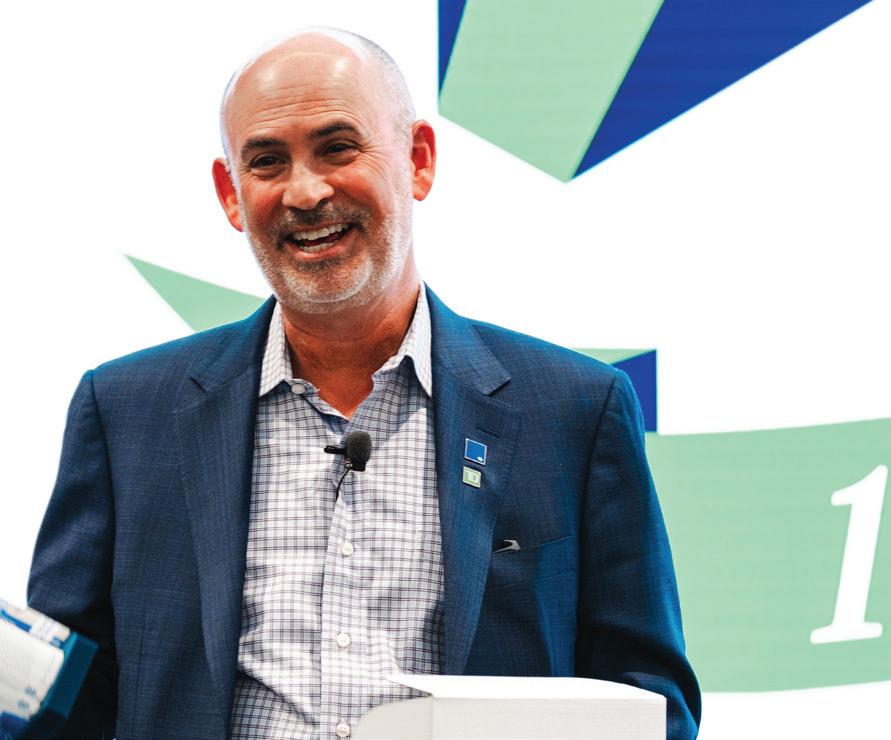
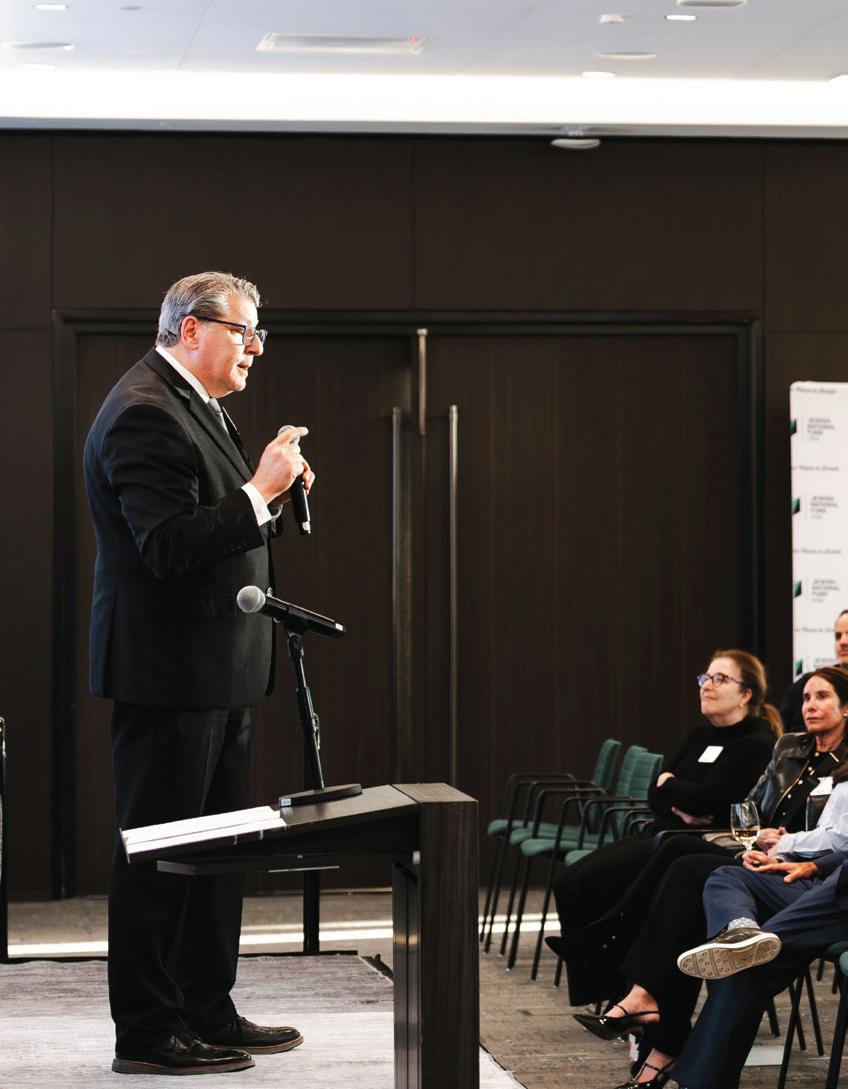
The event’s featured speaker was Jeff Solomon, former chair and CEO of Cowen and current senior advisor and vice chair of TD Bank US, who shared insights drawn from his distinguished career in executive leadership.
Solomon spoke about leading with empathy, making a difference beyond the workplace, and his personal journey combatting antisemitism, anti-Zionism and identitybased hate. He also delighted attendees by singing a song about the importance of giving tzedakah and was later
gifted a Jewish National Fund-USA blue box.
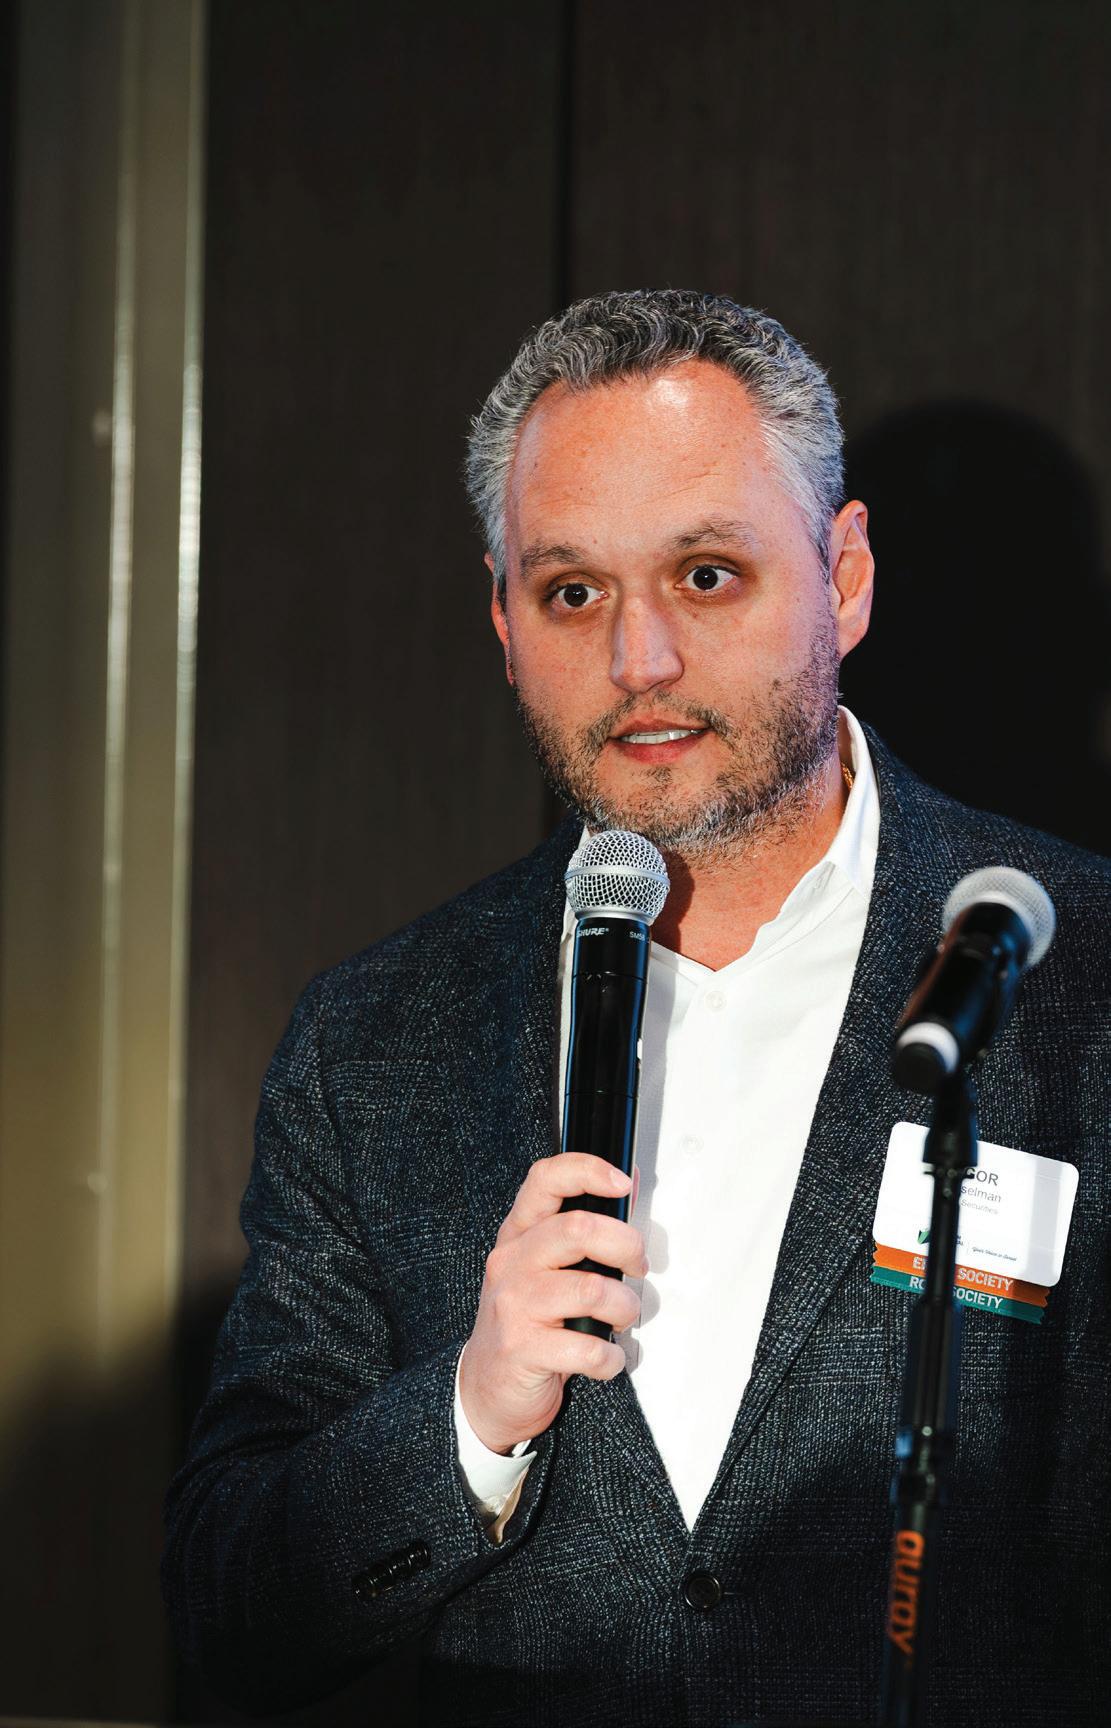
Through an engaging conversation and audience Q&A session, attendees explored how values-driven leadership and advocacy can coexist with professional success. The program was led by members of Jewish National FundUSA’s Finance for Israel community, including Yaron Werber, managing director at TD Cowen; Igor Biselman, managing director at TD Cowen and Alan Lovi, managing director at JP Morgan, who underscored the power of coming together as industry peers to support Israel through philanthropy, education and connection.
Finance for Israel is one of Jewish National FundUSA’s growing affinity groups, which also include Lawyers for Israel, Real Estate Division and others that unite likeminded professionals around shared values and meaningful impact. These groups provide opportunities to expand professional networks while directly supporting the land and people of Israel.
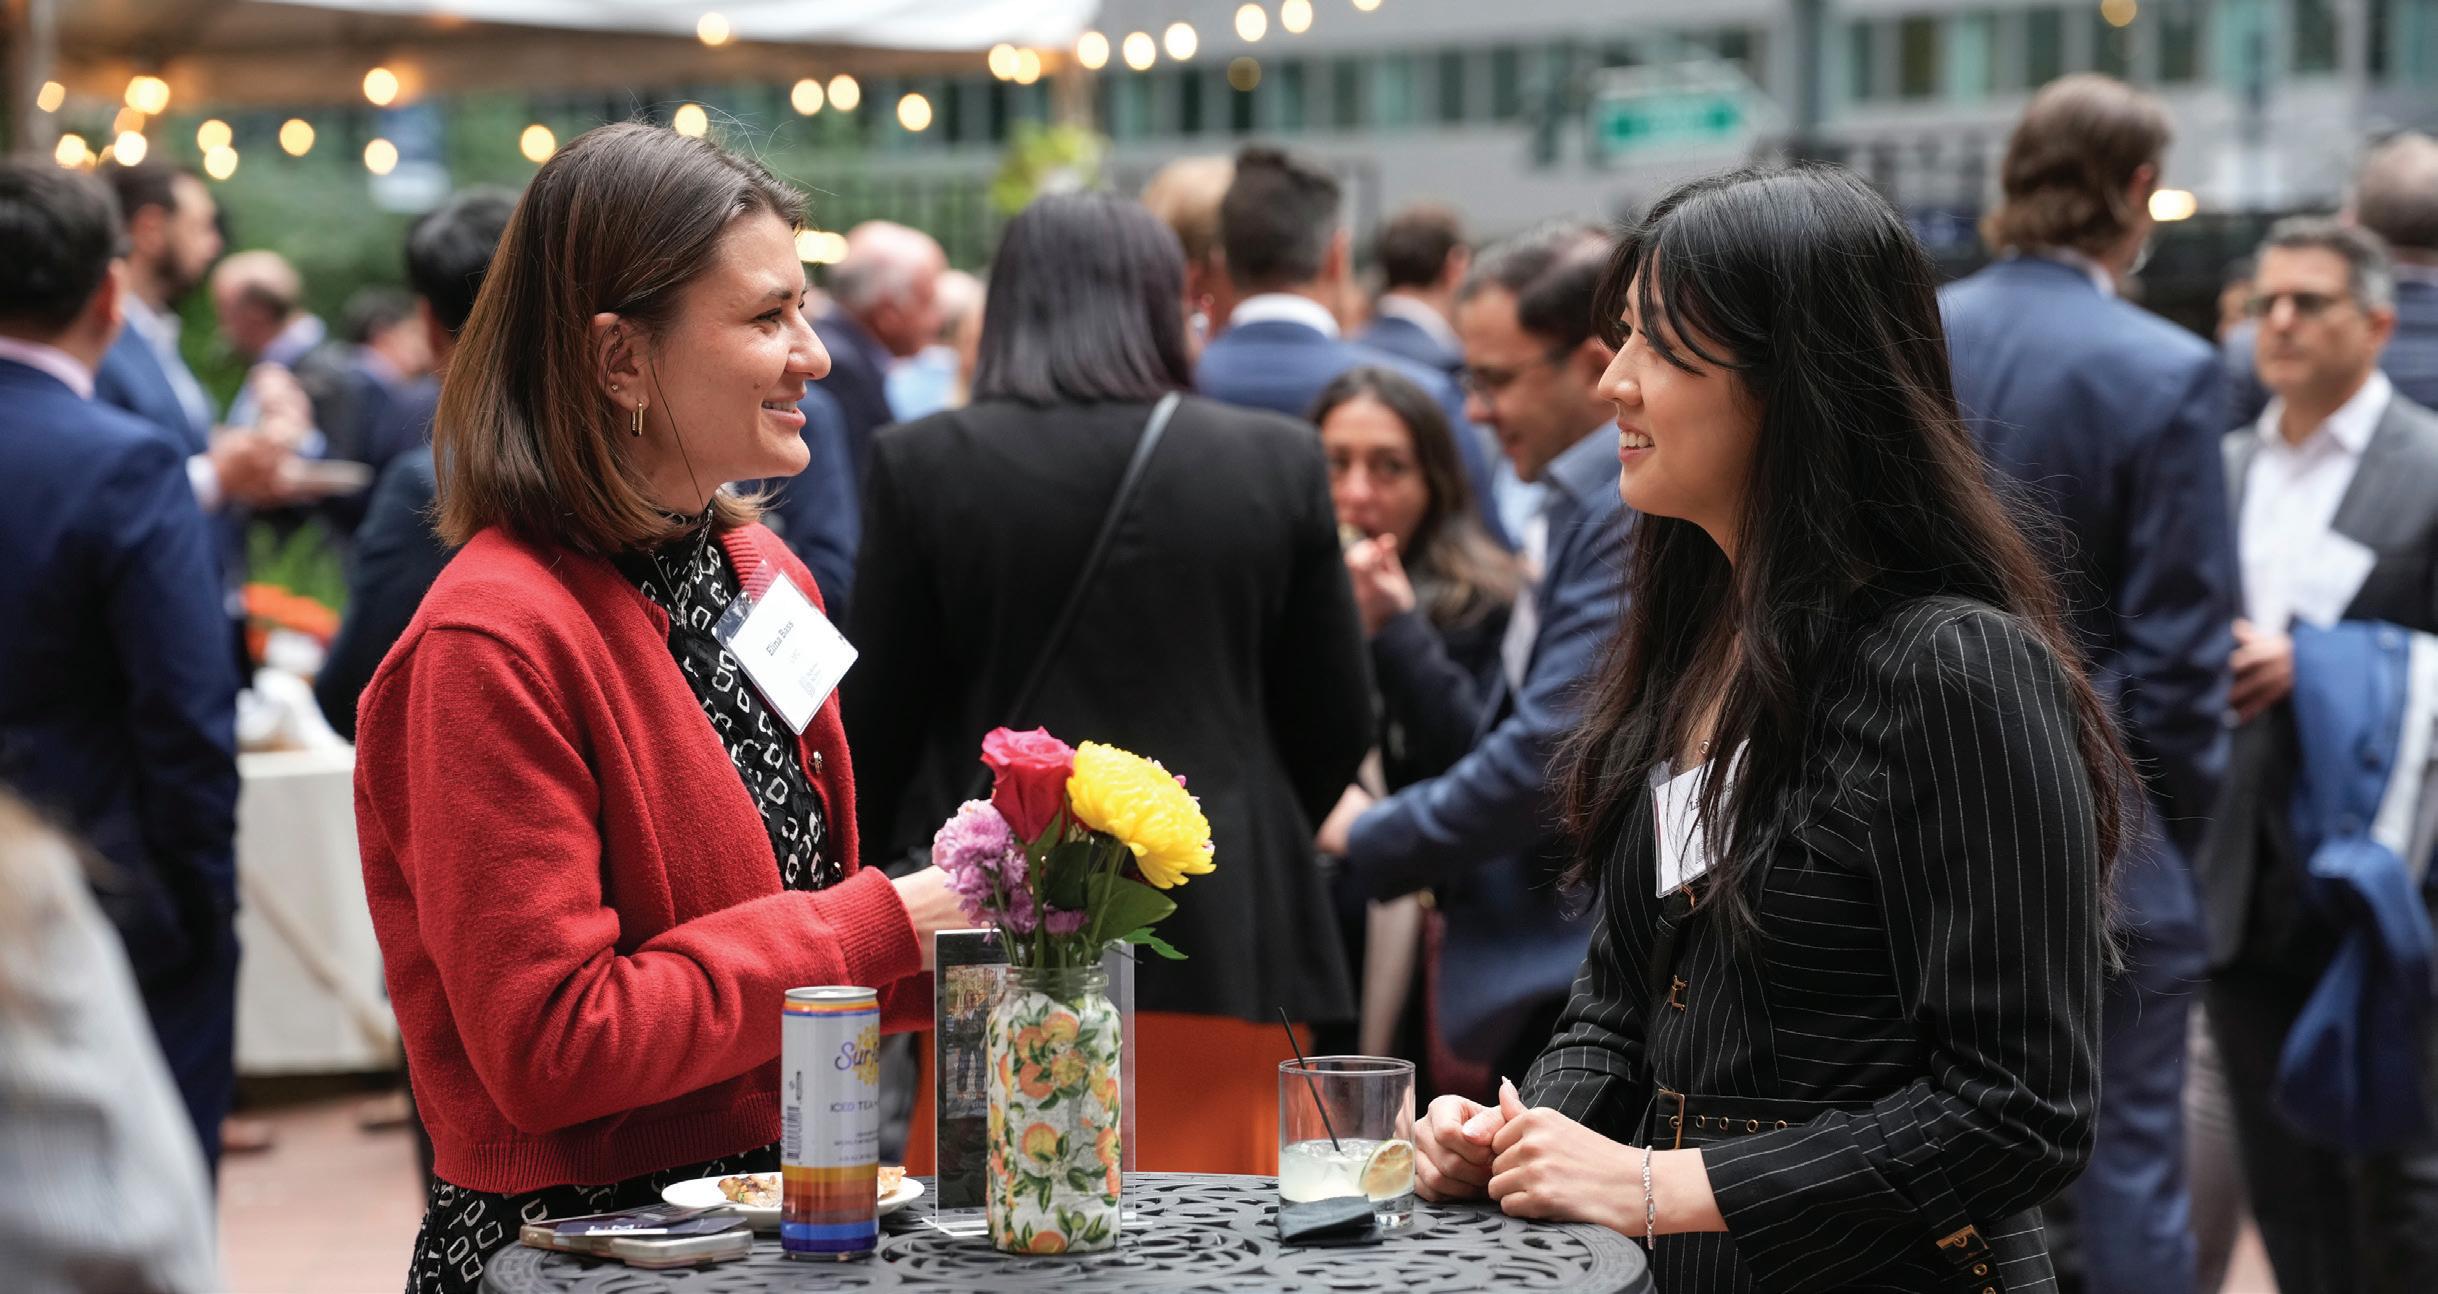
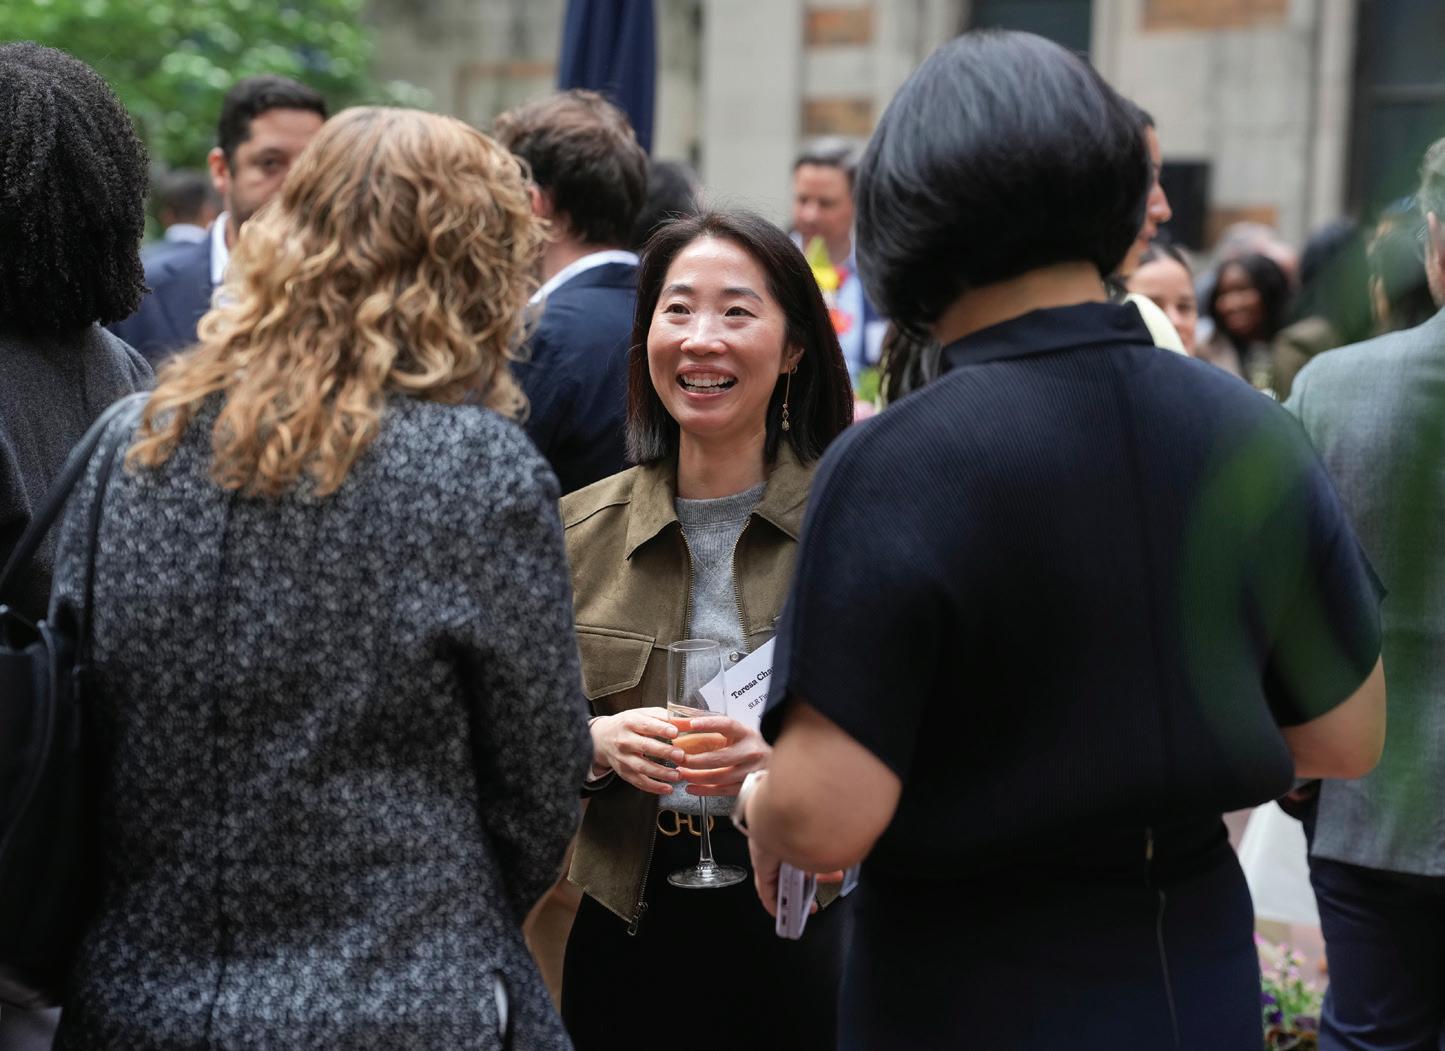
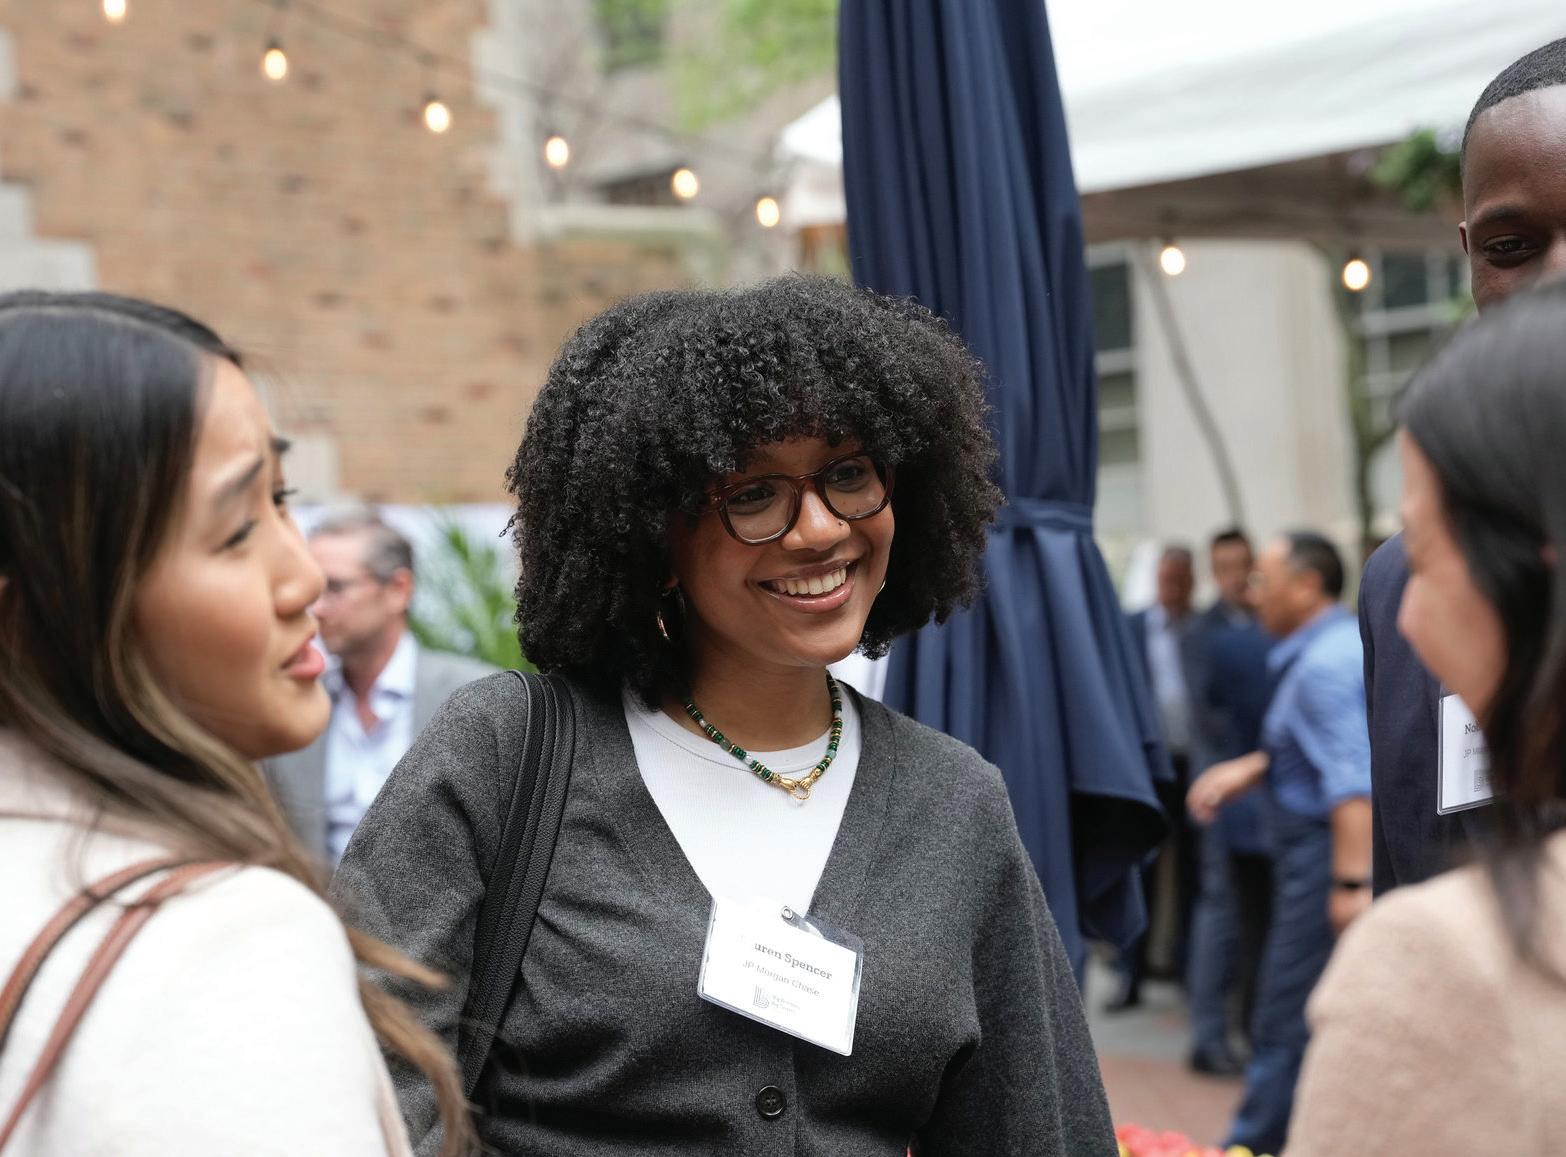
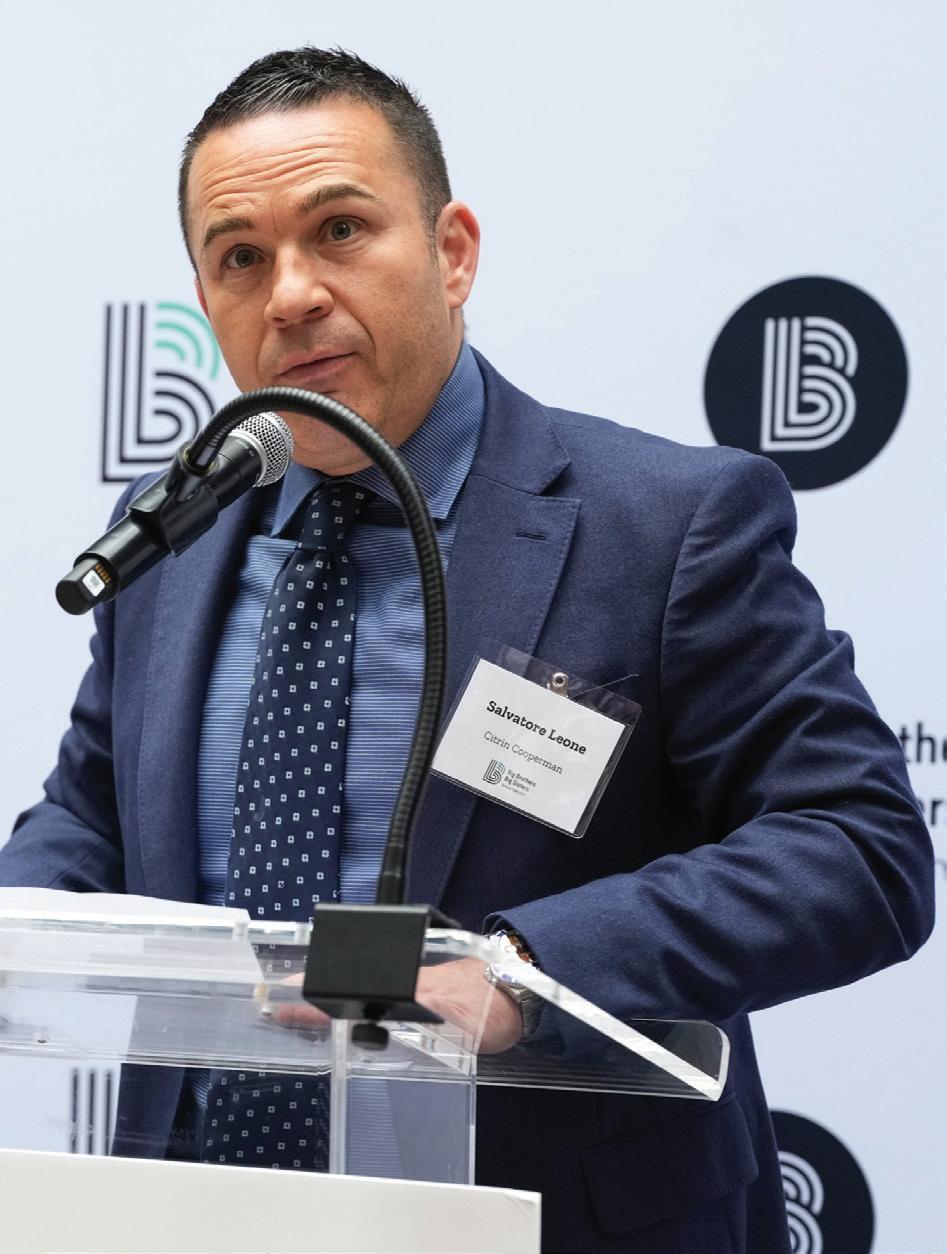
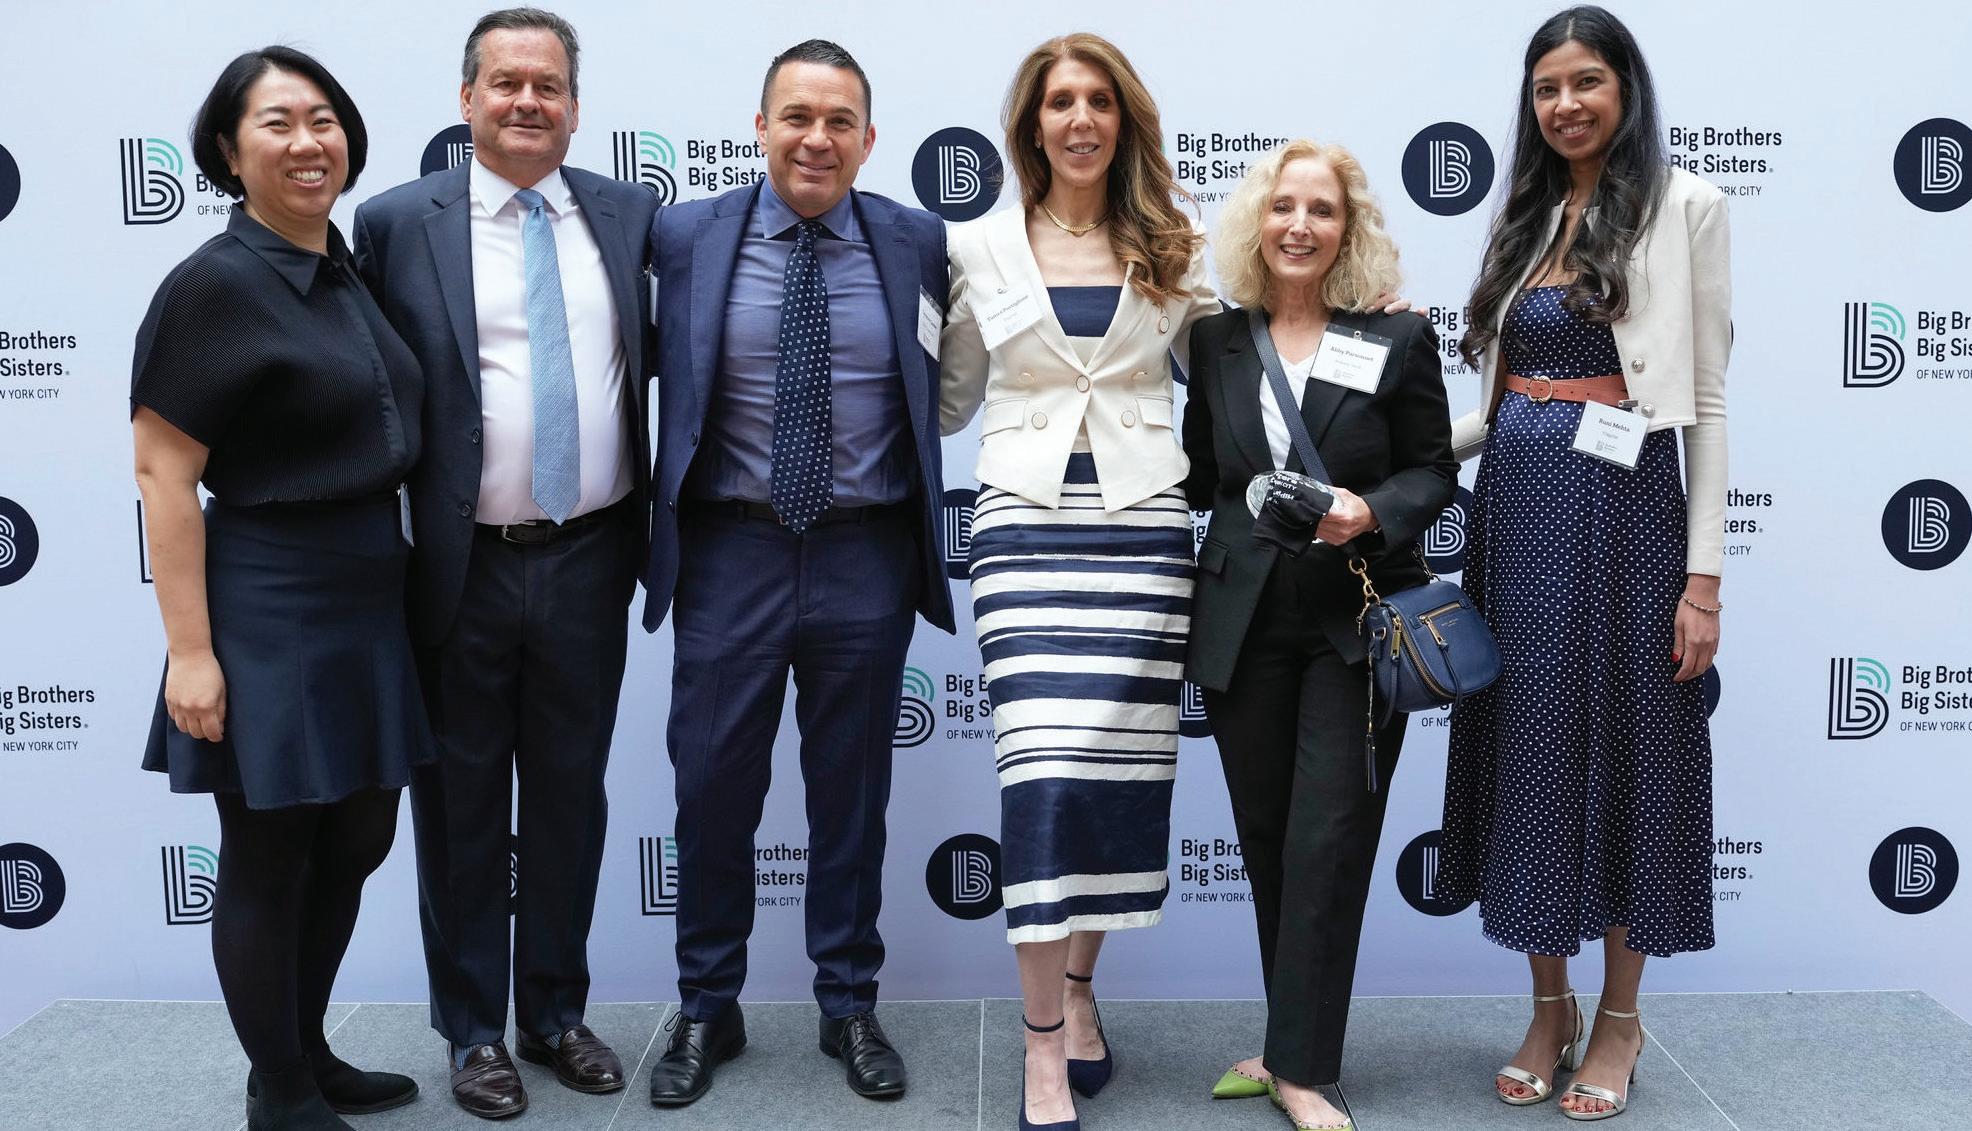
Big Brothers Big Sisters of New York City hosted its 28th annual Accountants and Bankers Reception at Inside Park at St. Bart’s. The event brought together more than 350 professionals from the banking, finance, accounting, legal, fashion and retail industries to celebrate mentorship and invest in the next generation of leaders.
The event raised more than $318,000 — enough to create 79 new mentoring matches between caring adult mentors and young people across New York City. These life-changing relationships help ignite potential, build confidence and empower the next generation of leaders.
The reception was co-chaired by Runi Mehta and Grace Mak, and honored Salvatore Leone of Citrin Cooperman, Tamra Postiglione of Flagstar Bank and Steven Rosenberg of Rosenberg & Fecci Consulting LLC for their commitment to mentorship and
youth opportunity. Their remarks underscored the importance of investing in young people and the lasting impact mentorship can have on future generations.
Special thanks were extended to Platinum Sponsor Flagstar Bank and to Legacy of Excellence Award recipient Abby Parsonnet, whose leadership and dedication have been instrumental to the success of the Accountants and Bankers Committee and the event over the years.
The organization also expressed its sincere appreciation to its sponsors, event committee members and all who contributed to such a meaningful evening. Their support continues to create a lasting impact for young people throughout New York City and helps shape the future of local communities.
Guests were encouraged to mark their calendars for the Annual Golf Outing on Sept. 28, 2026.
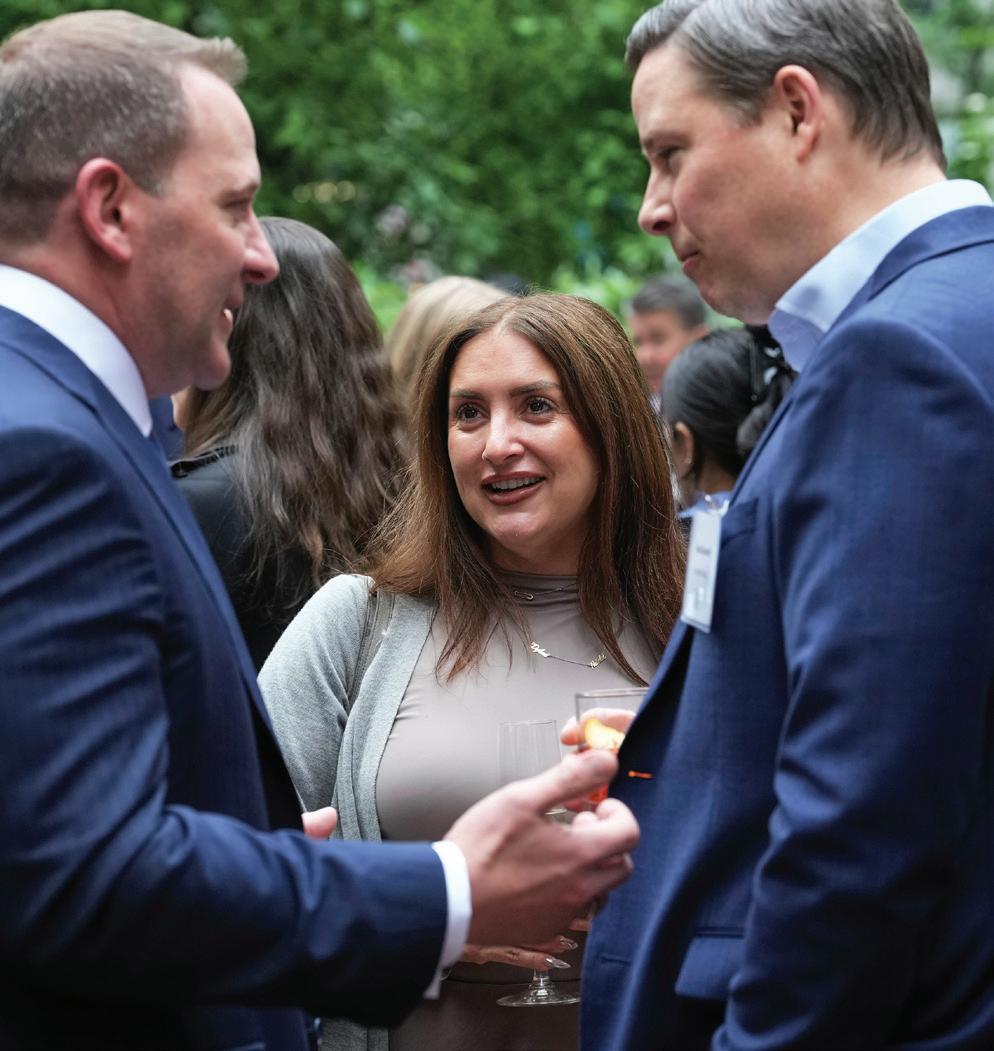



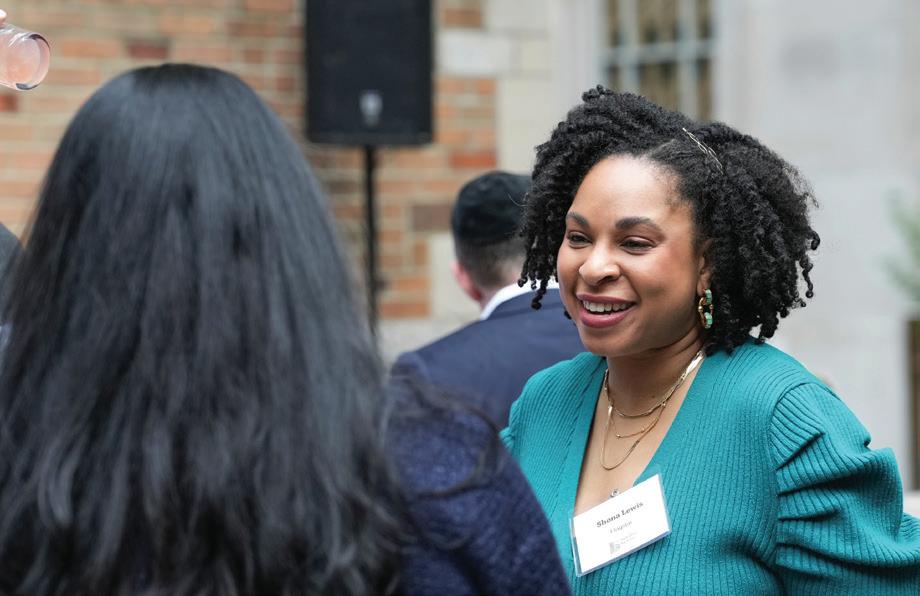
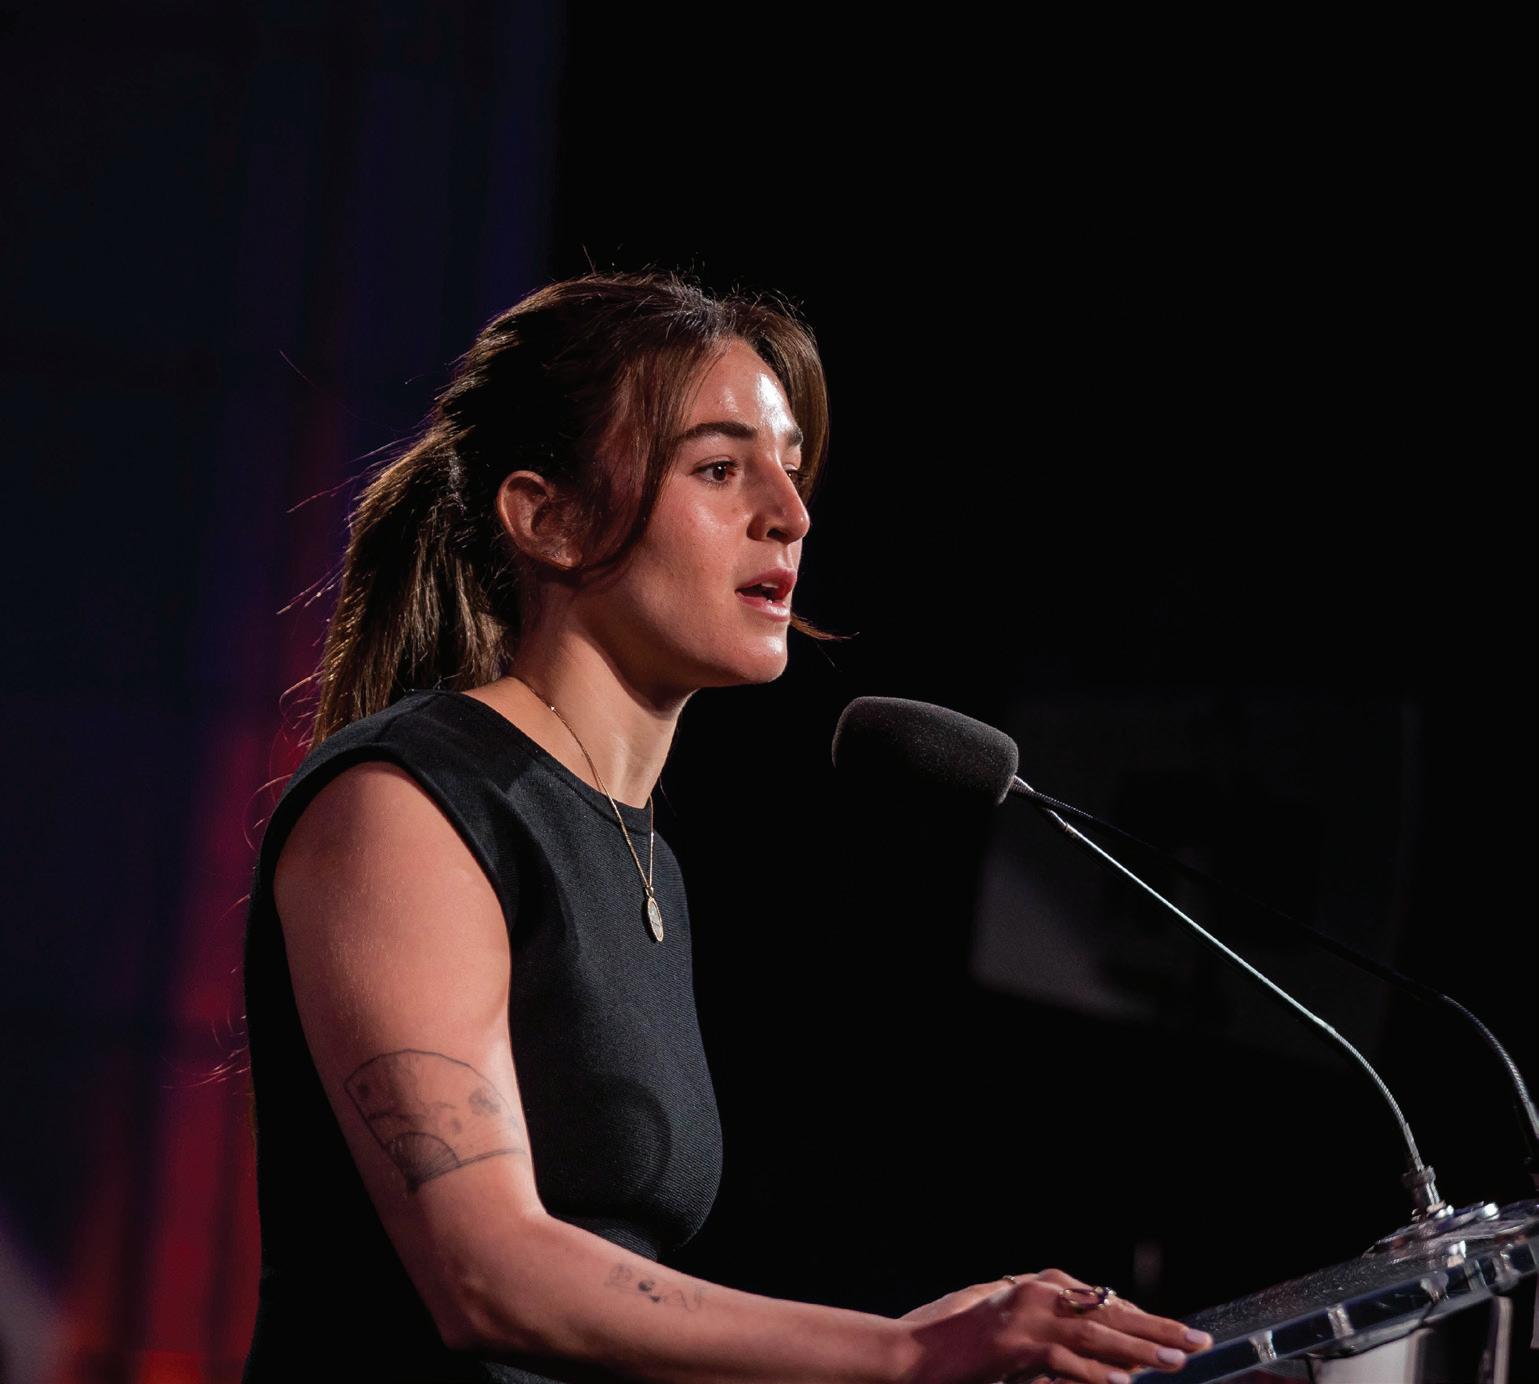
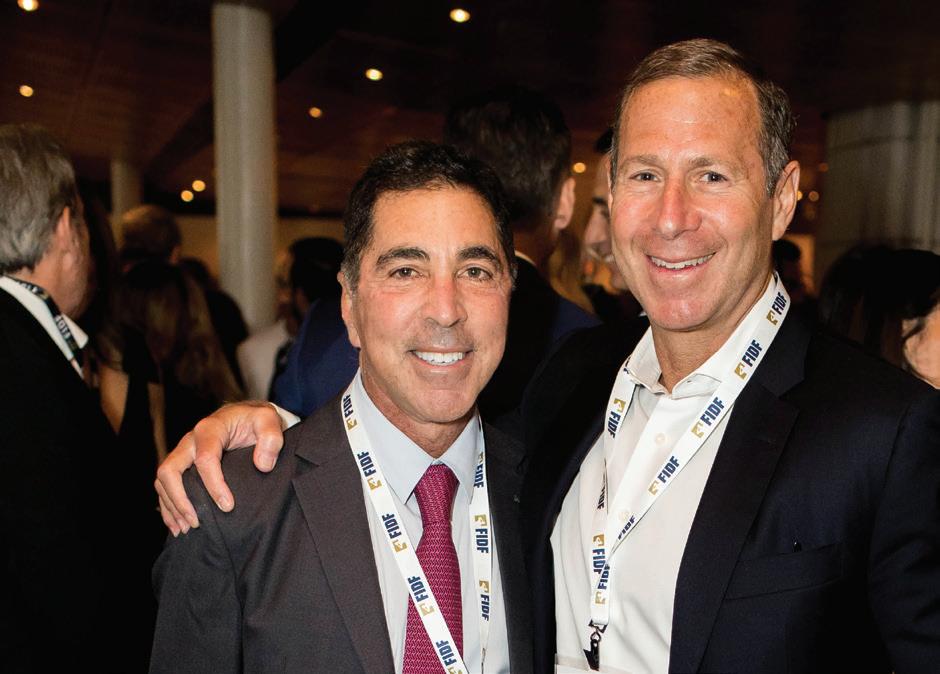
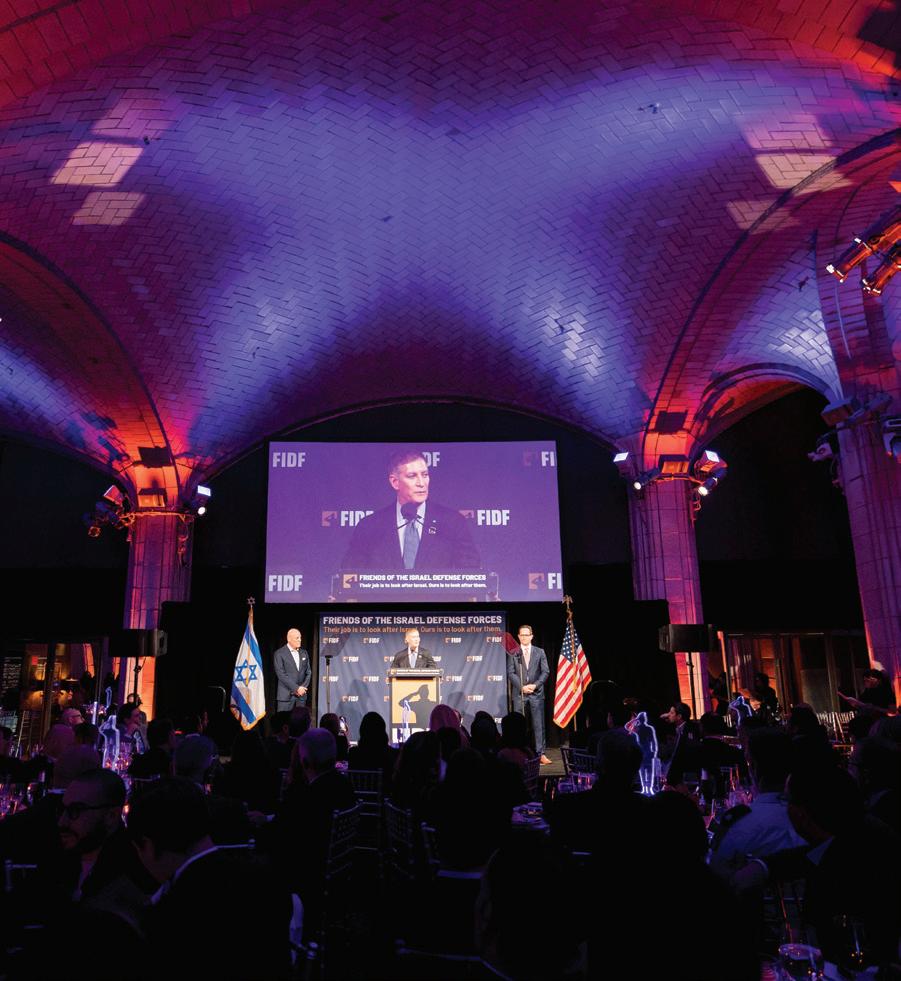
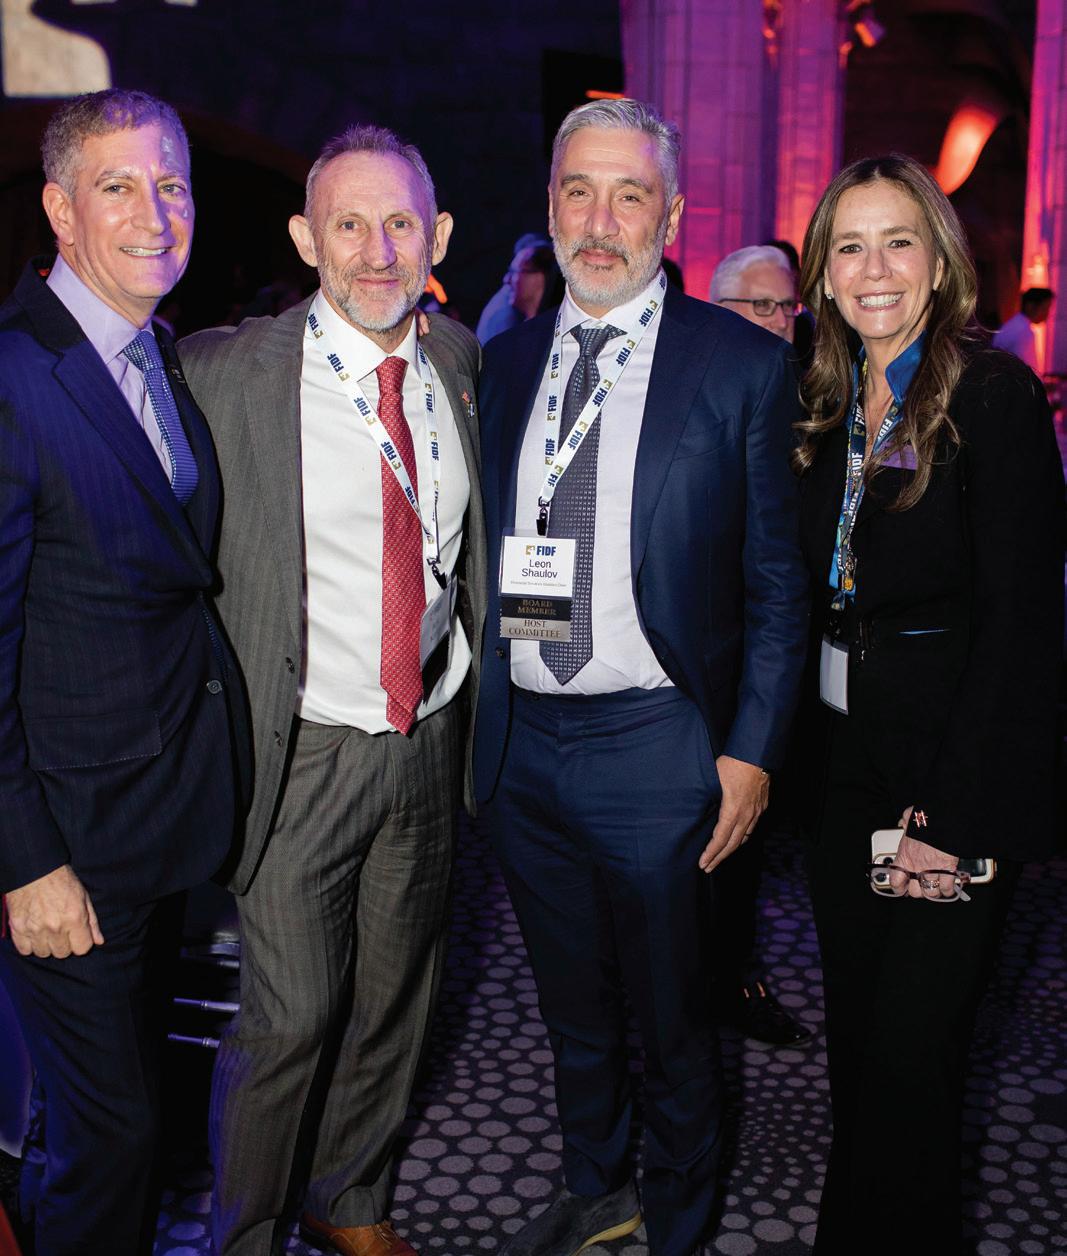
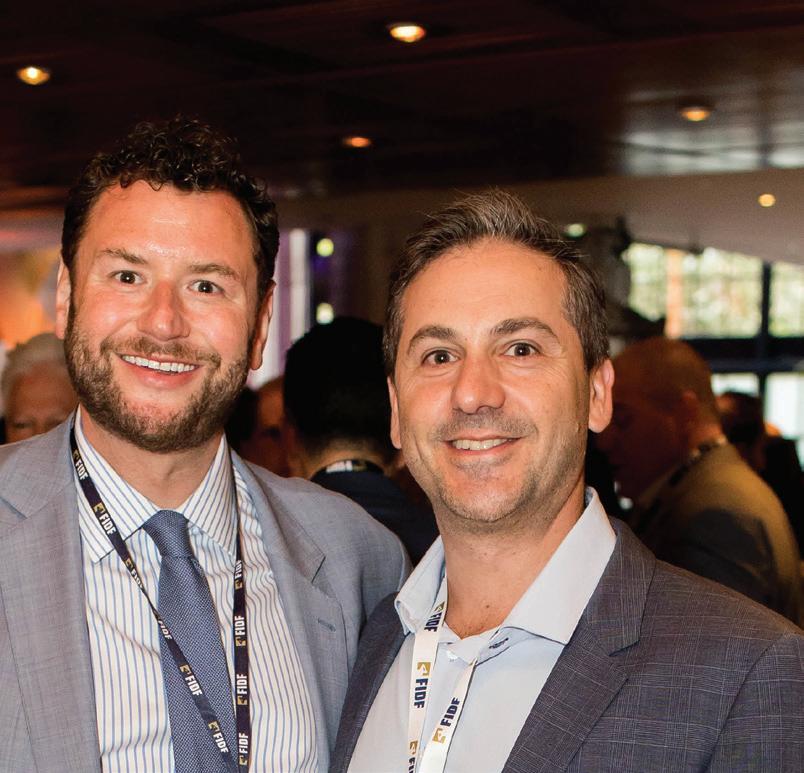
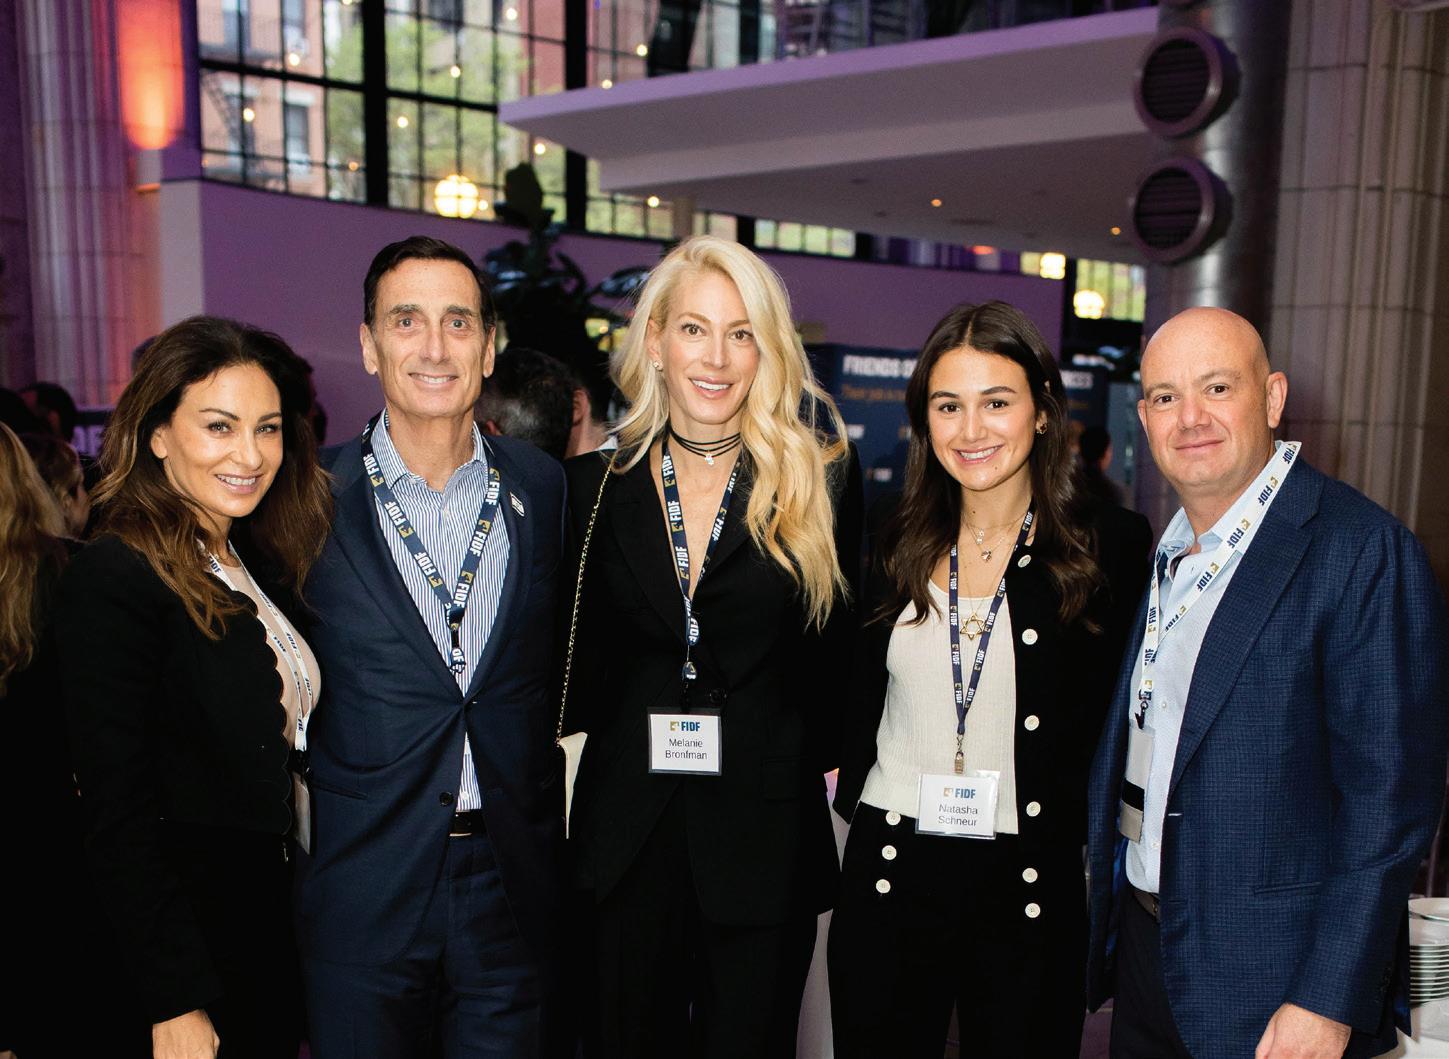
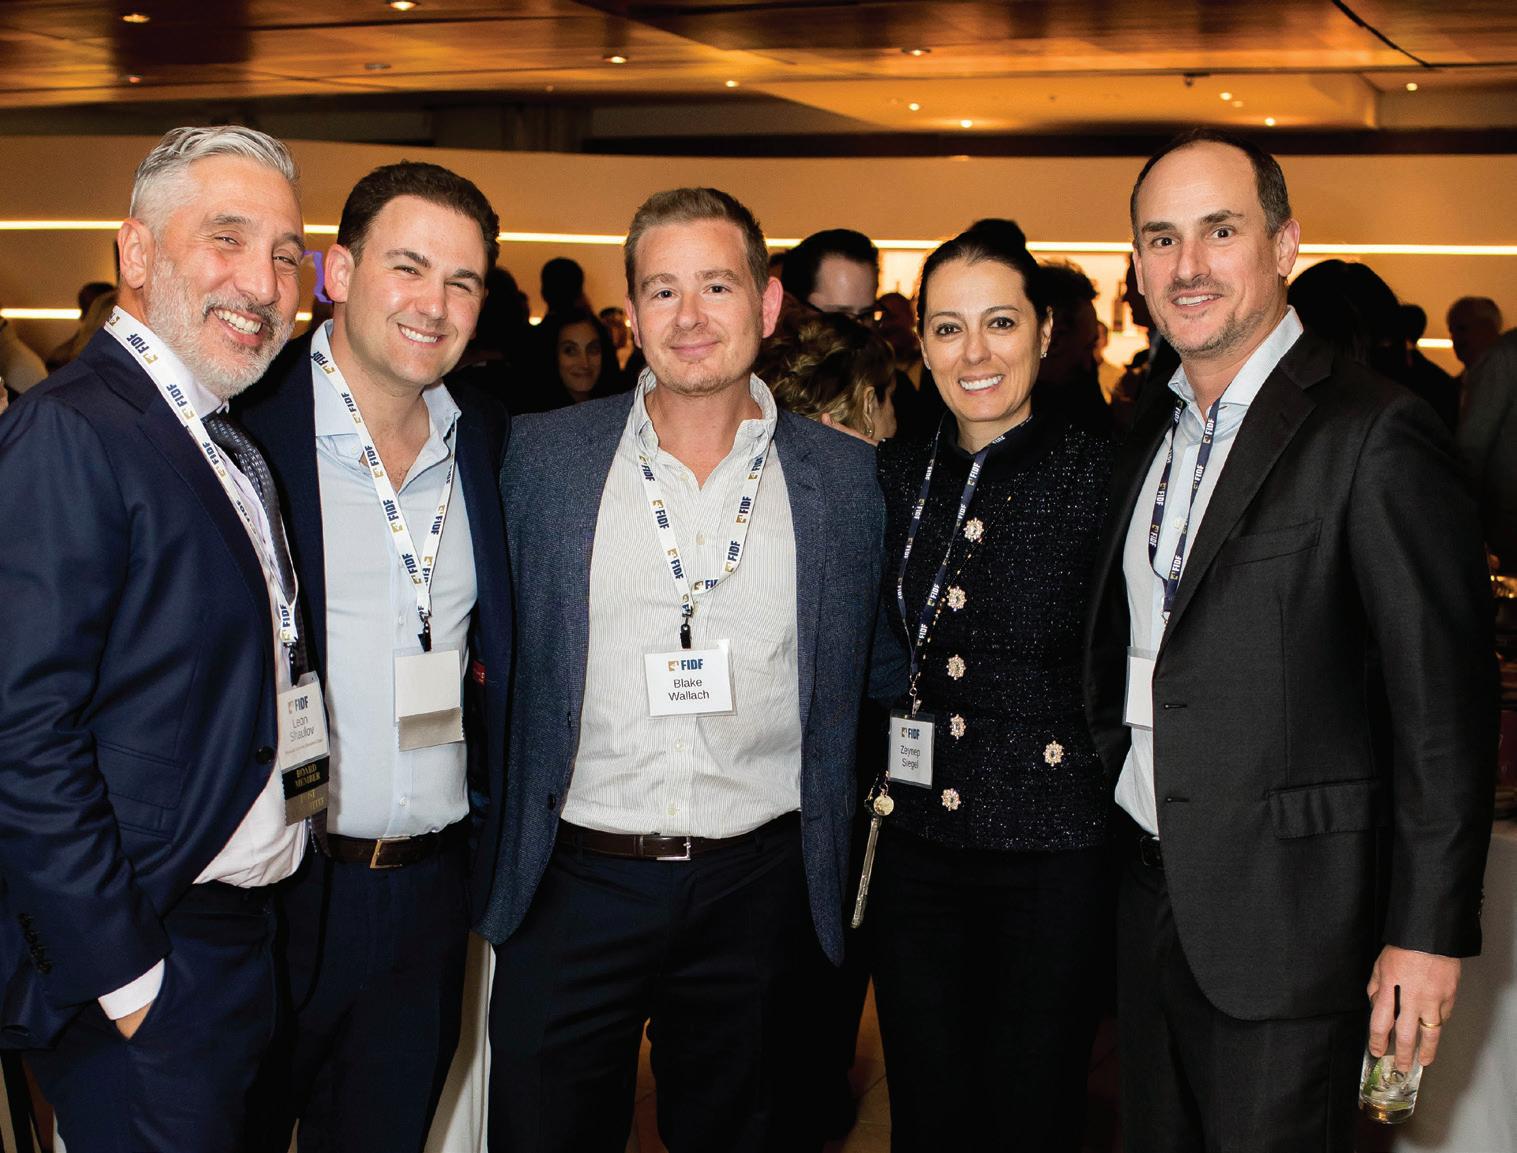
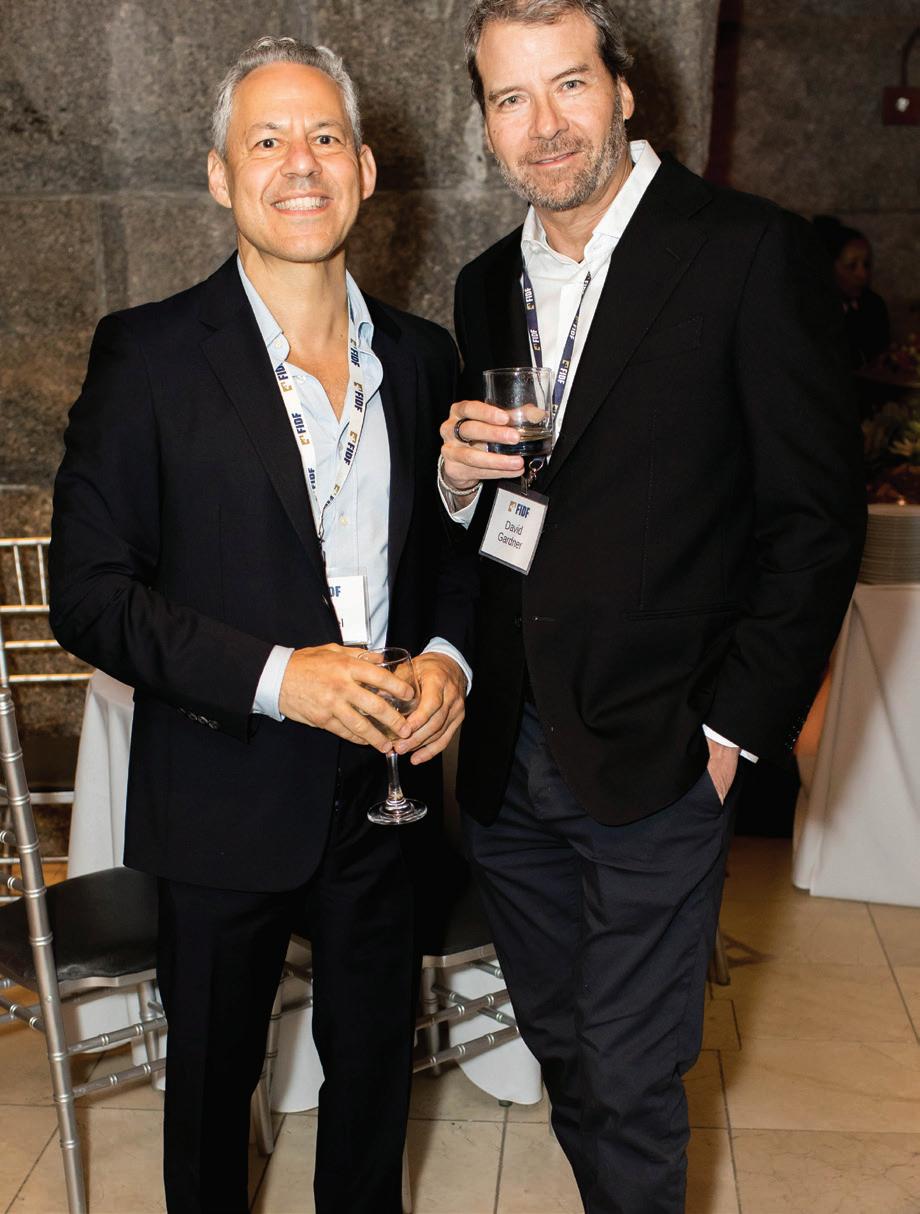
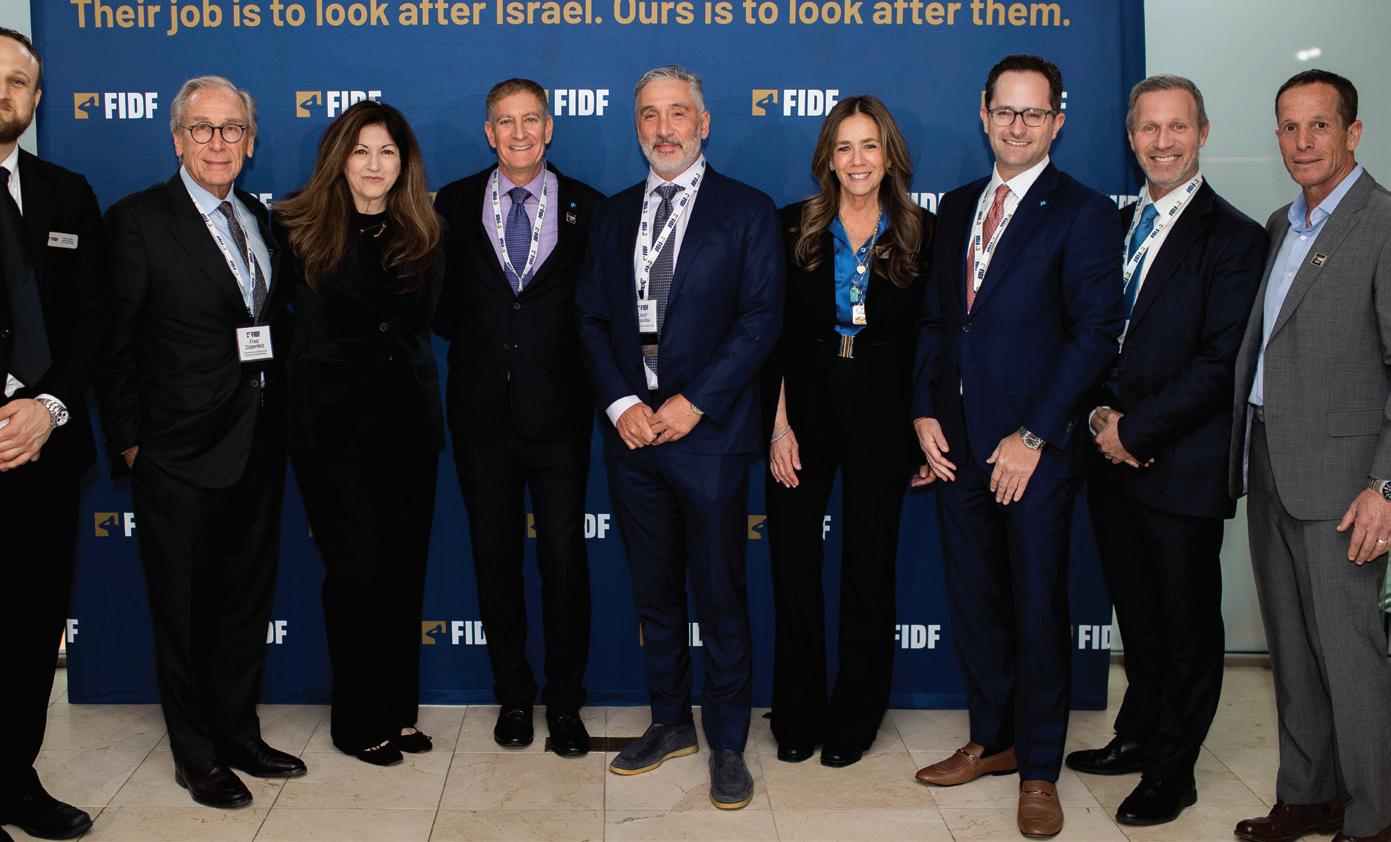
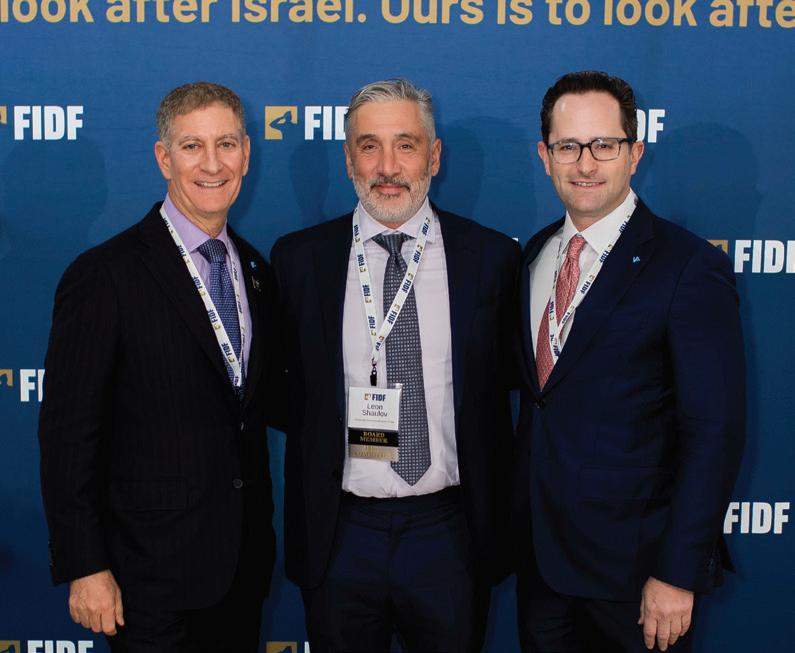
The Annual Real Estate & Financial Services Dinner held by the Friends of the Israel Defense Forces (FIDF) sold out, bringing together 500+ industry leaders. The evening united leaders across real estate and financial services in support of the men and women of the IDF.
At a time when the needs of Israel’s soldiers and their families are greater than ever, this level of commitment is not just
meaningful. It’s critical, the organization said.
FIDF provides essential support, including rehabilitation for wounded veterans, mental health services, care for bereaved families, and resources for reservists who have left their homes and careers to serve.
The organization send thanks to the Host Committee, partners and all who made the evening such a success.

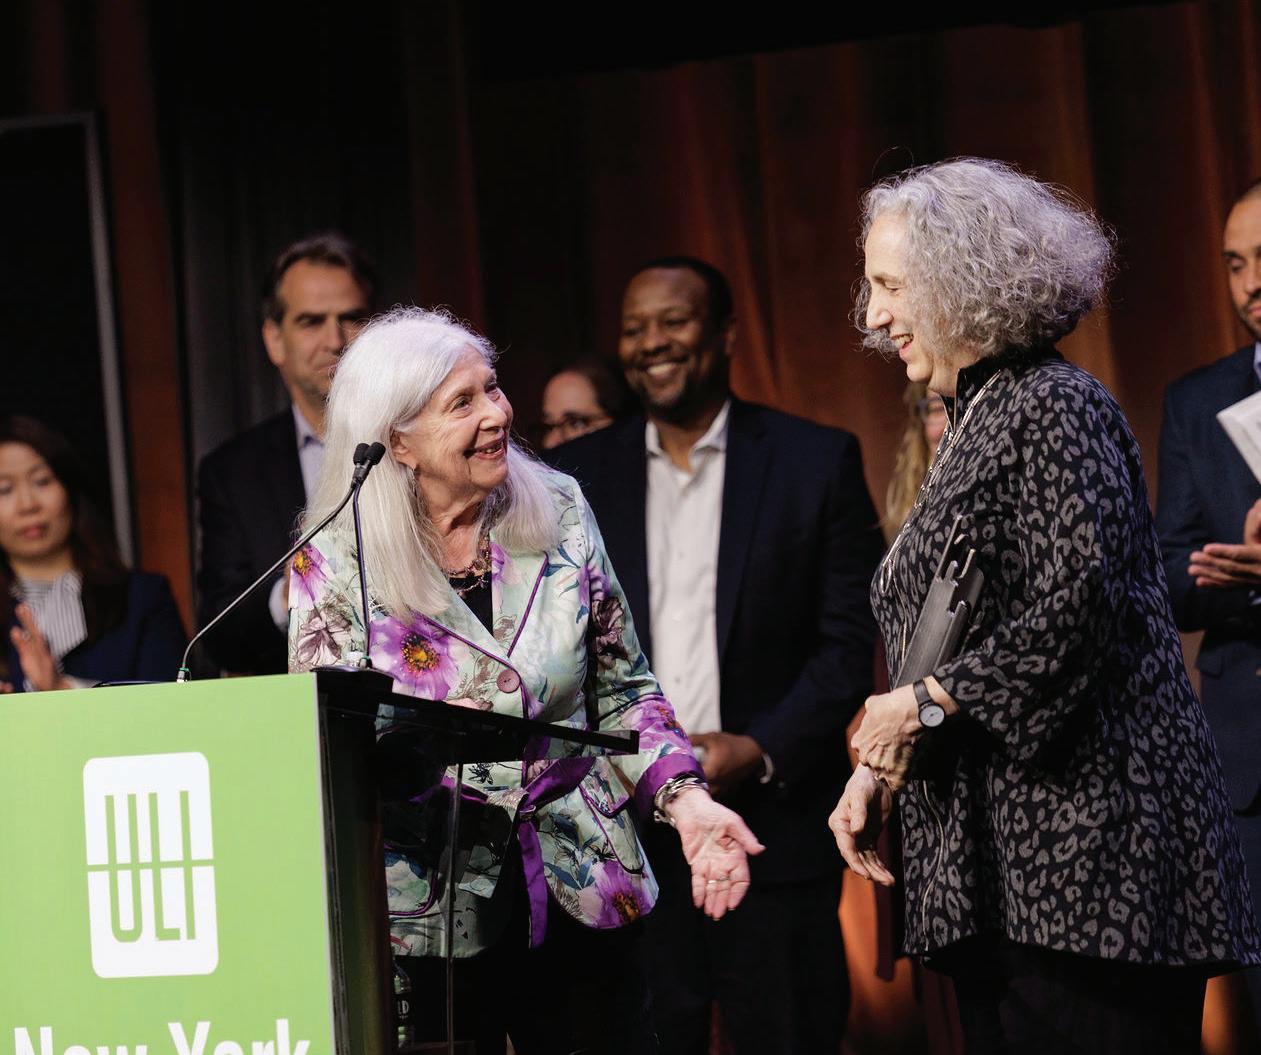
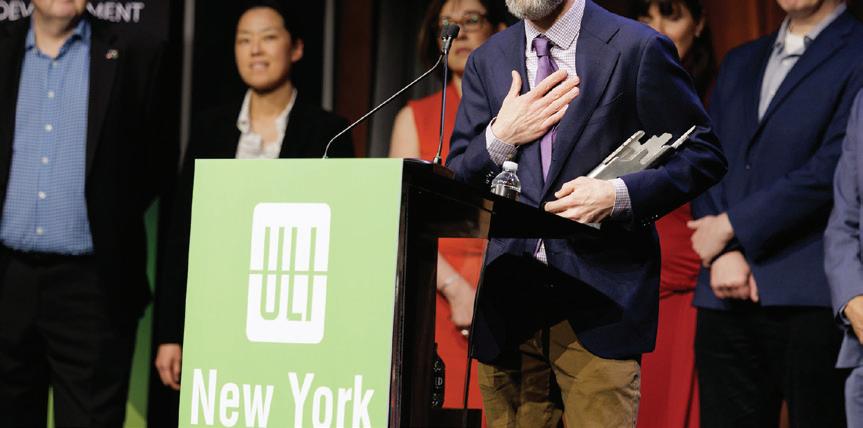
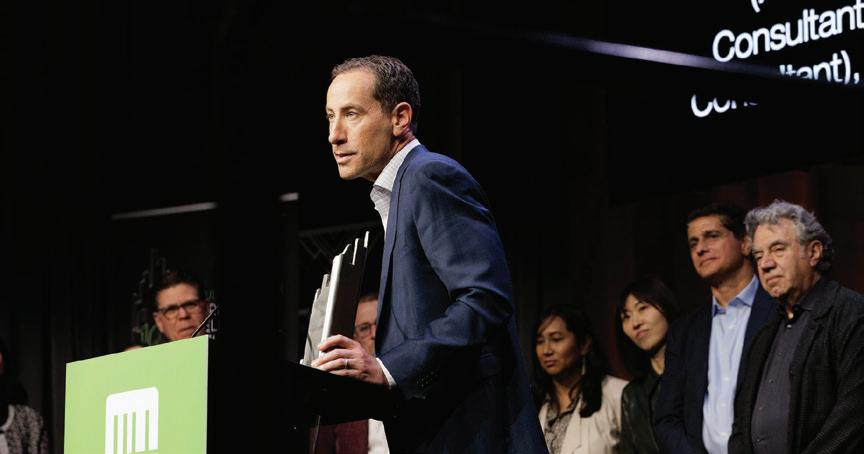
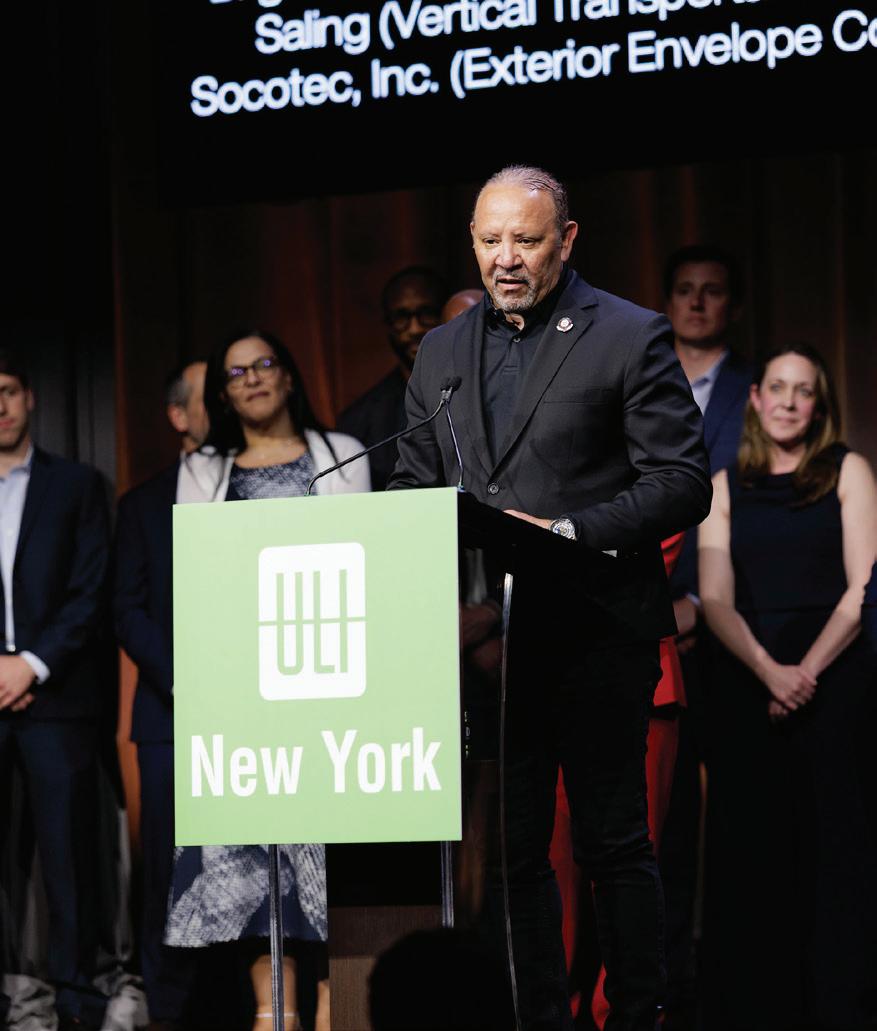
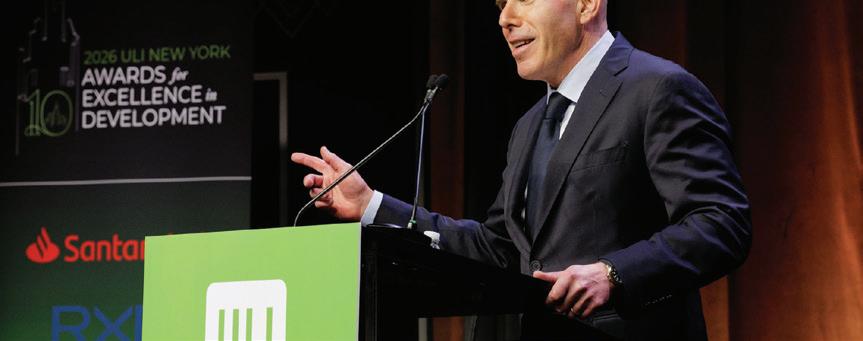
The Urban Land Institute New York (ULI New York) celebrated the 10th annual Awards for Excellence in Development at the Ziegfeld Ballroom, presenting Scott Rechler with the 2026 Visionary Leadership in Land Use Award in recognition of his work as a transformative leader in New York City real estate, renowned for leveraging public-private partnerships to advance large-scale development.
The evening also recognized seven category-winning projects across New York State, selected from a competitive field of finalists representing transformative work across housing, mixed-use development, adaptive reuse, office, infrastructure and communityfocused initiatives.
“We are proud to honor Scott Rechler and this year’s seven outstanding development projects, each of which demonstrates how thoughtful design, innovation, and community collaboration can transform New York’s built environment,” said Helen Hwang, current ULI New York chair and senior executive managing director at Meridian Investment Sales. “Scott’s visionary leadership and longstanding commitment to partnership-driven development, alongside the achievements of this year’s project winners, reflect how bold ideas and strong collaboration can create more resilient, inclusive and forward-looking communities.”
As chairman and CEO of RXR, Rechler has played a central role in shaping major urban projects, including the redevelopment of Terminal 6 at JFK Airport, the downtown New Rochelle master plan, and a 1,100-acre mixed-use project in Raleigh, N.C.
Through these efforts, Rechler has brought together government agencies, local communities and private stakeholders to create projects that balance economic growth with public benefit. His
collaborative, strategic approach to complex development challenges has made him a trusted figure in both civic and real estate circles, demonstrating how thoughtful partnerships can transform neighborhoods and set a model for sustainable urban growth.
both

The 2026 Awards for Excellence in Development Winners were:
• Fulton Community Reentry Center (Excellence in Adaptive Reuse), New York City — Developer: Osborne Association in partnership with NYC HPD and HDC.
• SoMA at 25 Water Street (Excellence in Market-Rate Housing Development), New York City — Developer: GFP Real Estate and Metro Loft Developers.
• One Madison Avenue (Excellence in Office Development), New York City
— Developer: SL Green Realty Corp. and Hines.
• The Eliza + Inwood Library –Joseph and Sheila Rosenblatt Building (Excellence in Affordable Housing Development), New York City — Developer: Ranger Properties; Housing Workshop; Community League of the Heights; The Children’s Village; Alembic Community Development with New York City partners and the New York Public Library
Housing Development), New Ranger Properties; Housing Workshop; Community League of the Heights; The Children’s Village; Alembic Development Delta Air Lines and the Port Authority of New York
• Delta’s Terminal C at LaGuardia Airport (Excellence in Civic & Institutional Development), Queens, N.Y. — Developer: Delta Air Lines and the Port Authority of New York and New Jersey
Urban League Empowerment Center (Excellence in Mixed-Use Development), New York City —
• Urban League Empowerment Center (Excellence in Mixed-Use Development), New York City — Developer: BRP Companies; L+M Development Partners; The Prusik Group; Taconic Partners with public partners.
• East Midtown Greenway (Excellence in Urban Open Space), New York City — Developer: NYCEDC; owned by NYC Parks

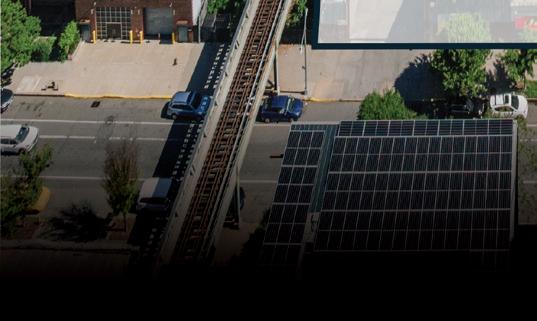
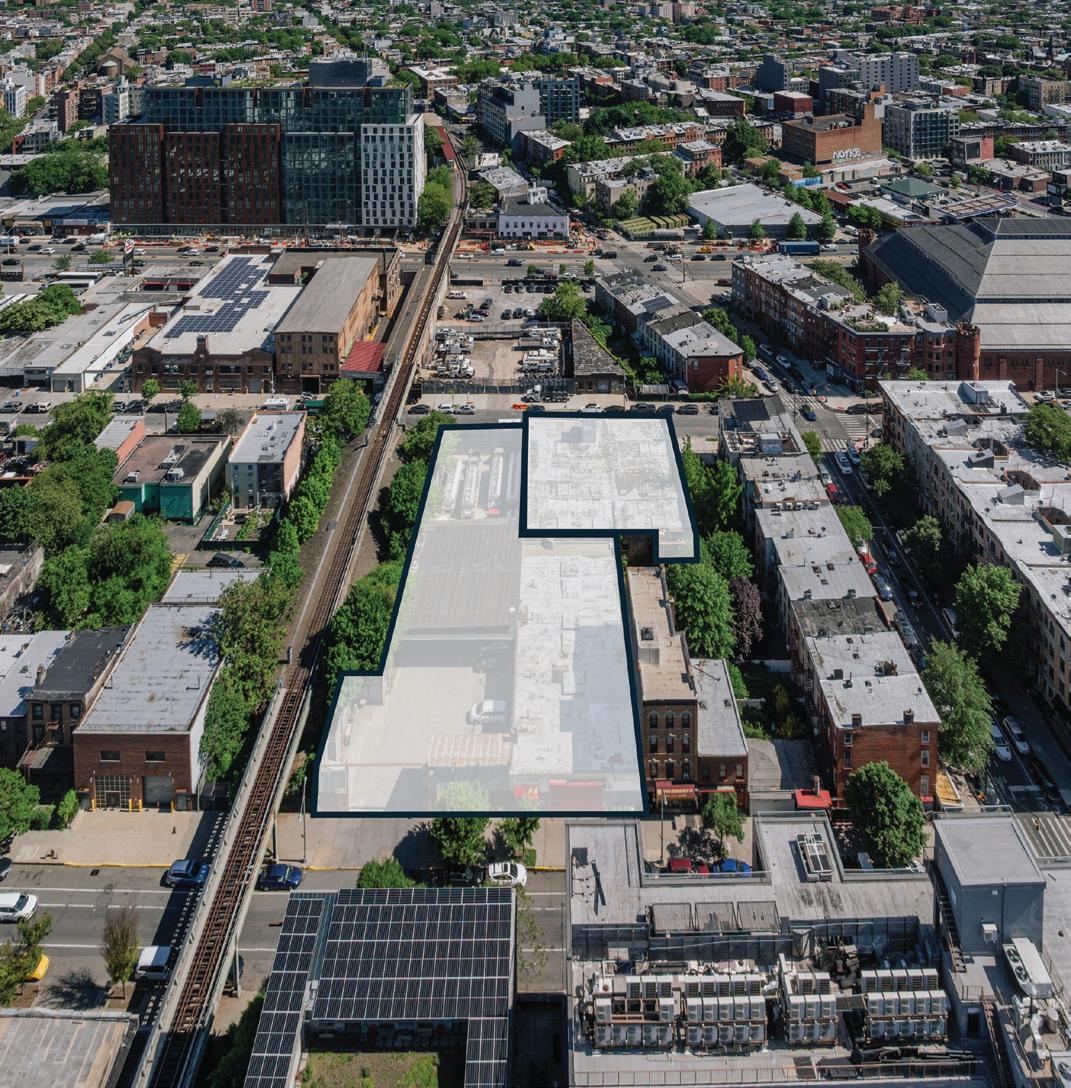
JLL Capital Markets has arranged the $25.15 million sale of two residential development sites located at 1029 Dean Street and 1104 Pacifi c Street in the Crown Heights neighborhood of Brooklyn. The transactions were completed in separate off-market deals.
JLL represented the sellers in both transactions and negotiated directly with the buyer, Brooklyn-based Castell Group and Montgomery Street Partners, which plan to build two large-scale residential projects on the parcels.
The sites are currently occupied by commercial properties. The two assets are situated contiguously and are located within the Atlantic Avenue Mixed-Use Plan (AAMUP) rezoning that was approved by the New York City Council in 2024 to enable new housing, including affordable units, and promote mixed-use development along the Atlantic Avenue corridor.
The JLL Capital Markets team was led by Mike Mazzara, Ethan Stanton and Brendan Maddigan.
Mazzara said, “We are in contract on a number of other sites in the neighborhood and AAMUP appears poised to be a big part of the next wave of residential development hub in Brooklyn. The area continues to see strong demand for housing, particularly when there is good access to transit and proximity to established employment and cultural hubs. These transactions underscore the importance of continued land use action to create additional housing opportunities across New York City.”
program, with approximately 25% of the residential units designated as permanently affordable.
“Trinity Church has been an exceptional partner, and we are deeply appreciative of the trust they have placed in us,” said MaryAnne Gilmartin, founder and CEO of MAG Partners. “Together, we are aligned in our commitment to delivering a best-in-class building that reflects the energy and evolution of Hudson Square. With innovative design leadership and our continued partnership with Global Holdings, we look forward to creating a project defined by quality, innovation and enduring value.”
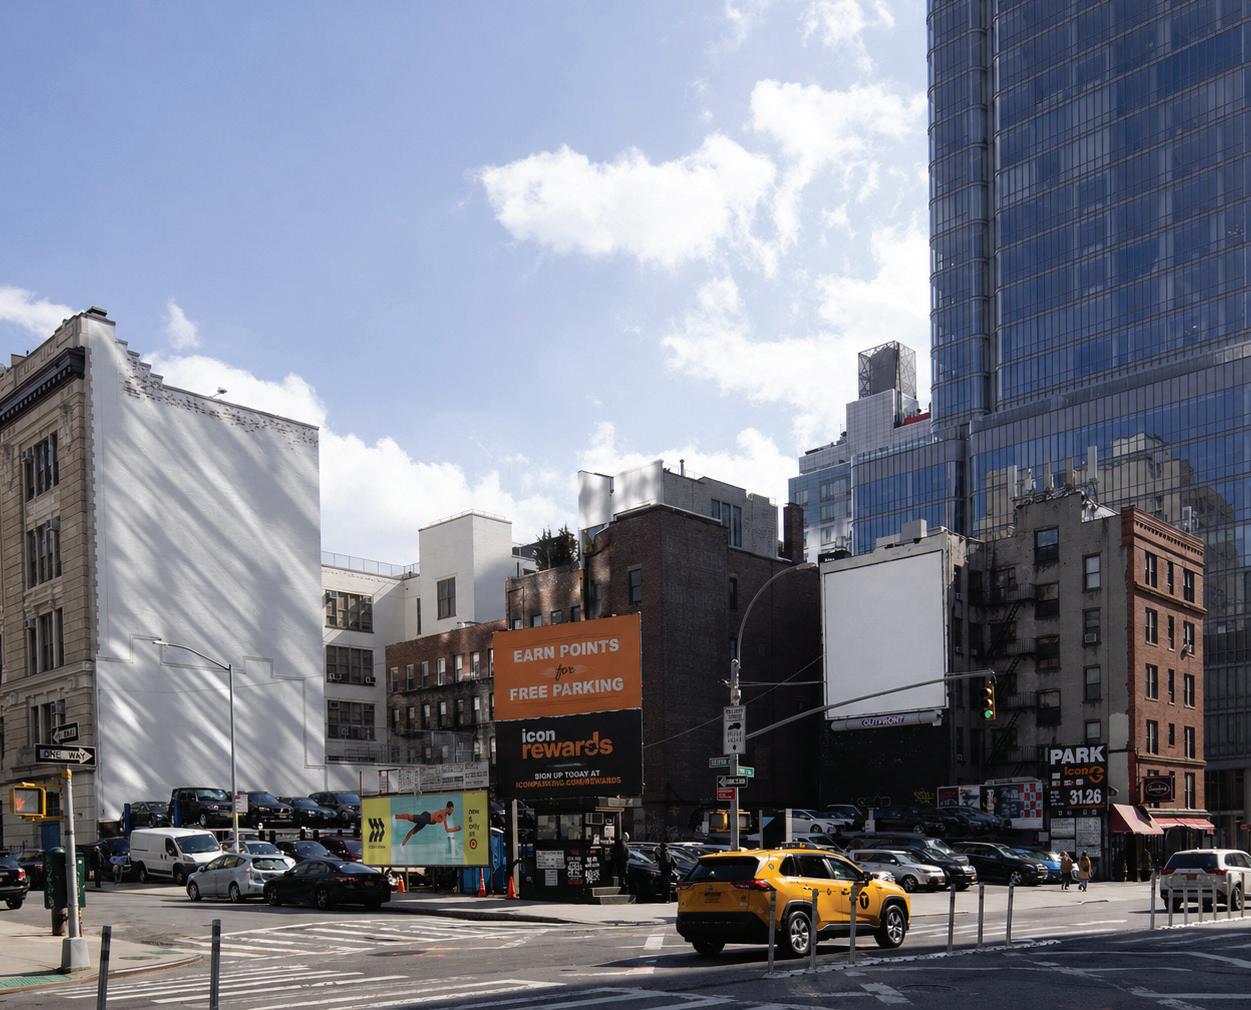
International real estate development and investment firm Global Holdings and real estate company MAG Partners announced a joint venture to develop a 149-unit residential tower at 122 Varick Street in Manhattan’s Hudson Square neighborhood under a long-term ground lease with Trinity Church.
The development at 122 Varick Street will comprise approximately 192,000 square feet in total, including over 5,000 square feet of ground-floor retail designed to activate the streetscape and contribute to the neighborhood’s vibrant pedestrian experience. The residential component will include 149 rental units delivered under the 485-x
The announcement comes on the heels of Global Holdings’ and MAG Partners’ successful partnership in the unveiling of Anagram Turtle Bay, a 194-unit, mixed-income residential building that is 87% leased.
“We are excited to deliver unparalleled living to the intersection of Hudson Square and SoHo, one of Manhattan’s most sought-after neighborhoods,” said Josh Feder, chief investment officer, Global Holdings, which was founded by Chairman Eyal Ofer. “This project represents our continued focus on creating exceptional residential environments in highly coveted locations, and we expect to deliver a spectacular building befitting Hudson Square.”
“Trinity Church NYC is excited to partner with MAG Partners and Global Holdings, whose proven execution and development expertise make them exceptional partners,” said Cynthia Maasry, deputy chief investment officer of Trinity Church NYC. “This collaboration reflects our shared long-term commitment to Hudson Square’s growth and to advancing the neighborhood as a vibrant, integrated live-work-play community.”
Kevin Donner from Cushman and Wakefield represented Trinity on the ground lease.
34th Street’s entire 18th and 19th fl oors.
With over two decades of experience managing hundreds of amenityrich shared workspaces, Corporate Suites tailors offi ce solutions, fully equipped executive suites and conference rooms. Its location at 16 East 34th Street will include a combination of large, light-filled furnished team offi ce spaces offering plug-and-play flexibility for corporate groups with a mix of smaller private offi ces, fully equipped conference and training rooms, open coworking areas, phone booths, complimentary café and an onsite team offering a high level of front desk services and support.
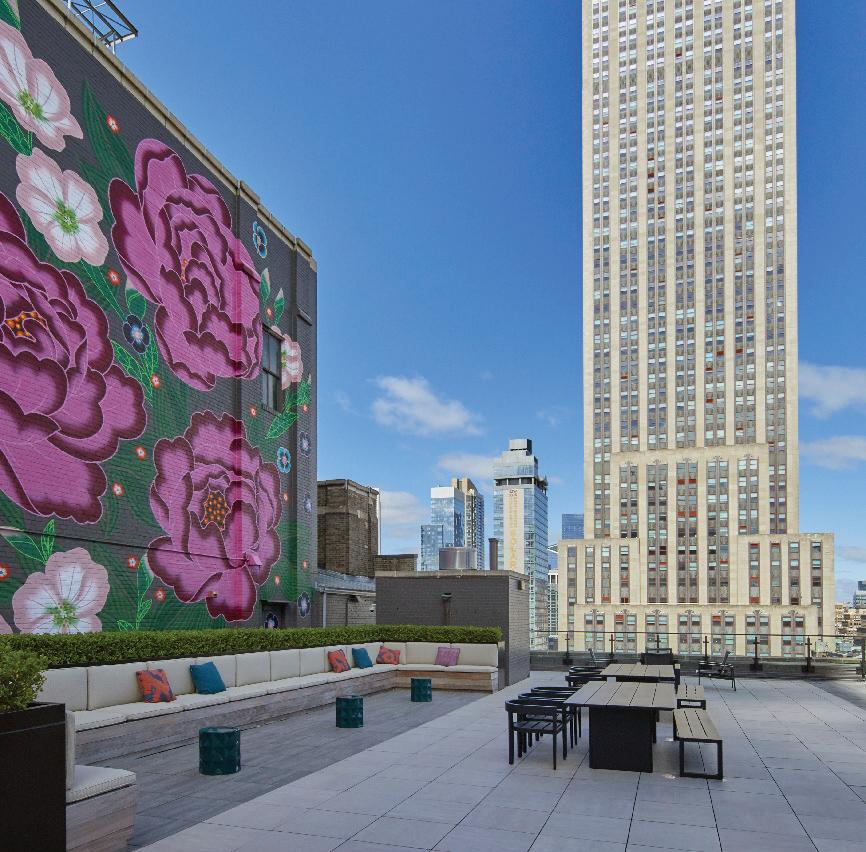
“As New York City’s offi ce market continues to rebound, flexible space and amenity access remain in high demand,” said George Comfort & Sons President and CEO Peter S. Duncan. “With an upgraded lobby and expansive roof deck, 16 East 34th Street is ideally positioned for companies seeking boutique space with unrivaled transit connectivity both throughout the city and surrounding suburbs.”
George Comfort & Sons and building owner Wohio Holding Inc. announced a new lease with Corporate Suites at 16 East 34th Street, a 22-story offi ce and retail building located between Madison and Fifth Avenues in Murray Hill.
Corporate Suites is one of the largest serviced offi ce space providers in New York City. As part of the 13-year lease, the coworking firm will open a location encompassing 34,857 square feet across 16 East
With its distinctive Art Deco architecture and Midtown South location, 16 East 34th Street blends historic character and modern functionality just steps from the Empire State Building. The 376,000-squarefoot tower recently underwent a series of renovations, including a redesigned lobby, new elevator cabs and the installation of an amenity roof deck with sweeping views of the New York City skyline accessible to all building tenants.
The building also features large, effi cient fl oor plates, including prebuilt suites. In addition, the property offers the unique option to create a building within a building on 33rd Street for a 100,000-square-foot user at its base.
Ownership was represented by George Comfort & Sons’ Duncan and Alexander Bermingham. Corporate Suites was represented by David Rosenbloom and Matthew Etlinger of Cushman & Wakefield.
“This refinancing is a clear validation of the strength of 9 West 57th Street and the collaborative success of lead lender Bank of America, and secondary leads Wells Fargo and Citibank,” Stefan Soloviev said.
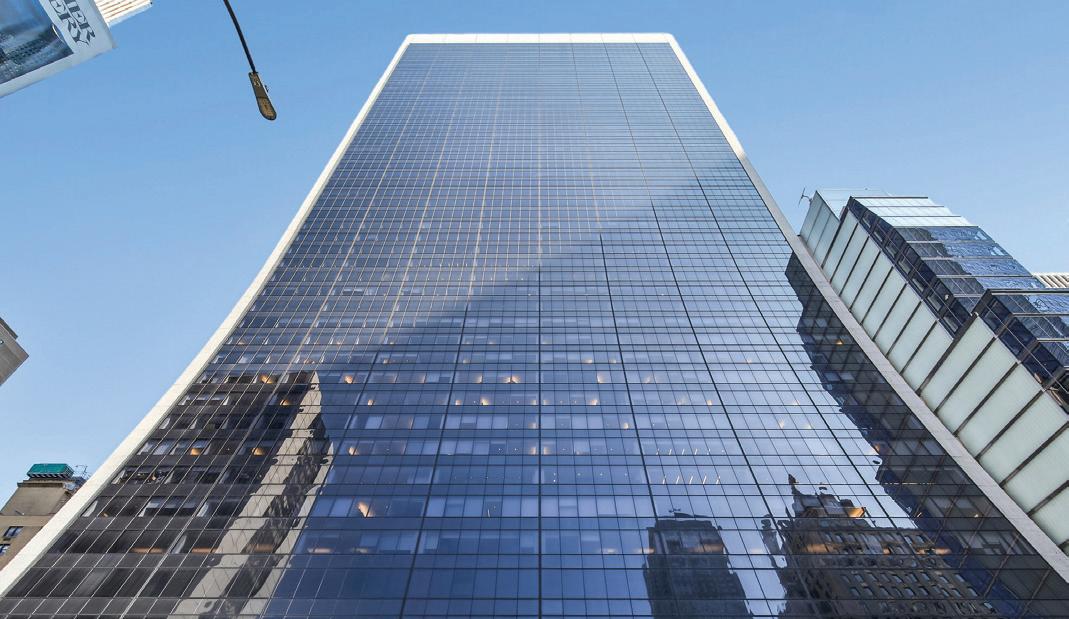
Soloviev Group together with lead lender Bank of America announced a $1.8 billion refinancing of its flagship tower, 9 West 57th Street, according to Chairman Stefan Soloviev.
As part of the execution, Soloviev Group hedged the index, significantly reducing the effective interest rate and further enhancing 9 West 57th Street’s long-term performance, the company said. Upon stabilization, the 50-story, 1.7 million-square-foot tower is expected to achieve a market valuation of $3.9 billion.
Stefan Soloviev recently announced a 10-year lease averaging $340 per rentable square foot, the highest rate ever achieved for the renowned building and what the company believes is the highest rent ever recorded in the New York City commercial marketplace.
Over the last several years, 9 West 57th Street has attracted the strongest roster of commercial tenants in New York City, most recently welcoming HBeyond, The U.S. Soccer Federation, Hess Group, Beaconlight Capital and Platinum Equity. The property’s list of tenants also includes longterm, large-footprint occupiers Apollo Global Management, Chanel, Loews Corporation, Qatar Investment Authority, Coatue, Veritas and Standard Industries. Other recent additions are Mousse Partners, Davidson Kempner, Tikehau Capital, Jain Capital and Panco Operations.
The skyscraper recently completed major upgrades to the lobby, elevator modernization and building system technology. Additionally, as part of its renewed commitment to bolstering the tenant experience, 9 West 57th Street introduced new amenities including a 20,000-square-foot amenity floor, offering Central Park views, modern conferencing, multifunctional meeting space, a grab and go coffee bar, executive dining and a hospitality area.
Holland & Knight’s New York Real Estate Practice Group and Real Estate Capital Markets Practice Group successfully closed deals worth more than $11.35 billion in 2024. From acquisitions, dispositions, development, condominium and cooperative formation and operation to hospitality, financing, leasing, land use and real estate capital markets, our attorneys do their utmost to deliver clients with exceptional results across all sectors.
Acquisitions and Dispositions: $1.93 billion
Financing: $4.1 billion
Leasing: $3.2 billion
Land Use: $290 million
Defaulted Loans, Workouts and Liquidations: $1.83 billion
www.hklaw.com
Stuart M. Saft, Partner | Real Estate Practice Group
Keith M. Brandofino, Partner | Real Estate Capital Markets Practice Group New York, NY | +1.212.513.3200
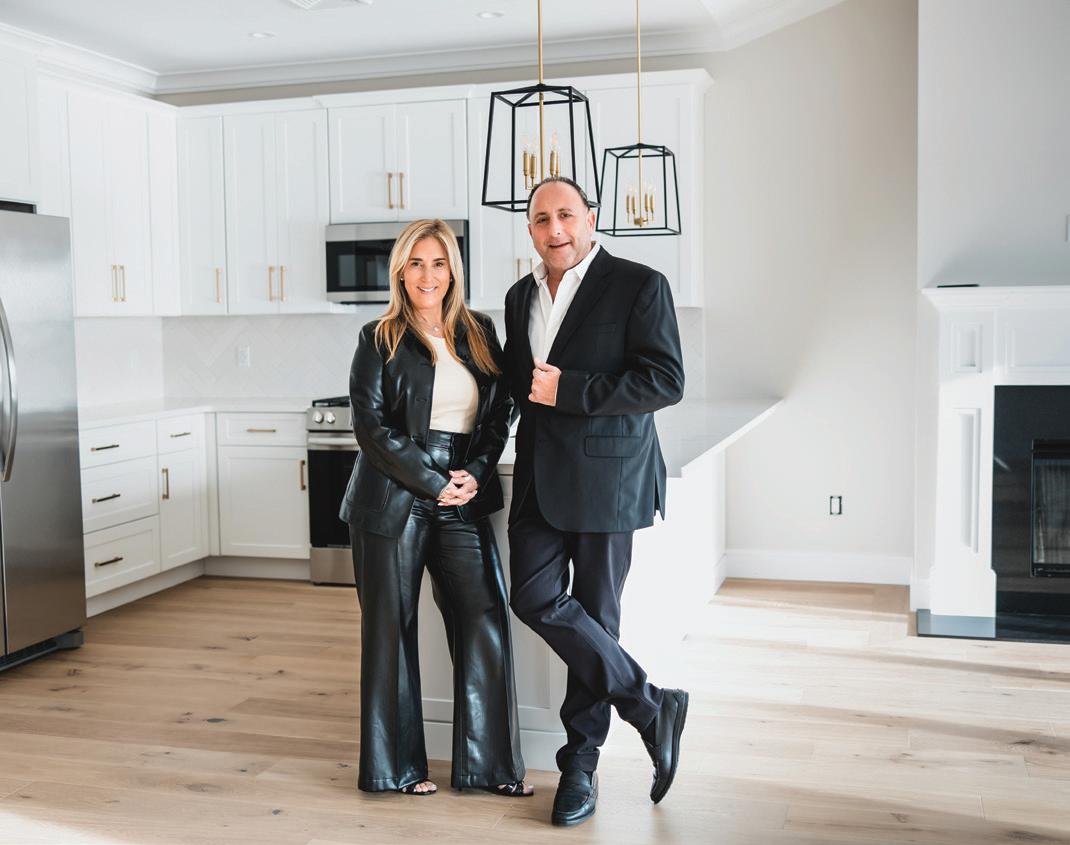
The expansion builds upon the firm’s foundation at its South Shore headquarters, located at 2878 Merrick Road, Bellmore, N.Y., and
reflects increasing demand from North Shore clients seeking a more personalized and elevated real estate experience.
“This has been a long time in the making,” said Mark Stempel, owner and broker of Blue Island Homes. “We have been preparing for this location for nearly two years. Once we found the right location, we felt it was the right time to expand our presence to the North Shore, where our clientele has been looking for us.”
Positioned just steps from the intersection of Northern Boulevard and Glen Cove Road, the new Greenvale office places Blue Island Homes at the center of one of Long Island’s most desirable and well-traveled corridors.
The office reflects the firm’s commitment to quality, design and innovation. Designed with both clients and agents in mind, the space features state-of-the-art technology, refined finishes and a level of craftsmanship that aligns with the brand’s established reputation for excellence. Every detail has been carefully considered to support a seamless and elevated real estate experience.
Blue Island Homes brings extensive experience and proven expertise in representing luxury estates across Long Island. The firm understands the nuances of high-end properties, from architectural significance and custom construction to discreet marketing and qualified buyer targeting. This depth of knowledge allows the company to deliver a highly strategic and tailored approach for sellers and buyers in the luxury market.
The Brennan Team at Engel and Völkers Brownstone Brooklyn has completed the sellout of 16 2nd Place, a four-unit luxury condominium redevelopment in Carroll Gardens.
The project averaged $1,830 per square foot, approximately 15% above initial underwriting, with individual three-bedroom residences closing for $3.25 million and $3.3 million, among the highest prices achieved for comparable units in the Carroll Gardens submarket.
The strong performance comes amid continued resilience in the Brooklyn housing market, where limited inventory and sustained buyer demand are supporting price growth. Median sale prices in the borough are up year-over-year, while price per square foot has seen double-digit gains. At the same time, days on market have declined, signaling that well-priced, high-quality product continues to transact quickly despite broader economic headwinds.
Originally acquired for $4.5 million in 2018 — 20% below the $5.5 million asking price — the property was redeveloped into four bespoke residences, each with private outdoor space. The project included both vertical and horizontal expansions, adding approximately 1,000 square feet of sellable space.
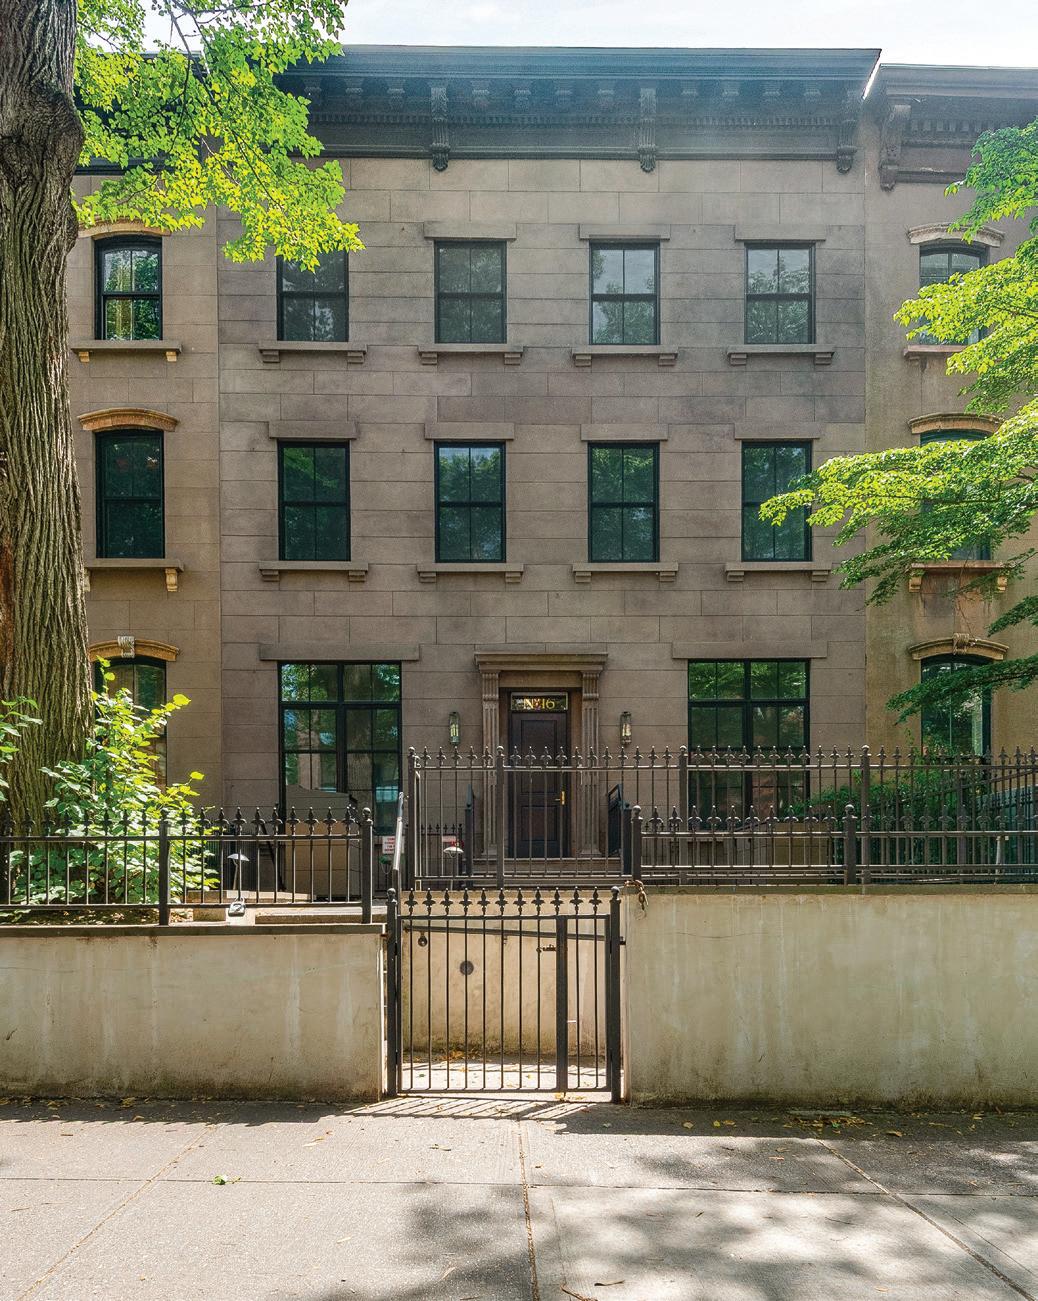
With architecture by The Brooklyn Studio and interiors by Carolyn Bever of Foundry House, the project design blends historic character with modern craftsmanship, featuring oversized windows, American white oak fl ooring, custom millwork and curated lighting.
The development was led by a first-time, brother-sister developer team, with The Brennan Team advising on acquisition, development strategy and sales.
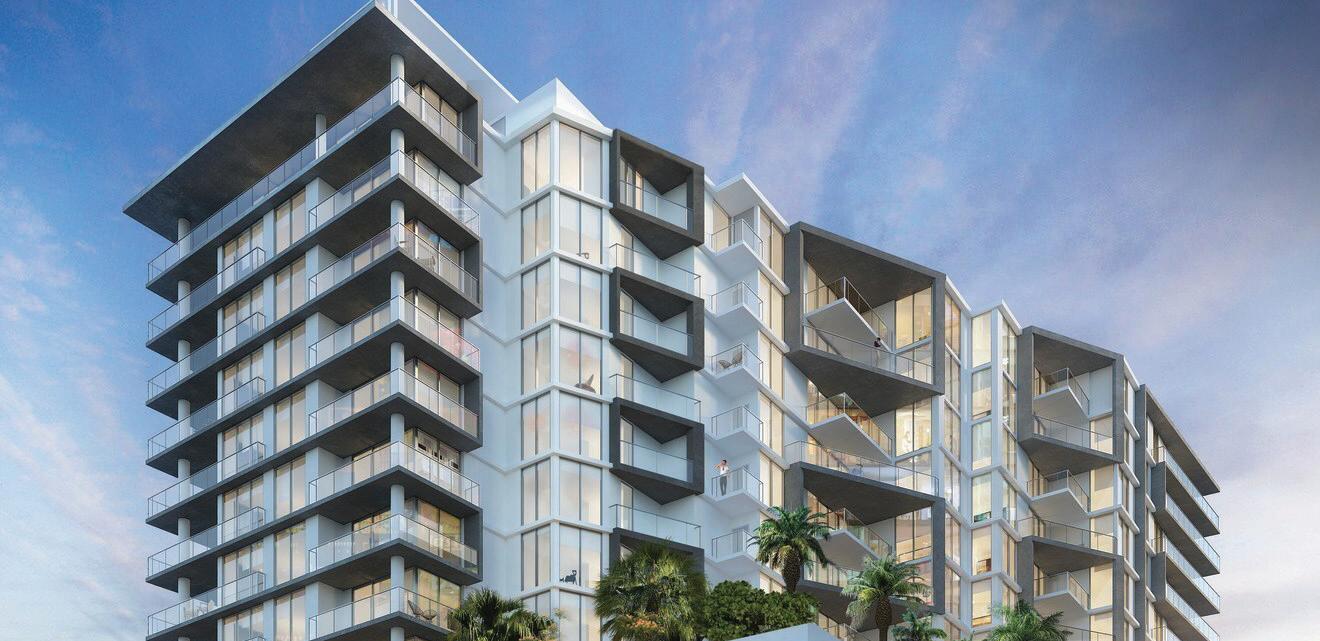
Resident occupancy has been scheduled for fall of 2026 at Avra at Metropolitan Naples, rising 15 stories above the intersection of Fifth Avenue South and Davis Boulevard in Naples, Fla., placing the best of downtown living just steps from home.
The collection of 56 residences showcases expansive fl oor plans that unite contemporary architecture with refi ned, high-end fi nishes. Floorto-ceiling glass invites abundant natural light, while chef-inspired kitchens and thoughtfully curated interiors refl ect a commitment to both design integrity and livability. Located in the heart of the downtown area, the building offers residents enjoy immediate access to the city’s fi ne dining, luxury retail and cultural destinations, placing the best of downtown living just steps from home.
Amenities include a rooftop infi nity-edge pool with sweeping bay, city and gulf views, a state-of-the-art fi tness center and lushly landscaped fi fth-fl oor outdoor environments complete with fire features and elegant lounge areas, designed for both relaxation and entertaining.
These residences feature two-, three- and four-bedroom fl oor plans spanning 1,890 to more than 6,300 square feet. Residences are priced from $2 million to $7 million.
Corcoran Group LLC has continued its international franchise expansion with the launch of Corcoran Micasamo, the brand’s entry into Spain.
Based in the Murcia region and led by CEO and Founder Darren Brown, the firm will serve clients across Costa Blanca, Costa Cálida and Costa Almería, some of the most dynamic and internationally sought-after real estate markets on the Iberian Peninsula.
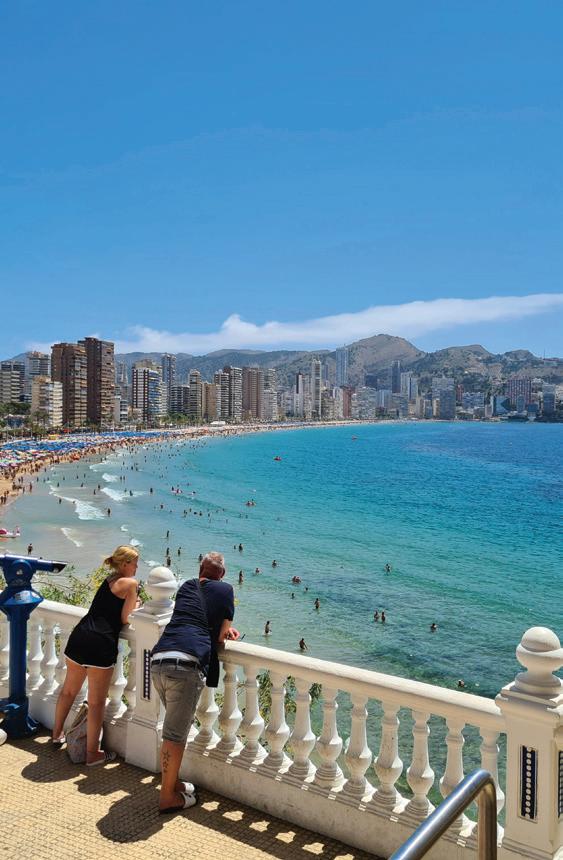
“Spain is one of Europe’s most compelling real estate destinations, drawing international buyers with its exceptional lifestyle, climate and extraordinary value proposition,” said Pamela Liebman, president and CEO of The Corcoran Group. “Darren and his team have built a remarkable business by deeply understanding the needs of international buyers and delivering a professional, brand-led experience that sets a new standard in these markets. We are proud to welcome Corcoran Micasamo as our first affiliate in Spain and look forward to the pivotal role they will play in establishing and growing the Corcoran brand across Europe.”
Founded in 2019 and operating full time since 2021, Micasamo Realty was established with a clear focus on delivering a more professional, brand-led real estate service to the greater Murcia and Costa Blanca regions. Over the past fi ve years, the company has grown steadily through digital marketing innovation, strong developer relationships and a consistent emphasis on international buyers, particularly from the United Kingdom and Northern Europe.
A key milestone in the company’s rise has been its ongoing presence on the U.K. television series “Sun, Sea and Selling Houses,” produced by Ricochet as part of Warner Bros. Television Studios, where Brown,
along with his wife and business partner, Natalie Brown, appear as “The Browns from Murcia” in eight to 10 episodes annually, reaching approximately one million viewers per episode and signifi cantly increasing the company’s brand visibility among U.K. buyers.
In addition, Micasamo has been involved in the sale of one of the highest-value residential properties in the Murcia region, achieving a transaction price of €4.125 million in 2025, refl ecting the company’s growing presence in the upper tier of the local market.
“Building a strong brand in real estate takes time, consistency, and the right platform,” said Darren Brown. “For us, it was important to align with an international brand that shared our values around professionalism, marketing and client experience, without losing our identity in the process. Corcoran stood out because it offers that balance: the strength of a recognized brand, while still allowing us to retain and build our own business locally. What really excited us was the opportunity to help establish the Corcoran brand in Spain. Being the first Corcoran affiliate in Spain brings a real sense of pride, but also a strong sense of responsibility. We’re not just joining a brand; we’re helping to build it, and we’re fully committed to making it a success.”
Northern Costa Blanca, encompassing Jávea, Dénia, Altea, Finestrat and Alicante, represents the premium luxury end of the market, attracting discerning international buyers seeking high-end villas and new developments. Southern Costa Blanca offers more accessible, entry-level opportunities, providing a wider variety of mid-market options at some of the most competitive price points in coastal Spain.
Costa Cálida delivers exceptional value combined with a strong lifestyle appeal, making it an increasingly popular choice for buyers seeking quality living at attainable prices. Meanwhile, Costa Almería stands out as a unique and fast-growing market, with major development activity underway and signifi cant potential for early movers. clientele. Corcoran Micasamo has an established expansion plan that includes the opening of multiple offi ces across key regions of Spain in the coming years.
The firm is focused on increasing brand visibility, strengthening its presence across both established luxury and emerging growth markets, and attracting high-quality agents who align with a professional, brandled approach to real estate.
Tennis Center and Detroit’s Ford Field, with a signifi cant reimagination of USTA’s Arthur Ashe Stadium and Cosm Detroit currently underway. The fi rm also brings deep experience in professional training and performance facilities, arenas and sports-anchored mixed-use districts — areas that complement and extend HOK’s existing sports, recreation and entertainment capabilities.
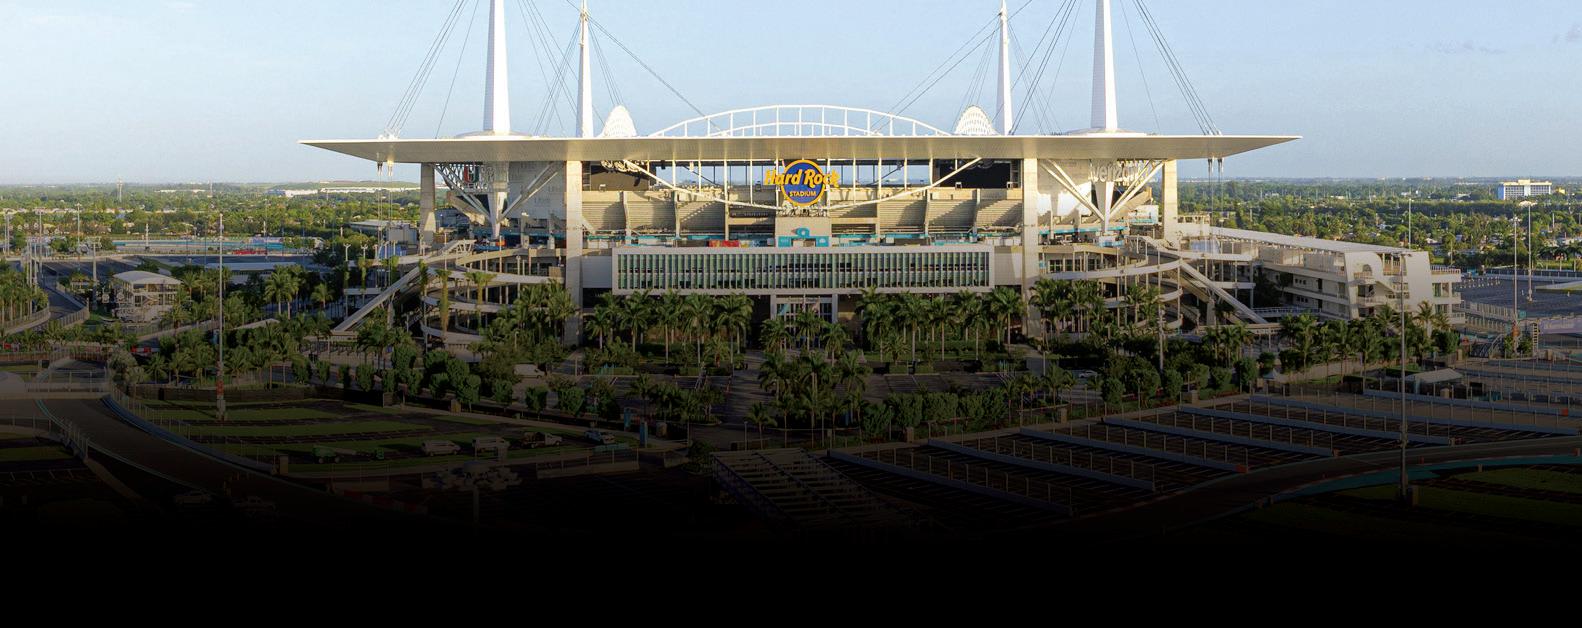
HOK has acquired Rossetti, a Detroit-based architecture fi rm recognized nationally for its sports venue design and renovation work. The merger strengthens HOK’s sports, recreation and entertainment design practices.
The combined fi rm will operate as HOK + Rossetti during the integration. Rossetti’s team, led by Matt Rossetti, FAIA, LEED AP, will continue to operate from Detroit — a market where HOK has long sought a physical presence and where Rossetti has been a fi xture for 57 years.
Rossetti’s portfolio includes the Formula 1 Crypto.com Miami Grand Prix, the U.S. Tennis Association (USTA) Billie Jean King National
“HOK has built a strong global sports practice over time. This partnership accelerates that trajectory with a fi rm whose expertise, culture and client relationships are exceptionally aligned with our own,” said HOK Co-CEO Eli Hoisington, AIA, LEED AP. “This strengthens every dimension of our Sports + Recreation + Entertainment practice while establishing a home in Detroit, a market we believe in deeply.”
Rossetti, who becomes a director of HOK’s Sports + Recreation + Entertainment practice, said the move provides his team with the resources and reach to compete at a new level.
“We built this fi rm on a commitment to design excellence and personal client service, and those values are shared completely by HOK,” he said. “Our clients will still work with the same people who know their projects and goals. The difference is that now those people have the backing of a global network with extraordinary depth across disciplines and markets. This is the right partnership at the right time.”
The combined HOK + Rossetti Sports + Recreation + Entertainment practice will be led by Directors Nate Appleman, Shannon Bartch, Amy Chase, John Rhodes, Matt Rossetti and Rashed Singaby. The Detroit studio will serve as a key hub for the practice while also strengthening HOK’s ability to serve clients throughout the Upper Midwest. HOK has already made its mark in Detroit, having designed Little Caesars Arena and the forthcoming home of Detroit FC.
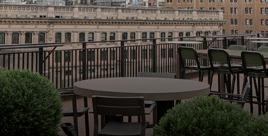
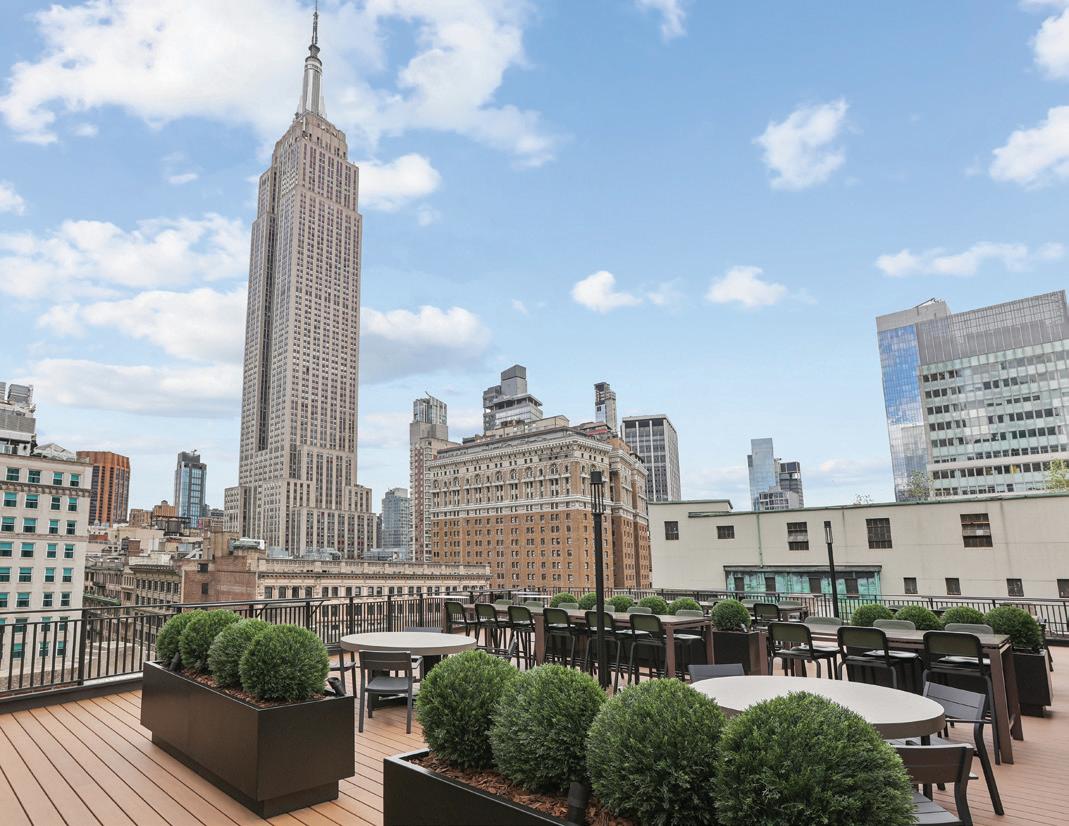
amenity package. The new rooftop lounge and outdoor venue in Midtown is available for daily use by, and special function reservations for, tenants of ESRT’s office portfolio.
“This is literally the crown of our portfolio amenities, a fantastic addition for all our tenant partners to our amenities package to assist them with employee recruitment, retention, and satisfaction,” said Ryan Kass, executive vice president, co-head and chief revenue officer of real estate at ESRT. “We are excited to welcome tenants to this brand-new rooftop that is steps from Grand Central and Penn Station.”
The rooftop features open and cabana seating areas, a wet bar, full audio and video capabilities, multiple charging stations, dedicated event and catering partners and unobstructed views of the Empire State Building.
Events can be reserved for up to 250 guests for corporate gatherings, client events, team celebrations and more.
The Rooftop at 1333 Broadway joins ESRT’s amenities collection that includes the Town Hall and Tenant Lounge at 1400 Broadway; tenantsonly conference facilities at both One Grand Central Place and the Empire State Building and the Empire State Building’s Empire Lounge.
For over a century, Kaufman has shaped New York City’s commercial real estate landscape. We combine deep market intelligence, trusted relationships, and tireless dedication to deliver results that build lasting value.
FROM VISION TO VALUE. NEW WORK STARTS HERE.
TENANT REPRESENTATION
LANDLORD REPRESENTATION
PROPERTY MANAGEMENT
CONSTRUCTION & OPERATIONS
ACCOUNTING & FINANCE
CONSULTING & EXPERTISE
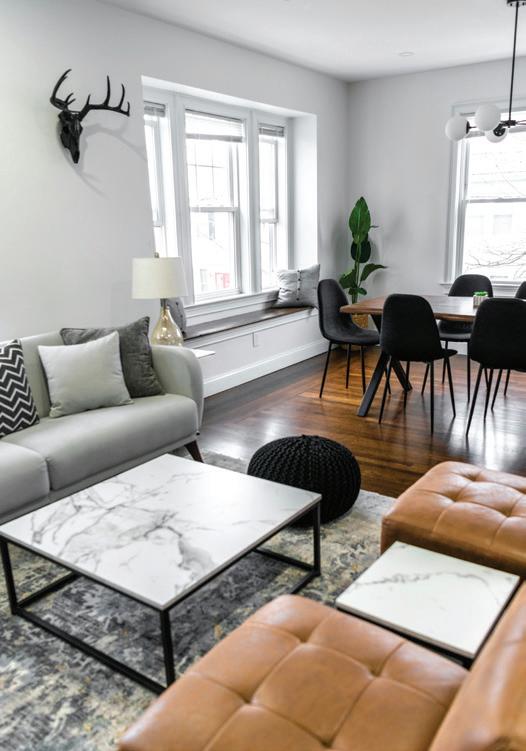
Gallery KBNY, a Manhattanbased design-build renovation fi rm specializing in apartment and townhouse renovations, announced the launch of its new Pre-Purchase Renovation Assessment service for prospective apartment buyers throughout Manhattan.
The new service was developed to help buyers evaluate renovation feasibility, construction timelines, projected costs and building-related constraints before purchasing apartments that require renovation.
As more Manhattan buyers pursue estate-condition and outdated apartments with plans to renovate, many enter contracts without a clear understanding of the scope, cost, approval requirements or hidden complexities associated with renovating in New York City’s highly regulated residential buildings.
Gallery KBNY’s Pre-Purchase Renovation Assessment provides
buyers with an objective, professional resource during the acquisition process, allowing them to make more informed purchasing decisions before closing.
“Our goal is to give buyers clarity before they make one of the largest fi nancial decisions of their lives,” said Avi Zikry, managing partner of Gallery KBNY. “In Manhattan, renovation complexity is driven by far more than fi nishes and square footage. Buyers need to understand building rules, infrastructure limitations, approval timelines, concealed conditions and feasibility constraints before they commit to a purchase. This service helps provide that clarity.”
The assessment includes renovation feasibility analysis; review of alteration agreements and building renovation policies; infrastructure evaluation, including plumbing, electrical and HVAC limitations; design feasibility guidance for layout modifi cations and system upgrades; realistic renovation budget ranges based on project scope; construction and approval timeline projections; identifi cation of potential concealed-condition risks and written summary reports delivered following the walkthrough.
The service was created specifi cally for buyers navigating Manhattan’s complex co-op and condominium renovation environment, where building regulations, Department of Buildings requirements and infrastructure limitations can signifi cantly affect both renovation cost and timeline.
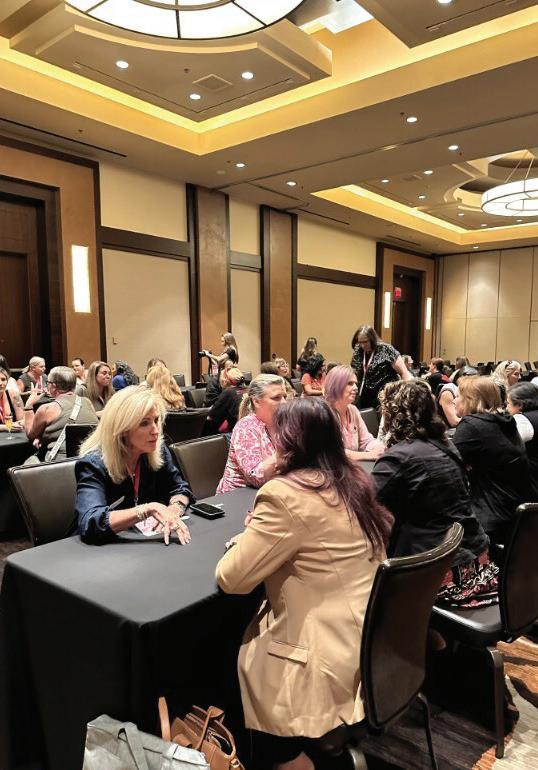
Women in HVACR (WHVACR), a nonprofit organization dedicated to empowering women in the heating, ventilation, air conditioning (HVAC) and refrigeration trades, is addressing the industry’s persistent gender gap through its Navigator Mentor Training Program, a structured mentorship and professional development training initiative designed to provide targeted mentorship training curriculum based on the specific needs of women in HVAC and refrigeration.
This training will equip women entering or advancing in this industry to have the mentoring skills critical to their own career growth, leadership development and long-term success, and share those skills with their peers and colleagues.
According to the U.S. Bureau of Labor Statistics, women make up only 3% of the HVACR workforce, reflecting longstanding barriers to entry and advancement within the trades. WHVACR members have identified the power of mentorship in helping them develop the skills and knowledge to be successful in their careers. Participation in the WHVACR Navigator program has tripled in size over the last two years and directly reflects the significant need for mentorship and trained mentors.
“The number one question I get asked by companies across the industry is around attracting and retaining women in their organization,” said Lisa Knapp, a WHVACR board member. “My response is, always, mentorship. Data collected from our members show that mentorship has been particularly valuable in employee retention and advancement. And now that we have seen the impact of our Navigator program, we want to flood the industry with women trained to be mentors to other women.”
Navigator was originally launched in 2024 and pairs emerging professionals with industry veterans who provide real-world insights and practical guidance to help mentees navigate obstacles to move forward in their careers. Knapp said the new training element ensures that mentors have the tools they need to guide other women through modern challenges.
The Navigator program is powered by MentorCity, a cloud-based, mentoring platform designed for organizations and individuals to foster professional growth through structured and automated mentormentee matching. Since its launch, Navigator has demonstrated strong participation and measurable impact, including more than 400 mentorship meetings, strong engagement across program discussion boards and more than 90 professional development goals set by mentees.
“Having a mentoring mindset is such a valuable part of leadership development,” said WHVACR President Jane Sidebottom. “We have such a strong mentorship committee, with deep coaching and mentoring experience. Their willingness to share this expertise in the form of training and in support of our members’ leadership development is a gift. It fills a gap for structured mentorship training in this industry.”
8:30
9:00
5:00 - 6:00 PM Hors
September 28, 2026
The Mann Charitable Foundation is having its annual golf outing this year at the wonderful Fresh Meadow Country Club on Monday, September 28, 2026. Formed by Irving and Marion Mann,The Mann Charitable Foundation supports research to fight life-threatening diseases. Expect another amazing outing, supporting causes of mainly geriatric diseases such as Alzheimer’s disease, Crohn’s and Colitis, Lymphoma, Macular Degeneration, liver disease and more. We have our honorees, one of which will be receiving the Michael Kerr Humanitarian Award in honor of one of my best friends, Michael Kerr. We hope to see you there supporting our causes and spreading the awareness for a better future.

Photo via PRNewswire
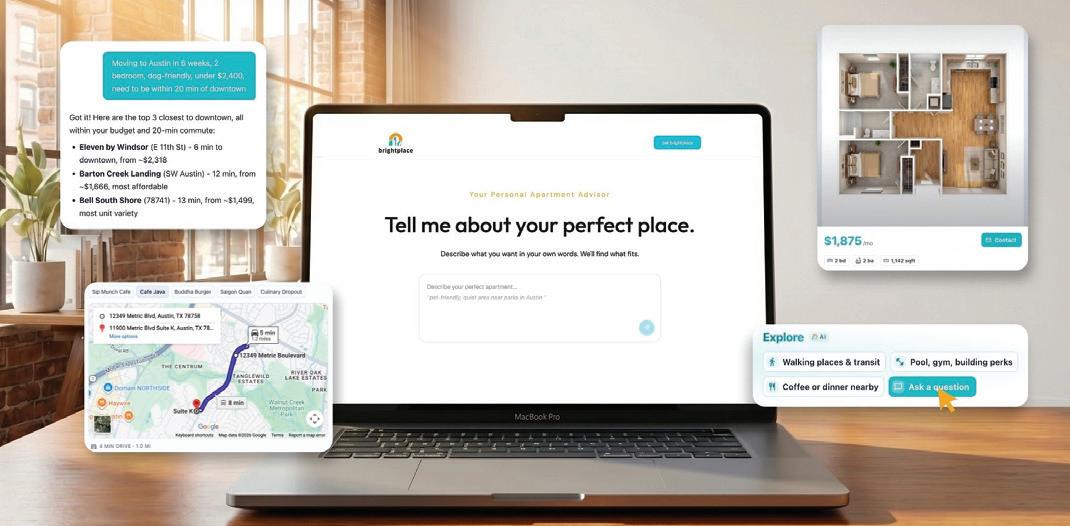
Today’s renters don’t just want a list of apartments. They want to understand what it’s actually like to live somewhere: the commute, the cost of living, the dining, the neighborhood feel, the quality of the community itself. Brightplace is the first apartment rental platform built entirely on artifi cial intelligence (AI) to answer those questions.
Founded by multiple-time founder and CEO Brian Lichtenberger and bootstrapped with a small team of AI-first engineers, Brightplace is a participant in the inaugural RET Ventures AI Accelerator cohort. Lichtenberger has two prior exits, both built at the intersection of data infrastructure and industry transformation.
At the center of Brightplace is the AI Rental Advisor, an intelligent agent that draws on a deep network of property, neighborhood, fi nancial and lifestyle data to answer the questions renters are actually asking. The Advisor works with enriched and aggregated apartment supply from across the multifamily industry, structured into a machine-readable format by the company’s proprietary technology platform, IntentOS. This includes resident experience context, local cost-of-living intelligence, commute data and neighborhood character profiles.
A renter can ask “Moving to Charlotte in three weeks with my family and dog, looking for a 2BR within 15 minutes of my job at Wells Fargo. We need a parking spot and a neighborhood with dog-friendly parks.” Instead of providing a filtered list, Brightplace returns a set of recommendations that weigh those tradeoffs against each other, explains why each option fi ts and gives the renter the context to compare across dozens of dimensions. From there, the renter can research even deeper: asking about actual commute times, mandatory fees beyond the advertised rent, resident reviews of a specifi c community or the daily life in a given neighborhood.
“For the first time, renters can get answers to questions no platform has ever been able to answer. What's it like to live in this unit? In this property? In this neighborhood? What will my true monthly cost be? Brightplace is the product built to deliver those answers,” said Lichtenberger.
Brightplace is built to serve both sides of the market. For operators, the challenge is straightforward: existing platforms deliver leads, but they cannot tell an operator what renters actually want, why they chose one property over another or what trade-offs they considered along the way. As renter discovery shifts to AI-powered channels, that gap will only widen.
Operators can deploy the AI Rental Advisor directly on their own websites, giving prospective residents superior search and contextual insights without leaving the operator’s brand experience. Every response generated by the advisor, whether on Brightplace or on an operator’s own site, passes through automated Fair Housing guardrails that screen for steering and protected-class bias in real time. Beyond their own sites, Brightplace aggregates, enriches and structures operator supply into a machine-readable format, making their properties discoverable across the growing ecosystem of AIpowered search.
management, particularly in markets where traditional AVMs struggle.
“This is not an incremental improvement — it’s a complete rearchitecture of the AVM using advanced AI,” said Rob Barber, CEO at Attom. “We’ve moved beyond static, comp-based approaches to a dynamic system that can learn from decades of market behavior and adapt to changing conditions in real time.”
Attom, a provider of property data, artifi cial intelligence (AI)-powered analytics and real estate intelligence solutions, launched its nextgeneration automated valuation model (AVM), a ground-up, AIfirst rebuild designed to move beyond the limitations of traditional comparable sales-based valuation models.
Traditional AVMs rely on recent comparable sales, which limits accuracy in a low-transaction housing market. Attom’s new model replaces this dependency with an AI-driven approach that leverages more than 30 years of time-adjusted transaction history, enabling more reliable valuations for underwriting, portfolio analysis and risk
“We model how each neighborhood has evolved over the past 30 years and use that temporal context to translate historical sales into accurate present-day values. This gives our valuation system a richer foundation to learn from, allowing each model to synthesize property characteristics, local market dynamics and price history into a single, informed estimate,” said Aaron Wagner, vice president of data science at Attom. “The result is consistent accuracy.”
Each valuation includes a confi dence score that provides a clear signal of reliability, enabling organizations to automate decisions with greater control and transparency.
The Attom AVM is built for enterprise use across mortgage, insurance, investment and proptech applications, and is delivered through fl exible solutions including APIs, bulk delivery and cloud platforms such as Snowflake and Databricks.
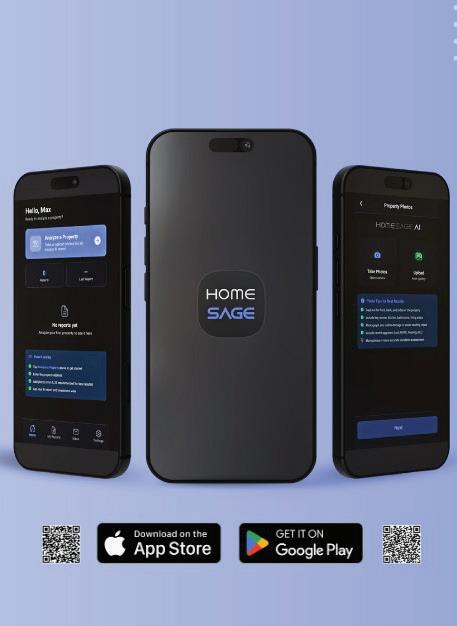
Homesage.ai announced the launch of its new mobile app designed to provide real estate investors and agents with AI-powered property analysis, real-time property reports and investment property insights directly from their smartphones.
The app enables users to evaluate properties, estimate home values and identify potential deals within seconds, thereby supporting faster, more informed investment decisions, the company said.
Real estate investors increasingly require timely, data-driven insights as market conditions shift rapidly, and competition for profitable properties intensifies. Traditional property analysis methods often involve multiple platforms and delayed data access, creating inefficiencies in identifying viable opportunities.
“Access to fast and reliable data is becoming essential in real estate investing,” said Blaze Dimov, CEO of Homesage.ai. “This mobile app brings AI property analysis directly into the hands of investors and agents, helping them evaluate opportunities and act with greater confidence in a competitive market.”
The Homesage.ai mobile app integrates several core features aimed at simplifying property evaluation and deal discovery:
• AI property analysis that evaluates key investment metrics, including estimated value, flip ROI, long-term rental and Airbnb potential renovation estimates and more.
• Real estate deal finder functionality that highlights properties with strong investment potential based on predefined criteria.
• Instant property reports that consolidate data points such as pricing trends, neighborhood insights and comparable sales.
• Home value estimator tools that provide quick, data-backed valuation ranges for residential properties.
• Investment property analysis dashboards that present clear summaries of risk and return factors.
The platform leverages Homesage.ai’s existing data infrastructure, which processes millions of property records across the United States. By combining machine learning models with large-scale property datasets, the app delivers insights in a format designed for quick interpretation on mobile devices. The release of the mobile app expands Homesage.ai’s product ecosystem beyond its web-based platform and API solutions.
The app is available for download on major mobile platforms and is designed to integrate seamlessly with existing Homesage.ai accounts. Users can use it to sync saved properties, reports and search preferences across devices, ensuring continuity between desktop and mobile workflows.
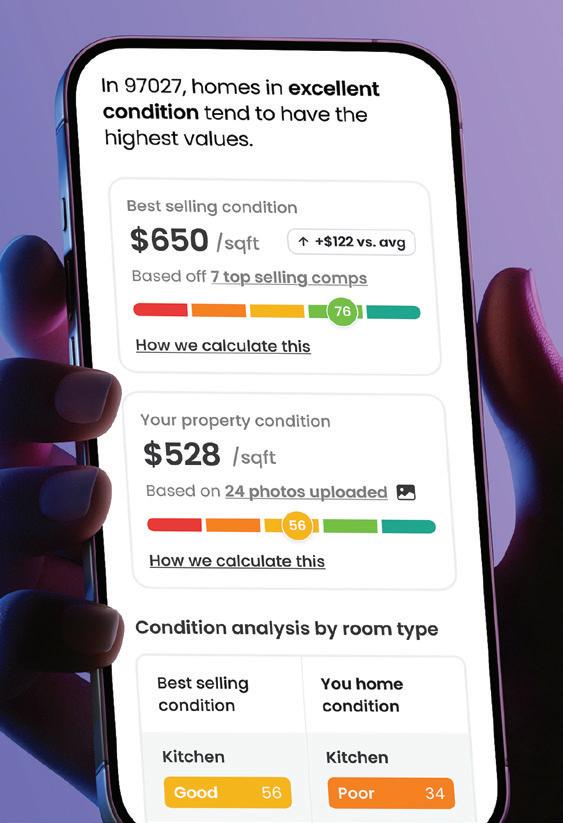
Home value optimization company Revive announced major upgrades to Revive AI, its artificial intelligence-powered platform that helps real estate agents show homeowners how strategic improvements can unlock more value before they sell. The upgraded platform brings together valuation intelligence, local market insights, home condition analysis, homeowner financial modeling and investment scenarios in one place.
Revive AI now gives real estate agents more data and features to show homeowners not just what their home is worth today, but what it could be worth with targeted updates and improvements before they sell. The update also marks a significant step forward for Revive AI with expanded data insights, including recent sales, that bring its AI-powered renovation and valuation intelligence directly into the workflows agents already use to deliver a wider and more reliable selection of comps.
“Agents don’t need another estimate of what a home is worth today. They need home value intelligence that helps show clients what it could be worth,” said Dalip Jaggi, co-founder and COO of Revive. “After more than
a year of meeting with agents every week, listening to their feedback and continuously improving the product around how they actually work, Revive AI has become the next-generation home value intelligence tool agents have been asking for.”
Key upgrades include:
• Smart value comparison, which brings automated estimates from trusted industry sources into one place to help agents explain where those automated valuations may fall short.
• Expanded local market insights, helping agents show homeowners neighborhood trends, current buyer expectations and how their property compares with nearby homes.
• Improved home condition analysis, offering a room-by-room look at a property’s current state with targeted recommendations designed to increase resale potential.
• Renovation estimates, helping agents and homeowners evaluate whether a home may benefit from repairs, a strategic refresh or no updates at all based on how its condition compares with the overall condition of the neighborhood.
• Home financial overview, allowing homeowners to input mortgage details and visualize current equity, estimated value and potential upside with and without renovations.
• Investment scenarios, available through Revive’s Flip360 program, that help agents model potential returns and evaluate renovation strategies for investor clients. These insights are provided by the agent and are not accessed directly by consumers, homeowners or individual investors through Revive AI.
With over 75 years of experience and deep understanding of industry challenges, IDB’s Commercial Real Estate team supports property owners, developers and builders across every type of financing requirement. We can help you keep pace with changes in the marketplace, while maintaining high credit quality levels and providing the personalized service, efficiency and flexibility to fit your specific needs.
For more information about financing solutions that meet your specific needs, visit idbny.com.
PGIM, the $1.4 trillion global investment management business of Prudential Financial Inc., announced that the PGIM Real Estate Fund Inc. has completed its 10th property acquisition with the purchase of The Arbor, a 127-unit housing community in the Riverdale neighborhood in the Bronx, N.Y., at a gross capitalization of $73.5 million. The transaction marks $260 million in capital deployed by the fund.
The fund acquired the asset in a joint venture with Fetner Properties
through a sale and leaseback with the seller, Columbia University. Beginning in July 2026, apartments are expected to be re-leased in two phases and will be operated as a residential property while it undergoes a value-add capital improvement program.
“Reaching 10 property acquisitions, $260 million in capital deployed and over $632 million in gross property value are important proof points for this fund and for our broader commitment to opening institutional-quality private real estate to a wider pool of investors,” said Darin Bright, senior portfolio manager for the PGIM Real Estate Fund. “The acquisition of The Arbor, which has very strong near-term growth potential, is a testament to that approach.”
The acquisition follows the fund’s recent conversion from a tender offer fund to an interval fund structure, completed on April 30, 2026.
“A sharp repricing in real estate and a slow, uneven recovery have set up a significant tailwind for the asset class,” said Soultana Reigle, head of U.S. Equity for PGIM’s Real Estate Investment Group. “Our real estate strategies invest in sectors tied to essential demand, including various housing formats and logistics, that persists through cycles regardless of the broader financial market backdrop. These stabilized real estate investments tend to generate resilient income with growth and lower volatility.”
PGIM’s Real Estate Investment Groupboasts $217 billion in gross assets under management and administration.
eventually some will be ready to sell. But today’s homeowners often take a longer, less predictable path from initial curiosity to listing. This creates a challenge for agents, who must balance immediate opportunities with long-term nurturing.
Constellation1, a provider of real estate technology solutions, announced the next evolution of HouseValues, the seller lead solution from Market Leader, marking what the company called “the most significant enhancement to the product in more than 25 years.”
For decades, HouseValues has helped real estate agents connect with homeowners and generate high quality seller opportunities, delivering more than 500,000 seller leads over the past three years alone. Now, HouseValues goes beyond lead generation by combining exclusive seller leads with monthly interactive equity reports, real time behavioral insights and a fully integrated engagement experience. The result is a smarter, more connected solution that helps agents identify intent earlier, engage more effectively and build lasting relationships throughout the entire homeowner journey.
For real estate professionals, seller lead generation has traditionally been a numbers game: connect with enough homeowners, and
At the heart of the new experience is the monthly HouseValues Equity Report — a personalized financial snapshot delivered directly to every homeowner. Fully branded to the agent, each report helps homeowners track their home’s value, monitor equity growth, evaluate refinance opportunities, estimate renovation returns and explore potential selling scenarios.
Combined with an integrated outreach program that surrounds the homeowner with 27 coordinated touchpoints in the first 60 days alone, agents can see who is engaging — and how — directly in their CRM. A greater percentage of leads now also includes validated phone numbers, giving agents a more complete picture from day one.
“HouseValues has been a cornerstone for seller leads for over 20 years, delivering an industry-leading success rate when they have the right agent support,” said Brant Morwald, president of Constellation Real Estate Group. “This update is all about making that connection more natural. We’re giving agents the kind of intelligence they need to reach out at exactly the right moment with information that actually matters to the homeowner. It’s a major step in our commitment to keeping our tech as modern and effective as the agents who use it.”
The new HouseValues experience became available on May 18, 2026, for new and existing Market Leader customers. Constellation1 plans to expand these enhanced seller lead capabilities across its broader real estate technology portfolio later this year.



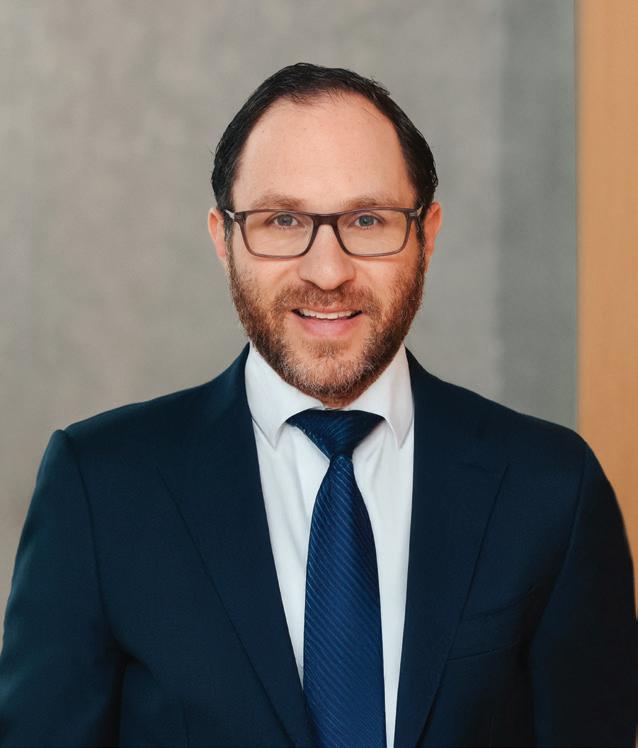
Argo Real Estate, a privately owned, fullservice real estate firm, has appointed Michael Marks as chief operating officer. Marks has more than two decades of leading complex, multiasset platforms across residential, commercial and high-service environments.
As COO of the legacy real estate firm founded in 1952, Marks will oversee operations across a portfolio of over 12,000 owned-and-operated units in the greater New York metro area, and drive performance across such in-house divisions as property management, brokerage, construction management and finance.
“Michael has a long record of building operational infrastructure, and we welcome his expertise and commitment,” said Mark Moskowitz, president and CEO of Argo Real Estate. “During an impressive career, he has managed global portfolios, led significant budgets and implemented systems that have improved efficiency, accountability and long-term asset performance.”
Prior to joining Argo, Marks held senior leadership positions at the City University of New York, Open Society Foundations and Allied Partners, where he directed real estate strategy, global operations and large-scale capital initiatives. His experience spans acquisitions, asset management, construction management and portfolio optimization across both institutional and privately held platforms.
Marks has a bachelor’s degree in finance and international business from George Washington University. His education credentials also include studies in real estate finance and investment at London School of Economics, construction management at Columbia University, executive leadership at Oxford Saïd Business School and international leadership and organizational behavior at University Bocconi in Milan.
He is a licensed real estate broker in New York and Florida.
has worked with global industry powerhouses that have contributed to the development, innovation and reshaping of U.S. real estate markets.
“Allen Matkins is known for its deep real estate bench and a highly collaborative approach that keeps the focus where it belongs, delivering practical, business-minded results for clients,” said Shapiro.
Drawing on over 20 years of experience, Shapiro has advised landlords in some of the largest office leases in New York City by square footage at the time of closing and has served as portfolio leasing counsel for numerous prominent commercial owners. He has also advised corporate tenants in headquarters and other significant leasing transactions.
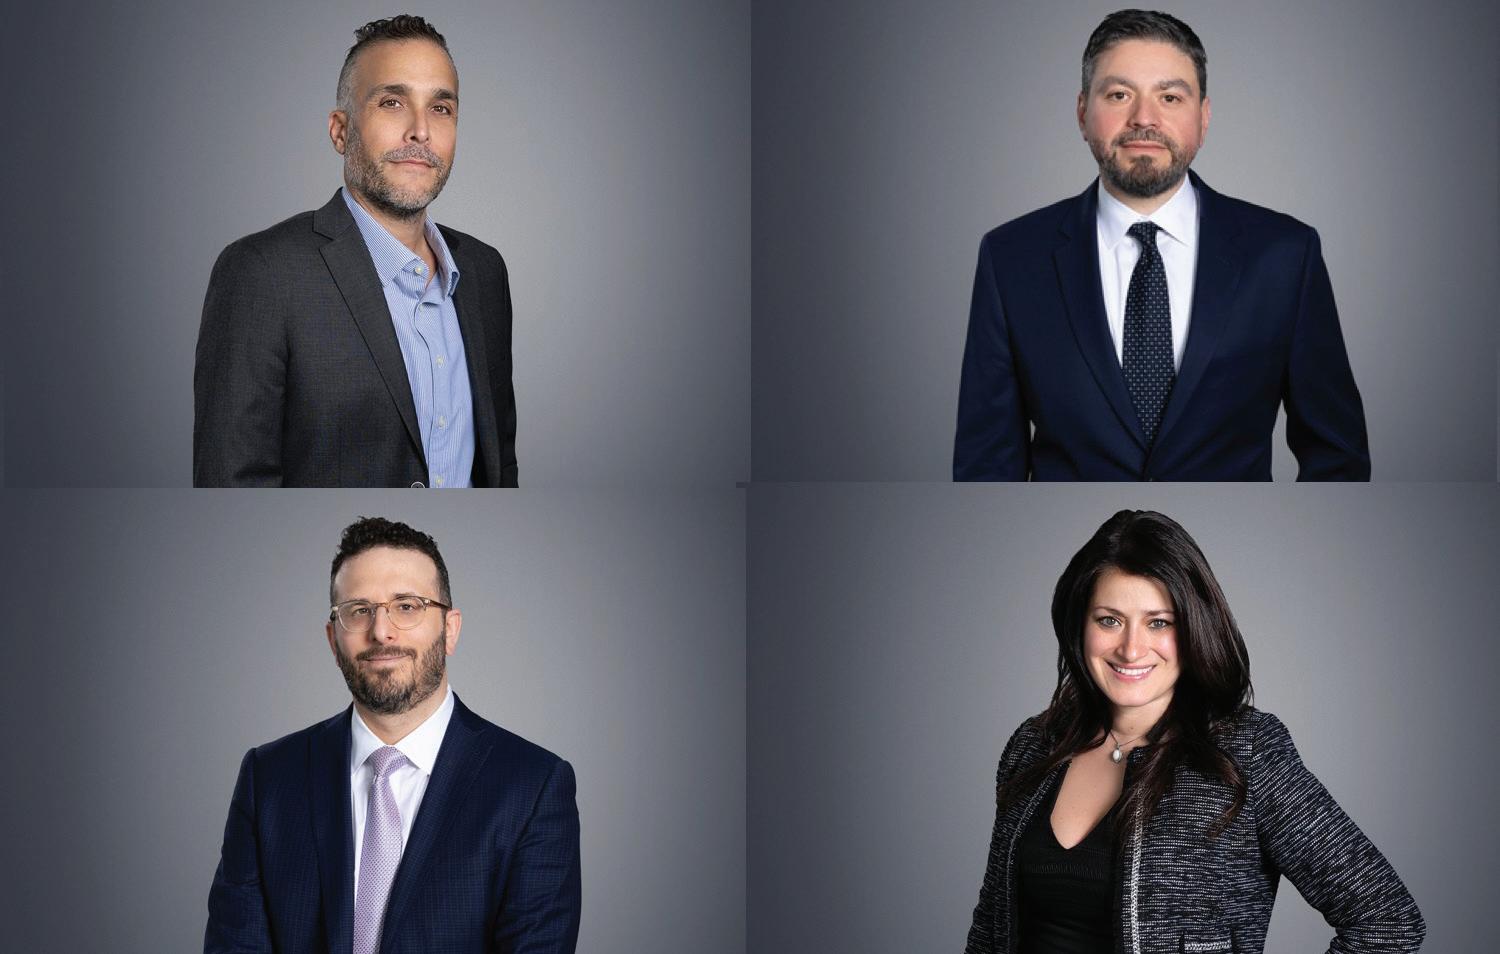
Allen Matkins announced that a real estate transactional team is joining the firm in its New York office. Partners Noah Shapiro, Russ Rabinovich and Lauren Margiano focus on sophisticated commercial leasing transactions, representing landlords and tenants in all aspects of office, retail, hotel and restaurant lease negotiations. In addition, Senior Counsel Jason Weaderhorn and Associate William Alesi will join the firm.
“Since 2023, we have been steadily investing in and expanding our New York real estate presence. Adding Noah, Russ and Lauren underscores our long-term commitment to the market and strengthens our ability to serve clients on sophisticated leasing and other transactions,” said Jeffrey Patterson, Allen Matkins’ managing partner.
“This group has negotiated some of the largest and most complex commercial leases in New York City that run the gamut of corporate landlords and tenants,” said Tony Natsis, name partner and chair of the firm’s Global Real Estate Group.
Allen Matkins’ growing real estate practice includes more than 170 real estate transactional lawyers across California and New York. The firm
Rabinovich advises a variety of clients in commercial leasing and other transactions. With more than two decades of experience, he has negotiated and structured some of New York City’s largest office leases, ranked by square footage at the time of closing, for institutional investors, REITs, asset managers and other commercial landlords. On the tenant side, he has closed headquarters and other office transactions for professional services firms, banks and corporate tenants.
Margiano has more than 15 years of experience advising landlords and tenants in office, retail and restaurant leases across New York City, including large-scale headquarters and portfolio-wide transactions. Along with her representation of preeminent landlords, she has a comprehensive tenant-side practice, counseling global banking and financial services firms, insurers, law firms and other sophisticated lessees in transactions across the U.S.
A transaction-oriented attorney, Weaderhorn represents landlords and tenants in New York and nationwide in leasing high-end properties, including office, retail, shopping center and mixed-use space.
Alesi focuses his practice on all areas of leasing office, retail and mixeduse projects nationwide. He has significant experience representing a variety of clients, including real estate investors, developers and managers with first-in-class portfolios located throughout the U.S.
BY DEBRA HAZEL
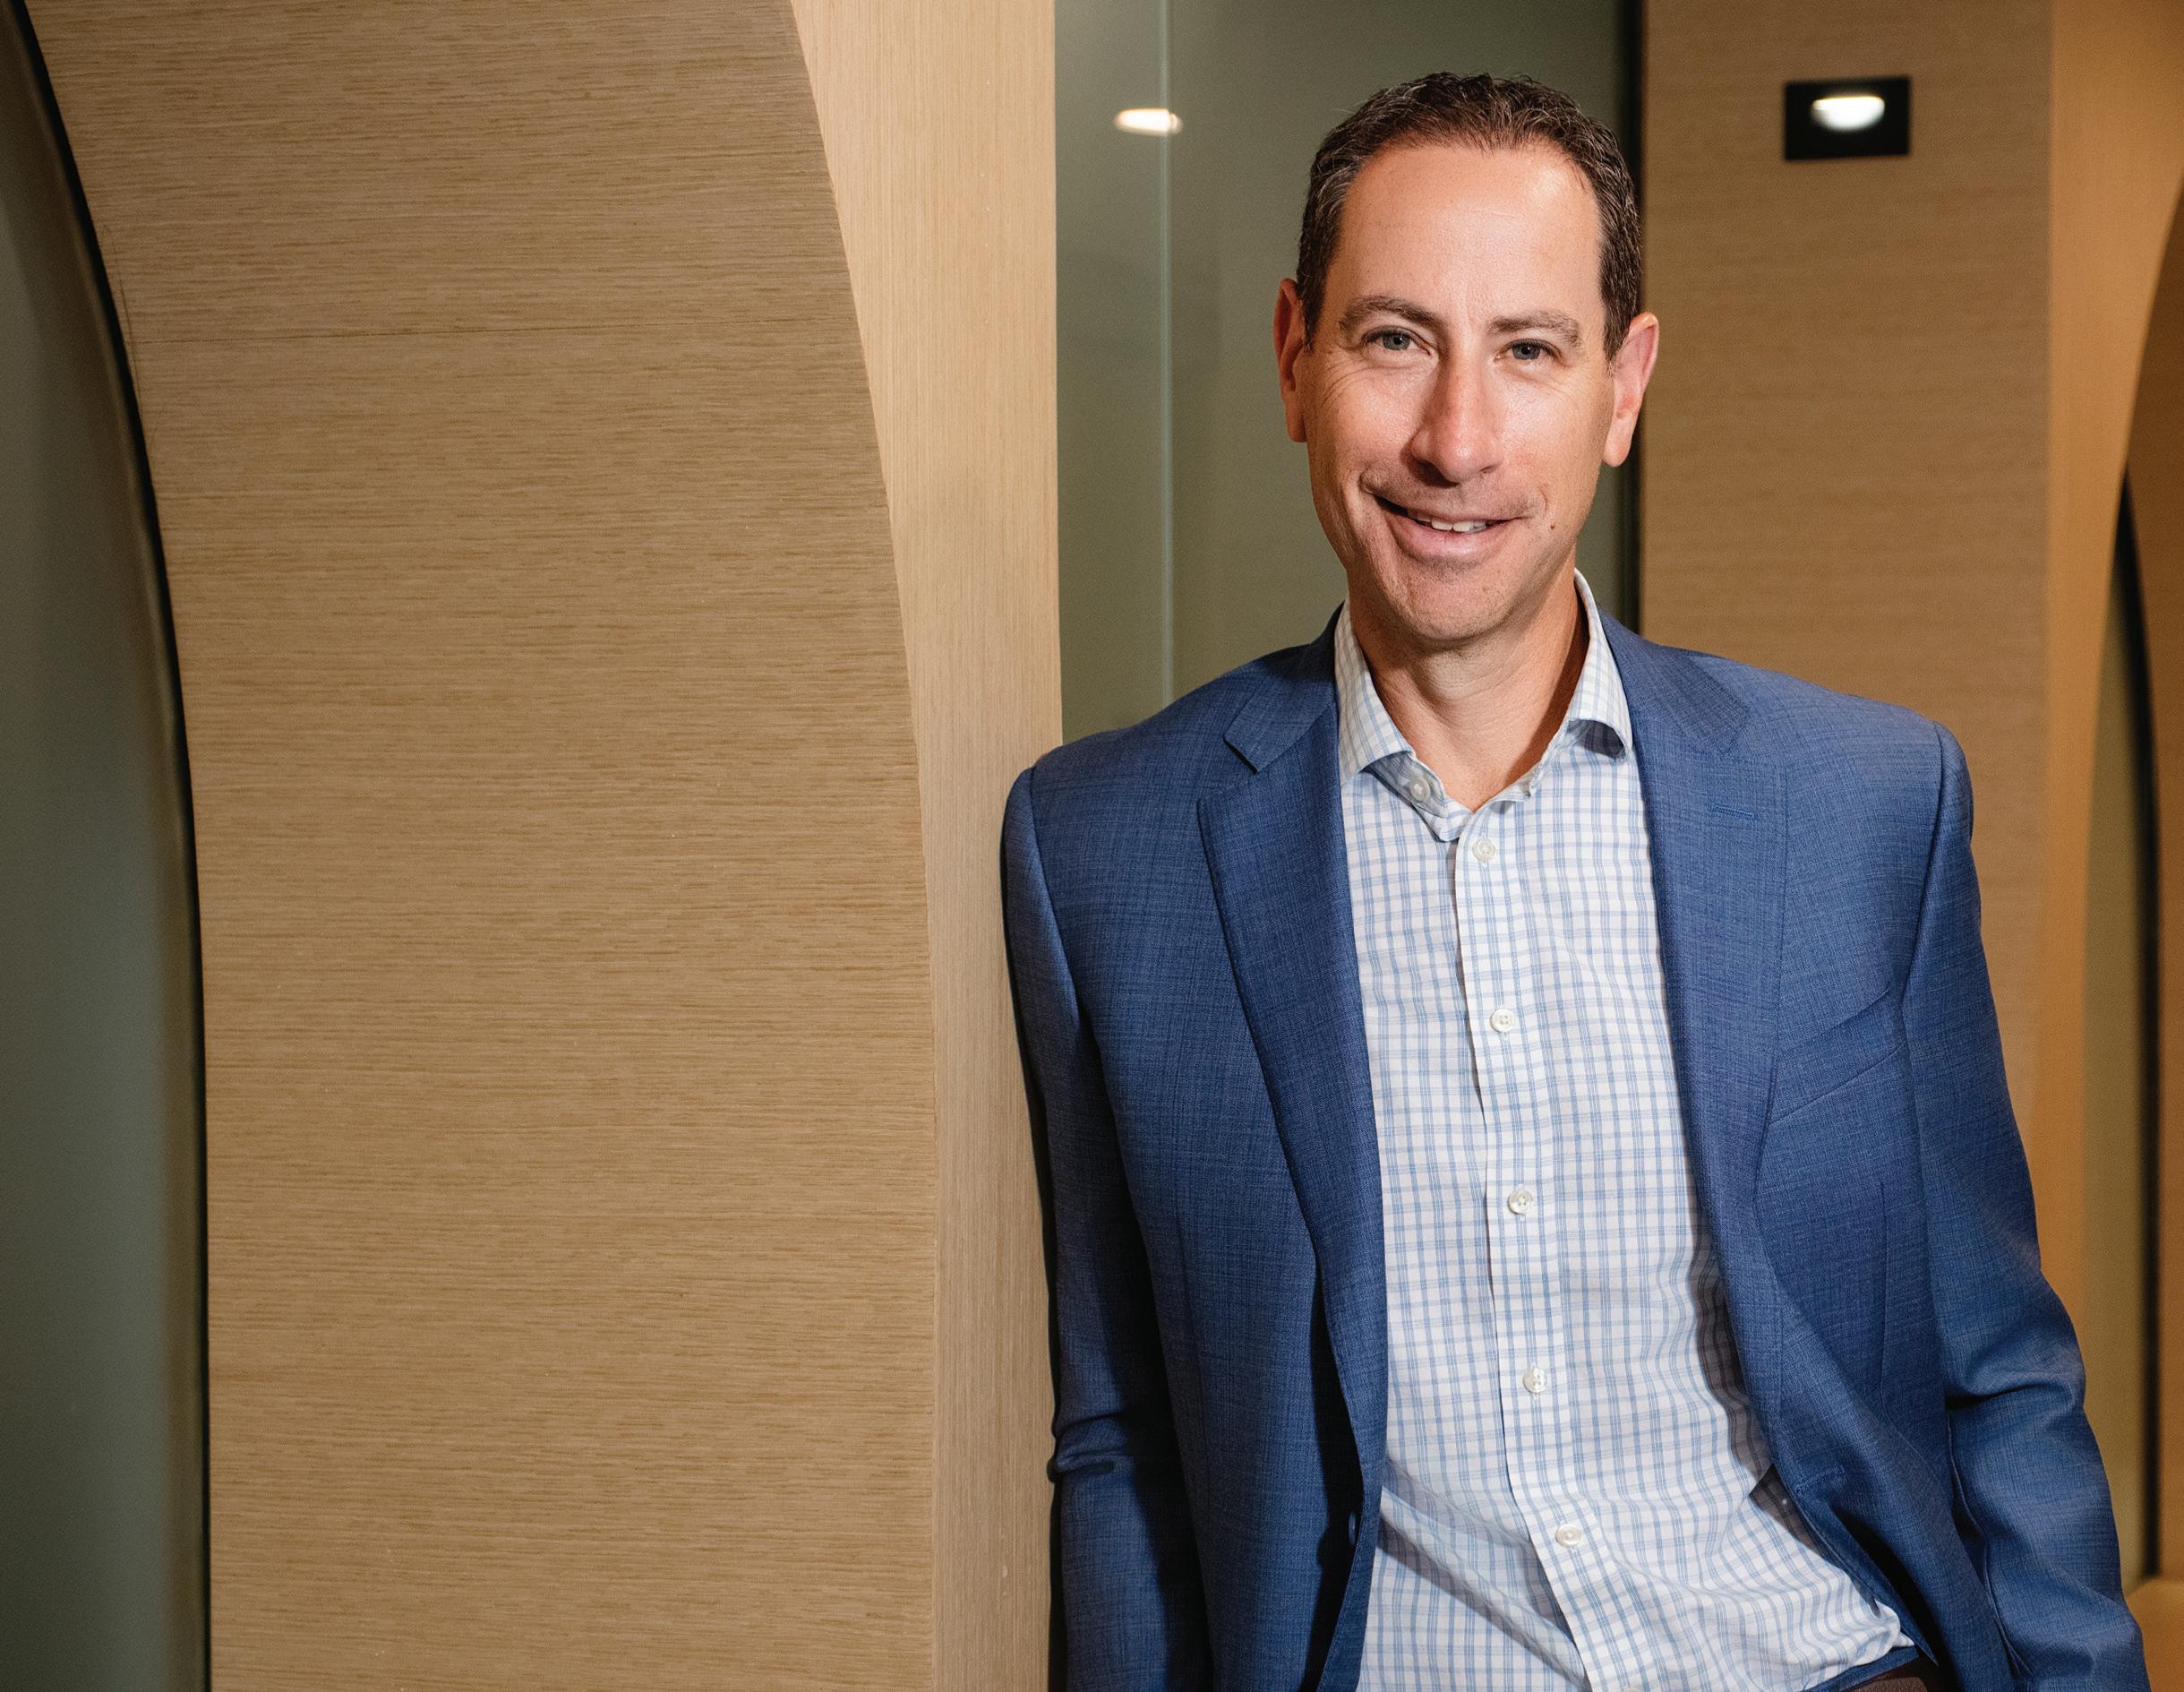
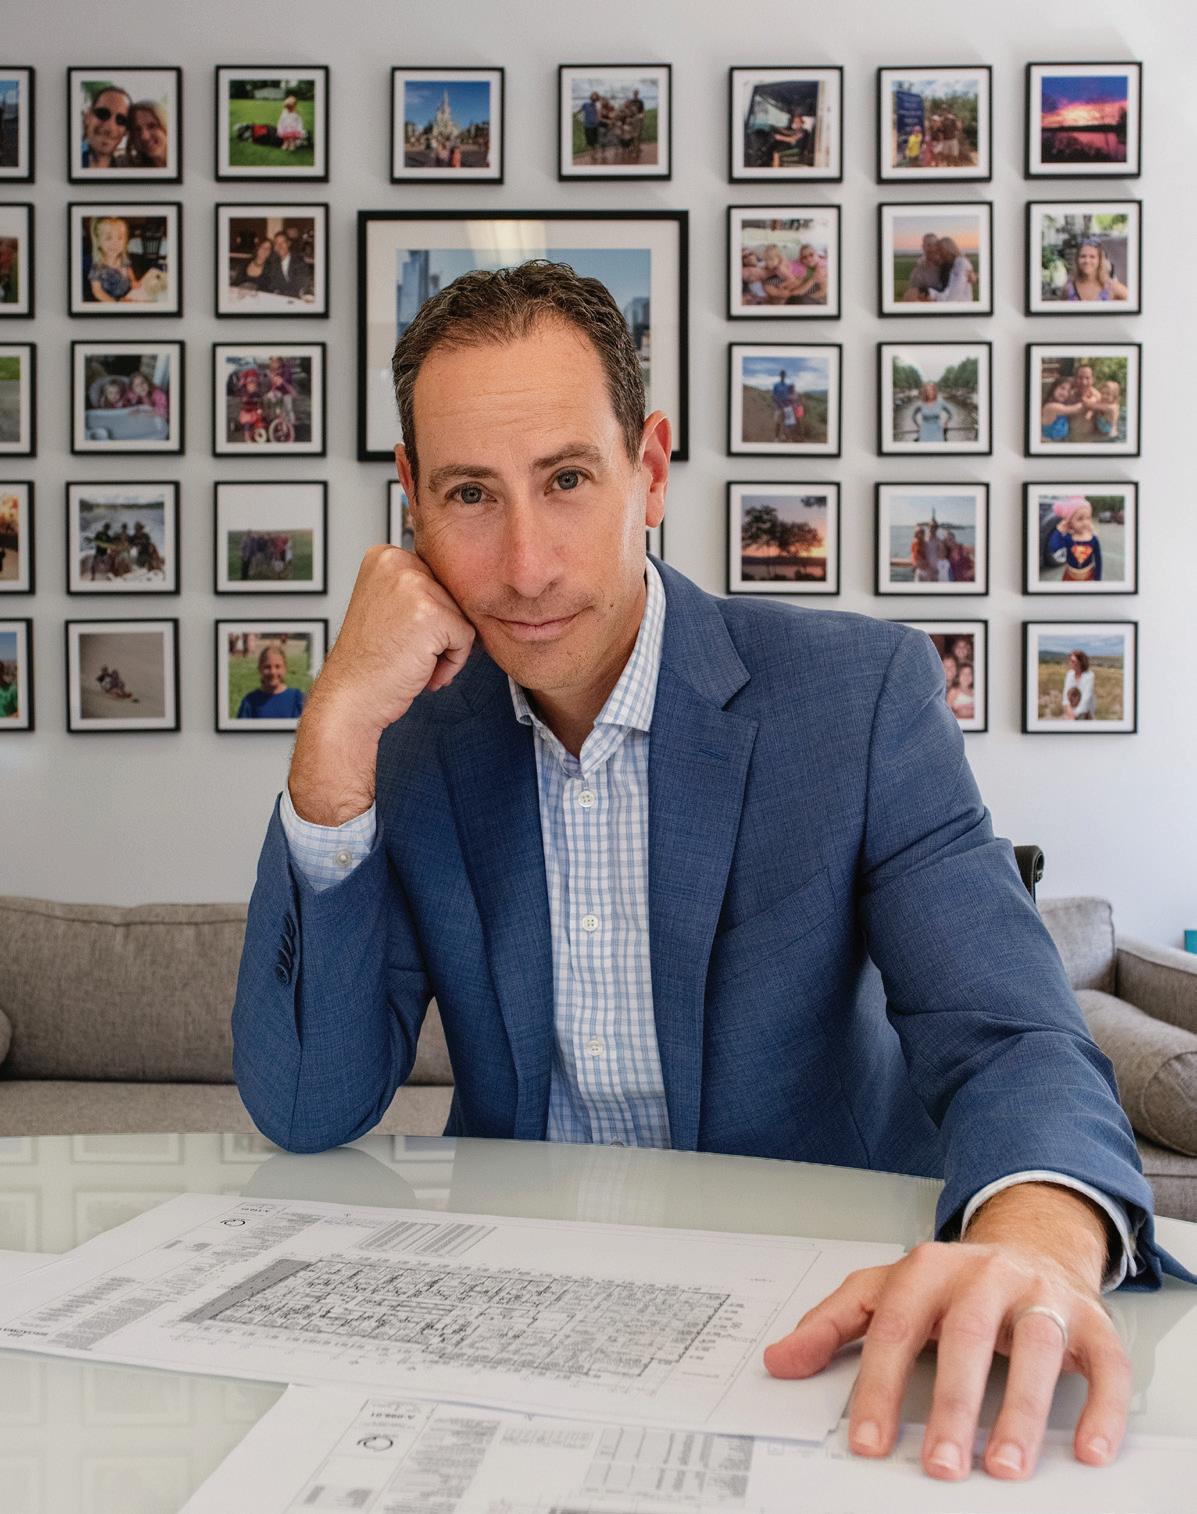
It’s no secret that developing in and around New York City is a challenge — yet GFP Real Estate LLC, long known for its massive office portfolio, has significantly expanded its focus on development with the launch of GFP Development. The new, affiliated company formalizes the firm’s development and construction platform as GFP continues to pursue large-scale development, repositioning and conversion opportunities throughout the New York City region.
is also advancing major redevelopment initiatives including the recently announced repositioning of 100 Gold Street in partnership with New York City, alongside additional conversion projects such as 40 Exchange Place, as GFP continues expanding its development pipeline across the region.
The formal launch comes at a time when distress in the office sector, evolving zoning policies and growing demand for adaptive reuse opportunities are reshaping New York City’s development landscape.
Patriarch Aaron Gural acquired Newmark & Co., a management and brokerage holding firm, in 1952 and began assembling what would become one of New York City’s largest privately held real estate portfolios. In the decades that followed, Jeffrey Gural helped expand the company’s ownership platform through acquisitions and repositionings across Manhattan, while longtime business partner Barry Gosin helped build and grow the brokerage business that would eventually become publicly traded Newmark Group.
By the 1990s and 2000s, additional members of the Gural family, including Jeffrey’s son Eric Gural and his sister, Jane Gural Senders, joined the business as the company continued expanding and modernizing its portfolio. When Brian, Jeffrey Gural’s nephew, joined the firm after business school, the company increasingly focused on large-scale acquisitions, adaptive reuse and development opportunities, including conversions of outdated office and manufacturing buildings into residential, student housing, life science and mixed-use projects. Eric Gural and Brian Steinwurtzel worked closely together on acquisitions, redevelopment and development
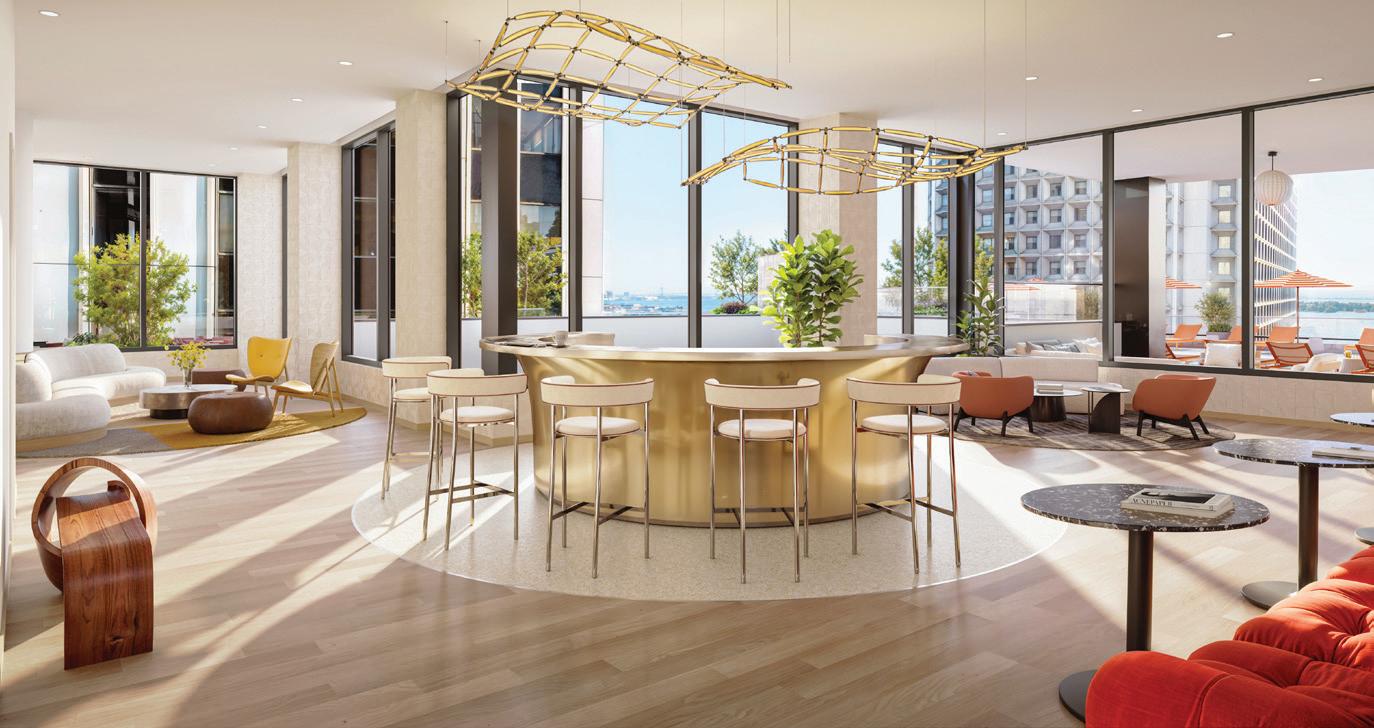
The new entity will be led by Brian Steinwurtzel, who will transition from his role as co-chief executive officer of GFP Real Estate to serve as chief executive officer of GFP Development.
“There’s a lot of opportunity when the market is uncertain. In fact, there’s more opportunity in an uncertain market than there is in a certain one,” Steinwurtzel said.
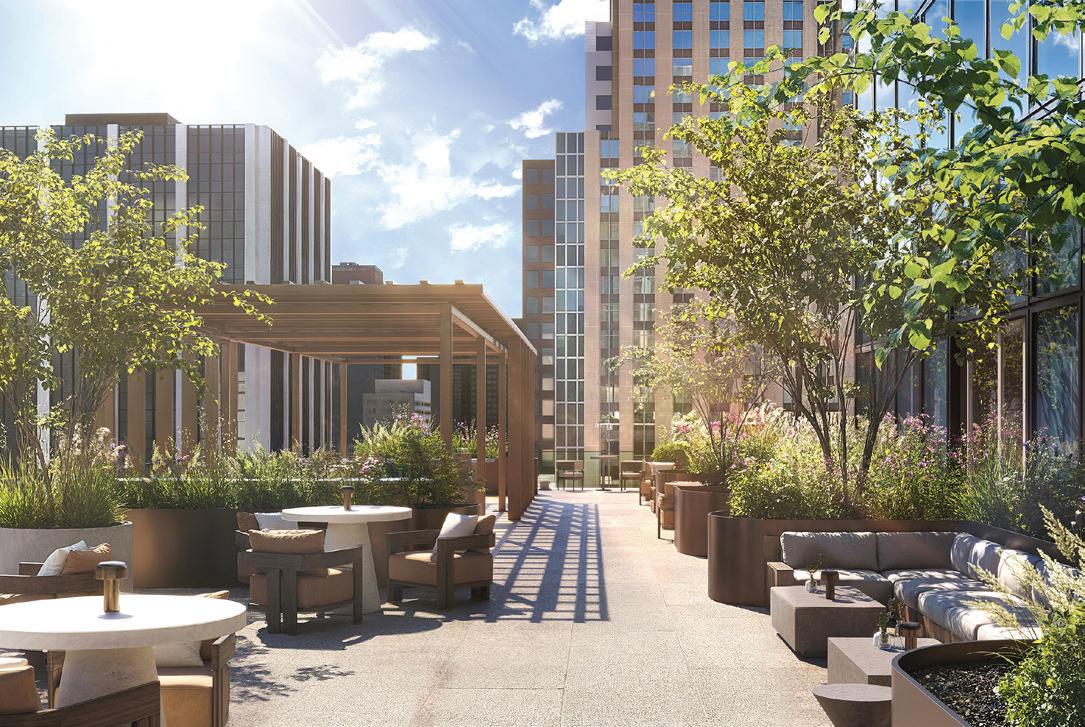
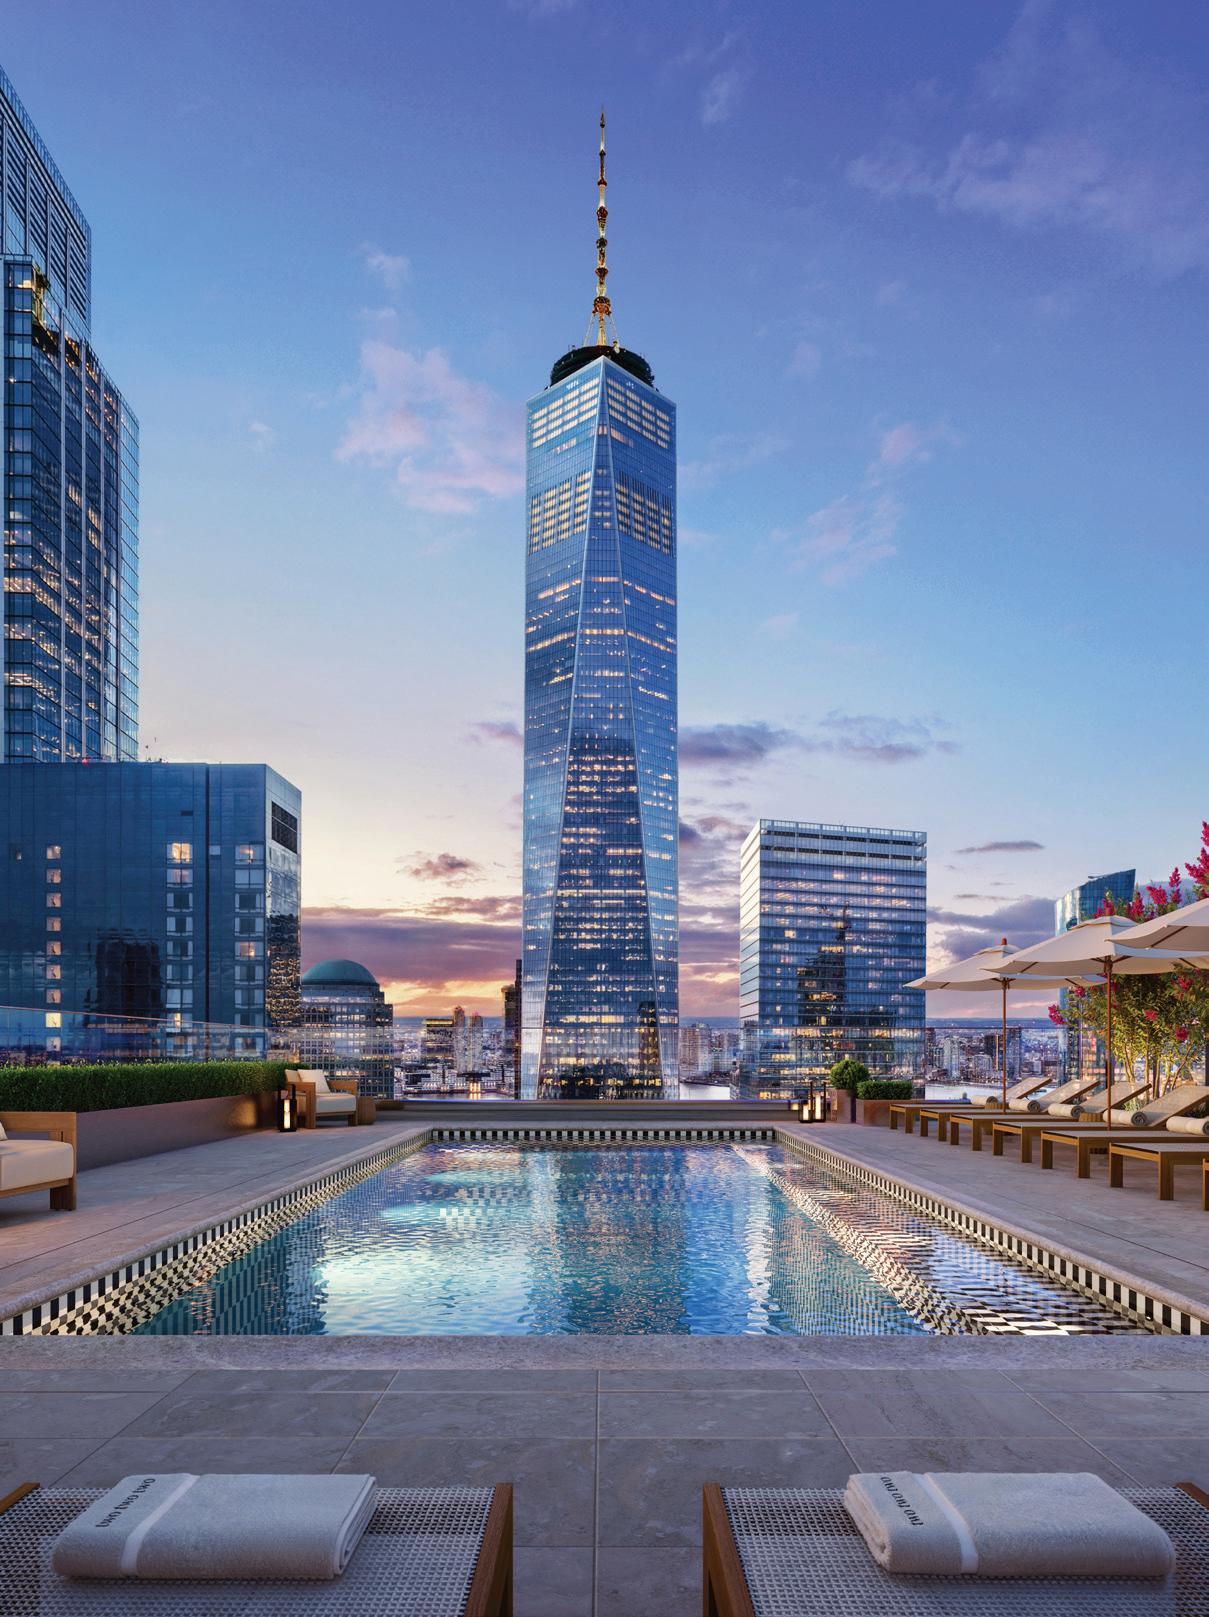
The launch of GFP Development formalizes a platform that has already overseen some of New York City’s most significant office-to-residential conversion projects, including 25 Water Street — now known as SoMA and one of the largest conversions in the country — and 222 Broadway, which reopened as the luxury rental property WREY. The company
initiatives through the end of 2021, helping to shape many of the projects and investment strategies that laid the foundation for GFP Development today.
In 2011, the company — then known as Newmark Knight Frank after other acquisitions — was sold to Cantor Fitzgerald spin-off BGC Partners. The Gurals retained Newmark Holdings’ portfolio, ultimately changing the company name to GFP Real Estate in 2017 to avoid confusion with Newmark Group. GFP Real Estate continues to operate that stable office portfolio.
“The legacy portfolio is one of the largest in New York City,” Steinwurtzel said. “It is the largest landlord of small- and mediumsized tenants in New York City, with a very successful portfolio of office
buildings, and the team that runs that does a phenomenal job running them.”
Growing up with people who would visit buildings and look up listings when they were on vacation would seem a direct path to entering the family business. However, Steinwurtzel wasn’t originally planning on a real estate career, especially with a childhood in the late 1980s, a difficult time in the industry. Instead, he spent his teens and early adulthood working in technology.
His first job out of college was in the technology consulting department at PricewaterhouseCoopers, where he analyzed the operations of large businesses including Caterpillar to determine if they could integrate technology into their company. He then joined a startup that was funded by Goldman Sachs that created a corporate analysis tool for investment banks that aggregated publicly available information.
“Then at business school, I studied in the real estate program at Columbia,” he said. “It brought me back, and I was fortunate enough that my uncle and the people at Newmark were willing to give me an opportunity to work with them. The rest is history.”
During business school, Steinwurtzel had worked for Newmark as an asset manager for a Times Square-area building. On graduation day, Jeff Gural put him straight to work building a bowling alley in Harlem.
“It was a fascinating experience to have to construct this facility, which was a multi-story bowling alley, and then to deal with an operating business,” he said.
After that, he took on various projects that others were too busy to handle.
“I was in my uncle’s office almost every day, and I would just ask him for more,” he said. “I felt very fortunate that he felt confident enough in me to put me in a position to do many of these things.”
One of those projects was the Film Center building at 630 Ninth Avenue, a personal favorite of Aaron Gural. Built for the movie industry, it offered storage for highly flammable nitrate film. For safety, each of the building’s 14 floors had a built-in film vault, with separate sprinklers and exhausts to the roof. The problem was that each higher level had its own exhaust as well as all of the others from the floors below. As a result, a significant portion of the 14th floor consisted of exhaust shafts.
By 2016, nitrate film was obsolete. Only two vaults were being rented.
“It was not an efficient way to use the building,” Steinwurtzel said.
He persuaded the New York City Department of Buildings that then-
Newmark could remove the vaults to create extra office space. It also moved the bathrooms and the hallways and consolidated them to make the building more efficient.
“The back of that building has tremendous views of Midtown. So, we removed most of the brick from the façade of that building and put in these brand new, gorgeous windows,” he said. “We recaptured a significant amount of space that we leased and opened up one whole side of the building to these gorgeous, expansive views. That project combined all sorts of elements — structural work, planning, very sophisticated rezoning and hiring and working with a great team of designers to reimagine the building.”
In many ways, The Film Center project set a tone for Steinwurtzel’s later work with GFP Real Estate. As the projects became more complex and sophisticated, Steinwurtzel rose through the ranks.
Jeffrey Gural had encouraged his team to pursue development projects over the years, and COVID-19 accelerated opportunities around distressed office assets and adaptive reuse. Projects including SoMA at 25 Water Street and WREY at 222 Broadway became defining examples of GFP’s growing development platform and helped lay the groundwork for GFP Development today.
Now, that will continue with GFP Development.
“This is an exciting evolution for our organization and a natural next step in GFP’s continued growth,” said Jeffrey Gural, chairman and CEO of GFP Real Estate, in the announcement. “Watching the business evolve across generations of our family while expanding into new areas of the industry has been incredibly rewarding. Brian has
done an exceptional job building our development platform, and with him leading GFP Development, I am confident the company is poised to accomplish even greater things in the years ahead.”
A number of developments are in the pipeline but cannot yet be announced. Though one early undertaking is a development of land GFP Real Estate has owned for decades in Jersey City, N.J., most GFP Development projects will be newly acquired, financed by large private equity funds, their own equity and more.
“We’ve built a team that includes Tom Ortinau, head of acquisitions, and Scott Beadle, head of development and construction. This team is acquiring mostly large-scale projects,” Steinwurtzel said. “A significant number of people work on these projects, and very senior people invest their own money into the deals as well. We are all deeply committed to these projects, and there’s no way that I could do any of this without them.”
In the 1980s, Jeffrey Gural had acquired 150 Bay Street in Jersey City, a 1908 landmarked warehouse that had been converted to residential, artist lofts, retail and a small office component. A small parking lot was also part of the parcel, and GFP acquired another. GFP Development aims to rezone the site into more residential.
“One of the most interesting things about the project is that if we are successful in that rezoning, a significant amount of resources will go to the local artists community. That entire area was zoned for artists years ago,” he said. “If we’re successful with it, it will ensure that the artist community will stay for years to come.”
GFP Development will focus on the New York City area, one the team knows well and boasts a multitude of opportunities, despite the challenges.
“We feel very good about the opportunities that are presenting themselves today,” Steinwurtzel said. “We are a family business that’s been investing for decades in New York City, and we are confident that the city will continue to be successful in a place that people want to live and work. We’re looking at opportunities no matter the market conditions.”
GFP Development will pursue projects across multiple sectors, including life science, student housing, office repositionings, adaptive reuse and ground-up residential development.
“These projects are really difficult. They’re very complicated,” Steinwurtzel said. “It’s fun and rewarding to find projects like 150 Bay Street where we can partner with local arts groups to create win/wins for not only us but for the local community and even include elements of affordable housing within these projects.”
Meanwhile, members of the four-generation Gural family continue to play an active role across GFP Real Estate. Jeffrey Gural will assume the title of chairman and chief executive officer of GFP Real Estate, continuing to oversee the company’s day-to-day operations and legacy portfolio. Jane Gural Senders and Eric Gural will continue to serve as principals alongside other family leaders including AnnyRose Pahl, principal and general counsel, as well as David Kaye, Neith Stone and Kephra Stone, who oversee various aspects of asset management and leasing across the portfolio.
“Culturally, it makes sense to have different firms,” Steinwurtzel
“It's fun and rewarding to find projects...where we can partner with local arts groups to create win/ wins for not only us but for the local community and even include elements of affordable housing within these projects.”
Brian Steinwurtzel
said. “At the same time, our core family values that we bring to both companies are the same. We will work together and help each other, just like we have in the past.”
In some ways, being in development was inevitable, as Steinwurtzel learned when he attended a large Gural family reunion in his 20s. He’d never met some of the attendees, a number of whom were from his great-grandparents’ generation and lived in other parts of the country. Chatting with one new acquaintance, he asked her to tell him about herself.
“She said, ‘I’m like everyone else here. I went into the family business,’” Steinwurtzel recalled. “Was there another family business I should be aware of? She wasn’t involved with Newmark. I asked her, ‘What do you mean?’ And she replied, ‘The real estate business. Every one of us is in the real estate business. It’s just in our blood.’”
SHIMON SHKURY
President & Founder, Ariel Property Advisors
Tree of Life® Award Honoree
MICHELLE KLEGER
Managing Director, Business Development, Kensington Vanguard National Land Services
Gregory A. Davis Leadership Award Recipient
TUESDAY, SEPTEMBER 15, 2026
6:00 pm | Upper East Side, Manhattan
EVENT CHAIRS
Laurent Morali, Kushner
Glen Weiss, Vornado Realty Trust
Ofer Yardeni, Stonehenge NYC
HONORARY CHAIRS
David R. Greenbaum, Vornado Realty Trust
Jeffrey E. Levine, Douglaston Development
More information
Sarah Azizi, Tristate Director, Manhattan sazizi@jnf.org • 212.879.9305 x505
JEWISH NATIONAL FUND - USA builds a strong, vibrant future for the land and people of Israel through bold initiatives and Zionist engagement.
Zetlin & De Chiara LLP, one of the country’s leading law firms, has built a reputation on counseling clients through complex issues. Whether negotiating a contract, resolving a dispute, or providing guidance to navigate the construction process, Zetlin & De Chiara is recognized as a “go-to firm for construction.”
By Lauren Dennison, Design Director, Vocon
For a long time, the office did not have to justify itself. It was simply where you went to work. In many cities, including New York City, that assumption no longer holds. When getting to work can take 45 minutes, an hour or sometimes more, people make a choice each morning about whether the trip is worth it. This has changed the role of the workplace in a fundamental way.
Value, benefits and unique experiences are what draw people to the office now rather than simply the habit of going into work everyday.
Employees are not looking for the office to mimic home, especially when many already have comfortable places to work remotely. They are looking for something that is harder to recreate on
their own: better conditions for certain tasks, easier access to colleagues, stronger moments of connection and a workday that feels more productive because they came in.
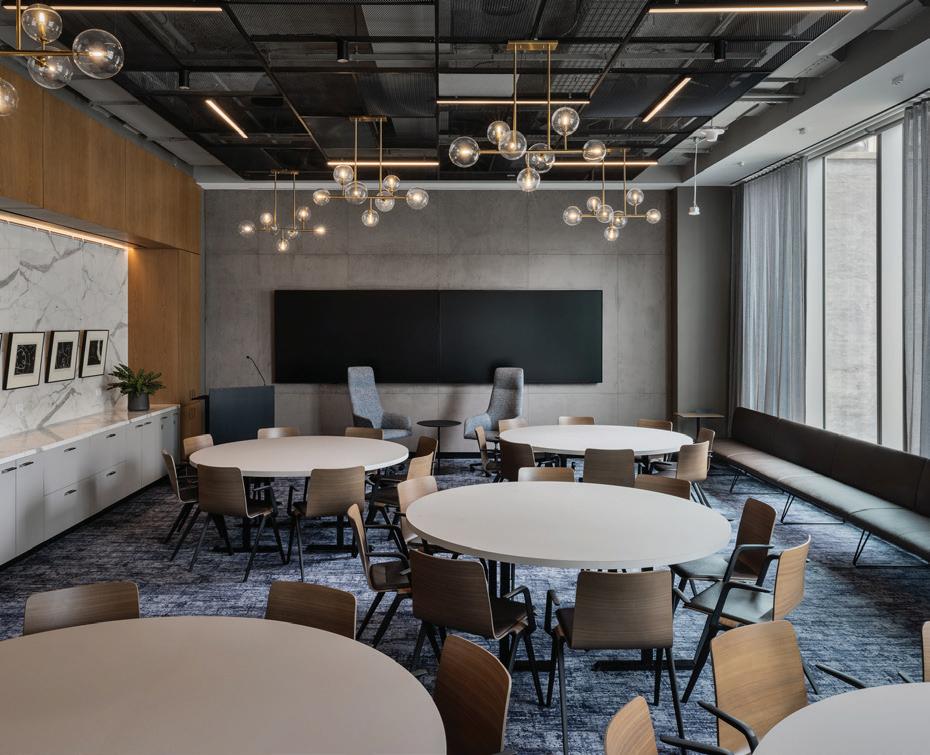
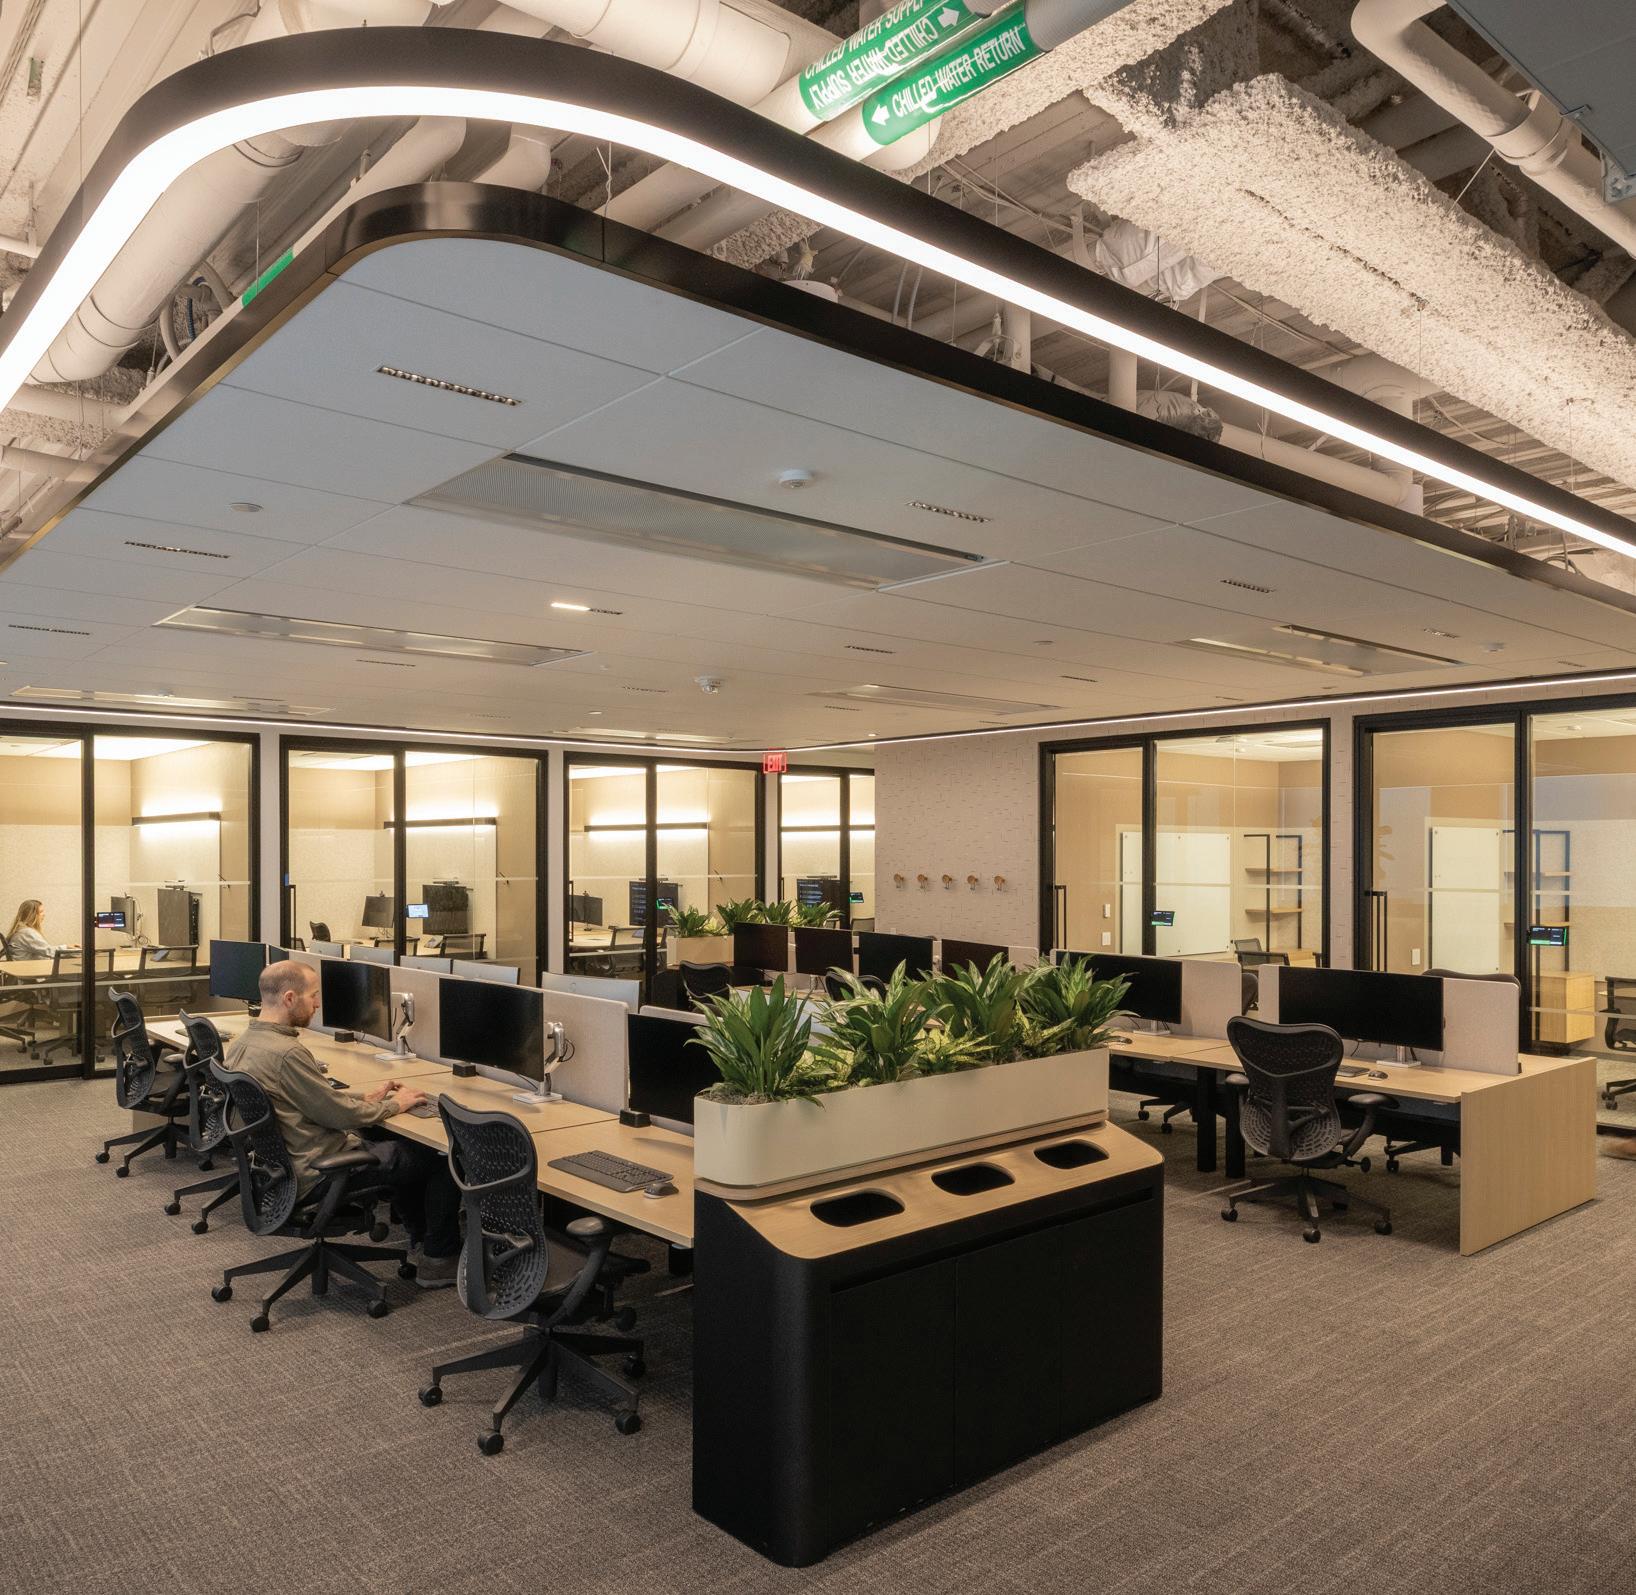
That shift is especially visible in New York City, where hybrid work has settled into the new norm. Many employees come in for only part of the week, often converging midweek, and that pattern puts a pressure on workplace design. The space has to perform when it is full, support different modes of work over the day and give people a clear answer to a simple question: why here and why today?
Recent workplace reporting from Work Better NYC and Work Design has pointed to the same evolution,
with offices increasingly expected to operate as intentional destinations rather than default settings for daily work.
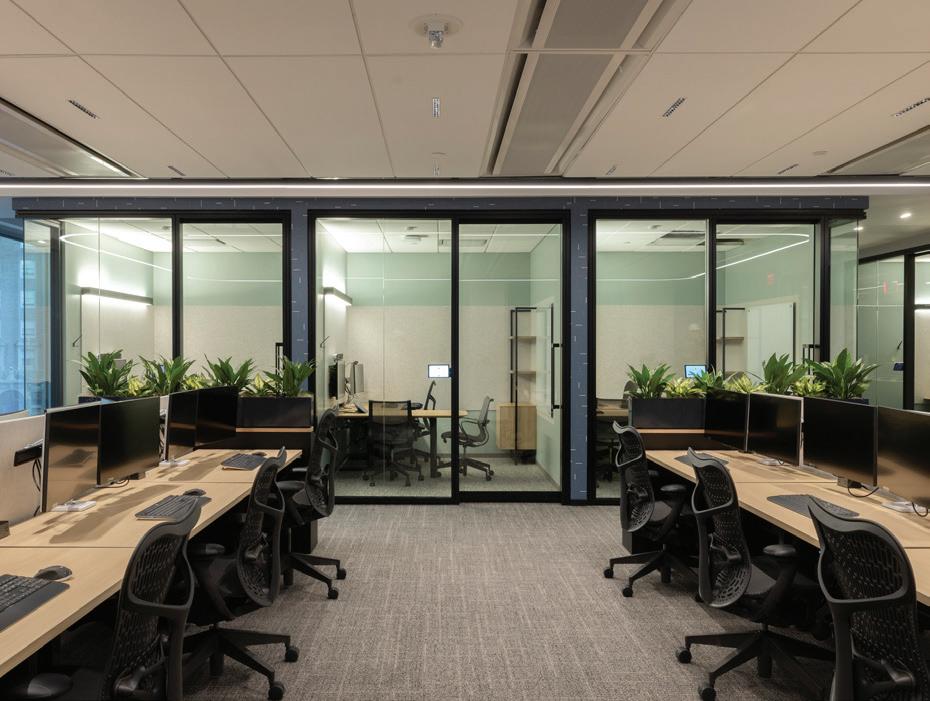
One of the clearest reasons people still want to come together is collaboration, and collaboration is expected to occur anywhere in the office, anytime in every kind of space. Open plans taught many companies a difficult lesson: more visibility does not automatically create better teamwork. In fact, without the right balance, it can do the opposite, making conversation easier at the expense of concentration.
The most effective workplaces are more strategic than that. They create distinct settings for distinct kinds of interaction. Some spaces should invite spontaneous exchange and social energy. Others should support focused, decision-oriented meetings with strong acoustics, dependable technology and enough privacy to let people actually solve problems.
For one client, we made this distinction very explicit within a single space. We designed a large, flexible room anchored by a curved screen and fully integrated audio but intentionally layered it to support both modes of collaboration. During working sessions, the room functions as a high-performance environment with U-shaped layouts, clear sightlines and the ability to focus on content and decision making.
At the same time, the space can quickly transition into a more social setting with round tables or an open plan for informal gatherings, shifting the energy toward connection and relationship building. What makes it effective is not just the flexibility, but the clarity of use; the room supports deep, outcome-driven work when needed and just as easily creates the conditions for more spontaneous, social interaction without those two modes competing. This matters even more on the busiest office days. In New York City, when attendance concentrates in the middle of the week, offices need to absorb those peaks without becoming noisy, chaotic or difficult to navigate. Collaboration may be a major reason people come in, but it only adds value when the environment is set up to support it.
Just as important, and often less discussed, is the office’s role in supporting individual work. Many workplaces still fall short in this area. Employees may have informal lounge setups at home, but they also often have something else there: control. Control over sound, interruptions, lighting, posture and routine. The office now needs to offer a better version of work, especially for tasks that require uninterrupted concentration. That means desks that are comfortable and functional over long stretches, acoustics that reduce distraction rather than amplify it and a range of settings that recognize focus as something to design for, not squeeze in around the edges.
The challenge lies in balancing focused workplace settings with social spaces to create seamless flow throughout the workday. There is no one-size-fits-all solution, which is why this balance needs to be strategically explored and defined upfront for each organization.
In many ways, this is where the commute is won or lost. If
the workplace cannot help people do their hardest work well, its value begins to decline. Reports on hybrid workplace performance have increasingly pointed to noise, lack of privacy and poorly supported focus time as recurring weaknesses in traditional office environments. But these are issues that can be resolved through careful planning.
There is also a more practical layer to all of this, and it matters. A workplace can have beautiful finishes, up-to-date amenities and an impressive lobby, but if people struggle to book rooms, launch meetings, find the right setting for a task or move through the day without friction, the experience breaks down quickly.
Good workplace design is partly about atmosphere. It is also about performance. Technology has to work the first time. Meeting rooms should feel intuitive. The office should make common tasks easier, not more cumbersome. When those basics are handled well, people feel it immediately, even if they never describe it in design terms.
In New York City, where competition for talent remains intense, that standard is only getting higher. High-profile developments have raised expectations across the market, and the so-called “JP Morgan effect” has become part of the conversation around what a workplace now needs to offer.
That does not mean every office has to chase spectacle or pile on amenities in hopes of appearing relevant. If anything, the opposite is true. The strongest workplaces are the ones that are more intentional: clearer about what they are offering, better at supporting how people actually work and less interested in adding features for their own sake.
“Worth the trip” is less about standout amenities and more about how seamless and purposeful the day feels. It ’ s about better-calibrated space types, intuitive technology and a strong hospitality layer that supports the full day. True value isn ’ t found in “more;” it’s found in less friction. We focus on making the workday more productive, more social and intentionally different from working anywhere else.
People come to the office for the energy, inspiration and the value created when teams gather with purpose. They come in because conversations move faster in person, because many efforts benefit from proximity, and because culture is still shaped through shared experience. But none of this means the workplace can coast on atmosphere. Experience and utility have to work together.
That is the real challenge for office design now. The workplace has to create meaningful opportunities for connection while also supporting focus, efficiency and ease of use at a high level. As hybrid behavior continues, offices will be judged less by how well their spaces align with actual needs.
The commute, in other words, has to be earned. And the offices that earn that trip will be the ones that help people work better, together and individually, from the moment they arrive.
New York meets Miami with a true work of art — Related Group and Tricap, together with Sydell Group, have officially completed the NoMad Residences Wynwood, the first residential expression of the NoMad Hotels brand. Located at 2700 NW 2nd Avenue in Wynwood’s main corridor — steps from the Wynwood Walls — the nine-story, 329-home community is welcoming its first residents, with more than 90% of residences already accounted for.
The NoMad brand was born in New York City, where it anchored the evolution of a wholesale district into one of Manhattan’s most coveted addresses. In Wynwood, the brand’s blend of cultural sensibility, culinary vision and residential warmth aims to perfectly complement the neighborhood’s eclectic character.
“For Wynwood, a neighborhood built on the collision of art, culture
and creative ambition, the arrival of NoMad Residences feels less like a development milestone and more like an inevitability,” said Nick Pérez, president of Related Group’s Condominium Division. “We only partner with names that bring genuine character and depth to a project, and NoMad does that better than anyone. What we’ve built here is already a community landmark, one that will define this neighborhood for generations to come.”
The result was shaped through a close collaboration of design firms Arquitectonica, DesignAgency and Sydell Group. The residences reflect the brand’s “artfully lived life” philosophy, blending old-world glamour, industrial edge and Wynwood’s creative energy into a single, seamless design language. Floorplans range from 464 square feet to 931 square feet and include studios through two-bedroom layouts.
Interiors balance modern and vintage-
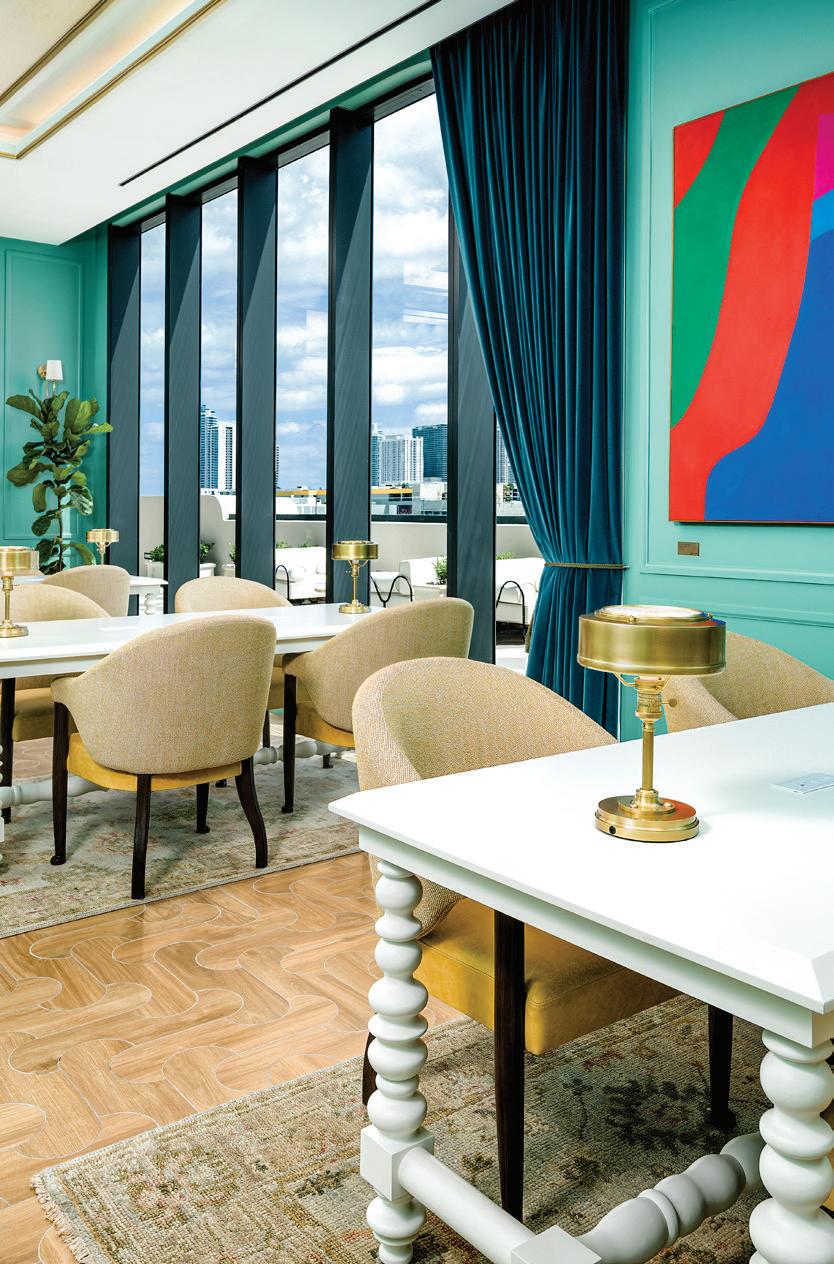
Retail occupancy remains strong and consumers remain resilient, but there are some concerns as the industry tries to grow, according to attendees at the annual ICSC@Las Vegas, held at the Wynn Las Vegas and the Las Vegas Convention Center from May 18 to 20.
New construction remains limited, benefi ting the sector in some ways, while also presenting challenges. As of the fi rst quarter of 2026, some 64.2 million square feet of retail space was under construction in the U.S., down from about 70 million square feet a year earlier, and far below the 90 million square feet-plus during previous expansions, reported CoStar. The result is major competition for nearly every vacant space.
And ironically, the very strength of the sector — vacancy around 4% nationwide, resulting in strong rents — could get in the way of future success as retailers rethink their growth plans.
“The constrained supply right now has a lot to do with the lack of new construction,” said Ebere Anotuke, Americas head of retail research at CBRE. “The fact that there is so little new construction and very little on the horizon was really making it diffi cult for these retailers to fi nd space. And a lot of them are opting to wait rather than overexpand.”
Site selection decisions can be expensive, he explained, making some companies cautious.
That same constraint may be preventing massive redevelopment of older properties, observed Adam Ifshin, founder and CEO of DLC Management Corp. With companies such as TJX Cos., Burlington, home furnishings and auto parts retaiers and more all competing for existing space, it simply doesn’t make sense to spend
BY DEBRA HAZEL
money on major rebuilding.
“The market is too good to do a wholesale redevelopment,” Ifshin observed.
Expect, on the other hand, individual retailers such as Home Depot, Target and Lowe’s to begin building secondary stores close to existing older units that can’t handle greatly increased demand.
“In the face of those volumes, they’re putting in a new store to intentionally cannibalize the sales,” Ifshin said. “Then, they can renovate.”
In some respects that strength is due to consumers, who continue to shop in physical stores despite higher prices for gas and even other basics such as groceries.
“I’ve been expecting more of a pullback,” said James Bohnaker, principal economist at Cushman & Wakefi eld. Shoppers may be assuaged by a strong stock market, “and won’t stop spending until they have to.”
But what’s really interesting is the kind of space that remains vacant, observed Brandon Isner, head of U.S. retail research at Newmark. Retailers continue to fl y to quality, with the result that nearly half (47%) of the space that is vacant now has been so for 24 months or longer. A vast majority of long-term vacancy is in older centers, and an argument can be made that no retailer will ultimately want the obsolete locations.
“A lot of that space will never be leased again,” Isner observed. But it could be acquired and turned into something else. Investors
continue to look for opportunities, and are fi nding some highquality locations, said Andy Graiser, co-president of A&G Real Estate Partners, which is marketing Walgreens, Saks Off Fifth and Offi ce Depot locations, among others.
“They’re also looking at college campuses, and there is demand for B quality distribution centers, some of which have a decent amount of land,” Graiser said.
“In retail, there is little to new development out there,” Graiser continued. The result, he said, is “very good demand and rents going up because vacancy is very low.”
Not surprisingly, experiences, value and necessities continue to dominate the retail categories that are growing. While many retailers may be opening fewer stores, new announcements are happening, with Isner citing ethnic grocers, pet foods and value retailers including Goodwill taking spaces.
“Those on the high end are doing quite well, those on the Lowe end are struggling,” said Herky Pollock, a founding partner of Legacy Realty Partners Pittsburgh, adding that deep discounters such as TJX and Marshalls continue to succeed as shoppers look for bargains. “Those in the middle are having the hardest time.”
Rising costs, Pollock continued, are preventing new entrepreneurs from opening.
“There will be more fi tness, and health and wellness,” Bohnaker said, extending beyond gyms and med spas to newer concepts including hot and cold plunge pool concepts.
Graiser remains optimistic about theaters, as good content is
Photos by
continuing to increase. Restaurants, he said, are something of a concern, as the sector may be overbuilt, and young adults are spending less on alcohol, normally a major profi t item.
Meanwhile, the very specialized luxury sector has its own challenges and opportunities. Luxury will continue to fl ock to the world’s great high streets, said Todd Siegel, president of U.S. retail of Savills, discussing the fi rm’s recently released “Global Luxury Retail 2026” report. The report ranked New York City as the world’s top luxury retail market, followed by Beijing, Paris, Bangkok, Milan, London, Los Angeles, Miami, Tokyo, Shanghai, Hong Kong and Singapore.
“There is a lack of availability on Madison Avenue, Bond Street, the Avenue des Champs-Élysées,” he said.
In seasonal luxury markets such as the Hamptons, Aspen, Colo., and Montecito, Calif., luxury retailers are taking advantage of the last aftereff ects of COVID-19 that depressed high street rents.
“Rents in the U.S. dropped so much during the pandemic, that this is now our moment,” Siegel said. “New York City, Rodeo Drive saw such an uptick over the last 12 months.”
That could mean opening smaller shops, especially in markets that are less dependent on tourism and are supported by local wealth, such as Silicon Valley and Dallas. Conglomerates such as LVMH and Richemont that control dozens of global brands are moving quickly when they see an available space.
The key is to “get closer to the customer,” Siegel said.
As it is for all retail.
At some point in the next 12 months, a real estate agent reading this will sit across from a buyer who mentions, almost as an aside, that most of their wealth is in crypto. As reported in Newsweek, nearly 40% of Americans under 40 own digital assets. That client is not an edge case anymore. What happens next in that conversation will determine whether the deal closes.
The instinct is often to note it and move on. The mortgage side of a crypto transaction is genuinely unsettled, and the guidance
available to agents is either too technical to be useful or too vague to act on. The result is that buyers with substantial digital assets too often end up with the wrong lender or arrive at application with expectations that don’t match what conventional underwriting can do for them. By then, course-correcting is hard.
The good news is that an agent doesn’t need to understand mortgage underwriting to help a crypto-holding buyer get to the right place. They need to know which questions to ask
By Eric Bernstein, President and Co-founder of LendFriend Mortgage
before they make that referral.
The First Conversation Is the One That Counts
Crypto disclosure is a qualification signal, and it should be treated the way a disclosure of self-employment income would be. Neither disqualifies a buyer, but both determine which lenders will be equipped to help.
Be specific with your questions.
Which assets does the buyer hold? Bitcoin
and Ethereum are the only digital assets most lenders will currently consider. A buyer whose wealth sits primarily in altcoins, regardless of market cap, is in a fundamentally different position than one holding Bitcoin. They should know that before they’re deep into a property search, and you should know it before you pick up the phone.
Where are the holdings? This matters more than most buyers realize. Assets held on a verifiable, centralized exchange can be documented to underwriting standards. Holdings in cold storage cannot currently be independently verified, regardless of their size. That distinction matters for which lenders can work with this buyer, and surfacing it early gives everyone time to respond to it.
How long has the buyer held the position? A portfolio with a two-year track record on a major exchange tells a very different story than one that materialized three months ago. Lenders working these transactions are looking for evidence of stability — consistent holdings signal that the wealth is real and the buyer isn’t a flight risk.
And there is the question that often goes unasked: can the buyer fund the down payment in cash, or do they need to convert crypto to do it? That single answer shapes which mortgage options are even on the table. It is worth knowing it before you recommend anyone.
You don’t need to be a mortgage expert to serve a crypto-holding buyer well. But understanding, at a basic level, that there are two very different ways digital assets can factor into a home purchase will help you recognize whether a buyer is being pointed in the right direction.
Some lenders will ask a buyer to pledge their crypto as collateral against the loan. Those assets get locked into a lender-controlled account for the life of the loan, and if the value drops below a certain threshold, the buyer can face a margin call: an obligation to post additional collateral or risk forced liquidation.
That risk doesn’t end at closing. It follows the buyer for as long as the loan is active. For many buyers, that’s not a structure they fully understand until they’re already in it.
Other lenders use what’s called an asset depletion approach, where the buyer’s holdings are verified but never pledged. The crypto stays in the buyer’s control throughout the transaction, and once the loan closes, they can do whatever they want with it: convert to cash, move to a different asset or hold it. For most people buying a home, this is the structure that fits their situation.
Your job isn’t to steer a buyer toward one or the other. That’s the lender’s conversation to have, based on the borrower’s full picture and what the lender can offer.
But if you’re referring a buyer to someone who can only offer the collateralized version, and that buyer doesn’t fully understand what they’re signing up for, that’s worth knowing before the referral happens.
One point worth flagging to buyers early: converting crypto to cash for a down payment is often a taxable event, and many buyers don’t realize it until it’s too late. A lender who works regularly with digital asset holders will know how to talk through this. One who doesn’t may not raise it at all.
The right lender for a crypto-holding buyer isn’t the nearest one. It’s one who has worked these transactions before and can speak to them with specificity.
Ask whether they’ve closed purchases where digital assets were part of the qualification. Ask which assets they can work with. Ask what documentation they’ll need and how far in advance a buyer should have it in order.
A lender who can answer those questions clearly has done this before. One who hedges or generalizes probably hasn’t.
Documentation matters as much as portfolio size in these transactions. A buyer with a consistent, well-documented holding history on a verifiable exchange is in a stronger position than one with a larger but messier picture. The latter includes recent unexplained transfers, assets spread across wallets, and holdings in tokens most lenders won’t touch.
The right lender will tell a buyer this upfront and, given enough lead time, structure the transaction so the borrower qualifies for the loan they want. Getting that conversation started before the property search does is worth more than most buyers realize.
Credit still matters too. Digital asset wealth opens doors that conventional underwriting might otherwise close, but it doesn’t replace a responsible financial profile. The lenders best equipped to help these buyers will be honest about that.
The generation now entering peak homebuying years built wealth in ways that traditional mortgage systems weren’t designed to read. That isn’t going to reverse.
The regulatory environment is moving toward broader recognition of digital assets. Slowly and inconsistently, but moving. Lenders who work these transactions are getting better at them.
An agent doesn’t need to get ahead of that curve to serve their buyers well. They need to know enough to ask the right questions, recognize the right lender and make the introduction before the wrong assumptions have a chance to take hold.
By Joel Horwitz, CEO, Synter
It is Monday morning. Your broker or managing partner pulls up an artificial intelligence (AI) assistant and asks it to build next month’s advertising plan. Ninety seconds later, the screen fills with a polished strategy that includes target audience segments; platform recommendations across Google, Meta, Spotify and Nextdoor; budget allocation by channel and creative angles tailored to three different homebuyer and seller personas.
They print it out and set it down on the desk.
Now what?
AI tools have become remarkably capable at generating strategy. However, they are equally incapable of executing it. No AI assistant, regardless of how sophisticated its output appears, can log into your Google Ads account, configure your Meta campaigns, set your bid strategies, build your exclusion lists or push spend to a connected TV platform.
The reality is this: strategy and execution still live in completely separate systems, and that gap is where performance breaks down. For most real estate brokerages, this is quietly consuming tens of thousands of dollars every year.
What’s missing is not better prompts or more data. It’s infrastructure — systems that can translate strategy into live campaigns, continuously optimize them and execute decisions in real time across platforms.
When a brokerage has a wellwritten AI strategy but lacks an integrated execution layer, the outcome typically follows one of three paths. In the first, the broker or team lead hands the plan to an employee who is not a paid media specialist. The implementation is inconsistent, platform-blind and expensive.
Alternatively, the strategy goes to an agency, which charges a retainer plus an additional 15% to 25% of total ad spend, while still relying on fragmented, manual processes the brokerage is trying to move beyond.
In the third scenario, that strategy sits on the desk, and nothing happens.
All three outcomes share the same core problem: the intelligence of the strategy never reaches the campaign layer where decisions are actually made.
There is a second, less visible drain running alongside the execution gap. Independent research from firms including DoubleVerify and Integral Ad Science consistently estimates that 20% to 40% of digital ad traffic carries some form of quality issue, including impressions served to non-human sources. For a brokerage spending $20,000 per month on digital advertising, a 20% waste rate represents impressions that never reached a real home buyer or seller actively searching in your market.
The AI assistant that wrote your strategy did not build geographic exclusions to filter low-quality traffic sources. It did not configure fraud filters or set platform-level brand safety controls. Those actions require execution, not recommendation. And the major advertising platforms, whose revenue models are built on impressions and clicks rather than outcomes, are not structured to flag this problem on your behalf.
The brokerages gaining ground right now are not using AI only to plan. They are connecting AI to their execution infrastructure so that a strategic recommendation can become a live, optimized campaign without requiring a specialist for every platform. This approach, sometimes called an agentic advertising model, allows a brokerage to run across eight or 10 platforms with the same internal team that previously managed two.
Equally important is where guardrails are applied. Effective execution embeds protections at the campaign level: geographic exclusions to block low-quality traffic, frequency caps to prevent ad fatigue and CRM-integrated suppression lists to stop serving prospecting ads to existing customers and employees.
These are not advanced tactics reserved for enterprise advertisers. They are the baseline requirements for spending responsibly, and they only work when they are systemically enforced at the execution layer.
The metric that exposes whether any of this is working is cost per acquisition. Most brokerages optimize for clicks and impressions because those are the numbers their platforms surface most prominently.
But 1,000 clicks from the wrong audience are worth nothing. One hundred clicks from in-market buyers within your drive market are worth a great deal.
Real estate brokerages operate in one of the most demanding local advertising environments in existence. Your listings changes weekly, which means your ad strategy must change with it. An AIgenerated plan that recommends promoting specific property types does not account for listings that go under contract, unless it is connected to your live data and capable of adjusting campaigns automatically.
Your clients generally transact within a 15to 25-mile radius, which means campaigns without tight geographic parameters are burning budget.
The right question for any broker evaluating their current approach is not which AI model powers the tool. The question is whether the system can actually execute, adapt and optimize automatically across your entire advertising stack. If the answer is a report or a recommendation that someone else has to act on, the execution gap remains open.
Audit your current stack and identify how many of your AI tools generate strategy versus execute it. Calculate your cost per acquisition by platform; if that number is unavailable, that is your first problem to solve. Run a geographic traffic audit on your last 90 days of campaign data and examine where your clicks are actually originating. Connect your CRM suppression list to every active ad platform before your next campaign launch.
AI has made it possible for any broker principal to develop a sophisticated, multiplatform advertising strategy in minutes. That is a genuine and meaningful shift. But having a strategy feels like progress without necessarily being progress.
The brokerages that pull ahead in the next 24 months will be the ones that close the gap between what their AI recommends and what actually goes live. The technology to do that exists. The question is whether yours is connected to it.
Synter is a technology company focused on agentic AI advertising execution for real estate brokerages and local businesses.

ISRAEL’S HOME FRONT NEEDS YOU JOIN US IN SOLIDARITY FOR THIS SPECIAL EVENT
JEWISH NATIONAL FUND - USA INVITES YOU TO OUR ANNUAL
Monday August 10 9:00 AM
The Mill River Club
Monday, August 10
9:00am
SPONSORSHIP
MORE INFORMATION
HONORING
Steve Pinchasick, Principal, EBMG LLC & Accredited Property Management
Howard Ingram, Associate Executive Director, Long Island hingram@jnf.org • 516.678.6805 x110
Ashley Emrani, Tri-State Director, Long Island and New York aemrani@jnf.org • 212.879.9305 x501
Please contact Neil B. Garfinkel, Managing Partner, to see how AGMB can assist you.
Abrams Garfinkel Margolis Bergson, LLP is a full-service law firm dedicated to smart, practical and cost-effective counsel. NEIL B. GARFINKEL, ESQ.
Broker Counsel to REBNY
Abrams Garfinkel Margolis Bergson, LLP (212) 201-1173
Efax: (646) 778-3710 ngarfinkel@agmblaw.com www.agmblaw.com
Carol A. Sigmond Partner Nossaman LLP
12 East 49th Street
22nd Floor
New York, NY 10017
For many years, service on boards of managers or directors for condominium and cooperative residential buildings was a privilege and source of influence within a building. Today, between the unfunded mandates, rising operating costs and increasing contentiousness within buildings, board service has become more burdensome.
Boards are facing unfunded mandates, including fair housing requirements, the threat of the Corporate Transparency Act (CTA) and various local laws. For many years, boards of directors in cooperative apartments had unfettered discretion to turn down prospective purchasers. Fair housing laws have effectively restricted that authority to financial issues. Statutes that were intended to protect ex-offenders from housing discrimination have also made it difficult to avoid ex-offender purchasers except for some on the sex offender registry. If a board is considering rejecting a proposed purchaser for any reason, the file should be fully documented with the support of the board’s counsel.
The CTA is currently being enforced against international non-domestic entities. However, pressures from law enforcement for more disclosure of ownership of companies in the cryptocurrency and money-laundering space may force a change in the enforcement of the CTA. For boards, this will require new disclosures and reporting requirements. Many businesspeople who make desirable board members may pass on the opportunity if the CTA takes effect.
Boards are also facing unfunded mandates for energy efficiency and other obligations from local and state governments. These demands are clashing with the second group of issues facing boards, namely the rising costs of maintenance, utilities, insurance and property taxes. Boards struggle to raise money from unit owners, because routine maintenance costs are rising and Manhattan-based cooperative and condo buildings are paying hugely disproportionate property taxes.
When a middle-value condo or coop unit in Manhattan pays five times more in property taxes than a similarly valued home in the outer boroughs, and amounts equal the property taxes paid by highvalue brownstones, the system is broken. It also means that unit owners are so overtaxed that they have no stomach for a board on a spending program, even to
support climate initiatives.
Against this backdrop, boards are struggling to raise maintenance to cover staff, utilities and maintenance. Whether The Real Estate Board of New York (REBNY) is serving the interests of coop and condos is questionable. REBNY seems to serve commercial buildings, not residential buildings.
Boards need flexibility to reduce staff, particularly as energy efficiency reduces workload. For example, the amount of time dedicated to changing light bulbs has decreased over time given the longer life of LED bulbs.
To date, no effort has been made to allow boards to modify staff as needs change. Obviously, this has to happen at some point. Utilities are costly in part due to property and other taxes charged by local and state government. For overtaxed Manhattan apartment owners, it is adding insult to injury. It is another example of the broken property tax system in New York City.
Board members are facing contentiousness within their buildings as well, including new demands on buildings for access agreements that were not favorable to coops and condos and claims of breach of fiduciary duty and liability.
Consider that some buildings are older and were built under older codes. Disgruntled unit owners or shareholders can make complaints of non-compliance with current code in buildings that cannot comply based on the physical attributes of the building.
Sadly, NYC uses the complaint system as a supplemental tax system, so buildings which are subject to the 1968 or 1938 codes for violations see fines, not constructive assistance from the New York City Department of Buildings. This only emboldens unreasonable demands, increases the insurance premiums for buildings and provides no enhanced safety or operations.
Why anyone wants to be a board member is this environment is a mystery.
This column presents a general discussion. This column does not provide legal advice. Please consult your attorney for specific legal advice.
Kris Kiser
Outdoor Power Equipment Institute
TurfMutt Foundation Equip Expo
1605 King St. Alexandria, VA 22314 turfmutt.com opei.org (703)549-7600
For many years, the American lawn was a status symbol of uniform green and seen as a quiet, aesthetic backdrop of a home. But in 2026 we are witnessing a paradigm shift.
The lawn is as important as ever but the “just for looks” yard has evolved into a high-performance, purposeful sanctuary. Your personal green space is a strategic investment in your family’s physical and mental health, environmental resiliency and community connectivity.
As the weather warms and attention shifts to our outdoor spaces, the TurfMutt Foundation highlights these trends that define intentionality as the new foundation of American landscaping:
Green Space Growth Movement
Homeowners recognize the power of backyards, parks, school yards and sports fields to foster family wellness, create environmental resiliency and nurture neighborhood connectedness. To that end, they are embracing a “Green Space Growth Movement” to put in more green space — or improve what they already have — to contribute to a more vibrant and healthier lifestyle.
Micro-Zoning to Make Every Square Foot Count
Whether you have a sprawling suburban yard or a compact urban area like a balcony, you can create purpose-driven zones. The goal is to maximize the ROI of your property’s footprint.
For small spaces, we’ll see a rise in living walls and vertical container gardens. For large estates, there is a shift toward dedicated areas for remote work, outdoor fitness or even hobby farming.
The Rise of the Four-Season Yard
Homeowners are no longer content with a oneseason backyard. The 365-Day Landscape is the new standard. The focus isn’t just on planting for immediate blooms but on strategic, year-round planning. By utilizing tools like the USDA Plant Hardiness Zone Map, homeowners can select a mix of species that provide visual interest in the winter, shade in the summer and hardiness in the fall.
Data Driven Landscaping
Guesswork in caring for green space has been replaced by precision technology. From AI-driven soil analysis apps to smart irrigation systems that track micro-climates, homeowners are using data to ensure their plants thrive.
Unleashing Backyard “Barkitecture”
Pets are taking center stage in landscape design with the rise of “barkitecture” that focuses on “zoomie zones,” pet-safe plant selections and puppy splash pads. Designing a yard that is as comfortable for our four-legged friends as it is for the humans — and ensuring it seamlessly integrates with the overall vibe of the property — is a top priority.
Homeowners increasingly see themselves as stewards of the environment, and their backyards as a conduit for conservation. Personal mini parks of small, dense stands of native trees reflect a desire for neighborhood connectivity and turn individual backyards into a vital part of a larger, healthy ecosystem.
Lawn mowers, hedge or string trimmers and other outdoor power equipment help keep your yard in tip-top shape, and more homeowners are demanding commercial-grade power and durability from their outdoor equipment.
There is a type of power equipment for every need, but remember to keep safety in mind:
• Read and follow the owner’s manual. Every piece of equipment is different, which impacts how to use it safely.
• Walk your yard before mowing, cutting or digging to pick up any debris and lose objects that could be hit by your mower. Don’t forget to inspect trees that might require pruning.
• Look over equipment before use, checking the air filter, oil level and gasoline tank.
• Never disable or alter manufacturer-installed safety equipment.
• Protect your power by using only E10 or less fuel in gasoline-powered equipment if it is not designed for higher ethanol blends.
• Only use battery packs specified by the manufacturer for electronic equipment.
• Always keep children and pets away from operating outdoor power equipment. Period.
• Keep your equipment clean and store equipment in a dry place, avoiding damp or wet environments.
TurfMutt encourages homeowners to invest in a landscape that performs for your family’s lifestyle, pets and the planet.
To learn more about creating the yard of your dreams, go to turfmutt.com.
Debra Hazel
Debra Hazel Communications
North Las Vegas, NV (201)618-5247
It’s a Northern invasion — Canadian tourists may be slowing down on visiting the U.S. these days, but Canadian retailers are crossing the border in ever greater numbers in search of growth.
Canadian residents returned from 2.6 million trips to the U.S. in March, down 6.4% from the previous year, continuing a trend over the last year, according to StatCan. But new companies are entering the retail fray here, including one category that might surprise you — home furnishings and décor.
JLL and Retail by Mona recently announced a 10,146-square-foot, 10-year lease for Cozey to open its first permanent U.S. store at 160 Fifth Avenue in Manhattan’s Flatiron District. Founded by Montreal-based entrepreneur Frédéric Aubé as an online brand in 2020, Cozey designs and sells modern, modular home furnishings. The company is known for its omnichannel approach, offering customers a curated, fl exible product assortment delivered quickly across North America. The company has four stores in Canada.
“Our fi rst permanent U.S. fl agship in New York City is a major step in Cozey’s growth journey,” said Aubé in the announcement. “We’re excited to bring our unique retail experience to the Flatiron District and continue building meaningful connections with our customers in one of the world’s most dynamic markets.”
On the West Coast, Article, a Vancouver, B.C.based modern furniture brand with one physical store in its home town, announced store locations in San Francisco and Bellevue, Wash., before the end of this year, based largely on its e-commerce sales. In fact, the company said, the U.S. is the company’s largest customer base.
“We see physical retail as an extension of the business we built online and are approaching expansion with discipline,” said Aamir Baig, Cofounder and CEO of Article. “The West Coast has always been core to our business and represents roughly a quarter of total purchases. It’s where our company is headquartered and where we built early infrastructure to support customer demand. Expanding our retail footprint to California and Washington is a natural next step.”
Article plans to have up to five store locations, including Vancouver and Toronto, by early 2027.
The trend continues beyond home décor companies. T&T Supermarket, the largest Asian grocer in the country and a subsidiary of giant Loblaw Cos., is expanding into California after opening its first U.S. location in Bellevue, Wash., in late 2024 and a second in Lynwood, Wash., last year. Premium luggage brand Monos
is opening boutiques in major cities including Boston, Los Angeles, Chicago, New York City and Washington, D.C. Several boast an adjacent lounge offering food and beverage to mimic the travel experience.
They join longer-established brands such as Aritzia, Lululemon, Canada Goose and Mejuri in operating in the U.S.
Why? Market saturation at home is certainly a factor. Canada’s population of 41.5 million is dwarfed by the U.S. 349 million. That’s a lot of opportunity. And domestic retail is dominated by a handful of companies: Loblaws on the grocery side; Alimentation Couche-Tard for convenience stores; Canadian Tire, which also sells hardware and sporting goods, and Canadian divisions of TJX, Costco and Walmart. It’s difficult for young companies, especially those that began online, to make a mark.
But the path hasn’t always been easy and remains a challenge.
Back in the late 1980s/early 1990s, some Canadian retailers tested stores across the border, but quickly retreated — currency issues, taxes and even holiday scheduling just made logistics too difficult back then. Black Friday as an official start to the holiday shopping season was a completely foreign concept, one company told me at the time.
Some of those challenges still exist, especially foreign exchange. According to Airwallex, a Canadian AI platform for retailers, various Canadian financial institutions charge from 2.6% to 3.3% fees on foreign exchange transactions. That might not seem like much, but in an industry with tight margins, it can make the difference between success and failure.
Language is another issue. Labels and other documents prepared in English and French for Canadian stores might need to be transitioned to English and Spanish.
And then we have tariffs. As I write this, the tariff is 25% on most Canadian goods coming into the U.S., which has already had an impact on Oak + Fort, a contemporary lifestyle apparel brand from Vancouver. The company has 12 stores in the U.S., including the Boston, New York, Los Angeles and Chicago metro areas, out of a total of 30 across North America. But in June 2025, it fi led for creditor protection, citing those tariff s as a major factor in its struggles. The stores remain open as the company restructures.
So, let’s welcome these newcomers, which keep our own retail scene lively — and keep an eye on cross-border shopping.
Langsam Property Services Corp. is a Bronx-based real estate management company. These buildings are located in the Bronx, Manhattan, Queens, Brooklyn, and lower Westchester County.
Langsam is designated as an Accredited Management Organization (AMO), a standard of excellence in management conferred by the Institute of Real Estate Management (IREM).
1601 Bronxdale Avenue
Bronx, New York 10462
Tel: 718. 518. 8000
Fax: 718.518. 8585
Michael Siino
CPA, Managing Director, Regional Real Estate Practice Leader CBIZ
New York, NY
Decisions about building design go far beyond aesthetics. They shape long-term value, performance and marketability. Energy efficiency and sustainability and environmental, social and governance (ESG) principles are redefining the real estate landscape and how developers, investors and tenants evaluate space.
Sustainable design strategies, energy incentives and increasing regulatory pressures shape building operations and asset value. Because early design decisions have lasting implications for performance, cost and market competitiveness, integrating tax planning with ESG upgrades can unlock incentives and depreciation benefits that enhance project value.
The timing and structure of these investments also affect eligibility for incentives, depreciation schedules, after-tax cash flow and overall return on investment.
Sustainable Design Drives Value
Sustainability is now a business imperative. Developers incorporate high-performance glazing, low-carbon materials, water-efficient systems and advanced lighting controls to meet tenant expectations and reduce energy consumption. These features attract investors, improve tenant retention and create value beyond initial construction costs.
Thoughtful design also enhances the occupant experience. Natural light, improved air quality and efficient climate control support comfort, productivity and tenant satisfaction. In competitive markets, LEEDcertified or Well Standard buildings often command higher rents and lease faster, reinforcing the financial benefits of ESG-aligned design.
Efficient buildings also reduce operational volatility, which appeals to long-term investors seeking stable returns. Industry research suggests that ESGcompliant properties may achieve higher occupancy rates, demonstrating that sustainability decisions can directly affect financial performance. When paired with tax-aware planning, these strategies can further strengthen ROI and portfolio performance.
Energy Incentives Turn Costs into Opportunity
Incentive programs can offset the cost of sustainability investments. Federal tax credits, state rebates and utility grants help offset upfront costs for energyefficient HVAC systems, solar infrastructure and smart building technologies. Although complex, these incentives strengthen project economics and support strategic design planning.
Incorporating solar readiness, high-efficiency mechanical systems or automated lighting controls early in the design process reduces retrofit costs and improves eligibility for incentives. These measures lower costs, accelerate payback and demonstrate ESG commitment, while a tax-informed approach helps maximize long-term financial benefits.
Tax treatment also affects the economics of ESGrelated improvements. Depending on the asset and scope, owners may claim deductions or credits and accelerate depreciation through cost segregation and related strategies. Evaluating these benefits early can improve after-tax project returns.
Regulatory Pressures Shape Design Decisions Policy is turning sustainability goals into requirements. Regulations now tie energy performance, emissions and sustainability disclosures to permitting, financing and occupancy approvals. This creates challenges for owners who must balance capital constraints, tenant needs and evolving energy systems. In some cases, standards depend on factors outside owners’ control, such as utility energy sources or infrastructure constraints.
This gap between policy and implementation poses an ongoing challenge. Owners must advance ESG objectives even when key variables remain outside their control, making flexibility and long-term planning essential.
ESG expectations now span across entire portfolios. Improving one property can affect leasing, capital planning, and compliance across others. Tenants increasingly demand ESG-aligned space, and investors incorporate ESG performance into valuations. Properties that fall behind may face slower lease-up, lower rents and reduced investor demand.
Regional differences matter. Strategies that work in newer urban properties may be less practical in older buildings. Leaders must weigh infrastructure, energy sources and building age when evaluating opportunities. Aligning ESG investments with tax strategy, financing and long-term planning supports better decision-making and helps prioritize upgrades.
Sustainable design requires balancing near-term costs with long-term impact. Initial expenditures may be higher, and integrating new materials and technologies requires coordination. However, long-term value is clear: lower energy use, reduced maintenance costs and stronger tenant satisfaction support performance.
Features such as solar panels, energy-efficient façades and water-conservation systems generate savings while enhancing market appeal. As ESG reporting standards evolve, these investments improve transparency and comparability, which investors and lenders increasingly value. Over time, they can strengthen performance and asset valuation.
Sustainable, energy-efficient and regulation-conscious design has become essential. Developers and investors who embrace ESG principles can reduce risk, improve returns and create long-term value. Buildings designed for performance, adaptability and compliance are better positioned to respond to evolving regulations and market demands.
These investments also strengthen tenant relationships, support predictable operating costs and enhance long-term stability. ESG is no longer optional; it’s a strategic lens for navigating today’s environment and safeguarding future portfolio value. When paired with thoughtful financial and tax planning, ESG-driven design supports performance and long-term value. Buildings designed today are investments in resilience, efficiency and competitive advantage.
Bob Knakal Chairman and CEO
BKREA
New York City (917)509-9501
One of the greatest misconceptions in business and in life is that success happens accidentally. People often look at elite performers and assume their outcomes were driven primarily by intelligence, talent, timing, luck, connections or circumstance. Those things can matter, but after 42 years in commercial real estate, after personally selling more than 2,401 buildings and observing thousands of careers unfold, I believe that one characteristic consistently separates people who merely drift through life from those who create extraordinary outcomes: intentionality.
Intentionality is not intensity. It is not motivation. It is not optimism. Intentionality is deciding who you want to become and then aligning your behavior with that vision repeatedly over long periods of time. Most people allow life to happen to them. Intentional people decide how they want life to happen. That distinction changes everything.
One of the lines I have used recently in my speaking engagements is this: “Your life ultimately becomes a collection of days you were intentional … or days you weren’t.” The older I get, the more I believe that is true. Most people dramatically underestimate the compounding effect of small daily decisions. They think life changes through massive moments, giant breakthroughs or sudden transformations.
In reality, life usually changes quietly. It changes in the invisible moments. Through routines. Through habits. Through standards. Through repeated choices that often seem insignificant in the moment but become enormously significant over time.
People frequently say they want better outcomes, but very few people are truly intentional about creating the systems necessary to produce those outcomes. They want to be healthier, but are not intentional about sleep, nutrition, training or recovery. They want financial success, but are not intentional about learning, prospecting, specialization or relationship building. They want stronger marriages, deeper friendships and closer families, but are not intentional about presence, attention, listening or time allocation. In many cases, people are emotionally attached to outcomes while remaining behaviorally attached to habits that make those outcomes impossible.
I have also come to believe that intentionality creates clarity, not the other way around. Many people spend years waiting to “find themselves” before they fully commit to something. They wait for certainty. They wait for perfect clarity. They wait for confidence. Elite performers often move before clarity arrives. The movement itself creates the clarity. Action reveals direction. Momentum reveals purpose. Movement creates meaning.
I certainly did not have everything figured out when I started in 1984. I did not fully understand my “why.” I simply knew I wanted to become exceptional at something. So, I became intentional about learning, about specialization, about
information gathering, about relationships and about execution. Over time, the deeper understanding of purpose followed.
This is one reason that specialization is so powerful. Generalists often live reactively. Specialists live intentionally. Specialists decide exactly what they want to become great at, then organize their lives around developing that expertise. They deliberately narrow their focus in order to create disproportionate value. In every business, the market tends to reward the people who become undeniable at something specific.
Generalists get considered. Specialists get selected.
Intentionality also matters enormously during difficult periods, because the market always has been, is and always will be cyclical. Through no fault of your own, there will be periods where conditions become extraordinarily challenging. Markets contract. Transactions slow. Deals die. Confidence disappears. During those periods, people without intentionality often drift emotionally along with the market. Their standards deteriorate. Their discipline weakens. Their focus disappears. Intentional people behave differently. They maintain routines during hard times. They continue building relationships. They continue learning. They continue prospecting. They continue executing. They understand that consistency during difficult periods is often what will position them to dominate when conditions improve.
Intentionality is not about perfection. Nobody operates intentionally every moment of every day. We all waste time, become distracted, have periods where we lose focus. The objective is not perfection. The objective is awareness. The objective is reducing drift. Because drift is dangerous. Drift quietly steals years. Drift convinces people they have more time than they actually do. Drift causes people to wake up one day wondering how decades passed so quickly without becoming the person they intended to become.
In my presentations, I often compress the entire history of the Earth into a 24-hour day. Human existence occupies only the final seconds before midnight. Our individual lives represent a tiny fraction of those final seconds. When you truly internalize how limited time actually is, intentionality stops becoming an abstract concept and starts becoming an urgent responsibility.
Ultimately, intentionality is really about ownership. Ownership of your standards, your habits, your time, your mindset and your future. Because if you are not intentional about your life, eventually someone else will be. And when that happens, you may discover you spent years building a life that was not fully your own.
And there are very few regrets greater than realizing you spent decades being reactive when you had the ability to be intentional all along.
Stuart M. Saft
Partner and Real Estate Practice Group Leader Holland & Knight LLP
787 Seventh Avenue, Suite 3100 New York, NY 10019 stuart.saft@hklaw.com (212)513-3308
For four centuries, New York City has been in the business of business, and has survived and prospered in times of war, disease, fire, pestilence, terrorist attack and market collapse. For four centuries, New York City has welcomed immigrants and turned them into Americans. It did not make a difference where they came from, what they did in the old country, their religion, race, creed or any other factors that caused them to leave and take a perilous journey to the new world where they did not know the language, the customs or their future.
They came to this country and this city because “the streets were paved with gold” and they could be free. No one came to America for socialism because, if they worked hard, obeyed the law and studied, they or more likely their children and grandchildren would have a future. Birth did not define a person, but rather their willingness to work hard.
Since its founding as a mercantile outpost, New York City has had wealthy and poor people live side by side and support each other. I grew up poor; went to New York City public schools; worked since my teenage years; paid city, state and federal taxes; employed many people and helped them become self-sufficient and then financially secure and supported charitable causes. Now all I hear is, “Make the rich pay their fair share.” I am not rich, but I do pay over 50% of my income in taxes, which means I work from January to early July to support the government.
Over the years I have written endlessly about the housing crisis in New York, which was not caused by the landlords or developers but by legislation that failed to address the issue while the legislators continue to double down and come up with even more draconian legislation ignoring the actual cause of the problems.
For a moment, let’s consider the facts. In 2012, New York City’s budget was $68.5 billion and in 2026 the proposed budget is $115.9 billion, a 69% increase. In 2012, New York City’s capital budget was $7.1 billion. In 2026, the mayor proposed a 10-year capital
budget of $173.4 billion or $17.3 billion a year, a 41% increase. In 2012, the public school budget was $23.7 billion and in 2026 the proposed public school budget is $33 billion, a 39% increase — but the school population has gone from 1.1 million children to 859,000 children, a 22% decrease.
It has also been reported that the exodus of wealthy and middle-income people and job-producing employers has been enormous. Instead of trying to stop the outflow of the people who pay the taxes and provide high-paying jobs, the goal is to tax those who are remaining and those who might consider moving here even more, thereby increasing the migration of the very people we need to stay.
However, what we have seen in the last dozen years is that there is no limit as to how much money New York City officials want to spend. Most families and businesses have budgets and cannot spend more than they earn, but not New York City, which just keeps spending or demanding its residents spend in unfunded mandates. The taxpayers cannot pay for everything the politicians propose.
Yes, New York City has an affordability problem, which is getting worse. If you look at the Consumer Price Index over the last 12 years, guess what? The biggest single factor in making New York City unaffordable is the cost of housing. Why is housing so expensive? Because there has not been enough housing produced. What is being done about it? Nothing other than recognizing that it is the laws and regulations that have caused these problems.
Perhaps it is time for the public to stand up and demand an explanation for why the situation is so bad and getting worse rather than chasing the wealthy and high-earning individuals away by standing in front of their homes screaming “Tax the Rich” and “The wealthy should pay their fair share” while ignoring that the source of the $115.9 billion in revenue needed to fund a bloated city government is being paid primarily by those people at whom the curses are directed.
More than 35 years of real estate, condominium & cooperative experience
WilkinGuttenplan uses expert industry knowledge in accounting, audit, and tax services to assist New York City real estate owners, developers, and investors of commercial and residential properties identify opportunities and guide them on implementing strategies to stay ahead of changing times.


Eric Bramlett
Broker-owner
Bramlett Partners
6850 Austin Center Blvd, Bldg. II | Suite 180 Austin, TX 78731 (512)872-4487
Most brokerages have adopted artificial intelligence (AI). Most have also stopped at the wrong place.
Writing a property description with ChatGPT is adoption in the same way that buying a treadmill is fitness. The tool might exist, but the outcome doesn’t follow automatically. In real estate, the gap between agencies that have deployed AI as a writing assistant and agencies that have rebuilt their operations around it is widening every quarter.
Generative AI alone could unlock up to $180 billion in value for the real estate industry, according to McKinsey. Broader AI adoption could add 1.5 percentage points to annual U.S. productivity growth over the next decade, said Goldman Sachs. That value is sitting inside operational infrastructure that most brokerages have yet to build.
Before that infrastructure gets built, the industry has to clear a misconception that is slowing adoption down.
The loudest concern in real estate AI conversations is agent replacement. It is also the wrong one. AI is coming for the coordination layer: the admin work, compliance audits, call reviews and reporting that surrounds the agent’s job. Judgment, relationships and negotiation under pressure remain irreducibly human.
The real risk runs in the opposite direction. Brokerages that refuse to modernize will watch their best agents leave for ones that have built better infrastructure. The threat is structural noncompetitiveness, and it lands on the brokerage rather than the agent.
There’s a spectrum worth naming here: non-adopters on one end, with builders on the other, constructing proprietary systems on top of AI APIs that actually change how the business runs. In between are adopters using off-the-shelf tools and calling it transformation. The builders are separating from the field, and the distance is compounding.
Generative AI produces content. You give it a prompt; it gives you text. Real estate agencies are finding genuine leverage in it: agents drafting client communications around rate changes or difficult pricing conversations; feeding raw market data into a model and getting a first newsletter draft back in their own voice; turning a 45-minute CMA prep task into a 10-minute review. These real efficiency gains belong in the operating stack. But generative AI does not transform brokerage operations.
Agentic AI takes autonomous action. It pulls production data, cross-references it against leads distributed, flags agents whose conversion has fallen
below threshold, drafts coaching notes and delivers a finished work product. That is a different category of change from faster drafting, and it requires different infrastructure: real database integrations, real permission architecture and a willingness to build rather than subscribe.
Brokerages that have made that investment, automating call analysis, lead routing and agent coaching on top of AI APIs, are running a structurally different business. The default question has flipped for those agencies. They ask whether they should build something before they ask what they should buy.
The governing question for any brokerage implementing agentic systems is what AI should do, not simply what it can.
The answer comes down to whether a task has a defensible right answer. Lead routing has one. Compliance checks have one. Onboarding coordination has one. These are machine tasks, and keeping humans on them is a cost decision disguised as a culture decision.
Negotiating a repair credit has no defensible right answer. Neither does telling an agent their production is falling short of the brokerage minimum, or sitting with a client whose transaction is unraveling. These are human tasks, and the test is propriety rather than capability. Any capable model can draft the difficult message. It takes a human, though, to deliver that message with poise, nuance and genuine understanding.
The consumer trust question resolves the same way. AI belongs back-of-house. When built correctly, it makes the agent who picks up the phone more informed and better prepared before the first sentence is spoken. An agent who walks into a listing appointment having worked through AI-synthesized market analysis and pressure-tested their pricing conversation is sharper because of that preparation. The client experiences the difference without needing to understand the infrastructure behind it.
Brokerages running well-built agentic systems are already seeing the results: leaner operations ratios, stronger agent retention and a marginal cost of growth that no longer scales with headcount. The competitive gap those outcomes create is structural. It does not close on its own.
The question is not whether agentic AI will reshape brokerage operations. It will. The only remaining question is whether your agency is building toward that now or inheriting the disadvantage of waiting.






Nicolette R. Sinatra, Esq.
Sales Representative Fidelity National Title
485 Lexington Ave. New York, NY 10017
nicolette.sinatra@fnf.com
When purchasing real property, buyers naturally focus on the aspects of the property that are easily identified, such as location, asset type, condition, price and financing terms. However, one of the most important aspects of purchasing any property is understanding the “title, ” the legal ownership history of the property.
It is critically important to have a thorough title search run as part of a buyer’s due diligence of any property, whether commercial or residential. A review of a property’s current and back title will reveal the present legal owner and prior ownership history of the property in addition to the existence of liens, easements, covenants, restrictions and other encumbrances affecting the title. Failure to perform this critical step can result in missing current and future conditions which may negatively affect the use and operation of the property and future costs to correct these unknown conditions.
Once the search results are obtained, the buyer will have a detailed picture of the property history along with any issues that may need to be resolved. This allows the purchaser, with the aid of their counsel, to raise objections with the seller and decide whether to move ahead with the transaction. If the buyer chooses to proceed to closing, they have the option to purchase an owner’s title insurance policy which will be effective as of the date of the transfer of title.
A title policy’s purpose is to protect against losses arising from defects in a property’s title. Unlike other types of insurance that cover future events, title insurance addresses problems rooted in the past. These issues include, but are by no means limited to, clerical errors in public records, undisclosed heirs claiming ownership, forged documents, mechanic’s liens, liens from unpaid debts or mistakes in legal descriptions of the property. Even with a thorough title search conducted before closing, some defects may remain hidden, making title insurance an essential safeguard for potential buyers.
Purchasing a title policy provides financial protection for an owner. If a title defect emerges after the purchase, such as a previously unknown lien or ownership claim, the owner may have a claim against the insurance company for legal fees and potential losses, up to the policy limit. Without this protection, the property owner would be responsible for resolving the issue, which could involve expensive litigation or even the loss of the property.
The availability of title insurance acts to mitigate risks for all parties and, therefore, facilitates real
estate transactions. Lenders almost always require a lender’s title insurance policy as a condition for issuing a mortgage. This protects the lender’s interest in the property, ensuring that their loan is secured by a valid and enforceable lien.
Without the benefit of title insurance, lenders would face significant risk, which could make obtaining financing more difficult or expensive for buyers. A lender’s policy only protects the lender’s interest, not the borrower’s/owner’s equity. If there is no owner’s policy and a title issue arises, the borrower could still face financial loss even if the lender is protected.
Unlike other insurance policies that require ongoing premiums, title insurance coverage typically involves a single payment made at closing. This one-time fee provides coverage for as long as the property owner or their heirs own the property. Considering the longterm protection it offers, the cost of title insurance is a relatively small investment compared to the potential risks it mitigates.
From a public policy standpoint, the availability of title insurance contributes to the overall stability of the real estate market. By ensuring that property ownership and any third-party interests therein are clearly defined and legally protected, it reduces disputes and increases confidence among buyers, sellers, and lenders.
Critics sometimes argue that title insurance is unnecessary or overly expensive, especially given the thoroughness of modern title searches and the availability of public information. However, even the most diligent searches cannot uncover every potential issue. Public records may contain errors, and certain claims — such as those involving fraud or undisclosed heirs — may not be discoverable until after the transaction is complete. Title insurance acts as a safety net for these unpredictable risks. Without the benefit of a title insurance policy, resolving these issues could result in unexpected costs, lengthy and expensive litigation, and possibly the loss of the asset.
Title insurance is a fundamental component of any real estate transaction. It protects against hidden defects in a property’s ownership history, provides financial security and ensures peace of mind for both buyers and lenders. While it may seem like just another closing cost, its value becomes clear when unexpected issues arise. For anyone purchasing or financing real property, investing in title insurance is not just a precaution — it is a smart and necessary step in safeguarding some of the most significant asset investments.
President
The Protocol School of Washington
20 F Street NW, 7th Floor
Washington, DC 20001
(202)575-5600
It’s graduation season, which means two million newly credentialed professionals are entering the workforce, according to Education Data Initiative.
To put that in perspective, that’s a talent pool the size of the entire population of Houston suddenly appearing on our payrolls, ready to take on their summer internships and entry-level analyst roles across the commercial real estate (CRE) and capital sectors.
They have real technical competence. They are data fluent, AI-native and digitally hyperconnected.
They also struggle with a significant soft skills gap.
According to a recent and much-discussed survey by Intelligent.com, 60% of employers say they’ve fired at least one new hire out of their college, citing a lack of motivation, poor communication skills and poor professional etiquette.
We can’t let this be the final verdict on Gen Z’s potential. We need what they bring — the analytical instincts, the comfort with new tools, the willingness to question old workflows.
That’s why it’s no longer enough to expect young professionals to know how to show up at work intuitively. Instead, CRE leaders must proactively build professional presence and communication training into their onboarding and development programs.
Bridging the Professionalism Gap
Solving the problem requires understanding more than external behaviors.
Perhaps most notably, recent graduating classes experienced heavily disrupted, remote schooling during their formative high school or college years. When coupled with a highly digital, artificial intelligence (AI)-driven world where screen time often replaces face-to-face interactions, it’s easy to see why many Gen Z graduates missed out on observing traditional workplace dynamics.
The results are familiar. We frequently hear from clients about new hires who arrive technically strong, but in the small moments, subtle warning signs begin to compound. They join meetings late, offer minimal in-person engagement, send unpolished follow-ups or miss obvious opportunities to build rapport.
Individually, these missteps seem minor. Taken together, they define a reputation. Over time, they shape perception. In a relationship-driven industry like commercial real estate, those subtle signals can quietly erode trust, credibility and performance.
We must bridge this gap by making the implicit explicit, turning unwritten rules and expectations of professional conduct into a tangible toolkit that will equip interns and recent grads with the interpersonal skills they need to match their technical potential.
As you prepare to welcome summer interns and new graduates, here is how you can integrate these principles into your firm.
1. Establish and teach a standard. Define what professionalism looks like for your specific firm. Do not assume young hires know the unwritten rules. You must ensure there is a standard and then teach it directly.
2. Interpret dress codes in context. Teach new hires how to read and apply workplace dress and grooming expectations across the settings they will encounter, from the office to tenant meetings to broker lunches.
3. Focus on authentic relationship building. In CRE, the real deals often happen through networking. Provide explicit guidance on relationship-building and networking strategies that create lasting impressions in the real estate and capital sectors.
4. Create space to practice and reinforce. Build safe environments for new hires to practice introductions and conversations. Follow up and reinforce these skills with positive, specific feedback.
That work does not happen by accident. It happens when leaders decide to make it part of the job.
Closing the Gap Starts This Summer Summer interns and new hires are an opportunity to onboard the next generation of CRE professionals. They create a sustainable talent pipeline that builds institutional resilience and agility.
Gen Z brings capabilities our industry genuinely needs. What they often lack is the lived experience of watching seasoned professionals navigate a room, handle a difficult client call or recover from a misstep with grace.
This is a gap we can close, and the firms that close it will build stronger teams, retain talent longer and protect the relationships that drive every deal.
Dress the part. Choose neutral, tailored attire; ensure grooming is polished, shoes shined and wear your name badge on your right shoulder for easy visibility.
Approach a group with confidence. Make eye contact, smile and say, “May I join you?” then pause and enter naturally.
Greet each person individually. Maintain eye contact and offer a firm (not bone-crushing) handshake.
Introduce yourself. Say your first and last name clearly, speaking with confidence and warmth.
Start the conversation. Ask a simple question to the group — “Is this your first time attending the forum?” If there’s a reason to connect, exchange business cards or virtually.
Ernest Rrika Director of Operation Peninsula Property Management
390 5th Ave
New York, NY 10018
(212)204-1728
The deadline came, and most of New York filed.
By the city’s preliminary tally, roughly 91% of covered buildings, representing about 93% of covered properties, submitted their Local Law 97 emissions reports on time. By any procedural measure, the second annual filing cycle was a success. The portal held. The reports went in. The Department of Buildings has what it needs to begin running this year’s penalty calculations at $268 per metric ton of CO₂-equivalent over the cap.
If you manage New York real estate, don’t take that as good news. It is, in fact, the single most misleading data point in the LL97 conversation today, and the longer the industry treats a high filing rate as a proxy for actual compliance, the more brutal the 2030 reset will be.
The 2030 Cliff is Real
The 2024-2029 limits were set deliberately above the existing emissions profile of most covered properties. Less than 10% of buildings exceeded their cap in this first compliance window. The point of the first period was never to penalize widely; it was to harden the data and stand up the enforcement infrastructure. The first period worked as designed.
The actual ramp begins in 2030, and it is significantly steeper than most owners are pricing into their capital plans. The 2030-2034 limits are roughly 40% stricter. For multifamily residential, the cap drops from 6.75 to 3.35 kilograms of CO₂equivalent per square foot per year. On current consumption patterns, about 57% of covered properties would exceed their 2030 cap. A quarter of multifamily buildings will need to cut emissions by 20% to 40% to comply.
Let’s translate that into management terms. A 10-story pre-war coop with a 1970s steam system and oil-fired hot water is not getting to 3.35 kg by changing light bulbs. The 2030 limits are a heat-pump, envelope and electrical-service conversation, and the projects implied by those conversations have multi-year design, permitting and capital horizons. The 2029 reporting cycle is the last filing before the new limits take effect. That filing is closer than it feels.
A meaningful slice of buildings projected to exceed the 2024–2029 limits availed themselves of the Good Faith Effort (GFE) pathway, filing a decarbonization plan with DEP rather than paying penalties up front. In 2024, that looked like a release valve. In 2026, it looks more like convertible debt.
May 1, 2026 was also the midpoint milestone for GFE buildings, the point at which owners were expected to demonstrate completed efficiency work sufficient to hit the 2024-2029 limit, or to submit a detailed decarbonization plan with specific measures and quantified emissions reductions. Buildings that filed weak plans or cannot show verifiable progress are now at real risk of losing GFE status, which would expose them to retroactive penalties for both 2024 and 2025 emissions exceedances at the full $268 per ton.
Every building that took GFE relief in the first filing must now treat its decarbonization plan as a regulatory commitment, not an aspiration.
The most common mistake that I see is treating LL97 as a sustainability or engineering file, something the chief engineer handles in a corner of operations. That made sense in 2022. It does not make sense in 2026. LL97 is now a capital, governance and disclosure problem, and the management firm is the right home for all three.
Three things should be on every manager’s desk this quarter. First, build a five-to-sevenyear decarbonization capital plan, not a oneyear operating plan. The 2030 cliff is a capital exenditures problem and the planning horizon must match the equipment life and reserve-funding cycle of the building.
Second, run the penalty model both ways. Owners deserve a transparent comparison between absorbing post-2030 penalties annually, staging a partial decarbonization and committing to a full electrification path on a defined schedule. The right answer is building-specific, but the analysis must be on the table.
Third, audit your GFE plans. If your firm signed off on decarbonization plans during the first filing cycle, this summer is the time to reread them, line by line, against what has actually been done at the property. If there are gaps, you should close them before DEP asks.
The 91% filing rate is the kind of number that closes meetings. We filed, we’re fine, what’s next. What this cycle actually showed is that the easy part of LL97 is over. The next period is not designed to be survivable on inertia. Buildings that wait will pay; buildings that planned will not. The portfolios that come through 2030 in good shape will be the ones whose managers treated 2026 not as a filing event, but as the last quiet year before the work has to be real.
Preiss, a national student housing and multifamily owner, developer and operator, in partnership with boutique real estate investment and development firm FD Stonewater, announced its latest residential developments: Signature at Varsity in Raleigh, N.C., located near North Carolina State University, and Signature on Grand in Knoxville, Tenn., serving the University of Tennessee, Knoxville.
Both properties are slated for delivery in fall 2027, bringing a combined 1,207 beds of high-end, purpose-built student housing to two prominent university markets.
“As a company rooted in Raleigh, we are especially proud to deepen our presence near NC State while simultaneously expanding our footprint at UT Knoxville,” said Jeff
Bartholomew, executive vice president of development and construction services at Preiss. “Raleigh and Knoxville are two of the most dynamic university markets in the country, and we believe Signature at Varsity and Signature on Grand will meet the growing demand for premier, walkable and tech-forward off-campus housing options.”
Located at 1400 Crest Road, Signature at Varsity boasts a flagship location across from North Carolina State’s Greek Village.
The 679-bed development is designed to be the premier residential hub for the university’s Greek Life and student leaders, offering a blend of high-energy social spaces and wellness-focused amenities just steps from campus.
Residents will enjoy a rooftop pool and poolside jumbotron, a two-story fitness
center and expansive courtyard spaces for socializing. Additional highlights include a putting green, collaborative lounge spaces, and a first-in-the-market Lenovo Esports gaming lounge. The project is slated for a Fall 2027 delivery.
Signature on Grand, located at 1727 Grand Ave., offers an off-campus residential retreat nestled in Knoxville’s Fort Sanders neighborhood. Scheduled for a Fall 2027 delivery, the 528-bed development offers modern architecture and convenient urban connectivity for the UTK student population, while offering welcome relief from the frequently congested Cumberland Avenue corridor.
The property will feature a courtyard pool with poolside jumbotron, a two-story fitness center and outdoor TV lounge areas. To support an active and balanced student
lifestyle, the community will also feature dedicated study spaces as well as a bike and e-scooter storage facility.
Both Signature properties will offer studio, one-, two-, three-, four- and five-bedroom floor plans. Every unit comes fully furnished with a premium furniture package and elevated finishes, such as hardwood-style flooring throughout, granite countertops, stainless steel appliances and LED vanities.
Select floor plans at both locations will also feature private patios or balconies, walk-in closets and glass shower enclosures.
The living experience is bolstered by a techforward, smart-home infrastructure designed for both convenience and sustainability.
Residents will benefit from mobile walletintegrated smart locks that allow for seamless,
keyless entry to both individual units and bedrooms. This high-tech experience is further supported by smart thermostats and direct fiber-to-unit internet connectivity delivering ultra-fast speeds of up to 1 Gbps.
Beyond the individual units, the communities support eco-conscious living through advanced leak detection systems and on-site EV charging stations.
Community areas will be further enhanced by innovative partnerships including Living Plant Walls powered by Miravel and Intelligent Vending powered by Tulu, which will provide the residents with on-demand access to household essentials and equipment rentals.
FD Stonewater is a vertically integrated real estate platform with national capabilities in development, investment and brokerage.
“Raleigh and Knoxville are two of the most dynamic university markets in the country, and we believe Signature at Varsity and Signature on Grand will meet the growing demand for premier, walkable and tech-forward off campus housing options.”
Jeff Bartholomew
From financing considerations, to property performance metrics, today’s real estate business is inundated with both challenges and opportunities.
PKF O’Connor Davies has decades of experience working with a variety of assets including industrial, office and residential sites. Our experience in this complex field gives us the expertise to deliver strategic advice that drives real value.
With the PKF O’Connor Davies Real Estate Team, our clients know greater service, know greater insights, Know Greater Value.
Edward O’Connor, Partner 201.712.9800
eoconnor@pkfod.com
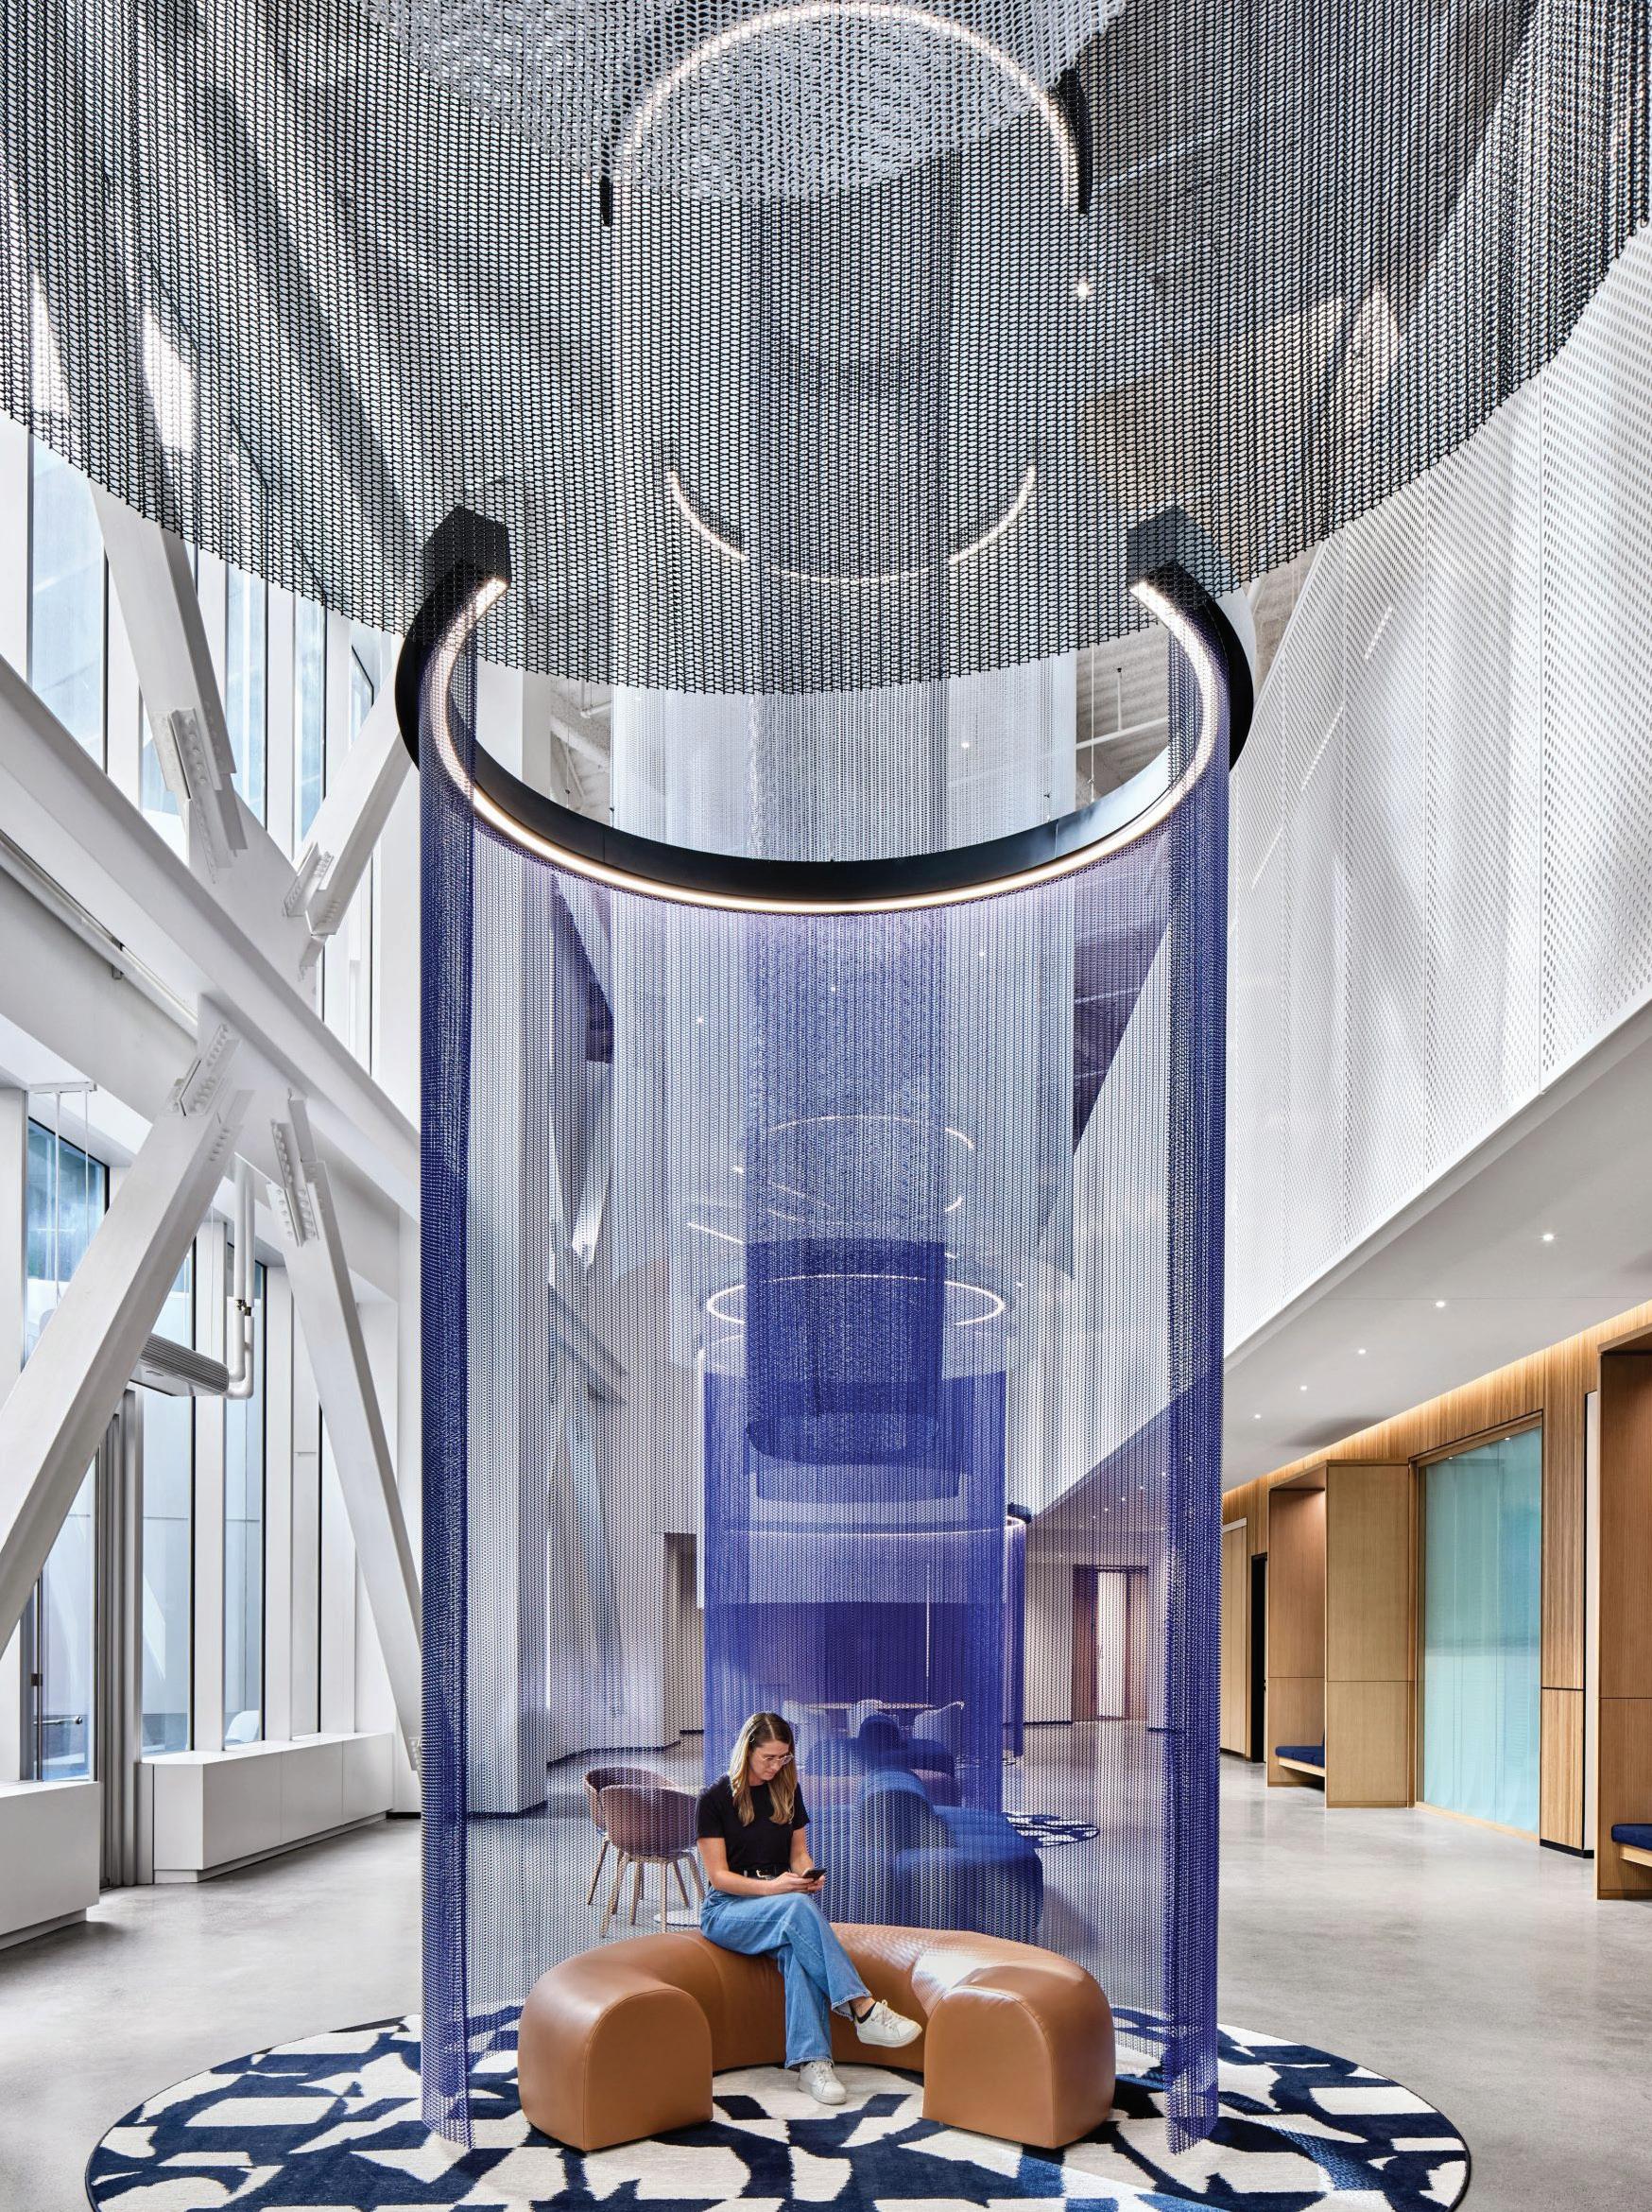
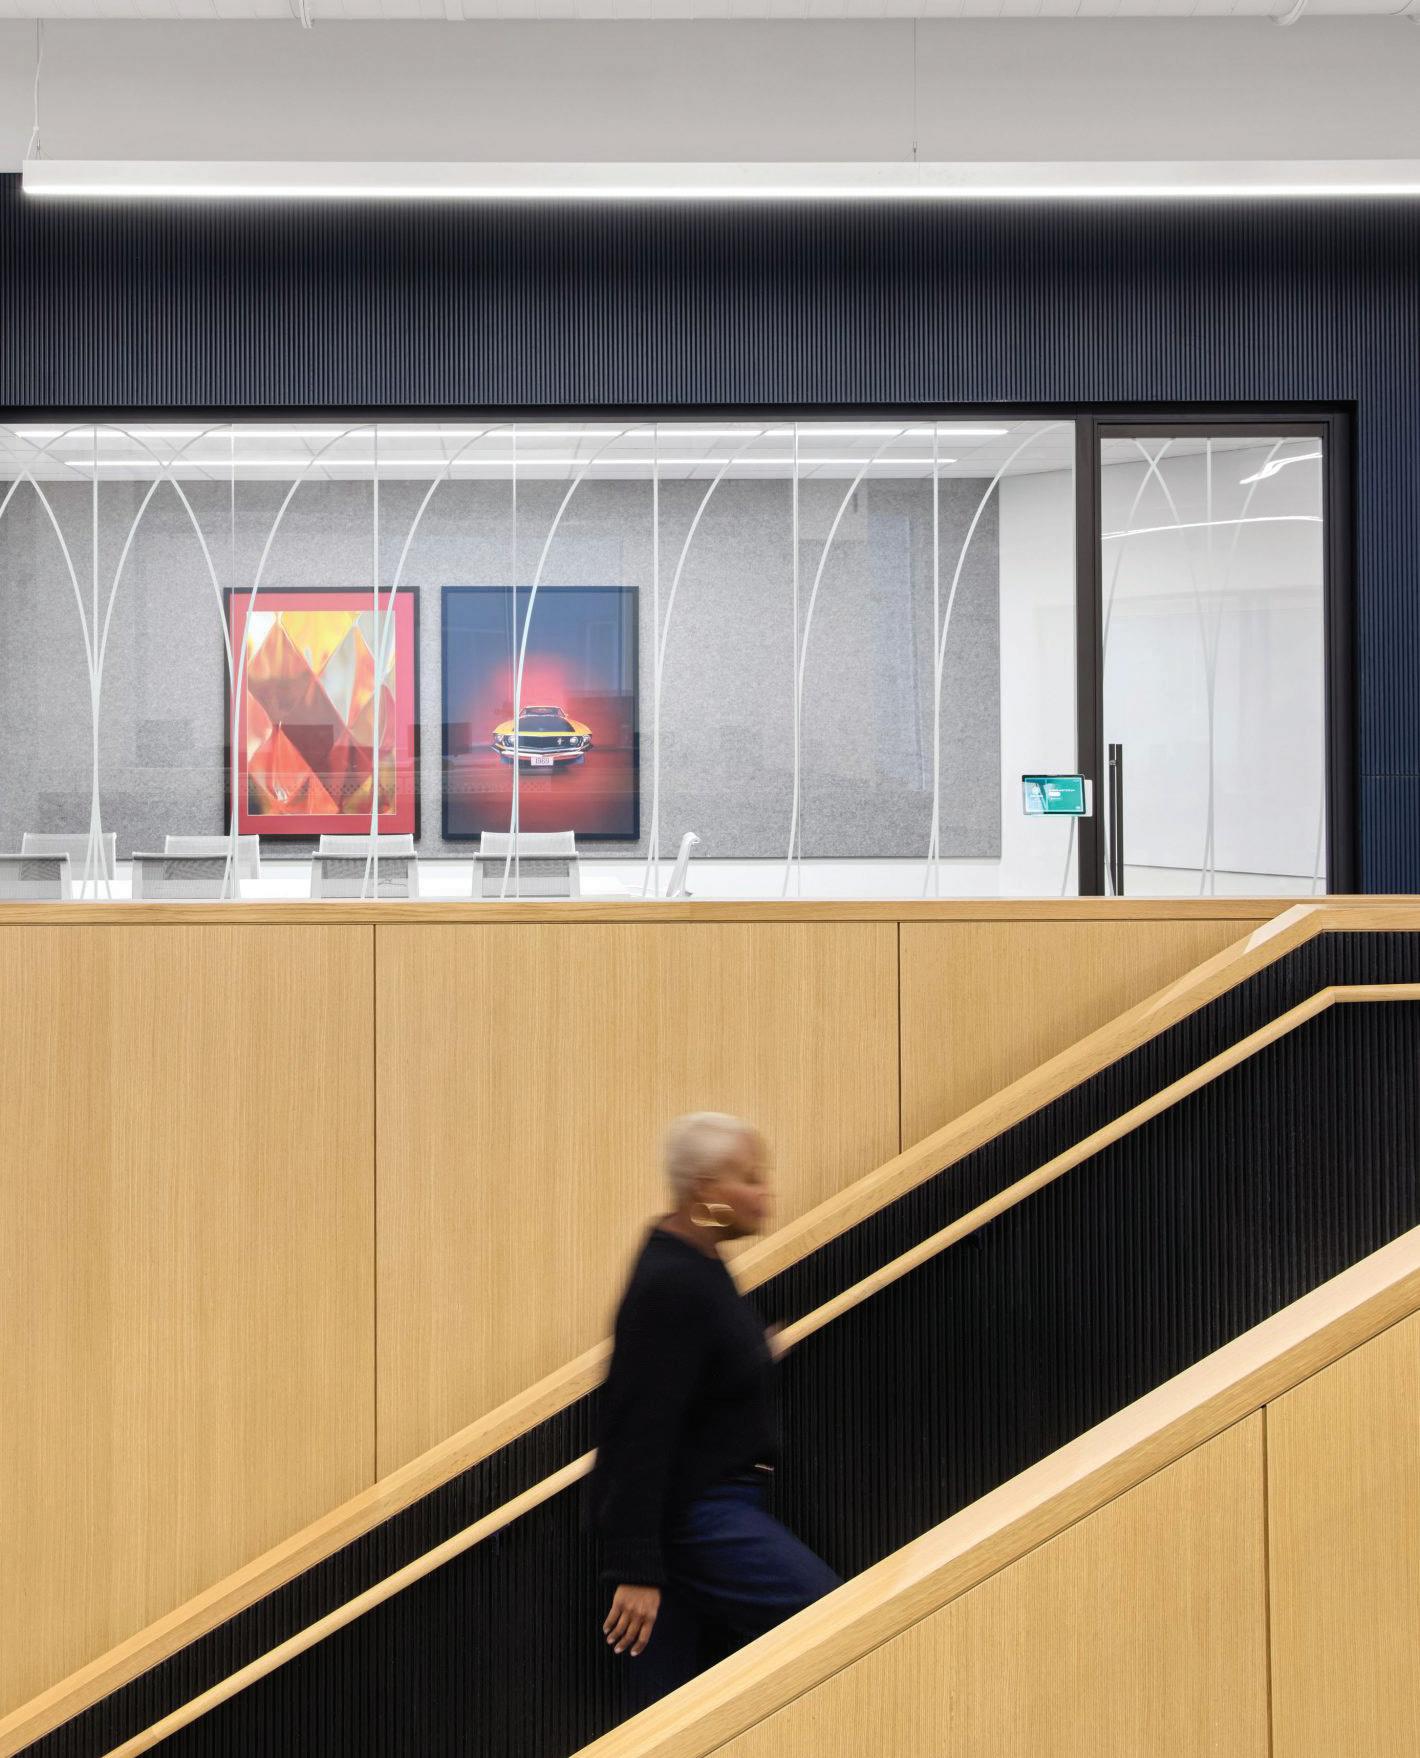
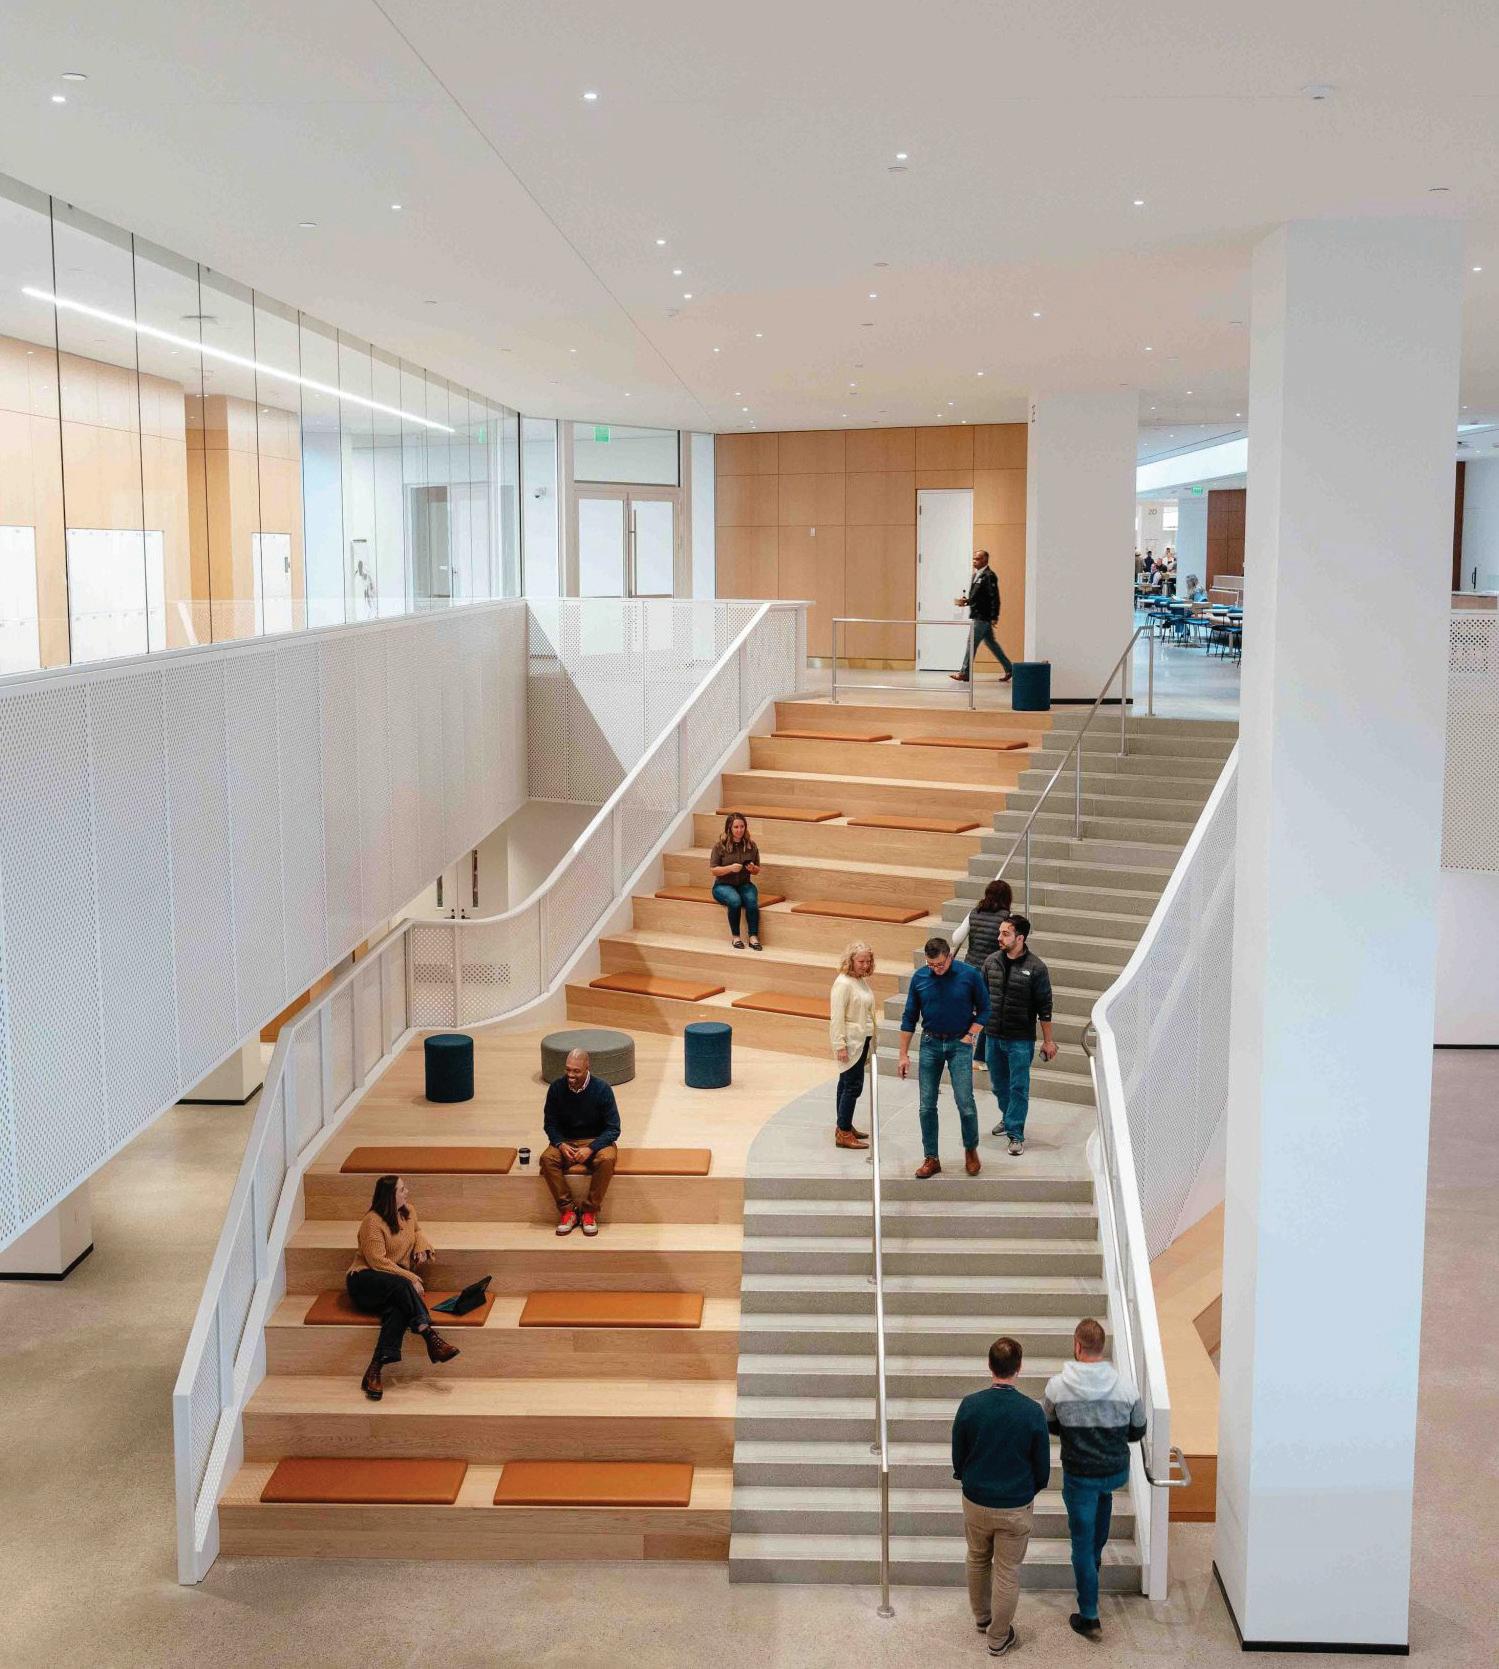
ynergi, an international engineering, fabrication and installation firm specializing in turnkey architectural stair systems and complex metalwork, announced its contribution to Ford Motor Company’s new World Headquarters in Dearborn, Mich., where the firm delivered a custom stair and architectural metal package for the 2.1 million-square-foot campus centerpiece.
Designed by Snøhetta in collaboration with Arcadis, IBI Group and Ford’s in-house design team, and constructed by Barton Malow, the fourstory headquarters anchors the company’s broader 700-acre Dearborn campus transformation and will accommodate approximately 4,000 employees across the company ’ s research, design, engineering and office functions.
As part of the project, Synergi engineered, fabricated and installed custom stair systems, perforated metal guardrails and architectural paneling integrated throughout key circulation and gathering spaces within the building.
The scope contributes to the headquarters’ industrial yet refined architectural language while supporting the functionality, durability and movement required within a high-performance workplace.
“The Ford Hub project has been a standout opportunity for our team and a strong example of what early collaboration can accomplish on a complex build,” said Kyle Simmons, senior project
manager at Synergi. “By joining during the designassist phase, we were able to identify constructability challenges early, introduce practical solutions and support both budget and schedule objectives. Coordinating early stair installation before the curtain wall was enclosed also created major efficiencies for fabrication, installation and overall site logistics.”
The architectural metal scope was designed to complement the headquarters’ broader material palette of terrazzo, exposed concrete, white-oak millwork and industrial detailing, reinforcing a design vision centered on durability, flexibility and timelessness.
Spanning 2.1 million square feet, Ford’s new headquarters serves as both a workplace and product development hub, bringing design, engineering, executive leadership and collaborative amenities together under one roof. The facility also features advanced showrooms, fabrication spaces and specialized vehicle review environments that support Ford’s next generation of innovation.
Synergi’s role on the project reflects the firm’s expertise in delivering technically complex stair and architectural metal systems for high-profile commercial and institutional developments worldwide. With offices across North America and Europe, the firm partners with leading architects, developers and contractors to execute precision-driven solutions where design intent and constructability must align.
Yes, sometimes New York City subway construction finishes on time — or even early. Case in point: general contractor Forte Construction Corp.’s replacement of three elevators at the125th St. and St. Nicholas Avenue subway station in Harlem, completed two months ahead of schedule.
The station advances the Metropolitan Transportation Authority’s (MTA) ongoing Americans with Disabilities Act (ADA) accessibility program and improves access for riders on the A, C, B and D lines between West and Central Harlem.
Built in 1932, the 125th St. station is one of the busiest transit hubs in the MTA system, serving tens of thousands of riders on an average weekday, according to the most recent MTA ridership data.
Working in close collaboration with the MTA and lead designer Goldman Copeland, Forte replaced decadesold hydraulic elevators and upgraded machine rooms, equipment, elevator shafts and pits, establishing reliable ADAaccessible connections between the street level, mezzanine and platform for riders on the A, C, B and D lines along St. Nicholas Ave.
Construction was conducted primarily
during off-peak hours and overnight shifts to minimize disruptions to the public.
“The 125th St. station at St. Nicholas Ave. is among the most utilized stations in the system” said Project Manager Elif Chavez. “Working with the MTA to enhance the rider experience and expand access across Harlem is something we are proud of. It means more people can get to where they need to go, whether that’s to work, to school or to one of the many community landmarks that make this neighborhood so special.”
Forte has long been a trusted partner in Harlem’s transit transformation. In 2017, the company led a comprehensive elevator replacement and full systems upgrade — electrical, communications, fire alarm, plumbing and HVAC — at the 125th St. and Lexington Avenue station, a critical intermodal hub connecting the 4, 5 and 6 subway lines with MetroNorth’s Hudson, Harlem and New Haven commuter rail lines.
In 2019, Forte renovated the 145th Street Station as part of a joint venture, installing new CCTV, public address systems, digital information screens, lighting and communications infrastructure and partnering with Boldyn Networks to bring Wi-Fi service to the station and surrounding tunnels.

EVENT CHAIRS (in formation)
Stephen Siegel • Gadi Peleg • Yale Stogel • Philip Altheim Beth Miller Eidman • Yoav Oelsner
COMMITTEE (in formation)
Adan Elias Kornfeld • Jonathan Friedman • Brad Gerla
Laura Gilbert • Bradley Hamburger • Karl Held • Daniel Kaplan
James Orphanides • Jason Rohlman • Ron Roman • Uzi Saban Andy Sachs • Robin Thompson • Glenn Tolchin
AFRMC BOARD OF DIRECTORS
A. Mitti Liebersohn • Stephen Siegel • Warren Diamond • David Schwartz
Beth Miller Eidman • Robert Sorin • Richard Chera • Michael Frain • Bess Freedman
Gary Jacob • Magalie Laguerre Wilkinson • Mitchell Moinian • Bruce Mosler
Mitchell Rudin • Harrison Sitomer • Phyllis Trobman • Philippe Visser



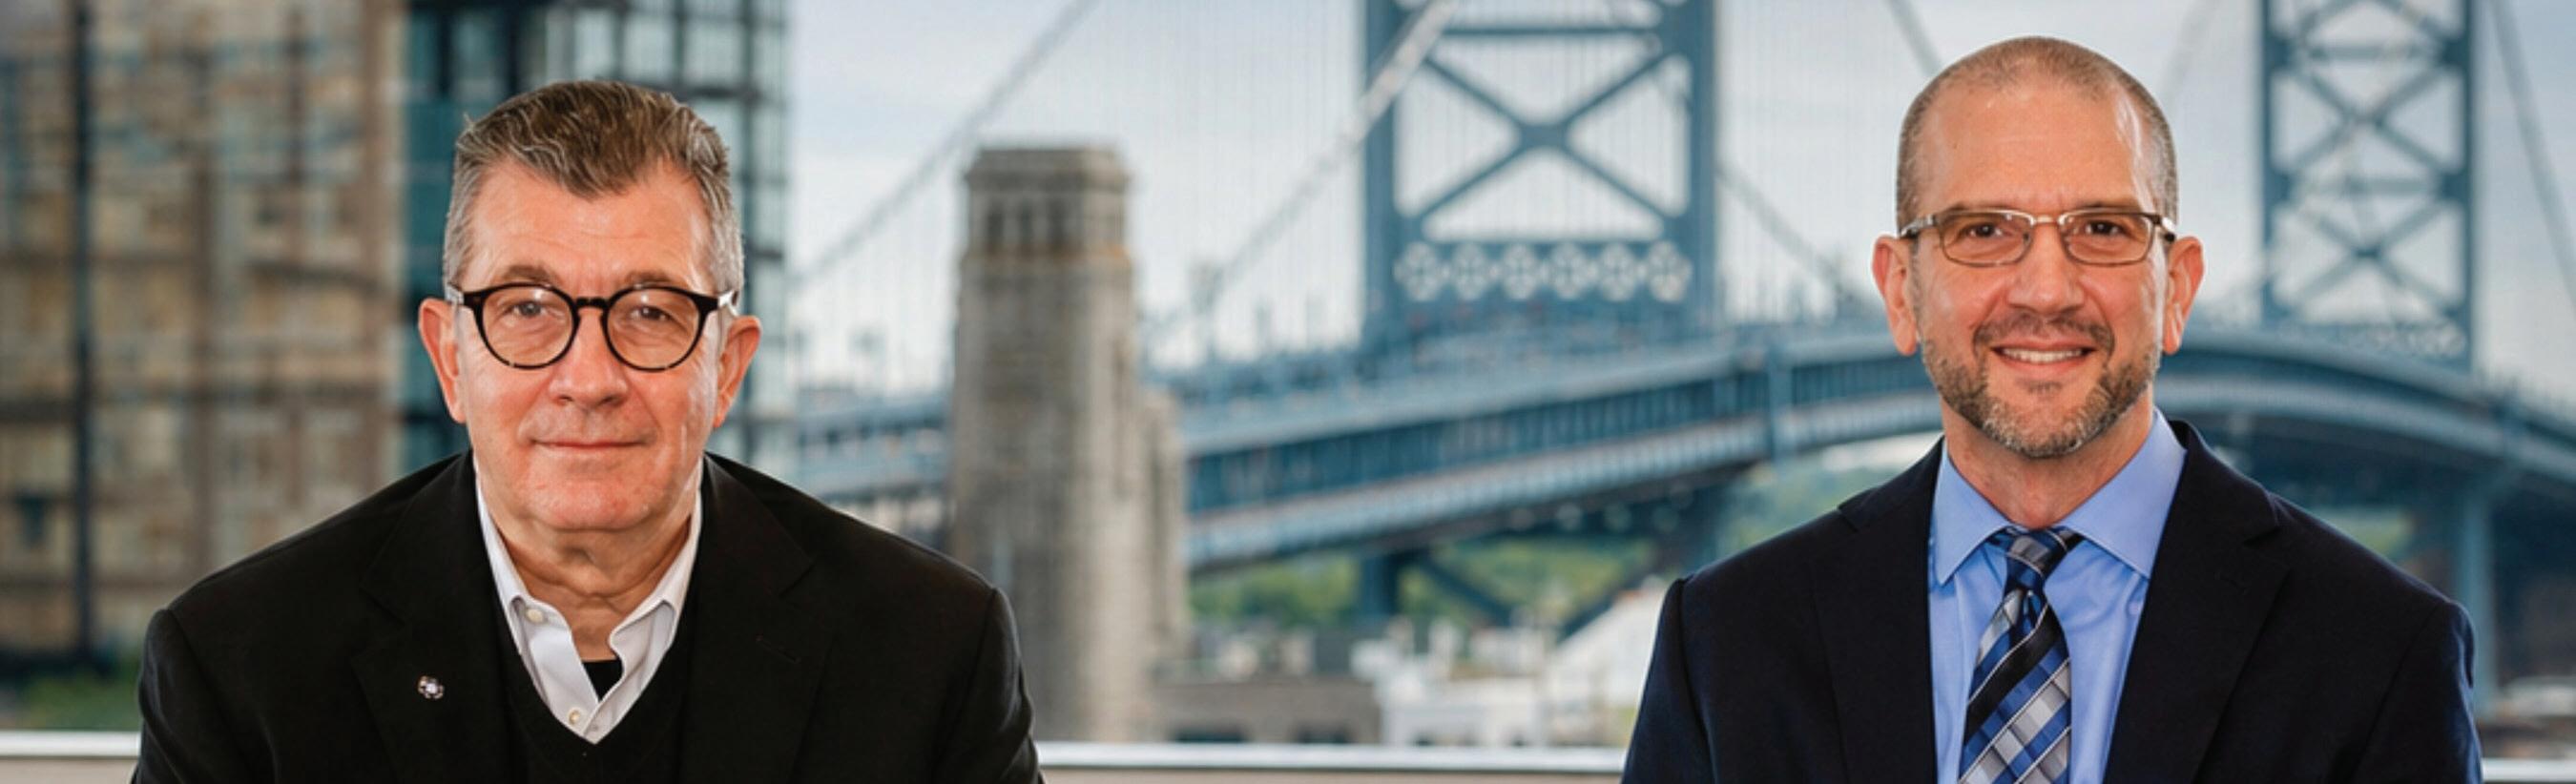
EwingCole, an award-winning architecture, engineering, interior design and planning firm, has announced a new executive leadership team as part of its long-standing leadership rotation model, a distinctive approach within the industry that reinforces continuity, shared ownership and long-term growth.
John L. Capelli, AIA, principal and director of the firm’s government practice, has been named chief executive officer and will guide the firm’s strategic direction, with a focus on strengthening its national practice model and aligning expertise across offices and markets. Jason E. Fierko, PE, CEM, LEED AP, principal and director of healthcare operations, has been named president, responsible for translating firm strategy into consistent execution across offices.
“We’ve built a foundation rooted in collaboration, design excellence and the depth of our people,” said Capelli. “Moving forward, we are bringing our expertise together more intentionally, strengthening how we deliver work, and creating a clearer, more consistent experience for our clients across every market we serve.”
“EwingCole has always been defined by its people,” said Fierko. “My focus is strengthening our offices by investing in local leadership and improving how we work together across the firm. By connecting our expertise more effectively,
we’re building a more cohesive organization and a stronger foundation to better serve our clients and pursue new opportunities.”
Peter J. Welsh, PE, SE, principal and director of operations, will serve as executive vice president and chief operating officer. Aitor Sanchez-Prado, PE, principal and director of life sciences, has been named senior vice president, leading national development and business growth. Sara J. Eastman, AIA, NCARB, principal and director of science and technology, will serve as vice president, leading firmwide talent and expertise initiatives.
Occurring every nine years, the leadership transition reflects a deliberate governance structure established by founder Alec Ewing to sustain a multigenerational firm while adapting to evolving market demands.
Following their tenures, Jared J. Loos, Robert McConnell and Keith Fallon are transitioning from their current executive roles. Under their leadership, EwingCole strengthened its multidisciplinary practice, expanded its geographic reach and advanced its reputation for delivering high-performing, design-driven solutions. Loos will assume the role of chairman of the board and treasurer, providing strategic oversight across both EwingCole and its construction management affiliate, ECBuild.
Ralph P. Giordano has joined Resolution Real Estate, a fully integrated, full-service commercial real estate firm and member of NAI Global, as executive director, head of brokerage.
Giordano’s career spanning roles in real estate management, investments and brokerage across all commercial asset classes and geographics to corporate clients and property owners.
Having held senior positions at Alti Global, CBRE, Colliers ABR and Okada, he has advised organizations
including Citibank, JP Morgan Chase, Shiseido, Screen Actors Guild, Coty and Random House. He has led transactions in 14 countries, including headquarters in New York, Los Angeles, Paris and Frankfurt, and R&D center projects in Geneva and Monaco.
“Having Ralph lead our brokerage team sets us on an important course for expansion in New York and other global markets,” said Gerard Nocera, managing partner, Resolution Real Estate. “Anthony [McElroy, managing partner] and I are excited to have him join us and welcome his leadership and expertise.”
Flash, a mobility technology company connecting property owners, operators and drivers, has appointed Peter Weiss as chief business officer. Weiss will lead Flash’s newly established Office of Real Estate and oversee the company’s marketing strategy, with a mandate to expand owner relationships and position parking as a measurable source of NOI across portfolios. Based in New York, he reports directly to Chief Executive Officer Chris Donus.
“With more than two decades of experience spanning real estate investment, banking, ownership, and operations, Peter brings a strong understanding of how real estate owners evaluate assets, operations, and long-term value creation,” Donus said. “He will help us strengthen our relationships with commercial property owners while sharpening how we bring Flash’s value proposition to market. Peter will work with owners and parking operators to unlock greater value from parking, mobility, EV charging and related technology as contributors to
portfolio performance and customer experience.”
Flash delivers demand by routing millions of drivers to owner assets via its own ParkWhiz app and through relationships with Google Maps, Waze, ParkMobile and Ticketmaster, among other digital channels.
That demand reach is paired with technology that manages every stage of the driver journey — from search and reservation through entry, payment and exit — ensuring every visitor interaction is consistent, controlled and reflective of the asset it serves.
Weiss most recently served as chief real estate officer at Latch (now operating as Door), where he led direct-toowner growth through relationships with the nation’s largest multifamily owners and developers. Earlier in his career, Weiss held senior roles at Capital Properties and Ackman-Ziff Real Estate Group, where he closed more than $6 billion in transactions across the capital stack.
National affordable housing preservation company Hudson Valley Property Group (HVPG) has appointed Kristin Koch as managing director, head of capital raising. The firm promoted Diana Bellizzi to managing director, head of investor relations, and Matt Doty to chief financial officer and chief compliance officer.
Koch joins HVPG to lead capital raising efforts, with a particular focus on expanding the firm’s global investor base across institutional, sovereign and private wealth channels. She brings significant experience raising capital within the affordable housing and impact investment sectors, including helping raise more than $1.4 billion for affordable housing at Jonathan Rose Companies.
Bellizzi, who has been with HVPG since 2019, has been promoted in recognition of her leadership in building the firm’s investor relations function. She will lead investor engagement, oversee operational due diligence and manage reporting and onboarding, helping to strengthen HVPG’s long-term limited partner (LP) relationships.
Together, Koch and Bellizzi will lead HVPG’s newly formalized Investor Solutions group, which brings together capital raising and investor relations under a unified structure overseeing the full capital lifecycle from investor origination through ongoing relationship management, including fundraising, diligence, onboarding and communications.
In his expanded role, Doty will oversee all financial operations across the firm, including corporate, fund and development accounting, as well as financial planning, analysis and compliance. His promotion reflects the continued development of HVPG’s institutional infrastructure and the increasing sophistication of its investor base.
HVPG also announced the promotions of Anna Perez to director of design and diligence and George Dandolos to associate director of construction on its Design and Construction team and Max Wofse to asset manager on the Asset & Portfolio Management team.
Riverview Landscapes announced the acquisition of Giannini Landscaping and Holiday Lighting by Giannini, a commercial landscaping, holiday lighting and snow management provider headquartered in Lindenhurst, N.Y. The transaction marks Riverview’s first branch location on Long Island proper.
Founded in 1977 by Mitch Giannini, Giannini has built a strong reputation for delivering high-quality, recurring landscaping and seasonal services. Mike Kaplan, a former long-time employee of Giannini, acquired the business in 2019 to accelerate growth and expand the service offering.
“This acquisition not only establishes our first physical presence on Long Island proper but also strengthens our ability to grow organically in the region,” said Liam Burrell, CFO of Riverview Landscapes. “With Giannini’s in-house holiday lighting expertise, Riverview will be able to expand this offering during the winter months.”
The Lindenhurst location will serve as Riverview’s West Suffolk County branch. The branch will continue operations under the leadership of Mike Laudando, a 20plus year veteran of Giannini who has served in account management and operations roles.
Thomas A. Kucharski has served as president and CEO of Invest Buffalo Niagara since 2000. Under his leadership, Invest Buffalo Niagara has grown from a start-up initiative to an innovative regional economic development organization that has secured more than 400 successful project wins representing $4.4 billion in investment in the region and over 42,000 jobs created and/or retained. From the onset, he helped Invest Buffalo Niagara form strong, enduring partnerships with business, development and academic leaders throughout the Buffalo Niagara region.
Today, more than 150 organizations work with Invest Buffalo Niagara to provide support and expertise to companies from the U.S., Canada and other parts of the world looking to set up shop in Western New York.
How long have you been in the business?
I have spent more than 40 years in economic development, and for more than 25 of those years I have had the privilege of leading Invest Buffalo Niagara. It has been deeply meaningful to do this work in a region I care about so much, and I have never lost sight of what an honor that is.
How did you enter the industry?
I was drawn to economic development because it is, at its heart, about people. Yes, it is about business growth and investment, but it is also about helping communities create opportunity, restore confidence and build a future that people want to be part of. Early in my career, I saw how much that work matters, and it stayed with me. It is what has made this profession so rewarding over the years.
Who inspires you?
I am inspired by people who commit themselves to building something larger than themselves. In Buffalo Niagara, that includes employers who keep investing here, educators and workforce leaders who open doors for others and community partners who show up every day because they believe in this place. There is a quiet strength to that kind of commitment, and I have always found it deeply inspiring.
How has Buffalo reversed decades of population flight?
I would describe it less as a finished turnaround and more as meaningful momentum. Buffalo’s 2020 Census population rose to 278,349 from 261,310 in 2010, which mattered not only because of the numbers, but because it reflected renewed confidence in the city after decades of decline.
More recent estimates remind us that this work is ongoing, but I think what has changed is that Buffalo has been creating real reasons for people to believe again: stronger employers, visible investment, neighborhood energy and a growing sense that the future here can look different from the past. That kind of progress takes time, and it happens because many people and institutions keep doing the work, year after year.
What types of skills are taught at the Northland Training Center?
Northland is helping prepare people for careers in advanced manufacturing and clean
Tom Kucharski CEO
Invest Buffalo Niagara
energy, and that matters for a region like ours. Its training model connects people to practical, in-demand skills while surrounding them with support that helps turn training into opportunity. What makes Northland so powerful is that it reflects something Buffalo does well at its best: connecting community, workforce and industry in a way that is both hopeful and practical.
Can this be a prototype for other cities around the country?
I believe it can. For legacy industrial cities, one great challenge is connecting reinvestment with real opportunity for people and neighborhoods. Northland offers a strong example of workforce development that is place-based, employer-informed and centered on long-term possibility. It shows that when a city invests thoughtfully, it can create something that is not only effective, but worthy of being replicated.
What keeps you up at night?
What keeps me up at night are the things that matter most to a region’s future: whether we have the sites and buildings ready when opportunity comes, whether we are growing the workforce we need and whether we are moving with enough urgency to meet the moment. But I also carry a great deal of hope. Buffalo Niagara understands itself more clearly today than it once did. We know our strengths, we know our challenges, and we have more people working together to meet them. That gives me real confidence in what lies ahead.
The financial backing of a global bank, and the streamlined structure and agility of a boutique bank that will keep your business moving forward.
BHI offers full commercial banking services that combine the personal attention of a prestigious boutique bank with the expertise and financial strength of Bank Hapoalim – the leading financial institution in Israel.
With a footprint in the largest U.S. metropolitan areas, we are committed to creating innovative funding solutions for your short– and long-term needs and providing convenient banking and liquidity products for your everyday business needs.
www.bhiusa.com
Even the youngest baby boomers are beginning to eye retirement, and the design sector is seeing the e ects. The number of architects has declined slightly, and the number who use artificial intelligence remains relatively small. Will those trends continue? Time will tell, but a changing of the guard is underway, as we can see by the numbers
$96,690
e median annual wage for architects in May 2024. (U.S. Bureau of Labor Statistics)
116,005
e number of licensed architects in the U.S. in 2024, down 4% from the previous year. (National Council of Architectural Registration Boards)
6% to 8%
e percentage of architects who said they use arti cial intelligence regularly on the job. (American Institute of Architects)
157,000
e number of interior design businesses in the U.S. in 2026 (IBISWorld)
45%
e share of interior designers who are self-employed in 2024. (American Society of Interior Designers)
14%
e average pro t margin for landscape architecture rms. (American Society of Landscape Architects)


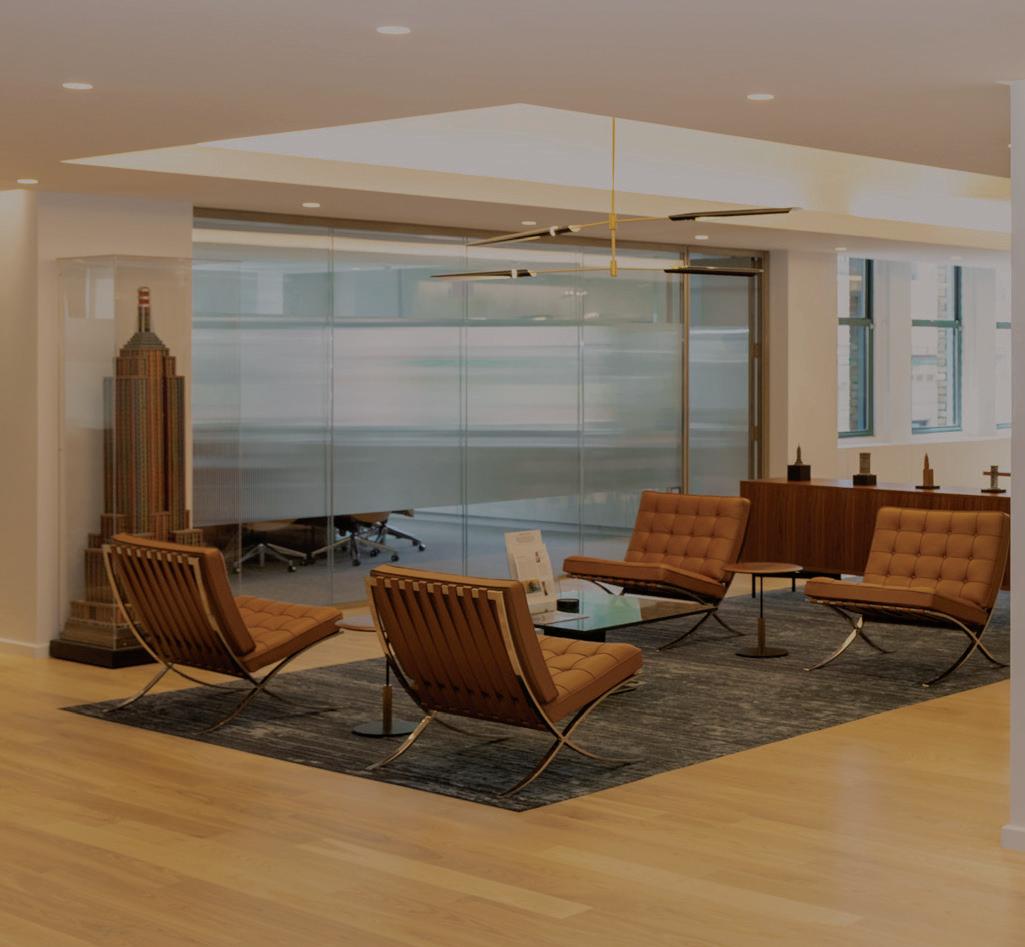
Looking for clarity in a market filled with trade-offs — growth, risk, and profitability?
CBIZ turns complexity into opportunity with integrated insights and solutions. From strategy to operations, we help you protect margins, navigate change, and unlock growth.
Abe Schlisselfeld National Real Estate Leader