LOCAL EXPERTS MAGAZINE localexpertsmagazine.com
August 2026 · Issue 10 HOUSTON, TX
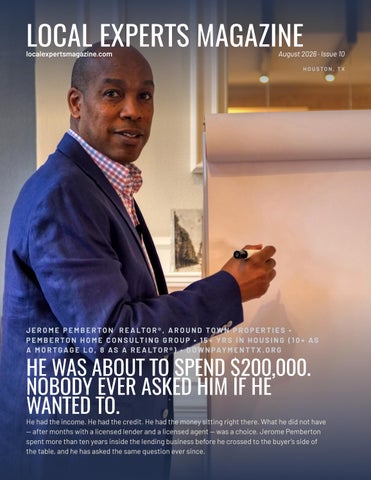
J E R O M E P E M B E R T O N R E A LT O R ® , A R O U N D T O W N P R O P E R T I E S • P E M B E R T O N H O M E C O N S U LT I N G G R O U P • 1 5 + Y R S I N H O U S I N G ( 1 0 + A S A M O R T G A G E L O , 8 A S A R E A LT O R ® ) • D O W N P AY M E N T T X . O R G
HE WAS ABOUT TO SPEND $200,000. NOBODY EVER ASKED HIM IF HE WANTED TO.
He had the income. He had the credit. He had the money sitting right there. What he did not have — after months with a licensed lender and a licensed agent — was a choice. Jerome Pemberton spent more than ten years inside the lending business before he crossed to the buyer’s side of the table, and he has asked the same question ever since.
LOCAL EXPERTS MAGAZINE
localexpertsmagazine.com
HE WAS ABOUT TO SPEND $200,000. NO BODY EVER ASKED HIM IF HE WANTED TO. He had the income. He had the credit. He had the money sitting right there. What he did not have — after months with a licensed lender and a licensed agent — was a choice. Jerome Pemberton spent more than ten years inside the lending business before he crossed to the buyer’s side of the table, and he has asked the same question ever since.
T
he number was two hundred thousand dollars.
That was what the man had in his head when he sat down with Jerome Pemberton. He was buying a million-dollar house. He had the income for it, the credit for it, the savings for it. And he had two hundred thousand dollars earmarked for the down payment, because that is what a house like that costs to get into. The lender had told him so. The agent had told him so. Pemberton did not confirm the number. He asked a question instead. “Do you want to put two hundred thousand dollars down?” The man stopped. He asked what Pemberton meant. Everything in this article lives inside that pause. Months of house hunting. A licensed lender. A licensed agent. Professional after professional looking straight at this man’s account balance — and not one of them had ever presented the two hundred thousand dollars as a decision. It had been presented as a fact. As the price of admission. As simply the way things are. “He didn’t even know he had that option,” Pemberton says. “He didn’t even know.” That moment is the one Jerome Pemberton has built an entire practice around, and he did not arrive at it by accident. He is a licensed Texas REALTOR® with Around Town Properties in Houston and the founder of Pemberton Home Consulting Group. Before any of that, he spent more than ten years as a mortgage loan officer — on the other side of the desk, learning exactly what it takes to get a person approved. Most realtors know houses. Most loan officers know money. Pemberton spent a decade in one world and now works in the other, and the crossing left him with the only question he has ever really needed to ask a client: Do you want to use your own money, or do you want to use the bank’s money?
PAGE 2
LOCAL EXPERTS MAGAZINE
localexpertsmagazine.com
He is careful about what he is not. He does not originate loans. He does not approve anyone. He does not hand out a dollar. “I’m not the bank,” he says. “We just follow guidelines.” What he does is read those guidelines — every bank writes its own, and almost nobody reads them to the buyer out loud — and then put the question on the table. The Texas State Affordable Housing Corporation credits him with helping more than 100 Texas buyers get into homes through its down payment assistance pro grams. Every one of them got asked. Then he builds the plan around the answer.
“
Do you want to use your own money, or do you want to use the bank’s money?
100+
Tex a s b u ye r s h e l p e d t h r o u g h T S A H C d ow n payment assistance
15+
Ye a r s i n h o u s i n g — 1 0 + as a mortgage LO, 8 as a R E A LTO R ®
30+
$0
D ow n p a y m e n t a s s i s D ow n required on tance programs in his some programs — sub l e n d i n g n e t wo r k ject to lender guide lines
THE HOUSE IS THE EASY PART Ask Pemberton to describe his process and he starts somewhere most agents never go. Not the listings. Not the neighborhoods. Not the pre-approval letter. He starts with the plan. “The first thing we do is talk to the client and find out what their goals are,” he says. “We know goal number one is they want to buy a house. But it’s more than that. Find out how much money they have, and what’s going to be the budget.” He pauses on that word deliberately. Not what’s the price — what’s the budget. What is this person actually willing to part with, and why has nobody asked them?
PAGE 3
LOCAL EXPERTS MAGAZINE
localexpertsmagazine.com
From there, the work runs in two directions at once. On one side, the money: getting fully qualified up front, which he calls the single biggest way to cut a buyer’s risk. On the other side, the property: resale or new construction, and what it will realistically take to win an offer in that particular pocket of the market. What he does not do is send the client off to a lender with a shrug. “Most traditional competitors are going to say, ‘I’m a realtor, go talk to my guy, do whatever he tells you to do — and come back to me when you’re ready.‘ That’s what we hear all the time.” For the million-dollar buyer, the work took months. Not months of house hunting — months of positioning. His credit had to reach a specific threshold to meet one particular bank’s guidelines. His income had to be documented to satisfy that bank’s rules at that price point. The house itself was almost an afterthought. “We’re getting him ready to meet the bank’s guidelines,” Pemberton says. “The house part is the easy part. The difficult part for him is that he’s using somebody else’s money — so he doesn’t have to take his money out. His money is still growing.” That is the whole thesis, compressed into two sentences. The money stays in the market, earning. The house gets bought anyway. And the client, who walked in believing he had one option, walks out having made a choice. Had he gone with the other firm — the one that hands him off to a lender and tells him to come back when he’s ready — Pemberton is blunt about the outcome. “He’s going to have to shell out that two hundred thousand dollars. He’s going to spend more money. That’s what’s going to happen.”
PAGE 4
LOCAL EXPERTS MAGAZINE
localexpertsmagazine.com
The house is the easy part — the financing plan is what should come first.
IT STARTED IN NEW JERSEY, WITH NOBODY ABLE TO ANSWER Pemberton was in college when he first heard the idea that would define his career. He was listening to Carleton Sheets tapes — the old real-estate courses — and the claim that stopped him was that investors were buying property using other people’s money. He spent hours on it. And then, when he left college and went looking for his first house in New Jersey, he tried to do it himself. Nobody could tell him how. “Everybody I went to, from the realtor to the loan officer, couldn’t tell me how to do it,” he says. He bought that first house at twenty-four years old and put three percent down, using an FHA loan, because three percent was the best answer anyone would give him. It bothered him. It has apparently never stopped bothering him. “There were resources, there were programs — and the majority of people didn’t know about them, nor could tell me about them.”
PAGE 5
LOCAL EXPERTS MAGAZINE
localexpertsmagazine.com
He was a teacher at the time. He left teaching for the mortgage business, not be cause he wanted to sell loans but because he wanted to understand the machinery. He spent more than a decade as a loan officer studying what the banks actually had on the shelf, how the guidelines really read, and how two products could be layered together so that a buyer didn’t have to drain an account to close. Then he crossed over. Today he is a realtor, not a loan officer — a distinction he draws carefully and often. He does not originate loans. He does not approve anyone. What he does is know, in unusual detail, what the banks will and will not do, and then build a plan that meets them where they are.
“
The house part is the easy part.
It started in New Jersey: a family that couldn’t get anyone to answer the question that mattered.
THE MISCONCEPTION THAT COSTS FAMILIES THE MOST Say the words down payment assistance to almost anyone in real estate and watch what they picture: a first-time buyer, a modest income, a starter home somewhere at the affordable end of the market. Pemberton has spent years trying to break that image, and it is the thing he most wants to be known for.
PAGE 6
LOCAL EXPERTS MAGAZINE
localexpertsmagazine.com
“The biggest misconception is that people think it’s only for first-time home buyers,” he says. “We have more people in a second and third house — coming back, keeping their money when they sell, and using the bank’s money instead.” Push him on what he’d like his reputation to be a year from now, and the answer comes out fully formed: “I want to be known for the diversity of it — not just the misconception that people who make lesser income need down payment assistance. I want to be known for people over a half a million dollars using strategies to use somebody else’s money.” The logic is not charity. It is arithmetic. A buyer with capital in the market faces a real question: if that money is earning a return, do you really want to pull it out and bury it in a down payment? For some buyers the answer is yes. For a surprising number, Pemberton says, the answer is no — they simply were never told there was an answer. “They can continue to get the appreciation as house values go up,” he says, “and have their own money keep growing. Get both lanes.” He has watched agents state the opposite as fact. He has heard the ceiling quoted out loud — that assistance programs are fine for houses up to a certain price and irrelevant above it. He has structured deals that make the claim look silly.
The costliest myth in housing — that a big down payment is the price of admission.
PAGE 7
LOCAL EXPERTS MAGAZINE
localexpertsmagazine.com
“I’M NOT THE BANK. WE JUST FOLLOW GUIDELINES.” There is a line Pemberton repeats so often it functions as a philosophy, and it is worth understanding exactly what he means by it. He is not the bank. He follows guidelines. He is not being modest. He is being precise. There is no hidden door in what Pemberton does. There is a filing cabinet. Every program, at every bank, is a set of written rules — and the rules differ, bank to bank, in ways most buyers never learn. One lender layers on extra requirements. Another does not. One counts a student loan payment heavily; another counts it differently. The programs themselves come and go: a credit union recently rewrote one of its offerings, called his office, and walked his team through the changes. And the cabinet is deeper than most buyers imagine. Between his lending partners and the wider network they work through, better than three hundred loan programs are in reach — and more than thirty of them are built around down payment assistance. Pemberton’s job is not to fund any of them. It is to know which drawer to open. “We’re not the one giving out the money,” he says. “We follow the guidelines of the bank, and we tell people that.” This matters more than it sounds, because it is the source of two of the most common objections he hears. The first is that all banks are basically the same. “A lot of people assume all banks have the same programs,” he says. “Which is completely false.” The assumption feels safe. It costs people money. The second is that people simply do not believe him when he describes what is available. It sounds too good. And in an era where buyers arrive having already researched their situation on social media or an AI chatbot and formed a firm opinion, disbelief has gotten harder to move. “People believe everything they read,” he says. “And now it’s tough to believe what you see and what you read — whether it’s real or not.” So he stops arguing and starts showing. He gets people to the property. He gets them on the phone with the bank. He lets the guidelines speak.
“
How dare you try to spend his family’s money when he doesn’t want to — because you didn’t even ask him.
PAGE 8
LOCAL EXPERTS MAGAZINE
localexpertsmagazine.com
WHAT IT LOOKS LIKE WHEN NOBODY PLANS A woman called Pemberton’s office recently. She was relocating to Texas from the East Coast, moving to be near her grandchildren, and she had been working with an agent for a full year. They had put her on a contract. She was going to bring nineteen thousand dollars to the closing table. “My clients don’t bring nineteen thousand,” Pemberton told her. “If they’re on a plan, they bring it only if they want to.” She was self-employed. She was paying for her own move. And she had spent twelve months with a professional who never built her a plan — never mapped her cost to close, never asked whether the money had to come out of her pocket, never explored whether a different structure existed. By the time she reached Pember ton, she was too deep in the deal to fix it. She told him she felt bad about it. “I don’t feel bad,” he says. “This is business.” It sounds hard until you understand what he means. His view is that the license carries an obligation. “I feel like, because I have this license, I’m responsible for helping you get the money you said you were looking for. And if they weren’t able to give it to you, then I need to go find it for you — if you qualify for it. That’s what I consider a professional.” The woman is not buying that house. She is getting her earnest money back, making her move, seeing her grandchildren — and then, Pemberton says, they will build the plan she should have had a year ago. “You will be in a house in Texas. You just need a better plan. And the team you were working with wasn’t able to do that for you.”
THE BUYER WHO WAS GOING TO BRING $38,000 Then there is the client closing this month. PAGE 9
LOCAL EXPERTS MAGAZINE
localexpertsmagazine.com
She is not a first-time buyer. She owned a home in another state, relocated to Texas, and landed in a market she was still learning while her income temporarily dropped. On the path she was on, she would have needed to bring roughly ten percent to the table — about thirty-eight thousand dollars — and given where her credit stood, Pemberton doesn’t think the purchase would have happened at all. “If she had gone with someone else, I know for a fact she would still not be able to buy a house,” he says. Instead, she went on a plan. Her file was structured, her credit positioned, her program matched to her situation. She closes this month. “That’s what motivates me,” Pemberton says. “To continue putting more programs together so people can buy. Because a lot of people give up.”
“
You can buy a house. You just don’t like the amount of down payment you’d have to put down.
COUNTING OTHER PEOPLE’S MONEY Ask Pemberton what genuinely angers him about his industry and the answer arrives fast. “People count other people’s money.” He means it literally. He means the loan officer who looks at a client’s bank balance and decides, without asking, that the client should spend it. He describes a caller whose son was heading off to college — seventy thousand dollars a year, tuition and room and board, staring the family in the face — while the professionals around him casually assumed a down payment should come out of the same account. He describes another client, a six-figure earner with a hundred thousand dollars in the bank. The man could buy today. Instead, Pemberton’s team is working with him on his credit first, specifically so he doesn’t have to deplete his savings to close. Then he describes correcting someone on his own team about it, and his voice sharpens: “That client doesn’t want to spend all of the money in his bank account. How dare you try to spend his family’s money when he doesn’t want to — because you didn’t
PAGE 10
LOCAL EXPERTS MAGAZINE
localexpertsmagazine.com
even ask him if he wanted to. He didn’t even know he had an option until he met with us.” The plan, in his hands, is not a document. It is an act of asking.
The real question: do you want to use your own money, or the bank’s?
THE HALF OF THE STRATEGY NOBODY USES: SELLING Here is where Pemberton’s thinking turns in a direction almost no one in residential real estate follows. Down payment programs are not just a tool for buyers. They are a tool for sellers — and almost nobody uses them that way. He points to a property he was asked to look at recently. It had been sitting for more than eight months. The only advice the listing agent had offered the owners was the advice listing agents almost always offer. Drop the price. “That’s not the problem,” Pemberton says. The problem, as he sees it, is that nobody marketed to the person who might actually buy it — a buyer sitting on capital that is earning a return, who assumes they need to put five or ten or twenty percent down, and who has quietly decided they would rather keep renting than liquidate. PAGE 11
LOCAL EXPERTS MAGAZINE
localexpertsmagazine.com
“If you’ve got that money in the market and it’s making a good return — do you really want to take it out and put it into a house?” Show that same buyer they can move in with little or nothing out of pocket, and the calculation changes entirely. The house didn’t need a lower price. It needed a different buyer, reached with a different message. His advice to the builder was blunt: market directly to people, not to agents. And on the price-cut reflex, he is withering: “The only strategy they have is drop the price. And then they call that marketing.”
Half the strategy nobody uses — the sell side, where an agent who knows the math saves you thousands.
THE WORDS THAT SHUT PEOPLE DOWN For all his program knowledge, one of Pemberton’s sharpest observations is about language. The phrase down payment assistance — the very phrase his specialty is named after — makes some buyers stop listening. “Once you use the words ‘down payment assistance,’” he says, “some people’s minds just shut off.”
PAGE 12
LOCAL EXPERTS MAGAZINE
localexpertsmagazine.com
So he changes the words. Sometimes he says creative financing. Sometimes he says special programs — “this house qualifies for a special program” — and then simply names the number it would take to move in. Even the industry’s favorite shorthand fails: zero down, zero move-in is jargon, and he has watched buyers nod along without any idea what it means. He tells a story about a major credit union running a campaign with language he was certain the public couldn’t parse. When he raised it, the response was a blank look. “Did you do a survey to ask people coming into the bank whether they understand what they’re reading? It blows my mind how marketers don’t test whether people understand the messaging that’s put out there.”
“YOU CAN BUY A HOUSE. YOU JUST DON’T LIKE THE DOWN PAYMENT.” Over the years, Pemberton has kept a running list of the questions people actually ask him. They are not sophisticated questions. That is the point. Can I buy a house with no money down? How much do I really need? I’m tired of paying rent. I want to own a home but I don’t know where to start. Can I buy while I’m still paying student loans? Can I qualify if I’m self-employed? Is my credit good enough? That last one draws his best answer, and it reframes the entire conversation. “People say, ‘My credit score is 550, I can’t buy a house.‘ I say — no. You can buy a house. You can get a mortgage. You just don’t like the amount of down payment you’d have to put down.” Sit with that for a second, because it inverts the way the question is usually handled. The typical response is a closed door: you don’t qualify for that program. Pemberton’s response separates two things the industry routinely fuses together — whether you can buy at all, and what it will cost you to get in. The first is almost always yes. The second is the thing worth negotiating. Then there is the buyer earning a healthy six-figure income who has been told, flatly, that they make too much money to use assistance. “You hear that all the time,” he says. And the buyers who spent years saving for a down payment they never needed — who arrive at his office, run the numbers, and realize what the waiting cost them. “They were literally saving for years, stressing themselves out trying to reach that goal. And then it’s: you mean I could have bought a house two or three years ago?” He lets it land. “That’s frustrating.”
PAGE 13
LOCAL EXPERTS MAGAZINE
localexpertsmagazine.com
WHERE THE EXPERTISE COMES FROM Pemberton holds a Texas real estate license through Around Town Properties and is a member of the Houston Association of REALTORS® and the National Association of REALTORS®. He has spent the past eight years as a REALTOR® — the second act of a career that opened with more than a decade as a mortgage loan officer, better than fifteen years in the housing business all told. He holds certifications in down payment assistance and is a licensed life insurance agent, and he works alongside financial planners to structure deals that account for more than the house. The community work runs wide: non-profit organizations, schools, credit unions, churches, shelters, and housing authorities have all asked him to come speak. He resists the word education. “I don’t like to use the word ‘education,’” he says. “But have discussions about different topics, so people can get a better understanding of how things really work out here.”
THE CHOICE, FINALLY OFFERED Strip away the programs, the guidelines, the structures, and what Pemberton is selling is not a product at all. It is the existence of a choice — one that most buyers are never told they have. The man buying the million-dollar house didn’t know. The woman relocating to be near her grandchildren didn’t know. The saver who lost three years to a down payment they never needed didn’t know. In every case, someone with a license had already spoken to them, and in every case, the choice was never presented. “Do you want to use your own money,” Pemberton asks, “or do you want to use the bank’s money?” You may well decide to use your own. That is a perfectly good answer. But you should be the one who decides. Jerome Pemberton is a licensed Texas REALTOR® with Around Town Properties and the founder of Pemberton Home Consulting Group. Programs, eligibility, and terms PAGE 14
LOCAL EXPERTS MAGAZINE
localexpertsmagazine.com
are set by participating lenders and program administrators and are subject to their guidelines; qualification is not guaranteed. Equal Housing Opportunity.
ABOUT JEROME PEMBERTON Jerome Pemberton is a licensed Texas REALTOR® with Around Town Properties and the founder of Pemberton Home Consulting Group in Houston. After more than a decade as a mortgage loan officer, he crossed to the realtor side — eight years ago now — to do what almost nobody in the industry does: build the financing plan before the house. The Texas State Affordable Housing Corporation has recognized him for helping more than 100 Texas families buy through down payment assistance programs.
Before you go house-hunting, build the financing plan first. See your down payment assis tance options at downpaymenttx.org or call (281) 220-9960.
downpaymenttx.org • (281) 220-9960 • Jerome Pemberton, REALTOR®, Around Town Properties • Pemberton Home Consulting Group • Equal Housing Opportunity
FIND JEROME PEMBERTON ON GOOGLE
Down Payment Assistance Texas · View on Google → PAGE 15