LOCAL EXPERTS MAGAZINE localexpertsmagazine.com
August 2026 · Issue 11 HOUSTON, TX
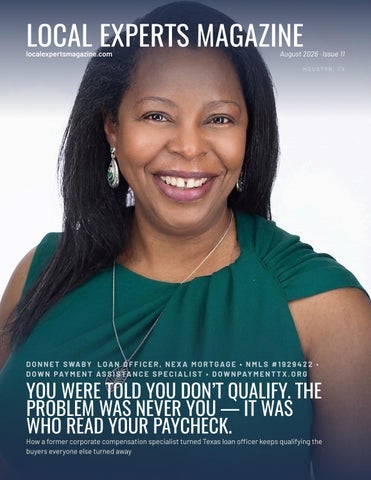
D O N N E T S WA B Y L O A N O F F I C E R , N E X A M O R T G A G E • N M L S # 1 9 2 9 4 2 2 • D O W N P AY M E N T A S S I S T A N C E S P E C I A L I S T • D O W N P AY M E N T T X . O R G
YOU WERE TOLD YOU DON’T QUALIFY. THE PROBLEM WAS NEVER YOU — IT WAS WHO READ YOUR PAYCHECK.
How a former corporate compensation specialist turned Texas loan officer keeps qualifying the buyers everyone else turned away
LOCAL EXPERTS MAGAZINE
localexpertsmagazine.com
YOU WERE TOLD YOU DON’T QUALIFY. THE PROBLEM WAS NEVER YOU — IT WAS WHO READ YOUR PAYCHECK.
How a former corporate compensation specialist turned Texas loan officer keeps quali fying the buyers everyone else turned away
I
t’s a quiet sentence, and it has kept more Texas families renting than any
interest rate ever did: you don’t qualify. Too little saved. Score too low. You thanked them, hung up, and quietly filed your own home under someday. But here’s what that bank couldn’t tell you — most of the time, “you don’t qualify” isn’t the truth about you. It’s the truth about them: a lender that never signed up for the programs that could have gotten you in. Donnet Swaby signed up. A Houston loan officer who spent more than two decades in corporate compensation before she ever wrote a mortgage, she reads a paycheck the way the people who build pay structures read it — finding the income the bank’s first pass missed, and shopping a single credit pull across more than thirty down payment assistance programs. She knows the door is there because she walked through it herself, buying her own home for about six hundred dollars out of pocket. “That bank doesn’t have a down payment assistance program because they didn’t sign up for it,” she says. It is the single most important sentence in her business, and she repeats it constantly, because almost no one she talks to understands what it means. When a lender tells you that you don’t qualify for help with your down payment, most of the time they are not describing you. They are describing them selves — an institution that never enrolled in the programs that could have gotten you into a home. She did enroll. And her niche — the corner of the mortgage world most of the industry quietly avoids — is exactly that: down payment assistance. What makes her unusual is not just that she embraces it. It is where she learned to see numbers in the first place.
PAGE 2
LOCAL EXPERTS MAGAZINE
“
localexpertsmagazine.com
That bank doesn’t have a down payment assistance program because they didn’t sign up for it.
300+
Loan programs in her n e t wo r k
30+
1
D ow n p a y m e n t a s s i s C r e d i t p u l l , s h o p p e d tance programs across all
11 days
Fa s t e s t c l e a n c l o s e
FROM THE PAY-STUB SIDE OF THE DESK Before Swaby ever originated a loan, she spent more than two decades inside corporate finance and compensation — much of it within the lineage of firms that eventually became Morgan Stanley, back when the names on the door still read Shearson Lehman Brothers, then Smith Barney, then Citigroup. Her world was ex ecutive comp, pay structures, the human-resources side of how large companies actually pay people. Bonuses. Deferred compensation. The difference between what a paycheck says and what a paycheck means. “Numbers was my thing,” she says. “It’s just a numbers game.” That sentence sounds like a throwaway line until you understand what it does for the people who work with her. Most loan officers come to the business from sales, or from real estate, or from a bank teller window. They learn to read a pay stub the way the software teaches them to — base salary, hourly rate, done. Swaby learned to read a pay stub the way the person who built the pay structure reads it. She knows where companies hide income in plain sight, because she used to be the one putting it there. When she describes how she got into lending, though, she doesn’t start with the résumé. She starts somewhere else entirely. “First of all,” she says, laughing, “it was God’s business.” The practical version came in 2021, when she became a licensed loan officer and finally pointed all of that numbers fluency at a single problem: getting ordinary PAGE 3
LOCAL EXPERTS MAGAZINE
localexpertsmagazine.com
people into homes. She started in retail lending at a company she still speaks about warmly — the shop that “first gave me my start” and taught her the mechanics of the job, from structuring a file to talking to real estate agents. But retail lending came with a ceiling she couldn’t live under.
Two decades in corporate compensation taught her to read a paycheck the way the people who build them do.
THE BUSINESS NOBODY WANTED HER TO DO Here is a fact the mortgage industry rarely says out loud: for years, many lenders actively discouraged their own loan officers from doing down payment assistance loans. Not by banning them — by making them unprofitable for the person doing the work. “A lot of companies, if I did a down payment assistance loan, they’d lower my com pensation,” Swaby says. “It’s discouraging. That’s why a lot of loan officers probably don’t advertise or want to do down payment assistance — because most of these organizations they’re working for tend to lower a loan officer’s compensation when it comes to providing it.” Read that again, because it explains something you may have experienced without knowing why. If you have ever felt like a lender was gently steering you away from down payment help — treating it as a hassle, a last resort, a thing for “other” buyers — PAGE 4
LOCAL EXPERTS MAGAZINE
localexpertsmagazine.com
you were not imagining it. You may have been sitting across from someone whose own paycheck shrank the moment they helped you. Swaby cycled through a couple of shops chasing a place that would let her do this work without penalizing her for it. One local Texas lender was short-lived. So was a national one. The pattern was always the same: companies that talked about down payment programs but, as she puts it, “when you get into the niche of everything, they really don’t” want to do them. “They didn’t back me up in terms of the products, the customers, the loans I was bringing to the table.” Then she moved to NEXA, a mortgage brokerage, and everything changed — not because she got better, but because the incentives finally pointed the same direc tion she did. “Here I’m able to offer my clients more programs. Down payment assistance is not frowned upon, because it is my business,” she says. “I’m not working toward somebody else’s bottom line, so it makes it easier.”
“
First of all, it was God’s business.
One credit pull, shopped across 30+ down payment assistance programs — not four banks, four hits.
ONE CREDIT REPORT, THIRTY DOORS
PAGE 5
LOCAL EXPERTS MAGAZINE
localexpertsmagazine.com
The switch from a retail bank to a brokerage is the part most buyers don’t under stand, and it is worth slowing down for, because it directly affects your credit score and your wallet. When you walk into a single bank — call it Chase, or Wells Fargo, or any name on a downtown building — that bank can only offer you the loans that bank makes. If its answer is no, you walk down the street to the next bank, which runs your credit again. Then the next one. Four banks, four separate “hard inquiries” on your credit report, each one nicking your score at the exact moment you need it highest. A broker works the other way. Swaby’s brokerage gives her access to a lending network of more than 300 loan programs, including a roster of 30-plus down pay ment assistance programs across her partner lenders — and she can shop a single application across all of them. She also works with certain Texas banks outside that network when a client’s situation calls for it. “I give one hard inquiry, and I can use that same credit report for all the programs I have,” she says. “Whereas if a client goes to an individual bank, and then goes somewhere else, they’re going to run their credit four different times, because it’s four different banks. So the client would have four inquiries. For me, it’s only one.” One pull. Dozens of doors. If the score doesn’t fit one program’s requirements, she carries the same report to the next lender without touching the client’s credit again. For a buyer whose approval is riding on a 640, that difference is not academic. It can be the whole ballgame.
PAGE 6
LOCAL EXPERTS MAGAZINE
localexpertsmagazine.com
On many programs the assistance behaves like a grant: no monthly payment, forgiven after 36 months in the home.
WHAT DOWN PAYMENT ASSISTANCE ACTUALLY IS Somewhere along the way, “down payment assistance” picked up a reputation it doesn’t deserve — a whiff of charity, of last resort, of a program for people who couldn’t quite make it on their own. Swaby spends a lot of energy dismantling that idea, and she has a credential most loan officers can’t claim: she used it herself. Around 2018, she bought her own home using a 100-percent financing program. The seller covered the closing costs. Her total out-of-pocket expense was roughly $600 — for a pool inspection, put on a credit card. “That was it,” she says. She is not describing a handout. She is describing a strategy — the same one wealthy buyers use instinctively, sometimes called “creative financing” or, more bluntly, using other people’s money. The programs she works with are frequently structured not as loans that pile a second payment on top of your mortgage, but closer to a grant. On many of them, the assistance carries no monthly payment at all. It simply sits quietly behind your mortgage, and after you make thirty-six months of on-time payments in the home, a good portion of it is forgiven outright. (Terms vary by program, and not every buyer or property fits every one — which is precisely why matching the buyer to the right program is the whole job.) The point Swaby wants buyers to sit with is this: the money to bridge the gap between “I can afford the payment” and “I have the cash to get in the door” already exists. It has existed the entire time. Most people were simply talking to institutions that never signed up to offer it.
“
I give one hard inquiry, and I can use that same credit report for all the programs I have.
PAGE 7
LOCAL EXPERTS MAGAZINE
localexpertsmagazine.com
She hunts every dollar an underwriter will legitimately count — shift differential, quarterly commission, overtime.
READING INCOME THE WAY ONLY A COMP SPECIALIST CAN This is where her old career stops being a biographical detail and starts being the reason her clients close. Qualifying for a mortgage comes down to income — how much of your money the underwriter is willing to count. And most pay is not as simple as forty hours times a wage. People earn shift differentials. Quarterly commissions. Overtime that comes and goes. Bonuses that hit once a year. The average loan officer, and the average underwriter’s first pass, misses a lot of it — sometimes because the buyer doesn’t even know it’s there. “Some individuals have shift differential on their pay stubs, or commissions that are only paid quarterly, so you have to dive into it a little bit more,” Swaby says. “Sometimes, honestly, they don’t even know until I see a pay stub and I’m asking, ‘So it shows here you get this amount of money?’ And they’re like, ‘Oh yeah, I get a quarterly commission.’” That is a comp specialist talking. She reads a year-end pay stub the way a forensic accountant reads a ledger, hunting for every dollar the system will legitimately let her count toward an approval. It is the difference between a file that gets declined and a file that gets a “yes.” The clearest example she gives involves a buyer who had already been to a large national lender — the kind whose ads are impossible to avoid. That lender told him he needed to put ten percent down and, even then, struggled to get him approved. He came to Swaby with the same contract, the same income, the same credit.
PAGE 8
LOCAL EXPERTS MAGAZINE
localexpertsmagazine.com
“I took a look at his credit report, and he didn’t even have to pay anything off,” she says. “In my system, I was able to get him approved with just putting five percent down on the home he was already under contract for — and I got him some credit based on the interest rate.” Same buyer. Same house. Half the money at the table, plus a credit he didn’t have before. The only variable that changed was the person reading the numbers.
WHO THIS IS ACTUALLY FOR Because of the charity myth, buyers routinely assume down payment assistance has a tight income ceiling — that if you earn a decent living, you’re disqualified. Swaby watches that assumption cost people money. Her favorite counterexample is a professional out of the Austin area who came to her earning $250,000 a year. During the approval process, the woman was promoted, pushing her income to roughly $300,000. She still qualified for down payment assistance. She came to the closing table with a few thousand dollars total on a home most people would assume required a fortune up front. “Some programs don’t have an income cap,” Swaby says — a sentence that lands like a small detonation on everything buyers think they know. So who is the ideal client? Swaby’s answer is refreshingly ordinary. Someone earning $100,000 or more in household income — and she is quick to say income is income, whether it arrives as salary, hourly wages, commission, or overtime, as long as there’s a two-year history behind it. A middle credit score in the neighbor hood of 640, which opens up the widest menu of programs (though she works with scores lower than that). And ideally three to four months of the future mortgage payment sitting in savings or a retirement account — not because she needs to spend it, but because reserves strengthen an approval. “Not that we’re going to use the savings,” she clarifies. “It just really helps to boost the approval on the file.” Notice what’s absent from that profile: any requirement to be poor, or desperate, or a first-timer scraping pennies. Down payment assistance, in Swaby’s hands, is a
PAGE 9
LOCAL EXPERTS MAGAZINE
localexpertsmagazine.com
tool for the solidly employed person who has the income to own a home and simply hasn’t been shown the door.
“
Some programs don’t have an income cap.
Pre-qual in 24–48 hours, under contract in days: her fastest clean close was 11 days.
FASTER THAN ANYONE BELIEVES The second great fear Swaby fights, after “I won’t qualify,” is “this will take forever.” Buyers walk in braced for months of purgatory. What she tells them sounds, at first, like a sales pitch. “If you get me all the documentation I’m asking for upfront, you can get your prequalification within a 24-to-48-hour time period,” she says. “They don’t believe that. They also don’t believe that once I get them a pre-qualification, they can go shop for their home and be under contract within three days and close on their loan in less than thirty days. They don’t believe any of that stuff.” PAGE 10
LOCAL EXPERTS MAGAZINE
localexpertsmagazine.com
Then it happens to them. One buyer she worked with — a man who’d braced himself for an ordeal — kept remarking, afterward, on how painless it had been. “He literally said the process was so easy and smooth,” she recalls. “It was unbelievable for him.” Her personal record is a clean close in eleven days: contract to fully underwritten and ready for title in under two weeks. “That means a person could literally get the keys — if the house is vacant — in eleven days,” she says. Not every file moves that fast, and much of it depends on how quickly a buyer hands over documents. But the ceiling is far higher, and the floor far lower, than the months of dread most people carry into her office. A lot of that speed is really just communication. Swaby talks her clients through what is about to happen at each step, which is less common in the industry than it should be — and it is what turns a terrifying process into a manageable one.
THE ONE FILE THAT EXPLAINS HER WHOLE APPROACH There was a buyer with about $11,000 in savings — enough that he didn’t consider himself short on cash, but not enough to cover both a down payment and closing costs on the home he wanted. When Swaby ran his credit, she saw a few items that could sink his approval. Rather than push a doomed file through, she told him plainly what needed to come off his report and sent him away. Months later, he called back. He’d done the work. “I ran the credit again, and the items I’d asked him to take care of were taken care of,” she says. She had his pre-qualification letter to him fast. Three days later he was under contract. He received more than $14,000 in down payment assistance — the forgivable kind, with no monthly payment attached — and walked into his closing owing a fraction of what he’d feared, held up only because his seller hadn’t offered a concession. Had the seller chipped in, she notes, he might have come to the table with almost nothing. That file has everything her business is built on inside it: the honesty to tell a buyer not yet instead of chasing a commission, the patience to coach rather than dismiss, and the numbers fluency to know exactly which items on a credit report actually
PAGE 11
LOCAL EXPERTS MAGAZINE
localexpertsmagazine.com
matter. He got his keys. And he got them from the loan officer that a retail bank’s compensation structure would have quietly discouraged from taking his call at all.
“
He literally said the process was so easy and smooth.
THE DOOR WAS NEVER LOCKED Ask Swaby what she wishes every Texas renter understood, and it comes back to that first, poisonous sentence — you don’t qualify — and everything the industry has built to make people believe it. The higher rates buyers panic about don’t have to keep them out. “As long as you can make the payment, you can buy a house,” is how her program director puts it, and the strategies to bring the cash-to-close down — seller concessions, the right assistance program, an agent who understands the math — are exactly what she spends her days assembling. The down payment that felt like a wall was, for a lot of people, a door. It was simply a door that most lenders never learned to open, because opening it cost them money. Donnet Swaby learned to open it — first for herself, for $600 out of pocket, and now for Texas families who were told, somewhere along the way, that homeownership wasn’t for them. They were told wrong. Donnet Swaby is a licensed mortgage loan officer (NMLS #1929422) with NEXA Mort gage, LLC (NMLS #1660690), an Equal Housing Lender, serving home buyers across Texas. To see which down payment assistance programs you may qualify for, visit downpaymenttx.org.
ABOUT DONNET SWABY Donnet Swaby is a Houston-based mortgage loan officer with NEXA Mortgage who specializes in down payment assistance. After more than two decades in corporate compensation and finance, she brings a numbers-first eye to qualifying buyers other lenders turn away — and used a down payment assistance program to buy her own home. She serves home buyers across Texas.
PAGE 12
LOCAL EXPERTS MAGAZINE
localexpertsmagazine.com
See which down payment assistance programs you may qualify for — one application, one credit pull. Visit downpaymenttx.org or call 713-258-0299.
downpaymenttx.org • 713-258-0299 • DSWABY@NEXAMORTGAGE.COM • Donnet Swaby NMLS #1929422 • NEXA Mortgage, LLC NMLS #1660690 • Equal Housing Lender
FIND DONNET SWABY ON GOOGLE
Down Payment Assistance Texas · View on Google → PAGE 13