
“SHE WORKED WHAT FELT LIKE MAGIC.”
AMI DESAI WOULD RATHER YOU KNEW WHAT IT ACTUALLY WAS.
Eighteen years. Nine states. A perfect five stars on Experience.com, Zillow and Redfin alike. And the truth behind that sentence is something far more boring — and far harder to copy.
The review is one sentence long, and it doesn’t name the person who wrote it.
It says this:
“I had a set budget and a tight timeline — she worked what felt like magic and made it happen.”
Read it twice, and notice what isn’t in it.
There’s no mention of a rate. No mention of a fast closing, either. Her reviews say other things instead. A first-time buyer, seven months into the process, writes that she “is amazing with everything and so patient.” Another says she was “always available any time of the day to explain any and everything I may of been confused about.” A third runs four words long: “She explains every detail.”
Nobody hires a lender for explaining. It’s what her clients keep coming back to anyway.
Which brings us back to that first word. Magic. Somebody sat down with a hard number and a hard date — two things that famously do not bend — and watched them fit together anyway. Reaching for a word afterward, the best one they could find was the word people use when they’ve just watched work they couldn’t see.
Because there was no magic. There is never any magic — not in a business run on guidelines, investor overlays, and a document stack the size of a phone book. There was a branch manager in Cockeysville doing something entirely ordinary and entirely specific. And that ordinary, specific thing is the most useful fact you’ll learn about Ami Desai today.
Here’s the fastest way to see it.
Think of the last mortgage ad you saw. Then the one before it. Low rate. Great service. Fast closing. That’s the whole menu, and it’s what nearly every lender in
Maryland is advertising this morning — because those three things are what a mortgage is supposed to do when nothing goes wrong.
Nobody advertises the other thing.
Nobody puts it on a billboard, because it doesn’t fit on one, and because out loud it sounds like nothing at all: I will go find out.
Five words. No promise attached. It’s a terrible slogan — it doesn’t tell you what the answer will be. Only that somebody is going looking for it.
Which is exactly why nobody runs it. And exactly why, eighteen years in, it’s the only thing Ami Desai has ever really sold.
Here’s what going and finding out actually costs.
“ She worked what felt like magic and made it happen. — Experience.com
WHAT GOING AND FINDING OUT ACTUALLY COSTS
Start with the arithmetic of the job, because the arithmetic explains everything. A mortgage originator is paid when a file closes. Not when it’s worked. Not when it’s researched. When it closes. That single fact shapes the entire business, and it shapes it in one direction: toward the file that closes itself. There is always another file that closes itself — cleaner income, simpler documentation, a borrower who fits the box on the first pass. The math rewards volume, and volume rewards moving on.
So when a file gets complicated — when the income won’t calculate cleanly, when a guideline appears to close the door, when the whole thing needs an exception somebody has to write — the economics are pushing hard, the entire time, toward the easy answer.
The easy answer is no.
Ami goes and reads.
She’ll spend an hour inside a program guideline hunting the sentence that applies to this specific borrower. She’ll work the phones — underwriting, then title, then the investor — until she’s reached the person who actually knows rather than the person who merely answered. She’ll go through a manual line by line instead of assuming what it says. She’ll dig for a down payment assistance program the borrower has never heard of. When one path closes, she goes looking for the other nine.
None of that shows up anywhere. Not on the closing disclosure, not on a billboard, not in the rate she quotes you. It’s an hour that bills nothing and photographs badly, spent on a file that might not close, in a job that only pays when files close.
That’s the cost. It’s why “I will go find out” doesn’t fit on a billboard — and it’s why it’s worth something. Anyone can promise you a low rate; a rate is free to promise and set by a market nobody in the transaction controls. The willingness to spend the hour is the one thing on the menu that has an actual price, and the one thing a competitor can’t simply decide to advertise tomorrow.
Her clients don’t experience any of this as research. They experience it as somebody who wouldn’t let their file die.
EIGHTEEN YEARS, NINE STATES, AND ONE NUMBER THAT MATTERS
The credentials are straightforward, and every one of them is verifiable.
Ami Desai is Branch Manager at All Western Mortgage in Cockeysville, Maryland. She has spent eighteen years in the mortgage business — nearly two decades of files, rate cycles, underwriting regimes and problems that never quite repeat. She is licensed in nine states: Colorado, Florida, Georgia, Maryland, Michigan, North Carolina, Ohio, Tennessee and Virginia. NMLS #245984. She holds a B.S. in Marketing from Towson University.
She was born and raised in Maryland, and she still works it — a baseball mom and a soccer mom whose business has been built referral by referral out of the same communities her own kids grew up in.
And across every platform where her clients are free to rate her — Experience.com, Zillow, Redfin — she carries a 5.0.
That last number deserves a moment of honesty, because five-star averages are cheap in this business. Reviews get requested at the closing table, on the happiest day of the transaction, from people holding keys. Nearly everyone’s average looks good. A 5.0 is not, by itself, evidence of anything. What isn’t cheap is why hers read the way they do.
Go read them. Almost nobody mentions the rate. They mention her patience. They mention that she picked up the phone at an hour she didn’t have to. They mention that something hard — something they’d half accepted wasn’t going to happen — got done. That’s not a review of a mortgage. That’s a review of a person, and it tells you exactly what her clients believe they were actually buying.
Eighteen years is the part that can’t be shortcut. Guidelines change, programs appear and disappear, investors tighten and loosen. The originator who has seen a problem before doesn’t need the hour — she needs ten minutes and a phone number. Experience, in this job, isn’t a credential. It’s inventory.
“ I will go find out. Five words. It’s a terrible slogan — which is exactly why nobody runs it.
SHE EXPLAINS IT UNTIL IT ACTUALLY MAKES SENSE
The second thing Ami’s clients say has nothing to do with problem-solving at all. It’s about being talked to like an adult.
A mortgage is the largest transaction most people will ever sign their name to, and it is conducted almost entirely in a language they do not speak. Escrow. LTV. Seasoning. Debt-to-income. Reserves. The whole vocabulary arrives at once, from professionals who use it forty times a day, at a moment when the borrower is too far in to admit they’re lost. And most borrowers do nod along — because saying I don’t understand is uncomfortable when everyone else in the room sounds certain.
Ami’s clients describe the opposite experience, and they describe it over and over in their own words: “Ami was always available any time of the day to explain any and everything I may of been confused about.” Another puts it in four words: “She explains every detail.”
There’s a strategic reason this matters well beyond good manners.
A borrower who genuinely understands their file makes better decisions inside it. They bring the right documents the first time. They don’t panic when the underwriter comes back with a third request — because they were told, in advance, that a third request is normal. They don’t blow up their own approval by financing a car three weeks before closing, because somebody explained why that would.
Education isn’t a courtesy Ami extends after the real work is done. It’s a substantial part of why her difficult files close at all.
And it’s patient work. One first-time buyer, Krystal S., went through a seven-month process with Ami before finally reaching the closing table. Her review does not complain about the seven months. It says: “She is amazing with everything and so patient.”
Seven months is a long time to stay in someone’s corner on a file that may never pay.
THE DOWN PAYMENT NOBODY TOLD THEM ABOUT
Here is the single assumption that costs Maryland families more money than any interest rate ever will:
I don’t have the down payment. So I can’t buy yet. It is, very often, simply not true.
Down payment assistance in Maryland is real, it’s available, and it goes systematically underused — not because it’s a secret, but because it’s fragmented, badly explained, and takes genuine work to match to one specific buyer’s income, county, credit profile and property. It is money that already exists, sitting in programs, waiting for somebody to go and find it.
Which makes it the purest possible example of the hour. There’s no way to shortcut it and no way to advertise it. You either go looking or you don’t, and the buyer never finds out either way — because a person who assumes they can’t afford a house doesn’t call a lender to check. They just don’t call.
Ami has gone deep enough on this that she’s building a dedicated Maryland down payment assistance resource — an effort to get the information in front of buyers before they’ve talked themselves out of the whole idea.
That’s the instinct aimed upstream. Instead of solving the file in front of her, going after the reason a whole category of qualified people never opens a file at all.
For a first-time buyer who’s quietly been assuming they need another three years of saving before they’re allowed to start, this isn’t a small conversation. It’s the one that moves up their entire timeline.
“
THE PERSON WHO KNOWS WHO TO CALL
Eighteen years in one market builds something that doesn’t fit anywhere on a résumé: a phone full of the right people.
A mortgage doesn’t close in isolation. It closes because a title issue got untangled by someone who’d seen that exact issue before. Because a Realtor and a builder got onto the same page about a timeline. Because an underwriter picked up the
She is amazing with everything and so patient. — Krystal S.
phone for a branch manager they’ve dealt with for a decade and trust. Because an attorney answered a question the same afternoon instead of the following week.
Ami sits in the middle of that network in Maryland — lending, title, real estate, construction, law — and the practical effect for a borrower is simple: their problem gets routed to a name instead of into a queue.
It’s why the magic reads as fast. It isn’t fast, exactly. It’s that she already knows who to call — which is just the hour again, spent years ago, on somebody else’s file.
WHAT IT SOUNDS LIKE WHEN IT WORKS
Read enough of Ami Desai’s reviews and the pattern is hard to miss. Almost none of them are about mortgages.
“I had a set budget and a tight timeline — she worked what felt like magic and made it happen.”
“She is amazing with everything and so patient.” — Krystal S.
“Ami was always available any time of the day to explain any and everything I may of been confused about.”
“She explains every detail.”
Nobody writes about the rate. They write about the outcome, and about the person who got them there. Which tells you precisely what they thought they were buying — and it wasn’t a loan.
“ Nobody writes about the rate. They write about the person who got them there.
WORK WITH AMI DESAI
If your situation is straightforward, almost any lender in Maryland can handle it, and you should feel free to shop on rate. That’s what a rate is for.
If it isn’t — if you’re self-employed and your returns don’t tell the whole story, if your timeline is tight, if you’re a first-time buyer who’s been assuming the down payment puts this years out of reach — that’s the call Ami wants.
Bring her the one that looks impossible. That’s the part she enjoys.
Ami Desai · Branch Manager, All Western Mortgage · NMLS #245984
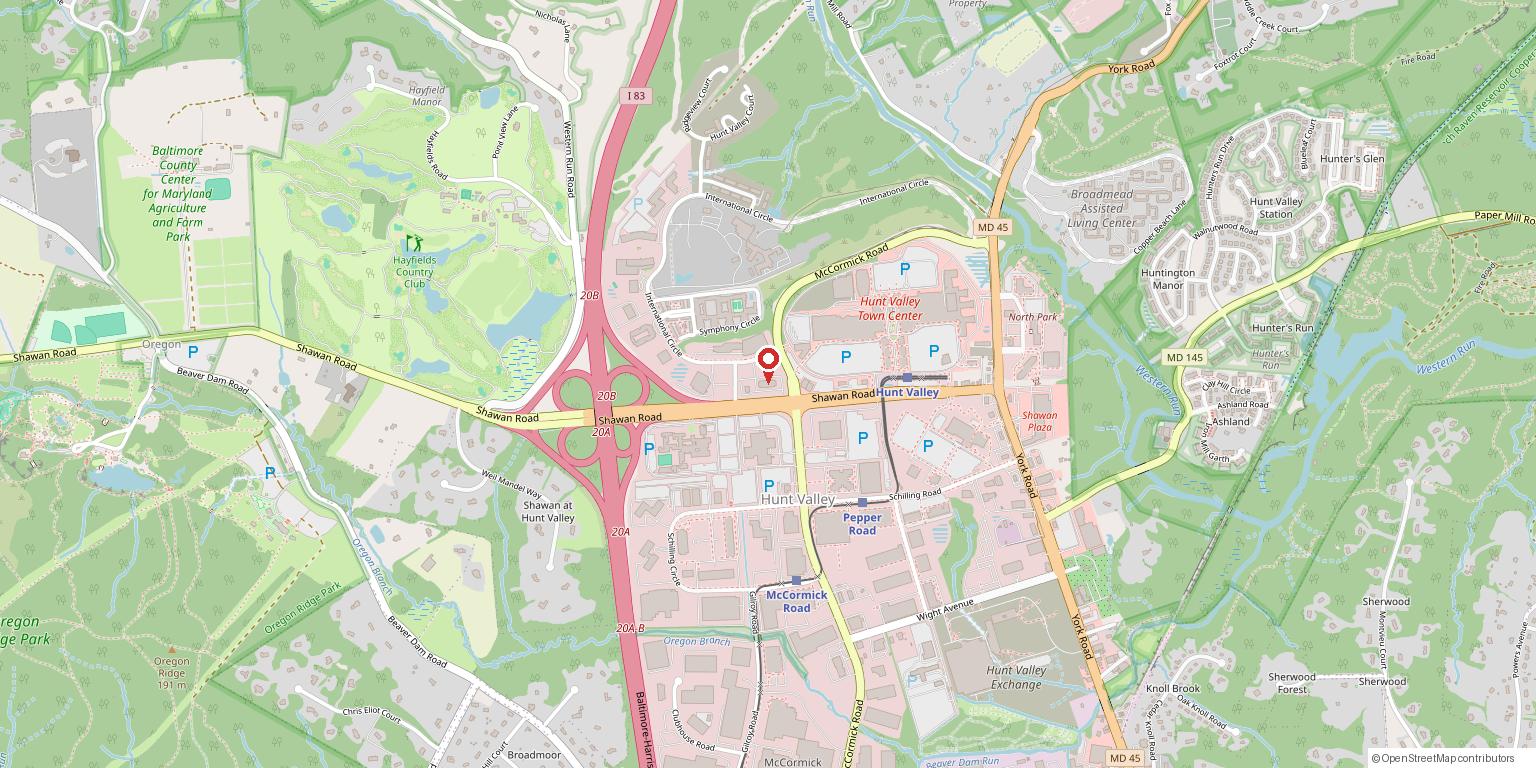
201 International Circle, Suite 238, Cockeysville, MD
(443) 375-2279 · ami@allwestern.com
ABOUT AMI DESAI
Ami Desai is Branch Manager at All Western Mortgage in Cockeysville, Maryland, with 18 years in the mortgage business and licenses in nine states. She specializes in the files other lenders find complicated.
Bring her the one that looks impossible. Call (443) 375-2279 or email ami@allwestern.com.
Ami Desai, All Western Mortgage · View on Google →