

MARKET REPORT
Portland-Vancouver-Hillsboro, OR-WA CBSA February 2022 YOY Change
MARKET OVERVIEW New Home Sales
L12M New Home Sales
Monthly Sales Rate
L12M Avg Sales Rate
539 -21.0%
5,360 -22.3%
2.9 12.0%
2.0 13.9%
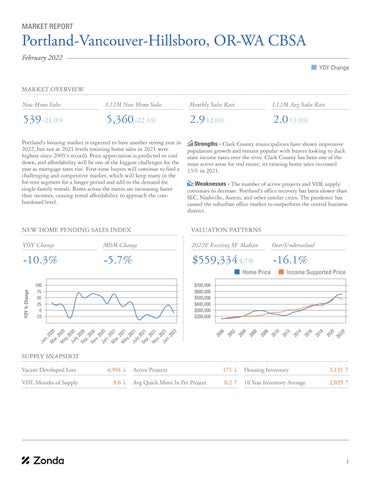
Portland's housing market is expected to have another strong year in 2022, but not at 2021 levels (existing home sales in 2021 were highest since 2005's record). Price appreciation is predicted to cool down, and affordability will be one of the biggest challenges for the year as mortgage rates rise. First-time buyers will continue to find a challenging and competitive market, which will keep many in the for-rent segment for a longer period and add to the demand for single-family rentals. Rents across the metro are increasing faster than incomes, causing rental affordability to approach the costburdened level.
Strengths - Clark County municipalities have shown impressive population growth and remain popular with buyers looking to duck state income taxes over the river. Clark County has been one of the most active areas for real estate; its existing home sales increased 13% in 2021. Weaknesses - The number of active projects and VDL supply continues to decrease. Portland's office recovery has been slower than SLC, Nashville, Austin, and other similar cities. The pandemic has caused the suburban office market to outperform the central business district.
NEW HOME PENDING SALES INDEX
VALUATION PATTERNS
YOY Change
MOM Change
2022F Existing SF Median
Over/Undervalued
-10.3%
-5.7%
$559,334 4.7%
-16.1% Income Supported Price
F 22
20
20
18
20
16
20
14
20
12
20
10
20
08
20
20
06
04
20
20
02
M
Ja
n.
20
00
$700,000 $600,000 $500,000 $400,000 $300,000 $200,000
20
100 75 50 25 0 -25
20 2 ar 0 .2 0 M 20 ay 2 Ju 020 ly 2 Se 020 p. 2 No 020 v. 2 Ja 020 n. 2 M 021 ar .2 M 021 ay 2 Ju 021 ly 2 Se 021 p. 2 No 021 v. 2 Ja 021 n. 20 22
YOY % Change
Home Price
SUPPLY SNAPSHOT Vacant Developed Lots VDL Months of Supply
4,994 ↓ 9.6 ↓
Active Projects
171 ↓
Housing Inventory
3,131 ↑
Avg Quick Move In Per Project
0.2 ↑
10 Year Inventory Average
2,029 ↑
1
Portland-Vancouver-Hillsboro, OR-WA CBSA, Feb. 28, 2022
YOY Change
SUPPLY Last 12 Months Starts
Last 12 Months Sales
Last 12 Months Closings
6,260 1.2%
5,360 -22.3%
5,671 -3.9%
ANNUAL STARTS VS. ANNUAL CLOSINGS
NEW HOME SALES
Starts
Closings
8,000 7,000 6,000 5,000 4,000 3,000 2,000
800 700 600 500
02 0 ar .2 02 M 0 ay 20 Ju 20 ly 20 Se 20 p. 20 No 20 v. 20 Ja 20 n. 20 M 21 ar .2 0 M 21 ay 20 Ju 21 ly 20 Se 21 p. 20 No 21 v. 20 Ja 21 n. 20 22
Ja n
M
.2
Q4 21
Q3
20
20
20
Q1 20
19
Q3 20
17
Q1 20
16
Q3 20
14
Q1 20
13
Q3 11 20
20
10
Q1
400
HOUSING INVENTORY Under Construction
Finished Vacant
Models
4,000 3,200 2,400 1,600
Q4 21
Q2
20
20
21
Q3 20
20
Q4 20
19
Q1 20
19
Q2 20
18
Q3 20
17
Q4 20
16
Q1 20
16
Q2 20
15
Q3 20
14
Q4 20
13
Q1 20
13
Q2 20
12
Q3 20
11
Q4 10 20
20
10
Q1
800
MEDIAN CLOSING PRICE New
Existing
$563,000 22.9%
$505,000 16.1%
1 02
No v. 2
1 02
Se p
.2
21 20 ly
Ju
20 ay M
ar .2
02
21
1
21 M
20 n.
02
0 Ja
No v. 2
0 02
Se p
.2
20 20 ly
Ju
20 ay M
M
ar .2
02
20
0
20 n.
20
9 Ja
01
9
No v. 2
01 .2
19
Se p
20
Ju
20 ay
ly
19
9 01 M
ar .2 M
20 n. Ja
No v. 2
01
8
19
$660,000 $605,000 $550,000 $495,000 $440,000 $385,000
2
Portland-Vancouver-Hillsboro, OR-WA CBSA, Feb. 28, 2022
YOY Change
ZILLOW LISTINGS
RESALE DAYS TO PENDING
Listings
Days To Pending
31 days↑
5,600 5,200 4,800 4,400 4,000 3,600
35 30 25 20
02 0-
18
-1
20
21
04
9-0
20
21
21
9-
8-
-0
20
21
07
-0
20
21
24
8-
7-
-0
20
21
10
-0
20
21
26
7-
6-
-0
20
21
12
-0
20
21
29
6-0
20
21
15
5-
5-
-0
20
21
01
-0
20
21
17 4-
-0
-0
20
21 20
21
-1
21
20
5-
02
11
0-
25 20
21
-0
9-
07
9-
20
21
-0
8-
28 20
21
-0
8-
17 20
21
-0
7-
03 20
21
-0
7-
05 20
21
-0
6-
12 20
21
-0
6-
08 20
21
-0
5-
22 20
21
-0
5-
20
21
-0
5-
4-
-0
-0
21
21
20
20
01
15
24
Listings
4,935 13.1%
JOBS VS. UNEMPLOYEMENT Annual Job Growth
81,800↑
1,208,000 7.3%
4.1%↓
F 23 20
21 20
19 20
17 20
15 20
20
20
20
20
20
20
20
13
4.0
11
8.0
-100,000
09
12.0
-50,000
07
16.0
0
05
20.0
50,000
03
100,000
01
New Jobs
Unemployment Rate
Unemployment Rate
Total Jobs
HOUSEHOLD GROWTH 2027 Forecast
20,320 2.1%
1,092,837 1.4% % Growth
22 20
19 20
17 20
15 20
13 20
11 20
09 20
07 20
20
05
6.0 5.0 4.0 3.0 2.0 1.0
03
1,120,000 1,050,000 980,000 910,000 840,000 770,000
20
Households
Households
% Growth
2022 Household Growth
3
SUPPLY
Portland-Vancouver-Hillsboro, OR-WA CBSA, Feb. 28, 2022
YOY Change
SUPPLY HIGHLIGHTS In the Portland-Vancouver-Hillsboro, OR-WA region, total residential building permit activity increased 16.6% year-over-year to an annualized rate of 15,471 units in November. In the twelvemonth period ending November, single-family building permit issuance increased 9.9% to 8,366 units while multi-family permit issuance increased 25.6% to 7,105 units.
Active Projects
Quarterly Starts
171 -31.3%
1,585 4.9%
Housing Inventory
Months Of Inventory
3,131 23.2%
6.6 32.4%
HOUSING DEMAND Total Housing Supply
Total Housing Demand
VDL
Months Of Supply
4,994 -19.1%
9.6 -26.9%
F 23 2.9K
$8
00
K+
349
$6
50
K-
$8
00
K
329
50 K00
$5 K50 $3
$6
00
0K 35 <$
Q4 21
Q2
20
21
Q4
20
20
Q2
20
Q4
20 20
19
Q2
20
Q4
19 20
20
18
Q2 18
Q4 17
20
Q2
20
Q4
17 20
16 20
847
K
520
K
51
$5
10,000 9,000 8,000 7,000 6,000 5,000
NA
VACANT DEVELOPED LOTS BY PRICE
20
21
VACANT DEVELOPED LOTS
20
19 20
17 20
15 20
13 20
11 20
09 20
07 20
05 20
03 20
20
01
1,200,000 1,120,000 1,040,000 960,000 880,000 800,000
4
Portland-Vancouver-Hillsboro, OR-WA CBSA, Feb. 28, 2022
YOY Change
BUILDING PERMITS VS. E/P RATIO Last 12 Months Total Permits
E/P Ratio
2022 E/P Ratio Forecast
15,471 16.6%
0.7 6.3%
3.4 1.8% E/P Ratio
ACTIVE PROJECTS
F 23
21
20
20
19 20
20
NA
K+
K K-
$8
$8
50
50
K
Closings
$7
50
K-
$7
50
K 50 $6
$5
50
K-
$6
50
K 50
$4
50
K-
$5
50 $4
35
50 $3
$7
50
K-
$8
<$
50
0K
NA
K+
K 50 $8
50 K-
$7
50 $6
50
K-
$6
50 50 $5
$4
50
K-
$4 K50
$5
50
0K 35
K
15
K
8
K
45 30
K
24 16
K
VDL 75 60
<$
Last 12 Months
Lot Deliveries
40 32
$3
20
VDL VS. CLOSINGS BY PRICE
K-
Starts
20
20
20
20
20
20
20
STARTS VS. LOT DELIVERIES BY PRICE Last 12 Months
17
-12.0
15
6,000
13
-6.0
11
12,000
09
0.0
07
18,000
05
6.0
03
12.0
24,000
E/P Ratio
MF Permits
30,000
01
Permits
SF Permits
AVG QMI PER PROJECT
Detached
135 -35.4%
Attached
Feb. 2022
36 -10.0%
0.2↑
450 360 270 180 90
1.5 1.0
C 22
21
20
20
b.
c.
Fe
De
Oc
t.
20
21
21
21
20 g.
Au
ne
20
1 02
r. 2
Ju
Ap
20
21
20 20
b. Fe
c.
De
Oc
t.
20
20
20
20
20 g.
20
Au
Ju
ne
02
20
r. 2
Ap
20 b. Fe
0
C 22
20
b.
Fe
De
c.
20
21
21
21
Oc
t.
20 g.
Au
20
21 20
1 Ju
ne
02
Ap
r. 2
21 20
b. Fe
De
c.
20
20
20
20
Oc
t.
20
20
20
g. Au
ne
20
0 02 Ju
r. 2
Ap
Fe
b.
20
20
0.5
5
n.
1
02
v. 2
Closings
21
20 +
.2M
$1
n. 2
600 500 400 300 200 100
2
02
1
02
Detached
Ja
21
20
21
21 20
No v. 2
Se p.
ly
Ju
20
1
2015
7.0 6.0 5.0 4.0 3.0 2.0
7,000 6,000 5,000 4,000 3,000 Sales Rate
SALES BY AVG PRICE
No
p.
M
1.2
-$
New Home Sales
Se
21
.1M
.1M
$1
K-
ay
02
1
02
US
20
$1
K
M
ar .2
M
n. 2
0
02
2.6↑
Portland
ly
21
20
00
$9
K
00
$9
K-
50
$7
K
50
$7
K-
00
$6
Ja
20
20
20
20
20
0
02
0
02
20
No v. 2
Se p.
ly
Ju
ay
M
ar .2
M
9
01
n. 2
Ja
19
20
19
20
19
9
01
9
01
20
No v. 2
Se p.
ly
Ju
ay
M
ar .2
M
n. 2
Ja
Sales
2.9↑
Ju
ay
M
1
02
21
20
ar .2
M
n.
00
K
50
$6
K-
50
$4
$4
K-
00
$3
Sales
Avg Sales Rate
Ja
0
02
20
20
v. 2
No
p.
20
20
20
20
Last 3 Months
Se
ly
Ju
ay
Sales Rate
7.0 6.0 5.0 4.0 3.0 2.0
M
0
600 500 400 300 200 100
02
20
20
ar .2
n.
+
00
3,5
0
,50
-3
00
3,0
0
0
,00
-3
00
2,5
,50
-2
00
0
SALES BY AVG UNIT SIZE
M
Ja
9
01
v. 2
19
20
19
20
19
20
2,0
,00
-2
00
1,5
0
,50
<1
Sales
New Home Sales
No
p.
Se
ly
Ju
ay
M
9
01
19
20
8
01
ar .2
M
Ja
v. 2
No
SALES Portland-Vancouver-Hillsboro, OR-WA CBSA, Feb. 28, 2022
AVG SALES RATE
2022
NEW HOME SALES Attached
1,000 800 600 400 200
Last 3 Months
Avg Sales Rate
CLOSINGS % New
40.0 32.0 24.0 16.0 8.0
6
Portland-Vancouver-Hillsboro, OR-WA CBSA, Feb. 28, 2022
TOP ACTIVE PROJECTS
By Sales Rate
AVG PRICE
AVG SIZE
AVG PRICE PER SQ FT
SALES RATE↓
Detached
-
-
-
11.9
Battle Gro
Detached
-
-
-
11.0
D.R. Horton
Gresham
Detached
$504,662
1,776
$283
10.3
Hazel Dell Landing
D.R. Horton
Vancouver
Attached
-
-
-
8.9
5
Spring Village
D.R. Horton
Vancouver
Detached
$399,995
1,315
$304
8.8
6
Faraday Hills
Holt Homes
Estacada
Detached
$525,460
2,366
$222
8.7
7
Hazel Dell Landing/Alleys D.R. Horton
Vancouver
Attached
$347,995
1,362
$255
8.7
8
Pleasant Valley Villages
Holt Homes
Happy Valley Detached
$576,136
1,731
$327
8.6
9
Harvest Park
D.R. Horton
Vancouver
Detached
$390,995
1,382
$282
8.0
10
Si Ellen Farms
New Traditi
Vancouver
Detached
$779,900
3,445
$226
7.8
$503,592
1,911
$271
9.3
RANK
PROJECT NAME
BUILDER
CITY
TYPE
1
Middlebrook
Holt Homes
Sherwood
2
River Bend Phase 1
Aho Constru
3
Brookside/Phase 5
4
Averages:
c
,
,
,
,
,
o
u
7
Portland-Vancouver-Hillsboro, OR-WA CBSA, Feb. 28, 2022
ACTIVE BUILDERS Top 15 RANK
BUILDER
1
By Market Share # OF PROJECTS
AVG PRICE
# OF YTD SALES
MARKET SHARE ↓
AVG SALES RATE
REMAINING UNITS
Lennar
18
$573,107
795
14.7%
4.31
461
2
Holt Homes
10
$512,441
662
12.3%
5.69
313
3
D.R. Horton, Inc.
7
$403,404
469
8.7%
7.92
143
4
Taylor Morrison
7
$476,839
388
7.2%
2.76
205
5
Pahlisch Homes
9
$602,762
304
5.6%
2.63
292
6
New Tradition Homes
4
$572,577
209
3.9%
5.63
37
7
Richmond American Homes
5
$617,900
198
3.7%
2.37
30
8
Pacific Lifestyle Homes
4
$553,607
173
3.2%
3.74
67
9
LGI Homes
3
$466,627
162
3.0%
2.35
130
10
David Weekley Homes
5
$661,640
159
2.9%
1.84
25
11
Stone Bridge Homes NW
3
$722,605
137
2.5%
2.17
21
12
Toll Brothers
2
$949,798
135
2.5%
4.36
77
13
West Hills Homes Northwest
2
$782,446
92
1.7%
2.04
21
14
Icon Construction and Develo
3
$729,602
84
1.6%
1.60
25
15
Ichijo USA
3
$632,015
78
1.4%
1.96
83
5.7
$617,158
269
74.9%
3.42
128
Totals & Averages:
p
8
PRICES
Portland-Vancouver-Hillsboro, OR-WA CBSA, Feb. 28, 2022
YOY Change
PRICE HIGHLIGHTS The median closing price for a new detached home in the Portland-Vancouver-Hillsboro, ORWA region increased 18.0% from 2021 to $565,400 in November while the median closing price for a new attached home increased 12.2% over the same period to $402,293. Homes priced between $400,000 and $500,000 experienced the most closing activity over the past year. The new home affordability ratio for a detached home reached 36.0% in November.
Avg New List Price
Median Price/Sq Ft, New vs. Existing
$543,952 18.8%
$285 57.5% / $299 35.9%
Median Existing Closed Price
New Premium, Detached vs. Attached
$505,000 16.1%
7%↑ / 11%↓
DETACHED MEDIAN CLOSING PRICE New
ATTACHED MEDIAN CLOSING PRICE
Existing
$565,400 18.0%
$525,000 16.7%
$402,293 12.2%
Existing
$360,000 26.3%
AVG NEW HOME LIST PRICE Detached
$605,100 11.3%
No v. 2 Ja 019 n. 2 M 020 ar .2 M 020 ay 2 Ju 020 ly 2 Se 020 p. 2 No 020 v. 2 Ja 020 n. 2 M 021 ar .2 M 021 ay 2 Ju 021 ly 2 Se 021 p. 2 No 021 v. 20 21
$3,300,000 $2,750,000 $2,200,000 $1,650,000 $1,100,000 $550,000
No v. 2 Ja 019 n. 2 M 020 ar .2 M 020 ay 2 Ju 020 ly 2 Se 020 p. 2 No 020 v. 2 Ja 020 n. 2 M 021 ar .2 M 021 ay 2 Ju 021 ly 2 Se 021 p. 2 No 021 v. 20 21
$720,000 $660,000 $600,000 $540,000 $480,000 $420,000
New
MEDIAN CLOSING PRICE PER SQ FT Attached
$482,805 29.8%
Attached $/SF
$302 27.9%
$280 27.9%
20
M
n. Ja
No v. 20 Ja 19 n. 20 2 M ar 0 .2 M 020 ay 20 Ju 20 ly 20 Se 20 p. 20 No 20 v. 20 Ja 20 n. 2 M 021 ar .2 0 M 21 ay 20 Ju 21 ly 20 Se 21 p. 20 No 21 v. 20 21
$330 $300 $270 $240 $210 $180
2 ar 0 .2 0 M 20 ay 2 Ju 020 ly 2 Se 020 p. 2 No 020 v. 2 Ja 020 n. 2 M 021 ar .2 M 021 ay 2 Ju 021 ly 2 Se 021 p. 2 No 021 v. 2 Ja 021 n. 20 22
$660,000 $600,000 $540,000 $480,000 $420,000 $360,000
Detached $/SF
9
1
02
1
02
No v. 2
$5
$5
$6
K
K
K
K+
00
00
$6
K-
50
50
$5
K-
00
00
$5
K
Prior 12 Months
.2
21
20
21
20
1
K-
50
50
$4
K-
00
K
00
$7
00
$6
00
$5
00
$4
00
$3
K+
K
00
K
00
K
00
K
00
K
00
K
00
00
$8
$8
K-
$7
K-
$6
K-
$5
K-
$4
K-
$3
K-
Prior 12 Months
Se p
ly
Ju
ay
M
02
$4
$4
00
$4
K-
50
K
Last 12 Months
ar .2
21
20
0
02
$3
50
$3
0K
Last 12 Months
M
n.
Ja
New K-
00
15,000 12,500 10,000 7,500 5,000 2,500
0
EXISTING DETACHED CLOSINGS BY PRICE
02
20
<$
150
No v. 2
$3
00
$2
300
.2
0K
30
<$
450 300
20
900 600
Se p
K+
K
00
K
50
K
00
K
50
K
00
K
50
00
$6
$6
K-
$5
K-
$5
K-
$4
K-
$4
K-
$3
0K
750 600
20
K+
00
50
$5
00
$5
50
$4
00
$4
50
$3
K-
30
<$
1,500 1,200
ly
36%↓
20
20
0
02
$9
K
K
K
K
K
K
00
$3
NEW DETACHED CLOSINGS BY PRICE
Ju
ay
M
20
20
ar .2
M
n.
Ja
00
$9
K-
00
00
$8
K-
00
00
$7
00
$6
K-
00
K-
00
00
$5
K-
00
00
$4
K-
00
0K
30
<$
Prior 12 Months
9
$8
$7
$6
$5
$4
$3
Prior 12 Months
01
No v. 2
9
01
19
20
19
20
.2
Se p
ly
Ju
ay
M
9
01
19
20
ar .2
M
n.
Ja
8
01
No v. 2
Affordability (%)
Portland-Vancouver-Hillsboro, OR-WA CBSA, Feb. 28, 2022
NEW ATTACHED CLOSINGS BY PRICE Last 12 Months
EXISTING ATTACHED CLOSINGS BY PRICE Last 12 Months
2,700 2,250 1,800 1,350 900 450
AFFORDABILITY RATIO
Existing
39.4%↓
64.0 56.0
48.0 40.0
32.0
10
DISTRESS
Portland-Vancouver-Hillsboro, OR-WA CBSA, Feb. 28, 2022
YOY Change
DISTRESS HIGHLIGHTS The region experienced 5 foreclosures in November, a decrease of 66.7% year-over-year. Meanwhile, Notices of Default registered at 25 for the month, a decrease of 39.0% over last year.
Notices Of Default
Foreclosures
25 -39.0%
5 -66.7%
Foreclosures Market Share
0.1%↓ NOTICES OF DEFAULT
FORECLOSURES
Last 12 Months
Last 12 Months
708 -76.6%
59 -81.0% 75 60 45 30
v. 2
0 Ja 19 n. 20 M 20 ar .2 0 M 20 ay 20 Ju 20 ly 20 Se 20 p. 20 No 20 v. 20 Ja 20 n. 2 M 021 ar .2 0 M 21 ay 20 Ju 21 ly 20 Se 21 p. 20 No 21 v. 20 21
15
No
No
v. 20 Ja 19 n. 20 M 20 ar .2 0 M 20 ay 20 Ju 20 ly 20 Se 20 p. 20 No 20 v. 20 Ja 20 n. 2 M 021 ar .2 0 M 21 ay 20 Ju 21 ly 20 Se 21 p. 20 No 21 v. 20 21
600 500 400 300 200 100
11
ECONOMY
Portland-Vancouver-Hillsboro, OR-WA CBSA, Feb. 28, 2022
YOY Change
ECONOMY HIGHLIGHTS Total nonfarm employment in the PortlandVancouver-Hillsboro, OR-WA metropolitan statistical area increased 7.3% from the same period last year to 1,208,000 payrolls in December 2021. There are approximately 81,800 more jobs than December of last year. The local unemployment rate remained flat at 4.1% in December 2021 compared to 4.1% in the previous month. December’s jobless rate is lower than it was this time last year when it stood at 6.3%. Forecasts from Moody’s Analytics show that the region’s unemployment rate will finish the year at 5.1%.
Total Jobs
CBSA Unemployment Rate
1,208,000 7.3%
4.1%↓
MOM Job Growth
OR Unemployment Rate
5,600
4.1%↓
YOY Job Growth
USA Unemployment Rate
81,800
4.0%↓
JOB GROWTH RATE
NEW JOBS USA
2022 Jobs Forecast
2023 Jobs Forecast
7.3%↑
4.7%↑
1.23M 5.0%
1.27M 3.5%
Ap 20 r. 2 Ju 020 ne 2 Au 020 g. 20 Oc 20 t. 2 De 020 c. 20 Fe 20 b. 20 Ap 21 r. 2 Ju 021 ne 2 Au 021 g. 20 Oc 21 t. 2 De 021 c. 20 21
20
b.
Fe
c. 2
01
9
195,000 130,000 65,000 0 -65,000 -130,000
De
21.0 14.0 7.0 0.0 -7.0 -14.0
No v. 2 Ja 019 n. 2 M 020 ar .2 M 020 ay 2 Ju 020 ly 2 Se 020 p. 2 No 020 v. 2 Ja 020 n. 2 Ap 021 r. 2 Ju 021 ne 2 Au 021 g. 20 Oc 21 t. 2 De 021 c. 20 21
% Growth
CBSA
JOB GROWTH BY INDUSTRY CBSA % TOTAL (NON-FARM)
USA % TOTAL (NON-FARM)
YOY JOBS CHANGE
YOY CHANGE
3-YEAR GROWTH FORECAST
Trade, Transport & Utilities
20.4%
20.0%
10,100
4.6%
14,086
Education & Health
16.1%
16.8%
8,500
4.8%
18,804
Professional & Business Services
18.3%
15.8%
14,880
8.0%
20,112
Government
12.9%
15.8%
5,500
3.9%
11,916
Hospitality
9.7%
10.5%
18,560
21.4%
23,040
10.8%
8.4%
4,170
3.5%
2,934
Finance
6.5%
6.3%
1,970
2.8%
4,380
Information
2.2%
2.1%
1,710
6.8%
2,234
Other
3.2%
4.2%
1,800
4.8%
2,449
INDUSTRY
Manufacturing
12
COMMUNITY
Portland-Vancouver-Hillsboro, OR-WA CBSA, Feb. 28, 2022
YOY Change
COMMUNITY HIGHLIGHTS Population
Households
2,523,991 0.0%
984,233 0.0%
Household Income
Housing Costs as % of Income
$79,883 3.3%
50.1%↑
HOUSEHOLDS BY AGE
2025 Forecast
2025 Forecast
2,611,348
1,017,800 % Growth
75
+
74
64
to 65
to
54 to
44
45
to
35
25
to
34
5 <2
+
75.0 50.0 25.0 0.0 -25.0
75
74 to
64
HOUSEHOLDS BY TYPE
2027 Forecast
275,000 220,000 165,000 110,000 55,000
65
54
55
to
44
to 45
35
to
<2
25
to
34
100.0 75.0 50.0 25.0 0.0
2022
Households
% Growth
% Growth
2027 Forecast
1,000,000 800,000 600,000 400,000 200,000
5
HOUSEHOLD INCOME 2025 Forecast
$83,172 2027 Forecast
% Growth
5.0
70,000
0.0
00 $2
20 -$
15 $1
50
K
-$ K
25
00
K
-$
12
10 -$ $1
$1
K 75 $7
5K
-$
$5
0K
<
19.3% Non-Family
$5
Single - No children under 18
K+
10.0
140,000
8.3%
0K
15.0
210,000
0K
280,000
34.7% Married - No children under 18
5K
20.0
0K
350,000
10.9% Single - Children under 18
0K
26.8% Married - Children under 18
% Growth
2022
Households
Population
2022
% Growth
POPULATION BY AGE
55
The current population for the PortlandVancouver-Hillsboro, OR-WA metropolitan area is approximately 2,523,991 people. Population in the area is projected to increase by 0.0% in 2022. There are approximately 984,233 households in the region which is down 0.0% year-over-year. Forecasts show that current household formation is expected to increase by an annual growth rate of 3.6% for 2025. Incomes increased 3.3% from the previous year to $79,883.
13
MARKET HEALTH
Portland-Vancouver-Hillsboro, OR-WA CBSA, Feb. 28, 2022
YOY Change
MARKET HEALTH FORECAST 2021E
2022F
Total Jobs
1,247,875 / 2.5%
1,309,158 / 4.9%
1,357,734 / 3.7%
-/-
Households
1,045,112 / 1.6%
1,062,161 / 1.6%
1,079,252 / 1.6%
-/-
Single-Family Permits
8,098 / 7.8%
9,019 / 11.4%
9,344 / 3.6%
-/-
Multifamily Permits
8,608 / 45.1%
8,202 / -4.7%
7,919 / -3.4%
-/-
Units Over/Underbuilt
28,535 / -19.1%
-4,925 / -117.3%
-25,657 / 420.9%
-/-
% Over/Underbuilt
2.7% Overbuilt
0.5% Underbuilt
2.4% Underbuilt
-/-
Median Household Income
$83,991 / 5.0%
$85,835 / 2.2%
$88,349 / 2.9%
-/-
Median Existing SF Price
$534,388 / 19.3%
$559,334 / 4.7%
$573,086 / 2.5%
-/-
% Over/Undervalued
6.1% Overvalued
16.1% Overvalued
17.5% Overvalued
-/-
MARKET HEALTH
2023F
2024F
10-YEAR ANNUAL HISTORY 2020
CURRENT MONTH / QUARTER
AVG
MIN
MAX
-/-
-/-
-
-
-
Lot Deliveries
3,570 / -37.3%
1,313 / 18.8%
4,097
767
8,068
VDL
6,173 / -25.3%
4,994 / -19.1%
7,106
4,825
10,596
VDL Months of Supply
13.1 / -28.6%
9.6 / -26.9%
20.8
9.0
57.2
Starts
5,658 / 4.6%
1,585 / 4.9%
4,596
1,585
6,773
Housing Inventory
2,542 / -14.8
3,131 / 23.2
2,029
1,058
3,131
New Home Sales
6,378 / 29.9%
-/-
4,409
3,217
6,378
Closings - New
6,076 / 11.0%
4,724 / -22.3%
4,004
462
6,076
$462,425 / 1.7%
$483,795 / 4.6%
$427,676
$274,975
$563,000
Affordability Ratio - New
40.9% / 7.9%
36.0% / 20.4%
42.4%
34.7%
56.7%
Foreclosures
283 / -60.3%
36 / -87.3%
1,762
5
4,812
Future Lots
Median New Price
14
Portland-Vancouver-Hillsboro, OR-WA CBSA, Feb. 28, 2022
DEFINITIONS AND METHODOLOGY
ABOUT US
All information presented involved the assembly of data sources that we consider to be reliable, including the Bureau of Labor Statistics, CoreLogic, Moody’s Analytics, Neustar, Public Record Data, U.S. Bureau of the Census, Zillow, various regional Multiple Listing Service providers and Zonda. We do not guarantee any data accuracy as all information is subject to human errors, omissions, and/or changes. Forecasts and projections within this report are based on data available at the time the forecast was made and are subject to change given uctuating market conditions. Abbreviations AVG - Average C - Current CBSA - Core Based Statistical Area CHG - Change CM - Current Month E - Estimated F - Forecast
MF - Multifamily P - Partial QMI - Quick Move-In SF - Single-Family VDL - Vacant Developed Lots YTD - Year To Date YOY - Year Over Year
Affordability Ratio - e percentage of households in the CBSA that earn at or above the qualifying income. e qualifying income is based on an estimated monthly payment that assumes the current median detached new home price, 20% down payment, property taxes, and current 30-year xed mortgage. is calculation assumes that 30% of the buyer’s household income is used toward housing.
We’re Zonda. We create data-driven solutions for the homebuilding & multifamily industries focused on providing data intelligence, insights, and engagement. We o er personalized, comprehensive, and intelligent solutions through the most advanced national homebuilding database to help builders, mortgage clients, managers, and developers stay informed, work smarter, and get ahead. Get More Out Of Zonda Expand coverage to nearby regions to investigate new markets. Get More Out Of Services
Annual Turnover Rate - e percentage of renter-occupied and owner-occupied households within the CBSA that moved during the most recent Census survey period.
Understand segmentation needs of your market.
Average Sales Rate - Re ects the total number of new home contract sales in a given month divided by the number of actively selling new home projects as collected by Zonda.
Contact Us www.zondahome.com hello@zondahome.com (858) 381-4390
E/P Ratio - e ratio of new jobs (employment) to building permits that are issued in a given year. Finished Vacant Inventory - A home that is completely constructed and ready for move-in without signs of occupancy. Housing Inventory - Housing units that have begun or completed construction but are not occupied by a buyer. is includes Models, Finished Vacant, and Under Construction units. Housing Supply (Over/Underbuilt) - e ratio between the total measure of nonfarm jobs and the total measure of housing of all types in a given region for a given month, as it compares to Zonda’s measure of long-term equilibrium.
Th
fl
fi
Th
Th
Th
fl
Th
ff
Th
Th
15
Portland-Vancouver-Hillsboro, OR-WA CBSA, Feb. 28, 2022
Housing Valuation Patterns (Over/Undervalued) - Over/undervaluation is based on the value of housing (inclusive of mortgage rates) relative to the long-term relationship between housing value & household incomes or income supported home price. Lot Deliveries quarter.
e number of new, active lots added to the market in a given
New Home Sales - Zonda conducts a monthly survey of actively selling new home projects by production homebuilders. is survey of monthly contract sales provides a leading indicator of housing activity. New Home List Price - Re ects the average list price at all actively selling projects tracked by Zonda. e average price is weighted based on the number of sales at each project during a given time period. New Home Pending Sales Index (PSI) - e New Home PSI blends the cumulative sales of actively and recently sold out projects with the average sales rate per community, which adjusts for uctuations in supply. e Index is adjusted based on each markets’ speci c seasonality, removes outliers, and uses June 2016 as the base month. New Home Premium - Represents the di erence between the average new home list price as collected by Zonda and the median existing home price per recorded deed data. Quick Move-Ins - Standing inventory or quick delivery homes. e report represents the average number of quick move-in homes per project. Data is based on the available inventory at the end of each month as captured from builders advertising through NewHomeSource.com. Starts Lot.
e point at which a foundation or slab is poured on a Vacant Developed
Total Housing Demand - Proprietary estimate based on current jobs and other factors relative to the long-term jobs-to-housing relationship. Total Housing Supply - Proprietary estimate based on US Census estimates of housing inventory and permits. Vacant Developed Lots - Represents the lots on a recorded plat with streets and utilities in place, ready for a home to be built.
Th
Th
Th
ff
Th
fl
fl
Th
fi
Th
Th
16