May 2026
Kaiser Partner Privatbank AG reports a significant increase in results for 2025
May 2026
Kaiser Partner Privatbank AG reports a significant increase in results for 2025
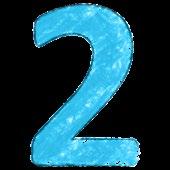
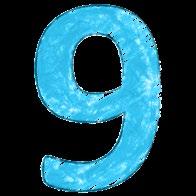
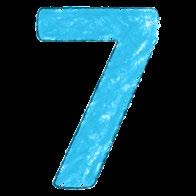
Kaiser Partner Privatbank AG looks back on a very successful financial year in 2025. In an environment marked by geopolitical tensions and economic uncertainty, the bank was able to further accelerate its growth and strengthen its market position.
Gross income rose to CHF 60 million (+11.9 %), whilst net profit for the year increased to CHF 12.2 million (+34.4 %).
Net new money inflows amounted to CHF 1.49 billion, bringing client assets under management to CHF 9.7 billion (+17.9 %).
This development reflects a clear strategic focus: as a family-run private bank based in Liechtenstein, Kaiser Partner combines long-term thinking with consistently values-based advice. The Values Compass forms the basis for decisions and shapes our day-to-day work with clients.
At the heart of our approach lies an interdisciplinary methodology that brings together expertise in banking, fiduciary services and asset management. This enables us to develop solutions that take a holistic view of complex financial situations and are geared towards long-term stability.
The bank is systematically expanding its range of services, particularly in the areas of private markets, alternative investments and digital assets, and is deploying new technologies where they create sustainable value.
Liechtenstein provides a stable framework for this: legal certainty, continuity and international networks create an environment that strengthens trust and enables long-term prospects.
“Trust is built on values put into practice – and on a genuine connection with our customers,” says Fritz Kaiser, Chairman of the Board of Directors.
Christian Reich, CEO, adds: “Our growth is a reflection of a clear stance. What matters is that we offer our clients reliability, quality and safe navigation through uncertainty, even in a challenging environment.”
Kaiser Partner Privatbank AG thus reaffirms its commitment to being a reliable and forward-looking partner, even in a changing environment.
The physical shortage of black gold could already become acute in a few weeks’ time.
High price of oil causing headaches
The closure of the Strait of Hormuz in recent weeks has gone into overtime, at least probably by the US administration’s reckoning. President Trump’s nerves evidently are badly frayed, judging by an analysis of the frequency, volatility, and tone of his tweets. But participants in the crude oil market are also gradually losing patience with an Iranian regime that holds the upper hand for the moment. The physical shortage of black gold could already become acute in a few weeks’ time. Even an immediate resolution of the oil tanker backup in the Persian Gulf would not quickly result in a return to normal.
New all-time highs
Equity markets around the world rebounded in April from the geopolitical shock triggered in March and made a V-shaped recovery. The MSCI World index recently already climbed back to new all-time highs. It once again paid off for investors to buy the dip, following a pattern that has been amply practiced during the current almost four-year-old bull market and which has reliably led to success. There indeed are good reasons to pay no mind to a politics-driven stock market: that’s because the current macro- and microeconomic
picture differs in a positive way from the tough climate for markets that prevailed in the year 2022.
Prediction markets: The price of truth
Terms like Polymarket and Kalshi have increasingly been popping up in the world of finance over the last few months, causing confusion at times. The talk is about prediction markets, where people can bet on the outcome of future real-world occurrences ranging from sports events and US Federal Reserve interestrate decisions to Nobel prize winners. What sounds at first like pure gambling could in fact effectively supplement surveys and expert opinions as forecasting tools in the future.
of the Month
The countdown to the biggest initial public offering ever is ticking. SpaceX filed documents for the IPO with the US Securities and Exchange Commission at the end of March. Elon Musk’s conglomerate, which combines rocket-launch services provider SpaceX, satellite telecom company Starlink, and artificial intelligence startup xAI and includes the social media platform X, could debut on the stock-market trading floor by as early as June and would instantly become one of the world’s ten largest publicly traded enterprises, with a valuation targeted at USD 1.75 trillion. The IPO would inject up to USD 75 billion into SpaceX’s coffers and would make Musk a trillionaire. However, the colossal IPO also comes with looming risks and side effects. Given its sheer size, index providers are amending their rules in order to allow SpaceX early admission to indices (and to push up demand for index funds). Individual private investors are also being heavily courted, but they risk climbing aboard at astronomical prices. The space industry has a lot of growth potential, but it would already be priced into SpaceX at an expected price-to-sales multiple of over 70x.
The closure of the Strait of Hormuz in recent weeks has gone into overtime, at least probably by the US administration’s reckoning. President Trump’s nerves evidently are badly frayed, judging by an analysis of the frequency, volatility, and tone of his tweets. But participants in the crude oil market are also gradually losing patience with an Iranian regime that holds the upper hand for the moment. Investment banks lately have been taking turns raising their oil-price forecasts. And crude oil futures prices for December delivery already hit new highs in late April. The physical shortage of black gold could already become acute in a few weeks’ time. It is already clear today that even an immediate resolution of the oil tanker backup in the Persian Gulf would not quickly result in a return to normal. Meanwhile, OPEC, too, finds itself facing an altered reality. The United Arab Emirates recently announced that it would exit the oil cartel on May 1. That news is suggestive of a tendency toward lower oil prices, at least in the longer run.
The acceleration in Eurozone economic growth actually envisaged for 2026 has gotten further postponed (yet again) by the Iran conflict. A period of stagflation looms for now. The Eurozone purchasing managers’ index fell in April to 48.6 points (from 50.7 in March), its lowest level since November 2024. The Bloomberg consensus forecasts that projected second- and third-quarter GDP growth rates of +0.2 % and +0.3 %, respectively, for the Eurozone are likely to prove overly optimistic. At the same time, inflation has increased sharply in recent weeks and looks set to climb to above 3% this summer. After three years of near-zero growth, a significant pickup in economic activity was also on the schedule for Germany as this year got underway. But the country’s federal government likewise has had to acknowledge the change in underlying conditions. In April, it cut its economic growth forecast for 2026 by half to now just +0.5 %. But postponed doesn’t mean cancelled. Rising defense spending in particular looks set to make an added contribution to economic output in the years ahead.
Personnel shuffle at central banks
In the face of inflation rates that are far overshooting their targets, central banks currently find themselves confronted with yet another test of their mettle. Markets expect to see a raising of policy interest rates this summer, particularly by the European Central Bank (ECB). However, it is likely to wait until the very last minute to avoid maneuvering incorrectly as far as possible because, theoretically, the current burst of inflation should prove temporary. Hence, a last-minute decision is likely at the ECB’s June monetary policy meeting. Speculating on staffing policy usually is hardly helpful, especially in connection with (independent) central banks. Christine Lagarde, in response to questions about a potential early resignation, recently let it be understood that the captain does not leave the ship when big clouds appear on the horizon – and clouds of that kind are definitely visible at the moment, she said. Meanwhile, another personnel change has been set in motion after a lengthy delay: Kevin Warsh will take over the helm of the US Federal Reserve at the next FOMC meeting. Jerome Powell, however, will stay on the Fed’s board of governors for a while yet.
Markets expect to see a raising of policy interest rates this summer, particularly by the European Central Bank (ECB).
Sources: Bloomberg, Kaiser Partner Privatbank
Fixed Income
Sovereign bonds
Corporate bonds
Microfinance
Inflation-linked bonds
High-yield bonds Japan
Emerging-market bonds
Insurance-linked bonds
Convertible bonds
Emerging markets
Alternative Assets
Duration Hedge funds
Currencies
US dollar
Swiss franc
Structured products
Private equity
Private credit
Euro Infrastructure
British pound
Equities: New all-time highs
After a period of underperformance, the US hyperscalers Amazon, Alphabet, Microsoft, and Meta posted disproportionately strong share-price gains in April. Asset Allocation Monitor
• Equity markets around the world rebounded in April from the geopolitical shock triggered in March and made a V-shaped recovery. The MSCI World index recently already climbed back to new all-time highs. It once again paid off for investors to buy the dip, following a pattern that has been amply practiced during the current almost four-year-old bull market and which has reliably led to success. There indeed are good reasons to pay no mind to a politics-driven stock market in general and to ignore contradictory tweets from Donald Trump in particular. That’s because the current macro- and microeconomic picture differs in a positive way from the tough climate for markets that prevailed in the year 2022. Notably this time, central banks are unlikely to see themselves compelled to vigorously tighten the interest-rate screw because the rise in inflation is much smaller than back then and a price-wage spiral doesn’t loom, plus the economy isn’t overheated. And finally, corporate earnings momentum is much better today than it was in 2022. Analysts’ earnings estimates have constantly been revised upward in recent weeks, not just in the USA, but also in Europe. Earnings growth of +20 % is being projected for the USA for 2026. After flat growth last year, Europe looks set to regain a lot of ground and is poised to reach similarly robust momentum.
Real estate
Macro
Monetary / fiscal policy
Corporate earnings
Valuation
Trend
Investor sentiment
• After a period of underperformance, the US hyperscalers Amazon, Alphabet, Microsoft, and Meta posted disproportionately strong share-price gains in April. Investors’ fears that those companies’ massive investments in AI infrastructure might not pay off have faded into the background once more for now. In fact, another staggering 64 % year-on-year acceleration in AI infrastructure spending is expected for 2026. The relative strength of the Magnificent Seven is justified from a valuation standpoint. They were trading at around a 30 % premium to the broad market at last look, which doesn’t seem excessive considering their growth momentum. Stocks in “AI loser” sectors like software, media, and business services likewise rebounded in April. However, more wheat is likely to get separated from the chaff here over the next 12 to 18 months.
The MSCI Emerging Markets index rose by more than 15 % in April and surpassed its February high.
In the wake of big yield spikes in March, fixedincome markets, too, have recently decoupled from the present state of geopolitical limbo.
• Emerging-market countries also ranked among the big winners in recent weeks. The MSCI Emerging Markets index rose by more than 15 % in April and surpassed its February high. However, its gains rest on a pretty thin foundation: three semiconductor chip stocks – TSMC (Taiwan), Samsung Electronics and SK Hynix (both South Korea) – alone accounted for half of the index’s advance. The dominance of those stocks and countries, which respectively make up more than 20 % and 40 % of the MSCI Emerging Markets index, has resulted in a good performance over the past year, but it turns the index into another bet on the technology sector and thus decreases the diversification actually to be expected from an allocation to emerging markets. Moreover, it obscures the fact that the emerging-markets space also includes some economic losers of the Iran conflict. The equity markets of oil-importing countries like Indonesia, the Philippines, South Africa, and India have been slumping lately.
Fixed income: Yield spikes and their limits
• In the wake of big yield spikes in March, fixedincome markets, too, have recently decoupled from the present state of geopolitical limbo. The MOVE index, the risk barometer for US Treasury bonds, has outright crashed in recent weeks. The 4.5 % yield mark ultimately turned out to be a resistance hurdle and a good entry point in the case of 10-year US Treasury notes. This level remains a good one in the near future for buying in the event of a renewed selloff. That’s because, on one hand, the current rise in inflation being driven mainly by energy prices is likely to prove temporary. A return of inflation back to normal afterwards is bound to be accompanied by lower fixed-income yields and bond price gains. On the other hand, at the same time government bonds are also good insurance against an adverse scenario of a sharper slowdown in economic activity in the USA, which still cannot be ruled out. The longer the Iran conflict remains more or less frozen, the more this risk increases.
Alternative assets: Rare down month for hedge funds
• Most hedge funds and liquid alternatives are more liquid than private-market assets (exceptions confirm the rule), but it usually takes some weeks until new net asset values get disclosed and allow conclusions to be drawn. Consequently, the latest performance data for the extremely turbulent month of March on the financial market didn’t become known until the end of April. The bottom line is that the climate in March, which was marked by abrupt volatile gyrations in stocks, bonds, currencies, and commodities, was a very challenging one also for
hedge funds. After a lengthy winning streak, hedge funds registered a down month for the first time in quite a while. Even the big names among multistrategy funds like Millennium, Citadel, Exodus Point, and Balyasny sustained losses. This shows that diversification by means of numerous uncorrelated sources of return is not invulnerable, at least not when observed over short periods. However, the analysis also reveals something else: there was a sizable performance differential between the best and the worst managers, as is so often the case. In each hedge fund category (with the exception of long-biased), the top performers managed to achieve gains. Access to these top funds, many of which are little known by the public and have limited capacity, is crucial to investing successfully in liquid alternatives.
• In the midst of the general risk-on mood, cryptocurrencies also advanced in April as the price of Bitcoin broke out of its downward trend in place since last autumn. However, there was nary a trace of euphoria to be found. A narrative that would revitalize this young asset class is still missing. Until one emerges, Bitcoin and its cohorts will probably continue to work on forming a floor on their respective price charts, which would lay a better foundation for any subsequent revival.
Currencies: New Fed chairman = weak dollar?
• Market participants in April tried to look beyond the geopolitical volatility also on the currencies front even though the crisis isn’t over yet. The supposed winner of the crisis, in the form of the US dollar index, gave back half of its gains from the prior two months. The greenback in the meantime has been in a wide rangebound trend for a year now and is thus holding up better than the longstanding moderately to deeply negative sentiment toward the dollar would have led one to suspect. Even though the US dollar has corrected by around 10 % from its peak at the start of 2025, various factors indicate that its current valuation is still quite ambitious. However, at the moment there are no downward impulses in place to resume pushing the US currency toward its fair value, and it is unlikely that the US Federal Reserve under a new chairman Kevin Warsh would deliver any. The transition to a potentially somewhat more accommodative, dollar-weakening monetary policy is likely to occur only gradually, if it happens at all.
“Political stock markets are short-lived” – the Philadelphia Semiconductor Index recently delivered an example corroborating this equity market adage. On even the faintest signs of an easing of tensions in the Iran conflict, the barometer for US semiconductor stocks shot upward like the release of a submerged waterpolo ball. That happened because the fundamentals in the chip industry are simply too good at the moment to keep ignoring them. The revenue and earnings guidance from chip manufacturers has been revised upward at a scorching pace in recent weeks. Even legendary chipmaker Intel recently surprised analysts on the upside, which the stock market rewarded with a more than 20 % share-price jump. The uninterrupted 18-day rally in April gifted semiconductor stocks a roughly 50 % gain and was reminiscent of a similar episode that occurred shortly before the bursting of the internet bubble in the year 2000. The fundamentals this time are obviously much better than they were 25 years ago, but the sector is nonetheless overheated for the near term and is overdue for a pause to catch breath.
Terms like Polymarket and Kalshi have increasingly been popping up in the world of finance over the last few months, causing confusion at times. The talk is about prediction markets, where people can bet on the outcome of future real-world occurrences ranging from sports events and US Federal Reserve interest-rate decisions to Nobel prize winners. What sounds at first like pure gambling could in fact effectively supplement surveys and expert opinions as forecasting tools in the future.
On January 3 this year, before the first breaking reports reached news agencies, the probability of an immediate change of power in Venezuela skyrocketed on the Polymarket prediction platform while the country’s ruler, who has since been forced into retirement, was still fast asleep in bed. Mere hours later, official reports confirmed the arrest of Nicolás Maduro through a US-led operation. While diplomacy was still groping for words, markets had already priced in the incident.
The trading volume on prediction markets has multiplied since their establishment in the course of the US presidential election in 2024, during which they foretold the Republican victor much earlier than electoral polls did. While the monthly trading volume in August 2025 amounted to USD 1 billion, by March 2026 it had already surged to USD 10 billion on Polymarket alone. Some individual contracts by now exhibit bid volumes amounting to several hundred millions of dollars.
What started out as a niche for crypto enthusiasts and gamblers has since evolved into a global fever chart of reality.
A fascinatingly simple logic lies behind this phenomenon. A prediction market in essence is a trading venue for binary events. On prediction platforms – Kalshi and Polymarket being the two most prominent ones – participants trade contracts that take on a value of either 1 dollar (if the specified event outcome occurs) or 0 dollars (if the specified event outcome does not occur). The probability aggregated by the market thus can be directly deduced from the current market price of a contract of that kind. If a “yes contract” for a certain election outcome, for instance, costs 72 cents, this signifies a (theoretical) 72 % chance of occurrence. Classical sports betting, in contrast, does not operate on the principle of supply and demand, but instead has odds that are set by the bookmaker. The odds, in principle, are set to the disadvantage of the bettor, for it’s wellknown that the house always wins in the long run.
The prediction market principle can be carried to extremes. Anyone betting on Polymarket right now that Jesus Christ will return to Earth in 2026 pays 4 cents for that contract. The market is pricing in a paltry 4 % probability of a Second Coming this year. Whoever, though, possesses an information advantage – such as in the form of divine intuition – and accordingly bets USD 1,000 on “yes” can rejoice over a biblical return of USD 25,000 if that hunch proves true.
The decisive advantage over classical surveys or expert opinions lies in the economic incentive structure. Whereas responses from survey participants often reflect social desirability, disinterest, or incompetence, prediction markets force speculators to be painfully honest in the literal sense of putting their money where their mouth is. Anyone who bets wrong on prediction markets loses money. Whoever possesses information that is not yet reflected in the market has a financial incentive to divulge it by trading. Every bet influences the probability and adds new data to a public indicator that reflects the societal consensus. To an economist, this is market efficiency par excellence because predictions of this kind measure what people actually believe while surveys only measure what people say.
Polymarket fired the starting gun for its entry into the prediction business in the year 2020, though the platform’s decentralized blockchain foundation quickly ran afoul of US regulatory authorities. The bets were legally classified as a form of event-based binary options and were placed under strict transparency rules for futures exchanges. Without a corresponding designated contract market license, prediction markets were considered illegal over-the-counter businesses. Recent court rulings in favor of the platforms and the establishment of regulated operators like Kalshi marked a preliminary end to the “Wild West” era of prediction markets. A milestone in this evolution was the acquisition of a
Wagers rather than words | Probabilities on the platform PredictIt Comparing election forecasts in the 2024 US presidential election
Sources: Bloomberg, PredictIt, Kaiser Partner Privatbank
strategic stake in Polymarket by stock-exchange operator Intercontinental Exchange, the parent company of the New York Stock Exchange. Legal uncertainties nonetheless continue to exist: in the USA, the platforms are increasingly coming under pressure on matters concerning politically sensitive topics while a uniform framework is missing in Europe. Prediction markets mostly operate in Europe in a legal gray zone between tacit tolerance and national bans. Their technology transcends borders, but there is still a long road to the establishment of a global standard.
In the USA, the platforms are increasingly coming under pressure on matters concerning politically sensitive topics while a uniform framework is missing in Europe.
Unlike classical stock markets, which are often driven by narrative overstatement and by speculation on falling or rising prices, prediction markets correct on new information usually within fractions of a second, because whoever deliberately wants to skew a bet mainly creates a chance of winning for better-informed wagerers by doing so.
The wisdom of the crowd
But why are these markets often more accurate than panels of experts are? Behavioral economics provides an answer in the “wisdom of the crowd,” the collective sapience of the general public. When a diverse group of individuals make decisions independently from one another and risk their own money in the process, individual errors and ideological biases balance each other out. In the best case, emotions get filtered out of the market. Unlike classical stock markets, which are often driven by narrative overstatement and by speculation on falling or rising prices, prediction markets correct on new information usually within fractions of a second, because whoever deliberately wants to skew a bet mainly creates a chance of winning for betterinformed wagerers by doing so.
new toolkit for managing risk?
Institutional investors, particularly hedge funds and banks, have also recognized the potential of prediction markets in the meantime. They are being used primarily not as a speculation instrument (although that possibility is surely also being looked into), but as a highly sensitive supplemental risk management tool. In a world in which portfolios are increasingly threatened by event risks such as court rulings, corporate data releases, populist currents, and geopolitical escalations, prediction markets provide an implied probability curve. They act as an early warning system that enables hedging strategies to be assessed more precisely and implemented immediately. If, for example, an escalation of the conflict in the Middle East looms that would drive up the price of petroleum, one can bet on the
occurrence of a military clash on Polymarket or Kalshi. The winnings from a prediction of that kind could partially offset the losses caused by the oil shock. In contrast to classical hedges like gold that rise only in general in times of market uncertainty, the prediction market pays out only if a specific event takes place.
One particular advantage here is temporal continuity. Whereas many conventional surveys deliver data only on a monthly or quarterly basis, prediction markets provide probabilities in real time, which can be beneficial especially during crises. That’s why the platforms are increasingly finding their way into analytic and research processes in the financial sector and into politics and general research. Even a recent report by the US Federal Reserve affirms their potential as a valuable supplement to conventional forecasting tools.1 They have particularly high potential to aid in forecasting policy interest rate decisions and headline inflation.
It’s worthwhile also for individual private investors to take a look at Polymarket, Kalshi, and the like for the purpose of gathering information. The value here lies not in betting, but in capturing signals in real time. However, anyone entertaining thoughts of betting his or her own money on future event outcomes should beware that wagers of that kind normally are not worth it financially, particularly not if one lacks extensive expertise in a specialized field that can beat the market. On top of that, there are also platform-specific fees to pay and an additional fact to bear in mind: people with information advantages are particularly the ones that profit while uninformed investors get the short end of the stick.
Despite their potential, prediction markets are still in their infancy and sometimes harbor downsides. Criticism, for instance, has been leveled that individual contracts often have scant trading liquidity, which leads to vague probabilities. A single order can influence the price, and bid-ask spreads can widen. In addition, a moral dilemma arises when wagerers bet on catastrophes or political instability. Critics also find fault with the contradiction that unethical insider trading paradoxically can increase prediction accuracy and thus enhance market efficiency. Here’s a thought experiment to illustrate this: Suppose that a football player has disclosed that he would like to leave his current club to join another one. (Purported) experts and gamblers will bet on his most probable next club address on prediction markets. But what prevents the player from anonymously betting his own money on the club of his dreams or from even intentionally transferring to an improbable club to maximize his profit?
This seemingly trivial example has an important implication. It shows that prediction markets have the potential to “read the crystal ball” by indirectly influencing reality or, in other words, by actuating a self-fulfilling prophecy, except in the case of exogenous, non-reflexive events like the weather, for instance. However, insider trading, although it’s unfair to those not in the know, helps markets to learn faster. When the odds change, it is often a sign that somebody somewhere knows something, and that signal becomes public long before any corresponding announcement does. Nevertheless, prediction markets do not always correctly foretell the future. The wisdom of the crowd can also be wrong. Individual investors remain faced with the challenge of distinguishing between genuine signals and pure noise.
The financial market in the age of digitalization In all probability, prediction markets are not a passing fad, but rather a natural progression of financial markets in the information age. They are a testament to the fact that information itself has become a tradable good, no longer just in betting offices, but as a public indicator for everyone. In the future, the ability to interpret signals correctly will become a core competency in asset management. Signals give us no certainty about future occurrences, but they provide us with an additional market-based seismograph for a world increasingly affected by event risks.
1 Diercks, Anthony M., Jared Dean Katz, & Jonathan H. Wright (2026). “Kalshi and the Rise of Macro Markets,” Finance and Economics Discussion Series 2026-010. Washington: Board of Governors of the Federal Reserve System.
In all probability, prediction markets are not a passing fad, but rather a natural progression of financial markets in the information age.
8.85% Bloomberg US Corporate High Yield Index (USD) EU High Yield 0.39% 1.92% 4.61% 7.81% Bloomberg Pan-European High Yield Index (EUR) Others
This document constitutes neither a financial analysis nor an advertisement. It is intended solely for informational purposes. None of the information contained herein constitutes a solicitation or recommendation by Kaiser Partner Privatbank AG to purchase or sell a financial instrument or to take any other actions regarding any financial instruments. Furthermore, the information contained herein does not constitute investment advice. Any references in this document to past performance are no guarantee of a positive future performance. Kaiser Partner Privatbank AG assumes no liability for the completeness, correctness or currentness of the information contained herein or for any losses or damages arising from any actions taken on the basis of the information in this document. All contents of this document are protected by intellectual property law, particularly by copyright law. The reprinting or reproduction of all or any parts of this document in any way or form for public or commercial purposes is expressly prohibited unless prior written consent has been explicitly granted by Kaiser Partner Privatbank AG.
Publisher: Kaiser Partner Privatbank AG Herrengasse 23, Postfach 725 FL-9490 Vaduz, Liechtenstein HR-Nr. FL-0001.018.213-7
T: +423 237 80 00, F: +423 237 80 01 E: bank@kaiserpartner.com
Editorial Team: Oliver Hackel, Head of Private Markets & Liquid Alternatives Corsin Raguth Tscharner, Trainee Asset Management
Design & Print: 21iLAB AG, Vaduz, Liechtenstein