Japan MarketDynamics

Author Research
SeniorDirector
YutoOhigashi
Looking at the global direct real estate investment market in the 2025, the U S continued to attract the largest capital, followed by the U.K., with Japan ranking the third. That said, by city, Tokyo ranked the second largest investment volume in terms of U S dollaramount, despitetheyen's depreciation, closetoNew York.
Inadditiontotheweakcurrency,thecontrastingmonetarypolicyis an apparently headwind for Japan. While Europe and the U.S. are nowinarate-cuttingphasefollowinginflationsuppression,Bankof
Japan is currently moving towards monetary normalization (i.e., tightening) process Nonetheless, on a comparison of absolute interest rate levels, Japan's funding costs remain relatively low, with thespread betweenlong-terminterest ratesandexpectedreal estate investment yields maintaining a positive margin. As such, Japan remains one of the few markets globally where this "positive carry"situationcontinues.
Under these conditions, capital inflows into the office sector have been particularlynotableinJapan's real estate investment market While office markets globally suffered from rising vacancy rates and declining rents due to the permeation of remote working during the pandemic, Japan saw a relatively fast pace of return to office, driving the recovery in office demand at a relatively early stage,once theCOVID-relatedrestrictions wereliftedinMay2023. Furthermore, severe labor shortage is also contributing to the tightening of office market. Population decline has made securing new talents and improving existing employee satisfaction the urgent priorities for companies across all industries and sizes. This has resulted in rapidly growing interest in high-quality offices, Grade A offices, located in Central Tokyo with excellent transportation access and equipped with the latest facilities and securitysystems
In addition to these demand-side factors, delays in number of major development projects has led to fewer new supplies than had been anticipated previously. Higher demand and lower supply have driven the vacancy rate in Tokyo Central 5-Wards downto0.7%asoftheendofDecember2025.Grossrentsreached 38,252yenpertsubopermonth,up32%quarter-over-quarterand 9.4%year-over-year.
The supply of large-scale buildings in 2025 (which were above historical average) has been almost fully absorbed, and prospective tenants are now shifting towards properties slated for completion in 2026 or later. While the volume of new supply this yearissimilarto2025,themarketisalreadyseeingprogressinpreleasing, suggesting that the tight supply-demand situation is likely tocontinue
Against the backdrop of breaking free from three decades of deflation, an inflationary mindset is finally starting to take hold among tenant companies. Rent negotiations now start not with reductions (as had traditionally been the case), but with how much of an increase will be applied. As such, there is a possibility that rent will not only continue to increase, but do so at a faster pace, given thatthevacancy ratesareprojected toremainlow.
Globalrealestateinvestmentvolumescontinueto expand,drivenbydeclininginterestratesand improvedlendingconditions.Investorappetite hasrecovered, withfundraisingincreasingforthe firsttimeinfouryears.Rentalgrowthhas accelerated, particularlyforhigh-gradeoffice properties,asleasingdemandrecovers andnew developmentdecreases. Officeinvestmentis recoveringglobally.
Japan'sInvestmentVolumeExceedsJPY6 Trillion,Reachinga
Large-scaleofficeandlogisticsfacilitydisposalsby corporationscontinuedin4Q2025,maintaining highinvestmentvolumes.Full-year2025 investmentvolumereachedarecordhighofJPY 6.218trillion.Tokyorankedsecondinglobalcity rankings.
Supply-demandtightening,particularlyinthe officesector,andacceleratingrentalgrowthare encouraginginvestorinterest.Financial institutionscontinuetomaintainanaggressive lendingstance,supportingthebuoyancyofthe realestateinvestmentmarket.
Asrealestateinvestmentexpandsglobally,the investmentappetiteforJapaneserealestatefrom bothdomesticandinternationalinvestors remainshigh.Portfoliorestructuringbyinvestors andcorporaterealestatedisposalsare progressing,increasinginvestmentopportunities forwell-locatedproperties.Therealestate investmentvolumein2026isexpected toexceed 2025levels,reachingthemid-JPY6trillionrange.
• Japan'srealestateinvestment volume forfull-year 2025increased 13%y-o-y toJPY6.218trillion.
• Japan'srealestateinvestment volume for4Q25 decreased 8%y-o-ytoJPY1.508trillion.Theprimary reasonforthequarterlydecline wasthe concentration oflargetransactionsin4Q24,which reached thesecond-highest levelonrecord.
• Nevertheless, 4Q25sawmajortransactions,including NissanMotor'sglobalheadquarters andalarge-scale logisticsfacilityinKoto ward, contributing tothe largestannualinvestment volumesincedata collection beganin2007.
Source:JLL
• Bysector, officespacecontinued toaccountforthe largestshareofinvestment. Full-year2025investment volume reachedJPY2.692trillion,representing 43% oftotalvolume, asignificantincreasefrom36%in full-year2024.Investor interesthasfurtherintensified amidnotableofficerentalgrowth incentralareas.
• Retailsawitsinvestment sharerisefrom7%inthe previous yearto11%,driven bymultipletransactions, including largecommercial facilitiesinGinzaand suburbanshopping centres.
• Forlogisticsfacilities,multiplelargetransactionswere observed, includingmajorfacilitiesinTokyo. However, investment sharedeclined forthesecond consecutive year,to16%,asJ-REIT acquisitionsof portfolios fromtheirsponsorsdecreased.
• Whileinvestment demand forhotelsremainsrobust, investment sharedecreased to10%duetothe limitedsupplyofproperties forsale.
• Theinvestment shareofmultifamilyproperties increased to16%,driven bygrowing portfolio acquisitionsof10-20properties bydomestic and overseasinvestors.
Source:JLL
• Byregion, Tokyo CBDaccounted for42%offull-year 2025investment, exceeding 40%forthefirsttime since2022.Transactionsinvolving largeoffice buildingsandmultifamilyportfolios contributed to thisincreasedshare.
• Meanwhile,theGreaterOsakaregion's share remained at13%,contracting from 22%infull-year 2024,primarilyduetofewerlargeproperty disposals compared totheprevious year.
Source:JLL
Note:TokyoCBC(5-kus)referstoChiyoda-ku,Chuo-ku,Minato-ku,Shinjuku-kuandShibuya-ku;GreaterTokyoreferstoTokyo,Chiba,SaitamaandKanagawa;GreaterNagoyareferstoAichi, GifuandMie;Greater
• Strong leasingmomentum continued inQ4,withfull-yearnetabsorptionreaching arecord-breaking level
• Totalvacancydeclined byafurther20bpsto0.7%,underpinned byrobustdemand forprimeoffice space
• Rents increased fortheeighthconsecutive quarter
Netabsorption intheTokyo GradeAoffice marketreached124,700sqm, markingarecord year.Demand wasledbyprofessional services,IT firms,andmanufacturing sectors.Notableleasingactivityduringthequarterincluded therelocation ofthecorporate headquartersofalarge multinational corporation andthepre-leasingofalarge-scaleproject, scheduled forcompletion after2030,byamajordomestic company.
Onenew GradeAofficebuilding,AkasakaTrustTower (MinatoWard;43storeys;NLA105,800s.m.), entered themarketinQ42025withnear-full occupancy, accounting fornearly20%oftotalcompletions fortheyear.Tokyo’s GradeAofficevacancyrateaveraged 0.7%in Q42025,down 20 bpsq-o-q and210bpsy-o-y.
Averagemonthly grossrentsstoodatJPY38,252per tsuboattheend ofQ42025,reflecting anincreaseof3.3%q-o-q and9.4%y-o-y. Capital valuesroseascontinued rentalgrowth more thanoffseta5bpsincreaseincapitalisationratesfromtheprevious quarter.Notabletransactions included FPG’sacquisitionofanadditional stakeinKyobashiTrustTower forJPY14billion.
According toOxfordEconomics’ forecastsasofDecember 2025,realGDPgrowthfor2026wasrevisedupwardby10bpsto0.7%, whileend-2026 CPIprojections wereraisedto2.0%.Withpre-commitment levelsfor2026remaining robust,tenantdemand isexpected toshifttowardsnew supplythatareexpected tobecompleted after2027.Vacancylevels arelikelytoremaintightintheneartermandrentsare forecasted toriseby afurther9%nextyear.
Note:Financialandphysical indicatorsareforthe5KusGradeAofficemarket.Datais onanNLAbasis.
• Officeconsolidation demand fromgroup companies remained active,withnotablerelocations tonewly completed buildingsalong Umeda andMidosuji
• Thecompletion ofYodoyabashi GateTower resultedinatemporary increaseinOsakaGradeAvacancyratesto3.1%.
• Rents reached JPY26,313pertsuboper month, markingthesecond consecutive quarterofrecord highssincedatacollection began in2003.
Osaka’sGradeAofficemarketclosed2025onafirmfooting,withnetabsorptionreaching34,000sqminQ42025.Relocationactivitywasparticularlypronouncedas groupcompaniesconsolidatedbranchandsalesofficesintoprimelocationstoimproveoperationalefficiencyandenhancetalentattraction.Thistrendsupportedthe absorptionofvacanciesinexistingbuildings.
Duringthequarter,YodoyabashiGateTower(Chuo-ku;29storeysaboveground;totalfloorareaof132,000sqm)wascompleted.Whileleasingprogressedsteadily,the buildingopenedwithvacantspaces,contributingtoaq-on-qincreaseinthevacancyrateof60bpsto3.1%attheendofQ4.Despitethisshort-termincrease,the vacancyratedeclinedby130bpsy-on-y,reflectingsustainedunderlyingdemand.AveragerentsreachedJPY26,313pertsubopermonthattheendofQ4,representing a3.5%q-on-qincreaseanda12.4%y-on-yrise.HavingsurpassedthepreviouspeakofJPY24,647recordedinQ22020–thehighestlevelsincedatacollectionbeganin 2003–rentshavenowestablishednewrecordsfortwoconsecutivequarters.High-rentlease-upsinUmedacompletionscontinueddrivingrentalgrowth.
Intheinvestmentmarket,estimatedcapratesincreasedslightly,reflectingupwardpressurefromrisinglong-terminterestrates.Nevertheless,pricingroseby3.1%qon-qand16.0%y-on-y,drivenbystrongrentalgrowth.NotabletransactionsinQ4includedJapanPrimeRealtyInvestmentCorporation’sacquisitionfromTokyo Tatemonoof4.6%co-ownershipinterestsinGrandFrontOsaka’sUmekitaPlazaSouthandNorthbuildingsforJPY9.2billionandJPY8.0billion,respectively,atNOI yieldsof4.0%and4.1%. Outlook
AccordingtoOxfordEconomicsforecastsasofDecember2025,OsakaCity’srealGDPgrowthisprojectedat+0.3%in2026and+0.2%in2027.OnlyoneGradeAoffice buildingisscheduledforcompletioninQ32026–Honmachi4-chomeProject(Chuo-ku;totalfloorareaof45,000sqm)–withnoadditionalsupplyexpectedthrough 2030.Strongleasingactivityisexpectedtodrivevacancyratesdownto2.8%byQ42026,whilerentsareforecasttocontinuesettingnewrecordsamidtightsupplydemandconditions.Capitalvaluesareexpectedtoincreaseinlinewithrentalgrowth,supportingcontinuedinvestorinterest inOsaka’sofficemarket.
2025NetAbsorption
Note:Financialandphysical indicatorsareforthe5KusGradeAofficemarket.Datais onanNLAbasis.
• Expansion relocationstorecently completed buildingsarenotableduetobusinessgrowth
• Vacancyratedropped by240bpsq-o-q to4.2%,mainlyduetoabsorptionofvacantspaceinFukuoka'slargestbuildings
• Rent growthrateaccelerated again,withmonthly rentatJPY22,509per tsubo,up3.1%fromtheprevious period
Netabsorption inFukuoka'sGradeAofficemarketreached 13,000sqminQ42025.WithnonewsupplyinQ4andminimalsecondary vacancy generation, demand wasdriven byexpansion relocations andin-building expansions duetobusinessgrowth. Byindustry, relocations were observed among professional servicesfirmssuchaslawfirmsandconsultingfirms,aswellasIT-related companies.
Thisquartersawsignificantprogress intenantleasingatONEFUKUOKABLDG.,whichboastsFukuoka'slargeststandardfloorplateareaof approximately 4,600sqm,contributing greatlytothevacancy ratedecline. Thevacancyrateattheend ofQ4reached 4.2%,down 240bpsq-o-q and280bpsy-o-y. Whilenew supplyfromTenjin BigBangandHakataConnected hascontinued intermittently, vacancyrateshadremained above5%since2023,butthisquartermarkedthefirsttimeinapproximately threeyearsthatthevacancy ratefellbelow5%.
Averagerentsreached JPY22,509per tsubopermonth attheend ofQ4,up3.1%q-o-q and7.9%y-o-y. Whilethepaceofrentgrowthhadshown signsofslowingsinceentering 2025,existingbuildingssawwidespread rentincreasesthisquarter,withthegrowthrateaccelerating once again.
According toOxfordEconomics forecastsasofDecember 2025,FukuokaCity'srealGDPgrowthrateisprojected at+0.7%in2026and+0.5%in 2027.Onenewsupplyisscheduled forQ12026(Nishi-Nippon CityBuilding:Hakata-ku,totalfloorarea76,000sqm, Marchcompletion). Asthe newsupplyfromTenjin BigBangandHakataConnected approachesitsfinalphase,leasingconditions areexpected tobecome morefavorable tolandlords. In2026,threenew buildingsarescheduled fordelivery (totalNLA75,000sqm),andsecondary vacanciesareexpected toemerge as tenants relocate tonewbuildings,leading toananticipated riseinvacancy ratesonce again.
2025NetAbsorption
Note: FinancialandphysicalindicatorsareforFukuoka’sGradeAofficemarket. DataisonaNLAbasis.
(thousands)
Netabsorption Newsupply Vacancyrate
• Hybridworkcontinues toproliferateanddemand forflexspaceisrobust
• Large-scalenewopenings continue toexpand inthesecond halfoftheyear
• Monthlyraterises10%y-o-y
In2H25,thenewsupplyofflexibleofficeinTokyo 5-ku’swasup12,900sqmwithfullyearvolumesat34,800sqm.Asoftheend of2025,total stockofTokyo flexofficeincreased7.8%y-o-y. Large-scalenewopenings inthesecond halfof2025included Regus-operated Signature, SENQ (NittochiTatemono), Workstyling(MitsuiFudosan)and HumanFirstOffice(NomuraFudosan).
Theoccupancy ratesofexistinglocationsarestableathighlevels,supported bydemand from awiderangeofuserssuchasstartupstolarge corporations. Varioususesareobserved including swingspace(orthetemporary useduring officerenovations andrelocations, etc.), satellite offices,project spaces,andcorporate headquarters. Withrisingconstruction andfit-outcosts,demand remains strongforworkspacesthat havelowinitialcosts.
Themonthly rateperseatforflexibleofficeinTokyo's fivecentral wardsrose10%y-o-yin4Q25.Inaddition torisingoccupancy levels,monthly ratehavebeen increasingsince2024duetoexpansion byexistingcompanies andlaunchofnew locationsandseriesbyflexoperators.
Companies aresupporting flexibleworkarrangements fortheiremployees whilealsoencouraging areturntotheofficetoimprove productivity. Demand forflexibleofficesorso-called'thirdplaces'thatfulfilltheseneeds willlikelyincrease.Althoughofficevacancy islimited, multiplelarge-scalenew openings arescheduledforthefirsthalfof2026,andflexspaceisexpected tocontinue expanding steadilygoing forward.
• LimitedNewSupply DrivesVacancyRateDown to8.8%
• Rents Continue toRise,Reflecting HigherConstruction Costs
• Investment Demand Remains Solid, Supporting FurtherPriceGrowth
Demandfrome-commercecompaniesandthird-partylogistics(3PL)operatorsremainedrobust,withnewdemandreaching221,000sqminQ42025.Although demandhadsoftenedinperipheralareasduetohighertransportationcostsstemmingfromtheongoingshortageoftruckdrivers,lowerrentallevelsinthese locationsarenowbeingviewedmorefavourablybysometenants,indicatingearlysignsofrecoveryintenantdemand.
Newsupplytotalledjustonefacility(85,000sqm)thisquarter thefirstsingle-buildingcompletionineightyears,sinceQ42017.Withdemandcontinuingto outpacesupply,theGreaterTokyovacancyratedeclinedforthesecondconsecutivequarterto8.8%,representinga0.3ppdecreasequarter-on-quarter(q-o-q) anda0.7ppdeclineyear-on-year(y-o-y).
TheaveragemonthlyrentinGreaterTokyorosetoJPY4,780pertsubo,increasing1.2%q-o-q and2.0%y-o-y. Thesharpriseinconstructioncostshasledto higherrentsfornewlycompletedproperties,whichinturnisexertingupwardpressureonrentsinsurroundingexistingfacilities.
JLL’sestimatedcapitalvalueforlogisticsfacilitiesinGreaterTokyoincreased0.2%q-o-q and0.8%y-o-y, reflectingrentalgrowth.Althoughlong-terminterest rateshavecontinuedtorise,compressingyieldmargins,strongunderlyingdemandhassustainedpricingmomentum.Thelargesttransactionbyvaluethis quarterwasBlackstoneGroup’sacquisitionofalarge-scalelogisticsfacilityinTokyo’sKotoWard.
Stabledemandfrome-commerceand3PLoccupiers,combinedwithrestrictednewdevelopmentduetorisingconstructioncosts,isexpectedtosustainupward pressureonrentsacrosstheGreaterTokyomarket.However,peripheralareas,wherevacancyratesarecomparativelyhigherandtransportcostsareincreasing, arelikelytoexperienceonlymodestrentalgrowth.
AlthoughOxfordEconomicsforecastsfurtherinterestrateincreases,investmentappetitefrombothdomesticandinternationalinvestorsremainsstrong.Asa result,anycaprateexpansionisexpectedtobelimited,andcapitalvaluesareprojectedtocontinuerising,particularlyforassetsandsubmarketswithstrong rentalgrowthpotential.
Note:TokyologisticsreferstotheGreaterTokyoprimelogisticsmarket.Dataisonan NLAbasis.
• NewCompletions FullyLeased;VacancyRateDeclinesasExistingSpace isAbsorbed
• CapRatesEdge Higher,butCapitalValuesContinue toRiseonSustainedRentalGrowth
• VacancyExpected toRemain Around 3%withFurtherRent Growthin2026
Strongtenantdemandwasabsorbedacrossbothnewlycompletedandexistingfacilities,withnewdemandreaching377,000sqminQ42025,thehighest quarterlyfigureinthepasteightyears.Leasingactivitywasdrivenbyadiversifiedoccupierbase,includinge-commercecompanies,3PLoperatorsandretailers, reflectingthebroad-basedstrengthofthelogisticsmarket.
Newsupplytotalledtwobuildings(306,000sqm),bothofwhichwerefullyoccupieduponcompletion,underscoringrobustdemandforhigh-specification,welllocatedlogisticsfacilities.Vacancyalsocontractedacrossexistingstock,withtheGreaterOsakavacancyratedecliningby 1.5ppq-o-qto3.0%.Whilevacancy hadtemporarilyincreasedearlierin2025,reaching4.9%inQ2duetoawaveofnewcompletions,themarketsubsequentlyabsorbedthespacesteadily.Bythe endofQ4,thevacancyratehadnearlyreturnedtoitslate-2024level,remainingonly0.2pphighery-o-y.
TheaveragemonthlyrentinGreaterOsakaincreasedtoJPY4,291pertsubo,representinggrowthof1.1%q-o-qand3.2%y-o-y.Higherrentsfornewly completedprimefacilitieshaveliftedratesatsurroundingexistingproperties,reinforcingthemarket’sbroaderrentalgrowthtrajectory.
Reflectingrisinglong-terminterestrates,theestimatedcaprateedgedupslightly.However,capitalvaluescontinuedtorise, supportedbysustainedrental growth.Aspricingincreasinglyincorporatesexpectationsoffuturerentgrowth,propertiescurrentlyleasedbelowmarketlevelscontinuetotradeatrelatively lowcaprates.
Outlook:
Intheleasingmarket,someconcernremainsregardingpotentialsecondaryvacanciesarisingfromtenantrelocationsintonewfacilitiescompletedin2025. However,newsupplyin2026isexpectedtodeclinesharplyfromthepreviousyear,supportingcontinuedleasingmomentumandmaintainingvacancyrates aroundthelow3%level.
Rentsareexpectedtocontinuerising,drivenbyhigherconstructioncostsfornewdevelopmentsandspillovereffectsintoexistingfacilities.Althoughsome tenantsmayfaceaffordabilitypressures,overalldemandremainsstrong,underpinnedbystructuralgrowthine-commerceandongoingdistributionnetwork upgrades.Giventhehighoccupancyofexistingstock,themarketisexpectedtoremainlandlord-favourable,withtherentalgrowthtrendacrossGreaterOsaka continuingthrough2026.
Note:OsakalogisticsreferstotheGreaterOsakaprimelogisticsmarket.Dataisonan NLAbasis.
• Thequartersawno newsupply;themarketremainsgenerally stable
• Whilerentswereflatq-o-q, therearesomesignsofpotential bifurcation
• Increaseinnew supplyin2026meanssomeproperties mayseedownward pressureonrents
InQ42025,no newsupply was recorded inthe GreaterFukuokalogisticsmarket. Meanwhile,demandremains stable, led bylocallogisticscompanies duringthe quarter
The vacancy rate declined to 6.7%, down 80 bps q-o-q, driven mainly by leasing progress in the Tosu area. Several properties which attracted inquiries from prospective tenants proceeded to contract closings, including one by a local logistics company. Meanwhile, no major tenant movements were observed in the FukuokaBayareaoraroundtheFukuokaIC,whereavailablespaceremainslimited.
Gross rent inGreater Fukuoka stood atJPY 3,547per tsubo permonth, remaining flatq-o-q, andmarkingamodest increase of04%y-o-y While some mid-sized facilitiessawdownwardrentadjustments,rentsatlarge-scalefacilitieswereunchanged.
Estimate cap rates remained unchanged q-o-q. One transaction was recorded in inland areas during the quarter. While rising interest have prompted some investorstoadoptamorecautiousstance,investmentappetiteforGreaterFukuokalogisticsfacilitiesremainssound Outlook.
IntheGreaterFukuokalogisticsleasingmarket,newsupplyin2026isexpectedtoreach262,600sq.m.,representinga55%increasey-o-y. Inparticular,theTosu areawillseeanewcompletionofapproximately65,000sq.m.duringthefirstquarter,withadditionalprojectsscheduledforcompletionthereafter. Asaresult, thereisagrowingawarenessofanupsiderisktovacancyrates,especiallyinthisarea.
Differencesinthetimerequiredtoreachfulloccupancyarealsoexpectedtowiden,drivenbyfactorssuchaslocation,buildingspecifications,andtheflexibilityof unitconfigurations.
Withmorenewsupply,somepropertiesmayseerevisionstoaskingtermsordownwardrentadjustments.Meanwhile,high-specfacilitiesandhighlyversatile propertiesareexpectedtocontinueachievingrelativelyhighrentallevels. Goingforward,tenantselectionbasedonlocation,buildingspecifications,andunit-sizeflexibilityislikelytointensify,leadingtoanevenclearerpolarizationin themarket.
Note:FukuokalogisticsreferstotheGreaterFukuokaprimelogisticsmarket.Datais onanNLAbasis.
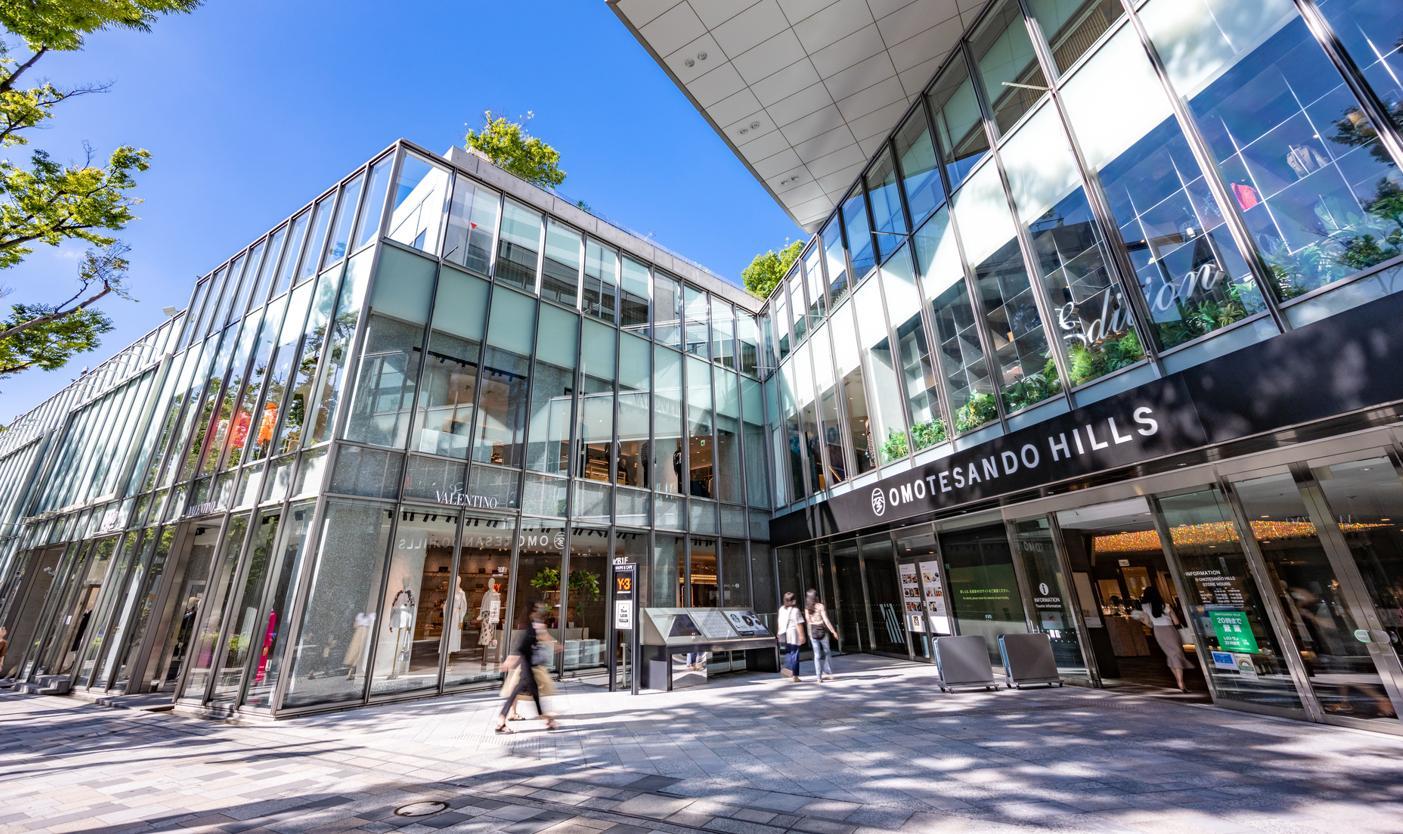
• Luxurygoods salesrecover growthtrend.
• Seiwa GinzaBuildingcompletes onChuo-doriinGinza.
• Rents andcapitalvaluescontinue growthtrend.
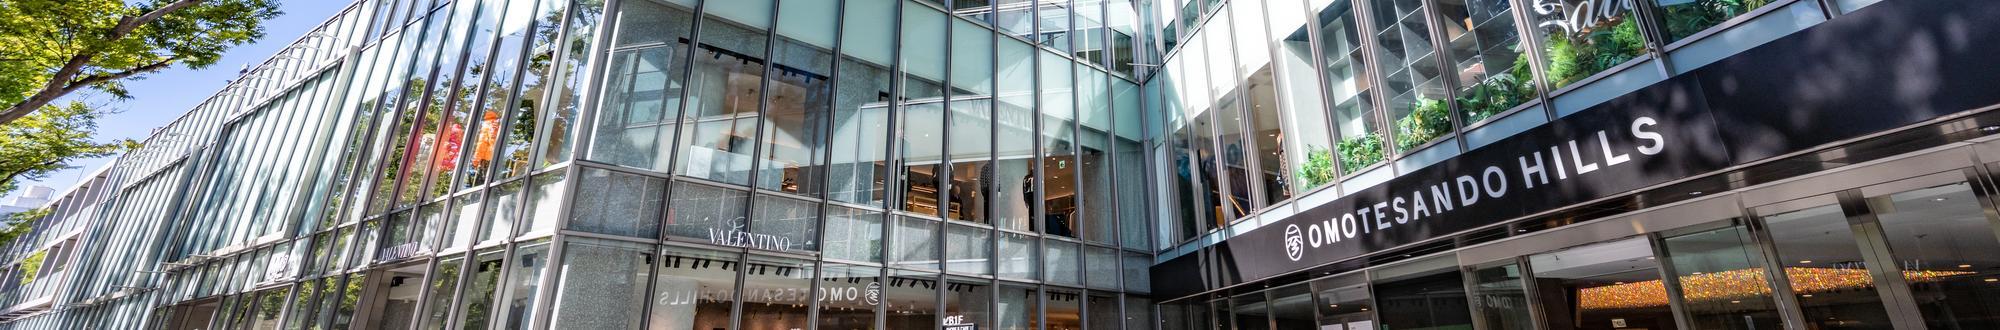
Grossrent JPY104,154per tsubop.m.
Rentgrowth Y-o-Y 5.5%
Stage inrental cycle GrowthSlowing
Note:FinancialindicatorsarefortheprimeretailmarketsofGinzaandOmotesando DataisonanNLAbasis.RetailsalesgrowthfiguresareforTokyoPrefecture. Domesticconsumption remained stableduetorecovering income andsentiment. Luxurygoods salesresumedgrowth inSeptember, followed bytwoconsecutive months of20%y-o-y growth. Inbound consumption stayedstrong amidrecord foreign visitorarrivals.Notablenew openings inQ4included Loewe andLäderachonChuo-dori, andUGGonMatsuya-doriinGinza.InOmotesando, Diptyque opened alongside CatStreet.
NewsupplyinQ4included SeiwaGinzaBuilding, atwo-building redevelopment project thatalsofeaturesGinzaDai-IchiBldg(officebuilding). TheretailbuildingoffersaGFAof4,700sqmacross13above-ground floors,withLoeweoccupying fourstoreys.TheoutlineofOmotesando Grid Tower wasmade public.Theoffice-led mixed-usedevelopment, with38above-ground floors,willofferaGFAof46,000sqmuponcompletion in Q12026.Retailspacewillbeprovided on theground andbasementfloors withwithoccupiers including Salon23ku
Rents inQ4reached JPY104,154pertsubopermonth, increasing 1.9%q-o-q and5.5%y-o-y. Growthcontinued, albeitataslower pace, primarilybecausemajorbrandswithstrongrentaffordabilityhadcompleted theirexpansion cycle. CapitalvaluesinQ4increased 1.7%q-o-q and4.2%y-o-y, driven byrent growthamidstablecaprates.Notabletransactionsinthequarterincluded domestic realestatecorporation MantomiAssetManagement's acquisitionofGinzagCUBE(priceundisclosed).
According toeconomic forecastsbyOxfordEconomics asofDecember, privateconsumption y-o-ygrowth wasrevisedupto1.2%in2025and 0.7%in2026.Risksincludetheimpact ofcontinued inflationon consumer sentiment. Rent growthisexpected tocontinue, driven bythetight demand-supply balancefrom independent international brandsandnear-fullycommitted futuresupply.Investment marketcapitalvalues shouldincreasegraduallyalongside rentgrowthwhilecapratesremainstable.
Source:JapanDepartmentStoresAssociation
Note:Luxurygoodsrefertoart,jewellery,andprecious metals
• Growthcontinues, driven byrobustinbound tourismdemand.
• Theopening ofnewinternational luxuryhotelsinTokyo continues.
• Continued record-high performance forADRandRevPAR.
Thenumberofforeign visitorstoJapanhassurpassed40millionforthefirsttime, reaching42.68millionin2025.Theweak yen andother tailwindshavecontinued toboosttheincreaseininternational visitors,leadingtorecord highsfortwoconsecutive years. Meanwhile,according toMLIT,thenumber ofovernight staysinTokyo inthefirst10months of2025declined by2.5%compared tothesameperiod lastyear. Although thenumberofinternational guestsincreased by6.8%Y-o-Y duringtheperiod, accounting for56%ofthetotal,thenumber ofdomestic guests declined by12.3%Y-o-Y, losingmajorityshare.
InQ42025,JWMarriottHotelTokyo opened on2October, followed byCaptionbyHyattKabutocho Tokyo on7October. ParkHyattTokyo also reopened on9December afterclosinginMay2024formajorrenovations. Numberofinternational luxuryhotelsarescheduledtoopen inthe coming years.Theseinclude theopening of1HotelTokyo in2026;Waldorf AstoriaTokyo andPullmanTokyo Ginzain2027;and Canopy by HiltonTokyo Akasaka,Dorchester Collection andRafflesTokyo in2028.
Tokyo continued toseeanincreaseintradingperformance acrossallhotelsegments inQ4.Theongoing increaseininbound visitorshasdriven asustainedriseinADR,whileoccupancy hasalsoshownsteadyrecovery. Intheluxuryandupper-upscale segments, althoughthepace of growthhasslowedin2025compared to2024,bothADRandRevPAR havecontinued toreachrecord highseachquarter. Occupancy in2025has improved slightlyY-o-Ybutisstillbelowpre-pandemic levels.
Althoughgeopolitical riskspersist,inbound demand isexpected toremainrobust,boostedbytheweakyen. Strong performance trends in Tokyo's hotelindustryarelikelytocontinue through2026.Robustinbound demand andcontinued yen depreciation arelikelytosustainthe upwardtrend inADRthrough2026.Luxuryandupscalehotelsarefocusingon raisingADRratherthanoccupancy, sothepaceof occupancy recovery mayremainslow.
Note:TokyoHotelsrefertoTokyo'soverallhotelmarket.
• Green buildingcertification acquisitionincreases,with20LEED-certifiedprojects including existingMICEfacilities.
• Wellness certificationacquisitiondecreases, withWELLachieving threePlatinumcertificationsforoffices.
• TheJapaneseversion ofSustainabilityMarketDynamics featurestrends inrealestatesustainabilityresponse inJapan.
LEED: Twenty projects acquired certification in 4Q25, bringing the total number of LEED-certified projects since 2009 to 377, representing a5.6%q-o-q increase.
CASBEE-BD: Twenty-one projects acquired certification in 4Q25 below the number expiring decreasing the total number of CASBEE-BD-certifiedprojects by30%q-o-q to526
CASBEE-RE: Certification was acquired by 233 projects in 4Q25, predominantly in the multi-family sector, increasing the total numberofCASBEE-RE-certified projects by6.9%q-o-q to2,927.
WELL: Three projects acquired certification in 4Q25, with three projects expiring, keeping the total number of WELL-certified projects unchanged at66.
Fitwel: No projects acquired certification in 4Q25, leaving the total number of Fitwel-certified projects unchanged at five for the seventh consecutive quarter.
CASBEE-WO: Six projects acquired certification in 4Q25 below the number expiring decreasing the total number of CASBEEWO-certified projects by05%q-o-q to194

JLL Japan Energy & Sustainability Services (ESS) analyzed the client inquiries received over the past three years to understand the trends in real estate sustainability response in Japan. The number of inquiries were roughly equal between investors and operators, as well as between foreign companies and domestic companies, but there was a significant difference between owners (80%) and tenants (20%). The following trends were observed based on client attributes and service categories: (1) Green building certification acquisition generates the most inquiries, followed by energy efficiency diagnostics; (2) Inquiries from investors seeking third-party evaluation (other than certification bodies) to verify whether target real estate meets ESG investment criteria are increasing; (3) Inquiries from the IT industry are increasing, particularly for green building certification for data centers; (4) Tenant inquiries account for only 20%, with more than halfseekinggreen buildingcertifications.
Metrics
Note:LEED,WELLandFitwelrefertoallratings.CASBEE-BD,CASBEE-REand CASBEEWOrefertoB+andabove.
Source:JLL,USGBC,IBECs,IWBI,Fitwel
Historicalvalidgreencertificationbycertifiedyear
Jones Lang LaSalle K.K.
Tokyo Headquarters
KioiTower,
Tokyo Garden TerraceKioicho 1-3Kioi-cho Chiyoda-ku, Tokyo 102-0094
+81343611800
Research
HeadofResearch
HiroshoOkubo
hiroshi.okubo@jll.com
Kansai
Nippon Life
YodoyabashiBuilding
3-5-29KitahamaChuo-ku, Osaka541-0041
+81676628400
Officeteamleader
YutoOhigashi Senior Director yuto.ohigashi@jll.com
Office:Osaka/Fukuoka
HarukaMatsumaru Manager haruka.matsumaru@jll.com
Hotels & Hospitality Group
HeadofAdvisory
KuraudoOhashi
ExecutiveVicePresident kuraudo.ohashi@jll.com
Fukuoka
FukuokaDaimyoGardenCity
2-6-50Daimyo, Chuo-ku,Fukuoka-shi
Fukuoka810-0041
+81922336801
Investment・Logistics teamleader ManabuTaniguchi
Senior Director manabu.taniguchi@jll.com
Office:Flexibleoffice
TomoyoNakamaru
AssistantManager tomoyo.namakaru@jll.com
Retail・Datacenter NaokoIwanaga Senior Director naoko.iwanaga@jll.com
Logistics:Fukuoka YokoYamad Manager yoko.yamada@jll.com
Nagoya
JPTowerNagoya
1-1-1Meieki, Nakamura-ku,Nagoya-shi
Aichi450-6321
+81528563357
Sustainability
TomomiKemmochi
Senior Manager tomomi.kemmochi@jll.com
JLL’s research team delivers intelligence, analysis and insight through marketleading reports and services that illuminate today’s commercial real estate dynamics and identify tomorrow’s challenges and opportunities Our more than 550 global research professionals track and analyze economic and property trends and forecast future conditions in over 60 countries, producing unrivalled local and global perspectives Our research and expertise, fueled by real-time information and innovative thinking around the world, creates a competitive advantage for our clientsanddrives successfulstrategiesandoptimal realestatedecisions
JLL (NYSE:JLL) is a leading global commercial real estate services and investment management company with annual revenue of $261 billion, operations in over 80 countries and a global workforce of more than 113,000 as of December 31, 2025 For over 200 years, clients have trusted JLL, a Fortune 500® company, to help them confidently buy, build, occupy, manage and invest across a variety of industries and property types, including office, industrial, hotel, multi-family, retail and data center properties. Driven by our purpose to shape the future of real estate for a better world, we help our clients, people and communities SEE A BRIGHTER WAY Powered by rich global datasets and leading technology capabilities, we provide coordinated, end-to-end delivery of real estate services for a broad range of global clients who represent a wide variety of industries. Through LaSalle Investment Management, we invest for clients on a global basis in both private assetsandpubliclytraded realestatesecurities Forfurtherinformation, visitjll com
Thisreporthasbeenpreparedsolelyforinformationpurposesanddoesnotnecessarilypurporttobeacompleteanalysisofthetopicsdiscussed,whichareinherentlyunpredictable.Ithasbeenbasedonsourceswebelievetobe reliable,butwehavenotindependentlyverifiedthosesourcesandwedonotguaranteethattheinformationinthereportis accurateorcomplete.Anyviewsexpressedinthereportreflectourjudgmentatthisdateandaresubject tochangewithoutnotice.Statementsthatareforward-lookinginvolveknownandunknownrisksanduncertaintiesthatmaycausefuturerealitiestobemateriallydifferentfromthoseimpliedbysuchforward-lookingstatements. Advicewegivetoclientsinparticularsituationsmaydifferfromtheviewsexpressedinthisreport.Noinvestmentorother businessdecisionsshouldbemadebasedsolelyontheviewsexpressedinthisreport.