Japan MarketDynamics

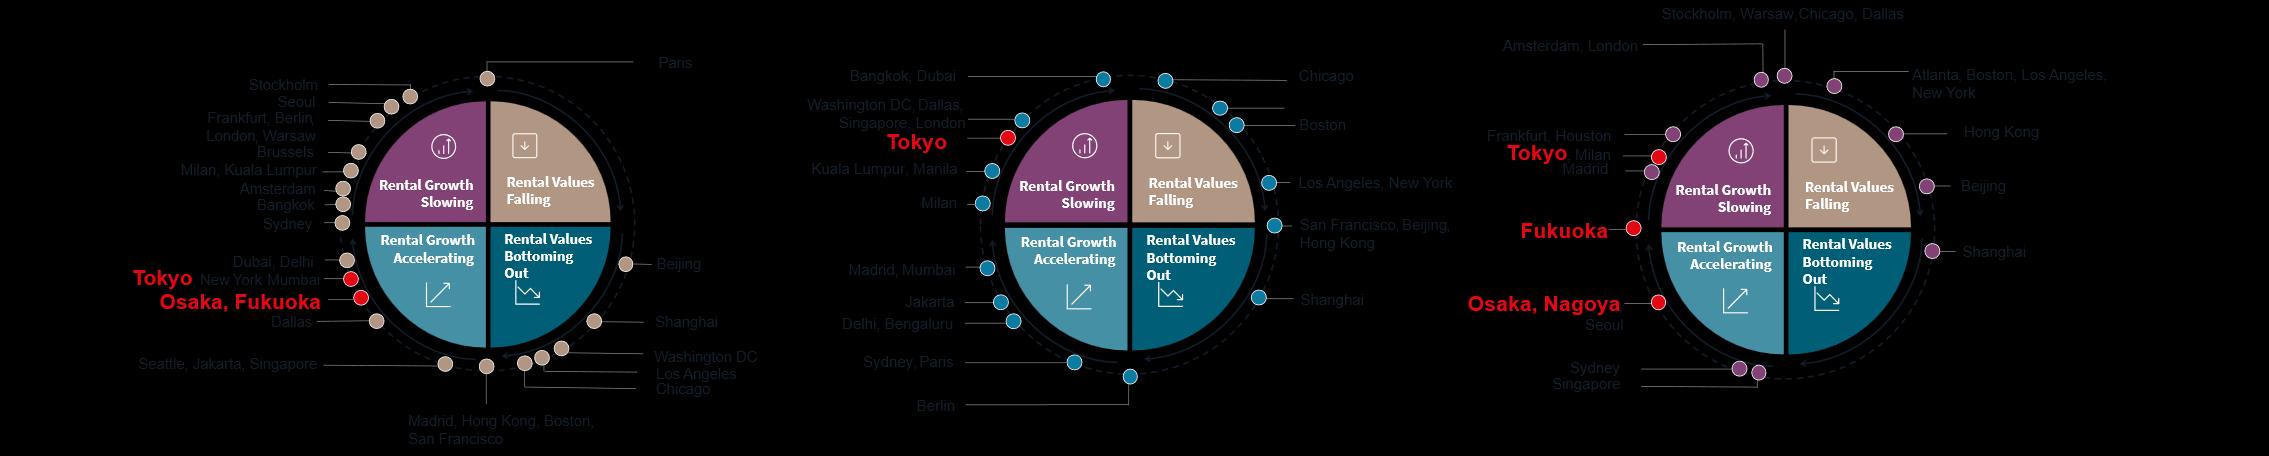
Despite rising global interest rates driven by heightened uncertainty and concerns over renewed inflation, Japan's commercial real estate investment market recorded JPY 2.075 trillion in Q1 2026, representing a modest 1.0% decline y-o-y Considering that the previous year set a recordhighfor first-quarter activity, the current period's performance at nearly equivalent levels demonstrates that the market remainsrobust
Investment by overseas investors have also remained at elevated levels following the previous year's strong performance. Amid the current global uncertainty, investor interest in Japan's real estate market-the most liquid in the Asia-Pacific region appears to be increasing, partly driven by risk diversification, although this is hardly the sole factor. Traditionally, the appeal of Japanese real estate investment has centered on "liquidity" and "stability" However, rental growth has been accelerating in core asset classes, particularly offices, adding "growth potential" as a new attractive dimension This evolving market environment is also considered a contributing factor to heightened interest in Japan's real estate market from both domestic and internationalinvestors
HeadofResearch
HiroshiOkubo
Author Research
Assistant
Manager
TomoyoNakamaru
In the second half of 2025, the new supply of flexible office space in Tokyo’s five central wards increased by 12,900 sqm. According to the latest edition of JLL Research’s semi-annual report, Tokyo
Flexible Office Market Dynamics 2H25, this brought the full-year totalsupplyto34,800sqm, markingastrongfinishtotheyear
By the end of 2025, the total flex space stock in Tokyo increased 78%year-on-year(y-o-y),anaccelerationfromalmost nogrowth in 2024.
Flexoperatorsarereportingrobustdemandfrombothstartupsand blue-chip companies, driven by the growth of hybrid work styles and increased digitalisation in central Tokyo. Occupancy rates are steadily improving, while operators are expanding their networks by opening new locations, adding more space to existing centres andclosingunderperforming sites
TotalNetLeasableArea(sqm)
Source:JLL
Operators are increasingly choosing prime locations for their network as the flight-to-quality trend is driving demand for workspace in central Tokyo. For example, Singapore-based operator JustCo launched its flagship premium brand, The Collective, on the 9th floor of Gran Tokyo South Tower (within the same building as its JustCo centre), focusing on providing the highestqualityservices.
In April, Mitsubishi Estate-operated XLINK opened in Marunouchi Building and in the second half of 2025, the third high-end Signature centre opened in the Nissay Marunouchi Building, anticipating further demand for luxury workspaces with state-ofthe-artfeaturesandamenities.
New openings have also launched in recently completed Grade A officebuildings,suchasMitaMachiTerrace(completedin October 2025), where domestic developer Chuo Nittochi Tatemono opened its 6th SENQ location, occupying two floors Mitsui Fudosan’s Workstylingbrand hasalsoaddednewsitesinIidabashi GranBloom andShibuyaSakuraStage.
Operators who had stopped expansion in recent years have reentered themarket,indicating growing confidence inthesector
In Q4 2025, the average monthly membership rate per seat for flex spaceinTokyo’sfivecentralwardsrosebyapproximately10%y-oy. This increase was driven by both rising occupancy at existing locations and the continued introduction of premium flex space offerings
Looking ahead, we expect momentum in central Tokyo’s flex space market to continue with the proliferation of AI in full momentum. Already, in the first half of 2026, several flex operators have announced new locations including a new Signature centre in Shinjuku Island (set to open in April 2026) and The Executive Centre’s new site in the grade A office building, TOFROM YAESU TOWER, located across from Tokyo Station. Future pipeline will continue into the second half of the year with numerous announcements oflargescalenewflexfacilities
Globalrealestateinvestmentvolumecontinuesto expand,supportedbyfavorablefinancing conditions.Investmentinofficebuildingsis growingworldwideduetorecovering leasing demandandreduced newdevelopmentactivity.
Tightsupply-demandbalance,particularlyfor officesector,andacceleratingrentgrowthare stimulatinginvestorappetite.Medium-tolongtermrentgrowthexpectationsareincreasingdue tofactorssuchasthegrowingadoptionofCPIlinkedrents,whichisexpected tooffsetthe negativeimpactofrisinginterestrate.
Japan'sInvestmentVolumeExceedsJPY2 Trillion,On
InQ12026,investmentvolumeexceeded JPY2 trillion,matchingQ12025,whichrecorded the highestfirstquartervolumeinhistory.Thisquarter sawtransactionsofalarge-scaleofficebuilding andalarge-scalehotelinTokyoCBD.
Bothdomesticandoverseas investorshavestrong investmentappetiteforJapaneserealestate. Constraintsonnewsupplyduetorising constructioncostsandlaborshortageswillfurther encourageinvestmentinexistingproperties.Real estateinvestmentvolumein2026isexpected to exceed 2025levels,reachingthemid-JPY6trillion range.
• Japan'srealestateinvestment volume inQ12026 reached JPY2.075trillion,down 1%y-o-y. Thismarks onlythesecond timequarterlyinvestment volume hasexceeded JPY2trillion,following Q12025,which recorded thehighestfirstquartervolume inhistory.
• Strong appetite frominvestors andcontinued provision ofinvestment opportunities aresustaining activemarketconditions. Thisquartersawseveral large-scaletransactions(exceeding JPY100billion), including theDentsuheadquartersbuildingandHyatt Regency Tokyo.
• Japan'srealestateinvestment markethasseen almostnoimpactfromtheMiddleEastsituationthus far.Lookingahead,whilethereareconcerns that prolonged conflictcould stagnatecorporate activity, risingenergy pricesandmaterialshortagescould potentially leadtofurtherconstraints onnewsupply.
Source:JLL
• Bysector, officecontinued toaccount forthelargest shareofinvestment. Investment inofficeinQ12026 wasJPY989.1billion,representing 48%ofthetotal, continuing theincreaseinsharefromalowof33%in full-year2023.Asofficerentgrowth becomes more pronounced, investor interestisintensifying further, withJ-REITs alsoincreasing newacquisitions.
• Forlogisticsfacilities,acquisitionsbyJ-REITs remain sluggish,andtheinvestment sharecontinues to decline to12%.
• Forhotels,theinvestment shareincreased to15% duetotransactionsoflarge-scaleproperties andan increaseinthenumber ofdealsthemselves.
• Formultifamilyproperties, theinvestment share increased to19%,driven byfactorssuchasoverseas investoracquisitionsofco-living facilities.
Source:JLL
JapanMarketDynamics -Q12026
• Byregion, Tokyo CBDaccounted for46%inQ12026, anincreasefrom42%infull-year2025.Inaddition to transactionsofalarge-scaleofficebuildinganda large-scalehotel, numberofmid-sizedofficebuilding transactionscontributed totheincreaseinshare.
• GreaterOsakaarea'ssharereached 16%,upfrom13% infull-year2025.Atransactionoflarge-scaleoffice buildingwasobserved inOsakaCBD.
Source:JLL
Note:TokyoCBC(5-kus)referstoChiyoda-ku,Chuo-ku,Minato-ku,Shinjuku-kuandShibuya-ku;GreaterTokyoreferstoTokyo,Chiba,SaitamaandKanagawa;GreaterNagoyareferstoAichi, GifuandMie;GreaterOsakareferstoOsaka,Hyogo,KyotoandNara; GreaterFukuokareferstoFukuoka,Saga,Nagasaki,Kumamoto,Oita,Miyazaki,KagoshimaandOkinawa.
JapanMarketDynamics -Q12026
• Furtherincreaseinnetabsorptiondriven bystrong occupier demand
• Vacancyrateremainsunchanged q-o-q at0.7%.
• Rents risefortheninthconsecutive quarter
Netabsorption inTokyo's GradeAoffice marketreached69,000tsuboinQ12026,increasingfrom38,000tsubointheprevious quarter. Demand hasbeen driven byemployees returning toofficesandbusinessexpansion, primarilycentered onmanufacturing, IT,andprofessionalservices sectors.
FournewGradeAofficebuildings,including Tofrom YaesuTower (NLA:31,300tsubo),TakanawaGatewayCityTheLinkpillar2(NLA:26,900 tsubo)andSumitomo FudosanShibaKoen (NLA:6,200tsubo),andOmotesando GridTower (NLA:3,300tsubo)werecompleted inQ1 2026, increasingtotalstockby3.5%.Tokyo's GradeAofficevacancyrateinQ12026was0.7%,unchanged q-o-q anddown 1.8ppy-o-y.
Theaveragemonthly grossrentpertsubowasJPY40,247,up5.2%q-o-q and13.2%y-o-yinQ12026.CapitalvaluesinQ12026rose5.5%q-o-q and16.4%y-o-y, accelerating fromQ42025,asstrongrentmomentum offsetrisingcaprates.NotableGradeAtransactionsincluded the purchaseofDentsuHQBuildingbyBrookfield for300billionJPY.
According toOxfordEconomics' forecastasofMarch2026,projections forrealGDPgrowth in2026werereviseddown to0.3%onthebackofthe conflict intheMiddleEast.InTokyo's GradeAofficeleasingmarket,solidtenant demand continues whiledelaysinnewbuildingcompletions areoccurring duetolaborshortagesandrisingconstruction costs.Withthesupply-demand balancetightening, rentsareexpected tomaintain anupwardtrend going forward.
Note:Financialandphysical indicatorsareforthe5KusGradeAofficemarket.Datais onanNLAbasis.
Tsubo(thousands)
• Relocation demand driven bytalentconsiderations expanded fromlargecorporations tomid-sizedandsmallcompanies
• Thequartersawno newsupplyandcontinued take-upinexistingpremises.
• Rents reached JPY27,104pertsuboper month, up3.0%q-o-q and13.9%y-o-y
Osaka’sGradeAofficemarketstarted2026strongly, withnetabsorptiontotalling7,000tsuboinQ12026.Therewasnosignificantconcentration among tenantsthatrelocated, withawide rangeofsectorsrepresented, including long-establishedmanufacturers,wholesalersandIT companies.
Therewasno newsupplydelivered duringthequarter. YodoyabashiGateTower, whichcompleted lastquarterwithaGFAof40,000tsuboand 29storeys,hasmade steadyprogress inleasing.TheQ12026vacancy ratefellto2.2%,down 0.9ppbothq-o-q andy-o-y. Buildingscompleted after2024,whichpreviously hadavailablespace, arenowseeing theirtotalvacancysignificantlyreduced, indicating tightermarketconditions.
Theaveragemonthly grossrentpertsubowasJPY27,104,up3.0%q-o-q and13.9%y-o-y, markingthefirsttimeannualrental growthhas exceeded 13%sincetrackingbegan in2003.Risesinrents attop-tier buildingsaredriving theoverallincrease.Capitalvaluesrose2.9%q-o-q and14.6%y-o-yinQ1,driven byrisingrents.Notabletransactionsannounced inthequarterincluded MeijiYasudaLifeInsurance'sacquisition ofHulicOsakaBuilding.Thebuyerisplanning to rebuildtheacquired building.
According toOxfordEconomics forecastsasofMarch2026,OsakaCity'srealGDPgrowthisprojected at+0.5%in2026.Thevacancy rateis expected tocontinue declining. Withfuturenewsupplyscheduled tobeextremely limited, theonly buildingdueforcompletion inJuly2026is notable. Tenant demand remains strong, anditisexpected tobefullyletshortlyaftercompletion. Therefore, thevacancyrateatendQ42026is forecasttodecline to2.0%.Vacanciesintop-tier buildingsaregetting scarceinearnest.Withavailablefloorspacebecoming limited, the upwardtrend inrents iscontinuing, andtheannualrentalgrowthratefor2026isprojected tobearound10%.
Note:Financialandphysical indicatorsareforthe5KusGradeAofficemarket.Datais onanNLAbasis.
Tsubo(thousands)
• Activerelocation demand driven bytalentacquisitionstrategiesthroughimproved locationsandenvironments, aswellasnew workplace development
• Nishi-NipponCityBuildingcompleted withsmoothleasingprogress
• Rent reached JPY23,276per tsubopermonth, up3.4%q-o-q and9.5%y-o-y
Netabsorption inFukuoka'sGradeAofficemarketreached +5,000tsuboinQ12026.Relocation demand persistsfortalent-focused locations, improved environments, andnewworkplace creation. However, sometenantsarebecoming cautiousorabandoning movesduetorisingcosts, indicating aslightdeceleration indemand momentum.
Thisquarterthevacancy ratewas4.4%,up0.2pp q-o-q butdown 1.6ppy-o-y, duetolimitedactivityinexistingbuildings andsome remaining vacanciesinnewly constructed building.Nishi-Nippon CityBuilding(Hakata-ku,14floorsaboveground, totalfloorareaapproximately 22,900 tsubo)wascompleted. AllGradeAofficebuildingsupplyin2025wasintheTenjin area,makingthisbuildingthefirstnewsupplyintheHakata Stationareainapproximately twoyearssinceMarch2024.Tenant leasinghasprogressed smoothly, withWeWork, theleading flexibleoffice provider, announcing itsoccupancy oftwofloors.
Averagerentsreached JPY23,276per tsubopermonth, up3.4%q-o-q and9.5%y-o-y. High-renttransactionsinnewlysupplied buildings pushedupthemarketaverage.
OneGradeAoffice buildingremainsinthe2026new supplypipeline (Tenjin BusinessCenter II:Chuo-ku,totalfloorarea19,000tsubo) scheduled forthesecond quarter.TheTenjin 1-7Project, originallyscheduled forcompletion inDecember 2026,hasbeen postponed to2027. Nevertheless, totalnewleasablefloorareain2026willbeapproximately 16,000tsubo,thelargestlevelinrecent years,andthevacancyrateis expected totemporarily riseto6.7%byyear-end 2026.However, rentsareexpected toriseapproximately 5.0%for2026,driven bythesupplyof newly constructed buildingswithpremium rentsamong GradeAproperties, aswellasincreasingupwardrent pressurefrominflation.
Note: FinancialandphysicalindicatorsareforFukuoka’sGradeAofficemarket. DataisonaNLAbasis.
• Demand frome-commerce and3PLcompanies remains robust
• Vacancyratedeclines forthirdconsecutive quarterto8.2%
• Rents continue toriseduetoconstruction costincreasesandtightsupply-demand balance
Demandfrome-commerceand3PLcompaniesremainsrobust,withnetabsorptioninQ12026reaching179,000tsubo.Strongdemandwasobservedbothin peripheralareassuchastheKen-OExpresswayareaandinhigh-rentareassuchastheGaikanExpresswayarea.
Newsupplytotaled142,000tsuboacrosssixproperties,upfromthepreviousquarterbutlessthanthefive-yearaverage.Asnetabsorptionexceededsupply,the vacancyratedeclinedforthethirdconsecutivequarterto8.2%,down0.6ppq-o-q and2.2ppy-o-y.
Rentsstandat4,823yenpertsubopermonth,up0.9%q-o-qand3.1%y-o-y.Risingconstructioncostshavedrivenuprentsfornewproperties,pushingup existingpropertyrents.Somewell-locatedpropertiessawaskingrentsincreasebyover10%followingtenantdepartures.
Capitalvaluesrose0.1%q-o-qand1.2%y-o-y.Althoughcapratesroseslightly,partiallyreflectinghigherbondyields,valuesincreasedreflectingrentgrowth.
Outlook:
RentgrowthacrossGreaterTokyoisexpectedtocontinue,supportedbystabledemandandthefactthatnewdevelopmentremainsconstrainedandselective duetorisingconstructioncosts.However,inperipheralareaswherepropertiesmustappealtotenantswithlowerrents,rent increasesareexpectedtobemore moderate.
AccordingtoOxfordEconomics,furtherinterestrateincreasesareanticipated,butcaprateincreasesareexpectedtobelimited.Thisisduetorisingrental growthexpectations,asevidencedbythepenetrationofCPI-linkedrents.Assuch,capitalvaluesareexpectedtocontinuerising,particularlyforwell-located, high-gradepropertieswherefurtherrentgrowthisanticipated.
Note:TokyologisticsreferstotheGreaterTokyoprimelogisticsmarket.Dataisonan NLAbasis.
(thousands)
• Demand fornewandrecently builtproperties significantlyexceeds supply
• Vacancyrateexpected toremain inthe2%rangein2026duetoreduced supply
• Rents continue toriseinlandlord-favorable marketenvironment
Stabledemandabsorbedexistingvacancies,withnetabsorptioninQ12026reaching48,000tsubo.Demandwasobservedforseveralrecentlybuiltproperties thathadremainedvacantduetoaskingrentsabovemarketlevels.
Newsupplyconsistedofoneproperty(24,000tsubo)intheKyotoarea,whichwasfullyleasedatcompletion.Whilemultiplelarge-scalelogisticsfacilitiesare scheduledfordeliveryintheKyotoarea,thisresultsuggestsstrongdemandforthearea.Combinedwithabsorptionofexistingvacancies,theoverallvacancy rateforGreaterOsakadeclined1.0ppq-o-q to2.1%.
RentsinGreaterOsakastandatJPY4,303pertsubopermonth,up0.3%q-o-qand2.8%y-o-y.Rentincreasesforrecentlybuiltpropertiesareripplingthroughto askingrentsforexistingproperties.
Althoughestimatedcapratesroseslightlyinresponsetorisingbondyields,capitalvaluesremainedalmostflatduetorentincreases.
Outlook:
Intheleasingmarket,newsupplyin2026isexpectedtodeclinesignificantlycomparedtothepreviousyear,andstabledemandisanticipatedtokeepthe vacancyrateatalowlevelinthe2%range.From2027onward,newsupplywillbeconcentratedintheKyotoarea,withlimiteddevelopmentplanselsewhere.As aresult,areasoutsideKyotoareexpectedtobecomeextremelytight.
Additionally,rentsfornewpropertiesareexpectedtorisefurther,reflectingrisingconstructioncosts,withcontinuedspillovereffectstoexistingproperties. Giventhehighoccupancyofexistingproperties,alandlord-favorablemarketenvironmentwillcontinue,andtheupwardrenttrendacrossGreaterOsakais expectedtopersist.
YTD
Note:OsakalogisticsreferstotheGreaterOsakaprimelogisticsmarket.Dataisonan NLAbasis.
Historicalsupplyanddemandtrends
• Demand remains sound, driven primarilybye-commerce operators, 3PLproviders, andlocal logisticscompanies
• Vacancyraterisesduetolarge-scalecompletion, butincreaseremains limitedasexistingproperties continue tobeabsorbed
• Tenant turnover drivesrentrevisions, underpinning rentalgrowth
In Q1 2026, net absorption(*) in the Greater Fukuoka logistics market reached 15,000 tsubo, falling short of new supply of 18,000 tsubo However, leasing activity forexistingpropertiesintheTosuareaprogressedsteadily,withdealsconfirmedbye-commerceoperators,3PLproviders,andlocallogisticscompanies
The vacancy rate increased to 71%, up 04pp q-o-q While the completion of a large-scale logistics facility in the Tosu area with significant vacancy temporarily liftedvacancy levels,absorption of existing properties in the Ogori-Tosu area proceeded smoothly, and overall demand across the market remains sound In the FukuokaBayareaandaroundtheFukuokaIC,newsupplyremainslimited,andvacancyratescontinuetostaylow
GrossrentinGreaterFukuokastoodatJPY3,568pertsubopermonth,up06%q-o-qand07%y-o-y During thequarter,someexistingpropertieswheretenants had decided to vacate began marketing at higher rents compared to previous levels This trend is spilling over to nearby properties, prompting rent increases uponleaserenewals Thisdynamicisnotlimitedtonewerbuildingsandiscontributingtoupwardpressureonrentsacrossthemarketasawhole
Oneinvestmenttransactionwasrecorded intheTosuareaduringthequarter.Whilerisinginterestrateshavepromptedsomeinvestorstoadoptamorecautious stance,investorappetiteforGreaterFukuokalogisticsfacilitiesremainssound.Estimatecapratesremainedunchangedq-o-q.
Outlook
For full-year 2026, new supply is expected to reach approximately 79,000 tsubo, with supply-side momentum continuing to outpace demand, particularly in the Tosu area. As aresult,theoverallmarketvacancy ratemayface short-term upwardpressure. However, multipleinquiries andsomepre-leasing agreementshave alreadybeen confirmed for properties scheduled for completion inthe coming quarters,indicating stable demand. Supported by the expansion of e-commerce, as well as warehousing and distributionneeds from manufacturing sectors particularly semiconductors and automotive most of the new supply is likely to be absorbed within approximately one year. Going forward, tenant selection based on location, building specifications, and unit-size flexibility is expected to intensifyfurther.Whilepropertieswithinferiorlocationsorspecificationsmayseerevisionstoaskingtermsordownwardrentadjustments,themarketasawhole isexpectedtomaintainamoderateupwardtrendinrents.
Note:FukuokalogisticsreferstotheGreaterFukuokaprimelogisticsmarket.Datais onanNLAbasis.
tsubo(thousands)
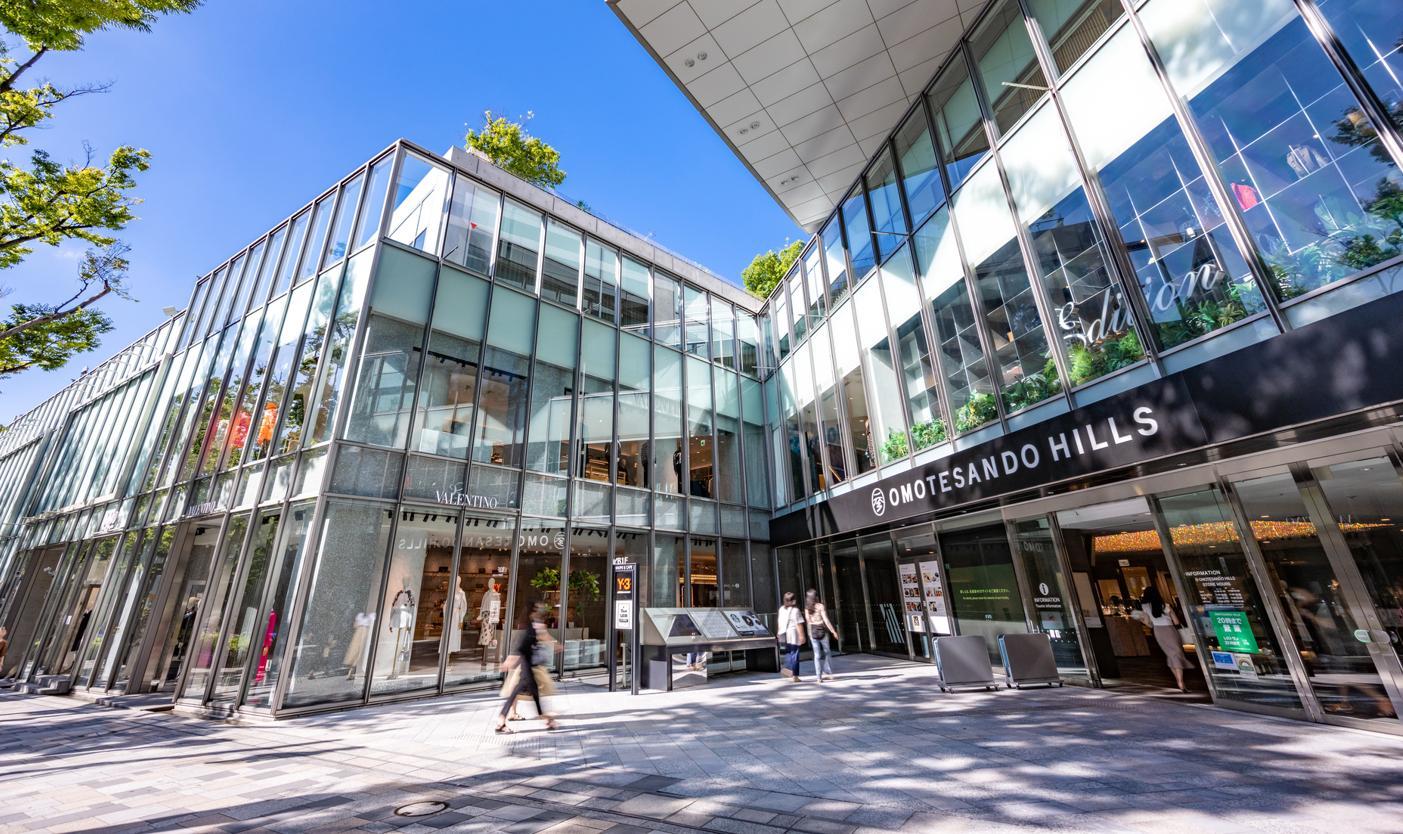
• Newopening demand remainsstableintheprime retailarea.
• GinzaNovo undergoes auseconversion, withaportion oftheF&Bareascheduledtobe converted andadded totheexisting nightclubarea.
• Rentalgrowth trends continue onbothground floorsandupperfloorsonthebackofextremely limited supply.
Note:FinancialindicatorsarefortheprimeretailmarketsonChuo-doriinGinzaarea andonOmotesandobetweenAoyama-doriandMeiji-dori inOmotesandoarea.Data isonanNLAbasis.LuxurygoodssalesgrowthfiguresareforTokyoDistrict. Tokyo luxurysalesgrew20%y-o-yinJan-Feb.Inbound consumption increased 3%y-o-yinQ1,asforeign visitorarrivalsedged up1%y-o-y. This wasdespite amarkedslowdown invisitorsfromChinawhichdecreased 55%y-o-y. Notablenewopenings inQ1included Jinsopening aglobal flagshipstoreonChuo-doriinGinza.InOmotesando, Milletopened aflagshipstoreontheHarajukusideofCatStreet.
Nonewsupplyentered theprime retailmarketinTokyo inQ1.TheGinzaNovo (formerly TokyuPlazaGinza),completed itsconversion inMarch, whichincluded converting aportion oftheF&Bareaintoanightclub.
Rents reached JPY109,179per tsubopermonth inQ1,up4.8%q-o-q and9.6%y-o-yfrom 1.9%inthepriorquarter. Growthcontinued despite moderating luxurydemand, driven bycasualapparelandvisibility-seekingretailersamidseverely limitedsupply. CapitalvaluesinQ1increased by5.0%q-o-q and8.1%y-o-y, driven byrentgrowthamidstablecaprates.Nonotableprime retailtransactionswere confirmed during the quarter.
According toeconomic forecastsbyOxfordEconomics asofMarch,privateconsumption growth wasrevised down to0.5%y-o-yin2026,given thesituationintheMiddleEast.Signsofweakening consumer sentiment implyfurtherdownside risk.Whiledemand frommajor luxurybrand groupshasmoderated, strongdemand forhigh-visibilitylocationsshouldpersistamidconstrained supply. Rentsareexpected togrow ata slowerpace. Capitalvaluesshouldrisegraduallywithrents,whilecapratesremainstable.
Source:JapanDepartmentStoresAssociation
Note:Luxurygoodsrefertoart,jewellery,andprecious metals
JapanMarketDynamics -Q12026
• Japaninbound tourismgrowth slowsto1.4%inQ12026amid55%drop inChinesevisitors
• Theopening ofnewinternational luxuryhotelsinTokyo continues
• ADRgrowthremains strongacrossallsegments
According toJNTO, foreign visitorstoJapanfromJanuarytoMarch2026reached10,683,481,up1.4%Y-o-Y. However, thepreviously robust growthininbound tourismdemand wascurtailedbydeteriorating Japan-Chinarelationssincelate2025,resultingina55%decline inChinese visitors.According toMLIT,totalovernight staysinTokyo in2025remained nearlyflatversus2024.An8%decline inJapanese guestswasoffset byan8%increaseinforeign guests.Theproportion offoreign guests,whichfirstexceeded 50%in2024,rosefrom51.2%to55.7%.
InQ12026,1HotelTokyo opened on5March.Manyinternational luxuryhotelsarescheduled toopen inthecoming years.Theseinclude the PullmanTokyo GinzaandWaldorfAstoriaTokyo in2027,Canopy byHiltonTokyo Akasaka,DorchesterCollection andRafflesTokyo in2028and TheHouseCollective Tokyo in2029.
Q12026hotelperformance showed continued ADRgrowth acrossallsegments, supported byrisingforeign guests,thoughgrowth rates decelerated. OCCimproved slightlyacrossallsegments except luxury,suggestingthatsourcemarketdiversificationsuccessfullyoffsetreduced Chinesevisitation.Theluxurysegment sawaslightoccupancy decline, likelyduetotheimpactoftheMiddleEastconflict. However, whileother segments experienced flatordecelerated ADRgrowth, luxuryposted 14.1%growth, demonstrating strongpricing power amidmarket challenges.
Althoughgeopolitical riskspersist,inbound demand isexpected toremainrobust,supported bytheweakyen. Whiletherecovery ofChinese tourismmaybepostponed, growing sourcemarkets,includingtheUSandSouthKorea, areexpected tomitigatetheimpactonhotel performance. ADRgrowthisexpected toremainstablethrough2026,supported byrobustinbound demand, thoughatadecelerating pace. The impactoftheMiddleEastconflictremains limitedcurrently, however risingflightcostsmayaffectoverallperformance going forward.
YTDroomadditions
RevPAR growth trendY-o-Y
Stage inRevPAR cycle
Note:TokyoHotelsrefertoTokyo'soverallhotelmarket.
Source:JLL,industrysources,STR
• Green buildingcertification acquisitionincreases,with15LEED-certifiedprojects including luxuryboutiques.
• Wellness certificationacquisitionincreases,withWELLachieving seven Platinumcertifications foroffices.
• TheJapaneseversion ofSustainabilityMarketDynamics featuresstrengthening regulationsonCO2emissionreduction inrealestate.
LEED: Fifteen projects acquired certification in 1Q26, bringing the total number of LEED-certified projects since 2009 to 383, representing a4.1%q-o-q increase.
CASBEE-BD: Thirty-nine projects acquired certification in 1Q26 below the number expiring decreasing the total number of CASBEE-BD-certifiedprojects by38%q-o-q to510
CASBEE-RE: Certification was acquired by 237 projects in 1Q26, predominantly in the multi-family sector, increasing the total numberofCASBEE-RE-certified projects by5.0%q-o-q to3,103.
WELL: Nine projects acquired certification in 1Q26, bringing the total number of WELL-certified projects, including undergoing recertification, totaled 73,increasing 12.3%q-o-q.
Fitwel: No projects acquired certification in 1Q26, leaving the total number of Fitwel-certified projects unchanged at five for the eighthconsecutive quarter.
CASBEE-WO: Eight projects acquired certification in 1Q26, increasing the total number of CASBEE-WO-certified projects by 15%q-o-q to198

Out of Japan's total CO2 emissions, operational carbon generated during building operations accounts for 30%, while embodied carbon from construction, maintenance, and demolition represents 10% The momentum toward real estate decarbonization is set to accelerate with several developments planned within the next few years: mandatory building LCA (calculation and evaluation of environmental impact throughout the entire lifecycle of buildings), full operation of GX-ETS (emissionstradingsystemundertheGXPromotion Act),disclosure obligations based on SSBJ (Sustainability information disclosure standards in securities reports), and revisions to the GHG Protocol (international standard for calculating and reporting greenhouse gas emissions by companies and organizations) This quarter’s special feature provides an overview of the latest trends in buildingLCAandGX-ETS, andtheirimpactonrealestate.
Note:LEED,WELLandFitwelrefertoallratings.CASBEE-BD,CASBEE-REand CASBEEWOrefertoB+andabove.
Source:JLL,USGBC,IBECs,IWBI,Fitwel
validgreencertificationbycertifiedyear
Source:JLL,USGBC,IBECs
Jones Lang LaSalle K.K.
Tokyo Headquarters
KioiTower,
Tokyo Garden TerraceKioicho 1-3Kioi-cho Chiyoda-ku, Tokyo 102-0094
+81343611800
Research
HeadofResearch
HiroshoOkubo
hiroshi.okubo@jll.com
Kansai
Nippon Life
YodoyabashiBuilding
3-5-29KitahamaChuo-ku, Osaka541-0041
+81676628400
Officeteamleader
YutoOhigashi Senior Director yuto.ohigashi@jll.com
Office:Osaka/Fukuoka
HarukaMatsumaru Manager haruka.matsumaru@jll.com
Hotels & Hospitality Group
HeadofAdvisory
KuraudoOhashi
ExecutiveVicePresident kuraudo.ohashi@jll.com
Fukuoka
FukuokaDaimyoGardenCity
2-6-50Daimyo, Chuo-ku,Fukuoka-shi
Fukuoka810-0041
+81922336801
Investment・Logistics teamleader ManabuTaniguchi
Senior Director manabu.taniguchi@jll.com
Office:Flexibleoffice
TomoyoNakamaru
AssistantManager tomoyo.namakaru@jll.com
Retail・Datacenter NaokoIwanaga Senior Director naoko.iwanaga@jll.com
Logistics:Fukuoka YokoYamad Manager yoko.yamada@jll.com
Nagoya
JPTowerNagoya
1-1-1Meieki, Nakamura-ku,Nagoya-shi
Aichi450-6321
+81528563357
Sustainability
TomomiKemmochi
Senior Manager tomomi.kemmochi@jll.com
JLL’s research team delivers intelligence, analysis and insight through marketleading reports and services that illuminate today’s commercial real estate dynamics and identify tomorrow’s challenges and opportunities Our more than 550 global research professionals track and analyze economic and property trends and forecast future conditions in over 60 countries, producing unrivalled local and global perspectives Our research and expertise, fueled by real-time information and innovative thinking around the world, creates a competitive advantage for our clientsanddrives successfulstrategiesandoptimal realestatedecisions
JLL (NYSE:JLL) is a leading global commercial real estate services and investment management company with annual revenue of $26.1 billion, operations in over 80 countries and a global workforce of more than 113,000as of March 31,2026 For over 200 years, clients have trusted JLL, a Fortune 500® company, to help them confidently buy, build, occupy, manage and invest across a variety of industries and property types, including office, industrial, hotel, multi-family, retail and data center properties. Driven by our purpose to shape the future of real estate for a better world, we help our clients, people and communities SEE A BRIGHTER WAY. Powered by rich global datasets and leading technology capabilities, we provide coordinated, end-to-end delivery of real estate services for a broad range of global clients who represent a wide variety of industries. Through LaSalle Investment Management, we invest for clients on a global basis in both private assetsandpubliclytraded realestatesecurities.Forfurtherinformation, visitjll.com.
OPYRIGHT©JONESLANGLASALLE IP,INC.2026
This report has beenpreparedsolelyfor information purposes anddoesnot necessarily purport tobe acomplete analysis ofthe topics discussed, which areinherentlyunpredictable. Ithasbeen basedon sources we believeto be reliable,butwehavenotindependentlyverifiedthosesourcesandwedonotguaranteethattheinformationinthereportisaccurateorcomplete.Anyviewsexpressedinthereportreflectourjudgmentatthisdateandaresubject to change without notice. Statements that are forward-looking involve known and unknown risks and uncertainties that maycause future realities to be materially different from those implied by such forward-looking statements. Advicewegivetoclientsinparticularsituationsmaydifferfromtheviewsexpressedinthisreport.Noinvestmentorotherbusinessdecisionsshouldbemadebasedsolelyontheviewsexpressedinthisreport.