Charlotte's Luxury Market Surges Upward After Delayed Start Due to Geopolitical Concerns
COMMUNITY UPDATES
SouthPark, Carmel, & Quail
Myers Park & Eastover
Lake Wylie & The Palisades
Providence, Weddington, & Waxhaw
Ballantyne & South Carolina
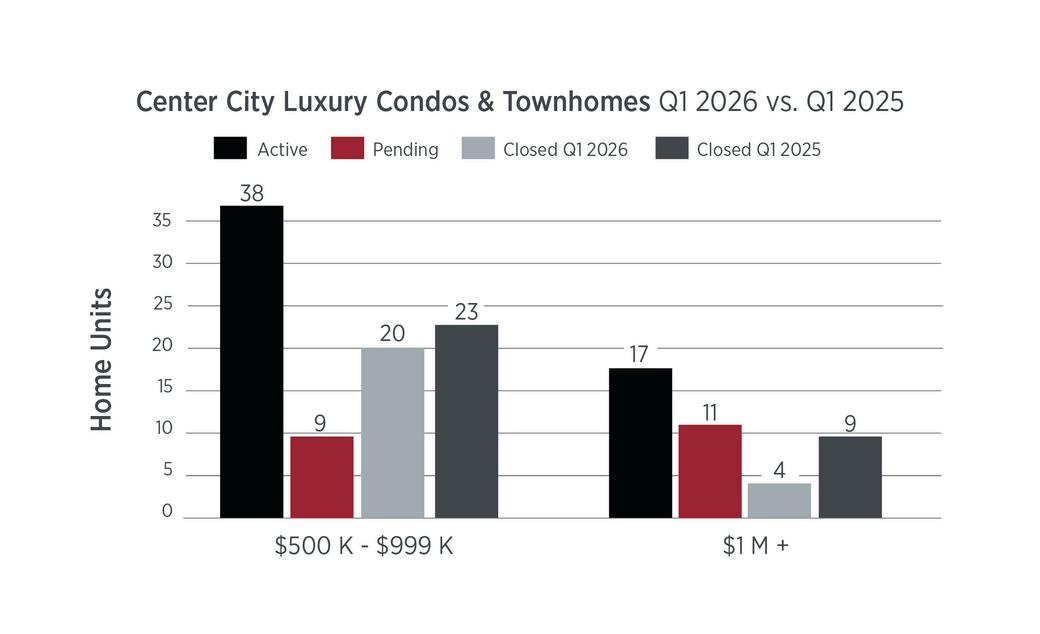
Center City Luxury Condos & Townhomes
FORECAST
Entering the second quarter, the Charlotte market shows clear segmentation rather than broad based weakness
FEATURED LISTINGS
View Our Featured Listings on IvesterJackson com Visit Our Blog And Follow Us On Social Media For Market Forecasts, Interviews, and Marketing Ideas
IvesterJackson com/Blog @IvesterJacksonCharlotte
Charlotte's Luxury Market Surges Upward After
Delayed Start Due to Geopolitical Concerns
The Charlotte luxury market traded very similarly to the start of 2025 in this year ' s first three months, with most areas showing flat or slight declines in sell-through across the board In recent weeks, the market has rebounded and now shows signs of more traditional surging forward into the spring selling season. Like last year, which saw some geopolitical upheaval in April that pushed activity back, this year ' s May activity seems to be trending upward Showing activity in the MLS system has mirrored last year ' s activity at this time, which points to a similar summer and second half provided outside influences settle the market into more activity
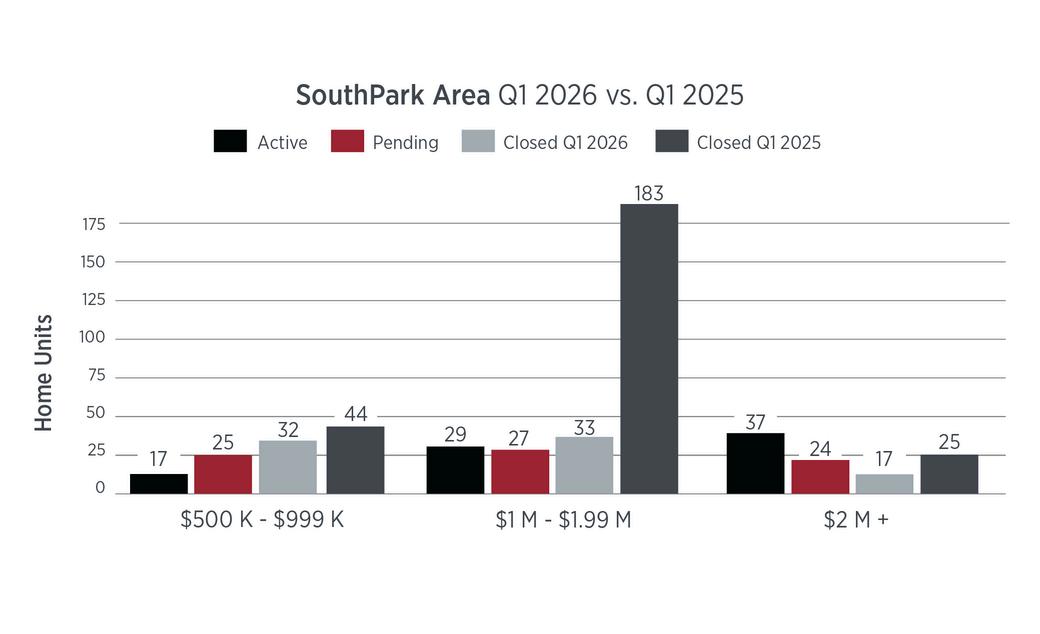
SOUTHPARK, CARMEL, & QUAIL
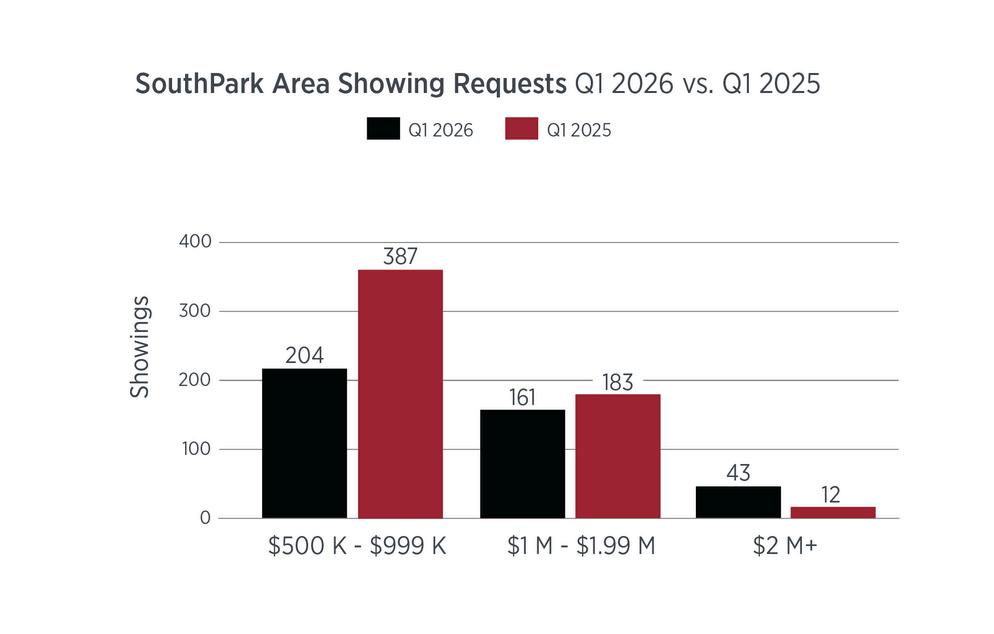
The market is sharply segmented: $1M–$1 99M sales declined materially, while $2M+ closings increased and are supported by rising pendings. Inventory turnover is weakest in the upper‑mid luxury range, but strongest at the true luxury tier. Capital driven buyers are active, while discretionary move up buyers remain cautious
Highlight: Barbell market, $2M+ is strong while $1M–$2M range is under pressure.
SOUTHPARK AREA Q1 HOMES
SOLD & SHOWINGS
MYERS PARK & EASTOVER
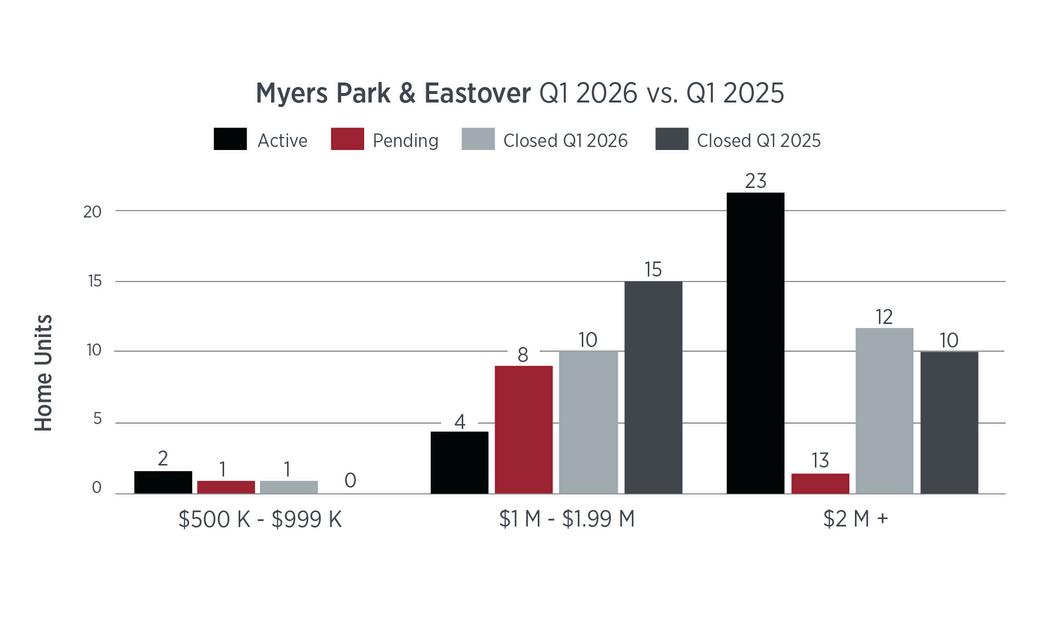
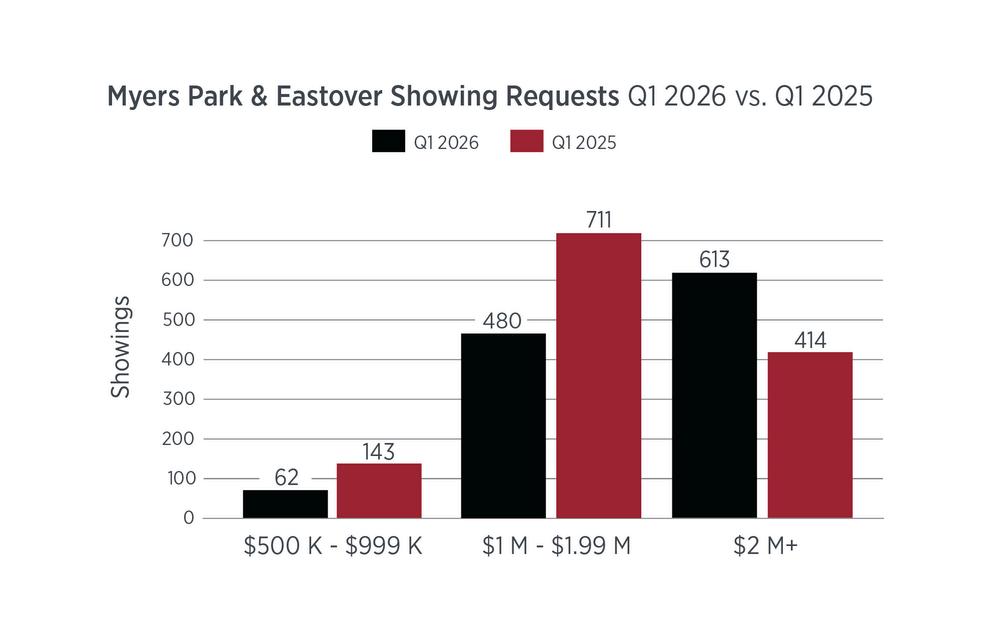
Ultra‑luxury, $2M+, sales improved notably year‑over‑year, supported by steady pending activity. In contrast, $1M–$1.99M sales declined sharply, with slower absorption versus available inventory. This reinforces a widening gap between needs‑based and choice‑based buyers
Highlight: Elite price points remain resilient; mid‑luxury demand has softened.
MYERS PARK & EASTOVER
HOMES SOLD & SHOWINGS
LAKE WYLIE & THE PALISADES
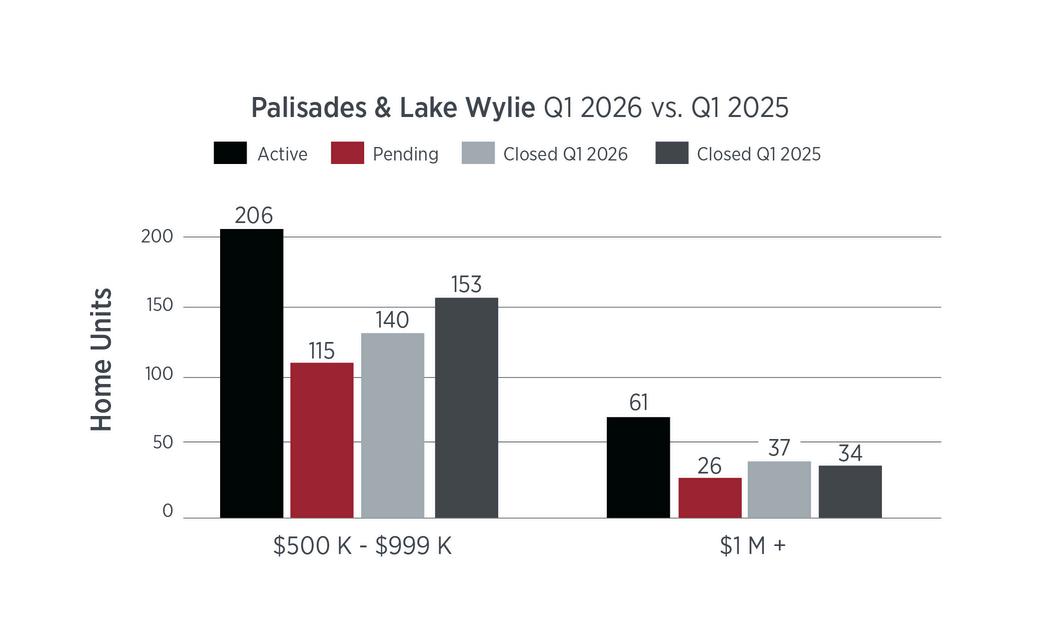
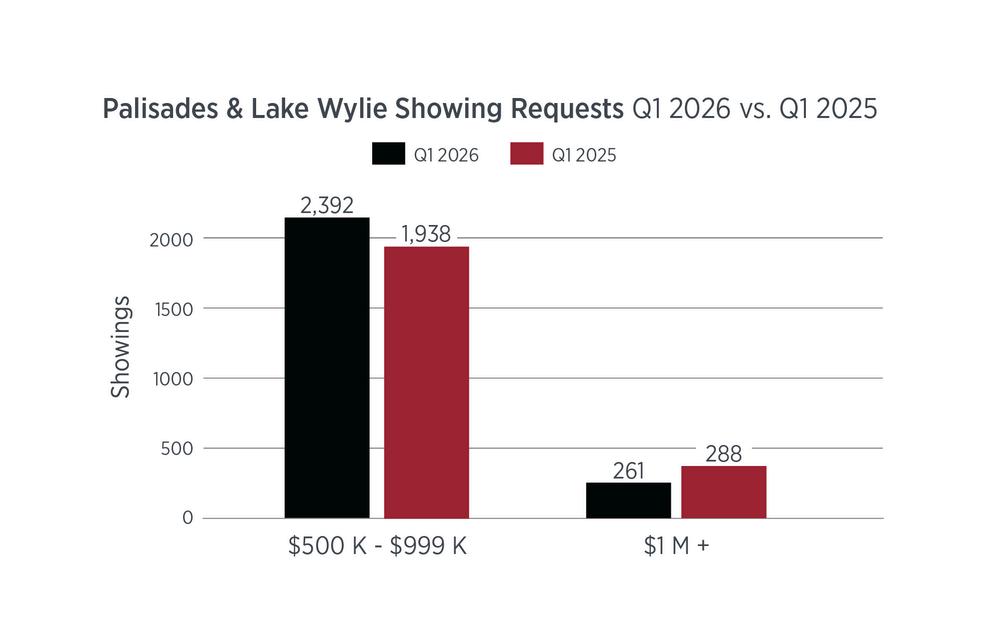
Sales volumes remain relatively stable year‑over‑year, but inventory growth has outpaced new pending contracts. The active‑to‑pending ratio has slipped, pointing to softening absorption even before it shows up clearly in closed sales. Without an improvement in contract velocity, this area risks a softer second quarter close rate
Highlight: Leading indicator market, pending slowdown suggests future sales pressure.
LAKE WYLIE & PALISADES
Q1 HOMES SOLD & SHOWINGS
PROVIDENCE, WEDDINGTON, & WAXHAW
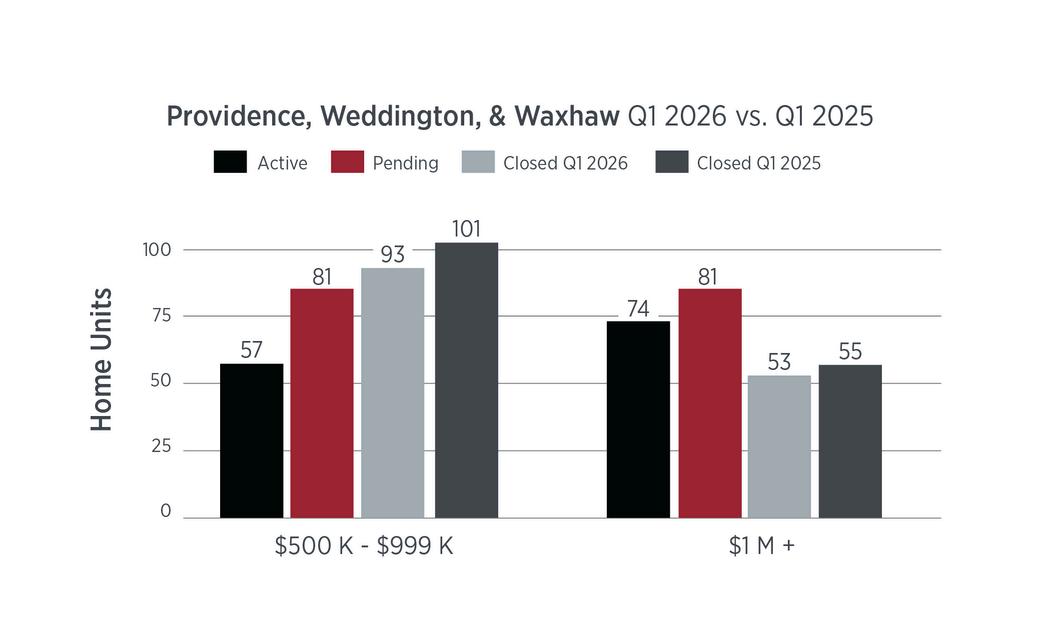
This area posted one of the strongest results, with mid‑price,
$500K–$999K, closings up more than 10% year‑over‑year
Pending contracts exceed active inventory on a 40‑day turn basis, confirming that sales growth is demand‑driven.
Momentum here appears durable heading into this year ’ s second quarter.
Highlight: Best supply‑demand balance in the metro with clear forward momentum.
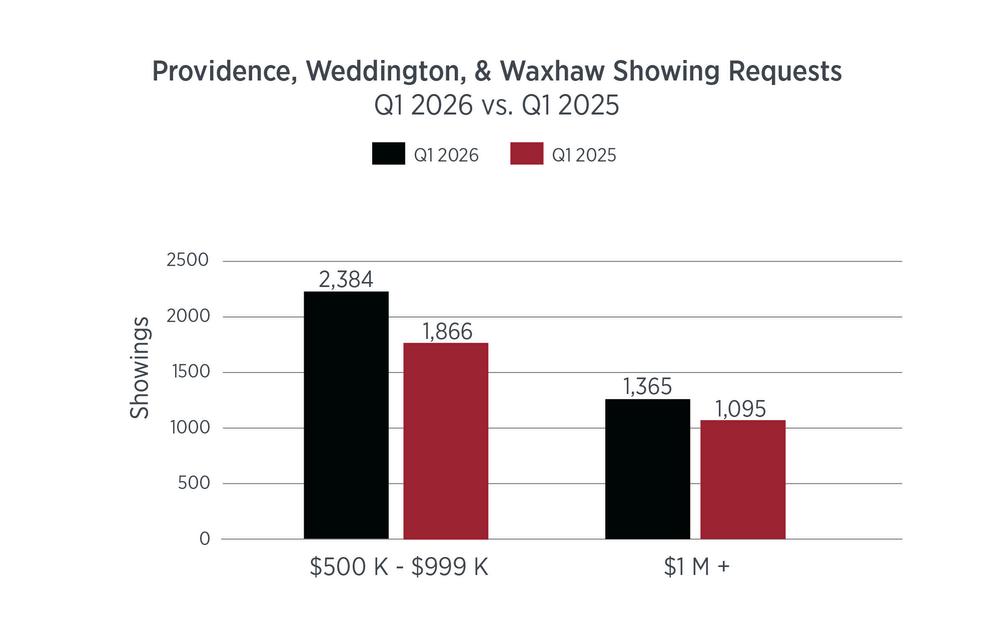
PROVIDENCE,WEDDINGTON, & WAXHAW Q1 HOMES SOLD
&
SHOWINGS
BALLANTYNE & SOUTH CAROLINA
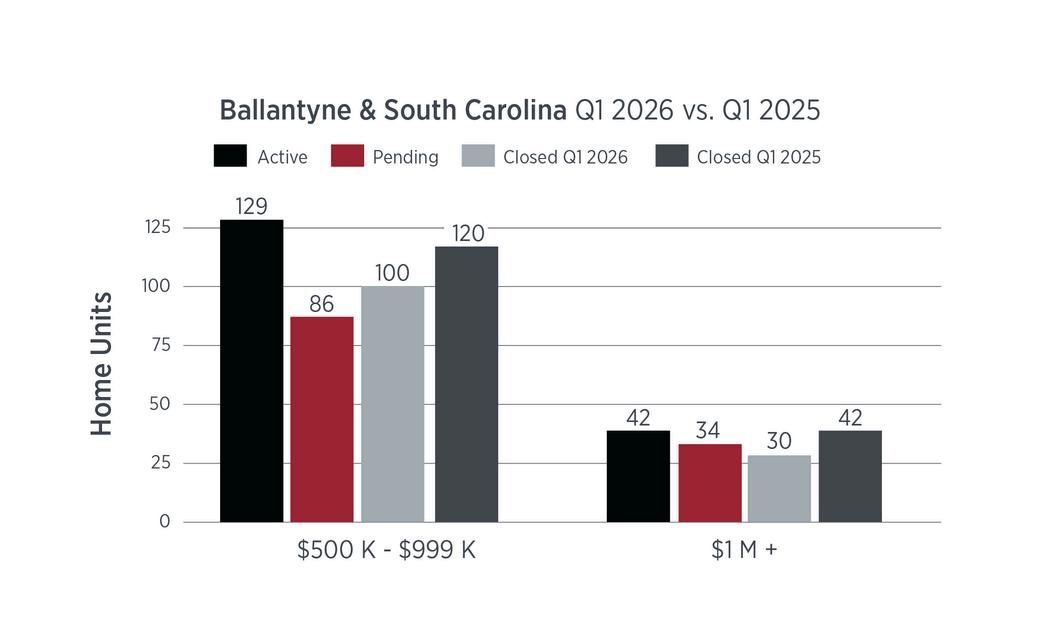
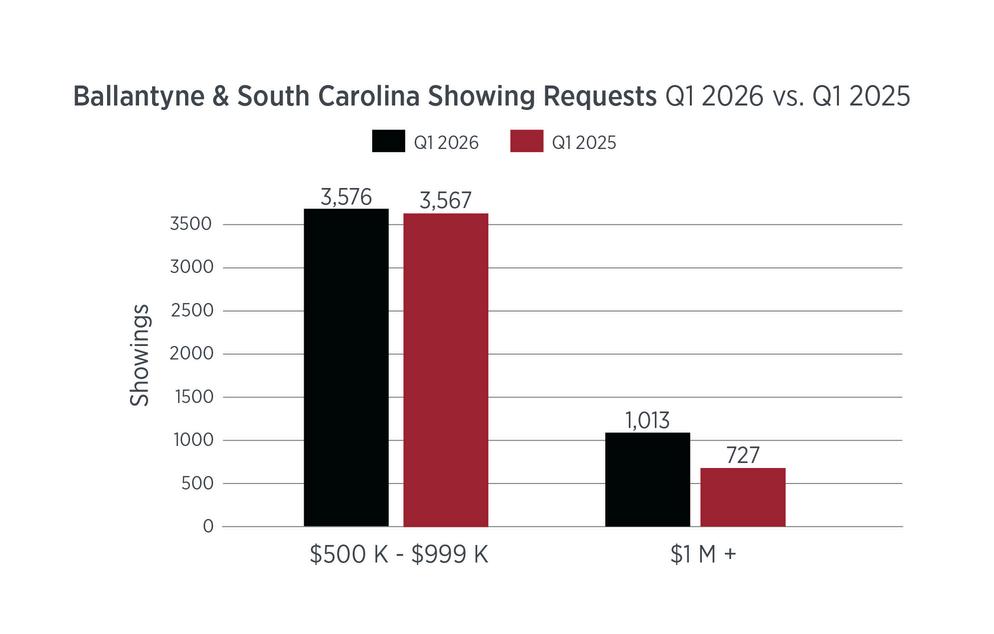
Quarter one ’ s sold activity declined meaningfully in both the $500K–$999K and $1M+ segments, despite healthy showing activity. Pending contracts are not keeping pace with active inventory, particularly at the high end, indicating buyer hesitation rather than lack of interest This disconnect suggests continued pressure on pricing and longer days on market into the early second quarter.
Highlight: Strong buyer interest, but decisiveness, especially above $1M, has weakened
BALLANTYNE & SOUTH CAROLINA Q1 HOMES SOLD & SHOWINGS
CENTER CITY LUXURY CONDOS & TOWNHOMES
Condo sales declined significantly, especially above $1M, and pending contracts remain low relative to active inventory Absorption is weak on a 40‑day turn basis, signaling ongoing challenges tied to rate sensitivity and total cost of ownership. No clear short‑term catalyst for recovery is evident.
Highlight: Structurally weak segment with limited near‑term upside
CENTER CITY CONDOS & TOWNHOMES Q1 HOMES SOLD
g q , segmentation rather than broad‑based weakness Pending contract trends support continued strength in select suburban family markets, notably Providence South, and core luxury neighborhoods above $2M, while mid‑luxury, $1M–$2M, and condo segments face headwinds.
Active to pending ratios suggest overall absorption will remain uneven, with inventory building where buyer confidence is most rate‑sensitive
Interest rates are expected to move modestly sideways to slightly lower over the next 90–120 days, which may stabilize, but not materially accelerate, mid‑market demand. As a result, second quarter closings should track flat to slightly down overall, with positive performance concentrated in markets already showing strong pending velocity Pricing power will remain localized rather than regional