Monthly Highlights
Expert Opinion Interviews
Check out our interviews on our website, featuring new conversations between industry experts and members of the LevinPro editorial team...
Watch here
Healthcare M&A Quarterly
Check out our recently published report covering the deals and trends from the first quarter of 2026....
Read more on LevinPro HC
Table of Contents
Lead Story Page 1
Top Stories .............................................. Page 3
Health System News Page 9
Private Equity News Page 9
Healthcare Real Estate News Page 10
Top Deals Page 12
Stat of the Month Page 13
Monthly Chart Page 14
Top Deals of April 2026
REITs, health systems, private equity and more all made moves
April wasn't an especially active month in the healthcare M&A market, reaching only 135 deals, but there were still notable announcements worth exploring. Here are the top transactions captured in our LevinPro HC database for April 2026.
Orlando Health acquires Regional Medical Center
Orlando Health, one of the largest health systems of the southeastern United States, announced it was acquiring Regional Medical Center (RMC) in Anniston, Alabama. RMC is a short-term acute care hospital and one of the region's largest employers, supported by more than 1,800 team members, 300 volunteers and more than 200 physicians across a broad range of specialties.
Under the agreement, RMC will become part of Orlando Health’s Alabama Region. All current employees will transition to Orlando Health on day one, with their existing titles and pay. Orlando Health has a
Continued on page 2
McGuireWoods' PE Conference
Discipline, AI and selectivity reshape healthcare investing
McGuireWoods’ 2026 Healthcare Private Equity and Finance Conference brought together private equity (PE) investors, lenders, healthcare executives, investment bankers and legal advisors to examine strategies for deploying capital and creating long-term value in a market shaped by selectivity and uncertainty. Held April 29-30, 2026, at The Ritz-Carlton Chicago, the event served as a key forum for examining the evolving investment landscape in 2026.
Panels throughout the conference highlighted the growing discipline required in today’s healthcare deal environment. Economic uncertainty persists alongside strong, long-term demand for quality healthcare services. Sessions covered a wide range of topics, including PE strategy in a disciplined market, AI-enabled care delivery models, private credit trends, healthcare banking dynamics, digital health ROI, life sciences funding pathways....Read more on LevinPro HC
growing presence in Alabama following its 2024 acquisition of Brookwood Baptist Health in Birmingham.
Juniper Advisory served as a transaction advisor to RMC, supporting strategic evaluation, partnership outreach and transaction execution.
For more details on the deal between Orlando Health and RMC, you can view those here
A new investor for TEAM Services Group
Alpine Investors has decided to sell TEAM Services Group to General Atlantic, a private equity firm with more than $120 billion in assets. TEAM Services Group provides household employment and home care solutions in all 50 states. Its subsidiary, TEAM Public Choices, provides home care for participants in government-sponsored disability and aging programs, with an emphasis on self-directed care. The deal is valued at approximately $3 billion, including debt.
Under Alpine Investors, TEAM grew significantly, reporting more than 10 add-on transactions in the past few years.
The sale of TEAM is the largest home health transaction of the year so far, followed by KinderHook Industries' $1.1 billion acquisition of Enhabit, Inc. in February.
A major REIT in the healthcare M&A space gets taken private
Blue Owl Real Estate Capital LLC, an affiliate of Blue Owl Capital, announced a $2.4 billion deal to acquire Sila Realty Trust, Inc., one of the most prolific healthcare REITs in the industry. According to data captured in our LevinPro HC platform, Sila Realty has announced 20 deals in the healthcare M&A market since 2020, buying 16 properties for a total value of $640 million.
The transaction will help expand Blue Owl Capital's real estate portfolio, which already has roughly 6,000 properties. Once the deal is complete, Sila Realty will stop trading on the New York Stock Exchange and become a private company owned by Blue Owl.
Missouri's largest health insurer acquires PAbased Highmark, Inc.
ISSN#: 2375-7612
Published monthly by:
Irving Levin Associates LLC
P.O. Box 1117, New Canaan, CT 06840
Phone: 800-248-1668 Fax: 203-846-8300
info@levinassociates.com
www.levinassociates.com
Editor: Dylan Sammut
Associate Editor: Avery Swett
Analyst: Kate Humphrey
Advertising: Cristina Blazek-Hearty
The full, annual subscription includes 51 weekly e-newsletters, 12 monthly issues, four quarterly reports
©2026 Irving Levin Associates, LLC All rights reserved. Reproduction or quotation in whole or part without permission is forbidden.
This publication is not a complete analysis of every material fact regarding any company, industry or security. Opinions expressed are subject to change without notice. Statements of fact have been obtained from sources considered reliable but no representation is made as to their completeness or accuracy.
Blue Cross & Blue Shield of Kansas City announced it purchased Highmark, Inc., which serves 4.9 million health plan members in Pennsylvania, West Virginia and Delaware. Nationally, it employs more than 20,000 people and provides health, dental, vision and supplemental health products and services to 34.4 million customers.
Founded in 1938, Blue Cross & Blue Shield of Kansas City is the largest not-for-profit health insurer in Missouri and the only not-for-profit commercial health insurer in Kansas City. Blue Cross provides coverage to more than one million residents in the greater Kansas City area.
Cain Brothers, a division of KeyBanc Capital Markets, acted as exclusive financial advisor to Blue Cross. Terms were not disclosed.
Accelerate your advantage.
Deliver insights that drive smarter healthcare real estate decisions.
Sun Pharmaceutical Industries buys Organon
In one of the largest healthcare M&A deals of the year so far, Sun Pharmaceutical Industries Ltd. acquired Organon & Co. for $11.75 billion, including debt.
Founded in 2020, Organon is a pharmaceutical company specializing in reproductive medicine, contraception, psychiatry, hormone replacement therapy and anesthesia. The company reported full-year 2025 revenue of $6.2 billion. Sun Pharmaceutical Industries, a specialty generic pharmaceutical company, manufactures and markets pharmaceutical formulations and active pharmaceutical ingredients in India and internationally.
Sun Pharmaceutical’s generic sales have been declining in the United States, so it acquired Organon to push into higher-margin specialty medicines with a sharper focus on areas such as dermatology, oncology and obesity. The acquisition will double Sun's revenue and EBITDA, adding $6.2 billion in sales with 30% EBITDA margins.
This acquisition is the second in about a year for Sun Pharmaceutical; in March 2025, it acquired Checkpoint Therapeutics, Inc., a commercial-stage company focused on developing novel treatments for patients with solid-tumor cancers, for $355 million.
Top Stories of April 2026
CEO Scotte Hudsmith’s View on Specialized Dental Partners's Acquisition Strategy
Specialized Dental Partners (SDP) is one of the most active buyers in the dental practice market, announcing multiple transactions per year. A portfolio company of Quad-C Management, SDP is a leading specialty dental service organization that provides comprehensive support services to endodontic specialists across the United States.
According to data captured in the LevinPro HC database, the dental industry is experiencing a slight
increase in deal volume. In the first quarter of 2026, 62 dental transactions were publicly announced, a small increase from the 59 reported in both Q4:25 and Q1:25. However, there was a 6% drop between full year 2024 (267 deals) and full year 2025 (251 deals).
Since SDP changed its name from US Endo Partners in late 2023 to widen its scope beyond endodontics, SDP has expanded by more than 50 practices and more than 80 physicians.
In 2026, the company has already announced the acquisition of Pittsburgh Endodontics, a two-physician practice in Monroeville, Pennsylvania, as well as Post Falls Periodontics & Implant Dentistry, which is run by Dr. Joseph K. McCombs in Post Falls, Idaho.
The LevinPro HC team sat down with Scotte Hudsmith, CEO of SDP, to discuss the company’s acquisition strategy and current market conditions.
While SDP’s focus on endodontics, periodontics and oral surgery represents only a fraction of the broader dental market, its specialization allows for a more disciplined strategy. This means its approach to partnerships is significantly more selective than general dentistry, as it builds its base around endodontics.
A challenge that faces many concentrated dental groups is providing care in rural communities, which often lack the infrastructure to deliver even general dental care. Hudsmith noted that, as SDP has a footprint in most markets across the country, geography is not often a factor in their acquisition strategy.
“If we’re entering a new market, our anchor is typically an endodontic practice, and then we add perio or oral surgery over time,” said Hudsmith. He even highlighted SDP’s significant presence in the rural communities of West Texas, Montana and New Mexico, citing these locations as evidence of SDP’s ability to navigate challenging markets.
When discussing what has made SDP such a successful investor, Hudsmith credited the company’s focus on longevity. According to Hudsmith, SDP does not do
transactions with physicians who are looking to retire immediately, noting that the average age of physicians SDP partners with is in the mid-40s. Not only does this help maintain stability and longevity for the practice, but it is also less likely to disrupt the patients’ experience. To Hudsmith, SDP is a people company first and foremost and will always do what it can to improve the patient journey.
“We actually won’t do a transaction with someone if they’re not in it for at least a five-year window,” commented Hudsmith. “If all they’re interested in is money and getting out, we’re not the right fit.” He even added that SDP is known for walking away from a potential partnership if they felt the physician wasn’t interested in a long-term partnership.
To further illustrate SDP’s emphasis on the patient journey, Hudsmith highlighted AI as a recent tool that improves the patient (and the physician) experience because it provides a second opinion. He even noted that SDP is currently piloting several clinical and administrative AI tools.
“AI can provide the data and the physician can review it,” said Hudsmith. “So, it frees up a lot of time from that standpoint on the clinical side.”
Burnout among physicians is largely driven by the dual pressure of heavy administrative burdens and high patient demand. Hudsmith believes that by integrating AI tools, doctors can streamline these tasks to provide faster, more comprehensive patient care.
In addition to discussing SDP’s acquisition strategy, Hudsmith also touched on current trends affecting dealmaking and the broader market. When speaking about the strength and stability of the dental industry, Hudsmith attributed it to past investors taking advantage of low-interest rates while not fully having a plan for the future.
“When interest rates were low, some thought that it was really easy to buy a bunch of assets and stick them together. I call them EBITDA stackers,” said Hudsmith, as to why previous years’ deal volume was higher. “They
didn’t build a business or infrastructure for long-term scale or stability. As a result, a lot of those practices are struggling financially or have been taken over by lenders.”
The rise in quarter-over-quarter deal volume may signal a return to a more normal market. Hudsmith anticipates that as more practices face operational struggles, an influx of motivated sellers will continue to drive volume upward. However, he cautioned that while activity is increasing, valuations and multiples remain suppressed and are unlikely to return to their previous peaks.
“Because we know there’s multiple compression on the top end, we have been lowering our offers in the process,” he said.
Beyond lower valuations impacting the market, Hudsmith also addressed a broader context that may lead to buyer hesitation.
“There’s going to be some noise in the market because of oil prices and economic challenges,” he noted. “Hopefully that ends soon and we can get back to normal.”
But, Hudsmith left the conversation with a feeling of quiet optimism. He believes that COVID-19 forced those in the dental industry to learn how to operate successfully on thin margins. Because of this, he believes that current investors are stronger and better equipped to survive economic ebbs and flows. With all the tailwinds in the market, anticipate a strong year for dental deal volume.
Health System M&A 2026 Round-Up
In 2026, health systems across the United States are navigating challenging market conditions, turning to M&A to expand their networks. Based on data captured in our LevinPro HC platform, here are the top health system trends and deals of the year, so far.
Health System M&A has surged this year
U.S.-based health systems have announced 48 transac-
tions through the final week of April, a 30% increase in volume compared with the same time last year. There have been 10 deals in 2026 targeting hospitals, with only one health system merger.
In January, Englewood Health agreed to merge with RWJBarnabas Health, creating one of the largest health systems in New Jersey. Englewood Health is anchored by a hospital and a statewide physician network and generated nearly $1.17 billion in net patient revenue in 2024, according to recent financial documents.
A modest amount of activity from health systems has focused on outpatient medical buildings (six deals) and ancillary services (seven deals). Health systems have announced 21 deals for physician groups, especially in high-value specialties such as orthopedics (six deals), internal medicine (four) and gastroenterology (four).
Notable deals this year include Medical University of South Carolina’s purchase of Palmetto Primary Care Physicians for $110 million, and Northwell Health’s acquisition of Garden OB/GYN, a fertility and women's health clinic with 10 locations in New York.
Hospital deals remain small
In the first four months of 2026, Hospital transactions have been smaller and strategic. The average revenue of acquired hospitals is down year over year: $243.5 million in 2026 versus $298.1 million in 2025, according to recorded transactions in our LevinPro HC database. Average bed counts are under 150, and nearly every deal is for a single, unaffiliated hospital. With only one health system merger this year as well, the results indicate that organizations are much more selective in their acquisition strategy, not just chasing scale for its own sake.
Universal Health Services’ acquisition of Talkspace
The largest deal from a health system was Universal Health Services’ (UHS) $835 million acquisition of Talkspace, one of the most widely known telebehavioral healthcare companies in the United States. The deal is one of the largest investments by a health system in telehealth and will help UHS expand its reach in outpatient and talk therapy.
Talkspace has a network of about 6,000 professionals offering virtual therapy, psychiatry and medication management. Patients can connect with their clinicians via video, audio, chat or asynchronous text messaging. Talkspace’s platform serves both employers and health plans. According to its 2025 annual report, it generated $228.9 million in revenue.
UHS already has a significant presence in inpatient behavioral health, with nearly 350 facilities nationwide, but Talkspace will help supplement that revenue stream and bring more patients into its ecosystem.
While other health systems are focusing on building their outpatient networks through brick-and-mortar locations, UHS is taking a different approach by leaning into telehealth and digital health instead.
Florida and Texas remain geographic hot spots, but Ohio has emerged as a top destination
In the healthcare M&A industry, Florida and Texas (along with California) are typically popular states with investors due to their demographics, favorable reimbursement structures and specific regulatory shifts. That remains true in 2026 for health systems, with four deals in Florida and six in Texas. There has also been plenty of activity in Ohio, with organizations looking to expand their market share in the state.
TriHealth and The Christ Hospital, two Ohio-based health systems, have both been acquiring outpatient medical buildings in the state. Organizations such as Dayton Children's and Cincinnati Children's Hospital each added a new pediatric physician group to their networks.
Ohio is also experiencing a population surge, prompting healthcare organizations to expand to meet the increased demand. And unlike states such as Florida, which are dominated by systems like HCA Healthcare and Orlando Health, Ohio has far less competition, giving organizations room to expand.
UMass Memorial Adds Hopedale Cardiology to Its Network
UMass Chan Medical School, a public medical school
affiliated with UMass Memorial Health, announced that it had added Hopedale Cardiology to its network.
Hopedale Cardiology is based in Upton, Massachusetts, and delivers a range of cardiology services, including cardiac catheterization, echo and stress testing, transesophageal echocardiography and pacemaker and implantable cardioverter defibrillator procedures at Milford Regional Medical Center. The practice is led by Dr. Scott Brownstein and six other physicians, according to the press release.
UMass Memorial Health and Milford Regional Medical Center entered into a corporate affiliation on October 1, 2024. Under this new deal, Hopedale Cardiology joins UMass Memorial Medical Group, expanding the health system’s cardiovascular services across the region.
There have been four acquisitions of physician groups by academic medical centers this year, according to data captured in our LevinPro HC platform, including UPMC's purchase of Pennsylvania Gastroenterology and UAB Health System's purchase of Southview Medical Group
The largest was the Medical University of South Carolina's $110 million acquisition of Palmetto Primary Care Physicians, an independent multi-specialty group practice with 90 physicians based in North Charleston.
Navigating Complexity: AHLA 2026 Health Care Transactions Conference Recap
The American Health Law Association’s 2026 Health Care Transactions Conference brought together leading healthcare attorneys, private equity investors and M&A advisors to explore the latest legal, regulatory and strategic challenges shaping healthcare M&A.
Held April 13-15, 2026 at the Grand Hyatt Nashville, the event served as a key forum for examining the evolving dealmaking landscape in 2026.
Panels throughout the conference underscored the growing complexity of healthcare transactions as regulatory scrutiny intensifies and policy uncertainty persists. Antitrust and regulatory panels featured direct insights from FTC representatives, state attorneys
general and CMS officials on enforcement priorities and compliance strategies. Fraud and abuse sessions examined diligence red flags and risk mitigation under the Stark Law, Anti-Kickback Statute and False Claims Act.
Other notable discussions addressed physician practice consolidation trends, sophisticated joint venture structuring and emerging issues around AI and digital health transactions.
Sessions on workforce and labor issues in deals, postclosing integration strategies, AI contracting and physician compensation further equipped participants with practical tools for navigating operational and regulatory hurdles in an increasingly selective market.
Networking was also a highlight of the conference. Receptions and informal conversations gave attorneys, private equity investors M&A advisors and compliance professionals the chance to connect, compare notes and discuss practical ways to address the regulatory and compliance issues raised during the panels.
The LevinPro HC team attended the conference and engaged with a wide range of industry professionals. A consistent takeaway was that while healthcare M&A activity continues, it is increasingly defined by complexity, selectivity and a more disciplined approach to risk. Market participants are adapting in real time, balancing strong long-term demand for healthcare services with a more challenging transactional environment.
Take a look at additional coverage from the conference, including deeper dives into key takeaways and perspectives from industry leaders, on the LevinPro HC platform.
Astorg Acquires Thermo Fisher's Microbiology Business for $1.075 Billion
Thermo Fisher Scientific announced that it sold its microbiology business to Astorg, a private equity group.
Astorg is buying the business for consideration of approximately $1.075 billion, consisting of cash and a $50 million seller note.
The microbiology business provides antimicrobial susceptibility testing and culture media solutions for clini-
cal, pharmaceutical and food safety testing. The business generated $645 million in revenue in 2025 and is part of Thermo Fisher's Specialty Diagnostics segment. Astorg is a global private equity firm with €15 billion ($15.8 billion USD) of assets under management.
For Thermo Fisher, Cravath, Swaine & Moore LLP is serving as principal deal counsel, Axinn, Veltrop & Harkrider LLP as regulatory counsel, Hogan Lovells as ex-U.S. counsel and Perella Weinberg Partners and Wells Fargo as financial advisors. For Astorg, Evercore and Moelis are serving as financial advisors and Latham & Watkins as legal counsel.
Heartland Dental Expands in Florida and Texas
Heartland Dental announced the addition of two practices to its network, expanding its presence in both Florida and Texas.
Prime Dentistry is a dental practice with one location in Coconut Creek, Florida. The practice provides the full range of dental care, including cosmetic and restorative dentistry. According to its website, it is run by Dr. Hugues Jean and a team of five employees.
Soto Dental Partners is a dental practice with two locations in El Paso, Texas. The practice provides the full scope of dental services including dentures, veneers, crowns and implants. According to its website, the practice is run by a team of two physicians: Dr. Obed Soto and Dr. Abigail Soto.
Heartland Dental is a dental support organization providing non-clinical, administrative support services with more than 3,000 doctors in more than 1,800 locations across 39 states. The company is majority-owned by KKR, a global investment firm.
These transactions mark Heartland Dental’s sixth and seventh acquisitions of 2026. The financial terms for neither of the deals were disclosed. Throughout 2025, Heartland Dental announced 11 transactions.
RadNet and Saint Alphonsus Health System Announce Joint Venture Through Acquisition
On April 30, RadNet and Saint Alphonsus Health System announced the formation of a joint venture through the acquisition of Intermountain Medical Imaging, LLC
Intermountain Medical Imaging is a comprehensive outpatient radiology imaging center with five locations in the Boise, Idaho MSA.
Saint Alphonsus Health System is a four-hospital regional, faith-based Catholic ministry with more than 2,000 medical staff professionals. It serves more than 700,000 people in Idaho and Oregon, with outreach services to Utah, Montana and Nevada. Saint Alphonsus consists of primary and specialty care providers at five acute care hospitals and more than 170 clinic locations, all of which are members of the Saint Alphonsus Health Alliance, a clinically integrated network of employed and independent providers. It is part of Trinity Health.
RadNet is a provider of freestanding, fixed-site diagnostic imaging services and related information technology solutions in the United States. RadNet has a network of 407 owned and/or operated outpatient imaging centers. It was founded in 1985 and has more than 11,000 employees.
The new joint venture is projected to generate approximately $30 million in annual revenue for RadNet. Terms of the deal were not disclosed.
Playground Pediatrics Expands in Four States
On April 28, Playground Pediatrics announced that it expanded its presence with the acquisition of four practices: Cobb Pediatrics, Purcell Pediatrics, Kids Kare Pediatrics, Smyrna Pediatrics and PAK Pediatrics.
Cobb Pediatrics is a pediatric practice with one location in Marietta, Georgia. It provides comprehensive pediatric primary care through a team of six physicians and three advanced practice providers, offering preventive visits, immunizations and ongoing support for patients.
Serving families in Laurinburg and Rockingham, North Carolina, Purcell Pediatrics provides comprehensive pediatric primary care. It has a team of five physicians and four advanced practice providers, offering walk-in sick care and extended hours to improve access to its communities. Purcell Pediatrics joined Playground in March. This deal builds on Playground’s existing presence in North Carolina.
Kids Kare Pediatrics is a two-location pediatric practice in Tennessee. It provides a full spectrum of pediatric primary care. According to its website, there are two doctors and five advanced practice providers on staff. Kids Kare Pediatrics joined Playground in December 2025.
Smyrna Pediatrics is a pediatric practice in Smyrna, Tennessee. It has two physicians and one advanced practice provider on staff. Smyrna Pediatrics joined Playground's network in March, expanding its position in Tennessee.
PAK Pediatrics is based in four locations in Pennsylvania. The practice is run by a team of five doctors and two nurse practitioners. The practice joined Playground in October of 2025.
A portfolio company of Norwest Venture Partners, Playground Pediatrics provides pediatric practices with financial and operational support. It has eight practices under its umbrella, spanning Tennessee, Pennsylvania, North Carolina and Georgia.
Lilly Acquires Kelonia Therapeutics for $3.25 Billion Upfront
Lilly announced that it acquired Kelonia Therapeutics for an upfront price of $3.25 billion.
For Lilly, Kirkland & Ellis LLP is acting as legal counsel. For Kelonia, Jefferies LLC is acting as financial advisor, and Goodwin Procter LLP is acting as legal counsel.
Under the terms of the agreement, Kelonia shareholders will receive up to $7 billion in cash, inclusive of an upfront payment of $3.25 billion, and subsequent payments upon achievement of certain clinical, regulatory and commercial milestones.
Kelonia is a clinical-stage biotechnology company pioneering a new wave of genetic medicines using its in vivo gene placement system. Kelonia's in vivo gene delivery technology uses an advanced lentiviral vector particle harboring envelope modification to improve in vivo gene transfer efficiency and tropism molecules to facilitate tissue-specific delivery.
Kelonia's lead program, KLN-1010, is an investigational, one-time intravenous gene therapy that generates antiB-cell maturation antigen (BCMA) CAR-T cells, targeting the BCMA protein expressed on the surface of multiple myeloma cells.
Lilly (formerly known as Eli Lilly and Company) is an American pharmaceutical company headquartered in Indianapolis, Indiana, with offices in 18 countries. Lilly discovers, develops, manufactures and sells pharmaceutical products worldwide. Its products are sold in 125 countries. According to its FY 2025 report, the company generated revenue of $65.2 billion and EBITDA of about $27.7 billion.
Health System News & Activity
April was a slow month for health systems in the healthcare M&A, with only 11 transactions announced, on par with the 10 announcements in March. Hospital deals were light in April, with only three completed transactions, and just two in the United States. Orlando Health acquired Regional Medical Center in Alabama, further expanding its presence in that market, and Baptist Health in Arkansas added Magnolia Regional Medical Center, a short-term acute care hospital with 29 beds.
Most of the announcements from health systems were focused on outpatient care or ancillary services. After years of completing only divestments, Community Health Systems, Inc. decided to expand its network, acquiring an undisclosed Anchorage, Alaska outpatient surgery center. No specific terms were disclose, but it is the 37th surgery center in Community Health System's network.
In Oklahoma, Saint Francis Health System purchased nine MedWise urgent care facilities from QuikTrip in the Tulsa metro area. A sale price was not disclosed, but QuikTrip said it will direct the proceeds back to MedWise employees through measures such as reten-
tion bonuses. The deal does not include QuikMed, QuikTrip’s network of internal primary care facilities for company employees, which remains operational.
Over in Florida, HCA Healthcare acquired Avecina Medical, a urgent care center and operator based in Saint Johns. HCA Healthcare has dedicated most of its M&A resources to expanding in the outpatient care market, buying urgent care centers, medical outpatient buildings and other sites of care, especially in Florida. In 2022, the system announced a $594 million deal for MD Now Urgent Care, a network of approximately 60 urgent care sites. In 2023, it bought 41 FastMed urgent care centers for an undisclosed sum.
There were also three announcements for physician groups in April. UMass Chan Medical School, an affiliated of UMass Memorial Health, acquired Hopedale Cardiology, a seven-physician practice, and Delta Health System bought Alliance Cancer Center in Greenville, Mississippi.
In New York, NYU Langone Health added Pediatric Associates of NYC, a 10-physician pediatric group practice with three offices in New York. Its physicians are affiliated with New York University Medical Center and Beth Israel Medical Center. No terms were disclosed in these transactions.
Private Equity News & Activity
Private equity (PE) activity in healthcare M&A held relatively steady in April 2026, with PE buyers and/or their portfolio companies involved in 46 of the 136 total healthcare transactions, representing 34% of overall volume. Activity in April was on par with March, which had 47 PE deal announcements.
Like most months, Physician Medical Group (PMG) remained the most active sector for PE buyers in April. There was 21 PE transactions announced during the month out of 33 total PMG deals.
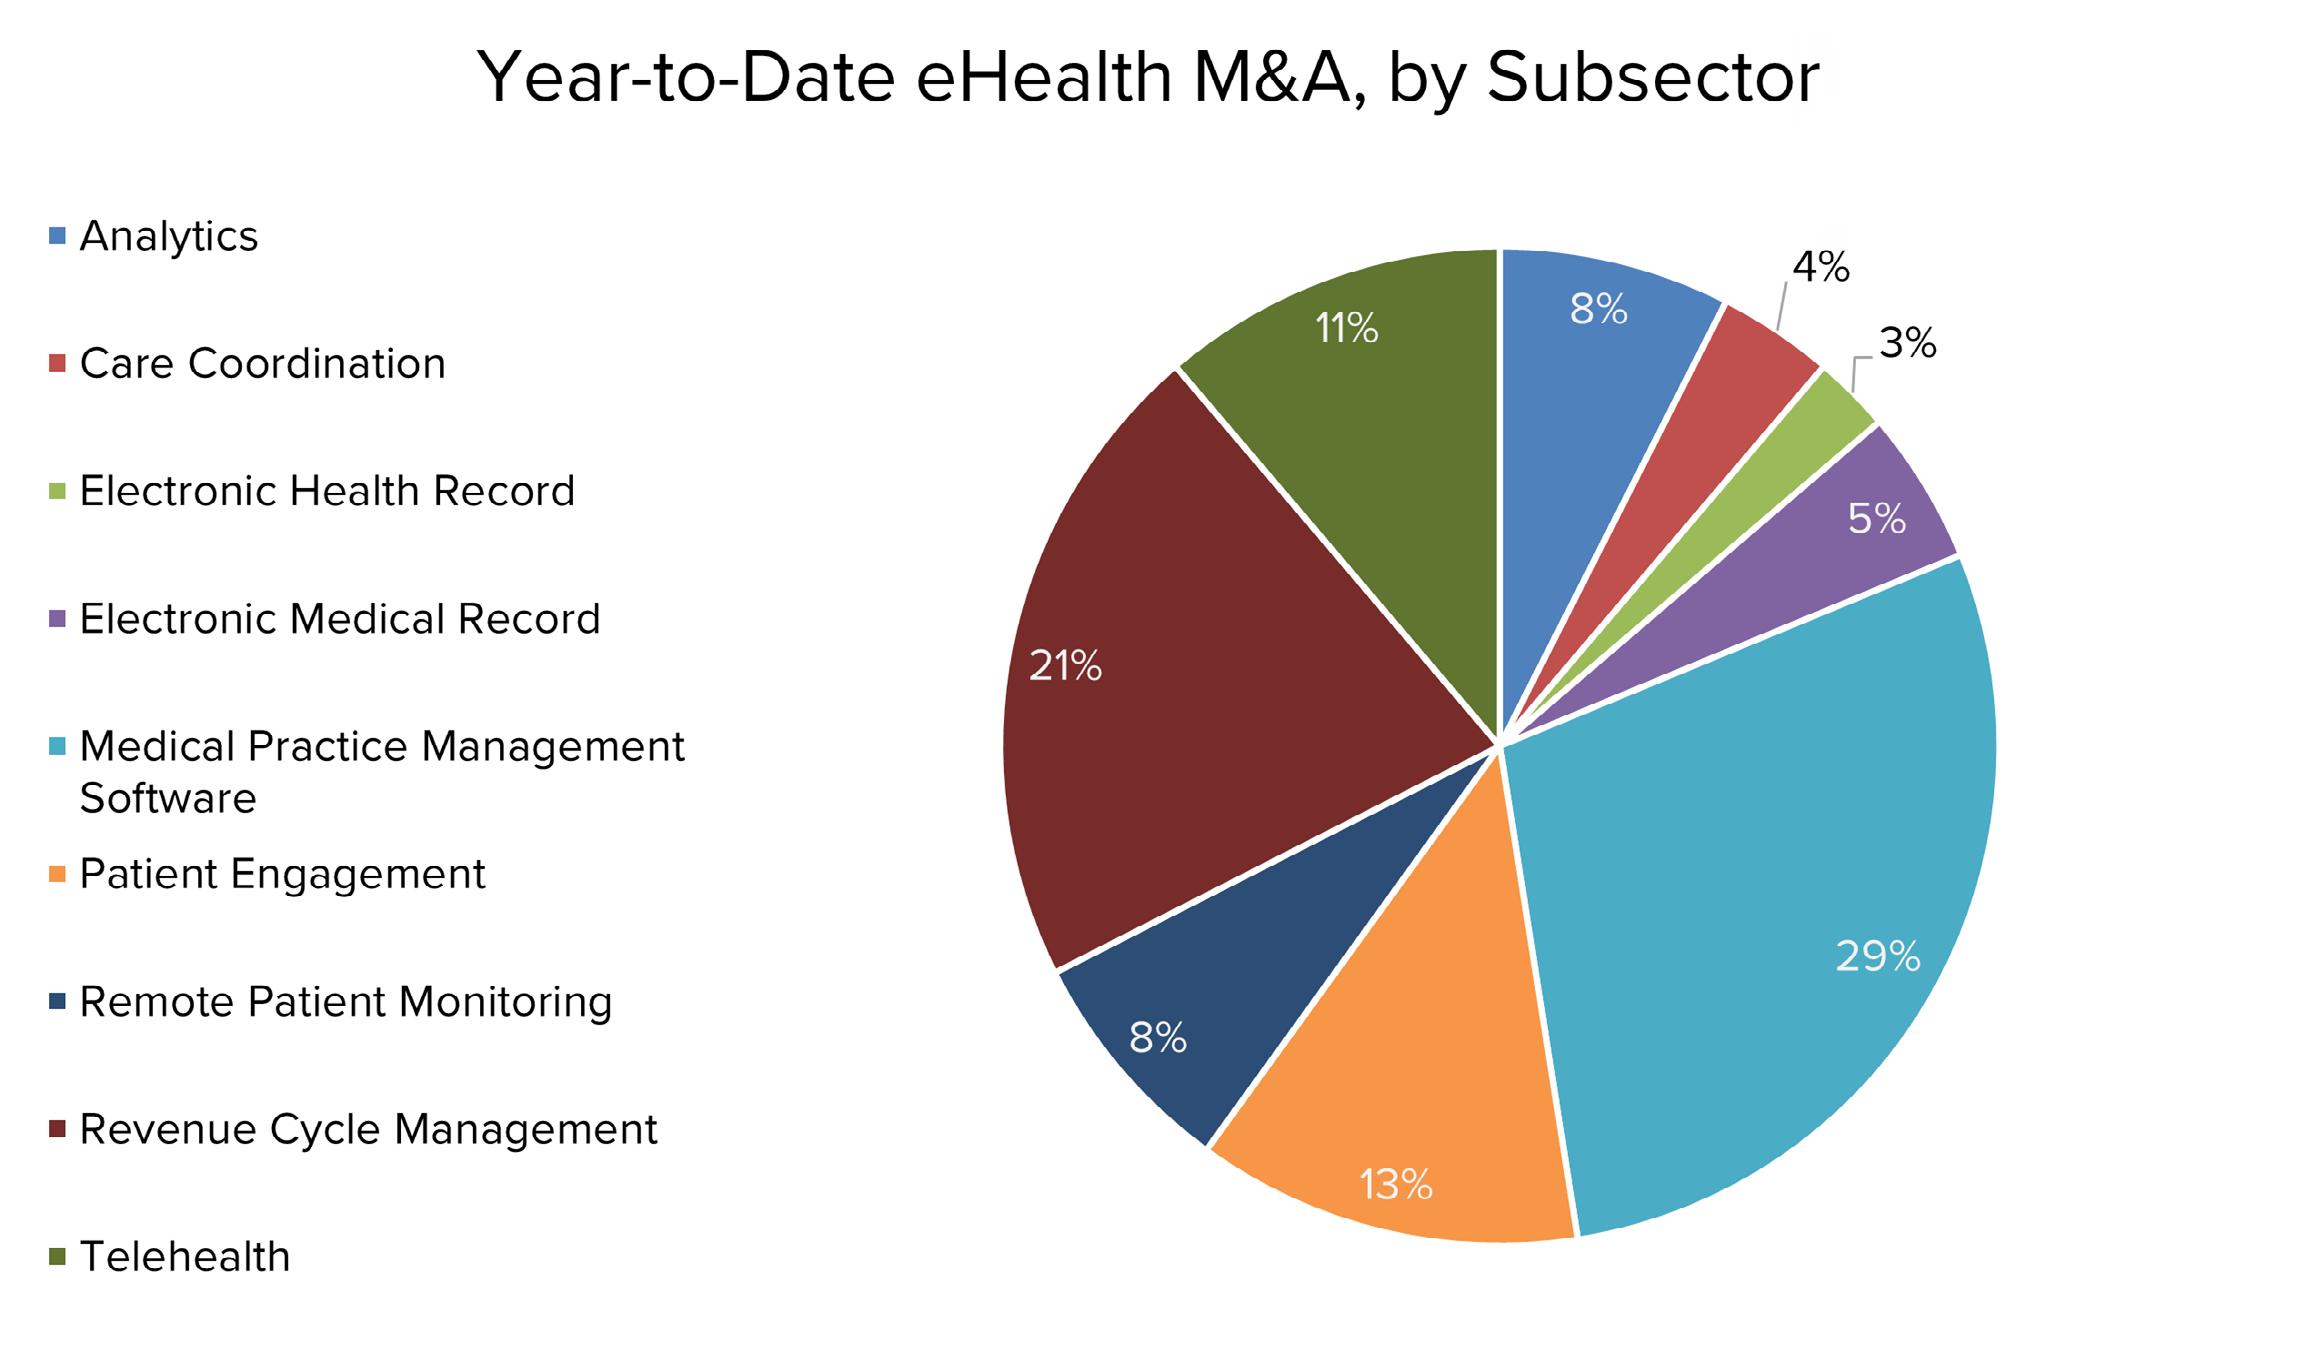
eHealth ranked second with seven PE-backed deals out of 16 total. Key transactions in the space included ModMed’s acquisition of Bonsai Health and TPG’s acquisition of Optum UK.
Home Health & Hospice came in third with four PEbacked deals. The sector featured the month’s largest
transaction by disclosed purchase price: General Atlantic’s acquisition of TEAM Services Group for $3 billion. General Atlantic initially reached an agreement earlier in 2026 to purchase TEAM Services from Alpine Investors, though the negotiations remained undisclosed until after closing in April.
Notably, the month also saw two other large PE transactions exceeding $1 billion. American Industrial Partners acquired Avanos Medical, Inc. for more than $1.27 billion, and Astorg acquired Thermo Fisher’s microbiology business for nearly $1.08 billion. Disclosed purchase prices are relatively uncommon in healthcare PE deals because most buyers and sellers prefer to keep valuation details private.
Overall, April reflected PE’s measured but active approach in healthcare M&A. The month stood out for its cluster of three billion-dollar-plus transactions, showing buyers were willing to commit substantial capital on the right opportunities. This combination of disciplined platform work and larger strategic moves suggests growing confidence heading into the rest of the year.
Healthcare Real Estate News & Activity
There were 12 Medical Outpatient Building (MOB) transactions captured in our LevinPro HC database for April, marking a notable decrease from the 20 reported in March 2026 and the 19 announced in April 2025. Since the start of 2026, there have been a total of 81 MOBs deals reported. The continuing decline in MOB M&A deal volume throughout the year signals a waning of investor confidence in the space.
Disclosed spending totaled $57.7 million across three transactions, a significant decrease from the $491.6 million reported across eight transactions in March. It is also a notable decrease from the $155.47 million reported across seven deals in April 2025.
The largest purchase price was Stonemont Financial Group’s acquisition of Northside East Cobb Medical Center for $32.5 million. The facility is a 103,184-squarefoot property in Marietta, Georgia and is 100% occupied, with tenants including Northside Hospital,
the main anchor, as well as Northside’s Imaging, Orthopedics & Sports Medicine and other primary care and urgent care providers.
The other two deals with disclosed terms were Compass Capital Investments’ $18.2 million acquisition of a 71,971-square-foot property in San Diego, California and Maple Street Management’s $7 million acquisition of a Tucker, Georgia property comprising 18,972 square feet.
Throughout the month, total acquired square footage surpassed 1.45 million square feet across 22 facilities. There were four transactions in which the square footage exceeded 100,000 square feet.
The deal with the most square footage was Bain Capital Real Estate and Evergreen Medical Properties’ joint purchase of a six-building portfolio in the Atlanta, Georgia MSA, totalling more than 665,000 square feet. The MOB is also occupied by Northside Hospital, but it does not appear that the transactions are related. Additionally, this was the only healthcare real estate transaction of the month to be completed by a private equity group.
No buyers announced multiple transactions, which is uncommon and points to heightened investor caution. But acquirers that have been on the active side throughout the year like Montecito Medical Real Estate and Remedy Medical Properties, announced only one deal in April, each.
Real estate investment firms led the MOB buyers with eight announced transactions. At 80% of the activity, this marks a nominal increase from March 2026 when they accounted for 50% of the buyers. It is also a drop from the 12 announced in April 2025. The other buyers were either not disclosed or private investors.
CBRE reported that it completed four transactions in April, making it the most active advisor. Brown Gibbons Lang & Company, Cushman & Wakefield, Matthews Real Estate Investment Services and Realty Trust Group each announced one deal.