Hospital M&A Mid-Year Report
Experts from Kaufman Hall give their take on the market
In the first six months of 2026 (H1 2026), Hospital M&A activity was strong, driven by aggressive, proactive growth strategies by health systems and other investors in the market. In this article, we’re going to take a deep dive into the Hospital and health system M&A industries, breaking down the trends and deals that have defined the year so far.
M&A Numbers & Trends
According to data captured on the LevinPro HC platform, there were 21 U.S.-based Hospital deal announcements, a 40% increase over the same period in 2025. Most Hospital transactions involved short-term acute care hospitals (13 deals), but there were a few acquisitions of critical access hospitals, a specialty hospital and four health system mergers.
“We’ve seen continued momentum into the second quarter, and it’s
Continued on page 2
Ascendia Gets PE Investment
Cathay Capital throws its support behind Ascendia Autism Care
Cathay Capital has made an investment in Ascendia Autism Care, a newly formed platform dedicated to expanding access to evidence-based applied behavior analysis therapy for children with autism spectrum disorder and their families.
The investment is sized to fund both the founding transaction and substantial growth capital for the platform’s continued expansion. Financial terms were not disclosed.
Ascendia Autism Care began operations with a founding affiliate that operates 20 centers across eight states. The platform plans to continue growing through de novo expansion and additional partnerships with leading clinical providers......Read more on LevinPro HC
driven by a myriad of factors, but I think a lot of activity is from pent-up demand and forward-thinking organizations taking charge,” said Courtney Midanek, Managing Director, Consulting, at Kaufman Hall, a Vizient company.
Kaufman Hall is a leading healthcare consulting firm, advising in everything from M&A to strategy and business transformation to clinical solutions.
Midanek’s comments touch on trends we’re seeing in our data. Historically, hospitals seek out mergers or partnerships when they’re in financial distress. But at least in 2026, that trend is changing, with hospitals in stronger financial positions hitting the M&A market. Excluding health system mergers, the average net patient revenue of an acquired hospital reached $172.3 million in H1 2026, up 16% from $147.6 million in H1 2025. Analyzing average EBITDA tells a similar story: in H1 2025, it was in the red at -$11.5 million per acquired facility, while in H1 2026, it swung back into the positive at $9.06 million per acquired facility.
Health systems have also accelerated their M&A activity, announcing 67 deals in H1 2026, a 26% increase from H1 2025. The health system mergers we’ve seen this year involve organizations with more than $1 billion in revenue, all of which are established leaders in their respective markets.
“I would say activity is measured and accelerating,” said Kris Blohm, Managing Director, Consulting, Kaufman Hall. “Organizations are being proactive, evaluating a variety of partnerships, trying to set themselves up optimally.”
The largest health system merger was the agreement between California-based Sutter Health and Minnesota-based Allina Health to form a $26 billion not-forprofit health system with a network of nearly 40 hospitals. Under the terms of the merger, Allina will become the Upper Midwest Division of Sutter Health, maintaining the Allina Health name, brand and regional headquarters in Minneapolis. Sutter Health would maintain its headquarters in Northern California. The combined organization would also have more than 400 primary and specialty care sites and 18,000 physicians.
ISSN#: 2375-7612
Published monthly by:
Irving Levin Associates LLC
P.O. Box 1117, New Canaan, CT 06840
Phone: 800-248-1668 Fax: 203-846-8300
info@levinassociates.com
www.levinassociates.com
Editor: Dylan Sammut
Associate Editor: Avery Swett
Analyst: Kate Humphrey
Advertising: Cristina Blazek-Hearty
The full, annual subscription includes 51 weekly e-newsletters, 12 monthly issues, four quarterly reports
©2026 Irving Levin Associates, LLC All rights reserved. Reproduction or quotation in whole or part without permission is forbidden.
This publication is not a complete analysis of every material fact regarding any company, industry or security. Opinions expressed are subject to change without notice. Statements of fact have been obtained from sources considered reliable but no representation is made as to their completeness or accuracy.
Other notable mergers announced this year include the agreement between RWJBarnabas Health and Englewood Health in New Jersey and UPMC's acquisition of Trinity Health System in Ohio from CommonSpirit Health.
“The spirit behind the decision to enter into exploratory partnership discussions has shifted from ‘have-to-do’ to ‘get-to-do,” Midanek said. “It’s not just distressed organizations deciding to explore partnership anymore; many are proactively leaning in. Scale matters, but you need the right definition of scale, so organizations are thinking long-term in their strategies."
Outpatient & Non-Acute Care Are Still Priority for Health Systems
For the past few years, health systems have turned their M&A efforts toward the outpatient and non-acute care space, and that trend continued in H1 2026. According to our transaction data in LevinPro HC, 71% of
July 15, 2026 at 1 pm Eastern
About the webinar
The SeniorCare Investor is convening a panel to discuss all of the options available to owners and operators that are looking to grow in seniors housing and care, and not just through traditional M&A. There are whole operating company acquisitions and mergers, growth through management contracts and leases, creative partnerships and joint ventures, as well as exploring third-party ancillary services acquisitions. levinassociates.com/2607webinar Register Today
PANELISTS:
Ben Swett, Managing Editor, The SeniorCare Investor (moderator)
K. Nicholas Glaisner, Managing Director, Ziegler
Joel Thiesen, CEO, LifeSpark
Raj Patel, CEO, Optalis Healthcare Sponsored
deals announced by health systems were for non-hospital entities, including physician groups, home health agencies, medical outpatient buildings and outpatient surgery centers.
The largest deal we saw in the non-acute space this year was Universal Health Services‘ (UHS) acquisition of the popular telehealth platform Talkspace for $835 million. It is one of the largest investments by a health system into telehealth the market has ever seen, and will help UHS expand its reach in the outpatient and talk therapy space.
Talkspace has a network of about 6,000 professionals offering virtual therapy, psychiatry and medication management. Patients can connect with their clinicians via video, audio, chat or asynchronous text messaging. It serves both employers and health plans.
UHS already has a significant presence in inpatient behavioral health, with nearly 350 facilities nationwide, but Talkspace will help supplement that revenue stream and bring more patients into its ecosystem. While other health systems are focusing on building their outpatient networks through brick-and-mortar locations, UHS is taking a different approach by leaning into telehealth and digital health instead.
Exploring Outside the M&A Space
Health systems and hospitals are increasingly looking outside M&A to expand and reinforce themselves against headwinds.
“The ones that have caught my attention have been those that cross for-profit to not-for-profit types of transactions, and it’s not just mergers,” said Blohm. “We’re seeing not-for-profit systems leapfrog out of the nonprofit space to work with financially-backed non-acute providers, other commercial care delivery organizations and even tech companies. It’s an evolving strategy we’re seeing from systems and organizations.”
Multiple systems, such as Mount Sinai Health System, Advocate Health and Allina Health, have announced partnerships with an AI platform to integrate the tech-
nology into their care delivery, enabling virtual nursing, clinical decision support, analytics and more.
Some systems went even further, developing the technology themselves. In May, Mayo Clinic and Bayesian Health co-developed an AI solution to “identify hospitalized patients who may benefit from palliative care earlier in their stay.”
“The solution is designed to support timely consultations, with the objective of improving goal-concordant care for patients with serious illness and reducing nonbeneficial readmissions,” stated the article announcing the partnership.
Future Outlook
The Hospital M&A and health system market in the second half of 2026 will mirror much of what we’ve seen in the first half, including divestments, large mergers and a focus on outpatient care.
“I think we’re going to continue to see more organizations focus on portfolio balance, and more $1 billion+ organizations hit the market as they try to be proactive in their strategies,” said Midanek.
Illinois-based CommonSpirit Health is looking to divest more hospitals in North Dakota and Ohio as it works to narrow its operating deficit and execute a $6 billion turnaround plan over the next 24 to 30 months, and Providence is divesting selective assets as part of its plan to stabilize its balance sheet.
As for outpatient care, we expect significant activity in this space. In its 2026 strategic guidance, HCA Healthcare emphasized a dedicated capital allocation strategy focusing heavily on "outpatient-focused high-value specialties."
“We’re monitoring activity in the non-acute space, which has been a big focus for health systems lately,” said Blohm. "We expect them to be proactive this year, trying to identify partners that are strategically aligned with their objectives.”
Top Healthcare M&A Deals H1 of 2026
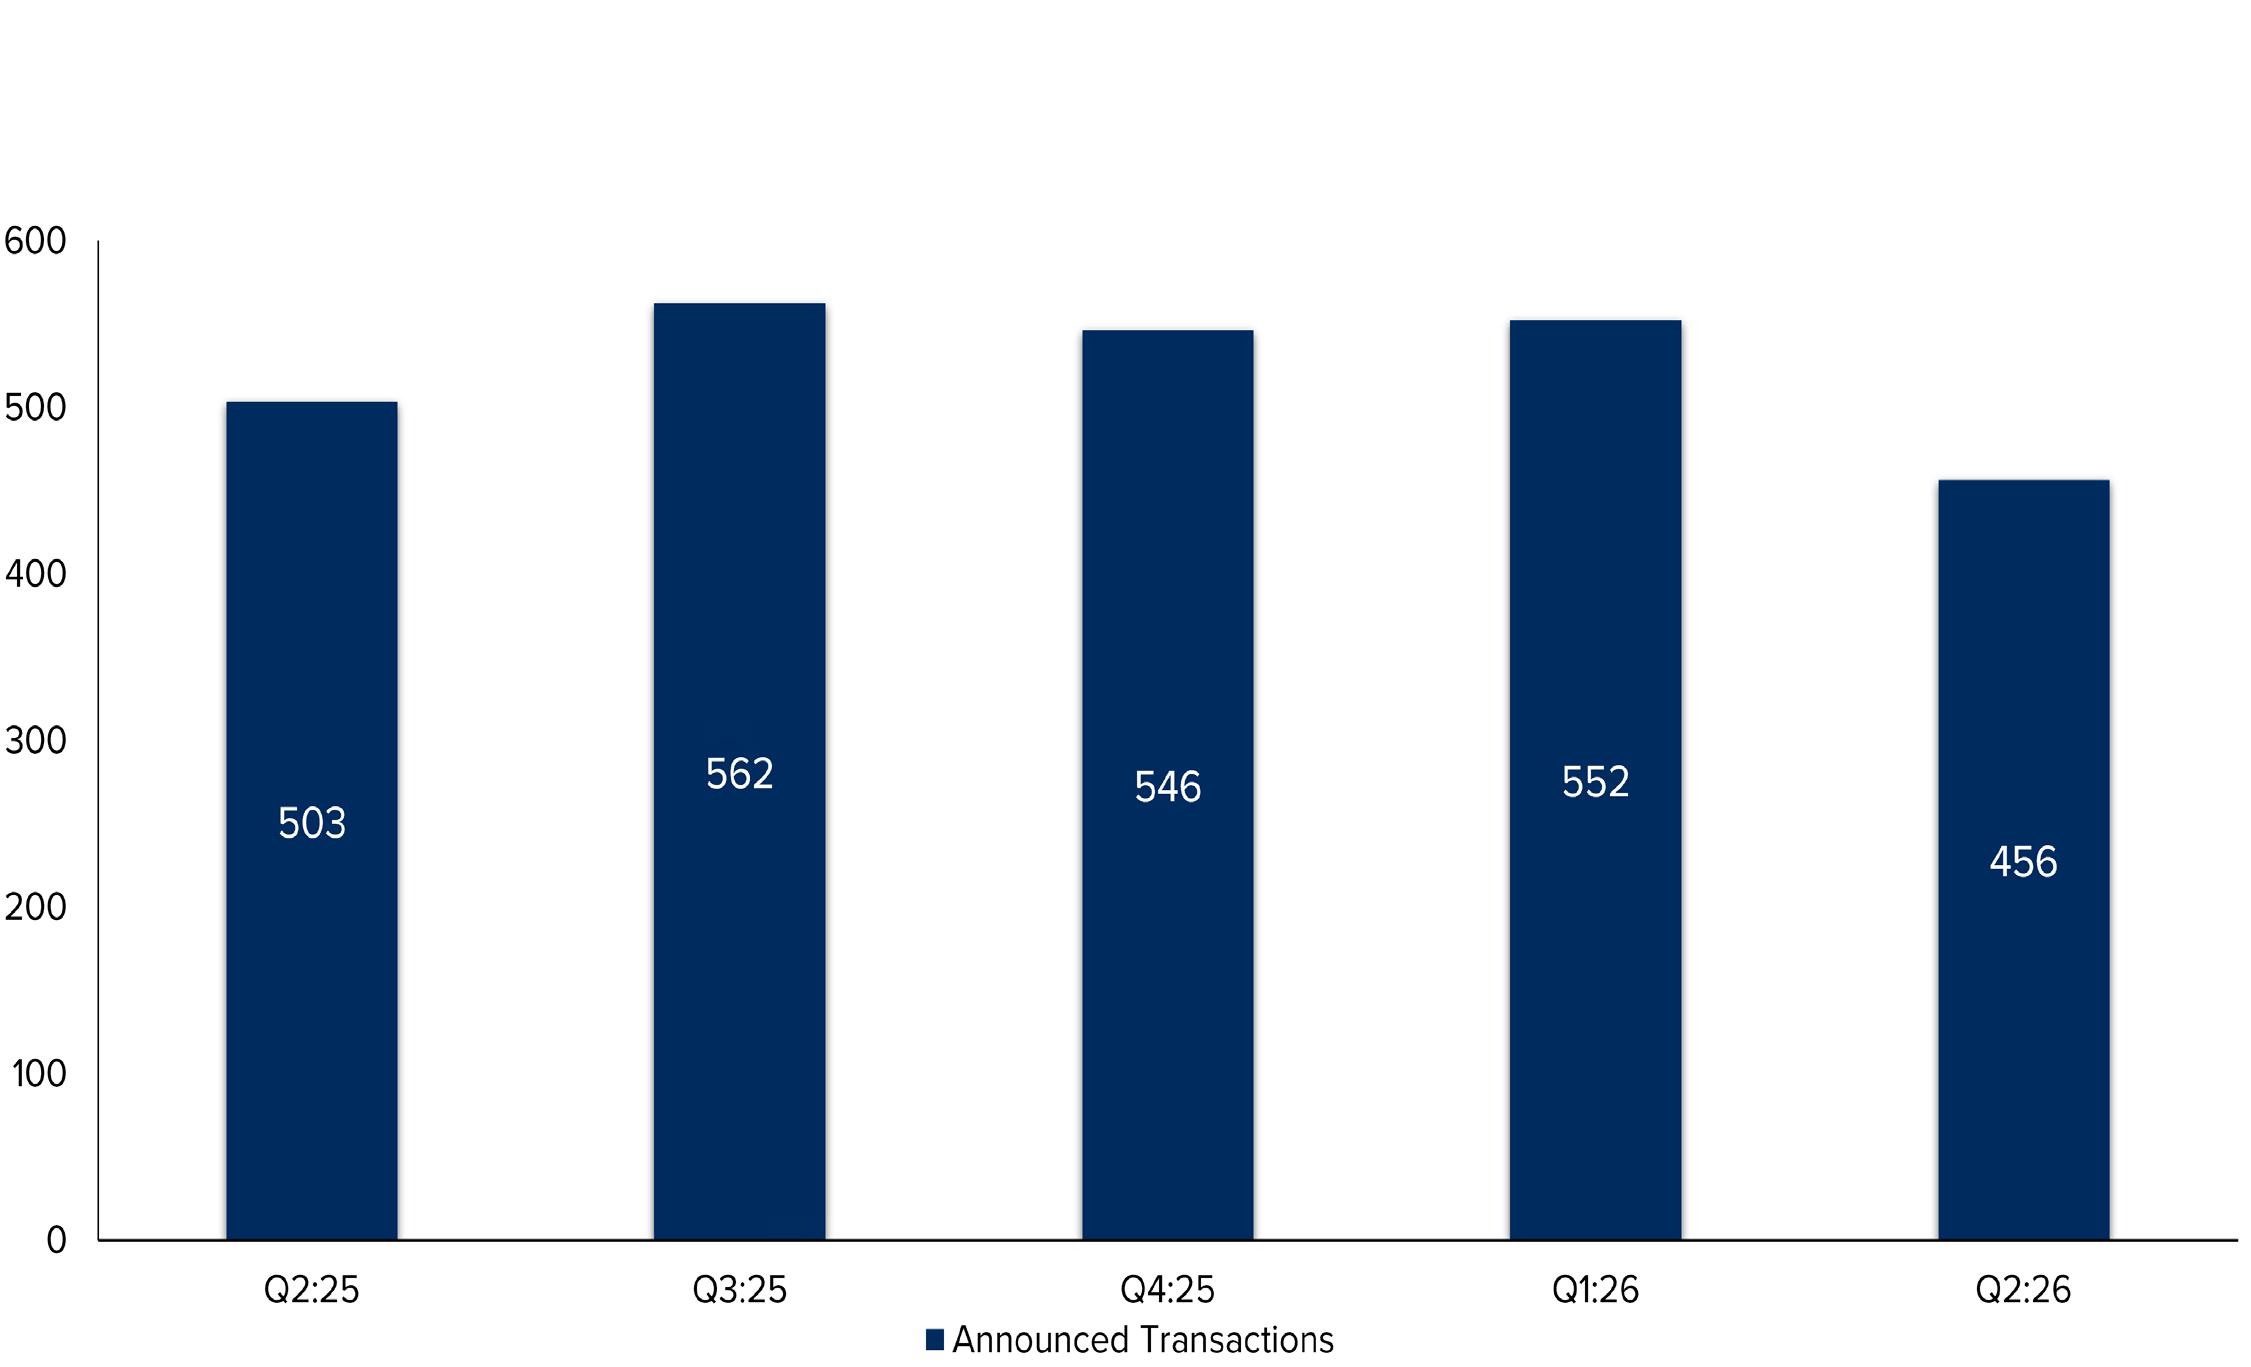
As we reach the halfway point of 2026, we decided it was time to review the top deals in the healthcare M&A market and which investors have been driving the industry. Compared with the first half of 2025, deal volume has slowed by approximately 5%, with 1,008 deals announced in the first half of 2026.
Investors are still bullish on the Physician Medical Group (PMG) sector, which has accounted for 25% of all deal activity this year, followed by a healthy appetite for Medical Outpatient Buildings (11% of all deals). Here are the most notable healthcare M&A deals so far this year.
Kinderhook Industries Acquires Enhabit, Inc.
In February, private equity firm Kinderhook Industries agreed to acquire Enhabit, Inc., a national home health and hospice provider, in an all-cash transaction with a total enterprise value of approximately $1.1 billion. The deal represents a 24.4% premium to Enhabit’s unaffected share price, with stockholders slated to receive $13.80 per share in cash.
Headquartered in Dallas, Texas, Enhabit has a nationwide footprint spanning 249 home health locations and 117 hospice locations across 34 states. According to its most recent annual filing, Enhabit generated approximately $1.06 billion in revenue during fiscal year 2025 and reported an adjusted EBITDA of $108.5 million.
This transaction closed succesfully in May.
Select Medical Holdings Gets Taken Private
Back in March, Select Medical Corporation, one of the largest operators in the Rehabilitation space, was taken private by Welsh, Carson, Anderson & Stowe (WCAS) and an entity affiliated with a consortium led by Select Medical executives. According to the terms of the agreement, WCAS and the consortium acquired all outstanding common stock of Select Medical not already
owned by the consortium for a cash price of $16.50 per share, representing an enterprise value of $3.9 billion.
Select Medical Corporation is one of the largest operators of critical illness recovery hospitals, rehabilitation hospitals and outpatient rehabilitation clinics in the United States based on the number of facilities. As of December 31, 2025, Select Medical operated 104 critical illness recovery hospitals in 28 states, 38 rehabilitation hospitals in 15 states and 1,917 outpatient rehabilitation clinics in 39 states and the District of Columbia.
According to the company's 2025 financial earnings report, Select Medical had nearly $3.82 billion in total liabilities and generated $5.452 billion in revenue with $483.2 million in EBITDA.
General Atlantic Acquires TEAM Services Group
In one of the largest private equity transactions in the healthcare M&A space, Alpine Investors sold TEAM Services Group to General Atlantic.
TEAM Services Group provides household employment and home care solutions across all 50 states. Its subsidiary, TEAM Public Choices, provides home care for participants in government-sponsored disability and aging programs, with an emphasis on self-directed care.
The deal is valued at approximately $3 billion, including debt. Under Alpine Investors, TEAM grew significantly, completing more than 10 add-on acquisitions in recent years.
Blue Owl Capital Buys Sila Realty in a $2.4 billion Deal
Blue Owl Real Estate Capital LLC, an affiliate of Blue Owl Capital, announced a $2.4 billion deal to acquire Sila Realty Trust, Inc., one of the most prolific healthcare REITs in the industry. According to data captured in our LevinPro HC platform, Sila Realty has announced 32 deals in the healthcare M&A market since 2020, buying 32 properties for a total value of $640 million.
The transaction will help expand Blue Owl Capital's real estate portfolio, which already has roughly 6,000 properties. Once the deal is complete, Sila Realty will stop
trading on the New York Stock Exchange and become a private company owned by Blue Owl.
EyeSouth Partners Divests its Retina Business
Cencora announced that its portfolio company, Retina Consultants of America, entered into an agreement to acquire EyeSouth Partners’ retina business. The purchase price of $1.1 billion makes it the largest eye care purchase price in the last five years and the largest PMG deal of 2026 so far.
Based in Atlanta, Georgia, EyeSouth Partners, a portfolio company of Olympus Partners as of 2022, is an eye care services organization. EyeSouth’s affiliate network comprises more than 400 doctors providing medical and surgical eye care at more than 275 locations across 14 states. Additionally, it operates 26 surgery centers throughout 12 states.
The press release noted that this deal builds on Cencora’s mission to expand past drug distribution by adding high-margin health services to its portfolio. In line with that strategy, this transaction follows Cencora’s 2025 acquisition of OneOncology from TPG for $5 billion.
HPS Investment Partners Takes Majority Ownership of Discovery Behavioral Health
Investment funds managed by HPS Investment Partners have agreed to assume majority ownership of Discovery Behavioral Health in a transaction that includes a substantial reduction of the company’s debt obligations. The deal, announced June 2, 2026, is subject to regulatory approval and other consents.
Discovery Behavioral Health is a Van Nuys, Californiabased national provider of evidence-based treatment for mental health conditions, eating disorders and substance use disorders in children, adolescents and adults. The company operates more than 100 programs across 12 states, delivering the full spectrum of recovery care: residential treatment centers, in-person and virtual partial hospitalization and intensive outpatient programs, professional psychiatric services and transcranial magnetic stimulation.
HPS Investment Partners, headquartered in New York City, focuses on private credit, public credit, private equity and real estate assets. This transaction formalizes HPS’s transition from a major lender to majority owner, significantly strengthening Discovery Behavioral Health’s balance sheet and providing greater operational and financial flexibility.
As part of the broader restructuring, Discovery Behavioral Health appointed a new Board of Directors and a new Chief Executive Officer, Pete Clarke, who also joins the board. Clarke is a seasoned healthcare executive with more than 20 years of experience leading complex, large-scale transformation initiatives. His background includes senior leadership roles at DaVita and Fresenius Medical Care, where he focused on operational efficiency, values-driven cultures and developing multi-center organizations.
"In my first two months, I have visited dozens of our programs across the country. It is one thing to know we have many examples of industry-leading, peerreviewed published outcomes. It is another to see the work in action," Clarke said. "What I have seen confirms what drew me to Discovery Behavioral Health: a consistently strong level of care. In many of our programs, we are already the preferred provider and partner for patients, families, and payors, and a place where the best behavioral health professionals want to do their life's work. My focus is on ensuring that's true everywhere we operate."
All Discovery Behavioral Health programs, referral relationships, payor contracts, clinical leadership, licensing, accreditation and regulatory standing remain unchanged. Patient care continues uninterrupted throughout the ownership transition.
The transaction follows a period of financial restructuring for the company. It resolves prior debt challenges and positions Discovery Behavioral Health for continued expansion in the behavioral health sector while leveraging its strong clinical outcomes and preferredprovider status with many payors.
The deal is expected to enable Discovery Behavioral Health to further invest in its programs, care teams and the patients and families it serves, reinforcing its position as a leading national behavioral health provider.
Nova Orthopedic and Spine Expands Florida Network to 12 Locations
Nova Orthopedic and Spine has added Southeastern Surgery Center to its clinical facilities network. Financial terms of the private transaction were not disclosed.
Southeastern Surgery Center is an outpatient surgery center located in Tallahassee, Florida. The single-site facility contains three operating rooms and three treatment rooms tailored for localized clinical interventions.
Woodbridge, Virginia-based Nova Orthopedic and Spine, delivers comprehensive surgical and non-surgical treatments for musculoskeletal injuries, including physical therapy, ultrasound, diagnostics and orthotics. Nova has operated as a portfolio company of healthcare services holding company Cardiff Lexington Corporation since 2021.
The addition marks the 12th surgical facility integrated under the Nova brand umbrella. The transaction establishes Nova's initial physical presence in the Florida capital, advancing its broader strategy to scale advanced orthopedic, spine and pain management clinical access across the southeastern and mid-Atlantic regions.
Merck KGaA to Acquire Bio-Techne for $11.3 Billion
Merck KGaA, Darmstadt, Germany has agreed to acquire Bio-Techne Corporation for $73 per share in cash, representing a total enterprise value of approximately $11.3 billion and a 36% premium to Bio-Techne’s one-month volume-weighted average trading price. The transaction is expected to close by late 2026 or early 2027.
Bio-Techne Corporation is a Minneapolis, Minnesotabased global provider of life science tools, analytical technologies and consumables. The company has more than 3,000 employees, with approximately 2,300 based in the United States.
It operates 34 global locations and 15 manufacturing facilities across the United States, Canada, the United Kingdom, Switzerland and China. According to its most recent annual filing, Bio-Techne reported a full-year fis-
cal 2025 revenue of $1.22 billion, and EBITDA of $213 million.
Merck KGaA, Darmstadt, Germany is a leading science and technology company operating across healthcare, life science and electronics. It employs roughly 62,000 people and generated sales of €21.1 billion (approximately $24.1 billion USD) in 2025 across 65 countries.
Guggenheim Securities and J.P. Morgan are acting as financial advisors to Merck, and Sullivan & Cromwell LLP is acting as the legal counsel of Merck. Goldman Sachs is acting as exclusive financial advisor to BioTechne, and Sidley Austin LLP is acting as Bio-Techne's legal counsel.
This also marks the third-largest deal by transaction value announced across all of healthcare this year, behind only Boston Scientific’s $14.5 billion acquisition of Penumbra and Sun Pharmaceutical Industries’ $11.75 billion acquisition of Organon & Co.
AbbVie to Acquire Apogee Therapeutics for $10.9 Billion
AbbVie and Apogee Therapeutics announced that they have entered into a definitive agreement under which AbbVie will acquire Apogee and its diverse pipeline of multiple clinical-stage candidates in development across inflammatory and immunological diseases, including atopic dermatitis and asthma.
Under the terms of the definitive agreement, AbbVie will acquire all outstanding Apogee common stock for $135.11 per share in cash, for a total equity value of approximately $10.9 billion. The acquisition complements AbbVie's existing immunology portfolio and accelerates AbbVie's clinical presence in the respiratory space.
Apogee Therapeutics is a biotechnology company advancing therapies to address the needs of the millions of people living with immunological and inflammatory disorders. Apogee's lead asset, zumilokibart (APG777), is a late-stage, half-life extended monoclonal antibody targeting IL-13, in development for patients with atopic dermatitis. According to its most recent annual report, Apogee Therapeutics reported $0 in revenue for its full fiscal year 2025, and reported an EBITDA loss of $284.2 million.
AbbVie Inc. is a biopharmaceutical company that discovers, develops, manufactures and sells pharmaceutical products worldwide. The company focuses on several therapeutic areas, including immunology, oncology, neuroscience, eye care, virology and gastroenterology, in addition to products and services across its Allergan Aesthetics portfolio.
According to its full-year 2024 financial results, the company delivered full-year net revenues of nearly $61.2 billion and EBITDA of about $17.4 billion.
The boards of directors of both companies have unanimously approved the transaction. This transaction is expected to close in the third quarter of 2026.
Thurston Group Consolidates DSOs Under SGA Dental Partners Umbrella
SGA Dental Partners has acquired Gen4 Dental Partners and MODIS Dental Partners in a private transaction. Financial terms of the multi-asset acquisition were not disclosed. Under the agreement, both Gen4 and Modis will be integrated into and operate under the SGA Dental Partners organizational umbrella.
Based in Tempe, Arizona, Gen4 Dental Partners manages 15 southwest locations originally formed by private equity sponsor Thurston Group through the consolidation of five initial group practices.
MODIS Dental Partners, based in Philadelphia, Pennsylvania, is a dental services organization specializing in specialized dental surgical services.
Richmond Hill, Georgia-based SGA Dental Partners is also a portfolio company of Thurston Group. The company was formed in 2022 through the merging of Dental Partners of Southwest Georgia, Garner Dental Group and South Georgia Dental Management
The transaction increases SGA's geographic scale, expanding its combined operational footprint to support more than 500 dentists across upwards of 250 dental sites spanning 26 states.
Sanford Health Equip Expands North Dakota Reach
Sanford Health Equip has acquired Great Plains Restorative Services, a home medical equipment provider serving Bismarck, Dickinson and surrounding rural communities in North Dakota. Patients currently receiving services will transition to Sanford Health Equip. Financial terms of the deal were not disclosed.
Sanford Health Equip offers a wide range of home healthcare accessories and durable medical equipment, including mobility aids, respiratory and CPAP equipment, enteral nutrition supplies, orthotics and prosthetics and daily living aids.
Lucent Health Group Acquires Chambers Home Health & Hospice
Lucent Health Group has acquired Chambers Home Health & Hospice, a provider of home health and hospice services across Northeast Texas. Cross Keys Capital served as exclusive financial advisor to Chambers Home Health & Hospice, while Calhoun, Bhella & Sechrest provided legal counsel to the seller. Financial terms of the transaction were not disclosed.
Chambers operates through three agencies: Chambers Home Health, Chambers Hospice and Healthcare Associates LLC. It operates out of several locations including Mt. Pleasant, Texarkana, Paris, Longview and Sulphur Springs. The acquisition expands Lucent Health Group’s presence in Texas and adds to its network of home-based care providers.
The transaction strengthens Lucent’s regional footprint in home-based care and adds density in markets where demand for post-acute and end-of-life services continues to shift toward community-based settings.
Soleo Health Buys Realo Specialty Care Pharmacy and BluHaven Management
Soleo Health announced that it has acquired Realo Specialty Care Pharmacy and BluHaven Management from parent company Realo Drugs. The entire Realo Specialty Care and BluHaven team will join Soleo Health. Financial terms of the deal were not disclosed.
Realo Specialty Care Pharmacy is a specialty pharmacy that provides advanced clinical support and care coordination for patients on complex specialty therpies. Founded in 2015, it delivers specialty pharmacy services that combine clinical expertise with a patientcentered model.
BluHaven Management manages an ambulatory infusion center, BluHaven Health, that provides clinically supervised infusion therapy services in a patient-focused environment. The center complements regional specialty pharmacy operations by supporting a wide range of complex treatment needs.
Soleo Health, a portfolio company of H.I.G. Capital, provides complex specialty pharmacy and infusion services administered in the home or at alternate sites of care.
It operates 28 specialty pharmacies and more than 30 ambulatory infusion suites and centers throughout the United States with national nursing coverage and pharmacy licensure in 50 states.
The acquisition expands Soleo Health’s footprint in the Mid-Atlantic region, primarily in North Carolina, South Carolina, Virginia and Maryland.
Biogen to Acquire RayThera in Up to $1 Billion Immunology Deal
Biogen has entered into an agreement to acquire RayThera Inc., a private biotechnology company focused on small molecule therapies in immunology.
Biogen will make an upfront payment (amount not disclosed) with RayThera shareholders eligible for clinical and regulatory milestone payments for a total potential deal value of up to $1 billion. The transaction is expected to close in the third quarter of 2026, subject to customary regulatory approvals.
Based in San Diego, California, RayThera’s portfolio includes multiple anti-inflammatory assets that could potentially treat immune-mediated conditions across a range of indications. The lead candidate is expected to enter Phase 1 development in early Q3 2026. In April 2025, RayThera completed a Series A financing co-led by Foresite Capital and OrbiMed Advisors, with participation from TTM Capital
Founded in 1978, Biogen discovers, develops and delivers therapies for people living with serious neurological and neurodegenerative diseases. The company reported $9.9 billion in annual revenue during 2025, and $2.48 billion in annual EBITDA.
Upon closing, Biogen will lead development, manufacturing and global commercialization of the assets, further expanding its immunology pipeline.
Assort Health Raises $102 Million to Scale Agentic AI Patient Experience Platform
San Francisco, California-based Assort Health announced on June 24 that it has raised $120 million in Series C funding led by Menlo Ventures. The round values the company at $1.2 billion post-money and brings total funding raised to more than $222 million.
Assort Health deploys autonomous AI agents that handle the full patient journey, including scheduling, intake, referrals, document processing, medication refills, eligibility verification and payments across specialty practices and health systems.
Its proprietary Synapse model, trained on more than 190 million specialty patient interactions, 62,000 care protocols and 1.6 million decision pathways, enables high automation rates even in complex specialty workflows. The company has delivered 20x revenue growth over the last 15 months.
The round included participation from Lightspeed Venture Partners, Felicis, First Round Capital, Chemistry, Joe Montana, Tau Ventures and Quiet Capital JP Sanday, partner at Menlo Ventures, will join Assort's Board, and fellow partner Matt Murphy, will serve as a Board observer. Proceeds will fuel expansion into health systems and continued scaling of its AI agent platform.
Assort is bringing the platform, already the largest AIpowered patient access deployment among provider groups, to health systems ranging from large community-based organizations to academic medical centers. Several health systems, such as John Muir Health, are partnering with Assort as demand grows for platforms that can support increasingly complex ambulatory operations.
Health System News & Activity
June was a slow month for health systems in the healthcare M&A market, with only eight transactions announced, most of them in the Hospital sector. In the largest deal of the month, West Virginia University Health System acquired Independence Health System, which consists of five hospitals and nearly 1,000 beds.
The system was established in January 2023 through the merger of Butler Health System and Excela Health, and has more than 1,000 physicians and advanced practice providers, as well as 7,300 employees on staff. Independence Health System is the third-largest healthcare system in western Pennsylvania, serving a population base of 750,000 in a footprint spanning a multicounty region.
According to its financial reports, Independence Health System generated $1.17 billion in net patient revenue and $28.85 million in EBITDA in the 12 months ending June 30, 2025.
As part of this transaction, the West Virginia University Health System has agreed to make an investment of $800 million in Independence Health System’s five hospitals. These investments will include a new electronic medical record system, significant facility upgrades and expansions and enhanced clinical capabilities. The transaction is expected to close in late September or early October 2026.
Down in North Carolina, UNC Health, a not-for-profit, state-owned integrated healthcare system based in Chapel Hill, acquired Onslow Memorial Hospital. The terms of the deal include a $150 million investment to support the integration.
Onslow Memorial Hospital was founded in 1944 and is a 162-bed acute-care community hospital located in coastal North Carolina, serving the city of Jacksonville and the greater Onslow County. It is nationally accredited by The Joint Commission.
According to WCTI12, a local news station, the Onslow County Board of Commissioners approved this deal. The agreement will occur in three phases, with UNC Health taking full control by 2029.
Private Equity News & Activity
Private equity (PE) activity in healthcare M&A slowed in June 2026, with PE buyers and/or their portfolio companies involved in 46 deals out of 169 total healthcare transactions, representing 27% of overall volume. This marks a decline from May’s 56 PE deals out of 143 and is roughly in line with June 2025, which recorded 47 PE deals out of 155 total.
As usual, Physician Medical Group (PMG) remained the most active sector for PE buyers in June. There were 12 PE transactions announced during the month out of 30 total PMG deals. Dental continued to lead within the sector with seven deals. Specialized Dental Partners was the most active acquirer, announcing the acquisition of Peninsula Endodontics and Southern Roots Periodontics and Dental Implant Specialists
eHealth ranked second with seven PE-backed deals out of 24 total. Med-Metrix, LLC, backed by A&M Capital Partners, was the most active acquirer in the space, completing two transactions: the $147 million acquisition of Vitalware and the purchase of CanAide.
Life Sciences R&D came in third with five PE deals, four of which were in the clinical trials specialty. The sector also featured the month’s largest disclosed transaction by a PE firm: Altaris’ acquisition of Simulations Plus for $375 million.
Medical Devices and Other Services each recorded four PE deals. Within Other Services, activity included two healthcare product distributor deals, along with one medical physics deal and one infusion services deal.
Home Health & Hospice had three PE-backed deals. Acquirers in the space included Advent International (acquired Japan Wellbeing), Bristol Hospice (Hope Hospice & Palliative Care) and Gemspring Capital (Freedom Senior Services).
Several sectors saw one or two PE-backed deals each, including Behavioral Health Care, Healthcare Staffing, Hospitals, Laboratories/MRI and Dialysis, Managed Care, Medical Outpatient Building, Rehabilitation and Specialty Pharmacy.
Healthcare Real Estate News & Activity
There were 24 Medical Outpatient Building (MOB) transactions captured in our LevinPro HC database for June. This marks an 85% increase from the 13 reported in May 2026, as well as a 71% increase from the 14 announced in June 2025. In the first two quarters of 2026, there have been a total of 120 MOB deals reported, which is a notable increase from the 99 announced in the first two quarters of 2025.
Continuing the year-over-year increase, total disclosed square footage also rose. In June, more than 1.43 million square feet were sold across 31 facilities, which is nearly double the 779,686 square feet across 16 facilities that were sold in June 2025. However, it is less than the 1.44 million square feet sold across 29 facilities in May 2025.
While this is the first month in several months to experience a surge in total number of transactions, the deal volume and square footage point to a continued shift from small single-property transactions to larger portfolio deals to obtain market dominance.
There were four deals that totaled more than 100,000 square feet; the largest was National Real Estate Advisors, LLC’s acquisition of a two-building portfolio in Great Falls, Montana and Winter Garden, Florida. The portfolio totals 293,520 square feet. The Montana campus consists of multiple buildings anchored by Great Falls Clinic, including an ambulatory surgery center and a 46-bed hospital. The Florida asset is fully leased to Post Acute Medical
Disclosed spending for the month totaled $106.84 million across seven transactions. The largest was Shore Capital Partners’ and RX Health & Science Trust’s (RXHST) $48 million acquisition of a two-facility MOB portfolio in Mesa, Arizona. The tenants were not disclosed. Cushman & Wakefield represented the seller, a joint venture partnership between Harbert Management Corporation and Cypress Office Properties.
As the sole investor to announce more than one acquisition throughout June, Montecito Medical Real Estate reaffirmed its place as one of the most active MOB buyers with six acquisitions. Square footage of the deals surpassed 174,000 square feet. Additionally, in May 2026, Montecito also announced six acquisitions for a total of 273,560 square feet. Since the start of 2026, Montecito has now acquired more than 1.16 million square feet across 34 facilities.
Additionally, RXHST also reported two deals; one acquisition and one divestment. RXHST, alongside Transwestern Investment Group, sold a 92,109-squarefoot MOB in Gilbert, Arizona to Fidelity Investments. Cushman & Wakefield’s Healthcare Capital Markets Team represented the sellers. For its second acquisition, RXHST purchased a MOB in Mesa, Arizona that totaled 181,898 square feet. The sellers were Cypress Office Properties, LLC and Harbert Management Corporation.
Other active buyers in June include Flagship Healthcare Properties, BGO and Anchor Health Properties in a joint venture and Remedy Medical Properties
Fueled by Montecito’s activity, real estate investment firms were the most active buyer type throughout the month with 13 transactions. This accounts for 54% of the MOB activity throughout the month, which is less than May 2026 when they accounted for 77% of the activity (10 deals).
Private equity, in a continuation of its low activity in the MOB space, accounted for one transaction; Woodside Health, LLC, based in Cleveland, Ohio purchased a 27,600-square-foot MOB in Naples, Florida. In May, Woodside Health, as the only private equity group to announce deals in the sector, reported two transactions, expanding its footprint by 855,000 square feet in Florida and North Carolina.
CBRE Group, Inc., Colliers International and Cushman & Wakefield all announced two transactions, each. Bass, Berry & Sims, Berkadia, Blueprint and Marcus & Millichap also reported one deal, each.
Let Us Help Build Your Ad Campaign. Secure your space today to reach key decisions-makers in the Seniors Housing & Care and Healthcare M&A industries
Advertising Opportunities include:
•Print/Publication Ads
•Digital Banner Ad Campaigns
•Thought-Leadership Sponsorships
•Lead Generation Options
Download our Media Kit - Book Your Campaign Today!
Top Deals June 2026
Bio-Techne Corporation
Laboratories, MRI and Dialysis
NASDAQ: Merck KGaA, Darmstadt ETR: MRK 6/25/2026
Minneapolis, MN TECH Darmstadt, Germany
In Brief: Bio-Techne Corporation is a Minneapolis, Minnesota-based global provider of life science tools, analytical technologies and consumables. The company has more than 3,000 employees, with approximately 2,300 employees based in the United States. It operates 34 global locations and 15 manufacturing facilities across the United States, Canada, the United Kingdom, Switzerland and China.
Top Deals June 2026
Arizona property portfolio
Medical Outpatient Building
Shore Capital
Mesa, AZ Chicago, IL
In Brief: Two Class A medical outpatient buildings (MOB) in Mesa, Arizona were acquired. The MOBs total 181,898 square feet. The tenants were not disclosed.
Top Deals June 2026
InnovativeRx assets N/A
Specialty Pharmacy
Mountain View, CA
In Brief: InnovativeRx is a compounded pharmacy. The assets that were sold include InnovativeRx US Holdings, Inc. The deal was done through the merger of the operating subsidiaries of InnovativeRx, including InnovativeRx North Ohio, Inc. and Flywheel Healthcare, LLC, into a wholly owned subsidiary of Custom Health effective June 3, 2026.
Top Deals June 2026
Edgewise Therapeutics assets N/A
N/A Suresnes, France
Biotechnology & Pharmaceuticals
In Brief: The sale includes the muscular dystrophy business of Edgewise Therapeutics, a biopharmaceutical company focused on the discovery, development and commercialization of treatments for severe, rare neuromuscular and cardiac disorders for which there is significant unmet medical need.
Nuvalent, Inc.
NASDAQ: GSK Plc
NYSE: GSK 6/9/2026
$10,600,000,000 Cambridge, MA NUVL Brentford, United Kingdom
In Brief: Nuvalent, Inc. is a clinical-stage biopharmaceutical company focused on creating precisely targeted therapies for patients with cancer, designed to overcome the limitations of existing therapies for clinically proven kinase targets. Nuvalent develops small molecules that have the potential to overcome resistance, minimize adverse events, address brain metastases and drive more durable responses.
Apogee Therapeutics Private AbbVie Inc.
NYSE: ABBV 6/22/2026
$10,900,000,000 Waltham, MA North Chicago, IL
In Brief: Apogee Therapeutics is a biotechnology company advancing therapies to address the needs of the millions of people living with immunological and inflammatory disorders. Apogee's lead asset, zumilokibart (APG777), is a late-stage, half-life extended monoclonal antibody targeting IL-13, in development for patients with atopic dermatitis.