SEP - OCT 2026
Issue 60 Volume 26
UK £4 Europe €5.35 US $6
www.internationalfinance.com
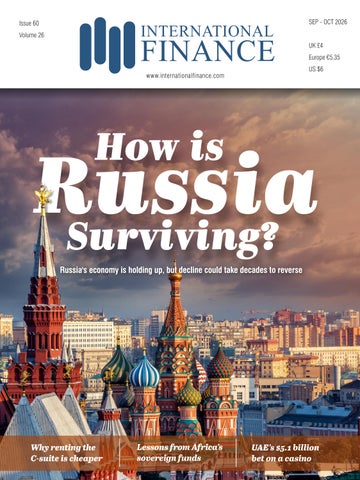
Russia's economy is holding up, but decline could take decades to reverse
Why renting the C-suite cheaper 1 | Sept - Octis 2026 | International Finance
Lessons from Africa’s sovereign funds
UAE’s $5.1 billion bet on a casino
EDITOR’S NOTE
SEP - OCT 2026 VOLUME 26 ISSUE 60
Behind the Iron Curtain
W
hat exactly is happening inside Russia? It is the question on everyone’s lips. While the country has been heavily bruised by Western sanctions over its war with Ukraine, the conflict in the Middle East has inadvertently provided a financial lifeline, driving up global demand for Russian crude in the absence of steady Gulf supplies. Otherwise, however, it has been a long, rough ride for the world's largest nation by landmass. After a high-ranking official let slip far more than the Kremlin would have liked, we took a deep dive into the true impact of these sanctions for this month's cover story. Beyond geopolitics, the NGX turned out to be the world’s bestperforming equity market over the past year, riding a boom fuelled primarily by domestic investors flocking to the trading floor. A closer look reveals that this achievement was not without its share of anomalies, including a tenuous link to US President Donald Trump. Our feature story has all the details. Turning to Asia, we look at China's staggering humanoid robotics breakthrough. A machine named Tianzhuo blitzed the 100-metre sprint in an astonishing 9.39 seconds. For context, Usain Bolt’s legendary human world record is 9.58 seconds. The catch? Tianzhuo had no reliable way of stopping. In another part of Asia, the Al Marjan Island in the UAE is the site for the most consequential experiment in Gulf tourism policy in a generation: The region’s first full-scale, licenced casino. It’s designed, unapologetically, to compete with Macau, Singapore and Las Vegas for a slice of Asia’s gaming dollar. Read our story on what this means for the UAE. As always, we look forward to hearing your thoughts.
editor@ifinancemag.com www.internationalfinance.com
International Finance | Sept - Oct 2026 | 3
INSIDE
IF SEP - OCT 2026
22
IN CONVERSATION EQUITY RALLY: 32 NGX CONSTRAINTS EXIST;
DIRECTION OF TRAVEL CHANGED The Nigerian stock exchange has been the best-performing equity market globally in dollar terms in 2026
RUSSIA’S ECONOMY IS HOLDING, BUT...HOW? Russia has been the target of the most extensive sanctions ever applied to a major economy, but the nation has not collapsed ECONOMY
INDUSTRY
16
54
THE WORLD IS ON FIRE AND THE MONEY IS GOING SOUTH
UAE’S $5.1 BILLION BET ON A CASINO OFF RAS AL KHAIMAH
Geopolitics and volatile AI market have not stopped money flowing into developing economies
Wynn Al Marjan is designed to compete with global hubs for a slice of Asia’s gaming dollar
INDUSTRY
TECHNOLOGY
FEATURES
40
Africa’s sovereign wealth funds: What sets them apart?
58
Germany’s industrial crown jewel under pressure
90
New property rules rattle banks in Australia
102 Wall Street’s capital truce collapses over Fed rulebook
BUSINESS DOSSIER
96
116
NVIDIA TURNS ITS CHIPS INTO WALL STREET’S NEWEST ASSET CLASS
THE ROBOT THAT BEAT USAIN BOLT... AND BROKE INTO PIECES
As Big Tech faces cash crunch, Jensen Huang eyes shifting the AI burden onto private credit
Whether China becomes the great robotics disruptor depends on a problem it has not yet solved
4 | Sept - Oct 2026 | International Finance
46
BDB: Digital arm reshaped how SMEs engage with our banking services
80
Saudi mining industry thrives with ESNAD guidance
108 Ranhill SAJ powers Johor’s long-
term water transformation journey
www.internationalfinance.com
Director & Publisher Sunil Bhat Editor Dhiraj Shetty Editorial Agnivesh Harshan, Prabuddha Ghosh Production Merlin Cruz
ANALYSIS
12
The debt bomb: America’s $40 trillion reckoning
28
At NGX, Share Prices Rise Faster Than Profits
50
Why the fractional executive is finding more takers
66
Dismantling: The Great Ooredoo Break-Up
84
Wall Street’s AI agents stop advising, start working
112 META and youth addiction: A problematic affair
Design & Layout Vikas Kapoor Technical Team Prashanth V Acharya, Bharath Kumar Business Analysts Alice Parker, Indra Kala, Stallone Edward, Jessica Smith, Harry Wilson, Susan Lee, Mark Pinto, Richard Samuel, Merl John Business Development Managers Christy John, Alex Carter, Gwen Morgan, Janet George Business Development Directors Sid Jain, Sarah Jones, Sid Nathan
OPINION DAVID COLINDRES GEOPOLITICAL RISK IS RESHAPING AIRCRAFT REGISTRY DECISIONS
78
The industry is becoming more conscious that aircraft registration is not simply a compliance exercise
REGULAR EDITOR'S NOTE
03 06 08
Behind the Iron Curtain
TRENDING Meet Apple's 'faster' Mac mini
NEWS Unique UK wedding venue gets honeymoon
Head of Operations Ryan Cooper Accounts Angela Mathews Registered Office INTERNATIONAL FINANCE is the trading name of INTERNATIONAL FINANCE Publications Ltd 843 Finchley Road, London, NW11 8NA Phone +44 (0) 208 123 9436 Fax +44 (0) 208 181 6550 Email info@ifinancemag.com Press Contact editor@ifinancemag.com Associate Office Zredhi Solutions Pvt. Ltd. 5th Floor, Sai Complex, #114/1, M G Road, Bengaluru 560001 Ph: +91-80-409901144
International Finance | Sept - Oct 2026 | 5
# TRENDING Meet Apple's 'faster' Mac mini
T E CH NOLOGY
Governed AI Framework for Private Equity
Navatar announced a governed AI framework for private markets firms that combines its purpose-built CRM and AI capabilities with Salesforce Agentforce and Claude. Private markets firms are rapidly adopting tools such as Claude for research, deal analysis, document summarization, and drafting. But the opportunity comes with an equally important question: how can a firm use powerful external AI models without exposing confidential information on LPs, targets, portfolio companies, investment theses, and internal decision-making? Navatar’s approach is to make AI usage selective, structured, and governed - not a choice between an open-ended model and a static CRM.
The tech giant's powerful Mac mini has been made keeping in mind consumers looking to host AI agents remotely. The new mini comes with either the tech giant's new M6 chip or the M5 Pro. One variant has been powered by Apple's 2-nanometer M6 chip, which delivers up to four times faster AI performance and double the graphics and storage speeds compared with the previous M4-powered model
At a Glance Top Eight US Trading Partners (In Billions USD) Mexico
$976.1 Canada
$877.2
Nexa Lighthouse to Fund ISS expands partnership Climate Innovation with MNC customer Grand Challenges Canada, AVPN, and global partners launched Nexa Lighthouse at the AVPN Global Conference 2026 to fund innovations that address the health impact of climate change across Asia and the Pacific. Innovations may take the form of a product, process, service, or delivery model that can deliver better outcomes than existing approaches. Nexa Lighthouse will provide catalytic funding for growth-stage climate and health innovations that strengthen health systems adaptation and resilience, and have strong potential for impact and scale. BA NK ING
6 | Sept - Oct 2026 | International Finance
ISS, a Copenhagen-based leader in workplace experience and facility services, has expanded its partnership with an MNC customer through the addition of multiple sites across key global markets. ISS drives the engagement and well-being of people, minimises the impact on the environment, and protects and maintains property. Under the expanded scope, ISS will provide integrated facility services, including food services, across countries in Europe, Asia and the Americas, with the US representing the largest share of the expanded scope. IN DUS T R Y
China
$660.7 United Kingdom
$373.8 Germany
$337.5 Japan
$328.2 Ireland
$286.0 Taiwan
$284.8 Source: US Census Bureau and US Bureau of Economic Analysis
NEWS | INSIGHTS | UPDATES | DATA
Ones to Watch
E CONOM Y
Challenges of wooing affluent customers
HUSAM FEZZANI CEO Integrated Quantum Technologies appointed Husam Fezzani as its new CEO. He succeeds Alan Guibord, who will transition to Chairman of the Board
Fintechs’ combined share of revenue among the world’s largest banks and fintechs rose from 10% in 2021 to 17% in 2025, according to McKinsey’s Global Banking Annual Review. Fintechs are maturing from niche challengers into full-scale competitors for broad customer relationships, not just individual transactions. Facing the competition, many banks are looking past standard segmentation toward more personalised, identity-driven relationships with affluent
and aspirational customers. This group is not easy to win or keep. Ultra-highnet-worth individuals collectively spend $280 billion on luxury goods annually, according to analyst Altrata. Also, aspirational consumers pursuing that lifestyle account for a significant share of premium brand purchases. Overall, the global luxury market is projected to reach $700 billion by the end of the decade, growing 4% to 6% annually, according to McKinsey consumer research.
By the Numbers
DANIEL SEVERIN HEAD OF GLOBAL MOBILITY INSURANCE Roamly, the speciality insurance provider of The Ride Platform, appointed Daniel Severin as Head of Global Mobility Insurance as its flagship London office
Top 10 Countries Facing the Highest Trump Tariffs Canada
Vietnam
European Union
China
Japan
Taiwan
Brazil
South Korea
India
50% 31.6% 37.5%
12.5% 12.5% 12.5%
10% 10% 10%
Source: USTR | The 10%-12% Ratio Has Been Decided Based On The Outcome Of The Section 301 Forced Labor Probe (Data Compiled as of August 2026)
ANTHONY GALLO CHIEF PRODUCT OFFICER TrueCommerce, a leading global supply chain network and integration platform, appointed Anthony Gallo as Chief Product Officer to lead the next phase of AI-driven supply chain modernisation
International Finance | Sept - Oct 2026 | 7
IN THE NEWS
FINANCE
BANKING
INDUSTRY
TECHNOLOGY
Loved up couples now have an even more stunning setting to say ‘I do’ at architectural landmark in Blackpool promenade
Size of delegation at LEAP 2026 in Saudi Arabia reflects a coordinated national effort rather than a single organisation’s appearance
Unique UK wedding venue gets makeover The Wedding Chapel, which has hosted more than 6,000 weddings since it first opened almost 15 years ago, is shining bright again on Blackpool promenade after a refurbishment. Blackpool building company Evolution carried out work on the roof of the Wedding Chapel, known for its stand-out architectural design. The 629m² building, which features a restaurant as well as the wedding venue, is an architectural landmark, designed by dRMM and gaining a RIBA (Royal Institute of British Architects) Award in 2012. The Wedding Chapel, which is part of Festival House, is set to celebrate its 15th anniversary of its opening in December. It was on January 12, 2012, that the first couple exchanged their vows at the chapel. Since then, more than 6,000 couples have married at the iconic venue, including approximately 400 couples in 2025, and more than 250 so far this year. Couples come from all over the United Kingdom, from up in Scotland and down in Devon, and even worldwide, to get married at the famous chapel.
8 | Sept - Oct 2026 | International Finance
Ben Reader, Evolution’s Contracts Manager who led the work, said, “The Wedding Chapel has a really striking design with an overhanging cantilevered balcony. None of our team had worked on anything like it before. It was a really interesting project to be involved in.” Evolution’s team, including two apprentices and site manager Leon Iddon, carried out the work before new steelwork was added, the reroofing completed, and new glazing inserted. Ben said, “Once the glass was all in, we returned to site to install all the composite decking. So we were the first team on site and the last team off it. It was very satisfying to have been there at the beginning and be back there to complete it.” Cllr Mark Smith, Blackpool Council’s Cabinet Member for Economy and Built Environment, added, "Festival House is part of our growing offer for couples who want to get married here, either as locals or because Blackpool holds a special place in their hearts." "We’re continually investing in the building so that hundreds more couples can get married here in the future," the senior official added further.
Pakistan makes a splash at LEAP 2026 Pakistan’s presence at LEAP 2026 in Riyadh, Saudi Arabia reflects the country’s continued commitment to strengthening its global technology footprint. Pakistan has arrived at LEAP 2026 with one of the largest national delegations the technology show has seen from the country, a signal of how quickly Pakistan’s IT sector has moved from emerging supplier to serious regional contender. Under the banner ‘Think Tech, Think Pakistan’, the Pakistan Software Export Board (PSEB), operating under Pakistan’s Ministry of IT & Telecommunication, led a national delegation of close to 1,000 delegates and exhibiting staff at the Kingdom’s flagship technology and AI event, that ran from August 31 to September 3 at RECC Malham. The scale of the presence reflects a coordinated national effort rather than a single organisation’s appearance. Eighteen companies exhibited under the PSEB-led Pakistan Pavilion, spanning fintech, enterprise AI, cybersecurity, engineering talent, and smart-city technology. Alongside them, ten startups exhibited through Ignite, Pakistan’s national technology fund, and more than ten additional Pakistani
companies put up independent stalls. The delegation includes eighteen representatives from PMTF and twenty-five from the Pakistan Software Houses Association (P@SHA), rounding out a presence that spans government, industry associations, and the private sector. The trip comes as Pakistan’s technology exports continue to climb. The country’s ICT exports reached $4.6 billion in FY2025–26, part of a broader push by the Ministry of IT & Telecommunication, under Federal Minister Shaza Fatima Khawaja, to position Pakistan as a serious partner for the Gulf’s digital transformation and AI ambitions, rather than solely a source of outsourced engineering talent. Among the independent exhibitors on the show floor were Systems Limited, 10Pearls and Abacus. For Saudi Arabia and the wider Gulf, the timing lines up with the region’s own technology ambitions. As Vision 2030 accelerates investment in AI, smart cities, and digital infrastructure, Pakistan’s pitch is straightforward: proven engineering capacity, a fast-growing AI sector, and companies already delivering for regional clients, including several with existing operations inside the Kingdom.
International Finance | Sept - Oct 2026 | 9
IN THE NEWS
FINANCE
BANKING
INDUSTRY
TECHNOLOGY
As AI continues to accelerate how software is built, Duolingo believes exceptional human creativity remains a critical differentiator
NetBet is one of Europe's leading online gaming operators, offering players a premium online casino experience across multiple regulated markets
Duolingo acquires Animade
G+D Brings New Colours to Convego
Duolingo, a mobile learning platform, has acquired Animade, a London-based animation and motion design studio. The acquisition expands Duolingo's Design Studio, strengthening a capability that has become increasingly important to delivering engaging product experiences and accelerating innovation. As AI continues to accelerate how software is built, Duolingo believes exceptional human creativity remains a critical differentiator. By investing in worldclass design talent, the company is strengthening its ability to create intuitive, delightful experiences that help millions of learners stay motivated and achieve their goals. Animade is known for creating expressive motion systems, interactive experiences, and product storytelling for some of the world's leading technology companies and brands.
Giesecke+Devrient (G+D) is expanding its Convego Ceramic payment card line with a wide range of new on-trend colours. It takes the material beyond the black and dark tones that have defined it so far, giving banks a new tool for physical differentiation as they compete with fintechs for affluent customers. This is the specific space G+D is addressing with its updated Convego Ceramic line, adding a variety of colours to a portfolio that has so far been almost exclusively black. A wide range of colours can be produced. Further customisation options, such as laser engraving for background textures and electroplating, are also available. G+D launched the Convego ceramic card in black some time ago as the first payment card on the market made entirely of ceramic, except for its electronic components and antenna.
The Top 10 Global Goods Exporters China
$3.77 Trillion
10 | Sept - Oct 2026 | International Finance
United States
Germany
Netherlands
$2.18 Trillion
$1.76 Trillion
$989 Billion
Hong Kong
Italy
United Arab Emirates
$754 Billion
$726 Billion
$707 Billion
Japan
South Korea
France
$738 Billion
$709 Billion
$683 Billion
The Top 10 Global Goods Importers United States
$3.51 Trillion
Resort in Sharjah gets biodigester
Peter & Sons Partners with NetBet
Coral Beach Resort Sharjah has begun operating a biodigester. The resort is now the first hotel in Sharjah to have a fully operational biodigester system, reinforcing its position as a pioneer in responsible tourism and environmental stewardship. The state-ofthe-art biodigester uses natural microorganisms and oxygen to safely break down organic kitchen waste into greywater. By processing food waste on-site instead of sending it to landfill, the system significantly reduces methane emissions and lowers the carbon footprint associated with conventional waste collection and transportation. The biodigester also supports the Coral Beach Resort's water conservation efforts. The nutrient-rich greywater produced through the process is reused to irrigate the resort’s landscaped gardens and greenery.
Barcelona-based creative iGaming studio Peter & Sons has expanded its partnership with NetBet, bringing its award-winning portfolio live across their brands in the United Kingdom, Greece, Ireland and Finland. Peter & Sons is a Yerevan and Barcelona-based game development studio transforming online gambling with uniquely styled, high-performing video slots and casino games. NetBet is one of Europe's leading online gaming operators, offering players a premium online casino experience across multiple regulated markets. Through the new collaboration, Peter & Sons titles are now available to NetBet players across several regulated jurisdictions, further expanding the studio's European footprint while reinforcing the operator's commitment to delivering premium gaming entertainment.
China
Netherlands
Japan
$2.58 Trillion
$870 Billion
$756 Billion
Germany
Hong Kong
India
$1.54 Trillion
$832 Billion
$753 Billion
United Kingdom
France
Mexico
$949 Billion
$786 Billion
$683 Billion International Finance | Sept - Oct 2026 | 11 Source: FAO Homes
ECONOMY
ANALYSIS
DEBT UNITED STATES
The debt has doubled in a decade under two Presidents and two parties, and the bond market has finally started charging for it
The debt bomb: America’s $40 trillion reckoning IF CORRESPONDENT
The United States crossed a line in August that its own official forecasters had not expected to see until the end of the decade. Total public debt outstanding reached $40.05 trillion on August 18, according to the Treasury's daily statement, comprising roughly $32.3 What is not trillion held by the public symbolic is the and $7.8 trillion in intraprice investors governmental holdings. are now Back in 2023, the charging to hold Congressional Budget Office American paper. had pencilled in 2028 for The 30-year that milestone. It arrived two Treasury bond has been yielding years early, and barely five around 5.25%, months after the debt passed a level last seen $39 trillion. before the 2008 The number itself is financial crisis, symbolic. What is not symbolic and the 10-year is the price investors are now has pushed close charging to hold American to 4.7% paper. The 30-year Treasury bond has been yielding around 5.25%, a level last seen before the 2008 financial crisis, and the 10-year has pushed close to 4.7%. Treasury Secretary Scott Bessent surprised markets on August 19 by at least doubling the size of the department's buyback operations in longerdated debt. Yields dropped for a few hours, then climbed straight back. That reversal is the story in miniature. Washington still has technical tools. It
12 | Sept - Oct 2026 | International Finance
is running short of ones that convince anybody. Dollar hovered near multi-month lows on August 24, as the market got unsettled by the Treasury's promise to buy back more long-dated bonds. Apart from traders’ anxious wait on the Trump administration’s Iran sanctions package, trade tensions with Canada emerged as a big factor as well. While Washington imposed 50% tariffs on Canadian goods after the failed negotiations, Ottawa returned the favour with equal vigour, creating an intense trade war.
A decade of doubling The debt has doubled in less than ten years, and neither party can claim the high ground. Gross federal debt stood at $19.95 trillion in January 2017. It rose by about $7.8 trillion across Donald Trump's first term, with more than half of that piling up in the final nine months as the pandemic response ran through the Treasury. It rose by a further $8.4 trillion under Joe Biden. Since Trump returned in January 2025, it has added about $3.8 trillion more, taking the total accumulated across his two terms to roughly $11.6 trillion. Roughly a third of the entire increase since 2017 is attributable to the two years of emergency borrowing after Covid-19 arrived, and that borrowing was bipartisan. The remainder is the product of choices made in calmer conditions, which is what worries the ratings agencies and the bond
desks far more than the pandemic bill ever did.
Two parties, two spending styles The pattern of the borrowing differs even where the totals do not. Trump's first term opened with the Tax Cuts and Jobs Act of 2017, which lowered the corporate rate to 21% and reduced federal revenue by close to $2 trillion over a decade. Then came the CARES Act in March 2020, worth $2.2 trillion, and a further $900 billion package that December. The Biden years front-loaded transfers and then pivoted to industrial policy. The American Rescue Plan of March 2021 was worth $1.9 trillion. The Infrastructure Investment and Jobs Act followed in November that year with $1.2 trillion headline value and roughly $550 billion in genuinely new money for roads, rail, ports, water systems, and broadband. The CHIPS and Science Act of August 2022 committed about $280 billion, including $52.7 billion in direct semiconductor subsidies. The Inflation Reduction Act, passed the same month, carried an official clean energy price tag near $390 billion, though its uncapped tax credits pushed
later estimates considerably higher. The political argument for all of this was that the outlay would pay for itself through factories, chips and cheaper power. The fiscal reality was that it was borrowed. Trump's second term produced its own landmark in the ‘One Big Beautiful Bill Act’. The Congressional Budget Office originally scored it at $3.4 trillion of added deficits over 2025 to 2034. Its most recent outlook, which accounts for economic effects and the extra debt service, puts the impact at $4.7 trillion from 2026 to 2035. The Committee for a Responsible Federal Budget reckons the figure climbs past $5.5 trillion if the temporary provisions are made permanent, as sponsors have signalled they intend to. In the near term, the law is adding around $500 billion to the fiscal 2026 deficit alone.
Why the cuts never landed Trump's second term began with an explicit promise of retrenchment. The Department of Government Efficiency (DOGE) was set up to find savings, and Elon Musk initially spoke of $2 trillion. That target was halved, then cut to $150 billion, then quietly
International Finance | Sept - Oct 2026 | 13
ECONOMY
ANALYSIS
DEBT UNITED STATES
abandoned. DOGE closed on July 4 without issuing a final report. The Government Accountability Office later found that it could not verify 96% of the grant savings the body had claimed, covering some $110 billion. What actually reached the statute book was a $9 billion rescissions package aimed at public broadcasting and foreign aid, plus a pocket rescission of around $5 billion. Congress rejected the great bulk of the discretionary cuts the White House proposed for fiscal 2026. Of thirty programmes the administration wanted slashed or scrapped, one was eliminated. The 2026 appropriations bills spend more than the 2025 ones did. Then came the revenue shock. On February 20, 2026, the Supreme Court ruled six to three that the 'International Emergency Economic Powers Act’ does not give a President the power to impose tariffs. Roughly $166 billion already collected became refundable, and more than $100 billion had gone back out of the door by July. Net customs receipts turned negative for three consecutive months. The CBO now expects fiscal 2026 customs revenue to come in about $250 billion below its February projection, and estimates the ruling opens a hole of around $900 billion over the decade once lost duties and extra interest are counted. The administration has been rebuilding a tariff wall through Section 122 and Section 301 authorities, but at lower rates and with a lag.
Where the money goes now Strip out the politics and the
14 | Sept - Oct 2026 | International Finance
arithmetic is dull and immovable. In the first ten months of fiscal 2026 federal spending rose by $309 billion, or 5%. Medicare accounted for $131 billion of that increase, a 16% jump driven by enrolment and payment rates. Veterans’ benefits rose $51 billion, also 16%. Social Security added $71 billion, Medicaid $45 billion, and national defence $46 billion. Homeland Security has become a genuine growth item, with the fiscal 2026 request running to $178 billion and the bulk of the increase directed at immigration enforcement, border technology, and detention capacity. Above all sits the interest bill. Net interest reached $963 billion in ten months, and the annual figure is now around $1.1 trillion, roughly 15% of all federal spending. In fiscal 2025, debt service overtook the Pentagon for the first time.
This year it has overtaken Medicare, leaving Social Security as the only line item larger. About 19% of federal tax revenue is now consumed simply by servicing what has already been borrowed. That is the compounding trap. Every dollar of new deficit raises the interest bill, which raises the deficit again.
What the Treasury can and cannot do Bessent's toolkit is real but narrow. The department can change the maturity mix of what it issues, and it has leaned heavily on short-term bills, taking advantage of a threemonth yield near 3.8% against a long bond above 5%. It can buy back illiquid long-dated securities, which is what it did in August, lifting operations from $2 billion to at least $4 billion. It can adjust the quarterly refunding schedule,
The debt by presidency (gross federal debt, Treasury data) • January 2017: Start of Donald Trump's first term, $19.95 trillion • January 2021: Start of Joe Biden's term, $27.75 trillion (rise of $7.8 trillion) • January 2025: Start of Trump's second term, $36.21 trillion (rise of $8.4 trillion) • August 18, 2026: $40.05 trillion (rise of $3.8 trillion so far) • Split on August 18, 2026: $32.27 trillion held by the public, $7.78 trillion intra-governmental • Debt per head of US population: Roughly $117,000
and coordinate with the Federal Reserve on liquidity facilities. None of this reduces the debt. It changes who holds it and for how long, and it can smooth a disorderly market for a few sessions. It also carries a cost. Tilting the stock towards bills means a larger share of the debt reprices whenever rates move. Any future tightening feeds through to the budget almost immediately. Jefferies described the surprise buyback expansion as shot from the hip, a pointed criticism of a department whose reputation rests on being regular and predictable. Bessent has confirmed that a broader fiscal consolidation plan is coming, drawn up with budget director Russ Vought, and argues the deficit has probably peaked. Markets are waiting for the detail. There is not much. About
two-thirds of federal spending is mandatory, and the three programmes driving the increase are the three that no administration facing mid-terms will touch. Discretionary cuts have already been tried and largely rejected by a Republican Congress. Tariff revenue, the one new income stream the administration built, has been struck down and only partially rebuilt. Tax increases are off the table by design, and the pressure inside the party runs towards making the expiring cuts permanent, which costs more. Bessent's own benchmark, a deficit of 3% of GDP, sits against a fiscal 2026 gap of about $2.1 trillion, close to double that target. He has said there is nothing magic about the $40 trillion number, and technically he is right. The magic, if that is the word, is in the interest line.
Inflation and the Fed Monetary policy is now working against the fiscal position rather than cushioning it. Consumer price inflation ran at 3.4% in July, easing for a second month but still well above the 2% target, with core at 2.5%. The energy shock from
the conflict with Iran is fading but gasoline remains around a quarter higher than a year ago. The Federal Open Market Committee, now chaired by Kevin Warsh, held rates at 3.5% to 3.75% in July on a nine to three vote, with the three dissenters wanting an increase. Markets put meaningful odds on a hike before the year is out. For the Treasury, that is an uncomfortable combination. Mild inflation erodes the real value of existing fixed-rate debt, which flatters the ratio, but it also lifts the coupon demanded on every new issue and on the enormous stock of bills being rolled over. Long yields have risen since June on a mixture of deficit worry, sticky inflation, and a wave of corporate borrowing tied to artificial intelligence investment, all of it competing for the same pool of savings. The rise is largely term premium, the extra compensation investors want for holding American duration risk. That is a judgement on fiscal credibility, and no buyback programme can argue with it.
editor@ifinancemag.com
International Finance | Sept - Oct 2026 | 15
NORTHERN SEA ROUTE ARCTIC SHIPPING
16 | Sept - Oct 2026 | International Finance
FEATURE EMERGING MARKETS
The world is on fire and the money is going South Iran war, a shut chokepoint, and an AI market that swings by the week have not stopped record sums flowing into developing economies IF CORRESPONDENT
W
ar in the Gulf, a shut chokepoint, and an AI market that swings by the week have not stopped record sums flowing into developing economies. Emerging markets are no longer where investors run from in a crisis. They are increasingly where investors hide The rule that has governed global finance for forty years has been that when something breaks, money leaves the developing world. It happened in 1994, in 1997, in 2008, in 2013 when the US Federal Reserve merely hinted at slowing its bond purchases, and again
after 2020, when the COVID pandemic shock pushed Zambia into default that November, and Sri Lanka and Ghana into default two years later. By that rule, 2026 should have been a bloodbath. A war that began in late February has effectively closed the Strait of Hormuz, the passage that carried roughly a fifth of the world's oil. Brent crude has traded near $89 a barrel in mid-August, up about a quarter on pre-war levels after touching $110 earlier in the year. Fertiliser prices have followed, and behind them food. The yield on the 10year US Treasury note, the number against which almost all developing
country borrowing is priced, sits near 4.65%, against 3.97% before the fighting started. Traders have spent the summer arguing not about how quickly the Fed will cut rates, but whether it will have to raise them. The rule did not hold. Institute of International Finance data shows foreign investors put $214.4 billion into emerging market debt in the first seven months of 2026, against $177.7 billion in the same stretch of 2025, the strongest run in more than two decades. Governments have exploited the appetite. Roughly $19 billion of sovereign bonds were sold in July alone, about twice the average for that month over the past ten years, taking issuance for the year to a record $187 billion. Something has changed, and it is worth being precise about what.
The comparison that flatters the developing world Ask whether emerging economies have handled geopolitical disruption better than rich ones and the honest answer is that they have handled their own bal-
International Finance | Sept - Oct 2026 | 17
ECONOMY
FEATURE EMERGING MARKETS
DEVELOPING ECONOMIES FUND FLOW
The flows, 2026 year to date
ance sheets better, which is not quite the same thing. The IMF's April 2026 Fiscal Monitor put global public debt just under 94% of GDP in 2025, on course to cross 100% by 2029, a year earlier than the fund projected only twelve months previously. The accumulation is driven overwhelmingly by the largest economies. On the fund's April World Economic Outlook database, US general government gross debt is projected at 126% of GDP this year and 142% by 2031, the biggest absolute increase in the advanced world. Japan sits above 200%. Twenty-three economies now carry gross debt above 100% of output, and the list is dominated by rich countries, not poor ones. Set against that, the emerging market picture looks almost conservative. Central banks across Latin America, Asia and Africa spent the 2022 to 2024 inflation shock raising rates early and hard, which left them with real yields that are genuinely positive, and room to cut when their advanced counterparts have none. Reserve buffers are thicker. Central bank independence, which was a slogan in the 1990s, is now closer to institutional fact in Brazil, Mexico and South Africa. Ratings agencies have noticed. Pakistan, Ghana, Ecuador, Nigeria and Argentina have all collected upgrades. Oman and Azerbaijan have reached investment grade. Fund managers report the strongest upgrade momentum among lower rated sovereigns in over a decade, an unusual thing to say in a year of war. Political risk, meanwhile, has migrated. The disorder that investors once priced into Latin American and African assets now shows up in a record US government shutdown, fractured European coalitions, and defence spending commitments that nobody has explained
18 | Sept - Oct 2026 | International Finance
$214.4
$187
$86
$18.8
Foreign inflows into emerging market debt, January to July 2026, $214.4 billion, against $177.7 billion in the same period in 2025. Strongest in more than two decades
Sovereign bond issuance year to date, a record $187 billion, with July alone accounting for about $19 billion, roughly twice the ten-year average for the month
Emerging market equity outflows over the same period, $86 billion, nearly ten times the 2025 figure
Net emerging market inflows in July, $18.8 billion, after two months of outflows. Equity outflows narrowed to $7.8 billion from $46.1 billion in June
billion
billion
billion
billion
Source: IIF, JPMorgan, UBS, VanEck, IMF Global Financial Stability Report, April 2026
how to fund. The growth arithmetic points the same way. The IMF's July update expects emerging market and developing economies to grow 3.8% this year and 4.5% in 2027, against 1.7% and 1.8% for advanced economies. Global growth of 3.0% in 2026 recovering to 3.4% in 2027 is what the fund calls a V shaped path around the war shock. The caveat matters, though, and it is a heavy one. The World Bank's June Global Economic Prospects cut its global forecast to 2.5% for 2026, the weakest since the pandemic, and downgraded two-thirds of economies. South Asia, the fastest growing region, decelerates from 7% to 6.3%. Low-income countries manage 5.4%, three-tenths lower than previously expected, with fertiliser driven food inflation doing much of the damage. Most sobering, the bank calculates that by 2028
developing economies other than China and India will have spent nearly a decade making no progress at all in closing the income gap with rich countries. So, the financial resilience is real. The developmental resilience is not. Bond markets and living standards have decoupled, and anyone reading the inflow numbers as evidence of broad-based prosperity is reading them wrong.
Why the money is moving For a decade-and-a-half, global portfolios were built on a single assumption, that American assets were the default, and everything else was a satellite allocation. That assumption is being quietly unwound. The IMF has begun writing about the erosion of the US Treasury's safety premium in its own fiscal surveillance. Investors who spent 2025 watching
FEATURE EMERGING MARKETS
$4
trillion Cumulative portfolio flows to emerging markets since the global financial crisis, up eightfold to about $4 trillion, with 80% now supplied by non-banks
6.9% Emerging market bond yield, about 6.9% as of February 2026, against 4.2% for US bonds and 3.6% globally
the dollar post its sharpest annual fall in eight years have concluded they are over allocated to one jurisdiction, and, in a fragmenting world, they want to be spread across many. The mechanics reinforce the mood. For Japanese and other Asian institutions, hedging US Treasuries back into home currency now wipes out most of the yield, which makes local Asian bonds structurally more attractive than they were. Emerging market debt was yielding around 6.9% in February, against roughly 4.2% for US bonds and 3.6% globally. Rising Treasury yields have narrowed that gap since, but not closed it. The pull side is the story of a decade of quiet plumbing work. Emerging economies have built domestic capital pools deep enough to reduce their dependence on foreign money altogether.
Local currency sovereign bonds outstanding totalled roughly $13 trillion by the end of 2024, against about $1.4 trillion of international hard currency sovereign debt, according to research from JP Morgan and UBS. Large economies, such as Brazil and South Africa, now fund themselves overwhelmingly at home, in their own currency, from their own pension funds and insurers. That changes the physics of a shock. When foreign investors sell, domestic institutions are on the other side of the trade. Fund managers describe the result as an absence of the liquidity crunches that used to define emerging market sell-offs. Prices fall, but the market does not gasp. Positioning is the third leg. After what Bank of America's head of emerging market fixed income strategy David Hauner, speaking to Reuters, called the ‘valley of tears’ running from roughly 2015 to 2025, a stretch of strong dollar, US exceptionalism, and serial defaults, global investors are still structurally underweight. Emerging economies hold about 60% of the world's population and produce around 40% of global output, yet account for barely a tenth of the 'MSCI All Country World Index.' Several months of inflows barely dent a decade of under-investment. There is a risk buried in the composition of the money, and the IMF flagged it in April. Portfolio flows to emerging markets have risen eightfold since the global financial crisis to about $4 trillion in cumulative terms. Portfolio debt liabilities now average around 15% of GDP, against roughly 9% in 2006. About 80% of that capital comes from non-banks, twice the share of twenty years ago, and non-bank money is faster money.
Private credit in emerging markets, opaque by design, has grown fivefold in a decade to somewhere between $50 billion and $100 billion. Deeper markets have not abolished the sudden stop. They have changed who would cause one.
Safe haven, or simply the least crowded trade The safe haven question deserves a careful answer, because the marketing departments have got ahead of the evidence. A true safe haven does two things. It holds value when everything else falls, and it stays liquid when liquidity vanishes. Emerging market assets do neither reliably. What they have done in 2026 is something narrower and still significant. They have offered diversification at a moment when the traditional refuges look compromised. Look at the split inside the flows. While $214.4 billion went into debt, roughly $86 billion came out of emerging market equities in the same seven months, nearly ten times the outflow at the same point in 2025. This is not a wall of money buying an asset class. It is a discriminating reallocation into yield, and away from concentrated technology risk. The performance record is similarly mixed. The JP Morgan GBI-EM Global Diversified index of local currency debt lost 2.25% in the first quarter as the dollar strengthened on safe haven demand, then gained 3.85% in the second. An index of inflation linked emerging market local currency government debt has returned 11.3% this year, against 1.5% for the broader local debt index, and a small loss for the Bloomberg Global Aggregate. The winners are specific, not general. Currencies tell the same story. Emerging market currencies erased their 2026 gains by the start of July as
International Finance | Sept - Oct 2026 | 19
ECONOMY
FEATURE EMERGING MARKETS
DEVELOPING ECONOMIES FUND FLOW
speculation about higher US rates revived the dollar. Capital Economics' aggregate currency risk indicator has nonetheless stayed near multi-year lows, which is the more interesting fact. Currencies weakened without anyone fearing a crisis. The deepest evidence for a structural shift comes from official reserve managers rather than fund managers, though it needs reading carefully. The dollar's share of global reserves has fallen from roughly 71% in 1999 to 57.1% in the first quarter of 2026. That latest reading, however, was up from 56.4% three months earlier, and the IMF is at pains to point out that much of the recent movement reflects exchange rate valuation effects rather than central banks actively selling dollars. Intent shows up more clearly in what reserve managers say and in what they buy instead. In the World Gold Council's 2026 survey, 74% of central banks expected the dollar's share to be moderately or significantly lower within five years. Official gold buying ran at an estimated 244 tonnes in the first quarter, ahead of both the previous quarter and the five-year average, with Poland the largest single purchaser. Central banks are not calling emerging markets a haven. They are calling the ‘Old Haven’ crowded, and looking for anything neutral. Emerging market debt is one beneficiary of that search. Gold is the bigger one. Professional investors are behaving accordingly. Several large houses, BlackRock's investment institute among them, have cooled on emerging market equities and hard currency debt even as flows continue. Managers describe themselves as highly selective, ignoring benchmarks, avoiding countries with debt problems
20 | Sept - Oct 2026 | International Finance
and skipping those where yields no longer compensate. That is not haven behaviour. It is careful, well-paid risk taking.
What the institutions are actually saying The IMF's July update describes an economy pulled by two crosscurrents, a war shock that punishes energy importers and vulnerable states, and an AI investment boom that lifts anyone plugged into the technology value chain. Global disinflation has stalled. Headline inflation is expected to rise from 4.1% in 2025 to 4.7% in 2026 before easing to 3.9% in 2027, with energy and food doing the work. The Fiscal Monitor adds the geopolitical arithmetic. IMF staff estimate that a one standard deviation shock to their geopolitical fragmentation index is associated with public debt ratios rising about 1.5 percentage points of GDP over the medium term. Fragmentation is not an abstraction. It has a price, it is paid in borrowing costs, and it is being paid now. The World Bank supplies the development warning. Its June report is explicit that emerging economies unable to build the ecosystem and policy environment for wide AI adoption risk falling further behind, and that private investment growth in developing economies has been declining since the 2000s even as public balance sheets improve. The US Energy Information Administration expects Brent to average $87 a barrel across 2026 and does not see Middle East production returning to near pre-conflict levels until early 2027. The IEA has warned of the widest global supply deficit in five years. For oil importing developing economies, that is another eighteen months of imported inflation. Fund managers add the risk nobody
controls. The threats most often named to the flow story are not war headlines but food prices, fertiliser costs, and El Nino. A drought does more damage to a frontier sovereign's fiscal position than a missile does.
The next shock is already priced, badly If the world has survived geopolitics, artificial intelligence (AI) is the test that has not yet started. And the strange thing about emerging markets in 2026 is that they are simultaneously the most exposed and the least prepared. Start with the index. As of July 31, information technology accounted for 40.8% of the MSCI Emerging Markets Index. Taiwan is the largest country weight at 26.6%, China 21.4%, and South Korea 20.3%. Taiwan and Korea together are almost half the benchmark. In January those weights were 21% and 15.7%, with technology at 30.3%. India, meanwhile, has slid from roughly 20% of the index in mid-2024 to under 12%. Its equities are down around 5% in local currency terms this year, with the Sensex at 77,728 on August 17, having lagged badly through the first half before a July rally that pulled about $1.6 billion of foreign money back in. Expensive crude and a weaker rupee did most of the damage. The emerging market equity benchmark is now, to a first approximation, a leveraged bet on the AI semiconductor cycle. That has been enormously profitable. It also means every boom and bust in AI sentiment transmits straight into an asset class marketed as diversification. Korea's Kospi moving 3.7% in a single session on AI earnings is not an emerging market story at all. It is a Silicon Valley story with a Seoul postcode. Then there is the labour market,
FEATURE EMERGING MARKETS
The pressure points, who is carrying what
94%
Global public debt, just under 94% of GDP in 2025, reaching 100% by 2029. US at 126% of GDP in 2026 rising to 142% by 2031, Japan above 200%.
4.5%
Growth in 2026, emerging and developing economies 3.8% rising to 4.5% in 2027, advanced economies 1.7% then 1.8%. Global growth 3.0%.
job exposure, 60% of employment in advanced economies, 40% in emerging markets, 28% in low-income 60% AIcountries. IMF AI Preparedness Index, published 2024, India 0.49, United States 0.77, Singapore 0.80
6.3%
World Bank global forecast, 2.5% for 2026, weakest since the pandemic, with two-thirds of economies downgraded, and South Asia slowing from 7% to 6.3%
4.1%
Global headline inflation, 4.1% in 2025 rising to 4.7% in 2026
Emerging Markets Index composition at July 31, 2026, information technology 40.8%, Taiwan 26.6%, 40.8% MSCI China 21.4%, South Korea 20.3%, India 11.7%. In January, technology was 30.3% and Taiwan 21.0%
57.1%
Dollar share of global reserves, 57.1% in the first quarter of 2026, up from 56.4% in the previous quarter but down from roughly 71% in 1999
74%
In the World Gold Council's 2026 survey, 74% of central banks expect it to lower still within five years. Official gold buying, an estimated 244 tonnes in the first quarter
crude, near $89 a barrel in mid-August, about 24% above pre-war levels, forecast to average $87 across 24% Brent 2026. US 10-year Treasury yield 4.65%, against 3.97% before the Iran war Source:IMF
where the exposure runs the other way. IMF research puts around 40% of global employment in occupations exposed to AI, rising to 60% in advanced economies but sitting at 40% in emerging markets and 28% in low-income countries. The fund's 2026 work on new job creation finds AI related skills appearing in almost 5% of US job postings by 2025, with incidence in emerging economies roughly half that. The comfortable reading is that developing economies face less immediate disruption. The correct reading is that they face less immediate disruption because they have fewer of the cognitive jobs that AI both threatens and rewards, and they are much less equipped to capture the productivity gains. The IMF's AI Preparedness Index, which covered 174 economies when it was published in 2024, places India at 0.49 against 0.77 for the US and 0.80 for Singapore. Bangladesh scores 0.38.
For countries whose development model runs through services exports, business process outsourcing, back-office work, entry level coding and customer support, this is the central strategic question of the next decade, and it is barely being discussed in the same rooms where capital flows are celebrated. Cheap labour was the comparative advantage. AI attacks precisely the tasks that made it valuable. The economies best placed are the ones already inside the hardware chain, Taiwan and Korea above all, along with the handful of middle-income economies drawing data centre investment on the strength of cheap power. The ones most at risk are populous middle-income countries with young workforces, thin digital infrastructure, and social safety nets designed for a different century.
rests on three things holding. That the Fed does not have to raise rates. That Hormuz reopens before food inflation does structural damage to importing sovereigns. That the reallocation away from American assets is a strategic decision rather than a carry trade wearing a strategic costume. The first two are out of the hands of finance ministries from Accra to Jakarta. The third is not. Governments that use this window to extend maturities, deepen domestic investor bases, and build the digital and educational infrastructure that AI adoption requires, will look, in five years, as though they earned something. Those that simply enjoy the cheaper borrowing will find out that the oldest rule in global finance was not repealed in 2026. It was merely suspended.
What to watch out for The bull case for emerging markets
editor@ifinancemag.com
International Finance | Sept - Oct 2026 | 21
COVER STORY
UKRAINE WAR RUSSIA SANCTIONS
ECONOMY
Russia has been the target of the most extensive sanctions regime ever applied to a major economy, but the economy has not collapsed
22 | Sept - Oct 2026 | International Finance
FEATURE RUSSIA
Russia’s economy is holding, but decline could take decades to reverse
International Finance | Sept - Oct 2026 | 23
ECONOMY
FEATURE RUSSIA
UKRAINE WAR RUSSIA SANCTIONS
IF CORRESPONDENT
M
oscow says the war economy is resilient and Western sanctions have failed. The sacking of a state development bank's chief economist, and the numbers behind his warning, tell a more complicated story. Within the space of a single week in August, the world was handed two irreconcilable accounts of the same economy. In the first, Russian officials told global media that the domestic economy has kept a strong and healthy profile despite what they described as unprecedented foreign pressure since the fullscale invasion of Ukraine in early 2022. The Russian embassy in London told CNBC that the country's fiscal position remains ‘significantly stronger’ than that of many Western economies, pointing to foreign public debt of around $57 billion, and noting that this is ‘considerably less’ than what the United States, the United Kingdom, Italy or France spend on debt servicing alone. In the second account, Andrei Klepach, for twelve years the chief economist of the state development corporation VEB.RF and before that a deputy economy minister, was removed from his post on August 16 after remarks he made in May began circulating in Russian media. He had told a gathering of economists at the Moscow Exchange's Nikitsky Club that the country was losing the technological and economic contest, that
24 | Sept - Oct 2026 | International Finance
it would not win a war of attrition, and that the country was heading towards a social crisis. Both accounts contain truths. The gap between them is where the real story sits.
Absorbing four-and-a-half years of sanctions Russia has been the target of the most extensive sanctions regime ever applied to a major economy, but it has not collapsed. It has not come close. The adaptation happened along three main lines. Trade was redirected, with crude and refined products rerouted from Europe to India, China and Turkey, moved on a shadow fleet of ageing tankers that has grown faster than Western authorities can designate it. The European Union's 20th sanctions package, adopted in April 2026, added 46 more vessels to the port access ban, taking the designated total past 630, which is itself an indication of how large the fleet has become. Second, the state stepped into the vacuum left by departing Western firms. Public spending, above all the defence order, replaced private investment as the engine of demand. In 2023 and 2024 that produced growth above 4% a year, which was less a boom than a fiscal injection with a growth rate attached. Third, the macroeconomic plumbing held. The central bank under Elvira Nabiullina defended the rouble aggressively, ran a genuinely orthodox inflation-targeting policy, and imposed
rates that reached 21% before easing began. Inflation was brought down from around 9.5% to below 6%. Sovereign external debt stayed low, which is exactly the point the embassy is making. So, the headline claim survives scrutiny. Russia's external public debt is modest, its banking system has not seized up, its shops are stocked, its currency has not spiralled, and unemployment sat at 2.2% in June. Anyone who predicted a 2022-style implosion was wrong.
Where things have actually deteriorated Low foreign public debt is partly a symptom of exclusion rather than a sign of health. Russia cannot borrow abroad because foreign capital markets are shut to it, so the debt it does not owe overseas is a measure of what it cannot access, not of what it has chosen to avoid. The pressure has simply moved to the domestic
FEATURE RUSSIA
The fiscal squeeze, January to July 2026
Growth, prices and the two-speed economy
• Federal budget deficit 6.46 trillion roubles (approx. $79bn), against a full-year plan of 3.79 trillion roubles
• Q1 2026 GDP -0.2% | Q2 2026 GDP +1.3% | H1 2026 GDP +0.6%
• Oil and gas revenues 4.6 trillion roubles, down 16.8% year on year
• 2023 and 2024 growth above 4% | 2025 growth around 1% | Economy Ministry 2026 forecast 0.4%, cut from 1.3%
• VAT receipts 9.8 trillion roubles, up 24.9% after the rate rose to 22%
• Bank of Russia key rate 14%, inflation forecast raised to 6-7% for 2026
• Government procurement, including the state defence order, up roughly 40% to 8.44 trillion roubles, already 80% of the annual plan
• Civilian manufacturing, excluding oil, around 4% below its 2024 monthly average
• National Wealth Fund liquid assets around 2% of GDP, against 7.3% before the invasion balance sheet, and there the numbers are less comfortable. Between January and July 2026, the federal budget ran a deficit of 6.46 trillion roubles, roughly $79 billion. That is already well beyond the full-year target of 3.79 trillion roubles, which was set at 1.6% of GDP. Depending on the GDP base used, the seven-month gap works out at some-
• Refinery runs at roughly 3.6-3.9 million barrels a day in July, the lowest in more than two decades
where between 2.5% and 2.8% of output. Former deputy central bank chairman Sergei Aleksashenko expects the fullyear figure to land between 7 and 7.5 trillion roubles, roughly 3% of GDP. The composition of that gap matters more than its size. Oil and gas revenues fell 16.8% year on year to 4.6 trillion roubles, despite a Middle East conflict that
briefly pushed crude sharply higher. The domestic fuel damper mechanism, which compensates refiners for selling into the home market below export parity, consumed most of the windfall. Meanwhile, spending has run ahead of plan, with government procurement including the state defence order up around 40% year-on-year to 8.44 trillion roubles by the end of July, some 80% of the entire annual allocation. The finance ministry raised 2.3 trillion roubles through OFZ bond issuance in the first seven months, largely absorbed by state banks, and then paused placements because yields near 16% made the exercise punitively expensive. Debt servicing has become one of the largest single lines in federal spending. Around 460 billion roubles was drawn from the ‘National Wealth Fund’, about 200 billion roubles came from selling nationalised assets, and roughly 3.5 trillion was covered by running down Treasury balances parked in commercial banks, with a little over 4.5 trillion left in that pool. The cushion that made the first years of the war survivable has largely gone. Before February 2022, the National Wealth Fund held around $113 billion in liquid assets, equal to 7.3% of GDP. It is now worth roughly a third of that in real terms, at about 2% of GDP. A fund designed to co-finance pensions has been spent covering a war. The corporate picture behind those aggregates is weakening in parallel. More than half of Russia's large companies closed 2025 with lower profits, and many have cut or frozen investment programmes outright. The coal sector, hit by falling global prices, sanctions and rising rail tariffs, has been running at a loss across a majority of its enterprises. Regional financ-
International Finance | Sept - Oct 2026 | 25
ECONOMY
FEATURE RUSSIA
UKRAINE WAR RUSSIA SANCTIONS
es have deteriorated alongside, with the great bulk of Russia's regions running deficits simultaneously for the first time. None of this shows up in a sovereign external debt figure. The rest of the bill has been passed on to households and firms. VAT went to 22% at the start of 2026, the highest rate since 1992, and the revenue threshold at which smaller businesses must register for it was cut sharply. VAT receipts rose almost 25% in the first seven months. That is not economic growth. It is a transfer from the private sector to the treasury, and it is being made in an economy where growth has already stalled.
What Klepach actually said Klepach's speech on May 21 was not a dissident manifesto. It was a technical diagnosis delivered to a room of professional economists, which is part of why it was so damaging when it surfaced. He began by apportioning blame for the slowdown. Around half of it, he argued, came from the central bank's extremely tight monetary policy, which had crushed investment and, in combination with reduced subsidised lending, dampened consumer demand. Roughly 30% he attributed to industrial policy failure, citing the surrender of the vehicle market to Chinese manufacturers, who now account for close to half of passenger car sales and more than 70% including local assembly, and 60% of trucks. He then went through the sectors. Design and technical problems in the new domestic civil aircraft programme. Weak demand in construction materials and metallurgy. Raw material shortages and import dependence in light industry. His conclusion on monetary policy was pointed. Not every barrier, he said, comes from the central bank, and even
26 | Sept - Oct 2026 | International Finance
Andrei Klepach, former chief economist of Russia's state development bank VEB
a substantial rate cut would not deliver rapid growth. His medium-term ceiling for the economy, assuming the war continues and sanctions hold, was 2% to 2.5% a year. Then came the passages that ended his career. "We won't win the competition in this war of attrition," he said, adding that Russia was losing not only to China and the United States but in some ways to Ukraine, which he acknowledged was an unpleasant thing for him to say. Ukraine's economy is partly destroyed and demographically shattered, he noted, but it is being financed by the West at a scale that dwarfs Russian capital outflows. The assumption that it would simply collapse has not held, and will not hold. His summary was that Russia would not fall apart and would not suffer economic collapse, but that its lag would keep widening, and that he was almost certain the country was heading for a social crisis. He added that these things arrive when nobody expects them, and reminded his audience that ‘no one ex-
pected the February Revolution either’. VEB.RF Chairman Igor Shuvalov reportedly acted after a call from above. An acquaintance told the business daily Vedomosti that the dismissal was related to personal and harsh assessments that could not be reconciled with the corporation's official position.
Testing his analysis against the data The striking thing about Klepach's assessment is how closely it tracks the official numbers, including the ones Rosstat published after he spoke. Second-quarter GDP grew 1.3% yearon-year, beating both the central bank's 0.8% estimate and the economy ministry's 0.9%. Taken alone, it reads as vindication for Moscow. Taken in context, it does not. The first quarter contracted 0.2%, the first decline since 2023, so firsthalf growth came to just 0.6%, around half of last year's pace and a fraction of the wartime surge of 2023 and 2024. The quarterly rebound also rests on temporary supports. There were 5%
FEATURE RUSSIA
more working days than a year earlier. Federal spending in the quarter rose about 13% to 11.5 trillion roubles, with government procurement up 38.5%. Retail turnover jumped 7.2%. The economy ministry itself cut its 2026 growth forecast threefold in May, from 1.3% to 0.4%, and the central bank in July projected a range of zero to 1%. Underneath the aggregate, the twospeed structure Klepach described is visible in the data. Industrial output growth accelerated only because a defence complex flush with orders offset declines elsewhere. Civilian manufacturing, excluding oil, fell 2.1% in June and remains close to 4% below its 2024 monthly average, on calculations by the Centre for Macroeconomic Analysis and Short-Term Forecasting. Civilian industry as a whole has been contracting by more than 3% year-on-year. The energy picture has deteriorated faster than he could have anticipated in May. Sustained Ukrainian drone strikes have pushed Russian refinery runs to roughly 3.6 to 3.9 million barrels a day in July, the lowest in more than two decades and about a third below the seasonal norm, with 18 refineries targeted in that month alone. The resulting petrol shortages forced export restrictions and drove the central bank to raise its 2026 inflation forecast to between 6% and 7% while cutting the key rate by only a quarter point to 14%. Most of the damage will not appear in the national accounts until third-quarter data. The labour market completes the picture. Unemployment of 2.2% sounds like strength, but it reflects a workforce hollowed out by casualties, emigration and recruitment, with authorities projecting a shortfall of around 3.1 million workers by 2030. An economy cannot grow out of stagnation with no spare
labour, no spare capital, and a central bank rate in double digits.
Reading the social crisis warning Klepach was careful about his terms, and the care is the substance of the argument. He explicitly ruled out collapse. What he described is slower, less dramatic, and harder to reverse. The mechanism runs roughly as follows. Growth settles near zero while inflation stays around 6%, so real incomes barely move. Growth in real disposable income could be as little as 0.6% this year. Inequality, which narrowed in 2023 and 2024 as military wages and defence sector pay lifted incomes in poorer regions, has begun widening again. Pensions are falling further behind wages. Tax rises are squeezing small and medium-sized businesses hardest, and those firms employ the people who are not on the defence payroll. Klepach also cited survey evidence that perceived healthcare quality is deteriorating, which is what happens when nearly 40% of federal spending goes to defence and security. There is also a quieter adjustment happening beneath the headline employment figure. Vacancies have been falling while the number of CVs in circulation rises, a pattern that usually signals hidden unemployment rather than a tight market. Employers have responded to cost pressure by cutting hours, freezing pay, and shedding administrative staff rather than by making formal redundancies, which keeps the official rate low while incomes stagnate. Demand for second jobs has risen sharply. A labour market can look fully employed and still be delivering falling living standards, and that combination is exactly what produces political surprises. The politics of this are more delicate
than the economics. The war economy created a large constituency of beneficiaries, from contract soldiers and their families to defence plant workers in regions that had seen no investment in decades. A social crisis in Klepach's sense is what happens when that constituency stops growing and starts shrinking, when the payments stop rising in real terms, when the coal towns and civilian factories that were already unprofitable finally close, and when veterans return to a labour market with no room for them. His invocation of February 1917 was not a prediction of revolution. It was a reminder that this category of breakdown is not forecastable from a spreadsheet.
Slow decline The embassy is right that Russia is not about to default or implode, and Western policymakers who keep waiting for a cliff edge will keep being disappointed. Klepach is right that an economy running at 0.4% growth, financing a war by taxing its own citizens and draining its Treasury balances, with its refining base under weekly attack and its technological gap widening, is not healthy in any sense that matters over a decade. The indicators worth tracking are the full-year deficit against Aleksashenko's 7 to 7.5 trillion rouble estimate, the resumption or otherwise of OFZ issuance, third-quarter GDP once the fuel crisis lands in the data, and real disposable income growth into 2027. The most telling signal, though, has already been given. When a state corporation dismisses one of the country's most respected macroeconomists for describing the contents of its own government's forecasts, the problem is no longer only economic. editor@ifinancemag.com
International Finance | Sept - Oct 2026 | 27
ECONOMY
ANALYSIS
NIGERIAN STOCK EXCHANGE NIGERIA EQUITY
Nigerian stock market emerged as the world’s bestperforming equity market, but that achievement came with a certain amount of scrutiny
At NGX, Share Prices Rise Faster Than Profits RONALD ADAMOLEKUN
The Nigerian stock market, which recently took the top spot in the pecking order of the world’s best-performing equity markets, is riding a boom fuelled by increasingly positive investor sentiment, coming mainly from local investors, who have been flocking to the market, and have never testThanks to the ed the waters. optimism in Nigerian stocks, So forceful has the bonanza the benchmark been that it is turbocharging index of the the share prices of stocks with country’s equity fundamentals and those withmarket hit its out them alike, in several cases all-time pinnacle to heights never before seen. in August, when It was thanks to that optiyear-to-date yield reached 59.7%, mism in Nigerian stocks that pushing market the benchmark index of the capitalisation to country’s equity market hit $117.5 billion its all-time pinnacle in August, when year-to-date yield reached 59.7%, pushing market capitalisation to $117.5 billion. In the banking sector, big-cap equities, like First HoldCo, Zenith and Ecobank Transnational Incorporated, stand out in terms of their year-todate yields, which stood at 169%, 93.2%, and 66.5% in that order as of August 26. First HoldCo, the only one of the three to have released its half-year financial results, reported an annual net profit growth rate of 85.4% for the six
28 | Sept - Oct 2026 | International Finance
months to June. It emerged in recent weeks as Nigeria’s most capitalised stock with a valuation of N5.87 trillion as of August 26. Demand pressure in the stock has been driven by its top shareholder and billionaire tycoon Femi Otedola, who has splurged millions of dollars this year to increase his stake in the company. Generally, the valuation of bank stocks, which have yielded 63.2% since January, has accelerated sharply on the back of the positive market sentiment created by a recently concluded recapitalisation, which raised N4.7 billion ($3.5 billion) from local and international investors.
What is driving demand? One of the reasons why stock prices may jump faster than valuation is when ‘a major investor is acquiring more shares, which could signal to the broader market that there could be something in store for the company’, Abeeblahi Rufai, senior analyst (research and strategy) at Lagos-based multi-asset investment management firm CardinalStone, told International Finance. That was the case with First HoldCo, where Otedola, who has a huge social media following and is seen by many as a charismatic investment role model, has been buying shares since 2021, when he became the top shareholder. In the oil & gas sector, Aradel Holdings, part of the consortium that acquired Shell onshore oper-
ations in 2025, has been the top-performing stock this year, yielding 105%. In comparison, its halfyear net profit grew by 30% above the level seen a year ago. The major spur, analysts said, is the optimism that soaring oil prices from the US-Israel war against Iran is generating among investors, making the yield on energy stocks, at 85.6%, the highest of the five sector indexes tracked by the NGX. “What has propelled prices within that space is the global oil price shock because of the war between the US and Iran,” Benedict Egwuchukwu, investment research associate at Afrinvest West Africa told International Finance. “That is affecting how people are seeing the oil and gas sector within Nigeria because there is a lot of profit to be made from this.” In the cement sub-sector, an acute housing deficit and an infrastructure shortage in Nigeria, Africa's biggest country by population, are stoking a construction boom that is driving up the demand for cement. That has led to spikes in cement prices, which, in turn, have boosted interest in cement stocks. HBM Nigeria, the local unit of Chinese-based
Huaxin Cement, is the biggest gainer this year at 148% as of August 26. Its half-year net profit growth rate of 57% significantly trails that. Sector giant Dangote Cement, owned by Africa’s richest man Aliko Dangote, reported a 22% jump in after-tax profit at half year. The stock, one of the most capitalised on the exchange at N17.4 trillion (nearly $13 billion), has yielded 69.8% this year. BUA Cement, majority owned by Abdulsamad Rabiu, Africa’s third richest man according to Forbes Billionaire Ranking, posted a modest 12.4% jump in post-tax profit in the six months to June, compared to a year ago. Its market value, however, has enlarged by 77% this year as of August 2026.
Speculative excess? Beyond these favourable industry factors, other catalysts, notably speculative excess, are also making stock valuations advance at a swifter pace than profits. Nigeria has a bandwagon culture when it comes to the flavour of the moment in business and investment securities as though a gravitational or supernatural force no one can resist is pulling everybody in one di-
International Finance | Sept - Oct 2026 | 29
ECONOMY
ANALYSIS
NIGERIAN STOCK EXCHANGE NIGERIA EQUITY
rection, sometimes prompting newbie investors to ignore caution. The boom owes its debt in part to that.
Intervention by authorities Recognising the harm that could do, the Securities and Exchange Commission stepped in this June to bar the promotion and marketing of a yet-tobe-approved IPO of Dangote Refinery, the world’s biggest single-train oil refinery owned by Dangote. The frenzy around the $5 billion public share sale, touted as Africa’s largest-ever IPO and now slated for October, was so huge that people that knew next to nothing about equity investment were reported to be opening trading accounts with brokers ahead of key regulatory approvals. The SEC’s intervention was timely, given that a similar flurry of interest in Nigerian stocks birthed a bubble before equities tanked eighteen years ago, making Nigeria one of the markets worst hit by the 2008 global financial crisis.
Power of optimism That massive optimism from retail local investors is stoking a prolonged market-wide rally across all sectors of the stocks listed on the Nigerian Exchange (NGX). It mirrors how domestic participation has steadily grown to be the pivot of all the major surges the market has recorded since 2021, when international investors, who until then were the driving force, exited the country in droves after pandemic lockdowns spurred a far-reaching dollar squeeze. Latest market data shows foreign participation in equity trading stood at 5.6%. That was way
30 | Sept - Oct 2026 | International Finance
weaker than pre-pandemic levels. The figure for September 2019, for instance, three months before the pandemic broke out, was as high as 66.8%. Such factors have broadly lifted most companies’ valuations this year, a number of which have accelerated at a far more rapid pace than their net profits. Curiously, loss-making firms feature among stocks that are the best performers since the start of the year.
Obscure Companies Lead Nigeria’s World-Beating Rally Seven little-known companies emerged in August as the best-performing stocks year to date on the 147-company strong bourse. All but one are penny stocks – a class of stocks that have been noted by analysts as particularly susceptible to share price manipulation – which has necessitated an urgency for regulators and watchdogs to subject trading in such equities to rigorous surveillance and scrutiny. Penny stocks ‘are easily manipulated because of their volatility and exposure to speculators’, Rufai told International Finance. “Manipulating penny stocks, too, could probably not bring as much attention or scrutiny as bluechip stocks, as they're not held by a lot of investors. Hence, it could easily go under the radar, making it easier to manipulate,” he added. The entry of Zichis Agro Allied Industries, the second biggest gainer this year, into the market is a case in point. Its market capitalisation, which was N1.1 billion ($765,511) at listing, had ballooned to N10.1 billion ($7.2 million) barely a month after. The company, which is involved
in oil palm, poultry and fish farming as well as animal feed production and crop cultivation, posted an 859.1% gain in less than five weeks after its listing on the NGX, prompting analysts and the SEC to raise eyebrows. In the last week of February, the regulator suspended trading in the stock and opened an investigation into its market activities. Olufemi Shobanjo, head of the regulation arm of the NGX, said at the time, “Our primary responsibility is to maintain a level playing field where market participants can trade with confidence, backed by timely and accurate information. “This advisory is a routine communication, reinforcing that sound fundamentals, not speculation, remain the foundation for sustainable investment outcomes.” Muktar Mohammed, finance analyst and non-executive director at Lagos-based Blue Marina Securities, told local TV News Central that a dramatic upward price trajectory in so short a time is unprecedented. "It has never happened in the history of the exchange to see a stock gain 772% just one month from its listing," he said. “When we talk about listing by introduction, there is a certain flow that you will make available for the public. And what we’ve seen over and over is that some of this flow is not made available. Then the demand is high, the supply is low. Definitely the price will go up.” He was alluding to the NGX’s free float rule, which requires the investors who are insiders to hold at least a certain percentage of a company’s stock, 15% in the case of Zichis.
Its most recent financial report covering the first half of this year showed post-tax profit quickened by 502% to N457 million from a year ago. That compares to its valuation, which, as of August 25, had been up by 754% since listing. In a market bulletin issued in March, the NGX stated that it ‘has concluded its investigation into the trading activities in the company’s shares and has implemented corrective measures to safeguard market integrity’. Fortis Global Insurance (formerly Standard Alliance Insurance), which has been technically insolvent for more than five years as its liabilities have consistently outstripped liabilities, is miraculously this year’s top performer. Since the first quarter of 2025, the insurer has been heaping up losses, with loss after tax for the half-year 2026 standing at N2.6 billion, 158.3% higher than a year ago. Yet, it has gained 925% this year, outperforming the market by more than sixteen times. Until January, the underwriter
had been under a trading suspension on account of its failure to publish its corporate accounts for years. Between August 2021 and April 2025, Fortis Global Insurance did not publish the reports until it started doing so on April 11, 2025. In the first week after trading resumption, it gained 65%. Fortis Global owed its overnight share price turnaround in part to a share consolidation it executed in July. The 1-for-4 share consolidation was a major contributor to the spell of strong gains it recorded between July and August as the move cut back its outstanding shares by 75%. The market capitalisation automatically surged by 260.6%, reflecting the boost that prices of stock typically receive from such share reduction. But the major driver of its sharply higher valuation has been the impact of buy pressure on its shares ever since the consolidation, with availability of its tradable shares now far lower than before, consequently boosting share price. SCOA Nigeria, a low-liquidity
stock, is the third best performer, having added 365% from the start of the year to August 26. Meanwhile, profit after tax tumbled 54.7% to N147.9 million in the first half of the year. The company, which is involved in the sales, maintenance and leasing of vehicles, is a subsidiary of Paris-based investment holding company SCOA International S.A. Until July 1, 2025, Lebanese-American Massad Fares Boulos was the MD of SCOA Nigeria. At present, Massad Fares Boulos is a senior advisor to US President Donald Trump on Arab and African affairs. SCOA Nigeria is majority-owned by Michel Zouhair Fadoul, who, according to the New York Times, is the father of Boulos’s wife, Sarah. Interestingly, their son Michael is married to Tiffany, Trump’s daughter. SCOA Nigeria has been reticent about its corporate activities and key decisions. No corporate disclosure document about the firm is available for the whole of 2015, 2016, 2019 and 2023 on the NGX, leaving the market and potential investors in the dark at the best of times. Only one of such documents has been released this year, just two throughout 2025, one in 2024, one in 2022, two in 2021, and one in 2020. The company didn’t hold its annual general meeting for six years in a row (2019-2024), all under Boulos’s leadership. It secured a court order to do so in September 2025, two months after Boulos exited the company.
editor@ifinancemag.com
International Finance | Sept - Oct 2026 | 31
ECONOMY
IN CONVERSATION
DELE KELVIN OYE CHAIRMAN, ALLIANCE FOR ECONOMIC RESEARCH AND ETHICS
The Nigerian stock exchange has been the best-performing equity market globally in dollar terms in 2026
NGX equity rally: Constraints exist; direction of travel changed PRABUDDHA GHOSH Nigerian stock exchange (NGX) has achieved a tremendous feat by becoming the best-performing equity market globally in dollar terms in 2026, with a 67% return. S&P Dow Jones Indices recently suggested upgrading Nigeria to frontier market status, news that will sound like music to the ears of investors searching for emerging markets to make their money work. To know more about the NGX's bull run, International Finance sought out Dele Kelvin Oye, who serves as Chairperson of two key bodies: Alliance for Economic Research and Ethics Ltd/GTE and the Nigeria–Turkiye Business Council. Kelvin Oye talked in detail about the various facets of the stock market uptick, including the key sectors driving the rally, the key numbers and data that everyone should take note from the bull run, and most importantly, how the Bola Tinubu administration's reform drive helped in Nigeria earning the confidence of investors. Excerpts from the interview.
International Finance: With a 67% return, Nigeria's stock market has been the best-performing equity market globally in dollar terms in 2026. What were the key factors driving the rally? Dele Kelvin Oye: Three years ago, many investors would have regarded a sustained Nigerian equity-market rally as improbable. Nigeria was widely associated with frontier-market risk: foreign-exchange uncertainty, shallow liquidity, uneven policy transmission, and difficulty in converting local currency returns into reliable dollar outcomes. That scepticism was not irrational. It reflected real institutional and macroeconomic constraints. The important point today is not that those constraints have disap-
32 | Sept - Oct 2026 | International Finance
STOCK MARKET NIGERIAN STOCK EXCHANGE
peared. It is that the direction of travel has changed. Nigeria’s equity market has responded to a combination of reform expectations, bank recapitalisation, improved foreign-exchange liquidity, stronger market infrastructure, corporate capital raising, and renewed interest in Nigeria's long-term productive capacity. Bloomberg data across 92 global exchanges indicated that Nigeria’s benchmark equity index had delivered a 67% return in US-dollar terms since the beginning of 2026, narrowly ahead of South Korea’s KOSPI at 66%. A market rally is not a referendum on one policy or one administration. It is a forward-looking aggregation of expectations about earnings, liquidity, currency, interest rates, commodity prices, governance, and political risk. The Nigerian Exchange is therefore pricing both improvement and uncertainty. The task before policymakers and market institutions is to convert a powerful repricing into durable capital formation. The reform programme began with difficult decisions, including the removal of the petrol subsidy and the movement toward a more unified, market-based foreign-exchange regime. The social costs have been substantial, and responsible economic leadership must acknowledge them. The IMF’s 2026 assessment recognised improved macroeconomic resilience
while also warning that poverty and food insecurity remained severe. Stability that is not eventually translated into lower living costs, employment, energy reliability, and wider opportunity will not possess enduring legitimacy. At the Alliance for Economic Research and Ethics, we view the current market through four lenses: the strengthening of bank balance sheets, the arrival and prospective arrival of strategic issuers, the interaction between currency conditions and asset prices, and the continuing influence of oil and gas on Nigeria’s external and fiscal position. These are not guarantees of perpetual appreciation. They are the principal mechanisms through which reform expectations are being transmitted into market prices.
S&P Dow Jones Indices has suggested upgrading Nigeria to frontier market status. How do you view this development? S&P Dow Jones Indices’ decision to place Nigeria on its 2027 Country Classification Watchlist is significant, but the language must be precise. Nigeria is being considered for possible reclassification from Standalone Market to Frontier Market; this is not an upgrade from an existing frontier classification.
International Finance | Sept - Oct 2026 | 33
ECONOMY
IN CONVERSATION
DELE KELVIN OYE CHAIRMAN, ALLIANCE FOR ECONOMIC RESEARCH AND ETHICS
NGX reported that Nigerian banks raised and listed an estimated 2.25 trillion in 2025. Total NGX listings were estimated at 6.34 trillion, including 3.79 trillion in Federal Government bonds, and 299.69 billion naira in other corporate listings
The distinction matters because index classification is not a ceremonial label. It affects how global investors define their investable universe, how benchmark providers construct portfolios, and how asset owners assess operational accessibility. A possible reclassification would signal that Nigeria’s market infrastructure, regulatory environment, transparency, enforcement, and accessibility are moving closer to the requirements of a recognised frontier-market universe. It would not, by itself, create sustainable foreign inflows. Nor should we confuse a watchlist with a completed decision. S&P DJI has indicated that consistent policy implementation and operational resilience will be important to the review. The appropriate Nigerian response is neither triumphalism nor defensiveness. It is to keep improving the practical experience of investing: timely settlement, reliable price discovery, predictable regulation, credible enforcement, transparent corporate actions, and efficient repatriation through authorised channels. The broader lesson is that market credibility is accumulated through repetition. One successful transaction is encouraging; a decade of consistent execution is transformative.
Which sectors have driven the NGX's bull run? The available H1 2026 data show a market that is broad in direction, and concentrated in leadership and magnitude. BusinessDay newspaper, citing NGX index performance, reported H1 gains of approximately 90.2% for Oil & Gas and 79.0% for Industrial Goods. The NGX’s weekly report for the period ended June 26 recorded broadly similar year-to-date figures. Banking has also been a major contributor. The CBN’s recapitalisation framework requires minimum capital of 500 billion naira for commercial banks
34 | Sept - Oct 2026 | International Finance
with international authorisation, 200 billion naira for national banks, and 50 billion naira for regional banks. The exercise has encouraged banks to raise equity, strengthen their balance sheets, reassess their strategic scale, and prepare for a more competitive regional environment. NGX reported that Nigerian banks raised and listed an estimated 2.25 trillion naira in 2025. Total NGX listings were estimated at 6.34 trillion naira, including 3.79 trillion naira in Federal Government bonds, and 299.69 billion naira in other corporate listings. These figures are evidence of a more active primary market. They are not, by themselves, proof that every new issue will create value or that the secondary market has become deep enough for all investors. Consumer Goods also gained, although more modestly, while the Insurance sector was negative. It is, therefore, more accurate to say that the market has experienced meaningful sectoral participation with pronounced leadership from Oil & Gas, Industrial Goods, and selected financial and energy names. The result is impressive, but it should not be described as an evenly distributed, all-sector advance. This distinction is important for investors and policymakers alike. Breadth of participation matters, but concentration matters too. A market driven by a few large constituents can produce a strong index return while leaving liquidity and valuation risks unresolved elsewhere.
Can you break down some of the key data and numbers behind the NGX's valuation rise in 2026? The NGX All-Share Index closed at approximately 74,800 points at the end of 2023 and stood at 245,209.34 points on August 6. The arithmetic implies a nominal naira index increase of approximately 227.8% over that interval. That is an extraordinary movement, but it is a price-index return, not a claim that the underlying economy or every listed company increased in value by the same amount. Market capitalisation also rose sharply. Contemporary reports placed it at approximately 158.3 trillion naira in early August 2026, compared with about 30 trillion naira at the end of 2023. Market capitalisation is a valuable measure of the market’s scale, but it is not identical to real wealth creation. It can change because share
STOCK MARKET NIGERIAN STOCK EXCHANGE
NXG Top Gainers Companies
Stock Price
Yearly Gain
Market Cap
Dangote Cement
1,000.00
92.23%
13.87 Billion
MTN Nigeria
807
85.52%
12.61 Billion
BUA Cement
28100.00%
85.11%
7.54 Billion
Seplat
13,552.60
151.94%
4.86 Billion
Lafarge Africa
357.2
216.11%
4.34 Billion
First HoldCo
146.7
357.01%
3.21 Billion
Zenith Bank
126.8
97.35%
2.88 Billion
Stanbic IBTC Bank
156.25
56.33%
1.51 Billion
Okomu Oil Palm
1276.2
25.12%
991.77 Million
Guinness Nigeria
356.5
174.23%
643.72 Million
prices rise, new securities are issued, companies are admitted to the market, corporate actions alter the share count, or the currency and nominal price level change. The strongest international comparison is the one that is explicitly dated and denominated. NGX reported that the benchmark delivered 67% in USD terms since the start of 2026, ahead of South Korea’s KOSPI at 66% in the Bloomberg comparison cited by NGX. Naira returns and dollar returns answer different questions. A domestic investor experiences the local-currency return; an international investor also experiences the movement of the naira against the dollar. Liquidity deserves the same precision. NGX reported that banks and other issuers contributed materially to the 6.34 trillion-naira of 2025 listings, while the broader market’s daily trading depth remains a separate question. A larger market is not automatically a liquid market. Liquidity is the capacity to transact meaningful size at reasonable cost, with dependable two-way prices, and without materially moving the market. The proper conclusion is therefore measured: the rally has been substantial, participation has widened, and primary-market activity has strengthened, but the durability of the repricing will ultimately be tested by earnings, free cash flow, governance, valuation, and the ability to trade and repatriate capital under pressure.
Since the beginning of 2026, the naira has strengthened by about 4% against the US dollar, amplifying returns for international investors. How do you read the currency's renewed strength and the NGX's meteoric rise? The naira and the NGX have moved in a relationship that deserves careful analysis. When the currency is volatile, a foreign investor may make a profit in naira and still lose money in dollars. That possibility creates what can be described as confidence deficit. The movement toward a more market-based FX regime has, therefore, been important, even though it has not eliminated liquidity, documentation, or execution risks. NGX reported an approximate 4% appreciation of the naira against the USD since January in the context of its July 2026 market report. The IMF, using a different comparison period, reported a 10% year-on-year appreciation against the dollar in March 2026. These figures are not necessarily inconsistent; they measure different intervals and may use different reference points. A responsible speaker must always state the date range and exchange-rate basis. A currency can influence equity performance through several channels. It affects the translated value of hard-currency earnings, the naira value of foreign assets and liabilities, import costs, interest-rate
International Finance | Sept - Oct 2026 | 35
ECONOMY
IN CONVERSATION
DELE KELVIN OYE CHAIRMAN, ALLIANCE FOR ECONOMIC RESEARCH AND ETHICS
A currency can influence equity performance through several channels. It affects the translated value of hard-currency earnings, the naira value of foreign assets and liabilities, import costs, interest-rate expectations, and the willingness of international investors to hold local securities expectations, and the willingness of international investors to hold local securities. It can also produce accounting gains that are not the same as recurring operating earnings. That is why FX revaluation gains should never be treated as a substitute for durable business performance. The IMF has rightly welcomed the Nigerian government's commitment to a flexible exchange-rate regime while continuing to call for the reduction of remaining exchange restrictions, capital-flow measures, and multiple-currency practices as conditions permit. The mature position is neither to deny progress nor to claim completion. Nigeria has moved in the direction of a more unified market-based system; the work of building deep, predictable, and trusted FX liquidity continues.
The naira's depreciation created a powerful incentive for foreign investors to seek inflation hedges in equities. Can you elaborate on this dynamic? Currency depreciation can encourage investors to seek assets with pricing power, inflation protection, or hard-currency earnings. In Nigeria, companies with export exposure, regulated pricing, strong brands, or the ability to reprice products may be perceived as better positioned than businesses whose revenues are fixed in naira while their costs are imported. But this mechanism must not be presented as a universal law. Depreciation can also weaken household purchasing power, increase working-capital requirements, raise debt-service burdens, and reduce the real value of domestic savings. In banks, FX movements can generate large reported gains or losses that may not recur. In consumer businesses, the ability to pass on costs depends on demand, competition, and the consumer’s capacity to pay. The more defensible conclusion is that depreciation may redirect capital toward selected equities, especially
36 | Sept - Oct 2026 | International Finance
where investors perceive a hedge against inflation or currency weakness. It does not make equities immune to macroeconomic damage. If currency deterioration becomes disorderly, the market’s valuation, financing conditions, and earnings quality can all suffer. For the next phase, returns must increasingly be earned through revenue growth, productivity, stronger balance sheets, dividends, and disciplined capital allocation. The depreciation trade is not a development strategy. It is, at most, a transitional feature of a market adjusting to a new nominal environment.
How much have the government reforms contributed to the NGX's bull run? President Bola Ahmed Tinubu’s reforms have been important to the market’s change in direction, but it would be too simple to attribute the entire rally to one administration or one announcement. Investor confidence is built through a chain of expectations: the belief that prices are becoming more transparent, that contracts will be respected, that capital can be moved through lawful channels, that financial institutions are resilient, and that policy will be implemented consistently and predictably. The Central Bank of Nigeria (CBN) states that Nigeria moved toward a new foreign-exchange framework in June 2023, including a willing-buyer, willing-seller model. This was a significant policy shift. It should not, however, be described as a guarantee of a permanently single exchange rate or frictionless access to dollars. The IMF’s 2026 assessment continued to identify remaining exchange restrictions and multiple-currency practices as matters for further reform. The same principle applies to fiscal reform. President Tinubu assented to four tax-reform Acts on June 26, 2025, with the principal provisions scheduled to commence on January 1, 2026. That is a consequential legislative achievement. Yet, enactment is not the same as successful implementation. The credibility of Nigeria's tax reform will depend on administrative clarity, institutional capacity, taxpayer confidence, and the quality of public expenditure. The market does not require government to promise perfection. It requires government to demonstrate a credible process: explain the objective, publish the rules, apply them fairly, measure the results, and cor-
STOCK MARKET NIGERIAN STOCK EXCHANGE
NXG Bull Run Details Period
Benchmark ASI Performance Milestone
Core Market Driver & Context
Sep-25
98,386 points
Market kicked off Q4 holding steady above the 98k floor as robust early Q3 institutional corporate volumes set a firm foundation.
Oct-25
154,126 points
A Massive Breakout (+8.0% MoM). High-cap banking and industrial giants surged back-toback during a massive 20-day consecutive winning streak.
Nov-25
143,064 points
Technical Pullback (-7.18% QoQ adjustment). The index fell back into local monthly consolidation as asset managers engaged in swift profit-locking sweeps.
Dec-25
155,613 points
Year-End Wrap (+51.19% Full-Year Return). Total market capitalization closed at ₦99.38 trillion, fueled by a strong Santa Claus rally across consumer and industrial goods.
Jan-26
165,517 points
Up +6.27% for the month. Hit an intra-month all-time psychological record peak of 165,837.33 points on January 13.
Feb-26
196,263 points
Up +18.56% MoM. A blowout month for financial tickers; the banking index alone skyrocketed on immense corporate FX revaluation windfalls.
Mar-26
200,913 points
Breached the 200k Milestone. The market effectively crossed into historical uncharted territory, anchored by massive institutional interest in energy and heavy growth assets.
April – May 2026
210,420 points (Established Cap Equivalents)
A ₦160 Trillion Market Cap Ceiling. Aggressive local aggregate positioning pushed the NGX into a top global rank for equity performance in real dollar terms.
June – July 2026
Consolidation Ranges
The market experienced localized mid-year correction buffers as foreign liquidity channels began reorganizing structural portfolio flows.
Aug-26
244,199 points
High Volatility Adjustment. Reached a sharp multi-month high early in the month before facing a brief ₦6 trillion profit-taking pullback across 13 negative sessions.
Sep-26
246,082.63 points (Current Bulls Regain Control (+58.1% YTD position). Staged an immediate ₦1.22 trillion single-day Peak) recovery rally right before the official FTSE Russell Frontier Market Reclassification goes live on September 21.
rect errors without destroying predictability. That is the foundation of a genuine credibility dividend.
The NGX is eagerly awaiting the listing of Dangote Petroleum Refinery. Do you see the listing triggering another bull run? A potential listing of Dangote Petroleum Refinery could become an important event for Nigeria’s capital market. It would bring a large strategic industrial asset into the public-market conversation, broaden
sectoral representation, create an opportunity for price discovery, and test the NGX’s capacity to support a transaction of global significance. The word potential is essential. Current reporting points to a proposed offering, but the reported stake, timing, valuation, and proceeds have changed across accounts. Reuters reported in August 2026 that the refinery was aiming to raise $5 billion through a proposed October 2026 listing, following a reported $2.5 billion private placement for a 6% stake that implied a
International Finance | Sept - Oct 2026 | 37
ECONOMY
IN CONVERSATION
DELE KELVIN OYE CHAIRMAN, ALLIANCE FOR ECONOMIC RESEARCH AND ETHICS
The next wave will be determined by the willingness of credible companies to accept the disciplines of public ownership: audited reporting, timely disclosure, independent oversight, investor relations, and accountability to minority shareholders. Those disciplines are not bureaucratic burdens. They are the infrastructure of trust
valuation of approximately $40 billion. Those reported terms should not be confused with a final prospectus or approved offer document. Nor should investors assume that a large listing automatically creates a bull market. The effect would depend on valuation, free float, governance, disclosure, dividend policy, the treatment of foreign-currency earnings, and the ability of local and international investors to trade the shares. Reports of possible dollar-denominated dividends should remain described as a proposed feature until formally documented in the offer materials, and approved through the relevant regulatory process. The strategic significance would nevertheless be considerable. Nigeria needs more large, transparent, productive companies represented in the public market — not only banks and consumer companies, but energy, infrastructure, technology, healthcare, agriculture, and industrial businesses. A successful offering would be valuable not because size alone is virtuous, but because it could establish a higher standard for disclosure, governance, research coverage, and long-term ownership.
Do you see more IPO opportunities arriving at the NGX amid the ongoing bull run? What sectors or companies could potentially drive the next wave of listings? Nigeria has a credible opportunity to deepen the pipeline of public-market issuers, but the language should be realistic. Energy infrastructure, gas processing, power, agriculture, food manufacturing, healthcare, logistics, and technology all require long-term capital. The NGX can become an important channel for that capital if it continues to improve listing standards, research coverage, settlement, market making, and investor education.
38 | Sept - Oct 2026 | International Finance
The history of recent listings also teaches us to distinguish between a primary capital raising and a listing by introduction. Geregu Power was admitted to the NGX in October 2022, BUA Foods in January 2022, Transcorp Power in March 2024, and Aradel Holdings in October 2024. Several of these were listings by introduction rather than public offerings that raised new equity at the time of admission. Nevertheless, the listings were strategically important. They broadened the investable universe, enhanced visibility, improved price discovery, and created a public-market platform that could support future financing. But precision matters. A listing can be a major capital-market event without being a primary IPO. The next wave will be determined by the willingness of credible companies to accept the disciplines of public ownership: audited reporting, timely disclosure, independent oversight, investor relations, and accountability to minority shareholders. Those disciplines are not bureaucratic burdens. They are the infrastructure of trust.
What must the Tinubu administration do to sustain both the momentum? The first requirement is policy consistency, understood not as stubbornness but as predictable governance. Reforms should be evaluated honestly, adjusted where evidence demands it, and protected from arbitrary reversals. Policy stability is strongest when it is supported by transparent rules and institutions rather than by personal assurances. The second requirement is deeper liquidity. The market needs more market makers, more institutional participation, more credible research, more investable products, and more large-cap issuers. Pension funds and insurance companies can contribute significant patient capital, but the regulatory framework must balance development objectives with fiduciary responsibility. Encouraging equity investment is not the same as compelling it. The third requirement is investor protection. The SEC, NGX, NGX Regulation, and market-infrastructure institutions must maintain high standards of enforcement, disclosure, settlement, and corporate governance. A market cannot become globally investable
STOCK MARKET NIGERIAN STOCK EXCHANGE
NXG Bull Run: Companies Providing Maximum Stock Returns Stock / Company
Sector
Trajectory and Key Metric
Market Rationale / Driver
Veritas Kapital Assurance
Insurance
+744.30% Return
Riding massive sector inflows and improved underwriting discipline
McNichols Plc
Process Industries
+273.18% Return
Leading mid-cap consumer/process goods rallies
Berger Paints Nigeria
Industrial Goods
+208.00% YTD Return
One of the top-performing industrial names on the board
First HoldCo Plc
Banking
+180.00% YTD Return
A standout tier-1 banking stock hitting a 10% daily ceiling frequently
Aradel Holdings Plc
Energy (Oil & Gas)
+145.00% YTD Return
Fueled by strong crude production, high oil prices, and asset tracking
Lafarge Africa Plc (WAPCO)
Industrial Goods
+120.00% YTD Return
Massive valuation jump following corporate acquisition news
Ecobank Transnational
Banking
+106.96% Q2 Surge
The fastest-moving commercial banking stock over the mid-year window
Zenith Bank Plc
Banking
+67.67% Return
Anchoring the banking index rally with record 1 trillion profits
Source: www.nairametrics.com
if minority shareholders do not trust the quality and timeliness of information. The fourth requirement is social legitimacy. Investors do not allocate capital to statistics; they allocate capital to economies populated by people, firms, institutions, and consumers. Reforms must, therefore, be judged by whether they improve productivity and opportunity, not only by whether they produce a stronger index in a particular year.
Higher crude prices have boosted government revenue and profitability in the energy sector. Do you see this rally sustaining in the long run? Higher oil prices can support Nigeria’s fiscal revenues, foreign-exchange availability, and energy-sector earnings. A prolonged oil-price decline would create pressure through the budget, the external account, the currency, and investor sentiment. That vulnerability remains real.
Yet, Nigeria’s long-term market story cannot be an oil-price story alone. The sustainable objective is to use periods of favourable commodity income to build nonoil productive capacity, improve tax administration, strengthen infrastructure, and invest in human capital. The IMF projects continued growth in both oil and non-oil activity while identifying fiscal, external, security, and social risks that must be managed. Diversification is not a slogan. It means that more Nigerian firms should earn revenue from manufacturing, food processing, improved mining investment climate, solid minerals processing and value addition, services, technology, logistics, healthcare, and regional trade. It means that the capital market should finance those firms transparently and at a cost that rewards discipline.
editor@ifinancemag.com
International Finance | Sept - Oct 2026 | 39
ECONOMY
FEATURE AFRICA
AFRICAN SOVEREIGN WEALTH FUNDS NSIA NIGERIA
Africa’s sovereign wealth funds: What sets them apart?
From Nigeria's top-ranked NSIA to Angola's hard-won governance turnaround, the continent's strongest sovereign funds share the same quiet discipline — and its weakest share the same fatal flaw 40 | Sept - Oct 2026 | International Finance
FEATURE AFRICA
IF CORRESPONDENT For a continent still associated, unfairly in many quarters, with the ‘resource curse’, Africa's sovereign wealth funds tell a more interesting story than the one usually told about them. It is not a story of uniform failure, nor of uniform success. It is a story of institutions built at wildly different speeds, with wildly different mandates, that are now producing wildly different results — and the gap between the best and the rest has rarely been more instructive. Roughly twenty African countries now run some version of a sovereign wealth fund. Collectively, they oversee a slice of a global sovereign investment industry that has swollen to well over $14 trillion, though Africa's share of that pool remains stubbornly under one percent — a reminder of how thin the continent's fiscal surpluses are relative to the Gulf states or Norway. Yet, within that modest total, a handful of funds have begun to do something that matters more than
raw size: they have started to compound. They have built governance structures that outlast the ministers who created them. They publish numbers that can be checked. They are, increasingly, delivering returns that would not embarrass an endowment manager in London or Toronto. What separates these funds from the many African sovereign vehicles that remain, in effect, government slush accounts with a fancier name? The answer turns out to have less to do with how much oil, gas, or diamonds a country has, and rather more to do with four unglamorous things: independence from the treasury, discipline about withdrawals, a genuine investment mandate rather than a political one, and transparency that is enforced by habit rather than by law alone.
The scoreboard that keeps everyone honest Any serious conversation about sovereign fund performance in 2026 now runs, sooner or later,
International Finance | Sept - Oct 2026 | 41
ECONOMY
FEATURE AFRICA
AFRICAN SOVEREIGN WEALTH FUNDS NSIA NIGERIA
through the Governance, Sustainability and Resilience Scoreboard published annually by the research firm Global SWF. The seventh edition of the index, released at the end of June, assessed 25 separate governance, sustainability, and resilience criteria across the world's 200 largest state-owned investors, which between them manage some $34 trillion. Only nine institutions worldwide earned a perfect score. One of them is African: Nigeria's Sovereign Investment Authority, universally known by its acronym NSIA. It sits alongside NBIM of Norway, Singapore's Temasek, Australia's Future Fund, and Canada's La Caisse — genuine company for a fund capitalised with a comparatively modest $1 billion in seed money fifteen years ago. It is worth dwelling on that fact before moving to the numbers, because it reframes the entire debate. The story of Africa's best sovereign funds is no longer a story about scale. It is a story about institutional design.
Nigeria's NSIA: The outlier that proves the rule NSIA has become, almost by default, the reference case for what an African sovereign fund can achieve when insulated properly from political interference. Established by an 'Act of the National Assembly' in 2011 and structured around three ring-fenced pools — a 'Stabilisation Fund,' a 'Future Generations Fund,' and a 'Nigeria Infrastructure Fund' — the Authority has now posted thirteen consecutive years of earnings and asset growth, a run that has taken its net asset value from roughly $2 billion in seed and government contributions to $3.4 billion, a compound annual growth rate of close to 11%. The 2025 numbers, presented in
42 | Sept - Oct 2026 | International Finance
Abuja earlier this year, show total assets rising 10.9% year-on-year to nearly 4.91 trillion, driven by fresh capital contributions and core earnings of 478.8 billion. Strip out the headline naira figures, which were flattered in 2024 by a weak currency and then normalised in 2025 as the naira stabilised, and the underlying story is one of patient, diversified asset allocation rather than one-off windfalls. The Future Generations Fund returned 15.44% against a policy benchmark of US inflation plus four percentage points — an outperformance of more than 800 basis points. The Nigeria Infrastructure Fund returned 14.55% against its own inflation-linked target, and the Stabilisation Fund, which by design holds the most liquid and conservative assets, still managed 9.27% against a target pegged to US CPI alone. Management has been candid, too, about the parts of the balance sheet that look less flattering on paper. Pre-tax return on equity fell from 73.4% in 2023 to 57.8% in 2024 once the currency effects are stripped out, and headline profit for 2025 dropped sharply once the one-off foreign exchange gains of the previous year washed out of the base. NSIA's leadership has framed this, reasonably, as a return to a more normal earnings pattern rather than a sign of deterioration — the kind of frank public accounting that is itself part of what earns a fund credibility with outside analysts. Three structural choices explain why NSIA keeps outperforming both its African peers and its own modest starting capital. First, the tripartite fund structure separates money that might be needed tomorrow from money that will not be touched for a generation, which allows each pool to be invested accord-
ing to its actual time horizon rather than a single, compromised risk appetite. Second, the Authority has been unusually aggressive about co-investment and blended finance, pairing its own capital with partners such as Japan's development agency JICA on start-up financing, and with private investors on healthcare infrastructure, including a diagnostics and cancer-treatment network under its Medserve platform that is expanding well beyond its original three centres. Third, and most important, NSIA has resisted becoming a piggy bank. Where other African funds have been raided during fiscal emergencies, Nigeria's has largely been left alone to compound — a political discipline that is rarer on the continent than any investment technique.
Botswana's cautionary counter-example No feature on African sovereign funds would be complete without Botswana's 'Pula Fund', and it earns its place here as much as a warning as a model. Established in 1993 to preserve diamond export revenues for future generations, the Pula Fund was for years held up as the African gold standard: professionally run out of the central bank, invested conservatively in global equities and bonds, and governed under the same Santiago Principles that underpin best practice worldwide. But a fund is only as disciplined as the government that owns it. Botswana's fiscal position has deteriorated as the diamond industry, hit hard by falling global demand and competition from lab-grown stones, has passed its peak contribution to the economy. Repeated withdrawals to plug budget and balance-of-payments gaps have shrunk the
FEATURE AFRICA
AFRICA'S SOVEREIGN FUNDS AT A GLANCE Country
Fund
Established
AUM (approx)
Type
2026 GSR Score
Botswana
Pula Fund
1993
~$142m**
Stabilisation / Savings
24%
Nigeria
NSIA
2011
$3.4bn
Stabilisation / Savings / Infrastructure
100%
Angola
FSDEA
2011
$4bn
Savings / Strategic
64%
Ghana
Ghana Petroleum Funds
2011
$1.42bn
Stabilisation / Heritage
36%
Rwanda
Agaciro Development Fund
2012
$400m
Sovereign Development
48%
Senegal
FONSIS
2012
$1bn
Strategic Investment
Not yet rated
Egypt
TSFE
2018
$12bn
Strategic (asset monetisation)
40%
Ethiopia
Ethiopia Investment Holdings
2024
$150bn*
Strategic (state-enterprise holding)
Not yet rated
*EIH's figure reflects consolidated state-enterprise assets rather than a traditional liquid investment portfolio, and is not directly comparable to the others.
fund from roughly $1.8 billion in 2018 to a reported $142 million by August 2025, according to Bank of Botswana data cited by regional media — a startling collapse for what was once southern Africa's flagship savings vehicle. The economy contracted an estimated 3% in 2024, with the IMF projecting a further contraction into 2025, and diamonds still account for roughly 80% of exports, and a third of fiscal revenue, leaving Gaborone dangerously exposed to a single commodity cycle. Botswana's response has been to launch an entirely new, more ambitious fund, tasked not only with investing surplus revenue but with restructuring loss-making state enterprises that have required repeated bailouts. Officials say only investment returns, not capi-
**Down from $1.8bn in 2018, following repeated fiscal withdrawals.
tal, will be drawn from the new vehicle. Whether that discipline holds where the old fund's did not is the open question — and it underlines the central lesson of this entire sector: a well-designed mandate is worth little without a legal or political firewall that keeps a finance ministry from treating the fund as a current account.
Rwanda's Agaciro: Small, deliberate, and citizen-owned If NSIA demonstrates what independence and diversified mandates can achieve at reasonable scale, Rwanda's 'Agaciro Development Fund' shows what discipline can achieve almost regardless of scale. Launched in 2012 following a national dialogue chaired by President Paul Kagame, Agaciro — the
Kinyarwanda word for dignity — remains unusual globally for having been seeded not by oil or mineral windfalls but by voluntary contributions from Rwandan citizens, the diaspora and the private sector, later supplemented by government transfers. The fund has grown steadily to around $400 million in assets, modest by continental standards but run with a consistency that shows up in the governance data: Agaciro scored 48% on the 2026 Global SWF assessment, respectable for a fund of its size, with particular strength on governance criteria. Roughly 70% of the portfolio sits in equities, with the balance in government securities, a relatively aggressive stance for a fund explicitly designed to reduce Rwanda's dependence on aid and donor
International Finance | Sept - Oct 2026 | 43
ECONOMY
FEATURE AFRICA
AFRICAN SOVEREIGN WEALTH FUNDS NSIA NIGERIA
goodwill. Management has signalled ambitions to grow the fund toward $1 billion partly through more infrastructure and co-investment activity, including in data centres and power generation to support the country's push into digital services. What Agaciro offers that larger, resource-backed funds cannot is a genuine political constituency. Because part of its capital came from citizens rather than the state alone, withdrawing from it carries a reputational cost that goes beyond fiscal arithmetic — a subtle but real form of accountability that has, so far, kept the fund from becoming a target for emergency raids.
Angola's FSDEA: Proof that redemption is possible Perhaps the most dramatic turnaround on the continent belongs to Angola's 'Fundo Soberano de Angola.' Established in 2011 with an initial $5 billion endowment, FSDEA spent its early years mired in allegations of self-dealing and opaque investment practices under the fund's first chairman, who happened to be the son of the then president — a textbook illustration of the governance failures that give African sovereign funds their poor global reputation. Since 2017, under President João Lourenço's anti-corruption drive, the fund has been rebuilt almost from scratch. A new board, greater disclosure, and a transparency score of 8 out of 10 from the Sovereign Wealth Fund Institute have accompanied a genuine financial recovery. FSDEA posted record net profit in 2023, more than tripling the prior year's result, and has more recently reported annual returns in the region of 10%. Armando Manuel, who returned to lead the fund in late 2023 after helping
44 | Sept - Oct 2026 | International Finance
launch it more than a decade earlier, and later serving stints at the IMF and World Bank, has been explicit that rebuilding trust meant insisting investment decisions no longer flow through the presidency. The fund, now with roughly $4 billion under management, has diversified into regional infrastructure, including a $1 billion commitment to the Lobito Corridor rail project linking Angola, Zambia, and the Democratic Republic of Congo — a bet that connectivity, not just financial assets, is where long-term African sovereign capital can do the most good. FSDEA's case matters because it demolishes the idea that governance failure is a permanent condition. A fund that was, ten years ago, a byword for cronyism now scores among the better-governed institutions on the continent, according to Global SWF's most recent assessment. The lesson is less about any particular investment technique than about political will: reform happened because a president decided it should, and was sustained because the new leadership treated the Santiago Principles as a floor rather than a public-relations exercise.
Ethiopia, Egypt and the new generation of ‘strategic’ funds Not every fast-growing African sovereign vehicle fits the classic savings-fund mould, and the newest entrants complicate the performance conversation in useful ways. Ethiopia Investment Holdings, barely two years old, has already amassed an estimated $150 billion in assets under management by consolidating some thirty state-owned enterprises, including Ethiopian Airlines, under one holding structure — making it, at least on paper, the largest sovereign fund on the continent. Its mandate is less about
generating portfolio returns than about modernising the management of state assets, entering partnerships, such as a solar power joint venture with the UAE's Masdar, and preparing to launch the Ethiopian Stock Exchange. Whether EIH's headline asset figure translates into anything resembling Norway-style investment performance is a question that will only be answerable once its accounts mature, and its state-enterprise holdings are independently valued — a caution worth noting given how differently ‘strategic’ funds like Ethiopia's, Gabon's FGIS, or Angola's FSDEA are constructed compared with pure savings vehicles like Botswana's. Egypt's Sovereign Fund, known as TSFE, sits somewhere in between. Established in 2018 to monetise underused state assets, the fund has been expanding rapidly, with plans to absorb hundreds more state enterprises and to launch dedicated sub-funds for tourism, healthcare, financial services and infrastructure, alongside an Africa-focused vehicle. Its 40% GSR score reflects a fund still building out its governance architecture even as its balance
FEATURE AFRICA
framework has not been immune to political pressure — recent amendments to the governing law have loosened some spending restrictions in favour of infrastructure financing, prompting warnings from resource-governance watchdogs about the risk of diversion into short-term political priorities. But the underlying architecture, with parliamentary oversight and a published, auditable track record stretching back over a decade, remains one of the more transparent among Africa's commodity-financed funds, and offers a template other nations continue to study. sheet grows quickly, a reminder that scale and institutional maturity do not always arrive together. TSFE's approach — attracting private co-investors into state assets rather than accumulating a traditional savings pool — mirrors a broader shift among newer African funds toward what practitioners call ‘strategic’ investing: less concerned with hoarding foreign exchange reserves, more concerned with catalysing private capital into infrastructure, healthcare, and industry at home.
Ghana's petroleum funds: Small, rules-bound, and quietly effective Ghana offers a smaller but instructive case of rules-based discipline. Its two petroleum funds, the 'Ghana Heritage Fund' and 'Ghana Stabilisation Fund,' were created in 2011 under a Petroleum Revenue Management Act that legally mandates the split of oil revenue between the two vehicles, and requires regular public reporting by the Bank of Ghana. Together, they held about $1.42 billion at the end of the first half of 2025, with the Heritage Fund's closing book value alone reaching $1.36 billion on the back of steady investment income. The
Senegal's FONSIS and the diversification play Senegal's Fund for Strategic Investments, known as FONSIS, illustrates a different route to relevance: rather than accumulating a single large pool of liquid assets, it operates through five specialised subsidiaries spanning healthcare, agriculture, real assets, and private equity, and has built roughly $1 billion in assets under management since its creation in 2012. Its model — smaller, sector-specific investment vehicles feeding off a central sovereign platform — has influenced how several newer West African funds are being designed, including Guinea's planned $1 billion fund, expected to launch by mid-2026, built around revenue from the giant Simandou iron-ore project.
The common threads Pull these case studies apart and a pattern emerges that has little to do with geology and everything to do with institutional plumbing. The funds that perform best over time — NSIA above all, but also the reformed FSDEA and the disciplined, citizen-anchored Agaciro —
share a few features. Their investment decisions are taken by professional boards operating at arm's length from the finance ministry, not by presidencies or cabinets. Their withdrawal rules are either legally binding or politically costly to break. They publish enough detail, consistently enough, that independent assessors, such as Global SWF and the International Forum of Sovereign Wealth Funds, can actually verify performance rather than take it on faith. And, critically, they have all, at some point, survived a moment when a government under fiscal pressure was tempted to raid them — and didn't, or did and then rebuilt. Botswana's Pula Fund shows what happens when that last safeguard fails even after decades of good practice. Angola's FSDEA shows that failure is not necessarily terminal. Ethiopia and Egypt show that scale can now be built astonishingly fast when a government consolidates state assets under a single sovereign umbrella, though the jury is still out on whether size will translate into the kind of risk-adjusted returns that older, more conservatively run funds have delivered. For a continent long defined in this space by extractive-industry dependence and governance scandals, that is a meaningfully different story than the one still told about it in most boardrooms outside Africa. The best-performing funds are not the ones sitting on the biggest reserves of oil, diamonds or iron ore. They are the ones that have figured out how to say no to their own governments — and have been allowed, by design or by hard-won reform, to keep saying it.
editor@ifinancemag.com
International Finance | Sept - Oct 2026 | 45
Business Dossier - Bahrain Development Bank
Digital arm reshaped how SMEs engage with our banking services
B
Through tijara, BDB enabled businesses to open accounts with minimal documentation and significantly lower entry barriers compared to the competition
ahrain Development Bank won two awards from International Finance for Best CEO Strategies in Digital Transformation - Banking - Ms. Dalal Al Qais - Bahrain 2025, and Most Innovative Islamic SME Finance Bank - Bahrain 2025. Bahrain Development Bank is one of leading financial institutions in the Gulf country. In an exclusive interview, Dalal Ahmed Al Qais, Group Chief Executive Officer, Bahrain Development Bank told International Finance how the bank is tackling the challengers being thrown up by the digital transformation that is underway around the world.
fore, focused on building a holistic ecosystem around the clients, enabled by digital infrastructure that is scalable, efficient, and responsive to evolving business needs.
What strategic vision have you implemented to drive digital transformation at Bahrain Development Bank? When I joined BDB, it was clear that digital transformation could not be approached as a technology upgrade alone. It had to be a fundamental shift in how we serve SMEs and how we position ourselves within Bahrain’s economic ecosystem. Our vision was to move from a traditional, product-led institution to a true development bank that delivers integrated, digital-first financial and non-financial solutions. We translated that vision in 2022 into a structured fouryear transformation strategy focused on customer centricity, digitisation, and sustainable growth. A key part of this was establishing a dedicated Strategy and Transformation division to function as both a delivery engine, and a longterm thinking partner for the organisation. Equally important was redefining our role as a key enabler. SME requirements today are far beyond funding and working capital; they also encompass market access and tools that support their growth journey. Our strategy, there-
What have been some of the most impactful digital initiatives introduced under your leadership that have improved customer experience and operational efficiency? One of our most defining initiatives has been the launch of tijara, our digital arm, which fundamentally reshaped how SMEs engage with our banking services. Through tijara, we introduced a seamless digital onboarding journey, enabling businesses to open accounts with minimal documentation and significantly lower entry barriers compared to the market. We also introduced solutions such as invoice discounting, which directly addresses one of the most pressing challenges SMEs face, namely cash flow constraints caused by delayed payments. This allowed us to move beyond traditional lending and provide liquidity solutions that are aligned with real business needs. On the operational side, we undertook a comprehensive modernisation of our core banking systems and migrated key functions to the cloud. This resulted in a marked im-
46 | Sept - Oct 2026 | International Finance
D
alal Al Qais is an accomplished banking professional with over 22 years of experience in the financial sector, spanning retail banking, SME financing, digital transformation, and risk management. Her expertise extends across conventional, Islamic, and international banking institutions. Before joining Bahrain Development Bank as Group Chief Executive Officer in December 2021, Dalal served as Chief Retail Banking and Wealth Management Officer at Bahrain Islamic Bank. During the course of her career, she held several senior leadership roles at Standard Chartered Bank, including Head of Consumer Banking, Head of Integrated Distribution, and Head of Distribution & Regional Channels and Call Centre. Dalal holds a Bachelor of Science in Management and Marketing from the University of Bahrain, and a Master’s in Finance. In 2020, she completed the Oxford Fintech Programme at the University of Oxford, and is currently pursuing a Doctorate in Business Administration at the Swiss Business School.
International Finance | Sept - Oct 2026 | 47
Business Dossier - Bahrain Development Bank
provement in performance, including a significant reduction in downtime and enhanced service reliability. The impact has been tangible. We have seen strong growth in digital transactions, customer acquisition, and onboarding, alongside a notable improvement in customer satisfaction. These outcomes reinforce that when digital transformation is done with purpose, it delivers measurable value for both the customer and the institution. Digital change often requires cultural and organisational shifts. How have you encouraged innovation and digital adoption within your teams? Digital transformation is essentially about people. Technology can enable change, but it is culture that sustains it. From the beginning, our focus was on building an organisation that is open to new ways of working and willing to challenge established processes. One of the first steps was restructuring the organisation and bringing in a high-calibre management team with diverse experience across banking, technology, and strategy. This created the foundation for a more progressive and agile culture. We also introduced a Transformation Management Office to ensure that initiatives are executed with discipline and pace, while maintaining clear accountability across the organisation. At the same time, we streamlined processes to remove inefficiencies and empower teams to focus on value-adding activities. Importantly, we embedded a data-driven mindset. Detailed analytics and insights have better equipped our teams to understand customer behaviour and make informed decisions. This has helped shift the culture from reactive to proactive, where innovation is not a one-off effort but a continuous process. What emerging technologies or digital trends do you believe will shape the next phase of banking transformation at Bahrain Development Bank? The next phase of transformation will be defined by how effectively banks integrate intelligence into their operating models. Data analytics and artificial intelligence will play a central role in enabling more personalised, predictive, and responsive financial services. For development banks like ours, this is particularly important. SMEs are not a homogeneous client segment as their needs vary significantly depending on their size, sector, and stage of growth. Advanced analytics will allow us to tailor solutions more precisely and anticipate challenges before they arise. We also see continued growth in embedded finance and 48 | Sept - Oct 2026 | International Finance
platform-based ecosystems. Banking services will increasingly be delivered within broader business environments, rather than as standalone offerings. This aligns closely with our direction of building an ecosystem that connects finance with market access and advisory support. Resilience and security will also remain critical. As digital adoption grows, so does the need for robust infrastructure and governance frameworks that ensure trust and stability across all customer interactions. How does Bahrain Development Bank support entrepreneurs and small businesses through its Islamic financing solutions? Islamic finance is a cornerstone of our offering, representing a significant portion of our portfolio and client base. It provides a framework that is both ethically grounded and commercially viable, which resonates strongly with SMEs in Bahrain. We have developed a range of Islamic financing solutions that address different stages of the business lifecycle, from starting up to scaling. This includes working capital, fixed asset financing, and specialised programmes delivered in collaboration with national institutions such as Tamkeen. This holistic approach allows us to support entrepreneurs in a way that is practical, scalable, and aligned with the broader economic objectives of the Kingdom. What specific gaps in SME financing did the bank aim to address through its innovative Islamic banking offerings? One of the key gaps we identified was accessibility. Many SMEs, particularly micro and small enterprises, face challenges in meeting traditional banking requirements, whether in terms of documentation, minimum balances, or credit history. We addressed this by simplifying our processes and lowering entry barriers. For example, through our digital offerings, we reduced the minimum balance required to open accounts and streamlined onboarding, making it easier for businesses to access financial services. Another critical gap is working capital. SMEs often struggle with liquidity due to delayed payments, which can hinder their ability to operate and grow. Our introduction of invoice discounting provided a direct solution to this issue, allowing businesses to unlock cash tied up in receivables. We also recognised the need for targeted support for specific segments, such as women entrepreneurs. Through programmes like Riyadat, we have been able to offer subsidised, Sharia’a-compliant financing that enables more inclusive participation in the economy. Overall, our focus has been on designing solutions that
BDB Signs Invoice Discounting Agreement with Alba Ms. Dalal Al Qais, Chief Executive Officer of Bahrain Development Bank Group, and Mr. Ali Al Baqali, Chief Executive Officer of Alba
are practical, accessible, and aligned with the realities of SME operations. Beyond financing, what types of advisory services, partnerships, or development programmes does the bank provide to help SMEs grow sustainably? We see ourselves as an enabler of growth rather than just a provider of capital. This means supporting SMEs across multiple dimensions, including market access and capability development. Our partnerships play a central role in this. Through collaborations with entities such as Tamkeen and the Supreme Council for Women, we deliver programmes that combine financing with training, mentorship, and business development support. We also provide access to opportunities such as government procurement and export support, helping businesses expand beyond their immediate markets. This is particularly important in an economy like Bahrain, where growth often depends on the ability to scale regionally and internationally. How can Islamic finance further evolve to strengthen SME ecosystems and contribute to long-term econom-
ic diversification in Bahrain? Islamic finance has a unique opportunity to play a more transformative role in SME ecosystems by evolving beyond traditional financing structures and embracing more innovative, partnership-based models. One area of potential is the expansion of risk-sharing instruments that align the interests of financiers and entrepreneurs. This can encourage more investment into highgrowth sectors and early-stage businesses, which are critical for economic diversification. There is also scope to integrate Islamic finance more closely with digital platforms and ecosystems. By leveraging technology, we can make these solutions more accessible, efficient, and responsive to the needs of SMEs. Finally, collaboration is an absolute must. Strengthening partnerships between financial institutions, government entities, and private sector stakeholders can create a more cohesive support system for SMEs. Initiatives such as the planned National SMEs Growth Fund are a step in this direction, providing targeted capital to priority sectors that drive long-term economic value. Ultimately, the goal is to position Islamic finance as a strategic enabler of sustainable growth and diversification.
International Finance | Sept - Oct 2026 | 49
INDUSTRY
ANALYSIS
FRACTIONAL EXECUTIVE FRACTIONAL CFO
A $5.7 billion market is turning the corner office into a subscription, and seasoned leaders are the ones cashing in
Why the fractional executive is finding more takers IF CORRESPONDENT
For most of the past century, a company that wanted a chief financial officer bought one outright. It paid a search firm, waited six months, then signed a package running well into six figures with equity stapled on top. That model is now being unbundled. A growing tier of companies has decided it does A growing tier not need a full-time chief of companies anything. It needs the judgehas decided ment, two days a week, on a it does not monthly invoice. The global need a fullfractional executive market time chief has topped $5.7 billion, and anything. is growing at roughly 14% It needs the a year, with North America judgement, accounting for 43.7% of that two days value at about $4.1 billion a week, on in 2025. What began as a a monthly stopgap for cash-poor startinvoice ups has become a deliberate sourcing strategy for the mid-market. The numbers behind the shift are unusually blunt. Gartner expects more than 30% of mid-size enterprises to have at least one fractional executive on retainer by 2027. Some 72% of chief executives say they plan to increase their use of fractional leaders within the next 12 months. A quarter of US businesses already hire this way, a figure projected
50 | Sept - Oct 2026 | International Finance
to reach 35% by the end of 2026, with demand up 46% year on year.
The maths that broke the full-time hire The arithmetic driving this is not complicated. A fulltime chief marketing officer typically costs between $275,000 and $400,000 a year once salary, bonus, equity and benefits are loaded in. For a business turning over $20 million, that is a substantial fixed cost attached to a single person whose value is concentrated in a handful of strategic decisions a quarter. The fractional alternative re-prices that exposure. Average monthly retainers sit between $6,000 and $15,000, with hourly rates generally ranging from $150 to $350 depending on function and complexity. Industry estimates put the saving at 40% to 60% against a full-time equivalent, with no equity dilution and no severance risk. Sara Daw, chief executive of The CFO Centre, has described the gap plainly. A lot of ‘companies need CFOs but can't afford them full-time’, she told Forbes, and fractional arrangements are built precisely for that space. Crucially, this is not consulting rebadged. A fractional executive is embedded leadership accountable for outcomes, not a vendor who hands over a slide deck and walks away. They sit in leadership meetings, own a roadmap, and answer to the board. The difference from a permanent hire is cadence and cost, not scope.
Finance and marketing built the category Two functions matured first, and both did so for the same reason. Their value is legible on a spreadsheet. Finance leads. The US market for fractional chief financial officers exceeds $3.2 billion in 2026 and is projected to double to $6.4 billion by 2028. Marketing follows close behind. The fractional CMO market reached $1.27 billion in 2026, with projections of $2.68 billion by 2031. Chief Outsiders, one of the earliest firms to industrialise the model, now fields a network of more than 120 fractional chief marketing officers and chief sales officers across the United States. Its West region managing partner, Karen Hayward, argues that most mid-market chief executives are working from an outdated picture of their own customers, ‘managing growth on assumptions that no
Finance leads. The US market for fractional chief financial officers exceeds
$3.2 billion in 2026
and is projected to double to
$6.4 billion by 2028
longer reflect how buyers actually buy’. That diagnosis explains the appeal. The problem such companies face is rarely a shortage of marketing activity. It is a shortage of senior pattern recognition, and pattern recognition does not require a desk five days a week. Revenue leadership is the next segment to mature. The population of fractional sales leaders across the
International Finance | Sept - Oct 2026 | 51
INDUSTRY
ANALYSIS
FRACTIONAL EXECUTIVE FRACTIONAL CFO
US and Canada grew from 5,000 in 2020 to 9,000 in 2024, an increase of 80%.
The AI officer is the new frontier Nowhere is the pressure sharper than in artificial intelligence, where demand for leadership has comprehensively outrun supply. IBM's 2026 CEO Study, covering 2,000 chief executives across 33 geographies, found that 76% of organisations now have a chief AI officer, up from 26% a year earlier. Postings for chief AI officer and equivalent senior titles grew roughly 400% between 2023 and early 2026. The role is measurably useful. Organisations with a CAIO scale 10% more AI initiatives and move generative-AI prototypes into production at a rate of 44%, against 36% for those without one. A full-time CAIO commands a median base salary of $353,220, with a typical range of $264,915 to $494,507, according to Glassdoor's June 2026 data. Once bonus, equity, benefits and the team they must build are included, the first-year investment can easily exceed $1.5 million to $2 million. Other estimates put the salaried cost of a full-time CAIO at $400,000 to $700,000 before the search even begins. Few companies below $300 million in revenue can justify that, and fewer still can fill the seat. Fractional CAIOs typically work one to four days a week for $10,000 to $30,000 a month, an annual cost of roughly $180,000 to $480,000 with no equity attached. Paul Okhrem, a Prague-based fractional chief AI officer who ad-
52 | Sept - Oct 2026 | International Finance
vises boards across the US, UK, Europe and the Gulf, frames his own value against the advisory industry. "Most AI consultants will tell you what to buy." His counter-argument is operating credibility. He has run production AI inside two companies he founded, Elogic Commerce and Uvik Software, reporting roughly 30% operational efficiency gains. Fractional CAIO engagements start from $30,000 a month, typically running six to eighteen months at one to three days a week.
Why the executives are opting in The demand story only works because the supply story changed first. Senior leaders are choosing this deliberately, and in numbers. LinkedIn profiles combining ‘fractional’ with a C-suite title rose from roughly 2,000 in 2022 to more than 110,000 by late 2024, an increase of about 5,400%. The wider fractional professional population doubled from 60,000 in 2022 to 120,000 in 2024, with projections above 200,000 by 2027. This is not a holding pattern between permanent jobs. Heidrick & Struggles' 2026 Talent Lens Survey found that 85% of interim leaders have worked independently for more than a year, while new entrants to the field jumped from 6% in 2020 to 15% in 2025. Roughly 72.8% of fractional leaders have 15 or more years of experience, and 92.8% win clients through referral. The pull factors are familiar to anyone who has watched senior professionals reassess their working lives since 2020. Multiple cli-
Fractional CAIOs typically work one to four days a week for $10,000 to $30,000 a month, an annual cost of roughly $180,000 to
$480,000 with no equity attached
ents means diversified income and reduced single-employer risk. Portfolio work suits leaders with grown children, slowing partners, or simply no appetite for another decade of internal politics. More than half of fractional professionals report six-figure annual incomes, which removes the obvious objection. Karen Hayward's own trajectory is illustrative. She held executive posts at EarthLink Business, CenterBeam, Accelio, BeyondWork and Xerox Canada before joining Chief Outsiders, converting three decades of operating experience into a repeatable practice rather than a single seat.
Britain becomes the second centre of gravity The model is not confined to North
America. UK fractional jobs have grown 340% since 2019, and 78% of British scale-ups have either used a fractional executive or are considering one, with day rates running between £800 and £1,500. and London commanding the top of the band. Europe is following, though more slowly, and the pattern is broadening by sector. Finance, manufacturing and healthcare are now the fastest-growing buyers, displacing technology as the category's centre. More than 40% of US small and mid-market companies are projected to use fractional leadership by the end of 2026.
Where the model strains None of this makes fractional leadership a universal answer, and the sector's own advocates concede as much.
Bandwidth is the obvious constraint. An executive splitting attention across three or four clients cannot absorb a crisis at all of them simultaneously. Cultural embedding is harder part-time, and a leader with no equity and a 30-day notice period has structurally less skin in the game than one whose net worth depends on the outcome. There is also a data problem for anyone reporting on the category. Much of the market sizing originates with the platforms and firms that profit from growth. Methodologies vary widely, and figures for the same segment can differ by an order of magnitude. ZipRecruiter's fractional CAIO index alone spans $111,000 to $800,000, because the label covers everyone from one-day-a-week advisers to interim
full-time executives. The direction of travel is unambiguous. The precision is not. The more durable point is structural. The broader executive search market stands at $58.13 billion in 2025 and is forecast to reach $94.73 billion by 2030, and interim solutions are increasingly sold alongside permanent placement rather than against it. Companies are not abandoning the full-time C-suite. They are learning to buy leadership in units smaller than a career. For a generation of executives who spent twenty years earning the title, that turns out to be an opportunity rather than a demotion.
editor@ifinancemag.com
International Finance | Sept - Oct 2026 | 53
INDUSTRY
FEATURE WYNN AL MARJAN
UAE CASINO AL MARJAN ISLAND
UAE’s $5.1 billion bet on a casino off Ras Al Khaimah IF CORRESPONDENT
54 | Sept - Oct 2026 | International Finance
Wynn Al Marjan Island is designed, unapologetically, to compete with Macau, Singapore and Las Vegas for a slice of Asia’s gaming dollar
R
ising 352 metres out of an artificial archipelago off Ras Al Khaimah, the bronze-and-gold tower of Wynn Al Marjan Island is meant to be seen from a long way off. By the time it opens – now pushed to 2027 after what Wynn Resorts calls a ‘modest delay’ caused by shipping disruptions on account of the Iran conflict, according to comments from chief executive Craig Billings on the company’s investor call – it will be the tallest building in the northern part of the Emirates and the centrepiece of the most consequential experiment in Gulf tourism policy in a generation: The region’s first full-scale, licenced casino. The numbers alone justify the attention. At $5.1 billion, Wynn Al Marjan is more than a resort; it’s a statement of intent by an emirate that until recently was best known as Dubai’s quieter, cheaper neighbour. The property will have 1,530 rooms and suites, 22 restaurants, a 101-berth marina built for superyachts, and a licenced gaming floor of more than 20,000 square metres, plus a second ‘sky casino’ on the 22nd floor.
International Finance | Sept - Oct 2026 | 55
INDUSTRY
FEATURE WYNN AL MARJAN
UAE CASINO AL MARJAN ISLAND
Analysts have pencilled in annual property cash flow in the $450-600 million range, comparing favourably with Wynn’s existing Macau and Boston properties. The company has spoken of revenue potential north of a billion dollars a year once the property matures. This isn’t a discreet card room appended to a beach resort. It’s designed, unapologetically, to compete with Macau, Singapore and Las Vegas for a slice of Asia’s gaming dollar. That ambition explains why the project has taken as long as it has to get off the ground, and why it’s worth examining critically. Financing alone required a $2.4 billion construction facility (reportedly the largest hospitality financing deal in UAE history) on top of equity contribution from Wynn, Marjan and RAK Hospitality Holding. Wynn holds a 40% stake in the joint venture, a structure that limits its financial exposure but also its control, more typical of an emerging-market bet than a flagship. And the ‘modest delay’ language is corporate understatement for a project that’s already weathered a construction pause, materials rerouted around a closed Strait of Hormuz, and a workforce of more than 22,000 labouring through a live regional conflict at its doorstep. None of this is disqualifying – delays are the rule rather than the exception for integrated resorts at this scale – but the project’s fortunes are tied to a neighbourhood that remains volatile in ways Macau and Singapore simply aren’t.
A licence, not a liberalisation The regulatory story here matters as much as the architecture. Wynn Al Marjan holds the first, and, so far only, land-based commercial gaming licence
56 | Sept - Oct 2026 | International Finance
issued by the UAE’s General Commercial Gaming Regulatory Authority, a federal body created by decree in 2023 and chaired by Jim Murren, the former chief executive of MGM Resorts. The GCGRA’s design is deliberately narrow: Each of the UAE’s seven emirates may opt in to a single land-based casino licence and a single online gaming licence, no more. Only Ras Al Khaimah has done so for a physical casino; Dubai, notably, has not, despite MGM Resorts building a large non-gaming hotel there, and reportedly circling an Abu Dhabi application. Abu Dhabi and Ras Al Khaimah have between them allowed one online operator, Play971, to go live, quietly, in late 2025. This is regulated scarcity, not a free market – a model that borrows more from Singapore’s tightly capped duopoly than from Macau’s crowded strip. It's also required real legal engineering. Gambling contracts were, until this year, technically void under the UAE’s civil code even where a GCGRA licence existed. A decree-law that took effect on June 1, 2026, finally removed that contradiction, giving licenced gaming contracts the enforceability investors need – while leaving unlicenced gambling, online and off, a criminal offence. It’s a narrow, surgical liberalisation: Permission for one heavily vetted operator in one Emirate, wrapped in anti-money-laundering and responsible-gaming obligations pitched, the regulator says, at standards comparable with New Jersey and the UK. Who exactly will be allowed onto the gaming floor remains one of the project’s more interesting unresolved questions. Early analyst notes assumed Emirati citizens – roughly 10-11% of the UAE’s population – would be barred
outright, consistent with the religious sensitivities involved. More recent regulatory guidance suggests no nationality-based restriction has actually been written into the rules, only an age floor of 21 and valid identification, with final entry conditions to be confirmed closer to opening. That ambiguity is itself telling: It suggests Abu Dhabi is deliberately keeping its options open rather than committing either way, aware that the answer carries real domestic sensitivity.
Gambling and the Islamic conscience That sensitivity is not incidental. Gambling – maisir – is explicitly proscribed in the Quran, grouped with intoxicants as a corrupting influence on society, and Islamic jurisprudence across schools treats it as unambiguously haram (forbidden). It’s this consensus that has kept the Gulf casino-free for decades, and that
FEATURE WYNN AL MARJAN
makes the UAE’s move genuinely startling to many in the region. Riyadh’s approach makes a useful mirror It shows there’s no single ‘Islamic’ answer here, only a spectrum of political calculations about how far economic diversification can be allowed to stretch religious tradition. Commentary across the Arab press has been sharp. Critics have accused Abu Dhabi of prioritising tourism revenue over religious and cultural tradition, and of building what amounts to a two-tier system: A foreign-facing playground for tourists, expatriates and global elites – who make up roughly 89% of the UAE’s population – insulated from a citizenry with little formal say in the decision. Supporters counter that this simply extends a model the UAE has run for decades, from alcohol licencing to Dubai’s nightlife economy: Permissive enough to draw global capital and visitors, calibrated carefully enough not to
disturb the domestic social contract.
The market case The commercial logic isn’t hard to see. Estimates put the UAE gaming market’s potential at $3-5 billion in annual gross gaming revenue, and industry analysts increasingly talk of the country becoming a fourth major global gaming hub behind Macau, Las Vegas and Singapore. The addressable market is enormous and under-served: Wealthy travellers from India, Pakistan, Iran and the wider Gulf currently fly to Macau, Genting Highlands or, further afield, Las Vegas to gamble. A resort 50 minutes from Dubai International Airport intercepts that demand far more efficiently, alongside European and Russian high rollers already resident in the Emirates. Wynn’s acquisition of London’s Aspinalls casino, rebranded Wynn Mayfair, looks explicitly designed as a feeder property, channelling British clientele
toward Ras Al Khaimah. Regional trend lines support the bet too: Gambling revenue across the Middle East and Africa remains a sliver of the global total but is forecast to grow faster than almost anywhere else through 2031, with the Gulf specifically tipped for growth above 4% annually. There’s also a wider Asian dimension worth noting. Japan’s own long-delayed integrated-resort experiment in Osaka, and Thailand’s on-again, offagain casino legislation, show how difficult it is even for governments without religious constraints to translate gaming ambition into open floors – years of licencing battles, community pushback, and financing hurdles are the norm, not the exception. Ras Al Khaimah’s advantage is that it faces none of that domestic political friction: A single ruling family, a compliant federal regulator, and no electorate to persuade. That’s precisely what has let the Emirate move from announcement to near-completion in barely five years, a pace unmatched anywhere else attempting to build an integrated resort from scratch. Whether Ras Al Khaimah becomes the Macau of the Middle East or a well-financed cautionary tale will depend on execution as much as appetite – on whether the delayed opening holds through 2027, on how strictly access is policed, and on whether Abu Dhabi’s calculated ambiguity toward its own citizens survives contact with a fully operational casino floor. What isn’t in doubt is that the Gulf’s relationship with gambling, quietly settled for half-a-century, has just been reopened for negotiation.
editor@ifinancemag.com
International Finance | Sept - Oct 2026 | 57
INDUSTRY
FEATURE AUTOMOBILE
VOLKSWAGEN MERCEDES-BENZ
One after another, German automobile companies are announcing restructuring plans, only to meet opposition and scrutiny from labour unions
58 | Sept - Oct 2026 | International Finance
FEATURE AUTOMOBILE
Germany’s industrial crown jewel under
pressure IF CORRESPONDENT
T
he April 2026 report from the London-based marketing consultant Brand Finance found four of the top five most valuable automobile brands are from Germany. However, all that glitters is not gold. Apply the proverb to the real-world scenario and you will find it sitting perfectly with Germany's crown jewel. Beneath so-called top rankings, lies weak consumer demand, slowing electric vehicle (EV) sales, intense competition from Chinese manufacturers, rising production costs, geopolitical uncertainty, and the expensive transition toward electrification, that are squeezing profits across the industry. One after another, companies are announcing restructuring plans, only to meet opposition and scrutiny from labour unions. The current industrial downturn do not appear to be a cyclical one. The issue reflects a painful structural transformation, that is forcing German automakers to rethink their business models, putting millions of jobs at risk.
An ongoing bloodbath Let’s start with Volkswagen. The company's operating profit fell 9.5% in the April-to-June
International Finance | Sept - Oct 2026 | 59
INDUSTRY
FEATURE AUTOMOBILE
VOLKSWAGEN MERCEDES-BENZ
period to €3.5 billion euro ($3.98 billion). With revenues of €82.4 billion, the group was somehow able to keep its operating margin within the 4.0% to 5.5% target range for the full year, at 4.2% in the second quarter. The group no longer expects revenue growth, and instead the automaker is bracing up for profit decline of up to 3% in 2026. CEO Oliver Blume has been uncompromising on the need of the automaker becoming competitive against Chinese rivals, both at home and abroad, by large-scale cost-cutting. Blume believes Volkswagen is facing more than 150 Chinese competitors right now, with some of them even challenging the German giant successfully in its home turf. Blume's restructuring plans have met with resistance from the powerful labour unions. They believe that, more than job cuts, progress on technology and product development will help the company stage a comeback. Mercedes-Benz, another German major, has seen its core car business suffering an 8% fall in the second quarter. In China, the sales drop was a whopping 30% compared to the same period in 2025. The automaker posted a higher Q2 profit, as the figure rose 22% to €1.5 billion ($1.7 billion), thanks to its financial services and vans. As per CEO Ola Kaellenius, Mercedes' German factories are in need of an intense push for leaner production (read potential job losses). The automaker is already diversifying its operations to open up new profit streams. It is boosting its production presence in cheaper Eastern European countries, such as Hungary and Poland. In Argentina, during May this year, the company
60 | Sept - Oct 2026 | International Finance
inaugurated a $110 million industrial truck plant, with the goal of producing up to 10,000 units per year.
No one is spared BMW too will cut several thousand jobs in Germany by 2027-end in response to a squeeze in profits and weak demand. The automaker's Q2 deliveries shrunk by 4.9% and following the loss-making patterns of its domestic peers, BMW saw heavy sales drop in China. A 30.2% downfall in the world's largest auto market couldn't be offset by the combined 19.5% growth seen in the American and European markets. The automaker will now trim its product portfolio, reviewing model variants in certain markets as electric vehicle adoption diverges between countries such as China, where EVs dominate,
and the US, where combustion-engine vehicles remain popular. It has also signed a long-term deal with Qualcomm to acquire chips for its future digital cockpit and advanced driver-assistance systems, that will come as built-in features for its next-generation vehicles. The company has concluded a $1.7 billion investment in its production plants in South Carolina, gearing up for the launch of EV production in the United States. Luxury carmaker Porsche will cut around one in five jobs by 2035, with 9,000 positions to be axed in total (from the total workforce of 42,600), toeing the restructuring line of parent Volkswagen and its brands. Michael Leiters, who became the CEO earlier 2026, has been tasked with
FEATURE AUTOMOBILE
overhauling the business, with sales in Porsche's once highly lucrative China market collapsing and its EV strategy stalling. Porsche has given its workers the guarantee of keeping sites open for another five years, until the end of 2035, as well as €2.1 billion ($2.39 billion) in investments in its main factory in Stuttgart-Zuffenhausen and its R&D centre in Weissach.
Things spill at supply chain front too The automotive sector is the backbone of the German economy, with an estimated three million people directly and indirectly employed by household names, including Volkswagen, Mercedes and BMW. According to a June 2026 report pub-
lished by the Boston Consulting, "For decades, Europe’s car industry had underpinned the continent’s most powerful manufacturing networks with deep supplier systems, highly skilled labour, and scale-driven efficiency but that stability had been turned upside down." The study found that Europe’s production capacity now exceeded demand by ‘more than five million vehicles a year’, or the equivalent of ‘35 production sites’ across the continent. Both Europe and China have one common enemy: overcapacity. However, China has found a solution, by exporting and selling cheap EVs on a global scale, including in Europe, while the continent’s automakers have failed to generate enough demand in their backyard, resulting in poor financials. In Germany’s case, the mess has
spilled over to the supplier level too. Bosch, a global engineering and technology giant, that operates across mobility (auto parts and software) and industrial technology (factory automation), received a massive jolt in June as Volkswagen walked away from a €1.5-billion ($1.7 billion) investment in its automated driving partnership with the supply chain giant, citing a sweeping cost-cutting drive. Since then, things have not gone smoothly for the supply chain giant. It has decided to cut roughly 13,000 to 22,000 jobs through 2030, due to a €2.5-billion cost gap, weak market demand, and intense price competition from Chinese EV and tech manufacturers. The rubber and plastics division of Continental recently reached an agreement with German labour representatives on a cost-saving programme involving around 1,600 job cuts. Following the agreement, Continental will launch a voluntary programme offering eligible employees at the ContiTech business the option to leave under agreed conditions. German machine and car parts maker Schaeffler has cut its medium-term sales target, citing weaker market expectations, particularly for passenger cars and light commercial vehicles. The company now expects 2028 sales between €24 billion and €26 billion ($27.6 billion and $29.9 billion), respectively, down from an earlier range of €27 billion to €29 billion. For Schaeffler, to make matters worse, major American customers have withdrawn component orders, something that the CEO Klaus Rosenfeld said was not included in the venture's 2025 planning assumptions. While Schaeffler, despite cutting its sales outlook, confirmed its 2028 group
International Finance | Sept - Oct 2026 | 61
INDUSTRY
FEATURE AUTOMOBILE
VOLKSWAGEN MERCEDES-BENZ
targets for an adjusted operating profit margin of 6% to 8%, and adjusted free cash flow of €400-600 million, it has decided to move ahead with its partial retirement programme in Germany to lower costs at its domestic sites. The measure, expected to be taken up by around 1,300 workers, had been agreed with employee representatives, and would result in a one-off charge of about €51 million ($59 million) in 2026, with savings expected from 2027. A financial analysis by Strategy&, PwC's German consulting arm, found average interest expenses at Germany's leading auto suppliers rising for a fourth consecutive year in 2025 to 102% of operating earnings, far exceeding levels in the rest of Europe and China. Apart from severe debt loads, the study also discovered another pressing financial problem for these companies: lower average equity ratios than their competitors, leaving them more exposed to financial stress. Suppliers themselves are under pressure to compete, with Strategy& terming the cost gap between German and Chinese suppliers as a ‘widened one’ between 2019 and 2025. "While German suppliers' overhead costs worsened during that period, Chinese competitors became more efficient, reducing both overhead and manufacturing costs as a share of revenue," the analysis noted.
China looms large Europe's auto market, especially the EV segment, saw sales growth in June 2026, offsetting a sharp decline in petrol and diesel sales, according to data from the European Automobile Manufacturers’ Association (ACEA). While total car registrations rose 13.1% to 1,407,332 vehicles, battery-elec-
62 | Sept - Oct 2026 | International Finance
Best-Selling Car Brands in Germany in 2026 (First Half) Brand
2026 (HY)
%Change
%Share
(From HY 2025) (H1 2026)
Volkswagen
73,747
-4.3
18.4
Skoda
128,218
+17.6
8.6
BMW
126,766 +6.5
8.5
Mercedes 125,960 -0.8
8.5
Audi
106,422 +8.9
7.2
Seat
79,094 -5.7
5.3
Opel Hyundai
70,403 +14.5
4.7
48,306
+4.1
3.3
Ford
48,255
-9.2
3.3
Fiat
35,832
+28.8
2.4
Source: Car Sales Statistics (Best-Selling Cars)
tric, plug-in hybrid and hybrid car registrations climbed 51%, 22.7% and 17.1%, respectively, together accounting for almost 70% of all new vehicles. The uptick helped Chinese brands expand their footprint further across the European Union, Britain and the European Free Trade Association. BYD, Chery and Leapmotor sold almost three and six times more than what they did in 2025. SAIC and Geely witnessed their sales rising more than 50% and 11%, respectively. Registrations at Renault, Stellantis and Volkswagen rose between 3.6% and 7.3%, which are nowhere close to their Chinese rivals.
The EU’s tariffs on Chinese BEVs, which can add up to 45.3% in costs, have done little to blunt the cost advantage. BYD’s Dolphin Surf Boost is priced in Europe from €26,990 ($30,800), still 3% cheaper than the comparable Renault 5 E-Tech. Closely following the European market trends, the automaker is increasingly leaning on plug-in hybrids (PHEVs), which escape the additional tariff altogether. The strategy change resulted in the automaker's May sales growing by 140. Germany, in the beginning of the year, introduced a new incentive, worth up to €6,000 for BEVs and PHEVs,
FEATURE AUTOMOBILE
while Sweden and Italy have expanded their own policy support. The consumer response got reflected in the continent’s Q1 2026 sales numbers. Total electrified vehicle market share sat at 67.5%, with China emerging as the winner Given the intense pace of the global protectionism, local production is emerging as the new reality, and the Chinese are again aware of that. Leapmotor is set to assemble SUVs at a Stellantis plant in Spain. Chery recently opened a European headquarters in Barcelona.
Chinese players are consolidating their grip Beijing hosted the world’s largest auto
show this year too, amid the growing shadow of the global energy crisis in the backdrop of the Iran war and the Hormuz disruption. The 2026 edition featured 1,451 vehicles, including 181 world premieres and 71 concept cars, across a record-breaking 380,000 square metres of exhibition space. Instead of competing with the Western carmakers on the internal combustion engine front, China decided to take the game to the next level: electric. In May 2014, the then Communist Party Chairman Xi Jinping (and now the President) outlined the goal during a visit to SAIC Motor. What followed was a series of priority state fundings and an inter-
national talent recruitment program. During the Covid years, as international executives stayed away from China, the domestic industry made remarkable advances, both on the vehicle and the supply chain fronts. It resulted in CATL and BYD now dominating global battery supply chains, apart from leading in innovation and disruption fronts, with low-cost sodium batteries all set to come to market in 2026. China excels in making small, affordable EVs, without compromising on the feature front. It has beaten its global peers on the innovation front. Every 18–24 months, a new vehicle emerges, against the global average of five–sev-
International Finance | Sept - Oct 2026 | 63
INDUSTRY
FEATURE AUTOMOBILE
VOLKSWAGEN MERCEDES-BENZ
en years. While Tesla developed a 48V architecture for its Cybertruck (up from 12V), Chery is believed to have put the vehicle's Chinese counterpart under mass production. Bugatti, which had held the all-time speed record for six years, with its W16 hitting 489 kilometres per hour, got beaten by BYD’s Yangwang U9 Xtreme, that did 496 kilometres per hour with four electric motors and a 1,200V lithium iron phosphate battery pack. The Xtreme was reportedly built in just 18 months. BYD, ranked as China's second-largest battery manufacturer, recently broke new ground by developing a car battery with what it calls ‘Megawatt charging technology’. In just five minutes of charging, this battery can travel up to 250 miles. Chinese EV brands are now branching out into batteries, semiconductors, and other products related to their industry, to expedite their own vehicle manufacturing. Their global peers, including the Germans, are dependent on external partners. Vertically-integrated supply chains, or the lack of it, have become the make-or-break factors here.
China vs Germany: A statistical comparison The harsher side of China's rise as a global EV powerhouse has been its domestic front. As per Carscoops, apart from BYD, Xiaomi, and Leapmotor, no more than four additional companies are expected to break even by 2030. The challenging earnings environment has pushed automakers to expand more aggressively into overseas markets. Data from the China Passenger Car Association showed that sales of BEVs and PHEVs, in the world's largest car market, totalled 1.04 million units in June, down
64 | Sept - Oct 2026 | International Finance
7% from the same month in 2025. Sales for the first half of 2026 fell 13% year-on-year to 4.73 million vehicles. The reason? A dampened consumer demand due to economic uncertainty, expectations of further price declines, and the gradual withdrawal of government support. Beijing has revised its subsidy programme, phasing out tax incentives for EV manufacturers, a process that will be completed in January 2027. Analysts estimate the vehicle export tally to be around 10 million by the end of 2026, a 41% increase from 2025. The removal of tax rebates has hit German ventures too. The sales share held by Volkswagen, Audi, BMW, Mercedes-Benz, and Porsche went down to just 1.6%. That is the lowest on record, with only 19,200 new EVs from these brands registered between January and March, a 55% drop year-over-year. Volkswagen’s EV sales alone fell by
more than 72%, while BMW dropped nearly 65%, and that of Mercedes-Benz slipped by around 14%. However, it would be unfair to blame the lack of tax rebates alone. Let’s take BMW as an example. The company is betting on its ‘Neue Klasse’ electric cars to revive its fortunes in China after two years of declining sales. But shareholders and analysts see the fiveyear development process as a slow one, against the break-neck R&D speed of its Chinese rivals. Supporters of German cars may say their favourite brands excel on quality. So does China. Nio reportedly drove its flagship ET9 sedan over speed bumps with a tower of champagne glasses balanced on the bonnet, without spilling a drop, to showcase the vehicle's advanced suspension system. While Chinese premium brands are openly targeting customers of BMW, Audi, Porsche and Mercedes, only about
FEATURE AUTOMOBILE
German brands are now tightening ties with Chinese automakers in an effort to steady the numbers. Audi launched its Chinaonly AUDI brand with SAIC in 2025, and is currently preparing a third all-electric model. Volkswagen has teamed up with Xpeng and recently unveiled the ID. Aura T6 and ID. Unyx 09 at the Beijing Auto Show 5% of BMW's sales in the world's largest automobile market have remained fully electric, according to Global Mobility data. In a market where EVs account for 46% of vehicle sales, the stat is more than disappointing. And that has resulted in BMW's China sales going down in both 2024 and 2025. Sales at Mercedes and Volkswagen's Audi brand have also been down, dropping 28% and 19%, respectively, in the H1 2026. According to Shanghai consultancy LandRoads, BMW's average transaction price in China in 2025 was 341,000 yuan ($50,200), below local brands such as Nio, Aito and Denza. Among German premium brands, only Audi was priced lower, at 287,000 yuan.
Predicting the situation ahead German brands are now tightening ties with Chinese automakers in an effort to steady the numbers. Audi launched
its China-only AUDI brand with SAIC in 2025, and is currently preparing a third all-electric model. Volkswagen has teamed up with Xpeng and recently unveiled the ID. Aura T6 and ID. Unyx 09 at the Beijing Auto Show. Developing these cars locally has cut costs by at least 40%, a figure that explains much of the strategy. Mercedes will sell its all-electric GLC EQ and the new electric C-Class in China, while partnering with a local company to produce models exclusively for the country. Similarly, BMW has gone it alone with the new iX3 and i3, both of which will be sold in China in long-wheelbase form. Volkswagen, apart from its aggressive cost-cutting, now sees a revised product offering as a solution, including a new pick-up truck, an avenue for expansion in the United States. Pick-up trucks and large SUVs are in strong demand in the world's largest economy.
As per reports, while the automaker doesn't offer pick-up truck in its line-up, it plans to bring one into the US market before the end of the decade. While the American market remains attractive for sellers of combustion engine trucks and SUVs, Volkswagen will face stiff competition from Ford, Ram-maker Stellantis and General Motors. As of now, it looks like collaboration with Chinese players and expansion elsewhere in the world have emerged as preferred survival options for German automakers.
editor@ifinancemag.com
International Finance | Sept - Oct 2026 | 65
INDUSTRY
ANALYSIS
TELECOM OOREDOO RESTRUCTURING
Why Qatar's telecom giant is carving itself into towers, data centres and cables
Dismantling: The Great Ooredoo Break-Up IF CORRESPONDENT
Something unusual is happening to one of the Middle East's biggest mobile operators. Piece by piece, Qatar's Ooredoo is taking itself apart. Not in crisis, not under pressure from creditors, but deliberately, with the enthusiasm of a company that has discovered its parts are worth more than the whole. The data centres now sit inside a company called Ooredoo's Syntys. The mobile masts in half-year Qatar have moved into a new results read firm named Al Abraj. The less like undersea cables and internaa telecom tional fibre routes are being earnings bundled into Ooredoo Fibre statement Networks. And a long-gesand more like tating venture with Kuwait's a progress Zain and the Dubai-based report on a TASC Towers would pool demolition roughly 30,000 telecommuschedule nication tower assets across Qatar, Kuwait, Algeria, Tunisia, Iraq and Jordan into a jointly owned independent tower company. Each move follows the same logic. Investors will pay handsomely for a business that owns physical kit and collects steady rent for decades, the way they pay for a motorway or a power station. They will pay far less for a firm that simply sells phone contracts. Ooredoo's half-year results read less like a telecom earnings statement and more like a progress
66 | Sept - Oct 2026 | International Finance
report on a demolition schedule.
A solid half, and a strategy laid bare The numbers themselves were respectable. Revenue grew 4.6% year-on-year to QAR 12.5 billion as demand for connectivity and data services held up across its markets, EBITDA rose 7.4% to QAR 5.5 billion, and free cash flow climbed 7.7% to QAR 3.9 billion. The group's customer base reached 147.5 million, including Indosat Ooredoo Hutchison. Net profit attributable to shareholders slipped 5.1% to QAR 1.8 billion because of a one-off legal provision in Algeria. Group chief executive Aziz Aluthman Fakhroo called the first half ‘another period of solid execution for Ooredoo’ on the earnings call, pointing to higher revenue, EBITDA and normalised profit across the footprint. Aziz added, “International connectivity and subsea infrastructure are already among the most strategic digital assets in the world, and demand is accelerating with AI, cloud, and hyperscale growth… We have set a clear ambition to grow our international infrastructure and subsea cable business from 3% to 12% of Group revenues over time.” But the more revealing material came later. A key milestone was the launch of Al Abraj, a standalone company established to independently manage Ooredoo's passive tower infrastructure in Qatar following regulatory approval, part of a portfolio
optimisation strategy aimed at improving capital efficiency. The group also expanded its digital infrastructure arm through Syntys, which acquired Q Data QFZ LLC in Qatar, adding 12.5MW of hyperscale data centre capacity. Management told analysts that the first close of the Al Abraj tower transaction should be completed by the next investor call, with the equalisation payment formula agreed with Zain Group unchanged. In other words, the strategy is on schedule. The question is what the strategy leaves behind.
The pieces on the table Start with the masts. Al Abraj launched in June as a standalone company that will independently operate and manage Ooredoo Qatar's passive tower infrastructure, after approvals from the Communications Regulatory Authority, marking the first
operational carve-out under Ooredoo's TowerCo initiative. Khalid Barzak, a 16-year telecom veteran, was appointed General Director. Qatar is only the opening act. The bigger prize is the joint venture with Zain and TASC, a $2.2 billion independent tower company estimated to turn over $500 million a year and generate EBITDA after leases of more than $200 million once fully operational, with Ooredoo and Zain each controlling 49.3%. When the deal was signed, the three chief executives issued a joint statement describing it as ‘placing the MENA region on the world telecom tower map’. Then the data centres. Syntys, established in 2025 as a spin-off from Ooredoo, operates facilities in Qatar, Kuwait, Tunisia, Oman and Iraq. It has been growing at pace. The Q Data acquisition took its operational IT capacity in Qatar to 26MW and total installed capacity to 30MW, on the way to a long-term goal of 120MW by 2030. Management now believes it can get there early.
International Finance | Sept - Oct 2026 | 67
INDUSTRY
ANALYSIS
TELECOM OOREDOO RESTRUCTURING
With 17.9MW of capacity either under construction or fully contracted, the group expects to reach the 120MW target about two years ahead of schedule, by 2028, if current demand holds. The customer mix tells its own story. In the first quarter of 2026, Syntys recorded QAR 51 million in revenue and QAR 22 million in EBITDA, with hyperscalers accounting for 76% of revenue in Qatar, backed by a $1 billion investment programme. Iron Mountain, the global data centre and information management group, acquired a minority equity stake in Syntys, an early sign that outside infrastructure capital wants in. Finally the cables. In February, Ooredoo announced the formation of Ooredoo Fibre Networks, a unit led by Khalid Hassan Al-Hamadi, with the carve-out expected to complete by 2027. Aziz said the company wants to grow its international infrastructure and subsea cable business from 3% to 12% of group revenues over time. The anchor asset is the FIG subsea cable system, under development with Alcatel Submarine Networks and spanning approximately 1,900 kilometres, alongside further submarine and terrestrial investments designed to create a new regional connectivity corridor between Europe and Asia.
Why the sum of the parts beats the whole The financial logic is brutally simple, and analysts have been happy to spell it out. Elie Abouatme, EMEA head of telecom, media and enter-
68 | Sept - Oct 2026 | International Finance
tainment at ServiceNow, told AGBI that integrated telecom operators typically trade at around four to six times earnings, while infrastructure platforms can command ten to fifteen times, because cable providers offer predictable, long-term, utility-like cash flows attractive to infrastructure investors. As he put it, "Historically, this model unlocks significant shareholder value." The same maths applies to towers and data centres. A mast does not care whose antenna hangs on it. A data hall does not care whose servers hum inside. Once separated from the parent, these assets can sign long contracts with multiple tenants, borrow cheaply against those contracts, and be valued like real estate rather than like a consumer business fighting price wars over prepaid SIM cards. Telecoms analyst Vakai Muntambirwa (BMI / Fitch) said, “By separating their division, Ooredoo gives OFN the operational inde-
pendence and strategic focus to become a dedicated infrastructure provider with a clearer focus to expand routes, add capacity, and maximise utilisation of subsea cable and fibre infrastructure.” The AI boom sharpens all of this. Training and running large models demand exactly what Ooredoo is unbundling. Compute needs data centres. Data centres need connectivity. Connectivity needs cables and towers. Aziz made the connection explicit when OFN launched, describing international connectivity and subsea infrastructure as ‘among the most strategic digital assets in the world’, and noting that demand is accelerating with AI, cloud and hyperscale growth. Nor is Ooredoo alone. Other Middle Eastern telcos have established regional tower operators in the hunt for efficiency and asset monetisation, from Saudi Arabia's TAWAL to Oman Tower Company, and the wholesale connectivity market is
Ooredoo H1 2026 in numbers Revenue QAR 12.5 billion, up 4.6% year on year EBITDA QAR 5.5 billion, up 7.4% Free cash flow QAR 3.9 billion, up 7.7% Net profit QAR 1.8 billion, down 5.1% on an Algeria legal provision customer base 147.5 million, including Indosat Ooredoo Hutchison
The pieces of the break-up Syntys data centres, 26MW live in Qatar, 30MW installed, 120MW target possibly reached by 2028 Al Abraj towers, first carve-out live in Qatar, June 2026 Zain and TASC towerco, around 30,000 towers across six countries, valued at $2.2 billion, projected $500 million annual revenue Ooredoo Fibre Networks, carve-out complete by 2027, FIG subsea cable of roughly 1,900km, international connectivity to grow from 3% to 12% of group revenue bracing for the newcomer. Brendan Swan, senior analyst at GlobalData, predicted, “The emergence of Ooredoo Fiber Networks will likely cause some disruption in the market, with incumbents looking to protect their turf and maintain their status in the region.” In a LinkedIn post marking the Al Abraj launch, Aziz wrote that the carve-out was a milestone in the company's plan to ‘evolve from a traditional telecom operator into a leading digital infrastructure provider’, and told followers that Qatar was only the first market under the multi-market TowerCo initiative. "Watch this space," he added.
So what is left of the phone company? Here is the uncomfortable part of the story. Strip out the towers, the data centres and the cables, and what remains of Ooredoo is a retail brand, a spectrum licence, a billing system and a customer base of prepaid and postpaid subscribers in fiercely competitive markets. The half-year results already show the texture of that business. Growth came from Algeria and Tunisia on the back of data demand, while core Gulf markets faced device-related revenue pressures, and Iraq wrestled with government salary payment disruptions.
And yes, the operator will pay rent on what it built. That is the entire design. The Zain venture will operate as an independent standalone entity providing passive infrastructure as a service throughout the region, which means Ooredoo becomes a tenant on masts it erected over decades. The sale-and-leaseback template is well established. Zain Iraq previously agreed a 15-year deal to sell and lease back its portfolio of nearly 5,000 towers to TASC for $180 million. Defenders of the model argue this is not weakness but discipline. Capital tied up in steel and concrete earns a telco nothing extra. Released, it can fund fintech, 5G spectrum and dividends, while the infrastructure companies raise their own money at better multiples. Sceptics counter that a telco without assets is a marketing operation with a network attached, permanently exposed to rent escalations negotiated by landlords it once owned, and that the premium being paid for AI infrastructure today may not survive the cycle. Ooredoo is 68% owned by Qatari state-related entities. So. this is also sovereign strategy, an attempt to make Doha a regional connectivity powerhouse rather than a national operator. The break-up will probably create value on paper, and quickly. Whether the phone company at the centre of it thrives as a capital-light service brand, or slowly discovers it sold the family silver to buy back cutlery, is the question the next few years of rent invoices will answer.
editor@ifinancemag.com
International Finance | Sept - Oct 2026 | 69
INDUSTRY
FEATURE AVIATION
IRAN WAR PAIN IN FLIGHT
Soaring costs, squeezing profits:
Airlines’ ‘Iran’ headache IF CORRESPONDENT
70 | Sept - Oct 2026 | International Finance
FEATURE AVIATION
While the budget carriers have felt the worst of the volatile geopolitics, the industry's hedging programmes too faced an acid test
International Finance | Sept - Oct 2026 | 71
INDUSTRY
FEATURE AVIATION
IRAN WAR PAIN IN FLIGHT
I
n the first week of August, Germany major Lufthansa, also Europe's second-largest airline group, cut its profit outlook and warned earnings could fall by 2026-end. However, Lufthansa's profit outlook followed the same pattern of its global peers, with these being the common factors mentioned across the aviation industry's earning documents: Iran war, higher jet fuel prices, and capacity revisions.
While the budget carriers have felt the worst of the crisis, fuel-related costs have managed to pressurise the airlines' hedging programmes too.
One after another, disappointing numbers arrive Let's start with Lufthansa, whose latest forecast 2026 adjusted earnings before interest and tax (Adjusted EBIT) stands at €1.7 billion-€2.2 billion ($2.0 billion to $2.5 billion). It had previously expected adjusted EBIT well above 2025's €1.96 billion. After peaking in June 2026, the carrier's stock has gone down about 2%. Lufthansa's capacity fell about 3% in the Q2, partly due to the staff strikes in April. However, its full-year capacity plans remain unchanged and are expected to be broadly flat. Adjusted EBIT fell to €383 million in the second quarter from €870 million a year earlier, well below analysts' average forecast of €401 million. The company now expects 2026 fuel costs of €8.66 billion, compared with an earlier forecast of €8.9 billion. As per the Chief Financial Officer (CFO) Till Streichert, the second half of the year remained uncertain as customers were booking closer to departure dates. Still, Lufthansa has decided to maintain its longer-term targets, including an operating margin of 8% to 10% between 2028 and 2030, despite geopolitical disruptions.
72 | Sept - Oct 2026 | International Finance
The company added that 86% of its fuel needs for this year are hedged, while CEO Carsten Spohr told reporters that fuel supplies are expected to remain stable. For Air France-KLM, things were a bit different in Q2, as it beat profit expectations on revenue gains from premium and long-haul travel. However, Iran war was the spoilsport here, as the carrier trimmed its annual capacity guidance. The airline group, in the coming days, will be leveraging its premium offering and ticket price increases to sustain profits through an industry downturn. However, Dutch arm KLM said improvements were not good enough to strengthen its financial foundations. The Franco-Dutch group posted second-quarter adjusted operating profit of €484 million ($552.5 million), down from €736 million in the same period in 2025 but higher than the €327 million consensus from analysts polled by the company. Air France-KLM has lowered fullyear capacity expectations, now guiding for a 1% drop in short and medium-haul flights and a group increase of between 2% and 3%. That is a second cut from the 3% to 5% forecast made before things got heated up in the Middle East. The capacity cuts will mainly materialise in the Q4 and will include fewer daily flights through European cities such as Dusseldorf and London.
The company also trimmed its April fuel bill projection for 2026 by 4% to $8.9 billion, citing newer and more efficient aircraft as well as jet fuel hedging. With €6.8 billion in net cash and €3.5 billion in undrawn credit lines (at the end of June), the airline group may look to go for cheap consolidation opportunities.
Budget carriers face cost pressure The environment is forcing smaller and budget carriers to seek restructuring or buyouts. Portugal's TAP, one such carrier, has emerged as Air France-KLM's acquisition target, with Lufthansa being the other interested party. TAP has slots linking its Lisbon hub with Brazil, Portuguese-speaking African countries, and the United States, markets that can potentially become lucrative expansion opportunities for the winner. British Airways owner IAG, while publishing its Q2 results in July, trimmed its 2026 capacity outlook to flat, after reporting a 16% profit drop due to soaring fuel costs and weaker travel demand. IAG, which also owns Iberia and Aer Lingus, said its fuel costs for the year would be between €8.3 billion and €8.6 billion ($9.6-$9.9 billion), slightly lower than the roughly €9 billion forecast i n May. The company said it was about 57%
FEATURE AVIATION
The environment is forcing smaller and budget carriers to seek restructuring or buyouts. Portugal's TAP, one such carrier, has emerged as Air France-KLM's acquisition target, with Lufthansa being the other interested party booked for the second half of the year, with booked revenue in line with a year earlier. It continues to expect to offset about 60% of its higher fuel bill through higher ticket prices and cost-cutting measures. EasyJet, before its acquisition by Apollo Global, saw the Iran war and the resultant price pressure on jet fuel contributing heavily to its 70% profit downfall. Ryanair, a prominent name in the
European budget flying segment, witnessed its profit slumping by a third in its most recent quarter on higher fuel costs and lower fares that look set to remain weak through the key summer period amid renewed consumer nervousness due to the Iran war. The Irish airline reported after-tax profit of €538 million ($616 million) for its fiscal first quarter through June 30, down 34% from the previous year, and short of a forecast of €579 million in a
company poll of analysts. However, the budget carrier maintained about being ‘better positioned’ than most rivals because 80% of its fuel requirements to the end of March 2027 are hedged at $67 per barrel. The management also stepped in to hedge 15% of its fuel needs for the following year at $85 per barrel during the recent interim ceasefire. Wizz Air, another budget airline, saw its operating losses further deepening in the first quarter. It now expects revenue per seat to keep falling in the current quarter after it cut fares to attract passengers. Despite the headwinds, it has decided to keep on expanding its operational capacities, by inducting new Airbus aircraft in its fleet. The budget carrier has hedged 76%
International Finance | Sept - Oct 2026 | 73
INDUSTRY
FEATURE AVIATION
IRAN WAR PAIN IN FLIGHT
of its full-year jet fuel needs using zero-cost collars, instruments that would cap the business' exposure at $826 per metric tonne. However, under the same mechanism, prices falling below $759 may end up becoming counter-productive, as it will prevent the carrier from benefiting from the windfall.
Same story everywhere In the United States, domestic airfares have been 26.5% higher than a year ago, according to June’s consumer price in-
74 | Sept - Oct 2026 | International Finance
dex data. Analysts, after decoding the data, found prices going up, both in domestic and global front, by 25%-30% compared with 2025. Strong demand for travel and reduced global oil refining capacity have resulted in upward trajectory of jet fuel prices. The commodity was trading about $149 a barrel as of August 4, up from $90 at the start of 2026 – a 65% increase. Crude-oil prices are up about 30% since January, trading around $76 a barrel.
"Jet fuel costs rise slightly higher than oil prices because on average, only about 10% of refined oil can be turned into jet fuel. The more limited the product, the more vulnerable it is to these supply shocks," said Louise Burke, the global head of aviation at Argus Media, a commodities data provider, while interacting with the Guardian. "There has been a substantial amount of refinery closures, a key to why jet fuel prices have soared so much higher than standard crude oil. A new
FEATURE AVIATION
refinery in west Africa has helped bring on supply, and refiners are making tweaks to boost output to about 12%14% to take advantage of the higher jet fuel prices, which has helped to alleviate some of the shortages," she noted. As per John Grant, the chief analyst at OAG, jet fuel prices are the biggest operating cost for airlines and the hardest to control. Costs range between 30% and 35%. In a set-up like this, airlines get a little elbow room. Some may hedge their fuel
costs to limit losses, but others buy on the volatile spot market. Demand for flying in the world's largest economy has also persisted despite higher airfares, giving airlines more leeway to continue charging higher prices. Legacy carriers such as American Airlines, United Airlines and Delta Air Lines said in recent earnings calls that higher airfares helped to offset some of the higher fuel costs, but the volatility of prices makes it hard to forecast the effects. In China, in separate filings to the Hong Kong and Shanghai stock exchanges on July 14, China Southern Airlines, Air China, and China Eastern Airlines reported anticipated interim losses that add up to between RMB 7.37–8.97 billion ($1.1–$1.3 billion). And this is not about China, Europe or the United States. Everywhere, it’s the same scenario. As per the International Air Transport Association's (IATA) latest financial outlook for the global airline industry, overall sector profitability will get halved due to the geopolitics, with high fuel prices acting as the constant irritant. Airlines are expected to achieve a combined total net profit of $23.0 billion in 2026, roughly half the previously projected $41 billion. The net profit margin is expected to be 2.0% in 2026, roughly half the previously projected 3.9%. It is also less than half the 4.2% estimate for the 2025 net profit margin. Total industry revenues are expected to reach $1.165 trillion in 2026, up by paltry 9.4% on the $1.065 trillion in 2025. Only silver lining will be the passenger load factor, that is forecast to continue to set record highs with airlines expected to fill 84.0% of all seats over the
year. This will be an improvement on 2025's ratio of 83.5%.
What's happening at the fuel price front? In the United States, the price for a gallon of Jet-A fuel rose 70 cents in August 2026 when compared to July figures to settle at an average price of $8.31 per gallon. Europe has been able to offset lower Middle Eastern jet fuel shipments by importing cargoes from the United States and Nigeria. The continent brought around 750,000 barrels per day (bpd) of jet fuel in June, the highest level since October 2025, and maintained a similar pace in July. On August 10, imported jet cargoes were assessed at a discount of $24 per metric tonne to gasoil futures, the widest discount since July 2025, according to LSEG and Argus Media. At the height of the Iran war in March, jet fuel had traded at a premium of more than $500 per barrel over the benchmark. However, the current situation is much better than the one seen a couple of months ago, when the International Energy Agency (IEA) warned about the continent having ‘maybe six weeks of jet fuel left’. The reality is that Gulf exports constitute the largest source of jet fuel to the global market. Refineries in other major exporting countries, such as Korea, India and China, are themselves highly dependent on crude oil imports from the conflict-ridden region. Europe has, over the years, relied on the Middle East for about 75% of its jet fuel imports. As per the IEA's estimates, despite United States and Nigeria acting as the guardian angels currently, they would be able to replace only a little over
International Finance | Sept - Oct 2026 | 75
INDUSTRY
FEATURE AVIATION
IRAN WAR PAIN IN FLIGHT
half of the lost supplies. Houston-based Chris Russo, associate director for energy in North America at Publicis Sapient, sees the crisis leaving a long-term imprint on the airlines' profit books. Russo, while speaking at the Aviation Week Window Seat podcast, stated that even if Iran war ended tomorrow and the Strait of Hormuz fully reopened, jet fuel prices would remain high for months to come. In fact, if the crisis gets worse again, some low-cost carriers may not survive a prolonged period of higher costs. He believes that China and the United States have relied on their strategic oil reserves since the beginning of the Iran war. However, the world has been facing a nearly one-billion-barrel supply shortage. “This hasn’t been factored into the prices of crude. That will come back to bite because it will jack up prices again in the future and cause problems downstream for things like jet fuel. This is going to be a challenge for airlines for a long while," Russo said. For him, airlines, from now onwards, should take a long-term view about how to procure fuel and manage the processes like the commodity's smart management. Beyond reactive steps, like cutting routes or frequencies, or even fuel hedging, carriers should closely examine the contracts they have with suppliers to guarantee some amount of fuel over the next 12 or 24 months. Russo said working those options could save an airline one to four cents per barrel, a meaningful saving when so many barrels are being bought.
Fuel Hedging: Where things stand now In April, Ryanair CEO Michael O’Leary
76 | Sept - Oct 2026 | International Finance
warned that the European aviation sector, as a whole, will face ‘financial difficulties’ if jet fuel prices stay high. Then, the following month, discount American carrier Spirit Airlines decided to cease its operations, after repeated attempts to secure creditor support for a government bailout plan met with failure. Spirit once accounted for 5% of US flights. The news broke out on May 2. A day before that, the carrier's board blamed the increase in oil prices and ‘other pressures’ on the business for the carrier’s deteriorating financial outlook, that ultimately led to its bankruptcy. Talking about the Iran war and its impact on Spirit, the carrier’s restructuring plan assumed jet fuel costs of about $2.24 a gallon in 2026 and $2.14 in 2027. However, geopolitics shot prices up to around $4.51 a gallon by the end of April, making fresh financing a must
for the survival of the business, which it couldn't manage. However, things have changed since then. According to S&P Global's July data, while talking about the industry’s fuel hedging trends, "European airlines' fuel hedging programmes have absorbed the bulk of this year's conflict-driven jet fuel price shock, industry data showed, widening a structural cost divide with largely unhedged US carriers as coverage ratios begin to thin into 2027.” Air France-KLM has lifted hedge cover to 87% of consumption on a horizon extending two years forward, while Lufthansa entered the crisis roughly 82% hedged for the Q1 2026 and 77% for the full year. IAG's coverage stood at 75% in the first quarter, declining to 50% in the Q4 2025, while Air France-KLM's quarterly profile ranged from 70% in the first
FEATURE AVIATION
“This (fuel shortage) hasn’t been factored into the prices of crude. That will come back to bite because it will jack up prices again in the future and cause problems downstream for things like jet fuel" — Chris Russo, Associate Director for Energy in North America at Publicis Sapient quarter to 47% in the fourth quarter. Among low-cost carriers, EasyJet was 84% hedged for the H1 2026, 62% for the H2 and 43% for H1 2027, while Ryanair has locked in roughly 80% of next year's fuel requirement. Wizz Air has described itself as mostly hedged through 2026. IATA sees the North American airlines largely moving away from fuel hedging, and jet fuel cost increases transmitted more directly and rapidly into the region's airlines' cost bases. Should prices remain elevated as legacy contracts roll off, carriers will face a choice between re-hedging at structurally higher forward levels, absorbing the cost into margins, or passing it through to fares.
Pain everywhere In July, Iran war found its mention in the International Monetary Fund’s (IMF)
outlook, with the global monetary body cutting its 2026 global growth forecast for the second time this year. Since then, the headwind has been accompanied by heatwaves (in Europe) and record high food prices. Consumers are already facing a costof-living heat. Central banks are showing reluctance to cut their interest rates. And if April's report from the consultancy Teneo is to be believed, the Iran war has ended up triggering a surge in air fares, with the lowest-priced economy tickets costing 24% more on average than they did a year ago. The war, in its sixth month, saw a ceasefire being signed and broken by Washington and Tehran. Post-June, Qatar, Oman, Kuwait, Jordan and Bahrain have all faced missile and drone attacks, resulting in flight cancellations. Several international airlines have resorted to route cancellations to the
Middle East after the European Union Aviation Safety Agency (EASA) extended its conflict zone advisory for the Gulf, urging airlines to avoid the contested airspace until August 31. A lack of a permanent ceasefire will mean avoiding the contested airspace, which will result in taking alternative yet longer routes, leading to more fuel consumption. Higher ticket prices will remain as airlines will be looking to recover fuel costs. Budget carriers, whose popularity hinges solely on low-cost flying, will find it difficult to pass on the costs. After the pandemic, airlines began focusing on expansion. The Iran war has forced them to once again focus on survival, cost control and balance-sheet protection, whether the industry likes it or not. editor@ifinancemag.com
International Finance | Sept - Oct 2026 | 77
INDUSTRY
THOUGHT LEADERSHIP
AIRCRAFT REGISTRATION SAN MARINO AIRCRAFT REGISTRY
DAVID COLINDRES PRESIDENT SAN MARINO AIRCRAFT REGISTRY
Aircraft registration is not simply a compliance exercise. It also contributes to the overall perception of the asset
Geopolitical risk is reshaping aircraft registry decisions In previous decades, there was a tendency to evaluate aircraft registration from a purely pragmatic and administrative perspective. The aircraft owners and operators primarily considered operational familiarity, financing arrangements, administrative efficiency, and logistics related to international use. Although these elements still have an important role in determining which registry is chosen, the environment surrounding aviation assets has changed quite substantially over the past several years. This shift is affecting not only ultra-high-networth individuals or large multinational operators, but also family offices, corporate flight departments, leasing companies, and financiers seeking greater certainty in an unpredictable global environment. Why? Several key factors are reshaping the current landscape and influencing the discussion.
documentation, oversight, recognition between authorities, financing structures, insurance compliance, and international acceptance. When geopolitical tensions affect any part of that framework, uncertainty can quickly emerge. This has led many owners and financiers to prioritise jurisdictions that offer regulatory consistency, internationally respected oversight, political neutrality, and legal predictability. Respected registries apply international sanctions and compliance frameworks rigorously — stability never means lighter compliance. In practical terms, owners increasingly want reassurance that the jurisdiction associated with their aircraft will remain stable, credible, and internationally recognised, regardless of broader geopolitical developments. That represents a meaningful evolution in how registries are evaluated.
Stability has become a competitive advantage
The impact of sanctions has changed industry thinking
Business aviation is inherently international. Aircraft routinely cross borders, interact with multiple regulatory systems, and depend on smooth coordination between authorities, financial institutions, insurers, airports, and operators. In periods of geopolitical stability, many owners may not fully appreciate how interconnected these systems are. However, when geopolitical tensions rise, the importance of legal clarity and jurisdictional stability becomes far more visible. Aircraft are highly mobile assets, but they are also highly regulated assets. Their operation depends on
78 | Sept - Oct 2026 | International Finance
Reputable aircraft registries fully enforce applicable international sanctions regimes, including appropriate due diligence on aircraft and beneficial ownership. This helps protect the integrity of the registry and the wider international aviation system. Recent geopolitical tensions have directly affected aviation operations and the ability to operate certain aircraft. What was not possible or imaginable five years ago suddenly became reality on a scale few anticipated. This has resulted in greater awareness of the po-
tential consequences of operating and moving aircraft across borders when tensions arise. As such, some owners and operators find themselves making decisions based on geopolitical considerations. All of this has caused many aircraft owners and financiers to consider the long-term implications of choosing a registry. Aircraft owners are, therefore, asking more sophisticated questions than before. They want to understand how internationally respected the registry is, how stable the jurisdiction may be over the long term, and whether the regulatory framework is clear and predictable. There is also a greater focus on how effectively creditor and lessor remedies can be exercised under the Cape Town Convention and through an IDERA, particularly where circumstances change unexpectedly.
Reputation now influences operational confidence Aircraft registries are often discussed in legal or administrative terms, but their influence extends far beyond day-to-day aviation activity. Registry reputation can affect how an aircraft is perceived by financial institutions, insurers, maintenance providers, international authorities, and prospective buyers. In a more scrutinised geopolitical environment, credibility matters. This is particularly important for aircraft involved in international charter operations, cross-border corporate travel, leasing environments, and complex ownership structures. The industry is becoming more conscious that aircraft registration is not simply a compliance exercise. It contributes to the overall perception of the asset. That perception can influence financing discussions, operational flexibility, insurance relationships, and ultimately long-term asset liquidity.
Aircraft registration is now part of risk management One of the most significant changes in recent years is that aircraft registration is increasingly viewed through a risk management lens. This does not mean owners are expecting political instability everywhere. Rather, it reflects a broader recognition that aviation operates within a global system in which external events can quickly and unexpectedly influence operations. As a result, owners and financiers are taking a
more comprehensive approach when evaluating jurisdictions. They are considering long-term stability, governance quality, operational predictability, legal resilience, and international recognition alongside traditional operational considerations. This represents a maturation of the conversation surrounding aircraft registration. The focus is shifting away from short-term administrative considerations toward long-term strategic confidence.
The importance of international cooperation No registry operates in isolation. Modern aviation depends on strong international cooperation between authorities, operators, manufacturers, financiers, and technical organisations. In times of geopolitical uncertainty, collaborative relationships become even more important. Registries that maintain strong communication channels, uphold internationally recognised standards, and demonstrate regulatory consistency help support stability across the aviation ecosystem. This is one reason why ICAO alignment and international credibility remain so important. At the San Marino Aircraft Registry, a Cape Town Convention contracting state since 2015, the emphasis has always been on maintaining internationally recognised standards while supporting operators with professionalism, responsiveness, and regulatory clarity. Those principles become even more valuable in periods of global uncertainty.
Looking ahead I believe the registries that will matter in the next decade will be those that combine stability with uncompromising compliance. Meanwhile, business aviation remains global. It allows owners to fly across borders with relative ease. Aircraft owners still need legal certainty and legitimate asset protection within a framework of full international compliance. In today’s geopolitical climate, aircraft owners are increasingly concerned with these aspects.
David Colindres is President of San Marino Aircraft Registry editor@ifinancemag.com
International Finance | Sept - Oct 2026 | 79
Business Dossier - ESNAD
Saudi mining industry thrives with ESNAD E guidance At the core of ESNAD’s success is its relentless commitment to digital transformation, a cornerstone of efficiency, transparency, and innovation
80 | Sept - Oct 2026 | International Finance
stablished in 2020 to serve as the executive and operational arm of the Ministry of Industry and Mineral Resources in the Kingdom, the Saudi Mining Services Company (ESNAD) plays a central role in implementing the ‘National Mining Strategy’, which positions mining as the third pillar of the Saudi economy alongside oil and petrochemicals. Its mission is to develop the mining sector in a balanced and sustainable manner, ensuring responsible resource management while supporting the Kingdom’s vision for economic diversification. At the recently concluded 13th Annual International Finance Awards, ESNAD was honoured as ‘Best Digital Transformation Strategies – Mining – Saudi Arabia 2025’ and ‘Best Stakeholder Communications Strategy – Mining – Saudi Arabia 2025’. The awards are a testament to ESNAD’s role in supporting the mining sector across the Kingdom, reflecting the company’s
THE MISSION
Develop the mining sector in a balanced and sustainable manner, ensuring responsible resource management while supporting the Kingdom’s vision for economic diversification
International Finance | Sept - Oct 2026 | 81
Business Dossier - ESNAD
commitment to innovation, operational excellence, and sustainable mining practices, in close alignment with the objectives of the Ministry of Industry and Mineral Resources. Through its focus on Licensing, Digital Transformation, and Mining Compliance, the company continues to enhance the investment environment, and contribute to building a transparent, efficient, and future-ready mining ecosystem that supports the Kingdom’s economic goals. ESNAD’s operations are grounded in a clear mandate to create a transparent, efficient, reliable mining environment that attracts investments, safeguards resources, and promotes environmental and social responsibility. By combining regulatory oversight with digital innovation, ESNAD has transformed how mining operations are managed and monitored, ensuring full alignment with 'Saudi Vision 2030' goals. Through collaboration with government entities, investors, and private-sector partners, ESNAD promotes an integrated mining ecosystem built on excellence, sustainability, and accountability. Its approach balances economic growth with environmental protection, creating value for industry, local communities, and future generations.
Commitment to digitalisation and sustainability
At the core of ESNAD’s success is its relentless commitment to digital transformation, a cornerstone of efficiency, transparency, and innovation. Through the development of advanced digital services, ESNAD has redefined licensing and compliance processes, streamlining investor interactions, automating approvals, and significantly reducing processing times. These advancements have helped position the Kingdom as one of the most attractive destinations for mining investment. ESNAD also integrates artificial intelligence (AI), drones, and satellite imagery to enhance monitoring and regulatory compliance. By analysing aerial and spatial data, the company detects irregularities, assesses environmental impact, and measures resource extraction 82 | Sept - Oct 2026 | International Finance
in real time. These innovations improve inspection efficiency, strengthen compliance, and support informed decision-making across the sector. At the same time, in line with the “Saudi Green Initiative,” ESNAD has strengthened environmental stewardship through rehabilitation and afforestation programmes. Its efforts include planting millions of trees in mining complexes such as Al-Summan and Al-Armah, in cooperation with investors and local communities. These projects reflect ESNAD’s commitment to restoring landscapes and mitigating environmental impact. By promoting cleaner operations, responsible waste management, and biodiversity protection, ESNAD ensures that the Kingdom’s mineral wealth is developed sustainably. The company also applies environmental, social, and governance (ESG) principles aligned with global best practices, reinforcing its role as a responsible mining enabler.
Financial and regulatory excellence Beyond technology and sustainability, ESNAD ensures financial compliance and regulatory integrity across the sector. It has built comprehensive mechanisms to monitor financial guarantees, enhance collection systems, and minimise operational risks. By enforcing robust governance standards, ESNAD safeguards public resources, supports investor confidence, and ensures financial sustainability. Through its inspection and licensing programmes, ESNAD guarantees that mining operations comply with the highest standards. ESNAD conducted thousands of inspections and issued hundreds of mining and exploration licenses, demonstrating its dedication to operational efficiency and sectoral growth.
Human capital and collaboration
ESNAD believes that people are central to sustainable progress. The company invests in developing national talent through training, upskilling, and leadership programmes
designed to prepare Saudi professionals for the future of mining. In this context, it would be appropriate to mention two initiatives. ESNAD’s "Graduate Development Program" is a year-long initiative designed to prepare Saudi graduates for the mining sector through hands-on field training, expert mentorship, and exposure to global best practices. In addition, ESNAD has introduced "REKAZ Future Leaders Development Program" in collaboration with INSEAD, offering a 10-month curriculum focused on strategic thinking, decision-making, and innovative leadership. This focus on human capital enhances ESNAD’s operational excellence and contributes to the Kingdom’s broader goal of empowering national capabilities. The company also works with ministries, research institutions, and international
partners to exchange expertise and adopt global best practices. Through this cooperative framework, ESNAD promotes innovation, enhances efficiency, and supports the Kingdom’s ambition to become a leading global mining hub. ESNAD’s journey represents a model of transformation built on vision, innovation, and responsibility. By integrating digital excellence, environmental care, and human development, ESNAD is redefining the future of mining in Saudi Arabia. As the Kingdom advances toward Vision 2030, ESNAD remains dedicated to enabling sustainable development, driving diversification, and ensuring that the mining sector continues to serve as a foundation for national prosperity, for today and generations to come.
International Finance | Sept - Oct 2026 | 83
BANKING AND FINANCE
ANALYSIS
AGENTIC AI WALL STREET
JPMorgan and Morgan Stanley are moving beyond chatbots to software that acts on its own, and central banks are already asking who stops it
Wall Street’s AI agents stop advising, start working IF CORRESPONDENT
Ask most bank executives about artificial intelligence in 2024 and they would describe a chatbot. Staff typed in a question, the software produced a paragraph, and somebody in the technology division counted it as adoption. The systems now being installed across the largest American banks work differently. They are handed JPMorgan an objective rather than a quesspends around tion. They break it into steps, $2 billion a open whichever internal sysyear on AI. tems those steps require, pull That sits the data, carry out the task, and within a report back when it is finished. technology The industry calls this agentic budget the AI. In practice, it means softbank raised ware that is given a job rather to about $19.8 than asked for an opinion. billion for 2026, Whether this is a genuine a 10% hike break with what came before, from 2025 or the same technology with more permissions attached, is a fair question. What is not in doubt is that the banks are spending as though it is the former.
What JPMorgan has built JPMorgan Chase has been unusually open about its programme, which makes it the easiest place to see the shift. Its platform is called LLM Suite. It started in
84 | Sept - Oct 2026 | International Finance
2023 as a secure internal version of ChatGPT for drafting emails and summarising documents. Around 250,000 employees now have access to it, and roughly half use it on any given working day. The platform is model agnostic, meaning it routes work to systems built by outside AI firms, including OpenAI and Anthropic, rather than depending on a single supplier. It is updated roughly every eight weeks as the bank wires it into more of its own databases and applications. That wiring is the slow part of the project and the part that determines whether any of it works. A capable AI model that cannot reach a bank's payment records, client files or risk systems produces confident text, and nothing else. The value only appears once the model can see the underlying data and act on what it finds. Derek Waldron, the bank's chief analytics officer, has described the goal to CNBC as a ‘fully AI-connected enterprise’, with an assistant for every employee, agents running back-office processes and AI shaping client interactions. In a demonstration for the broadcaster, the system assembled an investment banking pitch deck, including news, earnings figures and peer comparisons, in about thirty seconds. That is work which previously occupied a team of junior bankers for most of a night. The bank has been automating document work for longer than the current wave suggests. A tool
called COiN, short for Contract Intelligence, was reported by Bloomberg in 2017 to have taken over the review of commercial loan agreements that previously consumed around 360,000 hours a year of work by lawyers and loan officers. That was conventional machine learning applied to one narrow, high-volume document type rather than a large language model. What has changed is the range of work now in scope. The bank is training systems to draft confidential merger memoranda, which bankers then check.
The return on investment is still an open question JPMorgan spends around $2 billion a year specifically on AI. That sits within a technology budget the bank raised to about $19.8 billion for 2026, an increase of roughly 10% on the previous year. Jamie Dimon has said the AI investment has already paid for itself. The claim is harder to pin down than it first
appears, and Dimon has said so himself. Pressed by analysts at the same investor event, he replied that ‘the hardest thing to measure has always been tech projects’, adding that time saved is often too vague to quantify. Both statements were made in the same session. He believes the money is coming back, and he cannot demonstrate it line by line. Chief financial officer Jeremy Barnum was blunter about the cost side, telling investors that technology remains a major driver of the bank's expense growth. Paying for itself would in any case mean breaking even, roughly two billion dollars of benefit set against two billion dollars of cost. That is a modest outcome for a technology being described as transformational. It looks impressive mainly by comparison, because a large majority of companies attempting generative AI projects cannot show any measurable financial effect at all. There is a further difficulty. The savings that are easiest to evidence come from the least exciting work, meaning contract review, code generation and sum-
International Finance | Sept - Oct 2026 | 85
BANKING AND FINANCE
ANALYSIS
AGENTIC AI WALL STREET
marisation. Those are real hours removed from real cost centres. The claims attached to client-facing AI, personalisation, better service and deeper relationships, are the ones the bank is least able to price. Whether the second category ever produces returns of the kind the spending assumes is not yet established, by JPMorgan or anyone else. What the bank has done with its accounting is more revealing than the figures. It has moved AI spending out of the discretionary innovation category, the line that is cut first when results disappoint, and placed it alongside data centres, payment systems and core risk controls. That reclassification commits the bank to the spending regardless of what the next few years of returns look like.
Morgan Stanley is letting outside agents in Morgan Stanley is doing something structurally different, and it has attracted less attention than it probably deserves. The bank runs two platforms, ShareWorks and Equity Edge, which administer employee share schemes for around 3,400 corporate clients. The work involves grants, vesting schedules, option exercises, tax handling and compliance reporting. It matters commercially because administering a company's share plan puts Morgan Stanley in front of employees before those employees become wealthy. Executives have credited the workplace strategy with gathering some $1.2 trillion in assets. The bank is now opening those platforms so that clients' own AI
86 | Sept - Oct 2026 | International Finance
JPMorgan
250,000
access, roughly half using it daily
employees with LLM Suite
Platform updated every eight weeks Investment banking pitch deck built in about 30 seconds COiN contract review, around
360,000
hours removed a year
$2 billion annual AI spend $19.8 billion technology budget for 2026, up about 10% Operations staff to fall by at least 10% over five years
agents can connect directly, bypassing the interfaces built for human administrators. Mark Mitchell, chief product officer of Morgan Stanley at Work, told CNBC that in future corporate clients ‘will not be logging into ShareWorks or Equity Edge’ at all, and will instead run agentic tools inside their own companies that interact with the bank's platforms directly. He has argued that the firms which survive
will be the ones holding proprietary data and business logic, which he describes as the foundation of what Morgan Stanley sells. A small number of clients have early access, with a wider rollout planned across the client base. The technology behind this is the Model Context Protocol, or MCP. It is worth being precise here, because it is often described as an investment in AI infrastructure. MCP is
Sector 15,000 jobs shed at six large US banks in Q1 2026 $47 billion combined Q1 profit at those six banks Citigroup committed to cutting 20,000 posts Regulation
Morgan Stanley
3,400
and Equity Edge
corporate clients on ShareWorks
$1.2 trillion
through the workplace strategy
in assets gathered
Connection built on MCP, an open standard created in late 2024 and handed to the Linux Foundation in late 2025
not a Morgan Stanley product, and the bank has not funded its development. It is an open standard, created by Anthropic in late 2024, and handed to the Linux Foundation at the end of 2025, where it is now governed by an industry body with backing from Google, Microsoft, Amazon and OpenAI. Think of it as a USB-C port for AI systems. Before it existed, every connection between an AI model and a
piece of business software needed its own custom integration, which is a large part of why so many corporate AI projects stalled between the demonstration and the deployment. MCP standardises the socket. Build the connection once, and any compatible system can use it. The decision to adopt a shared standard rather than build a proprietary one tells you what Morgan Stanley expects. It is planning for
FPC Financial Stability Report published July 7, 2026 FSB consultation, 12 sound practices, comments closed July 22, final report due October 2010 flash crash, around
$1 trillion in five minutes clients who arrive already running their own AI, and it would rather be the system those agents connect to than the one they work around. Whether corporate clients actually take this up at scale is untested. The rollout is still ahead of the bank, not behind it.
Headcount is already moving The commercial argument being made to clients is about hiring.
International Finance | Sept - Oct 2026 | 87
BANKING AND FINANCE
ANALYSIS
AGENTIC AI WALL STREET
Fast-growing technology and biotechnology companies want to run increasingly complex share schemes without adding administrators. Internally, Mitchell has said Morgan Stanley sees agentic AI as a way to scale customer support, plan administration, and the wealth management funnel without adding thousands of employees. Across the sector, the numbers have started to reflect that. In the first quarter of 2026, six of the largest American banks shed around 15,000 jobs while posting roughly $47 billion in combined profit, up sharply on the previous year. The rhetoric has shifted just as fast. Bank of America chief executive Brian Moynihan, asked on television what he would tell his employees about AI replacing human work, said they did not have to worry. Within months. his bank was crediting AI for reductions achieved through attrition. Dimon has been more direct, saying AI will eliminate jobs and that ‘people should stop sticking their heads in the sand’, while pointing to attrition, retraining and redeployment as alternatives to mass redundancy. Citigroup chief executive Jane Fraser has told staff that some roles will change, some will emerge, and others will no longer be required, as part of a turnaround that includes cutting 20,000 posts. Among posts cut were employees from Citi's own internal programme dedicated to persuading colleagues to adopt AI. How much of this is genuinely attributable to AI is contested. Banks reduce headcount in tight years and have done so for decades,
88 | Sept - Oct 2026 | International Finance
and AI is a convenient explanation for decisions that might have been taken anyway. The clearer signal is which roles are exposed. Work that involves moving structured information between systems is the easiest to redesign around agents, and that covers much of the back office along with a growing share of the analyst work that has traditionally been the way into the industry. JPMorgan's consumer banking head has told investors that operations staff will fall by at least 10% over five years.
Trading, and the regulators arriving early The claim that machines will soon trade rather than advise turns out to be the part regulators are least worried about today, and most worried about tomorrow. In a speech titled Agents of change, delivered at the European Central Bank's Sintra forum on June 30, Bank of England deputy governor Sarah Breeden said the evidence suggests trading firms currently use autonomous AI mostly for lower-risk operational work, such as research, while warning that this could change quickly. Her more immediate concern was not markets at all. It was cyber security, which she described as her most proximate financial stability worry, driven by a steep change in what agentic systems can do when hunting software vulnerabilities. She cited the heads of the Five Eyes cyber agencies, who said in June that the relevant timeline is months rather than years. On trading, her argument was
about correlation. If agents respond similarly to the same prompts or triggers, they could amplify volatility under stress, particularly if their objectives drift from what their designers or public policy intended. The financial stability question, she said, is no longer only whether individual firms use models well, but whether the system can observe and contain how those models behave together. That is why the kill switch idea has been raised, and it is worth reporting accurately. Breeden did not propose one. She set out a research agenda, including work with the Bank for International Settlements innovation hub and the Bundesbank on which features of agent design drive herding, and asked whether guardrails analogous to circuit breakers or market-wide kill switches might eventually be needed. Her broader conclusion was
blunt. "Our frameworks were not built to contemplate autonomous agents," she said, adding that relying on a human approving every agent action is unlikely to be realistic. Markets absorb shocks because participants disagree. If several large institutions run agents built on the same small set of underlying models, trained on similar data and pointed at similar objectives, that disagreement could thin out at the moment it is most needed. The 2010 flash crash removed around a trillion dollars of value in five minutes, and the algorithms involved were considerably simpler and less autonomous than what is being deployed now. The Bank's Financial Policy Committee published its updated assessment on July 7. Rapid advances in frontier AI, the committee concluded, have increased financial stability risks connected to cyber and operational resilience.
That is a firmer position than it held in April, and the Treasury Committee questioned the Governor on it a week later. Internationally, the machinery is already turning. The Financial Stability Board (FSB), chaired by Bank of England governor Andrew Bailey, published a consultation in June setting out twelve sound practices for responsible AI adoption, covering governance, the stages of AI development and deployment, and cyber and third-party risk. Comments closed on July 22, and a final report is due in October as a G20 deliverable. Michelle Bowman, who chairs the FSB committee behind the work and serves as vice-chair for supervision at the US Federal Reserve, said the report reflected collaboration on an accelerated timeframe to keep pace with AI. The board was careful to add that the practices are not an international
standard and were not designed for the frontier model risks that have emerged most recently.
What remains unresolved The argument about whether banks will use AI is settled. The open question is what happens when agents stop being tools inside a single institution and start operating across the boundaries between them. Morgan Stanley opening its systems to external agents is the first real test of that. Once a client's AI can act inside a bank's infrastructure, the line between the two organisations becomes a question of permissions rather than architecture. Nobody has yet had to supervise that arrangement under stress.
editor@ifinancemag.com
International Finance | Sept - Oct 2026 | 89
BANKING AND FINANCE
FEATURE REAL ESTATE
AUSTRALIA NEGATIVE GEARING
New property rules rattle banks in Australia IF CORRESPONDENT
90 | Sept - Oct 2026 | International Finance
FEATURE REAL ESTATE
Canberra's negative gearing and capital gains overhaul have resulted in falling prices and a 20% slump in mortgage applications
C
anberra's negative gearing and capital gains overhaul was sold as a lifeline for first-home buyers. Six weeks after it became law, falling prices and a 20% slump in mortgage applications have made the lenders the earliest casualty On August 10, Westpac Banking Corp gave the market a number that summed up the mood in Australian housing. New mortgage applications were running 20% below the previous quarter, twice the drop the bank had recorded in the weeks straight after the May budget. The lender also told investors that credit growth for housing investors would more or less halve next year, from 9.1% in 2026 to about 4.5% in 2027. Westpac shares fell as much as 5.9% on the day, the bank's worst session since April 2025. Commonwealth Bank of Australia, National Australia Bank and ANZ all dropped more than 2% alongside.
International Finance | Sept - Oct 2026 | 91
BANKING AND FINANCE
FEATURE REAL ESTATE
None of this was supposed to be the story. The Treasury Laws Amendment (Tax Reform No. 1) Act 2026 was framed as a housing affordability measure, a way of tilting the market back towards people trying to buy their first home rather than people buying their fourth. Six weeks after it cleared parliament, the clearest evidence of its bite is not in the hands of first-home buyers. It is in the loan books of the four institutions that sit at the centre of almost every property transaction in the country.
What the law actually does The package was announced in the 2026-27 federal budget on May 12, introduced in the House of Representatives on May 28, and passed both chambers on June 25 after a short and bad-tempered committee process. The Greens sided with the government in the Senate to block a Coalition attempt to delay the vote. The lower house passed the amended bill 98 votes to 39. It was enacted the following day. Under a month from introduction to law is fast by any standard, and the speed is part of why the reform is still being argued about. Two changes matter most, and both start on July 1 2027. The first restricts negative gearing on residential property to new builds. Negative gearing lets an investor deduct the shortfall between rental income and costs, mostly loan interest, against their other income, including wages. From July 2027, investors who bought an established dwelling after 7.30 pm AEST on May 12, 2026 will no longer be able to do that. Losses on those properties are quarantined instead. They can be carried forward and offset against residential rental income or against future capital
92 | Sept - Oct 2026 | International Finance
AUSTRALIA NEGATIVE GEARING
gains on rental property, but not against salary in the year they occur. Grandfathering is generous. Anyone holding a property at budget night, including buyers who had exchanged contracts but not yet settled, keeps the existing treatment until they sell. Eligible new builds keep both negative gearing and the 50% capital gains discount. Build-to-rent projects, properties in widely held trusts and superannuation funds, and private investment supporting government housing programmes are all carved out. The second change is broader and reaches far beyond housing. For capital gains events on or after July 1, 2027, the 50% CGT discount for individuals, trusts and partnerships is replaced by cost base indexation using the consumer price index, so that only real gains are taxed, together with a new minimum tax rate of 30% on capital gains. The change applies prospectively, to gains accruing after the start date, with taxpayers establishing a value for their assets as on that day. It also ends the pre-CGT shelter that has protected assets acquired before September 20, 1985 for four decades. Late amendments softened some edges. The turnover threshold for the small business 50% active asset reduction was lifted from AUSD 2 million to AUSD 10 million, deductible gifts and donations now reduce gains caught by the 30% minimum, and some ministerial instrument-making powers were trimmed. On June 18, the government also flagged an Innovative Business CGT Concession for founders, employee share scheme participants, and early-stage investors, after complaints that the regime punished people who had built companies from a low-cost base.
Why the backlash has been so fierce The first is political. Prime Minister Anthony Albanese ruled out touching negative gearing and the capital gains discount repeatedly during the 2025 election campaign. Legislating both inside the following parliamentary term, and doing it in five weeks, handed the opposition a straightforward argument about mandate and trust. It is the second significant tax reversal in eight months, after the government's retreat on superannuation late last year. The government's answer is that the problem could not be deferred any longer. That may be true, and it does not settle the question of whether voters were told. The second is about rents. Australia's rental market entered this reform
FEATURE REAL ESTATE
with almost no slack. Vacancy is running near 1.6% nationally and advertised rents are climbing close to 6% a year. Critics argue that discouraging investors from buying established homes does not remove a single dwelling from the country, but it does change who owns it, and a first-home buyer moving into a house that was previously tenanted takes one rental off the market while removing one household from the queue. The offsetting effect is real but slow, and the timing gap falls on renters. The third is about who gets caught. The quarantining rule is blunt in a way that works against small investors. An investor with a single leveraged property and no other rental income has nothing to offset the loss against, so the deduction sits unused for years. An investor with a portfolio can ab-
sorb the loss against rent from other holdings almost immediately. Around two-thirds of Australia's landlords own one property. The reform, aimed at speculation, lands hardest on the smallest participants and on people who were about to become landlords for the first time. Complexity is the quieter complaint. Advisers point out that almost every resident individual and trust holding a capital asset now needs a defensible valuation as on July 1, 2027, that succession and exit planning has to be reworked, and that the loss of pre-CGT status will surface in family businesses and farms that have nothing to do with housing.
The experts do not agree, and that matters The construction and property lobby moved early. Modelling by Qaive and
Tulipwood Economics, commissioned jointly by the Housing Industry Association, Master Builders Australia, the Property Council of Australia and the Real Estate Institute of Australia, tested several versions of the reform and found housing starts falling in everyone. The harshest scenario, removing negative gearing except for one property per investor, produced 45,500 fewer dwelling starts over the five years to 2029-30, a AUSD 3.1 billion hit to GDP in net present value terms, and about 4,250 fewer construction jobs a year. The version closest to what parliament passed, restricting the concession to new construction while grandfathering existing holdings, pushed rents up by almost 1% a year above the baseline. HIA managing director Jocelyn Martin's argument is simple enough to fit on a placard, that taxing property more heavily produces fewer homes. Master Builders chief executive Denita Wawn called the findings unequivocal. The Grattan Institute reaches a very different conclusion from the same starting point, projecting national price falls of one to two percent with limited rental disruption, on the reasoning that the tax concessions mostly inflate the price of existing stock rather than fund new supply. Reserve Bank and Australian Bureau of Statistics data give that view some support, since the overwhelming majority of investor lending has historically gone to established dwellings rather than new construction. A Senate committee inquiry in March recommended cutting the discount for much the same reason, arguing the settings distorted the market in favour of investors over owner-occupiers. Both camps are arguing honestly, and the honest read is that the outcome de-
International Finance | Sept - Oct 2026 | 93
BANKING AND FINANCE
FEATURE REAL ESTATE
AUSTRALIA NEGATIVE GEARING
• Bill passed both houses June 25, 2026, enacted June 26. Lower house voted 98 to 39 pends almost entirely on design. Whether the new build exemption is workable, and how the term is defined in the regulations still to come, will decide whether investor money rotates into construction or simply leaves housing.
A market already turning The reform arrived into a downturn it did not cause but has clearly sharpened. Cotality's national Home Value Index fell 0.4% in June, the third consecutive monthly decline, and the largest since December 2022. July was worse at 0.7%, and the weakness stopped being a Sydney and Melbourne problem. Sydney values fell 1.4% over the month and Melbourne 1.2%, with Melbourne having peaked in November and Sydney in January. Brisbane fell 0.6% and Adelaide 0.2%, second consecutive monthly declines for both after revisions. Perth is the case that best illustrates how quickly the ground has shifted. The city was recording monthly gains above 3% as recently as November, and is still up more than 20% year-on-year. It posted a nominal 0.1% rise in July, but only after Cotality revised its June figure from a 0.7% gain to a 0.5% fall, leaving the quarter negative, and PropTrack has the city declining outright. Flat is the fair description of a market that was the country's engine room a few months ago. The composition of the fall is revealing. Over the three months to July, upper-quartile values fell 3.2% nationally while lower-quartile values edged up 0.3%. Expensive stock is bearing the correction, partly because higher borrowing costs bite hardest on large loans, partly because first-home buyer schemes support demand below the median, and partly because investors selling ahead of the 2027 start date are concentrated in premium property.
94 | Sept - Oct 2026 | International Finance
• Negative gearing and CGT measures commence July 1, 2027 • Cut-off for grandfathering, 7.30pm AEST, May 12, 2026 • 50% CGT discount replaced by CPI cost base indexation plus a 30% minimum tax rate on gains • Cotality national Home Value Index, June 2026 down 0.4%, July 2026 down 0.7%, the sharpest monthly fall since December 2022 • July monthly falls: Sydney down 1.4%, Melbourne down 1.2%, Brisbane down 0.6%, Adelaide down 0.2%, Perth up 0.1% after a revised 0.5% June fall • Upper quartile values down 3.2% over the three months to July, lower quartile up 0.3% Source: Statista
• Capital city sales volumes down 16.2% year-on-year. Auction clearance rates below 50% since late May The wider backdrop is unforgiving. The cash rate sits at 4.35% after 75 basis points of increases this year, consumer sentiment is deeply negative, capital city sales volumes are running 16.2% below a year ago, and auction clearance rates have been under 50% since late May, the weakest in six years. Investor mortgage rates average about 6.4% against a gross yield of 3.5%, which makes leveraged residential investment hard to justify on income alone even before the tax change lands. Most economists now expect the first rate cut around the middle of 2027, not this year. Forecasters have adjusted accordingly. CBA cut its December 2026 price growth forecast to 3% from 5%, citing the negative gearing changes and expecting the sharpest impact in apartments and cheaper stock where investors cluster. Westpac IQ now expects prices to finish the calendar year flat nationally. Domain sees Sydney and Melbourne
house prices falling over the year to June 2027 while Perth, Adelaide and Brisbane reach fresh records, a divergence that is arguably the real story of this cycle.
Why this lands on the banks Mortgages account for roughly 60% of the big four's combined credit books, against 40% to 50% at global peers, and that share has grown as the banks retreated from wealth management, advice and offshore assets. The four control more than 70% of the national mortgage market, with CBA alone holding about a quarter of home lending. Foreign investors now own somewhere between a quarter and a third of the majors, drawn by the same qualities that made the sector a domestic staple, reliable fully franked dividends underwritten by rising property values and benign credit losses. The banks touch every stage of a transaction. They set serviceability
FEATURE REAL ESTATE
• Cash rate 4.35% after 75 basis points of increases in 2026 • Westpac, mortgage applications down 20%. NAB, down about 15% over the June quarter • Westpac forecast, investor housing credit growth 9.1% in 2026 to 4.5% in 2027 and 4.4% in 2028. Total housing credit 6.8% to 4.7% • Mortgages are about 60% of the big four's combined credit books, against 40% to 50% for global peers • Big four control more than 70% of the mortgage market. CBA leads with a 25% share • Industry modelling: 45,500 fewer dwelling starts and A$3.1 billion off GDP in net present value terms over five years under the harshest scenario tested • National rental vacancy about 1.6%, advertised rents rising 5.9% a year • Investor mortgage rates averaging 6.4% against a gross rental yield of 3.5% buffers that determine what a buyer can bid. They commission the valuations that decide whether a deal settles at the agreed price. They price investor loans above owner-occupier loans and earn more on them. They fund the broker channel that originates most new lending, sell lenders mortgage insurance on high loan-tovalue deals, and securitise the resulting book. Crucially, serviceability assessments for investors have long incorporated the tax benefit of negative gearing. Strip that out for established dwellings and the same borrower qualifies for a smaller loan, which reduces both volume and average loan size at once. That is precisely what the numbers now show. Westpac's applications are down 20%, with investor applications down about 26% and owner-occupier applications down 18%, according to Morningstar's read of the update, which suggests rate rises are doing as much
damage as the tax change. NAB reported applications down about 15% over the June quarter with application values off 9%, attributing part of it to uncertainty over the reform. Westpac's third-quarter cash earnings came in at AUSD 1.8 billion with stable margins and 2% loan growth, respectable numbers that the market ignored in favour of the forward guidance. Analysts are now questioning the sector's core promise. Jarden's Matthew Wilson describes a difficult earnings environment built on weaker volumes, margin pressure and longer-run credit quality concerns, and his team has flagged a separate problem. Average mortgage risk weights across the majors have climbed to about 23%, from 14% in 2014, meaning the same loan book consumes materially more capital. Payout ratios set when home lending was growing faster than corporate lending start to look stretched.
Jarden holds sell ratings on CBA, NAB and Westpac, and prefers ANZ. Morningstar forecasts fiscal 2027 home loan growth of just 2.5%, well below Westpac's own 4.7%, and considers Westpac shares roughly 20% overvalued on a forward multiple above 17 times. The market has been moving that way for months. Between late February and late May, NAB fell 23%, Westpac nearly 14.5%, ANZ 11.2% and CBA 5.6%, making them the worst performers among Asian bank stocks. Several majors have already begun job cuts, offshoring and automation programmes, moves analysts expect to accelerate if revenue growth stays weak. Argo Investments senior investment officer Andy Forster captured the consensus, that dividends can probably be defended but are unlikely to grow.
What to watch Nothing in the law takes effect for another eleven months, and that gap is the immediate risk. Investors selling ahead of the start date add listings into a falling market, while buyers wait for regulations that will define what counts as a new build. Both behaviours depress prices in the interim, regardless of where the reform settles in the long run. For the banks, the pressure is measurable and already booked into forecasts. For renters, the squeeze arrives before any relief. For first-home buyers, whose interests justified the whole exercise, the benefit depends on whether cheaper established housing arrives faster than the rental market tightens around them. Canberra has made a structural bet on the answer. The transmission is running through the banking system first. editor@ifinancemag.com
International Finance | Sept - Oct 2026 | 95
BANKING AND FINANCE
FEATURE NVIDIA
96 | Sept - Oct 2026 | International Finance
WALL STREET AI BOOM
FEATURE NVIDIA
As the AI boom outgrows Big Tech's cash reserves, Jensen Huang's answer is to shift the burden onto private credit
Nvidia turns its chips into Wall Street’s newest asset class IF CORRESPONDENT
O
n the morning of August 10, six of the most powerful men in global finance sat down together in a television studio alongside Jensen Huang. Goldman Sachs chief executive David Solomon was there. So were Blackstone president Jon Gray, Apollo president Jim Zelter and Brookfield chief executive Bruce Flatt. KKR sent Waldemar Szlezak, who runs its digital infrastructure business. Larry Fink of BlackRock joined by video link from the road. The segment ran for more than half-an-hour and contained remarkably little detail. What it contained instead was a message, delivered with the theatrical confidence that has become Huang's trademark. Nvidia had signed memorandums of understanding (MoU) with all six firms to create what it called independent compute financing platforms, with the aim of mobilising more than $500 billion of third-party capital for the construction of AI data centres and the purchase of Nvidia hardware. No deals had actually been signed. There is no fixed timetable. The $500 billion figure, as Bloomberg later reported, is a round number combining transactions already under discussion with a forecast of demand still to come. Each lender will
International Finance | Sept - Oct 2026 | 97
BANKING AND FINANCE
FEATURE NVIDIA
WALL STREET AI BOOM
The cash squeeze that made the deal necessary vet borrowers individually before committing a cent. And yet, the announcement may prove to be one of the most consequential financial events of the AI era. Because what Huang was really doing was not raising money. He was proposing a new asset class.
The problem nobody could keep paying for To understand why Nvidia needed to stand on a stage with six financiers, look at what has happened to the balance sheets of its biggest customers. For most of the last decade, Big Tech funded its own expansion. Cloud businesses threw off enormous operating cash flow, and capital spending, however large, stayed comfortably inside it. That relationship has now broken. Alphabet, Amazon, Meta, and Microsoft have collectively guided to something close to $700 billion of capital expenditure in 2026, a rise of roughly three quarters on the previous year's already record figure. Bank of America projects aggregate hyperscaler capex will top $860 billion this year, and approach $1.2 trillion in 2027. Goldman Sachs now models more than $5 trillion of combined capex for the big four between fiscal 2025 and fiscal 2030. The cash consequences arrived faster than most investors expected. Alphabet posted its first negative free cash flow quarter since its 2004 listing in the second quarter of 2026, burning $5.9 billion as capital spending surged past $44 billion in three months. It then raised the top end of its full year capex guidance by as much as $15 billion. Amazon's trailing 12-month free cash flow swung to negative $7.6 billion after three consecutive positive years.
98 | Sept - Oct 2026 | International Finance
• Combined 2026 capex guidance, Alphabet, Amazon, Meta and Microsoft, close to $700 billion • Alphabet Q2 2026 free cash flow, negative $5.9 billion, its first negative quarter since listing in 2004 • Amazon trailing 12-month free cash flow, negative $7.6 billion after three positive years • Share of hyperscaler capex funded by new debt, up from 9% in FY24 to 32% by mid-2026 • Morgan Stanley funding gap estimate to 2028, $1.5 trillion, of which roughly $800 billion is expected from private credit • Alphabet equity raise, June 2026, $84.75 billion, the largest by a listed corporate
Research house Epoch AI, fitting growth curves to quarterly filings, calculated that aggregate hyperscaler cash capex would overtake operating cash flow somewhere around the third quarter of 2026. That crossover point is now behind us. Microsoft remains the outlier, the only one of the American hyperscalers still generating meaningful free cash flow, and it has managed that partly by leasing rather than buying, adding some $26 billion of finance lease assets over four quarters rather than issuing senior bonds. The rest have gone shopping for outside money, and at extraordinary scale. FactSet calculates that incremental annual debt has risen from 9% of hyperscaler capex in fiscal 2024 to 32% by mid-2026. Equity has returned to the funding mix too. Alphabet priced an $84.75 billion raise in June 2026, the largest eq-
uity capital transaction ever completed by a listed company, including a $10 billion private placement with Berkshire Hathaway. Oracle, the most leveraged of the group, raised $43 billion of debt and $5 billion of equity in fiscal 2026, and plans roughly $40 billion more. Then, there is the arithmetic that hangs over the whole sector. Morgan Stanley's widely circulated estimate puts global data centre capital expenditure through 2028 at around $2.9 trillion, against hyperscaler operating cash flow capable of covering perhaps $1.4 trillion of it. The remaining $1.5 trillion has to come from somewhere else. In Morgan Stanley's own bridge, the largest single share, about $800 billion, is allocated to private credit, with roughly $200 billion from corporate bonds and $150 billion from securitised products.
FEATURE NVIDIA
That $1.5 trillion hole is the reason six financiers were sitting in a television studio in August.
Why Nvidia cannot simply write the cheque Nvidia is not short of money. It reported record revenue of $81.6 billion in the first quarter of fiscal 2027, up 85% yearon-year, with data centre revenue of $75.2 billion and gross margins around 75%. It has authorised a further $80 billion of share buybacks and raised its dividend 25-fold. Its market capitalisation sits around $5.5 trillion. But Huang has said publicly that AI infrastructure spending could reach $3 trillion to $4 trillion a year by the end of the decade. At that scale, no single corporate balance sheet is adequate, including his own. There is a second problem, and it is arguably more urgent. Nvidia's growth increasingly depends on customers who are not hyperscalers. Frontier laboratories, such as OpenAI and Anthropic, specialist AI clouds, sovereign projects and enterprises, want compute at scale, but many of them lack the credit rating or the cash to buy millions of dollars of silicon outright. Meanwhile, the hyperscalers, Nvidia's traditional customers, are busy designing their own accelerators. Broadening the buyer base is a strategic necessity, and the constraint on that broadening is no longer chip supply or data centre shells. It is financing. Nvidia's earlier attempts to solve this itself produced exactly the reaction it feared. The company has invested in customers, including CoreWeave, contributed billions to an OpenAI funding round, and joined a consortium backing xAI. Analysts began describing the pattern as circular financing, the vendor funding its
own demand, and comparisons to the telecom vendors’ financing collapse of the dot com era followed quickly. The reaction sharpened when reports emerged that Nvidia was weighing a $250 billion guarantee for an OpenAI data centre project in Ohio. Nvidia shares fell 5%, and the price of credit default swaps on Nvidia bonds recorded their largest intraday move since they began trading actively. The company subsequently trimmed that guarantee to under $120 billion, covering only the first phase. Seen against that background, the six-way partnership is a deliberate correction. Nvidia will still provide credit support, but Huang clarified after the announcement that its guarantees would cover as much as 25% of an opportunity, assessed project by project. The other 75%, and the origination, structuring, distribution and warehousing of the risk, belongs to Wall Street. The chipmaker keeps the demand and sheds most of the balance sheet.
The intellectual move at the centre of the deal Huang's contention is that a rack of Nvidia GPUs should be treated the way a lender treats a warehouse, a toll road, or a power station. In his framing, Nvidia compute is an investable infrastructure asset, productive, revenue generating, and fungible across the entire market. Nvidia's own statement described its compute as broadly adopted, transferable between customers and operators, and continuously improved by CUDA software updates that extend its useful life. If that classification holds, everything else follows. Loans can be secured against the hardware itself alongside the offtake agreements that guaran-
tee its use. Special purpose vehicles can own chips and lease them to Nvidia's customers, keeping the debt off the customer's balance sheet and off Nvidia's. Those vehicles can then issue bonds, some expected to run to tens of billions of dollars each. If a borrower fails, the chips can be re-rented to somebody else, which limits the damage from any single default. Insurance capital, pension money, and sovereign wealth funds can buy the resulting paper, because it looks and behaves like infrastructure debt. If the classification does not hold, the whole edifice is a very large pile of fast depreciating electronics dressed up as real estate.
The case against An H100 that changed hands for roughly $30,000 in 2023 was trading at around $8,000 by the middle of 2026, a fall of about 73% in three years. Hourly rental rates for the same chip peaked near $8, collapsed to between $1 and $2 as supply arrived, recovered, then softened again. CUDA's ecosystem of more than six million developers may guarantee that a buyer exists for repossessed hardware. It does not guarantee the price. Michael Burry, who made his name calling the last credit crisis, has attacked the depreciation schedules underpinning the sector, arguing that a two-tothree-year hardware upgrade cycle cannot support five- and six-year useful life assumptions, and estimating that understated depreciation could distort reported earnings by around $176 billion between 2026 and 2028. Accounting specialists have pushed back on the strongest version of that claim, but the debate has moved from technical footnotes to the front of investor decks. Then, there is China. Bernstein Re-
International Finance | Sept - Oct 2026 | 99
BANKING AND FINANCE
FEATURE NVIDIA
search expects Nvidia's share of the Chinese AI chip market to collapse from roughly 40% to around 8% by the end of 2026, with Huawei approaching half the market. Should Chinese production flood the world with cheap compute, the collateral behind these loans could erode faster than the loans amortise. One analyst estimate suggests investors will price GPUs as high depreciation equipment rather than property, and demand yields of 11% to 17% depending on their position in the capital structure. That is high yield pricing, and it sits well above what a hyperscaler pays in the corporate bond market. Rating agency methodology for GPU backed securitisations, meanwhile, is still being worked out. Fitch has yet to publish a settled approach.
What Wall Street actually gets Fees, and a lot of them. Alternative managers earn management fees on committed capital, typically 1.5% to 2%, plus carried interest on profits. Fee related earnings are what analysts prize, because they are recurring and predictable. Apollo reported record fee related earnings of $785 million in the second quarter of 2026, up 25% year-on-year, on $74 billion of originations. Strikingly, that figure excluded the $35 billion Broadcom AI infrastructure financing entirely, because Apollo books volume at closing rather than announcement, leaving roughly $50 billion of signed deals to feed later quarters. Management has also noted a shift towards structures that recognise fees across multiple quarters or years rather than upfront, smoothing earnings in a way public shareholders reward. Goldman, the only participant with a full investment banking apparatus, collects the underwriting and distribution eco-
100 | Sept - Oct 2026 | International Finance
WALL STREET AI BOOM
nomics on top. A home for permanent capital. The deeper motivation is a liability problem. The five largest listed alternative managers now oversee about $1.5 trillion of perpetual capital, roughly 40% of their combined assets, much of its insurance and annuity money gathered through platforms such as Apollo's Athene, KKR's Global Atlantic, and Blackstone's insurance mandates. Annuity liabilities are long dated and require long dated, contracted, investment grade style assets to match them. Those assets are scarce. A twelveyear lease on a GPU cluster with an investment grade offtaker attached is, in principle, exactly the instrument these balance sheets are hungry for. Apollo's private credit assets alone stand at roughly $405 billion, Blackstone's credit and insurance arm at about $465 billion, BlackRock at around $220 billion after its HPS and GIP acquisitions, and KKR at about $140 billion. All of that money needs somewhere to go. Ownership of a new market at its inception. Asset classes are created rarely. Whoever writes the first documentation, sets the advance rates, defines the residual value assumptions, and builds the ratings dialogue, tends to own the league tables for a decade. Data centre securitisation issuance ran near $27 billion in 2025, and is projected by JPMorgan at $30 billion to $40 billion annually in 2026 and 2027, a rising share of the combined asset backed and commercial mortgage-backed market. CoreWeave has already priced an $8.5 billion investment grade rated GPU collateralised transaction. Nvidia has now handed six firms a franchise position in the market that follows. Better risk for the same yield. Nvidia's willingness to backstop up to a quarter of a transaction materially changes
the credit maths. A lender writing a loan against hardware alone is exposed to residual value. A lender writing the same loan with a first loss cushion from a company with 75% gross margins and a $5.5 trillion market capitalisation is in a different business. Combine that with collateral that mixes the chips themselves with contracted offtake, and with the ability to re-rent hardware to a different tenant on default, and the risk adjusted return starts to look attractive even at spreads well inside 11%. Distribution is where the real prize sits. These firms do not intend to hold the paper. They intend to originate it and sell it. Executives are already sounding out sovereign wealth funds, pension schemes and insurers, and indicated during the announcement that some of the capital could come from retail investors. That last point matters more than it sounds. American regulators have recently opened the roughly $13 trillion defined contribution market to private credit managers, while Europe's revised ELTIF regime has broadened what long term investment funds may hold. Non-traded business development companies and evergreen vehicles are growing quickly. A manufacturing line for long dated, contracted, AI linked credit feeding those channels is a business with obvious compounding characteristics. Apollo is expanding a trading operation to sell down chunks of what it originates and make markets in the paper afterwards, which adds a second fee layer. Adjacency. The financing will not be a single product. As Mercer's global head of real assets observed after the announcement, the partnerships are likely to spawn strategies across infrastructure, real estate credit, and possibly pri-
FEATURE NVIDIA
The pipeline and the prize for Wall Street • Headline commitment, more than $500 billion of thirdparty capital, six memorandums of understanding, no fixed timeframe • The six partners - Apollo, BlackRock, Blackstone, Brookfield, Goldman Sachs and KKR • Nvidia's own exposure, guarantees capped at about 25% of any single opportunity, assessed case by case • Apollo Q2 2026 fee related earnings: a record $785 million, up 25% year-on-year • Perpetual capital held by the five largest listed alternative managers: about $1.5 trillion, roughly 40% of their combined AUM • Data centre securitisation issuance: about $27 billion in 2025, forecast at $30 billion to $40 billion a year in 2026 and 2027 vate equity, giving investors multiple access routes. Data centres need land, power, transmission, cooling, and construction finance. A firm that anchors the compute layer is well placed to sell the rest. Competitive necessity. Nobody wanted to be left out. Huang has said he approached only these six and none refused. Within minutes of the announcement, Morgan Stanley published a framework to facilitate $1.5 trillion of funding for American innovation and national security, with AI and advanced computing at the top of the list. JPMorgan's asset management arm is reportedly discussing how to participate. Broadcom set the template weeks earlier, tapping Apollo and Blackstone as anchor investors for more than 20 gigawatts of compute for frontier laboratories through 2028, with $35 billion already
committed and the borrowing structured to sit off Broadcom's balance sheet.
Where the win-win could break The mutuality depends on one assumption holding for a decade. Chips must remain productive long enough, and generate enough revenue, to service the debt raised against them. Apollo's own published view illustrates the tension. The firm has argued that more than $5 trillion of expected data centre capital expenditure implies $1.5 trillion to $2 trillion of annual AI revenue by 2030, against $40 billion to $60 billion today. That is the gap the entire structure is betting will close. The risk is no longer confined to technology shareholders. It now runs through special purpose vehicles, private credit originators, securitisation trusts, and ultimately into pension port-
folios and insurance reserves. Insurance regulators have already tightened capital treatment for collateralised loan obligations and overhauled how collateral loans are charged, moving from a flat charge to a framework tied to what actually backs the loan. American law firms are circulating client alerts on litigation risk in AI data centre financing. The Federal Reserve Bank of Chicago has noted that direct bank exposure to AI adjacent industries averages under 1% of assets, while cautioning that indirect exposure through lending to private credit funds is harder to see. One person close to the announcement described Huang's intention as building a debt shopfront, an advertisement aimed simultaneously at customers and at nervous investors. If the deals do not materialise as promised, or if they sour, the reputational cost lands on all seven names.
The final take Nvidia has done something clever. It has kept the demand, capped its exposure at roughly a quarter, and persuaded the deepest pools of capital in the world to carry the rest. Wall Street, for its part, has been handed a manufacturing line for exactly the kind of long dated, contracted, high yielding asset its insurance balance sheets and retail distribution channels have been starved of. Both sides get what they want. Whether the arrangement is a win for the pensioners and policyholders who end up owning the paper depends entirely on a question none of the seven firms on that stage could answer, which is how long a graphics processor stays valuable. editor@ifinancemag.com
International Finance | Sept - Oct 2026 | 101
BANKING AND FINANCE
FEATURE WALL STREET
FEDERAL RESERVE CAPITAL RULE
Wall Street’s capital truce collapses over one line in Fed rulebook
102 | Sept - Oct 2026 | International Finance
FEATURE WALL STREET
A change to how the Federal Reserve measures short-term funding pits JPMorgan and Bank of America against Goldman Sachs and Morgan Stanley
International Finance | Sept - Oct 2026 | 103
BANKING AND FINANCE
FEATURE WALL STREET
FEDERAL RESERVE CAPITAL RULE
IF CORRESPONDENT
F
or the best part of a decade, America's largest banks spoke with something close to one voice on capital regulation. They funded the same trade bodies, signed the same comment letters, ran the same advertisements, and told regulators the same story about credit, competitiveness, and the cost of holding idle equity. That campaign has largely worked. The Federal Reserve is now finishing a rewrite of capital rules that will leave the biggest lenders holding less capital than they do today. And that is precisely where the alliance has broken. JPMorgan, Bank of America, Goldman Sachs, and Morgan Stanley are now feuding over a single technical adjustment inside the Fed's proposal, with billions of dollars at stake, according to public documents and four people familiar with the discussions who spoke to Reuters. The disagreement is narrow, highly technical and almost entirely invisible to anyone outside the regulatory bar. It is also worth more to the banks involved than most of the rest of the package combined.
What the surcharge does The instrument at the centre of the argument is the capital surcharge applied to global systemically important banks, known as GSIBs. There are eight of them in the United States, namely JPMorgan Chase, Bank of America, Citigroup, Wells Fargo, Goldman Sachs, Morgan Stanley, BNY Mellon, and State Street. The surcharge is an extra layer of common equity tier 1 capital they must hold on top of everyone else's requirements, calibrated to the damage their
104 | Sept - Oct 2026 | International Finance
failure would inflict on the wider system. The Fed built the surcharge after the 2007 to 2009 financial crisis, originally around five systemic risk factors carrying equal weight of 20% each, one of which was short-term wholesale funding. The logic was drawn straight from the wreckage of that period. Before the crash, the largest Wall Street firms funded their balance sheets aggressively with short-term liabilities that, for several of them, disappeared almost overnight, a dynamic that accelerated the collapse of Lehman Brothers and forced Morgan Stanley and Goldman Sachs to convert into bank holding companies. Short-term wholesale funding, or STWF, covers repurchase agreements, commercial paper, brokered and uninsured wholesale deposits, and similar instruments. It is cheap, flexible and prone to vanishing at exactly the moment a bank needs it most.
The tweak that split the room In March, the Fed proposed changes it said would make the surcharge more risk-sensitive, including a revision to how short-term wholesale funding is treated. The mechanics matter here. At present, the Fed measures shortterm wholesale funding as a ratio of risk-weighted assets. That normalised comparisons across the eight banks, but it also pushed the effective weighting of
the funding measure to roughly 30% of the overall calculation. The Fed has proposed scrapping the ratio and simply measuring the absolute dollar amount of short-term wholesale funding a bank carries. The recalibration is designed to bring the funding component back to around 20% of aggregate Method 2 GSIB scores, its originally intended weight, with the Fed attributing the drift to early data limitations. Strip out the jargon and the change is simple. Today, a bank's funding risk is judged relative to how risky its assets are. Under the proposal, it would be judged on its own, in dollars. That single substitution redistributes billions across the industry, because the eight banks look very different once the denominator disappears.
Winners, losers, and the maths behind them The banks that benefit are the ones
FEATURE WALL STREET
same directional conclusion, namely that the two investment banks stand to benefit most.
The Main Street argument
with small risk-weighted asset books relative to their funding. The banks that lose are the universal lenders with enormous balance sheets that were, in effect, being flattered by a large denominator. According to 2026 federal data, short-term wholesale funding accounted for 37% of Morgan Stanley's liabilities, and 30% of Goldman Sachs's. For Bank of America, the figure was 24%, and for JPMorgan 21%. The scoring effects are stark. Morgan Stanley currently carries the highest funding score among the eight at 333 basis points, despite ranking only fifth in absolute terms with $503 billion of short-term wholesale funding because its comparatively small $529 billion risk-weighted asset base inflates the ratio. Under the proposal, its score would fall to 116 basis points, a decline of 65%. JPMorgan runs by far the largest shortterm wholesale funding book at $903 billion, yet ranks only fourth on the
current measure at 165 basis points, because its $1.9 trillion risk-weighted asset denominator dilutes the result. Under the proposal, JPMorgan would move to the top of the table at 208 basis points. Goldman Sachs, second highest today at 271 basis points on $552 billion of funding, would drop to 127 basis points. Translated into capital, the numbers are large enough to explain the sudden loss of solidarity. The overall package still reduces requirements for all of them, but JPMorgan told the Fed in a June letter that the funding tweak would cost it $13 billion of additional relief it would otherwise have received, and Bank of America $9 billion. In the same letter JPMorgan estimated that Goldman Sachs and Morgan Stanley would each pick up a further $1 billion to $2 billion, a figure that is its own calculation of a rival's gain rather than an independent one. Better Markets has reached the
The change caught executives at JPMorgan and Bank of America by surprise, the people told Reuters, because the two largest US lenders sit on deep deposit funding, and the revision hands the advantage to commercial rivals who rely more heavily on wholesale markets. To them, it also sat awkwardly with the stated rationale for capital relief under President Donald Trump's regulators, which has been to expand lending into the real economy. That has become the core of their public case. According to the same account, JPMorgan and Bank of America executives have lobbied Fed officials, at times in joint meetings, to kill the proposed change, arguing that the new formula could constrain lending and support riskier trading activity instead. JPMorgan's business banking chief Stevie Baron made the argument publicly in a blog post in August, warning that the proposal as drafted would encourage trading over lending to small businesses and customers. The formal objections were filed in June. In separate comment letters submitted on June 18, JPMorgan and Bank of America told the Fed it had not adequately justified removing risk-weighted assets from the denominator, arguing the change could distort how reliance on short-term funding is measured and produce uneven outcomes across the largest US banks. Bank of America's chief financial officer Alastair Borthwick wrote that a gross funding measure with no denominator risks overstating the danger posed by a larger firm whose relative reliance
International Finance | Sept - Oct 2026 | 105
BANKING AND FINANCE
FEATURE WALL STREET
FEDERAL RESERVE CAPITAL RULE
on such funding is low. Bank of America has kept its public language broad. A spokesperson said the bank supports changes that drive Main Street lending, job creation, and affordability. The Fed, JPMorgan, Goldman Sachs, and Morgan Stanley all declined to comment.
The case for absolute dollars The two investment banks take the opposite view, and they have the more orthodox regulatory argument on their side. Goldman Sachs and Morgan Stanley filed their own letters backing the revision, on the grounds that it would improve the accuracy of the surcharge by better aligning the funding measure with the risk it is meant to capture. Goldman argued the change would produce a more transparent and economically grounded measure, while Morgan Stanley, which two of the people who spoke to Reuters described as especially active in pressing the case, told the Fed the revision could improve liquidity in the Treasury market by cutting the capital banks must hold against dealing in government bonds. Financial reform advocates, who agree with almost nothing else in the Fed's package, agree with them on this point. Better Markets argues that the damage a funding run inflicts depends on the absolute dollar volume of run-prone liabilities, not their ratio to a risk-weighted figure, since a bank forced into a fire sale must liquidate real assets at real prices regardless of what risk weights those assets carried. The group also notes that scaling by risk-weighted assets creates a perverse incentive, because banks that successfully optimise their risk weights downwards see their funding scores rise, while banks that become genuinely riskier see them fall.
106 | Sept - Oct 2026 | International Finance
Source: Statista
Christopher Appel, director of banking policy at Better Markets and a Fed official from 2019 until March, said the surcharge is a key remaining safeguard as regulators trim overall capital levels, and that the revision would better gauge funding risk. "It's absolutely critical that the Fed get this right," he said. Appel was among many staff who left the central bank this year as the administration overhauled federal agencies.
The wider package The funding dispute sits inside a far larger rewrite. On March 19, the agencies released a linked set of proposals covering Basel III implementation, a revised standardised approach and the GSIB surcharge methodology, marking a decisive retreat from the 2023 drafts that would have pushed capital requirements sharply higher across the industry. Fed Vice-Chair for Supervision Michelle Bowman set out the logic a week
earlier, saying the Basel III element would raise requirements slightly for the largest banks while the surcharge proposal would produce a modest decrease, leaving a small net reduction. The surcharge proposal does several other things beyond the funding measure. It adjusts the fixed systemic indicator coefficients to account for economic growth and inflation, replaces year-end snapshots with daily and monthly averages, and narrows the Method 2 surcharge bands from 50 basis points to 10 basis points to soften the cliff effects of moving between buckets. Industry economists have long complained that fixed denominators calibrated to 2012 and 2013 activity levels cause Method 2 scores to drift upwards over time for reasons unconnected to systemic risk, with a bank holding a constant global market share seeing its size score rise by 29% over the period. The aggregate figures are substantial. The surcharge proposal alone is expected to cut common equity tier 1 require-
FEATURE WALL STREET
ments for GSIBs by roughly 3.8%. Taken together, the March package is estimated to reduce required CET1 by up to 4.8% for Category I and II GSIB organisations, 5.2% for Category III and IV regional banks, and 7.8% for community banks. Not everyone at the Fed agreed. Governor Michael Barr put the surcharge cut at $33 billion, and said that once the recent changes to the enhanced supplementary leverage ratio are included, tier 1 requirements for GSIBs fall by 6.0%, or $60 billion. "These significant reductions in capital requirements are unnecessary and unwise," he said, while accepting that some elements, including annual averaging and narrower scoring bands, were genuine improvements.
Why the banks still object It is worth noting that even the banks winning relief are unhappy with the headline outcome. Jamie Dimon told shareholders in April that the proposals remain flawed in specific areas and that
some aspects are, in his words, nonsensical, while backing timely finalisation because everyone wants to move on. On JPMorgan's first-quarter call, executives said the bank was planning for a surcharge of 5.2% in 2028, a 70-basis point increase on the current 4.5%, which combined with the Basel III risk-weighted asset changes would mean roughly $20 billion more GSIB capital on its present balance sheet. That is the frame JPMorgan has adopted throughout. It is not arguing that the surcharge should disappear. It is arguing that the calibration remains disconnected from the Fed's own stated rationale, and that the funding tweak makes the disconnection worse. The timing explains much of the urgency. The infighting risks complicating the Fed's effort to finalise the reforms before 2027, when Democrats are widely expected to take the House of Representatives and step up scrutiny of the administration's regulators. Access has not been the constraint. JPMorgan and Morgan Stanley executives have each met Fed officials on the GSIB proposal at least four times since March, according to public Fed memos reviewed by Reuters. The four people cited by the agency said it was unclear who will prevail. Bowman has told banks to limit their feedback, and three of them believe she will stay close to the current draft, partly because she wants the rule done by year-end. All four banks support the overhaul in principle. What has changed is that a rare window has opened to maximise individual gains at a rival's expense. The industry pushed for years to soften the surcharge with limited success, and only made progress when the Fed's 2022 capital review triggered an un-
precedented and unified backlash. Unity was the tactic that worked. It has not survived contact with the spoils.
What to watch Three things will determine how this lands. The first is whether the Fed keeps the absolute-dollar measure intact, softens it with a partial denominator, or phases it in. A compromise that preserves the principle while smoothing the distributional effect is the most likely landing zone for a regulator trying to close a file before the calendar turns. The second is the Treasury market question. Morgan Stanley's argument that lower capital charges on repo activity would deepen liquidity in government bonds is the one strand of this dispute with consequences well beyond bank shareholders, and it is the argument most likely to resonate inside a central bank that has spent years worrying about Treasury market fragility. The third is durability. Better Markets has pointed out an internal tension in the package, arguing that if risk-weighted assets cannot be trusted as a denominator for the funding measure, the accompanying Basel III proposal doubles down on the same metric across the rest of the capital framework. A rule finalised in December on a narrow supervisory majority, into a Congress about to change hands, is not obviously a settled rule. Four of the most powerful financial institutions in the world spent a decade arguing that capital regulation was too blunt to reflect real risk. The Fed has finally accepted a version of that argument, and two of them have discovered they preferred the blunt version after all. editor@ifinancemag.com
International Finance | Sept - Oct 2026 | 107
Business Dossier - Ranhill SAJ
Ranhill SAJ powers Johor’s long-term water transformation journey Ranhill SAJ, a subsidiary of Ranhill Utilities Berhad
(Ranhill), is the Malaysian group's leading water operator, a position that it has achieved and consolidated through over two decades of strategic, performance-driven transformation. The utility company currently manages 47 water treatment plants (WTPs) in the Southern State of Johor, Malaysia, with a combined treatment capacity of 2,375 million litres per day (MLD), through an extensive infrastructure network that includes 799 reservoirs and approximately 24,639 kilometres of pipelines. The company has been a pivotal force in the state of Johor, in ensuring a reliable and safe water supply to over four million domestic and industrial users in the region. 108 | Sept - Oct 2026 | International Finance
Since the privatisation of its operations in the state of Johor in 1999, it has built a solid track record, positioning itself to support future development needs through operational readiness and long-term planning. "This journey was marked by consistent foresight, disciplined execution, and continuous investment in governance, infrastructure, people, security, and sustainability. From pioneering NRW reduction efforts to establishing an ESG-focused leadership model, the company’s growth exemplifies robust institutional development, delivering superior performance and aligning with national priorities and international best practices in utility management," the company told International Finance.
Under Ranhill SAJ's watchful eyes, Johor launched a pioneering structured NRW reduction programme
A successful NRW reduction programme
With a strong focus on operational excellence, sustainability, and customer satisfaction, the company has been advancing water infrastructure and services to meet growing demand and environmental challenges in the state. The utility player has been equally innovative when it comes to dealing with the problem of non-revenue water (NRW), a phenomenon in which treated water gets lost before reaching consumers due to leaks, theft, or metering errors, costing the industry billions annually. Johor was not immune to the problem either. To address that, the company adopted a different mindset, viewing NRW as a manageable operational is-
sue that could be tackled systematically through strong governance, targeted infrastructure investments, and accountability measures. Initial efforts in leakage control, pipe rehabilitation, and operational monitoring gradually yielded measurable improvements. Under Ranhill SAJ's watchful eyes, Johor launched a pioneering structured International Finance | Sept - Oct 2026 | 109
Business Dossier - Ranhill SAJ
NRW reduction programme. Over time, the initiative gained national recognition and was acknowledged by the National Water Services Commission (SPAN) as a benchmark model for other states. "During this period, NRW levels were successfully reduced and maintained below 24%, establishing Johor as the lowest NRW-performing state in Malaysia. A key milestone in validating this strategy is its consistent performance under Malaysia’s Matching Grant (MG) NRW Reduction Programme, a federal initiative that incentivises water operators to meet verified NRW targets. Under MG2021, NRW was reduced from 26.2% to 25.1%, earning a 75% reimbursement of RM142 million and demonstrating strong operational discipline with tangible results," the company said. "The momentum continued with MG2023, where the company exceeded expectations by achieving a 25.0% NRW against a target of 25.5%, resulting in a 50% reimbursement of RM120 million. Most recently, under MG2024, NRW was recorded at 24.1%, outperforming the target of 25.0%. The reimbursement for this achievement is currently under review by the SPAN-appointed auditor, further affirming the regulator’s confidence in the company’s reporting integrity, governance, and operational excellence," it added. The utility player has implemented an integrated geographical information system (GIS) and SCADA technology, enabling real-time monitoring, centralised control, and faster responses as part of its digitisation efforts and modernising Johor’s water distribution. This shift from manual to data-driven operations improved system reliability, visibility, and efficiency, helping to reduce NRW and enhance overall water management. By leveraging technology, it aligns with its commitment to continuous improvement in utility operations. Ranhill SAJ’s dedication to excellence was further solidified through various prestigious recognitions across operational, environmental, laboratory, and security sectors. It was honoured with the "IKM Laboratory Excellence Award 2025" in recognition of the outstanding performance of the Ranhill SAJ Sri Gading Laboratory. This accolade underscores the company's commitment to maintaining the highest technical standards, implementing rigorous quality assurance, and upholding professional laboratory management practices that ensure safe and dependable water services. In the same year, it was also honoured with the "Environmental Sustainability Award for Water Stewardship and Conservation" at the ESG PLUS Awards 2025, reflecting 110 | Sept - Oct 2026 | International Finance
the utility giant’s leadership in integrating sustainability into water resource management through conservation initiatives, efficient water use, and long-term environmental protection strategies, while balancing operational performance with national sustainability objectives. Ranhill SAJ received key recognitions for national security and operational resilience, including the Certified Johor’s Key Installation for managing critical water infrastructure and the Star Award of The Office of The Chief Government Security Officer for high compliance with
Business Dossier - Ranhill SAJ
(IMELC), promoting water conservation and environmental responsibility among students through interactive activities and workshops. IMELC alone has involved over 100,000 students from 909 schools across the state, supported by agencies such as Johor State Education Department (JPNJ), Iskandar Regional Development Authority (IRDA), Universiti Teknologi Malaysia (UTM), and United Nations Children's Fund (UNICEF). These efforts reflect the company’s commitment to fostering sustainability and community resilience beyond infrastructure security.
Establishing organisational resilience
Malaysia's National Critical Infrastructure Security Policy. These awards followed thorough inspections at six major water treatment plants and dams. Initiatives such as e-Vetting, security planning, contingency readiness, and risk assessments highlight the organisation’s ability to protect critical infrastructure and ensure a continuous water supply. In parallel, it is actively engaging with the community through outreach programmes such as Water Saving Generation and the Iskandar Malaysia Eco-Life Challenge
The company has also adopted a holistic approach to employee well-being, focusing on physical health, mental wellness, safety, career growth, and work-life balance. Through wellness programmes, safety improvements, and engagement initiatives, it supports both operational and administrative staff. Training, leadership development, and succession planning, on the other hand, ensure organisational resilience, while facilities such as the "Water Academy" foster technical skills and knowledge transfer. "Employee engagement is strengthened via transparent communication, leadership interactions, and recognition programmes. Inclusive policies on diversity, equality, and merit promote fairness and opportunity. These practices boost morale, retention, and cohesion, underpinning the company’s commitment to sustainable long-term performance," Ranhill SAJ commented. The transformation journey demonstrates that excellence in water management is achieved through consistency, strategic patience, and ongoing investment. By combining operational discipline with innovation, regulatory credibility, security, sustainability, and workforce well-being, the company has reduced losses, increased efficiency, and set new standards for water utility governance in Malaysia. This integrated approach enables the organisation to deliver long-term value to stakeholders and strengthen its role as a leading water operator for the future. International Finance | Sept - Oct 2026 | 111
TECHNOLOGY
ANALYSIS
META FACEBOOK
The social media conglomerate has been facing legal heat on a global scale, in terms of improperly collecting and using children's personal data
META and youth addiction: A problematic affair IF CORRESPONDENT
The week spanning from August 18- 25 was a huge one for American Big Tech. A coalition of 29 states sued the Mark Zuckerberg-led Meta with a damning claim: Facebook and Instagram were harming young users' mental health. The lawsuit rotated around these questions: Did Move fast and Meta design Facebook and break things Instagram to be addictive to was a mantra children and teens? Did the at Meta, which social media conglomerate took a don't mislead consumers about ask, don't tell the safety of its platforms for approach to young users? Most impormonitoring tantly, what about the allegawhether chiltions about the platforms imdren under 13 properly collecting and using were online children’s personal data, in violation of federal law? The hi-profile hearing at the Californian Federal Court had an EU link. In 2024, European regulators opened a formal investigation into Meta on the similar issue, citing potential breaches of online content rules related to child safety on Facebook and Instagram. The European Commission (EC), back then, expressed concerns over the algorithmic systems used by the popular social media platforms, that was allegedly recommending videos and posts that could ‘exploit the weaknesses and inexperience of
112 | Sept - Oct 2026 | International Finance
children and stimulate addictive behaviour’. In 2026, the EC published preliminary findings of that two-year investigation, finding the Meta in breach of the Digital Services Act (DSA). The tech giant was asked to implement several design changes to curb its platforms' ‘compulsive use’.
A self-inflicted wound for Meta During the hearing, four lead states, California, Colorado, Kentucky and New Jersey, accused the social media conglomerate of designing Facebook and Instagram to hook young users, apart from fuelling anxiety, depression, and even suicide, and most importantly, misleading consumers about the platforms' safety. All 29 states accused Meta of violating federal law by improperly collecting and using children's personal data. Meta's lawyer Paul Schmidt countered the charges by mentioning that there was ‘no dispute’ that some social media users face struggles, but that research showed no clear link between adolescents' social media use and a lack of well-being. Former Meta safety engineer Arturo Bejar, a vocal critique of the defective nature of Meta's child safety tools, also testified. He said, "Move fast and break things was a mantra at Meta, which took a don't ask, don't tell approach to monitoring whether children under 13 were online. Many products were shipped into the
world, such as Reels short-form videos, and safety was not a consideration in how it was initially deployed."
Meta saved its piggy bank, somehow Meta finally winked, on August 25, by agreeing to cough up to $18 billion to the 29 states. It also agreed to introduce nationwide changes to its services for teenage users. Meta has also agreed to implement teen safeguards, including a default two-hour daily limit across Facebook and Instagram, overnight blocks from midnight to morning 6 am, age-checking measures and disabling push notifications during school hours of 8 am to 3 p m for teen users. The social media conglomerate will be paying the 70% of the settlement, or roughly $12.7 billion, over a decade. The remaining amount, around $5 billion, will only be released if rivals Snap, TikTok and YouTube adopt similar measures. Meta has also added the condition of the rival platforms agreeing to make similar payments to the states. Likes and reactions will be hidden from teens by default, including on their own posts, and those of others.
The $18 billion figure, despite being among the largest ever settlements paid by a technology company, won't strain a business that earned more than $60 billion in 2025. The settlement also left untouched the personalised feeds and ad targeting, known as Meta's profit-making machines. The spike in Meta’s shares after the news coming out suggested that investors welcomed an outcome that will cost the company far less than the $1.4 trillion in penalties it said the states were seeking before trial.
The 2021 Whistleblower Testimony That Started the Saga The hearing in the Californian court and the multistate investigation into Instagram and Facebook's impact on young users were the follow-up actions of the 2021 testimony by Meta whistleblower Frances Haugen. Haugen, back then, informed the Senate committee that the company knew its products could harm young users and how to make them safer, but chose not to make those changes in favour of pursuing higher profits. Haugen came armed with ‘internal documents’, that revealed how Meta knowingly prioritised high profits and user engagement over children's safety. The papers contained Meta's own internal studies
International Finance | Sept - Oct 2026 | 113
TECHNOLOGY
ANALYSIS
META FACEBOOK
showing how Instagram worsened mental health and self-esteem issues for a significant percentage of teenage girls. Known as the ‘Facebook Papers’ and reported exclusively by The Wall Street Journal, the documents also showed Meta downplaying these findings publicly. "The platform’s engagement-driven algorithms actively steered young users toward harmful 'rabbit hole' content relating to eating disorders and toxic comparisons," reported the WSJ. While company executives took note of the negative psychological footprint of their products, they declined to implement safety-first structural changes over the alleged worries about the reforms ‘reducing’ user screen time and ad revenue. Meta also turned a blind eye to underage accounts (those below 13), failing to implement strict and verifiable age controls.
Plethora of lawsuits By 2022, hundreds of personal injury lawsuits from parents and over 200 US school districts got filed against Meta. They accused Instagram of causing severe youth depression, anxiety, eating disorders, and self-harm, forcing schools to expend massive resources on mental health counselling. By 2023, states’ allegations against Meta got further specific: developing algorithms intended to keep users on the platform as long as possible, even compulsively; creating visual filters it knows can contribute to body dysmorphia; and presenting content in an ‘infinite scroll’ format that makes it hard for
114 | Sept - Oct 2026 | International Finance
State-by-State Payout Estimates (Youth Addiction Case) State AGs have disclosed their expected minimum allocations over the next decade from the primary multi-state fund
State Minimum Projected Payout California At least $1.5 billion (up to $2.2 billion max) Texas $1.0 billion (Separate individual settlement)
New Jersey
At least $525 million
Massachusetts
At least $366 million
Virginia
At least $353 million
Washington At least $237 million (up to $339 million max) Georgia Close to $100 million (up to $135 million max) Source: CBS News
children to disengage. The legal luminaries found overwhelming support among the educators, who raised alarms over social media's negative impacts on kids’ mental health, especially the ability to learn. Noted Physician and the then US Surgeon General Vivek Murthy too came out against Meta. In an opinion piece published in The Washington Post, he wrote, “We do not have enough evidence
to conclude that social media is sufficiently safe for our kids. In fact, there is increasing evidence that social media use during adolescence — a critical stage of brain development — is associated with harm to mental health and well-being."
Seattle and New Mexico pleas changed the game In fact, in January 2023, Seattle Public Schools became the first-ever educational institution to file a
lawsuit on the above-mentioned constraint. The district claimed that the number of students in the school system reporting that they feel ‘so sad or hopeless almost every day for two weeks or more in a row that they stopped doing some usual activities’ rose 30% since 2009. The district asked for the social media companies named in its suit to pay for damages as well as preventative education and treatment for problematic social media use, among other remedies. Meta, Snap, ByteDance, and Alphabet were accused of designing and operating their respective platforms ‘in ways that exploit the psychology and neurophysiology of their users into spending more and more time on their platforms’. Seattle's lawsuit stated that, as a result of social media usage issues, the district's educational set-ups were forced to ‘take steps to mitigate the harm and disruption caused by defendants' conduct’, including hiring additional personnel to address mental, emotional, and social health issues, apart from increasing training for teachers and staff to identify students exhibiting symptoms affecting their mental, emotional, and social health. New Mexico followed it up with its own lawsuit, with Attorney General Raul Torrez charging the social media conglomerate of creating a ‘breeding ground’ for child sexual exploitation and ignoring safety gaps on Instagram. Judge Bryan Biedscheid, in August 2026, ordered Meta to pay another $567 million for its failure to warn the public about dangers its
platforms posed to children. The amount was an add-on to the previous figure of $375 million, that the social media conglomerate was already ordered to pay in the case. The grand total came at $942 million; the largest fine imposed on the company in the lead-up to the California trial. Throughout 2024 and 2025, federal courts were consolidating thousands of individual, school, and state cases into a massive Multi-District Litigation (MDL) block in the Northern District of California. Meta attempted to dismiss the lawsuits multiple times, arguing its algorithms are protected by Section 230 and the First Amendment. In March 2026, a Los Angeles court found Meta and Google liable for social media addiction, anxiety, and depression of a young girl, awarding her $6 million in damages. Then a month after, Meta agreed to a bellwether settlement with the Brevard County School District in Kentucky to avoid a massive public trial, helping set a precedent for thousands of pending school district claims. And then came the moment of reckoning at the Californian Federal Court, where the social media conglomerate had to bow down to the combined might of 29 states and promise to implement changes that will address the concerns related with the mental health of vulnerable young users.
Countries are watching
proposed by the social media conglomerate to curb potentially addictive features for young users should ideally be applied worldwide. Seoul's stand is clear: Not just Meta, every social media company operating within its territory needs to take greater responsibility for protecting children and teenagers. Australian Communications Minister Anika Wells said that social media companies ‘have the tools at their disposal to protect young people from their addictive features but have chosen not to use them’. Philippines Department of Information and Communications Technology Secretary Henry Aguda told Reuters about both Meta and gaming platform Roblox pledging in a meeting on August 27 about tightening age verification processes in the Southeast Asian country, apart from expanding parental controls and implementing time limits on the social media. Meta has also given hints to Brazil's National Data Protection Authority about discussing children's safety online. Both United Kingdom and European Commission will keep their eyes on the social media conglomerate's next set of actions. The social media conglomerate might have successfully avoided a huge dent in its bank balance, but the message from the Californian court has been sent in a crystal-clear manner: Big Tech is not big enough to escape legal glare, especially when it comes to protecting the mental well-being of teenagers.
South Korea's media regulator, while reacting to the news of Meta reaching a settlement in the California court, observed that measures
editor@ifinancemag.com
International Finance | Sept - Oct 2026 | 115
TECHNOLOGY
FEATURE ROBOT
CHINA HUMANOID
China has emerged as a humanoid giant. Whether that makes it the industry's great disruptor depends on a problem the country has not yet solved
IF CORRESPONDENT
O
n the evening of August 22, inside the Beijing oval built for the 2022 Winter Olympics, three humanoid robots crouched at the start of a 100-metre lane. A gun fired. Nine and a bit seconds later, a machine called Tianzhuo, built by the Beijing Innovation Centre of Humanoid Robotics, crossed the line a body length clear of the field in 9.39 seconds. Usain Bolt's world record, set in Berlin in 2009, is 9.58 seconds. Then Tianzhuo carried on running, because it had no reliable way of stopping, hit a padded barrier, and came apart. Stretcher-bearers carried the pieces away. Bolt, in 2009, jogged a victory lap. That sequence is the most honest summary of Chinese robotics available anywhere this year. The acceleration is real and it is astonishing. Twelve months earlier, at the first edition of these games, the best 100-metre time was 21.5 seconds. The braking is not there yet. Which makes the timing of a remark from Wang Xiaogang, chairman of the embodied AI startup ACE Robotics and a co-founder of SenseTime, worth pausing over. Speaking at the ‘World Robot Conference’ in Beijing the day before the race, he told Reuters he expects to reach the ‘ChatGPT moment’ for embodied intelligence by the end of 2027, driven by world models and the capture of environmental data. Xiaogang then added the part that rarely survives the headline. Even if that inflection point arrives in late 2027, he said, broad commercial use across sectors is another four or five years beyond.
116 | Sept - Oct 2026 | International Finance
The robot that beat Usain Bolt...
FEATURE DEMIS HASSABIS
....and broke into pieces International Finance | Sept - Oct 2026 | 117
TECHNOLOGY
FEATURE ROBOT
CHINA HUMANOID
Who actually ships humanoid robots
• Global humanoid shipments, H1 2026: 19,100 to 22,000 units, depending on the tracker So, the question for the industry is not whether China is fast. It is whether speed in hardware converts into control of a market that does not yet properly exist.
• Growth on H1 2025: 272% to 300%
The shipment numbers are extraordinary, and contested
• AgiBot, H1 2026: roughly 8,400 to 9,700 units, 43% to 44% share
Counterpoint Research puts global humanoid robot shipments above 22,000 units in the first half of 2026, a rise of nearly 300% year-on-year. Smart Analytics Global counts 19,100 units against 5,100 a year earlier, a 272% jump. Both agree on the important part. Chinese vendors accounted for more than 97% of global shipments, and China itself represented more than 85% of global demand. Shanghai-based AgiBot has taken the lead from Unitree, shipping somewhere between 8,400 and 9,700 units depending on whose ledger you trust, for a global share of roughly 44%. Unitree follows with about 5,900 units and 31%. Between them, two Chinese firms account for three-quarters of every humanoid robot shipped on Earth. Add Galbot, UBTech, and Leju, and the top five control 86% of the category. Four of the five are Chinese, and the fifth is also Chinese. There is one number worth treating with care. Counterpoint reports that entertainment, performance, data production, and research still account for more than 60% of shipments, with intelligent manufacturing at 13%, and warehousing and logistics at 5%. Smart Analytics Global says industrial and commercial applications are already above 70%. Those two claims cannot both be true, and the gap is not a rounding error. Part of the explanation is that state-backed training centres in China buy robots in volume purely to harvest movement data, which shows up as a sale and as a deployment without a customer having
118 | Sept - Oct 2026 | International Finance
• Chinese vendors' share of global shipments: over 97% • China's share of global demand: over 85% • Unitree, H1 2026: roughly 5,900 units, 31% share • UBTech, H1 2026: 4.4% share, fourth globally • Top five vendors combined: 86% of shipments • Full-year 2026 forecasts: 50,000 units (Counterpoint), 60,000 units and $1.6 billion revenue (Smart Analytics Global), 85,000 units in China alone (HRAA) found a use for the machine. When an industry's own trackers disagree by this margin about what the robots are for, the shipment totals should be read as a measure of production capability rather than of demand. The revenue attached to all this remains small. The whole humanoid market is worth roughly $2 billion to $3 billion today. Full-year 2026 shipments are forecast at 50,000 to 60,000 units globally, generating perhaps $1.6 billion, though the Humanoid Robot Scene Application Alliance expects Chinese shipments alone to exceed 85,000 against domestic capacity above 100,000 units. That last pairing is the one to watch, because capacity running ahead of shipments is how price wars begin.
Capital has arrived at a speed the sector cannot absorb Chinese embodied AI companies raised RMB 73.5 billion, about $10.8 billion, across 2025. In the first half of 2026 alone, disclosed funding exceeded RMB 46 billion, roughly $6.39 billion. The first quarter produced 210 financing events worth more than RMB 30 billion,
with Shenzhen leading on 44 deals, Beijing on 40, Shanghai on 38, and Hangzhou on 24. Crunchbase data shows China now accounts for more than 43% of global robotics venture investment. Globally, robotics startups had raised $18.8 billion by July 2026, already ahead of the $15 billion raised across the whole of 2025. The individual rounds are startling for companies with almost no shipping history. TARS Robotics, one year old, raised a $513 million seed at a $1.9 billion valuation before selling a commercial unit. AI² Robotics raised roughly $735 million at close to $3 billion. LimX Dynamics took $200 million in a pre-IPO round at $2.21 billion. Galbot closed RMB 2.5 billion with the national AI industry investment fund, Sinopec, and CITIC on the register. At least 25 Chinese embodied intelligence startups now carry valuations above RMB 10 billion, and 15 of them crossed that line in the first six months of this year. Then came the listing. Unitree's Shanghai STAR Market debut on August 19 raised RMB 6.1 billion, about
FEATURE ROBOT
$904 million, for 10% of its enlarged share capital. Nearly 9.8 million retail accounts chased 9.7 million shares. The stock opened 629% above its offer price, briefly valuing the company at RMB 445 billion, and closed up 460% at a market value near RMB 342 billion. The average first-day gain for Chinese new listings this year is 279%. Even by the standards of a frothy market, this listing stood out. It did so on a day when the STAR Market Composite fell 7.2%. Unitree is the sector's most defensible business. It shipped more than 5,500 humanoids in 2025 on revenue of RMB 1.699 billion, and, unlike almost every peer, it turns a profit. It is also the company whose first-quarter 2026 net profit fell 52% year-on-year even as its shares were being bid up on the promise of what comes next. That combination, verified volume alongside compressing margins, is the tension inside the whole Chinese proposition.
Why China got here first, and it is not mainly about robots China installed 295,000 industrial robots in 2024, some 54% of world installations,
and operates more than two million factory robots. The United States installed 34,200 in the same year. That installed base means factories already designed around machines, technicians who know how to maintain them, and buyers who understand the payback maths. More important is the electric vehicle supply chain. Actuators, the motor and gear assemblies at each joint, are the most expensive and most performance-critical part of a humanoid. Elsewhere in the world they are a bottleneck, because suppliers will not build dedicated high-volume lines for orders measured in dozens, and orders stay small because low-volume components keep prices high. In the Yangtze River Delta, that deadlock never formed. The precision motors, reducers and sensors that went into China's EV boom are substantially transferable, and suppliers sit within a two-hour logistics radius of the assemblers. A prototype that takes twelve weeks in Germany turns around in ten to fourteen days in Shenzhen. Unitree makes its motors, reducers and sensors inhouse. UBTech spent RMB 1.67 billion buying control of component maker Fenglong in April to pull actuator supply inside the company. Beneath that sits raw material. China dominates rare earth processing, and permanent magnets built on neodymium, terbium and dysprosium are what make compact high-torque joint motors possible. Beijing introduced export licencing on several rare earth items in 2025. In August, Bank of America analysts returning from Beijing concluded that China holds an early lead built on control of both critical materials and downstream manufacturing capacity. Then there is the state. Embodied intelligence, a term that barely appeared in
Chinese policy documents before 2023, now has its own inset box among the top ten new industry tracks in the 15th FiveYear Plan covering 2026 to 2030. That designation unlocks the RMB 60 billion National AI Industry Investment Fund, provincial matching money and a wider trillion-yuan state venture vehicle for AI and emerging technology. The Ministry of Industry and Information Technology set up a humanoid robot standardisation committee in December 2025, and published a national standard system covering the industry's full lifecycle by March 2026. China is leading formulation of international standards for elder-care robots. The playbook is the one used in 5G and high-speed rail. Set the domestic standard, build scale on it, then export it as the norm. Demand is being manufactured too. A joint directive targets 10,000 commercial humanoids in use by the end of 2026, and the MIIT action plan aims at 100,000 deployed units by 2027. Shanghai subsidises up to 30% of project costs, and offers compute vouchers. Shenzhen offers up to RMB 100 million for approved special projects. Unitree's own prospectus discloses RMB 76 million in tax incentives in the first nine months of 2025, and RMB 32 million in direct government grants since 2022. This is industrial policy operating on the supply side, the demand side, and the standards layer simultaneously. Nothing comparable exists in the United States or Europe.
The brain is the part China has not bought Everything described so far concerns bodies. What determines whether humanoids become a large industry or an
International Finance | Sept - Oct 2026 | 119
TECHNOLOGY
FEATURE ROBOT
CHINA HUMANOID
expensive novelty is whether they can do useful work in places nobody prepared for them. That is a software problem, and by the admission of the people building these machines, it is unsolved. Wang Xiaogang's late-2027 forecast is the optimistic end of the range. Wang Xingxing, Unitree's founder, said in the same week that a dramatic breakthrough in robot brains is two to three years away at the earliest. Both men point to the same bottleneck, which is high-quality real-world training data. Language models had the internet. Robots have no equivalent corpus, because the data has to be generated by machines physically doing things and failing. ACE Robotics aims to collect tens of millions of hours within two years, and plans deployments across 1,000 stores. That is the shape of the race now, not the sprint track. The dependency question cuts against China here. Its embodied AI sector still leans heavily on Nvidia chips and the surrounding software ecosystem, even as the hardware supply chain localises rapidly. And the frontier of world models is genuinely contested. Alibaba's Qwen-Robot Suite, ByteDance's world model programme, and a wave of Chinese vision-language-action architectures sit alongside American and European efforts that have more verified operating hours in commercial settings. That last point deserves weight. Figure AI's robots at BMW's Spartanburg plant have logged more than 1,250 hours loading sheet-metal parts, handling over 90,000 components at better than 99% placement accuracy. It is a small deployment, but it is audited, paid for by a customer, and productive. Tesla, meanwhile, has slipped Optimus production milestones repeat-
120 | Sept - Oct 2026 | International Finance
edly and had no external deployments as of mid-2026, despite committing $20 billion of capital expenditure this year. UBTech's Walker S2 has 1,079 audited unit sales in 2025, and contracts with Foxconn, BYD and Audi FAW, and the company expects humanoids to exceed 80% of its revenue in 2026, though it remains loss-making and lifted its Walker S delivery guidance to 5,000 units only after previously guiding to 2,000. Nobody, anywhere, has deployed humanoids above the low hundreds of units in a sustained commercial environment. The Chinese lead is a lead in production, not in usefulness.
The wall that Washington built On July 28, the US Federal Communications Commission added foreign-produced humanoid and quadruped robots, along with power inverters, to its Covered List. The practical effect is that new device models cannot obtain the equipment authorisation almost every electronic product needs before it can be imported, marketed, or sold in the United States. Models already authorised are unaffected, federal government use is exempt, and producers can seek conditional approval through the Department of War. Chairman Brendan Carr framed the move as an effort to secure America's critical supply chains. The commission insists the action is country neutral, and turns on place of production rather than ownership. Nobody is fooled by the framing. China holds roughly 85% of the global humanoid market, and Beijing's foreign ministry said it would take all measures necessary to defend Chinese firms, calling the restrictions protectionism. Running in parallel is a Commerce Department Section 232 national secu-
rity investigation into imports of robotics and industrial machinery, opened in September 2025, and explicitly covering parts and components. Previous Section 232 actions under this administration produced 50% tariffs on steel, aluminium and copper derivatives, and 25% on vehicles and parts. Here is the strategic wrinkle. Because more than 85% of humanoid demand is currently Chinese, the ban does less immediate damage than it appears to. What it does is foreclose the future. AgiBot already has deployments live in the United Kingdom and Germany. The American market, the one Morgan Stanley expects to hold 77.7 million humanoids by 2050 against 302.3 million in China, is being walled off before Chinese firms could reach it. Disruption requires access to the market being disrupted.
The involution problem The domestic market has its own hazard, and Chinese founders name it
FEATURE ROBOT
The money and the mandate
• China embodied AI financing, 2025: RMB 73.5bn (about $10.8bn) • Disclosed funding, H1 2026: over RMB 46bn (about $6.39bn) • Q1 2026 financing events: 210, led by Shenzhen (44), Beijing (40), Shanghai (38), Hangzhou (24) • Chinese startups valued above RMB 10bn: 25, of which 15 crossed the line in H1 2026 • Typical cash runway across that cohort: 18 to 24 months • China's share of global robotics venture investment: over 43% • National AI Industry Investment Fund: RMB 60bn (about $8.2bn) • MIIT Humanoid Robot Action Plan target: 100,000 deployed units by 2027 • Unitree IPO, August 19, 2026: RMB 6.1bn raised, shares opened 629%t above offer, closed up 460% • Morgan Stanley 2050 scenario: 302.3 million humanoids in China against 77.7 million in the US
themselves. By MIIT's count, China had more than 140 humanoid manufacturers and over 330 products by the end of 2025. Executives at AgiBot have publicly warned that the industry is already showing signs of involution, the self-destructive price competition that hollowed out margins across the EV sector, particularly in semi-humanoid and entertainment machines where barriers are low and prices are falling fast. Chinese carmakers, fresh from their own price war, are pouring into embodied intelligence and repurposing factories for it. Most of the 25 startups now valued above RMB 10 billion carry cash runways of 18 to 24 months. That is the clock. Consolidation, down rounds and outright failures are the arithmetic consequence of 15 companies reaching billion-dollar-plus valuations in a single half-year while the entire global category generates under $2 billion of revenue.
Valuation compounds it. Unitree's first-day close implied a multiple in the region of 200 times its 2025 revenue. That price only makes sense if the ChatGPT moment arrives roughly on Wang Xiaogang's schedule, and the commercial ramp behind it arrives faster than he himself expects. If the breakthrough slips to Wang Xingxing's two-to-three-year horizon, or if it lands and useful deployment still takes another four or five years after that, a lot of Chinese paper wealth has been created against a revenue line that will not appear inside the average fund's holding period.
So, disruptor or not On manufacturing and cost, China has already disrupted the industry and the outcome is not in serious doubt. It sets the price floor, it owns the component base, it controls the magnet supply, and its 97% shipment share reflects a structural advantage built over two decades
in electronics and EVs that no rival can replicate quickly. Unitree's G1 sells at RMB 99,000 against Western full-size platforms that cost an order of magnitude more. On intelligence, the outcome is open. The world model race is early, the data bottleneck is universal, and the most credible verified deployments to date belong to an American firm working inside a German carmaker's plant. Chinese executives are the ones saying this most plainly. On markets, China is being contained in real time, and the containment is arriving before the product is ready. That is unusual. Export controls normally chase a mature industry. This time, the wall went up while the robots were still falling over. The honest reading is that China has won the phase of this industry that rewards building things, but the phase that decides who captures the value has not started. Watch three things over the next eighteen months. Whether the entertainment and research share of shipments falls decisively below half, which would show real demand replacing subsidised demand. Whether any Chinese firm publishes audited operating hours from a paying industrial customer at the level Figure has. And, whether the first serious down round lands in that cohort of 25 unicorns. The robot beat Bolt. It could not stop, turn, or walk off the track. Both facts are the story.
editor@ifinancemag.com
International Finance | Sept - Oct 2026 | 121
TECHNOLOGY
FEATURE NEURONS
BIOLOGICAL COMPUTING NATIONAL UNIVERSITY OF SINGAPORE
Singapore has switched on a computer built from living human neurons. The remarkable feat of engineering is giving rise to many questions
The server rack that has to be fed every 3 days 122 | Sept - Oct 2026 | International Finance
FEATURE NEURONS
IF CORRESPONDENT
Singapore has switched on a computer built from living human neurons. The engineering is remarkable, the energy maths is seductive, but the hardest questions have barely been asked Somewhere inside the Life Sciences Institute at the National University of Singapore, a technician arrives every third day to feed a computer. This is not a metaphor. The machine in question is a 20-unit server rack holding Cortical Labs CL1 biological computing units, each one containing lab-grown human neurons living on a silicon chip. The cells need a nutrient solution. They need their temperature held steady, their gas mixture regulated, their waste filtered away. Left alone, they die. Managed properly, they survive for about six months, after which they are replaced.
International Finance | Sept - Oct 2026 | 123
TECHNOLOGY
FEATURE NEURONS
BIOLOGICAL COMPUTING NATIONAL UNIVERSITY OF SINGAPORE
The system went live on July 16, 2026. On August 6, more than 80 guests from industry, government and academia watched a live demonstration of the units running, complete with microelectrode array integration and real-time neural network activity on screen. The formal unveiling followed on August 17. NUS Medicine, which built the prototype with Singapore data centre operator DayOne and Melbourne-based biotechnology firm Cortical Labs, describes it as the world's first independently operated biologically integrated server rack.
What is actually in the box Every CL1 unit is a self-contained life support system with a computer attached. Human neurons, grown from induced pluripotent stem cells that were themselves reprogrammed from adult donor skin or blood samples, are cultured across a planar electrode array. The array is essentially metal and glass. Electrodes send electrical impulses into the neural tissue and read the responses back out. Cortical Labs wraps this in what it calls biOS - Biological Intelligence Operating System. The software runs a simulated environment and feeds information about that environment directly into the culture. The neurons fire in response, and their firing changes the simulated world. Read, act, write, repeat, in loops that close in under a millisecond. Developers can deploy code to the unit the way they would to any other machine. There is a touchscreen showing the cells' vital signs, and USB ports for cameras or actuators. The neuron count is worth pausing over, because the public numbers do not agree. NUS and several outlets have described each unit as holding at least 200,000 neurons.
124 | Sept - Oct 2026 | International Finance
Cortical Labs' own published specification for the CL1, going back to its commercial launch in 2025, puts the figure at roughly 800,000 per unit, which is also the number implied by the widely reported total of 16 million living neurons across the 20-unit rack. The gap may reflect a conservative floor rather than a contradiction. It has not been formally reconciled, and anyone modelling the technology should treat the per-unit figure as unsettled. Either way, the scale is modest. A human brain holds something in the region of 86 billion neurons. Sixteen million is a rounding error against that, and no one involved is claiming otherwise.
Why this is not a neuromorphic chip The distinction that matters here is easy to miss. Neuromorphic computing has existed for years. Intel's Loihi, IBM's TrueNorth, and a growing cluster of European research programmes all build chips that imitate the way neurons behave, using spiking architectures and event-driven design to cut power draw. The Netherlands is assembling a neuro-
morphic hub on exactly this principle. Every one of those systems is made of transistors. They mimic biology. They are not biology. The CL1 inverts that. It uses actual human neurons as the computing substrate, and treats the silicon as the interface rather than the processor. That is the uniqueness of the concept, and it produces properties that no transistor design can replicate. Biological neurons store and process information in the same place, as opposed to the memory and compute separation that has bottlenecked conventional computer architecture since the 1940s. They rewire themselves in response to stimuli, which means they adapt rather than being trained in the way a neural network is trained. They operate on chemistry rather than switching voltage, which is why the power figures look the way they do. They also die, which no transistor does, and that single fact reshapes the entire commercial proposition.
The energy arithmetic Cortical Labs says a single CL1 draws
FEATURE NEURONS
The power arithmetic • Single CL1 biological computing unit, roughly 25 to 30 watts • Full 20-unit CL1 rack, 850 to 1,000 watts • Single Nvidia H100 GPU, 700 watts • Conventional AI server rack, tens of kilowatts • Global data centre electricity use, 415 TWh in 2024 • Projected global data centre electricity use, around 945 TWh by 2030 • Singapore's installed data centre capacity, roughly 1.4 GW across 70-plus facilities
roughly 25 to 30 watts. The full 20-unit rack in Singapore consumes between 850 and 1,000 watts. For comparison, one Nvidia H100 accelerator draws around 700 watts on its own, and a conventional AI server rack runs into the tens of kilowatts. Set that against the macro picture and the appeal is obvious. Global data centre electricity consumption reached 415 terawatt hours in 2024, about 1.5% of world demand, and the International Energy Agency projects it will roughly double to around 945 terawatt hours by 2030, close to Japan's entire annual electricity use. Consumption from AI-focused facilities is set to triple over the same period. Capital expenditure by the largest technology companies passed $400 billion in 2025, and is expected to rise by another three-quarters this year, which is more than global investment in oil and gas production. Against that backdrop, a rack that sips a kilowatt looks like an escape route. It is not, or not yet. The comparison flatters the biology because the workloads are not equivalent. An H100 is do-
ing matrix multiplication at industrial scale for a specific and enormously valuable set of tasks. Sixteen million neurons in a nutrient bath are not doing that, and will not be doing that soon. The honest version of the claim is that biological computing might eventually be efficient at a different category of problem, not that it is efficient at the same problems. Nobody is replacing a training cluster with a fish tank. There is also a hidden energy cost that rarely appears in the comparisons. Growing neurons from stem cells is expensive, laborious, and takes place in laboratories that consume power of their own. Replacing every culture twice a year across a large deployment is a recurring biological and financial burden with no silicon equivalent. A rack that draws a kilowatt but needs a molecular biology facility standing behind it has a total cost profile that no wattage figure captures.
Why Singapore, and why now The location is not incidental. Singapore has spent seven years managing a collision between digital ambition and phys-
ical constraint. In 2019, the government imposed a de facto moratorium on new large-scale data centre approvals, driven by concern over energy, water, and land. The pause held until 2022, when a pilot Data Centre Call for Applications reopened the door on strictly selective terms. Roughly 80 megawatts went to four operators in 2023, among them Equinix, Microsoft, GDS, and an AirTrunk-ByteDance consortium. In May 2024, the Infocomm Media Development Authority published its Green Data Centre Roadmap, promising at least 300 megawatts of additional near-term capacity, and tying it explicitly to efficiency and green energy conditions. A second call, DC-CFA2, launched on December 1, 2025, offered at least 200 megawatts. Applications had to befiled on or before March 31, 2026. Applicants had to demonstrate best-in-class efficiency, a power usage effectiveness ceiling of 1.25 at full load, and at least half their power drawn from approved green sources. Singapore now hosts more than 70 data centres totalling roughly 1.4 gigawatts, in a country of 730 square kilometres with no domestic energy resources to speak of. Vacancy rates have fallen close to one per cent. Every additional megawatt is rationed. That is precisely the environment in which a technology promising radical efficiency gets a hearing it would not receive in Virginia or Johor. Singapore cannot build its way out of the constraint. It has to compute its way out, and that makes it unusually willing to host experiments that larger markets would leave in the laboratory.
The commercial calculation DayOne's involvement is the part that
International Finance | Sept - Oct 2026 | 125
TECHNOLOGY
FEATURE NEURONS
BIOLOGICAL COMPUTING NATIONAL UNIVERSITY OF SINGAPORE
turns a neuroscience project into a business story. The company was carved out of Chinese operator GDS Holdings in 2022 to hold assets outside the mainland, rebranded as DayOne in early 2025, and has since become one of Asia's most aggressively capitalised infrastructure platforms. It closed a $4.5 billion Series C in June 2026, led by Coatue and Hillhouse with participation from Indonesia's sovereign wealth fund, at a reported valuation near $20 billion. It has secured more than 1.5 gigawatts of customer bookings across Asia Pacific and Europe, is negotiating a corporate loan facility of up to $7 billion, and has confidentially filed for a US listing that could raise $5 billion. A company at that stage of its life does not attach itself to a university biology project for the science. The NUS rack is a validation phase, structured to transition into a live deployment inside a commercial DayOne facility in Singapore. The stated ambition is a large-scale biological data centre, the first outside Australia, eventually housing as many as 1,000 CL1 units subject to regulatory approval and safety testing. For an operator heading into public markets during an AI infrastructure boom, being the only listed name with a credible biological computing asset is worth something regardless of whether the technology works at scale. Investors have shown a consistent willingness to pay a premium for optionality on the next architecture. That is not a criticism of DayOne. It is simply the commercial logic that makes a project like this fundable at all. The pricing tells a similar story. A CL1 sells outright for around $35,000, falling to roughly $20,000 per unit when bought in 30-unit racks. Cortical
126 | Sept - Oct 2026 | International Finance
Labs also runs a cloud model it calls Wetware-as-a-Service, originally priced at $300 per week. Reporting around the Singapore launch has put access at about $2,200 a month, roughly half what major cloud platforms charge for comparable highend AI chip access. Undercutting the hyperscalers on price is a recognisable go-to-market strategy. It also implies that the company expects to be compared with them, which is a bolder claim than the science currently supports.
What it can actually do Cortical Labs made its name in 2022 with DishBrain, a peer-reviewed study in which human and rodent neurons were connected to a simulated game of Pong, and appeared to improve under closed-loop feedback. The work was genuinely significant. It also demonstrated learning in a very narrow sense, not general intelligence, and certainly
not readiness for enterprise workloads. Four years on, the capability question remains the weakest link in the story. Founder and chief executive Hon Weng Chong says the prototype shifts the conversation from research to commercial application, and points to drug discovery, humanoid robotics, cybersecurity, and fraud detection as the promising areas. The common thread is that these are domains where data is scarce, unpredictable or expensive to simulate, which is where adaptive biological systems might plausibly outperform statistical models trained on enormous corpora. NUS Medicine's own interest is more concrete and arguably more defensible. Professor Rickie Patani, who directs the Neurobiology Programme at the Life Sciences Institute and supervises the cultures, has emphasised the platform's value for studying learning and adaptation at their biological source, for modelling neurological disease, and for
FEATURE NEURONS
The commercial picture • CL1 units in the NUS rack, 20 Neurons per unit, at least 200,000 by NUS accounting, roughly 800,000 by Cortical Labs' published specification • Neuron viability, up to six months • Feeding cycle, every three days • CL1 outright purchase price, about $35,000, falling to roughly $20,000 per unit in 30-unit racks • Reported monthly access cost, about $2,200 against roughly $4,300 for comparable high-end AI chip access on major cloud platforms • Target scale-up, up to 1,000 CL1 units subject to regulatory approval • DayOne Series C close, $4.5 billion in June 2026 at a reported $20 billion valuation
a public backlash that damages legitimate medical research. Human neural organoids fall outside the regulatory structures governing both human and animal research. A March 2026 paper in Science called for international oversight specifically covering biocomputing applications, on the grounds that this use case sits in territory research ethics committees were never designed to police. Singapore, which has built its reputation on regulating emerging technology early and precisely, now hosts the most advanced deployment of a technology with no regulatory category. That is either an opportunity to write the rules first, or an oversight waiting to be noticed.
The honest assessment testing compounds on human neurons rather than animal tissue. That is a real and immediate use case with a clear ethical advantage over animal testing. Whether it justifies calling the installation a data centre is a separate question. A rack of 20 units in a university laboratory is a research instrument. The data centre framing belongs to the commercial roadmap, not to what exists today.
The question nobody has answered The ethics are unresolved, and the unresolved parts are not the ones that get the headlines. Public debate fixates on consciousness. Could a sufficiently large culture of human neurons, given sensory feedback and a simulated world, experience something? Bioethicists have argued that if biocomputers become conscious, they acquire moral status, which would place hard limits on permissible research. The trouble is that consciousness
has no agreed definition and, therefore, no agreed test. Sixteen million neurons is almost certainly nowhere near any plausible threshold. Nobody can say where the threshold is. The more immediate problem is consent. A comment published in Nature in July 2026 pointed out that donors whose skin or blood cells were reprogrammed into these neural cultures were not, in most cases, told that their tissue might end up as the computing substrate of a commercial machine. Existing consent frameworks were written for medical research, not for biocomputing. That gap is administrative rather than philosophical, and it is fixable, but it has not been fixed. Meanwhile the scientists who built the brain organoid field are increasingly uneasy. At a meeting at Asilomar in late 2025, researchers, ethicists and legal experts warned that inflated commercial claims about organoid intelligence risk
What has been switched on in Singapore is a demonstration of extraordinary engineering discipline that answers a question nobody has yet posed clearly. The energy comparison is real but not yet meaningful, because the workloads are not comparable. The commercial model is coherent but depends on capabilities that have not been shown. The scientific value, particularly for disease modelling and replacing animal testing, is the most solid part of the proposition, but receives the least attention. The rack does one thing unambiguously well. It forces a question that the AI industry has spent a decade avoiding, which is whether the path to more capable machines runs through more silicon or through a different substrate entirely. Feeding a computer every three days is an absurd way to run infrastructure. It is also the only computing architecture anyone has built that mimics how the human brain actually learns. editor@ifinancemag.com
International Finance | Sept - Oct 2026 | 127
LAST PAGE
Top destinations for corporate team-building trips As hybrid and remote work become permanent, business travel is shifting toward experiential connections
outdoors, whether that means sailing together or embarking on scavenger hunts.
As the back-to-work season approaches, companies are replacing virtual meetings with face-to-face retreats to address remote work fatigue and strengthen organisational culture. To identify where teams can genuinely build connections, Holafly has launched the Global Team-Building Index, ranking destinations based on group activity infrastructure, accessibility, overall experience, and value. The results identify Lisbon, Portugal as the world's leading destination, driven by its coastal activities, flight connectivity, and competitive costs.
The rise of the active corporate retreat As hybrid and remote work become permanent, business travel is shifting toward experiential connections. Organisations are prioritising places where employees can bond
Top 10 global destinations for team-building in 2026 1 Lisbon, Portugal 2 Barcelona, Spain 3 Prague, Czech Republic 4 Mallorca, Spain 5 Budapest, Hungary 6 Antalya, Turkey 7 Athens, Greece 8 Milan, Italy 9 Chamonix, France 10 Berlin, Germany
Top 10 Team-Building Destinations for Californians 1 Cabo San Lucas, Mexico 2 Denver, United States 3 Mexico City, Mexico 4 Portland, United States 5 Vancouver, Canada 6 Scottsdale, United States 7 Austin, United States 8 Jackson Hole, United States 9 Guanajuato, Mexico 10 Kauai, United States
128 | Sept - Oct 2026 | International Finance
The Iberian Peninsula takes the crown Lisbon secured the number one spot: the airport sits close to the city centre, while the river and coast provide a spectacular playground for sailing regattas and surfing challenges. Barcelona follows in second place with large hotel room blocks alongside high-end cultural experiences.
Eastern and Central Europe are budget-friendly champions To maximise budget efficiency without sacrificing quality, Central Europe offers compelling alternatives. Prague and Budapest rank high, with costs for dining, accommodation, and venue up to 30% lower than Western Europe. Both offer memorable group activities like medieval castle banquets and old-town scavenger hunts.
Top 5 team-building destinations for UK companies 1 Lisbon, Portugal 2 Barcelona, Spain 3 Mallorca, Spain 4 Chamonix, France 5 Prague, Czech Republic
Top 5 team-building destinations for German companies 1 Prague, Czech Republic 2 Lisbon, Portugal 3 Barcelona, Spain 4 Mallorca, Spain 5 Budapest, Hungary
AWARDS 2026
Experience the Joy of Winning The International Finance Awards is more than just an award ceremony — it’s a prestigious global platform
Celebrating Excellence
that brings together achievers and leaders. Celebrate excellence, build meaningful connections, and experience the unforgettable joy of winning.
Nominations Open for Asia-Pacific & EMEA Log on to: awards.internationalfinance.com International Finance | Sept - Oct 2026 | 129
access more potential
Through Tailor-Made Solutions in Trade Finance
The Access Bank UK Limited takes an innovative approach to trade finance, delivering financial solutions that are designed for the international market. / Export Letters of Credit / Import Letters of Credit / Standby Letters of Credit / Payment Guarantee / Risk Participation Contact us: tradefinancesbu@theaccessbankukltd.co.uk www.theaccessbankukltd.co.uk The Access Bank UK Ltd
more than banking
130 | Sept - Oct 2026 | International Finance
The Access Bank UK Limited is registered in England & Wales, Company Number 06365062. Registered Office: 4 Royal Court, Gadbrook Way, Gadbrook Park, Northwich, Cheshire, CW9 7UT. Authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and the Prudential Regulation Authority. FCA & PRA Registration Number 478415.