JAN - FEB 2026
Issue 56 Volume 26
UK £4 Europe €5.35
www.internationalfinance.com
US $6
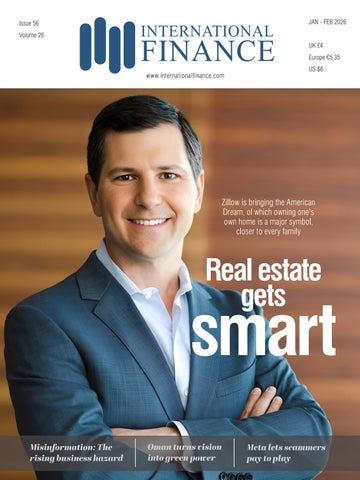
Zillow is bringing the American Dream, of which owning one’s own home is a major symbol, closer to every family
Real estate gets
smart Misinformation: The rising business hazard
Oman turns vision into green power
Meta lets scammers pay toFinance play International | Jan-Feb 2026 | 1
ﺗﻘﻮده اﻟﺮؤﻳﺔ،ُﺻﻨِﻊ ﻟﻠﺘﻐﻴﻴﺮ Built for Transformation Driven by Vision
info@gulaidholding.com www.gulaidholding.com 2 | Jan-Feb 2026 | International Finance
EDITOR’S NOTE
JAN - FEB 2026 VOLUME 26 ISSUE 56
Tech drives housing revolution
E
ntering 2026, Oman’s economy is experiencing a transformative shift. The Gulf nation is turning its green transition into a driver of growth, creating jobs, strengthening competitiveness, and building climate resilience. Oman Vision 2040 lays out a plan for a more diversified economy based on innovation, skilled employment, and sustainability. The plan also aims to protect natural beauty, improve global competitiveness, and demonstrate a long-term commitment to partners and markets. Another tech-led development is unfolding in the United States. DoorDash has taken its road-ready delivery robot, Dot, from testing to real-world use, launching an early access service across the Phoenix metro area. First unveiled at Dash Forward 2025, the compact electric vehicle uses an AI dispatcher to handle short local deliveries where a full-sized car is unnecessary, helping people get packages faster and reducing traffic congestion. Meanwhile, the United States continues its tariff battles, pressuring both allies and rivals for trade concessions that largely favour its economy. Despite these efforts, it has faced a rare setback with China. The Donald Trump administration has formally accepted the limits of trying to force Beijing into major structural economic reforms, signalling a shift in long-standing trade strategies and expectations. As International Finance prepares for its 13th annual awards, our cover story will focus on American PropTech giant Zillow. Since 2010, Zillow has reshaped the US real estate market. Beyond helping buyers find affordable homes, the company is evolving into a “Housing Super App,” offering a single digital platform that supports every stage of buying or selling a home, making the process simpler and more efficient for everyone involved.
editor@ifinancemag.com www.internationalfinance.com
International Finance | Jan-Feb 2026 | 3
INSIDE
IF JAN - FEB 2026
IN CONVERSATION
22
GUIDES 60 'EMPATHY WEALTH PLANNING'
The aim of Ma’an is not just to distribute wealth, but to carry forward the family’s values and intent
ZILLOW REWRITES THE AMERICAN DREAM Zillow is bringing the American Dream, of which owning one’s own home is a major symbol, closer to every family INDUSTRY
BANKING AND FINANCE
16
46
MISINFORMATION TRAP: THE RISING BUSINESS HAZARD
ARTIFICIAL INTELLIGENCE DRIVES CHANGE IN GLOBAL MARKETS
For companies, it’s no longer a question of if they will face a misinformation attack, but when
Machines now execute orders in microseconds, far faster than any trading floor
ECONOMY
TECHNOLOGY
78
100
GUNS & TEARS: EASTERN CONGO’S STOLEN FUTURE
HUMANS VS TECH: THE FIGHT FOR CREATIVE RIGHTS
Rwanda holds disproportionate global market shares in key Congolese minerals
The ultimate violation faced by creators is the commodification of their unique artistic style
4 | Jan-Feb 2026 | International Finance
FEATURES
30
Inside the hidden engine of sanctions
52
Oman turns vision into green power
84
China's defiance exposes US failures
110 Meta lets scammers pay to play
BUSINESS DOSSIER
38
Almamoon: A visionary approach to health insurance
70
POTAS: Elevating aviation fuel standards
92
Profuturo: A leader in Mexico's retirement services
106 Absa blends expertise & insight to fuel client success
www.internationalfinance.com
Director & Publisher Sunil Bhat
ANALYSIS
12 74
12
The Gulf’s new capital play
42
Fintech’s next revolution
74
Sudan’s war on survival
94
Is Dot the future of last-mile delivery?
INSIGHT
64
A DECADE OF DEBT EXPANSION The combination of higher yields, bespoke terms and less oversight makes private credit very attractive
Editorial Prajwal Wele, Agnivesh Harshan, CL Ramakrishnan, Prabuddha Ghosh Production Merlin Cruz Design & Layout Vikas Kapoor Technical Team Prashanth V Acharya, Bharath Kumar Business Analysts Alice Parker, Indra Kala, Stallone Edward, Jessica Smith, Harry Wilson, Susan Lee, Mark Pinto, Richard Samuel, Merl John Business Development Managers Christy John, Alex Carter, Gwen Morgan, Janet George Business Development Directors Sid Jain, Sarah Jones, Sid Nathan
THOUGHT LEADERSHIP
Head of Operations Ryan Cooper Accounts Angela Mathews
68
RICKSON D'SOUZA FAMILY DYNAMICS TRUMP DOCUMENTS
98
ALEXANDRA VIDYUK DEEP TECH: THE NEW GLOBAL BACKBONE
Phone +44 (0) 208 123 9436
As global markets face heightened volatility, the investment thesis shifts toward resilience
Fax +44 (0) 208 181 6550
Many first-generation founders built their wealth under constant pressure
Registered Office INTERNATIONAL FINANCE is the trading name of INTERNATIONAL FINANCE Publications Ltd 843 Finchley Road, London, NW11 8NA
Email info@ifinancemag.com
REGULAR EDITOR'S NOTE
03 06 08
Tech drives housing revolution
TRENDING Galaxy S26 on its way
Press Contact editor@ifinancemag.com Associate Office Zredhi Solutions Pvt. Ltd. 5th Floor, Sai Complex, #114/1, M G Road, Bengaluru 560001 Ph: +91-80-409901144
NEWS Starlink to conduct orbital reconfiguration
International Finance | Jan-Feb 2026 | 5
# TRENDING Galaxy S26 on its way
INDUST RY
Turkey starts Somalia oil drill
Turkey plans to send its drilling vessel, Cagri Bey, to Somalia in February for the country’s first deepwater exploration project abroad, Energy Minister Alparslan Bayraktar announced. The operation will target offshore areas in Somali waters, though details on reserves or investment size were not disclosed. This mission follows the 2024 energy exploration agreement between Turkey and Somalia. By doing this, Turkey aims to diversify its energy sources and reduce reliance on imports, investing in both domestic and international exploration projects. The Somali venture marks a significant step in Turkey’s expanding global energy strategy, highlighting its commitment to offshore exploration opportunities.
According to a recent report out of Korea, the Galaxy S26 series will be unveiled on February 25 in San Francisco, with Samsung releasing the trio in March. The Galaxy S26 will have a 4,300 mAh battery (300 mAh larger than its predecessor), the Galaxy S26+ will support 3x zoom HDR shooting, and the S26 Ultra will have a previously rumoured electronically controllable privacy display feature to prevent other people from looking at it. The Galaxy S26 Ultra will likely use the Snapdragon 8 Elite Gen 5 SoC.
At a Glance Top six leading mobile & wireless service companies and their market share AT&T
168.9B Verizon
133.6B
Trump Media launches crypto plan
Mawani awards SAR 500M contract
Deutsche Telekom
Trump Media and Technology Group will start distributing a new digital token to its shareholders, further expanding its foray into digital assets as support for cryptocurrencies in Washington grows. The family business empire, whose members have become a regular presence in the cryptocurrency world, has drawn criticism for potential conflicts of interest, with Trump vowing to make the United States the "crypto capital of the planet." The crypto climate has improved under the White House, with regulatory reforms.
The Saudi Ports Authority (Mawani) has awarded a contract to Arabian Chemical Terminals to build storage tanks for chemical and petrochemical products at Jubail Commercial Port, with an investment of more than SAR 500 million on 49,000 sqm. The project will enhance operational efficiency and increase handling capacity, in line with the goals of the "National Transport and Logistics Strategy" to solidify the Kingdom’s position as a global logistics hub under the "Vision 2030," while private sector will be tasked to support GDP growth.
140B
FIN T E CH
6 | Jan-Feb 2026 | International Finance
LOG IS T I C S
130B China Mobile China Telecom
75B China Unicom
54B In Billion US Dollar | Source: EZLoad
NEWS | INSIGHTS | UPDATES | DATA
Ones to Watch
E CONOM Y
US lead SWF investment in 2025
PETER NDEGWA CEO OF SAFARICOM Peter Ndegwa has led Safaricom to record profits and, in 2025, became the highest-paid CEO on the “Nairobi Securities Exchange,” earning KES 294.2 million amid strong mobile data and M-Pesa growth
In 2025, $132 billion of the roughly $255 billion sovereign wealth and public pension fund investors put their money into the United States, while big emerging markets attracted almost a third less than in 2024, an annual report showed. Sovereign wealth and public pension fund investors, along with central banks, had a record $60 trillion in assets under management in 2025, with two-thirds of sovereign wealth money invested in
the US during the period, according to the Global SWF report. According to the report, which tracks the assets and expenditures of the world's state-owned investors, including wealth and pension funds and central banks, using a combination of public data and official reports, sovereign wealth fund assets alone hit a new high of $15 trillion. Investments in sovereign wealth funds increased by 35% to $179.3 billion overall.
By the Numbers
MICHAEL NEISEN CEO OF ASAP GROUP Michael Neisen was honoured as 'Automotive Engineering CEO of the Year 2025' at the German CEO Excellence Awards, recognised for expanding ASAP’s engineering services and modern corporate culture
Industrial Machinery market size worldwide from 2016 to 2025 2016
2019
2022
2017
2020
2023
2018
2021
2024
550 580 610
640 535 560
592 546 673
In Billion US Dollars | Source: GlobeNewswire
2025
729
MAXIMILIAN TAYENTHAL CO FOUNDER OF N26 Maximilian Tayenthal announced his departure as co-CEO by the end of 2025, ahead of a transition to a sole CEO, amid increased regulatory scrutiny on the Berlin-based fintech
International Finance | Jan-Feb 2026 | 7
IN THE NEWS
FINANCE
BANKING
INDUSTRY
TECHNOLOGY
Lowering the satellites will cause Starlink orbits to condense, and will enhance space safety in multiple ways
Hyundai, along with its affiliate Kia, was the largest foreign carmaker in Russia, but it sold the plant in St. Petersburg in 2024
Starlink to conduct orbital reconfiguration SpaceX is planning to lower all of its satellites orbiting about 550 km (342 miles) to 480 km by 2026, and Starlink will begin this reconfiguration in 2026, said Michael Nicolls, SpaceX vice president of Starlink engineering. The goal is to reduce the potential for space collisions by lowering the orbit of the satellites, after Starlink said in December 2025 that one of its satellites had an anomaly in orbit that produced a small number of debris and ended communications with the spacecraft at 418 km (261 miles) altitude. The satellite, which is one of nearly 10,000 satellites in orbit for its broadband internet network, plummeted four kilometres in altitude, suggesting some sort of explosion on board. Lowering the satellites will cause Starlink orbits to condense and will enhance space safety in multiple ways, Nicolls said in a post on the social media platform X (formerly Twitter). "As solar mininum approaches, atmospheric density decreases which means the ballistic decay time at any given altitude increases," he wrote further. The number of spacecrafts in orbit has skyrocketed in recent years as companies and countries rush to
8 | Jan-Feb 2026 | International Finance
launch tens of thousands of satellites for internet constellations and other space-based services, such as communications and Earth imagery. With Starlink, a network of almost 10,000 satellites providing broadband internet to consumers, governments, and business clients, SpaceX, long recognised for its rocket launch business, has grown to become the world's largest satellite operator. Moreover, SpaceX broke its single-year launch record for a sixth straight year in 2025, with numbers getting increasingly ridiculous: 25 orbital liftoffs in 2020, 31 in 2021, 61 in 2022, 96 in 2023, 134 in 2024, and now 165. Not to mention five non-orbital Starship test flights by SpaceX, a launch almost every other day. SpaceX launched nearly twice as many orbital missions as China did in 2025, with the output representing approximately 85% of the United States' total. SpaceX carried out 165 of those launches using its workhorse Falcon 9, whose reusable first stage landed after all 162 of its launches but three — namely, two in January and October that placed massive Spainsat NG communications satellites into geostationary transfer orbit, and one in February 2024 that put the Starlink Gen 2-1 and 2-2 satellites into inclined orbits.
Hyundai won't buy back Russian plant South Korean automaker Hyundai is unable to repurchase its former manufacturing plant in Russia, with a buyback option scheduled to expire soon, as the ongoing Ukraine war continues to hinder the repurchase. Hyundai, along with its affiliate Kia, was the largest foreign carmaker in Russia, but it sold the plant in St. Petersburg in 2024. Operations at the facility had been suspended since March 2022, a month after Moscow invaded its smaller neighbour, triggering a wave of Western sanctions that disrupted supply chains and payments. Hyundai agreed to sell 100% of the facility to Russia's AGR Automotive Group for 140,000 won ($97), with a two-year buyback option, which expires in January 2026. While US President Donald Trump has made ending the war a priority for his administration and is pushing Kyiv and Moscow to sign a peace deal, fighting continues, and sanctions against Russia remain in place. The source did not elaborate on the specific reasons the company could not act on the buyback option, but said the war in Ukraine
was a factor. It was not certain whether missing the January deadline would result in the company losing its right to a buyback or whether the company would be able to negotiate an extension of the option. Most businesses withdrew from the Russian market, in part because their reputations were at stake and because Western sanctions prohibited foreign carmakers from continuing to operate factories in Russia. In 2024, Hyundai wrote off 287 billion won on the deal when it sold its Russian assets. Others, such as Hyundai, sold their plants to Russian players for pennies on the dollar and on options to repurchase after a certain period of time, intending to be able to come back one day. Japan's Mazda Motor was the first to lose its buyback rights in October when it opted not to exercise its option to repurchase 50% of its Russian factory from former partner Sollers. Renault, Ford, Nissan, and Mercedes-Benz have buyback options that expire between 2027 and 2029, while Toyota and Volkswagen sold their assets without buyback rights.
International Finance | Jan-Feb 2026 | 9
IN THE NEWS
FINANCE
BANKING
INDUSTRY
TECHNOLOGY
Beijing is trying to develop a fully self-sufficient semiconductor supply chain
The world's top oil exporter is roughly half-way through its "Vision 2030" plan to diversify its economy
China aims for local chip supply
Palace Group launches AYA
China is demanding that chipmakers use at least 50% domestically produced equipment when adding new capacity, as Beijing tries to develop a fully self-sufficient semiconductor supply chain. The rule has not been publicly codified, but authorities recently told the chipmakers that they need to prove through procurement tenders that at least half of their equipment will be Chinese-made to win state approval to build or expand their plants, sources said. It is one of the most stringent requirements Beijing has put in place to reduce its dependence on foreign technology, which has increased since 2023, when the United States banned sales of advanced AI chips and semiconductor equipment to the world's second-largest economy.
A key player in the UAE's luxury real estate sector, Palace Group announced the launch of AYA, a new residential development in Dubai's Jumeirah Garden City. AYA responds to a demand for contemporary, design-driven residences that balance intentional luxury with convenience and purposeful living. Designed by award-winning architects "John McAslan + Partners," and guided by the philosophy of "less to show, more to live," AYA by Palace Group combines refined architecture and thoughtful spatial planning to bring quiet, sophisticated authenticity to homes. AYA consists of 70 one- to two-bedroom residences over 12 floors of carefully considered open-air terraces and landscaped green pockets, promoting modern, yet mindful living.
Production of fertiliser worldwide from 2016 to 2025 (In Million Metric Tons) 2016
2017
180 185
2018
2019
2020
195 190 192
10 | Jan-Feb 2026 | International Finance
2021
2022
200 208
2023
192
2024
193
2025
199
Source: Statista
Saudi seals USD 13B utility loan
Waha joins Gulf’s income index
The National Debt Management Centre of Saudi Arabia has completed the arrangement of a $13 billion, seven-year syndicated loan to help fund power, water, and public utilities projects, part of its medium-term debt strategy to diversify funding sources and meet financing needs over the medium to long term. The centre said that the transaction would capitalise on market opportunities to carry out alternative government financing activities that support economic growth and development and infrastructure projects as part of the Kingdom's plan for economic transformation known as "Saudi Vision 2030." The world's top oil exporter is roughly halfway through its diversification plan, introduced by Crown Prince Mohammed bin Salman in 2016.
Waha Capital has been added to the "FTSE ADX Dividend Stars Index," the Gulf's first income-focused benchmark equity gauge, which was launched recently by the Abu Dhabi Securities Exchange (ADX) in partnership with FTSE Russell. The Managing Director of Waha Capital, Mohamed Hussain Al Nowais, said that Waha Capital’s inclusion in the FTSE ADX Dividend Stars Index reflected the strength, consistency, and sustainability of their earnings profile, and that their ability to deliver attractive dividends over time was anchored in their diversified business model, which was underpinned by disciplined capital allocation. He added that Abu Dhabi’s capital markets have remained focused on delivering long-term value as well as reliable shareholder income.
Consumption of fertiliser worldwide from 2016 to 2025 (In Million Metric Tons) 2020 2016
185
2017
2018
190 192
2019
2021 2022
202 2023 194 197 188 198
2024
2025
206 205
International Finance | Jan-Feb 2026Statista | 11 Source:
INDUSTRY
ANALYSIS
GULF SAUDI ARABIA
With risks now seen as lower, more investors are willing to compete for opportunities in the Gulf than ever before
The Gulf ’s new capital play IF CORRESPONDENT
Project finance in the Gulf Cooperation Council (GCC) region is undergoing a rapid transformation as markets mature and political risks recede, giving investors greater confidence to fund ambitious infrastructure projects. This confidence has facilitated a robust pipeline of deals across the GCC. International The region’s unique posibanks, armed tion is also a draw as the GCC with large offers a middle-ground risk pools of and return profile standing capital and between the low-risk, lowexpertise yield markets of the West and in complex the higher-risk, high-yield project opportunities in the East.
financing, are increasingly partnering with local GCC banks
Maturing markets reduce risk
Industry experts observe that the GCC’s political and economic environment has stabilised significantly in recent years. Hugh Morris, Senior Research Partner at the consultancy Z/Yen, explains that as the market matures, perceptions of geopolitical risk in the region have improved. A more stable environment has, in turn, enabled a growing pipeline of infrastructure projects. With risks now seen as lower, more investors are willing to compete for opportunities in the Gulf
12 | Jan-Feb 2026 | International Finance
than ever before. In a global investment climate where low-risk assets with decent yields are scarce, the GCC’s balanced risk-reward profile is especially compelling to international financiers. This improved climate has paved the way for greater collaboration among lenders. International banks, armed with large pools of capital and expertise in complex project financing, are increasingly partnering with local GCC banks that have invaluable on-the-ground knowledge and relationships. Together, these partnerships blend global financial power with local insight to ensure projects are funded and executed effectively. These synergies help major developments get off the ground, as each party brings complementary strengths to the table. Even with these positive trends, project finance deals are not without challenges. Many projects span 20 or more years, with loan repayment schedules commonly stretching over 12 to 25 years. Critically, loans are usually repaid from the project’s own revenues once it is operational, as sponsors do not typically guarantee the debt. This structure means lenders shoulder significant risk, since repayment hinges entirely on the project’s success. Naturally, banks expect to earn a premium interest rate in return for taking on this risk. However, competition in today’s market is pushing lenders to offer more attractive terms to win business, even as they must adhere to strict
capital adequacy rules. Balancing risk-based pricing with competitive financing packages has become a key focus for Gulf banks.
Diversification drives mega-projects Saudi Arabia and the United Arab Emirates (UAE) currently lead the region in large-scale project investments. A major driver behind this trend is the strategic push to diversify national economies away from oil and gas, building a sustainable postoil future. Both countries benefit from centralised decision-making as directives from top leadership translate swiftly into infrastructure initiatives on the ground. For example, Saudi Arabia has embarked on pioneering projects in green hydrogen energy, and the UAE has made a bold entry into nuclear power. Saudi Arabia’s $50 billion Al Diriyah development near Riyadh aims to create a cultural and tourist hub, echoing Dubai’s success in drawing international visitors. Despite this ambitious pipeline, not everything is rosy. A spokesperson for Bank ABC points out that there remains an estimated $5 trillion annual
investment gap globally for clean energy, highlighting shortcomings in meeting climate targets after COP29. The bank argues that financial institutions must play a greater leadership role in bridging this gap. This reality highlights why so many Gulf-based banks and investors are concentrating their efforts on funding renewable energy and other energy-transition projects.
Rise of social infrastructure Another notable shift in the Gulf’s project finance landscape is the growth of social infrastructure projects such as hospitals, schools, and public amenities, which are often structured as public-private partnerships (PPPs). Ehab Nassar, a director at Fitch Ratings, observes that this trend is driven by the same strategy of reducing reliance on oil revenues. Governments in the GCC have been ramping up PPP frameworks to tap private-sector capital and expertise for public projects. Until the late 2010s, true project finance deals outside the oil and gas sector were relatively limited. Since then, countries like Saudi Arabia and the UAE have introduced formal PPP programmes as part of their economic diversification agendas.
International Finance | Jan-Feb 2026 | 13
INDUSTRY
ANALYSIS
GULF SAUDI ARABIA
Not every major project in the region uses a PPP structure. For instance, Abu Dhabi’s Barakah nuclear power plant is a cornerstone of the UAE’s clean energy strategy. It was financed through a more traditional mix of government support and international investment rather than a typical PPP, combining debt and equity in its funding. It was backed by over $18 billion in loans from the Abu Dhabi government and international lenders (including KEXIM), plus an equity investment of $4.7 billion from a joint venture between Emirates Nuclear Energy Corporation (ENEC) and Korea Electric Power Corporation (KEPCO). Because the plant will help decarbonise the UAE’s power grid, the authorities classified its financing as a green loan, emphasising its contribution to the country’s green economy goals. In July 2023, once the plant was operational, two major Emirati lenders, Abu Dhabi Commercial Bank and First Abu Dhabi Bank, stepped in to refinance a large portion of the project’s debt, taking over the loan facilities that KEXIM had initially provided.
Innovative financing models Project financiers in the GCC are also experimenting with new deal structures to improve funding efficiency. One notable evolution, highlighted by Abbas Husain of Standard Chartered, is the use of “hard mini-perm” financing coupled with long-term off-take agreements. In these arrangements, a project’s initial bank loan might have a shorter tenor, effectively requir-
14 | Jan-Feb 2026 | International Finance
ing refinancing after a few years, while the project itself benefits from a long-term concession or purchase contract. This approach shifts much of the refinancing risk to the off-taker and offers two key benefits. There are lower initial financing costs and greater liquidity from banks to kick-start construction. Such projects often plan to refinance later by issuing project bonds or securing longer-term commercial loans once the development is operational. For infrastructure projects where the off-taker does not shoulder refinancing risk, developers typically secure long-term bank loans up front. Export credit agency (ECA) financing and other government-backed loans remain crucial in these cases, providing stability with low interest rates over long tenors and often coming with guarantees or insurance that enhance the project’s credit profile. By boosting the project’s credit quality in this way, such support makes it more attractive to a broader range of investors.
New trend in cost optimisation Once projects are up and running, many Gulf sponsors seek to refinance their debt on better terms. According to Mazen Singer, a partner in infrastructure finance at PwC Middle East, most project owners look to refinance about five to eight years after a project becomes operational. By that stage, construction is complete, operations have stabilised, and revenue streams are more predictable. The project’s risk profile improves significantly. Refinancing
GCC countries ranked by their investment appeal in 2025
UAE Saudi Arabia Qatar Oman Kuwait Bahrain Source: gccstat.org
at this point can lower the overall cost of capital and optimise the debt structure. In some cases, it even allows sponsors to free up capital for new developments. If one waits much longer, those advantages diminish, and once a loan’s remaining term becomes short, the potential savings from refinancing are far more limited. The pool of financiers and investors has also widened as the GCC market matures. Singer notes that more export credit agencies are now involved in Gulf projects. In addition, specialised infrastructure funds are drawn to mature, cash-generating (brownfield) assets, and local capital markets are growing more open to project bond issuances. Husain of Standard Chartered adds that improved regulatory and governance frameworks, clearer procurement processes, and high-calibre project sponsors have made banks much more comfortable with regional project risks.
Strong sovereign support underpins many deals, and often the off-taker is a state-owned utility or the obligation is backed by a government ministry. This backing substantially reduces perceived credit risk and has enabled banks to offer financing at more competitive rates than in the past. Thanks to an expanding track record of completed projects, investors now see a pipeline of successful ventures in the GCC, which builds confidence that each new project is a sound investment. These successes, and the collaborative financing behind them, demonstrate the Gulf governments’ determination to construct a prosperous post-oil future. However, industry veterans caution that financial discipline is still needed. Hugh Morris cautions that regulators must prevent investors from over-leveraging projects and taking excessive returns, as such practices could undermine long-term infrastructure sustainability.
The future of project financing While progress in Gulf project finance has been impressive, experts note certain challenges remain. One issue is the lack of historical precedent in the region for some project finance scenarios, which breeds uncertainty for lenders. For example, there is still little proven case law on how readily lenders can enforce their security interests if a project runs into trouble. Another concern is limited transparency and information sharing, which makes it harder for outside investors to gauge project risks. All of these gaps point to the need for stronger legal and regulatory frameworks across the GCC to reduce uncertainty and build long-term confidence. Notably, regulatory development is not uniform across the bloc. The UAE and Saudi Arabia boast the most advanced frameworks and capital markets, while smaller economies are still catching up. Industry analysts suggest several steps that could further
strengthen the Gulf’s project finance ecosystem. One suggestion is the standardisation of PPP frameworks. Uniform PPP laws and contracts across the region would make projects more bankable and attract international lenders. Another idea is to develop secondary markets. An active trading of infrastructure debt and equity would facilitate refinancing and let banks recycle capital into new projects. Finally, there is a shifting refinancing risk to off-takers. If utilities (project off-takers) bear future refinancing obligations, initial lenders can free up capacity, boosting liquidity for new projects. With ongoing regulatory advancements and collaboration among stakeholders, the GCC is positioned to become a leader in the next phase of global infrastructure finance. However, sustaining this momentum will require more than just money. It also calls for developing human capital. Analysts like Mazen Singer emphasise the importance of cultivating local expertise and institutional capacity in project finance. By training professionals and nurturing national champions in the industry, Gulf countries can ensure that the ambitious projects of today lead to a lasting legacy of knowledge and prosperity.
editor@ifinancemag.com
International Finance | Jan-Feb 2026 | 15
INDUSTRY
FEATURE MISINFORMATION
SOCIAL MEDIA BUSINESSES
For companies, it’s no longer a question of if they will face a misinformation attack, but when
Misinformation: The rising business hazard IF CORRESPONDENT
M
isinformation is no longer a fringe concern as it has become a fast-moving, reputation-wrecking force. As false narratives go viral, organisations must act swiftly to detect, counter, and contain the damage. Not long ago, companies barely considered “misinformation campaigns” a serious threat. The odds of a viral falsehood causing lasting damage seemed near zero. That complacency is now gone. Today, a single lie gaining traction online can indeed send a company’s stock plummeting overnight. All it takes is a critical mass of people believing a false claim. Say that a product is unsafe, made unethically, shoddy in quality, or linked to an extremist cause, and a customer boycott can erupt, wreaking havoc on the brand. The World Economic Forum's latest Global Risks Report emphasises the seriousness of this threat. It flags government-led misinformation and disinformation as a top short-term risk that can sow instability and erode trust in authority. Just as worrying, the report warns, is the potential impact on business. Entire industries could see growth and sales stifled by waves of
16 | Jan-Feb 2026 | International Finance
FEATURE MISINFORMATION
International Finance | Jan-Feb 2026 | 17
INDUSTRY
FEATURE MISINFORMATION
SOCIAL MEDIA BUSINESSES
misleading narratives. This is especially true for sectors like biotechnology, where self-styled “biohackers” and other unqualified influencers tout unproven health remedies while disparaging effective, regulated treatments. There’s also a geopolitical dimension. Some governments are now aggressively spreading falsehoods about products from rival countries. By poisoning public perception of a competitor’s goods, such state-sponsored lies can spark consumer boycotts. It’s a dangerous escalation amid today’s trade wars. The emergence of artificial intelligence could exacerbate the situation. Many AI-driven social media algorithms are programmed to maximise engagement by elevating trending posts and unintentionally turbocharging sensational falsehoods over accurate news. In other words, the very platforms companies rely on for marketing can become the channels that amplify lies about them. Companies also have limited legal recourse when misinformation strikes. There is often no simple way to stop those who sow lies online, and court remedies are notoriously difficult. In the United States, for example, internet platforms enjoy broad immunity from liability for user-posted content under Section 230 of the "Communications Decency Act." That law also shields websites that make good-faith efforts to moderate harmful content. Meanwhile, suing the originator of a damaging falsehood for defamation is usually a long shot and prohibitively expensive. It’s a gamble few organisations can afford.
When lies become weapons Not all misinformation is accidental or spread by misinformed individuals. In
18 | Jan-Feb 2026 | International Finance
some cases, it’s a deliberate act of sabotage against a company. During an interaction with World Finance, Ant Moore, a senior managing director in strategic communications at consultancy FTI Consulting, said, "At its worst, deliberate deception has the potential to destabilise or create severe financial and reputational damage." Moore explains that while everyday misinformation might start with someone innocently sharing a doctored photo or a counterfeit audio clip, thinking it’s real, true disinformation involves conscious intent. It’s the difference between a rumour gone wrong and a coordinated lie launched specifically to hurt a target. In all cases, Moore notes, society’s ability to discern fake content hasn’t caught up to the sophistication of today’s forgeries. There are many ways in which malicious misinformation can threaten a company’s well-being. For example, consumer boycotts and lost sales are extremely detrimental. False claims about a company’s products or practices can spark outrage and mass boycotts, causing an immediate hit to revenue. There is the erosion of brand trust to worry about. Once a damaging narrative takes hold, public perception can sour quickly. Customers may lose faith in the brand, even if the story is later debunked, leading to long-term reputation harm. Sometimes investors panic, and shareholders might dump the stock if they believe the negative buzz, driving the share price down and alarming the market. Also, workforce morale issues could disengage employees, and they might even quit if bombarded with false stories painting their employer as unethical. The company’s internal culture and productivity may suffer as a consequence. Finally, baseless but high-profile al-
In 2022, pharmaceutical giant Eli Lilly watched its stock price tumble by over 4% in a single day after a fake X (formerly Twitter) account impersonating the company announced that insulin would be given away for free legations can trigger investigations or demands for answers from regulators or politicians, forcing the company to spend time and resources addressing a non-issue. Real-world incidents illustrate how quickly a lie can erupt into a corporate crisis. In 2016, athletic brand New Balance faced a social media firestorm over false claims that it was aligned with farright politics. In 2022, pharmaceutical giant Eli Lilly watched its stock price tumble by over 4% in a single day after a fake Twitter account impersonating the company announced that insulin would be given away for free (given insulin’s high cost to patients at the time). And in 2023, Bud Light, America’s top-selling beer, saw sales plunge roughly 25% after a social media frenzy turned a promotional tie-in with a transgender influencer into a full-blown conservative boycott. The beer’s parent company blamed misinformation online for stoking the backlash. These
FEATURE MISINFORMATION
cases highlight how falsehoods can lead to significant financial harm for businesses, whether spread intentionally or unintentionally.
Exploitable info landscape According to communications experts, the only surprise is that more companies haven’t been blindsided sooner. Businesses today operate in an information environment that Chris Clarke, co-founder of agency Fire on the Hill, describes as “increasingly complex and globally connected.” New forms of digital media emerge constantly, and information now moves across the world in an instant. Controlling its flow is next to impossible. “In the current environment, which is chaotic, fragmented and lacking in trust, the ground is fertile for misinformation to go viral,” Clarke said. Bad actors are quick to exploit this chaos. Foreign adversaries, ideological agitators, or even unscrupulous com-
petitors or others might weaponise false stories to hurt a business. Companies must assume they will be targeted eventually and plan accordingly, making the fight against misinformation a top corporate priority rather than an afterthought.
Early detection and response When false stories can be fabricated with a few clicks and broadcast worldwide within minutes, speed is of the essence. Companies must learn to spot and counter malicious narratives in real time before they spiral out of control. The challenge, however, is knowing where to look. Rebecca Jones, associate director at business intelligence firm Sibylline, points out that many communications and PR teams still focus on tracking the major social media platforms like X (formerly Twitter), Instagram, or TikTok for mentions of their brand. “However, that is not where these disinformation campaigns begin, and
arguably, by the time disinformation hits these sites, the issue has already gone viral and you are in crisis,” Jones explains. In other words, by the time a lie about your company is trending on Twitter or being shared widely on Facebook, it’s probably too late to contain it. According to Jones, harmful rumours more often germinate in the internet’s shadows on alternative social sites and fringe forums where sensational claims find a receptive audience. A conspiracy theory or fabricated story might simmer in those corners, quietly gathering momentum over time, before jumping to mainstream platforms and exploding into public view. For companies, keeping an eye on these lesser-known channels can be a game-changer. If you can catch wind of a false narrative early, you might not be able to stop it entirely, but you can at least prepare. “Even if it can’t be stopped, hopefully, such an early warning mechanism
International Finance | Jan-Feb 2026 | 19
INDUSTRY
FEATURE MISINFORMATION
SOCIAL MEDIA BUSINESSES
enables teams to have a plan of action in place for when it does hit the mainstream. As your executives are prepped, the press team is ready to respond, and perhaps you have even taken steps to pre-bunk the story,” Jones noted. In fact, some businesses are now practising “pre-bunking,” which is pre-emptively debunking a looming false claim by releasing correct information or context before the lie goes viral. Another crucial defensive strategy is to proactively control the narrative about your own company. “Facts are more impressive than fiction,” says Chris Walker, managing director of consultancy “Be The Best Communications.” He advises organisations to compile clear evidence that disproves the false claim and to showcase the company’s genuine commitment to doing the right thing. By quickly sharing factual proof, a company can undermine a rumour’s credibility and reassure the public. Walker also suggests directly challenging the source of the fake news and demanding that they show proof for their sensational claim. Often those spreading a lie can’t back it up, and if pressed to “put up,” they’ll likely have to “shut up.” Building trust through direct communication channels is also increasingly important. Alice Regester, co-founder and CEO at communications agency 33Seconds, emphasises that companies should use their owned media, such as official websites, blogs, and verified social media accounts, to set the record straight quickly. By consistently putting out accurate information on these channels, a company builds a reputation as a trusted source. Then, when a crisis hits, con-
20 | Jan-Feb 2026 | International Finance
Frequency of seeing false or misleading information online among adults in the US in 2025
Daily
46%
Weekly
21%
Monthly
8%
Infrequent
9%
Never
2%
Not Sure
15% Source: Statista
sumers know they can check the official company outlets for the truth instead of relying on hearsay. In short, the faster and more credibly a company can present its side of the story, the better its chance to blunt the impact of a falsehood.
Collaborate and amplify Defending against misinformation is not a battle to fight alone. Companies can benefit from cultivating third-party champions, loyal customers, industry experts, and consumer advocates who will publicly counter false claims. When a false narrative emerges, these outside voices help amplify the truth. Partnering with independent fact-checkers or giving credible media outlets evidence to debunk rumours can further extend the reach of a company’s rebuttal. Another effective strategy is to build an influencer and fan community that will rally to the company’s defence.
Adam Blacker, PR director at HostingAdvice.com, said, "It is really hard to do everything yourself. You need to build a strong community of fans who love and support your brand. They, in turn, become brand ambassadors." These brand advocates can often counteract falsehoods faster and more credibly than any official corporate statement. Their genuine enthusiasm for the brand helps sway public sentiment in the company’s favour. In tandem with human allies, companies are also turning to technology for an early warning. Social listening software that continuously scans social media and online forums for mentions of a company or relevant keywords is becoming indispensable. By analysing conversations in real time, these tools alert teams to unusual spikes or trending topics, giving them a chance to verify alarming claims before they hit the mainstream. Catching a lie at the rumour stage (or at least early in its spread) means having a chance to intervene with correct information or prepare a measured response, rather than scrambling after the falsehood has already exploded. Even with all these measures, experts say organisations should shift from a reactive stance to a proactive defence posture. Andy Grayland, Chief Information Security Officer at threat intelligence firm Silobreaker, argues that cyber threat intelligence (CTI) solutions can serve as a crucial radar system for spotting disinformation campaigns. These advanced tools monitor a broad range of open sources from news sites and social networks to niche blogs, forums, and even parts of the deep web, looking for early indicators of threats to a company’s brand or interests. The moment something suspicious involving
FEATURE MISINFORMATION
the company starts bubbling up, CTI systems can raise an alert. Grayland notes that AI-powered intelligence platforms are increasingly essential for cutting through the noise of the internet and pinpointing real risks. They can also highlight patterns that suggest a coordinated effort to spread falsehoods. For instance, if an anti-vaccine group that typically mentions a particular pharmaceutical brand around 50 times a day suddenly ramps up to 500 mentions, a CTI platform would immediately flag the surge as suspicious. Armed with that knowledge, the company can quickly decide how to respond, whether by engaging with facts, informing authorities, or bracing for impact. Early detection translates into real business value. Companies that gain real-time visibility into brewing falsehoods have a chance to head off financial losses, prevent full-blown reputational crises, and stay ahead of any regulatory or shareholder fallout. In an age where lies can go viral in an instant, having this kind of rapid radar and response capability safeguards not just a company’s reputation but its bottom line as well.
Misinformation and its more deliberate counterpart, disinformation, are not new. Rumours and hoaxes have troubled businesses for ages. However, in the digital age, social media and AI have accelerated the speed and reach of this threat. A lie that once spread slowly via word of mouth can now hit millions within hours, making viral falsehoods a far more potent danger to companies than ever before. For companies, it’s no longer a question of if they will face a misinformation attack, but when. In this high-stakes environment, preparation is everything. By investing in early warning systems, building trust with stakeholders, and crafting rapid-response plans, businesses put themselves in a far stronger position to weather a misinformation storm. When a false narrative hits, a prepared organisation can respond swiftly with facts, rally supportive voices, and contain the damage. Combating viral falsehoods has essentially become part of the cost of doing business, and those that respond decisively are the ones most likely to protect their reputation and bottom line. Misinformation has evolved from an
inconvenient distraction into a systemic corporate threat. Companies that once treated false narratives as isolated crises must now recognise them as recurring hazards that can erode trust, market value, and even long-term viability. What makes the challenge more dangerous today is speed, as falsehoods can achieve global reach in minutes, amplified by algorithms, bots, and coordinated campaigns. In this environment, silence or delayed responses are no longer neutral options. They are liabilities. The lesson is clear: proactive defence is the only real safeguard. Monitoring fringe channels, detecting narratives early, and maintaining direct lines of communication with stakeholders are now core business functions, not optional extras. Pre-emptive storytelling, where companies anticipate disinformation and “inoculate” audiences with facts, has to complement traditional crisis management. Partnerships with fact-checkers, trusted influencers, and even competitors in vulnerable industries can create resilience against viral falsehoods. Ultimately, misinformation is not just a reputational issue but a strategic one. Companies that integrate misinformation defence into their governance and risk frameworks will be better placed to protect their brands, investors, and customers. Those that do not will continue to underestimate a threat that is already reshaping the business landscape.
editor@ifinancemag.com
International Finance | Jan-Feb 2026 | 21
COVER STORY INDUSTRY
Zillow
rewrites the American Dream
Zillow is bringing the American Dream, of which owning one’s own home is a major symbol, closer to every family
IF CORRESPONDENT
T
here is no way you would consider buying a house in America without getting on the Zillow app at some point in your hunt. Back in the day, when data was scarce, and your only point of information was a real estate agent, you were in the dark about how much your dream home really cost. You asked other agents, who were acting in a nexus to keep prices high and their share of the pie large, and you prayed to God that they didn’t rip you off.
22 | Jan-Feb 2026 | International Finance
L I S T E D
B Y
Jeremy Wacksman International Finance | Jan-Feb 2026 | 23
INDUSTRY
FEATURE ZILLOW
REAL ESTATE PROPTECH
As a result, if you weren’t savvy and didn't put in a considerable amount of footwork, you consistently overpaid on your down payments. Studies reveal that before Zillow’s data democratisation, an investor paid 2%-5% as an ignorance tax. If you were from out of town, you paid an additional 2%. The informed buyer who uses an app like Zillow saves 4.75% on their payments. The author of Freakonomics, Steven Levitt, examined the selling habits of real estate agents when it came to their own homes and found that they kept their properties on the market around 10 days longer and sold them for roughly 3% higher than those of their clients. This is not a trivial sum. To put things into context, the 5% overpayment is approximately $20,500 to $25,650 for the average American homebuyer. That can get you a brand new Honda Civic or Toyota Corolla, a full kitchen renovation, or the entire down payment for a first-time buyer. Zillow is a revolution in the real estate industry. It is a boon to the buyer, saving American homeowners $750 billion in aggregate since 2010. When Jeremy Wacksman took the helm as Zillow's CEO in late 2024, the company had just shuttered its ambitious home-flipping venture, Zillow Offers, after some spectacular miscalculations, leaving it holding properties it had overpaid for. Wall Street was sceptical. Agents were wary. Competitors were circling. Jeremy Wacksman proved the doubters wrong as Zillow made a miraculous comeback with mid-teens revenue growth, which got investors cheering. In a letter to shareholders, Zillow CEO Jeremy Wacksman and CFO Jeremy Hofmann wrote, “Our consistently strong performance reinforces that Zillow can grow regardless of what the residential real estate market is doing,” proving that Zillow has decoupled itself from the fate of interest rates and will continue to grow irrespective of the number of homebuyers. Jeremy Wacksman's vision is transforming Zillow into what he calls a "housing super app," a one-stop digital ecosystem that touches every step of buying or selling a home.
What exactly is PropTech, anyway? Before we deep dive into Zillow and its software-realty revolution, let’s look at the industry it operates in. Zillow can be classified as what economists and technologists call PropTech, just short for property
24 | Jan-Feb 2026 | International Finance
technology. The company uses information technology and digital platforms to give you, the consumer, insights into the real estate market, which is traditionally known for its opacity. Think of it as everything that happens when Silicon Valley meets the housing market. Even though the global real estate market is valued at hundreds of trillions, the technology that services it is in its adolescence, with annual revenues at around $35 to $45 billion and growing at roughly 12%-16% (in places like Bangkok and Manila, that rate is much higher at 19%). Among global giants like China and Europe, the US dominates PropTech, holding 35%-45% (approximately $12 billion to $16 billion) of the global market. The reason for that is companies like Zillow, CoStar, and Procore. America has a unique combination of standardised data (MLS), high transaction volume, and a tech-centric culture that encourages digital adoption. Zillow doesn’t control the housing market, but it is definitely in charge of the digital front door of the real estate business. It generated a revenue of $2.5 billion in 2025 and has a massive 15%-20% of the American PropTech market share. Over 60% of Americans who use their mobiles to browse real estate do so through Zillow, and in the residential sector, Zillow is the de facto search engine. It's Google for home buyers. While they only capture a small slice of the commission dollars (via agent fees), they control the flow of customers. And why is this happening? It’s because of three major technological shifts. For starters, generative AI is no longer about experimental chatbots and is adept at statistical analysis and can accurately predict which homeowners will sell their property. Artificial intelligence (AI) also performs exceptionally well in automated mortgage underwriting (which improves liquidity by reducing underwriting time from weeks to days), and writes listing descriptions tailored to each customer and with better precision than most human agents. Then there are immersive technologies like virtual tours and 3D walkthroughs, which help you visualise and feel which home is right for you. Finally, sustainability tech has emerged as a serious
COVER STORY ZILLOW
PropTech Think of it as everything that happens when Silicon Valley meets the housing market
value driver, especially in Europe, where buildings are increasingly valued based on their energy efficiency and carbon footprint. What makes PropTech fascinating is that it varies significantly by location. In Southeast Asia, it's about managing rapid urbanisation through state-level infrastructure; think government platforms that coordinate transit systems with residential development. In Europe, it's driven by sustainability regulations, with digital twins of buildings used primarily for energy optimisation and compliance. American PropTech solves a uniquely American problem. Companies like Zillow have figured out how to bring efficiency and transparency to a fragmented market dominated by 1.5 million independent agents and a patchwork of local Multiple Listing Services.
The story of Zillow Zillow, an idea thought up by Rich Barton and Lloyd Frink, was launched in 2004. What’s interesting is that both these men were former Microsoft employees who launched Expedia in the 1990s. It’s interesting because Expedia was a web portal that freed information from travel agents and ensured that ticketing and hotel prices were transparent. It was a data democratisation company that disrupted travel. All Barton and Frink
did was to apply the successful techniques they used in the travel industry to disrupt the real estate industry. The duo were about to revolutionise real estate by making all home values public. At the time, this was a radical move. Real estate data was locked away behind agent gates, and if you wanted to know what your neighbour's house sold for or what your own home might be worth, you had to call a real estate agent and hope they'd share that information. Zillow's "Zestimate" (an algorithmic home valuation tool) changed everything. Suddenly, anyone with an internet connection could get an instant estimate of any property's value. The industry opposed it, with agents concerned about job security and critics lamenting inaccuracies in price. However, consumers loved it. Within a few years, Zillow had become the most visited real estate website in America, attracting millions of people who were curious about home values, not necessarily looking to buy or sell. For years, Zillow operated as what insiders call a "media portal." It made money by selling advertising
International Finance | Jan-Feb 2026 | 25
INDUSTRY
FEATURE ZILLOW
REAL ESTATE PROPTECH
and leads to real estate agents through its Premier Agent programme. Think of it as the Google of real estate, a place where buyers started their search, but where the actual transaction happened elsewhere, facilitated by traditional agents and lenders. Then came the iBuying era. Flush with investor confidence and inspired by the success of companies that were "disrupting" traditional industries, Zillow launched Zillow Offers in 2018. The concept was a simple one. We will use data and algorithms to buy homes directly from sellers, make light renovations, and resell them at a profit. You cut the middleman off and inefficiencies of the traditional market, and capture more of the transactional value. It made absolute sense and was a bold move, championed by Barton,
26 | Jan-Feb 2026 | International Finance
who returned as CEO in 2019 to steer the ship through this "Moonshot." However, the algorithms miscalculated. The company overpaid for properties just as the market softened. By November 2021, the real estate market had become erratic, COVID-19 had hit, and home price appreciation was behaving unpredictably. Zillow’s algorithms, designed to forecast prices, struggled to keep up with the wild swings of a market influenced by a pandemic, inflation, and supply chain shocks. A simultaneous labour shortage and supply chain crisis meant that Zillow could not renovate and flip homes fast enough. The company discovered a backlog of inventory it could not clear, comprising thousands of homes that were depreciating each passing day. In the third quarter of 2021 alone, the Zillow Offers segment posted a staggering loss of $339.2 million, necessitating a write-down of over $540 million. Zillow Offers shut down, and a quarter of Zillow’s employees paid the price with unemployment. A truly humbling moment for a company that had spent years positioning itself as the smart data-driven disruptor.
COVER STORY ZILLOW
Innovation of the Housing Super App Instead of doubling down on Zillow Offers, caught in a vicious sunk cost fallacy, Zillow shut down the venture. The brilliance of this move became apparent in the years that followed. By exiting the capital-intensive, low-margin business of house flipping, Zillow was able to pivot back to its core strengths of audience, data, and software. This strategic retreat gave birth to the "Housing Super App" strategy, the engine driving Zillow’s success in 2025. So, the whole Super App vision is really about playing the role of the conductor in a real estate orchestra. It’s managing the transaction from start to finish without actually owning any of the assets involved. It integrates buying, selling, renting, and financing into a seamless, allin-one digital experience. Zillow profits at each stage, avoiding the headaches and risks associated with holding inventory. Jeremy Wacksman was the one who made this vision a reality. He was the COO right in the thick of that big pivot, and then he stepped up to CEO in August 2024. Under his guidance, this Super App approach has completely revamped Zillow's
By early 2025, Zillow had expanded its Enhanced Market footprint to cover 21% of its connections, with a clear path to 35% by year-end and a longterm goal of 75%
financial picture. The company shifted its focus to "Enhanced Markets," cities like Phoenix and Atlanta, where it deployed a full suite of integrated services. The results have been spectacular. In these markets, customer transaction share has increased by over 80% since 2022. By early 2025, Zillow had expanded its Enhanced Market footprint to cover 21% of its connections, with a clear path to 35% by year-end and a long-term goal of 75%. This pivot restored Zillow’s profitability and financial health. In 2024 and 2025, the company maintained gross margins above 75%, a figure characteristic of elite software firms rather than the slim margins of the construction industry. It's quite impressive how this company managed to make a major comeback. They achieved positive GAAP net income in Q1 2025, and projections indicate they will remain profitable throughout the entire fiscal year. This marks a significant shift from the substantial losses they experienced back in 2021. Their balance sheet? It's like a fortress now, sitting on $1.6 billion in cash and investments as of early 2025. That level of liquidity allows them to invest in innovation and weather any economic challenges that may arise. Zillow owes this turnaround to Jeremy Wacksman's leadership. As a former engineer at Xbox (another Microsoft subsidiary), he was well versed in that sharp, product-focused discipline. And he brought that over to the C-suite. His intellectual curiosity and willingness to admit ignorance when he did not know something were conducive to a team-based problem-solving approach crucial to tackle the crisis at hand. He took this fuzzy idea of a "Super App" and turned it into real, tangible products like Zillow Rentals, Zillow Home Loans, and the agent-facing Zillow Pro. Just look at Rentals now. It grew revenue by 33% year-over-year in Q1 2025, and aims for a $500 million run rate. Sure, detractors love to bring up the flop of Zillow Offers as some kind of permanent stain, but by 2025, industry folks see it as a "clarifying moment" that actually highlighted the company's resilience. It eliminated a distracting business model and encouraged everyone to focus on digital integration. The Zillow that emerged from that 2021 situation is leaner, more focused, and much more scalable. They realised their real strength
International Finance | Jan-Feb 2026 | 27
INDUSTRY
FEATURE ZILLOW
REAL ESTATE PROPTECH
isn't in owning actual homes, but in owning the digital backbone that makes homeownership happen. That lesson, earned the hard way, is what's driving all this optimism now. It’s shifting their strategy away from betting on market prices and toward capitalising on the efficiencies they build.
The future of home sales In 2025, Zillow really dug in this massive technological moat that's so deep and wide, it's struggling to seize its market share. They've ditched the old-school world of flat 2D photos and scattered data bits, and stepped right into the era of the "Digital Twin." We are talking about the super immersive, data-packed virtual copy of a home. It's not just for show, and this tech jump is what makes remote deals possible and sets Zillow miles apart from everyone else. The star of their tech lineup is "SkyTour," which they launched in July 2025 just for "Showcase" listings. SkyTour, a breakthrough in computer vision, is powered by this rendering method called "Gaussian Splatting." Instead of those clunky traditional 3D
28 | Jan-Feb 2026 | International Finance
models with meshes of triangles, it uses millions of "splats," which are these ellipsoidal bits that nail complex surfaces and lighting with spot-on photorealism. This stuff was once only for fancy movie effects and games, but now it lets you "fly" around a property on your phone, checking out the roof, backyard, and whole neighbourhood like you're piloting a drone. The engineering feat behind SkyTour is huge. Scientists like Will Hutchcroft and executives like Steve Anderson, who headed the Zillow crew, figured out how to tweak this heavy-duty process so it runs butter-smooth on regular web browsers and smartphones. It's basically made high-fidelity spatial data accessible to everyone, and that shifts how people think about house hunting. It gives buyers that "being there" vibe that plain pics can't touch, cutting down on in-person visits and speeding up decisions. The numbers back it up. Showcase listings with SkyTour pull in 79% more page views, 76% more saves, and 91% more shares than comparable non-Showcase ones. This initiates a
COVER STORY ZILLOW
Number of existing homes sold in the United States from 2015 to 2024 (In Million Units)
2015 2016 2017 2018 2019
5.25 5.45 5.51 5.34 5.34
2020 2021 2022 2023 2024
5.64 6.12 5.03 4.09 4.06 Source: Statista
do full-on conversational searches. No more fiddling with a ton of filters. Just type something like, "Find me a three-bedroom house in Austin with a big backyard under $500k that's near good schools." The AI gets the subtleties and serves up tailored results. This technology also enhances the agent tools. Through the "Zillow Pro" suite, AI analyses user habits to provide agents with "smart lists" and recommended actions. If a buyer keeps eyeing a listing or shares it with someone, the AI pings the agent to follow up, cranking up how well leads turn into deals.
What's next for Zillow? positive cycle where sellers are eager to utilise Zillow's premium marketing tools, generating additional revenue and enhancing the platform. But killer visuals are just one piece of Zillow's 2025 tech puzzle. They've gone all-in on weaving AI into the money and search sides of things, too. Take the "BuyAbility" tool. They have nailed it in 2025, and it hits right at the biggest worry for today's homebuyers: Can I afford this? Old mortgage calculators are rigid and often off-base, ignoring how credit scores, debt-to-income ratios, and changing interest rates all mix together. BuyAbility? It's live and adaptive. It retrieves real-time mortgage rates customised for your location and credit profile, producing a personalised "purchasing power" score that updates daily. As rates bounce around in the wild 2025 economy, your BuyAbility score updates on the spot. When you're scrolling the Zillow map, homes get marked as "Within BuyAbility," so you can ditch the ones that are a financial stretch and zero in on real options. But it doesn't stop at crunching numbers. It breaks down how boosting your credit or increasing your down payment tweaks your power, turning you into your personal digital money coach. And by baking Zillow Home Loans right in, they snag you when you're most ready, making the jump from looking to locking in financing seamless. On top of that, Zillow flipped the search game with Generative AI. They hooked up a ChatGPT plugin and natural language smarts, so you can
As Zillow looks toward 2030, its vision extends beyond profits to stewardship of the housing ecosystem. Through its Super App, the company wields technology for social good, exemplified by the Housing Connector partnership. Since 2019, this initiative has housed over 10,000 homeless individuals by linking case managers with flexible landlords, turning Zillow's database into a lifeline. Plans aim for 30,000 more placements, proving data can solve systemic crises. By 2030, the Super App may become the "One-Click Home," integrating title, escrow, and insurance for seamless transactions, targeting 45% EBITDA margins. The efficiencies of PropTech are saving tens of thousands of dollars for families at a time when housing prices are near inaccessible for most Americans. Zillow is bringing the American Dream, of which owning one’s own home is a major symbol, closer to every family. It will be a steady and slow process, with Wacksman proclaiming, “Affordability conditions are projected to improve... but it should be a gradual recovery and a year of 'small wins'.” In triumph, Zillow has overcome its iBuying woes, forging resilient software and partnerships. Spanning from the 2006 server crashes to the AI immersion of 2025, it empowers consumers, emerging as the optimistic, accessible, and enduring cornerstone of the digital infrastructure for the American Dream.
editor@ifinancemag.com
International Finance | Jan-Feb 2026 | 29
INDUSTRY
FEATURE SANCTIONS
RUSSIA OIL
Inside the hidden engine of sanctions IF CORRESPONDENT
Buyers will face growing compliance risks under the latest American sanctions
30 | Jan-Feb 2026 | International Finance
FEATURE SANCTIONS
International Finance | Jan-Feb 2026 | 31
INDUSTRY
FEATURE SANCTIONS
RUSSIA OIL
I
n October 2025, Russia's vital oil and gas revenues tumbled 27% from what they were a year earlier, a development that experts see as a sharp blow to the Kremlin's wartime finances just as new US sanctions tighten the screws on its energy exports. Moscow collected 888.6 billion rubles, or $10.9 billion, in oil and gas taxes, down from about 1.2 trillion rubles in October 2024, amid weak crude prices, a stronger ruble, and tightening Western sanctions over the Vladimir Putin administration and its associates. In the coming days, as the US Treasury Department's sanctions start taking their full financial toll on the Russia's largest oil companies, Rosneft and Lukoil, which together account for around 3 million barrels per day (nearly half of the country's seaborne oil exports), all eyes will be on Moscow’s next moves, which till now managed to keep its war machine going by rerouting much of its crude through a "shadow fleet," non-Western insurance, and non-dollar payment systems. However, buyers will face growing compliance risks under the latest American sanctions. Talking about sanctions, whenever the word comes into our mind, we immediately think about the economic warfare mechanism, which starves aggressor nations of the revenue needed to finance conflict and oppression. What was celebrated by Western capitals as an essential and powerful instrument of statecraft has recently been revealed to be nearly ineffective. The ongoing conflict in Ukraine has demonstrated that, beyond a poorly enforced system of voluntary compliance, sanctions are merely a hollow facade built on geopolitical self-deception. The brutal reality is that while dip-
32 | Jan-Feb 2026 | International Finance
lomats issued stern warnings and legislators passed sweeping restrictions, the essential infrastructure of Western finance, specifically the shadowy world of maritime insurance, actively functioned to undermine those very sanctions for the sake of profit, ensuring that billions of dollars continued to flow unimpeded into the coffers of Moscow and Tehran. As per veteran Reuters journalist Paul Carsten, this shocking failure of oversight centres on a single, unassuming company, Maritime Mutual (MMIA), an insurer based in a peripheral jurisdiction, New Zealand, which became the indispensable white-collar architect of the shadow fleet, providing the critical license to operate for the world’s most illicit energy cargoes. “The profound paradox at the heart of this scandal lies in its geography, a quiet insurance firm operating from a nondescript Auckland office, led by 75-year-old Briton Paul Rankin and his family, somehow managed to inject unprecedented instability into global security. This small, seemingly isolated entity emerged as a crucial nexus, a 'major power player' in the illicit global oil market, confirming that sanctions evasion is not managed from the dusty corners of pariah states but is facilitated by sophisticated financial mechanisms rooted deeply within democratic, sanction-compliant nations,” Carsten remarked. Maritime Mutual provided essential protection and indemnity (P&I) coverage, the non-profit mutual insurance for third-party liabilities required by all major ports and trading partners worldwide, a form of cover that is necessary for any ship to go to sea, including the vessels making up the so-called shadow fleet. Without valid P&I insurance, these tankers, which rely on false documentation and opaque ownership structures
to conceal their identities and cargoes, would be instantly barred from international waters and ports, rendering the entire illicit operation financially and physically impossible. Maritime Mutual facilitated this trade and provided the very lifeblood necessary for this massive, systematic evasion to survive and thrive. The financial scale of this betrayal is devastating, serving as irrefutable proof of a catastrophic lapse in both corporate responsibility and regulatory enforcement, figures that cannot be sanitised or dismissed as minor compliance hiccups. Since 2018, vessels insured by Maritime Mutual have been identified carrying oil and petroleum products valued at least $18.2 billion from Iran and a staggering $16.7 billion from Russia, a combined trade flow totalling nearly $35 billion, capital that has directly financed the geopolitical objectives and the mili-
FEATURE SANCTIONS
tary machines of both regimes. “To grasp the depth of MMIA’s involvement, one must look at its market saturation in the illicit sector. Investigations found that this single New Zealand insurer covered nearly one-sixth of all sanctioned shadow fleet tankers globally, confirming its role not as a marginal participant but as a deliberate and systemic enabler of sanctions evasion on a grand scale,” Carsten noted. Specific voyages highlight the calculated nature of this business, confirming that this was not a case of isolated oversight but continuous, high-volume trade. Reports detailed one tanker, the Yug, departing the Chinese port of Qingdao after offloading sanctioned Iranian oil around Christmas, another vessel ferrying Russian crude through treacherous Arctic waters on its way to India, and yet a third offloading Iranian
oil off the coast of Malaysia, all sharing that defining, necessary link, insurance provided by Maritime Mutual. The calculated exploitation of New Zealand’s relative obscurity by a British-led entity strongly suggests a deliberate strategy of regulatory arbitrage, choosing a smaller, less scrutinised jurisdiction to conduct high-risk, geopolitical business precisely because the scrutiny applied to financial centres like London, New York, or Frankfurt is immediate and intense. The sheer volume of the trade, $35 billion worth of risk being underwritten by a firm in a market the size of New Zealand, indicates that MMIA’s jurisdictional choice was a strategic attempt to find regulatory refuge while profiting immensely from the demand for P&I coverage in the non-compliant energy sector. The fundamental question that must
be asked is how the financial gatekeepers, those who provide the necessary capital and risk protection, were permitted to leave this critical choke point in the global sanctions framework so brazenly open for profit.
Unmasking the loophole The exposure of Maritime Mutual’s role quickly escalates the argument beyond a case of regional mismanagement, revealing an indictment of the entire global risk-transfer mechanism, proving that sanctions evasion was enabled and effectively subsidised by the world’s most elite financial institutions. Maritime Mutual based its claim to legitimacy on its structure, operating like an International Group P&I Club where risk is shared amongst members, a model that historically affords a degree of regulatory comfort.
International Finance | Jan-Feb 2026 | 33
INDUSTRY
FEATURE SANCTIONS
RUSSIA OIL
“Yet, crucially, MMIA simultaneously relied on external credibility, stating that its security was backed by a quality reinsurance programme provided by specialist Lloyd's Syndicates and highly rated London Market insurance companies, meaning MMIA was never operating in isolation; its risk was validated and ultimately underwritten by the core of global finance. This is the heart of the scandal, the mechanism that allowed illicit liabilities to be absorbed and legitimised by the wider financial system,” Carsten said. The evidence of this institutional complicity is quantitative and cannot be refuted by claims of accident or oversight, demonstrating a systematic failure of due diligence among the major global players. Of the 231 vessels Maritime Mutual insured between 2018 and the time of the investigation, at least 130 were found to have transported sanctioned Iranian or Russian oil, with 97 of those tankers later being formally added to sanctions lists imposed by the United States, the European Union, or the United Kingdom. This trajectory confirms that MMIA’s risk pool was actively providing coverage to ships that were either currently or imminently violating international sanctions, essentially providing a financial guarantee for criminal activity. This investigation is a devastating exposure of the entire reinsurance market, which provided the ultimate financial architecture necessary for the shadow fleet to achieve global operability. The list of those allegedly backing Maritime Mutual’s risk pool includes the titans of the reinsurance market, companies that profess adherence to the
34 | Jan-Feb 2026 | International Finance
most rigorous global compliance standards, but whose financial machinery enabled this vast evasion. Specifically, this includes Germany’s Munich Re Group, one of the largest reinsurers in the world, its German counterpart Hannover Re, and significant British insurance firms like MS Amlin and Atrium. These giants were receiving premiums derived directly from the illicit transport of sanctioned oil, meaning their profit motive tragically corrupted the fundamental need for stringent due diligence, suggesting a systemic failure of Know Your Customer (KYC) and Anti-Money Laundering (AML) obligations at the absolute highest level of global risk management. Furthermore, the sophisticated nature of this operation required the engagement of professional intermediaries, major British-American and American brokerage firms such as Aon and Lockton, which acted as key facilitators, placing the high-risk MMIA coverage with global reinsurers. This involvement directly links the failure back to the powerful compliance jurisdictions of London and the US, demonstrating that major market players, those expected to maintain the highest standards of financial integrity, provided the brokerage bridge that connected the peripheral New Zealand operation to the world’s capital markets. Entities like Atrium and Aon confirmed their working relationships with Maritime Mutual, solidifying the chain of financial complicity and confirming that the world’s sophisticated markets deliberately provided the vital capital necessary for the shadow fleet to operate globally. The inherent complexity of the P&I mutual structure, combined with outsourced management often seen in non-International Group clubs, is re-
The sophisticated nature of this operation required the engagement of professional intermediaries, major British-American and American brokerage firms such as Aon and Lockton, which acted as key facilitators, placing the high-risk MMIA coverage with global reinsurers
vealed here as an intentional feature that facilitates compliance failure because it creates significant opacity and distance. When the processes of management and ownership are separated, and risk is mutualised, accountability is diluted, making it easier for risk pools to accept dubious clients while the sophisticated reinsurers who provide security maintain plausible deniability regarding day-to-day underwriting decisions. The brokers, Aon and Lockton, while connecting the insurer to the reinsurers, must also face scrutiny for their due diligence failures, which allowed these highrisk placements to proceed unchecked across global financial markets. The financial integrity demanded by regulatory bodies around the world rests on the premise that these institutions act as responsible gatekeepers, yet the exposure of the MMIA network proves that this gatekeeping function was aban-
FEATURE SANCTIONS
doned when faced with the lure of billions of dollars in premium revenue.
The shadow fleet marches on The systemic failure laid bare by the Maritime Mutual scandal is ultimately a failure of state-level policy and regulation, where geopolitical strategy was fatally undermined by bureaucratic negligence and corporate complacency, demonstrating how regulatory divergence creates the exact operational cracks needed by evasion networks. The global sanctions landscape has been defined by both close coordination among the US, UK, and EU, and significant policy divergence, a combination that makes it exceedingly difficult for companies to navigate overlapping and sometimes contradictory rules, often leading to the selection of the most profitable, yet least compliant, path. Tellingly, the EU and UK have continually prioritised new measures against Russian entities following the
invasion of Ukraine, while the US, through the Office of Foreign Assets Control (OFAC), has simultaneously intensified its focus on enforcing restrictions against Iranian oil exports. MMIA, with its global insurance reach, successfully facilitated trade for both regimes, deftly exploiting the enforcement capacity limitations and the inherent complexity of navigating multiple, jurisdiction-specific sanctions lists. For years, experts have demanded deeper, enhanced upstream due diligence across complex supply chains and counterparties to detect concealed links to sanctioned entities, but the scale of the MMIA scandal proves that financial institutions either consciously disregarded these critical warnings or intentionally failed to resource their compliance departments adequately. The consequences of this structural negligence are evident in the sheer amount of sanctioned oil moved and
the operational freedom granted to the shadow fleet. The regulatory response has been characterised by a tragic lack of foresight, a reactive posture where regulators consistently play catch-up with criminals and evaders, allowing billions in revenue to leak through the system before corrective measures are finally instituted. It took until April 2025 for the US Treasury’s OFAC to issue a new, decisive maritime sanctions advisory that explicitly broadened the enforcement net beyond simple vessel owners and operators to include the crucial enablers, such as insurers, financial institutions, and brokers. “This official acknowledgement, while necessary, confirms that the regulatory framework was structurally inadequate for years, failing to recognise that the financial guarantee provided by P&I insurance was the most critical choke point available for enforcing maritime sanctions,” Carsten observed. The Trump administration's ongoing intensification of sanctions against Iran, targeting over 50 individuals and entities, as well as nearly two dozen shadow fleet vessels, represents a desperate attempt to undermine Iran's cash flow. This essential effort has been repeatedly undermined by systemic failures, such as those exemplified by Maritime Mutual. The disturbing reality that a small insurer based in New Zealand could become a linchpin in global geopolitical conflicts exposes a profound structural blindness where regulatory attention is disproportionately fixed on traditional financial centres, allowing vital ancillary services like P&I to operate with effective impunity from peripheral jurisdictions.
International Finance | Jan-Feb 2026 | 35
INDUSTRY
FEATURE SANCTIONS
RUSSIA OIL
Number of foreign companies in Russia by response to the war in Ukraine When faced with international scrutiny involving New Zealand, the US, the UK, and Australia, Maritime Mutual executed a textbook corporate manoeuvre of evasion, denying any wrongdoing and maintaining that it held a "zero-tolerance policy" on sanctions breaches. However, the firm’s subsequent actions are a far more truthful commentary on its operations than its public relations statements, because MMIA was quickly forced to announce that it would cease insuring vessels identified as part of the shadow fleet and those carrying Russian oil. This strategic retreat is an admission of guilt disguised as prudent business practice, yet their justification for this change is perhaps the most revealing indictment of all, citing the "disproportionate compliance burden" as their reason for withdrawal. This claim is a contemptible justification. For a sophisticated financial firm, the burden of compliance is the mandatory cost of legally operating in a complex global market. It is not an excuse for actively facilitating $35 billion in illicit trade, proving definitively that profit motives superseded every ethical, legal, and geopolitical obligation required of them. The fact that the burden only became "disproportionate" after the investigation shone a light on their activities strongly suggests that operating outside the law was vastly more profitable than operating within it, a perverse economic signal sent by weak regulatory oversight that persisted for years. Adding further context to this regulatory environment, New Zealand itself has struggled with significant systemic weaknesses within its financial sector, illustrated by the recent $19.5 million penalty imposed on IAG New Zealand
36 | Jan-Feb 2026 | International Finance
Withdrawal (totally halting Russian engagements or completely exiting Russia)
547 Suspension (temporarily curtailing most or nearly all operations while keeping return options open)
503 Scaling back (reducing some significant business operations but continuing some others)
151 Buying time (holding off new investments/development while continuing substantive business)
177 Digging in (defying demands for exit or reduction of activities, continuing business-as-usual in Russia)
212 Source: Statista
Limited for widespread historical system failures, miscalculations, and false representations. This pattern of regulatory lapse and underinvestment in core compliance
infrastructure within the jurisdiction suggests a local regulatory environment uniquely vulnerable to large-scale, sophisticated compliance failures, a vulnerability that shrewd global players like the British-led MMIA were clearly ready and able to exploit. The success of the shadow fleet, fuelled by MMIA’s insurance, injects continuous and significant volatility into the global oil market, undermining price stability and energy security globally. The untraceable flow of billions of dollars of discounted, illicit oil complicates efforts to predict supply and demand, distorting accurate financial forecasting and forcing established, legitimate corporate entities, such as Lukoil, to rapidly restructure or sell assets due to constrained operations. The cost of this structural failure is borne by governments as well as every legitimate oil and gas company striving for transparent and predictable market conditions.
Finding the corrective measures The exposure of Maritime Mutual’s central role in the shadow fleet is far more than an isolated case of insurance fraud; it stands as a damning, global symbol of Western financial hypocrisy, proving that the pursuit of short-term profits routinely triumphs over the collective security and the stated foreign policy goals of democratic nations. This failure represented a profound moral dereliction of duty, perpetrated not just by the directors in the unassuming Auckland office but by the sophisticated brokers in London and New York, and the senior executives at the powerful reinsurance giants in Germany, all of whom accepted revenue derived directly from state-sponsored tyranny and global instability. Every sanctioned ship insured
FEATURE SANCTIONS
by MMIA, every billion dollars of oil moved, translates directly into tangible, operational support for war, human rights abuses, and geopolitical destabilisation, confirming that this is a financial transaction with undeniable human consequences that can never be dismissed as a simple administrative oversight. The final denial of wrongdoing, the insistence on rigorous standards immediately followed by the admission that monitoring those standards was too commercially burdensome, constitutes an act of evasion, not accountability, demanding a punitive response that far exceeds the cost of a routine regulatory fine. To prevent the recurrence of this catastrophic structural failure, regulatory bodies must cease their perpetual game of catch-up and immediately implement an integrated, mandatory, and non-negotiable compliance system that
directly links P&I coverage to rigorous, real-time sanctions compliance checks across all jurisdictions. This system must be global in scope, ensuring there are no regulatory safe havens left for arbitrage. Crucially, there must be direct and punitive action taken against the major global reinsurers Munich Re Group, Hannover Re, the Lloyd’s syndicates, and others that provided the ultimate security and legitimacy for MMIA’s illicit risk pool, because their fundamental failure of due diligence enabled the entire $35 billion scheme to function. These institutions profited from the corruption of the sanctions regime, and they must now bear the cost of the structural cleanup. The P&I mutual structure, a model intended for shared protection, has been demonstrably corrupted into an instrument of systemic risk and sanctions evasion, requiring an immediate and radical overhaul of its oversight,
potentially placing all non-International Group P&I clubs under mandatory, intensified scrutiny from powerful regulators like OFAC and the UK’s OFSI. Furthermore, the regulators in New Zealand, including the FMA, must conclusively prove their capacity and willingness to regulate sophisticated global players operating on their soil, demonstrating that their jurisdiction will not continue to serve as a convenient and under-policed base for global financial arbitrage. Until the true enablers are subjected to the same ruthless enforcement pressure and sanctions as the vessels themselves, economic sanctions will remain nothing more than political theatre, an ineffective tool ensuring that financial integrity remains the most profound lie at the heart of global trade.
editor@ifinancemag.com
International Finance | Jan-Feb 2026 | 37
Business Dossier - Almamoon
Almamoon A visionary approach to health insurance
38 | Jan-Feb 2026 | International Finance
Almamoon’s service model emphasises the company’s operational values: convenience, transparency, and personalisation
S
audi Arabia-based Almamoon Insurance Broker is helping the Kingdom’s health insurance landscape evolve by consistently leading the way in redefining the broker’s role, not only as a policy intermediary but as a value-creating partner in the healthcare ecosystem. Taking note of Almamoon’s ongoing commitment to technology-driven solutions, regulatory excellence, and holistic client servicing, International Finance recently awarded the venture with the prestigious title of “Most Innovative Health Insurance Broker – Saudi Arabia 2025,” reaffirming the venture’s position as a market leader in digital health insurance transformation and customer-centric innovation. “Our journey is not just about offering insurance; it’s about enabling better health outcomes through smarter solutions. This award is a reflection of our team’s relentless pursuit of excellence,” said Mamdouh Tantawi, CEO of Almamoon, upon winning the honour.
Leading with technology and automation
At the core of Almamoon’s innovation strategy lies its proprietary digital infrastructure. The platform empowers clients with essential features such as real-time policy viewing, endorsement submission, access to up-to-date account statements, and an integrated ticketing system for complaints and service issues. These functionalities ensure transparency, efficiency, and streamlined communication across all touchpoints in the health insurance lifecycle. “Integration with top insurers and via secure
Mamdouh Tantawi, CEO of Almamoon APIs ensures seamless data flow between stakeholders, reducing manual effort and turnaround times. Moreover, Almamoon has implemented advanced Power BI dashboards, enabling HR and finance departments at client companies to visualise health benefits utilisation and monitor claims patterns with clarity,” Tantawi told International Finance.
Tailored products and value-based offerings
Understanding the diverse needs of its client base, Almamoon has collaborated with leading insurers to co-develop customised health insurance solutions for large enterprises, SMEs, financial institutions, and government or semigovernment entities. These tailored offerings go beyond regulatory compliance to promote employee well-being, featuring telemedicine access, wellness incentives, maternity support, and chronic disease management. Over the past 24 months, Almamoon has introduced several forward-looking enhancements to its group health propositions, such as nutrition coaching, mental health International Finance | Jan-Feb 2026 | 39
Business Dossier - Almamoon
support, and preventive health screenings, resulting in improved outcomes for insured employees and significantly higher retention rates among institutional clients.
Compliance-first, always
Almamoon operates with a deep commitment to regulatory excellence and ethical integrity, ensuring that every innovation is built on a foundation of full compliance. The company maintains robust governance frameworks, secure data practices, and transparent audit trails that instil confidence and trust across all stakeholders. By aligning its operations with both national regulations and Sharia principles, Almamoon delivers insurance solutions that are effective, innovative, responsible and values-driven. “As further validation of its commitment to excellence, Almamoon is ISO 9001 and ISO 10002 certified, reflecting its high standards in quality management and its structured, clientfocused approach to handling feedback and resolving customer concerns,” Tantawi noted.
Enhancing the customer journey
Almamoon’s service model emphasises the company’s operational values: convenience, transparency, and personalisation. Clients can engage the company through channels like mobile app, web, or WhatsApp. A dedicated health desk, staffed by qualified advisors, supports clients with claims, network queries, and service escalations. Almamoon continues to enhance its outpatient reimbursement process, achieving faster turnaround times and improved client satisfaction. This ongoing effort has led to consistently positive feedback, increased trust in employer-sponsored plans, and sustained improvements in satisfaction scores—reflecting Almamoon’s commitment to service excellence and continuous innovation.
Medical expertise at the heart of service
At the heart of Almamoon's service model is its dedicated doctor, a full-time, in-house medical expert who advises clients, guides 40 | Jan-Feb 2026 | International Finance
them through difficult claims, and negotiates directly with insurance companies on disputed or rejected cases. “This role bridges the gap between healthcare and insurance, ensuring clients receive fair, timely resolutions and professional medical guidance during their most critical moments. It’s a service rarely found in the brokerage industry, and one that sets Almamoon apart,” Tantawi remarked.
Strategic growth and market impact
Since 2022, Almamoon has achieved doubledigit annual growth in health GWP, fueled by strong performance across the SME, large corporate, and semi-government segments. This growth has been supported by tailored insurance solutions and strategic partnerships, including bundled offerings with leading
insurance companies that integrate health, auto, and life insurance. To support its continued expansion, Almamoon recently opened a new branch in Alkhobar, alongside its main branch in Jeddah and its other branch in Riyadh, to enhance its presence in the Kingdom’s Eastern Province and reinforce its nationwide reach. These efforts align with Almamoon’s broader mission to support “Vision 2030” by delivering accessible, client-centric, and innovative healthcare solutions across all sectors.
Culture of innovation
At the heart of Almamoon’s success is a bold culture of innovation fueled by agility, experimentation, and a relentless drive to lead. The leadership team fosters an environment where rapid pilots, cross-functional innovation
squads, and iterative feedback loops have become the default norm. Whether it’s enhancing chatbot capabilities or launching interactive wellness challenges, new ideas get conceived, tested, and deployed in weeks, not quarters. Looking ahead, Almamoon plans to roll out a self-service employer dashboard, introduce automated claims pre-authorisation workflows, and expand its smart policy renewal engine, each designed to enhance transparency, efficiency, and compliance. By continuing to invest in regulatory-aligned technology, data-driven insights, and client-centric tools, Almamoon remains at the forefront of reshaping health insurance brokerage in the Kingdom.
International Finance | Jan-Feb 2026 | 41
BANKING AND FINANCE
ANALYSIS
FINTECH REGTECH
Regulatory technology is becoming an increasingly important part of enterprise fintech plans
Fintech’s next revolution IF CORRESPONDENT
Financial technology is changing how companies conduct business, handle liquidity, and reduce risk — it is no longer merely an enabler. Fintech, from blockchain-powered payments to AI-driven automation, is transforming business finance at a rate never seen before. Blockchain is opening up new money flows, cross-border It is transactions are speeding up, anticipated and artificial intelligence (AI) that the total is revolutionising financial number of processes. cross-border At the same time, businessblockchain es are being forced by regutransactions latory changes to incorporate will have compliance technology, which increased by will ensure their resilience at a 48% year over time of increased scrutiny. year to B2B finance is at a turning $5 trillion point. In addition to changing the financial infrastructure, the convergence of these advances is radically changing how businesses control risk, streamline processes, and spur expansion. Businesses that successfully use fintech solutions will have a competitive advantage, while those that don't adjust quickly run the risk of becoming obsolete in the rapidly digitalised financial sector.
42 | Jan-Feb 2026 | International Finance
The quickening of business payments As businesses seek quicker, more affordable solutions, the global payment infrastructure is changing. By the end of 2025, it is anticipated that the total number of cross-border blockchain transactions will have increased by 48% year over year to $5 trillion. The demand for smooth, real-time settlement solutions is expected to propel the worldwide payment processing industry, valued at $79.6 billion in 2024, to more than double, reaching $161.9 billion by 2030. In addition to speeding up transactions, this development is forcing companies to reconsider their financial arrangements and hastening the use of financial products based on blockchain technology to improve liquidity management and maximise cash flow. This growing reliance on digital assets is ushering in a more automated and decentralised corporate finance ecosystem. Digital asset usage in corporate finance is becoming a strategic imperative rather than just conjecture. Blockchain technology is used by financial institutions and global firms to improve security, liquidity management, and transaction efficiency. Early blockchain projects were mostly limited to experimental pilots, but due to institutional demand, regulatory changes, and cost-saving advantages, corporate adoption has now moved to
full-scale implementation. Due to growing corporate adoption, the financial blockchain market is expected to reach $49.2 billion by 2030. Tokenisation is driving this change, as companies digitise financial instruments, commodities, and real estate to enhance liquidity and tradability. Experts predict that the demand for tokenised assets will surpass $600 billion. Tokenised assets are already being incorporated by businesses into trade settlement, supply chain finance, and cross-border transactions, which lowers counterparty risks and shortens settlement times from days to seconds. At the forefront of this change are institutions. Leading exchanges are modifying their models to include institutional-grade digital assets, while international banks and asset managers are introducing tokenisation platforms to enable blockchain-based financial instruments. The distinction between decentralised finance (DeFi) and traditional finance is starting to become less clear, opening up new avenues for investment vehicles and capital markets. But there are still obstacles in the way of widespread acceptance. As different jurisdictions adopt varying approaches to digital asset monitoring and compliance regimes, regulatory uncertainty remains a major concern. While some regions, like Singapore and the Eu-
ropean Union, have taken proactive measures to set clear regulatory norms, others are still figuring out where they stand. Businesses' approaches to risk reduction, security procedures, and compliance will be influenced by these changing policies. Businesses that successfully integrate tokenisation into their financial strategy will be positioned for longterm success in an increasingly digitised and decentralised global economy, even though adoption will move at varying rates across industries.
The institutional shift and CBDCs Central Bank Digital Currencies (CBDCs) are still developing, but more slowly than first thought. Citing the need for legislative clarity, interoperability testing, and risk assessment, about one-third of central banks have postponed their intentions to introduce digital versions of their currencies. Most, however, are still driven to keep control over monetary policy and currency issuance and are dedicated to eventual adoption. The increase in cross-border wholesale CBDC initiatives over the past few years is indicative of an institutional focus on improving interbank settlements and simplifying international financial flows. The People’s Bank of China (PBOC), the European Central Bank (ECB), and the United States Federal Reserve are among the central banks that have started pilot programmes to test the infrastructure for digital currency transactions at the wholesale level. Pro-
International Finance | Jan-Feb 2026 | 43
BANKING AND FINANCE
ANALYSIS
FINTECH REGTECH
Fintech industry revenue worldwide from 2017 to 2024 ject mBridge, which links banks in China, Thailand, the United Arab Emirates (UAE), Hong Kong, and Saudi Arabia, is one of them. Wholesale CBDCs are emerging as a more attractive option for largescale corporate transactions, liquidity management, and cross-border trade financing as central banks concentrate on improving interbank settlements and simplifying international financial flows. Adoption of CBDCs has important and encouraging ramifications for businesses. Reduced transaction costs, quicker settlement times, and less dependence on middlemen are all advantages for businesses involved in international trade. By facilitating quicker settlement times and lowering reliance on intermediary currencies, wholesale CBDCs have the potential to lower foreign exchange risks, especially in emerging markets where operational difficulties are caused by currency volatility. CBDCs could reduce the risks related to foreign exchange swings in cross-border payments by facilitating direct currency exchanges and improving transparency in cross-currency transactions. Despite these benefits, privacy laws, their influence on monetary policy, and cybersecurity issues remain major barriers to widespread adoption. The digital currency frameworks of some jurisdictions, like China and the UAE, are developing quickly, but others are still cautious and are waiting for more precise guidelines regarding the governance of CBDCs and their integration with current financial systems. Businesses must keep up with
44 | Jan-Feb 2026 | International Finance
changing technology and regulatory environments as CBDCs continue to grow. Navigating the next stage of financial digitisation will require an understanding of how digital currencies fit into global payment infrastructure, liquidity management, and corporate finance. This emphasis on ongoing learning and adaptation highlights the significance of remaining informed and proactive in the rapidly changing fintech world.
Future enterprise finance & AI Artificial intelligence is evolving from a tool for efficiency to a fundamental component of enterprise finance, changing everything from sophisticated financial modelling to real-time risk management. As businesses scramble to incorporate automation and machine learning into financial operations, investments in AI-driven compliance, fraud detection, and predictive analytics are increasing. The B2B banking industry has proven AI’s usefulness for automated risk assessment. It enables businesses to examine large financial data sets to identify irregularities and make previously unheard-of credit risk predictions. Real-time transactional behaviour analysis by AI-driven fraud detection systems, which are already integrated into international payment networks, can reduce financial crime losses by up to 50% by flagging questionable activity. Corporate finance is also changing as a result of the emergence of generative AI. Complex legal documents, contract analysis, and regulatory compliance reporting
2017 85.9 2018 98.8 2019 116.0 2020 135.3 2021 153.6 2022 170.8 2023 186.9 2024 201.9
(In Billion US Dollars) Source: DemandSage
are now processed by AI-powered automation, which can reduce processing times by up to 90%. Businesses now face additional security and regulatory problems as AI develops. Although AI improves financial decision-making, authorities are examining AI-driven financial services more closely, so companies must use understandable AI models to ensure compliance and transparency. For financial organisations, investing in AI is now a strategic need rather than an option. In an increasingly automated and data-driven economy, businesses that do not incorporate AI-powered financial solutions run the danger of falling behind.
Fintech for compliance Regulatory compliance is still a major concern as financial technology changes business interactions. Businesses are being forced to reconsider how they handle compliance as a result of the growing complexity of international finan-
cial regulations, as well as the emergence of digital assets, AI-driven financial services, and CBDCs. Regulatory technology (RegTech), which offers automated solutions for risk assessment, fraud prevention, and real-time monitoring, is becoming an increasingly important part of enterprise fintech plans. Several important causes are driving the need for RegTech. Businesses that conduct cross-border operations must adhere to several regulatory frameworks, which raises the cost and difficulty of reporting. Businesses may automate compliance procedures with AI-powered RegTech solutions, guaranteeing adherence to changing jurisdictional standards while lowering operational risks. As businesses enhance automation to manage regulatory complexity, the RegTech industry is expected to grow at a compound annual growth rate (CAGR) of 21.6% from its 2023 valuation of $11.7 billion to $83.8 billion by 2033, according to Allied Industry Research. AI is already being used to expedite manufacturing, healthcare, and financial regulatory procedures.
By automating risk assessments, fraud detection, and legal reporting, RegTech platforms powered by AI have been demonstrated to dramatically lower compliance costs. AI-based solutions have reduced document filing times in legal departments by 90%, improving operational effectiveness and reducing compliance expenses. Initiatives for digital compliance are also being accelerated by governments and financial institutions, especially in light of the growth of digital currencies and decentralised finance (DeFi). Regulatory frameworks must change as blockchain-based transactions and CBDCs become more popular in order to adequately supervise these financial innovations. Businesses that don't incorporate automated compliance solutions run the danger of facing fines from the governments, being investigated, and experiencing operational inefficiencies. Businesses can lower compliance expenses, improve fraud detection capabilities, and increase the effectiveness of regulatory reporting by utilising RegTech. Integrating
AI-powered compliance technologies enables businesses to manage changing regulations and reduce the dangers of financial crime. Businesses that proactively deploy RegTech solutions will be better equipped to handle the increasingly complicated global regulatory environment as financial technology continues to evolve at a rapid pace. In order to negotiate an increasingly complex legal environment, businesses must make sure that their infrastructure is ready for the integration of digital assets, engage in staff development to maximise AI applications, and have strict compliance procedures in place. Cybersecurity is still a major worry, and to protect digital transactions, firms must implement advanced risk mitigation techniques. Despite the traditional lag in B2B financial technology adoption compared to consumer finance, 2025 represents a significant shift. Failure to integrate financial technology puts businesses at risk of operational inefficiencies and decreased competitiveness, especially as the sector transitions to full-scale digitisation. Moving from trial adoption to strategic deployment is now essential, making sure that technology investments solve particular operational issues and provide quantifiable corporate value. Rapid fintech adoption creates opportunities, but firms lacking strategic planning risk falling behind in a dynamic financial environment shaped by early digital finance adopters. editor@ifinancemag.com
International Finance | Jan-Feb 2026 | 45
BANKING AND FINANCE
FEATURE MARKETS
TRADING HEDGE FUNDS
Machines can execute orders in microseconds and monitor markets around the clock, far faster than any trading floor
AI drives change in global markets IF CORRESPONDENT
A
rtificial intelligence (AI) is reshaping how financial markets operate. What once was all about human traders shouting orders on crowded floors has become an arena dominated by computer algorithms. Starting with early rule-based programmatic trading in the 1970s and 1980s, finance firms have long applied statistics and computing to markets. In the 1990s and 2000s, machine learning and neural networks added sophistication. For example, hedge funds like Renaissance Technologies hired PhDs to use AI for pattern recognition. Today, we stand at a new inflexion point with generative AI and large language models that can process massive streams of text and data and even suggest novel trading ideas. As one Wharton finance expert notes, AI’s evolution “from algorithmic trading to personalised advice” has made finance “fertile ground for AI innovation.”
46 | Jan-Feb 2026 | International Finance
FEATURE MARKETS
International Finance | Jan-Feb 2026 | 47
BANKING AND FINANCE
FEATURE MARKETS
TRADING HEDGE FUNDS
Global artificial intelligence market size from 2020 to 2025 Applications of AI in finance AI is now embedded in many financial processes. Broadly, AI serves in trading, analysis, and operations. In trading, automated systems place orders faster than any human can. High-frequency trading algorithms, often powered by machine learning (ML), make thousands of small trades every second to exploit tiny price discrepancies. Many of the largest trading venues are dominated by such “automated trading” in highly liquid assets. In other domains, AI systems read and summarise information. For example, NLP tools scan newsfeeds and social media to gauge market sentiment, a process known as sentiment analysis. A sudden burst of negative tweets about a company might trigger selling by algorithms. In risk modelling and compliance, AI churns through vast data to calculate creditworthiness or portfolio risk in real time. Advisors and insurers use AI to predict defaults or claims, while banks deploy chatbots to handle customer queries. In short, AI touches everything from trade execution to loan approvals and is effectively “democratising” access to analytics that only big institutions once had. The influence of AI and algorithms is clearest in a few headline-grabbing episodes. In January 2021, the GameStop saga showed the power of social sentiment and automated strategies. A surge of retail traders on Reddit’s WallStreetBets sent the share price of the video-game retailer GME skyrocketing over several days. Hedge funds that had short positions in the stock rushed to close them. Eventually, trading apps temporarily halted trading, igniting a political firestorm. Researchers note that “retail investors using the Robinhood platform”
48 | Jan-Feb 2026 | International Finance
collectively drove the sharp price swing. Although that episode was driven by human coordination online, it attracted algorithmic responses, with some trading bots detecting the rapid price trend and either piling in or pulling out, amplifying volatility. AI-driven trading has also featured in the activity of quantitative hedge funds. Firms like Renaissance Technologies, Two Sigma, DE Shaw, and others have long used machine learning to devise strategies. A 2019 survey identified those four as pioneers in AI-driven investing. These firms process vast alternative datasets, from satellite imagery of retail parking lots to aggregated price patterns, looking for subtle predictive signals. For example, AI can spot that a retail chain’s lawns are greener or read thousands of local news sites to update earnings estimates. In late 2022, Reuters reported Renaissance’s quant funds using models to target returns. Although strategies are secretive, experts agree that AI “provides a competitive advantage” in systematic trading. AI and social media can also combine in troubling ways. Studies and news accounts warn of sentiment manipulation using bots. In a recent report, experts imagined hundreds of AI-generated social media profiles pushing a narrative about a stock. Real people reacting to the buzz drive the price up or down, while those who detect the narrative profit. The danger is that neither the promoter nor some of the manipulators even realise they’re part of a larger AI-driven scheme, making enforcement hard. In practice, regulators have seen smaller-scale attempts in crypto and DeFi, where “malicious actors…deploy AI bots” on platforms like Telegram to hype assets.
2020 2021 2022 2023 2024 2025
62.35 93.52 119.78 149.63 191.00 275.00
(In Billion US Dollars)
Source: Statista
These examples highlight how automated sentiment analysis and engagement can influence markets, sometimes legitimately, with bots surfacing true trends and at other times through coordinated pumping.
Smarter markets at scale The attraction of AI in finance is clear, as it does things humans cannot. Speed and automation are paramount. Machines can execute orders in microseconds and monitor markets around the clock, far faster than any trading floor. This rapid processing tightens bid-ask spreads and improves liquidity in normal times. As the IMF notes, technology has “improved price discovery, deepened markets, and often dampened volatility” in normal periods. AI also excels at scalability and data processing. Financial markets generate enormous volumes of data on prices, news, social posts, filings, and satellite images, and AI can sift through it all. Advanced neural networks and LLMs (Large Language Models) can
FEATURE MARKETS
turn unstructured text into structured signals. For instance, a generative model can instantly read a regulatory filing or earnings call transcript, flagging risks or opportunities. The IMF notes that generative AI lets investors “process very large amounts of unstructured, often text-based, data,” which can improve forecasts and price accuracy. Another benefit is pattern recognition and precision. AI algorithms can spot complex statistical patterns that humans cannot see, such as nonlinear relationships or high-dimensional correlations. In portfolio management, for example, deep-learning models and reinforcement learning (RL) can adapt trading rules over time. Quantitative analysts now use RL to optimise asset allocation dynamically, a method well-suited for constantly shifting markets. These models “identify complex patterns in large datasets” by using millions of parameterised rules, going far beyond traditional formulae. In effect, AI can tailor strategies to ever-changing conditions, learning minute details of market microstructure.
This leads to efficiency and consistency, and routine tasks like compliance checks or customer service get automated via RegTech tools and chatbots, freeing humans for higher-level thinking. In trading, even a tiny improvement can be valuable. A recent AI pilot by HSBC reportedly found a quantum-enhanced model that improved trade-fill predictions by 34% over classical methods. Finally, AI can open new markets and lower costs. According to the IMF, AI tools are reducing barriers to entry and making it feasible for smaller firms or even individuals to analyse less-liquid markets like emerging debt or certain commodities. By automating research, coding, and data gathering, generative AI might lower the expertise needed to trade exotic assets. In retail finance, AI-powered robo-advisors have democratised wealth management. One report notes that about half of retail investors say they would use ChatGPT or similar AI to choose or rebalance investments. This suggests AI is making advanced analysis available to “anyone,”
not just Wall Street. Overall, proponents argue these gains, faster reactions to news, more thorough analysis, and automation, should make markets more efficient and investors more informed.
Herding, black boxes & volatility AI in finance may sound like an interesting and exciting concept, but it is not risk-free. A key concern is model correlation or “monoculture.” When many firms use similar data and algorithms, their trades tend to move together. Regulators and economists warn that this can amplify swings. For example, if numerous deeplearning models all see a similar signal, they might simultaneously sell stocks, creating a cascade. The Bank of England and the SEC have warned that advanced AI’s “hyper-dimensionality” and shared data sources could lead to just a few dominant models or data providers. In practical terms, a “monoculture” of strategies can increase market correlations and herding. In stressed markets, this may cause liquidity to evaporate suddenly.
International Finance | Jan-Feb 2026 | 49
BANKING AND FINANCE
FEATURE MARKETS
A recent IMF analysis noted that many algorithmic funds include safety mechanisms that can all activate at once, causing feedback loops. The 2010 “Flash Crash” is a cautionary example of an automated sell order in one market leading to a chain reaction, briefly knocking 1,000 points off the Dow within minutes. Though that crash predated today’s AI, it illustrates the danger of automated systems acting in unison. Experts now worry AI-driven trading could produce even faster and larger moves. Closely related is model opacity and explainability. Modern AI models are often “black boxes” that even their designers cannot fully explain how a specific trading decision was reached. This poses problems for oversight. If an AI fund suddenly accumulates a large position in an obscure asset, regulators might not understand why. The IMF notes that market participants insist on human oversight and explainable strategies, avoiding purely “black box” approaches. Likewise, a recent Sidley (law firm) report warns that deep-learning and reinforcement-learning systems can have “emergent behaviour” that current market rules aren’t built to catch. For example, if an AI learnt to detect fraud or manipulate prices in some non-obvious way, standard surveillance systems might miss it. The opacity also raises ethical concerns. How do we verify that AI decisions are fair and unbiased? Finance is littered with historical biases, so an AI trained on past records might perpetuate discrimination. Wharton researchers point out that “bias in AI models is particularly pertinent” in finance, especially lending and insurance. There are also privacy and manipulation issues. Bad actors can use AI to
50 | Jan-Feb 2026 | International Finance
TRADING HEDGE FUNDS
tailor scams or spread disinformation. Former SEC Chair Gary Gensler warns that AI-driven narrowcasting can facilitate fraud by zeroing in on individuals’ vulnerabilities. Indeed, regulators have already flagged concerns about AI-generated “deep fakes” of company announcements or rumours that could jolt markets. Finally, there is the risk of systemic volatility. Many worry that AI might make crises worse by speeding up decision-making. In turbulence, when computers pile into or out of trades in milliseconds, prices can swing violently. The Sidley report cites the IMF in noting that many AI strategies include circuit-breaker logic that all trigger together under unprecedented moves, risking a sudden freeze of liquidity. In other words, while AI may “damp down” routine volatility by making markets more efficient, it might also set the stage for faster, sharper shocks. Small errors or adversarial attacks on widely used models could propagate quickly across markets. There’s also a concentration risk, and just a few tech firms provide the most advanced AI services and cloud infrastructure, so outages or cyberattacks could disrupt financial systems more broadly.
Governance meets technology Awareness of these issues is growing. Governments and regulators worldwide are moving to govern AI in finance. In the EU, for example, the new AI Act will classify many financial AI systems as “high-risk” and impose strict obligations. Practices like AI-based credit scoring or risk pricing will have to meet transparency, data quality, and audit requirements. The stated goal is “consistency and equal treatment in the financial sector.”
Financial institutions are also starting to set their own AI governance. Many banks now require human signoff on automated strategies. Investment funds maintain “model risk management” teams to test how strategies behave under stress. After the GameStop episode, social platforms began cracking down on stock-promo groups. And financial regulators update rules in light of faster trading speeds. Still, experts say more will be needed. For example, regulators worry about a lack of transparency when nonbanks use cutting-edge AI outside full supervision. There are calls for international coordination, like the "Financial Stability Board" surveying AI preparedness in different countries. Another trend on the horizon is quantum computing. While today’s AI uses classical computers, quantum machines promise even more power. If scalable quantum computers arrive, they could revolutionise optimisation and simulation problems in finance. Banks are already experimenting. In 2025, HSBC announced a pilot with IBM showing that a quantum algorithm could predict bond trade outcomes 34%
FEATURE MARKETS
better than classical methods. UBS, Citigroup, and others are researching quantum for portfolio optimisation and risk analysis, and analysts estimate the “quantum technology” market could reach $100 billion by 2030. In plain terms, quantum computing could solve certain portfolio or pricing problems much faster than today’s fastest supercomputers. However, practical quantum advantage remains in early stages, and much of that promise is years away. Even so, finance leaders like HSBC’s quantum head call this a “new frontier” in computing for markets.
Tale of two traders The AI wave affects big institutions and small investors differently. Large financial firms such as banks, hedge funds, and trading firms have the resources to develop sophisticated AI. They run vast data centres, hire machine-learning experts, and deploy cutting-edge models. These institutional players have led the AI adoption for over a decade as they’ve used automated algorithms in HFT and complex derivatives trading. They also invest in AI for risk manage-
ment and compliance. Because of their scale, they have an edge in computing speed and data access. Retail investors have lagged but are catching up. The same chatbots and analysis tools that institutions use are now available to individuals in a lighter form. As one industry report noted, about half of retail investors say they would use AI tools to pick or adjust investments, and around 13% already do. User-friendly platforms now offer AI-driven advice and portfolio screening. For example, retail-friendly robo-advisors automate investing for individuals with modest accounts. Even individual day traders are experimenting with off-the-shelf AI bots or sentiment-tracker apps. Indeed,the widespread curiosity about ChatGPT and AI has “democratised” access to analysis once reserved for big banks. One former UBS analyst remarked that using ChatGPT for stock research was akin to “replicating many workflows” of an expensive Bloomberg terminal.
the IMF puts it, generative AI is the “latest stop on a journey” where technology incrementally improves markets. Its benefits in faster processing, new insights from data, and lower costs have already transformed many aspects of trading and investment. But the journey is not without bumps. Our analysis shows that there are real risks that correlate with AI models, as they could unintentionally synchronise market behaviour, create opaque algorithms, trigger flash crashes, and mislead investors. Addressing these issues will require vigilance and innovation on their own part. Regulators are awakening to the challenge, calling for AI governance frameworks and updating rules for our faster, more complex markets. Financial firms are instituting controls on things like explainability requirements and kill switches for trading bots. Meanwhile, new technologies on the horizon, like quantum computing, promise even more powerful tools. In the end, the AI transformation in finance mirrors other revolutions by creating opportunities and pitfalls. The central question will be how these systems are deployed. Used wisely, they can make markets more efficient and accessible to more people. Used recklessly, they could amplify our worst crashes or widen inequalities. For investors and policymakers alike, the task is to harness AI’s ingenuity while keeping our collective financial system resilient. Industry leaders must ensure AI markets remain “transparent, fair, and inclusive,” even as the algorithms get ever smarter.
Balancing innovation and stability AI’s role in finance is growing fast. As
editor@ifinancemag.com
International Finance | Jan-Feb 2026 | 51
BANKING AND FINANCE
FEATURE OMAN
GREEN FINANCE MONEY
Oman’s starting position is stronger than its critics concede, which is why urgency can coexist with confidence
52 | Jan-Feb 2026 | International Finance
FEATURE OMAN
Oman turns vision into green power IF CORRESPONDENT
A
round the world, capital is finally moving with purpose toward cleaner growth that can be measured, verified and trusted, and Oman is positioned to turn that momentum into jobs, competitiveness and climate resilience if it matches ambition with proof and policy discipline. Green finance has become a toolkit for funding real assets that cut emissions, protect natural resources and harden economies against climate shocks, from solar parks and efficient factories to cleaner transport, water systems that waste less and infrastructure that withstands heat and floods.
International Finance | Jan-Feb 2026 | 53
BANKING AND FINANCE
FEATURE OMAN
Investors who once chased stories now demand numbers, asking how many megawatt hours will be saved, how many tonnes of carbon will be avoided and whether those claims will stand up to independent verification over time. Green finance ties the use of proceeds or the performance of a borrower to quantifiable environmental outcomes that can be audited and priced, which is exactly what long-term capital wants in an era defined by risk, scrutiny and accountability. For Oman, the alignment is straightforward, since the vision set by “Oman Vision 2040” calls for a more diversified economy built on innovation, skilled jobs and sustainability that preserves natural beauty while boosting global competitiveness and signalling seriousness to partners and markets. The point is not to tick boxes for an external audience, it is to finance an economic transition that creates value locally, lowers costs of capital and strengthens the national balance sheet against volatility in a world already pricing climate risks. Capital will not come because green is fashionable. It will come because projects can demonstrate clear benefits, present bankable documentation and deliver verified outcomes that de-risk investor decisions and justify better pricing and longer maturities. The instruments are already proven, accessible and flexible enough to fit Omani priorities, which means the bottleneck is not novelty but execution with integrity. Green bonds and green loans direct money to labelled uses like solar generation, industrial retrofits or energy efficient desalination, where eligibility is clear, and the impacts can be tracked across the life of the asset.
54 | Jan-Feb 2026 | International Finance
GREEN FINANCE MONEY
Sustainability-linked loans and bonds go a step further by rewarding borrowers with lower coupons if they hit agreed performance targets, such as measurable reductions in energy use or increases in recycled water, which aligns incentives without restricting proceeds to a narrow list of assets. Carbon markets can add a complementary revenue stream when projects produce verified emissions reductions, improving project economics and attracting international finance that wants both returns and impact. When these tools are backed by honest data and credible reporting, the benefits compound, from access to new investor pools and longer duration money to a stronger national brand and more jobs across engineering, project
finance, digital monitoring, maritime services, logistics and the circular economy that ties waste to opportunity. Oman’s starting position is stronger than its critics concede, which is why urgency can coexist with confidence. Abundant solar and wind resources offer a comparative advantage for clean power and energy-intensive industries that want to decarbonise, while a strategic location and reliable institutions simplify supply chains and deal execution for investors who hate surprises more than anything else. A growing base of industrial and logistics expertise means capability is not being built from zero, it is being upgraded for the next wave of investment in green hydrogen, power grids, storage and cleaner manufacturing, where
FEATURE OMAN
GCC countries ranked by their involvement in green finance
Source: KPMG
scale, credibility and coordination determine winners. Local banks are building the right teams and tools, while policymakers are giving explicit signals, with the Central Bank of Oman encouraging sustainable finance practices and transparent disclosures and capital market rules now enabling green and sustainability bonds and sukuk to be issued with confidence inside a clear framework. Early movers matter in any market shift, and within banking, Sohar International has stepped out front by engaging clients, developing internal capacity and exploring climate-aligned lending so that more Omani projects qualify for green finance on terms that are fair, competitive and repeatable. This is how markets are built, by combining policy clarity with private capability and project-level data that turns goals into signed term sheets.
Proof beats promises Green finance rewards clarity, and in Oman, clarity is beginning to deliver funding for real economy use cases, not just glossy brochures. In shipping and logistics, an Omani company secured a green loan from international lenders by presenting an energy efficiency business case grounded in data with a credible plan to cut fuel use and emissions that third parties could verify, which is the difference between a marketing deck and a financing package. On rooftops and in small businesses, local retail programmes for solar and efficiency have already helped households and SMEs (small and medium businesses) lower bills, a reminder that the energy transition is not only about giga projects but about the cumulative effect of thousands of small decisions supported by accessible finance. In heavy industry and energy, a coordinated push around green hydro-
gen has started to attract global developers who bring capital and technology, which is precisely the blend needed to derisk first movers and get steel in the ground. The through line in each example is simple and repeatable, because clarity plus data equals money, and lenders will improve pricing and extend maturities when they can quantify savings or avoided emissions and see that those numbers have been independently checked. This is how to turn climate objectives into competitive financing: by answering the two questions lenders always ask, how will this project perform under stress, and who will verify that it is doing what it claims as conditions change. When the answers are precise, prices improve, and when the answers are weak or vague, projects stall and costs rise, which is why internal discipline inside firms will be as important
International Finance | Jan-Feb 2026 | 55
BANKING AND FINANCE
FEATURE OMAN
as external signalling by regulators. Preparedness at the enterprise level is the fastest way to convert interest into funding, because the cheapest loan is the one that does not get delayed by missing documents and shifting targets. Start with a simple sustainability plan that explains the project, defines the expected environmental benefits and sets out how results will be measured, because lenders finance what they can underwrite, and underwriters need a plan they can file and revisit. Build a baseline for emissions that covers Scope 1 and Scope 2 and the most material parts of Scope 3 where relevant, because credibility flows from showing where you stand before you promise how far you will go. Choose the right instrument for the job. A green loan or bond, when the use of proceeds is clearly green and a sustainability-linked structure, when the goal is to improve performance over time across a broader corporate platform. Collect facts early, from feasibility studies and permits to signed contracts and a one-page summary that states impact per rial invested, because the summary focuses attention and the appendices carry the evidence. Secure an external review to build trust and engage the bank at the start by asking what documentation, KPIs (key performance indicators) and reports it needs so that both sides are aligned on definitions, measurement and timing with no surprises later. This is about predictability, and predictable borrowers get better terms, more options and faster credit approvals from lenders trained to reward process discipline. The system moves faster when everyone shares the same language and templates, which is why a “Green Finance Starter Programme” would
56 | Jan-Feb 2026 | International Finance
GREEN FINANCE MONEY
pay for itself in velocity and volume. Many Omani SMEs want to participate but are unsure where to begin, so a national programme delivered through chambers and industry groups can teach teams to calculate a basic emissions baseline, select the right financing tool, prepare a short sustainability report and understand what assurance really means in practice. Training must also target bankers, credit officers and FDI professionals, because deals close when borrowers and lenders align on eligibility, KPIs, verification and reporting, and that alignment comes from repeated conversations across a shared technical vocabulary. Here, regulators can lean in with light but catalytic touch, as the Central Bank and investment authorities can back standard templates, share anonymised examples and celebrate early successes to create demonstration effects that pull others into the pipeline. The outcome is not bureaucracy, it is speed, because standardisation reduces ambiguity, reduces legal opinions and reduces time to funds disbursement for projects that meet the criteria. The more predictable the process, the lower the risk premium investors will demand, which is how a policy choice about templates becomes a macro lever for lowering national financing costs.
Sovereign first, global ready The fastest way to lose credibility is to appear to chase external agendas, which is why Omani green finance is rooted in national priorities and financial independence that serve domestic objectives first. The goal is neither to mimic another country’s taxonomy nor to accept conditionality that undermines sover-
eignty. The goal is to channel capital to projects that strengthen the economic base, build industrial competitiveness and enhance environmental resilience under rules set and enforced at home. Policy leadership by the Central Bank of Oman, the Capital Market Authority and the Ministry of Finance provides the backbone for this approach, ensuring that all green financing instruments are governed by clear disclosure and accountability standards that protect national interests while welcoming credible partners. That is how to be globally ready without being globally dependent, by
FEATURE OMAN
building a system that matches international best practice where it adds value while tailoring thresholds, definitions and reporting to Omani realities and sectoral priorities. Sovereignty is not a slogan in this context. It is a series of design choices that keep governance, verification and enforcement aligned with national strategy so that the shift to sustainability remains strategic and durable, not transient and reactive. Markets can smell incoherence, and when frameworks wobble, capital retreats, which is why a sovereign-led, transparent and practical architecture is a competitive
advantage in a crowded field of issuers and borrowers. A credible framework requires practical rules that are stable enough for companies and banks to plan around, because nothing kills a pipeline faster than moving goalposts. It also requires capability, which comes from short, targeted training that equips lenders and borrowers to measure and verify impact with confidence, so that KPIs are not just acronyms on a slide but metrics embedded in operations and covenants. Finally, it requires a visible pipeline of priority projects, from renewables
and storage to industrial efficiency, low carbon logistics and green hydrogen, because capital prefers to shop from a shelf where the products are labelled, documented and ready for due diligence. Publish the shelf and refresh it, then watch how swiftly roadshows turn into mandates when investors see a line of creditworthy projects under a consistent policy umbrella. Sovereign support should be targeted, not distorting, which is why a sustainable finance framework or a credit enhancement facility for early projects can attract private capital without crowding it out, especially in the first
International Finance | Jan-Feb 2026 | 57
BANKING AND FINANCE
FEATURE OMAN
wave, where demonstration effects matter more than marginal costs. The payoff is direct and measurable: lower financing costs, more international investment, stronger Omani enterprises and a stream of sustainable, high-quality jobs that anchor communities and expand the tax base. Evidence from within Oman already shows the logic working in microcosm, which should embolden a scale-up in the next budget cycle. The shipping example proves that when a borrower presents a credible plan with independently checkable metrics, international lenders will line up to price efficiency gains and share the upside in tighter spreads or better tenors. The household and SME programmes for rooftop solar and efficiency show that retail finance can be green, practical and popular when lower bills are visible within months, and repayment structures are simple, which builds a culture of demand that supports larger grid and storage investments. The early momentum in green hydrogen shows how policy focus can draw global developers with both capital and technology, and it underlines the need to connect upstream ambitions to midstream infrastructure and downstream offtake with contracts that allocate risk fairly across the chain. Stitch these strands together inside a coherent disclosure and assurance regime, and Oman will not have to persuade the market with slogans. It will persuade the market with term sheets and performance reports that speak for themselves.
Playbook for projects Every firm that wants to tap green finance in Oman can follow a playbook
58 | Jan-Feb 2026 | International Finance
GREEN FINANCE MONEY
that is short, disciplined and designed to survive sceptical due diligence, because scepticism is the default stance of any serious lender. First, define the project and its environmental logic in plain terms, then state the KPIs that will prove success and the methods for measuring them over time, which stops debates about purpose from consuming meetings that should be about terms and timelines. Following these, establish a baseline for emissions that covers direct and indirect energy and the most material value chain components, because a baseline makes future claims legible and comparable across reporting periods and market cycles. Third, match the instrument to the reality, using green loans or bonds for defined green uses of proceeds and sustainability-linked structures when the value lies in performance improvement against credible targets rather than in a single pool of assets. Fourth, pull together feasibility studies, permits and contracts, then condense the numbers into a one-page summary of impact per rial invested that lets decision makers grasp the economics and the environmental case at a glance without flipping through appendices in a marathon session. Fifth, seek an external review early to build trust and surface any weaknesses before they are handed to a lender, which prevents avoidable delays and demonstrates professionalism to counterparties who value preparedness. Finally, sit with the bank on day one and ask for its documentation, KPI and reporting expectations, then build your data room to that specification so there are no last-minute scrambles that raise doubts about execution capacity. This sequence is not glamorous, but it
wins mandates because it respects how credit committees think and how risk is priced in competitive markets that reward certainty. For SMEs, the path can be made even clearer through a national starter programme that demystifies the basics and lowers the cost of entry into green finance, which is where leverage per rial spent on training is highest. A programme delivered with chambers and industry groups can teach teams to calculate a basic baseline, choose a financing instrument, draft a short sustainability report and understand assurance, so that first-time borrowers arrive at banks with documents that are good enough to be taken seriously. Training should be reciprocal, with bankers, credit officers and FDI professionals learning the same technical
FEATURE OMAN
language so that meetings become exercises in alignment rather than translation, a shift that accelerates closings and reduces leakage in the pipeline. Regulators can help by standardising templates, sharing anonymised case studies and publicly celebrating early deals that went right, which normalises the process and signals to the market that this is not a fad but a policy-backed shift with institutional energy behind it. The net effect is compounding velocity, because the second wave of deals is always easier when the first wave created precedents that lawyers and lenders can reference without reinventing every clause.
The road to leadership The reasons to act now are practical,
not rhetorical, because global capital is already reweighting toward clean assets and credible frameworks, and the penalty for hesitation is opportunity lost to neighbours who move faster and offer better documentation. Oman has the resources, the institutions and the policy direction to compete for that capital at scale, but the deciding factor will be the boring excellence of documents, baselines, KPIs and third-party checks that earn trust across borders and credit cycles. Even the best solar resource does not finance itself. It needs a borrower who can prove savings, a regulator who can guarantee standards and a lender who can price risk with confidence, which is why the blocking and tackling described above will matter more than slogans on conference stages.
The good news is that the building blocks exist, from local banks assembling green finance capabilities to authorities enabling green and sustainability bonds and sukuk and early projects showing that money follows numbers when the numbers are honest. The next chapter will be written by teams that execute the playbook and by policymakers who protect national interests while opening the door to credible partners under rules that elevate trust over hype, process over improvisation and performance over promises. If that discipline holds, Oman can turn vision into velocity and make green finance not just a headline, but a competitive advantage that compounds across a generation. editor@ifinancemag.com
International Finance | Jan-Feb 2026 | 59
BANKING AND FINANCE
IN CONVERSATION
NAZNEEN ABBAS MA’AN
The aim of Ma’an is not just to distribute wealth, but to carry forward the family’s values and intent
'Empathy guides wealth planning' CL RAMAKRISHNAN While the UAE is considered an important global centre for wealth and legacy planning, Ma’an has become a reliable partner for families seeking clarity, structure, and continuity across generations. Founded by experienced financial advisor Nazneen Abbas, Ma’an combines technical knowledge with personal insight. It recognises that effective legacy planning involves relationships and values as much as it does assets and governance. Nazneen Abbas is a certified financial advisor from the Chartered Insurance Institute of London, and brings more than four decades of experience in navigating the complex intersection of wealth, family relationships, and long-term planning. Through Ma’an, she assists families across the Gulf, including high-net-worth individuals and multi-branch business households. She helps them create intergenerational structures based on empathy, purpose, and foresight. In an exclusive interview with International Finance, Ma’an founder Nazneen Abbas discusses the changing priorities of legacy planning in the UAE. She highlights the unique challenges faced by first-generation entrepreneurs and the increasing need for governance, clarity, and structured continuity. She explains how Ma’an helps families navigate legal reforms, cross-border complexities, and multi-generational dynamics, ensuring that wealth, values, and intent are preserved across branches and future generations.
IF: What unique challenges do first-generation entrepreneurs in the UAE face when planning to transfer their wealth across generations? Nazneen Abbas: In the UAE, many of today’s business owners are pioneers who built their enterprises from scratch, often without inherited structures
60 | Jan-Feb 2026 | International Finance
WEALTH LEGACY PLANNING
or precedents to follow. Their focus was growth, not governance. The most unique challenge they face is accepting that legacy planning must be treated as a formal part of their business plan. They are often unable to step back from the business and look at it as a family enterprise. To them, it remains my business, built through their own discipline, focus, and hard work. They often believe that the next generation will naturally follow the same discipline, focus, and systems they relied on. But the coming generation will not mirror their journey, and that is precisely why structured governance, continuity frameworks, and defined responsibilities must be put in place. The challenge often lies in accepting that their families genuinely need those frameworks.
How can Ma’an help guide the UAE’s first-generation business owners through the complexities of ensuring their legacy is passed down successfully? Our work at Ma’an begins with clarity. We bring families together to understand what legacy truly means to them beyond ownership and valuation. For most first-generation entrepreneurs, the business is their identity. So we help them separate emotional attachment from strategic planning without losing either.
We create frameworks that allow founders and their heirs to discuss everything from governance to liquidity, and from succession roles to shareholder protection. It’s never about telling them what to do; it's about facilitating a process where they themselves arrive at their own unique solutions. For instance, when families own multiple entities, we help them design continuity plans through structured financial solutions that account for valuation, liquidity, and tax implications. The goal is to preserve both the business and the relationships that sustain it.
How have recent changes in inheritance laws in the UAE impacted legacy planning for families, especially those with international connections? The UAE has made remarkable progress in building legal clarity around inheritance and succession. Expat families, both non-Muslim and Muslim, now have multiple avenues to register Wills and structure estates in alignment with their home jurisdictions. For families with global footprints, these changes have been transformative. They can now align UAE assets with offshore trusts, foundations, and holding companies. That harmony between local and international structures is what gives true continuity.
International Finance | Jan-Feb 2026 | 61
BANKING AND FINANCE
IN CONVERSATION
NAZNEEN ABBAS MA’AN
We help families align their UAE structures with global ones. Our role is to make sure the entire ecosystem functions seamlessly, without conflict or duplication
What are some of the most significant legal hurdles that families in the UAE still face when planning for succession, and how can these be overcome? The main challenge is fragmentation. For instance, families can tend to have real estate under one name, corporate holdings under another, and life’s savings scattered across jurisdictions. Another hurdle is understanding how inheritance laws interact across borders. At Ma’an, we bring this coordination into one framework to ensure that every legal structure speaks to the others. It’s what prevents future conflict and ensures that the founder’s intentions hold long after they are gone.
How does Ma’an approach multi-generational wealth planning, particularly in the context of extended family structures common in the Middle East? Most established business families in the Middle East are rarely nuclear. Many come from South Asian and Southeast Asian cultures where extended families traditionally live together, and it is common to find multiple family members involved in the same enterprise. Our approach begins with acknowledging that we are not here to advise families on what to do. We act as mediators. We provide the infrastructure to bring the decision-making members of the family together around one table. From there, we work to understand the shared vision of the family, because our aim is not just to distribute wealth, but to carry forward the family’s values and intent. As we often say, clarity at the top prevents confusion at the bottom. By helping the key members articulate what the family stands for and where they want to go, we establish a foundation that guides leadership transition, participation, and continuity across generations. Ultimately, our aim is not just to redistribute wealth but also wisdom.
62 | Jan-Feb 2026 | International Finance
What are the key considerations for families with diverse branches when planning for wealth transfer in the Middle Eastern context? The more diverse the family branches, the more important the framework becomes. When several members, entities, or assets are involved across generations, the structure must be designed thoughtfully and specifically for that family. Since no two families are alike, the solutions we offer differ markedly. For some, it may be a foundation, for others, holding companies, for some, it may be well-structured Wills, and for others, family constitutions or even perpetual family banks. Every family’s needs, culture, and vision are different, so the continuity framework must reflect their unique reality. Our role is to provide the right mechanisms for the right family to ensure that their wealth, values, and governance evolve cohesively across branches and generations.
How do you ensure that the needs of children of determination are fully integrated into a family’s legacy planning strategy? This is one of the most sensitive and deeply human parts of our work. For families with children of determination, legacy planning goes beyond inheritance and ventures more into security and dignity. We design special frameworks that ensure these children are financially protected for life while maintaining their rights within the broader family structure. This may involve setting up dedicated financial solutions or trusts that safeguard long-term care, education, and medical needs. More importantly, we help parents communicate these provisions to siblings so that there’s awareness, empathy, and inclusion. The most sustainable plan is one that the whole family understands and supports.
What are some of the common misconceptions families have when planning legacies for children of determination, and how does Ma’an address these? Contrary to common assumptions, families are generally well aware of their responsibilities. They come prepared, often having already drafted Wills, appointed trustees, and documented care instructions. The real misconception lies in placing too much
WEALTH LEGACY PLANNING
burden on siblings. So we help families move beyond the basics of naming trustees or allocating responsibilities. We create detailed financial plans, often in the form of structured, recurring income streams, so that funds reach the sibling supporting the family in a timely and responsible way. This avoids the challenges of easy lump-sum access, which can be mismanaged even without bad intent, especially in emergencies.
What makes the UAE an attractive destination for international families seeking to structure their estate plans, and how does Ma’an assist them in this process? The UAE has positioned itself as one of the most progressive jurisdictions globally for estate and succession planning. The legal infrastructure provides flexibility for expat families with various solutions. In addition to the civil-law system used by UAE courts, there are internationally recognised financial free zones like DIFC and ADGM, independent jurisdictions with their own common-law frameworks, regulators, and courts. For us, it is a case of creating a bridge between intent and implementation. We help families align their UAE structures with global ones. Our role is to make sure the entire ecosystem functions seamlessly, without conflict or duplication.
What are the key cross-border challenges you encounter when dealing with international estate planning, and how can these be managed effectively?
The most common challenge is jurisdictional overlap, where assets, heirs, and governing laws exist in three or four countries. A Will valid in one jurisdiction may be contested in another, or tax treatment may vary dramatically. We manage this by building collaboration across disciplines. Our framework integrates legal, financial, and tax perspectives from the start. We make sure the framework doesn’t wait for problems to arise but has already accounted for what’s to come. The goal is to ensure every document, every Will, trust, or foundation, works as part of one living plan rather than isolated pieces.
What do you believe is the most important factor in building a successful legacy plan that truly reflects a family’s values and vision? Authenticity. A family’s legacy must mirror who they are, not what others think they should be. Too often, families replicate structures they’ve seen elsewhere without asking whether those structures reflect their own values. When we work with clients, we start by asking questions that have nothing to do with money: What principles guided your journey? What values should your name carry forward? Once those answers are clear, the structures follow naturally. A successful legacy plan is a translation of a life’s purpose into continuity. editor@ifinancemag.com
International Finance | Jan-Feb 2026 | 63
BANKING AND FINANCE
INSIGHT
PRIVATE CREDIT INVESTMENT
The combination of higher yields, bespoke terms and less oversight makes private credit very attractive
A decade of debt expansion IF CORRESPONDENT
The private credit market has grown 10-fold from 2009 to 2023. The industry added $1 trillion in the last 18 months alone. It has $3 trillion in AUM (Assets Under Management) and is one of the fastest-growing segments of the financial system over the past 15 years, according to American multinational strategy and management consulting firm McKinsey. The primary reason is the retrenchment from traditional banking that followed the 2007-2008 global financial crisis. The phenomenon led to a shift away from legacy lending, while debt markets and shadow banking took centre stage. Since then, we have seen global economic uncertainty in the form of the COVID-19 pandemic, the Russia-Ukraine war, geopolitical volatility in the Middle East and more recently, whenever United States President Donald Trump says something on social media or is in front of a camera. The reductions in workforce are not solely a result of market volatility; they are also influenced by increasing regulatory pressures. This includes proposals related to the "Basel III Endgame," which will require banks to strengthen their cap-
64 | Jan-Feb 2026 | International Finance
ital reserves across various lending sectors. Additionally, liquidity regulations are likely to reduce banks' willingness to extend longer-term loans, noted McKinsey. Sensitive to market shocks and stymied by policy, private credit has come in, with a recent EY report suggesting that "Europe accounts for roughly 30% of the private credit market." Investment in infrastructure and energy is an important driver of growth across the continent, and private credit is "likely to be a key enabler of the global green energy transition" with "estimates suggesting that between $100 trillion and $300 trillion will be needed by 2050," the EY report said. Private credit has seemingly become a staple of the financial landscape, a counter-cyclical hero in economic downturns, but what happens when private capital encounters jurisdictions with geopolitical instability, and to what extent are financial markets exposed to risks that remain invisible to them?
Private credit explosion After the global financial crisis (GFC), the collapse
INSIGHT PRIVATE CREDIT
US private credit AUM (Funds + BDCs) from 2016 to 2023
Distribution of private credit allocated worldwide by sector
2016 2017 2018 2019 2020 2021 2022 2023
IT & Business Services Healthcare Industrials Financials Consumer Discretionary Others
373.9 426.2 493.2 552.0 683.2 831.6 897.5 1022.1
22% 16% 12% 12% 6% 32% Source: CRISIL
(In Billion US Dollars) Source: Statista
and near collapse of some of the too big to fail banks served to kickstart the "Great Recession," the worst global downturn since the "Great Depression," during which millions lost their homes, their savings and their jobs. Although the economic downturn impacted private credit, the data show that historically, private equity portfolios have generally shown shallower peak-to-trough declines than the public markets, and while the banks had to curtail their exposure, the private deal-making environment rebounded in the second half of the recession, in 2009. The post-GFC environment was the first true stress test for private equity, and it barely passed. A 2019 study of private equity during the "Great Recession" outlined that despite the increase in deals, fund managers in private equity "failed to take advantage of opportunities to buy high-quality assets at steep discounts." Analysts point to three characteristics that explain why private credit grew so rapidly in the past. Unlike the banks, PE has easier access to capital and more freedom to deploy it, and as a result, PE can grow market share and assets faster during
a crisis. Active management is also the norm in most global funds, and value creation is heavily weighted. This gave funds the green light to build new capabilities and initiate transformation projects. Finally, private equity is not very liquid, which can help insulate investors from the panic selling that usually occurs in times of economic downturns, when it often brings losses of 5%-10% higher. The combination of higher yields, bespoke terms and less oversight makes private credit very attractive. While private credit has exploded over the last 15 years, the success story contains reasons for caution, most notably the illiquidity risk (the ability to get money out of an investment quickly is normally a good thing, but it can be especially helpful in a downturn). And with geopolitical instability rarely priced in adequately, cracks could develop very quickly, especially when it comes to geopolitical risks, which are particularly hard to hedge against due to the sudden and severe effects of political instability, trade disputes, war, cyberattacks, climate change and natural disasters.
International Finance | Jan-Feb 2026 | 65
BANKING AND FINANCE
INSIGHT
PRIVATE CREDIT INVESTMENT
Value of private credit assets under management worldwide from 2016 to 2023 (In Billion US Dollars)
2016 600 2017 667 2018 755 2019 683 2020 471 2021 550 2022 680 2023 700 Source: CRISIL
Just weeks before Russia invaded Ukraine, Horizon Capital, the largest private equity group in Ukraine, had launched its fourth flagship fund. Sarah de St Croix, head of private funds at law firm Stephenson Harwood, said that it was essential to have provisions in place to allow fund managers to react to geopolitical events. For example, “managers affected by a geopolitical event could lean on their common law right to force an investor to exit the fund where their continued participation violates law or regulation.” Although these clauses had not been written with specific timing in mind, funds were able to "handle the situation of having a sanctioned investor in a commingled pool after widespread sanctions against Russian individuals were imposed in 2022." The GFC came after private credit went global, and geopolitical risk was not top of mind, but Weijian Shan, executive chairman and co-founder of investment firm PAG, said that "the geopolitical risks are very real now, you used not to have to think very much about it. Now you really need to think about decoupling risks; you really need to think about restrictions to the international flow of goods, people and capital."
66 | Jan-Feb 2026 | International Finance
Resource nationalism This is a fairly hard-edged way to look at it. Still, it does come into sharper focus about sanctions risks, political instability or local capital controls that would strand foreign investments, or populist governments reneging on investor protections. Indonesia, a key global exporter of coal, palm oil, copper, gold and other minerals, produces 37% of the world’s nickel and has been pursuing a form of resource nationalism for a decade. This has overlapped with heavy demand from China, and as Dr Eve Warburton of the Australian National University explains, “over this same period, the Indonesian Government introduced increasingly nationalist policies: new divestment obligations for foreign miners, a ban on the export of raw mineral ores, stringent new local content requirements and restrictions on foreign investment in the oil and gas sector, and observers noted increasing court cases and popular mobilisation against foreign companies.” This matters given the key role nickel plays in the batteries of electric vehicles and in renewable energy storage, making Indonesia a central part of the global energy transition. If the private credit market is not to become a
INSIGHT PRIVATE CREDIT
Leading private credit funds worldwide 2023, by closed size (In Billion US Dollars)
Oaktree Opportunities Fund XII West Street Strategic Solutions Fund I Barings North American Private Loan Fund III PIMCO Corporate Opportunities Fund IV Blackstone Tactical Opportunities Fund IV Brookfield Infrastructure Debt Fund III
Value of private credit fundraising worldwide between 2019 and 2023 (In Billion US Dollars)
18.0 10.0 5.0 5.0 4.5 4.0
2019 2020 2021 2022 2023
115 175 271 203 95 Source: CRISIL
Source: CRISIL
victim of its own success, it will have to surmount some significant hurdles. Rapid growth has pushed funds into new niches, often in emerging and frontier markets where yields and risks are highest. According to the Institute for Economics and Peace, "Today geopolitical risks are higher than at any time during the Cold War due to greater military spending, stalled nuclear disarmament, and a reduction in the power of multilateral institutions such as the United Nations," and this is coupled with active wars in Ukraine and Gaza, US-China decoupling, growing political instability and polarisation, misinformation, and an increase in cross-border sanctions and capital controls. Another issue for the industry is the risk of financial contagion. As any investor who has taken on private credit knows, that means anyone who has loaded up on private credit, whether pension funds, sovereign wealth funds or insurers, has more of their capital in opaque, illiquid private deals that are more vulnerable to losses that were neither expected nor fully priced for. A crisis in the private credit market would pose a systemic threat to the wider financial system. The greater the reach of private credit funds into higher-risk jurisdictions to satisfy expecta-
tions for higher yields, the more the potential for sudden, catastrophic losses increases. Access to capital, flexibility, and the ability to go where banks will not go are the hallmarks of private credit’s success, but in an unstable world, those advantages can rapidly turn into liabilities. The next market crisis is unlikely to begin on Wall Street or in the bond markets. But it is a must in a foreign ministry, a war room, or a populist parliament. Private credit needs to be ready.
editor@ifinancemag.com
International Finance | Jan-Feb 2026 | 67
BANKING AND FINANCE
THOUGHT LEADERSHIP
WEALTH FINANCIAL PLANNING
RICKSON D'SOUZA HNWI LIFE INSURANCE SPECIALIST CONTINENTAL GROUP
Many first-generation founders built their wealth under constant pressure
Succession breaks where silence lives Wealth today is mobile in a way earlier generations could not imagine. Families build businesses in one jurisdiction, buy homes in another, and educate children in a third. Bank accounts, operating companies, and properties sit under different legal systems and tax rules. This kind of diversity in modern financial layers provides a healthy amount of resilience. But on the flipside, such a system is most exposed when control begins to change hands. Succession is often treated as a technical exercise. Families are advised on companies, foundations, trusts, shareholder agreements, and life insurance. The documents are signed and there is a sense that the plan is “done”. The real vulnerabilities lie in human dynamics, unspoken expectations, and unresolved questions of what the family is actually trying to preserve.
Survival mode and residue it leaves behind Many first-generation founders built their wealth under constant pressure. Business demands invariably came first, so emotional conversations at home were easy to postpone. That does not necessarily make anyone a poor parent, but it can leave residue on the dynamics. From that point, even well drafted structures can strain. Decisions that appear to be about strategy or valuation often carry
68 | Jan-Feb 2026 | International Finance
older emotional weight. A disagreement over governance is also a dispute about recognition. A debate about liquidity is also a conversation about trust.
Patterns that repeat across generations Parents can sometimes confuse their own unmet needs with their children’s needs. A child who wants responsibility may receive only protection. Another who needs space may feel held in place by a structure designed to “keep the family together.” Over time, frustration can turn into mistrust or a quiet determination to prove a point. Consider the splitting of a restaurant bill. When ten friends split a bill evenly, some will have eaten less or ordered modestly. Many still pay their share, but a few quietly feel that the split was unfair. Repeated often enough, that feeling hardens into resentment. Family enterprises replicate this dynamic at scale. By the time a formal transition arrives, perceptions may have already hardened.
Tools are not necessarily the starting point From a technical and structural perspective, cross-border families have many tools. We’re talking of holding structures to align assets with jurisdictions, vehicles to ring-fence wealth, agreements that separate management
from control, and life insurance to create liquidity where most wealth is locked into operating businesses or property. None of these can compensate for the absence of alignment. A structure designed to preserve capital will not satisfy heirs who believe the real objective should be independence. A governance charter will not resolve a decade of unspoken resentment about who carried the load. A cross-border life insurance policy can ease a liquidity crunch, but it cannot tell a family how to measure fairness.
The question that keeps the boat moving After years of underperformance, a British rowing team adopted a simple filter before every decision: “Does this make the boat go faster?” If the answer was yes, they did it. If the answer was no, they did not. Families need their own version of that question, while understanding that the specific answer may differ, but agreeing on one shared objective changes the conversation. Once that principle is explicit, the role of advisors and structures becomes clearer. It’s important to re-
member that governance is designed to serve a purpose, not to compensate for the lack of one. Liquidity planning supports a chosen definition of fairness instead of trying to replace it, and cross-border complexity becomes a problem of implementation rather than identity.
Rickson D'Souza, HNWI Life Insurance Specialist at Continental Group, brings nearly 25 years of experience gained through reputable companies in the UAE. He is not merely a seasoned insurance advisor, but someone with a deep and nuanced understanding of the viability of various products in the Emirates. His unique advantage also stems from the pedigree of his family’s six decades of experience in the insurance and financial services industry. Carrying the baton forward, Rickson has branched out into multiple insurance verticals while specialising in high-value solutions for leading entrepreneurs and HNWIs editor@ifinancemag.com
International Finance | Jan-Feb 2026 | 69
POTAS
Elevating aviation fuel standards POTAS Akdeniz Akaryakıt Dağıtım A.Ş. has redefined the standards of aviation fuel operations in Turkey through its forward-looking approach to infrastructure development, financial discipline, and strategic collaboration. Established in 2023 as a joint venture between ATS Antalya Akaryakıt Dağıtım A.Ş. and Petrol Ofisi A.Ş., POTAS is currently operating under a 15-year aviation-fuel storage license issued by the Energy Market Regulatory Authority (EPDK). Based at Antalya Airport, one of Turkey’s most important tourism and aviation hubs, the company serves well over 100 airlines operating to over 200 destinations. Handling nearly 39 million passengers annually, Antalya has become one of Europe’s key gateways, and POTAS is now the engine that is fuelling its growth. POTAS was recently honoured by International 70 | Jan-Feb 2026 | International Finance
Finance for being the “Best New Strategic Partnership in Fuel Storage and Supply – Türkiye 2025,” as the company continues to strengthen its position as a leading force in the aviation energy sector. While interacting with International Finance, POTAS CEO Hüseyin Hilmi Aslanoğlu said, “This award reflects the strength of our partnerships, the precision of our engineering, and the trust we have built in the global aviation community. Every decision we make is guided by responsibility to our partners, to our country, and to the future of sustainable aviation energy.” The award highlights POTAS’s successful completion of an 85,000 m³ fuel-storage investment at Antalya Airport, built in parallel with the airport’s major expansion project. The new facility replaced outdated infrastructure, creating a state-of-the-art aviation-energy hub designed to reach 150,000 m³
Business Dossier - POTAS
Hüseyin Hilmi Aslanoğlu CEO, POTAS
The scale of POTAS’ achievement and its steady capacity-building process to fulfil its vision have been visible in its operational results by 2030. Supported by a 26-kilometre underground pipeline network, the system drastically reduces tanker traffic, increases safety, and minimises environmental impact while accelerating fuel-delivery efficiency. "As part of the Antalya Airport Expansion Project, POTAS commenced operations on January 2, 2024, and aims to achieve a total aviation fuel storage capacity of 150,000 m3 within the concession period. In connection with this project, the hydrant pipeline expansion works carried out over 22 kilometres of the total 42-kilometre pipeline operated to supply fuel to aircraft in the apron area have been completed, and the system has been commissioned. With our advanced technological infrastructure, commitment to sustainability, and strong operational capacity, we continue to support Antalya Airport in its development as a world-class aviation hub," Aslanoğlu noted.
“Some areas of aviation energy leave no room for compromise. For us, safety is one of them. We invested heavily in risk mitigation because reliability defines trust. Every litre of fuel we deliver must meet international specifications, every procedure must be traceable, and every partner must be confident in our system,” the CEO added. POTAS envisions itself as the most innovative and customer-oriented leading firm in the aviation fuel industry, offering reliable, high-quality and fully sustainable solutions in line with carbon neutrality targets. Explaining things further, Aslanoğlu said, "The primary focus of our operational activities is to ensure that the procurement of Jet A-1 fuel and other inputs from local or international sources, their transfer to POTAS Antalya Air Supply Facility, and their subsequent delivery to end users is conducted in a cost-effective and timely manner, with strict adherence to international standards and legal regulations, maintaining stringent quality assurance, preserving environmental integrity, and ensuring compliance with technical safety rules." The scale of POTAS’ achievement and its steady capacity-building process to fulfil its vision have been visible in its operational results. The company can now refuel up to 600 aircraft per day, essentially one every minute, and has recently achieved a national milestone: on July 26, 2025, 606 aircraft were refuelled in a single day, delivering 6.7 million litres of jet fuel. This record-breaking day demonstrated both the reliability of the new system and the resilience of the team managing it.
Laser-eyes focus on safety
Safety lies at the heart of every step POTAS takes. The Antalya facility integrates advanced gas-detection sensors, automatic leak-prevention systems, digital monitoring architectures, and firesuppression networks developed in partnership with international experts. These were jointly tested with the Antalya Airport Fire Brigade, ensuring response precision that meets and often exceeds European Union standards. International Finance | Jan-Feb 2026 | 71
Business Dossier - POTAS
The company’s comprehensive quality-control process follows each batch of fuel from refinery production to aircraft refuelling, adhering to Defence Standard 91-09191-091 and ASTM D1655 standards and verified through routine IATA and airline audits. These efforts also resulted in POTAS earning the ISO 9001 Quality Management and ISO 45001 Occupational Health and Safety Management Systems certificates. Environmental responsibility defines the next phase of POTAS’s growth. The company has launched a zero-emission fleet programme, replacing its refuelling trucks with electric vehicles. A fleet of 25 new units already been commissioned to reduce local emissions and operational noise. Energyefficient lighting, water-reuse systems, and paperfree documentation now complement every new infrastructure project. Under Aslanoglu’s leadership, these initiatives are guided by a clear philosophy: progress through
Çağıl Koçhan, Chief Financial Officer, POTAS
72 | Jan-Feb 2026 | International Finance
responsibility. Yet progress also requires financial discipline, a domain led by the company’s Chief Financial Officer, Çağıl Koçhan, whose strategy ensures that every initiative is sustainable, measurable, and economically sound. “Our capital strategy is built on controlled growth and transparent governance. Aviation energy is a capital-intensive sector; our role is to ensure that every Turkish lira invested generates measurable value. From the Antalya facility to our digital systems, every project is designed to enhance efficiency, reduce cost per litre, and strengthen long-term returns for all partners,” Koçhan said.
POTAS’ key performing unit
Koçhan’s finance division has implemented a performance-based budgeting framework that connects operational metrics directly to financial outcomes. Through automation and predictive analytics, POTAS has reduced operational losses, improved inventory accuracy, and enhanced cost forecasting, enabling precise control of liquidity and capital flow even under volatile global fuel price conditions. “Financial discipline enables innovation. Our systems are data-driven; they let us evaluate risk in real time and optimise capital allocation without sacrificing reliability or safety. Efficiency is not only an operational term but a financial responsibility,” Koçhan added.
“Efficiency is not only an operational term but a financial responsibility” — Çağıl Koçhan
This balance between innovation and discipline has positioned POTAS as a model of integrated management. The company’s three strategic pillars, infrastructure excellence, operational innovation, and sustainable partnership, govern every decision, ensuring that expansion aligns with both safety and profitability. The results are measurable. Refuelling capacity has more than doubled since 2023, storage efficiency has increased by 40%, and automation has cut response times during peak operations by over 30%. Each figure represents a clear return on investment, proof that financial stewardship and operational excellence can advance together.
Capitalising on human resources
The human element remains central to POTAS’ recent operational successes, as the venture’s multidisciplinary team of engineers, operators, and finance professionals has built a culture grounded in accountability and continuous learning. Frequent safety drills, international audits, and staff training ensure that every employee upholds global standards of quality and transparency. “At POTAS, partnership means shared accountability for the future of aviation energy. We build relationships that endure because consistency
and reliability are as vital as technology itself. Our mission is to enable trust across every level of the aviation ecosystem,” Aslanoğlu reiterated. Looking ahead, POTAS plans to extend its proven model to other major airports in Turkey, exporting its integrated systems of infrastructure, finance, and innovation. The company is also evaluating renewable energy integration and smart data platforms that will advance its role in the global energy transition. The International Finance award reaffirms POTAS’ hard work in uniting world-class engineering with financial discipline, while promoting a culture of trust to shape the next generation of aviation-fuel infrastructure. In doing so, the company has set a new benchmark for reliability, governance, and partnership, demonstrating that true strength in aviation energy lies in a unified vision, precision of execution, and continuity of purpose. “Sustainability is both an environmental and financial imperative. Our responsibility is to maintain profitability while investing in technologies that reduce our footprint and secure the future of aviation energy. Success, for us, is measured not only in litres delivered but in value sustained,” Koçhan concluded.
International Finance | Jan-Feb 2026 | 73
ECONOMY
ANALYSIS
SUDAN INFLATION
United Nations updates since early 2025 have called Sudan the most devastating humanitarian and displacement crisis in the world
Sudan’s war on survival IF CORRESPONDENT
Sudan is crumbling under the weight of hyperinflation. In the middle of a brutal civil war and a collapsing economy, ordinary Sudanese are being buried under numbers that defy belief. The IMF (International Monetary Fund) says inflation hit nearly 177% in 2024 and could still hover around The IMF says 100% in 2025. Triple-digit inflation hit inflation again, in a country nearly 177% already brought to its knees. in 2024 and Approximately 30,000 could still people have died in the fighthover around ing, and, when accounting 100% in 2025. for starvation and disease, Triple-digit the total number of casualinflation ties exceeds 400,000. After again, in Omar al-Bashir was overa country thrown in a coup in 2019 already by the Sudan Armed Forces brought to its (SAF) and the Rapid Support knees Forces (RSF), some believed this could mark a new beginning for the nation. However, the formerly allied factions went back on their promises and began battling for power instead of working to restore civilian rule. This situation serves as a stark reminder of what can happen when political discourse breaks down, and a nation becomes fractured due to political and economic greed.
74 | Jan-Feb 2026 | International Finance
What the numbers really show The IMF’s April 2025 World Economic Outlook places Sudan’s consumer price inflation at 100% for 2025 on average, a projection that reflects the scale and persistence of price pressures. Complementing that, the IMF country page for Sudan shows consumer prices rising at triple digits, with real GDP projected to contract slightly in 2025, highlighting a stagflationary environment, which is a rare combination of high inflation, slow economic growth, and highly elevated unemployment, a squeeze that is both deep and sustained. World Bank monitoring confirms continued macro fragility, with the May 2025 “Sudan Economic Update” describing entrenched supply constraints, administrative dislocation, and conflict-driven disruptions that keep inflation elevated and unstable. A World Bank Macro Poverty Outlook note for Sudan indicates inflation decelerated to 78.4% year over year by July 2025, which is a notable moderation that still leaves households struggling as broad money growth, foreign exchange scarcity, and a persistent parallel premium feed through to prices. When factories are looted, the farms burned, the roads severed, and banks shuttered or relocated under duress, price signals stop disciplining markets and start reflecting scarcity, fear, and speculation.
What fuels inflation? How can anyone stabilise prices when the country is being torn apart by a civil war that began in April 2023 and has displaced millions, severed supply chains, and turned food, fuel, and cash into instruments of leverage? United Nations updates since early 2025 have called Sudan the most devastating humanitarian and displacement crisis in the world. The World Bank’s Sudan overview makes the connection explicit, describing how conflict has produced wide-ranging economic and social damage that constrains production, distorts logistics, and crushes livelihoods, which elevate price pressures and entrench volatility. Moreover, standard economic analysis often misses the "shadow economy" of resource theft. In Sudan, this is not a small detail. It is the primary engine of the conflict. Official reports state that Sudan produced 64 tonnes of gold in 2024. This record amount should have injected billions into the banking system. It did not. The reason is simple. Data indicates that between 50% and 80% of this gold is smuggled out of the country. Economic analysts estimate this results in a loss of up to $7 billion in annual revenue.
This massive sum bypasses the government entirely. Instead of backing the currency, the wealth flows directly to armed factions like the RSF, who control key mines in Darfur. Investigations reveal that over 90% of this gold eventually lands in the United Arab Emirates. The proceeds then return to Sudan in the form of weapons rather than food or medicine. This creates a self-sustaining "Gold-for-Guns" loop. The inflation crisis will never end while the nation's most valuable asset is used to purchase the very bullets destroying it.
Currency collapse and the price spiral Currencies are stories about credibility, and Sudan’s story has been a slow-motion implosion that turned precipitous as the war intensified. Radio Dabanga reported that the US dollar surpassed 2,100 Sudanese pounds on the parallel market by July 2024. This violent depreciation quickly translated to increased prices for imported goods and basic necessities linked to import cost structures. Further reporting captured the widening spread between official and parallel rates, with banks quoting markedly below street prices as the market premium crystallised into a daily tax on transacting outside privileged channels.
International Finance | Jan-Feb 2026 | 75
ECONOMY
ANALYSIS
SUDAN INFLATION
The World Bank’s 2025 update documents an official rate around 2,019 pounds per US dollar by March against a parallel rate near 2,679, quantifying an approximate 21% premium that distorts price discovery, encourages hoarding, and penalises the poorest who cannot arbitrage. By June 2025, Xinhua described a further slide with the dollar trading at 2,760 on the parallel market and the official rate at 2,100, which is an exchange rate anatomy that maps directly onto continued price instability. None of this is abstract because every currency gap creates space for speculation, counterfeiting, and rent extraction that show up as empty wallets and thinner meals for ordinary households. Sudan executed a dramatic exchange rate adjustment in February 2021, moving the official rate from 55 to 375 pounds per dollar as part of a push to unify rates and restore competitiveness, a necessary step that proved insufficient in the face of political upheaval and then allout conflict. Any talk of new exchange rate reforms without parallel moves on security, revenue, and banking resilience will founder on the same rocks because credibility is earned through results that people can see on shelves and in markets. That is why the IMF’s WEO snapshots matter less as forecasts to memorise and more as calls to restore the basic preconditions for price stability, starting with security, access, and institutional capacity.
76 | Jan-Feb 2026 | International Finance
Human cost of inflation The numbers tell a story of collapse, but behind them are people, millions of them. According to UN assessments in 2025, tens of millions of Sudanese now depend on aid just to survive. Entire families are on the move, fleeing violence and hunger, while basic services such as water, health, and electricity fall around them. The World Bank says poverty is surging and the economy has shrunk again, year after year. Latest data suggests that 26 million (around half the population) are starving, and the nation has more people living in famine than the rest of the world combined. There is also a 40% drop in income, and food inflation has tripled. People have no money for food, medicine, or fuel. Even if inflation slows a little by mid-2025, it is still devastating. Prices are still high. And because food, housing, and transport make up most of what people spend on, it is the poorest who bear the most. Humanitarian groups like ACAPS have been sounding the alarm for months. Food prices are spiking far above their multi-year averages. For example, the price of grains like Sorghum and millets in 2024 is 500% higher, which is six times, than in 2023. And it seems to be getting worse. Markets are fractured. Imports are stuck. Traders are being taxed by armed groups at every checkpoint. Sudanese traders are being taxed or asked for protection money by both the Sudanese Armed Forces (SAF) and the Rapid Support Forces (RSF), as well as civil authorities and local militia. The cost of transit
GDP in current prices in Sudan from 2015 to 2024 (In Billion US Dollars)
2015 2016 2017 2018 2019 2020 2021 2022 2023 2024
64.53 64.89 48.91 33.59 31.48 35.24 35.14 33.50 36.98 29.18 Source: Statista
for goods itself is appalling. For a single truck to make a return trip in South Sudan, the cost of taxes and bribes to all competing parties is about a whopping $3,000. There are reports that supply trucks pass through almost 100 checkpoints controlled by rival factions on a one-way trip. It is a human catastrophe that shows, in real time, what happens when war, misrule, and neglect destroy not only a country’s currency but its capacity to care for its people. The displacement map is also a price map because each wave of movement shifts demand toward fragile urban centres and import-dependent corridors where logistics are already elevated.
Almost 13 million people have been displaced, and 8–10 million are internally displaced. It means that they have fled their homes but are still in Sudan. The rest have fled to Chad, Egypt, South Sudan, and Ethiopia. In that environment, the line between profiteering and survival blurs, and public authority’s absence invites every private tax imaginable, each one manifested in the final price paid in cash or in kind. Inflation erodes purchasing power, social cohesion, trust in institutions, and the perceived fairness of the economic game, which, in turn, depresses participation and investment.
A broken banking system If conflict is the match, policy failure is the kindling, and fiscal dominance is the wind that keeps the blaze alive. Sudan’s central bank has not operated with full independence in years, subordinated to urgent fiscal needs that have encouraged money creation and administrative con-
trols rather than credible anchors and transparent rule-making. The World Bank’s country work points to disrupted cash replacement, mobile money curbs, and administrative interventions that respond to immediate pressures but often add frictions that widen parallel gaps and degrade confidence. Banking infrastructure has been looted, relocated, or shuttered across key corridors, with more than half the system at times effectively disabled, which means intermediation is impaired and the transmission of policy signals is weak to non-existent. When broad money grows 29% in six months, as the World Bank notes for early 2025, in a context of supply destruction and FX scarcity, the predictable result is persistent inflation, even if the monthly path wobbles with seasonal harvests and sporadic aid. There is an irony here that should not be lost on anyone. The more the state leans on the banking
system to absorb shocks it cannot price, the more fragile and politicised that system becomes, and the less able it is to perform the basic tasks of payments, savings, and credit without distortion. There is no visible horizon for the conflict, and the Sudanese people are experiencing one of the worst economic crises of our times, comparable to the people of Palestine, Yemen, and Ukraine. Humanitarian access must expand quickly as an inflation management tool that floods famine-threatened regions with food and health services, breaks speculative hoarding, and normalises logistics so that price expectations can reset. Diplomatic leverage must prioritise a ceasefire that enables corridors and markets to function safely because every day of war deepens scarcity and every week of scarcity hardens inflation expectations.
editor@ifinancemag.com
International Finance | Jan-Feb 2026 | 77
ECONOMY
FEATURE CONGO
GOLD RWANDA
Rwanda holds disproportionate global market shares in key Congolese minerals
Eastern Congo’s
stolen future IF CORRESPONDENT
T
he decades-long catastrophe unfolding in the eastern Democratic Republic of Congo is a crime of calculated policy, a geopolitical masterclass in profit-driven plunder, sustained by neighbouring state actors who have perfected the art of weaponising proximity. Why must we accept the premise that a nation so unbelievably rich in gold, coltan, and tungsten, a nation that should be an economic powerhouse, is instead condemned to perpetual, bloody volatility? Tell me why, when the answer is staring us directly in the face, who profits? The chaos you observe in Eastern DRC is manufactured, financed, and a guaranteed revenue stream for the powerful patrons operating just across the border, using their immediate geographical advantage as an economic tool. Look at the resurgence of the March 23 Movement, the M23, a powerful armed group whose very origins are rooted in the devastating aftermath of the 1990s Rwandan genocide, confirming that this cycle of conflict is deep, historical, and externally driven. The M23 claims to fight against systemic discrimination of ethnic Tutsis, a convenient political
78 | Jan-Feb 2026 | International Finance
FEATURE CONGO
International Finance | Jan-Feb 2026 | 79
ECONOMY
FEATURE CONGO
GOLD RWANDA
fiction designed to provide cover for their true, brutal objective, the military and economic control over the vast mineral wealth of North Kivu. Their security claims are merely a shield, a flimsy pretext for securing lucrative, unregulated artisanal mining sectors, ensuring that external patrons can deny responsibility while the resource drain continues unabated. The M23's latest offensive is the most damning evidence of their capabilities and their explicit state-level backing. This was a sophisticated military campaign culminating in the seizure of Goma, the provincial capital of North Kivu, in January 2025, a decisive military and logistical victory. Immediately after the conquest, the M23 plunged hundreds of thousands of civilians into chaos, creating a humanitarian siege by severely restricting crucial aid access and consolidating territorial control through sheer terror. This pattern is clear: M23 advances directly correlate with spikes in resource extraction and export by neighbouring states, proving that state policy is deliberately designed to maintain chaos just across the border, creating a vast, lawless, and profitable extraction zone disguised as a conflict zone, a war sustained by calculated, cold-blooded design.
Who truly arms the proxy How can we continue to describe the M23 as a local rebel force operating independently or on scraps of local funding? It is an absurdity. How can a decentralised militia repeatedly defeat a national army, capture strategic cities like Goma, and even push towards Bukavu, utilising military tactics and resources only available to a sovereign state? The answer is laid bare in the explicit and ab-
80 | Jan-Feb 2026 | International Finance
solutely damning findings of the United Nations Group of Experts. The evidence presented by the United Nations (UN) is conclusive, it is undeniable, and an indictment. As far back as December 2022, the UN Group of Experts provided clear, verifiable evidence that a neighbouring state, specifically naming the Rwandan Defence Force, provided material, operational, and logistical support to the March 23 Movement. This is a documented indictment of state sponsorship of an armed group involved in systematic atrocities, representing a serious violation of international law and the sovereignty of the DRC, is it not? The final 2024 report of the Group of Experts, S/2024/432, confirmed the profound and continuing external involvement, noting the unauthorised presence of external forces operating in the Eastern DRC in a manner inconsistent with the sovereignty and territorial integrity of the DRC. The most crucial, most strategically significant detail confirming this state-level involvement is the documented deployment of sophisticated weaponry, including surface-to-air missiles, by this neighbouring state, alongside occurrences of GPS jamming and spoofing activities. It confirms only one thing: the M23 is acting as a fully integrated, heavily armed proxy force, directly challenging DRC sovereignty and escalating the conflict far beyond traditional guerrilla warfare. This is a professionalised, state-sponsored military project, where the M23 is used as a shield to test advanced military doctrines and technologies, all while the sponsoring state denies direct involvement to avoid international sanctions and accountability.
Despite these explicit UN findings detailing state sponsorship, the deployment of SAMs, and sovereignty violation, effective international sanctions targeting the sponsoring state have been conspicuously absent, sending a clear, criminal signal that the financial benefits of the war economy currently outweigh the political will to enforce accountability. What an outrage.
How conflict minerals escape The core motivation for sustaining this violence is simple: it is rapacious, it is entirely about resources. Eastern DRC holds some of the world’s most extensive deposits of critical raw materials, minerals essential to global electronics and high-end consumer markets, including gold and the so-called 3Ts, Cassiterite, Coltan, and Wolframite, the sources of tin, tantalum, and tungsten. These minerals move through sup-
FEATURE CONGO
ply chains that are intentionally opaque, beginning in isolated artisanal mines and ending up in your smartphones, your medical devices, and your aircraft components, illustrating the direct, bloody connection between Congolese suffering and global consumption. The structure of this resource extraction maximises profit while minimising local benefit. The majority of mining in Eastern DRC is artisanal, conducted with minimal mechanisation, existing either in a legal grey area or entirely outside government control. This extra-legal status is fundamentally critical because it leaves the miners, who have no recourse to legitimate government protection, completely open to ruthless exploitation by armed groups. The M23 and other militias enforce systemic exploitation and what the UN refers to as modern slavery, subjecting miners, including children, to inhu-
mane working conditions to secure their revenue streams, the hidden human cost of your digital life. Once extracted, these resources, which include gold generating millions of dollars yearly for armed groups, are immediately moved through local sales agents, negociants, and trading houses, comptoirs. This is the moment of laundering, the critical juncture where the Congolese blood mineral is washed clean by being deliberately blended with minerals sourced from other, supposedly conflict-free sources. Neighbouring countries, including Rwanda, Uganda, Burundi, and Tanzania, play a significant and necessary role in these routes, acting as jurisdictional laundering hubs, providing the final, sanitised export receipt. Groups like the FDLR and other armed factions obtain millions of dollars yearly from gold alone, gold that is
immediately trafficked through neighbouring countries like Uganda and Burundi. The M23, leveraging its state backing, taps directly into this immense resource drain, ensuring its substantial war chest remains perpetually full regardless of international outcry. Resource extraction and re-export constitute a core, illicit component of the economic policy of M23's patrons, designed to capture and monetise Congolese wealth under the convenient cover of legitimate commodity trading. Despite international mandates like the "US Dodd-Frank Act" requiring due diligence for these minerals, the system is demonstrably porous and totally ineffective, allowing countries with advanced processing capacity, like Rwanda with its gold refinery, to act as essential hubs, meaning global consumers are unwittingly subsidising the M23’s campaign of terror. Is that not a sickening reality?
Statistical proof of fraud If the political pronouncements of neighbouring capitals are built on systematic denials, then the trade statistics are the hard, quantifiable evidence of their deep economic deception. We must confront the trade figures directly. How, we must ask, do countries with relatively small-scale domestic mining operations suddenly become disproportionate global exporters of high-value Congolese minerals? The data consistently reveals an undeniable economic fraud, a "Great Mineral Mirage" constructed solely to mask massive resource theft from the DRC. Look at the stark contradiction evident in Rwanda’s coltan exports. Coltan is essential for capacitors in mobile devices, and its trade is subject to international scrutiny. Since 2022, the
International Finance | Jan-Feb 2026 | 81
ECONOMY
FEATURE CONGO
GOLD RWANDA
Largest gold mines in Africa as of 2022, by production volume (In 1,000 Ounces) precise period that coincides with the M23’s latest, most destructive offensive, Rwanda’s coltan exports have increased sharply, yet its domestic tantalum production has demonstrably stagnated, an impossible economic feat without illicit imports. This is a statistical confession, mirroring patterns from the 1990s when Rwandan forces controlled much of the DRC, and Rwanda became a leading coltan exporter despite mining none of the mineral themselves at the time. The M23 provides the military mechanism, and Kigali provides the legally sanitised export documentation. The gold trade offers an even more egregious statistical disparity that quantifies the sheer scale of the theft. Rwanda exported an enormous $555.7 million in gold in 2022. Contrast this enormous sum with the official bilateral trade figures from the DRC, which show that it exported only $3.5 million in gold to Uganda in 2023. This massive, hundreds of millions of dollars gap in highly liquid, untraceable wealth demonstrates conclusively that the vast majority of Congolese gold, forcibly extracted by armed groups, is being illegally funnelled directly into neighbouring states' official export ledgers. Rwanda also holds disproportionate global market shares in other key Congolese minerals, reporting 31% of total global tungsten exports and 14% of total tin exports in 2022, confirming Rwanda’s role as the primary consolidation and re-export hub for 3Ts forcibly sourced from the DRC. The figures confirming the reliance on laundered resources are indisputable.
The toll of unchecked violence We have established the financial incentives and the geopolitical machi-
82 | Jan-Feb 2026 | International Finance
Kibali, DRC Loulo Gounkoto, Mali Fekola, Mali Ahafo, Ghana Tasiast, Mauritania Tarkwa, Ghana Geita, Tanzania Essakane, Burkina Faso Sukari, Egypt Akyem, Ghana nations fuelling this conflict, but we must never, ever allow the statistics of trade to overshadow the staggering human price paid for every illicit ounce of gold and every illicit shipment of coltan that leaves the Congo. This is an escalating human rights catastrophe, where the M23’s advances translate directly into mass death, displacement, and systematic terror, confirmed by the evidence. The humanitarian landscape in Eastern DRC was already dire, with over 21 million people requiring humanitarian aid, one of the highest figures worldwide. The M23’s renewed offensive has exacerbated this crisis to unimaginable levels. Between January and February 2025 alone, the M23’s expansion displaced over 1.15 million individuals across North and South Kivu. Critically, 660,513 of these were people who had already been displaced, confirming that the M23 specifically targets vulnerable populations to maximise territorial clearance and control. Approximately one million people have been forced to seek refuge in neighbour-
750 684 599 574 539 532 521 480 441 420
Source: Statista
ing countries, an entire population dispossessed. The M23’s method of conquest involves war crimes and atrocities utilised as a systematic tool of control, not accidental collateral damage. Reports from Amnesty International and Human Rights Watch confirm summary executions, arbitrary killings, and the widespread use of gender-based violence, constituting war crimes and potentially crimes against humanity. In Goma, following the January 2025 occupation, Human Rights Watch documented the summary execution of at least 21 civilians in the Kasika neighbourhood, emphasising that these were deliberate acts carried out to solidify control through sheer terror. Witnesses recounted M23 fighters going house-tohouse, summarily killing every adult male they found and subjecting scores of women to rape, heinous, unspeakable crimes. The deliberate targeting of infrastructure and aid demonstrates the clear intent to maximise civilian suffering and create a humanitarian siege. Humani-
FEATURE CONGO
tarian infrastructure and warehouses have been systematically looted, severely compromising the necessary humanitarian response, with large quantities of food, medicine, and essential medical supplies lost in targeted attacks on UN agencies and non-governmental organisations. With the Goma airport closed and most roads connecting the city inaccessible due to M23 restrictions, the control exerted by the proxy force effectively isolates vulnerable populations, weaponising hunger and disease to drive displacement and secure unpopulated mineral zones. It is monstrous.
Global accountability is essential The narrative is now undeniably clear. The evidence, presented by the United Nations and confirmed by trade statistics, is overwhelming. The M23 conflict is a sophisticated, self-funding economic enterprise, a cycle of violence deliberately orchestrated by state patrons and fuelled by the illicit profits of gold and coltan. We have seen the UN indictments, we have seen the quantifiable
statistical anomalies, and we have documented the devastating human cost, so why, why does the world remain silent? It is a question of profound moral failure. The international paralysis is fundamentally geopolitical, driven by the very interests that profit from the conflict. Regional diplomatic efforts intended to broker peace, such as the Luanda and Nairobi processes, have repeatedly collapsed under the weight of vested interests and profound mistrust between Kinshasa and the neighbouring capitals. When the DRC government insisted that the Luanda Process remain strictly between sovereign states, refusing to commit to dialogue with the M23, the sponsoring state effectively cancelled a scheduled peace agreement, demonstrating that the proxy force itself is utilised as the central obstruction to a durable peace, a cynical display of power. The failure of regional mechanisms, coupled with the lack of decisive international action following the UN’s explicit findings of external state support and the deployment of sophisticated
weaponry, creates an environment of absolute, total impunity. The operational nexus of the war economy is undeniable. External state support enables M23 operations, which secures artisanal mines through systematic terror, which funds the armed groups, which funnels resources through neighbouring export hubs, and this entire, horrific cycle is successfully shielded by global diplomatic inertia. How can we stand for this? The current system of supply chain due diligence, designed to prevent conflict mineral trade, has failed spectacularly, demonstrably. What more proof do we need? We must recognise that until the financial lifeline of the M23 is severed, the violence will continue unabated. Therefore, the international community has a profound moral and legal obligation to act decisively, to stop hiding behind process, and to impose targeted accountability. This requires immediate, verifiable sanctions targeting the specific corporate entities, the trading houses, and the smelters operating in neighbouring states that participate in mineral blending and laundering. We must move beyond the abstract notion of "conflict minerals" to target the concrete financial structures that monetise the violence, directly targeting the estimated millions of dollars yearly that bankroll this war. The world must starve the war economy, impose rigorous accountability upon the state patrons who enable it, and demand that the flow of blood minerals stops funding the conflict that continues to condemn one of the world's richest nations to absolute poverty and ceaseless violence. We must break this cycle, or we will remain eternally complicit in the crime. editor@ifinancemag.com
International Finance | Jan-Feb 2026 | 83
ECONOMY
FEATURE CHINA
TRADE WAR UNITED STATES
84 | Jan-Feb 2026 | International Finance
FEATURE CHINA
China weaponised the benefits of global integration to strengthen its state apparatus and industrial planning
IF CORRESPONDENT
T
he current situation is a definitive political
China's defiance exposes US failures
surrender, a tactical retreat by the world’s self-
proclaimed superpower, the United States. After years of aggressive tariff deployment and diplomatic posturing, Washington has formally conceded that its primary objective, forcing Beijing to undertake fundamental structural economic reform, is simply unattainable. The ultimate goal of the trade war, changing the ideological basis of China’s economy, has become a lost cause, a monumental failure. The recent defeat is reflected in the significant decline of US diplomatic expectations. Wendy Cutler, a former US trade negotiator, confirmed to the Wall Street Journal that current trade negotiations have entirely set aside structural matters.
International Finance | Jan-Feb 2026 | 85
ECONOMY
FEATURE CHINA
TRADE WAR UNITED STATES
The objective is no longer advancing the relationship through fundamental change but achieving mere de-escalation and stability. Uncle Sam’s strategy has devolved from demanding systemic change, such as forcing a shift to domestic consumption or ending industrial subsidies, to simply managing crisis stability, confirming that years of tariff warfare yielded nothing but tactical adjustments and an exhausted diplomatic corps. The US trade war's unintended primary achievement was proving that China could withstand external economic pressure. By lowering expectations from achieving profound structural reform to settling for simple relationship stabilisation, the United States has signalled to Beijing that its state-led economic model, driven by the Chinese Communist Party, is unassailable. This undermines the US’ credibility in future negotiations globally, a geopolitical price that far outweighs any temporary trade concessions. The US deployed its greatest economic weapon, access to its immense market, to demand change. When Beijing retaliated by weaponising its dominance over rare-earth metals and disrupting the US’ agricultural sector, the cost of sustained friction became politically prohibitive for the American system, forcing this abandonment of structural goals. This tactical surrender is a direct, quantifiable measure of the effectiveness of China’s counter-coercion tactics. The decades-long faith in engagement, pursued through successive US administrations, was a profound political delusion, an act of intellectual self-comforting that ignored the clear warning signs. The historical premise of this policy rested on the belief that drawing China into the global trading system, notably through its accession to the World Trade
86 | Jan-Feb 2026 | International Finance
Organisation in 2001, would inevitably lead to political liberalisation. That hope has been comprehensively dashed. The ensuing decades saw not political openness, but the reverse. Chinese leader Xi Jinping, who consolidated power in 2012, has systematically tightened his control over the domestic political system and civil society more broadly. This failure was inherently ensured by Beijing’s rigid political identity. Evidence suggests that the Chinese Communist Party fundamentally rejects the idea that the rule of law should take precedence over the Party’s leadership role in governing the state. This stance creates significant obstacles to any transition toward a true, open market economy. Furthermore, the failure of engagement was significantly exacerbated by the failure of global enforcement. The US and the international community failed to utilise the tools available under the WTO to hold China rigorously accountable for its commitments, providing Beijing the space to pivot sharply toward a state-centric, CCP-run economy. This political tragedy confirms that the US supported China's entry on terms that proved wholly ineffective in securing Beijing’s embrace of an open, market-oriented trade regime. China weaponised the benefits of global integration to strengthen its state apparatus and industrial planning. The policy of engagement was a Trojan horse that ceded geopolitical advantage and accelerated CCP power.
Collapse of tariff warfare The Donald Trump administration, armed with tariffs and rhetorical fury, thought its economic might could intimidate history and force a fundamental shift in Beijing’s economic DNA. They were tragically, predictably wrong. The flawed strategy sought to move China away from
what was correctly identified as a mercantilist policy of subsidised manufacturing and export focus. The mechanism was based purely on market mechanics, imagining that tariffs would squeeze exports and compel Beijing to initiate painful social reforms, specifically overhauling health and social welfare systems, which would allow China’s 1.4 billion consumers to spend more and save less. The idea was that by pressuring exports, China would be forced to find new sources of growth at home, boosting global consumption and shrink-
FEATURE CHINA
ing its massive trade surplus. This strategy failed catastrophically because it entirely ignored China's ideological commitment to its state model. Oliver Melton, a director at Rhodium Group, states plainly that Washington has very little ability to influence China’s macroeconomic strategy because the two nations hold fundamentally different ideological understandings of what drives economic growth and development. China’s commitment to manufacturing and industrial production as the wellspring of national prosperity is abso-
lute. Beijing viewed the trade war not as a simple economic negotiation over market access, but as a severe test of national will and security. The failure of tariffs to achieve structural change confirms that Beijing is willing to absorb immense short-term economic pain and dislocation to defend its foundational industrial state model, a resolve the US completely underestimated.
Why Beijing refuses to spend The weak level of household consump-
tion in China is a deliberate political choice essential for funding the industrial state apparatus. Analysis confirms that China’s long-term economic stability absolutely requires a transition to household consumption as its investment-led model yields diminishing returns. Even some Chinese officials grudgingly acknowledge that the country’s consumption is far too weak and express a desire for some rebalancing. However, the necessary structural reforms are gargantuan, requiring a fiscal overhaul that Beijing views as politically unacceptable. Meaningfully boosting consumption requires structural reforms to address issues like the rural-urban divide, the precarious position of migrant workers, and the deep misallocation of capital currently controlled by stateowned enterprises and banks. The total fiscal resources required to fund social infrastructure, public services, and ongoing social transfers needed for a durable shift would amount to tens of trillions of RMB, approximately 30% of China’s GDP. Such a massive fiscal commitment is an existential threat to the powerful nexus of state-owned enterprises, local governments, and central planners that currently control the flow of capital. The efforts seen so far have been piecemeal, stymied by ideological attachment to industrial production and wariness of politically painful reforms in taxation, healthcare, and social welfare. For Xi Jinping and the Chinese Communist Party, redistributing 30% of the nation’s capital to the populace to boost consumption is perceived as an act of weakness that would destabilise the existing political system and threaten the Party’s command over the economy, hence the resolute refusal to change the growth model.
International Finance | Jan-Feb 2026 | 87
ECONOMY
FEATURE CHINA
TRADE WAR UNITED STATES
Beijing’s response to the American tariff assault was immediate, disciplined, and ruthlessly strategic, a calibrated move that forced the United States onto the defensive and rapidly exposed the limitations of American economic coercion. Rather than capitulating, Beijing retaliated with stiff countermeasures, using its leverage over critical supply chains and strategically targeting politically sensitive US sectors, such as halting purchases of soybeans to punish America’s agricultural ecosystem. This counter-coercion was built upon decades of deliberate industrial policy aimed at securing dominance in strategic materials. China weaponised its near-monopoly position on rare-earth elements, critical minerals essential for defence, electric vehicles, advanced semiconductors, and green energy technology. China established its leverage through decades of concerted industrial policy and now accounts for approximately 91% of global rare-earth refining. When the trade war heated up, Beijing imposed stringent export controls on these critical materials, establishing an economic weapon that allows it to inflict targeted pain directly on American companies reliant on these inputs. The American assumption that high tariffs alone would secure surrender proved far less damaging than China’s targeted, chokepoint-based retaliation, cementing China as an economic peer rival capable of defying the world's longstanding superpower. The systematic failure of the United States to achieve its stated goals is laid bare by key economic metrics, which confirm the persistence of China's export-driven imbalance and the scale of the necessary, yet politically impossible, consumption reforms.
88 | Jan-Feb 2026 | International Finance
Xi’s chokepoint strategy Henry Farrell, a professor of international affairs, argues that the trade war taught Xi Jinping the necessity of reducing reliance on the United States in critical areas such as semiconductors, confirming that Washington's pressure was entirely counterproductive. In response, Beijing strategically hardened its system. China systematically identified perceived “chokepoints,” sectors where it was reliant on foreign inputs, and launched a determined, whole-of-nation strategy to achieve self-sufficiency, rapidly building up domestic industries, developing alternative sources for inputs, and carefully husbanding its strengths. The ultimate geopolitical goal articulated by this strategy is not improved trade balance, but political autonomy. Beijing seeks to maximise its freedom to pursue its own national interests without the United States being capable of determining its destiny through technological or economic coercion. This shift elevates industrial policy from a matter of economic efficiency to a core mandate of national security and geopolitical warfare. Beijing’s official policy response to American pressure, the “Dual Circulation Strategy,” is a fortress doctrine designed for resilience and siege, not for peace or global integration. The blueprint for China’s future was made clear in its latest five-year plan, which confirmed Beijing’s absolute intention to double down on this path. The plan reemphasised its commitment to technological self-sufficiency, pledging to pour more investment into advanced manufacturing and boosting exports. The “Dual Circulation Strategy” aims to insulate the domestic market from external shocks by vertically integrating production and eliminating bottlenecks in technology and natural resources. This
Volume of United States imports of trade goods from China from 2015 to 2024 (In Billion US Dollars)
2015
483.20
2016
462.42
2017
505.17
2018
538.51
2019
449.11
2020
432.55
2021
504.29
2022
536.31
2023
427.23
2024
438.95 Source: Statista
involves focusing heavily on the internal market while leveraging the "Belt and Road Initiative" to secure reliable external demand and open markets in the emerging world. This inward pivot, born from the pressures of the trade war, is a powerful dual threat to the global economy. By aggressively seeking self-sufficiency in high-end inputs, China deliberately cuts off major high-tech exporters like the United States, Japan, and Germany. Simultaneously, the external circulation component ensures China will use its growing geopolitical reach to export its industrial overcapacity and deflationary pressures globally, creat-
FEATURE CHINA
ing new and pervasive structural trade friction worldwide.
China’s industrial backbone While Washington obsessed over tariffs and finished goods, Beijing executed a strategic masterstroke by weaving itself so deeply into the core machinery of global production that true decoupling became an impossibility. China has strategically shifted its focus from being merely the final assembler of finished products to dominating intermediate goods and core components. Dinny McMahon, head of markets research at Trivium China, told the Wall Street Journal that the consequence
is pervasive; virtually any manufactured goods purchased globally, no matter origin, now carries some exposure to Chinese supply chains. This dominance is structural and non-replicable in the short term. China holds dominant positions in multiple critical electronic products and raw materials. Mainland China hosts over 50% of global manufacturing for Printed Circuit Boards (PCBs), the fundamental backbone of all electronics. Furthermore, China’s chemical industry alone contributes over 40% of global chemical production, a critical input for countless industrial processes. Experts confirm that relocating final assembly processes is relatively straight-
forward, but the real obstacle, the "difficult middle stages," lies in replicating China's established infrastructure and expertise in complex component production, such as metal moulding and speciality chemicals. The US strategy fundamentally failed to comprehend that the centre of global manufacturing gravity had moved. China has successfully forced the world into a state of strategic interdependence where Beijing holds the most essential chokepoints, allowing it to overcome decoupling efforts and export restrictions by leveraging its deep local supply chains. China is suffering from domestic economic malaise and is actively weaponis-
International Finance | Jan-Feb 2026 | 89
ECONOMY
FEATURE CHINA
TRADE WAR UNITED STATES
ing its internal crisis, exporting deflation and systemic instability to the world. The rampant, state-subsidised production in China continues to far outstrip weak domestic consumption, leading to menacing domestic deflationary pressures. China is an exceptional case, the first G20 economy to report a year-on-year decline in consumer prices since August 2021. This crisis is now a global problem. China’s export prices are collapsing, pushing inflation rates down globally. Between April and December 2023, Chinese export prices fell by 6%. Crucially, prices for machinery and electrical equipment, inputs essential for Western industry and technology, dropped 8.4%. This overproduction, particularly in sectors like steel, aluminium, and advanced clean energy technology, is now flooding global markets and aggressively suppressing prices. The systematic undercutting of global prices in key strategic future industries, such as electric vehicles and solar panels, is an effective extension of China’s mercantilist industrial policy. This forces foreign firms into unhealthy, unsustainable competition, capturing global market share by systematically destroying the profitability of rival industries in advanced economies. This is economic warfare waged with weaponised low prices, supported by state funding, subsidies, and cheap financing. Perhaps the most profound moral indictment of China’s rigid, export-focused system is its detrimental effect on the development pathways of poorer nations. Eswar Prasad, a professor of trade policy, notes that China's ballooning goods surplus and resolute refusal to rebalance its model actively stifles manufacturing in other countries. This specifically targets poorer economies trying to nurture a domestic factory sector, as China refuses to cede significant
90 | Jan-Feb 2026 | International Finance
ground in lower-value manufacturing, even as it achieves dominance in high-value goods like aircraft and chips. The historical promise that China's rise up the value chain would create growing markets for labour-intensive manufactured goods from other emerging markets has been systematically dashed. Developing economies are being crowded out of manufacturing by Chinese overcapacity, blocking their essential path up the value chain. China increasingly competes headon with these nations in the low-tech and mid-tech space. The consequence is a Global South dilemma, where China remains primarily a source of supply, not a reliable source of demand, creating profound structural imbalances and mounting trade friction even with its supposed developing partners. Beijing must
undertake aggressive reforms, including allowing the renminbi to strengthen and boosting imports, to ease the intense pressures these trade flows are creating. The trade war was doomed before the first tariff was levied because Washington and Beijing are locked in a conflict between two mutually exclusive economic ideologies. The US insists on painful reforms toward consumption-led growth, but Beijing’s leadership reemphasises its absolute commitment to industry-led technological self-sufficiency and boosting exports. This is the unmovable object meeting the unstoppable force. The structural reality is clear: without aggressive, politically traumatic reforms to restructure the economy, China’s growth trajectory will inevitably slow while trade friction with every trade partner, both in the North and the South, will
FEATURE CHINA
Developing economies are being crowded out of manufacturing by Chinese overcapacity, blocking their essential path up the value chain
increase dramatically. The world must now prepare for a future defined by China’s chronic structural imbalances, a reality created by the failure of the United States to understand the ideological foundations of its rival. The quantitative evidence for China’s systematic export of its industrial surplus and deflationary pressure is overwhelming.
Necessity of a new strategy The US trade war achieved nothing of its stated goals, confirming only the profound political and ideological resilience of China. The American effort resulted in the confirmation of China’s resolve, cementing its status as an unyielding peer rival fully capable of determining its own destiny. Uncle Sam’s objective was inverted. Washington now accepts tactical de-es-
calation, having squandered years on a flawed, unilateral campaign that only taught Beijing how to harden its system and solidified its commitment to industry-led growth. The comprehensive failure of unilateral American tariffs against a centrally controlled, cohesive state apparatus demands a multilateral reckoning. The only viable path forward in response to China’s entrenched industrial model and its resulting weaponised deflation requires coordinated, unified action. This unified front must encompass Europe, Japan, and other critical partners globally. The strategy should go beyond simply applying tariffs. It must focus on systematically neutralising China’s leverage at critical points, countering the systemic instability caused by its enforced overcapacity, and offering alternative development
paths for emerging economies that are currently being overwhelmed by Chinese overproduction. This is the final verdict on the grand delusion, the profound political naivete that defined decades of US-China engagement. The geopolitical tragedy is that China leveraged that era of hope to construct a state fully immune to American economic coercion. The trade war showed Xi Jinping how essential it is for China to reduce reliance on the US and develop economic weapons to strike back. China, having successfully defied the world’s superpower on the matter of structural reform, now moves forward along an unchangeable path of technological autonomy and industrial dominance. The world must now adapt to China’s reality, a geopolitical shift that ensures escalating global friction and will redefine the structure of the 21st-century economy.
editor@ifinancemag.com
International Finance | Jan-Feb 2026 | 91
Business Dossier - Profuturo
Arturo García Profuturo CEO
Profuturo
A leader in Mexico's retirement services Financial education is one of the pillars of Profuturo’s institutional strategy
92 | Jan-Feb 2026 | International Finance
W
ith 28 years of experience in the market, Profuturo has solidified its position as a frontrunner in pension fund management, earning recognition as the "Best Pension Fund Manager in Mexico for 2025" and "Best Afore Provider in Mexico for 2025" by International Finance. This double distinction reaffirms Profuturo's leadership in the retirement services industry, highlighting its commitment to the financial well-being of all Mexicans and validating its client-focused approach, constant innovation, and operational excellence. Profuturo has developed a strong value proposition by combining a long-term strategy with a culture of continuous improvement. By integrating technology, personalised consulting, and innovation, the company has enhanced its service model. Through digital platforms designed to inform and empower users, Profuturo provides tools that enable individuals to make better financial decisions from an early age. As a specialised asset manager, Profuturo allocates its clients' assets across a diverse portfolio to achieve sustainable long-term returns. This strategy takes into account various financial stress scenarios and periods of high volatility. It is backed by one of the largest investment teams in the industry, known for its technical expertise and dedication to prudent and responsible asset management. Through this strategy, the company has
achieved the highest returns in the industry for over eight consecutive years, strengthening its status as a leading company and demonstrating why millions of Mexicans trust this organisation. Profuturo’s recognition as the Best Afore in Mexico also demonstrates the consistency and discipline with which the company has managed the resources of millions of Mexicans, maintaining outstanding performance even under challenging financial conditions. The combination of a long-term strategic vision, robust investment processes, and a longstanding commitment to transparency has allowed Profuturo to establish itself as a trusted and solid benchmark in the retirement services industry. One of Profuturo’s main strengths is its ability to offer differentiated experiences based on each client’s life stage. The company’s multigenerational approach allows it to adapt to the unique needs of children, youth, adults, and seniors, supporting them with useful content, timely advice, and clear language at every stage of their lives. In addition to its client-centred vision, Profuturo has set itself apart through its commitment to social responsibility. Over the years, the company has promoted initiatives focused on financial inclusion, gender equality, and early financial education. This comprehensive vision has created both economic value and measurable social impact. Financial education is one of the pillars of Profuturo’s institutional strategy. With a robust offering of digital content, interactive programmes, and its presence in specialised forums, this organisation seeks to strengthen Mexicans’ financial knowledge so they can make informed decisions and achieve
a better quality of life in the future. In this context, Profuturo’s participation in key events such as National Financial Literacy Week and Global Money Week has been instrumental in reaching new audiences and generating a wider conversation about savings and retirement planning. Through engaging activities, specialised talks, and educational materials, the company has fostered a stronger culture of financial preparedness in Mexico. Innovation has been a constant feature of Profuturo’s trajectory. This award-winning organisation has modernised its customer service channels and created accessible, functional, and user-friendly platforms that respond to the needs of today’s digital environment. Profuturo’s technological vision not only seeks to facilitate processes but also to improve the customer experience in every interaction. This recognition as the Best Afore in Mexico reflects an organisational culture based on integrity, commitment, and teamwork. At the heart of this achievement are thousands of team members
who all share the same mission: safeguarding the financial future of the Mexican people through ethical and responsible actions. Profuturo understands that each person has different needs throughout their life, so it has developed a strategy that supports each client with sensitivity and clarity. Initiatives focused on older adults, women transitioning into retirement, and school-age children demonstrate the company’s commitment to building a more equitable, fair, and informed future. Through this recognition by one of the most prestigious publications in the international financial world, Profuturo has further consolidated its industry-leading role and, more importantly, strengthened the trust of those who have chosen this company as their ally in achieving the future they’ve always dreamt of. Today, Profuturo celebrates this special honour with the same conviction it embraces every day: providing the best possible service and advice so that its clients may be able to make more informed financial decisions and fully experience the future they envision.
TECHNOLOGY
ANALYSIS
DOT DOORDASH
DoorDash says Dot has been tested across millions of simulated and real-world miles
Is Dot the future of last-mile delivery? IF CORRESPONDENT DoorDash has moved its road-going delivery robot called Dot from stage to street in early access service across the Phoenix metro after unveiling it at "Dash Forward 2025," positioning a compact electric vehicle and an AI dispatcher to take on short local trips where a full-size car is overkill. The pitch is simple and provocative as Dot targets Dot is a neighbourhood distances at compact up to twenty miles per hour four-wheeled with a thirty-pound payload electric while an "Autonomous Devehicle that livery Platform" decides in DoorDash real time whether a robot, a describes as human Dasher, a sidewalk roughly onetenth the size bot, or a drone is the best of a car, built option.
to travel up to twenty miles per hour
Why this robot now?
The last mile has always been a series of last metres, and DoorDash argues that many everyday errands do not require a car, which is why Dot is designed to move through streets, bike lanes, sidewalks, and driveways rather than living only on the curb or only on the road. Phoenix and its nearby cities provide the proving ground with broad lanes, active cycling infrastructure, and a mix of suburban and urban blocks that let a small robot show it can coexist without clogging sidewalks or becoming a rolling hazard.
94 | Jan-Feb 2026 | International Finance
The company frames early access as a data gathering phase that tunes dispatch logic, improves merchant handoffs, and learns from friction in parking lots, curb cuts, and crosswalks before expanding to reach an estimated one and a half million residents in the region. That choice reflects hard lessons in autonomy where reliability at scale tends to favour orchestration over a single mode and where flexibility beats bravado in diverse neighbourhoods and rulesets. The test is not just whether a robot can drive a good route on a good day, but whether a blended system can deliver on time, keep food quality high, minimise interventions, and earn enough goodwill among pedestrians, cyclists, and drivers to share space peacefully. DoorDash’s public stance is that autonomy is additive rather than subtractive, with robots taking lightweight, predictable trips so people can focus on complex, time-sensitive, or higher-touch deliveries that still demand judgment and access skills. That hybrid approach aims to absorb demand spikes and detours by matching each order to the right agent in real time, informed by distance, traffic weight, and readiness rather than one-size-fitsall dispatch. It is a bet that the future of local logistics looks less like an all-or-nothing automation moonshot and more like a network that quietly blends people and machines to reduce cost and delay without compromising safety or access.
What Dot actually is Dot is a compact four-wheeled electric vehicle that DoorDash describes as roughly one-tenth the size of a car, built to travel up to twenty miles per hour while carrying up to thirty pounds, which is enough room for about six large pizza boxes inside a front-opening storage bay. The robot is designed to handle the transitions that often trip small sidewalk bots, including threading through driveways, crossing curb cuts without blocking traffic, and navigating parking lots to reach pickup counters rather than stalling at the edge of a plaza. Company materials highlight a six-to-eighthour battery endurance window with a swappable pack architecture to keep utilisation high during peak periods instead of tanking throughput on long charge cycles. The platform emphasises visibility and legibility at a human scale with a bright red hull and lighting that reads clearly to other road and sidewalk users, which matters when operating near strollers, wheelchairs, scooters, cyclists, and cars. Sensors and perception stacks combine cameras, radar, and lidar in configurations intended to
perceive complex urban scenes where occlusions, construction, and parked trucks often mask cross traffic and pedestrians until the last moment. The cargo area supports modular inserts such as cup holders or coolers so merchants can secure drinks and temperature-sensitive orders to reduce spills and condensation, because real-world delivery quality depends on small choices that prevent messes and go far beyond route planning. Every design choice is meant to serve a simple thesis that a slightly larger, faster, and more robust robot than a sidewalk cooler can preserve food quality by moving at neighbourhood speeds without demanding the footprint of a car. The point is to demonstrate predictability and courtesy, allowing a robot to blend into bike lanes and low-speed roads without becoming an obstacle or an irritant. This is exactly how trust is built, one quiet trip at a time.
The brains behind the wheels Dot is only as useful as the dispatcher that assigns trips, which is why DoorDash launched an "Autonomous Delivery Platform" that weighs speed, cost, location, order composition, and conditions to route an
International Finance | Jan-Feb 2026 | 95
TECHNOLOGY
ANALYSIS
DOT DOORDASH
order to a robot, a person, a sidewalk bot, or a drone. SmartScale sits on the merchant side, using AI to validate bag weights, signal readiness, and improve order accuracy so the dispatcher does not send an overweight or mispacked order to a constrained mode that cannot carry it safely. The idea is to cut idle time and avoid preventable errors, which are the small hinges that swing big doors in unit economics by reducing rework and lowering intervention rates across the fleet. DoorDash says Dot has been tested across millions of simulated and real-world miles, which reflects an industry-wide shift toward deploying learning machines with structured fallbacks rather than claiming literal full autonomy that ignores operational realities. Remote assistance and documented handoff procedures are treated as part of the system because real streets throw edge cases constantly, and the fastest way to improve perception, prediction, and planning is to keep the service live while capturing those edge cases for training. The platform’s advantage lies in more than route choice. It involves the orchestration across people and multiple types of robots, enabling each agent to handle what it does best while the system as a whole smooths surges and detours that would otherwise jam a single mode. That is why the early Phoenix footprint includes Tempe and Mesa, where Dot has already navigated bike lanes, parking lots, and sidewalks, placing real stress on the full stack from dispatch to the final
96 | Jan-Feb 2026 | International Finance
handoff at curbs and driveways. The company and press observers have stressed that safety and reliability matter more than flashy demos and that the metric to watch is not a viral video but consistent ontime deliveries with minimal friction for everyone sharing the lane.
What history says If this sounds ambitious, it is also tempered by recent history as companies with deep pockets rethought sidewalk robots when support costs and exception handling overwhelmed early optimism. Amazon scaled back its Scout programme, and FedEx shut down Roxo, illustrating that last-mile autonomy is a grind that punishes naive scaling plans and underestimates of the real-world complexity. Coverage of those decisions emphasised that robotics remains a strategic pillar at both companies even as they redirected resources away from costly field tests that did not meet near-term value requirements. The lesson is less that robots cannot deliver and more that the operational design domain matters, which is why Dot’s remit includes streets, bike lanes, and driveways rather than constraining itself to narrow sidewalks with constant obstacles. It also explains DoorDash’s hybrid posture that centres Dashers and multiple modes, because a blended network can keep service flowing when a single mode would stall due to rules, blockages, or unexpected detours. Meanwhile, Serve Robotics has shown an urban path with sidewalk
DoorDash revenue from 2017 to 2024 (In Billion US Dollars)
2017 2018 2019 2020 2021 2022 2023 2024
0.11 0.55 0.85 2.88 4.88 6.58 8.63 10.72
Source: Business of Apps
bots integrated onto platforms like Uber Eats, crossing the 1000-robot milestone and reiterating plans to reach about 2000 deployed by the end of 2025. Serve’s disclosures focus attention on the levers that decide winners in autonomy: utilisation, intervention rates, and software revenue per unit, rather than raw robot counts, which is why cutting remote assists and idle time is the boring frontier that matters most. DoorDash’s scale as the largest American food delivery marketplace could provide a data advantage if its dispatcher consistently routes robot-fit orders to bots while keeping humans on the hairier trips, improving network flow without stepping on the customer experience.
True test of success The near-term markers to watch
are pragmatic expansion pace in Phoenix, the diversity of merchants participating, and any disclosures around delivery completion times and intervention rates once the honeymoon phase gives way to the long tail of weird Tuesdays. Local rules and public sentiment will shape the path because cities are still figuring out how to regulate small delivery vehicles on sidewalks and bike lanes in ways that protect accessibility and safety for everyone sharing the space. Company materials and media coverage have underscored Dot’s ability to blend into bike lanes and low-speed roads without becoming a hazard, a design mission that must be lived on the street day after day rather than asserted on a stage. If Dot consistently expands the range of trips where a small electric self-driving vehicle is the
fastest, most affordable, and least impactful option, it will become a commonplace utility. That commonality will then be the true measure of success. If interventions stay high and public patience runs thin, the platform will fall back on Dashers for routes robots cannot handle economically at scale, and the orchestration layer will remain the product that quietly allocates work to the right hands and wheels. In the end, the case for Dot is a system shot, and Phoenix will show whether brains and form factor can outpace the city’s appetite for new edge cases while maintaining speed, safety, and goodwill. So here is the test that matters: not the demo reel but the daily grind of orders, lanes, curb cuts, and human patience that does not care about press releases. Can an AI
dispatcher keep choosing the right agent and shaving minutes without fraying nerves or spilling soup when the bike lane is blocked, and the driveway is tight? If Dot keeps interventions low and completion times tight, the economics tip from novelty to inevitability and scale follows quietly. If exceptions dominate and goodwill thins, the platform routes work back to people and redraws the robot’s map with humility. Phoenix is only chapter one, and the verdict arrives when dinner arrives hot and on time, which is the only referendum that counts.
editor@ifinancemag.com
International Finance | Jan-Feb 2026 | 97
TECHNOLOGY
THOUGHT LEADERSHIP
DEEP TECH ENERGY
ALEXANDRA VIDYUK CEO & GENERAL PARTNER BEYOND EARTH VENTURES
As global markets face heightened volatility, the investment thesis shifts toward resilience
Deep tech: The new global backbone The era of easy capital and purely digital disruption is closing. In its place, we are witnessing the rise of a new asset class defined not by viral growth, but by critical necessity: Deep tech. As global markets face heightened volatility, supply chain fragmentation, and geopolitical friction, the investment thesis for 2026 and beyond is shifting toward resilience. We are no longer just funding software that optimises existing behaviours; we are funding the physical infrastructure that will secure the future of the global economy. For institutional investors, this represents a fundamental pivot. The last decade was defined by "growth at all costs." The next decade will be defined by "resilience at any price." Deep tech—specifically the convergence of space infrastructure, advanced energy, and industrial robotics—is no longer a speculative frontier. It is the defensive backbone of the modern state and the offensive engine of future industrial productivity.
Space: The invisible infrastructure Space technology has graduated from scientific curiosity to critical utility. It is a mistake to view space as vertical; it is a horizontal enabler, an "invisible infrastructure" akin to the internet or GPS, upon which terrestrial industries now depend. We are seeing a shift from launch-focused investments to orbital utility.
98 | Jan-Feb 2026 | International Finance
The most valuable opportunities lie in "Earth-first" applications. Sovereign nations and multinational corporations are demanding independent satellite constellations for secure communications, climate monitoring, and resource management. We are moving toward a real-time, sensor-rich planetary interface. Investors who recognise space assets as the ultimate high-ground real estate—delivering proprietary data and connectivity to agriculture, logistics, and defence—will capture returns that are uncorrelated with traditional consumer market cycles.
Energy security as an asset class Energy access is now a critical issue of national security. The fragility of global energy grids has exposed a desperate need for decentralised, high-density power sources. This drives our conviction in next-generation nuclear capabilities, such as micro-reactors and radioisotope power systems, alongside breakthroughs in hydrogen and fusion. The winners in this sector will not just be those who generate power, but those who solve the "storage and mobility" paradox. We are investing in technologies that decouple energy availability from geography. Whether powering a remote data centre for AI training or a lunar outpost, the physics are the same. By backing companies that miniaturise and
ruggedise energy systems, we are effectively buying options on industrial continuity in an unstable world.
The era of physical intelligence While Large Language Models (LLMs) have dominated headlines, the true productivity revolution awaits the arrival of "Physical AI"—intelligence embodied in robotics. The industrial base is suffering from a chronic labour shortage that demographic trends will only worsen. Software cannot change the physical world; robots can. We are witnessing the transition from rigid automation to adaptive autonomy. Robots are acquiring the ability to perceive, reason, and act in unstructured environments. This is the bridge between the digital brain and the physical hand. For investors, the alpha lies in "vertical robotics"—machines purpose-built for specific, high-value workflows in manufacturing, mining, and construction. This is not about replacing humans; it is about re-industrialising economies with higher margins and anti-fragility. Deep tech is for those who understand compound-
ing and harbour those who seek generational impact, challenging the investor mindset. It requires an investor mindset that balances the rigours of physics with the realities of finance. As we look toward 2026, the question for Limited Partners is not "is it too risky?" but rather "can we afford to be excluded from the infrastructure that will run the world?" At Beyond Earth Ventures, we believe the future belongs to the builders.
Alexandra Vidyuk is a physicist-turned-investor and General Partner at Beyond Earth Ventures, a global deep tech fund. She bridges the gap between scientific breakthroughs and commercial scale, investing in dual-use technologies across space, robotics, and energy. Building on her background as a senior banker, she brings institutional rigour and strategic discipline to early-stage frontier investing editor@ifinancemag.com
International Finance | Jan-Feb 2026 | 99
TECHNOLOGY
FEATURE CREATORS
COPYRIGHT GENERATIVE AI
The ultimate psychological and financial violation faced by creators is the commodification of their unique artistic style
The fight for creative rights IF CORRESPONDENT
T
he number is stark, terrifying, and impossible to ignore. Nearly all professional creators now admit they utilise artificial intelligence tools in their daily work, a statistic that, on its surface, might appear to herald a golden age of streamlined efficiency and boundless production. Approximately 86% of 16,000 professionals worldwide surveyed by Adobe in 2025 reported actively using AI in their creative workflows. It’s no longer futuristic; it is the reality of our times. One would imagine that AI tools would free people from the difficulties of labour and prolonged work hours. However, the opposite is happening. Instead of leisure, workers around the world are met with demands for unyielding speed and inhuman productivity. We must decide whether this universal integration signifies genuine technological progress or whether it simply marks the moment human artistic labour becomes economically mandatory to execute at the pace dictated by
100 | Jan-Feb 2026 | International Finance
Silicon Valley's algorithms. There is an immense economic pressure forcing creative professionals to comply or face immediate market obsolescence. The data confirms that AI is deeply integrated into creative workflows, yet this utility must not be mistaken for ethical merit or long-term soundness. Creative professionals do see genuine, tantalising opportunities, with over half reporting that AI helps them explore new mediums and a remarkable 46% believing it helps them create higher-quality work. This is the lure, the captivating promise of instantaneous enhancement and boundless efficiency, a promise designed to mask the underlying erosion of value and independence. The current analytical view of AI’s labour impact is dangerously complacent, focusing almost exclusively on macro-economic trends while entirely ignoring the microscopic, fundamental erosion occurring at the individual creator level. Technophiles often point to recent analyses showing that the broader labour market has
FEATURE CREATORS
International Finance | Jan-Feb 2026 | 101
TECHNOLOGY
FEATURE CREATORS
COPYRIGHT GENERATIVE AI
Top drivers for Generative AI in the media and entertainment industry in 2024 (In Percentage) not experienced a discernible disruption since the public release of major generative AI systems, a finding that allegedly undercuts fears of immediate mass job losses across the entire economy. This fact is often presented as reassurance, suggesting a measured, benign adoption trajectory, yet it hides a critical, predatory truth, namely that AI first displaces value and incentive long before it ever displaces employment.
Copyright and corporate capture To understand the core immorality of the generative AI revolution, we must look no further than the fuel source that powers it, which is the massive, unprecedented datasets of human creative expression upon which these models are trained. These datasets, which developers use as a neutral shorthand for copyrighted works, are the products of millions of human lives, careers, and artistic struggles. The training process, executed often without explicit permission, licensing, or any financial compensation, represents the original, defining sin of this entire industry, effectively turning the intellectual property and life’s work of millions of artists into free, disposable energy for a burgeoning multi-trillion-dollar technological complex. The fear among creators is profoundly visceral and absolutely justified, because unlicensed training will fatally corrode the creative ecosystem, permitting AI-generated content to directly and unfairly compete in the marketplace with the very artists whose works were ingested and repurposed without consent. The US legal system is currently caught in the paralysing gridlock of this crisis, embroiled in dozens of high-
102 | Jan-Feb 2026 | International Finance
Opportunity to accelerate content/media production Opportunity to reduce production costs Opportunity to improve viewer/customer experience Innovation
61% 55% 51% 49%
Source: Statista
stakes lawsuits that specifically focus on the strained application of copyright’s fair use doctrine to the mass ingestion required for AI training. These legal challenges have exposed the staggering scale of the alleged infringement, including claims against powerful entities like Meta for allegedly using its corporate IP addresses to download nearly 2,400 copyrighted adult movies via BitTorrent for the explicit purpose of training its AI systems, a transgression that puts the potential damages well over $350 million. The stakes in these legal battles are existential, with some developers arguing that requiring formal licensing would irreparably throttle a transformative, world-changing technology, while creators fear, with equal passion, that allowing this unlicensed exploitation will mean the inevitable death of the human creative community. The public interest demands striking an effective balance, one that allows technological innovation to flourish without dismantling the thriving community of creators who feed it. In terms of intellectual property protection, the American courts have established one clear and critical legal marker, confirming that human authorship is a foundational, bedrock requirement for copyright protection, thereby establishing a critical and necessary distinction between a human using a sophisticated tool and the tool itself attempting to claim the rights to its output.
This decision affirms the principle that intellectual property rights must apply to works generated by humans. The ruling addresses only the resulting output, leaving the foundational injustice of the mass, uncompensated training data capture entirely unresolved, a loophole large enough to drive a generative AI truck through.
Crowding out true innovation The deployment of generative AI has led to a fundamental economic revaluation of creative labour, posing an existential threat to the long-term health of the artistic community. When AI provides sophisticated tools that enable individuals without traditional, hardwon artistic skills to produce high-quality, technically sound work in fields like illustration, design, or digital music, it fundamentally lowers the barrier to entering the market. While accessibility sounds like a profound social good, the immediate economic consequence is brutally clear: this widespread capability devalues the artistic skills honed over years of craft, study, and sacrifice, diminishing their perceived market worth and making the professional’s work less appreciated or undervalued. This devaluation sets the stage for the most dangerous economic outcome, the widely observed "crowding out" effect. Generative AI excels at creating high-volume, low-variance, and highly
FEATURE CREATORS
formulaic work at nearly zero marginal cost, making these formulaic outputs significantly cheaper than traditional human creations. The lower cost of this technically proficient content then acts as an economic steamroller, systematically forcing out the more costly, experimental, and risky human creations that are essential for driving long-term innovation and stylistic evolution in culture. This phenomenon is not theoretical; the marketplace is already providing clear warning signs, with consumers sometimes showing a direct taste for the influx of AI-generated images, selecting them over human-generated works, confirming that increased competition and variety for buyers come at the devastating cost of financially crippling the creators who fuel the market. The ultimate psychological and financial violation faced by creators is the commodification of their unique artistic style. Creative professionals are acutely aware of this profound threat, which
is why surveys indicate a significant majority express keen interest in being paid specifically to license their unique artistic style (58%) or getting paid for having the models trained on their specific body of work (55%). Generative AI seeks to distil the most subjective, intangible, and unique element of an artist, his/her individual aesthetic footprint, into a fungible, replicable, and licensable commodity. If a distinct style can be captured, licensed, and then replicated infinitely by a machine for a small fee, the intrinsic, irreplaceable value of the human hand, the individual struggle, and the unique history behind that style, everything, gets tragically erased. Yet here lies the supreme, glaring irony, the self-defeating nature of the AI developers' exploitation. The fundamental truth of machine learning is that the output of these complex models is fundamentally limited by the volume and, more importantly, the quality of the input, the human-generated works
they ceaselessly ingest. Suppose the economic displacement and devaluation of human creators continue unabated, and their financial incentives diminish to the point of collapse. In that case, the flow of new, high-quality, experimental, and challenging human work, the raw fuel of the entire system, will inevitably degrade. Machines are capable of regurgitation. They can modify existing work. But the true fuel of the creative economy is raw, high-quality human work. And this model ensures that there will be recycling and no innovation or radical experimentation in the field of creative arts. It demonstrates that a thriving and compensated creative community is necessary for technological advancement, not merely an optional luxury. It’s important to recognise that not all creatives oppose technology. They are simply asking to be remunerated for the work they put in. A massive 83% of creative professionals think genuine transparency around whether artwork
International Finance | Jan-Feb 2026 | 103
TECHNOLOGY
FEATURE CREATORS
COPYRIGHT GENERATIVE AI
was created using generative AI is essential, and the same high percentage demands transparency about the specific data used to train the models. This urgent need for verifiable provenance has spurred important initiatives, such as the Coalition for Content Provenance and Authenticity (C2PA), which now provides open technical standards for publishers, creators, and consumers to establish the origin and edits of digital content, thereby providing verifiable assertions about content origins and, most importantly, ensuring a necessary baseline of trust in this increasingly murky digital marketplace. The advent of these transparency tools, which allow users to know the source of the information they are receiving, is the only possible path toward stabilising an ethical market where human and machine creations can coexist.
Ghost in the machine AI can make skills slightly redundant. But true creativity and imagination come from intentionality and lived experiences. Human imperfection mixed with imagination is necessary for art. It can be mimicked, but machines cannot create anything new that is also relatable to the human psyche. We must draw a clear and forceful distinction between sophisticated computation and genuine, conscious creation. Marvin Minsky, one of the foundational pioneers of AI, famously imagined machines capable of complex human reasoning. Yet the 21st-century generative AI has emerged primarily as the product of immense computational capacity and sophisticated algorithms, fundamentally departing from that initial, perhaps overly optimistic, vision. The core difference remains immutable. Human creativity is intrinsi-
104 | Jan-Feb 2026 | International Finance
cally rooted in genuine vision derived from living within a specific physical world, from experiencing the emotional complexity of loss, the transformative power of joy, and navigating complex cultural nuances. AI may function as a superb mimic and an incredibly fast learner, generating complex linguistic experimentation if prompted, but mimicry is not the same as true insight, and the resulting art risks lacking the genuine human depth that separates mere image generation from soulful expression. Philosophical analysis strongly suggests that mass AI-generated artifacts cannot be legitimately defined as bona fide "art" because they fundamentally lack the sort of intentional control that is plausibly accepted as a necessary precondition for the label of "arthood." The aesthetic experiences created by mass-produced AI are often similar to those found in inorganic nature, relying solely on formal properties. Because the work is the result of statistical probability and algorithmic iteration rather than struggle, conscious choice, or personal commitment, it risks meaning nothing to the AI and consequently risks meaning substantially less to us, the audience. This absence of a discernible consciousness or intentional struggle creates an aesthetic void.
Need for accountability We stand at a profound cultural and economic precipice, facing an existential crisis that must be addressed with clarity and legislative courage. The problem isn’t the technology, which promises genuine improvements to people in all fields of life. As usual, the culprit is corporate greed and unchecked power that boardrooms wield. These entities have ruthlessly lev-
We cannot possibly maintain a functioning, free creative ecosystem if the people in possession of the truth and the facts, the creators whose work defines our culture, are unable to win eraged this transformative capability to systematically dismantle existing legal and economic frameworks for their own profit, establishing an innovation structure that demands the consumption of past creativity while vehemently refusing to compensate the millions of creators whose labour and intellectual property fuel their systems. The question we face today is fully comparable in its magnitude and complexity to the social shifts that accompanied the advent of the printing press centuries ago, demanding that society urgently debate and establish entirely new, robust frameworks for genuinely rewarding creativity and ensuring that information provenance is transparent and trustworthy. We cannot possibly maintain a functioning, free creative ecosystem if the people in possession of the truth and the facts, the creators whose work defines our culture, are unable to win the necessary legal and rhetorical argument
FEATURE CREATORS
against powerful, highly capitalised corporate interests. To effectively preserve the unique and irreplaceable value of human creativity and ensure a stable future for the arts, our political and regulatory response must be swift, comprehensive, and absolute, demanding three non-negotiable elements. The first essential requirement is transparency and provenance, mandating the full, detailed disclosure of training data used by all generative models. Furthermore, we must implement verifiable authentication systems, such as the standards offered by C2PA, to provide immediate, verifiable confirmation of content origins, allowing both consumers and competitive creators to know exactly when the output is the result of a machine and statistical inference. This clarity is the minimum requirement for a fair market. The second non-negotiable element is compensation and licensing, requiring
an immediate end to the cynical reliance on tenuous fair use arguments for mass, systematic data ingestion. Governments must proactively establish robust collective licensing organisations or statutory compensation mechanisms that ensure genuine financial arrangements for all artists whose work is used to train these models. Creator participation must be predicated on appropriate financial arrangements, recognising that they hold the key intellectual assets that allow the algorithms to function. The third critical element is the preservation of authorship, legally reinforcing the established principle that copyright ownership must belong only to human beings, recognising the inherent distinction between human creation and machine replication. This ensures that the unique human elements, including personal stories, genuine emotional resonance, and complex cultural nuance, remain the legally protected, recognised, and invaluable
core of the creative economy, serving as the ultimate differentiator against the sea of machine-generated competence. Not too long ago, we envisioned artificial intelligence handling the mundane tasks, like data entry, dishwashing, and manual labour, allowing us to focus on pursuits such as poetry, painting, and philosophy. However, the exact opposite has occurred. We are now automating creative endeavours like poetry and painting for profit, while humans are left to deal with the administrative remnants. We risk building a world where creating things is seen as a problem to fix, not a human act. Creation becomes just a product. A machine can make a sad story, but it cannot feel sadness. When we read or look at art, we look for another person. Without that, culture becomes empty and lonely. At any cost, we must protect human work and human culture. editor@ifinancemag.com
International Finance | Jan-Feb 2026 | 105
Business Dossier - Absa Islamic Banking
Absa blends expertise & insight to fuel client success Absa refined its segmentation and coverage model to ensure it meets the diverse and complex needs of business clients
Shaheen Suliman Executive, Absa Islamic Banking
106 | Jan-Feb 2026 | International Finance
Q
uick evolution has become the new normal in the 21st-century business, as technological advancement and shifting consumer behaviours reign supreme. In South Africa, businesses are navigating unique challenges such as resource constraints, rising costs, and economic headwinds, and they need financial partners who can do more than provide traditional banking services. They need banks that can walk alongside them, understand their unique challenges, and deliver holistic solutions that unlock growth. Johannesburg-based Absa has positioned its Commercial Business Bank as that kind of partner, with a clear value proposition centred on three core principles: client centricity, holistic solutioning, and personalised partnerships. Stonie Steenkamp, Managing Executive for Commercial at Absa Business Banking, said, “At Absa Commercial Business Banking, we don’t just see ourselves as financial service providers. We are trusted advisors, partners in our clients’ ecosystems, and growth enablers. By combining deep sector expertise with tailored, holistic solutions, we ensure that our clients are empowered to succeed." In 2024, Absa refined its segmentation and coverage model to ensure it meets the diverse and complex needs of commercial clients. The model is delivered through dedicated client teams that include a trio of “Relationship Executive,” “Transactional Banker,” and “Credit Analyst,” supported by product and sector specialists. The result is personalised service, informed advice, and holistic solutions aligned to client complexity and ambition. Absa’s sector focus is central to its future-fit approach. From agriculture and manufacturing to transport, renewables, wholesale, retail and franchise, public sector, and tourism, Absa leverages decades of experience and in-depth knowledge to support clients with tailored solutions. For example, as the largest financier of agriculture, Absa has financed the sector for more than a century and provides farmers with strategic insights through its AgriTrends report, while partnerships with industry leaders such as John Deere and Rovic Leers unlock further
value. When it comes to renewables, Absa has financed more than 1,500 projects and grown its ambition 17-fold in five years, helping businesses adopt clean energy solutions that ensure sustainability and resilience. These sector-led strategies are combined with a holistic product offering, from Islamic Banking to advanced payment acceptance solutions that enable clients to grow, run, and optimise their businesses. Whether it's working capital management, cash flow optimisation, or international banking, Absa ensures that businesses are equipped with the right tools to compete and succeed. Absa’s commitment to clients extends beyond financial products. Their value proposition is enriched with beyond-banking offerings such as advanced data analytics that provide actionable insights into customer behaviour, and employee banking propositions that support financial wellness in the workplace. These solutions create shared value, benefiting businesses, their employees and communities. The game-changer called ecosystem banking SMEs form the backbone of the South African economy, as enterprises act as the engines International Finance | Jan-Feb 2026 | 107
Business Dossier - Absa Islamic Banking
of innovation, job creation, and community development. However, many SMEs face obstacles that prevent them from realising their full potential. While access to finance often serves as one of the barriers, entrepreneurs face a wider range of other challenges, which include a lack of skills, networks, and difficulty accessing markets. The latest Small Business Growth Index (SBGI), a partnership between Absa Business Banking and the South African Chamber of Commerce and Industry (SACCI) and independently conducted by the Bureau of Market Research (BMR) at Unisa, highlighted issues like poor financial management, lack of digital knowledge, and cash flow management skills hurting the small businesses. Skills gaps exacerbate these issues and continue to hinder growth and long-term sustainability. The solution lies in "Ecosystem
Banking," which combines access to capital with essential non-financial support such as training, mentorship, and networking opportunities. This approach recognises that while financial resources are vital, they are insufficient to boost sustainable growth. Absa’s solutions have revolutionised this approach. “As the Bank of the Entrepreneur, we believe that SMEs need more than capital to succeed. That is why we design solutions that support the full entrepreneurial ecosystem. Our financial offerings provide the flexibility required to manage working capital or expand operations, while our non-financial initiatives offer access to skills, markets, and digital tools to drive competitiveness. Partnerships play a vital role as well. By working with government, corporates, and industry associations,
“At Absa Commercial Business Banking, we don’t just see ourselves as financial service providers. We are trusted advisors, partners in our clients’ ecosystems, and growth enablers”
Stonie Steenkamp Managing Executive for Commercial at Absa Business Banking
108 | Jan-Feb 2026 | International Finance
“As the Bank of the Entrepreneur, we believe that SMEs need more than capital to succeed”
Vignesh Subramani Managing Executive (Interim) for SME Business at Absa Business Banking we can strengthen supply chains and create an environment where SMEs can thrive,” said Vignesh Subramani, Head of Sales and Distribution for SME Business at Absa Business Banking. This commitment to holistic SME support was recently recognised when Absa was named “Most Innovative SME Bank – South Africa – 2025” by the International Finance Awards. In addition, Absa also received the “Most Innovative Commercial Bank – South Africa – 2025” and “Best Shariah Compliant Banking Solutions Provider – South Africa – 2025” awards. “The accolade acknowledges our role in building digital-first solutions, developing skills training programmes, and nurturing partnerships that give SMEs access to markets and networks. It recognises our ability to create an ecosystem where entrepreneurs can access funding, mentorship, knowledge, and growth opportunities,” Subramani stated.
CEO Amy Chong
Performing on the climate front as well Absa actively supports clients in adopting environmentally and socially responsible practices, aligning with the global “Sustainable Development Goals.” Through initiatives such as green financing for renewable energy and climate-conscious business models, Absa helps businesses future-proof their operations while contributing to a just energy transition. An example is Absa’s active participation in the Energy Bounce Back Scheme, a National Treasury and SARB-backed initiative that makes solar financing more accessible. By March 2025, Absa had financed over R626 million through this scheme, helping businesses mitigate energy risks while contributing to South Africa’s low-carbon transition.
International Finance | Jan-Feb 2026 | 109
TECHNOLOGY
FEATURE META
SCAMS ADVERTISING
It's important to keep in mind that Meta is partly responsible for one-third of all successful scams in the US today
Meta lets scammers pay to play IF CORRESPONDENT
M
eta, the parent company of Instagram, Facebook, and WhatsApp, is a quintessential part of our lives, helping us connect with our loved ones, apart from networking efficiently. Most of us are hooked on our devices partly because of Meta's dopamine addiction hamster wheel. Despite the myriad reasons for harm, Meta claims to be a force for good and is genuinely useful to people around the world, and the market rewards it for it. In 2024, Meta Platforms reported revenue of $164.50 billion. As of September 30, 2025, the social media giant’s revenue was approximately $189.46 billion. It's a titan of industry that share-
110 | Jan-Feb 2026 | International Finance
holders love, and that loves its shareholders. But the excessive love of shareholders is the root of all corporate sin. Despite its skyrocketing revenue and incredible technological prowess, Meta doesn't think it should regulate its market or protect its customers from fraud and harm. The digital advertising ecosystem, once heralded as a democratisation of commercial reach, has metastasised into a complex marketplace where the distinctions between legitimate commerce and predatory fraud are increasingly obscured by algorithmic opacity.
FEATURE META
International Finance | Jan-Feb 2026 | 111
TECHNOLOGY
FEATURE META
SCAMS ADVERTISING
Internal projections for the fiscal year 2024 indicate that advertisements promoting scams, illegal goods, and prohibited content generated approximately $16 billion, representing roughly 10% of the company's total annual revenue. This revenue is safeguarded by a penalty bid pricing mechanism that monetises high-risk advertisers rather than removing them, a policy framework that sets enforcement thresholds at a staggering 95% certainty level and a corporate governance structure that explicitly caps revenue losses from safety enforcement at a fraction of the profits generated by the fraud. So, what does this mean? Meta will even let bad actors sell horse dung or magic remedies if they are willing to pay a premium for their risky endeavour. While the company has long faced scrutiny regarding data privacy and political influence, investigations surfacing in late 2024 and throughout 2025 have illuminated a far more tangible structural crisis: the institutionalisation of revenue derived from fraudulent advertising.
What's really happening? In November 2025, a Reuters investigation, corroborated by a cache of internal documents spanning 2021 to 2025, revealed a stark internal projection. Meta anticipated $16 billion in revenue for 2024, specifically from ads for scams and banned goods. To contextualise this figure, $16 billion exceeds the annual revenue of major global entities such as Spotify or eBay (Fortune 500 companies). It is a sum that materially impacts the company's earnings per share and, consequently, its stock valuation. This revenue stream is categorised internally under various euphemisms, including "violating revenue" or seg-
112 | Jan-Feb 2026 | International Finance
ments associated with higher legal risk. The existence of such specific forecasting line items indicates that this revenue is not accidental. Financial modelling that explicitly accounts for illicit revenue suggests a fiduciary dependency; removing this revenue stream would require a voluntary correction of the company’s top line by nearly 10%, a move that would likely trigger a shareholder revolt in an environment where growth in legitimate user acquisition has plateaued. To put things into context, Meta shows 15 billion scam ads a day. A lesser entity would be penalised and shut down in most countries, but the mighty titan of the digital industry has thus far been immune to its amoral position on the safety of its consumers. Upper management at Meta does not care if an online casino, a pump-and-dump investment scheme, fake websites, or purveyors of illegal drugs flood their platform with misleading ads, as long as their pockets are full. After the Reuters investigation and some high-profile cases against it globally, most notably the Calise vs Meta lawsuit and the Brazil AGU lawsuit, the company is trying its best at crisis management. Calise vs Meta is a class-action lawsuit in the Ninth Circuit pursuing claims of unjust enrichment, arguing that Meta actively solicited and profited from third-party fraud and thus should disgorge the revenue. The Brazilian Attorney General’s Office has also filed suit to recover revenue from 1,770 specific fraudulent ads that used government symbols to scam citizens, demanding that the funds be deposited into a rights defence fund. Something similar is happening in the United Kingdom as well. Regulators in the European
country found that Meta platforms were involved in 54% of all authorised push payment scams (where users are tricked into sending money). The Instagram parent company says only 10% of its revenue came from scams in 2024 and aims to cut it to 7.3% in 2025 and 5.8% by 2027. The claim seems absurd. They have the tools to stop it now, but choose to roll it out slowly to protect their profits and please shareholders. Of the $16 billion ad revenue they received from bad actors, $7 billion was from higher-risk parties (possibly ex-
FEATURE META
rails for safety teams. In one specific instance, a fraud prevention initiative was restricted to actions that would not reduce total ad revenue by more than 0.15% (approximately $135 million). This explicit capping of safety measures based on revenue impact demonstrates that the risk premium is a protected income stream, insulated from the full force of the company’s own trust and safety capabilities.
Who is profiting and how?
tremely dubious or problematic). It is ironic because Meta's own system files it as such. The most critical insight from the internal disclosures is the calculated decision to tolerate this revenue stream based on a comparison with potential regulatory penalties. The documents suggest a stark cost-benefit analysis. While the revenue from scam ads is estimated at nearly $7 billion annually, the company’s internal risk models projected that regulatory fines for these violations would likely cap at around $1 billion. Instead of pun-
ishing or deplatforming, they merely charge a higher fee from these individuals and organisations. It's important to keep in mind that Meta is partly responsible for one-third of all successful scams in the US today. Worldwide, the total cost of ad fraud was estimated at $81 billion in 2022 and was expected to surpass $100 billion in 2023, showing that current measures aren’t keeping up with increasingly sophisticated scams. Furthermore, internal memos revealed the existence of revenue guard-
The digital advertising ecosystem, once heralded as a precision instrument for commercial democratisation, has metamorphosed into a complex adversarial theatre where the economic interests of platforms and the operational methodologies of fraudsters have become dangerously aligned. These systems prioritise engagement metrics such as "Click-Through Rate" and Estimated Action Rate (EAR) over content veracity, creating a fertile substrate where fraudulent actors do not merely survive but thrive. At the core of the ad delivery engine lies the auction formula, a mathematical arbiter that decides which advertisement is shown to a user at any given millisecond. You don’t win the bid with money on platforms like Google, Facebook, or Instagram; you win it with a combination of ad quality and EAR. When a fraudster runs a campaign promising "Guaranteed 500% Returns in 24 Hours" or "Miracle Weight Loss Without Dieting," users interact with these ads at high rates. The algorithm, blind to the veracity of the claim and optimising strictly for the probability of action, registers this high interaction as a signal of quality and relevance. Consequently, the auction mechanism rewards the fraudster with a higher EAR, which inversely lowers their "Cost
International Finance | Jan-Feb 2026 | 113
TECHNOLOGY
FEATURE META
SCAMS ADVERTISING
Per Mille" or "Cost Per Click." In effect, the platform’s efficiency algorithms subsidise the distribution of scam content, allowing fraudsters to reach vast audiences at a fraction of the cost paid by legitimate brands. The digital ad fraud ecosystem has matured into a sophisticated business-to-business economy. While the end-point scammers running fake crypto exchanges or counterfeit e-commerce stores bear the operational risk, a vast shadow supply chain of service providers extracts guaranteed profits at every stage of the fraudulent lifecycle. These entities operate with the efficiency of legitimate SaaS (Software-as-a-Service) companies, often earning monthly recurring revenue (MRR) regardless of whether the scammer’s campaign succeeds or fails. The primary beneficiaries are vendors of evasion technology. Cloaking services, which filter traffic to hide malicious landing pages from platform moderators, have evolved into subscription-based platforms. Services like “TrafficArmor” and “Cloaking House” operate openly, charging tiered monthly fees ranging from $30 to $600, or utilising pay-per-click models where scammers pay premium rates (e.g., $129 for 32,500 clicks) to ensure their ads survive automated review. These companies profit by effectively selling invisibility, creating a technological tollbooth that every high-end fraudster must pay to access the audience. Supporting this is the "Bulletproof Hosting industry." Unlike legitimate hosts that comply with takedown requests, providers like Strox or SpeedHost247 charge premiums (e.g., $85/ month or $3/day) to host malicious landing pages on servers explicitly designed to ignore abuse reports and law
114 | Jan-Feb 2026 | International Finance
Meta ad revenue from 2014 to 2023 (In Million US Dollars)
2014 2015 2016 2017 2018 2019 2020 2021 2022 2023
11,492 17,079 26,885 39,942 55,013 69,655 84,169 114,934 113,642 131,948 Source: Statistico
enforcement inquiries. By commoditising resilience, they ensure that even when a scam is detected, the infrastructure remains operational long enough to be profitable. Fraud requires a constant supply of fresh identities to bypass platform bans. This has enriched Dark Web marketplaces and account brokers, who act as wholesalers of digital reputation. The most lucrative commodities are "Verified Business Managers" who hack or farm Facebook/Meta ad accounts with high spending limits and histories of legitimate activity. A verified BM can
fetch $120 to $250, while aged accounts (which look less suspicious to algorithms) sell for $45–$50. This sector also profits from the Stolen Credit model. Brokers sell stolen credit card details for as little as $10–$40, which fraudsters then link to compromised agency accounts. This arbitrage allows scammers to run thousands of dollars in ads using other people's money, while the identity brokers secure risk-free profit from the initial data sale. Perhaps the most significant evolution is the shift to Scam-as-a-Service
FEATURE META
global wage disparities to defeat advanced behavioural biometrics. By providing the human touch that algorithms crave, these farms monetise the very mechanism designed to stop them,” Horwitz said. And it doesn’t stop there. The data collected at these farms is often resold. If you’ve been the victim of a cybercrime, there’s a 34% chance it will happen again if you’re an individual, and an 84% chance if you’re a business. Once scammed, you can end up on what’s called a ‘suckers list,’ marking you as an easy target. These lists are valuable, and people are willing to pay a lot to get them.
How is the world reacting to it?
(ScaaS). Technical syndicates now build and lease entire fraud kits (pre-coded phishing sites, crypto drainer scripts, and back-end management panels) to lower-level criminals. “Instead of charging a flat fee, these developers often take a commission. For instance, the Inferno Drainer malware operated on a 20% commission model, syphoning off a fifth of all stolen funds from its affiliates, generating over $87 million in illicit profit before ceasing operations. This franchise model allows technical groups to scale their revenue infinitely without ever directly engag-
ing with a victim,” said Reuters journalist Jeff Horwitz, who has been covering the alleged ad-related irregularities involving Meta. Finally, the demand for human engagement signals has created a labour economy in Southeast Asia (e.g., Vietnam, Myanmar) and parts of Eastern Europe. “Click Farms” or “Fraud Farms” employ low-wage workers to manually interact with ads, solve CAPTCHAs, and warm up accounts. “These operations charge roughly $1 per 1,000 clicks/likes, creating a volume-based revenue stream that exploits
The world is reacting to the industrialisation of ad fraud with a shift from “user beware” to platform liability. In 2024 and 2025, governments and industries moved to dismantle the economic impunity of platforms, forcing them to bear the costs of the fraud they facilitate. The most significant development is the regulatory move to force reimbursement. For example, the UK Payment Systems Regulator implemented in 2024 a mandatory reimbursement requirement for Authorised Push Payment (APP) fraud. Crucially, the liability is now split 50:50 between the sending bank and the receiving payment service provider. While this primarily targets banks, it has created immense pressure from the financial sector on tech platforms. Banks, now on the hook for millions in refunds, are aggressively lobbying for a “polluter pays” model, arguing that since 60%–80% of scams originate on Meta's platforms, the tech giants should contribute to the reimbursement pot. Effective December 2024, Singa-
International Finance | Jan-Feb 2026 | 115
TECHNOLOGY
FEATURE META
SCAMS ADVERTISING
pore’s framework assigns specific duties to financial institutions and telcos to mitigate phishing scams. If banks fail to send real-time transaction alerts or impose cooling-off periods, they are liable for losses. This creates a regulatory precedent where infrastructure providers are held financially accountable for gatekeeping failures. Governments are moving beyond voluntary codes of conduct to enforceable legislation with massive financial penalties. The “UK Online Safety Act,” fully enforceable in 2025, requires platforms to proactively prevent fraudulent advertising. Non-compliance can result in fines of up to £18 million or 10% of global annual turnover (potentially billions for Meta). In Europe, something similar is happening with the “Digital Services Act.” The European Commission has opened investigations into “Very Large Online Platforms” regarding their risk mitigation for fraudulent ads. The DSA empowers the European Union to fine companies up to 6% of their global turnover if they fail to manage systemic risks, including the spread of financial scams. In Australia, the “Scams Prevention Framework,” which was passed in early 2025, introduces mandatory codes for banks, telcos, and digital platforms. It includes fines of up to AUD 50 million for non-compliance, specifically targeting the failure to detect and remove scam content. There is also other litigation from celebrities. For example, Andrew Forrest vs Meta is an ongoing case where Australian billionaire Andrew Forrest pursued Meta in both Australian and US courts over the proliferation of crypto scams using his likeness. While the Australian criminal case was dropped due to evidential hurdles, the US civil lawsuit
116 | Jan-Feb 2026 | International Finance
survived a motion to dismiss in 2024. This case is pivotal as it challenges Section 230 immunity often claimed by platforms, arguing that Meta’s ad tools contributed to the content creation, thereby stripping them of neutral publisher status. Even the "Australian Competition and Consumer Commission" sued Meta for aiding and abetting false conduct by publishing scam ads featuring public figures, arguing that Meta's algorithms actively targeted these scams to susceptible users. Meta has, under immense pressure, reversed its 2021 decision to abandon facial recognition. In late 2024, the company began testing facial recognition technology to combat “celeb-bait” scams. The system compares faces in suspected ads against the profile pictures of public figures. If a match is found and the ad is a scam, it is blocked. This marks a significant concession, as it acknowledges that privacy concerns regarding biometrics are outweighed by the need to stop the financial bleeding caused by industrial-scale fraud. Major players like Meta, Coinbase, and Match Group have formed coalitions to share intelligence on pig-butchering operations, aiming to sever the communication lines between the scam compounds and their victims.
Engagement fuels fraud risks This is the aftermath of prioritising engagement over verification. You end up with an ecosystem where scams and fraud flourish, and customers get hurt. At the heart of this crisis lies the EAR algorithm, a mechanism that inadvertently subsidises deception by rewarding the hyper-engaging nature of scams with lower distribution costs. This economic
The era of anonymous algorithmic bidding must yield to a “Know Your Business” standard, where access to the ad auction is predicated on verified identity rather than mere creditworthiness.
alignment between the platform's profit motives and the fraudster's operational goals has created a “Market for Lemons,” where predatory content effectively crowds out legitimate commerce. The “Retargeting Loop” further exacerbates this by trapping vulnerable populations in algorithmic echo chambers, commoditising their susceptibility, and reselling it through the secondary market of recovery scams. Technologically, the ecosystem has evolved into an asymmetric arms race, where enforcement is consistently outpaced by evasion. The transition from simple static landing pages to Generation 4 cloaking technologies, which are capable of analysing device telemetry, battery status, and gyroscopic movements in milliseconds, demonstrates
AWARDS 2026
International Finance Awards recognises industry talent, leadership skills, industry net worth and capability on an international platform. After careful consideration of nominations by a qualified research team, winners are declared on the strength of their application and past accomplishments. Winning an International Finance Award is a recognition of their continual efforts and commitment to improving business performance.
Celebrating Excellence Nominations Open for Asia-Pacific & EMEA Log on to: awards.internationalfinance.com International Finance | Jan-Feb 2026 | 117
TECHNOLOGY
FEATURE META
SCAMS ADVERTISING
that fraud is no longer the domain of opportunistic amateurs. It has industrialised into a sophisticated Fraud-as-aService economy. This shadow supply chain, composed of bulletproof hosting providers, identity brokers on the dark web, and commercial cloaking services, operates with the efficiency of the legitimate software sector. By lowering the technical barrier to entry, these enablers have democratised access to high-end evasion tools, allowing even low-skilled actors to launch enterprise-grade attacks against global platforms. The failure of self-regulation is now evident in the global legislative pivot toward platform liability. For over a decade, the industry operated under a “user beware” paradigm, but the sheer scale
118 | Jan-Feb 2026 | International Finance
of financial loss has forced a regulatory correction. Initiatives like the United Kingdom’s mandatory reimbursement requirement and Singapore’s “Shared Responsibility Framework” signal the end of platform immunity. By shifting the financial burden of fraud from the victim to the infrastructure providers, regulators are attempting to realign economic incentives. Only when the cost of hosting a scam exceeds the revenue generated from its ads will platforms invest the necessary resources to close the technological loopholes they currently tolerate. Ultimately, the future of the digital advertising economy hinges on a fundamental shift from plausible deniability to mandatory verification. The era of anonymous algorithmic bidding
must yield to a “Know Your Business” standard, where access to the ad auction is predicated on verified identity rather than mere creditworthiness. As Generative AI threatens to flood the web with infinite synthetic content, the only viable defence is a strict chain of custody for digital identity. If structural reform doesn’t ensue soon, corporate social media platforms will slowly transform into a black market without oversight. For now, as a reader and consumer, be careful, any ad you see on Instagram or Facebook could be a scam, backed by Meta Platforms, the world’s biggest advertiser.
editor@ifinancemag.com