Human Capital Management
Q1 2024 Report


Q1 2024 Report
In the first quarter of 2024, the Human Capital Management industry witnessed strengthening levels of M&A activity, representing the third most active quarter over the past 5 years. There were a total of 106 acquisitions, a 14% increase from the 93 deals in the fourth quarter of 2023. The talent management sector had the highest levels of M&A activity, as strategics in the learning and leadership development verticals ramped up their inorganic growth strategies Strategics view M&A as a key component of growth and PE players have record levels of dry powder to deploy Our outlook remains optimistic that activity will continue at these levels throughout 2024 as companies will continue to attract interest from buyers, despite geopolitical turbulence and recession fears.
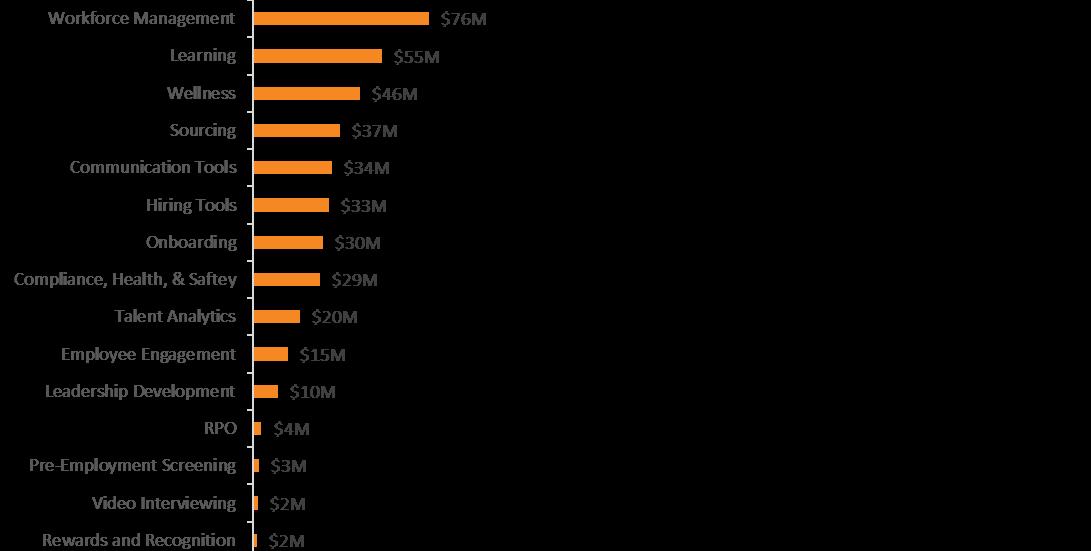
The number of venture capital deals increased slightly from the first quarter of 2023 while the amount of funding decreased significantly. Investors are exercising caution as strong headwinds, including inflationary concerns and high interest rates, have decreased early-stage pre-money valuations, which have dropped significantly from the unprecedented 2021 highs (Page 12) The non-cyclical Core HR sector has remained active and accounted for 58% of all VC dollars raised this quarter, consistent with the sector focus on mission-critical functions There are some promising signs of healthy VC activity as for the first time since Q 4 2022, there were two newly minted unicorns: payroll provider DailyPay and workforce management platform Deputy (Page 13).
M&A was highly selective in Q1. Large consolidators remain on the hunt for true competitive advantages – differentiated services, predictable revenue streams, or entry / expansion into high-margin / highperforming end markets – and PE firms are opportunistically considering platform investments. Additionally, PE-backed companies continue to drive add-on activity in Executive Search.
Staffing:
• PE firm MidOcean Partners acquired The Re-Sourcing Group, a leading provider of strategic staffing, consulting, and direct hire solutions, from McNally Capital
• INSPYR Solutions, a portfolio company of A&M Capital Partners, acquired Advantis Global, a leader in highly-specialized technology consultants and solutions
Executive Search:
• ZRG, a portfolio company of RFE, has continued to consolidate: Ignata Finance (backed by Hamilton Bradshaw), a UK-based executive search and finance recruitment business, and Wiser Partners, a Cincinnati-based marketing and sales firm
In the Core HR sector, M&A activity was driven by acquisitions of payroll and compensation & benefits companies. Automated payroll providers are increasing pay access and filing data transparency. Benefits providers are personalizing packages to retain employees in different life stages.
Payroll:
• The payroll business unit of Alight (NYS: ALIT) was acquired by H.I.G. Capital for $1.2B, and will partner with Alight to continue its services
• HiBob, a benefits provider and HRIS, acquired UK-based automated payroll platform Pento to add to their “all-in-one” service offering Compensation & Benefits:
• Alliant Insurance Services expanded their employee benefits capabilities by acquiring consulting firm Aldrich Benefits and the employee benefits division of PBC Insurance
• Employee benefits platform Vivup was acquired by Great Hill Partners to scale their go-to-market capabilities. The funds were used to merge with Perkbox, a global benefits and rewards platform
With 30 deals, the talent management sector had the highest M&A activity of the HCM sectors tracked, a 30% increase from Q1 2023 transaction levels. The learning and leadership development sectors accounted for over 50% of the acquisitions within talent management, as companies track and improve their continuous up- and re-skilling.
Learning:
• Employee learning provider Eloomi was acquired by Dayforce (NYS: DAY) to extend their enterprise people development capabilities
• Workplace LMS Learning Pool acquired Onscreen, a digital walkthrough platform, to train their clients on software applications
Leadership Development:
• Executive coaching agency Rovertson Lowstuter was acquired by total revenue performance consultancy Center for Sales Strategy to help clients increase productivity and find talent synergies
• True Capital Partners and LLR Partners acquired True Advance, a provider of leadership assessments and performance enhancement
• Create Impact Ventures acquired The Pipeline, a women’s leadership development, assessment, and coaching platform
The talent acquisition sector had the lowest public company performance of the HCM sectors tracked (Page 2), reflecting a higher exposure to the labor market cycle. M&A activity included notable deals in the background screening and RPO industries, driven by demand for reliable and cost-effective screening and recruiting solutions.
Pre-Employment Screening:
• Two of the largest players join as First Advantage (NAS:FA) will acquire Sterling (NAS: STER) for $2.2B to invest in AI automation. In Q1, Sterling acquired First Hospital Labs and Vault Workforce
• HireRight (NYSE: HRT) announced that they will be acquired by General Atlantic and Stone Point Capital at a $1.7B valuation Recruitment Processing Outsourcing:
• Student learning platform Podium Education acquired engineering and IT recruiting service Untapped to close the college-to-career gap
• Aya Healthcare acquired healthcare RPO managed service provider ID Medical to expand services into the UK-based NHS
3/31/2023 3/31/2024
Source: PitchBook, Data as of March 2024








Driven by 45%+ decreases in EBITDA
3/31/2023 3/31/2024
Driven by a 38% decrease in EBITDA from Seek, the largest Talent Acquisition company





Driven by 25%+ increases in EV from two >$220B companies: Oracle and SAP






The S&P 500 outperformed all four HCM indexes during this period. The Core HR index emerged as the topperforming HCM index, with 6 of the 18 stocks increasing their enterprise value by >45% (AOF, BBSI, SAP, SGE, TNET). The Talent Acquisition index performed poorly, with 4 of the 9 stocks decreasing over 25% (NWO, FVRR, ZIP, DHX)
Source: Refinitiv
Excludes companies not traded prior to 4/1/2023






The Rule of 40 is a financial ratio that assesses a company's performance by adding its revenue growth rate to its EBITDA margin The rule states that a company's combined growth rate and EBITDA margin should be 40% or higher. Notably, the Rule of 40 is not necessarily correlated with a stock’s performance, and several HCM companies that have had a combined revenue growth and EBITDA margin below 40 have experienced year-over-year enterprise value growth For example, TriNet Group and BBSI have grown their YoY Enterprise Value by ~50% while having a Rule of 40 metric of <15%.
TTM EBITDA Margin
YOY Revenue Growth % - Rule of 40 Baseline






$2.2B FEB 2024
• Sterling Check Corp is a public provider of technology-enabled background screening, credential verification, and ongoing risk monitoring services.
• The transaction combines two of the largest pre-employment screening players, allows First Advantage to invest in AI-driven automation, and is expected to deliver $50M in synergies.
$413M FEB 2024
UNDISCLOSED MAR 2024

$165M MAR 2024


$1.2B MAR 2024

UNDISCLOSED JAN 2024

UNDISCLOSED FEB 2024


UNDISCLOSED MAR 2024


• HireRight is a global provider of background screening, verification, identification, monitoring, and drug and health screening services.
• General Atlantic and Stone Point Capital will acquire the remaining 25% of HireRight they do not already own at a total enterprise value of $1.65B.
• PaySpace offers cloud-based software with multi-country, multi-language human capital management and payroll solutions.
• Deel will become the first global payroll & Employer of Record (EOR) with its own full-stack payroll engine localized in 50 countries.
• Perkbox, a global benefits and reward platform and Vivup, a provider of health and wellbeing benefits will merge, following a majority investment from Great Hill Partners.
• The acquisition will help the newly integrated organization scale its go-to-market capabilities, innovate product offerings, and accelerate organic and inorganic growth.
• Alight (NYS: ALIT), a cloud-based human capital technology and services provider, announced that it will sell its Payroll & HCM Outsourcing business units.
• The transaction accelerates Alight’s evolution into a more simplified and focused employee wellbeing and benefits platform company.
• MidOcean Partners made a platform investment into The Re-Sourcing Group, which provides staffing with a focus personnel in legal, IT, finance / accounting, and HR and will look to grow the company organically, as well as through acquisitions.
• MidOcean is also invested in GHR Healthcare (healthcare staffing) and was previously invested in staffing firms System One and The Planet Group.
• A&M Capital Partners-backed INSPYR Solutions acquired Advantis Global in a transaction that merges two of the larger IT Staffing Firms (INSPYR is no. 30 and Advantis is no. 62 on SIA’s Largest IT Staffing Firms list).
• The combined company will have a significantly-expanded market reach and a broad range of enhanced technology and talent solutions for clients.
• RFE-backed ZRG, the seventh-largest executive search firm in the U.S., completed two strategic bolt-on acquisitions, continuing to add to its global capabilities and by-industry expertise.
• Since December 2021, ZRG has also acquired Seba International, The Registry, Helbling and Associates, Hub Recruiting, RoseRyan Inc., Terra Search Partners and Brimstone Consulting Group.
At this year’s SIA Executive Forum North America in Las Vegas, HVA met with a broad range of staffing and recruiting companies – and also attended the inaugural pop-up SIA Staffing Tech Summit. The content of the SIA Staffing Tech Summit was particularly noteworthy as many firms are actively wrestling with critical technology questions prompted by the age of digital transformation – what to adopt? how much to spend? what is the competition investing in? The Tech Summit keynote address broke down how technology is currently impacting strategy decisions made by staffing and recruiting firms, as well as the broader competitive landscape
Staffing firms with >$100M of revenue have automated ~64% of worker processes and just over 30% of client processes – these percentages distinctly decline when looking at smaller companies
Staffing firms are spending less on tech (hardware, software, services) than other types of companies – ~0.73% of revenue (or ~2.75% of gross margin) vs. a broader average of ~3-5% of revenue
AI, Big Data, and RPA investments are seeing the largest ROI (Sourcing Automation Tools, Analytics and Benchmarking, Recruitment Chatbots, etc.) – AI is most likely to disrupt Candidate Screening / Skills Assessments, Matching and Selection, and Redeployment in the near term
Staffing firms are facing increased competition from tech-savvy Hiring Platforms, Temporary Staffing Platforms, and Talent Platforms, many of which are recording 70%+ Gross Margins
SIA continues to offer extensive technology guidance for staffing and recruiting firms, from IT self-assessment frameworks to research and education on key topics, such as how to leverage an SPaaS solution. The messaging is clear: Digital transformation is not just about modernizing for efficiency and keeping important data safe – but also using technology for a competitive advantage in the marketplace.
Source: SIA, Gartner
Larger
Early-stage pre-money valuations have stabilized below 2021 highs
$175M JAN 2024
RECEIVED INVESTMENT FROM Payroll
$95M JAN 2024
RECEIVED INVESTMENT FROM Performance Management

$50M MAR 2024
RECEIVED INVESTMENT FROM Payroll


$37M MAR 2024
RECEIVED INVESTMENT FROM Workforce Management
























Mar-24
Mar-24
Mar-24
Mar-24
Mar-24
Mar-24
Feb-24
Feb-24
Feb-24
Feb-24
Feb-24
Jan-24
Jan-24
Jan-24
Jan-24
Jan-24
Jan-24
Jan-24
Jan-24
Jan-24
Jan-24
Jan-24
Jan-24
Feb-24
Jan-24
Jan-24
Jan-24
Jan-24
Jan-24
Jan-24
Jan-24
Jan-24
Jan-24
Jan-24
Jan-24




















the
and
Industrials, and Consumer.
and

The material in this report is for information purposes only and is not intended to be relied upon as financial, accounting, tax, legal or other professional advice. This report does not constitute and should not be construed as soliciting or offering any investment or other transaction, identifying securities for you to purchase or offer to purchase, or recommending the acquisition or disposition of any investment. Harbor View Advisors does not guarantee the accuracy or reliability of any data provided from third party resources. Although we endeavor to provide accurate information from third party sources, there can be no guarantee that such information is accurate as of the date it is received or that it will continue to be accurate in the future.