Mortgage rates have been volatile lately, there's no doubt about it. And if you’re thinking about buying a home, that can make it harder to plan. But there are still things you can do to get the best rate possible in today’s market. It starts with having the right information.
Data from Mortgage News Daily shows the recent volatility. After trending down for well over a year, rates have been rising for the past few months (see graph below):
While it’s easy to be distracted (or even discouraged) by the changes, here’s what you need to try to remember. Rates are reacting to what’s happening in the world. Recent global uncertainty, tensions overseas, and inflation that hasn’t fully cooled are all weighing on rates. Even oil plays a role. When oil prices climb, inflation usually follows, and that pushes mortgage rates higher. So, rates didn't spike out of nowhere. But here’s what you really need to know.
When all of those factors finally calm down, rates should stabilize too. But it likely won’t happen overnight. These things take time. But while you can’t control what’s happening with rates, there are still things you can do to help you get the best rate possible in today’s market.
Your credit score plays a big role in the rate you qualify for. Even a small improvement can make a noticeable difference in your monthly payment. So, make sure you do what you can to keep your credit score up. If you’re not sure what your score is or how you can improve it, talk to a trusted loan officer. As Bankrate puts it:
“Your credit score is one of the most important factors lenders consider when you apply for a mortgage. Not just to qualify for the loan itself, but for the conditions: Typically, the higher your score, the lower the interest rates and better terms you’ll qualify for.”
There are also different types of home loans – and each one can have unique requirements, benefits, and rates for qualified buyers. That’s why it’s so important to explore your options with a lender. You may even want to talk to multiple lenders to see how the options vary. The Consumer Financial Protection Bureau (CFPB) explains:
“There are several broad categories of mortgage loans, such as conventional, FHA, USDA, and VA loans. Lenders decide which products to offer, and loan types have different eligibility requirements. Rates can be significantly different depending on what loan type you choose.”
The length of your loan matters too. Most lenders typically offer 15, 20, or 30-year loans. Again, to figure out what makes the most sense for your budget and long-term goals, have a lender walk you through all your options. Freddie Mac offers this advice:
“. . . it’s important to consider the loan term, which is the length of time it will take you to repay your loan before you fully own your home. Your loan term will affect your interest rate, monthly payment, and the total amount of interest you will pay over the life of the loan.”
Thinking about buying right now? The best advice is to accept that you can’t control where rates are going to go from here. What you can do is work with a trusted lender and take steps that’ll help you get the best rate possible.
Experts say rates will stay pretty much where they are now – but some volatility is to be expected. So, you shouldn't try to time the market. It's better to focus on how any change impacts your future mortgage payment. Source:
Did you try to buy a home last year, but you ended up pressing pause? Maybe you couldn’t find a home that really fit your needs. Or maybe the ones you liked just weren’t affordable. According to a recent survey from NerdWallet, those were the top two reasons buyers gave up on their search in 2025.
But this year, there's one trend that could help fix both of those frustration points: the number of homes for sale is growing. Take a look at the graph below. It uses data from Realtor.com to prove inventory is making a slow and steady comeback:
1,198,4451,102,0741,137,210
Active
Each year we’ve been inching closer to the inventory levels we had back in 2017-2019. And that’s a good thing. That’s what’s considered normal for the market.
Now, it’s worth noting, nationally we’re not there yet – and having more inventory won’t suddenly “fix” everything. But the growth the market has seen lately still changes how competitive it feels.
• When there are more homes for sale, buyers gain time, options, and leverage.
• When there aren’t, the pressure ramps up quickly.
In the years since 2020, there haven’t been enough homes for sale, and that’s made the market feel rushed. Stressful. Intimidating. But now it’s finally getting better.
If the number of homes for sale rises another 5% this year, that could actually be a big milestone. Because, if you graph that out you can see that growth (shown in the dotted line) has us hitting typical 2017-2019 inventory levels roughly this Winter. (the gray lines).
Now, it’s worth saying that, depending on where you live, inventory growth is going to vary. Some places are bouncing back faster than others. But overall, the story is clear: you’re getting more choices for your move. In other words, the market is starting to work with buyers again – not against them. And that should help in two big ways:
• More chances to find what you’re looking for
• More homes for sale in your target price point
Inventory isn’t back to normal everywhere. But it’s moving in the right direction. If you’ve been waiting for a moment when you have options, and a little breathing room, this is the strongest setup buyers have seen in a long time.
Housing inventory has risen from its postpandemic low . . . giving buyers more negotiating power.
If you've always assumed a newly built home is just not in your budget, you should know the math just got a little friendlier. The median sale price of a newly built home is now at its lowest level since 2021, according to the Census. And on top of that, builders are still rolling out incentives to bring buyers through the door.
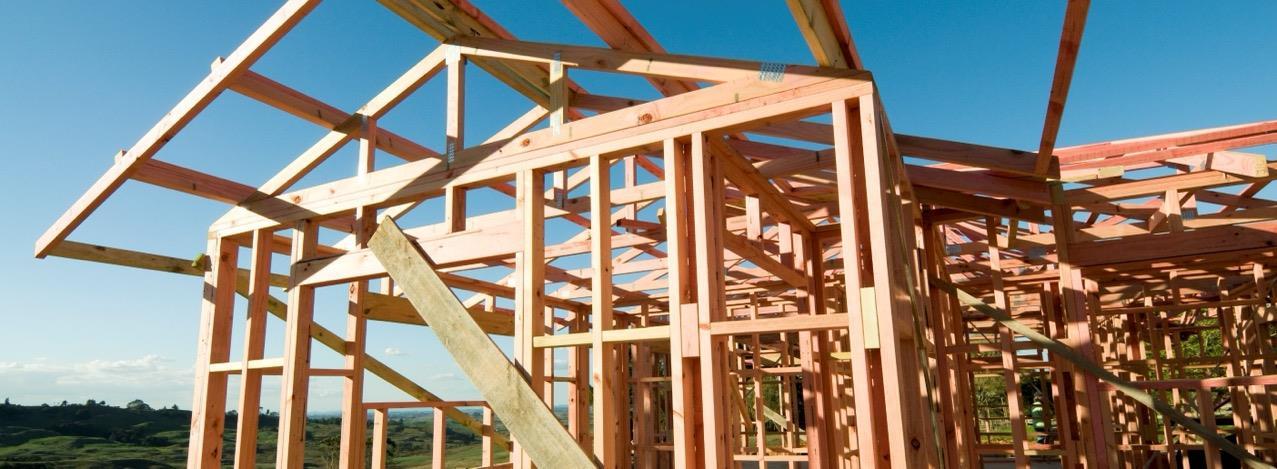
After a steep climb during the pandemic years, prices have eased a bit. The median sale price of newly built homes is sitting at about $422,500. That’s compared to a peak of $460,300 just a few years back. And in January this year they hit the lowest they’ve been in 5 years (see graph below):
Median Sales Price of Newly Built Homes
$470,000
$450,000
$430,000
$390,000 $410,000
$290,000 $310,000 $330,000 $350,000 $370,000
$460,300
$422,500
Source: Census
While local markets are going to vary, this could work in your favor, especially if you’re a firsttime buyer. According to Zonda, prices in the entry-level price range have dropped 3% over the past 12 months – more than any other price tier.
That doesn't mean every home in every market is suddenly affordable. But it does mean that, broadly, you’ll see the best prices on new builds since 2021, if you’re buying now.
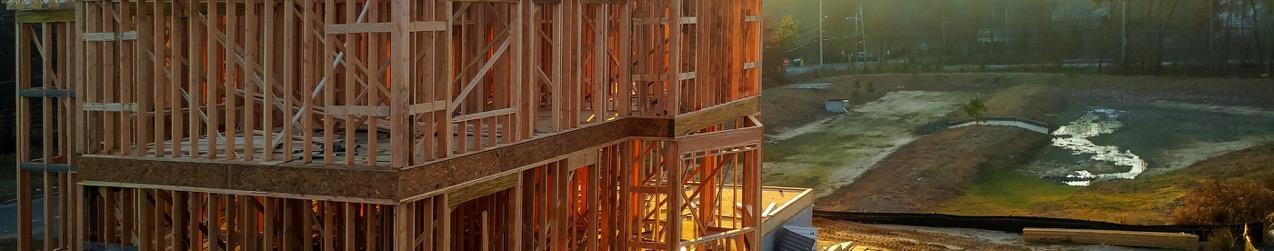
And just in case you’re thinking it, lower prices don't mean the new home market is in trouble. Builders today are being intentional about how much inventory they have, so it doesn't pile up the way it did in 2008. Even after the recent improvement in new home prices, they’re still higher than pre-pandemic norms. So, this isn’t a crash. It’s a strategy to keep inventory moving.
And lower sticker prices aren't the only break buyers are getting. According to the National Association of Home Builders (NAHB), 61% of builders are currently offering some form of incentive to attract buyers. Those typically include:
• Help with closing costs: Some builders are covering thousands of dollars in fees to reduce the upfront cost of buying.
• Extra upgrades: Think premium finishes, appliance packages, and designer features, often added at no extra cost.
• Mortgage rate buydowns: When the builder pays to lower your mortgage rate, which reduces your monthly payment.
• Price cuts: Almost one in three builders (32%) are cutting prices right now, averaging about 6% off list price. (see graph on the right).
of builders are doing price cuts right now
Source: NAHB
That last point catches a lot of buyers off guard – most assume that builders won’t negotiate on price. But builders need to move what they've built. That's a different mindset than a homeowner deciding whether to budge on price.
Builder incentives and lower new home prices are working to your advantage in a way they haven't in years. Want to see what's available in your area and what kind of deal a builder may be willing to make? Let's connect.
If you’re torn on whether you want to focus your search on new construction homes or existing ones, here are some differences that could help you decide.
A wider variety of floor plans and styles
Details that add charm and character
Ability to customize certain features during the build
Won’t need repairs or renovation work up front
More mature landscaping and neighborhoods
Energy efficient features may be standard
Both options have their perks; it just depends on what matters most to you.
If you have questions about what’s available in our area, let’s connect.
There's a lot of dramatic headlines and social posts out there. And if you're thinking about buying a home, that can make you feel a little less sure about your decision. But a lot of what you're hearing is based more on misconceptions. Not facts. So, let's break it down and separate fact from fiction.
One idea doing its rounds on social is that mortgage rates are going to drop dramatically soon. So, it’s better to wait to buy. But is that really what’s expected?
While mortgage rates have come down overall these last few years, forecasts don’t show a major drop ahead. The most likely scenario is that rates stay somewhere in the low to mid 6% range this year. And that’s not a big change from where rates are now (see graph below):
Of course, this depends on where inflation and the economy go from here. But, based on what we know today, waiting for a big drop in rates may not work out the way some people hope. As U.S. News explains:
“Mortgage rates aren't expected to change much over the next several quarters . . .”
You’ve probably heard inventory is up. And nationally, it is. It’s been growing for the past few years. And in 2026 so far, the number of homes for sale is 5% higher than this time last year. It’s one of the reasons you have a bit more breathing room right now.
The problem is the headlines are making something good, sound bad. They’re focusing on how this is the most inventory we’ve had since 2019 or how many homes builders are building. And that can make it sound like the number of homes for sale is rising too far, too fast. But that’s not what the bigger picture shows.
Data from Realtor.com proves that, even though inventory is up compared to last year, it’s still nearly 13% lower than it was during the last normal housing market (2017-2019):
Source: Realtor.com
While it can vary a lot based on where you live, only 15 states have more inventory than pre-pandemic today. That’s a key reason why there still aren’t enough homes for sale to trigger something like the crash back in 2008.
You’ve probably seen this one, too. The confusion is coming from the fact that some metros are experiencing slight price declines. And influencers are running with that and saying prices are crashing. But that’s not the reality.
Most areas are seeing prices rise, not fall. And that’s because:
• Many homeowners aren’t selling because they don’t want to give up the low mortgage rate they locked in a few years ago. And that’s keeping a lid on how much inventory can grow.
• Since inventory is still below pre-pandemic norms, there aren’t enough homes for sale to cause a price crash.
• Some sellers are choosing to pull their homes off the market instead of cutting prices.
And those are 3 big reasons prices aren’t headed for a crash.
Even in the markets experiencing mild declines, the drops aren’t enough to cancel out the big gains most homeowners have seen in the last 5 years (see graph below):
Online posts are going to make things sound worse than they are. If you want a true, databound look at what’s really happening in today’s market, lean on a real estate agent. That way you have someone to separate fact from fiction.
In today’s market, you’ll want to be sure you get your advice from a team of professionals. Here are the top two mistakes other buyers are making right now, and how your agent or lender can help you avoid each one.
As part of the homebuying process, a lender will look at your finances to figure out what they’re willing to let you borrow for your mortgage. This will help you really wrap your head around the financial side of things before you start looking at homes.
While house hunting can be a lot more fun than talking about finances, you don’t want to do this out of order.
Make sure you get your pre-approval first before you go house hunting. As CNET explains:
“If you wait to get preapproved until the last minute, you might be scrambling to contact a lender and miss the opportunity to put a bid on a home.”
With today’s mortgage rates and home prices, it’s even more important to avoid stretching your budget too far. This is especially true because other housing expenses like home insurance and taxes are on the rise.
Be sure to factor these expenses into your budget so you don’t overextend. Bankrate offers this advice:
“Focus on what monthly payment you can afford rather than fixating on the maximum loan amount you qualify for. Just because you can qualify for a $300,000 loan doesn’t mean you can comfortably handle the monthly payments that come with it along with your other financial obligations.”
73% faster
The good news is, you don’t have to deal with any of these headaches if you have the right partner by your side. Let’s connect so you have a pro who can help you avoid these costly mistakes.
As part of the homebuying process, once a lender has reviewed your finances, you want to be as consistent as possible.
Don’t change bank accounts.
Don’t deposit cash into your accounts before speaking with your bank or lender.
Don’t apply for new credit or close any credit accounts.
Don’t co-sign other loans for anyone.
Don’t make any large purchases.
The best advice? Once you’ve submitted your mortgage application, always talk to your lender before doing anything financial in nature.
Buying a home is exciting. But let’s be honest, it can also feel overwhelming. And with today’s housing market constantly changing, it’s easy to feel like you’re making one of the biggest financial decisions of your life while trying to keep up with moving goalposts.
That’s exactly why having a trusted real estate agent matters.
A great agent does a lot more than unlock doors and schedule showings. They help you make sense of the process, avoid costly mistakes, and feel confident in your decisions along the way. And according to the National Association of Realtors (NAR), buyers are crystal clear about the support they value most from an agent today (see visual below):
Percentage Distribution, All Buyers
The takeaway? Buyers don’t just want access to listings. They want someone they can trust who can guide them through the entire experience. Here are the biggest ways an agent delivers all that and more:
Finding a house online is easy. Finding the right one for your lifestyle, budget, and long-term goals? That’s a different story. A good agent helps you narrow the list, spot opportunities you may miss on your own, and avoid homes that aren’t the right fit, even if they look good online. Because buying the wrong home can cost you more than waiting another week for the right one.
A local agent helps you understand what a home is really worth based on what similar homes are actually selling for in that area, not just the list price. They also help you craft a strong offer strategy that gives you the best shot without stretching beyond what makes sense financially.
In many places, buyers have more leverage than they’ve had in years. That means more room to ask for repairs, closing cost help, or a better price – but it varies based on your local market and the home you’re buying. Knowing when to push, what to ask for, and how far to go is where a great agent shines. Because having someone in your corner who knows the market and how to negotiate can make a huge difference in the outcome.
Disclosures, contingencies, timelines… there’s a lot packed into a real estate contract, and missing something important can create major issues later. An agent helps you understand what everything means before you sign, so you can move forward with confidence.
Headlines change constantly – and that can breed uncertainty. A great agent helps cut through all that noise. They can explain what’s happening in your local market, how quickly homes are selling, where buyers have leverage, and what trends really matter for your search.
The right agent doesn’t just help you buy a house. They help you make smarter decisions, avoid costly mistakes, and feel more confident through every step of the process. And in today’s market, that expertise is a must.
The housing market—like so many other markets—is almost impossible to time. The best time for prospective buyers is when they find a home that they like, that meets their family’s current and foreseeable needs, and that they can afford.
Orphe Divounguy Senior Macroeconomist, Zillow Home Loans
Do you have questions about something you read here or about buying a home in general? Don’t hesitate to reach out.
Whether it’s housing market-related, or something about your specific situation, I’ve helped other buyers find success – and I can help you too.
