Finance Derivative Awards is established with the aim of honoring excellence in performance and rewarding Companies across different domains of business & financial world.
Our award honors companies and their key players who have performed extraordinarily well and who strive for fineness & provide a platform for recognition.
Check our online publication at www.financederivative.com
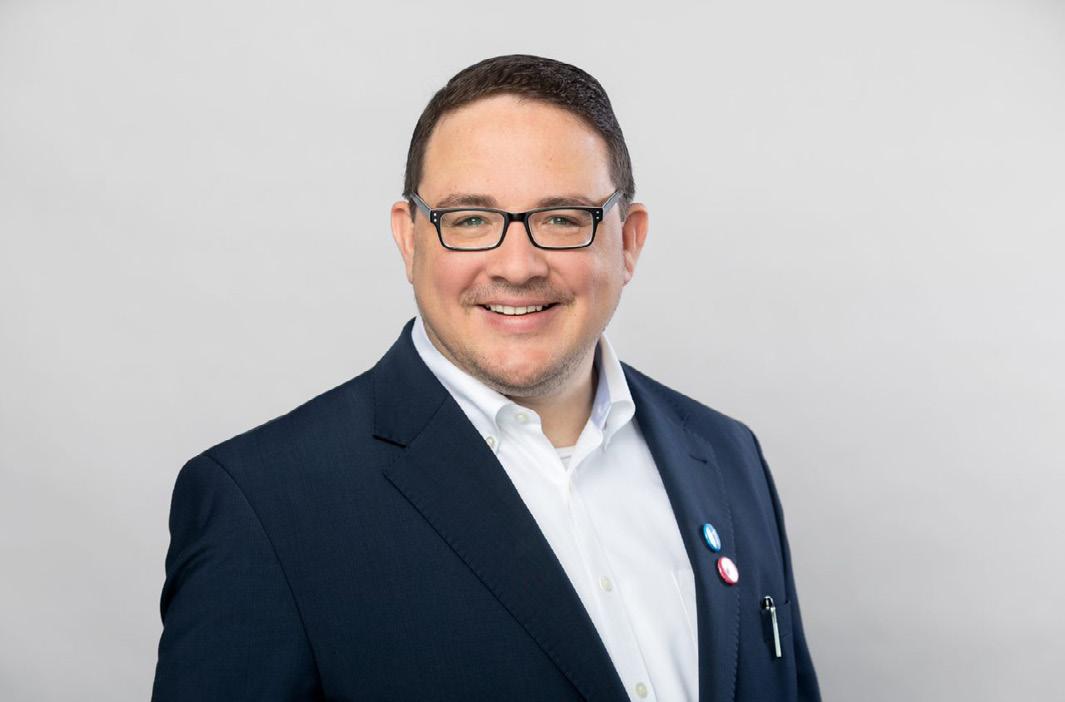
FROM THE CEO
Dear Readers,
As we release Issue 13 of Finance Derivative, I am proud to see how far our publication has come in shaping conversations around finance, technology, and global business. This edition highlights the pressing themes of our time — from digital sovereignty and BNPL regulation to agentic AI in accounting and digital asset recoverability.
This issue captures the transformative shifts redefining finance and technology. We explore how cloud sovereignty is reshaping geopolitical risk, why proportionate BNPL oversight is vital for consumer trust, and how agentic ROI is becoming the benchmark for AI adoption in accounting.
We also spotlight the urgent need for Digital Company IDs to combat fraud and unlock SME growth, alongside the critical infrastructure of stablecoin recoverability. Each article is designed to bridge rhetoric with operational reality, offering practical insights for leaders and innovators.
Our mission remains clear: to provide trusted insights that empower leaders to navigate uncertainty and seize opportunities. The Finance Derivative Awards continue to honor excellence across industries, and I encourage you to submit nominations to celebrate those driving innovation and resilience.
As always, our goal is to inform, challenge, and inspire. I invite you to engage with these ideas, share your perspectives, and continue shaping the future of finance with us.
Happy Reading !!
Warm regards,
Mehtab Chisti CEO
The Accountant’s Guide to Agentic ROI
In 2026, one thing is becoming clear. The novelty phase of agentic AI is over. The era of flashy demonstrations has faded. Chief technology officers are no longer being asked what AI might do. They are being asked what it has delivered - and where the return on investment sits.
Whilst this trend is being heavily felt across the world of finance, the accounting and bookkeeping industry finds itself in a state of limbo. With a strong tradition built on accuracy and trust, the sector generally takes a measured approach to adopting new technology. Milestones like Sage bringing products such as Sage 50 fully to the cloud in 2026 reflect a broader, steady evolution rather than sudden change.
However, the result is a market at a crossroads with many accountants and bookkeepers actively exploring agentic AI, but others still working to separate practical value from noise. Equally, with the technology evolving at a rapid speed, there is still an underlying, industry-wide pressure to justify the hype. The question now is how do you turn ambition around agentic AI into commercial value?
The Foundation: Audited Data as a Prerequisite
An agentic AI system is an echo of its training history and in accounting and bookkeeping, ‘clean’ data is not a high enough bar. This must be audited at a bare minimum, with a clear focus on ongoing data health. That means ensuring data isn’t only accurate at one point in time, but complete, standardised and
regularly maintained. Errors will naturally occur, but without processes to correct and reconcile them, agents will simply automate and scale those weaknesses across every output.
To move the needle, you must prioritise labelled, high-trust financial datasets that embed real bookkeeping judgment and maintain consistency over time. This includes standardised inputs and consistent categorisation rules across systems. Ultimately, an AI agent performing tax categorisation or variance analysis is only as reliable as the guidance it is using. If the same transaction is treated differently across periods, the outputs quickly become unreliable.
However, the real value of high-quality, consistent data sits in the insights it can generate. This allows agentic AI to move beyond processing and start identifying patterns, flagging anomalies and surfacing risks in real time. In the context of accounting and bookkeeping, this could result in spotting early signs of cash flow pressure or identifying gaps in revenue collection.
When data health is strong, these insights become actionable and support better decision making but when this isn’t the case, the outputs may look convincing but crucially lack substance. At that point, you’re amplifying uncertainty rather than generating insights.
Transparency Beyond the Black Box
The defining characteristic of an agent is its ability to apply reasoning on your behalf. However, most AI systems function as black boxes. When an agent moves funds or categorises a complex transaction, the ‘why’ is often buried in a hidden layer of weights and biases. This opacity is the greatest risk to financial stability.
We need systems that convert ‘habitual’ human knowledge into explicit guidance.
For example, many accountants and bookkeepers struggle to explain exactly why they treat a specific accrual a certain way - it is often an instinct honed over decades but effective agentic AI must extract this guidance.
Imagine an agent flagging a complex VAT treatment on an international invoice. Instead of merely choosing a value, the system provides a hover-over explanation: "I have categorised this as X because your standing instruction for EU-based software services is Y, and this vendor matches the Z criteria." This level of granular justification makes the system explainable. It allows the human to see the logic, edit the underlying guidance, and ensure the agent stays aligned with evolving regulations.
Crucially, the agent can also audit that guidance over time - surfacing inconsistencies or suggesting improvements - while leaving the final decision with the professional, where context is critical.
Accuracy at Scale: The Case for SLMs
Finance is a zero-tolerance environment for ‘close enough’. While Large Language Models (LLMs) are impressive generalists, they are often too ‘creative’ for the rigid requirements of a balance sheet. To achieve true accuracy, the value of specialist Small Language Models (SLMs) can’t be underestimated.
These models are leaner, faster, andcrucially - trained on narrow, domain-specific financial logic. Because an SLM isn't distracted by the vast, irrelevant data of the general internet, it is less prone to the ‘drift’ that plagues larger models. This specialisation allows for accuracy at a massive scale.
Can your system process hundreds of millions of documents and maintain a 99.9% precision rate? To guarantee this,
there is a need to move beyond simple spot-checks and implement automated sampling and verification loops. If an agentic system cannot explain its sampling methodology or pass a rigorous stress test of its own outputs, it is a liability, not an asset.
The Rise of the Chief Assurance Officer
As workflows become increasingly autonomous, the role of the accountants and bookkeepers will not diminish; they’ll elevate. Similar to most technologies, it’s likely the efficiency gains of agentic AI will usher in the Jevons Paradox. This means the better the agents become at processing, the greater the demand for oversight from professionals becomes.
In other words, we are witnessing the rise of accountants and bookkeepers becoming ‘Assurance Officers’. In this context, their real value lies in being the system's ultimate auditor, who still leverage AI to cross-examine its work, but deliver the final approval to ensure there’s a robust level of accountability, explainability and trust.
Accountants and bookkeepers will spend less time doing the work and more time interrogating the anomalies identified by the agents. They will safeguard the standards, tune the SLMs, and provide the final stamp of human credibility on machine-led outputs. The commercial value of agentic AI will only be fully unlocked when the human remains firmly in the loop as the architect of trust.
Stephen Edginton, Chief Product and Technology Officer at Dext
Systemic Change Across Financial Institutions Will Welcome More Women Investors
TWe are on the cusp of the greatest generational wealth transfer in financial history, with women primed to hold their largest ever stake in the economy. By 2030, women in the US are expected to control $30-34 trillion in financial assets. What will these women want and need from their financial institutions; how will it differ from their male counterparts; and why are too many institutions unprepared to meet this moment?
he investment industry, both traditional and digital/alternative asset providers, must do more to welcome, support and champion female investors. Systems are outdated, designed to accommodate a singular investor profile. But investing isn’t a onesize-fits-all approach, and that’s never been more true. If we fumble this moment, there may be no coming back and it will be to the detriment of our whole industry.
Recent studies show that women over 50 are more worried than their male peers about long-term financial stability and whether their money will last through retirement. Additionally, 1 in 5 women don’t have emergency funds or cash savings, even as many prioritize
long-term planning. So, even though the looming wealth transfer provides an incredible opportunity for women to invest, current participation still lags behind the male investor. The culprit isn’t female disinterest, but the way our financial systems are still structured toward men and their historical investor behavior.
Risk: Different Realities, Blunt Tools
Women live longer, earn less over a lifetime, and have different priorities than men. As a result, they tend to trade less often and take a long view/goals-based approach to investing, achieving similar (if not better) returns than men. Yet, risk profiling tools tend to be limited in categorizing potential investments (conservative, moderate, aggressive).
The challenge isn’t to “fix” women’s risk preferences, but to design products that respect those preferences. That includes greater access to asset classes like private markets and digital assets, where the interfaces and narratives still overwhelmingly assume a male, trading-oriented user, rather than the trust- and community-driven on-ramps many women prefer.
Round-the-clock Market Accessibility
We know that women still carry a disproportionate level of invisible labor in the workplace and home, leaving them with less time dedicated to investing. This time imbalance is further compounded by traditional markets, which are only open for a fraction of the time that alternative asset platforms allow.
These platforms often better serve the female investor reality: mobile-first, self-directed, and available whenever she is ready to act. There is a massive benefit in 24/7 access for those that manage complex, non-linear schedules to manage their own positions based on real-time news and research.
Advice Beyond the Advisor
Financial advisors still largely cater to their perceived primary client: an older man with his advisor on speed dial. The future demands more investor independence and self-direction. For women, nearly half rely on themselves for investment information, with most researching on their own without professional advice — often focusing on how to protect what they’ve built, how to structure it correctly, and how to preserve hard-won savings.
To best reach and support this female investor, a quarterly review and glossy brochure isn’t enough. She desires
transparent data, scenario tools, and always-on support that enables her to do the work on her terms.
Empowering the Rise of the Female Investor
The time is now. The financial industry needs to get serious about serving the next generation of female investors, especially in alternatives and digital assets. That means removing the systemic frictions directly:
Build for real schedules, not market hours. Make platforms mobile-first, 24/7 and asynchronous, so women can fund and rebalance in the time windows they actually have.
Modernize risk tools for women’s realities. Go beyond conservative, moderate, or aggressive to account for longer lifespans and life events like career breaks, caregiving, divorce or the death of a spouse – and make it easy to take measured positions in alternatives and digital assets with clear guardrails.
●Design for independent decision‑makers. Assume she’s doing her own homework. Put plain-language explainers, transparent fees and interactive scenario tools right next to every product, instead of burying them in PDFs or advisor-only portals.
While the rise of female investment in digital assets isn’t inevitable, we believe that we’re leading the way on creating an environment that best meets her needs. When we reduce the friction that stands between women and the systems that already exist, we unlock trillions in assets and opportunities for all. It will be one of the defining financial moments of this decade.
Kevin Maloney, CEO, iTrustCapital
What digital sovereignty means for Britain and beyond
In a political landscape marked by tariffs, tension in the Middle East, and growing uncertainty around the United States’ involvement with NATO, European countries and companies are evaluating their security. When contemplating security, people often consider nuclear capabilities, volatile leader personalities, and violent nonstate actors. Not everyone thinks about who owns digital infrastructure, and what that may mean for national security.
With American providers owning 85% of Europe’s digital cloud infrastructure, some are sounding the alarm. As today’s businesses and governments rely heavily on the cloud and Microsoft services, computers have become an essential part of operations around the world. Yet, most organisations have not thoroughly evaluated the potential cyber risks that could result from foreign ownership of the systems they rely on daily.
Sovereignty risk adds a new dimension to cyber risk: it’s not just hackers and criminals anymore. Now, organisations may face incidents for geopolitical reasons, rather than solely financial ones.
Why businesses must consider digital sovereignty
Digital sovereignty is not just a concern for governments, but the private sector as well. For example, a Gartner survey
found that over 60% of Western European Chief Information Officers (CIOs) stated that they will rely on regional cloud providers due to geopolitical factors, with 55% saying that open-source technology will serve as a major part of their plans.
If tensions between territories continue to grow, access to foreign technology may become strained or unreliable. Unreliable technology does not bode well in the business world.
The gap between political rhetoric and operational reality
While European business leaders may speak about reducing foreign dependencies, the operational reality of the situation does not necessarily reflect political rhetoric.
Foreign ownership comes with foreign governance. For example, the 2018 Cloud Act states that the American government has the right to access data stored outside of the US, meaning that American cloud providers like Google, Microsoft, and AWS may provide the American government with non-American data. However, it is not immediately clear what this may mean for businesses or their clients and their clients’ data.
Businesses may be interrupted due to service shutdowns and embargos, or even have their confidential data accessed by foreign governments. Just as political rhetoric may not match the operational reality, awareness of these IT risks often are not reflected in financial terms or terms that leaders can act on.
To solve this issue, businesses must shift from measuring vulnerabilities to measuring consequences. How much would it cost a company if their factory stops working because a critical provider
has banned you? What about if a foreign government accessed proprietary information, which was then leaked to a foreign competitor?
Without a quantitative, financial risk analysis, companies and governments will struggle to know what types of incidents will really cost them. Cyber risk quantification analyses potential cyber loss scenarios, which are then translated into financial terms. Without this financial explanation, many may struggle to understand the impact of the cyber risks, or what cyber risk looks like in reality.
What digital sovereignty looks like in today’s globalised world
Considering how much of the European digital infrastructure is owned by US operators, some may wonder what digital sovereignty would look like in practice. In short, organisations would prioritise open-source, local providers rather than those based overseas.
However, avoiding American-made technology is not convenient. Many businesses will be unwilling and unable to change providers, and those that do switch may have long lead times until their data is fully switched over to European providers (if they exist in that field at all).
Yet, the risk does not disappear. Company leaders need to get out of the paralysis that the scale of the problem causes, and start putting numbers to the costs as well as the risks. Risk quantification can identify the most critical scenarios and business processes, which helps break down the risk and makes the problem more actionable. Simply being aware of cyber risk is no longer enough, C-suite leaders must take action, or face the consequences.
- Asdrubal Pichardo
Buy Now, Pay Later (BNPL) regulation represents an important inflection point for the future of consumer finance. From this July, the Financial Conduct Authority (FCA) will bring the sector under formal oversight, signalling that BNPL is no longer an emerging trend, but an established tool helping millions of people manage their spending.
Introducing proportionate regulation will ensure the sector can balance innovation with robust consumer protection; helping to build trust, support sustainable growth, and define the role BNPL will play within a modern, inclusive consumer
What Buy Now, Pay Later regulation means for the future of consumer finance
finance system. BNPL offers a simple, interest-free alternative to other credit products, allowing people to buy the things they need, when they need, at a time when credit card APR is at its highest level in 20 years. Our data has shown that 42% of UK adults who are aware of BNPL have said that it has made it easier to buy what they need, whilst 32% who have used it have done so to manage their monthly cash flow.
Why regulation matters
Clearpay was built with consumer protection in mind, ensuring they are supported to manage their money responsibly. We
start customers on low spending limits that increase only when there is a history of on-time repayments, we pause accounts if a single payment is missed, and we cap late fees. As a result, 96% of Clearpay transactions globally are paid on time and 98% never incur a late fee.
As BNPL adoption continues to grow, it’s important that consumer protection keeps pace, while still embracing the benefits that have made BNPL so appealing such as its simplicity and digital-first design. That’s why we’ve consistently supported thoughtful, fit-for-purpose regulation that protects consumers without holding back innovation.
What regulation will mean in practice
Firstly, regulation will strengthen existing protections for consumers by bringing all BNPL providers in line, for example by making sure affordability checks consistently take place and requiring all providers to give clear, standardised information to make the process better for consumers. It will ensure they can rely on the same legal protections they have access to when using other forms of credit, including Section 75 and the Financial Ombudsman Service.
Secondly, regulation will foster even greater trust with consumers and create a more sustainable foundation for the future of BNPL. Our research showed that 71% believe it is important for BNPL to be subject to UK financial legislation, whilst 48% are more likely to use BNPL once regulation is in place.
Finally, this regulatory framework will level the playing field, allowing firms to innovate responsibly while ensuring consumer protection. In doing so it will accelerate improvements across the fintech sector and enhance the experience for customers. The benefits extend beyond consumers. Many small businesses are already seeing increased sales by offering BNPL at checkout and regulation is set to build further confidence in this payment option. In fact, 40% of shoppers say they are more likely to shop in-store once BNPL is regulated, demonstrating the fintech sector’s potential to support
high street retail growth at a time when many businesses are under pressure. 2
How the fintech sector can ensure success
Moving forward, the success of BNPL regulation in shaping the future of consumer finance will depend on how closely providers and regulators work together. This isn’t just about putting new rules in place; as an industry we need to make sure that consumers understand them, so that they can confidently use BNPL to manage their everyday spending.
BNPL has created the most successful shake up to the credit industry in the past 60 years. The solution that gives consumers access to short term credit with no interest has demonstrated that a payment option that benefits both consumers and merchants simultaneously is possible. Proportionate regulation will define BNPL’s role in a more accessible, transparent, and inclusive financial system; a future-facing system that balances innovation with strong consumer safeguards.
Clearpay commissioned Public First to conduct an online survey of 2,053 UK adults between 15 and 25 August 2025. Quotas were used to ensure a representative sample and all results are weighted using Iterative Proportional Fitting, or 'Raking'. Weighting targets are based on interlocking age & gender, region, and social grade to Nationally Representative Proportions.
Clearpay commissioned Censuswide to conduct a survey of 3000 UK adults between 7 – 13 February 2025. Censuswide abides by and employs members of the Market Research Society and follows the MRS code of conduct and ESOMAR principles. Censuswide is also a member of the British Polling Council.
Rich Bayer, CEO, Clearpay
Digital assets need more than regulation to win institutional trust, they need recoverability
Digital assets are no longer a speculative frontier. Banks and financial institutions are actively developing products to meet rising client demand, particularly as stablecoins and tokenisation move closer to mainstream financial use.
That demand is increasingly shaped by a preference for structure and transparency. Data from EY shows that 62% of institutional investors would rather gain
exposure to crypto through regulated vehicles, reinforcing the importance of clear rules and governed environments. In markets like the UK, policymakers are beginning to respond. Collaboration between the Bank of England and the FCA on regulated stablecoins signals a coordinated effort to integrate digital assets into the financial system.
But regulation alone will not be enough to unlock long-term adoption. Institutions
are not only concerned with how digital assets are issued or governed, they are focused on how they behave under stress. A more fundamental question – and one that is uniquely a digital asset issue – is operational: what happens when access is lost?
Regulation sets the framework, but not the outcome
Regulatory clarity plays a critical role in
reducing uncertainty. Rules around issuance, custody and governance provide the foundation for institutions to participate and encourage stablecoin adoption with confidence. They enable firms to build products, define responsibilities and manage risk within a recognised framework.
However, trust in financial services has never been built on regulation alone. It is grounded in operational certainty and the assurance that systems will function as expected, particularly when something goes wrong. In traditional finance, the loss of access to an account or asset does not result in permanent loss. Recovery processes exist, even if they are tightly controlled and subject to verification. There
is, for all intents and purposes, a ‘forgot password’ button. In much of the digital asset ecosystem, though the technology exists, this assumption does not yet hold.
Recoverability is the missing layer of infrastructure
In many current models, if private keys are lost, seed phrases are compromised or access credentials fail, assets can become permanently inaccessible. This is a deep-rooted issue and represents a structural gap in how digital assets are delivered and managed.
For institutions, this creates an unacceptable form of operational risk. No bank or regulated financial provider can scale a product where loss of access equates to permanent loss of funds. The issue is not that digital assets are inherently more fragile, but that the safeguards taken for granted in traditional finance around access, governance and continuity are often absent or underdeveloped, not because they don’t exist, but because institutions underestimate the inherent risk or prefer to self-back up their private key.
Addressing this gap requires treating access recoverability as core infrastructure. That includes implementing governance frameworks for key management, establishing processes for access restoration and ensuring resilience against events such as internal control failures, staff turnover or compromised credentials. These are standard considerations in any other area of financial services; digital assets cannot remain an exception.
Why this matters for stablecoins
The urgency of access recoverability becomes even clearer in the context of stablecoins. As institutions explore their use in payments, treasury management and on-chain settlement, stablecoins begin to
resemble critical financial plumbing rather than standalone assets.
In these use cases, uninterrupted access is essential. A failed payment or inaccessible account is not just a user issue, it’s a business continuity problem. Without robust recovery mechanisms, the reliability of stablecoin-based systems is fundamentally undermined.
If stablecoins are to support institutional scale activity, they must offer the same baseline assurances as traditional financial infrastructure. In other words, be able to safeguard assets and ensure that operational failures do not result in irreversible loss.
From feature to prerequisite
The institutional case for digital assets is increasingly well defined, and the regulatory direction is becoming clearer. But neither will be sufficient on their own to establish lasting confidence.
What will ultimately determine adoption is whether institutions can deliver digital asset services with the same operational safeguards that visibly underpin the rest of the financial system. That means ensuring that loss of access is not treated as final, but as a manageable and recoverable event.
For stablecoins and the broader digital asset ecosystem to scale sustainably, recoverability cannot be an afterthought or a differentiator. It must become a foundational component of the infrastructure itself.
Anthony Yeung, Chief Commercial Officer of CoinCover
THE IMPACT OF TECHNOLOGY ON ACCOUNTANCY
THistorically, whilst most financial accounting was undertaken manually, leading to heaps of paperwork and copious amounts of on-and-off site filing systems, the benefit was always keeping a record of every transaction. Fast forward to today, and all VAT-registered business are required by law to keep digital records and file tax returns using compatible software.
he introduction and continued evolution of technology and accounting practices are seen simply as changes to the profession that have enabled it to be more efficient in billing units of time. These challenges for business and personal tax means that more people are turning to professional accountancy services to support them through the digital taxation minefield.
But what exactly does this mean for the profession?
The key tech challenges facing accountancy firms
For the technologists in accountancy, whether a CIO in a large firm, an IT Manager or partner responsible for IT in a smaller organisation, they all share similar concerns:
• Service availability – ensuring always-on services, especially at critical times in the accountancy calendar, i.e. self-assessment deadline and Government budgets.
• Systems performance – meeting staff expectations for speed, accuracy and availability.
• Data security – ensuring that all client data remains secure and knowing exactly where it resides.
• Data sovereignty – ensuring data remains within preferred jurisdictions.
• Shadow IT – the use and expansion of uncontrolled SaaS applications.
How do accountancy firms address these common challenges?
1. Improving efficiency
In the accountancy business, time is money, and technology should be there to enable the business, not restrict it. By using appropriate and secure cloud-based solutions, processes can be streamlined, helping to maximise performance, whilst minimising the risk of downtime where systems are unavailable, resulting in improvements in the overall efficiency of staff.
Cloud computing also offers the flexibility and scalability required to respond to these changes in demand, particularly at tax year-end and key budgeting periods. They empower teams to scale IT resources without the need for
additional investment, paying for what is consumed, only when it needs to be consumed.
2. Enhanced collaboration
Collaboration is essential in an accountancy practice, where cross-functional teams must work together to meet customer expectations and regulatory requirements. By using cloud-based collaboration tools and unified communications solutions, teams can work together on projects, share files, and communicate in real-time, improving delivery speed and reducing errors.
3. Customer engagement
Through cloud services, as well as collaboration internally, these communication channels can be used to collect and share data with customers in a controlled and secure manner, making it simpler to conform to regulatory compliance. Where the customer is tech savvy,
activities can be reviewed and digitally signed by the customer to accelerate the point at which the client can be invoiced.
4. Data security
Data security is always a significant concern in any industry where sensitive customer data must, by law, be protected. Cloud solutions need to be supported heavily by security measures including, but not limited to, next-generation firewalls, intrusion detection systems, encryption, and vulnerability scanning - all essential in the protection of sensitive data.
As new applications and services come to market, technologists need to be the enabler, and have processes to quickly assimilate services that add value to the tech portfolio. Having a proven methodology for accelerated assessment, ensuring any service is secure, robust and conforms to legislative requirements,
and then ensuring adoption is key to containing shadow IT.
Where a service does not conform, the process must document why it is excluded and then prohibit it from the company portfolio.
As the Making Tax Digital deadline approaches, getting ahead of the curve with technology is important now more than ever. Accountancy firms should be securing processes, locking in software and ensuring the transition is as smooth as possible.
Neil Hall, Strategy Consultant at Wavenet.
How Digital Company IDs are the key to unlocking growth for the UK
Identity fraud costs the UK economy over £6.8 billion every year, accounting for more than 40% of all crime in England and Wales. In the first half of 2025 alone, there were over 2 million incidents of fraud, a 17% increase compared to the same period in 2024. While political noise around personal Digital IDs is ramping up as the government has relaunched the scheme as a voluntary project, it raises the question of what this means for the commercial sector.
- Anna Wallace, CEO of the Centre for Finance, Innovation and Technology
Digital Company ID is no longer a nice-to-have; it is the infrastructure the UK economy urgently needs to unlock growth across the UK’s financial and SME landscape. A secure, interoperable Digital Company ID will empower businesses to prove who they are, what they do, and how they operate, mitigating fraud risk, reducing compliance costs, and enabling the UK to compete in the global digital economy.
However, delivering trusted digital identity for businesses is not a simple challenge. It requires deep technical expertise, cross-sector coordination and alignment between industry, policymakers and regulators – many of whom operate in different parts of the digital economy.
But how can this be achieved in practice?
The cost of stagnation
Over £600 million was stolen by fraudsters through payment fraud and scams in the first half of 2025. This is a staggering amount, the burden of which is primarily felt by UK’s 5.5 million SMEs - the backbone of the British economy. While financial services firms spend £34.2 billion annually on compliance to tackle this issue, Digital Company IDs offer a more cost-effective solution.
By providing a single, reusable, and verified source of corporate identity, businesses and financial institutions can have the confidence to combat economic crime and support the widespread adoption of secure digital identities. Research conducted with over 1,000 UK SMEs found that 80% of respondents were willing to pay for Digital Company ID. In return, this can help cut costs associated with business verification and bank KYB procedures by over 50% and reduce the time required to verify and onboard businesses by 60%.
This isn't theoretical demand – it is real market readiness. The necessary infrastructure already exists to support a faster, more competitive UK. However, the scalability of this technology is hindered by fragmentation between key stakeholders.
Multi-stakeholder collaboration
Banks, technology providers, regulators and marketplaces all rely on identity verification, but historically they have approached the challenge in isolation. The scale and sophistication of fraud have increased significantly in recent years, with criminal networks now operating in highly organised, technology-enabled ways. Industry body UK Finance estimates that criminals successfully stole £1.17 billion through banking fraud and scams in 2024.
Digital Company ID has the potential to deliver an annual
economic boost of £600 million. But it’s not something that one organisation or sector can scale alone. This is a systemic challenge that requires a systemic response.
By bringing together leaders from finance, technology, academia and regulators, supported by interoperable infrastructure and clear governance frameworks, we have both the technical feasibility and commercial viability to scale Digital Company IDs. The next step is implementation.
Keeping pace with the EU
To embed trusted digital identity into core financial processes – from onboarding to payments – we must move from a reactive approach to fraud towards a more proactive and preventative model. To do this there needs to be a trust and governance framework that defines roles, standards, and responsibilities across the entire Digital Company ID ecosystem.
The European Union is aggressively moving toward the EU Digital Identity Wallet, which will mandate every member states to provide these to businesses and citizens by the end of 2026. By 2027, payment service providers across the EU will be legally required to accept them.
If the UK fails to maintain a high degree of interoperability and standardisation with these global shifts, it risks falling behind. SMEs need to be able to seamlessly verify their credentials across borders. To keep pace, the UK must accelerate its regulatory framework, ensuring domestic standards align with international protocols to prevent friction in cross-border trade.
Moving forward
The market is ready to move – but it needs clear, consistent policy foundations to do so at pace and with confidence. Whether through shared infrastructure or the development of common standards that enable multiple players to build and compete. CFIT’s Digital Company ID MVP – being built to enable effective data exchange between SMEs, ID data providers and banks – being accepted into the FCA’s Regulatory Sandbox is a testament to the importance of a collaborative effort to enable a clearer pathway to adopting Digital Company IDs at scale.
But this is only the beginning. If the government wants to create a more competitive and innovative financial system in the UK, they need to encourage greater cross-sector collaboration between the financial and technology sectors to adopt and scale Digital Company IDs. Only then will we be able to combat the harmful consequences of fraud and economic crime.
Understanding how the disappearance of cash is changing workforce economics
The UK’s move away from cash payments is now well established, with under 10% of all transactions in 2024 still made using physical currency. The downward trend is set to continue and is expected to hit just 4% in the longer term.
Clearly, there are many benefits to the near-universal availability of digital payments, but, as is well understood, the disappearance of cash is not ideal for everyone. Among the most disadvantaged groups are those sectors of the economy where cash has always been part of the payment culture, with hospitality perhaps the most obvious example.
The sector has been under significant financial pressure for years, with
challenging trading conditions and rising costs forcing the closing of thousands of businesses. Recent increases in business rates and the withdrawal of pandemic-era discounts have only compounded the challenges owners and staff face.
Tipping troubles
One of the main areas where the gradual disappearance of cash is having a direct operational and personal impact is tipping. UK tipping culture has seen significant change over the past 12 months or so, largely driven by the introduction of the Employment (Allocation of Tips) Act, which requires operators to pass 100% of tips to workers and to maintain transparent records.
By Swati Deshpande, PAYNT
As everyone knows, tipping has historically operated as an informal exchange between customers and staff, often handled in cash and largely outside established business systems. Today, however, tips are increasingly paid digitally and processed alongside regular customer payments via the same financial systems used for bill payments. The big problem this
creates for employers is that the gratuities process has morphed into formal financial transactions that businesses must manage properly.
In day-to-day practical terms, these micro-payments, which can occur at very high volumes, can easily create a major administrative headache for finance and HR teams, particularly as they are now subject to targeted compliance requirements.
For instance, rather than being handed directly to staff in cash, many tips are increasingly processed alongside the main customer transaction, and, to comply with the law, they must be separated from the bill amount and tracked independently of revenue.
Tips must then be accurately reconciled and then distributed to employees, many of whom work across multiple roles or teams. Employers must also ensure tips are paid promptly, adding an extra step to payroll coordination. The net result is a significant increase in operational complexity, particularly for larger businesses that may need to process thousands of tipping transactions each month.
It comes as no surprise, therefore, that a significant number of hospitality businesses have yet to update their tipping processes. For example, industry research conducted last year assessed how the industry and workers have responded to the Tipping Act, revealing a significant gap in understanding and implementation.
Specifically, 25% of hospitality employers said they had made no changes to how they handle tips since the law took effect. Part of the problem is that over a quarter (26%) of employers say they have struggled to understand the legislation and how to apply it within their businesses. In fact, only just over half (53%) of employers correctly knew that 100% of tips must be passed on to staff.
A lesson for the wider economy
As cash retreats from everyday use, the transformation of tipping in hospitality serves as a microcosm of wider changes across the economy. In businesses everywhere, the adoption of digital payments means that even the smallest transactions are more deeply integrated
into the overall financial infrastructure, with those processing high volumes of micro-payments experiencing disproportionate operational overheads.
And it’s not just operators who must adapt. There is also a direct impact on workforce economics, as payments once handed over directly are now processed through financial systems that employees have little choice but to trust. In this context, business owners have a responsibility not only to collect payments effectively but to ensure that staff receive the money intended for them.
The problem is that a quarter of hospitality staff report they have not seen any change in how their employers handle tips since the tipping law was passed.
Most worrying of all, a further 23% say they have actually received fewer tips, strongly suggesting that tipping processes, or the lack of them, are often failing to protect the interests of employees, many of whom rely on tips or service charges to supplement their regular income.
Ensuring that workforce economics continue to work in the best interests of everyone involved, there is a clear need to build trust in how earnings are processed and distributed as payments become increasingly digital. Without better checks and balances in place across the board, there is a risk that confidence in these systems will erode, with employees most likely to suffer.
CASS 15 is coming: how should FinTechs be preparing?
Karen Allan, Partner, HaysMac
From 7 May onwards, FinTechs operating in the UK will find themselves operating in a new, and perhaps unfamiliar, regulatory environment. The reason is that the latest iteration of the FCA’s Client Asset Sourcebook (CASS) rules will come into force and, for the first time, will bring a large number of FinTech, payments, and e-money firms in scope.
Indeed, from 7 May onwards, any API or EMI firm which holds or expects to hold over £100,000 of relevant funds within a 53-year period will be subject to the rules. Crucially, this means that they will be required to conduct a regulatory audit executed by a statutory auditor. This is not only a marked change from the previous safeguarding regime, but also a requirement that the clock is already ticking on as firms will need to complete their first audit within six months of the new regulations coming into force. Moving forwards, audits will need to be completed within four months of the year-end.
Audits are not the only regulatory requirement that firms will need to contend with either. Rather, CASS 15 will also introduce monthly reporting requirements on safeguarding funds and daily reconciliations, whilst firms also need to implement the measures in the CASS 15 resolution pack to demonstrate how they are planning for possible failures.
However, whilst this may seem like it has set up a challenging few months for FinTechs, CASS 15 shouldn’t be seen as a compliance headache but instead as a powerful opportunity.
A signal to the market
Firms do need to prepare for the changes introduced by CASS 15, but those that make the right preparations will be sending a powerful signal to the market that they have robust governance procedures in place. In a competitive fundraising environment, being able to demonstrate the strength of their resilience and compliance with the regulations will help fintechs to set themselves apart from competitors. After all, good governance is a green flag for investors and can instill confidence at every stage of a firm’s growth.
The key for firms will be to invest in the right expertise now to ensure that they are equipped to stay on the right side of the rules once these are in force. The starting point for this, as with most things, should be with management, as the firm’s management will set the tone for the entire business and so its essential they show support for regulatory oversight and compliance. They should also of course practice what they preach by taking steps to ensure they are themselves complying with the relevant rules and regulations.
FinTech firms should also put together a team of advisors to guide them through the changes. This must include a statutory auditor, and building a strong partnership with their auditor should be a priority. This should help to ensure that the CASS 15 audits can be executed as seamlessly as possible. Similarly, firms will need a compliance advisor to assist with the preparedness reviews.
Another crucial role will be a ‘head of compliance’. Concentrating responsibility for this with an expert will help ensure that firms are able to navigate the rules, as
Karen Allan
well as spot potential challenges and structural concerns before they become a problem by identifying the right approach to tackling them.
Timing will be critical here as the sooner these teams and partnerships are built, the better. Indeed, in an ideal world, an auditor would already have been appointed, but if not then it should be a top priority for management. That’s in part because, although its important to have an auditor in place as soon as possible, it’s equally important this process isn’t rushed. For one thing, this is a new world for auditors as well as FinTech firms, so it’s crucial that the auditors have the right expertise and the required resources to complete the audit.
One consideration that will be particularly important (and will require careful scrutiny) is whether the management
team feel confident in the auditor’s ability to challenge them. It is almost inevitable that there will be challenges that need to be overcome as the sector comes to grips with the new regulations, with both auditor and auditee likely to be learning on the job to some extent.
As a result, a thorough interview process will be needed to ensure that firms and their auditors are properly aligned. The same can be said of the process for selecting a head of compliance.
Reaping the rewards
Once the right expertise is in place, FinTech firms will need to take steps to foster a truly collaborative environment as this will lay the foundations for success. Naturally, this collaboration will need to be a two-way street as the auditors will need to be able ‘look under
the bonnet’ of the FinTech firm and both parties will need to ensure they have a thorough understanding of the others processes.
However, whilst that might be relatively time consuming in the short-term, it is an investment that is well-worth making because the long-term benefits should be substantial. Most importantly, as compliance procedures are bedded in, founders and business leaders will be freed up to do what they do best – drive the growth of their company.
They will also be able to do so safe in the knowledge that their business is built on solid financial foundations and operating in full compliance with the regulators. That should also make for a more compelling pitch when speaking with investors
Why AI agents are the new era of UK Retail Banking
By Andreea Plesea, PhD, Co-Founder and COO of Druid AI.
How retail banks can usher in a new era of AI agents to support customer journeys
Retail banking has become a digital-first industry with 88% of UK adults, roughly 48 million people, now using some form of online or remote banking to check balances, make payments and manage their finances. This shift has turned digital channels into the primary and highest-volume touchpoints between banks and their customers.
With customers reaching for their mobile device long before visiting a branch, digital banking is no longer a differentiator - it is a baseline expectation. The real
challenge facing retail banks now is whether their digital services can consistently resolve customer needs from start to finish without introducing operational risk and friction.
Neobanks such as Monzo, Starling and Revolut, as well as branchless banks, have been built on digital-first experiences, a shift that challenged traditional retail banks to rethink digital strategies in order to compete.
Although competitive rates are a crucial factor for customer retention, industry data reveals that relying on rates alone is not enough. In Q3 2025, more than 265,000 bank switches were recorded in the UK. Of
those who switched, over two-thirds (69%) preferred their new bank, with online banking (44%) and customer service (35%) both ranking higher than the interest earned (33%) as their main reasons for preferring their new bank.
These figures underline how service quality and digital experiences have become critical and that the competitive advantage lies not in digital access, but in how quickly and reliably banks resolve customer requests across digital channels.
Building AI agents for the new era of digital banking
The success of Interactive Voice Response (IVR) and chatbots remains limited, with 40% of customers reporting a poor experience with a chatbot. In many cases, they become deflection-only systems that frustrate customers and increase pressure on frontline staff, because the actual request still needs to be resolved elsewhere in the organisation.
Chatbots and IVRs are built on pre-scripted data, and they struggle with context and stall when presented with non-linear tasks. While they are useful for directing customers to service pages and answering basic questions, human intervention is eventually required along the service chain, leaving the actual impact on customer experience in doubt.
The deployment of proven AI agents is an opportunity for UK retail banks to move away from scripted bots toward multi-step workflow execution that operates within clearly defined governance and policy boundaries.
By acting as an orchestration layer, AI agents can coordinate tasks across multiple internal systems and platforms simultaneously, going beyond answering questions to executing customer requests such as retrieving records, guiding loan applications or updating account information. AI technology has evolved beyond answering basic customer queries to actually resolving customer enquiries.
Why operating models are a bottleneck for AI adoption
A common misconception is that AI agents can simply be ‘plugged’ into systems without changing the way teams work. That is partly true for knowledge-based AI solutions, where agents can look up information or answer questions based on internal documents, but this changes when an AI agent is embedded into a workflow.
Risk arises when it is assumed that adding more automation and service channels will improve customer satisfaction. In reality, this inadvertently adds complexity and further fragments existing service models, leading to inconsistent outcomes.
Retail banking leaders need to prioritise established workflows, system design and governance. Adopting AI without a unified orchestration layer is effectively skipping a step and could be the difference between a series of isolated pilot projects and scalable AI solutions.
Rather than acting as a simple support tool, an AI agent becomes a digital co-worker embedded within operational workflows that makes decisions based on defined rules and interacts with customers or teams in real time.
To scale this capability, banking leaders need to focus on clear process ownership, defined escalation paths and continuous optimisation. If these elements are missing from the operating model, the agent either underperforms or forces teams to build informal workarounds that undermine efficiency rather than improve it.
Ultimately, adopting agentic AI is an operating-model question, not just a technical one. Treating AI agents as a bolton tool that can be implemented and then forgotten about will result in any deployment moving beyond a proof of concept.
Andreea Plesea
What retail banks need to focus on
Most banks already have enough systems, data and infrastructure in place to start using AI agents in a meaningful way. The challenge is identifying which workflows are best suited for automation and where staff are currently bottlenecked with routine service requests that could be handled by an AI agent.
For example, automation should not be applied to high-risk compliance or financial decisions if the surrounding data environment is not mature enough to support secure and auditable outcomes. When data quality is poor, systems are fragmented, or audit trails are incomplete, AI agents cannot operate reliably as they depend on complete, well-governed information to function properly.
When these foundations are in place, however, the same systems can help apply policies, enforce approved language and ensure consistency across customer interactions. This is critical for retail banking, where regulatory expectations around accuracy, privacy, auditability and policy adherence are exceptionally high. In such an environment, a wrong answer can impact major financial decisions or disrupt access to essential banking services.
Banks that view AI agents as a technical tool only, without reflecting on their own systems and governance, will see slower adoption. Without clarity on what can or should be automated, where decisions are made and which outcomes are desired, no amount of technology will compensate for that uncertainty.
Future-proofing the retail banking sector
The UK is moving toward a cashless society, with cash payments expected to account for only 4% of transactions by 2034. As physical branches continue to close, the demand for more efficient online banking experiences is no longer a peripheral concern but an operational necessity.
For retail banking leaders, adopting the right technical tools is only the first step towards enhancing service delivery. To move beyond isolated pilot projects and avoid siloed systems, banks need to prioritise data reliability and system governance.
Only by establishing these foundations can banks move beyond fragmented digital tools and deliver the seamless, responsive service customers are increasingly expecting.
How technology can be used to identify vulnerable customers
Financial services firms are under significant pressure to strengthen their identification and support for vulnerable customers. Yet much of the sector’s technology investment still flows towards efficiency and cost savings rather than vulnerability management and safeguarding.
In financial services, the contact centre is often the first and most frequent point of interaction for customers. Whether they are speaking to a credit agency, an insurance provider, a loan company, or a bank, it is the customer-facing team that shapes the experience and ensures fair treatment from the very first interaction. This is particularly important for customers who may be vulnerable or experiencing financial hardship.
There’s an opportunity for businesses to recognise AI's important role in improving early vulnerability detection. Rather than just deploying AI projects to focus on operational efficiency, it could, and should be
used to identify behavioural cues that could suggest risk factors, while also facilitating more consistent and proactive responses. It shifts the AI focus to more responsible, customer-centred outcomes.
It's less about efficiency and more about responsibility.
With rising numbers of customers experiencing hardship, financial institutions need to invest in technology that can strengthen their ability to recognise risk much earlier and intervene more effectively.
In many interactions, automation can handle the endto-end process with clear guardrails and escalation to trained agents where needed. For financial services, which deal with a high volume of routine queries, this shift can be transformative.
AI-enabled systems can already carry out a range of tasks that have traditionally required an individual employee’s time, including:
- Sending automated payment reminders
- Guiding customers through instant payment processes
- Creating and managing payment plan
- Answering common questions about complex documents, policies or contracts
These tasks can now take place within a single journey, with AI seamlessly shifting the customer to the most suitable path. It assesses context, detects changes in behaviour and adjusts the interaction instantly.
But the real game changer is recognising that the technology can help identify and flag potential indicators of financial difficulty.
For financial service businesses, this means improved operational capacity without compromising the quality of support. It also means that agents are freed from repetitive transactional tasks and can be redeployed to handle more complex or vulnerable customer cases where human interaction makes the greatest difference.
Detecting hardship without expecting customers to explicitly ask for help
One of the challenges facing many banks, credit lenders, or insurers is that customers often do not explicitly say, or even recognise, when they are vulnerable and in need of help. Instead, they may hint at difficulty, use tentative language, or become hesitant when discussing payments. These nuances can be easy to miss during a busy shift in a contact centre.
But advances in conversational intelligence mean that AI can rapidly analyse language patterns and behaviour to identify early cues of financial distress in real-time. It can recognise patterns in tone and phrasing, identify repeated uncertainty, and pick up signs that a customer may be struggling even when they do not say so explicitly.
The technology does not make decisions on behalf of the organisation, but it can highlight where additional care may be needed. That might involve escalating the case to a specialist team, directing the customer to a short-term hardship
pathway or prompting a manual review.
For regulated financial institutions, this level of support can reduce the likelihood of customers receiving inconsistent advice. The technology is now capable of working far more intuitively and proactively by escalating cases much sooner and directly connecting customers to the right team.
Ensuring
compliance and building a reliable
audit trail
Ensuring that every customer receives correct, compliant information is one of the most demanding challenges in contact centres, particularly for financial organisations dealing with credit, lending and debt recovery.
Businesses know that they will be scrutinised for their record-keeping processes. They need real-time access to an auditable log of consistent communications, particularly when contact centre employees handle high volumes of calls, payments, or disputes.
The value of AI-driven contact centre technology lies in its ability to ensure that
- Ben Booth, CEO, MaxContact
each interaction is consistent and compliant with strict standards. The use of automated tools will make it much easier to log actions on client accounts, including payment attempts, transcript details, and support requests. Each log can be accompanied by accurate timestamps and approved messaging. The contact centre technology can also trigger vulnerability workflows and feed complete records directly into CRM systems without any manual input from contact centre agents.
This level of automation creates a reliable audit trail and reduces the chance of human error, while also giving leaders greater visibility of risk across the entire operation.
Technology should be there to support people, not replace them.
As the cost-of-living crisis continues to place pressure on households, financial service providers are dealing with more hardship cases than ever before. The challenge is not only volume but the complexity of individual circumstances.
That’s why it’s important to consider how technological advancements can be used to identify vulnerable customers earlier. Combining automated systems, multipath journeys, and skilled human agents enables businesses to provide the right level of support to those in need. This balance is increasingly important as businesses seek new ways to better support vulnerable customers without adding operational strain.
Biography: Ben is the CEO and co-founder of MaxContact, which has rapidly become one of the North’s top 50 fastest-growing tech companies. As CEO, Ben sets the strategic direction for the business, leads the senior leadership team and champions MaxContact's distinctive culture of distributed leadership and transparency. He oversees all aspects of the company's growth, from product innovation and AI technology advancement to team development and market positioning.
Using Intelligence-in-Motion and Agentic AI to boost finance customer loyalty
Mark Scrivens, FPT UK Chief Executive Officer, FPT Corporation
Agentic AI has driven powerful transformation across the finance industry, going beyond automation to give reasoning, decision-making, and adaptability to enterprise systems. But AI is continually offering new opportunities for enhancement. For the next stage in their Agentic AI journey, banking, financial services, and insurance organisations (BSFIs) are turning to Intelligence-in-Motion as a way to ensure Agentic AI delivers safer, smarter, and more human-aligned outcomes. Intelligence-in-Motion can amplify and support Agentic AI strategies to redefine competitive edge and elevate customer loyalty.
Far from replacing Agentic AI, Intelligencein-Motion is a step beyond the isolated automation of GenAI to a connected intelligence economy where fintechs operate with agility, precision, and resilience. It ensures data flows, decisions, and actions
are synchronised across people, processes, and technology, with examples from real-time loan processing and adaptive fraud detection to regulatory compliance automation.
As technology has advanced, the significance of customer loyalty has also surged in the financial services sector. Retention is key in online financial services, as some studies suggest that just a 5% increase in customer retention can boost profits by at least 25%. The pressure is on to offer a seamless digital journey.
How Intelligence-in-Motion enhances Agentic AI
Intelligence-in-Motion is best defined as the seamless orchestration of multiple AI, automation, and data intelligence solutions—each acting as an individual component, working collaboratively to learn, adapt, and continuously optimise.
It creates a dynamic ecosystem where Agentic AI agents, predictive analytics, GenAI models, and traditional tools collaborate to turn isolated AI capabilities into connected, outcome-driven intelligence. For BFSIs, this means loan approvals that adjust to risk in real time, compliance systems that self-audit, fraud detection that anticipates emerging threats before they materialise, and increased customer loyalty.
By enabling transparent orchestration between humans and AI systems, BFSIs can achieve a balance between automation and empathy, efficiency and ethics. Employees become “AI conductors”, guiding the system’s output toward responsible and customer-first outcomes.
The role of Intelligence-in-Motion in finance
Enhancing customer loyalty in the BFSI sector delivers substantial strategic and financial value. Loyal customers not only cost less to serve but also drive higher revenues and improve employee engagement. As loyalty grows, employees generate more revenue through cross-selling and longer relationships, leading to greater lifetime value and diversified income streams. Moreover, loyalty provides market stability and resilience during downturns, while emotionally engaged customers become advocates who help attract new clients at lower acquisition costs.
With customer acquisition expenses rising across financial services, retention becomes a powerful efficiency driver. In embracing technology and AI organisations can optimise operations and deliver highly personalised experiences that keep customers returning.
Real world use cases in the finance industry
In the finance industry, Intelligence-inMotion is already being deployed alongside Agentic AI to enhance customer loyalty and create greater operational efficiencies. By acting as the connective tissue that links Agentic AI with existing enterprise ecosystems, it facilitates data orchestration across departments. This works to ensure the integrity and traceability of every AI-driven decision. This level of accountability enables operational efficiencies that can positively impact bottom-line revenue.
For instance, one effective use case is real-time loan processing. With intelligent orchestration, application turnaround can be cut from days to hours, while preserving human oversight at key decision points.
Also, in adaptive fraud detection the crossagent collaboration enables systems to share intelligence, detect anomalies faster and respond instantly. This can tackle one of the greatest challenges for fraud teams, that of reducing false positives and losses.
In another complex field of regulatory compliance, multi-agent systems automatically align policies with the latest standards which updates audit trails and documentation in real time.
To optimise customer experience, AI-driven assistants can now coordinate personalised product recommendations, financial planning insights, and support interactions, all within one intelligent framework.
Through integrating Agentic AI with Intelligence-in-Motion, BFSIs achieve fluid coordination between data, models, and human operators, taking an essential step toward AI maturity and regulatory trust.
Essential infrastructure elements for Intelligence-in-Motion
To sustain this orchestration layer, some key infrastructure elements must be built for Intelligence-in-Motion to ensure trust in AI. Some resilient digital foundations for BFSIs to invest in include:
● AI-optimised infrastructure, to consist of various tech provisions including GPUs, AI-specific silicon, and in-memory data processing to support large-scale Agentic AI operations. These must be in place to meet AI’s requirements.
● A unified data strategy, which means breaking down data silos and using frameworks such as Retrieval-Augmented Generation (RAG). This can transform unstructured data, such as videos and photo files in the insurance industry, into usable intelligence which is vital for enterprises whose data is growing exponentially.
● Secure and ethical AI governance which is essential for protecting an organisation’s data and people. Transparency, bias mitigation, explainability, and continuous monitoring each play critical roles in ensuring safe outcomes.
With these three key elements in place, Intelligence-in-Motion becomes a trust engine. This ensures that each AI action remains auditable, explainable, and aligned with organisational values.
Taking the next stage in the Agentic AI journey
There are numerous applications already in operation that demonstrate how Agentic AI is reshaping businesses to be smarter, faster, and more resilient. Intelligence in Motion works to boost Agentic AI’s capabilities, to drive customer engagement, and improve operational efficiencies for financial organisations. Together, they lead the shift from isolated automation to a connected intelligence economy, where financial institutions operate with agility, precision, and resilience.
For organisations in the financial services industry, Intelligence-in-Motion is a strategic decision to advance AI’s potential for the business. Those who invest in orchestrating their AI capabilities with intelligence today will keep up with customer expectations in the fast-changing future of finance.
Can AI fix the merchant onboarding KYB bottleneck?
By Mateusz Pniewski, CEO of TransactionLink
Merchant onboarding continues to be a bottleneck for Payment Service Providers (PSPs) and acquirers due to its complexity and increasing pressures from external regulators. Unlike Know Your Customer (KYC), Know Your Business (KYB) features complex ownership structures, potentially consisting of different jurisdictions, which is becoming increasingly difficult to navigate in a timely manner.
Traditional onboarding workflows are no longer effective. When conducted manually, onboarding calls for individuals to chase documents in a fragmented and unattainable format, which not only increase approval delays, but also raise concerns surrounding consistency and data accuracy.
Regulatory standards can change quickly, increasing the pressure on acquirers to not only adapt to new standards, but ensure their customers uphold their compliance over time. As a result, merchants are becoming frustrated and compliance teams are being stretched beyond their limits.
The business impact of traditional onboarding
One of the main areas of operational friction for PSPs is traditional onboarding, which creates immense and adverse business impacts. For many acquirers, scaling has become nearly impossible to achieve, due to
increased risks, disconnected frameworks and operational bottlenecks.
Standard human-led and linear onboarding processes prevent scaling, fail to meet increases in volume and ultimately lead to backlogs. To scale in a linear fashion, hiring more staff is essential, which is often unachievable for acquirers. Human error is a frustrating, yet expected setback for scaling as manual data entries often lead to reworking documents and mistakes can inevitably cause reputational damage. Individuals are a lot more likely to miss fraudulent activity or misplace a document, which creates an unsteady foundation for scaling. When service providers manually manage their compliance, they add to their workload by having to regularly update their policies and provide staff training to ensure compliance is maintained. Moreover, manual processes lead to inconsistent decisions, placing acquirers at risk of fraud and regulatory shortfalls.
The traditional systems PSPs possess are creating KYB bottlenecks when it comes to expanding their portfolio and network. As they fail to gain a competitive advantage in the market, PSPs must start looking at new and improved ways to onboard and monitor their clients. Traditional onboarding has become completely unsustainable and automated compliance systems have provided the solution to these pressing concerns.
How can intelligent automation help?
In the past, static, one-time checks were the standard for acquirers looking to verify and onboard new businesses. However, regulatory and efficiency concerns have emphasised the long-term applications of innovations such as AI for financial verification and compliance. AI can reduce KYB bottlenecks by automating the existing fragmented onboarding structure, helping PSPs to scale without delays.
For many PSPs, implementing KYB can be an overwhelming challenge, which reduces the rate in which they can onboard new clients and exposes institutions to regulatory risks. The leading organisations are understanding that compliance is no longer a mainstream part of business, but a differentiator. The value of Ongoing Due Diligence (ODD) cannot be underestimated for those striving to grow and establish trust, while addressing changing risks. Intelligence automation does not just help acquirers verify new clients against thousands of platforms simultaneously, but it also automates AML screening processes, reducing delays, without increasing risk. By combining automation and traditional data sources with artificial intelligence and human review, acquirers can promote ODD, enhance their compliance and provide the perfect environment for scaling.
Those paving the way in the industry are employing AI alongside ODD to improve the overall customer experience of onboarding by highlighting inconsistencies within applications and providing AI agents for businesses having difficulties with completing their onboarding applications.
Now, continuous monitoring is the key for regulatory and compliance for acquirers, which is extremely hard to sustain when managed by teams of individuals. AI and automation provide accessible and efficient solutions for targeting commonly encountered KYB bottlenecks and PSPs striving to verify businesses faster while maintaining robust compliance oversight.
- Mateusz Pniewski
Banks Want Innovation, but their Infrastructure is Stuck in 2010 - Here's
What Breaks First
Banks talk endlessly about innovation. They sponsor hackathons, launch glossy apps, and announce partnerships with fast-moving startups. This is all great, but much of their core infrastructure still reflects decisions made around 2010 - or even earlier. When new ideas collide with old systems, something always gives. The question is not whether things break, but what breaks first.
The first fault line usually appears in customer experience. A bank might roll out a sleek mobile feature that promises instant account opening. On the surface, it works: a customer uploads ID, takes a selfie, and gets a confirmation screen within minutes. What is actually happening is a chain of batch processes designed for overnight updates is being put into overdrive. As a consequence, the customer logs in expecting a live account, only to find missing balances or delayed access. What looked like “instant” turns into confusion and calls to customer support.
Payments are often the next point of failure. New services demand real-time movement of money, but older systems were designed for predictable, scheduled flows. When a bank tries to layer real-time payments on top of this, cracks appear. Transactions may show as “sent” in the app while still sitting in a queue internally. Reconciliation teams then spend hours tracking mismatches between what customers see and what the system actually processed. This is where the gap between neo and legacy banks is truly apparent and why established ecosystems need fresh talent to orchestrate a more dynamic and frictionless customer experience.
The Co-Op bank had this issue in 2024 when customers saw duplicate payments had been taken from their accounts, as a result some were pushed into their overdraft, the issue particularly affected small businesses. Glitches happen, but these kind of mistakes don’t need to occur if banks have robust infrastructure.
Then there’s the issue of partnerships. Embedded finance depends on banks connecting smoothly with other companies - retailers, platforms, software providers. These partners expect simple, reliable connections. But many banks still rely on rigid interfaces that were never built for constant interaction. Each new partner becomes a custom project, taking months of work.
Companies like Shopify or Uber expect APIs that are clean, reliable, and fast to integrate. However, many banks still operate with rigid, custom-built interfaces. Every integration becomes a bespoke project.
Fraud and risk controls also begin to strain. Older systems tend to rely on fixed rules, updated infrequently. Modern financial services, especially those embedded in other platforms, generate a constant stream of activity that changes by the minute. When banks try to apply static controls to dynamic behaviour, they either block too much or miss too much.
By Philipp Buschmann, co-founder and CEO of AAZZUR
Finally, internal teams themselves feel the pressure. Product teams promise features that engineering teams struggle to deliver within the limits of legacy systems. Workarounds pile up. Small changes take weeks. Over time, even simple updates, like adjusting transaction limits or adding a new notification, become complex projects.
What breaks first, then, is not a single system but the connection between expectation and reality. Customers expect immediacy, partners expect flexibility, and teams expect speed. Infrastructure built for a different era cannot meet all three at once. The banks that navigate this tension successfully do not try to mask the problem with surface-level improvements. They focus on rebuilding the parts of their systems that handle movement of money,
data, and decisions. They reduce reliance on overnight processes, simplify how systems talk to each other, and design for constant activity rather than periodic updates.
Innovation in banking is not held back by a lack of ideas. It is held back by the friction of systems that were never meant to support today’s demands. Until that changes, every new feature will carry the risk of exposing what lies beneath.
About Philipp Buschmann, Co-Founder and CEO at AAZZUR
Philipp Buschmann is co-Founder and CEO at AAZZUR, a one-stop-shop for smart embedded finance experience. Recognised as a rising star in the FinTech space, AAZZUR’s mission is to build profitable banking whilst at the same time empowering consumers to have access to better informed financial choices.
Philipp is a serial entrepreneur with extensive experience of working in Challenger Banking, Financial Services, IT and Energy across the world. He took one of his businesses public - Ignis Petroleum was publicly listed in the US and Germany.
Having started as a developer in Financial Services, Philipp has first-hand experience of the banking revolution from both a technology and financial perspective. His interest in behavioural economics helped inspire AAZZUR’s revolutionary work on customer centricity in banking.
Philipp holds an MBA from the London Business School. He is passionate about entrepreneurship and loves exchanging ideas, insights and discussing FinTech's future. He has spoken at major Fintech events including Money 20/20, MoneyLive, Finovate, Fintech Matters, and the Future of Retail Banking.
Cross-Border Complexity Is Testing SME Survival
International ambition has long been part of the SME growth story. Increasingly, that ambition is tested by how reliably and seamlessly money is able once a deal has been completed. For small and medium-sized enterprises operating across borders, the mechanics of payments have become a significant operational concern rather than a minor back-office detail.
Across the next year, the IMF expects global growth to remain modest and below longer-term averages, with uncertainty and downside risks still elevated. In that environment, external conditions can shift faster than many SMEs are able to adapt. As this trend continues to unfold, building resilience now depends on understanding how those payment behaviours shape the broader organisation.
The erosion of certainty in cross-border cycles
Many SMEs align their operational planning with the times that funds usually land. If that timing drifts, even by an hour, the consequences can ripple across the entire organisation.
Even in long trade cycles, small delays near a reporting deadline can push liquidity off balance and unsettle decisions that depend on accurate forecasting. Convera’s AYRF 2026 outlook shows that internationally exposed firms are having difficulties planning due to the rapid shifts in market conditions. What was once a predictable inflow is now a variable input, with variability becoming the norm in 2026. Settlement behaviour is no longer consistent across corridors; each route reflects local clearing practices, time zone differences, intermediary involvement and varying data standards.
Over time, these inconsistencies chip away at confidence in the internal forecasts that guide pricing and hedging choices. When it’s unclear when cash will be available, an organisation’s ability to act decisively weakens.
It’s becoming more common for firms to track in real-time how routes perform to pinpoint where timing tends to slip, allowing planning to recover its footing and build more realistic liquidity models. While this plan is not foolproof, it does reduce surprises. It allows businesses to protect liquidity without stalling expansion and to commit to long-term plans with confidence.
Reframing payments as an information flow
But timing is just one part of the puzzle that small and medium businesses need to get right.
Many SMEs also encounter inconsistencies between the amount sent and received. Shortfalls, tied to intermediary deductions, take time to trace and often appear without warning.
When SMEs must operate to on tight margins, these differences introduce unnecessary pressure in places that rarely feature on dashboards. Chiefly, in reconciliation, supplier communication, and the credibility of internal numbers. Finance teams must then spend time tracing these deductions, diverting attention from important parts of their roles.
These shortfalls often stem from how correspondent chains are structured. Every handoff creates room for value to be removed, often without clear signals to the sender or recipient. These delays absorb time that should be spent managing the business.
A more resilient model comes to fruition when payments travel with richer, standardised information and fewer touchpoints. ISO 20022, the global standard for structured financial messaging, includes expanded data fields also allow payments
to move with clearer context and fewer interruptions. Payment providers with local account networks can settle transactions domestically in key markets, which reduces reliance on correspondent chains.
For SMEs next year, this shift is about removing the reoccurring pressures that erode the capacity of their teams. The aim is to remove small distractions so that finance teams can redirect their focus towards planning and higher value decision-making.
Confidence built on consistency
2026 will continue to present an environment where SMEs will have to navigate widening currency ranges and intricate compliance demands. Unfortunately, none of these forces are in a firm's control.
What they can control is how effectively their payment infrastructure absorbs those shocks.
When payment flows are predictable and transparent, leaders gain a clearer view of liquidity. Decisions about hiring and investment can be made from a position of
insight instead of reaction. When payment behaviour is erratic, even the strongest commercial performance can feel fragile.
And the connection between payment operations and organisational resilience is only becoming more explicit. Stability creates strategic headroom. It gives SMEs the breathing space to plan, adjust and act without being distracted by avoidable frictions.
Resilience now rests on how well firms treat cross-border payments as a core component of risk management. When SMEs gain clearer sight of where their money is and how it moves, many of the pressures that once felt inevitable start to ease. Payments stop being a weak link in the chain and begin to offer a firmer footing for the wider business.
Scott Johnson, Vice President, Program Management, Convera
Digital Sovereignty: an EU mission impossible?
The recent attacks on data centres in the middle east have pushed the data sovereignty debate centre stage. In case of turmoil and geopolitical tension, this latest incident has highlighted the significance of data residence and ownership. Under increasing pressure by the US, Canada has made the issue a key part of its forward trajectory: speaking at a conference in Montreal in September, Canada’s AI minister Evan Solomon said building digital sovereignty is “the most pressing policy and democratic issue of our time”.
In Europe the debate has been heating up ever since in June 2025, when the European Commission declared that: “The ability to build capacity, resilience and security by reducing strategic
dependencies, preventing reliance on foreign actors and single service providers, and safeguarding critical technologies and infrastructure”. This position was further cemented in November 2025 by the signing of the Declaration for European Digital Sovereignty in Berlin which homes in on the definition as the: “ability to act autonomously and to freely choose their own solutions.”
While action does need to be taken, the response that is emerging in Europe is shortsighted and risks creating a larger economic problem. In fact, rather than strengthening competition across its markets, Europe is leaning toward heavier regulation, more certification schemes, and policies aimed at promoting domestic technology champions. Companies must already navigate
the AI Act, the General Data Protection Regulation (GDPR), cybersecurity directives such as NIS2, and a growing number of sector-specific frameworks: a complex web that is stifling for smaller players and new entrants. EU startups face delayed access to frontier AI tools, with around 60% reporting product launch delays and over a third forced to strip features to comply with regulation; additional regulation will only worsen the burden.
What these startups in the EU really need to develop digital sovereignty is a resilient innovation ecosystem. This system is one where businesses compete fairly and users choose freely, negotiate terms, and switch when better solutions emerge. This is not a system where a few favoured “champions” are heavily
subsidized, distorting the market and destroying healthy competition.
Technological leadership historically has rarely emerged from regulatory protection. This is because governments often struggle to identify which firms will succeed, and companies that have been subsidized are difficult to wean off.
The ecosystem in Europe is already strong enough to create human talent and unicorn companies but it fails to retain them due to lack of investment, poor talent incentives and mobility, outdated infrastructure, and land use regulation. The data centres required for true technological leadership require abundant physical space and electricity: both come at a premium in Europe where energy costs and grid congestion limit the pace at which new computing capacity can be deployed. To tackle the lack of land, Europe is already experimenting with
pre-designated sites with shorter permitting times.
Beyond infrastructure, the war for talent may be Europe's fiercest battleground. The continent produces world-class researchers and engineers, yet too many of them build their companies outside the union. Streamlined visa pathways for international specialists, frictionless mobility across EU borders, and appealing equity compensation frameworks may encourage more talent to remain in the EU.
In addition to this, Europe's technology sector lacks the long-term capital that high-growth companies need to scale. The culprit is well known: European pension funds deploy a fraction of the capital into venture and growth equity that their North American counterparts do, leaving a financing gap that no amount of public subsidy can fully bridge. Deepening
capital markets and giving institutional investors both the mandate and the incentives to back domestic innovation would do more for Europe's technology ambitions than any national champion programme.
The case for digital resilience is solid, but building it on additional regulation is a damaging contradiction. The result will be a system that protects incumbents, burdens challengers, and ultimately weakens the very ecosystem it claims to defend. Durable technological sovereignty cannot be mandated. It grows from open, competitive markets where capital flows efficiently, talent moves freely, and the best ideas win regardless of their origin. That is the only version of digital sovereignty that can hold its own on the global stage.
"The Hidden Cost of AI Regulations: A Survey of EU, UK, and U.S. Companies"ACT | The App AssociationOctober 15, 2025
- Daniele Viappiani, Economics and Venture Capital Advisor
AWARDS WINNERS LIST 2026
Winners Titles
1Cover
Ak Portföy
AsiaPay
Banky
BCI
BCI
Cardinal Stone
Cardinal Stone
Commercial Bank of Ceylon PLC
Commercial Bank of Ceylon PLC
Dunav Voluntary Pension Fund Management Company
eBSEG
eBSEG
Encompass Corporation
Faraday Venture Capital SGEIC
First Capital Bank Botswana
First Capital Bank Zambia
Followme
FOO
Fosun International Limited
Ghazanfar Bank
GIG Insurance Egypt
GIG Insurance Egypt
Ilani Concepts
JFD Brokers
JSC Galt and Taggart
KBC Asset Management NV
KCB Group PLC
KCB Group PLC
kDEDEC CONSULTANCY AND TRAINING COMPANEY
Keepz
Liviti
Most Outstanding Travel Insurance Company Australia 2026
Best in Innovative Investment Solutions Turkey 2026
Best Payment Solutions Provider Hongkong 2026
Best Banking Products Comparison Platform Egypt 2026
Best Commercial Bank Mozambique 2026
Most Leading Financial Institution Mozambique 2026
Best Fund Manager Nigeria 2026
Best Securities House Nigeria 2026
Best SME Bank in Sri Lanka
Best Retail Bank In Sri Lanka
Best Pension Fund Management Company Serbia 2026
Most Innovative AI-Powered Chatbot Platform Egypt 2026
Most Innovative AI Solutions for Financial Services Egypt 2026
Best Global Business Entity Verification Solution Provider UK 2026
Best Venture Capital Firm Spain 2026
Best Corporate Bank Botswana 2026
Best Corporate Banking App Zambia 2026
Best Copy Trading Community Platform Indonesia 2026
Most Innovative Fintech Company UAE 2026
Best Company for ESG Practices Hong Kong 2026
Fastest Growing Commercial Bank Afghanistan 2026
Best Insurance CEO Egypt 2026 – Mr. Alaa El Zoheiry
Best General Insurance Company Egypt 2026
Best Web Design company Kenya 2026
Best Multi-Asset Investment Broker Cyprus 2026
Most Leading Investment Bank Georgia 2026
Best Sustainable Asset Management Company Belgium 2026
Best Banking CEO Kenya 2026- Mr. PAUL RUSSO
Best Bank Kenya 2026
Best Aviation Consultancy and Traınıng Company Turkey 2026
Most Innovative Digital Payment Solution Georgia 2026
Most Trusted Property Consultants Firm Australia 2026
Mashreq
Winners Titles
One Asset Management Limited
Pacific Risk Advisors Ltd.
Pan Asia Banking Corporation PLC
Permutable AI
PETRONAS Dagangan Berhad
PETRONAS Dagangan Berhad
PT KVB Futures Indonesia
Qatar Insurance Company
Samuel and Co Trading
Shoplazza
Best Retail Bank UAE 2026
Most Innovative Asset Management Company Thailand 2026
Best ESG Risk Advisory Firm Hongkong 2026
Best Bank for Remittances Sri Lanka 2026
Best New Market Analysis data provider UK 2026
Best Investor Relations Team Malaysia 2026
Most Outstanding Energy Solutions Provider Company Malaysia 2026
Best Forex Broker Indonesia 2026
Best General Insurance Company Qatar 2026
Best Forex Education & Training Platform Provider UK 2026
Most Innovative AI Commerce Technology Company Canada 2026
SQB Best Retail Bank Uzbekistan 2026
SQB Digital Transformation of the Year Uzbekistan 2026
Stanbic IBTC
STANBIC IBTC TRUSTEES LIMITED
Subotiz
Sukoon Insurance
Sukoon Insurance
Sukoon Takaful
Summer Atlantic Capital
Summer Atlantic Capital
Taipei Fubon Bank
Tayseer Arabian Company
TrioMarkets
Ultima Markets
VT Markets
VT Markets
ziyzo
Best Bank in Mortgage Finance Nigeria 2026
Best Trust Company Nigeria 2026
Most Innovative Fintech Platform For AI SaaS Businesses USA 2026
Digital Transformation of the Year UAE 2026
Most Innovative Insurance Application mySukoon App UAE 2026
Most Innovative Takaful Provider UAE 2026
Best Cross-Border Strategy and Governance CEO USA 2026- Mr. Sebright Chen
Excellent Sustainable and Responsible Investment Strategy USA 2026
Best Risk Management Bank Taiwan 2026
Fastest Growing Asset-based Finance Company Saudi Arabia 2026
Most Trusted Forex Broker Mauritius 2026
Fastest Growing Forex Trading Platform Hong Kong 2026
Fastest Growing Multi Asset Brokerage Company UK 2026
Most Outstanding Multi Asset Brokerage Company UAE 2026
Fastest Growing CRM service provider for MSME Kenya 2026
Paul Cragg, Chief Technology Officer at NormCyber
Cyber resilience is now a board priority and firms must learn how to measure it
Financial services organisations are under growing pressure to show they can withstand and recover from cyber incidents. What's more, cyber risk is increasingly being discussed in the same terms as financial or operational risk. Boards want clearer answers about how disruption would affect customers and services, regulators expect stronger evidence of resilience, and partners are paying closer attention to the security of the organisations they depend on. But despite significant investment in cyber security tools and processes, many firms still struggle to clearly explain how resilient they actually are.
Financial services organisations must now move beyond occasional reporting towards more consistent ways of measuring and demonstrating resilience across the business. Increasingly, the focus is shifting from simply proving that controls are in place to showing how well systems and services would hold up under real disruption.
The new scrutiny landscape
Last year, 65 percent of UK firms faced a cyber attack, with incidents impacting financial services increasing from 864 to 1,858 year-on-year. The sector’s high level of interconnectivity and the volume of sensitive customer data it holds have made it a prime target for attackers.
Regulation has responded accordingly. The Digital Operational Resilience Act (DORA) introduces a Europe-wide
framework designed to ensure organisations can withstand and recover from technology failures and cyber incidents. Research shows that 96 percent of European financial organisations surveyed believe their current level of data resilience falls short of DORA compliance. Fines for non-compliance can be up to two percent of the organisation's global annual turnover, or 10 million euros, whichever is higher.
However, compliance does not automatically equal preparedness. The threat landscape itself is accelerating, with attackers using AI to increase the speed and scale of incidents. Last year, AI-enabled attacks increased the speed of cyber incidents by 65 percent, forcing financial services organisations to recognise that their visibility and response capabilities must evolve. Together, these pressures are forcing organisations to
think more seriously about how resilience is measured and demonstrated.
Why traditional cyber metrics are not landing in the boardroom
At board level, there is limited clarity around whether cyber investment is reducing risk. Security leaders aim to demonstrate the business value of cyber security as a top priority, but achieving this is far more difficult than reporting on technical activity.
Many security teams track metrics such as patch coverage, vulnerability volumes, and mean time to detect. Operationally, these metrics are useful, however they rarely connect with the issues boards care most about, such as operational disruption, customer impact, regulatory exposure, and financial risk. The result is that cyber reporting often feels disconnected from wider business discussions. Not surprisingly then, only half of leaders believe their board members fully understand the risks facing their organisation.
How to quantify resilience
For many CISOs, the next phase is not about producing more reports but improving how resilience is measured. Security and IT teams need ways to present resilience in formats boards can understand quickly and act on with confidence. That includes benchmarks that allow organisations to compare themselves with peers and consistent views of resilience that can be shared with regulators and auditors.
Providing a single quantified measure across a firm’s environment helps turn complex technical signals into a clear, measurable view of risk. This should show how quickly threats can be detected and contained, and how exposed critical systems and customer data are at any given moment.
Instead of static reports or periodic audits, organisations need a continuously updated view of resilience so that boards can quickly understand if controls are working and whether they would hold up under a real attack.
Beyond business continuity, cyber resilience now also shapes how organisations are viewed externally. Customers and investors increasingly expect clear evidence that firms can keep their data safe, with almost a quarter of consumers in the US and UK considering a bank’s approach to cyber security when deciding whether to open an account.
Procurement and due diligence processes also tend to move faster when firms can provide clear evidence of how their systems will perform under pressure. Finally, cyber resilience ties directly to third parties. If internal resilience can be measured clearly then firms increasingly expect this from their partners. Providers that can evidence their resilience therefore gain a clear advantage over those that cannot.
The real question for 2026 is no longer whether firms are investing in cyber security. What matters now is whether that investment is producing resilience that can be clearly measured and communicated.
Measurable resilience as a differentiator
Can Zero-Knowledge Technology Play a Valuable Role in Web2 Security?
By The wave of cyberattacks we saw in 2025 exposed the fragile security architecture underpinning major enterprises. In the Salesforce supply-chain campaign, attackers exploited compromised OAuth tokens from a third-party integration to silently extract data from hundreds of corporate CRM instances, hitting huge corporations from Google to FedEx to Disney. This didn’t happen because Salesforce lacked the security controls to prevent it. Despite the platform having scoped OAuth permissions, token rotation, and API access auditing, hundreds of well-resourced enterprises, staffed by highly capable security teams, failed to deploy those controls correctly. This signals that the model itself demands
more operational perfection than organisations can sustainably deliver.
The victims of the Salesforce supply chain campaign weren't obscure companies running outdated systems - they were enterprises that spent millions on cybersecurity. And the breach didn't require exploiting zero-day vulnerability or cracking an encryption. By means of a single third-party app, attackers compromised OAuth tokens and used those tokens to systematically export data from customer instances. The data was all sitting there, accessible. The truth of the matter is: when every failure of operational discipline leads to catastrophic exposure, the root of the issue lies in the expectations placed on the architecture.
The Danger of Systems That Know Too Much
Most financial enterprise technology is built on a foundational assumption that the more data a system holds, the more useful it becomes. But this assumption has become its biggest liability and this thinking exposes an increasing volume of data to attacks. To clarify, modern SaaS platforms do offer data-layer defenses — they establish field-level encryption, customer-managed encryption keys, row-level security, and dynamic data masking. When properly deployed, these controls work. Breaches happen in the gap between "available" and "consistently deployed across hundreds of integrations". The Salesforce campaign exploited the reality that maintaining
perfect configuration hygiene across every third-party integration, API scope, token lifecycle, is a task that scales faster than security teams can cope with.
The problem isn't that enterprises have bad security teams. The problem is that the dominant architecture forces systems to hold and potentially expose more data than is ever actually required by the transaction, and then relies on an increasing surface area of access controls to be perfectly maintained. Solving this requires rethinking security not as a wall to protect the data that’s there, but as a series of architectural layers that reduce what can be accessed and stolen in the first place.
First Layer - ZK Proofs
Zero-knowledge (ZK) cryptography offers an entirely different point of entry. Instead of collecting, storing, and then trying to put up walls around sensitive data, ZK proofs allow one group to prove a statement to another without revealing the underlying information. The verifier gets to have mathematical certainty about the claim without learning anything beyond the definitive validity of the statement.
The most immediate use case for this technology is at verification boundaries: the points where systems need to share data to prove something. Consider identity verification (KYC): a financial institution collects and keeps on file government IDs, dates of birth, addresses old and new, and income documentation. This data then sits in a centralised database, sometimes replicated across subsidiaries. With ZK implemented into this process, a customer completes verification once, and that verification is encoded into a cryptographic credential they control. When a second party needs to confirm regulatory compliance, the customer presents their ZK
proof demonstrating "I have passed AML screening" without the need to transmit any personal data. In this version of the process, nothing is stored, transmitted, or potentially exposed to threat outside what is needed as a minimum.
Second Layer - ZK-Gated Execution
The deeper architectural shift that’s needed comes from a model I'd call ZK-Gated Execution, where ZK proofs don't simply verify claims at the boundary, going one step further to gate what computation can occur, inside an environment where no one can see the underlying data.
What’s the distinction? In the standard model, you prove you're authorised first, then you access the data store. By comparison, in ZK-Gated Execution, you prove your eligibility with a ZK application that executes a set of authorisation rules, followed by a specific, constrained computation runs inside a secure enclave. The operator who runs this environment can't see the inputs and the third party never touches the raw data.
This doesn't eliminate all risk, unfortunately no architecture can do that. But the fundamentals of an attack have changed.
Time is Running Out
ZK doesn't remove the need for good overall security hygiene. The right first investment for many organisations is still deploying MFA, monitoring, access controls, and proper configuration discipline. ZK (particularly in its ZK-Gated Execution form) addresses the structural vulnerability that makes breaches catastrophic even when operational security is strong: the presence of nonessential vast stores of sensitive plaintext data. The best protection against attackers is having nothing for them to find.
Deepthi Kumar, Co-CEO at o1Labs
Stopping Payment Fraud Without Testing Customer Loyalty
Stephanie Mitchell, Director of Product Management, FMM, Finastra
When it comes to protecting against payment fraud, European customers put the responsibility on their financial institution. Nearly half of respondents to a recent survey by FICO said that banks need better detection systems to reduce instances of fraud. At the same time, customers are far less willing to participate in the security steps these banking systems often require.
Nearly 40% of younger generations say they resent taking time for even simple security measures, such as entering a pin, and almost 30% of older generations feel the same way, according to data from EY. Sentiments like these highlight a need for frictionless payments, an experience factor that is often derailed by current fraud controls.
Datos Insights’ data from February 2025 shows that the AML models in use by many financial institutions routinely generate 90% to 95% false positive rates. If the customer receives too many false positives, accounts or cards are then blocked. Legitimate transactions are delayed, and customers must expend significant time to unfreeze related banking assets.
Step-up authentication is another fraud-busting tactic that causes considerable friction in the payments process. While Microsoft indicated in a recent cybersecurity whitepaper that multi-factor authentication reduces the risk of account compromise by as much as 99.22%, customers find it frustrating and resent the additional steps required to make a simple payment transaction.
But just as customers know what they don’t like, they also seem to intuitively understand what enhances the payment experience. For banks, listening to customer preferences may be the fastest way to develop stringent fraud controls that support more seamless payment transactions:
• 39% of consumers surveyed by FICO say they strongly prefer biometric controls, such as fingerprint authentication, over other fraud deterrents.
• 33% of consumers surveyed by FICO are open to fraud warnings about a purchase from banking apps and heed messages when they receive them.
• In the UK, 66% of respondents to a survey conducted by Fido Alliance said they are using passkeys to protect online accounts, while more than half of respondents from France and Germany said the same.
In the end, the evidence is clear. Customers prefer fraud controls that are
simple and require little time to enact. They show an equal dislike for those that require channel switching, waiting for authorization or repeated challenges.
Providing Customer-Friendly Transactions and Strong Fraud Controls
For banks, developing controls that accurately identify fraud without negatively impacting the customer experience is not a one and done prospect. As fraud tactics continue to evolve, banks need flexible platforms capable of quickly adding new data sources, adjusting thresholds according to new intelligence, and introducing new fraud controls without reconstructing entire systems. Modular, component based architecture is key, allowing banks to add new services as the threat landscape evolves.
However, fraud systems are only as good as the data that informs actions, and clean data is the key to reducing friction in the customer experience while ensuring high confidence decisions. Clean data refers to accurate and complete data
that is consistent across channels and timely enough to reflect current customer behavior.
Fraud prevention systems rely on a wide range of signals. Transaction history, behavioral patterns, and device intelligence all provide the basis on which high-confidence fraud decisions are made. When underlying data is incomplete, inaccurate, biased or not linked across channels, systems may miss valuable inputs, generating unnecessarily conservative decisions based on inaccurate or outdated signals.
While well orchestrated identity verification technologies, such as secure authentication or confirmation of payee, are necessary fraud deterrents in the payments setting, creating a seamless flow within the customer experience is highly dependent upon clean data. Banks that can ensure data quality minimize false positives, reduce uncertainty and are more likely to block only fraudulent transactions.
Andrew George, Managing Director and Solutions Architect, 3forge
Reimagining Financial Systems for AI-Driven Performance
Companies across industries are rapidly increasing their use of AI – and finance is no exception. Yet, even as interest in this technology expands and companies increasingly develop various AI models and co-pilots, directly embedding AI into core systems remains a work in progress, a gap clearly reflected in how workers perceive AI in the workplace. Only 12% of workers strongly agree that AI is transforming how work gets done, highlighting the significant untapped potential for production-grade AI value.
In finance, this gap is even more extensive. Legacy architecture often makes integrating modern technologies an ambitious endeavor. As a result, firms, who require continuous operations, have had to repeatedly modify traditional infrastructure to facilitate accessibility without triggering an extensive overhaul that would disrupt live environments. This creates a situation in which effectively leveraged AI would have to pull data from and operate across disconnected platforms, a feat that has proven challenging.
To realize AI’s full potential in meaningful, deployment-ready ways, financial institutions need the right foundation. This often starts by unifying fragmented
legacy technology stacks, implementing a governed AI gateway, and introducing AI-native workflows on top of an established base to mitigate existing complications.
This three-step process ultimately enables a shift from AI as an assistive layer to AI as an operational one capable of interacting with live systems, coordinating workflows, and generating outputs directly within production environments.
Why AI Requires a New Layer on Top of Legacy Systems
The current baseline in financial environments consists of layers of disconnected databases, streaming tools, middleware, UI frameworks, and security controls.
Each of these components functions independently but requires significant effort to integrate correctly.
When financial organizations combine these systems, the stack introduces:
● Lengthy development cycles.
● Increased reintegration costs.
● Performance bottlenecks.
● Governance enforcement difficulties.
These issues create an environment that cannot fully support AI capabilities. Rather than rebuilding this groundwork, financial institutions must introduce layers on top of existing architecture, enabling AI functionality without requiring a full infrastructure overhaul.
A Practical Path to AI-Native Finance
Firms can extend AI into production, without rebuilding core systems, by introducing targeted architectural layers. To facilitate AI deployment into these complex environments and bridge production gaps, financial teams should employ the following steps:
● Step One: Virtualize Legacy Access. Firms should build a single abstraction layer that provides AI access to static and streaming data, while producing natural-language interrogation, system virtualization, and safe AI interactions.
● Step Two: Establish a Governed AI Gateway. Financial institutions should implement an AI governance gateway that works in tandem with the abstraction layer to produce repeatable outputs, maintain full visibility into activity, and ensure governed execution.
● Step Three: Deploy AI-Native Workflows on Top. Firms should build intelligent workflows on top of these platforms to reduce code surface area and shorten audit cycles while generating layouts, workflows, and full applications.
While this approach is effective for starting the AI integration process, the challenge now is executing this approach consistently across complex environments. Many financial organizations are finding that enacting this strategy in the complex software environments created by years of incremental development remains a challenge. In these cases, the best approach is to examine how other industries have overcome similar obstacles.
The Playbook Already Exists
Other industries hit modernization roadblocks earlier in their development processes. In response, these industries decided they needed a software foundation that could support future development without requiring an infrastructure rework with each new progression.
To establish a base, many of these industries adopted application engines. Gaming created Unity/Unreal, e-commerce established Shopify, and general CRM formed Salesforce. These bases allowed companies to focus on technological differentiation rather than internal plumbing. This differentiation introduced
a way for organizations to leverage what already exists while making room for future progress. If developers purpose-built these systems for finance, financial institutions could establish a foundation that equips firms with the tools needed to fully capture AI’s benefits, all within trusted boundaries.
From Possibility to Production: The Future of AI in Finance
As AI moves deeper into financial systems, the opportunity is not just to deploy models, but to fundamentally expand what can be built and automated within existing infrastructure. Financial institutions can virtualize legacy access, create a governed gateway, and establish AI-powered processes to smoothly operationalize firm performance within existing infrastructure.
Application engines provide a strategic path for AI adoption to play out in live environments. When firms situate AI-native workflows on a unified foundation, they can simplify operations in meaningful, production-grade ways while maintaining trust and control.
Banking brands have Gen Z’s attention; what they need is its loyalty
John Clark, Coley Porter Bell
With younger generations under increasing financial pressure – be that paying back student loans,
exorbitant rent or other budget considerations – money matters a great deal to them. So Gen Z already understands banking, what they are really evaluating is whether banks understand them.
For bank brands capturing attention is relatively easy, but earning long-term loyalty through constructive reasons to stay, is far more difficult. As younger people reach pivotal life stages, their interest extends beyond current accounts and debit cards to long-term savings and investments. Gen Z are more likely than the
average Brit to be thinking about opening a savings account, ISA or taking out a credit card – and more likely to switch bank accounts too.
With the current rising cost of living, money management is crucial for those at the start of their careers, so there’s a clear role for banking brands to demonstrate what they can do for younger customers, so they feel heard. For banks looking to build lasting loyalty with Gen Z, legacy and behemoth status are no longer an automatic route to adoption.
Utility is reshaping the banking experience for Gen Z
At first glance, challenger brands such as Monzo, Wise and Revolut seem to be getting it right for the younger cohort.
On paper, Monzo looks like a Gen Z success story. According to figures from WPP’s BAV database, it scores a near-perfect 99 on Differentiation and an equally impressive 99 on perceived helpfulness. Gen Z finds it genuinely useful and meaningfully different from everything else in the category. Revolut tells a similar story from a different angle. It scores 93 on Differentiation and leads the field on Consideration (76), meaning Gen Z is genuinely open to it.
Their success has not come from shouting louder than traditional banks, but from embedding themselves into everyday financial behaviour. They understand that mobile banking is routine for Gen Z, with over 40% using banking apps daily and a further 39% checking them several times a week.
Monzo and Revolut apps are designed to make managing finances feel rewarding and fun. Features like budgeting prompts and emoji-enhanced payment notifications turn everyday banking into a more engaging experience. Rather than simply displaying account balances, these platforms actively guide users through their financial decisions so it feels supportive and accessible.
But dig a little deeper and a different story emerges. Monzo has high Relevance and Knowledge, but Esteem is only at 50. And Loyalty ranks at just 27 and Advocacy at 27. In plain terms: Gen Z has real affection for Monzo, but not deep commitment to it.
Revolut tells a similar story from a different angle. It scores 93 on Differentiation and leads the field on Consideration (76), meaning Gen Z is genuinely open to it. But Advocacy collapses to 23 — the lowest in the set — and Gaining in Popularity ranks at just 33. People consider it; they don't champion it.
So what might it take for banks to earn Gen Z trust?
But when it comes to money, the absolute vital element – more than app performance and engaging interactions –is trust. People want their money to be safe. Trust in banks does exist among Gen Z, but it comes with a strong dose of scepticism. More than half of Gen Z (57%) say they trust banks and building societies, yet around one in three (33%) believe banks try to trick customers out of their money.
So, beyond user-friendly digital services, how can banks show they’re on their side? Education, personalisation and outlook may help brands here.
When it comes to education, Gen Z are more likely than previous generations to educate themselves on financial matters, including student loans, before incurring debt: In a 2023 Mastercard study, 73% of teens said they wanted more personal finance education, perhaps because 52% worry about financial security and stability — more than double older generations
However, traditional financial education efforts like webinars and formal campaigns may not resonate. This generation responds more positively to, relatable content on social media. Short-form videos and real customer stories of people navigating similar financial problems are more likely to engage Gen Z because
they value authenticity.
A recent Stylus report found “People are growing weary of expert-led financial advice that glosses over the reality of debt, emotion fueled spending and stagnant salaries. Instead, many are turning to their peers for guidance’ - and as a recommendation driven audience, Gen Z are at the forefront of this.
Beyond education, personalisation is a powerful driver. From workouts to travel itineraries to menu choices, this generation lives in a world that’s been algorithmically optimised and personalised to them. Gen Z expects financial tools to adapt to them, not the other way around. Personalisation is no longer considered a premium feature but an expectation. Suggested budgeting and “Spotify Wrapped”-style annual financial summaries are the tailored experiences that resonate with Gen Z. They like goalbased financial journeys, whether saving for holidays or home deposits, that make banking brands feel more integrated into everyday life. Cashback is most effective when tied to real shopping habits, while rewards that help ease real financial pressures such as housing costs or utility bills demonstrate empathy and understanding. Meaningful financial relief builds far deeper loyalty than small, generic discounts ever could.
Lastly outlook - Gen Z doesn’t want banking to feel intimidating or emotionally heavy. Brands need to flip the serious narrative, money should be an optimistic topic. That means moving away from the traditional language of authority and seriousness, and toward communication that feels genuinely human and transparent. Gen Z will respond to brands that make managing money feel less like a source of anxiety and more like a tool for building the life they want.
The compliance era of data and why ethical data is becoming a competitive advantage
By Adam Herbert, CEO, Go Live Data
For a very long time, data has been treated as a numbers game, consisting of bigger databases, more contacts and more activity. It’s that approach which built an entire industry. But it also created a lot of noise, poor targeting and in many cases, opens the path to bad decision-making.
That however, I’m pleased to say is starting to change. We’re now operating in a compliance-driven environment where how you use data matters just as much as having it. And in that shift, something quite important is happening; businesses that use data properly are starting to outperform those that don’t.
The problem with ‘accepted’ data
In most cases organisations assume their data is good enough. The list has either been bought or built; it feeds reports, campaigns and key decisions. Therefore, it must be fine… But when you look closer at that data, it’s often not the case. You’ll find companies registered at addresses they don’t operate from and decision-makers who’ve moved on months ago. Businesses that might have changed direction, yet they still sit in the same category within the database.
In financial services and corporate environments, which has a knock-on effect:
• Risk gets misjudged
• Targeting becomes inefficient
• Pipelines are filled with the wrong opportunities
• Decisions are made on a false picture
The issue isn’t just bad data. It’s the assumption that it’s
accurate without so much as questioning it, and that’s where problems can start.
Compliance is tightening and so are expectations
Regulation has already forced change, with GDPR and PECR making businesses think harder about how they collect and use data. But what’s also shifting is expectation. It’s no longer enough to technically tick the box, as the increasing focus is on whether the use of data makes sense, which has created a different standard.
• Is it relevant?
• Is there an apparent reason for using it?
• Would the recipient expect to be contacted?
In financial services, where trust underpins everything, this matters even more. As for companies that are somehow misusing data, this will create regulatory risk while damaging credibility of the business at the same time. And unfortunately, once that’s happens, it’s extremely difficult to reverse.
Ethical data use is better business
There’s a misconception that ethical data use slows things down, when in reality, it sharpens everything. When you focus on accuracy and relevance, you are naturally:
• Target better
• Communicate more clearly
• Waste less time
• Get better results
At Go Live Data, we focus on intent data. By understanding when a business is actually in a position to engage, rather than pushing messages out at volume. For us that means fewer, more considered interactions with the recipient which works. It encourages higher engagement, better conversion rates and stronger relationships. Not only this, but it also reduces complaints, improves compliance and protects the brand.
The cost of getting it wrong
A lot of businesses are what we call busy with data, but they aren’t necessarily effective with it. A campaign will go out, reports get produced and on paper, marketing activity
looks strong. While in reality, the data isn’t doing the job it’s supposed to, with out-of-date contacts, segmentation is too broad and generic messaging which just doesn’t land, leading to inferior performance while also creating risk. Every irrelevant email or poorly targeted campaign increases the chance of scrutiny. And in regulated sectors, that’s not something you can ignore.
Data quality is a leadership issue
What’s changing in financial and corporate environments is where the responsibility sits. Data quality used to be seen as an operational issue, however that has changed.
It affects:
• Risk modelling
• Investment decisions
• Market analysis
• M&A targeting
If the data is wrong, so is the output which Boards are starting to recognise and the questions being asked are more direct:
• Where has this data come from?
• How current is it?
• What are we basing decisions on?
• What’s the downside if it’s wrong?
Transparency is becoming non-negotiable
There’s also a growing expectation around visibility, about what data is being used and how you’re using it, including things such as:
• Clear data sources
• How it’s been verified
• How it’s being applied
• Who is accountable
For financial services, this is particularly important. Clients, regulators and partners all expect a clear line of transparency.
Where the advantage sits
Compliance alone doesn’t give you an advantage, but how you respond to it does. Some businesses will do the minimum required and continue as they are, while others will use it as a reason to improve how they work and it’s those businesses that will continue to move forward effectively and successfully. Because when your data is accurate and your approach is considered, your marketing targeting improves, as do your insights as well as your customer relationships, which all has a significant commercial impact.
If you’re operating in a financial or corporate environment, there are a number of things you need to get right:
Look at your data properly - Not how much you have, but how much of it is actually usable.
Prioritise accuracy over scale – Quality over quantity and ensure its up to date. Anything over three months old, by our standards needs updating.
Be clear on intent - If you can’t explain why you’re using
data, that’s a problem.
Connect compliance to performance – Should sit side by side in terms of priorities.
Take ownership at leadership level - This is more than a systems matter. It’s a business issue.
The way businesses use data is under more scrutiny than ever and it’s forcing better standards. The businesses that adapt quickly and treat data as something to be managed properly, not just used at volume will be in a stronger position. The differences between success and failure comes down to how well you use it.
About Adam Herbert
Adam Herbert is the CEO and co-founder of Go Live Data, one of the UK’s fastest-growing data and marketing intelligence companies. With over 20 years in the industry, he’s a leading voice in ethical outbound marketing and is known for challenging outdated marketing norms.