International
Higginbotham Public Sector
833-894-4524
iltexas@hps.higginbotham.net
Medical Coverage
TRS ActiveCare
866-355-5999
www.bcbstx.com/trsactivecare
Medical Pharmacy
Express Scripts
844-367-6108
www.express-scripts.com/trsactivecare
Prescription Savings
Clever RX
Group Number 1085 | Member ID 3530
800-873-1195 www.cleverrx.com/iltexas
Telemedicine
Recuro
844-979-0313 www.recurohealth.com
Dental Coverage
Cigna
Group Number 3346275
800-244-6224
my.cigna.com/web/public/guest
Vision Coverage
EyeMed Group Number 1060982
866-804-0982
www.eyemed.com/member
Health Savings Account
EECU
817-882-0800
www.eecu.org
Flexible Spending Accounts
National Benefit Services
Group Number NBS632577
800-274-0503
service@nbsbenefits.com
Basic and Voluntary Life and AD&D
Chubb
Group Number 100000208
888-499-0425
cwbspecialmarketservice@chubb.com
Educator Disability
Chubb
Group Number 100000208
888-499-0425
cwbspecialmarketservice@chubb.com
Employee Assistance Program
ComPsych Web ID CHUBB 844-266-0712
www.guidanceresources.com
Accident Insurance
PanAmerican Group Number 98213 844-624-8110
888-499-0425
cwbspecialmarketservice@chubb.com
100000208
888-499-0425
cwbspecialmarketservice@chubb.com
Hospital Indemnity Insurance Chubb Group Number 100000208
888-499-0425
cwbspecialmarketservice@chubb.com
Identity Theft Protection ID Watchdog 866-513-1518
Retirement Plan (403(b)/457) National Benefit Services 800-274-0503 *5 www.nbsbenefits.com
877-853-9799 www.metlife.com/getpetquote
We are pleased to offer a full benefits package to you and your eligible dependents. Read this guide to know what benefits are available to you. You may only enroll for or make changes to your benefits during Open Enrollment or when you have a Qualifying Life Event.
Your plan offers medical coverage options. To help you make an informed choice, review each plan’s Summary of Benefits and Coverage (SBC) available by accessing www.mybenefitshub.com/iltexas.
Your New Benefits Begin and End September 1, 2026 – August 31, 2027
If you (and/or your dependents) have Medicare or will become eligible for Medicare in the next 12 months, federal law gives you more choices for your prescription drug coverage. Please see Important Notices for more details.


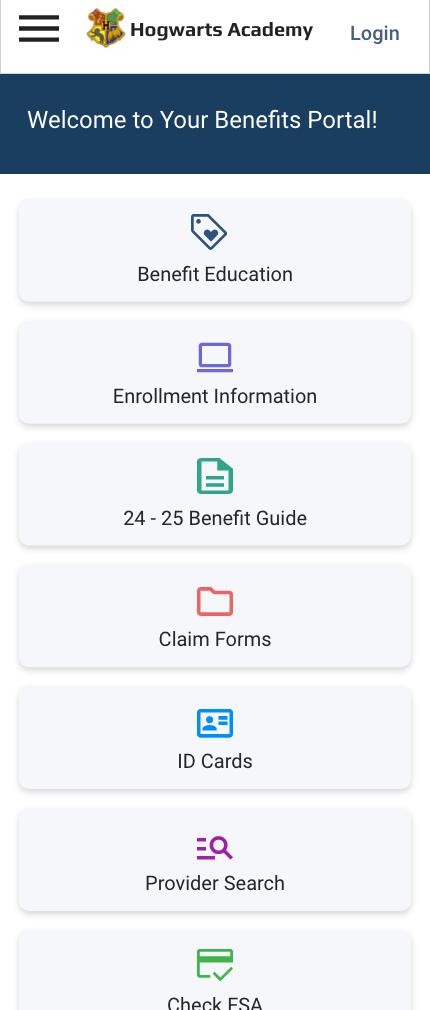

1. Go to www.mybenefitshub.com/iltexas. Scan the QR code to the right.
2. Click Login.
3. Enter your information:
• Last name
• Date of birth
• Last four digits of your Social Security number
Note: THEbenefitsHUB uses this information to check behind the scenes to confirm your employment status.
Email iltexas@hps.higginbotham.net or benefits@iltexas.org.
Call Higginbotham Public Sector at 833-894-4524
4. Once confirmed, the Additional Security Verification page will list the contact options from your profile. Select either the Text, Email, Call, or Ask Admin options to receive a code to complete the final verification step.
5. Enter the code you receive and click Verify to begin your benefits enrollment.
6. Review your personal information and verify covered dependents. Contact your employer with any discrepancies.
7. Select and confirm the dependent(s) who are to be covered on each benefit screen (medical, dental, etc.). If a dependent is not selected for a benefit, it will not be provided. NOTE: Dependents cannot be double-covered by married spouses within the district as both employees and dependents.
What if I miss the enrollment deadline?
You may only enroll for or change your benefits during Open Enrollment or if you have a Qualifying Life Event.
Is there an age limit for dependents to be covered under my benefits?
You may cover dependents up to age 26 on most benefit plans, but there are exceptions. See the Eligibility section for more details.
Where do I find benefit summaries and forms?
Access www.mybenefitshub.com/iltexas and click on the benefit plan you need (i.e., Dental). Forms and benefits information are under the Benefits and Form section.
How do I find an in-network provider?
Access www.mybenefitshub.com/iltexas and click on the benefit plan for the provider you need to find. Click on the Quick Links section to find provider search links.
will I get my ID cards?
If the medical carrier provides ID cards and there is a plan change, new cards usually arrive within four weeks of your effective date. If there are no plan changes, a new card may not be issued.
You may not need a card for dental and vision plans. Simply give your provider the insurance company’s name and phone number to verify benefits. You can also print a temporary card by visiting the insurance company’s website.
Email iltexas@hps.higginbotham.net or benefits@iltexas.org
Call Higginbotham Public Sector at 833-894-4524
The following limitations and exclusions may apply when obtaining coverage as a married couple or for your dependents.
Can I cover my family — a spouse or a dependent — as dependents on my benefits if we work for the same employer?
Some benefits may not allow you to do this if you work for the same employer. Review the applicable plan documents, contact Higginbotham Public Sector, or contact the insurance carrier for spouse and dependent eligibility.
Are there FSA/HSA limitations for married couples?
Yes, generally. Married couples may not enroll in both a Flexible Spending Account (FSA) and a Health Savings Account (HSA). If your spouse is covered under an FSA that reimburses for medical expenses then you and your spouse are not HSA-eligible – even if you would not use your spouse’s FSA to reimburse your expenses. However, there are some exceptions to the general limitation for specific types of FSAs. Contact the FSA and/or HSA provider before you enroll or reach out to your tax advisor for further guidance.
Disclaimer: You acknowledge that you have read the limitations and exclusions that may apply to obtaining spouse and dependent coverage, including limitations and exclusions that may apply to enrollment in Flexible Spending Accounts and a Health Savings Account as a married couple. You, the enrollee, shall hold harmless, defend, and indemnify Higginbotham Public Sector, LLC from any and all claims, actions, suits, charges, and judgments whatsoever that arise out of your enrollment in spouse and/or dependent coverage, including enrollment in an FSA and HSA.
You are eligible for coverage if you are a regular, full-time employee. You may only enroll for coverage when:
• You are a new hire
• It is Open Enrollment (OE)
• You have a Qualifying Life Event (QLE)
See Important Limitations and Exclusions section.
Eligibility Requirements for 2026-2027 Plan Year
• Basic Life Eligibility: Full-time employees only, working 30+ hours a week
• Supplemental Product Eligibility: Employees working 20+ hours a week
• Medical Eligibility: TRS standard of 10+ hours a week
• Medical Employer Contribution Eligibility: Full-time employees only, working 30+ hours a week
• Enroll by the deadline given by the Benefits Department
When Coverage Starts
• First of the month following or coinciding with the date of hire
You must be Actively at Work on the date your coverage becomes effective. Your coverage must be in effect for your spouse’s and eligible children’s coverage to take effect. See plan documents for specific details.
Eligibility Requirements for 2026-2027 Plan Year
• Basic Life Eligibility: Full-time employees only, working 30+ hours a week
• Supplemental Product Eligibility: Employees working 20+ hours a week
• Medical Eligibility: TRS standard of 10+ hours a week
• Medical Employer Contribution Eligibility: Full-time employees only, working 30+ hours a week
• Enroll during OE or when you have a QLE
• You must be actively at work on the plan effective date for new benefits to be effective
• QLE: Ask Benefits Department email: benefits@iltexas.org
• Your legal spouse
• Child(ren) under age 26, regardless of student, dependency, or marital status
• Child(ren) over age 26 who are fully dependent on you for support due to a mental or physical disability and who are indicated as such on your federal tax return
When to Enroll
• You must enroll the dependent(s) during OE or when you have a QLE
• When covering dependents, you must enroll for and be on the same plans
• Dependents cannot be double-covered by married spouses within the district as both employees and dependents
When Coverage Starts
• Based on OE or QLE effective dates
You may only change coverage during the plan year if you have a Qualifying Life Event, such as:
Marriage
Divorce
Legal separation
Annulment
Death
Birth
Adoption
Placement for adoption
Change in benefits eligibility
Death
You have 31 days from the event to notify Benefits Department and complete your changes. You may need to provide documents to verify the change.
Undergoing FMLA, COBRA event, court judgment, or decree
Becoming eligible for Medicare, Medicaid, or TRICARE
Receiving a Qualified Medical Child Support Order
Gain or loss of benefits coverage
Change in employment status affecting benefits Significant change in cost of spouse’s coverage
Our medical plans protect you and your family from major financial hardship in the event of illness or injury. You have a choice of three plans:
• TRS ActiveCare Primary
• TRS ActiveCare Primary+
• TRS ActiveCare HD – This plan is an HDHP.
• TRS ActiveCare 2 (current enrollees only)
TRS-ActiveCare Primary and TRSActiveCare Primary+
These plans require you to choose a Primary Care Provider who coordinates your care and makes specialist referrals when needed. You have predictable costs for doctor visits and prescriptions, access to a broad statewide network, and coverage options for dependents who live out of state.
TRS-ActiveCare HD is a high-deductible plan that pairs with a Health Savings Account (HSA). You must meet your deductible before the plan begins to pay for most services. This plan does not require a Primary Care Provider or referrals for specialist visits, offering more flexibility in choosing your care. It features a broad nationwide network, including coverage outside Texas, and also provides out-of-network benefits. Prescription coverage includes specialty medications, and the plan’s compatibility with an HSA allows you to save pretax dollars for medical expenses.
Except Arlington ISD
TRS is committed to accessibility. If you have trouble accessing this content, contact TRS at WebAccessibility@trs.texas.gov to request an alternative format.
• PREMIUM: The monthly amount you pay for health care coverage.
• DEDUCTIBLE: The annual amount for medical expenses you’re responsible to pay before your plan begins to pay.
• COPAY: The set amount you pay for a covered service at the time you receive it. The amount can vary based on the service.
• COINSURANCE: The portion you’re required to pay for services after you meet your deductible. It’s often a specified percentage of the costs; e.g., you pay 20% while the health care plan pays 80%.
• TIERING: Grouping doctors and facilities into tiers based on quality, cost and best practice clinical guidelines. This helps you compare choices. Tier 1 providers and facilities offer top performance and best value. You pay less when you choose Tier 1 and may pay more when you choose Tier 2.
• OUT-OF-POCKET MAXIMUM: The maximum amount you pay each year for medical costs. After reaching the out-of-pocket maximum, the plan pays 100% of allowable charges for covered services.
Ask your Benefits Administrator for your district’s specific premiums.
• $0 preventive services
• One-on-one health coaches
• Weight loss programs and nutrition
• TRS Virtual Health
• Member Rewards is even better. Now you’ll get a check when you use Member Rewards and choose low-cost, highquality doctors and facilities – up to $599* per tax year.
• Airrosti Remote Recover y gives you inhome virtual physical therapy to relieve common aches and pains at no cost.*
* Eligibility rules may apply.
See the Annual Enrollment Guide for more details.
You have in-office and virtual benefits:
• TRS-ActiveCare Primary Plan: $30 copay for office visits or $0 with Teladoc
• TRS-ActiveCare Primary+ Plan: $15 copay for office visits or $0 with Teladoc
• TRS-ActiveCare HD Plan: 30% coinsurance after deductible or $42 with Teladoc
• TRS-ActiveCare 2 Plan: $20 copay for office visits or $12 with Teladoc
This plan is closed to new enrollees. Current TRS-ActiveCare 2 participants can stay enrolled.
Closed to new enrollees.
Our dental plans help you maintain good oral health through affordable options for preventive care, including regular checkups and other dental work.
If you enroll in the DHMO plan, you will be assigned a Primary Care Dentist (PCD) from the DHMO network directory to manage your care. The Patient Charge Schedule applies only when covered dental services are performed by your network dentist. Not all Network Dentists perform all listed services and it is suggested to check with your Network Dentist in advance of receiving services. Dental services are unlimited; you pay fixed copays, there are no deductibles and there are no claim forms to file. There is no coverage for services provided without a referral from your PCD or if you seek care from out-of-network providers. Please refer to the DHMO plan document at www.mybenefitshub.com/iltexas for complete patient charge schedule details.
There are two DPPO Dental Plans — High and Medium — offering in-network and out-of-network coverage. You may see any dental provider for care, but you will pay less and get the highest level of benefits with in-network providers. You will pay more if you use an out-of-network provider.
Call 800-244-6224. Group # 3346275.
and
$3,050 You Pay You Pay
Diagnostic and Preventive Services
Class I: Oral Evaluations Prophylaxis: routine cleanings X-rays: routine X-rays: non-routine Fluoride Application Sealants: per tooth Space Maintainers: non-orthodontic Emergency Care to Relieve Pain (Note: This service is administrated at the in-network coinsurance level.)
Basic Restorative
Class II: Basic Restorative: fillings Endodontics: minor and major Periodontics: minor and major Oral Surgery: minor and major Anesthesia: general and IV sedation Repairs: Bridges, Crowns and Inlays Repairs: Dentures Denture Relines, Rebases and Adjustments
Major Services
Inlays and Onlays Prosthesis Over Implant Crowns: prefabricated stainless steel / resin Crowns: permanent cast and porcelain Bridges and Dentures
Preventive Services
Oral Evaluations Prophylaxis: routine cleanings X-rays: routine X-rays: non-routine Fluoride Application Sealants: per tooth Space Maintainers: non-orthodontic Emergency Care to Relieve Pain (Note: This service is administrated at the in network coinsurance level.)
Basic Restorative
Class II: Basic Restorative: fillings Endodontics: minor and major Periodontics: minor and major Oral Surgery: minor and major Anesthesia: general and IV sedation Repairs: Bridges, Crowns and Inlays Repairs: Dentures Denture Relines, Rebases and Adjustments
Major Services
Inlays and Onlays Prosthesis Over Implant Crowns: prefabricated stainless steel / resin Crowns: permanent cast and porcelain Bridges and Dentures
Treatment for cancer is often lengthy and expensive. While your health insurance helps pay the medical expenses for cancer treatment, it does not cover the cost of nonmedical expenses, such as out-of-town treatments, special diets, daily living, and household upkeep. In addition to these non-medical expenses, you are responsible for paying your health plan deductibles and/or coinsurance. Cancer insurance helps pay for these direct and indirect treatment costs so you can focus on your health.
Accident insurance provides affordable protection against a sudden, unforeseen accident. These plans help offset the direct and indirect expenses resulting from an accident such as copayments, deductible, ambulance, physical therapy, childcare, rent, and other costs not covered by traditional health plans. See the plan document for full details.
1 Percentage of benefit paid for dismemberment is dependent on type of loss.
Questions? Call 844-624-8110 for Member Services.
To file a claim: Visit www.mypalic.com to download a claim form and email it to benefits.service@palig.com.
UNIQUE FEATURES
Child Exclusive Alerts
Dual Enrollment
Digital Privacy Scans
Equifax child credit monitoring, Social media monitoring including cyberbullying, weapons, profanity, drugs and discrimination, Sex offenders (with map, photo, offense and address), Identity monitoring: dark web, high-risk transactions, subprime loan, public records, and USPS address monitoring.
Allows members to add additional family members—who may not qualify for other benefits—“under roof and wallet” through our online portal (optional, at no cost, and can be activated at any time).
Automated digital privacy scans and removal, monthly scans, and automated removal from over 100+ online search sites.
ID Watchdog is the only benefits provider with 3-Bureau PreCheck, Equifax Child Credit Lock feature for eligible children and Instant-On Child Credit Monitoring.
3 bureau pre check allows users to help stop fraud before it happens by prompting lenders to contact you and verify identity before extending credit
Enhanced AI-powered phishing and malware alerts you if our scans detect that one of your devices has exposed your personal information due to phishing, malware or botnet attack.
Educator Disability insurance combines features of short-term and long-term disability into one plan. Disability insurance protects part of your income if you are unable to work due to a covered accident, illness, or pregnancy. We offer Educator Disability insurance for you to purchase and allow you to choose the coverage amount and waiting period that best suits your needs.
Benefits Begin
The first number indicates the number of days you must be disabled due to Injury and the second number indicates the number of days you must be disabled due to Sickness
Percentage of Earnings You Receive Up to 66.67%
Maximum Monthly Benefit Between $200 and $10,000
Maximum Benefit Period SSNRA (Injury and Illness)
Pre-existing Condition Exclusion 3/122
1 Hospitalization during elimination period. If your elimination period is 30 days or less and you are confined to a hospital for 24 hours or more, the elimination period will be waived. Benefits begin from Day one.
2 Pre-existing condition limitation. No benefits paid for conditions treated within three months prior to your effective date until 12 months of coverage. If disabled from such a condition, benefits will be payable for the first 8 weeks.
What is disability insurance?
Disability insurance protects one of your most valuable assets: your paycheck. This insurance replaces part of your income if you are physically unable to work due to sickness or injury for an extended period of time. The educator disability plan is unique in that it includes both short- and long-term coverage in one convenient plan.
this plan have pre-existing condition limitations?
Yes. However, all plans will include pre-existing condition limitations that could impact you if you are a first-time enrollee in your employer’s disability plan (including your initial new hire enrollment). Review the plan documents for full details.
Your disability benefit may be reduced by other income you receive or are eligible to receive due to your disability, such as:
• Social Security disability insurance
• State teacher retirement disability plans
• Workers’ compensation
• Other employer-based disability insurance coverage you may have
• Unemployment benefits
• Retirement benefits that your employer fully or partially pays for (such as a pension plan)
Your disability plan selection should be a two-step approach.
Choose your elimination period, or waiting period. This is how long you are disabled and unable to work before your benefit will begin. It will be displayed as two numbers, such as 0/7, 14/14, 60/60, etc.
The first number indicates the number of days you must be disabled due to Injury and the second number indicates the number of days you must be disabled due to Sickness
When choosing your elimination period, determine how long you could go without a paycheck. The 60-, 90-, and 180-day elimination periods are the number of days that must be satisfied before benefits can begin. During this time, no benefits are payable. Choose your elimination period based on your answer. Note: Some plans will waive the elimination period if you choose 30/30 or less and you are confined as an inpatient to the hospital for a specific time period. Review your plan details to see if this feature is available to you.
Choose your benefit amount. This is the maximum amount of money you would get from the carrier on a monthly basis once your disability claim is approved by the carrier.
When choosing your monthly benefit, consider how much money you need to pay your monthly bills. Choose your monthly benefit amount based on your answer.
Visit www.mybenefitshub.com/iltexas for rates.
Life and Accidental Death and Dismemberment (AD&D) insurance is important to your financial security, especially if others depend on you for support or vice versa.
With Life insurance, you or your beneficiary(ies) can use the coverage to pay off debts such as credit cards, loans, and bills. AD&D coverage provides specific benefits if an accident causes bodily harm or loss (e.g., the loss of a hand, foot, or eye). If death occurs from an accident, 100% of the AD&D benefit would be paid to you or your beneficiary(ies).
Basic Term Life and AD&D insurance are provided at no cost to you. You are automatically covered at $50,000 * for each benefit.
* No reductions.
If you need more coverage than Basic Term Life and AD&D, you may buy Supplemental Term Life for yourself and your dependent(s). If you do not elect Supplemental Term Life insurance when first eligible, or if you want to increase your benefit amount at a later date, you may need to show proof of good health.
A beneficiary is the person or entity you elect to receive the death benefits of your Life and AD&D insurance policies. You can name more than one beneficiary, and you can change beneficiaries at anytime. If you name more than one beneficiary, you must identify how much each beneficiary will receive (e.g., 50% or 25%).
Supplemental AD&D coverage is separate and apart from your Basic and Supplemental Term Life insurance coverage. It provides benefits beyond your disability or life insurance for covered losses that are the result of an accidental injury or loss of life. The full amount of AD&D coverage you select is called the Full Amount and is equal to the benefit payable for the loss of life. Benefits for other losses — such as loss of sight, speech or hearing; coma; or paralysis — are payable as a predetermined percentage of the full amount.
Your Supplemental AD&D amount is equal to your Supplemental Term Life amount. You can also cover your dependent spouse and child(ren). Dependent coverage amounts will be equal to their Dependent Term Life coverage amounts.
• Portable – keep your supplemental coverage if you leave your current employer
• Convertible – convert your group term life insurance benefits to an individual whole life policy if your coverage ends
• Accelerated Benefits Option – get up to 75% of your life insurance benefit if you (or your spouse) are terminally ill and have less than 24 months to live. Note: this benefit is not the same as long term care insurance.
Some limitations and exclusions apply, so see the plan documents for details.
Note: The employer for the insured must complete their portion of the claim form before the claim can be submitted.
A 403(b) plan, also known as a Tax-Sheltered Annuity (TSA), is a tax-deferred retirement plan provided for employees of certain tax-exempt, governmental organizations or public education institutions.
What are the benefits of contributing to a 403(b) Plan?
The 403(b) contributions you make can be on a pretax basis. This means that the money used to invest in the 403(b) plan is not taxed until the funds are withdrawn. For example, if your federal marginal income tax rate is 25%, and you contribute $100 a month to a 403(b) plan, you have reduced your federal income taxes by nearly $25. In effect, your $100 contribution costs you only $75. The tax savings grow with the size of your 403(b) contribution.
In your 403(b) plan, interest and earnings grow tax-deferred. This means that your interest will grow tax-free until the time of your withdrawal. The compounding interest on your 403(b) plan allows your account to grow more quickly than money saved in a taxable account where interest and earnings are taxed each year.
Contributing to a 403(b) retirement plan helps you take control of your future retirement needs. Other sources of retirement income, including state pension plans and Social Security, often do not adequately replace a person’s salary upon retirement. A 403(b) plan can be a great way to supplement your income at retirement.
Pretax contributions may put you in a lower tax bracket, reducing your overall tax rate.
Either you or your beneficiary will be able to withdraw your vested balance when one of the following occurs:
1. Retirement
2. Termination of Employment
3. Attainment of Age 59 ½
4. Total Disability
5. Death
The vendors may require additional paperwork.
You may borrow up to 50% of your vested balance up to $50,000 (whichever is less). Contact your current vendor about their specific loan provisions.
Annual contribution limits are much higher than those of an IRA.
You may elect to save:
• 100% of your income up to $24,500 (2026)
• Extra $8,000 if age 50+
Limits are completely separate from those made to 403(b) or 401(k) accounts.
Your employer has provided investment option(s) for you. A list of approved vendor(s) and the Salary Reduction Agreement (“SRA”) can be found by visiting the National Benefit Services website at http://www.nbsbenefits.com/non-erisa-403b-forms/ or by contacting NBS.
Once you have chosen an approved vendor, please open a 403(b) account directly with them. To begin investing, send the completed SRA form to NBS who will work with your employer to begin contributions.
Annuity contracts made available through insurance companies or custodial accounts through a retirement account custodian are allowed in 403(b) plans. You will need to contact the vendor for a comprehensive listing and information regarding the available investment options.
As a participant in the 403(b) plan, you have the option to move funds, or “exchange” tax-free between different vendors within the same plan.
You also have the option of rolling retirement funds from previous employers to your current employer’s plan, thus simplifying retirement management.
You may also choose to invest part of your income on an aftertax (Roth) basis. Roth contributions are taxed at the time of the investment though contributions and earnings grow tax-free until withdrawn. Qualified distributions will allow you to withdraw your money tax-free.
An in-service hardship distribution may be allowed if you satisfy certain criteria. Contact NBS for more information about the requirements.
A 457 plan is a tax-deferred compensation plan provided for employees of certain tax-exempt, governmental organizations or public education institutions.
The 457 contributions you make can be on a pretax basis. This means that the money used to invest in the 457 plan is not taxed until the funds are withdrawn. For example, if your federal marginal income tax rate is 25%, and you contribute $100 a month to a 457 plan, you have reduced your federal income taxes by nearly $25. In effect, your $100 contribution costs you only $75. The tax savings grow with the size of your 457 contribution.
In your 457 plan, interest and earnings grow tax-deferred. This means that your interest will grow tax-free until the time of your withdrawal. The compounding interest on your 457 plan allows your account to grow more quickly than money saved in a taxable account where interest and earnings are taxed each year.
Contributing to a 457 plan helps you take control of your future retirement needs. Other sources of retirement income, including state pension plans and Social Security, often do not adequately replace a person’s salary upon retirement. A 457 plan can be a great way to supplement your income at retirement.
Pretax contributions may put you in a lower tax bracket, reducing your overall tax rate.
As a participant in the 457 plan, you have the option to move funds, or “transfer” tax-free between different vendors within the same plan.
You also have the option of rolling retirement funds from previous employers to your current employer’s plan thus simplifying retirement management.
DISTRIBUTIONS FROM THE PLAN
You or your beneficiary will be able to withdraw your vested balance when one of the following occurs:
1. Retirement
2. Termination of Employment
3. Attainment of Age 59 1/2
4. Total Disability
5. Death
The vendors may require additional paperwork.
Annual contribution limits are much higher than those of an IRA.
How much can you contribute to a 457 Plan?
You may elect to save:
• 100% of your income up to $24,500 in 2026
• Extra $8,000 if age 50+
Limits are completely separate from those made to 403(b) or 401(k) accounts.
Distributions are required at age 73. Exceptions may apply.
Your employer has provided investment option(s) for you. A list of approved vendor(s) and the Salary Reduction Agreement (“SRA”) can be found by visiting the National Benefit Services website at http://www.nbsbenefits.com/non-erisa-403b-forms/ or by contacting NBS.
Once you have chosen an approved vendor, please open a 457 account directly with them. To begin investing, send the completed SRA form to NBS who will work with your employer to begin contributions.
Annuity contracts made available through insurance companies or custodial accounts through a retirement account custodian are allowed in 457 plans. You will need to contact the vendor for a comprehensive listing and information regarding the available investment options.
An in-service unforeseeable emergency distribution may be allowed if you satisfy certain criteria. Contact NBS for more information about the requirements.
You may also choose to invest part of your income on an aftertax (Roth) basis. Roth contributions are taxed at the time of the investment though contributions and earnings grow tax-free until withdrawn. Qualified distributions will allow you to withdraw your money tax-free.
Visit www.nbsbenefits.com/457b for additional information.
A Flexible Spending Account (FSA) allows you to set aside pretax dollars from each paycheck to pay for certain IRS-approved health and dependent care expenses.
The Health Care FSA covers qualified medical, dental, and vision expenses for you or your eligible dependents. Eligible expenses include:
• Dental and vision expenses
• Medical deductibles and coinsurance
• Prescription copays
• Hearing aids and batteries
You may not contribute to a Health Care FSA if you enrolled in a High Deductible Health Plan (HDHP) and contribute to a Health Savings Account (HSA).
A Limited Purpose Health Care FSA is available if you enrolled in the HDHP medical plan and contribute to an HSA. You can use a Limited Purpose Health Care FSA to pay for eligible outof-pocket dental and vision expenses only, such as:
• Dental and orthodontia care (e.g., fillings, X-rays, and braces)
• Vision care (e.g., eyeglasses, contact lenses, and LASIK surgery)
You can access the funds in your Health Care or Limited Purpose FSA two different ways:
• Use your FSA debit card to pay for qualified expenses, doctor visits, and prescription copays.
• Pay out-of-pocket and submit your receipts for reimbursement:
• Call – 800-274-0503
• Email – service@nbsbenefits.com
• Online – www.my.nbsbenefits.com.
• Fax – 800-478-1528
Note: You may file claims incurred during the plan year for another 90 days.
The Dependent Care FSA helps pay for expenses associated with caring for elder or child dependents so you or your spouse can work or attend school full-time. You can use the account to pay for daycare or babysitter expenses for your children under age 13 and qualifying older dependents, such as dependent parents. Reimbursement from your Dependent Care FSA is limited to the total amount deposited in your account at that time. To be eligible, you (and your spouse, if married) must be gainfully employed, looking for work, a full-time student, or incapable of self-care.
• Overnight camps are not eligible for reimbursement (only day camps can be considered).
• If your child turns 13 midyear, you may only request reimbursement for the part of the year when the child is under age 13.
• You may request reimbursement for care of a spouse or dependent of any age who spends at least eight hours a day in your home and is mentally or physically incapable of self-care.
• The dependent care provider cannot be your child under age 19 or anyone claimed as a dependent on your income taxes.
A Health Savings Account (HSA) is more than a way to help you and your family cover health care costs – it is also a tax-exempt tool to supplement your retirement savings and cover health expenses during retirement. An HSA can provide the funds to help pay current health care expenses as well as future health care costs.
A type of personal savings account, an HSA is always yours even if you change health plans or jobs. The money in your HSA (including interest and investment earnings) grows tax-free and spends tax-free if used to pay for qualified medical expenses. There is no “use it or lose it” rule — you do not lose your money if you do not spend it in the calendar year — and there are no vesting requirements or forfeiture provisions. The account automatically rolls over year after year.
You are eligible to open and contribute to an HSA if you are:
• Enrolled in an HSA-eligible HDHP (High Deductible Health Plan)
• Not covered by another plan that is not a qualified HDHP, such as your spouse’s health plan
• Not enrolled in a Health Care Flexible Spending Account, nor should your spouse be contributing towards a Health Care
Flexible Spending Account
• Not eligible to be claimed as a dependent on someone else’s tax return
• Not enrolled in Medicare or TRICARE
• Not receiving Veterans Administration benefits
• Not receiving Veterans Administration benefits
You can use the money in your HSA to pay for qualified medical expenses now or in the future. You can also use HSA funds to pay health care expenses for your dependents, even if they are not covered under your HDHP.
Having an HSA is a smart financial move!
Your HSA contributions may not exceed the annual maximum amount established by the Internal Revenue Service. The annual contribution maximum for 2026 is based on the coverage option you elect:
$4,400 Individual
$8,750 Family
You decide whether to use the money in your account to pay for qualified expenses or let it grow for future use. If you are 55 or older, you may make a yearly catch-up contribution of up to $1,000 to your HSA. If you turn 55 at any time during the plan year, you are eligible to make the catch-up contribution for the entire plan year.
If you meet the eligibility requirements, you may open an HSA administered by EECU. You will receive a debit card to manage your HSA account reimbursements. Keep in mind, available funds are limited to the balance in your HSA.
• Always ask your health care provider to file claims with your medical provider so network discounts can be applied. You can pay the provider with your HSA debit card based on the balance due after discount.
• You, not your employer, are responsible for maintaining ALL records and receipts for HSA reimbursements in the event of an IRS audit.
• You may open an HSA at the financial institution of your choice, but only accounts opened through EECU are eligible for automatic payroll deduction and company contributions.
HSA contributions are tax-deductible and grow tax-deferred.
Withdrawals for qualifying medical expenses are tax-free.
• Online/Mobile: Sign in for 24/7 account access to check your balance, pay bills and more.
• Call/Text: 817-882-0800 EECU’s dedicated member service representatives are available to assist you with any questions. Their hours of operation are Monday through Friday from 8:00 a.m. to 7:00 p.m. CT, Saturday 9:00 a.m. to 1:00 p.m. CT and closed on Sunday.
• Lost/Stolen Debit Card: Call the 24/7 debit card hotline at 800-333-9934
• Stop by a local EECU financial center: www.eecu.org/ locations
Knowing the difference between a Health Savings Account (HSA) and Flexible Spending Account (FSA) can help you choose the best option for you and your family.
Description
An HSA is an actual bank account in your name that allows you to save and pay for unreimbursed qualified medical expenses tax-free.
Employer Eligibility A qualified High Deductible Health Plan
An FSA allows you to pay out-of-pocket expenses tax-free for:
• copays, deductibles, and certain services not covered by medical plan
• qualifying dependent care
employers Contribution Source You and/or your employer You and/or your employer
$3,400 family
$4,400 single
2026 Maximum Contribution
$8,750 family
$1,000 age 55+ catch-up
Permissible Use of Funds
Cash-Outs of Unused Amounts (if no medical expenses)
Year-to-year rollover of account balance?
Use any way you wish. If used for nonqualified medical expenses, funds are subject to the current tax rate plus a 20% penalty.
$3,400
Reimbursement for qualified medical expenses as defined in Section 213(d) of the Internal Revenue Code.
Permitted, but subject to current tax rate plus 20% penalty (waived after age 65). Not permitted
Yes, it will roll over to use for subsequent year’s health coverage.
No. Access to some funds may be extended if your employer’s plan contains a 2½-month grace period or $680 (2026) rollover provision.
Does the account earn interest? Yes No
Portable?
Yes, it is portable year-to-year and between jobs. No
The products and services listed below are examples of medical expenses eligible for payment under your Health Care FSA or HSA.* This list is not all-inclusive; additional expenses may qualify, and the items listed are subject to change in accordance with IRS regulations. Please refer to IRS Publication 502 Medical and Dental Expenses at www.irs.gov for a complete description of eligible medical and dental expenses.
Abdominal supports
Acupuncture
Ambulance
Anesthetist
Arch supports
Artificial limbs
Blood tests
Braces
Cardiographs
Chiropractor
Crutches
Dental treatment
Dentures
*Excludes Dependent Care FSA.
Dermatologist
Diagnostic fees
Eyeglasses
Gynecologist
Healing services
Hearing aids and batteries
Hospital bills
Insulin treatment
Lab tests
Metabolism tests
Neurologist
Nursing
Obstetrician
Operating room costs
Ophthalmologist/Optician/Optometrist
Orthopedic shoes
Orthopedist
Osteopath
Physician
Postnatal treatments
Prenatal care
Prescription medicines
Psychiatrist
Therapy equipment
Wheelchair X-rays
An Employee Assistance Program (EAP) helps you and family members cope with a variety of personal or work-related issues. Get confidential counseling and support services from licensed professionals at little or no cost to help with:
The EAP also offers up to six face-to-face visits, six virtual visits, and access to will preparation assistance.
Stress and anxiety
Grief and loss
Child and elder care resources
Substance abuse
The Hospital Indemnity plans help you with the high cost of medical care by paying you a cash benefit when you have an inpatient hospital stay. Unlike traditional insurance which pays a benefit to the hospital or doctor, these plans pay you directly. It is up to you how you want to use the cash benefit. These costs may include meals, travel, childcare or eldercare, deductibles, coinsurance, medication, or time away from work. See the plan document for full details.
Critical Illness insurance helps pay the cost of non-medical expenses related to a covered critical illness or cancer. The plan provides a lumpsum benefit payment to you upon first and second diagnosis of any covered critical illness or cancer. The benefit can help cover expenses such as lost income, out-of-town treatments, special diets, daily living, and household upkeep costs. This coverage is portable. See the plan document for full details.
Employee
Spouse
$10,000; $20,000; $30,000; or $40,000 face amounts
$10,000; $20,000; $30,000; or $40,000 face amounts
Children Included in the employee rate
Full Coverage
Benign brain tumor, coma, loss of speech, loss of hearing, loss of sight, heart attack, major organ transplant, ALS, Alzheimer’s disease, multiple sclerosis, advanced Parkinson’s disease, severe burns, stroke
Childhood Diseases
Cerebral Palsy, Congenital Birth Defects, Heart, Lung, Cleft Lip, Palate, etc, Cystic Fibrosis, Down Syndrome, Gaucher Disease, Muscular Dystrophy, and Type 1 Diabetes
Health Screening/Wellness Benefit
Pre-existing Condition Limitations
100% of benefit amount
100% of benefit amount
$50 Payable once per insured per year
No benefits will be paid for a date of diagnosis that occurs prior to the coverage effective date. Covered individuals must be cancer-free for 12 months prior to the treatment, free from cancer for 12 months prior to the diagnosis date, and in complete remission.
Alongside your medical coverage is access to quality telehealth services through Recuro Health. Connect anytime day or night with a board-certified doctor via your mobile device or computer.
While telemedicine does not replace your primary care physician, it is a convenient and cost-effective option when you need care and:
• Have a non-emergency issue and are considering an after hours health care clinic, urgent care clinic, or emergency room for treatment
• Are on a business trip, vacation, or away from home
• Are unable to see your primary care physician
Managing stress or life changes can be overwhelming but it’s easier than ever to get help right in the comfort of your own home. Visit a counselor or psychiatrist by phone, secure video, or app.
• Talk to a licensed counselor or psychiatrist from your home, office, or on the go!
• Affordable, confidential online therapy for a variety of counseling needs.
Register with Recuro Health so you are ready to use this valuable service when and where you need it.
Visit www.recurohealth.com
Call 1-855-6RECURO.
Download the Recuro app.
Use telemedicine for minor conditions such as:
• Sore throat
• Headache
• Stomachache
• Cold
• Flu
• Mental health issues
• Allergies
• Fever
• Urinary tract infections
Do not use telemedicine for serious or lifethreatening emergencies.
All tiers under the Recuro Health plan are priced at a flat rate of $12 per month.
MASA Medical Transport Solutions (MASA MTS) helps you prepare for the unexpected with affordable medical emergency air and ground transportation.
If you or your family members need emergency medical transport, your insurance coverage and Medicare may not cover all of the costs.
Following your medical crisis, MASA MTS will negotiate with your medical plan provider and cover your remaining balance on your medical transportation bills. Participation in this plan is voluntary.
3
4 Worldwide coverage to include any region with the exclusion of Antarctica and not prohibited by U.S. law or U.S. travel advisories
Disclaimer: This material is for informational purposes only and does not provide any coverage. The benefits listed, and the descriptions thereof, do not guarantee coverage and do not represent the full terms and conditions applicable for usage and may only be offered in some memberships or policies. Premiums, benefits, and coverage vary depending on the plan selected. For a complete list of benefits, premiums, terms, conditions, and restrictions, please refer to the applicable member services agreement or policy for your state. For additional information and disclosures about MASA plans, visit: https://info.masaglobal.com/disclaimers.
Disclaimer: This material is for informational purposes only and does not provide any coverage. The benefits listed, and the descriptions thereof, do not guarantee coverage and do not represent the full terms and conditions applicable for usage and may only be offered in some memberships or policies. Premiums, benefits, and coverage vary depending on the plan selected. For a complete list of benefits, premiums, terms, conditions, and restrictions, please refer to the applicable member services agreement or policy for your state.
Pet Insurance can help reimburse you for covered vet visits, accidents, illness and more. Plus, it can help keep your pet safe and healthy with preventive care like X-rays and ultrasounds.
Insurance can help take the worry out of covering the cost of unexpected
• The average annual cost for a routine vet visit is $212 for a dog and $160 for a cat.
• The average annual cost for a surgical vet visit is $426 for a dog and $214 for a cat.
• A small monthly payment can help plan for these expenses.
• Pet insurance may not cover pre-existing conditions, so enroll your pet when they’re healthy.
Choose the plan that works for you and your pet. Options include:
• Levels of coverage from $500–unlimited
• $0–$2,500 deductible options
• Reimbursement percentages from 50%–100%
• Accidental injuries
• Illnesses
What is Covered
Coverage Also Includes
Additional Value
• Exam fees
• Surgeries
• Hip dysplasia
• Hereditary conditions
• Congenital conditions
• Chronic conditions
• Medications
• Ultrasounds
• Hospital stays
• X-rays and diagnostic tests
• Alternative therapies
• Holistic care
• And much more
• Take your pet to any licensed veterinarian, specialist or emergency clinic in the U.S.
• If you’re claim-free in a policy year, we’ll automatically decrease your deductible by $25 or $50.
This brochure highlights the main features of the International Leadership of Texas employee benefits program. It does not include all plan rules, details, limitations, and exclusions. The terms of your benefit plans are governed by legal documents, including insurance contracts. Should there be an inconsistency between this brochure and the legal plan documents, the plan documents are the final authority. International Leadership of Texas reserves the right to change or discontinue its employee benefits plans anytime.