OCTOBER 2025
HUD HOMES MAGAZINE
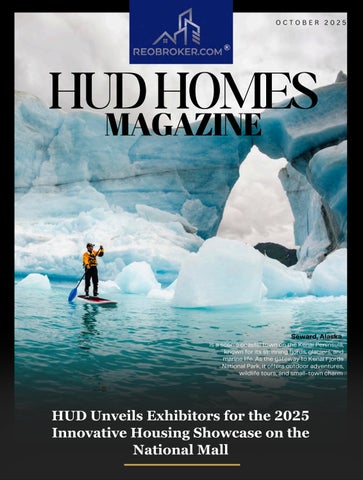
Seward, Alaska is a scenic coastal town on the Kenai Peninsula, known for its stunning fjords, glaciers, and marine life. As the gateway to Kenai Fjords National Park, it offers outdoor adventures, wildlife tours, and small-town charm.
HUD Unveils Exhibitors for the 2025 Innovative Housing Showcase on the National Mall
PUBLISHER: Brandy Nelson Executive Director REOBroker.com Equity Union Broker Associate 70115 Hwy 111 Rancho Mirage, CA 92270 Phone: 760-238-0552 Email: brandy@reobroker.com www.reobroker.com
REOBROKER VOL 01
Contact REOBROKER
Mike Samborn Executive Director REOBroker.com All Star Real Estate Broker/Owner 108 N. Henry Street Bay City, MI 48706 Phone: 989-922-6800 Email: Mike@mikesanborn.com
WEBSITE FACEBOOK INSTAGRAM
ADMINISTRATOR:
YOUTUBE
Eric Lawrence Frazier (714) 475-8629 ext 703 PRODUCTION TEAM: •Thepowerisnowmedia.com •Alvin Magua •Leonna Rose Berame •Sharon Rose Barellano
LINKED IN
a
ACTIVE RAIN
TWITTER PINTEREST TIK TOK
Editor’s Note
REOBROKER.COM
Welcome to this month’s issue of the HUD Real Estate Magazine, a publication dedicated to providing clarity, perspective, and actionable insights for professionals navigating today’s real estate and housing markets. At a time when housing affordability, foreclosure dynamics, and community revitalization remain central to national conversations, the role of timely information has never been more essential. This magazine is designed to bring together the most important updates from national real estate organizations, including the U.S. Department of Housing and Urban Development (HUD), Fannie Mae, the National Association of Realtors (NAR), the National Association of Real Estate Brokers (NAREB), and several others. These organizations issue regular press releases and market insights that not only inform policy and regulation but also shape the strategies of agents, brokers, investors, and property managers nationwide. By consolidating these updates, we aim to provide readers with a reliable, single source of information that highlights both immediate developments and longer-term trends. In addition to these press releases, the magazine also features selected HUD listings, reflecting the ongoing opportunities that exist within government-managed housing programs. These listings provide investors and agents with insight into available inventory, while also spotlighting HUD’s efforts to stabilize neighborhoods, preserve affordability, and expand access to homeownership. For those who specialize in REO and distressed property markets, HUD listings often represent an essential component of portfolio planning and community engagement. Why Press Releases Matter Press releases from organizations like HUD, Fannie Mae, NAR, and NAREB are more than routine announcements; they are critical signals about the direction of the housing market.
Whether it’s HUD announcing a new foreclosure relief initiative, Fannie Mae reporting on delinquency trends, or NAR providing analysis of seasonal housing demand, these updates help stakeholders anticipate shifts in supply, financing, and buyer sentiment. NAREB’s community-focused releases, meanwhile, remind us of the equity challenges that remain embedded in housing policy and practice. Together, they offer a wellrounded view of the industry, ensuring our readers remain not just informed but also strategically prepared. A Window Into HUD Listings HUD’s property listings deserve special attention in this publication because they bridge the gap between national housing policy and the day-to-day realities of real estate professionals. These listings often represent homes that have gone through foreclosure and returned to the market under HUD’s management. They can present opportunities for investors seeking affordable acquisitions, for agents looking to match buyers with entry-level housing, and for communities in need of revitalization. Including HUD listings alongside institutional press releases helps illustrate the realworld application of housing policy. Readers can see, for example, how foreclosure moratoriums, loan modification programs, or financing rule adjustments directly influence the flow of properties into HUD’s portfolio. These connections turn abstract policy discussions into tangible market opportunities. Preparing for What’s Ahead As the housing market continues to experience shifts in affordability, interest rates, and foreclosure activity, our goal is to ensure readers are equipped with the information needed to adapt. Press releases provide early warning signs of change— whether it’s new lending standards, proposed regulatory updates, or shifts in credit performance. HUD listings, meanwhile, give an on-the-ground view of how these macro-level policies manifest in available properties and investment opportunities. By engaging with both, real estate professionals gain a dual perspective: the high-level understanding necessary for strategic planning and the practical, asset-level detail required for day-to-day decision-making. Our Commitment As publishers of the HUD Real Estate Magazine, our commitment is to create a platform where policy meets practice. Each issue will highlight the voices of national housing organizations, translate institutional updates into actionable insights, and showcase HUD’s role in stabilizing the housing market through its listings and programs. We encourage our readers to approach this magazine not only as a source of information but also as a tool for strategic growth. Whether you are an investor looking for your next acquisition, an agent aiming to expand your knowledge, or a property manager navigating evolving regulatory landscapes, the HUD Real Estate Magazine is here to support your goals. Thank you for joining us for this issue. We look forward to bringing you more insights, updates, and opportunities in the months to come.
ARIZONA Bob Zachmeier
602-810-1561
Tucson
Arizona
Clay Strawn
480-250-0131
Chandler Mesa Tempe
Arizona
Jeff Miller
909-226-8038
Phoenix
Arizona
Julie Bruckner
602-810-1561
Lake Havasu
Arizona
ARKANSAS John Mason
501-985-0755
Pulaski Lonoke & Surrounding
Arkansas
CALIFORNIA Bob Siegmeth
818-425-0330
Porter Ranch
California
Brandy Nelson
760-238-0552
Palm Desert/Palm Springs
California
Darrell Isaacs
209-649-8593
Stockton/San Joaquin County
California
David Roth
707-446-1211
Vacaville
California
Deanna Lantieri
760-924-5091
Mammoth Lakes
California
Dennis Mulvihill
408-489-2904
Los Gatos
California
Don Kelber
805-338-9682
Westlake Village
California
Elysia Moon
949-212-6474
South Orange County
California
Gina Bocage
510-552-6480
Fremont / East Bay
California
James Outland
805-748-2262
Pismo Beach
California
Joe Mayol
661-618-1442
Lancastor
California
John Costigan
619-990-3044
San Diego / El Cajon
California
Justin Potier
562-480-9884
Los Angeles County
California
Mike Potier
562-708-0870
Long Bch South Bay
California
Nat Genis
909-376-0879
Temecula
California
Pete Nyiri
951-529-6606
Corona
California
Richard Hauff
559-593-8665
Clovis Fresno
California
Ronald Cedillo
209-321-0445
Tracy & Stanislaus County
California
Sigifredo Ponce
805-895-1109
Salinas
California
Timm Delaney
714-925-5544
Santa Barbara
California
Tom Moon
831-261-3758
Orange County
California
Warren Adams
916-208-2220
Sacramento
California
Wendell Turner
909-721-0714
Beaumont
California
Yolanda Castro
805-797-4526
Camarillo
California
COLORADO Tom Lazzaro
719-641-3544
El Paso County
Colorado
CONNETICUT Larry Madow
203-623-0763
Wallingford
Connecticut
Mark Porriello
860-539-9100
West Hartford
Connecticut
Teri Bennett
203-913-5899
Stamford
Connecticut
DELAWARE Colin & Stephanie Lehane
302-358-2617
Smyrna
Delaware
FLORIDA Barbara Zorn
321-799-0300
Cocoa Beach
Florida
Bob Hagmann
239-791-7653
Cape Coral
Florida
Debrah Bennett
786-395-8446
Florida Keys
Florida
Gerri Rosenthal Al Spry
352-267-7147
Leesburg
Florida
Joseph Doher
407-325-8165
Orlando
Florida
Michelle Pietrzyk
941-391-5257
Port Charlotte
Florida
Patricia Orsini
305-582-7816
Miami Lakes
Florida
Robin Burgarella
772-913-0533
Sebastian
Florida
Stephanie See
727-422-4202
Pinellas Pasco Hillsborough
Florida
GEORGIA Kent Miller
404-456-7137
Jonesboro
Georgia
Marc Oppenheimer
678-296-6550
Atlanta
Georgia
Sabriya Scott
912-844-0682
Savannah
Georgia
IOWA Julie Fischer
712-251-7506
Sioux City & Tri State Area
lowa
ILLINOIS Andrea Poling
217-202-8847
Champaign
Illinois
Marisa Barragan
630-202-3342
Aurora & Surrounding
Illinois
Richard Wolnik
847-338-8452
Chicago
Illinois
INDIANA Opal Sermersheim
812-582-0776
Jasper
Indiana
Robert (Bob) Smith
812-589-5253
Evansville
Indiana
Scott Smith
317-507-4663
Greenwood
Indiana
KANSAS Adam & Trice Massey
913-980-1399
Johnson Wyandotte & Surrounding
Kansas
KENTUCKY Mark Hass
502-744-7770
Louisville
Kentucky
LOUISIANA Rohn McManus
337-214-4575
Lake Charles
Louisiana
MARYLAND Anthony Dozier
301-440-7226
Crofton
Maryland
MASSACHUSETTS Joy E. Riley
401-952-7887
Suffolk Bristol Berkshire Co
Massachusetts
MICHIGAN Anthony Raffin
586-634-4761
Detroit SE Michigan
Michigan
Francine Willingham
734-564-7471
Whitmore Lake
Michigan
James Criteser
269-441-5575
Battle Crk Portage Kzoo
Michigan
Michael Balsitis
616-871-9200
Caledonia
Michigan
Michael Samborn
989-239-3662
Bay Saginaw Midland
Michigan
Zena Dakroub
313-485-8772
Dearborn & Surrounding
Michigan
MINNESOTA Frances Altman
320-260-2233
Central Minnesota
Minnesota
MISSOURI Adam & Trice Massey
913-980-1399
Johnson Wyandotte & Surrounding
Missouri
Jim Godwin
816-866-1159
Kansas Kansas City
Missouri
NEVADA Mary Baca
702-588-8944
Henderson Las Vegas
Nevada
Terry Lynn Rasner
775-560-2232
Reno Lake Tahoe & Surrounding
Nevada
NEW HAMPSHIRE Steven Cotran
603-626-5002
Manchester
New Hampshire
NEW JERSEY Anthony Nelson
973-930-4667
Ridgewood
New Jersey
Bill Flagg
908-377-7700
North Central New Jersey
New Jersey
Jay Koslowitz
732-364 6767
Lakewood
New Jersey
Lisa Lopez
609-384-5109
Manahawkin
New Jersey
Sharonn ThomasPope
215-669-4470
Cherry Hill
New Jersey
NEW MEXICO Maria Martinez
505-379-5698
Santa Fe/Albuquerque
New Mexico
NEW YORK Joe Hasselt
646-765-3592
Bronx/Westchester
New York
Ken MacBride
989-239-3662
Brooklyn Queens Staten Island
New York
Larry Mogguilli
585-359-2000
Rochester
New York
Mike Carroll
631-260-3328
West Babylon Long Island
New York
NORTH CAROLINA Michael Headley
336-655-5370
Greensboro
North Carolina
Nancy Braun
704-488-3109
Charlotte
North Carolina
Rudolph Mebane Jr
252-902-9740
Greenville
North Carolina
OREGON Derrick Emmert
503-581-6042
Salem
Oregon
Lizbeth Hale
503-757-1869
Happy Valley
Oregon
RHODE ISLAND Joy E. Riley
401-952-7887
All Counties
Rhode Island
SOUTH CAROLINA Rusty Williams
864-921-8280
Greenvile Spartanburg
South Carolina
TENNESSEE Ahmad Washington
615-479-0553
Nashville
Tennessee
TEXAS Alex Guerrero
915-592-4658
El Paso
Texas
Caryn Beard
832-867-7575
Houston area
Texas
Kelly Anne Porter
214-499-8369
Dallas North Texas Surrounding
Texas
Larry "Donnell" Durham
(713)785-7070
Livingston
Texas
Patricia Stampley
972-741-0770
Plano & Surrounding
Texas
Rohn McManus
337-884-7646
Beaumont
Texas
UTAH Robyn Moody
801-859-2539
Salt Lake & surrounding
Utah
VIRGINIA Michael Poole
703-973-2609
McLean
Virginia
WASHINGTON Ed Laine
206-229-5515
Sammamish
Washington
Scott Anthony
360-907-8499
Vancouver
Washington
Todd Sullivan
509-879-3362
Spokane
Washington
WASHINGTON DC Larry Daniels
202-491-6866
Washington DC
Washington DC
WEST VIRGINIA Elizabeth McDonald
304-283-8640
Charles Town
West Virginia
WISCONSIN David Vander Schaaf
608-393-6642
South Central Wisconsin
Wisconsin
Jennifer Vozka
715-490-5363
Rhinelander
Wisconsin
TABLE OF CONTENT
ALABAMA
CONNECTICUT
INDIANA
ALASKA
DELAWARE
KANSAS
ARIZONA
FLORIDA
KENTUCKY
ARKANSAS
GEORGIA
LOUISIANA
CALIFORNIA
IOWA
MARYLAND
COLORADO
ILLINOIS
MASSACHUSETTS
TABLE OF CONTENT
MICHIGAN
NEW MEXICO
TEXAS
MINNESOTA
NEW YORK
UTAH
MISSISSIPPI
NORTH CAROLINA
VIRGINIA
MISSOURI
OREGON
WASHINGTON
NEVADA
RHODE ISLAND
WASHINGTON DC
NEW HAMPSHIRE
SOUTH CAROLINA
WEST VIRGINIA
NEW JERSEY
TENNESSEE
WISCONSIN
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
ZONA
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
RADO
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
WARE
back to back to content content
back to back to content content
FLOR
IDA
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
GEOR
RGIA
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
IOW
WA
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
ILLIN
NOIS
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
INDI
ANA
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
KAN
SAS
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
KENTU
UCKY
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
LOUIS
IANA
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
MARY
LAND
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
MASSAC
HUSETTS
back to back to content content
REOBROKER.COM REO | RESIDENTIAL | COMMERICAL SALES | REAL ESTATE DEVELOPMENT
Brandy Nelson Executive Director REOBroker.com Equity Union Broker Associate Phone 760-238-0552 brandy@reobroker.com www.reobroker.com
Mike Samborn, Broker/Owner Executive Director REOBroker.com All Star Real Estate Phone (989) 922-6800 mike@mikesamborn.com www.reobroker.com
Business Adress: 70115 Hwy 111, Rancho Mirage, CA 92270
VISIT OUR WEBSITE
MICH
IGAN
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
MINNE
SOTA
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
MISSIS
SIPPI
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
MISSO
OURI
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
NEVA
ADA
back to back to content content
back to back to content content
back to back to content content
back to back to content content
NEW HAM
MPSHIRE
NO
LISTING YET IN
THIS
CONTACT
STATE
US
FOR
YET.
UPDAT
REOBROKER.COM REO | RESIDENTIAL | COMMERICAL SALES | REAL ESTATE DEVELOPMENT
Brandy Nelson Executive Director REOBroker.com Equity Union Broker Associate Phone 760-238-0552 brandy@reobroker.com www.reobroker.com
Mike Samborn, Broker/Owner Executive Director REOBroker.com All Star Real Estate Phone (989) 922-6800 mike@mikesamborn.com www.reobroker.com
Business Adress: 70115 Hwy 111, Rancho Mirage, CA 92270
VISIT OUR WEBSITE
NEW JE
ERSEY
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
NEW M
EXICO
back to back to content content
back to back to content content
back to back to content content
back to back to content content
NEW Y
YORK
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
REOBROKER.COM REO | RESIDENTIAL | COMMERICAL SALES | REAL ESTATE DEVELOPMENT
Brandy Nelson Executive Director REOBroker.com Equity Union Broker Associate Phone 760-238-0552 brandy@reobroker.com www.reobroker.com
Mike Samborn, Broker/Owner Executive Director REOBroker.com All Star Real Estate Phone (989) 922-6800 mike@mikesamborn.com www.reobroker.com
Business Adress: 70115 Hwy 111, Rancho Mirage, CA 92270
VISIT OUR WEBSITE
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
back to back to content content
PRESSRELEASES& HUD NEWS HUD and Census Bureau Report New Residential Sales in July 2025 HUD Unveils Exhibitors for the 2025 Innovative Housing Showcase on the National Mall HUD Announces Sponsors for the 2025 Innovative Housing Showcase HUD Regional Administrator Quinonez on HUD’s Support for Foster Youth in Texas Forecasting the Future of REO Markets: What the Next 5 Years Hold Buyer Behavior Shift: From Fixer-Upper Favorability to Turnkey Demand in REOs Preparing REO Buyers for Longer Sales Cycles: A Financial Guide Regional REO Hotspots: Texas, California & Florida Lead the Pack From Listings to Showrooms: Bringing REO Properties to Life with Home-Staging Trends Tech-Enhanced REO Hunting: How Analytics Are Reshaping How Agents Spot Bank-Owned Deals REO Myths Debunked: You Don’t Need Perfect Credit to Buy Foreclosures How Lowering Mortgage Rates Could Shift REO Market Dynamics Where REO Discounts Are Deepest: A State-by-State Analysis REO-to-Rental: A Strategic Pivot for Investors and Lenders The Lock-In Effect: Why Homeowners Staying Put Boosts REO Listings REOs Meet Affordability Pressures: How Price Trends Are Shifting Bargain Dynamics Cooling Listings and Rising Patience: What Slowed Sales Mean for REO Investors Myth-Busting REO: Debunking Misconceptions About Bank-Owned Homes REO Reality Check: Is Rising Foreclosure Activity Signaling Opportunity or Risk?
PRESS RELEASE HUD NEWS
HUD and Census Bureau Report New Residential Sales in July 2025 WASHINGTON (August 25, 2025) - The U.S. Census Bureau and the U.S. Department of Housing and Urban Development jointly announced the following new residential sales statistics for July 2025:
New Home Sales Sales of new single-family houses in July 2025 were at a seasonally-adjusted annual rate of 652,000, according to estimates released jointly today by the U.S. Census Bureau and the Department of Housing and Urban Development. This is 0.6 percent (±15.5 percent)* below the June 2025 rate of 656,000, and is 8.2 percent (±14.0 percent)* below the July 2024 rate of 710,000. For Sale Inventory and Months' Supply The seasonally-adjusted estimate of new houses for sale at the end of July 2025 was 499,000. This is 0.6 percent (±1.2 percent)* below the June 2025 estimate of 502,000, and is 7.3 percent (±5.7 percent) above the July 2024 estimate of 465,000. This represents a supply of 9.2 months at the current sales rate. The months' supply is virtually unchanged (±16.7 percent)* from the June 2025 estimate of 9.2 months, and is 16.5 percent (±19.0 percent)* above the July 2024 estimate of 7.9 months. Sales Price The median sales price of new houses sold in July 2025 was $403,800. This is 0.8 percent (±5.9 percent)* below the June 2025 price of $407,200, and is 5.9 percent (±8.5 percent)* below the July 2024 price of $429,000. The average sales price of new houses sold in July 2025 was $487,300. This is 3.6 percent (±8.0 percent)* below the June 2025 price of $505,300, and is 5.0 percent (±8.6 percent)* below the July 2024 price of $513,200. The August report is scheduled for release on September 24, 2025. View the full schedule in the Economic Briefing Room. The full text and tables for this release can be found here.
EXPLANATORY NOTES These statistics are estimated from sample surveys. They are subject to sampling variability as well as nonsampling error including bias and variance from response, nonreporting, and undercoverage. Estimated average relative standard errors of the preliminary data are shown in the tables. Whenever a statement such as “2.5 percent (±3.2%) above” appears in the text, this indicates the range (-0.7 to +5.7 percent) in which the actual percent change is likely to have occurred. All ranges given for percent changes are 90-percent confidence intervals and account only for sampling variability. If a range does not contain zero, the change is statistically significant. If it does contain zero, the change is not statistically significant; that is, it is uncertain whether there was an increase or decrease. The same policies apply to the confidence intervals for percent changes shown in the tables. Changes in seasonally adjusted statistics often show irregular movement. It takes 3 months to establish a trend for new houses sold. Preliminary new home sales figures are subject to revision due to the survey methodology and definitions used. The survey is primarily based on a sample of houses selected from building permits. Since a “sale” is defined as a deposit taken or sales agreement signed, this can occur prior to a permit being issued. An estimate of these prior sales is included in the sales figure. On average, the preliminary seasonally adjusted estimate of total sales is revised about 3.2 percent. Changes in sales price data reflect changes in the distribution of houses by region, size, etc., as well as changes in the prices of houses with identical characteristics. Explanations of confidence intervals and sampling variability can be found on our website. The Census Bureau has reviewed SOC monthly and quarterly tables to ensure appropriate access, use, and disclosure avoidance protection of the confidential source data (Disclosure Review Board (DRB) approval number: CBDRBFY25-0286). API
C O N T E N T
The Census Bureau’s application programming interface lets developers create custom apps to reach new users and makes key demographic, socio-economic and housing statistics more accessible than ever before. FRED Mobile App Receive the latest updates on the nation’s key economic indicators by downloading the FRED App for both Apple and Android devices. FRED, the signature database of the Federal Reserve Bank of St. Louis, now incorporates the Census Bureau’s 13 economic indicators. * The 90 percent confidence interval includes zero. In such cases, there is insufficient statistical evidence to conclude that the actual change is different from zero.
HUD Unveils Exhibitors for the 2025 Innovative Housing Showcase on the National Mall Showcase Returns on September 6th-10th to Celebrate 250 Years of the American Home WASHINGTON - The U.S. Department of Housing and Urban Development (HUD) announced more than 25 exhibitors that will showcase innovative housing and construction technologies on the National Mall during HUD’s annual Innovative Housing Showcase, taking place September 6th-10th. “HUD is proud to champion public-private partnerships across the nation,” said HUD Secretary Scott Turner. “This year’s Innovative Housing Showcase is historic. We look forward to welcoming thousands of attendees as they join us in celebrating American ingenuity, endurance, and free market innovation to see firsthand how Americans are making housing great again – all as part of the America 250 Initiative.” This year’s theme, “The American Home Is the American Dream,” spotlights the American Dream of homeownership, the future of housing innovation, and history-defining events in housing. Part of the America 250 Initiative, the showcase commemorates America’s 250th birthday and the American values of independence and opportunity. Founded in 2019 by former HUD Secretary Ben Carson, the showcase will feature a variety of full-scale housing models including manufactured, 3D printed, and modular homes built by American companies from across the nation. To view the list of 2025 exhibitors, click here: https://www.huduser.gov/portal/ihs/Exhibitors-2025.html.
More Details About the 2025 Innovative Housing Showcase A family-friendly event, the showcase is open to the public on the National Mall and expected to attract thousands of attendees, including Members of Congress, industry leaders, and community stakeholders. Visitors can view and enter exhibits on the Mall and attend expert-led panel discussions highlighting housing innovations. The panels are open to the public for in-person or virtual attendance. Register here: https://www.huduser.gov/portal/event/ihs2025.html. To view photos from past showcases, please visit IHS Past Showcases | HUD USER. For more information, please visit the Innovative Housing Showcase webpage.
C O N T E N T
HUD Announces Sponsors for the 2025 Innovative Housing Showcase The Historic Showcase Returns to the National Mall September 6th - 10th Highlighting 250 Years of Innovation in American Housing
WASHINGTON - Today the U.S. Department of Housing and Urban Development (HUD) announced the presenting sponsors for the 2025 Innovative Housing Showcase: The International Code Council (ICC), The Manufactured Housing Institute (MHI), The Structural Building Components Association (SBCA), and The Home Depot. As a proud part of the America 250 Initiative, the showcase will feature the theme, “The American Home Is The American Dream,” celebrating the evolution of homeownership over 250 years and how the American home is representative of the American values of independence, opportunity, and the unshakable drive to build a better life. “This year’s Innovative Housing Showcase puts the spotlight on American grit and free market innovation - a powerful reminder that free enterprise, not big government, drives the American Dream of Homeownership,” said HUD Secretary Scott Turner. “HUD will continue to spotlight solutions that support quality, affordable homeownership opportunities for hardworking Americans. Together, we will usher in the Golden Age of American Homeownership.”
Founded in 2019 by former HUD Secretary Ben Carson, the showcase will feature a variety of full-scale housing models including manufactured, 3D printed, and modular homes from across the country displayed on the National Mall. “The International Code Council is committed to supporting and facilitating the innovations necessary to make housing more affordable,” said John Belcik, Chief Executive Officer, International Code Council (ICC). “We are pleased to join HUD and other sponsors to highlight what is currently possible, and the policies, codes and standards that will continue to facilitate future progress.”
“MHI is excited to partner again with HUD to bring the 2025 Innovative Housing Showcase to the National Mall in celebration of the Showcase’s fifth year running and America’s 250th birthday. HUD Code manufactured homes have been bringing quality, attainable homeownership to Americans nationwide for fifty years. MHI welcomes the opportunity to demonstrate the beauty and innovation in design, scalability, and efficiency of today’s manufactured homes and the solutions they offer to address the nation’s housing supply needs,” said Lesli Gooch, Chief Executive Officer, Manufactured Housing Institute (MHI). “SBCA is excited to return to the National Mall as a co-sponsor and exhibitor for HUD’s Innovative Housing Showcase," said Jess Lohse, Executive Director, Structural Building Components Association (SBCA). “This event is a powerful platform for sharing solutions to the housing challenges our country faces. As the voice of the structural building components industry, SBCA is proud to demonstrate how trusses and wall panels provide scalable, efficient building methods supporting greater housing availability, accessibility, and affordability. We’re honored to join HUD and our fellow co-sponsors in presenting methodologies and technologies that are moving construction and housing forward.” “We’re proud to sponsor the Department of Housing and Urban Development’s Innovative Housing Showcase,” said Chip Devine, Senior Vice President of Pro Sales, The Home Depot. “At The Home Depot, we’re dedicated to driving growth in the housing industry by equipping professionals with the resources, tools, and partnerships they need to succeed. This event underscores the importance of advancing housing solutions nationwide, and addressing challenges like the skilled trades gap, which continues to be a barrier to progress.” Additional Details About 2025 Innovative Housing Showcase
C O N T E N T
A family-friendly event, the showcase is open to the public on the National Mall and expected to attract thousands of attendees, including Members of Congress, industry leaders, and community stakeholders. Visitors can view and enter exhibits on the Mall and attend expert-led panel discussions highlighting housing innovations. In years past, the showcase has attracted thousands of attendees from across the country. To view photos from past showcases, please visit IHS Past Showcases | HUD USER. For more information, please visit the Innovative Housing Showcase webpage.
ICYMI | HUD Regional Administrator Quinonez on HUD’s Support for Foster Youth in Texas HUD Celebrates the Sixth Anniversary of the Foster Youth to Independence Initiative TEXAS - U.S. Department of Housing and Urban Development (HUD) Southwest Regional Administrator Ashlea Quinonez penned an opinion piece discussing the continued impact of HUD’s investment in youth transitioning out of foster care in Texas. This year marks the sixth anniversary of HUD’s Foster Youth to Independence program, which gives these vulnerable youth the tools and resources they need to achieve success and selfsufficiency as they transition to adulthood. “[HUD] has delivered more than $5 million in investment nationwide since President Trump returned to the White House,” wrote HUD Southwest Regional Administrator Ashlea Quinonez. “Nearly $250,000 of that investment went to Texas foster youth, providing them with stable temporary housing and supportive services as they build their futures.” Read the full op-ed below: Each year, more than 20,000 young Americans transition from foster care, many with no safety net, no stable housing, and no clear path forward. It’s estimated a quarter of them become homeless shortly after leaving the foster care system. For these youth, the transition from foster care to adulthood marks a crossroads—one that can either lead to opportunity or derail their chance to achieve Ashlea Quinonez HUD Southwest Regional Administrator
the American Dream.
The U.S. Department of Housing and Urban Development (HUD) recognizes that this transition point is critical. It’s a moment when targeted investment can transform futures. That’s why, in 2019, HUD launched the Foster Youth to Independence (FYI) initiative. FYI provides local public housing authorities funding to help young Americans transitioning from foster care avoid homelessness and begin their new chapters as responsible adults. In addition to temporary rental assistance, the program includes support for services like skills training and job preparation. HUD’s investment in foster youth is equipping them with tools for success so they can enjoy housing stability, dignity, and independence. This year, we are celebrating the sixth anniversary of this important program, which has delivered more than $5 million in investment nationwide since President Trump returned to the White House. Nearly $250,000 of that investment went to Texas foster youth, providing them with stable temporary housing and supportive services as they build their futures. As HUD’s Southwest Regional Administrator, I have witnessed firsthand the impact HUD has made on these young people’s lives. They are resilient, ambitious, and full of promise-and they can thrive if given a chance. At HUD, we’re investing in more than housing, we’re investing in foster youths’ futures. We are committed to working with local communities to ensure foster C O N T E N T
youths are empowered, not forgotten. Under the leadership of HUD Secretary Scott Turner, we remain steadfast in ensuring that foster youth are not left to navigate this tough transition period alone. We will continue to support them so they can not only survive but thrive.
Forecasting the Future of REO Markets: What the Next 5 Years Hold Picture a landscape where opportunity surfaces in unexpected corners—where bank-owned properties quietly shift from overlooked inventory to strategic assets. The realm of REO properties holds such intrigue for investors, agents, and property managers. As we look ahead to the next five years, understanding how this sector will evolve becomes essential for anyone aiming to thrive in the real estate field. Recent housing market studies suggest that while home sales may see modest upward movement, price gains are expected to flatten. This backdrop frames the REO market’s likely trajectory through 2030. In this post, we’ll explore what moderate sales growth coupled with subdued price appreciation means for REO strategies nationwide, offering clarity on how to position for the future in this pivotal market segment. Sales Growth Amid Flat Price Trends Analysts anticipate that existing home sales will climb steadily in the coming years. Forecasts show a 7–12% increase in sales in the near term, with even stronger momentum expected further out. At the same time, projections from multiple sources point to a slowdown in home price appreciation—expected to hover at roughly 3–4% annually, a noticeable dip from prior years. Additional estimates suggest this moderate trajectory may extend into the latter half of the decade as affordability slowly improves. These dual trends—rising transactions paired with softer pricing—shape a predictable environment for REO activity. What This Means for the REO Market With sales rising and prices plateauing, REO properties could become more competitive—but only for the well-positioned. Auction volume is expected to decline; as of early 2025, REOs fell about 25% year-over-year, though short-term foreclosure starts ticked up by approximately 1%. Forecast models from auction platforms suggest a continued downward trend of around 8% in distressed auction volume this year, under baseline conditions. - Lower foreclosure rates suggest that REO inventory may tighten, even as demand stabilizes—especially if home equity and borrower resilience remain strong.
Strategic Implications for Stakeholders Investors: With fewer REO listings expected, competition for available properties could increase. Savvy players may need to act swiftly on new listings and maintain strong relationships with lenders and servicers. Agents: Success may hinge on quick access and marketing precision. With supply tight, differentiating REO listings through staging, accurate pricing, and targeted outreach will matter. Property Managers: Efficient management of REO assets—handling repairs, clean-outs, and listing preparation promptly—will give you a competitive edge in a lean market. Collectively, these trends signal a market where volume gains will rely on efficiency and timing, while price stability reinforces need for strategic focus rather than speculative upside. In summary, the coming half-decade offers a measured but promising horizon for REO markets. As home sales improve modestly and pricing growth remains subdued, the REO landscape may narrow, becoming more competitive and precision-driven. For those prepared to act decisively—whether through quick listing cycles, optimal marketing, or seamless management—this environment offers consistent opportunity. The key will be in watching market indicators, forging trusted connections, and staying nimble as conditions evolve through 2030. If you’re ready to navigate the changing landscape of REO markets with confidence and insight, let us support your journey. At REObroker.com, we C O N T E N T
specialize in connecting investors, agents, and property managers with real opportunities in this sector. Visit our website at https://www.reobroker.com or reach out directly via email at info@reobroker.com or call us at 760-238-0552. Let’s explore how strategic guidance and timely access can elevate your success in the years ahead.
Buyer Behavior Shift: From Fixer-Upper Favorability to Turnkey Demand in REOs
In today’s real estate landscape, something noteworthy is unfolding. Investors, agents, and property managers are witnessing a shift in buyer behavior: homes that once attracted DIY enthusiasts are being sidelined in favor of fully prepared, ready-to-go properties. This trend matters because it signals a fresh reality in the REO (real estate owned) market—one where speed and convenience increasingly outweigh the charm and potential of fixer-uppers. Gone are the days when buyers gravitated toward properties labeled “needs work” or “fixer,” drawn by lower purchase prices and renovation promise. Today, especially in 2025, there’s growing appetite for homes that require no immediate repairs—homes that buyers can simply walk into and begin living in or renting out. This article explores the forces behind this change, examines its impact on REO buyer profiles, and offers insights for professionals navigating this evolving terrain. We’ll look at the data driving buyer preference for move-in ready homes, the market conditions fostering this trend, and what it all means for stakeholders across the board. A Clear Turn Toward Move-in Ready Properties Market data shows a decisive pivot. Recent findings reveal that remodeled homes are generating about 26% more “saves” on listing platforms than fixer-upper properties, while listings labeled in need of repair have seen their sale-price premiums shrink to a 7–8% discount—the largest decline in years. Buyers now appear willing to pay close to 4% more—roughly $13,000 extra—for homes that are already updated.
Why Demand Is Shifting Several factors underscore this shift: Rising renovation costs and labor shortages are making buyer-led rehabs less appealing. With materials and contractor rates climbing, many prefer to avoid the hassle entirely. Economic uncertainty and cautious borrowing behavior have buyers favoring straightforward investments, particularly as mortgage rates remain a concern; yet, they’re preparing for gradual downward movement too. Increased inventory—nearly 25% year-over-year growth—means more options, but properties presented in excellent condition still sell fastest, encouraging buyers to act quickly. Implications for REO Buyer Profiles The traditional REO buyer—seeking discounted homes to restore and resell or rent— is now sharing the stage with a growing cohort focused on turnkey listings. These buyers, often investors or occupants with limited appetite for renovation, want assurance of quality, lower risk, and immediate usability. Financing also plays a role: bundling repair costs into standard financing spreads out expenditures, whereas cash renovations require upfront capital and carry more uncertainty. Agents, investors, and property managers should take note. Presenting REO homes as turnkey—highlighting recently completed updates, warranties, or staging—can dramatically enhance appeal. Renovation budgets should be carefully considered, and quick cosmetic touches may produce outsized returns. In short, the buyer lens has shifted: move-in readiness now often trumps the “potential” narrative once tied to fixer-uppers.
C O N T E N T
In 2025, the REO market is undergoing a noteworthy transformation. Buyers— particularly investors and ready-to-occupy occupants—are demonstrating a clear preference for homes that require little to no work. Renovation costs, market uncertainty, and attractive financing options for updated properties contribute to this shift away from fixer-uppers. For agents, property managers, and investors alike, recognizing and adapting to this tilt toward turnkey demand is critical. Emphasizing convenience, minimizing friction, and investing selectively in cosmetic upgrades or ready-to-go presentation may yield stronger interest and faster turnovers. If your work involves navigating this evolving REO market—whether sourcing, presenting, or managing properties—let REObroker.com be your partner in success. At REObroker.com, we specialize in showcasing and connecting investors, agents, and managers with REOs that match the modern demand: move-in ready, efficiently presented, and value-conscious. Explore our listings and resources at https://www.reobroker.com or reach out directly via email at info@reobroker.com or call us at 760-238-0552. We’re here to help you stay ahead in today’s market and turn opportunities into quick, confident transactions.
REO BROKER
PREPARING REO BUYERS FOR LONGER SALES CYCLES: A FINANCIAL GUIDE
In today’s buyer-friendly landscape, many bank-owned properties are lingering on the market longer than they once did. This shift creates both opportunity and challenge for investors, agents, and property managers alike. With more time comes added financial exposure—holding costs, inspection delays, and tough negotiations can all threaten your bottom line. Understanding how to navigate these longer sales cycles effectively isn’t just smart—it’s essential. This article will guide you through the essentials of budgeting for carrying costs, allocating resources for inspections and repairs, and negotiating strategically when the pace slows. You’ll walk away with clear, actionable strategies that keep your finances on track, even when sales drag. Ready to master the extended timeline? Let’s dig into the financial roadmap designed to protect profits and drive success. 1. Budgeting for Carrying Costs When properties stay unsold for weeks or months, cumulative holding expenses can chip away at your returns. These may include property taxes, insurance, utilities, and general upkeep. Reports recommend building a buffer—estimating holding costs at a conservative 2–4% of the property’s value per month—depending on location and type. Plus, align your budget with market averages to avoid surprise expenses. Some investors underestimate holding fees and find themselves eroding profit margins considerably.
2. Prioritizing Inspection and Repair Planning In slower markets, inspections offer a unique advantage: negotiating power. A thorough pre-offer inspection—if permitted—can uncover hidden repair needs and form the basis for either major concessions or a walk-away strategy. Agents and investors frequently overlook this step and end up overextended. Always plan for both cosmetic and structural budget contingencies. Choosing contractors early and locking in quotes can help you manage timelines and cost escalation during slower sale periods. 3. Strategic Negotiation in a Slower Market Extended listing durations often position sellers—banks or lenders—to be more flexible. To leverage that, support your offers with solid market data. Conduct a comparative market analysis to highlight why your price is fair and grounded in recent sales. Show that you’re serious: secure pre-approval or demonstrate access to funding, be it cash or hard money, to strengthen your negotiating stance. Remember that REO sellers usually provide limited contingencies, short inspection windows, and insist on “as-is” terms—so be ready but realistic. 4. Examples and Realistic Scenarios Imagine a property listed at a 20% discount in an open market. Holding costs of $1,500/month over 3 extra months can cut deeply into that margin. By negotiating a reduction based on estimated repair needs and slower buyer interest, you might recover $5,000–$10,000 and still stay profitable. In another case, bringing in a trusted contractor early could reveal roof or foundation issues—knowledge you can use for stronger negotiation leverage—or choose to walk if the risk outweighs the reward. These scenarios illustrate how preparation and clear financial margins can shift a slower market from threat to opportunity.
C O N T E N T
Longer sales cycles in bank-owned property markets are not just challenges—they’re opportunities to sharpen financial strategy. By planning realistically for carrying costs, leveraging inspections, and negotiating with precision, investors, agents, and managers can protect profitability and even gain advantage. The key is preparation: building in buffers, anticipating delays, and staying ready to pivot. With the right outlook, what may seem like extended holding periods can instead become calculated moves toward a more secure and rewarding deal. If you're looking to navigate the complexities of bank-owned property investing with confidence and clarity, REObroker.com is here to help. At REObroker.com, we specialize in providing expert guidance that helps you budget wisely, assess properties thoroughly, and negotiate advantageously—even when markets slow. Reach out to us via info@reobroker.com or give us a call at 760-238-0552 to start building a smarter, smoother strategy for your investments—because every day you wait should move you closer to profit, not farther from it.
In the current real estate market, regions where bank-owned properties (REOs) cluster are capturing keen interest from investors, agents, and property managers. Right now, three areas stand out as the most active REO hotspots, drawing attention for both challenge and opportunity. With significant numbers of REOs emerging, professionals need to understand not just the data, but how to respond strategically at the local level. Recent data from July 2025 highlights how concentrated REO activity has become, with Texas recording 377 bank repossessions, California following closely with 360, and Florida reporting 241. These figures point to markets under stress—but also to windows of potential for savvy players.
REGIONAL REO HOTSPOTS: TEXAS, CALIFORNIA & FLORIDA LEAD THE PACK
This article will first unpack where REOs are most concentrated and then offer tailored strategies that agents and investors can deploy in these regions. By examining real numbers and local trends, we’ll clarify how to approach these hotspots with an informed, opportunity-driven mindset. The Numbers & What They Reveal July 2025 data paints a clear picture: Texas leads the nation with 377 REO properties—the highest count among all states—closely followed by California’s 360 and Florida’s 241. These numbers reflect completed bank repossessions, signaling areas where foreclosure activity has gone through to conclusion, reaching the point of bank acquisition of property. Why These Regions Stand Out Texas: A booming population and diverse economic landscape create broad exposure to market shifts. Houston, for example, shows high foreclosure activity, indicating that agents dealing with REOs must be prepared for fast-paced market changes. California: Urban centers such as Bakersfield are marked by high foreclosure rates—one in every 1,538 housing units—making these areas critical for targeted REO efforts. Florida: Cities like Cape Coral (1 in every 1,735 housing units) and Lakeland (1 in every 1,802 units) face elevated foreclosure challenges, suggesting persistent demand for bank-owned properties.
Strategies for Agents & Investors Localized Market Intelligence -Conduct deep research into county- and metro-level foreclosure filings. Knowing where rates are highest—such as greater Houston or particular California metros—helps tailor outreach, valuations, and offers. Proactive Outreach to Banks and Servicers -Build relationships with institutions handling REOs. Texas, with the highest numbers, likely involves numerous local and regional bank partners. Early awareness of properties entering REO status can lead to advantageous deals. Adaptive Marketing and Pricing Strategies -In competitive markets, readiness to adjust pricing in response to demand and inventory changes is vital. Agents can benefit from leveraging local comps and foreclosure trends to position REOs effectively. Value-Add Tactics for Property Managers and Investors -Offer renovation and property preservation services to improve marketability. In places like Florida—where foreclosure pressure is acute—value-add improvements can differentiate REO listings from traditional listings. Community-Specific Messaging -Tailor outreach and marketing to local culture. Whether highlighting affordability in certain Texas regions or forecasting seasonal demand shifts in Florida, context-sensitive communication builds trust and effectiveness. The July 2025 data places Texas, California, and Florida at the forefront of REO activity, offering both challenges and opportunities for real estate professionals. High counts of bank-owned properties reflect stress in key markets—but also provide fertile ground for well-prepared agents, investors, and managers. By combining local intelligence with strategic outreach, dynamic pricing, and value-add services, industry professionals in these hotspots can turn elevated REO activity into lasting success. Ready to turn opportunity into action? Connect with REObroker.com for tailored insights and expert support in navigating these REO-rich markets. Whether you're investing, managing, or brokering bank-owned properties, our team is ready to guide you—visit https://www.reobroker.com or reach out via email at info@reobroker.com or by phone at 760238-0552. Let’s work together to maximize the potential of REO hotspots and secure your next win. C O N T E N T
From Listings to Showrooms: Bringing REO Properties to Life with Home-Staging Trends Imagine stepping into a gallery where every home on display feels welcoming, aspirational, and primed for action—that’s the aspiration behind the latest wave in property marketing. In today’s market, properties needing value-add attention—like REOs—can benefit immensely from next-level staging. While traditional clean and decluttered layouts once dominated, now it’s about immersion: model sales galleries that showcase lifestyle potential, alongside virtual and sensory staging tools gaining momentum. These techniques help investors, agents, and property managers shift perception from "foreclosed asset" to "high-potential opportunity." This article explores how these staging innovations can transform REOs, helping properties sell faster and command stronger offers. 1. Model Sales Galleries: The New Standard for Appeal Model sales galleries—essentially showroom versions of homes—are gaining ground in real estate. These curated environments let buyers experience high-end finishes, layouts, and mood of a property before committing. A leading design editorial predicts showrooms will become essential tools in sales strategies, offering immersive, handson previews for prospective buyers. These galleries highlight finishes and amenity quality in a way photos often can’t. For REOs, which may need visible improvements to feel move-in ready, creating a minimal “gallery” space can meaningfully boost emotional engagement. A clean, tastefully furnished room signals care, potential, and readiness—helping overcome typical buyer skepticism.
2. Immersive Virtual Staging: Affordable, Scalable, Impactful Virtual staging continues to surge as a cost-effective staging solution. Advances now allow interactive AR or VR walkthroughs, where users can customize furniture, finishes, and layouts in real time. Market projections show high growth—virtual staging is expected to leap from roughly USD 1.2 billion in 2024 to USD 5.5 billion by 2033, with compound annual growth nearing 18.5 percent. This makes virtual staging ideal for REOs needing flexible, budget-friendly ways to demonstrate potential. Instead of empty rooms, prospective buyers see possibilities. The immersive experience increases engagement, even before a physical visit. 3. Data-Led Impact: Faster Sales, Better Offers Staging isn’t just aesthetic—it delivers measurable returns. A recent industry overview found that staging can sell homes significantly faster and yield offers up to 20 percent above asking price. Home staging also reduces market time, with around 30 percent of agents seeing faster sales. Notably, the most critical area to stage remains the living room—37 percent of buyer agents rate it as essential, followed by primary bedroom (34 percent) and kitchen (23 percent). For REOs, focusing staging efforts on these core zones—whether physically or virtually—delivers the best strategic return. 4. Balancing Trend and Timelessness While staging benefits from design flair, over-personalized choices can alienate buyers. Experts caution against overused grays, bold paint, wallpaper, or heavy drapery— preferring earthy neutrals such as taupe, soft white, or greige to maintain broad appeal. Meanwhile, emerging design trends like color-drenching with accessories (pillows, small accents), layered textures, and a mix of vintage and modern touches can create sensory interest without overwhelming. Blending subtle trend cues within a neutral foundation helps REO properties feel fresh and relevant while remaining broadly appealing.
C O N T E N T
Conclusion Model sales galleries and immersive virtual staging are redefining how properties— especially those needing improvement—can be presented to buyers. By offering tangible experience through showrooms or engaging digital previews, REOs can shift from overlooked listings to thoughtfully curated spaces. Stage the living areas, apply subtle design accents, and use immersive staging tools to deliver a polished, confident presentation. These strategies are proven to attract stronger interest, command higher offers, and accelerate sales cycles. If you're ready to elevate your REO listings with compelling staging that drives results, reach out today. At REObroker.com, our team specializes in turning listings into experiences. Visit https://www.reobroker.com or contact us via email at info@reobroker.com or by phone at 760-238-0552 to explore how we can bring your next property to life. Let us help you create showrooms and virtual showcases that engage buyers and accelerate your success.
Tech-Enhanced REO Hunting: How Analytics Are Reshaping How Agents Spot Bank-Owned Deals Imagine unlocking a toolkit that shines a spotlight on the most promising bank-owned listings before they even hit mainstream markets. That’s the power analytics bring to the hunt for repossessed properties. For savvy investors, agents, and property managers, knowing where to look—and when—can mean the difference between chasing dead ends and closing profitable deals. Over the last few years, property data platforms have transformed traditional listing searches into precision operations. Platforms such as ATTOM and Realtor.com now deliver foreclosure and listing data with unprecedented depth and clarity. By tapping into this rich information flow, industry professionals can pinpoint opportunities with confidence and efficiency. In this article, we’ll explore how these platforms arm users with actionable insights— from foreclosure filings, auctions, and bank-owned inventory to listing trends and regional forecasts. We’ll examine how leveraging these tools can sharpen targeting for REO opportunities and ultimately help streamline your workflow and bottom line. Platforms Powering Insight ATTOM stands out as a leading source of foreclosure and related data. With coverage spanning over 155 million residential and commercial properties—covering nearly the entire population—its database includes detailed records for every stage of the foreclosure pipeline, including auctions, default notices, and bank repossessions. This level of granularity allows agents and investors to analyze opening bids, timelines, and local patterns with ease. On the other hand, Realtor.com delivers real-time access to bank-owned listings flagged as foreclosure, helping users view photos, status, and historical listing trends in one platform. Its expansive MLS-based database combines multiple listing feeds into robust visualizations, aiding both strategic decision-making and timely action.
Turning Data into Strategy For agents and property managers, this data becomes a tactical asset. ATTOM allows users to compare foreclosure activity by state, county, or ZIP code, helping identify “hot zones” where filings or completed repossessions are spiking. Such insights empower targeted marketing, better price assessments, and quicker responses to auctions before competition heats up. Realtor.com complements this by showcasing visible inventory, enabling professionals to monitor new REO listings as they surface. Combining both sources—ATTOM for macro trends and Realtor.com for active inventory—gives a powerful, 360-degree view of opportunity and timing. Real-World Example Consider Chicago, which led the nation in foreclosure starts during early 2025, followed by major metro areas like New York and Houston. An investor could use ATTOM to track rising filing rates in key neighborhoods, then switch to Realtor.com to monitor when corresponding bank-owned listings become active—acting swiftly to evaluate and bid. Value for Property Managers For property managers juggling multiple assets and markets, this combination of broad analytics and real-time listing alerts helps anticipate shifts in bank-owned inventory, assess localized risk exposure, and align maintenance, marketing, or leasing strategies with projected foreclosure waves. In sum, analytics have elevated the way real estate professionals hunt for bank-owned listings. ATTOM equips users with deep foreclosure intelligence—covering filings, auctions, and repossessions—while Realtor.com fills in the details of what’s actually available in the market today. When used together, they help agents, investors, and managers anticipate, locate, and act on REO opportunities with precision and speed.
C O N T E N T
By blending comprehensive trend analysis with live inventory tracking, you gain a clear edge in spotting value, reacting faster, and crafting smarter outreach strategies. Embracing these platforms means turning what was once guesswork into guided decision-making—saving time, reducing risk, and unlocking new opportunities for growth. Ready to take your approach to REO opportunities to the next level? Reach out to REObroker.com, where we combine cutting-edge analytics with expert insight to help you target the right bank-owned deals with clarity and confidence. Whether you’re an investor, agent, or property manager, let us guide you through the numbers and connect you with premium listings. Visit us at https://www.reobroker.com or send your questions to info@reobroker.com, or call us directly at 760-238-0552— our team is here to help you act smarter and grow your portfolio.
REO Myths Debunked: You Don’t Need Perfect Credit to Buy Foreclosures Foreclosures often evoke visions of perfect credit and endless paperwork. Yet for many investors, agents, and property managers, this perception is simply not accurate. While the idea of purchasing bank-owned properties may sound intimidating, the truth is more inviting: you don't need a flawless credit history to successfully navigate these opportunities. Across the market, distressed properties—those repossessed by lenders—present compelling value, frequently priced to move. However, a widespread myth persists: that only buyers with pristine credit and ample cash can access these deals. In reality, financing options and institutional buyer flexibility have opened the door to a wider range of purchasers. This article will explore and debunk common misconceptions surrounding credit requirements and bureaucratic hurdles in REO purchases. You’ll gain clear guidance on workable financing paths, expectations, and strategies to confidently pursue bank-owned properties—even with less-than-perfect credit. Myth 1: You Must Have Pristine Credit to Qualify It’s commonly believed that only buyers with excellent credit scores can secure financing for bank-owned properties. In fact, many mortgage programs exist for credit scores in the mid500s to 600s. For example, an FHA loan may accept a credit score around 580 with a modest down payment of approximately 3.5%—though property condition and eligibility still apply. VA loans are another path where credit and down payment requirements can be relaxed for qualified buyers. Moreover, certain lender or agency-run REO programs often feature competitive terms designed to attract more buyers, especially in markets flush with inventory. The evolving landscape of financing has made these properties more accessible than many assume.
Myth 2: You’ll Face Excessive Red Tape While banks do adhere to protocol, buying a bank-owned property often follows a process much like a standard real estate transaction—especially once the home transitions into an REO listing. Many of these properties are now listed on the MLS alongside traditional homes, streamlining exposure and accessibility. It’s true that lenders may delay responses or require unique paperwork, especially if managing large volumes of listings. But smart buyers work with experienced agents, get preapproved, and tailor their offers to align with bank timelines—reducing friction. Ethical waiver of contingencies (like inspection periods) can also strengthen offers—but should never be done without a proper inspection strategy. Myth 3: Cash Offers Are Always Required Another misconception: every REO purchase demands full cash. In auction scenarios, this may occasionally apply—but most REO listings are handled like traditional real estate sales, meaning mortgage financing is accepted and used by many buyers. That said, banks may favor cash offers in cases where the property’s condition is poor. But for better-maintained listings, financing is often available—and in some instances, buyer assistance programs or specialized loans can even make these deals feasible for those with modest credit. In summary, the path to acquiring bank-owned properties is more accessible than many believe. You don’t need perfect credit, nor are you always blocked by red tape—or forced to pay cash. With the right preparation—from understanding available loan programs to partnering with knowledgeable agents—REO purchases can be viable and rewarding even for buyers with moderate credit profiles. C O N T E N T
By breaking down these misconceptions, this article lays out practical strategies: use flexible loan programs, leverage agent expertise, and craft offers that balance competitiveness with caution. With clarity and persistence, investors, agents, and managers alike can tap into these hidden opportunities and cultivate success in the foreclosure space. If you're ready to explore REO opportunities and want expert guidance tailored to your situation, we're here to help. At REObroker.com, our dedicated team specializes in helping buyers and professionals navigate the foreclosure market—regardless of credit profile. Visit us at https://www.reobroker.com or reach out anytime at info@reobroker.com or by calling 760-238-0552. Let us help you turn common misconceptions into real, tangible opportunities.
How Lowering Mortgage Rates Could Shift REO Market Dynamics When mortgage rates ease to their lowest point of the year, the ripple effects reach far beyond traditional homebuyers. Suddenly, properties owned by lenders and sitting idle—the ones waiting for a new owner—spring into focus. For investors, real estate professionals, and property managers, this shift isn't just about better affordability for buyers—it could reshape how these properties move through the market. As borrowing costs fall, more buyers gain access to financing, potentially accelerating the pace at which these lender-owned properties move off the market. In turn, this could heighten competition for distressed listings and alter standard strategies around pricing, marketing, and turnaround timelines. In this article, we’ll explore how a drop in mortgage rates can speed up sales within this segment, attract new bidders, and influence your approach as a stakeholder in the space.
1. Improvements in Affordability Fuel Interest
When rates dip—even modestly —monthly payments become more manageable for a wider range of buyers. For instance, recent reports show the average 30-year fixed-rate mortgage now stands around 6.58%, the lowest since last fall. That eased cost threshold can make lenderowned property listings, often priced aggressively, even more appealing. As financing becomes more accessible, these properties may begin attracting buyers beyond investors—firsttime homeowners, for example— who are now able to participate in bidding where previously they'd been priced out.
2. Faster Turnover of Lender-Owned Inventory With affordability creeping upward, buyers won’t linger as long on the sidelines. Recent data indicates existing home sales rose by 2.0%, partly driven by a drop in mortgage rates. This uptick suggests increased confidence and purchasing activity. In parallel, properties in foreclosure—let go to lender ownership—may clear inventory more quickly as both demand and financing align favorably. 3. Sharper Competition for Distressed Listings As mortgage rates pull back, previously cautious buyers might reenter the market, joining seasoned investors in the race for lender-owned deals. Reports note investor activity now accounts for roughly 20% of home sales, up from 13% a year ago. As demand intensifies, even those who traditionally avoid bidding wars may reconsider, escalating competition for these listings. That scenario pushes prices upward and can reshape negotiation dynamics for agents and managers overseeing such properties. 4. Impacts on Strategy: Pricing, Marketing, and Timing
C O N T E N T
Pricing strategies may need recalibrating. Properties that were once positioned as bargains may no longer be perceived that way in a lower-rate environment. Investors and agents should evaluate comparable sales more closely. Marketing efforts could amplify as a broader pool of qualified buyers emerges. Highlighting favorable financing terms could turn casual interest into serious offers. Timing matters—with inventory turnover potentially quicker, efficiency in valuation, repairs, and listing becomes key. A streamlined process offers competitive advantage in securing buyers promptly. Lower mortgage rates may not deliver seismic shifts overnight, but even modest easing can unlock latent demand, particularly for lender-held properties. Improved financing conditions can galvanize buyers, hasten inventory movement, and elevate competition for distressed listings. For investors, agents, and property managers, the takeaway is clear: adapting to a market where affordability improves—even incrementally—can sharpen strategy and maximize outcomes. By aligning pricing, marketing, and timing with these rateinfluenced trends, professionals in this space can both anticipate change and leverage it effectively. If you're looking to stay ahead of these shifts and capitalize on emerging opportunities, let REObroker.com be your trusted partner. From market insights to listing execution, our team is committed to delivering responsive, tailored support. Visit us at https://www.reobroker.com or get in touch via info@reobroker.com or 760-238-0552—we’re here to help you navigate this evolving market and achieve your objectives with confidence.
Where REO Discounts Are Deepest: A State-by-State Analysis Imagine uncovering a property that’s priced significantly lower than its surroundings, not because it’s undesirable, but because it’s owned by a lender eager to move it on. That’s the reality for those seeking opportunities in bank-owned real estate. These listings can translate to meaningful savings for investors, agents, and property managers—but the extent of that discount can vary widely across different regions. In some states, REO properties—homes seized by banks and then put on the market—sell at notably lower prices than similar, non-distressed homes, making them attractive targets. The degree of discount depends on a range of factors: local market strength, property condition, and how swiftly the lender wants to liquidate the asset. In this article, we’ll look at how these discounts differ by region, using concrete examples such as the situation in Massachusetts with its valuation challenges and steep discounts. We’ll explore where the deepest savings are, what drives them, and how savvy professionals can use this knowledge to their advantage.
Regional Differences in REO Pricing Some regions see REO homes sell at 25–30% below comparable market values. A study analyzing two decades of home sales in Massachusetts found that foreclosure-related sales are discounted on average by about 28% relative to what similar homes might fetch. That’s an eye-opening figure for investors evaluating returns or agents advising clients on pricing strategies. Deep Discount Zones: Massachusetts Case Study Massachusetts offers a revealing case. Analysis of REO transactions from mid-2007 to 2008 shows that sales prices frequently lagged behind market levels, in part due to fast liquidations and appraisal inconsistencies amid market turmoil. Forced-sales often arise in neighborhoods with lower incomes or high mortgage leverage, where lenders are motivated to offload properties quickly—resulting in sharper price drops. Furthermore, spatial and appraisal challenges can lead to larger valuation gaps and steeper discounts. Why Discounts Vary State-by-State Multiple factors influence discount depth. In areas with slower housing turnover or economic stress, lenders accept lower offers to limit holding costs and risks—a stance informed by research on REO pricing rarely reflecting ongoing comparisons to current market values. Some regions—particularly those hit harder by economic downturns—show even deeper REO discounts due to local distress, stigma around lender-owned properties, or lack of buyer confidence. Variations Across Markets Other analyses, for instance, comparing requests for foreclosure discounts across local markets, reveal clear geographic variance. Estimates show foreclosure discounts in some states like Indiana are higher than in others like Florida, with pricing differences influenced by neighborhood characteristics and market conditions. This heterogeneity underscores the need for state-specific investigation rather than relying on national averages.
C O N T E N T
Across the country, bank-owned properties often command prices well below market comps—but the magnitude of that discount can differ dramatically by state and neighborhood. In Massachusetts, for example, REO sales have historically traded around 28% below typical values, driven by market conditions and expedited sales strategies. For investors, agents, and property managers, understanding these state-level differences is essential. It enables smarter decision-making, more accurate evaluations, and the ability to leverage opportunity where property is priced most attractively. Regional nuance matters—and recognizing where REO discounts are deepest can yield substantial yields. Ready to explore the most compelling REO opportunities tailored to your market? Reach out to REObroker.com to get expert insights into state-specific trends and unmatched listings that could deliver your next big win. Whether you're seeking data-driven evaluations or hands-on brokerage support, our team is here to guide you. Visit https://www.reobroker.com, drop us a note at info@reobroker.com, or give us a call at 760-238-0552—let us help you navigate the REO landscape with confidence and precision.
REO-to-Rental: A Strategic Pivot for Investors and Lenders
Imagine a slow but steady solution to the growing inventory of troubled properties blanketing neighborhoods. What if, instead of watching these homes deteriorate or dumping them on the market, they could be transformed into steady rental income? That’s the essence of a strategic shift gaining renewed attention: converting these properties into rentals. This approach benefits both investors looking for yield and entities seeking to stabilize markets. In this article, you’ll learn how an experimental strategy from years past could be reshaped for today’s housing landscape. We’ll explain how pilot projects have worked, the challenges and advantages involved, and why now might be the right moment to revisit this opportunity. Pilot Programs Lighting the Way A few years back, an initiative was launched where pools of distressed, institution-held homes were offered to investors with the stipulation that they be converted into long-term rentals. The aim was twofold: draw in private capital while absorbing excess housing stock and helping local markets recover. Early pilots demonstrated potential by leveraging investor resources for both financial return and community stability. Benefits for Investors For investors and operators, this model offers access to property portfolios often sold at favorable prices.
The approach aligns with known strategies like acquiring below market cost and generating ongoing rental revenue. In favorable markets, the increased value from stable rental income can even yield benefits upon eventual resale. Advantages for Markets and Communities Importantly, this model delivers more than financial upside. It helps stabilize neighborhoods by filling vacant properties, reducing deterioration, and bringing consistent occupancy. Initial pilot efforts revealed that converting empty homes into rentals can counter declining property values and elevate local morale. Lessons Learned from Pilots While promising, these programs also highlighted practical hurdles—investor vetting was sometimes uneven, and oversight lacked clarity. Regulatory bodies learned that to scale these efforts effectively, frameworks must ensure that investor partners are both financially capable and operationally reliable. Clear monitoring, goals, and assessments are essential for future iterations. Why It Matters Today As foreclosure and distressed-property volumes rise again, investors are scouting low-entry opportunities. Rental demand remains strong in many markets, making this model especially relevant now. For both capital providers and property professionals, reviving REO-to-Rental strategies opens a path that balances profit with neighborhood renewal.
C O N T E N T
Transforming distressed housing into rental assets offers a compelling dual benefit: investors gain reliable income streams, and communities regain stability and occupancy. While past pilot programs taught us that program design and oversight are critical, current market pressures and demand for rentals make this strategic pivot more promising than ever. Embracing such initiatives could be a savvy, socially responsible step forward. If you’re intrigued by the potential of REO-to-Rental pathways and want to explore how this approach could serve your investment goals or empower your brokerage or property management strategies, reach out. At REObroker.com, we're dedicated to helping investors and professionals turn opportunity into action. Visit us at https://www.reobroker.com or email info@reobroker.com. Want to talk? Call 760-238-0552 today to discover how converting challenging properties into rental solutions can align profit with purpose.
The Lock-In Effect: Why Homeowners Staying Put Boosts REO Listings Imagine a homeowner who's proudly maintained their mortgage at a very low interest rate—perhaps locked in a 3-4 percent fixed-rate loan a few years ago. Today, selling their home means taking on a much higher rate—maybe 6 or 7 percent—and that’s a heavy financial burden. This scenario sets up a powerful disincentive to move. At the same time, mortgage-rate volatility makes owners hesitant to list their properties. Over time, as economic stress grows or income falters, some of these locked-in homeowners do end up defaulting. That creates a wave of real estate owned (REO) listings, increasing overall inventory. This article explores how the lock-in effect works, why it suppresses for-sale inventory, and how it eventually spins off into higher REO levels. The Mortgage Lock-In Effect and Market Behavior When interest rates climb, homeowners with low fixed-rate mortgages hesitate to move because they’d lose favorable terms. Studies show that each 1-point rise in rates can reduce the probability of a sale by over 18%, and raise home prices by around 5.7% due to constrained supply, despite the direct cooling impact of higher rates on demand. One research analysis found the average borrower may be sacrificing $50,000 in cumulative mortgage cost savings to hold on to their low rate, a deterrent powerful enough to cut mobility significantly.
Inventory Shortages and Market Strain With so many homeowners entrenched in their homes, listings fall sharply. At one point, existing-home listings were down by up to 35 percent compared to prepandemic norms. Surveys confirm that a substantial share of homeowners staying put cite low rates as a primary reason alongside home attachment or high prices. Eventually, Defaults Rise and REO Increases Lower listing rates tighten inventory, raising prices—but not indefinitely. Economic stress, job loss, or rising insurance and tax costs can push homeowners toward default. Many eventually end up in foreclosure, turning properties into REOs. Historical data during the earlier housing crisis shows how foreclosures flooded markets and created REO surges. The Lock-In Effect’s Broader Impacts Long term, the lock-in effect foments inequality: homeowners who locked in low rates benefit enormously, while newer or prospective buyers face steeper costs and limited options. This widening gap strains affordability and market dynamics. Conclusion In short, rising mortgage rates create a lock-in effect that keeps many homeowners from selling. While this suppresses inventory and props up prices in the short term, financial pressures eventually drive some into default—boosting REO listings. For investors, agents, and property managers, recognizing this pattern is vital: supply may be tight now, but future REO inventory could surge as locked-in owners face hardship. C O N T E N T
If you’d like to stay ahead of this trend—whether by spotting upcoming REO opportunities or positioning your portfolio for evolving market shifts—set up a chat with us at REObroker.com. Reach out via our website (https://www.reobroker.com) or drop us an email at info@reobroker.com. Prefer a direct conversation? Give us a call at 760-238-0552—we’d be happy to discuss how you can benefit from tomorrow’s inventory dynamics.
REOs Meet Affordability Pressures: How Price Trends Are Shifting Bargain Dynamics
There’s a subtle yet meaningful shift underway in the real estate market—one that savvy investors, agents, and property managers can’t afford to ignore. While median listing prices have inched upward—hovering near $439,450, up roughly 0.5% year over year—overall home value growth has stalled at just about 0.3%. This mismatch between listing expectations and actual valuation is creating a fresh kind of affordability pressure, especially for those eyeing bank-owned or distressed properties. In this landscape, real estate–owned (REO) opportunities are being redefined: no longer automatic bargains, they're now weighed carefully against shifting market realities. This article explores how these affordability constraints are influencing REO buyer behavior, detailing what that means for different market participants. We’ll examine the trends driving cautious buying approaches, how pricing strategies are adapting, and what this means for your investment or portfolio strategy. Let’s dive into the forces reshaping bargain dynamics in today’s housing market. Affordability Squeezes Buyer Leverage The modest rise in listing prices, paired with nearly static home value growth— from a national average home value of about $368,580, up just 0.3%—is squeezing buyer power. Even though inventory is gradually increasing, the balance still favors sellers in many markets, keeping REO discounts in check.
Inventory Shifts and Price Pressures Data shows inventory of active listings has climbed steadily for many months, helping rebalance the market. Despite this, sellers often hold firm, anchoring to peak-era price expectations and avoiding deep discounts—even on REO listings. This makes thorough due diligence crucial, especially as price cuts are still noticeable across one in five listings. Regional Divergence Shapes Tactics Affordability dynamics are not uniform. Midwest and Northeast markets have seen modest value growth, offering more balanced conditions. In the West and South— where building restrictions, high demand, or coastal pressures persist—savvier buyers may face inflated listing prices with fewer traditional REO opportunities. Understanding these differences can help tailor pricing expectations and negotiation strategies. REO Buyer Behavior: Strategy Over Speculation Today’s REO purchasers are taking a more measured stance. Rather than snapping up distressed listings purely for discounts, they’re evaluating total return, cost of repairs, and financing realities. In markets where a 5%–10% growth forecast over five years is plausible, long-term value creation becomes the rationale, even if immediate deals look less compelling. Moreover, as one industry expert noted, a modest gain in affordability—due to easier mortgage payments or slightly lower rates—can breathe life into buyer interest. Still, many are cautious: rising cash purchases and investor activity signal that access to capital remains a key advantage for navigating tight markets.
C O N T E N T
As affordability remains stretched and price growth subdued, REO buyers are adapting their playbooks. Bargain-hunting is no longer just about securing a discount; it’s about aligning expectations with market realities, focusing on longterm value, and tailoring strategies by region. Rising listing prices, steady—but slow —value growth, and uneven inventory trends mean investors and agents must balance ambition with pragmatism. REO opportunities persist, but success now depends on sharp analysis, flexible pricing, and local market awareness. Understanding when and where value can emerge is the key. If you're looking for expert guidance navigating REO opportunities in today’s affordability-challenged market, reach out to REObroker.com. Our team at https://www.reobroker.com is ready to help you uncover the insights and strategies that match your investment or property management goals—just drop us a line at info@reobroker.com or call 760-238-0552. Let us be your partner in identifying smart, value-oriented REO options and making informed decisions that deliver meaningful results. We look forward to helping you unlock real potential in every deal.
REO BROKER
COOLING LISTINGS AND RISING PATIENCE: WHAT SLOWED SALES MEAN FOR REO INVESTORS
If you're involved in property investment—whether as an investor, agent, or property manager—you’re likely noticing something important: homes are taking longer to move. This slowdown in 39 of the 50 largest metro areas, especially across the South and West, is more than just a statistic; it's reshaping the landscape for REO investors in real time. As listings linger, inventory builds, and buyer behavior shifts, the balance of power is nudging toward those with capital and flexibility. This article will explore how longer listing times are influencing REO pricing strategies, giving investors stronger negotiating positions, and helping refine the timing of acquisitions and dispositions. With careful insights and practical examples, we'll unpack what slowed sales mean for your bottom line—and how you can turn these shifts to your advantage. 1. Slower Sales, More Listings—A Shift in Market Dynamics Recent data shows that 39 out of the 50 largest metros are experiencing increased time on the market. In particular, cities like Nashville are seeing homes sit for an extra 20 days, Orlando and Miami about 15 days, and Tucson 12 days longer compared to last year. This extended exposure is driving up active inventory across broad swathes of the market.
This trend is especially pronounced in the Sun Belt, where elevated prices and rising mortgage rates have tempered demand. Builders have also responded, adding to supply with fresh listings in a holdover from the pandemic-era housing boom. 2. Pricing Power and Negotiation Leverage for REO Investors With demand cooling and listings lingering, buyers—including institutional or smallerscale REO investors—find themselves in a stronger position. In many regions, over half of homes that eventually sell are closing below asking price, with a national average sales drop of around $45,000 under list price. Sellers are growing increasingly unwilling to budge, with many instead pulling listings off the market entirely rather than negotiate. In markets like Miami, sellers are particularly stubborn—choosing to delist rather than offer price reductions. Delistings there have surged, hitting 59% in June, outpacing the national norm of 21%. For REO investors, this extended time on market and heightened seller resistance can be an invitation to craft more creative offers, backed by data, to secure better terms or added concessions such as repairs, credits, or favorable financing. 3. Strategic Timing: When to Act (and When to Wait) Longer listing times also open new timing strategies. Investors can monitor stale listings—those sitting for weeks without price adjustments. These homes may represent motivated opportunities, especially when combined with growing inventory and falling sales activity. At the same time, sellers withdrawing listings change the calculus. A temporarily removed property might re-enter with revised expectations—making it ripe for acquisition when it returns. For REO investors, patience, paired with market tracking, can yield acquisition advantages.
C O N T E N T
A market where homes stay on the shelf longer offers a renewed advantage for savvy REO investors. Slower sales and rising supply empower negotiators to shape deals more favorably. At the same time, the evolving inventory dynamics call for attentive timing—knowing when to strike and when to wait can make all the difference. By reading these signs and acting decisively, investors, agents, and property managers can capitalize on a shifting market regime—turning patience into performance. If you're ready to strategically navigate this evolving market, REObroker.com is here to help. Whether you’re looking to buy, sell, or evaluate REO opportunities, our team offers sharp insights and dedicated support to guide every move. Visit us at https://www.reobroker.com or reach out via email at info@reobroker.com or by phone at 760-238-0552 to connect. Let REObroker.com be your partner in turning market delay into your next opportunity.
Myth-Busting REO: Debunking Misconceptions About BankOwned Homes
Imagine uncovering an opportunity many dismiss—homes owned by financial institutions, often overlooked, sitting just beneath the surface of mainstream real estate. Yet, contrary to popular belief, these properties can deliver surprising value to savvy investors, agents, and property managers. The idea that all bank-owned listings are mere money pits, teeming with unseen damage or requiring perfect credit to navigate, persists—but it’s time to challenge those assumptions. In the current market landscape, these homes can offer genuine advantages—discount pricing, financing flexibility, and diverse investment paths. This article will challenge three common myths: that these properties are always dilapidated, demand total renovation, or are inaccessible to those without flawless credit. Drawing on recent data and expert insights, we'll illuminate the true potential of these opportunities—and how professionals in the field can approach them with clarity, confidence, and strategy. Myth 1: All Bank-Owned Homes Are in Terrible Condition It’s easy to assume foreclosure equates to neglect—but that’s not always the case. While some homes do reflect deferred maintenance, many lenders invest in basic repairs before listing. According to real estate professionals, “banks are remodeling the homes they take ownership of before selling,” so overlooked properties may surprise buyers with fresh finishes or improved utilities. Moreover, recent commentary emphasizes that many foreclosures were entrusted to lenders simply due to financial hardship—not intentional abandonment.
Myth 2: Every Bank-Owned Home Requires Full-Scale Renovation A widespread misconception is that these homes are automatically renovation projects—but that isn’t universally true. Some homes require cosmetic updates, while others may need minimal improvements. Still, professionals caution that estimating repair costs can be tricky. One industry guide notes: "One of the most frequent mistakes investors make is underestimating the cost of repairs"—highlighting the importance of a professional inspection when possible. Strategically, a selective renovation approach—prioritizing upgrades that add maximum value—can yield strong returns without overspending. Myth 3: You Need Perfect Credit or Cash to Buy Perhaps the most discouraging myth: the belief that buyers must have perfect credit or pay in cash. In reality, numerous financing paths exist. Investors and buyers can utilize conventional mortgages, hard-money loans, VA/FHA/USDA loans, private lending, and even financing options provided directly by the lender holding the property. Some lenders are motivated to facilitate a sale and may be more flexible than traditional expectations anticipate. Strategic Advantages and Considerations These properties often sell at or near market value—and sometimes below, depending on condition and demand. The advantages extend beyond price: they typically come with clear title (freed from lingering liens or taxes), multiple financing options, and motivated sellers. Challenges include “as-is” sales, limited property history, and competitive bidding environments. The antidote lies in preparation: secure financing early, work with agents experienced in these listings, conduct inspections, and build realistic cost contingencies. Far from being universally dreary or out of reach, bank-owned homes offer pragmatic opportunities—often presenting value in surprising ways. While it’s true some properties require more attention than others, many are in better shape or financeable than commonly believed. The real key is informed decision-making: proper inspections, careful budgeting, and utilizing flexible financing can unlock positive outcomes for investors, agents, and property managers alike. C O N T E N T
By setting aside misconceptions and approaching these opportunities strategically, professionals can uncover real potential where others see only risk. This space deserves more thoughtful exploration—not dismissal. Ready to turn misconceptions into opportunity? Reach out to REObroker.com to learn how bank-owned properties can work for your goals. At REObroker.com, we offer tailored guidance, expert listings, and financing insights to help you capitalize confidently—whether you're investing, managing, or brokering. Visit our website at https://www.reobroker.com or send us an email at info@reobroker.com to start a conversation. Prefer to talk directly? Call us at 760-238-0552 and let’s transform myth into advantage together.
REO Reality Check: Is Rising Foreclosure Activity Signaling Opportunity or Risk? A meaningful shift is quietly underway in the housing market: foreclosure filings have climbed by 13% year over year, and completed foreclosures (REOs) are up 18%. These increases are gaining attention from investors, agents, and property managers alike. What’s behind the rise, and what does it mean for stakeholders looking to navigate changing conditions? This surge arrives against a backdrop of tightening economic conditions—rising rates, operating costs, and squeezed household finances. Yet, overall property values remain healthy enough to help many homeowners preserve equity, offering some balance to the stress signals.
In
this
article,
we’ll
explore
whether the expanding inventory of REO properties presents a golden opportunity, a warning sign, or both. We’ll break down what the numbers actually show, consider the drivers behind the trends, and consider how savvy professionals what’s unfolding.
can
interpret
1. Numbers Tell the Story Recent data indicates 36,128 properties had foreclosure filings in July—up 13% from a year earlier. Foreclosure starts are up 11%, while completed foreclosures rose by 18% year over year, though they dipped slightly from June. That uptick in REOs reflects growing inventory for investors and agents looking for value—but also points to higher strain on borrowers. The fact that completed foreclosures are increasing more than starts suggests a backlog clearing, rather than a spike in new distress. 2. Opportunity: More Inventory, Better Pricing Potential Rising REOs mean more properties hitting the market—often priced below typical market value—and available to investors and managers prepared to act. Markets such as Chicago, New York, Detroit, Houston, and Los Angeles show higher volumes of completed foreclosures, offering more prospects. For investors, REOs can offer margin for value-add projects. Agents and property managers can leverage these properties to help distressed sellers or local governments stabilize neighborhoods. 3. Risk: Underlying Economic Strain and Distribution Concerns Those filing rates aren’t uniform. Certain states—like Nevada, Florida, Maryland, South Carolina, and Illinois—face the highest foreclosure rates, with one in every C O N T E N T
~2,300 to ~2,700 housing units affected. This concentration suggests localized financial distress—resulting from factors like job losses, regional downturns, or unaffordable borrowing conditions. Moreover, while increasing REOs may signal opportunity, they also signal that more homeowners are under stress, which could weigh on property values in certain markets. Agents and managers must watch for signs of weakening demand or declining neighborhoods.
4. Balanced View: Opportunity and Caution Hand in Hand The truth is nuanced. Growing REO inventory offers buying and management potential—but it’s also a symptom of deeper economic challenges. For investors and agents, success lies in selective market targeting, rigorous due diligence, and strong risk management. This is not a nationwide flood of foreclosures; yet persistent upward trends warrant attention. The key is distinguishing regions with manageable opportunities from those with underlying vulnerabilities. The rise in foreclosure activity and REOs reflects both opportunity and caution. For professionals who move wisely, it offers a chance to acquire properties at favorable margins and deliver real value. At the same time, uneven stress levels across markets signal that risk is very real. Understanding the data, staying alert to regional differences, and applying strategic judgement will set investors, agents, and property managers on the right side of this shift. As always, being informed—and nimble—will matter most. Ready to explore promising REO opportunities while navigating risk with confidence? Reach out to REObroker.com to connect with a team that specializes in matching motivated buyers and managers with high-value inventory. Visit https://www.reobroker.com or send an email to info@reobroker.com and let our professionals guide you through emerging markets with precision. You can also call us directly at 760-238-0552 to discuss how the current foreclosure landscape aligns with your strategic goals. Let’s partner together to turn today’s market shifts into tomorrow’s success.
Real Estate Solutions with REOBroker.com Agents Services We Provide:
How We Can Assist You:
Residential: From single-family homes to high-rise apartments.
Broker Price Opinions: Accurate property valuations.
Commercial: Office spaces, retail outlets, and more. Industrial: Warehouses, factories, and other industrial properties. Multi-Family: Duplexes, triplexes, and larger apartment complexes. Land: Raw land, development sites, and agricultural plots.
Trusted by Industry Leaders: REOBroker.com agents have an extensive track record of collaboration with: C O N T E N T
-Asset Management Companies Corporate/Hedge Funds Institutional Lenders Private Lenders - Servicers
-Investment Groups -Private Note Holders - Attorneys - Probates/Trustees
Brandy Nelson Executive Director REOBroker.com Equity Union Broker Associate Phone 760-238-0552 brandy@reobroker.com www.reobroker.com
Occupancy Verifications: Ensure properties are occupied as expected. Door Knock/Postings: Direct outreach and postings for property management. Property Management: Property management services for all property types. Property Preservation: Preservation arrangements Eviction Services: Coordinating legal evictions and securing the property post-eviction. Inspection Services: Regular inspections are done to ensure properties are well-maintained and to identify any issues early.
Choose REOBroker.com for a proven partnership in real estate excellence!!
Mike Samborn, Broker/Owner Executive Director REOBroker.com All Star Real Estate Phone (989) 922-6800 mike@mikesamborn.com www.reobroker.com
SCAN HERE